 filings.tools
Item 1. Business
23K characters. Original on sec.gov · Markdown
Item 1. Business
Effective August 8, 2019, Torchmark Corporation changed its corporate name to Globe Life Inc. The New York Stock Exchange (NYSE) ticker was changed to "GL" on August 9, 2019. The name change is part of a brand alignment strategy which will enhance the Company's ability to build name recognition with potential customers and agent recruits through the use of a single brand. The underwriting companies owned by Globe Life Inc. (the Parent Company) will continue to exist as legal entities, but over a period of time will go to market under the Globe Life name to leverage branding initiatives implemented at Globe Life And Accident Insurance Company in recent years.
"Globe Life" and the "Company" refer to Globe Life Inc., an insurance holding company incorporated in Delaware in 1979, and its subsidiaries and affiliates. Its primary subsidiaries are Globe Life And Accident Insurance Company, American Income Life Insurance Company, Liberty National Life Insurance Company, Family Heritage Life Insurance Company of America, and United American Insurance Company.
Globe Life's website is: www.globelifeinsurance.com. Globe Life makes available free of charge through its website, its annual report on Form 10-K, its quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments to those reports as soon as reasonably practicable after they have been electronically filed with or furnished to the Securities and Exchange Commission. Other information included in Globe Life's website is not incorporated into this filing.
GL 2019 FORM 10-K
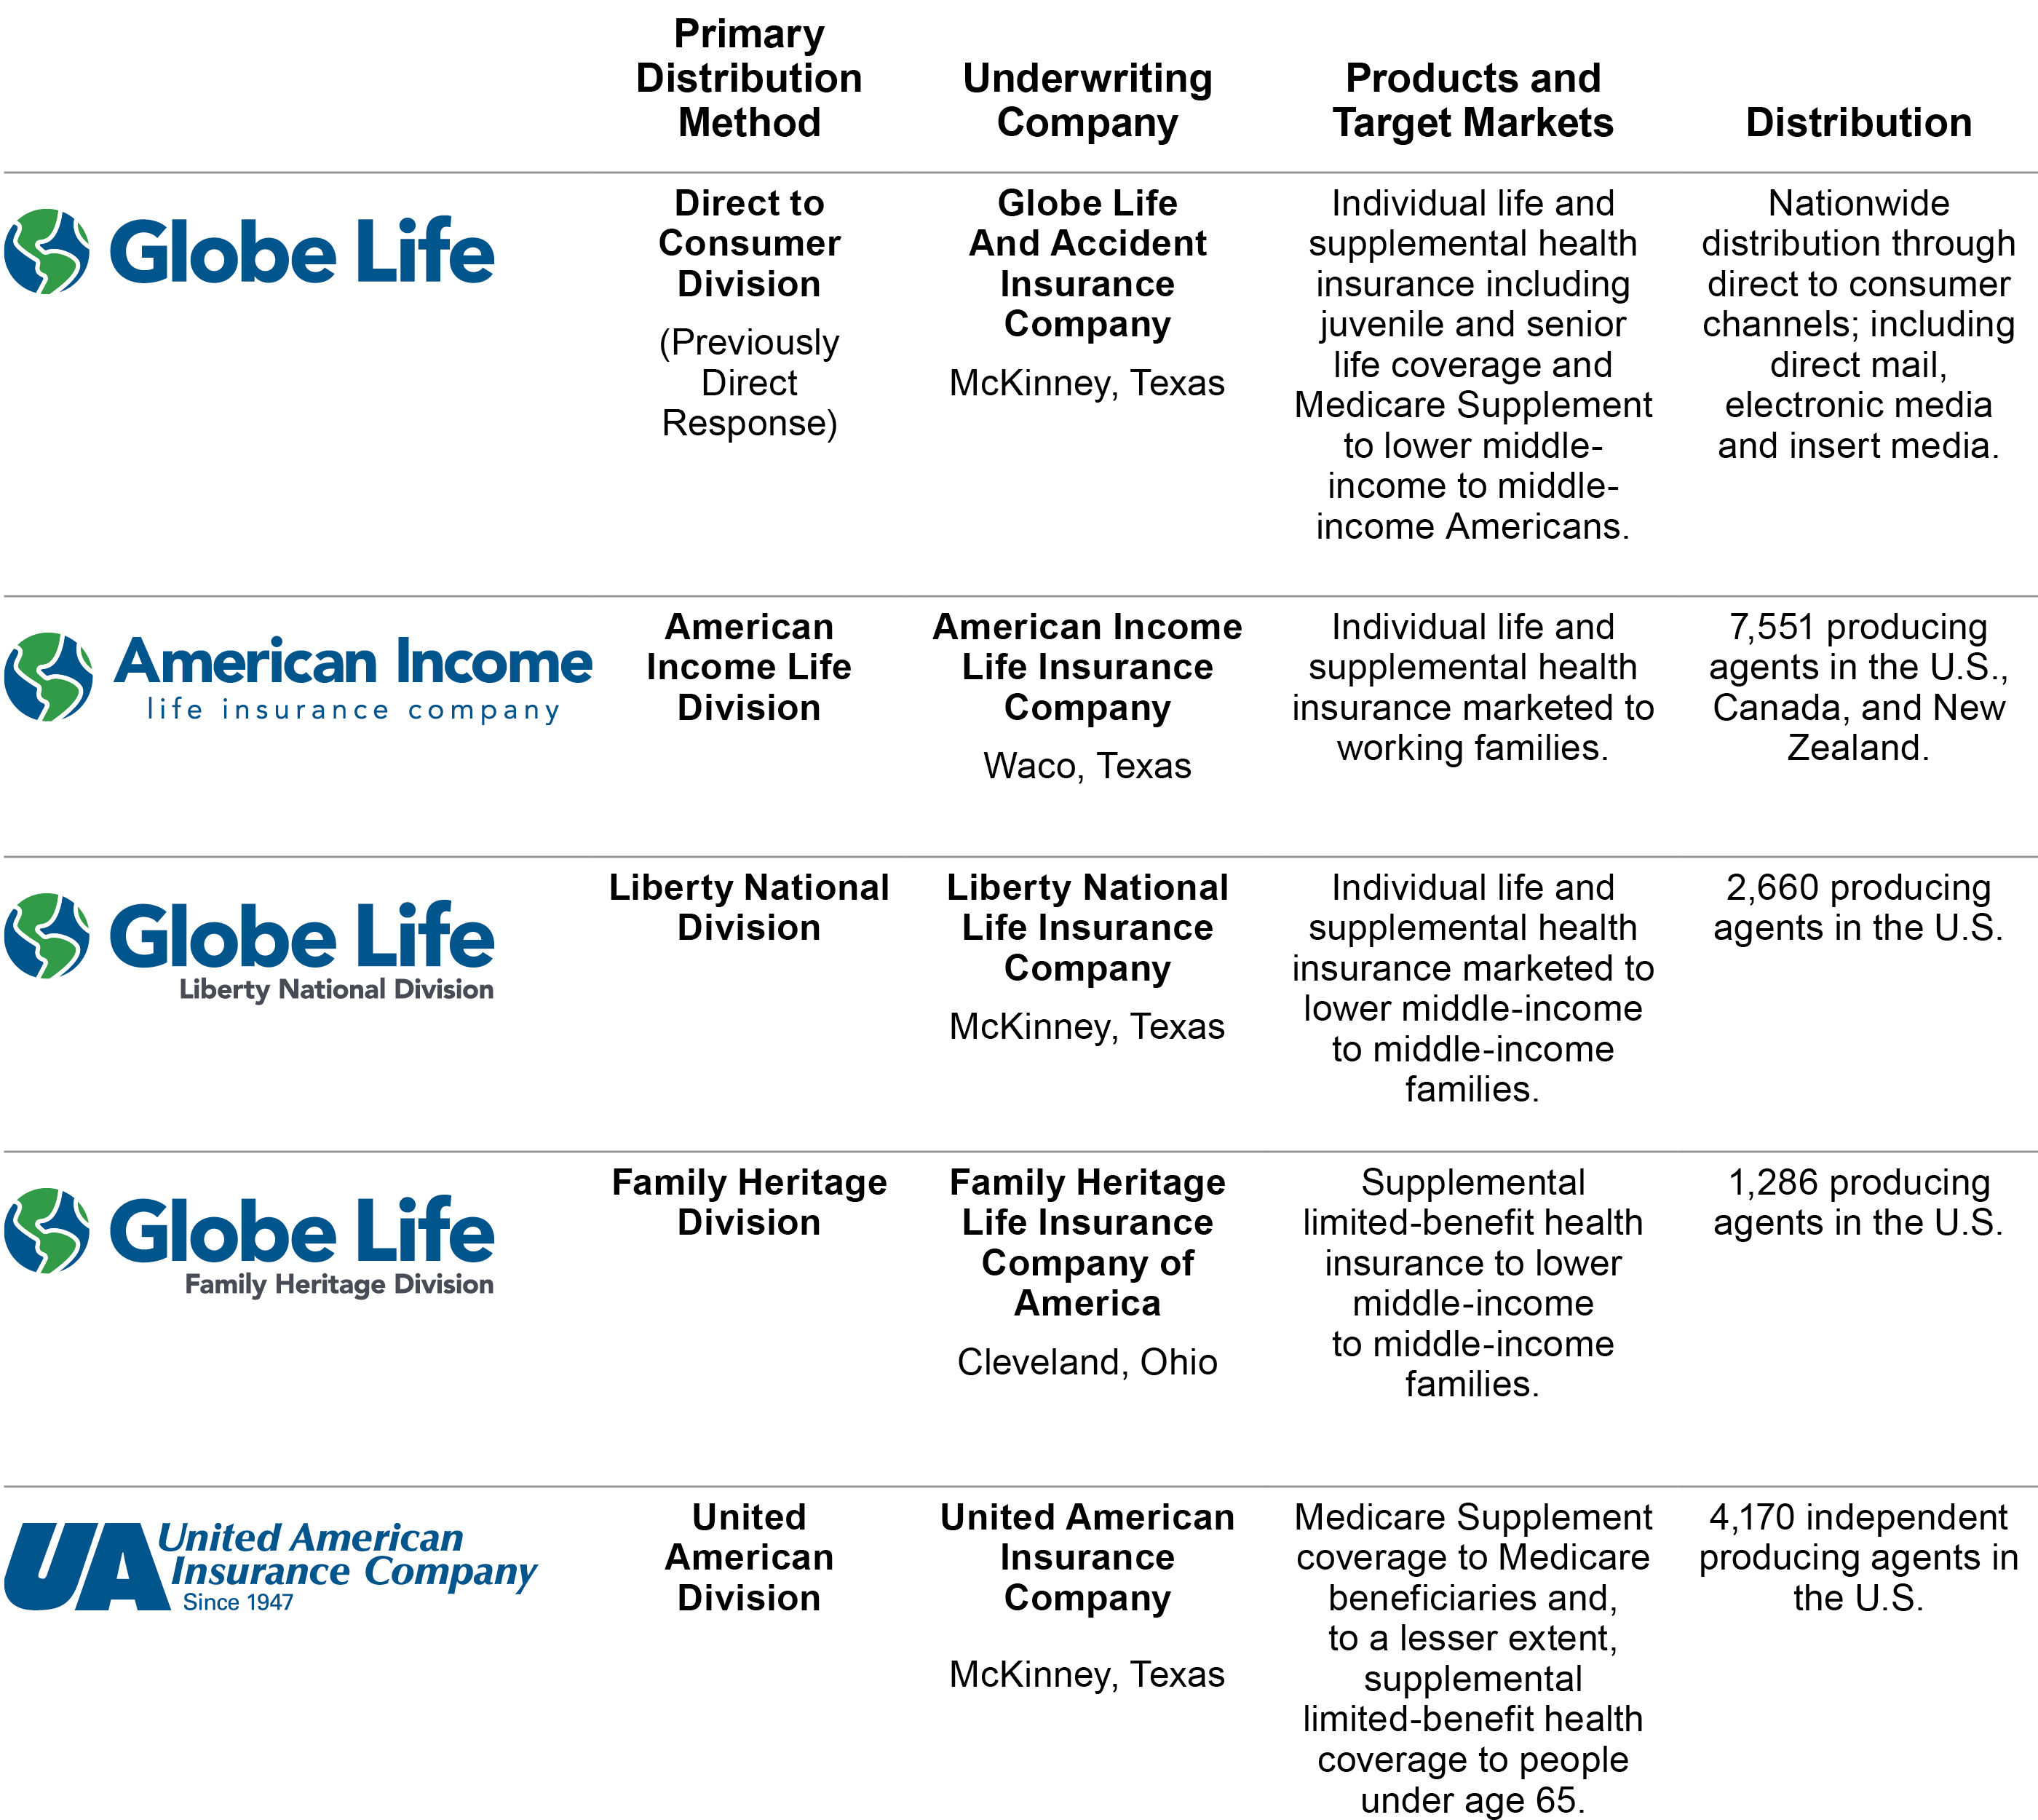
The following table presents Globe Life's business by primary marketing distribution method.
GL 2019 FORM 10-K
The Company's primary subsidiaries are Globe Life And Accident Insurance Company, American Income Life Insurance Company, Liberty National Life Insurance Company, Family Heritage Life Insurance Company of America, and United American Insurance Company. Our distribution channels consist of the following exclusive agencies: American Income Life Division (American Income), Liberty National Division (Liberty National) and Family Heritage Division (Family Heritage); an independent agency, United American Division (United American); and our Direct to Consumer Division (formerly referred to as Globe Life Direct Response distribution channel). Additional information concerning industry segments may be found in Management’s Discussion and Analysis and in Note 14—Business Segments within the Notes to the Consolidated Financial Statements**.
Insurance
Life Insurance
The distribution channels for life insurance products include direct to consumer, exclusive agents, and independent agents. These methods are described in greater detail within the primary marketing distribution channel chart seen on the previous page. The following table presents annualized premium in force for the three years ended December 31, 2019 by distribution method:
| Annualized Premium in Force(1) (Dollar amounts in thousands) | |||||||||||||||||||||||||||||
| 2019 | 2018 | 2017 | |||||||||||||||||||||||||||
| Direct to Consumer | $ | 831,739 | $ | 812,780 | $ | 796,628 | |||||||||||||||||||||||
| Exclusive agents: | |||||||||||||||||||||||||||||
| American Income | 1,220,483 | 1,129,384 | 1,059,216 | ||||||||||||||||||||||||||
| Liberty National | 309,792 | 300,846 | 295,235 | ||||||||||||||||||||||||||
| Independent agents: | |||||||||||||||||||||||||||||
| United American | 10,211 | 11,094 | 12,121 | ||||||||||||||||||||||||||
| Other | 209,403 | 210,624 | 209,899 | ||||||||||||||||||||||||||
| $ | 2,581,628 | $ | 2,464,728 | $ | 2,373,099 |
(1)See definition of annualized premium in force under Results of Operations in Management's Discussion & Analysis**.
Globe Life's insurance subsidiaries write a variety of nonparticipating ordinary life insurance products. These include traditional whole life, term life, and other life insurance. The Company does not currently sell interest-sensitive whole life products. The following tables present selected information about Globe Life's life insurance products.
| Annualized Premium in Force (Dollar amounts in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2019 | 2018 | 2017 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amount | % of Total | Amount | % of Total | Amount | % of Total | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Whole life: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Traditional | $ | 1,737,794 | 67 | $ | 1,643,122 | 67 | $ | 1,567,077 | 66 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-sensitive | 38,691 | 2 | 41,414 | 2 | 44,286 | 2 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Term | 683,869 | 26 | 671,840 | 27 | 664,558 | 28 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | 121,274 | 5 | 108,352 | 4 | 97,178 | 4 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | 2,581,628 | 100 | $ | 2,464,728 | 100 | $ | 2,373,099 | 100 |
GL 2019 FORM 10-K
| Policy Count and Average Face Amount Per Policy (Dollar amounts in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2019 | 2018 | 2017 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Policy Count | Average Face Amount per Policy | Policy Count | Average Face Amount per Policy | Policy Count | Average Face Amount per Policy | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Whole life: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Traditional | 8,477,406 | $ | 14.2 | 8,112,745 | $ | 13.9 | 8,045,522 | $ | 13.6 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-sensitive | 208,822 | 20.3 | 209,948 | 20.6 | 219,487 | 20.5 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Term | 4,313,709 | 14.8 | 4,459,850 | 14.9 | 4,351,901 | 15.0 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | 399,365 | 13.7 | 376,632 | 12.9 | 355,053 | 12.3 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 13,399,302 | $ | 14.5 | 13,159,175 | $ | 14.3 | 12,971,963 | $ | 14.1 |
Health Insurance
The following table presents Globe Life's health insurance annualized premium in force for the three years ended December 31, 2019 by distribution channel.
| Annualized Premium in Force (Dollar amounts in thousands) | |||||||||||||||||||||||||||||
| 2019 | 2018 | 2017 | |||||||||||||||||||||||||||
| Direct to Consumer | $ | 78,229 | $ | 79,325 | $ | 76,672 | |||||||||||||||||||||||
| Exclusive agents: | |||||||||||||||||||||||||||||
| Liberty National | 197,163 | 201,294 | 205,136 | ||||||||||||||||||||||||||
| American Income | 96,447 | 88,237 | 84,775 | ||||||||||||||||||||||||||
| Family Heritage | 312,479 | 290,186 | 268,584 | ||||||||||||||||||||||||||
| Independent agents: | |||||||||||||||||||||||||||||
| United American | 454,720 | 414,656 | 382,853 | ||||||||||||||||||||||||||
| $ | 1,139,038 | $ | 1,073,698 | $ | 1,018,020 |
Globe Life offers Medicare Supplement and limited-benefit supplemental health insurance products that include primarily critical illness and accident plans. These products are designed to supplement health coverage that applicants already own. Medicare Supplements are offered to enrollees in the traditional fee-for-service Medicare program. Medicare Supplement plans are standardized by federal regulation and are designed to pay deductibles and co-payments not paid by Medicare.
The following table presents supplemental health annualized premium in force information for the three years ended December 31, 2019 by product category.
| Annualized Premium in Force (Dollar amounts in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2019 | 2018 | 2017 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amount | % of Total | Amount | % of Total | Amount | % of Total | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Medicare Supplement | $ | 557,982 | 49 | $ | 524,415 | 49 | $ | 495,982 | 49 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Limited-benefit plans | 581,056 | 51 | 549,283 | 51 | 522,038 | 51 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | 1,139,038 | 100 | $ | 1,073,698 | 100 | $ | 1,018,020 | 100 |
GL 2019 FORM 10-K
Annuities
Annuity products include single-premium and flexible-premium deferred annuities. Annuities in each of the three years ended December 31, 2019 comprised less than 1% of premium. The Company does not currently market annuity products.
Pricing
Premium rates for life and health insurance products are established using assumptions as to future mortality, morbidity, persistency, investment income, expenses, and target profit margins. These assumptions are based on Company experience and projected investment earnings. Revenues for individual life and health insurance products are primarily derived from premium income, and, to a lesser extent, through policy charges to the policyholder account values on annuity products and certain individual life products. Profitability is affected by actual experience deviations from the pricing assumptions and to the extent investment income varies from that required for policy reserves.
Collections for annuity products and certain life products are not recognized as revenues, but are added to policyholder account values. Revenues from these products are derived from charges to the account balances for insurance risk and administrative costs. Profits are earned to the extent these revenues exceed actual costs. Profits are also earned from investment income in excess of the amounts required for policy reserves.
Underwriting
The underwriting standards of each Globe Life insurance subsidiary are established by management. Each subsidiary uses information obtained from the application and, in some cases, telephone interviews with applicants, including, but not limited to inspection reports, pharmacy data, doctors’ statements and/or medical examinations to determine whether a policy should be issued in accordance with the application, with a different rating, with a rider, with reduced coverage, or rejected.
Reserves
The life insurance policy reserves reflected in Globe Life's consolidated financial statements as future policy benefits are calculated based on accounting principles generally accepted in the United States of America (GAAP). These reserves, with premiums to be received in the future and the interest thereon compounded annually at assumed rates, must be sufficient to cover policy and contract obligations as they mature. Generally, the mortality and persistency assumptions used in the calculations of reserves are based on Company experience. Similar reserves are held on most of the health insurance policies written by Globe Life's insurance subsidiaries, since these policies generally are issued on a guaranteed-renewable basis. The assumptions used in the calculation of Globe Life's reserves are reported in Note 1—Significant Accounting Policies**. Reserves for annuity products and certain life products consist of the policyholders’ account values and are increased by policyholder deposits and interest credited and are decreased by policy charges and benefit payments.
Reinsurance
Globe Life has historically participated in very limited third-party reinsurance contracts as a result of the low face amounts of the policies sold by the Company. See Schedule IV and Note 6—Commitments and Contingencies for more information.
Investments
The nature, quality, and percentage mix of insurance company investments are regulated by state laws. The investments of Globe Life insurance subsidiaries consist predominantly of high-quality, investment-grade securities. Approximately 95% of our invested assets at fair value are fixed maturities at December 31, 2019 (see Note 4—Investments and Management’s Discussion and Analysis).
GL 2019 FORM 10-K
Competition
Globe Life competes with other insurance carriers through policyholder service, price, product design, and sales efforts. While there are insurance companies competing with Globe Life, no individual company dominates any of Globe Life's life or health insurance markets.
Globe Life's health insurance products compete with, in addition to the products of other health insurance carriers, health maintenance organizations, preferred provider organizations, and other health care-related institutions which provide medical benefits based on contractual agreements.
Management believes our companies operate at lower policy acquisition and administrative expense levels than peer companies. This allows Globe Life to have competitive rates while maintaining higher underwriting margins.
Regulation
Insurance—Insurance companies are subject to regulation and supervision in the states in which they do business. The laws of the various states establish agencies with broad administrative and supervisory powers which include, among other things, granting and revoking licenses to transact business, regulating trade practices, licensing agents, approving policy forms, approving certain premium rates, setting minimum reserve and loss ratio requirements, determining the form and content of required financial statements, and prescribing the type and amount of investments permitted. Insurance companies are also required to file detailed annual reports with supervisory agencies, and records of their business are subject to examination at any time. Under the rules of the National Association of Insurance Commissioners (NAIC), insurance companies are examined periodically by one or more of the supervisory agencies.
Risk-Based Capital (RBC)—The NAIC requires that a risk-based capital formula be applied to all life and health insurers. The risk-based capital formula is a threshold formula rather than a target capital formula. It is designed only to identify companies that require regulatory attention and is not to be used to rate or rank companies that are adequately capitalized. All Globe Life's insurance subsidiaries are more than adequately capitalized under the risk-based capital formula. See further discussion of RBC in Capital Resources**.
Guaranty Assessments—State guaranty laws provide for assessments from insurance companies to be placed into a fund which is used, in the event of failure or insolvency of an insurance company, to fulfill the obligations of that company to its policyholders. The amount which a company is assessed is based on its proportional share of the premium in each state. A significant portion of assessments are recoverable as offsets against state premium taxes.
Holding Company—States have enacted legislation requiring registration and periodic reporting by insurance companies domiciled within their respective jurisdictions that control or are controlled by other corporations so as to constitute a holding company system. Globe Life and its subsidiaries have registered as a holding company system pursuant to such legislation in Indiana, Nebraska, Ohio, and New York.
Insurance holding company system statutes and regulations impose various limitations on investments in subsidiaries, and may require prior regulatory approval for material transactions between insurers and affiliates and for the payment of certain dividends and other distributions.
Personnel
At the end of 2019, Globe Life had 3,196 employees.
GL 2019 FORM 10-K
Previous: Cover and table of contents · Next: Item 1A. Risk Factors