 filings.tools
Generac Holdings 10-K 2013-12-31
Filed 2014-03-03. 21 sections, 346K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 form10k.htm GENERAC FORM 10-K 12-31-2013
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 10-K
| (Mark One) | |
|---|---|
| x | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
| For the fiscal year ended December 31, 2013 Or | |
| o | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
| For the transition period from to |
Commission File Number 001-34627
GENERAC HOLDINGS INC.
(Exact name of registrant as specified in its charter)
| DELAWARE (State or other jurisdiction of incorporation or organization) | 20-5654756 (IRS Employer Identification No.) |
|---|---|
| S45 W29290 Hwy. 59, Waukesha, WI (Address of principal executive offices) | 53189 (Zip Code) |
| (262) 544-4811 (Registrant’s telephone number, including area code) | |
| SECURITIES REGISTERED PURSUANT TO SECTION 12(B) OF THE ACT: | |
| Common Stock, $0.01 par value (Title of class) | New York Stock Exchange (Name of exchange on which registered) |
| SECURITIES REGISTERED PURSUANT TO SECTION 12(G) OF THE ACT: None |
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes x No o
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes o No x
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes x No o
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes x No o
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§ 229.405 of this chapter) is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. o
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See definitions of “large accelerated filer,” “accelerated filer,” and “smaller reporting company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer x | Accelerated filer o | Non-accelerated filer o (Do not check if a smaller reporting company) | Smaller reporting company o |
|---|
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes o No x
The aggregate market value of the voting common equity held by non-affiliates of the registrant on June 28, 2013, the last business day of the registrant’s most recently completed second fiscal quarter, was approximately $2,175,882,000 based upon the closing price reported for such date on the New York Stock Exchange.
As of February 24, 2014, 68,779,944 shares of registrant's common stock were outstanding.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of the registrant’s Proxy Statement for the 2014 Annual Meeting of Stockholders (the “2014 Proxy Statement”), which will be filed by the registrant on or prior to 120 days following the end of the registrant’s fiscal year ended December 31, 2013, are incorporated by reference into Part III of this Form 10-K.
2013 FORM 10-K ANNUAL REPORT
TABLE OF CONTENTS
PART I
Forward-Looking Statements
This annual report contains forward-looking statements that are subject to risks and uncertainties. Forward-looking statements give our current expectations and projections relating to our financial condition, results of operations, plans, objectives, future performance and business. You can identify forward-looking statements by the fact that they do not relate strictly to historical or current facts. These statements may include words such as “anticipate,” “estimate,” “expect,” “forecast,”“project,” “plan,” “intend,” “believe,” “confident,” “may,” “should,” “can have,” “likely,” “future” and other words and terms of similar meaning in connection with any discussion of the timing or nature of future operating or financial performance or other events.
The forward-looking statements contained in this annual report are based on assumptions that we have made in light of our industry experience and on our perceptions of historical trends, current conditions, expected future developments and other factors we believe are appropriate under the circumstances. As you read and consider this report, you should understand that these statements are not guarantees of performance or results. They involve risks, uncertainties (some of which are beyond our control) and assumptions. Although we believe that these forward-looking statements are based on reasonable assumptions, you should be aware that many factors could affect our actual financial results and cause them to differ materially from those anticipated in the forward-looking statements. The forward-looking statements contained in this annual report include estimates regarding:
| · | our business, financial and operating results and future economic performance; |
|---|
| · | proposed new product and service offerings; and |
|---|
| · | management's goals, expectations and objectives and other similar expressions concerning matters that are not historical facts. |
|---|
Factors that could affect our actual financial results and cause them to differ materially from those anticipated in the forward-looking statements include:
| · | demand for our products; |
|---|
| · | frequency and duration of major power outages; |
|---|
| · | availability, cost and quality of raw materials and key components used in producing our products; |
|---|
| · | the impact on our results of the substantial increases in our outstanding indebtedness and related interest expense due to the dividend recapitalization transactions completed in May 2012 and 2013; |
|---|
| · | the possibility that the expected synergies, efficiencies and cost savings of our acquisitions will not be realized, or will not be realized within the expected time period; |
|---|
| · | the risk that our acquisitions will not be integrated successfully; |
|---|
| · | difficulties we may encounter as our business expands globally; |
|---|
| · | competitive factors in the industry in which we operate; |
|---|
| · | our dependence on our distribution network; |
|---|
| · | our ability to invest in, develop or adapt to changing technologies and manufacturing techniques; |
|---|
| · | loss of our key management and employees; |
|---|
| · | increase in product and other liability claims; and |
|---|
| · | changes in environmental, health and safety laws and regulations. |
|---|
Should one or more of these risks or uncertainties materialize, or should any of these assumptions prove incorrect, our actual results may vary in material respects from those projected in any forward-looking statements. A detailed discussion of these and other factors that may affect future results is contained in Item 1A of this Annual Report on Form 10-K.
Any forward-looking statement made by us in this report speaks only as of the date on which we make it. Factors or events that could cause our actual results to differ may emerge from time to time, and it is not possible for us to predict all of them. We undertake no obligation to update any forward-looking statement, whether as a result of new information, future developments or otherwise, except as may be required by law.
Item 1. Business
We are a leading designer and manufacturer of a wide range of power generation equipment and other engine powered products serving the residential, light commercial, industrial and construction markets. Power generation is our main focus, which differentiates us from our primary competitors that also have broad operations outside of the generator market. As the only significant market participant focused predominantly on these products, we have one of the leading market positions in the power equipment market in North America and an expanding presence internationally. We believe we have one of the widest range of products in the marketplace, including residential, commercial and industrial standby generators, as well as portable and mobile generators used in a variety of applications. Other engine powered products that we design and manufacture include light towers which provide temporary lighting for various end markets and a broad product line of power washers for residential and commercial use.
We design, manufacture, source and modify engines, alternators, transfer switches and other components necessary for our products, which are fueled by natural gas, liquid propane, gasoline, diesel and Bi-Fuel™. Our products are available primarily across the U.S and Canada, with an expanding presence internationally in the Latin America, Europe, Middle East, Africa and Asia/Pacific regions. Products are sold into these regions through a broad network of independent dealers, retailers, wholesalers and equipment rental companies under the Generac®, Magnum™, Ottomotores and Tower Light brand names. We also sell direct to certain national and regional account customers that are the end users of our products.
We have a significant market share in the residential and light commercial generator markets, which we believe are currently under penetrated. We believe that our leading market position is largely attributable to our strategy of providing a broad product line of high-quality, innovative and affordable products through our extensive and multi-layered distribution network. In addition, through recent acquisitions, we are also a leading provider of light towers and mobile generators, as well as a supplier of industrial diesel generators ranging in sizes up to 3,250kW.
History
Generac Holdings Inc. is a Delaware corporation whose principal operating subsidiary is Generac Power Systems, Inc., or Generac Power Systems (collectively Generac). Generac Power Systems was founded in 1959 to market a line of affordable portable generators that offered superior performance and features. Through innovation and focus, we have grown to be a leading provider of power generation equipment to the residential, commercial, industrial, and construction markets.
Key events in our history include the following:
| - | In 1980, we expanded beyond portable generators into the industrial market with the introduction of our first stationary generators that provided up to 200 kW of power output. |
|---|
| - | We introduced our first residential standby generator in 1989, and expanded our product development and global distribution system in the 1990s, forming a series of alliances that tripled our higher output generator sales. |
|---|
| - | In 1998, we sold our Generac® portable products business (which included portable generator and pressure washer product lines) to a private equity firm who eventually sold this business to another company. |
|---|
| - | Our growth accelerated in 2000 as we expanded our residential automatic standby generator product offering, implemented our multi-layered distribution philosophy, and introduced our quiet-running QT Series generators in 2005, accelerating our penetration in the commercial market. |
|---|
| - | In 2006, the founder of Generac Power Systems sold the company to affiliates of CCMP Capital Advisors, LLC or CCMP, together with certain other investors and members of our management (CCMP Transaction). |
|---|
| - | In 2008, we successfully expanded our position in the portable generator market after the expiration of our non-compete agreement that was entered into when we sold our Generac® portable products business in 1998. |
|---|
| - | In February 2010, we completed our initial public offering (IPO) of 20.7 million primary shares of our common stock (including additional share allotment). |
|---|
| - | In early 2011, we re-entered the market for gasoline-powered pressure washers (or power washers), which we previously exited in 1998 with the sale of our Generac® portable products business. |
|---|
| - | In October 2011, we purchased substantially all the assets of the Magnum Products business (Magnum or Magnum Products) which is the number one light tower manufacturer in the U.S. and has a growing share of the mobile generator market. |
|---|
| - | In December 2012, we purchased all of the equity of Ottomotores UK Limited and its affiliates (Ottomotores) which is one of the largest manufacturers of industrial generators in Mexico. |
|---|
| - | In August 2013, we purchased all of the equity of Tower Light Srl and its wholly-owned subsidiaries (Tower Light) which is a leading developer and supplier of mobile light towers throughout Europe, the Middle East and Africa. |
|---|
| - | In August 2013, CCMP completed the last of a series of sale transactions that began in November 2012 by which it sold substantially all of the shares of common stock that it owned as of the initial public offering. |
|---|
| - | In November 2013, we purchased substantially all the assets of the generator division of Baldor Electric Company, a wholly-owned subsidiary of ABB Group (Baldor Generators), which offers a complete line of standby and prime rated products ranging from 3kW up to 2,500kW throughout the US. And Canada. |
|---|
Today, we manufacture a full line of power products for a wide variety of applications and markets. We have demonstrated a long track record of achieving significant revenue growth through product innovation, expanded distribution and increased awareness of our products. We have experienced organic revenue growth of nearly 20% during the past 10 years on a compounded annual basis. Our success is built on engineering expertise, manufacturing & sourcing excellence and our innovative approaches to the market.
Products
We design and manufacture stationary, portable and mobile generators with single-engine outputs ranging between 800W and up to 3,250kW, with the ability to expand the power range for certain stationary generator solutions to much larger multi-megawatt systems through our Modular Power Systems, an integrated paralleling configuration. Other engine powered products that we design and manufacture include light towers, power washers and pumps. We classify our products into three classes based on similar range of power output geared for varying end customer uses: Residential power products, Commercial & Industrial power products; and Other products. The following summary outlines our portfolio of products, including their key attributes and customer applications.
Residential power products
Our residential automatic standby generators range in output from 6kW to 60kW, with manufacturer's suggested retail prices, or MSRPs, from approximately $1,900 to $16,700. These products operate on natural gas, liquid propane or diesel and are permanently installed with an automatic transfer switch, which we also manufacture. Air-cooled engine residential standby generators range in outputs from 6kW to 20kW, are available in steel and aluminum enclosures and serve as an emergency backup for small to medium-sized homes. Liquid-cooled engine generators serve as emergency backup for larger homes and small businesses and range in output from 22kW to 60kW. Liquid-cooled brands include the Guardian® Series and the premium Quietsource® Series, which have a quiet, low-speed engine and a standard aluminum enclosure.
In late 2013, we introduced a line of compact diesel generators developed specifically for residential and light-commercial users called Protector® Series, which offers the industry’s smallest and most compact footprint at price points well below those of larger, more traditional diesel generator sets in the marketplace.
Also during 2013, we introduced a new cellular remote monitoring system for home standby generators called Mobile Link™, which allows our customers to check the status of their generator conveniently from a desktop PC, tablet computer or mobile phone and also provides the capability to receive maintenance or service alerts.
We provide portable generators that are fueled predominantly by gasoline that range in size from 800W to 17,500W. These products serve as an emergency home backup and are also used for construction and recreational purposes. We currently have five portable product lines: the GP series, targeted at homeowners, ranging from 1,800W to 17,500W; the LP series, that runs on propane and is also targeted at homeowners, ranging from 3,250W to 5,500W; the XG series, targeted at the premium homeowner markets, ranging from 4,000 to 10,000W; the XP series, targeted at the professional contractor market, ranging from 3,600 to 10,000W; and the iX series, targeted at the recreational market, ranging from 800W to 2,000W. In addition, we offer manual transfer switches to supplement our portable generator product offering.
We also provide a broad product line of engine driven power washers, which are also fueled by gasoline, that range in PSI from 2,000 to 4,000 that are used for residential and commercial use.
Residential power products comprised 56.8%, 60.0% and 62.0%, respectively, of total net sales in 2013, 2012 and 2011.
Commercial & Industrial power products
We offer a full line of commercial & industrial generators fueled by diesel, natural gas, liquid propane and Bi-Fuel™. Ranging from 22kW up to 3,250kW, we believe we have one of the broadest product offerings in the industry.
Our light-commercial standby generators include a full range of affordable systems from 22kW to 150kW and related transfer switches, providing three-phase power sufficient for most small and mid-sized businesses including grocery stores, convenience stores, restaurants, gas stations, pharmacies, retail banks and small health care facilities. Our light-commercial generators run on natural gas and liquid propane, and in late 2013 we introduced a product line of compact, diesel-fueled generators called Protector® Series.
We also manufacture a broad line of standard and configured standby generators and related transfer switches for industrial applications. Our single-engine industrial generators range in output from 10kW up to 3,250kW with our Modular Power System (MPS) technology extending our product range up to much larger multi-megawatt systems through an integrated paralleling configuration. We offer four fuel options for our industrial generators, including diesel, natural gas, liquid propane or Bi-Fuel™. Bi-Fuel™ generators operate on a combination of both diesel and natural gas to allow our customers the advantage of multiple fuel sources and extended run times. Our industrial generators are primarily used as emergency backup for large healthcare, telecom, datacom, commercial office, municipal and manufacturing customers.
The acquisition of Baldor Generators in November 2013 enables us, for the first time, to offer single-engine industrial generators larger than 600kW within the U.S. and Canada. The Baldor Generators product offering includes stationary and containerized packages up to 2,500kW that can be used in standby applications and in certain configurations in prime power applications. The addition of these products significantly expands our industrial product offering and the addressable domestic market that our distribution partners can serve.
Our MPS technology combines the power of several smaller generators to produce the output of a larger generator, providing our customers with redundancy and scalability in a cost-effective manner. For larger industrial applications, our MPS products offer customers an efficient, affordable way to scale their standby power needs. The MPS product line also offers superior reliability given its built-in redundancy which allows individual units to be taken off-line for routine maintenance while retaining coverage for critical circuits.
Our light towers and mobile generators provide temporary lighting and power for various end markets, such as road and commercial construction, energy, mining, military and special events. We also manufacture mobile pumps which utilize wet and dry-priming pump systems for a wide variety of wastewater applications. The acquisition of Tower Light in August 2013 provides us an expanded product offering of light towers to support additional geographic markets, allowing us to participate in the growing rental market outside the U.S.
Commercial & Industrial power products comprised 38.4%, 34.9% and 31.6% respectively, of total net sales in 2013, 2012 and 2011.
Other power products
We sell aftermarket service parts to our dealers and proprietary engines to third-party original equipment manufacturers, or OEMs.
Other power products comprised 4.8%, 5.1% and 6.4%, respectively, of total net sales in 2013, 2012 and 2011.
Distribution channels and customers
We distribute our products through several channels to increase awareness of our product categories and the Generac®, Magnum®, OttomotoresTM and Tower LightTM brands, and to ensure our products reach a broad customer base. This distribution network includes independent residential and industrial dealers, national retailers, e-commerce merchants, electrical wholesalers (including certain private label arrangements), catalogs, equipment rental companies and equipment dealers. We also sell direct to certain national account customers that are the end users of our products.
We believe our distribution network is a competitive advantage that has strengthened over the last decade as a result of adding and expanding the various distribution channels through which we sell our products. Our network is well balanced with no customer providing more than 6% of our sales in 2013.
Our overall dealer network, which is located principally in the United States, Canada and Latin America, is the industry's largest network of factory direct independent generator contractors. In addition, the acquisition of Tower Light in August 2013 provides access to numerous independent distributors in over 50 countries.
Our residential/commercial dealer network sells, installs and services our residential and light-commercial products to end users. We have increased our level of investment in recent years by focusing on a variety of initiatives to more effectively market and sell our home standby products and better align our dealer network with Generac.
Our industrial dealer network provides industrial and commercial end users with ongoing sales and product support. Our industrial dealers maintain the local relationships with commercial electrical contractors, specifying engineers and national account regional buying offices. In recent years, we have been particularly focused on expanding our dealer network in Latin America and other regions of the world in order to expand our international sales opportunities.
Our retail distribution network includes thousands of locations and includes regional and national home improvement chains, retailers, clubs, buying groups and farm supply stores. These physical retail locations are supplemented by a number of catalogue and e-commerce retailers. This network primarily sells our residential standby, portable and light-commercial generators as well as our power washers.
Our wholesaler network distributes our residential and light-commercial generators and consists of selling branches of both national and local distribution houses for electrical and HVAC products.
On a selective basis, we have established private label and licensing arrangements with third party partners to provide residential, light-commercial and industrial generators. These partners include leading home equipment, electrical equipment and construction machinery companies, each of which provides access to incremental channels of distribution for our products.
The distribution for our mobile products includes international, national and regional equipment rental companies, equipment dealers and construction companies, which primarily serve non-residential building construction, road construction and energy markets.
We sell direct to certain national account customers that are the end users of our products covering a number of end market verticals, including telecommunication, retail, banking, convenience stores, and other light commercial applications.
Additionally, we sell certain engines directly to OEM manufacturers and after-market dealers for use in the lawn, garden and rental markets.
Business strategy
We believe our growth over the last several years is due in part to the development and execution of our "Powering Ahead” strategy. Since shortly after our initial public offering in 2010, this strategic plan has served as the framework for the significant investments we have made to drive the growth of Generac. As we continue to move the Powering Ahead plan into the future, we are focused on a number of initiatives that are driven by the same four key objectives:
Growing the residential standby generator market. As the leader in the home standby generator category, it is incumbent upon us to continue to drive growth and increase the penetration rate of these products in households across the United States. Central to this strategy is to increase the awareness, availability and affordability of home standby generators. Ongoing power outage activity, combined with expanding our dealer base and overall distribution in affected regions, are key drivers in elevating the awareness of home standby generators over the long term. We intend to continue to supplement these key growth drivers with targeted sales and marketing initiatives to further extend the awareness of home standby generators. In addition, we intend to continue to focus on innovation in this emerging product category and introduce new products into the marketplace. With only approximately 3.0% penetration of the addressable market of U.S. homes (which we define as single-family detached, owner-occupied households with a home value of over $100,000, as defined by the U.S. Census Bureau's 2011 American Housing Survey for the United States), we believe there are opportunities to further penetrate the residential standby generator market.
Gaining commercial and industrial market share. Our growth strategy for commercial and industrial power generation products is focused on incremental market share gains. Key to this objective are our efforts to develop and improve our industrial distribution, increase our addressable market with new products and increase the rate at which our products are specified in C&I power generation applications. In addition, we will attempt to garner incremental market share through our leading position in the growing market for cleaner burning, more cost effective natural gas fueled back-up power solutions. While still a much smaller portion of the overall C&I market, we believe demand for these products continues to increase at a faster rate than traditional diesel fueled generators as a result of their lower capital and operating costs. We also believe there is an opportunity to provide smaller, more cost effective generators marketed aggressively towards the underpenetrated “optional” standby market which includes smaller footprint commercial buildings. With our scale in these smaller commercial products, our distribution capabilities, and our national account customer focus, we believe we have an opportunity to penetrate these markets by using a targeted marketing approach and funneling opportunities to our distribution partners.
Diversifying end markets by expanding product offerings and services. In recent years, we have worked hard to diversify Generac's end markets with new products and services. Much of this diversification has been achieved with our strategic acquisitions over the last three years. We now have access to several new products, new markets and new customers through the purchase of the Magnum Products business in October 2011, the Ottomotores businesses in December 2012, Tower Light in August 2013 and Baldor Generators in November 2013. As a result of these acquisitions, we now have access to a broad lineup of mobile power products, as well as products that serve the oil & gas and other infrastructure power markets. Additionally, our re-entry into the market for power washers in 2011 provides us with an opportunity to further diversify our company with the addition of this platform. As we continue to build upon our recent diversification efforts, we intend to evaluate other products and services which we believe could further diversify our end markets.
Expanding into new geographies. During 2013, approximately 8% of our revenues were shipped to regions outside the U.S. and Canada. Given that the global market for power generation equipment is estimated to exceed $15 billion annually, we believe there are growth opportunities for Generac by expanding into new geographies. Prior to 2013, these efforts had been mostly organic with the creation of a dedicated sales team and the addition of over 100 new distribution points around the globe, with many of those in Latin America. The acquisitions of the Ottomotores and Tower Light businesses provide us with an enhanced platform and immediate scale for our international growth initiatives and accelerates our efforts to become a more global player in the markets for backup power and mobile power equipment. As we look forward, we intend to leverage these recent acquisitions while also evaluating other opportunities to expand into other regions of the world.
We believe the investments we have made to date, due in part to our Powering Ahead strategy, have helped to capitalize on the macro, secular growth drivers for our business and are an important part of our efforts to diversify and globalize our business. See “Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations – Business drivers and trends” for additional drivers that influence demand for our products and other trends affecting the markets that we serve.
Manufacturing
We operate several manufacturing plants located principally in Wisconsin (USA), Mexico, Italy and Brazil totaling over three million square feet. We also maintain inventory warehouses in the United States that accommodate material storage and rapid response requirements of our customers.
In recent years, we have added manufacturing capacity through investments in automation, improved utilization and the expansion of our manufacturing footprint through organic means as well as through acquisitions. We believe we have sufficient capacity to achieve our business goals for the near-to-intermediate term.
Research and development
Our primary focus on generators and engine powered equipment drives technological innovation, specialized engineering and manufacturing competencies. Research and development is a core competency and includes a staff of over 250 engineers working on numerous active projects. Our sponsored research and development expense was $29.3 million, $23.5 million and $16.5 million for the years ended December 2013, 2012 and 2011, respectively. Research and development is conducted at each of our manufacturing facilities and additionally at our technical center in Suzhou, China with dedicated teams for each product line. Research and development is focused on developing new technologies and product enhancements as well as maintaining product competitiveness by improving manufacturing costs, safety characteristics, reliability and performance while ensuring compliance with regulatory standards. We have over 30 years of experience using natural gas engines and have developed specific expertise with fuel systems and emissions technology. In the residential and light commercial markets, we have developed proprietary engines, cooling packages, controls, fuel systems and emissions systems. We believe that our expertise in engine powered equipment gives us the capability to develop new products that will allow continued diversification in our end markets.
Intellectual property
We rely on a combination of patents and trademarks to establish and protect our proprietary rights. Our commitment to research and development has resulted in a portfolio of over 100 U.S. and international patents and patent applications. Our patents expire between 2016 and 2030 and protect certain features and technologies we have developed for use in our products including fuel systems, air flow, electronics and controls, noise reduction and air-cooled engines. New U.S. patents that are issued generally have a life of 20 years from the date the patent application is initially filed. U.S. and international trademark registrations generally have a perpetual duration if they are properly maintained and renewed. We believe the existence of these patents and trademarks, along with our ongoing processes to register additional patents and trademarks, protect our intellectual property rights and enhance our competitive position. We also use proprietary manufacturing processes that require customized equipment.
Suppliers of raw materials
Our primary raw material inputs are steel, copper and aluminum, all of which are purchased from third parties and, in many cases, as part of machined or manufactured components. We have developed an extensive network of reliable, low-cost suppliers in the United States and abroad. Our strategic global sourcing function continuously evaluates the cost structure of our products and assesses the capabilities of our supply chain. Components are sourced accordingly based on this evaluation. Our supplier quality engineers conduct on-site audits of major supply chain partners and help to maintain the reliability of critical sourced components. In 2013, we sourced approximately 60% of our materials and components from outside the United States.
Competition
The market for power generation equipment is competitive. We face competition from a variety of large diversified industrial companies as well as smaller generator manufacturers abroad. However, most of the traditional participants in the generator market compete on a more specialized basis, focused on specific applications within their larger diversified product mix. We are the only significant market participant focused predominantly on standby, portable and mobile generators with broad capabilities across the residential, light commercial, industrial and construction generator markets. We believe that our engineering capabilities and core focus on generators provide us with manufacturing flexibility and enable us to maintain a first-mover advantage over our competition for product innovation. We also believe our broad product offering and diverse distribution model provide for additional advantages as well.
A summary of the primary competitors across our main product classes are as follows:
Residential standby generators – Kohler, Briggs & Stratton and Cummins (Onan division), each of which also have broad operations in other manufacturing businesses.
Portable generators – Honda, Briggs & Stratton, Pramac and Techtronics International (TTI), along with a number of smaller domestic and foreign competitors.
Power washers – Briggs & Stratton, TTI, FNA Group, Mi-T-M and Karcher.
Standby commercial and industrial generators – Caterpillar, Cummins, Kohler, MTU, most of which focus on the market for diesel generators as they are also diesel engine manufacturers.
Mobile generators – Doosan, Wacker and MultiQuip
Light towers – Terex, Allmand, Wacker and Atlas Copco
There are a number of other standby generator manufacturers and packagers located outside North America, but most supply their products mainly to their respective regional markets. In a continuously evolving sector, we believe our scale and broad capabilities make us well positioned to remain competitive.
We compete primarily on the basis of brand reputation, quality, reliability, pricing, innovative features, breadth of product offering and product availability.
Employees
As of December 31, 2013, we had 3,380 employees (3,032 full time and 348 part-time and temporary employees). Of those, 2,094 employees were directly involved in manufacturing at our manufacturing facilities.
Domestically, we have had an “open shop” bargaining agreement for the past 48 years. The current agreement, which expires October 17, 2016, covers our Waukesha and Eagle, Wisconsin facilities. Additionally, our plants in Mexico, Italy and Brazil are operated under various local or national union groups. Our other facilities are not unionized.
Regulation, including environmental matters
As a manufacturing company, our operations are subject to a variety of foreign, federal, state and local laws and regulations covering environmental, health and safety matters. Applicable laws and regulations include those governing, among other things, emissions to air, discharges to water, noise and employee safety, as well as the generation, handling, storage, transportation, treatment and disposal of waste and other materials. In addition, our products are subject to various laws and regulations relating to, among other things, emissions and fuel requirements, as well as labeling and marketing.
Our products sold in the United States are regulated by the U.S. Environmental Protection Agency (“EPA”), California Air Resources Board (“CARB”) and various other state and local air quality management districts. These governing bodies continue to pass regulations that require us to meet more stringent emission standards, and all of our engines and engine-driven products are regulated within the United States and its territories. Other countries have various degrees of regulation depending upon product application and fuel types. New regulations could require us to redesign our products and could affect market growth for our products.
Segment information
We refer you to Note 2, “Segment Reporting,” of our consolidated financial statements included in Item 8 of this Annual Report on Form 10-K for information about our business segment and geographic areas.
Available Information
The Company’s principal executive offices are located at S45 W29290 Highway 59, Waukesha, Wisconsin, 53189 and the Company’s telephone number is (262) 544-4811. The Company’s annual report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments to those reports are available free of charge through the “Investors” portion of the Company’s web site, www.generac.com, as soon as reasonably practical after they are filed with the Securities and Exchange Commission, or the “SEC”. The SEC maintains a web site, www.sec.gov, which contains reports, proxy and information statements, and other information filed electronically with the SEC by the Company. The information provided on these websites is not part of this report and is therefore not incorporated herein by reference.
Executive officers
The following table sets forth information regarding our executive officers:
| Name Age Position | ||||
|---|---|---|---|---|
| Aaron P. Jagdfeld | 42 | President, Chief Executive Officer and Director | ||
| York A. Ragen | 42 | Chief Financial Officer | ||
| Terrence J. Dolan | 48 | Executive Vice President, Global Commercial & Industrial Products | ||
| Russell S. Minick | 53 | Executive Vice President, Global Residential Products | ||
| Roger F. Pascavis | 53 | Executive Vice President, Strategic Global Supply | ||
| Allen D. Gillette | 57 | Executive Vice President, Global Engineering | ||
| Robert Stoppek | 42 | Senior Vice President, Global Operations | ||
| Clement Feng | 50 | Senior Vice President, Marketing |
Aaron P. Jagdfeld has served as our Chief Executive Officer since September 2008 and as a director since November 2006. Prior to becoming Chief Executive Officer, Mr. Jagdfeld worked for Generac for 15 years. He began his career in the finance department in 1994 and became our Chief Financial Officer in 2002. In 2007, he was appointed President and was responsible for sales, marketing, engineering and product development. Prior to joining Generac, Mr. Jagdfeld worked in the audit practice of the Milwaukee, Wisconsin office of Deloitte and Touche. Mr. Jagdfeld holds a Bachelor of Business Administration in Accounting from the University of Wisconsin-Whitewater.
York A. Ragen has served as our Chief Financial Officer since September 2008. Prior to becoming Chief Financial Officer, Mr. Ragen held Director of Finance and Vice President of Finance positions at Generac. Prior to joining Generac in 2005, Mr. Ragen was Vice President, Corporate Controller at APW Ltd., a spin-off from Applied Power Inc., now known as Actuant Corporation. Mr. Ragen began his career in the Audit division of Arthur Andersen's Milwaukee office. Mr. Ragen holds a Bachelor of Business Administration in Accounting from the University of Wisconsin-Whitewater.
Terrence J. Dolan began serving as our Executive Vice President, Industrial Products in October 2011, with this title being expanded in January 2014 to Executive Vice President, Global Commercial & Industrial Products. Prior to becoming Executive Vice President of Industrial Products, he served as our Senior Vice President of Sales from January 2010 to October 2011. Prior to joining Generac, Mr. Dolan was Senior Vice President of Business Development and Marketing at Boart Longyear from 2007 to 2008, Vice President of Sales and Marketing at Ingersoll Rand from 2002 to 2007, and Director of Strategic Accounts at Case Corporation from 1991 to 2001. Mr. Dolan holds a B.A. in Management and Communications from Concordia University.
Russell S. Minick began serving as our Executive Vice President, Residential Products in October 2011, with this title being expanded in January 2014 to Executive Vice President, Global Residential Products. Prior to joining Generac, Mr. Minick was President & CEO of Home Care Products for Electrolux from 2006 to 2011, President of The Gunlocke Company at HNI Corporation from 2003 to 2006, Senior Vice President of Sales, Marketing and Product Development at True Temper Sports from 2002 to 2003, and General Manager of Extended Warranty Operations for Ford Motor Company from 1998 to 2002. Mr. Minick is a graduate of the University of Northern Iowa, and holds a degree in marketing.
Roger Pascavis has served as our Executive Vice President, Strategic Global Supply since March 2013. Prior to becoming Executive Vice President of Strategic Global Supply, he served as the Senior Vice President of Operations since January 2008. Mr. Pascavis joined Generac in 1995 and has served as Director of Materials and Vice President of Operations. Prior to joining Generac, Mr. Pascavis was a Plant Manager for MTI in Waukesha, Wisconsin. Mr. Pascavis holds a B.S. in Industrial Technology from the University of Wisconsin, Stout and an M.B.A. from Lake Forest Graduate School of Management.
Allen D. Gillette is our Executive Vice President of Global Engineering. Mr. Gillette joined Generac in 1998 and has served in numerous engineering positions involving increasing levels of responsibilities and corresponding titles. Prior to joining Generac, Mr. Gillette was Manager of Engineering at Transamerica Delaval Enterprise Division, Chief Engineer—High-Speed Engines at Ajax-Superior Division and Manager of Design & Development, Cooper-Bessemer Reciprocating Products Division. Mr. Gillette holds an M.S. in Mechanical Engineering from Purdue University and a B.S. in Mechanical Engineering from Gonzaga University.
Robert Stoppek has served as our Senior Vice President of Global Operations since March 2013 when he joined Generac. Prior to joining Generac, Mr. Stoppek spent over 16 years at Sauer-Danfoss holding various executive level business positions both domestically and internationally and most recently as Chief Supply Chain Officer-Vice President Global Supply Chain & Procurement with IDEX Corporation. Mr. Stoppek holds an MBA from Northwestern University’s Kellogg School of Business and a Masters in Mechanical Engineering from Iowa State University.
Clement Feng has served as our Senior Vice President of Marketing since August 2013 when he re-joined Generac after three years as Vice President – Global Marketing with the Fluke Corporation. Mr. Feng served as our Senior Vice President of Marketing from 2007 until 2010. Mr. Feng holds a B.S. in Chemical Engineering from Stanford University and an M.B.A. from the University of Chicago- Booth School of Business.
Item 1A. Risk Factors
You should carefully consider the following risks. These risks could materially affect our business, results of operations or financial condition, cause the trading price of our common stock to decline materially or cause our actual results to differ materially from those expected or those expressed in any forward-looking statements made by us or on our behalf. These risks are not exclusive, and additional risks to which we are subject include, but are not limited to, the factors mentioned under “Forward-Looking Statements” and the risks of our businesses described elsewhere in this Annual Report.
Risk factors related to our business and industry
Demand for our products is significantly affected by unpredictable major power-outage events that can lead to substantial variations in, and uncertainties regarding, our financial results from period to period.
Sales of our products are subject to consumer buying patterns, and demand for our products is affected by power outage events caused by thunderstorms, hurricanes, ice storms, blackouts and other grid reliability issues. The impact of these outage events on our sales can vary depending on the location and severity of the outages. Sustained periods without major power disruptions can lead to reduced consumer awareness of the benefits of standby and portable generator products and can result in reduced sales growth rates and excess inventory. The lack of major power-outage events can affect our net sales in the years following a given storm season. Unpredictable fluctuations in demand are therefore part of managing our business, and these fluctuations could have an adverse effect on our net sales and profits. Despite their unpredictable nature, we believe major power outages create awareness and accelerate adoption for our home standby products.
Demand for our products is significantly affected by durable goods spending by consumers and businesses and other macroeconomic conditions.
Our business is affected by general economic conditions, and uncertainty or adverse changes such as the prolonged downturn in U.S. residential investment and the impact of more stringent credit standards could lead to a decline in demand for our products and pressure to reduce our prices. Our sales of light-commercial and industrial generators are affected by conditions in the non-residential construction sector and by the capital investment trends for small and large businesses and municipalities. If these businesses and municipalities cannot access credit markets or do not utilize discretionary funds to purchase our products as a result of the economy or other factors, our business could suffer and our ability to realize benefits from our strategy of increasing sales in the light-commercial and industrial sectors through, among other things, our focus on innovation and product development, including natural gas engine and modular technology, could be adversely affected. In addition, consumer confidence and home remodeling expenditures have a significant impact on sales of our residential products, and prolonged periods of weakness in consumer durable goods spending could have a material impact on our business. Typically, we do not have contracts with our customers which call for committed volume, and we cannot guarantee that our current customers will continue to purchase our products. If general economic conditions or consumer confidence were to worsen, or if the non-residential construction sector or rate of capital investments were to decline, our net sales and profits would likely be adversely affected. Additionally, timing of capital spending by our national account customers can vary from quarter-to-quarter based on capital availability and internal capital spending budgets.
Decreases in the availability and quality, or increases in the cost, of raw materials and key components we use could materially reduce our earnings.
The principal raw materials that we use to produce our products are steel, copper and aluminum. We also source a significant number of component parts from third parties that we utilize to manufacture our products. The prices of those raw materials and components are susceptible to significant fluctuations due to trends in supply and demand, transportation costs, government regulations and tariffs, price controls, economic conditions and other unforeseen circumstances beyond our control. We do not have long-term supply contracts in place to ensure the raw materials and components we use are available in necessary amounts or at fixed prices. If we are unable to mitigate raw material or component price increases through product design improvements, price increases to our customers, manufacturing productivity improvements, or hedging transactions, our profitability could be adversely affected. Also, our ability to continue to obtain quality materials and components is subject to the continued reliability and viability of our suppliers, including in some cases, suppliers who are the sole source of certain important components. If we are unable to obtain adequate, cost efficient or timely deliveries of required raw materials and components, we may be unable to manufacture sufficient quantities of products on a timely basis. This could cause us to lose sales, incur additional costs, delay new product introductions or suffer harm to our reputation.
The industry in which we compete is highly competitive, and our failure to compete successfully could adversely affect our results of operations and financial condition.
We operate in markets that are highly competitive. Some of our competitors have established brands and are larger in size or are divisions of large diversified companies and have substantially greater financial resources. Some of our competitors may be willing to reduce prices and accept lower margins in order to compete with us. In addition, we could face new competition from large international or domestic companies with established industrial brands that enter our end markets. Demand for our products may also be affected by our ability to respond to changes in design and functionality, to respond to downward pricing pressure, and to provide shorter lead times for our products than our competitors. If we are unable to respond successfully to these competitive pressures, we could lose market share, which could have an adverse impact on our results. For more information, see “Item 1—Business—Competition.”
Our industry is subject to technological change, and our failure to continue developing new and improved products and to bring these products rapidly to market could have an adverse impact on our business.
New products, or refinements and improvements of existing products, may have technical failures, their introduction may be delayed, they may have higher production costs than originally expected or they may not be accepted by our customers. If we are not able to anticipate, identify, develop and market high quality products in line with technological advancements that respond to changes in customer preferences, demand for our products could decline and our operating results could be adversely affected.
We rely on independent dealers and distribution partners, and the loss of these dealers and distribution partners, or of any of our sales arrangements with significant private label, telecommunications, retail or equipment rental customers, would adversely affect our business.
In addition to our direct sales force and manufacturer sales representatives, we depend on the services of independent distributors and dealers to sell our products and provide service and aftermarket support to our end customers. We also rely upon our distribution channels to drive awareness for our product categories and our brands. In addition, we sell our products to end users through private label arrangements with leading home equipment, electrical equipment and construction machinery companies, arrangements with top retailers and equipment rental companies, and our direct national accounts with telecommunications and industrial customers. Our distribution agreements and any contracts we have with large telecommunications, retail and other customers are typically not exclusive, and many of the distributors and customers with whom we do business offer products and services of our competitors. Impairment of our relationships with our distributors, dealers or large customers, loss of a substantial number of these distributors or dealers or of one or more large customers, or an increase in our distributors' or dealers' sales of our competitors' products to our customers or of our large customers' purchases of our competitors' products could materially reduce our sales and profits. Also, our ability to successfully realize our growth strategy is dependent in part on our ability to identify, attract and retain new distributors at all layers of our distribution platform, and we cannot be certain that we will be successful in these efforts.
Our business could be negatively impacted if we fail to adequately protect our intellectual property rights or if third parties claim that we are in violation of their intellectual property rights.
We view our intellectual property rights as very important assets. We seek to protect our intellectual property rights through a combination of patent, trademark, copyright and trade secret laws, as well as licensing and confidentiality agreements. These protections may not be adequate to prevent third parties from using our intellectual property without our authorization, breaching any confidentiality agreements with us, copying or reverse engineering our products, or developing and marketing products that are substantially equivalent to or superior to our own. The unauthorized use of our intellectual property by others could reduce our competitive advantage and harm our business. Not only are intellectual property-related proceedings burdensome and costly, but they could span years to get a conclusion and we may not prevail. We cannot guarantee that any patents, issued or pending, will provide us with any competitive advantage or will not be challenged by third parties. Moreover, the expiration of our patents may lead to increased competition with respect to certain products.
In addition, we cannot be certain that we do not or will not infringe third parties' intellectual property rights. Any such claim, even if it is without merit, may be expensive and time-consuming to defend, subject us to damages, cause us to cease making, using or selling certain products that incorporate the disputed intellectual property, require us to redesign our products, divert management time and attention and/or require us to enter into costly royalty or licensing arrangements. Furthermore, in connection with our sale of Generac Portable Products to a private equity firm in 1998, we granted the private equity firm an exclusive perpetual license for the use of the “Generac Portable Products” trademark in connection with the manufacture and sale of certain engine driven consumer products. This perpetual license was eventually transferred to another company when the private equity firm sold that business. Currently, this trademark is not being used in commerce and, as such, there is a rebuttable presumption that the trademark has been abandoned. However, in the event that this trademark is used in the future, we could suffer competitive confusion and our business could be negatively impacted.
Our operations are subject to various environmental, health and safety laws and regulations, and non-compliance with or liabilities under such laws and regulations could result in substantial costs, fines, sanctions and claims.
Our operations are subject to a variety of foreign, federal, state and local environmental, health and safety laws and regulations including those governing, among other things, emissions to air, discharges to water, noise, the generation, handling, storage, transportation, treatment and disposal of waste and other materials. In addition, under federal and state environmental laws, we could be required to investigate, remediate and/or monitor the effects of the release or disposal of materials both at sites associated with past and present operations and at third-party sites where wastes generated by our operations were disposed. This liability may be imposed retroactively and whether or not we caused, or had any knowledge of, the existence of these materials and may result in our paying more than our fair share of the related costs. Violations of or liabilities under such laws and regulations could result in substantial costs, fines and civil or criminal proceedings or personal injury and workers' compensation claims.
Our products are subject to substantial government regulation.
Our products are subject to extensive statutory and regulatory requirements governing, among other things, emissions and noise, including standards imposed by the federal Environmental Protection Agency (“EPA”), state regulatory agencies, such as California Air Resources Board (“CARB”), and other regulatory agencies around the world. These laws are constantly evolving and many are becoming increasingly stringent. Changes in applicable laws or regulations, or in the enforcement thereof, could require us to redesign our products and could adversely affect our business or financial condition in the future. Developing and marketing products to meet such new requirements could result in substantial additional costs that may be difficult to recover in some markets. In some cases, we may be required to modify our products or develop new products to comply with new regulations, particularly those relating to air emissions. For example, we were required to modify our spark-ignited air-cooled gaseous engines to comply with the 2011 EPA and CARB regulations, as well as the continued implementation of Tier 4 nonroad diesel engine changes associated with acquisitions serving the mobile product markets. Typically, additional costs associated with significant compliance modifications are passed on to the market. While we have been able to meet previous deadlines, failure to comply with other existing and future regulatory standards could adversely affect our position in the markets we serve.
We may incur costs and liabilities as a result of product liability claims.
We face a risk of exposure to product liability claims in the event that the use of our products is alleged to have resulted in injury or other damage. Although we currently maintain product liability insurance coverage, we may not be able to obtain such insurance on acceptable terms in the future, if at all, or obtain insurance that will provide adequate coverage against potential claims. Product liability claims can be expensive to defend and can divert the attention of management and other personnel for long periods of time, regardless of the ultimate outcome. A significant unsuccessful product liability defense could have a material adverse effect on our financial condition and results of operations. In addition, we believe our business depends on the strong brand reputation we have developed. If our reputation is damaged, we may face difficulty in maintaining our market share and pricing with respect to some of our products, which could reduce our sales and profitability.
The loss of any key members of our senior management team or key employees could disrupt our operations and harm our business.
Our success depends, in part, on the efforts of certain key individuals, including the members of our senior management team, who have significant experience in the power products industry. If, for any reason, our senior executives do not continue to be active in management, or if our key employees leave our company, our business, financial condition or results of operations could be adversely affected. Failure to continue to attract these individuals at reasonable compensation levels could have a material adverse effect on our business, liquidity and results of operations. Although we do not anticipate that we will have to replace any of these individuals in the near future, the loss of the services of any of our key employees could disrupt our operations and have a material adverse effect on our business.
Disruptions caused by labor disputes or organized labor activities could harm our business.
We may from time to time experience union organizing activities in our non-union facilities. Disputes with the current labor union or new union organizing activities could lead to work slowdowns or stoppages and make it difficult or impossible for us to meet scheduled delivery times for product shipments to our customers, which could result in loss of business. In addition, union activity could result in higher labor costs, which could harm our financial condition, results of operations and competitive position.
We may experience material disruptions to our manufacturing operations.
While we seek to operate our facilities in compliance with applicable rules and regulations and take measures to minimize the risks of disruption at our facilities, a material disruption at one of our manufacturing facilities could prevent us from meeting customer demand, reduce our sales and/or negatively impact our financial results. Any of our manufacturing facilities, or any of our equipment within an otherwise operational facility, could cease operations unexpectedly due to a number of events, including:
| · | equipment or information technology infrastructure failure; |
|---|
| · | disruptions in the transportation infrastructure including roads, bridges, railroad tracks; |
|---|
| · | fires, floods, tornados, earthquakes, or other catastrophes; and |
|---|
| · | other operational problems. |
|---|
In addition, the majority of our manufacturing and production facilities are located in Wisconsin within a 100-mile radius. We could experience prolonged periods of reduced production due to unforeseen events occurring in or around our manufacturing facilities in Wisconsin. In the event of a business interruption at our facilities, in particular our Wisconsin facilities, we may be unable to shift manufacturing capabilities to alternate locations, accept materials from suppliers or meet customer shipment needs, among other severe consequences. Such an event could have a material and adverse impact on our financial condition and results of our operations.
A significant portion of our purchased components are sourced in foreign countries, exposing us to additional risks that may not exist in the United States.
We source a significant portion of our purchased components overseas, primarily in Asia and Europe. Our international sourcing subjects us to a number of potential risks in addition to the risks associated with third-party sourcing generally. Such risks include:
| · | inflation or changes in political and economic conditions; |
|---|
| · | unstable regulatory environments; |
|---|
| · | changes in import and export duties; |
|---|
| · | domestic and foreign customs and tariffs; |
|---|
| · | currency rate fluctuations; |
|---|
| · | trade restrictions; |
|---|
| · | labor unrest; |
|---|
| · | logistical and communications challenges; and |
|---|
| · | other restraints and burdensome taxes. |
|---|
These factors may have an adverse effect on our ability to efficiently and cost effectively source our purchased components overseas. In particular, if the U.S. dollar were to depreciate significantly against the currencies in which we purchase raw materials from foreign suppliers, our cost of goods sold could increase materially, which would adversely affect our results of operations.
We are vulnerable to supply disruptions from single-sourced suppliers.
We single-sourced certain types of parts in our product designs during 2013. Any delay in our suppliers’ deliveries may impair our ability to deliver products to our customers. A wide variety of factors could cause such delays including, but not limited to, lack of capacity, economic downturns, availability of credit, weather events or natural disasters.
As a U.S. corporation that conducts business in a variety of foreign countries including, but not limited to, Mexico, Italy and Brazil, we are subject to the Foreign Corrupt Practices Act and a variety of anti-corruption laws worldwide. A determination that we violated any of these laws may affect our business and operations adversely.
As a U.S. corporation that conducts business in a variety of foreign countries including, but not limited to, Mexico, Italy and Brazil, we are subject to the regulations imposed by a variety of anti-corruption laws worldwide. The U.S. Foreign Corrupt Practices Act, or the FCPA, generally prohibits U.S. companies and their intermediaries from making improper payments to foreign officials for the purpose of obtaining or keeping business. The United Kingdom Bribery Act, or the UKBA, prohibits domestic and foreign bribery of the private sector as well as public officials. Any determination that we have violated any anti-corruption laws could have a material adverse effect on our financial position, operating results and cash flows.
Our total assets include goodwill and other indefinite-lived intangibles. If we determine these have become impaired in the future, net income could be materially adversely affected.
Goodwill represents the excess of cost over the fair market value of net assets acquired in business combinations. Indefinite-lived intangibles are comprised of certain trade names. At December 31, 2013, goodwill and other indefinite-lived intangibles totaled $891.1 million, most of which arose from the CCMP Transaction. We review goodwill and other intangibles at least annually for impairment and any excess in carrying value over the estimated fair value is charged to the statement of operations. A reduction in net income resulting from the write-down or impairment of goodwill or indefinite-lived intangibles could have a material adverse effect on our financial statements.
Goodwill and identifiable intangible assets are recorded at fair value on the date of acquisition. In accordance with FASB Accounting Standards Codification (ASC) Topic 350-20, goodwill and indefinite lived intangibles are reviewed at least annually for impairment and definite-lived intangible assets are reviewed for impairment whenever events or changes in circumstances indicate that their carrying value may not be recoverable. Future impairment may result from, among other things, deterioration in the performance of an acquired business or product line, adverse market conditions and changes in the competitive landscape, adverse changes in applicable laws or regulations, including changes that restrict the activities of an acquired business or product line, and a variety of other circumstances. The amount of any impairment is recorded as a charge to the statement of operations. We may never realize the full value of our intangible assets. Any future determination requiring the write-off of a significant portion of intangible assets would have an adverse effect on our financial condition and results of operations. See “Item 7—Management's Discussion and Analysis of Financial Condition and Results of Operations” for details.
We may need additional capital to finance our growth strategy or to refinance our existing credit facilities, and we may not be able to obtain it on acceptable terms, or at all, which may limit our ability to grow.
We may require additional financing to expand our business. Financing may not be available to us or may be available to us only on terms that are not favorable. The terms of our senior secured credit facilities limit our ability to incur additional debt. In addition, economic conditions, including a downturn in the credit markets, could impact our ability to finance our growth on acceptable terms or at all. If we are unable to raise additional funds or obtain capital on acceptable terms, we may have to delay, modify or abandon some or all of our growth strategies. On May 31, 2013, we amended and restated our term loan credit agreement, pursuant to which we incurred $1,200 million of a senior secured term loan to replace our prior $900 million term loan facility. Following the refinancing, we used the available proceeds from the new term loan and cash on hand to fund a special cash dividend to our stockholders of $5.00 per share and to pay related financing fees and expenses. In the future, if we are unable to refinance such facilities on acceptable terms, our liquidity could be adversely affected.
We are unable to determine the specific impact of changes in selling prices or changes in volumes of our products on our net sales.
Because of the wide range of products that we sell, the level of customization for many of our products, the frequent rollout of new products and the fact that we do not apply pricing changes uniformly across our entire portfolio of products, we are unable to determine with specificity the effect of volume changes or changes in selling prices on our net sales.
We may not realize all of the anticipated benefits of our acquisitions or those benefits may take longer to realize than expected. We may also encounter significant unexpected difficulties in integrating acquired businesses.
Our ability to realize the anticipated benefits of our acquisitions will depend, to a large extent, on our ability to integrate the acquired businesses with our business. The combination of independent businesses is a complex, costly and time-consuming process. Further, integrating and managing businesses with international operations may pose challenges not previously experienced by our management. As a result, we will be required to devote significant management attention and resources to integrating the business practices and operations of any acquired businesses with ours. The integration process may disrupt our business and, if implemented ineffectively, would preclude realization of the full benefits expected by us. Our failure to meet the challenges involved in integrating an acquired business into our existing operations or otherwise to realize the anticipated benefits of the transaction could cause an interruption of, or a loss of momentum in, our activities and could adversely affect our results of operations.
In addition, the overall integration of our acquired businesses may result in material unanticipated problems, expenses, liabilities, competitive responses, loss of customer relationships, and diversion of management's attention, and may cause our stock price to decline.
The difficulties of combining the operations of acquired businesses with ours include, among others:
| · | managing a larger company; |
|---|
| · | maintaining employee morale and retaining key management and other employees; |
|---|
| · | integrating two business cultures, which may prove to be incompatible; |
|---|
| · | the possibility of faulty assumptions underlying expectations regarding the integration process; |
|---|
| · | retaining existing customers and attracting new customers; |
|---|
| · | consolidating corporate and administrative infrastructures and eliminating duplicative operations; |
|---|
| · | the diversion of management's attention from ongoing business concerns and performance shortfalls as a result of the diversion of management's attention to the acquisition; |
|---|
| · | unanticipated issues in integrating information technology, communications and other systems; |
|---|
| · | unanticipated changes in applicable laws and regulations; |
|---|
| · | managing tax costs or inefficiencies associated with integrating the operations of the combined company; |
|---|
| · | unforeseen expenses or delays associated with the acquisition; |
|---|
| · | difficulty comparing financial reports due to differing financial and/or internal reporting systems; and |
|---|
| · | making any necessary modifications to internal financial control standards to comply with the Sarbanes-Oxley Act of 2002 and the rules and regulations promulgated thereunder. |
|---|
Many of these factors will be outside of our control and any one of them could result in increased costs, decreases in the amount of expected revenues and diversion of management's time and energy, which could materially impact our business, financial condition and results of operations. In addition, even if the operations of our acquired businesses are integrated successfully with our operations, we may not realize the full benefits of the transaction, including the synergies, cost savings or sales or growth opportunities that we expect. These benefits may not be achieved within the anticipated time frame, or at all. Or, additional unanticipated costs may be incurred in the integration of our businesses. All of these factors could cause dilution to our earnings per share, decrease or delay the expected accretive effect of the acquisition, and cause a decrease in the price of our common stock. As a result, we cannot assure you that the combination of our acquisitions with our business will result in the realization of the full benefits anticipated from the transaction.
Risks related to our common stock
If securities or industry analysts do not publish research or reports about our business, if they adversely change their recommendations regarding our common stock or if our results of operations do not meet their expectations, our common stock price and trading volume could decline.
The trading market for our common stock will be influenced by the research and reports that industry or securities analysts publish about us or our business. If one or more of these analysts cease coverage of our company or fail to publish reports on us regularly, we could lose visibility in the financial markets, which in turn could cause our stock price or trading volume to decline. Moreover, if one or more of the analysts who cover us downgrade recommendations regarding our stock, or if our results of operations do not meet their expectations, our stock price could decline and such decline could be material.
Anti-takeover provisions in our amended and restated certificate of incorporation and by-laws could prohibit a change of control that our stockholders may favor and could negatively affect our stock price.
Provisions in our amended and restated certificate of incorporation and by-laws may make it more difficult and expensive for a third party to acquire control of us even if a change of control would be beneficial to the interests of our stockholders. These provisions could discourage potential takeover attempts and could adversely affect the market price of our common stock. These provisions may also prevent or frustrate attempts by our stockholders to replace or remove our management. For example, our amended and restated certificate of incorporation and by-laws:
| · | permit our board of directors to issue preferred stock with such terms as they determine, without stockholder approval; |
|---|
| · | provide that only one-third of the members of the board are elected at each stockholders meeting and prohibit removal without cause; |
|---|
| · | require advance notice for stockholder proposals and director nominations; and |
|---|
| · | contain limitations on convening stockholder meetings. |
|---|
These provisions make it more difficult for stockholders or potential acquirers to acquire us without negotiation and could discourage potential takeover attempts and could adversely affect the market price of our common stock.
We do not anticipate paying dividends on our common stock in the foreseeable future.
While we declared a special dividend in both June 2012 and June 2013, we do not anticipate paying any further dividends in the foreseeable future on our common stock. We intend to retain all future earnings for the operation and expansion of our business and the repayment of outstanding debt. In addition, the terms of our senior secured credit facilities limit our ability to pay dividends on our common stock. As a result, capital appreciation, if any, of our common stock will be the sole source of gain for the foreseeable future. While we may change this policy at some point in the future, we cannot assure that we will make such a change.
Risks related to our capital structure
We have a significant amount of indebtedness which could adversely affect our cash flow and our ability to remain in compliance with debt covenants and make payments on our indebtedness.
We have a significant amount of indebtedness. As of December 31, 2013, we had total indebtedness of $1,187.8 million. Our significant level of indebtedness increases the possibility that we may be unable to generate cash sufficient to pay, when due, the principal of, interest on or other amounts due in respect of our indebtedness. Our significant indebtedness, combined with our lease and other financial obligations and contractual commitments could have other important consequences. For example, it could:
| · | make it more difficult for us to satisfy our obligations with respect to our indebtedness, which could result in an event of default under the agreements governing our indebtedness; |
|---|
| · | make us more vulnerable to adverse changes in general economic, industry and competitive conditions and adverse changes in government regulation; |
|---|
| · | require us to dedicate a portion of our cash flow from operations to payments on our indebtedness, thereby reducing the availability of our cash flows to fund working capital, capital expenditures, acquisitions and other general corporate purposes; |
|---|
| · | limit our flexibility in planning for, or reacting to, changes in our business and the industry in which we operate; |
|---|
| · | place us at a competitive disadvantage compared to our competitors that have less debt; and |
|---|
| · | limit our ability to borrow additional amounts for working capital, capital expenditures, acquisitions, debt service requirements, execution of our business strategy or other purposes. |
|---|
Any of the above-listed factors could materially adversely affect our business, financial condition, results of operations and cash flows. While we maintain interest rate swaps covering a portion of our outstanding debt, our interest expense could increase if interest rates increase because debt under our credit facilities bears interest at a variable rate once above a certain LIBOR floor. If we do not have sufficient earnings to service our debt, we may be required to refinance all or part of our existing debt, sell assets, borrow more money or sell securities, none of which we can guarantee we will be able to do.
The terms of our credit facilities restrict our current and future operations, particularly our ability to respond to changes in our business or to take certain actions.
Our credit facilities contain, and any future indebtedness of ours or our subsidiaries would likely contain, a number of restrictive covenants that impose significant operating and financial restrictions on us and our subsidiaries, including restrictions on our ability to engage in acts that may be in our best long-term interests. These restrictions include, among other things, our ability to:
| · | incur liens; |
|---|
| · | incur or assume additional debt or guarantees or issue preferred stock; |
|---|
| · | pay dividends, or make redemptions and repurchases, with respect to capital stock; |
|---|
| · | prepay, or make redemptions and repurchases of, subordinated debt; |
|---|
| · | make loans and investments; |
|---|
| · | make capital expenditures; |
|---|
| · | engage in mergers, acquisitions, asset sales, sale/leaseback transactions and transactions with affiliates; |
|---|
| · | change the business conducted by us or our subsidiaries; and |
|---|
| · | amend the terms of subordinated debt. |
|---|
The operating and financial restrictions in our credit facilities and any future financing agreements may adversely affect our ability to finance future operations or capital needs or to engage in other business activities. A breach of any of the restrictive covenants in our credit facilities would result in a default. If any such default occurs, the lenders under our credit facilities may elect to declare all outstanding borrowings, together with accrued interest and other fees, to be immediately due and payable, or enforce their security interest, any of which would result in an event of default. The lenders will also have the right in these circumstances to terminate any commitments they have to provide further borrowings. Our existing credit facilities do not contain any financial maintenance covenants.
Item 1B. Unresolved Staff Comments
None.
Item 2. Properties
We own, operate or lease manufacturing and distribution facilities located principally in Wisconsin (USA), Mexico, Italy and Brazil totaling over 3 million square feet. We also operate a dealer training center at our Eagle, Wisconsin facility, which allows us to train new industrial and residential dealers on the service and installation of our products and provide existing dealers with training on product innovations. We also have inventory warehouses in the United States that accommodate material storage and rapid response requirements of our customers.
The following table shows the location and activities of our principal operations:
| Location | Owned / Leased | Square Footage | Activities |
|---|---|---|---|
| Waukesha, WI | Owned | 307,000 | Corporate headquarters, manufacturing, storage, research and development, service parts distribution |
| Eagle, WI | Owned | 242,000 | Manufacturing, office, training |
| Whitewater, WI | Owned | 491,000 | Manufacturing, office, distribution |
| Oshkosh, WI | Owned | 255,000 | Manufacturing, storage, research and development |
| Berlin, WI | Owned | 129,000 | Manufacturing, office |
| Berlin, WI | Leased | 123,000 | Manufacturing, storage, research and development |
| Fort Atkinson, WI | Leased | 237,000 | Storage |
| Edgerton, WI | Leased | 575,000 | Storage |
| Maquoketa, IA | Owned | 137,000 | Storage, rental property |
| Jefferson, WI | Owned | 253,000 | Manufacturing, distribution |
| Jefferson, WI | Leased | 441,000 | Recently leased, soon-to-be-storage |
| Mexico City, Mexico | Owned | 161,000 | Manufacturing, sales, distribution, storage, office |
| Curitiba, Brazil | Leased | 26,000 | Manufacturing, sales, distribution, storage, office |
| Milan, Italy | Leased | 118,000 | Manufacturing, sales, distribution, storage, office |
| Milton Keynes, England | Leased | 9,000 | Sales, distribution, storage, office |
As of December 31, 2013, substantially all of our owned properties are subject to collateral provisions under our senior secured credit facilities.
Item 3. Legal Proceedings
From time to time, we are involved in legal proceedings primarily involving product liability, patent and employment matters and general commercial disputes arising in the ordinary course of our business. As of December 31, 2013, we believe that there is no litigation pending that would have a material effect on our results of operations or financial condition.
Item 4. Mine Safety Disclosures.
Not Applicable.
PART II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Price Range of Common Stock
Shares of our common stock are traded on the New York Stock Exchange (NYSE) under the symbol “GNRC.” The following table sets forth the high and low sales prices reported on the NYSE for our common stock by fiscal quarter during 2013 and 2012, respectively.
| 2013 | ||||||||
|---|---|---|---|---|---|---|---|---|
| High | Low | |||||||
| Fourth Quarter | $ | 57.05 | $ | 39.01 | ||||
| Third Quarter | $ | 44.30 | $ | 37.11 | ||||
| Second Quarter | $ | 41.48 | $ | 32.41 | ||||
| First Quarter | $ | 41.40 | $ | 32.72 |
| 2012 | ||||||||
|---|---|---|---|---|---|---|---|---|
| High | Low | |||||||
| Fourth Quarter | $ | 39.18 | $ | 24.43 | ||||
| Third Quarter | $ | 25.33 | $ | 18.35 | ||||
| Second Quarter | $ | 30.61 | $ | 22.40 | ||||
| First Quarter | $ | 30.50 | $ | 24.27 |
The following table summarizes the stock repurchase activity for the twelve months ended December 31, 2013, which consisted of the withholding of shares upon the vesting of restricted stock awards to pay withholding taxes:
| (in thousands, except share and per share data) | Total Number of Shares Purchased | Average Price Paid per Share | Total Number Of Shares Purchased As Part Of Publicly Announced Plans Or Programs | Approximate Dollar Value Of Shares That May Yet Be Purchased Under The Plans Or Programs | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 01/01/13 - 01/31/13 | - | $ | - | N/A | N/A | |||||||||||
| 02/01/13 - 02/28/13 | 162,819 | $ | 40.18 | N/A | N/A | |||||||||||
| 03/01/13 - 03/31/13 | - | $ | - | N/A | N/A | |||||||||||
| 04/01/13 - 04/30/13 | - | $ | - | N/A | N/A | |||||||||||
| 05/01/13 - 05/31/13 | - | $ | - | N/A | N/A | |||||||||||
| 06/01/13 - 06/30/13 | - | $ | - | N/A | N/A | |||||||||||
| 07/01/13 - 07/31/13 | - | $ | - | N/A | N/A | |||||||||||
| 08/01/13 - 08/31/13 | 227 | $ | 42.09 | N/A | N/A | |||||||||||
| 09/01/13 - 09/30/13 | - | $ | - | N/A | N/A | |||||||||||
| 10/01/13 - 10/31/13 | - | $ | - | N/A | N/A | |||||||||||
| 11/01/13 - 11/30/13 | 412 | $ | 46.42 | N/A | N/A | |||||||||||
| 12/01/13 - 12/31/13 | - | $ | - | N/A | N/A | |||||||||||
| Total | 163,458 | $ | 40.20 |
For equity compensation plan information, please refer to note 10 in Item 8 in Part II of this 10-K.
Stock Performance Graph
The line graph below compares the cumulative total stockholder return on our common stock with the cumulative total return of the Standard & Poor’s S&P 500 Index and S&P 500 Industrials Index for the year ended December 31, 2013. The graph and table assume that $100 was invested on February 11, 2010 (first day of trading) in each of our common stock, the S&P 500 Index, S&P 500 Industrials Index, and that all dividends were reinvested. Cumulative total stockholder returns for our common stock, the S&P 500 Index, and the S&P 500 Industrials Index are based on our fiscal year.
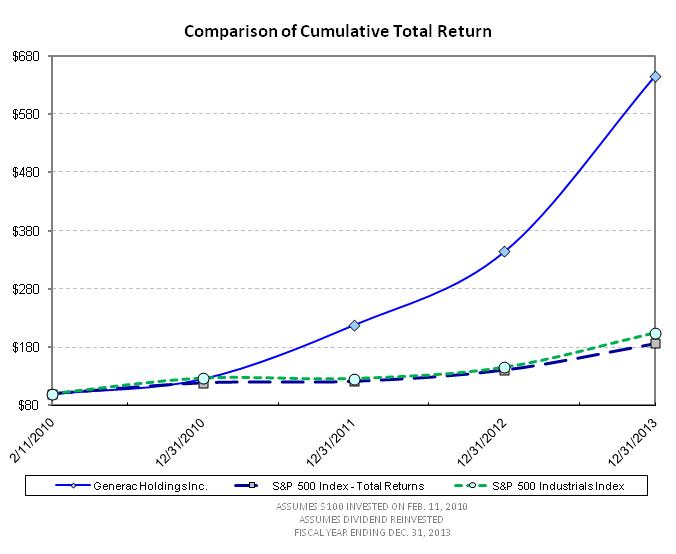
Holders
As of February 24, 2014, there were approximately 139 registered holders of record of Generac’s common stock. A substantially greater number of holders of Generac common stock are “street name” or beneficial holders, whose shares are held of record by banks, brokers, and other financial institutions.
Dividends
On June 21, 2013, the Company used a portion of the proceeds from the May 31, 2013 debt refinancing (see footnote #6 – Credit Agreements in Item 8 of this Annual Report on Form 10-K) to pay a special cash dividend of $5.00 per share on its common stock, resulting in payments totaling $340.8 million to stockholders. We currently do not have plans to pay any further dividends on our common stock in the near term. However, in the future, subject to factors such as general economic and business conditions, our financial condition and results of operations, our capital requirements, our future liquidity and capitalization and such other factors that our board of directors may deem relevant, we may change this policy and choose to pay dividends. Our ability to pay dividends on our common stock is currently restricted by the terms of our senior secured credit facilities and may be further restricted by any future indebtedness we incur. Our business is conducted through our subsidiaries, including our principal operating subsidiary, Generac Power Systems. Dividends from, and cash generated by our subsidiaries will be our principal sources of cash to repay indebtedness, fund operations and pay dividends. Accordingly, our ability to pay dividends to our stockholders is dependent on the earnings and distributions of funds from our subsidiaries, including Generac Power Systems.
Securities Authorized for Issuance Under Equity Compensation Plans
The information required by this item will be included in our 2014 Proxy Statement and is incorporated herein by reference.
Recent Sales of Unregistered Securities
None.
Use of Proceeds from Registered Securities
Not applicable.
Item 6. Selected Financial Data
The following table sets forth our selected historical consolidated financial data for the periods and at the dates indicated. The selected historical consolidated financial data for the years ended December 31, 2013, 2012 and 2011 are derived from our audited consolidated financial statements included elsewhere in this annual report. The selected historical consolidated financial data for the years ended December 31, 2010 and December 31, 2009 are derived from our audited historical consolidated financial statements not included in this annual report.
The results indicated below and elsewhere in this annual report are not necessarily indicative of our future performance. You should read this information together with “Item 7—Management's Discussion and Analysis of Financial Condition and Results of Operations” and our consolidated financial statements and related notes included in Item 8 of this Annual Report on Form 10-K.
| (Dollars in thousands, except per share data) | Year ended December 31, 2013 | Year ended December 31, 2012 | Year ended December 31, 2011 | Year ended December 31, 2010 | Year ended December 31, 2009 | |||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Statement of operations data: | ||||||||||||||||||||
| Net sales | $ | 1,485,765 | $ | 1,176,306 | $ | 791,976 | $ | 592,880 | $ | 588,248 | ||||||||||
| Costs of goods sold | 916,205 | 735,906 | 497,322 | 355,523 | 352,398 | |||||||||||||||
| Gross profit | 569,560 | 440,400 | 294,654 | 237,357 | 235,850 | |||||||||||||||
| Operating expenses: | ||||||||||||||||||||
| Selling and service | 107,515 | 101,448 | 77,776 | 57,954 | 59,823 | |||||||||||||||
| Research and development | 29,271 | 23,499 | 16,476 | 14,700 | 10,842 | |||||||||||||||
| General and administrative | 55,490 | 46,031 | 30,012 | 22,599 | 14,713 | |||||||||||||||
| Amortization of intangibles (1) | 25,819 | 45,867 | 48,020 | 51,808 | 51,960 | |||||||||||||||
| Trade name write-down (2) | — | — | 9,389 | — | — | |||||||||||||||
| Total operating expenses | 218,095 | 216,845 | 181,673 | 147,061 | 137,338 | |||||||||||||||
| Income from operations | 351,465 | 223,555 | 112,981 | 90,296 | 98,512 | |||||||||||||||
| Other income (expense): | ||||||||||||||||||||
| Interest expense | (54,435 | ) | (49,114 | ) | (23,718 | ) | (27,397 | ) | (70,862 | ) | ||||||||||
| (Loss) gain on extinguishment of debt (3) | (15,336 | ) | (14,308 | ) | (377 | ) | (4,809 | ) | 14,745 | |||||||||||
| Investment income | 91 | 79 | 110 | 235 | 2,205 | |||||||||||||||
| Costs related to acquisition | (1,086 | ) | (1,062 | ) | (875 | ) | — | — | ||||||||||||
| Other, net | (1,983 | ) | (2,798 | ) | (1,155 | ) | (1,105 | ) | (1,206 | ) | ||||||||||
| Total other expense, net | (72,749 | ) | (67,203 | ) | (26,015 | ) | (33,076 | ) | (55,118 | ) | ||||||||||
| Income before provision for income taxes | 278,716 | 156,352 | 86,966 | 57,220 | 43,394 | |||||||||||||||
| Provision (benefit) for income taxes (4) | 104,177 | 63,129 | (237,677 | ) | 307 | 339 | ||||||||||||||
| Net income | $ | 174,539 | $ | 93,223 | $ | 324,643 | $ | 56,913 | $ | 43,055 | ||||||||||
| Income per share - diluted: | ||||||||||||||||||||
| Common Stock (formerly Class A non-voting common stock) (5) | 2.51 | 1.35 | 4.79 | (1.65 | ) | (41,111 | ) | |||||||||||||
| Class B Common Stock (5) | n/a | n/a | n/a | 505 | 4,171 | |||||||||||||||
| Statement of cash flows data: | ||||||||||||||||||||
| Depreciation | 10,955 | 8,293 | 8,103 | 7,632 | 7,715 | |||||||||||||||
| Amortization | 25,819 | 45,867 | 48,020 | 51,808 | 51,960 | |||||||||||||||
| Expenditures for property and equipment | (30,770 | ) | (22,392 | ) | (12,060 | ) | (9,631 | ) | (4,525 | ) | ||||||||||
| Other financial data: | ||||||||||||||||||||
| Adjusted EBITDA (6) | 402,613 | 289,809 | 188,476 | 156,249 | 159,087 | |||||||||||||||
| Adjusted Net Income (7) | 301,664 | 220,792 | 147,176 | 115,954 | 83,643 |
| (Dollars in thousands) | As of December 31, 2013 | As of December 31, 2012 | As of December 31, 2011 | As of December 31, 2010 | As of December 31, 2009 | |||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Balance sheet data: | ||||||||||||||||||||
| Current assets | $ | 654,179 | $ | 522,553 | $ | 383,265 | $ | 272,519 | $ | 345,017 | ||||||||||
| Property, plant and equipment, net | 146,390 | 104,718 | 84,384 | 75,287 | 73,374 | |||||||||||||||
| Goodwill | 608,287 | 552,943 | 547,473 | 527,148 | 525,875 | |||||||||||||||
| Other intangibles and other assets | 389,349 | 423,633 | 537,671 | 334,929 | 392,977 | |||||||||||||||
| Total assets | $ | 1,798,205 | $ | 1,603,847 | $ | 1,552,793 | $ | 1,209,883 | $ | 1,337,243 | ||||||||||
| Total current liabilities | $ | 250,845 | $ | 294,859 | $ | 165,390 | $ | 86,685 | $ | 131,971 | ||||||||||
| Long-term borrowings, less current portion | 1,175,349 | 799,018 | 575,000 | 657,229 | 1,052,463 | |||||||||||||||
| Other long-term liabilities | 54,940 | 46,342 | 43,514 | 24,902 | 17,418 | |||||||||||||||
| Redeemable stock (8) | — | — | — | — | 878,205 | |||||||||||||||
| Stockholders' equity | 317,071 | 463,628 | 768,889 | 441,067 | (742,814 | ) | ||||||||||||||
| Total liabilities, redeemable stock and stockholders' equity (8) | $ | 1,798,205 | $ | 1,603,847 | $ | 1,552,793 | $ | 1,209,883 | $ | 1,337,243 |
(1) Our amortization of intangibles expenses includes the straight-line amortization of customer lists, patents and other finite-lived intangibles assets.
(2) During the fourth quarter of 2011, the Company decided to strategically transition certain products to their more widely known Generac brand. Based on this decision, the Company recorded a $9.4 million non-cash charge which primarily related to the write down of the impacted trade name to net realizable value.
(3) During 2013, the Company wrote-off a portion of deferred financing costs and original issue discount as a result of accelerated debt repayments in February and May 2013. Additionally, the Company recorded a loss on extinguishment of debt during 2013 as a result of the refinancing transaction that occurred on May 31, 2013. During 2012, the Company recorded a loss on extinguishment of debt related to the refinancing transactions that occurred on February 9, 2012 and May 30, 2012. During 2011 and 2010, the Company wrote-off a portion of deferred financing costs related to accelerated repayments of debt. During 2009, affiliates of CCMP acquired $9.9 million principal amount of first lien term loans and $20.0 million principal amount of second lien term loans for approximately $14.8 million. CCMP's affiliates exchanged this debt for 1,475.4596 shares of Series A Preferred Stock. The fair value of the shares exchanged was $14.8 million. We recorded this transaction as additional Series A Preferred Stock of $14.8 million based on the fair value of the debt contributed by CCMP's affiliates, which approximated the fair value of shares exchanged. The debt was held in treasury at face value. Consequently, we recorded a gain on extinguishment of debt of $14.7 million, which includes a write-off of deferred financing fees and other closing costs, in the consolidated statement of operations for the year ended December 31, 2009.
(4) The 2011 net tax benefit of $237.7 million includes a tax benefit of $271.4 million recorded due to the reversal of valuation allowances recorded on the Company’s net deferred tax assets. See Note 8 – Income Taxes in Item 8 of this Annual Report on Form 10-K for additional details.
(5) Diluted earnings per share reflects the impact of a reverse stock split which occurred immediately prior to the initial public offering (IPO). At the time of the IPO on February 17, 2010, all shares of Class B common stock were converted into shares of Class A common stock, and the Class A common stock became the one class of outstanding common stock.
(6) Adjusted EBITDA represents net income before interest expense, taxes, depreciation and amortization, as further adjusted for the other items reflected in the reconciliation table set forth below. The computation of adjusted EBITDA is based on the definition of EBITDA contained in Generac's New Term Loan Credit Agreement and New ABL Credit Agreement (terms defined in Item 7 - Management’s Discussion and Analysis of Financial Condition and Results of Operations – Liquidity and Financial Position), dated as of May 31, 2013, which is substantially the same definition that was contained in the Company’s previous credit agreements.
We view Adjusted EBITDA as a key measure of our performance. We present Adjusted EBITDA not only due to its importance for purposes of our New Term Loan Credit Agreement and New ABL Credit Agreement but also because it assists us in comparing our performance across reporting periods on a consistent basis because it excludes items that we do not believe are indicative of our core operating performance. Our management uses Adjusted EBITDA:
-
for planning purposes, including the preparation of our annual operating budget and developing and refining our internal projections for future periods;
-
to allocate resources to enhance the financial performance of our business;
-
as a benchmark for the determination of the bonus component of compensation for our senior executives under our management incentive plan, as described further in our Proxy Statement;
-
to evaluate the effectiveness of our business strategies and as a supplemental tool in evaluating our performance against our budget for each period; and
-
in communications with our board of directors and investors concerning our financial performance.
We believe Adjusted EBITDA is used by securities analysts, investors and other interested parties in the evaluation of our company. Management believes the disclosure of Adjusted EBITDA offers an additional financial metric that, when coupled with U.S. GAAP results and the reconciliation to U.S. GAAP results, provides a more complete understanding of our results of operations and the factors and trends affecting our business. We believe Adjusted EBITDA is useful to investors for the following reasons:
-
Adjusted EBITDA and similar non-GAAP measures are widely used by investors to measure a company's operating performance without regard to items that can vary substantially from company to company depending upon financing and accounting methods, book values of assets, tax jurisdictions, capital structures and the methods by which assets were acquired;
-
investors can use Adjusted EBITDA as a supplemental measure to evaluate the overall operating performance of our company, including our ability to service our debt and other cash needs; and
-
by comparing our Adjusted EBITDA in different historical periods, our investors can evaluate our operating performance excluding the impact of items described below.
The adjustments included in the reconciliation table listed below are provided for under our New Term Loan Credit Agreement and New ABL Credit Agreement and also are presented to illustrate the operating performance of our business in a manner consistent with the presentation used by our management and board of directors. These adjustments eliminate the impact of a number of items that:
-
we do not consider indicative of our ongoing operating performance, such as non-cash write-down and other charges, non-cash gains and write-offs relating to the retirement of debt, severance costs and other restructuring-related business optimization expenses;
-
we believe to be akin to, or associated with, interest expense, such as administrative agent fees, revolving credit facility commitment fees and letter of credit fees;
-
are non-cash in nature, such as share-based compensation; or
-
were eliminated following the consummation of our initial public offering.
We explain in more detail in footnotes (a) through (d) below why we believe these adjustments are useful in calculating Adjusted EBITDA as a measure of our operating performance.
Adjusted EBITDA does not represent, and should not be a substitute for, net income or cash flows from operations as determined in accordance with U.S. GAAP. Adjusted EBITDA has limitations as an analytical tool, and you should not consider it in isolation, or as a substitute for analysis of our results as reported under U.S. GAAP. Some of the limitations are:
-
Adjusted EBITDA does not reflect our cash expenditures, or future requirements for capital expenditures or contractual commitments;
-
Adjusted EBITDA does not reflect changes in, or cash requirements for, our working capital needs;
-
Adjusted EBITDA does not reflect the significant interest expense, or the cash requirements necessary to service interest or principal payments, on our debt;
-
although depreciation and amortization are non-cash charges, the assets being depreciated and amortized will often have to be replaced in the future, and Adjusted EBITDA does not reflect any cash requirements for such replacements;
-
several of the adjustments that we use in calculating Adjusted EBITDA, such as non-cash write-downs and other charges, while not involving cash expense, do have a negative impact on the value our assets as reflected in our consolidated balance sheet prepared in accordance with U.S. GAAP;
-
other companies may calculate Adjusted EBITDA differently than we do, limiting its usefulness as a comparative measure.
Furthermore, as noted above, one of our uses of Adjusted EBITDA is as a benchmark for determining elements of compensation for our senior executives. At the same time, some or all of these senior executives have responsibility for monitoring our financial results generally, including the items that are included as adjustments in calculating Adjusted EBITDA (subject ultimately to review by our board of directors in the context of the board's review of our financial statements). While many of the adjustments (for example, transaction costs and credit facility fees), involve mathematical application of items reflected in our financial statements, others involve a degree of judgment and discretion. While we believe that all of these adjustments are appropriate, and while the calculations are subject to review by our board of directors in the context of the board's review of our financial statements and certification by our chief financial officer in a compliance certificate provided to the lenders under our New Term Loan Credit Agreement and New ABL Credit Agreement, this discretion may be viewed as an additional limitation on the use of Adjusted EBITDA as an analytical tool.
Because of these limitations, Adjusted EBITDA should not be considered as a measure of discretionary cash available to us to invest in the growth of our business. We compensate for these limitations by relying primarily on our U.S. GAAP results and using Adjusted EBITDA only supplementally.
The following table presents a reconciliation of net income to Adjusted EBITDA:
| (Dollars in thousands) | Year ended December 31, 2013 | Year ended December 31, 2012 | Year ended December 31, 2011 | Year ended December 31, 2010 | Year ended December 31, 2009 | |||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Net income | $ | 174,539 | $ | 93,223 | $ | 324,643 | $ | 56,913 | $ | 43,055 | ||||||||||
| Interest expense | 54,435 | 49,114 | 23,718 | 27,397 | 70,862 | |||||||||||||||
| Depreciation and amortization | 36,774 | 54,160 | 56,123 | 59,440 | 59,675 | |||||||||||||||
| Income taxes provision (benefit) | 104,177 | 63,129 | (237,677 | ) | 307 | 339 | ||||||||||||||
| Non-cash write-down and other charges (income) (a) | 78 | 247 | 10,400 | (361 | ) | (1,592 | ) | |||||||||||||
| Non-cash share-based compensation expense (b) | 12,368 | 10,780 | 8,646 | 6,363 | — | |||||||||||||||
| Loss (gain) on extinguishment of debt (c) | 15,336 | 14,308 | 377 | 4,809 | (14,745 | ) | ||||||||||||||
| Transaction costs and credit facility fees (d) | 3,863 | 4,117 | 1,719 | 1,019 | 1,188 | |||||||||||||||
| Other | 1,043 | 731 | 527 | 362 | 305 | |||||||||||||||
| Adjusted EBITDA | $ | 402,613 | $ | 289,809 | $ | 188,476 | $ | 156,249 | $ | 159,087 |
(a) Represents the following non-cash charges:
-
for the years ended December 31, 2013 and 2012, includes loss on disposals of assets, unrealized mark-to-market adjustments on commodity contracts and adjustments to an earn-out obligation in connection with a permitted business acquisition, as defined in our credit agreement;
-
for the year ended December 31, 2011, primarily $9.4 million trade name write-down relating to the Comopany’s descision to strategically transition certain products to their more widely know Generac brand as further described in "Item 7 - Management's Discussion and Analysis of Financial Condition and Results of Operations—Critical accounting policies—Goodwill and other intangible assets." Also includes unrealized mark-to-market adjustments on copper forward contracts and loss on disposal of assets;
-
for the years ended December 31, 2010 and 2009, primarily unrealized mark-to-market adjustments on copper and Euro forward contracts and loss on disposal of assets;
We believe that adjusting net income for these non-cash charges is useful for the following reasons:
-
The loss on disposals of assets in several periods described above result from the sale of assets that are no longer useful in our business and therefore represent losses that are not from our core operations;
-
The adjustments for unrealized mark-to-market gains and losses on commodity and Euro forward contracts represent non-cash items to reflect changes in the fair value of forward contracts that have not been settled or terminated. We believe it is useful to adjust net income for these items because the charges do not represent a cash outlay in the period in which the charge is incurred, although Adjusted EBITDA must always be used together with our U.S. GAAP statements of income and cash flows to capture the full effect of these contracts on our operating performance;
-
The trade name write-down recorded in the year ended December 31, 2011 is a one-time charge that we believe does not reflect our ongoing operations;
(b) Represents share-based compensation expense to account for stock options, restricted stock and other stock awards over their vesting period.
(c) Represents the loss (gain) on extinguishment of debt from:
-
for the year ended December 31, 2013, represents the write-off of a portion of deferred financing costs and original issue discount related to accelerated repayments of debt in February and May 2013, as well as the loss on extinguishment of debt related to the refinancing transaction that occurred on May 31, 2013.
-
for the year ended December 31, 2012, represents the loss on extinguishment of debt related to the refinancing transactions that occurred on February 9, 2012 and May 30, 2012;
-
for the years ended December 31, 2011 and 2010, represents the write-off of a portion of deferred financing costs related to accelerated repayments of debt;
-
for the year ended December 31, 2009, represents non-cash gains on the extinguishment of debt repurchased by affiliates of CCMP, as described in note (3) above, which we do not expect to recur;
(d) Represents transaction costs incurred directly in connection with any investment, as defined in our credit agreement, equity issuance or debt issuance or refinancing, together with certain fees relating to our New Term Loan Credit Agreement and New ABL Credit Agreement, such as:
-
administrative agent fees and revolving credit facility commitment fees under our New Term Loan Credit Agreement and New ABL Credit Agreement, which we believe to be akin to, or associated with, interest expense and whose inclusion in Adjusted EBITDA is therefore similar to the inclusion of interest expense in that calculation;
-
transaction costs relating to the acquisition of a business;
-
other financing costs incurred relating to the dividend recapitalization transactions completed in May 2012 and 2013;
-
before 2011, transaction costs relating to repurchases of debt under our first and second lien credit facilities by affiliates of CCMP, which CCMP's affiliates contributed to our company in exchange for the issuances of securities, which repurchases we do not expect to recur;
(7) Adjusted Net Income is defined as net income before provision (benefit) for income taxes adjusted for the following items: cash income tax expense, amortization of intangible assets, amortization of deferred financing costs and original issue discount related to the Company’s debt, losses (gains) on extinguishment of the Company’s debt, intangible asset impairment charges, transaction costs and other purchase accounting adjustments, and certain non-cash gains and losses as reflected in the reconciliation table set forth below.
We believe Adjusted Net Income is used by securities analysts, investors and other interested parties in the evaluation of our company operations. Management believes the disclosure of Adjusted Net Income offers an additional financial metric that, when used in conjunction with U.S. GAAP results and the reconciliation to U.S. GAAP results, provides a more complete understanding of our results of operations, our cash flows, and the factors and trends affecting our business.
The adjustments included in the reconciliation table listed below are presented to illustrate the operating performance of our business in a manner consistent with the presentation used by investors and securities analysts. Similar to the Adjusted EBITDA reconciliation, these adjustments eliminate the impact of a number of items we do not consider indicative of our ongoing operating performance or cash flows, such as amortization costs, transaction costs and write-offs relating to the retirement of debt. We also make adjustments to present cash taxes paid as a result of our favorable tax attributes.
Similar to Adjusted EBITDA, Adjusted Net Income does not represent, and should not be a substitute for, net income or cash flows from operations as determined in accordance with U.S. GAAP. Adjusted Net Income has limitations as an analytical tool, and you should not consider it in isolation, or as a substitute for analysis of our results as reported under U.S. GAAP. Some of the limitations are:
-
Adjusted Net Income does not reflect changes in, or cash requirements for, our working capital needs;
-
although amortization is a non-cash charge, the assets being amortized may have to be replaced in the future, and Adjusted Net Income does not reflect any cash requirements for such replacements;
-
other companies may calculate Adjusted Net Income differently than we do, limiting its usefulness as a comparative measure.
The following table presents a reconciliation of net income to Adjusted Net Income:
| (Dollars in thousands) | Year ended December 31, 2013 | Year ended December 31, 2012 | Year ended December 31, 2011 | Year ended December 31, 2010 | Year ended December 31, 2009 | |||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Net income | $ | 174,539 | $ | 93,223 | $ | 324,643 | $ | 56,913 | $ | 43,055 | ||||||||||
| Provision (benefit) for income taxes | 104,177 | 63,129 | (237,677 | ) | 307 | 339 | ||||||||||||||
| Income before provision (benefit) for income taxes | 278,716 | 156,352 | 86,966 | 57,220 | 43,394 | |||||||||||||||
| Amortization of intangible assets | 25,819 | 45,867 | 48,020 | 51,808 | 51,960 | |||||||||||||||
| Amortization of deferred finance costs and original issue discount | 4,772 | 3,759 | 1,986 | 2,439 | 3,417 | |||||||||||||||
| Loss (gain) on extinguishment of debt | 15,336 | 14,308 | 377 | 4,809 | (14,745 | ) | ||||||||||||||
| Trade name write-down | — | — | 9,389 | — | — | |||||||||||||||
| Transaction costs and other purchase accounting adjustments | 2,842 | 3,317 | 875 | — | — | |||||||||||||||
| Adjusted net income before provision for income taxes | 327,485 | 223,603 | 147,613 | 116,276 | 84,026 | |||||||||||||||
| Cash income tax expense | (25,821 | ) | (2,811 | ) | (437 | ) | (322 | ) | (383 | ) | ||||||||||
| Adjusted net income | $ | 301,664 | $ | 220,792 | $ | 147,176 | $ | 115,954 | $ | 83,643 |
(8) Includes our Series A Preferred Stock and Class B Common Stock.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
The following discussion and analysis of our financial condition and results of operations should be read together with “Item 6 - Selected Financial Data” and the consolidated financial statements and the related notes included in Item 8 of this Annual Report on Form 10-K. This discussion contains forward-looking statements, based on current expectations and related to future events and our future financial performance, that involve risks and uncertainties. Our actual results may differ materially from those anticipated in these forward-looking statements as a result of many factors, including those set forth under “Item 1A - Risk Factors.”
Overview
We are a leading designer and manufacturer of a wide range of power generation equipment and other engine powered products serving the residential, light commercial, industrial and construction markets. Unlike our primary competitors in the generator market, power generation is our main focus. As the only significant market participant focused predominantly on these products, we have one of the leading market positions in the power equipment market in North America and an expanding presence internationally. We believe we have one of the widest range of products in the marketplace, including residential, commercial and industrial standby generators, as well as portable and mobile generators used in a variety of applications. Other engine powered products that we design and manufacture include light towers which provide temporary lighting for various end markets and a broad product line of power washers for residential and commercial use.
Business drivers and operational factors
In operating our business and monitoring its performance, we pay attention to a number of business drivers and trends as well as operational factors. The statements in this section are based on our current expectations.
Business drivers and trends
Our performance is affected by the demand for reliable power solutions by our customer base. This demand is influenced by several important drivers and trends affecting our industry, including the following:
Increasing penetration opportunity. Many potential customers are not aware of the costs and benefits of automatic backup power solutions. We estimate that penetration rates for home standby generators are only approximately 3.0% of U.S. single-family detached, owner-occupied households with a home value of over $100,000, as defined by the U.S. Census Bureau's 2011 American Housing Survey for the United States. The decision to purchase backup power for many light-commercial buildings such as convenience stores, restaurants and gas stations are more return-on-investment (ROI) driven and as a result these applications have relatively lower penetration rates as compared to buildings used in more code-driven or mission critical applications such as hospitals, wastewater treatment facilities, 911 call centers, data centers and certain industrial locations. In addition, the emergence of lower cost, cleaner burning natural gas fueled generators has helped to accelerate the penetration of standby generators in the light-commercial market. Also, the importance of backup power for telecommunications infrastructure is increasing due to the growing importance for uninterrupted voice and data services. We believe by expanding our distribution network, continuing to develop our product line, and targeting our marketing efforts, we can continue to build awareness and increase penetration for our standby generators.
Effect of large scale power disruptions. Power disruptions are an important driver of customer awareness and have historically influenced demand for generators. Increased frequency and duration of major power outage events caused by the aging U.S. power grid increases product awareness and may drive consumers to accelerate their purchase of a standby or portable generator during the immediate and subsequent period, which we believe may last for six to twelve months for standby generators. For example, the multiple major outage events that occurred during the second half of both 2011 and 2012 drove strong demand for portable and home standby generators, and the increased awareness of these products contributed to substantial organic revenue growth in 2012 with strong growth continuing during 2013. While there are localized power outages that occur practically every day across the U.S., major outage activity is unpredictable by nature and, as a result, our sales levels and profitability may fluctuate from period to period.
Impact of residential investment cycle. The market for residential generators is also affected by the residential investment cycle and overall consumer confidence and sentiment. When homeowners are confident of their household income, the value of their home and overall net worth, they are more likely to invest in their home. These trends can have an impact on demand for residential generators. Trends in the new housing market highlighted by residential housing starts can also impact demand for our residential products.
Impact of business capital investment cycle. The market for our commercial and industrial products is affected by the overall capital investment cycle, including non-residential building construction, durable goods and infrastructure spending as well as investments in the exploration and production of oil & gas, as businesses or organizations either add new locations or make investments to upgrade existing locations or equipment. These trends can have a material impact on demand for these products. The capital investment cycle may differ for the various commercial and industrial end markets that we serve including light commercial, retail, telecommunications, industrial, data centers, healthcare, construction, oil & gas and municipal infrastructure, among others. The market for these products is also affected by general economic conditions and credit availability in the geographic regions that we serve. In addition, we believe demand for our mobile power products will continue to benefit from a secular shift towards renting versus buying this type of equipment.
Factors affecting results of operations
We are subject to various factors that can affect our results of operations, which we attempt to mitigate through factors we can control, including continued product development, expanded distribution, pricing and cost control. Certain operational and other factors that affect our business include the following:
Effect of commodity, currency and component price fluctuations. Industry-wide price fluctuations of key commodities, such as steel, copper and aluminum and other components we use in our products, together with foreign currency fluctuations, can have a material impact on our results of operations. We have historically attempted to mitigate the impact of rising commodity, currency and component prices through improved product design and sourcing, manufacturing efficiencies, price increases and select hedging transactions. Our results are also influenced by changes in fuel prices in the form of freight rates, which in some cases are borne by our customers and in other cases are paid by us.
Seasonality. Although there is demand for our products throughout the year, in each of the past three years approximately 16% to 27% of our net sales occurred in the first quarter, 20% to 23% in the second quarter, 24% to 30% in the third quarter and 25% to 34% in the fourth quarter, with different seasonality depending on the presence, timing and severity of major power outage activity in each year. Major outage activity is unpredictable by nature and, as a result, our sales levels and profitability may fluctuate from period to period. For example, there were multiple major power outage events that occurred during the second half of both 2011 and 2012, which were significant in terms of severity. As a result, the seasonality experienced during this time
Showing the first 8K of 72K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
We are exposed to market risk from changes in foreign currency exchange rates, commodity prices and interest rates. To reduce the risk from changes in certain foreign currency exchange rates and commodity prices, we use financial instruments from time to time. We do not hold or issue financial instruments for trading purposes.
Foreign currency
We are exposed to foreign currency exchange risk as a result of purchasing from suppliers in other countries as well as operating businesses in foreign countries. Periodically, we utilize foreign currency forward purchase and sales contracts to manage the volatility associated with foreign currency purchases in the normal course of business. Contracts typically have maturities of one year or less. Realized and unrealized gains and losses on transactions denominated in foreign currency are recorded in earnings as a component of cost of goods sold. At December 31, 2012, we had no foreign exchange contracts outstanding. As of December 31, 2013, we had the following foreign currency contracts outstanding (in thousands):
| Currency Denomination | Effective Date | Notional Amount (Thousands) | Expiration Date | |||
|---|---|---|---|---|---|---|
| Number of Contracts Outstanding | Contract Date | Exchange Rate | ||||
| USD | 3 | October 23, 2013 | Various effective dates between 4/1/2014 and 7/14/2014 | 650 | (EUR:USD) 1.349-1.3515 | May 28, 2014 – October 31, 2014 |
| GBP | 4 | October 23, 2013 | Various effective dates between 2/3/2014 and 5/2/2014 | 4,000 | (EUR:GBP) 0.8384-0.8492 | April 30, 2014 – July 31, 2014 |
With the purchase of the Ottomotores businesses in December 2012 and the Tower Light business in August 2013, a small portion of revenues and expenses are now denominated in Euros, Mexican Pesos, Brazilian Real and British Pounds.
Commodity prices
We are a purchaser of commodities and of components manufactured from commodities, including steel, aluminum, copper and others. As a result, we are exposed to fluctuating market prices for those commodities. While such materials are typically available from numerous suppliers, commodity raw materials are subject to price fluctuations. We generally buy these commodities and components based upon market prices that are established with the supplier as part of the purchase process. Depending on the supplier, these market prices may reset on a periodic basis based on negotiated lags. To the extent that commodity prices increase and we do not have firm pricing from our suppliers, or our suppliers are not able to honor such prices, we may experience a decline in our gross margins to the extent we are not able to increase selling prices of our products or obtain manufacturing efficiencies or supply chain savings to offset increases in commodity costs.
Periodically, we engage in certain commodity risk management activities. The primary objectives of these activities are to understand and mitigate the impact of potential price fluctuations on our financial results. Generally, these risk management transactions will involve the use of commodity derivatives to protect against exposure resulting from significant price fluctuations.
We primarily utilize commodity contracts with maturities of one year or less. These are intended to offset the effect of price fluctuations on actual inventory purchases. The primary objective of the hedge is to mitigate the impact of potential price fluctuations of commodity on our financial results. As of December 31, 2013, we had the following commodity forward contracts outstanding (in thousands):
| Hedged Item | Number of Contracts Outstanding | Effective Date | Aggregate Notional Amount (Thousands) | Fixed Copper Price |
|---|---|---|---|---|
| Copper | 1 | October 1, 2013 to June 30, 2014 | $2,169 | $3.12 per LB |
For additional information on the Company’s commodity forward contracts, including amounts charged to the statement of comprehensive income during 2013, see Note 2 to our audited consolidated financial statements included in Item 8 of this Annual Report on Form 10-K.
Interest rates
As of December 31, 2013, all of the outstanding debt under our term loans was subject to floating interest rate risk. As of this date, we had the following interest rate swap contracts outstanding (in thousands):
| Hedged Item | Effective Date | Notional Amount (Thousands) | Expiration Date | ||
|---|---|---|---|---|---|
| Contract Date | Fixed LIBOR Rate | ||||
| Interest rate | October 23, 2013 | July 1, 2014 | $100,000 | 1.742% | July 1, 2018 |
| Interest rate | October 23, 2013 | July 1, 2014 | $100,000 | 1.737% | July 1, 2018 |
At December 31, 2013, the fair value of the swaps reduced for our credit risk and excluding any related accrued interest was an asset of $1.2 million. For additional information on the Company’s interest rate swaps, including amounts charged to the statement of comprehensive income during 2013, see Note 2 to our audited consolidated financial statements included in Item 8 of this Annual Report on Form 10-K. Even after giving effect to these swaps, we are exposed to risks due to changes in interest rates with respect to the portion of our term loans that are not covered by the swaps. A hypothetical change in the LIBOR interest rate of 100 basis points would have changed annual cash interest expense by approximately $4.9 million (or, without the swaps in place, $5.9 million). The existence of a 0.75% LIBOR floor provision in our New Term Loan Credit Agreement, effective May 31, 2013, limits the impact of a hypothetical 100 basis point change in LIBOR at current December 31, 2013 LIBOR rates.
Item 8. Financial Statements and Supplementary Data
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Stockholders of Generac Holdings Inc.
We have audited Generac Holdings Inc.’s internal control over financial reporting as of December 31, 2013, based on criteria established in Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (1992 Framework) (the COSO criteria). Generac Holdings Inc.’s management is responsible for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management’s Report on Internal Control Over Financial Reporting. Our responsibility is to express an opinion on the company’s internal control over financial reporting based on our audit.
We conducted our audit in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
As indicated in the accompanying Management’s Report on Internal Control Over Financial Reporting, management’s assessment of and conclusion on the effectiveness of internal control over financial reporting did not include the internal controls of the Tower Light or Baldor Generators businesses, which are included in the December 31, 2013 consolidated financial statements of Generac Holdings Inc. and constituted 4.2% and 15.1% of total and net assets, respectively, as of December 31, 2013 and 2.8% and 1.0% of revenues and net income, respectively, for the year then ended. Our audit of internal control over financial reporting of Generac Holdings Inc. also did not include an evaluation of the internal control over financial reporting of Tower Light or Baldor Generators.
In our opinion, Generac Holdings Inc. maintained, in all material respects, effective internal control over financial reporting as of December 31, 2013, based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated balance sheets as of December 31, 2013 and 2012, and related consolidated statements of comprehensive income, stockholders' equity and cash flows for each of the three years in the period ended December 31, 2013 of Generac Holdings Inc. and our report dated March 3, 2014 expressed an unqualified opinion thereon.
/s/ Ernst & Young LLP
Milwaukee, WI, USA
March 3, 2014
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Stockholders of Generac Holdings Inc.
We have audited the accompanying consolidated balance sheets of Generac Holdings Inc. (the Company) as of December 31, 2013 and 2012, and the related consolidated statements of comprehensive income, stockholders’ equity and cash flows for each of the three years in the period ended December 31, 2013. These financial statements are the responsibility of the Company's management. Our responsibility is to express an opinion on these financial statements based on our audits.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement. An audit includes examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements. An audit also includes assessing the accounting principles used and significant estimates made by management, as well as evaluating the overall financial statement presentation. We believe that our audits provide a reasonable basis for our opinion.
In our opinion, the financial statements referred to above present fairly, in all material respects, the consolidated financial position of Generac Holdings Inc. at December 31, 2013 and 2012, and the consolidated results of its operations and its cash flows for each of the three years in the period ended December 31, 2013, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), Generac Holdings Inc.’s internal control over financial reporting as of December 31, 2013, based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (1992 Framework) and our report dated March 3, 2014 expressed an unqualified opinion thereon.
/s/ Ernst & Young LLP
Milwaukee, WI, USA
March 3, 2014
| Generac Holdings Inc. | ||||||||
|---|---|---|---|---|---|---|---|---|
| Consolidated Balance Sheets | ||||||||
| (Dollars in Thousands, Except Share and Per Share Data) | ||||||||
| December 31, | ||||||||
| 2013 | 2012 | |||||||
| Assets | ||||||||
| Current assets: | ||||||||
| Cash and cash equivalents | $ | 150,147 | $ | 108,023 | ||||
| Restricted cash | 6,645 | – | ||||||
| Accounts receivable, less allowance for doubtful accounts of $2,658 at December 31, 2013 and $1,166 at December 31, 2012 | 164,907 | 134,978 | ||||||
| Inventories | 300,253 | 225,817 | ||||||
| Deferred income taxes | 26,869 | 48,687 | ||||||
| Prepaid expenses and other assets | 5,358 | 5,048 | ||||||
| Total current assets | 654,179 | 522,553 | ||||||
| Property and equipment, net | 146,390 | 104,718 | ||||||
| Customer lists, net | 42,764 | 37,823 | ||||||
| Patents, net | 62,418 | 70,302 | ||||||
| Other intangible assets, net | 4,447 | 5,783 | ||||||
| Deferred f |
Showing the first 8K of 128K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
There were no changes in, or disagreements with, accountants reportable herein.
Item 9A. Controls and Procedures
Evaluation of Disclosure Controls and Procedures
Disclosure controls and procedures are controls and other procedures that are designed to ensure that information required to be disclosed by us in reports we file or submit under the Securities Exchange Act of 1934, or the Exchange Act, is recorded, processed, summarized and reported within the time periods specified in the Securities and Exchange Commission rules and forms. Disclosure controls and procedures include, without limitation, controls and procedures designed to ensure that such information is accumulated and communicated to our management, including our Chief Executive Officer and Chief Financial Officer, as appropriate, to allow for timely decisions regarding required disclosure.
Our management, with the participation of our Chief Executive Officer and our Chief Financial Officer, has conducted an evaluation of the design and operation of our disclosure controls and procedures as defined in Rule 13a-15(e) and 15d-15(e) under the Exchange Act as of the end of the period covered by this report on Form 10-K. Based on that evaluation, our Chief Executive Officer and Chief Financial Officer concluded that our disclosure controls and procedures were effective in providing reasonable assurance that the information required to be disclosed in this report on Form 10-K has been recorded, processed, summarized and reported as of the end of the period covered by this report on Form 10-K.
Management’s Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting, as defined in Rule 13a-15(f) and 15d-15(f) under the Exchange Act. Our internal control over financial reporting is designed under the supervision of our Chief Executive Officer and Chief Financial Officer to provide reasonable assurance regarding the reliability of financial reporting and the preparation of the consolidated financial statements in accordance with U.S. generally accepted accounting principles.
Internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the Company; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of the financial statements in accordance with U.S. generally accepted accounting principles, and that receipts and expenditures of the Company are being made only in accordance with authorizations of management and directors of the Company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the Company’s assets that could have a material effect on the Company’s financial statements.
There are inherent limitations to the effectiveness of any internal control over financial reporting, including the possibility of human error or the circumvention or overriding of the controls. Accordingly, even an effective internal control over financial reporting can provide only reasonable assurance of achieving its objective. Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate, because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Under the supervision and with the participation of our Chief Executive Officer and Chief Financial Officer, our management conducted an assessment of the effectiveness of internal control over financial reporting as of December 31, 2013 based on the criteria established in the 1992 Internal Control – Integrated Framework, issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). Based on this assessment, our management has concluded that our internal control over financial reporting was effective as of December 31, 2013. In conducting this assessment, our management excluded the Tower Light and Baldor Generators businesses because they were acquired during 2013 and constituted 4.2% and 15.1% of total and net assets, respectively, as of December 31, 2013 and 2.8% and 1.0% of revenues and net income, respectively, for the year then ended.
Our independent registered public accounting firm has issued an attestation report on our internal control over financial reporting as of December 31, 2013. Its report appears in the consolidated financial statements included in this Annual Report on Form 10-K on page 36.
Changes in Internal Control Over Financial Reporting
There have been no changes in our internal control over financial reporting that occurred during the three months ended December 31, 2013 that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. Other Information
None
PART III
Item 10. Directors, Executive Officers and Corporate Governance
The information required by Item 10 not already provided herein under “Item 1 – Business – Executive Officers”, will be included in our 2014 Proxy Statement, and is incorporated by reference herein.
Item 11. Executive Compensation
The information required by this item will be included in our 2014 Proxy Statement and is incorporated herein by reference.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
The information required by this item will be included in our 2014 Proxy Statement and is incorporated herein by reference.
Item 13. Certain Relationships and Related Transactions, and Director Independence
The information required by this item will be included in our 2014 Proxy Statement and is incorporated herein by reference.
Item 14. Principal Accountant Fees and Services
The information required by this item will be included in our 2014 Proxy Statement and is incorporated herein by reference.
PART IV
Item 15. Exhibits and Financial Statement Schedules
(a)(1) Financial Statements
Included in Part II of this report:
| Page | |
|---|---|
| Report of Independent Registered Public Accounting Firm | 36 |
| Consolidated balance sheets as of December 31, 2013 and 2012 | 38 |
| Consolidated statements of comprehensive income for years ended December 31, 2013, 2012 and 2011 | 39 |
| Consolidated statements of stockholders’ equity for years ended December 31, 2013, 2012 and 2011 | 40 |
| Consolidated statements of cash flows for the years ended December 31, 2013, 2012 and 2011 | 41 |
| Notes to consolidated financial statements | 42 |
(a)(2) Financial Statement Schedules
All financial statement schedules have been omitted, since the required information is not applicable or is not present in amounts sufficient to require submission of the schedule, or because the information required is included in the consolidated financial statements and notes thereto.
(a)(3) Exhibits
See the Exhibits Index following the signature pages for a list of the exhibits being filed or furnished with or incorporated by reference into this Annual Report on Form 10-K.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| Generac Holdings Inc. | ||
|---|---|---|
| By: | /s/ Aaron Jagdfeld | |
| Aaron Jagdfeld | ||
| President and Chief Executive Officer |
Dated: March 3, 2014
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons and on behalf of the Registrant in the capacities and on the dates indicated.
| Signature | Title | Date | ||||||||
|---|---|---|---|---|---|---|---|---|---|---|
| /s/ Aaron Jagdfeld Aaron Jagdfeld | President, Chief Executive Officer and Director | March 3, 2014 | ||||||||
| /s/ York A. Ragen York A. Ragen | Chief Financial Officer and Chief Accounting Officer | March 3, 2014 | ||||||||
| /s/ TODD A. ADAMS Todd A. Adams | Director | March 3, 2014 | ||||||||
| /s/ john d. bowlin John D. Bowlin | Director | March 3, 2014 | ||||||||
| /s/ robert d. dixon Robert D. Dixon | Director | March 3, 2014 | ||||||||
| /s/ Barry J. Goldstein Barry J. Goldstein | Director | March 3, 2014 | ||||||||
| /s/ bennett morgan Bennett Morgan | Director | March 3, 2014 | ||||||||
| /s/ stephen murray Stephen Murray | Director | March 3, 2014 | ||||||||
| /s/ david ramon David Ramon | Director | March 3, 2014 | ||||||||
| /s/ timothy walsh Timothy Walsh | Director | March 3, 2014 |
EXHIBIT INDEX
| Exhibits Number | Description | |
|---|---|---|
| 2.1 | Agreement and Plan of Merger by and among Generac Power Systems, Inc., the representative named therein, GPS CCMP Acquisition Corp., and GPS CCMP Merger Corp., dated as of September 13, 2006 (incorporated by reference to Exhibit 2.1 of the Registration Statement on Form S-1 filed with the SEC on January 11, 2010). | |
| 2.2 | Amendment to Agreement and Plan of Merger by and among Generac Power Systems, Inc., the representative named therein, GPS CCMP Acquisition Corp., and GPS CCMP Merger Corp (incorporated by reference to Exhibit 2.1 of the Registration Statement on Form S-1 filed with the SEC on January 11, 2010). | |
| 3.1 | Third Amended and Restated Certificate of Incorporation of Generac Holdings Inc. (incorporated by reference to Exhibit 3.1 of the Company’s Annual Report on Form 10-K for the fiscal year ended December 31, 2010). | |
| 3.2 | Amended and Restated Bylaws of Generac Holdings Inc. (incorporated by reference to Exhibit 3.1 of the Company’s Current Report on Form 8-K filed with the SEC on April 10, 2013). | |
| 4.1 | Form of Common Stock Certificate (incorporated by reference to Exhibit 4.1 of the Registration Statement on Form S-1 filed with the SEC on January 25, 2010). | |
| 10.1 | Restatement Agreement, dated as of May 31, 2013, to that certain Credit Agreement, dated as of February 9, 2012, as amended and restated as of May 31, 2012, among Generac Power Systems, Inc., Generac Acquisition Corp., the lenders party thereto, JPMorgan Chase Bank, N.A., as Administrative Agent, and Bank of America, N.A. and Goldman Sachs Bank USA, as syndication agents (incorporated by reference to Exhibit 10.1 to the Company’s Current Report on Form 8-K filed with the SEC on June 4, 2013). | |
| 10.2 | Guarantee and Collateral Agreement, dated as of February 9, 2012, as amended and restated as of May 30, 2012, among Generac Holdings Inc., Generac Acquisition Corp., Generac Power Systems, Inc., certain subsidiaries of Generac Power Systems, Inc. and JPMorgan Chase Bank, N.A., as Administrative Agent (incorporated by reference to Exhibit 10.2 of the Company’s Current Report on Form 8-K filed with the SEC on May 31, 2012). | |
| 10.3 | Credit Agreement, dated as of February 9, 2012, as amended and restated as of May 30, 2012, as further amended and restated as of May 31, 2013, among Generac Power Systems, Inc., Generac Acquisition Corp., the lenders party thereto, JPMorgan Chase Bank, N.A., as Administrative Agent and Bank of America, N.A. and Goldman Sachs Bank USA, as syndication agent (incorporated by reference to Exhibit 10.2 to the Company’s Current Report on Form 8-K filed with the SEC on June 4, 2013). | |
| 10.4 | Guarantee and Collateral Agreement, dated as of May 30, 2012, among Generac Holdings Inc., Generac Acquisition Corp., Generac Power Systems, Inc., certain subsidiaries of Generac Power Systems, Inc. and Bank of America, N.A., as Administrative Agent (incorporated by reference to Exhibit 10.4 of the Company’s Current Report on Form 8-K filed with the SEC on May 31, 2012). | |
| 10.5 | First Amendment to Guarantee and Collateral Agreement, dated as of May 31, 2013, to that certain Guarantee and Collateral Agreement, dated as of February 9, 2012, as amended and restated as of May 30, 2012, among Generac Holdings Inc., Generac Acquisition Corp., Generac Power Systems, Inc., certain subsidiaries of Generac Power Systems, Inc. and JPMorgan Chase Bank, N.A., as Administrative Agent (incorporated by reference to Exhibit 10.3 to the Company’s Current Report on Form 8-K filed with the SEC on June 4, 2013). | |
| 10.6 | Credit Agreement, dated as of May 30, 2012, among Generac Power Systems, Inc., its Domestic Subsidiaries listed as Borrowers on the signature pages thereto, Generac Acquisition Corp., the lenders party thereto, Bank of America, N.A. as Administrative Agent, JPMorgan Chase Bank, N.A. and Goldman Sachs Bank USA, as syndication agents, and Wells Fargo Bank, National Association, as Documentation Agent (incorporated by reference to Exhibit 10.3 of the Company’s Current Report on Form 8-K filed with the SEC on May 31, 2012). | |
| 10.7 | Amendment No. 1 dated as of May 31, 2013 to the Credit Agreement, dated as of May 30, 2012, among Generac Power Systems, Inc., its Domestic Subsidiaries listed as Borrowers on the signature pages thereto, Generac Acquisition Corp., the lenders party thereto, Bank of America, N.A. as Administrative Agent, JPMorgan Chase Bank, N.A. and Goldman Sachs Bank USA, as syndication agents, and Wells Fargo Bank, National Association, as Documentation Agent (incorporated by reference to Exhibit 10.4 to the Company’s Current Report on Form 8-K filed with the SEC on June 4, 2013). | |
| 10.8 | First Amendment to the Guarantee and Collateral Agreement, dated as of May 31, 2013, to that certain Guarantee and Collateral Agreement, dated as of May 30, 2012, among Generac Holdings Inc., Generac Acquisition Corp., Generac Power Systems, Inc., certain subsidiaries of Generac Power Systems, Inc. and Bank of America, N.A., as Administrative Agent (incorporated by reference to Exhibit 10.5 to the Company’s Current Report on Form 8-K filed with the SEC on June 4, 2013). | |
| 10.9+ | 2009 Executive Management Incentive Compensation Program (incorporated by reference to Exhibit 10.46 of the Registration Statement on Form S-1 filed with the SEC on December 17, 2009). | |
| 10.10+ | Generac Holdings Inc. Amended and Restated 2010 Equity Incentive Plan (incorporated by reference to Appendix A to the Definitive Proxy Statement on Schedule 14A of the Company filed with the SEC on April 27, 2012) | |
| 10.11+ | Generac Holdings Inc. Annual Performance Bonus Plan (incorporated by reference to Exhibit 10.63 of the Registration Statement on Form S-1 filed with the SEC on January 25, 2010). | |
| 10.12+ | Amended and Restated Employment Agreement, dated January 14, 2010, between Generac and Aaron Jagdfeld (incorporated by reference to Exhibit 10.65 of the Registration Statement on Form S-1 filed with the SEC on January 25, 2010). | |
| 10.13+ | Employment Letter with Terrence Dolan (incorporated by reference to Exhibit 10.62 of the Registration Statement on Form S-1 filed with the SEC on January 25, 2010). | |
| 10.14+ | Form of Change in Control Severance Agreement (incorporated by reference to Exhibit 10.64 of the Registration Statement on Form S-1 filed with the SEC on January 25, 2010). | |
| 10.15 | Form of Confidentiality, Non-Competition and Intellectual Property Agreement (incorporated by reference to Exhibit 10.40 of the Registration Statement on Form S-1 filed with the SEC on November 24, 2009). | |
| 10.16+ | Form of Restricted Stock Award Agreement (incorporated by reference to Exhibit 10.44 of the Registration Statement on Form S-1 filed with the SEC on January 25, 2010). | |
| 10.17+ | Form of Nonqualified Stock Option Award Agreement (incorporated by reference to Exhibit 10.45 of the Registration Statement on Form S-1 filed with the SEC on January 25, 2010). | |
| 10.18+ | Amended Form of Restricted Stock Award Agreement pursuant to the 2010 Equity Incentive Plan (incorporated by reference to Exhibit 10.3 of the Quarterly Report on Form 10-Q filed with the SEC on May 8, 2012). | |
| 10.19+ | Amended Form of Nonqualified Stock Option Award Agreement pursuant to the 2010 Equity Incentive Plan (incorporated by reference to Exhibit 10.4 of the Quarterly Report on Form 10-Q filed with the SEC on May 8, 2012). | |
| 10.20+ | Amended Form of Restricted Stock Award Agreement with accelerated vesting pursuant to the 2010 Equity Incentive Plan (incorporated by reference to Exhibit 10.5 of the Quarterly Report on Form 10-Q filed with the SEC on May 8, 2012). | |
| 10.21 | Form of Generac Holdings Inc. Director Indemnification Agreement for Stephen Murray and Timothy Walsh (incorporated by reference to Exhibit 10.50 of the Registration Statement on Form S-1 filed with the SEC on January 11, 2010). | |
| 10.22 | Form of Generac Holdings Inc. Director Indemnification Agreement for Barry Goldstein, John D. Bowlin, Robert Dixon, David Ramon, Timothy W. Sullivan, Bennett Morgan and Todd A. Adams (incorporated by reference to Exhibit 10.51 of the Registration Statement on Form S-1 filed with the SEC on January 11, 2010). | |
| 10.23 | Form of Generac Holdings Inc. Officer Indemnification Agreement (incorporated by reference to Exhibit 10.52 of the Registration Statement on Form S-1 filed with the SEC on January 11, 2010). | |
| 10.24 | Form of Generac Power Systems, Inc. Director Indemnification Agreement for Stephen Murray and Timothy Walsh (incorporated by reference to Exhibit 10.53 of the Registration Statement on Form S-1 filed with the SEC on January 25, 2010). | |
| 10.25 | Form of Generac Power Systems, Inc. Indemnification Agreement for Barry Goldstein, John D. Bowlin, Aaron Jagdfeld, David Ramon, York A. Ragen, Dawn Tabat, Allen Gillette, Roger Schaus, Jr., Roger Pascavis, Russell S. Minick, Robert Stoppek and Clement Feng (incorporated by reference to Exhibit 10.54 of the Registration Statement on Form S-1 filed with the SEC on January 25, 2010). | |
| 10.26+ | Amended Form of Nonqualified Stock Option Award Agreement pursuant to the 2010 Equity Incentive Plan (incorporated by reference to Exhibit 10.1 of the Form 10-Q filed with the SEC on May 7, 2013). | |
| 10.27+ | Amended Form of Restricted Stock Award Agreement with accelerated vesting pursuant to the 2010 Equity Incentive Plan (incorporated by reference to Exhibit 10.2 of the Form 10-Q filed with the SEC on May 7, 2013). | |
| 10.28+ | Cash award agreement to non-executive chairman (incorporated by reference to Exhibit 10.3 of the Form 10-Q filed with the SEC on May 7, 2013). | |
| 10.29+ | Cash award agreement to non-executive chairman (incorporated by reference to Exhibit 10.6 of the Form 10-Q filed with the SEC on August 7, 2013). | |
| 21.1* | List of Subsidiaries of Generac Holdings Inc. | |
| 23.1* | Consent of Ernst & Young, Independent Registered Public Accounting Firm. | |
| 31.1* | Certification of Chief Executive Officer pursuant to Securities Exchange Act Rules 13a-14(a) and 15d-14(a), pursuant to Section 302 of the Sarbanes-Oxley Act of 2002. | |
| 31.2* | Certification of Chief Financial Officer pursuant to Securities Exchange Act Rules 13a-14(a) and 15d-14(a), pursuant to Section 302 of the Sarbanes-Oxley Act of 2002. | |
| 32.1** | Certification of Chief Executive Officer pursuant to 18 U.S.C. Section 1350, as adopted by Section 906 of the Sarbanes-Oxley Act of 2002. | |
| 32.2** | Certification of Chief Financial Officer pursuant to 18 U.S.C. Section 1350, as adopted by Section 906 of the Sarbanes-Oxley Act of 2002. | |
| 101* | The following financial information from the Company’s Annual Report on Form 10-K for the fiscal year ended December 31, 2013, filed with the SEC on March 3, 2014, formatted in eXtensible Business Reporting Language (XBRL): (i) Consolidated Balance Sheets at December 31, 2013 and December 31, 2012; (ii) Consolidated Statements of Comprehensive Income for the Fiscal Years Ended December 31, 2013, December 31, 2012 and December 31, 2011; (iii) Consolidated Statements of Stockholders' Equity (Deficit) for the Fiscal Years Ended December 31, 2013, December 31, 2012 and December 31, 2011; (iv) Consolidated Statements of Cash Flows for the Fiscal Years Ended December 31, 2013, December 31, 2012 and December 31, 2011; (v) Notes to Consolidated Financial Statements. |
| * | Filed herewith. |
|---|
| ** | Furnished herewith. |
|---|
| + | Indicates management contract or compensatory plan or arrangement. |
|---|