 filings.tools
Global Payments 2019 10-K Annual Report
GPN · CIK 1123360 · Form 10-K · Fiscal year ended December 31, 2019 · Filed February 21, 2020
Revenue rose 45.9% to $4.91 billion. Operating margin was 16.1%, against 21.9% the year before. Net income was $431 million.
18 sections, 431K characters. Original on sec.gov · ·
Risk FactorsBusinessMD&AFinancial StatementsWhat changed vs 2018
| Measure | Year ended Dec 31, 2019 | Year ended Dec 31, 2018 | Change |
|---|---|---|---|
| Revenue | $4.91B | $3.37B | +45.9% |
| Operating income | $791M | $737M | +7.4% |
| Net income | $431M | $452M | -4.7% |
| Diluted EPS | $2.16 | $2.84 | -23.9% |
| Free cash flow* | $1.08B | $893M | +21.4% |
| Cash and equivalents | $1.68B | $1.21B | +38.6% |
| Operating margin* | 16.1% | 21.9% | -5.8 pts |
From the XBRL facts tagged to this filing; both columns are as reported in this filing. * Computed by filings.tools: free cash flow is operating cash flow less capital spending; operating margin is operating income over revenue.
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
☒ ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended December 31, 2019
OR
☐ TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
For the transition period from to
Commission File No. 001-16111
GLOBAL PAYMENTS INC**.**
(Exact name of registrant as specified in charter)
| Georgia | 58-2567903 | |
| **(**State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
| 3550 Lenox Road | , | Atlanta | , | Georgia | 30326 | |
| (Address of principal executive offices) | (Zip Code) |
Registrant's telephone number, including area code: 770**-**829-8000
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading symbol | Name of each exchange on which registered | ||
| Common Stock, No Par Value | GPN | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act:
NONE
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or 15(d) of the Act. Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company” and “emerging growth company" in Rule 12b-2 of the Exchange Act.
Large accelerated filer ☒ Accelerated filer ☐
Non-accelerated filer ☐ Smaller reporting company ☐
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ☐ No ☒
The aggregate market value of the voting and non-voting common equity held by non-affiliates computed by reference to the price at which the common equity was last sold, or the average bid and asked price of such common equity, as of the last business day of the registrant's most recently completed second fiscal quarter was $24,916,809,935. The number of shares of the registrant's common stock outstanding at February 19, 2020 was 299,627,279 shares.
DOCUMENTS INCORPORATED BY REFERENCE
Specifically identified portions of the registrant's proxy statement for the 2020 annual meeting of shareholders are incorporated by reference in Part III.
GLOBAL PAYMENTS INC.
2019 ANNUAL REPORT ON FORM 10-K
CAUTIONARY NOTICE REGARDING FORWARD-LOOKING STATEMENTS
Unless the context requires otherwise, references in this report to "Global Payments," the "Company," "we," "our" or "us," refer to Global Payments Inc. and its subsidiaries.
Some of the statements we use in this report, and in some of the documents we incorporate by reference in this report, contain forward-looking statements concerning our business operations, economic performance and financial condition, including in particular: our business strategy and means to implement the strategy; measures of future results of operations, such as revenues, expenses, operating margins, income tax rates, and earnings per share; other operating metrics such as shares outstanding and capital expenditures; our success and timing in developing and introducing new services and expanding our business; and statements about the benefits of our acquisitions, including future financial and operating results, the combined company’s plans, objectives, expectations and intentions, and the successful integration of our future acquisitions. You can sometimes identify forward-looking statements by our use of the words "believes," "anticipates," "expects," "intends," "plan," "forecast," "guidance" and similar expressions. For these statements, we claim the protection of the safe harbor for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995.
Although we believe that the plans and expectations reflected in or suggested by our forward-looking statements are reasonable, those statements are based on a number of assumptions, estimates, projections or plans that are inherently subject to significant risks, uncertainties and contingencies, many of which are beyond our control, cannot be foreseen and reflect future business decisions that are subject to change. Accordingly, we cannot guarantee you that our plans and expectations will be achieved. Our actual revenues, revenue growth rates and margins, other results of operations and shareholder values could differ materially from those anticipated in our forward-looking statements as a result of many known and unknown factors, many of which are beyond our ability to predict or control. Important factors, among others, that may otherwise cause actual events or results to differ materially from those anticipated by such forward-looking statements include failure to realize the expected benefits of the merger with Total System Services, Inc. ("TSYS") or difficulties integrating the business of the combined company, higher than anticipated costs related to integrating the businesses, business disruptions or the risk of customer loss related to the merger with TSYS, our ability to safeguard our data; increased competition from larger companies and non-traditional competitors, our ability to update our services in a timely manner; our ability to maintain Visa and Mastercard registration and financial institution sponsorship; our reliance on financial institutions to provide clearing services in connection with our settlement activities; our potential failure to comply with card network requirements; risk associated with our indebtedness; potential systems interruptions or failures; software defects or undetected errors; increased attrition of merchants, referral partners or independent sales organizations; our ability to increase our share of existing markets and expand into new markets; development of market trends and technologies; a decline in the use of cards for payment generally; unanticipated increases in chargeback liability; increases in credit card network fees; change in laws, regulations or network rules or interpretations thereof; foreign currency exchange and interest rate risks; political, economic and regulatory changes in the foreign countries in which we operate; future performance, integration and conversion of acquired operations, including without limitation, difficulties and delays in integrating or fully realizing cost savings and other benefits of our acquisitions at all or within the expected time period; fully realizing anticipated annual interest expense savings from refinancing our credit facilities; our loss of key personnel and other risk factors presented in Item "1A - Risk Factors of this Annual Report on Form 10‑K," which we advise you to review. These cautionary statements qualify all of our forward-looking statements, and you are cautioned not to place undue reliance on these forward-looking statements.
Our forward-looking statements speak only as of the date they are made and should not be relied upon as representing our plans and expectations as of any subsequent date. While we may elect to update or revise forward-looking statements at some time in the future, we specifically disclaim any obligation to publicly release the results of any revisions to our forward-looking statements, except as required by law.
PART I
Item 1. BUSINESS
Global Payments, Inc. and its consolidated subsidiaries are referred to collectively as "Global Payments," the "Company," "we," "our" or "us," unless the context requires otherwise.
Introduction
We are a leading pure play payments technology company providing cutting edge payments and software solutions to approximately 3.5 million merchant locations and more than 1,300 financial institutions across more than 100 countries throughout North America, Europe, Asia-Pacific and Latin America. Our technologies, services and employee expertise enable us to provide a broad range of solutions that allow our customers to operate their businesses more efficiently across a variety of channels around the world. Headquartered in Georgia with approximately 24,000 employees worldwide, Global Payments is a member of the S&P 500. Our common stock is traded on the New York Stock Exchange under the symbol "GPN."
Merger with Total System Services, Inc.
On September 18, 2019, we consummated our merger with Total System Services, Inc. ("TSYS") (the "Merger") for total purchase consideration of $24.5 billion, primarily funded with shares of our common stock. Prior to the Merger, TSYS was a leading global payments provider, offering seamless, secure and innovative solutions to issuers, merchants and consumers. See "Note 2—Acquisitions" in the notes to the accompanying consolidated financial statements for further discussion of the Merger.
Industry Overview
The payments technology industry provides financial institutions, businesses and consumers with payment processing services, merchant acceptance solutions and related information and other value-added services. The industry continues to grow as a result of wider merchant acceptance, increased consumer use of credit and debit cards and advances in payment processing technology. The proliferation of credit and debit cards, as well as other digital payment solutions, has made the acceptance of electronic payments a virtual necessity for many businesses, regardless of size, in order to remain competitive. This increased use of cards and the availability of more sophisticated technology services to all market segments has resulted in a highly competitive and specialized industry.
Strategy
We seek to leverage the adoption of, and transition to, card, electronic and digital-based payments by expanding our share in our existing markets through our distribution channels and service innovation, as well as through acquisitions to improve our offerings and scale. We also seek to enter new markets through acquisitions, alliances and joint ventures around the world. We intend to continue to invest in and leverage our technology infrastructure and our people to increase our penetration in existing markets.
The key tenets of our strategy include the following:
| • | Grow and control our direct distribution by adding new channels and partners, including expanding our ownership of additional enterprise software solutions with a payments overlay in select vertical markets; |
| • | Deliver innovative services by developing value-added applications, enhancing existing services and developing new systems and services to blend technology with customer needs; |
| • | Continue to develop seamless multinational solutions for leading global customers; |
| • | Leverage technology and operational advantages across our business segments and throughout our global footprint; |
| • | Provide customer service at levels that exceed our competition, while investing in technology, training and enhancements to our service offerings; and |
| • | Pursue potential domestic and international acquisitions of, investments in and alliances with companies that have |
high growth potential, significant market presence, sustainable distribution platforms and/or key technological capabilities.
Competitive Strengths
We believe that our competitive strengths include the following:
| • | Global Footprint and Distribution - Our worldwide presence allows us to focus our investments on markets with promising gross domestic product fundamentals and favorable secular trends, makes us more attractive to customers with international operations and exposes us to emerging innovations that we can adopt globally, while diversifying our economic risk. |
| • | Technology Solutions - We provide innovative technology-based solutions, including enterprise software solutions, that enable our customers to operate their business more efficiently and simplify the payments process, regardless of the channel through which the transaction occurs. We believe our robust technology solutions will continue to differentiate us in the marketplace and will position us for continued growth. |
| • | Scalable Operating Environment and Technology Infrastructure - We operate with a multi-channel, global technology infrastructure, which provides scalable and innovative service offerings and a consistent service experience to our merchants, customers, financial institutions and other partners worldwide, while also driving sustainable operating efficiencies. |
| • | Strong, Long-lasting Partner Relationships - We have established strong, long-lasting relationships with many financial institutions, enterprise software providers, value-added resellers and other technology-based payment service providers, which enable us to deliver a set of diverse solutions to our customers. |
| • | Disciplined Acquisition Approach - Our proven track record for selectively and successfully sourcing, completing and integrating acquired businesses in existing and new markets positions us well for future growth and as an attractive partner for potential acquisition targets. |
Business Segments
Prior to the completion of the Merger, we operated in three reportable segments: North America, Europe and Asia-Pacific. As a result of the Merger, we assessed changes in our internal management reporting structure to incorporate the acquired operations of TSYS and the effects it has on our reportable segments. In the fourth quarter of 2019, we realigned our reportable segments to reflect the changes. As of December 31, 2019, we operated in three reportable segments: Merchant Solutions, Issuer Solutions and Business and Consumer Solutions. See "Note 15—Segment Information" in the notes to the accompanying consolidated financial statements for additional information about our segments, including revenues, operating income and depreciation and amortization by segment as well as financial information about geographic areas in which we operate.
In general, our consolidated results do not reflect pronounced seasonality. However, revenues and operating income for each segment and/or geographic channel may reflect stronger or weaker quarters given the nature of the underlying customer portfolios. Our foreign operations subject us to various risks, including, without limitation, currency exchange risks and political, economic and regulatory risks. See "Item 1A-Risk Factors" for additional information about these risks.
Merchant Solutions Segment
Through our Merchant Solutions segment, we provide payments technology and software solutions to customers globally. Our payment technology solutions are similar around the world in that we enable our customers to accept card, electronic, check and digital-based payments. Our comprehensive offerings include, but are not limited to, authorization services, settlement and funding services, customer support and help-desk functions, chargeback resolution, terminal rental, sales and deployment, payment security services, consolidated billing and statements and on-line reporting.
In addition, we offer a wide array of enterprise software solutions that streamline business operations to customers in numerous vertical markets. We also provide a variety of value-added services, including specialty point-of-sale solutions, analytic and engagement tools, payroll services and reporting that assist our customers with driving demand and operating their businesses more efficiently.
Our value proposition is to provide distinctive high-quality, responsive and secure services to all of our customers. We distribute our Merchant Solutions services globally through multiple channels and target customers in many vertical markets located throughout North America, Europe, Asia-Pacific and Latin America. The majority of our revenues is generated by services priced as a percentage of transaction value or a specified fee per transaction, depending on the payment type or the market. We also earn software subscription and licensing fees, as well as other fees based on specific value-added services that may be unrelated to the number or value of transactions.
Our primary mode of distribution is our direct distribution channels, including an extensive direct sales force selling our services and solutions across numerous vertical markets. Our technology-enabled solutions represented a substantial component of our revenues in North America for the year ended December 31, 2019. Our technology-enabled distribution in North America includes integrated and vertical market software solutions and ecommerce and omnichannel solutions. Our ecommerce and omnichannel solutions represent a growing percentage of the services we sell in Europe.
Direct Distribution
Our primary business model in the Merchant Solutions segment is to actively market and provide our payment services, enterprise software solutions and other value-added services directly to our customers through a variety of distribution channels. We offer high-touch services that provide our customers with reliable and secure solutions coupled with high quality and responsive support services. Through our direct sales force worldwide, as well as bank partnerships, we offer our payments technology services, software and other value-added solutions directly to customers in the markets we serve.
Many of our payment solutions are technology-enabled in that they incorporate or are incorporated into innovative, technology-driven solutions, including enterprise software solutions, designed to enable merchants to better manage their businesses. Our primary technology-enabled solutions include integrated solutions, vertical market software solutions and ecommerce and omnichannel solutions, each as described below.
Global Payments Integrated Solutions. Our integrated solutions provide advanced payments technology that is deeply embedded into business management software solutions that are owned by our technology partners who operate in numerous vertical markets, primarily in North America. We grow our integrated solutions business when new or existing merchants enable payments services through enterprise software solutions sold by our partners. Through Ezidebit, we offer integrated payment technology solutions in the Asia-Pacific region that focus on recurring payments verticals.
Vertical Markets Software Solutions. Our vertical markets software solutions provide advanced payments technology that is deeply integrated into business enterprise software solutions that we own. We distribute our vertical markets software solutions primarily through the following businesses:
| • | ACTIVE Network. Through ACTIVE Network, we deliver cloud-based enterprise software, including payment technology solutions, to event organizers in the communities and health and fitness markets. |
| • | AdvancedMD. Through AdvancedMD, we provide cloud-based enterprise solutions to small-to-medium sized ambulatory physician practices in the United States. |
| • | Education Solutions. We offer integrated payment solutions specifically designed for all levels of educational institutions. At the university level, we offer integrated commerce solutions, payment services, higher education loan services, credentialing services and open- and closed-loop payment solutions. For kindergarten through 12th grade, we provide ecommerce and in-person payments, cafeteria POS solutions and back-office management software, hardware, technical support and training. |
| • | Gaming. We offer a comprehensive suite of cash access solutions to the gaming market in North America. These solutions include credit and debit card cash advance, traditional and electronic check processing and other services specific to this market. |
| • | Xenial. Through Xenial, we offer leading-edge enterprise software solutions, integrated with our payment services and other adjacent business service applications, to the restaurant and hospitality and retail vertical markets. |
Ecommerce and Omnichannel. We offer ecommerce and omnichannel solutions to our customers that seamlessly blend payment gateway services, retail payment acceptance infrastructure and payment technology service capabilities through a unified commerce platform to allow merchants to accept various payment methods through any channel across our geographical footprint. We sell ecommerce and omnichannel solutions to customers of all sizes, from small businesses accepting payments
in a single country, to enterprise and multinational businesses that have complex payment needs and operate retail and online businesses in multiple countries.
Wholesale Distribution
Although our primary business model in the Merchant Solutions segment is to build high quality direct relationships with merchants, we also provide our services through a wholesale distribution channel where we do not maintain the face-to-face relationship with the merchant. Through our wholesale channel, our payment services are offered to merchants through independent sales organizations ("ISOs") and financial institutions.
Credit and Debit Card Transaction Processing
Credit and debit card transaction processing includes the processing of the world's major international card brands, including American Express, Discover Card ("Discover"), JCB, Mastercard, UnionPay International ("UPI") and Visa, as well as certain domestic debit networks, such as Interac in Canada. Credit and debit networks establish uniform regulations that govern much of the payment card industry. During a typical payment transaction, the merchant and the card issuer do not interface directly with each other, but instead rely on payments technology companies, such as Global Payments, to facilitate transaction processing services, including authorization, electronic draft capture, file transfers to facilitate funds settlement and certain exception-based, back office support services such as chargeback and retrieval resolution.
We process funds settlement under two models: a sponsorship model and a direct membership model. Under the sponsorship model, member clearing financial institutions ("Members") sponsor us and require our adherence to the standards of the networks. In certain markets, we have sponsorship or depository and clearing agreements with financial institution sponsors. These agreements allow us to route transactions under the Members' control and identification numbers to clear card transactions through Mastercard and Visa. In this model, the standards of the card networks restrict us from performing funds settlement or accessing merchant settlement funds, and, instead, require that these funds be in the possession of the Member until the merchant has been funded.
Under the direct membership model, we are direct members in various payment networks, allowing us to process and fund transactions without third-party sponsorship. In this model, we route and clear transactions directly through the card brand’s network and are not restricted from performing funds settlement. Otherwise, we process these transactions similarly to how we process transactions in the sponsorship model. We are required to adhere to the standards of the various networks in which we are direct members. We maintain relationships with financial institutions, which may also serve as our Member sponsors for other card brands or in other markets, to assist with funds settlement.
How a Card Transaction Works
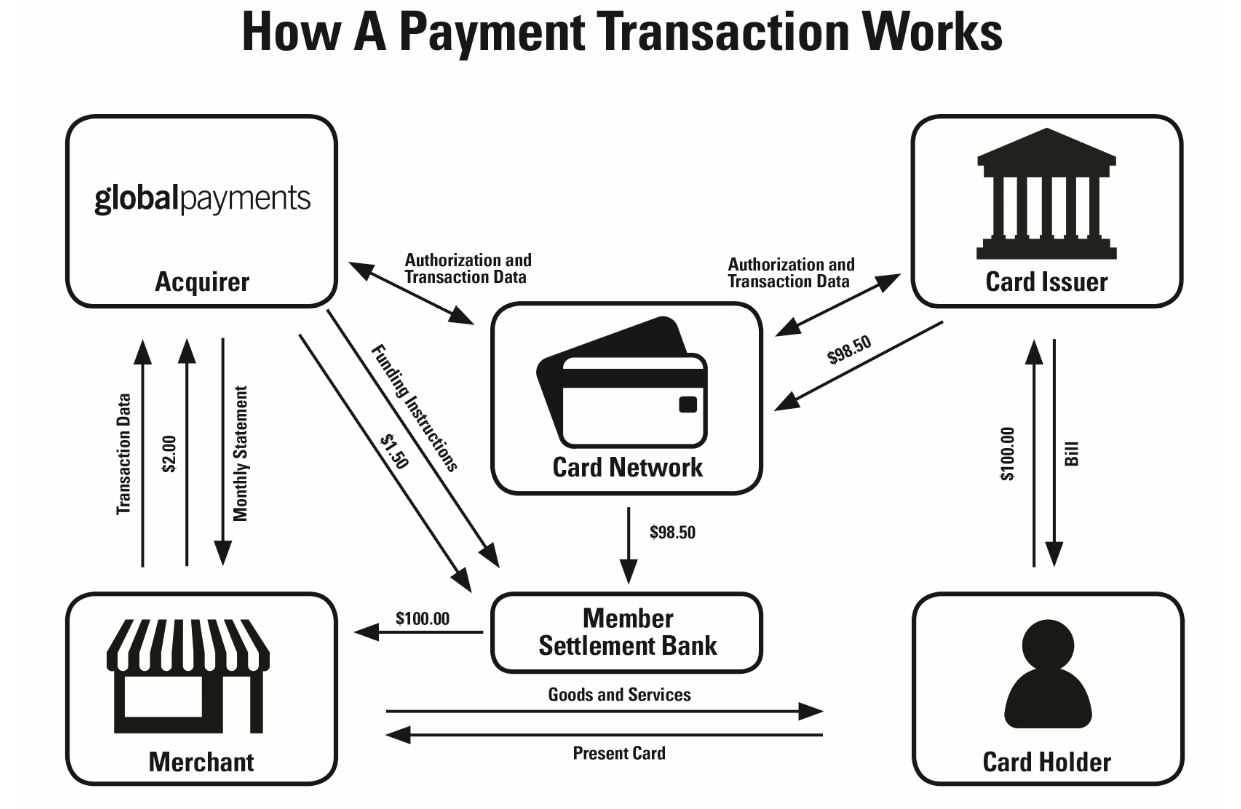
A typical payment transaction begins when a cardholder presents a card for payment at a merchant location where the card information is captured by a point-of-sale ("POS") terminal card reader or mobile device card reader, which may be sold or leased to the merchant and serviced by us. Alternatively, card and transaction information may be captured and transmitted to our network through a POS device or ecommerce portal by one of a number of services that we offer directly or through a value-added reseller. The card reader electronically records sales draft information, such as the card identification number, transaction date and transaction amount.
After the card and transaction information is captured, the POS device automatically connects to our network through the internet or other communication channel in order to receive authorization of the transaction. For a credit card transaction, authorization services generally refer to the process in which the card issuer indicates whether a particular credit card is authentic and whether the impending transaction amount will cause the cardholder to exceed defined credit limits. In a debit card transaction, we obtain authorization for the transaction from the card issuer through the payment network verifying that the cardholder has access to sufficient funds for the transaction amount.
As an illustration, shown below, on a $100.00 card transaction, the card issuer may fund the Member, our sponsor, (indirectly through the card network) $98.50 after retaining approximately $1.50 referred to as an interchange fee. The card issuer seeks reimbursement of $100.00 from the cardholder in the cardholder's monthly credit card statement. The Member would, in turn, pay the merchant $100.00. The net settlement after this transaction would require us to advance the Member $1.50. After the end of the month, we would bill the merchant a percentage of the transaction amount, or merchant discount, to cover the full amount of the interchange fee and our fee from the transaction. If our discount rate for the merchant in the above example was 2.00%, we would bill the merchant $2.00 after the end of the month for the transaction, reimburse ourselves for $1.50 in interchange fees and retain $0.50 as our fees for the transaction. Under some arrangements, we remit the net amount
of $98.00 to the merchant, rather than funding the full $100.00 and subsequently billing the merchant at the end of the month. Discount rates vary based on negotiations with merchants and the economic characteristics of transactions. Interchange rates also vary based on the economic characteristics of individual transactions. Accordingly, our fee per transaction varies across our merchant base and is subject to change based on changes in discount rates and interchange rates. Our profit on the transaction reflects the fee received less payment network fees and operating expenses, including systems cost to process the transaction and commissions paid to our sales force or ISO. Payment network fees are charged by the card brands, in part, based on the value of transactions processed through their networks.
Issuer Solutions Segment
Through our Issuer Solutions segment, we provide solutions that enable financial institutions and other financial service providers to manage their card portfolios, reduce technical complexity and overhead and offer a seamless experience for cardholders on a single platform. In addition, we provide flexible commercial payments and ePayables solutions that support business-to-business payment processes for businesses and governments. We also offer complementary services including account management and servicing, fraud solution services, analytics and business intelligence, cards, statements and correspondence, customer contact solutions and risk management solutions.
Issuer Solutions segment revenues are derived from long-term processing contracts with financial institutions and other financial services providers. Payment processing services revenues are generated primarily from charges based on the number of accounts on file, transactions and authorizations processed, statements generated and/or mailed, managed services, cards embossed and mailed, and other processing services for cardholders accounts on file. Most of these contracts have prescribed annual minimums, penalties for early termination, and service level agreements that may affect contractual fees if specific service levels are not achieved. Issuer Solutions revenues also include loyalty redemption services and professional services.
Business and Consumer Solutions Segment
Our Business and Consumer Solutions segment provides general purpose reloadable ("GPR") prepaid debit and payroll cards, demand deposit accounts and other financial service solutions to the underbanked and other consumers and businesses in the United States through our Netspend® brand. Through our Business and Consumer Solutions segment, we provide customers with access to depository accounts insured by the Federal Deposit Insurance Corporation ("FDIC") with a menu of
features specifically tailored to their needs. Business and Consumer Solutions has an extensive distribution and reload network comprising financial service centers and other retail locations throughout the United States, and is a program manager for FDIC-insured depository institutions that provide the services that the Business and Consumer Solutions segment develops, promotes and distributes. Business and Consumer Solutions currently has active agreements with five card issuing banks.
The Business and Consumer Solutions segment markets its services through multiple distribution channels, including alternative financial service providers, traditional retailers, direct-to-consumer and online marketing programs and contractual relationships with corporate employers. Business and Consumer Solutions segment revenues principally consist of fees collected from cardholders and fees generated by cardholder activity in connection with the programs that we manage. Customers are typically charged a fee for each purchase transaction made using their cards, unless the customer is on a monthly or annual service plan, in which case the customer is instead charged a monthly or annual subscription fee, as applicable. Customers are also charged a monthly maintenance fee after a specified period of inactivity. We also charge fees associated with additional services offered in connection with our accounts, including the use of overdraft features, a variety of bill payment options, card replacement, foreign exchange and card-to-card transfers of funds initiated through our call centers. Revenues are recognized net of fees charged by the payment networks for services they provide in processing transactions routed through them.
Competition
Our Merchant Solutions segment competes with financial institutions and merchant acquirers who provide businesses with merchant acquiring services and related services. We believe that as of December 31, 2019, we were one of the largest merchant acquirers in the small and medium-sized business segment (merchants who have less than $5 million in annual bankcard sales volume) in the United States. In the United States, we compete primarily with Fiserv, Inc. (and its alliances) ("Fiserv"), Fidelity National Information Services, Inc. ("FIS"), Chase Paymentech Solutions, LLC, Elavon, Inc., a subsidiary of U.S. Bancorp, Wells Fargo Bank, N.A and Square, Inc. While these are our primary competitors, some of our vertically focused business in the United States compete with other organizations.
Internationally, financial institutions remain the primary providers of payment technology services to merchants, although the outsourcing of these services to third-party service providers is becoming more prevalent. Payment services have become increasingly complex, requiring significant capital commitments to develop, maintain and update the systems necessary to provide these advanced services at competitive prices. In addition to financial institutions, competitors in Europe include Ayden N.V. and FIS.
Our Issuer Solutions segment encounters competition from credit card processing firms, third-party card processing software vendors and various other firms that provide products and services to credit card issuers in the United States and internationally. The United States market for third-party processing for credit card issuers is primarily serviced by three vendors, including TSYS, with our largest competitor being a subsidiary of Fiserv. We believe that as of December 31, 2019, we were the largest third-party processor for credit card issuers in North America and one of the largest in Europe based on net revenue derived from solutions for credit card issuers.
Our Business and Consumer Solutions segment primarily competes with other demand deposit account and prepaid debit account program managers to provide financial service solutions to the underbanked and other consumers and businesses. Our primary competitors in this space include Green Dot Corporation, InComm and Fiserv. As of December 31, 2019, we believe that we were one of the two largest prepaid program managers in the United States based on gross dollar volume (total spending on the accounts we manage) processed during 2019.
Safeguarding Our Business
In order to provide our services, we process and store sensitive business information and personal information, which may include credit and debit card numbers, bank account numbers, social security numbers, driver’s license numbers, names and addresses, and other types of personal information or sensitive business information. Some of this information is also processed and stored by financial institutions, merchants and other entities, as well as third-party service providers to whom we outsource certain functions and other agents, which we refer to collectively as our associated third parties. We may have responsibility to the card networks, financial institutions, and in some instances, our merchants, ISOs and/or individuals, for our failure or the failure of our associated third parties (as applicable) to protect this information.
We are subject to cyber security and information theft risks in our operations, which we seek to manage through cyber and information security programs, training and insurance coverage. To strengthen our security and cyber defenses, we continue to deploy multiple methods at different layers to defend our systems against misuse, intrusions and cyberattacks and to protect the data we collect. Further, we work with information security and forensics firms and employ advanced technologies to help
prevent, investigate and address issues relating to processing system security and availability. We also collaborate with third parties, regulators and law enforcement, when appropriate, to resolve security incidents and assist in efforts to prevent unauthorized access to our processing systems.
Intellectual Property
Our intellectual property is an important part of our strategy to be a leading provider of payment technology and software solutions. We use a combination of internal policies, intellectual property laws and contractual provisions to protect our proprietary technologies and brands. In addition, to protect our various brands, we seek and maintain registration of U.S. and international patents, trademarks, service marks and domain names that align with our brand strategy. We also enforce our trademarks against potential sources of confusion that could harm our brand and ability to compete. In addition to using our intellectual property in our own operations, we grant licenses to certain of our customers to use our intellectual property.
Employees and Labor
As of December 31, 2019, we had approximately 24,000 employees, many of whom are highly skilled in technical areas specific to payment technology and software solutions.
Regulation
Various aspects of our business are subject to regulation and supervision under federal, state and local laws in the United States, such as the California Consumer Privacy Act (the "CCPA"), and foreign laws, regulations and rules, including Directive 2007/64/EC in the European Union (the "Payment Services Directive"), as well as local escheat laws and privacy and information security regulations. In addition, we are subject to rules promulgated by the various payment networks, including American Express, Discover, Interac, Mastercard and Visa. Set forth below is a brief summary of some of the significant laws and regulations that apply to us. These descriptions are not exhaustive, and these laws, regulations and rules frequently change and are increasing in number.
Dodd-Frank Act
The Dodd-Frank Wall Street Reform and Consumer Protection Act of 2010 (the "Dodd-Frank Act") restricts the amounts of debit card fees that certain institutions can charge merchants. Pursuant to regulations promulgated by the Federal Reserve Board, debit interchange rates for card issuers with assets of $10 billion or more are capped at $0.21 per transaction and an ad valorem component of 5 basis points to reflect a portion of the issuer's fraud losses plus, for qualifying issuers, an additional $0.01 per transaction in debit interchange for fraud prevention costs.
In addition, the Dodd-Frank Act limits the ability of payment card networks to impose certain restrictions because it allows merchants to: (i) set minimum dollar amounts (not to exceed $10) for the acceptance of a credit card (and allows federal governmental entities and institutions of higher education to set maximum amounts for the acceptance of credit cards) and (ii) provide discounts or incentives to encourage consumers to pay with cash, checks, debit cards or credit cards.
The rules also contain prohibitions on network exclusivity and merchant routing restrictions that require a card issuer to enable at least two unaffiliated networks on each debit card, prohibit card networks from entering into exclusivity arrangements and restrict the ability of issuers or networks to mandate transaction routing requirements. The prohibition on network exclusivity has not significantly affected our ability to pass on network fees and other costs to our customers, nor do we expect it to in the future.
The Dodd-Frank Act also created the Consumer Financial Protection Bureau ("CFPB"), which has assumed responsibility for enforcing federal consumer protection laws, and the Financial Stability Oversight Council, which has the authority to determine whether any nonbank financial company, such as us, should be supervised by the Board of Governors of the Federal Reserve System (the "Federal Reserve") on the ground that it is "systemically important" to the U.S. financial system. Accordingly, we may be subject to additional systemic risk-related oversight.
Money Transmission, Sale of Checks and Payment Instrument Laws and Regulations
Our Business and Consumer Solutions segment is subject to money transfer and payment instrument licensing regulations. We have obtained licenses to operate as a money transmitter, seller of checks and/or provider of payment instruments in 49 states and the District of Columbia.
Our Business and Consumer Solutions segment is subject to direct supervision and regulation by the relevant state banking departments or similar agencies charged with enforcement of the relevant statutes and we must comply with various requirements, such as those related to the maintenance of a certain level of net worth, surety bonding, selection and oversight of our authorized agents, maintaining permissible investments in an amount equal to or in excess of our outstanding payment obligations, recordkeeping and reporting and disclosures to consumers. Our Business and Consumer Solutions segment is also subject to periodic examinations by the relevant licensing authorities, which may include reviews of our compliance practices, policies and procedures, financial position and related records, various agreements that we have with our issuing banks, distributors and other third parties, privacy and data security policies and procedures and other matters related to our business.
Banking Laws and Regulations
Because we provide electronic payment processing services to banks and other financial institutions, we are subject to examination by the Federal Financial Institutions Examination Counsel (the "FFIEC"), an interagency body comprised primarily of federal banking regulators, and also subject to examination by the various state financial regulatory agencies that supervise and regulate the financial institutions for which we provide electronic payment processing and other payment related services. The FFIEC examines large data processors in order to identify and mitigate risks associated with systemically significant service providers, including specifically the risks they may pose to the banking industry.
Privacy, Information Security and Other Business Practices Regulation
Aspects of our business are also subject, directly or indirectly, to business and trade practices regulation in the United States, the European Union and elsewhere. For example, in the United States, we and our financial institution customers are, respectively, subject to the Federal Trade Commission’s and the federal banking regulators’ privacy and information safeguarding requirements under the Gramm-Leach-Bliley Act. These requirements limit the manner in which personal information may be collected, stored, used and disclosed. The Federal Trade Commission’s information safeguarding rules require us to develop, implement and maintain a written, comprehensive information security program containing safeguards that are appropriate for our size and complexity, the nature and scope of our activities and the sensitivity of any customer information at issue. In many jurisdictions, including every U.S. State, consumers must be notified in the event of a data breach, and such notification requirements continue to increase in scope and cost. The changing privacy laws in the United States, Europe and elsewhere, including the adoption by the European Union of the General Data Protection Regulation, which became effective in May 2018, and the CCPA, which became effective in January 2020, create new individual privacy rights and impose increased obligations on companies handling personal data. In addition, multiple states, Congress and regulators outside the United States are considering similar laws or regulations which could create new individual privacy rights and impose increased obligations on companies handling personal data. See Item 1A. Risk Factors - "Any new implementation of or changes made to laws, regulations, card network rules or other industry standards affecting our business in any of the geographic regions in which we operate may require significant development efforts or have an unfavorable effect on our financial results and our cash flows."
Anti-Money Laundering and Counter Terrorist Requirements
In many countries, we are legally or contractually required to comply with the anti-money laundering laws and regulations, such as, in the United States, the Bank Secrecy Act, as amended by the USA PATRIOT Act (collectively, the "Bank Secrecy Act"), and similar laws of other countries, which require that customer identifying information be obtained and verified. In some countries, we are directly subject to these requirements; in other countries, we have contractually agreed to assist our sponsor financial institutions with their obligation to comply with anti-money laundering requirements that apply to them. In addition, we and our sponsor financial institutions are subject to the laws and regulations enforced by the Office of Foreign Assets Control ("OFAC"), which prohibit U.S. persons from engaging in transactions with certain prohibited persons or entities. Similar requirements apply in other countries. We have developed procedures and controls that are designed to monitor and address legal and regulatory requirements and developments and that allow our customers to protect against having direct business dealings with such prohibited countries, individuals or entities.
The Financial Crimes Enforcement Network of the U.S. Department of the Treasury ("FinCEN") has issued a rule regarding the applicability of the Bank Secrecy Act's anti-money laundering provisions to "prepaid access programs." This rulemaking clarifies the anti-money laundering obligations for entities, such as our Business and Consumer Solutions business and its distributors, engaged in the provision and sale of prepaid access devices like our GPR prepaid cards. Certain of our operating subsidiaries have registered with FinCEN as a money services business. This registration results in our having direct responsibility to maintain and implement an anti-money laundering compliance program.
State Wage Payment Laws and Regulations
The use of payroll card programs as a means for an employer to remit wages or other compensation to its employees or independent contractors is governed by state labor laws related to wage payments, which laws are subject to change. The paycard portion of our Business and Consumer Solutions segment includes payroll cards and convenience checks and is designed to allow employers to comply with applicable state wage and hour laws. Most states permit the use of payroll cards as a method of paying wages to employees, either through statutory provisions allowing such use or, in the absence of specific statutory guidance, the adoption by state labor departments of formal or informal policies allowing for their use. Nearly every state allowing payroll cards places certain requirements and/or restrictions on their use as a wage payment method, the most common of which involve obtaining the prior written consent of the employee, limitations on fees and disclosure requirements.
Escheat Laws
We are subject to unclaimed or abandoned property state laws in the United States and in certain foreign countries that require us to transfer to certain government authorities the unclaimed property of others that we hold when that property has been unclaimed for a certain period of time. Moreover, we are subject to audit by state and foreign regulatory authorities with regard to our escheatment practices.
Debt Collection and Credit Reporting Laws
Portions of our business may be subject to the Fair Debt Collection Practices Act ("FDCPA"), the Fair Credit Reporting Act ("FCRA") and similar state laws. These debt collection laws are designed to eliminate abusive, deceptive and unfair debt collection practices and may require licensing at the state level. The FCRA regulates the use and reporting of consumer credit information and also imposes disclosure requirements on entities that take adverse action based on information obtained from credit reporting agencies.
Telephone Consumer Protection Act
We are subject to the Telephone Consumer Protection Act ("TCPA") and various state laws to the extent we place telephone calls and short message service ("SMS") messages to customers and consumers. The TCPA regulates certain telephone calls and SMS messages placed using automatic telephone dialing systems or artificial or prerecorded voices.
Where to Find More Information
We file annual and quarterly reports, proxy statements and other information with the U.S. Securities and Exchange Commission ("SEC"). You may read and print materials that we have filed with the SEC from its website at www.sec.gov. In addition, certain of our SEC filings, including our annual reports on Form 10-K, our quarterly reports on Form 10-Q, our current reports on Form 8-K and amendments to them can be viewed and printed, free of charge, from the investor relations section of our website at www.globalpaymentsinc.com as soon as reasonably practicable after such material is electronically filed with or furnished to the SEC. Certain materials relating to our corporate governance, including our codes of ethics applicable to our directors, senior financial officers and other employees, are also available in the investor relations section of our website. Copies of our filings, specified exhibits and corporate governance materials are also available, free of charge, by writing us using the address on the cover of this Annual Report on Form 10-K. You may also telephone our investor relations office directly at (770) 829-8478. We are not including the information on our website as a part of, or incorporating it by reference into, this Annual Report on Form 10-K.
Item 1A. RISK FACTORS
An investment in our common stock involves a high degree of risk. You should consider carefully the following risks and other information contained in this Annual Report on Form 10-K and other SEC filings before you decide whether to buy our common stock. The risks identified below are not all encompassing but should be considered in establishing an opinion of our future operations. If any of the events contemplated by the following discussion of risks should occur, our business, results of operations, financial condition and cash flows could suffer significantly. As a result, the market price of our common stock could decline and you may lose all or part of your investment in our common stock.
Risks Related to Our Business and Operations
Our ability to protect our systems and data from continually evolving cybersecurity risks or other technological risks could affect our reputation among our customers and cardholders, adversely affect our continued card network registration or membership and financial institution sponsorship, and may expose us to penalties, fines, liabilities and legal claims.
In order to provide our services, we process and store sensitive business information and personal information, which may include credit and debit card numbers, bank account numbers, social security numbers, driver’s license numbers, names and addresses, and other types of personal information or sensitive business information. Some of this information is also processed and stored by financial institutions, merchants and other entities, as well as third-party service providers to whom we outsource certain functions and other agents, which we refer to collectively as our associated third parties. We may have responsibility to the card networks, financial institutions, and in some instances, our merchants, ISOs and/or individuals, for our failure or the failure of our associated third parties (as applicable) to protect this information.
We are a regular target of malicious third-party attempts to identify and exploit system vulnerabilities, and/or penetrate or bypass our security measures, in order to gain unauthorized access to our networks and systems or those of our associated third parties. Such access could lead to the compromise of sensitive, business, personal or confidential information. As a result, we follow a defense-in-depth model for cybersecurity, meaning we proactively seek to employ multiple methods at different layers to defend our systems against intrusion and attack and to protect the data we collect. However, we cannot be certain that these measures will be successful and will be sufficient to counter all current and emerging technology threats.
Our computer systems and/or our associated third parties’ computer systems could be subject to penetration, and our data protection measures may not prevent unauthorized access. The techniques used to obtain unauthorized access, disable or degrade service or sabotage systems change frequently and are often difficult to detect and continually evolve and become more sophisticated. Threats to our systems and our associated third parties’ systems can derive from human error, fraud or malice on the part of employees or third parties, including state-sponsored organizations with significant financial and technological resources. Computer viruses and other malware can be distributed and could infiltrate our systems or those of our associated third parties. In addition, denial of service or other attacks could be launched against us for a variety of purposes, including to interfere with our services or create a diversion for other malicious activities. Our defensive measures may not prevent downtime, unauthorized access or use of sensitive data. While we maintain first- and third-party insurance coverage that may cover certain aspects of cyber risks, such insurance coverage may be insufficient to cover all losses. Companies we acquire may require post-closing implementation of additional cyber defense methods to align with our standards and, as a result, there may be a period of increased risk between the closing of an acquisition and the completion of such implementation. Further, certain of our third-party relationships are subject to our vendor management program and governed by written contracts; however, we do not control the actions of our associated third parties, and any problems experienced by these third parties, including those resulting from breakdowns or other disruptions in the services provided by such parties or cyberattacks and security breaches, could adversely affect our ability to service our customers or otherwise conduct our business.
In addition, we cannot provide assurance that the contractual requirements related to use, security and privacy that we impose on our associated third parties who have access to this data will be followed or will be adequate to prevent the misuse of this data. Any misuse or compromise of personal information or failure to adequately enforce these contractual requirements could result in liability, protracted and costly litigation and, with respect to misuse of personal information of our customers, lost revenue and reputational harm.
Any type of security breach, attack or misuse of data described above or otherwise, whether experienced by us or an associated third party, could harm our reputation and deter existing and prospective customers from using our services or from making electronic payments generally, increase our operating expenses in order to contain and remediate the incident, expose us to unanticipated or uninsured liability, disrupt our operations (including potential service interruptions), distract our management, increase our risk of litigation or regulatory scrutiny, result in the imposition of penalties and fines under state, federal and foreign laws or by the card networks, and adversely affect our continued card network registration or membership and financial institution
sponsorship. Our removal from networks' lists of Payment Card Industry Data Security Standard compliant service providers could mean that existing customers, sales partners or other third parties may cease using or referring our services. Also, prospective merchant customers, financial institutions, sales partners or other third parties may choose to terminate negotiations with us, or delay or choose not to consider us for their processing needs. In addition, the card networks could refuse to allow us to process through their networks.
The payments technology industry is highly competitive, and some of our competitors are larger and have greater financial and operational resources than we do, which may give them an advantage with respect to the pricing of services offered to customers and the ability to develop new technologies.
We operate in the payments technology industry, which is highly competitive. In this industry, our primary competitors include other independent payment processors, credit card processing firms, as well as financial institutions, ISOs, prepaid programs managers and, potentially, card networks. We compete with many larger companies that have greater financial and operational resources than we have. Our competitors that are financial institutions or subsidiaries of financial institutions do not incur the costs associated with being sponsored by a direct member for participation in the card networks, as we do in certain jurisdictions, and may be able to settle transactions more quickly for merchants than we can. These financial institutions may also provide payment processing services to merchants at a loss in order to generate banking fees from the merchants. It is also possible that larger financial institutions could decide to perform in-house some or all of the services that we currently provide or could provide. These attributes may provide them with a competitive advantage in the market.
Additionally, the market for
Showing the first 8K of 71K characters. Open the full section
Item 2. PROPERTIES
We have properties located in the United States and in countries outside the United States to support the geographic markets in which we conduct business. Our properties include office space and data centers most of which we lease. We believe that all of our properties will be suitable and adequate for our business as presently conducted. See "Note 6—Leases" in the notes to the accompanying consolidated financial statements for further discussion of our leases.
Item 3. LEGAL PROCEEDINGS
We are party to a number of claims and lawsuits incidental to our business. In our opinion, the liabilities, if any, that may ultimately result from the outcome of such matters, individually or in the aggregate, are not expected to have a material adverse effect on our financial position, liquidity, results of operations or cash flows. See "Note 16—Commitments and Contingencies" in the notes to the accompanying consolidated financial statements for information about certain legal matters.
Part II
Item 5. MARKET FOR REGISTRANT'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Our common stock trades on the New York Stock Exchange under the ticker symbol "GPN." As of February 19, 2020, there were 14,180 shareholders of record.
Equity Compensation Plan Information
The information regarding our compensation plans under which equity securities are authorized for issuance is set forth in "Item 12—Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters" of this Annual Report.
Stock Performance Graph
In 2016, we changed our fiscal year-end from May 31 to December 31. We refer to the period consisting of the seven-months ended December 31, 2016 as the "2016 fiscal transition period."
The following graph compares our cumulative shareholder returns with the Standard & Poor's Information Technology Index and the Standard & Poor's 500 Index for the years ended December 31, 2019, 2018 and 2017, the 2016 fiscal transition period and the years ended May 31, 2016 and 2015. The line graph assumes the investment of $100 in our common stock, the Standard & Poor's ("S&P") 500 Index and the Standard & Poor's Information Technology Index on May 31, 2014 and assumes reinvestment of all dividends.
COMPARISON OF 5-YEAR CUMULATIVE TOTAL RETURN*
Among Global Payments Inc., the S&P 500 Index
and the S&P Information Technology Index
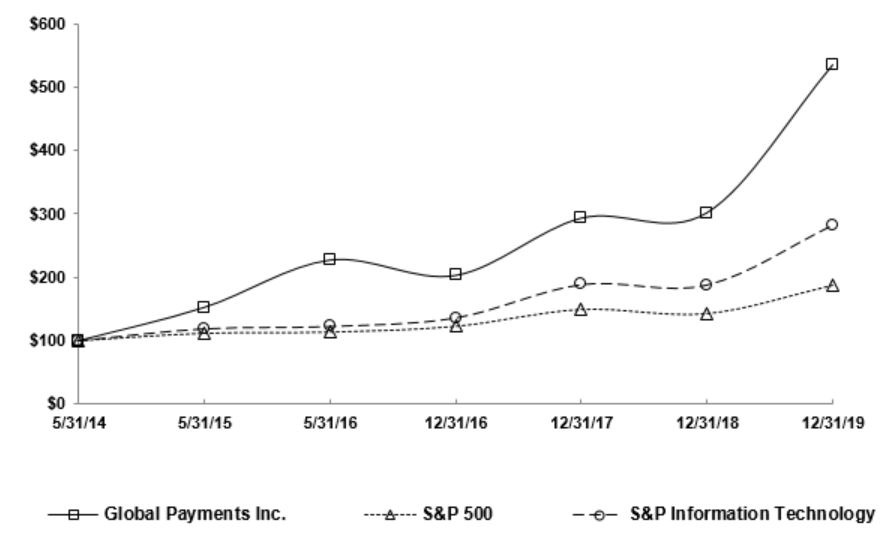
*$100 invested on May 31, 2014 in stock or index, including reinvestment of dividends.
Copyright© 2020 Standard & Poor's, a division of S&P Global. All rights reserved.
| Global Payments | S&P 500 Index | S&P Information Technology Index | ||||||||||
| May 31, 2014 | $ | 100.00 | $ | 100.00 | $ | 100.00 | ||||||
| May 31, 2015 | 152.39 | 111.81 | 118.81 | |||||||||
| May 31, 2016 | 226.99 | 113.72 | 122.52 | |||||||||
| December 31, 2016 | 202.85 | 122.94 | 136.07 | |||||||||
| December 31, 2017 | 293.09 | 149.78 | 188.91 | |||||||||
| December 31, 2018 | 301.65 | 143.21 | 188.37 | |||||||||
| December 31, 2019 | 534.68 | 188.31 | 283.10 |
Recent Sales of Unregistered Securities
There were no unregistered sales of equity securities during the year ended December 31, 2019.
Issuer Purchases of Equity Securities
Information about the shares of our common stock that we repurchased during the quarter ended December 31, 2019 is set forth below:
| Period | Total Number of Shares Purchased (1) | Approximate Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Maximum Number (or Approximate Dollar Value) of Shares that May Yet Be Purchased Under the Plans or Programs (2) | |||||||||
| (in millions) | |||||||||||||
| October 1-31, 2019 | 6,827 | $ | 160.70 | — | $ | 568.0 | |||||||
| November 1-30, 2019 | 6,357 | 172.00 | — | 568.0 | |||||||||
| December 1-31, 2019 | 629,195 | 182.06 | — | 568.0 | |||||||||
| Total | 642,379 | $ | 181.74 | — | $ | 473.4 |
| (1) | Our board of directors has authorized us to repurchase shares of our common stock through any combination of Rule 10b5-1 open-market repurchase plans, accelerated share repurchase plans, discretionary open-market purchases or privately negotiated transactions. |
During the quarter ended December 31, 2019, pursuant to our employee incentive plans, we withheld 122,617 shares at an average price per share of $180.77 in order to satisfy employees' tax withholding and payment obligations in connection with the vesting of awards of restricted stock, which we withheld at fair market value on the vesting date.
| (2) | On February 5, 2019, the board of directors increased its authorization to repurchase shares of our common stock to $750 million, inclusive of prior share repurchase programs authorized by the board and repurchases made thereunder. As of December 31, 2019, the approximate dollar value of shares that may yet be purchased under our share repurchase program was $473.4 million. The authorizations by our board of directors do not expire, but could be revoked at any time. In addition, we are not required by any of our board's authorizations or otherwise to complete any repurchases by any specific time or at all. |
Item 6. SELECTED FINANCIAL DATA
You should read the selected financial data set forth below in conjunction with (i) "Item 7 ‑ Management's Discussion and Analysis of Financial Condition and Results of Operations," (ii) "Item 8 ‑ Financial Statements and Supplementary Data" and (iii) the historical consolidated financial statements of Global Payments and the related notes presented in this Annual Report on Form 10-K.
| Years Ended December 31, | Seven Months Ended December 31, 2016 | Years Ended May 31, | |||||||||||||||||||||
| 2019 | 2018 | 2017 | 2016 | 2015 | |||||||||||||||||||
| (in thousands, except per share data) | |||||||||||||||||||||||
| Income statement data: | |||||||||||||||||||||||
| Revenues | $ | 4,911,892 | $ | 3,366,366 | $ | 3,975,163 | $ | 2,202,896 | $ | 2,898,150 | $ | 2,773,718 | |||||||||||
| Operating income | 791,417 | 737,055 | 558,868 | 237,951 | 424,944 | 456,597 | |||||||||||||||||
| Net income | 469,276 | 484,667 | 494,070 | 137,683 | 290,217 | 309,115 | |||||||||||||||||
| Net income attributable to Global Payments | 430,613 | 452,053 | 468,425 | 124,931 | 271,666 | 278,040 | |||||||||||||||||
| Per share data: | |||||||||||||||||||||||
| Basic earnings per share | $ | 2.17 | $ | 2.85 | $ | 3.03 | $ | 0.81 | $ | 2.05 | $ | 2.07 | |||||||||||
| Diluted earnings per share | 2.16 | 2.84 | 3.01 | 0.81 | 2.04 | 2.06 | |||||||||||||||||
| Cash dividends declared per common share | 0.225 | 0.04 | 0.04 | 0.02 | 0.04 | 0.04 | |||||||||||||||||
| Balance sheet data (at period end): | |||||||||||||||||||||||
| Total assets | $ | 44,480,162 | $ | 13,230,774 | $ | 12,998,069 | $ | 10,664,350 | $ | 10,509,952 | $ | 5,779,301 | |||||||||||
| Settlement lines of credit | 463,237 | 700,486 | 635,166 | 392,072 | 378,436 | 592,629 | |||||||||||||||||
| Long-term debt | 9,125,501 | 5,130,243 | 4,659,716 | 4,438,612 | 4,515,286 | 1,740,067 | |||||||||||||||||
| Total equity | 28,054,989 | 4,186,343 | 3,965,231 | 2,779,342 | 2,877,404 | 863,553 |
As more fully described in "Note 1—Basis of Presentation and Summary of Significant Accounting Policies" and "Note 3—Revenues" in the notes to the accompanying consolidated financial statements, we adopted a new revenue accounting standard on January 1, 2018 that results in revenue being presented net of certain fees that we pay to third parties, including payment networks. This change in presentation affected our reported revenues and operating expenses for all periods after the year ended December 31, 2017 by the same amount and had no effect on operating income.
The selected financial data in the table above reflect the effects of acquisitions and borrowings to fund certain of those acquisitions. Notably, in 2019, we completed the Merger for total purchase consideration of $24.5 billion, primarily funded with shares of our common stock. We also restructured our long-term debt facilities to include a $5.0 billion credit facility, consisting of a senior unsecured $2.0 billion term loan and a $3.0 billion revolving loan facility, and unsecured senior notes of $3.0 billion. In addition, we also assumed $3.0 billion of TSYS' unsecured senior notes in the Merger. See "Note 2—Acquisitions" and "Note 7—Long-Term Debt and Lines of Credit," respectively, in the notes to the accompanying consolidated financial statements for further discussion of our acquisitions and borrowing arrangements.
Operating income, net income, net income attributable to Global Payments and basic and diluted earnings per share in the table above reflect acquisition and integration expenses of $255.6 million for the year ended December 31, 2019, primarily related to the Merger, $56.1 million for the year ended December 31, 2018, $94.6 million for the year ended December 31, 2017, $91.6 million for the seven months ended December 31, 2016 and $51.3 million for the year ended May 31, 2016.
Net income, net income attributable to Global Payments and basic and diluted earnings per share in the table above also reflect the following:
(a) the effects of a net income tax benefit of $23.3 million in connection with adjustments made to accounting estimates associated with the U.S. Tax Cuts and Jobs Act of 2017 ("2017 U.S. Tax Act") for the year ended December 31, 2018 and a provisional net income tax benefit of $158.7 million recorded in connection with the 2017 U.S. Tax Act for
the year ended December 31, 2017. See "Note 9—Income Tax" in the notes to the accompanying consolidated financial statements for further discussion; and
(b) a gain of $41.2 million recognized in connection with the sale of our membership interests in Visa Europe Limited for the seven months ended December 31, 2016.
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following discussion and analysis of our financial condition and results of operations should be read in conjunction with "Item 6 - Selected Financial Data" and "Item 8 - Financial Statements and Supplementary Data." This discussion and analysis contains forward-looking statements about our plans and expectations of what may happen in the future. Forward-looking statements are based on a number of assumptions and estimates that are inherently subject to significant risks and uncertainties, and our actual results could differ materially from the results anticipated by our forward-looking statements as a result of many known and unknown factors, including but not limited to, those discussed in "Item 1A - Risk Factors." See "Cautionary Notice Regarding Forward-Looking Statements" located above in "Item 1 - Business."
Executive Overview
We are a leading pure play payments technology company delivering innovative software and services to our customers globally. Our technologies, services and employee expertise enable us to provide a broad range of solutions that allow our customers to operate their businesses more efficiently across a variety of channels around the world.
On September 18, 2019, we consummated our merger with Total System Services, Inc. ("TSYS") (the "Merger") for total purchase consideration of $24.5 billion, primarily funded with shares of our common stock. Prior to the Merger, TSYS was a leading global payments provider, offering seamless, secure and innovative solutions to issuers, merchants and consumers. See "Note 2—Acquisitions" in the notes to the accompanying consolidated financial statements for further discussion of the Merger.
We experienced strong business and financial performance around the world during the year ended December 31, 2019. Highlights related to our financial condition at December 31, 2019 and results of operations for the year then ended include the following:
| • | Consolidated revenues increased to $4,911.9 million compared to $3,366.4 million for the prior-year period, primarily due to additional revenues from TSYS. |
| • | Consolidated operating income increased to $791.4 million compared to $737.1 million for the prior-year period. Operating margin decreased to 16.1% compared to 21.9% for the prior-year period, primarily due to an increase in acquisition and integration expenses associated with the Merger. |
| • | Net income attributable to Global Payments decreased to $430.6 million compared to $452.1 million for the prior-year period, reflecting increases in acquisition and integration expenses, amortization of acquired intangibles and interest expense from the prior-year period. |
| • | Diluted earnings per share decreased to $2.16 compared to $2.84 for the prior-year period, reflecting the decrease in net income and an increase in the number of weighted-average shares outstanding as a result of issuing common shares as purchase consideration in the Merger. |
| • | In connection with the Merger, we achieved an investment grade debt structure, which now consists of a $5.0 billion senior unsecured term loan and revolving credit facility, unsecured senior notes of $3.0 billion that we issued and $3.0 billion of TSYS' unsecured senior notes that we assumed in the Merger. |
Emerging Trends
For a further discussion of trends, uncertainties and other factors that could affect our continuing operating results, see the section entitled "Risk Factors" in Item 1A in this Annual Report on Form 10-K.
The payments technology industry continues to grow worldwide and as a result, certain large payment technology companies, including us, have expanded operations globally by pursuing acquisitions and creating alliances and joint ventures. We expect to
continue to expand into new markets internationally and increase our scale and improve our competitiveness in existing markets by pursuing additional acquisitions and joint ventures.
We believe that the number of electronic payment transactions will continue to grow and that an increasing percentage of these will be facilitated through emerging technologies. As a result, we expect an increasing portion of our future capital investment will be allocated to support the development of new and emerging technologies; however, we do not expect our aggregate capital spending to support such technologies to increase materially from our current level of spending.
We also believe new markets will continue to develop in areas that have been previously dominated by paper-based transactions. We expect industries such as education, government and healthcare, as well as recurring payments and business-to-business payments, to continue to see transactions migrate to electronic-based solutions. We anticipate that the continued development of new services and the emergence of new vertical markets will be a factor in the growth of our business and our revenue in the future.
For a further discussion of trends, uncertainties and other factors that could affect our continuing operating results, see the section entitled "Risk Factors" in Item 1A in this Annual Report on Form 10-K.
Results of Operations
Prior to the completion of the Merger, we operated in three reportable segments: North America, Europe and Asia-Pacific. In the fourth quarter of 2019, as a result of the Merger, we realigned our executive management and organizational structures. Based on an evaluation performed in accordance with the guidance provided in Accounting Standards Codification Topic 280, Segment Reporting, we determined that our new reportable segments as of December 31, 2019 were: Merchant Solutions, Issuer Solutions, and Business and Consumer Solutions. In connection with the organizational realignment, the legacy Global Payments businesses are included in the Merchant Solutions segment, with the exception of a small portion of our European business that is included in the Issuer Solutions segment. Certain operating expenses, that prior to the Merger were considered "enterprise-wide" expenses and reported in Corporate, are now reflected in the Merchant Solutions segment. For further information about our reportable segments, see "Item 1. Business—Business Segments" and "Note 15—Segment Information" in the notes to the accompanying consolidated financial statements, incorporated herein by reference.
The following discussion of our results recasts our segments for prior periods to conform to our new segment presentation. For a discussion of our results of operations for fiscal 2018 compared to fiscal 2017, refer to "Part II, Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations" in our Form 10-K for the year ended December 31, 2018, which was filed with the SEC on February 21, 2019.
Revenues
Merchant Solutions. The majority of our Merchant Solutions segment revenues is generated by services priced as a percentage of transaction value or a specified fee per transaction, depending on card type or the vertical. We also earn software subscription and licensing fees, as well as other fees based on specific value-added services that may be unrelated to the number or value of transactions. These revenues depend upon a number of factors, such as demand for and price of our services, the technological competitiveness of our offerings, our reputation for providing timely and reliable service, competition within our industry and general economic conditions.
We provide payment technology and software solutions to customers and fund settlement either directly, in markets where we have direct membership with the payment networks, or through our relationship with a member financial institution in markets where we are sponsored. Revenues are recognized in the amount of customer billing, net of interchange fees and payment network fees. We market our services through a variety of sales channels, including a direct sales force, trade associations, agent and enterprise software providers and referral arrangements with value-added resellers ("VARs"), which we generally refer to as "direct distribution." We also sell services to ISOs and financial institutions through our wholesale channel. In certain of these contracts, the ISO receives a share of the customer profitability in the form of a monthly residual payment, which is reflected as a component of selling, general and administrative expenses in the consolidated statements of income.
Issuer Solutions. Issuer Solutions segment revenues are derived from long-term processing contracts with financial institutions and other financial services providers. Payment processing services revenues are generated primarily from charges based on the number of accounts on file, transactions and authorizations processed, statements generated and/or mailed, managed services, cards embossed and mailed, and other processing services for cardholders accounts on file. Most of these contracts have prescribed annual minimums, penalties for early termination, and service level agreements that may affect contractual fees if specific service levels are not achieved. Issuer Solutions revenues also include loyalty redemption services and professional services.
Business and Consumer Solutions. Business and Consumer Solutions segment revenues principally consist of fees collected from cardholders and fees generated by cardholder activity in connection with the programs that we manage. Customers are typically charged a fee for each purchase transaction made using their cards, unless the customer is on a monthly or annual service plan, in which case the customer is instead charged a monthly or annual subscription fee, as applicable. Customers are also charged a monthly maintenance fee after a specified period of inactivity. We also charge fees associated with additional services offered in connection with certain cards, including the use of overdraft features, a variety of bill payment options, card replacement, foreign exchange and card-to-card transfers of funds initiated through our call centers. Revenues are recognized net of fees charged by the payment networks for services they provide in processing transactions routed through them.
Operating Expenses
Cost of Service
Cost of service consists primarily of salaries, wages and related expenses paid to operations and technology-related personnel, including those who monitor our transaction processing systems and settlement functions; the cost of transaction processing systems, including third-party services; the cost of network telecommunications capability; depreciation and occupancy costs associated with the facilities supporting these functions; amortization of intangible assets; amortization of costs to fulfill customer contracts; provisions for operating losses; and, when applicable, integration expenses.
Selling, General and Administrative Expenses
Selling, general and administrative expenses consist primarily of salaries, wages, commissions and related expenses paid to sales personnel, customer support functions other than those supporting revenue, administrative employees and management; share-based compensation expense; amortization of costs to obtain customer contracts; residuals paid to ISOs; fees paid to VARs, independent contractors and other third parties; other selling expenses; occupancy costs of leased space directly related to these functions; advertising costs; and, when applicable, acquisition and integration expenses.
Operating Income and Operating Margin
For the purpose of discussing segment operations, we refer to "operating income," which is calculated by subtracting segment direct expenses from segment revenues. Overhead and shared expenses, including share-based compensation, are not allocated to segment operations; they are reported in the caption "Corporate." Similarly, we refer to "operating margin" regarding segment operations, which is calculated by dividing segment operating income by segment revenues.
Year Ended December 31, 2019 Compared to Year Ended December 31, 2018
The following table sets forth key selected financial data for the years ended December 31, 2019 and 2018, this data as a percentage of total revenues, and the changes between periods in dollars and as a percentage of the prior-period amount. The income statement data for the years ended December 31, 2019 and 2018 are derived from the accompanying consolidated financial statements included in Item 8 - Financial Statements and Supplementary Data.
| Year Ended December 31, | Year Ended December 31, | |||||||||||||||||||
| (dollar amounts in thousands) | 2019 | % of Revenue**(1)** | 2018 | % of Revenue**(1)** | Change | % Change | ||||||||||||||
| Revenues(2): | ||||||||||||||||||||
| Merchant Solutions | $ | 4,098,580 | 83.4 | % | $ | 3,345,181 | 99.4 | % | $ | 753,399 | 22.5 | % | ||||||||
| Issuer Solutions | 604,654 | 12.3 | % | 21,185 | 0.6 | % | 583,469 | NM | ||||||||||||
| Business and Consumer Solutions | 227,440 | 4.6 | % | — | — | % | 227,440 | NM | ||||||||||||
| Segment revenues | $ | 4,930,674 | 100.4 | % | $ | 3,366,366 | 100.0 | % | $ | 1,564,308 | 46.5 | % | ||||||||
| Less: intersegment revenues | (18,782 | ) | (0.4 | )% | — | — | % | (18,782 | ) | NM | ||||||||||
| Consolidated revenues | $ | 4,911,892 | 100.0 | % | $ | 3,366,366 | 100.0 | % | $ | 1,545,526 | 45.9 | % | ||||||||
| Consolidated operating expenses(2): | ||||||||||||||||||||
| Cost of service | $ | 2,073,803 | 42.2 | % | $ | 1,095,014 | 32.5 | % | $ | 978,789 | 89.4 | % | ||||||||
| Selling, general and administrative | 2,046,672 | 41.7 | % | 1,534,297 | 45.6 | % | 512,375 | 33.4 | % | |||||||||||
| Operating expenses | $ | 4,120,475 | 83.9 | % | $ | 2,629,311 | 78.1 | % | $ | 1,491,164 | 56.7 | % | ||||||||
| Operating income (loss)(2)(3): | ||||||||||||||||||||
| Merchant Solutions | $ | 1,148,975 | 23.4 | % | $ | 940,157 | 27.9 | % | $ | 208,818 | 22.2 | % | ||||||||
| Issuer Solutions | 82,172 | 1.7 | % | 14,084 | 0.4 | % | 68,088 | NM | ||||||||||||
| Business and Consumer Solutions | 19,473 | 0.4 | % | — | — | % | 19,473 | NM | ||||||||||||
| Corporate | (459,203 | ) | (9.3 | )% | (217,186 | ) | (6.5 | )% | (242,017 | ) | 111.4 | % | ||||||||
| Operating income | $ | 791,417 | 16.1 | % | $ | 737,055 | 21.9 | % | $ | 54,362 | 7.4 | % | ||||||||
| Operating margin(2): | ||||||||||||||||||||
| Merchant Solutions | 28.0 | % | 28.1 | % | (0.1 | )% | ||||||||||||||
| Issuer Solutions | 13.6 | % | NM | NM | ||||||||||||||||
| Business and Consumer Solutions | 8.6 | % | NM | NM |
NM = Not meaningful.
(1) Percentage amounts may not sum to the total due to rounding.
(2) Revenues, operating expenses, operating income and operating margin reflect the effects of acquired businesses from the respective dates of acquisition. For further discussion, see "Note 2—Acquisitions" in the notes to the accompanying consolidated financial statements.
(3) During the year ended December 31, 2019, operating income for our Merchant Solutions segment reflected the effect of acquisition and integration expenses of $56.1 million. Operating loss for Corporate included acquisition and integration expenses of $199.5 million and $56.1 million, respectively, during the years ended December 31, 2019 and 2018. Acquisition and integration expenses for 2019 were primarily related to the Merger.
Revenues
Consolidated revenues for the year ended December 31, 2019 increased by 45.9% to $4,911.9 million, compared to $3,366.4 million for the prior-year period, primarily due to additional revenues from the acquired operations of TSYS. For the year ended
December 31, 2019, currency exchange rate fluctuations reduced our consolidated revenues by approximately $44 million, compared to the prior-year period, calculated by converting revenues for the current year, excluding revenues from current year acquisitions, in local currencies using exchange rates for the prior-year period. The effect of exchange rate fluctuations on our revenues was almost exclusively in our Merchant Solutions segment.
Merchant Solutions Segment. Revenues from our Merchant Solutions segment increased by 22.5% to $4,098.6 million, compared to $3,345.2 million for the prior-year period, primarily due to additional revenues from the acquired operations of TSYS.
Issuer Solutions and Business and Consumer Solutions Segments. Revenues from our Issuer Solutions and Business and Consumer Solutions segments resulted primarily from the additional revenues from the acquired operations of TSYS.
Operating Expenses
Cost of Service. Cost of service for the year ended December 31, 2019 increased by 89.4% to $2,073.8 million, compared to $1,095.0 million for the prior-year period, primarily due to additional costs associated with the acquired operations of TSYS. Cost of service for the year ended December 31, 2019 reflects amortization of acquired intangibles of $667.1 million, compared to $377.7 million for the prior-year period, and integration expenses of $41.8 million primarily related to the Merger. Cost of service as a percentage of revenues increased to 42.2% for the year ended December 31, 2019, compared to 32.5% for the prior-year period, primarily due to the increase in amortization of acquired intangibles of $289.5 million.
Selling, General and Administrative Expenses. Selling, general and administrative expenses for the year ended December 31, 2019 increased by 33.4% to $2,046.7 million, compared to $1,534.3 million for the prior-year period. The increase in selling, general and administrative expenses was primarily due to additional costs associated with the acquired operations of TSYS. In addition, selling, general and administrative expenses for the year ended December 31, 2019 reflect acquisition and integration expenses of $213.8 million, primarily related to the Merger, compared to $56.1 million for the prior-year period. Selling, general and administrative expenses as a percentage of revenues was 41.7% for the year ended December 31, 2019, compared to 45.6% for the prior-year period.
Corporate. Corporate expenses increased by $242.0 million to $459.2 million for the year ended December 31, 2019, compared to $217.2 million for the prior-year period, primarily due to additional expenses associated with the acquired operations of TSYS and an increase in acquisition and integration expenses primarily due to the Merger. During the years ended December 31, 2019 and 2018, operating loss for Corporate included acquisition and integration expenses of $199.5 million and $56.1 million, respectively. Certain of these Merger-related integration activities resulted in the recognition of one-time employee termination benefits. During the year ended December 31, 2019, we recognized charges of $57.1 million for actions taken to date, which included $17.3 million of share-based compensation expense based on accelerated vesting periods for equity awards held by terminated employees. In addition, we wrote-off capitalized software and other assets of $40.2 million for legacy Global Payments technology that will no longer be utilized for the combined company. We expect to incur additional charges as Merger-related integration activities continue in 2020.
Operating Income and Operating Margin
Consolidated operating income for the year ended December 31, 2019 increased to $791.4 million, compared to $737.1 million for the prior year due to additional income from TSYS of $78.7 million. For the year ended December 31, 2019, currency exchange rate fluctuations reduced our consolidated operating income by approximately $21 million, compared to the prior-year period, calculated by converting operating income for the current year, excluding operating income from current year acquisitions, in local currencies using exchange rates for the prior-year period. The effect of exchange rate fluctuations on our operating income was almost exclusively in our Merchant Solutions segment.
Operating margin for the year ended December 31, 2019 decreased to 16.1%, compared to 21.9% for the prior-year period. Consolidated operating income for the year ended December 31, 2019 reflects an increase in acquisition and integration expenses of $199.5 million, primarily due to the Merger, compared to the prior-year period, which was the primary reason for the decrease in operating margin from the prior-year period.
Other Income/Expense, Net
Interest and other income for the year ended December 31, 2019 increased by $10.7 million to $31.4 million, compared to the prior-year period, as a result of interest earned on the net proceeds from the issuance of our unsecured senior notes while they were in escrow. Interest and other income for the year ended December 31, 2018 included a gain of $9.6 million recognized on the reorganization of a debit network association of which we were a member through one of our Canadian subsidiaries.
Interest and other expense for the year ended December 31, 2019 increased by $109.3 million to $304.9 million, compared to the prior-year period, as a result of the increase in our long-term debt, including debt of $3,295.3 million that we assumed in the Merger. Further, we incurred fees and charges of $30.4 million in connection with financing activities related to the Merger, which were included in interest expense for the year ended December 31, 2019. These fees and charges included fees associated with bridge financing and charges for the write-off of unamortized debt issuance costs related to borrowings under the credit facility that was extinguished prior to the completion of the Merger.
Income Tax Expense
Our effective income tax rates for the years ended December 31, 2019 and 2018 were 12.0% and 13.8%, respectively. Our effective tax rate for the year ended December 31, 2019 reflects the effects of the Merger on our state tax expense, foreign-derived intangible income deduction and tax credits. Our effective tax rate for the year ended December 31, 2018 reflects the reduction of our estimated transition tax liability associated with the U.S. Tax Cuts and Jobs Act of 2017.
Equity in Income of Equity Method Investments, Net of Tax
As a result of the Merger, we have a 44.56% investment in China UnionPay Data Co., Ltd. ("CUP Data"), which we account for using the equity method of accounting. Equity in income of equity method investments, net of tax, primarily reflects our proportional share of earnings from our investment in CUP Data.
Liquidity and Capital Resources
In the ordinary course of our business, a significant portion of our liquidity comes from operating cash flows and borrowings, including the capacity under our credit facilities. Cash flow from operating activities is used to make planned capital investments in our business, to pursue acquisitions that meet our corporate objectives, to pay dividends, to pay principal and interest on our outstanding debt and to repurchase shares of our common stock. Accumulated cash balances are invested in high-quality, marketable short-term instruments.
Our capital plan objectives are to support our operational needs and strategic plan for long-term growth while maintaining a low cost of capital. We use a combination of bank financing, such as borrowings under our credit facilities and senior note issuances, for general corporate purposes and to fund acquisitions. In addition, specialized lines of credit are also used in certain of our markets to fund merchant settlement prior to receipt of funds from the card network. We regularly evaluate our liquidity and capital position relative to cash requirements, and we may elect to raise additional funds in the future, through the issuance of debt or equity or by other means.
At December 31, 2019, we had cash and cash equivalents totaling $1,678.3 million. Of this amount, we consider $981.7 million to be available for general purposes, of which $27.0 million is undistributed foreign earnings considered to be indefinitely reinvested outside the United States. The available cash of $981.7 million does not include the following: (i) settlement-related cash balances, (ii) funds held as collateral for merchant losses ("Merchant Reserves") and (iii) funds held for customers. Settlement-related cash balances represent funds that we hold when the incoming amount from the card networks precedes the funding obligation to the merchant. Settlement-related cash balances are not restricted; however, these funds are generally paid out in satisfaction of settlement processing obligations the following day. Merchant Reserves serve as collateral to minimize contingent liabilities associated with any losses that may occur under the merchant's agreement. While this cash is not restricted in its use, we believe that designating this cash to collateralize Merchant Reserves strengthens our fiduciary standing with our member sponsors and is in accordance with the guidelines set by the card networks. Funds held for customers and the corresponding liability that we record in customer deposits include amounts collected prior to remittance on our customers' behalf.
Operating activities provided net cash of $1,391.3 million and $1,106.1 million for the years ended December 31, 2019 and 2018, respectively, which reflect net income adjusted for noncash items, including depreciation and amortization and changes in operating assets and liabilities. Fluctuations in operating assets and liabilities are affected primarily by timing of month-end and transaction volume, especially changes in settlement processing assets and obligations, and by the effects of businesses we acquire that have different working capital requirements. Changes in settlement processing assets and obligations increased operating cash flows by $213.7 million and $83.5 million during the years ended December 31, 2019 and 2018, respectively. The increase in cash flows from operating activities from the prior-year period was primarily due to the increase in earnings before certain noncash items, including amortization of acquired intangibles and depreciation and amortization of property and equipment.
We used net cash in investing activities of $917.1 million and $1,476.3 million during the years ended December 31, 2019 and 2018, respectively. Cash used for investing activities primarily represents cash used to fund acquisitions, net of cash acquired, and capital expenditures. During the year ended December 31, 2019, we used cash of $1,093.6 million for acquisitions, including $703.6 million for the repayment of TSYS' unsecured revolving credit facility (including accrued interest and fees) and for cash paid to TSYS shareholders in lieu of fractional shares, all of which was partially offset by cash acquired in the Merger and other acquisitions of $448.9 million. During the year ended December 31, 2018, we used cash of $1,274.9 million for acquisitions, which was partially offset by cash acquired of $15.2 million.
We made capital expenditures of $307.9 million and $213.3 million to purchase property and equipment during the years ended December 31, 2019 and 2018, respectively. These investments include software and hardware to support the development of new technologies, continued consolidation and enhancement of our operating platforms and infrastructure to support our growing business.
Financing activities include borrowings and repayments made under our various debt arrangements, as well as borrowings and repayments made under specialized lines of credit to fund daily settlement activities. Our borrowing arrangements are further described in "Note 7—Long-Term Debt and Lines of Credit" in the notes to the accompanying consolidated financial statements and below under "Long-Term Debt and Lines of Credit." Financing activities also include cash flows associated with common stock repurchase programs and share-based compensation programs, as well as cash distributions made to noncontrolling interests and our shareholders. We used net cash in financing activities of $28.7 million during the year ended December 31, 2019, and cash flows from financing activities provided net cash of $286.9 million during the year ended December 31, 2018.
In connection with financing activities associated with the Merger, we received proceeds of $2,973.2 million from the issuance of senior unsecured notes and $2,868.0 million from our senior unsecured term loan and revolving credit facilities. We used these proceeds to repay TSYS' unsecured revolving credit facility, to refinance certain of our existing indebtedness, to fund cash payments made in lieu of fractional shares and to pay transaction fees and costs related to the Merger.
Repayments of long-term debt were $6,484.7 million and $2,304.3 million for the years ended December 31, 2019 and 2018, respectively. Repayments of long-term debt consist of repayments that we make with available cash, from time-to-time, under our revolving credit facility, as well as scheduled principal repayments we make on our term loans. During the year ended December 31, 2019, repayments of long-term debt also included $5,127.5 million for the repayment of all outstanding principal under our secured term loan and revolving credit facility, which we extinguished in connection with the Merger.
Activity under our settlement lines of credit is affected primarily by timing of month-end and transaction volume. During the year ended December 31, 2019, we had net repayments of settlement lines of credit of $236.5 million, and during the year ended December 31, 2018, we had net borrowings from settlement lines of credit of $70.8 million.
From time to time, we repurchase our common stock, mainly through open market repurchase plans. During the years ended December 31, 2019 and 2018, we used cash of $311.4 million and $208.2 million, respectively, to repurchase shares of our common stock. As of December 31, 2019, we had $473.4 million of share repurchase authority remaining under a share repurchase program authorized by our board of directors.
We paid dividends to our common shareholders in the amounts of $63.5 million and $6.3 million during the years ended December 31, 2019 and 2018. During the year ended December 31, 2019, we funded assumed dividends payable (declared by TSYS' board of directors prior to consummation of the Merger) to former TSYS shareholders in the amount of $23.2 million. During the
years ended December 31, 2019 and 2018, we made distributions to noncontrolling interest in the amounts of $31.6 million and $5.7 million, respectively.
We believe that our current level of cash and borrowing capacity under our senior unsecured revolving credit facility, together with expected future cash flows from operations, will be sufficient to meet the needs of our existing operations and planned requirements for the foreseeable future.
Long-Term Debt and Lines of Credit
Bridge Facility
On May 27, 2019, in connection with our entry into the merger agreement with TSYS, we obtained commitments for a $2.75 billion, 364-day senior unsecured bridge facility (the "Bridge Facility"). On July 9, 2019, upon our entry into the senior unsecured term loan and revolving credit facilities described below, the aggregate commitments under the Bridge Facility were reduced to approximately $2.1 billion. Concurrently with the issuance of our senior unsecured notes, the remaining aggregate commitments under the Bridge Facility were reduced to zero and terminated. During the year ended December 31, 2019, we recognized $11.7 million of fees associated with the Bridge Facility in interest expense.
Senior Unsecured Credit Facilities
On July 9, 2019, we entered into a term loan credit agreement ("Term Loan Credit Agreement") and a revolving credit agreement ("Unsecured Revolving Credit Agreement") in each case with Bank of America, N.A., as administrative agent, and a syndicate of financial institutions, as lenders and other agents. The Term Loan Credit Agreement provides for a senior unsecured $2.0 billion term loan facility, and the Unsecured Revolving Credit Agreement provides for a senior unsecured $3.0 billion revolving credit facility.
Borrowings under the term loan facility were made in U.S. dollars and borrowings under the revolving credit facility are available to be made in U.S. dollars, euros, sterling, Canadian dollars and, subject to certain conditions, certain other currencies at our option. Borrowings in U.S. dollars and certain other London Interbank Offered Rate ("LIBOR")-quoted currencies will bear interest, at our option, at a rate equal to either (1) the rate (adjusted for any statutory reserve requirements for eurocurrency liabilities) for eurodollar deposits in the London interbank market, (2) a floating rate of interest set forth on the applicable LIBOR screen page designated by Bank of America or (3) the highest of (a) the federal funds effective rate plus 0.5%, (b) the rate of interest as publicly announced by Bank of America as its "prime rate" or (c) LIBOR plus 1.0%, in each case, plus an applicable margin. As of December 31, 2019, borrowings outstanding under the term loan facility and the revolving credit facility were $2.0 billion and $903.0 million, respectively.
As of December 31, 2019, the interest rates on the term loan facility and the revolving credit facility were 3.2% and 3.0%, respectively. In addition, we are required to pay a quarterly commitment fee with respect to the unused portion of the revolving credit facility at an applicable rate per annum ranging from 0.125% to 0.300% depending on our credit rating. Beginning on December 31, 2022, and at the end of each quarter thereafter, the term loan facility must be repaid in quarterly installments in the amount of 2.50% of original principal through the maturity date with the remaining principal balance due upon maturity in September 2024. The revolving credit facility also matures in September 2024.
We may issue standby letters of credit of up to $250 million in the aggregate under the revolving credit facility. Outstanding letters of credit under the revolving credit facility reduce the amount of borrowings available to us. The total available commitments under the revolving credit facility at December 31, 2019 were $2,077.5 million.
Senior Unsecured Notes
On August 14, 2019, we completed the public offering and issuance of $3.0 billion aggregate principal amount of senior unsecured notes, consisting of the following: (i) $1.0 billion aggregate principal amount of 2.650% senior notes due 2025; (ii) $1.25 billion aggregate principal amount of 3.200% senior notes due 2029; and (iii) $750.0 million aggregate principal amount of 4.150% senior notes due 2049. Interest on the senior notes is payable semi-annually in arrears on each February 15 and August 15, beginning on February 15, 2020. Each series of the senior notes is redeemable, at our option, in whole or in part, at any time and from time-to-time at the redemption prices set forth in the related indenture. We issued the senior notes at a total discount of $6.1 million and capitalized related debt issuance costs of $29.6 million.
From August 14, 2019 until the closing of the Merger on September 18, 2019, the proceeds from the issuance of the senior notes were held in escrow. Upon closing, the funds were released and used together with borrowings under the term loan facility and the revolving credit facility, as well as cash on hand, to repay TSYS' unsecured revolving credit facility, refinance certain of our existing indebtedness, fund cash payments made in lieu of fractional shares and pay transaction fees and costs related to the Merger.
In addition, in connection with the Merger, we assumed $3.0 billion aggregate principal amount of senior unsecured notes of TSYS, consisting of the following: (i) $750 million aggregate principal amount of 3.800% senior notes due 2021; (ii) $550 million aggregate principal amount of 3.750% senior notes due 2023; (iii) $550 million aggregate principal amount of 4.000% senior notes due 2023; (iv) $750 million aggregate principal amount of 4.800% senior notes due 2026; and (v) $450 million aggregate principal amount of 4.450% senior notes due 2028. For the 3.800% senior notes due 2021 and the 4.800% senior notes due 2026, interest is payable semi-annually each April 1 and October 1. For the 3.750% senior notes due 2023, the 4.000% senior notes due 2023 and the 4.450% senior notes due 2028, interest is payable semi-annually each June 1 and December 1.
Prior Credit Facility
Prior to completion of the Merger, we were party to a credit facility agreement with Bank of America, N.A., as administrative agent, and a syndicate of financial institutions, as lenders and other agents. The credit facility provided for secured financing comprised of (i) a $1.50 billion revolving credit facility; (ii) a $1.5 billion term loan; (iii) a $1.37 billion term loan; (iv) a $1.140 billion term loan; and (v) a $500.0 million term loan. Upon the consummation of the Merger, all borrowings outstanding and other amounts due under the credit facility were repaid and this credit facility was terminated.
Compliance with Covenants
The senior unsecured term loan and revolving credit facilities contain customary conditions to funding, affirmative covenants, negative covenants, financial covenants and events of default. As of December 31, 2019, financial covenants under the term loan facility required a leverage ratio of 3.50 to 1.00 and an interest coverage ratio of 3.00 to 1.00. We were in compliance with all applicable covenants as of December 31, 2019.
Settlement Lines of Credit
In various markets where we do business, we have specialized lines of credit, which are restricted for use in funding settlement. The settlement lines of credit generally have variable interest rates, are subject to annual review and are denominated in local currency but may, in some cases, facilitate borrowings in multiple currencies. For certain of our lines of credit, the available credit is increased by the amount of cash we have on deposit in specific accounts with the lender. Accordingly, the amount of the outstanding line of credit may exceed the stated credit limit. As of December 31, 2019 and 2018, a total of $74.5 million and $70.6 million, respectively, of cash on deposit was used to determine the available credit.
As of December 31, 2019, we had $463.2 million outstanding under these lines of credit with additional capacity to fund settlement of $981.8 million. During the year ended December 31, 2019, the maximum and average outstanding balances under these lines of credit were $882.6 million and $423.2 million, respectively. The weighted-average interest rate on these borrowings was 3.16% at December 31, 2019.
See "Note 6—Leases" and "Note 7—Long-Term Debt and Lines of Credit" in the notes to the accompanying consolidated financial statements for further information about our borrowing agreements and our lease liabilities.
Off-Balance Sheet Arrangements
We have not entered into any off-balance sheet arrangements that have, or are reasonably likely to have, a material effect on our financial condition, revenues, results of operations, liquidity, capital expenditures or capital resources, other than the guarantee services described in "Note 1—Basis of Presentation and Summary of Significant Accounting Policies" in the notes to the accompanying consolidated financial statements.
BIN/ICA Agreements
We have entered into sponsorship or depository and processing agreements with certain banks. These agreements allow us to use the banks' identification numbers, referred to as Bank Identification Number ("BIN") for Visa transactions and Interbank Card Association ("ICA") number for Mastercard transactions, to clear credit card transactions through Visa and Mastercard. Certain of such agreements contain financial covenants, and we were in compliance with all such covenants as of December 31, 2019.
Commitments and Contractual Obligations
The following table summarizes estimates of our contractual obligations and commitments as of December 31, 2019:
| Payments Due by Future Period | |||||||||||||||||||
| Total | Less than 1 Year | 1-3 Years | 3-5 Years | More Than 5 Years | |||||||||||||||
| (in thousands) | |||||||||||||||||||
| Long-term debt | $ | 8,986,456 | $ | 28,512 | $ | 804,944 | $ | 3,953,000 | $ | 4,200,000 | |||||||||
| Interest on long-term debt(1) | 2,544,547 | 337,627 | 626,346 | 484,473 | 1,096,101 | ||||||||||||||
| Operating lease obligations(2) | 576,669 | 106,787 | 186,696 | 106,067 | 177,119 | ||||||||||||||
| Settlement lines of credit | 463,237 | 463,237 | — | — | — | ||||||||||||||
| Purchase obligations(3) | 336,759 | 125,533 | 126,033 | 56,475 | 28,718 | ||||||||||||||
| Finance lease liabilities | 35,341 | 7,402 | 14,279 | 13,457 | 203 |
(1) Interest on long-term debt is based on effective rates and amounts borrowed as of December 31, 2019 and includes the estimated effect of interest rate swaps. Since the contractual rates for our long-term debt and settlements on our interest rate swaps are variable, actual cash payments may differ from the estimates provided.
(2) Operating lease obligations did not include approximately $64.0 million for operating leases that had not yet commenced at December 31, 2019.
(3) Includes an estimate of future payments for noncancelable contractual obligations related to service arrangements with suppliers for fixed or minimum amounts.
The table above excludes other obligations that we may have, such as employee benefit obligations and other noncurrent liabilities reflected in our consolidated balance sheet, because the timing of the related payments is not determinable or because there is no contractual obligation associated with the underlying obligations.
Critical Accounting Policies and Estimates
Our consolidated financial statements have been prepared in accordance with accounting principles generally accepted in the United States, which often require the judgment of management in the selection and application of certain accounting principles and methods. We consider the following accounting policies to be critical to understanding our consolidated financial statements because the application of these policies requires significant judgment on the part of management, and as a result, actual future developments may be different from those expected at the time that we make these critical judgments. We have discussed these critical accounting policies with the audit committee of the board of directors.
Accounting estimates necessarily require subjective determinations about future events and conditions. Therefore, the following descriptions of our critical accounting policies are forward-looking statements, and actual results could differ materially from the results anticipated by these forward-looking statements. You should read the following in conjunction with "Note 1—Basis of Presentation and Summary of Significant Accounting Policies" of the notes to the accompanying consolidated financial statements and the risk factors contained in "Item 1A - Risk Factors" of this Annual Report on Form 10-K.
Business Combinations
From time to time, we make strategic acquisitions that may have a material effect on our consolidated results of operations or financial position. We record the assets acquired and the liabilities assumed in a business combination at estimated fair value as of the acquisition date. The excess amount of the total consideration paid over the estimated fair value of the net identifiable assets acquired is recorded as goodwill.
The estimates we use to determine the fair value of long-lived assets, such as intangible assets, can be complex and require significant judgments. We use information available to us to make fair value determinations and engage independent valuation specialists, when necessary, to assist in the fair value determination of significant acquired long-lived assets. The estimated fair values of customer-related and contract-based intangible assets are generally determined using the income approach, which is based on projected cash flows discounted to their present value using discount rates that consider the timing and risk of the forecasted cash flows. The discount rates used represented the average estimated value of a market participant’s cost of capital and debt, derived using customary market metrics. These measures of fair value also require considerable judgments about future events, including forecasted revenue growth rates, forecasted customer attrition rates, contract renewal estimates and technology changes. Acquired technologies are generally valued using the replacement cost method, which requires us to estimate the costs to construct an asset of equivalent utility at prices available at the time of the valuation analysis, with adjustments in value for physical deterioration and functional and economic obsolescence. Trademarks and trade names are generally valued using the "relief-from-royalty" approach. This method assumes that trademarks and trade names have value to the extent that their owner is relieved of the obligation to pay royalties for the benefits received from them. This method requires us to estimate the future revenues for the related brands, the appropriate royalty rate and the weighted-average cost of capital. This measure of fair value requires considerable judgment about the value a market participant would be willing to pay in order to achieve the benefits associated with the trade name.
While we use our best estimates and assumptions to determine the fair values of the assets acquired and the liabilities assumed, our estimates are inherently uncertain and subject to refinement. As a result, during the measurement period, which may be up to one year from the acquisition date, we record adjustments to the assets acquired and liabilities assumed. Upon the conclusion of the measurement period, any subsequent adjustments are recorded to our consolidated statements of income. We are also required to estimate the useful lives of intangible assets to determine the amount of acquisition-related intangible asset amortization expense to record in future periods. The determination of asset lives affects our results of operations as different types of assets have different useful lives and certain assets may be considered to have indefinite useful lives. We periodically review the estimated useful lives assigned to our intangible assets to determine whether such estimated useful lives continue to be appropriate.
Goodwill—We perform our annual goodwill impairment test as of October 1 each year. We test goodwill for impairment at the reporting unit level annually and more often if an event occurs or circumstances change that indicate the fair value of a reporting unit is below its carrying amount. We have the option of performing a qualitative assessment of impairment to determine whether any further quantitative assessment for impairment is necessary. The option of whether or not to perform a qualitative assessment is made annually and may vary by reporting unit.
Factors we consider in the qualitative assessment include general macroeconomic conditions, industry and market conditions, cost factors, overall financial performance of our reporting units, events or changes affecting the composition or carrying amount of the net assets of our reporting units, sustained decrease in our share price, and other relevant entity-specific events. If we elect to bypass the qualitative assessment or if we determine, on the basis of qualitative factors, that the fair value of the reporting unit is more likely than not less than the carrying amount, a quantitative test would be required.
Prior to the Merger, our reporting units consisted of: North America Payments, Integrated Solutions and Vertical Markets, United Kingdom, Asia-Pacific, Central and Eastern Europe, Russia and Spain. As of October 1, 2019, we elected to perform a quantitative assessment of impairment for each of these reporting units, and determined on the basis of those assessments that the
fair value of each reporting unit is equal to or greater than its respective carrying amount. As of October 1, 2019, we had not allocated goodwill associated with the Merger to any of our reporting units; however, no indicators of impairment existed that warranted further evaluation of the provisional goodwill.
After October 1, 2019, as a result of the Merger, we realigned our reporting units based on new executive management and organizational structures so that they consisted of: North America Payment Solutions, Integrated Solutions, Vertical Market Software Solutions, Europe Merchant Solutions, Spain Merchant Solutions, Asia-Pacific Merchant Solutions, Issuer Solutions and Business and Consumer Solutions. After the reorganization of our reporting units, we performed a quantitative assessment of impairment for each of our new reporting units, and determined on the basis of those assessments that the fair value of each reporting unit is equal to or greater than its respective carrying amount. We believe that the fair value of each of our reporting units is substantially in excess of its carrying amount, except for Issuer Solutions and Business and Consumer Solutions for which the respective carrying amounts approximate fair value since they were recently acquired in the Merger.
Intangible and Long-lived Assets—Intangible assets are amortized over their estimated useful lives. The useful lives for customer-related intangible assets are determined based primarily on forecasted cash flows, which include estimates for the revenues, expenses, and customer attrition associated with the assets. The useful lives of contract-based intangible assets are equal to the terms of the agreements. The useful lives of amortizable trademarks and trade names are based on our plans to phase out the trademarks and trade names in the applicable markets. We use the straight-line method of amortization for our amortizable acquired technologies, trademarks and trade names and contract-based intangibles.
Amortization for most of our customer-related intangible assets is determined using an accelerated method. The first step in determining the amortization expense for any period is that we calculate the expected cash flows for that period that were used in determining the acquisition-date fair value of the asset divided by the expected total cash flows over the estimated life of the asset. We then multiply that percentage by the initial carrying amount of the asset to arrive at the amortization expense for that period. If the cash flow patterns that we experience differ significantly from our initial estimates, we adjust the amortization schedule prospectively. These cash flow patterns are derived using certain assumptions and cost allocations due to a significant number of asset interdependencies that exist in our business. We believe that our accelerated method reflects the expected pattern of the benefit to be derived from the acquired customer relationships. We did not make any significant adjustments to the amortization schedules of our intangible assets during the year ended December 31, 2019.
We regularly evaluate whether events and circumstances have occurred that indicate the carrying amount of property and equipment and finite-life intangible assets may not be recoverable. When factors indicate that these long-lived assets should be evaluated for possible impairment, we assess the potential impairment by determining whether the carrying amount of such long-lived assets will be recovered through the future undiscounted cash flows expected from use of the asset and its eventual disposition. The evaluation is performed at the asset group level, which is the lowest level of identifiable cash flows. If the carrying amount of the asset group is determined not to be recoverable and exceeds its fair value, an impairment loss is recorded, measured as the difference between the fair value and the carrying amount. Fair values are determined based on quoted market prices or discounted cash flow analysis as applicable. We regularly evaluate whether events and circumstances have occurred that indicate the useful lives of property and equipment and finite-life intangible assets may warrant revision.
Capitalization of Internal-Use Software
We develop software that is used in providing services to customers. Capitalization of internal-use software, primarily associated with operating platforms, occurs when we have completed the preliminary project stage, management authorizes the project, management commits to funding the project, it is probable the project will be completed and the project will be used to perform the function intended. The preliminary project stage consists of the conceptual formulation of alternatives, the evaluation of alternatives, the determination of existence of needed technology and the final selection of alternatives. Costs incurred during the preliminary project stage are expensed as incurred. Currently unforeseen circumstances in software development, such as a significant change in the manner in which the software is intended to be used, obsolescence or a significant reduction in revenues due to merchant attrition, could require us to implement alternative plans with respect to a particular effort, which could result in the impairment of previously capitalized software development costs. The carrying amount of internal-use software, including work-in-progress, at December 31, 2019 was $452.7 million. Costs capitalized during the year ended December 31, 2019 totaled $95.9 million. Internal-use software is amortized over its estimated useful life, which is typically 2 to 10 years, in a manner that best reflects the pattern of economic use of the assets.
During the fourth quarter of 2019, we preliminarily determined our target technology architecture for the combined company. As a result, we wrote-off capitalized software assets of $31.1 million related to legacy Global Payments technology that will no longer be utilized.
Revenue Recognition
We adopted Accounting Standards Update 2014-09, "Revenues from Contracts with Customers" as well as other clarifications and technical guidance issued by the Financial Accounting Standards Board related to this new revenue standard ("ASC 606") and ASC Subtopic 340-40: "Other Assets and Deferred Costs - Contracts with Customers" on January 1, 2018. We apply judgment in the determination of performance obligations in accordance with ASC 606, in particular related to large customer contracts within the Issuer Solutions segment. Performance obligations in a contract are identified based on the goods or services that will be transferred to the customer that are both capable of being distinct, whereby the customer can benefit from the service either on its own or together with other resources that are readily available from third parties or from us, and are distinct in the context of the contract, whereby the transfer of the services is separately identifiable from other promises in the contract. To the extent a contract includes multiple promised services, we must apply judgment to determine whether promised services are capable of being distinct and are distinct in the context of the contract. If these criteria are not met, the promised services are combined and accounted for as a single performance obligation. In addition, a single performance obligation may comprise a series of distinct goods or services that are substantially the same and that have the same pattern of transfer to the customer.
Income Taxes
We determine our provision for income taxes using management's judgments, estimates and the interpretation and application of complex tax laws in each of the jurisdictions in which we operate. Judgment is also required in assessing the timing and amounts of deductible and taxable items. These differences result in deferred tax assets and liabilities in our consolidated balance sheet.
We believe our tax return positions are fully supportable; however, we recognize the benefit for tax positions only when it is more likely than not that the position will be sustained based on its technical merits. Issues raised by a tax authority may be resolved at an amount different than the related benefit recognized. When facts and circumstances change (including an effective settlement of an issue or statute of limitations expiration), the effect is recognized in the period of change. The unrecognized tax benefits that exist at December 31, 2019 would affect our provision for income taxes in the future, if recognized. Judgment is required to determine whether or not some portion or all of our deferred tax assets will not be realized. To the extent we determine that we will not realize the benefit of some or all of our deferred tax assets, then these deferred tax assets are adjusted through our provision for income taxes in the period in which this determination is made.
Effect of New Accounting Pronouncements - Recently Issued Pronouncements Not Yet Adopted
Refer to "Note 1—Basis of Presentation and Summary of Significant Accounting Policies" in the notes to the accompanying consolidated financial statements for information on recently issued accounting pronouncements not yet adopted.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
Foreign Currency Exchange Rate Risk
Certain of our operations are conducted in foreign currencies. Consequently, a portion of our revenues and expenses may be affected by fluctuations in foreign currency exchange rates. We have not historically hedged our translation risk on foreign currency exposure, but we may do so in the future. For the year ended December 31, 2019, currency exchange rate fluctuations reduced our consolidated revenues by approximately $44 million and reduced our operating income by approximately $21 million compared to the prior-year period, calculated by converting revenues and operating income, respectively, for the current year, excluding revenues and operating income from current year acquisitions, in local currencies using exchange rates for the prior-year period.
Generally, the functional currency of our various subsidiaries is their local currency. We are exposed to currency fluctuations on transactions that are not denominated in the functional currency. Gains and losses on such transactions are included in determining
net income for the period. We seek to mitigate our foreign currency risk through timely settlement of transactions and cash flow matching, when possible. For the year ended December 31, 2019, our transaction gains and losses were insignificant.
Additionally, we are affected by currency fluctuations in our funds settlement process on merchant payment, chargeback and card network settlement transactions that are not denominated in the currency of the underlying credit or debit card transaction. Gains and losses on these transactions are included in revenues for the period.
We are also affected by fluctuations in exchange rates on our investments in foreign operations. Relative to our net investment in foreign operations, the assets and liabilities of subsidiaries whose functional currency is a foreign currency are translated at the period-end rate of exchange. The resulting translation adjustment is recorded as a component of other comprehensive income and is included in shareholders' equity. Transaction gains and losses on intercompany balances of a long-term investment nature are also recorded as a component of other comprehensive income.
Interest Rate Risk
We are exposed to market risk related to changes in interest rates on certain of our long-term borrowings and cash investments. We invest our excess cash in securities that we believe are highly liquid and marketable in the short term. These investments earn a floating rate of interest and are not held for trading or other speculative purposes.
We have a senior unsecured $2.0 billion term loan facility and a senior unsecured $3.0 billion revolving credit facility, as well as various lines of credit that we use to fund settlement in certain of our markets, each of which bears interest at rates that are based on market rates and fluctuate accordingly. As of December 31, 2019, the amount outstanding under these variable-rate debt arrangements and settlement lines of credit was $3.4 billion.
The interest earned on our invested cash and the interest paid on our debt are based on variable interest rates; therefore, the exposure of our net income to a change in interest rates is partially mitigated as an increase in rates would increase both interest income and interest expense, and a reduction in rates would decrease both interest income and interest expense. Under our current policies, we may selectively use derivative instruments, such as interest rate swaps or forward rate agreements, to manage all or a portion of our exposure to interest rate changes. We have entered into interest rate swaps that reduce a portion of our exposure to market interest rate risk on certain of our variable-rate debt as discussed in "Note 7—Long-Term Debt and Lines of Credit" in the notes to our accompanying consolidated financial statements.
Based on balances outstanding under variable-rate debt agreements and invested cash balances at December 31, 2019, a hypothetical increase of 50 basis points in applicable interest rates as of December 31, 2019 would increase our annual interest expense by approximately $7.4 million and increase our annual interest income by approximately $2.8 million.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the shareholders and the Board of Directors of Global Payments Inc.
Opinion on Internal Control over Financial Reporting
We have audited the internal control over financial reporting of Global Payments Inc. and subsidiaries (the "Company") as of December 31, 2019, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2019, based on criteria established in Internal Control - Integrated Framework (2013) issued by COSO.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated financial statements and financial statement schedule as of and for the year ended December 31, 2019, of the Company and our report dated February 21, 2020, expressed an unqualified opinion on those financial statements and included an explanatory paragraph regarding the Company's change in its method of accounting for revenue from contracts with customers in fiscal year 2018, due to the adoption of Accounting Standards Codification ("ASC") Topic 606, Revenue from Contracts with Customers and an explanatory paragraph regarding the Company’s change in its method of accounting for leases in fiscal year 2019 due to the adoption of ASC Topic 842, Leases. As described in Management's Report on Internal Control over Financial Reporting, the Company consummated its merger with Total System Services, Inc. ("TSYS") on September 18, 2019, and management excluded from its assessment of internal control over financial reporting the acquired operations of TSYS, which constituted approximately 32% of consolidated assets, excluding goodwill, approximately 25% of consolidated revenues, and approximately 10% of consolidated operating income, as of and for the year ended December 31, 2019. Accordingly, our audit did not include the internal control over financial reporting of the acquired operations of TSYS that is excluded from management’s assessment.
Basis for Opinion
The Company's management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management's Report on Internal Control over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control over Financial Reporting
A company's internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company's internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that
could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/ DELOITTE & TOUCHE LLP
Atlanta, Georgia
February 21, 2020
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the shareholders and the Board of Directors of Global Payments Inc.
Opinion on the Financial Statements
We have audited the accompanying consolidated balance sheets of Global Payments Inc. and subsidiaries (the "Company") as of December 31, 2019 and 2018, the related consolidated statements of income, comprehensive income, changes in equity, and cash flows, for each of the three years in the period ended December 31, 2019, and the related notes and the schedule listed in the Index at Item 15 (collectively referred to as the "financial statements"). In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company as of December 31, 2019 and 2018, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2019, in conformity with the applicable accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, 2019, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February 21, 2020, expressed an unqualified opinion on the Company's internal control over financial reporting.
Change in Accounting Principle
As discussed in Note 1 to the consolidated financial statements, the Company has changed its method of accounting for revenue from contracts with customers in fiscal year 2018 due to the adoption of Accounting Standards Codification Topic 606, Revenue from Contracts with Customers.
As discussed in Note 1 to the consolidated financial statements, the Company has changed its method of accounting for leases in fiscal year 2019 due to the adoption of Accounting Standards Codification Topic 842, Leases.
Basis for Opinion
These financial statements are the responsibility of the Company's management. Our responsibility is to express an opinion on the Company's financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material
Showing the first 8K of 200K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Evaluation of Disclosure Controls and Procedures
As of December 31, 2019, management carried out, under the supervision and with the participation of our principal executive officer and principal financial officer, an evaluation of the effectiveness of the design and operation of our disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934). Based on this evaluation, our principal executive officer and principal financial officer concluded that, as of December 31, 2019, our disclosure controls and procedures were effective in ensuring that information required to be disclosed by us in the reports that we file or submit under the Securities Exchange Act of 1934, as amended, is recorded, processed, summarized and reported within the time periods specified in applicable rules and forms and are designed to ensure that information required to be disclosed in those reports is accumulated and communicated to management, including our principal executive and principal financial officers, as appropriate to allow timely decisions regarding required disclosure.
Management's Report on Internal Control over Financial Reporting
Our management team is responsible for establishing and maintaining adequate internal control over financial reporting as defined in Rules 13a-15(f) and 15d-15(f) under the Securities Exchange Act of 1934. Our management assessed the effectiveness of our internal control over financial reporting as of December 31, 2019. In making this assessment, our management used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission the Internal Control — Integrated Framework (2013).
On September 18, 2019, we consummated our merger with Total System Services, Inc. ("TSYS"). As permitted by the SEC rules and regulations, management's assessment did not include the internal control of the acquired operations of TSYS, which are included in our consolidated financial statements as of December 31, 2019 and for the period from the acquisition date through December 31, 2019. In accordance with our integration efforts, we plan to incorporate the acquired operations of TSYS into our internal control over financial reporting program within the time period provided by applicable SEC rules and regulations. The assets, excluding goodwill, of the acquired operations of TSYS constituted approximately 32% of our total consolidated assets as of December 31, 2019. Operating results of the acquired operations of TSYS comprised approximately 25% of our total consolidated revenues and approximately of 10% our consolidated operating income for the year ended December 31, 2019.
Based on the results of its evaluation, which excluded assessments of the internal control of the acquired operations of TSYS, management believes that as of December 31, 2019, our internal control over financial reporting is effective based on those criteria.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect all misstatements. Projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions or that the degree of compliance with the policies or procedures may deteriorate. Internal control over financial reporting cannot provide absolute assurance of achieving financial reporting objectives because of its inherent limitations. Internal control over financial reporting is a process that involves human diligence and compliance and is subject to lapses in judgment and breakdowns resulting from human failures. Internal control over financial reporting also can be circumvented by collusion or improper management override. Due to such limitations, there is a risk that material misstatements may not be prevented or detected on a timely basis by internal control over financial reporting. However, these inherent limitations are known features of the financial reporting process. Therefore, it is possible to design into the process safeguards to reduce, though not eliminate, such risk.
Attestation Report of Public Accounting Firm
Deloitte & Touche LLP has issued an attestation report on our internal control over financial reporting, which is included herein as the Report of Independent Registered Public Accounting Firm under Item 8 - Financial Statements and Supplementary Data for the year ended December 31, 2019.
Changes in Internal Control over Financial Reporting
During the quarter ended December 31, 2019, as part of our ongoing integration activities following the Merger, we continued to apply our controls and procedures to the TSYS business and to augment our company-wide controls to address the risks inherent in an acquisition of this magnitude.
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
We incorporate by reference in this Item 10 information about our directors, executive officers and our corporate governance contained under the headings "Proposal 1: Election of Directors" and "Biographical Information About Our Executive Officers" and information about compliance with Section 16(a) of the Securities and Exchange Act of 1934 by our directors and executive officers under the heading "Delinquent Section 16(a) Reports" from our proxy statement to be delivered in connection with our 2020 Annual Meeting of Shareholders to be held on April 29, 2020 ("2020 Proxy Statement").
We have adopted codes of ethics that apply to our senior financial officers. The senior financial officers include our Chief Executive Officer, Chief Financial Officer, Chief Accounting Officer, Controller or persons performing similar functions. The code of ethics is available in the investor relations section of our website at www.globalpaymentsinc.com and as indicated in the section entitled "Where To Find Additional Information" in Part I to this Annual Report. We intend to satisfy the disclosure requirement under Item 5.05 of Form 8-K regarding an amendment to, or a waiver from, a provision of our code of ethics by posting such information on our website at the address and location set forth above.
Item 11. EXECUTIVE COMPENSATION
We incorporate by reference in this Item 11 the information relating to executive and director compensation and the report of the Compensation Committee contained under the headings "Compensation Discussion and Analysis" and "Board and Corporate Governance-Director Compensation" from our 2020 Proxy Statement.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
We incorporate by reference in this Item 12 the information relating to ownership of our common stock by certain persons contained under the headings "Common Stock Ownership-Common Stock Ownership by Management" and "Common Stock Ownership-Common Stock Ownership by Non-Management Shareholders" from our 2020 Proxy Statement.
The following table provides certain information as of December 31, 2019 concerning the shares of our common stock that may be issued under existing equity compensation plans. For more information on these plans, see "Note 11—Share-Based Awards and Options" in the notes to the accompanying consolidated financial statements.
| Plan category | Number of securities to be issued upon exercise of outstanding options, warrants and rights (a) | Weighted-average exercise price of outstanding options, warrants and rights (b) | Number of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in column (a)) (c) | ||||||
| Equity compensation plans approved by security holders | 1,166,520 | $ | 58.03 | 35,375,036 | |||||
| Equity compensation plans not approved by security holders | — | — | — | ||||||
| Total | 1,166,520 | $ | 58.03 | 35,375,036 |
The number of securities remaining available for future issuance under equity compensation plans reflected in column (c) above includes 10,242,552 shares authorized for issuance under our 2011 Amended and Restated Incentive Plan (the "2011 Incentive Plan"), all of which are available for issuance pursuant to grants of full-value stock awards, 2,076,737 shares authorized under our 2000 Employee Stock Purchase Plan (the "2000 ESPP"), 2,812 shares authorized under our Amended and Restated 2005 Incentive Plan, 22,822 shares authorized under our 2000 Non-Employee Director Stock Option Plan, 13,554,740 shares authorized under our Total System Services 2017 Omnibus Plan, 7,331,435 shares authorized under our Total System Services 2012 Omnibus Plan, 1,541,327 shares authorized under our Total System Services 2007 Omnibus Plan and 602,611 shares authorized under our
Amended and Restated NetSpend Holdings, Inc. 2004 Equity Incentive Plan for Options and Restricted Shares Assumed by Total System Services. We intend to issue future shares under the 2011 Incentive Plan and the 2000 ESPP only.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
We incorporate by reference in this Item 13 the information regarding certain relationships and related transactions between us and our affiliates and the independence of our directors contained under the headings "Additional Information--Relationships and Related Party Transactions" and "Board and Corporate Governance-Board Independence" from our 2020 Proxy Statement.
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
We incorporate by reference in this Item 14 the information regarding principal accounting fees and services contained under the heading "Proposal Four: Ratification of Reappointment of Auditors" from our 2020 Proxy Statement.
PART IV
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES:
The following documents are filed as part of this Annual Report on Form 10-K:
(1) Consolidated Financial Statements
Our consolidated financial statements listed below are set forth in "Item 8 - Financial Statements and Supplementary Data" of this Annual Report on Form 10-K:
| Page Number | |
| Reports of Independent Registered Public Accounting Firm | 44 |
| Consolidated Statements of Income for the years ended December 31, 2019, 2018 and 2017 | 49 |
| Consolidated Statements of Comprehensive Income for the years ended December 31, 2019, 2018 and 2017 | 50 |
| Consolidated Balance Sheets as of December 31, 2019 and 2018 | 51 |
| Consolidated Statements of Cash Flows for the years ended December 31, 2019, 2018 and 2017 | 52 |
| Consolidated Statements of Changes in Equity for the years ended December 31, 2019, 2018 and 2017 | 53 |
| Notes to Consolidated Financial Statements | 55 |
(2) Financial Statement Schedules
| Page Number | |
| Schedule II, Valuation and Qualifying Accounts | 97 |
All other schedules to our consolidated financial statements have been omitted because they are not required under the related instruction or are inapplicable, or because we have included the required information in our consolidated financial statements or related notes.
(3) Exhibits
The following exhibits either (i) are filed with this Annual Report on Form 10-K or (ii) have previously been filed with the SEC and are incorporated in this Item 15 by reference to those prior filings.
| 101.1* | The following financial information from the Annual Report on Form 10-K for the year ended December 31, 2019, formatted in Inline XBRL (eXtensible Business Reporting Language) and filed electronically herewith: (i) the Consolidated Statements of Income; (ii) the Consolidated Statements of Comprehensive Income; (iii) the Consolidated Balance Sheets; (iv) the Consolidated Statements of Cash Flows; (v) the Consolidated Statements of Changes in Equity; and (vi) the Notes to Consolidated Financial Statements. |
| 104* | Cover Page Interactive Data File (formatted as Inline XBRL and contained in Exhibit 101). |
- Filed herewith.
+ Management contract or compensatory plan or arrangement.
++ Certain schedules and exhibits to this agreement have been omitted pursuant to Item 601(b)(2) of Regulation S-K and Global Payments Inc. agrees to furnish supplementally to the SEC a copy of any omitted schedule and/or exhibit upon request.
(b) Exhibits
| Page Number | |
| Index to Exhibits | 100 |
(c) Financial Statement Schedules
See Item 15(2) above.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, Global Payments Inc. has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized, on February 21, 2020.
| GLOBAL PAYMENTS INC. | |
| By: | /s/ Jeffrey S. Sloan |
| Jeffrey S. Sloan | |
| Chief Executive Officer | |
| (Principal Executive Officer) | |
| By: | /s/ Paul M. Todd |
| Paul M. Todd | |
| Senior Executive Vice President and Chief Financial Officer | |
| (Principal Financial Officer) | |
| By: | /s/ David M. Sheffield |
| David M. Sheffield | |
| Senior Vice President and Chief Accounting Officer | |
| (Principal Accounting Officer) |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of Global Payments Inc. and in the capacities and on the dates indicated.
| Signature | Title | Date | |||
| /s/ M. Troy Woods* | Chairman of the Board | February 21, 2020 | |||
| M. Troy Woods | |||||
| /s/ Kriss Cloninger III* | Lead Independent Director | February 21, 2020 | |||
| Kriss Cloninger III | |||||
| /s/ F. Thaddeus Arroyo* | Director | February 21, 2020 | |||
| F. Thaddeus Arroyo | |||||
| /s/ Robert H.B. Baldwin, Jr.* | Director | February 21, 2020 | |||
| Robert H.B. Baldwin, Jr. | |||||
| /s/ John G. Bruno* | Director | February 21, 2020 | |||
| John G. Bruno | |||||
| /s/ William I Jacobs* | Director | February 21, 2020 | |||
| William I Jacobs | |||||
| /s/ Joia M. Johnson* | Director | February 21, 2020 | |||
| Joia M. Johnson | |||||
| /s/ Ruth Ann Marshall* | Director | February 21, 2020 | |||
| Ruth Ann Marshall | |||||
| /s/ Connie D. McDaniel* | Director | February 21, 2020 | |||
| Connie D. McDaniel | |||||
| /s/ William B. Plummer* | Director | February 21, 2020 | |||
| William B. Plummer | |||||
| /s/ John T. Turner* | Director | February 21, 2020 | |||
| John T. Turner | |||||
| /s/ Jeffrey S. Sloan | Director | February 21, 2020 | |||
| Jeffrey S. Sloan | |||||
| *By: | /s/ Jeffrey S. Sloan | Attorney-in-fact | February 21, 2020 | ||
| Jeffrey S. Sloan |