 filings.tools
Huntington Bancshares (HBAN) 10-K risk factor changes: FY2023 vs FY2022
The 2023-12-31 10-K against the 2022-12-31 one, compared heading by heading and sentence by sentence.
Item 1A34 rewritten21 added57 removed278 unchanged
All filing items1,690 rewritten1,074 added853 removed3,468 unchanged
Summary
counted, not written
- Item 1A lists 35 risk factor headings: 0 new, 0 reworded and 35 unchanged since FY2022. 3 headings from FY2022 no longer appear.
- Sentence by sentence, 1,074 added, 853 removed, 1,690 rewritten and 3,468 unchanged across 21 items that differ.
- New this year: Item 1C. Cybersecurity.
New Item 1A headings (0)
No risk factor heading in this filing is absent from FY2022.
Removed Item 1A headings (3)
- The transition away from LIBOR may adversely affect our business.
- The effects of COVID-19 have adversely impacted our operations and financial performance, and it, or a similar health crisis or pandemic, could have similar adverse impacts in future periods.
- If our regulators deem it appropriate, they can take regulatory actions that could result in a material adverse impact on our financial results, ability to compete for new business, or preclude mergers or acquisitions. In addition, regulatory actions could constrain our ability to fund our liquidity needs or pay dividends. Any of these actions could increase the cost of our services.
A heading is new when no FY2022 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
24 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2022. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
34 rewritten, 21 added, 57 removed, 278 unchanged
The risks and uncertainties listed below present risks that could have a material impact on Huntington’s financial condition, the results of [removed: operations] [added: operations,] or its business.
Additionally refer to factors set forth under the caption “Forward-Looking Statements.” For more information on how we manage risks, see discussion in the “[Risk [removed: Governance](#i3690470c99e54374bb9007e428dd5dc6_3184)”] [added: Governance](#ifc28720717254a2384ff7b9c2e90fea6_118)”] section of our MD&A.
Our ACL of [removed: $2.3] [added: $2.4] billion at December 31, [removed: 2022,] [added: 2023,] represented management’s estimate of the current expected losses in our loan and lease portfolio (ALLL) as well as our unfunded lending commitments (AULC).
In doing so, we consider probability of default, loss given [removed: default] [added: default,] and exposure at default depending on economic parameters for each month of the remaining contractual term of the credit exposure.
- A decrease in customer savings [removed: generally] [added: generally,] and in the demand for savings and investment products offered by us; [removed: and]
- An increase in the number of customers and counterparties who become delinquent, file for protection under bankruptcy laws, or default on their loans or other obligations to [removed: us.][added: us; and]
Other negative impacts [added: of a U.S. government debt default, budget deficit concerns, government shutdown, or related credit ratings downgrades] could [removed: be] [added: include] volatile capital markets, an adverse impact on the U.S. economy and the U.S. dollar, as well as increased default rates among borrowers in light of increased economic uncertainty.
Some of these impacts might occur even in the absence of an actual default [removed: but] [added: or government shutdown] as a consequence of extended political negotiations around the threat of such a default [removed: and a] [added: or] government shutdown.
In addition, [removed: decisions by] the Federal [removed: Reserve to increase] [added: Reserve’s monetary policies, including changes in the federal funds rate and increasing] or [removed: reduce] [added: reducing] the size of its balance [removed: sheet or to engage in tapering its purchase of assets] [added: sheet,] may also affect interest rates.
A decline in interest rates [removed: along with a flattening yield curve limits our ability to reprice deposits given the current historically low level of interest rates and] could result in declining net interest margins if longer duration assets reprice faster than deposits.
For more information, refer to “[Market [removed: Risk](#i3690470c99e54374bb9007e428dd5dc6_91)”] [added: Risk](#ifc28720717254a2384ff7b9c2e90fea6_127)” section] of the MD&A.
For more information, refer to [removed: “[Competition](#i3690470c99e54374bb9007e428dd5dc6_3208)”] [added: “[Competition](#ifc28720717254a2384ff7b9c2e90fea6_28)”] section of Item 1: Business.
The continued availability of this supply depends on customer willingness to maintain deposit balances with banks in [removed: general] [added: general,] and us in particular.
Additional information regarding dividend restrictions is provided in Item 1: Business - [removed: [Regulatory Matters](#i3690470c99e54374bb9007e428dd5dc6_28).][added: “[Regulatory Matters](#ifc28720717254a2384ff7b9c2e90fea6_34).”]
The macroeconomic environment in the [removed: United States] [added: U.S.] is susceptible to global events and volatility in financial markets.
For example, [added: global conflicts (including the continuing conflicts involving Ukraine and the Russian Federation and those in the Middle East) or other similar events, as well as government actions of other restrictions in connection with such events, and] trade negotiations between the U.S. and other nations [removed: remain uncertain and] could adversely impact economic and market conditions for the Company and its clients and counterparties.
In addition, global [removed: demand for products may exceed] supply [removed: during the economic recovery from the COVID-19 pandemic, and such shortages] [added: chain disruptions] may cause prolonged inflation, adversely impact consumer and business confidence, and adversely affect the economy as well as our financial condition and results.
A successful penetration or circumvention of system security could cause us serious negative consequences, [removed: including our] [added: including:] loss of customers and business [removed: opportunities,] [added: opportunities;] costs associated with maintaining business relationships after an attack or breach; significant business disruption to our operations and business, misappropriation, exposure, or destruction of our confidential information, intellectual property, funds, and/or those of our customers; or damage to our or our customers’ and/or third parties’ computers or [removed: systems, and could result in a violation of applicable privacy laws and other laws, litigation exposure, regulatory fines, penalties or intervention, loss of confidence in our security measures, reputational damage, reimbursement or other compensatory costs, additional compliance costs, and could adversely impact our results of operations, liquidity and financial condition.][added: systems.]
The federal bank regulatory agencies have proposed regulations that would enhance cyber risk management standards, which would apply to a wide range of large financial institutions and their third-party service providers, including us and the Bank, and would focus on cyber risk governance and management, management of internal and external dependencies, [removed: and] incident response, cyber resilience, and situational awareness.
[removed: Several] [added: Laws in all 50] states [removed: have also proposed or adopted cybersecurity legislation and regulations, which] [added: generally] require, among other things, notification to affected individuals when there has been a security breach of their personal [removed: data.][added: data under certain circumstances.]
For more information regarding cybersecurity and data privacy, refer to Item 1: Business - “[Regulatory [removed: Matters](#i3690470c99e54374bb9007e428dd5dc6_28).”][added: Matters](#ifc28720717254a2384ff7b9c2e90fea6_34).”]
For more information regarding data privacy laws and regulations, refer to Item 1: Business - “[Regulatory [removed: Matters](#i3690470c99e54374bb9007e428dd5dc6_28).”][added: Matters](#ifc28720717254a2384ff7b9c2e90fea6_34).”]
Acquisitions may be subject to the receipt of approvals from certain governmental authorities, including the Federal Reserve, the OCC, and the [removed: United States] [added: U.S.] Department of Justice, as well as the approval of our shareholders and the shareholders of companies that we seek to acquire.
We rely on third-party service [removed: providers] [added: providers, both domestically and offshore,] to leverage subject matter expertise and industry best practice, provide enhanced products and services, and reduce costs.
The [removed: Technology] [added: Risk Oversight] Committee of the [removed: board] [added: Board] of [removed: directors] [added: Directors] provides oversight related to the overall risk management process associated with third-party relationships.
For further discussion, see Note 2 - “[Accounting Standards [removed: Update](#i3690470c99e54374bb9007e428dd5dc6_184)”] [added: Update](#ifc28720717254a2384ff7b9c2e90fea6_223)”] to the Consolidated Financial Statements.
If an impairment loss is recorded, it will have little or no impact on the tangible book value of our Common Stock, or our regulatory capital levels, but such an impairment loss could significantly reduce the Bank’s earnings and thereby restrict the Bank’s ability to make dividend payments to us without prior regulatory approval, [removed: because Federal Reserve policy states the bank holding company dividends should be paid from current earnings.][added: which in turn could impact our ability to pay dividends.]
At December 31, [removed: 2022,] [added: 2023,] the book value of our goodwill was $5.6 billion, substantially all of which was recorded at the Bank.
These laws and regulations, [added: many of which are discussed in Item 1: Business - “[Regulatory Matters](#ifc28720717254a2384ff7b9c2e90fea6_34),”] among other matters, prescribe minimum capital requirements, impose limitations on our business activities (including foreclosure and collection practices), limit the dividend or distributions that we can pay, restrict the ability of institutions to guarantee our debt, and impose certain specific accounting requirements that may be more restrictive and may result in greater or earlier charges to earnings or reductions in our capital than accounting principles generally accepted in the [removed: United States.][added: U.S. Compliance with laws and regulations can be difficult and costly, and changes to laws and regulations often impose additional compliance costs.]
Both the scope of the laws and regulations and the intensity of the supervision to which we are subject [removed: increased] [added: may increase] in [removed: response to the] [added: times of] financial crisis, as well as [added: a result of] other factors such as technological and market changes.
For more information on litigation risks, see Note 22 - “[Commitments and Contingent [removed: Liabilities](#i3690470c99e54374bb9007e428dd5dc6_283)”] [added: Liabilities](#ifc28720717254a2384ff7b9c2e90fea6_322)”] to the Consolidated Financial Statements.
FinCEN, a unit of the Treasury Department that administers the Bank Secrecy Act, is authorized to impose significant civil money penalties for violations of those requirements and has recently engaged in coordinated enforcement efforts with the federal bank regulatory agencies, as well as the [removed: United States] [added: U.S.] Department of Justice, Drug Enforcement Administration, and IRS.
For more information regarding the Bank Secrecy Act, Patriot Act, anti-money laundering requirements and OFAC-administered sanctions, refer to Item 1: Business - “[Regulatory [removed: Matters](#i3690470c99e54374bb9007e428dd5dc6_28).”][added: Matters](#ifc28720717254a2384ff7b9c2e90fea6_34).”]
For more information regarding CCAR, stress testing, and capital and liquidity requirements, refer to Item 1: Business - “[Regulatory [removed: Matters](#i3690470c99e54374bb9007e428dd5dc6_28).”][added: Matters](#ifc28720717254a2384ff7b9c2e90fea6_34).”]
2023 Form 10-K 27
2023 Form 10-K 29
Our ability to access the capital markets, if needed, will depend on a number of factors, including the state of the financial markets.
Rising interest rates, disruptions in financial markets, negative perceptions of our business or our financial strength, negative perceptions of the overall banking industry or of other regional banks, or other factors may impact our ability to raise additional capital, if needed, on terms acceptable to us.
For example, in the event of future turmoil in the banking industry or other idiosyncratic events, there is no guarantee that the U.S. government will invoke the systemic risk exception, create additional liquidity programs, or take any other action to stabilize the banking industry or provide liquidity.
Any diminished ability to access short-term funding or capital markets to raise additional capital, if needed, could subject us to liability, restrict our ability to grow, require us to take actions that would affect our earnings negatively or otherwise adversely affect our business and our ability to implement our business plan, capital plan and strategic goals.
2023 Form 10-K 31
The occurrence of any of these events could result in a violation of applicable privacy laws and other laws, litigation exposure, regulatory fines, penalties or intervention, loss of confidence in our security measures, reputational damage, reimbursement or other compensatory costs, additional compliance costs, and could adversely impact our results of operations, liquidity and financial condition.
For more information regarding the Company’s process for assessing, identifying, and managing material risks from cybersecurity threats, refer to Item 1C: [Cybersecurity](#ifc28720717254a2384ff7b9c2e90fea6_3107).
2023 Form 10-K 33
For example, under California state law, the CCPA broadly defines personal information and substantially increases the rights of California residents to understand how their personal information is collected, used, and otherwise processed by commercial businesses, such as affording them the right to access and request deletion of their information and to opt out of certain sharing and sales of personal information.
2023 Form 10-K 35
2023 Form 10-K 37
The evolving regulatory and supervisory environment and uncertainty about the timing and scope of future laws, regulations and policies may contribute to decisions we may make to suspend, reduce, or withdraw from existing businesses, activities, or initiatives, which may result in potential lost revenue or significant restructuring or related costs or exposures.
In addition, regulatory responses in connection with severe market downturns or unforeseen stress events may alter or disrupt our planned future strategies and actions.
Adverse developments affecting the overall strength and soundness of other financial institutions, the financial services industry as a whole, and the general economic climate and U.S. Treasury market could have a negative impact on perceptions about the strength and soundness of our business even if we are not subject to the same adverse developments.
During 2023, the FDIC took control and was appointed receiver of Silicon Valley Bank, Signature Bank, and First Republic Bank, respectively.
The failure of other banks and financial institutions and the measures taken by governments and regulators in response to these events could adversely impact our business, financial condition, and results of operations.
2023 Form 10-K 39
We also face the risk of becoming subject to new or more stringent requirements in connection with the introduction of new regulations or modification of existing regulations, which could require us to hold more capital or liquidity or have other adverse effects on our businesses or profitability.
For example, proposed changes to applicable capital and liquidity requirements, such as the Basel III Endgame Proposal and the long-term debt proposal, could result in increased expenses or cost of funding, which could negatively affect our financial results or our ability to pay dividends and engage in share repurchases.
26 Huntington Bancshares Incorporated
In a rising interest rate environment, pension and other post-retirement obligations somewhat mitigate negative OCI impacts from securities and financial instruments.
2022 Form 10-K 27
The transition away from LIBOR may adversely affect our business.
Central banks around the world, including the Federal Reserve, have commissioned committees and working groups of market participants and official sector representatives to replace LIBOR and replace or reform other interest rate benchmarks.
The publication of most LIBOR rates ceased as of the end of December 2021, while certain U.S. dollar LIBOR tenors are expected to continue to be published until June 30, 2023.
A transition away from the widespread use of LIBOR to alternative rates and other potential interest rate benchmark reforms has begun and will continue over the course of the next few years.
These reforms may cause such rates to perform differently than in the past, or to disappear entirely, or have other consequences which cannot be predicted.
A group of market participants convened by the Federal Reserve, the Alternative Reference Rate Committee (ARRC), has selected SOFR as its recommended alternative to LIBOR.
The Federal Reserve Bank of New York started to publish SOFR in April 2018.
SOFR is a broad measure of the cost of overnight borrowings collateralized by Treasury securities that was selected by the ARRC due to the depth and robustness of the U.S. Treasury repurchase market.
In January of 2020, Huntington was added as an ARRC member.
The passage of the Adjustable Interest Rate (LIBOR) Act by Congress, and the Federal Reserve’s implementing rule, should decrease the risk of contracts that are not remediated prior to the cessation deadline by providing the terms for a transition to SOFR.
The market transition away from LIBOR to an alternative reference rate, such as SOFR, is complex and could have a range of adverse effects on our business, financial condition, and results of operations.
In particular, any such transition could:
- Adversely affect the interest rates paid or received on, the revenue and expenses associated with or the value of Huntington’s LIBOR-based assets and liabilities, which include certain variable rate loans, Huntington’s Series B preferred stock, certain of Huntington’s junior subordinated debentures, certain of the Bank’s senior notes and certain other securities or financial arrangements;
- Adversely affect the interest rates paid or received on, the revenue and expenses associated with or the value of other securities or financial arrangements, given LIBOR’s role in determining market interest rates globally;
- Prompt inquiries or other actions from regulators in respect of Huntington’s preparation and readiness for the replacement of LIBOR with an alternative reference rate; and
- Result in disputes, litigation, or other actions with counterparties regarding the interpretation and enforceability of certain fallback language in LIBOR-based contracts and securities.
Huntington implemented a LIBOR transition plan in 2018.
As of December 31, 2021, the company ceased issuance of new LIBOR loans.
Alternative reference rates at this time are predominantly SOFR-based.
Systems, products, and analytics have been effectively transitioned away from LIBOR and are utilizing alternative reference rates.
Remaining LIBOR transition project activities include remediation of remaining LIBOR products, including acquired products from TCF by June of 2023.
We continue to assess the impact on our customers, with any needed LIBOR exceptions escalated to ELT for approval.
The manner and impact of the transition from LIBOR to an alternative reference rate, as well as the effect of these developments on our funding costs, loan, and investment and trading securities portfolios, asset-liability management, and business, is uncertain.
2022 Form 10-K 29
The inability to access capital markets funding sources as needed could adversely impact our financial condition, results of operations, cash flows, and level of regulatory-qualifying capital.
2022 Form 10-K 31
For example, in June of 2018, the Governor of California signed into law the CCPA.
The CCPA, which became effective on January 1, 2020, applies to for-profit businesses that conduct business in California and meet certain revenue or data collection thresholds.
2022 Form 10-K 33
2022 Form 10-K 35
The effects of COVID-19 have adversely impacted our operations and financial performance, and it, or a similar health crisis or pandemic, could have similar adverse impacts in future periods.
Although U.S. and global economies have begun to recover from the COVID-19 pandemic as many health and safety restrictions have been lifted and vaccine distribution has increased, certain adverse consequences of the pandemic, including labor shortages, disruptions of global supply chains, and inflationary pressures, continue to impact the macroeconomic environment and could adversely affect our business.
The pandemic has caused us, and could continue to cause us, to recognize credit losses in our loan portfolios and increases in our allowance for credit losses should the effects of the pandemic continue for an extended period of time or worsen.
Furthermore, the pandemic could cause us to recognize impairment of our goodwill and our financial assets.
Sustained adverse effects may also increase our cost of capital, prevent us from satisfying our minimum regulatory capital ratios and other supervisory requirements, or result in downgrades in our credit ratings.
The COVID-19 pandemic has resulted in heightened operational risks.
Many of our colleagues continue to work remotely at least on a part-time basis, which may create additional cybersecurity risk and opportunities for cybercriminals to exploit vulnerabilities.
An excerpt. Shown here: all 34 rewritten, all 21 added and 40 of 57 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors in the FY2023 filing and the FY2022 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
541 rewritten, 430 added, 298 removed, 788 unchanged
The MD&A should be read in conjunction with the [Consolidated Financial [removed: Statements](#i3690470c99e54374bb9007e428dd5dc6_148),] [added: Statements](#ifc28720717254a2384ff7b9c2e90fea6_184),] [Notes to Consolidated Financial [removed: Statements](#i3690470c99e54374bb9007e428dd5dc6_175),] [added: Statements](#ifc28720717254a2384ff7b9c2e90fea6_214),] and other information contained in this report.
For further information, refer to Note 3 [added: -] “[Business [removed: Combinations](#i3690470c99e54374bb9007e428dd5dc6_190)”] [added: Combinations](#ifc28720717254a2384ff7b9c2e90fea6_229)”] of the Notes to Consolidated Financial Statements.
In May 2022, Huntington completed the acquisition of Torana, now known as Huntington [removed: Choice Pay,] [added: ChoicePay,] a digital [added: payments business focused on business to consumer payments.]
[added: This acquisition, along with the formation of our] enterprise-wide payments group, reflects one of our strategic priorities to accelerate our payments capabilities and expand the services provided to our customers.
[removed: 2022] [added: 2023] Financial Performance Review
[removed: In 2022, we reported net] [added: 2022 noninterest] income [removed: of $2.2] [added: was $2.0] billion, [removed: a $943] [added: an increase of $92] million, or [removed: 73%, increase] [added: 5%,] from the prior year.
Earnings per common share on a diluted basis for the year were [removed: $1.45, up 61%] [added: $1.24, down 14%] from the prior year.
The [removed: current year] [added: prior year’s] reported net income was negatively impacted by acquisition-related expenses totaling $95 million, or $76 million after tax ($0.05 per common [removed: share), compared to $701 million, or $566 million after tax ($0.44 per common share) in the prior year.][added: share).]
Net interest income for [removed: 2022] [added: 2023] was [removed: $5.3] [added: $5.4] billion, up [removed: $1.2 billion,] [added: $166 million,] or [removed: 29%,] [added: 3%,] from [removed: 2021.][added: 2022.]
FTE net interest income, a non-GAAP financial measure, increased [removed: $1.2 billion,] [added: $177 million,] or [removed: 29%,] [added: 3%,] from [removed: 2021.][added: 2022.]
Average earning asset growth included [removed: an $18.4] [added: a $5.7] billion, or [removed: 19%,] [added: 5%,] increase in [removed: average] loans and leases and [removed: an $8.9] [added: a $4.5] billion, or [removed: 27%,] [added: 92%,] increase in [added: interest-earning deposits with banks, partially offset by a $1.4 billion, or 3%, decrease in] average securities.
The [added: provision for credit losses increased $6 million due to a combination of loan and lease growth in 2022 and a] reduction in ACL coverage ratios over the course of [removed: 2021 reflected] [added: 2021, as there was] more clarity [removed: relating to] [added: around] the economic impacts of COVID-19.
The ACL was [removed: $2.3] [added: $2.4] billion, or [removed: 1.90%] [added: 1.97%] of total loans and leases, at December 31, [removed: 2022,] [added: 2023,] compared to [removed: $2.1] [added: $2.3] billion, or [removed: 1.89%] [added: 1.90%] of total loans and leases, at December 31, [removed: 2021.][added: 2022.]
[removed: Noninterest] [added: 2023 noninterest] income was [removed: $2.0] [added: $1.9] billion, [removed: up $92] [added: a decrease of $60] million, or [removed: 5%,] [added: 3%,] from the prior year.
Noninterest expense was [removed: $4.2] [added: $4.6] billion, [removed: down $174] [added: an increase of $373] million, or [removed: 4%,] [added: 9%,] from the prior year.
The tangible common equity to tangible assets ratio was [removed: 5.55%] [added: 6.14%] at December 31, [removed: 2022, down 133] [added: 2023, up 59] basis points from December 31, [removed: 2021,] [added: 2022,] primarily due to [removed: a decrease] [added: an increase] in tangible common equity related to [removed: the higher interest rates causing an increase] [added: earnings, net of dividends, and a decrease] in accumulated other comprehensive [removed: loss,] [added: loss due in part from a modest decline in interest rates at year-end,] partially offset by [removed: earnings.][added: higher tangible assets.]
CET1 risk-based capital ratio was [removed: 9.36%,] [added: 10.25%,] up from [removed: 9.33%] [added: 9.36%] at December 31, [removed: 2021.][added: 2022.]
The increase in regulatory capital ratios was primarily driven by [removed: earnings.][added: earnings and a decrease in risk-weighted assets, partially offset by dividends.]
- Build on our vision to be the country’s leading people-first, digitally powered [removed: bank][added: bank;]
- Drive sustainable long-term revenue growth and [removed: efficiency][added: efficiency;]
- Deliver a Category of One customer experience through our distinguished brand and [removed: culture][added: culture;]
- Extend our digital leadership with focus on ease of use, access to information, and self-service across products and [removed: services][added: services;]
- Leverage expertise and capabilities to acquire and deepen relationships and launching of select [removed: partnerships][added: partnerships;]
- Maintain positive operating leverage and execute disciplined capital [removed: management][added: management; and]
- [removed: Stability] [added: Provide stability] and resilience through risk management, [added: while] maintaining an aggregate moderate-to-low, through-the-cycle risk [removed: appetite][added: appetite.]
[removed: Credit continues to perform well in keeping] [added: We have continued our disciplined management of credit consistent] with our aggregate moderate-to-low, [removed: through the-cycle] [added: through-the-cycle] risk appetite.
A comprehensive discussion of legislative and regulatory matters affecting us can be found in Item 1: Business - “[Regulatory [removed: Matters](#i3690470c99e54374bb9007e428dd5dc6_28)”] [added: Matters](#ifc28720717254a2384ff7b9c2e90fea6_34)”] section of this Form 10-K.
| | | | | | | | | | Change from [removed: 2021] [added: 2022] | | | | | | | | | | | | | | | | | | Change from [removed: 2020] [added: 2021] | | | | | | | | | | | | | | |
| *(amounts in millions, except per share data)* | | | [removed: 2022] [added: 2023] | | | | | | Amount | | | | | | Percent | | | | | | [removed: 2021] [added: 2022] | | | | | | Amount | | | | | | Percent | | | | | | [removed: 2020] [added: 2021] | | |
| Interest income | | | $ | [removed: 5,969] [added: 8,916] | | | | | $ | [removed: 1,778] [added: 2,947] | | | | | [removed: 42] [added: 49] | | % | | | | $ | [removed: 4,191] [added: 5,969] | | | | | $ | [removed: 544] [added: 1,778] | | | | | [removed: 15] [added: 42] | | % | | | | $ | [removed: 3,647] [added: 4,191] | |
| Interest expense | | | [removed: 696] [added: 3,477] | | | | | | [removed: 607] [added: 2,781] | | | | | | [removed: NM] [added: 400] | | | | | | [removed: 89] [added: 696] | | | | | | [removed: (334)] [added: 607] | | | | | | [removed: (79)] [added: 682] | | | | | | [removed: 423] [added: 89] | | |
| Net interest income | | | [removed: 5,273] [added: 5,439] | | | | | | [removed: 1,171] [added: 166] | | | | | | [removed: 29] [added: 3] | | | | | | [removed: 4,102] [added: 5,273] | | | | | | [removed: 878] [added: 1,171] | | | | | | [removed: 27] [added: 29] | | | | | | [removed: 3,224] [added: 4,102] | | |
| Provision for credit losses | | | [removed: 289] [added: 402] | | | | | | [removed: 264] [added: 113] | | | | | | [removed: NM] [added: 39] | | | | | | [removed: 25] [added: 289] | | | | | | [removed: (1,023)] [added: 264] | | | | | | [removed: (98)] [added: NM] | | | | | | [removed: 1,048] [added: 25] | | |
| Net interest income after provision for credit losses | | | [removed: 4,984] [added: 5,037] | | | | | | [removed: 907] [added: 53] | | | | | | [removed: 22] [added: 1] | | | | | | [removed: 4,077] [added: 4,984] | | | | | | [removed: 1,901] [added: 907] | | | | | | [removed: 87] [added: 22] | | | | | | [removed: 2,176] [added: 4,077] | | |
| Mortgage banking income | | | [removed: 144] [added: 109] | | | | | | [removed: (165)] [added: (35)] | | | | | | [removed: (53)] [added: (24)] | | | | | | [removed: 309] [added: 144] | | | | | | [removed: (57)] [added: (165)] | | | | | | [removed: (16)] [added: (53)] | | | | | | [removed: 366] [added: 309] | | |
| Leasing revenue | | | [removed: 126] [added: 112] | | | | | | [removed: 27] [added: (14)] | | | | | | [removed: 27] [added: (11)] | | | | | | [removed: 99] [added: 126] | | | | | | [removed: 78] [added: 27] | | | | | | [removed: NM] [added: 27] | | | | | | [removed: 21] [added: 99] | | |
| Insurance income | | | [removed: 117] [added: 74] | | | | | | [removed: 12] [added: (5)] | | | | | | [removed: 11] [added: (6)] | | | | | | [removed: 105] [added: 79] | | | | | | [removed: 8] [added: (3)] | | | | | | [removed: 8] [added: (4)] | | | | | | [removed: 97] [added: 82] | | |
| Gain on sale of loans | | | [removed: 57] [added: 14] | | | | | | [removed: 48] [added: (43)] | | | | | | [removed: NM] [added: (75)] | | | | | | [removed: 9] [added: 57] | | | | | | [removed: (33)] [added: 48] | | | | | | [removed: (79)] [added: NM] | | | | | | [removed: 42] [added: 9] | | |
| Bank owned life insurance income | | | [removed: 56] [added: 66] | | | | | | [removed: (13)] [added: 10] | | | | | | [removed: (19)] [added: 18] | | | | | | [removed: 69] [added: 56] | | | | | | [removed: 5] [added: (13)] | | | | | | [removed: 8] [added: (19)] | | | | | | [removed: 64] [added: 69] | | |
| Net gains (losses) on sales of securities | | | [removed: —] [added: (7)] | | | | | | [removed: (9)] [added: (7)] | | | | | | NM | | | | | | [removed: 9] [added: —] | | | | | | [removed: 10] [added: (9)] | | | | | | NM | | | | | | [removed: (1)] [added: 9] | | |
Acquisitions and Divestitures
In March 2023, Huntington completed the sale of the RPS business and entered into an ongoing partnership with the purchaser.
The sale of our RPS business resulted in a $57 million gain including associated goodwill allocation, recorded within other noninterest income.
TCF was a financial holding company headquartered in Detroit, Michigan with operations across the Midwest.
The acquisition brought increased scale and market density, as well as added new markets and capabilities.
Our operating results include the impact of TCF subsequent to the acquisition on June 9, 2021.
For further information, refer to Note 3 - “[Business Combinations](#ifc28720717254a2384ff7b9c2e90fea6_229)” of the Notes to Consolidated Financial Statements.
Reporting Updates
During the fourth quarter of 2023, we updated the presentation of our noninterest income categories to align product and service types more closely with how we strategically manage our business.
For a description of each updated noninterest income revenue stream refer to Note 15 - “[Revenue from Contracts with Customers](#ifc28720717254a2384ff7b9c2e90fea6_289)” of the Notes to the Consolidated Financial Statements.
During the fourth quarter of 2023, we revised our FTP methodology for non-maturity deposits, which has been enhanced to consider the internally modeled weighted average life by non-maturity deposit type.
In general, the impact of the FTP methodology revision resulted in a higher cost of funds allocation as compared with the previous method.
To align with our strategic priorities, during the second quarter of 2023, we completed an organizational realignment and now report on two business segments: Consumer & Regional Banking and Commercial Banking.
Huntington’s business segments are based on our internally-aligned segment leadership structure, which is how management monitors results and assesses performance.
During the second quarter of 2023, we revised our process for assessing and monitoring the risk and performance of non-real estate secured commercial loans, primarily loans to REITs.
These loans were reclassified from commercial real estate to the commercial and industrial loan category to align reporting with this process revision.
For the reporting updates discussed above, prior period results have been adjusted to conform to the current presentation.
Selected Financial Data
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
In 2023, we reported net income of $2.0 billion, a $287 million, or 13%, decrease from the prior year.
The current year reported net income was negatively impacted by the recognition of the FDIC DIF special assessment totaling $214 million, or $169 million after tax ($0.11 per common share), to recover the cost associated with protecting uninsured depositors as part of the 2023 bank failures and $69 million, or $55 million after tax ($0.04 per common share), of expense from staffing related initiatives and the consolidation of corporate locations.
2023 Form 10-K 45
The increase in FTE net interest income reflected an increase in earning asset yields and the benefit of a $8.3 billion, or 5%, increase in average earning assets, partially offset by higher cost of funds and a $15.3 billion, or 13%, increase in average interest-bearing liabilities.
The growth in average interest-bearing liabilities included a $10.1 billion, or 10%, increase in average interest-bearing deposits and a $5.2 billion, or 46%, increase in average borrowings.
The provision for credit losses increased $113 million, or 39%, to $402 million, primarily driven by a combination of loan and lease growth and modest overall ACL coverage ratio builds throughout 2023 that is reflective of the current macroeconomic environment.
Noninterest income of $1.9 billion, decreased $60 million, or 3%, from the prior year primarily due to lower gain on sale of loans, customer deposit and loan fees, and mortgage banking income, in addition to $24 million of unfavorable mark-to-market on the pay-fixed swaptions program, partially offset by a $57 million gain on the sale of our RPS business and increases in payments and cash management revenue and wealth and asset management revenue.
Noninterest expense of $4.6 billion, increased $373 million, or 9%, from the prior year primarily due to the FDIC DIF special assessment of $214 million and an increase in personnel costs, partially offset by a decrease in acquisition-related expenses.
Total assets at December 31, 2023 were $189.4 billion, an increase of $6.5 billion, or 4%, compared to December 31, 2022.
The increase in total assets was primarily driven by increases in interest-earning deposits with banks of $3.6 billion, or 71%, and loans and leases of $2.5 billion, or 2%.
Total liabilities at December 31, 2023 were $170.0 billion, an increase of $4.8 billion, or 3%, compared to December 31, 2022.
The increase in total liabilities was primarily driven by increases in total deposits of $3.3 billion, or 2%, and borrowings of $1.3 billion, or 11%.
The decrease in risk-weighted assets was largely driven by the synthetic CRT related to an approximately $3 billion portfolio of on-balance sheet prime indirect auto loans.
Inflation continues to trend lower while remaining at levels above the Federal Reserve’s long run target.
Acquisitions
Historical periods prior to June 9, 2021 reflect results of legacy Huntington operations.
Subsequent to closing, results reflect all post-acquisition activity.
payments business focused on business to consumer payments.
This acquisition, along with the formation of our
The increase in FTE net interest income reflected the benefit of a $23.3 billion, or 17%, increase in average earning assets in addition to a 30 basis point increase in the FTE NIM to 3.25%.
Average balances across earning asset categories reflect organic growth in addition to the late second-quarter 2021 TCF acquisition.
The increase in average securities was additionally driven by the redeployment of excess liquidity into securities in the second half of 2021.
The NIM expansion was driven by the higher rate environment driving an increase in loan and lease and investment security yields, partially offset by higher cost of funds and the impact of lower accelerated PPP loan fees recognized upon forgiveness payments from the SBA in 2022.
The provision for credit losses increased $264 million to $289 million, primarily due to loan and lease growth and the likelihood of a worsening economic scenario throughout 2022.
The increase in the total ACL was primarily driven by loan and lease growth, but also recognizes the increased near-term recessionary risks at the end of 2022.
2022 Form 10-K 43
The changes in noninterest income and noninterest expense were impacted by the full-period impact of the TCF acquisition, completed in June 2021, in addition to the capital markets activity associated with the Capstone Partners acquisition, completed in June 2022.
Noninterest expense was additionally impacted by a decrease in acquisition-related expenses of $606 million and the execution of cost reduction initiatives associated with the TCF acquisition.
Growth in economic activity and demand for goods and services, alongside labor shortages, supply chain complications and geopolitical matters, have contributed to rising inflation.
In response, the Federal Reserve has raised interest rates and has been reducing the size of its balance sheet.
Furthermore, the Federal Reserve has signaled that it would continue to implement these policy actions in order to bring inflation down.
The timing and impact of inflation and rising interest rates on our business and related financial results will depend on future developments, which are highly uncertain and difficult to predict.
Our businesses and financial results may be impacted by a variety of other factors as well, such as an economic slowdown or recession.
Our baseline economic forecast assumes a mild recession in 2023 with modest GDP growth for the full year.
We expect the economy to exit the year on the path toward recovery with inflation gradually subsiding.
We delivered positive results in 2022, driven by broad-based loan and lease growth, growth in our deposit base, higher revenue, and disciplined expense management which were marked by the execution of strategic initiatives and acquisition synergies to further expand our capabilities.
The addition of Capstone Partners has expanded the expertise we bring to customers, is benefiting our continued efforts to deepen relationships with commercial customers, and is increasing our fee income opportunities.
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Service charges on deposit accounts | | | 384 | | | | | | 12 | | | | | | 3 | | | | | | 372 | | | | | | 71 | | | | | | 24 | | | | | | 301 | | |
| Card and payment processing income | | | 374 | | | | | | 40 | | | | | | 12 | | | | | | 334 | | | | | | 86 | | | | | | 35 | | | | | | 248 | | |
| Capital markets fees | | | 252 | | | | | | 101 | | | | | | 67 | | | | | | 151 | | | | | | 26 | | | | | | 21 | | | | | | 125 | | |
| Trust and investment management services | | | 249 | | | | | | 17 | | | | | | 7 | | | | | | 232 | | | | | | 43 | | | | | | 23 | | | | | | 189 | | |
| Marketing | | | 91 | | | | | | 2 | | | | | | 2 | | | | | | 89 | | | | | | 51 | | | | | | 134 | | | | | | 38 | | |
2022 Form 10-K 45
| Interest-bearing deposits at Federal Reserve Bank | | | $ | 4,626 | | | | | $ | 75 | | | | | 1.63 | | % | | | | $ | 8,129 | | | | | $ | 11 | | | | | 0.14 | | % | | | | $ | (3,503) | | | | | (43) | | % | | | | | | | | | | | | |
| Interest-bearing deposits in banks | | | 226 | | | | | | 8 | | | | | | 3.15 | | | | | | 372 | | | | | | 1 | | | | | | 0.04 | | | | | | (146) | | | | | | (39) | | | | | | | | | | | | | | |
| Commercial and industrial | | | 43,118 | | | | | | 1,875 | | | | | | 4.35 | | | | | | 36,898 | | | | | | 1,446 | | | | | | 3.92 | | | | | | 6,220 | | | | | | 17 | | | | | | | | | | | | | | |
| Commercial real estate | | | 15,768 | | | | | | 683 | | | | | | 4.33 | | | | | | 11,412 | | | | | | 362 | | | | | | 3.17 | | | | | | 4,356 | | | | | | 38 | | | | | | | | | | | | | | |
(5)Reflects the benefit of $89 million mark-to-market of interest rate caps for 2021.
2022 Form 10-K 47
| Interest-bearing deposits at Federal Reserve Bank | | | $ | 8,129 | | | | | $ | 11 | | | | | 0.14 | | % | | | | $ | 3,874 | | | | | $ | 6 | | | | | 0.15 | | % | | | | $ | 4,255 | | | | | 110 | | % | | | | | | | | | | | | |
| Interest-bearing deposits in banks | | | 372 | | | | | | 1 | | | | | | 0.04 | | | | | | 176 | | | | | | 1 | | | | | | 0.47 | | | | | | 196 | | | | | | 111 | | | | | | | | | | | | | | |
| Trading account securities | | | 50 | | | | | | 1 | | | | | | 3.32 | | | | | | 59 | | | | | | 2 | | | | | | 3.10 | | | | | | (9) | | | | | | (15) | | | | | | | | | | | | | | |
| Taxable | | | 19,767 | | | | | | 261 | | | | | | 1.32 | | | | | | 11,392 | | | | | | 237 | | | | | | 2.08 | | | | | | 8,375 | | | | | | 74 | | | | | | | | | | | | | | |
An excerpt. Shown here: 40 of 541 rewritten, 40 of 430 added and 40 of 298 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in the FY2023 filing and the FY2022 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
1 rewritten, 0 added, 0 removed, 0 unchanged
Information required by this item is set forth under the heading of “[Market [removed: Risk](#i3690470c99e54374bb9007e428dd5dc6_91)”] [added: Risk](#ifc28720717254a2384ff7b9c2e90fea6_127)”] in Item 7: MD&A, which is incorporated by reference into this item.
Item 1. Business
113 rewritten, 111 added, 112 removed, 292 unchanged
Through the Bank, we are committed to making people’s lives better, helping businesses thrive, and strengthening the communities we [removed: serve] [added: serve,] and [added: we] have [removed: over 150 years of] [added: been] servicing the financial needs of our [removed: customers.][added: customers since 1866.]
[removed: This includes,] [added: These include,] but [added: are] not limited to, payments, mortgage banking, automobile, recreational vehicle and marine financing, investment banking, capital markets, advisory, equipment financing, distribution [removed: finance (formerly referred to as inventory finance),] [added: finance,] investment management, trust, brokerage, [removed: insurance] [added: insurance,] and other financial products and services.
As of December 31, [removed: 2022,] [added: 2023,] our [removed: 1,032] [added: 999] full-service branches and private client group offices are primarily located in Ohio, Colorado, Illinois, Indiana, Kentucky, Michigan, Minnesota, Pennsylvania, West Virginia, and Wisconsin.
For each [removed: of our four] business [removed: segments,] [added: segment,] we expect the combination of our business model, investment in products and capabilities, and exceptional service to provide a competitive advantage that supports revenue and earnings growth.
A key strategic emphasis has been for our business segments to operate in cooperation to provide products and services to our customers and to build stronger and more profitable relationships using our OCR sales and service process, which [removed: align] [added: aligns] to our vision to be the leading people-first, digitally powered bank.
- Use a consultative and advisory sales approach to provide solutions that are specific to each [removed: customer.][added: customer;]
- Leverage each business segment in terms of its products and expertise to benefit [removed: customers.][added: customers; and]
Following is a description of our [removed: four] business segments and the Treasury / Other function:
- [removed: Commercial] [added: Commercial] Banking: The Commercial Banking segment provides expertise through bankers, capabilities, and digital channels, and includes a comprehensive set of product offerings.
Our target clients span from mid-market to large [removed: corporate (greater than $2 billion in revenue)] [added: corporates] across a national footprint.
The [added: Commercial Banking] segment [removed: is divided into five business units: (1)] [added: includes customers in] Middle Market Banking, [removed: (2)] Corporate, Specialty, and Government Banking, [removed: (3)] Asset Finance, [removed: (4)] Commercial Real Estate Banking, and [removed: (5)] Capital Markets.
[removed: We leverage] [added: Middle Market Banking serves the banking needs of mid-sized clients, leveraging] our local presence to serve our clients, [added: and] extending our full suite of banking products including lending, liquidity, treasury [removed: management,] [added: management] and [added: other payment services, and] capital markets.
Within this group, Huntington Community Development improves the quality of life for our communities and the residents of low-to-moderate income neighborhoods by developing and delivering innovative products and services to support affordable housing and neighborhood [removed: stabilization.][added: stabilization, including tax credit investments.]
Capital Markets delivers corporate risk management, institutional sales and trading, [removed: capital] [added: debt] and equity [removed: raising] [added: issuance,] and [added: additional] advisory [removed: services to all Commercial Banking clients.][added: services.]
[removed: Huntington serves] [added: We serve our] customers through our network of channels, including [removed: branches,] [added: branches and ATMs,] online [removed: banking,] [added: and] mobile banking, [removed: telephone banking,] and [removed: ATMs.][added: through our customer call centers.]
Our Fair Play banking suite of products includes 24-Hour Grace®, Asterisk-Free Checking®, Money [removed: Scout℠,] [added: Scout®,] $50 Safety [removed: Zone℠,] [added: Zone®,] Standby Cash®, Early Pay, Instant Access, [removed: The Hub,] [added: Savings Goal Getter®] and Huntington Heads Up®.
[removed: Business Banking] [added: Regional Banking, along with our business and specialty banking offerings,] is a dynamic part of our [removed: business,] [added: business] and we are committed to being the bank of choice for businesses in our markets.
Beyond conventional lending solutions, Huntington offers access to capital markets, [removed: treasury management,] practice [removed: finance] [added: finance,] and SBA lending capabilities.
We are the #1 SBA lender in the nation [removed: in units] [added: by loan volume] as of federal fiscal year end September 30, [removed: 2022.][added: 2023.]
Huntington continues to develop products and services that are designed specifically to meet the needs of [removed: small] business [added: customers] and [removed: look] [added: looks] for ways to help companies find solutions to their financing needs.
The [removed: products] [added: direct consumer loan products, including mortgage and home equity,] are [removed: distributed] [added: originated] through [removed: both branch] [added: branch, online,] and [removed: online] [added: third-party] channels.
- Treasury / Other: The Treasury / Other function includes technology and operations, [added: and] other unallocated assets, liabilities, revenue, and expense.
The financial results for each of these business segments are included in Note 25 - “[Segment [removed: Reporting](#i3690470c99e54374bb9007e428dd5dc6_298)”] [added: Reporting](#ifc28720717254a2384ff7b9c2e90fea6_337)”] of Notes to Consolidated Financial Statements and are discussed in the “[Business Segment [removed: Discussion](#i3690470c99e54374bb9007e428dd5dc6_115)”] [added: Discussion](#ifc28720717254a2384ff7b9c2e90fea6_151)”] of our MD&A.
| Chief ESG Officer | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | [removed: Risk Management Committee] [added: Climate Risk Director] | | | | | | | | | | | |
[added: Chief] ESG [added: Officer and] Strategy Team
[removed: The] [added: Our Chief] ESG [added: Officer leads an ESG] Strategy Team, [removed: led by our Chief ESG Officer, is] responsible for [added: (1)] advancing [removed: the] [added: enterprise] ESG strategy and facilitating implementation of the strategy at the [removed: segment- and] business [removed: unit-level;] [added: levels; (2)] ensuring consistent understanding of ESG strategy throughout the Company; [added: (3) leading ESG regulatory compliance efforts;] and [removed: assisting with] [added: (4) overseeing] ESG goal setting, reporting, and monitoring.
The [removed: Team] [added: team] also works to identify ESG-related innovation and advancement opportunities aligned with strategic [removed: planning for the enterprise.][added: planning.]
This group includes executive leaders across business segments and support [removed: units and meets regularly throughout the year.][added: units.]
Climate Risk [removed: Management] [added: Director and] Team
[removed: Our economic impact begins with a commitment] [added: We are committed] to delivering sustainable, long-term shareholder value through financial performance, while maintaining an aggregate moderate-to-low, through-the-cycle risk appetite and a well-capitalized position.
We align our corporate strategy to our purpose of helping others and building upon our market-leading, purpose-driven bank through focused efforts on the [removed: environmental, social] [added: environmental] and [removed: governance] [added: social] issues most important to our business and our stakeholders.
[removed: Following the acquisition of TCF, in] [added: In] June 2021, we [removed: committed] [added: made a five-year] $40 billion [added: commitment] toward [removed: a] [added: our] Community Plan to strengthen small businesses and foster economic justice [removed: through] [added: throughout] our [removed: footprint over the next five years.][added: footprint.]
[removed: The] [added: Our] Community Plan [removed: builds on the goals of our previous community plans, with expanded] [added: was developed to support communities by enabling and improving financial opportunities for people, businesses, and neighborhoods through] commitments focusing on increasing [removed: lending] [added: lending, investing,] and services to address economic, social, environmental, and racial equity areas of need as follows:
- Huntington expanded its Small Business lending programs into its [removed: new] [added: acquired TCF] footprint and committed $10 billion to the programs.
- Huntington committed $6.5 billion in [added: community development] loans and investments to establish programs and services that foster equity in areas such as affordable housing, small business financing, and community services.
Huntington has additionally developed a Lift Local Business® program, and made a commitment of $100 million, which supports [added: entrepreneurs who have been historically under-resourced, particularly] minority-, woman-, and veteran-owned small businesses throughout the business life cycle.
[removed: We demonstrate our commitment and transparency through our] [added: - Annual] disclosures to CDP, a global initiative [removed: that allows us to] [added: where we] track and submit data annually toward managing our carbon footprint and certain other aspects of our environmental [removed: impact, in addition to our reporting to the Task Force on Climate-Related Financial Disclosures framework.][added: impact;]
Huntington had [removed: 19,920] [added: 19,955] average full-time equivalent colleagues during [removed: 2022, all of] [added: 2023,] whom [removed: are encouraged] [added: we encourage] to [removed: live out] [added: support] a shared purpose of making our colleagues’ and customers’ lives better, helping businesses thrive, and strengthening the communities we serve.
[removed: 2022] [added: 2023] marked the [removed: ninth] [added: tenth] consecutive year we conducted a company-wide engagement survey to measure our colleagues’ experience with a strategic focus on culture, trust, and engagement – and the results were reaffirming.
In [removed: 2022, 87%,] [added: 2023,] 85%, [added: 82%,] and 84% of colleagues responded favorably on trust, culture, and engagement, respectively.
General Business Description
Business Segments
To align with our strategic priorities, during the second quarter of 2023, we completed an organizational realignment and now report on two business segments: Consumer & Regional Banking and Commercial Banking.
The organizational realignment primarily involved consolidating our previously reported Consumer and Business Banking, Vehicle Finance and RBHPCG, into one new business segment called Consumer & Regional Banking.
- Consumer & Regional Banking: The Consumer & Regional Banking segment provides a wide array of financial products and services to consumer and business customers including, but not limited to, deposits, lending, payments, mortgage banking, dealer financing, investment management, trust, brokerage, insurance, and other financial products and services.
2023 Form 10-K 7
Consumer & Regional Banking offers a comprehensive set of digitally powered consumer and business financial solutions to Consumer Lending, Regional Banking, Branch Banking, and Wealth Management customers.
Consumer Lending provides direct and indirect consumer loans, as well as dealer finance loans and deposits.
Indirect consumer loans are originated through deep relationships with dealerships to finance consumer purchases of automobiles, recreational vehicles, marine craft, and powersports.
We also provide dealer finance loans (including floorplan loans), deposits, and other financial products to these dealerships and their owners.
Regional Banking is defined as serving small to mid-sized businesses.
In addition, our payments business provides credit and debit cards and treasury management services to our customers.
Branch Banking provides a full range of financial products and services to consumer and business customers through our extensive branch and ATM network.
The branch network offers full-service branches that are primarily located in Ohio, Colorado, Illinois, Indiana, Kentucky, Michigan, Minnesota, Pennsylvania, West Virginia, and Wisconsin.
Wealth Management has a comprehensive product offering, including private banking, wealth management and legacy planning through investment and portfolio management, fiduciary administration and trust services, institutional custody services, and full-service retail brokerage investments.
In particular, our payments capabilities continue to expand as we develop unique solutions for our diverse client segments, including Huntington ChoicePay.
| Columbus, OH | | | | | | 1 | | | | | | $ | 41,638 | | | | | 40 | | % |
| Detroit, MI | | | | | | 4 | | | | | | 16,844 | | | | | | 9 | | |
| Cleveland, OH | | | | | | 2 | | | | | | 14,254 | | | | | | 11 | | |
| Chicago, IL | | | | | | 11 | | | | | | 9,149 | | | | | | 2 | | |
| Indianapolis, IN | | | | | | 5 | | | | | | 5,501 | | | | | | 6 | | |
| Akron, OH | | | | | | 1 | | | | | | 5,054 | | | | | | 28 | | |
| Cincinnati, OH | | | | | | 5 | | | | | | 4,497 | | | | | | 2 | | |
| Pittsburgh, PA | | | | | | 7 | | | | | | 4,422 | | | | | | 2 | | |
2023 Form 10-K 9
The scope of laws and regulations and the intensity of supervision to which we are subject has increased in response to the banking turmoil in early 2023, technological factors, market changes, and climate change concerns, and there is increased scrutiny and possible denials of bank mergers and acquisitions by federal banking regulators.
Huntington is a BHC under the BHC Act that has elected to be a FHC.
FHCs may engage in, and be affiliated with, companies engaging in a broader range of activities than those permitted for a BHC, so long as such activities are (i) financial in nature or incidental to such financial activity or (ii) complementary to a financial activity and that do not pose a substantial risk to the safety and soundness of a depository institution or to the financial system generally.
These activities include, for example, securities underwriting, securities dealing, making a market in securities, making merchant banking investments in non-financial companies, and engaging in insurance underwriting and agency activities.
To become and remain eligible for FHC status, a BHC and its subsidiary depository institutions must meet certain criteria, including capital, management, and CRA requirements.
Failure to meet such criteria could result, depending on which requirements were not met, in restrictions on new financial activities or acquisitions, or being required to discontinue existing activities that are not generally permissible for BHCs.
2023 Form 10-K 11
Long-term Debt Requirements
In August 2023, the U.S. banking agencies issued a proposed rule that would require certain large banking organizations such as Huntington to comply with long-term debt requirements and “clean holding company requirements” similar to those that currently only apply to U.S. global systemically important banking organizations.
This proposal would also impose a long-term debt requirement on certain categories of insured depository institutions that are not consolidated subsidiaries of U.S. global systematically important banking organizations, including insured depository institutions with $100 billion or more in total assets, such as the Bank.
If adopted, this proposal, would require Huntington and the Bank to each maintain a minimum outstanding eligible long-term debt amount of no less than the greater of (i) 6% of total risk-weighted assets, (ii) 2.5% of total leverage exposure (if subject to the supplementary leverage ratio), or (iii) 3.5% of average total consolidated assets.
To comply with the requirement, the Bank would be required to issue the minimum amount of eligible long-term debt to Huntington, and Huntington would be required to issue the minimum amount of eligible long-term debt externally.
The proposal allows banking organizations to include, as part of the required minimum outstanding eligible long-term debt amounts, certain existing long-term debt.
Once the rule is finalized, covered institutions would have three years to comply with the new requirements following a phased-in approach, with 25% of the long-term debt requirement by one year after finalization of the rule, 50% after two years, and 100% after three years.
In addition, if adopted as proposed, the “clean holding company requirements” would limit or prohibit Huntington from entering into certain transactions that could impede its orderly resolution, including, for example, prohibiting Huntington from entering into transactions that could spread losses to subsidiaries and third parties, as well as limiting the amount of the Company’s liabilities that are not eligible long-term debt.
On June 9, 2021, Huntington closed the acquisition of TCF Financial Corporation in an all-stock transaction valued at $7.2 billion.
TCF was a financial holding company headquartered in Detroit, Michigan with operations across the Midwest.
The acquisition brought increased scale and market density, as well as added new markets and capabilities.
Historical periods prior to June 9, 2021 reflect results of legacy Huntington operations.
Subsequent to closing, results reflect all post-acquisition activity.
For further information, refer to Note 3 “[Business Combinations](#i3690470c99e54374bb9007e428dd5dc6_190)” of the Notes to the Condensed Consolidated Financial Statements.
In May 2022, Huntington completed the acquisition of Torana, now known as Huntington Choice Pay, a digital payments business focused on business to consumer payments.
This acquisition along with the formation of our enterprise-wide payments group reflects one of our strategic priorities to accelerate our payments capabilities and expand the services provided to our customers.
In June 2022, Huntington completed the acquisition of Capstone Partners, a top tier middle market investment bank and advisory firm.
The transaction brings a national scale to serve middle market business owners throughout the corporate lifecycle, building on Huntington’s regional banking foundation.
Capstone Partners related revenue, including mergers and acquisitions, capital raising and other advisory-related fees, is recognized within capital markets fees in the Consolidated Statements of Income.
2022 Form 10-K 7
Middle Market Banking serves the banking needs of mid-sized clients (greater than $20 million in revenue) who reside in our geographic footprint.
- Consumer and Business Banking: The Consumer and Business Banking segment provides a wide array of financial products and services to consumer and small business customers including, but not limited to, checking accounts, savings accounts, money market accounts, CDs, investments, consumer loans, credit cards, and small business loans.
The Consumer and Business Banking segment leverages internal partnerships for mortgages, insurance, interest rate risk protection, foreign exchange, and treasury management.
Business Banking is defined as serving companies with annual revenues up to $20 million.
Consumer Payments and Lending provides consumer and small business credit and debit cards primarily to our deposit customers as well as unsecured personal loans, personal lines, and other direct secured loans.
The product suite is aimed at meeting our customers’ borrowing and transacting needs.
The team continues to explore ways to innovate and continue to meet the evolving and rapidly changing payment needs of customers.
Through Consumer and Business Banking, we originate consumer loans and mortgages for customers who are generally located in our primary banking markets.
Consumer and mortgage lending products are primarily distributed through the Consumer and Business Banking and RBHPCG segments, as well as through commissioned loan originators.
Consumer and Business Banking earns interest on portfolio loans and loans held-for-sale, earns fee income from the origination and servicing of mortgage loans, and recognizes gains or losses from the sale of mortgage loans.
Consumer and Business Banking supports the origination of mortgage loans across all segments.
- Vehicle Finance: Our products and services include providing financing to consumers for the purchase of automobiles, light-duty trucks, recreational vehicles, marine craft, and powersports at franchised and other select dealerships, and providing financing to franchised dealerships for the acquisition of new and used inventory.
Products and services are delivered through highly specialized relationship-focused bankers and product partners.
Huntington creates well-defined relationship plans which identify needs where solutions are developed and customer commitments are obtained.
The Vehicle Finance team services automobile dealerships, their owners, and consumers buying automobiles through these franchised dealerships.
Huntington has provided new and used automobile financing and dealer services throughout the Midwest since the early 1950s.
This consistency in the market and our focus on working with strong dealerships has allowed us to expand into select markets outside of the Midwest and to actively deepen relationships in 30 states while building a strong reputation.
Huntington also provides financing for the purchase by consumers of recreational vehicles and marine craft on an indirect basis through dealerships in 35 states and for the purchase of powersports on an indirect basis through dealerships in 17 states.
- Regional Banking and The Huntington Private Client Group: Regional Banking and The Huntington Private Client Group is closely aligned with our regional banking markets.
A fundamental point of differentiation is our commitment to be actively engaged within our local markets - building connections with community and business leaders and offering a uniquely personal experience delivered by colleagues working within those markets.
The core business of The Huntington Private Client Group is The Huntington Private Bank, which consists of Private Banking, Wealth & Investment Management, and Retirement Plan Services.
The Huntington Private Bank provides high net-worth customers with deposit, lending (including specialized lending options), and other banking services.
The Huntington Private Bank also delivers wealth management and legacy planning through investment and portfolio management, fiduciary administration, and trust services.
This group also provides retirement plan services to corporate businesses.
The Huntington Private Client Group also provides corporate trust services and institutional and mutual fund custody services.
2022 Form 10-K 9
| ESG Strategy Team | | | | | | | | | | | | | | | ESG Enterprise Working Group | | | | | | | | | | | | | | | Climate Risk Management Team | | | | | | | | | | | |
ESG Enterprise Working Group
An excerpt. Shown here: 40 of 113 rewritten, 40 of 111 added and 40 of 112 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2023 filing and the FY2022 filing.
Item 3. Legal Proceedings
1 rewritten, 0 added, 0 removed, 0 unchanged
Information required by this item is set forth in Note 22 - “[Commitments and Contingent [removed: Liabilities](#i3690470c99e54374bb9007e428dd5dc6_283)”] [added: Liabilities](#ifc28720717254a2384ff7b9c2e90fea6_322)”] of the Notes to Consolidated Financial Statements under the caption “Litigation and Regulatory Matters” and is incorporated into this Item by reference.
Cover and table of contents
39 rewritten, 37 added, 17 removed, 199 unchanged
For the fiscal year ended December 31, [removed: 2022][added: 2023]
[removed: ][added: ]
The aggregate market value of voting and non-voting common equity held by non-affiliates of the registrant as of June 30, [removed: 2022,] [added: 2023,] determined by using a per share closing price of [removed: $12.03,] [added: $10.78,] as quoted by Nasdaq on that date, was [removed: $17,092,209,908.][added: $15,337,338,365.]
As of January 31, [removed: 2023,] [added: 2024,] there were [removed: 1,443,016,884] [added: 1,448,345,863] shares of common stock with a par value of $0.01 outstanding.
Part III of this Form 10-K incorporates by reference certain information from the registrant’s definitive Proxy Statement for the [removed: 2023] [added: 2024] Annual Shareholders’ Meeting.
| | | | [Glossary of Acronyms and [removed: Terms](#i3690470c99e54374bb9007e428dd5dc6_13)] [added: Terms](#ifc28720717254a2384ff7b9c2e90fea6_13)] | | | [removed: [4](#i3690470c99e54374bb9007e428dd5dc6_13)] [added: [4](#ifc28720717254a2384ff7b9c2e90fea6_13)] | | |
| [Item [removed: 1.](#i3690470c99e54374bb9007e428dd5dc6_28)] [added: 1.](#ifc28720717254a2384ff7b9c2e90fea6_34)] | | | [removed: [Business](#i3690470c99e54374bb9007e428dd5dc6_22)] [added: [Business](#ifc28720717254a2384ff7b9c2e90fea6_22)] | | | [removed: [7](#i3690470c99e54374bb9007e428dd5dc6_22)] [added: [7](#ifc28720717254a2384ff7b9c2e90fea6_22)] | | |
| [Item [removed: 1A.](#i3690470c99e54374bb9007e428dd5dc6_31)] [added: 1A.](#ifc28720717254a2384ff7b9c2e90fea6_37)] | | | [Risk [removed: Factors](#i3690470c99e54374bb9007e428dd5dc6_31)] [added: Factors](#ifc28720717254a2384ff7b9c2e90fea6_37)] | | | [removed: [26](#i3690470c99e54374bb9007e428dd5dc6_31)] [added: [27](#ifc28720717254a2384ff7b9c2e90fea6_37)] | | |
| [Item [removed: 1B.](#i3690470c99e54374bb9007e428dd5dc6_40)] [added: 1B.](#ifc28720717254a2384ff7b9c2e90fea6_49)] | | | [Unresolved Staff [removed: Comments](#i3690470c99e54374bb9007e428dd5dc6_40)] [added: Comments](#ifc28720717254a2384ff7b9c2e90fea6_49)] | | | [removed: [40](#i3690470c99e54374bb9007e428dd5dc6_40)] [added: [40](#ifc28720717254a2384ff7b9c2e90fea6_49)] | | |
| [Item [removed: 2.](#i3690470c99e54374bb9007e428dd5dc6_43)] [added: 2.](#ifc28720717254a2384ff7b9c2e90fea6_52)] | | | [removed: [Properties](#i3690470c99e54374bb9007e428dd5dc6_43)] [added: [Properties](#ifc28720717254a2384ff7b9c2e90fea6_52)] | | | [removed: [40](#i3690470c99e54374bb9007e428dd5dc6_43)] [added: [42](#ifc28720717254a2384ff7b9c2e90fea6_52)] | | |
| [Item [removed: 3.](#i3690470c99e54374bb9007e428dd5dc6_46)] [added: 3.](#ifc28720717254a2384ff7b9c2e90fea6_61)] | | | [Legal [removed: Proceedings](#i3690470c99e54374bb9007e428dd5dc6_46)] [added: Proceedings](#ifc28720717254a2384ff7b9c2e90fea6_61)] | | | [removed: [41](#i3690470c99e54374bb9007e428dd5dc6_46)] [added: [42](#ifc28720717254a2384ff7b9c2e90fea6_61)] | | |
| [Item [removed: 4.](#i3690470c99e54374bb9007e428dd5dc6_49)] [added: 4.](#ifc28720717254a2384ff7b9c2e90fea6_64)] | | | [Mine Safety [removed: Disclosures](#i3690470c99e54374bb9007e428dd5dc6_49)] [added: Disclosures](#ifc28720717254a2384ff7b9c2e90fea6_64)] | | | [removed: [41](#i3690470c99e54374bb9007e428dd5dc6_49)] [added: [42](#ifc28720717254a2384ff7b9c2e90fea6_64)] | | |
| [Item [removed: 5.](#i3690470c99e54374bb9007e428dd5dc6_55)] [added: 5.](#ifc28720717254a2384ff7b9c2e90fea6_70)] | | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#i3690470c99e54374bb9007e428dd5dc6_55)] [added: Securities](#ifc28720717254a2384ff7b9c2e90fea6_70)] | | | [removed: [42](#i3690470c99e54374bb9007e428dd5dc6_55)] [added: [43](#ifc28720717254a2384ff7b9c2e90fea6_70)] | | |
| [Item [removed: 6.](#i3690470c99e54374bb9007e428dd5dc6_64)] [added: 6.](#ifc28720717254a2384ff7b9c2e90fea6_82)] | | | [removed: [\[Reserved\]](#i3690470c99e54374bb9007e428dd5dc6_61)] [added: [\[Reserved\]](#ifc28720717254a2384ff7b9c2e90fea6_79)] | | | [removed: [42](#i3690470c99e54374bb9007e428dd5dc6_61)] [added: [43](#ifc28720717254a2384ff7b9c2e90fea6_79)] | | |
| [Item [removed: 7.](#i3690470c99e54374bb9007e428dd5dc6_67)] [added: 7.](#ifc28720717254a2384ff7b9c2e90fea6_85)] | | | [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#i3690470c99e54374bb9007e428dd5dc6_67)] [added: Operations](#ifc28720717254a2384ff7b9c2e90fea6_85)] | | | [removed: [42](#i3690470c99e54374bb9007e428dd5dc6_67)] [added: [43](#ifc28720717254a2384ff7b9c2e90fea6_85)] | | |
| | | | [Executive [removed: Overview](#i3690470c99e54374bb9007e428dd5dc6_73)] [added: Overview](#ifc28720717254a2384ff7b9c2e90fea6_91)] | | | [removed: [43](#i3690470c99e54374bb9007e428dd5dc6_73)] [added: [44](#ifc28720717254a2384ff7b9c2e90fea6_91)] | | |
| | | | [Discussion of Results of [removed: Operations](#i3690470c99e54374bb9007e428dd5dc6_76)] [added: Operations](#ifc28720717254a2384ff7b9c2e90fea6_94)] | | | [removed: [46](#i3690470c99e54374bb9007e428dd5dc6_76)] [added: [47](#ifc28720717254a2384ff7b9c2e90fea6_94)] | | |
| | | | [Risk Management and [removed: Capital:](#i3690470c99e54374bb9007e428dd5dc6_82)] [added: Capital:](#ifc28720717254a2384ff7b9c2e90fea6_115)] | | | [removed: [52](#i3690470c99e54374bb9007e428dd5dc6_82)] [added: [53](#ifc28720717254a2384ff7b9c2e90fea6_118)] | | |
| | | | [Credit [removed: Risk](#i3690470c99e54374bb9007e428dd5dc6_85)] [added: Risk](#ifc28720717254a2384ff7b9c2e90fea6_121)] | | | [removed: [54](#i3690470c99e54374bb9007e428dd5dc6_85)] [added: [55](#ifc28720717254a2384ff7b9c2e90fea6_121)] | | |
| | | | [Market [removed: Risk](#i3690470c99e54374bb9007e428dd5dc6_91)] [added: Risk](#ifc28720717254a2384ff7b9c2e90fea6_127)] | | | [removed: [65](#i3690470c99e54374bb9007e428dd5dc6_91)] [added: [68](#ifc28720717254a2384ff7b9c2e90fea6_127)] | | |
| | | | [Business Segment [removed: Discussion](#i3690470c99e54374bb9007e428dd5dc6_115)] [added: Discussion](#ifc28720717254a2384ff7b9c2e90fea6_151)] | | | [removed: [78](#i3690470c99e54374bb9007e428dd5dc6_115)] [added: [81](#ifc28720717254a2384ff7b9c2e90fea6_151)] | | |
| [Item [removed: 7A.](#i3690470c99e54374bb9007e428dd5dc6_145)] [added: 7A.](#ifc28720717254a2384ff7b9c2e90fea6_181)] | | | [Quantitative and Qualitative Disclosures About Market [removed: Risk](#i3690470c99e54374bb9007e428dd5dc6_145)] [added: Risk](#ifc28720717254a2384ff7b9c2e90fea6_181)] | | | [removed: [86](#i3690470c99e54374bb9007e428dd5dc6_145)] [added: [88](#ifc28720717254a2384ff7b9c2e90fea6_181)] | | |
| [Item [removed: 8.](#i3690470c99e54374bb9007e428dd5dc6_148)] [added: 8.](#ifc28720717254a2384ff7b9c2e90fea6_184)] | | | [Financial Statements and Supplementary [removed: Data](#i3690470c99e54374bb9007e428dd5dc6_148)] [added: Data](#ifc28720717254a2384ff7b9c2e90fea6_184)] | | | [removed: [86](#i3690470c99e54374bb9007e428dd5dc6_148)] [added: [88](#ifc28720717254a2384ff7b9c2e90fea6_184)] | | |
| [Item [removed: 9.](#i3690470c99e54374bb9007e428dd5dc6_310)] [added: 9.](#ifc28720717254a2384ff7b9c2e90fea6_349)] | | | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure](#i3690470c99e54374bb9007e428dd5dc6_310)] [added: Disclosure](#ifc28720717254a2384ff7b9c2e90fea6_349)] | | | [removed: [161](#i3690470c99e54374bb9007e428dd5dc6_310)] [added: [160](#ifc28720717254a2384ff7b9c2e90fea6_349)] | | |
| [Item [removed: 9A.](#i3690470c99e54374bb9007e428dd5dc6_313)] [added: 9A.](#ifc28720717254a2384ff7b9c2e90fea6_352)] | | | [Controls and [removed: Procedures](#i3690470c99e54374bb9007e428dd5dc6_313)] [added: Procedures](#ifc28720717254a2384ff7b9c2e90fea6_352)] | | | [removed: [161](#i3690470c99e54374bb9007e428dd5dc6_313)] [added: [160](#ifc28720717254a2384ff7b9c2e90fea6_352)] | | |
| [Item [removed: 9B.](#i3690470c99e54374bb9007e428dd5dc6_316)] [added: 9B.](#ifc28720717254a2384ff7b9c2e90fea6_355)] | | | [Other [removed: Information](#i3690470c99e54374bb9007e428dd5dc6_316)] [added: Information](#ifc28720717254a2384ff7b9c2e90fea6_355)] | | | [removed: [161](#i3690470c99e54374bb9007e428dd5dc6_316)] [added: [160](#ifc28720717254a2384ff7b9c2e90fea6_355)] | | |
| [Item [removed: 9C.](#i3690470c99e54374bb9007e428dd5dc6_319)] [added: 9C.](#ifc28720717254a2384ff7b9c2e90fea6_358)] | | | [Disclosure Regarding Foreign Jurisdictions that Prevent [removed: Inspections.](#i3690470c99e54374bb9007e428dd5dc6_319)] [added: Inspections.](#ifc28720717254a2384ff7b9c2e90fea6_358)] | | | [removed: [161](#i3690470c99e54374bb9007e428dd5dc6_319)] [added: [160](#ifc28720717254a2384ff7b9c2e90fea6_358)] | | |
| [Item [removed: 10.](#i3690470c99e54374bb9007e428dd5dc6_325)] [added: 10.](#ifc28720717254a2384ff7b9c2e90fea6_364)] | | | [Directors, Executive Officers, and Corporate [removed: Governance](#i3690470c99e54374bb9007e428dd5dc6_325)] [added: Governance](#ifc28720717254a2384ff7b9c2e90fea6_364)] | | | [removed: [161](#i3690470c99e54374bb9007e428dd5dc6_325)] [added: [160](#ifc28720717254a2384ff7b9c2e90fea6_364)] | | |
| [Item [removed: 11.](#i3690470c99e54374bb9007e428dd5dc6_328)] [added: 11.](#ifc28720717254a2384ff7b9c2e90fea6_367)] | | | [Executive [removed: Compensation](#i3690470c99e54374bb9007e428dd5dc6_328)] [added: Compensation](#ifc28720717254a2384ff7b9c2e90fea6_367)] | | | [removed: [161](#i3690470c99e54374bb9007e428dd5dc6_328)] [added: [161](#ifc28720717254a2384ff7b9c2e90fea6_367)] | | |
| [Item [removed: 12.](#i3690470c99e54374bb9007e428dd5dc6_334)] [added: 12.](#ifc28720717254a2384ff7b9c2e90fea6_373)] | | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#i3690470c99e54374bb9007e428dd5dc6_334)] [added: Matters](#ifc28720717254a2384ff7b9c2e90fea6_373)] | | | [removed: [162](#i3690470c99e54374bb9007e428dd5dc6_334)] [added: [161](#ifc28720717254a2384ff7b9c2e90fea6_373)] | | |
| [Item [removed: 13.](#i3690470c99e54374bb9007e428dd5dc6_337)] [added: 13.](#ifc28720717254a2384ff7b9c2e90fea6_376)] | | | [Certain Relationships and Related Transactions, and Director [removed: Independence](#i3690470c99e54374bb9007e428dd5dc6_337)] [added: Independence](#ifc28720717254a2384ff7b9c2e90fea6_376)] | | | [removed: [162](#i3690470c99e54374bb9007e428dd5dc6_337)] [added: [161](#ifc28720717254a2384ff7b9c2e90fea6_376)] | | |
| [Item [removed: 14.](#i3690470c99e54374bb9007e428dd5dc6_340)] [added: 14.](#ifc28720717254a2384ff7b9c2e90fea6_379)] | | | [Principal Accounting Fees and [removed: Services](#i3690470c99e54374bb9007e428dd5dc6_340)] [added: Services](#ifc28720717254a2384ff7b9c2e90fea6_379)] | | | [removed: [162](#i3690470c99e54374bb9007e428dd5dc6_340)] [added: [161](#ifc28720717254a2384ff7b9c2e90fea6_379)] | | |
| [Item [removed: 15.](#i3690470c99e54374bb9007e428dd5dc6_346)] [added: 15.](#ifc28720717254a2384ff7b9c2e90fea6_385)] | | | [Exhibits and Financial Statement [removed: Schedules](#i3690470c99e54374bb9007e428dd5dc6_346)] [added: Schedules](#ifc28720717254a2384ff7b9c2e90fea6_385)] | | | [removed: [162](#i3690470c99e54374bb9007e428dd5dc6_346)] [added: [162](#ifc28720717254a2384ff7b9c2e90fea6_385)] | | |
| [Item [removed: 16.](#i3690470c99e54374bb9007e428dd5dc6_349)] [added: 16.](#ifc28720717254a2384ff7b9c2e90fea6_388)] | | | [Form 10-K [removed: Summary](#i3690470c99e54374bb9007e428dd5dc6_349)] [added: Summary](#ifc28720717254a2384ff7b9c2e90fea6_388)] | | | [removed: [162](#i3690470c99e54374bb9007e428dd5dc6_349)] [added: [162](#ifc28720717254a2384ff7b9c2e90fea6_388)] | | |
| AOCI | | | Accumulated Other Comprehensive Income [added: (Loss)] | | |
| CCPA | | | California Consumer Privacy Act of [removed: 2018] [added: 2018, as amended by the California Privacy Rights Act of 2020] | | |
| CET1 | | | Common [removed: equity tier] [added: Equity Tier] 1 on a [removed: transitional] Basel III basis | | |
| FTE | | | Fully-Taxable Equivalent [removed: or Full-Time Equivalent] | | |
| [removed: Capital and Liquidity] Tailoring [removed: Rule] [added: Rules] | | | Refers to the [added: Capital and Liquidity Tailoring Rule, which refers to] changes to applicability thresholds for regulatory and capital and liquidity requirements, issued by the OCC, the Federal Reserve, and the [removed: FDIC] [added: FDIC, and the EPS Tailoring Rule, which refers to the Prudential Standards for Large Bank Holding Companies and Savings and Loan Holding, issued by the Federal Reserve] | | |
| Depositary Shares (each representing a 1/40th interest in a share of 6.875% Series J Non-Cumulative, perpetual preferred stock) | | | HBANL | | | NASDAQ | | |
| [I](#ifc28720717254a2384ff7b9c2e90fea6_3107)[tem 1C.](#ifc28720717254a2384ff7b9c2e90fea6_3107) | | | [Cybersecurity](#ifc28720717254a2384ff7b9c2e90fea6_3107) | | | [41](#ifc28720717254a2384ff7b9c2e90fea6_3107) | | |
| | | | [Introduction](#ifc28720717254a2384ff7b9c2e90fea6_88) | | | [44](#ifc28720717254a2384ff7b9c2e90fea6_88) | | |
| | | | [R](#ifc28720717254a2384ff7b9c2e90fea6_118)[isk Governance](#ifc28720717254a2384ff7b9c2e90fea6_118) | | | [53](#ifc28720717254a2384ff7b9c2e90fea6_118) | | |
| | | | [Liquidity Risk](#ifc28720717254a2384ff7b9c2e90fea6_136) | | | [71](#ifc28720717254a2384ff7b9c2e90fea6_136) | | |
| | | | [Operational Risk](#ifc28720717254a2384ff7b9c2e90fea6_142) | | | [77](#ifc28720717254a2384ff7b9c2e90fea6_142) | | |
| | | | [Compliance Risk](#ifc28720717254a2384ff7b9c2e90fea6_145) | | | [78](#ifc28720717254a2384ff7b9c2e90fea6_145) | | |
| | | | [Capital](#ifc28720717254a2384ff7b9c2e90fea6_148) | | | [78](#ifc28720717254a2384ff7b9c2e90fea6_148) | | |
| | | | [Additional Disclosures](#ifc28720717254a2384ff7b9c2e90fea6_175) | | | [85](#ifc28720717254a2384ff7b9c2e90fea6_175) | | |
| [Signatures](#ifc28720717254a2384ff7b9c2e90fea6_394) | | | | | | [166](#ifc28720717254a2384ff7b9c2e90fea6_394) | | |
| ASU | | | Accounting Standards Update | | |
| BTFP | | | Bank Term Funding Program | | |
| CDS | | | Credit Default Swap | | |
| CEO | | | Chief Executive Officer | | |
| CFO | | | Chief Financial Officer | | |
| CODM | | | Chief Operating Decision Maker | | |
| CDP | | | Carbon Disclosure Project | | |
| CRO | | | Chief Risk Officer | | |
| CRT | | | Credit Risk Transfer | | |
| EOP | | | End of Period | | |
| ERM | | | Enterprise Risk Management | | |
| FRB | | | Federal Reserve Bank | | |
2023 Form 10-K 5
| | | | | | |
| | | | | | |
| | | | | | |
| RPS | | | Retirement Plan Services | | |
| RV | | | Recreational vehicle | | |
| | | | | | |
| | | | | | |
| TBA | | | To Be Announced | | |
| TCFD | | | Task Force on Climate-Related Financial Disclosures | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | [Introduction](#i3690470c99e54374bb9007e428dd5dc6_70) | | | [43](#i3690470c99e54374bb9007e428dd5dc6_70) | | |
| | | | [Liquidity Risk](#i3690470c99e54374bb9007e428dd5dc6_100) | | | [69](#i3690470c99e54374bb9007e428dd5dc6_100) | | |
| | | | [Operational Risk](#i3690470c99e54374bb9007e428dd5dc6_106) | | | [74](#i3690470c99e54374bb9007e428dd5dc6_106) | | |
| | | | [Compliance Risk](#i3690470c99e54374bb9007e428dd5dc6_109) | | | [75](#i3690470c99e54374bb9007e428dd5dc6_109) | | |
| | | | [Capital](#i3690470c99e54374bb9007e428dd5dc6_112) | | | [75](#i3690470c99e54374bb9007e428dd5dc6_112) | | |
| | | | [Additional Disclosures](#i3690470c99e54374bb9007e428dd5dc6_139) | | | [82](#i3690470c99e54374bb9007e428dd5dc6_139) | | |
| [Signatures](#i3690470c99e54374bb9007e428dd5dc6_355) | | | | | | [166](#i3690470c99e54374bb9007e428dd5dc6_355) | | |
| CARES Act | | | Coronavirus Aid, Relief, and Economic Security Act, as amended | | |
| CDI | | | Core Deposit Intangible | | |
| CPPA | | | California Privacy Protection Act | | |
| CPRA | | | California Privacy Rights Act | | |
| HPI | | | House Price Index | | |
| OPEC | | | Organization of the Petroleum Exporting Countries | | |
2022 Form 10-K 5
| EPS Tailoring Rule | | | Refers to Prudential Standards for Large Bank Holding Companies and Savings and Loan Holding, issued by the Federal Reserve | | |
| Tailoring Rules | | | Refers to the Capital and Liquidity Tailoring Rule and the EPS Tailoring Rule | | |
| UPB | | | Unpaid Principal Balance | | |
Item 1C. Cybersecurity
0 rewritten, 30 added, 0 removed, 0 unchanged
New section this year
Cybersecurity represents an important component of Huntington’s overall cross-functional approach to risk management.
Our cybersecurity practices are integrated into Huntington’s ERM approach, and cybersecurity risks are among the core enterprise risks identified for oversight by our Board of Directors (“Board”) through our annual ERM assessment.
See “Risk Factors—Operational Risks” for information on risks from cybersecurity threats.
Our cybersecurity policies and practices follow the cybersecurity framework of the National Institute of Standards and Technology and other applicable industry standards.
Consistent with Huntington’s overall ERM policies and practices, our cybersecurity program includes:
- Vigilance: We maintain a global cybersecurity threat operation designed to detect, contain, and respond to cybersecurity threats and incidents in a prompt and effective manner with the goal of minimizing disruptions to our business.
- Collaboration: We have established collaboration mechanisms with public and private entities, including intelligence and enforcement agencies, industry groups, and third-party service providers to identify and assess cybersecurity risks.
- Systems Safeguards: We deploy technical safeguards that are designed to protect our information systems from cybersecurity threats, including firewalls, intrusion prevention and detection systems, anti-malware functionality, access controls, and ongoing vulnerability assessments.
- Third-Party Management: We maintain a risk-based approach to identifying and overseeing cybersecurity risks presented by third parties, such as vendors, service providers, and other users of our systems.
- Education: We provide periodic and ongoing training for personnel regarding cybersecurity threats, with such training scaled to reflect the roles, responsibilities, and access of relevant personnel.
- Incident Response Planning: We have established and maintain incident response plans that address our response to a cybersecurity incident, and such plans are tested at least annually, or more frequently as needed.
- Communication and Coordination: We utilize a cross-functional approach to evaluating the risk from cybersecurity threats, involving management personnel from the technology, operations, legal, risk management, internal audit, and other key business functions, as well as members of our Board and the Technology Committee of the Board regarding cybersecurity threats and incidents.
- Governance: The Board’s oversight of cybersecurity risk management is supported by the Technology Committee, which has responsibility for the development, implementation, maintenance, and risk management of the cybersecurity program and regularly interacts with Huntington’s ERM function, individual members of management, and relevant management committees.
A key part of Huntington’s strategy for managing risks from cybersecurity threats is the ongoing assessment and testing of our processes and practices through auditing, assessments, tabletop exercises, and other exercises focused on evaluating effectiveness.
We regularly engage third parties to perform assessments on our cybersecurity measures, including information security maturity assessments, and independent reviews of our information security control environment and operating effectiveness.
The results of such assessments and reviews are reported to the Technology Committee and the Board, and we adjust our cybersecurity processes and practices as necessary based on the information provided by the third-party assessments and reviews.
The Technology Committee of the Board oversees the management of risks from cybersecurity threats, including the policies, processes and practices that management implements to address risks from cybersecurity threats.
The Board and the Technology Committee each receive regular presentations and reports on cybersecurity risks which address a wide range of topics including, for example, recent developments, evolving standards, vulnerability assessments, third-party and independent reviews, the threat environment, technological trends, and information security considerations arising with respect to peers and vendors.
The Board and the Technology Committee also receive prompt information regarding the occurrence of any potentially material cybersecurity incidents, including ongoing updates, when applicable.
To keep the Board apprised of the continually shifting landscape, the Chief Information Security Officer provides updates to the Technology Committee on information security and cybersecurity matters on at least a quarterly basis, and more frequently as necessary.
The entire Board also participates in periodic cyber-related tabletop exercises.
2023 Form 10-K 41
Huntington’s Chief Information Security Officer is a member of our Information and Technology Risk Committee that is principally responsible for overseeing our cybersecurity risk management program, in partnership with other business leaders across Huntington.
The Chief Information Security Officer also works with members of the ELT, which includes our Chief Executive Officer, Chief Financial Officer, Chief Risk Officer, and General Counsel.
We believe our Board and management have the appropriate expertise, background, and depth of experience to manage risks arising from cybersecurity threats including applicable knowledge gained through industry experience, academia, ongoing internal and external training, and regular discussions with consultants and peers with applicable knowledge and expertise.
In particular, one of our Board members has an extensive cybersecurity background, including having most recently served as the first-ever U.S. National Cyber Director.
In addition, other members of our Board and management hold varying levels of relevant cybersecurity certifications.
The Company’s Chief Information Security Officer works collaboratively across Huntington to implement a program designed to identify and protect our information systems from cybersecurity threats and to promptly detect and respond to cybersecurity incidents.
To facilitate this program, multi-disciplinary teams throughout Huntington are deployed to address cybersecurity threats and to respond to cybersecurity incidents in accordance with Huntington’s incident response plan.
Through ongoing communications across the organization, the Chief Information Security Officer monitors the prevention, detection, mitigation, and remediation of cybersecurity incidents in real time, and reports such incidents to the CEO and the Technology Committee and the Board when appropriate, as discussed above.
Item 2. Properties
1 rewritten, 0 added, 0 removed, 10 unchanged
Additional information regarding our properties is set forth in Note 9 - “[Premises and [removed: Equipment](#i3690470c99e54374bb9007e428dd5dc6_220)”] [added: Equipment](#ifc28720717254a2384ff7b9c2e90fea6_259)”] and Note 10 - “[Operating [removed: Leases](#i3690470c99e54374bb9007e428dd5dc6_223)”] [added: Leases](#ifc28720717254a2384ff7b9c2e90fea6_262)”] of the Notes to Consolidated Financial Statements and is incorporated into this item by reference.
Item 4. Mine Safety Disclosures
0 rewritten, 1 added, 1 removed, 2 unchanged
42 Huntington Bancshares Incorporated
2022 Form 10-K 41
Item 5. Market for Registrant’s Common Equity, Related Shareholder Matters and Issuer Purchases of Equity Securities
8 rewritten, 3 added, 3 removed, 4 unchanged
The common stock of Huntington Bancshares Incorporated is traded on the Nasdaq Global Stock Market under the symbol “HBAN.” As of January 31, [removed: 2023,] [added: 2024,] we had [removed: 30,985] [added: 29,674] shareholders of record.
Information regarding restrictions on dividends, as required by this Item, is set forth in Item 1: “Business - [Regulatory [removed: Matters](#i3690470c99e54374bb9007e428dd5dc6_28)”] [added: Matters](#ifc28720717254a2384ff7b9c2e90fea6_34)”] and in Note 23 - “[Other Regulatory [removed: Matters](#i3690470c99e54374bb9007e428dd5dc6_292)”] [added: Matters](#ifc28720717254a2384ff7b9c2e90fea6_331)”] of the Notes to Consolidated Financial Statements and incorporated into this Item by reference.
The following graph shows the changes, over the five-year period, in the value of $100 invested in (i) shares of Huntington’s Common Stock; (ii) the Standard & Poor’s 500 Stock Index (the S&P 500 Index) and (iii) Keefe, Bruyette & Woods Bank Index, for the period December 31, [removed: 2017,] [added: 2018,] through December 31, [removed: 2022.][added: 2023.]
The index is composed of the largest banking companies and includes all money center banks and [added: many] regional banks, including Huntington.
An investment of $100 on December 31, [removed: 2017,] [added: 2018,] and the reinvestment of all dividends, are assumed.
[removed: ][added: 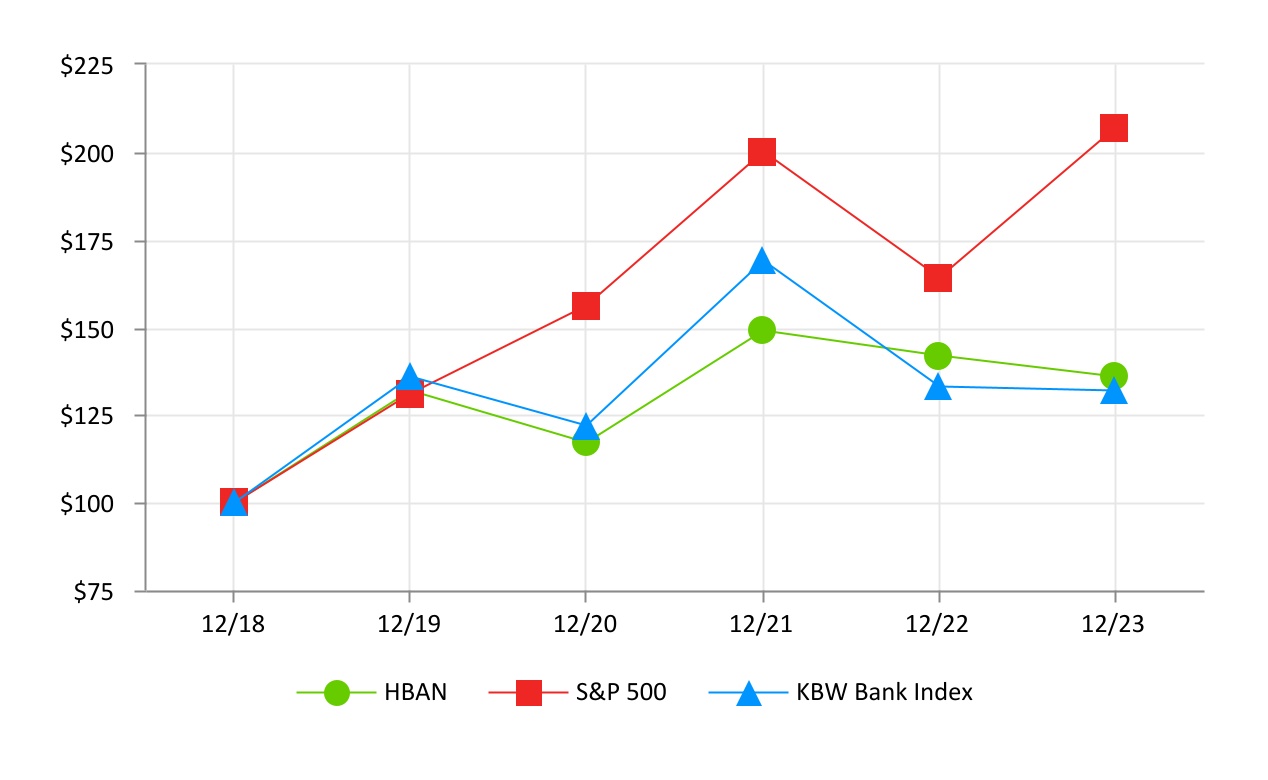]
| | | | [removed: 2017] [added: 2018] | | | | | | [removed: 2018] [added: 2019] | | | | | | [removed: 2019] [added: 2020] | | | | | | [removed: 2020] [added: 2021] | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2022] [added: 2023] | | |
For information regarding securities authorized for issuance under Huntington’s equity compensation plans, see Part III, [Item [removed: 12](#i3690470c99e54374bb9007e428dd5dc6_334).][added: 12](#ifc28720717254a2384ff7b9c2e90fea6_373).]
| HBAN | | | $100 | | | | | | $132 | | | | | | $117 | | | | | | $149 | | | | | | $142 | | | | | | $136 | | |
| S&P 500 | | | 100 | | | | | | 131 | | | | | | 156 | | | | | | 200 | | | | | | 164 | | | | | | 207 | | |
| KBW Bank Index | | | 100 | | | | | | 136 | | | | | | 122 | | | | | | 169 | | | | | | 133 | | | | | | 132 | | |
| HBAN | | | $100 | | | | | | $85 | | | | | | $111 | | | | | | $99 | | | | | | $126 | | | | | | $120 | | |
| S&P 500 | | | 100 | | | | | | 95 | | | | | | 125 | | | | | | 148 | | | | | | 190 | | | | | | 155 | | |
| KBW Bank Index | | | 100 | | | | | | 82 | | | | | | 112 | | | | | | 100 | | | | | | 138 | | | | | | 109 | | |
Item 6. [Reserved]
0 rewritten, 1 added, 1 removed, 1 unchanged
2023 Form 10-K 43
42 Huntington Bancshares Incorporated
Item 8. Financial Statements and Supplementary Data
912 rewritten, 421 added, 352 removed, 1,713 unchanged
Information required by this item is set forth in the [Reports of Independent Registered Public Accounting [removed: Firm](#i3690470c99e54374bb9007e428dd5dc6_154)] [added: Firm](#ifc28720717254a2384ff7b9c2e90fea6_190)] (PCAOB ID 238), [Consolidated Financial [removed: Statements](#i3690470c99e54374bb9007e428dd5dc6_160)] [added: Statements](#ifc28720717254a2384ff7b9c2e90fea6_199)] and [Notes to Consolidated Financial [removed: Statements](#i3690470c99e54374bb9007e428dd5dc6_175),] [added: Statements](#ifc28720717254a2384ff7b9c2e90fea6_214),] which is incorporated by reference into this item.
During [removed: 2022,] [added: 2023,] the audit committee of the board of directors met regularly with Management, Huntington’s internal auditors, and the independent registered public accounting firm, PricewaterhouseCoopers LLP, to review the scope of their audits and to discuss the evaluation of internal accounting controls and financial reporting matters.
Huntington’s Management assessed the effectiveness of the Company’s internal control over financial reporting as of December 31, [removed: 2022.][added: 2023.]
In making this assessment, Management used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) in *Internal Control—Integrated Framework (2013).* Based on that assessment, Management concluded that, as of December 31, [removed: 2022,] [added: 2023,] the Company’s internal control over financial reporting is effective based on those criteria.
The Company’s internal control over financial reporting as of December 31, [removed: 2022] [added: 2023] has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report appearing on the next page.
[removed: ][added: ]
[removed: ][added: ]
We have audited the accompanying consolidated balance sheets of Huntington Bancshares Incorporated and its subsidiaries (the “Company”) as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the related consolidated statements of income, of comprehensive income, of changes in shareholders' equity and of cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] including the related notes (collectively referred to as the “consolidated financial statements”).
We also have audited the Company's internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2022] [added: 2023] in conformity with accounting principles generally accepted in the United States of America.
Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
As described in Notes 1 and 6 to the consolidated financial statements, management’s estimate of the allowance for credit losses of [removed: $2.3] [added: $2.4] billion as of December 31, [removed: 2022] [added: 2023] includes a general reserve that consists of various risk-profile reserve components.
[removed: ][added: ]
| *(dollar amounts in millions)* | | | [added: 2023 | | | | | |] 2022 | | | | | | 2021 | | |
| Cash and due from banks | | | $ | [removed: 1,796] [added: 1,558] | | | | | $ | [removed: 1,811] [added: 1,796] | |
| [removed: Interest-bearing] [added: Change in interest bearing] deposits in banks | | | [removed: 214] [added: 23] | | | | | | [removed: 392] [added: 332] | | | [added: | | | 716 | | |]
| Trading account securities | | | [removed: 19] [added: 125] | | | | | | [removed: 46] [added: 19] | | |
| Available-for-sale securities | | | [removed: 23,423] [added: 25,305] | | | | | | [removed: 28,460] [added: 23,423] | | |
| Held-to-maturity securities | | | [removed: 17,052] [added: 15,750] | | | | | | [removed: 12,447] [added: 17,052] | | |
| Other securities | | | [removed: 854] [added: 725] | | | | | | [removed: 648] [added: 854] | | |
| Loans held for sale (includes [removed: $520] [added: $506] and [removed: $1,270] [added: $520] respectively, measured at fair value)(1) | | | [removed: 529] [added: 516] | | | | | | [removed: 1,676] [added: 529] | | |
| Loans and leases (includes [removed: $185] [added: $174] and [removed: $171] [added: $185] respectively, measured at fair value)(1) | | | [removed: 119,523] [added: 121,982] | | | | | | [removed: 111,267] [added: 119,523] | | |
| Allowance for loan and lease losses | | | [removed: (2,121)] [added: (2,255)] | | | | | | [removed: (2,030)] [added: (2,121)] | | |
| Net loans and leases | | | [removed: 117,402] [added: 119,727] | | | | | | [removed: 109,237] [added: 117,402] | | |
| Bank owned life insurance | | | [removed: 2,753] [added: 2,759] | | | | | | [removed: 2,765] [added: 2,753] | | |
| Accrued income and other receivables | | | [removed: 1,573] [added: 1,646] | | | | | | [removed: 1,319] [added: 1,573] | | |
| Premises and equipment | | | [removed: 1,156] [added: 1,109] | | | | | | [removed: 1,164] [added: 1,156] | | |
| Goodwill | | | [removed: 5,571] [added: 5,561] | | | | | | [removed: 5,349] [added: 5,571] | | |
| Servicing rights and other intangible assets | | | [removed: 712] [added: 672] | | | | | | [removed: 611] [added: 712] | | |
| Other assets | | | [removed: 4,944] [added: 5,150] | | | | | | [removed: 4,428] [added: 4,944] | | |
| Total assets | | | $ | [removed: 182,906] [added: 189,368] | | | | | $ | [removed: 174,064] [added: 182,906] | |
| Demand deposits—noninterest-bearing | | | $ | [removed: 38,242] [added: 30,967] | | | | | $ | [removed: 43,236] [added: 38,242] | |
| Interest-bearing | | | [removed: 109,672] [added: 120,263] | | | | | | [removed: 100,027] [added: 109,672] | | |
| Total deposits | | | [removed: 147,914] [added: 151,230] | | | | | | [removed: 143,263] [added: 147,914] | | |
| Short-term borrowings | | | [removed: 2,027] [added: 620] | | | | | | [removed: 334] [added: 2,027] | | |
| Long-term debt | | | [removed: 9,686] [added: 12,394] | | | | | | [removed: 7,108] [added: 9,686] | | |
| Other liabilities | | | [removed: 5,510] [added: 5,726] | | | | | | [removed: 4,041] [added: 5,510] | | |
| Total liabilities | | | [removed: 165,137] [added: 169,970] | | | | | | [removed: 154,746] [added: 165,137] | | |
| Preferred stock | | | [removed: 2,167] [added: 2,394] | | | | | | 2,167 | | |
| Common stock | | | [removed: 14] [added: 15] | | | | | | 14 | | |
February 16, 2024
February 16, 2024
| *(dollar amounts in millions)* | | | 2023 | | | | | | 2022 | | |
| Interest-earning deposits with banks | | | 8,765 | | | | | | 5,122 | | |
| Payments and cash management revenue | | | 585 | | | | | | 561 | | | | | | 501 | | |
| Wealth and asset management revenue | | | 328 | | | | | | 300 | | | | | | 269 | | |
| Customer deposit and loan fees | | | 312 | | | | | | 350 | | | | | | 310 | | |
| Capital markets and advisory fees | | | 248 | | | | | | 265 | | | | | | 156 | | |
| Balance, beginning of year | | | $ | 2,167 | | | | | 1,449,390 | | | | | | $ | 14 | | | | | $ | 15,309 | | | | | (6,322) | | | | | | $ | (80) | | | | | $ | (3,098) | | | | | $ | 3,419 | | | | | $ | 17,731 | | | | | $ | 38 | | | | | $ | 17,769 | |
| Repurchase of preferred stock | | | (90) | | | | | | | | | | | | | | | | | | — | | | | | | | | | | | | | | | | | | | | | | | | 8 | | | | | | (82) | | | | | | | | | | | | (82) | | |
| Preferred | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | (142) | | | | | | (142) | | | | | | | | | | | | (142) | | |
| Balance, end of year | | | $ | 2,394 | | | | | 1,455,723 | | | | | | $ | 15 | | | | | $ | 15,389 | | | | | (7,403) | | | | | | $ | (91) | | | | | $ | (2,676) | | | | | $ | 4,322 | | | | | $ | 19,353 | | | | | $ | 45 | | | | | $ | 19,398 | |
2023 Form 10-K 95
(1) Includes cash and due from banks and interest-earning deposits at the Federal Reserve Bank, included within Interest-earning deposits with banks on our Consolidated Balance Sheets.
2023 Form 10-K 96
Through its subsidiaries, including its bank subsidiary, The Huntington National Bank (the Bank), Huntington is engaged in providing full-service commercial and consumer deposit, lending, and other banking services.
Huntington updated the presentation of our noninterest income categories during the 2023 fourth quarter to align product and service types more closely with how we strategically manage our business.
See Note 15 - “[Revenue from Contracts wi](#ifc28720717254a2384ff7b9c2e90fea6_289)[th Customers](#ifc28720717254a2384ff7b9c2e90fea6_289)” for a description of our major noninterest income categories.
Effective January 1, 2023, Huntington adopted ASU 2022-02 *Financial Instruments - Credit Losses (Topic 326) Troubled Debt Restructurings (TDR) and Vintage Disclosures,* which removed the existing measurement and disclosure requirements for TDR loans and added additional disclosure requirements related to modifications provided to borrowers experiencing financial difficulty.
Prior to adoption a change in contractual terms of a loan where a borrower was experiencing financial difficulty and received a concession not available through other sources the loan was required to be disclosed as a TDR, whereas now a borrower that is experiencing financial difficulty and receives a modification in the form of principal forgiveness, interest rate reduction, an other-than-insignificant payment delay or a term extension in the current period is disclosed as a modification to a borrower experiencing financial difficulty.
Huntington may modify loans to borrowers experiencing financial difficulty as a way of managing risk and mitigating credit loss from the borrower.
Huntington may make various types of modifications and may in certain circumstances use a combination of modification types in order to mitigate future loss.
2023 Form 10-K 98
Refer to Note 15 - “[Revenue from Contracts with Customers](#ifc28720717254a2384ff7b9c2e90fea6_289)” for details related to revenue from contracts with customers within the scope of ASC Topic 606, Revenue from Contracts with Customers (“ASC 606”).
| ASU 2023-02 - Investments - Equity Method and Joint Ventures (Topic 323): Accounting for Investments in Tax Credit Structures Using the Proportional Amortization Method Issued: March 2023 | | | •Permits the election of the proportional amortization method for any tax equity investment that meets specific criteria. •Requires that the election be made on a tax-credit-program-by-tax-credit-program basis. •Receipt of tax credits must be accounted for using the flow through method. •Requires that a liability be recorded for delayed equity contributions. •Expands disclosure requirements for the nature of investments and financial statement effect. | | | •Effective for fiscal years beginning after December 15, 2023, including interim periods within those fiscal years. •Huntington adopted the standard effective January 1, 2024. on a modified retrospective basis. •Huntington does not expect adoption of the standard to have a material impact on its Consolidated Financial Statements. | | | | | | | | |
| ASU 2023-07 - Segment Reporting (Topic 280): Improvement to Reportable Segments | | | •Requires disclosure of the position and title of the CODM and significant segment expenses that the CODM is regularly provided. •Requires the disclosure of other segment items representing the difference between segment revenue and expense and the profit and loss measure of the segment. •Allows for the CODM to use more than one measure of segment profit and loss, as long as one measure is consistent with GAAP. | | | •Effective for fiscal years beginning after December 15, 2023, and interim periods within fiscal years beginning after December 15, 2024. •Early adoption is permitted. •The amendments are to be applied retrospectively to all periods presented and segment expense categories should be based on the categories identified at adoption. •Huntington does not expect adoption of the standard to have a material impact on its Consolidated Financial Statements. | | | | | | | | |
| ASU 2023-09 - Income Taxes (Topic 740): Improvements to Income Tax Disclosures | | | •Requires a tabular rate reconciliation using both percentages and reporting currency amounts between the reported amount of income tax expense (or benefit) to the amount of statutory federal income tax at current rates for specified categories using specified disaggregation criteria. •The amount of net income taxes paid for federal, state, and foreign taxes, as well as the amount paid to any jurisdiction that net taxes exceed a 5% quantitative threshold. •The amendments will require the disclosure of pre-tax income disaggregated between domestic and foreign, as well as income tax expense disaggregated by federal, state, and foreign. •The amendment also eliminates certain disclosures related to unrecognized tax benefits and certain temporary differences. | | | •Effective for fiscal years beginning after December 15, 2024. •Early adoption is permitted in any annual period where financial statements have not yet been issued. •The amendments should be applied on a prospective basis but retrospective application is permitted. •Huntington does not expect adoption of the standard to have a material impact on its Consolidated Financial Statements. | | | | | | | | |
| At December 31, 2023 | | | | | | | | | | | | | | | | | | | | | | | |
| U.S. Treasury | | | $ | 2,855 | | | | | $ | 1 | | | | | $ | — | | | | | $ | 2,856 | |
| Residential CMO | | | 3,592 | | | | | | — | | | | | | (408) | | | | | | 3,184 | | |
| Residential MBS | | | 13,155 | | | | | | 3 | | | | | | (1,776) | | | | | | 11,382 | | |
| Commercial MBS | | | 2,536 | | | | | | — | | | | | | (709) | | | | | | 1,827 | | |
| Other agencies | | | 161 | | | | | | — | | | | | | (6) | | | | | | 155 | | |
| Municipal securities | | | 3,536 | | | | | | 2 | | | | | | (165) | | | | | | 3,373 | | |
| Corporate debt | | | 2,202 | | | | | | 79 | | | | | | (238) | | | | | | 2,043 | | |
| Residential CMO | | | $ | 4,770 | | | | | $ | 6 | | | | | $ | (664) | | | | | $ | 4,112 | |
| Residential MBS | | | 9,368 | | | | | | 1 | | | | | | (1,145) | | | | | | 8,224 | | |
| Commercial MBS | | | 1,509 | | | | | | — | | | | | | (224) | | | | | | 1,285 | | |
The basis adjustments totaled $619 million and represent a reduction to the amortized cost of the securities being hedged.
(2)Excluded from the amortized cost are portfolio level basis adjustments for securities designated in fair value hedges under the portfolio layer method.
The selected quarterly financial data is no longer required.
There were no material retrospective changes to any quarters in the two most recent fiscal years that would require this
disclosure.
86 Huntington Bancshares Incorporated
February 17, 2023
2022 Form 10-K 87
*Change in Accounting Principle*
As discussed in Note 1 to the consolidated financial statements, the Company changed the manner in which it accounts for the allowance for credit losses as of January 1, 2020.
2022 Form 10-K 89
| | | | | | | | | | | | |
| Interest-bearing deposits at Federal Reserve Bank | | | 4,908 | | | | | | 3,711 | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Service charges on deposit accounts | | | 384 | | | | | | 372 | | | | | | 301 | | |
| Card and payment processing income | | | 374 | | | | | | 334 | | | | | | 248 | | |
| Trust and investment management services | | | 249 | | | | | | 232 | | | | | | 189 | | |
2022 Form 10-K 91
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | Preferred Stock | | | | | | Common Stock | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | AOCI | | | | | | | | | | | | | | | | | | Non-controlling | | | | | | | | |
| Amount | | | | | | Shares | | | | | | Amount | | | | | | Surplus | | | | | | Shares | | | | | | Amount | | | | | | | | | Earnings | | | | | | Total | | | | | | Interest | | | | | | Equity | | | | | | | | |
2022 Form 10-K 93
| Balance, beginning of year | | | $ | 1,203 | | | | | 1,024,541 | | | | | | $ | 10 | | | | | $ | 8,806 | | | | | (4,537) | | | | | | $ | (56) | | | | | $ | (256) | | | | | $ | 2,088 | | | | | $ | 11,795 | | | | | $ | — | | | | | $ | 11,795 | |
| Cumulative-effect of change in accounting principle, net of tax | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | (306) | | | | | | (306) | | | | | | | | | | | | (306) | | |
| Preferred | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | (100) | | | | | | (100) | | | | | | | | | | | | (100) | | |
| Balance, end of year | | | $ | 2,191 | | | | | 1,022,258 | | | | | | $ | 10 | | | | | $ | 8,781 | | | | | (5,062) | | | | | | $ | (59) | | | | | $ | 192 | | | | | $ | 1,878 | | | | | $ | 12,993 | | | | | $ | — | | | | | $ | 12,993 | |
| Change in interest bearing deposits in banks | | | 332 | | | | | | 716 | | | | | | (81) | | |
95 Huntington Bancshares Incorporated
Effective in the 2022, a new classification within the Consolidated Balance Sheet of accrued income and other receivables was established comprised of activity that was previously classified as loans and leases (other consumer loans and leases) and other assets.
2022 Form 10-K 96
Troubled debt restructurings are loans for which the original contractual terms have been modified to provide a concession to a borrower experiencing financial difficulties.
Loan modifications are considered TDRs when the concessions provided are not available to the borrower through either normal channels or other sources.
However, not all loan modifications are TDRs.
Modifications resulting in troubled debt restructurings may include changes to one or more terms of the loan, including, but not limited to, an interest rate concession, an extension of the repayment period, a reduction in payment amount, and partial forgiveness or deferment of principal or accrued interest.
On January 1, 2020, Huntington adopted ASC Topic 326 using the modified retrospective method for all financial assets in scope of the standard.
Upon adoption, Huntington recorded an increase to the ACL of $393 million and a corresponding decrease to retained earnings of $306 million, net of tax.
2022 Form 10-K 98
contemporaneously with, or in contemplation of, the transfer, even if they were not entered into at the time of transfer.
The fixed fee is recognized over a period of time while the transaction fee is recognized when a specific service (e.g., execution of wire-transfer) is rendered to the customer.
future reversals due to the insignificance of the amounts.
*•Card and payment processing income* includes interchange fees earned on debit cards and credit cards.
An excerpt. Shown here: 40 of 912 rewritten, 40 of 421 added and 40 of 352 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data in the FY2023 filing and the FY2022 filing.
Item 9A. Controls and Procedures
3 rewritten, 0 added, 0 removed, 6 unchanged
Huntington’s management, with the participation of its Chief Executive Officer and the Chief Financial Officer, evaluated the effectiveness of Huntington’s disclosure controls and procedures (as such term is defined in Rules 13a-15(e) and 15d-15(e) under the Exchange Act) as of December 31, [removed: 2022.][added: 2023.]
Based upon such evaluation, Huntington’s Chief Executive Officer and Chief Financial Officer have concluded that, as of December 31, [removed: 2022,] [added: 2023,] Huntington’s disclosure controls and procedures were effective.
There have not been any changes in our internal control over financial reporting (as such term is defined in Rules 13a-15(f) and 15d-15(f) under the Exchange Act) during the quarter ended December 31, [removed: 2022,] [added: 2023,] that have materially affected, or are reasonably likely to materially affect, internal control over financial reporting.
Item 9B. Other Information
0 rewritten, 4 added, 1 removed, 0 unchanged
Trading Plans
On November 20, 2023, Julie C.
Tutkovics, our Chief Marketing and Communications Officer, adopted a trading plan intended to satisfy the conditions under Rule 10b5-1(c) of the Exchange Act.
Ms. Tutkovics’ plan is for the sale of up to 178,395 shares of our common stock in amounts and prices determined in accordance with formulae set forth in the plan and terminates on the earlier of the date all the shares under the plan are sold and November 4, 2024.
Not applicable.
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections.
2 rewritten, 0 added, 0 removed, 2 unchanged
We refer in Part III of this report to relevant sections of our [removed: 2023] [added: 2024] Proxy Statement for the [removed: 2023] [added: 2024] Annual Meeting of shareholders, which will be filed with the SEC pursuant to Regulation 14A within 120 days of the close of our [removed: 2022] [added: 2023] fiscal year.
Portions of our [removed: 2023] [added: 2024] Proxy Statement, including the sections we refer to in this report, are incorporated by reference into this report.
Item 10. Directors, Executive Officers, and Corporate Governance
1 rewritten, 1 added, 0 removed, 0 unchanged
Information required by this item is set forth under the captions Election of Directors, Our Executive Officers, Family Relationships, Delinquent Section 16(a) Reports, Codes of Ethics, Proposals by Shareholders for the 2024 Annual Meeting, Recommendations for Directorship, and Board Committee Information of our [removed: 2023] [added: 2024] Proxy Statement, which is incorporated by reference into this item.
2023 Form 10-K 160
Item 11. Executive Compensation
1 rewritten, 0 added, 1 removed, 0 unchanged
Information required by this item is set forth under the captions Compensation of Executive Officers and Compensation of Directors of our [removed: 2023] [added: 2024] Proxy Statement, which is incorporated by reference into this item.
161 Huntington Bancshares Incorporated
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
5 rewritten, 2 added, 2 removed, 9 unchanged
The following table sets forth information about Huntington common stock authorized for issuance under Huntington’s existing equity compensation plans as of December 31, [removed: 2022.][added: 2023.]
(2)The numbers in this column (a) reflect shares of common stock to be issued upon exercise of outstanding stock options and the vesting of outstanding awards of [removed: RSAs, RSUs,] [added: restricted stock awards, restricted share units,] and [removed: PSUs,] [added: performance share units,] and the release of [removed: DSUs.][added: deferred share units.]
(3)As of December 31, [removed: 2022,] [added: 2023,] an additional [removed: 2,274,680] [added: 991,178] common shares, at a weighted-average exercise price of [removed: $3.32,] [added: $7.07,] are to be issued upon exercise or vesting under the TCF Incentive Plan, which was assumed in the acquisition of TCF, is no longer active, and for which Huntington has not reserved the right to make subsequent grants or awards.
(4)The weighted-average exercise prices in this column are based on outstanding options and do not take into account unvested awards of [removed: RSAs, RSUs] [added: restricted stock awards, restricted stock units] and [removed: PSUs] [added: performance share units] and unreleased [removed: DSUs] [added: deferred share units] as these awards do not have an exercise price.
The information related to item 403 of regulation S-K is set forth under the caption Ownership of Voting Stock of our [removed: 2023] [added: 2024] Proxy Statement, which is incorporated by reference into this item.
| Equity compensation plans approved by security holders | | | | | | 34,359,531 | | | | | | $ | 4.53 | | | | | 14,508,872 | | |
| Total | | | | | | 34,359,531 | | | | | | $ | 4.53 | | | | | 14,508,872 | | |
| Equity compensation plans approved by security holders | | | | | | 38,998,458 | | | | | | $ | 4.07 | | | | | 20,602,866 | | |
| Total | | | | | | 38,998,458 | | | | | | $ | 4.07 | | | | | 20,602,866 | | |
Item 13. Certain Relationships and Related Transactions, and Director Independence
1 rewritten, 0 added, 0 removed, 0 unchanged
Information required by this item is set forth under the captions Review, Approval, or Ratification of Transactions with Related Persons and Independence of Directors of our [removed: 2023] [added: 2024] Proxy Statement, which are incorporated by reference into this item.
Item 14. Principal Accounting Fees and Services
1 rewritten, 1 added, 0 removed, 1 unchanged
Information required by this item is set forth under the caption Audit Matters of our [removed: 2023] [added: 2024] Proxy Statement which is incorporated by reference into this item.
161 Huntington Bancshares Incorporated
Item 16. 10-K Summary
26 rewritten, 11 added, 8 removed, 156 unchanged
[removed: 2022] [added: 2023] Form 10-K [removed: 162][added: 162]
| [removed: 3.3] [added: 3.9] | | | [removed: [Bylaws] [added: [B](http://www.sec.gov/Archives/edgar/data/49196/000004919623000076/huntingtonbancsharesincorp.htm)[ylaws] of Huntington Bancshares Incorporated, as amended and restated on [removed: January 16, 2019.](http://www.sec.gov/Archives/edgar/data/49196/000004919619000005/hban-2019x01x16x8kxex33.htm)] [added: July 19, 2023](http://www.sec.gov/Archives/edgar/data/49196/000004919623000076/huntingtonbancsharesincorp.htm)] | | | [removed: [Current] [added: [C](http://www.sec.gov/Archives/edgar/data/49196/000004919623000076/huntingtonbancsharesincorp.htm)[urrent] Report on [removed: Form 8-K] [added: Form](http://www.sec.gov/Archives/edgar/data/49196/000004919623000076/huntingtonbancsharesincorp.htm) [8-K] dated [removed: January 16, 2019.](http://www.sec.gov/Archives/edgar/data/49196/000004919619000005/hban-2019x01x16x8kxex33.htm)] [added: July](http://www.sec.gov/Archives/edgar/data/49196/000004919623000076/huntingtonbancsharesincorp.htm) [19](http://www.sec.gov/Archives/edgar/data/49196/000004919623000076/huntingtonbancsharesincorp.htm)[, 2023](http://www.sec.gov/Archives/edgar/data/49196/000004919623000076/huntingtonbancsharesincorp.htm)] | | | [removed: [001-34073](http://www.sec.gov/Archives/edgar/data/49196/000004919619000005/hban-2019x01x16x8kxex33.htm)] [added: [001-34073](http://www.sec.gov/Archives/edgar/data/49196/000004919623000076/huntingtonbancsharesincorp.htm)] | | | [removed: [3.3](http://www.sec.gov/Archives/edgar/data/49196/000004919619000005/hban-2019x01x16x8kxex33.htm)] [added: [3.2](http://www.sec.gov/Archives/edgar/data/49196/000004919623000076/huntingtonbancsharesincorp.htm)] | | |
| [removed: 3.4] [added: 3.3] | | | [Articles Supplementary of Huntington Bancshares Incorporated, as of February 5, 2021.](https://www.sec.gov/Archives/edgar/data/49196/000119312521034332/d62360dex31.htm) | | | [Current Report on Form 8-K dated February 5, 2021](https://www.sec.gov/Archives/edgar/data/49196/000119312521034332/d62360dex31.htm) | | | [001-34073](https://www.sec.gov/Archives/edgar/data/49196/000119312521034332/d62360dex31.htm) | | | [3.1](https://www.sec.gov/Archives/edgar/data/49196/000119312521034332/d62360dex31.htm) | | |
| [removed: 3.5] [added: 3.4] | | | [Articles Supplementary of Huntington Bancshares Incorporated, as of August 5, 2020.](https://www.sec.gov/Archives/edgar/data/49196/000119312520215014/d79165dex31.htm) | | | [Current Report on Form 8-K dated August 5, 2020.](https://www.sec.gov/Archives/edgar/data/49196/000119312520215014/d79165dex31.htm) | | | [001-34073](https://www.sec.gov/Archives/edgar/data/49196/000119312520215014/d79165dex31.htm) | | | [3.1](https://www.sec.gov/Archives/edgar/data/49196/000119312520215014/d79165dex31.htm) | | |
| [removed: 3.6] [added: 3.5] | | | [Articles Supplementary of Huntington Bancshares Incorporated, as of May 28, 2020.](https://www.sec.gov/Archives/edgar/data/49196/000119312520159678/d937169dex31.htm) | | | [Current Report on Form 8-K dated May 28, 2020](https://www.sec.gov/Archives/edgar/data/49196/000119312520159678/d937169dex31.htm). | | | [001-34073](https://www.sec.gov/Archives/edgar/data/49196/000119312520159678/d937169dex31.htm) | | | [3.1](https://www.sec.gov/Archives/edgar/data/49196/000119312520159678/d937169dex31.htm) | | |
| [removed: 3.7] [added: 3.6] | | | [Articles Supplementary of Huntington Bancshares Incorporated, as of June 8, 2021](http://www.sec.gov/Archives/edgar/data/49196/000114036121020258/nt10025590x4_ex3-1.htm) | | | [Current Report on Form 8-K dated June 8, 2021](http://www.sec.gov/Archives/edgar/data/49196/000114036121020258/nt10025590x4_ex3-1.htm) | | | [001-34073](http://www.sec.gov/Archives/edgar/data/49196/000114036121020258/nt10025590x4_ex3-1.htm) | | | [3.1](http://www.sec.gov/Archives/edgar/data/49196/000114036121020258/nt10025590x4_ex3-1.htm) | | |
| [removed: 3.8] [added: 3.7] | | | [Articles of Amendment of Huntington Bancshares Incorporated to Articles of Restatement of Huntington Bancshares Incorporated, as of June 8, 2021](http://www.sec.gov/Archives/edgar/data/49196/000114036121020258/nt10025590x4_ex3-2.htm) | | | [Current Report on Form 8-K dated June 8, 2021](http://www.sec.gov/Archives/edgar/data/49196/000114036121020258/nt10025590x4_ex3-2.htm) | | | [001-34073](http://www.sec.gov/Archives/edgar/data/49196/000114036121020258/nt10025590x4_ex3-2.htm) | | | [3.2](http://www.sec.gov/Archives/edgar/data/49196/000114036121020258/nt10025590x4_ex3-2.htm) | | |
| [removed: 4.2] [added: 10.25] | | | [removed: [Description] [added: [*Executive Deferred Compensation Plan, amended as] of [removed: Securities](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex42-10k.htm)] [added: January 18, 2022.](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex1025-10k.htm)] | | | [Annual Report on Form 10-K for the year ended December 31, [removed: 2021.](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex42-10k.htm)] [added: 2021.](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex1025-10k.htm)] | | | [removed: [001-34073](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex42-10k.htm)] [added: [001-34073](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex1025-10k.htm)] | | | [removed: [4.2](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex42-10k.htm)] [added: [10.25](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex1025-10k.htm)] | | |
| 10.8 | | | [* Huntington Bancshares Incorporated 2007 Stock and Long-Term Incentive [removed: Plan.](http://www.sec.gov/Archives/edgar/data/49196/000119312507085352/ddefm14a.htm)] [added: Plan.](http://www.sec.gov/Archives/edgar/data/49196/000119312507085352/ddefm14a.htm#toc21747_111)] | | | [Definitive Proxy Statement for the 2007 Annual Meeting of [removed: Stockholders.](http://www.sec.gov/Archives/edgar/data/49196/000119312507085352/ddefm14a.htm)] [added: Stockholders.](http://www.sec.gov/Archives/edgar/data/49196/000119312507085352/ddefm14a.htm#toc21747_111)] | | | [removed: [000-02525](http://www.sec.gov/Archives/edgar/data/49196/000119312507085352/ddefm14a.htm)] [added: [000-02525](http://www.sec.gov/Archives/edgar/data/49196/000119312507085352/ddefm14a.htm#toc21747_111)] | | | [removed: [G](http://www.sec.gov/Archives/edgar/data/49196/000119312507085352/ddefm14a.htm)] [added: [G](http://www.sec.gov/Archives/edgar/data/49196/000119312507085352/ddefm14a.htm#toc21747_111)] | | |
| 10.15 | | | [*Huntington Bancshares Incorporated 2012 Long-Term Incentive [removed: Plan.](http://www.sec.gov/Archives/edgar/data/49196/000119312512102508/d257241ddef14a.htm)] [added: Plan.](http://www.sec.gov/Archives/edgar/data/49196/000119312512102508/d257241ddef14a.htm#toc257241_40)] | | | [Definitive Proxy Statement for the 2012 Annual Meeting of [removed: Shareholders.](http://www.sec.gov/Archives/edgar/data/49196/000119312512102508/d257241ddef14a.htm)] [added: Shareholders.](http://www.sec.gov/Archives/edgar/data/49196/000119312512102508/d257241ddef14a.htm#toc257241_40)] | | | [removed: [001-34073](http://www.sec.gov/Archives/edgar/data/49196/000119312512102508/d257241ddef14a.htm)] [added: [001-34073](http://www.sec.gov/Archives/edgar/data/49196/000119312512102508/d257241ddef14a.htm#toc257241_40)] | | | [removed: [A](http://www.sec.gov/Archives/edgar/data/49196/000119312512102508/d257241ddef14a.htm)] [added: [A](http://www.sec.gov/Archives/edgar/data/49196/000119312512102508/d257241ddef14a.htm#toc257241_40)] | | |
| [removed: 10.25] [added: 10.43] | | | [removed: [*Executive Deferred Compensation Plan,](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex1025-10k.htm) [amended as of](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex1025-10k.htm) [January 18, 2022.](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex1025-10k.htm)] [added: [*Form of 2022 Restricted Stock Unit Agreement](http://www.sec.gov/Archives/edgar/data/49196/000004919623000020/exhibit10432022stock-settl.htm)] | | | [Annual Report on Form 10-K for [removed: the] year ended December 31, [removed: 2021.](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex1025-10k.htm)] [added: 2022.](http://www.sec.gov/Archives/edgar/data/49196/000004919623000020/exhibit10432022stock-settl.htm)] | | | [removed: [001-34073](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex1025-10k.htm)] [added: [0](http://www.sec.gov/Archives/edgar/data/49196/000004919623000020/exhibit10432022stock-settl.htm)[0](http://www.sec.gov/Archives/edgar/data/49196/000004919623000020/exhibit10432022stock-settl.htm)[1](http://www.sec.gov/Archives/edgar/data/49196/000004919623000020/exhibit10432022stock-settl.htm)[\-](http://www.sec.gov/Archives/edgar/data/49196/000004919623000020/exhibit10432022stock-settl.htm)[34073](http://www.sec.gov/Archives/edgar/data/49196/000004919623000020/exhibit10432022stock-settl.htm)] | | | [removed: [10.25](http://www.sec.gov/Archives/edgar/data/49196/000004919622000023/hban20211231ex1025-10k.htm)] [added: [10.43](http://www.sec.gov/Archives/edgar/data/49196/000004919623000020/exhibit10432022stock-settl.htm)] | | |
| 10.38 | | | [*Amended and Restated TCF Financial 2015 Omnibus Incentive Plan.](http://www.sec.gov/Archives/edgar/data/814184/000081418418000022/ex-101omnibusincentiveplan.htm) | | | [TCF Financial Corporation Annual Report on Form 10-K for the year ended December 31, 2018.](http://www.sec.gov/Archives/edgar/data/814184/000081418418000022/ex-101omnibusincentiveplan.htm) | | | [001-10253](http://www.sec.gov/Archives/edgar/data/814184/000081418418000022/ex-101omnibusincentiveplan.htm) | | | [removed: [10(a)](http://www.sec.gov/Archives/edgar/data/814184/000081418418000022/ex-101omnibusincentiveplan.htm)] [added: [10.1](http://www.sec.gov/Archives/edgar/data/814184/000081418418000022/ex-101omnibusincentiveplan.htm)] | | |
[removed: 2022] [added: 2023] Form 10-K 164
| 14.1(P) | | | Code of Business Conduct and Ethics dated January 14, 2003 and revised on January 31, [removed: 2022] [added: 2023] and Financial Code of Ethics for Chief Executive Officer and Senior Financial Officers, adopted January 18, 2003, and revised on October [removed: 20, 2015,] [added: 17, 2023,] are available on our website at http://www.huntington.com/About-Us/corporate-governance | | | | | | | | | | | |
| [removed: [21.1](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex211-10k.htm)] [added: [21.1](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex211-10k.htm)] | | | [Subsidiaries of the [removed: Registrant](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex211-10k.htm)] [added: Registrant](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex211-10k.htm)] | | | | | | | | | | | |
| [removed: [22](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex22-10k.htm)] [added: [22](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex22-10k.htm)] | | | [Subsidiary Issuers of Guaranteed [removed: Securities](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex22-10k.htm)] [added: Securities](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex22-10k.htm)] | | | | | | | | | | | |
| [removed: [23.1](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex231-10k.htm)] [added: [23.1](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex231-10k.htm)] | | | [Consent of PricewaterhouseCoopers LLP, Independent Registered Public Accounting [removed: Firm.](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex231-10k.htm)] [added: Firm.](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex231-10k.htm)] | | | | | | | | | | | |
| [removed: [24.1](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex241-10k.htm)] [added: [24.1](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex241-10k.htm)] | | | [Power of [removed: Attorney](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex241-10k.htm)] [added: Attorney](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex241-10k.htm)] | | | | | | | | | | | |
| [removed: [31.1](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex311-10k.htm)] [added: [31.1](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex311-10k.htm)] | | | [Rule 13a-14(a) Certification – Chief Executive [removed: Officer.](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex311-10k.htm)] [added: Officer.](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex311-10k.htm)] | | | | | | | | | | | |
| [removed: [31.2](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex312-10k.htm)] [added: [31.2](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex312-10k.htm)] | | | [Rule 13a-14(a) Certification – Chief Financial [removed: Officer.](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex312-10k.htm)] [added: Officer.](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex312-10k.htm)] | | | | | | | | | | | |
| [removed: [32.1](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex321-10k.htm)] [added: [32.1](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex321-10k.htm)] | | | [Section 1350 Certification – Chief Executive [removed: Officer.](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex321-10k.htm)] [added: Officer.](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex321-10k.htm)] | | | | | | | | | | | |
| [removed: [32.2](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex322-10k.htm)] [added: [32.2](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex322-10k.htm)] | | | [Section 1350 Certification – Chief Financial [removed: Officer.](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/hban20221231ex322-10k.htm)] [added: Officer.](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex322-10k.htm)] | | | | | | | | | | | |
| 101 | | | The following material from Huntington’s Form 10-K Report for the year ended December 31, [removed: 2022,] [added: 2023,] formatted in Inline XBRL: (1) [Consolidated Balance [removed: Sheets](#i3690470c99e54374bb9007e428dd5dc6_160),] [added: Sheets](#ifc28720717254a2384ff7b9c2e90fea6_199),] (2) [Consolidated Statements of [removed: Income](#i3690470c99e54374bb9007e428dd5dc6_163),] [added: Income](#ifc28720717254a2384ff7b9c2e90fea6_202),] (3), [Consolidated Statements of Comprehensive [removed: Income](#i3690470c99e54374bb9007e428dd5dc6_166),] [added: Income](#ifc28720717254a2384ff7b9c2e90fea6_205),] (4) [Consolidated Statements of Changes in Shareholders’ [removed: Equity](#i3690470c99e54374bb9007e428dd5dc6_169),] [added: Equity](#ifc28720717254a2384ff7b9c2e90fea6_208),] (5) [Consolidated Statements of Cash [removed: Flows](#i3690470c99e54374bb9007e428dd5dc6_172),] [added: Flows](#ifc28720717254a2384ff7b9c2e90fea6_211),] and (6) the [Notes to the Consolidated Financial [removed: Statements](#i3690470c99e54374bb9007e428dd5dc6_175).] [added: Statements](#ifc28720717254a2384ff7b9c2e90fea6_214).] | | | | | | | | | | | |
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized, on the [removed: 17th] [added: 16th] Day of February, [removed: 2023.][added: 2024.]
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the Registrant and in the capacities indicated on the [removed: 17th] [added: 16th] Day of February, [removed: 2023.][added: 2024.]
[removed: 2022] [added: 2023] Form 10-K 166
| 3.8 | | | [A](http://www.sec.gov/Archives/edgar/data/49196/000119312523061394/d412387dex31.htm)[rticles Supplementary of Hunting](http://www.sec.gov/Archives/edgar/data/49196/000119312523061394/d412387dex31.htm)[ton Ban](http://www.sec.gov/Archives/edgar/data/49196/000119312523061394/d412387dex31.htm)[cshares Incorporated](http://www.sec.gov/Archives/edgar/data/49196/000119312523061394/d412387dex31.htm)[, as of March 3, 2023](http://www.sec.gov/Archives/edgar/data/49196/000119312523061394/d412387dex31.htm) | | | [Current Report on Form 8-K dated March 2, 2023](http://www.sec.gov/Archives/edgar/data/49196/000119312523061394/d412387dex31.htm) | | | [001-34073](http://www.sec.gov/Archives/edgar/data/49196/000119312523061394/d412387dex31.htm) | | | [3.1](http://www.sec.gov/Archives/edgar/data/49196/000119312523061394/d412387dex31.htm) | | |
| [4.2](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex42-10k.htm) | | | [Description of Securities](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex42-10k.htm) | | | | | | | | | | | |
| 10.44 | | | [*](http://www.sec.gov/Archives/edgar/data/49196/000004919623000097/exhibit101transitionletter.htm)[Separation A](http://www.sec.gov/Archives/edgar/data/49196/000004919623000097/exhibit101transitionletter.htm)[greement dated Aug](http://www.sec.gov/Archives/edgar/data/49196/000004919623000097/exhibit101transitionletter.htm)[ust 7, 2023 by and](http://www.sec.gov/Archives/edgar/data/49196/000004919623000097/exhibit101transitionletter.htm) [between The Huntington National Bank and Sandra E. Pierce.](http://www.sec.gov/Archives/edgar/data/49196/000004919623000097/exhibit101transitionletter.htm) | | | [Quarterly Report on Form 10-Q for the quarter ended September 30, 2023.](http://www.sec.gov/Archives/edgar/data/49196/000004919623000097/exhibit101transitionletter.htm) | | | [001-34073](http://www.sec.gov/Archives/edgar/data/49196/000004919623000097/exhibit101transitionletter.htm) | | | [10.1](http://www.sec.gov/Archives/edgar/data/49196/000004919623000097/exhibit101transitionletter.htm) | | |
| 10.45 | | | [*](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex1045-10k.htm)[Amendment to Executive Deferred Compensation Plan, dated April 28, 2023.](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/hban20231231ex1045-10k.htm) | | | | | | | | | | | |
| [97](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/exhibit97financialrestatem.htm) | | | [Financial Restatement Recoupment Policy](https://www.sec.gov/Archives/edgar/data/49196/000004919624000020/exhibit97financialrestatem.htm) | | | | | | | | | | | |
| Rafael Andres Diaz-Granados * | | | | | |
| Rafael Andres Diaz-Granados | | | | | |
| John C. Inglis * | | | | | |
| John C. Inglis | | | | | |
| */s/ Marcy C. Hingst | | | | | |
| Marcy C. Hingst | | | | | |
| 10.43 | | | *[Form of 2022 Restricted Stock Unit Agreement](https://www.sec.gov/Archives/edgar/data/49196/000004919623000020/exhibit10432022stock-settl.htm) | | | | | | | | | | | |
| | | | | | |
| Lizabeth Ardisana * | | | | | |
| Lizabeth Ardisana | | | | | |
| Robert S. Cubbin * | | | | | |
| Robert S. Cubbin | | | | | |
| */s/ Jana J. Litsey | | | | | |
| Jana J. Litsey | | | | | |