 filings.tools
Item 5. MARKET FOR THE HARTFORD'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
375K characters. Original on sec.gov · Markdown
Item 5. MARKET FOR THE HARTFORD'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
MARKET FOR THE HARTFORD'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
The Hartford’s common stock is traded on the New York Stock Exchange (“NYSE”) under the trading symbol “HIG”. As of February 17, 2022, the Company had approximately 9,679 registered holders of record of the Company's common stock. A substantially greater number of holders of our common stock are “street name” holders or beneficial holders, whose shares
are held of record by banks, brokers and other financial institutions.
The Hartford's cash dividends paid on common stock and expected payment of future cash dividends are discussed in the Summary of Capital Resources and Liquidity and Liquidity Requirements and Sources of Capital - Dividends sections of Part II, Item 7, MD&A — Capital Resources and Liquidity.
For information related to securities authorized for issuance under equity compensation plans, see Part III, Item 12, Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
Repurchases of common stock by the Company during the quarter ended December 31, 2021 are set forth below. During the period from January 1, 2022 through February 17, 2022, the Company repurchased 3.8 million shares for $274.
| Repurchases of Common Stock by the Issuer for the Three Months Ended December 31, 2021 | ||||||||||||||
| Period | Total Number of Shares Purchased | Average Price Paid Per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Approximate Dollar Value of Shares that May Yet Be Purchased Under the Plans or Programs [1] | ||||||||||
| (in millions) | ||||||||||||||
| October 1, 2021 - October 31, 2021 | 1,618,168 | $ | 72.42 | 1,618,168 | $ | 1,681 | ||||||||
| November 1, 2021 - November 30, 2021 | 3,165,842 | $ | 71.02 | 3,165,842 | $ | 1,456 | ||||||||
| December 1, 2021 - December 31, 2021 | 2,328,073 | $ | 67.86 | 2,328,073 | $ | 1,298 | ||||||||
| Total | 7,112,083 | $ | 70.31 | 7,112,083 |
[1]On December 17, 2020, the Board of Directors authorized a new equity repurchase plan for $1.5 billion for the period commencing January 1, 2021 through December 31, 2022. The Board of Directors increased this authorization by $1 billion on April 22, 2021 and by $500 on October 28, 2021, bringing the aggregate repurchase authorization to $3.0 billion through December 31, 2022. The timing of any repurchases of shares under the remaining equity repurchase authorization is dependent upon several factors, including the market price of the Company's securities, the Company's capital position, consideration of the effect of any repurchases on the Company's financial strength or credit ratings, the Company's blackout periods, and other considerations.
| |TOTAL RETURN TO STOCKHOLDERS |
The following tables present The Hartford’s annual return percentage and five-year total return on its common stock including reinvestment of dividends in comparison to the S&P
500 and the S&P Insurance Composite Index.
| Annual Return Percentage | ||||||||||||||||||||
| For the years ended | ||||||||||||||||||||
| Company/Index | 2017 | 2018 | 2019 | 2020 | 2021 | |||||||||||||||
| The Hartford Financial Services Group, Inc. | 20.25 | % | (19.24 | %) | 39.71 | % | (16.98 | %) | 44.27 | % | ||||||||||
| S&P 500 Index | 21.83 | % | (4.38 | %) | 31.49 | % | 18.40 | % | 28.71 | % | ||||||||||
| S&P Insurance Composite Index | 16.19 | % | (11.21 | %) | 29.38 | % | (0.44 | %) | 32.12 | % |
|
| Table of Contents |
Part II - Item 5. Market for the Hartford's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
| Cumulative Five-Year Total Return | |||||||||||||||||||||||||||||
| Base | |||||||||||||||||||||||||||||
| Period | For the years ended | ||||||||||||||||||||||||||||
| Company/Index | 2016 | 2017 | 2018 | 2019 | 2020 | 2021 | |||||||||||||||||||||||
| The Hartford Financial Services Group, Inc. | $ | 100 | $ | 120.25 | $ | 97.11 | $ | 135.68 | $ | 112.64 | $ | 162.51 | |||||||||||||||||
| S&P 500 Index | $ | 100 | $ | 121.83 | $ | 116.49 | $ | 153.18 | $ | 181.36 | $ | 233.43 | |||||||||||||||||
| S&P Insurance Composite Index | $ | 100 | $ | 116.19 | $ | 103.17 | $ | 133.48 | $ | 132.89 | $ | 175.57 |

|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| Item 7. |
MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
(Dollar amounts in millions, except for per share data, unless otherwise stated)
The Hartford provides projections and other forward-looking information in the following discussions, which contain many forward-looking statements, particularly relating to the Company’s future financial performance. These forward-looking statements are estimates based on information currently available to the Company, are made pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995 and are subject to the cautionary statements set forth on pages 4 and 5 of this Form 10-K. Actual results are likely to differ, and in the past have differed, materially from those forecast by the Company, depending on the outcome of various factors, including, but not limited to, those set forth in the following discussion and in Part I, Item 1A, Risk Factors, and those identified from time to time in our other filings with the Securities and Exchange Commission. The Hartford undertakes no obligation to publicly update any forward-looking statements, whether as a result of new information, future developments or otherwise.
On December 29, 2021, the Company completed the sale of all of the issued and outstanding equity of Navigators Holdings (Europe) N.V., a Belgium holding company, and its subsidiaries, Bracht, Deckers & Mackelbert N.V. (“BDM”) and Assurances Contintales Contintale Verzekeringen N.V. (“ASCO”), (collectively referred to as "Continental Europe Operations").
For discussion of reclassifications, acquisitions, and dispositions, see Note 1 - Basis of Presentation and Significant Accounting Policies, Note 2 - Business Acquisitions and Note 22 - Business Dispositions of Notes to Consolidated Financial Statements.
The Hartford defines increases or decreases greater than or equal to 200% as “NM” or not meaningful.
For discussion of the earliest of the three years included in the financial statements of the current filing, refer to Part 2, Item 7, Management's Discussion and Analysis of Financial Condition and Results of Operations in The Hartford’s 2020 Form 10-K Annual Report.
Index
Throughout the MD&A, we use certain terms and abbreviations, the more commonly used are summarized in the Acronyms section.
KEY PERFORMANCE MEASURES AND RATIOS
The Company considers the measures and ratios in the following discussion to be key performance indicators for its businesses. Management believes that these ratios and measures are useful in understanding the underlying trends in The Hartford’s businesses. However, these key performance indicators should only be used in conjunction with, and not in lieu of, the results presented in the segment discussions that follow in this MD&A. These ratios and measures may not be comparable to other performance measures used by the Company’s competitors.
Definitions of Non-GAAP and Other Measures and Ratios
Assets Under Management (“AUM”)- Include mutual fund and ETP assets. AUM is a measure used by the Company's Hartford Funds segment because a significant portion of the segments’s revenues and expenses are based upon asset values. These revenues and expenses increase or decrease with a rise or fall in AUM whether caused by changes in the market or through net flows.
Book Value per Diluted Share excluding accumulated other comprehensive income ("AOCI")- This is a non-GAAP per share measure that is calculated by dividing (a) common stockholders' equity, excluding AOCI, after tax, by (b) common shares outstanding
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
and dilutive potential common shares. The Company provides this measure to enable investors to analyze the amount of the Company's net worth that is primarily attributable to the Company's business operations. The Company believes that excluding AOCI from the numerator is useful to investors because it eliminates the effect of items that can fluctuate significantly from period to period, primarily based on changes in interest rates. Book value per diluted share is the most directly comparable U.S. GAAP measure.
Combined Ratio- The sum of the loss and loss adjustment expense ratio, the expense ratio and the policyholder dividend ratio. This ratio is a relative measurement that describes the related cost of losses and expenses for every $100 of earned premiums. A combined ratio below 100 demonstrates underwriting profit; a combined ratio above 100 demonstrates underwriting losses.
Core Earnings- The Hartford uses the non-GAAP measure core earnings as an important measure of the Company’s operating performance. The Hartford believes that core earnings provides investors with a valuable measure of the performance of the Company’s ongoing businesses because it reveals trends in our insurance and financial services businesses that may be obscured by including the net effect of certain items. Therefore, the following items are excluded from core earnings:
-
Certain realized gains and losses - Some realized gains and losses are primarily driven by investment decisions and external economic developments, the nature and timing of which are unrelated to the insurance and underwriting aspects of our business. Accordingly, core earnings excludes the effect of all realized gains and losses that tend to be highly variable from period to period based on capital market conditions. The Hartford believes, however, that some realized gains and losses are integrally related to our insurance operations, so core earnings includes net realized gains and losses such as net periodic settlements on credit derivatives. These net realized gains and losses are directly related to an offsetting item included in the income statement such as net investment income.
-
Restructuring and other costs - Costs incurred as part of a restructuring plan are not a recurring operating expense of the business.
-
Loss on extinguishment of debt - Largely consisting of make-whole payments or tender premiums upon paying debt off before maturity, these losses are not a recurring operating expense of the business.
-
Gains and losses on reinsurance transactions - Gains or losses on reinsurance, such as those entered into upon sale of a business or to reinsure loss reserves, are not a recurring operating expense of the business.
-
Integration and other non-recurring M&A costs - These costs, including transaction costs incurred in connection with an acquired business, are incurred over a short period of time and do not represent an ongoing operating expense of the business.
-
Change in loss reserves upon acquisition of a business - These changes in loss reserves are excluded from core earnings because such changes could obscure the ability to compare results in periods after the acquisition to results of periods prior to the acquisition.
-
Deferred gain resulting from retroactive reinsurance and subsequent changes in the deferred gain - Retroactive reinsurance agreements economically transfer risk to the reinsurers and including the full benefit from retroactive reinsurance in core earnings provides greater insight into the economics of the business.
-
Change in valuation allowance on deferred taxes related to non-core components of before tax income - These changes in valuation allowances are excluded from core earnings because they relate to non-core components of before tax income, such as tax attributes like capital loss carryforwards.
-
Results of discontinued operations - These results are excluded from core earnings for businesses sold or held for sale because such results could obscure the ability to compare period over period results for our ongoing businesses.
In addition to the above components of net income available to common stockholders that are excluded from core earnings, preferred stock dividends declared, which are excluded from net income available to common stockholders, are included in the determination of core earnings. Preferred stock dividends are a cost of financing more akin to interest expense on debt and are expected to be a recurring expense as long as the preferred stock is outstanding.
Net income (loss) and net income (loss) available to common stockholders are the most directly comparable U.S. GAAP measures to core earnings. Core earnings should not be considered as a substitute for net income (loss) or net income (loss) available to common stockholders and does not reflect the overall profitability of the Company's business. Therefore, The Hartford believes that it is useful for investors to evaluate net income (loss), net income (loss) available to common stockholders, and core earnings when reviewing the Company's performance.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Reconciliation of Net Income to Core Earnings
| For the years ended December 31, | |||||||||||
| 2021 | 2020 | 2019 | |||||||||
| Net income | $ | 2,365 | $ | 1,737 | $ | 2,085 | |||||
| Preferred stock dividends | 21 | 21 | 21 | ||||||||
| Net income available to common stockholders | $ | 2,344 | $ | 1,716 | $ | 2,064 | |||||
| Adjustments to reconcile net income available to common stockholders to core earnings: | |||||||||||
| Net realized losses (gains) excluded from core earnings, before tax | (505) | 18 | (389) | ||||||||
| Restructuring and other costs, before tax | 1 | 104 | — | ||||||||
| Loss on extinguishment of debt, before tax | — | — | 90 | ||||||||
| Loss on reinsurance transactions, before tax | — | — | 91 | ||||||||
| Integration and other non-recurring M&A costs, before tax | 58 | 51 | 91 | ||||||||
| Change in loss reserves upon acquisition of a business, before tax | — | — | 97 | ||||||||
| Change in deferred gain on retroactive reinsurance, before tax | 246 | 312 | 16 | ||||||||
| Income tax expense (benefit) [1] | 34 | (115) | 2 | ||||||||
| Core earnings | $ | 2,178 | $ | 2,086 | $ | 2,062 |
[1] Primarily represents the federal income tax expense (benefit) related to before tax items not included in core earnings and includes the effect of changes in net deferred taxes due to changes in enacted tax rates.
Core Earnings Margin- The Hartford uses the non-GAAP measure core earnings margin to evaluate, and believes it is an important measure of, the Group Benefits segment's operating performance. Core earnings margin is calculated by dividing core earnings by revenues, excluding buyouts and realized gains (losses). Net income margin, calculated by dividing net income by revenues, is the most directly comparable U.S. GAAP measure. The Company believes that core earnings margin provides investors with a valuable measure of the performance of Group Benefits because it reveals trends in the business that may be obscured by the effect of buyouts and realized gains (losses) as well as other items excluded in the calculation of core earnings. Core earnings margin should not be considered as a substitute for net income margin and does not reflect the overall profitability of Group Benefits. Therefore, the Company believes it is important for investors to evaluate both core earnings margin and net income margin when reviewing performance. A reconciliation of net income margin to core earnings margin is set forth in the Results of Operations section within MD&A - Group Benefits.
Current Accident Year Catastrophe Ratio- A component of the loss and loss adjustment expense ratio, represents the ratio of catastrophe losses incurred in the current accident year (net of reinsurance) to earned premiums. For U.S. events, a catastrophe is an event that causes $25 or more in industry insured property losses and affects a significant number of property and casualty policyholders and insurers, as defined by the Property Claim Services office of Verisk. For international events, the Company's approach is similar, informed, in part, by how Lloyd's of London defines catastrophes. Lloyd's of London is an insurance market-place operating worldwide ("Lloyd's"). Lloyd's does not underwrite risks. The Company accepts risks as the sole member of Lloyd's Syndicate 1221 ("Lloyd's Syndicate"). The current accident year catastrophe ratio includes the effect of catastrophe losses, but does not include the effect of reinstatement premiums.
Expense Ratio- For the underwriting segments of Commercial Lines and Personal Lines is the ratio of underwriting expenses less fee income, to earned premiums. Underwriting expenses include the amortization of deferred policy acquisition costs ("DAC") and insurance operating costs and expenses, including certain centralized services costs and bad debt expense. DAC include commissions, taxes, licenses and fees and other incremental direct underwriting expenses and are amortized over the policy term.
The expense ratio for Group Benefits is expressed as the ratio of insurance operating costs and other expenses including amortization of intangibles and amortization of DAC, to premiums and other considerations, excluding buyout premiums.
The expense ratio for Commercial Lines, Personal Lines and Group Benefits does not include integration and other transaction costs associated with an acquired business.
Fee Income- Is largely driven from amounts earned as a result of contractually defined percentages of assets under management in our Hartford Funds business. These fees are generally earned on a daily basis. Therefore, the growth in assets under management either through net inflows or favorable market performance will have a favorable impact on fee income. Conversely, either net outflows or unfavorable market performance will reduce fee income.
Gross New Business Premium- Represents the amount of premiums charged, before ceded reinsurance, for policies issued to customers who were not insured with the Company in the previous policy term. Gross new business premium plus gross renewal written premium less ceded reinsurance equals total written premium.
Loss and Loss Adjustment Expense Ratio- A measure of the cost of claims incurred in the calendar year divided by earned premium and includes losses and loss
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
adjustment expenses incurred for both the current and prior accident years. Among other factors, the loss and loss adjustment expense ratio needed for the Company to achieve its targeted return on equity ("ROE") fluctuates from year to year based on changes in the expected investment yield over the claim settlement period, the timing of expected claim settlements and the targeted returns set by management based on the competitive environment.
The loss and loss adjustment expense ratio is affected by claim frequency and claim severity, particularly for shorter-tail property lines of business, where the emergence of claim frequency and severity is credible and likely indicative of ultimate losses. Claim frequency represents the percentage change in the average number of reported claims per unit of exposure in the current accident year compared to that of the previous accident year. Claim severity represents the percentage change in the estimated average cost per claim in the current accident year compared to that of the previous accident year. As one of the factors used to determine pricing, the Company’s practice is to first make an overall assumption about claim frequency and severity for a given line of business and then, as part of the rate-making process, adjust the assumption as appropriate for the particular state, product or coverage.
Loss and Loss Adjustment Expense Ratio before Catastrophes and Prior Accident Year Development- A measure of the cost of non-catastrophe loss and loss adjustment expenses incurred in the current accident year divided by earned premiums. Management believes that the current accident year loss and loss adjustment expense ratio before catastrophes is a performance measure that is useful to investors as it removes the impact of volatile and unpredictable catastrophe losses and prior accident year development.
Loss Ratio, excluding Buyouts- Utilized for the Group Benefits segment and is expressed as a ratio of benefits, losses and loss adjustment expenses, excluding those related to buyout premiums, to premiums and other considerations, excluding buyout premiums. Since Group Benefits occasionally buys a block of claims for a stated premium amount, the Company excludes this buyout from the loss ratio used for evaluating the profitability of the business as buyouts may distort the loss ratio. Buyout premiums represent takeover of open claim liabilities and other non-recurring premium amounts.
Mutual Fund and Exchange-Traded Product Assets- Are owned by the shareholders of those products and not by the Company and, therefore, are not reflected in the Company’s Consolidated Financial Statements except in instances where the Company seeds new investment products.
Mutual fund and ETP assets are a measure used by the Company primarily because a significant portion of the Company’s Hartford Funds segment revenues and expenses are based upon asset values. These revenues and expenses increase or decrease with a rise or fall in AUM whether caused by changes in the market or through net flows.
Net New Business Premium- Represents the amount of premiums charged, after ceded reinsurance, for policies issued to customers who were not insured with the Company in the
previous policy term. Net new business premium plus renewal written premium equals total written premium.
Policy Count Retention- Represents the ratio of the number of renewal policies issued during the current year period divided by the number of policies issued in the previous calendar period before considering policies cancelled subsequent to renewal. Policy count retention is affected by a number of factors, including the percentage of renewal policy quotes accepted and decisions by the Company to non-renew policies because of specific policy underwriting concerns or because of a decision to reduce premium writings in certain classes of business or states. Policy count retention is also affected by advertising and rate actions taken by competitors.
Policy Count Retention, Net of Cancellations- Represents the ratio of the number of renewal policies issued net of cancellations during the current year period divided by the number of policies issued net of cancellations in the previous calendar period.
Policies in Force- Represents the number of policies with coverage in effect as of the end of the period. The number of policies in force is a growth measure used for Personal Lines and standard commercial lines (small commercial and middle market lines within middle & large commercial) within Commercial Lines and is affected by both new business growth and policy count retention.
Policyholder Dividend Ratio- The ratio of policyholder dividends to earned premium.
Prior Accident Year Loss and Loss Adjustment Expense Ratio- Represents the increase (decrease) in the estimated cost of settling catastrophe and non-catastrophe claims incurred in prior accident years as recorded in the current calendar year divided by earned premiums.
Reinstatement Premiums- Represents additional ceded premium paid for the reinstatement of the amount of reinsurance coverage that was reduced as a result of the Company ceding losses to reinsurers.
Renewal Earned Price Increase (Decrease)- Written premiums are earned over the policy term, which is six months for certain Personal Lines automobile business and twelve months for substantially all of the remainder of the Company’s Property and Casualty business. Since the Company earns premiums over the six to twelve month term of the policies, renewal earned price increases (decreases) lag renewal written price increases (decreases) by six to twelve months.
Renewal Written Price Increase (Decrease)- For Commercial Lines, represents the combined effect of rate changes, amount of insurance and individual risk pricing decisions per unit of exposure on commercial lines policies that renewed. For Personal Lines, renewal written price increases represent the total change in premium per policy since the prior year on those policies that renewed and includes the combined effect of rate changes, amount of insurance and other changes in exposure. For Personal Lines, other changes in exposure include, but are not limited to, the effect of changes in number of drivers, vehicles and incidents, as well as changes in customer policy elections, such as deductibles and limits. The rate
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
component represents the change in rate filed with and approved by state regulators during the period and the amount of insurance represents the change in the value of the rating base, such as model year/vehicle symbol for automobiles, building replacement costs for property and wage inflation for workers’ compensation. A number of factors affect renewal written price increases (decreases) including expected loss costs as projected by the Company’s pricing actuaries, rate filings approved by state regulators, risk selection decisions made by the Company’s underwriters and marketplace competition. Renewal written price changes reflect the property and casualty insurance market cycle. Prices tend to increase for a particular line of business when insurance carriers have incurred significant losses in that line of business in the recent past or the industry as a whole commits less of its capital to writing exposures in that line of business. Prices tend to decrease when recent loss experience has been favorable or when competition among insurance carriers increases. Renewal written price statistics are subject to change from period to period, based on a number of factors, including changes in actuarial estimates and the effect of subsequent cancellations and non-renewals, and modifications made to better reflect ultimate pricing achieved.
**Return on Assets ("ROA"), Core Earnings-**The Company uses this non-GAAP financial measure to evaluate, and believes is an important measure of, the Hartford Funds segment’s operating performance. ROA, core earnings is calculated by dividing annualized core earnings by a daily average AUM. ROA is the most directly comparable U.S. GAAP measure. The Company believes that ROA, core earnings, provides investors with a valuable measure of the performance of the Hartford Funds segment because it reveals trends in our business that may be obscured by the effect of items excluded in the calculation of core earnings. ROA, core earnings, should not be considered as a substitute for ROA and does not reflect the overall profitability of our Hartford Funds business. Therefore, the Company believes it is important for investors to evaluate both ROA, and ROA, core earnings when reviewing the Hartford Funds segment performance. A reconciliation of ROA to ROA, core earnings is set forth in the Results of Operations section within MD&A - Hartford Funds.
**Underlying Combined Ratio-**This non-GAAP financial measure of underwriting results represents the combined ratio before catastrophes, prior accident year development and current accident year change in loss reserves upon acquisition of a business. Combined ratio is the most directly comparable GAAP measure. The underlying combined ratio represents the combined ratio for the current accident year, excluding the impact of current accident year catastrophes and current accident year change in loss reserves upon acquisition of a business. The Company believes this ratio is an important measure of the trend in profitability since it removes the impact of volatile and unpredictable catastrophe losses and prior accident year loss and loss adjustment expense reserve development. The changes to loss reserves upon acquisition of a business are excluded from underlying combined ratio because such changes could obscure the ability to compare results in periods after the acquisition to results of periods prior to the acquisition as such trends are valuable to our investors' ability to assess the Company's financial performance. A reconciliation of combined ratio to underlying combined ratio is set forth in the Results of Operations section within MD&A - Commercial Lines and Personal Lines.
Underwriting Gain (Loss)- The Hartford's management evaluates profitability of the Commercial and Personal Lines segments primarily on the basis of underwriting gain or loss. Underwriting gain (loss) is a before tax non-GAAP measure that represents earned premiums less incurred losses, loss adjustment expenses and underwriting expenses. Net income (loss) is the most directly comparable GAAP measure. Underwriting gain (loss) is influenced significantly by earned premium growth and the adequacy of The Hartford's pricing. Underwriting profitability over time is also greatly influenced by The Hartford's underwriting discipline, as management strives to manage exposure to loss through favorable risk selection and diversification, effective management of claims, use of reinsurance and its ability to manage its expenses. The Hartford believes that the measure underwriting gain (loss) provides investors with a valuable measure of profitability, before tax, derived from underwriting activities, which are managed separately from the Company's investing activities.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Reconciliation of Net Income to Underwriting Gain (Loss)
| For the years ended December 31, | |||||||||||||||||
| 2021 | 2020 | 2019 | |||||||||||||||
| Commercial Lines | |||||||||||||||||
| Net income | $ | 1,757 | $ | 856 | $ | 1,192 | |||||||||||
| Adjustments to reconcile net income to underwriting gain (loss): | |||||||||||||||||
| Net servicing income | (13) | (4) | (2) | ||||||||||||||
| Net investment income | (1,502) | (1,160) | (1,129) | ||||||||||||||
| Net realized losses (gains) | (260) | 60 | (271) | ||||||||||||||
| Other expense | 18 | 35 | 38 | ||||||||||||||
| Loss on reinsurance transaction | — | — | 91 | ||||||||||||||
| Income tax expense | 402 | 176 | 270 | ||||||||||||||
| Underwriting gain (loss) | $ | 402 | $ | (37) | $ | 189 | |||||||||||
| Personal Lines | |||||||||||||||||
| Net income (loss) | $ | 385 | $ | 718 | $ | 318 | |||||||||||
| Adjustments to reconcile net income to underwriting gain (loss): | |||||||||||||||||
| Net servicing income | (19) | (14) | (13) | ||||||||||||||
| Net investment income | (157) | (157) | (179) | ||||||||||||||
| Net realized losses (gains) | (29) | 5 | (43) | ||||||||||||||
| Other expense | — | 1 | 1 | ||||||||||||||
| Income tax expense | 95 | 184 | 76 | ||||||||||||||
| Underwriting gain | $ | 275 | $ | 737 | $ | 160 | |||||||||||
| P&C Other Ops | |||||||||||||||||
| Net Income | $ | (95) | $ | (168) | $ | 61 | |||||||||||
| Adjustments to reconcile net income to underwriting gain (loss): | |||||||||||||||||
| Net investment income | (75) | (55) | (84) | ||||||||||||||
| Net realized losses (gains) | (13) | 1 | (20) | ||||||||||||||
| Other expense (income) | 1 | (1) | — | ||||||||||||||
| Income tax expense (benefit) | (28) | (46) | 12 | ||||||||||||||
| Underwriting loss | $ | (210) | $ | (269) | $ | (31) |
Written and Earned Premiums- Written premium represents the amount of premiums charged for policies issued, net of reinsurance, during a fiscal period. Premiums are considered earned and are included in the financial results on a pro rata basis over the policy period. Management believes that written premium is a performance measure that is useful to investors as it reflects current trends in the Company’s sale of property and casualty insurance products. Written and earned premium are recorded net of ceded reinsurance premium.
Traditional life and disability insurance type products, such as those sold by Group Benefits, collect premiums from policyholders in exchange for financial protection for the policyholder from a specified insurable loss, such as death or disability. These premiums, together with net investment income earned, are used to pay the contractual obligations under these insurance contracts.
Two major factors, new sales and persistency, impact premium growth. Sales can increase or decrease in a given year based on a number of factors including, but not limited to, customer demand for the Company’s product offerings, pricing competition, distribution channels and the Company’s reputation
and ratings. Persistency refers to the percentage of premium remaining in-force from year-to-year.
THE HARTFORD'S OPERATIONS
The Hartford conducts business principally in five reporting segments including Commercial Lines, Personal Lines, Property & Casualty Other Operations, Group Benefits and Hartford Funds, as well as a Corporate category. The Company includes in the Corporate category reserves for run-off structured settlement and terminal funding agreement liabilities, restructuring costs, capital raising activities (including equity financing, debt financing and related interest expense), transaction expenses incurred in connection with an acquisition, certain M&A costs, purchase accounting adjustments related to goodwill and other expenses not allocated to the reporting segments. Corporate also includes investment management fees and expenses related to managing third party business, including management of a portion of the invested assets of Talcott Resolution Life, Inc. and its subsidiaries as well as
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
certain affiliates. In addition, up until June 30, 2021, Corporate included a 9.7% ownership interest in Hopmeadow Holdings LP, the legal entity that acquired Talcott Resolution in May 2018 (Hopmeadow Holdings, LP, Talcott Resolution Life Inc., and its subsidiaries are collectively referred to as "Talcott Resolution"). The sale of Talcott Resolution to a new investor was completed on June 30, 2021. The Company received a total of $217 in connection with the sale of its 9.7% ownership interest, resulting in a realized gain of $46 before tax in 2021.
The Company derives its revenues principally from: (a) premiums earned for insurance coverage provided to insureds; (b) management fees on mutual fund and ETP assets; (c) net investment income; (d) fees earned for services provided to third parties; and (e) net realized gains and losses. Premiums charged for insurance coverage are earned principally on a pro rata basis over the terms of the related policies in-force.
The profitability of the Company's property and casualty insurance businesses over time is greatly influenced by the Company’s underwriting discipline, which seeks to manage exposure to loss through favorable risk selection and diversification, its management of claims, its use of reinsurance, the size of its in force block, actual mortality and morbidity experience, and its ability to manage its expense ratio which it accomplishes through economies of scale and its management of acquisition costs and other underwriting expenses. Pricing adequacy depends on a number of factors, including the ability to obtain regulatory approval for rate changes, proper evaluation of underwriting risks, the ability to project future loss cost frequency and severity based on historical loss experience adjusted for known trends, the Company’s response to rate actions taken by competitors, its expense levels and expectations about regulatory and legal developments. The Company seeks to price its insurance policies such that insurance premiums and future net investment income earned on premiums received will cover underwriting expenses and the ultimate cost of paying claims reported on the policies and provide for a profit margin. For many of its insurance products, the Company is required to obtain approval for its premium rates from state insurance departments and the Lloyd's Syndicate's ability to write business is subject to Lloyd's approval for its premium capacity each year. Most of Personal Lines written premium is associated with our exclusive licensing agreement with AARP, which is effective through December 31, 2032. This agreement provides an important competitive advantage given the size of the 50 plus population and the strength of the AARP brand.
Similar to property and casualty, profitability of the group benefits business depends, in large part, on the ability to evaluate and price risks appropriately and make reliable estimates of mortality, morbidity, disability and longevity. To manage the pricing risk, Group Benefits generally offers term insurance policies, allowing for the adjustment of rates or policy terms in order to minimize the adverse effect of market trends, loss costs, declining interest rates and other factors. However, as policies are typically sold with rate guarantees of up to three years, pricing for the Company’s products could prove to be inadequate if loss and expense trends emerge adversely during the rate guarantee period or if investment returns are lower than expected at the time the products were sold. For some of its products, the Company is required to obtain approval for its premium rates from state insurance departments. New and
renewal business for group benefits business, particularly for long-term disability, are priced using an assumption about expected investment yields over time. While the Company employs asset-liability duration matching strategies to mitigate risk and may use interest-rate sensitive derivatives to hedge its exposure in the Group Benefits investment portfolio, cash flow patterns related to the payment of benefits and claims are uncertain and actual investment yields could differ significantly from expected investment yields, affecting profitability of the business. In addition to appropriately evaluating and pricing risks, the profitability of the Group Benefits business depends on other factors, including the Company’s response to pricing decisions and other actions taken by competitors, its ability to offer voluntary products and self-service capabilities, the persistency of its sold business and its ability to manage its expenses which it seeks to achieve through economies of scale and operating efficiencies.
The financial results of the Company’s mutual fund and ETP businesses depend largely on the amount of assets under management and the level of fees charged based, in part, on asset share class and product type. Changes in assets under management are driven by the two main factors of net flows and the market return of the funds, which are heavily influenced by the return realized in the equity and bond markets. Net flows are comprised of new sales less redemptions by mutual fund and ETP shareholders. Financial results are highly correlated to the growth in assets under management since these products generally earn fee income on a daily basis.
The investment return, or yield, on invested assets is an important element of the Company’s earnings since insurance products are priced with the assumption that premiums received can be invested for a period of time before benefits, losses and loss adjustment expenses are paid. Due to the need to maintain sufficient liquidity to satisfy claim obligations, the majority of the Company’s invested assets have been held in available-for-sale securities, including, among other asset classes, corporate bonds, municipal bonds, government debt, short-term debt, mortgage-backed securities, asset-backed securities and collateralized loan obligations. The primary investment objective for the Company is to maximize economic value, consistent with acceptable risk parameters, including the management of credit risk and interest rate sensitivity of invested assets, while generating sufficient net of tax income to meet policyholder and corporate obligations. Investment strategies are developed based on a variety of factors including business needs, regulatory requirements and tax considerations.
Impact of COVID-19 on our financial condition, results of operations and liquidity
Impact to written and earned premiums
Despite the rollout of vaccines and states largely lifting restrictions allowing business to re-open, the COVID-19 pandemic continues to pose a threat to the economic recovery of the U.S. and other countries in which we operate. As one of the largest providers of small business insurance in the U.S., we were negatively affected by economic effects of the pandemic on small businesses beginning in March of 2020. An
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
improvement in economic conditions in 2021 has contributed to an increase of 11% in our small commercial written premiums. Our middle & large commercial business was also negatively affected by COVID-19 and written premium has rebounded with an increase of 12% in 2021. Overall, Commercial Lines written premium increased $1,072, or 12%, in 2021 with growth in workers' compensation, small commercial package business, general liability, U.S. wholesale, U.S. financial lines and global reinsurance.
Personal Lines written premium declined 1% in 2021 due to the effect of non-renewed premium exceeding new business, partially offset by the effect of premium credits given in the second quarter of 2020.
In Group Benefits, fully insured ongoing premium increased 4% in 2021, primarily due to higher in-force employer group
disability premiums and higher supplemental health product premiums.
Impact to direct benefits, losses and loss adjustment expenses from COVID-19 claims
Total pandemic-related losses were higher in 2021 compared to 2020 driven by higher excess mortality in our group life business and an increase in pandemic-related short-term disability claims, partially offset by a reduction of P&C COVID-19 incurred losses.
| For the year ended December 31, | |||||||||||||||||
| 2021 | 2020 | ||||||||||||||||
| Excess mortality claims on group life | $ | 583 | $ | 239 | |||||||||||||
| COVID-19 short-term disability claims [1] | 31 | (9) | |||||||||||||||
| Workers' compensation COVID-19 claims | 20 | 66 | |||||||||||||||
| Global specialty financial lines and other | 11 | 71 | |||||||||||||||
| Commercial property | — | 141 | |||||||||||||||
| Total direct COVID-19 and excess mortality claims | $ | 645 | $ | 508 |
[1]The year ended December 31, 2020 included both short-term disability and New York paid family leave claims related to COVID-19 and lower incurred losses due to fewer elective procedures during the early stages of the pandemic more than offset direct COVID-19 incurred losses.
Excess mortality in the group life business includes both claims where COVID-19 is specifically listed as the cause of death and indirect impacts of the pandemic such as causes of death due to patients deferring regular treatments of chronic conditions. The incidence of excess mortality claims is subject to significant uncertainty as it is dependent on a number of factors difficult to predict including, among others, the ultimate vaccination rate of the population, the potential spread of new COVID-19 variants, the effectiveness of the vaccines against new variants, the effectiveness of other treatments to prevent serious illness and death, the percentage of those infected who are of working age and the strain on the health care system preventing timely treatment of chronic illnesses.
Within P&C, direct COVID-19 incurred losses in 2021 were predominantly on workers' compensation claims incurred in the first quarter. We incur COVID-19 workers’ compensation losses when it is determined that workers were exposed to COVID-19 out of and in the course of their employment and in other cases where states have passed laws providing for the presumption of coverage for certain industry classes, including health care and other essential workers.
Apart from COVID-19 workers' compensation claims, net of favorable frequency, and incurred losses within financial lines, P&C COVID-19 incurred losses in 2020 primarily included $141 for property claims. There were no COVID-19 P&C property losses incurred in 2021. Nearly all of our property insurance policies require direct physical loss or damage to property and contain standard exclusions that we believe preclude coverage for COVID-19 related claims, and the vast majority of such policies contain exclusions for virus-related losses.
Other impacts from COVID-19
In Personal Lines automobile, miles driven and average claim severity increased in 2021, which has increased automobile loss costs. In addition, as the effects of favorable claim frequency
from lower miles driven during the pandemic have been factored into rates, we have experienced lower earned pricing increases resulting in a higher automobile loss ratio in 2021 than in 2020. Refer to Personal Lines Results of Operations for discussion of pricing and loss cost trends for the year ended December 31, 2021.
As we emerge from the pandemic, inflationary pressures in the economy have resulted in increased claim severity in 2021 in automobile and property lines of business in both Commercial Lines and Personal Lines. As expectations of inflationary pressures have increased, interest rates rose in 2021 and higher interest rates reduce the fair value of our investments in fixed maturity securities, available for sale ("AFS").
Aided by some improvement in the economy and the effect of the government’s economic stimulus payments to our customers, in 2021, we recorded a decrease of $47 in the allowance for credit losses ("ACL") on premiums receivable, reflecting a lower expectation of credit losses, though there remains an elevated risk of uncollectible premiums receivable relative to historical trends if economic conditions do not improve further.
As we emerge from the pandemic, we expect travel costs and certain employee benefits costs will increase relative to the lower level of those costs we have incurred in 2020 and 2021.
For information about resources the Company has to manage capital and liquidity, refer to the Capital Resources & Liquidity section of MD&A.
For additional information about the potential economic impacts to the Company of the COVID-19 pandemic, see the risk factor "The pandemic caused by the spread of COVID-19 has disrupted our operations and may have a material adverse
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
impact on our business results, financial condition, results of operations and/or liquidity" in Item 1A of Part I.
Operational transformation and cost reduction plan
In recognition of the need to become more cost efficient and competitive along with enhancing the experience we provide to agents and customers, on July 30, 2020, the Company announced an operational transformation and cost reduction plan it refers to as Hartford Next.Through reduction of its headcount, IT investments to further enhance our capabilities, and other activities, relative to 2019, the Company expects to achieve a reduction in annual insurance operating costs and other expenses of approximately $540 by 2022 and $625 by 2023.
To achieve those expected savings, we expect to incur approximately $401 over the course of the program, with $217
expensed cumulatively through December 31, 2021, and expected expenses of $89 in 2022, $38 in 2023 and $57 after 2023, with the expenses after 2023 consisting mostly of amortization of internal use software and capitalized real estate costs. Included in the estimated costs of $401, we expect to incur restructuring costs of approximately $130, including $48 of employee severance, and approximately $82 of other costs, including consulting expenses, lease termination expenses and the cost to retire certain IT applications. Restructuring costs are reported as a charge to net income but not in core earnings.
The following table presents Hartford Next program costs incurred, including restructuring costs, and expense savings relative to 2019 realized in 2021 and expected annual costs and expense savings relative to 2019 for the full year in 2022 and 2023:
| Hartford Next Costs and Expense Savings | |||||||||||||||||
| 2020 | 2021 | Estimate for 2022 | Estimate for 2023 | ||||||||||||||
| Employee severance | $ | 73 | $ | (25) | $ | — | $ | — | |||||||||
| IT costs to retire applications | 2 | 9 | 10 | — | |||||||||||||
| Professional fees and other expenses | 29 | 17 | 15 | — | |||||||||||||
| Estimated restructuring costs | 104 | 1 | 25 | — | |||||||||||||
| Non-capitalized IT costs | 30 | 46 | 45 | 22 | |||||||||||||
| Other costs | 19 | 17 | 14 | 6 | |||||||||||||
| Amortization of capitalized IT development costs [1] | — | — | 4 | 9 | |||||||||||||
| Amortization of capitalized real estate [2] | — | — | 1 | 1 | |||||||||||||
| Estimated costs within core earnings | 49 | 63 | 64 | 38 | |||||||||||||
| Total Hartford Next program costs | 153 | 64 | 89 | 38 | |||||||||||||
| Cumulative savings relative to 2019 beginning July 1, 2020 | (106) | (423) | (540) | (625) | |||||||||||||
| Net expense (savings) before tax | $ | 47 | $ | (359) | $ | (451) | $ | (587) | |||||||||
| Net expense (savings) before tax: | |||||||||||||||||
| To be accounted for within core earnings | $ | (57) | $ | (360) | $ | (476) | $ | (587) | |||||||||
| Restructuring costs recognized outside of core earnings | 104 | 1 | 25 | — | |||||||||||||
| Net expense (savings) before tax | $ | 47 | $ | (359) | $ | (451) | $ | (587) |
[1]Does not include approximately $34 of IT asset amortization after 2023.
[2]Does not include approximately $19 of real estate amortization after 2023.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
2021 FINANCIAL HIGHLIGHTS
| Net Income Available to Common Stockholders | Net Income Available to Common Stockholders per Diluted Share | Book Value per Diluted Share |


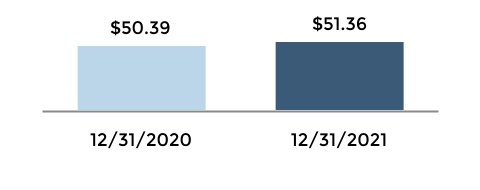
| Ý | Increased $628 or 37% | Ý | Increased $1.86 or 39% | Ý | Increased $0.97 or 1.9% | |||||||||||||||||||||||||||
| + | A change from net realized losses in the 2020 period to gains in the 2021 period | + | Increase in net income available to common stockholders | + | Net income in excess of common stockholder dividends and share repurchases | |||||||||||||||||||||||||||
| + | Increase in net investment income | + | Share repurchases | + | Decrease in dilutive shares from the prior year | |||||||||||||||||||||||||||
| + | Decrease in P&C COVID-19 incurred losses | - | Increase in dilutive shares under stock-based compensation largely due to an increase in the quarterly average stock price | |||||||||||||||||||||||||||||
| + | Higher earned premiums in Commercial Lines and a lower P&C underlying loss ratio before COVID-19 | - | Decrease in common stockholders' equity largely due to decrease in AOCI, driven by a decline in net unrealized gains on available for sale securities | |||||||||||||||||||||||||||||
| + | Lower restructuring costs | |||||||||||||||||||||||||||||||
| + | Increase in earnings from Hartford Funds | |||||||||||||||||||||||||||||||
| - | Higher excess mortality losses in group life and COVID-19 losses in group disability | |||||||||||||||||||||||||||||||
| - | A change from net favorable to net unfavorable P&C prior accident year reserve development | |||||||||||||||||||||||||||||||
| - | Higher current accident year catastrophes | |||||||||||||||||||||||||||||||
| - | An increase in personal automobile claim frequency and severity | |||||||||||||||||||||||||||||||
| - | Lower income from the former Talcott Resolution investment |
| Investment Yield, After Tax | Property & Casualty Combined Ratio | Group Benefits Net Income Margin |


| Ý | Increased 50 bps | Þ | Improved 0.1 points | Þ | Decreased 2.5 points | |||||||||||||||||||||||||||
| + | Greater returns on limited partnerships and other alternative investments | + | Decrease in COVID-19 incurred losses | - | Higher excess mortality in group life | |||||||||||||||||||||||||||
| - | Lower reinvestment rates and lower yield on variable rate securities | + | Lower current accident year loss ratio before COVID-19 in global specialty and workers' compensation | - | A higher group disability loss ratio primarily due to higher short-term and long-term disability claim incidence | |||||||||||||||||||||||||||
| - | A change to unfavorable prior accident year reserve development | - | A higher expense ratio | |||||||||||||||||||||||||||||
| + | Higher net investment income | |||||||||||||||||||||||||||||||
| - | Higher current accident year catastrophes | + | Greater net realized gains | |||||||||||||||||||||||||||||
| - | Higher personal automobile claim frequency and severity | |||||||||||||||||||||||||||||||
| - | An increase in underwriting expenses | |||||||||||||||||||||||||||||||
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
CONSOLIDATED RESULTS OF OPERATIONS
The Consolidated Results of Operations should be read in conjunction with the Company's Consolidated Financial Statements and the related Notes as well as with the segment operating results sections of the MD&A.
Consolidated Results of Operations
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | ||||||||||||||||||||||||||||
| Earned premiums | $ | 17,999 | $ | 17,288 | $ | 16,923 | 4 | % | 2 | % | ||||||||||||||||||||||
| Fee income | 1,488 | 1,277 | 1,301 | 17 | % | (2 | %) | |||||||||||||||||||||||||
| Net investment income | 2,313 | 1,846 | 1,951 | 25 | % | (5 | %) | |||||||||||||||||||||||||
| Net realized gains (losses) | 509 | (14) | 395 | NM | (104 | %) | ||||||||||||||||||||||||||
| Other revenues | 81 | 126 | 170 | (36 | %) | (26 | %) | |||||||||||||||||||||||||
| Total revenues | 22,390 | 20,523 | 20,740 | 9 | % | (1 | %) | |||||||||||||||||||||||||
| Benefits, losses and loss adjustment expenses | 12,729 | 11,805 | 11,472 | 8 | % | 3 | % | |||||||||||||||||||||||||
| Amortization of deferred policy acquisition costs | 1,680 | 1,706 | 1,622 | (2 | %) | 5 | % | |||||||||||||||||||||||||
| Insurance operating costs and other expenses | 4,779 | 4,480 | 4,580 | 7 | % | (2 | %) | |||||||||||||||||||||||||
| Loss on extinguishment of debt | — | — | 90 | — | % | (100 | %) | |||||||||||||||||||||||||
| Loss on reinsurance transactions | — | — | 91 | — | % | (100 | %) | |||||||||||||||||||||||||
| Interest expense | 234 | 236 | 259 | (1 | %) | (9 | %) | |||||||||||||||||||||||||
| Amortization of other intangible assets | 71 | 72 | 66 | (1 | %) | 9 | % | |||||||||||||||||||||||||
| Restructuring and other costs | 1 | 104 | — | (99 | %) | NM | ||||||||||||||||||||||||||
| Total benefits, losses and expenses | 19,494 | 18,403 | 18,180 | 6 | % | 1 | % | |||||||||||||||||||||||||
| Income before income taxes | 2,896 | 2,120 | 2,560 | 37 | % | (17 | %) | |||||||||||||||||||||||||
| Income tax expense | 531 | 383 | 475 | 39 | % | (19 | %) | |||||||||||||||||||||||||
| Net income | 2,365 | 1,737 | 2,085 | 36 | % | (17 | %) | |||||||||||||||||||||||||
| Preferred stock dividends | 21 | 21 | 21 | — | % | — | % | |||||||||||||||||||||||||
| Net income available to common stockholders | $ | 2,344 | $ | 1,716 | $ | 2,064 | 37 | % | (17 | %) |
Year ended December 31, 2021 compared to year ended December 31, 2020
Net income available to common stockholders increased by $628 primarily driven by:
-
A $523 before tax change from net realized losses in 2020 to net realized gains in 2021, primarily driven by changes in valuation and sales of equity securities from losses in the 2020 period to gains in the 2021 period;
-
An increase in net investment income of $467 before tax driven by higher returns on limited partnerships and other alternative investments;
-
A $103 before tax decrease in restructuring costs related to the Hartford Next operational transformation and cost reduction plan;
-
An increase in earnings from Hartford Funds; and
-
An increase in P&C underwriting results of $36 before tax, with a reduction in COVID-19 incurred losses, a lower Commercial Lines underlying loss and loss adjustment expense ratio before COVID-19 and the effect of earned premium growth largely offset by a change to net unfavorable prior accident year reserve development, higher personal automobile loss costs and higher underwriting expenses.
These increases were partially offset by:
-
A $384 before tax increase in excess mortality claims and COVID-19 related impacts to short-term-disability losses; and
-
Lower income from the Talcott Resolution investment, which was divested on June 30, 2021.
For a discussion of the Company's operating results by segment, see MD&A - Segment Operating Summaries. In addition, for further discussion of impacts resulting from the COVID-19 pandemic, refer to the Impact of COVID-19 on our financial condition, results of operations and liquidity section of this MD&A.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
REVENUE
Earned Premiums

*[1]*For the years ended 2020 and 2019, the total includes $9, and $10 respectively, recorded in Corporate other revenue.
Earned premiums increased primarily due to:
-
An increase in P&C reflecting a 7% increase in Commercial Lines and a 2% decrease in Personal Lines. Contributing to the increase in Commercial Lines was the effect of higher audit and endorsement premiums as the result of higher insured exposures given the economic recovery in 2021. For Personal Lines, the effect of non-renewals outpacing new business was partially offset by the effect of $81 in COVID-related premium credits in the 2020 period; and
-
An increase in Group Benefits earned premium of 3% year over year due to an increase in group disability and higher supplemental health product premiums, partially offset by the effect of buyout premium in the 2020 period.
Fee income increased, largely driven by Hartford Funds as a result of higher daily average assets under management due to an increase in equity market levels and net inflows.
Other revenues decreased by $45, primarily driven by lower income of $53 before tax from the Talcott Resolution investment, which was divested on June 30, 2021.
Net investment income increased primarily due to:
-
Greater income from limited partnerships and other alternative investments primarily driven by higher valuations and cash distributions within private equity funds and sales of underlying investments within real estate funds;
-
A higher level of invested assets;
Net Investment Income

-
Greater income from non-routine income items, including yield adjustments on prepayable securities; and
-
Higher yield from equity investments.
These increases were partially offset by:
- A lower yield on fixed maturity investments resulting from reinvesting at lower rates and a lower yield on floating rate investments.
Net realized gains (losses) changed from net losses in the 2020 period to net gains in the 2021 period, primarily driven by:
-
Gains on equity securities in the 2021 period driven by appreciation in value compared to losses on equity securities in the 2020 period, partially offset by net realized gains in the 2020 period upon termination of derivatives used to hedge against a decline in equity market levels;
-
A net reduction in ACL on mortgage loans and fixed maturities in the 2021 period due to an improved economic outlook, compared to increases in the ACL on mortgage loans and fixed maturities in the 2020 period;
-
A $46 before tax net realized gain in 2021 resulting from sale of the Company's 9.7% previously owned interest in Talcott Resolution;
-
A lower level of losses in 2021 than in 2020 related to the sale of the Continental Europe Operations; and
-
Higher net realized gains on sales of fixed maturity securities.
For further discussion of investment results, see MD&A - Investment Results, Net Realized Gains and MD&A - Investment Results, Net Investment Income.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
BENEFITS, LOSSES AND EXPENSES
P&C Losses and LAE Incurred

Benefits, losses and loss adjustment expenses increased due to:
-
An increase in incurred losses for Property & Casualty of $457 which was driven by:
-
An unfavorable change of $335 in P&C net prior accident year reserve development. Prior accident year reserve development in the 2021 period was a net unfavorable $199 before tax, driven by reserve increases for sexual molestation and sexual abuse claims, primarily to reflect claims made against the Boy Scouts of America ("BSA"), partially offset by reserve decreases in workers' compensation, catastrophes, package business, personal automobile, commercial property, and bond. Prior accident year development in the 2021 period also included adverse reserve development ceded to NICO under an adverse development cover ("ADC") of $155 before tax for A&E reserves and $91 before tax for Navigators reserves related to 2018 and prior accident years, both of which the Company recognized a deferred gain under retroactive reinsurance accounting. Prior accident year reserve development in 2020 was a favorable $136 before tax, driven by $529 of reserve reductions related to catastrophes, including decreases in estimated losses arising from wind and hail events in 2017, 2018 and 2019 and from the 2017 and 2018 California wildfires, including a $289 before tax subrogation benefit from PG&E Corporation and Pacific Gas and Electric Company (together, "PG&E"). Reserve development in 2020 also included a $254 before tax reserve increase for sexual molestation and abuse claims, a $208 before tax increase in A&E reserves and a $102 before tax of adverse development for Navigators related to 2018 and prior accident years. While $220 of A&E and $102 of Navigators’ reserve development in 2020 has been economically ceded to
Group Benefits Losses and LAE Incurred

NICO, the Company recognized a $312 deferred gain under retroactive reinsurance accounting with $10 of the $220 ceded A&E losses recognized as a benefit to income in 2020. For further discussion, see Note 12 - Reserve for Unpaid Losses and Loss Adjustment Expenses of Notes to Consolidated Financial Statements;
-
An increase in current accident year catastrophe losses of $58, before tax. Catastrophe losses in the 2021 period were principally from hurricane Ida and February winter storms, as well as from tornado, wind and hail events in Texas, the Midwest and Southeast. Catastrophe losses in 2020 were primarily from civil unrest, a number of hurricanes and tropical storms, Pacific Coast wildfires and Northeast windstorms as well as tornado, wind and hail events in the South, Midwest and Central Plains; and
-
An increase in P&C current accident year ("CAY") loss and loss adjustment expenses before catastrophes primarily due to the effect of higher earned premiums in commercial lines, higher personal automobile claim frequency and severity, and higher non-catastrophe property losses partially offset by a $247 before tax decrease in COVID-19 incurred losses and lower current accident year loss ratios before COVID-19 in global specialty, workers’ compensation and general liability.
-
An increase in Group Benefits of $475 primarily driven by a $344 before tax increase in excess mortality claims in group life, the effect of an increase in earned premiums and higher short-term and long-term disability claim incidence especially compared to the favorable incidence levels experienced during the early stages of the pandemic. The increased claim incidence was partially offset by a higher
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
favorable New York Paid Family Leave adjustment recognized in the 2021 period.
For further discussion of impacts resulting from the COVID-19 pandemic, refer to the impact of COVID-19 on our financial condition, results of operations and liquidity section of this MD&A.
Amortization of deferred policy acquisition costs decreased from the prior year period driven, in part, by a decrease in Personal Lines due to lower earned premiums.
Insurance operating costs and other expenses increased due to:
-
Higher variable costs of the Hartford Funds business due to higher daily average assets under management;
-
Higher variable incentive compensation costs;
-
An increase in supplemental and contingent commissions;
-
Increased costs in Group Benefits to handle elevated claim levels resulting from the pandemic, higher technology costs and increased AARP direct marketing costs in Personal Lines; and
-
Legal and consulting costs associated with the unsolicited proposals from Chubb Limited (“Chubb”) to acquire the Company.
These increases were partially offset by:
-
Lower staffing and other costs driven by the Company’s Hartford Next operational transformation and cost reduction plan; and
-
A decrease in the ACL on uncollectible premiums receivable in Property & Casualty and Group Benefits in the 2021 period compared to an increase in the 2020 period due to the economic impacts of COVID-19.
Restructuring and other costs decreased as the prior year period included severance costs related to the Company's Hartford Next operational transformation and cost reduction plan. For further discussion of impacts resulting from the Hartford Next initiative, see MD&A - The Hartford's Operations, The Hartford's Operations, Operational Transformation and Cost Reduction Plan and Note 23 - Restructuring and Other Costs of Notes to Consolidated Financial Statements.
Income tax expense increased primarily due to an increase in income before tax.
For further discussion of income taxes, see Note 17 - Income Taxes of Notes to Consolidated Financial Statements.
INVESTMENT RESULTS
| Composition of Invested Assets | |||||||||||||||||
| December 31, 2021 | December 31, 2020 | ||||||||||||||||
| Amount | Percent | Amount | Percent | ||||||||||||||
| Fixed maturities, available-for-sale ("AFS"), at fair value | $ | 42,847 | 74.2 | % | $ | 45,035 | 79.7 | % | |||||||||
| Equity securities, at fair value | 2,094 | 3.6 | % | 1,438 | 2.5 | % | |||||||||||
| Mortgage loans (net of ACL of $29 and $38) | 5,383 | 9.3 | % | 4,493 | 7.9 | % | |||||||||||
| Limited partnerships and other alternative investments | 3,353 | 5.8 | % | 2,082 | 3.7 | % | |||||||||||
| Other investments [1] | 375 | 0.7 | % | 201 | 0.4 | % | |||||||||||
| Short-term investments | 3,697 | 6.4 | % | 3,283 | 5.8 | % | |||||||||||
| Total investments | $ | 57,749 | 100.0 | % | $ | 56,532 | 100.0 | % |
[1] Primarily consists of fixed maturities, at fair value using the fair value option ("FVO"), equity fund investments, overseas deposits, consolidated investment funds and derivative instruments which are carried at fair value.
December 31, 2021 compared to December 31, 2020
Total investments increased primarily due to an increase in limited partnerships and other alternative investments, mortgage loans, and equity securities, partially offset by a decrease in fixed maturities, AFS.
Limited partnerships and other alternative investments increased primarily driven by increased valuations and additional investments in real estate joint ventures.
Mortgage loans increased largely due to funding of industrial, multifamily, and retail commercial whole loans.
Equity securities increased due to net purchases and appreciation in value due to higher equity market levels.
Fixed maturities, AFS decreased primarily due to a decrease in valuations due to higher interest rates, partially offset by tighter credit spreads. The decline was also due to the reinvestment into other asset classes.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| Net Investment Income | ||||||||||||||||||||||||||
| For the years ended December 31, | ||||||||||||||||||||||||||
| 2021 | 2020 | 2019 | ||||||||||||||||||||||||
| (Before tax) | Amount | Yield [1] | Amount | Yield [1] | Amount | Yield [1] | ||||||||||||||||||||
| Fixed maturities [2] | $ | 1,349 | 3.1 | % | $ | 1,442 | 3.4 | % | $ | 1,559 | 3.8 | % | ||||||||||||||
| Equity securities | 73 | 4.9 | % | 39 | 3.7 | % | 46 | 3.4 | % | |||||||||||||||||
| Mortgage loans | 181 | 3.7 | % | 172 | 3.9 | % | 165 | 4.4 | % | |||||||||||||||||
| Limited partnerships and other alternative investments | 732 | 31.8 | % | 222 | 12.3 | % | 232 | 14.4 | % | |||||||||||||||||
| Other [3] | 58 | 42 | 32 | |||||||||||||||||||||||
| Investment expense | (80) | (71) | (83) | |||||||||||||||||||||||
| Total net investment income | $ | 2,313 | 4.3 | % | $ | 1,846 | 3.6 | % | $ | 1,951 | 4.1 | % | ||||||||||||||
| Total net investment income excluding limited partnerships and other alternative investments | $ | 1,581 | 3.1 | % | $ | 1,624 | 3.3 | % | $ | 1,719 | 3.7 | % |
*[1]*Yields calculated using annualized net investment income divided by the monthly average invested assets at amortized cost, as applicable, excluding repurchase agreement and securities lending collateral, if any, and derivatives book value.
*[2]*Includes net investment income on short-term investments.
*[3]*Primarily includes changes in fair value of certain equity fund investments and income from derivatives that qualify for hedge accounting and are used to hedge fixed maturities.
Year ended December 31, 2021 compared to the year ended December 31, 2020
Total net investment income increased primarily due to:
-
Greater income from limited partnerships and other alternative investments primarily driven by higher valuations and cash distributions within private equity funds and sales of underlying investments within real estate funds;
-
A higher level of invested assets;
-
Greater income from non-routine items, including yield adjustments on prepayable securities; and
-
A higher yield from equity investments.
These increases were partially offset by a lower yield on fixed maturities resulting from reinvesting at lower rates and a lower yield on floating rate investments.
Annualized net investment income yield, excluding limited partnerships and other alternative investments, was down primarily due to lower reinvestment rates, partially offset
by greater income from non-routine income items and a higher yield on equity securities.
Average reinvestment rate, on fixed maturities and mortgage loans, excluding certain U.S. Treasury securities, for the year-ended December 31, 2021, was 2.6% which was below the average yield of sales and maturities of 3.0% for the same period. Average reinvestment rate for the year-ended December 31, 2020, was 2.5% which was below the average yield of sales and maturities of 3.4%.
For the 2022 calendar year, we expect the annualized net investment income yield, excluding limited partnerships and other alternative investments, to be lower than the portfolio yield earned in 2021 due to lower reinvestment rates. The estimated impact on annualized net investment income yield is subject to variability due to evolving market conditions, active portfolio management, and the level of non-routine income items, such as make-whole payments, prepayment penalties on mortgage loans and yield adjustments on prepayable securities.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| Net Realized Gains (Losses) | |||||||||||
| For the years ended December 31, | |||||||||||
| (Before tax) | 2021 | 2020 | 2019 | ||||||||
| Gross gains on sales of fixed maturities | $ | 319 | $ | 255 | $ | 234 | |||||
| Gross losses on sales of fixed maturities | (89) | (50) | (56) | ||||||||
| Equity securities [1] | 227 | (214) | 254 | ||||||||
| Net credit losses on fixed maturities, AFS [2] | 4 | (28) | |||||||||
| Change in ACL on mortgage loans [3] | 9 | (19) | |||||||||
| Intent-to-sell impairments [2] | — | (5) | — | ||||||||
| Net other-than-temporary impairment ("OTTI") losses recognized in earnings | (3) | ||||||||||
| Valuation allowances on mortgage loans | 1 | ||||||||||
| Other, net [4] | 39 | 47 | (35) | ||||||||
| Net realized gains (losses) | $ | 509 | $ | (14) | $ | 395 |
*[1]*The net unrealized gains on equity securities still held as of the end of the period and included in net realized gains (losses) were $155, $53, and $164 for the years ended December 31, 2021, 2020, and 2019, respectively.
*[2]*Due to the adoption of accounting guidance for credit losses on January 1, 2020, realized losses previously reported as OTTI are now presented as credit losses which are net of any recoveries. For further information refer to Note 1 - Basis of Presentation and Significant Accounting Policies. In addition, see Credit Losses on Fixed Maturities, AFS and Intent-to-Sell Impairments within the Investment Portfolio Risks and Risk Management section of the MD&A.
*[3]*Represents the change in ACL recorded during the period following the adoption of accounting guidance for credit losses on January 1, 2020. For further information refer to Note 1 - Basis of Presentation and Significant Accounting Policies. In addition, see ACL on Mortgage Loans within the Investment Portfolio Risks and Risk Management section of the MD&A.
*[4]*Includes gains (losses) on non-qualifying derivatives for 2021, 2020, and 2019 of $12, $104, and $(24), respectively, gains (losses) from transactional foreign currency revaluation of $(1), $(1) and (9), respectively, and a loss of $21 and $48, respectively, on the sale of Continental Europe Operations for the years ended December 31, 2021 and 2020. For the year-ended December 31, 2021, there was also a gain of $46 on the sale of the Company's previously owned interest in Talcott Resolution.
Year ended December 31, 2021
Gross gains and losses on sales were primarily due to net sales of corporate securities and tax-exempt municipals, in addition to sales of U.S. treasuries for duration and risk management.
Equity securities net gains were primarily driven by appreciation in value due to higher equity market levels and gains realized on exit of private equity direct investments.
Other, net gains and losses included a gain of $46 on the sale of the Company's 9.7% retained interest in Talcott Resolution, sold on June 30, 2021, and a loss of $21 related to the sale of the Company's Continental Europe Operations, which was completed on December 29, 2021. Also included were gains of $7 on credit derivatives driven by a decrease in credit spreads.
Year ended December 31, 2020
Gross gains and losses on sales were primarily driven by issuer-specific sales of corporate securities and tax-exempt municipal bonds, rebalancing within the foreign government sector, and sales of U.S. treasury securities for duration and/or liquidity management.
Equity securities net losses were driven by mark-to-market losses due to the decline in equity market levels in the first quarter and losses incurred on sales across multiple issuers as the Company reduced its exposure to equity securities, partially offset by mark-to-market gains on certain preferred equities.
Other, net gains are primarily due to $75 of realized gains on terminated derivatives used to hedge against a decline in equity market levels and $21 of gains on interest rate derivatives due to a decline in interest rates. These gains were partially offset by
a loss of $48, before tax, on the sale of the Company’s Continental Europe Operations which the Company agreed to sell in September of 2020.
CRITICAL ACCOUNTING ESTIMATES
The preparation of financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. Actual results could differ, and in the past have differed, from those estimates.
The Company has identified the following estimates as critical in that they involve a higher degree of judgment and are subject to a significant degree of variability:
-
property and casualty insurance product reserves, net of reinsurance;
-
group benefit LTD reserves, net of reinsurance;
-
evaluation of goodwill for impairment;
-
valuation of investments and derivative instruments including evaluation of credit losses on fixed maturities, AFS and ACL on mortgage loans; and
-
contingencies relating to corporate litigation and regulatory matters.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
In developing these estimates management makes subjective and complex judgments that are inherently uncertain and subject to material change as facts and circumstances develop. Although variability is inherent in these estimates, management believes the amounts provided are appropriate based upon the
facts available upon compilation of the financial statements. Certain of these estimates are particularly sensitive to market conditions, and deterioration and/or volatility in the worldwide debt or equity markets could have a material impact on the Consolidated Financial Statements.
|PROPERTY & CASUALTY INSURANCE PRODUCT RESERVES, NET OF REINSURANCE
P&C Loss and Loss Adjustment Expense Reserves, Net of Reinsurance, by Segment as of December 31, 2021

Loss and LAE Reserves, Net of Reinsurance as of December 31, 2021
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | % Total Reserves-net | ||||||||||||||||
| Workers’ compensation | $ | 11,259 | $ | — | $ | — | $ | 11,259 | 44.4% | |||||||||||
| General liability | 4,960 | — | — | 4,960 | 19.5% | |||||||||||||||
| Marine | 303 | — | — | 303 | 1.2% | |||||||||||||||
| Package business [1] | 1,924 | — | — | 1,924 | 7.6% | |||||||||||||||
| Commercial property | 530 | — | — | 530 | 2.1% | |||||||||||||||
| Automobile liability | 1,175 | 1,390 | — | 2,565 | 10.1% | |||||||||||||||
| Automobile physical damage | 14 | 40 | — | 54 | 0.2% | |||||||||||||||
| Professional liability | 1,261 | — | — | 1,261 | 5.0% | |||||||||||||||
| Bond | 434 | — | — | 434 | 1.7% | |||||||||||||||
| Homeowners | — | 364 | — | 364 | 1.4% | |||||||||||||||
| Asbestos and environmental | 110 | 10 | 604 | 724 | 2.9% | |||||||||||||||
| Assumed reinsurance | 285 | — | 96 | 381 | 1.5% | |||||||||||||||
| All other | 171 | 3 | 435 | 609 | 2.4% | |||||||||||||||
| Total reserves-net | 22,426 | 1,807 | 1,135 | 25,368 | 100.0% | |||||||||||||||
| Reinsurance and other recoverables | 4,480 | 37 | 1,564 | 6,081 | ||||||||||||||||
| Total reserves-gross | $ | 26,906 | $ | 1,844 | $ | 2,699 | $ | 31,449 |
*[1]*Commercial Lines policy packages that include property and general liability coverages are generally referred to as the package line of business.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
For descriptions of the coverages provided under the lines of business shown above, see Part I - Item1, Business.
Overview of Reserving for Property and Casualty Insurance Claims
It typically takes many months or years to pay claims incurred under a property and casualty insurance product; accordingly, the Company must establish reserves at the time the loss is incurred. Most of the Company’s policies provide for occurrence-based coverage where the loss is incurred when a claim event happens like an automobile accident, house or building fire or injury to an employee under a workers’ compensation policy. Some of the Company's policies, mostly for directors and officers insurance and errors and omissions insurance, are claims-made policies where the loss is incurred in the period the claim event is reported to the Company even if the loss event itself occurred in an earlier period.
Loss and loss adjustment expense reserves provide for the estimated ultimate costs of paying claims under insurance policies written by the Company, less amounts paid to date. These reserves include estimates for both claims that have been reported and those that have not yet been reported, and include estimates of all expenses associated with processing and settling these claims. Case reserves are established by a claims handler on each individual claim and are adjusted as new information becomes known during the course of handling the claim. Incurred but not reported (“IBNR”) reserves represent the difference between the estimated ultimate cost of all claims and the actual loss and loss adjustment expenses reported to the Company by claimants (“reported losses”). Reported losses represent cumulative loss and loss adjustment expenses paid plus case reserves for outstanding reported claims. For most lines, Company actuaries evaluate the total reserves (IBNR and case reserves) on an accident year basis. An accident year is the calendar year in which a loss is incurred, or, in the case of claims-made policies, the calendar year in which a loss is reported. For certain lines acquired from the Navigators Group book of business, total reserves are evaluated on a policy year basis and then converted to accident year. A policy year is the calendar year in which a policy incepts.
Factors that Change Reserve Estimates- Reserve estimates can change over time because of unexpected changes in the external environment. Inflation in claim costs, such as with medical care, hospital care, automobile parts, wages and home and building repair, would cause claims to settle for more than they are initially reserved. Changes in the economy can cause an increase or decrease in the number of reported claims (claim frequency). For example, an improving economy could result in more automobile miles driven and a higher number of automobile reported claims, or a change in economic conditions can lead to more or less workers’ compensation reported claims. An increase in the number or percentage of claims litigated can increase the average settlement amount per claim (claim severity). Changes in the judicial environment can affect interpretations of damages and how policy coverage applies which could increase or decrease claim severity. Over time, judges or juries in certain jurisdictions may be more inclined to determine liability and award damages. New legislation can also change how damages are defined or change the statutes of limitations for the filing of civil suits, resulting in greater claim frequency or severity. In addition, new
types of injuries may arise from exposures not contemplated when the policies were written. Past examples include pharmaceutical products, silica, lead paint, sexual molestation and sexual abuse and construction defects.
Reserve estimates can also change over time because of changes in internal Company operations. A delay or acceleration in handling claims may signal a need to increase or reduce reserves from what was initially estimated. New lines of business may have loss development patterns that are not well established. Changes in the geographic mix of business, changes in the mix of business by industry and changes in the mix of business by policy limit or deductible can increase the risk that losses will ultimately develop differently than the loss development patterns assumed in our reserving. In addition, changes in the quality of risk selection in underwriting and changes in interpretations of policy language could increase or decrease ultimate losses from what was assumed in establishing the reserves.
In the case of assumed reinsurance, all of the above risks apply. The Company assumes property and casualty risks from other insurance companies as part of its Global Re business acquired from Navigators Group and from certain pools and associations. Global Re, which is a part of the global specialty business, mostly assumes property, casualty and specialty risks. Changes in the case reserving and reporting patterns of insurance companies ceding to The Hartford can create additional uncertainty in estimating the reserves. Due to the inherent complexity of the assumptions used, final claim settlements may vary significantly from the present estimates of direct and assumed reserves, particularly when those settlements may not occur until well into the future.
Reinsurance Recoverables- Through both facultative and treaty reinsurance agreements, the Company cedes a share of the risks it has underwritten to other insurance companies. The Company records reinsurance recoverables for losses and loss adjustment expenses ceded to its reinsurers representing the anticipated recovery from reinsurers of unpaid claims, including IBNR.
The Company estimates the portion of losses and loss adjustment expenses to be ceded based on the terms of any applicable facultative and treaty reinsurance, including an estimate of IBNR for losses that will ultimately be ceded.
The Company provides an allowance for uncollectible reinsurance, reflecting management’s best estimate of reinsurance cessions that may be uncollectible in the future due to reinsurers’ unwillingness or inability to pay. The allowance for uncollectible reinsurance comprises an ACL and an allowance for disputed balances. The ACL primarily considers the credit quality of the Company's reinsurers while the allowance for disputes considers recent outcomes in arbitration and litigation in disputes between reinsurers and cedants and recent commutation activity between reinsurers and cedants that may signal how the Company’s own reinsurance claims may settle. Where its reinsurance contracts permit, the Company secures funding of future claim obligations with various forms of collateral, including irrevocable letters of credit, secured trusts, funds held accounts and group-wide offsets. The allowance for uncollectible reinsurance was $96 as of December 31, 2021, comprised of $42 related to Commercial Lines, $1 related to
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Personal Lines and $53 related to Property & Casualty Other Operations.
The Company’s estimate of reinsurance recoverables, net of an allowance for uncollectible reinsurance, is subject to similar risks and uncertainties as the estimate of the gross reserve for unpaid losses and loss adjustment expenses for direct and assumed exposures.
Review of Reserve Adequacy- The Hartford regularly reviews the appropriateness of reserve levels at the line of business or more detailed level, taking into consideration the variety of trends that impact the ultimate settlement of claims. For Property & Casualty Other Operations, asbestos and environmental (“Run-off A&E”) reserves are reviewed by type of event rather than by line of business.
Reserve adjustments, which may be material, are reflected in the operating results of the period in which the adjustment is determined to be necessary. In the judgment of management, information currently available has been properly considered in establishing the reserves for unpaid losses and loss adjustment expenses and in recording the reinsurance recoverables for ceded unpaid losses.
Reserving Methodology
The following is a discussion of the reserving methods used for the Company's property and casualty lines of business other than asbestos and environmental.
Reserves are set by line of business within the operating segments. A single line of business may be written in more than one segment. Lines of business for which reported losses emerge over a long period of time are referred to as long-tail lines of business. Lines of business for which reported losses emerge more quickly are referred to as short-tail lines of business. The Company’s shortest-tail lines of business are homeowners, commercial property, marine and automobile physical damage. The longest tail lines of business include workers’ compensation, general liability, professional liability and assumed reinsurance. For short-tail lines of business, emergence of paid losses and case reserves is credible and likely indicative of ultimate losses. For long-tail lines of business, emergence of paid losses and case reserves is less credible in the early periods after a given accident year and, accordingly, may not be indicative of ultimate losses.
Use of Actuarial Methods and Judgments- The Company’s reserving actuaries regularly review reserves for both current and prior accident years using the most current claim data. A variety of actuarial methods and judgments are used for most lines of business to arrive at selections of estimated ultimate losses and loss adjustment expenses. New methods may be added for specific lines over time to inform these selections where appropriate. The reserve selections incorporate input, as appropriate, from claims personnel, pricing actuaries and operating management about reported loss cost trends and other factors that could affect the reserve estimates. Most reserves are reviewed fully each quarter, including loss and loss adjustment expense reserves for homeowners, commercial property, marine property, automobile physical damage, automobile liability, package property business, and workers’ compensation. Other reserves, including most general liability and professional liability lines, are reviewed semi-annually. Certain additional reserves are also reviewed semi-
annually or annually, including reserves for losses incurred in accident years older than twelve years for Personal Lines and older than twenty years for Commercial Lines, as well as reserves for bond, assumed reinsurance, latent exposures such as construction defects, and unallocated loss adjustment expenses. For reserves that are reviewed semi-annually or annually, management monitors the emergence of paid and reported losses in the intervening quarters and, if necessary, performs a reserve review to determine whether the reserve estimate should change.
An expected loss ratio is used in initially recording the reserves for both short-tail and long-tail lines of business. This expected loss ratio is determined by starting with the average loss ratio of recent prior accident years and adjusting that ratio for the effect of expected changes to earned pricing, loss frequency and severity, mix of business, ceded reinsurance and other factors. For short-tail lines, IBNR for the current accident year is initially recorded as the product of the expected loss ratio for the period, earned premium for the period and the proportion of losses expected to be reported in future calendar periods for the current accident period. For long-tailed lines, IBNR reserves for the current accident year are initially recorded as the product of the expected loss ratio for the period and the earned premium for the period, less reported losses for the period.
As losses emerge or develop in periods subsequent to a given accident year, reserving actuaries use other methods to estimate ultimate unpaid losses in addition to the expected loss ratio method. These primarily include paid and reported loss development methods, frequency/severity techniques and the Bornhuetter-Ferguson method (a combination of the expected loss ratio and paid development or reported development method). Within any one line of business, the methods that are given more influence vary based primarily on the maturity of the accident year, the mix of business and the particular internal and external influences impacting the claims experience or the methods. The output of the reserve reviews are reserve estimates representing a range of actuarial indications.
Reserve Discounting- Most of the Company’s property and casualty insurance product reserves are not discounted. However, the Company has discounted liabilities funded through structured settlements and has discounted a portion of workers’ compensation reserves that have a fixed and determinable payment stream. For further discussion of these discounted liabilities, see Note 1 - Basis of Presentation and Significant Accounting Policies of Notes to Consolidated Financial Statements.
Differences Between GAAP and Statutory Basis Reserves- As of December 31, 2021 and 2020, U.S. property and casualty insurance product reserves for losses and loss adjustment expenses, net of reinsurance recoverables, reported under U.S. GAAP were lower than net reserves reported on a statutory basis, primarily due to reinsurance recoverables on two ceded retroactive reinsurance agreements that are recorded as a reduction of other liabilities under statutory accounting. One of the retroactive reinsurance agreements covers substantially all adverse development on asbestos and environmental reserves subsequent to 2016, up to a $1.5 billion limit, and the other covered adverse development on Navigators Insurers' existing net loss and allocated loss adjustment reserves as of December 31, 2018, up to a $300 limit. Under both agreements,
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
the Company cedes to NICO, a subsidiary of Berkshire Hathaway Inc. ("Berkshire").
Reserving Methods by Line of Business- Apart from Run-off A&E which is discussed in the following section on Property & Casualty Other Operations, below is a general discussion of which reserving methods are preferred by line of business. Because the actuarial estimates are generated at a
much finer level of detail than line of business (e.g., by distribution channel, coverage, accident period), other methods than those described for the line of business may also be employed for a coverage and accident year within a line of business. Also, as circumstances change, the methods that are given more influence will change.
Preferred Reserving Methods by Line of Business
| Commercial property, homeowners and automobile physical damage | These short-tailed lines are fast-developing and paid and reported development techniques are used as these methods use historical data to develop paid and reported loss development patterns, which are then applied to cumulative paid and reported losses by accident period to estimate ultimate losses. In addition to paid and reported development methods, for the most immature accident months, the Company uses frequency and severity techniques and the initial expected loss ratio. The advantage of frequency/severity techniques is that frequency estimates are generally easier to predict and external information can be used to supplement internal data in estimating average severity. | ||||
| Personal automobile liability | For personal automobile liability, and bodily injury in particular, in addition to traditional paid and reported development methods, the Company relies on frequency/severity techniques and Berquist-Sherman techniques. Because the paid development technique is affected by changes in claim closure patterns and the reported development method is affected by changes in case reserving practices, the Company reviews and often relies on Berquist-Sherman techniques which adjust these patterns to reflect current settlement rates and case reserving practices. The Company generally uses the reported development method for older accident years and a combination of reported development, frequency/severity and Berquist-Sherman methods for more recent accident years. For older accident periods, reported losses are a good indicator of ultimate losses given the high percentage of ultimate losses reported to date. For more recent periods, the frequency/severity techniques are not affected as much by changes in case reserve practices and changing disposal rates and the Berquist-Sherman techniques specifically adjust for these changes. | ||||
| Commercial automobile liability | The Company performs a variety of techniques, including the paid and reported development methods and frequency/severity techniques. For older, more mature accident years, the Company primarily uses reported development techniques. For more recent accident years, the Company relies on several methods that incorporate expected loss ratios, reported loss development, paid loss development, frequency/severity, case reserve adequacy, and claim settlement rates. | ||||
| Professional liability | Reported and paid loss development patterns for this line tend to be volatile. Therefore, the Company typically supplements the expected loss ratio method and paid and reported development methods with others such as individual claim reviews and frequency and severity techniques. | ||||
| General liability, bond and large deductible workers’ compensation | For these long-tailed lines of business, the Company generally relies on the expected loss ratio and reported development techniques. The Company generally weights these techniques together, relying more heavily on the expected loss ratio method at early ages of development and shifting more weight onto the reported development method as an accident year matures. For certain general liability lines the Company uses a Berquist-Sherman technique to adjust for changes in claim reserving patterns. The Company also uses various frequency/severity methods aimed at capturing large loss development and in some bond lines individual claim reviews are used. | ||||
| Workers’ compensation | Workers’ compensation is the Company’s single largest reserve line of business and a wide range of methods are used. Due to the long-tailed nature of workers' compensation, the selection of methods is driven by expected loss ratio methods ("ELR") at early evaluations with emphasis shifting first to Bornhuetter-Ferguson methods, then to paid and reported development methods (with more reliance placed on paid methods), and finally to methods that are responsive to the inventory of open claims. Across these techniques, there are adjustments related to changes in emergence patterns across years, projections of future cost inflation, outlier claims, and analysis of larger states. | ||||
| Marine | For marine liability, the Company generally relies on the expected loss ratio, Berquist-Sherman, and reported development techniques. The Company generally weights these techniques together, relying more heavily on the expected loss ratio method at early ages of development and then shifts towards Berquist-Sherman and then more towards the reported development method as an accident year matures. For marine property segments, the Company relies on a Berquist-Sherman method for early development ages then shifts to reported development techniques. | ||||
| Assumed reinsurance and all other | Standard methods, such as expected loss ratio, Berquist-Sherman and reported development techniques are applied. These methods and analyses are informed by underlying treaty by treaty analyses supporting the expected loss ratios, and cedant data will often inform the loss development patterns. In some instances, reserve indications may also be influenced by information gained from claims and underwriting audits. Policy quarter and policy year loss reserve estimates are then converted to an accident year basis. | ||||
| Allocated loss adjustment expenses ("ALAE") | For some lines of business (e.g., professional liability, assumed reinsurance, and the acquired Navigators Group book of business), ALAE and losses are analyzed together. For most lines of business, however, ALAE is analyzed separately, using paid development techniques and a ratio of paid ALAE to paid loss is applied to loss reserves to estimate unpaid ALAE. | ||||
| Unallocated loss adjustment expenses ("ULAE") | ULAE is analyzed separately from loss and ALAE. For most lines of business, future ULAE costs to be paid are projected based on an expected claim handling cost per claim year, the anticipated claim closure pattern and the ratio of paid ULAE to paid loss is applied to estimated unpaid losses. For some lines, a simplified paid-to-paid approach is used. |
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
The recorded reserve for losses and loss adjustment expenses represents the Company's best estimate of the ultimate settlement amount of unpaid losses and loss adjustment expenses. In applying judgment, the best estimate is selected after considering the estimates derived from a number of actuarial methods, giving more weight to those methods deemed more predictive of ultimate unpaid losses and loss adjustment expenses. The Company does not produce a statistical range or confidence interval of reserve estimates and, since reserving methods with more credibility are given greater weight, the selected best estimate may differ from the mid-point of the various estimates produced by the actuarial methods used.
Assumptions used in arriving at the selected actuarial indications consider a number of factors, including the immaturity of emerged claims in recent accident years, emerging trends in the recent past, and the level of volatility within each line of business.
Adjustments to reserves of prior accident years are referred to as “prior accident year development”. Increases in previous estimates of ultimate loss costs are referred to as either an increase in prior accident year reserves or as unfavorable reserve development. Decreases in previous estimates of ultimate loss costs are referred to as either a decrease in prior accident year reserves or as favorable reserve development. Reserve development can influence the comparability of year over year underwriting results.
For a discussion of changes to reserve estimates recorded in 2021, see Note 12 - Reserve for Unpaid Losses and Loss Adjustment Expenses in the Notes to Consolidated Financial Statements.
Current Trends Contributing to Reserve Uncertainty
The Hartford is a multi-line company in the property and casualty insurance business. The Hartford is, therefore, subject to reserve uncertainty stemming from changes in loss trends and other conditions which could become material at any point in time. As market conditions and loss trends develop, management must assess whether those conditions constitute a long-term trend that should result in a reserving action (i.e., increasing or decreasing the reserve).
General liability- Within Commercial Lines and Property & Casualty Other Operations, the Company has exposure to general liability claims, including from bodily injury, property damage and product liability. Reserves for these exposures can be particularly difficult to estimate due to the long development pattern and uncertainty about how cases will settle. In particular, the Company has exposure to bodily injury claims that is the result of long-term or continuous exposure to harmful products or substances. Examples include, but are not limited to, pharmaceutical products, silica, talcum powder, per-and polyfluoroalkyl substances ("PFAS"), head injuries and lead paint. The Company also has exposure to claims from construction defects, where property damage or bodily injury from negligent construction is alleged. In addition, the Company has exposure to claims asserted against religious institutions, and other organizations, including the Boy Scouts of America, relating to sexual molestation and sexual abuse. For additional information related to the Company's settlement agreement with
the Boy Scouts of America, see Note 12 - Reserve for Unpaid Losses and Loss Adjustment Expenses in the Notes to Consolidated Financial Statements. State “reviver” statutes, extending statutes of limitations for certain sexual molestation and sexual abuse claims, could result in additional litigation or could result in unexpected sexual molestation and sexual abuse losses. Such exposures may involve potentially long latency periods and may implicate coverage in multiple policy periods, which can raise complex coverage issues with significant effects on the ultimate scope of coverage. Such exposures may also be impacted by insured bankruptcies. These factors make reserves for such claims more uncertain than other bodily injury or property damage claims. With regard to these exposures, the Company monitors trends in litigation, the external environment including legislation, the similarities to other mass torts and the potential impact on the Company’s reserves. Additionally, uncertainty in estimated claim severity causes reserve variability, particularly with respect to changes in internal claim handling and case reserving practices.
Workers’ compensation- Included in both small commercial and in middle & large commercial, workers’ compensation is the Company’s single biggest line of business and the property and casualty line of business with the longest pattern of loss emergence. To the extent that patterns in the frequency of settlement payments deviate from historical patterns, loss reserve estimates would be less reliable. Medical costs make up approximately 50% of workers’ compensation payments. As such, reserve estimates for workers’ compensation are particularly sensitive to changes in medical inflation, the changing use of medical care procedures and changes in state legislative and regulatory environments. In addition, a deteriorating economic environment can reduce the ability of an injured worker to return to work and lengthen the time a worker receives disability benefits. In National Accounts, reserves for large deductible workers’ compensation insurance require estimating losses attributable to the deductible amount that will be paid by the insured; if such losses are not paid by the insured due to financial difficulties, the Company is contractually liable.
Commercial Lines automobile- Uncertainty in estimated claim severity causes reserve variability for commercial automobile losses including reserve variability due to changes in internal claim handling and case reserving practices as well as due to changes in the external environment.
Directors' and officers' insurance- Uncertainty regarding the number and severity of security class action suits can result in reserve volatility for directors' and officers' insurance claims. Additionally, the Company’s exposure to losses under directors’ and officers’ insurance policies, both domestically and internationally, is primarily in excess layers, making estimates of loss more complex.
Personal Lines automobile- While claims emerge over relatively shorter periods, estimates can still vary due to a number of factors, including uncertain estimates of frequency and severity trends. Severity trends are affected by changes in internal claim handling and case reserving practices as well as by changes in the external environment, such as due to inflation in labor and materials because of supply chain disruptions affecting repair costs. Changes in claim practices increase the uncertainty in the interpretation of case reserve data, which
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
increases the uncertainty in recorded reserve levels. Severity trends have increased in recent accident years, in part driven by more expensive parts associated with new automobile technology, causing additional uncertainty about the reliability of past patterns. In addition, the introduction of new products and class plans has led to a different mix of business by type of insured than the Company experienced in the past. Such changes in mix increase the uncertainty of the reserve projections, since historical data and reporting patterns may not be applicable to the new business.
Assumed reinsurance- While the pricing and reserving processes can be challenging and idiosyncratic for insurance companies, the inherent uncertainties of setting prices and estimating such reserves are even greater for the reinsurer. This is primarily due to the longer time between the date of an occurrence and the reporting of claims to the reinsurer, the diversity of development patterns among different types of reinsurance treaties or contracts, the necessary reliance on the ceding companies for information regarding reported claims and differing pricing and reserving practices among ceding companies. In addition, trends that have affected development of liabilities in the past may not necessarily occur or impact liability development in the same manner or to the same degree in the future. As a result, actual losses and LAE may deviate, perhaps substantially, from the expected estimates.
International business- In addition to several of the line-specific trends listed above, the International business acquired through the Navigators Group book of business may have additional uncertainty due to geopolitical, foreign currency, and trade dispute risks.
COVID-19 impacts- As further explained under the "Impact of COVID-19 on our financial condition, results of operations and liquidity" section of this MD&A, the Company incurred $31 of COVID-19 claims in 2021 within P&C, including in workers' compensation and financial lines. Under workers’ compensation, we have experienced a continuation of COVID-19 incurred losses, particularly due to laws or directives in certain states that require coverage of COVID-19 claims for health care and other essential workers based on a presumption that they contracted the virus while working. Under financial lines, we have experienced COVID-19 related claims under employment practices liability insurance policies. These claims tend to be low severity and we are monitoring emerging trends related to return to work and vaccine mandates. We continue to monitor exposure under director's and officer's insurance policies.
In addition to the direct impacts of COVID-19 mentioned above, we are monitoring for indirect impacts as well. This past year we have seen inflationary pressure on building material and labor costs due to supply chain disruption because of the pandemic. This has the potential to impact homeowners and commercial property severity and lengthen reporting patterns due to claim settlement delays. Supply chain disruption as a result of the pandemic has also had an impact on the automobile industry impacting physical damage severities.
Reserve estimates for COVID-19 claims are difficult to estimate. In establishing reserves for COVID-19 incurred claims through December 31, 2021, we have provided IBNR at a higher percentage of ultimate estimated incurred losses than usual as we expect longer claim reporting patterns given the effects of COVID-19. For example, we expect longer delays than usual between the time a worker is treated and the date the claim is
eventually submitted for workers' compensation coverage. Reserve estimates for directors’ and officers’ (“D&O”), errors and omissions ("E&O") and employment practices liability are subject to significant uncertainty given that estimates must be made of the expected ultimate severity of claims that have recently been reported. Changes in the legal environment and litigation process, including but not limited to court delays and closings, may also have potential impacts on development patterns for liability lines.
Catastrophes- Within Commercial Lines and Personal Lines, the Company is exposed to incurred losses from catastrophe events, primarily for damage to property. Reserves for hurricanes, tropical storms, tornado/hail, wildfires, earthquakes and other catastrophe events are subject to significant uncertainty about the number and average severity of claims arising from those events, particularly in cases where the event occurs near the end of a financial reporting period when there is limited information about the extent of damages. For example, after a catastrophe event, it may take a period of time before we are able to access the impacted areas limiting the ability of our claims adjusting staff to inspect losses, make estimates and determine the damages that are covered by the policy. To estimate catastrophe losses, we consider information from claim notices received to date, third party data, visual images of the affected area where we have exposures and our own historical experience of loss reporting patterns for similar events.
Impact of Key Assumptions on Reserves
As stated above, the Company’s practice is to estimate reserves using a variety of methods, assumptions and data elements within its reserve estimation. The Company does not use statistical loss distributions or confidence levels in the process of determining its reserve estimate and, as a result, does not disclose reserve ranges.
Across most lines of business, the most important reserve assumptions are future loss development factors applied to paid or reported losses to date. The trend in loss cost frequency and severity is also a key assumption, particularly in the most recent accident years, where loss development factors are less credible.
The following discussion discloses possible variation from current estimates of loss reserves due to a change in certain key indicators of potential losses. For automobile liability lines in both Personal Lines and Commercial Lines, the key indicator is the annual loss cost trend, particularly the severity trend component of loss costs. For workers’ compensation and general liability, loss development patterns are a key indicator, particularly for more mature accident years. For workers’ compensation, paid loss development patterns have been impacted by medical cost inflation and other changes in loss cost trends. For general liability, incurred loss development patterns have been impacted by, among other things, emergence of new types of claims (e.g., PFAS claims) and a shift in the mixture between smaller, more routine claims and larger, more complex claims.
Each of the impacts described below is estimated individually, without consideration for any correlation among key indicators or among lines of business. Therefore, it would be inappropriate to take each of the amounts described below and add them
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
together in an attempt to estimate volatility for the Company’s reserves in total. For any one reserving line of business, the estimated variation in reserves due to changes in key indicators is a reasonable estimate of potential reserve development that may occur in the future, likely over a period of several calendar years. The variation discussed is not meant to be a worst-case scenario, and, therefore, it is possible that future variation may be more than the amounts discussed below. Moreover, the variation discussed does not represent a complete statistical range of potential reserve outcomes, and factors exist beyond the key indicators considered which have the potential to drive additional variation to the Company's reserves.
| Possible Change in Key Indicator | Reserves, Net of Reinsurance December 31, 2021 | Estimated Range of Potential Reserve Development | |||||||||
| Personal Automobile Liability | +/- 2.5 points to the annual assumed change in loss cost severity for the two most recent accident years | $1.4 billion | +/- $65 | ||||||||
| Commercial Automobile Liability | +/- 2.5 points to the annual assumed change in loss cost severity for the two most recent accident years | $1.2 billion | +/- $30 | ||||||||
| Workers' Compensation | 2% change in paid loss development patterns | $11.3 billion | +/- $400 | ||||||||
| General Liability | 8% change in reported loss development patterns | $5.0 billion | +/- $500 |
Reserving for Asbestos and Environmental Claims
How A&E Reserves are Set- The process for establishing reserves for asbestos and environmental claims first involves estimating the required reserves gross of ceded reinsurance and then estimating reinsurance recoverables.
In establishing reserves for gross asbestos claims, the Company evaluates its insureds’ estimated liabilities for such claims by examining exposures for individual insureds and assessing how coverage applies. The Company considers a variety of factors, including the jurisdictions where underlying claims have been brought, past, pending and anticipated future claim activity, the level of plaintiff demands, disease mix, past settlement values of similar claims, dismissal rates, allocated loss adjustment expense, and potential impact of other defendants being in bankruptcy.
Similarly, the Company reviews exposures to establish gross environmental reserves. The Company considers several factors in estimating environmental liabilities, including historical values of similar claims, the number of sites involved, the insureds’ alleged activities at each site, the alleged environmental damage, the respective shares of liability of
potentially responsible parties, the appropriateness and cost of remediation, the nature of governmental enforcement activities or mandated remediation efforts and potential impact of other defendants being in bankruptcy.
After evaluating its insureds’ probable liabilities for asbestos and/or environmental claims, the Company evaluates the insurance coverage in place for such claims. The Company considers its insureds’ total available insurance coverage, including the coverage issued by the Company. The Company also considers relevant judicial interpretations of policy language, the nature of how policy limits are enforced on multi-year policies and applicable coverage defenses or determinations, if any.
The estimated liabilities of insureds and the Company’s exposure to the insureds depends heavily on an analysis of the relevant legal issues and litigation environment. This analysis is conducted by the Company’s lawyers and is subject to applicable privileges.
For both asbestos and environmental reserves, the Company also analyzes its historical paid and reported losses and expenses year by year, to assess any emerging trends, fluctuations or characteristics suggested by the aggregate paid and reported activity. The historical losses and expenses are analyzed on both a direct basis and net of reinsurance.
Once the gross ultimate exposure for indemnity and allocated loss adjustment expense is determined for its insureds by each policy year, the Company calculates its ceded reinsurance projection based on any applicable facultative and treaty reinsurance and the Company’s experience with reinsurance collections. See the section that follows entitled A&E Adverse Development Cover that discusses the impact the reinsurance agreement with NICO may have on future adverse development of asbestos and environmental reserves, if any.
Uncertainties Regarding Adequacy of A&E Reserves- A number of factors affect the variability of estimates for gross asbestos and environmental reserves including assumptions with respect to the frequency of claims, the average severity of those claims settled with payment, the dismissal rate of claims with no payment, resolution of coverage disputes with our policyholders and the expense to indemnity ratio. Reserve estimates for gross asbestos and environmental reserves are subject to greater variability than reserve estimates for more traditional exposures.
The process of estimating asbestos and environmental reserves remains subject to a wide variety of uncertainties, which are detailed in Note 15 - Commitments and Contingencies of Notes to Consolidated Financial Statements. The Company believes that its current asbestos and environmental reserves are appropriate. Future developments could continue to cause the Company to change its estimates of its gross asbestos and environmental reserves. Losses ceded under the adverse development cover ("A&E ADC") with NICO in excess of the ceded premium paid of $650 have resulted in a deferred gain resulting in a timing difference between when gross reserves are increased and when reinsurance recoveries are recognized. This timing difference results in a charge to net income until such periods when the recoveries are recognized. Consistent with past practice, the Company will continue to monitor its reserves in Property & Casualty Other Operations regularly,
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
including its annual reviews of asbestos liabilities, reinsurance recoverables, the allowance for uncollectible reinsurance, and environmental liabilities. Where future developments indicate, we will make appropriate adjustments to the reserves at that time.
Total P&C Insurance Product Reserves Development
In the opinion of management, based upon the known facts and current law, the reserves recorded for the Company’s property
and casualty insurance products at December 31, 2021 represent the Company’s best estimate of its ultimate liability for unpaid losses and loss adjustment expenses related to losses covered by policies written by the Company. However, because of the significant uncertainties surrounding reserves, it is possible that management’s estimate of the ultimate liabilities for these claims may change in the future and that the required adjustment to currently recorded reserves could be material to the Company’s results of operations and liquidity.
Rollforward of Property and Casualty Insurance Product Liabilities for Unpaid Losses and LAE for the Year Ended December 31, 2021
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | |||||||||||||||||
| Beginning liabilities for unpaid losses and loss adjustment expenses, gross | $ | 25,058 | $ | 1,836 | $ | 2,728 | $ | 29,622 | ||||||||||||
| Reinsurance and other recoverables | 4,271 | 28 | 1,426 | 5,725 | ||||||||||||||||
| Beginning liabilities for unpaid losses and loss adjustment expenses, net | 20,787 | 1,808 | 1,302 | 23,897 | ||||||||||||||||
| Provision for unpaid losses and loss adjustment expenses | ||||||||||||||||||||
| Current accident year before catastrophes | 5,407 | 1,840 | — | 7,247 | ||||||||||||||||
| Current accident year ("CAY") catastrophes | 496 | 168 | — | 664 | ||||||||||||||||
| Prior accident year development ("PYD") [1] | 141 | (144) | 202 | 199 | ||||||||||||||||
| Total provision for unpaid losses and loss adjustment expenses | 6,044 | 1,864 | 202 | 8,110 | ||||||||||||||||
| Change in deferred gain on retroactive reinsurance included in other liabilities [1] | (91) | — | (155) | (246) | ||||||||||||||||
| Payments | (4,316) | (1,865) | (214) | (6,395) | ||||||||||||||||
| Foreign currency adjustment | 2 | — | — | 2 | ||||||||||||||||
| Ending liabilities for unpaid losses and loss adjustment expenses, net | 22,426 | 1,807 | 1,135 | 25,368 | ||||||||||||||||
| Reinsurance and other recoverables | 4,480 | 37 | 1,564 | 6,081 | ||||||||||||||||
| Ending liabilities for unpaid losses and loss adjustment expenses, gross | $ | 26,906 | $ | 1,844 | $ | 2,699 | $ | 31,449 | ||||||||||||
| Earned premiums and fee income | $ | 9,575 | $ | 2,986 | ||||||||||||||||
| Loss and loss expense paid ratio [2] | 45.1 | 62.5 | ||||||||||||||||||
| Loss and loss expense incurred ratio | 63.4 | 63.1 | ||||||||||||||||||
| Prior accident year development (pts) [3] | 1.5 | (4.9) |
*[1]*Prior accident year development does not include the benefit of a portion of losses ceded under the Navigators and A&E ADCs which, under retroactive reinsurance accounting, is deferred and is recognized over the period the ceded losses are recovered in cash from NICO. For additional information regarding the two adverse development cover reinsurance agreements, refer to Note 12 - Reserve for Unpaid Losses and Loss Adjustment Expenses of Notes to Consolidated Financial Statements.
*[2]*The “loss and loss expense paid ratio” represents the ratio of paid losses and loss adjustment expenses to earned premiums and fee income.
[3]**“Prior accident year development (pts)” represents the ratio of prior accident year development to earned premiums.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| Current Accident Year Catastrophe Losses for the Year Ended December 31, 2021, Net of Reinsurance | |||||||||||
| Commercial Lines | Personal Lines | Total | |||||||||
| Wind and hail | $ | 157 | $ | 94 | $ | 251 | |||||
| Winter storms [1] | 151 | 18 | 169 | ||||||||
| Hurricanes and Tropical Storms | 151 | 43 | 194 | ||||||||
| Wildfires | 9 | 23 | 32 | ||||||||
| Losses ceded to the aggregate catastrophe treaty [2] | (29) | (10) | (39) | ||||||||
| Catastrophes before assumed reinsurance | 439 | 168 | 607 | ||||||||
| Global assumed reinsurance business [3] | 57 | — | 57 | ||||||||
| Total catastrophe losses | $ | 496 | $ | 168 | $ | 664 | |||||
*[1]*Includes catastrophe losses from the February winter storms in Texas and other areas within Commercial Lines and Personal Lines of $206 and $24, respectively, gross of reinsurance, and $151 and $18, respectively, net of reinsurance under the Company's per occurrence property catastrophe treaty covering events other than earthquakes and named hurricanes and tropical storms. The reinsurance covers 70% of up to $250 of losses in excess of $100 from such events occurring within a seven day time period, subject to a $50 annual aggregate deductible. These recoveries do not inure to the benefit of the aggregate property catastrophe treaty reinsurers. For further information on the treaty, refer to Enterprise Risk Management — Insurance Risk section of this MD&A.
*[2]*For further information on the aggregate catastrophe treaty, refer to Enterprise Risk Management — Insurance Risk section of this MD&A.
*[3]*Catastrophe losses incurred on global assumed reinsurance business are not covered under the Company's aggregate property catastrophe treaty. For further information on the treaty, refer to Enterprise Risk Management — Insurance Risk section of this MD&A.
| Unfavorable (Favorable) Prior Accident Year Development for the Year Ended December 31, 2021 | ||||||||||||||
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | |||||||||||
| Workers’ compensation | $ | (190) | $ | — | $ | — | $ | (190) | ||||||
| Workers’ compensation discount accretion | 35 | — | — | 35 | ||||||||||
| General liability | 454 | — | — | 454 | ||||||||||
| Marine | 1 | — | — | 1 | ||||||||||
| Package business | (91) | — | — | (91) | ||||||||||
| Commercial property | (26) | — | — | (26) | ||||||||||
| Professional liability | (2) | — | — | (2) | ||||||||||
| Bond | (26) | — | — | (26) | ||||||||||
| Assumed reinsurance | (6) | — | — | (6) | ||||||||||
| Automobile liability | 9 | (90) | — | (81) | ||||||||||
| Homeowners | — | 3 | — | 3 | ||||||||||
| Net asbestos and environmental reserves | — | — | — | — | ||||||||||
| Catastrophes | (97) | (57) | — | (154) | ||||||||||
| Uncollectible reinsurance | (5) | — | (1) | (6) | ||||||||||
| Other reserve re-estimates, net | (6) | — | 48 | 42 | ||||||||||
| Prior accident year development before change in deferred gain | 50 | (144) | 47 | (47) | ||||||||||
| Change in deferred gain on retroactive reinsurance included in other liabilities | 91 | — | 155 | 246 | ||||||||||
| Total prior accident year development | $ | 141 | $ | (144) | $ | 202 | $ | 199 |
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Rollforward of Property and Casualty Insurance Product Liabilities for Unpaid Losses and LAE for the Year Ended December 31, 2020
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | ||||||||||||||
| Beginning liabilities for unpaid losses and loss adjustment expenses, gross | $ | 23,363 | $ | 2,201 | $ | 2,697 | $ | 28,261 | |||||||||
| Reinsurance and other recoverables [1] | 4,029 | 68 | 1,178 | 5,275 | |||||||||||||
| Beginning liabilities for unpaid losses and loss adjustment expenses, net | 19,334 | 2,133 | 1,519 | 22,986 | |||||||||||||
| Provision for unpaid losses and loss adjustment expenses | |||||||||||||||||
| Current accident year before catastrophes | 5,493 | 1,695 | — | 7,188 | |||||||||||||
| Current accident year catastrophes | 397 | 209 | — | 606 | |||||||||||||
| Prior accident year development [2] | 44 | (438) | 258 | (136) | |||||||||||||
| Total provision for unpaid losses and loss adjustment expenses | 5,934 | 1,466 | 258 | 7,658 | |||||||||||||
| Change in deferred gain on retroactive reinsurance included in other liabilities [2] | (102) | — | (210) | (312) | |||||||||||||
| Payments | (4,348) | (1,791) | (265) | (6,404) | |||||||||||||
| Net reserves transferred to liabilities held for sale | (45) | — | — | (45) | |||||||||||||
| Foreign currency adjustment | 14 | — | — | 14 | |||||||||||||
| Ending liabilities for unpaid losses and loss adjustment expenses, net | 20,787 | 1,808 | 1,302 | 23,897 | |||||||||||||
| Reinsurance and other recoverables | 4,271 | 28 | 1,426 | 5,725 | |||||||||||||
| Ending liabilities for unpaid losses and loss adjustment expenses, gross | $ | 25,058 | $ | 1,836 | $ | 2,728 | $ | 29,622 | |||||||||
| Earned premiums and fee income | $ | 8,940 | $ | 3,042 | |||||||||||||
| Loss and loss expense paid ratio [3] | 48.6 | 58.9 | |||||||||||||||
| Loss and loss expense incurred ratio | 66.5 | 48.7 | |||||||||||||||
| Prior accident year development (pts) [4] | 0.5 | (14.6) |
*[1]*Includes a cumulative effect adjustment of $1 and $(1) for Commercial Lines and Property & Casualty Other Operations respectively, representing an adjustment to the ACL recorded on adoption of accounting guidance for credit losses on January 1, 2020. See Note 1 - Basis of Presentation and Significant Accounting Policies of Notes to Consolidated Financial Statements for further information.
*[2]*Prior accident year development does not include the benefit of a portion of losses ceded under the Navigators and A&E ADCs which, under retroactive reinsurance accounting, is deferred and is recognized over the period the ceded losses are recovered in cash from NICO. For additional information regarding the two adverse development cover reinsurance agreements, refer to Note 12 - Reserve for Unpaid Losses and Loss Adjustment Expenses of Notes to Consolidated Financial Statements.
*[3]*The “loss and loss expense paid ratio” represents the ratio of paid losses and loss adjustment expenses to earned premiums and fee income.
[4]**“Prior accident year development (pts)” represents the ratio of prior accident year development to earned premiums.
| Current Accident Year Catastrophe Losses for the Year Ended December 31, 2020, Net of Reinsurance | |||||||||||
| Commercial Lines | Personal Lines | Total | |||||||||
| Wind and hail | $ | 167 | $ | 97 | $ | 264 | |||||
| Civil Unrest | 105 | — | 105 | ||||||||
| Hurricanes and Tropical Storms | 96 | 51 | 147 | ||||||||
| Wildfires | 21 | 61 | 82 | ||||||||
| Other | 8 | — | 8 | ||||||||
| Total catastrophe losses | $ | 397 | $ | 209 | $ | 606 | |||||
In December, 2019, the judge overseeing the bankruptcy of PG&E approved an $11 billion settlement of insurance subrogation claims to resolve all such claims arising from the 2017 Northern California wildfires and 2018 Camp wildfire. That settlement was contingent upon, among other things, the judge entering an order confirming PG&E’s chapter 11 bankruptcy plan (“PG&E Plan”) incorporating the settlement agreement. On June 20, 2020, the bankruptcy court judge approved the PG&E
Plan and PG&E subsequently transferred the $11 billion settlement amount to a trust designed to allocate and distribute the settlement among subrogation holders, including certain of the Company’s insurance subsidiaries. In the second quarter of 2020, the Company recorded an estimated $289 subrogation benefit though the ultimate amount it collects will depend on how the Company’s ultimate paid claims subject to subrogation compare to other insurers’ ultimate paid claims subject to
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
subrogation. In 2020, the Company received distributions, net of attorney costs, of $227.
| Unfavorable (Favorable) Prior Accident Year Development for the Year Ended December 31, 2020 | ||||||||||||||
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | |||||||||||
| Workers’ compensation | $ | (110) | $ | — | $ | — | $ | (110) | ||||||
| Workers’ compensation discount accretion | 35 | — | — | 35 | ||||||||||
| General liability | 237 | — | — | 237 | ||||||||||
| Marine | 3 | — | — | 3 | ||||||||||
| Package business | (58) | — | — | (58) | ||||||||||
| Commercial property | (4) | — | — | (4) | ||||||||||
| Professional liability | (14) | — | — | (14) | ||||||||||
| Bond | (19) | — | — | (19) | ||||||||||
| Assumed reinsurance | (6) | — | — | (6) | ||||||||||
| Automobile liability | 27 | (61) | — | (34) | ||||||||||
| Homeowners | — | 7 | — | 7 | ||||||||||
| Net asbestos and environmental reserves | — | — | (2) | (2) | ||||||||||
| Catastrophes | (149) | (380) | — | (529) | ||||||||||
| Uncollectible reinsurance | — | — | (8) | (8) | ||||||||||
| Other reserve re-estimates, net | — | (4) | 58 | 54 | ||||||||||
| Prior accident year development before change in deferred gain | (58) | (438) | 48 | (448) | ||||||||||
| Change in deferred gain on retroactive reinsurance included in other liabilities | 102 | — | 210 | 312 | ||||||||||
| Total prior accident year development | $ | 44 | $ | (438) | $ | 258 | $ | (136) |
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Rollforward of Property and Casualty Insurance Product Liabilities for Unpaid Losses and LAE for the Year Ended December 31, 2019
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | |||||||||||
| Beginning liabilities for unpaid losses and loss adjustment expenses, gross | $ | 19,455 | $ | 2,456 | $ | 2,673 | $ | 24,584 | ||||||
| Reinsurance and other recoverables | 3,137 | 108 | 987 | 4,232 | ||||||||||
| Beginning liabilities for unpaid losses and loss adjustment expenses, net | 16,318 | 2,348 | 1,686 | 20,352 | ||||||||||
| Navigators Group Acquisition | 2,001 | — | — | 2,001 | ||||||||||
| Provision for unpaid losses and loss adjustment expenses | ||||||||||||||
| Current accident year before catastrophes | 4,913 | 2,087 | — | 7,000 | ||||||||||
| Current accident year catastrophes | 323 | 140 | — | 463 | ||||||||||
| Prior accident year development [1] | (44) | (42) | 21 | (65) | ||||||||||
| Total provision for unpaid losses and loss adjustment expenses | 5,192 | 2,185 | 21 | 7,398 | ||||||||||
| Change in deferred gain on retroactive reinsurance included in other liabilities [1] | (16) | — | — | (16) | ||||||||||
| Payments | (4,161) | (2,400) | (187) | (6,748) | ||||||||||
| Foreign currency adjustment | (1) | — | — | (1) | ||||||||||
| Ending liabilities for unpaid losses and loss adjustment expenses, net | 19,333 | 2,133 | 1,520 | 22,986 | ||||||||||
| Reinsurance and other recoverables | 4,030 | 68 | 1,177 | 5,275 | ||||||||||
| Ending liabilities for unpaid losses and loss adjustment expenses, gross | $ | 23,363 | $ | 2,201 | $ | 2,697 | $ | 28,261 | ||||||
| Earned premiums and fee income | $ | 8,325 | $ | 3,235 | ||||||||||
| Loss and loss expense paid ratio [2] | 50.0 | 74.2 | ||||||||||||
| Loss and loss expense incurred ratio | 62.6 | 68.3 | ||||||||||||
| Prior accident year development (pts) [3] | (0.5) | (1.3) |
*[1]*Prior accident year development does not include the benefit of a portion of losses ceded under the Navigators and A&E ADCs which, under retroactive reinsurance accounting, is deferred and is recognized over the period the ceded losses are recovered in cash from NICO. For additional information regarding the two adverse development cover reinsurance agreements, refer to Note 12 - Reserve for Unpaid Losses and Loss Adjustment Expenses of Notes to Consolidated Financial Statements.
*[2]*The “loss and loss expense paid ratio” represents the ratio of paid losses and loss adjustment expenses to earned premiums and fee income.
[3]**“Prior accident year development (pts)” represents the ratio of prior accident year development to earned premiums.
| Current Accident Year Catastrophe Losses for the Year Ended December 31, 2019, Net of Reinsurance | |||||||||||
| Commercial Lines | Personal Lines | Total | |||||||||
| Wind and hail | $ | 157 | $ | 102 | $ | 259 | |||||
| Winter storms | 54 | 18 | 72 | ||||||||
| Tropical storms | 18 | 5 | 23 | ||||||||
| Hurricanes | 20 | 4 | 24 | ||||||||
| Wildfires | 4 | 4 | 8 | ||||||||
| Tornadoes | 53 | 7 | 60 | ||||||||
| Typhoons | 16 | — | 16 | ||||||||
| Other | 1 | — | 1 | ||||||||
| Total catastrophe losses | $ | 323 | $ | 140 | $ | 463 |
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| Unfavorable (Favorable) Prior Accident Year Development for the Year Ended December 31, 2019 | ||||||||||||||
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | |||||||||||
| Workers’ compensation | $ | (120) | $ | — | $ | — | $ | (120) | ||||||
| Workers’ compensation discount accretion | 33 | — | — | 33 | ||||||||||
| General liability | 61 | — | — | 61 | ||||||||||
| Marine | 8 | — | — | 8 | ||||||||||
| Package business | (47) | — | — | (47) | ||||||||||
| Commercial property | (11) | — | — | (11) | ||||||||||
| Professional liability | 29 | — | — | 29 | ||||||||||
| Bond | (3) | — | — | (3) | ||||||||||
| Assumed reinsurance | 3 | — | — | 3 | ||||||||||
| Automobile liability | 27 | (38) | — | (11) | ||||||||||
| Homeowners | — | 3 | — | 3 | ||||||||||
| Net asbestos and environmental reserves | — | — | — | — | ||||||||||
| Catastrophes | (40) | (2) | — | (42) | ||||||||||
| Uncollectible reinsurance | (5) | — | (25) | (30) | ||||||||||
| Other reserve re-estimates, net | 5 | (5) | 46 | 46 | ||||||||||
| Total prior accident year development | (60) | (42) | 21 | (81) | ||||||||||
| Change in deferred gain on retroactive reinsurance included in other liabilities | 16 | — | — | 16 | ||||||||||
| Total prior accident year development | $ | (44) | $ | (42) | $ | 21 | $ | (65) |
For discussion of the factors contributing to unfavorable (favorable) for the prior accident year reserve development 2021, 2020, and 2019 periods, refer to Note 12 - Reserve for
Unpaid Losses and Loss Adjustment Expenses of Notes to Consolidated Financial Statements.
|PROPERTY & CASUALTY OTHER OPERATIONS
Net reserves and reserve activity in Property & Casualty Other Operations are categorized and reported as asbestos, environmental, and “all other”. The “all other” category of reserves covers a wide range of insurance and assumed reinsurance coverages, including, but not limited to, potential liability for construction defects, lead paint, silica, pharmaceutical products, head injuries, sexual molestation and sexual abuse and other long-tail liabilities. In addition to various insurance and assumed reinsurance exposures, "all other" includes unallocated loss adjustment expense reserves. "All other" also includes the Company’s allowance for uncollectible reinsurance. When the Company commutes a ceded reinsurance contract or settles a ceded reinsurance dispute, net reserves for the related cause of loss (including asbestos, environmental or all other) are increased for the portion of the
allowance for uncollectible reinsurance attributable to that commutation or settlement.
Asbestos and Environmental Reserves
The vast majority of the Company's exposure to A&E relates to policy coverages provided prior to 1986, reported within the P&C Other Operations segment (“Run-off A&E”). In addition, since 1986, the Company has written asbestos and environmental exposures under general liability policies and pollution liability under homeowners policies, which are reported in the Commercial Lines and Personal Lines segments.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Run-off A&E Summary as of December 31, 2021
| Asbestos | Environmental | Total Run-off A&E | ||||||||||||
| Gross | ||||||||||||||
| Direct | $ | 1,247 | $ | 394 | $ | 1,641 | ||||||||
| Assumed Reinsurance | 460 | 68 | 528 | |||||||||||
| Total | 1,707 | 462 | 2,169 | |||||||||||
| Ceded- other than NICO | (444) | (68) | (512) | |||||||||||
| Total net reserves, before ceded losses to NICO | 1,263 | 394 | 1,657 | |||||||||||
| Ceded - NICO A&E ADC "Run-off"[1] | (1,053) | |||||||||||||
| Net | $ | 604 |
*[1]*Including $1,053 of ceded losses for Run-off A&E and a ($38) reduction in ceded losses for Commercial Lines and Personal Lines, cumulative net incurred losses of $1,015 have been ceded to NICO under an adverse development cover reinsurance agreement. See the section that follows entitled A&E Adverse Development Cover for additional information.
Rollforward of Run-off A&E Losses and LAE
| Asbestos | Environmental | Total Run-off A&E | |||||||||
| 2021 | |||||||||||
| Beginning net reserves before reinsurance recoverable from NICO | $ | 1,268 | $ | 419 | $ | 1,687 | |||||
| Losses and loss adjustment expenses incurred before ceding to NICO A&E ADC | 104 | 51 | 155 | ||||||||
| Losses and loss adjustment expenses paid | (112) | (76) | (188) | ||||||||
| Reclassification of allowance for uncollectible reinsurance [1] | 3 | — | 3 | ||||||||
| Ending net reserves before reinsurance recoverable from NICO | 1,263 | 394 | 1,657 | ||||||||
| Reinsurance recoverable from NICO A&E ADC | (1,053) | ||||||||||
| Ending net reserves | $ | 604 | |||||||||
| 2020 | |||||||||||
| Beginning net reserves before reinsurance recoverable from NICO | $ | 1,308 | $ | 346 | $ | 1,654 | |||||
| Losses and loss adjustment expenses incurred before ceding to NICO A&E ADC | 130 | 106 | 236 | ||||||||
| Losses and loss adjustment expenses paid | (172) | (33) | (205) | ||||||||
| Reclassification of allowance for uncollectible reinsurance [1] | 2 | — | 2 | ||||||||
| Ending net reserves before reinsurance recoverable from NICO | 1,268 | 419 | 1,687 | ||||||||
| Reinsurance recoverable from NICO A&E ADC | (898) | ||||||||||
| Ending net reserves | $ | 789 | |||||||||
| 2019 | |||||||||||
| Beginning net reserves before reinsurance recoverable from NICO | $ | 1,342 | $ | 321 | $ | 1,663 | |||||
| Losses and loss adjustment expenses incurred before ceding to NICO A&E ADC | 76 | 56 | 132 | ||||||||
| Losses and loss adjustment expenses paid | (111) | (32) | (143) | ||||||||
| Reclassification of allowance for uncollectible reinsurance [1] | 1 | 1 | 2 | ||||||||
| Ending net reserves before reinsurance recoverable from NICO | 1,308 | 346 | 1,654 | ||||||||
| Reinsurance recoverable from NICO A&E ADC | (660) | ||||||||||
| Ending liability — net | $ | 994 |
[1]Related to the reclassification of an allowance for uncollectible reinsurance from the "all other" category of P&C Other Operations reserves.
A&E Adverse Development Cover
Effective December 31, 2016, the Company entered into an A&E ADC reinsurance agreement with NICO, a subsidiary of Berkshire, to reduce uncertainty about potential adverse development. Under the A&E ADC, the Company paid a reinsurance premium of $650 for NICO to assume adverse net loss and allocated loss adjustment expense reserve development up to $1.5 billion above the Company’s existing net A&E reserves as of December 31, 2016 of approximately $1.7 billion, including both Run-off A&E and A&E reserves in Commercial Lines and Personal Lines. The $650 reinsurance premium was placed in a collateral trust account as security for
NICO’s claim payment obligations to the Company. The Company has retained the risk of collection on amounts due from other third-party reinsurers and continues to be responsible for claims handling and other administrative services, subject to certain conditions. The A&E ADC covers substantially all the Company’s A&E reserve development up to the reinsurance limit.
Under retroactive reinsurance accounting, net adverse A&E reserve development after December 31, 2016 results in an offsetting reinsurance recoverable up to the $1.5 billion limit. Cumulative ceded losses up to the $650 reinsurance
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
premium paid have been recognized as a dollar-for-dollar offset to direct losses incurred. Cumulative ceded losses exceeding the $650 reinsurance premium paid have resulted in a deferred gain. As of December 31, 2021, the Company has incurred a cumulative $1,015 in adverse development on A&E reserves that have been ceded under the A&E ADC treaty with NICO, including $1,053 for Run-off A&E reserves, partially offset by a $38 reduction for A&E reserves in Commercial Lines and Personal Lines. As such, $485 of coverage is available for future adverse net reserve development, if any. As a result, the Company has recorded a $365 deferred gain within other liabilities, representing the difference between the reinsurance recoverable of $1,015 and ceded premium paid of $650. The deferred gain is recognized over the claim settlement period in the proportion of the amount of cumulative ceded losses collected from the reinsurer to the estimated ultimate reinsurance recoveries. Consequently, until periods when the deferred gain is recognized as a benefit to earnings, cumulative adverse development of asbestos and environmental claims will result in charges against earnings, which may be significant.
Net and Gross Survival Ratios
Net and gross survival ratios are a measure of the quotient of the carried reserves divided by average annual payments (net of reinsurance and on a gross basis) and is an indication of the number of years that carried reserves would last (i.e. survive) if future annual payments were consistent with the calculated historical average.
Since December 31, 2016, asbestos and environmental net reserves have been declining since all adverse development has been ceded to NICO, up to a limit of $1.5 billion and the deferred gain on retroactive reinsurance has been recorded within other liabilities rather than in net loss and loss adjustment expense reserves. Recoveries from NICO will not be collected until the Company has cumulative loss payments of more than the attachment point of $1.7 billion which was based on the carrying value of net reserves as of December 31, 2016. Accordingly, the payment of losses without any current collection of recoveries from NICO has reduced the Company’s net loss reserves which decreases the net survival ratios such that, unadjusted, the net survival ratios would not be representative of the true number of years of average loss payments covered by the reserves. Therefore, the net survival ratios presented in the table below are calculated before considering the effect of the A&E ADC reinsurance agreement but net of other reinsurance in place.
Net and Gross Survival Ratios
| Asbestos | Environmental | |||||||||||||
| One year net survival ratio | 11.3 | 5.2 | ||||||||||||
| Three year net survival ratio | 9.6 | 8.4 | ||||||||||||
| One year gross survival ratio | 10.9 | 4.2 | ||||||||||||
| Three year gross survival ratio | 9.4 | 7.4 |
Run-off A&E Paid and Incurred Losses and LAE Development
| Asbestos | Environmental | Total A&E | ||||||||||||||||||
| Paid Losses & LAE | Incurred Losses & LAE | Paid Losses & LAE | Incurred Losses & LAE | Paid Losses & LAE | Incurred Losses & LAE | |||||||||||||||
| 2021 | ||||||||||||||||||||
| Gross | $ | 157 | $ | 148 | $ | 109 | $ | 55 | $ | 266 | $ | 203 | ||||||||
| Ceded- other than NICO | (45) | (44) | (33) | (4) | (78) | (48) | ||||||||||||||
| Net - Gross of ADC | 112 | 104 | 76 | 51 | 188 | 155 | ||||||||||||||
| Ceded - NICO A&E ADC | — | (155) | ||||||||||||||||||
| Net | $ | 188 | $ | — | ||||||||||||||||
| 2020 | ||||||||||||||||||||
| Gross | $ | 252 | $ | 170 | $ | 40 | $ | 141 | $ | 292 | $ | 311 | ||||||||
| Ceded- other than NICO | (80) | (40) | (7) | (35) | (87) | (75) | ||||||||||||||
| Net - Gross of ADC | 172 | 130 | 33 | 106 | 205 | 236 | ||||||||||||||
| Ceded - NICO A&E ADC | — | (238) | ||||||||||||||||||
| Net | $ | 205 | $ | (2) | ||||||||||||||||
| 2019 | ||||||||||||||||||||
| Gross | $ | 131 | $ | 115 | $ | 39 | $ | 95 | $ | 170 | $ | 210 | ||||||||
| Ceded- other than NICO | (20) | (39) | (7) | (39) | (27) | (78) | ||||||||||||||
| Net - Gross of ADC | 111 | 76 | 32 | 56 | 143 | 132 | ||||||||||||||
| Ceded - NICO A&E ADC | — | (132) | ||||||||||||||||||
| Net | $ | 143 | $ | — |
Annual Reserve Reviews
Review of Asbestos and Environmental Reserves
The Company performs its regular comprehensive annual review of asbestos and environmental reserves in the fourth quarter, including both Run-off A&E (P&C Other Operations) and asbestos and environmental reserves included in Commercial
Lines and Personal Lines. As part of the evaluation of asbestos and environmental reserves in the fourth quarter of 2021, the Company reviewed all of its open direct domestic insurance accounts exposed to asbestos and environmental liability, as well as assumed reinsurance accounts.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
2021 comprehensive annual reviews
As a result of the 2021 fourth quarter review, the Company increased estimated asbestos reserves before NICO reinsurance by $106, including $104 in P&C Other Operations, primarily due to an increase in claim settlement rates, claim settlement values, and defense costs, which more than offset the impact of a decline in claim filing frequency. Also contributing was an increase in the Company's estimated share of liability under pending or potential cost sharing agreements and settlements. The increase in asbestos reserves was offset by a $106 reinsurance recoverable under the NICO treaty.
As a result of the 2021 fourth quarter review, the Company increased estimated environmental reserves before NICO reinsurance by $49, including $51 in P&C Other Operations, primarily due to the settlement of a large coal ash remediation claim, an increase in legal defense costs and higher site remediation costs. The increase in environmental reserves was offset by a $49 reinsurance recoverable under the NICO treaty.
The total $155 increase in asbestos and environmental reserves in P&C Other Operations was offset by a $155 reinsurance recoverable under the NICO treaty. Since cumulative losses ceded to the A&E ADC exceed the $650 of ceded premium paid, the Company recognized a $155 increase in deferred gain on retroactive reinsurance, resulting in the Company recording a charge to earnings of $155 in 2021.
2020 comprehensive annual reviews
As a result of the 2020 fourth quarter review, the Company increased estimated asbestos reserves before NICO reinsurance in P&C Other Operations by $130, primarily due to an increase in the rate of asbestos claims settlements for both mesothelioma and non-mesothelioma claims. In addition, average settlement values and defense costs were higher than anticipated, driven by elevated plaintiff demands. Overall, the number of claim filings in the period covered by the 2020 study was roughly flat with the 2019 study, driven by an increase in non-mesothelioma claim filings, while the number of mesothelioma claim filings decreased as expected. The increase in asbestos reserves was offset by $132 reinsurance recoverable under the NICO treaty, recognizing ($2) in reserve releases not subject to the NICO treaty.
As a result of the 2020 fourth quarter review, the Company increased estimated environmental reserves before NICO reinsurance in P&C Other Operations by $106, primarily due to an increasing number of claims and suits alleging contamination from or exposure to PFAS. In addition, higher than anticipated remediation costs and legal defense costs also contributed to the reserve increase. The increase in environmental reserves was offset by a $106 reinsurance recoverable under the NICO treaty.
The total $236 increase in asbestos and environmental reserves in P&C Other Operations was offset by a $238 reinsurance recoverable under the NICO treaty, with a ($2) release in asbestos reserves not subject to the NICO treaty. Including a reduction of asbestos and environmental reserves in Commercial Lines and Personal Lines, the net increase in A&E reserves ceded to the A&E ADC in 2020 was $220 offset by a $220 increase in reinsurance recoverables under the NICO treaty. However, since cumulative losses ceded to the A&E ADC of $860 exceed the $650 of ceded premium paid, the Company recognized a $210 increase in deferred gain on retroactive
reinsurance, resulting in the Company recording a charge to earnings of $208 in 2020, consisting of the $210 deferred gain net of the $2 of favorable development on A&E reserves not subject to the NICO treaty.
For information regarding the 2019 comprehensive annual review, refer to Part 2, Item 7, Management's Discussion and Analysis of Financial Condition and Results of Operations in The Hartford’s 2020 Form 10-K Annual Report.
Major Categories of Asbestos Accounts
Direct asbestos exposures include both Known and Unallocated Direct Accounts.
-
Known Direct Accounts- includes both Major Asbestos Defendants and Non-Major Accounts, and represent approximately 71% of the Company's total Direct gross asbestos reserves as of December 31, 2021 compared to approximately 71% as of December 31, 2020. Major Asbestos Defendants have been defined as the “Top 70” accounts in Tillinghast's published Tiers 1 and 2 and Wellington accounts, while Non-Major accounts are comprised of all other direct asbestos accounts and largely represent smaller and more peripheral defendants. Major Asbestos Defendants have the fewest number of asbestos accounts.
-
Unallocated Direct Accounts- includes an estimate of the reserves necessary for asbestos claims related to direct insureds that have not previously tendered asbestos claims to the Company and exposures related to liability claims that may not be subject to an aggregate limit under the applicable policies. These exposures represent approximately 29% of the Company's Direct gross asbestos reserves as of December 31, 2021 compared to approximately 29% as of December 31, 2020.
Review of "All Other" Reserves in Property & Casualty Other Operations
Prior year development on all other reserves resulted in increases of $47, $50 and $21, respectively for calendar years 2021, 2020 and 2019. Included in the 2021 adverse reserve development was the portion of the increase in reserve for sexual molestation and sexual abuse claims recognized in P&C Other Operations, principally on assumed reinsurance. Also included in 2021 adverse development was an increase in reserves for ULAE, primarily due to an increase in expected aggregate claim handling costs associated with asbestos and environmental claims. For more information on the increase in reserves for sexual molestation and sexual abuse claims, see Note 12 - Reserve for Unpaid Losses and Loss Adjustment Expenses, of the Notes to Consolidated Financial Statements.
The Company provides an allowance for uncollectible reinsurance, reflecting management’s best estimate of reinsurance cessions that may be uncollectible in the future due to reinsurers’ unwillingness or inability to pay. In performing its assessment, the Company evaluates the collectibility of the reinsurance recoverables and the adequacy of the allowance for uncollectible reinsurance associated with older, long-term casualty liabilities reported in Property & Casualty Other Operations. In conducting these evaluations, the company used its most recent detailed evaluations of ceded liabilities reported in the segment. The Company analyzed the overall credit quality of the Company’s reinsurers, recent trends in arbitration and litigation outcomes in disputes between cedants and reinsurers,
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
and recent developments in commutation activity between reinsurers and cedants. As of 2021, 2020, and 2019 the allowance for uncollectible reinsurance for Property & Casualty Other Operations totaled $53, $60 and $71, respectively. Due to the inherent uncertainties as to collection and the length of time
before reinsurance recoverables become due, particularly for older, long-term casualty liabilities, it is possible that future adjustments to the Company’s reinsurance recoverables, net of the allowance, could be required.
|IMPACT OF RE-ESTIMATES ON PROPERTY & CASUALTY INSURANCE PRODUCT RESERVES
Estimating property and casualty insurance product reserves uses a variety of methods, assumptions and data elements. Ultimate losses may vary materially from the current estimates. Many factors can contribute to these variations and the need to change the previous estimate of required reserve levels. Prior accident year reserve development is generally due to the emergence of additional facts that were not known or anticipated at the time of the prior reserve estimate and/or due to changes in interpretations of information and trends.
The table below shows the range of annual reserve re-estimates experienced by The Hartford over the past ten years. The range of prior accident year development shown in the table below is net of losses ceded, including losses ceded under two adverse
development cover reinsurance agreements with NICO that are accounted for as a deferred gain on retroactive reinsurance. The amount of prior accident year development (as shown in the reserve rollforward) for a given calendar year is expressed as a percent of the beginning calendar year reserves, net of reinsurance. The ranges presented are significantly influenced by the facts and circumstances of each particular year and by the fact that only the last ten years are included in the range. Accordingly, these percentages are not intended to be a prediction of the range of possible future variability. For further discussion of the potential for variability in recorded loss reserves, see Preferred Reserving Methods by Line of Business and Impact of Key Assumptions on Reserves sections.
Range of Prior Accident Year Unfavorable (Favorable) Development for the Ten Years Ended December 31, 2021
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty [1] | |||||||||||
| Annual range of prior accident year unfavorable (favorable) development for the ten years ended December 31, 2021 | (1.3%) - 0.6% | (20.5%) - 8.3% | 0.9% - 9.8% | (1.9%) - 2.4% |
*[1]*Excluding the reserve increases for asbestos and environmental reserves, over the past ten years, reserve re-estimates for total property and casualty insurance ranged from (1.9%) to 1.0%.
The potential variability of the Company’s property and casualty insurance product reserves would normally be expected to vary by segment and the types of loss exposures insured by those segments. Illustrative factors influencing the potential reserve variability for each of the segments are discussed under Critical Accounting Estimates for Property & Casualty Insurance Product Reserves and Asbestos and Environmental Reserves. See the section entitled Property & Casualty Other Operations, Annual Reserve Reviews about the impact that the A&E ADC retroactive reinsurance agreement with NICO has on net reserve changes of asbestos and environmental reserves.
The following table summarizes the effect of reserve re-estimates, net of reinsurance, on calendar year operations for the ten-year period ended December 31, 2021. The total of each column details the amount of reserve re-estimates made in the indicated calendar year and shows the accident years to which the re-estimates are applicable. The amounts in the total column on the far right represent the cumulative reserve re-estimates during the ten year period ended December 31, 2021 for the indicated accident year in each row. This table does not include Navigators Group reserve re-estimates for periods prior to the acquisition of the business on May 23, 2019.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Effect of Net Reserve Re-estimates on Calendar Year Operations
| Calendar Year | |||||||||||||||||||||||||||||||||||
| 2012 | 2013 | 2014 | 2015 | 2016 | 2017 | 2018 | 2019 | 2020 | 2021 | Total | |||||||||||||||||||||||||
| By Accident Year | |||||||||||||||||||||||||||||||||||
| 2011 & Prior | $ | (4) | $ | 173 | $ | 326 | $ | 362 | $ | 310 | $ | 93 | $ | (26) | $ | 19 | $ | 277 | $ | 569 | $ | 2,099 | |||||||||||||
| 2012 | 19 | — | (55) | (35) | (12) | (15) | (15) | (25) | (14) | (152) | |||||||||||||||||||||||||
| 2013 | (98) | (43) | (29) | (33) | (2) | (26) | (15) | (35) | (281) | ||||||||||||||||||||||||||
| 2014 | (14) | 20 | (19) | (54) | (29) | (28) | (59) | (183) | |||||||||||||||||||||||||||
| 2015 | 191 | (41) | (93) | 19 | (16) | (70) | (10) | ||||||||||||||||||||||||||||
| 2016 | (29) | 14 | (11) | (38) | (83) | (147) | |||||||||||||||||||||||||||||
| 2017 | 9 | (116) | (204) | (111) | (422) | ||||||||||||||||||||||||||||||
| 2018 | 78 | (307) | (96) | (325) | |||||||||||||||||||||||||||||||
| 2019 | (92) | (47) | (139) | ||||||||||||||||||||||||||||||||
| 2020 | (101) | (101) | |||||||||||||||||||||||||||||||||
| Increase (decrease) in net reserves [1] | (4) | 192 | 228 | 250 | 457 | (41) | (167) | (81) | (448) | (47) | 339 | ||||||||||||||||||||||||
| Change in deferred gain on retroactive reinsurance included in other liabilities | 16 | 312 | 246 | ||||||||||||||||||||||||||||||||
| Total unfavorable (favorable) prior accident year development | $ | (65) | $ | (136) | $ | 199 |
*[1]*Increase (decrease) in net reserves by accident year in the above table is net of losses ceded, including losses ceded under two adverse development cover reinsurance agreements with NICO accounted for as a deferred gain on retroactive reinsurance. One agreement covers substantially all A&E reserve development for 2016 and prior accident years (the “A&E ADC”) up to an aggregate limit of $1.5 billion and the other covered substantially all reserve development of Navigators Insurance Company and certain of its affiliates for 2018 and prior accident years (“Navigators ADC”) up to an aggregate limit of $300. For calendar years before 2017, the 2011 and prior accident year development includes adverse development for A&E reserves. For additional information regarding the two adverse development cover reinsurance agreements, refer to Note 12 – Reserve for Unpaid Losses and Loss Adjustment Expenses of Notes to Consolidated Financial Statements.
The commentary below explains, by accident year, the total prior accident year development recognized over the past 10 years.
Accident year 2011 and Prior
The net increases in estimates of ultimate losses for accident years 2011 and prior were driven mostly by increased reserves for asbestos and environmental reserves, and also by increased estimates for customs bonds, sexual molestation and sexual abuse and other mass torts claims. Also contributing was an increase in workers' compensation and commercial automobile liability, offset by favorable development in personal automobile liability.
Accident years 2012 and 2013
Estimates of ultimate losses were decreased for accident years 2012 and 2013 due to favorable frequency and/or medical severity trends for workers’ compensation and favorable professional liability claim emergence. Favorable emergence of property lines of business, including catastrophes, for the 2013 accident year, was partially offset by increased reserves in automobile liability due to increased severity of large claims.
Accident years 2014 and 2015
Changes in estimates of ultimate losses for accident years 2014 and 2015 were largely driven by favorable frequency and medical severity trends for workers' compensation, partially offset by unfavorable frequency and severity trends for personal and commercial automobile liability and increased severity of liability claims on package business.
Accident year 2016
Estimates of ultimate losses were decreased for the 2016 accident year largely due to reserve decreases on workers' compensation and personal automobile liability due to lower
estimated severity, partially offset by unfavorable reserve estimates for higher hazard general liability exposures due to increased frequency and severity trends, higher estimated severity in middle & large commercial and on the acquired Navigators Group book of business related to U.S. construction, premises liability, products liability and excess casualty.
Accident year 2017
Ultimate loss estimates were decreased for the 2017 accident year mainly due to release of reserves related to catastrophes, lower reserve estimates in personal automobile liability due to emergence of lower estimated severity and lower reserve estimates for workers’ compensation related to lower than previously estimated claim severity, partially offset by increases in estimates of ultimate losses in general liability and bond. Partially offsetting was an increase to general liability reserves that was related to high hazard exposures which experienced increased frequency and severity trends. In addition, unfavorable bond reserve re-estimates were driven by large claims.
Accident year 2018
Ultimate loss estimates were decreased for the 2018 accident year mainly due to reduction in estimated catastrophe reserves for California wildfires and for various wind and hail events. Reserve estimates were also reduced, to a lesser extent, for personal automobile liability which decreased due to lower than previously expected claim severity. These reserve decreases were partially offset by increases in commercial automobile liability and general liability. Commercial automobile liability reserve increases were related to higher estimated severity on middle & large commercial claims. Increases in general liability reserves for middle market and complex liability claims were also largely due to higher than previously expected severity.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Accident year 2019
Ultimate loss estimates were decreased for the 2019 accident year mainly due to favorable emergence of property lines of business, primarily related to catastrophes. In addition, reduced reserve estimates for personal automobile liability were largely offset by higher reserve estimates for commercial automobile liability.
Accident year 2020
Ultimate loss estimates were decreased for the 2020 accident year mainly due to favorable emergence of property lines of business, inclusive of catastrophes. Reserve estimates were also reduced, to a lesser extent, for personal automobile liability due to lower estimated severity and for general liability.
|GROUP BENEFIT RESERVES, NET OF REINSURANCE
The Company establishes reserves for group life and accident & health contracts, including long-term disability coverage, for both reported claims and claims related to insured events that the Company estimates have been incurred but have not yet been reported. As long-term disability reserves are long-tail claim liabilities, they are discounted because the payment pattern and the ultimate costs are reasonably fixed and determinable on an individual claim basis. The Company held $6,437 and $6,494 of LTD unpaid losses and loss adjustment expenses, net of reinsurance, as of December 31, 2021 and 2020, respectively.
Reserving Methodology
How Reserves are Set - A Disabled Life Reserve ("DLR") is calculated for each LTD claim. The DLR for each claim is the expected present value of all future benefit payments starting with the known monthly gross benefit which is reduced for estimates of the expected claim recovery due to return to work or claimant death, offsets from other income including offsets from Social Security benefits, and discounting where the discount rate is tied to expected investment yield at the time the claim is incurred. Estimated future benefit payments represent the monthly income benefit that is paid until recovery, death or expiration of benefits. Claim recoveries are estimated based on claim characteristics such as age and diagnosis and represent an estimate of benefits that will terminate, generally as a result of the claimant returning to work or being deemed able to return to work. For claims recently closed due to recovery, a portion of the DLR is retained for the possibility that the claim reopens upon further evidence of disability. In addition, a reserve for estimated unpaid claim expenses is included in the DLR.
The DLR also includes a liability for potential payments to pending claimants beyond the elimination period who have not yet been approved for LTD. In these cases, the present value of future benefits is reduced for the likelihood of claim denial based on Company experience.
Estimates for IBNR claims are made by applying completion factors to expected emerged experience by line of business. Included within IBNR are bulk reserves for claims reported but still within the waiting period until benefits are paid, typically 3 or 6 months depending on the contract. Completion factors are derived from standard actuarial techniques using triangles that display historical claim count emergence by incurral month. These estimates are reviewed for reasonableness and are adjusted for current trends and other factors expected to cause a change in claim emergence. The reserves include an estimate of unpaid claim expenses, including a provision for the cost of initial set-up of the claim once reported.
For all products, including LTD, there is a period generally ranging from two to twelve months, depending on the product and line of business, where emerged claims for an incurral year
are not yet credible enough to be a basis for estimating reserves. In these cases, the ultimate loss is estimated using earned premium multiplied by an expected loss ratio based on pricing assumptions of claim incidence, claim severity, and earned pricing.
Impact of Key Assumptions on Reserves
The key assumptions affecting long-term disability, which is the largest reserve within Group Benefits, include:
Discount Rate - The discount rate is the interest rate at which expected future claim cash flows are discounted to determine the present value. A higher selected discount rate results in a lower reserve. If the discount rate is higher than our future investment returns, our invested assets will not earn enough investment income to cover the discount accretion on our claim reserves which would negatively affect our profits. For each incurral year, the discount rates are estimated based on investment yields expected to be earned net of investment expenses. The incurral year is the year in which the claim is incurred and the estimated settlement pattern is determined. Once established, discount rates for each incurral year are unchanged except that LTD reserves assumed from the acquisition of Aetna's U.S. group life and disability business are all discounted using rates as of the November 1, 2017 acquisition date. The weighted average discount rate on LTD reserves was 3.3% and 3.4% in 2021 and 2020, respectively. Had the discount rate for each incurral year been 10 basis points lower at the time they were established, our LTD unpaid loss and loss adjustment expense reserves would be higher by $28, before tax, as of December 31, 2021.
Claim Termination Rates (inclusive of mortality, recoveries, and expiration of benefits) - Claim termination rates are an estimate of the rate at which claimants will cease receiving benefits during a given calendar year. Terminations result from a number of factors, including death, recoveries and expiration of benefits. The probability that benefits will terminate in each future month for each claim is estimated using a predictive model that uses past Company experience, contract provisions, job characteristics and other claimant-specific characteristics such as diagnosis, time since disability began, and age. Actual claim termination experience will vary from period to period. Over the past 10 years, claim termination rates for a single incurral year have generally increased and have ranged from 5% below to 8% above current assumptions over that time period. For a single recent incurral year (such as 2021), a one percent decrease in our assumption for LTD claim termination rates would increase our reserves by $10. For all incurral years combined, as of December 31, 2021, a one percent decrease in our assumption for our LTD claim
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
termination rates would increase our Group Benefits unpaid losses and loss adjustment expense reserves by $23.
Impact of COVID-19 on 2021 Results of Operations
Within Group Benefits, the Company experienced excess mortality in its group life business of $583 in 2021, primarily caused by direct and indirect impacts of COVID-19. Within the group disability business, in 2021 the Company recognized $31 of COVID-19 related losses from short-term disability claims.
Current Trends Contributing to Reserve Uncertainty
While we have not seen a significant change in claim recovery patterns to date due to COVID-19, we have observed delays in
the Social Security Administration’s processing of disability claims. Other potential pandemic-related risks, such as delays in medical care or return-to-work and the emerging risk of long-COVID symptoms are being monitored. Also, due to the effects on the economy, we could experience an increase in claim incidence on long-term disability claims.
We hedge our interest rate exposure over a three year period at the time we price and sell long-term disability policies and our weighted average discount rate assumption for the 2021 incurral year is down slightly from that of the 2020 incurral year.
|EVALUATION OF GOODWILL FOR IMPAIRMENT
Goodwill balances are reviewed for impairment at least annually, or more frequently if events occur or circumstances change that would indicate that a triggering event for a potential impairment has occurred. The recognition and measurement of goodwill impairment is based on the excess of the carrying value of the reporting unit over its estimated fair value, up to the amount of the reporting unit’s goodwill.
The estimated fair value of each reporting unit incorporates multiple inputs into discounted cash flow calculations including assumptions that market participants would make in valuing the reporting unit. Assumptions include levels of economic capital, future business growth, earnings projections, assets under management for Hartford Funds and the weighted average cost of capital used for purposes of discounting. Decreases in business growth, decreases in earnings projections and increases in the weighted average cost of capital will all cause a reporting unit’s fair value to decrease, increasing the possibility of impairment.
A reporting unit is defined as an operating segment or one level below an operating segment. The Company’s reporting units for which goodwill has been allocated consist of Commercial Lines, Personal Lines, Group Benefits and Hartford Funds.
The carrying value of goodwill was $1,911 as of December 31, 2021 and was comprised of $659 for Commercial Lines, $119 for Personal Lines, $861 for Group Benefits, and $272 for Hartford Funds.
The annual goodwill assessment for the reporting units was completed as of October 31, 2021, and resulted in no write-downs of goodwill for the year ended December 31, 2021. All reporting units passed the annual impairment test with a significant margin. For information regarding the 2021 and 2020 impairment tests see Note 11 - Goodwill & Other Intangible Assets of Notes to Consolidated Financial Statements.
|VALUATION OF INVESTMENTS AND DERIVATIVE INSTRUMENTS
Fixed Maturities, Equity Securities, Short-term Investments, and Derivatives
The Company generally determines fair values using valuation techniques that use prices, rates, and other relevant information evident from market transactions involving identical or similar instruments. Valuation techniques also include, where appropriate, estimates of future cash flows that are converted into a single discounted amount using current market expectations. The Company uses a "waterfall" approach comprised of the following pricing sources which are listed in priority order: quoted prices, prices from third-party pricing services, internal matrix pricing, and independent broker quotes. The fair value of derivative instruments is determined primarily using a discounted cash flow model or option model technique and incorporate counterparty credit risk. In some cases, quoted market prices for exchange-traded transactions and transactions cleared through central clearing houses ("OTC-cleared") may be used and in other cases independent broker quotes may be
used. For further discussion, see the Fixed Maturities, Equity Securities, Short-term Investments and Derivatives section in Note 5 - Fair Value Measurements of Notes to Consolidated Financial Statements.
Evaluation of Credit Losses on Fixed Maturities, AFS and ACL on Mortgage Loans
Each quarter, a committee of investment and accounting professionals evaluates investments to determine if a credit loss is present for fixed maturities, AFS or an ACL is required for mortgage loans. This evaluation is a quantitative and qualitative process, which is subject to risks and uncertainties. For further discussion of the accounting policies, see the Significant Investment Accounting Policies Section in Note 1 - Basis of Presentation and Significant Accounting Policies of Notes to Consolidated Financial Statements. For a discussion of credit losses recorded, see the Credit Losses on Fixed Maturities, AFS and Intent-to-Sell Impairments and ACL on Mortgage Loans
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
sections within the Investment Portfolio Risks and Risk Management section of the MD&A.
|CONTINGENCIES RELATING TO CORPORATE LITIGATION AND REGULATORY MATTERS
Management evaluates each contingent matter separately. A loss is recorded if probable and reasonably estimable. Management establishes reserves for these contingencies at its “best estimate,” or, if no one number within the range of possible losses is more probable than any other, the Company records an estimated reserve at the low end of the range of losses.
The Company has a quarterly monitoring process involving legal and accounting professionals. Legal personnel first identify outstanding corporate litigation and regulatory matters posing a reasonable possibility of loss. These matters are then jointly reviewed by accounting and legal personnel to evaluate the facts and changes since the last review in order to determine if a provision for loss should be recorded or adjusted, the amount that should be recorded, and the appropriate disclosure. The outcomes of certain contingencies currently being evaluated by
the Company, which relate to corporate litigation and regulatory matters, are inherently difficult to predict, and the reserves that have been established for the estimated settlement amounts are subject to significant changes. Management expects that the ultimate liability, if any, with respect to such lawsuits, after consideration of provisions made for estimated losses, will not be material to the consolidated financial condition of the Company. In view of the uncertainties regarding the outcome of these matters, as well as the tax-deductibility of payments, it is possible that the ultimate cost to the Company of these matters could exceed the reserve by an amount that would have a material adverse effect on the Company’s consolidated results of operations and liquidity in a particular quarterly or annual period.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| SEGMENT OPERATING SUMMARIES |
| |COMMERCIAL LINES - RESULTS OF OPERATIONS |
Underwriting Summary
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Written premiums | $ | 10,041 | $ | 8,969 | $ | 8,452 | 12 | % | 6 | % | |||||||
| Change in unearned premium reserve | 500 | 59 | 162 | NM | (64 | %) | |||||||||||
| Earned premiums | 9,541 | 8,910 | 8,290 | 7 | % | 7 | % | ||||||||||
| Fee income | 34 | 30 | 35 | 13 | % | (14 | %) | ||||||||||
| Losses and loss adjustment expenses | |||||||||||||||||
| Current accident year before catastrophes | 5,407 | 5,488 | 4,913 | (1 | %) | 12 | % | ||||||||||
| Current accident year catastrophes [1] | 496 | 397 | 323 | 25 | % | 23 | % | ||||||||||
| Prior accident year development [1] | 141 | 44 | (44) | NM | NM | ||||||||||||
| Total losses and loss adjustment expenses | 6,044 | 5,929 | 5,192 | 2 | % | 14 | % | ||||||||||
| Amortization of DAC | 1,398 | 1,397 | 1,296 | — | % | 8 | % | ||||||||||
| Underwriting expenses | 1,678 | 1,594 | 1,600 | 5 | % | — | % | ||||||||||
| Amortization of other intangible assets | 29 | 28 | 18 | 4 | % | 56 | % | ||||||||||
| Dividends to policyholders | 24 | 29 | 30 | (17 | %) | (3 | %) | ||||||||||
| Underwriting gain (loss) | 402 | (37) | 189 | NM | (120 | %) | |||||||||||
| Net servicing income | 13 | 4 | 2 | NM | 100 | % | |||||||||||
| Net investment income [2] | 1,502 | 1,160 | 1,129 | 29 | % | 3 | % | ||||||||||
| Net realized gains (losses) [2] | 260 | (60) | 271 | NM | (122 | %) | |||||||||||
| Loss on reinsurance transaction | — | — | (91) | — | % | 100 | % | ||||||||||
| Other (expenses) | (18) | (35) | (38) | 49 | % | 8 | % | ||||||||||
| Income before income taxes | 2,159 | 1,032 | 1,462 | 109 | % | (29 | %) | ||||||||||
| Income tax expense [3] | 402 | 176 | 270 | 128 | % | (35 | %) | ||||||||||
| Net income | $ | 1,757 | $ | 856 | $ | 1,192 | 105 | % | (28 | %) |
*[1]*For additional information on current accident year catastrophes and prior accident year development, see MD&A - Critical Accounting Estimates, Property and Casualty Insurance Product Reserves Development, Net of Reinsurance and Note 12- Reserve for Unpaid Losses and Loss Adjustment Expenses of Notes to Consolidated Financial Statements.
*[2]*For discussion of consolidated investment results, see MD&A - Investment Results.
*[3]*For discussion of income taxes, see Note 17 - Income Taxes of Notes to Consolidated Financial Statements.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Premium Measures
| 2021 | 2020 | 2019 | ||||||||||||
| Small Commercial: | ||||||||||||||
| Net new business premium | $ | 673 | $ | 557 | $ | 646 | ||||||||
| Policy count retention [1] | 84 | % | 83 | % | 82 | % | ||||||||
| Policy count retention, net of cancellations [1] | 87 | % | 84 | % | 83 | % | ||||||||
| Renewal written price increases | 3.0 | % | 2.0 | % | 1.7 | % | ||||||||
| Renewal earned price increases | 2.6 | % | 2.1 | % | 1.9 | % | ||||||||
| Policies in-force as of end of period (in thousands) | 1,366 | 1,283 | 1,291 | |||||||||||
| Middle Market [2]: | ||||||||||||||
| Net new business premium | $ | 532 | $ | 479 | $ | 584 | ||||||||
| Policy count retention [1] | 82 | % | 78 | % | 81 | % | ||||||||
| Policy count retention, net of cancellations [1] | 83 | % | 78 | % | 81 | % | ||||||||
| Renewal written price increases | 6.0 | % | 7.7 | % | 3.9 | % | ||||||||
| Renewal earned price increases | 7.3 | % | 6.5 | % | 2.8 | % | ||||||||
| Global Specialty: | ||||||||||||||
| Global specialty gross new business premium [3] | $ | 912 | $ | 752 | ||||||||||
| U.S. global specialty renewal written price increases | 11.5 | % | 17.3 | % | ||||||||||
| U.S. global specialty renewal earned price increases | 16.6 | % | 13.0 | % | ||||||||||
| International global specialty renewal written price increases [4] | 19.6 | % | 41.8 | % | ||||||||||
| International global specialty renewal earned price increases [4] | 42.8 | % | 41.3 | % | ||||||||||
*[1]*Policy count retention represents the ratio of the number of renewal policies issued during the current year period divided by the number of policies issued in the previous calendar year period before considering policies cancelled subsequent to renewal. Policy count retention, net of cancellations, represents the ratio of the number of renewal policies issued net of cancellations during the current year period divided by the number of policies issued net of cancellations in the previous calendar year period.
*[2]*Except for net new business premium, metrics for middle market exclude loss sensitive and programs businesses.
*[3]*Excludes Global Re and Continental Europe Operations and is before ceded reinsurance.
*[4]*Excludes offshore energy policies, political violence and terrorism policies, and any business under which the managing agent of our Lloyd's Syndicate delegates underwriting authority to coverholders and other third parties.
Underwriting Ratios
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Loss and loss adjustment expense ratio | |||||||||||||||||
| Current accident year before catastrophes | 56.7 | 61.6 | 59.3 | (4.9) | 2.3 | ||||||||||||
| Current accident year catastrophes | 5.2 | 4.5 | 3.9 | 0.7 | 0.6 | ||||||||||||
| Prior accident year development | 1.5 | 0.5 | (0.5) | 1.0 | 1.0 | ||||||||||||
| Total loss and loss adjustment expense ratio | 63.3 | 66.5 | 62.6 | (3.2) | 3.9 | ||||||||||||
| Expense ratio | 32.2 | 33.5 | 34.7 | (1.3) | (1.2) | ||||||||||||
| Policyholder dividend ratio | 0.3 | 0.3 | 0.4 | — | (0.1) | ||||||||||||
| Combined ratio | 95.8 | 100.4 | 97.7 | (4.6) | 2.7 | ||||||||||||
| Impact of current accident year catastrophes and prior year development | (6.7) | (5.0) | (3.4) | (1.7) | (1.6) | ||||||||||||
| Impact of current accident year change in loss reserves upon acquisition of a business [1] | — | — | (0.3) | — | 0.3 | ||||||||||||
| Underlying combined ratio | 89.1 | 95.5 | 94.0 | (6.4) | 1.5 |
*[1]*Upon acquisition of Navigators Group and a review of Navigators Insurers reserves, the year ended December 31, 2019 included $68 of prior accident year reserve increases and $29 of current accident year reserve increases which were excluded for the purposes of the underlying combined ratio calculation.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Net Income

Year ended December 31, 2021 compared to the year ended December 31, 2020
Net income increased primarily due to a change from an underwriting loss to an underwriting gain, higher net investment income and a change from net realized losses to net realized gains. For further discussion of investment results, see MD&A - Investment Results.
Underwriting Gain (Loss)

Year ended December 31, 2021 compared to the year ended December 31, 2020
Underwriting gain in 2021 compared with an underwriting loss in 2020 with the improvement primarily due to lower current accident year losses before catastrophes, partially offset by higher net unfavorable prior accident year development and higher current accident year catastrophes. The decrease in current accident year losses before catastrophes was primarily driven by $278 before tax of COVID-19 incurred losses in 2020 compared with $31 before tax of COVID-19 incurred losses in 2021, partially offset by the impact of higher earned premium on incurred losses. Underwriting expenses increased due to higher contingent and supplemental commissions, incentive compensation, technology costs and marketing expenses, partially offset by a decrease in the allowance for credit losses on premiums receivable in the 2021 period compared to an increase in the 2020 period and savings from Hartford Next initiatives.
Earned Premiums

*[1]*Other of $42, $43 and $43 for 2019, 2020 and 2021, respectively, is included in the total.
Written Premiums

*[1]*Other written premiums of $41, $41 and $43 for the year ended December 31, 2019, 2020 and 2021, respectively, is included in the total.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Year ended December 31, 2021 compared to the year ended December 31, 2020
Earned premiums increased in 2021 due to written premium increases over the prior 12 months as well as due to higher premiums from audits and endorsements, principally in workers’ compensation due to an increasing exposure base from higher payrolls as the economy recovers from the pandemic.
Written premiums increased in 2021 driven by growth in small commercial, middle & large commercial and global specialty across most lines of business.
The Company recognized renewal written pricing increases in all lines in 2021, with moderating price increases across most lines in middle market and global specialty. In global specialty, our U.S. wholesale book achieved an approximate 16% renewal written price increase, led by excess casualty. Global specialty international lines achieved a nearly 20% price increase, led by D&O. In small commercial, renewal written price increases were higher in 2021 than 2020, with workers' compensation pricing slightly positive in 2021 due to rising wages, along with mid-single digit increases in most other lines. In middle market, the Company recognized high single-digit to low double-digit rate increases in most middle market lines other than workers’ compensation, which experienced low single-digit written pricing increases.
Written premium increased across all three lines of business.
-
Small commercial written premium increased in 2021 driven by exposure growth from higher audit and endorsement premium, higher policy count retention, renewal written pricing increases in all lines as well as new business growth. Written premium grew in all lines of business, with the most significant growth in package business and workers’ compensation.
-
Middle & large commercial written premium increased in 2021 driven by exposure growth from higher audit and endorsement premium, improved retention, renewal written pricing increases in all lines as well as new business growth. Written premium grew in most lines of business, including general industries, national accounts, complex liability solutions and specialized industries.
-
Global specialty written premium increased in 2021 driven by continued strong written pricing increases, higher retention and growth in gross new written premium. Written premium grew in all lines except international, with the most significant growth in U.S. wholesale, financial lines and global reinsurance.
Current Accident Year Loss and LAE Ratio before Catastrophes

Year ended December 31, 2021 compared to the year ended December 31, 2020
Current Accident Year Loss and LAE ratio before catastrophes decreased in 2021 primarily due to lower COVID-19 incurred losses in 2021 as well as due to lower loss ratios in global specialty and workers’ compensation. The lower loss ratios in global specialty were largely the result of rate and underwriting actions to improve profitability in those lines and was driven by U.S. financial lines, global reinsurance, U.S. wholesale and international.
2021 included COVID-19 incurred losses of $31 before tax, including losses of $20 in workers’ compensation and $11 in financial and other lines. 2020 included COVID-19 incurred losses of $278 before tax, including losses of $141 in property, $66 in workers’ compensation, net of favorable frequency on other workers' compensation claims, and $71 in financial and other lines.
Included in the $141 of COVID-19 property incurred losses and loss adjustment expenses in 2020 were $101 of losses arising from a small number of property policies that do not require direct physical loss or damage and from policies intended to cover specific business needs, including crisis management and performance disruption as well as a reserve of $40 for legal defense costs. Workers’ compensation COVID-19 incurred losses include claims in both states with presumptive coverage and in other states where the claimant must prove their COVID-19 illness was contracted at work. Financial lines COVID-19 claims include exposures in D&O, E&O and employment practices liability and the recessionary impacts on the surety book of business.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Catastrophes and Unfavorable (Favorable) Prior Accident Year Development

Y****ear ended December 31, 2021 compared to the year ended December 31, 2020
Current accident year catastrophe losses for 2021 included losses from tornado, wind and hail events, mostly concentrated in the Midwest, Texas and Southeast as well as hurricane Ida, and February winter storms primarily in the South.
Current accident year catastrophe losses for 2020 were primarily from civil unrest, a number of hurricanes and tropical storms, Pacific Coast wildfires, and Northeast windstorms as well as tornado, wind and hail events in the South, Midwest and Central Plains.
Prior accident year development was net unfavorable for 2021. Reserve development in 2021 included an increase in general liability that included a reserve increase related to the settlement with Boy Scouts of America on sexual molestation and sexual abuse claims, largely offset by reserve decreases for workers' compensation, package business, catastrophes, commercial property and bond.
Net unfavorable reserve development for 2020 included reserve increases for general liability driven primarily by increases in reserves for sexual molestation and sexual abuse claims, and increases in commercial automobile liability reserves, partially offset by net reserve decreases for catastrophes, workers' compensation and package business. Partially offsetting was
favorable development on prior year catastrophe reserves in 2020 due to recognizing a $29 before tax subrogation benefit from a settlement with PG&E over certain of the 2017 and 2018 California wildfires and a reduction in estimated catastrophe losses from a number of wind and hail events that occurred in 2017, 2018 and 2019.
Prior accident year development in both 2021 and 2020 included reserve increases related to Navigators Group on 2018 and prior accident years that was economically ceded to NICO but for which the benefit was not recognized in earnings as it has been recorded as a deferred gain on retroactive reinsurance.
2022 Outlook
The Company expects Commercial Lines written premiums in 2022 to be 4% to 5% higher than written premiums in 2021, with growth across small commercial, middle & large commercial, and global specialty. In small commercial, policy retention is expected to remain strong with new business growth across all lines of business. In middle & large commercial, we expect written premium growth in our general industries book of business driven by improved retention and new business growth, as well as an increase in new business in specialized industries. In global specialty, premium growth in 2022 is expected primarily in wholesale and financial lines in the U.S., as well as in global reinsurance and international.
In 2022, management expects positive renewal written pricing in most lines, though workers' compensation pricing is expected to be flat to slightly negative. Across the rest of Commercial Lines, mid single-digit rate increases are expected to continue in most lines with written pricing increases in the high single-digits in wholesale and ocean marine. Written pricing increases in 2022 in lines other than workers’ compensation are driven by a number of factors including the effects of social inflation, increased catastrophe losses due to changing weather patterns, and a prolonged low interest rate environment, that puts added pressure on the need for underwriting profits to make up for the lost investment yield.
The Company expects the Commercial Lines combined ratio will be 90.0 to 92.0 in 2022, compared to 95.8 in 2021, primarily due to lower current accident year catastrophe losses expected in 2022, and the effect of a prior accident year reserve increase and COVID-19 incurred claims in 2021. Apart from lower expected COVID-19 claims, we expect earned pricing increases in excess of loss costs in most lines except workers’ compensation, while the expense ratio is expected to improve driven, in part, by additional savings from Hartford Next initiatives. The underlying combined ratio is expected to be 86.5 to 88.5 in 2022 compared to 89.1 in 2021.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| | PERSONAL LINES - RESULTS OF OPERATIONS |
Underwriting Summary
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Written premiums | $ | 2,908 | $ | 2,936 | $ | 3,131 | (1 | %) | (6 | %) | |||||||
| Change in unearned premium reserve | (46) | (72) | (67) | 36 | % | (7 | %) | ||||||||||
| Earned premiums | 2,954 | 3,008 | 3,198 | (2 | %) | (6 | %) | ||||||||||
| Fee income | 32 | 34 | 37 | (6 | %) | (8 | %) | ||||||||||
| Losses and loss adjustment expenses | |||||||||||||||||
| Current accident year before catastrophes | 1,840 | 1,695 | 2,087 | 9 | % | (19 | %) | ||||||||||
| Current accident year catastrophes [1] | 168 | 209 | 140 | (20 | %) | 49 | % | ||||||||||
| Prior accident year development [1] | (144) | (438) | (42) | 67 | % | NM | |||||||||||
| Total losses and loss adjustment expenses | 1,864 | 1,466 | 2,185 | 27 | % | (33 | %) | ||||||||||
| Amortization of DAC | 230 | 244 | 259 | (6 | %) | (6 | %) | ||||||||||
| Underwriting expenses | 615 | 591 | 625 | 4 | % | (5 | %) | ||||||||||
| Amortization of other intangible assets | 2 | 4 | 6 | (50 | %) | (33 | %) | ||||||||||
| Underwriting gain | 275 | 737 | 160 | (63 | %) | NM | |||||||||||
| Net servicing income [2] | 19 | 14 | 13 | 36 | % | 8 | % | ||||||||||
| Net investment income [3] | 157 | 157 | 179 | — | % | (12 | %) | ||||||||||
| Net realized gains (losses) [3] | 29 | (5) | 43 | NM | (112 | %) | |||||||||||
| Other income (expenses) | — | (1) | (1) | 100 | % | — | % | ||||||||||
| Income before income taxes | 480 | 902 | 394 | (47 | %) | 129 | % | ||||||||||
| Income tax expense [4] | 95 | 184 | 76 | (48 | %) | 142 | % | ||||||||||
| Net income | $ | 385 | $ | 718 | $ | 318 | (46 | %) | 126 | % |
*[1]*For discussion of current accident year catastrophes and prior accident year development, see MD&A - Critical Accounting Estimates, Property and Casualty Insurance Product Reserves, Net of Reinsurance and Note 12 - Reserve for Unpaid Losses and Loss Adjustment Expenses.
*[2]*Includes servicing revenues of $80, $81, and $83 for 2021, 2020, and 2019, respectively and includes servicing expenses of $61, $67, and $70 for 2021, 2020, and 2019, respectively.
*[3]*For discussion of consolidated investment results, see MD&A - Investment Results.
*[4]*For discussion of income taxes, see Note 17 - Income Taxes of Notes to Consolidated Financial Statements.
Written and Earned Premiums
| Written Premiums | 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | ||||||||||||
| Product Line | |||||||||||||||||
| Automobile | $ | 1,997 | $ | 2,003 | $ | 2,176 | — | % | (8 | %) | |||||||
| Homeowners | 911 | 933 | 955 | (2 | %) | (2 | %) | ||||||||||
| Total | $ | 2,908 | $ | 2,936 | $ | 3,131 | (1 | %) | (6 | %) | |||||||
| Earned Premiums | |||||||||||||||||
| Product Line | |||||||||||||||||
| Automobile | $ | 2,035 | $ | 2,058 | $ | 2,221 | (1 | %) | (7 | %) | |||||||
| Homeowners | 919 | 950 | 977 | (3 | %) | (3 | %) | ||||||||||
| Total | $ | 2,954 | $ | 3,008 | $ | 3,198 | (2 | %) | (6 | %) |
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Premium Measures
| 2021 | 2020 | 2019 | |||||||||||||||
| Policies in-force end of period (in thousands) | |||||||||||||||||
| Automobile | 1,317 | 1,369 | 1,422 | ||||||||||||||
| Homeowners | 773 | 826 | 877 | ||||||||||||||
| New business written premium | |||||||||||||||||
| Automobile | $ | 219 | $ | 223 | $ | 220 | |||||||||||
| Homeowners | $ | 60 | $ | 63 | $ | 73 | |||||||||||
| Policy count retention [1] | |||||||||||||||||
| Automobile | 84 | % | 84 | % | 83 | % | |||||||||||
| Homeowners | 85 | % | 84 | % | 83 | % | |||||||||||
| Policy count retention, net of cancellations [1] | |||||||||||||||||
| Automobile | 84 | % | 86 | % | 85 | % | |||||||||||
| Homeowners | 84 | % | 86 | % | 85 | % | |||||||||||
| Renewal written price increase | |||||||||||||||||
| Automobile | 2.2 | % | 2.4 | % | 4.6 | % | |||||||||||
| Homeowners | 8.5 | % | 6.4 | % | 6.5 | % | |||||||||||
| Renewal earned price increase | |||||||||||||||||
| Automobile | 2.1 | % | 3.4 | % | 5.5 | % | |||||||||||
| Homeowners | 8.1 | % | 5.7 | % | 8.4 | % | |||||||||||
*[**1]*Policy count retention represents the ratio of the number of renewal policies issued during the current year period divided by the number of policies issued in the previous calendar period before considering policies cancelled subsequent to renewal. Policy count retention, net of cancellations, represents the ratio of the number of renewal policies issued net of cancellations during the current year period divided by the number of policies issued net of cancellations in the previous calendar period.
Underwriting Ratios
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Loss and loss adjustment expense ratio | |||||||||||||||||
| Current accident year before catastrophes | 62.3 | 56.3 | 65.3 | 6.0 | (9.0) | ||||||||||||
| Current accident year catastrophes | 5.7 | 6.9 | 4.4 | (1.2) | 2.5 | ||||||||||||
| Prior accident year development | (4.9) | (14.6) | (1.3) | 9.7 | (13.3) | ||||||||||||
| Total loss and loss adjustment expense ratio | 63.1 | 48.7 | 68.3 | 14.4 | (19.6) | ||||||||||||
| Expense ratio | 27.6 | 26.8 | 26.7 | 0.8 | 0.1 | ||||||||||||
| Combined ratio | 90.7 | 75.5 | 95.0 | 15.2 | (19.5) | ||||||||||||
| Impact of current accident year catastrophes and prior year development | (0.8) | 7.7 | (3.1) | (8.5) | 10.8 | ||||||||||||
| Underlying combined ratio | 89.9 | 83.1 | 91.9 | 6.8 | (8.8) |
Product Combined Ratios
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Automobile | |||||||||||||||||
| Combined ratio | 92.9 | 85.5 | 96.6 | 7.4 | (11.1) | ||||||||||||
| Underlying combined ratio | 95.9 | 88.0 | 97.9 | 7.9 | (9.9) | ||||||||||||
| Homeowners | |||||||||||||||||
| Combined ratio | 86.8 | 54.2 | 91.7 | 32.6 | (37.5) | ||||||||||||
| Underlying combined ratio | 76.5 | 72.5 | 78.3 | 4.0 | (5.8) |
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Net Income

Year ended December 31, 2021 compared to the year ended December 31, 2020
Net income decreased in 2021, largely driven by a decrease in underwriting gain, partially offset by a change from net realized losses to net realized gains and an increase in net servicing income.
Underwriting Gain

Year ended December 31, 2021 compared to the year ended December 31, 2020
Underwriting gain decreased in 2021, primarily due to a decrease in favorable prior accident year catastrophe reserve development and higher current accident year personal automobile loss costs. Also contributing was an increase in underwriting expenses and higher current accident year non-catastrophe property losses, partially offset by lower current accident year catastrophe losses. Contributing to the increase in underwriting expenses in 2021 was higher costs for AARP direct marketing, incentive compensation, and technology, partially offset by cost savings from the Hartford Next initiative.
Earned Premiums

Year ended December 31, 2021 compared to the year ended December 31, 2020
Earned premiums decreased in 2021 due to the effect of a decline in written premium over the prior twelve months in both Agency channels and in AARP Direct due to non-renewals exceeding new business. The decrease was partially offset by the effect of $81 of premium credits given to automobile policyholders in the second quarter of 2020 in recognition of shelter-in-place guidelines that reduced miles driven in 2020.
Written Premiums

Written premiums decreased in automobile for 2021 due to the effect of non-renewed premium exceeding new business, partially offset by the effect of the premium credits given in the 2020 period. Written premium declined in homeowners due to the effect of non-renewed premium exceeding new business. For automobile and homeowners new business decreased in 2021 compared to the prior year.
Renewal written pricing increases were down modestly in automobile for 2021 while renewal written pricing increases for homeowners were higher in 2021 in response to recent loss cost trends.
Policy count retention was flat for automobile and was up slightly for homeowners.
Policies in-force decreased in the 2021 period in both automobile and homeowners driven by not generating enough new business to offset the loss of non-renewed policies.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Current Accident Year Loss and Loss Adjustment Expense Ratio before Catastrophes

Year ended December 31, 2021 compared to the year ended December 31, 2020
Current accident year loss and LAE ratio before catastrophes increased in 2021 by 7.1 points in automobile and 3.1 points in homeowners. The increase in automobile was due to higher claim frequency, due to an increase in miles driven, and an increase in average claim severity. For 2021, the homeowners current accident year loss and LAE ratio before catastrophes increased due to an increase in weather and non-weather severity, partially offset by the effect of earned pricing increases. Contributing to the increase in homeowners severity was the effect of higher rebuilding costs and a greater number of large losses.
Current Accident Year Catastrophes and Unfavorable (Favorable) Prior Accident Year Development

Year ended December 31, 2021 compared to the year ended December 31, 2020
Current accident year catastrophe losses decreased in 2021 compared to the prior year. Current accident year catastrophe losses for 2021 included losses from hurricane Ida, tropical storms, California wildfires, and February winter storms as well as losses largely from tornado, wind and hail events, mostly concentrated in Texas, the Southeast, Midwest and Mountain West.
Current accident year catastrophe losses for 2020 were primarily from Pacific Coast wildfires, tropical storm Isaias, hurricane Laura, and various tornado, wind and hail events in the South, Midwest and Central Plains.
Prior accident year development was less favorable in 2021, with the decrease largely due to lower reserve reductions for prior year catastrophes. Prior accident year development was favorable in 2021, with a reduction in personal automobile liability and a decrease in catastrophe reserves, driven by reductions in estimates for prior year hurricanes, tornado & hail and wildfires, including the benefit of higher expected subrogation recoveries related to the 2017 and 2018 California wildfires. Prior accident year development was favorable in 2020 with reserve reductions in catastrophes and, to a lesser extent, personal automobile liability. The reduction in catastrophe reserves for 2020 was driven by lower estimated losses for the 2017 and 2018 California wildfires, including a $260 subrogation benefit from PG&E, as well as a reduction in losses for various 2018 and 2019 wind and hail events.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
2022 Outlook
Written premium is expected to decrease in 2022 compared with 2021 as non-renewal of premium more than offsets new business. While new business conversions are expected to increase with the continued rollout of the Prevail automobile and home product in additional states, new business premium is expected to be lower despite expected higher conversion rates as the Company transitions from 12-month automobile policies to 6-month automobile policies for AARP members.
In 2022, the Company expects written pricing increases in automobile to be in the low to mid-single digits throughout the year as the effect of recent claim frequency and severity trends are reflected in rate filings. Written pricing increases in homeowners are expected to be in the mid-to-high single digits.
The Company expects the combined ratio for Personal Lines will be 97.0 to 99.0 in 2022 compared to 90.7 in 2021 as 2021
benefited from claim frequency that was still below pre-pandemic levels as well as from lower current accident year catastrophe losses and favorable prior accident year development. The underlying combined ratio for Personal Lines is expected to be 90.0 to 92.0 in 2022 compared to 89.9 in 2021 due to an increase in the current accident year loss and loss adjustment expense ratio before catastrophes in both automobile and homeowners with supply chain disruptions causing an increase in severity through 2022. For automobile, we expect the underlying combined ratio to increase driven by an increase in both claim frequency and severity. The underlying combined ratio for homeowners is also expected to increase in 2022, primarily driven by a return to a higher, more normal, level of non-catastrophe weather loss experience, partially offset by the effect of earned pricing increases.
| | PROPERTY & CASUALTY OTHER OPERATIONS - RESULTS OF OPERATIONS |
Underwriting Summary
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Change in unearned premium reserve | $ | — | $ | — | $ | (2) | — | % | 100 | % | |||||||
| Earned premiums | — | — | 2 | — | % | (100 | %) | ||||||||||
| Losses and loss adjustment expenses | |||||||||||||||||
| Prior accident year development [1] | 202 | 258 | 21 | (22 | %) | NM | |||||||||||
| Total losses and loss adjustment expenses | 202 | 258 | 21 | (22 | %) | NM | |||||||||||
| Underwriting expenses | 8 | 11 | 12 | (27 | %) | (8 | %) | ||||||||||
| Underwriting loss | (210) | (269) | (31) | 22 | % | NM | |||||||||||
| Net investment income [2] | 75 | 55 | 84 | 36 | % | (35 | %) | ||||||||||
| Net realized gains (losses) [2] | 13 | (1) | 20 | NM | (105 | %) | |||||||||||
| Other income (expenses) | (1) | 1 | — | NM | NM | ||||||||||||
| Income (loss) before income taxes | (123) | (214) | 73 | 43 | % | NM | |||||||||||
| Income tax expense (benefit) [3] | (28) | (46) | 12 | 39 | % | NM | |||||||||||
| Net income (loss) | $ | (95) | $ | (168) | $ | 61 | 43 | % | NM |
*[1]*For discussion of prior accident year development, see MD&A - Critical Accounting Estimates, Property and Casualty Insurance Product Reserves, Net of Reinsurance and Note 12 - Reserve for Unpaid Losses and Loss Adjustment Expenses of Notes to Consolidated Financial Statements.
*[2]*For discussion of consolidated investment results, see MD&A - Investment Results.
*[3]*For discussion of income taxes, see Note 17 - Income Taxes of Notes to Consolidated Financial Statements.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Net Income (Loss)

Year ended December 31, 2021 compared to the year ended December 31, 2020
Net loss in 2021 decreased compared to 2020, primarily due to lower unfavorable prior accident year reserve development, higher net investment income and a change from net realized losses to net realized gains.
Underwriting loss in 2021 decreased from 2020 primarily due to a lower increase in A&E reserves. Unfavorable prior
accident year development in 2021 included a $155 increase in A&E reserves, an increase in reserves for sexual molestation and sexual abuse claims, primarily on assumed reinsurance, and a $14 increase in ULAE reserves, partially offset by a reduction in the allowance for uncollectible reinsurance. Unfavorable prior accident year development in 2020 primarily included a $208 increase in A&E reserves, and a $35 increase in ULAE reserves. In both periods, the increase in ULAE reserves was primarily driven by the higher estimate for A&E claims.
Before NICO reinsurance in 2021, A&E reserves were increased by $155 in P&C Other Operations, including $104 for asbestos and $51 for environmental. Cumulative adverse A&E reserve development on both ongoing operations and P&C Other Operations totaled $1,015 through December 31, 2021 and since this amount exceeds ceded premium paid for the A&E ADC of $650, the Company has recognized a $365 deferred gain on retroactive reinsurance as of December 31, 2021, within other liabilities, including a $155 increase in deferred gain in 2021 recognized within P&C Other Operations.
Asbestos reserves prior accident year development in 2021 before NICO reinsurance of $104 was primarily due to an increase in claim settlement rates, claim settlement values, and defense costs, which more than offset the impact of a decline in claim filing frequency. Also contributing was an increase in the Company's estimated share of liability under pending or potential cost sharing agreements and settlements.
Environmental reserves prior accident year development in 2021 before NICO reinsurance of $51 was primarily due to the settlement of a large coal ash remediation claim, an increase in legal defense costs and higher site remediation costs.
| |GROUP BENEFITS - RESULTS OF OPERATIONS |
Operating Summary
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Premiums and other considerations | $ | 5,687 | $ | 5,536 | $ | 5,603 | 3 | % | (1 | %) | |||||||
| Net investment income [1] | 550 | 448 | 486 | 23 | % | (8 | %) | ||||||||||
| Net realized gains [1] | 130 | 22 | 34 | NM | (35 | %) | |||||||||||
| Total revenues | 6,367 | 6,006 | 6,123 | 6 | % | (2 | %) | ||||||||||
| Benefits, losses and loss adjustment expenses | 4,612 | 4,137 | 4,055 | 11 | % | 2 | % | ||||||||||
| Amortization of DAC | 40 | 50 | 54 | (20 | %) | (7 | %) | ||||||||||
| Insurance operating costs and other expenses | 1,373 | 1,308 | 1,311 | 5 | % | — | % | ||||||||||
| Amortization of other intangible assets | 40 | 40 | 41 | — | % | (2 | %) | ||||||||||
| Total benefits, losses and expenses | 6,065 | 5,535 | 5,461 | 10 | % | 1 | % | ||||||||||
| Income before income taxes | 302 | 471 | 662 | (36 | %) | (29 | %) | ||||||||||
| Income tax expense [2] | 53 | 88 | 126 | (40 | %) | (30 | %) | ||||||||||
| Net income | $ | 249 | $ | 383 | $ | 536 | (35 | %) | (29 | %) |
*[1]*For discussion of consolidated investment results, see MD&A - Investment Results.
*[2]*For discussion of income taxes, see Note 17 - Income Taxes of Notes to the Consolidated Financial Statements.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Premiums and Other Considerations
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Fully insured — ongoing premiums | $ | 5,502 | $ | 5,305 | $ | 5,416 | 4 | % | (2 | %) | |||||||
| Buyout premiums | 2 | 56 | 7 | (96 | %) | NM | |||||||||||
| Fee income | 183 | 175 | 180 | 5 | % | (3 | %) | ||||||||||
| Total premiums and other considerations | $ | 5,687 | $ | 5,536 | $ | 5,603 | 3 | % | (1 | %) | |||||||
| Fully insured ongoing sales, excluding buyouts | $ | 760 | $ | 717 | $ | 647 | 6 | % | 11 | % |
Ratios, Excluding Buyouts
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Group disability loss ratio | 68.2 | % | 66.1 | % | 67.3 | % | 2.1 | (1.2) | |||||||||
| Group life loss ratio | 101.9 | % | 87.5 | % | 79.5 | % | 14.4 | 8.0 | |||||||||
| Total loss ratio | 81.1 | % | 74.5 | % | 72.3 | % | 6.6 | 2.2 | |||||||||
| Expense ratio [1] | 25.5 | % | 25.2 | % | 24.5 | % | 0.3 | 0.7 |
[1]Integration and transaction costs related to the acquisition of Aetna's U.S. group life and disability business are not included in the expense ratio.
Margin
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Net income margin | 3.9 | % | 6.4 | % | 8.8 | % | (2.5) | (2.4) | |||||||||
| Adjustments to reconcile net income margin to core earnings margin: | |||||||||||||||||
| Net realized losses (gains) excluded from core earnings, before tax | (2.0 | %) | (0.4 | %) | (0.5 | %) | (1.6) | 0.1 | |||||||||
| Integration and other non-recurring M&A costs, before tax | 0.1 | % | 0.3 | % | 0.6 | % | (0.2) | (0.3) | |||||||||
| Income tax benefit | 0.5 | % | — | % | — | % | 0.5 | 0.0 | |||||||||
| Impact of excluding buyouts from denominator of core earnings margin | — | % | 0.1 | % | — | % | (0.1) | 0.1 | |||||||||
| Core earnings margin | 2.5 | % | 6.4 | % | 8.9 | % | (3.9) | (2.5) |
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Net Income

Year ended December 31, 2021 compared to the year ended December 31, 2020
Net income decreased largely driven by higher excess mortality and short-term disability losses and higher operating expenses, partially offset by an increase in net realized gains, an increase in net investment income and increased earned premiums.
Insurance operating costs and other expenses were higher year over year as an increase in incentive compensation, technology costs and claim costs to handle elevated claim levels resulting from the pandemic was partially offset by lower staffing and other costs due to the Hartford Next operational transformation and cost reduction program and a decrease in integration costs.
In addition, 2021 included a decrease in the allowance for credit losses on premiums receivable compared to an increase in the allowance in the prior year.
Fully Insured Ongoing Premiums

Year ended December 31, 2021 compared to the year ended December 31, 2020
Fully insured ongoing premiums increased primarily due to an increase in exposure on existing accounts as our customers emerge from the pandemic, as well as strong persistency and sales.
Fully insured ongoing sales, excluding buyouts increased with increases in group disability and other partially offset by a decrease in group life.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Ratios

Year ended December 31, 2021 compared to the year ended December 31, 2020
Total loss ratio increased 6.6 points for 2021 reflecting a higher group life loss ratio and higher group disability loss ratio. The group life loss ratio increased 14.4 points driven by a 14.5 point increase in excess mortality claims compared to the twelve month period ended December 31, 2020. For the twelve month periods ended December 31, 2021 and 2020, excess mortality losses were $583 and $239, respectively. The group disability loss ratio increased 2.1 points over the twelve-month period ended December 31, 2020. Both the short-term and long-term disability loss ratios reflect increased claim incidence especially compared to the favorable incidence levels experienced during the early stages of the pandemic. The increased claim incidence was partially offset by a higher favorable New York Paid Family Leave adjustment recognized in the 2021 period.
Expense ratio increased 0.3 points in 2021 driven by an increase in incentive compensation, technology costs and claim costs to handle elevated claim levels resulting from the pandemic, partially offset by lower staffing and other costs as a result of the Hartford Next operational transformation and cost reduction program, and higher earned premiums. Also included was a decrease in the allowance for credit losses on premiums receivable compared to an increase in the allowance in the prior year period.
2022 Outlook
The Company expects Group Benefits fully insured ongoing premiums to increase approximately 2% in 2022 due to higher book persistency and continued strong sales. We expect net income in 2022 to benefit from lower excess mortality and pandemic related short-term disability losses, partially offset by the effects of downward pressure on pricing due to recent historical favorable long-term disability claim incidence, an expectation of higher claim incidence and less favorable recoveries on long-term disability claims in 2022 and lower expected investment yields. For 2022, we have assumed excess mortality losses of $100 to $200 before tax and COVID-19 short-term disability losses of approximately $25 before tax. The level of excess mortality losses is subject to significant uncertainty as it is dependent on a number of factors difficult to predict including, among others, the ultimate vaccination rate of the population, the continued effectiveness of the vaccines, the potential spread of new COVID-19 variants, the percentage of those infected who are of working age and the strain on the health care system preventing timely treatment of chronic illnesses. Compared to the net income margin of 3.9% in 2021, the net income margin in 2022 will largely depend on the level of excess mortality claims and other COVID-19 impacts. Based on the assumed range of excess mortality and COVID-19 short-term disability losses, the core earnings margin is expected to be 3.1% to 5.4% in 2022 compared to the 2.5% core earnings margin reported in 2021.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| |HARTFORD FUNDS - RESULTS OF OPERATIONS |
Operating Summary
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Fee income and other revenue | $ | 1,189 | $ | 989 | $ | 999 | 20 | % | (1 | %) | |||||||
| Net investment income | 5 | 4 | 7 | 25 | % | (43 | %) | ||||||||||
| Net realized gains | 4 | 8 | 5 | (50 | %) | 60 | % | ||||||||||
| Total revenues | 1,198 | 1,001 | 1,011 | 20 | % | (1 | %) | ||||||||||
| Amortization of DAC | 12 | 14 | 12 | (14 | %) | 17 | % | ||||||||||
| Operating costs and other expenses | 913 | 773 | 813 | 18 | % | (5 | %) | ||||||||||
| Total benefits, losses and expenses | 925 | 787 | 825 | 18 | % | (5 | %) | ||||||||||
| Income before income taxes | 273 | 214 | 186 | 28 | % | 15 | % | ||||||||||
| Income tax expense [1] | 56 | 44 | 37 | 27 | % | 19 | % | ||||||||||
| Net income | $ | 217 | $ | 170 | $ | 149 | 28 | % | 14 | % | |||||||
| Daily average total Hartford Funds segment AUM | $ | 151,347 | $ | 120,908 | $ | 117,914 | 25 | % | 3 | % | |||||||
| Return on Assets ("ROA") [2] | 14.3 | 14.1 | 12.5 | 0.2 | 1.6 | ||||||||||||
| Adjustments to reconcile ROA to ROA, core earnings: | |||||||||||||||||
| Effect of net realized gains, excluded from core earnings, before tax | (0.3) | (0.7) | (0.3) | 0.4 | (0.4) | ||||||||||||
| Effect of income tax expense | 0.1 | 0.1 | — | 0.0 | 0.1 | ||||||||||||
| Return on Assets ("ROA"), core earnings [2] | 14.1 | 13.5 | 12.2 | 0.6 | 1.3 |
*[1]*For discussion of income taxes, see Note 17 - Income Taxes of Notes to Consolidated Financial Statements.
*[2]*Represents annualized earnings divided by a daily average of assets under management, as measured in basis points.
Hartford Funds Segment AUM
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Mutual Fund and ETP AUM - beginning of period | $ | 124,627 | $ | 112,533 | $ | 91,557 | 11 | % | 23 | % | |||||||
| Sales - mutual fund | 32,399 | 28,604 | 22,479 | 13 | % | 27 | % | ||||||||||
| Redemptions - mutual fund | (28,653) | (31,412) | (23,624) | 9 | % | (33 | %) | ||||||||||
| Net flows - ETP | 121 | (276) | 1,332 | 144 | % | (121 | %) | ||||||||||
| Net Flows - mutual fund and ETP | 3,867 | (3,084) | 187 | NM | NM | ||||||||||||
| Change in market value and other | 14,138 | 15,178 | 20,789 | (7 | %) | (27 | %) | ||||||||||
| Mutual Fund and ETP AUM - end of period | 142,632 | 124,627 | 112,533 | 14 | % | 11 | % | ||||||||||
| Talcott Resolution life and annuity separate account AUM [1] | 15,263 | 14,809 | 14,425 | 3 | % | 3 | % | ||||||||||
| Hartford Funds AUM - end of period | $ | 157,895 | $ | 139,436 | $ | 126,958 | 13 | % | 10 | % |
*[1]*Represents AUM of the life and annuity business sold in May 2018 that is still managed by the Company's Hartford Funds segment.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Mutual Fund AUM by Asset Class
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Equity | $ | 95,703 | $ | 82,123 | $ | 71,629 | 17 | % | 15 | % | |||||||
| Fixed Income | 20,113 | 17,034 | 16,130 | 18 | % | 6 | % | ||||||||||
| Multi-Strategy Investments [1] | 23,610 | 22,645 | 21,332 | 4 | % | 6 | % | ||||||||||
| Exchange-traded products | 3,206 | 2,825 | 3,442 | 13 | % | (18 | %) | ||||||||||
| Mutual Fund and ETP AUM | $ | 142,632 | $ | 124,627 | $ | 112,533 | 14 | % | 11 | % |
*[1]*Includes balanced, allocation, and alternative investment products.
Net Income

Year ended December 31, 2021 compared to the year ended December 31, 2020
Net income increased primarily due to higher fee income as a result of an increase in daily average assets under management, partially offset by higher variable costs and the effect of a $12 reduction in contingent consideration payable associated with the acquisition of Lattice that was recognized in first quarter 2020.
Hartford Funds AUM

December 31, 2021 compared to December 31, 2020
Hartford Funds AUM increased primarily due to net inflows and an increase in market values over the previous twelve months. Net inflows on mutual fund and ETP of $3.9 billion in 2021 compared to net outflows of $3.1 billion for the year ended December 31, 2020.
2022 Outlook
Assuming net inflows and continued growth in equity markets in 2022, the Company expects net income for Hartford Funds to increase from 2021.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| |CORPORATE - RESULTS OF OPERATIONS |
Operating Summary
| 2021 | 2020 | 2019 | Increase (Decrease) From 2020 to 2021 | Increase (Decrease) From 2019 to 2020 | |||||||||||||
| Fee income [1] | $ | 50 | $ | 49 | $ | 50 | 2 | % | (2 | %) | |||||||
| Net investment income | 24 | 22 | 66 | 9 | % | (67 | %) | ||||||||||
| Net realized gains | 73 | 22 | 22 | NM | — | % | |||||||||||
| Other revenue | (10) | 53 | 96 | (119 | %) | (45 | %) | ||||||||||
| Total revenues | 137 | 146 | 234 | (6 | %) | (38 | %) | ||||||||||
| Benefits, losses and loss adjustment expenses [2] | 7 | 15 | 19 | (53 | %) | (21 | %) | ||||||||||
| Insurance operating costs and other expenses [1] | 90 | 76 | 83 | 18 | % | (8 | %) | ||||||||||
| Loss on extinguishment of debt [3] | — | — | 90 | — | % | (100 | %) | ||||||||||
| Interest expense [3] | 234 | 236 | 259 | (1 | %) | (9 | %) | ||||||||||
| Restructuring and other costs | 1 | 104 | — | (99 | %) | NM | |||||||||||
| Total benefits, losses and expenses | 332 | 431 | 451 | (23 | %) | (4 | %) | ||||||||||
| Loss before income taxes | (195) | (285) | (217) | 32 | % | (31 | %) | ||||||||||
| Income tax benefit [4] | (47) | (63) | (46) | 25 | % | (37 | %) | ||||||||||
| Net loss | (148) | (222) | (171) | 33 | % | (30 | %) | ||||||||||
| Preferred stock dividends | 21 | 21 | 21 | — | % | — | % | ||||||||||
| Net loss available to common stockholders | $ | (169) | $ | (243) | $ | (192) | 30 | % | (27 | %) |
*[1]*Includes investment management fees and expenses related to managing third party business, including management of a portion of the invested assets of Talcott Resolution.
*[2]*Includes benefits expense on life and annuity business previously underwritten by the Company.
*[3]*For discussion of debt, see Note 14 - Debt of Notes to Consolidated Financial Statements.
*[4]*For discussion of income taxes, see Note 17 - Income Taxes of Notes to Consolidated Financial Statements.
Net Loss

Year ended December 31, 2021 compared to the year ended December 31, 2020
Net loss available to common stockholders decreased from 2020 primarily due to a decrease in restructuring and other costs and greater net realized gains, partially offset by a change from income to loss from the Company’s previously owned equity interest in Talcott Resolution and higher insurance operating costs and other expenses.
Income (loss) from the Company’s previously owned equity interest in Talcott Resolution was $(11) and $42, respectively, for 2021 and 2020. The increase in operating costs and other expenses for 2021 was primarily driven by legal and consulting costs associated with the unsolicited proposals from Chubb Limited to acquire the Company, partially offset by lower consulting fees. Net realized gains for 2021 included a $46 gain on sale of the Company’s 9.7% retained equity interest in Talcott Resolution.
Interest Expense

|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Year ended December 31, 2021 compared to the year ended December 31, 2020
Interest expense in 2021 was relatively consistent with 2020 due to the repayment of our 5.5% senior notes in March
2020 offset by the issuance of the 2.9% senior notes in September 2021.
ENTERPRISE RISK MANAGEMENT
The Company’s Board of Directors has ultimate responsibility for risk oversight, as described more fully in our Proxy Statement, while management is tasked with the day-to-day management of the Company’s risks.
The Company manages and monitors risk through risk policies, controls and limits. At the senior management level, an Enterprise Risk and Capital Committee (“ERCC”) oversees the risk profile and risk management practices of the Company. As illustrated below, a number of functional committees sit underneath the ERCC, providing oversight of specific risk areas and recommending risk mitigation strategies to the ERCC.
| ERCC Members | ||
| CEO (Chair) | ||
| President | ||
| Chief Financial Officer | ||
| Chief Investment Officer | ||
| Chief Risk Officer | ||
| Chief Underwriting Officer | ||
| General Counsel | ||
| Others as deemed necessary by the Committee Chair |
| ERCC | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset Liability Committee | Underwriting Risk Committee | Emerging Risk Steering Committee | Operational Risk Committee | Economic Capital Executive Committee | Model Oversight Committee |
The Company's enterprise risk management ("ERM") function supports the ERCC and functional committees, and is tasked with, among other things:
-
risk identification and assessment;
-
the development of risk appetites, tolerances, and limits;
-
risk monitoring; and
-
internal and external risk reporting.
The Company categorizes its main risks as insurance risk, operational risk and financial risk, each of which is described in more detail below.
|INSURANCE RISK
Insurance risk is the risk of losses of both a catastrophic and non-catastrophic nature on the P&C and Group Benefits products the Company has sold. Catastrophe insurance risk is the exposure arising from both natural (e.g., weather, earthquakes, wildfires, pandemics) and man-made catastrophes (e.g., terrorism, cyber-attacks) that create a concentration or
aggregation of loss across the Company's insurance or asset portfolios.
Sources of Insurance Risk Non-catastrophe insurance risks exist within each of the Company's segments except Hartford Funds and include:
-
Property-** Risk of loss to personal or commercial property from automobile related accidents, weather, explosions, smoke, shaking, fire, theft, vandalism, inadequate installation, faulty equipment, collisions and falling objects, and/or machinery mechanical breakdown resulting in physical damage and other covered perils.
-
Liability-** Risk of loss from automobile related accidents, uninsured and underinsured drivers, lawsuits from accidents, defective products, breach of warranty, negligent acts by professional practitioners, environmental claims, latent exposures, fraud, coercion, forgery, failure to fulfill obligations per contract surety, liability from errors and omissions, losses from political and credit coverages, losses from derivative lawsuits, and other securities actions and covered perils.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
-
Mortality-** Risk of loss from unexpected trends in insured deaths impacting timing of payouts from group life insurance, personal or commercial automobile related accidents, and death of employees or executives during the course of employment, while on disability, or while collecting workers compensation benefits.
-
Morbidity-** Risk of loss to an insured from illness incurred during the course of employment or illness from other covered perils.
-
Disability-** Risk of loss incurred from personal or commercial automobile related losses, accidents arising outside of the workplace, injuries or accidents incurred during the course of employment, or from equipment, with each loss resulting in short term or long-term disability payments.
-
Longevity-** Risk of loss from increased life expectancy trends among policyholders receiving long-term benefit payments.
-
Cyber Insurance**- Risk of loss to property, breach of data and business interruption from various types of cyber-attacks.
Catastrophe risk primarily arises in the property, automobile, workers' compensation, casualty, group life, and group disability lines of business. Not all insurance losses arising from catastrophe risk are categorized as catastrophe losses within the segment operating results. For example, losses arising from the COVID-19 pandemic were not categorized as catastrophe losses within either the P&C or Group Benefits segments as the pandemic was not identified as a catastrophe event by the Property Claim Service in the U.S. See the term Current Accident Year Catastrophe Ratio within the Key Performance Measures section of MD&A for an explanation of how the Company defines catastrophe losses in its financial reporting.
Impact Non-catastrophe insurance risk can arise from unexpected loss experience, underpriced business and/or underestimation of loss reserves and can have significant effects on the Company’s earnings. Catastrophe insurance risk can arise from various unpredictable events and can have significant effects on the Company's earnings and may result in losses that could constrain its liquidity.
Management The Company's policies and procedures for managing these risks include disciplined underwriting protocols, exposure controls, sophisticated risk-based pricing, risk modeling, risk transfer, and capital management strategies. The Company has established underwriting guidelines for both individual risks, including individual policy limits, and risks in the aggregate, including aggregate exposure limits by geographic zone and peril. The Company uses both internal and third-party models to estimate the potential loss resulting from various catastrophe events and the potential financial impact those events would have on the Company's financial position and results of operations across its businesses.
In addition, certain insurance products offered by The Hartford provide coverage for losses incurred due to cyber events and the Company has assessed and modeled how those products would respond to different events in order to manage its aggregate exposure to losses incurred under the insurance policies we sell. The Company models numerous deterministic scenarios including losses caused by malware, data breach, distributed denial of service attacks, intrusions of cloud environments and attacks of power grids.
Among specific risk tolerances set by the Company, risk limits are set for natural catastrophes, terrorism risk and pandemic risk.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| Risk | Definition | Details and Company Limits | ||||||||||||
| Natural catastrophe | Exposure arising from natural phenomena (e.g., earthquakes, wildfires, etc.) that create a concentration or aggregation of loss across the Company's insurance or asset portfolios and the inherent volatility of weather or climate pattern changes. | The Company generally limits its estimated before tax loss as a result of natural catastrophes for property & casualty exposures from a single 250-year event to less than 30% of the reported capital and surplus of the property and casualty insurance subsidiaries prior to reinsurance and to less than 15% of the reported capital and surplus of the property and casualty insurance subsidiaries after reinsurance. The Company generally limits its estimated before tax loss from an aggregation of multiple natural catastrophe events for an all-peril annual aggregate 100-year event to less than 18% reported capital and surplus of the property and casualty insurance subsidiaries after reinsurance. From time to time the estimated loss from natural catastrophes may fluctuate above or below these limits due to changes in modeled loss estimates, exposures or statutory surplus. [1] The table below represents the estimated before tax catastrophe loss exceedance probabilities, from an aggregate of all catastrophe events occurring in a one-year timeframe before and after reinsurance and from a single hurricane or earthquake occurrence. | ||||||||||||
| Modeled Loss Gross and Net of Reinsurance [2] | ||||||||||||||
| Probability of Loss Exceedance [3] | Gross of Reinsurance | Net of Reinsurance | ||||||||||||
| Aggregate annual all-peril (1-in-100) (1.0%) | $ | 2,062 | $ | 1,160 | ||||||||||
| Aggregate annual all-peril (1-in-250) (0.4%) | $ | 2,893 | $ | 1,726 | ||||||||||
| Hurricane single occurrence (1-in-100) (1.0%) | $ | 1,106 | $ | 459 | ||||||||||
| Hurricane single occurrence (1-in-250) (0.4%) | $ | 1,854 | $ | 904 | ||||||||||
| Earthquake single occurrence (1-in-100) (1.0%) | $ | 783 | $ | 414 | ||||||||||
| Earthquake single occurrence (1-in-250) (0.4%) | $ | 1,482 | $ | 661 | ||||||||||
| Terrorism | The risk of losses from terrorist attacks, including losses caused by single-site and multi-site conventional attacks, as well as the potential for attacks using nuclear, biological, chemical or radiological weapons (“NBCR”). | Enterprise limits for terrorism apply to aggregations of risk across property & casualty, group benefits and specific asset portfolios and are defined based on a deterministic, single-site conventional terrorism attack scenario. The Company manages its potential estimated loss from a conventional terrorism loss scenario, up to $2.0 billion net of reinsurance and $2.5 billion gross of reinsurance, before coverage under TRIPRA. In addition, the Company monitors exposures monthly and employs both internally developed and vendor-licensed loss modeling tools as part of its risk management discipline. Our modeled exposures to conventional terrorist attacks around landmark locations may fluctuate above and below our stated limits. | ||||||||||||
| Pandemic | The exposure to loss arising from widespread influenza or other pathogens or bacterial infections that create an aggregation of loss across the Company's insurance or asset portfolios. | The Company generally limits its estimated before tax loss from a single 250 year pandemic event to less than 18% of the aggregate reported capital and surplus of the property and casualty and group benefits insurance subsidiaries. In evaluating these scenarios, the Company assesses the impact on group life, short-term disability, long-term disability and property & casualty claims. While ERM has a process to track and manage these limits, from time to time, the estimated loss for pandemics may fluctuate above or below these limits due to changes in modeled loss estimates, exposures, or statutory surplus. In addition, the Company assesses losses in the investment portfolio associated with market declines in the event of a widespread pandemic. [1] |
*[1]*For U.S. insurance subsidiaries, reported capital and surplus is equal to actual U.S. statutory capital and surplus. For Navigators Insurers in non-U.S. jurisdictions, reported capital and surplus is equal to U.S. GAAP equity of those subsidiaries less certain assets such as goodwill and intangible assets.
*[2]*The loss estimates represent total property modeled losses for hurricane single occurrence events, property and workers' compensation modeled losses for earthquake single occurrence events, and modeled aggregate annual losses for natural catastrophes from all perils (hurricane, flood, earthquake, hail, tornado, wildfire and winter storms). The net loss estimates provided assume that the Company is able to recover all losses ceded to reinsurers under its reinsurance programs. The Company also manages natural catastrophe risk for group life and group disability, which in combination with property and workers compensation loss estimates are subject to separate enterprise risk management net aggregate loss limits as a percent of enterprise surplus.
*[3]*The modeled probability of loss exceedance represents the likelihood of a loss from single peril occurrence or from an aggregate of catastrophe events from all perils to exceed the indicated amount in a one-year time frame.
Reinsurance as a Risk Management Strategy
The Company uses reinsurance to transfer certain risks to reinsurance companies based on specific geographic or risk concentrations. A variety of traditional reinsurance products are used as part of the Company's risk management strategy, including excess of loss occurrence-based products that reinsure property and workers' compensation exposures, and individual risk (including facultative reinsurance) or quota share arrangements, that reinsure losses from specific classes or lines of business. The Company has no significant finite risk contracts in place and the statutory surplus benefit from all such prior year
contracts is immaterial. The Hartford also participates in governmentally administered reinsurance facilities such as the Florida Hurricane Catastrophe Fund (“FHCF”), TRIPRA and other reinsurance programs relating to particular risks or specific lines of business.
Reinsurance for Catastrophes- The Company utilizes various reinsurance programs to mitigate catastrophe losses including excess of loss occurrence-based treaties covering property and workers’ compensation, and an aggregate property catastrophe treaty as well as individual risk agreements (including facultative reinsurance) that reinsure losses from specific classes or lines
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
of business. The aggregate property catastrophe treaty covers the aggregate of catastrophe events designated by the Property Claim Services office of Verisk and, for international business, net losses arising from two or more risks involved in the same loss occurrence totaling at least $500 thousand, in excess of a $700 retention. The occurrence-based property catastrophe treaties respond in excess of $100 per occurrence for all perils other than earthquakes and named hurricanes and tropical
storms (subject to a $50 annual aggregate deductible). Beginning with the January 1, 2021 renewal, our per occurrence property catastrophe treaty and workers’ compensation catastrophe treaty incepting January 1, 2021 do not cover pandemic losses, as most industry reinsurance programs exclude communicable disease. The Company has reinsurance in place to cover individual group life losses in excess of $1 per person.
Primary Catastrophe Treaty Reinsurance Coverages as of January 1, 2022 [1]
| Portion of losses reinsured | Portion of losses retained by The Hartford | |||||||
| Per Occurrence Property Catastrophe Treaty from 1/1/2022 to 12/31/2022 [1] [2] | ||||||||
| Losses of $0 to $100 | None | 100% retained | ||||||
| Losses of $100 to $350 for earthquakes and named hurricanes and tropical storms [3] | None | 100% retained | ||||||
| Losses of $100 to $350 from one event other than earthquakes and named hurricanes and tropical storms (subject to a $50 Annual Aggregate Deductible ("AAD")) [3] | 70% of $250 in excess of $100 | 30% co-participation | ||||||
| Losses of $350 to $500 from one event (all perils) | 75% of $150 in excess of $350 | 25% co-participation | ||||||
| Losses of $500 to $1.1 billion from one event [4] (all perils) | 90% of $600 in excess $500 | 10% co-participation | ||||||
| Aggregate Property Catastrophe Treaty for 1/1/2022 to 12/31/2022 [5] | ||||||||
| $0 to $700 of aggregate losses | None | 100% retained | ||||||
| $700 to $900 of aggregate losses | 100% | None | ||||||
| Workers' Compensation Catastrophe Treaty for 1/1/2022 to 12/31/2022 | ||||||||
| Losses of $0 to $100 from one event | None | 100% retained | ||||||
| Losses of $100 to $450 from one event [6] | 80% of $350 in excess of $100 | 20% co-participation |
*[1]*These treaties do not cover the assumed reinsurance business which purchases its own retrocessional coverage.
*[2]*In addition to the Per Occurrence Property Catastrophe Treaty, for Florida wind events, The Hartford has purchased the mandatory FHCF reinsurance for the annual period starting at June 1, 2021. Retention and coverage varies by writing company. The writing company with the largest coverage under FHCF is Hartford Insurance Company of the Midwest, with coverage estimated at approximately 90% of $52 in per event losses in excess of a $21 retention (estimates are based on best available information at this time and are periodically updated as information is made available by Florida).
*[3]*Named hurricanes and tropical storms are defined as any storm or storm system declared to be a hurricane or tropical storm by the US National Hurricane Center, US Weather Prediction Center, or their successor organizations (being divisions of the US National Weather Service).
*[4]*Portions of this layer of coverage extend beyond a traditional one year term.
*[5]*The aggregate treaty is not limited to a single event; rather, it is designed to provide reinsurance protection for the aggregate of all catastrophe events (up to $350 per event), either designated by the Property Claim Services office of Verisk or, for international business, net losses arising from two or more risks involved in the same loss occurrence totaling at least $500 thousand. All catastrophe losses, except assumed reinsurance business losses, apply toward satisfying the $700 attachment point under the aggregate treaty.
*[6]*In addition to the limits shown, the workers' compensation reinsurance includes a non-catastrophe, industrial accident layer, providing coverage for 80% of $30 in per event losses in excess of a $20 retention.
In addition to the property catastrophe reinsurance coverage described in the above table, the Company has other reinsurance agreements that cover property catastrophe losses. The Per Occurrence Property Catastrophe Treaty, and Workers' Compensation Catastrophe Treaty include a provision to reinstate one limit in the event that a catastrophe loss exhausts limits on one or more layers under the treaties.
Reinsurance for Terrorism**-** For the risk of terrorism, private sector catastrophe reinsurance capacity is generally limited and largely unavailable for terrorism losses caused by nuclear, biological, chemical or radiological attacks. As such, the Company's principal reinsurance protection against large-scale terrorist attacks is the coverage currently provided through TRIPRA to the end of 2027.
TRIPRA provides a backstop for insurance-related losses resulting from any “act of terrorism”, which is certified by the
Secretary of the Treasury, in consultation with the Secretary of Homeland Security and the Attorney General, for losses that exceed a threshold of industry losses of $200. Under the program, in any one calendar year, the federal government will pay a percentage of losses incurred from a certified act of terrorism after an insurer's losses exceed 20% of the Company's eligible direct commercial earned premiums of the prior calendar year up to a combined annual aggregate limit for the federal government and all insurers of $100 billion. The percentage of losses paid by the federal government is 80% . The Company's estimated deductible under the program is $1.7 billion for 2022. If an act of terrorism or acts of terrorism result in covered losses exceeding the $100 billion annual industry aggregate limit, Congress would be responsible for determining how additional losses in excess of $100 billion will be paid.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Reinsurance for A&E and Navigators Group Reserve Development - The Company has two ADC reinsurance agreements in place, both of which are accounted for as retroactive reinsurance. One agreement covers substantially all A&E reserve development for 2016 and prior accident years (the “A&E ADC”) up to an aggregate limit of $1.5 billion and the other covered substantially all reserve development of Navigators Insurance Company and certain of its affiliates for 2018 and prior accident years (“Navigators ADC”) up to an aggregate limit
of $300. As the Company has ceded all of the $300 available limit under the Navigators ADC, there is no remaining limit available as of December 31, 2021. Any net adverse loss development above the $300 limit is reflected in the Company's results from operations. For more information on the A&E ADC and the Navigators ADC, see Note 1, Basis of Presentation and Significant Accounting Policies, and Note 12, Reserve for Unpaid Losses and Loss Adjustment Expenses of Notes to Consolidated Financial Statements.
Reinsurance Recoverables
Property and Casualty insurance product reinsurance recoverables represent loss and loss adjustment expense recoverables from a number of entities, including reinsurers and pools. A portion of the total gross reinsurance recoverables balance relates to the Company’s participation in various mandatory (assigned) and involuntary risk pools and the value of annuity contracts held under structured settlement agreements.
Group Benefits and Corporate reinsurance recoverables represent reserves for future policy benefits and unpaid loss and loss adjustment expenses and other policyholder funds and benefits payable that are recoverable from a number of reinsurers.
The table below shows the gross and net reinsurance recoverables reported in the Property and Casualty and Group Benefits reporting segments as well as Corporate.
To manage reinsurer credit risk, a reinsurance security review committee evaluates the credit standing, financial performance, management and operational quality of each potential reinsurer.
In placing reinsurance, the Company considers the nature of the risk reinsured, including the expected liability payout duration, and establishes limits tiered by reinsurer credit rating. Where its contracts permit, the Company secures future claim obligations with various forms of collateral or other credit enhancement,
including irrevocable letters of credit, secured trusts, funds held accounts and group wide offsets. As part of its reinsurance recoverable review, the Company analyzes recent developments in commutation activity between reinsurers and cedants, recent trends in arbitration and litigation outcomes in disputes between cedants and reinsurers and the overall credit quality of the Company’s reinsurers. For further discussion on reinsurance recoverables, including details of recoverables by AM Best credit rating, see Note 9 – Reinsurance of Notes to Consolidated Financial Statements.
Annually, the Company completes evaluations of the reinsurance recoverable asset associated with older, long-term casualty liabilities reported in the Property & Casualty Other Operations reporting segment and the allowance for uncollectible reinsurance reported in the Commercial Lines and Group Benefits reporting segments as well as the Corporate category. For a discussion regarding the results of the evaluation of older, long-term casualty liabilities reported in the Property & Casualty Other Operations reporting segment, see MD&A - Critical Accounting Estimates, Property and Casualty Insurance Product Reserves, Net of Reinsurance. For a discussion of the allowance for uncollectible reinsurance, see Note 9 – Reinsurance of Notes to Consolidated Financial Statements.
Reinsurance Recoverables as of December 31,
| Property and Casualty | Group Benefits | Corporate | Total | |||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | 2021 | 2020 | 2021 | 2020 | |||||||||||||||||||
| Paid loss and loss adjustment expenses | $ | 319 | $ | 269 | $ | 5 | $ | 6 | $ | — | $ | — | $ | 324 | $ | 275 | ||||||||||
| Unpaid loss and loss adjustment expenses | 5,774 | 5,297 | 246 | 239 | 278 | 308 | 6,298 | 5,844 | ||||||||||||||||||
| Gross reinsurance recoverables | 6,093 | 5,566 | 251 | 245 | 278 | 308 | 6,622 | 6,119 | ||||||||||||||||||
| Allowance for uncollectible reinsurance | (96) | (105) | (1) | (1) | (2) | (2) | (99) | (108) | ||||||||||||||||||
| Net reinsurance recoverables | $ | 5,997 | $ | 5,461 | $ | 250 | $ | 244 | $ | 276 | $ | 306 | $ | 6,523 | $ | 6,011 |
Guaranty Funds and Other Insurance-related Assessments
As part of its risk management strategy, the Company regularly monitors the financial strength of other insurers and, in particular, activity by insurance regulators and various state guaranty associations in the U.S. relating to troubled insurers. In all states, insurers licensed to transact certain classes of insurance are required to become members of a guaranty fund.
|OPERATIONAL RISK
Operational risk is the risk of loss resulting from inadequate or failed internal processes and systems, human error, or from external events.
Sources of Operational Risk Operational risk is inherent in the Company's business and functional areas. Operational risks include: compliance with laws and regulation, cybersecurity, business disruption, technology failure, inadequate execution or process management, reliance on
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
model and data analytics, internal fraud, external fraud, third party dependency and attraction and retention of talent.
Impact Operational risk can result in financial loss, disruption of our business, regulatory actions or damage to our reputation.
Management Responsibility for day-to-day management of operational risk lies within each business unit and functional area. ERM provides an enterprise-wide view of the Company's operational risk on an aggregate basis. ERM is responsible for establishing, maintaining and communicating the framework, principles and guidelines of the Company's operational risk management program. Operational risk mitigation strategies include the following:
-
Establishing policies and monitoring risk tolerances and exceptions;
-
Conducting business risk assessments and implementing action plans where necessary;
-
Validating existing crisis management protocols;
-
Identifying and monitoring emerging risks; and
-
Purchasing insurance coverage.
In response to COVID-19 the Company continues to assess evolving risks related to COVID-19 while monitoring guidance and regulations to maintain certain practices in the interest of the health and welfare of our employees and to reduce operational risk. Among others, current practices include enabling work from home and hybrid work arrangements, mandating protocols that employees must follow when they are in the office and established contact tracing processes for in-office and customer facing individuals who have had exposure to COVID-19. We also continue to work with vendors to ensure they have business continuity plans in place.
Cybersecurity Risk
The Hartford has implemented an information protection program with established governance routines that promote an adaptive approach for assessing and managing risks. The Hartford employs a ‘defense-in-depth’ strategy that uses multiple security measures to protect the integrity of the Company's information assets. This ‘defense-in-depth’ strategy aligns to the National Institute of Standards and Technology ("NIST") Cyber Security Framework and provides preventative, detective and responsive measures that collectively protects the Company. The Hartford continually assesses cyber capabilities and threat detection. Various cyber assurance methods, including security metrics, third party security assessments, external penetration testing, red team exercises, and cyber incident response exercises are used to test the effectiveness of the overall cybersecurity control environment. Additionally, The Company collaborates with industry associations, government authorities, peers and external advisors to monitor the threat environment and to inform our security practices.
The Hartford, like many other large financial services companies, blocks attempted cyber intrusions on a daily basis. In the event of a cyber intrusion, the Company invokes its Cyber Incident Response Program (the "Program") commensurate with the nature of the intrusion. While the actual methods employed differ based on the event, our approach uses internal teams and outside advisors with specialized skills to support the response and recovery efforts and requires elevation of issues, as necessary, to senior management. In addition, we have
procedures to ensure timely notification of critical cybersecurity incidents pursuant to the Program to help identify employees who may have material non-public information and to implement blackout restrictions on trading the Company's securities during the investigation and assessment of such cybersecurity incidents.
From a governance perspective, senior members of our Enterprise Risk Management, Information Protection and Internal Audit functions provide detailed, regular reports on cybersecurity matters to the Board, including the Finance, Investment, and Risk Management Committee ("FIRMCo"), a committee consisting of all directors and the Audit Committee, which oversees controls for the Company's major risk exposures, and has principal responsibility for oversight of cybersecurity risk. The topics covered by these updates include the Company's activities, policies and procedures to prevent, detect and respond to cybersecurity incidents, as well as lessons learned from cybersecurity incidents and internal and external testing of our cyber defenses.
|FINANCIAL RISK
Financial risks include direct and indirect risks to the Company's financial objectives from events that impact financial market conditions and the value of financial assets. Some events may cause correlated movement in multiple risk factors. The primary sources of financial risks are the Company's invested assets.
Consistent with its risk appetite, the Company establishes financial risk limits to control potential loss on a U.S. GAAP, statutory, and economic basis. Exposures are actively monitored and managed, with risks mitigated where appropriate. The Company uses various risk management strategies, including limiting aggregation of risk, portfolio re-balancing and hedging with over-the-counter ("OTC") and exchange-traded derivatives with counterparties meeting the appropriate regulatory and due diligence requirements. Derivatives are utilized to achieve the following Company-approved objectives: (1) hedging risk arising from interest rate, equity market, commodity market, credit spread and issuer default, price or currency exchange rate risk or volatility; (2) managing liquidity; (3) controlling transaction costs; and (4) engaging in income generation covered call transactions and synthetic replication transactions. Derivative activities are monitored and evaluated by the Company’s compliance and risk management teams and reviewed by senior management. The Company identifies different categories of financial risk, including liquidity, credit, interest rate, equity, and foreign currency exchange.
Liquidity Risk
Liquidity risk is the risk to current or prospective earnings or capital arising from the Company's inability or perceived inability to meet its contractual funding obligations as they come due.
Sources of Liquidity Risk Sources of liquidity risk include funding risk, company-specific liquidity risk and market liquidity risk resulting from differences in the amount and timing of sources and uses of cash as well as company-specific and general market conditions. Stressed market conditions may impact the ability to sell assets or otherwise transact business and may result in a significant loss in value.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Impact Inadequate capital resources and liquidity could negatively affect the Company’s overall financial strength and its ability to generate cash flows from its businesses, borrow funds at competitive rates, and raise new capital to meet operating and growth needs.
Management The Company has defined ongoing monitoring and reporting requirements to assess liquidity across the enterprise under both current and stressed market conditions. The Company measures and manages liquidity risk exposures and funding needs within prescribed limits across legal entities, taking into account legal, regulatory and operational limitations to the transferability of liquid assets among legal entities. The Company also monitors internal and external conditions, and identifies material risk changes and emerging risks that may impact operating cash flows or liquid assets. The liquidity requirements of The Hartford Financial Services Group, Inc. ("HFSG Holding Company") have been and will continue to be met by the HFSG Holding Company's fixed maturities, short-term investments and cash, and dividends from its subsidiaries, principally its insurance operations, as well as the issuance of common stock, debt or other capital securities and borrowings from its credit facilities as needed. The Company maintains multiple sources of contingent liquidity including a revolving credit facility, an intercompany liquidity agreement that allows for short-term advances of funds among the HFSG Holding Company and certain affiliates, and access to collateralized advances from the Federal Home Loan Bank of Boston ("FHLBB") for certain affiliates. The Company's CFO has primary responsibility for liquidity risk.
Refer to the Capital Resources & Liquidity section of MD&A for the discussion of what the Company is doing to manage liquidity during the COVID-19 pandemic.
Credit Risk and Counterparty Risk
Credit risk is the risk to earnings or capital due to uncertainty of an obligor’s or counterparty’s ability or willingness to meet its obligations in accordance with contractually agreed upon terms. Credit risk is comprised of three major factors: the risk of change in credit quality, or credit migration risk; the risk of default; and the risk of a change in value due to changes in credit spreads.
Sources of Credit Risk The majority of the Company’s credit risk is concentrated in its investment holdings and use of derivatives, but it is also present in the Company’s ceded reinsurance activities and various insurance products.
Impact A decline in creditworthiness is typically reflected as an increase in an investment’s credit spread and an associated decline in the investment's fair value, potentially resulting in recording an ACL and an increased probability of a realized loss upon sale. In certain instances, counterparties may default on their obligations and the Company may realize a loss on default. Premiums receivable, including premiums for retrospectively rated plans, reinsurance recoverable and deductible losses recoverable are also subject to credit risk based on the counterparty’s inability to pay.
For a discussion of impacts resulting from the COVID-19 pandemic, refer to the Impact of COVID-19 on our financial condition, results of operations and liquidity section of this MD&A.
Management The objective of the Company’s enterprise credit risk management strategy is to identify, quantify, and manage credit risk in aggregate and to limit potential losses in accordance with the Company's credit risk management policy. The Company manages its credit risk by managing aggregations of risk, holding a diversified mix of issuers and counterparties across its investment, reinsurance, and insurance portfolios and limiting exposure to any specific reinsurer or counterparty. Potential credit losses can be mitigated through diversification (e.g., geographic regions, asset types, industry sectors), hedging and the use of collateral to reduce net credit exposure.
The Company manages credit risk through the use of various surveillance, analyses and governance processes. The investment and reinsurance areas have formal policies and procedures for counterparty approvals and authorizations, which establish criteria defining minimum levels of creditworthiness and financial stability for eligible counterparties. Potential investments are subject to underwriting reviews and private securities are subject to management approval. Mitigation strategies vary across the three sources of credit risk, but may include:
-
Investing in a portfolio of high-quality and diverse securities;
-
Selling investments subject to credit risk;
-
Hedging through use of credit default swaps;
-
Clearing derivative transactions through central clearing houses that require daily variation margin;
-
Entering into derivative and reinsurance contracts only with strong creditworthy institutions;
-
Requiring collateral; and
-
Non-renewing policies/contracts or reinsurance treaties.
The Company has developed credit exposure thresholds which are based upon counterparty ratings. Aggregate counterparty credit quality and exposure are monitored on a daily basis utilizing an enterprise-wide credit exposure information system that contains data on issuers, ratings, exposures, and credit limits. Exposures are tracked on a current and potential basis and aggregated by ultimate parent of the counterparty across investments, reinsurance receivables, insurance products with credit risk, and derivatives.
As of December 31, 2021, the Company had no investment exposure to any credit concentration risk of a single issuer or counterparty greater than 10% of the Company's stockholders' equity, other than the U.S. government and certain U.S. government agencies. For further discussion of concentration of credit risk in the investment portfolio, see the Concentration of Credit Risk section in Note 6 - Investments of Notes to Consolidated Financial Statements.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Assets and Liabilities Subject to Credit Risk
Investments Essentially all of the Company's invested assets are subject to credit risk. In 2021, there were net credit recoveries on fixed maturities, AFS and a decrease in the ACL on mortgage loans of $4 and $9 respectively, primarily due to an improved economic environment. In 2020, there were net credit losses on fixed maturities, AFS and an increase in the ACL on mortgage loans of $28 and $19 respectively, due primarily to the negative economic impacts resulting from the pandemic. Refer to the Investment Portfolio Risk section of Financial Risk Management under “Credit Losses on Fixed Maturities, AFS and Intent-to-Sell Impairments" and "ACL on Mortgage Loans”.
Reinsurance recoverables Reinsurance recoverables, net of an allowance for uncollectible reinsurance, were $6,523 and $6,011 as of December 31, 2021 and 2020 respectively. Refer to the Enterprise Risk Management section of the MD&A under “Reinsurance as a Risk Management Strategy.”
Premiums receivable and agents' balances Premiums receivable and agents’ balances, net of an ACL, were $4,445 and $4,268, as of December 31, 2021 and 2020, respectively. For a discussion regarding collectibility of these balances, see Note 8 - Premiums Receivable and Agents' Balances of Notes to Consolidated Financial Statements.
Credit Risk of Derivatives
The Company uses various derivative counterparties in executing its derivative transactions. The use of counterparties creates credit risk that the counterparty may not perform in accordance with the terms of the derivative transaction.
Downgrades to the credit ratings of the Company’s insurance operating companies may have adverse implications for its use of derivatives. In some cases, downgrades may give derivative counterparties for OTC derivatives and clearing brokers for OTC-cleared derivatives the right to cancel and settle outstanding derivative trades or require additional collateral to be posted. In addition, downgrades may result in counterparties and clearing brokers becoming unwilling to engage in or clear additional derivatives or may require additional collateralization before entering into any new trades.
Managing the Credit Risk of Counterparties to Derivative Instruments
The Company also has derivative counterparty exposure policies which limit the Company’s exposure to credit risk. The Company monitors counterparty exposure on a monthly basis to ensure compliance with Company policies and statutory limitations. The Company’s policies with respect to derivative counterparty exposure establishes market-based credit limits, favors long-term financial stability and creditworthiness of the counterparty and typically requires credit enhancement/credit risk reducing agreements, which are monitored and evaluated by the Company’s risk management team and reviewed by senior management.
The Company minimizes the credit risk of derivative instruments by entering into transactions with high quality counterparties primarily rated A or better. The Company also generally requires that OTC derivative contracts be governed by an International
Swaps and Derivatives Association ("ISDA") Master Agreement, which is structured by legal entity and by counterparty and permits right of offset. The Company enters into credit support annexes in conjunction with the ISDA agreements, which require daily collateral settlement based upon agreed upon thresholds.
The Company also has derivative counterparty exposure policies which limit the Company’s exposure to credit risk. Credit exposures are generally quantified based on the prior business day’s net fair value, including income accruals, of all derivative positions transacted with a single counterparty for each separate legal entity. The notional amount of derivative contracts represents the basis upon which pay or receive amounts are calculated and are not reflective of credit risk. The Company enters into collateral arrangements in connection with its derivatives positions and collateral is pledged to or held by, or on behalf of, the Company to the extent the exposure is greater than zero, subject to minimum transfer thresholds, if applicable. In accordance with industry standards and the contractual requirements, collateral is typically settled on the same business day. For further discussion, see the Derivative Commitments section of Note 15 - Commitments and Contingencies of Notes to Consolidated Financial Statements.
Use of Credit Derivatives
The Company may also use credit default swaps to manage credit exposure or to assume credit risk to enhance yield.
Credit Risk Reduced Through Credit Derivatives
The Company uses credit derivatives to purchase credit protection with respect to a single entity or referenced index. The Company purchases credit protection through credit default swaps to economically hedge and manage credit risk of certain fixed maturity investments across multiple sectors of the investment portfolio. As of December 31, 2021 and 2020, the notional amount related to credit derivatives that purchase credit protection was $112 and $6, respectively, while the fair value was $(2) and less than $(1), respectively. These amounts do not include positions that are in offsetting relationships.
Credit Risk Assumed Through Credit Derivatives
The Company also enters into credit default swaps that assume credit risk as part of replication transactions. Replication transactions are used as an economical means to synthetically replicate the characteristics and performance of assets that are permissible investments under the Company’s investment policies. These swaps primarily reference investment grade single corporate issuers and indexes. As of December 31, 2021, the Company did not hold credit default swaps that assume credit risk. As of December 31, 2020, the notional amount related to credit derivatives that assume credit risk was $675 and the fair value was $21. These amounts do not include positions that are in offsetting relationships.
For further information on credit derivatives, see Note 7 - Derivatives of Notes to Consolidated Financial Statements.
Credit Risk of Business Operations
A portion of the Company's Commercial Lines business is written with large deductibles or under retrospectively-rated plans. Under some commercial insurance contracts with a large deductible, the Company is obligated to pay the claimant the full amount of the claim and the Company is subsequently reimbursed by the policyholder for the deductible amount. As such, the Company is subject to credit risk until reimbursement
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
is made. Retrospectively-rated policies are utilized primarily for workers' compensation coverage, whereby the ultimate premium is adjusted based on actual losses incurred. Although the premium adjustment feature of a retrospectively-rated policy substantially reduces insurance risk for the Company, it presents credit risk to the Company. The Company’s results of operations could be adversely affected if a significant portion of such policyholders failed to reimburse the Company for the deductible amount or the amount of additional premium owed under retrospectively-rated policies. The Company manages these credit risks through credit analysis, collateral requirements, and regular monitoring. For more information, see Note 8- Premiums Receivable and Agents' Balances of Notes to the Consolidated Financial Statements.
Interest Rate Risk
Interest rate risk is the risk of financial loss due to adverse changes in the value of assets and liabilities arising from movements in interest rates. Interest rate risk encompasses exposures with respect to changes in the level of interest rates, the shape of the term structure of rates and the volatility of interest rates. Interest rate risk does not include exposure to changes in credit spreads.
Sources of Interest Rate Risk The Company has exposure to interest rate risk arising from investments in fixed maturities and commercial mortgage loans, issuances by the Company of debt securities, preferred stock and similar securities, discount rate assumptions associated with the Company’s claim reserves and pension and other postretirement benefit obligations, and assets that support the Company's pension and other postretirement benefit plans.
Impact Changes in interest rates from current levels can have both favorable and unfavorable effects for the Company.
| Change in Interest Rates | Favorable Effects | Unfavorable Effects | ||||||
| Ý | •Additional net investment income due to reinvesting at higher yields and higher yields on variable rate securities | •Decrease in the fair value of the fixed income investment portfolio | ||||||
| •Higher interest expense on variable rate debt obligations | ||||||||
| Þ | •Increase in the fair value of the fixed income investment portfolio | •Lower net investment income due to reinvesting at lower yields and lower yields on variable rate securities | ||||||
| •Lower interest expense on variable rate debt obligations | •Acceleration in paydowns and prepayments or calls of certain mortgage-backed and municipal securities |
Management The Company manages its exposure to interest rate risk by constructing investment portfolios that seek
to protect the Company from the economic impact associated with changes in interest rates by setting portfolio duration targets that are aligned with the duration of the liabilities that they support. The Company analyzes interest rate risk using various models including parametric models and cash flow simulation under various market scenarios of the liabilities and their supporting investment portfolios. Key metrics that the Company uses to quantify its exposure to interest rate risk inherent in its invested assets and the associated liabilities include duration, convexity and key rate duration.
The Company primarily utilizes interest rate swaps and, to a lesser extent, futures to mitigate interest rate risk associated with its investment portfolio or liabilities and to manage portfolio duration. Interest rate swaps are primarily used to convert interest receipts or payments to a fixed or variable rate. The use of such swaps enables the Company to customize contract terms and conditions to desired objectives and manage the duration profile within established tolerances. As of December 31, 2021 and 2020, notional amounts pertaining to derivatives utilized to manage interest rate risk, including offsetting positions, totaled $9.9 billion and $10.7 billion, respectively, and primarily relate to hedging invested assets. The fair value of these derivatives was $(46) and $(69) as of December 31, 2021 and 2020, respectively.
Assets and Liabilities Subject to Interest Rate Risk
Fixed income investments The fair value of fixed income investments, which include fixed maturities, commercial mortgage loans, and short-term investments, was $51.9 billion and $52.8 billion at December 31, 2021 and 2020, respectively. The weighted average duration of the portfolio, including derivative instruments, was approximately 4.3 years and 4.9 years as of December 31, 2021 and 2020, respectively. Changes in the fair value of fixed maturities due to changes in interest rates are reflected as a component of AOCI.
Long-term debt obligations The Company's variable rate debt obligations will generally result in increased interest expense as a result of higher interest rates; the inverse is true during a declining interest rate environment. Changes in the value of long-term debt as a result of changes in interest rates will impact the fair value of these instruments but not the carrying value in the Company's Consolidated Balance Sheets.
Group life and disability product liabilities The cash outflows associated with contracts issued by the Company's Group Benefits segment, primarily group life and short and long-term disability policy liabilities, are not interest rate sensitive but vary based on timing. Though the aggregate cash flow payment streams are relatively predictable, these products rely upon actuarial pricing assumptions (including mortality and morbidity) and have an element of cash flow uncertainty. As of December 31, 2021 and 2020, the Company had $8,609 and $8,653, respectively of reserves for group life and disability contracts. Changes in the value of the liabilities as a result of changes in interest rates will impact the fair value of these instruments but not the carrying value in the Company's Consolidated Balance Sheets.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Pension and other postretirement benefit obligations The Company’s pension and other postretirement benefit obligations are exposed to interest rate risk based upon the sensitivity of present value obligations to changes in liability discount rates as well as the sensitivity of the fair value of investments in the plan portfolios to changes in interest rates. The discount rate assumption is based upon an interest rate yield curve that reflects high-quality fixed income investments consistent with the maturity profile of the expected liability cash flows. The Company is exposed to the risk of having to make additional plan contributions if the plans’ investment returns, including from investments in fixed maturities, are lower than expected. (For further discussion of discounting pension and other postretirement benefit obligations, refer to Note 19 - Employee Benefit Plans of Notes to Consolidated Financial Statements.)
Interest Rate Sensitivity
Group Life and Disability Reserves and Invested Assets Supporting Them
Included in the following table is the before tax change in the net economic value of contracts issued by the Company’s Group Benefits segment, primarily group life and disability, for which fixed valuation discount rate assumptions are established based upon investment returns assumed in pricing, along with the corresponding invested assets. Also included in this analysis are the interest rate sensitive derivatives used by the Company to hedge its exposure to interest rate risk in the investment portfolios supporting these contracts. This analysis does not include the assets and corresponding liabilities of other insurance products such as automobile, property, workers' compensation and general liability insurance. Certain financial instruments, such as limited partnerships and other alternative investments, have been omitted from the analysis as the interest rate sensitivity of these investments is generally lower and less predictable than fixed income investments. The calculation of the estimated hypothetical change in net economic value below assumes a 100 basis point upward and downward parallel shift in the yield curve.
The selection of the 100 basis point parallel shift in the yield curve was made only as an illustration of the potential hypothetical impact of such an event and should not be construed as a prediction of future market events. Actual results could differ materially from those illustrated below due to the nature of the estimates and assumptions used in the analysis. The Company’s sensitivity analysis calculation assumes that the composition of invested assets and liabilities remain materially consistent throughout the year and that the current relationship between short-term and long-term interest rates will remain constant over time. As a result, these calculations may not fully capture the impact of portfolio re-allocations, significant product sales or non-parallel changes in interest rates.
Interest Rate Sensitivity of Group Benefits Short and Long-term Disability Reserves and Invested Assets Supporting Them
| Change in Net Economic Value as of December 31, | ||||||||||||||
| 2021 | 2020 | |||||||||||||
| Basis point shift | -100 | +100 | -100 | +100 | ||||||||||
| Increase (decrease) in economic value, before tax | $ | 101 | $ | (94) | $ | 137 | $ | (133) |
The carrying value of assets related to the businesses included in the table above was $11.3 billion and $12.1 billion, as of December 31, 2021 and 2020, respectively, and included fixed maturities, commercial mortgage loans and short-term investments. The assets are monitored and managed within set duration guidelines and are evaluated on a daily basis, as well as annually, using scenario simulation techniques in compliance with regulatory requirements.
Invested Assets not Supporting Group Life and Disability Reserves
The following table provides an analysis showing the estimated before tax change in the fair value of the Company’s investments and related derivatives, excluding assets supporting group life and disability reserves which are included in the table above, assuming 100 basis point upward and downward parallel shifts in the yield curve as of December 31, 2021 and 2020. Certain financial instruments, such as limited partnerships and other alternative investments, have been omitted from the analysis as the interest rate sensitivity of these investments is generally lower and less predictable than fixed income investments.
Interest Rate Sensitivity of Invested Assets Not Supporting Group Benefits Short and Long-term Disability Reserves
| Change in Fair Value as of December 31, | ||||||||||||||
| 2021 | 2020 | |||||||||||||
| Basis point shift | -100 | +100 | -100 | +100 | ||||||||||
| Increase (decrease) in fair value, before tax | $ | 1,841 | $ | (1,730) | $ | 2,054 | $ | (1,906) |
The carrying value of fixed maturities, commercial mortgage loans and short-term investments related to the businesses included in the table above was $40.6 billion and $40.7 billion as of December 31, 2021 and 2020, respectively.
Long-term Debt
A 100 basis point parallel decrease in the yield curve would result in an increase in the fair value of long-term debt by $732 and $670 as of December 31, 2021 and 2020, respectively. A 100 basis point parallel increase in the yield curve would result in a decrease in the fair value of long-term debt by $600 and $551 as of December 31, 2021 and 2020, respectively. Changes in the value of long-term debt as a result of changes in interest rates will not impact the carrying value in the Company's Consolidated Balance Sheets.
Pension and Other Postretirement Plan Obligations
A 100 basis point parallel decrease in the yield curve would
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
impact both the value of the underlying pension assets and the value of the liabilities, resulting in an increase in the unfunded liabilities (or decrease in asset) for pension and other postretirement plan obligations of $36 and $196 as of December 31, 2021 and 2020, respectively. A 100 basis point parallel increase in the yield curve would have the inverse effect and result in a decrease in the unfunded liabilities (or increase in assets) for pension and other postretirement plan obligations of $17 and $148 as of December 31, 2021 and 2020, respectively. Gains or losses due to changes in interest rates on the pension and postretirement plan obligations are recorded within AOCI and are amortized into the actuarial loss component of net periodic benefit cost when they exceed a threshold.
Discontinuation of LIBOR In July 2017, the U.K. Financial Conduct Authority ("FCA") announced that by the end of 2021 it intended to stop persuading or compelling banks to report information used to set LIBOR. On March 5, 2021, the FCA announced that publication of certain LIBOR settings in currencies other than U.S. dollars would cease immediately after December 31, 2021, and that publication of U.S. dollar LIBOR on a representative basis would cease for the one-week and two-month settings immediately after December 31, 2021 and for the remaining U.S. dollar settings immediately after June 30, 2023. Although the most widely used settings of U.S. dollar LIBOR continue to be published and used in existing transactions, regulatory pressures and other factors have resulted in a general decline in new U.S. dollar LIBOR-based transactions. The Company continues to monitor the potential impacts of the discontinuation of LIBOR, which is used as a benchmark or reference rate for certain investments and derivatives the Company owns and floating rate debt the Company has issued.
The Company has identified three principal types of outstanding contracts that may be affected by the discontinuance of or transition from LIBOR to an alternative reference rate, including floating rate fixed maturity investments the Company holds in its investment portfolio; derivative instruments that hedge interest rate risk; and one class of junior subordinated debentures that mature after June 30, 2023.
-
Using our best estimate of expected future cash flows including prepayments and maturities, the book value of LIBOR referenced floating rate fixed maturities that the Company owns as of December 31, 2021 and that the Company expects to be outstanding after June 2023 is $4 billion. The Company has performed a review of the LIBOR replacement language on these assets and believes that greater than 90% have language that supports a transition to a new standard benchmark rate. The Company will continue to assess the remaining holdings and work with counterparties, as appropriate, to determine LIBOR replacement language or manage the assets in other ways, such as through asset sales.
-
The notional amount of derivative instruments as of December 31, 2021 with a floating rate component that references LIBOR that the Company expects to be outstanding after June 30, 2023, considering maturities, is $8.1 billion, with $7.9 billion being cleared through an exchange or clearinghouse. The Company anticipates that substantially all existing derivatives referencing LIBOR, whether or not cleared through an exchange or clearing
house, will transition from LIBOR to SOFR or other market alternative rates in line with new market standards.
- The Company has issued $1.1 billion of junior subordinated debentures that mature after June 30, 2023 with LIBOR referenced floating interest rates. The Company expects to call its $600 of 7.875% junior subordinated debentures at par in April of 2022 and, for the $500 of 3 month LIBOR + 2.125% notes, is assessing options to manage the risk associated with the transition away from LIBOR.
The uncertainty regarding the continued use and reliability of LIBOR, including the timing of such transition, could reduce the value of some of our floating rate fixed maturity investments and increase the interest the Company pays on the junior subordinated debentures.
There is also a risk that certain derivatives may no longer qualify for hedge accounting if reference rates change on derivative contracts but the reference interest rate of the instruments being hedged do not change in a substantially similar manner, particularly for cash flow hedges of floating rate investments the Company owns and junior subordinated debentures the Company has issued. The loss of hedge accounting could result in the recognition of gains or losses on derivatives in the income statement rather than in accumulated other comprehensive income. The Company has adopted the FASB's temporary guidance which allows for contract modifications made solely due to rate reform (such as replacing LIBOR with another reference rate) as continuations of existing contracts and to maintain hedge accounting when the hedging effectiveness between the financial instrument and its hedge is only affected by the change to the reference rate. The FASB is deliberating revised guidance which would extend the accounting relief for contract modifications made and hedge relationships entered into or evaluated through December 31, 2024, after which there is uncertainty whether certain outstanding derivative contracts will continue to qualify for hedge accounting either because the replacement rate of the financial instrument being hedged is not sufficiently matched to the reference rate of the derivative contract or because replacement rate language for the hedged instrument has not been determined. For a discussion of risks related to the discontinuance of LIBOR, see Part I, Item 1A, - Risk Factors for the risk factor "The discontinuance of LIBOR may adversely affect the value of certain investments we hold and floating rate securities we have issued, and another other assets or liabilities whose value may be tied to LIBOR."
Equity Risk
Equity risk is the risk of financial loss due to changes in the value of global equities or equity indices.
Sources of Equity Risk
The Company has exposure to equity risk from invested assets, assets that support the Company’s pension and other postretirement benefit plans, and fee income derived from Hartford Funds assets under management.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Impact The investment portfolio is exposed to losses from market declines affecting equity securities and derivatives, which could negatively impact the Company's reported earnings. In addition, investments in limited partnerships and other alternative investments generally have a level of correlation to domestic equity market levels and can expose the Company to losses in earnings if valuations decline; however, earnings impacts are recognized on a lag as results from private equity investments and other funds are generally reported on a three-month delay. For assets supporting pension and other postretirement benefit plans, the Company may be required to make additional plan contributions if equity investments in the plan portfolios decline in value. Hartford Funds earnings are also significantly influenced by the U.S. and other equity markets. Generally, declines in equity markets will reduce the value of average daily assets under management and the amount of fee income generated from those assets. Increases in equity markets will generally have the inverse impact.
Management The Company uses various approaches in managing its equity exposure, including limits on the proportion of assets invested in equities, diversification of the equity portfolio, and, at times, hedging of changes in equity indices. For assets supporting pension and other postretirement benefit plans, the asset allocation mix is reviewed on a periodic basis. In order to minimize risk, the pension plans maintain a listing of permissible and prohibited investments and impose concentration limits and investment quality requirements on permissible investment options.
Assets and Liabilities Subject to Equity Risk
Investment portfolio The investment portfolio is exposed to losses from market declines affecting equity securities and derivatives, and certain alternative assets and limited partnerships. Generally, declines in equity markets will reduce the value of these types of investments and could negatively impact the Company’s earnings while increases in equity will have the inverse impact. For equity securities, the changes in fair value are reported in net realized gains and losses. For alternative assets and limited partnerships, the Company's share of earnings for the period is recorded in net investment income, though typically on a delay based on the
availability of the underlying financial statements. For a discussion of equity sensitivity, see below.
Assets supporting pension and other postretirement benefit plans The Company may be required to make additional plan contributions if equity investments in the plan portfolios decline in value. For a discussion of equity sensitivity, see below.
Declines in value are recognized as unrealized losses in AOCI. Increases in equity markets are recognized as unrealized gains in AOCI. Unrealized gains and losses in AOCI are amortized into the actuarial loss component of net periodic benefit cost when they exceed a threshold. For further discussion of equity risk associated with the pension plans, see Note 19 - Employee Benefit Plans of Notes to Consolidated Financial Statements.
Assets under management Assets under management in Hartford Funds may decrease in value during equity market declines, which would result in lower earnings because fee income is earned based upon the value of assets under management.
Equity Sensitivity
Investment portfolio and the assets supporting pension and other postretirement benefit plans
Included in the following tables are the estimated before tax change in the economic value of the Company’s invested assets and assets supporting pension and other postretirement benefit plans with sensitivity to equity risk. The calculation of the hypothetical change in economic value below assumes a 20% upward and downward shock to the Standard & Poor's 500 Composite Price Index ("S&P 500"). For limited partnerships and other alternative investments, the movement in economic value is calculated using a beta analysis largely derived from historical experience relative to the S&P 500.
The selection of the 20% shock to the S&P 500 was made only as an illustration of the potential hypothetical impact of such an event and should not be construed as a prediction of future market events. Actual results could differ materially from those illustrated below due to the nature of the estimates and assumptions used in the analysis. These calculations do not capture the impact of portfolio re-allocations.
Equity Sensitivity
| As of December 31, 2021 | As of December 31, 2020 [1] | ||||||||||||||||||||||
| Shock to S&P 500 | Shock to S&P 500 | ||||||||||||||||||||||
| (Before tax) | Fair Value | +20% | -20% | Fair Value | +20% | -20% | |||||||||||||||||
| Investment Portfolio | $ | 5,447 | $ | 641 | $ | (641) | $ | 3,520 | $ | 397 | $ | (397) | |||||||||||
| Assets supporting pension and other postretirement benefit plans | $ | 1,245 | $ | 167 | $ | (167) | $ | 1,573 | $ | 240 | $ | (240) |
*[1]*Table excludes the Company's investment in Hopmeadow Holdings LP which was reported in other assets on the Company's Consolidated Balance Sheets prior to being sold on June 30, 2021.
Hartford Funds assets under management
Hartford Funds earnings are significantly influenced by the U.S. and other equity markets. If equity markets were to hypothetically decline 20% and remain depressed for one year, the estimated before tax impact on reported earnings for that one year period is approximately $65 as of December 31, 2021.
The selection of the 20% shock to the S&P 500 was made only as an illustration of the potential hypothetical impact of such an event and should not be construed as a prediction of future market events. Actual results could differ materially due to the nature of the estimates and assumptions used in the analysis.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Foreign Currency Exchange Risk
Foreign currency exchange risk is the risk of financial loss due to changes in the relative value between currencies.
Sources of Currency Risk The Company has foreign currency exchange risk in non-U.S. dollar denominated cash, fixed maturities, equities, and derivative instruments. In addition, the Company has non-U.S. subsidiaries, some with functional currencies other than U.S. dollar, and which transact business in multiple currencies resulting in assets and liabilities denominated in foreign currencies.
Impact Changes in relative values between currencies can create variability in cash flows and realized or unrealized gains and losses on changes in the fair value of assets and liabilities. The impact on the fair value of fixed maturities, AFS due to changes in foreign currency exchange rates, in relation to functional currency, is reported in unrealized gains or losses as part of other comprehensive income. The realization of gains or losses resulting from investment sales or from changes in investments that record changes in fair value through the income statement due to changes in foreign currency exchange rates is reflected through net realized gains and losses.
In regards to insurance and reinsurance contracts that the Company enters into for which we are obligated to pay losses in a foreign currency, the impact of changes in foreign currency exchange rates on assets and liabilities related to these contracts is reflected through net realized gains and losses. These assets or liabilities include, but are not limited to, cash and cash equivalents, premiums receivable, reinsurance recoverables, and unpaid losses and loss adjustment expenses. Additionally, the Company translates the assets, liabilities, and income of non-U.S. dollar functional currency legal entities into U.S. dollar. This translation amount is reported as a component of other comprehensive income.
Management The Company manages its foreign currency exchange risk primarily through asset-liability matching and through the use of derivative instruments. However, legal entity capital is invested in local currencies in order to satisfy regulatory requirements and to support local insurance operations. The foreign currency exposure of non-U.S. dollar denominated investments will most commonly be reduced through the sale of the assets or through hedges using foreign currency swaps and forwards.
Assets and Liabilities Subject to Foreign Currency Exchange Risk
Investment portfolio The Company is exposed to foreign exchange risk affecting non-U.S. dollar denominated cash, fixed maturities, equities and derivative instruments. Changes in relative values between currencies can positively or negatively impact net realized gains and losses or unrealized gains (losses) as part of other comprehensive income.
Assets supporting pension plan Changes in relative values between currencies can positively or negatively impact unrealized gains and losses in AOCI. Unrealized gains and losses in AOCI are amortized into the actuarial loss component of net periodic benefit cost when they exceed a threshold. As of December 31, 2021 and 2020, the Company had pension plan assets of $97 and $95, respectively, of non-U.S. dollar investments in multiple currencies. These amounts are excluded from the sensitivity analysis below.
Insurance contract related assets and liabilities The Company has non-U.S. dollar denominated insurance and reinsurance contracts and associated premiums receivable, reinsurance recoverables and unpaid losses and loss adjustment expenses, that are exposed to foreign exchange risk. For contracts that are within U.S, dollar functional currency legal entities, changes in foreign currency exchange rates can positively or negatively impact net realized gains and losses. For contracts within non-U.S. dollar functional currency legal entities, changes in foreign currency exchange rates can positively or negatively impact other comprehensive income.
Foreign Currency Sensitivity
For the Company’s primary currencies that create foreign exchange risk, the following table provides the estimated impact of a hypothetical 10% unfavorable change in exchange rates. Actual results could differ materially due to the nature of the estimates and assumptions used in the analysis. The amounts presented are in U.S. dollars and before tax.
Foreign Currency Sensitivity [1]
| GBP | CAD | 10% Unfavorable Change | |||||||||
| December 31, 2021 | |||||||||||
| Net assets (liabilities) | $ | 287 | $ | 132 | $ | (38) | |||||
| December 31, 2020 | |||||||||||
| Net assets (liabilities) | $ | 296 | $ | 189 | $ | (44) |
*[1]*Amount excludes currencies where the value of net assets in U.S. dollar equivalent is less than 1% of total net assets of the Company.
|
| Table of Contents | Index to MD&A |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Financial Risk on U.S. Statutory Capital
U.S. Statutory surplus amounts and RBC ratios may increase or decrease in any period depending upon a variety of factors and may be compounded in extreme scenarios or if multiple factors occur at the same time. At times, the impact of changes in certain market factors or a combination of multiple factors on RBC ratios can be counterintuitive. Factors include:
-
A decrease in the value of certain fixed-income and equity securities in our investment portfolio, due in part to credit spreads widening, an increase in interest rates, or a decline in equity market levels, may result in a decrease in statutory surplus and RBC ratios;
-
A decline in investment yields may reduce our net investment income, which may result in a decrease in statutory surplus and RBC ratios;
-
Decreases in the value of certain derivative instruments that do not get hedge accounting, may reduce statutory surplus and RBC ratios; and
-
Non-market factors can also impact the amount and volatility of either our actual or potential obligation, as well as the related statutory surplus and RBC ratios.
Most of these factors are outside of the Company’s control. Among other factors, rating agencies consider the level of statutory capital and surplus of our U.S. insurance subsidiaries as well as the level of a measure of GAAP capital held by the Company in determining the Company’s financial strength and credit ratings. Rating agencies may implement changes to their internal models that have the effect of increasing or decreasing the amount of capital we must hold in order to maintain our current ratings.
Investment Portfolio Risk
The following table presents the Company’s fixed maturities, AFS, by credit quality. The credit ratings referenced throughout this section are based on availability and are generally the midpoint of the available ratings among Moody’s, S&P, and Fitch. If no rating is available from a rating agency, then an internally developed rating is used. Accrued interest receivable
related to fixed maturities are recorded in other assets on the Consolidated Balance Sheets and are not included in the amortized cost or fair value of the fixed maturities. For further information refer to Note 6 - Investments.
Fixed Maturities, AFS by Credit Quality
| December 31, 2021 | December 31, 2020 | ||||||||||||||||||||||
| Amortized Cost | Fair Value | Percent of Total Fair Value | Amortized Cost | Fair Value | Percent of Total Fair Value | ||||||||||||||||||
| United States Government/Government agencies | $ | 5,706 | $ | 5,881 | 13.7 | % | $ | 4,872 | $ | 5,214 | 11.6 | % | |||||||||||
| AAA | 5,917 | 6,133 | 14.3 | % | 6,482 | 6,848 | 15.2 | % | |||||||||||||||
| AA | 7,279 | 7,718 | 18.0 | % | 7,840 | 8,453 | 18.8 | % | |||||||||||||||
| A | 10,277 | 10,962 | 25.6 | % | 10,500 | 11,595 | 25.7 | % | |||||||||||||||
| BBB | 9,196 | 9,708 | 22.7 | % | 9,831 | 10,856 | 24.1 | % | |||||||||||||||
| BB & below | 2,413 | 2,445 | 5.7 | % | 2,036 | 2,069 | 4.6 | % | |||||||||||||||
| Total fixed maturities, AFS | $ | 40,788 | $ | 42,847 | 100.0 | % | $ | 41,561 | $ | 45,035 | 100.0 | % |
The fair value of fixed maturities, AFS decreased as compared to December 31, 2020, primarily due a decrease in valuations due to higher interest rates, partially offset by tighter credit spreads. The decline was also due to the reinvestment into other asset classes.
Fixed maturities, FVO, included within other investments on the Consolidated Balance Sheets, are not included in the preceding table. For further discussion on FVO securities, see Note 5 - Fair Value Measurements of Notes to Consolidated Financial Statements.
|
| Table of Contents | Index to MD&A |
Previous: Item 3. LEGAL PROCEEDINGS · Next: Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations