 filings.tools
Item 2. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
38K characters. Original on sec.gov · Markdown
Item 2. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
(Dollars in tables and graphs in millions, except per share amounts)
The following Management's Discussion and Analysis of Financial Condition and Results of Operations is intended to help the reader understand the results of operations and financial condition of Honeywell International Inc. and its consolidated subsidiaries (Honeywell, we, us, our, or the Company) for the three months ended March 31, 2024. The financial information as of March 31, 2024, should be read in conjunction with the Consolidated Financial Statements for the year ended December 31, 2023, contained in our 2023 Annual Report on Form 10-K. See Note 3 Acquisitions and Divestitures of Notes to Consolidated Financial Statements for a discussion of acquisition and divestiture activity during the three months ended March 31, 2024. Certain prior year amounts are reclassified to conform to the current year presentation.
BUSINESS UPDATE
MACROECONOMIC CONDITIONS
We continue to monitor the impacts of ongoing macroeconomic conditions and geopolitical events. In the first quarter of 2024, material inflation continued to moderate with some preliminary signs of stabilization across most industrial sectors. Slowing global growth relieved pressure on logistics freight and service capacity and provided supply chain redundancy. We continue to leverage short-term and long-term mitigation strategies to reduce the impact of supply chain disruptions, including digital solutions to assist in identifying and managing shortages.
Our mitigation strategies include pricing actions, longer term planning for constrained materials, new supplier development, material supply tracking tools, and direct engagement with key suppliers to meet customer demand. Our relationships with primary and secondary suppliers allow us to reliably source key components and raw materials. In areas where we cannot procure key components or raw materials, we consider altering existing products and developing new products to satisfy customer needs. Alterations to existing products and the development of new products undergo product quality controls and engineering qualification prior to releasing to our customers. In addition, we assist certain suppliers facing manufacturing challenges by committing our own resources to their sites and facilities. We believe these mitigation strategies enable us to reduce supply risk, accelerate new product innovation, and expand our penetration in the markets we serve. Additionally, due to the strenuous quality controls and product qualification we perform on a new or altered product, we do not expect these mitigation strategies to impact product quality or reliability.
Global conflicts continue to create volatility in global financial and energy markets and contribute to supply chain shortages adding to the inflationary pressures in the global economy. We actively collaborate with our suppliers to minimize impacts of supply shortages on our manufacturing capabilities.
To date, our strategies have successfully mitigated our exposure to these conditions. However, if we are not successful in sustaining or executing these strategies, these macroeconomic conditions could have a material adverse effect on our consolidated results of operations or operating cash flows.
32 Honeywell International Inc.
RESULTS OF OPERATIONS
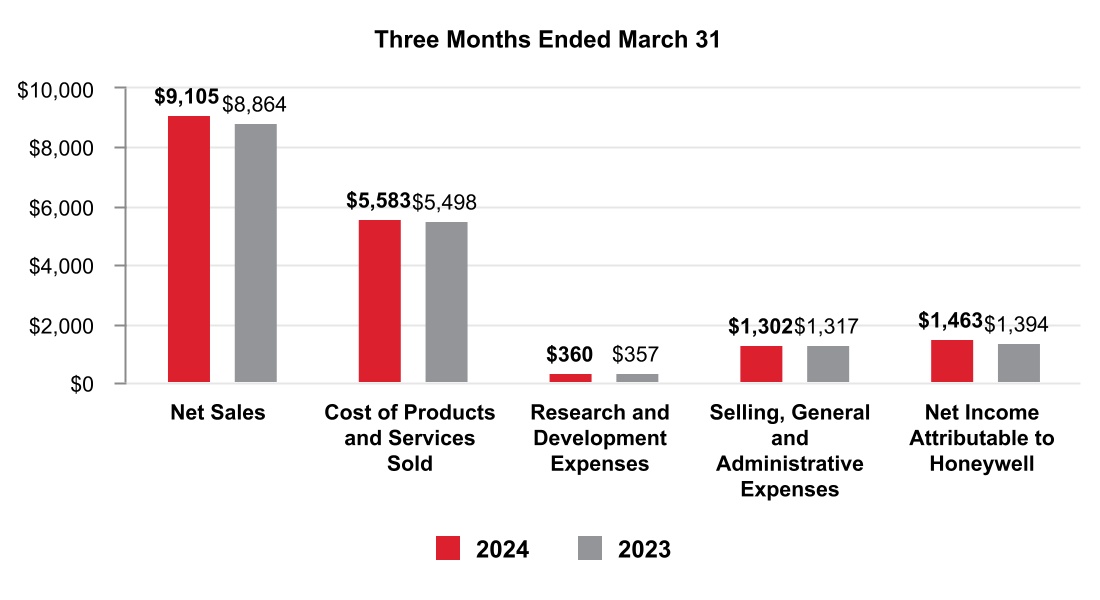
Consolidated Financial Results
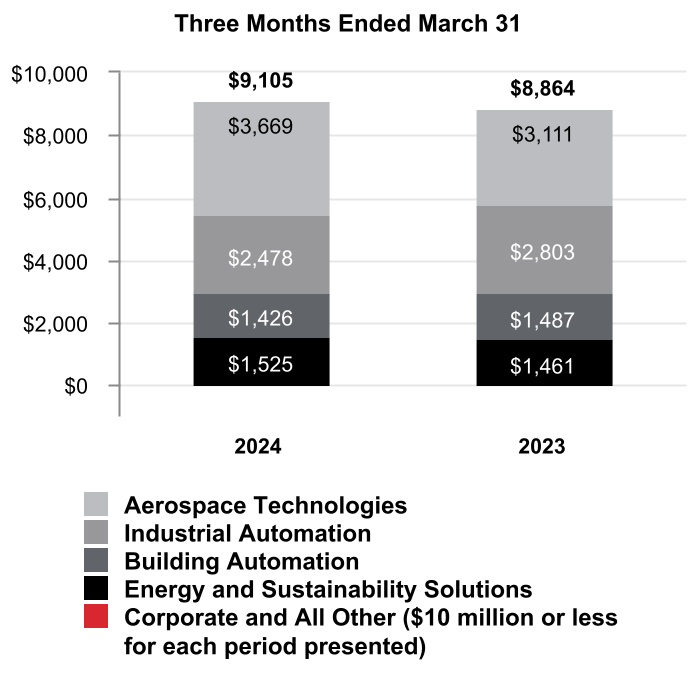
Net Sales by Segment
33 Honeywell International Inc.
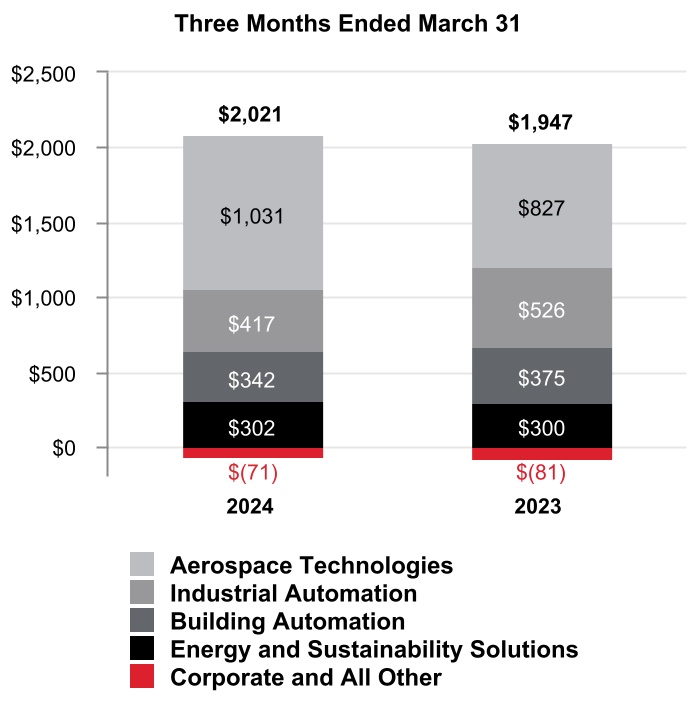
Segment Profit by Segment
34 Honeywell International Inc.
CONSOLIDATED OPERATING RESULTS
Net Sales
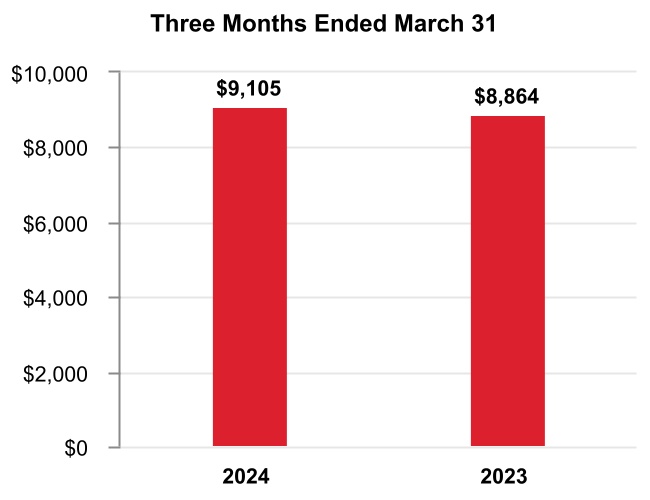
The change in Net sales was attributable to the following:
| Q1 2024 vs. Q1 2023 | ||||||||||||||||||||||||||
| Volume | —% | |||||||||||||||||||||||||
| Price | 3% | |||||||||||||||||||||||||
| Foreign currency translation | —% | |||||||||||||||||||||||||
| Acquisitions, divestitures, and other, net | —% | |||||||||||||||||||||||||
| Total % change in Net sales | 3% |
A discussion of Net sales by reportable business segment can be found in the Review of Business Segments section of this Management's Discussion and Analysis.
Q1 2024 compared with Q1 2023
Net sales increased due to increased pricing and price adjustments to offset inflation.
35 Honeywell International Inc.
Cost of Products and Services Sold
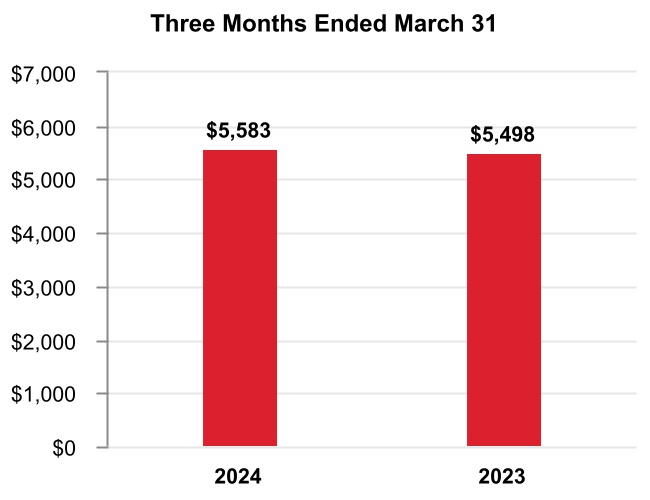
Q1 2024 compared with Q1 2023
Cost of products and services sold increased due to the following:
-
Higher direct and indirect material costs and higher labor costs of approximately $0.2 billion or 4%,
-
Partially offset by higher productivity of approximately $0.1 billion or 2%.
Gross Margin
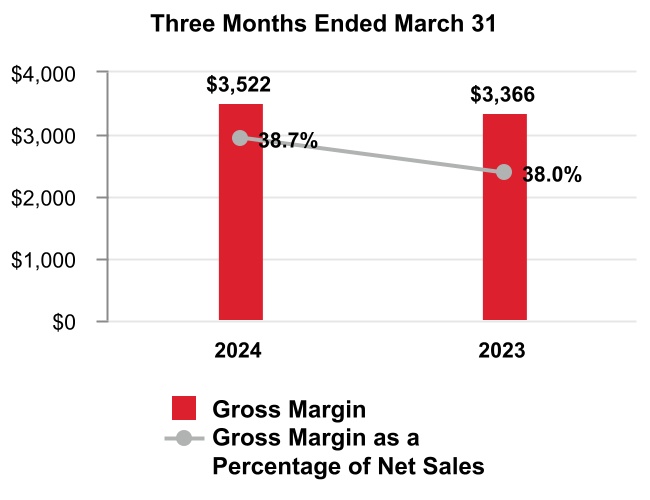
Q1 2024 compared with Q1 2023
Gross margin increased by approximately $0.2 billion and gross margin percentage increased 70 basis points to 38.7% compared to 38.0% for the same period of 2023.
36 Honeywell International Inc.
Research and Development Expenses
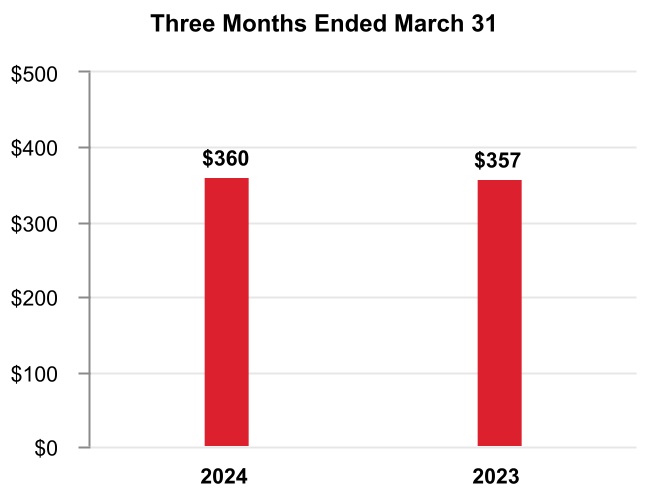
Q1 2024 compared with Q1 2023
Research and development expenses were largely unchanged.
Selling, General and Administrative Expenses
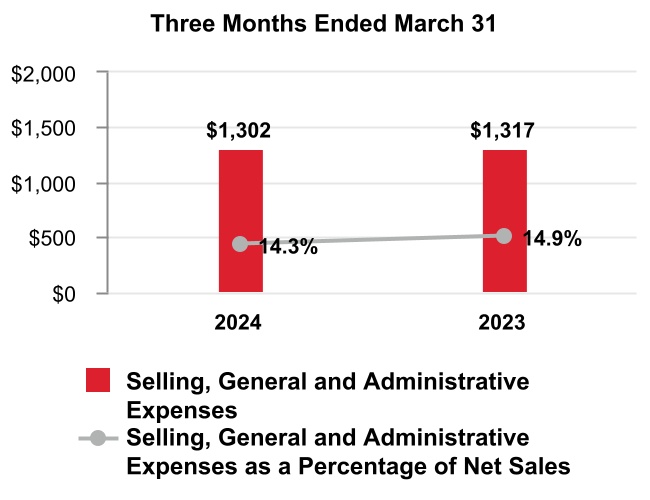
Q1 2024 compared with Q1 2023
Selling, general and administrative expenses were largely unchanged.
Other (Income) Expense
| Three Months Ended March 31, | |||||||||||||||||||||||||||||
| 2024 | 2023 | ||||||||||||||||||||||||||||
| Other (income) expense | $ | (231) | $ | (260) |
Q1 2024 compared with Q1 2023
Other income declined slightly.
37 Honeywell International Inc.
Tax Expense
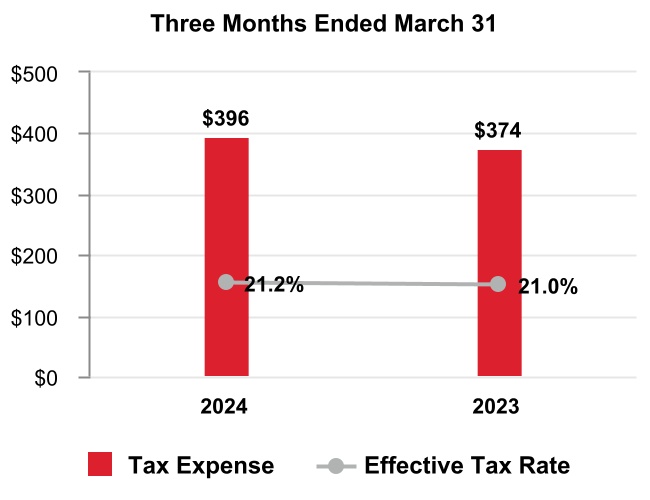
Q1 2024 compared with Q1 2023
The effective tax rate increased as a result of incremental tax expense from reduced tax reserve activity, partially offset by increased tax benefits from employee-share based compensation and other accrued taxes, representing a 20 basis-point increase.
Net Income Attributable to Honeywell
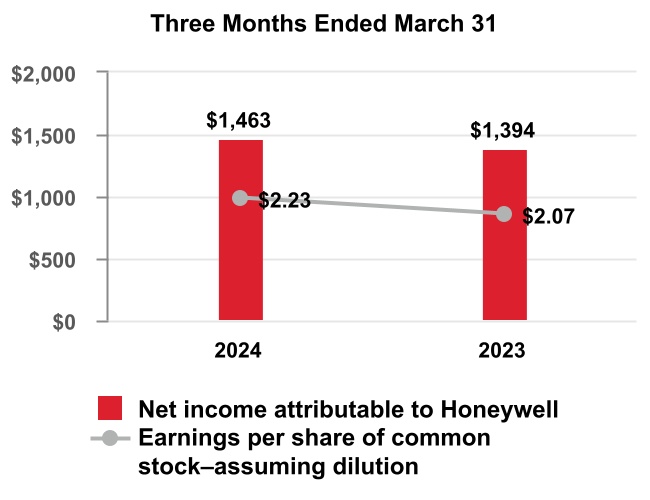
Q1 2024 compared to Q1 2023
Earnings per share of common stock–assuming dilution increased due to the following:
-
Higher segment profit ($0.09 after tax),
-
Lower repositioning and other charges ($0.06 after tax),
-
Higher interest income ($0.03 after tax), and
-
Lower share count ($0.05 after tax),
-
Partially offset by higher interest expense (loss of $0.06 after tax).
38 Honeywell International Inc.
REVIEW OF BUSINESS SEGMENTS
During the first quarter of 2024, the Company realigned certain of its business units as reflected in Note 18 Segment Financial Data, which impacts the composition of its reportable segments. The Company recast historical periods to reflect this change in segment presentation. See Note 18 Segment Financial Data to Notes to Consolidated Financial Statements for further discussion.
We globally manage our business operations through four reportable business segments: Aerospace Technologies, Industrial Automation, Building Automation, and Energy and Sustainability Solutions.
AEROSPACE TECHNOLOGIES
Net Sales
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||||||||
| 2024 | 2023 | % Change | |||||||||||||||||||||||||||||||||||||||
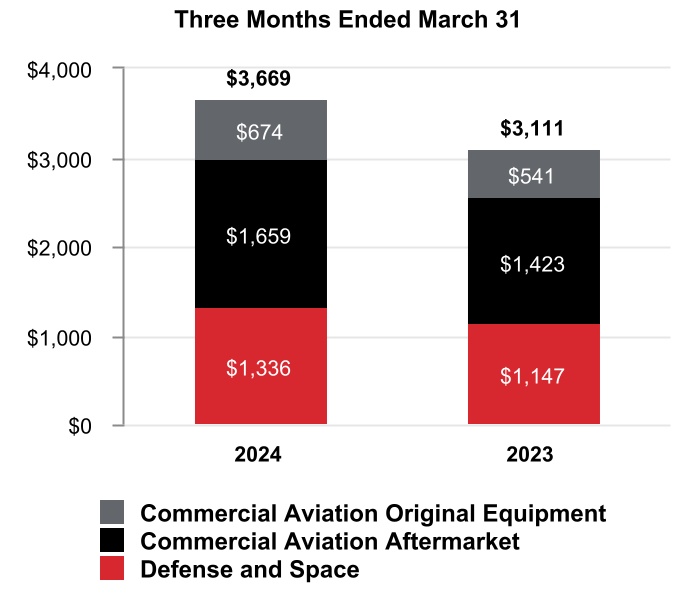
| Net sales | $ | 3,669 | $ | 3,111 | 18 | % | |||||||||||||||||||||||||||||||||||
| Cost of products and services sold | 2,221 | 1,936 | |||||||||||||||||||||||||||||||||||||||
| Selling, general and administrative and other expenses | 417 | 348 | |||||||||||||||||||||||||||||||||||||||
| Segment profit | $ | 1,031 | $ | 827 | 25 | % |
| 2024 vs. 2023 | |||||||||||||||||||||||||||||
| Three Months Ended March 31, | |||||||||||||||||||||||||||||
| Factors Contributing to Year-Over-Year Change | Net Sales | Segment Profit | |||||||||||||||||||||||||||
| Organic1 | 18 | % | 25 | % | |||||||||||||||||||||||||
| Foreign currency translation | — | % | — | % | |||||||||||||||||||||||||
| Acquisitions, divestitures, and other, net | — | % | — | % | |||||||||||||||||||||||||
| Total % change | 18 | % | 25 | % |
| 1 | Organic sales % change, presented for all of our reportable business segments, is defined as the change in Net sales, excluding the impact on sales from foreign currency translation and acquisitions, net of divestitures, for the first 12 months following the transaction date. We believe this non-GAAP measure is useful to investors and management in understanding the ongoing operations and analysis of ongoing operating trends. |
39 Honeywell International Inc.
Q1 2024 compared to Q1 2023
Sales increased $558 million due to higher organic sales of $237 million in Commercial Aviation Aftermarket driven by higher sales volumes in air transport due to an increase in flight hours, higher organic sales of $187 million in Defense and Space driven by higher sales volumes due to increased shipments, and higher organic sales of $132 million in Commercial Aviation Original Equipment driven by higher sales volumes due to increased shipments.
Segment profit increased $204 million and segment margin percentage increased 150 basis points to 28.1% compared to 26.6% for the same period of 2023.
INDUSTRIAL AUTOMATION
Net Sales
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||||||||
| 2024 | 2023 | % Change | |||||||||||||||||||||||||||||||||||||||
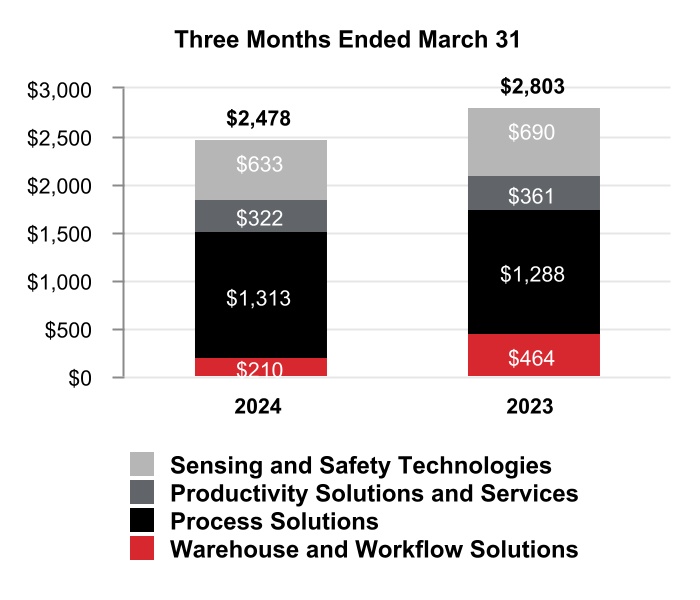
| Net sales | $ | 2,478 | $ | 2,803 | (12) | % | |||||||||||||||||||||||||||||||||||
| Cost of products and services sold | 1,503 | 1,724 | |||||||||||||||||||||||||||||||||||||||
| Selling, general and administrative and other expenses | 558 | 553 | |||||||||||||||||||||||||||||||||||||||
| Segment profit | $ | 417 | $ | 526 | (21) | % |
| 2024 vs. 2023 | |||||||||||||||||||||||||||||
| Three Months Ended March 31, | |||||||||||||||||||||||||||||
| Factors Contributing to Year-Over-Year Change | Net Sales | Segment Profit | |||||||||||||||||||||||||||
| Organic | (13) | % | (21) | % | |||||||||||||||||||||||||
| Foreign currency translation | — | % | — | % | |||||||||||||||||||||||||
| Acquisitions, divestitures, and other, net | 1 | % | — | % | |||||||||||||||||||||||||
| Total % change | (12) | % | (21) | % |
Q1 2024 compared to Q1 2023
Sales decreased $325 million due to lower organic sales of $254 million in Warehouse and Workflow Solutions driven by lower demand for projects and lower organic sales of $55 million in Sensing and Safety Technologies driven by lower demand for sensing products.
Segment profit decreased $109 million and segment margin percentage decreased 200 basis points to 16.8% compared to 18.8% for the same period in 2023.
40 Honeywell International Inc.
BUILDING AUTOMATION
Net Sales
| Three Months Ended March 31, | ||||||||||||||||||||||||||||||||||||||
| 2024 | 2023 | % Change | ||||||||||||||||||||||||||||||||||||
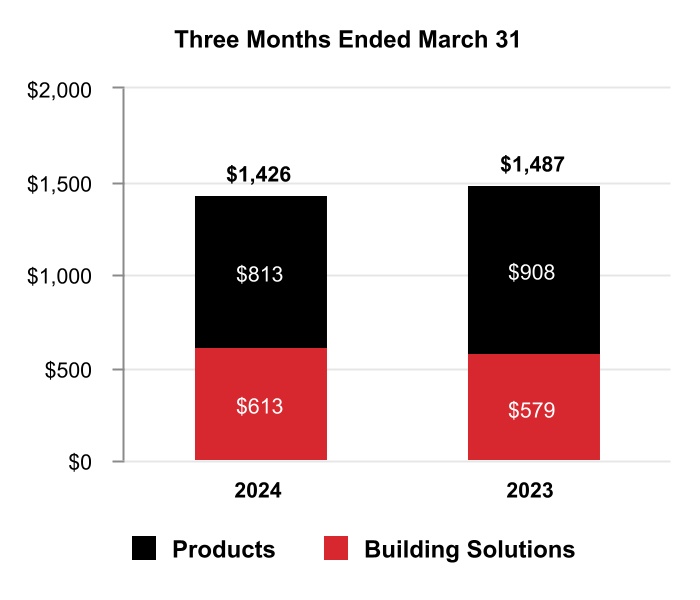
| Net sales | $ | 1,426 | $ | 1,487 | (4) | % | ||||||||||||||||||||||||||||||||
| Cost of products and services sold | 769 | 792 | ||||||||||||||||||||||||||||||||||||
| Selling, general and administrative and other expenses | 315 | 320 | ||||||||||||||||||||||||||||||||||||
| Segment profit | $ | 342 | $ | 375 | (9) | % |
| 2024 vs. 2023 | ||||||||||||||||||||||||||
| Three Months Ended March 31, | ||||||||||||||||||||||||||
| Factors Contributing to Year-Over-Year Change | Net Sales | Segment Profit | ||||||||||||||||||||||||
| Organic | (3) | % | (8) | % | ||||||||||||||||||||||
| Foreign currency translation | (1) | % | (1) | % | ||||||||||||||||||||||
| Acquisitions, divestitures, and other, net | — | % | — | % | ||||||||||||||||||||||
| Total % change | (4) | % | (9) | % |
Q1 2024 compared to Q1 2023
Sales decreased $61 million due to lower organic sales of $89 million in Products driven by lower demand partially offset by higher organic sales of $38 million in Building Solutions driven by higher demand in building projects.
Segment profit decreased $33 million and segment margin percentage decreased 120 basis points to 24.0% compared to 25.2% for the same period of 2023.
41 Honeywell International Inc.
ENERGY AND SUSTAINABILITY SOLUTIONS
Net Sales
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||||||||
| 2024 | 2023 | % Change | |||||||||||||||||||||||||||||||||||||||
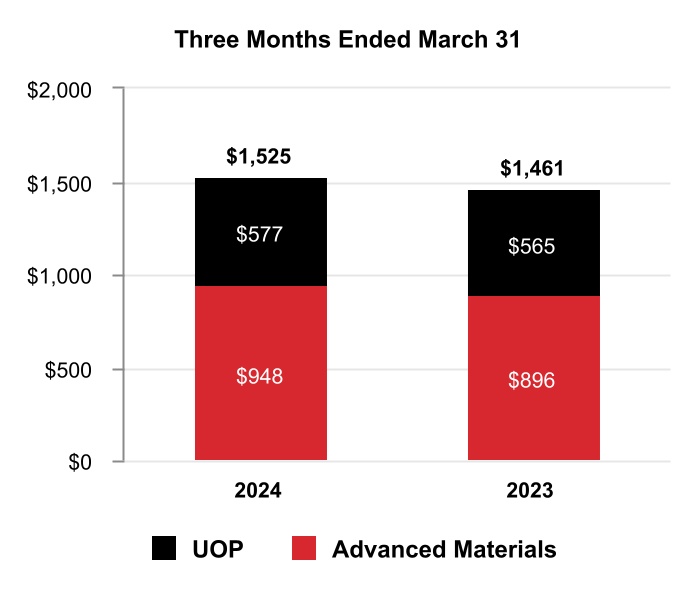
| Net sales | $ | 1,525 | $ | 1,461 | 4 | % | |||||||||||||||||||||||||||||||||||
| Cost of products and services sold | 1,000 | 949 | |||||||||||||||||||||||||||||||||||||||
| Selling, general and administrative and other expenses | 223 | 212 | |||||||||||||||||||||||||||||||||||||||
| Segment profit | $ | 302 | $ | 300 | 1 | % |
| 2024 vs. 2023 | |||||||||||||||||||||||||||||
| Three Months Ended March 31, | |||||||||||||||||||||||||||||
| Factors Contributing to Year-Over-Year Change | Net Sales | Segment Profit | |||||||||||||||||||||||||||
| Organic | 5 | % | 2 | % | |||||||||||||||||||||||||
| Foreign currency translation | (1) | % | (1) | % | |||||||||||||||||||||||||
| Acquisitions, divestitures, and other, net | — | % | — | % | |||||||||||||||||||||||||
| Total % change | 4 | % | 1 | % |
Q1 2024 compared to Q1 2023
Sales increased $64 million due to higher organic sales of $55 million in Advanced Materials driven by higher demand for fluorine products.
Segment profit increased $2 million and segment margin percentage decreased 70 basis points to 19.8% compared to 20.5% for the same period of 2023.
42 Honeywell International Inc.
CORPORATE AND ALL OTHER
Corporate and All Other primarily includes unallocated corporate costs, interest expense on holding-company debt, and the controlling majority-owned interest in Quantinuum. Corporate and All Other is not a separate reportable business segment as segment reporting criteria is not met. The Company continues to monitor the activities in Corporate and All Other to determine the need for further reportable business segment disaggregation.
REPOSITIONING CHARGES
See Note 5 Repositioning and Other Charges of Notes to Consolidated Financial Statements for a discussion of our repositioning actions and related charges incurred in the three months ended March 31, 2024, and 2023. Cash spending related to our repositioning actions was $50 million in the three months ended March 31, 2024, and was funded through operating cash flows.
43 Honeywell International Inc.
LIQUIDITY AND CAPITAL RESOURCES
(Dollars in tables in millions)
We manage our businesses to maximize operating cash flows as the primary source of liquidity. Each of our businesses is focused on increasing operating cash flows through revenue growth, margin expansion, and improved working capital turnover. Additional sources of liquidity include U.S. cash balances, and the ability to access non-U.S. cash balances, short-term debt from the commercial paper market, long-term borrowings, committed credit lines, and access to the public debt and equity markets.
CASH
As of March 31, 2024, and December 31, 2023, we held $12.0 billion and $8.1 billion, respectively, of cash and cash equivalents, including our short-term investments. We monitor the third-party depository institutions that hold our cash and cash equivalents on a daily basis. Our emphasis is primarily safety of principal and secondarily maximizing yield of those funds. We diversify our cash and cash equivalents among counterparties to minimize exposure to any one counterparty.
As of March 31, 2024, $5.7 billion of the Company’s cash, cash equivalents, and short-term investments were held by non-U.S. subsidiaries. We do not have material amounts related to any jurisdiction subject to currency control restrictions that impact our ability to access and repatriate such amounts. Under current laws, we do not expect taxes on repatriation or restrictions on amounts held outside of the U.S. to have a material effect on our overall liquidity.
CASH FLOW SUMMARY
Our cash flows from operating, investing, and financing activities, as reflected in the Consolidated Statement of Cash Flows, are summarized as follows:
| Three Months Ended March 31, | |||||||||||||||||
| 2024 | 2023 | Variance | |||||||||||||||
| Cash and cash equivalents at beginning of period | $ | 7,925 | $ | 9,627 | $ | (1,702) | |||||||||||
| Operating activities | |||||||||||||||||
| Net income attributable to Honeywell | 1,463 | 1,394 | 69 | ||||||||||||||
| Noncash adjustments | 289 | 572 | (283) | ||||||||||||||
| Changes in working capital | (468) | (546) | 78 | ||||||||||||||
| NARCO Buyout payment | — | (1,325) | 1,325 | ||||||||||||||
| Other operating activities | (836) | (879) | 43 | ||||||||||||||
| Net cash provided by (used for) operating activities | 448 | (784) | 1,232 | ||||||||||||||
| Net cash used for investing activities | (273) | (29) | (244) | ||||||||||||||
| Net cash provided by (used for) financing activities | 3,696 | (1,973) | 5,669 | ||||||||||||||
| Effect of foreign exchange rate changes on cash and cash equivalents | (40) | 28 | (68) | ||||||||||||||
| Net increase (decrease) in cash and cash equivalents | 3,831 | (2,758) | 6,589 | ||||||||||||||
| Cash and cash equivalents at end of period | $ | 11,756 | $ | 6,869 | $ | 4,887 |
Three months ended March 31, 2024
Net cash provided by operating activities was $448 million, driven by $1,463 million of Net income attributable to Honeywell, adjusted for $291 million of depreciation and amortization, partially offset by a $603 million decrease in Accrued liabilities, driven by a decrease in accrued employee compensation and benefits costs, and a $381 million decrease in Accounts payable, due to decreased material receipts.
Net cash used for investing activities was $273 million, driven by $233 million of capital expenditures.
Net cash provided by financing activities was $3,696 million, driven by $5,710 million of proceeds from issuance of long-term debt primarily to fund the Carrier acquisition, partially offset by $703 million of cash dividends paid, $671 million of repurchases of common stock, and $573 million of payments of long-term debt.
44 Honeywell International Inc.
Three months ended March 31, 2024 compared with three months ended March 31, 2023
Net cash provided by operating activities increased by $1,232 million due to the $1,325 million payment made by the Company pursuant to the NARCO Amended Buyout Agreement in 2023, partially offset by $283 million decrease of noncash adjustments, driven by a $222 million decline in deferred income taxes.
Net cash used for investing activities increased by $244 million due to a $243 million net increase in investments.
Net cash provided by financing activities increased by $5,669 million due to a $5,710 million increase of proceeds from issuance of long-term debt, $790 million decrease in payments of long-term debt, and $107 million increase in proceeds from the issuance of common stock, partially offset by $1,058 million decrease in net proceeds of commercial paper.
CASH REQUIREMENTS AND ASSESSMENT OF CURRENT LIQUIDITY
In addition to our normal operating cash requirements, we expect our principal future cash requirements will be to fund capital expenditures, share repurchases, dividends, strategic acquisitions, and debt repayments. On April 24, 2023, the Board of Directors authorized the repurchase of up to $10 billion of Honeywell common stock, including approximately $2.1 billion of remaining availability under the previously announced $10 billion share repurchase authorization. During the three months ended March 31, 2024, we repurchased common stock of $671 million. Refer to the section titled Liquidity and Capital Resources of our 2023 Form 10-K for a discussion of our expected capital expenditures, share repurchases, mergers and acquisitions activity, and dividends for 2024.
We continually seek opportunities to improve our liquidity and working capital efficiency, which includes the extension of payment terms with our suppliers and transfer of our trade receivables to unaffiliated financial institutions on a true sale basis. The impact of these programs is not material to our overall liquidity.
We continue to assess the relative strength of each business in our portfolio as to strategic fit, market position, profit, and cash flow contribution in order to identify target investment and acquisition opportunities in order to upgrade our combined portfolio. We identify acquisition candidates that will further our strategic plan and strengthen our existing core businesses. We also identify businesses that do not fit into our long-term strategic plan based on their market position, relative profitability, or growth potential. These businesses are considered for potential divestiture, restructuring, or other repositioning actions, subject to regulatory constraints.
In early 2023, we made payments of approximately $1.5 billion in connection with the NARCO Buyout and UOP Matters. Pursuant to the NARCO Amended Buyout Agreement, we received proceeds of $275 million from the HWI Sale during the year ended December 31, 2023, and may receive additional consideration in future periods if certain conditions under the definitive sale agreement for the HWI Sale are met. These payments and receipts have not materially impacted our liquidity position. See Note 12 Fair Value Measurements of Notes to Consolidated Financial Statements for additional discussion related to the fair value of future proceeds from the HWI Sale.
Based on past performance and current expectations, we believe that our operating cash flows will be sufficient to meet our future operating cash needs. Our available cash, committed credit lines, and access to the public debt and equity markets provide additional sources of short-term and long-term liquidity to fund current operations, debt maturities, and future investment opportunities.
See Note 9 Long-term Debt and Credit Agreements of Notes to Consolidated Financial Statements for additional discussion of items impacting our liquidity.
BORROWINGS
We leverage a variety of debt instruments to manage our overall borrowing costs. As of March 31, 2024, and December 31, 2023, our total borrowings were $25.3 billion and $20.4 billion, respectively.
| March 31, 2024 | December 31, 2023 | |||||||||||||
| Commercial paper | $ | 1,817 | $ | 2,083 | ||||||||||
| Variable rate notes | 22 | 22 | ||||||||||||
| Fixed rate notes | 23,714 | 18,530 | ||||||||||||
| Other | 215 | 219 | ||||||||||||
| Fair value of hedging instruments | (208) | (166) | ||||||||||||
| Debt issuance costs | (304) | (245) | ||||||||||||
| Total borrowings | $ | 25,256 | $ | 20,443 |
45 Honeywell International Inc.
A primary source of liquidity is our ability to access the corporate bond markets. Through these markets, we issue a variety of long-term fixed rate notes, in a variety of currencies, to manage our overall funding costs.
Another primary source of liquidity is our ability to access the commercial paper market. Commercial paper notes are sold at a discount or premium and have a maturity of 365 days or less from date of issuance. Borrowings under the commercial paper program are available for general corporate purposes as well as for financing acquisitions.
We also have the following revolving credit agreements:
-
A $1.5 billion 364-day credit agreement (the 364-Day Credit Agreement) with a syndicate of banks, dated as of March 18, 2024. Amounts borrowed under the 364-Day Credit Agreement are required to be repaid no later than March 17, 2025, unless (i) we elect to convert all then outstanding amounts into a term loan, upon which such amounts shall be repaid in full on March 17, 2026, or (ii) the 364-Day Credit Agreement is terminated earlier pursuant to its terms. The 364-Day Credit Agreement replaced the previously reported $1.5 billion 364-day credit agreement dated as of March 20, 2023, which was terminated in accordance with its terms effective March 18, 2024. As of March 31, 2024, there were no outstanding borrowings under our 364-Day Credit Agreement.
-
A $4.0 billion five-year credit agreement (the 5-Year Credit Agreement) with a syndicate of banks, dated as of March 18, 2024. Commitments under the 5-Year Credit Agreement can be increased pursuant to the terms of the 5-Year Credit Agreement to an aggregate amount not to exceed $4.5 billion. The 5-Year Credit Agreement amended and restated the previously reported $4.0 billion amended and restated five-year credit agreement dated as of March 20, 2023. As of March 31, 2024, there were no outstanding borrowings under our 5-Year Credit Agreement.
See Note 9 Long-Term Debt and Credit Agreements of Notes to Consolidated Financial Statements for additional information regarding our debt instruments.
We also have a current shelf registration statement filed with the SEC under which we may issue additional debt securities, common stock, and preferred stock that may be offered in one or more offerings on terms to be determined at the time of the offering. We anticipate that net proceeds of any offering would be used for general corporate purposes, including repayment of existing indebtedness, share repurchases, capital expenditures, and acquisitions.
CREDIT RATINGS
Our ability to access the global debt capital markets and the related cost of these borrowings is affected by the strength of our credit rating and market conditions. Our credit ratings are periodically reviewed by the major independent debt-rating agencies. As of March 31, 2024, S&P Global Inc. (S&P), Fitch Ratings Inc. (Fitch), and Moody’s Investor Service (Moody's) have ratings on our debt set forth in the table below:
| S&P | Fitch | Moody's | |||||||||||||||
| Outlook | Stable | Stable | Positive | ||||||||||||||
| Short-term | A-1 | F1 | P1 | ||||||||||||||
| Long-term | A | A | A2 |
OTHER MATTERS
LITIGATION
We are subject to a number of lawsuits, investigations, and claims (some of which involve substantial amounts) arising out of the conduct of our business. See Note 15 Commitments and Contingencies of Notes to Consolidated Financial Statements for further discussion of environmental, asbestos, and other litigation matters.
CRITICAL ACCOUNTING ESTIMATES
There have been no material changes to our Critical Accounting Estimates presented in our 2023 Annual Report on Form 10-K. For a discussion of the Company’s Critical Accounting Estimates, see the section titled Critical Accounting Estimates in our 2023 Annual Report on Form 10-K.
46 Honeywell International Inc.
RECENT ACCOUNTING PRONOUNCEMENTS
See Note 2 Summary of Significant Accounting Policies of Notes to Consolidated Financial Statements for a discussion of recent accounting pronouncements.
Previous: Cover and table of contents · Next: Item 3. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISKS