 filings.tools
Interactive Brokers Group 10-K 2019-12-31
Filed 2020-02-28. 22 sections, 471K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the year ended December 31**, 2019**
Commission File Number: 001-33440
INTERACTIVE BROKERS GROUP, INC.
(Exact name of registrant as specified in its charter)
| Delaware (State or other jurisdiction of incorporation or organization) | 30-0390693 (I.R.S. Employer Identification No.) |
One Pickwick Plaza
Greenwich**,** Connecticut 06830
(Address of principal executive office)
(203) 618-5800
(Registrant’s telephone number, including area code)
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol | Name of the exchange on which registered |
| Common Stock, par value $.01 per share | IBKR | The Nasdaq Global Select Market |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark whether the registrant is a well-known seasoned issuer, as defined in Rule 405 of the securities act. Yes x No o
Indicate by check mark whether the registrant is not required to file reports pursuant to Section 13 or 15(d) of the act. Yes o No x
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes x No o
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes x No o
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See the definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act. (Check one):
| Large accelerated filer x | Accelerated filer o | Non-accelerated filer o | Smaller reporting company o | Emerging growth company o |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. o
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes o No x
The aggregate market value of the voting and non-voting common equity stock held by non-affiliates of the registrant was approximately $4,032,724,571 computed by reference to the $54.20 closing sale price of the common stock on the Investors Exchange LLC, on June 28, 2019, the last business day of the registrant’s most recently completed second fiscal quarter.
As of February 25, 2020, there were 76,750,794 shares of the issuer’s Class A common stock, par value $0.01 per share, outstanding and 100 shares of the issuer’s Class B common stock, par value $0.01 per share, outstanding.
Documents Incorporated by Reference: Portions of Registrant’s definitive proxy statement for its 2020 annual meeting of shareholders are incorporated by reference in Part III of this Form 10-K.
ANNUAL REPORT ON FORM 10**-**K FOR THE YEAR ENDED DECEMBER 31, 2019
Table of Contents
i
**CAUTIONARY NOTE REGARDING FORWARD-**LOOKING STATEMENTS
We have included or incorporated by reference in this Annual Report on Form 10-K, and from time to time our management may make statements that may constitute “forward-looking statements” within the meaning of the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. Forward-looking statements are not historical facts, but instead represent only our beliefs regarding future events, many of which, by their nature, are inherently uncertain and outside our control. These statements include statements other than historical information or statements of current condition and may relate to our future plans and objectives and results, among other things, and may also include our belief regarding the effect of various legal proceedings, as set forth under “Legal Proceedings and Regulatory Matters” in Part I, Item 3 of this Annual Report on Form 10-K, as well as statements about the objectives and effectiveness of our liquidity policies, statements about trends in or growth opportunities for our businesses, included in “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in Part II, Item 7 of this Annual Report on Form 10-K. By identifying these statements for you in this manner, we are alerting you to the possibility that our actual results may differ, possibly materially, from the anticipated results indicated in these forward-looking statements. Important factors that could cause actual results to differ from those in the forward-looking statements include, among others, those discussed below and under “Risk Factors” in Part I, Item 1A of this Annual Report on Form 10-K and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in Part II, Item 7 of this Annual Report on Form 10-K.
Factors that could cause actual results to differ materially from any future results, expressed or implied, in these forward-looking statements include, but are not limited to, the following:
-
general economic conditions in the markets where we operate;
-
increased industry competition and downward pressures on electronic brokerage commissions and on bid/offer spreads in the remaining market making business we operate;
-
risks inherent to the electronic brokerage and market making businesses;
-
implied versus actual price volatility levels of the products in which we continue to make markets;
-
the general level of interest rates;
-
failure to protect or enforce our intellectual property rights in our proprietary technology;
-
our ability to keep up with rapid technological change;
-
system failures, cyber security threats and other disruptions;
-
non-performance of third-party vendors;
-
conflicts of interest and other risks due to our ownership and holding company structure;
-
the loss of key executives and failure to recruit and retain qualified personnel;
-
the risks associated with the expansion of our business;
-
our possible inability to integrate any businesses we acquire;
-
the impact of accounting standards issued but not yet adopted;
-
compliance with laws and regulations, including those relating to the securities industry; and
-
other factors discussed under “Risk Factors” in Part I, Item 1A of this Annual Report on Form 10-K or elsewhere in this Annual Report on Form 10-K.
We undertake no obligation to publicly update or revise any forward-looking statements to reflect events or circumstances that may arise after the date of this Annual Report on Form 10-K.
PART I
Item 1. BUSINESS
Overview
Interactive Brokers Group, Inc. (“IBG, Inc.” or the “Company”) is an automated global electronic broker and market maker (although, we have substantially exited the options market making business - see Note 2 - Discontinued Operations and Costs Associated with Exit or Disposal Activities to the audited consolidated financial statements in Part II, Item 8 of this Annual Report on Form 10-K). We custody and service accounts for hedge and mutual funds, registered investment advisors, proprietary trading groups, introducing brokers and individual investors. We specialize in routing orders while striving to achieve best executions and processing trades in stocks, options, futures, foreign exchange instruments (“forex”), bonds, mutual funds and exchange traded funds (“ETFs”) on more than 135 electronic exchanges and market centers around the world. In the United States of America (“U.S.”), we conduct our business primarily from our headquarters in Greenwich, Connecticut, and from Chicago, Illinois. Abroad, we conduct our business through offices located in Canada, the United Kingdom, Luxembourg, Switzerland, India, China (Hong Kong and Shanghai), Japan, and Australia. As of December 31, 2019, we had 1,643 employees worldwide.
IBG, Inc. is a holding company whose primary asset is the ownership of approximately 18.5% of the membership interests of IBG LLC (the “Group”), the current holding company for our businesses. IBG, Inc. is the sole managing member of IBG LLC.
When we use the terms “we,” “us,” and “our,” we mean IBG, Inc. and its subsidiaries (including IBG LLC). Unless otherwise indicated, the terms “common stock” and “IBKR shares” refer to the Class A common stock of IBG, Inc.
We are a successor to the market making business founded by our Chairman, Mr. Thomas Peterffy, on the floor of the American Stock Exchange in 1977. Since our inception, we have focused on developing proprietary software to automate broker-dealer functions. During that time, we have been a pioneer in developing and applying technology as a financial intermediary to increase liquidity and transparency in the capital markets in which we operate. The proliferation of electronic exchanges since the early 1990s has provided us with the opportunity to integrate our software with an increasing number of exchanges and market centers to create one automatically functioning, computerized platform that requires minimal human intervention. Over four decades of developing our automated trading platforms and our automation of many middle and back office functions have allowed us to become one of the lowest cost providers of broker-dealer services and significantly increase the volume of trades we handle.
Our activities are divided into two principal business segments: electronic brokerage and market making (being discontinued). For a description of these segments and the products and services they provide, refer to “Business Segments” below in this Item 1.
Our internet address is www.interactivebrokers.com and the investor relations section of our website is located at www.interactivebrokers.com/ir. We make available free of charge, on or through the investor relations section of our website, this Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Securities Exchange Act of 1934, as well as proxy statements, registration statements, prospectus supplements, and Section 16 filings for our directors and officers, as soon as reasonably practicable after we electronically file such material with, or furnish it to, the U.S. Securities and Exchange Commission (“SEC”). The SEC maintains an internet site, www.sec.gov, that contains annual, quarterly and current reports, proxy and information statements and other information that issuers file electronically with the SEC. Our electronic SEC filings are made available to the public on the SEC’s internet site. In addition, posted on our website are our Bylaws, our Amended and Restated Certificate of Incorporation, charters for the Audit Committee, Compensation Committee and Nominating and Corporate Governance Committee of our board of directors, our Accounting Matters Complaint Policy, our Whistle Blower Hotline, our Corporate Governance Guidelines and our Code of Business Conduct and Ethics governing our directors, officers and employees. Within the time periods required by SEC and the Nasdaq Stock Market LLC (“Nasdaq”), we will post on our website any amendment to the Code of Business Conduct and Ethics and any waiver applicable to any executive officer, director or senior financial officer. In addition, our website includes information concerning purchases and sales of our equity securities by our executive officers and directors, as well as disclosure relating to certain non-GAAP financial measures, if any, (as defined in Regulation G) promulgated under the Securities Act of 1933, as amended (the “Securities Act”) and the Securities Exchange Act of 1934, as amended (the “Exchange Act”) that we may make public orally, telephonically, by webcast, by broadcast or by similar means from time to time.
Our Investor Relations Department can be contacted at Interactive Brokers Group, Inc., Two Pickwick Plaza, Greenwich, Connecticut 06830, Attn: Investor Relations, telephone: 203-618-4070, e-mail: investor-relations@interactivebrokers.com.
Our Organizational Structure and Overview of Recapitalization Transactions
The graphic below illustrates our current ownership structure and reflects current ownership percentages. The graphic below does not display the subsidiaries of IBG LLC.
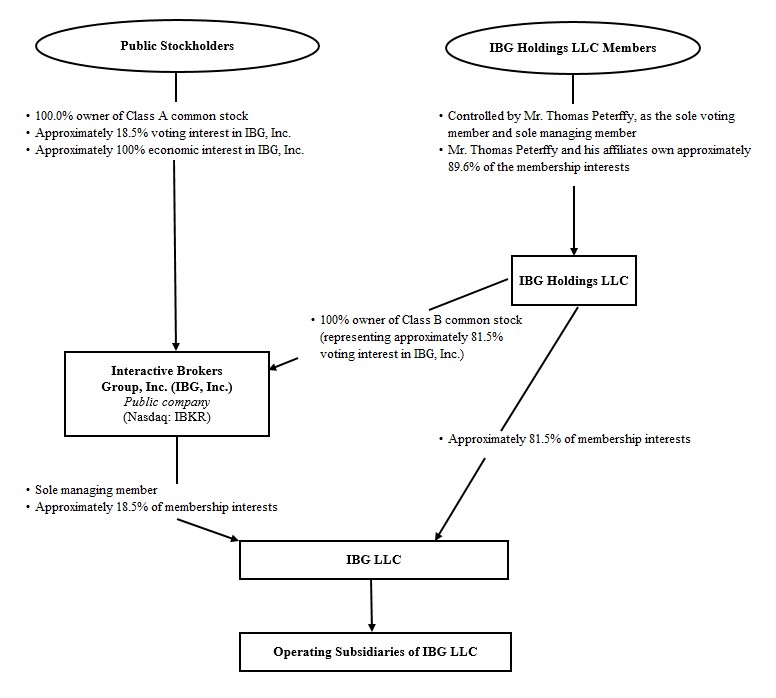
(1)In connection with redemption transactions in 2018, as of December 31, 2019, IBG Holdings LLC held for sale for the benefit of certain of its members 869,135 shares of IBG, Inc. Class A common stock, representing an additional 0.21% of the voting interests in IBG, Inc.
Our primary assets are our ownership of approximately 18.5% of the membership interests of IBG LLC, the current holding company for our businesses, and our controlling interest and related contractual rights as the sole managing member of IBG LLC. The remaining approximately 81.5% of IBG LLC membership interests are held by IBG Holdings LLC (“Holdings”), a holding company that is owned directly and indirectly by our founder and Chairman, Mr. Thomas Peterffy and his affiliates, management and other employees of IBG LLC, and certain other members. The IBG LLC membership interests held by Holdings will be subject to purchase by us over time in connection with offerings by us of shares of our common stock.
The table below presents the amount of IBG LLC membership interests held by IBG, Inc. and Holdings as of December 31, 2019.
| IBG, Inc. | Holdings | Total | ||||
| Ownership % | 18.5% | 81.5% | 100.0% | |||
| Membership interests | 76,759,595 | 338,670,642 | 415,430,237 |
Purchases of IBG LLC membership interests, held by Holdings, by the Company are governed by the exchange agreement among us, IBG LLC, Holdings and the historical members of IBG LLC, (the “Exchange Agreement”), a copy of which was filed as an exhibit to our Quarterly Report on Form 10-Q for the quarter ended September 30, 2009 and filed with the SEC on November 9, 2009. The Exchange Agreement, as amended June 6, 2012, provides that the Company may facilitate the redemption by Holdings of interests held by its members through the issuance of shares of common stock through a public offering in exchange for the interests in IBG LLC being redeemed by Holdings. Periodically since June 2011, with the consent
Showing the first 8K of 73K characters. Open the full section
Item 1A. RISK FACTORS
We face a variety of risks that are substantial and inherent in our businesses, including market, liquidity, credit, operational, legal and regulatory. In addition to the risks identified elsewhere in this Annual Report on Form 10-K, the following risk factors apply to our business results of operations and financial condition:
Risks Related to Our Company Structure
Control by Mr. Thomas Peterffy of a majority of the combined voting power of our common stock may give rise to conflicts of interests and could discourage a change of control that other stockholders may favor, which could negatively affect our stock price, and adversely affect stockholders in other ways.
Mr. Thomas Peterffy, our founder and Chairman, and his affiliates beneficially own approximately 89.6% of the economic interests and all of the voting interests in Holdings, which owns all of our Class B common stock, representing approximately 81.5% of the combined voting power of all classes of our voting stock. As a result, Mr. Thomas Peterffy has the ability to elect all of the members of our board of directors and thereby to control our management and affairs, including determinations with respect to acquisitions, dispositions, material expansions or contractions of our business, entry into new lines of business, borrowings, issuances of common stock or other securities, and the declaration and payment of dividends on our common stock. In addition, Mr. Thomas Peterffy is able to determine the outcome of all matters requiring stockholder approval and will be able to cause or prevent a change of control of our company or a change in the composition of our board of directors and could preclude any unsolicited acquisition of our company. The concentration of ownership could discourage potential takeover attempts that other stockholders may favor and could deprive stockholders of an opportunity to receive a premium for their common stock as part of a sale of our company and this may adversely affect the market price of our common stock.
Moreover, because of Mr. Thomas Peterffy’s substantial ownership, we are eligible to be and are, treated as a “controlled company” for purposes of the Nasdaq Rules. As a result, we are not required by Nasdaq to have a majority of independent directors or to maintain Compensation and Nominating and Corporate Governance Committees composed entirely of independent directors to continue to list the shares of our common stock on Nasdaq. Our Compensation Committee is comprised of Messrs. Thomas Peterffy (Chairman of the Compensation Committee) and Earl H. Nemser (our Vice Chairman). Mr. Thomas Peterffy’s membership on the Compensation Committee may give rise to conflicts of interests in that Mr. Thomas Peterffy is able to influence all matters relating to executive compensation, including his own compensation.
We are dependent on IBG LLC to distribute cash to us in amounts sufficient to pay our tax liabilities and other expenses.
We are a holding company and our primary assets are our approximately 18.5% equity interest in IBG LLC and our controlling interest and related rights as the sole managing member of IBG LLC and, as such, we operate and control all of the business and affairs of IBG LLC and are able to consolidate IBG LLC’s financial results into our financial statements. We have no independent means of generating revenues. IBG LLC is treated as a partnership for U.S. federal income tax purposes and, as such, is not subject to U.S. federal income tax. Instead, its taxable income is allocated on a pro rata basis to Holdings and us. Accordingly, we incur income taxes on our proportionate share of the net taxable income of IBG LLC, and also incur expenses related to our operations. We intend to cause IBG LLC to distribute cash to its members in amounts at least equal to that necessary to cover their tax liabilities, if any, with respect to the earnings of IBG LLC. To the extent we need funds to pay such taxes, or for any other purpose, and IBG LLC is unable to provide such funds, it could have a material adverse effect on our business, financial condition and results of operations.
We are required to pay Holdings for the benefit relating to additional tax depreciation or amortization deductions we claim as a result of the tax basis step**-**up our subsidiaries received in connection with our initial public offering and certain subsequent redemptions of Holdings membership interests.
In connection with our initial public offering (“IPO”), we purchased interests in IBG LLC from Holdings for cash. In connection with redemptions of Holdings membership interests, we acquired additional interests in IBG LLC by issuing shares of Class A common stock in exchange for an equivalent number of shares of member interests in IBG LLC (the “Redemptions”). In addition, IBG LLC membership interests held by Holdings may be sold in the future to us and financed by our issuances of shares of our common stock. The initial purchase and the Redemptions did, and the subsequent purchases may, result in increases in the tax basis of the tangible and intangible assets of IBG LLC and its subsidiaries that otherwise would not have been available. Such increase will be approximately equal to the amount by which our stock price at the time of the purchase exceeds the income tax basis of the assets of IBG LLC underlying the IBG LLC interests acquired by us. These increases in tax basis will result in increased deductions in computing our taxable income and resulting tax savings for us generally over the 15 year period which commenced with the initial purchase. We have agreed to pay 85% of these tax savings, if any, to Holdings as they are realized as additional consideration for the IBG LLC interests that we acquire.
As a result of the IPO and the Redemptions by Holdings, the increase in the tax basis attributable to our interest in IBG LLC is $1.3 billion. The tax savings that we would actually realize as a result of this increase in tax basis likely would be significantly less than this amount multiplied by our effective tax rate due to a number of factors, including the allocation of a portion of the increase in tax basis to foreign or non-depreciable fixed assets, the impact of the increase in the tax basis on our ability to use foreign tax credits and the rules relating to the amortization of intangible assets, for example. Based on facts and assumptions as of December 31, 2019, including that subsequent purchases of IBG LLC interests will occur in fully taxable transactions, the potential tax basis increase resulting from the historical and future purchases of the IBG LLC interests held by Holdings could be as much as $9.0 billion. The Tax Receivable Agreement requires 85% of such tax savings, if any, to be paid to Holdings, with the balance to be retained by us. The actual increase in tax basis depends, among other factors, upon the price of shares of our common stock at the time of the purchase and the extent to which such purchases are taxable and, as a result, could differ materially from this amount. Our ability to achieve benefits from any such increase, and the amount of the payments to be made under the Tax Receivable Agreement, depends upon a number of factors, as discussed above, including the timing and amount of our future income.
The tax basis of $9.0 billion assumes that (a) all remaining IBG LLC membership interests held by Holdings are purchased by us in a taxable transaction and (b) such purchases in the future are made at prices that reflect the closing share price as of December 31, 2019. In order to have a $9.0 billion tax basis, the offering price per share of Class A common stock in such future public offering will need to exceed the then current cost basis per share of Class A common stock by approximately $29.93.
If either immediately before or immediately after any purchase or the related issuance of our stock, the Holdings members own or are deemed to own, in the aggregate, more than 20% of our outstanding common stock, then all or part of any increase in the tax basis of goodwill may not be amortizable and, thus, our ability to realize the annual tax savings that otherwise would have resulted if such tax basis were amortizable may be significantly reduced. Although the Holdings members are prohibited under the Exchange Agreement from purchasing shares of Class A common stock in a public offering, grants of our common stock to employees and directors who are also members or related to members of Holdings and the application of certain tax attribution rules, such as among family members and partners in a partnership, could result in Holdings members being deemed for tax purposes to own shares of Class A common stock.
If the Internal Revenue Services (“IRS”) successfully challenges the tax basis increase, under certain circumstances, we could be required to make payments to Holdings under the Tax Receivable Agreement in excess of our cash tax savings.
Future sales of our common stock in the public market could lower our stock price, and any additional capital raised by us through the sale of equity or convertible securities may dilute your ownership in us.
The members of Holdings have the right to cause the redemption of their Holdings membership interests over time in connection with offerings of shares of our common stock. We intend to sell additional shares of common stock in public offerings in the future, which may include offerings of our common stock to finance future purchases of IBG LLC membership interests which, in turn, will finance corresponding redemptions of Holdings membership interests. These offerings and related transactions are anticipated to occur at least annually into the future. The size and occurrence of these offerings may be affected by market conditions. We may also issue additional shares of common stock or convertible debt securities to finance future acquisitions or business combinations. We currently have approximately 77 million outstanding shares of common stock. Assuming no anti-dilution adjustments based on combinations or divisions of our common stock, the offerings referred to above could result in the issuance by us of up to an additional approximately 339 million shares of common stock. It is possible, however, that such shares could be issued in one or a few large transactions.
We cannot predict the size of future issuances of our common stock or the effect, if any, that future issuances and sales of shares of our common stock may have on the market price of our common stock. Sales of substantial amounts of our common stock (including shares issued in connection with an acquisition), or the perception that such sales could occur, may cause the market price of our common stock to decline.
Certain provisions in our amended and restated certificate of incorporation may prevent efforts by our stockholders to change our direction or management.
Provisions contained in our amended and restated certificate of incorporation could make it more difficult for a third-party to acquire us, even if doing so might be beneficial to our stockholders. For example, our amended and restated certificate of incorporation authorizes our board of directors to determine the rights, preferences, privileges and restrictions of unissued series of preferred stock, without any vote or action by our stockholders. We could issue a series of preferred stock that could impede the completion of a merger, tender offer or other takeover attempt. These provisions may discourage potential acquisition proposals and may delay, deter or prevent a change of control of us, including through transactions, and, in particular, unsolicited transactions, that some or all of our stockholders might consider to be desirable. As a result, efforts by our stockholders to change our direction or management may be unsuccessful.
Risks Related to Our Business
Our business may be harmed by global events beyond our control, including overall slowdowns in securities trading.
Like other brokerage and financial services firms, our business and profitability are directly affected by elements that are beyond our control, such as economic and political conditions, broad trends in business and finance, changes in volume of securities and futures transactions, changes in the markets in which such transactions occur and changes in how such transactions are processed. A weakness in equity markets, such as a slowdown causing reduction in trading volume in U.S. or foreign securities and derivatives, has historically resulted in reduced transaction revenues and would have a material adverse effect on our business, financial condition and results of operations.
Our business could be harmed by a systemic market event.
Some market participants could be overleveraged. In case of sudden, large price movements, such market participants may not be able to meet their obligations to brokers who, in turn, may not be able to meet their obligations to their counterparties. As a result, the financial system or a portion thereof could collapse, and the impact of such an event could be catastrophic to our business.
Our future success will depend on our response to the demand for new services, products and technologies.
The demand for our services that rely on electronic communications gateways, is characterized by:
-
rapid technological change;
-
changing customer demands;
-
the need to enhance existing services and products or introduce new services and products; and
-
evolving industry standards.
New services, products and technologies may render our existing services, products and technologies less competitive. Our future success will depend, in part, on our ability to respond to the demand for new services, products and technologies on a timely and cost-effective basis and to adapt to technological advancements and changing standards to address the increasingly sophisticated
requirements and varied needs of our customers and prospective customers. We cannot assure you that we will be successful in developing, introducing or marketing new services, products and technologies. In addition, we may experience difficulties that could delay or prevent the successful development, introduction or marketing of these services and products, and our new service and product enhancements may not achieve market acceptance. Any failure on our part to anticipate or respond adequately to technological advancements, customer requirements or changing industry standards, or any significant delays in the development, introduction or availability of new services, products or enhancements could have a material adverse effect on our business, financial condition and results of operations.
Our reliance on our computer software could cause us great financial harm in the event of any disruption or corruption of our computer software. We may experience technology failures while developing our software.
We rely on our computer software to receive and properly process internal and external data. Any disruption in the proper functioning of our software due to, for example, erroneous or corrupted data, or cyber-attacks, may cause us to make erroneous trades or suspend our services and could cause us great financial harm. To maintain our competitive advantage, our software is under continuous development. As we identify and enhance our software, there is risk that software failures may occur and result in service interruptions and have other unintended consequences.
We depend on our proprietary technology, and our future results may be impacted if we cannot maintain technological superiority in our industry.
Our success in the past has largely been attributable to our sophisticated proprietary technology that has taken many years to develop. We have benefited from the fact that the type of proprietary technology equivalent to that which we employ has not been widely available to our competitors. If our technology becomes more widely available to our current or future competitors for any reason, our operating results may be adversely affected. Additionally, adoption or development of similar or more advanced technologies by our competitors may require that we devote substantial resources to the development of more advanced technology to remain competitive. The markets in which we compete are characterized by rapidly changing technology, evolving industry standards and changing trading systems, practices and techniques. Although we have been at the forefront of many of these developments in the past, we may not be able to keep up with these rapid changes in the future, develop new technology, realize a return on amounts invested in developing new technologies or remain competitive in the future.
The loss of our key employees would materially adversely affect our business.
Our key executives have substantial experience and have made significant contributions to our business, and our continued success is dependent upon the retention of our key management executives, as well as the services provided by our staff of trading system, technology and programming specialists and a number of other key managerial, marketing, planning, financial, technical and operations personnel. The loss of such key personnel could have a material adverse effect on our business. Growth in our business is dependent, to a large degree, on our ability to retain and attract such employees.
We may not pay dividends on our common stock at any time in the foreseeable future.
As a holding company for our interest in IBG LLC, we will be dependent upon the ability of IBG LLC to generate earnings and cash flows and distribute them to us so that we may pay any dividends to our stockholders. To the extent (if any) that we have excess cash, any decision to declare and pay dividends in the future will be made at the discretion of our board of directors and will depend on, among other things, our results of operations, financial conditions, cash requirement, contractual restrictions and other factors that our board of directors may deem relevant. Since the second quarter of 2011, we have declared and paid a quarterly cash dividend of $0.10 per share. Although not required, we currently intend to pay quarterly dividends of $0.10 per share to our common stockholders for the foreseeable future.
Our future efforts to sell shares or raise additional capital may be delayed or prohibited by regulations.
As certain of our subsidiaries are members of FINRA, we are subject to certain regulations regarding changes in control of our ownership. FINRA Rule 1017 generally provides that FINRA approval must be obtained in connection with any transaction resulting in a change in control of a member firm. FINRA defines control as ownership of 25% or more of the firm’s equity by a single entity or person and would include a change in control of a parent company. IBC, IBUK, IBEU, IBKRFS and IBHK are subject to similar change in control regulations promulgated by the IIROC in Canada, the FCA in the United Kingdom, the CSSF in Luxembourg, FINMA in Switzerland and the SFC in Hong Kong, respectively. As a result of these regulations, our future efforts to sell shares or raise additional capital may be delayed or prohibited. We may be subject to similar restrictions in other jurisdictions in which we operate.
Regulatory and legal uncertainties could harm our business.
The securities and derivatives businesses are heavily regulated. Firms in financial service industries have been subject to an increasingly regulated environment over recent years, and penalties and fines sought by regulatory authorities have increased accordingly. This regulatory and enforcement environment has created uncertainty with respect to various types of transactions that historically had been entered into by financial services firms and that were generally believed to be permissible and appropriate. Our broker-dealer subsidiaries are subject to regulations in the U.S. and abroad covering all aspects of their business. Regulatory bodies include, in the U.S., the SEC, FINRA, the Board of Governors of the Federal Reserve System, the Chicago Board Options Exchange, the Chicago Mercantile Exchange, the CFTC, and the NFA; in Canada, the IIROC and various Canadian securities commissions; in the United Kingdom, the FCA; in Luxembourg, the CSSF; in Switzerland, FINMA; in India, the Securities and Exchange Board of India; in Hong Kong, the SFC; in Japan, the FSA and the Japan Securities Dealers Association; and in Australia, the Australian Securities and Investment Commission. Our mode of operation and profitability may be directly affected by additional legislation changes in rules promulgated by various domestic and foreign government agencies and self-regulatory organizations that oversee our businesses, and changes in the interpretation or enforcement of existing laws and rules, including the potential imposition of transaction taxes. Noncompliance with applicable laws or regulations could result in sanctions being levied against us, including fines and censures, suspension or expulsion from a certain jurisdiction or market or the revocation or limitation of licenses. Noncompliance with applicable laws or regulations could adversely affect our reputation, prospects, revenues and earnings. In addition, changes in current laws or regulations or in governmental policies could adversely affect our business, financial condition and results of operations.
We are subject to regulatory oversight and examination by numerous governmental and self-regulatory authorities. We are currently providing information to certain of such authorities, including FINRA, the SEC, the CFTC and the United States Department of Justice, and cooperating with those authorities. The regulators are focused on compliance practices, including anti money laundering and Bank Secrecy Act practices. We periodically review these practices to make them more robust and to keep pace with changing regulatory standards, and we have been enhancing and augmenting our procedures and personnel in these areas over the past several years. While the outcome of the examinations and inquiries currently in progress cannot be predicted, we do not believe that they are likely to have a materially adverse effect on our financial results.
Domestic and foreign stock exchanges, other self-regulatory organizations and state and foreign securities commissions can censure, fine, issue cease-and-desist orders, suspend or expel a broker-dealer or any of its officers or employees. Our ability to comply with all applicable laws and rules is largely dependent on our internal system to ensure compliance, as well as our ability to attract and retain qualified compliance personnel. We could be subject to disciplinary or other actions in the future due to claimed noncompliance, which could have a material adverse effect on our business, financial condition and results of operations. To continue to operate and to expand our services internationally, we may have to comply with the regulatory controls of each country in which we conduct, or intend to conduct business, the requirements of which may not be clearly defined. The varying compliance requirements of these different regulatory jurisdictions, which are often unclear, may limit our ability to continue existing international operations and further expand internationally.
Our direct market access clearing and non**-**clearing brokerage operations face intense competition.
With respect to our direct market access brokerage business, the market for electronic and interactive bidding, offering and trading services in connection with equities, options and futures is rapidly evolving and intensely competitive. We expect competition to continue and intensify in the future. Our current and potential future competition principally comes from five categories of competitors:
-
prime brokers who, in an effort to satisfy the demands of their customers for hands-on electronic trading facilities, universal access to markets, smart routing, better trading tools, lower commissions and financing rates, have embarked upon building such facilities and product enhancements;
-
direct market access and online options and futures firms;
-
direct market access and online equity brokers;
-
software development firms and vendors who create global trading networks and analytical tools and make them available to brokers; and
-
traditional brokers.
In addition, we compete with financial institutions, mutual fund sponsors and other organizations, many of which provide online, direct market access or other investing services. A number of brokers provide our technology and execution services to their customers, and these brokers will become our competitors if they develop their own technology. Some of our competitors in this area have greater name recognition, longer operating histories and significantly greater financial, technical, marketing and other resources than we have and offer a wider range of services and financial products than we do. Some of our competitors may also have an ability
to charge lower or zero commissions. We cannot assure you that we will be able to compete effectively or efficiently with current or future competitors. These increasing levels of competition in the online trading industry could significantly harm this aspect of our business.
We are subject to potential losses as a result of our clearing and execution activities.
As a clearing member firm providing financing services to certain of our brokerage customers, we are ultimately responsible for their financial performance in connection with various securities and derivatives transactions. Our clearing operations require a commitment of our capital and, despite safeguards implemented by our software, involve risks of losses due to the potential failure of our customers to perform their obligations under these transactions. If our customers default on their obligations, we remain financially liable for such obligations, and although these obligations are collateralized, we are subject to market risk in the liquidation of customer collateral to satisfy those obligations. There can be no assurance that our risk management procedures will be adequate. Any liability arising from clearing operations could have a material adverse effect on our business, financial condition and results of operations.
As a clearing member firm of securities and derivatives clearing houses in the U.S. and abroad, we are also exposed to clearing member credit risk. Securities and derivatives clearing houses require member firms to deposit cash, stock and/or government securities for margin requirements and to clearing funds. If a clearing member defaults in its obligations to the clearing house in an amount larger than its own margin and clearing fund deposits, the shortfall is absorbed pro rata from the deposits of the other clearing members. Many clearing houses of which we are members also have the authority to assess their members for additional funds if the clearing fund is depleted. A large clearing member default could result in a substantial cost to us if we are required to pay such assessments.
We are exposed to risks associated with our international operations.
During 2019, approximately 21% of our net revenues were generated by our operating subsidiaries outside the U.S. We are exposed to risks and uncertainties inherent in doing business in international markets, particularly in the heavily regulated brokerage industry. Such risks and uncertainties include political, economic and financial instability; unexpected changes in regulatory requirements, tariffs and other trade barriers; exchange rate fluctuations; applicable currency controls; and difficulties in staffing, including reliance on newly hired local experts, and managing foreign operations. These risks could cause a material adverse effect on our business, financial condition and results of operations.
We do not have fully redundant systems. System failures could harm our business.
If our systems fail to perform, we could experience unanticipated disruptions in operations, slower response times or decreased customer service and customer satisfaction. Our ability to facilitate transactions successfully and provide high quality customer service also depends on the efficient and uninterrupted operation of our computer and communications hardware and software systems. Our service has experienced periodic system interruptions, which we believe will continue to occur from time to time. Our systems and operations also are potentially vulnerable to damage or interruption from human error, cyber-attacks, natural disasters, power loss, telecommunication failures, break-ins, sabotage, computer viruses, intentional acts of vandalism and similar events. While we currently maintain redundant servers to provide limited service during system disruptions, we do not have fully redundant systems, and our formal disaster recovery plan does not include restoration of all services. For example, we have backup facilities at our disaster recovery site that enable us, in the case of complete failure of our main North America data center, to recover and complete all pending transactions, provide customers with access to their accounts to deposit or withdraw money, transfer positions to other brokers and manage their risk by continuing trading through the use of marketable orders. These backup services are currently limited to U.S. markets. We do not currently have separate backup facilities dedicated to our non-U.S. operations. It is our intention to provide for and progressively deploy backup facilities for our global facilities over time. In addition, we do not carry business interruption insurance to compensate for losses that could occur to the extent not required. Any system failure that causes an interruption in our service or decreases the responsiveness of our service could impair our reputation, damage our brand name and materially adversely affect our business, financial condition and results of operations.
Failure of third**-**party systems on which we rely could adversely affect our business.
We rely on certain third-party computer systems or third-party service providers, including clearing systems, exchange systems, banking systems, Internet service, co-location facilities, communications facilities and other facilities. Any interruption in these third-party services, or deterioration in their performance, could be disruptive to our business. If our arrangement with any third-party is terminated, we may not be able to find an alternative source of systems support on a timely basis or on commercially reasonable terms. This could have a material adverse effect on our business, financial condition and results of operations.
Internet**-**related issues may reduce or slow the growth in the use of our services in the future.
Critical issues concerning the commercial use of the Internet, such as ease of access, security, privacy, reliability, cost, and quality of service, remain unresolved and may adversely impact the growth of Internet use. If Internet usage continues to increase rapidly, the Internet infrastructure may not be able to support the demands placed on it by this growth, and its performance and reliability may decline. Although our larger institutional customers use leased data lines to communicate with us, our ability to increase the speed with which we provide services to consumers and to increase the scope and quality of such services is limited by and dependent upon the speed and reliability of our customers’ access to the Internet, which is beyond our control. If periods of decreased performance, outages or delays on the Internet occur frequently or other critical issues concerning the Internet are not resolved, overall Internet usage or usage of our web based products could increase more slowly or decline, which could have a material adverse effect on our business, financial condition and results of operations.
Our computer infrastructure may be vulnerable to security breaches. Any such problems could jeopardize confidential information transmitted over the Internet, cause interruptions in our operations or cause us to have liability to third persons.
Our computer infrastructure is potentially vulnerable to physical or electronic computer break-ins, cyber-attacks, viruses and similar disruptive problems and security breaches. Any such problems or security breaches could cause us to have liability to one or more third parties, including our customers, and disrupt our operations. A party able to circumvent our security measures could misappropriate proprietary information or customer information, jeopardize the confidential nature of information transmitted over the Internet or cause interruptions in our operations. Concerns over the security of Internet transactions and the privacy of users could also inhibit the growth of the Internet or the electronic brokerage industry in general, particularly as a means of conducting commercial transactions. To the extent that our activities involve the storage and transmission of proprietary information such as personal financial information, security breaches could expose us to a risk of financial loss, litigation and other liabilities. Our estimated annual losses from reimbursements to customers whose accounts have been negatively affected by unauthorized access have historically been less than $500,000 annually and were significantly reduced since the widespread introduction of our Secure Login System. Our current insurance program may protect us against some, but not all, of such losses. Any of these events, particularly if they (individually or in the aggregate) result in a loss of confidence in our company or electronic brokerage firms in general, could have a material adverse effect on our business, financial condition and results of operations.
We may not be able to protect our intellectual property rights or may be prevented from using intellectual property necessary for our business.
We rely primarily on trade secret, contract, copyright, patent and trademark laws to protect our proprietary technology. It is possible that third parties may copy or otherwise obtain and use our proprietary technology without authorization or otherwise infringe on our rights. We may also face claims of infringement that could interfere with our ability to use technology that is material to our business operations.
In the future, we may have to rely on litigation to enforce our intellectual property rights, protect our trade secrets, determine the validity and scope of the proprietary rights of others or defend against claims of infringement or invalidity. Any such litigation, whether successful or unsuccessful, could result in substantial costs and the diversion of resources and the attention of management, any of which could negatively affect our business.
We are subject to risks relating to litigation and potential securities laws liability.
We are exposed to substantial risks of liability under federal and state securities laws, other federal and state laws and court decisions, as well as rules and regulations promulgated by the SEC, the CFTC, the Federal Reserve, state securities regulators, self-regulatory organizations and foreign regulatory agencies. We are also subject to the risk of litigation and claims that may be without merit. We could incur significant legal expenses in defending ourselves against and resolving lawsuits or claims. An adverse resolution of any future lawsuits or claims against us could result in a negative perception of the Company and have a material adverse effect on our business, financial condition and results of operations. See “Legal Proceedings and Regulatory Matters” in Part I, Item 3 of this Annual Report on Form 10-K.
We are subject to counterparty risk whereby defaults by parties with whom we do business can have an adverse effect on our business, financial condition and results of operations.
In our electronic brokerage business, our customer margin credit exposure is to a great extent mitigated by our policy of automatically evaluating each account throughout the trading day and closing out positions automatically for accounts that are found to be under-margined. While this methodology is effective in most situations, it may not be effective in situations in which no liquid market exists for the relevant securities or commodities or in which, for any reason, automatic liquidation for certain accounts has been disabled. If no liquid market exists or automatic liquidation has been disabled, we are subject to risks inherent in extending credit, especially during periods of rapidly declining markets. Any loss or expense incurred due to defaults by our customers in failing to
repay margin loans or to maintain adequate collateral for these loans would cause harm to our business, financial condition and results of operations.
Any future acquisitions may result in significant transaction expenses, integration and consolidation risks and risks associated with entering new markets, and we may be unable to profitably operate our consolidated company.
Although our growth strategy has not focused historically on acquisitions, we may in the future engage in evaluations of potential acquisitions and new businesses. We may not have the financial resources necessary to consummate any acquisitions in the future or the ability to obtain the necessary funds on satisfactory terms. Any future acquisitions may result in significant transaction expenses and risks associated with entering new markets in addition to integration and consolidation risks. Because acquisitions historically have not been a core part of our growth strategy, we have little experience in successfully utilizing acquisitions. We may not have sufficient management, financial and other resources to integrate any such future acquisitions or to successfully operate new businesses and we may be unable to profitably operate our expanded company.
Because our revenues and profitability depend on trading volume, they are prone to significant fluctuations and are difficult to predict.
Our revenues are dependent on the level of trading activity on securities and derivatives exchanges in the U.S. and abroad. In the past, our revenues and operating results have varied significantly from period to period primarily due to movements and trends in the underlying markets and to fluctuations in trading levels. As a result, period to period comparisons of our revenues and operating results may not be meaningful, and future revenues and profitability may be subject to significant fluctuations or declines.
We may incur material trading losses from our market making activities.
A portion of our revenues and operating profits is derived from our trading as principal in our role as a market maker. We may incur trading losses relating to these activities since each primarily involves the purchase or sale of securities for our own account. In any period, we may incur trading losses in a significant number of securities for a variety of reasons including:
-
price changes in securities;
-
lack of liquidity in securities in which we have positions; and
-
the required performance of our market making obligations.
These risks may limit or restrict our ability to either resell securities we purchased or to repurchase securities we sold. In addition, we may experience difficulty borrowing securities to make delivery to purchasers to whom we sold short, or lenders from whom we have borrowed. From time to time, we have large position concentrations in securities of a single issuer or issuers engaged in a specific industry or traded in a particular market. Such a concentration could result in higher trading losses than would occur if our positions and activities were less concentrated.
In our role as a market maker, we attempt to derive a profit from the difference between the prices at which we buy and sell, or sell and buy, securities. However, competitive forces often require us to match the quotes other market makers display and to hold varying amounts of securities in inventory. By having to maintain inventory positions, we are subjected to a high degree of risk. We cannot assure you that we will be able to manage such risk successfully or that we will not experience significant losses from such activities, which could have a material adverse effect on our business, financial condition and results of operations.
Reduced spreads in securities pricing, levels of trading activity and trading through market makers could harm our business.
Computer-generated buy/sell programs and other technological advances and regulatory changes in the marketplace may continue to tighten spreads on securities transactions. Tighter spreads and increased competition could make market making activities less profitable.
We may incur losses in our market making activities in the event of failures of our proprietary pricing model.
Our market making business is substantially dependent on the accuracy of our proprietary pricing mathematical model, which continuously evaluates and monitors the risks inherent in our portfolio, assimilates market data and reevaluates our outstanding quotes many times per second. Our model is designed to automatically rebalance our positions throughout the trading day to manage risk exposures on our positions in options, futures and the underlying securities. In the event of a flaw in our pricing model and/or a failure in the related software, our pricing model may lead to unexpected and/or unprofitable trades, which may result in material trading losses.
The valuation of the financial instruments we hold may result in large and occasionally anomalous swings in the value of our positions and in our earnings in any period.
The market prices of our long and short positions are reflected on our books at closing prices which are typically the last trade price before the official close of the primary exchange on which each such security trades. If prices of derivatives and their underlying securities close out of alignment, there may be large and occasionally anomalous swings in the value of our positions daily and, accordingly, in our earnings in any period. This is especially true on the last business day of each calendar quarter.
We are exposed to losses due to lack of perfect information.
As market makers, we provide liquidity by buying from sellers and selling to buyers. Quite often, we trade with others who have different information than we do, and as a result, we may accumulate unfavorable positions preceding large price movements in companies. Should the frequency or magnitude of these events increase, our losses will likely increase correspondingly.
Rules governing designated market makers may require us to make unprofitable trades or prevent us from making profitable trades.
Designated market makers are granted certain rights and have certain obligations to “make a market” in a particular security. They agree to specific obligations to maintain a fair and orderly market. In acting as a designated market maker, we are subjected to a high degree of risk by having to support an orderly market. In this role, we may at times be required to make trades that adversely affect our profitability. In addition, we may at times be unable to trade for our own account in circumstances in which it may be to our advantage to trade, and we may be obligated to act as a principal when buyers or sellers outnumber each other. In those instances, we may take a position counter to the market, buying or selling securities to support an orderly market. Additionally, the rules of the markets which govern our activities as a designated market maker are subject to change. If these rules are made more stringent, our trading revenues and profits as a designated market maker could be adversely affected.
We face competition in our market making activities.
In our market making activities, we compete with other firms based on our ability to provide liquidity at competitive prices and to attract order flow. These firms include registered market makers as well as HFTs that act as market makers. Both types of competitors range from sole proprietors with very limited resources to a few highly sophisticated groups which have substantially greater financial and other resources, including research and development personnel, than we do. These larger and better capitalized competitors may be better able to respond to changes in the market making industry, to compete for skilled professionals, to finance acquisitions, to fund internal growth and to compete for market share generally. HFTs that are not registered market makers have certain advantages over registered market making firms that may allow them to bypass regulatory restrictions and trade more quickly and cheaply than registered market makers at some exchanges. We may not be able to compete effectively against HFTs or market makers with greater financial resources, and our failure to do so could materially and adversely affect our business, financial condition and results of operations. As in the past, we may in the future face enhanced competition, resulting in narrowing bid/offer spreads in the marketplace that may adversely impact our financial performance. This is especially likely if HFTs continue to receive advantages in capturing order flow or if others can acquire systems that enable them to predict markets or process trades more efficiently than we can.
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 2. PROPERTIES
Our headquarters are located in Greenwich, Connecticut. We lease office and data center facilities in 24 cities throughout the world where we conduct our operations as set forth below. Unless otherwise indicated, all properties are used by both our electronic brokerage and market making segments. We believe our present facilities, together with our current options to extend lease terms, are adequate for our current needs.
The table below presents certain information with respect to our leased facilities as of December 31, 2019.
| Location | Space (sq. feet) | Principal Usage | ||||
| North America | ||||||
| Greenwich, CT | 163,510 | Headquarters | ||||
| Chicago, IL | 60,276 | Office space and data center | ||||
| Other (7 locations) | 28,662 | Office space and data center | ||||
| Europe | ||||||
| Zug, Switzerland | 25,009 | Office space | ||||
| London, United Kingdom | 12,969 | Office space | ||||
| Tallinn, Estonia | 11,010 | Office space | ||||
| Other (4 locations) | 19,980 | Office space | ||||
| Asia - Pacific | ||||||
| Mumbai, India | 54,275 | Office space | ||||
| Hong Kong | 17,565 | Office space and data center | ||||
| Other (4 locations) | 19,741 | Office space |
Item 3. LEGAL PROCEEDINGS AND REGULATORY MATTERS
The securities and commodities industry is highly regulated and many aspects of our business involve substantial risk of liability. In past years, there has been an increasing incidence of litigation involving the brokerage industry, including class action suits that generally seek substantial damages, including in some cases punitive damages. Compliance and trading problems that are reported to federal, state and provincial regulators, exchanges or other self-regulatory organizations by dissatisfied customers are investigated by such regulatory bodies, and, if pursued by such regulatory body or such customers, may rise to the level of arbitration or disciplinary action. We are also subject to periodic regulatory audits and inspections.
Like other brokerage firms, we have been named as a defendant in lawsuits and from time to time we have been threatened with, or named as a defendant in arbitrations and administrative proceedings. The following contains information regarding potentially material pending litigation and pending regulatory inquiries. We may in the future become involved in additional litigation or regulatory proceedings in the ordinary course of our business, including litigation or regulatory proceedings that could be material to our business.
Trading Technologies Matter
On February 3, 2010, Trading Technologies International, Inc. (“Trading Technologies”) filed a complaint in the U.S. District Court for the Northern District of Illinois, Eastern Division, against IBG LLC and IB LLC (“Defendants”). The complaint, as amended, alleges that the Defendants have infringed and continue to infringe twelve U.S. patents held by Trading Technologies. Trading Technologies is seeking, among other things, unspecified damages and injunctive relief. The Defendants filed an answer to Trading Technologies’ amended complaint, as well as related counterclaims. The Defendants deny Trading Technologies’ claims, assert that the asserted patents are not infringed and are invalid, and assert several other defenses as well.
The asserted patents were the subject of petitions before the United States Patent and Trademark Office (“USPTO”) seeking Covered Business Method Review (“CBM Review”). The USPTO Patent Trial Appeal Board (“PTAB”) found all claims of ten of the twelve asserted patents to be invalid. Of the remaining two patents, 53 of the 56 claims of one patent were held invalid and the other patent survived CBM Review proceedings. Appeals were filed by either Defendants or Trading Technologies on all PTAB determinations.
The United States Court of Appeals for the Federal Circuit vacated the CBM Review determinations of invalidity for four patents, concluding that these patents were not eligible for CBM Review. The District Court trial with respect to these four patents is scheduled for May 2020; however, the parties have filed a motion with the District Court to move the trial to November 2020.
While it is difficult to predict the outcome of the matter, the Company believes it has meritorious defenses to the allegations made in the complaint and intends to defend itself vigorously against them. However, litigation is inherently uncertain and there can be no guarantee that the Company will prevail or that the litigation can be settled on favorable terms.
Class Action Matter
On December 18, 2015, a former individual customer filed a purported class action complaint against IB LLC, IBG, Inc., and Thomas Frank, PhD, the Company’s Executive Vice President and Chief Information Officer, in the U.S. District Court for the District of Connecticut. The complaint alleges that the purported class of IB LLC’s customers were harmed by alleged “flaws” in the computerized system used to close out (i.e., liquidate) positions in customer brokerage accounts that have margin deficiencies. The complaint seeks, among other things, undefined compensatory damages and declaratory and injunctive relief.
On September 28, 2016, the District Court issued an order granting the Company’s motion to dismiss the complaint in its entirety, and without providing plaintiff leave to amend. On September 28, 2017, plaintiff appealed to the United States Court of Appeals for the Second Circuit. On September 26, 2018, the Court of Appeals affirmed the dismissal of plaintiff’s claims of breach of contract and commercially unreasonable liquidation but vacated and remanded back to the District Court plaintiff’s claims for negligence. On November 30, 2018, the plaintiff filed a second amended complaint. The Company filed a motion to dismiss the new complaint on January 15, 2019, which was denied on September 30, 2019. On December 9, 2019, the Company filed a motion requesting that the District Court certify to the Connecticut Supreme Court two questions of Connecticut law directly relevant to the motion to dismiss. Briefing has only recently been completed, and the District Court has not yet ruled on the motion. Regardless of the outcome of this motion, the Company does not believe that a purported class action is appropriate given the great differences in portfolios, markets and many other circumstances surrounding the liquidation of any particular customer’s margin deficient account. IB LLC and the related defendants intend to continue to defend themselves vigorously against the case and, consistent with past practice in connection with this type of unwarranted action, any potential claims for counsel fees and expenses incurred in defending the case may be fully pursued against the plaintiff.
Regulatory Matters
The Company is currently providing information to the Financial Industry Regulatory Authority (“FINRA”), the SEC, the Commodities and Futures Trading Commission (“CFTC”) and the United States Department of Justice focused on anti-money laundering and Bank Secrecy Act practices. The Company periodically reviews these practices to make them more robust and to keep pace with changing regulatory standards, and the Company has been enhancing and augmenting its procedures and personnel in these areas over the past several years. While the outcome of the examinations and inquiries currently in progress cannot be predicted, the Company does not believe that they are likely to have a materially adverse effect on its results of operations.
Pending Regulatory Inquiries
Our businesses are heavily regulated by state, federal and foreign regulatory agencies as well as numerous exchanges and self-regulatory organizations. Most of our companies are regulated under some or all of the following: state securities laws, U.S. and foreign securities, commodities and financial services laws and the rules of the more than 120 exchanges, market centers and self-regulatory organizations of which one or more of our companies may be members. In the current era of dramatically heightened regulatory scrutiny of financial institutions, we have incurred increased compliance costs, along with the industry as a whole. Increased regulation also creates increased barriers to entry. We have built and continue to build human and automated infrastructure in light of increasing regulatory scrutiny, which provides us with a possible advantage over potential newcomers to the business.
We receive thousands of regulatory inquiries each year in addition to being subject to frequent regulatory examinations. The great majority of these inquiries do not lead to fines or any further action against us. Most often, regulators do not inform us as to when and if an inquiry has been concluded. We are currently the subject of active or dormant regulatory inquiries regarding subjects including, but not limited to: audit trail reporting, trade reporting, best execution and order execution procedures, short sales, margin lending, anti-money laundering or potentially manipulative trading by customers, procedures for transfers and trading of U.S. Micro-Cap securities, procedures for accounts managed by independent financial advisors or referred by third parties, technology development practices, business continuity planning and other topics of recent regulatory interest. The Company has procedures for evaluating whether potential regulatory fines are probable, estimable and material and for updating its contingency reserves and disclosures accordingly. In the current climate, we expect to pay significant and increasing regulatory fines on various topics on an ongoing basis, as other regulated financial services businesses do. The amount of any fines, and when and if they will be incurred, typically is impossible to predict given the nature of the regulatory process.
Item 4. MINE SAFETY DISCLOSURES
Not applicable.
PA****RT II
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY; RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Common Stock Information
Interactive Brokers Group Inc.’s Class A common stock trades under the symbol “IBKR” on the Nasdaq Stock Market LLC. As of February 24, 2020, there were seventeen holders of record, which does not reflect those shares held beneficially or those shares held in “street” name. Accordingly, the number of beneficial owners of our common stock exceeds this number
Dividends and Other Restrictions
We currently intend to pay quarterly dividends of $0.10 per share to our common stockholders for the foreseeable future.
Stockholder Return Performance Graph
The graph below compares cumulative total stockholder return on our common stock, the S&P 500 Index and the Nasdaq Financial-100 Index from December 31, 2014 to December 31, 2019. The comparison assumes $100 was invested on December 31, 2014 in our common stock and each of the foregoing indices and assumes reinvestment of dividends before consideration of income taxes.
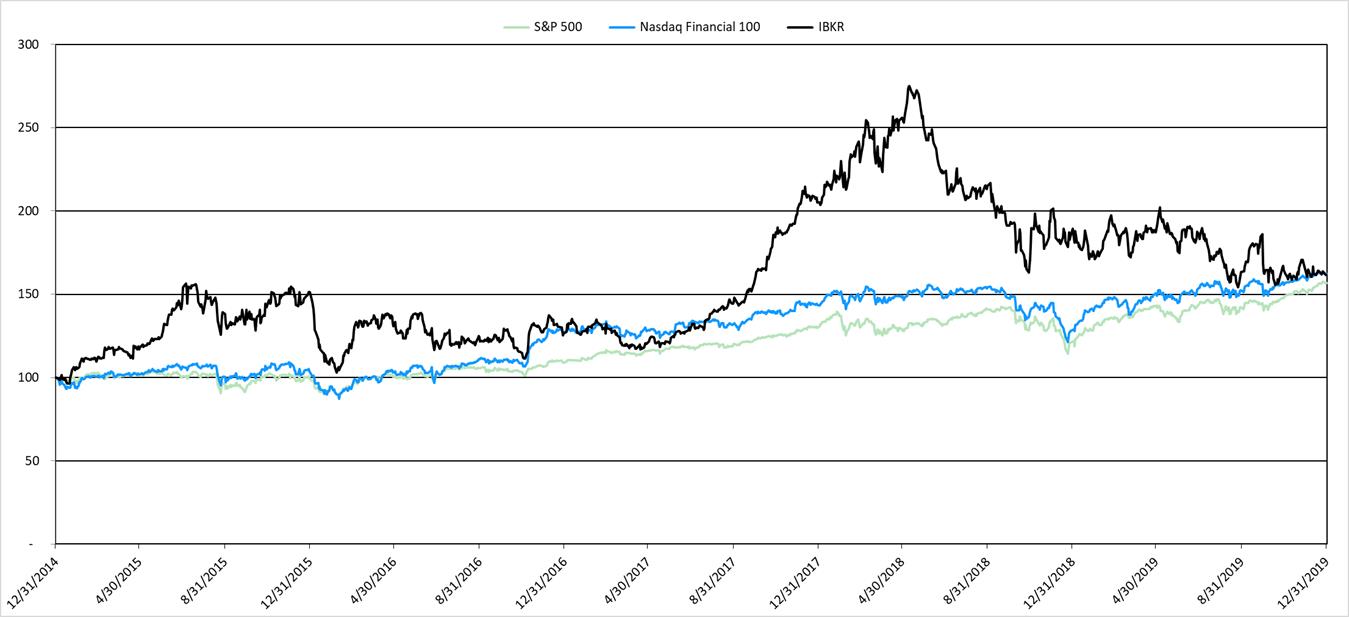
(1)The Nasdaq Financial-100 Index includes 100 of the largest domestic and international financial securities listed on The Nasdaq Stock Market based on market capitalization. They include companies classified according to the Industry Classification Benchmark as Financials, which are included within the Nasdaq Bank, Nasdaq Insurance, and Nasdaq Other Finance Indexes.
(2)The S&P 500 Index includes 500 large cap common stocks actively traded in the U.S. The stocks included in the S&P 500 are those of large publicly held companies that trade on either of the two largest American stock markets, the New York Stock Exchange and Nasdaq.
The stock performance depicted in the graph above is not to be relied upon as indicative of future performance. The stock performance graph shall not be deemed to be incorporated by reference into any of our filings under the Securities Act or the Exchange Act, except to the extent that we specifically incorporate the same by reference, nor shall it be deemed to be “soliciting material” or to be “filed” with the SEC or subject to Regulations 14A or 14C or to the liabilities of Section 18 of the Exchange Act.
Use of Proceeds
On October 7, 2019, the Company filed a Prospectus Supplement on Form 424B (File Number 333-219552) with the SEC to register up to 1,000,000 shares of common stock, offering the opportunity for eligible persons to receive awards in the form of such shares by participating in one or more promotions that are designed to attract new customers to the Company’s brokerage platform, increase assets held with the Company’s brokerage subsidiaries and enhance customer loyalty. As of December 31, 2019, the Company has issued 10,000 shares to IBG LLC for distribution to eligible customers of certain of its subsidiaries. Assuming all shares were issued, IBG, Inc.’s interest in IBG LLC would increase from 18.5% to 18.7%.
Securities Authorized for Issuance under Equity Compensation Plans
The table below presents information about shares of common stock available for future awards under all the Company’s equity compensation plans as of December 31, 2019. The Company has not made grants of common stock outside of its equity compensation plans.
| Number of securities to be | Number of securities | ||||
| issued upon exercise of | Weighted-average exercise | remaining available for | |||
| outstanding options, | price of outstanding options | future awards under | |||
| warrants and rights | warrants and rights | equity compensation plans**(1)** | |||
| Equity compensation plans | |||||
| approved by security holders | N/A | N/A | 4,659,381 | ||
| Total | — | — | 4,659,381 |
(1)Amount represents restricted stock units available for future issuance of grants under the Company’s amended 2007 Stock Incentive Plan.
Item 6. SELECTED FINANCIAL DATA
The tables below present selected historical consolidated financial and other data of the Company for the periods indicated.
| Year-Ended December 31, | |||||||||||||||
| 2019 | 2018 | 2017 | 2016 | 2015 | |||||||||||
| Consolidated Statement of Comprehensive Income Data | (in millions, except share and per share amounts) | ||||||||||||||
| Revenues | |||||||||||||||
| Commissions | $ | 706 | $ | 777 | $ | 647 | $ | 612 | $ | 617 | |||||
| Interest income | 1,726 | 1,392 | 908 | 606 | 492 | ||||||||||
| Trading gains | 27 | 39 | 40 | 163 | 269 | ||||||||||
| Other (loss) income (1) | 121 | 158 | 332 | 94 | (122) | ||||||||||
| Total revenues | 2,580 | 2,366 | 1,927 | 1,475 | 1,256 | ||||||||||
| Interest expense | 643 | 463 | 225 | 79 | 67 | ||||||||||
| Total net revenues | 1,937 | 1,903 | 1,702 | 1,396 | 1,189 | ||||||||||
| Non-interest expenses | |||||||||||||||
| Execution, clearing and distribution fees | 251 | 269 | 241 | 244 | 231 | ||||||||||
| Fixed expenses | 485 | 434 | 410 | 385 | 354 | ||||||||||
| Customer bad debt (2) | 44 | 4 | 2 | 6 | 146 | ||||||||||
| Total non-interest expenses | 780 | 707 | 653 | 635 | 731 | ||||||||||
| Income before income taxes | 1,157 | 1,196 | 1,049 | 761 | 458 | ||||||||||
| Income tax expense (1) | 68 | 71 | 256 | 62 | 43 | ||||||||||
| Net income | 1,089 | 1,125 | 793 | 699 | 415 | ||||||||||
| Less net income attributable to noncontrolling interests | 928 | 956 | 717 | 615 | 366 | ||||||||||
| Net income available for common stockholders | $ | 161 | $ | 169 | $ | 76 | $ | 84 | $ | 49 | |||||
| Earnings per share | |||||||||||||||
| Basic | $ | 2.11 | $ | 2.30 | $ | 1.09 | $ | 1.28 | $ | 0.80 | |||||
| Diluted | $ | 2.10 | $ | 2.28 | $ | 1.07 | $ | 1.25 | $ | 0.78 | |||||
| Comprehensive income available for common stockholders | $ | 165 | $ | 156 | $ | 87 | $ | 80 | $ | 39 | |||||
| Comprehensive income attributable to noncontrolling interests | $ | 948 | $ | 890 | $ | 771 | $ | 594 | $ | 313 | |||||
| Comprehensive earnings per share | |||||||||||||||
| Basic | $ | 2.18 | $ | 2.12 | $ | 1.24 | $ | 1.21 | $ | 0.64 | |||||
| Diluted | $ | 2.16 | $ | 2.09 | $ | 1.22 | $ | 1.19 | $ | 0.62 | |||||
| Weighted average common shares outstanding | |||||||||||||||
| Basic | 76,121,570 | 73,438,209 | 69,926,933 | 66,013,247 | 61,043,071 | ||||||||||
| Diluted | 76,825,863 | 74,266,370 | 70,904,921 | 67,299,413 | 62,509,796 | ||||||||||
(1)The results for 2017 include the impact of the Tax Cuts and Job Act (“Tax Act”) which was enacted on December 22, 2017. The Tax Act resulted in additional income tax expense of $62 million for the one-time transition tax on deemed repatriation of earnings of some of our foreign subsidiaries and $115 million from the remeasurement of the Company’s deferred tax assets at the reduced corporate income tax rate of 21%. Other income includes a $93 million gain from the remeasurement of Tax Receivable Agreement liability, payable to Holdings, which is associated with and offsetting to the expense on remeasurement of deferred tax assets. See Note 4 – “Equity and Earnings per Share” and Note 11 – “Income Taxes” to the audited consolidated financial statements, in Part II, Item 8 of this Annual Report on Form 10-K.
(2)The results for 2019 include an unusual loss of $42 million recorded as customer bad debt which reflects losses recognized on margin lending to a small number of our brokerage customers that had taken relatively large positions in a security listed on a major U.S. exchange, which lost a substantial amount of its value in a very short timeframe. See Note 14 – “Commitments, Contingencies and Guarantees” to the audited consolidated financial statements in Part II, Item 8 of this Annual Report on Form 10-K for additional details.
The results for 2015 include an unusual loss of $137 million recorded as customer bad debt. On January 15, 2015, in an unprecedented action, the Swiss National Bank removed a previously instituted and repeatedly confirmed cap of the currency relative to the euro, causing a sudden move in the value of the Swiss franc. Several of our customers holding currency futures and spot positions suffered losses in excess of their deposits with us. We took immediate action to hedge our exposure to the foreign currency receivables from these customers. As of December 31, 2019, we have incurred cumulative losses, net of hedging activity and debt collection efforts, of $115 million. We continue to actively pursue collection of the debts. The ultimate effect of this incident on our results will depend upon the outcome of our debt collection efforts.
| December 31, | |||||||||||||||
| 2019 | 2018 | 2017 | 2016 | 2015 | |||||||||||
| (in millions) | |||||||||||||||
| Consolidated Statement of Financial Condition Data | |||||||||||||||
| Cash, cash equivalents and short-term investments (1) | $ | 33,217 | $ | 26,937 | $ | 23,999 | $ | 26,053 | $ | 23,105 | |||||
| Total assets (2), (3) | $ | 71,676 | $ | 60,547 | $ | 61,162 | $ | 54,673 | $ | 48,734 | |||||
| Total liabilities(3) | $ | 63,736 | $ | 53,391 | $ | 54,729 | $ | 48,853 | $ | 43,390 | |||||
| Stockholders' equity | $ | 1,452 | $ | 1,282 | $ | 1,090 | $ | 974 | $ | 863 | |||||
| Noncontrolling interests | $ | 6,488 | $ | 5,874 | $ | 5,343 | $ | 4,846 | $ | 4,481 |
(1)Cash, cash equivalents and short-term investments represent cash and cash equivalents, cash and securities segregated under federal and other regulations, short-term investments and securities purchased under agreements to resell.
(2)As of December 31, 2019, approximately $71.1 billion, or 99.2%, of total assets were considered liquid and consisted primarily of cash, marketable securities and collateralized receivables.
(3)As a result of the Company’s acquisition from Holdings of IBG LLC membership interests, the Company received not only an interest in IBG LLC but also, for federal income tax purposes, a step-up to the federal income tax basis of the assets of IBG LLC underlying such additional interest. This increased tax basis is expected to result in tax benefits as a result of increased amortization deductions. The Company will retain 15% of the tax benefits actually realized. As set forth in the Tax Receivable Agreement the Company entered into with Holdings, the Company will pay the remaining 85% of the realized tax benefits relating to any applicable tax year to Holdings. The deferred tax asset was $116 million, $140 million, $146 million, $273 million, and $288 million and the corresponding payable to Holdings was $139 million, $171 million, $187 million, $285 million, and $291 million as of December 31, 2019, 2018, 2017, 2016, and 2015, respectively. See “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in Part II, Item 7 of this Annual Report on Form 10-K for additional details related to the impact of the Tax Act on the Company.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following discussion should be read in conjunction with the audited consolidated financial statements and the related notes in Part II, Item 8, of this Annual Report on Form 10-K. In addition to historical information, the following discussion also contains forward-looking statements that include risks and uncertainties. Our actual results may differ materially from those anticipated in these forward-looking statements as a result of certain factors, including those set forth under the heading “Risk Factors” in Part I, Item 1A of this Annual Report on Form 10-K.
Business Overview
We are an automated global electronic broker and market maker (although, we have substantially exited our options market making business - see Note 2 – “Discontinued Operations and Costs Associated with Exit or Disposal Activities” to the audited consolidated financial statements in Part II, Item 8 of this Annual Report on Form 10-K). We custody and service accounts for hedge and mutual funds, registered investment advisers, proprietary trading groups, introducing brokers and individual investors. We specialize in routing orders and executing and processing trades in stocks, options, futures, forex, bonds, mutual funds and ETFs on more than 135 electronic exchanges and market centers around the world. Since our inception in 1977, we have focused on developing proprietary software to automate broker-dealer functions. The proliferation of electronic exchanges over nearly the last three decades has provided us with the opportunity to integrate our software with an increasing number of exchanges and market centers into one automatically functioning, computerized platform that requires minimal human intervention.
Our primary assets are our ownership of approximately 18.5% of the membership interests of IBG LLC, the current holding company for our businesses, and our controlling interest and related contractual rights as the sole managing member of IBG LLC. The remaining approximately 81.5% of IBG LLC membership interests are held by Holdings, a holding company that is owned by our founder and Chairman, Mr. Thomas Peterffy and his affiliates, management and other employees of IBG LLC, and certain other members. The IBG LLC membership interests held by Holdings will be subject to purchase by us over time in connection with offerings by us of shares of our common stock.
Business Segments
We report our results in two operating business segments, electronic brokerage and market making (being discontinued). These segments are analyzed separately as these are the two principal business activities from which we derive our revenues and to which we allocate resources.
Electronic Brokerage. As an electronic broker, we execute, clear and settle trades globally for both institutional and individual customers. Capitalizing on our proprietary technology, our systems provide our customers with the capability to monitor multiple markets around the world simultaneously and to execute trades electronically in these markets at a low cost, in multiple products and currencies from a single trading account. We offer our customers access to all classes of tradable, primarily exchange-listed products, including stocks, options, futures, forex, bonds, mutual funds and ETFs traded on more than 135 electronic exchanges and market centers in 33 countries and in 25 currencies seamlessly around the world. The emerging complexity of multiple market centers has provided us with the opportunity to build and continuously adapt our order routing software to secure excellent execution prices.
Our customer base is diverse with respect to geography and segments. Currently, approximately 70% of our customers reside outside the U.S. in over 200 countries and territories, and over 50% of new customers come from outside the U.S. Approximately 65% of our customers’ equity is in institutional accounts such as hedge funds, financial advisors, proprietary trading desks and introducing brokers. Specialized products and services that we have developed are successfully attracting these accounts. For example, we offer prime brokerage services, including financing and securities lending to hedge funds; our model portfolio technology and automated share allocation and rebalancing tools are particularly attractive to financial advisors; and our trading platform, global access and low pricing attract introducing brokers.
Market Making. As previously announced, we transferred our U.S. options market making operations to Two Sigma Securities, LLC effective September 29, 2017 and also exited the majority of our options market making activities outside the U.S. by December 31, 2017. During 2019, we exited our Canadian market making operations. We intend to continue conducting certain proprietary trading activities in stocks and related instruments to facilitate our electronic brokerage customers’ trading in products such as ETFs, ADRs, CFDs and other financial instruments, as well as exchange-traded market making activities in a few select markets outside of the U.S. However, we do not expect the remaining activity to be of sufficient size as to require reporting as a separate segment in the future.
Business Environment
During 2019, U.S. market volatility was generally lower than in the prior year, amid greater optimism about global economic growth and continued monetary easing by central banks. Equity market indices around the globe were predominantly up, led by the U.S., where the S&P 500 index rose 29%. U.S. interest rates were lowered three times by the Federal Reserve in 2019, nearly reversing all the rate hikes of the prior year, while trends in benchmark rates of other currencies were mixed.
Among our customer base, volatility is highly correlated with customer trading activity across product types. In 2019, lower volatility led to decreases in trading volume, notably in the U.S., as our customers’ trading activity, which is sensitive to overall market trends, showed declines. In addition, lower benchmark interest rates, which can be beneficial by reducing the rate of interest paid on customer cash, can also give us fewer opportunities to earn more net interest income on fully interest-sensitive balances.
In an improving market environment, with mainly lower interest rates and rising asset values, customer account growth was robust, with total customer accounts increasing 15% from 2018 to 690 thousand. Healthy inflows from customers, combined with securities market increases that generally benefited customers’ investment values, led to customer equity growth of 36% to $174.1 billion. Institutional customers, such as hedge funds, mutual funds, introducing brokers, proprietary trading groups and financial advisors, comprised approximately 50% of total accounts and approximately 65% of total customer equity at the end of 2019. We continue to attract large customers that seek our superior technology and execution capabilities, high interest rates on cash balances, and low costs, as well as our securities finance services, including margin lending and short sale support.
The following is a summary of the key profit drivers that affect our business and how they compared to 2018:
Global trading volumes. According to data received from exchanges, volumes in exchange-listed equity-based options decreased by approximately 13% in the U.S. for the year ended December 31, 2019, compared to 2018. Further, U.S. volumes decreased in exchange-listed futures by 19% and in equities by 20%, due to the decline in volatility among other factors. See the “Trading Volumes and Brokerage Statistics” section below in this Item 7 for additional details regarding our trade volumes, contract and share volumes, and brokerage statistics.
Volatility. Based on the Chicago Board Options Exchange Volatility Index (“VIX®”), average U.S. market volatility decreased to 15.4 in 2019, down 7% from the average of 16.6 in 20
Showing the first 8K of 97K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
We are exposed to various market risks. Our exposures to market risks arise from assumptions built into our pricing models, equity price risk, foreign currency exchange rate fluctuations related to our international operations, changes in interest rates and risks relating to the extension of margin credit to our customers.
Market risk refers to the risk that a change in the level of one or more market prices, rates, indices, implied volatilities (the price volatility of the underlying instrument imputed from option prices), correlations or other market factors, such as market liquidity, will result in losses for a position or portfolio. Generally, we incur trading-related market risk as a result of activities in the market making segment, where the substantial majority of our Value-at-Risk (“VaR”) for market risk exposures is generated. In addition, we incur non-trading-related market risk primarily from investment activities and from foreign currency exposure held in the equity of our foreign subsidiaries, i.e., our non-U.S. brokerage subsidiaries and information technology subsidiaries, and held to meet target balances in our currency diversification strategy.
We use various risk management tools in managing our market risk, which are embedded in our real-time market making systems. We employ certain hedging and risk management techniques to protect us from a severe market dislocation. Our risk management policies are developed and implemented by our Chairman and our steering committee, which is comprised of senior executives of our various companies. Our market making strategy is to calculate quotes a few seconds ahead of the market and execute small trades at a tiny but favorable differential as a result. This is made possible by our proprietary pricing model, which evaluates and monitors the risks inherent in our portfolio, assimilates external market data and reevaluates the outstanding quotes in our portfolio many times per second. Our model automatically rebalances our positions throughout each trading day to manage risk exposures on our options and futures positions and the underlying securities, and will price the increased risk that a position would add to the overall portfolio into the bid and offer prices we post. Under risk management policies implemented and monitored primarily through our computer systems, reports to management, including risk profiles, profit and loss analysis and trading performance, are prepared on a real-time basis as well as daily and periodical bases. Although our market making is completely automated, the trading process and our risk are monitored by a team of individuals who, in real time, observe various risk parameters of our consolidated positions. Our assets and liabilities are marked-to-market daily for financial reporting purposes and re-valued continuously throughout the trading day for risk management and asset/liability management purposes.
We use a covariant VaR methodology to measure, monitor and review the market risk of our market making portfolios, with the exception of fixed income products, and our currency exposures. The risk of fixed income products, which comprise primarily U.S. government securities, is measured using a stress test.
Pricing Model Exposure
As described above, our proprietary pricing model, which continuously evaluates and monitors the risks inherent in our portfolio, assimilates external market data and reevaluates the outstanding quotes in our entire portfolio many times per second. Certain aspects of the model rely on historical prices of securities. If the behavior of price movements of individual securities diverges substantially from what their historical behavior would predict, we might incur trading losses. We attempt to limit such risks by diversifying our portfolio across many different options, futures and underlying securities and avoiding concentrations of positions based on the same underlying security. Historically, our losses from these events have been immaterial in comparison to our annual trading profits.
Foreign Currency Exposure
As a result of our international activities and accumulated earnings in our foreign subsidiaries, our income and net worth is exposed to fluctuations in foreign exchange rates. For example, our European operations and some of our Asian operations are conducted by our Swiss subsidiary, IBKRFS. IBKRFS is regulated by the Swiss Financial Market Supervisory Authority as a securities dealer and its financial statements are presented in Swiss francs. Accordingly, IBKRFS is exposed to certain foreign exchange risks as described below:
IBKRFS buys and sells securities denominated in various currencies and carries bank balances and borrows and lends such currencies in its regular course of business. At the end of each accounting period, IBKRFS’ assets and liabilities are revalued into Swiss francs for presentation in its financial statements. The resulting foreign currency gains or losses are reported in IBKRFS’ income statement and, as translated into U.S. dollars for U.S. GAAP purposes, in our consolidated statement of comprehensive income as a component of other income.
IBKRFS’ financial statements are presented in Swiss francs (i.e., its functional currency) as noted above. At the end of each accounting period, IBKRFS’ net worth is translated at the then prevailing exchange rate into U.S. dollars and the resulting translation gain or loss is reported as OCI in our consolidated statement of financial condition and consolidated statement of comprehensive income. OCI is also produced by our other non-U.S. subsidiaries.
Historically, we have taken the approach of not hedging the above exposures, based on the notion that the cost of constantly hedging over the years would amount to more than the random impact of rate changes on our non-U.S. dollar balances. For instance, an increase in the value of the Swiss franc would be unfavorable to the earnings of IBKRFS but would be counterbalanced to some extent by the fact that the translation gain or loss into U.S. dollars is likely to move in the opposite direction.
Our risk management systems incorporate cash forex to hedge our currency exposure at little or no cost throughout each day on a continuous basis. The majority of currency spot positions held as part of our currency diversification strategy are regularly transferred to the parent holding company, IBG LLC, where they are held and reported in the corporate segment. In connection with the development of our currency diversification strategy, we determined to base our net worth in GLOBALs, a basket of currencies.
Because we conduct business in many countries and many currencies and because we consider ourselves a global enterprise based in a diversified basket of currencies rather than a U.S. dollar based company, we actively manage our global currency exposure by maintaining our equity in GLOBALs. The U.S. dollar value of the GLOBAL decreased 0.06% as of December 31, 2019 compared to December 31, 2018. As of December 31, 2019, approximately 30% of our equity was denominated in currencies other than the U.S. dollar.
The table below presents a comparison of the U.S. dollar equivalent of the GLOBAL for the periods indicated.
| As of 12/31/2018 | As of 12/31/2019 | |||||||||||||||||||||||
| GLOBAL in | % of | Net Equity | GLOBAL in | % of | Net Equity | CHANGE in | ||||||||||||||||||
| Currency | Composition | FX Rate | USD Equiv. | Comp. | (in USD millions) | FX Rate | USD Equiv. | Comp. | (in USD millions) | % of Comp. | ||||||||||||||
| USD | 0.68 | 1.0000 | 0.680 | 70.3% | $ | 5,031 | 1.0000 | 0.680 | 70.3% | $ | 5,586 | 0.0% | ||||||||||||
| EUR | 0.09 | 1.1467 | 0.103 | 10.7% | 763 | 1.1213 | 0.101 | 10.4% | 829 | -0.2% | ||||||||||||||
| JPY | 4.41 | 0.0091 | 0.040 | 4.2% | 298 | 0.0092 | 0.041 | 4.2% | 333 | 0.0% | ||||||||||||||
| GBP | 0.02 | 1.2760 | 0.026 | 2.6% | 189 | 1.3261 | 0.027 | 2.7% | 218 | 0.1% | ||||||||||||||
| HKD | 0.14 | 0.1277 | 0.018 | 1.8% | 132 | 0.1284 | 0.018 | 1.9% | 147 | 0.0% | ||||||||||||||
| INR | 1.10 | 0.0144 | 0.016 | 1.6% | 117 | 0.0140 | 0.015 | 1.6% | 126 | 0.0% | ||||||||||||||
| CHF | 0.02 | 1.0190 | 0.020 | 2.1% | 151 | 1.0334 | 0.021 | 2.1% | 170 | 0.0% | ||||||||||||||
| CAD | 0.02 | 0.7332 | 0.015 | 1.5% | 108 | 0.7699 | 0.015 | 1.6% | 127 | 0.1% | ||||||||||||||
| CNH | 0.10 | 0.1456 | 0.015 | 1.5% | 108 | 0.1437 | 0.014 | 1.5% | 118 | 0.0% | ||||||||||||||
| AUD | 0.02 | 0.7052 | 0.014 | 1.5% | 104 | 0.7017 | 0.014 | 1.5% | 115 | 0.0% | ||||||||||||||
| MXN | 0.17 | 0.0509 | 0.009 | 0.9% | 64 | 0.0528 | 0.009 | 0.9% | 74 | 0.0% | ||||||||||||||
| SEK | 0.05 | 0.1129 | 0.006 | 0.6% | 42 | 0.1068 | 0.005 | 0.6% | 44 | 0.0% | ||||||||||||||
| NOK | 0.03 | 0.1157 | 0.003 | 0.4% | 26 | 0.1139 | 0.003 | 0.4% | 28 | 0.0% | ||||||||||||||
| DKK | 0.02 | 0.1536 | 0.003 | 0.3% | 23 | 0.1501 | 0.003 | 0.3% | 25 | 0.0% | ||||||||||||||
| 0.967 | 100.0% | $ | 7,156 | 0.967 | 100.0% | $ | 7,940 | 0.0% |
The effects of our currency diversification strategy appear in two places in the consolidated financial statements: (1) as a component of other income in the consolidated statement of comprehensive income and (2) as OCI in the consolidated statement of financial condition and the consolidated statement of comprehensive income. The full effect of the GLOBAL is captured in the consolidated statement of comprehensive income.
Reported results on a comprehensive basis reflect the U.S. GAAP convention that requires the reporting of currency translation results contained in OCI as part of reportable earnings.
Interest Rate Risk
We had no variable-rate debt outstanding as of December 31, 2019.
We pay our electronic brokerage customers interest based on benchmark overnight interest rates in various currencies, on cash balances above $10 thousand (or equivalent) in securities accounts holding more than $100 thousand and at lower, tiered rates for accounts holding less than $100 thousand (or equivalent) net asset value. In a normal rate environment, we typically invest a portion of these funds in U.S. government securities with maturities of up to two years. If interest rates were to increase rapidly and substantially, our net interest income would not increase proportionally with the interest rates for the portion of the funds invested in the U.S. government securities with fixed yields. In addition, the mark-to-market changes in the value of these fixed rate securities will be reflected in other income, instead of net interest income. Based on customer balances and investments outstanding as of December 31, 2019, and assuming reinvestment of maturing instruments in instruments of short-term duration, an unexpected increase of 0.25% over current U.S. dollar interest rate levels would increase our net interest income by approximately $20 million over the first year and $22 million on an annualized basis, assuming the full effect of reinvestment at higher rates. Our interest rate sensitivity estimate contains separate assumptions for U.S. dollar rates from other currencies’ rates and it isolates the effects of a rate increase on reinvestments. We do not approximate mark-to-market impact from interest rate changes; if U.S. government securities whose prices were to fall under these scenarios were held to maturity, as intended, then the reduction in other income would be temporary, as the securities would mature at par value.
We also face the potential for reduced net interest income from customer deposits due to interest rate spread compression in a low rate environment. Based on customer balances and investments outstanding as of December 31, 2019, and assuming reinvestment of maturing instruments in instruments of short-term duration, an unexpected decrease in U.S. dollar interest rates of 0.25% would decrease our net interest income by approximately $17 million over the first year and $22 million on an annualized basis, assuming the full effect of reinvestment at lower rates.
We also face interest rate risk due to positions carried in our market making business to the extent that long or short stock positions may have been established for future or forward dates on options or futures contracts and the value of such positions are impacted by interest rates. The amount of such risk cannot be quantified, however, the reduction of market making positions has substantially reduced this exposure.
Dividend Risk
We face dividend risk in our market making business as we derive revenues and incur expenses in the form of dividend income and expense, respectively, from our inventory of equity securities, and must make payments in lieu of dividends on short positions in equity securities within our portfolio. Projected future dividends are an important component of pricing equity options and other derivatives, and incorrect projections may lead to trading losses. The amount of such risk cannot be quantified, however, the reduction of market making positions has substantially reduced this exposure.
Margin Loans
We extend margin loans to our customers, which are subject to various regulatory requirements. Margin loans are collateralized by cash and securities in the customers’ accounts. The risks associated with margin credit increase during periods of fast market movements or in cases where collateral is concentrated and market movements occur. During such times, customers who utilize margin loans and who have collateralized their obligations with securities may find that the securities have a rapidly depreciating value and may not be sufficient to cover their obligations in the event of a liquidation. We are also exposed to credit risk when our customers execute transactions, such as short sales of options and equities that can expose them to risk beyond their invested capital.
We expect this kind of exposure to increase with the growth of our overall business. Because we indemnify and hold harmless our clearing houses and counterparties from certain liabilities or claims, the use of margin loans and short sales may expose us to significant off-balance-sheet risk in the event that collateral requirements are not sufficient to fully cover losses that customers may incur and those customers fail to satisfy their obligations. As of December 31, 2019, we had $31.3 billion in margin loans extended to our customers. The amount of risk to which we are exposed from the margin loans we extend to our customers and from short sale transactions by our customers is unlimited and not quantifiable as the risk is dependent upon analysis of a potential significant and undeterminable rise or fall in stock prices. Our account level margin requirements meet or exceed those required by Regulation T of the Board of Governors of the Federal Reserve and FINRA portfolio margin rules, as applicable. As a matter of practice, we enforce real-time margin compliance monitoring and liquidate customers’ positions if their equity falls below required margin requirements.
We have a comprehensive policy implemented in accordance with regulatory standards to assess and monitor the suitability of investors to engage in various trading activities. To mitigate our risk, we also continuously monitor customer accounts to detect excessive concentration, large orders or positions, patterns of day trading and other activities that indicate increased risk to us.
Our credit exposure is to a great extent mitigated by our policy of automatically evaluating each account throughout the trading day and closing out positions automatically for accounts that are found to be under-margined. While this methodology is effective in most situations, it may not be effective in situations where no liquid market exists for the relevant securities or commodities or where, for any reason, automatic liquidation for certain accounts has been disabled. Our Risk Management Committee continuously monitors and evaluates our risk management policies, including the implementation of policies and procedures to enhance the detection and prevention of theoretical events to mitigate margin loan losses.
Value**-at-**Risk
We estimate VaR using an historical approach, which uses the historical daily price returns of underlying assets as well as estimates of the end of day implied volatility for options. Our one-day VaR is defined as the unrealized loss in portfolio value that, based on historically observed market risk factors, would have been exceeded with a frequency of one percent, based on a calculation with a confidence interval of 99%.
Our VaR model generally takes into account exposures to equity and commodity price risk and foreign exchange rates.
We use VaR as one of a range of risk management tools. Among their benefits, VaR models permit estimation of a portfolio’s aggregate market risk exposure, incorporating a range of varied market risks and portfolio assets. One key element of the VaR model is that it reflects risk reduction due to portfolio diversification or hedging activities. However, VaR has various strengths and limitations, which include, but are not limited to: use of historical changes in market risk factors, which may not be accurate predictors of future market conditions, and may not fully incorporate the risk of extreme market events that are outsized relative to observed historical market behavior or reflect the historical distribution of results beyond the confidence interval; and reporting of losses in a single day, which does not reflect the risk of positions that cannot be liquidated or hedged in one day. A small proportion of market risk generated by trading positions is not included in VaR. The modeling of the risk characteristics of some positions relies on approximations that, under certain circumstances, could produce significantly different results from those produced using more precise measures. VaR is most appropriate as a risk measure for trading positions in liquid financial markets and will understate the risk associated with severe events, such as periods of extreme illiquidity.
The VaR calculation simulates the performance of the portfolio based on several years of the daily price changes of the underlying assets and determines the VaR as the calculated loss that occurs at the 99th percentile.
Since the reported VaR statistics are estimates based on historical data, VaR should not be viewed as predictive of our future revenues or financial performance or of our ability to monitor and manage risk. There can be no assurance that our actual losses on a particular day will not exceed the indicated VaR or that such losses will not occur more than one time in 100 trading days. VaR does not predict the magnitude of losses which, should they occur, may be significantly greater than the VaR amount.
Stress Test
We estimate the market risk of our fixed income portfolio using a risk analysis model provided by a leading external vendor. For corporate bonds, this stress test is configured to calculate the change in value of each fixed income security in the portfolio over one day in seven scenarios each of which represents a parallel shift of the U.S. Treasury yield curve. The scenarios are shifts of +/−100, +/−200 and +/−300 basis points. For U.S. government securities, the stress test is configured to calculate the change in value of each fixed income security in the portfolio over one day in three scenarios each of which represents a parallel shift of the U.S. Treasury yield curve. The scenarios are shifts of +/−25 basis points.
VaR and Stress Test Measures
| At December 31, | At December 31, | Average | High | |||||||||
| Market Risk Category | 2019 | 2018 | 2019 | 2019 | ||||||||
| (in millions) | ||||||||||||
| Trading (1) | ||||||||||||
| Equities and Currencies (2) | $ | 7 | $ | 7 | $ | 7 | $ | 8 | ||||
| Fixed Income (3) | - | - | - | - | ||||||||
| Trading Total | $ | 7 | $ | 7 | $ | 7 | $ | 8 | ||||
| Non-Trading (1) | ||||||||||||
| Equities and Currencies | $ | 17 | $ | 15 | $ | 15 | $ | 18 | ||||
| Fixed Income, Other (4) | 2 | 4 | 4 | 6 | ||||||||
| Non-Trading Total | $ | 19 | $ | 19 | $ | 19 | $ | 24 |
(1)The product categories displayed in the table as “Trading” reflect activities undertaken in the Company's market making segment. The “Non-trading” category reflects investment activities and foreign currency exposures held in the equity of the Company's non-market making subsidiaries, i.e., its brokerage subsidiaries and information technology subsidiaries. This category also includes corporate segment activities in foreign exchange designed to achieve the Company's currency diversification strategy.
The average and high VaR amounts for equities and currencies are based on end of day calculations performed in 2019. The fixed income stress amounts are based on the four quarter ending calculations performed in 2019.
(2)Equities and currencies held for market making purposes are combined because these products are part of an integrated, hedged market making portfolio, on which the risk is measured using VaR.
(3)The Trading – Fixed Income category contains primarily foreign government securities held in connection with market making activities. The risks on these products were managed separately and measured using the stress test analysis.
(4)The Non-Trading – Fixed Income, Other category contains primarily U.S. government securities held in segregated safekeeping accounts for the exclusive benefit of our brokerage customers, on which the risk is measured using a stress test analysis.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
Index to Consolidated Financial Statements
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the Stockholders and the Board of Directors of
Interactive Brokers Group, Inc.
Greenwich, CT
Opinion on the Financial Statements
We have audited the accompanying consolidated statements of financial condition of Interactive Brokers Group, Inc. and subsidiaries (the "Company") as of December 31, 2019 and 2018, the related consolidated statements of comprehensive income, changes in equity, and cash flows, for each of the three years in the period ended December 31, 2019, and the related notes (collectively referred to as the "financial statements"). In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company as of December 31, 2019 and 2018, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2019, in conformity with accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, 2019, based on criteria established in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February 28, 2020, expressed an unqualified opinion on the Company's internal control over financial reporting.
Basis for Opinion
These financial statements are the responsibility of the Company's management. Our responsibility is to express an opinion on the Company's financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements. We believe that our audits provide a reasonable basis for our opinion.
Critical Audit Matter
The critical audit matter communicated below is a matter arising from the current-period audit of the financial statements that was communicated or required to be communicated to the audit committee and that (1) relates to accounts or disclosures that are material to the financial statements and (2) involved our especially challenging, subjective, or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
Income taxes — Refer to Notes 2 and 11 to the consolidated financial statements
Critical Audit Matter Description
The Company’s income tax expense, deferred tax assets and liabilities (net of valuation allowance, if any), and reserves for unrecognized tax benefits are based on enacted tax laws and reflects management's best assessment of estimated future taxes to be paid. The Company is subject to income taxes in both the U.S. and numerous foreign jurisdictions. The Company has deferred tax assets resulting from the tax basis step-up received in connection with the Company’s public equity offerings. Determining income tax expense requires significant management judgments and estimates.
We identified management’s calculation of income tax expense, deferred tax assets and liabilities (net of valuation allowance, if any), and reserves for unrecognized tax benefits as a critical audit matter because of the significant judgments and estimates management makes to determine these amounts. This required a high degree of audit judgment and an increased effort, including the need to involve our income tax specialists when performing audit procedures to evaluate the reasonableness of management’s interpretation of tax law in multiple countries, and its estimate of the associated provisions, tax charges, and uncertain tax positions.
How the Critical Audit Matter Was Addressed in the Audit
Our audit procedures related to income taxes included, among others, the following:
We tested the design and operating effectiveness of controls over income tax balances, including the provision for income taxes, deferred tax assets and liabilities (including valuation allowance) and unrecognized tax benefits.
With the assistance of our income tax specialists, we assessed the Company’s income tax expense by:
-Evaluating the Company’s income tax provision calculation, including testing the appropriateness of income tax rates applied and of income allocations among the taxing jurisdictions, application of the provisions in the Tax Act, and the mathematical accuracy of the calculation.
-Evaluating the Company’s analyses supporting its conclusions as to the recognition and measurement of deferred tax assets and liabilities, including the calculation of the deferred tax asset related to the tax basis step-up received in connection with the Company’s public equity offering.
-Evaluating management’s assessment of the Company’s ability to utilize the net deferred tax assets in future years.
-Evaluating the appropriateness of the Company having no significant unrecognized tax benefits.
/s/ Deloitte & Touche LLP
New York, New York
February 28, 2020
We have served as the Company's auditor since 1990.
Interactive Brokers Group, Inc. and Subsidiaries
Consolidated Statements of Financial Condition
| December 31, | ||||||
| (in millions, except share amounts) | 2019 | 2018 | ||||
| Assets | ||||||
| Cash and cash equivalents | $ | 2,882 | $ | 2,597 | ||
| Cash - segregated for regulatory purposes | 9,400 | 7,503 | ||||
| Securities - segregated for regulatory purposes | 17,824 | 15,595 | ||||
| Securities borrowed | 3,916 | 3,331 | ||||
| Securities purchased under agreements to resell | 3,111 | 1,242 | ||||
| Financial instruments owned, at fair value | ||||||
| Financial instruments owned | 1,755 | 1,931 | ||||
| Financial instruments owned and pledged as collateral | 161 | 188 | ||||
| Total fina |
Showing the first 8K of 171K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Conclusion Regarding the Effectiveness of Disclosure Controls and Procedures
The Company maintains disclosure controls and procedures that are designed to provide reasonable assurance that information required to be disclosed in the reports it files or submits under the Securities Exchange Act of 1934 (the “Exchange Act”) is recorded, processed, summarized and reported accurately and within the time periods specified in the SEC’s rules and forms. Disclosure controls and procedures include, without limitation, controls and procedures designed to ensure that information required to be disclosed by the Company in the reports that it files or submits under the Exchange Act is accumulated and communicated to management, including the Chief Executive Officer (“CEO”) and Chief Financial Officer (“CFO”), as appropriate, to allow timely decisions regarding required disclosure.
Under the supervision and with the participation of our management, including our CEO and our CFO, we conducted an evaluation of our disclosure controls and procedures; as such term is defined under Exchange Act Rule 13a-15(e). Based on this evaluation, our CEO and our CFO concluded that our disclosure controls and procedures were effective as of the end of the period covered by this annual report.
Management’s Report on Internal Control over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting. IBG, Inc.’s internal control over financial reporting is designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with U.S. generally accepted accounting principles.
Our internal control over financial reporting includes those policies and procedures that pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of IBG, Inc.; provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with U.S. generally accepted accounting principles, and that our receipts and expenditures are being made only in accordance with authorizations of IBG, Inc.’s management and directors; and provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use or disposition of our assets that could have a material effect on our financial statements.
In 2012, the Company’s management created the Accounting Policy Committee (the “APC”) to provide a robust framework for the design and implementation of all relevant controls. The APC is comprised of eight (8) experienced subject matter experts from within the Company’s accounting and regulatory disciplines, and includes the CFO and the Chief Accounting Officer. The APC is responsible for assessing the effects of complex transactions and related accounting guidance on the Company’s financial statements and to report the results of its assessments to management and to the Audit Committee. The APC’s mandate includes review and approval of the adoption and implementation of accounting guidance (new or newly applicable) by the Company.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Management, including our CEO and our CFO, assessed the effectiveness of IBG, Inc.’s internal control over financial reporting as of December 31, 2019. In making this assessment, management used the criteria set forth in Internal Control-Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (“COSO”). Based on management’s assessment and those criteria, management concluded that IBG, Inc. maintained effective internal control over financial reporting as of December 31, 2019.
The effectiveness of the Company’s internal control over financial reporting as of December 31, 2019, has been audited by Deloitte & Touche LLP, an independent registered public accounting firm, as stated in their report, which appears herein.
Changes to Internal Control over Financial Reporting
No changes to our internal control over financial reporting for the year ended December 31, 2019 have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the Stockholders and the Board of Directors of
Interactive Brokers Group, Inc.
Greenwich, CT
Opinion on Internal Control over Financial Reporting
We have audited the internal control over financial reporting of Interactive Brokers Group, Inc. and subsidiaries (the “Company”) as of December 31, 2019, based on criteria established in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2019, based on criteria established in Internal Control — Integrated Framework (2013) issued by COSO.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated statements of financial condition as of December 31, 2019 and 2018 and the related consolidated statements of comprehensive income, cash flows, and changes in equity for each of the three years in the period December 31, 2019 , of the Company and our report dated February 28, 2020, expressed an unqualified opinion on those financial statements.
Basis for Opinion
The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management's Report on Internal Control over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/ Deloitte & Touche LLP
New York, New York
February 28, 2020
Item 9B. OTHER INFORMATION
Not applicable.
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
Information related to the Company’s directors and nominees under the following captions in the Company’s Proxy Statement is incorporated by reference herein:
-
“Item 1 - Election of Directors”
-
“Item 1 - Election of Directors - Board Meetings and Committees”
Code of Ethics
IBG, Inc.’s Code of Ethics and Business Conduct applies to all directors, officers and employees, including its Chief Executive Officer, its Chief Financial Officer and its Chief Accounting Officer. Information relating to our Code of Business Conduct and Ethics is included in Part I, Item 1 of this Annual Report on Form 10-K. We will post any amendments to the Code of Ethics and Business Conduct, and any waivers that are required to be disclosed by the rules of either the SEC or Nasdaq on the investor relations section of our website located at www.interactivebrokers.com/ir.
Item 11. EXECUTIVE COMPENSATION
Information relating to director and executive officer compensation under the following captions in the Company’s Proxy Statement is incorporated by reference herein:
-
“Compensation of Directors”
-
“Executive Compensation”
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
Other information relating to security ownership of certain beneficial owners and management is set forth under the caption “Beneficial Ownership of Directors, Executive Officers and Owners of More than Five Percent” in the Company’s Proxy Statement and such information is incorporated by reference herein.
Item 13. TRANSACTIONS WITH RELATED PERSONS, PROMOTERS AND CERTAIN CONTROL PERSONS
Information regarding certain relationships and related transactions under the following caption in the Company’s Proxy Statement and such information is incorporated by reference herein:
- “Certain Relationships and Related Transactions”
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
Information regarding principal accounting fees and under the following caption in the Company’s Proxy Statement is incorporated by reference herein:
- “Item 3 - Ratification of Appointment of Independent Registered Public Accounting Firm”
PA****RT IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
Documents filed as part of this report
**1.**Consolidated Financial Statements
The consolidated financial statements required to be filed in the Annual Report on Form 10-K are listed on page F-1 hereof and in Part II, Item 8 hereof.
**2.**Financial Statement Schedule
The financial statement schedule required in the Annual Report on Form 10-K is listed on page F-1 hereof. The required schedule appears on pages F-1 through F-5 hereof.
**3.**Exhibits
** Previously filed; incorporated herein by reference.
+ These exhibits relate to management contracts or compensatory plans or arrangements.
- Attached as Exhibit 101 to this Annual Report on Form 10-K for the annual period ended December 31, 2019, are the following materials formatted in iXBRL (Inline eXtensible Business Reporting Language) (i) the Consolidated Statements of Financial Condition, (ii) the Consolidated Statements of Comprehensive Income, (iii) the Consolidated Statements of Cash Flows, (iv) the Consolidated Statement of Changes in Stockholders’ Equity and (v) Notes to the Consolidated Financial Statements tagged in detail levels 1-4.
ITEMS. 15 (a)(1) and 15 (a)(2) INDEX TO FINANCIAL STATEMENTS AND FINANCIAL STATEMENT SCHEDULE
Financial Statement Schedule
| Schedule I—Condensed Financial Information of Registrant (Parent Company Only) | |
| Report of Independent Registered Public Accounting Firm | F - 1 |
| Condensed Statements of Financial Condition as of December 31, 2019 and 2018 | F - 2 |
| Condensed Statements of Comprehensive Income for the Years ended December 31, 2019, 2018, and 2017 | F - 3 |
| Condensed Statements of Cash Flow for the Years ended December 31, 2019, 2018, and 2017 | F - 4 |
| Notes to Condensed Financial Statements | F - 5 |
Item 16. 10-K SUMMARY
None.
REPORT OF INDEPENDENT REGISTERE****D PUBLIC ACCOUNTING FIRM
To the Stockholders and the Board of Directors of
Interactive Brokers Group, Inc.
Greenwich, CT
Opinion on the Financial Statement Schedules
We have audited the consolidated financial statements of Interactive Brokers Group, Inc. and subsidiaries (the “Company”) as of December 31, 2019 and 2018, and for each of the three years in the period ended December 31, 2019, and the Company’s internal control over financial reporting as of December 31, 2019, and have issued our reports thereon dated February 28, 2020; such consolidated financial statements and reports are included elsewhere in this Form 10-K. Our audits also included the financial statement schedules of the Company listed in the Index at Item 15. These condensed financial statement schedules are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s financial statement schedules based on our audits. In our opinion, such condensed financial statement schedules, when considered in relation to the consolidated financial statements taken as a whole, present fairly, in all material respects, the information set forth therein.
/s/ Deloitte & Touche LLP
New York, New York
February 28, 2020
We have served as the Company’s auditor since 1990
F - 1
| INTERACTIVE BROKERS GROUP, INC. | ||||||
| (Parent Company Only) | ||||||
| CONDENSED STATEMENTS OF FINANCIAL CONDITION | ||||||
| December 31, | ||||||
| (in millions, except share amounts) | 2019 | 2018 | ||||
| Assets | ||||||
| Cash and cash equivalents | $ | 1 | $ | 1 | ||
| Investments in subsidiaries, equity basis | 1,469 | 1,302 | ||||
| Other assets | 143 | 152 | ||||
| Total assets | $ | 1,613 | $ | 1,455 | ||
| Liabilities and Equity | ||||||
| Liabilities: | ||||||
| Payable to affiliates | $ | 152 | $ | 171 | ||
| Accrued expenses and other liabilities | 9 | 2 | ||||
| 161 | 173 | |||||
| Stockholders' equity: | ||||||
| Common stock, $0.01 par value per share: | ||||||
| Class A – Authorized - 1,000,000,000, Issued - 76,889,040 and 75,230,400 shares, Outstanding – 76,750,110 and 75,100,952 shares as of December 31, 2019 and 2018 | 1 | 1 | ||||
| Class B – Authorized, Issued and Outstanding – 100 shares as of December 31, 2019 and 2018 | — | — | ||||
| Additional paid-in capital | 934 | 898 | ||||
| Retained earnings | 520 | 390 | ||||
| Accumulated other comprehensive income, net of income taxes $0 and $0 as of December 31, 2019 and 2018 | — | (4) | ||||
| Treasury stock, at cost, 138,930 and 129,448 shares as of December 31, 2019 and 2018 | (3) | (3) | ||||
| Total equity | 1,452 | 1,282 | ||||
| Total liabilities and equity | $ | 1,613 | $ | 1,455 |
See accompanying notes to the condensed financial statements.
F - 2
| INTERACTIVE BROKERS GROUP, INC. | |||||||||
| (Parent Company Only) | |||||||||
| CONDENSED STATEMENTS OF COMPREHENSIVE INCOME | |||||||||
| Year-Ended December 31, | |||||||||
| (in millions) | 2019 | 2018 | 2017 | ||||||
| Income (loss) before income from subsidiaries | $ | (2) | $ | 2 | $ | 92 | |||
| Undistributed gains of subsidiaries, net | 208 | 206 | 147 | ||||||
| Income tax expense | 45 | 39 | 163 | ||||||
| Net income | $ | 161 | $ | 169 | $ | 76 | |||
| Net income available for common stockholders | $ | 161 | $ | 169 | $ | 76 | |||
| Cumulative translation adjustment, net of tax | 4 | (13) | 11 | ||||||
| Comprehensive income available for common stockholders | $ | 165 | $ | 156 | $ | 87 |
See accompanying notes to the condensed financial statements.
F - 3
| INTERACTIVE BROKERS GROUP, INC. | |||||||||
| (Parent Company Only) | |||||||||
| CONDENSED STATEMENTS OF CASH FLOWS | |||||||||
| Year-Ended December 31, | |||||||||
| (in millions) | 2019 | 2018 | 2017 | ||||||
| Cash flows from operating activities | |||||||||
| Net income | $ | 161 | $ | 169 | $ | 76 | |||
| Adjustments to reconcile net income to net cash provided by operating activities | |||||||||
| Undistributed gains of subsidiaries, net | (208) | (206) | (147) | ||||||
| Deferred income taxes | 23 | 23 | 149 | ||||||
| Gain on remeasurement of Tax Receivable Agreement liability | — | (3) | (93) | ||||||
| Changes in operating assets and liabilities | (1) | 15 | (9) | ||||||
| Net cash used in operating activities | (25) | (2) | (24) | ||||||
| Cash flows provided by investing activities | 81 | 74 | 56 | ||||||
| Cash flows used in financing activities | (60) | (58) | (43) | ||||||
| Effect of exchange rate changes on cash and cash equivalents | 4 | (13) | 11 | ||||||
| Net increase in cash and cash equivalents | — | 1 | — | ||||||
| Cash and cash equivalents at beginning of period | 1 | — | — | ||||||
| Cash and cash equivalents at end of period | $ | 1 | $ | 1 | $ | — | |||
| Supplemental disclosures of cash flow information | |||||||||
| Cash paid for interest | $ | 2 | $ | 1 | $ | — | |||
| Cash paid for taxes, net | $ | 20 | $ | 14 | $ | 13 | |||
| Non-cash investing activities: | |||||||||
| Non-cash distributions from subsidiaries | $ | — | $ | 2 | $ | — |
See accompanying notes to the condensed financial statements.
F - 4
INTERACTIVE BROKERS GROUP, INC.
(Parent Co****mpany Only)
NOTES TO CONDEN****SED FINANCIAL STATEMENTS
1. Basis of Presentation
The accompanying condensed financial statements (the “Parent Company Financial Statements”) of Interactive Brokers Group, Inc. (“IBG, Inc.”), a Delaware holding company, including the notes thereto, should be read in conjunction with the consolidated financial statements of IBG, Inc. and its subsidiaries (the “Company”) and the notes thereto. IBG, Inc.’s primary asset is its ownership interest in IBG LLC, an automated global electronic broker and market maker specializing in executing and clearing trades in securities, futures, foreign exchange instruments, bonds and mutual funds on more than 135 electronic exchanges and market centers around the world and offering custody, prime brokerage, securities and margin lending services to customers.
The preparation of the Parent Company Financial Statements in conformity with accounting principles generally accepted in the United States requires management to make estimates and assumptions that affect the reported amounts and disclosures in the condensed financial statements and accompanying notes.
Income Taxes
Refer to Note 2 to the consolidated financial statements.
2. Related Party Transactions
As of December 31, 2019, there were no receivables from affiliates. Dividends received from IBG LLC for the three years ended December 31, 2019, 2018, and 2017, were $81 million, $76 million and $56 million, respectively.
As of December 31, 2019, and 2018, respectively, payable to affiliates of $152 million and $171 million consisted primarily of amounts payable to Holdings under the Tax Receivable Agreement.
3. Stockholders’ Equity
Refer to Note 4 to the consolidated financial statements.
4. Employee Incentive Plans
Refer to Note 10 to the consolidated financial statements.
5. Commitments, Contingencies and Guarantees
Refer to Note 14 to the consolidated financial statements.
6. Subsequent Events
As required by FASB ASC Topic, “Subsequent Events,” IBG, Inc. has evaluated subsequent events for adjustment to or disclosure in its condensed financial statements through the date the condensed financial statements were issued.
Except as disclosed in Note 4 and Note 14 to the consolidated financial statements, no other recordable or disclosable events occurred.
F - 5
SIGNA****TURES
Pursuant to the requirements of Section 13 or 15(d) the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned thereunto duly authorized.
| INTERACTIVE BROKERS GROUP, INC. | ||
| /s/ Paul J. Brody | ||
| Name: | Paul J. Brody | |
| Title: | Chief Financial Officer, Treasurer and Secretary | |
| (Signing both in his capacity as a duly authorized officer and as principal financial officer of the registrant) |
Date: February 28, 2020
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed by the following persons on behalf of the registrant and in the capacities and on the dates indicated:
| Signature | Title | Date | ||
| /s/ Thomas Peterffy Thomas Peterffy | Chairman of the Board of Directors | February 28, 2020 | ||
| /s/ Milan Galik Milan Galik | Chief Executive Officer and President (Principal Executive Officer) | February 28, 2020 | ||
| /s/ Denis mendonca Denis Mendonca | Chief Accounting Officer (Principal Accounting Officer) | February 28, 2020 | ||
| /s/ Lawrence E. Harris Lawrence E. Harris | Director | February 28, 2020 | ||
| /s/ GARY KATZ Gary Katz | Director | February 28, 2020 | ||
| /s/ Philip Uhde Philip Uhde | Director | February 28, 2020 |