 filings.tools
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
296K characters. Original on sec.gov · Markdown
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
INDEX TO CONSOLIDATED FINANCIAL STATEMENTS
REPORT OF MANAGEMENT ON INTERNAL CONTROL OVER FINANCIAL REPORTING
Our management is responsible for the preparation and integrity of the consolidated financial statements appearing in our Annual Report on Form 10-K. The financial statements were prepared in conformity with generally accepted accounting principles appropriate in the circumstances and, accordingly, include certain amounts based on our best judgments and estimates.
Our management is responsible for establishing and maintaining adequate internal control over financial reporting as such term is defined in Rule 13a-15(f) and 15d-a5(f) under the Securities Exchange Act of 1934 (“Exchange Act”). Our internal control over financial reporting is designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of the consolidated financial statements. Our internal control over financial reporting is supported by a program of internal audits and appropriate reviews by management, written policies and guidelines, careful selection and training of qualified personnel and a written Global Code of Business Conduct adopted by our Board of Directors, applicable to all of our directors and all officers and all of our employees.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements and even when determined to be effective, can only provide reasonable assurance with respect to financial statement preparation and presentation. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Management assessed the effectiveness of our internal control over financial reporting as of December 31, 2022. In making this assessment, management used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission (“COSO”) in Internal Control - Integrated Framework (2013 framework). Based on our assessment, management believes that we maintained effective internal control over financial reporting as of December 31, 2022.
Our independent auditors, Ernst & Young LLP, a registered public accounting firm, are appointed by the Audit Committee, subject to ratification by our stockholders. Ernst & Young LLP has audited and reported on our consolidated financial statements and the effectiveness of our internal control over financial reporting. The reports of our independent registered public accounting firm are contained in this Annual Report.
| /s/ Jeffrey C. Sprecher | /s/ A. Warren Gardiner | |||||||
| Jeffrey C. Sprecher | A. Warren Gardiner | |||||||
| Chair and Chief Executive Officer | Chief Financial Officer | |||||||
| February 2, 2023 | February 2, 2023 |
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
ON INTERNAL CONTROL OVER FINANCIAL REPORTING
To the Stockholders and the Board of Directors of Intercontinental Exchange, Inc.
Opinion on Internal Control over Financial Reporting
We have audited Intercontinental Exchange, Inc. and Subsidiaries’ internal control over financial reporting as of December 31, 2022, based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria). In our opinion, Intercontinental Exchange, Inc. and Subsidiaries (the Company) maintained, in all material respects, effective internal control over financial reporting as of December 31, 2022, based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of the Company as of December 31, 2022 and 2021, the related consolidated statements of income, comprehensive income, changes in equity and redeemable non-controlling interest, and cash flows for each of the three years in the period ended December 31, 2022, and the related notes, and our report dated February 2, 2023 expressed an unqualified opinion thereon.
Basis for Opinion
The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying “Report of Management on Internal Control over Financial Reporting”. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects.
Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/ Ernst & Young LLP
Atlanta, Georgia
February 2, 2023
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
ON THE FINANCIAL STATEMENTS
To the Stockholders and the Board of Directors of Intercontinental Exchange, Inc.
Opinion on the Financial Statements
We have audited the accompanying consolidated balance sheets of Intercontinental Exchange, Inc. and Subsidiaries (the Company) as of December 31, 2022 and 2021, the related consolidated statements of income, comprehensive income, changes in equity and redeemable non-controlling interest, and cash flows for each of the three years in the period ended December 31, 2022, and the related notes (collectively referred to as the “consolidated financial statements”). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company at December 31, 2022 and 2021, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2022, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company’s internal control over financial reporting as of December 31, 2022, based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 Framework), and our report dated February 2, 2023 expressed an unqualified opinion thereon.
Basis for Opinion
These financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements. We believe that our audits provide a reasonable basis for our opinion.
Critical Audit Matter
The critical audit matter communicated below is a matter arising from the current period audit of the financial statements that was communicated or required to be communicated to the audit committee and that: (1) relates to accounts or disclosures that are material to the financial statements and (2) involved our especially challenging, subjective or complex judgments. The communication of the critical audit matter does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
Accounting for Income Taxes
Description of the Matter 0As discussed in Note 13 to the consolidated financial statements, the Company operates in the United States and multiple international tax jurisdictions and is therefore subject to various tax treaty arrangements and where applicable, transfer pricing guidelines for intercompany transactions. Consolidated income tax expense, including the liability for unrecognized tax benefits, is an estimate based on management’s understanding and interpretation of current enacted tax laws and tax rates of each tax jurisdiction. For the year-ended December 31, 2022, the Company recognized consolidated income tax expense of $310 million, and as of December 31, 2022, the Company accrued liabilities of $247 million for unrecognized tax benefits.
Auditing the Company's accounting for consolidated income tax expense was complex because management’s calculation of consolidated income tax expense involves application and interpretation of complex tax laws. Further, the identification and measurement of unrecognized tax benefits requires significant management judgment and estimation. Each tax position may involve unique facts and circumstances to be evaluated, and there may be uncertainties around initial recognition and de-recognition of tax positions, including regulatory changes, litigation and examination activity.
How we Addressed the
Matter in Our Audit We tested the Company’s controls that address the risks of material misstatement relating to the Company’s consolidated income tax expense. For example, we tested controls over management’s calculation of the federal, state and foreign components of income tax expense including management’s controls over the identification and ongoing review of its unrecognized tax benefits.
To test consolidated income tax expense, we performed audit procedures that included, among others, recalculation of consolidated income tax expense and agreeing the data used in the calculations to the Company’s underlying books and records. We involved our tax professionals to evaluate the application of tax law to management’s calculation methodologies and tax positions. We also evaluated assumptions the Company used to develop its tax positions and related unrecognized tax benefit amounts by jurisdiction. For example, we compared the estimated liabilities for unrecognized tax benefits to similar positions in prior periods and assessed management’s consideration of current tax controversy and litigation and trends in similar positions challenged by tax authorities. We also evaluated the adequacy of the Company’s disclosures included in Note 13 in relation to these tax matters.
/s/ Ernst & Young LLP
We have served as the Company’s auditor since 2002.
Atlanta, Georgia
February 2, 2023
Intercontinental Exchange, Inc. and Subsidiaries
Consolidated Balance Sheets
(In millions, except per share amounts)
| As of December 31, | |||||||||||
| 2022 | 2021 | ||||||||||
| Assets: | |||||||||||
| Current assets: | |||||||||||
| Cash and cash equivalents | $ | 1,799 | $ | 607 | |||||||
| Short-term restricted cash and cash equivalents | 6,149 | 1,035 | |||||||||
| Cash and cash equivalent margin deposits and guaranty funds | 141,990 | 145,936 | |||||||||
| Invested deposits, delivery contracts receivable and unsettled variation margin | 5,382 | 4,493 | |||||||||
| Customer accounts receivable, net of allowance for doubtful accounts of $22 and $24, respectively | 1,169 | 1,208 | |||||||||
| Prepaid expenses and other current assets | 458 | 1,021 | |||||||||
| Total current assets | 156,947 | 154,300 | |||||||||
| Property and equipment, net | 1,767 | 1,699 | |||||||||
| Other non-current assets: | |||||||||||
| Goodwill | 21,111 | 21,123 | |||||||||
| Other intangible assets, net | 13,090 | 13,736 | |||||||||
| Long-term restricted cash and cash equivalents | 405 | 398 | |||||||||
| Other non-current assets | 1,018 | 2,246 | |||||||||
| Total other non-current assets | 35,624 | 37,503 | |||||||||
| Total assets | $ | 194,338 | $ | 193,502 | |||||||
| Liabilities and Equity: | |||||||||||
| Current liabilities: | |||||||||||
| Accounts payable and accrued liabilities | $ | 866 | $ | 703 | |||||||
| Section 31 fees payable | 223 | 57 | |||||||||
| Accrued salaries and benefits | 352 | 354 | |||||||||
| Deferred revenue | 170 | 194 | |||||||||
| Short-term debt | 4 | 1,521 | |||||||||
| Margin deposits and guaranty funds | 141,990 | 145,936 | |||||||||
| Invested deposits, delivery contracts payable and unsettled variation margin | 5,382 | 4,493 | |||||||||
| Other current liabilities | 184 | 153 | |||||||||
| Total current liabilities | 149,171 | 153,411 | |||||||||
| Non-current liabilities: | |||||||||||
| Non-current deferred tax liability, net | 3,493 | 4,100 | |||||||||
| Long-term debt | 18,118 | 12,397 | |||||||||
| Accrued employee benefits | 160 | 200 | |||||||||
| Non-current operating lease liability | 254 | 252 | |||||||||
| Other non-current liabilities | 381 | 394 | |||||||||
| Total non-current liabilities | 22,406 | 17,343 | |||||||||
| Total liabilities | 171,577 | 170,754 | |||||||||
| Commitments and contingencies | |||||||||||
| Equity: | |||||||||||
| Intercontinental Exchange, Inc. stockholders’ equity: | |||||||||||
| Preferred stock, $0.01 par value; 100 shares authorized; none issued or outstanding | — | — | |||||||||
| Common stock, $0.01 par value; 1,500 authorized; 634 and 559 shares issued and outstanding at December 31, 2022, respectively, and 631 and 561 shares issued and outstanding at December 31, 2021, respectively | 6 | 6 | |||||||||
| Treasury stock, at cost; 75 and 70 shares at December 31, 2022 and December 31, 2021, respectively | (6,225) | (5,520) | |||||||||
| Additional paid-in capital | 14,313 | 14,069 | |||||||||
| Retained earnings | 14,943 | 14,350 | |||||||||
| Accumulated other comprehensive loss | (331) | (196) | |||||||||
| Total Intercontinental Exchange, Inc. stockholders’ equity | 22,706 | 22,709 | |||||||||
| Non-controlling interest in consolidated subsidiaries | 55 | 39 | |||||||||
| Total equity | 22,761 | 22,748 | |||||||||
| Total liabilities and equity | $ | 194,338 | $ | 193,502 |
See accompanying notes.
Intercontinental Exchange, Inc. and Subsidiaries
Consolidated Statements of Income
(In millions, except per share amounts)
| Year Ended December 31, | ||||||||||||||||||||
| 2022 | 2021 | 2020 | ||||||||||||||||||
| Revenues: | ||||||||||||||||||||
| Exchanges | $ | 6,415 | $ | 5,878 | $ | 5,839 | ||||||||||||||
| Fixed income and data services | 2,092 | 1,883 | 1,810 | |||||||||||||||||
| Mortgage technology | 1,129 | 1,407 | 595 | |||||||||||||||||
| Total revenues | 9,636 | 9,168 | 8,244 | |||||||||||||||||
| Transaction-based expenses: | ||||||||||||||||||||
| Section 31 fees | 499 | 248 | 622 | |||||||||||||||||
| Cash liquidity payments, routing and clearing | 1,845 | 1,774 | 1,586 | |||||||||||||||||
| Total revenues, less transaction-based expenses | 7,292 | 7,146 | 6,036 | |||||||||||||||||
| Operating expenses: | ||||||||||||||||||||
| Compensation and benefits | 1,407 | 1,462 | 1,188 | |||||||||||||||||
| Professional services | 131 | 159 | 144 | |||||||||||||||||
| Acquisition-related transaction and integration costs | 93 | 102 | 105 | |||||||||||||||||
| Technology and communication | 683 | 666 | 549 | |||||||||||||||||
| Rent and occupancy | 83 | 84 | 81 | |||||||||||||||||
| Selling, general and administrative | 226 | 215 | 185 | |||||||||||||||||
| Depreciation and amortization | 1,031 | 1,009 | 751 | |||||||||||||||||
| Total operating expenses | 3,654 | 3,697 | 3,003 | |||||||||||||||||
| Operating income | 3,638 | 3,449 | 3,033 | |||||||||||||||||
| Other income/(expense): | ||||||||||||||||||||
| Interest income | 108 | 1 | 10 | |||||||||||||||||
| Interest expense | (616) | (423) | (357) | |||||||||||||||||
| Other income/(expense), net | (1,322) | 2,671 | 80 | |||||||||||||||||
| Total other income/(expense), net | (1,830) | 2,249 | (267) | |||||||||||||||||
| Income before income tax expense | 1,808 | 5,698 | 2,766 | |||||||||||||||||
| Income tax expense | 310 | 1,629 | 658 | |||||||||||||||||
| Net income | $ | 1,498 | $ | 4,069 | $ | 2,108 | ||||||||||||||
| Net income attributable to non-controlling interest | (52) | (11) | (19) | |||||||||||||||||
| Net income attributable to Intercontinental Exchange, Inc. | $ | 1,446 | $ | 4,058 | $ | 2,089 | ||||||||||||||
| Earnings per share attributable to Intercontinental Exchange, Inc. common stockholders: | ||||||||||||||||||||
| Basic | $ | 2.59 | $ | 7.22 | $ | 3.79 | ||||||||||||||
| Diluted | $ | 2.58 | $ | 7.18 | $ | 3.77 | ||||||||||||||
| Weighted average common shares outstanding: | ||||||||||||||||||||
| Basic | 559 | 562 | 552 | |||||||||||||||||
| Diluted | 561 | 565 | 555 |
See accompanying notes.
Intercontinental Exchange, Inc. and Subsidiaries
Consolidated Statements of Comprehensive Income
(In millions)
| Year Ended December 31, | |||||||||||||||||
| 2022 | 2021 | 2020 | |||||||||||||||
| Net income | $ | 1,498 | $ | 4,069 | $ | 2,108 | |||||||||||
| Other comprehensive income/(loss): | |||||||||||||||||
| Foreign currency translation adjustments, net of tax benefit | (128) | (16) | 43 | ||||||||||||||
| Change in equity method investment, net of tax expense | — | 1 | — | ||||||||||||||
| Employee benefit plan net gains/(losses), net of tax benefit/(expense) | (7) | 11 | 8 | ||||||||||||||
| Other comprehensive income/(loss) | (135) | (4) | 51 | ||||||||||||||
| Comprehensive income | $ | 1,363 | $ | 4,065 | $ | 2,159 | |||||||||||
| Comprehensive income attributable to non-controlling interest | (52) | (11) | (19) | ||||||||||||||
| Comprehensive income attributable to Intercontinental Exchange, Inc. | $ | 1,311 | $ | 4,054 | $ | 2,140 |
See accompanying notes.
Intercontinental Exchange, Inc. and Subsidiaries
Consolidated Statements of Changes in Equity and Redeemable Non-Controlling Interest
(In millions)
| Intercontinental Exchange, Inc. Stockholders' Equity | Non- Controlling Interest in Consolidated Subsidiaries | Total Equity | Redeemable Non-controlling Interest | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Common Stock | Treasury Stock | Additional Paid-in Capital | Retained Earnings | Accumulated Other Comprehensive Income/(Loss) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Shares | Value | Shares | Value | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Balance, as of December 31, 2019 | 607 | $ | 6 | (53) | $ | (3,879) | $ | 11,742 | $ | 9,629 | $ | (243) | $ | 31 | $ | 17,286 | $ | 78 | |||||||||||||||||||||||||||||||||||||||||
| Impact of adoption of ASU 2016-13, net of tax | — | — | — | — | — | (10) | — | — | (10) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other comprehensive income | — | — | — | — | — | — | 51 | — | 51 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Stock consideration issued for acquisition | 18 | — | — | — | 1,895 | — | — | — | 1,895 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Exercise of common stock options | 1 | — | — | — | 31 | — | — | — | 31 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Repurchases of common stock | — | — | (14) | (1,247) | — | — | — | — | (1,247) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Payments relating to treasury shares | — | — | (1) | (74) | — | — | — | — | (74) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Stock-based compensation | — | — | — | — | 141 | — | — | — | 141 | 11 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Issuance under the employee stock purchase plan | 1 | — | — | — | 33 | — | — | — | 33 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Warrants issued to minority interest holders | — | — | — | — | 3 | — | — | — | 3 | 2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Issuance of restricted stock | 2 | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Distributions of profits | — | — | — | — | — | — | — | (31) | (31) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Dividends paid to stockholders | — | — | — | — | — | (669) | — | — | (669) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Redeemable non-controlling interest | — | — | — | — | — | — | — | — | — | 10 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Issuance of non-controlling interest | — | — | — | — | — | — | — | 9 | 9 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net income attributable to non-controlling interest | — | — | — | — | — | (19) | — | 27 | 8 | (8) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net income | — | — | — | — | — | 2,108 | — | — | 2,108 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Balance, as of December 31, 2020 | 629 | $ | 6 | (68) | $ | (5,200) | $ | 13,845 | $ | 11,039 | $ | (192) | $ | 36 | $ | 19,534 | $ | 93 | |||||||||||||||||||||||||||||||||||||||||
| Other comprehensive loss | — | — | — | — | — | — | (4) | — | (4) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Exercise of common stock options | — | — | — | — | 17 | — | — | — | 17 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Repurchases of common stock | — | — | (1) | (250) | — | — | — | — | (250) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Payments relating to treasury shares | — | — | (1) | (70) | — | — | — | — | (70) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Stock-based compensation | — | — | — | — | 168 | — | — | — | 168 | 27 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Issuance under the employee stock purchase plan | — | — | — | — | 42 | — | — | — | 42 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Issuance of restricted stock | 2 | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Distributions of profits | — | — | — | — | — | — | — | (21) | (21) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Dividends paid to stockholders | — | — | — | — | — | (747) | — | — | (747) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Bakkt deconsolidation adjustment | — | — | — | — | (3) | — | — | — | (3) | (107) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net income attributable to non-controlling interest | — | — | — | — | — | (11) | — | 24 | 13 | (13) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net income | — | — | — | — | — | 4,069 | — | — | 4,069 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Balance, as of December 31, 2021 | 631 | $ | 6 | (70) | $ | (5,520) | $ | 14,069 | $ | 14,350 | $ | (196) | $ | 39 | $ | 22,748 | $ | — | |||||||||||||||||||||||||||||||||||||||||
| Other comprehensive loss | — | — | — | — | — | — | (135) | — | (135) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Exercise of common stock options | — | — | — | — | 22 | — | — | — | 22 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Repurchases of common stock | — | — | (4) | (632) | — | — | — | — | (632) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Payments relating to treasury shares | — | — | (1) | (73) | — | — | — | — | (73) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Stock-based compensation | — | — | — | — | 172 | — | — | — | 172 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Issuance under the employee stock purchase plan | 1 | — | — | — | 50 | — | — | — | 50 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Issuance of restricted stock | 2 | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Distributions of profits | — | — | — | — | — | — | — | (36) | (36) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Dividends paid to stockholders | — | — | — | — | — | (853) | — | — | (853) | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net income/(loss) attributable to non-controlling interest | — | — | — | — | — | (52) | — | 52 | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net income | — | — | — | — | — | 1,498 | — | — | 1,498 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Balance, as of December 31, 2022 | 634 | $ | 6 | (75) | $ | (6,225) | $ | 14,313 | $ | 14,943 | $ | (331) | $ | 55 | $ | 22,761 | $ | — |
See accompanying notes.
Intercontinental Exchange, Inc. and Subsidiaries
Consolidated Statements of Cash Flows
(In millions)
| Year Ended December 31, | ||||||||||||||||||||
| 2022 | 2021 | 2020 | ||||||||||||||||||
| Operating activities: | ||||||||||||||||||||
| Net income | $ | 1,498 | $ | 4,069 | $ | 2,108 | ||||||||||||||
| Adjustments to reconcile net income to net cash provided by operating activities: | ||||||||||||||||||||
| Depreciation and amortization | 1,031 | 1,009 | 751 | |||||||||||||||||
| Stock-based compensation | 155 | 188 | 139 | |||||||||||||||||
| Deferred taxes | (593) | 537 | 92 | |||||||||||||||||
| Gain on deconsolidation of Bakkt | — | (1,419) | — | |||||||||||||||||
| Gains on equity investments | (41) | (1,261) | (55) | |||||||||||||||||
| Net losses/(income) from and impairment of unconsolidated investees | 1,340 | 42 | (71) | |||||||||||||||||
| Other | 41 | 45 | 46 | |||||||||||||||||
| Changes in assets and liabilities: | ||||||||||||||||||||
| Customer accounts receivable | 20 | (5) | (149) | |||||||||||||||||
| Other current and non-current assets | (196) | (100) | (83) | |||||||||||||||||
| Section 31 fees payable | 166 | (150) | 69 | |||||||||||||||||
| Deferred revenue | (27) | 34 | 2 | |||||||||||||||||
| Other current and non-current liabilities | 160 | 134 | 32 | |||||||||||||||||
| Total adjustments | 2,056 | (946) | 773 | |||||||||||||||||
| Net cash provided by operating activities | 3,554 | 3,123 | 2,881 | |||||||||||||||||
| Investing activities: | ||||||||||||||||||||
| Capital expenditures | (225) | (179) | (207) | |||||||||||||||||
| Capitalized software development costs | (257) | (273) | (203) | |||||||||||||||||
| Cash paid for acquisitions, net of cash acquired | (59) | (66) | (9,446) | |||||||||||||||||
| Purchases of equity and equity method investments | (73) | (117) | — | |||||||||||||||||
| Proceeds from the sales of equity investments | 741 | 1,237 | — | |||||||||||||||||
| Proceeds from other investments, net | 2 | 1 | 4 | |||||||||||||||||
| Purchases of invested margin deposits | (6,935) | (5,050) | (3,371) | |||||||||||||||||
| Proceeds from sales of invested margin deposits | 7,483 | 3,661 | 2,840 | |||||||||||||||||
| Other | — | — | 22 | |||||||||||||||||
| Net cash used in investing activities | 677 | (786) | (10,361) | |||||||||||||||||
| Financing activities: | ||||||||||||||||||||
| Proceeds from debt offerings, net | 7,891 | — | 9,606 | |||||||||||||||||
| Repayments of debt | (2,705) | (1,246) | (2,004) | |||||||||||||||||
| Proceeds from/(redemption of) commercial paper, net | (1,012) | (1,393) | 1,094 | |||||||||||||||||
| Repurchases of common stock | (632) | (250) | (1,247) | |||||||||||||||||
| Dividends to stockholders | (853) | (747) | (669) | |||||||||||||||||
| Change in cash and cash equivalent margin deposits and guaranty funds | (4,493) | 65,697 | 19,256 | |||||||||||||||||
| Payments relating to treasury shares received for restricted stock tax payments and stock option exercises | (73) | (70) | (74) | |||||||||||||||||
| Other | 36 | 35 | 38 | |||||||||||||||||
| Net cash provided by/(used in) financing activities | (1,841) | 62,026 | 26,000 | |||||||||||||||||
| Effect of exchange rate changes on cash, cash equivalents, restricted cash and cash equivalents, and cash and cash equivalent margin deposits and guaranty funds | (23) | (6) | 8 | |||||||||||||||||
| Net increase in cash, cash equivalents, restricted cash and cash equivalents, and cash and cash equivalent margin deposits and guaranty funds | 2,367 | 64,357 | 18,528 | |||||||||||||||||
| Cash, cash equivalents, restricted cash and cash equivalents and cash and cash equivalent margin deposits and guaranty funds at beginning of year | 147,976 | 83,619 | 65,091 | |||||||||||||||||
| Cash, cash equivalents, restricted cash and cash equivalents and cash and cash equivalent margin deposits and guaranty funds at end of year | $ | 150,343 | $ | 147,976 | $ | 83,619 | ||||||||||||||
| Supplemental cash flow disclosures: | ||||||||||||||||||||
| Common stock issued for acquisition | $ | — | $ | — | $ | 1,895 | ||||||||||||||
| Cash paid for income taxes | $ | 882 | $ | 1,057 | $ | 642 | ||||||||||||||
| Cash paid for interest | $ | 550 | $ | 406 | $ | 298 |
See accompanying notes.
Intercontinental Exchange, Inc. and Subsidiaries
Notes to Consolidated Financial Statements
**1.**Description of Business
Nature of Business and Organization
Intercontinental Exchange, Inc. is a provider of market infrastructure, data services and technology solutions to a broad range of customers including financial institutions, corporations and government entities. These products, which span major asset classes including futures, equities, fixed income and United States, or U.S., residential mortgages, provide our customers with access to mission critical tools that are designed to increase asset class transparency and workflow efficiency. Our business is conducted through three reportable business segments:
-
Exchanges: We operate regulated marketplaces for the listing, trading and clearing of a broad array of derivatives contracts and financial securities.
-
Fixed Income and Data Services: We provide fixed income pricing, reference data, indices, analytics and execution services as well as global credit default swap, or CDS, clearing and multi-asset class data delivery solutions.
-
Mortgage Technology: We provide a technology platform that offers customers comprehensive, digital workflow tools that aim to address the inefficiencies that exist in the U.S. residential mortgage market, from application through closing and the secondary market.
We operate marketplaces, technology and provide data services in the U.S., United Kingdom, or U.K., European Union, or EU, Canada, Asia Pacific and the Middle East.
**2.**Summary of Significant Accounting Policies
Basis of Presentation
The accompanying consolidated financial statements have been prepared by us in accordance with U.S. generally accepted accounting principles, or U.S. GAAP. These statements include the accounts of our wholly-owned and controlled subsidiaries. For consolidated subsidiaries in which our ownership is less than 100% and for which we have control over the assets and liabilities and the management of the entity, the outside stockholders’ interests are shown as non-controlling interests.
All intercompany balances and transactions between us and our wholly-owned and controlled subsidiaries have been eliminated in consolidation. The financial results of companies we acquire are included from the acquisition dates and the results of companies we sold are included up to the disposition dates. The accounting policies used to prepare these financial statements are the same as those used to prepare the consolidated financial statements in prior years.
Use of Estimates
Preparing financial statements in conformity with U.S. GAAP requires us to make certain estimates and assumptions that affect the amounts reported in our consolidated financial statements and accompanying disclosures. Actual amounts could differ from those estimates.
Comprehensive Income
Other comprehensive income includes foreign currency translation adjustments, comprehensive income from a change in an equity method investment, and amortization of the difference in the projected benefit obligation and the accumulated benefit obligation associated with benefit plan liabilities, each of which is net of tax.
Segment and Geographic Information
As of December 31, 2022, our business is conducted through three reportable business segments: Exchanges, Fixed Income and Data Services, and Mortgage Technology. This presentation is reflective of how our chief operating decision maker reviews and operates our business. The majority of our identifiable assets are located in the U.S and U.K. (see Note 19).
Cash and Cash Equivalents, Short-Term and Long-Term Restricted Cash and Cash Equivalents, and Cash and Cash Equivalent Margin Deposits and Guaranty Funds
Cash and Cash Equivalents
We consider all short-term, highly liquid investments with maturities of three months or less at the time of purchase to be cash equivalents.
Short-Term and Long-Term Restricted Cash and Cash Equivalents
We classify all cash and cash equivalents that are not available for immediate or general business use by us as restricted in the accompanying consolidated balance sheets (see Note 7). This includes amounts set aside due to regulatory requirements, earmarked for specific purposes, or restricted by specific agreements. We also invest a portion of funds in excess of short-term operating needs in term deposits and investment-grade marketable debt securities, including government or government-sponsored agencies and corporate debt securities. These are classified as cash equivalents, are short-term in nature and carrying amount approximates fair value.
Cash and Cash Equivalent Margin Deposits and Guaranty Funds (Cash and Cash Equivalent Margin)
Original margin, variation margin and guaranty funds received by our clearing houses may be in the form of cash, government obligations, certain agency debt, letters of credit or on rare occasions, gold (see Note 14). We hold the cash deposits at central banks, highly-rated financial institutions or at times secure the cash through reverse repurchase agreements or direct investments, certain of which are not cash equivalents. See "Credit Risk and Significant Customers", below. Although not included in short term restricted cash and cash equivalents, cash and cash equivalent margin represent a form of restricted cash, and exclude invested deposits, delivery contracts receivable and unsettled variation margin since those amounts represent invested cash and not a form of restricted cash.
Consolidated Statement of Cash Flows Presentation
A reconciliation of the components of cash and cash equivalents, restricted cash and cash equivalents, and cash and cash equivalent margin deposits and guaranty funds as presented in the consolidated statements of cash flows to the balance sheet is as follows (in millions):
| As of December 31, 2022 | As of December 31, 2021 | As of December 31, 2020 | |||||||||||||||
| Cash and cash equivalents | $ | 1,799 | $ | 607 | $ | 583 | |||||||||||
| Short-term restricted cash and cash equivalents | 6,149 | 1,035 | 1,000 | ||||||||||||||
| Long-term restricted cash and cash equivalents | 405 | 398 | 408 | ||||||||||||||
| Cash and cash equivalent margin deposits and guaranty funds | 141,990 | 145,936 | 81,628 | ||||||||||||||
| Total | $ | 150,343 | $ | 147,976 | $ | 83,619 |
Investments
We have made various investments in the equity securities of other companies. We also invest in mutual funds and fixed income securities. We classify all other investments that are not cash equivalents with original maturity dates of less than one year as short-term investments and all investments that we intend to hold for more than one year as long-term investments. Short-term and long-term investments are included in other current and other non-current assets, respectively, in the accompanying consolidated balance sheets.
Equity Investments
Investments in equity securities, or equity investments, are carried at fair value and included in other non-current assets, with changes in fair value, whether realized or unrealized, recognized in net income. For those investments that we do not control and which do not have readily determinable fair market values, such as those which are not publicly-listed companies, we have made a fair value policy election under Accounting Standards Update, or ASU, No. 2016-01, Financial Instruments - Overall (Subtopic 825-10): Recognition and Measurement of Financial Assets and Financial Liabilities, or ASU 2016-01. The election requires us to only adjust the fair value of such investments if and when there is an observable price change in an orderly transaction of a similar or identical investment, with any change in fair value recognized in net income.
Equity Method Investments
When we do not have a controlling financial interest in an entity but exercise significant influence over the entity’s operating and financial policies, such investments are accounted for using the equity method and included in other non-current assets. We recognize dividends when declared as a reduction in the carrying value of our equity method investments. We evaluate our equity method investments for impairment whenever events or changes in circumstances indicate that a decline in value has occurred that is other than temporary. If the investment is determined to have a decline in value deemed to be other than temporary it is written down to estimated fair value. Other than the impairment of our equity method investment in Bakkt (see Note 4), we did not record any other impairment charges on our equity method investments as of December 31, 2022.
Property and Equipment
Property and equipment is recorded at cost, reduced by accumulated depreciation (see Note 8). Depreciation and amortization is computed using the straight-line method based on estimated useful lives of the assets, or in the case of leasehold improvements, the shorter of the lease term or the estimated useful life of the improvement. We review the remaining estimated useful lives at each balance sheet date and make adjustments whenever events or changes in circumstances indicate that the remaining useful lives have changed. Gains on disposals are included in other income and losses on disposals are included in depreciation expense. Maintenance and repair costs are expensed as incurred.
Allowance for Doubtful Accounts
Under ASU 2016-13, Financial Instruments - Measurement of Credit Losses on Financial Instruments, or ASU 2016-13, we estimate our allowance for doubtful accounts using an aging method, disaggregated based on major revenue stream categories as well as other unique revenue stream factors. The allowance for doubtful accounts is maintained at a level that we believe to be sufficient to absorb probable losses over the expected life in our accounts receivable portfolio. The allowance is based on several factors, including continuous assessments of risk characteristics, specific customer events that may impact its ability to meet its financial obligations, and other reasonable and supportable economic characteristics. Accounts receivable are written-off against the allowance for doubtful accounts when collection efforts cease.
Software Development Costs
We capitalize costs related to software we develop or obtain for internal use*.* The costs capitalized include both internal and external direct and incremental costs. General and administrative costs related to developing or obtaining such software are expensed as incurred. Development costs incurred during the preliminary or maintenance project stages are expensed as incurred. Costs incurred during the application development stage are capitalized and amortized using the straight-line method over the useful life of the software, generally not exceeding three years (except for certain ICE Data Services, ICE Mortgage Technology and NYSE platforms, which have seven-year useful lives). Amortization begins when the software is ready for its intended use.
Accrued Employee Benefits
We have a defined benefit pension plan and other postretirement benefit plans, or collectively the “benefit plans,” covering certain of our U.S. operations. The benefit accrual for the pension plan is frozen. We recognize the funded status of the benefit plans in our consolidated balance sheets, measure the fair value of plan assets and benefit obligations as of the date of our fiscal year-end, and provide additional disclosures in the footnotes (see Note 17).
Benefit plan costs and liabilities are dependent on assumptions used in calculating such amounts. These are provided by a third-party specialist and include discount rates, health care cost trend rates, benefits earned, interest cost, expected return on assets, mortality rates and other factors. Actual results that differ from the assumptions are accumulated and amortized over future periods and, therefore, generally affect recognized expense and the recorded obligation in future periods. However, certain of these unrecognized amounts are recognized when triggering events occur, such as when a settlement of pension obligations in excess of total interest and service costs occurs. While we believe that the assumptions used are appropriate, differences in actual experience or changes in assumptions may affect our pension and other post-retirement obligations and future expense recognized.
Goodwill and Indefinite-Lived Intangible Assets
Goodwill represents the excess of the purchase price of our acquisitions over the fair value of identifiable net assets acquired, including other identified intangible assets (see Note 9). We recognize specifically-identifiable intangibles when a specific right or contract is acquired. That value is determined with the assistance of third-party valuation specialists.
Goodwill has been allocated to our reporting units for purposes of impairment testing based on the portion of synergy, cost savings and other expected future cash flows expected to benefit the reporting units at the time of the acquisition. The reporting units identified for our goodwill testing are: the NYSE, Other Exchanges, Fixed Income and Data Services, and Mortgage Technology. Goodwill impairment testing is performed annually at the reporting unit level in the fiscal fourth quarter or more frequently if conditions exist that indicate that it may be impaired, or if changes are made to the reporting units.
We also evaluate indefinite-lived intangible assets for impairment annually in our fiscal fourth quarter or more frequently if conditions exist that indicate that an asset may be impaired.
For both goodwill and indefinite-lived impairment testing we have the option to first perform a qualitative assessment to determine whether it is more likely than not that the fair value of a reporting unit or indefinite lived intangible asset is less than its carrying amount. If the fair value of the reporting unit or indefinite-lived intangible asset is less than its carrying value, an impairment loss is recognized in earnings in an amount equal to the difference. Alternatively, we may choose to bypass the qualitative option and perform quantitative testing to determine if the fair value is less than carrying value. For our goodwill impairment testing, we have elected to bypass the qualitative assessment and apply the quantitative approach. For our testing of indefinite-lived intangible assets, we apply qualitative and quantitative approaches.
Long-Lived Assets and Finite-Lived Intangible Assets
We review our long-lived and finite-lived intangible assets for impairment whenever events or changes in circumstances indicate that the carrying amount may not be fully recoverable. When these indicators exist, we project undiscounted net future cash flows over the remaining life of such assets. If the sum of the projected cash flows is less than the carrying amount, an impairment would exist, measured based upon the difference between the carrying amount and the fair value of the assets. Finite-lived intangible assets are generally amortized using the straight-line method or an accelerated method over the lesser of their contractual or estimated useful lives.
All costs related to internally developed patents and trademarks are expensed as incurred. All costs related to purchased patents, trademarks and internet domain names are recorded as other intangible assets and are amortized using a straight-line method over their estimated useful lives. All costs related to licensed patents are capitalized and amortized using a straight-line method over the term of the license.
Derivatives and Hedging Activity
Periodically, we may use derivative financial instruments to manage exposure to changes in currency exchange rates. All derivatives are recorded at fair value. We generally do not designate these derivatives as hedges for accounting purposes. Accordingly, changes in fair value are recognized in income.
We entered into foreign currency hedging transactions during 2022, 2021 and 2020 as economic hedges to help mitigate a portion of our foreign exchange risk exposure. The gains and losses on these transactions were not material during these years.
Income Taxes
We recognize income taxes under the liability method. We recognize a current tax liability or tax asset for the estimated taxes payable or refundable on tax returns for the current year. We recognize deferred tax assets and liabilities for the expected future tax consequences of temporary differences between the financial statement carrying amounts and the tax bases of assets and liabilities. We establish valuation allowances if we believe that it is more likely than not that some or all of our deferred tax assets will not be realized. Deferred tax assets and liabilities are measured using current enacted tax rates in effect. We do not recognize a tax benefit unless we conclude that it is more likely than not that the benefit will be sustained on audit by the taxing authority based solely on the technical merits of the associated tax position. If the recognition threshold is met, we recognize a tax benefit measured at the largest amount of the tax benefit that, in our judgment, is greater than 50 percent likely to be realized. We recognize accrued interest and penalties related to uncertain tax positions as a component of income tax expense. We recognize the tax effects related to Global Intangible Low-Taxed Income in the period it is incurred.
We are subject to tax in numerous domestic and foreign jurisdictions primarily based on our operations in these jurisdictions. Significant judgment is required in assessing the future tax consequences of events that have been recognized in our financial statements or tax returns. Fluctuations in the actual outcome of these future tax consequences could have a material impact on our financial position or results of operations.
We use a portfolio approach with respect to pension, postretirement benefits plan obligations and currency translation matters when we determine the timing and extent to which stranded income tax effects from items that were previously recorded in accumulated other comprehensive income are released.
Revenue Recognition
Our revenues primarily consist of revenues for transactions executed and/or cleared through our global electronic derivatives trading and clearing exchanges and cash equities trading as well as revenues related to our fixed income, data services, mortgage technology services and listings. We recognize revenue when we transfer promised goods or services to customers in an amount that reflects the consideration to which we expect to be entitled in exchange for those goods or services. We enter into contracts that can include various combinations of products and services, which are generally capable of being distinct and accounted for as separate performance obligations. We also evaluate all contracts in order to determine appropriate gross versus net revenue reporting.
Substantially all of our revenues are considered to be revenues from contracts with customers. The related accounts receivable balances are recorded in our balance sheets as customer accounts receivable. We do not have obligations for warranties, returns or refunds to customers, other than rebates, which are settled each period and therefore do not result in variable consideration. We do not have significant revenue recognized from performance obligations that were satisfied in prior periods, and we do not have any transaction price allocated to unsatisfied performance obligations other than in our deferred revenue. Certain judgments and estimates are used in the identification and timing of satisfaction of performance obligations and the related allocation of transaction price. We believe that these represent a faithful depiction of the transfer of services to our customers.
Deferred revenue represents our contract liabilities related to our annual, original and other listings revenues, certain data services, clearing services, mortgage technology services and other revenues. Deferred revenue is our only significant contract asset or liability. See Note 6 for our discussion of deferred revenue balances, activity, and expected timing of recognition.
We have elected not to provide disclosures about transaction price allocated to unsatisfied performance obligations if contract durations are less than one year, or if we are not required to estimate the transaction price. For all of our contracts with customers, except for listings and certain data, mortgage and clearing services, our performance obligations are short term in nature and there is no significant variable consideration. In addition, we have elected the practical expedient of excluding sales taxes from transaction prices. We have assessed the costs incurred to obtain or fulfill a contract with a customer and determined them to be immaterial.
Activity Assessment Fees and Section 31 Fees
We pay the Securities and Exchange Commission, or SEC, fees pursuant to Section 31 of the Securities Exchange Act of 1934 for transactions executed on our U.S. equities and options exchanges. These Section 31 fees are designed to recover the costs to the government for supervising and regulating the securities markets and securities professionals. We (or the Options Clearing Corporation, or OCC, on our behalf), in turn, collect activity assessment fees, which are included in exchanges revenues in the accompanying consolidated statements of income, from member organizations clearing or settling trades on the U.S. equities and options exchanges and recognize these amounts as revenue. Fees received are included in cash at the time of receipt and, as required by law, the amount due to the SEC is remitted semi-annually and recorded as an accrued liability until paid. The activity assessment fees are designed so that they are equal to the Section 31 fees paid by us to the SEC. As a result, Section 31 fees do not have an impact on our net income.
Stock-Based Compensation
We currently sponsor stock option plans, restricted stock plans and our Employee Stock Purchase Plan, or ESPP, to provide additional and incentive-based compensation to our employees and directors (see Note 11). Stock options and restricted stock are granted at the discretion of the Compensation Committee of the Board of Directors. We measure and recognize compensation expense for share-based payment awards, including employee stock options, restricted stock and shares purchased under the ESPP based on estimated fair values on the date of grant. The value of the portion of the award that is ultimately expected to vest is recognized as stock-based compensation expense over the requisite service period.
We use the Black-Scholes pricing model to value stock option awards as well as shares purchased as part of our ESPP. The values estimated by the model are affected by the price of our stock as well as subjective variables that include assumed interest rates, our expected dividend yield, our expected share price volatility over the term of the awards and actual and projected employee stock option exercise behavior. Under our ESPP, employees may purchase shares of our
common stock at a price equal to 85% of the lesser of the fair market value of the stock on the first or the last trading day of each offering period. We record compensation expenses related to the discount given to our participating employees.
Treasury Stock
We record treasury stock activities under the cost method whereby the cost of the acquired stock is recorded as treasury stock (see Note 12). In the event it occurs in the future, our accounting policy upon the formal retirement of treasury stock is to deduct the par value from common stock and to reflect any excess of cost over par value as a deduction from additional paid-in capital (to the extent created by previous issuances of the shares) and retained earnings.
Credit Risk and Significant Customers
Our clearing houses are exposed to credit risk as a result of maintaining clearing member cash deposits at various financial institutions (see Note 14). Cash deposit accounts are established at large, highly-rated financial institutions and entered into so that they restrict the rights of offset or imposition of liens by the banks. We also limit our risk of loss by holding the majority of the cash deposits in cash accounts at the Federal Reserve Bank of Chicago, high quality short-term sovereign debt reverse repurchase agreements with several different counterparty banks or direct investments in short-term high quality sovereign and supranational debt issues primarily with original maturities of less than three months. While we seek to achieve a reasonable rate of return which may generate interest income for our clearing members, we are primarily concerned with preservation of capital and managing the risks associated with these deposits. As the clearing houses may pass on interest revenues, minus costs, to the members, this could include negative or reduced yield due to market conditions.
When engaging in reverse repurchase agreements, our clearing houses take delivery of the underlying securities in custody accounts under clearing house control. Additionally, the securities purchased have a market value greater than the reverse repurchase amount. The typical haircut received for high quality sovereign debt is 2% of the reverse repurchase amount. Thus, in the event that a reverse repurchase counterparty defaults on its obligation to repurchase the underlying reverse repurchase securities, our clearing house will have possession of securities with a value potentially greater than the reverse repurchase counterparty’s obligation to the clearing house.
ICE Clear Credit, a systemically important financial market utility as designated by the Financial Stability Oversight Council, maintains a U.S. dollar account at the Federal Reserve Bank of Chicago as of December 31, 2022. ICE Clear Europe maintains a euro-denominated account at the European Central Bank, or ECB, the central bank of the Netherlands, as well as pounds sterling- and euro-denominated accounts at the Bank of England, or BOE, the central bank of the U.K. These accounts provide the flexibility for ICE Clear Europe to place euro- and pounds sterling-denominated cash margin securely at national banks, in particular during periods when liquidity in the euro and pounds sterling repo markets may temporarily become contracted. Such accounts are intended to decrease ICE Clear Credit and ICE Clear Europe’s custodial, liquidity and operational risk as compared to alternative custodial and investment arrangements.
Our futures businesses have minimal credit risk as the majority of their transaction revenues are currently cleared through our clearing houses. Our accounts receivable related to fixed income and data services revenues, cash trading, listing revenues, technology revenues, CDS and bilateral over-the-counter, or OTC, energy transaction revenues and mortgage technology services subjects us to credit (collection) risk, as we do not require these customers to post collateral. We limit our risk of loss by terminating a customer's ability to remain listed or receive data or terminating other services for entities with delinquent accounts. The concentration of risk on accounts receivable is also mitigated by the large number of entities comprising our customer base. Excluding clearing members, there were no individual accounts receivable balances greater than 10% of total consolidated accounts receivable as of December 31, 2022 or December 31, 2021. Our accounts receivable are stated at the billed amount.
Leases
We record our leases in accordance with ASU No. 2016-02, Leases, or ASU 2016-02. This standard requires recognition of both assets and liabilities arising from finance and operating leases, along with additional qualitative and quantitative disclosures. ASU 2016-02 requires lessees to recognize a right-of-use asset representing a right to use the underlying asset over the lease term, and a corresponding lease liability on the balance sheet. Operating lease right-of-use assets and liabilities are recorded at the lease commencement date based on the present value of the lease payments to be made over the lease term using its incremental borrowing rate based on the information available at the lease commencement date. As the rate implicit in the lease is not readily determinable in most of our leases, we use our incremental borrowing rate based on the information available at the commencement date in determining the present value of lease payments. Rent expense is recognized on a straight-line basis over the lease term. Rent expense is
included in rent and occupancy expenses and technology and communication expenses in the accompanying consolidated statements of income (see Note 15).
Acquisition-Related Transaction and Integration Costs
We incur incremental costs relating to our completed and potential acquisitions and other strategic opportunities. This includes fees for investment banking advisors, lawyers, accountants, tax advisors and public relations firms, as well as costs associated with credit facilities and other external costs directly related to the proposed or closed transactions. In accordance with ASC 805, Business Combinations, acquisition-related transaction and integration costs, excluding costs to issue debt or equity securities, are expensed in the period in which these costs are incurred and the services are received and are not included in the purchase price.
The acquisition-related transaction and integration costs incurred during 2022 are primarily due to legal and consulting expenses related to our pending acquisition of Black Knight and our integration of Ellie Mae. The acquisition-related transaction and integration costs incurred during 2021 are primarily related to our integration of Ellie Mae and the Bakkt transaction. The acquisition-related transaction and integration costs incurred during 2020 primarily relate to costs incurred for our acquisitions of Ellie Mae and Bridge2 Solutions (see Note 3).
Fair Value of Financial Instruments
Fair value is the price that would be received from selling an asset or paid to transfer a liability (an exit price) in the principal or most advantageous market for the asset or liability in an orderly transaction between market participants at the measurement date. Our financial instruments consist primarily of certain short-term and long-term assets and liabilities, customer accounts receivable, margin deposits and guaranty funds, equity and equity method investments, and short-term and long-term debt (see Note 18).
The fair value of our financial instruments is measured based on a three-level hierarchy:
-
Level 1 inputs** — quoted prices for identical assets or liabilities in active markets.
-
Level 2 inputs** — observable inputs other than Level 1 inputs such as quoted prices for similar assets and liabilities in active markets or inputs other than quoted prices that are directly observable.
-
Level 3 inputs** — unobservable inputs supported by little or no market activity and that are significant to the fair value of the assets or liabilities.
Foreign Currency Translation Adjustments and Foreign Currency Transaction Gains and Losses
Our functional and reporting currency is the U.S. dollar. We have exposure to foreign currency translation gains and losses arising from our net investment in certain U.K., continental European, Asian and Canadian subsidiaries. The revenues, expenses and financial results of these subsidiaries are recorded in the functional currency of the countries that these subsidiaries are located in, which are primarily pounds sterling and euros. The financial statements of these subsidiaries are translated into U.S. dollars using a current rate of exchange, with gains or losses, net of tax as applicable, included in the cumulative translation adjustment account, a component of equity. As of December 31, 2022 and 2021, the portion of our equity attributable to accumulated other comprehensive loss from foreign currency translation adjustments was $278 million and $150 million, respectively.
We have foreign currency transaction gains and losses related to the settlement of foreign currency denominated assets, liabilities and payables that occur through our operations. These transaction gains and losses are due to the increase or decrease in the foreign currency exchange rates between periods. Forward contracts on foreign currencies are entered into to manage the foreign currency exchange rate risk. Gains and losses from foreign currency transactions are included in other income/(expense) in the accompanying consolidated statements of income and resulted in net losses of $9 million, $13 million and $5 million in 2022, 2021 and 2020, respectively.
Earnings Per Common Share
Basic earnings per common share is calculated using the weighted average common shares outstanding during the year. Common equivalent shares from stock options and restricted stock awards, using the treasury stock method, are included in the diluted per share calculations unless the effect of inclusion would be antidilutive (see Note 20).
Recently Adopted Accounting Pronouncements
| Standard/Description | Effective Date and Adoption Considerations | Effect on Financial Statements | ||||||
| ASU 2021-08*, Business Combinations (Topic 805), Accounting for Contract Assets and Contract Liabilities from Contracts with Customers,* requires the recognition and measurement of contract assets and contract liabilities acquired in a business combination in accordance with ASC 606, Revenue from Contracts with Customers. Considerations to determine the amount of contract assets and contract liabilities to record at the acquisition date include the terms of the acquired contract, such as timing of payment, identification of each performance obligation in the contract and allocation of the contract transaction price to each identified performance obligation on a relative standalone selling price basis as of contract inception. This standard is effective beginning in the first quarter of 2023 and should be applied prospectively for acquisitions occurring on or after the effective date of the amendment, with early adoption permitted. | We adopted this standard early as of December 31, 2022. | We evaluated this guidance to determine the impact on our consolidated financial statements. Based on our assessment, we concluded the impact of adoption of this guidance was not material. | ||||||
| ASU No. 2016-13, Financial Instruments - Measurement of Credit Losses on Financial Instruments, applies to all financial instruments carried at amortized cost including held-to-maturity debt securities and accounts receivable. It requires financial assets carried at amortized cost to be presented at the net amount expected to be collected and requires entities to record credit losses through an allowance for credit losses on available-for-sale debt securities. | We adopted on January 1, 2020 on a modified retrospective basis. | We evaluated this guidance to determine the impact on our consolidated financial statements. Based on our assessment, we concluded the impact of adoption of this guidance was not material. Further disclosures and details on our adoption are discussed below. | ||||||
| ASU 2017-04, Simplifying the Test for Goodwill Impairment, removes the second step of the goodwill impairment test, which requires a hypothetical purchase price allocation if the fair value of a reporting unit is less than its carrying value. Goodwill impairment will now be measured using the difference between the carrying value and the fair value of the reporting unit, and any loss recognized should not exceed the total amount of goodwill allocated to that reporting unit. | We adopted on January 1, 2020 on a prospective basis. | We evaluated this guidance to determine the impact on our consolidated financial statements. Based on our assessment, we concluded the impact of adoption of this guidance was not material. The fair values of our reporting units have been greater than their corresponding carrying values in recent years. Changes in future projections, market conditions, and other factors may cause a change in the excess of fair value of our reporting units over their corresponding carrying values. |
| Standard/Description | Effective Date and Adoption Considerations | Effect on Financial Statements | ||||||
| ASU 2018-15, Customer's Accounting for Implementation Costs Incurred in a Cloud Computing Arrangement that is a Service Contract, helps entities evaluate the accounting for fees paid by a customer in a cloud computing arrangement by providing guidance for determining when an arrangement includes a software license and is solely a hosted service. Customers will now apply the same criteria for capitalizing implementation costs as they would for a software license arrangement. The guidance also prescribes the balance sheet, income statement, and cash flow classification of the capitalized implementation costs and related amortization expense, and requires additional quantitative and qualitative disclosures. | We adopted on January 1, 2020 and apply the rules prospectively to eligible costs incurred on or after the effective date. | We evaluated this guidance to determine the impact on our consolidated financial statements. Based on our assessment, we concluded the impact of adoption of this guidance was not material. | ||||||
| ASU No. 2019-12, Simplifying the Accounting for Income Taxes, eliminates certain exceptions related to the approach for intraperiod tax allocation, the methodology for calculating income taxes in an interim period and the recognition of deferred tax liabilities for outside basis differences. It clarifies that single-member limited liability companies, and other similar disregarded entities that are not subject to income tax, are not required to recognize an allocation of consolidated income tax expense in their separate financial statements. Further, it simplifies the accounting for franchise taxes, enacted changes in tax laws or rates and transactions that result in a step-up in the tax basis of goodwill. | Effective for fiscal years beginning after December 15, 2020 with early adoption permitted. We elected early adoption and adopted on January 1, 2020. | We evaluated this guidance to determine the impact on our consolidated financial statements. Based on our assessment, we concluded the impact of adoption of this guidance was not material. | ||||||
We do not currently expect that any pending accounting pronouncements will have a material impact on our financial statements.
Adoption of ASU 2016-13, Financial Instruments - Measurement of Credit Losses on Financial Instruments
On January 1, 2020, we adopted ASU 2016-13 using the modified retrospective approach through a cumulative-effect adjustment of $10 million, net of tax, to retained earnings. ASU 2016-13 primarily impacted the calculation of our allowance for doubtful accounts on accounts receivable utilizing the expected credit losses model. We do not currently hold available-for-sale debt securities, off-balance-sheet credit exposures, or other material financial assets impacted by the standard, besides those mentioned below.
We consider our material financial assets within scope, including our cash equivalents, short-term and long-term restricted cash equivalents as well as our clearing members' cash equivalent and reverse repurchase receivables, and determined that such assets have a de minimis risk of credit loss. We invest our cash and clearing members' cash by placing it in highly-rated government securities, primarily U.S. Treasury securities and other sovereign debt with original maturities of less than three months which we consider to be cash equivalents, or into reverse repurchase agreements, referred to as reverse repos, with primarily overnight maturities. Reverse repos are valued daily and are subject to collateral maintenance provisions whereby the counterparty must provide additional collateral if the value of the underlying securities lose value, in an amount sufficient to maintain collateralization of at least 102%. Therefore, as of and for the year ended December 31, 2022 we have not recorded a credit loss for these financial assets.
Based on the high turnover and collectability of our accounts receivable, the mitigated default and concentration risks due to the high quality and large number of entities comprising our customer base, and the monthly billing process for the majority of our revenue, we have not experienced a significant increase in the loss provision recognized upon adoption of the CECL model.
A reconciliation of the beginning and ending amount of allowance for doubtful accounts is as follows for the years ended December 31, 2022, 2021, and 2020 (in millions):
| Year Ended December 31, | |||||||||||||||||
| 2022 | 2021 | 2020 | |||||||||||||||
| Beginning balance of allowance for doubtful accounts | $ | 24 | $ | 27 | $ | 8 | |||||||||||
| Impact of adoption of ASU 2016-13 | — | — | 13 | ||||||||||||||
| Bad debt expense | 11 | 13 | 16 | ||||||||||||||
| Charge-offs | (13) | (16) | (10) | ||||||||||||||
| Ending balance of allowance for doubtful accounts | $ | 22 | $ | 24 | $ | 27 |
Charge-offs in the table above represent the write-off of uncollectible receivables, net of recoveries. These amounts also include the impact of foreign currency translation adjustments.
**3.**Acquisitions and Divestitures
Acquisitions and Divestitures
| Company | Transaction Date | Primary Segment | Description | ||||||||
| Bakkt Holdings, LLC, or Bakkt | Deconsolidated on 10/15/2021 | Exchanges | Bakkt is a business with an integrated platform that enables consumers and institutions to transact in digital assets. The Bakkt platform consists of three complementary aspects: a digital asset marketplace, loyalty redemption services and an alternative payment method. In 2021, Bakkt completed its merger with VPC Impact Acquisition Holdings, or VIH, a special purpose acquisition company sponsored by Victory Park Capital, or VPC. Following the closing, as a consequence of our inability to meet the power criterion through our variable interest and because of holding a minority voting interest in the combined company, during the fourth quarter of 2021 we deconsolidated Bakkt upon loss of control and prospectively treat it as an equity method investment within our financial statements. | ||||||||
| Ellie Mae Intermediate Holdings I, Inc., and its indirect wholly owned subsidiary, Ellie Mae, Inc. (collectively, Ellie Mae) | Acquired on 9/4/2020 | Mortgage Technology | Ellie Mae is a cloud-based technology solution provider for the mortgage finance industry, and expanded our ICE Mortgage Technology portfolio. Through its digital lending platform, Ellie Mae provides technology solutions to participants in the mortgage supply chain, including over 3,000 customers and thousands of partners and investors who participate on its open network. Originators rely on Ellie Mae to securely manage the exchange of data across the mortgage ecosystem to enable the origination of mortgages while adhering to various local, state and federal compliance requirements. See below for the Ellie Mae purchase price allocation and supplemental pro forma financial information. | ||||||||
During 2022 and 2021, we acquired multiple companies which were not material to our operations.
Pending Acquisition of Black Knight, Inc.
On May 4, 2022, we announced that we had entered into a definitive agreement to acquire Black Knight, Inc., or Black Knight, a software, data and analytics company that serves the housing finance continuum, including real estate data, mortgage lending and servicing, as well as the secondary markets. Pursuant to that certain Agreement and Plan of Merger, dated as of May 4, 2022, among ICE, Sand Merger Sub Corporation, a wholly owned subsidiary of ICE, or Sub, and Black Knight, which we refer to as the “merger agreement,” Sub will merge with and into Black Knight, which we refer to as the “merger,” with Black Knight surviving as a wholly owned subsidiary of ICE. As of May 4, 2022, the transaction was valued at approximately $13.1 billion, or $85 per share of Black Knight common stock, with cash comprising 80% of the value of the aggregate transaction consideration and shares of our common stock comprising 20% of the value of the aggregate transaction consideration at that time. The aggregate cash component of the transaction consideration is fixed at $10.5 billion, and the value of the aggregate stock component of the transaction consideration will fluctuate with the market price of our common stock and will be determined based on the average of the volume weighted averages of the trading prices of our common stock on each of the ten consecutive trading days ending three trading days prior to the
closing of the merger. This transaction builds on our position as a provider of electronic workflow solutions for the rapidly evolving U.S. residential mortgage industry.
Black Knight provides a comprehensive and integrated ecosystem of software, data and analytics solutions serving the real estate and housing finance markets. We believe the Black Knight ecosystem adds value for clients of all sizes across the mortgage and real estate lifecycles by helping organizations lower costs, increase efficiencies, grow their businesses, and reduce risk.
On August 19, 2022, our preliminary proxy statement/prospectus on Form S-4 was declared effective by the SEC, and on September 21, 2022, Black Knight stockholders approved the transaction. The transaction is expected to close in the first half of 2023 following the receipt of regulatory approvals and the satisfaction of customary closing conditions.
Ellie Mae Acquisition
On September 4, 2020, we acquired Ellie Mae for aggregate consideration of $11.4 billion from private equity firm Thoma Bravo. The purchase price consisted of $9.5 billion in cash, as adjusted for $335 million of cash and cash equivalents held by Ellie Mae on the date of acquisition, and approximately $1.9 billion, or approximately 18.4 million shares of our common stock, based on our stock price on the acquisition date. ICE funded the cash portion of the purchase price with net proceeds from our offering of new senior notes in August 2020, together with the issuance of commercial paper and borrowings under a new senior unsecured term loan facility (see Note 10). We have evaluated the impact of this acquisition and related disclosures under ASC 805- Business Combinations.
The purchase price has been allocated to the net tangible and identifiable intangible assets and liabilities based on the respective estimated fair values on the date of acquisition, as determined with the assistance of a third-party valuation specialist. The excess of purchase price over the net tangible and identifiable intangible assets has been recorded as goodwill. Goodwill represents potential revenue synergies related to new product development, various expense synergies and opportunities to enter new markets. The purchase price allocation is as follows (in millions):
| Purchase Price Allocation | |||||
| Cash and cash equivalents | $ | 335 | |||
| Property and equipment | 125 | ||||
| Goodwill | 7,731 | ||||
| Identifiable intangibles | 4,442 | ||||
| Other assets and liabilities, net | 48 | ||||
| Deferred tax liabilities on identifiable intangibles | (1,253) | ||||
| Total purchase price allocation | $ | 11,428 |
In performing the purchase price allocation, we considered, among other factors, the intended future use of acquired assets, analysis of historical financial performance and estimates of future performance of the Ellie Mae business.
The following table sets forth the components of the intangible assets associated with the acquisition as of December 31, 2022 (in millions, except years):
| Acquisition-Date Fair Value | Accumulated Amortization | Net Book Value | Useful Life (Years) | ||||||||||||||||||||
| Customer relationships | $ | 3,136 | $ | (377) | $ | 2,759 | 10 to 20 | ||||||||||||||||
| Backlog | 300 | (139) | 161 | 5 | |||||||||||||||||||
| Trademark/Tradenames | 200 | (25) | 175 | 5 to 20 | |||||||||||||||||||
| Developed Technology | 739 | (262) | 477 | 7 | |||||||||||||||||||
| In-process Research & Development | 67 | — | 67 | N/A | |||||||||||||||||||
| Total | $ | 4,442 | $ | (803) | $ | 3,639 |
From the acquisition date through December 31, 2020, Ellie Mae revenues of $351 million, were included in our mortgage technology revenues, and operating expenses of $250 million were recorded in our consolidated income statement.
The financial information in the table below summarizes the combined results of operations of ICE and Ellie Mae, on a pro forma basis, as though the companies had been combined as of the beginning of the period presented. The unaudited pro forma financial information is presented for informational purposes only and is not indicative of the results of operations that would have been achieved if the acquisition had taken place at the beginning of the period presented. Such
unaudited pro forma financial information is based on the historical financial statements of ICE and Ellie Mae. This unaudited pro forma financial information is based on estimates and assumptions that have been made solely for purposes of developing such unaudited pro forma information, including, without limitation, purchase accounting adjustments, interest expense on debt issued to finance the purchase price, acquisition-related transaction costs, the removal of historical Ellie Mae intangible asset amortization and the addition of intangible asset amortization related to this acquisition. The unaudited pro forma financial information does not reflect any synergies or operating cost reductions that have been and may be achieved from the combined operations. The unaudited pro forma financial information combines the historical results for us and Ellie Mae for 2020 in the following table (in millions).
| Year Ended December 31, 2020 | |||||
| Total revenues, less transaction-based expenses | $ | 6,644 | |||
| Net income attributable to ICE | $ | 2,193 | |||
Transaction-based expenses included within revenues, less transaction-based expenses in the table above, were not impacted by pro forma adjustments and agree to the amounts presented historically in our consolidated income statements as they relate solely to ICE and not to Ellie Mae.
Bakkt Transaction
On October 15, 2021, Bakkt completed its merger with VPC Impact Acquisition Holdings, or VIH, a special purpose acquisition company sponsored by Victory Park Capital, or VPC. The business combination between Bakkt and VIH resulted in enterprise value of approximately $2.1 billion, including approximately $479 million of cash on the combined company’s balance sheet, reflecting a contribution of up to $123 million of cash held in VIH’s trust account, and a $325 million concurrent private investment in public equity, or PIPE, of Class A common stock of the combined company and $31 million of cash held in Bakkt accounts. The PIPE was priced at $10.00 per share and included a $47 million commitment from us. The newly combined company has been renamed Bakkt Holdings, Inc. and is listed on the New York Stock Exchange, or NYSE.
As part of the transaction, Bakkt’s existing equity holders and management rolled 100% of their equity into the combined company through a retained variable interest in Bakkt and are subject to a six-month lockup period. Certain shareholders of VIH exercised their redemption rights, and at closing, Bakkt equity holders, including ICE, owned approximately 81% of the combined company, VIH’s public shareholders owned approximately 5%, VPC owned 2%, and PIPE investors (a group that also includes us) owned approximately 12% of the issued and outstanding equity of the combined company.
Following completion of the business combination, we held an approximate 68% economic interest, which includes both our variable interest and PIPE investment. As a result of limitations on ICE from the Bakkt voting agreement entered into in connection with the transaction, we hold a minority voting interest in the combined company. Prior to the closing, Bakkt revenues and operating expenses were reported within our consolidated revenues and operating expenses. Following the closing, as a consequence of our inability to meet the power criterion through our variable interest and because of holding a minority voting interest in the combined company, during the fourth quarter of 2021 we deconsolidated Bakkt upon loss of control and prospectively treat it as an equity method investment within our financial statements. We recorded a pre-tax gain on the transaction of $1.4 billion during the fourth quarter of 2021, which is included in other non-operating income within our consolidated income statement. The pre-tax gain is a result of recording an equity method investment value of $1.7 billion plus the removal of our redeemable non-controlling interest liability of $107 million, partially offset by the deconsolidation of Bakkt net assets of $295 million and our additional PIPE contribution of $47 million.
The merger of Bakkt and VIH triggered a market condition event on the Bakkt equity incentive awards. As a result, during 2021, we incurred a $31 million non-cash compensation expense related to these awards which we recorded as an acquisition-related cost prior to deconsolidating Bakkt (see Note 11).
Bridge2 Solutions Acquisition Considerations
Bridge2 Solutions is a leading provider of loyalty solutions for merchants and consumers. Subsequent to its acquisition by us in February 2020, Bridge2 Solutions was contributed to Bakkt in combination with its capital call. To fund the acquisition of Bridge2 Solutions, Bakkt completed a capital call for $300 million in funding by ICE and the minority investors. This acquisition-related capital call triggered a market condition of certain Bakkt equity incentive awards, and as a result, we incurred a $10 million non-cash compensation expense in 2020 related to these awards which was recorded as an acquisition-related cost (see Note 11).
The following summarizes our purchase price allocation for Bridge2 Solutions to the respective net tangible and identifiable intangible assets and liabilities based on the respective estimated fair values on the date of acquisition. The excess of the purchase price over the net tangible and identifiable intangible assets has been recorded as goodwill. Revenues and expenses were not material to the periods presented.
| Acquisition Purchase Price Allocation (dollars in millions) | ||||||||||||||
| Bridge2 Solutions | Useful Life (Years) | |||||||||||||
| Customer relationship intangibles | $ | 54 | 12 | |||||||||||
| Developed technology intangibles | 12 | 7 | ||||||||||||
| Trade name intangibles | — | 1 | ||||||||||||
| Total identifiable intangible assets | $ | 66 | ||||||||||||
| Goodwill | 217 | |||||||||||||
| Other working capital adjustments | (22) | |||||||||||||
| Total purchase price cash consideration | $ | 261 |
As of October 15, 2021, following the Bakkt transaction discussed above, we no longer consolidate Bridge2 Solutions in our financial statements.
Non-Controlling Interest
During 2020, we received a contribution from a group of minority investors for a non-controlling interest in ICE Futures Abu Dhabi.
Minority investors hold a net profit sharing interest in our CDS clearing subsidiaries of 26.7% ownership interest as of December 31, 2022.
In December 2018, Bakkt was capitalized with $183 million in initial funding with ICE as the majority owner, along with a group of other minority investors, and in March 2020, an additional $300 million in funding occurred with ICE maintaining its majority ownership. We held a call option over these interests subject to certain terms. Similarly, the non-ICE partners in Bakkt held a put option to require us to repurchase their interests subject to certain terms. These minority interests were reflected as redeemable non-controlling interests in temporary equity within our consolidated balance sheet. Following the October 2021 Bakkt merger discussed above, we no longer consolidate Bakkt and therefore did not record a redeemable non-controlling interest in Bakkt as of December 31, 2022 or 2021.
**4.**Investments
Equity Investments Subject to ASU 2016-01
Our equity investments are subject to valuation under ASU 2016-01, Financial Instruments- Overall (Subtopic 825-10): Recognition and Measurement of Financial Assets and Financial Liabilities, or ASU 2016-01. See Note 18 for a discussion of our determination of fair value of our financial instruments.
Investment in Euroclear
We previously owned a 9.8% stake in Euroclear, plc, or Euroclear, that we originally purchased for $631 million. We appointed a director to the Euroclear Board of Directors, and classified our investment in Euroclear as an equity investment.
On May 20, 2022, we completed the sale of our 9.8% stake in Euroclear. The carrying value of our investment was $700 million at the time of the sale and was classified within other current assets on our balance sheet. We recorded a net gain on the sale of $41 million, which is included in other income in 2022.
We did not receive a dividend from Euroclear during 2022 or 2020. We recognized dividend income of $60 million in 2021 from Euroclear, included in other income.
Investment in Coinbase
On December 1, 2014, we acquired preferred stock of Coinbase Global, Inc., or Coinbase, which operates a cryptocurrency exchange platform, for $10 million, representing a 1.4% ownership share on a fully-diluted, as-converted
basis. On April 14, 2021, Coinbase completed an initial public offering, or IPO. On April 15, 2021, we completed the sale of our investment in Coinbase for $1.24 billion and recorded a gain of $1.23 billion, or $892 million net of tax, as other income in our consolidated statement of income.
Equity Method Investments
Our equity method investments include OCC and Bakkt, among others. Our equity method investments are included in other non-current assets in the accompanying consolidated balance sheets. We carry our equity method investments at cost and assess the carrying value periodically if impairment indicators are present. At the end of each reporting period, we record our share of profits or losses of our equity method investments as equity earnings included in other income. In addition, if and when our equity method investments issue cash dividends to us, we deduct the amount of these dividends from the carrying amount of that investment.
We recognized ($1.3 billion), ($42 million) and $71 million as our share of estimated profits/(losses) and impairment, net, from our equity method investments other income/(expense) during 2022, 2021 and 2020, respectively. The estimated losses during 2022 and 2021 are primarily related to our investment in Bakkt, and the estimated profits during 2020 are related to our investment in OCC. Each period includes adjustments to reflect the difference between reported prior period actual results from our original estimates.
When performing our assessment of the carrying value of our investments, we consider, among other things, the length of time and the extent to which the market value has been less than our cost basis, if applicable, the investee's financial condition and near-term prospects, the economic or technological environment in which our investees operate, weakening of the general market condition of the related industry, whether an investee can continue as a going concern, any impairment charges recorded by an investee on goodwill, intangible or long-lived assets, and our intent and ability to retain the investment for a period of time sufficient to allow for any anticipated recovery in market value.
Investment in OCC
We own a 40% interest in OCC through a direct investment by the NYSE. OCC is regulated by the SEC as a registered clearing agency and by the Commodity Futures Trading Commission, or CFTC, as a derivatives clearing organization. OCC serves as a clearing house for securities options, security futures, commodity futures and options on futures traded on various independent exchanges. OCC clears securities options traded on NYSE Arca and NYSE Amex Options, along with other non-affiliated exchanges.
We recognized $15 million, $51 million and $71 million during 2022, 2021 and 2020, respectively, of equity earnings as our share of OCC's estimated profits, which is included in other income.
Investment in Bakkt
Following Bakkt's October 15, 2021 merger with VIH, we held an approximate 68% economic interest and treat it as an equity method investment (see Note 3). We recorded estimated equity losses and impairment of $1.4 billion during 2022 related to our investment in Bakkt.
During 2022, Bakkt reported an impairment of goodwill and intangible assets. As of December 31, 2022, after recording our share of Bakkt's equity method losses, which included Bakkt's impairment charge, we recorded an impairment in our investment in Bakkt to its fair value as other expense. This was based on what we consider to be an other-than-temporary decline in fair value as a result of the factors noted above, including consideration for the impairment charge recorded by Bakkt. As of December 31, 2022, the carrying value of our investment in Bakkt was determined to be $208 million.
We have concluded that Bakkt meets the significance test under Rule 3-09 of Regulation S-X for 2022. Bakkt’s total assets and liabilities as of September 30, 2022 were $879 million and $220 million, respectively, and Bakkt’s net revenues and net loss for the nine months ended September 30, 2022 were $39 million and ($1.7 billion), respectively. Bakkt’s total assets and liabilities as of December 31, 2021 were $2.4 billion and $120 million, respectively, and Bakkt’s net revenues and net loss for the period from October 15, 2021 through December 31, 2021 were $11 million and ($165 million), respectively. In accordance with Rule 3-09 of Regulation S-X, financial statements for Bakkt as of and for the year ended December 31, 2022 will be filed subsequently as an amendment to this Form 10-K.
**5.**Revenue Recognition
Our primary revenue contract classifications are described below. These categories best represent those with similar economic characteristics of the nature, amount, timing and uncertainty of our revenues and cash flows.
Exchanges Revenues
- Futures and Options:** Revenues in our futures and options trading businesses primarily represent fees charged for the performance obligations of derivatives trading and clearing. In our derivatives markets, we earn transaction and clearing revenues from both counterparties to each contract that is traded and/or cleared.
Our transaction and clearing revenues are primarily included in our Exchanges segment with the exception of our CDS and fixed income transaction and clearing revenues which are discussed below and are included in our Fixed Income and Data Services segment. Derivatives trading and clearing fees contain two performance obligations: (1) trade execution/clearing novation and (2) risk management of open interest. While we allocate the transaction price between these two performance obligations, since they generally are satisfied almost simultaneously, there is no significant deferral of revenue. Our Exchanges segment futures and options transaction and clearing revenues are reported net of rebates. Rebates were $815 million, $982 million and $933 million in 2022, 2021 and 2020, respectively. Transaction and clearing fees can be variable based on trade volume discounts used in the determination of rebates, however virtually all volume discounts are calculated and recorded on a monthly basis. Transaction and clearing fees, as well as any volume discounts rebated to our customers, are calculated and billed monthly in accordance with our published fee schedules.
-
Cash Equities and Equity Options: Revenues in our cash equity and equity options markets represent trade execution fees. Cash trading and equity options contain one performance obligation related to each transaction which occurs instantaneously, and the revenue is recorded at the point in time of the transaction. We make liquidity payments to certain customers, as well as charge routing fees related to orders in our markets which are routed to other markets for execution and recognize those payments as a cost of revenue. In addition, we pay NYSE regulatory oversight fees to the SEC and collect equal amounts from our customers. These are also considered a cost of revenue, and both of these NYSE-related fees are included in transaction-based expenses. For one of our equity option exchanges, revenues are reported net of rebates. Rebates for that exchange were $50 million, $51 million and $29 million in 2022, 2021 and 2020, respectively.
-
Listings:** Our listings revenues include original and annual listings fees, and other corporate action fees. Each distinct listing fee is allocated to multiple performance obligations including original and incremental listing and investor relations services, as well as a customer’s material right to renew the option to list on our exchanges. In performing this allocation, the standalone selling price of the listing services is based on the original and annual listing fees and the standalone selling price of the investor relations services is based on its market value. All listings fees are billed upfront and the identified performance obligations are satisfied over time. Revenue related to the investor relations performance obligation is recognized ratably over the period these services are provided, with the remaining revenue recognized ratably over time as customers continue to list on our exchanges. Listings fees related to other corporate actions are considered contract modifications of our listing contracts and are recognized ratably over time as customers continue to list on our exchanges.
-
Data and Connectivity Services:** Our data and connectivity services revenues are related to the various data and connectivity services that we provide which are directly attributable to our exchange venues. Exchange data services include, among other offerings, proprietary real-time and historical pricing data, as well as order book and transaction information related to our global futures markets and the NYSE exchanges. In addition, we receive a share of revenue from the National Market System, or NMS, Plan. Separately, we also provide connectivity services directly related to our futures, cash equity and options exchanges and clearing houses. Data and connectivity services revenues are primarily subscription-based, billed monthly, quarterly or annually in advance and recognized ratably over time as our performance obligations of data delivery are met consistently throughout the period. Considering that these contracts primarily consist of single performance obligations with fixed prices, there is no variable consideration and no need to allocate the transaction price.
*•*OTC and Other: Our OTC revenues are generated in our bilateral energy markets where we offer electronic trading on contracts based on physically settled natural gas, power and refined oil contracts. Other revenues primarily include interest income on certain clearing margin deposits, regulatory penalties and fines, fees for use of our facilities, regulatory fees charged to member organizations of our U.S. securities exchanges, designated market maker service fees, exchange membership fees and agricultural grading and certification fees. Generally, fees for OTC and other revenues contain one performance obligation. Because these contracts primarily consist of single performance obligations with fixed prices, there is no variable consideration and no need to allocate the transaction price. Services for OTC and other revenues are primarily satisfied at a point in time. Therefore, there is no need to allocate the fee and no deferral results as we have no further obligation to the customer at that time.
In certain of our revenue share arrangements with third parties we control the delivered contract; in these arrangements we are acting as a principal and the revenue is recorded gross.
Fixed Income and Data Services Revenues
-
Fixed Income Execution: Execution fees are reported net of rebates, and can be variable based on trade volume discounts used in the determination of rebates, however virtually all volume discounts are calculated and recorded on a monthly basis. Execution fees and rebates are calculated and billed monthly in accordance with our published fee schedules. Fixed income execution rebates were nominal in 2022, 2021 and 2020. In addition, we earn fixed income transaction fees on the trade execution of agency trades, commissions and net markups and markdowns on riskless principal trades. Fixed income execution fees contain one performance obligation related to each transaction which occurs instantaneously, and the revenue is recorded at the point in time. Fixed income revenues also include interest income on certain clearing margin deposits related to our CDS clearing business which are satisfied at a point in time and consists of a single performance obligations.
-
CDS Clearing: CDS clearing revenues are reported net of rebates. Rebates were nominal in 2022, 2021 and 2020. We provide clearing services to the global CDS market and the timing and nature of our CDS transaction and clearing revenue is similar in nature to the Exchanges Segment transaction and clearing revenues discussed above. The CDS derivatives trading and clearing fees contain two performance obligations: (1) trade execution/clearing novation and (2) risk management of open interest. While we allocate the transaction price between these two performance obligations, since they generally are satisfied almost simultaneously, there is no significant deferral of revenue.
-
Fixed Income Data and Analytics, and Other Data and Network Services: Fixed income data and analytics services revenues are recurring in nature and include evaluated pricing and reference data and analytics including sovereign, corporate and municipal bonds, mortgage and asset-backed securities, as well as leveraged loans. Other data and network services include those related to the ICE Global Network and our consolidated feeds business, as well as desktops and other multi-asset class analytics.
The nature and timing of each contract type for the data services above are similar in nature. Data services revenues are primarily subscription-based, billed monthly, quarterly or annually in advance and recognized ratably over time as our performance obligations of data delivery are met consistently throughout the period. Considering that these contracts primarily consist of single performance obligations with fixed prices, there is no variable consideration and no need to allocate the transaction price. In certain of our data contracts, where third parties are involved, we either arrange for the third party to transfer the services to our customers, or we transfer third-party data to our customers; in these arrangements we are acting as an agent and revenue is recorded net.
Mortgage Technology Revenues
- Origination Technology:** Our origination technology acts as a system of record for the mortgage transaction, automating the gathering, reviewing, and verifying of mortgage-related information and enabling automated enforcement of rules and business practices designed to help ensure that each completed loan transaction is of high quality and adheres to secondary market standards. These revenues are based on recurring Software as a Service, or SaaS, subscription fees, with an additive transaction-based success-based pricing fee as lenders exceed the number of loans closed that are included with their monthly base subscription.
In addition, the ICE Mortgage Technology network provides originators connectivity to the mortgage supply chain and facilitates the secure exchange of information between our customers and a broad ecosystem of third-party service providers, as well as lenders and investors that are critical to consummating the millions of loan transactions that occur on our origination network each year. Revenue from the ICE Mortgage Technology network is largely transaction-based.
Performance obligations consist of a series of distinct services and support services. Mortgage subscription customers simultaneously receive and consume benefits from our performance and revenues are recognized over time as our performance obligations are met consistently throughout the period. Contracts generally range from one year to five years. Success-based contracts are subject to monthly billing calculations whereby customers are obligated to pay the greater of a contractual base fee or variable closed loan fee based on the number of closed loan transactions processed by the customer in the specific month. Under success-based contracts, monthly base fees are recognized ratably over the contract terms as subscription performance obligations are satisfied and closed loan fees in excess of base fees are considered variable consideration.
For the majority of contracts that include variable consideration, such fees are recognized in the month in which they are earned because the terms of the variable payments relate specifically to the outcome from transferring the distinct time increment (one month) of service and because such amounts reflect the fees to which we expect to be entitled for providing access to the Encompass platform for that period, consistent with the allocation objective of Topic 606. For certain contracts where the allocation objective would not be met by allocating variable consideration in this way, total variable consideration to be received is estimated at contract inception and recognized ratably over the contract term considering historical trends, industry data, and contract specific factors to determine an expected amount to which we expect to be entitled. The amount of variable consideration included in the transaction price is constrained to ensure that it is probable that a significant reversal in the amount of cumulative revenue recognized will not occur when the amount of variable consideration is subsequently resolved. When agreements involve multiple distinct performance obligations, we allocate arrangement consideration to all performance obligations at the inception of an arrangement based on the relative standalone selling prices of each performance obligation.
-
Closing Solutions:** Our closing solutions connect key participants such as lenders, title and settlement agents and individual recorders together to digitize the closing and recording process. For these services, we act as agent and revenues are recorded net. Revenues for these services primarily contain one performance obligation related to each transaction which occurs instantaneously, and the revenues are primarily recorded at the point in time of the transaction. Closing solutions also includes revenues from our Mortgage Electronic Registrations Systems, Inc., or MERS database, which provides a system of record for recording and tracking changes and servicing rights and beneficial ownership interests in loans secured by U.S. residential real estate. MERS database revenues contain multiple performance obligations related to each new loan registration and future transfers, and the revenues are primarily recorded at the point in time of each transaction. Closing solutions revenues may include a fixed-fee subscription component recognized ratably over the contract term, as this method best depicts our pattern of performance.
-
Data and Analytics:** Revenues include those related to ICE Mortgage Technology’s Automation, Intelligence, Quality, or AIQ, offering which applies machine learning to the entire loan origination process, offering customers greater efficiency by streamlining data collection and validation through our automated document recognition and data extraction capabilities. AIQ revenues can be both recurring and transaction-based in nature. In addition, our data offerings include real-time industry and peer benchmarking tools, which provide originators a granular view into the real-time trends of the U.S. residential mortgage market. We also provide a Data as a Service, or DaaS, offering through private data clouds for lenders to access their own data and origination information. Revenues related to our data products are largely subscription-based and recurring in nature and recognized ratably over time as this method best depicts our pattern of performance. Our performance obligations of data delivery are met consistently throughout the period.
-
Other:** Other revenues include professional services fees, as well as revenues from ancillary products. Other revenues can be both recurring and transaction-based in nature.
The following table depicts the disaggregation of our revenue according to business line and segment (in millions). Amounts here have been aggregated as they follow consistent revenue recognition patterns, and are consistent with the segment information in Note 19:
| Exchanges Segment | Fixed Income and Data Services Segment | Mortgage Technology Segment | Total Consolidated | ||||||||||||||||||||
| Year ended December 31, 2022 | |||||||||||||||||||||||
| Total revenues | $ | 6,415 | $ | 2,092 | $ | 1,129 | $ | 9,636 | |||||||||||||||
| Transaction-based expenses | 2,344 | — | — | 2,344 | |||||||||||||||||||
| Total revenues, less transaction-based expenses | $ | 4,071 | $ | 2,092 | $ | 1,129 | $ | 7,292 | |||||||||||||||
| Timing of Revenue Recognition | |||||||||||||||||||||||
| Services transferred at a point in time | $ | 2,307 | $ | 370 | $ | 455 | $ | 3,132 | |||||||||||||||
| Services transferred over time | 1,764 | 1,722 | 674 | 4,160 | |||||||||||||||||||
| Total revenues, less transaction-based expenses | $ | 4,071 | $ | 2,092 | $ | 1,129 | $ | 7,292 |
| Exchanges Segment | Fixed Income and Data Services Segment | Mortgage Technology Segment | Total Consolidated | ||||||||||||||||||||
| Year ended December 31, 2021 | |||||||||||||||||||||||
| Total revenues | $ | 5,878 | $ | 1,883 | $ | 1,407 | $ | 9,168 | |||||||||||||||
| Transaction-based expenses | 2,022 | — | — | 2,022 | |||||||||||||||||||
| Total revenues, less transaction-based expenses | $ | 3,856 | $ | 1,883 | $ | 1,407 | $ | 7,146 | |||||||||||||||
| Timing of Revenue Recognition | |||||||||||||||||||||||
| Services transferred at a point in time | $ | 2,166 | $ | 216 | $ | 820 | $ | 3,202 | |||||||||||||||
| Services transferred over time | 1,690 | 1,667 | 587 | 3,944 | |||||||||||||||||||
| Total revenues, less transaction-based expenses | $ | 3,856 | $ | 1,883 | $ | 1,407 | $ | 7,146 |
| Exchanges Segment | Fixed Income and Data Services Segment | Mortgage Technology Segment | Total Consolidated | ||||||||||||||||||||
| Year ended December 31, 2020 | |||||||||||||||||||||||
| Total revenues | $ | 5,839 | $ | 1,810 | $ | 595 | $ | 8,244 | |||||||||||||||
| Transaction-based expenses | 2,208 | — | — | 2,208 | |||||||||||||||||||
| Total revenues, less transaction-based expenses | $ | 3,631 | $ | 1,810 | $ | 595 | $ | 6,036 | |||||||||||||||
| Timing of Revenue Recognition | |||||||||||||||||||||||
| Services transferred at a point in time | $ | 2,045 | $ | 249 | $ | 439 | $ | 2,733 | |||||||||||||||
| Services transferred over time | 1,586 | 1,561 | 156 | 3,303 | |||||||||||||||||||
| Total revenues, less transaction-based expenses | $ | 3,631 | $ | 1,810 | $ | 595 | $ | 6,036 |
The Exchanges segment and the Fixed Income and Data Services segment revenues above include data services revenues. Our data services revenues are transferred over time, and a majority of those revenues are performed over a short period of time of one month or less and relate to subscription-based data services billed monthly, quarterly or annually in advance. These revenues are recognized ratably over time as our data delivery performance obligations are met consistently throughout the period.
The Exchanges segment revenues transferred over time in the table above also include services related to listings, services related to risk management of open interest performance obligations and services related to regulatory fees, trading permits, and software licenses.
The Fixed Income and Data Services segment revenues transferred over time in the table above also include services related to risk management of open interest performance obligations, primarily in our CDS business.
The Mortgage Technology segment revenues transferred over time in the table above primarily relate to our origination technology revenue where performance obligations consist of a series of distinct services and are recognized over the contract terms as subscription performance obligations are satisfied, and to a lesser extent, professional services revenues and revenues from certain of our data and analytics offerings.
The components of services transferred over time for each of our segments are as follows:
| Year ended December 31, | |||||||||||||||||
| 2022 | 2021 | 2020 | |||||||||||||||
| Exchanges Segment: | |||||||||||||||||
| Data services revenues | $ | 877 | $ | 838 | $ | 790 | |||||||||||
| Services transferred over time related to risk management of open interest performance obligations | $ | 262 | $ | 260 | $ | 241 | |||||||||||
| Services transferred over time related to listings | $ | 515 | $ | 479 | $ | 446 | |||||||||||
| Services transferred over time related to regulatory fees, trading permits, and software licenses | $ | 110 | $ | 113 | $ | 109 | |||||||||||
| Total | $ | 1,764 | $ | 1,690 | $ | 1,586 | |||||||||||
| Fixed Income Data Services Segment: | |||||||||||||||||
| Data services revenues | $ | 1,686 | $ | 1,639 | $ | 1,532 | |||||||||||
| Services transferred over time related to risk management of open interest performance obligations in our CDS business | $ | 36 | $ | 28 | $ | 29 | |||||||||||
| Total | $ | 1,722 | $ | 1,667 | $ | 1,561 | |||||||||||
| Mortgage Technology Segment: | |||||||||||||||||
| Subscription revenues | $ | 643 | $ | 553 | $ | 155 | |||||||||||
| Professional service revenues and other | $ | 31 | $ | 34 | $ | 1 | |||||||||||
| Total | $ | 674 | $ | 587 | $ | 156 | |||||||||||
| Total consolidated revenues transferred over time | $ | 4,160 | $ | 3,944 | $ | 3,303 |
6. Deferred Revenue
Our contract liabilities, or deferred revenue, represent consideration received that is yet to be recognized as revenue. Total deferred revenue was $254 million as of December 31, 2022, including $170 million in current deferred revenue and $84 million in other non-current liabilities. Total deferred revenue was $284 million as of December 31, 2021, including $194 million in current deferred revenue and $90 million in other non-current liabilities. See Note 5 for a description of our annual listing, original listing, other listings, data services and mortgage technology services revenues and the revenue recognition policy for each of these revenue streams. The changes in our deferred revenue during 2022 and 2021 are as follows (in millions):
| Annual Listing Revenue | Original Listing Revenues | Other Listing Revenues | Data Services and Other Revenues | Mortgage Technology | Total | ||||||||||||||||||||||||||||||
| Deferred revenue balance at January 1, 2021 | $ | — | $ | 13 | $ | 92 | $ | 95 | $ | 59 | $ | 259 | |||||||||||||||||||||||
| Additions | 403 | 39 | 44 | 451 | 83 | 1,020 | |||||||||||||||||||||||||||||
| Amortization | (403) | (33) | (43) | (453) | (63) | (995) | |||||||||||||||||||||||||||||
| Deferred revenue balance at December 31, 2021 | — | 19 | 93 | 93 | 79 | 284 | |||||||||||||||||||||||||||||
| Additions | 437 | 34 | 47 | 451 | 72 | 1,041 | |||||||||||||||||||||||||||||
| Amortization | (437) | (34) | (44) | (456) | (100) | (1,071) | |||||||||||||||||||||||||||||
| Deferred revenue balance at December 31, 2022 | $ | — | $ | 19 | $ | 96 | $ | 88 | $ | 51 | $ | 254 |
The Mortgage Technology deferred revenue balance as of December 31, 2022 primarily relates to origination technology subscription services for which the performance obligations have not yet been provided as of the balance sheet date but for which billings or payments have been received in advance. Performance obligations for origination technology revenue consist of a series of distinct services and are recognized over the contract terms as subscription performance obligations are satisfied. Contracts generally range from one year to five years.
Included in the amortization recognized in 2022, $195 million was related to the deferred revenue balance as of January 1, 2022. Included in the amortization in 2021, $152 million was related to the deferred revenue balance as of January 1, 2021. As of December 31, 2022, the remaining deferred revenue balance will be recognized over the period of time we satisfy our performance obligations. As of December 31, 2022, we estimate that our deferred revenue will be recognized in the following years (in millions):
| Original Listing Revenues | Other Listing Revenues | Data Services and Other Revenues | Mortgage Technology | Total | |||||||||||||||||||||||||||||||
| 2023 | $ | 13 | $ | 33 | $ | 78 | $ | 46 | $ | 170 | |||||||||||||||||||||||||
| 2024 | 3 | 25 | 4 | 5 | 37 | ||||||||||||||||||||||||||||||
| 2025 | 2 | 18 | 2 | — | 22 | ||||||||||||||||||||||||||||||
| 2026 | 1 | 12 | 2 | — | 15 | ||||||||||||||||||||||||||||||
| 2027 | — | 7 | 1 | — | 8 | ||||||||||||||||||||||||||||||
| Thereafter | — | 1 | 1 | — | 2 | ||||||||||||||||||||||||||||||
| Total | $ | 19 | $ | 96 | $ | 88 | $ | 51 | $ | 254 |
7. Short-Term and Long-Term Restricted Cash and Cash Equivalents
Our total restricted cash and cash equivalents, including short-term and long-term portions, consisted of the following (in millions):
| As of December 31, | |||||||||||||||||
| 2022 | 2021 | ||||||||||||||||
| Restricted cash and cash equivalents: | |||||||||||||||||
| Short-term restricted cash and cash equivalents: | |||||||||||||||||
| ICE Futures Europe | $ | 100 | $ | 100 | |||||||||||||
| ICE Clear Europe | 730 | 550 | |||||||||||||||
| CFTC Regulated Entities | 287 | 289 | |||||||||||||||
| Other Regulated Entities | 73 | 76 | |||||||||||||||
| Other | 4,959 | 20 | |||||||||||||||
| Total short-term restricted cash and cash equivalents | 6,149 | 1,035 | |||||||||||||||
| Long-term restricted cash and cash equivalents: | |||||||||||||||||
| ICE Clearing House Portion of the Guaranty Fund Contribution | 405 | 398 | |||||||||||||||
| Total long-term restricted cash and cash equivalents | 405 | 398 | |||||||||||||||
| Total restricted cash and cash equivalents | $ | 6,554 | $ | 1,433 |
Short-Term Restricted Cash and Cash Equivalents
Our short-term restricted cash and cash equivalents in the table above consist of the following:
-
ICE Futures Europe: ICE Futures Europe operates as a U.K. Recognized Investment Exchange, and is required by the U.K. Financial Conduct Authority to maintain financial resources sufficient to properly perform its relevant functions equivalent to a minimum of six months of operating costs, subject to certain deductions.
-
ICE Clear Europe: ICE Clear Europe operates as a U.K. Recognized Clearing House. As such, ICE Clear Europe is required by the BOE and the European Market Infrastructure Regulation, or EMIR, to restrict as cash, cash equivalents or investments in an amount to reflect an estimate of the capital required to wind down or restructure the activities of the clearing house, cover operational, legal and business risks and to reserve capital to meet credit, counterparty and market risks not covered by the members' margin and guaranty funds. The increase in the regulatory capital restricted cash at ICE Clear Europe as of December 31, 2022 was due to the growth of our clearing businesses, a related increase in costs and the consequential additional regulatory capital buffers required by the BOE. ICE Clear Europe, in addition to being regulated by the BOE, is also regulated by the CFTC as a U.S. Derivatives Clearing Organization, or DCO. The regulatory capital available to ICE Clear Europe, as described above, exceeds the CFTC requirements.
-
CFTC Regulated Entities:** Our CFTC regulated U.S. Designated Contract Market, or DCM, ICE Futures U.S., our CFTC regulated U.S. DCOs, ICE Clear U.S. and ICE Clear Credit, our CFTC regulated U.S. Swap Data Repository, or SDR, ICE Trade Vault, LLC, and our U.S. Swap Execution Facility, or SEF, ICE Swap Trade, are required to maintain financial resources including cash, in an amount that would cover certain operating costs for a one-year period, subject to certain deductions, to satisfy at least six months of such operating costs at all times. For our U.S. DCOs, ICE Clear U.S. and ICE Clear Credit, these amounts include voluntarily-held additional reserves consistent with the EMIR requirements to cover operational, legal and business risks and to reserve
capital to meet credit, counterparty and market risks not covered by the member margin and guaranty funds. In addition, ICE NGX is registered by the CFTC as a Foreign Board of Trade and a DCO and the CFTC requires ICE NGX to maintain financial resources including cash, in an amount that would cover certain operating costs for a one-year period. ICE NGX is regulated by both the CFTC and the Alberta Securities Commission.
-
Other Regulated Entities:** Restricted cash on our various regulated entities and exchanges includes ICE Benchmark Administration, ICE Clear Netherlands, ICE Trade Vault U.K., ICE Endex, ICE Futures Singapore and ICE Futures Abu Dhabi. It also includes the clearing member requirements of ICE Securities Executions & Clearing, LLC and included restricted cash related to Bakkt Trust Company, LLC prior to our deconsolidation of Bakkt in October 2021.
-
Other: Other restricted cash is primarily related to $4.9 billion of net proceeds from the SMR Notes that are separately invested (see Note 10).
Long-Term Restricted Cash and Cash Equivalents
Our long-term restricted cash and cash equivalents in the table above consist of the following:
- ICE Clearing House Portion of the Guaranty Fund Contribution: Our clearing houses, other than ICE NGX, require each clearing member to make deposits to a fund known as the guaranty fund. Included in the total contribution to ICE Clear U.S. as of December 31, 2022, is $15 million from Bakkt, solely applicable to any losses associated with a default in Bitcoin contracts and other digital assets that ICE Clear U.S. may clear in the future. In addition, we have a $15 million first-loss amount related to ICE NGX insurance and included in our contribution to its guaranty fund. See Note 14 for additional information on the guaranty funds and our contributions of cash to our clearing houses guaranty funds.
8. Property and Equipment
Property and equipment consisted of the following (in millions):
| As of December 31, | Depreciation Period (Years) | ||||||||||||||||
| 2022 | 2021 | ||||||||||||||||
| Software and internally developed software | $ | 1,599 | $ | 1,407 | 3 to 7 | ||||||||||||
| Computer and network equipment | 811 | 792 | 3 to 5 | ||||||||||||||
| Land | 155 | 156 | N/A | ||||||||||||||
| Buildings and building improvements | 352 | 342 | 15 to 30 | ||||||||||||||
| Right-of-use lease assets | 278 | 278 | 1 to 20 | ||||||||||||||
| Leasehold improvements | 331 | 322 | 4 to 15 | ||||||||||||||
| Equipment, aircraft and office furniture | 339 | 335 | 4 to 12 | ||||||||||||||
| Total property and equipment | 3,865 | 3,632 | |||||||||||||||
| Less accumulated depreciation and amortization | (2,098) | (1,933) | |||||||||||||||
| Property and equipment, net | $ | 1,767 | $ | 1,699 |
In 2022, 2021 and 2020, amortization of software and internally developed software was $247 million, $213 million and $190 million, respectively, and depreciation of all other property and equipment was $174 million, $174 million and $173 million, respectively. As of December 31, 2022 and 2021, unamortized software and internally developed software was $427 million and $361 million, respectively.
9. Goodwill and Other Intangible Assets
The following is a summary of the activity in our goodwill balance (in millions):
| Goodwill balance at January 1, 2021 | $ | 21,291 | |||
| Acquisitions | 50 | ||||
| Divestitures | (233) | ||||
| Foreign currency translation | (7) | ||||
| Other activity, net | 22 | ||||
| Goodwill balance at December 31, 2021 | $ | 21,123 | |||
| Acquisitions | 46 | ||||
| Foreign currency translation | (55) | ||||
| Other activity, net | (3) | ||||
| Goodwill balance at December 31, 2022 | $ | 21,111 |
The following is a summary of the activity in our other intangible assets balance (in millions):
| Other intangible assets balance at January 1, 2021 | $ | 14,408 | |||
| Acquisitions | 26 | ||||
| Divestitures | (58) | ||||
| Foreign currency translation | (6) | ||||
| Amortization of other intangible assets | (622) | ||||
| Other activity, net | (12) | ||||
| Other intangible assets balance at December 31, 2021 | $ | 13,736 | |||
| Acquisitions | 14 | ||||
| Foreign currency translation | (53) | ||||
| Amortization of other intangible assets | (610) | ||||
| Other activity, net | 3 | ||||
| Other intangible assets balance at December 31, 2022 | $ | 13,090 |
We completed our divestiture of Bakkt in 2021 (see Note 3).
Foreign currency translation adjustments result from a portion of our goodwill and other intangible assets being held at our U.K., EU and Canadian subsidiaries, whose functional currencies are not the U.S. dollar. The changes in other activity, net, in the tables above primarily relate to adjustments to the fair value of the net tangible and intangible assets made within one year of acquisitions, with a corresponding adjustment to goodwill. We have performed an analysis of impairment indicators and did not recognize any impairment losses on goodwill or other intangible assets in 2022, 2021 or 2020.
Other intangible assets and the related accumulated amortization consisted of the following (in millions):
| As of December 31, | Useful Life (Years) | ||||||||||||||||
| 2022 | 2021 | ||||||||||||||||
| Finite-lived intangible assets: | |||||||||||||||||
| Customer relationships | $ | 7,966 | $ | 7,958 | 3 to 25 | ||||||||||||
| Technology | 1,380 | 1,379 | 2.5 to 11 | ||||||||||||||
| Trading products with finite lives | 242 | 237 | 20 | ||||||||||||||
| Data/databases | 150 | 150 | 4 to 10 | ||||||||||||||
| Market data provider relationships | 11 | 11 | 20 | ||||||||||||||
| Non-compete agreements | 42 | 42 | 1 to 5 | ||||||||||||||
| Other | 254 | 253 | 1 to 5 | ||||||||||||||
| Total finite-lived intangible assets | 10,045 | 10,030 | |||||||||||||||
| Less accumulated amortization | (3,461) | (2,814) | |||||||||||||||
| Total finite-lived intangible assets, net | 6,584 | 7,216 | |||||||||||||||
| Indefinite-lived intangible assets: | |||||||||||||||||
| Exchange registrations, licenses and contracts with indefinite lives | 6,218 | 6,232 | |||||||||||||||
| Trade names and trademarks with indefinite lives | 280 | 280 | |||||||||||||||
| Other | 8 | 8 | |||||||||||||||
| Total indefinite-lived intangible assets | 6,506 | 6,520 | |||||||||||||||
| Total other intangible assets, net | $ | 13,090 | $ | 13,736 |
In 2022, 2021 and 2020, amortization of other intangible assets was $610 million, $622 million and $388 million, respectively. Collectively, the remaining weighted average useful lives of the finite-lived intangible assets is 14.4 years as of December 31, 2022. We expect future amortization expense from the finite-lived intangible assets as of December 31, 2022 to be as follows (in millions):
| 2023 | $ | 600 | |||
| 2024 | 581 | ||||
| 2025 | 558 | ||||
| 2026 | 511 | ||||
| 2027 | 464 | ||||
| Thereafter | 3,870 | ||||
| $ | 6,584 |
**10.**Debt
Our total debt, including short-term and long-term debt, consisted of the following (in millions):
| As of December 31, | ||||||||||||||
| 2022 | 2021 | |||||||||||||
| Debt: | ||||||||||||||
| Short-term debt: | ||||||||||||||
| Commercial Paper | $ | — | $ | 1,012 | ||||||||||
| 2022 Senior Notes (2.35% senior notes due September 15, 2022) | — | 499 | ||||||||||||
| Other short-term debt | 4 | 10 | ||||||||||||
| Total short-term debt | 4 | 1,521 | ||||||||||||
| Long-term debt: | ||||||||||||||
| 2023 Senior Notes (0.70% senior notes due June 15, 2023) | — | 997 | ||||||||||||
| 2023 Senior Notes (3.45% senior notes due September 21, 2023) | — | 399 | ||||||||||||
| 2023 Senior Notes (4.00% senior notes due October 15, 2023) | — | 797 | ||||||||||||
| 2025 Senior Notes (3.65% senior notes due May 23, 2025) | 1,243 | — | ||||||||||||
| 2025 Senior Notes (3.75% senior notes due December 1, 2025) | 1,247 | 1,246 | ||||||||||||
| 2027 Senior Notes (4.00% senior notes due September 15, 2027) | 1,487 | — | ||||||||||||
| 2027 Senior Notes (3.10% senior notes due September 15, 2027) | 498 | 497 | ||||||||||||
| 2028 Senior Notes (3.75% senior notes due September 21, 2028) | 594 | 594 | ||||||||||||
| 2029 Senior Notes (4.35% senior notes due June 15, 2029) | 1,240 | — | ||||||||||||
| 2030 Senior Notes (2.10% senior notes due June 15, 2030) | 1,235 | 1,234 | ||||||||||||
| 2032 Senior Notes (1.85% senior notes due September 15, 2032) | 1,485 | 1,483 | ||||||||||||
| 2033 Senior Notes (4.60% senior notes due March 15, 2033) | 1,488 | — | ||||||||||||
| 2040 Senior Notes (2.65% senior notes due September 15, 2040) | 1,231 | 1,230 | ||||||||||||
| 2048 Senior Notes (4.25% senior notes due September 21, 2048) | 1,231 | 1,230 | ||||||||||||
| 2050 Senior Notes (3.00% senior notes due June 15, 2050) | 1,221 | 1,220 | ||||||||||||
| 2052 Senior Notes (4.95% senior notes due June 15, 2052) | 1,464 | — | ||||||||||||
| 2060 Senior Notes (3.00% senior notes due September 15, 2060) | 1,471 | 1,470 | ||||||||||||
| 2062 Senior Notes (5.20% senior notes due June 15, 2062) | 983 | — | ||||||||||||
| Total long-term debt | 18,118 | 12,397 | ||||||||||||
| Total debt | $ | 18,122 | $ | 13,918 | ||||||||||
Credit Facilities
- Credit Facility:** We have a $3.9 billion senior unsecured revolving credit facility, or the Credit Facility, with future capacity to increase our borrowings under the Credit Facility by an additional $1.0 billion, subject to the consent of the lenders funding the increase and certain other conditions. On October 15, 2021, we agreed with the lenders to extend the date of the Credit Facility from August 21, 2025 to October 15, 2026, among other items. On May 25, 2022, we agreed with the lenders to extend the maturity date of the Credit Facility from October 15, 2026, to May 25, 2027, among other items. We also exercised our option to increase the amount of the Credit Facility from $3.8 billion to $3.9 billion. We incurred new debt issuance costs of $4 million during both 2022 and 2021 relating to the Credit Facility and these costs are represented in the accompanying consolidated balance sheet as other non-current assets and will be amortized over the remaining life of the Credit Facility. No amounts were outstanding under the Credit Facility as of December 31, 2022.
As of December 31, 2022, of the $3.9 billion that was available for borrowing under the Credit Facility, $171 million was required to support certain broker-dealer and other subsidiary commitments. We did not have any notes outstanding under our U.S. dollar commercial paper program, or the Commercial Paper Program, as of December 31, 2022. Therefore, there was not a required amount to backstop the Commercial Paper Program. Amounts required to back-stop notes outstanding under the Commercial Paper Program will fluctuate as we increase or decrease our commercial paper borrowings. The remaining $3.7 billion is available for working capital and general corporate purposes including, but not limited to, acting as a back-stop to future increases in the amounts outstanding under the Commercial Paper Program.
We also pay an annual commitment fee for unutilized amounts payable in arrears at a rate that ranges from 0.08% to 0.20% determined based on our current long-term debt rating. As of December 31, 2022, the applicable rate for commitments to October 2026 was 0.13%. Amounts borrowed under the facility may be prepaid at any time without premium or penalty.
The Credit Facility also contains customary representations and warranties, covenants and events of default, including a leverage ratio, limitations on liens on our assets, indebtedness of non-obligor subsidiaries, the sale of all or substantially all of our assets, and other matters.
-
2022 Bridge Facility:** On May 4, 2022, we entered into a 364-day senior unsecured bridge facility in an aggregate principal amount not to exceed $14.0 billion, or the Bridge Facility. The commitments that the Company obtained for the Bridge Facility have been permanently reduced from $14.0 billion and there were no amounts outstanding as of December 31, 2022 as a result of (i) the amendment and extension of the Credit Facility, (ii) the issuance by the Company of certain senior unsecured notes on May 23, 2022, (iii) Euroclear divestment proceeds, (iv) the generation of cash internally by the Company, and (v) the effectiveness of our term loan facility.
-
2022 Term Loan:** On May 25, 2022, we entered into a $2.4 billion two-year senior unsecured delayed draw term loan facility, or Term Loan. Draws under the Term Loan bear interest on the principal amount outstanding at either (a) Term Secured Overnight Financing Rate, or Term SOFR, plus an applicable margin plus a credit spread adjustment of 10 basis points or (b) a "base rate" plus an applicable margin. The applicable margin ranges from 0.625% to 1.125% for Term SOFR loans and from 0.000% to 0.125% for base rate loans, in each case, based on a ratings-based pricing grid. The proceeds from borrowings under the Term Loan will be used to fund a portion of the purchase price for the Black Knight acquisition. We incurred new debt issuance costs of $4 million relating to the Term Loan and these costs are represented in the accompanying consolidated balance sheet as other non-current assets and will be amortized over the remaining life of the Term Loan. We have the option to prepay outstanding amounts under the Term Loan in whole or in part at any time. No amounts were outstanding under the Term Loan as of December 31, 2022.
-
2020 Term Loan: On August 21, 2020, we entered into a $750 million 18-month senior unsecured delayed draw term loan facility with a maturity date of February 21, 2022. We borrowed in full under the facility on September 3, 2020, and the proceeds were used to fund a portion of the purchase price for the Ellie Mae acquisition. We had the option to prepay the facility in whole or in part at any time, and paid off the full balance of the loan on December 16, 2020. Interest on borrowings under this term loan facility were based on the principal amount outstanding at the London Interbank Offered Rate, or LIBOR, plus an applicable margin, which was equal to 1.125%. We incurred new debt issuance costs of $3 million during 2020 relating to this term loan and these costs were fully amortized when the term loan was repaid on December 16, 2020.
-
Other:** Our India subsidiaries maintain $14 million of credit lines for their general corporate purposes. As of December 31, 2022, they had borrowed $4 million, which is reflected as "other short-term debt" in the table above.
Commercial Paper Program
Our Commercial Paper Program is currently backed by the borrowing capacity available under the Credit Facility, as described above. The effective interest rate of commercial paper issuances does not materially differ from short-term interest rates, which fluctuate due to market conditions and as a result may impact our interest expense.
We had net repayments of $1.0 billion under the Commercial Paper Program during 2022 funded, in part, by the May 2023 net proceeds from our Senior Notes offering, discussed below. We had net repayments of $1.4 billion under the Commercial Paper Program during 2021. We used $1.2 billion of proceeds received from the sale of our Coinbase investment to pay down the commercial paper balance. We had net issuances of $1.1 billion under the Commercial Paper Program during 2020 the proceeds of which were primarily used to fund a portion of the purchase price for the Ellie Mae acquisition. We repaid a portion of the amounts outstanding under the program during 2022, 2021 and 2020 with cash flows from operations.
As of December 31, 2022, we did not have any notes outstanding under our Commercial Paper Program. As of December 31, 2021, commercial paper notes of $1.0 billion with original maturities ranging from three to 73 days were outstanding with a weighted average interest rate of 0.33% per annum, and a weighted average remaining maturity of 26 days.
New Senior Notes
On May 23, 2022, we issued $8.0 billion in aggregate principal amount of new fixed rate senior notes, comprised of the following:
-
$1.25 billion in aggregate principal amount of 3.65% senior notes due in 2025, or the 2025 Notes;
-
$1.5 billion in aggregate principal amount of 4.00% senior notes due in 2027, or the 2027 Notes;
-
$1.25 billion in aggregate principal amount of 4.35% senior notes due in 2029, or the 2029 Notes;
-
$1.5 billion in aggregate principal amount of 4.60% senior notes due in 2033, or the 2033 Notes;
-
$1.5 billion in aggregate principal amount of 4.95% senior notes due in 2052, or the 2052 Notes; and
-
$1.0 billion in aggregate principal amount of 5.20% senior notes due in 2062, or the 2062 Notes, collectively, the Notes.
We intend to use the net proceeds of $4.9 billion from the offering of the 2025 Notes, the 2027 Notes, the 2029 Notes and the 2062 Notes, or collectively, the SMR Notes, together with the issuance of commercial paper and/or borrowings under the Credit Facility, cash on hand or other immediately available funds and borrowings under the Term Loan, discussed below, to finance the cash portion of the purchase price for Black Knight. The SMR Notes are subject to a special mandatory redemption feature pursuant to which we will be required to redeem all of the outstanding SMR Notes at a redemption price equal to 101% of the aggregate principal amount of the SMR Notes, plus accrued and unpaid interest, in the event that the Black Knight acquisition is not consummated on or prior to May 4, 2023, subject to two automatic extensions of three months each, to August 4, 2023 and to November 4, 2023, respectively, if U.S. antitrust clearance or a related law, injunction, order or other judgment, in each case whether temporary, preliminary or permanent, that restrains, enjoins or otherwise prohibits the consummation of the Black Knight merger remains outstanding and all other conditions to closing are satisfied (or in the case of conditions that by their terms are to be satisfied at the closing, are capable of being satisfied if the closing were to occur on such date) at each extension date, or if the Black Knight merger agreement is terminated at any time prior to such date. The $4.9 billion of net proceeds from the SMR Notes are separately invested and recorded as short-term restricted cash and cash equivalents in our consolidated balance sheet as of December 31, 2022.
We used the $3.0 billion of net proceeds from the offering of the 2033 Notes and the 2052 Notes to redeem $2.7 billion aggregate principal amount of four series of senior notes that would have matured in 2022 and 2023. The balance of the net proceeds was used for general corporate purposes, which included paying down a portion of the amounts outstanding under our Commercial Paper Program. We recorded $30 million in costs associated with the extinguishment and re-financing of our existing debt in connection with our May 2022 debt refinancing which includes a make-whole redemption of $18 million, duplicative interest of $7 million and $5 million of accelerated unamortized deferred debt costs. These costs are included in interest expense in our consolidated statements of income for 2022.
We incurred debt issuance costs of $67 million relating to the issuance of the Notes and these costs are presented in the accompanying consolidated balance sheet as a deduction from the carrying amount of the related debt liability and will be amortized over the remaining term of each series of the Notes. The Notes contain affirmative and negative covenants, including, but not limited to, certain redemption rights, limitations on liens and indebtedness and limitations on certain mergers, sales, dispositions and lease-back transactions.
Fixed Rate Senior Notes
- Senior Notes Issued in August 2020: On August 20, 2020, we issued $6.5 billion in aggregate principal amount of new senior notes, comprised of $1.25 billion in aggregate principal amount of floating rate senior notes due in 2023, or the Floating Rate Notes, $1.0 billion in aggregate principal amount of 0.70% senior notes due in 2023, $1.5 billion in aggregate principal amount of 1.85% senior notes due in 2032, $1.25 billion in aggregate principal amount of 2.65% senior notes due in 2040, and $1.5 billion in aggregate principal amount of 3.00% senior notes
due in 2060 (collectively, the August 2020 Notes). We used the net proceeds to fund a portion of the purchase price for the Ellie Mae acquisition.
We incurred debt issuance costs of $53 million relating to the issuance of the August 2020 Notes and these costs are presented in the accompanying consolidated balance sheet as a deduction from the carrying amount of the related debt liability and will be amortized over the remaining term of each series of the August 2020 Notes.
In September 2021, we used the proceeds from commercial paper issuances and cash on hand to fund the redemption of $1.25 billion of the Floating Rate Notes and recorded $4 million of accelerated unamortized deferred loan costs, included in interest expense in our consolidated statements of income for 2021.
In May 2022, we used the proceeds from the Notes to fund the redemption of $1.0 billion in aggregate principal amount of 0.70% senior notes due in 2023.
- Senior Notes Issued in May 2020: On May 26, 2020, we issued $2.5 billion in aggregate principal amount of new senior notes comprised of $1.25 billion in aggregate principal amount of 2.10% senior notes due in 2030 and $1.25 billion in aggregate principal amount of 3.00% senior notes due in 2050 (collectively, the May 2020 Notes).
We used the net proceeds of the May 2020 Notes for general corporate purposes, including to fund the redemption of our $1.25 billion aggregate principal amount of 2.75% senior notes due December 2020, or the 2020 Senior Notes, which were redeemed in accordance with their terms on June 25, 2020, and to pay down a portion of our commercial paper outstanding. In connection with our issuance of the May 2020 Notes and our early redemption of the 2020 Senior Notes, we recorded an extinguishment payment of $14 million that includes both a make-whole redemption payment and duplicative interest. These costs are included in interest expense in our consolidated statements of income in 2020.
We incurred debt issuance costs of $23 million relating to the issuance of the May 2020 Notes and these costs are presented in the accompanying consolidated balance sheet as a deduction from the carrying amount of the related debt liability and will be amortized over the remaining term of each note series.
- Senior Notes Issued in August 2018: In August 2018, we issued $2.25 billion in new aggregate unsecured fixed-rate senior notes, including $400 million, 3.45% notes due in 2023, $600 million, 3.75% notes due in 2028, and $1.25 billion, 4.25% notes due in 2048. We used the proceeds for general corporate purposes, including to fund the redemption of the $600 million, 2.50% Senior Notes due October 2018 and to refinance all of our issuances under our Commercial Paper Program that resulted from acquisitions and investments in 2018. We incurred debt issuance costs of $21 million relating to these notes that we recorded as a deduction from the carrying amount of the debt and which is being amortized over the respective note lives.
In June 2022, we used the proceeds from the Notes to fund the redemption of $400 million in aggregate principal amount of 3.45% notes due in 2023.
- Senior Notes Issued in August 2017:** In August 2017, we issued $1.0 billion in aggregate senior unsecured fixed-rate notes, including $500 million, 2.35% notes due in 2022 and $500 million, 3.10% notes due in 2027. We used the majority of the proceeds of the offering to fund the redemption of $850 million, 2.00% senior unsecured fixed-rate NYSE Notes prior to the October 2017 maturity date. We incurred debt issuance costs of $8 million relating to these notes that we recorded as a deduction from the carrying amount of the debt and which is being amortized over the respective note lives.
In June 2022, we used the proceeds from the Notes to fund the redemption of $500 million in aggregate principal amount of 2.35% notes due in 2022.
-
Senior Notes Issued in November 2015:** In November 2015, we issued $2.5 billion in aggregate senior unsecured fixed-rate notes, including the 2020 Senior Notes, and $1.25 billion, 3.75% notes due 2025. We used the proceeds, together with $1.6 billion of borrowings under our Commercial Paper Program, to finance the cash portion of the purchase price of Interactive Data. The 2020 Senior Notes were paid off in June 2020 with net proceeds from the offering of the May 2020 Notes.
-
Senior Notes Issued in October 2013:** In October 2013, we issued $800 million, 4.00% senior unsecured fixed-rate notes due 2023. We used the net proceeds to finance a portion of the purchase price of the acquisition of NYSE.
In June 2022, we used the proceeds from the Notes to fund the redemption of $800 million in aggregate principal amount of 4.00% notes due in 2023.
All of our Senior Notes contain affirmative and negative covenants, including, but not limited to, certain redemption rights, limitations on liens and indebtedness and limitations on certain mergers, sales, dispositions and lease-back transactions.
Debt Repayment Schedule
As of December 31, 2022, the outstanding debt repayment schedule is as follows (in millions):
| 2023 | $ | 4 | |||
| 2024 | — | ||||
| 2025 | 2,500 | ||||
| 2026 | — | ||||
| 2027 | 2,000 | ||||
| Thereafter | 13,850 | ||||
| Principal amounts repayable | 18,354 | ||||
| Debt issuance costs | (136) | ||||
| Unamortized balance discounts on bonds, net | (96) | ||||
| Total debt outstanding | $ | 18,122 |
**11.**Share-Based Compensation
The non-cash compensation expenses recognized in our consolidated statements of income for stock options, restricted stock and under our employee stock purchase plan were $155 million, $188 million and $139 million in 2022, 2021 and 2020, respectively, net of $16 million, $13 million and $12 million, respectively, that was capitalized as software development costs. This includes the expense related to the Bakkt Incentive Units, described below. As of December 31, 2022, we had 40.2 million shares in total under various equity plans available for future issuance as stock option and restricted stock awards.
Stock Option Plans
Stock options are granted with an exercise price equal to the fair value of our common stock on the grant date. We may grant, under provisions of the plans, both incentive stock options and nonqualified stock options. The options generally vest over three or four years and may generally be exercised up to ten years after the date of grant, but generally expire either 14 or 60 days after termination of employment. The shares of common stock issued under our stock option plans are made available from authorized and unissued common stock or treasury shares.
The fair value is based on our closing stock price on the date of grant as well as certain other assumptions. Compensation expense arising from option grants is recognized ratably over the vesting period based on the grant date fair value, net of estimated forfeitures.
The following is a summary of our stock option activity:
| Number of Options (in thousands) | Weighted Average Exercise Price per Option | ||||||||||
| Outstanding at January 1, 2020 | 3,501 | $ | 51.87 | ||||||||
| Granted | 413 | $ | 92.63 | ||||||||
| Exercised | (723) | $ | 42.88 | ||||||||
| Forfeited | (44) | $ | 75.81 | ||||||||
| Outstanding at December 31, 2020 | 3,147 | $ | 58.96 | ||||||||
| Granted | 310 | $ | 114.19 | ||||||||
| Exercised | (493) | $ | 34.80 | ||||||||
| Forfeited | — | $ | — | ||||||||
| Outstanding at December 31, 2021 | 2,964 | $ | 68.77 | ||||||||
| Granted | 266 | $ | 129.76 | ||||||||
| Exercised | (417) | $ | 53.30 | ||||||||
| Forfeited | (26) | $ | 123.77 | ||||||||
| Outstanding at December 31, 2022 | 2,787 | $ | 76.38 |
Details of stock options outstanding as of December 31, 2022 are as follows:
| Number of Options (in thousands) | Weighted Average Exercise Price | Weighted Average Remaining Contractual Life (Years) | Aggregate Intrinsic Value (In millions) | ||||||||||||||||||||
| Vested or expected to vest | 2,787 | $ | 76.38 | 5.5 | $ | 83 | |||||||||||||||||
| Exercisable | 2,205 | $ | 65.97 | 4.7 | $ | 82 |
Details of stock options exercised during 2022, 2021 and 2020 are as follows:
| Year Ended December 31, | ||||||||||||||||||||
| Options exercised: | 2022 | 2021 | 2020 | |||||||||||||||||
| Total intrinsic value of options exercised (in millions) | $ | 28 | $ | 41 | $ | 38 |
| As of December 31, | ||||||||||||||||||||
| Options outstanding: | 2022 | 2021 | 2020 | |||||||||||||||||
| Number of options exercisable (in millions) | 2.2 | 2.2 | 2.3 | |||||||||||||||||
| Weighted-average exercise price | $ | 65.97 | $ | 59.03 | $ | 50.07 |
As of December 31, 2022, there were $8 million in total unrecognized compensation costs related to stock options, which are expected to be recognized over a weighted average period of 1.3 years as the stock options vest.
We use the Black-Scholes option pricing model to value our stock option awards. During 2022, 2021 and 2020, we used the assumptions in the table below to compute the value:
| Year Ended December 31, | ||||||||||||||||||||
| Assumptions: | 2022 | 2021 | 2020 | |||||||||||||||||
| Risk-free interest rate | 1.72% | 0.64% | 1.46% | |||||||||||||||||
| Expected life in years | 6.0 | 5.7 | 5.8 | |||||||||||||||||
| Expected volatility | 23% | 24% | 20% | |||||||||||||||||
| Expected dividend yield | 1.17% | 1.16% | 1.30% | |||||||||||||||||
| Estimated weighted-average fair value of options granted per share | $ | 28.18 | $ | 22.70 | $ | 16.65 |
The risk-free interest rate is based on the zero-coupon U.S. Treasury yield curve in effect at the date of grant. The expected life is derived from historical and anticipated future exercise patterns. Expected volatility is based on historical volatility data of our stock.
Restricted Stock Plans
Restricted shares are used as an incentive to attract and retain qualified employees and to align our and our stockholders' interests by linking actual performance to both short and long-term stockholder return. We issue awards that may contain a combination of time, performance and/or market conditions. The grant date fair value of each award is based on the closing stock price of our stock at the date of grant.
Granted but unvested shares are generally forfeited upon termination of employment, whereby compensation costs previously recognized for unvested shares are reversed. Until the shares vest and are issued, participants have no voting or dividend rights and the shares may not be sold, assigned, transferred, pledged or otherwise encumbered. Unvested restricted stock earns dividend equivalents which are paid in cash on the vesting date.
The grant date fair value of time-based restricted stock units is recognized as expense ratably over the vesting period, which is typically three or four years, net of forfeitures. Our equity plans include a change in control provision that may accelerate vesting on both the time-based and performance-based restricted shares if the awards are not assumed by an acquirer in the case of a change in control.
For awards with performance conditions, we recognize compensation costs, net of forfeitures, using an accelerated attribution method over the vesting period. Compensation costs are recognized only if it is probable that the performance condition will be satisfied. If we initially determine that it is not probable of being satisfied and later determine that it is, or vice versa, a cumulative catch-up adjustment is retroactively recorded in the period of change based on the new estimate. We recognize the remaining compensation costs over the remaining vesting period.
For awards with a market condition, fair value is estimated based on a simulation of various outcomes and includes inputs such as our stock price on the grant date, the valuation of historical awards with market conditions, the probability that the market condition will affect the number of shares granted (as the market condition only affects shares granted in excess of certain financial performance targets), and our expectation of achieving the financial performance targets.
In February 2022, we reserved a maximum of 0.7 million restricted shares for potential issuance as performance-based restricted shares to certain of our employees. The number of shares ultimately granted under this award is based on our actual financial performance as compared to financial performance targets set by our Board and the Compensation Committee for the year ending December 31, 2022, and is also subject to a market condition reduction based on how our 2022 total stockholder return, or TSR, compared to that of the S&P 500 Index. In 2022, we performed at a performance level "below-target". Based on our actual 2022 financial performance as compared to the 2022 financial performance level thresholds, and without a required TSR haircut since we were "below-target", 0.3 million restricted shares will be awarded. This results in $39 million in compensation expenses that will be expensed over the three-year accelerated vesting period, including $22 million expensed during 2022.
The following is a summary of nonvested restricted shares under all plans discussed above:
| Number of Restricted Stock Shares (in thousands) | Weighted Average Grant-Date Fair Value per Share | ||||||||||
| Nonvested at January 1, 2020 | 3,728 | 68.87 | |||||||||
| Granted | 1,697 | 91.83 | |||||||||
| Vested | (2,035) | 65.21 | |||||||||
| Forfeited | (154) | 79.24 | |||||||||
| Nonvested at December 31, 2020 | 3,236 | 82.73 | |||||||||
| Granted | 1,869 | 115.28 | |||||||||
| Vested | (1,619) | 78.07 | |||||||||
| Forfeited | (169) | 101.47 | |||||||||
| Nonvested at December 31, 2021 | 3,317 | 101.72 | |||||||||
| Granted | 1,526 | 126.98 | |||||||||
| Vested | (1,541) | 93.94 | |||||||||
| Forfeited | (307) | 118.23 | |||||||||
| Nonvested at December 31, 2022 | 2,995 | 116.90 |
| Year Ended December 31, | ||||||||||||||||||||
| 2022 | 2021 | 2020 | ||||||||||||||||||
| Time-based restricted stock units granted (in thousands) (1) | 1,067 | 1,196 | 910 | |||||||||||||||||
| Total fair value of restricted stock vested under all restricted stock plans (in millions) | $ | 191 | $ | 184 | $ | 194 |
(1) The remaining shares granted are performance-based.
Performance-based restricted shares have been presented in the table above to reflect the actual shares issued based on the achievement of past performance targets, also considering the impact of any market conditions. Non-vested performance-based restricted shares granted are presented in the table above at the target number of restricted shares that would vest if the performance targets are met. As of December 31, 2022, there were $174 million in total unrecognized compensation costs related to time-based and performance-based restricted stock. These costs are expected to be recognized over a weighted-average period of 1.4 years as the restricted stock vests.
Employee Stock Purchase Plan
We offer our employees participation in our ESPP, under which we have reserved and may sell up to 25 million shares of our common stock to employees. The ESPP grants participating employees the right to acquire our stock in increments of 1% of eligible pay, with a maximum contribution of 25% of eligible pay, subject to applicable annual Internal Revenue Service, or IRS, limitations. Under our ESPP, participating employees are limited to $25,000 of common stock annually, and a maximum of 1,250 shares of common stock each offering period. There are two offering periods each year, from January 1st (or the first trading day thereafter) through June 30th (or the last trading day prior to such date) and from July 1st (or the first trading day thereafter) through December 31st (or the last trading day prior to such date). The purchase
price per share of common stock is 85% of the lesser of the fair market value of the stock on the first or the last trading day of each offering period. We recorded compensation expenses of $13 million, $11 million and $8 million during 2022, 2021 and 2020, respectively, related to the discount given to our participating employees.
Bakkt Incentive Units
Prior to the Bakkt merger with VIH (see Note 3), we sponsored the Bakkt Equity Incentive Plan under which Bakkt issued various Bakkt preferred, common and phantom, or participation, equity unit awards. These awards were made to certain employees and board members of Bakkt. The units were unvested at the issuance date, were subject to the vesting terms in the award agreements and upon vesting were converted into Bakkt equity or cash.
During 2020, a $300 million capital call related to the acquisition of Bridge2 Solutions triggered a market condition of certain of these Bakkt equity incentive awards. The market condition was based on numerous possible Bakkt transaction or event scenarios established on the original date of grant, each of which have a fixed fair market value. Over the life of these awards, we were required to estimate the most likely outcome and reflect the cumulative financial statement impact of any changes between outcomes. As a result, during 2020, we incurred a $10 million non-cash compensation expense related to these awards that was recorded as an acquisition-related cost.
During 2021, the merger of Bakkt and VIH triggered a market condition of these Bakkt equity incentive awards. As a result, during 2021, we incurred $31 million of non-cash compensation expense related to these awards which we recorded as an acquisition-related cost prior to deconsolidating Bakkt.
**12.**Equity
Common Stock
We are authorized to issue 1.5 billion shares with a par value of $0.01 per share. Each holder of common stock is entitled to one vote for each share of common stock held of record by such holder on all matters on which stockholders are entitled to vote, including the election and removal of directors. There were 634 million and 559 million shares of common stock issued and outstanding, respectively, as of December 31, 2022. There were 631 million and 561 million shares of common stock issued and outstanding, respectively, as of December 31, 2021.
Preferred Stock
We are authorized to issue 100 million shares of preferred stock with a par value of $0.01 per share. The holders of a series of preferred stock shall be entitled only to such voting rights as shall expressly be granted thereto by the Certificate of Incorporation (including any certificate of designation relating to such series of preferred stock). As of December 31, 2022, no shares of preferred stock have been issued.
Treasury Stock
During each of 2022, 2021 and 2020, we received 1.0 million shares of common stock from employees to satisfy tax withholdings we made on their behalf for restricted stock and stock option exercises. We recorded the receipt of the shares as treasury stock.
Stock Repurchase Program
We periodically review whether to repurchase our stock. In making a determination regarding the timing and extent of any stock repurchases, we consider multiple factors that may include: overall stock market conditions, our common stock price performance, the remaining amount authorized for repurchases by our Board, the potential impact of a stock repurchase program on our debt ratings, our expected free cash flow and working capital needs, our current and future planned strategic growth initiatives, and other potential uses of our cash and capital resources.
Repurchases may be made from time to time on the open market, through established trading plans, in privately-negotiated transactions or otherwise, in accordance with all applicable securities laws, rules and regulations. We may begin or discontinue stock repurchases at any time and may amend or terminate a Rule 10b5-1 trading plan at any time or enter into additional plans.
We discontinued stock repurchases and terminated our Rule 10b5-1 trading plan in August 2020 in connection with the Ellie Mae acquisition. In November 2021, we resumed stock repurchases. In December 2021, our Board approved an aggregate of $3.15 billion for future repurchases of our common stock with no fixed expiration date that became effective January 1, 2022. The $3.15 billion replaces the previous amount approved by the Board. In December 2021 we entered
into a new Rule 10b5-1 trading plan that became effective in February 2022. In connection with our pending acquisition of Black Knight, on May 4, 2022, we terminated our Rule 10b5-1 trading plan and suspended share repurchases.
During 2022, 2021 and 2020, we repurchased 5.0 million shares, 1.8 million shares and 13.6 million shares, respectively, of our outstanding common stock at a cost of $632 million, $250 million and $1.2 billion, respectively, excluding shares withheld upon vesting of equity awards. The shares repurchased are held in treasury stock.
As of December 31, 2022, the remaining balance of Board approved funds for future repurchase was $2.5 billion. The approval of our Board for stock repurchases does not obligate us to acquire any particular amount of our common stock. In addition, our Board may increase or decrease the amount available for repurchases from time to time.
The table below sets forth the information with respect to purchases made by or on behalf of ICE or any “affiliated purchaser” (as defined in Rule 10b-18(a)(3) under the Exchange Act) of our common stock during the periods presented as follows:
| Shares Repurchased (in thousands) | Average Repurchase Price Per Share | Amount of Repurchases (in millions) | Total cumulative year-to-date shares purchased as part of publicly announced plans or programs (in thousands) | Approximate dollar value of shares that may yet be purchased under the plans or programs as of the end of the quarter (in millions) | |||||||||||||||||||||||||
| 2022 | |||||||||||||||||||||||||||||
| Fourth quarter | — | $ | — | $ | — | 4,955 | $ | 2,518 | |||||||||||||||||||||
| Third quarter | — | $ | — | $ | — | 4,955 | $ | 2,518 | |||||||||||||||||||||
| Second quarter | 1,281 | $ | 122.54 | $ | 157 | 4,955 | $ | 2,518 | |||||||||||||||||||||
| First quarter | 3,674 | $ | 129.30 | $ | 475 | 3,674 | $ | 2,675 | |||||||||||||||||||||
| Total common stock repurchases(1) | 4,955 | $ | 127.56 | $ | 632 | ||||||||||||||||||||||||
| 2021 | |||||||||||||||||||||||||||||
| Fourth quarter | 1,834 | $ | 136.31 | $ | 250 | 1,834 | $ | 903 | |||||||||||||||||||||
| Third quarter | — | $ | — | — | — | $ | — | ||||||||||||||||||||||
| Second quarter | — | $ | — | — | — | $ | — | ||||||||||||||||||||||
| First quarter | — | $ | — | — | — | $ | — | ||||||||||||||||||||||
| Total common stock repurchases(2) | 1,834 | $ | 136.31 | $ | 250 | ||||||||||||||||||||||||
| 2020 | |||||||||||||||||||||||||||||
| Fourth quarter | — | $ | — | $ | — | 13,603 | $ | 1,153 | |||||||||||||||||||||
| Third quarter | 1,576 | $ | 93.88 | 148 | 13,603 | $ | 1,153 | ||||||||||||||||||||||
| Second quarter | 4,384 | $ | 91.24 | 400 | 12,027 | $ | 1,301 | ||||||||||||||||||||||
| First quarter | 7,643 | $ | 91.50 | 699 | 7,643 | $ | 1,701 | ||||||||||||||||||||||
| Total common stock repurchases(3) | 13,603 | $ | 91.69 | $ | 1,247 |
(1) Includes 0.4 million shares purchased on the open market at a cost of $50 million and 4.6 million shares purchased under our Rule 10b5-1 trading plan at a cost of $582 million.
(2) All 1.8 million shares were purchased on the open market at a cost of $250 million.
(3) Includes 3.2 million shares purchased on the open market at a cost of $299 million and 10.4 million shares purchased under our Rule 10b5-1 trading plan at a cost of $948 million.
Dividends
Our Board has adopted a quarterly dividend declaration policy providing that the declaration of any dividends will be determined quarterly by the Board or the Audit Committee, taking into account such factors as our evolving business model, prevailing business conditions, our financial results and capital requirements, and other considerations which our Board deems relevant, without a predetermined annual net income payout ratio. We declared and paid cash dividends per share during the periods presented as follows:
| Dividends Per Share | Amount (in millions) | ||||||||||
| 2022 | |||||||||||
| Fourth quarter | $ | 0.38 | $ | 214 | |||||||
| Third quarter | 0.38 | 213 | |||||||||
| Second quarter | 0.38 | 213 | |||||||||
| First quarter | 0.38 | 213 | |||||||||
| Total cash dividends declared and paid | $ | 1.52 | $ | 853 | |||||||
| 2021 | |||||||||||
| Fourth quarter | $ | 0.33 | $ | 186 | |||||||
| Third quarter | 0.33 | 187 | |||||||||
| Second quarter | 0.33 | 187 | |||||||||
| First quarter | 0.33 | 187 | |||||||||
| Total cash dividends declared and paid | $ | 1.32 | $ | 747 | |||||||
| 2020 | |||||||||||
| Fourth quarter | $ | 0.30 | $ | 169 | |||||||
| Third quarter | 0.30 | 170 | |||||||||
| Second quarter | 0.30 | 164 | |||||||||
| First quarter | 0.30 | 166 | |||||||||
| Total cash dividends declared and paid | $ | 1.20 | $ | 669 |
Accumulated Other Comprehensive Income/(Loss)
The following tables present changes in the accumulated balances for each component of other comprehensive income/(loss) (in millions):
| Changes in Accumulated Other Comprehensive Income/(Loss) by Component | ||||||||||||||||||||||||||
| Foreign currency translation adjustments | Comprehensive income from equity method investment | Employee benefit plans adjustments | Total | |||||||||||||||||||||||
| Balance, as of January 1, 2020 | $ | (177) | $ | 1 | $ | (67) | $ | (243) | ||||||||||||||||||
| Other comprehensive income/(loss) | 43 | — | 11 | 54 | ||||||||||||||||||||||
| Income tax benefit/(expense) | — | — | (3) | (3) | ||||||||||||||||||||||
| Net current period other comprehensive income/(loss) | 43 | — | 8 | 51 | ||||||||||||||||||||||
| Balance, as of December 31, 2020 | (134) | 1 | (59) | (192) | ||||||||||||||||||||||
| Other comprehensive income/(loss) | (16) | 1 | 15 | — | ||||||||||||||||||||||
| Income tax benefit/(expense) | — | — | (4) | (4) | ||||||||||||||||||||||
| Net current period other comprehensive income/(loss) | (16) | 1 | 11 | (4) | ||||||||||||||||||||||
| Balance, as of December 31, 2021 | (150) | 2 | (48) | (196) | ||||||||||||||||||||||
| Other comprehensive income/(loss) | (130) | — | (10) | (140) | ||||||||||||||||||||||
| Income tax benefit/(expense) | 2 | — | 3 | 5 | ||||||||||||||||||||||
| Net current period other comprehensive income/(loss) | (128) | — | (7) | (135) | ||||||||||||||||||||||
| Balance, as of December 31, 2022 | $ | (278) | $ | 2 | $ | (55) | $ | (331) |
**13.**Income Taxes
Income before income taxes and the income tax provision consisted of the following (in millions), and our consolidated income tax provision for 2021 was elevated due to the income tax expense associated with the gains we recognized from the Coinbase and Bakkt transactions.
| Year Ended December 31, | |||||||||||||||||
| 2022 | 2021 | 2020 | |||||||||||||||
| Income before income taxes | |||||||||||||||||
| Domestic | $ | 184 | $ | 4,179 | $ | 1,449 | |||||||||||
| Foreign | 1,624 | 1,519 | 1,317 | ||||||||||||||
| Total | $ | 1,808 | $ | 5,698 | $ | 2,766 | |||||||||||
| Income tax provision | |||||||||||||||||
| Current tax expense: | |||||||||||||||||
| Federal | $ | 366 | $ | 533 | $ | 166 | |||||||||||
| State | 206 | 267 | 136 | ||||||||||||||
| Foreign | 331 | 292 | 264 | ||||||||||||||
| Total | $ | 903 | $ | 1,092 | $ | 566 | |||||||||||
| Deferred tax expense/(benefit): | |||||||||||||||||
| Federal | $ | (413) | $ | 258 | $ | 73 | |||||||||||
| State | (165) | 92 | (42) | ||||||||||||||
| Foreign | (15) | 187 | 61 | ||||||||||||||
| $ | (593) | $ | 537 | $ | 92 | ||||||||||||
| Total income tax expense | $ | 310 | $ | 1,629 | $ | 658 |
A reconciliation of the statutory U.S. federal income tax rate to our effective income tax rate is as follows:
| Year Ended December 31, | |||||||||||||||||
| 2022 | 2021 | 2020 | |||||||||||||||
| Statutory federal income tax rate | 21 | % | 21 | % | 21 | % | |||||||||||
| State and local income taxes, net of federal benefit | 5 | 4 | 3 | ||||||||||||||
| Foreign tax rate differential | (1) | — | (1) | ||||||||||||||
| Current year tax benefit from foreign derived intangible income | (3) | (1) | (1) | ||||||||||||||
| Deferred tax from foreign tax law change and Bakkt transaction | — | 4 | 2 | ||||||||||||||
| Unrecognized tax benefits | 1 | 1 | 1 | ||||||||||||||
| State apportionment changes | — | — | (1) | ||||||||||||||
| State deferred benefit of Bakkt impairment | (5) | — | — | ||||||||||||||
| Other | (1) | — | — | ||||||||||||||
| Total provision for income taxes | 17 | % | 29 | % | 24 | % |
The effective tax rate in 2022 was lower than in prior years primarily due to the deferred income tax benefit from the impairment of our equity investment in Bakkt recorded in the current year, and the deferred income tax expenses recorded in prior years from U.K. tax law changes in the prior years. In 2021, the U.K. enacted a corporate income tax rate increase from 19% to 25% effective April 1, 2023. In 2020, the U.K. enacted a corporate income tax rate increase from 17% to 19% effective April 1, 2020.
On November 15, 2021, the Infrastructure Investment and Jobs Act was signed into law. On March 11, 2021, the American Rescue Plan Act, or ARPA, was signed into law. The ARPA enacted certain provisions that are relevant to corporate income tax. On March 27, 2020, the CARES Act was enacted and certain income tax related relief was provided under the CARES Act. These provisions did not have a material impact on our income tax provision for 2022, 2021 or 2020.
Deferred Tax Assets and Liabilities
Deferred income taxes reflect the net tax effects of temporary differences between the carrying amounts of assets and liabilities for financial reporting purposes and the amounts used for income tax purposes. As a result of the U.K. corporate
income tax rate change from 19% to 25% enacted in June 2021, and from 17% to 19% enacted in 2020, we revalued the U.K. deferred tax assets and liabilities accordingly. Certain unrecognized tax benefits associated with our acquisition of Ellie Mae are presented as a reduction to related deferred tax assets. During the fourth quarter of 2021, we deconsolidated Bakkt and treat it as an equity investment within our consolidated financial statements resulting in a pre-tax gain of $1.4 billion (see Note 3). The deferred tax liability associated with our Bakkt equity method investment decreased significantly in 2022 due to the impairment of the investment. The deferred tax liability associated with property and equipment decreased significantly due to capitalized research and experimental expenditure requirements that became effective in 2022 under the Tax Cuts and Jobs Act. The following table summarizes the significant components of our deferred tax liabilities and assets as of December 31, 2022 and 2021 (in millions):
| As of December 31, | |||||||||||
| 2022 | 2021 | ||||||||||
| Deferred tax assets: | |||||||||||
| Deferred and stock-based compensation | $ | 78 | $ | 76 | |||||||
| Liability reserve | 66 | 59 | |||||||||
| Tax credits | 7 | 12 | |||||||||
| Loss carryforward | 91 | 115 | |||||||||
| Deferred revenue | 19 | 23 | |||||||||
| Lease liability | 77 | 77 | |||||||||
| Other | 31 | 20 | |||||||||
| Total | 369 | 382 | |||||||||
| Valuation allowance | (92) | (99) | |||||||||
| Total deferred tax assets, net of valuation allowance | $ | 277 | $ | 283 | |||||||
| Deferred tax liabilities: | |||||||||||
| Property and equipment | $ | (60) | $ | (172) | |||||||
| Acquired intangibles | (3,527) | (3,660) | |||||||||
| Right of use asset | (62) | (58) | |||||||||
| Equity investment | (121) | (493) | |||||||||
| Total deferred tax liabilities | $ | (3,770) | $ | (4,383) | |||||||
| Net deferred tax liabilities | $ | (3,493) | $ | (4,100) | |||||||
| Reported as: | |||||||||||
| Net non-current deferred tax liabilities | $ | (3,493) | $ | (4,100) | |||||||
A reconciliation of the beginning and ending amount of deferred income tax valuation allowance is as follows (in millions):
| Year Ended December 31, | |||||||||||||||||
| 2022 | 2021 | 2020 | |||||||||||||||
| Beginning balance of deferred income tax valuation allowance | $ | 99 | $ | 95 | $ | 119 | |||||||||||
| Charges against goodwill | — | — | 2 | ||||||||||||||
| Increases/(Decreases) | (7) | 4 | (26) | ||||||||||||||
| Ending balance of deferred income tax valuation allowance | $ | 92 | $ | 99 | $ | 95 |
We recognize valuation allowances on deferred tax assets if, based on the weight of the evidence, we believe that it is more likely than not that some or all of the deferred tax assets will not be realized. We recorded a valuation allowance for deferred tax assets of $92 million and $99 million as of December 31, 2022 and 2021, respectively. Decreases in 2022 and 2020 primarily related to taxable capital gain and certain tax attributes that expired, respectively. The increase in 2021 is primarily due to certain carried forward foreign tax attributes and foreign tax attributes generated in 2021 that became unrealizable during the year. Increases charged against goodwill in 2020 primarily relate to deferred tax assets arising on acquisitions.
The majority of our undistributed earnings of our non-U.S. subsidiaries are subject to the Global Intangible Low-Taxed Income provisions and, as such, are subject to immediate U.S. income taxation and can be distributed to the U.S. with no material additional income tax consequences in the future. Consequently, these earnings are not considered to be indefinitely reinvested and the related tax impact is included in our income tax provision for 2022, 2021 and 2020.
However, our non-U.S. subsidiaries’ cumulative undistributed earnings as of December 31, 2022, 2021 and 2020 that are not subject to the Global Intangible Low-Taxed Income provisions are considered to be indefinitely reinvested. Accordingly, no provision for U.S. federal and state income taxes has been made in the accompanying consolidated financial statements. Further, a determination of the unrecognized deferred tax liability is not practicable. An estimate of these indefinitely reinvested undistributed earnings as of December 31, 2022, based on post-income tax earnings under U.S. GAAP, is $5.8 billion.
As of December 31, 2022 and 2021, we have gross U.S. federal net operating loss carryforwards of $100 million and $120 million, respectively, and gross state and local net operating loss carryforwards of $76 million and $137 million, respectively. The net decrease of federal, state and local net operating loss carryforwards are primarily due to losses utilized in the current year. The net operating loss carryforwards are available to offset future taxable income until they expire, with amounts beginning in 2026. In addition, as of December 31, 2022 and 2021, we have gross foreign net operating loss carryforwards of $280 million and $293 million, respectively. The majority of gross foreign net operating losses are not expected to be realizable in future periods and have related valuation allowances.
A reconciliation of the beginning and ending amount of unrecognized tax benefits is as follows (in millions):
| Year Ended December 31, | |||||||||||||||||
| 2022 | 2021 | 2020 | |||||||||||||||
| Beginning balance of unrecognized tax benefits | 229 | 188 | $ | 103 | |||||||||||||
| Additions/(reductions) related to acquisitions | — | (1) | 58 | ||||||||||||||
| Additions based on tax positions taken in current year | 30 | 41 | 21 | ||||||||||||||
| Additions based on tax positions taken in prior years | — | 3 | 14 | ||||||||||||||
| Reductions based on tax positions taken in prior years | (3) | (2) | — | ||||||||||||||
| Reductions resulting from statute of limitation lapses | (9) | — | (5) | ||||||||||||||
| Reductions related to settlements with taxing authorities | — | — | (3) | ||||||||||||||
| Ending balance of unrecognized tax benefits | $ | 247 | $ | 229 | $ | 188 |
As of December 31, 2022 and 2021, the balance of unrecognized tax benefits which would, if recognized, affect our effective tax rate was $208 million and $194 million, respectively. It is reasonably possible, as a result of settlements of ongoing audits or statute of limitations expirations, that unrecognized tax benefits could increase as much as $30 million and decrease as much as $45 million within the next 12 months. Of the $247 million in unrecognized tax benefits as of December 31, 2022, $202 million is recorded within other non-current liabilities and $45 million is recorded within other current liabilities.
We recognize interest and penalties accrued on income tax uncertainties as a component of income tax expense. In 2022, 2021 and 2020, we recognized $12 million, $10 million and $6 million, respectively, of income tax expense for interest and penalties. As of December 31, 2022 and 2021, accrued interest and penalties were $61 million and $49 million, respectively. Of the $61 million in accrued interest and penalties as of December 31, 2022, $17 million is recorded within other non-current liabilities and $44 million is recorded within other current liabilities in the accompanying consolidated balance sheet.
We or one of our subsidiaries files income tax returns in the U.S. federal jurisdiction and various state and foreign jurisdictions. The following table summarizes open tax years by major jurisdiction:
| Jurisdiction | Open Tax Years | |||||||
| U.S. Federal | 2019 - 2022 | |||||||
| U.S. States | 2009 - 2022 | |||||||
| U.K. | 2020 - 2022 |
We have filed amended U.S. federal returns for the years prior to 2019 to claim additional credits and deductions and the associated refund claims are subject to review by the U.S. taxing authorities. Although the outcome of tax audits is always uncertain, we believe that adequate amounts of tax, including interest and penalties, have been provided for any adjustments expected to result from open tax years.
**14.**Clearing Operations
We operate six clearing houses, each of which acts as a central counterparty that becomes the buyer to every seller and the seller to every buyer for its clearing members or participants, or Members. Through this central counterparty function, the clearing houses provide financial security for each transaction for the duration of the position by limiting counterparty credit risk.
Our clearing houses are responsible for providing clearing services to each of our futures exchanges, and in some cases to third-party execution venues, and are as follows, referred to herein collectively as "the ICE Clearing Houses":
| Clearing House | Products Cleared | Exchange where Executed | Location | |||||||||||||||||
| ICE Clear Europe | Energy, agricultural, interest rates and equity index futures and options contracts and OTC European CDS instruments | ICE Futures Europe, ICE Futures U.S., ICE Endex, ICE Futures Abu Dhabi and third-party venues | U.K. | |||||||||||||||||
| ICE Clear U.S. | Agricultural, metals, foreign exchange, or FX, interest rate, equity index and digital asset futures and/or options contracts | ICE Futures U.S. | U.S. | |||||||||||||||||
| ICE Clear Credit | OTC North American, European, Asian-Pacific and Emerging Market CDS instruments | Creditex and third-party venues | U.S. | |||||||||||||||||
| ICE Clear Netherlands | Derivatives on equities and equity indices traded on regulated markets | ICE Endex | The Netherlands | |||||||||||||||||
| ICE Clear Singapore | Energy, metals and financial futures products and digital asset futures contracts | ICE Futures Singapore | Singapore | |||||||||||||||||
| ICE NGX | Physical North American natural gas and electricity | ICE NGX | Canada |
In 2022, we announced our decision to cease our CDS clearing service at ICE Clear Europe, our clearing house in the U.K., and thereafter our sole CDS clearing offering will be at our ICE Clear Credit clearing house in the U.S.
Original and Variation Margin
Each of the ICE Clearing Houses generally requires all Members to deposit collateral in cash or certain pledged assets. The collateral deposits are known as “original margin.” In addition, the ICE Clearing Houses may make intraday original margin calls in circumstances where market conditions require additional protection. The daily profits and losses to and from the ICE Clearing Houses due to the marking-to-market of open contracts is known as “variation margin.” With the exception of ICE NGX’s physical natural gas and physical power products discussed separately below, the ICE Clearing Houses mark all outstanding contracts to market, and therefore pay and collect variation margin, at least once daily.
The amounts that Members are required to maintain are determined by proprietary risk models established by each ICE Clearing House and reviewed by the relevant regulators, independent model validators, risk committees and the boards of directors of the respective ICE Clearing House. The amounts required may fluctuate over time. Each of the ICE Clearing Houses is a separate legal entity and is not subject to the liabilities of the others, or the obligations of Members of the other ICE Clearing Houses.
Should a particular Member fail to deposit its original margin or fail to make a variation margin payment, when and as required, the relevant ICE Clearing House may liquidate or hedge the defaulting Member's open positions and use their original margin and guaranty fund deposits to pay any amount owed. In the event that the defaulting Member's deposits are not sufficient to pay the amount owed in full, the ICE Clearing Houses will first use their respective contributions to the guaranty fund, often referred to as Skin In The Game, or SITG, to pay any remaining amount owed. In the event that the SITG is not sufficient, the ICE Clearing Houses may utilize the respective guaranty fund deposits and default insurance, or collect limited additional funds from their respective non-defaulting Members on a pro-rata basis, to pay any remaining amount owed.
As of December 31, 2022 and 2021, the ICE Clearing Houses had received or had been pledged $273.3 billion and $239.9 billion, respectively, in cash and non-cash collateral in original margin and guaranty fund deposits to cover price movements of underlying contracts for both periods.
Guaranty Funds and ICE Contribution
As described above, mechanisms have been created, called guaranty funds, to provide partial protection in the event of a Member default. With the exception of ICE NGX, each of the ICE Clearing Houses requires that each Member make deposits into a guaranty fund.
In addition, we have contributed our own capital that could be used if a defaulting Member’s original margin and guaranty fund deposits are insufficient. Included in the total contribution to ICE Clear U.S. as of December 31, 2022, is $15 million from Bakkt, solely applicable to any losses associated with a default in Bitcoin contracts and other digital assets that ICE Clear U.S. may clear in the future. Such amounts are recorded as long-term restricted cash and cash equivalents in our balance sheets and are as follows (in millions):
| ICE Portion of Guaranty Fund Contribution | Default insurance | |||||||||||||||||||||||||||||||
| As of December 31, | As of December 31, | |||||||||||||||||||||||||||||||
| Clearing House | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||||||||
| ICE Clear Europe | $247 | $247 | $100 | $75 | ||||||||||||||||||||||||||||
| ICE Clear U.S. | 90 | 83 | 25 | 25 | ||||||||||||||||||||||||||||
| ICE Clear Credit | 50 | 50 | 75 | 50 | ||||||||||||||||||||||||||||
| ICE Clear Netherlands | 2 | 2 | N/A | N/A | ||||||||||||||||||||||||||||
| ICE Clear Singapore | 1 | 1 | N/A | N/A | ||||||||||||||||||||||||||||
| ICE NGX | 15 | 15 | 200 | 100 | ||||||||||||||||||||||||||||
| Total | $405 | $398 | $400 | $250 |
We also maintain default insurance as an additional layer of clearing member default protection which is reflected in the table below. The default insurance was renewed in September 2022 and has a three-year term for the following clearing houses in the following amounts: ICE Clear Europe - $100 million; ICE Clear U.S. - $25 million; and ICE Clear Credit - $75 million. The default insurance layer resides after and in addition to the ICE Clear Europe, ICE Clear U.S. and ICE Clear Credit SITG contributions and before the guaranty fund contributions of the non-defaulting Members.
Similar to SITG, the default insurance layer is not intended to replace or reduce the position risk-based amount of the guaranty fund. As a result, the default insurance layer is not a factor that is included in the calculation of the Members’ guaranty fund contribution requirement. Instead, it serves as an additional, distinct, and separate default resource that should serve to further protect the non-defaulting Members’ guaranty fund contributions from being mutualized in the event of a default.
As of December 31, 2022, ICE NGX maintained a guaranty fund of $215 million, comprising $15 million in cash and a $200 million letter of credit backed by a default insurance policy of the same amount, discussed below.
Below is a depiction of our Default Waterfall which summarizes the lines of defense and layers of protection we maintain at ICE Clear Europe, ICE Clear U.S. and ICE Clear Credit.
ICE Clearing House Default Waterfall
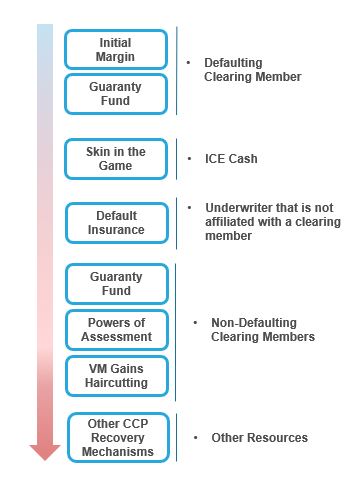
Cash and Invested Margin Deposits
We have recorded cash and invested margin and guaranty fund deposits and amounts due in our balance sheets as current assets with corresponding current liabilities to the Members. As of December 31, 2022, our cash and invested margin deposits were as follows (in millions):
| ICE Clear Europe (1) | ICE Clear Credit | ICE Clear U.S. | ICE NGX | Other ICE Clearing Houses | Total | ||||||||||||||||||||||||||||||
| Original margin | $ | 101,243 | $ | 31,277 | $ | 4,141 | $ | — | $ | 5 | $ | 136,666 | |||||||||||||||||||||||
| Unsettled variation margin, net | — | — | — | 749 | — | 749 | |||||||||||||||||||||||||||||
| Guaranty fund | 4,162 | 3,177 | 597 | — | 4 | 7,940 | |||||||||||||||||||||||||||||
| Delivery contracts receivable/payable, net | — | — | — | 2,017 | — | 2,017 | |||||||||||||||||||||||||||||
| Total | $ | 105,405 | $ | 34,454 | $ | 4,738 | $ | 2,766 | $ | 9 | $ | 147,372 |
As of December 31, 2021, our cash and invested margin deposits, were as follows (in millions):
| ICE Clear Europe (2) | ICE Clear Credit | ICE Clear U.S. | ICE NGX | Other ICE Clearing Houses | Total | ||||||||||||||||||||||||||||||
| Original margin | $ | 94,010 | $ | 39,372 | $ | 6,963 | $ | — | $ | 27 | $ | 140,372 | |||||||||||||||||||||||
| Unsettled variation margin, net | — | — | — | 226 | — | 226 | |||||||||||||||||||||||||||||
| Guaranty fund | 4,175 | 3,952 | 597 | — | 4 | 8,728 | |||||||||||||||||||||||||||||
| Delivery contracts receivable/payable, net | — | — | — | 1,103 | — | 1,103 | |||||||||||||||||||||||||||||
| Total | $ | 98,185 | $ | 43,324 | $ | 7,560 | $ | 1,329 | $ | 31 | $ | 150,429 |
(1) $97.6 billion and $7.8 billion is related to futures/options and CDS, respectively.
(2) $92.0 billion and $6.2 billion is related to futures/options and CDS, respectively.
The amount of cash and cash equivalent margin deposits on hand will fluctuate over time as a result of, among other things, the extent of open positions held at any point in time by market participants in contracts and the margin rates then in effect for such contracts, as well as the extent to which we invest in non-cash and cash equivalents. Our cash and
invested margin and guaranty fund deposits are maintained in accounts with national banks and highly-rated financial institutions or secured through direct investments, primarily in U.S. Treasury and other highly-rated foreign government securities, or reverse repurchase agreements with primarily overnight maturities. We primarily use Level 1 inputs when evaluating the fair value of the non-cash equivalent direct investments, as highly-rated government securities are quoted in active markets. The carrying value of these deposits are deemed to approximate fair value.
To provide a tool to address the liquidity needs of our clearing houses and manage the liquidation of margin and guaranty fund deposits held in the form of cash and high quality sovereign debt, ICE Clear Europe, ICE Clear Credit and ICE Clear U.S. have entered into Committed Repurchase Agreement Facilities, or Committed Repo. Additionally, ICE Clear Credit and ICE Clear Netherlands have entered into Committed FX Facilities to support these liquidity needs. As of December 31, 2022 the following facilities were in place:
-
ICE Clear Europe: $1.0 billion in Committed Repo to finance U.S. dollar, euro and pound sterling deposits.
-
ICE Clear Credit: $300 million in Committed Repo (U.S. dollar based) to finance U.S. dollar denominated sovereign debt and euro deposits, €250 million in Committed Repo (euro based) to finance euro and U.S. dollar denominated sovereign debt deposits, and €1.9 billion in Committed FX Facilities to finance euro payment obligations.
-
ICE Clear U.S.: $250 million in Committed Repo to finance U.S. dollar denominated sovereign debt deposits.
-
ICE Clear Netherlands: €10 million in Committed FX Facilities to finance euro payment obligations.
Details of our deposits are as follows (in millions):
| Cash and Cash Equivalent Margin Deposits and Guaranty Funds | ||||||||||||||||||||
| Clearing House | Investment Type | As of December 31, 2022 | As of December 31, 2021 | |||||||||||||||||
| ICE Clear Europe | National bank account (1) | $ | 17,390 | $ | 55,959 | |||||||||||||||
| ICE Clear Europe | Reverse repo | 65,352 | 25,518 | |||||||||||||||||
| ICE Clear Europe | Sovereign debt | 19,894 | 9,324 | |||||||||||||||||
| ICE Clear Europe | Demand deposits | 153 | 4,220 | |||||||||||||||||
| ICE Clear Credit | National bank account | 27,145 | 37,282 | |||||||||||||||||
| ICE Clear Credit | Reverse repo | 3,916 | 3,639 | |||||||||||||||||
| ICE Clear Credit | Demand deposits | 3,393 | 2,403 | |||||||||||||||||
| ICE Clear U.S. | Reverse repo | 4,266 | 6,485 | |||||||||||||||||
| ICE Clear U.S. | Sovereign debt | 472 | 1,075 | |||||||||||||||||
| Other ICE Clearing Houses | Demand deposits | 9 | 31 | |||||||||||||||||
| Total cash and cash equivalent margin deposits and guaranty funds | $ | 141,990 | $ | 145,936 | ||||||||||||||||
| Invested Deposits, Delivery Contracts Receivable and Unsettled Variation Margin | ||||||||||||||||||||
| Clearing House | Investment Type | As of December 31, 2022 | As of December 31, 2021 | |||||||||||||||||
| ICE NGX | Unsettled variation margin and delivery contracts receivable/payable | $ | 2,766 | $ | 1,329 | |||||||||||||||
| ICE Clear Europe | Invested deposits - sovereign debt | 2,616 | 3,164 | |||||||||||||||||
| Total invested deposits, delivery contracts receivable and unsettled variation margin | $ | 5,382 | $ | 4,493 |
(1) As of December 31, 2022, ICE Clear Europe held €11.7 billion ($12.5 billion based on the euro/U.S. dollar exchange rate of 1.0704 as of December 31, 2022) at European Central Bank, or ECB, £4.0 billion ($4.9 billion based on the pound sterling/U.S. dollar exchange rate of 1.2093 as of December 31, 2022) at the Bank of England, or BOE and €10 million ($11 million based on the above exchange rate) at the BOE. As of December 31, 2021, ICE Clear Europe held €47.2 billion ($53.7 billion based on the euro/U.S. dollar exchange rate of 1.1372 as of December 31, 2021) at ECB, £1.7 billion ($2.3 billion based on the pound sterling/U.S. dollar exchange rate of 1.3524 as of December 31, 2021) at the BOE and €10 million ($11 million based on the above exchange rate) at the BOE.
Other Deposits
Non-cash original margin and guaranty fund deposits are not reflected in the accompanying consolidated balance sheets as the risks and rewards of these assets remain with the clearing members unless the clearing houses have sold or re-
pledged the assets or in the event of a clearing member default, where the clearing member is no longer entitled to redeem the assets. Any income, gain or loss accrues to the clearing members.
In addition to the cash and invested deposits above, the ICE Clearing Houses have also received other assets from Members, which include government obligations, and may include other non-cash collateral such as letters of credit at ICE NGX, or gold on rare occasions at ICE Clear Europe, to mitigate credit risk. For certain deposits, we may impose discount or “haircut” rates to ensure adequate collateral if market values fluctuate. The value-related risks and rewards of these assets remain with the Members. Any gain or loss accrues to the Member. The ICE Clearing Houses do not, in the ordinary course, rehypothecate or re-pledge these assets. These pledged assets are not reflected in our balance sheets, and are as follows (in millions):
| As of December 31, 2022 | |||||||||||||||||||||||||||||||||||
| ICE Clear Europe | ICE Clear Credit | ICE Clear U.S. | ICE NGX | Total | |||||||||||||||||||||||||||||||
| Original margin: | |||||||||||||||||||||||||||||||||||
| Government securities at face value | $ | 74,964 | $ | 26,601 | $ | 14,855 | $ | — | $ | 116,420 | |||||||||||||||||||||||||
| Letters of credit | — | — | — | 5,434 | 5,434 | ||||||||||||||||||||||||||||||
| ICE NGX cash deposits | — | — | — | 2,357 | 2,357 | ||||||||||||||||||||||||||||||
| Total | $ | 74,964 | $ | 26,601 | $ | 14,855 | $ | 7,791 | $ | 124,211 | |||||||||||||||||||||||||
| Guaranty fund: | |||||||||||||||||||||||||||||||||||
| Government securities at face value | $ | 641 | $ | 805 | $ | 269 | $ | — | $ | 1,715 | |||||||||||||||||||||||||
| As of December 31, 2021 | |||||||||||||||||||||||||||||||||||
| ICE Clear Europe | ICE Clear Credit | ICE Clear U.S. | ICE NGX | Total | |||||||||||||||||||||||||||||||
| Original margin: | |||||||||||||||||||||||||||||||||||
| Government securities at face value | $ | 58,156 | $ | 8,425 | $ | 17,211 | $ | — | $ | 83,792 | |||||||||||||||||||||||||
| Letters of credit | — | — | — | 3,566 | 3,566 | ||||||||||||||||||||||||||||||
| ICE NGX cash deposits | — | — | — | 987 | 987 | ||||||||||||||||||||||||||||||
| Total | $ | 58,156 | $ | 8,425 | $ | 17,211 | $ | 4,553 | $ | 88,345 | |||||||||||||||||||||||||
| Guaranty fund: | |||||||||||||||||||||||||||||||||||
| Government securities at face value | $ | 740 | $ | 152 | $ | 273 | $ | — | $ | 1,165 | |||||||||||||||||||||||||
ICE NGX
ICE NGX owns a clearing house which administers the physical delivery of energy trading contracts. ICE NGX is the central counterparty to Members on opposite sides of its physically-settled contracts, and the balance related to delivered but unpaid contracts is recorded as a delivery contract net receivable, with an offsetting delivery contract net payable in our balance sheets. Unsettled variation margin equal to the fair value of open contracts is recorded as of each balance sheet date. There is no impact on our consolidated statements of income as an equal amount is recognized as both an asset and a liability. ICE NGX marks all of its outstanding physical natural gas and physical power contracts to market daily, but only collects variation margin when a Member's open position falls outside a specified percentage of its pledged collateral. Due to the highly liquid nature and the short period of time to maturity, the fair values of our delivery contract net payable and net receivable are determined to approximate carrying value.
ICE NGX requires Members to maintain cash or letters of credit to serve as collateral in the event of default. The cash is maintained in a segregated bank account for the benefit of the Member, and remains the property of the Member and, therefore, is not included in our balance sheets. ICE NGX maintains a committed daylight-overnight liquidity facility in the amount of $100 million with an additional $150 million uncommitted with a third-party Canadian chartered bank which provides liquidity in the event of a settlement shortfall, subject to certain conditions.
During 2022, ICE NGX increased its default insurance by $100 million, and as of December 31, 2022, ICE NGX maintains a guaranty fund of $215 million funded by a $200 million letter of credit issued by a major Canadian chartered bank and backed by default insurance underwritten by Export Development Canada, or EDC, a Crown corporation operated at arm’s length from the Canadian government, plus $15 million held as restricted cash to fund the first loss amount the ICE NGX is responsible for under the default insurance policy. In the event of a participant default where the Member’s collateral is depleted, the shortfall would be covered by a draw down on the letter of credit following which ICE NGX would file a claim under the default insurance to recover additional losses up to $200 million beyond the $15 million first-loss amount that ICE NGX is responsible for under the default insurance policy.
Clearing House Exposure
The net notional value of unsettled contracts was $2.8 trillion as of December 31, 2022. Each ICE Clearing House bears financial counterparty credit risk and provides a central counterparty guarantee, or performance guarantee, to its Members. To reduce their exposure, the ICE Clearing Houses have a risk management program with both initial and ongoing membership standards. Excluding the effects of original and variation margin, guaranty fund and collateral requirements and default insurance, the ICE Clearing Houses’ maximum estimated exposure for this guarantee is $228.3 billion as of December 31, 2022, which represents the maximum estimated value by the ICE Clearing Houses of a hypothetical one-day movement in pricing of the underlying unsettled contracts. This value was determined using proprietary risk management software that simulates gains and losses based on historical market prices, volatility and other factors present at that point in time for those particular unsettled contracts. Future actual market price volatility could result in the exposure being significantly different than this amount.
We also performed calculations to determine the fair value of our counterparty performance guarantee taking into consideration factors such as daily settlement of contracts, margining and collateral requirements, other elements of our risk management program, historical evidence of default payments, and estimated probability of potential default payouts by the ICE Clearing Houses. Based on these analyses, the estimated counterparty performance guarantee liability was determined to be nominal and no liability was recorded as of December 31, 2022 or 2021. The ICE Clearing Houses have never experienced an incident of a clearing member default which has required the use of the guaranty funds of non-defaulting clearing members or the assets of the ICE Clearing Houses.
15. Leases
We have lease agreements for office space, equipment facilities and certain computer equipment for lease terms up to eighteen years. All of our leases are classified as operating leases and we do not have any leases classified as finance leases.
At lease inception, we review the service arrangement and components of a contract to identify if a lease or embedded lease arrangement exists. An indicator of a contract containing a lease is when we have the right to control and use an identified asset over a period of time in exchange for consideration. Operating lease right-of-use assets and liabilities are recognized at the commencement date based on the present value of lease payments over the lease term. We have elected the short-term lease policy to recognize leases with a term of 12 months or less as rent expense on a straight-line basis over the lease term and do not recognize these short-term leases on our balance sheet. We have elected the practical expedient of not separating lease and non-lease components as our lease arrangements are not highly dependent on other underlying assets. We have elected to use a portfolio approach in consideration of our incremental borrowing rate to our population of lease agreements. Certain lease agreements include options to extend, renew or terminate the lease agreement. Our lease agreements do not contain any residual value guarantees. As of December 31, 2022, the weighted-average remaining lease term was 4.7 years and the weighted average discount rate was 3.0%. As of December 31, 2021, the weighted-average remaining lease term was 5.1 years and the weighted average discount rate was 3.1%. Our lease agreements do not contain any residual value guarantees.
We recognized $52 million, $61 million and $46 million of rent expense for office space as rent and occupancy expense in 2022, 2021, and 2020, respectively, and $26 million, $24 million and $22 million for data center facilities as technology and communication expense in 2022, 2021, and 2020, respectively, within our consolidated income statements. We do not have any significant variable lease costs related to building and maintenance costs, real estate taxes, or other charges.
Our lease assets are included within property, plant and equipment and our lease liabilities are included in current and noncurrent liabilities within our consolidated balance sheets. Details of our lease asset and liability balances are as follows (in millions):
| As of December 31, 2022 | As of December 31, 2021 | As of January 1, 2020 | |||||||||||||||
| Right-of-use lease assets | $ | 278 | $ | 278 | $ | 339 | |||||||||||
| Current operating lease liability | 65 | 72 | 69 | ||||||||||||||
| Non-current operating lease liability | 254 | 252 | 320 | ||||||||||||||
| Total operating lease liability | $ | 319 | $ | 324 | $ | 389 |
As of December 31, 2022, we estimate that our operating lease liability will be recognized in the following years (in millions):
| 2023 | $ | 73 | |||
| 2024 | 82 | ||||
| 2025 | 70 | ||||
| 2026 | 50 | ||||
| 2027 | 45 | ||||
| Thereafter | 22 | ||||
| Lease liability amounts repayable | $ | 342 | |||
| Interest costs | (23) | ||||
| Total operating lease liability | $ | 319 |
Supplemental cash flow information and non-cash activity related to our operating leases are as follows:
| Year Ended December 31, 2022 | Year Ended December 31, 2021 | ||||||||||||||||
| Cash paid for amounts included in the measurement of operating lease liability | $ | 89 | $ | 91 | |||||||||||||
| Right-of-use assets obtained in exchange for operating lease obligations | $ | 92 | $ | 13 |
16. Commitments and Contingencies
Legal Proceedings
In the ordinary course of our business, from time to time we are subject to legal proceedings, lawsuits, government investigations and other claims with respect to a variety of matters. In addition, we are subject to periodic reviews, inspections, examinations and investigations by regulators in the U.S. and other jurisdictions, any of which may result in claims, legal proceedings, assessments, fines, penalties, restrictions on our business or other sanctions. We record estimated expenses and reserves for legal or regulatory matters or other claims when these matters present loss contingencies that are probable and the related amount is reasonably estimable. Any such accruals may be adjusted as circumstances change. Assessments of losses are inherently subjective and involve unpredictable factors. While the outcome of legal and regulatory matters is inherently difficult to predict and/or the range of loss often cannot be reasonably estimable, we do not believe that the liabilities, if any, which may ultimately result from the resolution of the various legal and regulatory matters that arise in the ordinary course of our business, including the matters described below, are likely to have a material adverse effect on our consolidated financial condition, results of operations, or liquidity. It is possible, however, that future results of operations for any particular quarterly or annual period could be materially and adversely affected by any developments relating to these legal and regulatory matters.
City of Providence Litigation
In 2014, New York Stock Exchange LLC and NYSE Arca, Inc., two of our subsidiaries, were among more than 40 financial institutions and U.S.-based equity exchanges named as defendants in four purported class action lawsuits filed in the U.S. District Court for the Southern District of New York, or the Southern District, by the City of Providence, Rhode Island, and other plaintiffs. In a subsequent consolidated amended complaint filed against only the exchange defendants (which include exchanges owned and operated by Nasdaq and Cboe Global Markets,Inc.), the plaintiffs asserted claims on behalf of a class of “all public investors” who bought or sold stock from April 18, 2009 to the present on the named exchanges.
In 2015, the district court granted a motion to dismiss filed by the exchange defendants and dismissed the complaint with prejudice. The court held that the plaintiffs had failed to sufficiently state a claim under Sections 10(b) and 6(b) of the Exchange Act, and additionally that some of the claims were barred by the doctrine of self-regulatory organization immunity. The plaintiffs appealed, and in 2017 the U.S. Court of Appeals for the Second Circuit, or the Second Circuit, issued a decision vacating the dismissal and remanding the case to the district court for further proceedings. The Second Circuit held that the claims against the exchanges were not barred by the doctrine of self-regulatory organization immunity because (in the view of the Second Circuit) the exchanges were not carrying out regulatory functions while operating their markets and engaging in the challenged conduct at issue, and that the plaintiffs had adequately pleaded claims against the defendants under Section 10(b) of the Exchange Act. The Second Circuit directed that, on remand, the district court should address and rule upon various other defenses raised by the exchanges in their motion to dismiss (which the district court did not address in its prior opinion and order).
In 2019, the district court denied a new motion to dismiss filed by the defendants, and the exchanges filed answers to the complaint, denying the principal allegations of the plaintiffs, denying liability in the matter, and asserting various affirmative defenses. During 2021, the parties conducted discovery, relating largely to class certification issues; the plaintiffs filed a motion for class certification; and the defendants filed motions for summary judgment on the basis of preclusion and lack of standing.
On March 28, 2022, the district court entered an order granting the defendant exchanges’ motion for summary judgment on the ground that the plaintiffs lacked standing, and dismissing without prejudice the plaintiffs’ claims on this basis. Among other things, the court found that the plaintiffs failed to show that they had been injured and that, even putting aside this defect, the plaintiffs failed to produce evidence from which a jury could reasonably conclude that they suffered an injury traceable to any conduct of the exchanges. The district court also held that the opinions of the plaintiffs’ principal expert witness in this matter were fundamentally flawed and unreliable, and therefore inadmissible. In light of these holdings, the court denied as moot the plaintiffs’ motion for class certification and the exchanges’ motion for summary judgment on the basis of preclusion. On April 25, 2022, the plaintiffs filed a notice of appeal of the dismissal order. Effective as of June 6, 2022, the parties to the litigation executed settlement agreements pursuant to which, among other things, the plaintiffs withdrew their appeal with prejudice and provided the defendants a covenant not to sue (and additionally provided the NYSE and Cboe defendants a release of claims). No monetary payment was made by the defendants. The settlement agreements and dismissal of the appeal constitute the final resolution of this matter.
LIBOR Litigation
In 2019, three virtually identical purported class action complaints were filed in the Southern District against ICE and several of its subsidiaries, including ICE Benchmark Administration Limited, or IBA, collectively referred to as the ICE Defendants, as well as 18 multinational banks and various of their respective subsidiaries and affiliates, or the Panel Bank Defendants, by, respectively, Putnam Bank, a savings bank based in Putnam, Connecticut; two municipal pension funds affiliated with the City of Livonia, Michigan; and four retirement and benefit funds affiliated with the Hawaii Sheet Metal Workers Union. IBA is the administrator for various regulated benchmarks, including the ICE LIBOR benchmark that is calculated daily based upon the submissions from a reference panel (which includes the Panel Bank Defendants).
The plaintiffs sought to litigate on behalf of a purported class of all U.S.-based persons or entities who transacted with a Panel Bank Defendant by receiving a payment on an interest rate indexed to a one-month or three-month USD LIBOR-benchmarked rate during the period from 2014 to 2019. The plaintiffs alleged that the ICE Defendants and the Panel Bank Defendants engaged in a conspiracy to set the LIBOR benchmark at artificially low levels, with an alleged purpose and effect of depressing payments by the Panel Bank Defendants to members of the purported class.
Subsequent to the filing of the individual complaints, the various plaintiffs referenced above filed a consolidated amended complaint against the ICE Defendants and the Panel Bank Defendants. As with the individual complaints, the consolidated amended complaint asserted a claim for violations of the Sherman and Clayton Antitrust Acts and sought unspecified treble damages and other relief. The ICE Defendants and the Panel Bank Defendants filed motions to dismiss the consolidated amended complaint.
In 2020, the court issued a decision and order granting the ICE Defendants and the Panel Bank Defendants' motions to dismiss for failure to state a claim. Among other things, the court found that the amended complaint “…is made up of almost entirely conclusory allegations and is essentially devoid of any evidence, direct or circumstantial, to support the conclusion that Defendants colluded with one another.”
The plaintiffs appealed the decision to the Second Circuit. While briefing of the appeal was ongoing, each of the named plaintiffs withdrew from the case. DYJ Holdings, LLC, a New Jersey-based holding company, was permitted, over the objection of the defendants, to intervene for the purpose of serving as named plaintiff and representative of the purported class.
On February 14, 2022, the Second Circuit dismissed the appeal for lack of jurisdiction, holding that DYJ Holdings, LLC, the sole entity attempting to pursue the appeal, lacked standing to do so. The dismissal of the appeal constitutes the final resolution of this matter.
ICE Data Pricing & Reference Data Matter
Our subsidiary ICE Data Pricing & Reference Data, LLC, or PRD, is a registered investment advisor in the business of, among other things, providing clients with evaluated pricing and other information for fixed-income securities. PRD formerly had a business practice of passing through third-party price quotes, or broker quotes, in certain fixed income securities as-is to its clients when PRD did not believe it had the capability to model an evaluated price for such securities. Broker quoted securities were less than 2% of the securities PRD priced. A list of securities that were broker quoted, as distinguished from evaluated, was made available to PRD’s clients every day. PRD first notified its clients on December 16, 2019 that it would cease providing broker quotes and did so as of October 1, 2020.
On December 9, 2020, following an SEC investigation of PRD’s legacy business practices with respect to broker quotes, the SEC announced a settlement in which PRD, without admitting or denying the findings therein, agreed to pay an $8 million civil monetary penalty, together with certain non-monetary provisions. For further details about the settlement and underlying matter under investigation, please refer to Order Instituting Administrative and Cease-and-Desist Proceedings, Pursuant to Sections 203(e) and 203(k) of the Investment Advisers Act of 1940, Making Findings, and Imposing Remedial Sanctions and a Cease-and-Desist Order, Administrative Proceeding File No. 3-20164 (In the Matter of ICE Data Pricing & Reference Data, LLC).
Separately, PRD’s legacy business practices with respect to broker quotes received from a now-bankrupt entity named Live Well Financial, Inc., or Live Well, are relevant to potential civil claims against PRD. In August 2019, the SEC and the United States Department of Justice, respectively, filed civil and criminal charges against Live Well and certain of its executives, alleging that Live Well fraudulently provided over-stated “broker quotes” to a then-unnamed “industry-leading price service” (which was PRD). Certain of Live Well’s financial institution creditors and its bankruptcy trustee asserted to PRD that they believed they had putative claims against PRD related to Live Well’s actions. As of April 2022, PRD had resolved the potential claims of the trustee as well as all known claims of any of the financial institution creditors. With the resolution of those clams, there are no known unresolved assertions of liability against PRD relating to broker quotes PRD received from Live Well.
Tax Audits
We are engaged in ongoing discussions and audits with taxing authorities on various tax matters, the resolutions of which are uncertain. Currently, there are matters that may lead to assessments involving us or one of our subsidiaries, some of which may not be resolved for several years. Based on currently available information, we believe we have adequately provided for any assessments that could result from those proceedings where it is more likely than not that we will be assessed. We continuously review our positions as these matters progress.
17. Pension and Other Benefit Programs
Defined Benefit Pension Plan
We have a pension plan covering employees in certain of our U.S. operations whose benefit accrual has been frozen. Retirement benefits are derived from a formula, which is based on length of service and compensation.
We did not make any contributions to our pension plan during 2022, 2021 or 2020. The plan’s target allocation is 5% equity securities and 95% fixed income securities. The fixed income allocation includes corporate bonds of companies from diversified industries and U.S. government bonds. Our long-term objective is to keep the plan at or near full funding, while minimizing the risk inherent in pension plans. As a result, we don't anticipate that there will be a strong need for contributions in future years, and the pension plan will not be required to pay the Pension Benefit Guaranty Corporation variable rate premiums. We do not expect to make contributions to the pension plan in 2023. We will continue to monitor the plan’s funded status, and we will consider modifying the plan’s investment policy based on the actuarial and funding characteristics of the retirement plan, the demographic profile of plan participants, and our business objectives.
The fair values of our plan assets as of December 31, 2022, by asset category, are as follows (in millions):
| Fair Value Measurements | ||||||||||||||||||||||||||
| Asset Category | Quoted Prices in Active Markets for Identical Assets (Level 1) | Significant Observable Inputs (Level 2) | Significant Unobservable Inputs (Level 3) | Total | ||||||||||||||||||||||
| Cash | $ | 8 | $ | — | $ | — | $ | 8 | ||||||||||||||||||
| Equity securities: | ||||||||||||||||||||||||||
| U.S. large-cap | — | 20 | — | 20 | ||||||||||||||||||||||
| U.S. small-cap | — | 5 | — | 5 | ||||||||||||||||||||||
| International | — | 12 | — | 12 | ||||||||||||||||||||||
| Fixed income securities | 118 | 526 | 6 | 650 | ||||||||||||||||||||||
| Total | $ | 126 | $ | 563 | $ | 6 | $ | 695 |
The above table excludes trades pending settlement with a net loss of $8 million as of December 31, 2022. These trades settled in January 2023.
The fair values of our plan assets as of December 31, 2021, by asset category, are as follows (in millions):
| Fair Value Measurements | ||||||||||||||||||||||||||
| Asset Category | Quoted Prices in Active Markets for Identical Assets (Level 1) | Significant Observable Inputs (Level 2) | Significant Unobservable Inputs (Level 3) | Total | ||||||||||||||||||||||
| Cash | $ | 7 | $ | — | $ | — | $ | 7 | ||||||||||||||||||
| Equity securities: | ||||||||||||||||||||||||||
| U.S. large-cap | — | 26 | — | 26 | ||||||||||||||||||||||
| U.S. small-cap | — | 6 | — | 6 | ||||||||||||||||||||||
| International | — | 15 | — | 15 | ||||||||||||||||||||||
| Fixed income securities | 137 | 720 | 6 | 863 | ||||||||||||||||||||||
| Total | $ | 144 | $ | 767 | $ | 6 | $ | 917 |
The above table excludes trades pending settlement with a net benefit of $3 million as of December 31, 2021. These trades settled in January 2022.
The measurement dates for the pension plan are December 31, 2022 and 2021. The following table provides a summary of the changes in the pension plan’s benefit obligations and the fair value of assets measured using the valuation techniques described in Note 18, as of December 31, 2022 and 2021 and a statement of funded status of the pension plan as of December 31, 2022 and 2021 (in millions):
| As of December 31, | |||||||||||
| 2022 | 2021 | ||||||||||
| Change in benefit obligation: | |||||||||||
| Benefit obligation at beginning of year | $ | 846 | $ | 914 | |||||||
| Interest cost | 17 | 14 | |||||||||
| Actuarial gain | (169) | (35) | |||||||||
| Benefits paid | (47) | (47) | |||||||||
| Benefit obligation at year end | $ | 647 | $ | 846 | |||||||
| Change in plan assets: | |||||||||||
| Fair value of plan assets at beginning of year | $ | 920 | $ | 975 | |||||||
| Actual return on plan assets | (186) | (8) | |||||||||
| Benefits paid | (47) | (47) | |||||||||
| Fair value of plan assets at end of year | $ | 687 | $ | 920 | |||||||
| Funded status | $ | 40 | $ | 74 | |||||||
| Accumulated benefit obligation | $ | 647 | $ | 846 | |||||||
| Amounts recognized in the accompanying consolidated balance sheets: | |||||||||||
| Accrued pension plan asset | $ | 40 | $ | 74 |
The following shows the components of the pension plan expense for 2022, 2021 and 2020 (in millions):
| Year Ended December 31, | |||||||||||||||||
| 2022 | 2021 | 2020 | |||||||||||||||
| Interest cost | $ | 17 | $ | 14 | $ | 22 | |||||||||||
| Estimated return on plan assets | (21) | (19) | (25) | ||||||||||||||
| Amortization of loss | 2 | 6 | 5 | ||||||||||||||
| Aggregate pension (benefit)/expense | $ | (2) | $ | 1 | $ | 2 |
We use a market-related value of plan assets when determining the estimated return on plan assets. Gains/losses on plan assets are amortized over a four-year period and accumulate in other comprehensive income. We recognize deferred gains and losses in future net income based on a “corridor” approach, where the corridor is equal to 10% of the greater of the benefit obligation or the market-related value of plan assets at the beginning of the year.
The following shows the projected payments for the pension plan based on actuarial assumptions (in millions):
| 2023 | $ | 50 | |||
| 2024 | 50 | ||||
| 2025 | 50 | ||||
| 2026 | 50 | ||||
| 2027 | 49 | ||||
| Next 5 years | 235 |
Supplemental Executive Retirement Plan
We have a U.S. nonqualified supplemental executive retirement plan, or SERP, which provides supplemental retirement benefits for certain employees. The future benefit accrual of the SERP plan is frozen. To provide for the future payments of these benefits, we have purchased insurance on the lives of certain of the participants through company-owned policies. As of both December 31, 2022 and 2021, the cash surrender value of such policies was $61 million and is included in other non-current assets in the accompanying consolidated balance sheets. We also acquired a SERP through both the ICE NGX and CHX acquisitions. The following table provides a summary of the changes in the SERP benefit obligations (in millions):
| As of December 31, | |||||||||||
| 2022 | 2021 | ||||||||||
| Change in benefit obligation: | |||||||||||
| Benefit obligation at beginning of year | $ | 33 | $ | 38 | |||||||
| Interest cost | 1 | 1 | |||||||||
| Actuarial (gain) loss | (3) | (1) | |||||||||
| Benefits paid | (5) | (5) | |||||||||
| Benefit obligation at year end | $ | 26 | $ | 33 | |||||||
| Funded status | $ | (26) | $ | (33) | |||||||
| Amounts recognized in the accompanying consolidated balance sheets: | |||||||||||
| Other current liabilities | $ | (4) | $ | (4) | |||||||
| Accrued employee benefits | (22) | (29) |
SERP plan expense in the accompanying consolidated statements of income was $1 million each year in 2022, 2021 and 2020 and primarily consisted of interest cost. The following table shows the projected payments for the SERP plan based on the actuarial assumptions (in millions):
| Projected SERP Plan Payments | |||||
| 2023 | $ | 4 | |||
| 2024 | 4 | ||||
| 2025 | 3 | ||||
| 2026 | 3 | ||||
| 2027 | 2 | ||||
| Next 5 years | 10 |
Pension and SERP Plans Assumptions
The weighted-average assumptions used to develop the actuarial present value of the projected benefit obligation and net periodic pension/SERP costs in 2022, 2021 and 2020 are set forth below:
| Year Ended December 31, | |||||||||||||||||
| 2022 | 2021 | 2020 | |||||||||||||||
| Weighted-average discount rate for determining benefit obligations (pension/SERP plans) | 4.9% / 4.8% | 2.6% / 2.1% | 2.2% / 1.6% | ||||||||||||||
| Weighted-average discount rate for determining interest costs (pension/SERP plans) | 2.1% / 1.6% | 1.6% / 1.1% | 2.6% / 2.3% | ||||||||||||||
| Expected long-term rate of return on plan assets (pension/SERP plans) | 2.5% / N/A | 2.3% / N/A | 3.1% / N/A | ||||||||||||||
| Rate of compensation increase | N/A | N/A | N/A |
The assumed discount rate reflects the market rates for high-quality corporate bonds currently available. The discount rate was determined by considering the average of pension yield curves constructed on a large population of high quality corporate bonds. The resulting discount rates reflect the matching of plan liability cash flows to yield curves. To develop
the expected long-term rate of return on assets assumption, we considered the historical returns and the future expectations for returns for each asset class as well as the target asset allocation of the pension portfolio.
The determination of the interest cost component utilizes a full yield curve approach by applying the specific spot rates along the yield curve used in the determination of the benefit obligation to each year’s discounted cash flow.
Post-retirement Benefit Plans
Our defined benefit plans provide certain health care and life insurance benefits for certain eligible retired NYSE U.S. employees. These post-retirement benefit plans, which may be modified in accordance with their terms, are fully frozen. The net periodic post-retirement benefit costs were $3 million, $2 million and $2 million in 2022, 2021 and 2020, respectively. The defined benefit plans are unfunded and we currently do not expect to fund the post-retirement benefit plans. The weighted-average discount rate for determining the benefit obligation as of December 31, 2022 and 2021 was 4.9% and 2.6%, respectively. The weighted-average discount rate for determining the interest cost as of December 31, 2022 and 2021 is 2.1% and 1.6%, respectively. The following table shows the actuarial determined benefit obligation, interest costs, employee contributions, actuarial (gain)/loss, benefits paid during the periods and the accrued employee benefits (in millions):
| As of December 31, | |||||||||||
| 2022 | 2021 | ||||||||||
| Benefit obligation at the end of year | $ | 116 | $ | 145 | |||||||
| Interest cost | 3 | 2 | |||||||||
| Actuarial gain | (22) | (2) | |||||||||
| Employee contributions | 2 | 2 | |||||||||
| Benefits paid | (12) | (11) | |||||||||
| Amounts recognized in the accompanying consolidated balance sheets: | |||||||||||
| Other current liabilities | $ | (8) | $ | (8) | |||||||
| Accrued employee benefits | (108) | (136) |
The following table shows the payments projected for our post-retirement benefit plans (net of expected Medicare subsidy receipts of $9 million in aggregate over the next ten fiscal years) based on actuarial assumptions (in millions):
| Projected Post-Retirement Benefit by Year: | Projected Payment | |||||||
| 2023 | $ | 9 | ||||||
| 2024 | 9 | |||||||
| 2025 | 9 | |||||||
| 2026 | 9 | |||||||
| 2027 | 9 | |||||||
| Next 5 years | 43 |
For measurement purposes, we assumed a 5.6% annual rate of increase in the per capita cost of covered health care benefits in 2022 which will decrease on a graduated basis to 3.9% in the year 2049 and thereafter.
Accumulated Other Comprehensive Loss
The accumulated other comprehensive loss, after tax, as of December 31, 2022, consisted of the following amounts that have not yet been recognized in net periodic benefit cost (in millions):
| Pension Plans | SERP Plans | Post-retirement Benefit Plans | Total | ||||||||||||||||||||
| Unrecognized net actuarial losses/(gains), after tax | $ | 82 | $ | 3 | $ | (30) | $ | 55 |
Other Benefit Plans and Defined Contribution Plans
Our U.S. employees are eligible to participate in 401(k) and profit sharing plans and our non-U.S. employees are eligible to participate in defined contribution pension plans. Total contributions under the 401(k), profit sharing and defined contribution pension plans were $64 million, $63 million and $52 million in 2022, 2021 and 2020, respectively. No discretionary or profit sharing contributions were made during 2022, 2021 or 2020.
18. Fair Value Measurements
Financial assets and liabilities recorded or disclosed at fair value in the accompanying consolidated balance sheets as of December 31, 2022 and 2021 were classified in their entirety based on the lowest level of input that is significant to the asset or liability’s fair value measurement.
Our mutual funds are equity and fixed income mutual funds held for the purpose of providing future payments for the supplemental executive savings plan and SERP. These mutual funds are classified as equity investments and measured at fair value using Level 1 inputs with adjustments recorded in net income (see Note 17).
Excluding our equity investments without a readily determinable fair value, all other financial instruments are determined to approximate carrying value due to the short period of time to their maturities.
We did not use Level 3 inputs to determine the fair value of assets or liabilities measured at fair value on a recurring basis as of December 31, 2022 or 2021.
We measure certain assets, such as intangible assets and equity method investments, at fair value on a non-recurring basis. These assets are recognized at fair value if they are deemed to be impaired. During 2022, we evaluated these intangible assets and investments and determined that the value of our equity method investment in Bakkt was impaired using a Level 1 input, which was the publicly-traded closing stock price of Bakkt on December 30, 2022, the last trading day of 2022. As of December 31, 2022 and 2021, no other intangible assets or equity method investments were required to be recorded at fair value since no other impairments were recorded.
We measure certain equity investments at fair value on a non-recurring basis using our policy election under ASU 2016-01 (see Note 2). No fair value adjustments were required under our accounting policy election related to these investments (see Note 4).
See Note 14 for the fair value considerations related to our margin deposits, guaranty funds and delivery contracts receivable.
The table below displays the fair value of our debt as of December 31, 2022 and December 31, 2021. The fair values of our fixed rate notes were estimated using quoted market prices for these instruments. The fair value of our commercial paper as of December 31, 2021 includes a discount and other short-term debt approximates par value since the interest rates on this short-term debt approximate market rates as of December 31, 2022 and December 31, 2021.
| As of December 31, 2022 | As of December 31, 2021 | ||||||||||||||||||||||
| (in millions) | (in millions) | ||||||||||||||||||||||
| Carrying Amount | Fair value | Carrying Amount | Fair value | ||||||||||||||||||||
| Debt: | |||||||||||||||||||||||
| Commercial Paper | $ | — | $ | — | $ | 1,012 | $ | 1,012 | |||||||||||||||
| 2.35% Senior Notes due September 15, 2022 | — | — | 499 | 506 | |||||||||||||||||||
| Other short-term debt | 4 | 4 | 10 | 10 | |||||||||||||||||||
| 0.70% Senior Notes due June 15, 2023 | — | — | 997 | 1,000 | |||||||||||||||||||
| 3.45% Senior Notes due September 21, 2023 | — | — | 399 | 416 | |||||||||||||||||||
| 4.00% Senior Notes due October 15, 2023 | — | — | 797 | 844 | |||||||||||||||||||
| 3.65% Senior Notes due May 23, 2025 | 1,243 | 1,224 | — | — | |||||||||||||||||||
| 3.75% Senior Notes due December 1, 2025 | 1,247 | 1,218 | 1,246 | 1,351 | |||||||||||||||||||
| 4.00% Senior Notes due September 15, 2027 | 1,487 | 1,450 | — | — | |||||||||||||||||||
| 3.10% Senior Notes due September 15, 2027 | 498 | 465 | 497 | 533 | |||||||||||||||||||
| 3.75% Senior Notes due September 21, 2028 | 594 | 568 | 594 | 664 | |||||||||||||||||||
| 4.35% Senior Notes due June 15, 2029 | 1,240 | 1,210 | — | — | |||||||||||||||||||
| 2.10% Senior Notes due June 15, 2030 | 1,235 | 1,022 | 1,234 | 1,242 | |||||||||||||||||||
| 1.85% Senior Notes due September 15, 2032 | 1,485 | 1,130 | 1,483 | 1,440 | |||||||||||||||||||
| 4.60% Senior Notes due March 15, 2033 | 1,488 | 1,440 | — | — | |||||||||||||||||||
| 2.65% Senior Notes due September 15, 2040 | 1,231 | 871 | 1,230 | 1,217 | |||||||||||||||||||
| 4.25% Senior Notes due September 21, 2048 | 1,231 | 1,052 | 1,230 | 1,563 | |||||||||||||||||||
| 3.00% Senior Notes due June 15, 2050 | 1,221 | 841 | 1,220 | 1,266 |
| As of December 31, 2022 | As of December 31, 2021 | ||||||||||||||||||||||
| (in millions) | (in millions) | ||||||||||||||||||||||
| Carrying Amount | Fair value | Carrying Amount | Fair value | ||||||||||||||||||||
| 4.95% Senior Notes due June 15, 2052 | 1,464 | 1,395 | — | — | |||||||||||||||||||
| 3.00% Senior Notes due September 15, 2060 | 1,471 | 938 | 1,470 | 1,487 | |||||||||||||||||||
| 5.20% Senior Notes due June 15, 2062 | 983 | 951 | — | — | |||||||||||||||||||
| Total debt | $ | 18,122 | $ | 15,779 | $ | 13,918 | $ | 14,551 |
19. Segment Reporting
Our business is conducted through three reportable business segments, comprised of the following:
-
Exchanges: We operate regulated marketplaces for the listing, trading and clearing of a broad array of derivatives contracts and financial securities;
-
Fixed Income and Data Services: We provide fixed income pricing, reference data, indices, analytics and execution services, as well as global CDS clearing and multi-asset class data delivery solutions; and
-
Mortgage Technology: We provide a technology platform that offers customers comprehensive, digital workflow tools that aim to address the inefficiencies that exist in the U.S. residential mortgage market, from application through closing and the secondary market.
While revenues are recorded specifically in the segment in which they are earned or to which they relate, a significant portion of our operating expenses are not solely related to a specific segment because the expenses serve functions that are necessary for the operation of more than one segment. We directly allocate expenses when reasonably possible to do so. Otherwise, we use a pro-rata revenue approach as the allocation method for the expenses that do not relate solely to one segment and serve functions that are necessary for the operation of all segments.
Our chief operating decision maker does not review total assets or statements of income below operating income by segments; therefore, such information is not presented below. Our three segments do not engage in intersegment transactions.
Financial data for our business segments is as follows for 2022, 2021 and 2020 (in millions):
| Year Ended December 31, 2022 | ||||||||||||||||||||||||||
| Exchanges | Fixed Income and Data Services | Mortgage Technology | Consolidated | |||||||||||||||||||||||
| Revenues: | ||||||||||||||||||||||||||
| Energy futures and options | $ | 1,162 | $ | — | $ | — | $ | 1,162 | ||||||||||||||||||
| Agricultural and metals futures and options | 235 | — | — | 235 | ||||||||||||||||||||||
| Financial futures and options | 475 | — | — | 475 | ||||||||||||||||||||||
| Cash equities and equity options | 2,722 | — | — | 2,722 | ||||||||||||||||||||||
| OTC and other | 429 | — | — | 429 | ||||||||||||||||||||||
| Data and connectivity services | 877 | — | — | 877 | ||||||||||||||||||||||
| Listings | 515 | — | — | 515 | ||||||||||||||||||||||
| Fixed income execution | — | 101 | — | 101 | ||||||||||||||||||||||
| CDS clearing | — | 305 | — | 305 | ||||||||||||||||||||||
| Fixed income data and analytics | — | 1,098 | — | 1,098 | ||||||||||||||||||||||
| Other data and network services | — | 588 | — | 588 | ||||||||||||||||||||||
| Origination technology | — | — | 758 | 758 | ||||||||||||||||||||||
| Closing solutions | — | — | 229 | 229 | ||||||||||||||||||||||
| Data and analytics | — | — | 90 | 90 | ||||||||||||||||||||||
| Other | — | — | 52 | 52 | ||||||||||||||||||||||
| Revenues | 6,415 | 2,092 | 1,129 | 9,636 | ||||||||||||||||||||||
| Transaction-based expenses | 2,344 | — | — | 2,344 | ||||||||||||||||||||||
| Revenues, less transaction-based expenses | 4,071 | 2,092 | 1,129 | 7,292 | ||||||||||||||||||||||
| Operating expenses | 1,209 | 1,373 | 1,072 | 3,654 | ||||||||||||||||||||||
| Operating income | $ | 2,862 | $ | 719 | $ | 57 | $ | 3,638 | ||||||||||||||||||
| Year Ended December 31, 2021 | ||||||||||||||||||||||||||
| Exchanges | Fixed Income and Data Services | Mortgage Technology | Consolidated | |||||||||||||||||||||||
| Revenues: | ||||||||||||||||||||||||||
| Energy futures and options | $ | 1,236 | $ | — | $ | — | $ | 1,236 | ||||||||||||||||||
| Agricultural and metals futures and options | 228 | — | — | 228 | ||||||||||||||||||||||
| Financial futures and options | 394 | — | — | 394 | ||||||||||||||||||||||
| Cash equities and equity options | 2,377 | — | — | 2,377 | ||||||||||||||||||||||
| OTC and other | 326 | — | — | 326 | ||||||||||||||||||||||
| Data and connectivity services | 838 | — | — | 838 | ||||||||||||||||||||||
| Listings | 479 | — | — | 479 | ||||||||||||||||||||||
| Fixed income execution | — | 52 | — | 52 | ||||||||||||||||||||||
| CDS clearing | — | 192 | — | 192 | ||||||||||||||||||||||
| Fixed income data and analytics | — | 1,082 | — | 1,082 | ||||||||||||||||||||||
| Other data and network services | — | 557 | — | 557 | ||||||||||||||||||||||
| Origination technology | — | — | 971 | 971 | ||||||||||||||||||||||
| Closing solutions | — | — | 310 | 310 | ||||||||||||||||||||||
| Data and analytics | — | — | 73 | 73 | ||||||||||||||||||||||
| Other | — | — | 53 | 53 | ||||||||||||||||||||||
| Revenues | 5,878 | 1,883 | 1,407 | 9,168 | ||||||||||||||||||||||
| Transaction-based expenses | 2,022 | — | — | 2,022 | ||||||||||||||||||||||
| Revenues, less transaction-based expenses | 3,856 | 1,883 | 1,407 | 7,146 | ||||||||||||||||||||||
| Operating expenses | 1,333 | 1,354 | 1,010 | 3,697 | ||||||||||||||||||||||
| Operating income | $ | 2,523 | $ | 529 | $ | 397 | $ | 3,449 | ||||||||||||||||||
| Year Ended December 31, 2020 | ||||||||||||||||||||||||||
| Exchanges | Fixed Income and Data Services | Mortgage Technology | Consolidated | |||||||||||||||||||||||
| Revenues: | ||||||||||||||||||||||||||
| Energy futures and options | $ | 1,120 | $ | — | $ | — | $ | 1,120 | ||||||||||||||||||
| Agricultural and metals futures and options | 245 | — | — | 245 | ||||||||||||||||||||||
| Financial futures and options | 357 | — | — | 357 | ||||||||||||||||||||||
| Cash equities and equity options | 2,585 | — | — | 2,585 | ||||||||||||||||||||||
| OTC and other | 296 | — | — | 296 | ||||||||||||||||||||||
| Data and connectivity services | 790 | — | — | 790 | ||||||||||||||||||||||
| Listings | 446 | — | — | 446 | ||||||||||||||||||||||
| Fixed income execution | — | 70 | — | 70 | ||||||||||||||||||||||
| CDS clearing | — | 208 | — | 208 | ||||||||||||||||||||||
| Fixed income data and analytics | — | 1,018 | — | 1,018 | ||||||||||||||||||||||
| Other data and network services | — | 514 | — | 514 | ||||||||||||||||||||||
| Origination technology | — | — | 316 | 316 | ||||||||||||||||||||||
| Closing solutions | — | — | 238 | 238 | ||||||||||||||||||||||
| Data and analytics | — | — | 22 | 22 | ||||||||||||||||||||||
| Other | — | — | 19 | 19 | ||||||||||||||||||||||
| Revenues | 5,839 | 1,810 | 595 | 8,244 | ||||||||||||||||||||||
| Transaction-based expenses | 2,208 | — | — | 2,208 | ||||||||||||||||||||||
| Revenues, less transaction-based expenses | 3,631 | 1,810 | 595 | 6,036 | ||||||||||||||||||||||
| Operating expenses | 1,242 | 1,318 | 443 | 3,003 | ||||||||||||||||||||||
| Operating income | $ | 2,389 | $ | 492 | $ | 152 | $ | 3,033 | ||||||||||||||||||
No customers or clearing members accounted for more than 10% of our Exchanges revenues, less transaction-based expenses during 2022. Revenue from one member of our Exchanges segment comprised $443 million or 11% of our Exchanges revenue, less transaction-based expenses during 2021. No customers or clearing members accounted for more than 10% of our segment revenues or consolidated revenues, less transaction-based expenses, in 2020. Clearing members are primarily intermediaries and represent a broad range of principal trading firms. If a clearing member ceased its operations, we believe that the trading firms would continue to conduct transactions and would clear those transactions through another clearing member firm. No additional customers or clearing members accounted for more than 10% of our segment revenues or consolidated revenues in 2021.
Geographical Information
The following represents our revenues, less transaction-based expenses, net assets and net property and equipment based on the geographic location (in millions):
| United States | Foreign Countries | Total | |||||||||||||||
| Revenues, less transaction-based expenses: | |||||||||||||||||
| Year ended December 31, 2022 | $ | 4,867 | $ | 2,425 | $ | 7,292 | |||||||||||
| Year ended December 31, 2021 | $ | 4,832 | $ | 2,314 | $ | 7,146 | |||||||||||
| Year ended December 31, 2020 | $ | 3,933 | $ | 2,103 | $ | 6,036 | |||||||||||
| Net assets: | |||||||||||||||||
| As of December 31, 2022 | $ | 15,226 | $ | 7,535 | $ | 22,761 | |||||||||||
| As of December 31, 2021 | $ | 14,628 | $ | 8,120 | $ | 22,748 | |||||||||||
| Property and equipment, net: | |||||||||||||||||
| As of December 31, 2022 | $ | 1,598 | $ | 169 | $ | 1,767 | |||||||||||
| As of December 31, 2021 | $ | 1,494 | $ | 205 | $ | 1,699 |
The foreign countries category above primarily relates to the U.K. and to a lesser extent, EU, Israel, Canada and Singapore.
20. Earnings Per Common Share
The following is a reconciliation of the numerators and denominators of the basic and diluted earnings per common share computations in 2022, 2021 and 2020 (in millions, except per share amounts):
| Year Ended December 31, | |||||||||||||||||
| 2022 | 2021 | 2020 | |||||||||||||||
| Basic: | |||||||||||||||||
| Net income attributable to Intercontinental Exchange, Inc. | $ | 1,446 | $ | 4,058 | $ | 2,089 | |||||||||||
| Weighted average common shares outstanding | 559 | 562 | 552 | ||||||||||||||
| Basic earnings per common share | $ | 2.59 | $ | 7.22 | $ | 3.79 | |||||||||||
| Diluted: | |||||||||||||||||
| Weighted average common shares outstanding | 559 | 562 | 552 | ||||||||||||||
| Effect of dilutive securities - stock options and restricted stock | 2 | 3 | 3 | ||||||||||||||
| Diluted weighted average common shares outstanding | 561 | 565 | 555 | ||||||||||||||
| Diluted earnings per common share | $ | 2.58 | $ | 7.18 | $ | 3.77 |
Basic earnings per common share is calculated using the weighted average common shares outstanding during the periods. Changes in the weighted average common shares outstanding between years was primarily due to stock repurchases.
Common equivalent shares from stock options and restricted stock awards, calculated using the treasury stock method, are included in the diluted per share calculations unless the effect of their inclusion would be antidilutive. During 2022, 2021 and 2020 531,000, 281,000 and 372,000 outstanding stock options, respectively, were not included in the computation of diluted earnings per common share because to do so would have had an antidilutive effect. In addition, we excluded warrants and preferred and common incentive units under the Bakkt Equity Incentive Plan in 2020 because they were also antidilutive. None of these warrants and preferred/common units were outstanding as of December 31, 2022 or 2021 due to the deconsolidation of Bakkt. As of both December 31, 2022 and 2021, there were 50,000 restricted stock units that were vested but have not been issued that are included in the computation of diluted earnings per share. Certain figures in the table above may not recalculate due to rounding.
21. Subsequent Events
We have evaluated subsequent events and determined that no events or transactions met the definition of a subsequent event for purposes of recognition or disclosure in the accompanying financial statements.
ITEM 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Previous: Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS · Next: Item 9. (A). CONTROLS AND PROCEDURES