 filings.tools
Item 2. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
96K characters. Original on sec.gov · Markdown
Item 2. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following discussion and analysis of our financial condition and results of operations for the three and six months ended June 30, 2023 should be read in conjunction with our Condensed Consolidated Financial Statements and Notes thereto for the three and six months ended June 30, 2023, included herein, and our Consolidated Financial Statements and Notes thereto for the year ended December 31, 2022, included in our Annual Report on Form 10-K filed with the United States Securities and Exchange Commission ("SEC") on February 23, 2023 (our "Annual Report").
FORWARD-LOOKING STATEMENTS
We have made statements in this Quarterly Report that constitute "forward-looking statements" as that term is defined in the Private Securities Litigation Reform Act of 1995 and other securities laws. These forward-looking statements concern our current expectations regarding our future results from operations, economic performance, financial condition, goals, strategies, investment objectives, plans and achievements. These forward-looking statements are subject to various known and unknown risks, uncertainties and other factors, and you should not rely upon them except as statements of our present intentions and of our present expectations, which may or may not occur. When we use words such as "believes", "expects", "anticipates", "estimates", "plans", "intends", "pursue", "will" or similar expressions, we are making forward-looking statements. Although we believe that our forward-looking statements are based on reasonable assumptions, our expected results may not be achieved, and actual results may differ materially from our expectations. In addition, important factors that could cause actual results to differ from expectations include, among others:
-
our ability or inability to execute our strategic growth plan, including our ability to invest according to plan, grow our businesses (including through joint ventures), incorporate alternative technologies into our offerings, achieve satisfactory returns on new product offerings, continue our revenue management, expand and manage our global operations, complete acquisitions on satisfactory terms, integrate acquired companies efficiently and transition to more sustainable sources of energy;
-
changes in customer preferences and demand for our storage and information management services, including as a result of the shift from paper and tape storage to alternative technologies that require less physical space;
-
the impact of our distribution requirements on our ability to execute our business plan;
-
the costs of complying with and our ability to comply with laws, regulations and customer requirements, including those relating to data privacy and cybersecurity issues, as well as fire and safety and environmental standards;
-
the impact of attacks on our internal information technology ("IT") systems, including the impact of such incidents on our reputation and ability to compete and any litigation or disputes that may arise in connection with such incidents;
-
our ability to fund capital expenditures;
-
our ability to remain qualified for taxation as a real estate investment trust for United States federal income tax purposes ("REIT");
-
changes in the political and economic environments in the countries in which we operate and changes in the global political climate;
-
our ability to raise debt or equity capital and changes in the cost of our debt;
-
our ability to comply with our existing debt obligations and restrictions in our debt instruments;
-
the impact of service interruptions or equipment damage and the cost of power on our data center operations;
-
the cost or potential liabilities associated with real estate necessary for our business;
-
unexpected events, including those resulting from climate change or geopolitical events, could disrupt our operations and adversely affect our reputation and results of operations;
-
failures to implement and manage new IT systems;
-
other trends in competitive or economic conditions affecting our financial condition or results of operations not presently contemplated; and
-
the other risks described in our periodic reports filed with the SEC, including under the caption "Risk Factors" in Part I, Item 1A of our Annual Report on Form 10-K filed with the SEC on February 23, 2023.
Except as required by law, we undertake no obligation to update any forward-looking statements appearing in this report.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 30 |
Part I. Financial Information
OVERVIEW
The following discussions set forth, for the periods indicated, management's discussion and analysis of financial condition and results of operations. Significant trends and changes are discussed for the three and six months ended June 30, 2023 within each section. Trends and changes that are consistent for both the three and six month periods are not repeated and are discussed on a year to date basis only.
PROJECT MATTERHORN
In September 2022, we announced a global program designed to accelerate the growth of our business ("Project Matterhorn"). Project Matterhorn investments will focus on transforming our operating model to a global operating model. Project Matterhorn will focus on the formation of a solution-based sales approach that is designed to allow us to optimize our shared services and best practices to better serve our customers' needs. We will be investing to accelerate growth and to capture a greater share of the large, global addressable markets in which we operate. We expect to incur approximately $150.0 million in costs annually related to Project Matterhorn from 2023 through 2025. Costs are comprised of (1) restructuring costs, which include (i) site consolidation and other related exit costs, (ii) employee severance costs and (iii) certain professional fees associated with these activities, and (2) other transformation costs, which include professional fees such as project management costs and costs for third party consultants who are assisting in the enablement of our growth initiatives. There were no Restructuring and other transformation costs related to Project Matterhorn for the three and six months ended June 30, 2022. The following chart presents (in thousands) total Restructuring and other transformation costs related to Project Matterhorn from the inception of Project Matterhorn through June 30, 2023 and for the three and six months ended June 30, 2023:
| From the Inception of Project Matterhorn through June 30, 2023 |  | ||||
| For the Three Months Ended June 30, 2023 | 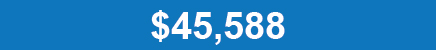 | ||||
| For the Six Months Ended June 30, 2023 |  |
See Note 11 to Notes to Condensed Consolidated Financial Statements included in this Quarterly Report for more information on Restructuring and other transformation costs.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 31 |
Part I. Financial Information
GENERAL
RESULTS OF OPERATIONS - KEY TRENDS
-
We have experienced steady volume in our Global RIM Business segment, with organic storage rental revenue growth driven primarily by revenue management. We expect organic storage rental revenue growth to benefit from revenue management and volume to be relatively stable in the near term.
-
Our organic service revenue growth is primarily due to increases in our service activity. We expect organic service revenue growth in 2023 to benefit from our new and existing digital offerings, as well as our traditional services.
-
We expect continued total revenue and Adjusted EBITDA growth in 2023 as a result of our focus on new product and service offerings, innovation, customer solutions and market expansion in line with our Project Matterhorn objectives.
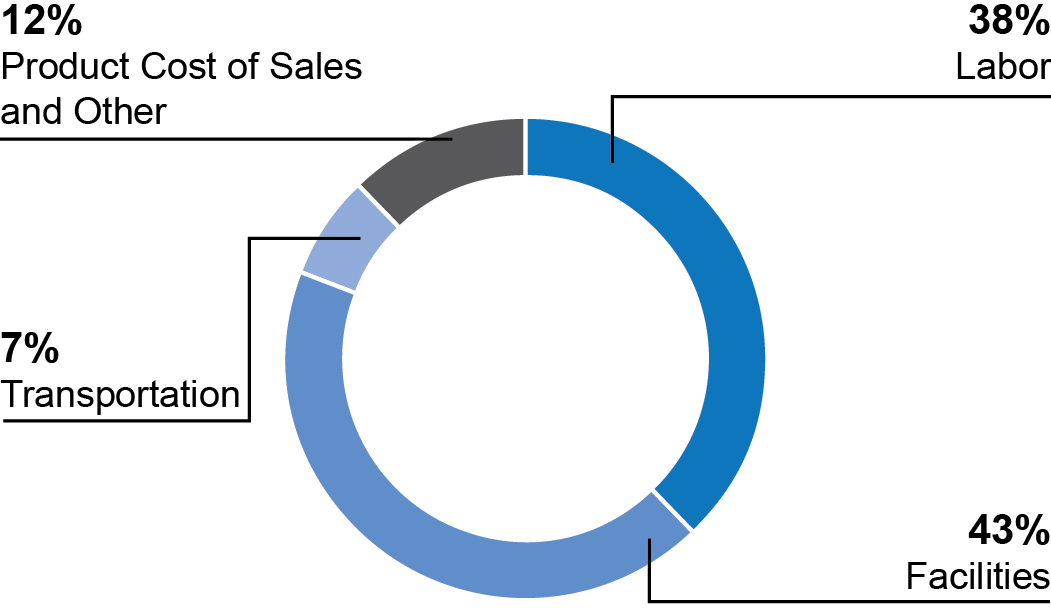
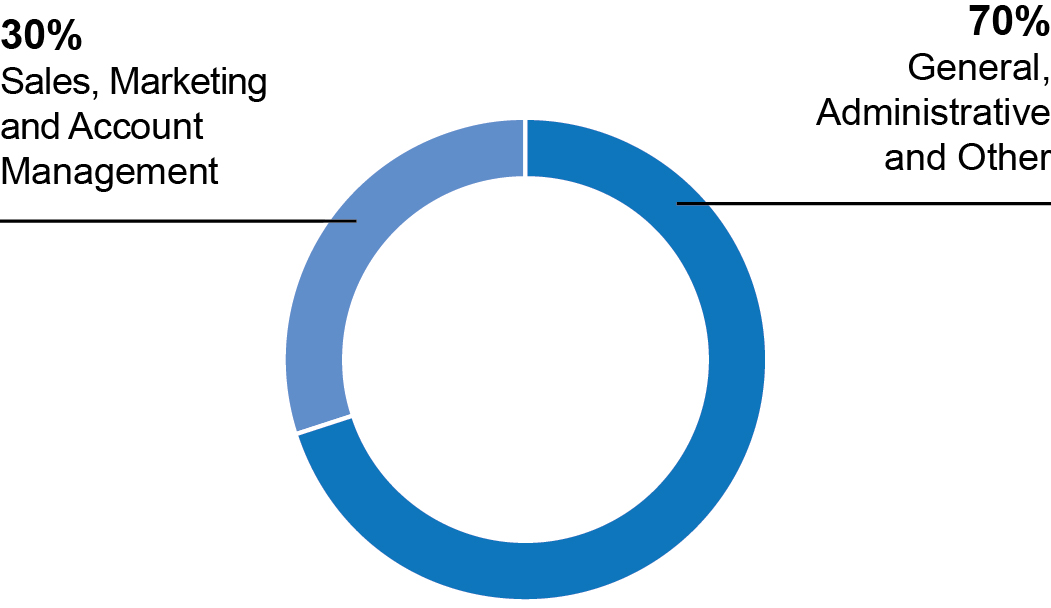
Cost of sales (excluding depreciation and amortization) and Selling, general and administrative expenses for the six months ended June 30, 2023 consists of the following:
| COST OF SALES | SELLING, GENERAL AND ADMINISTRATIVE EXPENSES | |||||||
 |  |
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 32 |
Part I. Financial Information
NON-GAAP MEASURES
ADJUSTED EBITDA
We define Adjusted EBITDA as net income (loss) before interest expense, net, provision (benefit) for income taxes, depreciation and amortization (inclusive of our share of Adjusted EBITDA from our unconsolidated joint ventures), and excluding certain items we do not believe to be indicative of our core operating results, specifically:
| EXCLUDED | ||||||||
| •Acquisition and Integration Costs (as defined below) •Restructuring and other transformation •(Gain) loss on disposal/write-down of property, plant and equipment, net (including real estate) | •Other expense (income), net •Stock-based compensation expense | |||||||
Adjusted EBITDA Margin is calculated by dividing Adjusted EBITDA by total revenues. We also show Adjusted EBITDA and Adjusted EBITDA Margin for each of our reportable segments under "Results of Operations – Segment Analysis" below.
Adjusted EBITDA excludes both interest expense, net and the provision (benefit) for income taxes. These expenses are associated with our capitalization and tax structures, which we do not consider when evaluating the operating profitability of our core operations. Adjusted EBITDA does not include depreciation and amortization expenses, in order to eliminate the impact of capital investments, which we evaluate by comparing capital expenditures to incremental revenue generated and as a percentage of total revenues. Adjusted EBITDA and Adjusted EBITDA Margin should be considered in addition to, but not as a substitute for, other measures of financial performance reported in accordance with accounting principles generally accepted in the United States of America ("GAAP"), such as operating income, net income (loss) or cash flows from operating activities.
RECONCILIATION OF NET INCOME (LOSS) TO ADJUSTED EBITDA (IN THOUSANDS):
| THREE MONTHS ENDED JUNE 30, | SIX MONTHS ENDED JUNE 30, | ||||||||||||||||||||||||||||||||||
| 2023 | 2022 | 2023 | 2022 | ||||||||||||||||||||||||||||||||
| Net Income (Loss) | $ | 1,143 | $ | 201,858 | $ | 66,678 | $ | 243,565 | |||||||||||||||||||||||||||
| Add/(Deduct): | |||||||||||||||||||||||||||||||||||
| Interest expense, net | 144,178 | 115,057 | 281,347 | 229,499 | |||||||||||||||||||||||||||||||
| Provision (benefit) for income taxes | 4,255 | 18,083 | 21,013 | 28,163 | |||||||||||||||||||||||||||||||
| Depreciation and amortization | 195,367 | 178,254 | 377,461 | 361,869 | |||||||||||||||||||||||||||||||
| Acquisition and Integration Costs(1) | 1,511 | 16,878 | 3,106 | 32,539 | |||||||||||||||||||||||||||||||
| Restructuring and other transformation | 45,588 | — | 82,501 | — | |||||||||||||||||||||||||||||||
| (Gain) loss on disposal/write-down of property, plant and equipment, net (including real estate) | (1,505) | (51,249) | (14,566) | (51,954) | |||||||||||||||||||||||||||||||
| Other expense (income), net, excluding our share of losses (gains) from our unconsolidated joint ventures | 58,694 | (46,103) | 76,185 | 7,412 | |||||||||||||||||||||||||||||||
| Stock-based compensation expense | 22,373 | 20,256 | 34,882 | 31,597 | |||||||||||||||||||||||||||||||
| Our share of Adjusted EBITDA reconciling items from our unconsolidated joint ventures | 4,054 | 1,672 | 7,859 | 3,010 | |||||||||||||||||||||||||||||||
| Adjusted EBITDA | $ | 475,658 | $ | 454,706 | $ | 936,466 | $ | 885,700 |
(1)Represent operating expenditures directly associated with the closing and integration activities of our business acquisitions that have closed, or are highly probable of closing, and include (i) advisory, legal and professional fees to complete business acquisitions and (ii) costs to integrate acquired businesses into our existing operations, including move, severance and system integration costs (collectively, "Acquisition and Integration Costs").
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 33 |
Part I. Financial Information
ADJUSTED EPS
We define Adjusted EPS as reported earnings per share fully diluted from net income (loss) attributable to Iron Mountain Incorporated (inclusive of our share of adjusted losses (gains) from our unconsolidated joint ventures) and excluding certain items, specifically:
| EXCLUDED | ||||||||
| •Acquisition and Integration Costs •Restructuring and other transformation •Amortization related to the write-off of certain customer relationship intangible assets •(Gain) loss on disposal/write-down of property, plant and equipment, net (including real estate) | •Other expense (income), net •Stock-based compensation expense •Non-cash amortization related to derivative instruments •Tax impact of reconciling items and discrete tax items | |||||||
We do not believe these excluded items to be indicative of our ongoing operating results, and they are not considered when we are forecasting our future results. We believe Adjusted EPS is of value to our current and potential investors when comparing our results from past, present and future periods.
RECONCILIATION OF REPORTED EPS—FULLY DILUTED FROM NET INCOME (LOSS) ATTRIBUTABLE TO IRON MOUNTAIN INCORPORATED TO ADJUSTED EPS—FULLY DILUTED FROM NET INCOME (LOSS) ATTRIBUTABLE TO IRON MOUNTAIN INCORPORATED:
| THREE MONTHS ENDED JUNE 30, | SIX MONTHS ENDED JUNE 30, | ||||||||||||||||||||||
| 2023 | 2022 | 2023 | 2022 | ||||||||||||||||||||
| Reported EPS—Fully Diluted from Net Income (Loss) Attributable to Iron Mountain Incorporated | $ | 0.00 | $ | 0.68 | $ | 0.22 | $ | 0.83 | |||||||||||||||
| Add/(Deduct): | |||||||||||||||||||||||
| Acquisition and Integration Costs | 0.01 | 0.06 | 0.01 | 0.11 | |||||||||||||||||||
| Restructuring and other transformation | 0.16 | — | 0.28 | — | |||||||||||||||||||
| Amortization related to the write-off of certain customer relationship intangible assets | — | — | — | 0.02 | |||||||||||||||||||
| (Gain) loss on disposal/write-down of property, plant and equipment, net (including real estate) | (0.01) | (0.18) | (0.05) | (0.18) | |||||||||||||||||||
| Other expense (income), net, excluding our share of losses (gains) from our unconsolidated joint ventures | 0.20 | (0.16) | 0.26 | 0.03 | |||||||||||||||||||
| Stock-based compensation expense | 0.08 | 0.07 | 0.12 | 0.11 | |||||||||||||||||||
| Non-cash amortization related to derivative instruments | 0.02 | — | 0.04 | — | |||||||||||||||||||
| Tax impact of reconciling items and discrete tax items(1) | (0.05) | (0.03) | (0.06) | (0.07) | |||||||||||||||||||
| Income (Loss) Attributable to Noncontrolling Interests | — | 0.01 | 0.01 | — | |||||||||||||||||||
| Adjusted EPS—Fully Diluted from Net Income (Loss) Attributable to Iron Mountain Incorporated(2) | $ | 0.40 | $ | 0.46 | $ | 0.83 | $ | 0.85 |
(1)The difference between our effective tax rates and our structural tax rate (or adjusted effective tax rates) for the three and six months ended June 30, 2023 and 2022 is primarily due to (i) the reconciling items above, which impact our reported net income (loss) before provision (benefit) for income taxes but have an insignificant impact on our reported provision (benefit) for income taxes and (ii) other discrete tax items. Our structural tax rate for purposes of the calculation of Adjusted EPS for the three and six months ended June 30, 2023 and 2022 was 14.0% and 16.5%, respectively. The Tax impact of reconciling items and discrete tax items is calculated using the current quarter's estimate of the annual structural tax rate. This may result in the current period adjustment plus prior period reported quarterly adjustments not summing to the full year adjustment.
(2)Columns may not foot due to rounding.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 34 |
Part I. Financial Information
FFO (NAREIT) AND FFO (NORMALIZED)
Funds from operations ("FFO") is defined by the National Association of Real Estate Investment Trusts as net income (loss) excluding depreciation on real estate assets, losses and gains on sale of real estate, net of tax, and amortization of data center leased-based intangibles ("FFO (Nareit)"). We calculate our FFO measures, including FFO (Nareit), adjusting for our share of reconciling items from our unconsolidated joint ventures. FFO (Nareit) does not give effect to real estate depreciation because these amounts are computed, under GAAP, to allocate the cost of a property over its useful life. Because values for well-maintained real estate assets have historically increased or decreased based upon prevailing market conditions, we believe that FFO (Nareit) provides investors with a clearer view of our operating performance. Our most directly comparable GAAP measure to FFO (Nareit) is net income (loss).
We modify FFO (Nareit), as is common among REITs seeking to provide financial measures that most meaningfully reflect their particular business ("FFO (Normalized)"). Our definition of FFO (Normalized) excludes certain items included in FFO (Nareit) that we believe are not indicative of our core operating results, specifically:
| EXCLUDED | ||||||||
| •Acquisition and Integration Costs •Restructuring and other transformation •(Gain) loss on disposal/write-down of property, plant and equipment, net (excluding real estate) •Other expense (income), net | •Stock-based compensation expense •Non-cash amortization related to derivative instruments •Real estate financing lease depreciation •Tax impact of reconciling items and discrete tax items | |||||||
RECONCILIATION OF NET INCOME (LOSS) TO FFO (NAREIT) AND FFO (NORMALIZED) (IN THOUSANDS):
| THREE MONTHS ENDED JUNE 30, | SIX MONTHS ENDED JUNE 30, | ||||||||||||||||||||||
| 2023 | 2022 | 2023 | 2022 | ||||||||||||||||||||
| Net Income (Loss) | $ | 1,143 | $ | 201,858 | $ | 66,678 | $ | 243,565 | |||||||||||||||
| Add/(Deduct): | |||||||||||||||||||||||
| Real estate depreciation | 81,558 | 75,008 | 157,687 | 154,341 | |||||||||||||||||||
| (Gain) loss on sale of real estate, net of tax | (1,853) | (48,978) | (17,599) | (48,764) | |||||||||||||||||||
| Data center lease-based intangible assets amortization | 4,907 | 4,040 | 11,036 | 8,163 | |||||||||||||||||||
| Our share of FFO (Nareit) reconciling items from our unconsolidated joint ventures | 562 | — | 694 | — | |||||||||||||||||||
| FFO (Nareit) | 86,317 | 231,928 | 218,496 | 357,305 | |||||||||||||||||||
| Add/(Deduct): | |||||||||||||||||||||||
| Acquisition and Integration Costs | 1,511 | 16,878 | 3,106 | 32,539 | |||||||||||||||||||
| Restructuring and other transformation | 45,588 | — | 82,501 | — | |||||||||||||||||||
| (Gain) loss on disposal/write-down of property, plant and equipment, net (excluding real estate) | (1,417) | (2,270) | 3,133 | (3,189) | |||||||||||||||||||
| Other expense (income), net, excluding our share of losses (gains) from our unconsolidated joint ventures(1) | 58,694 | (46,103) | 76,185 | 7,412 | |||||||||||||||||||
| Stock-based compensation expense | 22,373 | 20,256 | 34,882 | 31,597 | |||||||||||||||||||
| Non-cash amortization related to derivative instruments | 5,817 | — | 11,651 | — | |||||||||||||||||||
| Real estate financing lease depreciation | 3,008 | 3,427 | 5,996 | 7,207 | |||||||||||||||||||
| Tax impact of reconciling items and discrete tax items(2) | (13,278) | (8,250) | (18,491) | (20,876) | |||||||||||||||||||
| Our share of FFO (Normalized) reconciling items from our unconsolidated joint ventures | (500) | 374 | (274) | 354 | |||||||||||||||||||
| FFO (Normalized) | $ | 208,113 | $ | 216,240 | $ | 417,185 | $ | 412,349 |
(1)Includes foreign currency transaction (gains) losses, net and other, net. See Note 2.k. to Notes to Condensed Consolidated Financial Statements included in this Quarterly Report for additional information regarding the components of Other expense (income), net.
(2)Represents the tax impact of (i) the reconciling items above, which impact our reported net income (loss) before provision (benefit) for income taxes but have an insignificant impact on our reported provision (benefit) for income taxes and (ii) other discrete tax items. Discrete tax items resulted in a (benefit) provision for income taxes of $(5.0) million and $(5.5) million for the three and six months ended June 30, 2023, respectively, and $(0.2) million and $(10.2) million for the three and six months ended June 30, 2022, respectively.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 35 |
Part I. Financial Information
CRITICAL ACCOUNTING ESTIMATES
Our discussion and analysis of our financial condition and results of operations are based upon our Condensed Consolidated Financial Statements, which have been prepared in accordance with GAAP. The preparation of these financial statements requires us to make estimates, judgments and assumptions that affect the reported amounts of assets, liabilities, revenues and expenses, and related disclosure of contingent assets and liabilities at the date of the financial statements and for the period then ended. On an ongoing basis, we evaluate the estimates used. We base our estimates on historical experience, actuarial estimates, current conditions and various other assumptions that we believe to be reasonable under the circumstances. These estimates form the basis for making judgments about the carrying values of assets and liabilities and are not readily apparent from other sources. Actual results may differ from these estimates. Our critical accounting estimates include the following, which are listed in no particular order:
-
Revenue Recognition
-
Accounting for Acquisitions
-
Impairment of Tangible and Intangible Assets
-
Income Taxes
Further detail regarding our critical accounting estimates can be found in "Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations" in our Annual Report, and the Consolidated Financial Statements and the Notes included therein. We have determined that no material changes concerning our critical accounting estimates have occurred since December 31, 2022.
RESULTS OF OPERATIONS
COMPARISON OF THE THREE AND SIX MONTHS ENDED JUNE 30, 2023 TO THE THREE AND SIX MONTHS ENDED JUNE 30, 2022 (IN THOUSANDS):
| THREE MONTHS ENDED JUNE 30, | DOLLAR CHANGE | PERCENTAGE CHANGE | |||||||||||||||||||||
| 2023 | 2022 | ||||||||||||||||||||||
| Revenues | $ | 1,357,936 | $ | 1,289,534 | $ | 68,402 | 5.3 | % | |||||||||||||||
| Operating Expenses | 1,145,410 | 995,753 | 149,657 | 15.0 | % | ||||||||||||||||||
| Operating Income | 212,526 | 293,781 | (81,255) | (27.7) | % | ||||||||||||||||||
| Other Expenses, Net | 211,383 | 91,923 | 119,460 | 130.0 | % | ||||||||||||||||||
| Net Income (Loss) | 1,143 | 201,858 | (200,715) | (99.4) | % | ||||||||||||||||||
| Net Income (Loss) Attributable to Noncontrolling Interests | 1,029 | 1,777 | (748) | (42.1) | % | ||||||||||||||||||
| Net Income (Loss) Attributable to Iron Mountain Incorporated | $ | 114 | $ | 200,081 | $ | (199,967) | (99.9) | % | |||||||||||||||
| Adjusted EBITDA(1) | $ | 475,658 | $ | 454,706 | $ | 20,952 | 4.6 | % | |||||||||||||||
| Adjusted EBITDA Margin(1) | 35.0 | % | 35.3 | % |
| SIX MONTHS ENDED JUNE 30, | DOLLAR CHANGE | PERCENTAGE CHANGE | |||||||||||||||||||||
| 2023 | 2022 | ||||||||||||||||||||||
| Revenues | $ | 2,672,285 | $ | 2,537,580 | $ | 134,705 | 5.3 | % | |||||||||||||||
| Operating Expenses | 2,219,097 | 2,021,669 | 197,428 | 9.8 | % | ||||||||||||||||||
| Operating Income | 453,188 | 515,911 | (62,723) | (12.2) | % | ||||||||||||||||||
| Other Expenses, Net | 386,510 | 272,346 | 114,164 | 41.9 | % | ||||||||||||||||||
| Net Income (Loss) | 66,678 | 243,565 | (176,887) | (72.6) | % | ||||||||||||||||||
| Net Income (Loss) Attributable to Noncontrolling Interests | 1,969 | 1,185 | 784 | 66.2 | % | ||||||||||||||||||
| Net Income (Loss) Attributable to Iron Mountain Incorporated | $ | 64,709 | $ | 242,380 | $ | (177,671) | (73.3) | % | |||||||||||||||
| Adjusted EBITDA(1) | $ | 936,466 | $ | 885,700 | $ | 50,766 | 5.7 | % | |||||||||||||||
| Adjusted EBITDA Margin(1) | 35.0 | % | 34.9 | % |
(1)See "Non-GAAP Measures—Adjusted EBITDA" in this Quarterly Report for the definitions of Adjusted EBITDA and Adjusted EBITDA Margin, reconciliation of Net Income (Loss) to Adjusted EBITDA and a discussion of why we believe these non-GAAP measures provide relevant and useful information to our current and potential investors.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 36 |
Part I. Financial Information
REVENUES
Total revenues consist of the following (in thousands):
| THREE MONTHS ENDED JUNE 30, | PERCENTAGE CHANGE | ||||||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | DOLLAR CHANGE | ACTUAL | CONSTANT CURRENCY**(1)** | ORGANIC GROWTH**(2)** | IMPACT OF ACQUISITIONS | |||||||||||||||||||||||||||||||||||
| Storage Rental | $ | 830,756 | $ | 753,126 | $ | 77,630 | 10.3 | % | 10.9 | % | 10.8 | % | 0.1 | % | |||||||||||||||||||||||||||
| Service | 527,180 | 536,408 | (9,228) | (1.7) | % | (1.0) | % | (1.4) | % | 0.4 | % | ||||||||||||||||||||||||||||||
| Total Revenues | $ | 1,357,936 | $ | 1,289,534 | $ | 68,402 | 5.3 | % | 6.0 | % | 5.7 | % | 0.3 | % |
| SIX MONTHS ENDED JUNE 30, | PERCENTAGE CHANGE | ||||||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | DOLLAR CHANGE | ACTUAL | CONSTANT CURRENCY**(1)** | ORGANIC GROWTH**(2)** | IMPACT OF ACQUISITIONS | |||||||||||||||||||||||||||||||||||
| Storage Rental | $ | 1,640,845 | $ | 1,504,196 | $ | 136,649 | 9.1 | % | 10.6 | % | 11.0 | % | (0.4) | % | |||||||||||||||||||||||||||
| Service | 1,031,440 | 1,033,384 | (1,944) | (0.2) | % | 1.1 | % | 0.2 | % | 0.9 | % | ||||||||||||||||||||||||||||||
| Total Revenues | $ | 2,672,285 | $ | 2,537,580 | $ | 134,705 | 5.3 | % | 6.7 | % | 6.6 | % | 0.1 | % |
(1)Constant currency growth rates, which are a non-GAAP measure, are calculated by translating the 2022 results at the 2023 average exchange rates.
(2)Our organic revenue growth rate, which is a non-GAAP measure, represents the year-over-year growth rate of our revenues excluding the impact of business acquisitions, divestitures and foreign currency exchange rate fluctuations. Our organic revenue growth rate includes the impact of acquisitions of customer relationships.
TOTAL REVENUES
For the six months ended June 30, 2023, the increase in reported revenue was primarily driven by organic storage rental revenue growth. Foreign currency exchange rate fluctuations decreased our reported revenue growth rate for the six months ended June 30, 2023 by 1.4% compared to the prior year period.
STORAGE RENTAL REVENUE AND SERVICE REVENUE
Primary factors influencing the change in reported storage rental revenue and reported service revenue for the six months ended June 30, 2023 compared to the six months ended June 30, 2022 include the following:
| STORAGE RENTAL REVENUE | •organic storage rental revenue growth driven by increased volume in faster growing markets and our Global Data Center Business segment and revenue management; •a 0.1% increase in total global volume; and •a decrease of $20.0 million due to foreign currency exchange rate fluctuations. | |||||||
| SERVICE REVENUE | •organic service revenue growth driven by increased service activity levels in our Global RIM business, partially offset by service revenue declines in our asset lifecycle management business as a result of component price declines, partially offset by increased volume; and •a decrease of $13.6 million due to foreign currency exchange rate fluctuations. | |||||||
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 37 |
Part I. Financial Information
OPERATING EXPENSES
COST OF SALES
Cost of sales (excluding depreciation and amortization) consists of the following expenses (in thousands):
| THREE MONTHS ENDED JUNE 30, | PERCENTAGE CHANGE | % OF TOTAL REVENUES | PERCENTAGE CHANGE (FAVORABLE)/ UNFAVORABLE | ||||||||||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | DOLLAR CHANGE | ACTUAL | CONSTANT CURRENCY | 2023 | 2022 | |||||||||||||||||||||||||||||||||||||||||
| Labor | $ | 224,398 | $ | 203,459 | $ | 20,939 | 10.3 | % | 11.0 | % | 16.5 | % | 15.8 | % | 0.7 | % | |||||||||||||||||||||||||||||||
| Facilities | 255,535 | 213,795 | 41,740 | 19.5 | % | 20.3 | % | 18.8 | % | 16.6 | % | 2.2 | % | ||||||||||||||||||||||||||||||||||
| Transportation | 41,147 | 42,391 | (1,244) | (2.9) | % | (2.0) | % | 3.0 | % | 3.3 | % | (0.3) | % | ||||||||||||||||||||||||||||||||||
| Product Cost of Sales and Others | 71,564 | 96,831 | (25,267) | (26.1) | % | (25.7) | % | 5.3 | % | 7.5 | % | (2.2) | % | ||||||||||||||||||||||||||||||||||
| Total Cost of sales | $ | 592,644 | $ | 556,476 | $ | 36,168 | 6.5 | % | 7.2 | % | 43.6 | % | 43.2 | % | 0.4 | % |
| SIX MONTHS ENDED JUNE 30, | PERCENTAGE CHANGE | % OF TOTAL REVENUES | PERCENTAGE CHANGE (FAVORABLE)/ UNFAVORABLE | ||||||||||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | DOLLAR CHANGE | ACTUAL | CONSTANT CURRENCY | 2023 | 2022 | |||||||||||||||||||||||||||||||||||||||||
| Labor | $ | 443,929 | $ | 404,960 | $ | 38,969 | 9.6 | % | 11.3 | % | 16.6 | % | 16.0 | % | 0.6 | % | |||||||||||||||||||||||||||||||
| Facilities | 496,225 | 432,114 | 64,111 | 14.8 | % | 16.7 | % | 18.6 | % | 17.0 | % | 1.6 | % | ||||||||||||||||||||||||||||||||||
| Transportation | 81,122 | 77,659 | 3,463 | 4.5 | % | 6.2 | % | 3.0 | % | 3.1 | % | (0.1) | % | ||||||||||||||||||||||||||||||||||
| Product Cost of Sales and Others | 142,994 | 188,365 | (45,371) | (24.1) | % | (23.3) | % | 5.4 | % | 7.4 | % | (2.0) | % | ||||||||||||||||||||||||||||||||||
| Total Cost of sales | $ | 1,164,270 | $ | 1,103,098 | $ | 61,172 | 5.5 | % | 7.1 | % | 43.6 | % | 43.5 | % | 0.1 | % |
Primary factors influencing the change in reported Cost of sales for the six months ended June 30, 2023 compared to the six months ended June 30, 2022 include the following:
*•*an increase in labor costs driven by an increase in service activity, primarily within our Global RIM business;
*•*an increase in facilities expenses driven by increases in rent expense, reflecting the impact of our sale-leaseback activity during 2022 and the first six months of 2023, as well as increases in utilities costs and facility maintenance costs;
- a decrease in product cost of sales in our asset lifecycle management business as a result of component price declines, partially offset by increased volume; and
*•*a decrease of $15.8 million due to foreign currency exchange rate fluctuations.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 38 |
Part I. Financial Information
SELLING, GENERAL AND ADMINISTRATIVE EXPENSES
Selling, general and administrative expenses consists of the following expenses (in thousands):
| THREE MONTHS ENDED JUNE 30, | PERCENTAGE CHANGE | % OF TOTAL REVENUES | PERCENTAGE CHANGE (FAVORABLE)/ UNFAVORABLE | ||||||||||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | DOLLAR CHANGE | ACTUAL | CONSTANT CURRENCY | 2023 | 2022 | |||||||||||||||||||||||||||||||||||||||||
| General, Administrative and Other | $ | 217,965 | $ | 220,891 | $ | (2,926) | (1.3) | % | 0.3 | % | 16.1 | % | 17.1 | % | (1.0) | % | |||||||||||||||||||||||||||||||
| Sales, Marketing and Account Management | 93,840 | 74,503 | 19,337 | 26.0 | % | 26.5 | % | 6.9 | % | 5.8 | % | 1.1 | % | ||||||||||||||||||||||||||||||||||
| Total Selling, general and administrative expenses | $ | 311,805 | $ | 295,394 | $ | 16,411 | 5.6 | % | 7.0 | % | 23.0 | % | 22.9 | % | 0.1 | % |
| SIX MONTHS ENDED JUNE 30, | PERCENTAGE CHANGE | % OF TOTAL REVENUES | PERCENTAGE CHANGE (FAVORABLE)/ UNFAVORABLE | ||||||||||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | DOLLAR CHANGE | ACTUAL | CONSTANT CURRENCY | 2023 | 2022 | |||||||||||||||||||||||||||||||||||||||||
| General, Administrative and Other | $ | 424,988 | $ | 427,207 | $ | (2,219) | (0.5) | % | 1.6 | % | 15.9 | % | 16.8 | % | (0.9) | % | |||||||||||||||||||||||||||||||
| Sales, Marketing and Account Management | 181,337 | 148,910 | 32,427 | 21.8 | % | 23.3 | % | 6.8 | % | 5.9 | % | 0.9 | % | ||||||||||||||||||||||||||||||||||
| Total Selling, general and administrative expenses | $ | 606,325 | $ | 576,117 | $ | 30,208 | 5.2 | % | 7.2 | % | 22.7 | % | 22.7 | % | — | % |
Primary factors influencing the change in reported Selling, general and administrative expenses for the six months ended June 30, 2023 compared to the six months ended June 30, 2022 include the following:
-
an increase in sales, marketing and account management expenses, driven by higher compensation expense, primarily reflecting increased headcount; and
-
a decrease of $10.6 million due to foreign currency exchange rate fluctuations.
DEPRECIATION AND AMORTIZATION
Depreciation expense increased by $17.9 million, or 7.6%, for the six months ended June 30, 2023 compared to the prior year period. See Note 2.i. to Notes to Consolidated Financial Statements included in our Annual Report for additional information regarding the useful lives over which our property, plant and equipment is depreciated.
Amortization expense decreased by $2.3 million, or 1.8%, for the six months ended June 30, 2023 compared to the prior year period.
ACQUISITION AND INTEGRATION COSTS
Acquisition and Integration Costs for the six months ended June 30, 2023 and 2022 were approximately $3.1 million and $32.5 million, respectively.
RESTRUCTURING AND OTHER TRANSFORMATION
Restructuring and other transformation costs for the six months ended June 30, 2023 were $82.5 million and related to operating expenses associated with the implementation of Project Matterhorn. There were no Restructuring and other transformation costs for the six months ended June 30, 2022.
(GAIN) LOSS ON DISPOSAL/WRITE-DOWN OF PROPERTY, PLANT AND EQUIPMENT, NET
Gain on disposal/write-down of property, plant and equipment, net for the six months ended June 30, 2023 was approximately $14.6 million. The gains primarily consist of a gain of approximately $18.5 million associated with a sale-leaseback transaction of a facility in Singapore during the first quarter of 2023.
Gain on disposal/write-down of property, plant and equipment, net for the six months ended June 30, 2022 was approximately $52.0 million. The gains primarily consist of gains of approximately $49.0 million associated with sale and sale-leaseback transactions of 11 facilities and parcels of land in the United States during the second quarter of 2022.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 39 |
Part I. Financial Information
OTHER EXPENSES, NET
INTEREST EXPENSE, NET
Interest expense, net increased by $51.8 million to $281.3 million in the six months ended June 30, 2023 from $229.5 million in the prior year period. The increase is primarily due to higher average debt outstanding during the six months ended June 30, 2023 compared to the prior year period as well as an increase in our weighted average interest rate. Our weighted average interest rate, inclusive of the fees associated with our outstanding letters of credit, was 5.4% and 4.6% at June 30, 2023 and 2022, respectively. See Note 6 to Notes to Condensed Consolidated Financial Statements included in this Quarterly Report for additional information regarding our indebtedness.
OTHER EXPENSE (INCOME), NET
Other expense (income), net for the three and six months ended June 30, 2023 and 2022 consists of the following (in thousands):
| THREE MONTHS ENDED JUNE 30, | DOLLAR CHANGE | SIX MONTHS ENDED JUNE 30, | DOLLAR CHANGE | |||||||||||||||||||||||||||||||||||
| DESCRIPTION | 2023 | 2022 | 2023 | 2022 | ||||||||||||||||||||||||||||||||||
| Foreign currency transaction losses (gains), net(1) | $ | 15,063 | $ | (55,039) | $ | 70,102 | $ | 29,487 | $ | (68,240) | $ | 97,727 | ||||||||||||||||||||||||||
| Debt extinguishment expense | — | — | — | — | 671 | (671) | ||||||||||||||||||||||||||||||||
| Other, net(2) | 47,887 | 13,822 | 34,065 | 54,663 | 82,253 | (27,590) | ||||||||||||||||||||||||||||||||
| Other Expense (Income), Net | $ | 62,950 | $ | (41,217) | $ | 104,167 | $ | 84,150 | $ | 14,684 | $ | 69,466 |
(1)The losses for the three and six months ended June 30, 2023 primarily consist of the impact of changes in the exchange rate of the British pound sterling against the United States dollar on our intercompany balances with and between certain of our subsidiaries.
(2)Other, net for the six months ended June 30, 2023 consists primarily of a loss of approximately $38.0 million associated with the remeasurement to fair value of our previously held equity interest in the Clutter JV. See the Investments section of Liquidity and Capital Resources for additional information. We also recognized losses on our equity method investments and the change in value of the Deferred Purchase Obligation (as defined in Note 3 to Notes to Consolidated Financial Statements included in our Annual Report).
PROVISION FOR INCOME TAXES
We provide for income taxes during interim periods based on our estimate of the effective tax rate for the year. Our effective tax rates for the three and six months ended June 30, 2023 and 2022 are as follows:
| THREE MONTHS ENDED JUNE 30, | SIX MONTHS ENDED JUNE 30, | ||||||||||||||||||||||
| 2023**(1)** | 2022 | 2023**(1)** | 2022 | ||||||||||||||||||||
| Effective Tax Rate | 78.8 | % | 8.2 | % | 24.0 | % | 10.4 | % |
(1)The primary reconciling items between the federal statutory tax rate of 21.0% and our overall effective tax rate for the three and six months ended June 30, 2023 were (i) the loss of approximately $38.0 million recorded in Other, net a component of Other expense (income), net during the second quarter of 2023 to reflect the remeasurement of our previously held equity interest in the Clutter JV to fair value, for which there was no tax impact, (ii) the benefits derived from the dividends paid deduction and (iii) the differences in the tax rates to which our foreign earnings are subject.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 40 |
Part I. Financial Information
NET INCOME (LOSS) AND ADJUSTED EBITDA
The following table reflects the effect of the foregoing factors on our net income (loss) and Adjusted EBITDA (in thousands):
| THREE MONTHS ENDED JUNE 30, | DOLLAR CHANGE | PERCENTAGE CHANGE | |||||||||||||||||||||
| 2023 | 2022 | ||||||||||||||||||||||
| Net Income (Loss) | $ | 1,143 | $ | 201,858 | $ | (200,715) | (99.4) | % | |||||||||||||||
| Net Income (Loss) as a percentage of Revenue | 0.1 | % | 15.7 | % | |||||||||||||||||||
| Adjusted EBITDA | $ | 475,658 | $ | 454,706 | $ | 20,952 | 4.6 | % | |||||||||||||||
| Adjusted EBITDA Margin | 35.0 | % | 35.3 | % |
| SIX MONTHS ENDED JUNE 30, | DOLLAR CHANGE | PERCENTAGE CHANGE | |||||||||||||||||||||
| 2023 | 2022 | ||||||||||||||||||||||
| Net Income (Loss) | $ | 66,678 | $ | 243,565 | $ | (176,887) | (72.6) | % | |||||||||||||||
| Net Income (Loss) as a percentage of Revenue | 2.5 | % | 9.6 | % | |||||||||||||||||||
| Adjusted EBITDA | $ | 936,466 | $ | 885,700 | $ | 50,766 | 5.7 | % | |||||||||||||||
| Adjusted EBITDA Margin | 35.0 | % | 34.9 | % |
| Adjusted EBITDA Margin for the six months ended June 30, 2023 increased by 10 basis points compared to the same prior year period driven by improved service revenue trends, revenue management and ongoing cost containment measures, partially offset by lower Adjusted EBITDA Margin in our asset lifecycle management business. | ↑ INCREASED BY $50.8 MILLION OR 5.7% Adjusted EBITDA | ||||
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 41 |
Part I. Financial Information
SEGMENT ANALYSIS
See Note 9 to Notes to Condensed Consolidated Financial Statements included in this Quarterly Report for a description of our reportable segments.
GLOBAL RIM BUSINESS (IN THOUSANDS)
| THREE MONTHS ENDED JUNE 30, | PERCENTAGE CHANGE | ||||||||||||||||||||||||||||||||||||||||
| DOLLAR CHANGE | ACTUAL | CONSTANT CURRENCY | ORGANIC GROWTH | IMPACT OF ACQUISITIONS | |||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | ||||||||||||||||||||||||||||||||||||||||
| Storage Rental | $ | 704,011 | $ | 649,771 | $ | 54,240 | 8.3 | % | 9.2 | % | 9.2 | % | — | % | |||||||||||||||||||||||||||
| Service | 455,856 | 420,705 | 35,151 | 8.4 | % | 9.3 | % | 9.3 | % | — | % | ||||||||||||||||||||||||||||||
| Segment Revenue | $ | 1,159,867 | $ | 1,070,476 | $ | 89,391 | 8.4 | % | 9.2 | % | 9.2 | % | — | % | |||||||||||||||||||||||||||
| Segment Adjusted EBITDA | $ | 499,062 | $ | 469,368 | $ | 29,694 | |||||||||||||||||||||||||||||||||||
| Segment Adjusted EBITDA Margin | 43.0 | % | 43.8 | % |
| SIX MONTHS ENDED JUNE 30, | PERCENTAGE CHANGE | ||||||||||||||||||||||||||||||||||||||||
| DOLLAR CHANGE | ACTUAL | CONSTANT CURRENCY | ORGANIC GROWTH | IMPACT OF ACQUISITIONS | |||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | ||||||||||||||||||||||||||||||||||||||||
| Storage Rental | $ | 1,391,680 | $ | 1,299,858 | $ | 91,822 | 7.1 | % | 8.7 | % | 9.3 | % | (0.6) | % | |||||||||||||||||||||||||||
| Service | 894,713 | 819,509 | 75,204 | 9.2 | % | 10.9 | % | 11.4 | % | (0.5) | % | ||||||||||||||||||||||||||||||
| Segment Revenue | $ | 2,286,393 | $ | 2,119,367 | $ | 167,026 | 7.9 | % | 9.5 | % | 10.1 | % | (0.6) | % | |||||||||||||||||||||||||||
| Segment Adjusted EBITDA | $ | 976,846 | $ | 918,163 | $ | 58,683 | |||||||||||||||||||||||||||||||||||
| Segment Adjusted EBITDA Margin | 42.7 | % | 43.3 | % |
SIX MONTHS ENDED YEAR OVER YEAR SEGMENT ANALYSIS: GLOBAL RIM BUSINESS (IN MILLIONS)
| Storage Rental Revenue | Service Revenue | Segment Revenue | Segment Adjusted EBITDA |
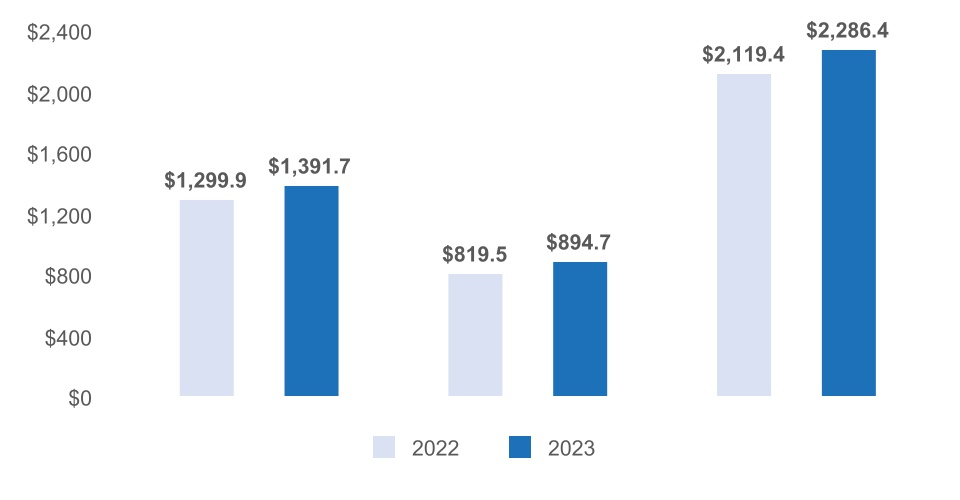
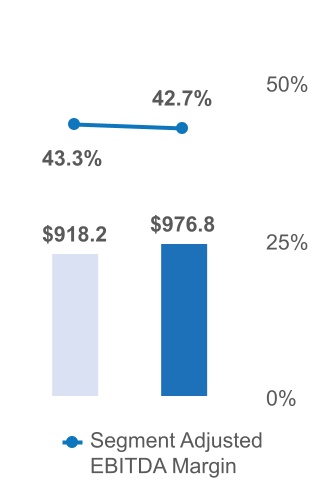
Primary factors influencing the change in revenue and Adjusted EBITDA Margin in our Global RIM Business segment for the six months ended June 30, 2023 compared to the prior year period include the following:
-
organic storage rental revenue growth driven by revenue management;
-
organic service revenue growth primarily driven by increases in our traditional service activity levels and growth in our Global Digital Solutions business;
*•*a decrease in revenue of $31.7 million due to foreign currency exchange rate fluctuations; and
*•*a 60 basis point decrease in Adjusted EBITDA Margin primarily driven by an increase in compensation and other employee-related costs, partially offset by revenue management.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 42 |
Part I. Financial Information
GLOBAL DATA CENTER BUSINESS (IN THOUSANDS)
| THREE MONTHS ENDED JUNE 30, | PERCENTAGE CHANGE | ||||||||||||||||||||||||||||||||||||||||
| DOLLAR CHANGE | ACTUAL | CONSTANT CURRENCY | ORGANIC GROWTH | IMPACT OF ACQUISITIONS | |||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | ||||||||||||||||||||||||||||||||||||||||
| Storage Rental | $ | 110,990 | $ | 89,768 | $ | 21,222 | 23.6 | % | 23.0 | % | 22.3 | % | 0.7 | % | |||||||||||||||||||||||||||
| Service | 7,043 | 10,320 | (3,277) | (31.8) | % | (33.2) | % | (32.4) | % | (0.8) | % | ||||||||||||||||||||||||||||||
| Segment Revenue | $ | 118,033 | $ | 100,088 | $ | 17,945 | 17.9 | % | 17.1 | % | 16.7 | % | 0.4 | % | |||||||||||||||||||||||||||
| Segment Adjusted EBITDA | $ | 53,809 | $ | 42,307 | $ | 11,502 | |||||||||||||||||||||||||||||||||||
| Segment Adjusted EBITDA Margin | 45.6 | % | 42.3 | % |
| SIX MONTHS ENDED JUNE 30, | PERCENTAGE CHANGE | ||||||||||||||||||||||||||||||||||||||||
| DOLLAR CHANGE | ACTUAL | CONSTANT CURRENCY | ORGANIC GROWTH | IMPACT OF ACQUISITIONS | |||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | ||||||||||||||||||||||||||||||||||||||||
| Storage Rental | $ | 218,425 | $ | 177,219 | $ | 41,206 | 23.3 | % | 23.6 | % | 23.0 | % | 0.6 | % | |||||||||||||||||||||||||||
| Service | 11,913 | 19,856 | (7,943) | (40.0) | % | (40.1) | % | (39.8) | % | (0.3) | % | ||||||||||||||||||||||||||||||
| Segment Revenue | $ | 230,338 | $ | 197,075 | $ | 33,263 | 16.9 | % | 17.2 | % | 16.7 | % | 0.5 | % | |||||||||||||||||||||||||||
| Segment Adjusted EBITDA | $ | 104,444 | $ | 84,284 | $ | 20,160 | |||||||||||||||||||||||||||||||||||
| Segment Adjusted EBITDA Margin | 45.3 | % | 42.8 | % |
SIX MONTHS ENDED YEAR OVER YEAR SEGMENT ANALYSIS: GLOBAL DATA CENTER BUSINESS (IN MILLIONS)
| Storage Rental Revenue | Service Revenue | Segment Revenue | Segment Adjusted EBITDA |
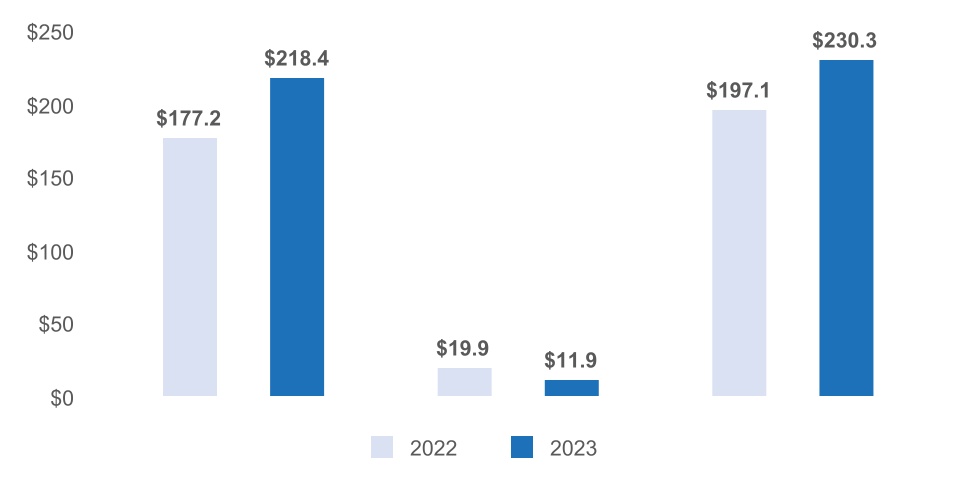
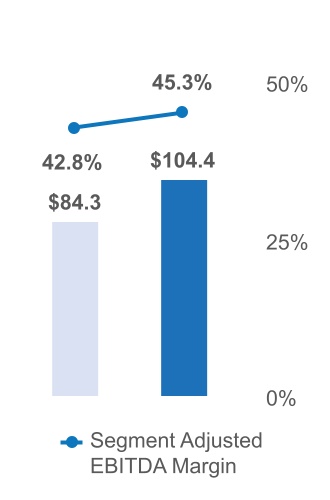
Primary factors influencing the change in revenue, Adjusted EBITDA and Adjusted EBITDA Margin in our Global Data Center Business segment for the six months ended June 30, 2023 compared to the prior year period include the following:
- organic storage rental revenue growth from leases that commenced during the first six months of 2023 and in prior periods, improved pricing and higher pass-through power costs, partially offset by churn of 280 basis points;
*•*an increase in Adjusted EBITDA primarily driven by organic storage rental revenue growth; and
*•*a 250 basis point increase in Adjusted EBITDA Margin reflecting ongoing cost management and a decline in lower margin project revenue, partially offset by higher pass-through power costs.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 43 |
Part I. Financial Information
CORPORATE AND OTHER (IN THOUSANDS)
| THREE MONTHS ENDED JUNE 30, | PERCENTAGE CHANGE | ||||||||||||||||||||||||||||||||||||||||
| DOLLAR CHANGE | ACTUAL | CONSTANT CURRENCY | ORGANIC GROWTH | IMPACT OF ACQUISITIONS | |||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | ||||||||||||||||||||||||||||||||||||||||
| Storage Rental | $ | 15,755 | $ | 13,587 | $ | 2,168 | 16.0 | % | 15.8 | % | 11.5 | % | 4.3 | % | |||||||||||||||||||||||||||
| Service | 64,281 | 105,383 | (41,102) | (39.0) | % | (38.9) | % | (41.0) | % | 2.1 | % | ||||||||||||||||||||||||||||||
| Revenue | $ | 80,036 | $ | 118,970 | $ | (38,934) | (32.7) | % | (32.6) | % | (35.0) | % | 2.4 | % | |||||||||||||||||||||||||||
| Adjusted EBITDA | $ | (77,213) | $ | (56,969) | $ | (20,244) |
| SIX MONTHS ENDED JUNE 30, | PERCENTAGE CHANGE | ||||||||||||||||||||||||||||||||||||||||
| DOLLAR CHANGE | ACTUAL | CONSTANT CURRENCY | ORGANIC GROWTH | IMPACT OF ACQUISITIONS | |||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | ||||||||||||||||||||||||||||||||||||||||
| Storage Rental | $ | 30,740 | $ | 27,119 | $ | 3,621 | 13.4 | % | 14.1 | % | 10.0 | % | 4.1 | % | |||||||||||||||||||||||||||
| Service | 124,814 | 194,019 | (69,205) | (35.7) | % | (35.3) | % | (42.4) | % | 7.1 | % | ||||||||||||||||||||||||||||||
| Revenue | $ | 155,554 | $ | 221,138 | $ | (65,584) | (29.7) | % | (29.2) | % | (36.0) | % | 6.8 | % | |||||||||||||||||||||||||||
| Adjusted EBITDA | $ | (144,824) | $ | (116,747) | $ | (28,077) |
Primary factors influencing the change in revenue and Adjusted EBITDA in Corporate and Other for the six months ended June 30, 2023 compared to the prior year period include the following:
- a decrease in service revenue in our asset lifecycle management business as a result of component price declines, which we expect to improve from current levels, partially offset by increased volume; and
*•*a decrease in Adjusted EBITDA driven by the flow through of service revenue declines in our asset lifecycle management business.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 44 |
Part I. Financial Information
LIQUIDITY AND CAPITAL RESOURCES
GENERAL
We expect to meet our short-term and long-term cash flow requirements through cash generated from operations, cash on hand, borrowings under our Credit Agreement (as defined below) and proceeds from monetizing a small portion of our total industrial real estate assets, as well as other potential financings (such as the issuance of debt). Our cash flow requirements, both in the near and long term, include, but are not limited to, capital expenditures, the repayment of outstanding debt, shareholder dividends, potential business acquisitions and normal business operation needs.
PROJECT MATTERHORN
As disclosed above, in September 2022, we announced Project Matterhorn. We estimate that the implementation of Project Matterhorn will result in costs of approximately $150.0 million per year from 2023 through 2025. Total costs related to Project Matterhorn during the three and six months ended June 30, 2023 were approximately $45.6 million and $82.5 million, respectively, and are included in Restructuring and other transformation in our Condensed Consolidated Statement of Operations. Total costs from inception of the program to June 30, 2023 were approximately $124.4 million. There were no Restructuring and other transformation costs related to Project Matterhorn for the three and six months ended June 30, 2022.
CASH FLOWS
The following is a summary of our cash balances and cash flows (in thousands) as of and for the six months ended June 30,
| 2023 | 2022 | ||||||||||
| Cash Flows from Operating Activities | $ | 446,094 | $ | 345,924 | |||||||
| Cash Flows from Investing Activities | (645,282) | (991,103) | |||||||||
| Cash Flows from Financing Activities | 209,827 | 542,000 | |||||||||
| Cash and Cash Equivalents, End of Period | 149,493 | 144,746 |
A. CASH FLOWS FROM OPERATING ACTIVITIES
For the six months ended June 30, 2023, net cash flows provided by operating activities increased by $100.2 million compared to the prior year period, primarily due to an increase in cash from working capital of $105.3 million, primarily related to the timing of accounts receivable collections, partially offset by a decrease in net income (excluding non-cash charges) of $5.1 million.
B. CASH FLOWS FROM INVESTING ACTIVITIES
Our significant investing activity during the six months ended June 30, 2023 included cash paid for capital expenditures of $600.8 million. Additional details of our capital spending are included in the "Capital Expenditures" section below.
C. CASH FLOWS FROM FINANCING ACTIVITIES
Our significant financing activities during the six months ended June 30, 2023 included:
-
Net proceeds of $990.0 million associated with the issuance of the 7% Notes due 2029 (as defined below).
-
Net payments of $403.2 million primarily associated with repayments on our Revolving Credit Facility (as defined in Note 6 to Notes to Condensed Consolidated Financial Statements included in this Quarterly Report).
-
Payment of dividends in the amount of $367.1 million on our common stock.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 45 |
Part I. Financial Information
CAPITAL EXPENDITURES
The following table presents our capital spend for the six months ended June 30, 2023 and 2022, organized by the type of the spending as described in our Annual Report (in thousands):
| SIX MONTHS ENDED JUNE 30, | |||||||||||
| NATURE OF CAPITAL SPEND | 2023 | 2022 | |||||||||
| Growth Investment Capital Expenditures: | |||||||||||
| Data Center | $ | 417,861 | $ | 183,815 | |||||||
| Real Estate | 104,862 | 66,855 | |||||||||
| Innovation and Other | 37,644 | 20,958 | |||||||||
| Total Growth Investment Capital Expenditures | 560,367 | 271,628 | |||||||||
| Recurring Capital Expenditures: | |||||||||||
| Real Estate | $ | 19,552 | $ | 23,672 | |||||||
| Non-Real Estate | 34,662 | 37,834 | |||||||||
| Data Center | 6,415 | 5,678 | |||||||||
| Total Recurring Capital Expenditures | 60,629 | 67,184 | |||||||||
| Total Capital Spend (on accrual basis) | $ | 620,996 | $ | 338,812 | |||||||
| Net (decrease) increase in prepaid capital expenditures | (630) | 1,407 | |||||||||
| Net (increase) decrease in accrued capital expenditures | (19,608) | (9,999) | |||||||||
| Total Capital Spend (on cash basis) | $ | 600,758 | $ | 330,220 |
Excluding capital expenditures associated with potential future acquisitions, we expect total capital expenditures of approximately $1,200.0 million for the year ending December 31, 2023. Of this, we expect our capital expenditures for growth investment to be approximately $1,055.0 million, and our recurring capital expenditures to approach $145.0 million.
DIVIDENDS
See Note 8 to Notes to Condensed Consolidated Financial Statements included in this Quarterly Report for a listing of dividends that we declared during the first six months of 2023 and fiscal year 2022.
On August 3, 2023, we declared a dividend to our stockholders of record as of September 15, 2023 of $0.65 per share, payable on October 5, 2023.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 46 |
Part I. Financial Information
FINANCIAL INSTRUMENTS AND DEBT
Financial instruments that potentially subject us to credit risk consist principally of cash and cash equivalents (including money market funds) and accounts receivable. The only significant concentration of liquid investments as of June 30, 2023 is related to cash and cash equivalents held in money market funds. See Note 2.e. to Notes to Condensed Consolidated Financial Statements included in this Quarterly Report for information on our money market funds.
Long-term debt as of June 30, 2023 is as follows (in thousands):
| JUNE 30, 2023 | |||||||||||||||||
| DEBT (INCLUSIVE OF DISCOUNT) | UNAMORTIZED DEFERRED FINANCING COSTS | CARRYING AMOUNT | |||||||||||||||
| Revolving Credit Facility(1) | $ | 679,500 | $ | (5,332) | $ | 674,168 | |||||||||||
| Term Loan A(1) | 234,375 | — | 234,375 | ||||||||||||||
| Term Loan B(1)(3) | 662,685 | (3,122) | 659,563 | ||||||||||||||
| Australian Dollar Term Loan | 196,333 | (543) | 195,790 | ||||||||||||||
| UK Bilateral Revolving Credit Facility | 177,277 | — | 177,277 | ||||||||||||||
| 37/8% GBP Senior Notes due 2025 (the "GBP Notes") | 506,506 | (2,231) | 504,275 | ||||||||||||||
| 47/8% Senior Notes due 2027 (the "47/8% Notes due 2027")(2) | 1,000,000 | (6,043) | 993,957 | ||||||||||||||
| 51/4% Senior Notes due 2028 (the "51/4% Notes due 2028")(2) | 825,000 | (5,609) | 819,391 | ||||||||||||||
| 5% Senior Notes due 2028 (the "5% Notes due 2028")(2) | 500,000 | (3,678) | 496,322 | ||||||||||||||
| 7% Senior Notes due 2029 (the "7% Notes due 2029")(2) | 1,000,000 | (11,853) | 988,147 | ||||||||||||||
| 47/8% Senior Notes due 2029 (the "47/8% Notes due 2029")(2) | 1,000,000 | (9,041) | 990,959 | ||||||||||||||
| 51/4% Senior Notes due 2030 (the "51/4% Notes due 2030")(2) | 1,300,000 | (10,655) | 1,289,345 | ||||||||||||||
| 41/2% Senior Notes due 2031 (the "41/2% Notes")(2) | 1,100,000 | (9,539) | 1,090,461 | ||||||||||||||
| 5% Senior Notes due 2032 (the "5% Notes due 2032") | 750,000 | (11,858) | 738,142 | ||||||||||||||
| 55/8% Senior Notes due 2032 (the "55/8% Notes")(2) | 600,000 | (5,275) | 594,725 | ||||||||||||||
| Real Estate Mortgages, Financing Lease Liabilities and Other | 457,724 | (483) | 457,241 | ||||||||||||||
| Accounts Receivable Securitization Program | 343,100 | (426) | 342,674 | ||||||||||||||
| Total Long-term Debt | 11,332,500 | (85,688) | 11,246,812 | ||||||||||||||
| Less Current Portion | (102,582) | — | (102,582) | ||||||||||||||
| Long-term Debt, Net of Current Portion | $ | 11,229,918 | $ | (85,688) | $ | 11,144,230 |
(1)Collectively, the “Credit Agreement”.
(2)Collectively, the "Parent Notes".
(3)Due to the discontinuance of the London Interbank Offered Rate ("LIBOR") reference rate on June 30, 2023, we transitioned the Term Loan B from an interest rate of LIBOR plus 1.75% to a synthetic LIBOR rate plus 1.75%, effective July 1, 2023.
See Note 7 to Notes to Consolidated Financial Statements included in our Annual Report and Note 6 to Notes to Condensed Consolidated Financial Statements included in this Quarterly Report for additional information regarding our long-term debt.
MAY 2023 OFFERING
On May 15, 2023, Iron Mountain Incorporated completed a private offering of (in thousands):
| SERIES OF NOTES | AGGREGATE PRINCIPAL AMOUNT | MATURITY DATE | INTEREST PAYMENT DUE | PAR CALL DATE**(1)** | ||||||||||
| 7% Notes due 2029 | $ | 1,000,000 | February 15, 2029 | February 15 and August 15 | August 15, 2025 |
(1)We may redeem the 7% Notes due 2029 at any time, at our option, in whole or in part. Prior to the par call date, we may redeem the 7% Notes due 2029 at the redemption price or make-whole premium specified in the indenture governing the 7% Notes due 2029, together with accrued and unpaid interest to, but excluding, the redemption date. On or after the par call date, we may redeem the 7% Notes due 2029 at a price equal to 100% of the principal amount being redeemed, together with accrued and unpaid interest to, but excluding, the redemption date.
The 7% Notes due 2029 were issued at 100% of par. The total net proceeds of approximately $990.0 million from the issuance of the 7% Notes due 2029, after deducting the initial purchasers' commissions, were used to repay a portion of the outstanding borrowings under our Revolving Credit Facility.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 47 |
Part I. Financial Information
ACCOUNTS RECEIVABLE SECURITIZATION PROGRAM
On June 8, 2023, we amended the Accounts Receivable Securitization Program (as defined in Note 7 to Notes to Consolidated Financial Statements included in our Annual Report) to increase the maximum borrowing capacity from $325.0 million to $360.0 million. All other material terms of the Accounts Receivable Securitization Program remain the same as what was disclosed in Note 7 to Notes to Consolidated Financial Statements included in our Annual Report.
LETTERS OF CREDIT
As of June 30, 2023, we had outstanding letters of credit totaling $40.4 million, of which $4.4 million reduce our borrowing capacity under the Revolving Credit Facility. The letters of credit expire at various dates between September 2023 and July 2025.
DEBT COVENANTS
The Credit Agreement, our bond indentures and other agreements governing our indebtedness contain certain restrictive financial and operating covenants, including covenants that restrict our ability to complete acquisitions, pay cash dividends, incur indebtedness, make investments, sell assets and take other specified corporate actions. The covenants do not contain a rating trigger. Therefore, a change in our debt rating would not trigger a default under the Credit Agreement, our bond indentures or other agreements governing our indebtedness. The Credit Agreement requires that we satisfy a net total lease adjusted leverage ratio and a fixed charge coverage ratio on a quarterly basis and our bond indentures require that, among other things, we satisfy a leverage ratio (not lease adjusted) or a fixed charge coverage ratio (not lease adjusted) as a condition to taking actions such as paying dividends and incurring indebtedness.
The Credit Agreement uses earnings before interest, taxes, depreciation and amortization and rent expense ("EBITDAR") based calculations and the bond indentures use earnings before interest, taxes, depreciation and amortization ("EBITDA") based calculations as the primary measures of financial performance for purposes of calculating leverage and fixed charge coverage ratios. The EBITDAR- and EBITDA-based leverage calculations include our consolidated subsidiaries, other than those we have designated as "Unrestricted Subsidiaries" as defined in the Credit Agreement and bond indentures. Generally, the Credit Agreement and the bond indentures use a trailing four fiscal quarter basis for purposes of the relevant calculations and require certain adjustments and exclusions for purposes of those calculations, which make the calculation of financial performance for purposes of those calculations under the Credit Agreement and bond indentures not directly comparable to Adjusted EBITDA as presented herein. These adjustments can be significant. For example, the calculation of financial performance under the Credit Agreement and certain of our bond indentures includes (subject to specified exceptions and caps) adjustments for non-cash charges and for expected benefits associated with (i) completed acquisitions, (ii) certain executed lease agreements associated with our data center business that have yet to commence, and (iii) restructuring and other strategic initiatives. The calculation of financial performance under our other bond indentures includes, for example, adjustments for non-cash charges and for expected benefits associated with (i) completed acquisitions and (ii) events that are extraordinary, unusual or non-recurring.
Our leverage and fixed charge coverage ratios under the Credit Agreement as of June 30, 2023 are as follows:
| JUNE 30, 2023 | MAXIMUM/MINIMUM ALLOWABLE | ||||||||||||||||
| Net total lease adjusted leverage ratio | 5.1 | Maximum allowable of 7.0 | |||||||||||||||
| Fixed charge coverage ratio | 2.3 | Minimum allowable of 1.5 | |||||||||||||||
We are in compliance with our leverage and fixed charge coverage ratios under the Credit Agreement, our bond indentures and other agreements governing our indebtedness as of June 30, 2023. Noncompliance with these leverage and fixed charge coverage ratios would have a material adverse effect on our financial condition and liquidity.
Our ability to pay interest on or to refinance our indebtedness depends on our future performance, working capital levels and capital structure, which are subject to general economic, financial, competitive, legislative, regulatory and other factors which may be beyond our control. There can be no assurance that we will generate sufficient cash flow from our operations or that future financings will be available on acceptable terms or in amounts sufficient to enable us to service or refinance our indebtedness or to make necessary capital expenditures.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 48 |
Part I. Financial Information
DERIVATIVE INSTRUMENTS
INTEREST RATE SWAP AGREEMENTS
In July 2019, we entered into forward-starting interest rate swap agreements to limit our exposure to changes in interest rates on a portion of our floating rate indebtedness. These forward-starting interest rate swap agreements commenced in March 2022 with a total notional amount of $350.0 million and provided variable rate interest payments associated with the notional amount of each interest rate swap, based upon one-month LIBOR, in exchange for the payment of fixed interest rates as specified in the respective interest rate swap agreements. In April 2023, we terminated these agreements in anticipation of the discontinuance of the LIBOR reference rate on June 30, 2023. The terminated swap agreements had associated unrealized gains at the termination date of approximately $10.1 million. These gains are included in Accumulated other comprehensive items, net and will be reclassified into earnings as reductions to interest expense from the date of termination through March 2024, the original maturity date of the swaps.
In April 2023, we entered into interest rate swap agreements to limit our exposure to changes in interest rates on a portion of our floating rate indebtedness. Under these interest rate swap agreements, we receive variable rate interest payments associated with the notional amount of each interest rate swap, based upon one-month Secured Overnight Financing Rate, in exchange for the payment of fixed interest rates as specified in the interest rate swap agreements. As of June 30, 2023, we have $350.0 million in notional value outstanding associated with these interest rate swap agreements, which expire in February 2026.
In November 2022, we entered into a forward-starting interest rate swap agreement to limit our exposure to changes in interest rates on future borrowings under our Virginia Credit Agreement (as defined in Note 7 to Notes to Consolidated Financial Statements included in our Annual Report). This forward-starting interest rate swap agreement commenced in July 2023 and expires in October 2025. As of both June 30, 2023 and December 31, 2022, we have $4.8 million in notional value outstanding on this forward-starting interest rate swap agreement.
We have designated each of the interest rate swap agreements described above as cash flow hedges. These interest rate swap agreements are marked to market at the end of each reporting period, representing the fair values of the interest rate swap agreements, and any changes in fair value are recognized as a component of Accumulated other comprehensive items, net. Unrealized gains are recognized as assets, while unrealized losses are recognized as liabilities.
CROSS-CURRENCY SWAP AGREEMENTS
We utilize cross-currency interest rate swaps to hedge the variability of exchange rate impacts between the United States dollar and the Euro. As of both June 30, 2023 and December 31, 2022, we have approximately $469.2 million in notional value outstanding on cross-currency interest rate swaps, with maturity dates ranging from August 2023 through February 2026.
We have designated these cross-currency swap agreements as hedges of net investments in certain of our Euro denominated subsidiaries and they require an exchange of the notional amounts at maturity. These cross-currency swap agreements are marked to market at the end of each reporting period, representing the fair values of the cross-currency swap agreements, and any changes in fair value are recognized as a component of Accumulated other comprehensive items, net. Unrealized gains are recognized as assets while unrealized losses are recognized as liabilities. The excluded component of our cross-currency swap agreements is recorded in Accumulated other comprehensive items, net and amortized to interest expense on a straight-line basis.
ACQUISITIONS
CLUTTER
On June 29, 2023, in order to further expand our on-demand consumer storage business, we acquired 100% of the outstanding shares of Clutter Intermediate, Inc. and control of all assets of the Clutter JV (collectively, "Clutter") for total consideration of $59.1 million (the “Clutter Acquisition”). During the third quarter of 2023, we anticipate offering up to 15% equity interest in Clutter to certain former stakeholders of the Clutter JV.
INVESTMENTS
CLUTTER JOINT VENTURE
In February 2022, the joint venture formed by MakeSpace Labs, Inc. and us (the "MakeSpace JV") entered into an agreement with Clutter, Inc. pursuant to which the equityholders of the MakeSpace JV contributed their ownership interests in the MakeSpace JV, and Clutter, Inc.’s shareholders contributed their ownership interests in Clutter, Inc., to create a newly formed venture (the "Clutter JV"). In exchange for our 49.99% interest in the MakeSpace JV, we received an approximate 27% interest in the Clutter JV (the "Clutter Transaction"). As a result of the Clutter Transaction, we recognized a gain related to our contributed interest in the MakeSpace JV of approximately $35.8 million, which was recorded to Other, net, a component of Other expense (income), net, during the first quarter of 2022.
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 49 |
Part I. Financial Information
On June 29, 2023, we completed the Clutter Acquisition. In connection with the Clutter Acquisition, our previously held approximately 27% interest in the Clutter JV was remeasured to fair value at the closing date of the Clutter Acquisition. As a result, we recognized a loss of approximately $38.0 million to Other, net, a component of Other expense (income), net, during the second quarter of 2023.
WEB WERKS JOINT VENTURE
In April 2021, we closed on an agreement to form a joint venture (the "Web Werks JV") with the shareholders of Web Werks India Private Limited, a colocation data center provider in India. Through December 31, 2022, we made two investments totaling approximately 7,500.0 million Indian rupees (or approximately $96.2 million, based upon the exchange rates between the United States dollar and Indian rupee on the closing date of each investment) in exchange for a noncontrolling interest in the form of convertible preference shares in the Web Werks JV. On July 7, 2023, we made our final contractual investment in the Web Werks JV of approximately 3,750.0 million Indian rupees (or approximately $45.3 million, based upon the exchange rate between the United States dollar and Indian rupee on the closing date of this investment). After the final contractual payment, our interest in the Web Werks JV increased to 63.39% and we assumed control of its board of directors. For financial reporting periods beginning after July 7, 2023, the Web Werks JV will be consolidated within our Global Data Center Business segment.
JOINT VENTURE SUMMARY
The following joint ventures are accounted for as equity method investments and are presented as a component of Other within Other assets, net in our Condensed Consolidated Balance Sheets. The carrying values and equity interests in our joint ventures at June 30, 2023 and December 31, 2022 are as follows (in thousands):
| JUNE 30, 2023 | DECEMBER 31, 2022 | ||||||||||||||||||||||
| CARRYING VALUE | EQUITY INTEREST | CARRYING VALUE | EQUITY INTEREST | ||||||||||||||||||||
| Web Werks JV | $ | 98,650 | 53.58 | % | $ | 98,278 | 53.58 | % | |||||||||||||||
| Joint venture with AGC Equity Partners | 59,394 | 20.00 | % | 37,194 | 20.00 | % | |||||||||||||||||
| Clutter JV | — | — | % | 54,172 | 26.73 | % |
| IRON MOUNTAIN JUNE 30, 2023 FORM 10-Q | 50 |
Part I. Financial Information
Previous: Item 1. UNAUDITED CONDENSED CONSOLIDATED FINANCIAL STATEMENTS · Next: Item 4. CONTROLS AND PROCEDURES