 filings.tools
J.B. Hunt Transport Services 10-K 2018-12-31
Filed 2019-02-22. 21 sections, 200K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 jbht20181231_10k.htm FORM 10-K
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF
THE SECURITIES EXCHANGE ACT OF 1934
| For the fiscal year ended | Commission file number |
|---|---|
| December 31, 2018 | 0-11757 |
J.B. HUNT TRANSPORT SERVICES, INC.
(Exact name of registrant as specified in its charter)
| Arkansas | 71-0335111 | ||
|---|---|---|---|
| (State or other jurisdiction of | (I.R.S. Employer | ||
| incorporation or organization) | Identification No.) | ||
| 615 J.B. Hunt Corporate Drive | 72745-0130 | ||
| Lowell, Arkansas | (ZIP Code) | ||
| (Address of principal executive offices) |
Registrant’s telephone number, including area code: 479**-**820-0000
Securities registered pursuant to Section 12(b) of the Act: None
Securities registered pursuant to Section 12(g) of the Act: Common Stock, $0.01 Par Value
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act.
Yes X No _____
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or 15(d) of the Act.
Yes _____ No X
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days.
Yes X No _____
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files).
Yes X No _____
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§229.405 of this chapter) is not contained herein, and will not be contained, to the best of the registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. [ ]
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
Large accelerated filer X Accelerated filer _____ Non-accelerated filer _____ Smaller reporting company _____ Emerging growth company
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. [ ]
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act).
Yes _____ No X
The aggregate market value of 86,721,074 shares of the registrant’s $0.01 par value common stock held by non-affiliates as of June 30, 2018, was $10.5 billion (based upon $121.55 per share).
As of February 12, 2019, the number of outstanding shares of the registrant’s common stock was 108,738,788.
DOCUMENTS INCORPORATED BY REFERENCE
Certain portions of the Notice and Proxy Statement for the Annual Meeting of Stockholders, to be held April 18, 2019, are incorporated by reference in Part III of this Form 10-K.
J.B. HUNT TRANSPORT SERVICES, INC.
Form 10-K
For The Fiscal Year Ended December 31, 2018
Table of Contents
| Page | ||
|---|---|---|
| PART I | ||
| Item 1. Business 2 | ||
| Item 1A. Risk Factors 6 | ||
| Item 1B. Unresolved Staff Comments 9 | ||
| Item 2. Properties 10 | ||
| Item 3. Legal Proceedings 10 |
Item 4. Mine Safety Disclosures 11
| | | | | | | | | | PART II | | | | | | Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities 12 Item 6. Selected Financial Data 14 Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations 15 Item 7A. Quantitative and Qualitative Disclosures About Market Risk 25 Item 8. Financial Statements and Supplementary Data 26 Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure 26 Item 9A. Controls and Procedures 26
Item 9B. Other Information 27
| | | | | | | | | | PART III | | | | | | Item 10. Directors, Executive Officers and Corporate Governance 27 Item 11. Executive Compensation 27 Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters 27 Item 13. Certain Relationships and Related Transactions, and Director Independence 28 Item 14. Principal Accounting Fees and Services 28 | | | | | | | | | | PART IV | | | | | | Item 15. Exhibits, Financial Statement Schedules 29 | Signatures | | 31 |
FORWARD-LOOKING STATEMENTS
This report, including documents whic__h are incorporated by reference and other documents which we file periodically with the Securities and Exchange Commission (SEC), contains statements that may be considered to be “forward-looking statements.” Such statements relate to our predictions concerning future events or operations and are within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements are inherently uncertain, subject to risks, and should be viewed with caution. These statements are based on our belief or interpretation of information currently available. Stockholders and prospective investors are cautioned that actual results and future events may differ materially from the__se forward-looking statements as a result of many factors. Some of the factors and events that are not within our control and that could have a material impact on future operating results include: general economic and business conditions, competition and competitive rate fluctuations, cost and availability of diesel fuel, ability to attract and retain qualified drivers and delivery personnel_, a loss of one or more major customers, interference with or termination of our relationships with certain railroads,_ rail service delays, insurance costs and availability, claims expense, retention of key employees, terrorist attacks or actions, acts of war, adverse weather conditions, disruption or failure of information systems, new or different environmental or other laws and regulations, operational disruption or adverse effects of business acquisitions, increased costs for new revenue equipment or decreases in the value of used equipment_,_ and the ability of revenue equipment manufacturers to perform in accordance with agreements for guarant__e__ed equipment trade-in values.
You should understand that many important factors, in addition to those listed above, could impact us financially. Our operating results may fluctuate as a result of these and other risk factors or events as described in our filings with the SEC. Some important factors that could cause our actual results to differ from estimates or projections contained in the forward-looking statements are described under “Risk Factors” in Item 1__A_. We assume no obligation to update any forward-looking statement to the extent we become aware that it will not be achieved for any reason._
PART I
Item 1. BUSINESS
O****VERVIEW
We are one of the largest surface transportation, delivery, and logistics companies in North America. J.B. Hunt Transport Services, Inc. is a publicly held holding company that, together with our wholly owned subsidiaries, provides safe and reliable transportation and delivery services to a diverse group of customers and consumers throughout the continental United States, Canada, and Mexico. Unless otherwise indicated by the context, “we,” “us,” “our,” the “Company”, and “JBHT” refer to J.B. Hunt Transport Services, Inc. and its consolidated subsidiaries. We were incorporated in Arkansas on August 10, 1961, and have been a publicly held company since our initial public offering in 1983. Our service offerings include transportation of full-truckload containerized freight, which we directly transport utilizing our company-controlled revenue equipment and company drivers or independent contractors. We have arrangements with most of the major North American rail carriers to transport freight in containers or trailers. We also provide customized freight movement, revenue equipment, labor, systems, and delivery services that are tailored to meet individual customers’ requirements and typically involve long-term contracts. These arrangements are generally referred to as dedicated services and may include multiple pickups and drops, local and home deliveries, freight handling, specialized equipment, and freight network design. Our local and home delivery services typically are provided through a network of cross-dock service centers throughout the continental United States. Utilizing a network of thousands of reliable third-party carriers, we also provide comprehensive transportation and logistics services. In addition to full-load, dry-van operations, these unrelated outside carriers also provide flatbed, refrigerated, less-than-truckload (LTL), and other specialized equipment, drivers, and services. Our customers’ business activities are extremely diverse, and our customer base includes a large number of Fortune 500 companies.
We believe our ability to offer multiple services, utilizing our four business segments and a full complement of logistics services through third parties, represents a competitive advantage. These segments include Intermodal (JBI), Dedicated Contract Services® (DCS), Integrated Capacity Solutions (ICS), and Truckload (JBT). Our business is somewhat seasonal, with slightly higher freight volumes typically experienced during August through early November. Our DCS segment is subject to somewhat less seasonal variation than our other segments.
Additional general information about us is available at jbhunt.com. We make a number of reports and other information available free of charge on our website, including our annual report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K and all amendments to those reports as soon as reasonably practicable after such material is electronically filed with or furnished to the SEC pursuant to Section 13(a) or 15(d) of the Securities Exchange Act of 1934. Our website also contains corporate governance guidelines, our code of ethics, our whistleblower policy, Board committee charters, and other corporate policies. The information on our website is not, and shall not be deemed to be, a part of this annual report on Form 10-K or incorporated into any other filings we make with the SEC.
Our Mission and Strategy
We forge long-term partnerships with key customers that include supply-chain management as an integral part of their strategies. Working in concert, we strive to drive out excess cost, add value and function as an extension of their enterprises. Our strategy is based on utilizing an integrated, multimodal approach to provide capacity-oriented solutions centered on delivering customer value and industry-leading service. We believe our unique operating strategy can add value to customers and increase our profits and returns to stockholders.
We continually analyze where we believe additional capital should be invested and management’s resources should be focused to provide added benefits to our customers. These actions should, in turn, yield increasing returns to our stockholders.
Increasingly, our customers are seeking energy-efficient transportation solutions to reduce both cost and greenhouse-gas emissions. Our intermodal service addresses both demands. Further, we are customizing dedicated solutions aimed at minimizing transportation-related carbon emissions. Efforts to improve fleet fuel efficiency are ongoing, and we are an Environmental Protection Agency (EPA) SmartWaySM Transport Partner.
As always, we continue to ingrain safety into our corporate culture and strive to conduct all of our operations as safely as possible.
operating segments
Segment information is also included in Note 13 to our Consolidated Financial Statements.
JBI Segment
The transportation service offerings of our JBI segment utilize arrangements with most major North American rail carriers to provide intermodal freight solutions for our customers throughout the continental United States, Canada, and Mexico. Our JBI segment began operations in 1989, forming a unique partnership with what is now the BNSF Railway Company (BNSF); this was a watershed event in the industry and the first agreement that linked major rail and truckload carriers in a joint service environment. JBI draws on the intermodal services of rail carriers for the underlying linehaul movement of its equipment between rail ramps. The origin and destination pickup and delivery services (drayage) are handled by our company-owned tractors for the majority of our intermodal loads, while third-party dray carriers are used where economical. By performing our own drayage services, we are able to provide a cost-competitive, seamless coordination of the combined rail and dray movements for our customers.
JBI operates 88,739 pieces of company-owned trailing equipment systemwide. The fleet primarily consists of 53-foot, high-cube containers and is designed to take advantage of intermodal double-stack economics and superior ride quality. We own and maintain our own chassis fleet, consisting of 81,442 units. The containers and chassis are uniquely designed so that they may only be paired together, which we feel creates an operational competitive advantage. JBI also manages a fleet of 5,017 company-owned tractors, 633 independent contractor trucks, and 6,208 company drivers. At December 31, 2018, the total JBI employee count was 7,081. Revenue for the JBI segment in 2018 was $4.72 billion.
DCS Segment
DCS focuses on private fleet conversion and creation in replenishment, specialized equipment, and final-mile delivery services. We specialize in the design, development, and execution of supply-chain solutions that support a variety of transportation networks. Our final-mile delivery services are supported with a network of approximately 102 cross-dock and other delivery system network locations nationwide, with 98% of the continental U.S. population living within 150 miles of a network location. Contracts with our customers are long-term, ranging from three to 10 years, with the average being approximately five years. Pricing of our contracts typically involves cost-plus arrangements, with our fixed costs being recovered regardless of equipment utilization, but is customized based on invested capital and duration.
At December 31, 2018, this segment operated 9,652 company-owned trucks, 412 customer-owned trucks, and 51 independent contractor trucks. DCS also operates 20,344 owned pieces of trailing equipment and 6,366 customer-owned trailers. The DCS segment employed 13,747 people, including 11,331 drivers, at December 31, 2018. DCS revenue for 2018 was $2.16 billion.
ICS Segment
ICS provides traditional freight brokerage and transportation logistics solutions to customers through relationships with thousands of third-party carriers and integration with our owned equipment. By leveraging the J.B. Hunt brand, systems, and network, we provide a broader service offering to customers by providing flatbed, refrigerated, expedited, and LTL, as well as a variety of dry-van and intermodal solutions. ICS provides single-source logistics management for customers desiring to outsource their transportation functions and utilize our proven supply-chain technology and design expertise to improve efficiency. ICS operates 44 remote sales offices or branches, as well as on-site logistics personnel working in direct contact with customers.
At December 31, 2018, the ICS segment employed 1,142 people, with a carrier base of approximately 73,100. ICS revenue for 2018 was $1.33 billion.
JBT Segment
The service offering in this segment is full-load, dry-van freight, utilizing tractors operating over roads and highways. We typically pick up freight at the dock or specified location of the shipper and transport the load directly to the location of the consignee. We use our company-owned tractors and employee drivers or independent contractors who agree to transport freight in our trailers.
At December 31, 2018, the JBT segment operated 1,139 company-owned tractors and employed 1,440 people, 1,200 of whom were drivers. At December 31, 2018, we had 973 independent contractors operating in the JBT segment. JBT revenue for 2018 was $417 million.
Marketing and Operations
We transport, or arrange for the transportation of, a wide range of freight, including general merchandise, specialty consumer items, appliances, forest and paper products, food and beverages, building materials, soaps and cosmetics, automotive parts, agricultural products, electronics, and chemicals. Our customers’ business activities are extremely diverse, and our customer base includes a large number of Fortune 500 companies. We provide a broad range of transportation services to shippers seeking to use a variety of transportation options to optimize their supply-chain logistics needs.
We generally market all of our service offerings through a nationwide sales and marketing network. We use a specific sales force in DCS due to the length, complexity, and specialization of the sales cycle. In accordance with our typical arrangements, we bill the customer for all services, and we, in turn, pay all third parties for their portion of transportation services provided.
People
We believe that one of the factors differentiating us from our competitors is our service-oriented people. As of December 31, 2018, we had 27,621 employees, which consisted of 18,739 company drivers, 7,589 office personnel, and 1,293 maintenance technicians. We also had arrangements with approximately 1,657 independent contractors to transport freight in our trailing equipment. None of our employees are represented by unions or covered by collective bargaining agreements.
Revenue Equipment
Our JBI segment utilizes uniquely designed high-cube containers and chassis, which can only be paired with each other and can be separated to allow the containers to be double-stacked on rail cars. The composition of our DCS trailing fleet varies with specific customer requirements and may include dry-vans, flatbeds, temperature-controlled, curtain-side vans, straight trucks, and dump trailers. We primarily utilize third-party carriers’ tractor and trailing equipment for our ICS segment. Our JBT segment operates primarily 53-foot dry-van trailers.
As of December 31, 2018, our company-owned tractor and truck fleet consisted of 15,808 units. In addition, we had 1,657 independent contractors who operate their own tractors but transport freight in our trailing equipment. We operate with standardized tractors in as many fleets as possible, particularly in our JBI and JBT fleets. Due to our customers’ preferences and the actual business application, our DCS fleet is extremely diversified. We believe operating with relatively newer revenue equipment provides better customer service, attracts quality drivers, and lowers maintenance expense. At December 31, 2018, the average age of our combined tractor fleet was 2.3 years, while our containers averaged 6.4 years of age and our trailers averaged 6.3 years. We perform routine servicing and preventive maintenance on our equipment at our regional terminal facilities.
Competition and the Industry
The freight transportation markets in which we operate are frequently referred to as highly fragmented and competitive. Our JBI segment competes with other intermodal marketing companies; other full-load carriers that utilize railroads for a portion of the transportation service; and, to a certain extent, some railroads directly. The diversified nature of the services provided by our DCS segment attracts competition from customers’ private fleets, other private fleet outsourcing companies, equipment leasing companies, local and regional delivery service providers, and some truckload carriers. Our ICS segment utilizes the fragmented nature of the truck industry and competes with other non-asset-based logistics companies and freight brokers, as well as full-load carriers. The full-load freight competition of our JBT segment includes thousands of carriers, many of which are very small. While we compete with a number of smaller carriers on a regional basis, only a limited number of companies represent competition in all markets across the country.
We compete with other transportation service companies primarily in terms of price, on-time pickup and delivery service, availability and type of equipment capacity, and availability of carriers for logistics services.
Regulation
Our operations as a for-hire motor carrier are subject to regulation by the U.S. Department of Transportation (DOT) and the Federal Motor Carrier Safety Administration (FMCSA), and certain business is also subject to state rules and regulations. The DOT periodically conducts reviews and audits to ensure our compliance with federal safety requirements, and we report certain accident and other information to the DOT. Our operations into and out of Canada and Mexico are subject to regulation by those countries. We are also subject to a variety of requirements of national, state, and local governments, including the U.S. Environmental Protection Agency and the Occupational Safety and Health Administration.
We continue to monitor the actions of the FMCSA and other regulatory agencies, and evaluate all proposed rules to determine their impact on our operations.
Item 1A. RISK FACTORS
In addition to the forward-looking statements outlined previously in this Form 10-K and other comments regarding risks and uncertainties, the following risk factors should be carefully considered when evaluating our business. Our business, financial condition or financial results could be materially and adversely affected by any of these risks.
Our business is dependent upon a number of factors that may have a material adverse effect on the results of our operations, many of which are beyond our control. In addition to general U.S. economic trends, and to a lesser extent global economic trends, these factors include interference with or termination of our relationships with certain railroads; rail service delays; disruptions to U.S. port-of-call activity; significant increases or rapid fluctuations in fuel prices, fuel taxes, interest rates, insurance premiums, self-insurance levels, excess capacity in the intermodal or trucking industries, or license and registration fees; terrorist attacks or actions; acts of war; adverse weather conditions; disruption or failure of information technology systems; increased costs for new revenue equipment or decreases in the value of used equipment; increased tariffs assessed on or disruptions in the procurement of imported revenue equipment; volatile financial credit markets; operational disruption or adverse effects of business acquisitions; and difficulty in attracting and retaining qualified drivers, independent contractors, and third-party carriers.
We are also affected by recessionary economic cycles and downturns in customers’ business cycles, particularly in market segments and industries where we have a significant concentration of customers. Economic conditions represent a greater potential for loss, and we may be required to increase our reserve for bad debt losses. In addition, our results of operations may be affected by seasonal factors. Customers tend to reduce shipments after the winter holiday season, and our operating expenses tend to be higher in the winter months, primarily due to colder weather, which causes higher fuel consumption from increased idle time and higher maintenance costs.
We depend on third parties in the operation of our business.
Our JBI business segment utilizes railroads in the performance of its transportation services. The majority of these services are provided pursuant to contractual relationships with the railroads. While we have agreements with a number of Class I railroads, the majority of our business travels on the BNSF and the Norfolk Southern railways. A material change in the relationship with, the ability to utilize one or more of these railroads or the overall service levels provided by these railroads could have a material adverse effect on our business and operating results. In addition, a portion of the freight we deliver is imported to the United States through ports of call that are subject to labor union contracts. Work stoppages or other disruptions at any of these ports could have a material adverse effect on our business.
In January 2017, we exercised our right to utilize the arbitration process to review the division of revenue collected beginning May 1, 2016, as well as to clarify other issues, under our Joint Service Agreement with BNSF. BNSF requested the same, and the arbitration process is on-going. On October 5, 2018, we received the arbitrators’ Interim Award. The details of the Interim Award are confidential and require the parties to submit additional information requested by the arbitrators to decide certain unresolved matters. For the determined components of the Interim Award, we recorded an $18.3 million pre-tax charge in the third quarter 2018, related to certain charges claimed by BNSF for specific services requested for customers from April 2014 through May 2018. On December 7, 2018 the arbitrators’ issued their Clarified Interim Award of October 5, 2018 resulting from some of the parties’ additional submissions to the Panel regarding certain issues related to determining the revenue division between the parties. On January 11, 2019, the Panel issued its Second Interim Award ordering that $89.4 million is due from the Company to BNSF resulting from the adjusted revenue divisions relating to the 2016 period at issue ($52.1 million) and for calendar year 2017 ($37.3 million). The parties have been instructed to make further submissions on the revenue divisions for calendar year 2018 and going forward, as well as other confidential issues raised during the arbitration process so that the panel can issue an appropriate interim and/or final award regarding all issues raised during the proceeding. We recorded pretax charges for contingent liabilities in the fourth quarter 2018 of $89.4 million claimed by the BNSF for the period May 1, 2016 through December 31, 2017 and $44.6 million for the period January 1, 2018 through December 31, 2018, for a total of $134 million.
The other financial implications from the Interim Award and the Clarified Interim Award will not be fully determined until the arbitrators issue additional award(s) following their review of each party’s requested additional submissions. At this time, we are unable to reasonably predict the final outcome of the arbitration, and, as such, no further gain or loss contingency can be determined or recorded. If decided adversely, this matter could result in a liability material to our financial condition or results of operations. BNSF provides a significant amount of rail transportation services to our JBI business segment. Normal commercial business activity between the parties, including load tendering, load tracing, billing and payments, is expected to continue on a timely basis.
We also utilize independent contractors and third-party carriers to complete our services. These third parties are subject to similar regulation requirements, which may have a more significant impact on their operations, causing them to exit the transportation industry. Aside from when these third parties may use our trailing equipment to fulfill loads, we do not own the revenue equipment or control the drivers delivering these loads. The inability to obtain reliable third-party carriers and independent contractors could have a material adverse effect on our operating results and business growth.
Rapid changes in fuel costs could impact our periodic financial results.
Fuel costs can be very volatile. We have a fuel surcharge revenue program in place with the majority of our customers, which has historically enabled us to recover the majority of higher fuel costs. Most of these programs automatically adjust weekly depending on the cost of fuel. However, there can be timing differences between a change in our fuel cost and the timing of the fuel surcharges billed to our customers. In addition, we incur additional costs when fuel price increases cannot be fully recovered due to our engines being idled during cold or warm weather and empty or out-of-route miles that cannot be billed to customers. Rapid increases in fuel costs or shortages of fuel could have a material adverse effect on our operations or future profitability. As of December 31, 2018, we had no derivative financial instruments to reduce our exposure to fuel-price fluctuations.
I****nsurance and claims expenses could significantly reduce our earnings.
Our future insurance and claims expenses might exceed historical levels, which could reduce our earnings. If the number or severity of claims for which we are self-insured increases, our operating results could be adversely affected. We have policies in place for 2019 with substantially the same terms as our 2018 policies for personal injury, property damage, workers’ compensation, and cargo loss or damage, with the exception of decreasing our self-insured portion of workers’ compensation claims to zero for nearly all states. We purchase insurance coverage for the amounts above which we are self-insured. If these expenses increase and we are unable to offset the increase with higher freight rates, our earnings could be materially and adversely affected.
We derive a significant portion of our revenue from a few major customers, the loss of one or more of which could have a material adverse effect on our business.
For the calendar year ended December 31, 2018, our top 10 customers, based on revenue, accounted for approximately 30% of our revenue. Our JBI, ICS, and JBT segments typically do not have long-term contracts with their customers. While our DCS segment business may involve long-term written contracts, those contracts may contain cancellation clauses, and there is no assurance that our current customers will continue to utilize our services or continue at the same levels. A reduction in or termination of our services by one or more of our major customers could have a material adverse effect on our business and operating results.
We operate in a regulated industry, and increased direct and indirect costs of compliance with, or liability for violation of, existing or future regulations could have a material adverse effect on our business.
The DOT, FMCSA, and various state agencies exercise broad powers over our business, generally governing matters including authorization to engage in motor carrier service, equipment operation, safety, and financial reporting. We are audited periodically by the DOT to ensure that we are in compliance with various safety, hours-of-service, and other rules and regulations. If we were found to be out of compliance, the DOT could restrict or otherwise impact our operations. Our failure to comply with any applicable laws, rules or regulations to which we are subject, whether actual or alleged, could expose us to fines, penalties or potential litigation liabilities, including costs, settlements and judgments. Further, these agencies could institute new laws, rules or regulations or issue interpretation changes to existing regulations at any time. Compliance with new laws, rules or regulations could substantially impair labor and equipment productivity, increase our costs or impact our ability to offer certain services.
Difficulty in attracting and retaining drivers and delivery personnel could affect our profitability and ability to grow.
If we are unable to attract and retain the necessary quality and number of employees, we could be required to significantly increase our employee compensation package, let revenue equipment sit idle, dispose of the equipment altogether, or rely more on higher-cost third-party carriers, which could adversely affect our growth and profitability. In addition, our growth could be limited by an inability to attract third-party carriers upon whom we rely to provide transportation services.
A determination that independent contractors are employees could expose us to various liabilities and additional costs.
Tax and other regulatory authorities often seek to assert that independent contractors in the transportation service industry are employees rather than independent contractors. There can be no assurance that interpretations that support the independent contractor status will not change or that various authorities will not successfully assert a position that re-classifies independent contractors to be employees. If our independent contractors are determined to be our employees, that determination could materially increase our exposure under a variety of federal and state tax, workers’ compensation, unemployment benefits, labor, employment and tort laws, as well as our potential liability for employee benefits. In addition, such changes may be applied retroactively, and if so, we may be required to pay additional amounts to compensate for prior periods. Any of the above increased costs would adversely affect our business and operating results.
We may be subject to litigation claims that could result in significant expenditures**.**
We by the nature of our operations are exposed to the potential for a variety of litigation, including personal injury claims, vehicular collisions and accidents, alleged violations of federal and state labor and employment laws, such as class-action lawsuits alleging wage and hour violations and improper pay, commercial and contract disputes, cargo loss and property damage claims. While we purchase insurance coverage at levels we deem adequate, future litigation may exceed our insurance coverage or may not be covered by insurance. We accrue a provision for a litigation matter according to applicable accounting standards based on the ongoing assessment of the strengths and weaknesses of the litigation, its likelihood of success, and an evaluation of the possible range of loss. Our inability to defend ourselves against a significant litigation claim, could have a material adverse effect on our financial results.
We rely significantly on our information technology systems**, a** disruption, failure or security breach of which could have a material adverse effect on our business.
We rely on information technology throughout all areas of our business to initiate, track, and complete customer orders; process financial and nonfinancial data; compile results of operations for internal and external reporting; and achieve operating efficiencies and growth. Our information technology systems may be susceptible to various interruptions, including equipment or network failures, failed upgrades or replacement of software, user error, power outages, natural disasters, cyber-attacks, terrorist attacks, computer viruses, hackers, or other security breaches. We have mitigated our exposure to these risks through the establishment and maintenance of technology security programs and disaster recovery plans, but these mitigating activities may not be sufficient. A significant disruption, failure or security breach in our information technology systems could have a material adverse effect on our business, which could include operational disruptions, loss of confidential information, external reporting delays or errors, legal claims, or damage to our business reputation.
We operate in a competitive and highly fragmented industry. Numerous factors could impair our ability to maintain our current profitability and to compete with other carriers and private fleets.
We compete with many other transportation service providers of varying sizes and, to a lesser extent, with LTL carriers and railroads, some of which have more equipment and greater capital resources than we do. Additionally, some of our competitors periodically reduce their freight rates to gain business, especially during times of reduced growth rates in the economy, which may limit our ability to maintain or increase freight rates or to maintain our profit margins.
In an effort to reduce the number of carriers it uses, a customer often selects so-called “core carriers” as approved transportation service providers, and in some instances, we may not be selected. Many customers periodically accept bids from multiple carriers for their shipping needs, and this process may depress freight rates or result in the loss of some business to competitors. Also, certain customers that operate private fleets to transport their own freight could decide to expand their operations, thereby reducing their need for our services.
Extreme or unusual weather conditions can disrupt our operations, impact freight volumes**,** and increase our costs, all of which could have a material adverse effect on our business results.
Certain weather conditions such as ice and snow can disrupt our operations. Increases in the cost of our operations, such as towing and other maintenance activities, frequently occur during the winter months. Natural disasters such as hurricanes and flooding can also impact freight volumes and increase our costs.
Our operations are subject to various environmental laws and regulations, the violation of which could result in substantial fines or penalties.
We are subject to various environmental laws and regulations dealing with the handling of hazardous materials, underground fuel storage tanks, and discharge and retention of storm water. We operate in industrial areas, where truck terminals and other industrial activities are located and where groundwater or other forms of environmental contamination have occurred. Our operations involve the risks of fuel spillage or seepage, environmental damage, and hazardous waste disposal, among others. We also maintain bulk fuel storage and fuel islands at several of our facilities. If a spill or other accident involving hazardous substances occurs, or if we are found to be in violation of applicable laws or regulations, it could have a material adverse effect on our business and operating results. If we should fail to comply with applicable environmental regulations, we could be subject to substantial fines or penalties and to civil and criminal liability.
Acquisitions or business combinations may disrupt or have a material adverse effect on our operations or earnings.
We could have difficulty integrating acquired companies’ assets, personnel and operations with our own. Regardless of whether we are successful in making an acquisition or completing a business combination, the negotiations could disrupt our ongoing business, distract our management and employees, and increase our operating costs. Acquisitions and business combinations are accompanied by a number of inherent risks, including, without limitation, the difficulty of integrating acquired companies and operations; potential disruption of our ongoing businesses and distraction of our management or the management of acquired companies; difficulties in maintaining controls, procedures and policies; potential impairment of relationships with employees and partners as a result of any integration of new management personnel; potential inability to manage an increased number of locations and employees; failure to realize expected efficiencies, synergies and cost savings; or the effect of any government regulations which relate to the businesses acquired.
Our business could be materially impacted if and to the extent that we are unable to succeed in addressing any of these risks or other problems encountered in connection with an acquisition or business combination, many of which cannot be presently identified.
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 2. PROPERTIES
We own our corporate headquarters in Lowell, Arkansas. In addition, we own or lease a number of buildings in Lowell that we utilize for administrative support, customer service, freight dispatch, data processing and warehousing, and data backup and disaster recovery. We also own or lease 43 other significant facilities across the United States where we perform maintenance on our equipment, provide bulk fuel, and employ personnel to support operations. These facilities vary in size from 2 to 39 acres. Each of our business segments utilizes these facilities. In addition, we have 98 leased facilities in our DCS cross-dock and other delivery system networks, with the remaining four locations outsourced, and 44 leased or owned remote sales offices or branches in our ICS segment. We also own or lease multiple small facilities, offices, and parking yards throughout the country that support our customers’ business needs.
A summary of our principal facilities in locations throughout the U.S. follows:
| Type | Acreage | Maintenance Shop/ Cross-dock Facility (square feet) | Office Space (square feet) | |||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Maintenance and support facilities | 443 | 1,020,000 | 190,000 | |||||||||
| Cross-dock and delivery system facilities | 24 | 2,308,000 | 124,000 | |||||||||
| Corporate headquarters, Lowell, Arkansas | 88 | - | 407,000 | |||||||||
| Offices and data center, Lowell, Arkansas | 8 | - | 60,000 | |||||||||
| Branch sales offices | - | - | 92,000 | |||||||||
| Other facilities, offices, and parking yards | 343 | 211,000 | 129,000 |
Item 3. LEGAL PROCEEDINGS
We are a defendant in certain alleged class-action lawsuits in which the plaintiffs are current and former California-based drivers who allege claims for unpaid wages, failure to provide meal and rest periods, and other items. In the lead class-action, we reached an agreement and recorded a reserve in September 2018 to resolve all pending claims for a class settlement payment of $15 million, subject to Court approval. The Court granted preliminary settlement approval in November 2018. Notice of the settlement has been mailed to all settlement class members and the deadline for objections to the settlement passed without any objections filed. We expect the Court’s order granting final approval to be issued in April 2019. The overlapping claims in the other alleged class-action lawsuits remain stayed pending final approval of the settlement in the lead class-action case.
In January 2017, we exercised our right to utilize the arbitration process to review the division of revenue collected beginning May 1, 2016, as well as to clarify other issues, under our Joint Service Agreement with BNSF. BNSF requested the same, and the arbitration process is on-going. On October 5, 2018, we received the arbitrators’ Interim Award. The details of the Interim Award are confidential and require the parties to submit additional information requested by the arbitrators to decide certain unresolved matters. For the determined components of the Interim Award, we recorded an $18.3 million pre-tax charge in the third quarter 2018, related to certain charges claimed by BNSF for specific services requested for customers from April 2014 through May 2018. On December 7, 2018 the arbitrators’ issued their Clarified Interim Award of October 5, 2018 resulting from some of the parties’ additional submissions to the Panel regarding certain issues related to determining the revenue division between the parties. On January 11, 2019, the Panel issued its Second Interim Award ordering that $89.4 million is due from the Company to BNSF resulting from the adjusted revenue divisions relating to the 2016 period at issue ($52.1 million) and for calendar year 2017 ($37.3 million). The parties have been instructed to make further submissions on the revenue divisions for calendar year 2018 and going forward, as well as other confidential issues raised during the arbitration process so that the panel can issue an appropriate interim and/or final award regarding all issues raised during the proceeding. We recorded pretax charges for contingent liabilities in the fourth quarter 2018 of $89.4 million claimed by the BNSF for the period May 1, 2016 through December 31, 2017 and $44.6 million for the period January 1, 2018 through December 31, 2018, for a total of $134 million.
The other financial implications from the Interim Award and the Clarified Interim Award will not be fully determined until the arbitrators issue additional award(s) following their review of each party’s requested additional submissions. At this time, we are unable to reasonably predict the final outcome of the arbitration, and, as such, no further gain or loss contingency can be determined or recorded. If decided adversely, this matter could result in a liability material to our financial condition or results of operations. BNSF provides a significant amount of rail transportation services to our JBI business segment. Normal commercial business activity between the parties, including load tendering, load tracing, billing and payments, is expected to continue on a timely basis.
We are involved in certain other claims and pending litigation arising from the normal conduct of business. Based on present knowledge of the facts and, in certain cases, opinions of outside counsel, we believe the resolution of these claims and pending litigation will not have a material adverse effect on our financial condition, results of operations or liquidity.
ITEM 4. MINE SAFETY DISCLOSURES
Not applicable.
PART II
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Our common stock is traded on the NASDAQ Global Select Market (NASDAQ) under the symbol “JBHT.” At December 31, 2018, we were authorized to issue up to 1 billion shares of our common stock, and 167.1 million shares were issued. We had 108.7 million and 109.8 million shares outstanding as of December 31, 2018 and 2017, respectively. On February 12, 2019, we had 1,133 stockholders of record of our common stock.
Dividend Policy
Our dividend policy is subject to review and revision by the Board of Directors, and payments are dependent upon our financial condition, liquidity, earnings, capital requirements, and any other factors the Board of Directors may deem relevant. On January 23, 2019, we announced an increase in our quarterly cash dividend from $0.24 to $0.26 per share, which will be paid February 22, 2019, to stockholders of record on February 8, 2019. We currently intend to continue paying cash dividends on a quarterly basis. However, no assurance can be given that future dividends will be paid.
Purchases of Equity Securities
The following table summarizes purchases of our common stock during the three months ended December 31, 2018:
| Period | Number of Common Shares Purchased | Average Price Paid Per Common Share Purchased | Total Number of Shares Purchased as Part of a Publicly Announced Plan (1) | Maximum Dollar Amount of Shares That May Yet Be Purchased Under the Plan (in millions) (1) | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| October 1 through October 31, 2018 | - | $ | - | - | $ | 421 | ||||||||||
| November 1 through November 30, 2018 | - | - | - | 421 | ||||||||||||
| December 1 through December 31, 2018 | 493,905 | 101.86 | 493,905 | 371 | ||||||||||||
| Total | 493,905 | $ | 101.86 | 493,905 | $ | 371 |
(1) On April 20, 2017, our Board of Directors authorized the purchase of up to $500 million of our common stock.
Stock Performance Graph
The following graph compares the cumulative 5-year total return of stockholders of our common stock with the cumulative total returns of the S&P 500 index and two customized peer groups. The peer group labeled “Peer Group 2017” consists of 13 companies: C.H. Robinson Worldwide Inc., CSX Corp, Expeditors International Of Washington Inc., Hub Group Inc., Kansas City Southern, Norfolk Southern Corp, Old Dominion Freight Line Inc., Republic Services Inc., Ryder System Inc., Schneider National Inc., Stericycle Inc., Waste Management Inc. and XPO Logistics Inc. The peer group labeled “Peer Group 2018” consists of 14 companies: C.H. Robinson Worldwide Inc., CSX Corp, Expeditors International Of Washington Inc., Hub Group Inc., Kansas City Southern, Knight-Swift Transportation Holdings Inc., Norfolk Southern Corp, Old Dominion Freight Line Inc., Republic Services Inc., Ryder System Inc., Schneider National Inc., Stericycle Inc., Waste Management Inc. and XPO Logistics Inc. The graph assumes the value of the investment in our common stock, in the index, and in each of the peer groups (including reinvestment of dividends) was $100 on December 31, 2013, and tracks it through December 31, 2018. The stock price performance included in this graph is not necessarily indicative of future stock price performance.
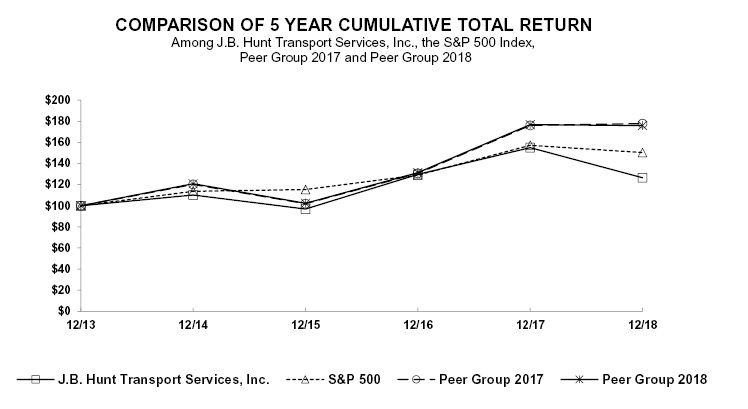
| Years Ended December 31, | ||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2013 | 2014 | 2015 | 2016 | 2017 | 2018 | |||||||||||||||||||
| J.B. Hunt Transport Services, Inc. | $ | 100.00 | $ | 110.12 | $ | 96.88 | $ | 129.61 | $ | 155.01 | $ | 126.48 | ||||||||||||
| S&P 500 | 100.00 | 113.69 | 115.26 | 129.05 | 157.22 | 150.33 | ||||||||||||||||||
| Peer Group 2017 | 100.00 | 120.17 | 102.00 | 130.72 | 176.06 | 177.76 | ||||||||||||||||||
| Peer Group 2018 | 100.00 | 120.90 | 102.35 | 131.32 | 176.84 | 175.96 |
Item 6. SELECTED FINANCIAL DATA
The following selected financial data should be read in conjunction with the Consolidated Financial Statements and notes thereto, Management’s Discussion and Analysis of Financial Condition and Results of Operations, and other financial data included elsewhere in this annual report.
(Dollars in millions, except per share amounts)
| Earnings data for the years ended December 31, | 2018 | 2017 | 2016 | 2015 | 2014 | |||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating revenues | $ | 8,615 | $ | 7,190 | $ | 6,555 | $ | 6,188 | $ | 6,165 | ||||||||||
| Operating income | 681 | 624 | 721 | 716 | 632 | |||||||||||||||
| Net earnings | 490 | 686 | 432 | 427 | 375 | |||||||||||||||
| Basic earnings per share | 4.48 | 6.24 | 3.84 | 3.69 | 3.20 | |||||||||||||||
| Diluted earnings per share | 4.43 | 6.18 | 3.81 | 3.66 | 3.16 | |||||||||||||||
| Cash dividends per share | 0.96 | 0.92 | 0.88 | 0.84 | 0.80 | |||||||||||||||
| Operating expenses as a percentage of operating revenues: | ||||||||||||||||||||
| Rents and purchased transportation | 51.5 | % | 50.8 | % | 49.7 | % | 48.4 | % | 50.0 | % | ||||||||||
| Salaries, wages and employee benefits | 22.4 | 22.4 | 22.4 | 22.5 | 20.9 | |||||||||||||||
| Fuel and fuel taxes | 5.3 | 4.8 | 4.3 | 5.1 | 7.4 | |||||||||||||||
| Depreciation and amortization | 5.1 | 5.3 | 5.5 | 5.5 | 4.8 | |||||||||||||||
| Operating supplies and expenses | 3.5 | 3.6 | 3.6 | 3.6 | 3.5 | |||||||||||||||
| General and administrative expenses, net of asset dispositions | 1.8 | 1.8 | 1.3 | 1.1 | 0.8 | |||||||||||||||
| Insurance and claims | 1.5 | 1.7 | 1.2 | 1.2 | 1.3 | |||||||||||||||
| Operating taxes and licenses | 0.6 | 0.6 | 0.7 | 0.7 | 0.7 | |||||||||||||||
| Communication and utilities | 0.4 | 0.3 | 0.3 | 0.3 | 0.4 | |||||||||||||||
| Total operating expenses | 92.1 | 91.3 | 89.0 | 88.4 | 89.8 | |||||||||||||||
| Operating income | 7.9 | 8.7 | 11.0 | 11.6 | 10.2 | |||||||||||||||
| Net interest expense | 0.5 | 0.4 | 0.4 | 0.4 | 0.4 | |||||||||||||||
| Earnings before income taxes | 7.4 | 8.3 | 10.6 | 11.2 | 9.8 | |||||||||||||||
| Income taxes | 1.7 | (1.2 | ) | 4.0 | 4.3 | 3.7 | ||||||||||||||
| Net earnings | 5.7 | % | 9.5 | % | 6.6 | % | 6.9 | % | 6.1 | % | ||||||||||
| Balance sheet data as of December 31, | 2018 | 2017 | 2016 | 2015 | 2014 | |||||||||||||||
| Working capital ratio | 1.11 | 1.45 | 1.65 | 1.61 | 1.11 | |||||||||||||||
| Total assets (millions) | $ | 5,092 | $ | 4,465 | $ | 3,951 | $ | 3,630 | $ | 3,374 | ||||||||||
| Stockholders’ equity (millions) | $ | 2,101 | $ | 1,839 | $ | 1,414 | $ | 1,300 | $ | 1,205 | ||||||||||
| Current portion of long-term debt (millions) | $ | 251 | - | - | - | $ | 250 | |||||||||||||
| Total debt (millions) | $ | 1,149 | $ | 1,086 | $ | 986 | $ | 998 | $ | 929 | ||||||||||
| Total debt to equity | 0.55 | 0.59 | 0.70 | 0.77 | 0.77 | |||||||||||||||
| Total debt as a percentage of total capital | 35 | % | 37 | % | 41 | % | 43 | % | 44 | % |
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following discussion of our results of operations and financial condition should be read in conjunction with our financial statements and related notes in Item 8. This discussion contains forward-looking statements. Please see “Forward-looking Statements” and “Risk Factors” for a discussion of items, uncertainties, assumptions and risks associated with these statements.
Critical Accounting Policies and Estimates
The preparation of our financial statements in accordance with U.S. generally accepted accounting principles requires us to make estimates and assumptions that impact the amounts reported in our Consolidated Financial Statements and accompanying notes. Therefore, the reported amounts of assets, liabilities, revenues, expenses and associated disclosures of contingent liabilities are affected by these estimates. We evaluate these estimates on an ongoing basis, utilizing historical experience, consultation with third parties and other methods considered reasonable in the particular circumstances. Nevertheless, actual results may differ significantly from our estimates. Any effects on our business, financial position or results of operations resulting from revisions to these estimates are recognized in the accounting period in which the facts that give rise to the revision become known. We consider our critical accounting policies and estimates to be those that require us to make more significant judgments and estimates when we prepare our financial statements and include the following:
Workers’ Compensation and Accident Costs
We purchase insurance coverage for a portion of expenses related to employee injuries, vehicular collisions, accidents, and cargo damage. Certain insurance arrangements include a level of self-insurance (deductible) coverage applicable to each claim. We have umbrella policies to limit our exposure to catastrophic claim costs. We are substantially self-insured for loss of and damage to our owned and leased revenue equipment.
The amounts of self-insurance change from time to time based on measurement dates, policy expiration dates, and claim type. We have policies in place for 2019 with substantially the same terms as our 2018 policies for personal injury, property damage, workers’ compensation, and cargo loss or damage, with the exception of decreasing our self-insured portion of workers’ compensation claims to zero for nearly all states.
Our claims accrual policy for all self-insured claims is to recognize a liability at the time of the incident based on our analysis of the nature and severity of the claims and analyses provided by third-party claims administrators, as well as legal, economic, and regulatory factors. Our safety and claims personnel work directly with representatives from the insurance companies to continually update the estimated cost of each claim. The ultimate cost of a claim develops over time as additional information regarding the nature, timing, and extent of damages claimed becomes available. Accordingly, we use an actuarial method to develop current claim information to derive an estimate of our ultimate claim liability. This process involves the use of loss-development factors based on our historical claims experience and includes a contractual premium adjustment factor, if applicable. In doing so, the recorded liability considers future claims growth and provides a reserve for incurred-but-not-reported claims. We do not discount our estimated losses. At December 31, 2018, we had an accrual of approximately $260 million for estimated claims. In addition, we record receivables for amounts expected to be reimbursed for payments made in excess of self-insurance levels on covered claims. At December 31, 2018, we have recorded $261 million of expected reimbursement for covered excess claims, other insurance deposits, and prepaid insurance premiums.
Revenue Equipment
We operate a significant number of tractors, trucks, containers, chassis, and trailers in connection with our business. This equipment may be purchased or acquired under lease agreements. In addition, we may rent revenue equipment from various third parties under short-term rental arrangements. Purchased revenue equipment is depreciated on the straight-line method over the estimated useful life to an estimated salvage or trade-in value. We periodically review the useful lives and salvage values of our revenue equipment and evaluate our long-lived assets for impairment. We have not identified any impairment to our assets at December 31, 2018.
We have agreements with our primary tractor suppliers for residual or trade-in values for certain new equipment. We have utilized these trade-in values, as well as other operational information such as anticipated annual miles, in accounting for depreciation expense. If our suppliers were unable to perform under the terms of our agreements for trade-in values, it could have a material adverse effect on our financial results.
Revenue Recognition
We record revenues on the gross basis at amounts charged to our customers because we control and are primarily responsible for the fulfillment of promised services. Accordingly, we serve as a principal in the transaction. We invoice our customers, and we maintain discretion over pricing. Additionally, we are responsible for selection of third-party transportation providers to the extent used to satisfy customer freight requirements.
We recognize revenue from customer contracts based on relative transit time in each reporting period and as other performance obligations are provided, with related expenses recognized as incurred. Accordingly, a portion of the total revenue that will be billed to the customer is recognized in each reporting period based on the percentage of the freight pickup and delivery performance obligation that has been completed at the end of the reporting period.
Our trade accounts receivable includes amounts due from customers that have been reduced by an allowance for uncollectible accounts and revenue adjustments. The allowance for uncollectible accounts and revenue adjustments is based on historical experience, as well as any known trends or uncertainties related to customer billing and account collectability. The adequacy of our allowance is reviewed quarterly.
Income Taxes
We account for income taxes under the liability method. Our deferred tax assets and liabilities represent items that will result in a tax deduction or taxable income in future years for which we have already recorded the related tax expense or benefit in our statement of earnings. Deferred tax accounts arise as a result of timing differences between when items are recognized in our Consolidated Financial Statements and when they are recognized in our tax returns. We assess the likelihood that deferred tax assets will be recovered from future taxable income or the reversal of temporary timing differences. To the extent we believe recovery does not meet the more-likely-than-not threshold, a valuation allowance is established. To the extent we establish a valuation allowance, we include an expense as part of our income tax provision.
The Tax Cuts and Jobs Act (the Act) was enacted in December 2017. Beginning in 2018, the Act reduced the U.S. federal corporate tax rate from 35% to 21%. At December 31, 2017, we made a reasonable estimate of the effects on our existing deferred tax assets and liabilities based on the rates at which they were expected to reverse in the future, which was generally 21%. The provisional amount recorded resulting from the remeasurement of our deferred tax balance was $309.2 million, which was included as a component of 2017 income tax from continuing operations. During 2018, we finalized our calculations for our 2017 federal income tax return, which was filed based on the law prior to the Act, resulting in no significant change to the initial measurement of these balances. Remaining aspects of the Act were not relevant to our operations.
Significant judgment is required in determining and assessing the impact of complex tax laws and certain tax-related contingencies on our provision for income taxes. As part of our calculation of the provision for income taxes, we assess whether the benefits of our tax positions are at least more likely than not to be sustained upon audit based on the technical merits of the tax position. For tax positions that are not more likely than not to be sustained upon audit, we accrue the largest amount of the benefit that is not more likely than not to be sustained in our Consolidated Financial Statements. Such accruals require us to make estimates and judgments, whereby actual results could vary materially from these estimates. Further, a number of years may elapse before a particular matter for which we have established an accrual is audited and resolved. See Note 7, Income Taxes, in our Consolidated Financial Statements for a discussion of our current tax contingencies.
RESULTS OF OPERATIONS
The following table sets forth items in our Consolidated Statements of Earnings as a percentage of operating revenues and the percentage increase or decrease of those items compared with the prior year.
| Percentage of Operating Revenues | Percentage Change Between Years | |||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | ||||||||||||||||
| Operating revenues | 100.0 | % | 100.0 | % | 100.0 | % | 19.8 | % | 9.7 | % | ||||||||||
| Operating expenses: | ||||||||||||||||||||
| Rents and purchased transportation | 51.5 | 50.8 | 49.7 | 21.5 | 12.1 | |||||||||||||||
| Salaries, wages and employee benefits | 22.4 | 22.4 | 22.4 | 19.8 | 9.5 | |||||||||||||||
| Fuel and fuel taxes | 5.3 | 4.8 | 4.3 | 32.1 | 22.6 | |||||||||||||||
| Depreciation and amortization | 5.1 | 5.3 | 5.5 | 13.7 | 6.1 | |||||||||||||||
| Operating supplies and expenses | 3.5 | 3.6 | 3.6 | 18.0 | 10.3 | |||||||||||||||
| General and administrative expenses, net of asset dispositions | 1.8 | 1.8 | 1.3 | 29.7 | 44.6 | |||||||||||||||
| Insurance and claims | 1.5 | 1.7 | 1.2 | 4.7 | 57.6 | |||||||||||||||
| Operating taxes and licenses | 0.6 | 0.6 | 0.7 | 14.0 | (2.5 | ) | ||||||||||||||
| Communication and utilities | 0.4 | 0.3 | 0.3 | 28.9 | 20.1 | |||||||||||||||
| Total operating expenses | 92.1 | 91.3 | 89.0 | 20.8 | 12.5 | |||||||||||||||
| Operating income | 7.9 | 8.7 | 11.0 | 9.2 | (13.5 | ) | ||||||||||||||
| Net interest expense | 0.5 | 0.4 | 0.4 | 40.8 | 13.2 | |||||||||||||||
| Earnings before income taxes | 7.4 | 8.3 | 10.6 | 7.7 | (14.5 | ) | ||||||||||||||
| Income taxes | 1.7 | (1.2 | ) | 4.0 | 266.1 | (134.5 | ) | |||||||||||||
| Net earnings | 5.7 | % | 9.5 | % | 6.6 | % | (28.7 | %) | 58.8 | % |
2018 Compared With 201****7
Consolidated Operating Revenues
Our total consolidated operating revenues increased 19.8% to $8.61 billion in 2018, compared to $7.19 billion in 2017, primarily due to overall increased load volume and higher revenue per load in all four of our segments. Fuel surcharge revenues increased 40.2% to $1.1 billion in 2018, compared to $754 million in 2017. If fuel surcharge revenues were excluded from both years, our 2018 revenue increased 17.4% over 2017.
Consolidated Operating Expenses
Our 2018 consolidated operating expenses increased 20.8% from 2017, while year-over-year revenue increased 19.8%, resulting in a 2018 operating ratio of 92.1% compared to 91.3% in 2017. Rents and purchased transportation costs increased 21.5% in 2018, primarily due to increased rail and truck purchased transportation rates and the increase in load volume, which increased services provided by third-party rail and truck carriers within JBI and ICS segments. In addition, our JBI segment incurred charges of $152.3 million to rail purchase transportation expense related to the ongoing arbitration with BNSF. Salaries, wages and employee benefit costs increased 19.8% in 2018 from 2017. This increase was primarily related to increases in driver pay and office personnel compensation due to an increase in the number of employees and a tighter supply of qualified drivers.
Fuel and fuel taxes expense increased 32.1% in 2018 compared with 2017, due primarily to an increase in road miles and increases in the price of fuel during 2018. We have fuel surcharge programs in place with the majority of our customers. These programs typically involve a specified computation based on the change in national, regional, or local fuel prices. While these programs may address fuel cost changes as frequently as weekly, most also reflect a specified miles-per-gallon factor and require a certain minimum change in fuel costs to trigger a change in fuel surcharge revenue. As a result, some of these programs have a time lag between when fuel costs change and when this change is reflected in revenues. Due to these programs, this lag negatively impacts operating income in times of rapidly increasing fuel costs and positively impacts operating income when fuel costs decrease rapidly.
It is not meaningful to compare the amount of fuel surcharge revenue or the change in fuel surcharge revenue between reporting periods to fuel and fuel taxes expense, or the change of fuel expense between periods, as a significant portion of fuel cost is included in our payments to railroads, dray carriers and other third parties. These payments are classified as purchased transportation expense.
Depreciation and amortization expense increased 13.7% in 2018, primarily due to additions to our JBI segment tractor, container and chassis fleets to support additional business demand and equipment purchased related to new DCS long-term customer contracts.
Operating supplies and expenses increased 18.0%, driven primarily by higher equipment maintenance and tire expenses due to increased equipment counts, higher travel costs, increased toll costs, and higher building maintenance expenses. General and administrative expenses increased 29.7% from 2017, primarily due to increased building and computer rentals, higher professional fees, higher advertising costs, higher bad debt expense driven by a customer bankruptcy, and increased net losses from asset sales and disposals, partially offset by the 2017 inclusion of a $20.2 million reserve of a cash advance for the purchases of new trailing equipment from a manufacturer that did not meet delivery. Additionally, net losses from sale or disposal of assets were $12.1 million in 2018, compared to net losses of $7.4 million in 2017. Insurance and claims expense increased 4.7% in 2018, primarily due to higher incident volume.
Net interest expense for 2018 increased by 40.8% compared with 2017, due to an increase in average debt levels, higher effective interest rates on our debt, and expenses incurred to refinance our revolving line of credit compared to 2017.
Our effective income tax rate was 23.6% in 2018 and (15.29%) in 2017. The increase in 2018 was primarily due to a $309.2 million decrease in income tax expense in 2017 resulting from adjustments to our deferred tax balances at December 31, 2017, for the change in future tax rates prescribed by the Tax Cuts and Jobs Act.
Segments
We operated four business segments during calendar year 2018. The operation of each of these businesses is described in our Notes to Consolidated Financial Statements. The following tables summarize financial and operating data by segment:
| Operating Revenue by Segment | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Years Ended December 31, (in millions) | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| JBI | $ | 4,717 | $ | 4,084 | $ | 3,796 | ||||||
| DCS | 2,163 | 1,719 | 1,533 | |||||||||
| ICS | 1,335 | 1,025 | 852 | |||||||||
| JBT | 417 | 378 | 388 | |||||||||
| Total segment revenues | 8,632 | 7,206 | 6,569 | |||||||||
| Intersegment eliminations | (17 | ) | (16 | ) | (14 | ) | ||||||
| Total | $ | 8,615 | $ | 7,190 | $ | 6,555 | ||||||
| Operating Income by Segment | ||||||||||||
| Years Ended December 31, (in millions) | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| JBI | $ | 401 | $ | 407 | $ | 450 | ||||||
| DCS | 193 | 171 | 205 | |||||||||
| ICS | 50 | 23 | 36 | |||||||||
| JBT | 37 | 23 | 30 | |||||||||
| Total | $ | 681 | $ | 624 | $ | 721 |
Operating Data by Segment
| Years Ended December 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2018 | 2017 | 2016 | ||||||||||
| JBI | ||||||||||||
| Loads | 2,049,014 | 1,999,807 | 1,916,303 | |||||||||
| Average length of haul (miles) | 1,648 | 1,681 | 1,657 | |||||||||
| Revenue per load | $ | 2,302 | $ | 2,042 | $ | 1,981 | ||||||
| Average tractors during the period(1) | 5,551 | 5,362 | 5,222 | |||||||||
| Tractors (end of period) | ||||||||||||
| Company-owned | 5,017 | 4,776 | 4,581 | |||||||||
| Independent contractor | 633 | 764 | 695 | |||||||||
| Total tractors | 5,650 | 5,540 | 5,276 | |||||||||
| Net change in trailing equipment during the period | 6,262 | 4,016 | 5,637 | |||||||||
| Trailing equipment (end of period) | 94,902 | 88,610 | 84,594 | |||||||||
| Average effective trailing equipment usage | 88,739 | 82,969 | 77,179 | |||||||||
| DCS | ||||||||||||
| Loads | 2,981,344 | 2,575,245 | 2,401,332 | |||||||||
| Average length of haul (miles) | 177 | 178 | 177 | |||||||||
| Revenue per truck per week(2) | $ | 4,534 | $ | 4,226 | $ | 4,077 | ||||||
| Average trucks during the period(3) | 9,264 | 7,946 | 7,307 | |||||||||
| Trucks (end of period) | ||||||||||||
| Company-owned | 9,652 | 8,124 | 6,976 | |||||||||
| Independent contractor | 51 | 59 | 15 | |||||||||
| Customer-owned (DCS-operated) | 412 | 544 | 410 | |||||||||
| Total trucks | 10,115 | 8,727 | 7,401 | |||||||||
| Trailing equipment (end of period) | 26,710 | 25,811 | 22,688 | |||||||||
| Average effective trailing equipment usage | 26,806 | 24,550 | 22,827 | |||||||||
| ICS | ||||||||||||
| Loads | 1,234,632 | 992,834 | 852,179 | |||||||||
| Revenue per load | $ | 1,081 | $ | 1,032 | $ | 999 | ||||||
| Gross profit margin | 15.4 | % | 13.3 | % | 14.3 | % | ||||||
| Employee count (end of period) | 1,142 | 954 | 824 | |||||||||
| Approximate number of third-party carriers (end of period) | 73,100 | 56,700 | 50,900 | |||||||||
| JBT | ||||||||||||
| Loads | 355,038 | 370,591 | 385,298 | |||||||||
| Average length of haul (miles) | 427 | 435 | 455 | |||||||||
| Loaded miles (000) | 151,322 | 160,932 | 175,038 | |||||||||
| Total miles (000) | 181,718 | 192,433 | 207,998 | |||||||||
| Average nonpaid empty miles per load | 85.5 | 85.1 | 85.6 | |||||||||
| Revenue per tractor per week(2) | $ | 4,148 | $ | 3,556 | $ | 3,458 | ||||||
| Average tractors during the period(1) | 1,990 | 2,098 | 2,191 | |||||||||
| Tractors (end of period) | ||||||||||||
| Company-owned | 1,139 | 1,291 | 1,376 | |||||||||
| Independent contractor | 973 | 741 | 752 | |||||||||
| Total tractors | 2,112 | 2,032 | 2,128 | |||||||||
| Trailing equipment (end of period) | 6,800 | 7,120 | 7,642 | |||||||||
| Average effective trailing equipment usage | 6,513 | 7,066 | 6,956 |
| (1) | Includes company-owned and independent contractor tractors |
|---|---|
| (2) | Using weighted workdays |
| (3) | Includes company-owned, independent contractor, and customer-owned trucks |
JBI Segment
JBI segment revenue increased 15% to $4.72 billion in 2018, from $4.08 billion in 2017. This increase in revenue was primarily a result of a 2% increase in load volume and a 13% increase in revenue per load, which is the combination of changes in freight mix, customer rates, and fuel surcharge revenue. Eastern network loads grew at 10% and transcontinental loads decreased 2% compared to 2017. Average length of haul decreased 2% in 2018 when compared to 2017. Revenue per load excluding fuel surcharges increased approximately 10% compared to 2017.
Operating income of the JBI segment decreased to $401 million in 2018, from $407 million in 2017. Benefits from volume growth and increased revenue per load were offset by increases in rail purchased transportation costs, which included $152.3 million of additional expense related to the ongoing arbitration with BNSF. Benefits where further offset by higher driver wage and retention costs, higher driver recruiting expenses, higher outsourced dray costs, increased costs for onboarding and integration of container tracking technologies, higher equipment ownership costs, and costs of reduced efficiency and disruptions within the rail network. In addition, 2017 included a $20.2 million expense for the reserve of a cash advance for the purchases of new trailing equipment from a manufacturer that did not meet delivery.
DCS Segment
DCS segment revenue increased 26% to $2.16 billion in 2018, from $1.72 billion in 2017. Productivity, defined as revenue per truck per week, increased 7% when compared to 2017. Productivity excluding fuel surcharge revenue increased 5% from 2017. The increase in productivity was primarily a result of better integration of assets between customer accounts, customer rate increases, and increased customer supply chain fluidity during 2018 compared to 2017. In addition, the growth in DCS revenue includes an increase of $113 million in Final Mile Services (FMS) revenue, approximately $66 million of which was derived from the 2017 acquisition of Special Logistics Dedicated, LLC (SLD). DCS ended 2018 with a net additional 1,388 revenue-producing trucks when compared to 2017.
Operating income of our DCS segment increased to $193 million in 2018, from $171 million in 2017. Increased revenue and improved asset integration was offset by higher costs from the expanded FMS network, increased driver wages and recruiting costs, higher non-driver salaries, wages and benefits, increased maintenance costs on equipment scheduled to be traded in the current year, higher overall insurance and claims costs, implementation costs for new customer contracts and approximately $4.4 million in additional non-cash amortization expense compared to 2017.
ICS Segment
ICS segment revenue increased 30% to $1.33 billion in 2018, from $1.02 billion in 2017. Overall volumes increased 24%. Revenue per load increased 5% primarily due to increased contractual and spot rates. Contractual business was approximately 70% of the total load volume and 48% of the total revenue in the 2018, compared to 70% of the total load volume and 53% of the total revenue in 2017.
Operating income increased to $50 million in 2018, from $23 million in 2017. Gross profit margin improved to 15.4% in the current year compared to 13.3% in 2017 primarily due to improved contractual margins and increased spot market activity. This increase in gross profit margin was partially offset by higher personnel costs, higher technology development costs, and increase bad debt expense due to a customer bankruptcy. Approximately $558 million of ICS revenue for 2018 was executed through the marketplace for JBHunt360. ICS’s carrier base increased 29%, and the employee count increased 20% when compared to 2017.
JBT Segment
JBT segment revenue increased 10% to $417 million in 2018, from $378 million in 2017. Excluding fuel surcharges, revenue for 2018 increased 9% compared to 2017, primarily from a 16% increase in rates per loaded mile, partially offset by an 4% decrease in load count.
JBT segment had operating income of $37 million in 2018 compared with $23 million in 2017. The increase in operating income was driven primarily by higher rates per loaded mile and lower equipment ownership costs, partially offset by increased driver wage and retention costs, higher driver and independent contractor recruiting expenses, and higher independent contractor costs per mile.
201****7 Compared With 201****6
Consolidated Operating Revenues
Our total consolidated operating revenues increased 9.7% to $7.19 billion in 2017, compared to $6.56 billion in 2016, primarily due to overall increased load volume and higher revenue per load in our JBI, DCS, and ICS segments. Fuel surcharge revenues increased 37.5% to $754 million in 2017, compared to $548 million in 2016. If fuel surcharge revenues were excluded from both years, our 2017 revenue increased 7.1% over 2016.
Consolidated Operating Expenses
Our 2017 consolidated operating expenses increased 12.5% from 2016, while year-over-year revenue increased 9.7%, resulting in a 2017 operating ratio of 91.3% compared to 89.0% in 2016. Rents and purchased transportation costs increased 12.1% in 2017, primarily due to increased rail and truck purchased transportation rates and the increase in load volume, which increased services provided by third-party rail and truck carriers within JBI and ICS segments. Salaries, wages and employee benefit costs increase 9.5% in 2017 from 2016. This increase was primarily related to increases in driver pay and office personnel compensation due to an increase in the number of employees and a tighter supply of qualified drivers. In addition, 2016 included a $15.2 million benefit recorded to reflect a change in our employee paid time off policy.
Fuel and fuel taxes expense increased 22.6% in 2017 compared with 2016, due primarily to increases in the price of fuel during 2017. Depreciation and amortization expense increased 6.1% in 2017, primarily due to additions to our JBI segment tractor, container and chassis fleets to support additional business demand and equipment purchased related to new DCS long-term customer contracts.
Operating supplies and expenses increased 10.3%, driven primarily by increased mileage activity and tire expense. General and administrative expenses increased 44.6% from 2016, primarily due to a $20.2 million reserve of a cash advance for the purchases of new trailing equipment from a manufacturer that did not meet delivery, increased building rental expense, higher professional fee expenses, higher computer software subscription costs, and increased net losses from asset sales and disposals in 2017. Net losses from sale or disposal of assets were $7.4 million in 2017, compared to net losses of $5.5 million in 2016. Insurance and claims expense increased 57.6% in 2017, primarily due to higher incident volume and accident severity and an $18.6 million increase in reserves for certain claims not covered by insurance.
Net interest expense for 2017 increased by 13.2% compared with 2016, due to an increase in average debt levels and higher effective interest rates on our debt during 2017.
Our effective income tax rate was (15.29)% in 2017 and 37.90% in 2016. The decrease in 2017 was primarily due to a $309.2 million decrease in income tax expense resulting from adjustments to our deferred tax balances at December 31, 2017, for the change in future tax rates prescribed by the Tax Cuts and Jobs Act.
JBI Segment
JBI segment revenue increased 7.6% to $4.08 billion in 2017, from $3.80 billion in 2016. This increase in revenue was primarily a result of an 4.4% increase in load volume and a 3.1% increase in revenue per load, which is the combination of changes in freight mix, customer rates, and fuel surcharge revenue. Load volume in our transcontinental loads grew 7.2% while our eastern network was relatively flat compared to 2016. Average length of haul increased 1.4% in 2017 when compared to 2016. Revenue per load excluding fuel surcharge was flat in 2017 when compared to 2016.
Operating income of the JBI segment decreased to $407 million in 2017, from $450 million in 2016. Benefits from volume growth and increased revenue per load were offset by increases in rail purchased transportation costs, rail inefficiencies, higher driver wages and recruiting costs, higher equipment ownership costs, increased insurance and claims costs, which included an $8.5 million increase in reserves for certain insurance and claims, and the $20.2 million expense for the reserve of a cash advance for the purchases of new trailing equipment from a manufacturer that did not meet delivery. In addition, 2016 included a $5.7 million, one-time benefit from the change in paid time off policy.
DCS Segment
DCS segment revenue increased 12.1% to $1.72 billion in 2017, from $1.53 billion in 2016. Productivity, defined as revenue per truck per week, increased 3.7% when compared to 2016. Revenue, excluding fuel surcharges, increased 10.0% in 2017 compared to 2016, and productivity excluding fuel surcharge revenue increased 1.6% from 2016. The increase in revenue in 2017 was primarily a result of better integration of assets among customer accounts and customer rate increases, partially offset by lower productivity under new customer contracts, compared to 2016. DCS ended 2017 with a net additional 1,326 revenue-producing trucks when compared to 2016.
Operating income of our DCS segment decreased to $171 million in 2017, from $205 million in 2016. The increase in revenue and improved asset utilization were offset by higher driver wages and recruiting costs, increased insurance and claims cost, which included a $7.6 million increase in reserves for certain insurance and claims, increased start up expenditures for new customer contracts, higher equipment ownership costs, and the addition of acquisition costs and intangible asset amortization associated with the purchase of SLD when compared to 2016. In addition, 2016 included a $7.3 million, one-time benefit from the change in paid time off policy.
ICS Segment
ICS segment revenue increased 20.3% to $1.02 billion in 2017, from $852 million in 2016. Overall volumes increased 16.5%. Revenue per load increased 3.3% primarily due to freight mix changes driven by customer demand. Contractual business was approximately 70% of the total load volume and 53% of the total revenue in the 2017, compared to 74% of the total load volume and 64% of the total revenue in 2016.
Operating income decreased to $23 million in 2017, from $36 million in 2016, primarily due to lower gross profit margins, increased insurance and claims cost, which included a $1.8 million increase in reserves for certain insurance and claims, increased number of branches less than two years old, and higher technology development costs. ICS gross profit margin decreased to 13.3% for 2017 from 14.3% for 2016. ICS’s carrier base increased 11.4%, and the employee count increased 15.8% when compared to 2016. In addition, 2016 included a $1.0 million, one-time benefit from the change in paid time off policy.
JBT Segment
JBT segment revenue decreased 2.4% to $378 million in 2017, from $388 million in 2016, primarily from a 3.8% decrease in load count partially offset by a 1.4% increase in revenue per load. Excluding fuel surcharges, revenue for 2017 decreased 4.5% compared to 2016, primarily due to the reduction in load volume and a 4.4% decrease in length of haul.
JBT segment had operating income of $23 million in 2017 compared with $30 million in 2016. The decrease in operating income was driven primarily by lower revenue, increased driver wages and recruiting costs, higher independent contractor cost per mile, increased insurance and claims cost, which included an $0.7 million increase in reserves for certain insurance and claims, and increased tractor maintenance costs compared to 2016. In addition, 2016 included a $1.2 million, one-time benefit from the change in paid time off policy.
LIQUIDITY AND CAPITAL RESOURCES
Net cash provided by operating activities totaled $1.09 billion in 2018, compared to $855 million in 2017. This increase was primarily due to the increase in pre-tax earnings and the reduction in the U.S. federal corporate tax rate as a result of the Tax Cuts and Jobs Act, in 2018.
Net cash used in investing activities totaled $887 million in 2018, compared with $651 million in 2017. The increase resulted primarily from an increase in equipment purchases, net of proceeds from the sale of equipment, in 2018, partially offset by the 2017 purchase of SLD.
Net cash used in financing activities was $208 million in 2018, compared with $196 million in 2017. This increase resulted primarily from lower proceeds from long-term debt issuances, net of long-term debt repayments, partially offset by a decrease in treasury stock purchased in 2018.
Our dividend policy is subject to review and revision by the Board of Directors, and payments are dependent upon our financial condition, liquidity, earnings, capital requirements, and other factors the Board of Directors may deem relevant. We paid a $0.22 per share quarterly dividend in 2016, a $0.23 per share quarterly dividend in 2017, and a $0.24 per share quarterly dividend in 2018. On January 23, 2019, we announced an increase in our quarterly cash dividend from $0.24 to $0.26 per share, which will be paid February 22, 2019, to stockholders of record on February 8, 2019. We currently intend to continue paying cash dividends on a quarterly basis. However, no assurance can be given that future dividends will be paid.
Liquidity
Our need for capital has typically resulted from the acquisition of containers, chassis, trucks, tractors, and trailers required to support our growth and the replacement of older equipment. We are frequently able to accelerate or postpone a portion of equipment replacements depending on market conditions. We obtain capital through cash generated from operations, revolving lines of credit, and long-term debt issuances. We have also periodically utilized capital and operating leases for revenue equipment.
In September 2018, we replaced our $500 million senior revolving credit facility dated September 2015 with a new credit facility authorizing us to borrow up to $750 million under a senior revolving line of credit, which is supported by a credit agreement with a group of banks and expires September 2023. This senior credit facility allows us to request an increase in the total commitment by up to $250 million and to request a one-year extension of the maturity date. The applicable interest rate under this agreement is based on the Prime Rate, the Federal Funds Rate, or LIBOR, depending upon the specific type of borrowing, plus an applicable margin based on our credit rating and other fees. At December 31, 2018, we had $309 million outstanding at an average interest rate of 3.47% under this agreement.
Our senior notes consist of three separate issuances. The first and second issuances are $250 million of 2.40% senior notes due March 2019 and $250 million of 3.85% senior notes due March 2024, respectively, both of which were issued in March 2014. Interest payments under both notes are due semiannually in March and September of each year. The third issuance is $350 million of 3.30% senior notes due August 2022, issued in August 2015. Interest payments under this note are due semiannually in February and August of each year. We may redeem for cash some or all of these notes based on a redemption price set forth in the note indenture. We currently have interest rate swap agreements which effectively convert our $250 million of 2.40% fixed-rate senior notes due March 2019 and our $350 million of 3.30% fixed-rate senior notes due August 2022 to variable rates, resulting in interest rates of 3.63% and 3.97%, respectively, at December 31, 2018. The applicable interest rates under these swap agreements are based on LIBOR plus an established margin. For our senior notes maturing in 2019, it is our intent to pay the entire outstanding balances in full, on or before the maturity dates, using our existing senior revolving line of credit or other sources of long-term financing. In addition, we have a shelf registration filed with the SEC and may draw upon it as warranted.
Our financing arrangements require us to maintain certain covenants and financial ratios. We were in compliance with all covenants and financial ratios at December 31, 2018.
As previously mentioned above, the Tax Cuts and Jobs Act was enacted in December 2017. Beginning in 2018, the Act reduced the U.S. federal corporate tax rate from 35% to 21%, which had a positive effect on our overall liquidity.
We believe our liquid assets, cash generated from operations, and various financing arrangements will provide sufficient funds for our operating and capital requirements for the foreseeable future.
We are currently committed to spend approximately $381.6 million, net of proceeds from sales or trade-ins, during 2019 and 2020, which is primarily related to the acquisition of containers, chassis, and tractors.
Off-Balance Sheet Arrangements
In addition to our net purchase commitments of $381.6 million, our only other off-balance sheet arrangements are related to operating leases. As of December 31, 2018, we had approximately $117.8 million of obligations, primarily related to facility leases.
Contractual Obligations and Commitments
The following table summarizes our expected obligations and commitments (in millions) as of December 31, 2018:
| Total | 2019 | 2020-2021 | 2022-2023 | 2024 and thereafter | ||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating leases | $ | 117.8 | $ | 34.9 | $ | 50.6 | $ | 21.9 | $ | 10.4 | ||||||||||
| Long-term debt obligations | 1,159.0 | 250.0 | - | 659.0 | 250.0 | |||||||||||||||
| Interest payments on debt (1) | 154.3 | 36.1 | 68.5 | 47.3 | 2.4 | |||||||||||||||
| Commitments to acquire revenue equipment and facilities | 381.6 | 381.6 | - | - | - | |||||||||||||||
| Total | $ | 1,812.7 | $ | 702.6 | $ | 119.1 | $ | 728.2 | $ | 262.8 |
(1) Interest payments on debt are based on the debt balance and applicable rate at December 31, 2018.
We had standby letters of credit outstanding of approximately $1.3 million at December 31, 2018, that expire at various dates in 2019, which are related to certain operating agreements and our self-insured retention levels for casualty and workers’ compensation claims. We plan to renew these letters of credit in accordance with our third-party agreements. The table above excludes $56.8 million of liabilities related to uncertain tax positions, including interest and penalties, as we are unable to reasonably estimate the ultimate timing of settlement. See Note 7, Income Taxes, in the Notes to Consolidated Financial Statements for further discussion.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
Interest rate risk can be quantified by measuring the financial impact of a near-term adverse increase in short-term interest rates on variable-rate debt outstanding. Our total long-term debt consists of both fixed and variable interest rate facilities. Our senior notes have fixed interest rates ranging from 2.40% to 3.85%. These fixed-rate facilities reduce the impact of changes to market interest rates on future interest expense. Our senior revolving line of credit has variable interest rates, which are based on the Prime Rate, the Federal Funds Rate, or LIBOR, depending upon the specific type of borrowing, plus any applicable margins. We currently have interest rate swap agreements which effectively convert our $250 million of 2.40% fixed-rate senior notes due March 2019 and our $350 million of 3.30% fixed-rate senior notes due August 2022 to variable rates. The applicable interest rates under these swap agreements are based on LIBOR plus an established margin. Our earnings would be affected by changes in these short-term variable interest rates. At our current level of borrowing, a one-percentage-point increase in our applicable rate would reduce annual pretax earnings by $9.1 million.
Although we conduct business in foreign countries, international operations are not material to our consolidated financial position, results of operations, or cash flows. Additionally, foreign currency transaction gains and losses were not material to our results of operations for the year ended December 31, 2018. Accordingly, we are not currently subject to material foreign currency exchange rate risks from the effects that exchange rate movements of foreign currencies would have on our future costs or on future cash flows we would receive from our foreign investment. To date, we have not entered into any foreign currency forward exchange contracts or other derivative financial instruments to hedge the effects of adverse fluctuations in foreign currency exchange rates.
The price and availability of diesel fuel are subject to fluctuations due to changes in the level of global oil production, seasonality, weather, and other market factors. Historically, we have been able to recover a majority of fuel-price increases from our customers in the form of fuel surcharges. We cannot predict the extent to which volatile fluctuations in fuel prices will continue in the future or the extent to which fuel surcharges could be collected to offset fuel-price increases. As of December 31, 2018, we had no derivative financial instruments to reduce our exposure to fuel-price fluctuations.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
Our Consolidated Financial Statements, Notes to Consolidated Financial Statements, and reports thereon of our independent registered public accounting firm as specified by this Item are presented following Item 15 of this report and include:
Reports of Independent Registered Public Accounting Firm
Consolidated Balance Sheets as of December 31, 2018 and 2017
Consolidated Statements of Earnings for years ended December 31, 2018, 2017, and 2016
Consolidated Statements of Stockholders’ Equity for years ended December 31, 2018, 2017, and 2016
Consolidated Statements of Cash Flows for years ended December 31, 2018, 2017, and 2016
Notes to Consolidated Financial Statements
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Disclosure Controls and Procedures
We maintain controls and procedures designed to ensure that the information we are required to disclose in the reports we file with the SEC is recorded, processed, summarized and reported, within the time periods specified in the SEC rules, and that such information is accumulated and communicated to our management, including our Chief Executive Officer and Chief Financial Officer, as appropriate, to allow timely decisions regarding required disclosure. As of the end of the period covered by this report, we carried out an evaluation, under the supervision and with the participation of our management, including our Chief Executive Officer and Chief Financial Officer, of the effectiveness of the design and operation of our disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934, as amended). Based upon that evaluation, our Chief Executive Officer and Chief Financial Officer concluded that our disclosure controls and procedures were effective as of December 31, 2018.
The certifications of our Chief Executive Officer and Chief Financial Officer required under Section 302 of the Sarbanes-Oxley Act have been filed as Exhibits 31.1 and 31.2 to this report.
Management’s Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining effective internal control over financial reporting as defined in Rules 13a-15(f) under the Securities Exchange Act of 1934. Our internal control over financial reporting is designed to provide reasonable assurance to our management and Board of Directors regarding the preparation and fair presentation of published financial statements.
Because of its inherent limitation, internal control over financial reporting may not prevent or detect misstatements. Therefore, even those systems determined to be effective can provide only reasonable assurance with respect to financial statement preparation and presentation.
Management assessed the effectiveness of our internal control over financial reporting as of December 31, 2018. In making this assessment, management used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) in Internal Control – Integrated Framework (2013 Framework)__. Based on our assessment, we believe that as of December 31, 2018, our internal control over financial reporting is effective based on those criteria.
The effectiveness of internal control over financial reporting as of December 31, 2018, has been audited by Ernst & Young LLP, an independent registered public accounting firm that also audited our Consolidated Financial Statements. Ernst & Young LLP’s report on internal control over financial reporting is included herein (following Item 15).
Changes in Internal Control Over Financial Reporting
There has been no change in our internal control over financial reporting during the fourth quarter ended December 31, 2018, that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
ITEM 9B. OTHER INFORMATION
None.
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
The information required for Item 10 is hereby incorporated by reference from the Notice and Proxy Statement for the Annual Meeting of Stockholders to be held April 18, 2019.
Item 11. EXECUTIVE COMPENSATION
The information required for Item 11 is hereby incorporated by reference from the Notice and Proxy Statement for the Annual Meeting of Stockholders to be held April 18, 2019.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
Except as set forth below, the information required for Item 12 is hereby incorporated by reference from the Notice and Proxy Statement for the Annual Meeting of Stockholders to be held April 18, 2019.
Securiti****es Authorized For Issuance Under Equity Compensation Plans
The following table summarizes, as of December 31, 2018, information about compensation plans under which equity securities of the Company are authorized for issuance.
| Plan Category(1) | Number of Securities To Be Issued Upon Exercise of Outstanding Options, Warrants, and Rights | Weighted-average Exercise Price of Outstanding Options, Warrants, and Rights | Number of Securities Remaining Available for Future Issuance Under Equity Compensation Plans (Excluding Securities Reflected in Column (A)) | ||||||
|---|---|---|---|---|---|---|---|---|---|
| (A) | (B) | (C) | |||||||
| Equity compensation plans approved by security holders | 1,606,347 | $ - (2) | 6,260,958 |
| (1) | We have no equity compensation plans that are not approved by security holders. |
|---|
| (2) | Currently, only restricted share units remain outstanding under our equity compensation plan. Upon vesting, restricted share units are settled with shares of our common stock on a one-for-one basis and, accordingly, do not include an exercise price. |
|---|
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
The information required for Item 13 is hereby incorporated by reference from the Notice and Proxy Statement for the Annual Meeting of Stockholders to be held April 18, 2019.
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
The information required for Item 14 is hereby incorporated by reference from the Notice and Proxy Statement for the Annual Meeting of Stockholders to be held April 18, 2019.
PART IV
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES
| (A) | Financial Statements, Financial Statement Schedules and Exhibits: |
|---|
| (1) | Financial Statements |
|---|
The financial statements included in Item 8 above are filed as part of this annual report.
| (2) | Financial Statement Schedules |
|---|
Schedule II – Valuation and Qualifying Accounts (in millions)
| Allowance for Doubtful Accounts, Revenue Adjustments and Other for the Years Ended: | Balance at Beginning of Year | Charged to Expense/ Against Revenue | Write-Offs, Net of Recoveries | Balance at End of Year | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| December 31, 2016 | 9.9 | 19.5 | (16.0 | ) | 13.4 | |||||||||||
| December 31, 2017 | 13.4 | 29.3 | (18.7 | ) | 24.0 | |||||||||||
| December 31, 2018 | 24.0 | 35.7 | (23.9 | ) | 35.8 |
All other schedules have been omitted either because they are not applicable or because the required information is included in our Consolidated Financial Statements or the notes thereto.
| (3) | Exhibits |
|---|
| 10.8 | Fourth Supplemental Indenture (incorporated by reference from Exhibit 4.3 of the Company’s current report on Form 8-K, filed August 6, 2015) | ||
|---|---|---|---|
| 10.9 | Credit Agreement and related documents (incorporated by reference from Exhibit 10.1 of the Company’s current report on Form 8-K, filed September 28, 2018) | ||
| 21.1 | Subsidiaries of J.B. Hunt Transport Services, Inc. | ||
| 23.1 | Consent of Ernst & Young LLP | ||
| 31.1 | Rule 13a-14(a)/15d-14(a) Certification | ||
| 31.2 | Rule 13a-14(a)/15d-14(a) Certification | ||
| 32.1 | Section 1350 Certification | ||
| 99.1 | Equity Interests Purchase Agreement dated July 20, 2017 (incorporated by reference from Exhibit 99.1 of the Company’s current report on Form 8-K, filed July 25, 2017) | ||
| 101.INS | XBRL Instance Document | ||
| 101.SCH | XBRL Taxonomy Extension Schema Document | ||
| 101.CAL | XBRL Taxonomy Extension Calculation Linkbase Document | ||
| 101.DEF | XBRL Taxonomy Extension Definition Linkbase Document | ||
| 101.LAB | XBRL Taxonomy Extension Label Linkbase Document | ||
| 101.PRE | XBRL Taxonomy Extension Presentation Linkbase Document |
SIGNATURES
Pursuant to the requirements of Sections 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned thereunto duly authorized, in the City of Lowell, Arkansas, on the 22nd day of February 2019.
| J.B. HUNT TRANSPORT SERVICES, INC. | ||||
|---|---|---|---|---|
| (Registrant) | ||||
| By: | /s/ John N. Roberts, III | |||
| John N. Roberts, III | ||||
| President and Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on the 22nd day of February 2019, on behalf of the registrant and in the capacities indicated.
| /s/ John N. Roberts, III | President and Chief Executive Officer, Member | ||
|---|---|---|---|
| John N. Roberts, III | of the Board of Directors | ||
| (Principal Executive Officer) | |||
| /s/ David G. Mee | Executive Vice President, Finance and | ||
| David G. Mee | Administration, Chief Financial Officer | ||
| (Principal Financial Officer) | |||
| /s/ John Kuhlow | Senior Vice President Finance, Controller, | ||
| John Kuhlow | Chief Accounting Officer | ||
| /s/ Kirk Thompson | Chairman of the Board of Directors | ||
| Kirk Thompson | |||
| /s/ James L. Robo | Member of the Board of Directors | ||
| James L. Robo | (Lead Director) | ||
| /s/ Douglas G. Duncan | Member of the Board of Directors | ||
| Douglas G. Duncan | |||
| /s/ Francesca M. Edwardson | Member of the Board of Directors | ||
| Francesca M. Edwardson | |||
| /s/ Wayne Garrison | Member of the Board of Directors | ||
| Wayne Garrison | |||
| /s/ Sharilyn S. Gasaway | Member of the Board of Directors | ||
| Sharilyn S. Gasaway | |||
| /s/ Gary C. George | Member of the |
Showing the first 8K of 95K characters. Open the full section