 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF RESULTS OF OPERATIONS AND FINANCIAL CONDITION
75K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF RESULTS OF OPERATIONS AND FINANCIAL CONDITION
Organization and Business Segments
Description of the Company and Business Segments
Johnson & Johnson and its subsidiaries (the Company) have approximately 132,200 employees worldwide engaged in the research and development, manufacture and sale of a broad range of products in the health care field. The Company conducts business in virtually all countries of the world with the primary focus on products related to human health and well-being.
The Company is organized into three business segments: Consumer, Pharmaceutical and Medical Devices. The Consumer segment includes a broad range of products used in the baby care, oral care, beauty, over-the-counter pharmaceutical, women’s health and wound care markets. These products are marketed to the general public and sold both to retail outlets and distributors throughout the world. The Pharmaceutical segment is focused on six therapeutic areas, including immunology, infectious diseases, neuroscience, oncology, pulmonary hypertension, and cardiovascular and metabolic diseases. Products in this segment are distributed directly to retailers, wholesalers, hospitals and health care professionals for prescription use. The Medical Devices segment includes a broad range of products used in the orthopaedic, surgery, interventional solutions (cardiovascular and neurovascular) and eye health fields. These products are distributed to wholesalers, hospitals and retailers, and used principally in the professional fields by physicians, nurses, hospitals, eye care professionals and clinics.
The Executive Committee of Johnson & Johnson is the principal management group responsible for the strategic operations and allocation of the resources of the Company. This Committee oversees and coordinates the activities of the Consumer, Pharmaceutical and Medical Devices business segments.
In all of its product lines, the Company competes with other companies both locally and globally, throughout the world. Competition exists in all product lines without regard to the number and size of the competing companies involved. Competition in research, involving the development and the improvement of new and existing products and processes, is particularly significant. The development of new and innovative products, as well as protecting the underlying intellectual property of the Company's product portfolio, is important to the Company’s success in all areas of its business. The competitive environment requires substantial investments in continuing research. In addition, the development and maintenance of customer demand for the Company’s consumer products involves significant expenditures for advertising and promotion.
Management’s Objectives
With “Our Credo” as the foundation, the Company’s purpose is to blend heart, science and ingenuity to profoundly change the trajectory of health for humanity. The Company is committed to bringing its full breadth and depth to ensure health for people today and for future generations. United around this common ambition, the Company is poised to fulfill its purpose and successfully meet the demands of the rapidly evolving markets in which it competes.
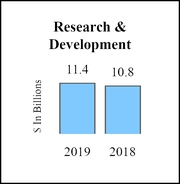
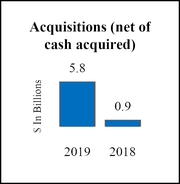
The Company is broadly based in human healthcare, and is committed to creating value by developing accessible, high quality, innovative products and services. New products introduced within the past five years accounted for approximately 25% of 2019 sales. In 2019, $11.4 billion was invested in research and development and $5.8 billion spent on acquisitions, reflecting management’s commitment to create life-enhancing innovations and to create value through partnerships that will profoundly change the trajectory of health for humanity.
A critical driver of the Company’s success is the 132,200 diverse employees worldwide. Employees are empowered and inspired to lead with the Company’s Our Credo and purpose as guides. This allows every employee to use the Company’s reach and size to advance the Company's purpose, and to also lead with agility and urgency. Leveraging the extensive resources across the enterprise, enables the Company to innovate and execute with excellence. This ensures the Company can remain focused on addressing the unmet needs of society every day and invest for an enduring impact, ultimately delivering value to its patients, consumers and healthcare professionals, employees, communities and shareholders.
| 17 |
Results of Operations
Analysis of Consolidated Sales
For discussion on results of operations and financial condition pertaining to the fiscal years 2018 and 2017 see the Company’s Annual Report on Form 10-K for the fiscal year ended December 30, 2018, Item 7. Management's Discussion and Analysis of Results of Operations and Financial Condition.
In 2019, worldwide sales increased 0.6% to $82.1 billion as compared to an increase of 6.7% in 2018. These sales changes consisted of the following:
| Sales increase/(decrease) due to: | 2019 | 2018 | ||||
| Volume | 3.7 | % | 8.5 | % | ||
| Price | (0.9 | ) | (2.2 | ) | ||
| Currency | (2.2 | ) | 0.4 | |||
| Total | 0.6 | % | 6.7 | % |
The net impact of acquisitions and divestitures on the worldwide sales growth was a negative impact of 1.7% in 2019 and a positive impact of 0.8% in 2018.
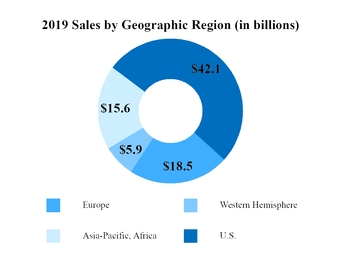
Sales by U.S. companies were $42.1 billion in 2019 and $41.9 billion in 2018. This represents increases of 0.5% in 2019 and 5.1% in 2018. Sales by international companies were $40.0 billion in 2019 and $39.7 billion in 2018. This represents an increase of 0.7% in 2019 and 8.5% in 2018.
The five-year compound annual growth rates for worldwide, U.S. and international sales were 2.0%, 3.9% and 0.2%, respectively. The ten-year compound annual growth rates for worldwide, U.S. and international sales were 2.9%, 3.1% and 2.6%, respectively.
In 2019, sales by companies in Europe experienced a sales decline of 1.5% as compared to the prior year, which included operational growth of 3.8% offset by a negative currency impact of 5.3%. Sales by companies in the Western Hemisphere (excluding the U.S.) experienced a sales decline of 2.8% as compared to the prior year, which included operational growth of 5.7% offset by a negative currency impact of 8.5%. Sales by companies in the Asia-Pacific, Africa region achieved growth of 4.9% as compared to the prior year, including operational growth of 6.9% partially offset by a negative currency impact of 2.0%.
In 2019, the Company utilized three wholesalers distributing products for all three segments that represented approximately 15.0%, 12.0% and 11.0% of the total consolidated revenues. In 2018, the Company had three wholesalers distributing products for all three segments that represented approximately 14.0%, 11.0% and 11.0% of the total consolidated revenues.
| 18 |
Analysis of Sales by Business Segments
Consumer Segment
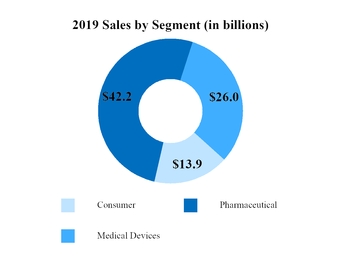
Consumer segment sales in 2019 were $13.9 billion, an increase of 0.3% from 2018, which included 3.0% operational growth and a negative currency impact of 2.7%. U.S. Consumer segment sales were $5.8 billion, an increase of 1.4%. International sales were $8.1 billion, a decrease of 0.4%, which included 4.2% operational growth and a negative currency impact of 4.6%. In 2019, acquisitions and divestitures had a net positive impact of 1.6% on the operational sales growth of the worldwide Consumer segment.
Major Consumer Franchise Sales:
| % Change | ||||||||||
| (Dollars in Millions) | 2019 | 2018 | ’19 vs. ’18 | |||||||
| Beauty | $ | 4,593 | 4,382 | 4.8 | % | |||||
| OTC | 4,444 | 4,334 | 2.5 | |||||||
| Baby Care | 1,675 | 1,858 | (9.9 | ) | ||||||
| Oral Care | 1,528 | 1,555 | (1.7 | ) | ||||||
| Women’s Health | 986 | 1,049 | (6.0 | ) | ||||||
| Wound Care/Other | 671 | 675 | (0.6 | ) | ||||||
| Total Consumer Sales | $ | 13,898 | 13,853 | 0.3 | % |
The Beauty franchise sales of $4.6 billion increased 4.8% as compared to the prior year. Growth was primarily driven by incremental sales from the acquisition of Ci:z Holdings Co., Ltd., (DR.CI:LABO) in Japan as well as market growth and share gains of NEUTROGENA® and AVEENO® products. Growth was partially offset by the divestitures of RoC® and NIZORAL® in the fiscal year 2018.
The Over-the-Counter (OTC) franchise sales of $4.4 billion increased 2.5% as compared to the prior year. Growth was primarily driven by incremental sales from the acquisition of ZARBEES®. Additional contributors to the growth were TYLENOL®, Children's MOTRIN®, digestive health products and anti-smoking aids.
The Baby Care franchise sales were $1.7 billion in 2019, a decrease of 9.9% compared to the prior year, primarily due to JOHNSON’s® competitive pressures coupled with comparisons to prior year relaunch activities and the Baby Center divestiture.
The Oral Care franchise sales of $1.5 billion decreased 1.7% as compared to the prior year. Growth in LISTERINE® Mouthwash and Ready Tabs outside the U.S. was offset by share declines and retailer destocking in the U.S. and the negative impact of currency.
The Women’s Health franchise sales were $1.0 billion in 2019, a decrease of 6.0% as compared to the prior year. The decline was primarily driven by the negative impact of currency and weakness in liners partially offset by strength in napkins in Asia Pacific and Latin America.
The Wound Care/Other franchise sales were $0.7 billion in 2019, a decrease of 0.6% as compared to the prior year. The decline was primarily driven by the divestiture of COMPEED® outside the U.S. and the negative impact of currency.
| 19 |
Pharmaceutical Segment
Pharmaceutical segment sales in 2019 were $42.2 billion, an increase of 3.6% from 2018, which included operational growth of 5.8% and a negative currency impact of 2.2%. U.S. sales were $23.9 billion, an increase of 2.5%. International sales were $18.3 billion, an increase of 5.0%, which included 10.1% operational growth and a negative currency impact of 5.1%. In 2019, the net impact of acquisitions and divestitures on the Pharmaceutical segment operational sales growth was negligible. Adjustments to previous reserve estimates, as compared to the prior year, positively impacted the Pharmaceutical segment operational growth by approximately 1.3%, primarily in the Immunology and Cardiovascular/Metabolism/Other therapeutic areas.
Major Pharmaceutical Therapeutic Area Sales:
| % Change | ||||||||||
| (Dollars in Millions) | 2019 | 2018 | ’19 vs. ’18 | |||||||
| Total Immunology | $ | 13,950 | 13,120 | 6.3 | % | |||||
| REMICADE® | 4,380 | 5,326 | (17.8 | ) | ||||||
| SIMPONI®/SIMPONI ARIA® | 2,188 | 2,084 | 5.0 | |||||||
| STELARA® | 6,361 | 5,156 | 23.4 | |||||||
| TREMFYA® | 1,012 | 544 | 85.9 | |||||||
| Other Immunology | 10 | 10 | 4.5 | |||||||
| Total Infectious Diseases | 3,413 | 3,304 | 3.3 | |||||||
| EDURANT®/rilpivirine | 861 | 816 | 5.6 | |||||||
| PREZISTA®/ PREZCOBIX®/REZOLSTA®/SYMTUZA® | 2,110 | 1,955 | 8.0 | |||||||
| Other Infectious Diseases | 441 | 533 | (17.3 | ) | ||||||
| Total Neuroscience | 6,328 | 6,077 | 4.1 | |||||||
| CONCERTA®/methylphenidate | 696 | 663 | 4.9 | |||||||
| INVEGA SUSTENNA®/XEPLION®/INVEGA TRINZA®/TREVICTA® | 3,330 | 2,928 | 13.7 | |||||||
| RISPERDAL CONSTA® | 688 | 737 | (6.7 | ) | ||||||
| Other Neuroscience | 1,614 | 1,749 | (7.7 | ) | ||||||
| Total Oncology | 10,692 | 9,844 | 8.6 | |||||||
| DARZALEX® | 2,998 | 2,025 | 48.0 | |||||||
| IMBRUVICA® | 3,411 | 2,615 | 30.4 | |||||||
| VELCADE® | 751 | 1,116 | (32.7 | ) | ||||||
| ZYTIGA® /abiraterone acetate | 2,795 | 3,498 | (20.1 | ) | ||||||
| Other Oncology | 739 | 590 | 25.0 | |||||||
| Total Pulmonary Hypertension | 2,623 | 2,573 | 1.9 | |||||||
| OPSUMIT® | 1,327 | 1,215 | 9.2 | |||||||
| TRACLEER® /bosentan | 341 | 546 | (37.5 | ) | ||||||
| UPTRAVI® | 819 | 663 | 23.5 | |||||||
| Other Pulmonary Hypertension | 135 | 149 | (9.4 | ) | ||||||
| Total Cardiovascular / Metabolism / Other | 5,192 | 5,816 | (10.7 | ) | ||||||
| XARELTO® | 2,313 | 2,477 | (6.6 | ) | ||||||
| INVOKANA®/ INVOKAMET® | 735 | 881 | (16.5 | ) | ||||||
| PROCRIT®/EPREX® | 790 | 988 | (20.0 | ) | ||||||
| Other | 1,353 | 1,470 | (8.0 | ) | ||||||
| Total Pharmaceutical Sales | $ | 42,198 | 40,734 | 3.6 | % |
| 20 |
Immunology products sales were $14.0 billion in 2019, representing an increase of 6.3% as compared to the prior year. Growth was driven by strong uptake of STELARA® (ustekinumab) in Crohn's disease, and TREMFYA® (guselkumab) in Psoriasis, expanded indications of SIMPONI®/SIMPONI ARIA® (golimumab), and the U.S. immunology market growth. Immunology was negatively impacted by lower sales of REMICADE® (infliximab) due to increased discounts/rebates and biosimilar competition.
The patents for REMICADE® (infliximab) in certain countries in Europe expired in February 2015. Biosimilar versions of REMICADE® have been introduced in certain markets outside the U.S., resulting in a reduction in sales of REMICADE® in those markets. Additional biosimilar competition will likely result in a further reduction in REMICADE® sales in markets outside the United States. In the U.S., a biosimilar version of REMICADE® was introduced in 2016, and additional competitors continue to enter the market. Continued infliximab biosimilar competition in the U.S. market will result in a further reduction in U.S. sales of REMICADE®. See Note 21 to the Consolidated Financial Statements for a description of legal matters regarding the REMICADE® patents.
Infectious disease products sales were $3.4 billion in 2019, representing an increase of 3.3% as compared to the prior year. Strong sales of SYMTUZA® and the launch of JULUCA® (dolutegravir/rilpivirine) were partially offset by lower sales of PREZISTA® and PREZCOBIX®/REZOLSTA® (darunavir/cobicistat) due to increased competition and loss of exclusivity of PREZISTA® in certain countries outside the U.S.
Neuroscience products sales were $6.3 billion, representing an increase of 4.1% as compared to the prior year. Strong sales of long-acting injectables INVEGA TRINZA®/TREVICTA®(paliperidone palmitate) and INVEGA SUSTENNA®/XEPLION® were partially offset by cannibalization of RISPERDAL CONSTA® (risperidone).
Oncology products achieved sales of $10.7 billion in 2019, representing an increase of 8.6% as compared to the prior year. Contributors to the growth were strong sales of DARZALEX® (daratumumab) with continued market growth and share gain, IMBRUVICA® (ibrutinib) due to increased patient uptake globally. Additionally, sales from the launch of ERLEADA™ (apalutamide) contributed to the growth. Growth was negatively impacted from a decline in U.S. sales of ZYTIGA® (abiraterone acetate) driven by generic competition partially offset by increased sales outside the U.S. Lower sales of VELCADE® (bortezomib) were also due to generic competition.
Pulmonary Hypertension products achieved sales of $2.6 billion, representing an increase of 1.9% as compared to the prior year. Sales of OPSUMIT® (macitentan) and UPTRAVI® (selexipag) were due to continued market growth and increased share gains while sales of TRACLEER® (bosentan) were negatively impacted by generics and cannibalization from OPSUMIT®.
Cardiovascular/Metabolism/Other products sales were $5.2 billion, a decline of 10.7% as compared to the prior year. XARELTO® (rivaroxaban) sales volume growth was offset by higher discounts and rebates. Lower sales of INVOKANA®/INVOKAMET® (canagliflozin) were due to share loss from competitive pressure and a safety label update in the U.S. and lower sales of PROCRIT®/ EPREX® (epoetin alfa) were due to biosimilar competition.
| 21 |
During 2019, the Company advanced its pipeline with several regulatory submissions and approvals for new drugs and additional indications for existing drugs as follows:
| Product Name (Chemical Name) | Indication | US Approval | EU Approval | US Filing | EU Filing |
| BALVERSA™ (erdafitinib) | Treatment of locally advanced or metastatic urothelial cancer | Ÿ | |||
| DARZALEX® (daratumumab) | Combination Regimen for Newly Diagnosed, Transplant-eligible Patients with Multiple Myeloma | Ÿ | Ÿ | ||
| Newly diagnosed patients with Multiple Myeloma in combination with Lenalidomide and Dexamethasone | Ÿ | ||||
| Split-dosing regimen | Ÿ | ||||
| Combination therapy for transplant ineligible Multiple Myeloma patients | Ÿ | Ÿ | |||
| Subcutaneous Formulation in Multiple Myeloma | Ÿ | Ÿ | |||
| ERLEADA™ (apalutamide) | Treatment of Metastatic Castration-Sensitive Prostate Cancer | Ÿ | |||
| Treatment of Metastatic Hormone-Sensitive Prostate Cancer | Ÿ | ||||
| IMBRUVICA® (ibrutinib) | Expanded Use in Combination with Obinutuzumab in Adult Patients with Previously Untreated Chronic Lymphocytic Leukemia and in Combination with Rituximab in Waldenström's Macroglobulinemia | Ÿ | |||
| Treatment for Chronic Lymphocytic Leukemia in combination with obinutuzumab | Ÿ | ||||
| INVOKANA® (canagliflozin) | Treatment of Diabetic Kidney Disease | Ÿ | |||
| rilpivirine and cabotegravir | For Monthly, Injectable, Two Drug Regimen for Treatment of HIV | Ÿ | Ÿ | ||
| SPRAVATO® (esketamine) | Treatment-resistant depression | Ÿ | Ÿ | ||
| Rapid Reduction of Depressive Symptoms in Adults with Major Depressive Disorder who have Active Suicidal Ideation with Intent | Ÿ | ||||
| STELARA® (ustekinumab) | Extended Use for the Treatment of Moderately to Severely Active Ulcerative Colitis | Ÿ | Ÿ | ||
| Treatment of Pediatric Patients with Moderate to Severe Plaque Psoriasis | Ÿ | ||||
| TREMFYA® (guselkumab) | One-press patient-controlled injector | Ÿ | |||
| Treatment of Adults with Active Psoriatic Arthritis | Ÿ | Ÿ | |||
| XARELTO® (rivaroxaban) | For the prevention of Blood Clots in Acutely Ill Medical Patients | Ÿ |
| 22 |
Medical Devices Segment
The Medical Devices segment sales in 2019 were $26.0 billion, a decrease of 3.8% from 2018, which included an operational decrease of 1.7% and a negative currency impact of 2.1%. U.S. sales were $12.4 billion, a decrease of 3.5% as compared to the prior year. International sales were $13.6 billion, a decrease of 4.1% as compared to the prior year, with an operational decrease of 0.1% and a negative currency impact of 4.0%. In 2019, the net impact of acquisitions and divestitures on the Medical Devices segment worldwide operational sales growth was a negative 5.6% of which, the divestitures of LifeScan and Advanced Sterilization Products (ASP) had an impact of approximately 3.8% and 1.6%, respectively.
Major Medical Devices Franchise Sales:
| % Change | ||||||||||
| (Dollars in Millions) | 2019 | 2018 | ’19 vs. ’18 | |||||||
| Surgery | $ | 9,501 | 9,901 | (4.0 | )% | |||||
| Advanced | 4,095 | 4,002 | 2.3 | |||||||
| General | 4,480 | 4,557 | (1.7 | ) | ||||||
| Specialty | 926 | 1,342 | (31.0 | ) | ||||||
| Orthopaedics | 8,839 | 8,885 | (0.5 | ) | ||||||
| Hips | 1,438 | 1,418 | 1.4 | |||||||
| Knees | 1,480 | 1,502 | (1.4 | ) | ||||||
| Trauma | 2,720 | 2,699 | 0.8 | |||||||
| Spine & Other | 3,201 | 3,266 | (2.0 | ) | ||||||
| Vision | 4,624 | 4,553 | 1.6 | |||||||
| Contact Lenses/Other | 3,392 | 3,302 | 2.7 | |||||||
| Surgical | 1,232 | 1,251 | (1.6 | ) | ||||||
| Interventional Solutions | 2,997 | 2,646 | 13.3 | |||||||
| Diabetes Care**(1)** | — | 1,009 | ***** | |||||||
| Total Medical Devices Sales | $ | 25,963 | 26,994 | (3.8 | )% |
(1)LifeScan was divested in the fiscal fourth quarter of 2018.
*Percentage greater than 100% or not meaningful
The Surgery franchise sales were $9.5 billion in 2019, a decrease of 4.0% from 2018. Growth in Advanced Surgery was primarily driven by endocutter, biosurgery and energy products. The decline in General Surgery was primarily driven by the negative impact of currency partially offset by growth of wound closure products. The decline in Specialty Surgery was primarily driven by the divestiture of the sterilization business (ASP) partially offset by growth of aesthetic products.
The Orthopaedics franchise sales were $8.8 billion in 2019, a decrease of 0.5%, including operational growth of 1.2% offset by a negative currency impact of 1.7% as compared to the prior year. The growth in hips was driven by leadership position in the anterior approach, strong market demand for the ACTIS® stem and the KINCISE™ surgical automated system. Knees grew outside the U.S. from new products coupled with continued global uptake of ATTUNE® Revision, offset by a negative currency impact. Growth in trauma was due to strong market growth coupled with continued uptake of new products. The decline in Spine & Other was primarily driven by base business declines in Spine partially offset by growth in Sports which was led by new products, MONOVISC® in the U.S. and growth in Asia Pacific.
The Vision franchise achieved sales of $4.6 billion in 2019, an increase of 1.6% from 2018. Growth was primarily driven by the strength of daily disposable lenses in the ACUVUE® OASYS contact lenses category. The Surgical operational growth was primarily driven by the strength of cataracts outside the U.S. partially offset by competitive pressures in the U.S.
The Interventional Solutions franchise achieved sales of $3.0 billion in 2019, an increase of 13.3% from 2018. Strong growth in the electrophysiology business was driven by Atrial Fibrillation procedure growth and with strong THERMOCOOL SMARTTOUCH® SF Contact Force Sensing Catheter and diagnostic catheter sales.
| 23 |
Analysis of Consolidated Earnings Before Provision for Taxes on Income
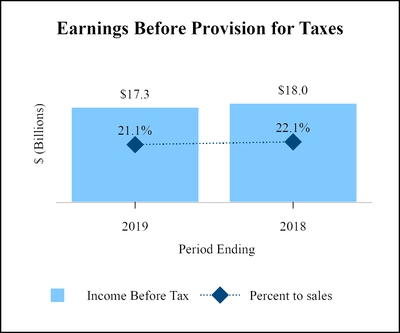
Consolidated earnings before provision for taxes on income was $17.3 billion and $18.0 billion for the fiscal years ended 2019 and 2018, respectively. As a percent to sales, consolidated earnings before provision for taxes on income was 21.1% and 22.1%, in 2019 and 2018, respectively.
Cost of Products Sold and Selling, Marketing and Administrative Expenses: Cost of products sold and selling, marketing and administrative expenses as a percent to sales were as follows:
| % of Sales | 2019 | 2018 | ||||
| Cost of products sold | 33.6 | % | 33.2 | |||
| Percent point increase/(decrease) over the prior year | 0.4 | (0.1 | ) | |||
| Selling, marketing and administrative expenses | 27.0 | % | 27.6 | |||
| Percent point increase/(decrease) over the prior year | (0.6 | ) | (0.5 | ) |
In 2019, cost of products sold as a percent to sales increased to 33.6% from 33.2% as compared to the same period a year ago primarily driven by the negative impact of currency in the Pharmaceutical business as well as increased intangible asset amortization expense. Intangible asset amortization expense of $4.5 billion was included in cost of products sold for 2019 as compared to $4.4 billion in 2018. There was a decrease in the percent to sales of selling, marketing and administrative expenses in 2019 as compared to the prior year, primarily due to favorable segment mix with a higher percentage of sales coming from the Pharmaceutical business, planned prioritization and reduced brand marketing expense in the Consumer business partially offset by increased selling and marketing investments in the Medical Devices business.
Research and Development Expense: Research and development expense by segment of business was as follows:
| 2019 | 2018 | ||||||||||||
| (Dollars in Millions) | Amount | % of Sales* | Amount | % of Sales* | |||||||||
| Consumer | $ | 493 | 3.5 | % | 565 | 4.1 | |||||||
| Pharmaceutical | 8,834 | 20.9 | 8,446 | 20.7 | |||||||||
| Medical Devices | 2,028 | 7.8 | 1,764 | 6.5 | |||||||||
| Total research and development expense | $ | 11,355 | 13.8 | % | 10,775 | 13.2 | |||||||
| Percent increase/(decrease) over the prior year | 5.4 | % | 1.7 |
| *As a percent to segment sales |
| 24 |
Research and development activities represent a significant part of the Company's business. These expenditures relate to the processes of discovering, testing and developing new products, upfront payments and developmental milestones, improving existing products, as well as ensuring product efficacy and regulatory compliance prior to launch. The Company remains committed to investing in research and development with the aim of delivering high quality and innovative products. In 2019, worldwide costs of research and development activities increased by 5.4% compared to 2018 primarily driven by increased investment in the Medical Devices business related to robotics and digital surgery platforms along with higher upfront and developmental milestone payments, primarily from the argenx collaboration in the Pharmaceutical business.
Research facilities are located in the U.S., Belgium, Brazil, China, France, Germany, India, Israel, the Netherlands, Poland, Singapore, Sweden, Switzerland and the United Kingdom with additional R&D support in over 30 other countries.
In-Process Research and Development (IPR&D): In the fiscal first quarter of 2019, the Company recorded an IPR&D charge of $0.9 billion for the remaining intangible asset value related to the development program of AL-8176, an investigational drug for the treatment of Respiratory Syncytial Virus (RSV) and human metapneumovirus (hMPV) acquired with the 2014 acquisition of Alios Biopharma Inc. The impairment charge was based on additional information, including clinical data, which became available and led to the Company's decision to abandon the development of AL-8176. In the fiscal third quarter of 2018, the Company recorded an impairment charge of $1.1 billion which included a partial impairment charge of $0.8 billion related to the development program of AL-8176 and an impairment charge of $0.3 billion for the discontinuation of the development project for an anti-thrombin antibody associated with the 2015 acquisition of XO1 Limited.
Other (Income) Expense, Net: Other (income) expense, net is the account where the Company records gains and losses related to the sale and write-down of certain investments in equity securities held by Johnson & Johnson Innovation - JJDC, Inc. (JJDC), unrealized gains and losses on investments, gains and losses on divestitures, certain transactional currency gains and losses, acquisition-related costs, litigation accruals and settlements, as well as royalty income.
The change in other (income) expense, net for the fiscal year 2019 was additional net expense of $1.1 billion primarily attributable to litigation expense of $5.1 billion in 2019, primarily related to the agreement in principle to settle opioid litigation of $4.0 billion, as compared to litigation expense of $2.0 billion in 2018. This was partially offset by divestiture gains in 2019 of $2.2 billion of which $2.0 billion related to the divestiture of the ASP business. In addition, the fiscal year 2019 included higher unrealized gains on securities of $0.7 billion, an equity step-up gain of $0.3 billion related to the Company's previously held equity investment in DR. CI:LABO, and lower restructuring related expense of $0.2 billion as compared to the same period a year ago. Divestiture gains were approximately $1.2 billion in 2018 and included the LifeScan business, NIZORAL®, RoC® and certain non-strategic Pharmaceutical products. Additionally, 2018 included a reversal of a contingent liability of $0.2 billion.
Interest (Income) Expense: The fiscal year 2019 included net interest income as compared to an expense in the fiscal year 2018. This was primarily due to the positive effect of net investment hedging arrangements and certain cross currency swaps, and a lower average debt balance. Cash, cash equivalents and marketable securities totaled $19.3 billion at the end of 2019, and averaged $19.5 billion as compared to the cash, cash equivalents and marketable securities total of $19.7 billion and $19.0 billion average cash balance in 2018. The total debt balance at the end of 2019 was $27.7 billion with an average debt balance of $29.1 billion as compared to $30.5 billion at the end of 2018 and an average debt balance of $32.5 billion. The decrease in debt was due to the retirement of long-term debt.
Income Before Tax by Segment
Income before tax by segment of business were as follows:
| Income Before Tax | Segment Sales | Percent of Segment Sales | ||||||||||||||||
| (Dollars in Millions) | 2019 | 2018 | 2019 | 2018 | 2019 | 2018 | ||||||||||||
| Consumer | $ | 2,061 | 2,320 | 13,898 | 13,853 | 14.8 | % | 16.7 | ||||||||||
| Pharmaceutical | 8,816 | 12,568 | 42,198 | 40,734 | 20.9 | 30.9 | ||||||||||||
| Medical Devices | 7,286 | 4,397 | 25,963 | 26,994 | 28.1 | 16.3 | ||||||||||||
| Total (1) | 18,163 | 19,285 | 82,059 | 81,581 | 22.1 | 23.6 | ||||||||||||
| Less: Net expense not allocated to segments (2) | 835 | 1,286 | ||||||||||||||||
| Earnings before provision for taxes on income | $ | 17,328 | 17,999 | 82,059 | 81,581 | 21.1 | % | 22.1 |
| (1) | See Note 18 to the Consolidated Financial Statements for more details. |
| (2) | Amounts not allocated to segments include interest (income) expense and general corporate (income) expense. |
| 25 |
Consumer Segment: In 2019, the Consumer segment income before tax as a percent to sales was 14.8%, versus 16.7% in 2018. The decrease in the income before tax as a percent of sales in 2019 as compared to 2018 was primarily attributable to higher expenses for litigation of $0.1 billion, intangible asset amortization of $0.1 billion and restructuring of $0.1 billion in the fiscal year 2019 as compared to the fiscal year 2018. This was partially offset by planned prioritization and brand marketing expense reductions. The fiscal year 2019 included a gain of $0.3 billion related to the Company's previously held equity investment in DR. CI:LABO. Divestiture gains for the fiscal year of 2018 included a gain of $0.3 billion from the divestiture of NIZORAL®.
Pharmaceutical Segment: In 2019, the Pharmaceutical segment income before tax as a percent to sales was 20.9% versus 30.9% in 2018. The decrease in the income before tax as a percent of sales was primarily due to higher litigation expense of $4.3 billion, primarily due to the agreement in principle to settle opioid litigation of $4.0 billion, increased spending in research and development, including a $0.3 billion upfront payment to argenx. This was partially offset by $0.8 billion of higher unrealized gains on securities, a lower in-process research and development charge of $0.2 billion, and lower Actelion acquisition and integration related costs as compared to the fiscal year 2018. In addition, the fiscal year 2018 included a contingent liability reversal of $0.2 billion and higher divestiture gains of $0.2 billion.
Medical Devices Segment: In 2019, the Medical Devices segment income before tax as a percent to sales was 28.1% versus 16.3% in 2018. The increase in the income before tax as a percent to sales was primarily attributable to higher divestiture gains in 2019. Divestiture gains in the fiscal 2019 included a gain of $2.0 billion related to the ASP business. Divestiture gains for the fiscal year of 2018 included a gain of $0.5 billion related to LifeScan. Additionally, the fiscal year 2019 included lower litigation expense of $1.3 billion, lower restructuring charges of $0.2 billion and lower intangible asset amortization expense of $0.1 billion as compared to the fiscal year 2018. This was partially offset by increased investment in robotics and digital solutions.
Restructuring: In the fiscal second quarter of 2018, the Company announced plans to implement actions across its global supply chain that are intended to enable the Company to focus resources and increase investments in critical capabilities, technologies and solutions necessary to manufacture and supply its product portfolio of the future, enhance agility and drive growth. The Company expects these supply chain actions will include expanding its use of strategic collaborations, and bolstering its initiatives to reduce complexity, improving cost-competitiveness, enhancing capabilities and optimizing its network. Discussions regarding specific future actions are ongoing and are subject to all relevant consultation requirements before they are finalized. In total, the Company expects these actions to generate approximately $0.6 to $0.8 billion in annual pre-tax cost savings that will be substantially delivered by 2022. The Company expects to record pre-tax restructuring charges of approximately $1.9 to $2.3 billion. The Company estimates that approximately 70% of the cumulative pre-tax costs will result in cash outlays. In 2019, the Company recorded a pre-tax charge of $0.6 billion, which is included on the following lines of the Consolidated Statement of Earnings, $0.3 billion in restructuring, $0.2 billion in other (income) expense and $0.1 billion in cost of products sold. Total project costs of approximately $0.8 billion have been recorded since the restructuring was announced.
See Note 22 to the Consolidated Financial Statements for additional details related to the restructuring programs.
Provision for Taxes on Income: The worldwide effective income tax rate was 12.7% in 2019 and 15.0% in 2018.
For discussion related to the fiscal 2019 provision for taxes refer to Note 8 to the Consolidated Financial Statements.
On September 28, 2018 the Swiss Parliament approved the Federal Act on Tax Reform and AHV Financing (TRAF). On May 19, 2019 a public referendum was held in Switzerland that approved the federal reform proposals. In the fiscal third quarter of 2019, the Swiss Federal Council enacted TRAF which became effective on January 1, 2020. On February 9, 2020 a public referendum on the legislative change was held in the last remaining canton where the Company has significant operations. The legislation was approved by the voters and formal enactment is expected in the fiscal first half of 2020. The Company has not yet elected the transitional provision in this canton. However, the net financial benefit is estimated to be between $0.2 billion and $0.5 billion in the fiscal first half of 2020. The Company does not believe that TRAF will have a material impact to the Company’s ongoing consolidated effective tax rate beginning in fiscal year 2020.
| 26 |
Liquidity and Capital Resources
Liquidity & Cash Flows
Cash and cash equivalents were $17.3 billion at the end of 2019 as compared to $18.1 billion at the end of 2018. The primary sources and uses of cash that contributed to the $0.8 billion decrease were approximately $23.4 billion of cash generated from operating activities. This was offset by $6.2 billion net cash used by investing activities and $18.0 billion net cash used by financing activities. In addition, the Company had $2.0 billion in marketable securities at the end of 2019 and $1.6 billion at the end of 2018. See Note 1 to the Consolidated Financial Statements for additional details on cash, cash equivalents and marketable securities.
Cash flow from operations of $23.4 billion was the result of $15.1 billion of net earnings and $9.1 billion of non-cash expenses and other adjustments for depreciation and amortization, stock-based compensation, assets write-downs (primarily related to the Alios IPR&D asset), and favorable increases in accounts payable, accrued liabilities and other liabilities of $5.5 billion. This was reduced by $1.6 billion related to an increase in accounts receivable, inventories, other current and non-current assets. as well as non-cash expenses and other adjustments of $2.5 billion for the increase in the deferred tax provision and a net gain on sale of assets/businesses of $2.2 billion (primarily related to the ASP divestiture).
Investing activities use of $6.2 billion of cash was primarily used for acquisitions of $5.8 billion primarily related to the acquisitions of Auris Health, Inc. and DR. CI:LABO, additions to property, plant and equipment of $3.5 billion and $0.5 billion from the net purchases of investments. Investing activities also included a source of $3.3 billion of proceeds from the disposal of assets/businesses, primarily the ASP divestiture, and proceeds from credit support agreements of $0.3 billion.
Financing activities use of $18.0 billion of cash was primarily used for dividends to shareholders of $9.9 billion, the repurchase of common stock of $6.7 billion and the net retirement of short and long term debt of $2.9 billion. Financing activities also included sources of $1.5 billion from proceeds of stock options exercised/employee withholding tax on stock awards, and other financing activities.
On December 17, 2018, the Company announced that its Board of Directors approved a share repurchase program, authorizing the Company to purchase up to $5.0 billion of the Company's shares of common stock. Shares acquired are available for general corporate purposes. The Company financed the share repurchase program through available cash. As of September 29, 2019, $5.0 billion was repurchased under the program and the program was completed.
As of December 29, 2019, the Company's notes payable and long-term debt was in excess of cash, cash equivalents and marketable securities. As of December 29, 2019, the net debt position was $8.4 billion as compared to the prior year of $10.8 billion. There was a decrease in the net debt position due to retirement of debt. The debt balance at the end of 2019 was $27.7 billion as compared to $30.5 billion in 2018. In 2019, the Company continued to have access to liquidity through the commercial paper market. Additionally, as a result of the TCJA, the Company has access to its cash outside the U.S. at a significantly reduced cost. The Company anticipates that operating cash flows, the ability to raise funds from external sources, borrowing capacity from existing committed credit facilities and access to the commercial paper markets will continue to provide sufficient resources to fund operating needs, including the agreement in principle to settle opioid litigation to be potentially paid over the next two to three years. As discussed in Note 8 to the Consolidated Financial Statements, the Internal Revenue Service (IRS) has completed its audit for the tax years through 2009 and is currently auditing the tax years 2010-2012. The Company currently expects completion of this audit and settlement of the related tax liabilities in the fiscal year 2020. As of December 29, 2019, the Company has classified unrecognized tax benefits and related interest of approximately $0.9 billion as a current liability in the “Accrued taxes on Income” line in the Consolidated Balance Sheet. This is the amount expected to be paid over the next 12 months with respect to the IRS audit. Subsequent to December 29, 2019, the Company made a payment for approximately $0.6 billion to the U.S. Treasury related to the estimated 2010-2012 tax audit liability in anticipation of the final settlement later in fiscal 2020. The completion of this tax audit may result in additional adjustments to the Company’s unrecognized tax benefit liability that may have a material impact on the Company’s future operating results or cash flows in the period that the audit is substantially completed.
The Company monitors the global capital markets on an ongoing basis and from time to time may raise capital when market conditions are favorable. The Company filed a shelf registration on February 27, 2017, which will enable it to issue debt securities on a timely basis and will be updated as required. For additional details on borrowings, see Note 7 to the Consolidated Financial Statements.
Financing and Market Risk
The Company uses financial instruments to manage the impact of foreign exchange rate changes on cash flows. Accordingly, the Company enters into forward foreign exchange contracts to protect the value of certain foreign currency assets and liabilities and to hedge future foreign currency transactions primarily related to product costs. Gains or losses on these contracts are offset by the gains or losses on the underlying transactions. A 10% appreciation of the U.S. Dollar from the December 29, 2019 market rates would increase the unrealized value of the Company’s forward contracts by $271 million. Conversely, a
| 27 |
10% depreciation of the U.S. Dollar from the December 29, 2019 market rates would decrease the unrealized value of the Company’s forward contracts by $331 million. In either scenario, the gain or loss on the forward contract would be offset by the gain or loss on the underlying transaction, and therefore, would have no impact on future anticipated earnings and cash flows.
The Company hedges the exposure to fluctuations in currency exchange rates, and the effect on certain assets and liabilities in foreign currency, by entering into currency swap contracts. A 1% change in the spread between U.S. and foreign interest rates on the Company’s interest rate sensitive financial instruments would either increase or decrease the unrealized value of the Company’s swap contracts by approximately $1,043 million. In either scenario, at maturity, the gain or loss on the swap contract would be offset by the gain or loss on the underlying transaction, and therefore, would have no impact on future anticipated cash flows.
The Company does not enter into financial instruments for trading or speculative purposes. Further, the Company has a policy of only entering into contracts with parties that have at least an investment grade credit rating. The counter-parties to these contracts are major financial institutions and there is no significant concentration of exposure with any one counter-party. Management believes the risk of loss is remote. During the fiscal second quarter of 2017, the Company entered into credit support agreements (CSA) with certain derivative counterparties establishing collateral thresholds based on respective credit ratings and netting agreements. See Note 6 to the Consolidated Financial Statements for additional details on credit support agreements.
The Company invests in both fixed rate and floating rate interest earning securities which carry a degree of interest rate risk. The fair market value of fixed rate securities may be adversely impacted due to a rise in interest rates, while floating rate securities may produce less income than predicted if interest rates fall. A 1% (100 basis points) change in spread on the Company’s interest rate sensitive investments would either increase or decrease the unrealized value of cash equivalents and current marketable securities by approximately $7 million.
The Company has access to substantial sources of funds at numerous banks worldwide. In September 2019, the Company secured a new 364-day Credit Facility. Total credit available to the Company approximates $10 billion, which expires on September 10, 2020. Interest charged on borrowings under the credit line agreement is based on either bids provided by banks, the prime rate, London Interbank Offered Rates (LIBOR), or other applicable market rate as allowed under the terms of the agreement, plus applicable margins. Commitment fees under the agreement are not material.
Total borrowings at the end of 2019 and 2018 were $27.7 billion and $30.5 billion, respectively. The decrease in borrowings was due to the retirement of debt in 2019. In 2019, net debt (cash and current marketable securities, net of debt) was $8.4 billion compared to net debt of $10.8 billion in 2018. Total debt represented 31.8% of total capital (shareholders’ equity and total debt) in 2019 and 33.8% of total capital in 2018. Shareholders’ equity per share at the end of 2019 was $22.59 compared to $22.44 at year-end 2018.
A summary of borrowings can be found in Note 7 to the Consolidated Financial Statements.
Contractual Obligations and Commitments
The Company’s contractual obligations are primarily for the recently enacted tax legislation, leases, debt and unfunded retirement plans. There are no other significant obligations. To satisfy these obligations, the Company will use cash from operations. The following table summarizes the Company’s contractual obligations and their aggregate maturities as of December 29, 2019 (see Notes 7, 8, 10 and 16 to the Consolidated Financial Statements for further details):
| (Dollars in Millions) | Tax Legislation (TCJA) | Debt Obligations | Interest on Debt Obligations | Unfunded Retirement Plans | Leases | Total | |||||||||||||
| 2020 | $ | 528 | 1,100 | 886 | 103 | 215 | 2,832 | ||||||||||||
| 2021 | 812 | 1,797 | 841 | 107 | 254 | 3,811 | |||||||||||||
| 2022 | 812 | 2,106 | 796 | 113 | 197 | 4,024 | |||||||||||||
| 2023 | 1,522 | 1,552 | 764 | 118 | 141 | 4,097 | |||||||||||||
| 2024 | 2,029 | 1,474 | 729 | 127 | 86 | 4,445 | |||||||||||||
| After 2024 | 2,536 | 19,565 | 8,121 | 749 | 201 | 31,172 | |||||||||||||
| Total | $ | 8,239 | 27,594 | 12,137 | 1,317 | 1,094 | 50,381 |
For tax matters, see Note 8 to the Consolidated Financial Statements. For other retirement plan and post-employment medical benefit information, see Note 10 to the Consolidated Financial Statements. The table does not include activity related to business combinations.
| 28 |
Dividends
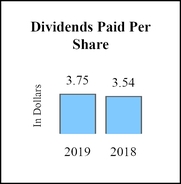
The Company increased its dividend in 2019 for the 57th consecutive year. Cash dividends paid were $3.75 per share in 2019 and $3.54 per share in 2018.
Other Information
Critical Accounting Policies and Estimates
Management’s discussion and analysis of results of operations and financial condition are based on the Company’s consolidated financial statements that have been prepared in accordance with accounting principles generally accepted in the U.S. (GAAP). The preparation of these financial statements requires that management make estimates and assumptions that affect the amounts reported for revenues, expenses, assets, liabilities and other related disclosures. Actual results may or may not differ from these estimates. The Company believes that the understanding of certain key accounting policies and estimates are essential in achieving more insight into the Company’s operating results and financial condition. These key accounting policies include revenue recognition, income taxes, legal and self-insurance contingencies, valuation of long-lived assets, assumptions used to determine the amounts recorded for pensions and other employee benefit plans and accounting for stock based awards.
Revenue Recognition: The Company recognizes revenue from product sales when obligations under the terms of a contract with the customer are satisfied; generally, this occurs with the transfer of control of the goods to customers. The Company's global payment terms are typically between 30 to 90 days. Provisions for certain rebates, sales incentives, trade promotions, coupons, product returns and discounts to customers are accounted for as variable consideration and recorded as a reduction in sales. See Note 1 to the Consolidated Financial Statements for the Accounting Standards Update related to revenue which was adopted in 2018.
Product discounts granted are based on the terms of arrangements with direct, indirect and other market participants, as well as market conditions, including consideration of competitor pricing. Rebates are estimated based on contractual terms, historical experience, patient outcomes, trend analysis and projected market conditions in the various markets served. The Company evaluates market conditions for products or groups of products primarily through the analysis of wholesaler and other third-party sell-through and market research data, as well as internally generated information.
Sales returns are estimated and recorded based on historical sales and returns information. Products that exhibit unusual sales or return patterns due to dating, competition or other marketing matters are specifically investigated and analyzed as part of the accounting for sales return accruals.
Sales returns allowances represent a reserve for products that may be returned due to expiration, destruction in the field, or in specific areas, product recall. The sales returns reserve is based on historical return trends by product and by market as a percent to gross sales. In accordance with the Company’s accounting policies, the Company generally issues credit to customers for returned goods. The Company’s sales returns reserves are accounted for in accordance with the U.S. GAAP guidance for revenue recognition when right of return exists. Sales returns reserves are recorded at full sales value. Sales returns in the Consumer and Pharmaceutical segments are almost exclusively not resalable. Sales returns for certain franchises in the Medical Devices segment are typically resalable but are not material. The Company infrequently exchanges products from inventory for returned products. The sales returns reserve for the total Company has been approximately 1.0% of annual net trade sales during the fiscal reporting years 2019 and 2018.
Promotional programs, such as product listing allowances and cooperative advertising arrangements, are recorded in the same period as related sales. Continuing promotional programs include coupons and volume-based sales incentive programs. The redemption cost of consumer coupons is based on historical redemption experience by product and value. Volume-based incentive programs are based on the estimated sales volumes for the incentive period and are recorded as products are sold. These arrangements are evaluated to determine the appropriate amounts to be deferred or recorded as a reduction of revenue. The Company also earns profit-share payments through collaborative arrangements of certain products, which are included in sales to customers. For all years presented, profit-share payments were approximately 2.0% of the total revenues and are included in sales to customers.
In addition, the Company enters into collaboration arrangements that contain multiple revenue generating activities. Amounts due from collaborative partners for these arrangements are recognized as each activity is performed or delivered, based on the relative selling price. Upfront fees received as part of these arrangements are deferred and recognized over the performance period. See Note 1 to the Consolidated Financial Statements for additional disclosures on collaborations.
Reasonably likely changes to assumptions used to calculate the accruals for rebates, returns and promotions are not anticipated to have a material effect on the financial statements. The Company currently discloses the impact of changes to assumptions in the quarterly or annual filing in which there is a material financial statement impact.
| 29 |
Below are tables that show the progression of accrued rebates, returns, promotions, reserve for doubtful accounts and reserve for cash discounts by segment of business for the fiscal years ended December 29, 2019 and December 30, 2018.
Consumer Segment
| (Dollars in Millions) | Balance at Beginning of Period | Accruals | Payments/Credits | Balance at End of Period | |||||||||
| 2019 | |||||||||||||
| Accrued rebates (1) | $ | 271 | 841 | (828 | ) | 284 | |||||||
| Accrued returns | 57 | 128 | (122 | ) | 63 | ||||||||
| Accrued promotions | 497 | 2,119 | (2,129 | ) | 487 | ||||||||
| Subtotal | $ | 825 | 3,088 | (3,079 | ) | 834 | |||||||
| Reserve for doubtful accounts | 32 | 21 | (18 | ) | 35 | ||||||||
| Reserve for cash discounts | 23 | 198 | (204 | ) | 17 | ||||||||
| Total | $ | 880 | 3,307 | (3,301 | ) | 886 | |||||||
| 2018 | |||||||||||||
| Accrued rebates(1) | $ | 186 | 836 | (751 | ) | 271 | |||||||
| Accrued returns | 68 | 98 | (109 | ) | 57 | ||||||||
| Accrued promotions | 481 | 2,233 | (2,217 | ) | 497 | ||||||||
| Subtotal | $ | 735 | 3,167 | (3,077 | ) | 825 | |||||||
| Reserve for doubtful accounts | 31 | 10 | (9 | ) | 32 | ||||||||
| Reserve for cash discounts | 23 | 204 | (204 | ) | 23 | ||||||||
| Total | $ | 789 | 3,381 | (3,290 | ) | 880 |
| (1) | Includes reserve for customer rebates of $54 million at December 29, 2019 and $57 million at December 30, 2018, recorded as a contra asset. |
Pharmaceutical Segment
| (Dollars in Millions) | Balance at Beginning of Period | Accruals | Payments/Credits**(2)** | Balance at End of Period | |||||||||
| 2019 | |||||||||||||
| Accrued rebates (1) | $ | 7,510 | 26,868 | (25,365 | ) | 9,013 | |||||||
| Accrued returns | 436 | 354 | (290 | ) | 500 | ||||||||
| Accrued promotions | 13 | 17 | (25 | ) | 5 | ||||||||
| Subtotal | $ | 7,959 | 27,239 | (25,680 | ) | 9,518 | |||||||
| Reserve for doubtful accounts | 47 | 2 | (13 | ) | 36 | ||||||||
| Reserve for cash discounts | 53 | 936 | (924 | ) | 65 | ||||||||
| Total | $ | 8,059 | 28,177 | (26,617 | ) | 9,619 | |||||||
| 2018 | |||||||||||||
| Accrued rebates (1) | $ | 4,862 | 22,644 | (19,996 | ) | 7,510 | |||||||
| Accrued returns | 362 | 385 | (311 | ) | 436 | ||||||||
| Accrued promotions | 35 | 46 | (68 | ) | 13 | ||||||||
| Subtotal | $ | 5,259 | 23,075 | (20,375 | ) | 7,959 | |||||||
| Reserve for doubtful accounts | 77 | 37 | (67 | ) | 47 | ||||||||
| Reserve for cash discounts | 55 | 860 | (862 | ) | 53 | ||||||||
| Total | $ | 5,391 | 23,972 | (21,304 | ) | 8,059 |
| (1) | Includes reserve for customer rebates of $93 million at December 29, 2019 and $89 million at December 30, 2018, recorded as a contra asset. |
| 30 |
| (2) | Includes adjustments |
Medical Devices Segment
| (Dollars in Millions) | Balance at Beginning of Period | Accruals | Payments/Credits | Balance at End of Period | |||||||||
| 2019 | |||||||||||||
| Accrued rebates(1) | $ | 1,218 | 5,487 | (5,692 | ) | 1,013 | |||||||
| Accrued returns | 114 | 673 | (669 | ) | 118 | ||||||||
| Accrued promotions | 42 | 106 | (102 | ) | 46 | ||||||||
| Subtotal | $ | 1,374 | 6,266 | (6,463 | ) | 1,177 | |||||||
| Reserve for doubtful accounts | 169 | 30 | (44 | ) | 155 | ||||||||
| Reserve for cash discounts | — | 106 | (96 | ) | 10 | ||||||||
| Total | $ | 1,543 | 6,402 | (6,603 | ) | 1,342 | |||||||
| 2018(2) | |||||||||||||
| Accrued rebates(1) | $ | 1,620 | 6,344 | (6,746 | ) | 1,218 | |||||||
| Accrued returns | 152 | 750 | (788 | ) | 114 | ||||||||
| Accrued promotions | 83 | 116 | (157 | ) | 42 | ||||||||
| Subtotal | $ | 1,855 | 7,210 | (7,691 | ) | 1,374 | |||||||
| Reserve for doubtful accounts | 183 | 29 | (43 | ) | 169 | ||||||||
| Reserve for cash discounts | 15 | 140 | (155 | ) | — | ||||||||
| Total | $ | 2,053 | 7,379 | (7,889 | ) | 1,543 |
| (1) | Includes reserve for customer rebates of $499 million at December 29, 2019 and $632 million at December 30, 2018, recorded as a contra asset. |
| (2) | Certain prior period amounts have been reclassified to conform to current year presentation. |
Income Taxes: Income taxes are recorded based on amounts refundable or payable for the current year and include the results of any difference between U.S. GAAP accounting and tax reporting, recorded as deferred tax assets or liabilities. The Company estimates deferred tax assets and liabilities based on enacted tax regulations and rates. Future changes in tax laws and rates may affect recorded deferred tax assets and liabilities.
The Company has unrecognized tax benefits for uncertain tax positions. The Company follows U.S. GAAP, which prescribes a recognition threshold and measurement attribute for the financial statement recognition and measurement of a tax position taken or expected to be taken in a tax return. Management believes that changes in these estimates would not have a material effect on the Company's results of operations, cash flows or financial position.
The Company has recorded deferred tax liabilities on all undistributed earnings prior to December 31, 2017 from its international subsidiaries. The Company has not provided deferred taxes on the undistributed earnings subsequent to January 1, 2018 from certain international subsidiaries where the earnings are considered to be indefinitely reinvested. The Company intends to continue to reinvest these earnings in those international operations. If the Company decides at a later date to repatriate these earnings to the U.S., the Company would be required to provide for the net tax effects on these amounts. The Company estimates that the total tax effect of this repatriation would be approximately $0.8 billion under current enacted tax laws and regulations and at current currency exchange rates.
See Note 8 to the Consolidated Financial Statements for further information regarding income taxes.
Legal and Self Insurance Contingencies: The Company records accruals for various contingencies, including legal proceedings and product liability claims as these arise in the normal course of business. The accruals are based on management’s judgment as to the probability of losses and, where applicable, actuarially determined estimates. The Company has self insurance through a wholly-owned captive insurance company. In addition to accruals in the self insurance program, claims that exceed the insurance coverage are accrued when losses are probable and amounts can be reasonably estimated.
The Company follows the provisions of U.S. GAAP when recording litigation related contingencies. A liability is recorded when a loss is probable and can be reasonably estimated. The best estimate of a loss within a range is accrued; however, if no estimate in the range is better than any other, the minimum amount is accrued.
| 31 |
See Notes 1 and 21 to the Consolidated Financial Statements for further information regarding product liability and legal proceedings.
Long-Lived and Intangible Assets: The Company assesses changes in economic conditions and makes assumptions regarding estimated future cash flows in evaluating the value of the Company’s property, plant and equipment, goodwill and intangible assets. As these assumptions and estimates may change over time, it may or may not be necessary for the Company to record impairment charges.
Employee Benefit Plans: The Company sponsors various retirement and pension plans, including defined benefit, defined contribution and termination indemnity plans, which cover most employees worldwide. These plans are based on assumptions for the discount rate, expected return on plan assets, mortality rates, expected salary increases, health care cost trend rates and attrition rates. See Note 10 to the Consolidated Financial Statements for further details on these rates and the effect a rate change to the health care cost trend would have on the Company’s results of operations.
Stock Based Compensation: The Company recognizes compensation expense associated with the issuance of equity instruments to employees for their services. Based on the type of equity instrument, the fair value is estimated on the date of grant using either the Black-Scholes option valuation model or a combination of both the Black-Scholes option valuation model and Monte Carlo valuation model, and is expensed in the financial statements over the service period. The input assumptions used in determining fair value are the expected life, expected volatility, risk-free rate and expected dividend yield. For performance share units the fair market value is calculated for each of the three component goals at the date of grant. The fair values for the sales and earnings per share goals of each performance share unit were estimated on the date of grant using the fair market value of the shares at the time of the award, discounted for dividends, which are not paid on the performance share units during the vesting period. The fair value for the relative total shareholder return goal of each performance share unit was estimated on the date of grant using the Monte Carlo valuation model. See Note 17 to the Consolidated Financial Statements for additional information.
New Accounting Pronouncements
Refer to Note 1 to the Consolidated Financial Statements for recently adopted accounting pronouncements and recently issued accounting pronouncements not yet adopted as of December 29, 2019.
Economic and Market Factors
The Company is aware that its products are used in an environment where, for more than a decade, policymakers, consumers and businesses have expressed concerns about the rising cost of health care. In response to these concerns, the Company has a long-standing policy of pricing products responsibly. For the period 2009 - 2019, in the U.S., the weighted average compound annual growth rate of the Company’s net price increases for health care products (prescription and over-the-counter drugs, hospital and professional products) was below the U.S. Consumer Price Index (CPI).
The Company operates in certain countries where the economic conditions continue to present significant challenges. The Company continues to monitor these situations and take appropriate actions. Inflation rates continue to have an effect on worldwide economies and, consequently, on the way companies operate. The Company has accounted for operations in Argentina (beginning in the fiscal third quarter of 2018) and Venezuela as highly inflationary, as the prior three-year cumulative inflation rate surpassed 100%. This did not have a material impact to the Company's results in the period. In the face of increasing costs, the Company strives to maintain its profit margins through cost reduction programs, productivity improvements and periodic price increases.
In June 2016, the United Kingdom (U.K.) held a referendum in which voters approved an exit from the European Union (E.U.), commonly referred to as “Brexit” and on January 31, 2020, the U.K. formally exited the E.U. Given the lack of comparable precedent, it is unclear what the ultimate financial, trade, regulatory and legal implications the withdrawal of the U.K. from the E.U. will have. Brexit creates global political and economic uncertainty, which may cause, among other consequences, volatility in exchange rates and interest rates, additional cost containment by third-party payors and changes in regulations. However, the Company currently does not believe that these and other related effects will have a material impact on the Company’s consolidated financial position or operating results. As of December 29, 2019, the business of the Company’s U.K. subsidiaries represented less than 3% of both the Company’s consolidated assets and fiscal twelve months revenues, respectively.
The Company is exposed to fluctuations in currency exchange rates. A 1% change in the value of the U.S. Dollar as compared to all foreign currencies in which the Company had sales, income or expense in 2019 would have increased or decreased the translation of foreign sales by approximately $390 million and net income by approximately $120 million.
Governments around the world consider various proposals to make changes to tax laws, which may include increasing or decreasing existing statutory tax rates. A change in statutory tax rate in any country would result in the revaluation of the Company’s deferred tax assets and liabilities related to that particular jurisdiction in the period in which the new tax law is enacted. This change would result in an expense or benefit recorded to the Company’s Consolidated Statement of Earnings. The Company closely monitors these proposals as they arise in the countries where it operates. Changes to the statutory tax rate
| 32 |
may occur at any time, and any related expense or benefit recorded may be material to the fiscal quarter and year in which the law change is enacted. For discussion on Federal Act on Tax Reform and AHV Financing (Swiss Tax Reform) see Provision for Taxes on Income in Management's Discussion and Analysis of Financial Condition and Results of Operations.
The Company faces various worldwide health care changes that may continue to result in pricing pressures that include health care cost containment and government legislation relating to sales, promotions and reimbursement of health care products.
Changes in the behavior and spending patterns of purchasers of health care products and services, including delaying medical procedures, rationing prescription medications, reducing the frequency of physician visits and foregoing health care insurance coverage, as a result of the current global economic downturn, may continue to impact the Company’s businesses.
The Company also operates in an environment increasingly hostile to intellectual property rights. Firms have filed Abbreviated New Drug Applications or Biosimilar Biological Product Applications with the FDA or otherwise challenged the coverage and/or validity of the Company's patents, seeking to market generic or biosimilar forms of many of the Company’s key pharmaceutical products prior to expiration of the applicable patents covering those products. In the event the Company is not successful in defending the patent claims challenged in the resulting lawsuits, generic or biosimilar versions of the products at issue will be introduced to the market, resulting in the potential for substantial market share and revenue losses for those products, and which may result in a non-cash impairment charge in any associated intangible asset. There is also a risk that one or more competitors could launch a generic or biosimilar version of the product at issue following regulatory approval even though one or more valid patents are in place. For further information, see the discussion on “REMICADE® Related Cases” and “Litigation Against Filers of Abbreviated New Drug Applications” in Note 21 to the Consolidated Financial Statements.
Legal Proceedings
Johnson & Johnson and certain of its subsidiaries are involved in various lawsuits and claims regarding product liability, intellectual property, commercial and other matters; governmental investigations; and other legal proceedings that arise from time to time in the ordinary course of business.
The Company records accruals for loss contingencies associated with these legal matters when it is probable that a liability will be incurred and the amount of the loss can be reasonably estimated. As of December 29, 2019, the Company has determined that the liabilities associated with certain litigation matters are probable and can be reasonably estimated. The Company has accrued for these matters and will continue to monitor each related legal issue and adjust accruals as might be warranted based on new information and further developments in accordance with ASC 450-20-25. For these and other litigation and regulatory matters discussed below for which a loss is probable or reasonably possible, the Company is unable to estimate the possible loss or range of loss beyond the amounts already accrued. Amounts accrued for legal contingencies often result from a complex series of judgments about future events and uncertainties that rely heavily on estimates and assumptions including timing of related payments. The ability to make such estimates and judgments can be affected by various factors including, among other things, whether damages sought in the proceedings are unsubstantiated or indeterminate; scientific and legal discovery has not commenced or is not complete; proceedings are in early stages; matters present legal uncertainties; there are significant facts in dispute; procedural or jurisdictional issues; the uncertainty and unpredictability of the number of potential claims; or there are numerous parties involved. To the extent adverse verdicts have been rendered against the Company, the Company does not record an accrual until a loss is determined to be probable and can be reasonably estimated.
In the Company's opinion, based on its examination of these matters, its experience to date and discussions with counsel, the ultimate outcome of legal proceedings, net of liabilities accrued in the Company's balance sheet, is not expected to have a material adverse effect on the Company's financial position. However, the resolution of, or increase in accruals for, one or more of these matters in any reporting period may have a material adverse effect on the Company's results of operations and cash flows for that period.
See Note 21 to the Consolidated Financial Statements for further information regarding legal proceedings.
Common Stock
The Company’s Common Stock is listed on the New York Stock Exchange under the symbol JNJ. As of February 12, 2020, there were 135,953 record holders of Common Stock of the Company.
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK