 filings.tools
Item 2. Management's Discussion and Analysis of Financial Condition and Results of Operations
133K characters. Original on sec.gov · Markdown
Item 2. Management's Discussion and Analysis of Financial Condition and Results of Operations
The following discussion should be read in conjunction with our audited consolidated financial statements and notes thereto in our Annual Report, as filed on February 25, 2021.
This Quarterly Report on Form 10-Q contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Exchange Act, including, in particular, statements about the impact of the global COVID-19 pandemic, inflation, future events, future financial performance, plans, strategies, expectations, prospects, competitive environment, regulation, labor matters, supply chain issues and availability of raw materials. Forward-looking statements include all statements that are not historical facts and can be identified by the use of forward-looking terminology such as “outlook,” “guidance,” “anticipate,” “expect,” “believe,” “could,” “estimate,” “feel,” “forecast,” “intend,” “may,” “plan,” “potential,” “project,” “should,” “target,” “will,” “would,” and similar words, phrases or expressions and variations or negatives of these words in this Quarterly Report on Form 10-Q. We have based these forward-looking statements on our current views with respect to future events and financial performance. Our actual financial performance could differ materially from those projected in the forward-looking statements due to the inherent uncertainty of estimates, forecasts and projections, and our financial performance may be better or worse than anticipated. Given these uncertainties, you should not put undue reliance on any forward-looking statements. All of the forward-looking statements are qualified in their entirety by reference to the factors discussed under "Risk Factors" in Part I, Item 1A of our Annual Report, as well as our subsequent filings with the SEC. Forward-looking statements represent our estimates and assumptions only as of the date that they were made. We do not undertake any duty to update the forward-looking statements, and the estimates and assumptions associated with them, after the date of this Quarterly Report on Form 10-Q, except to the extent required by applicable securities laws.
This Quarterly Report on Form 10-Q contains the names of some of our owned or licensed trademarks, trade names and service marks, which we refer to as our brands. All of the product names included in this Quarterly Report on Form 10-Q are either our registered trademarks or those of our licensors.
OVERVIEW
KDP is a leading beverage company in North America, with a diverse portfolio of flavored (non-cola) CSDs, NCBs, including water (enhanced and flavored), ready-to-drink tea and coffee, juice, juice drinks, mixers and specialty coffee, and is a leading producer of innovative single serve brewing systems. With a wide range of hot and cold beverages that meet virtually any consumer need, KDP key brands include Keurig, Dr Pepper, Canada Dry, Snapple, Bai, Mott's, Core, Green Mountain and The Original Donut Shop. KDP has some of the most recognized beverage brands in North America, with significant consumer awareness levels and long histories that evoke strong emotional connections with consumers. KDP offers more than 125 owned, licensed, and partner brands, including the top ten best-selling coffee brands and Dr Pepper as a leading flavored CSD in the U.S., according to IRi, which are available nearly everywhere people shop and consume beverages.
KDP operates as an integrated brand owner, manufacturer and distributor. We believe our integrated business model strengthens our route-to-market and provides opportunities for net sales and profit growth through the alignment of the economic interests of our brand ownership and our manufacturing and distribution businesses through both our DSD system and our WD delivery system. KDP markets and sells its products to retailers, including supermarkets, mass merchandisers, club stores, pure-play e-commerce retailers, and office superstores; to restaurants, hotel chains, office product and coffee distributors, and partner brand owners; and directly to consumers through its websites. Our integrated business model enables us to be more flexible and responsive to the changing needs of our large retail customers and allows us to more fully leverage our scale and reduce costs by creating greater geographic manufacturing and distribution coverage.
The beverage market is subject to some seasonal variations. Our cold beverage sales are generally higher during the warmer months, while hot beverage sales are generally higher during the cooler months. Overall beverage sales can be influenced by the timing of holidays and weather fluctuations. Sales of brewing systems and related accessories are generally higher during the second half of the year due to the holiday shopping season.
COFFEE SYSTEMS
Our Coffee Systems segment is primarily a producer of innovative single serve brewers and specialty coffee in the U.S. and Canada. We manufacture over 75% of the pods in the single-serve K-Cup pod format in the U.S. We manufacture and sell 100% of the K-Cup pods of the following brands to retailers, away from home channel participants and end-use consumers: Green Mountain Coffee Roasters, The Original Donut Shop, McCafé, Laughing Man, REVV, and Van Houtte.
We manufacture and sell K-Cup pods for the following brands to our partners, who in turn sell them to retailers: Starbucks, Smuckers, Peet's, Dunkin', Folgers, Newman’s Own Organics, Caribou Coffee, Eight O’Clock, Maxwell House, and Tim Hortons, as well as private label arrangements. Generally, we are able to sell these brands to our away from home channel participants and end-use consumers. We also have agreements for manufacturing, distributing, and selling K-Cup pods for tea under brands such as Celestial Seasonings, Lipton and Tazo in addition to K-Cup pods of our own brand, Snapple. We also produce and sell K-Cup pods for cocoa, including through a licensing agreement for the Swiss Miss brand, and hot apple cider, including under our own brand, Mott's.
Our Coffee Systems segment manufactures its K-Cup pods in facilities in North America that include specialty designed proprietary high-speed packaging lines using freshly roasted and ground coffee as well as tea, cocoa and other products. We offer high-quality coffee, including certified single-origin, organic, flavored, limited edition and proprietary blends. We carefully select our coffee beans and appropriately roast the coffees to optimize their taste and flavor differences. We engineer and design most of our single serve brewers, where we then utilize third-party contract manufacturers located in various countries in Asia for brewer appliance manufacturing. We distribute our brewers using third-party distributors, retail partners and through our website at www.keurig.com.
PACKAGED BEVERAGES
Our Packaged Beverages segment is principally a brand ownership, manufacturing and distribution business. In this segment, we primarily manufacture and distribute packaged beverages of our brands. Additionally, in order to maximize the size and scale of our manufacturing and distribution operations, we also distribute packaged beverages for our partner brands and manufacture packaged beverages for other third parties in the U.S. and Canada.
The larger CSD brands in this segment include Dr Pepper, Canada Dry, A&W, 7UP, Sunkist, Squirt, Big Red, RC Cola, and Vernors. The larger NCB brands in this segment include Snapple, Mott's, Bai, Clamato, Hawaiian Punch, Core, Yoo-Hoo, ReaLemon, evian, Vita Coco and Mr and Mrs T mixers.
The majority of our Packaged Beverages net sales come from the manufacturing and distribution of our own brands and the contract manufacturing of certain private label and emerging brand beverages. We also recognize net sales in this segment from the distribution of our partner brands such as evian, Vita Coco, Peet's RTD Coffee, A Shoc energy drinks, Runa energy drinks and Polar sparkling seltzer waters. We provide a route-to-market for third party brand owners seeking effective distribution for their new and emerging brands. These brands give us exposure in certain markets to fast growing segments of the beverage industry with minimal capital investment.
Our Packaged Beverages products are manufactured in multiple facilities across the U.S. and are sold or distributed to retailers and their warehouses by our own distribution network through our DSD and our WD systems, or by third party distributors, to all major retail channels.
BEVERAGE CONCENTRATES
Our Beverage Concentrates segment is principally a brand ownership business where we manufacture and sell beverage concentrates in the U.S. and Canada. Most of the brands in this segment are CSD brands. Key brands include Dr Pepper, Canada Dry, Crush, Schweppes, Sun Drop, Sunkist soda, A&W, 7UP, Squirt, Big Red, RC Cola and Hawaiian Punch. Almost all of our beverage concentrates are manufactured at our plant in St. Louis, Missouri. We are expanding our manufacturing capabilities to include a concentrate manufacturing facility in Ireland in the fourth quarter of 2021.
Beverage concentrates are shipped to third party bottlers, as well as to our own manufacturing systems, who combine them with carbonation, water, sweeteners and other ingredients, package the combined product in aluminum cans, PET containers and glass bottles, and sell them as a finished beverage to retailers through our Branded Concentrates operating segment. Beverage concentrates are also manufactured into syrup, which is shipped to fountain customers, such as fast food restaurants, who mix the syrup with water and carbonation to create a finished beverage at the point of sale to consumers through our FFS operating segment. Dr Pepper represents most of our FFS volume.
Our Beverage Concentrates brands are sold by our bottlers through all major retail channels.
LATIN AMERICA BEVERAGES
Our Latin America Beverages segment is a brand ownership, manufacturing and distribution business, with operations in Mexico representing approximately 90% of the segment's 2020 net sales. This segment participates mainly in the carbonated mineral water, flavored CSD, bottled water and vegetable juice categories. The largest brands include Peñafiel, Clamato, Squirt, Aguafiel and Crush.
VOLUME
In evaluating our performance, we consider different volume measures depending on whether we sell beverage concentrates, finished beverages, K-Cup pods or brewers.
Coffee Systems K-Cup Pod and Appliance Sales Volume
In our Coffee Systems segments, we measure our sales volume as the number of appliances and the number of individual K-Cup pods sold to our customers.
Packaged Beverages and Latin America Beverages Sales Volume
In our Packaged Beverages and Latin America Beverages segments, we measure volume as case sales to customers. A case sale represents a unit of measurement equal to 288 fluid ounces of packaged beverage sold by us. Case sales include both our owned brands and certain brands licensed to and/or distributed by us.
Beverage Concentrates Sales Volume
In our Beverage Concentrates segment, we measure our sales volume as concentrate case sales for concentrates sold by us to our bottlers and distributors. A concentrate case is the amount of concentrate needed to make one case of 288 fluid ounces of finished beverage, the equivalent of 24 twelve ounce servings. It does not include any other component of the finished beverage other than concentrate.
COMPARABLE RESULTS OF OPERATIONS
Management believes that there are certain non-GAAP financial measures that allow management to evaluate our results, trends and ongoing performance on a comparable basis. In order to derive the adjusted financial information, we adjust certain financial statement captions and metrics prepared under U.S. GAAP for certain items affecting comparability. See Non-GAAP Financial Measures for further information on the certain items affecting comparability used in the preparation of the financial information. These items are referred to within this Management's Discussion and Analysis discussion as Adjusted income from operations, Adjusted interest expense, Adjusted provision for income taxes, Adjusted net income and Adjusted diluted EPS.
EXECUTIVE SUMMARY
Financial Overview - Third Quarter of 2021 as compared to Third Quarter of 2020
As Reported, in millions (except EPS)

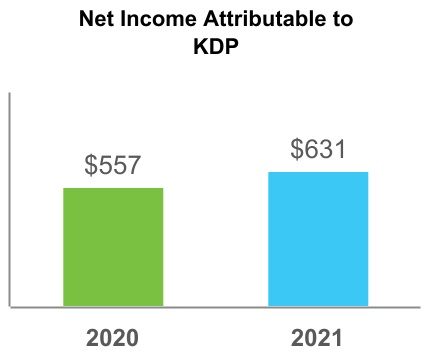
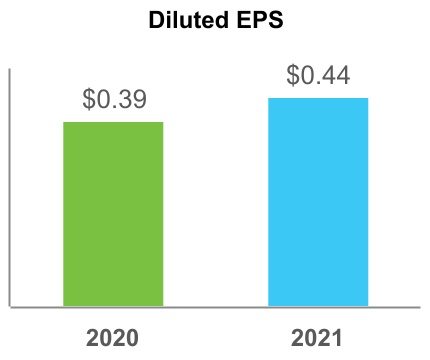
As Adjusted, in millions (except EPS)
Key Events During and Subsequent to the Third Quarter of 2021
During the third quarter of 2021, we made net repayments of our Notes, our commercial paper and our other credit agreements of $325 million.
On September 14, 2021, our Board of Directors declared a regular quarterly dividend of $0.1875 per share, which was paid on October 15, 2021 to shareholders of record as of October 1, 2021.
On October 1, 2021, we announced that our Board of Directors authorized a share repurchase program of up to $4 billion of our outstanding common stock, beginning on January 1, 2022, enabling us to opportunistically return value to shareholders.
On October 25, 2021, we acquired an ownership interest in Vita Coco for $20 million.
Uncertainties and Trends Affecting Our Business
We believe the North American beverage market is influenced by certain key trends and uncertainties. Refer to Item 1A, "Risk Factors", of our Annual Report, combined with the Uncertainties and Trends Affecting Liquidity section below, for more information about risks and uncertainties facing us.
Some of these items, such as the ongoing COVID-19 pandemic and its resulting impacts on the global economy, including supply chain constraints and labor shortages, have led to inflation in input costs, logistics, manufacturing and labor costs. During the third quarter of 2021, we have experienced supply chain disruptions and a significant inflationary impact compared to the prior year period. These impacts have created headwinds for our products that we expect to continue during the remainder of 2021 and into 2022.
As a result of these inflationary pressures, we have increased the pricing on a number of our products. As a result of these price increases, we may incur a reduction of volume or net sales, and combined with the inflationary pressures, could impact our margins and operating results.
Refer to Note 5 of the Notes to our Unaudited Condensed Consolidated Financial Statements and Item 3, Quantitative and Qualitative Disclosures About Market Risk for management's discussion of how we manage our exposure to commodity risk.
Impact of COVID-19 on our Financial Statements
The following table sets forth our reconciliation of significant COVID-19-related expenses. Employee compensation expense and employee protection costs, which impact our SG&A expenses and cost of sales, are included as the COVID-19 item affecting comparability and are excluded in our Adjusted financial measures. In addition, reported amounts under U.S. GAAP also include additional costs, not included as the COVID-19 item affecting comparability, as presented in tables below.
| Items Affecting Comparability**(1)** | |||||||||||||||||||||||||||||
| (in millions) | Employee Compensation Expense**(2)** | Employee Protection Costs**(3)** | Allowances for Expected Credit Losses**(4)** | Inventory Write-Downs**(5)** | Total | ||||||||||||||||||||||||
| For the third quarter of 2021: | |||||||||||||||||||||||||||||
| Coffee Systems | $ | 1 | $ | 1 | $ | — | $ | — | $ | 2 | |||||||||||||||||||
| Packaged Beverages | 1 | 1 | — | — | 2 | ||||||||||||||||||||||||
| Beverage Concentrates | — | — | — | — | — | ||||||||||||||||||||||||
| Latin America Beverages | — | — | — | — | — | ||||||||||||||||||||||||
| Total | $ | 2 | $ | 2 | $ | — | $ | — | $ | 4 | |||||||||||||||||||
| For the third quarter of 2020: | |||||||||||||||||||||||||||||
| Coffee Systems | $ | 7 | $ | 5 | $ | — | $ | — | $ | 12 | |||||||||||||||||||
| Packaged Beverages | 32 | 4 | — | — | 36 | ||||||||||||||||||||||||
| Beverage Concentrates | — | — | — | — | — | ||||||||||||||||||||||||
| Latin America Beverages | — | 1 | — | — | 1 | ||||||||||||||||||||||||
| Total | $ | 39 | $ | 10 | $ | — | $ | — | $ | 49 | |||||||||||||||||||
| For the first nine months of 2021: | |||||||||||||||||||||||||||||
| Coffee Systems | $ | 3 | $ | 14 | $ | (2) | $ | — | $ | 15 | |||||||||||||||||||
| Packaged Beverages | 7 | 6 | (8) | — | 5 | ||||||||||||||||||||||||
| Beverage Concentrates | — | — | (3) | — | (3) | ||||||||||||||||||||||||
| Latin America Beverages | — | 1 | — | — | 1 | ||||||||||||||||||||||||
| Total | $ | 10 | $ | 21 | $ | (13) | $ | — | $ | 18 | |||||||||||||||||||
| For the first nine months of 2020: | |||||||||||||||||||||||||||||
| Coffee Systems | $ | 14 | $ | 7 | $ | 2 | $ | 8 | $ | 31 | |||||||||||||||||||
| Packaged Beverages | 73 | 22 | 8 | — | 103 | ||||||||||||||||||||||||
| Beverage Concentrates | — | — | 4 | — | 4 | ||||||||||||||||||||||||
| Latin America Beverages | — | 1 | — | — | 1 | ||||||||||||||||||||||||
| Total | $ | 87 | $ | 30 | $ | 14 | $ | 8 | $ | 139 | |||||||||||||||||||
(1)Employee compensation expense and employee protection costs are both included as the COVID-19 items affecting comparability in the reconciliation of our Adjusted Non-GAAP financial measures.
(2)In 2021, amounts include pay for temporary employees, including the associated taxes, as well as incremental benefits provided to frontline workers such as extended sick leave, in order to maintain essential operations during the COVID-19 pandemic. In 2020, amounts primarily reflected temporary incremental frontline incentive pay and benefits, as well as pay for temporary employees, including the associated taxes. Impacts both cost of sales and SG&A expenses.
(3)Includes costs associated with personal protective equipment, temperature scans, cleaning and other sanitization services. Impacts both cost of sales and SG&A expenses.
(4)In 2020, allowances reflected the expected impact of the economic uncertainty caused by COVID-19, leveraging estimates of credit worthiness, default and recovery rates for certain of our customers. In 2021, reversals of those previously recorded allowances reflect improving economic conditions. Impacts SG&A expenses.
(5)Impacts cost of sales.
RESULTS OF OPERATIONS
We eliminate from our financial results all intercompany transactions between entities included in our consolidated financial statements and the intercompany transactions with our equity method investees.
References in the financial tables to percentage changes that are not meaningful are denoted by "NM".
Non-GAAP financial measures are provided in addition to U.S. GAAP measures. Such non-GAAP financial measures are excluded from the Results of Operations by Segment when there is no difference between the non-GAAP and the corresponding U.S. GAAP measure. See Non-GAAP Financial Measures for more information, including reconciliations to the corresponding U.S. GAAP measures.
Third Quarter of 2021 Compared to Third Quarter of 2020
Consolidated Operations
The following table sets forth our unaudited condensed consolidated results of operations for the third quarter of 2021 and 2020:
| Third Quarter | Dollar | Percentage | |||||||||||||||||||||
| ($ in millions, except per share amounts) | 2021 | 2020 | Change | Change | |||||||||||||||||||
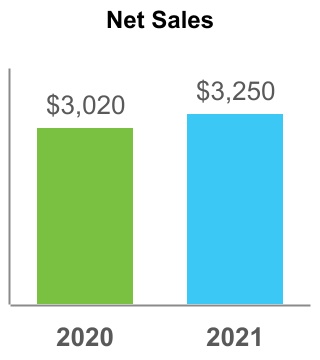
| Net sales | $ | 3,250 | $ | 3,020 | $ | 230 | 7.6 | % | |||||||||||||||
| Cost of sales | 1,415 | 1,316 | 99 | 7.5 | |||||||||||||||||||
| Gross profit | 1,835 | 1,704 | 131 | 7.7 | |||||||||||||||||||
| Selling, general and administrative expenses | 1,040 | 949 | 91 | 9.6 | |||||||||||||||||||
| Other operating expense (income), net | — | 2 | (2) | NM | |||||||||||||||||||
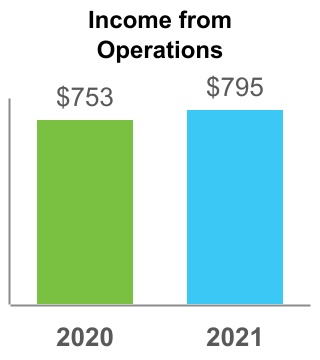
| Income from operations | 795 | 753 | 42 | 5.6 | |||||||||||||||||||
| Interest expense | 116 | 148 | (32) | (21.6) | |||||||||||||||||||
| Impairment of investments and note receivable | — | 16 | (16) | NM | |||||||||||||||||||
| Other expense (income), net | 1 | 5 | (4) | NM | |||||||||||||||||||
| Income before provision for income taxes | 678 | 584 | 94 | 16.1 | |||||||||||||||||||
| Provision for income taxes | 149 | 141 | 8 | 5.7 | |||||||||||||||||||
| Net income including non-controlling interest | 529 | 443 | 86 | 19.4 | |||||||||||||||||||
| Less: Net loss attributable to non-controlling interest | (1) | — | (1) | NM | |||||||||||||||||||
| Net income attributable to KDP | $ | 530 | $ | 443 | 87 | 19.6 | |||||||||||||||||
| Earnings per common share: | |||||||||||||||||||||||
| Basic | $ | 0.37 | $ | 0.31 | $ | 0.06 | 19.4 | % | |||||||||||||||
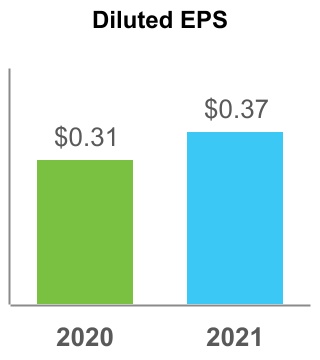
| Diluted | 0.37 | 0.31 | 0.06 | 19.4 | |||||||||||||||||||
| Gross margin | 56.5 | % | 56.4 | % | 10 bps | ||||||||||||||||||
| Operating margin | 24.5 | % | 24.9 | % | (40) bps | ||||||||||||||||||
| Effective tax rate | 22.0 | % | 24.1 | % | (210) bps |
Sales Volume. The following table sets forth changes in sales volume for the third quarter of 2021 compared to the prior year period:
| Percentage Change | ||||||||
| K-Cup pod volume | 6.3 | % | ||||||
| Brewer volume | 2.2 | |||||||
| CSD sales volume | 2.8 | |||||||
| NCB sales volume | (6.4) |
Net Sales. Net sales increased $230 million, or 7.6%, to $3,250 million for the third quarter of 2021 compared with $3,020 million in the prior year period. This performance reflected higher net price realization of 3.6%, volume/mix growth of 3.2% and favorable FX translation of 0.8%.
Gross Profit. Gross profit increased $131 million for the third quarter of 2021 compared with the prior year period. This performance primarily reflected higher net price realization, the impact of growth in volume/mix, the benefit of productivity and merger synergies, favorable FX impacts, including both transaction and translation, and lower COVID-19-related expenses. These benefits were partially offset by higher manufacturing costs, due to both inflation and the growth in volume/mix, an unfavorable change in unrealized commodity mark-to-market impacts, and increased costs to achieve productivity. Gross margin increased 10 bps versus the year ago period to 56.5%, driven by our Beverage Concentrates segment.
Selling, General and Administrative Expenses. SG&A expenses increased $91 million, or 9.6%, to $1,040 million for the third quarter of 2021 compared with $949 million in the prior year period. The increase was driven by increases in logistics, due to both inflation and volume/mix, higher marketing expense, an unfavorable comparison in unrealized mark-to-market on commodities, higher expenses associated with restructuring and integration projects and unfavorable FX impacts. These increases were partially offset by reduced expenses related to the COVID-19 pandemic and the benefit of productivity and merger synergies.
Income from Operations. Income from operations increased $42 million to $795 million for the third quarter of 2021 compared to $753 million in the prior year period due to the increase in gross profit, partially offset by increased SG&A expenses. Operating margin decreased 40 bps versus the year ago period to 24.5%.
Interest Expense. Interest expense decreased $32 million, or 21.6%, to $116 million for the third quarter of 2021 compared with $148 million in the prior year period. This change was driven by our strategic refinancing initiatives, continued deleveraging, and realized gains on interest rate contracts.
Impairment of Investments and Note Receivable. Impairment of investments and note receivable reflected a favorable comparison to a non-cash impairment charge of $16 million in the prior year period associated with our LifeFuels investment.
Effective Tax Rate. The effective tax rate decreased 210 bps to 22.0% for the third quarter of 2021, compared to 24.1% in the prior year period, which was primarily driven by the decrease on the revaluation of state deferred tax liabilities due to state legislative and apportionment changes in 2021, as well as the benefit received from U.S. provision-to-return adjustments.
Net Income Attributable to KDP. Net income increased $87 million to $530 million for the third quarter of 2021 as compared to $443 million in the prior year period, driven by improved income from operations, reduced interest expense and the favorable comparison to the impairment of our LifeFuels investment in the prior year period.
Diluted EPS. Diluted EPS increased 19.4% to $0.37 per diluted share for the third quarter of 2021 as compared to $0.31 in the prior year period.
Adjusted Results of Operations
The following table sets forth certain unaudited condensed consolidated adjusted results of operations for the third quarter of 2021 and 2020:
| Third Quarter | Dollar | Percent | |||||||||||||||||||||
| (in millions, except per share amounts) | 2021 | 2020 | Change | Change | |||||||||||||||||||
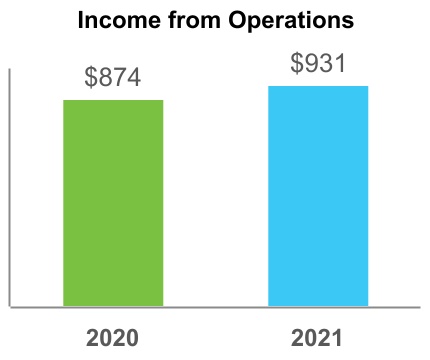
| Adjusted income from operations | $ | 931 | $ | 874 | $ | 57 | 6.5 | % | |||||||||||||||
| Adjusted interest expense | 110 | 139 | (29) | (20.9) | |||||||||||||||||||
| Adjusted provision for income taxes | 190 | 173 | 17 | 9.8 | |||||||||||||||||||
| Adjusted net income attributable to KDP | 631 | 557 | 74 | 13.3 | |||||||||||||||||||
| Adjusted diluted EPS | 0.44 | 0.39 | 0.05 | 12.8 | |||||||||||||||||||
| Adjusted operating margin | 28.6 | % | 28.9 | % | (30) bps | ||||||||||||||||||
| Adjusted effective tax rate | 23.2 | % | 23.7 | % | (50) bps |
Adjusted Income from Operations. Adjusted income from operations increased $57 million, or 6.5%, to $931 million for the third quarter of 2021 as compared to Adjusted income from operations of $874 million in the prior year period. Driving this performance in the quarter were the growth in net sales and the benefits of productivity and merger synergies. These benefits were partially offset by higher manufacturing costs, due to both the growth in volume/mix and inflation, and higher marketing expense. Adjusted operating margin declined 30 bps versus the year ago period to 28.6%.
Adjusted Interest Expense. Adjusted interest expense decreased $29 million, or 20.9%, to $110 million for the third quarter of 2021 compared to Adjusted interest expense of $139 million in the prior year period. This benefit was primarily the result of our reduced interest rates resulting from our strategic refinancing initiatives, continued deleveraging, and realized gains on interest rate contracts.
Adjusted Effective Tax Rate. The Adjusted effective tax rate decreased 50 bps to 23.2% for the third quarter of 2021, compared to the Adjusted effective tax rate of 23.7% in the prior year period. This decrease was primarily driven by the benefit received from U.S. provision-to-return adjustments.
Adjusted Net Income Attributable to KDP. Adjusted net income attributable to KDP increased 13.3% to $631 million for the third quarter of 2021 as compared to Adjusted net income attributable to KDP of $557 million in the prior year period, driven by the growth in Adjusted income from operations and the decreased in Adjusted interest expense.
Adjusted Diluted EPS. Adjusted diluted EPS increased 12.8% to $0.44 per diluted share for the third quarter of 2021 as compared to Adjusted diluted EPS of $0.39 per diluted share in the prior year period.
Results of Operations by Segment
The following tables set forth net sales and income from operations for our segments for the third quarter of 2021 and 2020, as well as the other amounts necessary to reconcile our total segment results to our consolidated results presented in accordance with U.S. GAAP:
| Third Quarter | |||||||||||
| (in millions) | 2021 | 2020 | |||||||||
| Segment Results — Net sales | |||||||||||
| Coffee Systems | $ | 1,155 | $ | 1,097 | |||||||
| Packaged Beverages | 1,547 | 1,447 | |||||||||
| Beverage Concentrates | 392 | 352 | |||||||||
| Latin America Beverages | 156 | 124 | |||||||||
| Net sales | $ | 3,250 | $ | 3,020 | |||||||
| Third Quarter | |||||||||||
| (in millions) | 2021 | 2020 | |||||||||
| Segment Results — Income from operations | |||||||||||
| Coffee Systems | $ | 334 | $ | 320 | |||||||
| Packaged Beverages | 288 | 260 | |||||||||
| Beverage Concentrates | 286 | 262 | |||||||||
| Latin America Beverages | 37 | 25 | |||||||||
| Unallocated corporate costs | (150) | (114) | |||||||||
| Income from operations | $ | 795 | $ | 753 |
COFFEE SYSTEMS
The following table provides selected information about our Coffee Systems segment's results:
| Third Quarter | Dollar | Percent | |||||||||||||||||||||
| (in millions) | 2021 | 2020 | Change | Change | |||||||||||||||||||
| Net sales | $ | 1,155 | $ | 1,097 | $ | 58 | 5.3 | % | |||||||||||||||
| Income from operations | 334 | 320 | 14 | 4.4 | |||||||||||||||||||
| Operating margin | 28.9 | % | 29.2 | % | (30) bps | ||||||||||||||||||
| Adjusted income from operations | $ | 377 | $ | 373 | 4 | 1.1 | % | ||||||||||||||||
| Adjusted operating margin | 32.6 | % | 34.0 | % | (140) bps |
Sales Volume. Volume growth for the Coffee Systems segment included K-Cup pod volume growth of 6.3%, reflecting growth in at-home pod shipments and improvement in our away-from-home businesses, which continues to be well below pre-pandemic levels. Brewer volume increased 2.2% in the quarter, as compared to 33.7% in the year ago period.
Net Sales. Net sales increased 5.3% to $1,155 million for the third quarter of 2021 compared to net sales of $1,097 million in the prior year period, reflecting volume/mix growth of 5.7% and favorable FX translation of 0.7%, which was partially offset by lower net price realization of 1.1%.
Income from Operations. Income from operations increased $14 million, or 4.4%, to $334 million for the third quarter of 2021, compared to $320 million for the prior year period, driven by the continued benefit of productivity and merger synergies, which impacted both cost of sales and SG&A, the benefit of volume/mix growth, and a favorable comparison to COVID-19-related expenses in the prior year period. These impacts were partially offset by inflation, strategic pricing initiatives and increased marketing expense. Operating margin decreased 30 bps versus the year ago period to 28.9%.
Adjusted Income from Operations. Adjusted income from operations increased $4 million, or 1.1%, to $377 million for the third quarter of 2021, compared with Adjusted income from operations of $373 million for the prior year period, driven by the continued benefit of productivity and merger synergies, which impacted both cost of sales and SG&A, and the benefit of volume/mix growth. These impacts were partially offset by inflation, strategic pricing initiatives and increased marketing expense. Adjusted operating margin decreased 140 bps versus the year ago period to 32.6%.
PACKAGED BEVERAGES
The following table provides selected information about our Packaged Beverages segment's results:
| Third Quarter | Dollar | Percent | |||||||||||||||||||||
| (in millions) | 2021 | 2020 | Change | Change | |||||||||||||||||||
| Net sales | $ | 1,547 | $ | 1,447 | $ | 100 | 6.9 | % | |||||||||||||||
| Income from operations | 288 | 260 | 28 | 10.8 | |||||||||||||||||||
| Operating margin | 18.6 | % | 18.0 | % | 60 bps | ||||||||||||||||||
| Adjusted income from operations | $ | 312 | $ | 304 | 8 | 2.6 | % | ||||||||||||||||
| Adjusted operating margin | 20.2 | % | 21.0 | % | (80) bps |
Sales Volume. Sales volume for the third quarter of 2021 increased 0.1%, as strength in CSDs, which benefited from the expansion of our route to market network, as well as increases in Polar and Mott’s, were mostly offset by declines in Snapple and Hawaiian Punch.
Net Sales. Net sales increased 6.9% to $1,547 million for the third quarter of 2021, compared with net sales of $1,447 million in the prior year period, driven by higher net price realization of 5.3%, due to the impact of lower trade and price increases, volume/mix growth of 1.5% and favorable FX translation of 0.1%.
Income from Operations. Income from operations increased $28 million, or 10.8%, to $288 million for the third quarter of 2021, compared with $260 million for the prior year period, driven by higher net price realization, the favorable comparison to COVID-19-related expenses in the prior year period, the benefits of productivity and merger synergies, and volume/mix growth. These growth drivers were partially offset by inflation, increased costs due to higher volumes, driven by an expansion of our route to market network, expenses associated with productivity projects, higher marketing expense and increases in other operating costs. Operating margin grew 60 bps versus the year ago period to 18.6%.
Adjusted Income from Operations. Adjusted income from operations increased $8 million, or 2.6%, to $312 million for the third quarter of 2021, compared with Adjusted income from operations of $304 million for the prior year period, driven by higher net price realization, the benefits of productivity and merger synergies, and volume/mix growth. These growth drivers were partially offset by inflation, increased costs due to higher volumes, driven by an expansion of our route to market network, higher marketing expense and increases in other operating costs. Adjusted operating margin declined 80 bps versus the year ago period to 20.2%.
BEVERAGE CONCENTRATES
The following table provides selected information about our Beverage Concentrates segment's results:
| Third Quarter | Dollar | Percent | |||||||||||||||||||||
| (in millions) | 2021 | 2020 | Change | Change | |||||||||||||||||||
| Net sales | $ | 392 | $ | 352 | $ | 40 | 11.4 | % | |||||||||||||||
| Income from operations | 286 | 262 | 24 | 9.2 | |||||||||||||||||||
| Operating margin | 73.0 | % | 74.4 | % | (140) bps | ||||||||||||||||||
| Adjusted income from operations | $ | 289 | $ | 265 | 24 | 9.1 | % | ||||||||||||||||
| Adjusted operating margin | 73.7 | % | 75.3 | % | (160) bps |
Sales volume. Sales volume for the third quarter of 2021 declined 0.6%, as improving trends in our fountain foodservice business, which services restaurants and hospitality, were more than offset by declines in our branded concentrates business, primarily driven by a shift in sales from concentrates to finished goods in our Packaged Beverages segment.
Net Sales. Net sales increased 11.4% to $392 million for the third quarter of 2021 compared to $352 million for the prior year period, reflecting higher net price realization of 11.4%, driven by the impact of our annual price increases and lower trade, as well as favorable FX translation of 0.6%, partially offset by unfavorable volume/mix of 0.6%.
Income from Operations. Income from operations increased $24 million, or 9.2%, to $286 million for the third quarter of 2021 compared to $262 million for the prior year period, driven by the impact of higher net sales, partially offset by higher marketing expense. Operating margin declined 140 bps from versus the year ago period to 73.0%.
Adjusted Income from Operations. Adjusted income from operations increased $24 million, or 9.1%, to $289 million for the third quarter of 2021 compared with Adjusted income from operations of $265 million for the prior year period, driven by the impact of higher net sales, partially offset by higher marketing expense. Adjusted operating margin declined 160 bps versus the year ago period to 73.7%.
LATIN AMERICA BEVERAGES
The following table provides selected information about our Latin America Beverages segment's results:
| Third Quarter | Dollar | Percent | |||||||||||||||||||||
| (in millions) | 2021 | 2020 | Change | Change | |||||||||||||||||||
| Net sales | $ | 156 | $ | 124 | $ | 32 | 25.8 | % | |||||||||||||||
| Income from operations | 37 | 25 | 12 | 48.0 | |||||||||||||||||||
| Operating margin | 23.7 | % | 20.2 | % | 350 bps | ||||||||||||||||||
| Adjusted income from operations | $ | 37 | $ | 25 | 12 | 48.0 | % | ||||||||||||||||
| Adjusted operating margin | 23.7 | % | 20.2 | % | 350 bps |
Sales Volume. Sales volume for the third quarter of 2021 increased 5.3% compared to the prior year period, driven primarily by Peñafiel, Squirt and Clamato.
Net Sales. Net sales increased 25.8% to $156 million for the third quarter of 2021 compared to $124 million for the prior year period, driven by favorable FX translation of 11.3%, favorable volume/mix of 10.5% and higher net price realization of 4.0%.
Income from Operations. Income from operations increased 48.0% to $37 million for the third quarter of 2021 compared to $25 million in the prior year period, driven by favorable volume/mix, favorable FX effects, including both transaction and translation, higher net pricing, and the benefits of productivity, partially offset by inflation, higher marketing investments and increased operating costs due to higher volumes. Operating margin increased 350 bps versus the year ago period to 23.7%.
Adjusted Income from Operations. Adjusted income from operations increased 48.0% to $37 million for the third quarter of 2021 compared to $25 million in the prior year period, driven by favorable volume/mix, favorable FX effects, including both transaction and translation, higher net pricing, and the benefits of productivity, partially offset by inflation, higher marketing investments and increased operating costs due to higher volumes. Adjusted operating margin grew 350 bps versus the prior year period to 23.7%.
First Nine Months of 2021 Compared to First Nine Months of 2020
Consolidated Operations
The following table sets forth our unaudited condensed consolidated results of operations for the first nine months of 2021 and 2020:
| First Nine Months | Dollar | Percentage | |||||||||||||||||||||
| ($ in millions, except per share amounts) | 2021 | 2020 | Change | Change | |||||||||||||||||||
| Net sales | $ | 9,292 | $ | 8,497 | $ | 795 | 9.4 | % | |||||||||||||||
| Cost of sales | 4,087 | 3,779 | 308 | 8.2 | |||||||||||||||||||
| Gross profit | 5,205 | 4,718 | 487 | 10.3 | |||||||||||||||||||
| Selling, general and administrative expenses | 3,040 | 2,978 | 62 | 2.1 | |||||||||||||||||||
| Other operating expense (income), net | (4) | (40) | 36 | NM | |||||||||||||||||||
| Income from operations | 2,169 | 1,780 | 389 | 21.9 | |||||||||||||||||||
| Interest expense | 381 | 458 | (77) | (16.8) | |||||||||||||||||||
| Loss on early extinguishment of debt | 105 | 4 | 101 | NM | |||||||||||||||||||
| Impairment of investments and note receivable | — | 102 | (102) | NM | |||||||||||||||||||
| Other expense (income), net | (6) | 21 | (27) | NM | |||||||||||||||||||
| Income before provision for income taxes | 1,689 | 1,195 | 494 | 41.3 | |||||||||||||||||||
| Provision for income taxes | 387 | 298 | 89 | 29.9 | |||||||||||||||||||
| Net income including non-controlling interest | 1,302 | 897 | 405 | 45.2 | |||||||||||||||||||
| Less: Net loss attributable to non-controlling interest | (1) | — | (1) | NM | |||||||||||||||||||
| Net income attributable to KDP | $ | 1,303 | $ | 897 | 406 | 45.3 | |||||||||||||||||
| Earnings per common share: | |||||||||||||||||||||||
| Basic | $ | 0.92 | $ | 0.64 | $ | 0.28 | 43.8 | % | |||||||||||||||
| Diluted | 0.91 | 0.63 | 0.28 | 44.4 | |||||||||||||||||||
| Gross margin | 56.0 | % | 55.5 | % | 50 bps | ||||||||||||||||||
| Operating margin | 23.3 | % | 20.9 | % | 240 bps | ||||||||||||||||||
| Effective tax rate | 22.9 | % | 24.9 | % | (200) bps |
Sales Volume. The following table provides the percentage increase in sales volumes compared to the prior year period:
| Percentage Change | ||||||||
| K-Cup Pods | 6.6 | % | ||||||
| Brewers | 22.5 | |||||||
| CSDs | 5.5 | |||||||
| NCBs | (7.3) |
Net Sales. Net sales increased $795 million, or 9.4%, to $9,292 million for the first nine months of 2021 compared to $8,497 million in the prior year period. This performance reflected volume/mix of 6.3%, net price realization of 2.1% and favorable FX translation of 1.0%.
Gross Profit. Gross profit increased $487 million, or 10.3%, to $5,205 million for the first nine months of 2021 compared to $4,718 million in the prior year period. This performance primarily reflected strong growth in net sales, the benefit of productivity and merger synergies, and a favorable change in unrealized commodity mark-to-market impacts. These benefits were partially offset by higher manufacturing costs, driven by both volume/mix growth and inflation. Gross margin increased 50 bps versus the year ago period to 56.0%.
Selling, General and Administrative Expenses. SG&A expenses increased $62 million, or 2.1%, to $3,040 million for the first nine months of 2021 compared to $2,978 million in the prior year period. The increase was driven by increases in logistics, driven by both inflation and higher volumes, higher marketing expense, FX effects and expenses associated with productivity projects. These increases were partially offset by reduced expenses related to the COVID-19 pandemic of $97 million, productivity and merger synergies, and a favorable change in commodity mark-to-market impacts of $60 million.
Other Operating Income, net. Other operating income, net had an unfavorable change of $36 million for the first nine months of 2021 compared to the prior year period, largely driven by the network optimization program gain of $42 million on the asset sale-leaseback of four facilities in the prior year period.
Income from Operations. Income from operations increased $389 million, or 21.9%, to $2,169 million for the first nine months of 2021 compared to $1,780 million in the prior year period, driven by the increase in gross profit, partially offset by the increase in SG&A expenses and the unfavorable change in other operating income, net. Operating margin increased 240 bps versus the year ago period to 23.3%.
Interest Expense. Interest expense decreased $77 million, or 16.8%, to $381 million for the first nine months of 2021 compared to $458 million for the prior year period. This change was primarily the result of the favorable change in unrealized interest rate swap mark-to-market impacts of $35 million, lower interest rates resulting from our strategic refinancing initiatives, and our continued deleveraging.
Loss on Early Extinguishment of Debt. Loss on early extinguishment of debt reflected expense of $105 million during the first nine months of 2021 due to our strategic refinancing initiatives.
Impairment of Investments and Note Receivable. Impairment on investments and note receivable reflected a favorable comparison to a non-cash impairment charge of $102 million in the prior year period associated with our Bedford and LifeFuels investments.
Effective Tax Rate. The effective tax rate decreased 200 bps to 22.9% for the first nine months of 2021, compared to 24.9% in the prior year period, primarily driven by the tax benefit received from excess tax deductions that were generated from the vesting of RSUs in the first nine months of 2021, as well as the benefit received from the Company’s election of the high-tax exception to the GILTI calculation and U.S. provision-to-return adjustments.
Net Income Attributable to KDP. Net income attributable to KDP increased $406 million, or 45.3%, to $1,303 million for the first nine months of 2021 as compared to $897 million in the prior year period, driven by improved income from operations and reduced interest expense, as well as the favorable comparison to the impairment on investments and note receivable, partially offset by the loss on early extinguishment of debt in the first nine months of 2021.
Diluted EPS. Diluted EPS increased 44.4% to $0.91 per diluted share as compared to $0.63 in the prior year period.
Adjusted Results of Operations
The following table sets forth certain unaudited condensed consolidated adjusted results of operations for the first nine months of 2021 and 2020:
| First Nine Months | Dollar | Percent | |||||||||||||||||||||
| (in millions, except per share amounts) | 2021 | 2020 | Change | Change | |||||||||||||||||||
| Adjusted income from operations | $ | 2,511 | $ | 2,333 | $ | 178 | 7.6 | % | |||||||||||||||
| Adjusted interest expense | 368 | 404 | (36) | (8.9) | |||||||||||||||||||
| Adjusted provision for income taxes | 510 | 474 | 36 | 7.6 | |||||||||||||||||||
| Adjusted net income attributable to KDP | 1,640 | 1,434 | 206 | 14.4 | |||||||||||||||||||
| Adjusted diluted EPS | 1.15 | 1.01 | 0.14 | 13.9 | |||||||||||||||||||
| Adjusted operating margin | 27.0 | % | 27.5 | % | (50) bps | ||||||||||||||||||
| Adjusted effective tax rate | 23.7 | % | 24.8 | % | (110) bps |
Adjusted Income from Operations. Adjusted income from operations increased $178 million, or 7.6%, to $2,511 million for the first nine months of 2021 compared to Adjusted income from operations of $2,333 million in the prior year period. Driving this performance in the current period were strong growth in net sales, the benefit of productivity and merger synergies, and favorable changes in unrealized commodity mark-to-market impacts, which impacted both SG&A and cost of sales. Partially offsetting these positive drivers were inflation, higher marketing expense, increased operating costs due to higher volumes, and an unfavorable comparison to a network optimization program gain of $42 million on the asset sale-leaseback of four facilities in the prior year period. Adjusted operating margin declined 50 bps versus the year ago period to 27.0%.
Adjusted Interest Expense. Adjusted interest expense decreased $36 million, or 8.9%, to $368 million for the first nine months of 2021 compared to Adjusted interest expense of $404 million in the prior year period, driven by reduced interest rates resulting from our strategic refinancing initiatives and continued deleveraging.
Adjusted Effective Tax Rate. The Adjusted effective tax rate decreased 110 bps to 23.7% for the first nine months of 2021, compared to 24.8% in the prior year period, primarily driven by the tax benefit received from excess tax deductions that were generated from the vesting of RSUs in the first nine months of 2021, as well as the benefit received from U.S. provision-to-return adjustments.
Adjusted Net Income Attributable to KDP. Adjusted net income attributable to KDP increased 14.4% to $1,640 million for the first nine months of 2021 as compared to Adjusted net income of $1,434 million in the prior year period. This performance was driven primarily by strong growth in Adjusted income from operations and the decrease in Adjusted interest expense.
Adjusted Diluted EPS. Adjusted diluted EPS increased 13.9% to $1.15 per diluted share as compared to Adjusted diluted EPS of $1.01 per diluted share in the prior year period.
Results of Operations by Segment
The following tables provide net sales and income from operations for our reportable segments for the first nine months of 2021 and 2020, as well as the other amounts necessary to reconcile our total segment results to our consolidated results presented in accordance with U.S. GAAP:
| (in millions) | First Nine Months | ||||||||||
| Segment Results — Net sales | 2021 | 2020 | |||||||||
| Coffee Systems | $ | 3,398 | $ | 3,113 | |||||||
| Packaged Beverages | 4,352 | 4,056 | |||||||||
| Beverage Concentrates | 1,095 | 967 | |||||||||
| Latin America Beverages | 447 | 361 | |||||||||
| Net sales | $ | 9,292 | $ | 8,497 | |||||||
| First Nine Months | |||||||||||
| (in millions) | 2021 | 2020 | |||||||||
| Segment Results — Income from operations | |||||||||||
| Coffee Systems | $ | 992 | $ | 882 | |||||||
| Packaged Beverages | 721 | 657 | |||||||||
| Beverage Concentrates | 778 | 679 | |||||||||
| Latin America Beverages | 95 | 73 | |||||||||
| Unallocated corporate costs | (417) | (511) | |||||||||
| Income from operations | $ | 2,169 | $ | 1,780 |
COFFEE SYSTEMS
The following table provides selected information about our Coffee Systems segment's results:
| First Nine Months | Dollar | Percent | |||||||||||||||||||||
| (in millions) | 2021 | 2020 | Change | Change | |||||||||||||||||||
| Net sales | $ | 3,398 | $ | 3,113 | $ | 285 | 9.2 | % | |||||||||||||||
| Income from operations | 992 | 882 | 110 | 12.5 | |||||||||||||||||||
| Operating margin | 29.2 | % | 28.3 | % | 90 bps | ||||||||||||||||||
| Adjusted income from operations | 1,137 | 1,083 | 54 | 5.0 | % | ||||||||||||||||||
| Adjusted operating margin | 33.5 | % | 34.8 | % | (130) bps |
Sales Volume. Sales volume growth in the first nine months of 2021 compared to the prior year period for the Coffee Systems segment included K-Cup pod volume growth of 6.6%, reflecting strength in at-home consumption and modest improvement in the away-from-home businesses. Brewer volume increased 22.5% in the first nine months of 2021, as compared to growth of 17.7% in the year-ago period, driven by our successful brewer innovation program.
Net Sales. Net sales increased 9.2% to $3,398 million for the first nine months of 2021 compared to $3,113 million in the prior year period, driven by volume/mix growth of 9.3% and favorable FX translation of 1.0%, partially offset by lower net price realization of 1.1%.
Income from Operations. Income from operations increased $110 million, or 12.5%, to $992 million for the first nine months of 2021, compared to $882 million in the prior year period, driven by the continued benefit of productivity and merger synergies, strong volume/mix, reduced costs associated with our productivity projects, a favorable comparison to an increase in our litigation reserve in the prior year, and favorable FX effects, including both transaction and translation. These benefits were partially offset by declines due to inflation, strategic pricing initiatives, and the unfavorable comparison to a network optimization program gain of $16 million on an asset sale-leaseback of a manufacturing facility in the prior year period. Operating margin grew 90 bps versus the year ago period to 29.2%.
Adjusted Income from Operations. Adjusted income from operations increased $54 million, or 5.0%, to $1,137 million for the first nine months of 2021, compared to $1,083 million in the prior year period, driven by the continued benefit of productivity, strong volume/mix, and favorable FX effects, including both transaction and translation. These benefits were partially offset by declines due to inflation, strategic pricing initiatives, and the unfavorable comparison to a network optimization program gain of $16 million on an asset sale-leaseback of a manufacturing facility in the prior year period. Adjusted operating margin declined 130 bps versus the year ago period to 33.5%.
PACKAGED BEVERAGES
The following table provides selected information about our Packaged Beverages segment's results:
| First Nine Months | Dollar | Percent | |||||||||||||||||||||
| (in millions) | 2021 | 2020 | Change | Change | |||||||||||||||||||
| Net sales | $ | 4,352 | $ | 4,056 | $ | 296 | 7.3 | % | |||||||||||||||
| Income from operations | 721 | 657 | 64 | 9.7 | |||||||||||||||||||
| Operating margin | 16.6 | % | 16.2 | % | 40 bps | ||||||||||||||||||
| Adjusted income from operations | 795 | 776 | 19 | 2.4 | % | ||||||||||||||||||
| Adjusted operating margin | 18.3 | % | 19.1 | % | (80) bps |
Sales Volume. Sales volume for the first nine months of 2021 increased 1.4% compared to the prior year period, due primarily to strength in CSDs, driven by our broad flavor portfolio, water, and the addition of Polar to our portfolio of partner brands. This was partially offset by declines in Hawaiian Punch and reductions in contract manufacturing.
Net Sales. Net sales increased 7.3% to $4,352 million in the first nine months of 2021, compared to $4,056 million in the prior year period, driven by volume/mix of 4.7%, net price realization of 2.4% and favorable FX translation of 0.2%.
Income from Operations. Income from operations increased $64 million, or 9.7%, to $721 million for the first nine months of 2021 compared to $657 million for the prior year period, driven primarily by strong volume/mix growth, higher net price realization, the favorable comparison to COVID-19-related expenses in the prior year period, and the benefit of productivity and merger synergies. These increases were partially offset by inflation, the unfavorable comparison to a network optimization gain of $26 million in the prior year period related to the asset sale-leaseback of three facilities, expenses associated with productivity projects, higher marketing expense and increased operating costs due to higher volumes, driven by an expansion of our route to market network. Operating margin grew 40 bps from the year ago period to 16.6%.
Adjusted Income from Operations. Adjusted income from operations increased $19 million, or 2.4%, to $795 million for the first nine months of 2021 compared to $776 million for the prior year period, driven primarily by strong volume/mix growth, higher net price realization and the benefit of productivity and merger synergies. These increases were partially offset by inflation, the unfavorable comparison to a network optimization gain of $26 million in the prior year period related to the asset sale-leaseback of three facilities, higher marketing expense and increased operating costs due to higher volumes, driven by an expansion of our route to market network. Adjusted operating margin decreased 80 bps versus the year ago period to 18.3%, primarily reflecting the aforementioned asset sale-leaseback gain in the year-ago period.
BEVERAGE CONCENTRATES
The following table provides selected information about our Beverage Concentrates segment's results:
| First Nine Months | Dollar | Percent | |||||||||||||||||||||
| (in millions) | 2021 | 2020 | Change | Change | |||||||||||||||||||
| Net sales | $ | 1,095 | $ | 967 | $ | 128 | 13.2 | % | |||||||||||||||
| Income from operations | 778 | 679 | 99 | 14.6 | |||||||||||||||||||
| Operating margin | 71.1 | % | 70.2 | % | 90 bps | ||||||||||||||||||
| Adjusted income from operations | 784 | 684 | 100 | 14.6 | % | ||||||||||||||||||
| Adjusted operating margin | 71.6 | % | 70.7 | % | 90 bps |
Sales Volume. Sales volume for the first nine months of 2021 increased 2.4% compared to the prior year period, reflecting improving trends in our fountain foodservice component of the business, which services restaurants and hospitality, driven by increasing levels of consumer mobility during the first nine months of 2021 compared to the year-ago period.
Net Sales. Net sales increased 13.2% to $1,095 million in the first nine months of 2021, compared to $967 million in the prior year period, reflecting higher net price realization of 9.7%, volume/mix growth of 3.0% and favorable FX translation of 0.5%.
Income from Operations. Income from operations increased $99 million, or 14.6%, to $778 million for the first nine months of 2021 compared to $679 million in the prior year period. This performance reflected the impact of net sales growth, partially offset by higher marketing expense. Operating margin increased 90 bps versus the year ago period to 71.1%.
Adjusted Income from Operations. Adjusted income from operations increased $100 million, or 14.6%, to $784 million for the first nine months of 2021 compared to $684 million in the prior year period. This performance reflected the impact of net sales growth, partially offset by higher marketing expense. Adjusted operating margin increased 90 bps versus the year ago period to 71.6%.
LATIN AMERICA BEVERAGES
The following table provides selected information about our Latin America Beverages segment's results:
| First Nine Months | Dollar | Percent | |||||||||||||||||||||
| (in millions) | 2021 | 2020 | Change | Change | |||||||||||||||||||
| Net sales | $ | 447 | $ | 361 | $ | 86 | 23.8 | % | |||||||||||||||
| Income from operations | 95 | 73 | 22 | 30.1 | |||||||||||||||||||
| Operating margin | 21.3 | % | 20.2 | % | 110 bps | ||||||||||||||||||
| Adjusted income from operations | 97 | 75 | 22 | 29.3 | % | ||||||||||||||||||
| Adjusted operating margin | 21.7 | % | 20.8 | % | 90 bps |
Sales Volume. Sales volume for the first nine months of 2021 as compared to the prior year period increased 2.6%, driven by Peñafiel and Clamato, partially offset by declines in Squirt and Crush.
Net Sales. Net sales grew 23.8% to $447 million for the first nine months of 2021, compared to $361 million in the prior year period, reflecting favorable FX translation of 9.1%, volume/mix growth of 8.6% and net price realization of 6.1%.
Income from Operations. Income from operations increased $22 million, or 30.1%, to $95 million for the first nine months of 2021 compared to $73 million in the prior year period, driven by higher net price realization and favorable volume/mix, partially offset by inflation and higher marketing expense. Operating margin increased 110 bps versus the year ago period to 21.3%.
Adjusted Income from Operations. Adjusted income from operations increased $22 million, or 29.3%, to $97 million for the first nine months of 2021 compared to $75 million in the prior year period, driven by higher net price realization and favorable volume/mix, partially offset by inflation and higher marketing expense. Adjusted operating margin improved 90 bps versus the year ago period to 21.7%.
CRITICAL ACCOUNTING ESTIMATES
The process of preparing our consolidated financial statements in conformity with U.S. GAAP requires the use of estimates and judgments that affect the reported amounts of assets, liabilities, revenue and expenses. Critical accounting estimates are both fundamental to the portrayal of a company’s financial condition and results and require difficult, subjective or complex estimates and assessments. These estimates and judgments are based on historical experience, future expectations and other factors and assumptions we believe to be reasonable under the circumstances. The most significant estimates and judgments are reviewed on an ongoing basis and revised when necessary. These critical accounting estimates are discussed in greater detail in our Annual Report.
LIQUIDITY AND CAPITAL RESOURCES
Overview
Our financial condition and liquidity remain strong. Net cash provided by operations was $1,933 million for the first nine months of 2021 compared to $1,666 million for the prior year period. Although there is continued uncertainty related to the impact of the ongoing COVID-19 pandemic on our future results, we believe we are uniquely positioned, with our broad portfolio and unmatched distribution network, to successfully navigate through this pandemic, and the steps we have taken over the course of the pandemic to strengthen our balance sheet leave us well positioned to manage our business. We continue to manage all aspects of our business, including, but not limited to, monitoring the financial health of our customers, suppliers and other third-party relationships, implementing gross margin enhancement strategies through our integration and productivity initiatives, and developing new opportunities for growth such as innovation and agreements with partners to distribute brands that are accretive to our portfolio.
The following summarizes our cash activity for the first nine months of 2021 and 2020:
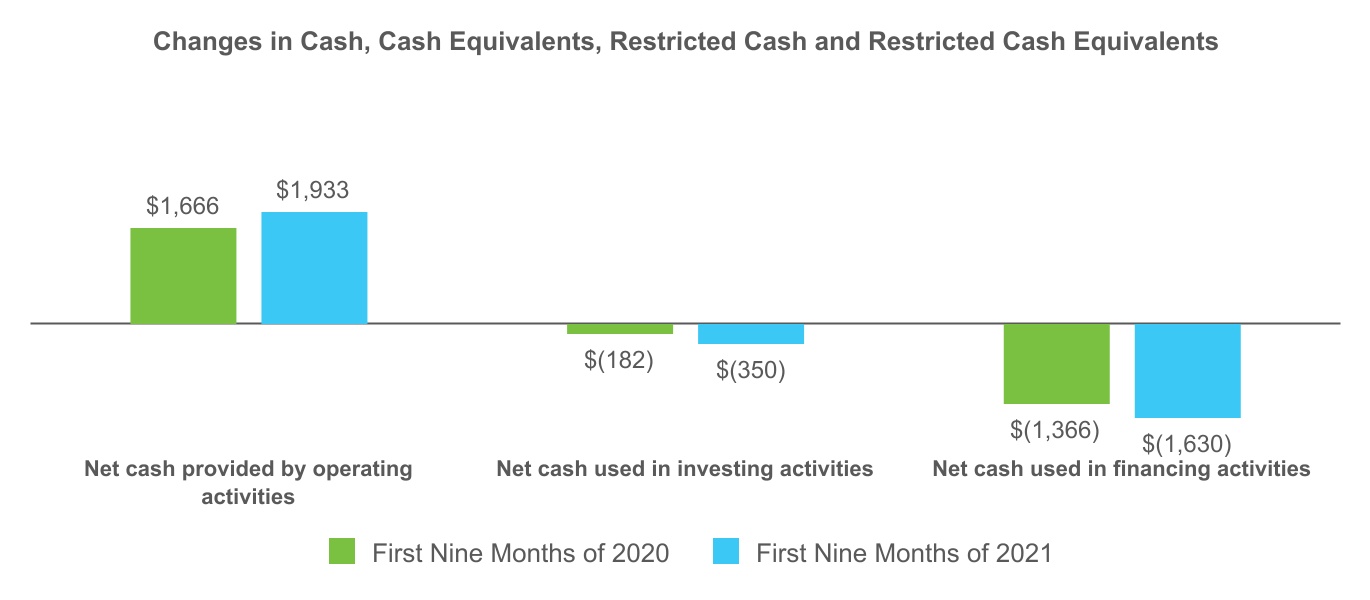
Cash, cash equivalents, restricted cash and restricted cash equivalents decreased $52 million from December 31, 2020 to September 30, 2021 primarily as a result of deleveraging, dividend payments and investments in property, plant and equipment, which outpaced cash generated from our operations.
Cash generated by our foreign operations is generally repatriated to the U.S. periodically as working capital funding requirements in those jurisdictions allow. Foreign cash balances were $163 million and $165 million as of September 30, 2021 and December 31, 2020, respectively.
Principal Sources of Capital Resources
Our principal sources of liquidity are our existing cash and cash equivalents, cash generated from our operations and borrowing capacity currently available under our KDP Revolver and 2021 364-Day Credit Agreement. Additionally, we have an uncommitted commercial paper program where we can issue unsecured commercial paper notes on a private placement basis. Based on our current and anticipated level of operations, we believe that our operating cash flows will be sufficient to meet our anticipated obligations for the next twelve months. To the extent that our operating cash flows are not sufficient to meet our liquidity needs, we may utilize cash on hand or amounts available under our financing arrangements, if necessary.
Sources of Liquidity - Operations
Net cash provided by operating activities increased $267 million for the first nine months of 2021, as compared to the first nine months of 2020, driven by the increase in net income adjusted for non-cash items, partially offset by a decline in working capital.
Cash Conversion Cycle
Our cash conversion cycle is defined as DIO and DSO less DPO. The calculation of each component of the cash conversion cycle is provided below:
| Component | Calculation (on a trailing twelve month basis) | |||||||
| DIO | (Average inventory divided by cost of sales) * Number of days in the period | |||||||
| DSO | (Accounts receivable divided by net sales) * Number of days in the period | |||||||
| DPO | (Accounts payable * Number of days in the period) divided by cost of sales and SG&A expenses |
Our cash conversion cycle improved 10 days to approximately 66 days as of September 30, 2021 as compared to 56 days in the prior year period. The following table summarizes our cash conversion cycle:
| September 30, | ||||||||||||||
| 2021 | 2020 | |||||||||||||
| DIO | 58 | 53 | ||||||||||||
| DSO | 33 | 34 | ||||||||||||
| DPO | 157 | 143 | ||||||||||||
| Cash conversion cycle | (66) | (56) |
Accounts Payable Program
As part of our ongoing efforts to improve our cash flow and related liquidity, we work with our suppliers to optimize our terms and conditions, which include the extension of payment terms. Excluding our suppliers who require cash at date of purchase or sale, our current payment terms with our suppliers generally range from 10 to 360 days. We also entered into agreements with third party administrators to allow participating suppliers to track payment obligations from us, and if voluntarily elected by the supplier, sell payment obligations from us to financial institutions. Suppliers can sell one or more of our payment obligations at their sole discretion and our rights and obligations to our suppliers are not impacted. We have no economic interest in a supplier’s decision to enter into these agreements and no direct financial relationship with the financial institutions. Our obligations to our suppliers, including amounts due and scheduled payment terms, are not impacted. We have been informed by the third party administrators that as of September 30, 2021 and December 31, 2020, $3,027 million and $2,578 million, respectively, of our outstanding payment obligations were voluntarily elected by the supplier and sold to financial institutions. The amounts settled through the program and paid to the financial institutions were $2,492 million and $2,022 million for the first nine months of 2021 and 2020, respectively.
Impact of the Cares Act
Beginning in the second quarter of 2020, we deferred payments of employer-related payroll taxes as allowed under the U.S. Coronavirus Aid, Relief and Economic Security Act, commonly known as the CARES Act. Payment of at least 50% of the deferred amount is due on January 3, 2022, with the remainder due by January 3, 2023. As of September 30, 2021, we have deferred a total of $59 million in such payments.
Sources of Liquidity - Financing
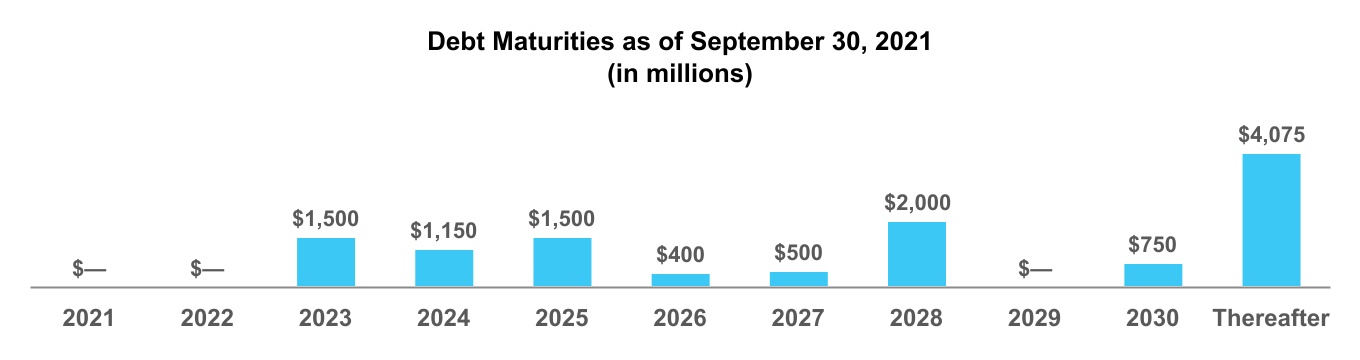
In March 2021, we undertook a strategic refinancing and issued $2,150 million aggregate face value of Notes, consisting of $1,150 million aggregate principal amount of 0.750% 2024 Notes, $500 million aggregate principal amount of 2.250% 2031 Notes, and $500 million aggregate principal amount of 3.350% 2051 Notes. The proceeds from the issuance were used to voluntarily prepay several tranches of our existing Notes and our 2019 KDP Term Loan in order to take advantage of current market conditions to refinance our debt maturities at more attractive interest rates, while also extending the duration of our debt. We also terminated our 2020 364-Day Credit Agreement, which would have expired in April 2021, and replaced it with our 2021 364-Day Credit Agreement, which has a term-out option allowing us to extend the maturity date by converting the facility into a term loan agreement for an additional one-year term.
Additionally, in March 2021, we filed a prospectus supplement with the SEC in order to sell up to 4,300,000 shares to or through Goldman in at-the-market offerings, known as an ATM Program. The ATM Program was completed effective March 15, 2021, and the net proceeds of approximately $140 million were primarily used to cover our obligation to remit cash to local, state and federal tax authorities in connection with the net settlement of vesting restricted stock units during the first quarter of 2021. Commissions and fees paid under the ATM program were less than $1 million for the first nine months of 2021.
Refer to Note 2 of the Notes to our Unaudited Condensed Consolidated Financial Statements for management's discussion of our financing arrangements.
We also have an active shelf registration statement, filed with the SEC on August 27, 2019, which allows us to issue an indeterminate number or amount of common stock, preferred stock, debt securities and warrants from time to time in one or more offerings at the direction of our Board of Directors.
Debt Ratings
As of September 30, 2021, our credit ratings were as follows:
| Rating Agency | Long-Term Debt Rating | Commercial Paper Rating | Outlook | Date of Last Change | ||||||||||
| Moody's | Baa2 | P-2 | Stable | February 26, 2021 | ||||||||||
| S&P | BBB | A-2 | Stable | May 14, 2018 |
These debt and commercial paper ratings impact the interest we pay on our financing arrangements. A downgrade of one or both of our debt and commercial paper ratings could increase our interest expense and decrease the cash available to fund anticipated obligations.
As of September 30, 2021, we were in compliance with all debt covenants and we have no reason to believe that we will be unable to satisfy these covenants.
Principal Uses of Capital Resources
Through the remainder of 2021, our principal uses of our capital resources following the DPS Merger are deleveraging, providing shareholder return to our investors through regular quarterly dividends, and investing in KDP to capture market share and drive growth through innovation and routes to market.
On October 1, 2021, we announced that our Board of Directors authorized a share repurchase program of up to $4 billion of our outstanding common stock, beginning on January 1, 2022, enabling us to opportunistically return value to shareholders. See Expansion of Our Capital Allocation Strategy below.
Deleveraging and Other Debt Repayments
In 2018, management set deleveraging targets for a 2-3 year time period following the DPS Merger in order to optimize our balance sheet, and we continue to be focused on achieving those targets. Since the DPS Merger, we have made net repayments of $4,047 million of our Notes, our commercial paper and our other credit agreements, including $872 million for the first nine months of 2021.
In May 2021, our 2021 Merger Notes were repaid at maturity, using cash generated from operations and the issuance of commercial paper.
Regular Quarterly Dividends
In February 2021, we announced that our Board of Directors approved a 25% increase in our annualized dividend rate to $0.75 per share, from the current annualized rate of $0.60 per share, effective with the Company’s regular quarterly dividend for the second quarter of 2021. For the first nine months of 2021, we have declared total dividends of $0.525 per share.
Capital Expenditures
We have significantly invested in state-of-the-art manufacturing and warehousing facilities, including expansive investments in new facilities in Newbridge, Ireland; Spartanburg, South Carolina; and Allentown, Pennsylvania, in 2021 and 2020, in order to optimize our supply chain network through integration and productivity projects and to mitigate risk of business interruption.
Purchases of property, plant and equipment were $325 million and $356 million for the first nine months of 2021 and 2020, respectively.
Capital expenditures, which includes both purchases of property, plant and equipment and amounts included in accounts payable and accrued expenses, for the first nine months of 2021 and 2020 primarily related to our continued investment in state-of-the-art manufacturing and warehousing facilities. Capital expenditures included in accounts payable and accrued expenses were $180 million and $255 million for the first nine months of 2021 and 2020, respectively, which primarily related to these investments.
As we begin to move past the three-year period after the DPS Merger, we expect that purchases of property, plant and equipment will be approximately 3% of net sales on an annualized basis.
Purchases of Intangible Assets
We have invested in the expansion of our DSD network through transactions with strategic independent bottlers to ensure competitive distribution scale for our brands. These transactions are generally accounted for as an asset acquisition, as the majority of the transaction price represents the reacquisition of our distribution rights. Purchases of intangible assets were $31 million and $26 million for the first nine months of 2021 and 2020, respectively.
Expansion of Our Capital Allocation Strategy
Beginning on January 1, 2022, we intend to expand our capital allocation strategy to include inorganic options to drive total shareholder return. Our primary inorganic option to drive total shareholder return will be through strategic acquisitions. However, to the extent our primary option does not occur, we may employ secondary options, which may include the repurchase of shares or special dividends. See Part II, Item 2, Unregistered Sales of Equity Securities and Use of Proceeds, for further information.
Uncertainties and Trends Affecting Liquidity
Disruptions in financial and credit markets, including those caused by the ongoing COVID-19 pandemic, may impact our ability to manage normal commercial relationships with our customers, suppliers and creditors. These disruptions could have a negative impact on the ability of our customers to timely pay their obligations to us, thus reducing our cash flow, or the ability of our vendors to timely supply materials.
Customer and consumer demand for our products may also be impacted by the risk factors discussed under "Risk Factors" in Part 1, Item 1A of our Annual Report, as well as subsequent filings with the SEC, that could have a material effect on production, delivery and consumption of our products, which could result in a reduction in our sales volume.
We believe that the following events, trends and uncertainties may also impact liquidity:
-
Our intention to drive significant cash flow generation to enable continued deleveraging through the end of 2021;
-
Our ability to access our committed financing arrangements, including our KDP Revolver and our 2021 364-Day Credit Agreement;
-
Our ability to issue unsecured uncommitted commercial paper notes on a private placement basis up to a maximum aggregate amount outstanding at any time of $2,400 million;
-
A significant downgrade in our credit ratings could limit i) a financial institution's willingness to participate in our accounts payable program and reduce the attractiveness of the accounts payable program to participating suppliers who may sell payment obligations from us to financial institutions, which could impact our accounts payable program; or ii) our ability to issue debt at terms that are favorable to us;
-
Our continued payment of regular quarterly dividends;
-
Our continued capital expenditures;
-
Future mergers or acquisitions, which may include brand ownership companies, regional bottling companies, distributors and/or distribution rights to further extend our geographic coverage;
-
Future opportunistic repurchases of our common stock or special dividends to drive total shareholder return;
-
Future equity investments;
-
Seasonality of our operating cash flows, which could impact short-term liquidity; and
-
Fluctuations in our tax obligations.
SUPPLEMENTAL GUARANTOR FINANCIAL INFORMATION
The Notes are fully and unconditionally guaranteed by certain of our direct and indirect subsidiaries (the "Guarantors"), as defined in the indentures governing the Notes. The Guarantors are 100% owned either directly or indirectly by us and jointly and severally guarantee, subject to the release provisions described below, our obligations under the Notes. None of our subsidiaries organized outside of the U.S., immaterial subsidiaries used for charitable purposes, any of the subsidiaries held by Maple Parent Holdings Corp. prior to the DPS Merger or any of the subsidiaries acquired after the DPS Merger (collectively, the "Non-Guarantors") guarantee the Notes. The subsidiary guarantees with respect to the Notes are subject to release upon the occurrence of certain events, including the sale of all or substantially all of a subsidiary's assets, the release of the subsidiary's guarantee of our other indebtedness, our exercise of the legal defeasance option with respect to the Notes and the discharge of our obligations under the applicable indenture.
The following schedules present the summarized financial information for Keurig Dr Pepper Inc. (the “Parent”) and the Guarantors on a combined basis after intercompany eliminations; the Parent and the Guarantors' amounts due from and amounts due to Non-Guarantors are disclosed separately. The consolidating schedules are provided in accordance with the reporting requirements of Rule 13-01 under SEC Regulation S-X for the issuer and guarantor subsidiaries.
The summarized financial information for the Parent and Guarantors were as follows:
| (in millions) | For the First Nine Months of 2021 | ||||
| Net sales | $ | 5,384 | |||
| Income from operations | 1,149 | ||||
| Net income attributable to KDP | 1,303 |
| (in millions) | September 30, 2021 | December 31, 2020 | |||||||||
| Current assets | $ | 1,774 | $ | 1,810 | |||||||
| Non-current assets | 43,821 | 43,333 | |||||||||
| Total assets(1) | $ | 45,595 | $ | 45,143 | |||||||
| Current liabilities | $ | 4,164 | $ | 5,148 | |||||||
| Non-current liabilities | 17,026 | 16,164 | |||||||||
| Total liabilities(2) | $ | 21,190 | $ | 21,312 |
(1)Includes $133 million and $423 million of intercompany receivables due to the Parent and Guarantors from the Non-Guarantors as of September 30, 2021 and December 31, 2020, respectively.
(2)Includes $37 million and $30 million of intercompany payables due to the Non-Guarantors from the Parent and Guarantors as of September 30, 2021 and December 31, 2020, respectively.
NON-GAAP FINANCIAL MEASURES
To supplement the consolidated financial statements presented in accordance with U.S. GAAP, we have presented for the third quarter and first nine months of 2021 and 2020 (i) Adjusted income from operations, (ii) Adjusted interest expense, (iii) Adjusted provision for income taxes, (iv) Adjusted net income attributable to KDP and (v) Adjusted diluted EPS, which are considered non-GAAP financial measures. The non-GAAP financial measures provided should be viewed in addition to, and not as an alternative for, results prepared in accordance with U.S. GAAP. The non-GAAP financial measures presented may differ from similarly titled non-GAAP financial measures presented by other companies, and other companies may not define these non-GAAP financial measures in the same way. The adjusted measures are not substitutes for their comparable U.S. GAAP financial measures, such as income from operations, net income, diluted EPS or other measures prescribed by U.S. GAAP, and there are limitations to using non-GAAP financial measures. We use these non-GAAP financial measures, in addition to U.S. GAAP financial measures, to evaluate our operating and financial performance and to compare such performance to that of prior periods and to the performance of our competitors. Additionally, we use these non-GAAP financial measures in making operational and financial decisions and in our budgeting and planning process. We believe that providing these non-GAAP financial measures to investors helps investors evaluate our operating performance, profitability and business trends in a way that is consistent with how management evaluates such performance and consistent with guidance previously provided by us.
For the third quarter and first nine months of 2021 and 2020, we define our Adjusted non-GAAP financial measures as certain financial statement captions and metrics adjusted for certain items affecting comparability. The items affecting comparability are defined below.
Items affecting comparability: Defined as certain items that are excluded for comparison to prior year periods, adjusted for the tax impact as applicable. Tax impact is determined based upon an approximate rate for each item. For each period, management adjusts for (i) the unrealized mark-to-market impact of derivative instruments not designated as hedges in accordance with U.S. GAAP and do not have an offsetting risk reflected within the financial results; (ii) the amortization associated with definite-lived intangible assets; (iii) the amortization of the deferred financing costs associated with the DPS Merger; (iv) the amortization of the fair value adjustment of the senior unsecured notes obtained as a result of the DPS Merger; (v) stock compensation expense and the associated windfall tax benefit attributable to the matching awards made to employees who made an initial investment in KDP; (vi) non-cash changes in deferred tax liabilities related to goodwill and other intangible assets as a result of tax rate or apportionment changes; and (vii) other certain items that are excluded for comparison purposes to prior year periods.
For the third quarter and first nine months of 2021, the other certain items excluded for comparison purposes include (i) restructuring and integration expenses related to significant business combinations; (ii) productivity expenses; (iii) costs related to significant non-routine legal matters; (iv) the loss on early extinguishment of debt related to the redemption of debt; (v) incremental costs to our operations related to risks associated with the COVID-19 pandemic; and (vi) gains from insurance recoveries related to the February 2019 organized malware attack on our business operation networks in the Coffee Systems segment.
For the third quarter and first nine months of 2020, the other certain items excluded for comparison purposes include (i) restructuring and integration expenses related to significant business combinations; (ii) productivity expenses; (iii) transaction costs for significant business combinations (completed or abandoned) excluding the DPS Merger; (iv) costs related to significant non-routine legal matters; (v) the loss on early extinguishment of debt related to the redemption of debt, (vi) incremental costs to our operations related to risks associated with the COVID-19 pandemic and (vii) impairment recognized on our equity method investments with Bedford and LifeFuels.
Incremental costs to our operations related to risks associated with the COVID-19 pandemic include incremental expenses incurred to either maintain the health and safety of our front-line employees or temporarily increase compensation to such employees to ensure essential operations continue during the pandemic. We believe removing these costs reflects how management views our business results on a consistent basis. See Impact of COVID-19 on our Financial Statements for further information.
For the third quarter and first nine months of 2021 and 2020, the supplemental financial data set forth below includes reconciliations of Adjusted income from operations, Adjusted interest expense, Adjusted provision for income taxes, Adjusted net income attributable to KDP and Adjusted diluted EPS to the applicable financial measure presented in the unaudited condensed consolidated financial statement for the same period.
KEURIG DR PEPPER INC.
RECONCILIATION OF CERTAIN REPORTED ITEMS TO CERTAIN NON-GAAP ADJUSTED ITEMS
For the Third Quarter of 2021
(Unaudited, in millions, except per share data)
| Cost of sales | Gross profit | Gross margin | Selling, general and administrative expenses | Income from operations | Operating margin | ||||||||||||||||||||||||||||||||||||||||||||||||
| Reported | $ | 1,415 | $ | 1,835 | 56.5 | % | $ | 1,040 | $ | 795 | 24.5 | % | |||||||||||||||||||||||||||||||||||||||||
| Items Affecting Comparability: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mark to market | 27 | (27) | (18) | (9) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of intangibles | — | — | (34) | 34 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Stock compensation | — | — | (3) | 3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Restructuring and integration costs | — | — | (53) | 53 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Productivity | (21) | 21 | (23) | 44 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Nonroutine legal matters | — | — | (7) | 7 | |||||||||||||||||||||||||||||||||||||||||||||||||
| COVID-19 | (3) | 3 | (1) | 4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Transaction costs | — | — | (1) | 1 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Malware incident | — | — | 1 | (1) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Adjusted | $ | 1,418 | $ | 1,832 | 56.4 | % | $ | 901 | $ | 931 | 28.6 | % |
| Interest expense | Income before provision for income taxes | Provision for income taxes | Effective tax rate | Net income attributable to KDP | Diluted earnings per share | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Reported | $ | 116 | $ | 678 | $ | 149 | 22.0 | % | $ | 530 | $ | 0.37 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Items Affecting Comparability: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mark to market | — | (9) | (3) | (6) | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of intangibles | — | 34 | 9 | 25 | 0.02 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of deferred financing costs | (2) | 2 | 2 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of fair value debt adjustment | (4) | 4 | 1 | 3 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Stock compensation | — | 3 | — | 3 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Restructuring and integration costs | — | 53 | 13 | 40 | 0.03 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Productivity | — | 44 | 11 | 33 | 0.02 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loss on early extinguishment of debt | — | — | (1) | 1 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Nonroutine legal matters | — | 7 | 2 | 5 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| COVID-19 | — | 4 | 1 | 3 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Transaction costs | — | 1 | — | 1 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Malware incident | — | (1) | (1) | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Change in deferred tax liabilities related to goodwill and other intangible assets | — | — | 7 | (7) | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Adjusted | $ | 110 | $ | 820 | $ | 190 | 23.2 | % | $ | 631 | $ | 0.44 |
Diluted earnings per common share may not foot due to rounding.
KEURIG DR PEPPER INC.
RECONCILIATION OF CERTAIN REPORTED ITEMS TO CERTAIN NON-GAAP ADJUSTED ITEMS
For the Third Quarter of 2020
(Unaudited, in millions, except per share data)
| Cost of sales | Gross profit | Gross margin | Selling, general and administrative expenses | Income from operations | Operating margin | ||||||||||||||||||||||||||||||||||||||||||
| Reported | $ | 1,316 | $ | 1,704 | 56.4 | % | $ | 949 | $ | 753 | 24.9 | % | |||||||||||||||||||||||||||||||||||
| Items Affecting Comparability: | |||||||||||||||||||||||||||||||||||||||||||||||
| Mark to market | 46 | (46) | (1) | (45) | |||||||||||||||||||||||||||||||||||||||||||
| Amortization of intangibles | — | — | (34) | 34 | |||||||||||||||||||||||||||||||||||||||||||
| Stock compensation | — | — | (6) | 6 | |||||||||||||||||||||||||||||||||||||||||||
| Restructuring and integration costs | — | — | (39) | 39 | |||||||||||||||||||||||||||||||||||||||||||
| Productivity | (10) | 10 | (20) | 30 | |||||||||||||||||||||||||||||||||||||||||||
| Nonroutine legal matters | — | — | (8) | 8 | |||||||||||||||||||||||||||||||||||||||||||
| COVID-19 | (19) | 19 | (30) | 49 | |||||||||||||||||||||||||||||||||||||||||||
| Adjusted | $ | 1,333 | $ | 1,687 | 55.9 | % | $ | 811 | $ | 874 | 28.9 | % |
| Interest expense | Impairment of investments and note receivable | Income before provision for income taxes | Provision for income taxes | Effective tax rate | Net income including non-controlling interest | Diluted earnings per share | |||||||||||||||||||||||||||||||||||||||||||||||
| Reported | $ | 148 | $ | 16 | $ | 584 | $ | 141 | 24.1 | % | $ | 443 | $ | 0.31 | |||||||||||||||||||||||||||||||||||||||
| Items Affecting Comparability: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mark to market | (1) | — | (44) | (13) | (31) | (0.02) | |||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of intangibles | — | — | 34 | 9 | 25 | 0.02 | |||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of deferred financing costs | (2) | — | 2 | 1 | 1 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of fair value debt adjustment | (6) | — | 6 | 1 | 5 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Stock compensation | — | — | 6 | 1 | 5 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Restructuring and integration costs | — | — | 39 | 8 | 31 | 0.02 | |||||||||||||||||||||||||||||||||||||||||||||||
| Productivity | — | — | 30 | 8 | 22 | 0.02 | |||||||||||||||||||||||||||||||||||||||||||||||
| Impairment on Investment | — | (16) | 16 | 4 | 12 | 0.01 | |||||||||||||||||||||||||||||||||||||||||||||||
| Nonroutine legal matters | — | — | 8 | 1 | 7 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| COVID-19 | — | — | 49 | 12 | 37 | 0.03 | |||||||||||||||||||||||||||||||||||||||||||||||
| Adjusted | $ | 139 | $ | — | $ | 730 | $ | 173 | 23.7 | % | $ | 557 | $ | 0.39 |
Diluted earnings per common share may not foot due to rounding.
KEURIG DR PEPPER INC.
RECONCILIATION OF CERTAIN REPORTED ITEMS TO CERTAIN NON-GAAP ADJUSTED ITEMS
For the First Nine Months of 2021
(Unaudited, in millions, except per share data)
| Cost of sales | Gross profit | Gross margin | Selling, general and administrative expenses | Income from operations | Operating margin | ||||||||||||||||||||||||||||||||||||||||||
| Reported | $ | 4,087 | $ | 5,205 | 56.0 | % | $ | 3,040 | $ | 2,169 | 23.3 | % | |||||||||||||||||||||||||||||||||||
| Items Affecting Comparability: | |||||||||||||||||||||||||||||||||||||||||||||||
| Mark to market | 53 | (53) | 32 | (85) | |||||||||||||||||||||||||||||||||||||||||||
| Amortization of intangibles | — | — | (101) | 101 | |||||||||||||||||||||||||||||||||||||||||||
| Stock compensation | — | — | (14) | 14 | |||||||||||||||||||||||||||||||||||||||||||
| Restructuring and integration costs | — | — | (145) | 145 | |||||||||||||||||||||||||||||||||||||||||||
| Productivity | (43) | 43 | (72) | 115 | |||||||||||||||||||||||||||||||||||||||||||
| Nonroutine legal matters | — | — | (23) | 23 | |||||||||||||||||||||||||||||||||||||||||||
| COVID-19 | (22) | 22 | (9) | 31 | |||||||||||||||||||||||||||||||||||||||||||
| Transaction costs | — | — | (1) | 1 | |||||||||||||||||||||||||||||||||||||||||||
| Malware incident | — | — | 3 | (3) | |||||||||||||||||||||||||||||||||||||||||||
| Adjusted | $ | 4,075 | $ | 5,217 | 56.1 | % | $ | 2,710 | $ | 2,511 | 27.0 | % |
| Interest expense | Loss on early extinguishment of debt | Income before provision for income taxes | Provision for income taxes | Effective tax rate | Net income attributable to KDP | Diluted earnings per share | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Reported | $ | 381 | $ | 105 | $ | 1,689 | $ | 387 | 22.9 | % | $ | 1,303 | $ | 0.91 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Items Affecting Comparability: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mark to market | 7 | — | (92) | (23) | (69) | (0.05) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of intangibles | — | — | 101 | 26 | 75 | 0.05 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of deferred financing costs | (6) | — | 6 | 2 | 4 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of fair value debt adjustment | (14) | — | 14 | 3 | 11 | 0.01 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Stock compensation | — | — | 14 | 14 | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Restructuring and integration costs | — | — | 145 | 35 | 110 | 0.08 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Productivity | — | — | 115 | 29 | 86 | 0.06 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loss on early extinguishment of debt | — | (105) | 105 | 24 | 81 | 0.06 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Nonroutine legal matters | — | — | 23 | 5 | 18 | 0.01 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| COVID-19 | — | — | 31 | 8 | 23 | 0.02 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Transaction costs | — | — | 1 | — | 1 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Malware incident | — | — | (3) | (1) | (2) | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Change in deferred tax liabilities related to goodwill and other intangible assets | — | — | — | 1 | (1) | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Adjusted | $ | 368 | $ | — | $ | 2,149 | $ | 510 | 23.7 | % | $ | 1,640 | $ | 1.15 |
Diluted earnings per common share may not foot due to rounding.
KEURIG DR PEPPER INC.
RECONCILIATION OF CERTAIN REPORTED ITEMS TO CERTAIN NON-GAAP ADJUSTED ITEMS
For the First Nine Months of 2020
(Unaudited, in millions, except per share data)
| Cost of sales | Gross profit | Gross margin | Selling, general and administrative expenses | Income from operations | Operating margin | ||||||||||||||||||||||||||||||||||||||||||
| Reported | $ | 3,779 | $ | 4,718 | 55.5 | % | $ | 2,978 | $ | 1,780 | 20.9 | % | |||||||||||||||||||||||||||||||||||
| Items Affecting Comparability: | |||||||||||||||||||||||||||||||||||||||||||||||
| Mark to market | 2 | (2) | (28) | 26 | |||||||||||||||||||||||||||||||||||||||||||
| Amortization of intangibles | — | — | (100) | 100 | |||||||||||||||||||||||||||||||||||||||||||
| Stock compensation | — | — | (21) | 21 | |||||||||||||||||||||||||||||||||||||||||||
| Restructuring and integration costs | — | — | (143) | 143 | |||||||||||||||||||||||||||||||||||||||||||
| Productivity | (28) | 28 | (75) | 103 | |||||||||||||||||||||||||||||||||||||||||||
| Nonroutine legal matters | — | — | (43) | 43 | |||||||||||||||||||||||||||||||||||||||||||
| COVID-19 | (38) | 38 | (79) | 117 | |||||||||||||||||||||||||||||||||||||||||||
| Adjusted | $ | 3,715 | $ | 4,782 | 56.3 | % | $ | 2,489 | $ | 2,333 | 27.5 | % |
| Interest expense | Loss on early extinguishment of debt | Impairment of investment and note receivable | Income before provision for income taxes | Provision for income taxes | Effective tax rate | Net income attributable to KDP | Diluted earnings per share | ||||||||||||||||||||||||||||||||||||||||
| Reported | $ | 458 | $ | 4 | $ | 102 | $ | 1,195 | $ | 298 | 24.9 | % | $ | 897 | $ | 0.63 | |||||||||||||||||||||||||||||||
| Items Affecting Comparability: | |||||||||||||||||||||||||||||||||||||||||||||||
| Mark to market | (28) | — | — | 54 | 13 | 41 | 0.03 | ||||||||||||||||||||||||||||||||||||||||
| Amortization of intangibles | — | — | — | 100 | 27 | 73 | 0.05 | ||||||||||||||||||||||||||||||||||||||||
| Amortization of deferred financing costs | (8) | — | — | 8 | 2 | 6 | — | ||||||||||||||||||||||||||||||||||||||||
| Amortization of fair value debt adjustment | (18) | — | — | 18 | 4 | 14 | 0.01 | ||||||||||||||||||||||||||||||||||||||||
| Stock compensation | — | — | — | 21 | 4 | 17 | 0.01 | ||||||||||||||||||||||||||||||||||||||||
| Restructuring and integration costs | — | — | 143 | 34 | 109 | 0.08 | |||||||||||||||||||||||||||||||||||||||||
| Productivity | — | — | — | 103 | 27 | 76 | 0.05 | ||||||||||||||||||||||||||||||||||||||||
| Loss on early extinguishment of debt | — | (4) | — | 4 | 1 | 3 | — | ||||||||||||||||||||||||||||||||||||||||
| Impairment of investment and note receivable | — | — | (102) | 102 | 25 | 77 | 0.05 | ||||||||||||||||||||||||||||||||||||||||
| Nonroutine legal matters | — | — | — | 43 | 10 | 33 | 0.02 | ||||||||||||||||||||||||||||||||||||||||
| COVID-19 | — | — | — | 117 | 29 | 88 | 0.06 | ||||||||||||||||||||||||||||||||||||||||
| Adjusted | $ | 404 | $ | — | $ | — | $ | 1,908 | $ | 474 | 24.8 | % | $ | 1,434 | $ | 1.01 |
Diluted earnings per common share may not foot due to rounding.
KEURIG DR PEPPER INC.
RECONCILIATION OF SEGMENT ITEMS TO CERTAIN NON-GAAP ADJUSTED SEGMENT ITEMS
(Unaudited)
| (in millions) | Reported | Items Affecting Comparability | Adjusted GAAP | ||||||||||||||
| For the third quarter of 2021: | |||||||||||||||||
| Income from Operations | |||||||||||||||||
| Coffee Systems | $ | 334 | $ | 43 | $ | 377 | |||||||||||
| Packaged Beverages | 288 | 24 | 312 | ||||||||||||||
| Beverage Concentrates | 286 | 3 | 289 | ||||||||||||||
| Latin America Beverages | 37 | — | 37 | ||||||||||||||
| Unallocated corporate costs | (150) | 66 | (84) | ||||||||||||||
| Total income from operations | $ | 795 | $ | 136 | $ | 931 | |||||||||||
| For the third quarter of 2020: | |||||||||||||||||
| Income from Operations | |||||||||||||||||
| Coffee Systems | $ | 320 | $ | 53 | $ | 373 | |||||||||||
| Packaged Beverages | 260 | 44 | 304 | ||||||||||||||
| Beverage Concentrates | 262 | 3 | 265 | ||||||||||||||
| Latin America Beverages | 25 | — | 25 | ||||||||||||||
| Unallocated corporate costs | (114) | 21 | (93) | ||||||||||||||
| Total income from operations | $ | 753 | $ | 121 | $ | 874 |
KEURIG DR PEPPER INC.
RECONCILIATION OF SEGMENT ITEMS TO CERTAIN NON-GAAP ADJUSTED SEGMENT ITEMS
(Unaudited)
| (in millions) | Reported | Items Affecting Comparability | Adjusted GAAP | ||||||||||||||
| For the first nine months of 2021: | |||||||||||||||||
| Income from Operations | |||||||||||||||||
| Coffee Systems | $ | 992 | $ | 145 | $ | 1,137 | |||||||||||
| Packaged Beverages | 721 | 74 | 795 | ||||||||||||||
| Beverage Concentrates | 778 | 6 | 784 | ||||||||||||||
| Latin America Beverages | 95 | 2 | 97 | ||||||||||||||
| Unallocated corporate costs | (417) | 115 | (302) | ||||||||||||||
| Total income from operations | $ | 2,169 | $ | 342 | $ | 2,511 | |||||||||||
| For the first nine months of 2020: | |||||||||||||||||
| Income from Operations | |||||||||||||||||
| Coffee Systems | $ | 882 | $ | 201 | $ | 1,083 | |||||||||||
| Packaged Beverages | 657 | 119 | 776 | ||||||||||||||
| Beverage Concentrates | 679 | 5 | 684 | ||||||||||||||
| Latin America Beverages | 73 | 2 | 75 | ||||||||||||||
| Unallocated corporate costs | (511) | 226 | (285) | ||||||||||||||
| Total income from operations | $ | 1,780 | $ | 553 | $ | 2,333 |
Previous: Item 1. Financial Statements (Unaudited) · Next: Item 3. Quantitative and Qualitative Disclosures About Market Risk