 filings.tools
KeyCorp (KEY) 10-K risk factor changes: FY2023 vs FY2022
The 2023-12-31 10-K against the 2022-12-31 one, compared heading by heading and sentence by sentence.
Item 1A172 rewritten392 added62 removed160 unchanged
All filing items2,168 rewritten1,553 added839 removed3,657 unchanged
Summary
counted, not written
- Item 1A lists 35 risk factor headings: 4 new, 4 reworded and 27 unchanged since FY2022. 2 headings from FY2022 no longer appear.
- Sentence by sentence, 1,553 added, 839 removed, 2,168 rewritten and 3,657 unchanged across 20 items that differ.
- New this year: Item 1C. CYBERSECURITY.
New Item 1A headings (4)
- Geopolitical destabilization could adversely impact our loan portfolios.
- We are subject to complex and evolving laws and regulations regarding privacy and cybersecurity, which could limit our ability to pursue business initiatives, increase the cost of doing business and subject us to compliance risks and potential liability.Cybersecurity
- Depressed market values for our common stock and adverse economic conditions sustained over a period of time may require us to write down all or some portion of our goodwill.
- Key is subject to environmental, social, and governance (ESG) risks that could adversely affect our reputation, the trading price of our common stock and/or our business and results of operations.
Removed Item 1A headings (2)
- Any failure by the U.S. federal government to increase the debt ceiling or any government shutdown could adversely affect the U.S. and global economy and our liquidity, financial condition and earnings.
- Uncertainty surrounding the transition from LIBOR to an alternate reference rate may adversely affect our business.
Reworded Item 1A headings (4)
- Various factors may cause our allowance for loan and lease losses to
[removed: increase.][added: increase or to be inadequate.] - We
[removed: are][added: are, and may in the future be,] subject to[removed: claims and][added: claims,] litigation, [added: investigations, and governmental proceedings,] which could result in significant financial liability and/or reputational[removed: risk.][added: harm.] - Societal [added: and governmental] responses to climate change could adversely affect Key’s business and performance, including indirectly through impacts on Key’s customers.
- Maintaining or increasing our market share depends upon our ability to adapt our products and services to evolving industry standards and consumer preferences, while maintaining competitive
[removed: prices.][added: products and services.]
A heading is new when no FY2022 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
24 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2022. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
172 rewritten, 392 added, 62 removed, 160 unchanged
As of December 31, [removed: 2022,] [added: 2023,] approximately 69% of our loan portfolio consisted of commercial and industrial loans, commercial real estate loans, including commercial mortgage and construction loans, and commercial leases.
Recent [removed: and ongoing] Federal Reserve monetary policy, including shrinkage of its balance sheet and incremental increases in target interest [removed: rates, have begun to impact the commercial and residential real estate markets.][added: rates early in 2023 followed by a sustained period of relatively high target interest rates throughout]
[removed: Capitalization rates] are rising, and property value appreciation has slowed or [removed: ceased altogether.][added: is now declining.]
In many markets within Key’s footprint, [removed: property values have begun to decrease.]
[removed: Multifamily and industrial properties continue to remain stable, but] office, [removed: retail,] hospitality, and single family detached properties are beginning to show [removed: early] signs of [removed: potential] deterioration.
[removed: Development] and construction continue, but at muted levels, and deliveries of additional units into the market have been supported.
The most severely impacted commercial real estate segments have been in [removed: office and retail.][added: office.]
Key’s non-owner occupied office [removed: and retail] exposures are [removed: 12%] [added: 5%] of our total commercial real estate exposure.
Substantial deterioration in property market fundamentals could negatively impact our portfolio, with a large portion of our clients active in real estate but in the comparatively better performing multifamily [removed: space.][added: space over the cycle.]
[removed: A] relatively small portion of our commercial real estate loans are construction loans.
New construction and value-add or rehabilitation construction projects [removed: are][added: may not be fully leased at loan origination.]
[removed: [Table](#i5a468b8a075b404bb1614017a87fbb3f_13) [of contents](#i5a468b8a075b404bb1614017a87fbb3f_13)][added: [Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)]
Many of our routine transactions expose us to credit risk, including the risk of default of our [removed: counterparty] [added: counterparties, which include other financial institutions,] or [removed: client.][added: clients.]
In deciding whether to extend credit or enter into other transactions, we rely on information furnished by or on [removed: behalf of counterparties and clients, including financial statements, credit reports and other information.]
[removed: We also rely] on representations of those counterparties, clients, or other third parties as to the accuracy and completeness of that information.
[removed: Given] [added: In addition, given] the Dodd-Frank legislative mandate to centrally clear eligible derivative contracts, we rely on central clearing counterparties to remain open and operationally viable at all times.
[removed: Various] [added: ◦Various] factors may cause our allowance for loan and lease losses to [removed: increase.][added: increase or to be inadequate.]
The level of the allowance at December 31, [removed: 2022] [added: 2023] represents management’s estimate of expected credit losses over the contractual life of our existing loan portfolio.
Changes in economic conditions affecting borrowers, the softening of certain macroeconomic variables that we are more susceptible to, such as GDP, unemployment, [removed: SOFR,] [added: SOFR and other interest rates, the] producer price index, [removed: industrial production, interest rates] and real estate values, along with updated information regarding existing loans, identification of additional problem loans and other factors, both within and outside of our control, may indicate the need for an increase in the ALLL.
During [removed: the Great Recession,] [added: periods of economic stress,] the volatility and disruption that the capital and credit markets [removed: experienced reached] [added: experience may reach, and have in the past reached,] extreme levels.
Asset price deterioration has a negative effect on the valuation of [added: collateral and] certain of the asset categories represented on our balance sheet and reduces our ability to sell assets at prices we deem acceptable.
The most recent recession, resulting from the impact of the COVID-19 pandemic, did not have significant lasting [removed: impact on collateral value.]
- [removed: Further supply] [added: Supply] chain issues such as closed factories and disrupted port [removed: activity] [added: activity,] as well as the impact of the Russia-Ukraine [removed: conflict] [added: war and the Israel-Hamas war] on [added: global] transportation and [added: the] availability of materials;
- Labor-supply [removed: constraints could continue longer than anticipated,] [added: constraints,] leading to slowing job growth and boosting wages along with inflation (wage-price spiral); and
- Negative [removed: GDP,] [added: GDP growth,] as a result of, in part, the Federal Reserve’s monetary policy efforts to arrest inflationary pressures within the broader economy.
As a financial services institution, we are subject to extensive federal and state regulation, supervision, and tax [removed: legislation.]
Banking regulations are primarily intended to protect depositors’ funds, the DIF, consumers, taxpayers, [removed: and the banking system as a whole, not our debtholders or shareholders.]
[removed: These regulations increase our costs and] affect our lending practices, capital structure, investment practices, dividend policy, ability to repurchase our common shares, and growth, among other things.
KeyBank and KeyCorp remain covered institutions under the Dodd-Frank Act’s heightened prudential standards [removed: and regulations, including its provisions designed to protect consumers from financial abuse.]
As new privacy-related laws and regulations, [removed: such as the California Consumer Privacy Act,] [added: and judicially-created frameworks,] are implemented in jurisdictions in which KeyBank operates, the time and resources needed for us to comply with such laws and regulations, as well as our potential liability for noncompliance and reporting obligations in the case of data breaches, may significantly increase.
Changes to existing statutes and regulations, and taxes (including industry-specific taxes and surcharges), or their [removed: interpretation or implementation, could affect us in substantial and unpredictable ways.]
[removed: Interpretation of consumer] banking-related regulations may evolve as the industry and the regulators seek to increase access to banking products and services by consumers.
Such changes may [added: subject us to additional costs, adversely impact our income, and increase our litigation risk should we fail to appropriately comply and may] also impact consumer behavior, limit the types of financial services and products we may offer, affect the investments we make, and change the manner in which we operate.
Certain federal regulations have been in existence for decades without modification to account for modern banking [removed: practices, such as digital delivery of products and services, which can create challenges in execution and in the examination process.]
Emerging technologies, such as cryptocurrencies, could limit KeyBank’s ability to track the [removed: movement of funds.]
KeyBank’s ability to comply with BSA/AML and other regulations is dependent on its ability to [removed: improve detection and reporting capabilities and reduce variation in control processes and oversight accountability.]
This enforcement authority includes, among other things, the ability to assess civil money penalties, fines, or restitution, [removed: to issue cease and desist or removal orders, and to initiate injunctive actions against banking organizations and affiliated parties.]
These enforcement actions may be initiated for violations of laws and regulations, for practices [removed: determined to be unsafe or unsound, or for practices or acts that are determined to be unfair, deceptive, or abusive.]
Failure to comply with these and other regulations, and supervisory expectations related thereto, may result in fines, [removed: penalties, lawsuits, regulatory sanctions, reputational damage, or restrictions on our business.]
[removed: Moreover, different] government administrations may have different regulatory priorities, which may impact the level of regulation of [removed: financial institutions and the enforcement environment.]
Summary of Risk Factors
The following is a summary of some of the material risks and uncertainties that could have an adverse effect on our business.
- Credit Risk
◦We have concentrated credit exposure in commercial and industrial loans, commercial real estate loans, and commercial leases.
◦Should the fundamentals of the commercial real estate market deteriorate, our financial condition and results of operations could be adversely affected.
◦We are subject to the risk of defaults by our loan clients and counterparties.
◦Declining asset prices could adversely affect us.
◦Geopolitical destabilization could adversely impact our loan portfolios.
- Compliance Risk
◦We are subject to extensive government regulation, supervision, and tax legislation.
◦We are subject to complex and evolving laws and regulations regarding privacy and cybersecurity, which could limit our ability to pursue business initiatives, increase the cost of doing business and subject us to compliance risks and potential liability.
◦Changes in accounting policies, standards, and interpretations could materially affect how we report our financial condition and results of operations.
- Operational Risk
◦We are subject to a variety of operational risks.
◦We and third parties on which we rely (including their downstream service providers) may experience a cyberattack, technology failure, information system or security breach or interruption.
◦We rely on third parties to perform significant operational services for us.
◦Our controls and procedures may fail or be circumvented, and our methods of reducing risk exposure may not be effective.
◦Our operations and financial performance could be adversely affected by severe weather and natural disasters exacerbated by climate change.
◦The increased use of remote work infrastructure has expanded potential attack vectors and resulted in increased operational risks.
- Liquidity Risk
◦Capital and liquidity requirements imposed by banking regulations require banks and BHCs to maintain more and higher quality capital and more and higher quality liquid assets.
◦Federal agencies’ actions to ensure stability of the U.S. financial system may have disruptive effects on us.
◦We rely on dividends by our subsidiaries for most of our funds.
◦We are subject to liquidity risk, which could negatively affect our funding levels.
◦Our credit ratings affect our liquidity position.
- Market Risk
◦A worsening of the U.S. economy and volatile or recessionary conditions in the U.S. or abroad could negatively affect our business or our access to capital markets.
◦We are subject to interest rate risk, which could adversely affect net interest income.
◦Our profitability depends upon economic conditions in the geographic regions where we have significant operations and in certain market segments in which we conduct significant business.
◦The soundness of other financial institutions could adversely affect us.
◦Depressed market values for our common stock and adverse economic conditions sustained over a period of time may require us to write down all or some portion of our goodwill.
- Reputation Risk
◦Damage to our reputation could significantly impact our business and major stakeholders.
◦Key is subject to environmental, social, and governance (ESG) risks that could adversely affect our reputation, the trading price of our common stock and/or our business and results of operations.
- Strategic Risk
◦We may not realize the expected benefits of our strategic initiatives.
◦We operate in a highly competitive industry.
◦We may not be able to attract and retain skilled people.
◦Acquisitions or strategic partnerships may disrupt our business and dilute shareholder value.
- Model Risk
However, our exposures in those markets are limited.
not fully leased at loan origination.
A large member failure or a cybersecurity breach could result in a counterparty or client disruption.
This severe market disruption led to the failure of several substantial financial institutions, which caused the credit markets to constrict and caused a widespread liquidation of assets.
These asset sales, along with asset sales by other leveraged investors, including some hedge funds, rapidly drove down prices and valuations across a wide variety of traded asset classes.
- Additional surges in COVID-19 cases leading to a decrease in economic activity;
Like similarly situated institutions, Key undergoes routine scrutiny from bank supervisors in the examination process and is subject to enforcement of regulations at the federal and state levels, particularly with respect to consumer banking-related practices, including fair and responsible banking, fair lending, unfair, deceptive or abusive practices, and the Community Reinvestment Act, as well as compliance with AML, BSA and Office of Foreign Assets Control efforts.
Federal rulemaking bodies continue to pass new, or modifications to, significant regulations with upcoming effective dates.
There has also been an increase in state legislative activity, particularly in areas such as student lending and privacy.
These changes may subject us to additional costs and increase our litigation risk should we fail to appropriately comply.
U.S. financial service
Over the last few years, several large companies have disclosed that they or their service providers suffered substantial data security breaches, compromising millions of user accounts and credentials.
The risk of cyberattacks has also increased and will continue to increase in connection with Russia’s invasion of Ukraine.
In light of the Ukraine war and other geopolitical events and dynamics, including ongoing tensions with North Korea, Iran and other countries, state-sponsored parties or their supporters may launch retaliatory cyberattacks, and may attempt to cause supply chain disruptions, or carry out other geopolitically motivated retaliatory actions that may adversely disrupt or degrade our operations and may result in data compromise.
State-sponsored parties have, and will continue, to conduct cyberattacks to achieve their goals that may include espionage, monetary gain, disruption, and destruction.
To accomplish their goals, state-sponsored parties and other cyber criminals have used, and may continue to use, various attack vectors and methods as discussed above.
For example, we previously announced that we plan to operate our primary platforms and applications on Google Cloud infrastructure.
If this planned transition is delayed or impacts the reliability and availability of our services, we may not realize our financial and strategic objectives.
If a critical third party is unable to meet our needs in a timely manner or if the services or products provided by such third party are terminated or otherwise delayed and if we are not able to identify or develop alternative sources for these services and products quickly and cost-effectively, it could have a material adverse effect on our business.
From time to time, customers, vendors, or other parties may make claims and take legal action against us.
The outcome of regulatory matters as well as the timing of ultimate resolution are inherently difficult to predict.
The systems may not work as
Natural disasters could have a material adverse effect on our financial position and results of operations, and the timing and effects of any natural disaster cannot accurately be predicted.
The frequency and severity of some types of natural disasters, including wildfires, tornadoes, severe storms, and hurricanes, have increased as a result of climate change, which further reduces our ability to predict their effects accurately.
These and other natural disasters could affect Key directly (for example, by interrupting our systems, damaging our facilities or otherwise preventing us from conducting our business in the ordinary course) or indirectly (for example, by damaging or destroying customer businesses or otherwise impairing customers’ ability to repay their loans, or by damaging or destroying property pledged as collateral for loans made by Key).
The results of these processes are difficult to predict due, among other things, to the Federal Reserve’s use of proprietary stress models that differ from our internal models and may result in the Federal Reserve imposing capital requirements in excess of our expectations which could require us, as applicable, to revise our stress-testing or capital management approaches, resubmit our capital plan or postpone, cancel, or alter or planned capital actions.
The discontinuation and, in some cases, reversal of such initiatives have since impacted financial markets and our business.
Additionally, new initiatives or legislation may not be implemented, or, if implemented, may not be adequate to counter any negative effects of discontinuing programs or, in the event of an economic downturn, to support and stabilize the economy.
Any failure by the U.S. federal government to increase the debt ceiling or any government shutdown could adversely affect the U.S. and global economy and our liquidity, financial condition and earnings.
U.S. debt ceiling and budget deficit concerns have increased the possibility of credit-rating downgrades and economic slowdowns, or a recession in the United States or globally.
The U.S. federal government hit its borrowing limit, or debt ceiling, on January 19, 2023.
If the government fails to increase the debt limit, the U.S. government’s sovereign credit rating may be downgraded and the U.S. government could default on its debts, which could adversely affect the U.S. and global financial markets, banking systems, and economic conditions.
Absent intervention by the Federal Reserve, these developments could cause interest rates and borrowing costs to further increase, which may negatively impact our ability to access the debt markets, including the corporate bond markets, on favorable terms.
In addition, disagreement over the federal budget has previously caused the U.S. federal government to shut down for periods of time.
An extended period of shutdown of portions of the U.S. federal government could negatively impact the financial performance of certain customers and could negatively impact customers’ future access to certain loan and guaranty programs.
Interest rates are highly sensitive to many factors that are beyond our control, including general economic conditions, the competitive environment within our markets, consumer preferences for specific loan and deposit products, and policies of various governmental and regulatory agencies, in particular, the Federal Reserve.
Changes in monetary policy, including changes in interest rate controls being applied by the Federal Reserve, could influence the amount of interest we receive on loans and securities, the amount of interest we pay on deposits and borrowings, our ability to originate loans and obtain deposits, and the fair value of our financial assets and liabilities.
Uncertainty surrounding the transition from LIBOR to an alternate reference rate may adversely affect our business.
On July 27, 2017, the Chief Executive of the United Kingdom Financial Conduct Authority (the “Authority”), which regulates LIBOR, announced that the Authority intends to stop persuading or compelling banks to submit rates for the calculation of LIBOR to the administrator of LIBOR after 2021.
On March 5, 2021, ICE Benchmark Administration (“IBA”), the Authority-regulated and authorized administrator of LIBOR, confirmed, following a consultation process occurring during the end of 2020 and beginning of 2021, its intention to cease one-week and two-month USD LIBOR settings at December 31, 2021, and cease the USD LIBOR panel at June 30, 2023, effectively ceasing all other USD LIBOR tenors.
An excerpt. Shown here: 40 of 172 rewritten, 40 of 392 added and 40 of 62 removed. The counts are complete. For every sentence, read Item 1A. RISK FACTORS in the FY2023 filing and the FY2022 filing.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
560 rewritten, 340 added, 275 removed, 923 unchanged
| [Long-term financial [removed: targets](#i5a468b8a075b404bb1614017a87fbb3f_55)] [added: targets](#id35963ddccc041b2ab203b7e536286e2_55)] | | | [removed: [48](#i5a468b8a075b404bb1614017a87fbb3f_55)] [added: [49](#id35963ddccc041b2ab203b7e536286e2_55)] | | |
| [Corporate [removed: strategy](#i5a468b8a075b404bb1614017a87fbb3f_58)] [added: strategy](#id35963ddccc041b2ab203b7e536286e2_58)] | | | [removed: [49](#i5a468b8a075b404bb1614017a87fbb3f_58)] [added: [50](#id35963ddccc041b2ab203b7e536286e2_58)] | | |
| [Strategic [removed: developments](#i5a468b8a075b404bb1614017a87fbb3f_61)] [added: developments](#id35963ddccc041b2ab203b7e536286e2_61)] | | | [removed: [49](#i5a468b8a075b404bb1614017a87fbb3f_61)] [added: [50](#id35963ddccc041b2ab203b7e536286e2_61)] | | |
| [Results of [removed: Operations](#i5a468b8a075b404bb1614017a87fbb3f_64)] [added: Operations](#id35963ddccc041b2ab203b7e536286e2_64)] | | | [removed: [50](#i5a468b8a075b404bb1614017a87fbb3f_64)] [added: [51](#id35963ddccc041b2ab203b7e536286e2_64)] | | |
| [Earnings [removed: overview](#i5a468b8a075b404bb1614017a87fbb3f_67)] [added: overview](#id35963ddccc041b2ab203b7e536286e2_67)] | | | [removed: [50](#i5a468b8a075b404bb1614017a87fbb3f_67)] [added: [51](#id35963ddccc041b2ab203b7e536286e2_67)] | | |
| [Net interest [removed: income](#i5a468b8a075b404bb1614017a87fbb3f_70)] [added: income](#id35963ddccc041b2ab203b7e536286e2_70)] | | | [removed: [50](#i5a468b8a075b404bb1614017a87fbb3f_70)] [added: [51](#id35963ddccc041b2ab203b7e536286e2_70)] | | |
| [Provision for credit [removed: losses](#i5a468b8a075b404bb1614017a87fbb3f_73)] [added: losses](#id35963ddccc041b2ab203b7e536286e2_73)] | | | [removed: [53](#i5a468b8a075b404bb1614017a87fbb3f_73)] [added: [54](#id35963ddccc041b2ab203b7e536286e2_73)] | | |
| [removed: [Noninterest income](#i5a468b8a075b404bb1614017a87fbb3f_76)] [added: Noninterest income] | | | [removed: [53](#i5a468b8a075b404bb1614017a87fbb3f_76)] | | | [added: up 5%+ | | |]
| [Noninterest [removed: expense](#i5a468b8a075b404bb1614017a87fbb3f_79)] [added: expense](#id35963ddccc041b2ab203b7e536286e2_79)] | | | [removed: [55](#i5a468b8a075b404bb1614017a87fbb3f_79)] [added: [56](#id35963ddccc041b2ab203b7e536286e2_79)] | | |
| [Income [removed: taxes](#i5a468b8a075b404bb1614017a87fbb3f_82)] [added: taxes](#id35963ddccc041b2ab203b7e536286e2_82)] | | | [removed: [57](#i5a468b8a075b404bb1614017a87fbb3f_82)] [added: [58](#id35963ddccc041b2ab203b7e536286e2_82)] | | |
| [Business Segment [removed: Results](#i5a468b8a075b404bb1614017a87fbb3f_85)] [added: Results](#id35963ddccc041b2ab203b7e536286e2_85)] | | | [removed: [57](#i5a468b8a075b404bb1614017a87fbb3f_85)] [added: [58](#id35963ddccc041b2ab203b7e536286e2_85)] | | |
| [Consumer [removed: Bank](#i5a468b8a075b404bb1614017a87fbb3f_88)] [added: Bank](#id35963ddccc041b2ab203b7e536286e2_88)] | | | [removed: [57](#i5a468b8a075b404bb1614017a87fbb3f_88)] [added: [58](#id35963ddccc041b2ab203b7e536286e2_88)] | | |
| [Commercial [removed: Bank](#i5a468b8a075b404bb1614017a87fbb3f_91)] [added: Bank](#id35963ddccc041b2ab203b7e536286e2_91)] | | | [removed: [58](#i5a468b8a075b404bb1614017a87fbb3f_91)] [added: [59](#id35963ddccc041b2ab203b7e536286e2_91)] | | |
| [Financial [removed: Condition](#i5a468b8a075b404bb1614017a87fbb3f_94)] [added: Condition](#id35963ddccc041b2ab203b7e536286e2_94)] | | | [removed: [60](#i5a468b8a075b404bb1614017a87fbb3f_94)] [added: [61](#id35963ddccc041b2ab203b7e536286e2_94)] | | |
| [Loans and loans held for [removed: sale](#i5a468b8a075b404bb1614017a87fbb3f_97)] [added: sale](#id35963ddccc041b2ab203b7e536286e2_97)] | | | [removed: [60](#i5a468b8a075b404bb1614017a87fbb3f_97)] [added: [61](#id35963ddccc041b2ab203b7e536286e2_97)] | | |
| [Deposits and other sources of [removed: funds](#i5a468b8a075b404bb1614017a87fbb3f_103)] [added: funds](#id35963ddccc041b2ab203b7e536286e2_106)] | | | [removed: [69](#i5a468b8a075b404bb1614017a87fbb3f_103)] [added: [70](#id35963ddccc041b2ab203b7e536286e2_106)] | | |
| [Off-Balance Sheet Arrangements and Aggregate Contractual [removed: Obligations](#i5a468b8a075b404bb1614017a87fbb3f_109)] [added: Obligations](#id35963ddccc041b2ab203b7e536286e2_112)] | | | [removed: [71](#i5a468b8a075b404bb1614017a87fbb3f_109)] [added: [73](#id35963ddccc041b2ab203b7e536286e2_112)] | | |
| [Off-balance sheet [removed: arrangements](#i5a468b8a075b404bb1614017a87fbb3f_112)] [added: arrangements](#id35963ddccc041b2ab203b7e536286e2_115)] | | | [removed: [71](#i5a468b8a075b404bb1614017a87fbb3f_112)] [added: [73](#id35963ddccc041b2ab203b7e536286e2_115)] | | |
| [Market risk [removed: management](#i5a468b8a075b404bb1614017a87fbb3f_127)] [added: management](#id35963ddccc041b2ab203b7e536286e2_130)] | | | [removed: [74](#i5a468b8a075b404bb1614017a87fbb3f_127)] [added: [76](#id35963ddccc041b2ab203b7e536286e2_130)] | | |
| [Liquidity risk [removed: management](#i5a468b8a075b404bb1614017a87fbb3f_130)] [added: management](#id35963ddccc041b2ab203b7e536286e2_133)] | | | [removed: [80](#i5a468b8a075b404bb1614017a87fbb3f_130)] [added: [82](#id35963ddccc041b2ab203b7e536286e2_133)] | | |
| [Credit risk [removed: management](#i5a468b8a075b404bb1614017a87fbb3f_133)] [added: management](#id35963ddccc041b2ab203b7e536286e2_136)] | | | [removed: [83](#i5a468b8a075b404bb1614017a87fbb3f_133)] [added: [85](#id35963ddccc041b2ab203b7e536286e2_136)] | | |
| [Operational and compliance risk [removed: management](#i5a468b8a075b404bb1614017a87fbb3f_136)] [added: management](#id35963ddccc041b2ab203b7e536286e2_139)] | | | [removed: [87](#i5a468b8a075b404bb1614017a87fbb3f_136)] [added: [88](#id35963ddccc041b2ab203b7e536286e2_139)] | | |
| [GAAP to Non-GAAP [removed: Reconciliations](#i5a468b8a075b404bb1614017a87fbb3f_139)] [added: Reconciliations](#id35963ddccc041b2ab203b7e536286e2_142)] | | | [removed: [89](#i5a468b8a075b404bb1614017a87fbb3f_139)] [added: [89](#id35963ddccc041b2ab203b7e536286e2_142)] | | |
| [Critical Accounting Policies and [removed: Estimates](#i5a468b8a075b404bb1614017a87fbb3f_172)] [added: Estimates](#id35963ddccc041b2ab203b7e536286e2_175)] | | | [removed: [90](#i5a468b8a075b404bb1614017a87fbb3f_172)] [added: [90](#id35963ddccc041b2ab203b7e536286e2_175)] | | |
| [Allowance for loan and lease [removed: losses](#i5a468b8a075b404bb1614017a87fbb3f_175)] [added: losses](#id35963ddccc041b2ab203b7e536286e2_178)] | | | [removed: [90](#i5a468b8a075b404bb1614017a87fbb3f_175)] [added: [91](#id35963ddccc041b2ab203b7e536286e2_178)] | | |
| [Derivatives and [removed: hedging](#i5a468b8a075b404bb1614017a87fbb3f_181)] [added: hedging](#id35963ddccc041b2ab203b7e536286e2_184)] | | | [removed: [93](#i5a468b8a075b404bb1614017a87fbb3f_181)] [added: [94](#id35963ddccc041b2ab203b7e536286e2_184)] | | |
| [Contingent liabilities, guarantees and income [removed: taxes](#i5a468b8a075b404bb1614017a87fbb3f_184)] [added: taxes](#id35963ddccc041b2ab203b7e536286e2_187)] | | | [removed: [93](#i5a468b8a075b404bb1614017a87fbb3f_184)] [added: [94](#id35963ddccc041b2ab203b7e536286e2_187)] | | |
| [Accounting and reporting [removed: developments](#i5a468b8a075b404bb1614017a87fbb3f_187)] [added: developments](#id35963ddccc041b2ab203b7e536286e2_190)] | | | [removed: [94](#i5a468b8a075b404bb1614017a87fbb3f_187)] [added: [95](#id35963ddccc041b2ab203b7e536286e2_190)] | | |
[removed: [Table](#i5a468b8a075b404bb1614017a87fbb3f_13) [of contents](#i5a468b8a075b404bb1614017a87fbb3f_13)][added: [Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)]
This section reviews the financial condition and results of operations of KeyCorp and its subsidiaries for [removed: 2022] [added: 2023] and [removed: 2021.][added: 2022.]
To review our financial condition and results of operations for [removed: 2020] [added: 2021] and a comparison between the [removed: 2020 and] 2021 [added: and 2022] results, see Item 7.
Management’s Discussion and Analysis of Financial Condition and Results of Operations of our [removed: [202](https://www.sec.gov/Archives/edgar/data/91576/000009157622000029/key-20211231.htm)[1](https://www.sec.gov/Archives/edgar/data/91576/000009157622000029/key-20211231.htm) [Form 10-K](https://www.sec.gov/Archives/edgar/data/91576/000009157622000029/key-20211231.htm)] [added: [2022 Form 10-K](https://www.sec.gov/ix?doc=/Archives/edgar/data/91576/000009157623000026/key-20221231.htm)] filed with the SEC on February 22, [removed: 2022,] [added: 2023,] which discussion is incorporated herein by reference.
[removed: 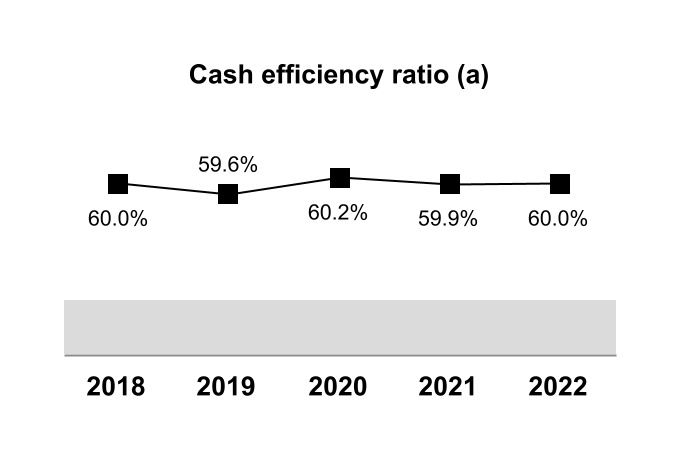][added: 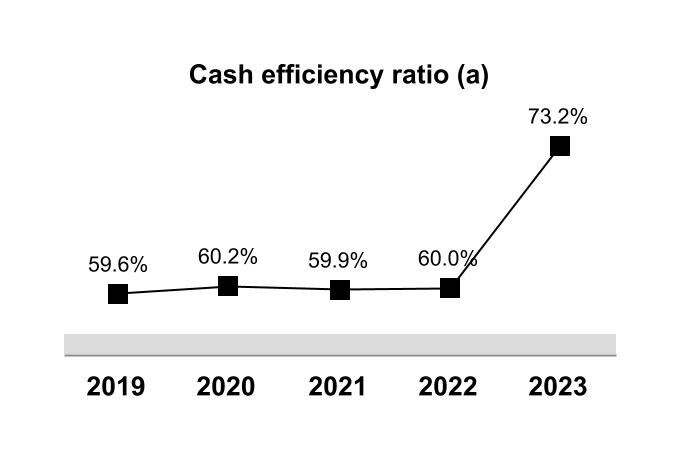]
[removed: ][added: 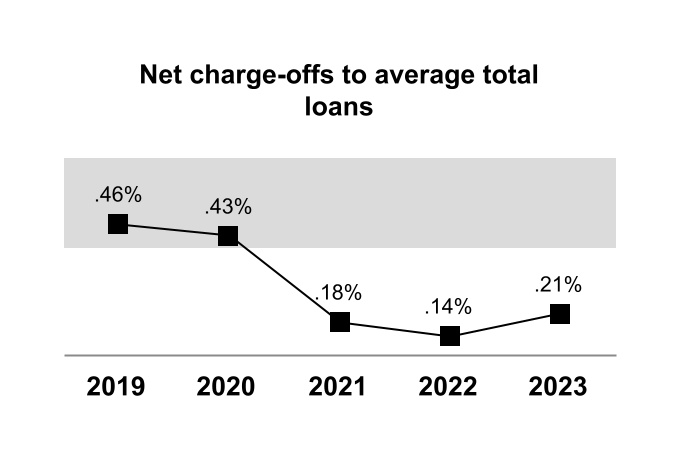]
[removed: 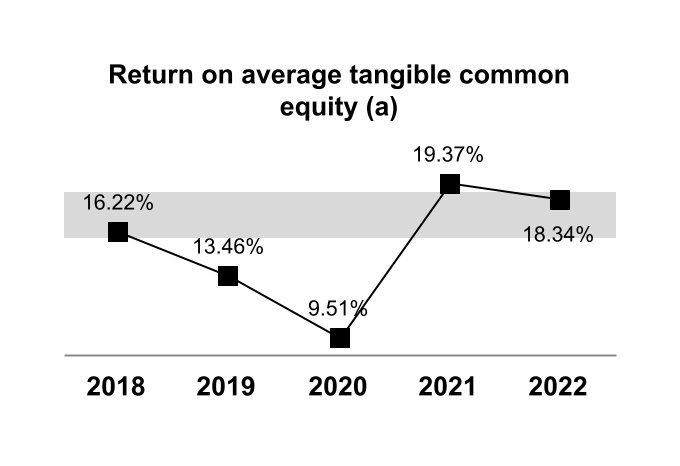][added: ]
Our net charge-offs to average loans ratio remains [removed: at a] [added: near] historically low [removed: level.][added: levels and continues to reflect our proven underwrite-to-distribute model.]
We remain committed to enhancing long-term shareholder value by continuing to execute our relationship-based business model, growing our franchise, and being disciplined [removed: in our] [added: with respect to] capital management.
We took the following actions during [removed: 2022] [added: 2023] in support of our corporate strategy:
At December 31, [removed: 2022,] [added: 2023,] our Common Equity Tier 1 and Tier 1 risk-based capital ratios stood at [removed: 9.10%] [added: 10.02%] and [removed: 10.60%,] [added: 11.67%,] respectively.
- We remained committed to our strategy to engage a high-performing, talented, and diverse workforce. We have been recognized by multiple organizations for our dedication to creating an environment where employees [added: are treated with respect and empowered to bring their authentic selves to work.]
| [Introduction](#id35963ddccc041b2ab203b7e536286e2_52) | | | [48](#id35963ddccc041b2ab203b7e536286e2_52) | | |
| [Noninterest income](#id35963ddccc041b2ab203b7e536286e2_76) | | | [54](#id35963ddccc041b2ab203b7e536286e2_76) | | |
| [Securities](#id35963ddccc041b2ab203b7e536286e2_103) | | | [67](#id35963ddccc041b2ab203b7e536286e2_103) | | |
| [Capital](#id35963ddccc041b2ab203b7e536286e2_109) | | | [71](#id35963ddccc041b2ab203b7e536286e2_109) | | |
| [Guarantees](#id35963ddccc041b2ab203b7e536286e2_121) | | | [74](#id35963ddccc041b2ab203b7e536286e2_121) | | |
| [Risk Management](#id35963ddccc041b2ab203b7e536286e2_124) | | | [74](#id35963ddccc041b2ab203b7e536286e2_124) | | |
| [Overview](#id35963ddccc041b2ab203b7e536286e2_127) | | | [74](#id35963ddccc041b2ab203b7e536286e2_127) | | |
| [Valuation methodologies](#id35963ddccc041b2ab203b7e536286e2_181) | | | [92](#id35963ddccc041b2ab203b7e536286e2_181) | | |
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
For the 2023 fiscal year, our cash efficiency ratio and operating leverage were affected by an increase in noninterest expense and a decrease in revenues.
Noninterest expense increased 7% from prior year including the impact of the FDIC special assessment as well as efficiency-related charges as we focused on expense management, including simplifying and streamlining our businesses.
Net interest income decreased 13% from prior year reflecting higher interest-bearing deposit costs and a shift in funding mix to higher cost deposits and borrowings.
Positive operating leverage remains one of our long-term financial targets.
Our full-year dividend for 2023 was $.82.
Our proactive balance sheet optimization efforts drove the increase in our CET1 ratio and improved our liquidity and funding profile.
We believe that these proactive efforts will better position Key to deliver sound, profitable growth and value for all of our stakeholders.
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
Our capital position remains strong, and we are well-positioned relative to our capital priorities.
- Throughout dynamic market conditions we continued to support our clients, growing in both commercial clients and consumer households and raising $80 billion in capital for our clients.
- We’ve continued to focus on relationships, primacy, and quality deposits, while de-emphasizing non-relationship business and significantly improving our funding and liquidity.
- Overall, credit quality remains strong reflecting our strong risk management discipline and our proven underwrite-to-distribute business model.
We’ve continued to maintain low exposure in high-risk categories such as leveraged lending and office properties.
- We proactively managed our balance sheet by reducing risk-weighted assets, improving our capital position.
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
Current year expectations - full year 2024 vs. full year 2023
| Category | | | | | | Expectations (a) | | |
| Average loans | | | | | | down 5% to 7%(c) | | |
| Average deposits | | | | | | flat to down 2% | | |
| Effective tax rate | | | | | | ~20% (FY2024) | | |
(a) Guidance range: relatively stable: +/- 2%.
(b) Excludes impact of the FDIC special assessment charge of $190 million, efficiency related expenses of $131 million, and a pension settlement charge of $18 million in 2023.
(c) Additional Guidance: End of period loans: relatively stable vs. year-end 2023 balances; Net interest income (TE): Up low-single digits vs. 4Q23 annualized exit rate, 10%+ 4Q24 vs. 4Q23.
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
The decline in net interest income (TE) and the net interest margin was driven by higher interest-bearing deposit costs and a shift in funding mix to higher cost deposits and borrowings.
Partly offsetting the decline in net interest income and the net interest margin were higher earning asset balances and yields.
The $6.7 billion increase was driven by growth in commercial and industrial loans and consumer mortgage balances during the first half of 2023.
Average deposits totaled $144.1 billion for 2023, a decrease of $2.8 billion compared to 2022.
The decrease was driven by changing client behavior as a result of higher interest rates.
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
| Money market deposits | | | $ | 34,539 | | $ | 666 | | 1.93 | | % | | | | $ | 35,966 | | $ | 52 | | .14 | | % | | | | $ | 36,959 | | $ | 15 | | .04 | | % |
| | | | | | |
| --- | --- | --- | --- | --- | --- |
| [Introduction](#i5a468b8a075b404bb1614017a87fbb3f_52) | | | [47](#i5a468b8a075b404bb1614017a87fbb3f_52) | | |
| [Securities](#i5a468b8a075b404bb1614017a87fbb3f_100) | | | [66](#i5a468b8a075b404bb1614017a87fbb3f_100) | | |
| [Capital](#i5a468b8a075b404bb1614017a87fbb3f_106) | | | [69](#i5a468b8a075b404bb1614017a87fbb3f_106) | | |
| [Guarantees](#i5a468b8a075b404bb1614017a87fbb3f_118) | | | [72](#i5a468b8a075b404bb1614017a87fbb3f_118) | | |
| [Risk Management](#i5a468b8a075b404bb1614017a87fbb3f_121) | | | [72](#i5a468b8a075b404bb1614017a87fbb3f_121) | | |
| [Overview](#i5a468b8a075b404bb1614017a87fbb3f_124) | | | [72](#i5a468b8a075b404bb1614017a87fbb3f_124) | | |
| [Valuation methodologies](#i5a468b8a075b404bb1614017a87fbb3f_178) | | | [91](#i5a468b8a075b404bb1614017a87fbb3f_178) | | |
Positive operating leverage was delivered for the 2022 fiscal year, marking the ninth time in the past ten years this was achieved.
We expect to again generate positive operating leverage in 2023.
Our full-year dividend for 2022 was $.79, reflecting a Board approved increase in the fourth quarter.
We remain committed to delivering value to all shareholders.
Our capital remains a competitive advantage for us.
- We continued the momentum of loan growth across both our consumer and commercial businesses as we continue to add clients and deepen our existing relationships.
- In the third quarter, we implemented new client-friendly fee terms, eliminating NSF fees and introducing Key Coverage Zone TM for overdraft fees.
- We continued to expand targeted client relationships in healthcare, growing relationships with nurses and significant healthcare providers, including healthcare systems and facilities.
- Our strong capital position allows us to continue to execute against each of our capital priorities of organic growth, dividends, and share repurchases.
During the fourth quarter, the Board of Directors announced an increase in the quarterly dividend to $.205 per common share resulting in a full-year dividend of $.79.
- We continued to grow profitably during 2022.
Positive operating leverage was achieved for the year, and we expect to deliver positive operating leverage in 2023.
- During 2022 we completed the acquisition of GradFin, one of the nation's leading Public Service Loan Forgiveness counseling providers.
The acquisition furthers Key's commitment to accelerate growth through targeted investments in digital, niche businesses.
- Overall, credit quality remains strong as our new loan originations in both our commercial and consumer book continue to meet our criteria for high quality loans as we continue to effectively manage risk and rewards. Our continuous focus on maintaining our risk discipline has and will continue to position us to perform well through all business cycles.
- Maintaining financial strength while driving long-term shareholder value was again a focus during 2022.
are treated with respect and empowered to bring their authentic selves to work.
Net interest income (TE) benefited from higher earning asset balances, higher interest rates, and a favorable balance sheet mix.
Net interest income (TE) and the net interest margin were negatively impacted by the sale of the indirect auto loan portfolio in the third quarter of 2021, higher interest-bearing deposit costs, and lower loan fees from PPP.
Commercial loans increased $6.5 billion, reflecting core commercial and industrial loan growth and an increase in commercial mortgage real estate loans, which mitigated the impact of a $4.7 billion decline in PPP balances.
Consumer loans increased $4.6 billion driven by Key’s consumer mortgage business and student loan originations from Laurel Road, partly offset by the sale of the indirect auto loan portfolio in the third quarter of 2021.
Average deposits totaled $146.9 billion for 2022, an increase of $1.8 billion compared to 2021.
The increase reflects growth from consumer and commercial relationships, partially offset by a decline in time deposits and non-operating commercial deposit balances.
| NOW and money market deposit accounts | | | $ | 85,673 | | $ | 234 | | .27 | | % | | | | $ | 84,736 | | $ | 41 | | .05 | | % | | | | $ | 75,733 | | $ | 206 | | .27 | | % |
| Loans | | | $ | 428 | | $ | 281 | | $ | 709 | | | | | | | | | | | | | |
| Total interest income (TE) | | | 509 | | | 536 | | | 1,045 | | | | | | | | | | | | | | |
| NOW and money market deposit accounts | | | — | | | 193 | | | 193 | | | | | | | | | | | | | | |
| Long-term debt | | | 52 | | | 202 | | | 254 | | | | | | | | | | | | | | |
| Total interest expense | | | 99 | | | 490 | | | 589 | | | | | | | | | | | | | | |
In 2021, our provision for credit losses was a net benefit due to reserve releases as the economic stress and uncertainty in the U.S. and globally caused by COVID-19 eased, along with significantly lower net loan charge-offs and improved asset quality.
In 2023 we expect net charge-offs to average loans to be in the range of 25 to 30 bps.
An excerpt. Shown here: 40 of 560 rewritten, 40 of 340 added and 40 of 275 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS in the FY2023 filing and the FY2022 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
2 rewritten, 0 added, 0 removed, 0 unchanged
The information included under the caption “Risk Management — Market risk management” in the MD&A beginning on page [removed: [74](#i5a468b8a075b404bb1614017a87fbb3f_127)] [added: [76](#id35963ddccc041b2ab203b7e536286e2_130)] is incorporated herein by reference.
[removed: [Table](#i5a468b8a075b404bb1614017a87fbb3f_13) [of contents](#i5a468b8a075b404bb1614017a87fbb3f_13)][added: [Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)]
Item 1. BUSINESS
106 rewritten, 107 added, 217 removed, 275 unchanged
We are a BHC under the BHCA and one of the nation’s largest bank-based financial services companies, with consolidated total assets of approximately [removed: $189.8] [added: $188.3] billion at December 31, [removed: 2022.][added: 2023.]
As of December 31, [removed: 2022,] [added: 2023,] these services were provided across the country through KeyBank’s [removed: 972] [added: 959] full-service retail banking branches and a network of [removed: 1,265] [added: 1,217] ATMs in 15 states, as well as additional offices, online and mobile banking capabilities, including our national digital bank, Laurel Road, and a telephone banking call center.
The Consumer Bank serves individuals and small businesses throughout our 15-state branch footprint and through our Laurel Road digital [removed: lending business] [added: brand] by offering a variety of deposit and investment products, personal finance and financial wellness services, lending, student loan refinancing, mortgage and home equity, credit card, treasury services, and business advisory services.
[removed: [Table](#i5a468b8a075b404bb1614017a87fbb3f_13) [of contents](#i5a468b8a075b404bb1614017a87fbb3f_13)][added: [Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)]
The operating segment includes the KBCM platform which provides a broad suite of capital markets products and services including syndicated finance, debt and equity capital markets, derivatives, foreign exchange, financial advisory, [removed: and] public [removed: finance.][added: finance, commercial payments, equipment finance, and commercial mortgage banking.]
[added: Risk Factors - “ We operate in a highly competitive industry.”] Mergers and acquisitions have also led to increased concentration in the banking industry, placing added competitive pressure on Key’s core banking products and services as we see competitors enter some of our markets or offer similar products.
We make investments to hire [added: and retain] the people we need to serve our customers and communities and regularly review our pay practices to reflect changing market and economic conditions.
We have [removed: steadily increased our starting minimum wage since 2015 and] made other [added: compensation] adjustments [removed: responding] [added: in response] to market trends, competitive [removed: pressures] [added: pressures,] and a dynamic market for talent.
Key’s benefits offerings include employee health and welfare plans, a 401(k) plan with competitive matching [removed: contributions,] [added: contributions (dollar for dollar, up to the first 7% of eligible pay contributed on a per pay period basis for eligible employees), up to ten weeks of] paid parental leave, a Discounted Stock Purchase Plan, wellness [removed: incentives] [added: incentives,] and a lifestyle reimbursement account [removed: program.][added: program for covered expenses related to health, mental wellness, family needs, and finances.]
[removed: With respect to pay, we] [added: We] design our compensation programs to balance risk and reward and align with the guidance of our regulators, and we regularly monitor these programs to remain within our risk tolerances.
We [removed: invest in our teammates’ growth and professional development through a variety of internal networking groups, formal and informal mentoring programs, and a suite of leadership development programs as well as by offering] [added: also offer] employees the opportunities to develop and enhance their skills through formal learning curricula and [removed: the opportunity] to obtain [added: tuition reimbursement for eligible] collegiate or post-collegiate education and relevant certifications.
In [removed: 2022,] [added: 2023,] we continued to focus on increasing minority representation in management and leadership roles, expanding our overall recruiting focus, developing diverse candidate [removed: slates and] pipelines, increasing supplier diversity, providing mentorship opportunities, offering implicit bias training, and leveraging our [removed: existing employee resource groups] [added: KBINGs] to strengthen both engagement and inclusion.
As of February [removed: 2022,] [added: 2023,] at KeyBank women earn on average more than 99% of what their male teammates earn, and people of color earn on average more than 99% of what their white teammates earn, after taking into account an employee’s job.
More information about our commitment to pay equity and our commitment to increasing diversity is available at [removed: www.key.com/about/diversity/pay-equity-commitment.jsp.][added: www.key.com/about/diversity/pay-equity-commitment.html.]
As of December 31, [removed: 2022,] [added: 2023,] our overall workforce was [removed: 58.7%] [added: 57.8%] female.
In addition, as of December 31, [removed: 2022,] [added: 2023,] our workforce was also [removed: 75.3%] [added: 74.9%] White, [removed: 9.1%] [added: 9.0%] Black/African American, [removed: 6.9%] [added: 7.0%] Hispanic/Latino, [removed: 6.1%] [added: 6.4%] Asian and 2.7% other.
Our Board of Directors is 46% diverse (six of our 13 total Directors are diverse, with four women, one of whom is also a minority, and two male minorities) and our Executive Leadership Team is [removed: 36%] [added: 42%] diverse (four women and one minority out of [removed: 14] [added: 12] total executives).
For more information about our diversity and inclusion efforts, a more detailed breakdown of employee diversity by EEO-1 categories, and information about how we work every day and in every way to help our clients, colleagues, and communities thrive, please see our website and our [removed: Corporate Responsibility] [added: annual Environmental, Social, and Governance] report at [removed: https://investor.key.com/esg-information/corporate-responsibility/.][added: https://www.key.com/about/diversity/diversity-and-inclusion.html.]
Key had an average of [removed: 17,660] [added: 17,692] full time equivalent employees in [removed: 2022.][added: 2023.]
As of December 31, [removed: 2022,] [added: 2023,] a total of [removed: 18,891] [added: 17,333] full-time and part-time employees worked in the following regions, which are generally aligned to the regions Key uses for its retail branch banking network:
[removed: 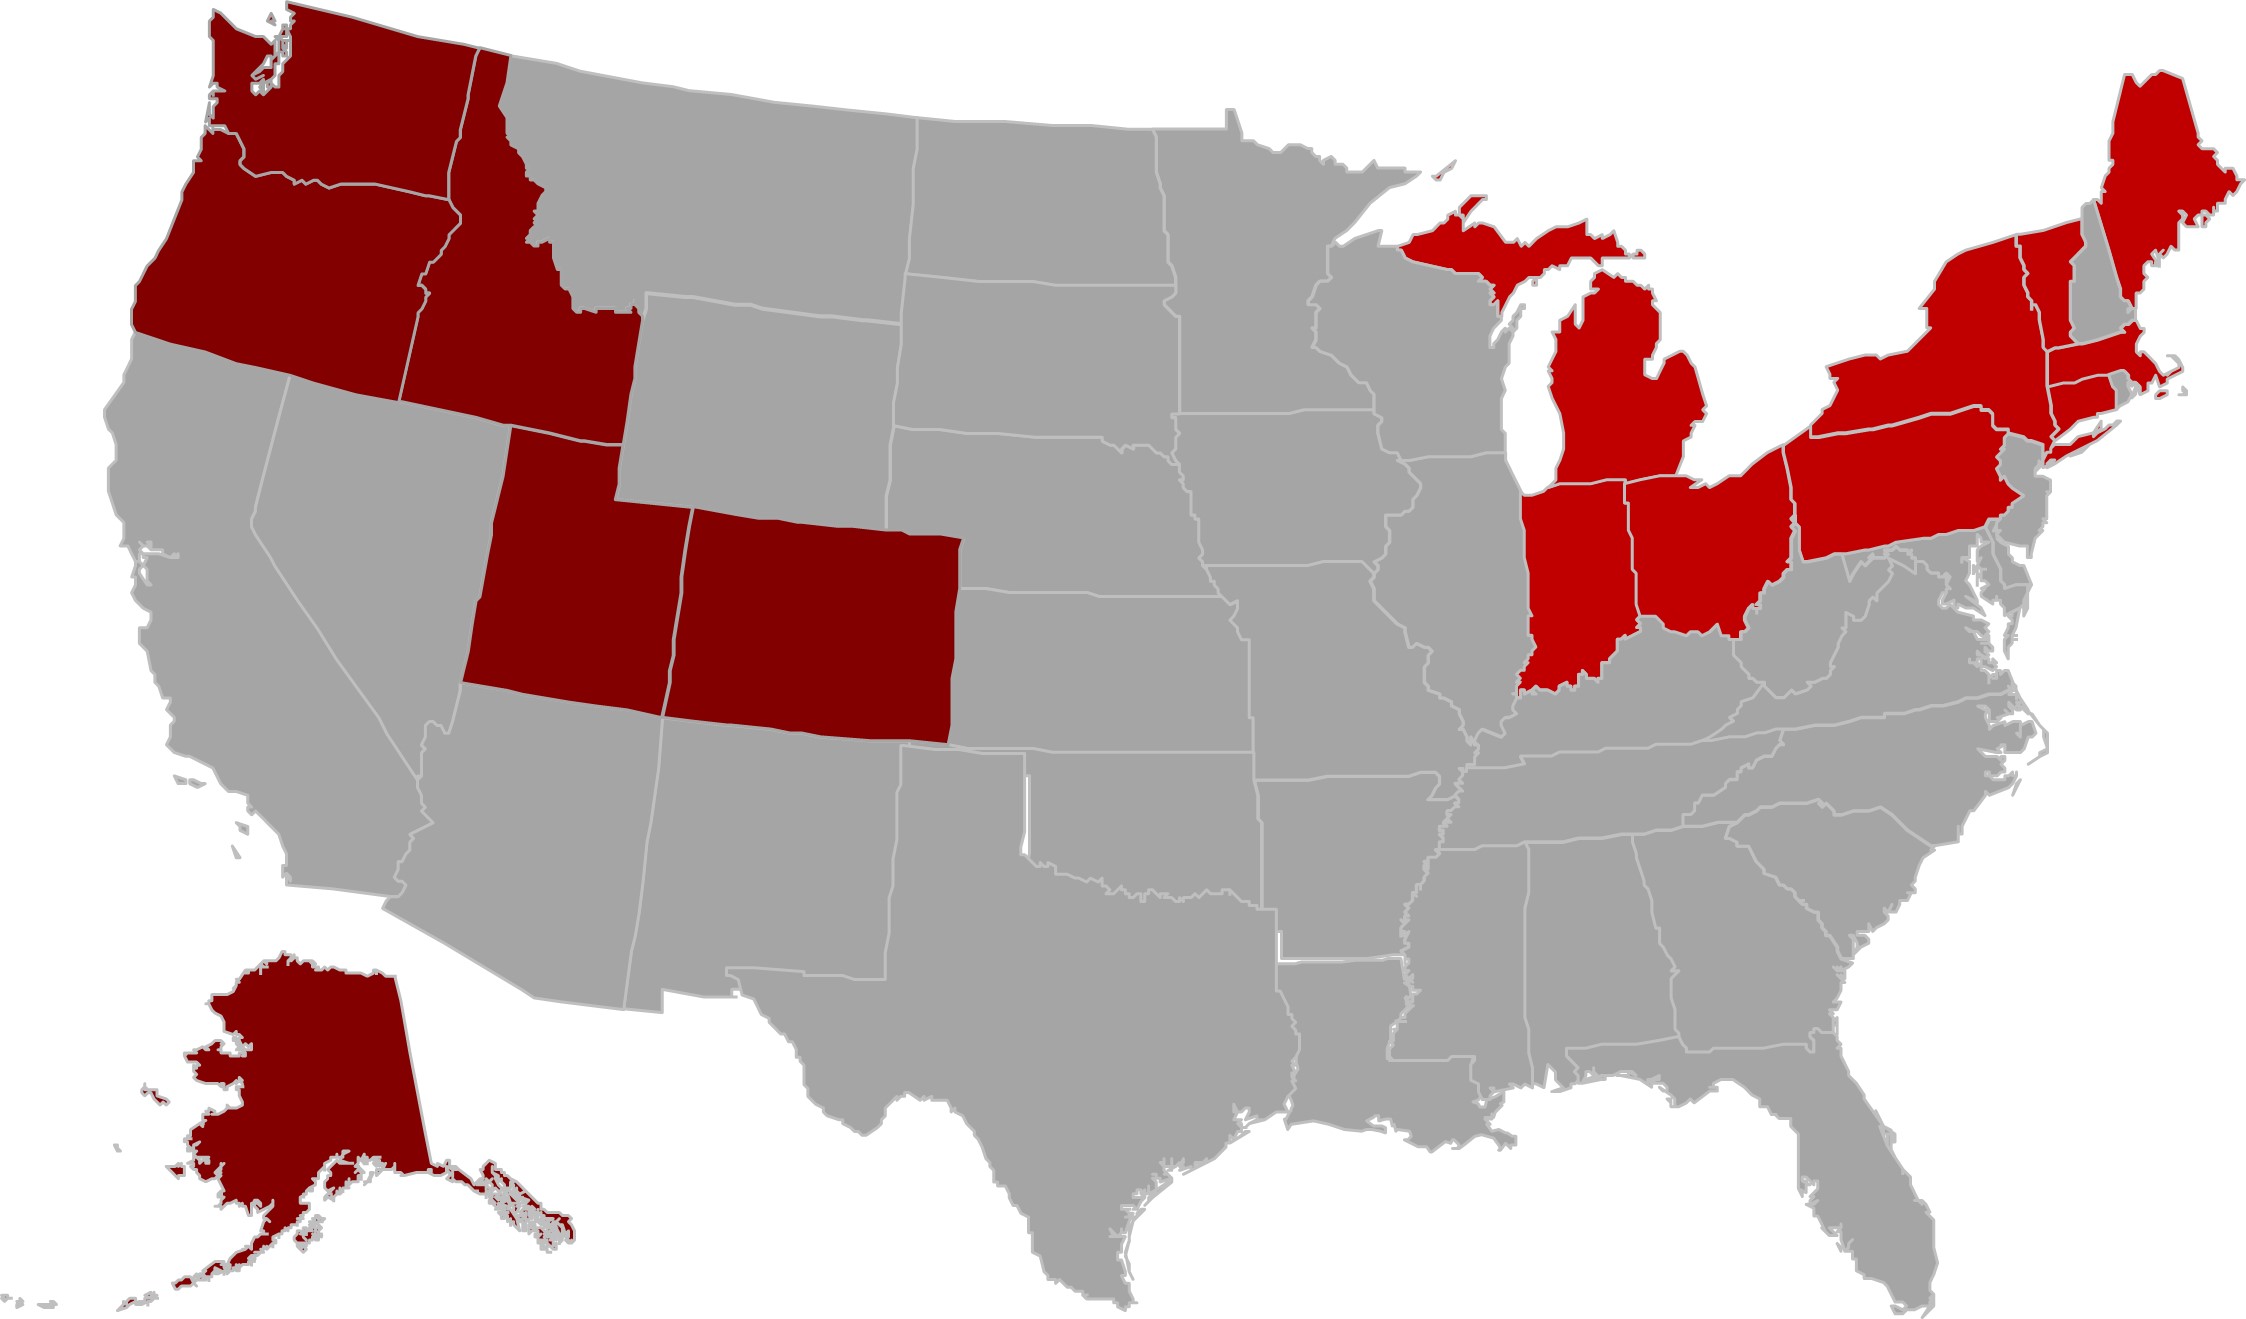][added: 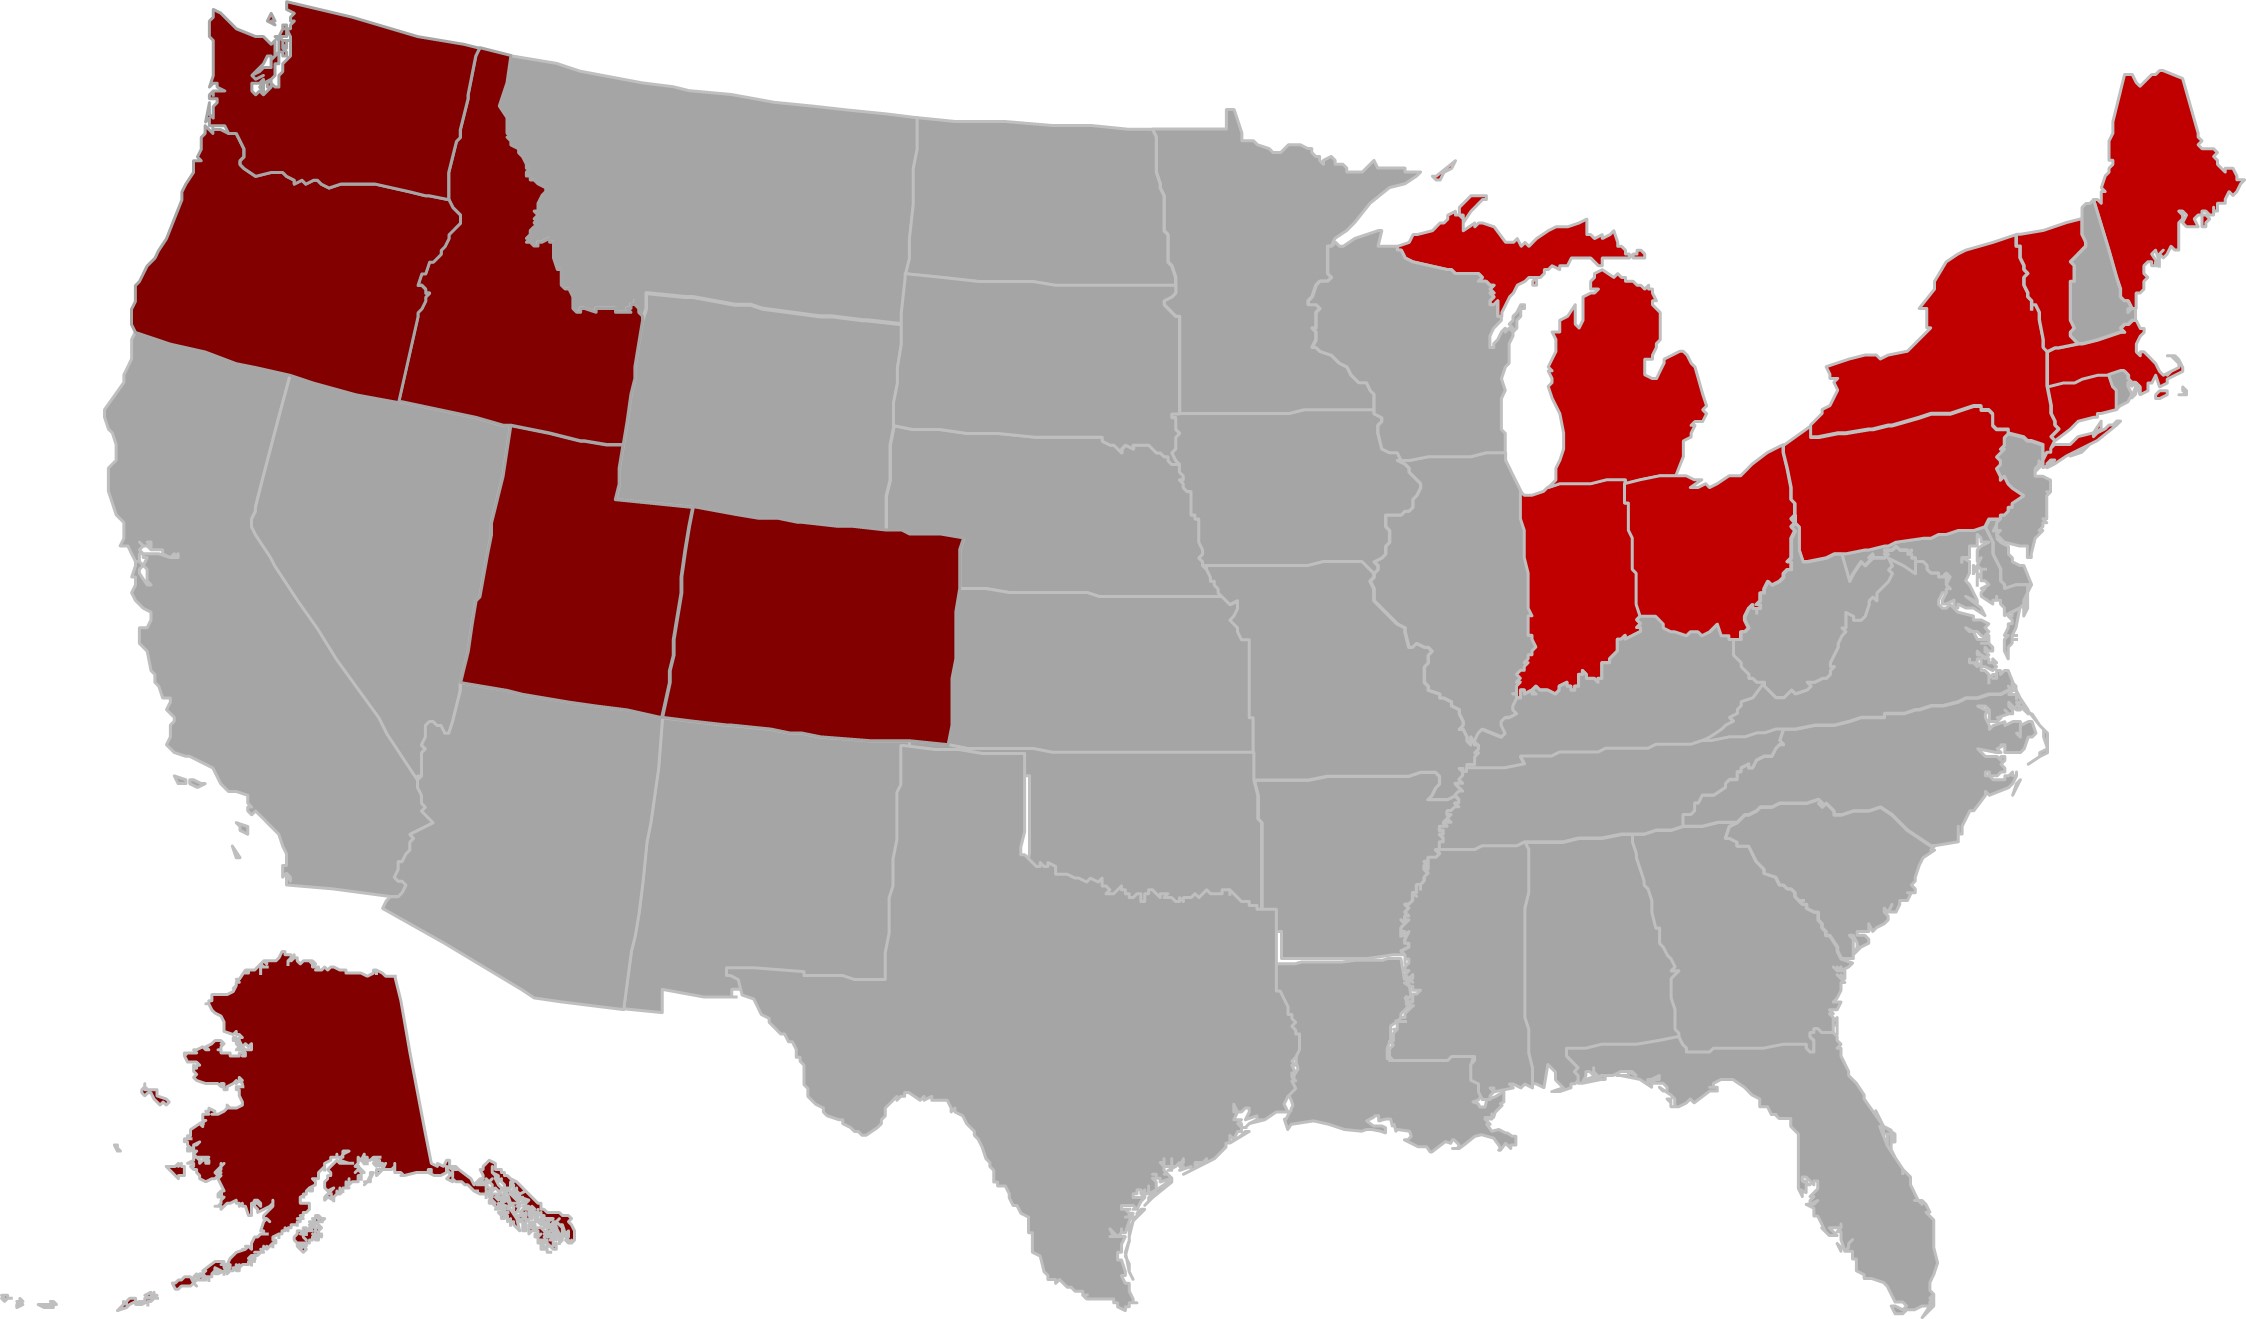]
| | | | All Other | | | [removed: 3,142] [added: 2,552] | | |
Set forth below are the names and ages of the executive officers of KeyCorp as of December 31, [removed: 2022,] [added: 2023,] the positions held by each at KeyCorp during the past five years, and the year each first became an executive officer of KeyCorp.
Because [added: Darrin Benhart and] James Waters [removed: has] [added: have] been employed at KeyCorp for less than five years, information is being provided concerning [removed: his] [added: their] prior business experience.
Alexander [removed: (43)] [added: (44)] - Mr. Alexander has been KeyCorp’s Head of Consumer Bank and an executive officer of KeyCorp since January 2020.
Brady [removed: (56)] [added: (57)] *-* Ms. Brady is KeyCorp’s Chief Information Officer, serving in that role since May 2012.
Evans [removed: (58)] [added: (59)] - Ms. Evans has been the Director of Corporate Center for KeyCorp since August 2012.
[removed: Fishel (57)] [added: Benhart (58)] - Mr. [removed: Fishel] [added: Benhart] became [removed: the] Chief [removed: Human Resources] [added: Risk] Officer and an executive officer of KeyCorp [removed: in May 2018.][added: on January 1,]
[removed: Gavrity (46)] [added: Jaime Warder (50)] - Mr. [removed: Gavrity] [added: Warder] has been Head of [removed: Enterprise Payments] [added: Digital Banking] since January 2019 and became an executive officer of KeyCorp in May 2021.
Prior to this, Mr. Gavrity served as Head of [added: Enterprise Payments from January 2019 to November 2023 and Head of] Commercial Payments from 2016 to 2019.
Gorman [removed: (62)] [added: (63)] - Mr. Gorman has been Chairman, Chief Executive Officer, and President of KeyCorp since May 1, 2020.
[removed: Clark H.I. Khayat (51) -] Mr. Khayat rejoined KeyCorp as Chief Strategy Officer in January [removed: 2018.][added: 2018 and served in that role until March 2023.]
Mr. Khayat [added: had] previously served as [removed: an Executive Vice President and] Head of Key’s Enterprise Commercial Payments group from April 2014 to June 2016.
Kidik [removed: (43)] [added: (44)] - Ms. Kidik has been the Chief Risk Review Officer and General Auditor and an executive officer of KeyCorp since July 2022.
[removed: Kimble (62)] [added: Schosser (53)] - Mr. [removed: Kimble] [added: Schosser] has been the Chief [removed: Financial] [added: Accounting] Officer [added: and an executive officer] of KeyCorp since [removed: June 2013.][added: May 2015.]
She previously served as [added: Head of Commercial Bank from May 2019 to November 2023 and] Co-Head of Key Corporate Bank from 2016 to May 2019.
Midkiff [removed: (60)] [added: (61)] - [added: On December 31, 2023,] Mr. Midkiff [removed: became] [added: was] Chief Risk Officer and an executive officer of KeyCorp [removed: in] [added: since] January 2018.
Paine III [removed: (53)] [added: (54)] - Mr. Paine [removed: is] [added: has been] the Head of Institutional [removed: Bank.][added: Bank since 2019.]
[removed: Schosser (52)] [added: Gavrity (47)] - Mr. [removed: Schosser] [added: Gavrity] has been [removed: the Chief Accounting Officer] [added: Head of Commercial Bank since November 2023] and [added: became] an executive officer of KeyCorp [removed: since] [added: in] May [removed: 2015.][added: 2021.]
Waters [removed: (56)] [added: (57)] - Mr. Waters became the General Counsel and Secretary and an executive officer of KeyCorp in July 2021.
For more information on competition and related risks, see Item 1A.
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
We have steadily increased our starting minimum wage since 2015, and as of December 31, 2023, 98% of employees earned $18 or more per hour, with 89% of employees earning $20 or more per hour.
Teammates can also participate in a variety of company-sponsored volunteer and giving opportunities, including Neighbors Make the Difference Day, our national employee volunteer day, and the Employee Matching Gift Program, which offers eligible employees the opportunity to support qualified nonprofit organizations and multiply their contributions through the KeyBank Foundation.
We have a pay-for-performance culture that is guided by the following three principles:
- Pay decisions are based on Key’s performance, business unit performance, and individual performance.
- We deliver pay in a way that balances short-term and long-term financial performance objectives and aligns to shareholder value creation.
- We support sustainable performance with policies that focus on prudent risk-taking and the balance between risk and reward.
We invest in our teammates’ growth and professional development through a variety of internal networking groups, including our twelve Key Business Impact and Networking Groups (“KBINGs”), formal and informal mentoring programs, including Key’s enterprise-wide formal mentoring program, MentorMe at Key, and a suite of leadership development programs.
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
Our pay equity and parity measures are evaluated annually, and we engage third-party partners to consult on our pay equity analysis and practices as needed.
| | | | East | | | 12,459 | | |
| | | | West | | | 2,322 | | |
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
We invest significant time and resources in creating an attractive work environment and competitive total rewards package that attracts and retains top talent.
Key’s annualized rate for voluntary turnover as of December 31, 2023, was 14.6%, lower than our annualized voluntary turnover rate for 2022, which was 18.0%, and lower than our previous five year historical average of 16.8%.
On January 1, 2024, Darrin J.
Benhart became Chief Risk Officer.
Darrin L.
2024.
Prior to that time, he served as Deputy Chief Risk Officer and Head of Enterprise Risk Management from
August 2023 to December 2023 and Chief Enterprise Risk Officer from July 2022 to August 2023.
Prior to July
2022, he served as a National Bank Examiner with the OCC from March 1992 to March 2022.
Clark H.I. Khayat (52) - Mr. Khayat has been Chief Financial Officer since March 2023 and an executive officer since September 2018.
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
Mago (58) - Ms. Mago has served as the Chief Human Resources Officer since November 2023.
In addition,
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
risk-weighted assets.
However, some of those additional requirements will apply to KeyCorp and KeyBank if proposed revisions to the Regulatory Capital Rules are adopted.
However, KeyCorp will be subject to the supplementary leverage ratio if proposed revisions to the Regulatory Capital Rules discussed below are adopted.
However, KeyCorp will be subject to the countercyclical capital buffer if proposed revisions to the Regulatory Capital Rules discussed below are adopted.
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
However, KeyCorp will be subject to the supplementary leverage ratio if proposed revisions to the Regulatory Capital Rules discussed below are adopted.
On July 27, 2023, the federal banking agencies issued a proposal (the “Capital Proposal”) that would make significant changes to the Regulatory Capital Rules applicable to banking organizations with total assets of $100 billion or more and their depository institution subsidiaries (“Large Banking Organizations”) (including KeyCorp and KeyBank) and banking organizations with significant trading activity.
This proposal would implement the final elements of the Basel III capital framework and make other changes to the Regulatory Capital Rules in response to the bank failures that occurred in 2023.
The Capital Proposal would establish a new framework for calculating risk-weighted assets (the “expanded risk-based approach”) that would apply to Large Banking Organizations.
The expanded risk-based approach would include a new more risk-sensitive standardized approach for measuring credit risk and operational risk.
Technological advances may diminish the importance of depository institutions and other financial institutions.
| | | | East | | | 13,775 | | |
| | | | West | | | 1,974 | | |
Brian L.
From 2013 to 2018, he served as the Director of Talent Management for KeyCorp.
He became an executive officer of KeyCorp in September 2018.
On November 17, 2022, KeyCorp announced that Mr. Khayat will succeed Donald R.
Kimble as Chief Financial Officer of KeyCorp effective upon Mr. Kimble’s retirement.
Donald R.
In 2017, Mr. Kimble was also named Vice Chairman.
In January 2020, Mr. Kimble was also appointed Chief Administrative Officer.
Mr. Kimble became an executive officer upon joining KeyCorp in June 2013.
On November 17, 2022, KeyCorp announced that Mr. Kimble will retire from KeyCorp effective May 1, 2023.
Mago (57) - Ms. Mago is the Head of Commercial Bank.
She also serves as Head of Real Estate Capital for Key, a role she has held since 2014.
Jaime Warder (49) - Mr. Warder has been Head of Digital Banking since January 2019 and became an executive officer of KeyCorp in May 2021.
Regulatory Capital Rules
The U.S. federal banking agencies released a statement announcing their support for the Basel Committee’s efforts, but cautioned that they will consider how to appropriately incorporate these revisions into the Regulatory Capital
Rules, and that any proposed changes based on the Basel Committee revisions would be subject to notice-and-comment rulemaking.
In view of the prohibition under the Dodd-Frank Act on the use of credit ratings in federal regulation, there is some uncertainty as to whether or how the agencies would implement the ratings-based aspects of the Basel Committee revisions to Basel III, as well as any other aspect of the Basel Committee revisions that permit the U.S. agencies to exercise home-country discretion, for example, due to differences in accounting or market practices, and legal requirements.
Subsequently, in December 2018, the Basel Committee released an update to its Pillar 3 disclosure framework, to more appropriately align it to the changes adopted under the Basel Committee’s final revisions to Basel III.
Before any action is taken by the federal banking agencies with respect to the revised Pillar 3 disclosure framework, the federal agencies must determine whether and to what extent they will implement the final revisions to Basel III released by the Basel Committee in December 2017.
On July 9, 2019, the federal banking agencies issued a final rule to simplify certain aspects of the Regulatory Capital Rules for standardized approach banking organizations, including Key.
The final rule simplifies, for these banking organizations, the regulatory capital requirements for mortgage servicing assets, certain deferred tax assets arising from temporary differences, and investments in the capital of unconsolidated financial institutions.
The final rule replaces multiple deduction thresholds with a single 25% deduction threshold for each of these categories and requires that a 250% risk weight be applied to mortgage servicing assets and deferred tax assets that are not deducted from capital.
The final rule also simplifies the calculation of the amount of capital issued by a consolidated subsidiary of a banking organization and held by third parties that is includable in regulatory capital.
In addition, the final rule makes certain technical amendments to the Regulatory Capital Rules that are applicable to standardized approach banking organizations as well as advanced approaches banking organizations.
The final rule provided an effective date of October 1, 2019, for the technical amendments and an effective date of April 1, 2020, for the simplification changes.
On November 13, 2019, the federal banking agencies published an amendment to the final rule to provide standardized approach banking organizations with the option to implement the simplification changes on either January 1, 2020, or April 1, 2020.
We chose to implement the simplification changes on April 1, 2020.
In November 2019, the federal banking agencies adopted a final rule to amend the Regulatory Capital Rules by revising the definition of a high volatility commercial real estate (“HVCRE”) exposure.
HVCRE exposures are subject to a heightened risk weight under the Regulatory Capital Rules.
The final rule, which became effective on April 1, 2020, conforms the HVCRE definition to statutory changes enacted in May 2018.
The final rule also clarifies the treatment under the revised HVCRE definition of credit facilities that finance one-to-four family residential properties as well as credit facilities that finance the development of land.
The agencies noted that this relief is being provided in order to allow banking organizations to better focus on lending to creditworthy households and businesses affected by recent strains on the U.S. economy caused by COVID-19.
The CARES Act, enacted on March 27, 2020, provides banking organizations with the option to not comply with CECL until the earlier of (i) the termination date of the national emergency concerning COVID-19 declared by the President under the National Emergencies Act; or (ii) December 31, 2020.
The federal banking agencies issued a statement on March 31, 2020, indicating that banking organizations that elect to use the optional, temporary statutory relief will be able to elect the remaining period of regulatory capital relief provided under the CECL Interim Final Rule after the end of the statutory relief period.
Alternatively, banking organizations may adopt CECL as planned in 2020 and use the regulatory capital relief provided under the CECL Interim Final Rule starting at the time of their adoption of CECL.
Like the CECL Interim Final Rule, the final rule gives eligible banking organizations the option to mitigate the estimated adverse effects on regulatory capital of CECL for two years, followed by a three-year transition period, which results in an optional five-year transition.
The final rule expands the group of institutions eligible for this optional five-year transition to include any institution adopting CECL in 2020.
An excerpt. Shown here: 40 of 106 rewritten, 40 of 107 added and 40 of 217 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2023 filing and the FY2022 filing.
Item 3. LEGAL PROCEEDINGS
1 rewritten, 0 added, 0 removed, 7 unchanged
Based on information currently available to us, advice of counsel, and available insurance coverage, we believe that our established reserves are adequate and [removed: the] [added: any] liabilities [removed: arising] [added: that may arise] from [removed: the] [added: outstanding] legal proceedings will not have a material adverse effect on our consolidated financial condition.
Cover and table of contents
37 rewritten, 21 added, 15 removed, 126 unchanged
[removed: [Table](#i5a468b8a075b404bb1614017a87fbb3f_13) [of contents](#i5a468b8a075b404bb1614017a87fbb3f_13)][added: [Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)]
[removed: ][added: ]
The aggregate market value of voting and non-voting common stock held by nonaffiliates of the Registrant was [removed: $16,069,430,913] [added: $8,646,175,313] (based on the June 30, [removed: 2022,] [added: 2023,] closing price of KeyCorp Common Shares of [removed: $17.23] [added: $9.24] as reported on the New York Stock Exchange).
As of February 20, [removed: 2023,] [added: 2024,] there were [removed: 931,825,509] [added: 933,841,692] Common Shares outstanding.
Certain specifically designated portions of KeyCorp’s definitive Proxy Statement for its [removed: 2023] [added: 2024] Annual Meeting of Shareholders are incorporated by reference into Part III of this Form 10-K.
- negative outcomes from [removed: claims] [added: claims, litigation, investigations,] or [removed: litigation;][added: governmental proceedings;]
- the soundness of other financial [removed: institutions;][added: institutions, including instability in the financial industry;]
- our ability to manage our reputational [added: risks, including ESG-related] risks;
Any forward-looking statements made by us or on our behalf speak only as of the date they are made, and we do not undertake any obligation to update any forward-looking statement to reflect the impact of subsequent events or [added: circumstances, except as required by applicable securities laws.]
- We use the phrase continuing operations in this document to mean all of our businesses other than our government-guaranteed and private education lending business, which [removed: have been] [added: are] accounted for as discontinued [removed: operations since 2009.][added: operations.]
The acronyms and abbreviations identified below are used [added: throughout this report, including] in the Notes to Consolidated Financial Statements [removed: as well as] [added: and] in the Management’s Discussion and Analysis of Financial Condition and Results of Operations.
| ABO: Accumulated benefit obligation. ALCO: Asset/Liability Management Committee. ALLL: Allowance for loan and lease losses. A/LM: Asset/liability management. AML: Anti-money laundering. AOCI: Accumulated other comprehensive income (loss). APBO: Accumulated postretirement benefit obligation. AQN Strategies: Arbitria Quum Notitia, LLC. ARRC: Alternative Reference Rates Committee. ASC: Accounting Standards Codification. ASR: Accelerated Stock Repurchase. ASU: Accounting Standards Update. ATMs: Automated teller machines. BSA: Bank Secrecy Act. BHCA: Bank Holding Company Act of 1956, as amended. BHCs: Bank holding companies. Board: KeyCorp Board of Directors. CAPM: Capital Asset Pricing Model. CARES Act: Coronavirus Aid, Relief, and Economic Security Act. CCAR: Comprehensive Capital Analysis and Review. Cain Brothers: Cain Brothers & Company, LLC. CECL: Current Expected Credit Losses. CFPB: Consumer Financial Protection Bureau, also known as the Bureau of Consumer Financial Protection. CFTC: Commodities Futures Trading Commission. CMBS: Commercial mortgage-backed securities. CMO: Collateralized mortgage obligation. Common Shares: KeyCorp common shares, $1 par value. CVA: Credit Valuation Adjustment. DCF: Discounted cash flow. DIF: Deposit Insurance Fund of the FDIC. Dodd-Frank Act: Dodd-Frank Wall Street Reform and Consumer Protection Act of 2010. EAD: Exposure at default. EBITDA: Earnings before interest, taxes, depreciation, and amortization. EPS: Earnings per share. ERISA: Employee Retirement Income Security Act of 1974. ERM: Enterprise risk management. ESG: Environmental, social, and governance EVE: Economic value of equity. FASB: Financial Accounting Standards Board. FDIA: Federal Deposit Insurance Act, as amended. FDIC: Federal Deposit Insurance Corporation. Federal Reserve: Board of Governors of the Federal Reserve System. FHLB: Federal Home Loan Bank of Cincinnati. FHLMC: Federal Home Loan Mortgage Corporation. FICO: Fair Isaac Corporation. FINRA: Financial Industry Regulatory Authority. First Niagara: First Niagara Financial Group, Inc. FNMA: Federal National Mortgage Association. [removed: | | |] FSOC: Financial Stability Oversight Council. [added: | | |] FVA: Fair value of employee benefit plan assets. GAAP: U.S. generally accepted accounting principles. GNMA: Government National Mortgage Association. HTC: Historic tax credit. [added: IDI: Insured depository institution.] IRS: Internal Revenue Service. ISDA: International Swaps and Derivatives Association. KBCM: KeyBanc Capital Markets, Inc. [added: KBING: Key Business Impact and Networking Groups.] KCC: Key Capital Corporation. KCDC: Key Community Development Corporation. KCIC: Key Community Investment Capital LLC. KEF: Key Equipment Finance. LCR: Liquidity coverage ratio. LGD: Loss given default. LIBOR: London Interbank Offered Rate. LIHTC: Low-income housing tax credit. LTV: Loan-to-value. Moody’s: Moody’s Investor Services, Inc. MRM: Market Risk Management group. MRC: Market Risk Committee. N/A: Not applicable. NAV: Net asset value. NFA: National Futures Association. N/M: Not meaningful. NMTC: New market tax credit. NOW: Negotiable Order of Withdrawal. NPR: Notice of proposed rulemaking. [added: NSF: Non-sufficient funds.] NYSE: New York Stock Exchange. OCC: Office of the Comptroller of the Currency. OCI: Other comprehensive income (loss). OREO: Other real estate owned. PBO: Projected benefit obligation. PCCR: Purchased credit card relationship. PCD: Purchased credit deteriorated. PD: Probability of default. PPP: Paycheck Protection Program. RMBS: Residential mortgage-backed securities. S&P: Standard and Poor’s Ratings Services, a Division of The McGraw-Hill Companies, Inc. SEC: U.S. Securities & Exchange Commission. SIFIs: Systemically important financial institutions, including large, interconnected BHCs and nonbank financial companies designated by FSOC for supervision by the Federal Reserve. SOFR: Secured Overnight Financing Rate. TDR: Troubled debt restructuring. TE: Taxable-equivalent. U.S. Treasury: United States Department of the Treasury. VaR: Value at risk. VEBA: Voluntary Employee Beneficiary Association. VIE: Variable interest entity. | | |
[removed: 2022] [added: 2023] FORM 10-K ANNUAL REPORT
| 1A | | | | | | [Risk [removed: Factors](#i5a468b8a075b404bb1614017a87fbb3f_22)] [added: Factors](#id35963ddccc041b2ab203b7e536286e2_22)] | | | [removed: [29](#i5a468b8a075b404bb1614017a87fbb3f_22)] [added: [25](#id35963ddccc041b2ab203b7e536286e2_22)] | | |
| 1B | | | | | | [Unresolved Staff [removed: Comments](#i5a468b8a075b404bb1614017a87fbb3f_25)] [added: Comments](#id35963ddccc041b2ab203b7e536286e2_25)] | | | [removed: [44](#i5a468b8a075b404bb1614017a87fbb3f_25)] [added: [42](#id35963ddccc041b2ab203b7e536286e2_25)] | | |
| 3 | | | | | | [Legal [removed: Proceedings](#i5a468b8a075b404bb1614017a87fbb3f_31)] [added: Proceedings](#id35963ddccc041b2ab203b7e536286e2_31)] | | | [removed: [44](#i5a468b8a075b404bb1614017a87fbb3f_31)] [added: [45](#id35963ddccc041b2ab203b7e536286e2_31)] | | |
| 4 | | | | | | [Mine Safety [removed: Disclosures](#i5a468b8a075b404bb1614017a87fbb3f_34)] [added: Disclosures](#id35963ddccc041b2ab203b7e536286e2_34)] | | | [removed: [44](#i5a468b8a075b404bb1614017a87fbb3f_34)] [added: [45](#id35963ddccc041b2ab203b7e536286e2_34)] | | |
| 5 | | | | | | [Market for the Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#i5a468b8a075b404bb1614017a87fbb3f_40)] [added: Securities](#id35963ddccc041b2ab203b7e536286e2_40)] | | | [removed: [45](#i5a468b8a075b404bb1614017a87fbb3f_40)] [added: [46](#id35963ddccc041b2ab203b7e536286e2_40)] | | |
| 7 | | | | | | [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#i5a468b8a075b404bb1614017a87fbb3f_49)] [added: Operations](#id35963ddccc041b2ab203b7e536286e2_49)] | | | [removed: [46](#i5a468b8a075b404bb1614017a87fbb3f_49)] [added: [47](#id35963ddccc041b2ab203b7e536286e2_49)] | | |
| 7A | | | | | | [Quantitative and Qualitative Disclosures About Market [removed: Risk](#i5a468b8a075b404bb1614017a87fbb3f_193)] [added: Risk](#id35963ddccc041b2ab203b7e536286e2_196)] | | | [removed: [94](#i5a468b8a075b404bb1614017a87fbb3f_193)] [added: [95](#id35963ddccc041b2ab203b7e536286e2_196)] | | |
| 8 | | | | | | [Financial Statements and Supplementary [removed: Data](#i5a468b8a075b404bb1614017a87fbb3f_196)] [added: Data](#id35963ddccc041b2ab203b7e536286e2_199)] | | | [removed: [95](#i5a468b8a075b404bb1614017a87fbb3f_196)] [added: [96](#id35963ddccc041b2ab203b7e536286e2_199)] | | |
| | | | | | | [Management’s Annual Report on Internal Control over Financial [removed: Reporting](#i5a468b8a075b404bb1614017a87fbb3f_199)] [added: Reporting](#id35963ddccc041b2ab203b7e536286e2_202)] | | | [removed: [96](#i5a468b8a075b404bb1614017a87fbb3f_199)] [added: [97](#id35963ddccc041b2ab203b7e536286e2_202)] | | |
| | | | | | | [Reports of Independent Registered Public Accounting [removed: Firm](#i5a468b8a075b404bb1614017a87fbb3f_202)] [added: Firm](#id35963ddccc041b2ab203b7e536286e2_205)] | | | [removed: [97](#i5a468b8a075b404bb1614017a87fbb3f_202)] [added: [98](#id35963ddccc041b2ab203b7e536286e2_205)] | | |
| | | | | | | [Consolidated Financial Statements and Related [removed: Notes](#i5a468b8a075b404bb1614017a87fbb3f_208)] [added: Notes](#id35963ddccc041b2ab203b7e536286e2_211)] | | | [removed: [100](#i5a468b8a075b404bb1614017a87fbb3f_208)] [added: [102](#id35963ddccc041b2ab203b7e536286e2_211)] | | |
| | | | | | | [Consolidated Statements of [removed: Comprehensive Income](#i5a468b8a075b404bb1614017a87fbb3f_217)] [added: Income](#id35963ddccc041b2ab203b7e536286e2_217)] | | | [removed: [102](#i5a468b8a075b404bb1614017a87fbb3f_217)] [added: [103](#id35963ddccc041b2ab203b7e536286e2_217)] | | |
| | | | | | | [Consolidated Statements of Changes in [removed: Equity](#i5a468b8a075b404bb1614017a87fbb3f_220)] [added: Equity](#id35963ddccc041b2ab203b7e536286e2_223)] | | | [removed: [103](#i5a468b8a075b404bb1614017a87fbb3f_220)] [added: [105](#id35963ddccc041b2ab203b7e536286e2_223)] | | |
| | | | | | | [Consolidated Statements of Cash [removed: Flows](#i5a468b8a075b404bb1614017a87fbb3f_223)] [added: Flows](#id35963ddccc041b2ab203b7e536286e2_226)] | | | [removed: [104](#i5a468b8a075b404bb1614017a87fbb3f_223)] [added: [106](#id35963ddccc041b2ab203b7e536286e2_226)] | | |
| | | | | | | [Notes to Consolidated Financial [removed: Statements](#i5a468b8a075b404bb1614017a87fbb3f_226)] [added: Statements](#id35963ddccc041b2ab203b7e536286e2_229)] | | | [removed: [105](#i5a468b8a075b404bb1614017a87fbb3f_229)] [added: [107](#id35963ddccc041b2ab203b7e536286e2_232)] | | |
| 9 | | | | | | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure](#i5a468b8a075b404bb1614017a87fbb3f_313)] [added: Disclosure](#id35963ddccc041b2ab203b7e536286e2_316)] | | | [removed: [176](#i5a468b8a075b404bb1614017a87fbb3f_313)] [added: [181](#id35963ddccc041b2ab203b7e536286e2_316)] | | |
| 9C | | | | | | [Disclosure Regarding Foreign Jurisdictions that Prevent [removed: Inspections](#i5a468b8a075b404bb1614017a87fbb3f_322)] [added: Inspections](#id35963ddccc041b2ab203b7e536286e2_325)] | | | [removed: [176](#i5a468b8a075b404bb1614017a87fbb3f_322)] [added: [181](#id35963ddccc041b2ab203b7e536286e2_325)] | | |
| 10 | | | | | | [Directors, Executive Officers and Corporate [removed: Governance](#i5a468b8a075b404bb1614017a87fbb3f_328)] [added: Governance](#id35963ddccc041b2ab203b7e536286e2_331)] | | | [removed: [176](#i5a468b8a075b404bb1614017a87fbb3f_328)] [added: [181](#id35963ddccc041b2ab203b7e536286e2_331)] | | |
| 12 | | | | | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#i5a468b8a075b404bb1614017a87fbb3f_334)] [added: Matters](#id35963ddccc041b2ab203b7e536286e2_337)] | | | [removed: [177](#i5a468b8a075b404bb1614017a87fbb3f_334)] [added: [182](#id35963ddccc041b2ab203b7e536286e2_337)] | | |
| 13 | | | | | | [Certain Relationships and Related Transactions, and Director [removed: Independence](#i5a468b8a075b404bb1614017a87fbb3f_337)] [added: Independence](#id35963ddccc041b2ab203b7e536286e2_340)] | | | [removed: [177](#i5a468b8a075b404bb1614017a87fbb3f_337)] [added: [182](#id35963ddccc041b2ab203b7e536286e2_340)] | | |
| 14 | | | | | | [Principal Accountant Fees and [removed: Services](#i5a468b8a075b404bb1614017a87fbb3f_340)] [added: Services](#id35963ddccc041b2ab203b7e536286e2_343)] | | | [removed: [177](#i5a468b8a075b404bb1614017a87fbb3f_340)] [added: [182](#id35963ddccc041b2ab203b7e536286e2_343)] | | |
| 15 | | | | | | [Exhibits and Financial Statement [removed: Schedules](#i5a468b8a075b404bb1614017a87fbb3f_346)] [added: Schedules](#id35963ddccc041b2ab203b7e536286e2_349)] | | | [removed: [177](#i5a468b8a075b404bb1614017a87fbb3f_346)] [added: [182](#id35963ddccc041b2ab203b7e536286e2_349)] | | |
| | | | | | | [(a) (1) Financial Statements — See listing in Item 8 [removed: above](#i5a468b8a075b404bb1614017a87fbb3f_349)] [added: above](#id35963ddccc041b2ab203b7e536286e2_352)] | | | [removed: [177](#i5a468b8a075b404bb1614017a87fbb3f_349)] [added: [182](#id35963ddccc041b2ab203b7e536286e2_352)] | | |
| | | | | | | [(a) (2) Financial Statement Schedules — None [removed: required](#i5a468b8a075b404bb1614017a87fbb3f_352)] [added: required](#id35963ddccc041b2ab203b7e536286e2_355)] | | | [removed: [177](#i5a468b8a075b404bb1614017a87fbb3f_352)] [added: [183](#id35963ddccc041b2ab203b7e536286e2_355)] | | |
December 31, 2023
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
- geopolitical destabilization;
- complex and evolving laws and regulations regarding privacy and cybersecurity;
- impairment of goodwill;
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
| 1 | | | | | | [Business](#id35963ddccc041b2ab203b7e536286e2_19) | | | [6](#id35963ddccc041b2ab203b7e536286e2_19) | | |
| 1C | | | | | | [Cybersecurity](#id35963ddccc041b2ab203b7e536286e2_2936) | | | [42](#id35963ddccc041b2ab203b7e536286e2_2936) | | |
| 2 | | | | | | [Properties](#id35963ddccc041b2ab203b7e536286e2_28) | | | [45](#id35963ddccc041b2ab203b7e536286e2_28) | | |
| 6 | | | | | | [RESERVED](#id35963ddccc041b2ab203b7e536286e2_43) | | | [47](#id35963ddccc041b2ab203b7e536286e2_43) | | |
| | | | | | | [Consolidated Balance Sheets](#id35963ddccc041b2ab203b7e536286e2_214) | | | [102](#id35963ddccc041b2ab203b7e536286e2_214) | | |
| | | | | | | [Consolidated Statements of Comprehensive Income](#id35963ddccc041b2ab203b7e536286e2_220) | | | [104](#id35963ddccc041b2ab203b7e536286e2_220) | | |
| 9A | | | | | | [Controls and Procedures](#id35963ddccc041b2ab203b7e536286e2_319) | | | [181](#id35963ddccc041b2ab203b7e536286e2_319) | | |
| 9B | | | | | | [Other Information](#id35963ddccc041b2ab203b7e536286e2_322) | | | [181](#id35963ddccc041b2ab203b7e536286e2_322) | | |
| 11 | | | | | | [Executive Compensation](#id35963ddccc041b2ab203b7e536286e2_334) | | | [182](#id35963ddccc041b2ab203b7e536286e2_334) | | |
| | | | | | | [(a) (3) Exhibits](#id35963ddccc041b2ab203b7e536286e2_358) | | | [184](#id35963ddccc041b2ab203b7e536286e2_358) | | |
| 16 | | | | | | [Form 10-K Summary](#id35963ddccc041b2ab203b7e536286e2_361) | | | [186](#id35963ddccc041b2ab203b7e536286e2_361) | | |
| | | | | | | [Signatures](#id35963ddccc041b2ab203b7e536286e2_364) | | | [187](#id35963ddccc041b2ab203b7e536286e2_364) | | |
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
December 31, 2022
- the impact of any failure by the U.S. government to increase the debt ceiling or any government shutdown;
- uncertainty surrounding the transition from LIBOR to an alternate reference rate;
circumstances, except as required by applicable securities laws.
| 1 | | | | | | [Business](#i5a468b8a075b404bb1614017a87fbb3f_19) | | | [7](#i5a468b8a075b404bb1614017a87fbb3f_19) | | |
| 2 | | | | | | [Properties](#i5a468b8a075b404bb1614017a87fbb3f_28) | | | [44](#i5a468b8a075b404bb1614017a87fbb3f_28) | | |
| 6 | | | | | | [RESERVED](#i5a468b8a075b404bb1614017a87fbb3f_43) | | | [46](#i5a468b8a075b404bb1614017a87fbb3f_43) | | |
| | | | | | | [Consolidated Balance Sheets](#i5a468b8a075b404bb1614017a87fbb3f_211) | | | [100](#i5a468b8a075b404bb1614017a87fbb3f_211) | | |
| | | | | | | [Consolidated Statements of Income](#i5a468b8a075b404bb1614017a87fbb3f_214) | | | [101](#i5a468b8a075b404bb1614017a87fbb3f_214) | | |
| 9A | | | | | | [Controls and Procedures](#i5a468b8a075b404bb1614017a87fbb3f_316) | | | [176](#i5a468b8a075b404bb1614017a87fbb3f_316) | | |
| 9B | | | | | | [Other Information](#i5a468b8a075b404bb1614017a87fbb3f_319) | | | [176](#i5a468b8a075b404bb1614017a87fbb3f_319) | | |
| 11 | | | | | | [Executive Compensation](#i5a468b8a075b404bb1614017a87fbb3f_331) | | | [177](#i5a468b8a075b404bb1614017a87fbb3f_331) | | |
| | | | | | | [(a) (3) Exhibits](#i5a468b8a075b404bb1614017a87fbb3f_355) | | | [178](#i5a468b8a075b404bb1614017a87fbb3f_355) | | |
| 16 | | | | | | [Form 10-K Summary](#i5a468b8a075b404bb1614017a87fbb3f_358) | | | [180](#i5a468b8a075b404bb1614017a87fbb3f_358) | | |
| | | | | | | [Signatures](#i5a468b8a075b404bb1614017a87fbb3f_361) | | | [181](#i5a468b8a075b404bb1614017a87fbb3f_361) | | |
Item 1C. CYBERSECURITY
0 rewritten, 140 added, 0 removed, 0 unchanged
New section this year
Cybersecurity Risk Management
As a financial services institution, Key faces heightened risk of cybersecurity incidents.
Risks and exposures related
to cybersecurity incidents are expected to remain high for the foreseeable future due to the rapidly evolving nature
and sophistication of cybersecurity threats and geopolitical events, as well as due to the expanding use of Internet and mobile banking and other technology-based products and services utilized by us and our clients.
To date, Key has not experienced material disruption to our operations, or material harm to our client base, from cyberattacks.
However, we have incurred, and may again incur, expenses related to the investigation of cybersecurity incidents involving third-party providers or related to the protection of our clients from identity theft as a result of such incidents.
We have also incurred, and may continue to incur, expenses to enhance our systems or processes to protect against cyber or other security incidents.
For more information, see “Risk Factors—We and third parties on which we rely (including their downstream service providers) may experience a cyberattack, technology failure, information system or security breach or interruption” in Item 1A.
Risk Factors of this report.
Key maintains an Information Security Program (the “IS Program”) to support the management of information security risk, including cybersecurity risk, across the organization.
The IS Program is designed to protect Key’s
clients, employees, third parties, and assets from threats by managing the confidentiality, availability, and integrity of
Key’s information assets.
Our Chief Information Security Officer (“CISO”), who is also the Enterprise Security
Executive, oversees the IS Program and its related policy and has overall responsibility for managing the appropriate identification and ownership of cybersecurity risks.
Key’s Corporate Information Security Team, under the oversight of the CISO, is responsible for maintaining the IS Program, assessing program-level risks and threats to our information assets, and overseeing the proper level of investment in security resources.
The IS Program is designed to provide safeguards for Key’s assets through a series of administrative, technical,
and physical controls.
Key employs a variety of security practices and controls to protect information and assets,
including, but not limited to, access controls, vulnerability scans, network monitoring, internal and external
penetration testing, monitoring of vendor vulnerability notices and patch releases, scanning of systems and emails
for malware and other vulnerabilities, firewalls and intrusion detection and prevention systems, and dedicated
security personnel.
As described in more detail in “Risk Management — Overview” in Item 7 of this report and in “Cybersecurity
Governance” below, Key employs the “Three Lines of Defense” in its risk governance framework.
Assessing,
identifying, and managing cybersecurity risk across the organization in support of the IS Program is a cross-functional effort that requires collaboration and direction from all lines of defense – the lines of business and support functions (First Line of Defense), Risk Management (Second Line of Defense), and the Risk Review Group (RRG), Key’s internal audit function (Third Line of Defense):
- First Line of Defense – Lines of Business and Support Functions.
Primary responsibility for day-to-day management of cybersecurity risk lies with the senior management of each of Key’s lines of business (LOB) and support functions.
The LOB and support functions own and manage the individual processes and procedures that are used throughout the IS Program, implement and manage business-specific security controls, and enforce behavioral controls throughout the management structure.
- Second Line of Defense – Risk Management.
Risk Management oversees risk and monitors the First Line of Defense controls.
Operational Risk Management performs review and challenge of controls, monitors the operational risk profile, and ensures Key operates within its operational risk appetite.
Compliance Risk Management provides an independent, enterprise-wide function that focuses on compliance with laws, rules, regulations, and guidance applicable to Key.
Privacy Compliance, which sits within Compliance Risk Management, provides advisory support, governance, and oversight of privacy-related statutes, regulations, and risks related to Key’s customers, employees, and other individuals from who Key collects personally identifiable information.
- Third Line of Defense – Risk Review Group.
The RRG reviews and evaluates the scope and breadth of security activities throughout Key and the effectiveness of the IS Program.
RRG conducts independent internal audits on Key’s LOBs, operations, information systems, and technologies.
These internal audits provide an independent
An excerpt. Shown here: all 0 rewritten, 40 of 140 added and all 0 removed. The counts are complete. For every sentence, read Item 1C. CYBERSECURITY in the FY2023 filing.
Item 2. PROPERTIES
3 rewritten, 0 added, 0 removed, 3 unchanged
At December 31, [removed: 2022,] [added: 2023,] Key leased approximately [removed: 418,812] [added: 375,414] square feet of the complex, encompassing the first floor branch, the [removed: 2nd] [added: 2nd, 3rd and 5th] through 9th office floors, the 12th floor, and the 54th through 56th floors of the 57-story Key Center.
In addition, Key owned two buildings in Brooklyn, Ohio, with office space that it operated from and totaling [removed: 586,616] [added: 584,930] square feet at December 31, [removed: 2022.][added: 2023.]
As of the same date, KeyBank owned [removed: 428] [added: 415] branches and leased [removed: 571] [added: 544] branches.
Item 4. MINE SAFETY DISCLOSURES
1 rewritten, 0 added, 0 removed, 2 unchanged
[removed: [Table](#i5a468b8a075b404bb1614017a87fbb3f_13) [of contents](#i5a468b8a075b404bb1614017a87fbb3f_13)][added: [Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)]
Item 5. MARKET FOR THE REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
7 rewritten, 11 added, 6 removed, 14 unchanged
The following graph compares the price performance of our Common Shares (based on an initial investment of $100 on December 31, [removed: 2017,] [added: 2018,] and assuming reinvestment of dividends) with that of the S&P 500 Index and a group of other banks that constitute our peer group.
[removed: 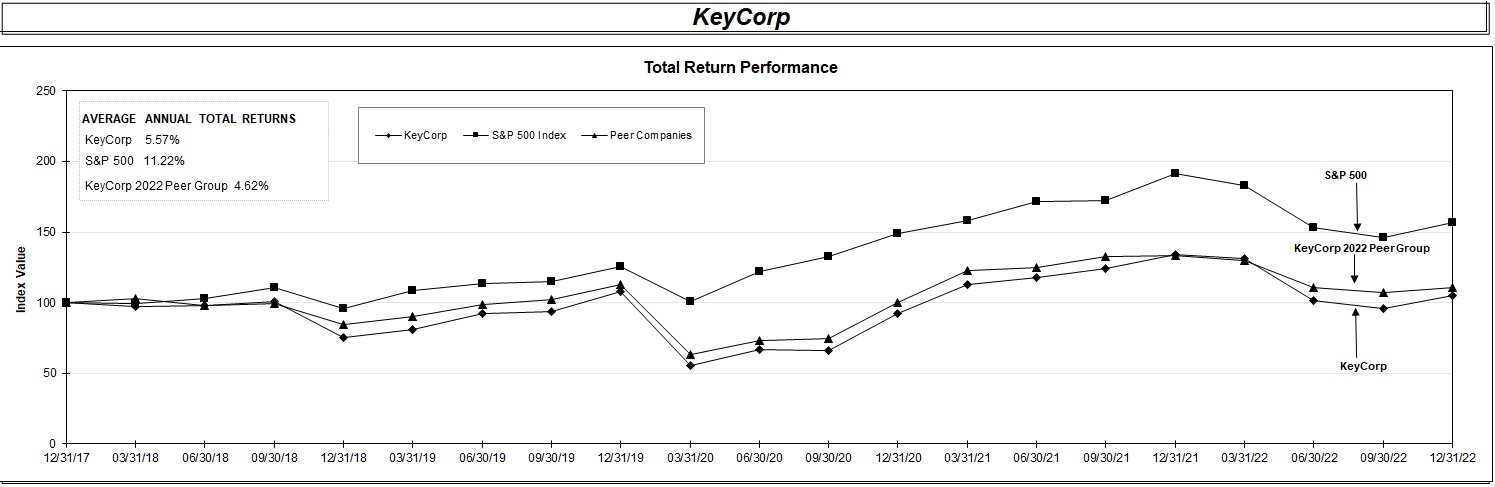][added: 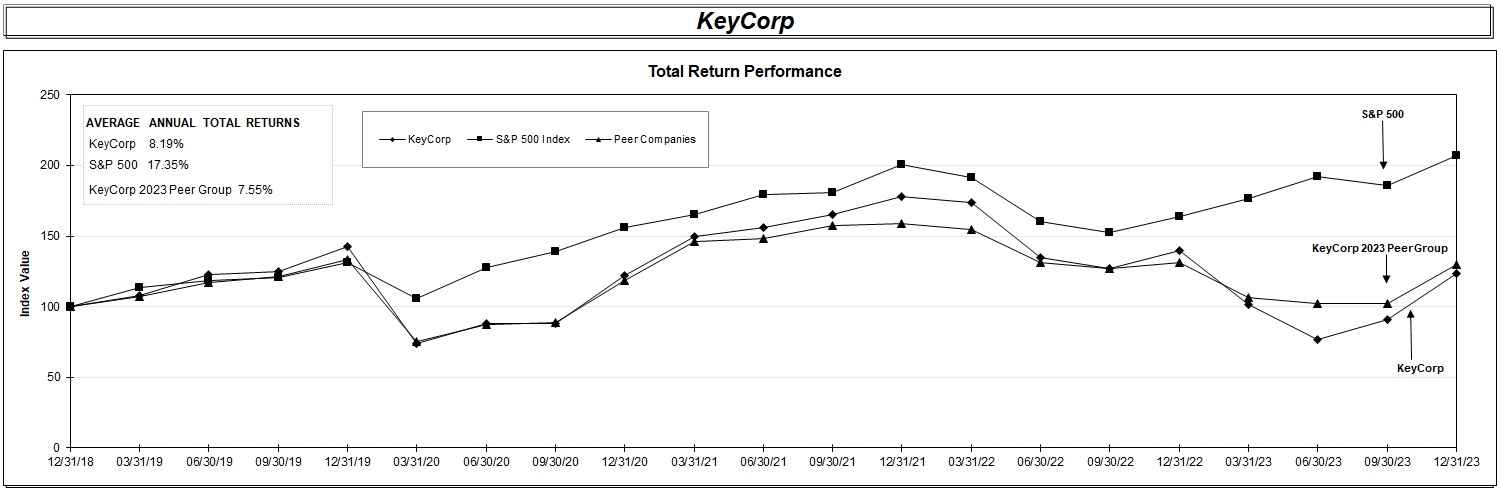]
[removed: As part of our previous 2021 capital plan, which was effective through the third quarter of 2022,] [added: In July 2021,] the Board [removed: had] [added: of Directors] authorized the repurchase of up to $1.5 billion of our Common [removed: Shares.][added: Shares, effective the third quarter of 2021 through the third quarter of 2022.]
In September 2022, the Board [added: of Directors] approved the extension of the previous authorization through the third quarter of 2023.
The following table summarizes our repurchases of our Common Shares for the three months ended December 31, [removed: 2022.][added: 2023.]
| Calendar month | | | Total number of shares repurchased(a) | | | Average price paid per share | | | Total number of shares purchased as part of publicly announced plans or [removed: programs(a)] [added: programs] | | | Dollar value of shares that may yet be purchased as part of publicly announced plans or programs [added: (b)] | | | [added: | | |]
[removed: [Table](#i5a468b8a075b404bb1614017a87fbb3f_13) [of contents](#i5a468b8a075b404bb1614017a87fbb3f_13)][added: [Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)]
This authorization expired as of September 30, 2023.
During the fourth quarter of 2023, Key repurchased less than $1 million of shares related to equity compensation programs.
| | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| October 1 - 31 | | | — | | | $ | — | | — | | | $ | — | | | | |
| November 1 - 30 | | | — | | | — | | | — | | | — | | | | | |
| December 1 -31 | | | 1,744 | | | 13.73 | | | — | | | — | | | | | |
| Total | | | 1,744 | | | $ | 13.73 | | — | | | | | | | | |
| | | | | | | | | | | | | | | | | | |
We did not complete any open market share repurchases in the fourth quarter of 2023.
(b)Our previous share purchase authorization expired as of September 30, 2023
| | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| October 1 - 31 | | | — | | | $ | — | | — | | | $ | 745,991,117 | |
| November 1 - 30 | | | — | | | — | | | — | | | 745,991,117 | | |
| December 1 - 31 | | | 2,401 | | | 17.89 | | | 2,401 | | | 745,948,169 | | |
| Total | | | 2,401 | | | $ | 17.89 | | 2,401 | | | | | |
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
1,217 rewritten, 511 added, 256 removed, 2,036 unchanged
| [Management’s Annual Report on Internal Control over Financial [removed: Reporting](#i5a468b8a075b404bb1614017a87fbb3f_199)] [added: Reporting](#id35963ddccc041b2ab203b7e536286e2_202)] | | | [removed: [96](#i5a468b8a075b404bb1614017a87fbb3f_199)] [added: [97](#id35963ddccc041b2ab203b7e536286e2_202)] | | |
| [Report of Independent Registered Public Accounting Firm on Internal Control over Financial [removed: Reporting](#i5a468b8a075b404bb1614017a87fbb3f_202)] [added: Reporting](#id35963ddccc041b2ab203b7e536286e2_205)] | | | [removed: [97](#i5a468b8a075b404bb1614017a87fbb3f_202)] [added: [98](#id35963ddccc041b2ab203b7e536286e2_205)] | | |
| [Report of Independent Registered Public Accounting [removed: Firm](#i5a468b8a075b404bb1614017a87fbb3f_205)] [added: Firm](#id35963ddccc041b2ab203b7e536286e2_208)] (PCAOB ID: 42) | | | [removed: [98](#i5a468b8a075b404bb1614017a87fbb3f_205)] [added: [99](#id35963ddccc041b2ab203b7e536286e2_208)] | | |
| [Consolidated Statements of [removed: Comprehensive Income](#i5a468b8a075b404bb1614017a87fbb3f_217)] [added: Income](#id35963ddccc041b2ab203b7e536286e2_217)] | | | [removed: [102](#i5a468b8a075b404bb1614017a87fbb3f_217)] [added: [103](#id35963ddccc041b2ab203b7e536286e2_217)] | | |
| [Consolidated Statements of Changes in [removed: Equity](#i5a468b8a075b404bb1614017a87fbb3f_220)] [added: Equity](#id35963ddccc041b2ab203b7e536286e2_223)] | | | [removed: [103](#i5a468b8a075b404bb1614017a87fbb3f_220)] [added: [105](#id35963ddccc041b2ab203b7e536286e2_223)] | | |
| [Consolidated Statements of Cash [removed: Flows](#i5a468b8a075b404bb1614017a87fbb3f_223)] [added: Flows](#id35963ddccc041b2ab203b7e536286e2_226)] | | | [removed: [104](#i5a468b8a075b404bb1614017a87fbb3f_223)] [added: [106](#id35963ddccc041b2ab203b7e536286e2_226)] | | |
| [Notes to Consolidated Financial [removed: Statements](#i5a468b8a075b404bb1614017a87fbb3f_226)] [added: Statements](#id35963ddccc041b2ab203b7e536286e2_229)] | | | [removed: [105](#i5a468b8a075b404bb1614017a87fbb3f_229)] [added: [107](#id35963ddccc041b2ab203b7e536286e2_232)] | | |
| [Note 1. Summary of Significant Accounting [removed: Policies](#i5a468b8a075b404bb1614017a87fbb3f_229)] [added: Policies](#id35963ddccc041b2ab203b7e536286e2_232)] | | | [removed: [105](#i5a468b8a075b404bb1614017a87fbb3f_229)] [added: [107](#id35963ddccc041b2ab203b7e536286e2_232)] | | |
| [Note 2. Earnings Per Common [removed: Share](#i5a468b8a075b404bb1614017a87fbb3f_232)] [added: Share](#id35963ddccc041b2ab203b7e536286e2_235)] | | | [removed: [116](#i5a468b8a075b404bb1614017a87fbb3f_232)] [added: [119](#id35963ddccc041b2ab203b7e536286e2_235)] | | |
| [Note 3. Restrictions on Cash, Dividends and Lending [removed: Activities](#i5a468b8a075b404bb1614017a87fbb3f_235)] [added: Activities](#id35963ddccc041b2ab203b7e536286e2_238)] | | | [removed: [117](#i5a468b8a075b404bb1614017a87fbb3f_235)] [added: [119](#id35963ddccc041b2ab203b7e536286e2_238)] | | |
| [Note 6. Fair Value [removed: Measurements](#i5a468b8a075b404bb1614017a87fbb3f_244)] [added: Measurements](#id35963ddccc041b2ab203b7e536286e2_247)] | | | [removed: [125](#i5a468b8a075b404bb1614017a87fbb3f_244)] [added: [130](#id35963ddccc041b2ab203b7e536286e2_247)] | | |
| [Note 8. Derivatives and Hedging [removed: Activities](#i5a468b8a075b404bb1614017a87fbb3f_250)] [added: Activities](#id35963ddccc041b2ab203b7e536286e2_253)] | | | [removed: [137](#i5a468b8a075b404bb1614017a87fbb3f_250)] [added: [142](#id35963ddccc041b2ab203b7e536286e2_253)] | | |
| [Note 9. Mortgage Servicing [removed: Assets](#i5a468b8a075b404bb1614017a87fbb3f_253)] [added: Assets](#id35963ddccc041b2ab203b7e536286e2_256)] | | | [removed: [144](#i5a468b8a075b404bb1614017a87fbb3f_253)] [added: [148](#id35963ddccc041b2ab203b7e536286e2_256)] | | |
| [Note 11. Premises and [removed: Equipment](#i5a468b8a075b404bb1614017a87fbb3f_259)] [added: Equipment](#id35963ddccc041b2ab203b7e536286e2_262)] | | | [removed: [148](#i5a468b8a075b404bb1614017a87fbb3f_259)] [added: [153](#id35963ddccc041b2ab203b7e536286e2_262)] | | |
| [Note 12. Goodwill and Other Intangible [removed: Assets](#i5a468b8a075b404bb1614017a87fbb3f_262)] [added: Assets](#id35963ddccc041b2ab203b7e536286e2_265)] | | | [removed: [148](#i5a468b8a075b404bb1614017a87fbb3f_262)] [added: [153](#id35963ddccc041b2ab203b7e536286e2_265)] | | |
| [Note 13. Variable Interest [removed: Entities](#i5a468b8a075b404bb1614017a87fbb3f_265)] [added: Entities](#id35963ddccc041b2ab203b7e536286e2_268)] | | | [removed: [149](#i5a468b8a075b404bb1614017a87fbb3f_265)] [added: [154](#id35963ddccc041b2ab203b7e536286e2_268)] | | |
| [Note 14. Income [removed: Taxes](#i5a468b8a075b404bb1614017a87fbb3f_268)] [added: Taxes](#id35963ddccc041b2ab203b7e536286e2_271)] | | | [removed: [151](#i5a468b8a075b404bb1614017a87fbb3f_268)] [added: [157](#id35963ddccc041b2ab203b7e536286e2_271)] | | |
| [Note 15. Acquisitions and Discontinued [removed: Operations](#i5a468b8a075b404bb1614017a87fbb3f_271)] [added: Operations](#id35963ddccc041b2ab203b7e536286e2_274)] | | | [removed: [153](#i5a468b8a075b404bb1614017a87fbb3f_271)] [added: [159](#id35963ddccc041b2ab203b7e536286e2_274)] | | |
| [Note 16. Securities Financing [removed: Activities](#i5a468b8a075b404bb1614017a87fbb3f_274)] [added: Activities](#id35963ddccc041b2ab203b7e536286e2_277)] | | | [removed: [154](#i5a468b8a075b404bb1614017a87fbb3f_274)] [added: [159](#id35963ddccc041b2ab203b7e536286e2_277)] | | |
| [Note 17. Stock-Based [removed: Compensation](#i5a468b8a075b404bb1614017a87fbb3f_277)] [added: Compensation](#id35963ddccc041b2ab203b7e536286e2_280)] | | | [removed: [154](#i5a468b8a075b404bb1614017a87fbb3f_277)] [added: [160](#id35963ddccc041b2ab203b7e536286e2_280)] | | |
| [Note 18. Employee [removed: Benefits](#i5a468b8a075b404bb1614017a87fbb3f_280)] [added: Benefits](#id35963ddccc041b2ab203b7e536286e2_283)] | | | [removed: [157](#i5a468b8a075b404bb1614017a87fbb3f_280)] [added: [162](#id35963ddccc041b2ab203b7e536286e2_283)] | | |
| [Note 19. Short-Term [removed: Borrowings](#i5a468b8a075b404bb1614017a87fbb3f_283)] [added: Borrowings](#id35963ddccc041b2ab203b7e536286e2_286)] | | | [removed: [163](#i5a468b8a075b404bb1614017a87fbb3f_283)] [added: [168](#id35963ddccc041b2ab203b7e536286e2_286)] | | |
| [Note 20. Long-Term [removed: Debt](#i5a468b8a075b404bb1614017a87fbb3f_286)] [added: Debt](#id35963ddccc041b2ab203b7e536286e2_289)] | | | [removed: [164](#i5a468b8a075b404bb1614017a87fbb3f_286)] [added: [169](#id35963ddccc041b2ab203b7e536286e2_289)] | | |
| [Note 21. Trust Preferred Securities Issued by Unconsolidated [removed: Subsidiaries](#i5a468b8a075b404bb1614017a87fbb3f_289)] [added: Subsidiaries](#id35963ddccc041b2ab203b7e536286e2_292)] | | | [removed: [165](#i5a468b8a075b404bb1614017a87fbb3f_289)] [added: [170](#id35963ddccc041b2ab203b7e536286e2_292)] | | |
| [Note 22. Commitments, Contingent Liabilities, and [removed: Guarantees](#i5a468b8a075b404bb1614017a87fbb3f_292)] [added: Guarantees](#id35963ddccc041b2ab203b7e536286e2_295)] | | | [removed: [166](#i5a468b8a075b404bb1614017a87fbb3f_292)] [added: [171](#id35963ddccc041b2ab203b7e536286e2_295)] | | |
| [Note 23. Accumulated Other Comprehensive [removed: Income](#i5a468b8a075b404bb1614017a87fbb3f_295)] [added: Income](#id35963ddccc041b2ab203b7e536286e2_298)] | | | [removed: [169](#i5a468b8a075b404bb1614017a87fbb3f_295)] [added: [174](#id35963ddccc041b2ab203b7e536286e2_298)] | | |
| [Note 24. Shareholders’ [removed: Equity](#i5a468b8a075b404bb1614017a87fbb3f_298)] [added: Equity](#id35963ddccc041b2ab203b7e536286e2_301)] | | | [removed: [170](#i5a468b8a075b404bb1614017a87fbb3f_298)] [added: [175](#id35963ddccc041b2ab203b7e536286e2_301)] | | |
| [Note 25. Business Segment [removed: Reporting](#i5a468b8a075b404bb1614017a87fbb3f_304)] [added: Reporting](#id35963ddccc041b2ab203b7e536286e2_307)] | | | [removed: [171](#i5a468b8a075b404bb1614017a87fbb3f_304)] [added: [177](#id35963ddccc041b2ab203b7e536286e2_307)] | | |
| [Note 26. Condensed Financial Information of the Parent [removed: Company](#i5a468b8a075b404bb1614017a87fbb3f_307)] [added: Company](#id35963ddccc041b2ab203b7e536286e2_310)] | | | [removed: [174](#i5a468b8a075b404bb1614017a87fbb3f_307)] [added: [179](#id35963ddccc041b2ab203b7e536286e2_310)] | | |
| [Note 27. Revenue from Contracts with [removed: Customers](#i5a468b8a075b404bb1614017a87fbb3f_310)] [added: Customers](#id35963ddccc041b2ab203b7e536286e2_313)] | | | [removed: [175](#i5a468b8a075b404bb1614017a87fbb3f_310)] [added: [180](#id35963ddccc041b2ab203b7e536286e2_313)] | | |
[removed: [Table](#i5a468b8a075b404bb1614017a87fbb3f_13) [of contents](#i5a468b8a075b404bb1614017a87fbb3f_13)][added: [Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)]
During [removed: 2022,] [added: 2023,] the Audit Committee of the Board of Directors met regularly with Management, internal audit, and the independent registered public accounting firm, Ernst & Young LLP, to review the scope of their audits and to discuss the evaluation of internal accounting controls and financial reporting matters.
Based on that assessment, we believe we maintained an effective system of internal control over financial reporting as of December 31, [removed: 2022.][added: 2023.]
The Corporation's internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] has been audited by Ernst & Young LLP, an independent registered public accounting firm, as stated in their accompanying report dated February 22, [removed: 2023.][added: 2024.]
[removed:  ][added:  ]
We have audited KeyCorp’s internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria).
In our opinion, KeyCorp maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of KeyCorp as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the related consolidated statements of income, comprehensive income, changes in equity and cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] and the related notes and our report dated February 22, [removed: 2023] [added: 2024] expressed an unqualified opinion thereon.
| [removed: ] [added: ] | | |
We have audited the accompanying consolidated balance sheets of KeyCorp as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the related consolidated statements of income, comprehensive income, changes in equity, and cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] and the related notes (collectively referred to as the “consolidated financial statements”).
| [Consolidated Balance Sheets](#id35963ddccc041b2ab203b7e536286e2_214) | | | [102](#id35963ddccc041b2ab203b7e536286e2_214) | | |
| [Consolidated Statements of Comprehensive Income](#id35963ddccc041b2ab203b7e536286e2_220) | | | [104](#id35963ddccc041b2ab203b7e536286e2_220) | | |
| [Note 4. Loan Portfolio](#id35963ddccc041b2ab203b7e536286e2_241) | | | [120](#id35963ddccc041b2ab203b7e536286e2_241) | | |
| [Note 5. Asset Quality](#id35963ddccc041b2ab203b7e536286e2_244) | | | [121](#id35963ddccc041b2ab203b7e536286e2_244) | | |
| [Note 7. Securities](#id35963ddccc041b2ab203b7e536286e2_250) | | | [140](#id35963ddccc041b2ab203b7e536286e2_250) | | |
| [Note 10. Leases](#id35963ddccc041b2ab203b7e536286e2_259) | | | [150](#id35963ddccc041b2ab203b7e536286e2_259) | | |
Gorman Clark H.
Khayat
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
| | | | | | | Goodwill Impairment Test of the Institutional Bank Reporting Unit | | |
| *Description of the Matter* | | | | | | KeyCorp has a goodwill balance of $2.8 billion as of December 31, 2023, of which $133 million is allocated to the Institutional Bank reporting unit. As discussed in Notes 1 and 12 of the financial statements, management performs an annual goodwill impairment test at the reporting unit level as of October 1, or more frequently as events occur or circumstances change that may indicate that it is more likely than not that the fair value of any reporting unit may be less than its carrying value. Management estimates the fair value of its reporting units by using a combination of income and market approaches. The income approach consists of discounted cash flow modeling that uses internal forecasts and various other inputs and assumptions. The market approach incorporates comparable public company multiples along with data related to recent merger and acquisition activity. Auditing management's annual goodwill impairment test for the Institutional Bank reporting unit was complex and highly judgmental due to the significant estimation required to determine the fair value of the reporting unit. In particular, the fair value estimate was sensitive to the (i) discounted cash flow method of the income approach and its significant assumptions, which include the terminal growth rate and discount rate and (ii) valuation multiples of comparable public companies and recent transaction information. | | |
| *How We Addressed the Matter in Our Audit* | | | | | | We obtained an understanding, evaluated the design and tested the operating effectiveness of controls over KeyCorp’s goodwill impairment review process, including controls over management’s review of the significant assumptions described above. With the assistance of EY specialists, we evaluated management’s fair value methodology, assessed the reasonableness of significant assumptions used in the discounted cash flow method, evaluated the appropriateness of selected multiples of comparable public companies and recent transaction information used in the market approach, developed an independent fair value range of the Institutional Bank reporting unit and compared the results to management’s fair value estimate and carrying value of the Institutional Bank reporting unit, and reconciled management’s estimated fair value of KeyCorp to its market capitalization as of the annual measurement date. | | |
|  | | |
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
| Income (loss) from discontinued operations, net of taxes | | | — | | | .01 | | | .01 | | |
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
| Net income (loss) | | | | | | | | | | | | | | | | | | 967 | | | | | | | | | | | | 967 | | |
| Series H Preferred Stock ( $1.55 per depositary share) | | | | | | | | | | | | | | | | | | (37) | | | | | | | | | | | | (37) | | |
| BALANCE AT DECEMBER 31, 2023 | | | 1,996 | | | 936,564 | | | $ | 2,500 | | $ | 1,257 | | $ | 6,281 | | $ | 15,672 | | $ | (5,844) | | $ | (5,229) | | | | | $ | 14,637 | |
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
| Net transfer of loans held for sale | | | — | | | — | | | — | | |
| Repurchases of long-term debt | | | (92) | | | — | | | — | | |
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
326), which eliminated the accounting for troubled debt restructurings while expanding loan modification and vintage disclosure requirements.
Under this guidance we assess all loan modifications to determine whether one is granted to a borrower experiencing financial difficulty, regardless of whether the modification loan terms include a
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
concession.
Modifications granted to borrowers experiencing financial difficulty may be in the form of an interest rate reduction, payment delay, other modifications, or some combination thereof.
A borrower is considered to be experiencing financial difficulty when there is significant doubt about the borrower’s ability to make required payments on the loan or to get equivalent financing from another creditor at a market rate for a similar loan.
Prior to the adoption of ASU 2022-02, a TDR occurred when a loan to a borrower experiencing financial difficulty was restricted with a concession provided that a creditor would not otherwise consider.
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
are determined based on an analysis of the present value of the loan's expected future cash flows or the fair
value of the collateral less costs to sell.
multiplied by the loan balance and the results are aggregated for purposes of measuring specific reserve
| [Consolidated Balance Sheets](#i5a468b8a075b404bb1614017a87fbb3f_211) | | | [100](#i5a468b8a075b404bb1614017a87fbb3f_211) | | |
| [Consolidated Statements of Income](#i5a468b8a075b404bb1614017a87fbb3f_214) | | | [101](#i5a468b8a075b404bb1614017a87fbb3f_214) | | |
| [Note 4. Loan Portfolio](#i5a468b8a075b404bb1614017a87fbb3f_238) | | | [117](#i5a468b8a075b404bb1614017a87fbb3f_238) | | |
| [Note 5. Asset Quality](#i5a468b8a075b404bb1614017a87fbb3f_241) | | | [118](#i5a468b8a075b404bb1614017a87fbb3f_241) | | |
| [Note 7. Securities](#i5a468b8a075b404bb1614017a87fbb3f_247) | | | [135](#i5a468b8a075b404bb1614017a87fbb3f_247) | | |
| [Note 10. Leases](#i5a468b8a075b404bb1614017a87fbb3f_256) | | | [145](#i5a468b8a075b404bb1614017a87fbb3f_256) | | |
Gorman Donald R.
Kimble
| Cleveland, Ohio | | |
| February 22, 2023 | | |
| NOW and money market deposit accounts | | | $ | 86,707 | | $ | 89,207 | |
| Savings deposits | | | 7,681 | | | 7,503 | | |
| Certificates of deposit ($100,000 or more) | | | 1,708 | | | 1,705 | | |
| Other time deposits | | | 5,665 | | | 2,153 | | |
For 2022, 2021, and 2020, we did not have any impairment losses related to securities.
See Notes to Consolidated Financial Statements.
| BALANCE AT DECEMBER 31, 2019 | | | 1,396 | | | 977,189 | | | $ | 1,900 | | $ | 1,257 | | $ | 6,295 | | $ | 12,469 | | $ | (4,909) | | $ | 26 | | | | | $ | 17,038 | |
| Cumulative effect from changes in accounting principle (a) | | | | | | | | | | | | | | | | | | (230) | | | | | | | | | | | | (230) | | |
| Other reclassification of AOCI | | | | | | | | | | | | | | | | | | (2) | | | | | | | | | | | | (2) | | |
(a) Includes the impact of implementing ASU 2016-13.
(b) See Note 24 (“Shareholders' Equity”) for additional detail regarding ASR program.
commitment fees, and the direct costs of originating or acquiring loans.
Credit Losses on Financial Instruments, which replaces the incurred-loss methodology that recognized losses when
a probable threshold was met with an expected-loss methodology, specifically, recognizing current expected credit
losses for the remaining life of the asset at the time of origination or acquisition.
adjusted as a provision for credit losses.
“Other securities” held in the available-for-sale portfolio consist of convertible preferred stock of privately held companies.
All of our mortgage-backed securities are issued by U.S. government-sponsored enterprises or GNMA, are highly rated by major rating agencies and have a long history of no credit losses.
Our asset backed securities consist primarily of senior notes from the sale and securitization of our indirect auto portfolio.
Other securities are comprised of State of Israel bonds denominated and paid in U.S. dollars.
Israel bonds have a long history of no credit losses.
Additionally, as of December 31, 2022, the State of Israel's credit rating is "stable" or “positive” among Fitch, Moody's, and S&P (A+, A1, AA-).
Adjustments are
| ASU 2020-04 and ASU 2021-01 — Reference Rate Reform (Topic 848) | | | March 12, 2020 through December 31, 2024 | | | London Interbank Offered Rate (LIBOR), a reference rate presumed to capture bank funding costs, is being phased out and will no longer be published. This transition to alternate rates will impact, among other things, contracts that reference LIBOR. This ASU provides relief from cumbersome accounting consequences for certain qualifying contract modifications undertaken as a result of reference rate reform. | | | Key has established an enterprise-wide program to identify and address all LIBOR related matters. We have elected to apply certain optional expedients for contract modifications and hedging relationships to derivative instruments impacted by the market-wide discounting transition. These optional expedients remove the requirement to remeasure contract modifications or dedesignate hedging relationships due to reference rate reform. We plan to elect any optional expedients for contract modifications and hedging relationships to any other financial instruments falling under the scope of reference rate reform. | | |
| ASU 2020-06, Debt—Debt with Conversion and Other Options (Subtopic 470-20) and Derivatives and Hedging— Contracts in Entity’s Own Equity (Subtopic 815-40) | | | January 1, 2022 | | | The ASU simplifies the accounting for convertible debt instruments by eliminating the legacy accounting models for convertible instruments with beneficial conversion features or cash conversion features. The guidance also amends the guidance used to determine if a freestanding financial instrument or an embedded feature qualifies for a scope exception from derivative accounting. For freestanding financial instruments and embedded features that have all the characteristics of a derivative instrument and are potentially settled in an entity’s own stock, the guidance simplifies the settlement assessment that entities are required to perform. Also, this update now requires the use of the if-converted method for all convertible instruments and includes the effect of potential share settlement in diluted EPS if the effect is more dilutive. The new guidance also makes clarifications to the EPS calculation. Further, the ASU expands disclosure requirements. The guidance should be applied on a modified retrospective or retrospective basis. | | | The adoption of this accounting guidance did not have a material effect on our financial condition or results of operations. | | |
stock-based awards.
| | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Commercial and industrial | | | $ | 551 | | $ | (141) | | $ | 410 | | $ | 585 | | | | | $ | (351) | | $ | 34 | | $ | 678 | |
| Total commercial loans | | | 751 | | | (124) | | | 627 | | | 839 | | | | | | (405) | | | 38 | | | 1,099 | | |
| Total consumer loans | | | 149 | | | 328 | | | 477 | | | 126 | | | | | | (117) | | | 41 | | | 527 | | |
An excerpt. Shown here: 40 of 1,217 rewritten, 40 of 511 added and 40 of 256 removed. The counts are complete. For every sentence, read Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA in the FY2023 filing and the FY2022 filing.
Item 9A. CONTROLS AND PROCEDURES
1 rewritten, 0 added, 0 removed, 5 unchanged
Management’s Annual Report on Internal Control over Financial Reporting, the Report of Independent Registered Public Accounting Firm on Internal Control over Financial Reporting, and the Report of Independent Registered Public Accounting Firm are included in Item 8 on pages [removed: [96](#i5a468b8a075b404bb1614017a87fbb3f_199), [97](#i5a468b8a075b404bb1614017a87fbb3f_202),] [added: [97](#id35963ddccc041b2ab203b7e536286e2_202), [98](#id35963ddccc041b2ab203b7e536286e2_205),] and [removed: [98](#i5a468b8a075b404bb1614017a87fbb3f_205),] [added: [99](#id35963ddccc041b2ab203b7e536286e2_208),] respectively.
Item 9B. OTHER INFORMATION
0 rewritten, 17 added, 1 removed, 0 unchanged
No director or officer (as defined in Rule 16a-1(f) of the Exchange Act) of KeyCorp adopted, modified,
or terminated any Rule 10b5-1 trading arrangement or any non-Rule 10b5-1 trading arrangement (as such terms
are defined in Item 408 of Regulation S-K of the Exchange Act) during the quarter ended December 31, 2023,
except as may be noted below.
We do not permit the use of Rule 10b5-1 trading arrangements by our directors or
executive officers.
Certain of our directors or officers have made elections to participate in, and are participating in, our KeyCorp
Second Amended and Restated Discounted Stock Purchase Plan, our Long-Term Incentive Deferral Plan, our
Directors’ Deferred Share Sub-Plan, and the Dividend Reinvestment Plan and dividend reinvestment features under
various compensation plans and arrangements, and previously made elections to participate in KeyCorp common
stock funds that are now frozen but were previously available as an investment option under our Deferred Savings
Plan and KeyCorp 401(k) plan.
By participating in these plans or stock funds, the directors or officers have made,
and/or may from time to time make, elections involving transactions in KeyCorp common shares which may be
designed to satisfy the affirmative defense conditions of Rule 10b5-1 under the Exchange Act or may constitute
non-Rule 10b5-1 trading arrangements (as such term is defined in Item 408(c) of Regulation S-K of the Exchange
Act).
Not applicable.
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
4 rewritten, 0 added, 0 removed, 6 unchanged
The other information required by this item will be set forth in the following sections of KeyCorp’s Definitive Proxy Statement for the [removed: 2023] [added: 2024] Annual Meeting of Shareholders to be held May [removed: 11, 2023] [added: 9, 2024] (the [removed: “2023] [added: “2024] Proxy Statement”), and these sections are incorporated herein by reference:
- “Additional Information — Other Proposals and Director Nominations for the [removed: 2024] [added: 2025] Annual Meeting of Shareholders”
KeyCorp expects to file the [removed: 2023] [added: 2024] Proxy Statement with the SEC on or about March [removed: 24, 2023.][added: 22, 2024.]
[removed: [Table](#i5a468b8a075b404bb1614017a87fbb3f_13) [of contents](#i5a468b8a075b404bb1614017a87fbb3f_13)][added: [Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)]
Item 11. EXECUTIVE COMPENSATION
1 rewritten, 0 added, 0 removed, 4 unchanged
The information required by this item will be set forth in the following sections of the [removed: 2023] [added: 2024] Proxy Statement and these sections are incorporated herein by reference:
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item will be set forth in the section captioned “Ownership of KeyCorp Equity Securities” contained in the [removed: 2023] [added: 2024] Proxy Statement, and is incorporated herein by reference.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
1 rewritten, 0 added, 0 removed, 2 unchanged
The information required by this item will be set forth in the following sections of the [removed: 2023] [added: 2024] Proxy Statement and these sections are incorporated herein by reference:
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
1 rewritten, 0 added, 0 removed, 1 unchanged
The information required by this item will be set forth in the sections captioned “Audit Matters — Ernst & Young’s Fees” and “Audit Matters — Pre-Approval Policies and Procedures” contained in the [removed: 2023] [added: 2024] Proxy Statement, and is incorporated herein by reference.
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
52 rewritten, 9 added, 4 removed, 51 unchanged
| [Report of Independent Registered Public Accounting Firm (PCAOB ID: [removed: 42)](#i5a468b8a075b404bb1614017a87fbb3f_205)] [added: 42)](#id35963ddccc041b2ab203b7e536286e2_208)] | | | [removed: [98](#i5a468b8a075b404bb1614017a87fbb3f_205)] [added: [99](#id35963ddccc041b2ab203b7e536286e2_208)] | | |
| [Consolidated Balance Sheets at December 31, [removed: 2022,] [added: 2023,] and [removed: 2021](#i5a468b8a075b404bb1614017a87fbb3f_211)] [added: 2022](#id35963ddccc041b2ab203b7e536286e2_214)] | | | [removed: [100](#i5a468b8a075b404bb1614017a87fbb3f_211)] [added: [102](#id35963ddccc041b2ab203b7e536286e2_214)] | | |
| [Consolidated Statements of [added: Comprehensive] Income for the Years Ended December 31, [added: 2023,] 2022, [removed: 2021,] and [removed: 2020](#i5a468b8a075b404bb1614017a87fbb3f_214)] [added: 2021](#id35963ddccc041b2ab203b7e536286e2_220)] | | | [removed: [101](#i5a468b8a075b404bb1614017a87fbb3f_214)] [added: [104](#id35963ddccc041b2ab203b7e536286e2_220)] | | |
| [Consolidated Statements of [removed: Comprehensive] Income for the Years Ended December 31, [removed: 2022, 2021,] [added: 2023, 202](#id35963ddccc041b2ab203b7e536286e2_217)[2] and [removed: 2020](#i5a468b8a075b404bb1614017a87fbb3f_217)] [added: 2021](#id35963ddccc041b2ab203b7e536286e2_217)] | | | [removed: [102](#i5a468b8a075b404bb1614017a87fbb3f_217)] [added: [103](#id35963ddccc041b2ab203b7e536286e2_217)] | | |
| [Consolidated Statements of Changes in Equity for the Years Ended December 31, [added: 2023,] 2022, [removed: 2021,] and [removed: 2020](#i5a468b8a075b404bb1614017a87fbb3f_220)] [added: 2021](#id35963ddccc041b2ab203b7e536286e2_223)] | | | [removed: [103](#i5a468b8a075b404bb1614017a87fbb3f_220)] [added: [105](#id35963ddccc041b2ab203b7e536286e2_223)] | | |
| [Consolidated Statements of Cash Flows for the Years Ended December 31, [added: 2023,] 2022, [removed: 2021,] and [removed: 2020](#i5a468b8a075b404bb1614017a87fbb3f_223)] [added: 2021](#id35963ddccc041b2ab203b7e536286e2_226)] | | | [removed: [104](#i5a468b8a075b404bb1614017a87fbb3f_223)] [added: [106](#id35963ddccc041b2ab203b7e536286e2_226)] | | |
| [Notes to Consolidated Financial [removed: Statements](#i5a468b8a075b404bb1614017a87fbb3f_226)] [added: Statements](#id35963ddccc041b2ab203b7e536286e2_229)] | | | [removed: [105](#i5a468b8a075b404bb1614017a87fbb3f_229)] [added: [107](#id35963ddccc041b2ab203b7e536286e2_232)] | | |
[removed: [Table](#i5a468b8a075b404bb1614017a87fbb3f_13) [of contents](#i5a468b8a075b404bb1614017a87fbb3f_13)][added: [Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)]
| [removed: 3.4] [added: 3.3] | | | | | | [removed: [First Amendment to the Third] [added: [Fourth] Amended and Restated [removed: Regulations,] [added: Regulations of KeyCorp,] effective [removed: May 13, 2021,] [added: September 21, 2023,] filed as Exhibit 3.1 to Form 8-K on [removed: May 14, 2021.*](https://www.sec.gov/Archives/edgar/data/0000091576/000119312521162024/d398498dex31.htm)] [added: September 22, 2023.](https://www.sec.gov/Archives/edgar/data/91576/000119312523240536/d505390dex31.htm)] | | |
| 4.1 | | | | | | [Description of KeyCorp’s Securities Registered Pursuant to Section 12 of the Securities Exchange Act of [removed: 1934.](https://www.sec.gov/Archives/edgar/data/91576/000009157623000026/key-123122xexx41.htm)] [added: 1934.](https://www.sec.gov/Archives/edgar/data/91576/000009157624000040/key-123123xexx41.htm)] | | |
| 4.16 | | | | | | [Form of Depositary [removed: Receipt](https://www.sec.gov/Archives/edgar/data/91576/000119312522228512/d376484dex43.htm) [](https://www.sec.gov/Archives/edgar/data/91576/000119312522228512/d376484dex43.htm)[related] [added: Receipt related] to Series H Preferred [removed: Stock](https://www.sec.gov/Archives/edgar/data/91576/000119312522228512/d376484dex43.htm) [(included] [added: Stock (included] as part of Exhibit 4.15), filed as Exhibit 4.4 to Form 8-K on August 24, 2022.*](https://www.sec.gov/Archives/edgar/data/91576/000119312522228512/d376484dex43.htm) | | |
| 10.2 | | | | | | [Form of Cash-settling Performance Shares Award Agreement [removed: (2020-2022),] [added: (2021-2023),] filed as Exhibit [removed: 10.6] [added: 10.8] to Form 10-K for the year ended December 31, [removed: 2020.*](https://www.sec.gov/Archives/edgar/data/0000091576/000009157621000044/key-123120xexx106.htm)] [added: 2020.*](https://www.sec.gov/Archives/edgar/data/91576/000009157621000044/key-123120xexx108.htm)] | | |
| 10.3 | | | | | | [Form of Stock-settling Performance Shares Award Agreement [removed: (2020-2022),] [added: (2021-2023),] filed as Exhibit [removed: 10.7] [added: 10.9] to Form 10-K for the year ended December 31, [removed: 2020.*](https://www.sec.gov/Archives/edgar/data/0000091576/000009157621000044/key-123120xexx107.htm)] [added: 2020.*](https://www.sec.gov/Archives/edgar/data/91576/000009157621000044/key-123120xexx109.htm)] | | |
| 10.4 | | | | | | [Form of Cash-settling Performance Shares Award Agreement [removed: (2021-2023),] [added: (2022-2024),] filed as Exhibit 10.8 to Form 10-K for the year ended December 31, [removed: 2020.*](https://www.sec.gov/Archives/edgar/data/91576/000009157621000044/key-123120xexx108.htm)] [added: 2021.*](https://www.sec.gov/Archives/edgar/data/91576/000009157622000029/key-123121xexx108.htm)] | | |
| 10.5 | | | | | | [Form of Stock-settling Performance Shares Award Agreement [removed: (2021-2023),] [added: (2023-2025),] filed as Exhibit [removed: 10.9](https://www.sec.gov/Archives/edgar/data/0000091576/000009157621000044/key-123120xexx109.htm) [to](https://www.sec.gov/Archives/edgar/data/0000091576/000009157621000044/key-123120xexx109.htm) [Form] [added: 10.7 to Form] 10-K for the year ended December 31, [removed: 2020.*](https://www.sec.gov/Archives/edgar/data/0000091576/000009157621000044/key-123120xexx109.htm).] [added: 2022.*](https://www.sec.gov/Archives/edgar/data/91576/000009157623000026/key-123122xexx107.htm).] | | |
| 10.6 | | | | | | [Form of Cash-settling Performance Shares Award Agreement [removed: (2022-2024), filed as Exhibit 10.8](https://www.sec.gov/Archives/edgar/data/91576/000009157622000029/key-123121xexx108.htm) [to](https://www.sec.gov/Archives/edgar/data/91576/000009157622000029/key-123121xexx108.htm) [Form 10-K for the year ended December 31, 2021.*](https://www.sec.gov/Archives/edgar/data/91576/000009157622000029/key-123121xexx108.htm)] [added: (2024-2026).](https://www.sec.gov/Archives/edgar/data/91576/000009157624000040/key-123123xexx106.htm)] | | |
| [removed: 10.8] [added: 10.7] | | | | | | [Form of Stock Option Award Agreement under KeyCorp 2013 Equity Compensation Plan, filed as Exhibit 10.7 to Form 10-K for the year ended December 31, 2016.*](http://www.sec.gov/Archives/edgar/data/91576/000009157617000013/key-123116exx107.htm) | | |
| [removed: 10.9] [added: 10.8] | | | | | | [Form of Stock Option Award Agreement under KeyCorp 2013 Equity Compensation Plan, effective 2019, filed as Exhibit 10.8 to Form 10-K for the year ended December 31, 2018.*](http://www.sec.gov/Archives/edgar/data/91576/000009157619000009/key-123118x10kexx108.htm) | | |
| [removed: 10.10] [added: 10.9] | | | | | | [Form of Stock Option Award Agreement under KeyCorp 2019 Equity Compensation Plan, effective 2020, filed as Exhibit 10.12 to Form 10-K for the year ended December 31, 2020.*](https://www.sec.gov/Archives/edgar/data/0000091576/000009157621000044/key-123120xexx1012.htm). | | |
| [removed: 10.11] [added: 10.10] | | | | | | [Form of Restricted Stock Unit Award Agreement under KeyCorp 2013 Equity Compensation Plan, effective 2019, filed as Exhibit 10.10 to Form 10-K for the year ended December 31, 2018.*.](http://www.sec.gov/Archives/edgar/data/91576/000009157619000009/key-123118x10kexx1010.htm) | | |
| [removed: 10.12] [added: 10.11] | | | | | | [Form of Restricted Stock Unit Award Agreement (New Hire/Retention) under KeyCorp 2019 Equity Compensation Plan, filed as Exhibit 10.4 to KeyCorp’s Registration Statement on Form S-8 on May 23, 2019, File No. 333-231689.*](http://www.sec.gov/Archives/edgar/data/91576/000119312519155006/d752581dex104.htm) | | |
| [removed: 10.13] [added: 10.12] | | | | | | [Form of Restricted Stock Unit Award Agreement (New Hire/Retention) under KeyCorp 2019 Equity Compensation Plan, effective 2020, filed as Exhibit 10.16 to Form 10-K for the year ended December 31, 2020.*](https://www.sec.gov/Archives/edgar/data/0000091576/000009157621000044/key-123120xexx1016.htm) | | |
| [removed: 10.14] [added: 10.13] | | | | | | [Form of Restricted Stock Unit Award Agreement under KeyCorp 2019 Equity Compensation Plan, effective 2020, filed as Exhibit 10.17 to Form 10-K for the year ended December 31, 2020.*](https://www.sec.gov/Archives/edgar/data/91576/000009157621000044/key-123120xexx1017.htm) | | |
| [removed: 10.15] [added: 10.14] | | | | | | [Form of Restricted Stock Unit Award Agreement (New Hire/Retention) under KeyCorp 2019 Equity Compensation Plan, filed as Exhibit 10.17 in Form 10-K for the year ended December 31, 2021.*](https://www.sec.gov/Archives/edgar/data/91576/000009157622000029/key-123121xexx1017.htm) | | |
| [removed: 10.16] [added: 10.15] | | | | | | [Form of Change of Control Agreement (Tier I) between KeyCorp and Certain Executive Officers of KeyCorp, dated as of March 8, 2012, filed as Exhibit 10.8 to Form 10-K for the year ended December 31, 2017.*](http://www.sec.gov/Archives/edgar/data/91576/000009157618000011/key-123117x10kex108.htm) | | |
| [removed: 10.17] [added: 10.16] | | | | | | [Form of Change of Control Agreement (Tier II Executives) between KeyCorp and Certain Executive Officers of KeyCorp, dated as of April 15, 2012, filed as Exhibit 10.9 to Form 10-K for the year ended December 31, 2017.*](http://www.sec.gov/Archives/edgar/data/91576/000009157618000011/key-123117x10kexx109.htm) | | |
| [removed: 10.18] [added: 10.17] | | | | | | [KeyCorp Executive Annual Performance Plan (effective March 13, 2019), filed as Exhibit 10.1 to Form 8-K on March 15, 2019.*](http://www.sec.gov/Archives/edgar/data/91576/000119312519076702/d722297dex101.htm) | | |
| [removed: 10.19] [added: 10.18] | | | | | | [KeyCorp Long-Term Incentive Deferral Plan, filed as Exhibit 10.14 to Form 10-K for the year ended December 31, 2018.*](http://www.sec.gov/Archives/edgar/data/91576/000009157619000009/key-123118x10kexx1014.htm) | | |
| [removed: 10.20] [added: 10.19] | | | | | | [KeyCorp 2010 Equity Compensation Plan (effective March 11, 2010), filed as Exhibit 10.16 to Form 10-K for the year ended December 31, 2015.*](http://www.sec.gov/Archives/edgar/data/91576/000119312516475914/d97852dex1016.htm) | | |
| [removed: 10.21] [added: 10.20] | | | | | | [KeyCorp 2013 Equity Compensation Plan (effective March 14, 2013), filed as Exhibit 10.17 to Form 10-K for the year ended December 31, 2018.](http://www.sec.gov/Archives/edgar/data/91576/000009157619000009/key-123118x10kexx1017.htm)* | | |
| [removed: 10.22] [added: 10.21] | | | | | | [KeyCorp 2019 Equity Compensation Plan (effective January 10, 2019), filed as Exhibit 10.1 to Form 8-K on May 24, 2019.*](http://www.sec.gov/Archives/edgar/data/91576/000119312519157021/d736948dex101.htm) | | |
| [removed: 10.35] [added: 10.36] | | | | | | [Trust Agreement for certain amounts that may become payable to certain executives and directors of KeyCorp, dated April 1, 1997, and amended as of August 25, 2003, filed as Exhibit 10.28 to Form 10-K for the year ended December 31, 2018.*](http://www.sec.gov/Archives/edgar/data/91576/000009157619000009/key-123118x10kexx1028.htm) | | |
| [removed: 10.36] [added: 10.37] | | | | | | [KeyCorp Deferred Savings Plan (effective January 1, 2015), filed as Exhibit 10.31 to Form 10-K for the year ended December 31, 2014.*](http://www.sec.gov/Archives/edgar/data/91576/000119312515072950/d831862dex1031.htm) | | |
| [removed: 10.37] [added: 10.38] | | | | | | [Amendment to the KeyCorp Deferred Savings Plan (effective January 1, [removed: 2023).](https://www.sec.gov/Archives/edgar/data/91576/000009157623000026/key-123122xexx1037.htm)] [added: 2023), filed as Exhibit 10.37 to Form 10-K for the year ended December 31, 2022.*](https://www.sec.gov/Archives/edgar/data/91576/000009157623000026/key-123122xexx1037.htm)] | | |
| [removed: 10.38] [added: 10.39] | | | | | | [Amendment to the KeyCorp Deferred Savings Plan (effective January 1, [removed: 2023).](https://www.sec.gov/Archives/edgar/data/91576/000009157623000026/key-123122xexx1038.htm)] [added: 2023), filed as Exhibit 10.38 to Form 10-K for the year ended December 31, 2022.*](https://www.sec.gov/Archives/edgar/data/91576/000009157623000026/key-123122xexx1038.htm)] | | |
| [removed: 10.39] [added: 10.40] | | | | | | [KeyCorp Second Deferred Savings Plan (effective January 1, 2019), filed as Exhibit 10.30 to Form 10-K for the year ended December 31, 2018.*](http://www.sec.gov/Archives/edgar/data/91576/000009157619000009/key-123118x10kexx1030.htm) | | |
| [removed: 10.40] [added: 10.42] | | | | | | [Amended and Restated KeyCorp Second Deferred Savings Plan (effective [removed: January 1, 2023).](https://www.sec.gov/Archives/edgar/data/91576/000009157623000026/key-123122xexx1040.htm)] [added: May 8, 2023).](https://www.sec.gov/Archives/edgar/data/91576/000009157624000040/key-123123xexx1042.htm)] | | |
| [removed: 10.41] [added: 10.43] | | | | | | [Amended and Restated First Niagara Bank and First Niagara Financial Group, Inc. Directors Deferred Fees Plan, filed as Exhibit 10.32 to Form 10-K for the year ended December 31, 2018.*](http://www.sec.gov/Archives/edgar/data/91576/000009157619000009/key-123118x10kexx1032.htm) | | |
| [removed: 10.42] [added: 10.44] | | | | | | [First Niagara Financial Group, Inc. 2012 Equity Incentive Plan, filed as Exhibit 10.33 to Form 10-K for the year ended December 31, 2017.*](http://www.sec.gov/Archives/edgar/data/91576/000009157618000011/key-123117x10kexx1033.htm) | | |
| [removed: 10.43] [added: 10.45] | | | | | | [First Niagara Financial Group, Inc. 2012 Equity Incentive Plan, Amendment Number One, filed as Appendix B to First Niagara Financial Group, Inc.’s Schedule 14A filed on March 21, 2014.*](http://www.sec.gov/Archives/edgar/data/1051741/000105174114000018/a2014proxy.htm#s7e6b8e6751c346858e14d2eef2c183e0) | | |
| [Consolidated Financial Statements](#id35963ddccc041b2ab203b7e536286e2_211) | | | [102](#id35963ddccc041b2ab203b7e536286e2_211) | | |
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
| 10.22 | | | | | | [KeyCorp Amended and Restated 2019 Equity Compensation Plan (incorporated herein by reference to Exhibit 99.1 to KeyCorp’s Registration Statement on Form S-8 filed with the Securities and Exchange Commission on May 11, 2023).*](https://www.sec.gov/Archives/edgar/data/91576/000119312523141902/d671215dex991.htm) | | |
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
| 10.35 | | | | | | [Amendment to the KeyCorp Second Excess Cash Balance Pension Plan (effective May 8, 2023).](https://www.sec.gov/Archives/edgar/data/91576/000009157624000040/key-123123xexx1035.htm) | | |
| 10.41 | | | | | | [Amended and Restated KeyCorp Second Deferred Savings Plan (effective January 1, 2023), filed as Exhibit 10.40 to Form 10-K for the year ended December 31, 2022.*](https://www.sec.gov/Archives/edgar/data/91576/000009157623000026/key-123122xexx1040.htm) | | |
| 97 | | | | | | [KeyCorp Compensation Recovery Policy.](https://www.sec.gov/Archives/edgar/data/91576/000009157624000040/key-123123xexx97.htm) | | |
[Table of](#id35963ddccc041b2ab203b7e536286e2_13) [contents](#id35963ddccc041b2ab203b7e536286e2_13)
| [Consolidated Financial Statements](#i5a468b8a075b404bb1614017a87fbb3f_208) | | | [100](#i5a468b8a075b404bb1614017a87fbb3f_208) | | |
| 3.3 | | | | | | [Third Amended and Restated Regulations of KeyCorp, effective May 23, 2019, filed as Exhibit 3.2 to Form 10-Q for the quarterly period ended June 30, 2019.*](http://www.sec.gov/Archives/edgar/data/91576/000009157619000029/key-063019xexx32.htm) | | |
| 10.7 | | | | | | [Form of Cash-settling Performance Shares Award Agreement (2023-2025).](https://www.sec.gov/Archives/edgar/data/91576/000009157623000026/key-123122xexx107.htm) | | |
| 10.45 | | | | | | [Letter agreement between KeyBank National Association and Kevin T. Ryan, dated as of July 2, 2022, filed as Exhibit 10.1 to Form 10-Q for the quarterly period ended September 30, 2022*](https://www.sec.gov/Archives/edgar/data/91576/000009157622000119/key-93022xexx101.htm) | | |
An excerpt. Shown here: 40 of 52 rewritten, all 9 added and all 4 removed. The counts are complete. For every sentence, read Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES in the FY2023 filing and the FY2022 filing.
Item 16. FORM 10-K SUMMARY
1 rewritten, 5 added, 3 removed, 38 unchanged
| [removed: *Donald R. Kimble] [added: Clark H. Khayat] | | | | | | Chief Financial Officer (Principal Financial Officer) | | |
| /s/ Clark H. Khayat | | |
| Clark H. Khayat | | |
| February 22, 2024 | | |
| February 22, 2024 | | |
| February 22, 2024 | | |
| /s/ Donald R. Kimble | | |
| Donald R. Kimble | | |
| February 22, 2023 | | |