 filings.tools
Kraft Heinz 10-K 2018-12-29
Filed 2019-06-07. 22 sections, 1059K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 form10-k2018.htm 10-K
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 10-K
(Mark One)
| x | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 29, 2018
or
| o | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the transition period from __________ to __________
Commission File Number 001-37482
The Kraft Heinz Company
(Exact name of registrant as specified in its charter)
| Delaware (State or other jurisdiction of incorporation or organization) | 46-2078182 (I.R.S. Employer Identification No.) | |
| One PPG Place, Pittsburgh, Pennsylvania (Address of Principal Executive Offices) | 15222 (Zip Code) |
Registrant’s telephone number, including area code: (412) 456-5700
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol | Name of exchange on which registered |
| Common stock, $0.01 par value | KHC | The Nasdaq Stock Market LLC |
Securities registered pursuant to Section 12(g) of the Act:
None.
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes o No x
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes o No x
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes o No x
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes o No x
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer x | Accelerated filer o | |
| Non-accelerated filer o | Smaller reporting company o | Emerging growth company o |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. o
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes o No x
The aggregate market value of the shares of common stock held by non-affiliates of the registrant, computed by reference to the closing price of such stock as of the last business day of the registrant’s most recently completed second quarter, was $38 billion. As of June 5, 2019, there were 1,219,938,804 shares of the registrant’s common stock outstanding.
Table of Contents
Unless the context otherwise requires, the terms “we,” “us,” “our,” “Kraft Heinz,” and the “Company” each refer to The Kraft Heinz Company and all of its consolidated subsidiaries.
Forward-Looking Statements
This Annual Report on Form 10-K contains a number of forward-looking statements. Words such as “anticipate,” “reflect,” “invest,” “see,” “make,” “expect,” “give,” “deliver,” “drive,” “believe,” “improve,” “assess,” “reassess,” “remain,” “evaluate,” “grow,” “will,” “plan,” and variations of such words and similar future or conditional expressions are intended to identify forward-looking statements. These forward-looking statements include, but are not limited to, statements regarding our plans, impacts of accounting standards and guidance, growth, legal matters, taxes, costs and cost savings, impairments, and dividends. These forward-looking statements are not guarantees of future performance and are subject to a number of risks and uncertainties, many of which are difficult to predict and beyond our control.
Important factors that may affect our business and operations and that may cause actual results to differ materially from those in the forward-looking statements include, but are not limited to, operating in a highly competitive industry; our ability to correctly predict, identify, and interpret changes in consumer preferences and demand, to offer new products to meet those changes, and to respond to competitive innovation; changes in the retail landscape or the loss of key retail customers; changes in our relationships with significant customers, suppliers, and other business relationships; our ability to maintain, extend, and expand our reputation and brand image; our ability to leverage our brand value to compete against private label products; our ability to drive revenue growth in our key product categories, increase our market share, or add products that are in faster-growing and more profitable categories; product recalls or product liability claims; unanticipated business disruptions; our ability to identify, complete, or realize the benefits from strategic acquisitions, alliances, divestitures, joint ventures, or other investments; our ability to realize the anticipated benefits from prior or future streamlining actions to reduce fixed costs, simplify or improve processes, and improve our competitiveness; our ability to successfully execute our strategic initiatives; the impacts of our international operations; economic and political conditions in the United States and in various other nations where we do business; changes in our management team or other key personnel and our ability to hire or retain key personnel or a highly skilled and diverse global workforce; risks associated with information technology and systems, including service interruptions, misappropriation of data, or breaches of security; impacts of natural events in the locations in which we or our customers, suppliers, distributors, or regulators operate; our ownership structure; our indebtedness and ability to pay such indebtedness; additional impairments of the carrying amounts of goodwill or other indefinite-lived intangible assets; exchange rate fluctuations; volatility in commodity, energy, and other input costs; volatility in the market value of all or a portion of the derivatives we use; increased pension, labor and people-related expenses; compliance with laws, regulations, and related interpretations and related legal claims or other regulatory enforcement actions, including additional risks and uncertainties related to our restatement and any potential actions resulting from the Securities and Exchange Commission’s ongoing investigation, as well as potential additional subpoenas, litigation, and regulatory proceedings; an inability to remediate the material weaknesses in our internal control over financial reporting or additional material weaknesses or other deficiencies in the future or the failure to maintain an effective system of internal controls; our failure to prepare and timely file our periodic reports; the restatement of certain of our previously issued consolidated financial statements, which resulted in unanticipated costs and may affect investor confidence and raise reputational issues; our ability to protect intellectual property rights; tax law changes or interpretations; the impact of future sales of our common stock in the public markets; our ability to continue to pay a regular dividend and the amounts of any such dividends; volatility of capital markets and other macroeconomic factors. For additional information on these and other factors that could affect our forward-looking statements, see Item 1A, Risk Factors. We disclaim and do not undertake any obligation to update or revise any forward-looking statement in this report, except as required by applicable law or regulation.
Explanatory Note
General
On May 2, 2019, management, in consultation with the Audit Committee of our Board of Directors, concluded that our audited consolidated financial statements and related disclosures for the fiscal years ended December 30, 2017 and December 31, 2016 included in our Annual Reports on Form 10-K, and each of our unaudited condensed consolidated financial statements for the quarterly and year-to-date periods in fiscal year 2017 and each of our unaudited condensed consolidated financial statements for the quarterly and year-to-date periods for the nine months ended September 29, 2018 included in our Quarterly Reports on Form 10-Q (unaudited condensed consolidated financial statements for the quarterly periods ended September 29, 2018, June 30, 2018, March 31, 2018, and September 30, 2017) and Form 10-Q/A (unaudited condensed consolidated financial statements for the quarterly periods ended July 1, 2017 and April 1, 2017) should no longer be relied upon due to misstatements that are described in greater detail below, and that we would restate such financial statements to make the necessary accounting corrections. We discussed this conclusion with our independent registered public accounting firm, PricewaterhouseCoopers LLP.
Restatement
This Annual Report on Form 10-K for the year ended December 29, 2018 includes audited consolidated financial statements at December 29, 2018 and December 30, 2017 and for the years ended December 29, 2018, December 30, 2017, and December 31, 2016, as well as relevant unaudited interim financial information for the quarterly periods ended December 29, 2018, September 29, 2018, June 30, 2018, March 31, 2018, December 30, 2017, September 30, 2017, July 1, 2017, and April 1, 2017. We have restated certain information within this Annual Report on Form 10-K, including our consolidated financial statements at December 30, 2017 and for the years ended December 30, 2017 and December 31, 2016, selected financial data at and for the year ended January 3, 2016, and the relevant unaudited interim financial information for the quarterly periods ended September 29, 2018, June 30, 2018, March 31, 2018, December 30, 2017, September 30, 2017, July 1, 2017, and April 1, 2017 (collectively known as the “Financial Statements”).
Restatement Background
As described in our Current Report on Form 8-K filed with the Securities and Exchange Commission (“SEC”) on May 6, 2019, management noted certain misstatements contained in the Financial Statements relating principally to the accounting treatment for supplier contracts and related arrangements. As previously disclosed, we received a subpoena from the SEC in October 2018related to our procurement area, specifically the accounting policies, procedures, and internal controls related to our procurement function, including, but not limited to, agreements, side agreements, and changes or modifications to agreements with our suppliers. Following the receipt of this subpoena, we, together with external counsel and forensic accountants, and subsequently, under the oversight of the Audit Committee of our Board of Directors (the “Audit Committee”), conducted an internal investigation into the procurement area and related matters. As a result of the findings from this internal investigation, which is now complete and which identified that multiple employees in the procurement area engaged in misconduct, we corrected prior period misstatements that generally increased the total cost of products sold in prior financial periods. These misstatements principally related to the incorrect timing of when certain cost and rebate elements associated with supplier contracts and related arrangements were initially recognized. The findings from the internal investigation did not identify any misconduct by any member of the senior management team. We continue to cooperate with the SEC concerning its investigation of these matters.
In connection with the internal investigation, we also conducted a comprehensive review of supplier contracts and related arrangements to identify other potential misstatements in the timing of the recognition of supplier rebates, incentive payments, and pricing arrangements. The review identified further misstatements, which we also investigated and have been unable to conclude if they resulted from the misconduct described above. These misstatements were primarily related to certain supplier contracts and related arrangements where the allocation of value of all or a portion of rebates and up-front payments to contractual elements in the current period should have been deferred and recognized over an applicable contractual period. We corrected these misstatements to defer the up-front consideration from suppliers when the retention or receipt of that consideration was contingent upon future events and to correctly recognize the consideration as a reduction of cost of products sold over the terms of the arrangements with the suppliers.
Our internal investigation and review identified adjustments that resulted in an understatement of cost of products sold totaling $208 million, including $175 million relating to the periods up through September 29, 2018 that are being restated in this Annual Report on Form 10-K. The misstatements of cost of products sold related to our internal investigation and review included $22 million for fiscal year 2018, $94 million for fiscal year 2017, $35 million for fiscal year 2016, and $24 million for fiscal year 2015. We do not believe that the misstatements are quantitatively material to any period presented in our prior financial statements. However, due to the qualitative nature of the matters identified in our internal investigation, including the number of years over which the misconduct occurred and the number of transactions, suppliers, and procurement employees involved, we determined that it would be appropriate to correct the misstatements in our previously issued consolidated financial statements by restating such financial statements. The restatement also included corrections for additional identified out-of-period and uncorrected misstatements in the impacted periods. Accordingly, we have restated our consolidated financial statements and the impacted amounts within the accompanying footnotes thereto.
In addition, the statements of income for fiscal years 2017 and 2016, as previously reported, did not originally reflect the adoption of accounting standards update (“ASU”) 2017-07 related to the presentation of net periodic benefit cost (pension and postretirement cost). This ASU was adopted in the first quarter of 2018 and was applied retrospectively for statement of income presentation of service cost components and other net periodic benefit cost components. The restated statements of income for fiscal years 2017 and 2016 reflect the retrospective application of ASU 2017-07 and are labeled “As Recast.”
Restatement of Previously Issued Consolidated Financial Statements
This Annual Report on Form 10-K restates amounts included in the 2017 Annual Report described above, including the audited consolidated financial statements at December 30, 2017 and for the fiscal years ended December 30, 2017 and December 31, 2016. In addition to the misstatements related to the supplier contracts and related arrangements, including the misstatements related to lease classification, we corrected additional identified out-of-period and uncorrected misstatements that were not material, individually or in the aggregate, to our consolidated financial statements. These misstatements were related to customer incentive program expense misclassifications, balance sheet misclassifications, income taxes, impairments, and other misstatements.
See Note 2, Restatement of Previously Issued Consolidated Financial Statements, in Item 8, Financial Statements and Supplementary Data, for additional information.
The relevant unaudited interim financial information for the quarterly periods ended September 29, 2018, June 30, 2018, March 31, 2018, December 30, 2017, September 30, 2017, July 1, 2017, and April 1, 2017, has also been restated. The 2018 quarterly restatements will be effective with the filing of our future 2019 unaudited interim condensed consolidated financial statement filings in Quarterly Reports on Form 10-Q.
See Note 23, Quarterly Financial Information (Unaudited), in Item 8, Financial Statements and Supplementary Data, for such restated information, and see Supplemental Unaudited Quarterly Financial Information, in Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations, for additional interim financial information.
Selected financial information for the fiscal year ended January 3, 2016 has also been restated. See Item 6, Selected Financial Data.
This restatement resulted in the following decreases to our results:
| For the Nine Months Ended | For the Year Ended | ||||||||||
| September 29, 2018 | December 30, 2017 | December 31, 2016 | |||||||||
| (in millions, except per share data) | |||||||||||
| Net income | $ | (2 | ) | $ | (58 | ) | $ | (36 | ) | ||
| Adjusted EBITDA(a) | (35 | ) | (106 | ) | (79 | ) | |||||
| Diluted earnings per common share | — | (0.04 | ) | (0.03 | ) | ||||||
| Adjusted EPS(a) | (0.01 | ) | (0.05 | ) | (0.02 | ) |
| (a) | Adjusted EBITDA and Adjusted EPS are non-GAAP financial measures. See the Non-GAAP Financial Measures section within Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations, for the related definitions and reconciliations. |
Control Considerations
In connection with the restatement, management has assessed the effectiveness of our internal control over financial reporting. Based on this assessment, management identified material weaknesses in our internal control over financial reporting resulting in the conclusion by our Chief Executive Officer and Chief Financial Officer that our disclosure controls and procedures were not effective as of December 29, 2018. Management has taken and is taking additional steps to remediate the material weaknesses in our internal control over financial reporting. See Item 9A, Controls and Procedures, for additional information related to these material weaknesses in internal control over financial reporting and the related remedial measures.
Additional Information Specific to Goodwill and Indefinite-Lived Intangible Asset Impairment
We announced on February 21, 2019 that as part of our normal quarterly reporting procedures and planning processes for the fourth quarter of 2018, the fair values of certain goodwill and intangible assets were below their carrying amounts. As a result, we announced non-cash impairment losses of $15.4 billion to lower the carrying amount of goodwill in certain reporting units, primarily U.S. Refrigerated and Canada Retail, and certain intangible assets, primarily the Kraft and Oscar Mayer brands. As disclosed in our Current Report on Form 8-K filed with the SEC on May 6, 2019, we subsequently identified errors in the calculations performed in connection with the interim goodwill and indefinite-lived intangible asset impairment testing in the fourth quarter of 2018. Specifically, we identified certain errors in projected net cash flows and allocations to certain brands. Correcting this allocation error resulted in an increase to the impairment losses initially calculated for brands of approximately $278 million, partially offset by a reduction to the impairment losses initially calculated for reporting units of approximately $171 million.
In addition, the corrections to the carrying values on our balance sheet at December 29, 2018 recorded as part of the correction of the procurement-related misstatements described above resulted in an adjustment to the carrying amounts of certain reporting units, and therefore resulted in a reduction to goodwill impairment losses of approximately $92 million. The net impact of these misstatements was an increase of approximately $15 million from the $15.4 billion total impairment losses in the fourth quarter of 2018 previously announced in our earnings release and investor call on February 21, 2019.
As discussed in Item 9A, Controls and Procedures, of this Annual Report on Form 10-K, we did not design and maintain effective controls to reassess the level of precision used to review the allocation of cash flow projections to certain brands used as a basis for performing our fourth quarter 2018 interim impairment assessments in response to the significant reduction in, and in certain instances elimination of, the excess fair value over carrying amount for certain brands that resulted from the changing business environment. This material weakness resulted in the errors in the calculations performed in connection with the interim goodwill and indefinite-lived intangible asset impairment testing in the fourth quarter of 2018, as described above, because approximately five to ten percent of cash flows were not subjected to our control procedures. This material weakness arose during our interim impairment testing in the fourth quarter of 2018 due to the significant reduction in excess fair value over carrying amount for certain brands as noted above, which required us to increase the percentage of cash flows subject to our control procedures to nearly one hundred percent. This did not result in a misstatement of any previously reported consolidated financial statements but was determined to be a material weakness because it could have resulted in a material misstatement that would not have been prevented or detected.
PART I
Item 1. Business.
General
For 150 years, we have produced some of the world’s most beloved products at The Kraft Heinz Company (Nasdaq: KHC). Our Vision is To Be the Best Food Company, Growing a Better World. We are one of the largest global food and beverage companies, with 2018 net sales of approximately $26 billion. Our portfolio is a diverse mix of iconic and emerging brands. As the guardians of these brands and the creators of innovative new products, we are dedicated to the sustainable health of our people and our planet.
On July 2, 2015, through a series of transactions, we consummated the merger of Kraft Foods Group, Inc. (“Kraft”) with and into a wholly-owned subsidiary of H.J. Heinz Holding Corporation (“Heinz”) (the “2015 Merger”). At the closing of the 2015 Merger, Heinz was renamed The Kraft Heinz Company, and H. J. Heinz Company changed its name to Kraft Heinz Foods Company.
Before the consummation of the 2015 Merger, Heinz was controlled by Berkshire Hathaway Inc. (“Berkshire Hathaway”) and 3G Global Food Holdings, L.P. (“3G Capital”) (together, the “Sponsors”), following their acquisition of H. J. Heinz Company on June 7, 2013.
Reportable Segments
We manage and report our operating results through four segments. We have three reportable segments defined by geographic region: United States, Canada, and Europe, Middle East, and Africa (“EMEA”). Our remaining businesses are combined and disclosed as “Rest of World.” Rest of World comprises two operating segments: Latin America and Asia Pacific (“APAC”).
Our segments reflect a change, effective in the first quarter of our fiscal year 2018, to reorganize our international businesses to better align our global geographies. We moved our Middle East and Africa businesses from the historical Asia Pacific, Middle East, and Africa (“AMEA”) operating segment into the historical Europe reportable segment, forming the new EMEA reportable segment. The remaining businesses from the AMEA operating segment became the APAC operating segment. We have reflected this change in all historical periods presented.
See Note 22, Segment Reporting, in Item 8, Financial Statements and Supplementary Data, for our geographic financial information by segment.
Trademarks and Intellectual Property
Our trademarks are material to our business and are among our most valuable assets. Depending on the country, trademarks generally remain valid for as long as they are in use or their registration status is maintained. Trademark registrations generally are for renewable, fixed terms. Significant trademarks by segment based on net sales in 2018 were:
| Majority Owned and Licensed Trademarks | ||
| United States | Kraft, Oscar Mayer, Heinz, Philadelphia, Lunchables, Velveeta, Planters, Maxwell House, Capri Sun*, Ore-Ida, Kool-Aid, Jell-O | |
| Canada | Kraft, Cracker Barrel, Heinz, Philadelphia, Maxwell House, Classico, McCafe*, P’Tit Quebec, Tassimo* | |
| EMEA | Heinz, Plasmon, Pudliszki, Honig, HP, Kraft, Benedicta, Karvan Cevitam | |
| Rest of World | Heinz, ABC, Master, Quero, Kraft, Golden Circle, Wattie's, Glucon-D, Complan |
*Used under license. Additionally, our license to use the McCafe brand in Canada will expire in December 2019.
In the fourth quarter of 2018, we announced our plans to divest certain assets and operations, predominantly in Canada and India, including the intellectual property rights to Cracker Barrel and P’Tit Quebec in Canada, as well as Glucon-D and Complan globally. See Note 5, Acquisitions and Divestitures, in Item 8, Financial Statements and Supplementary Data, for additional information on these transactions.
We sell certain products under brands we license from third parties. In 2018, brands used under licenses from third parties included Capri Sun packaged drink pouches for sale in the United States, TGI Fridays frozen snacks and appetizers in the United States and Canada, McCafe ground, whole bean, and on-demand single cup coffees in the United States and Canada, and Taco Bell Home Originals Mexican-style food products in U.S. grocery stores. In addition, in our agreements with Mondelēz International, Inc. (“Mondelēz International”) following the spin-off of Kraft from Mondelēz International in 2012, we each granted the other party various licenses to use certain of our and their respective intellectual property rights in named jurisdictions for certain periods of time.
We also own numerous patents worldwide. We consider our portfolio of patents, patent applications, patent licenses under patents owned by third parties, proprietary trade secrets, technology, know-how processes, and related intellectual property rights to be material to our operations. Patents, issued or applied for, cover inventions ranging from packaging techniques to processes relating to specific products and to the products themselves. While our patent portfolio is material to our business, the loss of one patent or a group of related patents would not have a material adverse effect on our business.
Our issued patents extend for varying periods according to the date of the patent application filing or grant and the legal term of patents in the various countries where patent protection is obtained. The actual protection afforded by a patent, which can vary from country to country, depends upon the type of patent, the scope of its coverage as determined by the patent office or courts in the country, and the availability of legal remedies in the country.
Research and Development
Our research and development focuses on achieving the following four objectives:
| • | product innovations, renovations, and new technologies to meet changing consumer needs and drive growth; |
| • | world-class and uncompromising food safety, quality, and consistency; |
| • | superior, customer-preferred product and package performance; and |
| • | continuous process improvement and product optimization in pursuit of cost reductions. |
Competition
Our products are sold in highly competitive marketplaces, which have experienced increased concentration and the growing presence of e-commerce retailers, large-format retailers, and discounters. Competitors include large national and international food and beverage companies and numerous local and regional companies. We compete with both branded and private label products sold by retailers, wholesalers, and cooperatives. We compete on the basis of product quality and innovation, brand recognition and loyalty, service, the ability to identify and satisfy consumer preferences, the introduction of new products and the effectiveness of our advertising campaigns and marketing programs, distribution, shelf space, merchandising support, and price. Improving our market position or introducing new products requires substantial advertising and promotional expenditures.
Sales and Customers
Our products are sold through our own sales organizations and through independent brokers, agents, and distributors to chain, wholesale, cooperative and independent grocery accounts, convenience stores, drug stores, value stores, bakeries, pharmacies, mass merchants, club stores, foodservice distributors, and institutions, including hotels, restaurants, hospitals, health care facilities, and certain government agencies. Our products are also sold online through various e-commerce platforms and retailers. Our largest customer, Walmart Inc., represented approximately 21% of our net sales in 2018, approximately 21% of our net sales in 2017, and approximately 22% of our net sales in 2016.
Additionally, we have significant customers in different regions around the world; however, none of these customers are individually material to our consolidated business. In 2018, the five largest customers in our U.S. segment accounted for approximately 49% of U.S. segment net sales, the five largest customers in our Canada segment accounted for approximately 71% of Canada segment net sales, and the five largest customers in our EMEA segment accounted for approximately 26% of our EMEA segment net sales.
Net Sales by Product Category
In 2018, we reorganized the products within our product categories to reflect how we manage our business. We have reflected this change for all historical periods presented. The product categories that contributed 10% or more to consolidated net sales in any of the periods presented were:
| December 29, 2018 | December 30, 2017 | December 31, 2016 | ||||||
| Condiments and sauces | 26 | % | 25 | % | 24 | % | ||
| Cheese and dairy | 20 | % | 21 | % | 21 | % | ||
| Ambient foods | 10 | % | 10 | % | 9 | % | ||
| Frozen and chilled foods | 10 | % | 10 | % | 10 | % | ||
| Meats and seafood | 10 | % | 10 | % | 10 | % |
Raw Materials and Packaging
We manufacture (and contract for the manufacture of) our products from a wide variety of raw materials. We purchase and use large quantities of commodities, including dairy products, meat products, coffee beans, nuts, tomatoes, potatoes, soybean and vegetable oils, sugar and other sweeteners, corn products, and wheat products, to manufacture our products. In addition, we purchase and use significant quantities of resins, metals, and cardboard to package our products and natural gas to operate our facilities. For commodities that we use across many of our product categories, such as corrugated paper and energy, we coordinate sourcing requirements and centralize procurement to leverage our scale. In addition, some of our product lines and brands separately source raw materials that are specific to their operations. We source these commodities from a variety of providers, including large, international producers and smaller, local, independent sellers. Where appropriate, we seek to establish preferred purchaser status and have developed strategic partnerships with many of our suppliers with the objective of achieving favorable pricing and dependable supply for many of our commodities. The prices of raw materials and agricultural materials that we use in our products are affected by external factors, such as global competition for resources, currency fluctuations, severe weather or global climate change, consumer, industrial or investment demand, and changes in governmental regulation and trade, tariffs, alternative energy, and agricultural programs.
Our procurement teams monitor worldwide supply and cost trends so we can obtain ingredients and packaging needed for production at competitive prices. Although the prices of our principal raw materials can be expected to fluctuate, we believe there will be an adequate supply of the raw materials we use and that they are generally available from numerous sources. We use a range of hedging techniques in an effort to limit the impact of price fluctuations on many of our principal raw materials. However, we do not fully hedge against changes in commodity prices, and our hedging strategies may not protect us from increases in specific raw material costs. We actively monitor changes to commodity costs so that we can seek to mitigate the effect through pricing and other operational measures.
Seasonality and Working Capital
Although crops constituting certain of our raw food ingredients are harvested on a seasonal basis, the majority of our products are produced throughout the year.
Seasonal factors inherent in our business change the demand for products, including holidays, changes in seasons, or other annual events. While these factors influence our quarterly net sales, operating income/(loss), and cash flows at the product level, unless the timing of such events shift period-over-period (e.g., a shift in Easter timing), this seasonality does not typically have a significant effect on our consolidated results of operations or segment results.
For information related to our cash flows provided by/(used for) operating activities, including working capital items, see Liquidity and Capital Resources in Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations, of this report.
Employees
We had approximately 38,000 employees as of December 29, 2018.
Regulation
The manufacture and sale of consumer food and beverage products is highly regulated. Our business operations, including the production, transportation, storage, distribution, sale, display, advertising, marketing, labeling, quality and safety of our products and their ingredients, and our occupational safety, health, and privacy practices, are subject to various laws and regulations. These laws and regulations are administered by federal, state, and local government agencies in the United States, as well as government entities and agencies outside the United States in markets where our products are manufactured, distributed or sold. In the United States, our activities are subject to regulation by various federal government agencies, including the Food and Drug Administration, U.S. Department of Agriculture, Federal Trade Commission, Department of Labor, Department of Commerce, and Environmental Protection Agency, as well as various state and local agencies. We are also subject to numerous similar and other laws and regulations outside of the United States, including but not limited to laws and regulations governing food safety, health and safety, anti-corruption, and data privacy. In our business dealings, we are also required to comply with the Foreign Corrupt Practices Act (“FCPA”), the U.K. Bribery Act, the Trade Sanctions Reform and Export Enhancement Act, and various other anti-corruption regulations in the regions in which we operate. We rely on legal and operational compliance programs, as well as in-house and outside counsel, to guide our businesses in complying with applicable laws and regulations of the countries in which we do business. In addition, the United Kingdom's impending withdrawal from the European Union (commonly referred to as “Brexit”) and other regulatory regime changes may add cost and complexity to our compliance efforts.
Environmental Regulation
Our activities throughout the world are highly regulated and subject to government oversight regarding environmental matters. Various laws concerning the handling, storage, and disposal of hazardous materials and the operation of facilities in environmentally sensitive locations may impact aspects of our operations.
In the United States, where a significant portion of our business operates, these laws and regulations include the Clean Air Act, the Clean Water Act, the Resource Conservation and Recovery Act, and the Comprehensive Environmental Response, Compensation, and Liability Act (“CERCLA”). CERCLA imposes joint and several liability on each potentially responsible party. We are involved in a number of active proceedings in the United States under CERCLA (and other similar state actions under similar legislation) related to our current operations and certain closed, inactive, or divested operations for which we retain liability.
As of December 29, 2018, we had accrued an amount we deemed appropriate for environmental remediation. Based on information currently available, we believe that the ultimate resolution of existing environmental remediation actions and our compliance in general with environmental laws and regulations will not have a material effect on our earnings or financial condition. However, it is difficult to predict with certainty the potential impact of future compliance efforts and environmental remedial actions and thus, future costs associated with such matters may exceed current reserves.
Information about our Executive Officers
The following are our executive officers as of June 5, 2019 and all persons chosen to become executive officers as of the filing date of this Annual Report on Form 10-K:
| Name | Age | Title | ||
| Bernardo Hees | 49 | Chief Executive Officer | ||
| Miguel Patricio | 53 | Advisor and Incoming Chief Executive Officer | ||
| David Knopf | 31 | Executive Vice President and Chief Financial Officer | ||
| Nina Barton | 45 | Zone President of Canada and President of Digital Growth | ||
| Paulo Basilio | 44 | President of U.S. Commercial Business | ||
| Pedro Drevon | 36 | Zone President of Latin America | ||
| Rashida La Lande | 45 | Senior Vice President, Global General Counsel and Head of CSR and Government Affairs; Corporate Secretary | ||
| Rafael Oliveira | 44 | Zone President of EMEA | ||
| Rodrigo Wickbold | 42 | Zone President of APAC |
Bernardo Hees became Chief Executive Officer upon the closing of the 2015 Merger. He had previously served as Chief Executive Officer of Heinz since June 2013. Previously, Mr. Hees served as Chief Executive Officer of Burger King Worldwide Holdings, Inc., a global fast food restaurant chain, from September 2010 to June 2013 and Burger King Worldwide, Inc. from June 2012 to June 2013 and as Chief Executive Officer of América Latina Logística (“ALL”), a logistics company, from January 2005 to September 2010. Mr. Hees has also been a partner at 3G Capital, a global investment firm, since July 2010. On April 22, 2019, we announced that Bernardo Hees will leave Kraft Heinz in 2019 to focus on other projects as a Partner of 3G Capital.
Miguel Patricio was appointed to succeed Mr. Hees as Chief Executive Officer and has served as Advisor to Kraft Heinz since May 5, 2019. Mr. Patricio has been Chief of Special Global Projects-Marketing at Anheuser-Busch Inbev SA/NV (“AB InBev”), a multinational drink and brewing holdings company, since January 1, 2019. Prior to that, he served as the Chief Marketing Officer at AB InBev since 2012. Prior to his role as Chief Marketing Officer, since joining AB InBev in 1998, he also served as Zone President Asia Pacific, Zone President North America, Vice President Marketing of North America, and Vice President Marketing. Mr. Patricio has also held several senior positions across the Americas at The Coca-Cola Company and Johnson & Johnson. Mr. Patricio also invests in the 3G Special Situation Fund III (the “Fund”); his investment represents less than 1% of the Fund’s assets.
David Knopf became Executive Vice President and Chief Financial Officer in October 2017. He had previously served as Vice President, Category Head of Planters Business since August 2016. Prior to that role, Mr. Knopf served as Vice President of Finance, Head of Global Budget & Business Planning, Zero-Based Budgeting, and Financial & Strategic Planning from July 2015 to August 2016. Prior to joining Kraft Heinz in July 2015, Mr. Knopf served in various roles at 3G Capital, including as an associate partner. Before joining 3G Capital in October 2013, Mr. Knopf served in various roles at Onex Partners, a private equity firm, and Goldman Sachs, a global investment banking, securities, and investment management firm. Mr. Knopf has also been a partner of 3G Capital since July 2015.
Nina Barton became Zone President of Canada and President of Digital Growth effective January 1, 2019. Prior to assuming her current role, Ms. Barton had served as President, Global Digital and Online Growth since October 2017, and from July 2015 through October 2017, she served as Senior Vice President of Marketing, Innovation and Research & Development for the U.S. business. From July 2013 through July 2015, she served as Vice President, Marketing at Kraft Foods Group, Inc. and managed the total coffee portfolio including the Maxwell House, Gevalia, and McCafe brands. Ms. Barton joined Kraft Foods in 2011 as Senior Marketing Director responsible for growing the Philadelphia cream cheese brand. Prior to that, Ms. Barton served in a variety of marketing and brand-building roles in the consumer products industry.
Paulo Basilio assumed his current role as President of the U.S. Commercial Business in October 2017. Mr. Basilio previously served as Executive Vice President and Chief Financial Officer upon the closing of the 2015 Merger until October 2017. He had previously served as Chief Financial Officer of Heinz since June 2013. Previously, Mr. Basilio served as Chief Executive Officer of ALL from September 2010 to June 2012, after having served in various roles at ALL, including Chief Operating Officer, Chief Financial Officer, and Analyst. Mr. Basilio has also been a partner of 3G Capital since July 2012.
Pedro Drevon assumed his current role as Zone President of Latin America in October 2017. Previously he served as Managing Director for Kraft Heinz Brazil since August 2015. Prior to joining Kraft Heinz in 2015, Mr. Drevon served in various capacities at 3G Capital. Before joining 3G Capital in 2008, Mr. Drevon served in various roles at Banco BBM, a financial advisory and wealth management firm. Mr. Drevon has also been a partner of 3G Capital since January 2011.
Rashida La Lande joined Kraft Heinz as Senior Vice President, Global General Counsel and Corporate Secretary in January 2018. In October 2018, Ms. La Lande’s responsibilities expanded to include leadership of our corporate social responsibility and government affairs functions, and she was later appointed Head of Corporate Social Responsibility and Government Affairs in addition to her role as Senior Vice President, Global General Counsel and Corporate Secretary. Prior to joining Kraft Heinz, Ms. La Lande was a partner at the law firm of Gibson, Dunn & Crutcher, where she advised clients with respect to mergers and acquisitions, leveraged buyouts, private equity deals, and joint ventures. Throughout Ms. La Lande’s career, she has advised companies and private equity sponsors in the consumer products, retail, financial services, and technology industries.
Rafael Oliveira assumed his current role as Zone President of EMEA in October 2016 after serving as the Managing Director of Kraft Heinz UK & Ireland. Mr. Oliveira joined Kraft Heinz in July 2014 and served as President of Kraft Heinz Australia, New Zealand, and Papua New Guinea until September 2016. Prior to joining Kraft Heinz, Mr. Oliveira spent 17 years in the financial industry, the final 10 of which he held a variety of leadership positions with Goldman Sachs.
Rodrigo Wickbold assumed his current role as Zone President of APAC in January 2018 after serving as Chief Marketing Officer of APAC since January 2016. Prior to joining Kraft Heinz in January 2016, Mr. Wickbold served in various marketing and business leadership roles at Unilever, a consumer products company, since 2000, including as Global Senior Brand Manager - Skin Care.
Available Information
Our website address is www.kraftheinzcompany.com. The information on our website is not, and shall not be deemed to be, a part of this Annual Report on Form 10-K or incorporated into any other filings we make with the Securities and Exchange Commission (the “SEC”). Our Annual Reports on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Securities Exchange Act of 1934, as amended, (the “Exchange Act”) are available free of charge on our website as soon as reasonably practicable after we electronically file them with, or furnish them to, the SEC. In addition, the SEC maintains a website at www.sec.gov that contains reports, proxy and information statements, and other information regarding issuers, including Kraft Heinz, that are electronically filed with the SEC.
Item 1A. Risk Factors.
Industry Risks
We operate in a highly competitive industry.
The food and beverage industry is highly competitive across all of our product offerings. Our principal competitors in these categories are manufacturers, as well as retailers with their own branded and private label products. We compete based on product innovation, price, product quality, nutritional value, service, taste, convenience, brand recognition and loyalty, effectiveness of marketing and distribution, promotional activity, and the ability to identify and satisfy changing consumer preferences.
We may need to reduce our prices in response to competitive and customer pressures, including pressures in relation to private label products that are generally sold at lower prices. These pressures have restricted and may in the future continue to restrict our ability to increase prices in response to commodity and other cost increases. Failure to effectively assess, timely change and set proper pricing, promotions, or trade incentives may negatively impact the achievement of our objectives.
The rapid emergence of new distribution channels, particularly e-commerce, may create consumer price deflation, affecting our retail customer relationships and presenting additional challenges to increasing prices in response to commodity or other cost increases. We may also need to increase or reallocate spending on marketing, retail trade incentives, materials, advertising, and new product or channel innovation to maintain or increase market share. These expenditures are subject to risks, including uncertainties about trade and consumer acceptance of our efforts. If we are unable to compete effectively, our profitability, financial condition, and operating results may decline.
Our success depends on our ability to correctly predict, identify, and interpret changes in consumer preferences and demand, to offer new products to meet those changes, and to respond to competitive innovation.
Consumer preferences for food and beverage products change continually and rapidly. Our success depends on our ability to predict, identify, and interpret the tastes and dietary habits of consumers and to offer products that appeal to consumer preferences, including with respect to health and wellness. If we do not offer products that appeal to consumers, our sales and market share will decrease, which could materially and adversely affect our product sales, financial condition, and operating results.
We must distinguish between short-term trends and long-term changes in consumer preferences. If we do not accurately predict which shifts in consumer preferences will be long-term, or if we fail to introduce new and improved products to satisfy those preferences, our sales could decline. In addition, because of our varied consumer base, we must offer an array of products that satisfy a broad spectrum of consumer preferences. If we fail to expand our product offerings successfully across product categories, or if we do not rapidly develop products in faster-growing or more profitable categories, demand for our products could decrease, which could materially and adversely affect our product sales, financial condition, and operating results.
Prolonged negative perceptions concerning the health implications of certain food and beverage products (including as they relate to obesity or other health concerns) could influence consumer preferences and acceptance of some of our products and marketing programs. We strive to respond to consumer preferences and social expectations, but we may not be successful in our efforts. Continued negative perceptions and failure to satisfy consumer preferences could materially and adversely affect our product sales, financial condition, and operating results.
In addition, achieving growth depends on our successful development, introduction, and marketing of innovative new products and line extensions. There are inherent risks associated with new product or packaging introductions, including uncertainties about trade and consumer acceptance or potential impacts on our existing product offerings. We may be required to increase expenditures for new product development. Successful innovation depends on our ability to correctly anticipate customer and consumer acceptance, to obtain, protect, and maintain necessary intellectual property rights, and to avoid infringing upon the intellectual property rights of others. We must also be able to respond successfully to technological advances by and intellectual property rights of our competitors, and failure to do so could compromise our competitive position and impact our product sales, financial condition, and operating results.
Changes in the retail landscape or the loss of key retail customers could adversely affect our financial performance.
Retail customers, such as supermarkets, warehouse clubs, and food distributors in our major markets, may continue to consolidate, resulting in fewer but larger customers for our business across various channels. Consolidation also produces larger retail customers that may seek to leverage their positions to improve their profitability by demanding improved efficiency, lower pricing, more favorable terms, increased promotional programs, or specifically-tailored product offerings. In addition, larger retailers have scale to develop supply chains that permit them to operate with reduced inventories or to develop and market their own private label products. Retail consolidation and increasing retailer power could materially and adversely affect our product sales, financial condition, and operating results.
Retail consolidation also increases the risk that adverse changes in our customers’ business operations or financial performance may have a corresponding material and adverse effect on us. For example, if our customers cannot access sufficient funds or financing, then they may delay, decrease, or cancel purchases of our products, or delay or fail to pay us for previous purchases, which could materially and adversely affect our product sales, financial condition, and operating results.
In addition, technology-based systems, which give consumers the ability to shop through e-commerce websites and mobile commerce applications, are also significantly altering the retail landscape in many of our markets. If we are unable to adjust to developments in these changing landscapes, we may be disadvantaged in key channels and with certain consumers, which could materially and adversely affect our product sales, financial condition, and operating results.
Changes in our relationships with significant customers, suppliers, or other business relationships could adversely impact us.
We derive significant portions of our sales from certain significant customers (see Sales and Customers within Item 1, Business). There can be no assurance that all of our significant customers will continue to purchase our products in the same mix or quantities or on the same terms as in the past, particularly as increasingly powerful retailers may demand lower pricing and focus on developing their own brands. The loss of a significant customer or a material reduction in sales or a change in the mix of products we sell to a significant customer could materially and adversely affect our product sales, financial condition, and operating results.
Disputes with significant suppliers, including disputes related to pricing or performance, could adversely affect our ability to supply products to our customers and could materially and adversely affect our product sales, financial condition, and operating results. In addition, terminations of relationships with other significant contractual counterparties, including licensors, could adversely affect our portfolio, product sales, financial condition, and operating results.
In addition, the financial condition of such customers, suppliers, and other significant contractual counterparties are affecte
Showing the first 8K of 78K characters. Open the full section
Item 1B. Unresolved Staff Comments.
None.
Item 2. Properties.
Our corporate co-headquarters are located in Pittsburgh, Pennsylvania and Chicago, Illinois. Our co-headquarters are leased and house certain executive offices, our U.S. business units, and our administrative, finance, legal, and human resource functions. We maintain additional owned and leased offices throughout the regions in which we operate.
We manufacture our products in our network of manufacturing and processing facilities located throughout the world. As of December 29, 2018, we operated 84 manufacturing and processing facilities. We own 81 and lease three of these facilities. Our manufacturing and processing facilities count by segment as of December 29, 2018 was:
| Owned | Leased | ||
| United States | 40 | 1 | |
| Canada | 2 | — | |
| EMEA | 12 | — | |
| Rest of World | 27 | 2 |
We maintain all of our manufacturing and processing facilities in good condition and believe they are suitable and are adequate for our present needs. We also enter into co-manufacturing arrangements with third parties if we determine it is advantageous to outsource the production of any of our products.
In the fourth quarter of 2018, we announced our plans to divest certain assets and operations, predominantly in Canada and India, including one owned manufacturing facility in Canada and one owned and one leased facility in India. See Note 5, Acquisitions and Divestitures, in Item 8, Financial Statements and Supplementary Data, for additional information on these transactions.
Item 3. Legal Proceedings.
See Note 18, Commitments and Contingencies, in Item 8, Financial Statements and Supplementary Data.
Item 4. Mine Safety Disclosures.
Not applicable.
PART II
Item 5. Market for Registrant's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
Our common stock is listed on Nasdaq under the ticker symbol “KHC”. At June 5, 2019, there were approximately 49,000 holders of record of our common stock.
See Equity and Dividends in Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations, for a discussion of cash dividends declared on our common stock.
Comparison of Cumulative Total Return
The following graph compares the cumulative total return on our common stock with the cumulative total return of the Standard & Poor's (“S&P”) 500 Index and the S&P Consumer Staples Food and Soft Drink Products, which we consider to be our peer group. Companies included in the S&P Consumer Staples Food and Soft Drink Products index change periodically and are presented on the basis of the index as it is comprised on December 29, 2018. This graph covers the period from July 6, 2015 (the first day our common stock began trading on Nasdaq) through December 28, 2018 (the last trading day of our fiscal year 2018). The graph shows total shareholder return assuming $100 was invested on July 6, 2015 and the dividends were reinvested on a daily basis.
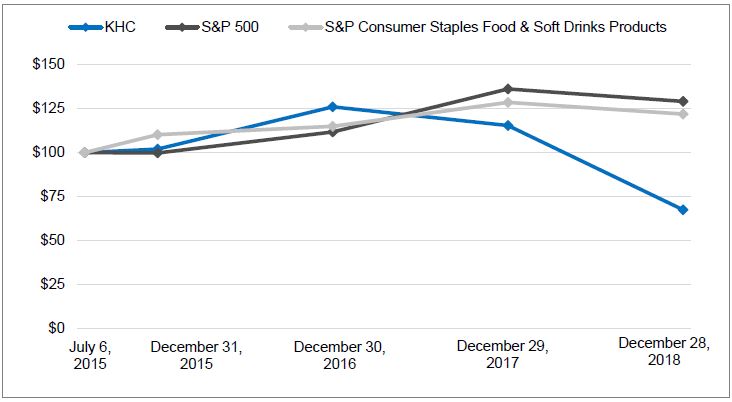
| Kraft Heinz | S&P 500 | S&P Consumer Staples Food and Soft Drink Products | |||||||||
| July 6, 2015 | $ | 100.00 | $ | 100.00 | $ | 100.00 | |||||
| December 31, 2015 | 102.07 | 99.85 | 110.18 | ||||||||
| December 30, 2016 | 125.99 | 111.79 | 114.98 | ||||||||
| December 29, 2017 | 115.44 | 136.20 | 128.53 | ||||||||
| December 28, 2018 | 67.49 | 129.11 | 121.93 |
The above performance graph shall not be deemed to be “soliciting material” or to be “filed” with the SEC or subject to Regulation 14A or 14C, or to the liabilities of Section 18 of the Exchange Act.
Issuer Purchases of Equity Securities During the Three Months Ended December 29, 2018
Our share repurchase activity in the three months ended December 29, 2018 was:
| Total Number of Shares Purchased(a) | Average Price Paid Per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs(b) | Approximate Dollar Value of Shares that May Yet Be Purchased Under the Plans or Programs | |||||||||||
| 9/30/2018 - 11/3/2018 | 48,358 | $ | 55.58 | — | $ | — | ||||||||
| 11/4/2018 - 12/1/2018 | 79,925 | 52.18 | — | — | ||||||||||
| 12/2/2018 - 12/29/2018 | 231,409 | 49.16 | — | — | ||||||||||
| Total | 359,692 | — |
| (a) | Includes the following types of share repurchase activity, when they occur: (1) shares repurchased in connection with the exercise of stock options (including periodic repurchases using option exercise proceeds), (2) shares withheld for tax liabilities associated with the vesting of restricted stock units, and (3) shares repurchased related to employee benefit programs (including our annual bonus swap program) or to offset the dilutive effect of equity issuances. |
| (b) | We do not have any publicly announced share repurchase plans or programs. |
Item 6. Selected Financial Data.
The following table presents selected consolidated financial data for the last five fiscal years. Our fiscal years 2018, 2017, and 2016 include a full year of Kraft Heinz results. Our fiscal year 2015 includes a full year of Heinz results and post-merger Kraft results. Our fiscal year 2014 includes a full year of Heinz results.
Certain prior period amounts have been restated for the correction of misstatements described below. This information should be read in conjunction with the “Explanatory Note” immediately preceding Item 1 of this Annual Report on Form 10-K, with Item 7, Management's Discussion and Analysis of Financial Condition and Results of Operations, and with our consolidated financial statements and notes thereto included elsewhere in this Annual Report on Form 10-K, including further details related to the misstatements discussed in Note 2, Restatement of Previously Issued Consolidated Financial Statements.
| As Restated | |||||||||||||||||||
| (Unaudited) | |||||||||||||||||||
| December 29, 2018 (52 weeks) | December 30, 2017 (52 weeks) | December 31, 2016 (52 weeks)(h) | January 3, 2016 (53 weeks) | December 28, 2014 (52 weeks) | |||||||||||||||
| (in millions, except per share data) | |||||||||||||||||||
| Period Ended: | |||||||||||||||||||
| Net sales(a)(b)(c) | $ | 26,268 | $ | 26,076 | $ | 26,300 | $ | 18,318 | $ | 10,922 | |||||||||
| Income/(loss)(c)(d)(e) | (10,254 | ) | 10,932 | 3,606 | 614 | 672 | |||||||||||||
| Income/(loss) attributable to common shareholders(c)(d)(e) | (10,192 | ) | 10,941 | 3,416 | (299 | ) | (63 | ) | |||||||||||
| Income/(loss) per common share: | |||||||||||||||||||
| Basic(c)(d)(e) | (8.36 | ) | 8.98 | 2.81 | (0.38 | ) | (0.17 | ) | |||||||||||
| Diluted(c)(d)(e) | (8.36 | ) | 8.91 | 2.78 | (0.38 | ) | (0.17 | ) | |||||||||||
| As Restated | |||||||||||||||||||
| (Unaudited) | |||||||||||||||||||
| December 29, 2018 | December 30, 2017 | December 31, 2016 | January 3, 2016 | December 28, 2014 | |||||||||||||||
| (in millions, except per share data) | |||||||||||||||||||
| As of: | |||||||||||||||||||
| Total assets(b)(c)(e) | 103,461 | 120,092 | 120,617 | 123,110 | 36,571 | ||||||||||||||
| Long-term debt(b)(c)(f) | 30,770 | 28,308 | 29,712 | 25,148 | 13,358 | ||||||||||||||
| Redeemable preferred stock(g) | — | — | — | 8,320 | 8,320 | ||||||||||||||
| Cash dividends per common share | 2.50 | 2.45 | 2.35 | 1.70 | — |
| (a) | As previously disclosed, we adopted a new accounting standard related to revenue recognition in the first quarter of 2018, and at the same time, we retrospectively corrected immaterial misclassifications in our statements of income principally related to customer incentive program expense misclassifications. This resulted in net sales decreases of $147 million in 2017, $152 million in 2016, and $55 million in 2015. |
| (b) | The increases in net sales in 2016 and in 2015 compared to the prior year, and the increases in total assets and long-term debt from December 28, 2014 to January 3, 2016, were primarily driven by the 2015 Merger. |
| (c) | We have restated previously disclosed consolidated financial data for fiscal years 2017, 2016, and 2015, as well as the related balance sheet dates, to correct misstatements principally related to supplier contracts and related arrangements, as well as other identified out-of-period and uncorrected misstatements. See Note 2, Restatement of Previously Issued Consolidated Financial Statements, in Item 8, Financial Statements and Supplementary Data, for additional information. |
| (d) | The increases in income/(loss), income/(loss) attributable to common shareholders, and basic and diluted income/(loss) per common share in 2017 compared to 2016 were primarily driven by U.S. Tax Reform, which was enacted in December 2017. See Note 11, Income Taxes, in Item 8, Financial Statements and Supplementary Data, for additional information. |
| (e) | The decreases in income/(loss), income/(loss) attributable to common shareholders, and basic and diluted income/(loss) per common share in 2018 compared to 2017, and the decrease in total assets from December 30, 2017 to December 29, 2018, were primarily driven by non-cash impairment losses in 2018. See Note 10, Goodwill and Intangible Assets, in Item 8, Financial Statements and Supplementary Data, for additional information. |
| (f) | Amounts exclude the current portion of long-term debt. |
| (g) | On June 7, 2016, we redeemed all outstanding shares of our 9.00% cumulative compounding preferred stock, Series A (“Series A Preferred Stock”). See Equity and Dividends in Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations, along with Note 19, Debt, and Note 20, Capital Stock, in Item 8, Financial Statements and Supplementary Data, for additional information. |
| (h) | On December 9, 2016, our Board of Directors approved a change to our fiscal year end from Sunday to Saturday. Effective December 31, 2016, we operate on a 52- or 53-week fiscal year ending on the last Saturday in December in each calendar year. In prior years, we operated on a 52- or 53-week fiscal year ending the Sunday closest to December 31. As a result, we occasionally have a 53rd week in a fiscal year. Our 2015 fiscal year includes a 53rd week of activity. |
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
Overview
The following discussion should be read in conjunction with the other sections of this Annual Report on Form 10-K, including the consolidated financial statements and related notes contained in Item 8, Financial Statements and Supplementary Data.
Restatement of Previously Issued Consolidated Financial Statements:
We have restated our previously issued consolidated financial statements contained in this Annual Report on Form 10-K. Refer to the “Explanatory Note” preceding Item 1, Business, for background on the restatement, the fiscal periods impacted, control considerations, and other information.
In addition, we have restated certain previously reported financial information at December 30, 2017 and for the fiscal years ended December 30, 2017 and December 31, 2016 in this Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations, including but not limited to information within the Consolidated Results of Operations, Results of Operations by Segment, and Non-GAAP Financial Measures sections. We have also included certain restated quarterly information in the Supplemental Quarterly Financial Information section at the end of this item.
See Note 2, Restatement of Previously Issued Consolidated Financial Statements, in Item 8, Financial Statements and Supplementary Data, for additional information related to the restatement, including descriptions of the misstatements and the impacts on our consolidated financial statements.
Description of the Company:
We manufacture and market food and beverage products, including condiments and sauces, cheese and dairy, meals, meats, refreshment beverages, coffee, and other grocery products throughout the world.
We manage and report our operating results through four segments. We have three reportable segments defined by geographic region: United States, Canada, and EMEA. Our remaining businesses are combined and disclosed as “Rest of World.” Rest of World comprises two operating segments: Latin America and APAC.
Our segments reflect a change, effective in the first quarter of our fiscal year 2018, to reorganize our international businesses to better align our global geographies. We moved our Middle East and Africa businesses from the historical AMEA operating segment into the historical Europe reportable segment, forming the new EMEA reportable segment. The remaining businesses from the AMEA operating segment became the APAC operating segment. We have reflected this change in all historical periods presented.
See Note 22, Segment Reporting, in Item 8, Financial Statements and Supplementary Data, to the consolidated financial statements for our financial information by segment.
Items Affecting Comparability of Financial Results
Impairment Losses:
Our 2018 results reflect goodwill and intangible asset impairment losses of $15.9 billion compared to $49 million in 2017. The increase was primarily driven by impairment losses of $15.5 billion recognized in the fourth quarter of 2018.
For the fourth quarter of 2018, in connection with the preparation of our year-end financial statements, we assessed the changes in circumstances that occurred during the quarter to determine if it was more likely than not that the fair values of any reporting units or brands were below their carrying amounts. Although our annual impairment test is performed during the second quarter, we perform this qualitative assessment each interim reporting period.
While there was no single determinative event or factor, the consideration in totality of several factors that developed during the fourth quarter of 2018 led us to conclude that it was more likely than not that the fair values of certain reporting units and brands were below their carrying amounts. These factors included: (i) a sustained decrease in our share price in November and December of 2018, which reduced our market capitalization below the book value of net assets; (ii) the completion of our fourth quarter results, which were below management’s expectations due to several factors such as higher than expected supply chain costs and increased competition; (iii) the development and approval of our 2019 annual operating plan in December 2018, which provided additional insights into expectations and priorities for the coming years, such as lower growth and margin expectations; (iv) the announcement in November 2018 to sell certain assets in our natural cheese portfolio in Canada, which changed the composition and use of the remaining assets and brands in the associated reporting unit; (v) fluctuations in foreign exchange rates in certain countries; (vi) increased interest rates in certain locations, including an increase in the United States in December 2018; and (vii) increased and prolonged economic and regulatory uncertainty in the United States and global economies as of the end of December 2018.
As we determined that it was more likely than not that the fair values of certain reporting units or brands were below their carrying amounts, we performed an interim impairment test as of December 29, 2018. As a result of our interim impairment test, we recognized goodwill impairment losses of $6.9 billion and indefinite-lived intangible asset impairment losses of $8.6 billion in the fourth quarter of 2018.
See Critical Accounting Estimates within this item and Note 10, Goodwill and Intangible Assets, in Item 8, Financial Statements and Supplementary Data, to the consolidated financial statements for additional information.
U.S. Tax Reform:
U.S. Tax Reform legislation enacted by the federal government on December 22, 2017 significantly changed U.S. tax laws by, among other things, lowering the federal corporate tax rate from 35.0% to 21.0%, effective January 1, 2018 and imposing a one-time toll charge on deemed repatriated earnings of foreign subsidiaries as of December 30, 2017. In addition, there were many new provisions, including changes to bonus depreciation, revised deductions for executive compensation and interest expense, a tax on global intangible low-taxed income (“GILTI”), the base erosion anti-abuse tax (“BEAT”), and a deduction for foreign-derived intangible income (“FDII”). While the corporate tax rate reduction was effective January 1, 2018, we accounted for this anticipated rate change in 2017, the period of enactment. As a result of U.S. Tax Reform, we recorded a net tax benefit of approximately $7.0 billion in 2017. As a result, U.S. Tax Reform significantly impacted our provision for/(benefit from) income taxes and our effective tax rate, primarily in 2017, resulting in a lack of comparability year over year.
See Note 11, Income Taxes, in Item 8, Financial Statements and Supplementary Data, for additional information.
Integration and Restructuring Expenses:
At the end of 2017, we had substantially completed our multi-year program announced following the 2015 Merger (the “Integration Program”), which was designed to reduce costs and integrate and optimize our combined organization. As of December 29, 2018, we had incurred cumulative pre-tax costs of $2,146 million related to the Integration Program. These costs primarily included severance and employee benefit costs (including cash and non-cash severance), costs to exit facilities (including non-cash costs such as accelerated depreciation), and other costs incurred as a direct result of integration activities. Approximately 60% of total Integration Program costs were cash expenditures. As of December 29, 2018, we had incurred approximately $1.4 billion in capital expenditures related to the Integration Program since its inception in 2015.
Related to our restructuring activities, including the Integration Program, we recognized expenses of $460 million in 2018, $434 million in 2017, and $1.0 billion in 2016. Integration Program expenses included in these totals were $92 million in 2018, $316 million, in 2017, and $887 million in 2016.
See Note 6, Integrat
Showing the first 8K of 133K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
We are exposed to market risks from adverse changes in commodity prices, foreign exchange rates, and interest rates. We monitor and manage these exposures as part of our overall risk management program. Our risk management program focuses on the unpredictability of financial markets and seeks to reduce the potentially adverse effects that volatility in these markets may have on our operating results. We maintain risk management policies that principally use derivative financial instruments to reduce significant, unanticipated fluctuations in earnings and cash flows that may arise from variations in commodity prices, foreign currency exchange rates, and interest rates. We manage market risk by incorporating parameters within our risk management strategy that limit the types of derivative instruments, the derivative strategies we use, and the degree of market risk that we hedge with derivative instruments. See Note 3, Significant Accounting Policies, and Note 14, Financial Instruments, in Item 8, Financial Statements and Supplementary Data, for details of our market risk management policies and the financial instruments used to hedge those exposures.
When we use financial instruments, we are exposed to credit risk that a counterparty might fail to fulfill its performance obligations under the terms of our agreement. We minimize our credit risk by entering into transactions with counterparties with investment grade credit ratings, limiting the amount of exposure we have with each counterparty, and monitoring the financial condition of our counterparties. All of our non-exchange traded derivative contracts are governed by an International Swaps and Derivatives Association master agreement. By policy, we do not engage in speculative or leveraged transactions, nor do we hold or issue financial instruments for trading purposes.
Effect of Hypothetical 10% Fluctuation in Market Prices:
The potential gain or loss on the fair value of our outstanding commodity contracts, foreign exchange contracts, and cross-currency swap contracts, assuming a hypothetical 10% fluctuation in commodity prices and foreign currency exchange rates, would have been (in millions):
| December 29, 2018 | December 30, 2017 | ||||||
| Commodity contracts | $ | 38 | $ | 23 | |||
| Foreign currency contracts | 100 | 173 | |||||
| Cross-currency swap contracts | 402 | 287 |
It should be noted that any change in the fair value of our derivative contracts, real or hypothetical, would be significantly offset by an inverse change in the value of the underlying hedged items. In relation to foreign currency contracts, this hypothetical calculation assumes that each exchange rate would change in the same direction relative to the U.S. dollar. Our utilization of financial instruments in managing market risk exposures described above is consistent with the prior year. Changes in our portfolio of financial instruments are a function of our results of operations, debt repayments and debt issuances, market effects on debt and foreign currency, and our acquisition and divestiture activities.
Effect of Hypothetical 1% Fluctuation in LIBOR and CDOR:
Based on our current variable rate debt balance as of December 29, 2018, a hypothetical 1% increase in LIBOR and CDOR would increase our annual interest expense by approximately $19 million.
Item 8. Financial Statements and Supplementary Data.
Report of Independent Registered Public Accounting Firm
To the Shareholders and Board of Directors of The Kraft Heinz Company
Opinions on the Financial Statements and Internal Control over Financial Reporting
We have audited the accompanying consolidated balance sheets of The Kraft Heinz Company and its subsidiaries (the “Company”) as of December 29, 2018 and December 30, 2017, and the related consolidated statements of income, comprehensive income, equity and cash flows for each of the three years in the period ended December 29, 2018, including the related notes and financial statement schedule listed in the index appearing under Item 15 (a) (collectively referred to as the “consolidated financial statements”). We also have audited the Company's internal control over financial reporting as of December 29, 2018, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 29, 2018 and December 30, 2017, and the results of its operations and its cash flows for each of the three years in the period ended December 29, 2018 in conformity with accounting principles generally accepted in the United States of America. Also in our opinion, the Company did not maintain, in all material respects, effective internal control over financial reporting as of December 29, 2018, based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO because material weaknesses in internal control over financial reporting existed as of that date related to the risk assessment component of internal control, as the Company did not appropriately design controls in response to the risk of material misstatement due to changes in their business environment. The risk assessment material weakness gave rise to additional material weaknesses as the Company did not design and maintain effective controls over the accounting for supplier contracts and related arrangements or to reassess the level of precision used to review the impairment assessments related to forecasted cash flows used within goodwill and indefinite-lived intangible asset impairment calculations.
A material weakness is a deficiency, or a combination of deficiencies, in internal control over financial reporting, such that there is a reasonable possibility that a material misstatement of the annual or interim financial statements will not be prevented or detected on a timely basis. The material weaknesses referred to above are described in Management's Report on Internal Control Over Financial Reporting appearing under Item 9A. We considered these material weaknesses in determining the nature, timing, and extent of audit tests applied in our audit of the 2018 consolidated financial statements, and our opinion regarding the effectiveness of the Company’s internal control over financial reporting does not affect our opinion on those consolidated financial statements.
Restatement of Previously Issued Financial Statements
As discussed in Note 2 to the consolidated financial statements, the Company has restated its 2017 and 2016 financial statements to correct misstatements.
Change in Accounting Principle
As discussed in Note 4 to the consolidated financial statements, the Company changed the manner in which it presents net periodic benefit costs in 2018.
Basis for Opinions
The Company's management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting included in management’s report referred to above. Our responsibility is to express opinions on the Company’s consolidated financial statements and on the Company's internal control over financial reporting based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud, and whether effective internal control over financial reporting was maintained in all material respects.
Our audits of the consolidated financial statements included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.
Definition and Limitations of Internal Control over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/ PricewaterhouseCoopers LLP
Chicago, Illinois
June 7, 2019
We have served as the Company’s or its predecessor’s auditor since 1979.
The Kraft Heinz Company
Consolidated Statements of Income
(in millions, except per share data)
| As Restated & Recast | |||||||||||
| December 29, 2018 | December 30, 2017 | December 31, 2016 | |||||||||
| Net sales | $ | 26,268 | $ | 26,076 | $ | 26,300 | |||||
| Cost of pr |
Showing the first 8K of 598K characters. Open the full section
Item 9. Changes in and Disagreements With Accountants on Accounting and Financial Disclosure.
None.
Item 9A. Controls and Procedures.
Evaluation of Disclosure Controls and Procedures
Our management, with the participation of our Chief Executive Officer and Chief Financial Officer, has evaluated the effectiveness of our disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Exchange Act) as of December 29, 2018. Based on that evaluation, our Chief Executive Officer and Chief Financial Officer have concluded that as of December 29, 2018, due to the existence of the material weaknesses in our internal control over financial reporting described below, our disclosure controls and procedures were not effective to provide reasonable assurance that the information required to be disclosed in the reports that we file or submit under the Exchange Act is recorded, processed, summarized, and reported within the time periods specified in the SEC’s rules and forms, and that such information is accumulated and communicated to management as appropriate to allow timely decisions regarding required disclosure.
Management’s Report on Internal Control Over Financial Reporting
Management is responsible for establishing and maintaining adequate internal control over financial reporting as defined in Rule 13a-15(f) under the Exchange Act. Our internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. Our internal control over financial reporting includes those written policies and procedures that:
| • | pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of assets; |
| • | provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles; |
| • | provide reasonable assurance that receipts and expenditures are being made only in accordance with management and director authorization; and |
| • | provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of assets that could have a material effect on the consolidated financial statements. |
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Under the supervision and with the participation of management, including our Chief Executive Officer and Chief Financial Officer, we conducted an evaluation of the effectiveness of our internal control over financial reporting as of December 29, 2018 based on the framework described in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). Based on this evaluation, our management concluded that we did not maintain effective internal control over financial reporting as of December 29, 2018 due to the material weaknesses described below.
A material weakness is a deficiency, or combination of deficiencies, in internal control over financial reporting, such that there is a reasonable possibility that a material misstatement of our annual or interim financial statements will not be prevented or detected on a timely basis.
We identified a material weakness in the risk assessment component of internal control as we did not appropriately design controls in response to the risk of misstatement due to changes in our business environment. This material weakness in risk assessment gave rise to the specific control deficiencies described below, which we also determined to be material weaknesses:
| • | Supplier Contracts and Related Arrangements: We did not design and maintain effective controls over the accounting for supplier contracts and related arrangements. Specifically, certain employees in our procurement organization engaged in misconduct and circumvented controls that included withholding information or directing others to withhold information related to supplier contracts that affected the accounting for certain supplier rebates, incentives, and pricing arrangements, in an attempt to influence the achievement of internal financial targets that became or were perceived to have become increasingly difficult to attain due to changes in our business environment. Additionally, in certain instances, we did not have a sufficient understanding or maintain sufficient documentation of the transaction to determine the appropriate accounting for certain cost and rebate elements and embedded leases. This material weakness resulted in misstatements that were corrected in the restatement included in this Annual Report on Form 10-K. |
| • | Goodwill and Indefinite-lived Intangible Asset Impairment Testing: We did not design and maintain effective controls to reassess the level of precision used to review the impairment assessments related to goodwill and indefinite-lived intangible assets as changes in our business environment occurred. Specifically, we did not design and maintain effective controls to reassess the level of precision used in the review of the allocation of cash flow projections to certain brands used as a basis for performing our fourth quarter 2018 interim impairment assessments in response to the significant reduction in, and in certain instances elimination of, the excess fair value over carrying amount of certain brands that resulted from changes in our business environment. This material weakness did not result in a misstatement of any previously issued consolidated financial statements. |
Additionally, the material weaknesses described above could result in a misstatement of the aforementioned account balances or disclosures that would result in a material misstatement of the annual or interim consolidated financial statements that would not be prevented or detected.
PricewaterhouseCoopers LLP, an independent registered public accounting firm that audited the consolidated financial statements included in this Annual Report on Form 10-K, has also audited the effectiveness of our internal control over financial reporting as of December 29, 2018, as stated in their report which appears herein under Item 8, Financial Statements and Supplementary Data.
Remediation of Material Weaknesses
We are evaluating the material weaknesses and developing a plan of remediation to strengthen our internal controls related to our risk assessment component of internal control over financial reporting, supplier contracts and related arrangements, and the level of precision applied to the goodwill and indefinite-lived intangible asset impairment testing process. The remediation efforts summarized below, which are in the process of being implemented, are intended to address the identified material weaknesses and enhance our overall internal control environment.
| • | Personnel Actions—A comprehensive disciplinary plan is in the process of being implemented for all employees found to have engaged in misconduct, including termination, written warnings, and appropriate training depending on the severity of the misconduct. |
| • | Performance Targets—We have identified and will be implementing several performance-based target enhancements as follows: (i) implementing checkpoints to evaluate significant changes in the environment that could adversely impact the attainability of management goals and targets; (ii) reassessing and adjusting the overall balance of performance measures provided to employees to help drive challenging but attainable targets; and (iii) enhancing our training and overall communication specific to the Management by Objective (“MBO”) process, including a focus on the process to request relief from previously established MBOs, to help ensure all eligible employees are aware of and understand the overall MBO waiver and relief process; (iv) reinforcing the importance of adherence to established internal controls and company policies and procedures through other formal communications, town hall meetings, and other employee trainings; and (v) reassessing certain employees’ key performance indicators. |
| • | Organizational Enhancements—We have identified and are in the process of implementing organizational enhancements as follows: (i) augmenting our procurement finance teams with additional professionals with the appropriate levels of accounting and controls knowledge, experience, and training in the area of supplier contracts and related arrangements; and (ii) realigning reporting lines whereby procurement finance now report directly to the finance organization. |
| • | Procurement Practices—We have evaluated our procurement practices and are in the process of implementing improvements to those practices, including: (i) developing more comprehensive contract approval policies and processes; (ii) enhancing required communication protocols among all functions involved in the procurement process (e.g., procurement, legal, accounting, and finance) to ensure all relevant parties are involved in the contract review process; (iii) standardizing contract documentation and analyses; and (iv) developing a more comprehensive accounting review process and monitoring controls over supplier contracts and related arrangements to ensure transactions are recorded in accordance with generally accepted accounting principles. |
| • | Training Practices—We are in the process of developing a comprehensive global procurement training program that will cover supplier contracts and related arrangements, including potential accounting implications. As part of this effort, we have held mandatory training for our global procurement function, which focused on our policies and procedures related to procurement, including the proper accounting for the contract terms that contributed to the material weakness. |
| • | Procurement Management Software—We have started to evaluate potential solutions to implement or upgrade the existing procurement management software to enhance the identification, tracking, and monitoring of supplier contracts and related arrangements. |
| • | Level of Precision Applied to Impairment Testing—We are in the process of implementing a plan to enhance the level of precision at which our internal controls over financial reporting relating to goodwill and indefinite-lived intangible asset impairment assessments are performed. Specifically, we will be implementing and executing additional procedures to (i) |
enhance our analysis of forecasted cash flows used in the impairment assessment and (ii) test the accuracy of forecasted cash flow allocations to specific brands.
We believe the measures described above will remediate the material weaknesses we have identified and strengthen our internal control over financial reporting. We are committed to continuing to improve our internal control processes and have begun to implement some of the steps described above. We will also continue to review, optimize, and enhance our financial reporting controls and procedures. As we continue to evaluate and work to improve our internal control over financial reporting, we may take additional measures to address control deficiencies or we may modify certain of the remediation measures described above. These material weaknesses will not be considered remediated until the applicable remediated controls operate for a sufficient period of time and management has concluded, through testing, that these controls are operating effectively.
Changes in Internal Control Over Financial Reporting
Our Chief Executive Officer and Chief Financial Officer, with other members of management, evaluated the changes in our internal control over financial reporting during the three months ended December 29, 2018. We determined that there were no changes in our internal control over financial reporting during the three months ended December 29, 2018 that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. Other Information.
Not applicable.
PART III
Item 10. Directors, Executive Officers and Corporate Governance.
EXECUTIVE OFFICERS
Information regarding executive officers is included in Part I of this Annual Report on Form 10-K under the caption “Information about our Executive Officers.”
BOARD OF DIRECTORS
Directors and Director Nominees
The table below provides summary information about each director and each person nominated by the Kraft Heinz Board of Directors (the “Board”) for election at our 2019 Annual Meeting of Stockholders (the “Annual Meeting”) as of June 5, 2019.
| Name | Age | Director Since | Independent | Audit Committee | Compensation Committee | Governance Committee | Operations & Strategy Committee | |||||||
| Gregory E. Abel | 57 | 2013 | Yes | X | ||||||||||
| Alexandre Behring (Chairman) | 52 | 2013 | Yes | X | Chair | X | ||||||||
| Joao M. Castro-Neves* | 52 | 2019 | Yes | Chair | X | X | ||||||||
| Tracy Britt Cool | 34 | 2013 | Yes | X | ||||||||||
| John T. Cahill (Vice Chairman) | 62 | 2015 | No | Chair | ||||||||||
| Feroz Dewan | 42 | 2016 | Yes | X | ||||||||||
| Jeanne P. Jackson | 67 | 2015 | Yes | X | X | X | ||||||||
| Jorge Paulo Lemann | 79 | 2013 | Yes | X | X | |||||||||
| John C. Pope | 70 | 2015 | Yes | Chair | X | X | ||||||||
| Alexandre Van Damme** | 57 | 2018 | Yes | X | ||||||||||
| George Zoghbi | 52 | 2018 | No |
| * | As previously disclosed, Marcel Hermann Telles decided to retire from the Board. His retirement will become effective on June 12, 2019. The Board elected Mr. Castro-Neves, effective June 12, 2019, and appointed him to the Compensation Committee, the Nominating and Corporate Governance Committee (the “Governance Committee”), and the Operations and Strategy Committee, effective June 12, 2019. |
| ** | The board appointed Mr. Van Damme to the Governance Committee, effective June 12, 2019. |
Gregory E. Abel, age 56, has served on our Board since July 2015 and previously served on the Heinz board from June 2013 to July 2015. In January 2018, Mr. Abel was elected to the Board of Directors of Berkshire Hathaway Inc., a diversified holding company, and appointed as its Vice Chairman, Non-Insurance Business Operations. In connection with this election in January 2018, Mr. Abel became Executive Chairman of the Board of Directors of Berkshire Hathaway Energy Company and resigned as the company’s Chief Executive Officer and President, roles that he had held since 2008 and 1998, respectively. He had previously served as Chairman of Berkshire Hathaway Energy Company since 2011. Berkshire Hathaway Energy Company is a diversified global holding company that owns subsidiaries principally engaged in energy businesses in the United States, Canada, Great Britain, and the Philippines.
Until January 2018, Mr. Abel also served as Chairman, Chief Executive Officer, and Director of PacifiCorp, an electric power company, as Chairman, President, Chief Executive Officer and Director of CE Casecnan Ltd., a water and energy company, as Chairman and Director of Northern Natural Gas Company, a natural gas company, Northern Powergrid Holdings Company, an electric power company, and NV Energy, Inc., a public utility company, as Director of AltaLink Management Ltd., an electricity transmission company, as Director and Vice Chairman of Edison Electric Institute, an association of U.S. investor-owned electric companies, and as Director of Nuclear Electric Insurance Limited, a mutual insurance company of nuclear power facilities.
Mr. Abel serves as Director of HomeServices of America, Inc., a residential real estate brokerage firm, and as Director and Vice Chairman of Associated Electric & Gas Insurance Services, Inc., a managing general agent for a mutual insurance company.
Mr. Abel has experience as chief executive officer and director of multiple energy companies. Due to his service as a director in a highly-regulated industry and his management experience, he provides the Board with strong regulatory and operational skills, including international experience.
Alexandre Behring, age 52, has served on our Board as Chairman since July 2015 and previously served as Chairman of the Heinz board from June 2013 to July 2015. Mr. Behring is a Founding Partner and has been Managing Partner and a board member of 3G Capital, a global investment firm, since 2004. He also has served as the Executive Chairman of the Board of Directors of Restaurant Brands International Inc. (“RBI”), the parent company of Burger King, Popeyes, and Tim Hortons, quick service restaurant companies, since December 2014. Previously, he had served on the Board of Directors of Burger King Worldwide, Inc. and its predecessor as Chairman from October 2010 until December 2014. Mr. Behring also served as a Director of AB InBev, a multinational drink and brewing holdings company, from April 2014 to April 2019.
Previously, Mr. Behring spent 10 years at GP Investments, including eight years as a partner and member of the firm’s Investment Committee. He served for seven years, from 1998 through 2004, as Chief Executive Officer of ALL, one of Latin America’s largest railroad and logistics companies. He served as a Director of ALL until December 2011. From July 2008 to May 2011, Mr. Behring served as a Director of CSX Corporation, a U.S. rail-based transportation company.
Mr. Behring’s extensive leadership experience in developing and operating both public and private companies brings an important perspective and ability to lead and motivate. Mr. Behring’s qualifications and operational, financial, logistics, and strategic skills strengthen the Board’s collective knowledge and capacities.
Joao M. Castro-Neves, age 52, has served on our Board since June 2019. He has been a partner with 3G Capital since July 2018. Previously, Mr. Castro-Neves served as Chief Executive Officer of Anheuser-Busch, AB InBev’s North American unit, and Zone President, North America of AB InBev, from January 2015 until December 2017. Mr. Castro-Neves joined Companhia de Bebidas das Americas S.A. (“AMBEV”), a predecessor of AB InBev, in 1996 and served in positions of increasing responsibility, including Chief Financial Officer from January 2005 until December 2006 and Chief Executive Officer from January 2009 until December 2014. He has also served as Chief Executive Officer of Quilmes Industrial S.A., a subsidiary of AMBEV based in Argentina, from January 2007 until December 2008. Mr. Castro-Neves is also a director of RBI.
The Board has elected Mr. Castro-Neves because of his extensive experience in the consumer goods industry in his various positions with AB InBev as well as his public company directorship experience at RBI. In addition, when electing him, the Board considered his knowledge of strategy, finance, operations, mergers and acquisitions, and business development.
Tracy Britt Cool, age 34, has served on our Board since July 2015 and previously served on the Heinz board from June 2013 to July 2015. Ms. Cool has served as Chief Executive Officer of The Pampered Chef, a direct seller of high-quality cooking tools, since November 2014. Ms. Cool has been with Berkshire Hathaway, The Pampered Chef’s parent company, since she joined in December 2009 as Financial Assistant to the Chairman. Ms. Cool is currently the Chairman of Benjamin Moore & Co., a leading manufacturer and retailer of paints and architectural coatings, Chairman of Larson-Juhl, a manufacturer and distributor of wood and metal framing products, and Chairman of Oriental Trading Company, a direct merchant of party suppliers, arts and crafts, toys, and novelties. Ms. Cool is also a director of Blue Apron Holdings, Inc., an ingredient-and-recipe meal kit service.
Ms. Cool’s background as a senior leader of several consumer product companies provides her with a strong fundamental understanding related to our business. She also brings important insight into financial, marketing, product development, and other complex subjects.
John T. Cahill, age 62, has served on our Board as Vice Chairman since July 2015, prior to which he had served as Chairman and Chief Executive Officer of Kraft since December 2014. Mr. Cahill previously served as Kraft’s non-executive Chairman from March 2014 to December 2014. Prior to that, he served as Kraft’s Executive Chairman since October 2012. Mr. Cahill joined Mondelēz International, a food and beverage company and Kraft’s former parent, in January 2012 as the Executive Chairman Designate, North American Grocery, and served in that capacity until the spin-off of Kraft from Mondelēz International in October 2012. Prior to that, he served as an Industrial Partner at Ripplewood Holdings LLC, a private equity firm, from 2008 to 2011. Mr. Cahill spent nine years with The Pepsi Bottling Group, Inc., a beverage manufacturing company, most recently as Chairman and Chief Executive Officer from 2003 to 2006 and Executive Chairman until 2007. Mr. Cahill previously spent nine years with PepsiCo, Inc., a food and beverage company, in a variety of leadership positions. He currently serves as Lead Independent Director of American Airlines Group and is also a director at Colgate-Palmolive Company and a former director of Kraft and Legg Mason, Inc.
Mr. Cahill has extensive experience in the food and beverage industry, having served as Chairman and Chief Executive Officer of Kraft and in various key roles at other food and beverage companies. Mr. Cahill brings global leadership, operating, marketing, and product development experience, as well as insight into corporate governance, accounting, and financial subjects.
Feroz Dewan, age 42, has served on our Board since October 2016. Mr. Dewan is CEO of Arena Holdings Management LLC, an investment holding company. Previously, Mr. Dewan has served in several positions with Tiger Global Management, an investment firm with approximately $20 billion under management across public and private equity funds, from 2003 to 2015, including most recently as Head of Public Equities. He also served as a Private Equity Associate at Silver Lake Partners, a private equity firm focused on leveraged buyout and growth capital investments in technology, technology-enabled, and related industries, from 2002 to 2003. Mr. Dewan has served as a Director of Fortive Corporation, a diversified industrial growth company, since July 2016.
Mr. Dewan has experience with technology and technology-related companies, including extensive experience in valuation, investments, financial reporting, capital allocation, operational oversight, and corporate governance.
Jeanne P. Jackson, age 67, has served on our Board since July 2015 and previously served on the Kraft Board of Directors from October 2012 to July 2015. Ms. Jackson served as President and Strategic Advisor, of NIKE, Inc., a designer, marketer, and distributor of athletic footwear, equipment, and accessories from June 2016 to August 2017, President, Product and Merchandising from July 2013 until April 2016, and President, Direct to Consumer from 2009 until July 2013. Prior to that, she founded and served as the Chief Executive Officer of MSP Capital, a private investment company, from 2002 to 2009, a role she returned to after retiring from NIKE, Inc. Before MSP, she served as Chief Executive Officer of Walmart.com, a private eCommerce enterprise, from 2000 to 2002. Ms. Jackson previously served in various leadership positions at Gap Inc., Victoria’s Secret, Saks Fifth Avenue, and Federated Department Stores, Inc., all clothing retailers, and Walt Disney Attractions, Inc., the theme parks and vacation resorts division of The Walt Disney Company, a mass media company. Ms. Jackson currently serves as a director of Delta Airlines, Inc. and McDonald’s Corporation and was formerly a director of Kraft.
As a former senior executive with several major consumer retailers and service as audit committee member of several public companies, Ms. Jackson brings knowledge of accounting and financial subjects as well as leadership, operating, and marketing experience.
Jorge Paulo Lemann, age 79, has served on our Board since July 2015 and previously served on the Heinz board from June 2013 to July 2015. Mr. Lemann is a Founding Partner and has been a board member of 3G Capital since 2004. Mr. Lemann founded and was Senior Partner of Banco de Investimentos Garantia S.A. in Brazil from 1971 through June 1998. He was also Chairman of the Latin American Advisory Committee of the New York Stock Exchange and formerly a Director of AB InBev. Mr. Lemann has been a member of JP Morgan International Council since 2012.
Mr. Lemann has experience as a director of a consumer products company and has strong international experience in the beverage industry. He also has broad knowledge of strategy, financial, investing, and business development.
John C. Pope, age 70, has served on our Board since July 2015 and previously served on the Kraft Board of Directors from August 2012 to July 2015. Mr. Pope has served as Chairman of PFI Group, LLC, a financial management firm, since 1994. Mr. Pope also serves as Chairman of the board of R.R. Donnelley and Sons Co., a marketing and business communication company, since May 2014, and from November 2004 to December 2011, he served as Chairman of the board of Waste Management, Inc., a provider of comprehensive waste management services. Mr. Pope also served as Chairman of the board of MotivePower Industries, Inc., a manufacturer and remanufacturer of locomotives and locomotive components, from December 1995 to November 1999. Prior to joining MotivePower Industries, Inc., Mr. Pope served in various capacities at United Airlines, a U.S.-based airline, and its parent, UAL Corporation, including as Director, Vice Chairman, President, Chief Operating Officer, Chief Financial Officer, and Executive Vice President, Marketing and Finance. Mr. Pope is currently Chairman of the board of R.R. Donnelley and Sons Co. and a director of Talgo S.A., a railcar manufacturer, and Waste Management, Inc. Mr. Pope was formerly a director of Con-way, Inc., Dollar Thrifty Automotive Group, Inc., Kraft, Mondelēz International, and Navistar International Corporation.
Mr. Pope has served as Chairman of a financial management firm and in several key leadership roles at global companies, including as Chief Financial Officer. Combined with his experience as an audit committee member of several public companies, Mr. Pope brings accounting and financial expertise, as well as leadership, operating, marketing, and international experience.
Alexandre Van Damme, age 57, has served on our Board since April 2018 and has served as a member of the board of RBI since December 2014. He previously served on the board of Burger King Worldwide, Inc. and its predecessor from December 2011 to December 2014. Mr. Van Damme has served as a member of the Board of Directors of AB InBev since 1992. He held various operational positions within Interbrew, a large Belgian-based brewing company until 1991. Mr. Van Damme was also a board member of Jacobs Douwe Egberts B.V., a global coffee and tea company, and its subsidiary Keurig Green Mountain through May 2018. He is also a director of DKMS, the largest bone marrow donor center in the world.
Mr. Van Damme’s long-term leadership at a large brewing company that is a major consumer brand gives him valuable expertise in business development, supply chain management, marketing, finance, risk assessment, and strategy.
George Zoghbi, age 52, has served on our Board since April 2018 and currently serves as a Special Advisor at Kraft Heinz, a role to which he transitioned in October 2017 after having served as our Chief Operating Officer of the U.S. Commercial business since the 2015 Merger. Mr. Zoghbi previously held key leadership roles at Kraft, including Chief Operating Officer from February 2015 until the 2015 Merger and, before that, as Vice Chairman, Operations, R&D, Sales and Strategy from June 2014 until February 2015, Executive Vice President and President, Cheese & Dairy and Exports from February 2013 until June 2014, and Executive Vice President and President, Cheese and Dairy from October 2012 to February 2013. Prior to that, he served as President, Cheese and Dairy at Mondelēz International. Prior to joining Kraft in 2007, Mr. Zoghbi held a number of roles with Fonterra Cooperative, a multinational dairy cooperative, and Associated British Foods, a multinational food processor and retailer. Mr. Zoghbi currently serves as a director of Brambles Limited, a global supply chain logistics company.
Mr. Zoghbi has a comprehensive understanding of, and a unique perspective on, the Kraft Heinz business and the food and beverage markets from his distinguished career at Kraft Heinz and Kraft. He served a key leadership role during the integration of Kraft and Heinz and has extensive experience of delivering on innovation, renovation, and new consumer trends.
CORPORATE GOVERNANCE AND BOARD MATTERS
Corporate Governance Guidelines
The Guidelines articulate our governance philosophy, practices, and policies in a range of areas, including: the Board’s role and responsibilities; the composition and structure of the Board; the establishment and responsibilities of the committees of the Board; executive and director performance evaluations; and succession planning. The Governance Committee reviews the Guidelines annually and recommends any changes to the Board.
Code of Business Conduct and Ethics for Non-Employee Directors and Code of Conduct for Employees
We have a written Code of Business Conduct and Ethics for Non-Employee Directors (the “Directors Ethics Code”) that is designed to deter wrongdoing and to promote:
| • | honest and ethical conduct; |
| • | due care, diligence, and loyalty; |
| • | confidentiality of our proprietary information; |
| • | compliance with applicable laws, rules, and regulations, including insider trading compliance; and |
| • | accountability for adherence to the Directors Ethics Code and prompt internal reporting of violations. |
Annually, each non-employee director acknowledges in writing that he or she has received, reviewed, and understands the Directors Ethics Code.
We also have a written Code of Conduct for employees (the “Code of Conduct”). The Code of Conduct includes a set of employee policies that cover ethical and legal practices for nearly every aspect of our business. The Code of Conduct reflects our values and contains important rules our employees must follow when conducting business to promote compliance and integrity. The Code of Conduct is part of our global compliance and integrity program that provides support and training throughout our Company and encourages reporting of wrongdoing by offering anonymous reporting options and a non-retaliation policy. We will disclose in the Corporate Governance section of our Web site (described below) any amendments to our Directors Ethics Code or Code of Conduct and any waiver granted to an executive officer or director under these codes.
Corporate Governance Materials Available on Our Web Site
Our Web site contains the Guidelines, our Board committee charters, the Code of Conduct, and the Directors Ethics Code. To view these documents, go to http://ir.kraftheinzcompany.com and click on “Corporate Governance.” We will promptly deliver free of charge, upon request, a copy of the Guidelines, the Board committee charters, the Code of Conduct, or the Directors Ethics Code to any stockholder requesting a copy. Requests should be directed to our Corporate Secretary at The Kraft Heinz Company, 200 East Randolph Street, Suite 7600, Chicago, IL 60601.
The information on our Web site is not, and will not be deemed to be, a part of this Annual Report on Form 10-K or incorporated by reference into any of our other filings with the SEC.
Delinquent Section 16(a) Reports
Section 16(a) of the Exchange Act requires our executive officers and directors, and persons who own more than 10% of our common stock (collectively, the “Reporting Persons”), to file reports of ownership and changes in ownership with the SEC. Based solely upon a review of Forms 3, 4 and 5 and amendments thereto filed electronically with the SEC by the Reporting Persons with respect to the fiscal year ended December 29, 2018, we believe that all filing requirements were complied with in a timely manner, except in two instances where Form 4s were inadvertently filed late on behalf of two directors to report certain transactions as follows: (i) in April 2018, to report three purchases of shares that were executed by the broker of one of our former directors, Mackey McDonald, on Mr. McDonald’s behalf without his knowledge or direction; and (ii) in June 2019, to report one transaction relating to the transfer of certain shares held in a trust for the benefit of Mr. Pope’s three adult children as a result of their election to exercise control over such shares in accordance with the terms of the trust that held these shares.
BOARD COMMITTEES AND MEMBERSHIP—AUDIT COMMITTEE
The Board established the Audit Committee in accordance with Section 3(a)(58)(A) and Rule 10A-3 under the Exchange Act. The Audit Committee consists entirely of independent directors, and each director meets the independence requirements set forth in the listing standards of Nasdaq, Rule 10A-3 under the Exchange Act and the Audit Committee charter. The Board has determined that each Audit Committee member is able to read and understand fundamental financial statements. In addition, the Board has determined that Ms. Jackson and Mr. Pope are “audit committee financial experts” within the meaning of SEC regulations. No Audit Committee member received any payments in 2018 from us other than compensation for service as a director.
BOARD COMMITTEES AND MEMBERSHIP—OPERATIONS AND STRATEGY COMMITTEE
Effective June 5, 2019, the Board established the Operations and Strategy Committee to assist it in overseeing and facilitating the development and implementation of our ongoing operations and corporate strategy. The Operations and Strategy Committee is led by John Cahill, Vice Chairman of the Board, and meets with management regularly to discuss, review and evaluate the development and implementation of our operational objectives and corporate strategy. The Operations and Strategy Committee is comprised of five directors appointed by the Board, based on nominations recommended to the Board by our Nominating and Corporate Governance Committee. Based on its review, the committee shares with management the Board’s expectations for the operations of the company and strategic planning process, makes recommendations to management on areas of improvement, and provides other feedback and guidance to management on behalf of the Board. The Operations and Strategy Committee’s responsibilities also include, among others, reviewing and making recommendations to the Board regarding:
| • | our corporate strategy, performance, and annual capital plan, as well as certain individual capital projects; |
| • | the impact of external developments and factors, such as any changes in economic and market conditions, competition in the industry, environmental and safety regulations, federal, state and local regulations and technology, on our corporate strategy and its execution; |
| • | identification of prospects and opportunities for corporate developments and growth initiatives, including acquisitions, divestitures, joint ventures and strategic alliances; and |
| • | implementation of our corporate strategy through corporate developments and growth initiatives, including acquisitions, divestitures, joint ventures and strategic alliances. |
Item 11. Executive Compensation.
BOARD COMMITTEES AND MEMBERSHIP—COMPENSATION COMMITTEE
Compensation Committee Interlocks and Insider Participation
The Board has determined that all of the directors who served on the Compensation Committee during fiscal year 2018 are independent within the meaning of the Nasdaq listing standards. No member of the Compensation Committee is a current, or during fiscal year 2018 was, a former, officer, or employee of Heinz, Kraft, Kraft Heinz, or any of their subsidiaries. During fiscal year 2018, no member of the Compensation Committee had a relationship that must be described under the SEC rules relating to disclosure of “related person transactions” (for a description of our policy on “related person transactions,” see “Independence and Related Person Transactions” in Item 13, Certain Relationships and Related Transactions, and Director Independence). During fiscal year 2018, none of our executive officers served on the board of directors or compensation committee of any entity that had one or more of its executive officers serving on the Board or the Compensation Committee.
Analysis of Risk in the Compensation Architecture
Annually, the Compensation Committee evaluates the risk profile of our executive and broad-based employee compensation programs. In its evaluation for fiscal year 2018, the Compensation Committee reviewed our executive compensation structure as well as our overarching compensation systems to determine whether our compensation policies and practices encourage our executive officers or other employees to take unnecessary or excessive risks and whether these policies and practices properly mitigate risk. In addition, Willis Towers Watson advised management with respect to the risk assessment of our Performance Bonus Plan.
As described under “Compensation Discussion and Analysis,” our compensation structure is designed to incentivize executives and employees to achieve Kraft Heinz financial and strategic goals as well as individual performance goals that promote long-term stockholder returns. However, certain employees within our procurement organization engaged in misconduct and circumvented controls that included withholding information or directing others to withhold information related to supplier contracts that affected the accounting for certain supplier rebates, incentives, and pricing arrangements, in an attempt to influence the achievement of internal financial targets that became or were perceived to have become increasingly difficult to attain due to changes in our business environment. We are undertaking various remedial efforts outlined in Item 9A, Controls and Procedures, and expect to revise the Performance Bonus Plan for 2019 to explicitly state applicable penalties such as score and/or percentage reductions and losses, up to and including ineligibility for and forfeiture of payments under the Performance Bonus Plan for misconduct. We also expect to revise the Performance Bonus Plan for 2019 to require that if the aforementioned misconduct is discovered after the payout under the Performance Bonus Plan, we would be entitled to seek equitable relief to recoup the amounts paid, including without limitation disgorgement, in addition to any other remedies under the law.
Compensation Committee Report
The Compensation Committee oversees our compensation programs on behalf of the Board. In fulfilling its oversight responsibilities, the Compensation Committee reviewed and discussed with management the Compensation Discussion and Analysis included in this Annual Report on Form 10-K. In reliance on that review and discussion, the Compensation Committee recommended to the Board that the Compensation Discussion and Analysis be included in this Annual Report on Form 10-K.
Compensation Committee:
Alexandre Behring, Chair
Jorge Paulo Lemann
Marcel Herrmann Telles
COMPENSATION OF NON-EMPLOYEE DIRECTORS
Following the 2015 Merger, the Board approved our non-employee director compensation program, which was designed to be similar to the program in place at Kraft prior to the 2015 Merger. The table below summarizes the annual cash and equity compensation elements in place for our non-employee directors.
| Compensation Element(1) | Fee ($) | ||
| Board Retainer | 110,000 | ||
| Chairman Retainer | 250,000 | ||
| Audit Committee Chair Retainer | 20,000 | ||
| Compensation Committee Chair Retainer | 20,000 | ||
| Governance Committee Chair Retainer | 10,000 | ||
| Operations and Strategy Committee Chair Retainer(2) | 20,000 | ||
| Stock Grant Value(3) | 125,000 |
| (1) | If a director serves as Chair of multiple committees, he or she receives fees for only one committee. Therefore, Mr. Behring does not receive a retainer for service as Chair of the Governance Committee. |
| (2) | Effective June 5, 2019, the Board established the Operations and Strategy Committee to assist it in overseeing and facilitating the development and implementation of our ongoing operations and corporate strategy. The Operations and Strategy Committee is led by John Cahill, Vice Chairman of the Board. |
| (3) | Non-employee directors are awarded Kraft Heinz deferred shares. Although the deferred shares are vested as of the award date, the shares are not distributed until six months following the date the non-employee director ceases to serve on our Board. When dividends are paid on our common stock, we accrue the value of the dividend paid and issue shares equal to the accrued value six months after the director’s departure. |
Non-employee directors receive an annual stock award that is granted effective immediately following our annual meeting of stockholders. We also pay the non-employee directors cash retainers on a quarterly basis. Non-employee directors also have the option to (i) defer up to 100% of their cash retainers in 25% increments into accounts that mirror certain funds in the Kraft Heinz 401(k) Plan pursuant to the Deferred Compensation Plan for Non-Management Directors or (ii) receive deferred shares annually in lieu of their cash retainer payable in arrears.
Our stock ownership guidelines require non-employee directors who elect to receive compensation for service as directors to hold shares of our common stock in an amount equal to five times the annual Board retainer (equivalent to $550,000) within five years. As all of our current directors have served following the 2015 Merger for less than five years, they are not yet required to meet the stock ownership requirement. We feel strongly that our director compensation program significantly aligns our non-employee directors’ and stockholders’ interests.
For as long as Mr. Zoghbi continues to serve as a Special Advisor at Kraft Heinz, it is anticipated that he will not receive compensation for his services as a director. For a discussion of Mr. Zoghbi’s compensation arrangement, please see “Compensation Arrangement” in Item 13, Certain Relationships and Related Transactions, and Director Independence.
The table below presents information regarding the compensation and stock awards that we have paid or granted to our non-employee directors.
2018 Non-Employee Director Compensation Table
| Name(1) | Fees Earned or Paid in Cash(2) ($) | Stock Awards(3) ($) | All Other Compensation ($) | Total ($) | ||||||||
| Gregory E. Abel | 110,054 | 125,050 | — | 235,104 | ||||||||
| Alexandre Behring | 270,000 | 125,050 | — | 395,050 | ||||||||
| John T. Cahill(4) | 110,000 | 125,050 | 500,000 | 735,050 | ||||||||
| Tracy Britt Cool | 110,054 | 125,050 | — | 235,104 | ||||||||
| Feroz Dewan | 110,054 | 125, |
Showing the first 8K of 82K characters. Open the full section
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
SECURITIES AUTHORIZED FOR ISSUANCE UNDER EQUITY COMPENSATION PLANS
The number of shares to be issued upon exercise or vesting of awards issued under, and the number of shares remaining available for future issuance under our equity compensation plans at December 29, 2018 were:
| Number of securities to be issued upon exercise of outstanding options, warrants and rights(1) | Weighted average exercise price per share of outstanding options, warrants and rights | Number of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in column (a)) | |||||||
| Plan Category | (a) | (b) | (c) | ||||||
| Equity compensation plans approved by security holders | 23,858,121 | $ | 44.64 | 43,920,379 | |||||
| Equity compensation plans not approved by security holders | — | — | — | ||||||
| Total | 23,858,121 | 43,920,379 |
| (1) | Includes the vesting of RSUs. |
OWNERSHIP OF EQUITY SECURITIES
The following table shows the number of shares of our common stock beneficially owned as of June 5, 2019, unless otherwise noted, by each current director, director nominee, and Named Executive Officer, as well as the number of shares beneficially owned by all of our current directors and executive officers as a group. None of our common stock owned by these individuals is subject to any pledge. Unless otherwise indicated, each of the named individuals has, to Kraft Heinz’s knowledge, sole voting and investment power with respect to the shares shown.
| Name of Beneficial Owner | Beneficially Owned Shares(1) (2) | Deferred Stock(3) | Total | ||||||
| Directors and Director Nominees: | |||||||||
| Gregory E. Abel | 22,166 | 20,878 | 43,044 | ||||||
| Alexandre Behring | 44,333 | 30,479 | 74,812 | ||||||
| John T. Cahill(4) | 781,338 | 8,799 | 790,137 | ||||||
| Joao M. Castro-Neves | — | — | — | ||||||
| Tracy Britt Cool | 22,166 | 22,261 | 44,427 | ||||||
| Feroz Dewan | — | 6,902 | 6,902 | ||||||
| Jeanne P. Jackson | 4,280 | 17,049 | 21,329 | ||||||
| Jorge Paulo Lemann | 22,166 | 20,878 | 43,044 | ||||||
| John C. Pope | 10,098 | 18,409 | 28,507 | ||||||
| Marcel Hermann Telles | 22,166 | 18,494 | 40,660 | ||||||
| Alexandre Van Damme | 6,000 | 2,269 | 8,269 | ||||||
| George Zoghbi | 240,161 | — | 240,161 | ||||||
| Named Executive Officers: | — | ||||||||
| Bernardo Hees | 1,486,199 | — | 1,486,199 | ||||||
| David Knopf | 1,106 | — | 1,106 | ||||||
| Paulo Basilio | 597,401 | — | 597,401 | ||||||
| Rafael Oliveira | 117,330 | — | 117,330 | ||||||
| Rashida La Lande | — | — | — | ||||||
| All directors and executive officers as a group (19 persons)(5) | 3,406,501 | 166,418 | 3,572,919 |
| (1) | Individual directors and executive officers as well as all directors and executive officers as a group beneficially own less than 1% of our issued and outstanding common stock as of June 5, 2019. |
| (2) | Includes the number of Kraft Heinz stock options that are exercisable, or will become exercisable, within 60 days after June 5, 2019 as follows: Mr. Abel-22,166; Mr. Behring-44,333; Ms. Cool-22,166; Mr. Cahill-633,017; Mr. Lemann-22,166; Mr. Zoghbi-180,799; and all of our current executive officers as a group-2,130,954. |
| (3) | Includes RSUs and deferred shares held in the stock deferral plan under the Kraft Heinz Deferred Compensation Plan for Non-Management Directors. These shares accumulate dividends, which are reinvested in common stock. For a description of these deferred shares, see “Compensation of Non-Employee Directors” above. |
| (4) | Mr. Cahill’s holdings include 148,321 shares of common stock held in grantor retained annuity trusts. |
| (5) | This group includes, in addition to the individuals named in the table, Pedro Drevon, Rodrigo Wickbold, and Nina Barton, who collectively have 29,591 beneficially owned shares and exercisable stock options. |
The following table displays information about persons we know were the beneficial owners of more than 5% of our outstanding common stock as of June 5, 2019.
| Name and Address of Beneficial Owner | Amount and Nature of Beneficial Ownership | Percent of Common Stock(1) | ||
| 3G Funds(2) c/o 3G Capital, Inc. 600 Third Avenue 37th Floor New York, New York 10016 | 270,097,373 | 22.1% | ||
| Warren E. Buffett(3) Berkshire Hathaway 3555 Farnam Street Omaha, Nebraska 68131 | 325,442,152 | 26.7% |
| (1) | Calculated based on 1,219,938,804 shares of our outstanding common stock as of June 5, 2019. |
| (2) | Based on the Schedule 13G/A filed on January 18, 2019 by (i) 3G Global Food Holdings, a Cayman Islands limited partnership, (ii) 3G Global Food Holdings GP LP, a Cayman Islands limited partnership (“3G Global Food Holdings GP”), (iii) 3G Capital Partners II LP, a Cayman Islands limited partnership (“3G Capital Partners II”), (iv) 3G Capital Partners Ltd., a Cayman Islands exempted company (“3G Capital Partners Ltd”), and (v) 3G Capital Partners LP, a Cayman Islands limited partnership (“3G Capital Partners LP” and, together with 3G Global Food Holdings, 3G Global Food Holdings GP, 3G Capital Partners II and 3G Capital Partners Ltd, the “3G Funds”). According to the Schedule 13G/A filing, the 3G Funds own dispositive power over an aggregate of 270,097,373 shares of Kraft Heinz common stock. As a result of the relationships described above under “Independence and Related Person Transactions” in Item 13, Certain Relationships and Related Transactions, and Director Independence, Berkshire Hathaway, Mr. Buffett and the 3G Funds may be deemed to be a group for purposes of Section 13(d) of the Exchange Act and therefore may be deemed to hold 595,539,525 shares of Kraft Heinz common stock. |
| (3) | Based on the Schedule 13G/A filed on February 15, 2017 by Warren E. Buffett and Berkshire Hathaway. As a result of the relationships described above under “Independence and Related Person Transactions” in Item 13, Certain Relationships and Related Transactions, and Director Independence, Berkshire Hathaway, Mr. Buffett and the 3G Funds may be deemed to be a group for purposes of Section 13(d) of the Exchange Act and therefore may be deemed to hold 616,169,839 shares of Kraft Heinz common stock. |
Item 13. Certain Relationships and Related Transactions, and Director Independence.
INDEPENDENCE AND RELATED PERSON TRANSACTIONS
Independence Determinations
The Guidelines require that a majority of the directors meet Nasdaq listing standards’ “independence” requirements. For a director to be considered independent, the Board must affirmatively determine, after reviewing all relevant information, that a director has no direct or indirect material relationship with Kraft Heinz that would interfere with his or her exercise of independent judgment in carrying out his or her responsibilities as a director. The Board determined that, under the Nasdaq listing standards, the following director nominees are independent: Mr. Abel, Mr. Behring, Ms. Cool, Mr. Dewan, Ms. Jackson, Mr. Lemann, Mr. Pope, Mr. Castro-Neves, and Mr. Van Damme. Warren Buffett and Mackey McDonald, who retired from Board service in 2018, and Marcel Herrmann Telles, who decided to retire from the Board, effective on June 12, 2019, were also determined to be independent during the periods they served. Mr. Cahill, the former Chief Executive Officer of Kraft and a current consultant to Kraft Heinz, and George Zoghbi, our former Chief Operating Officer of the U.S. Commercial business and Special Advisor at Kraft Heinz, are not independent.
In conducting its evaluations of Mr. Abel, Mr. Buffett, and Ms. Cool, the Board considered each individual’s affiliation with Berkshire Hathaway, which held approximately 27% of our outstanding common stock as of June 5, 2019, and its subsidiaries. Similarly, in conducting its evaluations of Mr. Behring, Mr. Lemann, Mr. Castro-Neves, and Mr. Telles, the Board considered each individual’s affiliation with 3G Capital, which held approximately 22% of our outstanding common stock as of June 5, 2019, and its subsidiaries. The Board also considered the service of Messrs. Behring, Castro-Neves, and Van Damme on the Board of Directors of RBI, a company in which 3G Capital invests and the parent company of Burger King and Tim Hortons, quick service restaurant companies that purchase certain of our products and conduct certain brand sponsorship and marketing activities for us, in conducting its evaluations of them.
Review of Transactions with Related Persons
The Board has adopted a written policy regarding the review, approval, or ratification of “related person transactions.” A “related person transaction” is one in which Kraft Heinz is a participant, the amount involved exceeds $120,000, and any “related person” had, has, or will have a direct or indirect material interest. In general, “related persons” include our directors, executive officers, and 5% stockholders and their immediate family members. In accordance with this policy, the Governance Committee reviews transactions that might qualify as “related person transactions.” If the Governance Committee determines that a transaction qualifies as a “related person transaction,” then the Governance Committee reviews, and approves, disapproves, or ratifies the “related person transaction.” The Governance Committee approves or ratifies only those “related person transactions” that are fair and reasonable to Kraft Heinz and in our and our stockholders’ best interests. Any member of the Governance Committee who is a “related person” with respect to a transaction under review may not participate in the deliberations or decisions regarding the transaction. The chair of the Governance Committee (or the Chair of the Audit Committee if the chair of the Governance Committee is a “related person” with respect to the transaction under review) will review and approve or ratify potential “related person transactions” when it is not practicable or desirable to delay review of a transaction until a Governance Committee meeting, and will report to the Governance Committee any transaction so approved or ratified. The Governance Committee, in the course of its review and approval or ratification of a related person transaction under this policy, considers, among other things:
| • | the commercial reasonableness of the transaction; |
| • | the materiality of the related person’s direct or indirect interest in the transaction; |
| • | whether the transaction may involve an actual, or the appearance of a, conflict of interest; |
| • | the impact of the transaction on the related person’s independence (as defined in the Guidelines and the Nasdaq listing standards); and |
| • | whether the transaction would violate any provision of our Directors Ethics Code or Code of Conduct. |
Registration Rights Agreement
In connection with the 2015 Merger, we entered into a registration rights agreement with 3G Global Food Holdings and Berkshire Hathaway. Pursuant to the registration rights agreement, we granted 3G Global Food Holdings and Berkshire Hathaway registration rights with respect to the shares of Kraft Heinz common stock held by 3G Global Food Holdings and Berkshire Hathaway as of the date of the closing of the 2015 Merger, representing shares of Kraft Heinz common stock acquired from Heinz in connection with the 2015 Merger and/or immediately prior to the 2015 Merger pursuant to a warrant. The registration rights only apply to registrable shares and not shares of Kraft Heinz common stock subsequently acquired by either party. These rights include demand registration rights, shelf registration rights, and “piggyback” registration rights, as well as customary indemnification. The rights are subject to certain holdback and suspension periods. We generally will bear all fees, costs, and expenses related to registrations, other than underwriting discounts and commissions attributable to the sale of shares of Kraft Heinz common stock by 3G Global Food Holdings and Berkshire Hathaway, as applicable.
Demand Registration Rights
The registration rights agreement grants each of 3G Global Food Holdings and Berkshire Hathaway demand registration rights. We will be required, upon the written request of 3G Global Food Holdings or Berkshire Hathaway, to file a registration statement pursuant to its demand rights under the registration rights agreement, as promptly as practicable and to use our reasonable best efforts to effect registration of shares of Kraft Heinz common stock requested to be registered by 3G Global Food Holdings or Berkshire Hathaway, subject to certain exceptions. Each of 3G Global Food Holdings and Berkshire Hathaway may request up to three demand registrations in the aggregate.
Shelf Registration Rights
The registration rights agreement also grants each of 3G Global Food Holdings and Berkshire Hathaway shelf registration rights. Subject to our eligibility to use a Registration Statement on Form S-3, each of 3G Global Food Holdings and Berkshire Hathaway may request that we file a shelf registration statement with respect to some or all of its shares of Kraft Heinz common stock, and, upon such request, we are required to file such registration statement promptly as practicable, subject to certain exceptions.
“Piggyback” Registration Rights
The registration rights agreement grants each of 3G Global Food Holdings and Berkshire Hathaway “piggyback” registration rights. If we register any of our shares of common stock, either for our own account or for the account of other stockholders, each of 3G Global Food Holdings and Berkshire Hathaway will be entitled, subject to certain exceptions, to include its shares of common stock in the registration.
Holdback Periods
Notwithstanding the registration rights described above, if there is an offering of shares of Kraft Heinz and the managing underwriters for the offering advise us that a public sale or distribution of shares outside the offering would adversely affect the offering, then, if requested, each of 3G Global Food Holdings and Berkshire Hathaway will not dispose of, or request the registration of, any registrable shares for a certain period, which we refer to as a holdback period. The holdback period will begin on the 10th day before the pricing date of the offering and extend for either (i) 120 days or (ii) an earlier date, if designated by the managing underwriters.
Suspension Periods
In addition, we may delay or suspend the filing, effectiveness, or use of a registration statement for a certain period, which we refer to as a suspension period, if we determine that (i) proceeding with the use or effectiveness of the registration statement would require us to disclose material non-public information and the disclosure of that information at that time would not be in our best interests or (ii) the registration or offering to be delayed or suspended would, if not delayed or suspended, materially adversely affect us or delay or otherwise materially adversely affect the success of any pending or proposed material transaction, including any debt or equity financing, any acquisition or disposition, any recapitalization or reorganization or any other material transaction, whether due to commercial reasons, a desire to avoid premature disclosure of information, or any other reason. During any calendar year, there will not be more than two suspension periods and the aggregate number of days included in all suspension periods in that year will not exceed 119 days.
Shareholders’ Agreement
In connection with the 2015 Merger, 3G Global Food Holdings and Berkshire Hathaway entered into a shareholders’ agreement that governs how each party and their affiliates will vote the shares of Kraft Heinz common stock held by them as of the date of closing of the 2015 Merger, with respect to supporting certain directors who are designated by either 3G Global Food Holdings or Berkshire Hathaway. Pursuant to the shareholders’ agreement, 3G Global Food Holdings agrees that for so long as Berkshire Hathaway and its affiliates control shares representing at least 66% of the voting power in election of directors of shares owned by Berkshire Hathaway as of the consummation of the 2015 Merger, 3G Global Food Holdings and its affiliates will vote their shares of Kraft Heinz common stock in favor of the three Kraft Heinz Board nominees designated by Berkshire Hathaway and not take any action to remove such designees without Berkshire Hathaway’s consent. Similarly, Berkshire Hathaway agrees that for so long as 3G Global Food Holdings and its affiliates control shares representing at least 66% of the voting power in elections of directors of shares owned by 3G Global Food Holdings as of the consummation of the 2015 Merger, Berkshire Hathaway and its affiliates will vote their shares of Kraft Heinz common stock in favor of the three Kraft Heinz Board nominees designated by 3G Global Food Holdings and not take any action to remove such designees without 3G Global Food Holdings’ consent. The shareholders’ agreement provides that each party’s foregoing rights and obligations will step down upon specified reductions in ownership below the 66% threshold described above by either 3G Global Food Holdings or Berkshire Hathaway and their respective affiliates, as applicable.
Consulting Agreement
On November 2, 2017, we entered into a consulting agreement with Mr. Cahill pursuant to which he provides advisory and consulting services to us related to current and historical finances, relationships with licensors, customers and vendors, employee matters, product development, marketing and distribution, government affairs and strategic opportunities. Mr. Cahill is paid $500,000 annually under this new consulting agreement, which was approved by the disinterested members of the Board. Mr. Cahill’s services under the consulting agreement are distinct from his duties as a director. Previously, Mr. Cahill had provided similar services under a consulting agreement entered into following the 2015 Merger, which had expired in July 2017.
Compensation Arrangement
Effective January 1, 2017, the Company entered into an offer letter (the “Offer Letter”) with Mr. Zoghbi in order to incent Mr. Zoghbi to extend his service with the Company past January 1, 2017, after a retention bonus pursuant to a prior offer letter entered into upon the closing of the 2015 Merger had been earned. Under the Offer Letter, Mr. Zoghbi: (i) continued his current base salary of $850,000; (ii) agreed to a 2017 target annual incentive award opportunity of 200% (with a maximum bonus multiplier of 130%); and (iii) was granted a long-term equity incentive award. The long-term equity incentive award was composed of (i) RSUs, which cliff vest after three years, and (ii) PSUs, which cliff vest after three years based on the achievement of U.S. sales growth targets and U.S. Adjusted EBITDA growth targets. The Offer Letter also eliminated the Section 280G gross-up rights that Mr. Zoghbi had been granted by Kraft compensation plans prior to the 2015 Merger. In October 2017, Mr. Zoghbi transitioned from his role as President of the U.S. Commercial business to his role as Special Advisor. As previously disclosed, Mr. Zoghbi was not eligible under the Offer Letter for an annual incentive award in 2018 based on 2017 performance. For as long as Mr. Zoghbi continues to serve as a Special Advisor at Kraft Heinz, it is anticipated that he will not receive compensation for his services as a director.
Item 14. Principal Accounting Fees and Services.
Independent Auditors’ Fees
Aggregate fees for professional services rendered by our independent auditors, PricewaterhouseCoopers LLP, are set forth in the table below (in thousands). All fees below include out-of-pocket expenses.
| For the Year Ended | |||||||
| December 29, 2018 | December 30, 2017 | ||||||
| Audit Fees(1) | $ | 19,234 | $ | 9,353 | |||
| Audit-Related Fees(2) | 442 | 401 | |||||
| Tax Fees(3) | 1,171 | 1,009 | |||||
| All Other Fees(4) | 46 | 5 | |||||
| Total | $ | 20,893 | $ | 10,768 |
| (1) | Include (a) the audit of our consolidated financial statements, including statutory audits of the financial statements of certain of our affiliates, and (b) the reviews of our unaudited condensed consolidated interim financial statements (quarterly financial statements). The increase from 2017 to 2018 primarily related to audit overruns associated with the procurement investigation, restatement, and impairment of goodwill and intangible assets. |
| (2) | Include professional services in connection with accounting consultations and procedures related to various other audit and special reports. |
| (3) | Include professional services in connection with tax compliance and advice. |
| (4) | Consist principally of software license fees related to research and benchmarking. |
Pre-Approval Policy
The Audit Committee’s policy is to pre-approve all audit and non-audit services provided by the independent auditors. These services may include audit services, audit-related services, tax services, and other permissible non-audit services. The pre-approval authority details the particular service or category of service that the independent auditors will perform. The Audit Committee’s policy also requires management to report at Audit Committee meetings throughout the year on the actual fees charged by the independent auditors for each category of service. The Audit Committee reviews this policy annually.
During the year, circumstances may arise when it may be necessary to engage the independent auditors for additional services not contemplated in the original pre-approval authority. In those instances, the Audit Committee approves the services before we engage the independent auditors. If pre-approval is needed before a scheduled Audit Committee meeting, the Audit Committee delegated pre-approval authority to its chair. The chair must report on such pre-approval decisions at the committee’s next regular meeting.
During fiscal year 2018, the Audit Committee pre-approved all audit and non-audit services provided by the independent auditors.
PART IV
Item 15. Exhibits, Financial Statement Schedules.
(a) Index to Consolidated Financial Statements and Schedules
Schedules other than those listed above have been omitted either because such schedules are not required or are not applicable.
(b) The following exhibits are filed as part of, or incorporated by reference into, this Annual Report:
Item 16. Form 10-K Summary.
None.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| The Kraft Heinz Company | |||
| Date: | June 7, 2019 | ||
| By: | /s/ David H. Knopf | ||
| David H. Knopf | |||
| Executive Vice President and Chief Financial Officer | |||
| (Principal Financial Officer) |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the date indicated:
| Signature | Title | Date | ||
| /s/ Bernardo Hees | Chief Executive Officer | June 7, 2019 | ||
| Bernardo Hees | (Principal Executive Officer) | |||
| /s/ David H. Knopf | Executive Vice President and Chief Financial Officer | June 7, 2019 | ||
| David H. Knopf | (Principal Financial Officer) | |||
| /s/ Vince Garlati | Vice President, Global Controller | June 7, 2019 | ||
| Vince Garlati | (Principal Accounting Officer) |
| Alexandre Behring* | Chairman of the Board | |
| John T. Cahill* | Vice Chairman of the Board | |
| Gregory E. Abel* | Director | |
| Tracy Britt Cool* | Director | |
| Feroz Dewan* | Director | |
| Jeanne P. Jackson* | Director | |
| Jorge Paulo Lemann* | Director | |
| John C. Pope* | Director | |
| Marcel Hermann Telles* | Director | |
| Alexandre Van Damme* | Director | |
| George Zoghbi* | Director |
| *By: | /s/ David H. Knopf |
| David H. Knopf | |
| Attorney-In-Fact | |
| June 7, 2019 |
The Kraft Heinz Company
Valuation and Qualifying Accounts
For the Years Ended December 29, 2018, December 30, 2017 and December 31, 2016
(in millions)
| Additions | Deductions | ||||||||||||||||||
| Description | Balance at Beginning of Period | Charged to Costs and Expenses | Charged to Other Accounts(a) | Write-offs and Reclassifications | Balance at End of Period | ||||||||||||||
| Year ended December 29, 2018 | |||||||||||||||||||
| Allowances related to trade accounts receivable | $ | 23 | $ | 8 | $ | — | $ | (7 | ) | $ | 24 | ||||||||
| Allowances related to deferred taxes | 80 | 1 | — | — | 81 | ||||||||||||||
| $ | 103 | $ | 9 | $ | — | $ | (7 | ) | $ | 105 | |||||||||
| Year ended December 30, 2017 | |||||||||||||||||||
| Allowances related to trade accounts receivable | $ | 20 | $ | 8 | $ | 1 | $ | (6 | ) | $ | 23 | ||||||||
| Allowances related to deferred taxes | 89 | (9 | ) | — | — | 80 | |||||||||||||
| $ | 109 | $ | (1 | ) | $ | 1 | $ | (6 | ) | $ | 103 | ||||||||
| Year ended December 31, 2016 | |||||||||||||||||||
| Allowances related to trade accounts receivable | $ | 32 | $ | 6 | $ | (4 | ) | $ | (14 | ) | $ | 20 | |||||||
| Allowances related to deferred taxes | 83 | 6 | — | — | 89 | ||||||||||||||
| $ | 115 | $ | 12 | $ | (4 | ) | $ | (14 | ) | $ | 109 |
| (a) | Primarily relates to acquisitions and currency translation. |
S-1