 filings.tools
Kimco Realty 2022 10-K Annual Report
KIM · CIK 879101 · Form 10-K · Fiscal year ended December 31, 2022 · Filed February 24, 2023
23 sections, 603K characters. Original on sec.gov · Markdown · JSON
Risk FactorsBusinessMD&AFinancial StatementsWhat changed vs 2021
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
☑ ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended December 31, 2022
OR
☐ TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the transition period from __________ to __________
Commission file number 1-10899 (Kimco Realty Corporation)
Commission file number 333-269102-01 (Kimco Realty OP, LLC)
KIMCO REALTY CORPORATION
KIMCO REALTY OP, LLC
(Exact name of registrant as specified in its charter)
| Maryland (Kimco Realty Corporation) Delaware (Kimco Realty OP, LLC) | 13-2744380 92-1489725 | |
|---|---|---|
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
500 North Broadway, Suite 201, Jericho, NY 11753
(Address of principal executive offices) (Zip Code)
(516) 869-9000
(Registrant’s telephone number, including area code)
Securities registered pursuant to Section 12(b) of the Act:
Kimco Realty Corporation
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | |
|---|---|---|---|
| Common Stock, par value $.01 per share. | KIM | New York Stock Exchange | |
| Depositary Shares, each representing one-thousandth of a share of 5.125% Class L Cumulative Redeemable, Preferred Stock, $1.00 par value per share. | KIMprL | New York Stock Exchange | |
| Depositary Shares, each representing one-thousandth of a share of 5.250% Class M Cumulative Redeemable Preferred Stock, $1.00 par value per share. | KIMprM | New York Stock Exchange |
Kimco Realty OP, LLC
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | |
|---|---|---|---|
| None | N/A | N/A |
Securities registered pursuant to section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act.
Kimco Realty Corporation Yes ☑ No ☐ Kimco Realty OP, LLC Yes ☑ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act.
Kimco Realty Corporation Yes ☐ No ☑ Kimco Realty OP, LLC Yes ☐ No ☑
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days.
Kimco Realty Corporation Yes ☑ No ☐ Kimco Realty OP, LLC Yes ☑ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files).
Kimco Realty Corporation Yes ☑ No ☐ Kimco Realty OP, LLC Yes ☑ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
Kimco Realty Corporation:
| Large accelerated filer ☑ | Accelerated filer ☐ | Non-accelerated filer ☐ | Smaller reporting company ☐ | Emerging growth company ☐ |
|---|
Kimco Realty OP, LLC:
| Large accelerated filer ☐ | Accelerated filer ☐ | Non-accelerated filer ☑ | Smaller reporting company ☐ | Emerging growth company ☐ |
|---|
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
Kimco Realty Corporation ☐ Kimco Realty OP, LLC ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report.
Kimco Realty Corporation ☑ Kimco Realty OP, LLC ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act).
Kimco Realty Corporation Yes ☐ No ☑ Kimco Realty OP, LLC Yes ☐ No ☑
The aggregate market value of the voting and non-voting common equity held by non-affiliates of Kimco Realty Corporation was approximately $12.0 billion based upon the closing price on the New York Stock Exchange for such equity on June 30, 2022.
(APPLICABLE ONLY TO CORPORATE REGISTRANTS)
Indicate the number of shares outstanding of each of the registrant's classes of common stock, as of the latest practicable date.
As of February 10, 2023, Kimco Realty Corporation had 618,609,347 shares of common stock outstanding.
DOCUMENTS INCORPORATED BY REFERENCE
Part III incorporates certain information by reference to the Kimco Realty Corporation's definitive proxy statement to be filed with respect to the Annual Meeting of Stockholders expected to be held on April 25, 2023.
Index to Exhibits begins on page 46.
KIMCO REALTY CORPORATION
KIMCO REALTY OP, LLC
ANNUAL REPORT ON FORM 10-K
FISCAL YEAR ENDED DECEMBER 31, 2022
EXPLANATORY NOTE
Prior to January 1, 2023, the business of Kimco Realty Corporation (the “Company”) was conducted through a predecessor entity also known as Kimco Realty Corporation (the “Predecessor”). On December 14, 2022, the Predecessor’s Board of Directors approved the entry into an Agreement and Plan of Merger (the “UPREIT Merger”) with the company formerly known as New KRC Corp., which was a Maryland corporation and wholly owned subsidiary of the Predecessor (the “Parent Company”), and KRC Merger Sub Corp., which was a Maryland corporation and wholly owned subsidiary of the Parent Company (“Merger Sub”), to effect the reorganization (the “Reorganization”) of the Predecessor’s business into an umbrella partnership real estate investment trust, or “UPREIT”.
On January 1, 2023, pursuant to the UPREIT Merger, Merger Sub merged with and into the Predecessor, with the Predecessor continuing as the surviving entity and a wholly-owned subsidiary of the Parent Company, and each outstanding share of capital stock of the Predecessor was converted into one equivalent share of capital stock of the Parent Company (each of which has continued to trade under their respective existing ticker symbol with the same rights, powers and limitations that existed immediately prior to the Reorganization).
In connection with the Reorganization, the Parent Company changed its name to Kimco Realty Corporation, and replaced the Predecessor as the New York Stock Exchange-listed public company. Effective as of January 3, 2023, the Predecessor converted into a limited liability company, organized in the State of Delaware, known as Kimco Realty OP, LLC, the entity we refer to herein as “Kimco OP”.
Following the Reorganization, substantially all of the Company’s assets are held by, and substantially all of the Company’s operations are conducted through, Kimco OP (either directly or through its subsidiaries), as the Company’s operating company, and the Company is the managing member of Kimco OP. The officers and directors of the Company are the same as the officers and directors of the Predecessor immediately prior to the Reorganization.
This Annual Report on Form 10-K (“Form 10-K” or “Annual Report”) pertains to the business and results of operations of the Predecessor for its fiscal year ended December 31, 2022. The Company and Kimco OP have elected to co-file such Annual Report of the Predecessor to ensure continuity of information to investors.
For additional information on our Reorganization, please see our Current Reports on Form 8-K filed with the SEC on January 3, 2023 and January 4, 2023.
Throughout this Annual Report, unless the context requires otherwise:
| ● | the “Company,” “we,” “our,” “us” or refer to: | |
|---|---|---|
| ○ for the period prior to January 1, 2023 (the period preceding the UPREIT Merger), the Predecessor and its business and operations conducted through its directly or indirectly owned subsidiaries; | ||
| ○ for the period on or after January 1, 2023, (the period from and following the UPREIT Merger), the Parent Company and its business and operations conducted through its directly or indirectly owned subsidiaries, including Kimco OP; and | ||
| ○ in statements regarding qualification as a real estate investment trust (“REIT”), such terms refer solely to the Predecessor or Parent Company, as applicable. |
| ● | “Kimco OP” refers to Kimco Realty OP, LLC, our operating company following the UPREIT Merger. |
|---|
| ● | References to “shares” and “shareholders” refer to the shares and stockholders of the Predecessor prior to January 1, 2023 and of the Parent Company on or after January 1, 2023, and not the limited liability company interests of Kimco OP. |
|---|
| Item No. | Form 10-K Report Page |
|---|
FORWARD-LOOKING STATEMENTS
This annual report on Form 10-K (“Form 10-K”), together with other statements and information publicly disseminated by the Company contains certain forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended (the “Securities Act”), and Section 21E of the Securities Exchange Act of 1934, as amended (the “Exchange Act”). The Company intends such forward-looking statements to be covered by the safe harbor provisions for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995 and includes this statement for purposes of complying with the safe harbor provisions. Forward-looking statements, which are based on certain assumptions and describe the Company’s future plans, strategies and expectations, are generally identifiable by use of the words “believe,” “expect,” “intend,” “commit,” “anticipate,” “estimate,” “project,” “will,” “target,” “forecast” or similar expressions. You should not rely on forward-looking statements since they involve known and unknown risks, uncertainties and other factors which, in some cases, are beyond the Company’s control and could materially affect actual results, performances or achievements. Factors which may cause actual results to differ materially from current expectations include, but are not limited to, (i) general adverse economic and local real estate conditions, (ii) the impact of competition, including the availability of acquisition or development opportunities and the costs associated with purchasing and maintaining assets; (iii) the inability of major tenants to continue paying their rent obligations due to bankruptcy, insolvency or a general downturn in their business, (iv) the reduction in the Company’s income in the event of multiple lease terminations by tenants or a failure of multiple tenants to occupy their premises in a shopping center, (v) the potential impact of e-commerce and other changes in consumer buying practices, and changing trends in the retail industry and perceptions by retailers or shoppers, including safety and convenience, (vi) the availability of suitable acquisition, disposition, development and redevelopment opportunities, and risks related to acquisitions not performing in accordance with our expectations, (vii) the Company’s ability to raise capital by selling its assets, (viii) disruptions and increases in operating costs due to inflation and supply chain issues, (ix) risks associated with the development of mixed-use commercial properties, including risks associated with the development and ownership of non-retail real estate, (x) changes in governmental laws and regulations, including, but not limited to, changes in data privacy, environmental (including climate change), safety and health laws, and management’s ability to estimate the impact of such changes, (xi) valuation and risks related to the Company’s joint venture and preferred equity investments and other investments, (xii) valuation of marketable securities and other investments, including the shares of Albertsons Companies, Inc. common stock held by the Company, (xiii) impairment charges, (xiv) criminal cybersecurity attacks disruption, data loss or other security incidents and breaches, (xv) impact of natural disasters and weather and climate-related events, (xvi) pandemics or other health crises, such as coronavirus disease 2019 (“COVID-19”), (xvii) our ability to attract, retain and motivate key personnel, (xviii) financing risks, such as the inability to obtain equity, debt or other sources of financing or refinancing on favorable terms to the Company, (xix) the level and volatility of interest rates and management’s ability to estimate the impact thereof, (xx) changes in the dividend policy for the Company’s common and preferred stock and the Company’s ability to pay dividends at current levels, (xxi) unanticipated changes in the Company’s intention or ability to prepay certain debt prior to maturity and/or hold certain securities until maturity, and (xxii) the Company’s ability to continue to maintain its status as a REIT for federal income tax purposes and potential risks and uncertainties in connection with its UPREIT structure, and (xxiii) the other risks and uncertainties identified under Item 1A, “Risk Factors” and elsewhere in this Form 10-K and in the Company’s other filings with the Securities and Exchange Commission (“SEC”). Accordingly, there is no assurance that the Company’s expectations will be realized. The Company disclaims any intention or obligation to update the forward-looking statements, whether as a result of new information, future events or otherwise. You are advised to refer to any further disclosures the Company makes or related subjects in the Company’s quarterly reports on Form 10-Q and current reports on Form 8-K that the Company files with the SEC.
Item 1. Business
Overview
The Company is North America’s largest publicly traded owner and operator of open-air, grocery-anchored shopping centers, and a growing portfolio of mixed-use assets. The Company’s mission is to create destinations for everyday living that inspire a sense of community and deliver value to our many stakeholders.
The Company began operations through its predecessor, The Kimco Corporation, which was organized in 1966 upon the contribution of several shopping center properties owned by its principal stockholders. In 1973, these principals formed the Company as a Delaware corporation, and, in 1985, the operations of The Kimco Corporation were merged into the Company. The Company completed its initial public stock offering (the “IPO”) in November 1991, and, commencing with its taxable year which began January 1, 1992, elected to qualify as a REIT in accordance with Sections 856 through 860 of the Internal Revenue Code of 1986, as amended (the “Code”). To qualify as a REIT, the Company must meet several organizational and operational requirements, and is required to annually distribute at least 90% of its net taxable income, determined without regard to the dividends paid deduction and excluding any net capital gain. In addition, the Company will be subject to federal income tax at regular corporate rates to the extent that it distributes less than 100% of its net taxable income, including any net capital gains. In January of 2023, the Company consummated the Reorganization into an UPREIT structure as described in the Explanatory Note at the beginning of this Annual Report. If, as the Company believes, it is organized and operates in such a manner so as to qualify and remain qualified as a REIT under the Code, the Company, generally will not be subject to U.S. federal income tax, provided that distributions to its stockholders equal at least the amount of its REIT taxable income, as defined in the Code. The Company maintains certain subsidiaries that made joint elections with the Company to be treated as taxable REIT subsidiaries (“TRSs”), that permit the Company to engage through such TRSs in certain business activities that the REIT may not conduct directly. A TRS is subject to federal and state taxes on its income, and the Company includes a provision for taxes in its consolidated financial statements. In 1994, the Predecessor reorganized as a Maryland corporation. In March 2006, the Predecessor was added to the S&P 500 Index, an index containing the stock of 500 Large Cap companies, most of which are U.S. corporations. The Company's common stock, Class L Depositary Shares and Class M Depositary Shares are traded on the New York Stock Exchange (“NYSE”) under the trading symbols “KIM”, “KIMprL”, and “KIMprM”, respectively.
The Company is a self-administered REIT and has not engaged, nor does it expect to retain, any REIT advisors in connection with the operation of its properties. The Company’s ownership interests in real estate consist of its consolidated portfolio and portfolios where the Company owns an economic interest, such as properties in the Company’s investment real estate management programs, where the Company partners with institutional investors and also retains management.
The Company began to expand its operations through the development of real estate and the construction of shopping centers but revised its growth strategy to focus on the acquisition and redevelopment of existing shopping centers that include a grocery component. The Company also expanded internationally within Canada, Mexico, Chile, Brazil and Peru, but has since exited all international investments. Additionally, the Company developed various residential and mixed-use operating properties and continues to obtain entitlements to embark on additional projects of this nature through re-development opportunities. In August 2021, the Company expanded through a merger with Weingarten Realty Investors (“Weingarten”), whereby Weingarten merged with and into the Predecessor, with the Predecessor continuing as the surviving public company (the “Merger”), pursuant to the definitive merger agreement (the “Merger Agreement”) between the Predecessor and Weingarten which was entered into on April 15, 2021. The Merger brought together two industry-leading retail real estate platforms with highly complementary portfolios and created the preeminent open-air shopping center and mixed-use real estate owner in the country. The Merger further enhanced the Company’s portfolio in coastal and sun belt regions.
The Company has implemented its investment real estate management format through the establishment of various institutional joint venture programs, in which the Company has noncontrolling interests. The Company earns management fees, acquisition fees, disposition fees as well as promoted interests based on achieving certain performance metrics.
In addition, the Company has capitalized on its established expertise in retail real estate by establishing other ventures in which the Company owns a smaller equity interest and provides management, leasing and operational support for those properties. The Company has also provided preferred equity capital to real estate professionals and, from time to time, provides real estate capital and management services to both healthy and distressed retailers. The Company has also made selective investments in secondary market opportunities where a security or other investment is, in management’s judgment, priced below the value of the underlying assets, however these investments are subject to volatility within the equity and debt markets.
As described in greater detail in the Explanatory Note to this Form 10-K, (i) on January 1, 2023, as a result of the Reorganization, the Parent Company, a Maryland corporation, became the successor issuer to the Predecessor, and (ii) on January 3, 2023 the Predecessor converted into Kimco OP, a limited liability company, organized in the State of Delaware. Parent Company is the managing member of Kimco OP and owns 100% of the limited liability company interests, and exercises exclusive control over Kimco OP.
As of December 31, 2022, the Company had interests in 532 shopping center properties (the “Combined Shopping Center Portfolio”), aggregating 90.8 million square feet of gross leasable area (“GLA”), located in 28 states. In addition, the Company had 23 other property interests, primarily through the Company’s preferred equity investments and other investments, totaling 5.7 million square feet of GLA.
Economic Conditions
The economy continues to face several issues including the lack of qualified employees, inflation risk, supply chain issues and new COVID-19 variants, which could impact the Company and its tenants. In response to the rising rate of inflation the Federal Reserve has steadily increased interest rates, and may continue to increase interest rates, until the rate of inflation begins to decrease. These increases in interest rates could adversely impact the business and financial results of the Company and its tenants. In addition, slower economic growth and the potential for a recession could have an adverse effect on the Company and its tenants. This could negatively affect the overall demand for retail space, including the demand for leasable space in the Company’s properties. As a result, the Company could feel pricing pressure on rents that it is able to charge to new or renewing tenants, such that future rents and rent spreads could be negatively impacted. Any of these events could materially adversely impact the Company’s business, financial condition, results of operations or stock price. The Company continues to monitor economic, financial, and social conditions and will assess its asset portfolio for any impairment indicators. If the Company determines that any of its assets are impaired, the Company would be required to take impairment charges, and such amounts could be material.
Business Objective and Strategies
The Company has developed a strong nationally diversified portfolio of open-air, shopping centers located in drivable first-ring suburbs primarily within 19 major metropolitan sun belt and coastal markets, which are supported by strong demographics, significant projected population growth, and where the Company perceives significant barriers to entry. As of December 31, 2022, the Company derived 85% of its annualized base rent from these top major metro markets. The Company’s shopping centers provide essential, necessity-based goods and services to the local communities and are primarily anchored by grocers, home improvement, and pharmacy.
The Company’s focus on high-quality locations has led to significant opportunities for value creation through the reinvestment in its assets to add density, replace outdated shopping center concepts, and better meet changing consumer demands. In order to add density to existing properties, the Company has obtained multi-family entitlements for 8,818 units of which 2,218 units have been constructed as of December 31, 2022. The Company continues to place strategic emphasis on live/work/play environments and in reinvesting in its existing assets, while building shareholder value. This philosophy is exemplified by the Company’s Signature SeriesTM properties which include key value creation projects in our portfolio that exemplify our transformation and highlight our focus on quality, concentration around core MSAs, and growth through redevelopment and development opportunities. Signature Series properties also include fully entitled, shovel-ready mixed-use projects, and opportunities that we continue to identify and entitle as we seek to achieve the highest and best use of our real estate, enhance our communities, and create value for our stakeholders for years to come.
The strength and security of the Company’s balance sheet remains central to its strategy. The Company’s strong balance sheet and liquidity position are evidenced by its investment grade unsecured debt ratings (Baa1/BBB+) by two major ratings agencies. The Company maintains one of the longest weighted average debt maturity profiles in the REIT industry, now at 9.5 years. The Company expects to continue to take steps to reduce leverage, unencumber assets and improve its debt coverage metrics as mixed-use projects and redevelopments continue to come online and contribute additional cash flow growth.
Business Objective
The Company’s primary business objective is to be the premier owner and operator of open-air, grocery-anchored shopping centers, and a growing portfolio of mixed-use assets, in the U.S. The Company believes it can achieve this objective by:
| ● | increasing the value of its existing portfolio of properties and generating higher levels of portfolio growth; |
|---|
| ● | increasing cash flows for reinvestment and/or for distribution to shareholders while maintaining conservative payout ratios; |
|---|
| ● | improving debt metrics and upgraded unsecured debt ratings |
|---|
| ● | continuing growth in desirable demographic areas with successful retailers, primarily focused on grocery anchors; and |
|---|
| ● | increasing the number of entitlements for residential use. |
|---|
Business Strategies
The Company believes with its strong core portfolio and its recent acquisitions, it will continue to achieve higher occupancy levels, increased rental rates and rental growth in the future. To effectively execute the Company’s strategy and achieve its strategic goals the Company identified the following growth components to focus on:
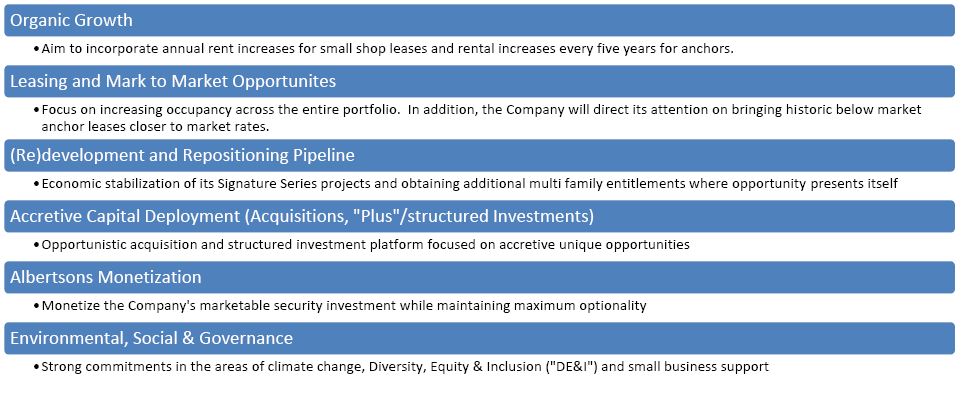
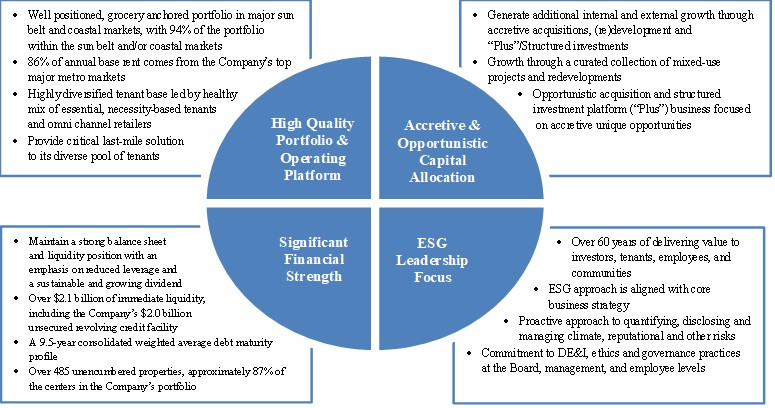
The Company believes it is well positioned for sustainable growth with its high-quality portfolio, accretive and opportunistic capital allocation, financial strength and environmental, social and governance leadership.
The Company has identified the following areas where it is well positioned for sustainable growth in the future.
The Company reduces its operating and leasing risks through diversification achieved by the geographic distribution of its properties and a large tenant base. As of December 31, 2022, no single open-air shopping center accounted for more than 1.3% of the Company's annualized base rental revenues, including the proportionate share of base rental revenues from properties in which the Company has less than a 100% economic interest, or more than 1.4% of the Company’s total shopping center GLA. Furthermore, at December 31, 2022, the Company’s single largest tenant represented only 3.7%, and the Company’s five largest tenants aggregated less than 11.4%, of the Company’s annualized base rental revenues, including the proportionate share of base rental revenues from properties in which the Company has less than a 100% economic interest.
As one of the original participants in the growth of the shopping center industry and the nation's largest owners and operators of open-air shopping centers, the Company has established close relationships with major national and regional retailers and maintains a broad network of industry contacts. Management is associated with and/or actively participates in many shopping center and REIT industry organizations. Notwithstanding these relationships, there are numerous regional and local commercial developers, real estate companies, financial institutions and other investors who compete with the Company for the acquisition of properties and other investment opportunities and in seeking tenants who will lease space in the Company’s properties.
Government Regulation
Compliance with various governmental regulations has an impact on our business, including our capital expenditures, earnings and competitive position, which can be material. We incur costs to monitor and take actions to comply with governmental regulations that are applicable to our business, which include, among others, federal securities laws and regulations, applicable stock exchange requirements, REIT and other tax laws and regulations, environmental and health and safety laws and regulations, local zoning, usage and other regulations relating to real property and the Americans with Disabilities Act of 1990.
In addition, see Item 1A. Risk Factors for a discussion of material risks to us, including, to the extent material, to our competitive position, relating to governmental regulations, and see “Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations” together with our audited consolidated financial statements and the related notes thereto for a discussion of material information relevant to an assessment of our financial condition and results of operations, including, to the extent material, the effects that compliance with governmental regulations may have upon our capital expenditures and earnings.
Human Capital Resources
The Company believes that our associates are one of our strongest resources and that a variety of perspectives and experiences found in a diverse workforce spark innovation and enrich company culture. The Company is committed to diversity, equity and inclusion best practices in all phases of the associate life cycle, including recruitment, training and development and promotion. By cultivating high levels of associate satisfaction and improving the diversity of our team, management’s goal is to ensure the Company will remain a significant driving force in commercial real estate well into the future.
The Company has been and will continue to be an equal opportunity employer committed to hiring, developing, and supporting a diverse, equitable, and inclusive workplace. To ensure full implementation of this equal employment policy, we take steps to ensure that persons are recruited, hired, assigned and promoted without regard to race, creed, national origin, ancestry, citizenship status, religion, age, color, sex, gender (including pregnancy, childbirth and related medical conditions), gender identity and expression, sexual orientation, marital status, disability, genetic information, protected veteran status, or any other characteristic protected by local, state, or federal laws, rules, or regulations. All of our employees must adhere to a Code of Business Conduct and Ethics that sets standards for appropriate behavior and includes required, regular internal training on preventing, identifying, reporting and stopping any type of discrimination and/or retaliation.
To attract and retain high performing individuals, we are committed to partnering with our associates to provide opportunities for their professional development and promote their health and well-being. We offer a broad range of benefits, and we believe our compensation package and benefits are competitive with others in our industry. Our benefits programs include a robust offering of medical, dental, vision, life, disability and a number of exciting ancillary benefits, all of which require very low associate contributions or are offered at no cost to associates. The Company also provides a Safe Harbor 401(k) program with both pretax and Roth offering including a robust, fully vested matching contribution.
The Company has been recognized as a Great Place to Work® for five consecutive years as well as a One of the 2022 Best Workplaces in Real Estate™, both of which are based on anonymous third-party surveys and feedback collected from our associates. Additionally, the Company was designated a Best Place to Work for LGBTQ+ Equality and has achieved a perfect score on the Human Rights Campaign Foundation’s 2022 Corporate Equality Index, a nationally recognized benchmarking survey and report measuring corporate policies and practices related to LGBTQ+ workplace equality.
The Company operates under a hybrid work model, which balances associates’ need for valuable face-to-face interactions with individual preferences for ideal work conditions. By continuing to focus on communication, collaboration, and innovation, and by encouraging associates to protect their personal time and be deliberate in where and how they choose to work, management is confident that the model results in a happier, engaged, and more efficient workforce.
The Company’s executive and management team promotes a true “open door” environment in which all feedback and suggestions are welcome. Whether it be through regular all employee calls, department meetings, frequent training sessions, Coffee Connections with the executive team, use of our BRAVO recognition program, awarding of iPads for Ideas, or participation in our LABS (Leaders Advancing Business Strategy) program, associates are encouraged to be inquisitive and share ideas. Those ideas have resulted in a number of programs and benefit enhancements.
The Company promotes physical health, including access to a national gym membership program for associates and their family members as well as host to regular wellness and nutrition seminars and health screenings. The Company also feels it is important that our associates are engaged and active in the community. Across our numerous offices, associates host volunteer and social activities. Whether we’re participating in walks, runs, food or toy drives, the Company promotes and supports associate volunteerism with two volunteer days off per year and a company matching program in support of each associates charitable endeavors. The Company also encourages associates to directly drive strategy around the Company’s environmental, social and governance initiatives through participation in five associate-driven KIMunity Councils focused in the areas of diversity, equity and inclusion, giving, wellness, sustainability, and tenant engagement.
The Company recognizes the importance of advanced education. Each year, the Company funds $100,000 in college scholarships to benefit the children of our associates. In addition, the Company recently announced, in partnership with ICSC, it is providing $100,000 in scholarships to students wishing to pursue careers in real estate, of which no less than 50% will be awarded to students of under-represented groups. Both programs are managed by independent third parties who consider an equal balance of academics and financial need as determining factors.
The Company's executive offices are located at 500 North Broadway, Suite 201, Jericho, NY 11753, a mixed-use property that is wholly owned by the Company, and its telephone number is (516) 869-9000 or 1-800-764-7114. Nearly all corporate functions, including legal, data processing, finance and accounting are administered by the Company from its executive offices in Jericho, New York and supported by the Company’s regional offices. As of December 31, 2022, a total of 639 persons were employed by the Company, of which 31% were located in our corporate office with the remainder located in 28 offices throughout the United States. The average tenure of our employees was 9.0 years.
Cybersecurity
The Company’s Audit Committee receives quarterly briefings from the Company’s Chief Information Officer regarding the emerging cybersecurity threat and risk landscape as well as the Company’s security program and related readiness, resiliency, and response efforts.
The Company has a Cyber Risk Committee (“Cyber Committee”) which reviews and reports on technology-based security issues. The Cyber Committee is comprised of senior management from various business units within the Company and meets quarterly to review the status of the Company’s overall security program as well as controls and procedures and to stay up-to-date of relevant legislative, regulatory and technical developments.
The Company utilizes a variety of administrative, technical and physical safeguards that take into account the nature of our IT environment, information assets and cyber risks posed by both internal and external threats. The Company has incorporated cybersecurity coverage in its insurance policies. The Company’s goal is to keep its data and systems, as well as its employees safe from cybersecurity threats.
The Company conducts employee security awareness training and internal phishing exercises. When security issues arise, the Company conducts a prompt investigation and initiates response protocols and other measures to protect the Company and its valued employees and key stakeholders.
Environmental, Social and Governance (“ESG”) Programs
The Company strives to build a thriving and viable business, one that succeeds by delivering long-term value for its stakeholders. We believe that the Company’s ESG programs are aligned with its core business strategy of creating destinations for everyday living that inspire a sense of community and deliver value to its many stakeholders.
The Company has identified the following five pillars that outline the Company’s current strategic priorities within our ESG program. The Company has defined 16 ESG goals that expand upon the Company’s commitment with clear targets in each pillar:
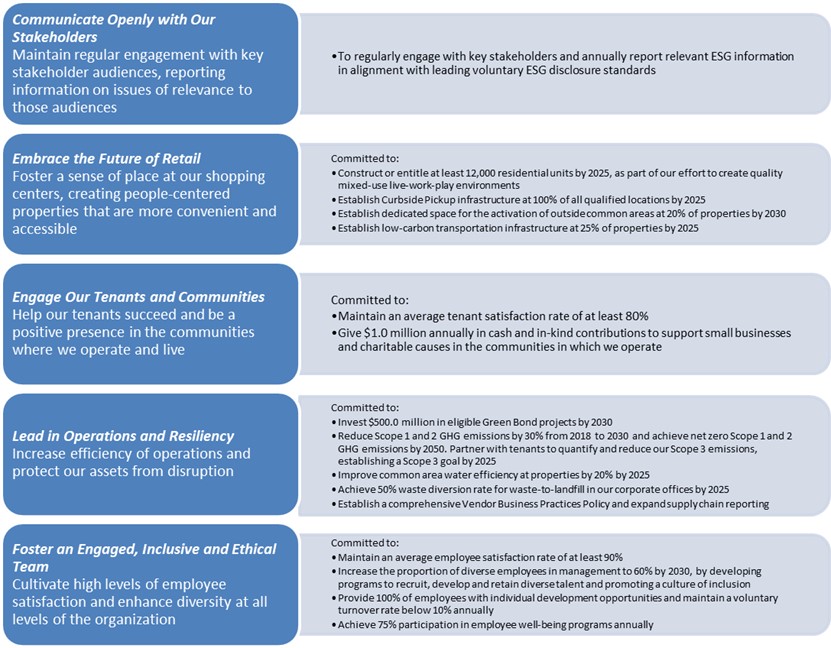
The Company has aligned its annual reporting with standards from the Global Reporting Initiative (“GRI”), Sustainability Accounting Standards Board (“SASB”) and Task Force on Climate-related Financial Disclosures (“TCFD”). The Company also discloses aggregate-level EEO-1 workforce diversity data that can be found on the Company’s website, which data and website contents are not incorporated by reference hereto. Additional ESG information of relevance to stakeholders can be found on the Company’s website, the contents of which are not incorporated by reference and do not form a part of this Form 10-K.
The Company’s Board of Directors sets the Company’s overall ESG program objectives and oversees enterprise risk management. The Nominating and Corporate Governance Committee of the Board of Directors is responsible for overseeing the Company's efforts with regard to the Company's ESG matters.
The Company recognizes that climate change is one of the most significant stakeholder issues of our times, threatening the viability of economic and environmental systems globally. The scientific community has studied climate change and a consensus exists that warming is occurring outside the boundaries of historical planetary trends due in significant part, to human activity. As a real estate portfolio owner, the Company monitors physical and transition risks as well as opportunities posed to its business by climate change and quantifies and discloses the climate impacts of its activities. The Company’s science-based GHG emissions reduction goals are aligned with the Paris Climate Accord and while there can be no guarantees, we believe they could put the Company on pace to achieve Scope 1 and Scope 2 net zero GHG emissions by 2050.
Climate risks and opportunities are generally evaluated at both the corporate and individual asset level. The following table summarizes relevant climate risks identified as a part of the Company’s ongoing risk assessment process. The Company may be subject to other climate risks not included below.
| Climate Risk | Description | |
|---|---|---|
| Physical | ||
| Windstorms | Increased frequency and intensity of windstorms, such as hurricanes, could lead to property damage, loss of property value and interruptions to business operations | |
| Sea Level Rise | Rising sea levels could lead to storm surge and other potential impacts for low-lying coastal properties leading to damage, loss of property value and interruptions to business operations | |
| Flooding | Change in rainfall conditions leading to increased frequency and severity of flooding could lead to property damage, loss of property value and interruptions to business operations | |
| Wildfires | Change in fire potential could lead to permanent loss of property, stress on human health (air quality) and stress on ecosystem services | |
| Heat and Water Stress | Increases in temperature could lead to droughts and decreased available water supply could lead to higher utility usage, supply interruptions and reputational issues in local communities | |
| Transition | ||
| Regulation | Regulations at the federal, state and local levels could impose additional operating and capital costs associated with utilities, energy efficiency, building materials and building design | |
| Reputation | Increased interest among retail tenants in building efficiency, sustainable design criteria and "green leases", which incorporate provisions intended to promote sustainability at the property, could result in decreased demand for outdated space |
The Company’s approach in mitigating these risks include but are not limited to (i) carrying additional insurance coverage relating to flooding and windstorms, (ii) maintaining a geographically diversified portfolio, which limits exposure to event driven risks and (iii) creating a form “green lease” for its tenants which incorporates varied criteria that align landlord and tenant sustainability priorities as well as establishing green construction criteria.
In 2020, the Company issued $500.0 million in 2.70% notes due 2030 in its inaugural green bond offering. The net proceeds from this offering are allocated to finance or refinance, in whole or in part, recently completed, existing or future eligible green projects, with projects are to be aligned with the four core components of the Green Bond Principles, 2018 as administered by the International Capital Market Association. Additionally, the Company’s $2.0 billion Credit Facility (as defined below) is a green credit facility which incorporates rate adjustments associated with attainment (or nonattainment) of Scope 1 and 2 greenhouse gas emissions reductions.
Information About Our Executive Officers
The following table sets forth information with respect to the executive officers of the Company as of December 31, 2022:
| Name | Age | Position | Joined Kimco |
|---|---|---|---|
| Milton Cooper | 93 | Executive Chairman of the Board of Directors | Co-Founder |
| Conor C. Flynn | 42 | Chief Executive Officer | 2003 |
| Ross Cooper | 40 | President and Chief Investment Officer | 2006 |
| Glenn G. Cohen | 58 | Executive Vice President, Chief Financial Officer and Treasurer | 1995 |
| David Jamieson | 42 | Executive Vice President, Chief Operating Officer | 2007 |
Available Information
The Company’s website is located at http://www.kimcorealty.com. The information contained on our website does not constitute part of this Form 10-K. On the Company’s website you can obtain, free of charge, a copy of this Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Exchange Act, as soon as reasonably practicable, after we file such material electronically with, or furnish it to, the SEC. The public may read and obtain a copy of any materials we file electronically with the SEC at http://www.sec.gov.
Item 1A. Risk Factors
We are subject to certain business and legal risks including, but not limited to, the following:
Risks Related to Our Business and Operations
Adverse global market and economic conditions may impede our ability to generate sufficient income and maintain our properties.
Our properties consist primarily of open-air shopping centers, including mixed-use assets, and other retail properties. Our performance, therefore, is generally linked to economic conditions in the market for retail space. The economic performance and value of our properties is subject to all of the risks associated with owning and operating real estate, including but not limited to:
| ● | changes in the national, regional and local economic climate; |
|---|
| ● | local conditions, including an oversupply of, or a reduction in demand for, space in properties like those that we own or operate; |
|---|
| ● | trends toward smaller store sizes as retailers reduce inventory and develop new prototypes; |
|---|
| ● | increasing use by customers of e-commerce and online store sites; |
|---|
| ● | the attractiveness of our properties to tenants; |
|---|
| ● | market disruptions due to global pandemics; |
|---|
| ● | the ability of tenants to pay rent, particularly anchor tenants with leases in multiple locations; |
|---|
| ● | tenants who may declare bankruptcy and/or close stores; |
|---|
| ● | competition from other available properties to attract and retain tenants; |
|---|
| ● | changes in market rental rates; |
|---|
| ● | the need to periodically pay for costs to repair, renovate and re-let space; |
|---|
| ● | ongoing consolidation in the retail sector; |
|---|
| ● | the excess amount of retail space in a number of markets; |
|---|
| ● | changes in operating costs, including costs for maintenance, insurance and real estate taxes; |
|---|
| ● | the expenses of owning and operating properties, which are not necessarily reduced when circumstances such as market factors and competition cause a reduction in income from the properties; |
|---|
| ● | changes in laws and governmental regulations, including those governing usage, zoning, the environment and taxes; |
|---|
| ● | acts of terrorism and war and acts of God, including physical and weather-related damage to our properties; |
|---|
| ● | the continued service and availability of key personnel; and |
|---|
| ● | the risk of functional obsolescence of properties over time. |
|---|
Competition may limit our ability to purchase new properties or generate sufficient income from tenants and may decrease the occupancy and rental rates for our properties.
Numerous commercial developers and real estate companies compete with us in seeking tenants for our existing properties and properties for acquisition. Open-air shopping centers, including mixed-use assets, or other retail shopping centers with more convenient locations or better rents may attract tenants or cause them to seek more favorable lease terms at or prior to renewal. Retailers at our properties may face increasing competition from other retailers, e-commerce, outlet malls, discount shopping clubs, telemarketing or home shopping networks, all of which could (i) reduce rents payable to us; (ii) reduce our ability to attract and retain tenants at our properties; or (iii) lead to increased vacancy rates at our properties. We may fail to anticipate the effects of changes in consumer buying practices, particularly of growing online sales and the resulting retailing practices and space needs of our tenants or a general downturn in our tenants’ businesses, which may cause tenants to close stores or default in payment of rent.
We face competition in the acquisition or development of real property from others engaged in real estate investment that could increase our costs associated with purchasing and maintaining assets. Some of these competitors may have greater financial resources than we do. This could result in competition for the acquisition of properties for tenants who lease or consider leasing space in our existing and subsequently acquired properties and for other investment or development opportunities.
Our performance depends on our ability to collect rent from tenants, including anchor tenants, our tenants’ financial condition and our tenants maintaining leases for our properties.
At any time, our tenants may experience a downturn in their business that may significantly weaken their financial condition. As a result, our tenants may delay a number of lease commencements, decline to extend or renew leases upon expiration, fail to make rental payments when due, close stores or declare bankruptcy. Any of these actions could result in the termination of tenants’ leases and the loss of rental income attributable to these tenants’ leases. In the event of a default by a tenant, we may experience delays and costs in enforcing our rights as landlord under the terms of the leases.
In addition, multiple lease terminations by tenants, including anchor tenants, or a failure by multiple tenants to occupy their premises in a shopping center could result in lease terminations or significant reductions in rent by other tenants in the same shopping centers under the terms of some leases. In that event, we may be unable to re-lease the vacated space at attractive rents or at all, and our rental payments from our continuing tenants could significantly decrease. The occurrence of any of the situations described above, particularly involving a substantial tenant with leases in multiple locations, could have a material adverse effect on our financial condition, results of operations and cash flows.
A tenant that files for bankruptcy protection may not continue to pay us rent. A bankruptcy filing by, or relating to, one of our tenants or a lease guarantor would bar all efforts by us to collect pre-bankruptcy debts from the tenant or the lease guarantor, or their property, unless the bankruptcy court permits us to do so. A tenant bankruptcy could delay our efforts to collect past due balances under the relevant leases and could ultimately preclude collection of these sums. If a lease is rejected by a tenant in bankruptcy, we would have only a general unsecured claim for damages. As a result, it is likely that we would recover substantially less than the full value of any unsecured claims we hold, if at all.
E-commerce and other changes in consumer buying practices present challenges for many of our tenants and may require us to modify our properties, diversify our tenant composition and adapt our leasing practices to remain competitive.
Many of our tenants face increasing competition from e-commerce and other sources that could cause them to reduce their size, limit the number of locations and/or suffer a general downturn in their businesses and ability to pay rent. We may also fail to anticipate the effects of changes in consumer buying practices, particularly of growing online sales and the resulting change in retailing practices and space needs of our tenants, which could have an adverse effect on our results of operations and cash flows. We are focused on anchoring and diversifying our properties with tenants that are more resistant to competition from e-commerce (e.g., groceries, essential retailers, restaurants and service providers), but there can be no assurance that we will be successful in modifying our properties, diversifying our tenant composition and/or adapting our leasing practices.
**Our expenses may remain constant or increase, even if income from our Combined Shopping Center Portfolio decreases, which could adver
Showing the first 8K of 63K characters. Open the full section
Item 1B. Unresolved Staff Comments
None.
Item 2. Properties
Real Estate Portfolio.
As of December 31, 2022, the Company had interests in 532 shopping center properties aggregating 90.8 million square feet of GLA located in 28 states. In addition, the Company had 23 other property interests, primarily through the Company’s preferred equity investments and other investments, totaling 5.7 million square feet of GLA. Open-air shopping centers comprise the primary focus of the Company's current portfolio. As of December 31, 2022, the Company’s Combined Shopping Center Portfolio, including noncontrolling interests, was 95.7% leased.
The Company's open-air shopping center properties, which are generally owned and operated through subsidiaries or joint ventures, had an average size of 170,754 square feet as of December 31, 2022. The Company generally retains its shopping centers for long-term investment and consequently pursues a program of regular physical maintenance together with redevelopment, major renovations and refurbishing to preserve and increase the value of its properties. This includes renovating existing facades, installing uniform signage, resurfacing parking lots and enhancing parking lot lighting. During 2022, the Company expended $113.9 million in connection with property redevelopments and $79.8 million related to improvements.
The Company's management believes its experience in the real estate industry and its relationships with numerous national and regional tenants gives it an advantage in an industry where ownership is fragmented among a large number of property owners. The Company's open-air shopping centers are usually "anchored" by a grocery store, home improvement centers, off-price retailer, discounter or service-oriented tenant. As one of the original participants in the growth of the shopping center industry and the nation's largest owner and operator of shopping centers, the Company has established close relationships with a large number of major national and regional retailers. Some of the major national and regional companies that are tenants in the Company's shopping center properties include TJX Companies, The Home Depot, Albertsons Companies, Ross Stores, Amazon/Whole Foods Market, PetSmart, Ahold Delhaize, Kroger, Burlington Stores and Walmart.
The Company reduces its operating and leasing risks through diversification achieved by the geographic distribution of its properties and a large tenant base. As of December 31, 2022, no single open-air shopping center accounted for more than 1.3% of the Company's annualized base rental revenues, including the proportionate share of base rental revenues from properties in which the Company has less than a 100% economic interest, or more than 1.4% of the Company’s total shopping center GLA. At December 31, 2022, the Company’s five largest tenants were TJX Companies, The Home Depot, Ross Stores, Albertsons Companies and Amazon/Whole Foods Market, which represented 3.7%, 2.1%, 1.9%, 1.9% and 1.8%, respectively, of the Company’s annualized base rental revenues, including the proportionate share of base rental revenues from properties in which the Company has less than a 100% economic interest.
A substantial portion of the Company's income consists of rent received under long-term leases. Most of the leases provide for the payment of fixed-base rentals monthly in advance and for the payment by tenants of an allocable share of the real estate taxes, insurance, utilities and common area maintenance expenses incurred in operating the shopping centers (certain of the leases provide for the payment of a fixed-rate reimbursement of these such expenses). Although many of the leases require the Company to make roof and structural repairs as needed, a number of tenant leases place that responsibility on the tenant, and the Company's standard small store lease provides for reimbursements by the tenant as part of common area maintenance. Additionally, many of the leases provide for reimbursements by the tenant of capital expenditures.
Minimum base rental revenues and operating expense reimbursements accounted for 97% and other revenues, including percentage rents, accounted for 3% of the Company's total revenues from rental properties for the year ended December 31, 2022. The Company's management believes that the base rent per leased square foot for many of the Company's existing leases is generally lower than the prevailing market-rate base rents in the geographic regions where the Company operates, reflecting the potential for future growth. Additionally, a majority of the Company’s leases have provisions requiring contractual rent increases. The Company’s leases may also include escalation clauses, which provide for increases based upon changes in the consumer price index or similar inflation indices.
As of December 31, 2022, the Company’s consolidated operating portfolio, comprised of 428 shopping center properties aggregating 70.6 million square feet of GLA, was 95.5% leased. The consolidated operating portfolio consists entirely of properties located in the U.S., inclusive of Puerto Rico. For the period of January 1, 2022 to December 31, 2022, the Company increased the average base rent per leased square foot, which includes the impact of tenant concessions, in its consolidated portfolio of open-air shopping centers from $19.05 to $19.60, an increase of $0.55. This increase primarily consists of (i) a $0.28 increase relating to rent step-ups within the portfolio and new leases signed, net of leases vacated, (ii) a $0.17 increase relating to acquisitions and (iii) a $0.10 increase relating to dispositions.
The Company has a total of 8,292 leases in the consolidated operating portfolio. The following table sets forth the aggregate lease expirations for each of the next ten years, assuming no renewal options are exercised. For purposes of the table, the Total Annual Base Rent Expiring represents annualized rental revenue, excluding the impact of straight-line rent, for each lease that expires during the respective year. Amounts in thousands, except for number of leases data:
| Year Ending December 31, | Number of Leases Expiring | Square Feet Expiring | Total Annual Base Rent Expiring | % of Gross Annual Rent | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| (1) | 167 | 469 | $ | 11,527 | 0.9 | % | ||||||||
| 2023 | 867 | 4,771 | $ | 89,735 | 7.2 | % | ||||||||
| 2024 | 1,185 | 7,648 | $ | 146,985 | 11.8 | % | ||||||||
| 2025 | 1,149 | 8,134 | $ | 152,931 | 12.3 | % | ||||||||
| 2026 | 1,071 | 9,563 | $ | 158,673 | 12.7 | % | ||||||||
| 2027 | 1,138 | 9,726 | $ | 175,091 | 14.0 | % | ||||||||
| 2028 | 790 | 7,860 | $ | 141,934 | 11.4 | % | ||||||||
| 2029 | 432 | 3,915 | $ | 73,695 | 5.9 | % | ||||||||
| 2030 | 321 | 2,612 | $ | 58,702 | 4.7 | % | ||||||||
| 2031 | 338 | 2,385 | $ | 54,674 | 4.4 | % | ||||||||
| 2032 | 402 | 2,901 | $ | 56,550 | 4.5 | % |
| (1) | Leases currently under a month-to-month lease or in process of renewal. |
|---|
During 2022, the Company executed 1,696 leases totaling 10.7 million square feet in the Company’s consolidated operating portfolio comprised of 525 new leases and 1,171 renewals and options. The leasing costs associated with these new leases are estimated to aggregate $107.4 million or $39.40 per square foot. These costs include $84.3 million of tenant improvements and $23.1 million of external leasing commissions. The average rent per square foot for (i) new leases was $21.76 and (ii) renewals and options was $18.20. The Company will seek to obtain rents that are higher than amounts within its expiring leases, however, there are many variables and uncertainties which can significantly affect the leasing market at any time; as such, the Company cannot guarantee that future leases will continue to be signed for rents that are equal to or higher than current amounts.
Ground-Leased Properties.
The Company has interests in 40 consolidated shopping center properties that are subject to long-term ground leases where a third party owns and has leased the underlying land to the Company to construct and/or operate a shopping center. The Company pays rent for the use of the land and generally is responsible for all costs and expenses associated with the building and improvements. At the end of these long-term leases, unless extended, the land together with all improvements reverts to the landowner.
More specific information with respect to each of the Company's property interests is set forth in Exhibit 99.1, which is incorporated herein by reference.
Item 3. Legal Proceedings
The Company is not presently involved in any litigation nor, to its knowledge, is any litigation threatened against the Company or its subsidiaries that, in management's opinion, would result in any material effect on the Company's ownership, management or operation of its properties taken as a whole, or which is not covered by the Company's insurance.
Item 4. Mine Safety Disclosures
Item 5. Market for the Registrant's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Market Information: The Company’s common stock is traded on the NYSE under the trading symbol "KIM".
Holders: The number of holders of record of the Company's common stock, par value $0.01 per share, was 2,767 as of January 31, 2023.
Dividends: Since the IPO, the Company has paid regular quarterly cash dividends to its stockholders. While the Company intends to continue paying regular quarterly cash dividends, future dividend declarations will be paid at the discretion of the Board of Directors and will depend on the actual cash flows of the Company, its financial condition, capital requirements, the annual distribution requirements under the REIT provisions of the Code and such other factors as the Board of Directors deems relevant. The Company’s Board of Directors will continue to evaluate the Company’s dividend policy on a quarterly basis as they monitor sources of capital and evaluate operating fundamentals. The Company is required by the Code to distribute at least 90% of its REIT taxable income determined without regard to the dividends paid deduction and excluding any net capital gain. In addition, the Company will be subject to federal income tax at regular corporate rates to the extent that it distributes less than 100% of its net taxable income, including any net capital gains. The actual cash flow available to pay dividends will be affected by a number of factors, including the revenues received from operating properties, the operating expenses of the Company, the interest expense on its borrowings, the ability of lessees to meet their obligations to the Company, the ability to refinance near-term debt maturities and any unanticipated capital expenditures. The following table reflects the income tax status of distributions per share paid to holders of shares of our common stock:
| Year Ended December 31, | ||||||||
|---|---|---|---|---|---|---|---|---|
| 2022 | 2021 | |||||||
| Dividend paid per share | $ | 0.84 | $ | 0.68 | ||||
| Ordinary income | 81 | % | 77 | % | ||||
| Capital gains | 16 | % | 3 | % | ||||
| Return of capital | 3 | % | 20 | % |
In addition to common stock offerings, the Company has capitalized on the growth in its business through the issuance of unsecured fixed rate medium-term notes, underwritten bonds, unsecured bank debt, mortgage debt and perpetual preferred stock. Borrowings under the Company's unsecured revolving credit facility have also been an interim source of funds to both finance the purchase of properties and other investments and meet any short-term working capital requirements. The various instruments governing the Company's issuance of its unsecured public debt, bank debt, mortgage debt and preferred stock impose certain restrictions on the Company regarding dividends, voting, liquidation and other preferential rights available to the holders of such instruments. See "Management's Discussion and Analysis of Financial Condition and Results of Operations" and Footnotes 13, 14 and 19 of the Notes to Consolidated Financial Statements included in this Form 10-K.
The Company does not believe that the preferential rights available to the holders of its Class L Preferred Stock and Class M Preferred Stock, the financial covenants contained in its public bond indentures, as amended, or the credit agreement for its Credit Facility will have an adverse impact on the Company's ability to pay dividends in the normal course to its common stockholders or to distribute amounts necessary to maintain its qualification as a REIT.
The Company maintains a dividend reinvestment and direct stock purchase plan (the "Plan") pursuant to which common and preferred stockholders and other interested investors may elect to automatically reinvest their dividends to purchase shares of the Company’s common stock or, through optional cash payments, purchase shares of the Company’s common stock. The Company may, from time-to-time, either (i) purchase shares of its common stock in the open market or (ii) issue new shares of its common stock for the purpose of fulfilling its obligations under the Plan.
Recent Sales of Unregistered Securities: None.
Issuer Purchases of Equity Securities:
The Company’s Board of Directors had authorized the repurchase of up to 900,000 depositary shares of Class L preferred stock and 1,058,000 depositary shares of Class M preferred stock through December 31, 2022, which represented up to an aggregate of 1,958 shares of the Company’s preferred stock, par value $1.00 per share. During the year ended December 31, 2022, the Company repurchased 54,508 depositary shares of Class L preferred stock and 90,760 depositary shares of Class M preferred stock for a purchase price of $1.3 million and $2.1 million, respectively.
During February 2018, the Company’s Board of Directors authorized a share repurchase program, which is scheduled to expire February 29, 2024. Under this program, the Company may repurchase shares of its common stock, par value $0.01 per share, with an aggregate gross purchase price of up to $300.0 million. The Company did not repurchase any shares under the share repurchase program during the year ended December 31, 2022. As of December 31, 2022, the Company had $224.9 million available under this common share repurchase program.
During the year ended December 31, 2022, the Company repurchased 567,450 shares of the Company’s common stock for an aggregate purchase price of $13.7 million (weighted average price of $24.11 per share) in connection with common shares surrendered or deemed surrendered to the Company to satisfy statutory minimum tax withholding obligations in connection with equity-based compensation plans.
The following table presents information regarding the shares of common stock repurchased by the Company during the three months ended December 31, 2022.
| Period | Total Number of Shares Purchased | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Approximate Dollar Value of Shares that May Yet Be Purchased Under the Plans or Programs (in millions) | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| October 1, 2022 – October 31, 2022 | 1,791 | $ | 18.63 | - | $ | 224.9 | ||||||||||
| November 1, 2022 – November 30, 2022 | - | - | - | $ | 224.9 | |||||||||||
| December 1, 2022 – December 31, 2022 | 4,472 | 21.49 | - | $ | 224.9 | |||||||||||
| Total | 6,263 | $ | 20.67 | - |
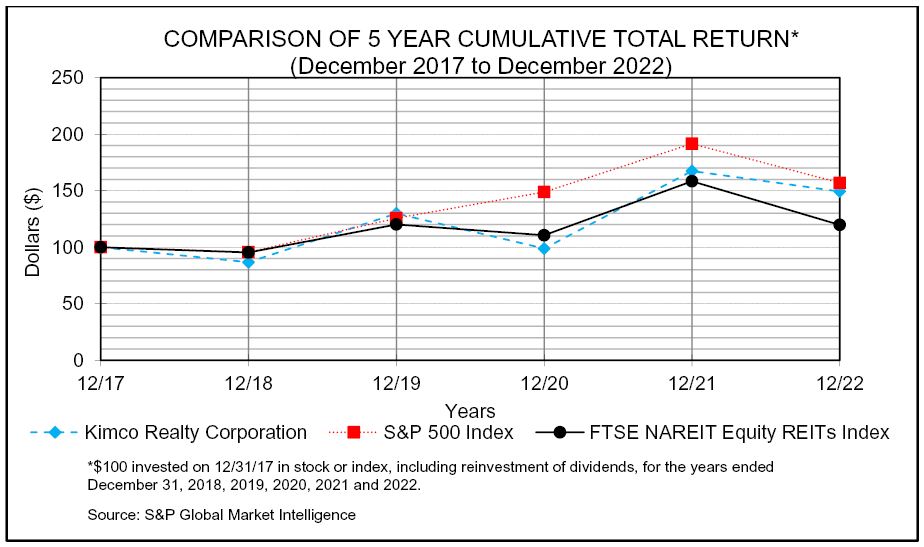
Total Stockholder Return Performance: The following performance chart compares, over the five years ended December 31, 2022, the cumulative total stockholder return on the Company’s common stock with the cumulative total return of the S&P 500 Index and the cumulative total return of the NAREIT Equity REITs Index (the “NAREIT Equity REITs”) prepared and published by the National Association of Real Estate Investment Trusts (“NAREIT”). The NAREIT Equity REITs Index is a free-float adjusted, market capitalization-weighted index of U.S. equity REITs. Constituents of the index include all tax-qualified REITs with more than 50% of total assets in qualifying real estate assets other than mortgages secured by real property.
Stockholder return performance, presented annually for the five years ended December 31, 2022, is not necessarily indicative of future results. All stockholder return performance assumes the reinvestment of dividends. The information in this paragraph and the following performance chart are deemed to be furnished, not filed.
| Comparison of 5 year cumulative total return data points | ||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Dec-17 | Dec-18 | Dec-19 | Dec-20 | Dec-21 | Dec-22 | |||||||||||||||||||
| Kimco Realty Corporation | $ | 100 | $ | 87 | $ | 130 | $ | 99 | $ | 167 | $ | 149 | ||||||||||||
| S&P 500 | $ | 100 | $ | 96 | $ | 126 | $ | 149 | $ | 192 | $ | 157 | ||||||||||||
| NAREIT Equity REITs | $ | 100 | $ | 95 | $ | 120 | $ | 111 | $ | 158 | $ | 120 |
Item 6. Reserved
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
The following discussion should be read in conjunction with the Consolidated Financial Statements and Notes thereto included in this Form 10-K. Historical results and percentage relationships set forth in the Consolidated Statements of Income contained in the Consolidated Financial Statements, including trends, should not be taken as indicative of future operations.
The Consolidated Financial Statements of the Company include the accounts of the Company, its wholly owned subsidiaries and all entities in which the Company has a controlling interest, including where the Company has been determined to be a primary beneficiary of a variable interest entity in accordance with the consolidation guidance of the FASB Accounting Standards Codification. The Company applies these provisions to each of its joint venture investments to determine whether the cost, equity or consolidation method of accounting is appropriate. The Company evaluates performance on a property specific or transactional basis and does not distinguish its principal business or group its operations on a geographical basis for purposes of measuring performance. Accordingly, the Company believes it has a single reportable segment for disclosure purposes in accordance with accounting principles generally accepted in the United States of America (“GAAP”).
Critical Accounting Estimates
The preparation of financial statements in conformity with GAAP requires management to make estimates and assumptions in certain circumstances that affect amounts reported in the accompanying Consolidated Financial Statements and related notes. In preparing these financial statements, management has made its best estimates and assumptions that affect the reported amounts of assets and liabilities. These estimates are based on, but not limited to, historical results, industry standards and current economic conditions, giving due consideration to materiality. The Company’s significant accounting policies are more fully described in Footnote 1 to the Consolidated Financial Statements. The Company is required to make subjective assessments, of which, the most significant assumptions and estimates relate to the recoverability of trade accounts receivable, depreciable lives, valuation of real estate and intangible assets and liabilities, and valuation of joint venture investments and other investments. The Company’s reported net earnings are directly affected by management’s estimate of impairments. Application of these assumptions requires the exercise of judgment as to future uncertainties, and, as a result, actual results could materially differ from these estimates.
Trade Accounts Receivable
The Company reviews its trade accounts receivable, related to base rents, straight-line rent, expense reimbursements and other revenues for collectability. The Company evaluates the probability of the collection of the lessee’s total accounts receivable, including the corresponding straight-line rent receivable balance on a lease-by-lease basis. Determining the probability of collection of substantially all lease payments during a lease term requires significant judgment. The Company’s analysis of its accounts receivable included (i) customer credit worthiness, (ii) assessment of risk associated with the tenant, and (iii) current economic trends. In addition, tenants in bankruptcy are analyzed and considerations are made in connection with the expected recovery of pre-petition and post-petition bankruptcy claims. The Company includes provision for doubtful accounts in Revenues from rental properties, net. If a lessee’s accounts receivable balance is considered uncollectible, the Company will write-off the receivable balances associated with the lease and will only recognize lease income on a cash basis. In addition to the lease-specific collectability assessment, the analysis also recognizes a general reserve, as a reduction to Revenues from rental properties, for its portfolio of operating lease receivables which are not expected to be fully collectible based on the Company’s historical and current collection experience and the potential for settlement of arrears. Although the Company estimates uncollectible receivables and provides for them through charges against Revenues from rental properties, actual results may differ from those estimates. For example, in the event that the Company’s collectability determinations are not accurate, and we are required to write off additional receivables equaling 1% of the outstanding accounts receivable balance at December 31, 2022, the Company’s rental income and net income would decrease by $3.0 million for the year ended December 31, 2022. If the Company subsequently determines that it is probable it will collect the remaining lessee’s lease payments under the lease term, any outstanding lease receivables (including straight-line rent receivables) are reinstated with a corresponding increase to rental income.
Real Estate
Valuation of Real Estate, and Intangible Assets and Liabilities
The Company’s investments in real estate properties are stated at cost, less accumulated depreciation and amortization. Expenditures for maintenance and repairs are charged to operations as incurred. Significant renovations and replacements, which improve and extend the life of the asset, are capitalized.
Transaction costs related to acquisitions that qualify as asset acquisitions are capitalized as part of the cost basis of the acquired assets, while transaction costs for acquisitions that are deemed to be business combinations are expensed as incurred. Also, upon acquisition of real estate operating properties in either an asset acquisition or business combination, the Company estimates the fair value of acquired tangible assets (consisting of land, building, building improvements and tenant improvements) and identified intangible assets and liabilities (consisting of above and below-market leases, in-place leases, and tenant relationships, where applicable), assumed debt and redeemable units issued at the date of acquisition, based on evaluation of information and estimates available at that date. Fair value is determined based on a market approach, which contemplates the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date.
Depreciation and amortization are provided on the straight-line method over the estimated useful lives of the assets, as follows:
| Buildings and building improvements (in years) | 5 to 50 | |
|---|---|---|
| Fixtures, leasehold and tenant improvements (including certain identified intangible assets) | Terms of leases or useful lives, whichever is shorter |
The Company is required to make subjective assessments as to the useful lives of its properties for purposes of determining the amount of depreciation to reflect on an annual basis with respect to those properties. These assessments have a direct impact on the Company’s net earnings.
During 2022, the Company acquired properties for a total purchase price of $524.9 million. $8.4 million, or less than 1.6% of the total purchase price, was allocated to above-market leases and $24.1 million, or 4.6% was allocated to below-market leases. If the amounts allocated in 2022 to above-market and below-market leases were each reduced by 1% of the total purchase price, the net annual market lease amortization through rental income would decrease by $0.9 million (using the weighted average life of above-market and below-market leases at each respective acquired property).
On a continuous basis, management assesses whether there are any indicators, including property operating performance, changes in anticipated holding period, general market conditions and delays of development, that the value of the real estate properties (including any related amortizable intangible assets or liabilities) may be impaired.
Showing the first 8K of 84K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
The Company’s primary market risk exposure is interest rate risk. The Company periodically evaluates its exposure to short-term interest rates and will, from time-to-time, enter into interest rate protection agreements which mitigate, but do not eliminate, the effect of changes in interest rates on its floating-rate debt. The Company has not entered, and does not plan to enter, into any derivative financial instruments for trading or speculative purposes. The following table presents the Company’s aggregate fixed rate and variable rate debt obligations outstanding, including fair market value adjustments and unamortized deferred financing costs, as of December 31, 2022, with corresponding weighted-average interest rates sorted by maturity date. The table does not include extension options where available (amounts in millions).
| 2023 | 2024 | 2025 | 2026 | 2027 | Thereafter | Total | Fair Value | |||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Secured Debt | ||||||||||||||||||||||||||||||||
| Fixed Rate | $ | 12.0 | $ | 14.9 | $ | 53.0 | $ | - | $ | 34.3 | $ | 244.4 | $ | 358.6 | $ | 293.8 | ||||||||||||||||
| Average Interest Rate | 3.23 | % | 4.87 | % | 3.50 | % | - | 4.01 | % | 4.23 | % | 4.10 | % | |||||||||||||||||||
| Variable Rate | $ | - | $ | - | $ | 18.3 | $ | - | $ | - | $ | - | $ | 18.3 | $ | 17.9 | ||||||||||||||||
| Average Interest Rate | - | - | 5.43 | % | - | - | - | 5.43 | % | |||||||||||||||||||||||
| Unsecured Debt | ||||||||||||||||||||||||||||||||
| Fixed Rate | $ | - | $ | 654.3 | $ | 752.9 | $ | 785.4 | $ | 436.8 | $ | 4,151.6 | $ | 6,781.0 | $ | 5,837.4 | ||||||||||||||||
| Average Interest Rate | - | 3.37 | % | 3.48 | % | 3.06 | % | 4.03 | % | 3.47 | % | 3.45 | % |
Based on the Company’s variable-rate debt balances, interest expense would have increased by $0.2 million for the year ended December 31, 2022, if short-term interest rates were 1.0% higher.
Item 8. Financial Statements and Supplementary Data
The response to this Item 8 is included in our audited Consolidated Financial Statements and Notes to Consolidated Financial Statements, which are contained in Part IV, Item 15 of this Form 10-K.
Item 9. Changes in and Disagreements With Accountants on Accounting and Financial Disclosure
None.
Item 9A. Controls and Procedures
Evaluation of Disclosure Controls and Procedures
The Company’s management, with the participation of the Company’s Chief Executive Officer and Chief Financial Officer, has evaluated the effectiveness of the Company’s disclosure controls and procedures (as such term is defined in Rules 13a-15(e) and 15d-15(e) under the Exchange Act) as of the end of the period covered by this report. Based on such evaluation, the Company’s Chief Executive Officer and Chief Financial Officer have concluded that the Company’s disclosure controls and procedures are effective as of December 31, 2022.
Changes in Internal Control Over Financial Reporting
There have not been any changes in the Company’s internal control over financial reporting (as such term is defined in Rules 13a-15(f) and 15d-15(f) under the Exchange Act) during the fourth fiscal quarter ended December 31, 2022, that have materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.
Management’s Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Exchange Act Rule 13a-15(f) and 15d-15(f). Under the supervision and with the participation of our management, including our Chief Executive Officer and Chief Financial Officer, we conducted an evaluation of the effectiveness of our internal control over financial reporting based on the framework in the Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission. Based on our evaluation under the framework in Internal Control - Integrated Framework (2013), our management concluded that our internal control over financial reporting was effective as of December 31, 2022.
The effectiveness of our internal control over financial reporting as of December 31, 2022 has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report which appears under Item 8.
Item 9B. Other Information
Director and Officer Indemnification Agreements
On or about February 23, 2023, the Company entered into, or will enter into, new indemnification agreements with each of its directors and executive officers (each, an “Indemnitee”). The indemnification agreements provide that the Company will indemnify the Indemnitee, in each case, against certain expenses and costs arising out of claims to which he or she becomes subject in connection with his or her service to the Company. The indemnification agreements contain customary terms and conditions and establish certain customary procedures and presumptions.
The above description of the indemnification agreements does not purport to be complete and is qualified in its entirety by reference to the Form of Indemnification Agreement filed as Exhibit 10.19 hereto and incorporated herein by reference.
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
Item 10. Directors, Executive Officers and Corporate Governance
The information required by this item is incorporated by reference to “Proposal 1—Election of Directors,” “Governance at Kimco,” “Officers,” “Other Matters” and if required, “Delinquent Section 16(a) Reports” in our definitive proxy statement to be filed with respect to the Annual Meeting of Stockholders expected to be held on April 25, 2023 (“Proxy Statement”).
We have adopted a Code of Conduct that applies to all directors, officers and employees, including our principal executive officer, principal financial officer and principal accounting officer. The Code of Conduct is available at the Investors/Governance/Governance Documents section of our website at www.kimcorealty.com. A copy of the Code of Conduct is available in print, free of charge, to stockholders upon request to us at the address set forth in Item 1 of this Form 10-K under the section “Business - Overview.” We intend to satisfy the disclosure requirements under the Exchange Act, as amended, regarding an amendment to or waiver from a provision of our Code of Conduct by posting such information on our website.
Item 11. Executive Compensation
The information required by this item is incorporated by reference to “Compensation Discussion and Analysis,” “Executive Compensation Committee Report,” “ Executive Compensation Tables,” “Governance at Kimco” and “Other Matters” in our Proxy Statement.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
The information required by this item is incorporated by reference to “Beneficial Ownership” and “Executive Compensation” in our Proxy Statement.
Item 13. Certain Relationships and Related Transactions, and Director Independence
The information required by this item is incorporated by reference to “Certain Relationships and Related Transactions” and “Governance at Kimco” in our Proxy Statement.
Item 14. Principal Accountant Fees and Services
Item 15. Exhibits and Financial Statement Schedules
Item 16. Form 10-K Summary
None.
- Filed herewith
** Furnished herewith
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| KIMCO REALTY CORPORATION | |||
|---|---|---|---|
| By: | /s/ Conor C. Flynn | ||
| Conor C. Flynn | |||
| Chief Executive Officer |
Dated: February 24, 2023
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| Signature | Title | Date | |
|---|---|---|---|
| /s/ Milton Cooper | Executive Chairman of the Board of Directors | February 24, 2023 | |
| Milton Cooper | |||
| /s/ Conor C. Flynn | Chief Executive Officer and Director | February 24, 2023 | |
| Conor C. Flynn | |||
| /s/ Frank Lourenso | Director | February 24, 2023 | |
| Frank Lourenso | |||
| /s/ Richard Saltzman | Director | February 24, 2023 | |
| Richard Saltzman | |||
| /s/ Philip Coviello | Director | February 24, 2023 | |
| Philip Coviello | |||
| /s/ Mary Hogan Preusse | Director | February 24, 2023 | |
| Mary Hogan Preusse | |||
| /s/ Valerie Richardson | Director | February 24, 2023 | |
| Valerie Richardson | |||
| /s/ Henry Moniz | Director | February 24, 2023 | |
| Henry Moniz | |||
| /s/ Glenn G. Cohen | Executive Vice President - | February 24, 2023 | |
| Glenn G. Cohen | Chief Financial Officer and Treasurer | ||
| /s/ Paul Westbrook | Vice President - | February 24, 2023 | |
| Paul Westbrook | Chief Accounting Officer |
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| KIMCO REALTY OP, LLC | |||
|---|---|---|---|
| BY: | KIMCO REALTY CORPORATION, managing member | ||
| By: | /s/ Conor C. Flynn | ||
| Conor C. Flynn | |||
| Chief Executive Officer |
Dated: February 24, 2023
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following directors and officers of Kimco Realty Corporation, the managing member of the registrant, and in the capacities and on the dates indicated.
| Signature | Title | Date | |
|---|---|---|---|
| /s/ Milton Cooper | Executive Chairman of the Board of Directors | February 24, 2023 | |
| Milton Cooper | |||
| /s/ Conor C. Flynn | Chief Executive Officer and Director | February 24, 2023 | |
| Conor C. Flynn | |||
| /s/ Frank Lourenso | Director | February 24, 2023 | |
| Frank Lourenso | |||
| /s/ Richard Saltzman | Director | February 24, 2023 | |
| Richard Saltzman | |||
| /s/ Philip Coviello | Director | February 24, 2023 | |
| Philip Coviello | |||
| /s/ Mary Hogan Preusse | Director | February 24, 2023 | |
| Mary Hogan Preusse | |||
| /s/ Valerie Richardson | Director | February 24, 2023 | |
| Valerie Richardson | |||
| /s/ Henry Moniz | Director | February 24, 2023 | |
| Henry Moniz | |||
| /s/ Glenn G. Cohen | Executive Vice President - | February 24, 2023 | |
| Glenn G. Cohen | Chief Financial Officer and Treasurer | ||
| /s/ Paul Westbrook | Vice President - | February 24, 2023 | |
| Paul Westbrook | Chief Accounting Officer |
ANNUAL REPORT ON FORM 10-K
Item 8. , ITEM 15 (a) (1) and (2)
INDEX TO FINANCIAL STATEMENTS
AND
FINANCIAL STATEMENT SCHEDULES
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Stockholders of Kimco Realty Corporation
Opinions on the Financial Statements and Internal Control over Financial Reporting
We have audited the consolidated financial statements, including the related notes, as listed in the index appearing under Item 15(a)(1), and the financial statement schedules listed in the index appearing under Item 15(a)(2), of Kimco Realty Corporation and its subsidiaries (the “Company”) (collectively referred to as the “consolidated financial statements”). We also have audited the Company's internal control over financial reporting as of December 31, 2022, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, 2022 and 2021, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2022 in conformity with accounting principles generally accepted in the United States of America. Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2022, based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
Basis for Opinions
The Company's management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting, included in Management’s Report on Internal Control Over Financial Reporting appearing under Item 9A. Our responsibility is to express opinions on the Company’s consolidated financial statements and on the Company's internal control over financial reporting based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud, and whether effective internal control over financial reporting was maintained in all material respects.
Our audits of the consolidated financial statements included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.
Definition and Limitations of Internal Control over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Critical Audit Matters
The critical audit matter communicated below is a matter arising from the current period audit of the consolidated financial statements that was communicated or required to be communicated to the audit committee and that (i) relates to accounts or disclosures that are material to the consolidated financial statements and (ii) involved our especially challenging, subjective, or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
Analysis of Real Estate Properties for Indicators of Impairment
As described in Notes 1 and 6 to the consolidated financial statements, the net carrying value of the Company’s real estate net was $15.0 billion. On a continuous basis, management assesses whether there are indicators, including proper
Showing the first 8K of 362K characters. Open the full section