 filings.tools
Item 1. BUSINESS
123K characters. Original on sec.gov · Markdown
Item 1. BUSINESS
Overview
We are a leading global investment firm that manages investments across multiple asset classes including private equity, energy, infrastructure, real estate, credit and hedge funds. We aim to generate attractive investment returns by following a patient and disciplined investment approach, employing world‑class people, and driving growth and value creation in the assets we manage. We invest our own capital alongside the capital we manage for fund investors and bring debt and equity investment opportunities to others through our capital markets business.
Our business offers a broad range of investment management services to our fund investors and provides capital markets services to our firm, our portfolio companies and third parties. Throughout our history, we have consistently been a leader in the private equity industry, having completed more than 260 private equity investments in portfolio companies with a total transaction value in excess of $515 billion. We have grown our firm by expanding our geographical presence and building businesses in areas, such as credit, special situations, hedge funds, collateralized loan obligations (“CLOs”), capital markets, infrastructure, energy and real estate. Our balance sheet has provided a significant source of capital in the growth and expansion of our business, and has allowed us to further align our interests with those of our fund investors. These efforts build on our core principles and industry expertise, allowing us to leverage the intellectual capital and synergies in our businesses, and to capitalize on a broader range of the opportunities we source. Additionally, we have increased our focus on meeting the needs of our existing fund investors and in developing relationships with new investors in our funds.
We conduct our business with offices throughout the world, providing us with a pre‑eminent global platform for sourcing transactions, raising capital and carrying out capital markets activities. Our growth has been driven by value that we have created through our operationally focused investment approach, the expansion of our existing businesses, our entry into new lines of business, innovation in the products that we offer investors in our funds, an increased focus on providing tailored solutions to our clients and the integration of capital markets distribution activities.
As a global investment firm, we earn management, monitoring, transaction, incentive fees and carried interest for providing investment management, monitoring and other services to our funds, vehicles, CLOs, managed accounts and portfolio companies, and we generate transaction‑specific income from capital markets transactions. We earn additional investment income from investing our own capital alongside that of our fund investors, from other assets on our balance sheet and from the carried interest we receive from our funds and certain of our other investment vehicles. A carried interest entitles the sponsor of a fund to a specified percentage of investment gains that are generated on third‑party capital that is invested.
Our investment teams have deep industry knowledge and are supported by a substantial and diversified capital base, an integrated global investment platform, the expertise of operating consultants and senior advisors and a worldwide network of business relationships that provide a significant source of investment opportunities, specialized knowledge during due diligence and substantial resources for creating and realizing value for stakeholders. These teams invest capital, a substantial portion of which is of a long duration and not subject to redemption. With over 75% of our fee paying assets under management not subject to redemption for at least 8 years from inception, we have significant flexibility to grow investments and select exit opportunities. We believe that these aspects of our business will help us continue to expand and grow our business and deliver strong investment performance in a variety of economic and financial conditions.
Our Firm
With offices around the world, we have established ourselves as a leading global investment firm. We have multilingual and multicultural investment teams with local market knowledge and significant business, investment, and operational experience in the countries in which we invest. We believe that our global capabilities have helped us to raise capital, capture a greater number of investment opportunities, and assist our portfolio companies in their increasing reliance on global markets and sourcing, while enabling us to diversify our operations.
Though our operations span multiple continents and asset classes, our investment professionals are supported by an integrated infrastructure and operate under a common set of principles and business practices that are monitored by a variety of committees. The firm operates with a single culture that rewards investment discipline, creativity, determination, and patience and the sharing of information, resources, expertise, and best practices across offices and asset classes. When appropriate, we staff transactions across multiple offices and businesses in order to take advantage of the industry‑ specific expertise of our investment professionals, and we hold regular meetings in which investment professionals throughout our offices share their
knowledge and experiences. We believe that the ability to draw on the local cultural fluency of our investment professionals while maintaining a centralized and integrated global infrastructure distinguishes us from other investment firms and has been a substantial contributing factor to our ability to raise funds, invest internationally and expand our businesses.
Since our inception, one of our fundamental philosophies has been to align the interests of the firm and our principals with the interests of our fund investors, portfolio companies and other stakeholders. We achieve this by putting our own capital behind our ideas. As of December 31, 2015, we and our employees and other personnel have approximately $12.3 billion invested in or committed to our own funds and portfolio companies, including $8.9 billion funded through our balance sheet, $1.4 billion of additional commitments from our balance sheet to investment funds, $1.0 billion in personal investments and $1.0 billion of additional commitments from personal investments.
Our Segments
Private Markets
Through our Private Markets segment, we manage and sponsor a group of private equity funds and co-investment vehicles that invest capital for long-term appreciation, either through controlling ownership of a company or strategic minority positions. We also manage and sponsor a group of funds and co-investment vehicles that invest capital in real assets, such as infrastructure, energy and real estate. These funds, vehicles and accounts are managed by Kohlberg Kravis Roberts & Co. L.P., an SEC registered investment adviser. As of December 31, 2015, the segment had $66.0 billion of AUM and FPAUM of $45.3 billion, consisting of $34.9 billion in private equity and $10.4 billion in real assets (including infrastructure, energy and real estate) and other strategies. Prior to 2010, FPAUM in the Private Markets segment consisted entirely of private equity funds.
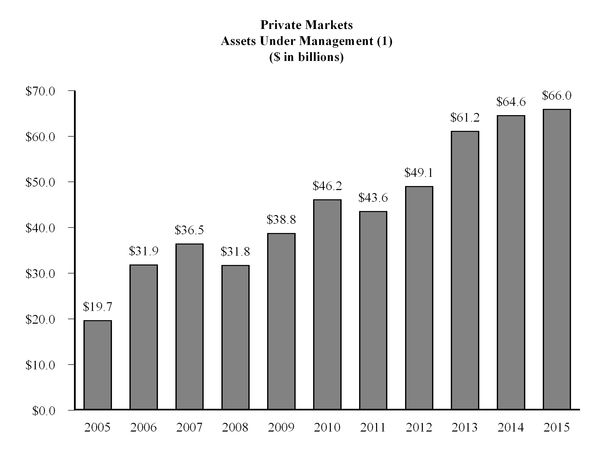
| (1) | For the years 2006 through 2008, assets under management are presented pro forma for the KPE Transaction, and therefore, exclude the net asset value of KPE and its former commitments to our investment funds. AUM as of and after December 31, 2014 has been adjusted to include capital commitments for which we are eligible to receive fees or carried interest upon deployment of capital. This item increased our AUM by approximately $3.1 billion as of December 31, 2014 but is excluded from AUM for all prior years presented. |
The table below presents information as of December 31, 2015 relating to our current private equity funds and other investment vehicles for which we have the ability to earn carried interest. This data does not reflect acquisitions or disposals of investments, changes in investment values or distributions occurring after December 31, 2015.
| Investment Period (1) | Amount ($ in millions) | |||||||||||||||||||||
| Commencement Date | End Date | Commitment (2) | Uncalled Commitments | Percentage Committed by General Partner | Invested | Realized | Remaining Cost (3) | Remaining Fair Value | ||||||||||||||
| Private Markets | ||||||||||||||||||||||
| Private Equity Funds | ||||||||||||||||||||||
| European Fund IV | 12/2014 | 12/2020 | $ | 3,468.0 | $ | 3,307.1 | 5.7% | $ | 160.9 | $ | — | $ | 160.9 | $ | 185.7 | |||||||
| Asian Fund II | 4/2013 | 4/2019 | 5,825.0 | 3,979.3 | 1.3% | 2,599.7 | 753.9 | 1,845.8 | 3,163.6 | |||||||||||||
| North America Fund XI | 9/2012 | 9/2018 | 8,718.4 | 3,704.0 | 2.9% | 5,932.1 | 1,733.8 | 4,635.4 | 6,983.8 | |||||||||||||
| China Growth Fund | 11/2010 | 11/2016 | 1,010.0 | 307.6 | 1.0% | 702.4 | 283.4 | 544.4 | 713.4 | |||||||||||||
| E2 Investors (Annex Fund) | 8/2009 | 11/2013 | 195.8 | — | 4.9% | 195.8 | 195.7 | 18.1 | 10.3 | |||||||||||||
| European Fund III | 3/2008 | 3/2014 | 6,121.8 | 812.1 | 4.6% | 5,309.7 | 4,447.2 | 3,224.2 | 4,240.2 | |||||||||||||
| Asian Fund | 7/2007 | 4/2013 | 3,983.3 | 129.5 | 2.5% | 3,853.8 | 5,397.4 | 1,918.7 | 2,534.0 | |||||||||||||
| 2006 Fund | 9/2006 | 9/2012 | 17,642.2 | 525.6 | 2.1% | 17,116.6 | 18,411.5 | 7,703.3 | 13,028.5 | |||||||||||||
| European Fund II | 11/2005 | 10/2008 | 5,750.8 | — | 2.1% | 5,750.8 | 6,611.1 | 825.0 | 2,003.2 | |||||||||||||
| Millennium Fund | 12/2002 | 12/2008 | 6,000.0 | — | 2.5% | 6,000.0 | 12,517.4 | 714.0 | 1,521.1 | |||||||||||||
| European Fund | 12/1999 | 12/2005 | 3,085.4 | — | 3.2% | 3,085.4 | 8,748.0 | — | 17.1 | |||||||||||||
| Total Private Equity Funds | 61,800.7 | 12,765.2 | 50,707.2 | 59,099.4 | 21,589.8 | 34,400.9 | ||||||||||||||||
| Co-Investment Vehicles | Various | Various | 5,774.0 | 2,709.6 | Various | 3,137.4 | 2,511.0 | 2,118.0 | 2,865.8 | |||||||||||||
| Total Private Equity | 67,574.7 | 15,474.8 | 53,844.6 | 61,610.4 | 23,707.8 | 37,266.7 | ||||||||||||||||
| Real Assets | ||||||||||||||||||||||
| Energy Income and Growth Fund | 9/2013 | 9/2018 | 1,974.2 | 1,142.6 | 12.8% | 831.6 | 143.9 | 757.1 | 544.3 | |||||||||||||
| Natural Resources Fund | Various | Various | 887.4 | 2.9 | Various | 884.5 | 96.6 | 809.9 | 200.1 | |||||||||||||
| Global Energy Opportunities | Various | Various | 1,026.4 | 808.7 | Various | 252.7 | 55.0 | 144.8 | 124.7 | |||||||||||||
| Global Infrastructure Investors | 9/2011 | 10/2014 | 1,039.9 | 100.9 | 4.8% | 967.0 | 216.4 | 847.8 | 972.7 | |||||||||||||
| Global Infrastructure Investors II | 10/2014 | 10/2020 | 3,028.3 | 2,685.7 | 4.1% | 346.5 | 8.9 | 338.9 | 354.0 | |||||||||||||
| Infrastructure Co-Investments | Various | Various | 1,125.0 | — | Various | 1,125.0 | 377.9 | 1,124.4 | 1,520.1 | |||||||||||||
| Real Estate Partners Americas | 5/2013 | 12/2016 | 1,229.1 | 598.2 | 16.3% | 777.5 | 314.5 | 630.5 | 740.7 | |||||||||||||
| Real Estate Partners Europe | 9/2015 | (4) | 591.3 | 591.3 | 10.9% | — | — | — | — | |||||||||||||
| Real Assets | 10,901.6 | 5,930.3 | 5,184.8 | 1,213.2 | 4,653.4 | 4,456.6 | ||||||||||||||||
| Unallocated Commitments | 1,361.2 | 1,361.2 | Various | — | — | — | — | |||||||||||||||
| Private Markets Total | $ | 79,837.5 | $ | 22,766.3 | $ | 59,029.4 | $ | 62,823.6 | $ | 28,361.2 | $ | 41,723.3 |
| (1) | The commencement date represents the date on which the general partner of the applicable fund commenced investment of the fund’s capital or the date of the first closing. The end date represents the earlier of (i) the date on which the general partner of the applicable fund was or will be required by the fund’s governing agreement to cease making investments on behalf of the fund, unless extended by a vote of the fund investors or (ii) the date on which the last investment was made. |
| (2) | The commitment represents the aggregate capital commitments to the fund, including capital commitments by third-party fund investors and the general partner. Foreign currency commitments have been converted into U.S. dollars based on (i) the foreign exchange rate at the date of purchase for each investment and (ii) the exchange rate that prevailed on December 31, 2015, in the case of uncalled commitments. |
| (3) | The remaining cost represents the initial investment of the general partner and limited partners, with the limited partners’ investment reduced for any return of capital and realized gains from which the general partner did not receive a carried interest. |
| (4) | Four years from final close. |
Performance
We take a long‑term approach to Private Markets investing and measure the success of our investments over a period of years rather than months. Given the duration of these investments, the firm focuses on realized multiples of invested capital and IRRs when deploying capital in these transactions. We have more than doubled the value of capital that we have invested in our Private Markets investment funds, turning $71.0 billion of capital into $147.4 billion of value from our inception in 1976 to December 31, 2015. Over this same period, the value of capital that we have invested in our Private Markets investment funds and that has been realized and partially realized has grown from $51.1 billion to $126.5 billion.
Amount Invested and Total Value for
Private Markets Investment Funds
As of December 31, 2015
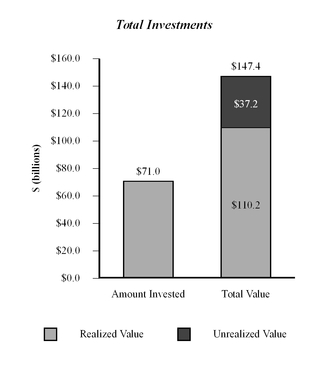

From our inception in 1976 through December 31, 2015, our investment funds with at least 36 months of investment activity generated a cumulative gross IRR of 25.6%, compared to the 11.7% and 8.7% gross IRR achieved by the S&P 500 Index and MSCI World Index, respectively, over the same period, despite the cyclical and sometimes challenging environments in which we have operated. The S&P 500 Index and MSCI World Index are unmanaged indices and such returns assume reinvestment of distributions and do not reflect any fees or expenses. Our past performance, however, may not be representative of performance in any given period. For example, as of March 31, 2009, the date of the lowest aggregate valuation of our private equity funds during the most recent downturn, the investments in certain of our private equity funds at the time were marked down to 67% of original cost. For additional information regarding impact of market conditions on the value and performance of our investments, see “Risk Factors-Risks Related to Our Business-Difficult market conditions can adversely affect our business in many ways, including by reducing the value or performance of the investments that we manage or by reducing the ability of our funds to raise or deploy capital, each of which could negatively impact our net income and cash flow and adversely affect our financial condition.” and “-Risks Related to the Assets We Manage-The historical returns attributable to our funds, including those presented in this report, should not be considered as indicative of the future results of our funds or of our future results or of any returns on our common units.”
The tables below present information as of December 31, 2015 relating to the historical performance of certain of our Private Markets investment vehicles since inception, which we believe illustrates the benefits of our investment approach. The information presented under Total Investments includes all of the investments made by the specified investment vehicle, while the information presented under Realized/Partially Realized Investments includes only those investments that have been disposed of or have otherwise generated disposition proceeds or current income including dividends that has been distributed
by the relevant fund. This data does not reflect additional capital raised since December 31, 2015 or acquisitions or disposals of investments, changes in investment values or distributions occurring after that date. Past performance is no guarantee of future results.
| Amount | Fair Value of Investments | ||||||||||||||||||||||||
| Private Markets Investment Funds | Commitment | Invested (5) | Realized (5) | Unrealized | Total Value | Gross IRR (5) | Net IRR (5) | Multiple of Invested Capital (5) | |||||||||||||||||
| ($ in millions) | |||||||||||||||||||||||||
| Total Investments | |||||||||||||||||||||||||
| Legacy Funds (1) | |||||||||||||||||||||||||
| 1976 Fund | $ | 31.4 | $ | 31.4 | $ | 537.2 | $ | — | $ | 537.2 | 39.5 | % | 35.5 | % | 17.1 | ||||||||||
| 1980 Fund | 356.8 | 356.8 | 1,827.8 | — | 1,827.8 | 29.0 | % | 25.8 | % | 5.1 | |||||||||||||||
| 1982 Fund | 327.6 | 327.6 | 1,290.7 | — | 1,290.7 | 48.1 | % | 39.2 | % | 3.9 | |||||||||||||||
| 1984 Fund | 1,000.0 | 1,000.0 | 5,963.5 | — | 5,963.5 | 34.5 | % | 28.9 | % | 6.0 | |||||||||||||||
| 1986 Fund | 671.8 | 671.8 | 9,080.7 | — | 9,080.7 | 34.4 | % | 28.9 | % | 13.5 | |||||||||||||||
| 1987 Fund | 6,129.6 | 6,129.6 | 14,949.2 | — | 14,949.2 | 12.1 | % | 8.9 | % | 2.4 | |||||||||||||||
| 1993 Fund | 1,945.7 | 1,945.7 | 4,143.3 | — | 4,143.3 | 23.6 | % | 16.8 | % | 2.1 | |||||||||||||||
| 1996 Fund | 6,011.6 | 6,011.6 | 12,476.9 | — | 12,476.9 | 18.0 | % | 13.3 | % | 2.1 | |||||||||||||||
| Subtotal - Legacy Funds | 16,474.5 | 16,474.5 | 50,269.3 | — | 50,269.3 | 26.1 | % | 19.9 | % | 3.1 | |||||||||||||||
| Included Funds | |||||||||||||||||||||||||
| European Fund (1999) (2) | 3,085.4 | 3,085.4 | 8,748.0 | 17.1 | 8,765.1 | 26.9 | % | 20.2 | % | 2.8 | |||||||||||||||
| Millennium Fund (2002) | 6,000.0 | 6,000.0 | 12,517.4 | 1,521.1 | 14,038.5 | 22.2 | % | 16.3 | % | 2.3 | |||||||||||||||
| European Fund II (2005) (2) | 5,750.8 | 5,750.8 | 6,611.1 | 2,003.2 | 8,614.3 | 6.4 | % | 4.7 | % | 1.5 | |||||||||||||||
| 2006 Fund (2006) | 17,642.2 | 17,116.6 | 18,411.5 | 13,028.5 | 31,440.0 | 11.6 | % | 8.9 | % | 1.8 | |||||||||||||||
| Asian Fund (2007) | 3,983.3 | 3,853.8 | 5,397.4 | 2,534.0 | 7,931.4 | 18.7 | % | 13.5 | % | 2.1 | |||||||||||||||
| European Fund III (2008) (2) | 6,121.8 | 5,309.7 | 4,447.2 | 4,240.2 | 8,687.4 | 15.2 | % | 9.6 | % | 1.6 | |||||||||||||||
| E2 Investors (Annex Fund) (2009) (2) | 195.8 | 195.8 | 195.7 | 10.3 | 206.0 | 1.5 | % | 1.1 | % | 1.1 | |||||||||||||||
| China Growth Fund (2010) | 1,010.0 | 702.4 | 283.4 | 713.4 | 996.8 | 15.1 | % | 8.0 | % | 1.4 | |||||||||||||||
| Natural Resources Fund (2010) | 887.4 | 884.5 | 96.6 | 200.1 | 296.7 | (45.8 | )% | (48.5 | )% | 0.3 | |||||||||||||||
| Global Infrastructure Investors (2011) (2) | 1,039.9 | 967.0 | 216.4 | 972.7 | 1,189.1 | 9.1 | % | 7.6 | % | 1.2 | |||||||||||||||
| North America Fund XI (2012) | 8,718.4 | 5,932.1 | 1,733.8 | 6,983.8 | 8,717.6 | 26.4 | % | 19.5 | % | 1.5 | |||||||||||||||
| Asian Fund II (2013) (3) | 5,825.0 | 2,599.7 | 753.9 | 3,163.6 | 3,917.5 | N/A | N/A | N/A | |||||||||||||||||
| Real Estate Partners Americas (2013) (3) | 1,229.1 | 777.5 | 314.5 | 740.7 | 1,055.2 | N/A | N/A | N/A | |||||||||||||||||
| Energy Income and Growth Fund (2013) (3) | 1,974.2 | 831.6 | 143.9 | 544.3 | 688.2 | N/A | N/A | N/A | |||||||||||||||||
| Global Infrastructure Investors II (2014) (2) (3) | 3,028.3 | 346.5 | 8.9 | 354.0 | 362.9 | N/A | N/A | N/A | |||||||||||||||||
| European Fund IV (2015) (2) (3) | 3,468.0 | 160.9 | — | 185.7 | 185.7 | N/A | N/A | N/A | |||||||||||||||||
| Real Estate Partners Europe (2015) (2) (3) | 591.3 | — | — | — | — | N/A | N/A | N/A | |||||||||||||||||
| Subtotal - Included Funds | 70,550.9 | 54,514.3 | 59,879.7 | 37,212.7 | 97,092.4 | 15.4 | % | 11.1 | % | 1.8 | |||||||||||||||
| All Funds | $ | 87,025.4 | $ | 70,988.8 | $ | 110,149.0 | $ | 37,212.7 | $ | 147,361.7 | 25.6 | % | 18.9 | % | 2.1 | ||||||||||
| Amount | Fair Value of Investments | ||||||||||||||||||||||||
| Private Markets Investment Funds | Commitment | Invested (5) | Realized (5) | Unrealized | Total Value | Gross IRR (5) | Net IRR (5) | Multiple of Invested Capital (5) | |||||||||||||||||
| ($ in millions) | |||||||||||||||||||||||||
| Realized/Partially Realized Investments (4) | |||||||||||||||||||||||||
| Legacy Funds (1) | |||||||||||||||||||||||||
| 1976 Fund | $ | 31.4 | $ | 31.4 | $ | 537.2 | $ | — | $ | 537.2 | 39.5 | % | 35.5 | % | 17.1 | ||||||||||
| 1980 Fund | 356.8 | 356.8 | 1,827.8 | — | 1,827.8 | 29.0 | % | 25.8 | % | 5.1 | |||||||||||||||
| 1982 Fund | 327.6 | 327.6 | 1,290.7 | — | 1,290.7 | 48.1 | % | 39.2 | % | 3.9 | |||||||||||||||
| 1984 Fund | 1,000.0 | 1,000.0 | 5,963.5 | — | 5,963.5 | 34.5 | % | 28.9 | % | 6.0 | |||||||||||||||
| 1986 Fund | 671.8 | 671.8 | 9,080.7 | — | 9,080.7 | 34.4 | % | 28.9 | % | 13.5 | |||||||||||||||
| 1987 Fund | 6,129.6 | 6,129.6 | 14,949.2 | — | 14,949.2 | 12.1 | % | 8.9 | % | 2.4 | |||||||||||||||
| 1993 Fund | 1,945.7 | 1,945.7 | 4,143.3 | — | 4,143.3 | 23.6 | % | 16.8 | % | 2.1 | |||||||||||||||
| 1996 Fund | 6,011.6 | 6,011.6 | 12,476.9 | — | 12,476.9 | 18.0 | % | 13.3 | % | 2.1 | |||||||||||||||
| Subtotal - Legacy Funds | 16,474.5 | 16,474.5 | 50,269.3 | — | 50,269.3 | 26.1 | % | 19.9 | % | 3.1 | |||||||||||||||
| Included Funds | |||||||||||||||||||||||||
| European Fund (1999) (2) | 3,085.4 | 3,085.4 | 8,748.0 | 17.1 | 8,765.1 | 26.9 | % | 20.2 | % | 2.8 | |||||||||||||||
| Millennium Fund (2002) | 6,000.0 | 5,599.4 | 12,517.4 | 1,402.2 | 13,919.6 | 25.0 | % | 19.4 | % | 2.5 | |||||||||||||||
| European Fund II (2005) (2) | 5,750.8 | 5,245.4 | 6,611.1 | 2,001.6 | 8,612.7 | 7.8 | % | 6.7 | % | 1.6 | |||||||||||||||
| 2006 Fund (2006) | 17,642.2 | 10,867.0 | 18,411.5 | 7,208.4 | 25,619.9 | 17.1 | % | 14.8 | % | 2.4 | |||||||||||||||
| Asian Fund (2007) | 3,983.3 | 2,953.6 | 5,397.4 | 1,791.2 | 7,188.6 | 22.3 | % | 19.1 | % | 2.4 | |||||||||||||||
| European Fund III (2008) (2) | 6,121.8 | 2,694.3 | 4,447.2 | 1,324.9 | 5,772.1 | 22.0 | % | 18.6 | % | 2.1 | |||||||||||||||
| E2 Investors (Annex Fund) (2009) (2) | 195.8 | 94.8 | 195.7 | — | 195.7 | 19.8 | % | 19.8 | % | 2.1 | |||||||||||||||
| China Growth Fund (2010) | 1,010.0 | 371.3 | 283.4 | 377.0 | 660.4 | 20.3 | % | 18.1 | % | 1.8 | |||||||||||||||
| Natural Resources Fund (2010) | 887.4 | 884.6 | 96.6 | 200.1 | 296.7 | (45.8 | )% | (48.5 | )% | 0.3 | |||||||||||||||
| Global Infrastructure Investors (2011) (2) | 1,039.9 | 765.1 | 216.3 | 711.5 | 927.8 | 7.8 | % | 7.8 | % | 1.2 | |||||||||||||||
| North America Fund XI (2012) | 8,718.4 | 2,074.9 | 1,733.9 | 2,551.7 | 4,285.6 | 49.6 | % | 48.7 | % | 2.1 | |||||||||||||||
| Asian Fund II (2013) (4) | 5,825.0 | — | — | — | — | — | — | — | |||||||||||||||||
| Real Estate Partners Americas (2013) (4) | 1,229.1 | — | — | — | — | — | — | — | |||||||||||||||||
| Energy Income and Growth Fund (2013) (4) | 1,974.2 | — | — | — | — | — | — | — | |||||||||||||||||
| Global Infrastructure Investors II (2014) (2) (4) | 3,028.3 | — | — | — | — | — | — | — | |||||||||||||||||
| European Fund IV (2015) (2) (4) | 3,468.0 | — | — | — | — | — | — | — | |||||||||||||||||
| Real Estate Partners Europe (2015) (2) (4) | 591.3 | — | — | — | — | — | — | — | |||||||||||||||||
| Subtotal - Included Funds | 70,550.9 | 34,635.8 | 58,658.5 | 17,585.7 | 76,244.2 | 19.4 | % | 16.1 | % | 2.2 | |||||||||||||||
| All Realized/Partially Realized Investments | $ | 87,025.4 | $ | 51,110.3 | $ | 108,927.8 | $ | 17,585.7 | $ | 126,513.5 | 25.8 | % | 20.8 | % | 2.5 |
(1)These funds were not contributed to KKR as part of the KPE Transaction.
| (2) | The capital commitments of the European Fund, European Fund II, European Fund III, E2 Investors (Annex Fund), European Fund IV, Global Infrastructure Investors, Global Infrastructure Investors II and Real Estate Partners Europe include euro-denominated commitments of €196.5 million, €2,597.5 million, €2,882.8 million, €55.5 million, €1,626.1 million, €30.0 million, €243.8 million and €275.6 million, respectively. Such amounts have been converted into U.S. dollars based on (i) the foreign exchange rate at the date of purchase for each investment and (ii) the exchange rate prevailing on December 31, 2015 in the case of unfunded commitments. |
| (3) | The gross IRR, net IRR and multiple of invested capital are calculated for our investment funds that have invested for at least 36 months prior to December 31, 2015. None of the Asian Fund II, Real Estate Partners Americas, Energy Income and Growth Fund, Global Infrastructure Investors II, European Fund IV or Real Estate Partners Europe have invested for at least 36 months as of December 31, 2015. We therefore have not calculated gross IRRs, net IRRs and multiples of invested capital with respect to those funds. |
| (4) | An investment is considered partially realized when it has been disposed of or has otherwise generated disposition proceeds or current income that has been distributed by the relevant fund. In periods prior to the three months ended September 30, 2015, realized proceeds excluded current income such as dividends and interest. None of the Asian Fund II, Real Estate Partners Americas, Energy Income and Growth Fund, Global Infrastructure Investors II, European Fund IV or Real Estate Partners Europe have any investments that are considered partially realized. We therefore have not calculated gross IRRs, net IRRs and multiples of invested capital with respect to the investments of those funds. |
| (5) | IRRs measure the aggregate annual compounded returns generated by a fund’s investments over a holding period. Net IRRs presented under Total Investments are calculated after giving effect to the allocation of realized and unrealized carried interest and the payment of any applicable management fees. Net IRRs presented under Realized/Partially Realized Investments are calculated after giving effect to the allocation of realized and unrealized carried interest, but before payment of any applicable management fees as management fees are applied to funds, not investments. Gross IRRs are calculated before giving effect to the allocation of carried interest and the payment of any applicable management fees. |
The multiples of invested capital measure the aggregate value generated by a fund’s investments in absolute terms. Each multiple of invested capital is calculated by adding together the total realized and unrealized values of a fund’s investments and dividing by the total amount of capital invested by the fund. Such amounts do not give effect to the allocation of any realized and unrealized returns on a fund’s investments to the fund’s general partner pursuant to a carried interest or the payment of any applicable management fees.
KKR Private Markets funds may utilize third party financing facilities to provide liquidity to such funds. In such event IRRs are calculated from the time capital contributions are due from fund investors to the time fund investors receive a related distribution from the fund, and the use of such financing
facilities generally decreases the amount of invested capital that would otherwise be used to calculate IRRs and multiples of invested capital, which tends to increase IRRs and multiples when fair value grows over time and decrease IRRs and multiples when fair value decreases over time. KKR Private Markets funds also generally provide in certain circumstances, which vary depending on the relevant fund documents, for a portion of capital returned to investors to be restored to unused commitments as recycled capital. For KKR's Private Markets funds that have a preferred return, we take into account recycled capital in the calculation of IRRs and multiples of invested capital because the calculation of the preferred return includes the effect of recycled capital. For KKR's Private Markets funds that do not have a preferred return, we do not take recycled capital into account in the calculation of IRRs and multiples of invested capital. The inclusion of recycled capital generally causes invested and realized amounts to be higher and IRRs and multiples of invested capital to be lower than had recycled capital not been included. The inclusion of recycled capital would reduce the composite net IRR of all Included Funds by 0.1% and the composite net IRR of all Legacy Funds by 0.5%, and would reduce the composite multiple of invested capital of Included Funds by less than 0.1 and the composite multiple of invested capital of Legacy Funds by 0.4.
For more information, see “Risk Factors-Risks Related to the Assets We Manage-The historical returns attributable to our funds, including those presented in this report, should not be considered as indicative of the future results of our funds or of our future results or of any returns on our common units.”
Private Equity
We are a world leader in private equity, having raised 19 funds with approximately $78.3 billion of capital commitments through December 31, 2015. We invest in industry‑leading franchises and attract world‑class management teams. Our investment approach leverages our capital base, sourcing advantage, global network and industry knowledge. It also leverages a sizeable team of operating consultants, who work exclusively with our investment professionals and portfolio company management teams and otherwise at our direction, as well as senior advisors, many of whom are former chief executive officers and leaders of the business community.
Portfolio
The following chart presents information concerning the amount of capital invested by private equity funds by geography through December 31, 2015. We believe that this data illustrates the benefits of our business approach and our ability to source and invest in deals in multiple geographies.

Our current private equity portfolio consists of over 108 companies with approximately $200 billion of annual revenues. These companies are headquartered in 21 countries and operate in 19 general industries which take advantage of our broad and deep industry and operating expertise. Many of these companies are leading franchises with global operations, strong management teams and attractive growth prospects, which we believe will provide benefits through a broad range of business conditions.
Investment Approach
Our approach to making private equity investments focuses on achieving multiples of invested capital and attractive risk‑adjusted IRRs by selecting high‑ quality investments that may be made at attractive prices, applying rigorous standards of due diligence when making investment decisions, implementing strategic and operational changes that drive growth and value creation in acquired businesses, carefully monitoring investments, and making informed decisions when developing investment exit strategies.
We believe that we have achieved a leading position in the private equity industry by applying a disciplined investment approach and by building strong partnerships with highly motivated management teams who put their own capital at risk. When making private equity investments, we seek out strong business franchises, attractive growth prospects, leading market positions, and the ability to generate attractive returns. In our private equity funds, we do not effect transactions that are “hostile”, meaning a target company’s board of directors makes an unfavorable recommendation with respect to the transaction or publicly opposes the consummation of the transaction.
Sourcing and Selecting Investments
We have access to significant opportunities for making private equity investments as a result of our sizeable capital base, global platform, and relationships with leading executives from major companies, commercial and investment banks, and other investment and advisory institutions. Members of our global network contact us with new investment opportunities, including a substantial number of exclusive investment opportunities and opportunities that are made available to only a limited number of other firms. We also proactively pursue business development strategies that are designed to generate deals internally based on the depth of our industry knowledge and our reputation as a leading financial sponsor.
To enhance our ability to identify and consummate private equity investments, we have organized our investment professionals in industry‑specific teams. Our industry teams work closely with our operating consultants and other advisors to identify businesses that can be grown and improved. These teams conduct their own primary research, develop a list of industry themes and trends, identify companies and assets in need of operational improvement, and seek out businesses and assets that they believe will benefit from our involvement. They possess a detailed understanding of the economic drivers, opportunities for value creation, and strategies that can be designed and implemented to improve companies across the industries in which we invest.
Due Diligence and the Investment Decision
When an investment team determines that an investment proposal is worth consideration, the proposal is formally presented to the applicable regional investment committee and the due diligence process commences if appropriate. The objective of the due diligence process is to identify attractive investment opportunities based on the facts and circumstances surrounding an investment and to prepare a framework that may be used from the date of an acquisition to drive operational improvement and value creation. When conducting due diligence, investment teams evaluate a number of important business, financial, tax, accounting, environmental, social, governance, legal and regulatory issues in order to determine whether an investment is suitable. While the due diligence process differs depending on the type of investment we make, generally, in connection with the private equity due diligence process, investment professionals spend significant amounts of time meeting with a company’s management and operating personnel, visiting plants and facilities, and where appropriate, speaking with other stakeholders interested in and impacted by the investment in order to understand the opportunities and risks associated with the proposed investment. Our investment professionals may also use the services of outside accountants, consultants, lawyers, investment banks, and industry experts as appropriate to assist them in this process. Investment committees monitor all due diligence practices, and the applicable investment committee must approve an investment before it may be made.
Building Successful and Competitive Businesses
Portfolio management committees are responsible for working with our investment professionals from the date on which a private equity investment is made until the time it is exited in order to ensure that strategic and operational objectives are accomplished and that the performance of the investment is closely monitored. When investing in a private equity portfolio company, we partner with management teams to execute on our investment thesis, and we rigorously track performance through regular monitoring of detailed operational and financial metrics as well as appropriate environmental, social and governance issues. We have developed a global network of experienced managers and operating executives who assist the private equity portfolio companies in making operational improvements and achieving growth. We augment these resources with operational guidance from operating consultants at KKR Capstone, senior advisors, and investment teams, and with “100‑Day Plans” that focus the firm’s efforts and drive our strategies. We seek to emphasize efficient capital management, top‑line growth, R&D spending, geographical expansion, cost optimization, and investment for the long‑term.
Realizing Investments
We have developed substantial expertise for realizing private equity investments. From our inception through December 31, 2015, the firm has generated approximately $110.2 billion of cash proceeds from the sale of our private equity portfolio companies in initial public offerings and secondary offerings, dividends, and sales to strategic buyers. When exiting private equity investments, our objective is to structure the exit in a manner that optimizes returns for fund investors and, in the case of publicly traded companies, minimizes the impact that the exit has on the trading price of the company’s securities. We believe that our ability to successfully realize investments is attributable in part to the strength and discipline of our portfolio management committees and capital markets business, as well as the firm’s longstanding relationships with corporate buyers and members of the investment banking and investing communities.
Private Equity Fund Structures
The private equity funds that we sponsor and manage have finite lives and investment periods. Each fund is organized as one or more partnerships, and each partnership is controlled by a general partner. Private equity fund investors are limited partners who agree to contribute a specified amount of capital to the fund from time to time for use in qualifying investments during the investment period, which generally lasts up to six years depending on how quickly capital is deployed. The investment period for certain funds may be terminated upon supermajority vote (based on capital commitment) of the fund’s limited partners or by the fund’s advisory committee. The term of our private equity funds generally last for 10 to 12 years and may last up to 15 years from the date of the fund’s first or last investment, subject to a limited number of extensions with the consent of the limited partners or the applicable advisory committee. Given the length of the investment periods and terms of our private equity funds and the limited conditions under which such periods can be terminated and commitments may be withdrawn, the AUM of our private equity funds provide a long‑term stable capital base.
Each private equity fund’s general partner is generally entitled to a carried interest that allocates to it 20% of the net profits realized by the limited partners from the fund’s investments. Our newer private equity funds, the North America Fund XI, Asian Fund II and European Fund IV have a performance hurdle which requires that we return 7%, compounded annually, to limited partners in the fund prior to receiving our 20% share of net profits realized by limited partners. Such performance hurdles are subject to a catch‑up allocation to the general partner after the hurdle has been reached. Our earlier private equity funds do not include a performance hurdle. The timing of receipt of carried interest in respect of investments of our carry funds is dictated by the terms of the partnership agreements that govern such funds, and is distributed to the general partner of a private equity fund only after all of the following are met: (i) a realization event has occurred (e.g., sale of a portfolio company, dividend, etc.); (ii) the vehicle has achieved positive overall investment returns since its inception, in excess of performance hurdles where applicable; and (iii) with respect to investments with a fair value below cost, cost has been returned to fund investors in an amount sufficient to reduce remaining cost to the investments’ fair value. For a fund that has a fair value above cost, overall, but has one or more investments where fair value is below cost, the shortfall between cost and fair value for such investments is referred to as a “netting hole.” See “Management’s Discussion and Analysis of Financial Condition and Results of Operations-Liquidity-Sources of Liquidity” for a discussion of netting holes. Net realized profit or loss is not netted between or among funds except for the Annex Fund as discussed below under “-Other Private Equity Investment Vehicles-E2 Investors (Annex Fund)”. In addition, the agreements governing KKR’s private equity funds generally include a “clawback” or, in certain instances, a “net loss sharing” provision that, if triggered, may give rise to a contingent obligation that may require the general partner to return or contribute amounts to the fund for distribution to fund investors at the end of the life of the fund. Our newer private equity funds do not have a net loss sharing provision. See “Management’s Discussion and Analysis of Financial Condition and Results of Operations-Critical Accounting Policies-Clawback Provision”, “Management’s Discussion and Analysis of Financial Condition-Critical Accounting Policies-Net Loss Sharing Provision” and “Risk Factors-The “clawback” or “net loss sharing” provisions in our governing agreements may give rise to a contingent obligation that may require us to return or contribute amounts to our funds and fund investors.”
We enter into management agreements with our private equity funds pursuant to which we receive management fees in exchange for providing the funds with management and other services. Gross management fees for our private equity funds generally range from 1% to 2% of committed capital during the fund’s investment period and is generally 0.75% to 1.25% of invested capital after the expiration of the fund’s investment period with subsequent reductions over time, which causes the fees to be reduced as investments are liquidated. These management fees are paid by private equity fund investors, who generally contribute capital to the fund in order to allow the fund to pay the fees to us. Our private equity funds generally require that management fees be returned to fund investors before a carried interest may be paid.
We also enter into monitoring agreements with our portfolio companies pursuant to which we receive periodic monitoring fees in exchange for providing them with management, consulting, and other services, and we typically receive transaction fees for providing portfolio companies with financial, advisory and other services in connection with specific transactions. Monitoring fees may provide for a termination payment following an initial public offering or change of control. In some cases,
we may be entitled to other fees that are paid by an investment target upon closing a transaction or when a potential investment is not consummated. Our private equity fund agreements typically require us to share 80% to 100% of any monitoring, transaction and other fees that are allocable to a fund (after reduction for expenses incurred allocable to a fund from unconsummated transactions) with fund investors.
In addition, the agreements governing our private equity funds enable investors in those funds to reduce their capital commitments available for further investments, on an investor‑by‑investor basis, in the event certain “key persons” (for example, both of Messrs. Kravis and Roberts, and, in the case of certain geographically or product focused funds, one or more of the investment professionals focused on such funds) cease to be actively involved in the management of the fund. While these provisions do not allow investors in our funds to withdraw capital that has been invested or cause a fund to terminate, the occurrence of a “key man” event could cause disruption in our business, reduce the amount of capital that we have available for future investments, and make it more challenging to raise additional capital in the future.
Because private equity fund investors typically are unwilling to invest their capital in a fund unless the fund’s manager also invests its own capital in the fund’s investments, our private equity fund documents generally require the general partners of the funds to make minimum capital commitments to the funds. The amounts of these commitments, which are negotiated by fund investors, generally range from 2% to 5% of a fund’s total capital commitments at final closing, but may be greater for certain funds pursuing newer strategies. When investments are made, the general partner contributes capital to the fund based on its fund commitment percentage and acquires a capital interest in the investment that is not subject to a carried interest or management fees.
Other Private Equity Investment Vehicles
E2 Investors (Annex Fund). We established the Annex Fund in 2009 to enable fund investors in the European Fund II and the Millennium Fund to make additional investments in portfolio companies of the European Fund II, which had already been fully invested. This fund has several features that distinguish it from our other private equity funds, including: (i) it does not pay a management fee to us; (ii) its general partner is only entitled to a carried interest after netting any losses, costs, and expenses relating to European Fund II and certain Millennium Fund investments from the profits of the Annex Fund investments; and (iii) no transaction or incremental monitoring fees are charged in connection with investments in which the Annex Fund participates. The Annex Fund reached the end of its investment period in November 2013.
Other Private Equity Products. We have offered significant co‑investment opportunities to both fund investors and other third parties. We have built out our capital markets and distribution capabilities and created new investment structures and products that allow us to syndicate a portion of the equity needed to finance acquisitions. These structures include co‑investment vehicles and a principal‑protected private equity product, which generally entitles the firm to receive management fees and/or a carried interest. In addition, we manage certain separately managed accounts in the form of separate investment vehicles based on terms that are separately negotiated with investors in those vehicles. We also offer multi‑strategy products, which invest in our funds, co‑investment vehicles and external funds and have launched a strategy focused on growth equity opportunities in the technology, media and telecommunications sector.
Real Assets
Energy
In 2010 we launched our first dedicated energy fund, which acquired and operated oil and natural gas properties in mature basins located primarily in the United States. In acquiring these properties, which are typically considered to be non‑core by their sellers, we sought to generate value through optimizing production , reducing operating costs, and optimizing commercial and marketing arrangements.
Since the launch of our first dedicated energy fund, we have invested in our capabilities, both with respect to our team of investment professionals and our relationships with technical partners. With these capabilities, we have expanded our energy platform to target real asset investment opportunities across the upstream and midstream segments of the oil and gas industry. As part of this effort, we have completed investments in oil and gas drilling development transactions with operating companies and have also acquired mineral and royalty interests. We invest in these energy strategies through the KKR Energy Income and Growth Fund. As of December 31, 2015, we have received $2.9 billion of capital commitments to our energy funds and $1.0 billion of capital commitments to this strategy through separately managed accounts.
Our energy business aims to deliver current returns to fund investors through distributions generated by producing and selling oil and natural gas reserves and capital appreciation. The goal is to provide investors with exposure to commodity prices
and optionality associated with future drilling and production. We work closely with external teams of technical and operational experts to assist in the selection, evaluation and operation of investments.
Infrastructure
We manage infrastructure investments and began investing through our first dedicated infrastructure fund, KKR Global Infrastructure Investors L.P., in 2011. We believe that the global infrastructure market provides an opportunity for the firm’s private investment, operational improvement capabilities and stakeholder engagement. This strategy seeks to achieve returns including current income through the acquisition and operational improvement of assets important to the functioning of the economy. Through this strategy we have made investments in parking, alternative energy, district heating and contracted electricity generation, water and wastewater, locomotive transportation, midstream and telecommunications infrastructure. As of December 31, 2015, we had received $4.1 billion of capital commitments to our infrastructure funds and $1.1 billion of capital commitments to this strategy through separately managed accounts and co‑investment vehicles.
Real Estate
The firm developed a dedicated real estate strategy beginning in 2011 using our own seed capital. Since launching our first dedicated real estate fund, KKR Real Estate Partners Americas, in 2013, we have expanded our real estate strategy to pursue real estate investments in Western Europe and real estate credit. In addition, we have the flexibility to invest in real estate transactions across the capital structure through various vehicles, including our private equity and alternative credit funds. We have also established investment platforms with strategic partners to invest in commercial real estate in Germany and the United States. Our real estate platform targets real estate opportunities, including direct investments in real property, debt, special situations transactions and businesses with significant real estate holdings that can benefit from KKR’s operational expertise. We seek to partner with real estate owners, lenders, operators, and developers to provide flexible capital to respond to transaction specific needs, including the outright purchase or financing of existing assets or companies and the funding of future development or acquisition opportunities. Through this strategy, we have made real estate investments in residential and commercial assets. As of December 31, 2015, we have received $1.8 billion of capital commitments through our real estate funds.
Real Asset Investment Process
Our energy, infrastructure and real estate funds have a similar investment process as that described under “-Private Equity.” Investment teams for a particular real asset strategy formally present investments to the applicable strategy oriented investment committee, which monitors all due diligence practices and must approve an investment before it may be made. Most of our real asset strategies also have a portfolio management committee that works with our investment professionals from the date on which an investment is made until the time it is exited in order to ensure that strategic and operational objectives are accomplished and that the performance of the investment is closely monitored. In addition to leveraging the resources of the firm, our energy and real estate investment teams partner with technical experts and operators to manage our real asset investments.
Real Asset Fund Structures
Our energy, infrastructure and real estate funds generally have investment periods of up to 6 years and generally have a fund term of up to 13 years. Management fees for such funds range from 0.75% to 1.5% on commitments, invested capital or net asset value during the investment period and on invested capital or net asset value for investments thereafter, subject to certain adjustments. These funds generally have performance hurdles of 8% to 10% subject to a catch‑up allocation to the general partner after the hurdle has been reached. Thereafter the general partners of such funds generally share in 10% to 20% of net profits realized by limited partners.
Public Markets
We operate and report our combined credit and hedge funds businesses through the Public Markets segment. Our credit business advises funds, CLOs, separately managed accounts, and investment companies registered under the Investment Company Act, including a business development company or BDC, undertakings for collective investment in transferable securities or UCITS, and alternative investments funds or AIFs, which invest capital in (i) leveraged credit strategies, such as leveraged loans, high yield bonds and opportunistic credit, and (ii) alternative credit strategies such as mezzanine investments, direct lending investments, special situations investments and long/short credit investment strategies. The funds, accounts, registered investment companies and CLOs in our leveraged credit and alternative credit strategies are managed by KKR Credit Advisors (US) LLC, which is an SEC‑registered investment adviser, KKR Credit Advisors (Ireland), regulated by the Central
Bank of Ireland, and KKR Credit Advisors (UK), regulated by the United Kingdom Financial Conduct Authority, or FCA. KKR Credit Advisors (Ireland) and KKR Credit Advisors (UK) (formerly known collectively as Avoca Capital) were acquired by KKR on February 19, 2014. Our Public Markets segment also includes our hedge funds business that offers a variety of investment strategies including customized hedge fund portfolios and hedge fund‑of‑fund solutions. The funds and accounts in our hedge fund business are managed by Prisma Capital Partners LP (KKR Prisma or Prisma), an SEC‑registered investment adviser. Through our Public Markets segment, we also have developed strategic partnerships by acquiring minority stakes in other hedge fund managers.
We intend to continue to grow the Public Markets business by leveraging our global investment platform, experienced investment professionals and the ability to adapt our investment strategies to different market conditions to capitalize on investment opportunities that may arise at various levels of the capital structure and across market cycles.
As of December 31, 2015, this segment had $53.5 billion of AUM, comprised of $17.4 billion of assets managed in our leveraged credit strategies, $15.5 billion of assets managed in our alternative credit strategies, $11.0 billion of assets managed in our hedge fund solutions strategies, $8.7 billion of assets managed in our strategic partnerships and $0.9 billion of assets managed in other strategies. Our alternative credit investments include $2.0 billion of assets managed in our mezzanine strategy, $6.5 billion of assets managed in our direct lending strategy, $6.6 billion of assets managed in our special situations strategies and $0.4 billion of assets managed in our long/short credit strategy. The following chart presents the growth in the AUM of our Public Markets segment from the commencement of its operations in August 2004 through December 31, 2015.
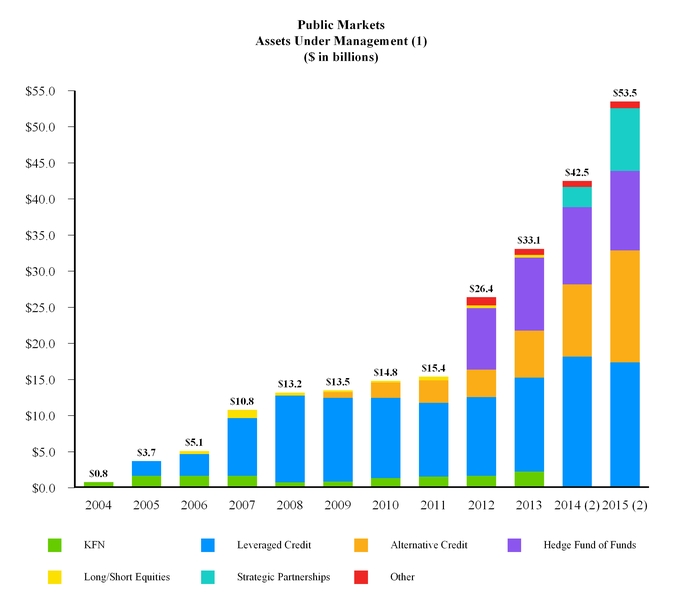
| (1) | For years 2006 through 2008, assets under management are presented pro forma for the KPE Transaction and, therefore, exclude the net asset value of KPE and its former commitments to our investment funds. Assets under management of KKR Prisma and Avoca are included in the years on and after the completion of the respective acquisitions. |
| (2) | AUM as of and after December 31, 2014 has been adjusted to include (i) KKR's pro-rata portion of AUM managed by other asset managers in which KKR holds a minority stake and (ii) capital commitments for which we are eligible to receive fees or carried interest upon deployment of capital. These two items increased our AUM by approximately $5.4 billion as of December 31, 2014 but are excluded from AUM for all prior years presented. |
Credit
Performance
We generally review our performance in our credit business by investment strategy. Our leveraged credit strategies principally invest in leveraged loans and high yield bonds, or a combination of both. In certain cases these strategies have meaningful track records and may be compared to widely‑known indices. The following table presents information regarding larger leveraged credit strategies managed by KKR from inception to December 31, 2015. Past performance is no guarantee of future results.
Leveraged Credit Strategies: Inception-to-Date Annualized Gross Performance vs. Benchmark by Strategy
| ($ in millions) | Inception Date | Gross Returns | Net Returns | Benchmark (1) | Benchmark Gross Returns | ||||||||
| Bank Loans Plus High Yield (2) | Jul 2008 | 8.07 | % | 7.41 | % | 65% S&P/ LSTA, 35% BoAML HY Master II Index (3) | 5.72 | % | |||||
| Opportunistic Credit (4) | May 2008 | 12.18 | % | 10.21 | % | BoAML HY Master II Index (4) | 6.96 | % | |||||
| Bank Loans (2) | Apr 2011 | 4.38 | % | 3.76 | % | S&P/ LSTA Loan Index (5) | 3.07 | % | |||||
| High Yield (2) | Apr 2011 | 5.50 | % | 4.92 | % | BoAML HY Master II Index (6) | 4.00 | % | |||||
| Bank Loans Conservative | Apr 2011 | 4.24 | % | 3.62 | % | S&P/ LSTA BB-B Loan Index (7) | 3.30 | % | |||||
| European Leveraged Loans (8) | Sep 2009 | 5.88 | % | 5.36 | % | CS Inst West European Leveraged Loan Index (9) | 4.92 | % |
| (1) | The Benchmarks referred to herein include the S&P/LSTA Leveraged Loan Index (the “S&P/LSTA Loan Index”), the Bank of America Merrill Lynch High Yield Master II Index (the “BoAML HY Master II Index”), the S&P European Leveraged Loan Index (the “ELLI”) and Credit Suisse Institutional Western European Leveraged Loan Index (the “CS Inst European Leveraged Loan Index”). The S&P/LSTA Loan Index is an index that comprises all loans that meet the inclusion criteria and that have marks from the LSTA/LPC mark-to-market service. The inclusion criteria consist of the following: (i) syndicated term loan instruments consisting of term loans (both amortizing and institutional), acquisition loans (after they are drawn down) and bridge loans; (ii) secured; (iii) U.S. dollar denominated; (iv) minimum term of one year at inception; and (v) minimum initial spread of LIBOR plus 1.25%. The BoAML HY Master II Index is a market value weighted index of below investment grade U.S. dollar denominated corporate bonds publicly issued in the U.S. domestic market. “Yankee” bonds (debt of foreign issuers issued in the U.S. domestic market) are included in the BoAML HY Master II Index provided that the issuer is domiciled in a country having investment grade foreign currency long-term debt rating. Qualifying bonds must have maturities of one year or more, a fixed coupon schedule and minimum outstanding of US$100 million. In addition, issuers having a credit rating lower than BBB3, but not in default, are also included. The ELLI is based upon Euro denominated facilities. The index reflects the market-weighted performance of institutional leveraged loan portfolios investing in European credits. All the index components are loans syndicated to European loan investors. The ELLI series uses real-time market weightings, spreads and interest payments. The Index was calculated monthly from January 1, 2002 to January 1, 2004; then weekly until May 2, 2013, and is currently calculated daily. The CS Inst European Leveraged Loan Index contains only institutional loan facilities priced above 90, excluding TL and TLa facilities and loans rated CC, C or are in default. It is designed to more closely reflect the investment criteria of institutional investors. While the returns of these strategies reflect the reinvestment of income and dividends, none of the indices presented in the chart above reflect such reinvestment, which has the effect of increasing the reported relative performance of these strategies as compared to the indices. Furthermore, these indices are not subject to management fees, incentive allocations or expenses. It is not possible to invest directly in unmanaged indices. |
| (2) | The AUM of the Bank Loans Plus High Yield strategy is also included in the AUM of the High Yield strategy and the AUM of the Bank Loans strategy. |
| (3) | Performance is based on a blended composite of Bank Loans Plus High Yield strategy accounts. The Benchmark used for purposes of comparison for the Bank Loans Plus High Yield strategy is based on 65% S&P/LSTA Loan Index and 35% BoAML HY Master II Index. |
| (4) | The Opportunistic Credit strategy invests in high yield securities and corporate loans with no preset allocation. The Benchmark used for purposes of comparison for the Opportunistic Credit strategy presented herein is based on the BoAML HY Master II Index. Funds within this strategy may utilize third party financing facilities to provide liquidity to such funds. In cases where financing facilities are used, the amounts drawn on the facility are deducted from the assets of the fund in the calculation of net asset value, which tends to increase returns when net asset value grows over time and decrease returns when net asset value decreases over time. |
| (5) | Performance is based on a composite of portfolios that primarily invest in leveraged loans. The Benchmark used for purposes of comparison for the Bank Loans strategy is based on the S&P/LSTA Loan Index. |
| (6) | Performance is based on a composite of portfolios that primarily invest in high yield securities. The Benchmark used for purposes of comparison for the High Yield strategy is based on the BoAML HY Master II Index. |
| (7) | Performance is based on a composite of portfolios that primarily invest in leveraged loans rated B-/Baa3 or higher. The Benchmark used for purposes of comparison for the Bank Loans strategy is based on the S&P/LSTA BB/B Loan Index. |
| (8) | The AUM amounts reflected have been converted to U.S. dollars based on the exchange rate prevailing on December 31, 2015. The returns presented are calculated based on local currency. |
(9) Performance is based on a composite of portfolios that primarily invest in higher quality leveraged loans. The Benchmark used for purposes of comparison for the European Senior Loans strategy is based on the CS Inst West European Leveraged Loan Index.
Our alternative credit strategies primarily invest in more illiquid instruments through private investment funds. The following table presents information regarding our Public Markets alternative credit funds where investors are subject to capital commitments from inception to December 31, 2015. Some of our alternative credit funds have begun investing more recently and therefore have not yet developed meaningful track records, and thus their performance is not included below. Past performance is no guarantee of future results.
Alternative Credit Strategies: Fund Performance
| Amount | Fair Value of Investments | ||||||||||||||||||||||||||||||
| Public Markets Investment Funds | Inception Date | Commitment | Invested* | Realized* | Unrealized | Total Value | Gross IRR** | Net IRR** | Multiple of Invested Capital*** | ||||||||||||||||||||||
| ($ in Millions) | |||||||||||||||||||||||||||||||
| Special Situations Fund | Dec-12 | $ | 2,257.6 | $ | 2,129.6 | $ | 257.6 | $ | 2,205.6 | $ | 2,463.2 | 9.6 | % | 7.0 | % | 1.2 | |||||||||||||||
| Special Situations Fund II | Dec-14 | 2,675.5 | 592.1 | — | 452.4 | 452.4 | N/A | N/A | N/A | ||||||||||||||||||||||
| Mezzanine Partners | Mar-10 | 1,022.8 | 872.2 | 541.0 | 634.3 | 1,175.3 | 13.8 | % | 8.4 | % | 1.3 | ||||||||||||||||||||
| Lending Partners | Dec-11 | 460.2 | 369.7 | 181.5 | 303.3 | 484.8 | 11.4 | % | 9.4 | % | 1.3 | ||||||||||||||||||||
| Lending Partners II | Jun-14 | 1,335.9 | 446.3 | 26.4 | 475.7 | 502.1 | 10.9 | % | 8.2 | % | 1.1 | ||||||||||||||||||||
| Lending Partners Europe | Mar-15 | 780.1 | 16.5 | — | 24.0 | 24.0 | N/A | N/A | N/A | ||||||||||||||||||||||
| Revolving Credit Partners | May-15 | 510.0 | — | — | (2.8 | ) | (2.8 | ) | N/A | N/A | N/A | ||||||||||||||||||||
| Private Credit Opportunities Partners II | Dec-15 | 350.0 | — | — | — | — | N/A | N/A | N/A | ||||||||||||||||||||||
| All Funds | $ | 9,392.1 | $ | 4,426.4 | $ | 1,006.5 | $ | 4,092.5 | $ | 5,099.0 | 1.2 |
- Recycled capital is excluded from the amounts invested and realized.
** KKR alternative credit funds may utilize third party financing facilities to provide liquidity to such funds, and in such event IRRs are calculated from the time capital contributions are due from fund investors to the time fund investors receive a related distribution from the fund. In cases where financing facilities are used, their use generally decreases the amount of invested capital that would otherwise be used to calculate IRRs, which tends to increase IRRs when fair value grows over time and decrease IRRs when fair value decreases over time. IRRs measure the aggregate annual compounded returns generated by a fund’s investments over a holding period and are calculated taking into account recycled capital. Net IRRs presented are calculated after giving effect to the allocation of realized and unrealized carried interest and the payment of any applicable management fees. Gross IRRs are calculated before giving effect to the allocation of carried interest and the payment of any applicable management fees.
*** The multiples of invested capital measure the aggregate value generated by a fund’s investments in absolute terms. Each multiple of invested capital is calculated by adding together the total realized and unrealized values of a fund’s investments and dividing by the total amount of capital invested by the fund. In cases where financing facilities are used, their use generally decreases the amount of invested capital that would otherwise be used to calculate multiples of invested capital, which tends to increase multiples when fair value grows over time and decrease multiples when fair value decreases over time. . Such amounts do not give effect to the allocation of any realized and unrealized returns on a fund’s investments to the fund’s general partner pursuant to a carried interest or the payment of any applicable management fees and are calculated without taking into account recycled capital.
Such past performance may not be representative of performance in any given period. For additional information regarding impact of market conditions on the value and performance of our investments, see “Risk Factors-Risks Related to Our Business-Difficult market conditions can adversely affect our business in many ways, including by reducing the value or performance of the investments that we manage or by reducing the ability of our funds to raise or deploy capital, each of which could negatively impact our net income and cash flow and adversely affect our financial condition.” and “-Risks Related to the Assets We Manage-The historical returns attributable to our funds, including those presented in this report, should not be considered as indicative of the future results of our funds or of our future results or of any returns on our common units.”
Investment Approach
Our approach to making investments focuses on creating investment portfolios that seek to generate attractive risk‑adjusted returns by selecting investments that may be made at attractive prices, subjecting investments to regular monitoring and oversight, and, for more liquid investments, making buy and sell decisions based on price targets and relative value parameters. The firm employs both “top‑down” and “bottom‑up” analyses when making investments. Our top‑down analysis involves, as appropriate, a macro analysis of relative asset valuations, long‑term industry trends, business cycles, regulatory trends, interest rate expectations, credit fundamentals and technical factors to target specific industry sectors and asset classes in which to invest. From a bottom‑up perspective, our investment decision is predicated on an investment thesis that is developed using our proprietary resources and knowledge and due diligence.
Sourcing and Selecting Investments
We source investment opportunities through a variety of channels, including internal deal generation strategies and the firm’s global network of contacts at major companies, corporate executives, commercial and investment banks, financial intermediaries, other private equity sponsors and other investment and advisory institutions. We are also provided with opportunities to invest in certain strategies, where appropriate, in the securities of KKR’s private equity portfolio companies, though there are limitations across the platform on the maximum size of such KKR‑affiliated investments.
Due Diligence and the Investment Decision
Once a potential investment has been identified, our investment professionals screen the opportunity and make a preliminary determination concerning whether we should proceed with further diligence. When evaluating the suitability of an investment for our funds, we typically employ a relative value framework and subject the investment to due diligence. This review considers many factors including, as appropriate, expected returns, capital structure, credit ratings, historical and projected financial data, the issuer’s competitive position, the quality and track record of the issuer’s management team, margin stability, and industry and company trends. Investment professionals use the services of outside advisors and industry experts as appropriate to assist them in the due diligence process and, when relevant and permitted, leverage the knowledge and experience of our Private Markets investment professionals. Strategy‑specific investment committees monitor all due diligence practices.
Monitoring Investments
We monitor our portfolios of investments using, as applicable, daily, quarterly and annual analyses. Daily analyses include morning market meetings, industry and company pricing runs, industry and company reports and discussions with the firm’s Private Markets investment professionals on an as‑needed basis. Quarterly analyses include the preparation of quarterly operating results, reconciliations of actual results to projections and updates to financial models (baseline and stress cases). Annual analyses involve conducting internal audits, and testing compliance with monitoring and documentation requirements.
Credit Strategies
Our credit strategies business pursues investments in debt securities ranging from liquid securities such as leveraged loans and high‑yield bonds to alternative credit including longer‑duration strategies such as mezzanine, special situations and direct lending and revolving credit. These investments may be made across a range of vehicles including funds, single‑ or cross‑strategy separately managed accounts, and registered investment companies. These managed accounts enable us to tailor an investment program to meet the specific risk, return and investment objective of investors in our funds.
Leveraged Credit. Our leveraged credit strategies are principally directed at investing in leveraged loans, high‑yield bonds or a combination of both. Our opportunistic credit strategy seeks to deploy capital across investment themes that take advantage of credit market dislocations, spanning asset types and liquidity profiles. These leveraged credit strategies are pursued primarily through separately managed accounts and registered investment companies, with a smaller amount of capital residing in funds. We are entitled to receive a fee or a combination of a fee and an incentive allocation for managing these vehicles.
Structured Credit Vehicles. We manage structured credit vehicles in the form of collateralized loan obligation transactions, or CLOs. CLOs are typically structured as bankruptcy‑remote, special purpose investment vehicles which acquire, monitor and, to varying degrees, manage a pool of credit assets. The CLOs serve as long term financing for credit investments and as a way to minimize refinancing risk, minimize maturity risk and secure a fixed cost of funds over an underlying market interest rate. We may receive a fee for managing certain CLOs.
Alternative Credit. Our alternative credit strategies leverage the knowledge and relationships developed in the leveraged credit business. These strategies include private credit strategies such as mezzanine and distressed investing and special situations strategies. As with our leveraged credit strategy, these are pursued through a combination of separately managed accounts, a BDC and funds. For managing these accounts and funds, we are entitled to receive either fees or a combination of fees and carried interest.
Direct Lending. We seek to make investments in proprietarily sourced primarily senior debt financings for middle‑market companies through our direct lending strategy. We closed our first dedicated direct lending fund, KKR Lending Partners L.P. in December 2012 and had AUM of $6.5 billion in this strategy as of December 31, 2015.
Mezzanine. We seek to make mezzanine investments in directly sourced third‑party mezzanine and mezzanine-like transactions through this strategy. These investments often consist of mezzanine debt, which generates a current yield, coupled with marginal equity exposure with additional upside potential. We closed our first dedicated mezzanine fund, KKR Mezzanine Partners I L.P. in August 2011 and had AUM of $2.0 billion in this strategy as of December 31, 2015.
Special Situations. We seek to make opportunistic investments largely in distressed companies through our special situations investment strategy. These investments include secondary market distressed investments (including post‑ restructuring equity), control‑oriented opportunities, rescue financing (debt or equity investments made to
address covenant, maturity or liquidity issues), debtor‑in‑possession or exit financing, structured principal investments, and other event‑driven investments in debt or equity. We closed our first dedicated special situations fund, KKR Special Situations Fund L.P., in December 2013 and had AUM of $6.6 billion in this strategy as of December 31, 2015.
Long/short credit. Our long/short credit strategy invests across capital structures with a focus primarily on corporate credit opportunities and had AUM of $0.4 billion in this strategy as of December 31, 2015.
Products for Individual Investors
KKR Credit Advisors (US) LLC serves as the registered investment adviser to an investment company registered under the Investment Company Act (or, in the case of the BDC we manage, as its sub‑adviser), which are subject to the Investment Company Act and the rules thereunder. The management fees we receive from these registered investment companies are generally paid on a regular basis (typically monthly) and proportionately increase or decrease based on the net asset value or gross assets of the investment company. The management fees we are paid for managing these investment companies will generally be subject to contractual rights that require their board of directors to provide prior notice (or, in the case of the BDC we manage, the investment adviser) in order to terminate our investment management services.
Hedge Funds
Overview
Our hedge fund business is comprised of customized hedge fund solutions and minority interests in other public markets managers and funds. We established our hedge fund business in October 2012 with the acquisition of Prisma Capital Partners LP through which we provide customized hedge fund portfolio and hedge fund‑of‑fund solutions. We expect to grow this business with the acquisition of majority and minority interests or stakes in third party hedge fund management companies or by seeding strategies with strategic hedge fund partners.
KKR Prisma
KKR Prisma constructs and manages customized hedge fund portfolios and hedge fund‑of‑funds. It seeks to deliver superior performance by utilizing portfolio construction techniques and an integrated, quantitative approach to risk management. KKR Prisma takes a specialist approach by seeking leading niche hedge fund managers in various alternative investment strategies. Various strategies are offered to investors, including moderate and low‑volatility, equity, credit and opportunistic, in both commingled and separate account portfolios. For the period beginning in June 2004 through December 31, 2015, our hedge fund-of-funds low volatility strategy, which consists of the majority of our hedge fund-of-funds AUM and FPAUM, generated a gross annualized return of 7.0%. As of December 31, 2015, our hedge fund-of-funds accounted for $11.0 billion of AUM.
Strategic Partnerships
Through our Public Markets segment, we also have developed strategic partnerships by acquiring minority stakes in other hedge fund managers. In this business we have a 24.9% interest in Marshall Wace LLP, a leading global liquid alternatives manager, a 24.9% interest in Nephila Capital Ltd., or Nephila, an investment manager focused on investing in natural catastrophe and weather risk, a 24.9% interest in BlackGold Capital Management L.P., or BlackGold, a credit‑oriented investment manager focused on investing in energy and hard asset investments. We have also seeded Acion Partners Limited, a Hong Kong based investment manager that manages Asian event driven investments.
Public Markets Vehicle Structures
The table below presents information as of December 31, 2015 relating to our Public Markets vehicles:
| ($ in millions) | AUM | FPAUM | Typical Management Fee Rate | Incentive Fee / Carried Interest | Preferred Return | Duration of Capital | ||||||||||
| Leveraged Credit: | ||||||||||||||||
| Leveraged Credit SMAs/Funds | $ | 7,129 | $ | 6,647 | 0.50%-1.50% | Various (1) | Various (1) | Subject to redemptions | ||||||||
| CLO’s | 9,021 | 9,021 | 0.50% | Various (1) | Various (1) | 10-14 Years (2) | ||||||||||
| Total Leveraged Credit | 16,150 | 15,668 | ||||||||||||||
| Alternative Credit Vehicles (3) | 13,463 | 7,340 | 0.75%-1.50% (4) | 10.00-20.00% | 8.00-12.00% | 8-15 Years (2) | ||||||||||
| Hedge Fund Solutions | 11,028 | 10,530 | 0.50%-1.50% | Various (1) | Various (1) | Subject to redemptions | ||||||||||
| Strategic Partnerships (6) | 8,737 | 8,737 | 0.75%-2.00% | Various | Various | Subject to redemptions | ||||||||||
| Corporate Capital Trust (5) | 4,138 | 4,138 | 1.00% | 10.00% | 7.00% | 7 years (5) | ||||||||||
| Total | $ | 53,516 | $ | 46,413 |
| (1) | Certain funds and CLOs are subject to a performance fee in which the manager or general partner of the funds share in up to 20% (in our hedge fund solutions business, up to 10%) of the net profits earned by investors in excess of performance hurdles (generally tied to a benchmark or index) and subject to a provision requiring the funds and vehicles to regain prior losses before any performance fee is earned. |
| (2) | Term for duration of capital is since inception. Inception dates for CLOs were between 2004 and 2015 and for separately managed accounts and funds investing in alternative credit strategies from 2009 through 2015. |
| (3) | AUM and FPAUM include all assets invested by vehicles that principally invest in alternative credit strategies, respectively, and consequently may include a certain amount of assets, currently less than $1.0 billion, invested in other strategies. |
| (4) | Lower fees on uninvested capital in certain vehicles. |
| (5) | Corporate Capital Trust is a BDC sub-advised by KKR. By December 31, 2018, the capital in the Corporate Capital Trust vehicle may have an indefinite duration. This vehicle invests in both leveraged credit and alternative credit strategies. |
| (6) | Includes KKR's pro rata portion of AUM and FPAUM managed by other asset managers in which KKR holds a minority interest. |
Capital Markets
Our Capital Markets segment is comprised primarily of our global capital markets business. Our capital markets business supports our firm, our portfolio companies and third-party clients by developing and implementing both traditional and non-traditional capital solutions for investments or companies seeking financing. These services include arranging debt and equity financing for transactions, placing and underwriting securities offerings and providing other types of capital markets services. When we underwrite an offering of securities or a loan on a firm commitment basis, we commit to buy and sell an issue of securities or indebtedness and generate revenue by purchasing the securities or indebtedness at a discount or for a fee. When we act in an agency capacity, we generate revenue for arranging financing or placing securities or debt with capital markets investors. We may also provide issuers with capital markets advice on security selection, access to markets, marketing considerations, securities pricing, and other aspects of capital markets transactions in exchange for a fee. KKR Capital Markets LLC is an SEC-registered broker-dealer and a FINRA member, and we are also registered or authorized to carry out certain broker-dealer activities in various countries in North America, Europe, Asia-Pacific and the Middle East. Our third party capital markets activities are generally carried out through Merchant Capital Solutions LLC, a joint venture with one other unaffiliated partner, and non-bank financial companies, or NBFCs, in India.
Client & Partner Group
We have a Client & Partner Group that is responsible for raising capital for us globally across all products, expanding our client relationships across asset classes and across types of fund investors, developing products to meet our clients’ needs, and servicing existing fund investors and products. We also provide fundraising services to fund managers in whom we have invested through our stakes business. As of December 31, 2015, we had 80 executives and professionals dedicated to our Client & Partner Group.
As of December 31, 2015, we had 895 investors in funds across all our strategies, which reflects the addition of over 100 investors during the year. On average, a fund investor is invested in approximately 1.7 of our products as of December 31, 2015. The following charts detail our investor base by type and geography as of December 31, 2015.
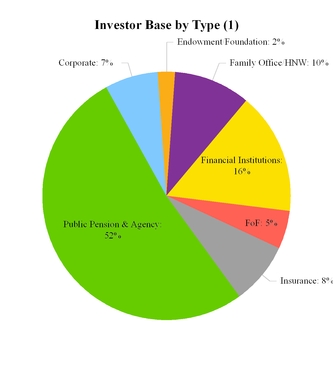
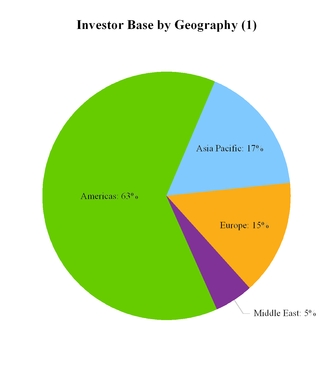
| (1) | Based on the AUM of our Private Markets investment funds, Private Markets co‑investment vehicles, and Public Markets separately managed accounts and investment funds. These charts exclude (a) commitments in connection with Private and Public Markets vehicles for which we are entitled to management fees or carried interest upon the satisfaction of certain conditions, which had not been met as of December 31, 2015 and (b) assets managed by other asset managers with which KKR has formed strategic partnerships where KKR does not hold more than a 50% ownership interest. Allocations are assigned to a type or geographic region according to subscriptions received from a limited partner. |
Principal Activities
Through our Principal Activities segment, we manage the firm’s own assets and deploy capital to support and grow our businesses. We use our Principal Activities assets to support our investment management and capital markets businesses. Typically, the funds in our Private Markets and Public Markets businesses contractually require us, as general partner of the funds, to make sizable capital commitments from time to time. We believe our general partner commitments are indicative of the conviction we have in a given fund’s strategy, which assists us in raising new funds from limited partners. We also deploy Principal Activities assets in order to help establish a track record for fundraising purposes in new strategies. We may also use our own capital to seed investments for new funds, to bridge capital selectively for our funds’ investments or finance strategic acquisitions and partnerships, although the financial results of an acquired business or strategic partnership have been reported in our other segments.
Our Principal Activities assets also provide the required capital to fund the various commitments of our Capital Markets business when underwriting or syndicating securities, or when providing term loan commitments for transactions involving our portfolio companies and for third parties. Our Principal Activities assets also may be utilized to satisfy regulatory requirements for our Capital Markets business and risk retention requirements for our CLO business.
We also make opportunistic investments through our Principal Activities segment, which include co-investments alongside our Private Markets and Public Markets funds, as well as make Principal Activities investments that do not involve our Private Markets or Public Markets funds.
We endeavor to use our balance sheet strategically and opportunistically to generate an attractive risk-adjusted return on equity in a manner that is consistent with our fiduciary duties and in compliance with applicable laws.
The chart below presents the holdings of our Principal Activities segment by asset class as of December 31, 2015.
Holdings by Asset Class (1)
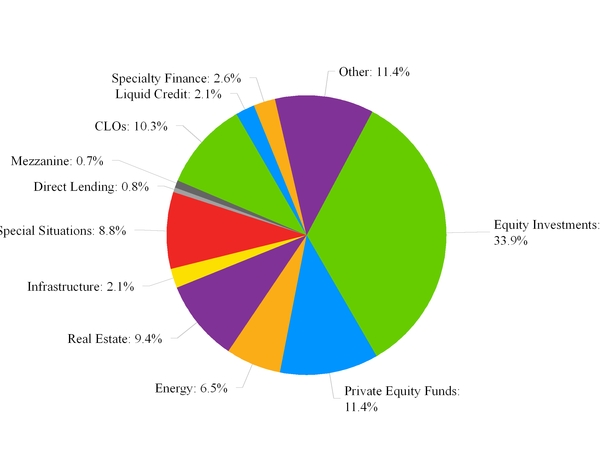
| (1) | General partner commitments in our funds are included in the various asset classes shown above. Assets and revenues of other asset managers with which KKR has formed strategic partnerships where KKR does not hold more than 50% ownership interest are not included in our Principal Activities business but are reported in the financial results of our other segments. Private equity funds represent holdings in KKR sponsored private equity funds. Equity investments consist of opportunistic investments including co-investments alongside such KKR sponsored private equity funds. However, equity investments in other asset classes, such as real estate, special situations and energy appear in these other asset classes. |
Competition
We compete with other investment managers for both fund investors and investment opportunities. The firm’s competitors consist primarily of sponsors of public and private investment funds, real estate development companies, business development companies, investment banks, commercial finance companies and operating companies acting as strategic buyers. We believe that competition for fund investors is based primarily on investment performance, investor liquidity and willingness to invest, investor perception of investment managers’ drive, focus and alignment of interest, business reputation, duration of relationships, quality of services, pricing, fund terms including fees, and the relative attractiveness of the types of investments that have been or are to be made. We believe that competition for investment opportunities is based primarily on the pricing, terms and structure of a proposed investment and certainty of execution. In addition to these traditional competitors within the global investment management industry, we also face competition from local and regional firms, financial institutions and sovereign wealth funds, in the various countries in which we invest. In certain emerging markets, local firms may have more established relationships with the companies in which we are attempting to invest. These competitors often fall into one of the aforementioned categories but in some cases may represent new types of fund investors, including high net worth individuals, family offices and state‑ sponsored entities.
There are numerous funds focused on private equity, real assets, credit and hedge fund strategies that compete for investor capital. Fund managers have also increasingly adopted investment strategies outside of their traditional focus. For example,
funds focused on credit and equity strategies have become active in taking control positions in companies, while private equity funds have acquired minority equity or debt positions in publicly listed companies. This convergence could heighten competition for investments. Furthermore, as institutional fund investors increasingly consolidate their relationships for multiple investment products with a few investment firms, competition for capital from such institutional fund investors may become more acute.
Some of the entities that we compete with as an investment firm may have greater financial, technical, marketing and other resources and more personnel than us and, in the case of some asset classes, longer operating histories, more established relationships or greater experience. Several of our competitors also have raised, or may raise, significant amounts of capital and have investment objectives that are similar to the investment objectives of our funds, which may create additional competition for investment opportunities. Some of these competitors may also have lower costs of capital and access to funding sources that are not available to us, which may create competitive advantages for them. For example, master limited partnerships, or MLPs, which typically invest in oil and gas assets, may have a lower cost of capital than, and may compete with our energy funds for investment opportunities. In addition, some of these competitors may have higher risk tolerances, different risk assessments or lower return thresholds, which could allow them to consider a wider range of investments and to bid more aggressively than us for investments. Strategic buyers may also be able to achieve synergistic cost savings or revenue enhancements with respect to a targeted portfolio company, which may provide them with a competitive advantage in bidding for such investments.
We expect to compete as a capital markets business primarily with investment banks and independent broker‑dealers in the North America, Europe, Asia‑ Pacific and the Middle East. We principally focus our capital markets activities on the firm, our portfolio companies and fund investors, but we also seek to service other third parties, principally through Merchant Capital Solutions LLC. While we generally target customers with whom we have existing relationships, those customers may have similar relationships with the firm’s competitors, many of whom will have access to competing securities transactions, greater financial, technical or marketing resources or more established reputations than us. The limited operating history of our capital markets business could make it difficult for us to compete with established investment banks or broker‑dealers, participate in capital markets transactions of issuers or successfully grow the firm’s capital markets business over time.
Competition is also intense for the attraction and retention of qualified employees and consultants. Our ability to continue to compete effectively in our businesses will depend upon our ability to attract new employees and consultants and retain and motivate our existing employees and consultants.
Employees, Consultants and Advisors
As of December 31, 2015, we employed approximately 1,200 people worldwide:
| Investment Professionals | 370 | |
| Other Professionals | 569 | |
| Support Staff | 257 | |
| Total Employees(1) | 1,196 | |
(1) Does not include consolidated consultants and other consultants who provide services to us or our funds.
Investment Professionals
Our 370 investment professionals come from diverse backgrounds in private equity, real assets, credit, hedge funds and other asset classes and include executives with operations, strategic consulting, risk management, liability management and finance experience. As a group, these professionals provide us with a strong global team for identifying attractive investment opportunities, creating value, and generating superior returns.
Other Professionals
Our 569 other professionals come from diverse backgrounds in capital markets, capital raising, client services, public affairs, finance, tax, legal, compliance, human resources, and information technology. As a group, these professionals provide us with a strong team for overseeing investments and performing capital markets activities, servicing our existing fund investors and creating relationships with new fund investors globally. Additionally, a majority of these other professionals are responsible for supporting the global infrastructure of KKR.
KKR Capstone
We have developed an institutionalized process for creating value in investments. As part of our effort, we utilize a team of 49 operating consultants at KKR Capstone, who are not KKR employees but work exclusively with our investment professionals and portfolio company management teams or our designees. With professionals in North America, Europe and the Asia‑Pacific, KKR Capstone provides additional expertise for assessing investment opportunities and assisting managers of portfolio companies in defining strategic priorities and implementing operational changes. During the initial phases of an investment, KKR Capstone’s work seeks to implement our thesis for value creation. These operating consultants may assist portfolio companies in addressing top‑line growth, cost optimization and efficient capital allocation and in developing operating and financial metrics. Over time, this work shifts to identifying challenges and taking advantage of business opportunities that arise during the life of an investment. KKR Capstone is consolidated in KKR’s financial results for GAAP purposes, but is not a subsidiary or affiliate of KKR.
Senior Advisors
To complement the expertise of our investment professionals, we have a team of senior advisors and other advisors. While not KKR employees, they provide us with additional operational and strategic insights. The responsibilities of senior advisors include serving on the boards of our portfolio companies, helping us source and evaluate individual investment opportunities and assisting portfolio companies with operational matters. These individuals include current and former chief executive officers, chief financial officers and chairmen of major corporations and leading positions of public agencies worldwide.
Organizational Structure
The following simplified diagram illustrates our organizational structure as of December 31, 2015, unless otherwise noted. Certain entities depicted below may be held through intervening entities not shown in the diagram.
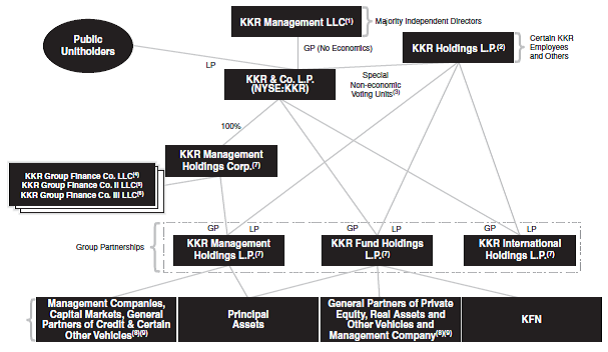
| (1) | KKR Management LLC serves as the general partner of KKR & Co. L.P., which is governed by a Board of Directors consisting of a majority of independent directors. KKR Management LLC does not hold any economic interests in KKR & Co. L.P. and is owned by senior KKR employees. |
| (2) | KKR Holdings is the holding vehicle through which certain of our current and former employees and other persons indirectly own their interest in KKR. KKR Group Partnership Units that are held by KKR Holdings are exchangeable for our common units on a one‑for‑one basis, subject to customary conversion rate adjustments for splits, unit distributions and reclassifications and compliance with applicable vesting and transfer restrictions. As limited partner interests, these KKR Group Partnership Units are non‑voting and do not entitle KKR Holdings to participate in the management of our business and affairs. As of December 31, 2015, KKR Holdings had a 44.1% interest in our business indirectly through its limited partner interests in the KKR Group Partnerships. |
| (3) | KKR Holdings holds special non‑economic voting units in our partnership that entitle it to cast, with respect to those limited matters that may be submitted to a vote of our unitholders, a number of votes equal to the number of KKR Group Partnership Units that it holds from time to time. |
| (4) | KKR Group Finance Co. LLC is a wholly‑owned subsidiary of KKR Management Holdings Corp. and the issuer of our $500 million aggregate principal amount of 6.375% Senior Notes due 2020 (the “2020 Senior Notes”). The 2020 Senior Notes are guaranteed by KKR & Co. L.P. and the KKR Group Partnerships. |
| (5) | KKR Group Finance Co. II LLC is a wholly‑owned subsidiary of KKR Management Holdings Corp. and the issuer of our $500 million aggregate principal amount of 5.500% Senior Notes due 2043 (the “2043 Senior Notes”), which were issued on February 1, 2013. The 2043 Senior Notes are guaranteed by KKR & Co. L.P. and the KKR Group Partnerships. |
| (6) | KKR Group Finance Co. III LLC is a wholly‑owned subsidiary of KKR Management Holdings Corp. and the issuer of our $1,000 million aggregate principal amount of 5.125% Senior Notes due 2044 (the “2044 Senior Notes”), which were issued on May 29, 2014 and on March 18, 2015. The 2044 Senior Notes are guaranteed by KKR & Co. L.P. and the KKR Group Partnerships. |
| (7) | Because the income of KKR Management Holdings L.P. is likely to be primarily non‑qualifying income for purposes of the qualifying income exception to the publicly traded partnership rules, we formed KKR Management Holdings Corp., which is subject to taxation as a corporation for U.S. federal income tax purposes, to hold our KKR Group Partnership Units in KKR Management Holdings L.P. Accordingly, our allocable share of the taxable income of KKR Management Holdings L.P. will be subject to taxation at a corporate rate. KKR Management Holdings L.P., which is treated as a partnership for U.S. federal income tax purposes, was formed to hold interests in our fee generating businesses and other assets that may not generate qualifying income for purposes of the qualifying income exception to the publicly traded partnership rules. KKR Fund Holdings L.P., which is also treated as a partnership for U.S. federal income tax purposes, was formed to hold interests in our businesses and assets that will generate qualifying income for purposes of the qualifying income exception to the publicly traded partnership rules. KKR International |
Holdings L.P. was formed generally to hold certain non‑U.S. assets that may generate non‑qualifying income under the U.S. federal income tax laws applicable to publicly traded partnerships. As of February 22, 2016, KKR International Holdings L.P. holds no assets.
| (8) | KKR Management Holdings L.P. is the parent company of Kohlberg Kravis Roberts & Co. L.P., the SEC‑registered investment adviser, which in turn is generally the parent company for most of KKR’s other management and capital markets subsidiaries including KKR Credit Advisors (US) LLC, Prisma Capital Partners LP and KKR Capital Markets Holdings L.P., the holding company for KKR Capital Markets LLC. KKR Fund Holdings L.P. is the parent company of KKR Credit Advisors (Ireland). |
| (9) | 40% of the carried interest earned in relation to our investment funds and carry paying co‑investment vehicles is allocated to a carry pool, from which carried interest is allocable to our employees and selected other individuals. No carried interest has been allocated with respect to co‑investments acquired from KPE in the KPE Transaction. |
Regulation
Our operations are subject to regulation and supervision in a number of jurisdictions. The level of regulation and supervision to which we are subject varies from jurisdiction to jurisdiction and is based on the type of business activity involved. We, in conjunction with our outside advisors and counsel, seek to manage our business and operations in compliance with such regulation and supervision. The regulatory and legal requirements that apply to our activities are subject to change from time to time and may become more restrictive, which may make compliance with applicable requirements more difficult or expensive or otherwise restrict our ability to conduct our business activities in the manner in which they are now conducted. Changes in applicable regulatory and legal requirements, including changes in their enforcement, could materially and adversely affect our business and our financial condition and results of operations. As a matter of public policy, the regulatory bodies that regulate our business activities are generally responsible for safeguarding the integrity of the securities and financial markets and protecting fund investors who participate in those markets rather than protecting the interests of our unitholders.
United States
Regulation as an Investment Adviser
We conduct our advisory business through our investment adviser subsidiaries, including Kohlberg Kravis Roberts & Co. L.P. and its wholly‑owned subsidiaries KKR Credit Advisors (US) LLC and Prisma Capital Partners LP, each of which is registered as an investment adviser with the SEC under the Investment Advisers Act. The investment advisers are subject to the anti‑fraud provisions of the Investment Advisers Act and to fiduciary duties derived from these provisions which apply to our relationships with our advisory clients globally, including funds that we manage. These provisions and duties impose restrictions and obligations on us with respect to our dealings with our fund investors and our investments, including for example restrictions on agency cross and principal transactions. Our registered investment advisers are subject to periodic SEC examinations and other requirements under the Investment Advisers Act and related regulations primarily intended to benefit advisory clients. These additional requirements relate, among other things, to maintaining an effective and comprehensive compliance program, recordkeeping and reporting requirements and disclosure requirements. The Investment Advisers Act generally grants the SEC broad administrative powers, including the power to limit or restrict an investment adviser from conducting advisory activities in the event it fails to comply with federal securities laws. Additional sanctions that may be imposed for failure to comply with applicable requirements include the prohibition of individuals from associating with an investment adviser, the revocation of registrations and other censures and fines.
KKR Credit Advisors (US) LLC is also subject to regulation under the Investment Company Act as an investment adviser to a registered investment company. The KKR Income Opportunities Fund is a closed‑end management company registered under the Investment Company Act. The closed‑end management company and KKR Credit Advisors (US) LLC are subject to the Investment Company Act and the rules thereunder, which among other things regulate the relationship between a registered investment company and its investment adviser and prohibit or restrict principal transactions and joint transactions.
Regulation as a Broker‑Dealer
KKR Capital Markets LLC, one of our subsidiaries, is registered as a broker‑ dealer with the SEC under the Exchange Act and in all 50 U.S. States and U.S. territories and is a member of the Financial Industry Regulatory Authority, or FINRA. MCS Capital Markets LLC is registered as a broker‑ dealer with the SEC under the Exchange Act and in 35 U.S. States. As registered broker‑dealers, KKR Capital Markets LLC and MCS Capital Markets LLC are subject to periodic SEC and FINRA examinations and reviews. A broker‑dealer is subject to legal requirements covering all aspects of its securities business, including sales and trading practices, public and private securities offerings, use and safekeeping of customers’ funds and securities, capital structure, record‑ keeping and retention and the conduct and qualifications of directors, officers, employees and other associated persons. These requirements include the SEC’s “uniform net capital rule,” which specifies the minimum
level of net capital that a broker‑dealer must maintain, requires a significant part of the broker‑ dealer’s assets to be kept in relatively liquid form, imposes certain requirements that may have the effect of prohibiting a broker‑dealer from distributing or withdrawing its capital and subjects any distributions or withdrawals of capital by a broker‑dealer to notice requirements. These and other requirements also include rules that limit a broker‑dealer’s ratio of subordinated debt to equity in its regulatory capital composition, constrain a broker‑dealer’s ability to expand its business under certain circumstances and impose additional requirements when the broker‑dealer participates in securities offerings of affiliated entities. Violations of these requirements may result in censures, fines, the issuance of cease‑and‑desist orders, revocation of licenses or registrations, the suspension or expulsion from the securities industry of the broker‑dealer or its officers or employees or other similar consequences by regulatory bodies.
United Kingdom
We have several subsidiaries which are authorized and regulated by the United Kingdom Financial Conduct Authority, or FCA, under the Financial Services and Markets Act 2000, or FSMA, and are authorized in the United Kingdom with permission to engage in certain specified activities. FSMA and related rules govern most aspects of investment business, including sales, research and trading practices, provision of investment advice, corporate finance, use and safekeeping of client funds and securities, regulatory capital, record keeping, margin practices and procedures, approval standards for individuals, anti‑money laundering, periodic reporting and settlement procedures. The FCA is responsible for administering these requirements and our compliance with the FSMA and related rules. Violations of these requirements may result in censures, fines, imposition of additional requirements, injunctions, restitution orders, revocation or modification of permissions or registrations, the suspension or expulsion from certain “controlled functions” within the financial services industry of officers or employees performing such functions or other similar consequences.
KKR Capital Markets Limited has permission to engage in a number of regulated activities regulated under FSMA, including dealing as principal or agent and arranging deals in relation to certain types of specified investments and arranging the safeguarding and administration of assets. KKR Capital Markets Limited also benefits from a passport under the single market directives to offer services cross border into all countries in the European Economic Area and Gibraltar. Kohlberg Kravis Roberts & Co. Partners LLP has permission to engage in a number of regulated activities including advising on and arranging deals relating to corporate finance business in relation to certain types of specified investments. KKR Asset Management Partners LLP has permission to engage in a number of regulated activities including and advising on and arranging deals in relation to certain types of specified investments. KKR Credit Advisors (UK) has permission to advise, arrange, manage and deal as agent in certain types of investments. Prisma Capital Management International LLP is authorized to carry on any investment services and activities on a regular basis except reception and transmission of orders in relation to one or more financial instruments or investment advice.
Other Jurisdictions
Certain other subsidiaries or funds that we advise are registered with, have been licensed by or have obtained authorizations to operate in their respective jurisdictions outside of the United States. These registrations, licenses or authorizations relate to providing investment advice, broker‑dealer activities, marketing of securities and other regulated activities. Failure to comply with the laws and regulations governing these subsidiaries and funds that have been registered, licensed or authorized could expose us to liability and/or damage our reputation.
KKR Credit Advisors (Ireland) and KKR Alternative Investment Management are regulated by the Central Bank of Ireland. KKR Credit Advisors (Ireland) is authorized to carry out a number of regulated activities including receiving and transmitting orders, portfolio management and providing investment advice. KKR Alternative Investment Management is an authorized EU alternative investment manager permitted to conduct portfolio management, risk management and certain administrative activities.
KKR Capital Markets LLC and MCS Capital Markets LLC, respectively, are also registered as an international dealer under the Securities Act (Ontario). This registration permits us to trade in non‑Canadian equity and debt securities with certain types of investors located in Ontario, Canada.
KKR Capital Markets Japan Limited, a joint stock corporation, is registered as a Type I and Type II Financial Instruments Business Operator (broker dealer) under the Financial Instruments and Exchange Act of Japan, and a money lender under the Money Lending Business Act of Japan.
KKR MENA Limited, a Dubai International Financial Centre company, is licensed to arrange credit or deals in investments, advise on financial products or credit, and manage assets, and is regulated by the Dubai Financial Services Authority.
KKR Saudi Limited is licensed by the Capital Market Authority in Saudi Arabia and is authorized for the activity of arranging in the securities business.
KKR Australia Pty Limited and KKR Australia Investment Management Pty Limited are Australian financial services licensed and are authorized to provide advice on and deal in financial products for wholesale clients, and are regulated by the Australian Securities and Investments Commission.
KKR Capital Markets Asia Limited is licensed by the Securities and Futures Commission in Hong Kong to carry on dealing in securities and advising on securities regulated activities.
KKR Singapore Pte. Ltd. holds a capital markets services license to conduct fund management for accredited and/or institutional investors only, and is regulated by Monetary Authority of Singapore.
KKR Holdings Mauritius, Ltd. and KKR Account Adviser (Mauritius), Ltd. are unrestricted investment advisers authorized to manage portfolios of securities and give advice on securities transactions, and are regulated by the Financial Services Commission, Mauritius.
KKR Account Adviser (Mauritius), Ltd. is registered as a Foreign Institutional Investor, or FII, with the Securities and Exchange Board of India ("SEBI"), under the SEBI (Foreign Institutional Investors) Regulations, 1995 pursuant to which it can make investments in listed and unlisted securities of Indian issuers.
KKR Mauritius Direct Investments I, Ltd. is registered as a Foreign Portfolio Investor, or FPI, with SEBI under the SEBI (Foreign Portfolio Investor) Regulations, 2014 pursuant to which it can make investments in listed and unlisted securities of Indian issuers, and is incorporated as an investment holding company in Mauritius regulated by the Financial Services Commission, Mauritius.
KKR India Financial Services Private Limited is registered with the Reserve Bank of India as a non‑deposit taking non‑banking financial company and is authorized to undertake lending and financing activities.
KKR Capital Markets India Private Limited is licensed by the SEBI as a merchant bank that is authorized to execute capital market mandates, underwrite issues, offer investment advisory and other consultancy/advisory services.
Silverview Investments Pte. Ltd., Silverview Portfolio Investments Pte. Ltd. (earlier known as KKR Asia II Portfolio Investors Pte. Ltd.), Moneyline Portfolio Investments Limited are registered with SEBI either as an FII sub‑account or an FPI pursuant to which they can make investments in listed and unlisted securities of Indian issuers.
KKR India Asset Finance Private Limited (formerly known as Motichand Finance Private Limited) is registered with the Reserve Bank of India as a non‑ deposit taking non‑banking financial company and is authorized to undertake lending and financing activities.
Daena Venture Capital Investments, Ltd. is incorporated as an investment holding company in Mauritius regulated by the Financial Services Commission, Mauritius and was registered with SEBI as a foreign venture capital investor, or FVCI; however the FVCI certificated of registration has been surrendered with effect from December 18, 2015.
KKR Asia II Venture Investments Pte Ltd. is registered with SEBI as a foreign venture capital investor, or FVCI, under the SEBI (Foreign Venture Capital Investors) Regulations, 2000 pursuant to which it can make certain investments in securities of Indian issuers and is incorporated as an investment holding company in Singapore.
From time to time, one or more of our investment funds or their related investment vehicles may be regulated as a mutual fund by the Cayman Islands Monetary Authority, regulated as an investment limited partnership by the Central Bank of Ireland, listed on the Irish Stock Exchange, notified with the Financial Services Agency of Japan for sale pursuant to certain private placement exemptions and/or for investment pursuant to certain exemption, registered with the Financial Supervisory Service of the Republic of Korea, licensed by or granted in principal approval from SEBI, subject to the regulatory supervision of the Commission de Surveillance du Secteur Financier of Luxembourg, notified with the Netherlands Authority for Financial Markets for sale pursuant to certain private placement exemptions, or registered under the Investment Company Act.
There are a number of legislative and regulatory initiatives in the United States and in Europe that could significantly affect our business. Please see “Risk Factors-Risks Related to Our Business-Extensive regulation of our businesses affects our activities and creates the potential for significant liabilities and penalties. The possibility of increased regulatory focus or legislative or regulatory changes could result in additional burdens on our business.”
Website and Availability of SEC Filings
Our website address is www.kkr.com. Information on our website is not incorporated by reference herein and is not a part of this Form 10‑K. We make available free of charge on our website or provide a link on our website to our Annual Report on Form 10‑K, Quarterly Reports on Form 10‑Q and Current Reports on Form 8‑K, and any amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Exchange Act, as soon as reasonably practicable after those reports are electronically filed with, or furnished to, the SEC. To access these filings, go to the “KKR & Co. L.P.” portion of our “Investor Center” page on our website, then click on “SEC Filings”. You may also read and copy any document we file at the SEC’s public reference room located at 100 F Street, N.E., Washington, DC 20549. Please call the SEC at 1‑800‑SEC‑0330 for further information on the public reference room. In addition these reports and the other documents we file with the SEC are available at a website maintained by the SEC at www.sec.gov.
From time to time, we may use our website as a channel of distribution of material information. Financial and other material information regarding our company is routinely posted on and accessible at www.kkr.com. In addition, you may automatically receive e‑mail alerts and other information about our company by enrolling your e‑mail address by visiting the “E‑ mail Alerts” section at under the “KKR & Co. L.P.” section of the “Investor Center” heading at www.kkr.com.
Previous: Cover and table of contents · Next: Item 1A. RISK FACTORS