 filings.tools
Southwest Airlines 10-K 2015-12-31
Filed 2016-02-03. 20 sections, 501K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 luv-12312015x10k.htm FORM 10-K
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
(Mark One)
| þ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
| For the fiscal year ended December 31, 2015 |
| or |
| ¨ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
| For the transition period from ________ to ________ |
Commission File No. 1-7259

Southwest Airlines Co.
(Exact name of registrant as specified in its charter)
| TEXAS | 74-1563240 |
| (State or other jurisdiction of | (IRS Employer |
| incorporation or organization) | Identification No.) |
| P.O. Box 36611 | |
| Dallas, Texas | 75235-1611 |
| (Address of principal executive offices) | (Zip Code) |
Registrant's telephone number, including area code: (214) 792-4000
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Name of Each Exchange on Which Registered | |
| Common Stock ($1.00 par value) | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act:
None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes þ No ¨
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ¨ No þ
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes þ No ¨
Indicate by checkmark whether the registrant has submitted electronically and posted on its corporate Website, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes þ No ¨
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. þ
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See the definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | þ | Accelerated filer | ¨ | Non-accelerated filer | ¨ | Smaller reporting company | ¨ |
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ¨ No þ
The aggregate market value of the common stock held by non-affiliates of the registrant was approximately $21,774,060,585 computed by reference to the closing sale price of the common stock on the New York Stock Exchange on June 30, 2015, the last trading day of the registrant’s most recently completed second fiscal quarter.
Number of shares of common stock outstanding as of the close of business on January 29, 2016: 638,070,032 shares
DOCUMENTS INCORPORATED BY REFERENCE
Portions of the Definitive Proxy Statement for the Company’s Annual Meeting of Shareholders to be held May 18, 2016, are incorporated into Part III of this Annual Report on Form 10-K.
TABLE OF CONTENTS
Showing the first 8K of 83K characters. Open the full section
Item 1A. Risk Factors
The airline industry is particularly sensitive to changes in economic conditions; in the event of unfavorable economic conditions or economic uncertainty, the Company’s results of operations could be negatively affected, which could require the Company to adjust its business strategies.
The airline industry, which is subject to relatively high fixed costs and highly variable and unpredictable demand, is particularly sensitive to changes in economic conditions. Historically, unfavorable U.S. economic conditions have driven changes in travel patterns and have resulted in reduced spending for both leisure and business travel. For some consumers, leisure travel is a discretionary expense, and short-haul travelers, in particular, have the option to replace air travel with surface travel. Businesses are able to forego air travel by using communication alternatives such as videoconferencing and the Internet or may be more likely to purchase less expensive tickets to reduce costs, which can result in a decrease in average revenue per seat. Unfavorable economic conditions have also historically hampered the ability of airlines to raise fares to counteract any increases in fuel, labor, and other costs. Although the U.S. economy has experienced moderate economic growth over the course of the past three years, any continuing or future U.S. or global economic uncertainty could negatively affect the Company’s results of operations and could cause the Company to adjust its business strategies.
The Company’s business can be significantly impacted by high and/or volatile fuel prices, and the Company’s operations are subject to disruption in the event of any delayed supply of fuel; therefore, the Company’s strategic plans and future profitability are likely to be impacted by the Company’s ability to effectively address fuel price increases and fuel price volatility and availability.
Airlines are inherently dependent upon energy to operate, and jet fuel and oil represented approximately 23 percent of the Company’s operating expenses for 2015. Although 2015 fuel prices were lower than in 2014, and dropped significantly beginning in the second half of 2014, the cost of fuel continues to be volatile and unpredictable, and even a small change in market fuel prices can significantly affect profitability. Furthermore, volatility in fuel prices can be due to many external factors that are beyond the Company’s control. For example, fuel prices can be impacted by political and economic factors, such as (i) dependency on foreign imports of crude oil and the potential for hostilities or other conflicts in oil producing areas; (ii) limited domestic refining or pipeline capacity; (iii) worldwide demand for fuel, particularly in developing countries, which can result in inflated energy prices; (iv) changes in U.S. governmental policies on fuel production, transportation, taxes, and marketing; and (v) changes in currency exchange rates.
If higher fuel prices were to return, the Company’s ability to effectively address fuel price increases could be limited by its ability to increase fares, which can be difficult in challenging economic environments when low fares are often used to stimulate traffic. The Company's ability to increase fares can also be limited by factors such as its historical low-fare reputation, the portion of its Customer base that purchases travel for leisure purposes, the competitive nature of the airline industry generally, and the risk that higher fares will drive a decrease in demand.
The Company attempts to manage its risk associated with volatile jet fuel prices by utilizing over-the-counter fuel derivative instruments to hedge a portion of its future jet fuel purchases. However, as evidenced by the extreme decline in jet fuel prices during the fourth quarter of 2014 and early 2015, and again in late 2015, energy prices can fluctuate significantly in a relatively short amount of time. Because the Company uses a variety of different derivative instruments at different price points, the Company is subject to the risk that the fuel derivatives it uses will not provide adequate protection against significant increases in fuel prices and could in fact result in additional volatility in the Company’s earnings. The Company is also subject to the risk that additional cash collateral may be required to be posted to fuel hedge counterparties, which could have a significant impact on the Company’s financial position and liquidity.
In addition, the Company is subject to the risk that its fuel derivatives will not be effective or that they will no longer qualify for hedge accounting under applicable accounting standards, which can create additional earnings volatility. Adjustments in the Company’s overall fuel hedging strategy, as well as the ability of the commodities used in fuel hedging to qualify for special hedge accounting, are likely to continue to affect the Company’s results of operations. In addition, there can be no assurance that the Company will be able to cost-effectively hedge against increases in fuel prices.
The Company’s fuel hedging arrangements and the various potential impacts of hedge accounting on the Company’s financial position, cash flows, and results of operations are discussed in more detail under “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” “Quantitative and Qualitative Disclosures About Market Risk,” and in Note 1 and Note 10 to the Consolidated Financial Statements.
The Company is also reliant upon the readily available supply and timely delivery of jet fuel to the airports that it serves. A disruption in that supply could present significant challenges to the Company’s operations and could ultimately cause the cancellation of flights and/or the inability of the Company to provide service to a particular airport.
The Company’s low-cost structure has historically been one of its primary competitive advantages, and many factors have affected and could continue to affect the Company’s ability to control its costs.
The Company’s low-cost structure has historically been one of its primary competitive advantages, as it has enabled it to offer low fares, drive traffic volume, and grow market share. The Company has limited control over fuel and labor costs, as well as other costs such as regulatory compliance costs. Jet fuel and oil constituted approximately 23 percent of the Company’s operating expenses during 2015, and the cost of fuel is subject to the external factors discussed in the second Risk Factor above. Salaries, wages, and benefits constituted approximately 41 percent of the Company’s operating expenses during 2015. The Company’s ability to control labor costs is limited by the terms of its collective-bargaining agreements, and increased labor costs have negatively impacted the Company’s low-cost competitive position. As discussed further under “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” the Company’s unionized workforce, which makes up the majority of its Employees, has had pay scale increases as a result of contractual rate increases. Furthermore, as indicated above under “Business - Employees,” the majority of Southwest’s unionized Employees, including its Pilots; Mechanics; Ramp, Operations, Provisioning, and Freight Agents; Flight Attendants; Material Specialists; Facilities Maintenance Technicians; Flight Crew Training Instructors; and Source of Support Representatives, are in unions currently in negotiations for labor agreements, which could continue to put pressure on the Company’s labor costs. As discussed above under “Business - Regulation,” the airline industry is heavily regulated, and the Company’s regulatory compliance costs are subject to potentially significant increases from time to time based on actions by the regulatory agencies. Additionally, when other airlines reduce their capacity, airport costs are then allocated among a fewer number of total flights, which can result in increased landing fees and other costs for the Company. The Company is also reliant upon third party vendors and service providers, and its low-cost advantage is also dependent in part on its ability to obtain and maintain commercially reasonable terms with those parties.
As discussed above under “Business - Insurance,” the Company carries insurance of types customary in the airline industry and, in the past, has also been provided supplemental, first-party, war-risk insurance coverage by the federal
government. Since the government-provided supplemental coverage from the Wartime Act was set to expire on September 30, 2014, the Company proactively canceled its government provided war-risk insurance coverage prior to that date and purchased comparable coverage via the commercial insurance marketplace. Although the Company was able to purchase comparable coverage via the commercial insurance marketplace, available commercial insurance in the future could be more expensive and/or have material differences in coverage than is currently provided and may not be adequate to protect against the Company's risk of loss from future acts of terrorism. In addition, an accident or other incident involving Southwest aircraft could result in costs in excess of its related insurance coverage, which costs could be substantial. Any aircraft accident or other incident, even if fully insured, could also have a material adverse effect on the public’s perception of the Company.
The Company cannot guarantee it will be able to maintain or improve upon its current level of low-cost advantage over many of its airline competitors. Some of the Company’s competitors have achieved lower employee pay scales through bankruptcy. Further, some competitors have continued to grow their fleets and expand their networks, potentially enabling them to better control costs per available seat mile. In addition, like Southwest, some competitors have plans to add a significant number of new aircraft to their fleets, which could potentially decrease their operating costs through better fuel efficiencies, and lower maintenance costs. Some of the Company’s competitors have taken advantage of reorganization in bankruptcy, and even the threat of bankruptcy, not only to lower employee pay scales, but also to decrease operating costs through renegotiated supply and financing agreements. In addition, some airlines have consolidated and reported significant cost synergies.
The Company is increasingly dependent on technology to operate its business and continues to implement substantial changes to its information systems; any failure, disruption, or breach in the Company’s information systems could materially adversely affect its operations.
The Company is increasingly dependent on the use of complex technology and systems to run its ongoing operations. In recent years the Company has been committed to technology improvements to support its ongoing operations and initiatives and, as discussed above under “Business - Technology Initiatives,” the Company has invested in significant technology changes. The Company is in the midst of a multi-year project to completely replace its reservation system. In 2014, the Company launched the Amadeus Altéa reservations solution to support the Company’s international service. The Company has since begun implementing Amadeus' Altéa reservations solution as the Company's future single reservation system for both domestic and international reservations. This single reservation system is expected to be implemented in 2017. The Company intends to continue to devote significant technology resources towards, among other things, (i) the continued development of systems to improve both revenue management and network optimization capabilities, (ii) the aforementioned replacement of Southwest's existing domestic reservation system with the comprehensive Amadeus' Altéa reservations solution, and (iii) tools to improve operational management.
Integration of complex systems and technology presents significant challenges in terms of costs, human resources, and development of effective internal controls. Integration also presents the risk of operational or security inadequacy or interruption, which could materially affect the Company’s ability to effectively operate its business. The Company is also reliant upon third party performance for timely and effective completion of many of its technology initiatives.
In the ordinary course of business, the Company’s systems will continue to require modification and refinements to address growth and changing business requirements, including requirements related to international operations. In addition, the Company’s systems may require modification to enable the Company to comply with changing regulatory requirements. Modifications and refinements to the Company’s systems have been and are expected to continue to be expensive to implement and may divert management’s attention from other matters. In addition, the Company’s operations could be adversely affected, or it could face imposition of regulatory penalties, if it were unable to timely or effectively modify its systems as necessary.
The Company may occasionally experience system interruptions and delays that make its websites and services unavailable or slow to respond, which could prevent the Company from efficiently processing Customer transactions or providing services. This in turn could reduce the Company’s operating revenues and the attractiveness of its services. The Company’s computer and communications systems and operations could be damaged or interrupted by catastrophic events such as fires, floods, earthquakes, tornadoes and hurricanes, power loss, computer and telecommunications failures, acts of war or terrorism, computer viruses, security breaches, and similar events or disruptions. Any of these events could cause system interruptions, delays, and loss of critical data, and could prevent the Company from
processing Customer transactions or providing services, which could make the Company’s business and services less attractive and subject the Company to liability. Any of these events could damage the Company’s reputation and be expensive to remedy.
The Company’s business is labor intensive; therefore, the Company would be adversely affected if it were unable to maintain satisfactory relations with its Employees or its Employees’ Representatives or if the Company were unable to employ sufficient numbers of qualified Employees to maintain its operations.
The airline business is labor intensive. Salaries, wages, and benefits represented approximately 41 percent of the Company’s operating expenses for the year ended December 31, 2015. In addition, as of December 31, 2015, approximately 83 percent of the Company’s Employees were represented for collective bargaining purposes by labor unions, making the Company particularly exposed in the event of labor-related job actions. Employment-related issues that may impact the Company’s results of operations, some of which are negotiated items, include hiring/retention rates, pay rates, outsourcing costs, work rules, and health care costs. The Company has historically maintained positive relationships with its Employees and its Employees’ Representatives. However, as indicated above under “Business - Employees,” the majority of Southwest’s unionized Employees, including its Pilots; Mechanics; Ramp, Operations, Provisioning, and Freight Agents; Flight Attendants; Material Specialists; Facilities Maintenance Technicians; Flight Crew Training Instructors; and Source of Support Representatives, are in unions currently in negotiations for labor agreements, which could continue to put pressure on the Company’s labor costs. Increasing labor costs could negatively impact the Company’s competitive position.
The Company’s success also depends on its ability to attract and retain skilled personnel. Competition for skilled personnel may intensify if overall industry capacity increases and/or if high levels of current personnel reach retirement age. The Company may be required to increase existing levels of compensation to retain or supplement its skilled workforce. The inability to recruit and retain skilled personnel or the unexpected loss of key skilled personnel could adversely affect the Company’s operations.
The Company is currently dependent on single aircraft and engine suppliers, as well as single suppliers of certain other parts; therefore, the Company would be materially adversely affected if it were unable to obtain additional equipment or support from any of these suppliers or in the event of a mechanical or regulatory issue associated with their equipment.
The Company is dependent on Boeing as its sole supplier for aircraft and many of its aircraft parts and is dependent on other suppliers for certain other aircraft parts. Although the Company is able to purchase some aircraft from parties other than Boeing, most of its purchases are directly from Boeing. Therefore, if the Company were unable to acquire additional aircraft from Boeing, or if Boeing were unable or unwilling to make timely deliveries of aircraft or to provide adequate support for its products, the Company’s operations would be materially adversely affected. In addition, the Company would be materially adversely affected in the event of a mechanical or regulatory issue associated with the Boeing 737 aircraft type, whether as a result of downtime for part or all of the Company’s fleet, increased maintenance costs, or because of a negative perception by the flying public. The Company believes, however, that its years of experience with the Boeing 737 aircraft type, as well as the efficiencies Southwest has historically achieved by operating with a single aircraft type, outweigh the risks associated with its single aircraft supplier strategy. The Company is also dependent on sole suppliers for aircraft engines and certain other aircraft parts and would therefore also be materially adversely affected in the event of the unavailability of, or a mechanical or regulatory issue associated with, engines and other parts.
Any failure of the Company to maintain the security of certain Customer-related information could result in damage to the Company’s reputation and could be costly to remediate.
The Company must receive information related to its Customers in order to run its business, and the Company’s online operations depend upon the secure transmission of information over public networks, including information permitting cashless payments. This information is subject to the risk of intrusion, tampering, and theft. Although the Company maintains systems to defend against this from occurring, these systems require ongoing monitoring and updating as technologies change, and security could be compromised, confidential information could be misappropriated, or system disruptions could occur. In the ordinary course of its business, the Company provides certain confidential, proprietary, and personal information to third parties. While the Company seeks to obtain assurances that these third parties will protect this information, there is a risk the confidentiality of data held by third parties could be breached. A compromise
of the Company’s security systems could adversely affect the Company’s reputation and disrupt its operations and could also result in litigation against the Company or the imposition of penalties. In addition, it could be costly to remediate. Although the Company has not experienced cyber incidents that are individually, or in the aggregate, material, the Company has experienced cyber attacks in the past, which have thus far been mitigated by preventative, detective, and responsive measures put in place by the Company.
The Company’s results of operations could be adversely impacted if it is unable to grow or to effectively execute its strategic plans.
Southwest has historically been regarded as a growth airline. However, organic growth remains challenging because (i) the opportunities for domestic expansion could be limited; (ii) the Company's international network is small and not yet developed; and (iii) the Company has faced an increased presence of other low-cost, low-fare carriers. As a result, the Company is reliant on the success of its revenue strategies to help offset certain increasing costs and to continue to improve Customer Service. The timely and effective execution of the Company's strategic plans could be negatively affected by (i) the Company’s ability to timely and effectively implement, transition, and maintain related information technology systems and infrastructure; (ii) the Company’s ability to effectively balance its investment of incremental operating expenses and capital expenditures related to its strategies against the need to effectively control costs; and (iii) the Company’s dependence on third parties with respect to its strategic plans.
Instability of credit, capital, and energy markets can result in pressure on the Company’s credit ratings and can also negatively affect the Company’s ability to obtain financing on acceptable terms and the Company’s liquidity generally.
While the Company’s credit rating is “investment grade,” factors such as future unfavorable economic conditions, a significant decline in demand for air travel, or instability of the credit, capital, and energy markets could result in future pressure on credit ratings, which could negatively affect (i) the Company’s ability to obtain financing on acceptable terms, (ii) the Company’s liquidity generally, and (iii) the availability and cost of insurance. A credit rating downgrade could subject the Company to credit rating triggers related to its credit card transaction processing agreements, the pricing related to any funds drawn under its revolving credit facility, and some of its hedging counterparty agreements. The potential effect of credit rating downgrades is discussed in more detail below under “Quantitative and Qualitative Disclosures About Market Risk.”
The airline industry has faced on-going security concerns and related cost burdens; further threatened or actual terrorist attacks, or other hostilities, could significantly harm the airline industry and the Company’s operations.
Terrorist attacks, actual and threatened, have from time to time materially adversely affected the demand for air travel and also have resulted in increased safety and security costs for the Company and the airline industry generally. Safety measures create delays and inconveniences and can, in particular, reduce the Company’s competitiveness against surface transportation for short-haul routes. Additional terrorist attacks, even if not made directly on the airline industry, or the fear of such attacks or other hostilities (including elevated national threat warnings or selective cancellation or redirection of flights due to terror threats) would likely have a further significant negative impact on the Company and the airline industry.
Airport capacity constraints and air traffic control inefficiencies could limit the Company’s growth; changes in or additional governmental regulation could increase the Company’s operating costs or otherwise limit the Company’s ability to conduct business.
Almost all commercial service airports are owned and/or operated by units of local or state governments. Airlines are largely dependent on these governmental entities to provide adequate airport facilities and capacity at an affordable cost. Similarly, the federal government singularly controls all U.S. airspace, and airlines are completely dependent on the FAA operating that airspace in a safe and efficient manner. The air traffic control system, which is operated by the FAA, could continue to face airspace and/or airport congestion challenges in the future, which could limit the Company’s opportunities for growth. As discussed above under “Business - Regulation,” airlines are also subject to other extensive regulatory requirements. These requirements often impose substantial costs on airlines. The Company’s strategic plans and results of operations could be negatively affected by changes in law and future actions taken by domestic and foreign governmental agencies having jurisdiction over its operations, including, but not limited to:
| • | increases in airport rates and charges; |
| • | limitations on airport gate capacity or use of other airport facilities; |
| • | limitations on route authorities; |
| • | actions and decisions that create difficulties in obtaining access at slot-controlled airports; |
| • | actions and decisions that create difficulties in obtaining operating permits and approvals; |
| • | changes to environmental regulations; |
| • | new or increased taxes or fees; |
| • | changes to laws that affect the services that can be offered by airlines in particular markets and at particular airports; |
| • | restrictions on competitive practices; |
| • | changes in laws that increase costs for safety, security, compliance, or other Customer Service standards; |
| • | changes in laws that may limit the Company's ability to enter into fuel derivative contracts to hedge against increases in fuel prices; |
| • | changes in laws that may limit or regulate the Company’s ability to promote the Company’s business or fares; and |
| • | the adoption of more restrictive locally-imposed noise regulations. |
Because expenses of a flight do not vary significantly with the number of passengers carried, a relatively small change in the number of passengers can have a disproportionate effect on an airline’s operating and financial results. Therefore, any general reduction in airline passenger traffic as a result of any of the factors listed above could adversely affect the Company’s results of operations. In addition, in instances where the airline industry shrinks, many airport operating costs are essentially unchanged and must be shared by the remaining operating carriers, which can therefore increase the Company’s costs.
The airline industry is affected by many conditions that are beyond its control, which can impact the Company’s business strategies and results of operations.
In addition to the unpredictable economic conditions and fuel costs discussed above, the Company, like the airline industry in general, is affected by conditions that are largely unforeseeable and outside of its control, including, among others:
| • | adverse weather and natural disasters; |
| • | outbreaks of disease; |
| • | changes in consumer preferences, perceptions, spending patterns, or demographic trends (including, without limitation, changes in government travel patterns due to government shutdowns or sequestration); |
| • | actual or potential disruptions in the air traffic control system (including, without limitation, as a result of potential FAA budget cuts due to government shutdowns or sequestration); |
| • | changes in the competitive environment due to industry consolidation, industry bankruptcies, and other factors; |
| • | air traffic congestion and other air traffic control issues; and |
| • | actual or threatened war, terrorist attacks, and political instability. |
The airline industry is intensely competitive.
As discussed in more detail above under “Business - Competition,” the airline industry is intensely competitive. The Company’s primary competitors include other major domestic airlines, as well as regional and new entrant airlines, surface transportation, and alternatives to transportation such as videoconferencing and the Internet. The Company’s revenues are sensitive to the actions of other carriers with respect to pricing, routes, frequent flyer programs, scheduling, capacity, Customer Service, comfort and amenities, cost structure, aircraft fleet, and code-sharing and similar activities.
The Company’s future results will suffer if it does not effectively manage its expanded operations, including its international operations.
As the Company expands its international flight offerings, the U.S. Customs and Border Protection (“CBP”) will become an increasingly important federal agency. CBP personnel and CBP-mandated procedures can affect the Company’s operations, costs, and Customer experience. The Company has made, and is continuing to make, significant investments in facilities, equipment, and technologies at certain airports in order to improve the Customer experience and to assist CBP with its inspection and processing duties; however, the Company is not able to predict the impact, if any, that various CBP measures or the lack of CBP resources will have on Company revenues and costs, either in the short-term or the long-term.
International flying requires the Company to modify certain processes, as the airport environment is dramatically different in certain international locations with respect to, among other things, common-use ticket counters and gate areas, local operating requirements, and cultural preferences. In addition, international flying exposes the Company to certain foreign currency risks to the extent the Company chooses to, or is required to, transact in currencies other than the U.S. dollar. To the extent the Company seeks to serve additional foreign destinations in the future, or to renew its authority to serve certain routes, it may be required to obtain necessary authority from the DOT and/or approvals from the FAA, as well as any applicable foreign government entity.
The Company’s expansion of its operations into non-U.S. jurisdictions also expands the scope of the laws to which the Company is subject, both domestically and internationally. In addition, operations in non-U.S. jurisdictions are in many cases subject to the laws of those jurisdictions rather than U.S. laws. Laws in some jurisdictions differ in significant respects from those in the United States, and these differences can affect the Company’s ability to react to changes in its business, and its rights or ability to enforce rights may be different than would be expected under U.S. laws. Furthermore, enforcement of laws in some jurisdictions can be inconsistent and unpredictable, which can affect both the Company’s ability to enforce its rights and to undertake activities that it believes are beneficial to its business. As a result, the Company’s ability to generate revenue and its expenses in non-U.S. jurisdictions may differ from what would be expected if U.S. laws governed these operations. Although the Company has policies and procedures in place that are designed to promote compliance with the laws of the jurisdictions in which it operates, a violation by the Company’s Employees, contractors, or agents or other intermediaries, could nonetheless occur. Any violation (or alleged or perceived violation), even if prohibited by the Company’s policies, could have an adverse effect on the Company’s reputation and/or its results of operations.
The Company is currently subject to pending litigation, and if judgment were to be rendered against the Company in the litigation, such judgment could adversely affect the Company’s operating results.
A complaint alleging violations of federal antitrust laws and seeking certification as a class action was filed against Delta Air Lines, Inc. and AirTran in the United States District Court for the Northern District of Georgia in Atlanta on May 22, 2009. The complaint alleged, among other things, that AirTran attempted to monopolize air travel in violation of Section 2 of the Sherman Act, and conspired with Delta in imposing $15-per-bag fees for the first item of checked luggage in violation of Section 1 of the Sherman Act. The initial complaint sought treble damages on behalf of a putative class of persons or entities in the United States who directly paid Delta and/or AirTran such fees on domestic flights beginning December 5, 2008. After the filing of the May 2009 complaint, various other nearly identical complaints also seeking certification as class actions were filed in federal district courts in Atlanta, Georgia; Orlando, Florida; and Las Vegas, Nevada. All of the cases were consolidated before a single federal district court judge in Atlanta. A Consolidated Amended Complaint was filed in the consolidated action on February 1, 2010, which broadened the allegations to add claims that Delta and AirTran conspired to reduce capacity on competitive routes and to raise prices in violation of Section 1 of the Sherman Act. In addition to treble damages for the amount of first baggage fees paid to AirTran and to Delta, the Consolidated Amended Complaint seeks injunctive relief against a broad range of alleged anticompetitive activities, as well as attorneys' fees. On August 2, 2010, the Court dismissed plaintiffs' claims that AirTran and Delta had violated Section 2 of the Sherman Act; the Court let stand the claims of a conspiracy with respect to the imposition of a first bag fee and the airlines' capacity and pricing decisions. On June 30, 2010, the plaintiffs filed a motion to certify a class, which AirTran and Delta have opposed. The parties have submitted briefs on class certification, and the parties have filed motions to exclude the class certification opinions of each other’s expert. The parties engaged in extensive discovery, and discovery has now closed. On June 18, 2012, the parties filed a Stipulation and Order that plaintiffs have abandoned their claim that AirTran and Delta conspired to reduce capacity.
On August 31, 2012, AirTran and Delta moved for summary judgment on all of plaintiffs' remaining claims, but discovery disputes between plaintiffs and Delta delayed further briefing on summary judgment. On August 5, 2015, the Court entered an order granting class certification, which was vacated on August 17, 2015, to permit further briefing on class certification and AirTran’s motion to exclude plaintiffs’ expert. Thereafter, the parties filed motions to exclude the opinions of the other parties’ experts. On January 8, 2016, the parties completed briefing on defendants’ motions for summary judgment, plaintiffs’ motion for class certification, and the motions to exclude the opinions of experts, and those motions have been submitted to the Court for decision. While AirTran has denied all allegations of wrongdoing, including those in the Consolidated Amended Complaint, and intends to defend vigorously any and all such allegations, results of legal proceedings such as this one cannot be predicted with certainty.
Also, on June 30, 2015, the U.S. Department of Justice (“DOJ”) issued a Civil Investigative Demand (“CID”) to the Company. The CID seeks information and documents about the Company’s capacity from January 2010 to the present including public statements and communications with third parties about capacity. In June 2015, the Company also received a letter from the Connecticut Attorney General requesting information about capacity; and on August 21, 2015, the Attorney General of the State of Ohio issued an investigative demand seeking information and documents about the Company’s capacity from December 2013 to the present. The Company is cooperating fully with the DOJ CID and these two state inquiries.
Further, on July 1, 2015, a complaint was filed in the United States District Court for the Southern District of New York on behalf of putative classes of consumers alleging collusion among the Company, American Airlines, Delta Air Lines, and United Airlines to limit capacity and maintain higher fares in violation of Section 1 of the Sherman Act. Since then, a number of similar class action complaints have been filed in the United States District Courts for the Central District of California, the Northern District of California, the District of Columbia, the Middle District of Florida, the Southern District of Florida, the Northern District of Georgia, the Northern District of Illinois, the Southern District of Indiana, the Eastern District of Louisiana, the District of Minnesota, the District of New Jersey, the Eastern District of New York, the Southern District of New York, the Middle District of North Carolina, the District of Oklahoma, the Eastern District of Pennsylvania, the Northern District of Texas, the District of Vermont, and the Eastern District of Wisconsin. The complaints seek treble damages for periods that vary among the complaints, costs, attorneys’ fees, and injunctive relief. On October 13, 2015, the Judicial Panel on Multi-District Litigation centralized the cases to the United States District Court in the District of Columbia. The Court has not yet entered a scheduling order establishing a date for defendants to respond to the complaints. While the Company intends to vigorously defend these civil cases, results of legal proceedings such as this one cannot be predicted with certainty.
In addition, on July 8, 2015, the Company was named as a defendant in putative class action filed in British Columbia, Canada alleging that the Company, Air Canada, American Airlines, Delta Air Lines and United Airlines colluded to restrict capacity and maintain higher fares for Canadian citizens traveling in the United States and for travel between the United States and Canada. Similar lawsuits were filed in Ontario, Quebec and Saskatchewan. The time for the Company to respond to the complaints has not yet expired. While the Company intends to vigorously defend these civil cases, results of legal proceedings such as this one cannot be predicted with certainty.
Regardless of merit, these litigation matters and any potential future claims against the Company or AirTran may be both time consuming and disruptive to the Company’s operations and cause significant expense and diversion of management attention. Should AirTran and the Company fail to prevail in these or other matters, the Company may be faced with significant monetary damages or injunctive relief that could materially adversely affect its business and might materially affect its financial condition and operating results.
The application of the acquisition method of accounting resulted in the Company recording a significant amount of goodwill in connection with the acquisition of AirTran, which could result in significant future impairment charges and negatively affect the Company’s financial results.
The Company recorded goodwill on its Consolidated Balance Sheet as a result of its acquisition of AirTran. Goodwill is not amortized, but is tested for impairment at least annually. Future impairment of Goodwill could be recorded in the Company's results of operations as a result of changes in assumptions, estimates, or circumstances, some of which are beyond the Company’s control. Factors which could result in an impairment, holding other assumptions constant, could include, but are not limited to: (i) reduced passenger demand as a result of domestic or global economic conditions; (ii) significantly higher prices for jet fuel; (iii) lower fares or passenger yields as a result of increased competition or
lower demand; (iv) a significant increase in future capital expenditure commitments; and (v) significant disruptions to the Company’s operations as a result of both internal and external events such as terrorist activities, actual or threatened war, labor actions by Employees, or further industry regulation. The Company can provide no assurance that a significant impairment charge will not occur in one or more future periods. Any such charges may materially negatively affect the Company’s financial results. See Note 1 to the Consolidated Financial Statements for further information.
Item 1B. Unresolved Staff Comments
None.
Item 2. Properties
Aircraft
Southwest operated a total of 704 Boeing 737 aircraft as of December 31, 2015, of which 95 and 28 were under operating and capital leases, respectively. The following table details information on the 704 aircraft as of December 31, 2015:
| Type | Seats | Average Age (Yrs) | Number of Aircraft | Number Owned (a) | Number Leased | |||||||||
| 737-300 (b) | 137 or 143 | 22 | 118 | 78 | 40 | |||||||||
| 737-500 | 122 | 24 | 11 | 9 | 2 | |||||||||
| 737-700 | 143 | 11 | 471 | 397 | 74 | |||||||||
| 737-800 | 175 | 2 | 104 | 97 | 7 | |||||||||
| Totals | 12 | 704 | 581 | 123 |
| (a) | As discussed further in Note 6 to the Consolidated Financial Statements, 181 of the Company's aircraft were pledged as collateral as of December 31, 2015, for secured borrowings and/or in the case that the Company has obligations related to its fuel derivative instruments with counterparties that exceed certain thresholds. |
| (b) | Of the total, 78 737-300 aircraft had 143 seats and 40 have 137 seats. |
As of December 31, 2015, the Company had firm deliveries and options for Boeing 737-700, 737-800, 737 MAX 7, and 737 MAX 8 aircraft as follows:
| The Boeing Company 737 NG | The Boeing Company 737 MAX | ||||||||||||||||
| -800 Firm Orders | Options | Additional -700 A/C | -7 Firm Orders | -8 Firm Orders | Options | Total | |||||||||||
| 2016 | 36 | — | 17 | — | — | — | 53 | ||||||||||
| 2017 | 35 | — | 14 | — | 14 | — | 63 | ||||||||||
| 2018 | 18 | 18 | 4 | — | 13 | — | 53 | ||||||||||
| 2019 | — | — | — | 15 | 10 | — | 25 | ||||||||||
| 2020 | — | — | — | 14 | 22 | — | 36 | ||||||||||
| 2021 | — | — | — | 1 | 33 | 18 | 52 | ||||||||||
| 2022 | — | — | — | — | 30 | 19 | 49 | ||||||||||
| 2023 | — | — | — | — | 24 | 23 | 47 | ||||||||||
| 2024 | — | — | — | — | 24 | 23 | 47 | ||||||||||
| 2025 | — | — | — | — | — | 36 | 36 | ||||||||||
| 2026 | — | — | — | — | — | 36 | 36 | ||||||||||
| 2027 | — | — | — | — | — | 36 | 36 | ||||||||||
| Total | 89 | 18 | 35 | (b) | 30 | 170 | (a) | 191 | 533 |
(a) The Company has flexibility to substitute MAX 7 in lieu of MAX 8 firm orders beginning in 2019.
(b) To be acquired in leases from various third parties.
Ground Facilities and Services
Southwest either leases or pays a usage fee for terminal passenger service facilities at each of the airports it serves, to which various leasehold improvements have been made. The Company leases the land and/or structures on a long-term basis for its aircraft maintenance centers (located at Dallas Love Field, Houston Hobby, Phoenix Sky Harbor, Chicago Midway, Hartsfield-Jackson Atlanta International Airport and Orlando International Airport), its flight training center at Dallas Love Field (which houses ten 737 simulators), and its main corporate headquarters building, also located at Dallas Love Field. The Company also leases a warehouse and engine repair facility in Atlanta. The Company owns an energy-efficient, modern building designed to house certain operational and training functions, including its 24-hour operations. This additional headquarters building is located across the street from the Company’s current headquarters building on land owned by the Company.
The Company’s international expansion in 2015 was facilitated by the completion of construction of a new five-gate international terminal at Houston’s William P. Hobby Airport with international passenger processing facilities, an expanded security checkpoint, and an upgraded Southwest ticketing area. The Company controlled this expansion and related financial terms pursuant to an Airport Use and Lease Agreement with the City of Houston. Additional information regarding this project is provided below under “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and in Note 4 to the Consolidated Financial Statements.
Pursuant to an agreement with Broward County, Florida, which owns and operates Fort Lauderdale-Hollywood International Airport, the Company is also overseeing and managing the design and construction of the airport’s Terminal 1 Modernization Project. In addition to significant improvements to the existing Terminal 1, the project includes the design and construction of a new five-gate Concourse A with an international processing facility. Major construction on the project began during third quarter 2015 and is estimated to be completed during 2017. Additional information regarding this project is provided below under “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and in Note 4 to the Consolidated Financial Statements.
Pursuant to a lease agreement with Los Angeles World Airports, which owns and operates Los Angeles International Airport, the Company is also overseeing and managing the design, development, financing, construction, and commissioning of the airport's Terminal 1 Modernization Project. Construction on the project began during fourth quarter 2014 and is estimated to be completed during 2018. Additional information regarding this project is provided below under “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and in Note 4 to the Consolidated Financial Statements.
The Company also managed the reconstruction of Dallas Love Field with modern, convenient air travel facilities (“Love Field Modernization Program”). The project consisted of the complete replacement of gate facilities with a new 20-gate facility, including infrastructure, systems and equipment, aircraft parking apron, fueling system, roadways and terminal curbside, baggage handling systems, passenger loading bridges and support systems, and other supporting infrastructure. The Love Field Modernization Program is discussed in more detail below under “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and in Note 4 to the Consolidated Financial Statements.
As of December 31, 2015, the Company operated seven Customer Support and Services call centers. The centers located in Atlanta, San Antonio, Chicago, Albuquerque, and Oklahoma City occupy leased space. The Company owns its Houston and Phoenix centers.
The Company performs substantially all line maintenance on its aircraft and provides ground support services at most of the airports it serves. However, the Company has arrangements with certain aircraft maintenance firms for major component inspections and repairs for its airframes and engines, which comprise the majority of the Company’s annual aircraft maintenance costs.
Item 3. Legal Proceedings
A complaint alleging violations of federal antitrust laws and seeking certification as a class action was filed against Delta Air Lines, Inc. and AirTran in the United States District Court for the Northern District of Georgia in Atlanta on May 22, 2009. The complaint alleged, among other things, that AirTran attempted to monopolize air travel in violation of Section 2 of the Sherman Act, and conspired with Delta in imposing $15-per-bag fees for the first item of checked luggage in violation of Section 1 of the Sherman Act. The initial complaint sought treble damages on behalf of a putative class of persons or entities in the United States who directly paid Delta and/or AirTran such fees on domestic flights beginning December 5, 2008. After the filing of the May 2009 complaint, various other nearly identical complaints also seeking certification as class actions were filed in federal district courts in Atlanta, Georgia; Orlando, Florida; and Las Vegas, Nevada. All of the cases were consolidated before a single federal district court judge in Atlanta. A Consolidated Amended Complaint was filed in the consolidated action on February 1, 2010, which broadened the allegations to add claims that Delta and AirTran conspired to reduce capacity on competitive routes and to raise prices in violation of Section 1 of the Sherman Act. In addition to treble damages for the amount of first baggage fees paid to AirTran and to Delta, the Consolidated Amended Complaint seeks injunctive relief against a broad range of alleged anticompetitive activities, as well as attorneys' fees. On August 2, 2010, the Court dismissed plaintiffs' claims that AirTran and Delta had violated Section 2 of the Sherman Act; the Court let stand the claims of a conspiracy with respect to the imposition of a first bag fee and the airlines' capacity and pricing decisions. On June 30, 2010, the plaintiffs filed a motion to certify a class, which AirTran and Delta have opposed. The parties have submitted briefs on class certification, and the parties have filed motions to exclude the class certification opinions of each other’s expert. The parties engaged in extensive discovery, and discovery has now closed. On June 18, 2012, the parties filed a Stipulation and Order that plaintiffs have abandoned their claim that AirTran and Delta conspired to reduce capacity. On August 31, 2012, AirTran and Delta moved for summary judgment on all of plaintiffs' remaining claims, but discovery disputes between plaintiffs and Delta delayed further briefing on summary judgment. On August 5, 2015, the Court entered an order granting class certification, which was vacated on August 17, 2015, to permit further briefing on class certification and AirTran’s motion to exclude plaintiffs’ expert. Thereafter, the parties filed motions to exclude the opinions of the other parties’ experts. On January 8, 2016, the parties completed briefing on defendants’ motions for summary judgment, plaintiffs’ motion for class certification, and the motions to exclude the opinions of experts, and those motions have been submitted to the Court for decision. AirTran denies all allegations of wrongdoing, including those in the Consolidated Amended Complaint, and intends to defend vigorously any and all such allegations.
Also, on June 30, 2015, the U.S. Department of Justice (“DOJ”) issued a Civil Investigative Demand (“CID”) to the Company. The CID seeks information and documents about the Company’s capacity from January 2010 to the present including public statements and communications with third parties about capacity. In June 2015, the Company also received a letter from the Connecticut Attorney General requesting information about capacity; and on August 21, 2015, the Attorney General of the State of Ohio issued an investigative demand seeking information and documents about the Company’s capacity from December 2013 to the present. The Company is cooperating fully with the DOJ CID and these two state inquiries.
Further, on July 1, 2015, a complaint was filed in the United States District Court for the Southern District of New York on behalf of putative classes of consumers alleging collusion among the Company, American Airlines, Delta Air Lines, and United Airlines to limit capacity and maintain higher fares in violation of Section 1 of the Sherman Act. Since then, a number of similar class action complaints have been filed in the United States District Courts for the Central District of California, the Northern District of California, the District of Columbia, the Middle District of Florida, the Southern District of Florida, the Northern District of Georgia, the Northern District of Illinois, the Southern District of Indiana, the Eastern District of Louisiana, the District of Minnesota, the District of New Jersey, the Eastern District of New York, the Southern District of New York, the Middle District of North Carolina, the District of Oklahoma, the Eastern District of Pennsylvania, the Northern District of Texas, the District of Vermont, and the Eastern District of Wisconsin. The complaints seek treble damages for periods that vary among the complaints, costs, attorneys’ fees, and injunctive relief. On October 13, 2015, the Judicial Panel on Multi-District Litigation centralized the cases to the United States District Court in the District of Columbia. The Court has not yet entered a scheduling order establishing a date for defendants to respond to the complaints. The Company intends to vigorously defend these civil cases.
In addition, on July 8, 2015, the Company was named as a defendant in putative class action filed in British Columbia, Canada alleging that the Company, Air Canada, American Airlines, Delta Air Lines and United Airlines colluded to
restrict capacity and maintain higher fares for Canadian citizens traveling in the United States and for travel between the United States and Canada. Similar lawsuits were filed in Ontario, Quebec and Saskatchewan. The time for the Company to respond to the complaints has not yet expired. The Company intends to vigorously defend these civil cases in Canada.
The Company is from time to time subject to various legal proceedings and claims arising in the ordinary course of business, including, but not limited to, examinations by the Internal Revenue Service.
The Company’s management does not expect that the outcome in any of its currently ongoing legal proceedings or the outcome of any proposed adjustments presented to date by the Internal Revenue Service, individually or collectively, will have a material adverse effect on the Company’s financial condition, results of operations, or cash flow.
Item 4. Mine Safety Disclosures
Not applicable.
EXECUTIVE OFFICERS OF THE REGISTRANT
The following information regarding the Company’s executive officers is as of February 1, 2016.
| Name | Position | Age |
| Gary C. Kelly | Chairman of the Board, President, & Chief Executive Officer | 60 |
| Robert E. Jordan | Executive Vice President & Chief Commercial Officer | 55 |
| Jeff Lamb | Executive Vice President Corporate Services | 53 |
| Thomas M. Nealon | Executive Vice President Strategy & Innovation | 54 |
| Tammy Romo | Executive Vice President & Chief Financial Officer | 53 |
| Michael G. Van de Ven | Executive Vice President & Chief Operating Officer | 54 |
| Mark R. Shaw | Senior Vice President, General Counsel, & Corporate Secretary | 53 |
Set forth below is a description of the background of each of the Company’s executive officers.
Gary C. Kelly has served as the Company’s Chairman of the Board since May 2008, as its President since July 2008, and as its Chief Executive Officer since July 2004. Mr. Kelly also served as Executive Vice President & Chief Financial Officer from June 2001 to July 2004 and Vice President Finance & Chief Financial Officer from 1989 to 2001. Mr. Kelly joined the Company in 1986 as its Controller.
Robert E. Jordan has served as the Company’s Executive Vice President & Chief Commercial Officer since September 2011 and as President of AirTran Airways, Inc. since May 2011. Mr. Jordan also served as Executive Vice President Strategy & Planning from May 2008 to September 2011, Executive Vice President Strategy & Technology from September 2006 to May 2008, Senior Vice President Enterprise Spend Management from August 2004 to September 2006, Vice President Technology from 2002 to 2004, Vice President Purchasing from 2001 to 2002, Controller from 1997 to 2001, Director Revenue Accounting from 1994 to 1997, and Manager Sales Accounting from 1990 to 1994. Mr. Jordan joined the Company in 1988 as a programmer.
Jeff Lamb has served as the Company’s Executive Vice President Corporate Services since July 2015. Mr. Lamb also served as Executive Vice President & Chief People & Administrative Officer from September 2011 to July 2015, Senior Vice President Administration & Chief People Officer from October 2007 to September 2011, Vice President People & Leadership Development from February 2006 to October 2007, and as Senior Director People Development from December 2004 until February 2006.
Thomas M. Nealon has served as the Company’s Executive Vice President Strategy & Innovation since January 2016. Prior to becoming an executive officer of the Company, Mr. Nealon served on the Company’s Board of Directors from December 2010 until November 2015. Mr. Nealon has also served as Group Executive Vice President of J.C. Penney Company, Inc., a retail company, from August 2010 until December 2011. In this role Mr. Nealon was responsible for Strategy, jcp.com, Information Technology, Customer Insights, and Digital Ventures. Mr. Nealon also served as J.C. Penney’s Executive Vice President & Chief Information Officer from September 2006 until August 2010. Prior to
joining J.C. Penney, Mr. Nealon was a partner with The Feld Group, a provider of information technology consulting services, where he served in a consultant capacity as Senior Vice President & Chief Information Officer for the Company from 2002 to 2006. Mr. Nealon also served as Chief Information Officer for Frito-Lay, a division of PepsiCo, Inc., from 1996 to 2000, and in various software engineering, systems engineering, and management positions for Frito-Lay from 1983 to 1996.
Tammy Romo has served as the Company’s Executive Vice President & Chief Financial Officer since July 2015. Ms. Romo also served as Senior Vice President Finance & Chief Financial Officer from September 2012 to July 2015, Senior Vice President of Planning from February 2010 to September 2012, Vice President of Financial Planning from September 2008 to February 2010, Vice President Controller from February 2006 to August 2008, Vice President Treasurer from September 2004 to February 2006, Senior Director of Investor Relations from March 2002 to September 2004, Director of Investor Relations from December 1994 to March 2002, Manager of Investor Relations from September 1994 to December 1994, and Manager of Financial Reporting from September 1991 to September 1994.
Michael G. Van de Ven has served as the Company’s Executive Vice President & Chief Operating Officer since May 2008. Mr. Van de Ven also served as Chief of Operations from September 2006 to May 2008, Executive Vice President Aircraft Operations from November 2005 through August 2006, Senior Vice President Planning from August 2004 to November 2005, Vice President Financial Planning & Analysis from 2001 to 2004, Senior Director Financial Planning & Analysis from 2000 to 2001, and Director Financial Planning & Analysis from 1997 to 2000. Mr. Van de Ven joined the Company in 1993 as its Director Internal Audit.
Mark R. Shaw has served as the Company’s Senior Vice President, General Counsel, & Corporate Secretary since July 2015. Mr. Shaw also served as Vice President, General Counsel, & Corporate Secretary from February 2013 to July 2015 and as Associate General Counsel - Corporate and Transactions from February 2008 to February 2013. Mr. Shaw joined the Company in 2000 as an Attorney in the General Counsel Department.
PART II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters, and Issuer Purchases of Equity Securities
The Company’s common stock is listed on the New York Stock Exchange ("NYSE") and is traded under the symbol “LUV.” The following table shows the high and low prices per share of the Company’s common stock, as reported on the NYSE Composite Tape, and the cash dividends per share declared on the Company’s common stock.
| Period | Dividend | High | Low | |||||||||
| 2015 | ||||||||||||
| 1st Quarter | $ | 0.06000 | $ | 47.17 | $ | 38.26 | ||||||
| 2nd Quarter | 0.07500 | 44.19 | 33.02 | |||||||||
| 3rd Quarter | 0.07500 | 40.87 | 31.36 | |||||||||
| 4th Quarter | 0.07500 | 51.34 | 37.00 | |||||||||
| 2014 | ||||||||||||
| 1st Quarter | $ | 0.04000 | $ | 24.17 | $ | 18.78 | ||||||
| 2nd Quarter | 0.06000 | 27.70 | 22.35 | |||||||||
| 3rd Quarter | 0.06000 | 35.49 | 25.86 | |||||||||
| 4th Quarter | 0.06000 | 43.19 | 28.40 |
The Company currently intends to continue declaring dividends on a quarterly basis for the foreseeable future; however, the Company’s Board of Directors may elect to alter the timing, amount, and payment of dividends on the basis of operational results, financial condition, cash requirements, future prospects, and other factors deemed relevant by the Board. As of January 29, 2016, there were approximately 13,518 holders of record of the Company’s common stock.
Stock Performance Graph
The following Performance Graph and related information shall not be deemed “soliciting material” or “filed” with the Securities and Exchange Commission, nor shall such information be incorporated by reference into any future filing under the Securities Act of 1933 or Securities Exchange Act of 1934.
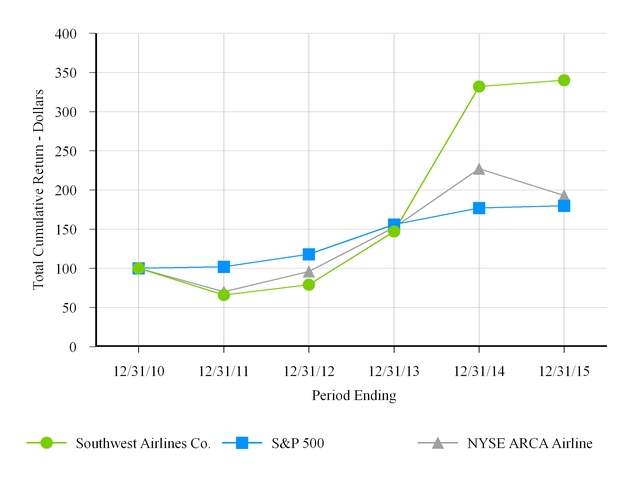
The following graph compares the cumulative total shareholder return on the Company’s common stock over the five-year period ended December 31, 2015, with the cumulative total return during such period of the Standard and Poor’s 500 Stock Index and the NYSE ARCA Airline Index. The comparison assumes $100 was invested on December 31, 2010, in the Company’s common stock and in each of the foregoing indices and assumes reinvestment of dividends. The stock performance shown on the graph below represents historical stock performance and is not necessarily indicative of future stock price performance.
COMPARISON OF FIVE YEAR CUMULATIVE TOTAL RETURN AMONG SOUTHWEST AIRLINES CO., S&P 500 INDEX, AND NYSE ARCA AIRLINE INDEX
| 12/31/2010 | 12/31/2011 | 12/31/2012 | 12/31/2013 | 12/31/2014 | 12/31/2015 | |||||||||||||||||||
| Southwest Airlines Co. | $ | 100 | $ | 66 | $ | 79 | $ | 147 | $ | 332 | $ | 340 | ||||||||||||
| S&P 500 | $ | 100 | $ | 102 | $ | 119 | $ | 156 | $ | 177 | $ | 180 | ||||||||||||
| NYSE ARCA Airline | $ | 100 | $ | 70 | $ | 96 | $ | 152 | $ | 227 | $ | 193 |
Issuer Repurchases
| Issuer Purchases of Equity Securities (1) | ||||||||||||||||
| (a) | (b) | (c) | (d) | |||||||||||||
| Total number of | Maximum dollar | |||||||||||||||
| shares purchased | value of shares that | |||||||||||||||
| Total number | Average | as part of publicly | may yet be purchased | |||||||||||||
| of shares | price paid | announced plans | under the plans | |||||||||||||
| Period | purchased | per share | or programs | or programs | ||||||||||||
| October 1, 2015 through October 31, 2015 | — | $ | — | — | $ | 700,000,000 | ||||||||||
| November 1, 2015 through November 30, 2015 | 3,213,009 | $ | — | (2 | ) | 3,213,009 | $ | 700,000,000 | ||||||||
| December 1, 2015 through December 31, 2015 | — | $ | — | — | $ | 700,000,000 | ||||||||||
| Total | 3,213,009 | 3,213,009 |
| (1) | In May 2015, the Company’s Board of Directors authorized the repurchase of up to $1.5 billion of the Company’s common stock. Repurchases are made in accordance with applicable securities laws in open market, private, or in accelerated repurchase transactions from time to time, depending on market conditions, and may be discontinued at any time. |
| (2) | Under an accelerated share repurchase program entered into by the Company with a third party financial institution in third quarter 2015 ("Third Quarter ASR Program"), the Company paid $500 million and received an initial delivery of 9,679,195 shares during third quarter 2015, representing an estimated 75 percent of the shares to be purchased by the Company under the Third Quarter ASR Program based on a volume-weighted average price of $38.74 per share of the Company’s common stock on the New York Stock Exchange during a calculation period between August 3, 2015 and August 20, 2015. Final settlement of this Third Quarter ASR Program occurred in November 2015 and was determined based generally on a discount to the volume-weighted average price per share of the Company's common stock during a calculation period completed in October 2015. Upon settlement, the third party financial institution delivered 3,213,009 additional shares of the Company’s common stock to the Company. In total, the average purchase price per share for the 12,892,204 shares repurchased under the Third Quarter ASR Program, upon completion of the Third Quarter ASR Program in November 2015, was $38.78. |
Item 6. Selected Financial Data
The following financial information, for the five years ended December 31, 2015, has been derived from the Company’s Consolidated Financial Statements. This information should be viewed in conjunction with the Consolidated Financial Statements and related notes thereto included elsewhere herein. This financial information includes the operations of AirTran from the May 2, 2011 acquisition date through the end of AirTran service on December 28, 2014. Any financial information presented prior to May 2, 2011, or after December 28, 2014, includes only the operations of Southwest unless otherwise indicated. The Company provides the operating data below because these statistics are commonly used in the airline industry and, therefore, allow readers to compare the Company’s performance against its results for prior periods, as well as against the performance of the Company’s peers.
| Year ended December 31, | ||||||||||||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||||||||||||
| Financial Data (in millions, except per share amounts): | ||||||||||||||||||||
| Operating revenues | $ | 19,820 | $ | 18,605 | $ | 17,699 | $ | 17,088 | $ | 15,658 | ||||||||||
| Operating expenses | 15,704 | 16,380 | 16,421 | 16,465 | 14,965 | |||||||||||||||
| Operating income | 4,116 | 2,225 | 1,278 | 623 | 693 | |||||||||||||||
| Other expenses (income) net | 637 | 409 | 69 | (62 | ) | 370 | ||||||||||||||
| Income before taxes | 3,479 | 1,816 | 1,209 | 685 | 323 | |||||||||||||||
| Provision for income taxes | 1,298 | 680 | 455 | 264 | 145 | |||||||||||||||
| Net income | $ | 2,181 | $ | 1,136 | $ | 754 | $ | 421 | $ | 178 | ||||||||||
| Net income per share, basic | $ | 3.30 | $ | 1.65 | $ | 1.06 | $ | 0.56 | $ | 0.23 | ||||||||||
| Net income per share, diluted | $ | 3.27 | $ | 1.64 | $ | 1.05 | $ | 0.56 | $ | 0.23 | ||||||||||
| Cash dividends per common share | $ | 0.2850 | $ | 0.2200 | $ | 0.1300 | $ | 0.0345 | $ | 0.0180 | ||||||||||
| Total assets at period-end (1) | $ | 21,312 | $ | 19,723 | $ | 19,177 | $ | 18,350 | $ | 17,805 | ||||||||||
| Long-term obligations at period-end | $ | 2,541 | $ | 2,434 | $ | 2,191 | $ | 2,883 | $ | 3,107 | ||||||||||
| Stockholders’ equity at period-end | $ | 7,358 | $ | 6,775 | $ | 7,336 | $ | 6,992 | $ | 6,877 | ||||||||||
| Operating Data: | ||||||||||||||||||||
| Revenue passengers carried | 118,171,211 | 110,496,912 | 108,075,976 | 109,346,509 | 103,973,759 | |||||||||||||||
| Enplaned passengers | 144,574,882 | 135,767,188 | 133,155,030 | 133,978,100 | 127,551,012 | |||||||||||||||
| Revenue passenger miles (RPMs) (000s) (2) | 117,499,879 | 108,035,133 | 104,348,216 | 102,874,979 | 97,582,530 | |||||||||||||||
| Available seat miles (ASMs) (000s) (3) | 140,501,409 | 131,003,957 | 130,344,072 | 128,137,110 | 120,578,736 | |||||||||||||||
| Load factor (4) | 83.6 | % | 82.5 | % | 80.1 | % | 80.3 | % | 80.9 | % | ||||||||||
| Average length of passenger haul (miles) | 994 | 978 | 966 | 941 | 939 | |||||||||||||||
| Average aircraft stage length (miles) | 750 | 721 | 703 | 693 | 679 | |||||||||||||||
| Trips flown | 1,267,358 | 1,255,502 | 1,312,785 | 1,361,558 | 1,317,977 | |||||||||||||||
| Seats flown (5) | 184,955,094 | 179,733,055 | 183,563,527 | 184,208,891 | 177,469,069 | |||||||||||||||
| Seats per trip (6) | 145.94 | 143.16 | 139.83 | 135.92 | 134.65 | |||||||||||||||
| Average passenger fare (12) | $ | 154.85 | $ | 159.80 | $ | 154.72 | $ | 147.17 | $ | 141.90 | ||||||||||
| Passenger revenue yield per RPM (cents) (7)(12) | 15.57 | 16.34 | 16.02 | 15.64 | 15.12 | |||||||||||||||
| Operating revenue per ASM (cents) (8) | 13.98 | 14.20 | 13.58 | 13.34 | 12.99 | |||||||||||||||
| Passenger revenue per ASM (cents) (9)(12) | 13.02 | 13.48 | 12.83 | 12.56 | 12.24 | |||||||||||||||
| Operating expenses per ASM (cents) (10) | 11.18 | 12.50 | 12.60 | 12.85 | 12.41 | |||||||||||||||
| Operating expenses per ASM, excluding fuel (cents) | 8.61 | 8.46 | 8.18 | 8.07 | 7.73 | |||||||||||||||
| Operating expenses per ASM, excluding fuel and profitsharing (cents) | 8.17 | 8.19 | 8.01 | 7.98 | 7.65 | |||||||||||||||
| Fuel costs per gallon, including fuel tax | $ | 1.90 | $ | 2.93 | $ | 3.16 | $ | 3.30 | $ | 3.19 | ||||||||||
| Fuel costs per gallon, including fuel tax, economic | $ | 2.07 | $ | 2.92 | $ | 3.12 | $ | 3.28 | $ | 3.19 | ||||||||||
| Fuel consumed, in gallons (millions) | 1,901 | 1,801 | 1,818 | 1,847 | 1,764 | |||||||||||||||
| Active fulltime equivalent Employees | 49,583 | 46,278 | 44,381 | 45,861 | 45,392 | |||||||||||||||
| Aircraft at end of period (11) | 704 | 665 | 681 | 694 | 698 |
| (1) | Historical amounts have been restated to align with current presentation. See Note 1 to the Consolidated Financial Statements for further information. |
| (2) | A revenue passenger mile is one paying passenger flown one mile. Also referred to as “traffic,” which is a measure of demand for a given period. |
| (3) | An available seat mile is one seat (empty or full) flown one mile. Also referred to as “capacity,” which is a measure of the space available to carry passengers in a given period. |
| (4) | Revenue passenger miles divided by available seat miles. |
| (5) | Seats flown is calculated using total number of seats available by aircraft type multiplied by the total trips flown by the same aircraft type during a particular period. |
| (6) | Seats per trip is calculated using seats flown divided by trips flown. Also referred to as “gauge.” |
| (7) | Calculated as passenger revenue divided by revenue passenger miles. Also referred to as “yield,” this is the average cost paid by a paying passenger to fly one mile, which is a measure of revenue production and fares. |
| (8) | Calculated as operating revenues, excluding special items, divided by available seat miles. Also referred to as "RASM" or "operating unit revenues," this is a measure of operating revenue production based on the total available seat miles flown during a particular period. Year ended 2015 RASM excludes a $172 million one-time non-cash special revenue adjustment. Additional information regarding this special item is provided in the Note Regarding Use of Non-GAAP Financial Measures and a reconciliation of revenue excluding special items related to accounting changes in the accompanying pages. |
| (9) | Calculated as passenger revenue divided by available seat miles. Also referred to as “passenger unit revenues,” this is a measure of passenger revenue production based on the total available seat miles flown during a particular period. |
| (10) | Calculated as operating expenses divided by available seat miles. Also referred to as “unit costs” or “cost per available seat mile,” this is the average cost to fly an aircraft seat (empty or full) one mile, which is a measure of cost efficiencies. |
| (11) | Aircraft in the Company's fleet at end of period, less Boeing 717-200s removed from service in preparation for transition out of the fleet. |
| (12) | Refer to Note 1 to the Consolidated Financial Statements for additional information regarding the impact from the July 2015 amended co-branded credit card agreement with Chase Bank USA, N.A. |
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Reconciliation of Reported Amounts to Non-GAAP Financial Measures (unaudited) (in millions, except per share and per ASM amounts)
| Year ended December 31, | Percent | |||||||||
| 2015 | 2014 | Change | ||||||||
| Total operating revenues, as reported | $ | 19,820 | $ | 18,605 | ||||||
| Deduct: Special revenue adjustment | (172 | ) | — | |||||||
| Operating revenues, Non-GAAP | $ | 19,648 | $ | 18,605 | 5.6 | % | ||||
| Fuel and oil expense, unhedged | $ | 3,362 | $ | 5,321 | ||||||
| Add (Deduct): Fuel hedge losses (gains) included in Fuel and oil expense | 254 | (28 | ) | |||||||
| Fuel and oil expense, as reported | $ | 3,616 | $ | 5,293 | ||||||
| Add (Deduct): Net impact from fuel contracts | 323 | (28 | ) | |||||||
| Fuel and oil expense, non-GAAP | $ | 3,939 | $ | 5,265 | (25.2 | )% | ||||
| Total operating expenses, as reported | $ | 15,704 | $ | 16,380 | ||||||
| Deduct: Union contract bonuses | (334 | ) | (9 | ) | ||||||
| Add (Deduct): Reclassification between Fuel and oil and Other (gains) losses, net, associated with current period settled contracts | 72 | (4 | ) | |||||||
| Add (Deduct): Contracts settling in the current period, but for which gains and/or (losses) have been recognized in a prior period* | 251 | (24 | ) | |||||||
| Deduct: Acquisition and integration costs | (39 | ) | (126 | ) | ||||||
| Add: Litigation settlement | 37 | — | ||||||||
| Total operating expenses, non-GAAP | $ | 15,691 | $ | 16,217 | (3.2 | )% | ||||
| Operating income, as reported | $ | 4,116 | $ | 2,225 | ||||||
| Deduct: Special revenue adjustment | (172 | ) | $ | — | ||||||
| Add: Union contract bonuses | 334 | 9 | ||||||||
| Add (Deduct): Reclassification between Fuel and oil and Other (gains) losses, net, associated with current period settled contracts | (72 | ) | 4 | |||||||
| Add (Deduct): Contracts settling in the current period, but for which gains and/or (losses) have been recognized in a prior period* | (251 | ) | 24 | |||||||
| Add: Acquisition and integration costs | 39 | 126 | ||||||||
| Deduct: Litigation settlement | (37 | ) | — | |||||||
| Operating income, non-GAAP | $ | 3,957 | $ | 2,388 | 65.7 | % | ||||
| Net income, as reported | $ | 2,181 | $ | 1,136 | ||||||
| Deduct: Special revenue adjustment (a) | (108 | ) | — | |||||||
| Add: Union contract bonuses (a) | 210 | 6 | ||||||||
| Add: Mark-to-market impact from fuel contracts settling in future periods | 373 | 251 | ||||||||
| Add (Deduct): Ineffectiveness from fuel hedges settling in future periods | (9 | ) | 5 | |||||||
| Add (Deduct): Other net impact of fuel contracts settling in the current or a prior period (excluding reclassifications) | (251 | ) | 24 | |||||||
| Deduct: Income tax impact of fuel contracts | (42 | ) | (104 | ) | ||||||
| Add: Acquisition and integration costs (a) | 24 | 79 | ||||||||
| Deduct: Litigation settlement (a) | (23 | ) | — | |||||||
| Net income, non-GAAP | $ | 2,355 | $ | 1,397 | 68.6 | % |
| Year ended December 31, | Percent | |||||||||
| 2015 | 2014 | Change | ||||||||
| Net income per share, diluted, as reported | $ | 3.27 | $ | 1.64 | ||||||
| Add: Net impact to net income above from fuel contracts divided by dilutive shares (a) | 0.06 | 0.25 | ||||||||
| Add: Impact of special items (a) | 0.19 | 0.12 | ||||||||
| Net income per share, diluted, non-GAAP | $ | 3.52 | $ | 2.01 | 75.1 | % | ||||
| Operating expenses per ASM (cents) | 11.18 | ¢ | 12.50 | ¢ | ||||||
| Deduct: Fuel expense divided by ASMs | (2.57 | ) | (4.04 | ) | ||||||
| Deduct: Impact of special items | (0.24 | ) | (0.10 | ) | ||||||
| Operating expenses per ASM, non-GAAP, excluding fuel and special items (cents) | 8.37 | ¢ | 8.36 | ¢ | 0.1 | % |
- As a result of prior hedge ineffectiveness and/or contracts marked to market through earnings.
(a) Amounts net of tax.
Return on Invested Capital (ROIC) (in millions) (unaudited)
| Year Ended | Year Ended | Year Ended | |||||||||
| December 31, 2015 | December 31, 2014 | December 31, 2013 | |||||||||
| Operating Income, as reported | $ | 4,116 | $ | 2,225 | $ | 1,278 | |||||
| Deduct: Special revenue adjustment | (172 | ) | — | — | |||||||
| Add: Union contract bonuses | 334 | 9 | — | ||||||||
| Add (Deduct): Net impact from fuel contracts | (323 | ) | 28 | 84 | |||||||
| Add: Acquisition and integration costs | 39 | 126 | 86 | ||||||||
| Deduct: Litigation settlement | (37 | ) | — | — | |||||||
| Operating Income, non-GAAP | 3,957 | 2,388 | 1,448 | ||||||||
| Net adjustment for aircraft leases (1) | 114 | 133 | 143 | ||||||||
| Adjustment for fuel hedge accounting | (124 | ) | (62 | ) | (60 | ) | |||||
| Adjusted Operating Income, non-GAAP | $ | 3,947 | $ | 2,459 | $ | 1,531 | |||||
| Average invested capital (2) | $ | 11,037 | $ | 11,470 | $ | 11,664 | |||||
| Equity adjustment for hedge accounting | 1,027 | 104 | 50 | ||||||||
| Adjusted average invested capital | $ | 12,064 | $ | 11,574 | $ | 11,714 | |||||
| ROIC, pre-tax | 32.7 | % | 21.2 | % | 13.1 | % |
(1) Net adjustment related to presumption that all aircraft in fleet are owned (i.e., the impact of eliminating aircraft rent expense and replacing with estimated depreciation expense for those same aircraft).
(2) Average invested capital is an average of the five most recent quarter end balances of debt, net present value of aircraft leases, and equity adjusted for hedge accounting.
Note Regarding Use of Non-GAAP Financial Measures
The Company's Consolidated Financial Statements are prepared in accordance with accounting principles generally accepted in the United States ("GAAP"). These GAAP financial statements include (i) unrealized non-cash adjustments and reclassifications, which can be significant, as a result of accounting requirements and elections made under accounting pronouncements relating to derivative instruments and hedging and (ii) other charges and benefits the Company believes are not indicative of its ongoing operational performance.
As a result, the Company also provides financial information in this filing that was not prepared in accordance with GAAP and should not be considered as an alternative to the information prepared in accordance with GAAP. The Company provides supplemental non-GAAP financial information, including results that it refers to as "economic," which the Company's management utilizes to evaluate its ongoing financial performance and the Company believes provides greater transparency to investors as supplemental information to its GAAP results. The Company's economic financial results differ from GAAP results in that
Showing the first 8K of 110K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
The Company has interest rate risk in its floating-rate debt obligations and interest rate swaps, commodity price risk in jet fuel required to operate its aircraft fleet, and market risk in the derivatives used to manage its fuel hedging program and in the form of fixed-rate debt instruments. As of December 31, 2015, Southwest operated a total of 123 aircraft under operating and capital lease. However, except for a small number of aircraft that have lease payments that fluctuate based in part on changes in market interest rates, the remainder of the leases are not considered market sensitive financial instruments and, therefore, are not included in the interest rate sensitivity analysis below. The Company also has 78 aircraft under operating and capital lease that have been subleased to another carrier. Further information about this sublease arrangement is disclosed in Note 7 to the Consolidated Financial Statements. The Company does not purchase or hold any derivative financial instruments for trading purposes. See Note 10 to the Consolidated Financial Statements for information on the Company’s accounting for its hedging program and for further details on the Company’s financial derivative instruments.
Hedging
The Company purchases jet fuel at prevailing market prices, but seeks to manage market risk through execution of a documented hedging strategy. The Company utilizes financial derivative instruments, on both a short-term and a long-term basis, as a form of insurance against the potential for significant increases in fuel prices. The Company believes there can be significant risk in not hedging against the possibility of such fuel price increases, especially in energy markets in which prices are high and/or rising. The Company expects to consume approximately 2 billion gallons of jet fuel in 2016. Based on this anticipated usage, a change in jet fuel prices of just one cent per gallon would impact
the Company’s Fuel and oil expense by approximately $20 million for 2016, excluding any impact associated with fuel derivative instruments held.
As of December 31, 2015, the Company held a net position of fuel derivative instruments that represented a hedge for a portion of its anticipated jet fuel purchases for each year from 2016 through 2018. See Note 10 to the Consolidated Financial Statements for further information. The Company may increase or decrease the size of its fuel hedge based on its expectation of future market prices, as well as its perceived exposure to cash collateral requirements contained in the agreements it has signed with various counterparties, while considering the significant cost that can be associated with different types of hedging strategies. The gross fair value of outstanding financial derivative instruments related to the Company’s jet fuel market price risk at December 31, 2015, was a net liability of $1.5 billion. In addition, $835 million in cash collateral deposits and $250 million in aircraft collateral were provided by the Company in connection with these instruments based on their fair value as of December 31, 2015. The fair values of the derivative instruments, depending on the type of instrument, were determined by use of present value methods or standard option value models with assumptions about commodity prices based on those observed in underlying markets. An immediate 10 percent increase or decrease in underlying fuel-related commodity prices from the December 31, 2015 (for all years from 2016 through 2018) prices would correspondingly change the fair value of the commodity derivative instruments in place by approximately $192 million. Fluctuations in the related commodity derivative instrument cash flows may change by more or less than this amount based upon further fluctuations in futures prices, as well as related income tax effects. In addition, this does not consider changes in cash, aircraft, or letters of credit utilized as collateral provided to or by counterparties, which would fluctuate in an amount equal to or less than this amount, depending on the type of collateral arrangement in place with each counterparty. This sensitivity analysis uses industry standard valuation models and holds all inputs constant at December 31, 2015, levels, except underlying futures prices.
The Company’s credit exposure related to fuel derivative instruments is represented by the fair value of contracts with a net positive fair value to the Company. At such times, these outstanding instruments expose the Company to credit loss in the event of nonperformance by the counterparties to the agreements. As of December 31, 2015, the Company had three counterparties in which the derivatives held were a net asset. To manage credit risk, the Company selects and will periodically review counterparties based on credit ratings, limits its exposure to a single counterparty with collateral support agreements, and monitors the market position of the program and its relative market position with each counterparty. However, if one or more of these counterparties were in a liability position to the Company and were unable to meet their obligations, any open derivative contracts with the counterparty could be subject to early termination, which could result in substantial losses for the Company. At December 31, 2015, the Company had agreements with all of its counterparties containing early termination rights triggered by credit rating thresholds and/or bilateral collateral provisions whereby security is required if market risk exposure exceeds a specified threshold amount based on the counterparty’s credit rating. The Company also had agreements with counterparties in which cash deposits, letters of credit, and/or pledged aircraft are required to be posted whenever the net fair value of derivatives associated with those counterparties exceeds specific thresholds—cash is either posted by the counterparty if the value of derivatives is an asset to the Company, or cash, letters of credit, and/or aircraft could be posted as collateral by the Company if the value of derivatives is a liability to the Company. Refer to the counterparty credit risk and collateral table provided in Note 10 to the Consolidated Financial Statements for the fair values of fuel derivatives, amounts posted as collateral, and applicable collateral posting threshold amounts as of December 31, 2015, at which such postings are triggered.
Due to the terms of the Company’s current fuel hedging agreements with counterparties and the types of derivatives held, in the Company’s judgment, it does not have significant additional exposure to future cash collateral requirements. As an example, if market prices for the commodities used in the Company’s fuel hedging activities were to decrease by 25 percent from market prices as of December 31, 2015, given the Company’s fuel derivative portfolio, its aircraft collateral facilities, and its investment grade credit rating, it would likely provide an additional $436 million in collateral which could be met by posting aircraft and/or letters of credit with its current counterparties. The Company has the option of providing cash, letters of credit, and/or pledging aircraft as collateral. At December 31, 2015, the Company had $1.4 billion in aircraft available to be posted as collateral. However, as it did in 2015, and expects to continue doing in first quarter 2016, the Company would expect to also benefit from lower market prices paid for fuel used in
its operations. Also, the Company has the ability to manage or reduce its derivative positions by entering into offsetting positions, as it did during 2015, for a portion of its future hedge portfolio.
The Company is also subject to the risk that the fuel derivatives it uses to hedge against fuel price volatility do not provide adequate protection. A portion of the fuel derivatives in the Company's hedge portfolio are based on the market price of West Texas intermediate crude oil ("WTI"). In recent years, jet fuel prices have been more closely correlated with changes in the price of Brent crude oil ("Brent"). The Company has attempted to mitigate some of this risk by entering into more fuel hedges based on Brent crude. Although the Company has some fuel derivatives based on the price of Brent, to the extent the Company holds WTI-based derivatives, changes in the fair value of these positions will continue to create income statement volatility and may not provide complete protection against jet fuel price volatility. In addition, to add further protection, the Company may periodically enter into jet fuel derivatives for short-term timeframes. Jet fuel is not widely traded on an organized futures exchange and, therefore, there are limited opportunities to hedge directly in jet fuel for time horizons longer than approximately 24 months into the future.
The Company also has agreements with each of its counterparties associated with its outstanding interest rate swap agreements in which cash collateral may be required based on the fair value of outstanding derivative instruments, as well as the Company’s and its counterparty’s credit ratings. As of December 31, 2015, no cash collateral deposits were provided by or held by the Company based on its outstanding interest rate swap agreements.
Due to the significance of the Company’s fuel hedging program and the emphasis that the Company places on utilizing fuel derivatives to reduce its fuel price risk, the Company has created a system of governance and management oversight and has put in place a number of internal controls designed so that procedures are properly followed and accountability is present at the appropriate levels. For example, the Company has put in place controls designed to: (i) create and maintain a comprehensive risk management policy; (ii) provide for proper authorization by the appropriate levels of management; (iii) provide for proper segregation of duties; (iv) maintain an appropriate level of knowledge regarding the execution of and the accounting for derivative instruments; and (v) have key performance indicators in place in order to adequately measure the performance of its hedging activities. The Company believes the governance structure that it has in place is adequate given the size and sophistication of its hedging program.
Financial Market Risk
The vast majority of the Company’s tangible assets are aircraft, which are long-lived. The Company’s strategy is to maintain a conservative balance sheet and grow capacity steadily and profitably under the right conditions. While the Company uses financial leverage, it strives to maintain a strong balance sheet and has a “BBB+” rating with Fitch, a “BBB” rating with Standard & Poor’s, and a “Baa1” credit rating with Moody’s as of December 31, 2015, all of which are considered “investment grade.” The Company’s French Credit Agreements due 2018 do not give rise to significant fair value risk but do give rise to interest rate risk because this borrowing was originally issued as floating-rate debt. In addition, as disclosed in Note 10 to the Consolidated Financial Statements, the Company has converted certain of its long-term debt to floating rate debt by entering into an interest rate swap agreement. Although there is interest rate risk associated with these floating rate borrowings, the risk of the French Credit Agreements due 2018 is somewhat mitigated by the fact that the Company may prepay this debt under certain conditions. See Note 6 to the Consolidated Financial Statements for more information on the material terms of the Company’s short-term and long-term debt.
As of December 31, 2015, excluding the notes or debentures that have been converted to a floating rate, the Company’s fixed-rate senior unsecured notes outstanding included its $300 million 5.75% senior unsecured notes 2016, its $300 million 5.125% senior unsecured notes due 2017, and its $100 million 7.375% senior unsecured notes due 2027. Each of these notes had at one point been converted to floating rates, but the Company subsequently terminated the fixed-to-floating interest rate swap agreements related to them. The effect of these terminations was that the interest associated with these debts prospectively reverted back to their original fixed rates. As a result of the gains realized on these transactions, which are being amortized over the remaining term of the corresponding notes, and based on projected interest rates at the date of termination, the Company does not believe its future interest expense, based on projected future interest rates at the date of termination, associated with these notes will significantly differ from the expense it
would have recorded had the notes remained at floating rates. The following table displays the characteristics of the Company’s secured fixed rate debt as of December 31, 2015:
| Principal amount (in millions) | Effective fixed rate | Final maturity | Underlying collateral | ||||||||
| Term Loan Agreement | $ | 143 | 6.315 | % | 5/6/2019 | 14 specified Boeing 737-700 aircraft | |||||
| Term Loan Agreement | 36 | 4.84 | % | 7/1/2019 | 4 specified Boeing 737-700 aircraft | ||||||
| Term Loan Agreement | 329 | 5.223 | % | 5/9/2020 | 21 specified Boeing 737-700 aircraft |
The carrying value of the Company’s floating rate debt totaled $859 million, and this debt had a weighted-average maturity of 4.36 years at floating rates averaging 1.47 percent for the year ended December 31, 2015. In total, the Company’s fixed-rate debt and floating rate debt represented 13.42 percent and 4.97 percent, respectively, of consolidated noncurrent assets at December 31, 2015.
The Company also has some risk associated with changing interest rates due to the short-term nature of its invested cash, which totaled $1.6 billion, and short-term investments, which totaled $1.5 billion at December 31, 2015. See Notes 1 and 11 to the Consolidated Financial Statements for further information. The Company currently invests available cash in certificates of deposit, highly rated money market instruments, investment grade commercial paper, treasury securities, U.S. government agency securities, and other highly rated financial instruments, depending on market conditions and operating cash requirements. As a result of previous turmoil in credit markets, the Company has discontinued further investments in auction rate securities. Because of the short-term nature of these investments, the returns earned parallel closely with short-term floating interest rates. The Company has not undertaken any additional actions to cover interest rate market risk and is not a party to any other material market interest rate risk management activities.
A hypothetical 10 percent change in market interest rates as of December 31, 2015, would not have a material effect on the fair value of the Company’s fixed-rate debt instruments. See Note 11 to the Consolidated Financial Statements for further information on the fair value of financial instruments. A change in market interest rates could, however, have a corresponding effect on earnings and cash flows associated with the Company’s floating-rate debt, invested cash (excluding cash collateral deposits held, if applicable), floating-rate aircraft leases, and short-term investments because of the floating-rate nature of these items. Assuming floating market rates in effect as of December 31, 2015 were held constant throughout a 12-month period, a hypothetical 10 percent change in those rates would have an immaterial impact on the Company’s net earnings and cash flows. Utilizing these assumptions and considering the Company’s cash balance (excluding the impact of cash collateral deposits held or provided to counterparties, if applicable), short-term investments, and floating-rate debt outstanding at December 31, 2015, an increase in rates would have a net negative effect on the Company’s earnings and cash flows, while a decrease in rates would have a net positive effect on the Company’s earnings and cash flows. However, a 10 percent change in market rates would not impact the Company’s earnings or cash flow associated with the Company’s publicly traded fixed-rate debt.
The Company is also subject to a financial covenant included in its revolving credit facility, and is subject to credit rating triggers related to its credit card transaction processing agreements, the pricing related to any funds drawn under its revolving credit facility, and some of its hedging counterparty agreements. Certain covenants include the maintenance of minimum credit ratings and/or triggers that are based on changes in these ratings. The Company’s revolving credit facility contains a financial covenant requiring a minimum coverage ratio of adjusted pre-tax income to fixed obligations, as defined. As of December 31, 2015, the Company was in compliance with this covenant and there were no amounts outstanding under the revolving credit facility. However, if conditions change and the Company fails to meet the minimum standards set forth in the revolving credit facility, there could be a reduction in the availability of cash under the facility, or an increase in the costs to keep the facility intact as written. The Company’s hedging counterparty agreements contain ratings triggers in which additional cash collateral could be required to be posted with the counterparty if the Company’s credit rating were to fall below investment grade by two of the three major rating agencies, and if the Company were in a net liability position with the counterparty. See Note 10 to the Consolidated Financial Statements for further information. As of December 31, 2015, $835 million in cash collateral deposits were
provided by the Company under these provisions. If the Company’s credit rating had been below investment grade as of that date, the Company would not have been required to post additional cash collateral deposits with fuel hedge counterparties because it had additional room available under its existing aircraft collateral facilities.
The Company currently has agreements with organizations that process credit card transactions arising from purchases of air travel tickets by its Customers utilizing American Express, Discover, and MasterCard/VISA. Credit card processors have financial risk associated with tickets purchased for travel because, although the processor generally forwards the cash related to the purchase to the Company soon after the purchase is completed, the air travel generally occurs after that time, and the processor will have liability if the Company does not ultimately provide the air travel. Under these processing agreements, and based on specified conditions, increasing amounts of cash reserves could be required to be posted with the counterparty.
A majority of the Company’s sales transactions are processed by Chase Paymentech. Should chargebacks processed by Chase Paymentech reach a certain level, proceeds from advance ticket sales could be held back and used to establish a reserve account to cover such chargebacks and any other disputed charges that might occur. Additionally, cash reserves are required to be established if the Company’s credit rating falls to specified levels below investment grade. Cash reserve requirements are based on the Company’s public debt rating and a corresponding percentage of the Company’s Air traffic liability.
As of December 31, 2015, the Company was in compliance with all credit card processing agreements. However, the inability to enter into credit card processing agreements would have a material adverse effect on the business of the Company. The Company believes that it will be able to continue to renew its existing credit card processing agreements or will be able to enter into new credit card processing agreements with other processors in the future.
Item 8. Financial Statements and Supplementary Data
Southwest Airlines Co.
Consolidated Balance Sheet
(in millions, except share data)
| December 31, 2015 | December 31, 2014 | ||||||
| ASSETS | |||||||
| Current assets: | |||||||
| Cash and cash equivalents | $ | 1,583 | $ | 1,282 | |||
| Short-term investments | 1,468 | 1,706 | |||||
| Accounts and other receivables | 474 | 365 | |||||
| Inventories of parts and supplies, at cost | 311 | 342 | |||||
| Prepaid expenses and other current assets | 188 | 232 | |||||
| Total current assets | 4,024 | 3,927 | |||||
| Property and equipment, at cost: | |||||||
| Flight equipment | 19,462 | 18,473 | |||||
| Ground property and equipment | 3,219 | 2,853 | |||||
| Deposits on flight equipment purchase contracts | 1,089 | 566 | |||||
| Assets constructed for others | 915 | 621 | |||||
| 24,685 | 22,513 | ||||||
| Less allowance for depreciation and amortization | 9,084 | 8,221 | |||||
| 15,601 | 14,292 | ||||||
| Goodwill | 970 | 970 | |||||
| Other assets | 717 | 534 | |||||
| $ | 21,312 | $ | 19,723 | ||||
| LIABILITIES AND STOCKHOLDERS' EQUITY | |||||||
| Current liabilities: | |||||||
| Accounts payable | $ | 1,188 | $ | 1,203 | |||
| Accrued liabilities | 2,591 | 1,565 | |||||
| Air traffic liability | 2,990 | 2,897 | |||||
| Current maturities of long-term debt | 637 | 258 | |||||
| Total current liabilities | 7,406 | 5,923 | |||||
| Long-term debt less current maturities | 2,541 | 2,434 | |||||
| Deferred income taxes | 2,490 | 2,782 | |||||
| Construction obligation | 757 | 554 | |||||
| Other noncurrent liabilities | 760 | 1,255 | |||||
| Stockholders' equity: | |||||||
| Common stock, $1.00 par value: 2,000,000,000 shares authorized; 807,611,634 shares issued in 2015 and 2014 | 808 | 808 | |||||
| Capital in excess of par value | 1,374 | 1,315 | |||||
| Retained earnings | 9,409 | 7,416 | |||||
| Accumulated other comprehensive loss | (1,051 | ) | (738 | ) | |||
| Treasury stock, at cost: 160,010,017 and 132,017,550 shares in 2015 and 2014 respectively | (3,182 | ) | (2,026 | ) | |||
| Total stockholders' equity | 7,358 | 6,775 | |||||
| $ | 21,312 | $ | 19,723 |
See accompanying notes.
Southwest Airlines Co.
Consolidated Statement of Income
(in millions, except per share amounts)
| Year ended December 31, | |||||||||||
| 2015 | 2014 | 2013 | |||||||||
| OPERATING REVENUES: | |||||||||||
| Passenger | $ | 18,299 | $ | 17,658 | $ | 16,721 | |||||
| Freight | 179 | 175 | 164 | ||||||||
| Special revenue adjustment | 172 | — | — | ||||||||
| Other | 1,170 | 772 | 814 | ||||||||
| Total operating revenues | 19,820 | 18,605 | 17,699 | ||||||||
| OPERATING EXPENSES: | |||||||||||
| Salaries, wages, and benefits | 6,383 | 5,434 | 5,035 | ||||||||
| Fuel and oil | 3,616 | 5,293 | 5,763 | ||||||||
| Maintenance materials and repairs | 1,005 | 978 | 1,080 | ||||||||
| Aircraft rentals | 238 | 295 | 361 | ||||||||
| Landing fees and other rentals | 1,166 | 1,111 | 1,103 | ||||||||
| Depreciation and amortization | 1,015 | 938 | 867 | ||||||||
| Acquisition and integration | 39 | 126 | 86 | ||||||||
| Other operating expenses | 2,242 | 2,205 | 2,126 | ||||||||
| Total operating expenses | 15,704 | 16,380 | 16,421 | ||||||||
| OPERATING INCOME | 4,116 | 2,225 | 1,278 | ||||||||
| OTHER EXPENSES (INCOME): | |||||||||||
| Interest expense | 121 | 130 | 131 | ||||||||
| Capitalized interest | (31 | ) | (23 | ) | (24 | ) | |||||
| Interest income | (9 | ) | (7 | ) | (6 | ) | |||||
| Other (gains) losses, net | 556 | 309 | (32 | ) | |||||||
| Total other expenses (income) | 637 | 409 | 69 | ||||||||
| INCOME BEFORE INCOME TAXES | 3,479 | 1,816 | 1,209 | ||||||||
| PROVISION FOR INCOME TAXES | 1,298 | 680 | 455 | ||||||||
| NET INCOME | $ | 2,181 | $ | 1,136 | $ | 754 | |||||
| NET INCOME PER SHARE, BASIC | $ | 3.30 | $ | 1.65 | $ | 1.06 | |||||
| NET INCOME PER SHARE, DILUTED | $ | 3.27 | $ | 1.64 | $ | 1.05 | |||||
| Cash dividends declared per common share | $ | .2850 | $ | .2200 | $ | .1300 |
See accompanying notes.
Southwest Airlines Co.
Consolidated Statement of Comprehensive Income
(in millions)
| Year ended December 31, | ||||||||||||
| 2015 | 2014 | 2013 | ||||||||||
| NET INCOME | $ | 2,181 | $ | 1,136 | $ | 754 | ||||||
| Unrealized gain (loss) on fuel derivative instruments, net of deferred taxes of ($181), ($430), and $31 | (308 | ) | (727 | ) | 52 | |||||||
| Unrealized gain on interest rate derivative instruments, net of deferred taxes of $6, $5, and $19 | 9 | 8 | 31 | |||||||||
| Unrealized gain (loss) on defined benefit plan items, net of deferred taxes of ($7), ($8), and $15 | (12 | ) | (16 | ) | 24 | |||||||
| Other, net of deferred taxes of $-, $-, and $7 | (2 | ) | — | 9 | ||||||||
| OTHER COMPREHENSIVE INCOME (LOSS) | $ | (313 | ) | $ | (735 | ) | $ | 116 | ||||
| COMPREHENSIVE INCOME | $ | 1,868 | $ | 401 | $ | 870 |
See accompanying notes.
Southwest Airlines Co.
Consolidated Statement of Stockholders' Equity
(in millions, except per share amounts)
| Year ended December 31, 2015, 2014, and 2013 | ||||||||||||||||||||||||
| Common Stock | Capital in excess of par value | Retained earnings | Accumulated other comprehensive income (loss) | Treasury stock | Total | |||||||||||||||||||
| Balance at December 31, 2012 | $ | 808 | $ | 1,210 | $ | 5,768 | $ | (119 | ) | $ | (675 | ) | $ | 6,992 | ||||||||||
| Repurchase of common stock | — | — | — | — | (540 | ) | (540 | ) | ||||||||||||||||
| Issuance of common and treasury stock pursuant to Employee stock plans | — | 12 | — | — | 84 | 96 | ||||||||||||||||||
| Net tax benefit (expense) of options exercised | — | (9 | ) | — | — | — | (9 | ) | ||||||||||||||||
| Share-based compensation | — | 18 | — | — | — | 18 | ||||||||||||||||||
| Cash dividends, $.1300 per share | — | — | (91 | ) | — | — | (91 | ) | ||||||||||||||||
| Comprehensive income | — |
Showing the first 8K of 162K characters. Open the full section
Item 9. Changes in and Disagreements With Accountants on Accounting and Financial Disclosure
None.
Item 9A. Controls and Procedures
Evaluation of Disclosure Controls and Procedures. The Company maintains disclosure controls and procedures (as defined in Rule 13a-15(e) of the Securities Exchange Act (the “Exchange Act”)) designed to provide reasonable assurance that the information required to be disclosed by the Company in the reports that it files or submits under the Exchange Act is recorded, processed, summarized, and reported within the time periods specified in the SEC’s rules and forms. These include controls and procedures designed to ensure that this information is accumulated and communicated to the Company’s management, including its Chief Executive Officer and Chief Financial Officer, as appropriate to allow timely decisions regarding required disclosure. Management, with the participation of the Company’s Chief Executive Officer and Chief Financial Officer, evaluated the effectiveness of the Company’s disclosure controls and procedures as of December 31, 2015. Based on this evaluation, the Company’s Chief Executive Officer and Chief Financial Officer have concluded that the Company’s disclosure controls and procedures were effective as of December 31, 2015, at the reasonable assurance level.
Management’s Annual Report on Internal Control over Financial Reporting. Management of the Company is responsible for establishing and maintaining adequate internal control over financial reporting (as defined in Rule 13a-15(f) of the Exchange Act). The Company’s internal control over financial reporting is a process, under the supervision of the Company’s Chief Executive Officer and Chief Financial Officer, designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with accounting principles generally accepted in the United States.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Therefore, even those systems determined to be effective can provide only reasonable assurance of achieving their control objectives.
Management, with the participation of the Company’s Chief Executive Officer and Chief Financial Officer, evaluated the effectiveness of the Company’s internal control over financial reporting as of December 31, 2015. In making this assessment, management used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) in Internal Control - Integrated Framework (2013 Framework). Based on this evaluation, management, with the participation of the Company’s Chief Executive Officer and Chief Financial Officer, concluded that, as of December 31, 2015, the Company’s internal control over financial reporting was effective.
Ernst & Young, LLP, the independent registered public accounting firm who audited the Company’s Consolidated Financial Statements included in this Form 10-K, has issued a report on the Company’s internal control over financial reporting, which is included herein.
Changes in Internal Control over Financial Reporting. There were no changes in the Company’s internal control over financial reporting (as defined in Rule 13a-15(f) of the Exchange Act) during the quarter ended December 31, 2015, that have materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.
Item 9B. Other Information
None.
PART III
Item 10. Directors, Executive Officers, and Corporate Governance
Directors and Executive Officers
The information required by this Item 10 regarding the Company’s directors will be set forth under the heading “Proposal 1 — Election of Directors” in the Proxy Statement for the Company’s 2016 Annual Meeting of Shareholders and is incorporated herein by reference. The information required by this Item 10 regarding the Company’s executive officers is set forth under the heading “Executive Officers of the Registrant” in Part I of this Form 10-K and is incorporated herein by reference.
Section 16(a) Compliance
The information required by this Item 10 regarding compliance with Section 16(a) of the Exchange Act will be set forth under the heading “Section 16(a) Beneficial Ownership Reporting Compliance” in the Proxy Statement for the Company’s 2016 Annual Meeting of Shareholders and is incorporated herein by reference.
Corporate Governance
Except as set forth in the following paragraph, the remaining information required by this Item 10 will be set forth under the heading “Corporate Governance” in the Proxy Statement for the Company’s 2016 Annual Meeting of Shareholders and is incorporated herein by reference.
The Company has adopted a Code of Ethics that applies to its principal executive officer, principal financial officer, and principal accounting officer or controller. The Company’s Code of Ethics, as well as its Corporate Governance Guidelines and the charters of its Audit, Compensation, and Nominating and Corporate Governance Committees, are available on the Company’s website, www.southwest.com. Copies of these documents are also available upon request to Investor Relations, Southwest Airlines Co., P.O. Box 36611, Dallas, TX 75235. The Company intends to disclose any amendments to, or waivers from, its Code of Ethics that apply to the Company’s principal executive officer, principal financial officer, and principal accounting officer or controller on the Company’s website, www.southwest.com, under the “About Southwest” caption, promptly following the date of any such amendment or waiver.
Item 11. Executive Compensation
The information required by this Item 11 will be set forth under the headings “Compensation of Executive Officers” and “Compensation of Directors” in the Proxy Statement for the Company’s 2016 Annual Meeting of Shareholders and is incorporated herein by reference.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
Except as set forth below regarding securities authorized for issuance under equity compensation plans, the information required by this Item 12 will be set forth under the heading “Voting Securities and Principal Shareholders” in the Proxy Statement for the Company’s 2016 Annual Meeting of Shareholders and is incorporated herein by reference.
Securities Authorized for Issuance under Equity Compensation Plans
The following table provides information as of December 31, 2015, regarding compensation plans (including individual compensation arrangements) under which equity securities of the Company are authorized for issuance.
Equity Compensation Plan Information
| Plan Category | Number of Securities to be Issued Upon Exercise of Outstanding Options, Warrants, and Rights (a) | Weighted-Average Exercise Price of Outstanding Options, Warrants, and Rights (b) | Number of Securities Remaining Available for Future Issuance Under Equity Compensation Plans (Excluding Securities Reflected in Column (a)) (c) | |||||||||||||
| Equity Compensation Plans Approved by Security Holders | 2,294,804 | (1 | ) | $ | 13.44 | (2 | ) | 32,761,701 | (3 | ) | ||||||
| Equity Compensation Plans not Approved by Security Holders | 12,548 | $ | 13.25 | — | ||||||||||||
| Total | 2,307,352 | $ | 13.44 | (2 | ) | 32,761,701 |
| (1) | Includes 809,727 shares of common stock issuable upon exercise of outstanding stock options and 1,485,077 restricted share units settleable in shares of the Company’s common stock. |
| (2) | The weighted-average exercise price does not take into account the restricted share units discussed in footnote (1) above because the restricted share units do not have an exercise price upon vesting. |
| (3) | Of these shares, (i) 9,995,360 shares remained available for issuance under the Company’s tax-qualified employee stock purchase plan; and (ii) 22,765,741 shares remained available for issuance under the Company’s 2007 Equity Incentive Plan in connection with the exercise of stock options and stock appreciation rights, the settlement of awards of restricted stock, restricted stock units, and phantom shares, and the grant of unrestricted shares of common stock; however, no more than 1,265,178 shares remain available for grant in connection with awards of unrestricted shares of common stock, stock-settled phantom shares, and awards to non-Employee members of the Board. These shares are in addition to the shares reserved for issuance pursuant to outstanding awards included in column (a). |
See Note 9 to the Consolidated Financial Statements for information regarding the material features of the above plans. Each of the above plans provides that the number of shares with respect to which options may be granted, the number of shares of common stock subject to an outstanding option, and the number of restricted share units granted shall be proportionately adjusted in the event of a subdivision or consolidation of shares or the payment of a stock dividend on common stock, and the purchase price per share of outstanding options shall be proportionately revised.
Item 13. Certain Relationships and Related Transactions, and Director Independence
The information required by this Item 13 will be set forth under the heading “Certain Relationships and Related Transactions, and Director Independence” in the Proxy Statement for the Company’s 2016 Annual Meeting of Shareholders and is incorporated herein by reference.
Item 14. Principal Accounting Fees and Services
The information required by this Item 14 will be set forth under the heading “Relationship with Independent Auditors” in the Proxy Statement for the Company’s 2016 Annual Meeting of Shareholders and is incorporated herein by reference.
PART IV
Item 15. Exhibits and Financial Statement Schedules
(a) 1. Financial Statements:
The financial statements included in Item 8. Financial Statements and Supplementary Data above are filed as part of this annual report.
- Financial Statement Schedules:
There are no financial statement schedules filed as part of this annual report, since the required information is included in the Consolidated Financial Statements, including the notes thereto, or the circumstances requiring inclusion of such schedules are not present.
- Exhibits:
| 3.1 | Restated Certificate of Formation of the Company, effective May 18, 2012 (incorporated by reference to Exhibit 3.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2012 (File No. 1-7259)). | |
| 3.2 | Amended and Restated Bylaws of the Company, effective November 19, 2009 (incorporated by reference to Exhibit 3.1 to the Company’s Current Report on Form 8-K filed November 20, 2009 (File No. 1-7259)). | |
| 4.1 | Specimen certificate representing common stock of the Company (incorporated by reference to Exhibit 4.2 to the Company’s Annual Report on Form 10-K for the year ended December 31, 1994 (File No. 1-7259)). | |
| 4.2 | Indenture dated as of February 14, 2005, between the Company and The Bank of New York Trust Company, N.A., Trustee (incorporated by reference to Exhibit 4.2 to the Company’s Current Report on Form 8-K filed February 14, 2005 (File No. 1-7259)). | |
| 4.3 | Indenture dated as of September 17, 2004, between the Company and Wells Fargo Bank, N.A., Trustee (incorporated by reference to Exhibit 4.1 to the Company’s Registration Statement on Form S-3 filed October 30, 2002 (File No. 333-100861)). | |
| 4.4 | Indenture dated as of February 25, 1997, between the Company and U.S. Trust Company of Texas, N.A. (incorporated by reference to Exhibit 4.12 to the Company’s Annual Report on Form 10-K for the year ended December 31, 1996 (File No. 1-7259)). | |
| The Company is not filing any other instruments evidencing any indebtedness because the total amount of securities authorized under any single such instrument does not exceed 10 percent of its total consolidated assets. Copies of such instruments will be furnished to the Securities and Exchange Commission upon request. | ||
| 10.1 | Purchase Agreement No. 1810, dated January 19, 1994, between The Boeing Company and the Company (incorporated by reference to Exhibit 10.4 to the Company’s Annual Report on Form 10-K for the year ended December 31, 1993 (File No. 1-7259)); Supplemental Agreement No. 1 (incorporated by reference to Exhibit 10.3 to the Company’s Annual Report on Form 10-K for the year ended December 31, 1996 (File No. 1-7259)); Supplemental Agreements Nos. 2, 3, and 4 (incorporated by reference to Exhibit 10.2 to the Company’s Annual Report on Form 10-K for the year ended December 31, 1997 (File No. 1-7259)); Supplemental Agreements Nos. 5, 6, and 7 (incorporated by reference to Exhibit 10.1 to the Company’s Annual Report on Form 10-K for the year ended December 31, 1998 (File No. 1-7259)); Supplemental Agreements Nos. 8, 9, and 10 (incorporated by reference to Exhibit 10.1 to the Company’s Annual Report on Form 10-K for the year ended |
| December 31, 1999 (File No. 1-7259)); Supplemental Agreements Nos. 11, 12, 13, and 14 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2000 (File No. 1-7259)); Supplemental Agreements Nos. 15, 16, 17, 18, and 19 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2001 (File No. 1-7259)); Supplemental Agreements Nos. 20, 21, 22, 23, and 24 (incorporated by reference to Exhibit 10.3 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2002 (File No. 1-7259)); Supplemental Agreements Nos. 25, 26, 27, 28, and 29 (incorporated by reference to Exhibit 10.8 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2003 (File No. 1-7259)); Supplemental Agreements Nos. 30, 31, 32, and 33 (incorporated by reference to Exhibit 10.1 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2003 (File No. 1-7259)); Supplemental Agreements Nos. 34, 35, 36, 37, and 38 (incorporated by reference to Exhibit 10.3 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2004 (File No. 1-7259)); Supplemental Agreements Nos. 39 and 40 (incorporated by reference to Exhibit 10.6 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2004 (File No. 1-7259)); Supplemental Agreement No. 41 (incorporated by reference to Exhibit 10.1 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2004 (File No. 1-7259)); Supplemental Agreements Nos. 42, 43, and 44 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2005 (File No. 1-7259)); Supplemental Agreement No. 45 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2005 (File No. 1-7259)); Supplemental Agreements Nos. 46 and 47 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2006 (File No. 1-7259)); Supplemental Agreement No. 48 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2006 (File No. 1-7259)); Supplemental Agreements Nos. 49 and 50 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2006 (File No. 1-7259)); Supplemental Agreement No. 51 (incorporated by reference to Exhibit 10.1 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2006 (File No. 1-7259)); Supplemental Agreement No. 52 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2007 (File No. 1-7259)); Supplemental Agreement No. 53 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2007 (File No. 1-7259)); Supplemental Agreements Nos. 54 and 55 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2007 (File No. 1-7259)); Supplemental Agreement No. 56 (incorporated by reference to Exhibit 10.1 to Southwest’s Annual Report on Form 10-K for the year ended December 31, 2007 (File No. 1-7259)); Supplemental Agreements Nos. 57, 58, and 59 (incorporated by reference to Exhibits 10.1, 10.2, and 10.3, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2008 (File No. 1-7259)); Supplemental Agreement No. 60 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2008 (File No. 1-7259)); Supplemental Agreement No. 61 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2008 (File No. 1-7259)); Supplemental Agreements Nos. 62 and 63 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2009 (File No. 1-7259)); Supplemental Agreement No. 64 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2010 (File No. 1-7259)); Supplemental Agreement No. 65 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2010 (File No. 1-7259)); Supplemental Agreement No. 66 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2010 (File No. 1-7259)); Supplemental Agreement No. 67 (incorporated by reference to Exhibit 10.1(a) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2010 (File No. 1-7259)); Supplemental Agreement No. 68 (incorporated by reference to Exhibit 10.1(b) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2010 (File No. 1-7259)); Supplemental Agreement No. 69 (incorporated by reference to Exhibit 10.1(c) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2010 |
| (File No. 1-7259)); Supplemental Agreement No. 70 (incorporated by reference to Exhibit 10.1(d) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2010 (File No. 1-7259)); Supplemental Agreements Nos. 71 and 72 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2011 (File No. 1-7259)); Supplemental Agreement No. 73 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2011 (File No. 1-7259)); Supplemental Agreement No. 74 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2011 (File No. 1-7259)); Supplemental Agreement No. 75 (incorporated by reference to Exhibit 10.1(a) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2011 (File No. 1-7259)); Supplemental Agreements Nos. 76 and 77 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2012 (File No. 1-7259)); Supplemental Agreements Nos. 78 and 79 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2012 (File No. 1-7259)); Supplemental Agreements Nos. 80 and 81 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2013 (File No. 1-7259)); Supplemental Agreements Nos. 82 and 83 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2013 (File No. 1-7259)); Supplemental Agreement No. 84 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2013 (File No. 1-7259)); Supplemental Agreement No. 85 (incorporated by reference to Exhibit 10.1(a) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2013 (File No. 1-7259)); Supplemental Agreement No. 86 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2014 (File No. 1-7259)); Supplemental Agreement No. 87 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2014 (File No. 1-7259)); Supplemental Agreement No. 88 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2014 (File No. 1-7259)); Supplemental Agreements Nos. 89 and 90 (incorporated by reference to Exhibits 10.1(a) and 10.1(b), respectively, to the Company’s Annual Report on Form 10-K for the year ended December 31, 2014 (File No. 1-7259)); Supplemental Agreement No. 91 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2015 (File No. 1-7259)); Supplemental Letter Agreement No. 1810-LA-1501773 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2015 (File No. 1-7259)). (1) | ||
| 10.1(a) | Supplemental Agreement No. 92 to Purchase Agreement No. 1810, dated January 19, 1994, between The Boeing Company and the Company. (1) | |
| 10.2 | Form of Amended and Restated Executive Service Recognition Plan Executive Employment Agreement between the Company and certain Officers of the Company (incorporated by reference to Exhibit 10.2 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2008 (File No. 1-7259)). (2) | |
| 10.3 | Southwest Airlines Co. 1996 Incentive Stock Option Plan (incorporated by reference to Exhibit 10.12 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2002 (File No. 1-7259)). (2) | |
| 10.4 | Letter Agreement between Southwest Airlines Co. and Gary C. Kelly, effective as of February 1, 2011 (incorporated by reference to Exhibit 99.1 to the Company’s Current Report on Form 8-K filed February 1, 2011 (File No. 1-7259)). (2) | |
| 10.5 | Southwest Airlines Co. Amended and Restated Severance Plan for Directors (as amended and restated effective May 19, 2009) (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2009 (File No. 1-7259)). | |
| 10.6 | Southwest Airlines Co. Outside Director Incentive Plan (as amended and restated effective May 16, 2007) (incorporated by reference to Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2007 (File No. 1-7259)). | |
| 10.7 | Southwest Airlines Co. 2002 Bonus SWAPA Non-Qualified Stock Option Plan (incorporated by reference to Exhibit 4.2 to the Company’s Registration Statement on Form S-8 filed August 27, 2002 (File No. 333-98761)). |
| 10.8 | Southwest Airlines Co. 2002 SWAPIA Non-Qualified Stock Option Plan (incorporated by reference to Exhibit 4.1 to the Company’s Registration Statement on Form S-8 filed October 30, 2002 (File No. 333-100862)). | |
| 10.9 | Southwest Airlines Co. Amended and Restated 2007 Equity Incentive Plan (incorporated by reference to Exhibit 99.1 to the Company’s Current Report on Form 8-K filed May 18, 2015 (File No. 1-7259)). (2) | |
| 10.10 | Southwest Airlines Co. 2007 Equity Incentive Plan Form of Notice of Grant and Terms and Conditions for Stock Option Grant (incorporated by reference to Exhibit 10.31 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2007 (File No. 1-7259)). (2) | |
| 10.11 | Southwest Airlines Co. Excess Benefit Plan (incorporated by reference to Exhibit 10.32 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2008 (File No. 1-7259)). (2) | |
| 10.12 | Amendment No. 1 to the Southwest Airlines Co. Excess Benefit Plan (incorporated by reference to Exhibit 10.33 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2008 (File No. 1-7259)). (2) | |
| 10.13 | Amendment No. 2 to the Southwest Airlines Co. Excess Benefit Plan (incorporated by reference to Exhibit 10.34 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2008 (File No. 1-7259)). (2) | |
| 10.14 | Amended and Restated Southwest Airlines Co. 2005 Excess Benefit Plan (as amended and restated effective for plan years beginning on and after January 1, 2015) (incorporated by reference to Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2014 (File No. 1-7259)). (2) | |
| 10.15 | Form of Indemnification Agreement between the Company and its Directors (incorporated by reference to Exhibit 10.1 to the Company’s Current Report on Form 8-K filed January 22, 2009 (File No. 1-7259)). | |
| 10.16 | Southwest Airlines Co. Amended and Restated 2007 Equity Incentive Plan Form of Notice of Grant and Terms and Conditions for Restricted Stock Unit grants (incorporated by reference to Exhibit 10.3 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2014 (File No. 1-7259)). (2) | |
| 10.17 | $1,000,000,000 Revolving Credit Facility Agreement among the Company, The Banks Party thereto, Morgan Stanley Senior Funding, Inc., as Syndication Agent, Bank of America, N.A., Barclays Bank PLC, Deutsche Bank Securities Inc., Goldman Sachs Bank USA, and Wells Fargo Bank, N.A., as Documentation Agents, Citibank, N.A. and JPMorgan Chase Bank, N.A., as Co-Administrative Agents, and Citibank, N.A., as Paying Agent, dated as of April 2, 2013 (incorporated by reference to Exhibit 10.1 to the Company’s Current Report on Form 8-K filed April 4, 2013 (File No. 1-7259)). | |
| 10.18 | Purchase Agreement No. 3729 and Aircraft General Terms Agreement, dated December 13, 2011, between The Boeing Company and the Company (incorporated by reference to Exhibit 10.28 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2011 (File No. 1-7259)); Supplemental Agreements Nos. 1 and 2 (incorporated by reference to Exhibits 10.3 and 10.4, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2013 (File No. 1-7259)); Supplemental Agreement No. 3 (incorporated by reference to Exhibit 10.27(a) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2013 (File No. 1-7259)). (1) | |
| 10.18(a) | Supplemental Agreement No. 4 to Purchase Agreement No. 3729, dated December 13, 2011, between The Boeing Company and the Company. (1) | |
| 10.19 | Southwest Airlines Co. Senior Executive Short Term Incentive Plan (incorporated by reference to Exhibit 99.1 to the Company’s Current Report on Form 8-K filed January 30, 2013 (File No. 1-7259)). (2) | |
| 10.20 | Southwest Airlines Co. Deferred Compensation Plan for Senior Leadership and Non-Employee Members of the Southwest Airlines Co. Board of Directors (incorporated by reference to Exhibit 99.1 to the Company’s Current Report on Form 8-K filed May 19, 2014 (File No. 1-7259)). (2) | |
| 10.21 | Southwest Airlines Co. Amended and Restated 2007 Equity Incentive Plan Form of Notice of Grant and Terms and Conditions for Performance-Based Restricted Stock Unit grants (incorporated by reference to Exhibit 10.4 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2014 (File No. 1-7259)). (2) |
| 21 | Subsidiaries of the Company. | |
| 23 | Consent of Ernst & Young LLP, Independent Registered Public Accounting Firm. | |
| 31.1 | Rule 13a-14(a) Certification of Chief Executive Officer. | |
| 31.2 | Rule 13a-14(a) Certification of Chief Financial Officer. | |
| 32 | Section 1350 Certification of Chief Executive Officer and Chief Financial Officer. (3) | |
| 101.INS | XBRL Instance Document | |
| 101.SCH | XBRL Taxonomy Extension Schema Document | |
| 101.CAL | XBRL Taxonomy Extension Calculation Linkbase Document | |
| 101.DEF | XBRL Taxonomy Extension Definition Linkbase Document | |
| 101.LAB | XBRL Extension Labels Linkbase Document | |
| 101.PRE | XBRL Taxonomy Extension Presentation Linkbase Document |
| (1) | Pursuant to 17 CFR 240.24b-2, confidential information has been omitted and has been filed separately with the Securities and Exchange Commission pursuant to a Confidential Treatment Application filed with the Commission. |
| (2) | Management contract or compensatory plan or arrangement. |
| (3) | This exhibit is being furnished rather than filed and shall not be deemed incorporated by reference into any filing, in accordance with Item 601 of Regulation S-K. |
A copy of each exhibit may be obtained at a price of 15 cents per page, $10.00 minimum order, by writing to: Investor Relations, Southwest Airlines Co., P.O. Box 36611, Dallas, Texas 75235-1611.
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned thereunto duly authorized.
| SOUTHWEST AIRLINES CO. | ||
| February 2, 2016 | By | /s/ Tammy Romo |
| Tammy Romo | ||
| Executive Vice President & Chief Financial Officer | ||
| (On behalf of the Registrant and in | ||
| her capacity as Principal Financial | ||
| & Accounting Officer) |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on February 2, 2016, on behalf of the registrant and in the capacities indicated.
| Signature | Title | |
| /s/ GARY C. KELLY | Chairman of the Board, President, & Chief Executive Officer (Principal Executive Officer) | |
| Gary C. Kelly | ||
| /s/ TAMMY ROMO | Executive Vice President & Chief Financial Officer (Principal Financial & Accounting Officer) | |
| Tammy Romo | ||
| /s/ RON RICKS | Vice Chairman of the Board | |
| Ron Ricks | ||
| /s/ DAVID W. BIEGLER | Director | |
| David W. Biegler | ||
| /s/ J. VERONICA BIGGINS | Director | |
| J. Veronica Biggins | ||
| /s/ DOUGLAS H. BROOKS | Director | |
| Douglas H. Brooks | ||
| /s/ WILLIAM H. CUNNINGHAM | Director | |
| William H. Cunningham | ||
| /s/ JOHN G. DENISON | Director | |
| John G. Denison | ||
| /s/ THOMAS W. GILLIGAN | Director | |
| Thomas W. Gilligan | ||
| /s/ NANCY B. LOEFFLER | Director | |
| Nancy B. Loeffler | ||
| /s/ JOHN T. MONTFORD | Director | |
| John T. Montford |
INDEX TO THE EXHIBITS
| 3.1 | Restated Certificate of Formation of the Company, effective May 18, 2012 (incorporated by reference to Exhibit 3.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2012 (File No. 1-7259)). | |
| 3.2 | Amended and Restated Bylaws of the Company, effective November 19, 2009 (incorporated by reference to Exhibit 3.1 to the Company’s Current Report on Form 8-K filed November 20, 2009 (File No. 1-7259)). | |
| 4.1 | Specimen certificate representing common stock of the Company (incorporated by reference to Exhibit 4.2 to the Company’s Annual Report on Form 10-K for the year ended December 31, 1994 (File No. 1-7259)). | |
| 4.2 | Indenture dated as of February 14, 2005, between the Company and The Bank of New York Trust Company, N.A., Trustee (incorporated by reference to Exhibit 4.2 to the Company’s Current Report on Form 8-K filed February 14, 2005 (File No. 1-7259)). | |
| 4.3 | Indenture dated as of September 17, 2004, between the Company and Wells Fargo Bank, N.A., Trustee (incorporated by reference to Exhibit 4.1 to the Company’s Registration Statement on Form S-3 filed October 30, 2002 (File No. 333-100861)). | |
| 4.4 | Indenture dated as of February 25, 1997, between the Company and U.S. Trust Company of Texas, N.A. (incorporated by reference to Exhibit 4.12 to the Company’s Annual Report on Form 10-K for the year ended December 31, 1996 (File No. 1-7259)). | |
| The Company is not filing any other instruments evidencing any indebtedness because the total amount of securities authorized under any single such instrument does not exceed 10 percent of its total consolidated assets. Copies of such instruments will be furnished to the Securities and Exchange Commission upon request. | ||
| 10.1 | Purchase Agreement No. 1810, dated January 19, 1994, between The Boeing Company and the Company (incorporated by reference to Exhibit 10.4 to the Company’s Annual Report on Form 10-K for the year ended December 31, 1993 (File No. 1-7259)); Supplemental Agreement No. 1 (incorporated by reference to Exhibit 10.3 to the Company’s Annual Report on Form 10-K for the year ended December 31, 1996 (File No. 1-7259)); Supplemental Agreements Nos. 2, 3, and 4 (incorporated by reference to Exhibit 10.2 to the Company’s Annual Report on Form 10-K for the year ended December 31, 1997 (File No. 1-7259)); Supplemental Agreements Nos. 5, 6, and 7 (incorporated by reference to Exhibit 10.1 to the Company’s Annual Report on Form 10-K for the year ended December 31, 1998 (File No. 1-7259)); Supplemental Agreements Nos. 8, 9, and 10 (incorporated by reference to Exhibit 10.1 to the Company’s Annual Report on Form 10-K for the year ended December 31, 1999 (File No. 1-7259)); Supplemental Agreements Nos. 11, 12, 13, and 14 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2000 (File No. 1-7259)); Supplemental Agreements Nos. 15, 16, 17, 18, and 19 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2001 (File No. 1-7259)); Supplemental Agreements Nos. 20, 21, 22, 23, and 24 (incorporated by reference to Exhibit 10.3 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2002 (File No. 1-7259)); Supplemental Agreements Nos. 25, 26, 27, 28, and 29 (incorporated by reference to Exhibit 10.8 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2003 (File No. 1-7259)); Supplemental Agreements Nos. 30, 31, 32, and 33 (incorporated by reference to Exhibit 10.1 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2003 (File No. 1-7259)); Supplemental Agreements Nos. 34, 35, 36, 37, and 38 (incorporated by reference to Exhibit 10.3 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2004 (File No. 1-7259)); Supplemental Agreements Nos. 39 and 40 (incorporated by reference to Exhibit 10.6 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2004 (File No. 1-7259)); Supplemental Agreement No. 41 (incorporated by reference to Exhibit 10.1 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2004 (File No. 1-7259)); Supplemental Agreements |
| Nos. 42, 43, and 44 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2005 (File No. 1-7259)); Supplemental Agreement No. 45 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2005 (File No. 1-7259)); Supplemental Agreements Nos. 46 and 47 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2006 (File No. 1-7259)); Supplemental Agreement No. 48 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2006 (File No. 1-7259)); Supplemental Agreements Nos. 49 and 50 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2006 (File No. 1-7259)); Supplemental Agreement No. 51 (incorporated by reference to Exhibit 10.1 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2006 (File No. 1-7259)); Supplemental Agreement No. 52 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2007 (File No. 1-7259)); Supplemental Agreement No. 53 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2007 (File No. 1-7259)); Supplemental Agreements Nos. 54 and 55 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2007 (File No. 1-7259)); Supplemental Agreement No. 56 (incorporated by reference to Exhibit 10.1 to Southwest’s Annual Report on Form 10-K for the year ended December 31, 2007 (File No. 1-7259)); Supplemental Agreements Nos. 57, 58, and 59 (incorporated by reference to Exhibits 10.1, 10.2, and 10.3, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2008 (File No. 1-7259)); Supplemental Agreement No. 60 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2008 (File No. 1-7259)); Supplemental Agreement No. 61 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2008 (File No. 1-7259)); Supplemental Agreements Nos. 62 and 63 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2009 (File No. 1-7259)); Supplemental Agreement No. 64 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2010 (File No. 1-7259)); Supplemental Agreement No. 65 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2010 (File No. 1-7259)); Supplemental Agreement No. 66 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2010 (File No. 1-7259)); Supplemental Agreement No. 67 (incorporated by reference to Exhibit 10.1(a) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2010 (File No. 1-7259)); Supplemental Agreement No. 68 (incorporated by reference to Exhibit 10.1(b) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2010 (File No. 1-7259)); Supplemental Agreement No. 69 (incorporated by reference to Exhibit 10.1(c) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2010 (File No. 1-7259)); Supplemental Agreement No. 70 (incorporated by reference to Exhibit 10.1(d) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2010 (File No. 1-7259)); Supplemental Agreements Nos. 71 and 72 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2011 (File No. 1-7259)); Supplemental Agreement No. 73 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2011 (File No. 1-7259)); Supplemental Agreement No. 74 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2011 (File No. 1-7259)); Supplemental Agreement No. 75 (incorporated by reference to Exhibit 10.1(a) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2011 (File No. 1-7259)); Supplemental Agreements Nos. 76 and 77 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2012 (File No. 1-7259)); Supplemental Agreements Nos. 78 and 79 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2012 (File No. 1-7259)); Supplemental Agreements Nos. 80 and 81 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2013 |
| (File No. 1-7259)); Supplemental Agreements Nos. 82 and 83 (incorporated by reference to Exhibits 10.1 and 10.2, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2013 (File No. 1-7259)); Supplemental Agreement No. 84 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2013 (File No. 1-7259)); Supplemental Agreement No. 85 (incorporated by reference to Exhibit 10.1(a) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2013 (File No. 1-7259)); Supplemental Agreement No. 86 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2014 (File No. 1-7259)); Supplemental Agreement No. 87 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2014 (File No. 1-7259)); Supplemental Agreement No. 88 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2014 (File No. 1-7259)); Supplemental Agreements Nos. 89 and 90 (incorporated by reference to Exhibits 10.1(a) and 10.1(b), respectively, to the Company’s Annual Report on Form 10-K for the year ended December 31, 2014 (File No. 1-7259)); Supplemental Agreement No. 91 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2015 (File No. 1-7259)); Supplemental Letter Agreement No. 1810-LA-1501773 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2015 (File No. 1-7259)). (1) | ||
| 10.1(a) | Supplemental Agreement No. 92 to Purchase Agreement No. 1810, dated January 19, 1994, between The Boeing Company and the Company. (1) | |
| 10.2 | Form of Amended and Restated Executive Service Recognition Plan Executive Employment Agreement between the Company and certain Officers of the Company (incorporated by reference to Exhibit 10.2 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2008 (File No. 1-7259)). (2) | |
| 10.3 | Southwest Airlines Co. 1996 Incentive Stock Option Plan (incorporated by reference to Exhibit 10.12 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2002 (File No. 1-7259)). (2) | |
| 10.4 | Letter Agreement between Southwest Airlines Co. and Gary C. Kelly, effective as of February 1, 2011 (incorporated by reference to Exhibit 99.1 to the Company’s Current Report on Form 8-K filed February 1, 2011 (File No. 1-7259)). (2) | |
| 10.5 | Southwest Airlines Co. Amended and Restated Severance Plan for Directors (as amended and restated effective May 19, 2009) (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2009 (File No. 1-7259)). | |
| 10.6 | Southwest Airlines Co. Outside Director Incentive Plan (as amended and restated effective May 16, 2007) (incorporated by reference to Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2007 (File No. 1-7259)). | |
| 10.7 | Southwest Airlines Co. 2002 Bonus SWAPA Non-Qualified Stock Option Plan (incorporated by reference to Exhibit 4.2 to the Company’s Registration Statement on Form S-8 filed August 27, 2002 (File No. 333-98761)). | |
| 10.8 | Southwest Airlines Co. 2002 SWAPIA Non-Qualified Stock Option Plan (incorporated by reference to Exhibit 4.1 to the Company’s Registration Statement on Form S-8 filed October 30, 2002 (File No. 333-100862)). |
| 10.9 | Southwest Airlines Co. Amended and Restated 2007 Equity Incentive Plan (incorporated by reference to Exhibit 99.1 to the Company’s Current Report on Form 8-K filed May 18, 2015 (File No. 1-7259)). (2) | |
| 10.10 | Southwest Airlines Co. 2007 Equity Incentive Plan Form of Notice of Grant and Terms and Conditions for Stock Option Grant (incorporated by reference to Exhibit 10.31 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2007 (File No. 1-7259)). (2) | |
| 10.11 | Southwest Airlines Co. Excess Benefit Plan (incorporated by reference to Exhibit 10.32 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2008 (File No. 1-7259)). (2) | |
| 10.12 | Amendment No. 1 to the Southwest Airlines Co. Excess Benefit Plan (incorporated by reference to Exhibit 10.33 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2008 (File No. 1-7259)). (2) | |
| 10.13 | Amendment No. 2 to the Southwest Airlines Co. Excess Benefit Plan (incorporated by reference to Exhibit 10.34 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2008 (File No. 1-7259)). (2) | |
| 10.14 | Amended and Restated Southwest Airlines Co. 2005 Excess Benefit Plan (as amended and restated effective for plan years beginning on and after January 1, 2015) (incorporated by reference to Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2014 (File No. 1-7259)). (2) | |
| 10.15 | Form of Indemnification Agreement between the Company and its Directors (incorporated by reference to Exhibit 10.1 to the Company’s Current Report on Form 8-K filed January 22, 2009 (File No. 1-7259)). | |
| 10.16 | Southwest Airlines Co. Amended and Restated 2007 Equity Incentive Plan Form of Notice of Grant and Terms and Conditions for Restricted Stock Unit grants (incorporated by reference to Exhibit 10.3 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2014 (File No. 1-7259)). (2) | |
| 10.17 | $1,000,000,000 Revolving Credit Facility Agreement among the Company, The Banks Party thereto, Morgan Stanley Senior Funding, Inc., as Syndication Agent, Bank of America, N.A., Barclays Bank PLC, Deutsche Bank Securities Inc., Goldman Sachs Bank USA, and Wells Fargo Bank, N.A., as Documentation Agents, Citibank, N.A. and JPMorgan Chase Bank, N.A., as Co-Administrative Agents, and Citibank, N.A., as Paying Agent, dated as of April 2, 2013 (incorporated by reference to Exhibit 10.1 to the Company’s Current Report on Form 8-K filed April 4, 2013 (File No. 1-7259)). | |
| 10.18 | Purchase Agreement No. 3729 and Aircraft General Terms Agreement, dated December 13, 2011, between The Boeing Company and the Company (incorporated by reference to Exhibit 10.28 to the Company’s Annual Report on Form 10-K for the year ended December 31, 2011 (File No. 1-7259)); Supplemental Agreements Nos. 1 and 2 (incorporated by reference to Exhibits 10.3 and 10.4, respectively, to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2013 (File No. 1-7259)); Supplemental Agreement No. 3 (incorporated by reference to Exhibit 10.27(a) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2013 (File No. 1-7259)). (1) | |
| 10.18(a) | Supplemental Agreement No. 4 to Purchase Agreement No. 3729, dated December 13, 2011, between The Boeing Company and the Company. (1) | |
| 10.19 | Southwest Airlines Co. Senior Executive Short Term Incentive Plan (incorporated by reference to Exhibit 99.1 to the Company’s Current Report on Form 8-K filed January 30, 2013 (File No. 1-7259)). (2) | |
| 10.20 | Southwest Airlines Co. Deferred Compensation Plan for Senior Leadership and Non-Employee Members of the Southwest Airlines Co. Board of Directors (incorporated by reference to Exhibit 99.1 to the Company’s Current Report on Form 8-K filed May 19, 2014 (File No. 1-7259)). (2) |
| 10.21 | Southwest Airlines Co. Amended and Restated 2007 Equity Incentive Plan Form of Notice of Grant and Terms and Conditions for Performance-Based Restricted Stock Unit grants (incorporated by reference to Exhibit 10.4 to the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2014 (File No. 1-7259)). (2) | |
| 21 | Subsidiaries of the Company. | |
| 23 | Consent of Ernst & Young LLP, Independent Registered Public Accounting Firm. | |
| 31.1 | Rule 13a-14(a) Certification of Chief Executive Officer. | |
| 31.2 | Rule 13a-14(a) Certification of Chief Financial Officer. | |
| 32 | Section 1350 Certification of Chief Executive Officer and Chief Financial Officer. (3) | |
| 101.INS | XBRL Instance Document | |
| 101.SCH | XBRL Taxonomy Extension Schema Document | |
| 101.CAL | XBRL Taxonomy Extension Calculation Linkbase Document | |
| 101.DEF | XBRL Taxonomy Extension Definition Linkbase Document | |
| 101.LAB | XBRL Extension Labels Linkbase Document | |
| 101.PRE | XBRL Taxonomy Extension Presentation Linkbase Document |
| (1) | Pursuant to 17 CFR 240.24b-2, confidential information has been omitted and has been filed separately with the Securities and Exchange Commission pursuant to a Confidential Treatment Application filed with the Commission. |
| (2) | Management contract or compensatory plan or arrangement. |
| (3) | This exhibit is being furnished rather than filed and shall not be deemed incorporated by reference into any filing, in accordance with Item 601 of Regulation S-K. |
A copy of each exhibit may be obtained at a price of 15 cents per page, $10.00 minimum order, by writing to: Investor Relations, Southwest Airlines Co., P.O. Box 36611, Dallas, Texas 75235-1611.