 filings.tools
Southwest Airlines 10-K 2023-12-31
Filed 2024-02-06. 24 sections, 673K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
(Mark One)
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2023
| or |
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
| For the transition period from ________ to ________ |
Commission File No. 1-7259
SOUTHWEST AIRLINES CO.
(Exact name of registrant as specified in its charter)
| Texas | 74-1563240 | |||||||
| (State or other jurisdiction of | (IRS Employer | |||||||
| incorporation or organization) | Identification No.) | |||||||
| P.O. Box 36611 | ||||||||
| Dallas, | Texas | 75235-1611 | ||||||
| (Address of principal executive offices) | (Zip Code) |
Registrant's telephone number, including area code: (214) 792-4000
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol | Name of each exchange on which registered | ||||||
| Common Stock ($1.00 par value) | LUV | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act:
None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes x No o
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes o No x
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes x No o
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes x No o
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of "large accelerated filer," "accelerated filer," "smaller reporting company," and "emerging growth company" in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | x | Accelerated filer | ☐ | ||||||||
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ | ||||||||
| Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨
Indicate by check mark whether the registrant has filed a report on and attestation to its management's assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. x
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements. Yes ☐ No x
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant's executive officers during the relevant recovery period pursuant to §240.10D-1(b). Yes ☐ No x
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ☐ No x
The aggregate market value of the common stock held by non-affiliates of the registrant was approximately $21,499,447,826 computed by reference to the closing sale price of the common stock on the New York Stock Exchange on June 30, 2023, the last trading day of the registrant’s most recently completed second fiscal quarter.
Number of shares of common stock outstanding as of the close of business on February 2, 2024: 596,664,523 shares
DOCUMENTS INCORPORATED BY REFERENCE
Portions of the Definitive Proxy Statement for the Company’s Annual Meeting of Shareholders to be held May 15, 2024, are incorporated into Part III of this Annual Report on Form 10-K.
TABLE OF CONTENTS
-PART I-
Item 1. Business
Company Overview
Southwest Airlines Co. (the “Company” or “Southwest”) operates Southwest Airlines, a major passenger airline that provides scheduled air transportation in the United States and near-international markets. Southwest commenced service on June 18, 1971, with three Boeing 737 aircraft serving three Texas cities: Dallas, Houston, and San Antonio. Southwest’s unique route network, low fares, and famous Hospitality continue to make the Company an attractive choice for Customers in cities across the United States and near-international destinations. As of December 31, 2023, Southwest had a total of 817 Boeing 737 aircraft in its fleet and served 121 destinations in 42 states, the District of Columbia, the Commonwealth of Puerto Rico, and ten near-international countries: Mexico, Jamaica, The Bahamas, Aruba, Dominican Republic, Costa Rica, Belize, Cuba, the Cayman Islands, and Turks and Caicos.
Industry
The airline industry has historically been an extremely volatile industry. Among other things, it has been cyclical, energy intensive, labor intensive, capital intensive, technology intensive, highly regulated, heavily taxed, and extremely competitive. The airline industry has also been particularly susceptible to detrimental events such as economic recessions, jet fuel price volatility, unscheduled maintenance disruptions, outbreaks of disease and/or pandemics, supply chain challenges, U.S. government shutdowns, acts of terrorism or war, geopolitical unrest, severe weather, and natural disasters.
In 2023, the U.S. airline industry continued to recover from the COVID-19 pandemic while facing challenges such as volatile fuel prices, inflationary cost pressures (particularly labor costs), delayed aircraft deliveries, labor availability (namely pilot availability), supply chain challenges, shifting travel demand patterns, economic uncertainty, disruptive weather events, and natural disasters such as the wildfires in Maui. Overall, the U.S. airline industry has experienced a strong recovery of domestic leisure travel demand since mid-2022, as reported COVID-19 cases declined throughout the United States and travel restrictions eased. International travel demand largely recovered to pre-pandemic levels in summer 2023. Business travel, while showing modest improvements over several years, remained at reduced levels throughout 2022 and 2023 compared with pre-pandemic levels, as corporate travel patterns continued to lag and evolve post-pandemic. In response to ever-evolving travel patterns, the Company and several other U.S. airlines have announced route network changes and slower capacity growth for early 2024, as compared with 2023 and/or previously announced plans.
Historically, airline industry results have been particularly susceptible to fuel price volatility. Although jet fuel prices were slightly lower in 2023 as compared with 2022, they remain at high levels and continue to be subject to extreme volatility based on a variety of factors.
Company Operations
Route Structure
Southwest has historically principally provided “point-to-point” service, rather than the “hub-and-spoke” service provided by most major U.S. airlines. A point-to-point system enables airlines to connect directly to destinations without providing a connecting service. By contrast, the hub-and-spoke system concentrates most of an airline's operations at a limited number of central hub cities and serves most other destinations in the system by providing one-stop or connecting service through a hub. By not concentrating operations exclusively through one or more central transfer points, Southwest's route structure has allowed for more direct nonstop routing than a traditional hub-and-spoke service. While the Company does not operate a traditional hub-and-spoke model, in recent years the Company has increasingly focused on designing its network around core stations in an effort to provide greater connectivity, and support operational reliability and recoverability. Southwest’s network blends intentional
connectivity offered by hub-and-spoke models and point-to-point nonstops, allowing the Company to capture nonstop demand and provide reliable one-stop itinerary options. Approximately 73 percent of the Company's Customers flew nonstop during 2023, compared with 74 percent during 2022 and 73 percent during 2021. As of December 31, 2023, Southwest served 805 nonstop city pairs, compared with 825 as of December 31, 2022, and 788 as of December 31, 2021. For 2023, the Company’s average aircraft trip stage length was 730 miles, with an average duration of approximately 2.0 hours, as compared with an average aircraft trip stage length of 728 miles and an average duration of approximately 2.0 hours in 2022, and an average aircraft trip stage length of 790 miles and an average duration of approximately 2.1 hours in 2021.
Southwest’s unique route network has also enabled it to provide its markets with frequent, conveniently timed flights and low fares. For example, Southwest currently offers 12 weekday roundtrips between Dallas Love Field and Houston Hobby (and an additional 3 to Houston Bush), 5 weekday roundtrips between Denver and Chicago Midway (and an additional 4 to Chicago O'Hare), 7 weekday roundtrips between Los Angeles International and Las Vegas, 8 weekday round trips between Burbank and Oakland, and 13 weekday roundtrips between Phoenix and Denver. Southwest complements its high-frequency short-haul routes with mid-range and long-haul nonstop service, including flights between Hawaii and California, Las Vegas, and Phoenix, and between markets such as Los Angeles and Nashville, New York LaGuardia and Houston, Los Angeles and Baltimore, Oakland and Houston, and San Diego and Baltimore.
The Company continually works to optimize its route network and schedule through the adjustment of flights in its existing markets and the addition of new markets and itineraries, while also pruning less profitable flights from its schedule. In 2023, the Company focused its efforts towards restoring the depth and breadth of its pre-pandemic network by adding back frequency in existing markets and reconnecting markets that have historically served as points of strength for the network. While the Company’s network and aircraft utilization were restored to pre-pandemic levels in late 2023, the network was not fully optimized for post-pandemic travel patterns. The Company’s near-term optimization efforts focus on evaluating its short-haul routes as business travel continues to lag pre-pandemic levels, offering the right number of flights at the right times of day, and reducing certain weekday flights to better match capacity to demand. The Company’s unique route network allows for these adjustments without structurally disrupting its airports in core markets and other large cities. The Company also remains focused on maturing newer markets introduced during the pandemic. The Company entered 18 new destinations during 2020 and 2021, expanding its network to new Customer bases, leisure destinations, and geographic regions. These services have created additional regional and international connectivity structured to grow the Company's presence in strategic markets that serve as cornerstones for its network and provide additional options for Customers to reach their final destinations. To further improve international connectivity with its domestic network, the Company has announced its plans to shift the bulk of its international service in Fort Lauderdale to Orlando. Further, in October 2023, the Company announced its plans to moderate capacity growth in 2024 to better match demand and Customer travel patterns, as well as to absorb its capacity growth from 2023.
Cost Structure
A key component of the Company's business strategy is its focus on cost discipline and charging competitively low fares. The Company's low-cost strategy includes, among other elements, (i) the use
Showing the first 8K of 127K characters. Open the full section
Item 1A. Risk Factors
The Company’s operations and financial results are subject to various risks and uncertainties, including but not limited to those described below. Other risks are described in “Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations,” “Item 7A. Quantitative and Qualitative Disclosures About Market Risk,” and the Consolidated Financial Statements and related Notes thereto. The Company's business could also be affected by additional risks and uncertainties not currently known to the Company or that it currently deems to be immaterial. If any of these risks actually occur, it could materially harm the Company's business, financial condition, or results of operations, or impair the Company's ability to implement its strategic plans. In that case, the market price of the Company's common stock could decline. The following risk factors are summarized as financial; operational; information technology; and legal, regulatory, compliance, and reputational.
Financial Risks
-
The airline industry is particularly sensitive to changes in economic conditions, and continued or future unfavorable economic conditions could negatively affect the Company’s results of operations and require the Company to adjust its business strategies.
-
The Company's business can be significantly impacted by the availability of jet fuel and high and/or volatile fuel prices, and the Company's operations are subject to disruption in the event of any delayed supply of fuel; therefore, the Company's strategic plans and future profitability are likely to be impacted by the Company's ability to effectively address fuel price increases and fuel price volatility and availability.
-
The Company's low-cost structure has historically been one of its primary competitive advantages, and many factors have affected and could continue to affect the Company's ability to control its costs.
-
The Company's results of operations could be adversely impacted if it is unable to effectively execute its strategic plans.
-
The airline industry is intensely competitive.
Operational Risks
- The Company is currently dependent on Boeing as the sole manufacturer of the Company's aircraft. If the MAX aircraft were to become unavailable for the Company's operations, or if the Company were to
experience prolonged delivery delays of MAX aircraft, the Company's business plans, strategies, and results of operations could be materially and adversely affected.
-
The Company's business is labor intensive, with most Employees represented by labor unions; therefore, the Company could be materially adversely affected in the event of conflict with its Employees or its Employees' representatives or if the Company were unable to employ and retain sufficient numbers of qualified Employees to maintain its operations.
-
The Company is currently dependent on a single engine supplier, as well as single suppliers of certain other aircraft parts and equipment; therefore, the Company could be materially adversely affected (i) if it were unable to obtain timely or sufficient delivery of aircraft parts or equipment from Boeing or other suppliers or adequate maintenance or other support from any of these suppliers at commercially reasonable terms, (ii) if Boeing or other suppliers were unable to achieve and/or maintain required regulatory certifications or approvals of their parts or equipment, or (iii) in the event of a mechanical or regulatory issue associated with the Company's aircraft parts or equipment.
-
The airline industry has faced on-going security concerns and related cost burdens; further threatened or actual terrorist attacks, war, or other hostilities, even if not made directly on the airline industry, could significantly harm the airline industry and the Company's operations.
-
Interruptions or disruptions in service at one of the Company’s core stations have had, and could in the future have, a material adverse impact on its operations.
-
The Company’s operations have been, and in the future may again be, materially and adversely disrupted by extreme weather events. An inability to quickly and effectively restore operations following adverse weather, a localized disaster, or disturbance in a key geography has adversely and materially impacted, and in the future could again adversely and materially impact, the Company’s business, results of operations, and financial condition.
-
The airline industry is made up of inherently complex systems and is affected by many conditions that are beyond its control, which can impact the Company's business strategies and results of operations.
Information Technology Risks
-
The Company is increasingly dependent on technology to operate its business and continues to implement substantial changes to its information systems; any failure, disruption, breach, or delay in implementation of necessary changes to the Company's information systems could materially adversely affect its operations.
-
Developing and expanding data security and privacy requirements could increase the Company's operating costs, and any failure of the Company to maintain the security of certain Customer, Employee, and business-related information could result in disruption to operations and damage to the Company's reputation and could be costly to remediate.
Legal, Regulatory, Compliance, and Reputational Risks
-
The Company is subject to extensive FAA regulation that may disrupt or necessitate modifications to the Company’s operations, business plans, and strategies.
-
Airport capacity constraints and air traffic control inefficiencies have limited and could continue to limit the Company's growth; changes in or additional governmental regulation could increase the Company's operating costs or otherwise limit the Company's ability to conduct business.
-
The Company is subject to various environmental requirements and risks, including increased regulation, changing consumer preferences, physical, environmental, and climate risks, and risks associated with climate change; the cost of compliance with more stringent environmental regulations, failure to comply with environmental regulations, or failure to otherwise manage the risks of climate change effectively could have a material adverse effect on the Company’s results of operations.
-
The Company is subject to risks related to its sustainability goals and disclosures, which may affect stakeholder sentiment and the Company’s reputation and brand.
-
The Company's future results will suffer if it is unable to effectively manage its international operations and/or Extended Operations.
-
The Company is currently subject to regulatory actions and pending litigation, and if judgment, penalties, or fines were to be rendered against the Company, such judgment, penalties, or fines could adversely affect the Company's operating results.
-
Conflicting federal, state, and local laws and regulations may impose additional requirements and restrictions on the Company’s operations, which could increase the Company’s operating costs, result in service disruptions, and increase litigation risk.
-
The Company’s reputation and brand could be harmed if it were to experience significant negative publicity through social media or otherwise, including with respect to the Company's voluntary ESG-related goals and disclosures.
-
The Company’s Bylaws designate specific courts as the exclusive forum for certain legal actions between the Company and its Shareholders, which could increase costs to bring a claim, discourage claims, or limit the ability of the Company’s Shareholders to bring a claim in a judicial forum viewed by the Shareholders as more favorable for disputes with the Company or the Company’s directors, officers, or other Employees.
Financial Risks
**The airline industry is particularly sensitive to changes in economic conditions; in the event of continued or future unfavorable economic conditions or
Showing the first 8K of 89K characters. Open the full section
Item 1B. Unresolved Staff Comments
None.
Item 1C. Cybersecurity
Cybersecurity Risk Management and Strategy
Risk Assessment and Management
The Company is increasingly dependent on the use of complex technology and systems to run its operations and support its strategic objectives. These technologies and systems include, among others, the Company's website and reservation system; flight dispatch and tracking systems; flight simulators; check-in kiosks; aircraft maintenance, planning, and record keeping systems; telecommunications systems; flight planning and scheduling systems; crew scheduling systems; human resources systems; and financial planning, management, and accounting systems. Additionally, the Company must receive certain confidential or personal information related to its Customers and
Employees to run its business, and the Company's operations depend upon secure collection, processing, retention, and transmission of such information. Therefore, the performance, reliability, and security of the Company's technology infrastructure and information systems are critical to the Company's operations and initiatives.
The Company has an enterprise risk management (“ERM”) program to identify, evaluate, and manage risks. Cybersecurity risks are evaluated alongside other critical business risks under the ERM program to align cybersecurity efforts with the Company's broader business goals and objectives. The Company believes that integrating cybersecurity risks into its ERM program fosters a proactive and holistic approach to cybersecurity, which helps safeguard the Company’s operations, financial condition, and reputation in an ever-evolving threat landscape.
The Company maintains a cybersecurity program that is designed to identify, protect from, detect, respond to, and recover from cybersecurity threats and risks, and protect the confidentiality, integrity, and availability of its information systems, including the information residing on such systems. The National Institute of Standards and Technology Cybersecurity Framework helps the Company inform its cybersecurity agenda and prioritize its cybersecurity activities. The Company takes a risk-based approach to cybersecurity, which begins with the identification and evaluation of cybersecurity risks or threats that could affect the Company’s operations, finances, legal or regulatory compliance, or reputation. Once identified, cybersecurity risks and related mitigation efforts are prioritized based on their potential impact, likelihood, velocity, and vulnerability, considering both quantitative and qualitative factors. Risk mitigation strategies are developed and implemented based on the specific nature of each cybersecurity risk. These strategies include, among others, the application of cybersecurity policies and procedures, implementation of administrative, technical, and physical controls, and Employee training, education, and awareness initiatives. The Company’s cybersecurity risk management also includes a Security Operations Center (“SOC”) that conducts ongoing monitoring of networks and systems for potential signs of suspicious activity. The SOC is a centralized function that monitors security alerts to initiate triage, verification, and remediation activities. Additionally, the Company’s cybersecurity program provides mechanisms for Employees to report any unusual or potentially malicious activity they observe. The Company tracks key performance indicators and cybersecurity metrics to evaluate the efficacy of its cybersecurity controls and practices. Further, the Company’s cybersecurity program is periodically reviewed by its Cybersecurity Leaders (as defined below) and adjusted in an effort to maintain the program’s agility and responsiveness as circumstances evolve, new cybersecurity threats emerge, and regulations change.
Incident Response
The Company has a dedicated cybersecurity incident response team responsible for managing and coordinating the Company’s cybersecurity incident response efforts. This team also collaborates closely with other teams in identifying, protecting from, detecting, responding to, and recovering from cybersecurity incidents. Cybersecurity incidents that meet certain thresholds are escalated to the Cybersecurity Leaders and cross-functional teams on an as-needed basis for support and guidance. Additionally, this team tracks cybersecurity incidents to help identify and analyze them. The Company’s cybersecurity incident response team partners with the Company’s internal cybersecurity teams as well as with external legal advisors, communication specialists, and other key stakeholders as appropriate to respond to cybersecurity incidents. The Company maintains a cybersecurity incident response plan to prepare for and respond to cybersecurity incidents. The incident response plan includes standard processes for reporting and escalating cybersecurity incidents to senior management. Additionally, the Company conducts at least one cybersecurity tabletop exercise on an annual basis, where members of a cross-functional team engage in a simulated cybersecurity incident scenario. This preparedness exercise is intended to provide hands-on training for the participants and helps the Company assess its processes and capabilities in addressing cybersecurity threats.
Use of Third Parties
Cybersecurity Service Providers and Third-Party Consultants. The Company engages cybersecurity consultants, auditors, and other third parties to assess and enhance its cybersecurity practices. These third parties conduct assessments, penetration testing, and vulnerability assessments to identify weaknesses and recommend
improvements. Additionally, the Company leverages a number of third-party tools and technologies as part of its efforts to enhance cybersecurity functions. This includes a managed security service provider to augment the Company’s dedicated SOC team, an endpoint detection and response system for continuous monitoring, detection, and response capabilities, and a security information and event management solution to automate real-time threat detection, investigation, and prioritization of high-fidelity alerts.
Oversight of Third-Party Service Providers. The Company also uses third-party service providers to support its operations and many of its technology initiatives. The Company evaluates third-party service providers from a cybersecurity risk perspective, which may include an assessment of that service provider’s cybersecurity posture or a recommendation of specific mitigation controls. Following an evaluation, the Company determines and prioritizes service provider risk based on potential threat impact and likelihood, and such risk determinations drive the level of due diligence and ongoing compliance monitoring required for each service provider.
Risks from Material Cybersecurity Threats
As of the date of this report, the Company has not identified any cybersecurity threats that have materially affected or are reasonably anticipated to have a material effect on the organization. Although the Company has not experienced cybersecurity incidents that are individually, or in the aggregate, material, the Company has experienced cyberattacks in the past, which the Company believes have thus far been mitigated by preventative, detective, and responsive measures put in place by the Company. For a detailed discussion of the Company’s cybersecurity related risks, see “Item 1.A Risk Factors—Information Technology Risks.”
Cybersecurity Governance
Board Oversight
The Board is responsible for overseeing management’s assessments of major risks facing the Company and for reviewing options to mitigate such risks. The Board’s oversight of major risks, including cybersecurity risks, occurs at both the full Board level and at the Board committee level through the Audit Committee.
The Board. The Chief Executive Officer, the Chief Operating Officer, the Chief Financial Officer, members of senior management, and other personnel and advisors, as requested by the Board, report on the Company’s financial, operating, and commercial strategies, as well as major related risks, which may include cybersecurity risks, at regularly scheduled meetings of the Board. Based on these reports, the Board requests follow-up data and presentations to address any specific concerns and recommendations. Additionally, the Audit Committee has opportunities to report regularly to the entire Board and review with the Board any major issues that arise at the committee level, which may include cybersecurity risks.
The Audit Committee. The Audit Committee reviews with management the Company’s technology and cybersecurity frameworks, policies, programs, opportunities, and risk profile at its regularly scheduled meetings. The Company’s Chief Information Officer (“CIO”), Chief Information Security Officer (“CISO”), members of the cybersecurity team, or other advisors, as requested by the Audit Committee, report quarterly on the Company’s technology, data privacy, and cybersecurity strategies and risks. Cybersecurity topics are presented to the Audit Committee on a quarterly basis and generally highlight any significant cybersecurity incidents, the cyber threat landscape, cybersecurity program enhancements, cybersecurity risks and related mitigation activities, and any other relevant cybersecurity topics. Management believes that this regular cadence of reporting helps to provide the Audit Committee with an informed understanding of the Company’s dynamic cybersecurity program and threat landscape. The Audit Committee further reviews with management the Company’s business continuity and disaster recovery plans and capabilities and the effectiveness of the Company’s escalation procedures. Based on these management reports, the Audit Committee may request follow-up data and presentations to address any specific concerns and recommendations. In addition to this regular reporting, significant cybersecurity risks or threats may also be escalated on as needed basis to the Audit Committee.
Management’s Role
The Company has a dedicated cybersecurity organization within its technology department that focuses on current and emerging cybersecurity matters. The Company’s cybersecurity function is led by the Company’s CISO, who reports to the Company’s CIO. The CISO and CIO (collectively, the Company’s “Cybersecurity Leaders”) are actively involved in assessing and managing cybersecurity risks. They are responsible for implementing cybersecurity policies, programs, procedures, and strategies. The responsibilities and relevant experience of each of the Cybersecurity Leaders are listed below:
-
The CIO provides leadership for the Company’s technology department. The CIO holds an undergraduate degree from Cornell and has served in various roles in information technology for over 20 years, including Vice President, Senior Director, Manager and Consultant.
-
The CISO is responsible for all aspects of cybersecurity across the Company’s facilities, airports, and aircraft fleet, which includes security engineering, security operations, incident response, threat intelligence, risk and compliance, and vulnerability management. The CISO has served in various roles in information technology for nearly 40 years at numerous technology companies and consulting firms. The CISO earned a Bachelor of Science in Industrial Engineering from Louisiana State University, a Master of Science in Management Information Systems from The University of Texas at Dallas, and a Master of Business Administration from Southern Methodist University.
The Company’s cybersecurity department is comprised of teams that engage in a range of cybersecurity activities such as threat intelligence, security architecture, and incident response. These teams conduct vulnerability management and penetration testing to identify, classify, prioritize, remediate, and mitigate vulnerabilities. Leaders from each team regularly meet with the Cybersecurity Leaders to provide visibility of major issues and seek alignment with strategy. As noted above under “Incident Response,” the Company’s cybersecurity incident response plan includes standard processes for reporting and escalating cybersecurity incidents to senior management. Cybersecurity incidents that meet certain thresholds are escalated to the Cybersecurity Leaders and cross-functional teams on an as-needed basis for support and guidance. The Company’s incident response team also coordinates with external legal advisors, communication specialists, and other key stakeholders.
Item 2. Properties
Aircraft
Southwest operated a total of 817 Boeing 737 aircraft as of December 31, 2023, of which 57 and 24 were under operating and finance leases, respectively. The following table details information on the 817 aircraft as of December 31, 2023:
| Type | Seats | Average Age (Yrs) | Number of Aircraft | Number Owned | Number Leased (a) | |||||||||||||||||||||||||||
| 737-700 | 143 | 18 | 387 | 352 | 35 | |||||||||||||||||||||||||||
| 737-800 | 175 | 8 | 207 | 190 | 17 | |||||||||||||||||||||||||||
| 737 -8 | 175 | 2 | 223 | 194 | 29 | |||||||||||||||||||||||||||
| Totals | 11 | 817 | 736 | 81 |
(a)See Note 8 to the Consolidated Financial Statements for more information on the Company's lease transactions.
In fourth quarter 2023, the Company entered into supplemental agreements with Boeing relating to its contractual order book for -7 and -8 aircraft. These agreements, which include an extended order book to 2031, provide flexibility in support of the Company's growth plans and fleet modernization. The delivery schedule below reflects contractual commitments, although the timing of future deliveries could be affected by any potential or prolonged delays in the manufacturing process or with the -7 certification. The Company retains significant flexibility to manage its fleet size, including opportunities to accelerate fleet modernization efforts if growth opportunities do not materialize.
As of December 31, 2023, the Company had firm deliveries and options for -7 and -8 aircraft as follows:
| The Boeing Company | ||||||||||||||||||||||||||||||||
| -7 Firm Orders | -8 Firm Orders | -7 or -8 Options | Total | |||||||||||||||||||||||||||||
| 2024 | 27 | 58 | — | 85 | (c) | |||||||||||||||||||||||||||
| 2025 | 59 | — | 15 | 74 | ||||||||||||||||||||||||||||
| 2026 | 59 | — | 26 | 85 | ||||||||||||||||||||||||||||
| 2027 | 19 | 46 | 25 | 90 | ||||||||||||||||||||||||||||
| 2028 | 15 | 50 | 25 | 90 | ||||||||||||||||||||||||||||
| 2029 | 38 | 34 | 18 | 90 | ||||||||||||||||||||||||||||
| 2030 | 45 | — | 45 | 90 | ||||||||||||||||||||||||||||
| 2031 | 45 | — | 45 | 90 | ||||||||||||||||||||||||||||
| 307 | (a) | 188 | (b) | 199 | 694 |
(a) The delivery timing for the -7 is dependent on the FAA issuing required certifications and approvals to Boeing and the Company. The FAA will ultimately determine the timing of the -7 certification and entry into service, and the Company therefore offers no assurances that current estimations and timelines are correct.
(b) The Company has flexibility to designate firm orders or options as -7s or -8s, upon written advance notification as stated in the contract.
(c) The Company currently plans for approximately 79 MAX aircraft deliveries in 2024.
Ground Facilities and Services
Southwest either leases or pays a usage fee for terminal passenger service facilities at each of the airports it serves to which various leasehold improvements have been made. The Company leases the land and/or structures on a long-term basis for its aircraft maintenance centers (located at Dallas Love Field, Houston Hobby, Phoenix Sky Harbor, Chicago Midway, Hartsfield-Jackson Atlanta International Airport, Denver International Airport, and Orlando International Airport) and its main corporate headquarters building, also located near Dallas Love Field. The
Company also leases a warehouse and engine repair facility in Atlanta. The Company has announced its intent to build a new aircraft maintenance facility, expected to be completed in 2025, at Baltimore-Washington International Airport.
The Company owns two additional headquarters buildings, located across the street from the Company's main headquarters building, on land owned by the Company, including (a) an energy efficient, modern building, called TOPS, which houses certain operational and training functions, including the Company's 24-hour operations and (b) the Wings Complex, consisting of a Leadership Education and Aircrew Development (“LEAD”) Center (housing the Company's 26 Boeing 737 flight simulators and classroom space for Pilot training), an additional office building, and a parking garage.
The Company has commitments associated with various airport improvement projects, including construction at Houston Hobby International Airport. This project includes the construction of new facilities and the rebuilding or modernization of existing facilities. In April 2023, the Company executed a ground lease agreement with Los Angeles World Airports (“LAWA”) at Los Angeles International Airport (LAX) which provides the Company the right to construct a 9-gate concourse (Concourse 0) adjacent to Terminal 1. The Company expects to manage the design, development, financing, construction, and commissioning of the project, and expects to commence construction in early 2025 with construction to be complete in late 2028 or early 2029. Prior to commencement of construction, LAWA and the Company will need to agree on scope and budget and have financing in place. Additional information regarding these projects is provided in Note 5 to the Consolidated Financial Statements.
The Company performs substantially all line maintenance on its aircraft and provides ground support services at most of the airports it serves. However, the Company has arrangements with certain aircraft maintenance providers for major component inspections and repairs for its airframes and engines, which comprise the majority of the Company's annual aircraft maintenance costs.
Item 3. Legal Proceedings
On June 30, 2015, the U.S. Department of Justice ("DOJ") issued a Civil Investigative Demand ("CID") to the Company. The CID sought information and documents about the Company’s capacity from January 2010 to the date of the CID, including public statements and communications with third parties about capacity. In June 2015, the Company also received a letter from the Connecticut Attorney General requesting information about capacity. The Company is cooperating fully with the DOJ CID and the state inquiry.
Further, on July 1, 2015, a complaint was filed in the United States District Court for the Southern District of New York on behalf of putative classes of consumers alleging collusion among the Company, American Airlines, Delta Air Lines, and United Airlines to limit capacity and maintain higher fares in violation of Section 1 of the Sherman Act. Since then, a number of similar class action complaints were filed in the United States District Courts for the Central District of California, the Northern District of California, the District of Columbia, the Middle District of Florida, the Southern District of Florida, the Northern District of Georgia, the Northern District of Illinois, the Southern District of Indiana, the Eastern District of Louisiana, the District of Minnesota, the District of New Jersey, the Eastern District of New York, the Southern District of New York, the Middle District of North Carolina, the District of Oklahoma, the Eastern District of Pennsylvania, the Northern District of Texas, the District of Vermont, and the Eastern District of Wisconsin. On October 13, 2015, the Judicial Panel on Multi-District Litigation centralized the cases to the United States District Court in the District of Columbia. On March 25, 2016, the plaintiffs filed a Consolidated Amended Complaint in the consolidated cases alleging that the defendants conspired to restrict capacity from 2009 to present. The plaintiffs seek to bring their claims on behalf of a class of persons who purchased tickets for domestic airline travel on the defendants' airlines from July 1, 2011 to present. They seek treble damages, injunctive relief, and attorneys' fees and expenses. On May 11, 2016, the defendants moved to dismiss the Consolidated Amended Complaint, which the Court denied on October 28, 2016. On December 20, 2017, the Company reached an agreement to settle these cases with a proposed class of all persons who purchased domestic airline transportation services from July 1, 2011, to the date of the settlement. The Company agreed to pay
$15 million and to provide certain cooperation with the plaintiffs as set forth in the settlement agreement. After notice was provided to the proposed settlement class and the Court held a fairness hearing the Court issued an order granting final approval of the settlement on May 9, 2019. On June 10, 2019, certain objectors filed notices of appeal to the United States Court of Appeals for the District of Columbia Circuit, which the Court dismissed on July 9, 2021, for lack of jurisdiction because the district court's order approving the settlements was not a final appealable order. The case is continuing as to the remaining defendants. The Company denies all allegations of wrongdoing.
On January 7, 2019, a complaint alleging a violation of the federal Uniformed Services Employment and Reemployment Rights Act (“USERRA”) and seeking a certification as a class action was filed against the Company in the United States District Court for the Northern District of California. The complaint alleges that the Company violates section 4316(b) of USERRA because it does not provide paid “short-term” military leave (i.e., a military leave of 14 days or fewer) but does provide paid jury duty leave, bereavement leave, and sick leave, which the plaintiff alleges are “comparable” forms of leave under USERRA and its implementing regulations. The complaint seeks declaratory and injunctive relief, damages, liquidated damages, interest, and attorneys’ fees, expert fees, and litigation costs. On February 3, 2021, the court granted the plaintiff’s motion for class certification and issued an order certifying a class comprised of current or former Employees who, during their employment with the Company at any time from October 10, 2004, through the date of judgment in this action, have taken short-term military leave and were subject to a collective bargaining agreement, except for Employees subject to the Transport Workers Union Local 550 agreement covering meteorologists. On January 11, 2022, the court granted the parties’ stipulated request to vacate the trial date as the Department of Defense had not yet produced the class members’ military pay and service records pursuant to the Company’s third-party subpoena. On August 18, 2022, the court entered an order that effectively stayed the action, except for attention to the third-party subpoena, until after the Ninth Circuit issued its opinion in the matter of Clarkson v. Alaska Airlines, Inc. and Horizon Industries, Inc., an appeal from an order by the United States District Court for the Eastern District of Washington granting summary judgment in defendants’ favor on substantially the same claims at issue in this action. The Ninth Circuit issued its order in Clarkson on February 1, 2023, reversing the district court’s grant of summary judgment and remanding the Clarkson case to the District Court with instructions to consider the “pay during leave” issue in the first instance. The Company denies all allegations of wrongdoing, believes the plaintiff’s positions are without merit, and intends to vigorously defend itself in all respects.
On February 19, 2020, a complaint alleging violations of federal securities laws and seeking certification as a class action was filed against the Company and certain of its officers in the United States District Court for the Northern District of Texas in Dallas (the “2020 Securities Litigation”). A lead plaintiff has been appointed in the case, and an amended complaint was filed on July 2, 2020. The amended complaint seeks damages on behalf of a putative class of persons who purchased the Company’s common stock between February 7, 2017, and January 29, 2020. The amended complaint asserts claims under Sections 10(b) and 20 of the Securities Exchange Act and alleges that the Company made material misstatements to investors regarding the Company’s safety and maintenance practices and its compliance with federal regulations and requirements. The amended complaint generally seeks money damages, pre-judgment and post-judgment interest, and attorneys’ fees and other costs. On August 17, 2020, the Company and the individual defendants filed a motion to dismiss. On October 1, 2020, the lead plaintiff filed a response in opposition to the motion to dismiss. The Company filed a reply on or about October 21, 2020. On September 20, 2023, the District Court issued an opinion granting the Company’s motion to dismiss as to all claims. On October 5, 2023, the District Court entered a final judgment dismissing the suit in its entirety with prejudice. The lead plaintiff has filed no timely notice of appeal. The Company denies all allegations of wrongdoing, including those in the amended complaint.
On June 22, 2020, a derivative action for breach of fiduciary duty was filed in the United States District Court for the Northern District of Texas naming the members of the Company's Board of Directors as defendants and the Company as a nominal defendant (the "Derivative Action"). The plaintiff alleges unspecified damage to Company’s reputation, goodwill, and standing in the community, as well as damage from exposure to civil and regulatory liability and defense costs. According to the lawsuit, these damages arise from the Company’s alleged failure to comply with safety and record maintenance regulations and false statements in public filings regarding the Company’s safety practices. The plaintiff alleges the Board, in the absence of good faith, exhibited reckless
disregard for its duties of oversight. On October 7, 2020, the Court entered an order staying and administratively closing the Derivative Action, pending the District Court’s final resolution of the Company’s motion to dismiss in the ongoing 2020 Securities Litigation brought under the federal securities laws or upon the occurrence of certain other conditions. On October 5, 2023, the District Court entered a final judgment dismissing the 2020 Securities Litigation in its entirety with prejudice, and the lead plaintiff has filed no timely notice of appeal from that dismissal. The plaintiff in the Derivative Action has taken no steps to lift the stay in the case, which remains stayed. The Board and Company deny all allegations of wrongdoing made in the Derivative Action.
On August 26, 2021, a complaint alleging breach of contract and seeking certification as a class action was filed against the Company in the United States District Court for the Western District of Texas in Waco. The complaint alleges that the Company breached its Contract of Carriage and other alleged agreements in connection with its use of the allegedly defective MAX aircraft manufactured by The Boeing Company. The complaint seeks damages on behalf of putative classes of customers who provided valuable consideration, whether in money or other form (e.g., voucher, miles/points, etc.), in exchange for a ticket for air transportation with the Company, which transportation took place between August 29, 2017, and March 13, 2019. The complaint generally seeks money damages, declaratory relief, and attorneys’ fees and other costs. On October 27, 2021, the Company filed a multi-faceted motion challenging the complaint based upon lack of subject matter jurisdiction, the existence of a prior-filed complaint on appeal in the Fifth Circuit (the “Sherman Complaint”), improper venue, and failure to state a claim, and seeking to have the complaint's class contentions stricken. That motion was fully briefed by both parties and was argued to a United States Magistrate Judge on June 27, 2022. On July 5, 2022, the Magistrate Judge granted the motion in part and ordered the case stayed until the issuance of the Fifth Circuit's opinion in the Sherman Complaint. On November 28, 2022, the parties jointly notified the Court of the Fifth Circuit's decision regarding the Sherman Complaint. On March 23, 2023, the parties jointly notified the Court of the dismissal of the Sherman Complaint for lack of jurisdiction. The case remains stayed. The Company denies all allegations of wrongdoing, believes the plaintiffs' positions are without merit, and intends to vigorously defend itself in all respects.
Two complaints alleging violations of federal securities laws and seeking certification as a class action have been filed (on January 10, 2023, and March 13, 2023, respectively) against the Company and certain of its officers in the United States District Court for the Southern District of Texas in Houston. The complaints seek damages on behalf of a putative class of persons who purchased or otherwise acquired the Company's common stock between June 13, 2020, and December 31, 2022. The complaints assert claims under Sections 10(b) and 20 of the Exchange Act and allege that the Company made material misstatements to investors regarding the Company's internal technology and alleged vulnerability to large-scale flight disruptions. The complaints generally seek money damages, pre-judgment and post-judgment interest, and attorneys' fees and other costs. The deadline in the first of these two cases to file a motion seeking appointment of lead plaintiff was March 13, 2023; four separate motions were filed, and three of the parties seeking appointment have continued to contest the issue. On July 17, 2023, the Court signed an order consolidating the two federal securities cases into the first-filed suit and also appointed plaintiff Michael Berry as lead plaintiff in the consolidated case, with his counsel of record to serve as lead counsel and liaison counsel. On September 15, 2023, the lead plaintiff filed an amended complaint that expanded the class period to include persons who purchased or otherwise acquired the Company's common stock between February 4, 2020, and March 14, 2023, while continuing to assert claims under Sections 10(b) and 20 of the Exchange Act based on alleged misstatements regarding the Company's internal technology and alleged vulnerability to large-scale flight disruptions. On November 20, 2023, the Company and the individual defendants filed a motion to dismiss the amended complaint for failure to state a claim. The parties’ respective briefing on the Company’s motion to dismiss is expected to be completed on or around February 21, 2024. The Company denies all allegations of wrongdoing in the complaint, believes the plaintiffs' positions are without merit, and intends to vigorously defend itself in all respects.
Since about January 24, 2023, the Company’s senior officers and Board of Directors have received multiple derivative demand letters from legal counsel for purported Southwest shareholders demanding that the Board investigate claims, initiate legal action, and take remedial measures in connection with the service disruptions occurring in December 2022. Generally, the demand letters broadly assert that the Company’s directors and senior officers did not make sufficient investments in internal technology systems to prevent large-scale flight disruptions,
did not exercise sufficient oversight over the Company’s operations, approved or received unwarranted compensation, caused the Company to make materially misleading public statements, and breached their fiduciary duties to the Company. Additionally, since January 27, 2023, the Company has received multiple letters from counsel for purported Southwest shareholders making statutory demands for the production of various books and records of the Company, purportedly in an effort to investigate possible derivative claims similar to those made the subject of the derivative demands discussed above. On June 13, 2023, a shareholder derivative suit was filed against certain of the Company’s current and former officers and directors in the 14th Judicial District Court of Dallas County, Texas, asserting claims for damages from alleged breach of fiduciary duty, waste of corporate assets, and unjust enrichment derivatively on the Company’s behalf against the individual defendants based on similar factual allegations as contained in the demand letters and in the federal class action complaints. On June 15, 2023, a second shareholder derivative suit was filed against certain of the Company’s current and former officers and directors in the United States District Court for the Northern District of Texas, asserting claims under Section 14(a) of the Exchange Act and for damages from alleged breach of fiduciary duty, indemnification, and unjust enrichment derivatively on the Company’s behalf against the individual defendants based on similar factual allegations as contained in the demand letters and in the federal class action complaints. On November 14, 2023, a third shareholder derivative suit was filed in the 134th Judicial District of Dallas County, Texas, by some of the same counsel involved in the June 13, 2023, suit against the same defendants in that suit and making allegations of the same operative facts and claims. The Company and its Board of Directors intend to address the derivative and books and records demands and the shareholder derivative suits in accordance with the applicable Texas statutes governing such demands and litigation. Pursuant to those statutes, a committee of independent and disinterested directors (“Special Litigation Committee”) has been appointed to conduct an inquiry regarding the allegations in the derivative suits and derivative demand letters. In that regard, on December 15, 2023, the plaintiffs in the two state court derivative cases filed an unopposed motion to consolidate the two state derivative cases, to appoint lead counsel, and to stay the consolidated state court derivative case pending the outcome of the ongoing inquiry of the Special Litigation Committee. Further, in light of the ongoing inquiry of the Special Litigation Committee, on December 19, 2023, the Company filed an unopposed motion to extend a stay of the federal derivative case until at least February 26, 2024.
Based on the Company's wide-scale operational disruption, which led to the cancelation of a significant number of flights between December 21 and December 29, 2022, the Company has been subject to inquiries and investigations by governmental agencies and could be subject to fines and/or penalties resulting from those inquiries and investigations, as well as litigation from Customers and Shareholders. On October 27, 2023, the DOT notified the Company that it had determined the Company failed to provide adequate customer service assistance, prompt flight status notifications, and proper and prompt refunds and that the assessment of a civil penalty was warranted. During fourth quarter 2023, the Company accrued an expense of $107 million associated with a settlement reached with the DOT based on their investigation into the disruption, which includes a cash penalty and incorporates a future commitment for Southwest Customer care with a new Customer compensation policy. An additional $33 million penalty was also assessed by the DOT, but was able to be credited against the substantial value the Company had already provided to its Customers impacted by the disruption, and therefore did not result in further impact to the Company's financial results for 2023.
The Company is from time to time subject to various legal proceedings and claims arising in the ordinary course of business, including, but not limited to, examinations by the Internal Revenue Service and state and local income tax authorities.
The Company’s management does not expect that the outcome in any of its currently ongoing legal proceedings or the outcome of any proposed adjustments presented to date by the Internal Revenue Service and state and local income tax authorities, individually or collectively, will have a material adverse effect on the Company’s financial condition, results of operations, or cash flow. Nevertheless, an adverse outcome for any of these matters could be material.
Item 4. Mine Safety Disclosures
Not applicable.
INFORMATION ABOUT OUR EXECUTIVE OFFICERS
The following information regarding the Company’s executive officers is as of February 1, 2024.
| Name | Position | Age | ||||||
| Gary C. Kelly | Executive Chairman of the Board | 68 | ||||||
| Robert E. Jordan | President & Chief Executive Officer | 63 | ||||||
| Andrew M. Watterson | Chief Operating Officer | 57 | ||||||
| Ryan C. Green | Executive Vice President & Chief Commercial Officer | 47 | ||||||
| Justin Jones | Executive Vice President Operations | 45 | ||||||
| Tammy Romo | Executive Vice President & Chief Financial Officer | 61 | ||||||
| Linda B. Rutherford | Chief Administration Officer | 57 | ||||||
| Mark R. Shaw | Executive Vice President & Chief Legal & Regulatory Officer & Corporate Secretary | 61 |
Set forth below is a description of the background of each of the Company’s executive officers.
Gary C. Kelly has served as the Company's Executive Chairman of the Board since February 2022 and has served as the Company's Chairman of the Board since May 2008. Mr. Kelly also served as Chief Executive Officer from July 2004 to February 2022, President from July 2008 to January 2017, Executive Vice President & Chief Financial Officer from June 2001 to July 2004, and Vice President Finance & Chief Financial Officer from 1989 to 2001. Mr. Kelly joined the Company in 1986 as its Controller.
Robert E. Jordan has served as the Company's Chief Executive Officer since February 2022 and as its President since January 2023. Mr. Jordan has been a member of the Company's Board of Directors since February 2022. Mr. Jordan also served as Executive Vice President & Incoming Chief Executive Officer from June 2021 to February 2022, Executive Vice President Corporate Services from July 2017 to June 2021, Executive Vice President & Chief Commercial Officer from September 2011 to July 2017, Executive Vice President Strategy & Planning from May 2008 to September 2011, Executive Vice President Strategy & Technology from September 2006 to May 2008, Senior Vice President Enterprise Spend Management from August 2004 to September 2006, Vice President Technology from 2002 to 2004, Vice President Purchasing from 2001 to 2002, Controller from 1997 to 2001, Director Revenue Accounting from 1994 to 1997, and Manager Sales Accounting from 1990 to 1994. Mr. Jordan joined the Company in 1988 as a programmer.
Andrew M. Watterson has served as the Company's Chief Operating Officer since October 2022. Mr. Watterson also served as Executive Vice President & Chief Commercial Officer from January 2020 to October 2022, Executive Vice President & Chief Revenue Officer from July 2017 to January 2020, Senior Vice President & Chief Revenue Officer from January 2017 to July 2017, Senior Vice President of Network & Revenue from January 2016 to January 2017, and as Vice President of Network Planning & Performance from October 2013 to January 2016.
Ryan C. Green has served as the Company’s Executive Vice President & Chief Commercial Officer since October 2022. Mr. Green also served as Senior Vice President & Chief Marketing Officer from February 2019 to October 2022, Vice President & Chief Marketing Officer from April 2017 to February 2019, Vice President Marketing from February 2016 to April 2017, Managing Director Customer Strategy and Development from October 2013 to February 2016, Senior Director Loyalty & Partnerships from July 2010 to October 2013, Director Customer Loyalty from November 2007 to July 2010, Senior Manager Loyalty Marketing from January 2007 to November 2007, and Manager Business Development from July 2004 to January 2007. Mr. Green joined the Company in 2002 in the Marketing Department.
Justin Jones has served as the Company’s Executive Vice President Operations since December 2023. Mr. Jones also served as Senior Vice President Operations & Design from December 2021 to December 2023, Vice President Planning & Performance, Technical Operations from September 2018 to December 2021, Vice President Operational Strategy & Performance from March 2016 to September 2018, Senior Director Pricing & Planning from October 2012 to March 2016, and Director Revenue Management from November 2008 to October 2012. Mr. Jones joined the Company in 2001 in the Revenue Management Department.
Tammy Romo has served as the Company's Executive Vice President & Chief Financial Officer since July 2015. Ms. Romo also served as Senior Vice President Finance & Chief Financial Officer from September 2012 to July 2015, Senior Vice President of Planning from February 2010 to September 2012, Vice President of Financial Planning from September 2008 to February 2010, Vice President Controller from February 2006 to August 2008, Vice President Treasurer from September 2004 to February 2006, Senior Director of Investor Relations from March 2002 to September 2004, Director of Investor Relations from December 1994 to March 2002, Manager of Investor Relations from September 1994 to December 1994, and Manager of Financial Reporting from September 1991 to September 1994.
Linda B. Rutherford has served as the Company’s Chief Administration Officer since October 2022. Ms. Rutherford also served as Chief Communications Officer from October 2022 to December 2023, Executive Vice President People & Communications from June 2021 to October 2022, Senior Vice President & Chief Communications Officer from October 2017 to June 2021, Vice President & Chief Communications Officer from January 2016 to October 2017, Vice President Communications & Strategic Outreach from April 2007 to January 2016, Vice President Public Relations & Community Affairs from December 2005 to April 2007, Director Public Relations from May 2001 to December 2005, Senior Manager Public Relations from February 1999 to May 2001, and Manager Public Relations from February 1997 to February 1999. Ms. Rutherford joined the Company in 1992 as a Public Relations Coordinator.
Mark R. Shaw has served as the Company's Executive Vice President & Chief Legal & Regulatory Officer since November 2018. Mr. Shaw has also served as the Company’s Corporate Secretary since August 2022. Mr. Shaw also served as Executive Vice President, Chief Legal & Regulatory Officer, & Corporate Secretary from August 2018 to November 2018, Senior Vice President, General Counsel, & Corporate Secretary from July 2015 to August 2018, Vice President, General Counsel, & Corporate Secretary from February 2013 to July 2015, and as Associate General Counsel - Corporate & Transactions from February 2008 to February 2013. Mr. Shaw joined the Company in 2000 as an Attorney in the General Counsel Department.
PART II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters, and Issuer Purchases of Equity Securities
The Company’s common stock is listed on the New York Stock Exchange ("NYSE") and is traded under the symbol "LUV." Although the Company previously suspended the payment of dividends in second quarter 2020 through September 30, 2022, pursuant to payroll funding support agreements with the U.S. Department of the Treasury, the Company reinstated and declared a quarterly cash dividend of $.18 per share on December 6, 2022, and has continued to pay quarterly dividends since the reinstatement. The Company currently intends to continue declaring dividends on a quarterly basis for the foreseeable future; however, the Board may elect to alter the timing, amount, and payment of dividends on the basis of operational results, financial condition, cash requirements, future prospects, and other factors deemed relevant by the Board. As of February 2, 2024, there were approximately 11,028 holders of record of the Company’s common stock.
Stock Performance Graph
The following Performance Graph and related information shall not be deemed "soliciting material" or "filed" with the Securities and Exchange Commission, nor shall such information be incorporated by reference into any future filing under the Securities Act of 1933 or Securities Exchange Act of 1934.
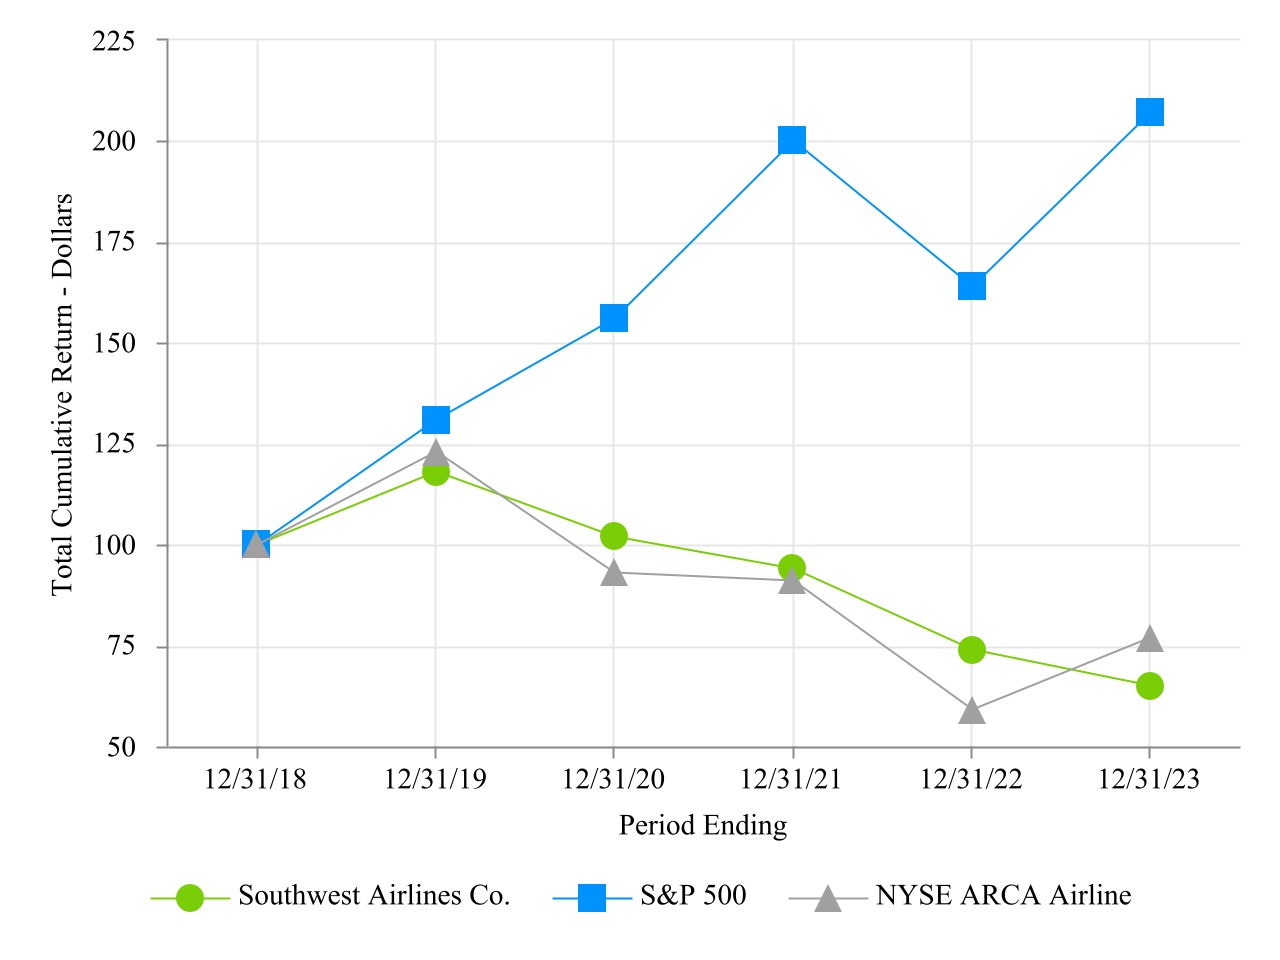
The following graph compares the cumulative total shareholder return on the Company’s common stock over the five-year period ended December 31, 2023, with the cumulative total return during such period of the Standard and Poor’s 500 Stock Index and the NYSE ARCA Airline Index. The comparison assumes $100 was invested on December 31, 2018, in the Company’s common stock and in each of the foregoing indices and assumes reinvestment of dividends. The stock performance shown on the graph below represents historical stock performance and is not necessarily indicative of future stock price performance.
COMPARISON OF FIVE YEAR CUMULATIVE TOTAL RETURN AMONG SOUTHWEST AIRLINES CO., S&P 500 INDEX, AND NYSE ARCA AIRLINE INDEX
| 12/31/2018 | 12/31/2019 | 12/31/2020 | 12/31/2021 | 12/31/2022 | 12/31/2023 | |||||||||||||||||||||||||||||||||
| Southwest Airlines Co. | $ | 100 | $ | 118 | $ | 102 | $ | 94 | $ | 74 | $ | 65 | ||||||||||||||||||||||||||
| S&P 500 | $ | 100 | $ | 131 | $ | 156 | $ | 200 | $ | 164 | $ | 207 | ||||||||||||||||||||||||||
| NYSE ARCA Airline | $ | 100 | $ | 123 | $ | 93 | $ | 91 | $ | 59 | $ | 77 |
Issuer Repurchases
On May 15, 2019, the Board authorized the repurchase of up to $2.0 billion of the Company’s common stock. Subject to certain conditions, repurchases may be made in accordance with applicable securities laws in open market or private, including accelerated, repurchase transactions from time to time, depending on market conditions. The Company has suspended share repurchase activity until further notice. The Company has approximately $899 million remaining under its current share repurchase authorization.
Item 6. [RESERVED]
Item 7. . Management's Discussion and Analysis of Financial Condition and Results of Operations
YEAR IN REVIEW
The Company had record full year 2023 revenue performance, producing operating revenues of $26.1 billion, due to healthy leisure demand and continued yield strength combined with record ancillary revenue, loyalty program revenue, and passengers carried. The Company’s 2022 results were somewhat impacted by the COVID-19 pandemic, as the Omicron variant of COVID-19 both impacted travel demand and created staffing challenges for the Company, particularly during January and February 2022. However, strong travel demand, especially associated with leisure travel, accelerated during March 2022 and continued through 2023. In 2023, the Company was able to focus on completing a comprehensive winter action plan, restoring its network and operational stability, reaching full utilization of its fleet, and delivering on significant new capabilities for its Customers.
In late December 2022, the Company experienced a wide-scale operational disruption as extreme winter weather across a significant portion of the United States impacted its operational plan and flight schedules. Subsequent to Winter Storm Elliott, the Company was challenged to realign flight crews, flight schedules, and aircraft for a period of several days during this peak demand travel period. This disruption and subsequent recovery efforts resulted in the cancellation of more than 16,700 flights during the period from December 21 through December 31, 2022. For fourth quarter 2022, the Company estimated the financial impact of this disruption was approximately $800 million on a pre-tax basis. A significant portion of this impact in fourth quarter 2022 was due to the loss of Operating revenue associated with the flight cancellations that was estimated to be approximately $410 million, and the remaining impact primarily related to a net increase of approximately $390 million in operating expenses, primarily due to travel expense reimbursements to Customers, the estimated value of Rapid Rewards points offered as a gesture of goodwill to Customers that were expected to be redeemed, and premium pay and additional compensation for Employees, which were partially offset by lower fuel and oil and profitsharing expenses. For first quarter 2023, these events also created a deceleration in bookings, largely isolated to January and February 2023, as well as additional expenses primarily in the form of reimbursing Customers for costs incurred as a result of the flight cancellations. The financial impact of this disruption on first quarter 2023 results was approximately $380 million on a pre-tax basis. On October 27, 2023, the Department of Transportation ("DOT") notified the Company that it determined the Company had failed to provide adequate customer service assistance, prompt flight status notifications, and proper and prompt refunds and that the assessment of a civil penalty was warranted. During fourth quarter 2023, the Company accrued an expense of $107 million associated with a settlement reached with the DOT in December 2023 based on their investigation into the disruption, which includes a cash penalty and incorporates a future commitment for Southwest Customer care with a new Customer compensation policy. An additional $33 million penalty was also assessed by the DOT, but was able to be credited against the substantial value the Company had already provided to its Customers impacted by the disruption, and therefore did not result in further impact to the Company's financial results for 2023. Other than the fourth quarter 2023 charge associated with the DOT settlement, there were no material impacts to operating revenues or expenses as a result of this disruption beyond first quarter 2023.
To boost operational resiliency in key areas across the Company and to mitigate the risk of a recurrence, the Company developed a three-part tactical action plan focused on improving winter operations, accelerating
operational-related investments, and enhancing cross-team collaboration. The Company's action plan was released in March 2023 and key winter operations steps were completed as of October 2023, as planned.
The Company recorded results for 2023 and 2022, on an accounting principles generally accepted in the United States ("GAAP") and non-GAAP basis, as noted in the following tables. See Note Regarding Use of Non-GAAP Financial Measures and the Reconciliation of Reported Amounts to Non-GAAP Financial Measures for additional detail regarding non-GAAP financial measures.
| (in millions, except per share amounts) | Year ended December 31, | |||||||||||||||||||||||||||||||
| GAAP | 2023 | 2022 | Change | |||||||||||||||||||||||||||||
| Operating income | $ | 224 | $ | 1,017 | (78.0) | |||||||||||||||||||||||||||
| Net income | $ | 465 | $ | 539 | (13.7) | |||||||||||||||||||||||||||
| Net income per share, diluted | $ | 0.76 | $ | 0.87 | (12.6) | |||||||||||||||||||||||||||
| Non-GAAP | ||||||||||||||||||||||||||||||||
| Operating income | $ | 893 | $ | 1,120 | (20.3) | |||||||||||||||||||||||||||
| Net income | $ | 980 | $ | 723 | 35.5 | |||||||||||||||||||||||||||
| Net income per share, diluted | $ | 1.56 | $ | 1.16 | 34.5 |
The Company's financial results, as shown above on a GAAP and non-GAAP basis for the year ended December 31, 2023 versus the year ended December 31, 2022, were affected by higher salaries, wages, and benefits expense and maintenance materials and repairs expense. On a GAAP basis, the Company's results for the year ended December 31, 2023 included incremental expense of $180 million for changes in estimate related to the contract ratification bonus for the Company's Flight Attendants as part of a tentative agreement reached in October 2023 and an incremental expense of $354 million for changes in estimate related to the contract ratification bonus for the Company's Pilots as part of a tentative agreement reached in December 2023, both of which were treated as special items and excluded from the Company's presentation of non-GAAP results. Additionally, due to the December 2022 operational disruption, as described above, the financial results on a GAAP and non-GAAP basis for the year ended December 31, 2023 included a negative financial impact of approximately $380 million on a pre-tax basis in first quarter 2023 and, on a GAAP basis, a $107 million charge on a pre-tax basis for the DOT settlement in fourth quarter 2023. The expense related to the tentative agreement with Pilots combined with the charge related to the settlement with the DOT resulted in the Company reporting a net loss of $252 million on a GAAP basis for fourth quarter 2023. Furthermore, on a GAAP and non-GAAP basis, the financial results for the year ended December 31, 2022 included a negative financial impact of approximately $800 million on a pre-tax basis in fourth quarter 2022 related to the December 2022 operational disruption and, on a GAAP basis, the financial results for the year ended December 31, 2022 included a $193 million pre-tax loss on extinguishment of debt
Showing the first 8K of 110K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
The Company has at times had interest rate risk in its interest rate swaps, commodity price risk in jet fuel required to operate its aircraft fleet, and market risk in the derivatives used to manage its fuel hedging program and in the form of fixed-rate debt instruments. As of December 31, 2023, the Company operated a total of 81 aircraft under operating and finance leases. However, except for a small number of aircraft that have lease payments that fluctuate based in part on changes in market interest rates, the remainder of the leases are not considered market sensitive financial instruments and, therefore, are not included in the interest rate sensitivity analysis below. The Company does not purchase or hold any derivative financial instruments for trading purposes. See Note 11 to the Consolidated Financial Statements for information on the Company’s accounting for its hedging program and for further details on the Company’s financial derivative instruments.
Hedging
The Company purchases jet fuel at prevailing market prices, but seeks to manage market risk through execution of a documented hedging strategy. The Company utilizes financial derivative instruments, on both a short-term and a long-term basis, as a form of insurance against the potential for significant, or catastrophic, increases in fuel prices. The Company believes there can be significant risk in not hedging against the possibility of such fuel price increases, especially in energy markets in which prices are high and/or rising. The Company currently expects to consume approximately 2.2 billion gallons of jet fuel in 2024. Based on this anticipated usage, a change in jet fuel prices of just one cent per gallon would impact the Company’s Fuel and oil expense by approximately $22 million for 2024, excluding any impact associated with fuel derivative instruments held.
As of December 31, 2023, the Company held a net position of fuel derivative instruments that represented a hedge for a portion of its anticipated jet fuel purchases for future periods through 2026. See Note 11 to the Consolidated Financial Statements for further information. The Company may increase or decrease the volume of fuel hedged based on its expectation of future market prices and its forecasted fuel consumption levels, while considering the significant premium cost that can be associated with different types of hedging strategies. The gross fair value of outstanding financial derivative instruments related to the Company’s jet fuel market price risk as of December 31, 2023, was an asset of $223 million. In addition, $50 million in cash collateral deposits were held by the Company in connection with these instruments based on their fair value as of December 31, 2023. The fair values of the derivative instruments, depending on the type of instrument, were determined by use of present value methods or standard option value models with assumptions about commodity prices based on those observed in underlying markets. An immediate 10 percent increase or decrease in underlying fuel-related commodity prices from prices as of December 31, 2023 would correspondingly change the fair value of the commodity derivative instruments in place by approximately $148 million. Fluctuations in the related commodity derivative instrument cash flows may change by more or less than this amount based upon further fluctuations in futures prices, as well as related income tax effects. In addition, this does not consider changes in cash or letters of credit utilized as collateral provided to or by counterparties, which would fluctuate in an amount equal to or less than this amount, depending on the type of collateral arrangement in place with each counterparty. This sensitivity analysis uses industry standard valuation models and holds all inputs constant as of December 31, 2023, levels, except underlying futures prices.
The Company’s credit exposure related to fuel derivative instruments is represented by the fair value of contracts that are in an asset position to the Company. At such times, these outstanding instruments expose the Company to credit loss in the event of nonperformance by the counterparties to the agreements. As of December 31, 2023, the Company had eight counterparties for which the derivatives held were an asset and none in a loss position. To manage credit risk, the Company selects and periodically reviews counterparties based on credit ratings, limits its exposure with respect to each counterparty, and monitors the market position of the fuel hedging program and its relative market position with each counterparty. However, if one or more of these counterparties were in a liability position to the Company and were unable to meet their obligations, any open derivative contracts with the counterparty could be subject to early termination, which could result in substantial losses for the Company. As of December 31, 2023, the Company had agreements with all of its active counterparties containing early termination rights and/or bilateral collateral provisions whereby security is required if market risk exposure exceeds a specified
threshold amount based on the counterparty’s credit rating. The Company also had agreements with counterparties in which cash deposits and/or letters of credit are required to be posted as collateral whenever the net fair value of derivatives associated with those counterparties exceeds specific thresholds. Refer to the counterparty credit risk and collateral table provided in Note 11 to the Consolidated Financial Statements for the fair values of fuel derivatives, amounts held as collateral, and applicable collateral posting threshold amounts as of December 31, 2023, at which such postings are triggered.
The Company is also subject to the risk that the fuel derivatives it uses to hedge against fuel price volatility do not provide adequate protection. The Company has found that financial derivative instruments in commodities, such as West Texas Intermediate ("WTI") crude oil, Brent crude oil, and refined products, such as heating oil and unleaded gasoline, can be useful in decreasing its exposure to jet fuel price volatility. In addition, to add further protection, the Company may periodically enter into jet fuel derivatives for short-term timeframes. Jet fuel is not widely traded on an organized futures exchange and, therefore, there are limited opportunities to hedge directly in jet fuel for time horizons longer than approximately 24 months into the future.
The Company also at times has agreements with each of its counterparties associated with its outstanding interest rate swap agreements in which cash collateral may be required based on the fair value of outstanding derivative instruments, as well as the Company’s and its counterparty’s credit ratings. As of December 31, 2023, the Company had no outstanding interest rate swap agreements and therefore no cash collateral deposits provided or held.
Due to the significance of the Company’s fuel hedging program and the emphasis that the Company places on utilizing fuel derivatives to reduce its fuel price risk, the Company has created a system of governance and management oversight and has put in place a number of internal controls designed so that procedures are properly followed and accountability is present at the appropriate levels. For example, the Company has put in place controls designed to: (i) create and maintain a comprehensive risk management policy; (ii) provide for proper authorization by the appropriate levels of management; (iii) provide for proper segregation of duties; (iv) maintain an appropriate level of knowledge regarding the execution of and the accounting for derivative instruments; and (v) have key performance indicators in place in order to adequately measure the performance of its hedging activities. The Company believes the governance structure that it has in place is adequate given the size and sophistication of its hedging program.
Financial Market Risk
The vast majority of the Company’s tangible assets are aircraft, which are long-lived. The Company’s long-term strategy is to maintain a conservative balance sheet and generate adequate profits and returns on capital, while growing capacity steadily under the right conditions. While the Company uses financial leverage, it strives to maintain a strong balance sheet and has a "BBB+" rating with Fitch, a "BBB" rating with Standard & Poor’s, and a "Baa1" credit rating with Moody’s as of December 31, 2023, all of which are considered "investment grade." See Note 7 to the Consolidated Financial Statements for more information on the material terms of the Company’s short-term and long-term debt.
The Company's senior unsecured notes outstanding as of December 31, 2023 are all fixed-rate obligations. See Note 7 to the Consolidated Financial Statements for further information.
The $100 million 7.375% debentures due 2027 had at one point been converted to a floating rate, but the Company subsequently terminated the fixed-to-floating interest rate swap agreements related to it. The effect of this termination was that the interest associated with this debt prospectively reverted back to its original fixed rate. As a result of the gain realized on this transaction, which is being amortized over the remaining term of the corresponding notes, and based on projected interest rates at the date of termination, the Company does not believe its future interest expense, based on projected future interest rates at the date of termination, associated with these notes will significantly differ from the expense it would have recorded had the notes remained at floating rates.
During fourth quarter 2023, the Company terminated $150 million notional value of forward-starting interest rate swap agreements. These swap agreements had been classified as cash flow hedges, and all fair market value changes were recorded to AOCI prior to their termination. The effect of this termination is that the value of the swaps originally recorded in AOCI, a gain of $23 million, will be amortized to Interest expense over the life of the debt, which will be within the years 2024-2027. See Note 11 to the Consolidated Financial Statements for further information.
The Company's total debt divided by total assets was 21.9 percent as of December 31, 2023.
The Company also has some risk associated with changing interest rates due to the short-term nature of its invested cash, which totaled $9.3 billion, and short-term investments, which totaled $2.2 billion as of December 31, 2023. See Notes 1 and 12 to the Consolidated Financial Statements for further information. The Company currently invests available cash in certificates of deposit, highly rated money market instruments, investment grade commercial paper, treasury securities, U.S. government agency securities, and other highly rated financial instruments, depending on market conditions and operating cash requirements. Because of the short-term nature of these investments, the returns earned parallel closely with short-term floating interest rates. The Company has not undertaken any additional actions to cover interest rate market risk and is not a party to any other material market interest rate risk management activities.
A hypothetical 10 percent change in market interest rates as of December 31, 2023, would have resulted in an approximate $74 million change in the fair value of the Company’s fixed-rate debt instruments. See Note 12 to the Consolidated Financial Statements for further information on the fair value of financial instruments. A change in market interest rates could, however, have a corresponding effect on earnings and cash flows associated with the Company’s invested cash (excluding cash collateral deposits held, if applicable) and short-term investments because of the floating-rate nature of these items. Assuming floating market rates in effect as of December 31, 2023 were held constant throughout a 12-month period, a hypothetical 10 percent change in those rates would have resulted in an approximate $59 million impact on the Company’s net earnings and cash flows. Utilizing these assumptions and considering the Company’s cash balance (excluding the impact of cash collateral deposits held from or provided to counterparties, if applicable) and short-term investments outstanding as of December 31, 2023, an increase in rates would have a net positive effect on the Company’s earnings and cash flows, while a decrease in rates would have a net negative effect on the Company’s earnings and cash flows. However, a 10 percent change in market rates would not impact the Company’s earnings or cash flow associated with the Company’s publicly traded fixed-rate debt.
The Company is also subject to a financial covenant included in its Amended Credit Agreement, and is subject to credit rating triggers related to its credit card transaction processing agreements, the pricing related to any funds drawn under its Amended Credit Agreement, and some of its hedging counterparty agreements. Certain covenants include the maintenance of minimum credit ratings and/or triggers that are based on changes in these ratings. The Company’s Amended Credit Agreement contains a financial covenant to maintain a Coverage Ratio (as defined therein) of 1.25 to 1.00, subject to the Company's one-time option to reduce this ratio requirement to 0.80 to 1.00 for two consecutive fiscal quarters. As of December 31, 2023, the Company was in compliance with this covenant and there were no amounts outstanding under the Amended Credit Agreement. However, if conditions change and the Company fails to meet the minimum standards set forth in the Amended Credit Agreement, there could be a reduction in the availability of cash under the facility, or an increase in the costs to keep the facility intact as written. The Company’s hedging counterparty agreements contain ratings triggers in which cash collateral could be required to be posted with the counterparty if the Company’s credit rating were to fall below investment grade by two of the three major rating agencies, and if the Company were in a net liability position with the counterparty. See Note 11 to the Consolidated Financial Statements for further information.
The Company currently has agreements with organizations that process credit card transactions arising from purchases of air travel tickets by its Customers utilizing American Express, Discover, and MasterCard/VISA. Credit card processors have financial risk associated with tickets purchased for travel because the processor generally forwards the cash related to the purchase to the Company soon after the purchase is completed, but the air travel generally occurs after that time; therefore, the processor will have liability if the Company does not ultimately
provide the air travel. Under these processing agreements, and based on specified conditions, increasing amounts of cash reserves could be required to be posted with the counterparty. There was no cash reserved for this purpose as of December 31, 2023.
A majority of the Company’s sales transactions are processed by Chase Paymentech. Should chargebacks processed by Chase Paymentech reach a certain level, proceeds from advance ticket sales could be held back and used to establish a reserve account to cover such chargebacks and any other disputed charges that might occur. Additionally, cash reserves are required to be established if the Company’s credit rating falls to specified levels below investment grade. Cash reserve requirements are based on the Company’s public debt rating and a corresponding percentage of the Company’s Air traffic liability. As of December 31, 2023, no holdbacks were in place.
As of December 31, 2023, the Company was in compliance with all credit card processing agreements. The inability to enter into credit card processing agreements would have a material adverse effect on the business of the Company. The Company believes that it will be able to continue to renew its existing credit card processing agreements or will be able to enter into new credit card processing agreements with other processors in the future.
Item 8. Financial Statements and Supplementary Data
Southwest Airlines Co.
Consolidated Balance Sheet
(in millions, except share data)
| December 31, 2023 | December 31, 2022 | ||||||||||
| ASSETS | |||||||||||
| Current assets: | |||||||||||
| Cash and cash equivalents | $ | 9,288 | $ | 9,492 | |||||||
| Short-term investments | 2,186 | 2,800 | |||||||||
| Accounts and other receivables | 1,154 | 1,040 | |||||||||
| Inventories of parts and supplies, at cost | 807 | 790 | |||||||||
| Prepaid expenses and other current assets | 520 | 686 | |||||||||
| Total current assets | 13,955 | 14,808 | |||||||||
| Property and equipment, at cost: | |||||||||||
| Flight equipment | 26,060 | 23,725 | |||||||||
| Ground property and equipment | 7,460 | 6,855 | |||||||||
| Deposits on flight equipment purchase contracts | 236 | 376 | |||||||||
| Assets constructed for others | 62 | 28 | |||||||||
| 33,818 | 30,984 | ||||||||||
| Less allowance for depreciation and amortization | 14,443 | 13,642 | |||||||||
| 19,375 | 17,342 | ||||||||||
| Goodwill | 970 | 970 | |||||||||
| Operating lease right-of-use assets | 1,223 | 1,394 | |||||||||
| Other assets | 964 | 855 | |||||||||
| $ | 36,487 | $ | 35,369 | ||||||||
| LIABILITIES AND STOCKHOLDERS' EQUITY | |||||||||||
| Current liabilities: | |||||||||||
| Accounts payable | $ | 1,862 | $ | 2,004 | |||||||
| Accrued liabilities | 3,606 | 2,043 | |||||||||
| Current operating lease liabilities | 208 | 225 | |||||||||
| Air traffic liability | 6,551 | 6,064 | |||||||||
| Current maturities of long-term debt | 29 | 42 | |||||||||
| Total current liabilities | 12,256 | 10,378 | |||||||||
| Long-term debt less current maturities | 7,978 | 8,046 | |||||||||
| Air traffic liability - noncurrent | 1,728 | 2,186 | |||||||||
| Deferred income taxes | 2,044 | 1,985 | |||||||||
| Noncurrent operating lease liabilities | 985 | 1,118 | |||||||||
| Other noncurrent liabilities | 981 | 969 | |||||||||
| Stockholders' equity: | |||||||||||
| Common stock, $1.00 par value: 2,000,000,000 shares authorized; 888,111,634 shares issued in 2023 and 2022 | 888 | 888 | |||||||||
| Capital in excess of par value | 4,153 | 4,037 | |||||||||
| Retained earnings | 16,297 | 16,261 | |||||||||
| Accumulated other comprehensive income | — | 344 | |||||||||
| Treasury stock, at cost: 291,599,001 and 294,111,813 shares in 2023 and 2022, respectively | (10,823) | (10,843) | |||||||||
| Total stockholders' equity | 10,515 | 10,687 | |||||||||
| $ | 36,487 | $ | 35,369 |
See accompanying notes.
Southwest Airlines Co.
Consolidated Statement of Income
(in millions, except per share amounts)
| Year ended December 31, | |||||||||||||||||||||||||||||
| 2023 | 2022 | 2021 | |||||||||||||||||||||||||||
| OPERATING REVENUES: | |||||||||||||||||||||||||||||
| Passenger | $ | 23,637 | $ | 21,408 | $ | 14,066 | |||||||||||||||||||||||
| Freight | 175 | 177 | 187 | ||||||||||||||||||||||||||
| Other | 2,279 | 2,229 | 1,537 | ||||||||||||||||||||||||||
| Total operating revenues | 26,091 | 23,814 | 15,790 | ||||||||||||||||||||||||||
| OPERATING EXPENSES, NET: | |||||||||||||||||||||||||||||
| Salaries, wages, and benefits | 11,152 | 9,376 | 7,743 | ||||||||||||||||||||||||||
| Payroll support and voluntary Employee programs, net | — | — | (2,960) | ||||||||||||||||||||||||||
| Fuel and oil | 6,217 | 5,975 | 3,310 | ||||||||||||||||||||||||||
| Maintenance materials and repairs | 1,188 | 852 | 854 | ||||||||||||||||||||||||||
| Landing fees and airport rentals | 1,789 | 1,508 | 1,456 | ||||||||||||||||||||||||||
| Depreciation and amortization | 1,522 | 1,351 | 1,272 | ||||||||||||||||||||||||||
| Other operating expenses | 3,999 | 3,735 | 2,394 | ||||||||||||||||||||||||||
| Total operating expenses, net | 25,867 | 22,797 | 14,069 | ||||||||||||||||||||||||||
| OPERATING INCOME | 224 | 1,017 | 1,721 | ||||||||||||||||||||||||||
| OTHER EXPENSES (INCOME): | |||||||||||||||||||||||||||||
| Interest expense | 259 | 340 | 467 | ||||||||||||||||||||||||||
| Capitalized interest | (23) | (39) | (36) | ||||||||||||||||||||||||||
| Interest income | (583) | (217) | (13) | ||||||||||||||||||||||||||
| Loss on extinguishment of debt | — | 193 | 28 | ||||||||||||||||||||||||||
| Other (gains) losses, net | (62) | 12 | (50) | ||||||||||||||||||||||||||
| Total other expenses (income) | (409) | 289 | 396 | ||||||||||||||||||||||||||
| INCOME BEFORE INCOME TAXES | 633 | 728 | 1,325 | ||||||||||||||||||||||||||
| PROVISION FOR INCOME TAXES | 168 | 189 | 348 | ||||||||||||||||||||||||||
| NET INCOME | $ | 465 | $ | 539 | $ | 977 | |||||||||||||||||||||||
| NET INCOME PER SHARE, BASIC |
Showing the first 8K of 230K characters. Open the full section
Item 9. Changes in and Disagreements With Accountants on Accounting and Financial Disclosure
None.
Item 9A. Controls and Procedures
Evaluation of Disclosure Controls and Procedures. The Company maintains disclosure controls and procedures (as defined in Rule 13a-15(e) of the Securities Exchange Act (the “Exchange Act”)) designed to provide reasonable assurance that the information required to be disclosed by the Company in the reports that it files or submits under the Exchange Act is recorded, processed, summarized, and reported within the time periods specified in the SEC’s rules and forms. These include controls and procedures designed to ensure that this information is accumulated and communicated to the Company’s management, including its Chief Executive Officer and Chief Financial Officer, as appropriate to allow timely decisions regarding required disclosure. Management, with the participation of the Company’s Chief Executive Officer and Chief Financial Officer, evaluated the effectiveness of the Company’s disclosure controls and procedures as of December 31, 2023. Based on this evaluation, the Company’s Chief Executive Officer and Chief Financial Officer have concluded that the Company’s disclosure controls and procedures were effective as of December 31, 2023, at the reasonable assurance level.
Management’s Annual Report on Internal Control over Financial Reporting. Management of the Company is responsible for establishing and maintaining adequate internal control over financial reporting (as defined in Rule 13a-15(f) of the Exchange Act). The Company’s internal control over financial reporting is a process, under the supervision of the Company’s Chief Executive Officer and Chief Financial Officer, designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with accounting principles generally accepted in the United States.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Therefore, even those systems determined to be effective can provide only reasonable assurance of achieving their control objectives.
Management, with the participation of the Company’s Chief Executive Officer and Chief Financial Officer, evaluated the effectiveness of the Company’s internal control over financial reporting as of December 31, 2023. In making this assessment, management used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) in Internal Control - Integrated Framework (2013 Framework). Based on this evaluation, management, with the participation of the Company’s Chief Executive Officer and Chief Financial Officer, concluded that, as of December 31, 2023, the Company’s internal control over financial reporting was effective.
Ernst & Young LLP, the independent registered public accounting firm who audited the Company’s Consolidated Financial Statements included in this Form 10-K, has issued an attestation report on the Company’s internal control over financial reporting, which is included herein.
Changes in Internal Control over Financial Reporting. There were no changes in the Company’s internal control over financial reporting (as defined in Rule 13a-15(f) of the Exchange Act) during the quarter ended December 31, 2023, that have materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.
Item 9B. Other Information
On February 2, 2024, the Company's Board of Directors approved the Company's Fourth Amended and Restated Bylaws ("Amended and Restated Bylaws"), effective as of such date. Among other matters, the Amended and Restated Bylaws are amended to permit Shareholders, at any meeting of Shareholders called expressly for that purpose, to remove directors with or without cause by vote of the holders of a majority of the shares then entitled to vote for the election of directors. The foregoing summary of the amendments to the Amended and Restated Bylaws does not purport to be complete and is qualified in its entirety by reference to the complete text of the Amended and Restated Bylaws, a copy of which is filed as Exhibit 3.2 to this Form 10-K and is incorporated herein by reference.
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
Not applicable.
PART III
Item 10. Directors, Executive Officers, and Corporate Governance
Directors and Executive Officers
The information required by this Item 10 regarding the Company’s directors will be set forth under the heading “Proposal 1 - Election of Directors” in the Proxy Statement for the Company’s 2024 Annual Meeting of Shareholders and is incorporated herein by reference. The information required by this Item 10 regarding the Company’s executive officers is set forth under the heading “Information about our Executive Officers” in Part I of this Form 10-K and is incorporated herein by reference.
Section 16(a) Compliance
If applicable, the information required by this Item 10 regarding compliance with Section 16(a) of the Exchange Act will be set forth under the heading “Delinquent Section 16(a) Reports” in the Proxy Statement for the Company’s 2024 Annual Meeting of Shareholders and is incorporated herein by reference.
Corporate Governance
Except as set forth in the following paragraph, the remaining information required by this Item 10 will be set forth under the heading “Corporate Governance” in the Proxy Statement for the Company’s 2024 Annual Meeting of Shareholders and is incorporated herein by reference.
The Company has adopted a Code of Ethics that applies to its principal executive officer, principal financial officer, and principal accounting officer or controller. The Company’s Code of Ethics, as well as its Corporate Governance Guidelines and the charters of its Audit, Compensation, and Nominating and Corporate Governance Committees, are available on the Company’s website, www.southwest.com. Copies of these documents are also available upon request to Investor Relations, Southwest Airlines Co., P.O. Box 36611, Dallas, TX 75235. The Company intends to disclose any amendments to, or waivers from, its Code of Ethics that apply to the Company’s principal executive officer, principal financial officer, and principal accounting officer or controller on the Company’s website, www.southwest.com, under the “About Southwest” caption, promptly following the date of any such amendment or waiver.
Item 11. Executive Compensation
The information required by this Item 11 will be set forth under the headings “Compensation of Executive Officers” and “Compensation of Directors” in the Proxy Statement for the Company’s 2024 Annual Meeting of Shareholders and is incorporated herein by reference.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
Except as set forth below regarding securities authorized for issuance under equity compensation plans, the information required by this Item 12 will be set forth under the heading “Voting Securities and Principal Shareholders” in the Proxy Statement for the Company’s 2024 Annual Meeting of Shareholders and is incorporated herein by reference.
Securities Authorized for Issuance under Equity Compensation Plans
The following table provides information as of December 31, 2023, regarding compensation plans under which equity securities of the Company are authorized for issuance.
Equity Compensation Plan Information
| Plan Category | Number of Securities to be Issued Upon Exercise of Outstanding Options, Warrants, and Rights (a) | Weighted-Average Exercise Price of Outstanding Options, Warrants, and Rights (b) | Number of Securities Remaining Available for Future Issuance Under Equity Compensation Plans (Excluding Securities Reflected in Column (a)) (c) | ||||||||||||||||||||||||||
| Equity Compensation Plans Approved by Security Holders | 3,962,911 | (1) | $ | — | (2) | 29,725,197 | (3) | ||||||||||||||||||||||
| Equity Compensation Plans not Approved by Security Holders | — | $ | — | — | |||||||||||||||||||||||||
| Total | 3,962,911 | $ | — | (2) | 29,725,197 |
(1)Restricted share units settleable in shares of the Company’s common stock.
(2)Restricted share units discussed in footnote (1) above do not have a weighted average exercise price because the restricted share units do not have an exercise price upon vesting.
(3) Of these shares, (i) 16,454,511 shares remained available for issuance under the Company’s tax-qualified employee stock purchase plan; and (ii) 13,270,686 shares remained available for issuance under the Company’s 2007 Equity Incentive Plan in connection with the exercise of stock options and stock appreciation rights, the settlement of awards of restricted stock, restricted stock units, and phantom shares, and the grant of unrestricted shares of common stock; however, no more than 956,310 shares remain available for grant in connection with awards of unrestricted shares of common stock, stock-settled phantom shares, and awards to non-Employee members of the Board. These shares are in addition to the shares reserved for issuance pursuant to outstanding awards included in column (a).
See Note 10 to the Consolidated Financial Statements for information regarding the material features of the above plans. Each of the above plans provides that the number of shares with respect to which options may be granted, the number of shares of common stock subject to an outstanding option, and the number of restricted share units granted shall be proportionately adjusted in the event of a subdivision or consolidation of shares or the payment of a stock dividend on common stock, and the purchase price per share of outstanding options shall be proportionately revised.
Item 13. Certain Relationships and Related Transactions, and Director Independence
The information required by this Item 13 will be set forth under the heading “Certain Relationships and Related Transactions, and Director Independence” in the Proxy Statement for the Company’s 2024 Annual Meeting of Shareholders and is incorporated herein by reference.
Item 14. Principal Accounting Fees and Services
The Company's independent registered public accounting firm is Ernst & Young LLP, Dallas, TX, Auditor Firm ID: 42.
The information required by this Item 14 will be set forth under the heading “Relationship with Independent Auditors” in the Proxy Statement for the Company’s 2024 Annual Meeting of Shareholders and is incorporated herein by reference.
PART IV
Item 15. Exhibits and Financial Statement Schedules
(a) 1. Financial Statements:
The financial statements included in Item 8. Financial Statements and Supplementary Data above are filed as part of this annual report.
- Financial Statement Schedules:
There are no financial statement schedules filed as part of this annual report, since the required information is included in the Consolidated Financial Statements, including the notes thereto, or the circumstances requiring inclusion of such schedules are not present.
- Exhibits:
| 21 | Subsidiaries of the Company. | |||||||
| 23 | Consent of Ernst & Young LLP, Independent Registered Public Accounting Firm. | |||||||
| 31.1 | Rule 13a-14(a) Certification of Chief Executive Officer. | |||||||
| 31.2 | Rule 13a-14(a) Certification of Chief Financial Officer. | |||||||
| 32 | Section 1350 Certification of Chief Executive Officer and Chief Financial Officer. (3) | |||||||
| 97.1 | Southwest Airlines Co. Clawback Policy, effective as of November 16, 2023. | |||||||
| 101.INS | XBRL Instance Document - The instance document does not appear in the Interactive Data File because its XBRL tags are embedded within the Inline XBRL document. | |||||||
| 101.SCH | Inline XBRL Taxonomy Extension Schema Document. | |||||||
| 101.CAL | Inline XBRL Taxonomy Extension Calculation Linkbase Document. | |||||||
| 101.DEF | Inline XBRL Taxonomy Extension Definition Linkbase Document. | |||||||
| 101.LAB | Inline XBRL Taxonomy Extension Label Linkbase Document. | |||||||
| 101.PRE | Inline XBRL Taxonomy Extension Presentation Linkbase Document. | |||||||
| 104 | Cover Page Interactive Data File (formatted as Inline XBRL and contained in Exhibit 101). |
(1)Certain confidential information contained in this agreement has been omitted because it is both not material and is of the type that the registrant treats as private or confidential.
(2)Management contract or compensatory plan or arrangement.
(3)This exhibit is being furnished rather than filed and shall not be deemed incorporated by reference into any filing, in accordance with Item 601 of Regulation S-K.
A copy of each exhibit may be obtained at a price of 15 cents per page, $10.00 minimum order, by writing to: Investor Relations, Southwest Airlines Co., P.O. Box 36611, Dallas, Texas 75235-1611.
Item 16. 10-K Summary
None.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned thereunto duly authorized.
| SOUTHWEST AIRLINES CO. | ||||||||
| February 6, 2024 | By | /s/ Tammy Romo | ||||||
| Tammy Romo | ||||||||
| Executive Vice President & Chief Financial Officer | ||||||||
| (On behalf of the Registrant and in | ||||||||
| her capacity as Principal Financial | ||||||||
| & Accounting Officer) |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on February 6, 2024, on behalf of the registrant and in the capacities indicated.
| Signature | Title | |||||||
| /s/ ROBERT E. JORDAN | President & Chief Executive Officer & Director (Principal Executive Officer) | |||||||
| Robert E. Jordan | ||||||||
| /s/ TAMMY ROMO | Executive Vice President & Chief Financial Officer (Principal Financial & Accounting Officer) | |||||||
| Tammy Romo | ||||||||
| /s/ GARY C. KELLY | Executive Chairman of the Board | |||||||
| Gary C. Kelly | ||||||||
| /s/ RON RICKS | Vice Chairman of the Board | |||||||
| Ron Ricks | ||||||||
| /s/ DAVID W. BIEGLER | Director | |||||||
| David W. Biegler | ||||||||
| /s/ J. VERONICA BIGGINS | Director | |||||||
| J. Veronica Biggins | ||||||||
| /s/ ROY BLUNT | Director | |||||||
| Roy Blunt | ||||||||
| /s/ DOUGLAS H. BROOKS | Director | |||||||
| Douglas H. Brooks | ||||||||
| /s/ EDUARDO F. CONRADO | Director | |||||||
| Eduardo F. Conrado | ||||||||
| /s/ WILLIAM H. CUNNINGHAM | Director | |||||||
| William H. Cunningham | ||||||||
| /s/ THOMAS W. GILLIGAN | Director | |||||||
| Thomas W. Gilligan | ||||||||
| /s/ DAVID P. HESS | Director | |||||||
| David P. Hess | ||||||||
| /s/ ELAINE MENDOZA | Director | |||||||
| Elaine Mendoza | ||||||||
| /s/ JOHN T. MONTFORD | Director | |||||||
| John T. Montford | ||||||||
| /s/ CHRISTOPHER P. REYNOLDS | Director | |||||||
| Christopher P. Reynolds | ||||||||
| /s/ JILL SOLTAU | Director | |||||||
| Jill Soltau |