 filings.tools
Mastercard 10-K 2022-12-31
Filed 2023-02-14. 22 sections, 632K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
| UNITED STATES SECURITIES AND EXCHANGE COMMISSION | |||||||||||||||||
| Washington, D.C. 20549 | |||||||||||||||||
| Form | 10-K | ||||||||||||||||
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2022
| Or | |||||
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 | ||||
| For the transition period from to |
Commission file number: 001-32877
 | ||||||||||||||||||||
| Mastercard Incorporated | ||||||||||||||||||||
| (Exact name of registrant as specified in its charter) | ||||||||||||||||||||
| Delaware | 13-4172551 | |||||||||||||||||||
| (State or other jurisdiction of incorporation or organization) | (IRS Employer Identification Number) | |||||||||||||||||||
| 2000 Purchase Street | ||||||||||||||||||||
| Purchase, | NY | 10577 | ||||||||||||||||||
| (Address of principal executive offices) | (Zip Code) |
(914) 249-2000
(Registrant’s telephone number, including area code)
| Securities registered pursuant to Section 12(b) of the Act: | ||||||||||||||
| Title of each class | Trading Symbol | Name of each exchange of which registered | ||||||||||||
| Class A Common Stock, par value $0.0001 per share | MA | New York Stock Exchange | ||||||||||||
| 2.1% Notes due 2027 | MA27 | New York Stock Exchange | ||||||||||||
| 1.0% Notes due 2029 | MA29A | New York Stock Exchange | ||||||||||||
| 2.5% Notes due 2030 | MA30 | New York Stock Exchange |
| Securities registered pursuant to Section 12(g) of the Act: | ||||||||||||||||||||
| Class B common stock, par value $0.0001 per share |
| Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. | Yes | ☒ | No | ☐ | |||||||||||||||||||
| Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. | Yes | ☐ | No | ☒ | |||||||||||||||||||
| Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. | Yes | ☒ | No | ☐ | |||||||||||||||||||
| Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). | Yes | ☒ | No | ☐ |
| Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act. (Check One): | |||||||||||||||||||||||
| Large accelerated filer | ☒ | Accelerated filer | ☐ | ||||||||||||||||||||
| Non-accelerated filer | ☐ | (do not check if a smaller reporting company) | Smaller reporting company | ☐ | |||||||||||||||||||
| Emerging growth company | ☐ | ||||||||||||||||||||||
| If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13 (a) of the Exchange Act. | ☐ | ||||||||||||||||||||||
| Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. | ☒ | ||||||||||||||||||||||
| If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements. | ☐ | ||||||||||||||||||||||
| Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b). | ☐ | ||||||||||||||||||||||
| Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). | Yes | ☐ | No | ☒ |
The aggregate market value of the registrant’s Class A common stock, par value $0.0001 per share, held by non-affiliates (using the New York Stock Exch
Showing the first 8K of 103K characters. Open the full section
Item 1. BUSINESS
Various forms of data localization requirements or data transfer restrictions are also under consideration in other countries and jurisdictions, including the European Union.
Anti-Money Laundering, Counter Financing of Terrorism, Economic Sanctions and Anti-Corruption. We are subject to anti-money laundering (“AML”) and counter-financing of terrorism (“CFT”) laws and regulations globally, including the U.S. Bank Secrecy Act and the USA PATRIOT Act, as well as the various economic sanctions programs, including those imposed and administered by the U.S. Office of Foreign Assets Control (“OFAC”). We have implemented a comprehensive AML/CFT program, comprised of policies, procedures and internal controls, including the designation of a compliance officer, which is designed to prevent our payments network from being used to facilitate money laundering and other illicit activity and to address these legal and regulatory requirements and assist in managing money laundering and terrorist financing risks. The economic sanctions programs administered by OFAC restrict financial transactions and other dealings with certain countries and geographies (specifically Crimea, the Donetsk People’s Republic and Luhansk People’s Republic regions of Ukraine, Cuba, Iran, North Korea and Syria) and with persons and entities included in OFAC sanctions lists including its list of Specially Designated Nationals and Blocked Persons (the “SDN List”). We take measures to prevent transactions that do not comply with OFAC and other applicable sanctions, including establishing a risk-based compliance program that has policies, procedures and controls designed to prevent us from having unlawful business dealings with prohibited countries, regions, individuals or entities. As part of this program, we obligate issuers and acquirers to comply with their local sanctions obligations and the U.S. sanctions programs, including requiring the screening of account holders and merchants, respectively, against OFAC sanctions lists (including the SDN List). Iran and Syria have been identified by the U.S. State Department as terrorist-sponsoring states, and we have no offices, subsidiaries or affiliated entities located in these countries and do not license entities domiciled there. We are also subject to anti-corruption laws and regulations globally, including the U.S. Foreign Corrupt Practices Act and the U.K. Bribery Act, which, among other things, generally prohibit giving or offering payments or anything of value for the purpose of improperly influencing a business decision or to gain an unfair business advantage. We have implemented policies, procedures and internal controls to proactively manage corruption risk.
Financial Sector Oversight. We are or may be subject to regulations related to our role in the financial industry and our relationship with our financial institution customers. In addition, we are or may be subject to regulation by a number of agencies charged with oversight of, among other things, consumer protection, cybersecurity, financial and banking matters. The regulators have supervisory and independent examination authority as well as enforcement authority that we may be subject to because of the services we provide to financial institutions that issue and acquire our products.
Issuer and Acquirer Practices Legislation and Regulation. Our issuers and acquirers are subject to numerous regulations and investigations applicable to banks, financial institutions and other licensed entities, impacting us as a consequence. Additionally, regulations such as the revised Payment Services Directive (commonly referred to as “PSD2”) in the EEA require financial institutions to provide third-party payment processors access to consumer payment accounts, enabling them to route transactions away from Mastercard products and provide payment initiation and account information services directly to consumers who use our products. PSD2 also requires a new standard for authentication of transactions, which necessitates additional verification information from consumers to complete transactions. This may increase the number of transactions that consumers abandon if we are unable to ensure a frictionless authentication experience under the new standards.
Regulation of Internet, Digital Transactions and High-Risk Merchant Categories. Various jurisdictions have enacted or have proposed regulation related to internet transactions. The legislation applies to payments system participants, including us and our customers, and is implemented through a federal regulation. We may also be impacted by evolving laws surrounding gambling, including fantasy sports, as well as certain legally permissible but high-risk merchant categories, such as adult content, firearms, alcohol and tobacco.
Privacy, Data and Information Security. Aspects of our operations or business are subject to increasingly complex privacy and data protection laws in the United States, the European Union and elsewhere around the world. For example, in the United States, we and our customers are respectively subject to Federal Trade Commission and federal banking agency information safeguarding requirements under the Gramm-Leach-Bliley Act that require the maintenance of a written, comprehensive information security program. In the European Union, we are subject to the General Data Protection Regulation (the “GDPR”), which requires a comprehensive privacy and data protection program to protect the personal and sensitive data of EEA residents. A number of regulators and policymakers around the globe are using the GDPR as a reference to adopt new or updated privacy and data protection laws. Due to increasing data collection and data flows, numerous data breaches and security incidents as well as the use of emerging technologies such as artificial intelligence, regulations in this area are constantly evolving with regulatory and legislative authorities in numerous parts of the world adopting proposals to regulate data and protect information. In addition, the interpretation and application of these privacy and data protection laws are often uncertain and in a state of flux, thus requiring constant monitoring for compliance.
24 MASTERCARD 2022 FORM 10-K
PART I
ITEM 1. BUSINESS
ESG. Various jurisdictions have adopted or are increasingly considering adopting laws and regulations impacting our reporting on ESG governance, strategy, risk management and metrics and targets. Regulations already adopted or being considered include required corporate reporting and disclosures on specific topics as well as broader ESG matters. Specific topics include climate (such as the U.K. Streamlined Energy and Carbon Reporting, the European Union Corporate Sustainability Reporting Directive, or “EU CSRD”, and the SEC proposed rules related to climate change) and human rights (such as the European Union Corporate Sustainability Due Diligence Directive). Broader ESG matters include other environmental matters, treatment of employees and diversity of workforce (such as the EU CSRD).
Additional Regulatory Developments. Various regulatory agencies also continue to examine a wide variety of issues that could impact us, including evolving laws surrounding buy-now-pay-later, digital currencies, marijuana, prepaid payroll cards, identity theft, account management guidelines, disclosure rules, security and marketing that would impact our customers directly.
Additional Information
Mastercard Incorporated was incorporated as a Delaware corporation in May 2001. We conduct our business principally through our principal operating subsidiary, Mastercard International Incorporated, a Delaware non-stock (or membership) corporation that was formed in November 1966. For more information about our capital structure, including our Class A common stock (our voting stock) and Class B common stock (our non-voting stock), see Note 16 (Stockholders' Equity) to the consolidated financial statements included in Part II, Item 8.
Website and SEC Reports
Our internet address is www.mastercard.com. From time to time, we may use our corporate website as a channel of distribution of material company information. Financial and other material information is routinely posted and accessible on the investor relations section of our corporate website. You can also visit “Investor Alerts” in the investor relations section to enroll your email address to automatically receive email alerts and other information about Mastercard.
Our annual report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K and amendments to those reports are available for review, without charge, on the investor relations section of our corporate website as soon as reasonably practicable after they are filed with, or furnished to, the U.S. Securities and Exchange Commission (the “SEC”). The information contained on our corporate website, including, but not limited to, our Corporate Sustainability Report, our Global Inclusion Report and our U.S. Consolidated EEO-1 Report, is not incorporated by reference into this Report. Our filings are also available electronically from the SEC at www.sec.gov.
Item 1A. Risk factors
| RISK HIGHLIGHTS | ||||||||||||||||||||||||||
| Legal and Regulatory | Business and Operations | |||||||||||||||||||||||||
| Payments Industry Regulation | Competition and Technology | Brand, Reputational Impact and ESG | ||||||||||||||||||||||||
| Preferential or Protective Government Actions | Information Security and Operational Resilience | Talent and Culture | ||||||||||||||||||||||||
| Privacy, Data and Security | Stakeholder Relationships | Acquisitions | ||||||||||||||||||||||||
| Other Regulation | Global Economic and Political Environment | Settlement and Third-Party Obligations | ||||||||||||||||||||||||
| Litigation | ||||||||||||||||||||||||||
| Class A Common Stock and Governance Structure | ||||||||||||||||||||||||||
MASTERCARD 2022 FORM 10-K 25
PART I
ITEM 1A. RISK FACTORS
Legal and Regulatory
Payments Industry Regulation
Global regulatory and legislative activity directly related to the payments industry may have a material adverse impact on our overall business and results of operations.
Jurisdictions increasingly have regulated or established and expanded authority over certain aspects of payments systems such as ours, or have sought to do so. These efforts established, and potentially further expand, obligations or restrictions with respect to the types of products and services that we may offer, the countries in which our integrated products and services may be used, the way we structure and operate our business and the types of consumers and merchants who can obtain or accept our products or services. New regulations and oversight could also relate to our clearing and settlement activities (including policies, procedures and requirements related to risk management, collateral, participant default, timely switching of financial transactions, and capital and financial resource). Several jurisdictions have also inquired about the network fees we charge to our customers (in some cases as part of broader market reviews of retail payments).
Several central banks or similar regulatory bodies around the world have also increased, or are seeking to increase, their formal oversight of the electronic payments industry. In several jurisdictions, we have been designated as a “systemically important payment system”, with other regulators considering similar designations. Parts of our business have also been deemed as a “specified service provider” and considered critical national infrastructure. These obligations, designations and restrictions result in heightened regulatory oversight and scrutiny. They may further expand and could conflict with each other as more jurisdictions impose oversight of payments systems. Moreover, these efforts may influence the approaches of other regulators around the world that are increasingly looking to replicate similar regulation of payments and other industries. Similarly, jurisdictions that regulate a particular product may extend their regulation to similar products (for example, debit regulations could lead to regulation of credit products or network fees). As a result, the risks to our business created by any one new law or regulation are magnified by the potential it has to be replicated in other jurisdictions or involve other products within any particular jurisdiction.
The expansion of our products and services as part of our multi-rail strategy have also created the need for us to obtain new types and increasing numbers of regulatory licenses, resulting in increased supervision and additional compliance burdens distinct from those imposed on our core payment network activities. For example, certain of our subsidiaries maintain money transfer licenses to support certain activities. These licenses typically impose supervisory and examination requirements, as well as capital, safeguarding, risk management and other business obligations.
Increased regulation and oversight of payments systems, as well as increased exposure to regulation resulting from changes to our products and services, have resulted and may continue to result in significant compliance and governance burdens or otherwise increase our costs. As a result, customers could be less willing to participate in our payments system and/or use our other products or services, reduce the benefits offered in connection with the use of our products (making our products less desirable to consumers), reduce the volume of domestic and cross-border transactions or other operational metrics, disintermediate us, impact our profitability and/or limit our ability to innovate or offer differentiated products and services, all of which could materially and adversely impact our financial performance. In addition, any regulation that is enacted related to the type and level of network fees we charge our customers could also materially and adversely impact our results of operations. Regulators could also require us to obtain prior approval for changes to our system rules, procedures or operations, or could require customization with regard to such changes, which could negatively impact us. Such changes could lead to new or different criteria for participation in and access to our payments system by financial institutions or other customers. Moreover, failure to comply with the laws and regulations to which we are subject could result in fines, sanctions, civil damages or other penalties, which could materially and adversely affect our overall business and results of operations, as well as have an impact on our brand and reputation.
Increased regulatory, legislative and litigation activity with respect to interchange rates could have an adverse impact on our business.
Interchange rates are a significant component of the costs that merchants pay in connection with the acceptance of products associated with our core payment network. Although we do not earn revenues from interchange, interchange rates can impact the volume of transactions we see on our payment products. If interchange rates are too high, merchants may stop accepting our products or route transactions away from our network. If interchange rates are too low, issuers may stop promoting our integrated products and services, eliminate or reduce loyalty rewards programs or other account holder benefits (e.g., free checking or low interest rates on balances), or charge fees to account holders (e.g., annual fees or late payment fees).
Governments and merchant groups in a number of countries have implemented or are seeking interchange rate reductions through legislation, competition law, central bank regulation and litigation. See “Business - Government Regulation” in Part I, Item 1 and Note 21 (Legal and Regulatory Proceedings) to the consolidated financial statements included in Part II, Item 8 for more details.
26 MASTERCARD 2022 FORM 10-K
PART I
ITEM 1A. RISK FACTORS
If issuers cannot collect or we are required to reduce interchange rates, issuers may be less willing to participate in our four-party payments system, or may reduce the benefits offered in connection with the use of our products, reducing the attractiveness of our products to consumers. These and other impacts could lower transaction volumes, and/or make proprietary three-party networks or other forms of payment more attractive. Issuers could reduce the benefits associated with our products or choose to charge higher fees to consumers to attempt to recoup a portion of the costs incurred for their services. In addition, issuers could seek a fee reduction from us to decrease the expense of their payment programs, particularly if regulation has a disproportionate impact on us as compared to our competitors in terms of the fees we can charge. This could make our products less desirable to consumers, reduce the volume of transactions and our profitability, and limit our ability to innovate or offer differentiated products.
We are devoting substantial resources to defending our right to establish interchange rates in regulatory proceedings, litigation and legislative activity. The potential outcome of any of these activities could have a more positive or negative impact on us relative to our competitors. If we are ultimately unsuccessful in defending our ability to establish interchange rates, any resulting legislation, regulation and/or litigation may have a material adverse impact on our overall business and results of operations. In addition, regulatory proceedings and litigation could result (and in some cases has resulted) in us being fined and/or having to pay civil damages, the amount of which could be material.
Limitations on our ability to restrict merchant surcharging could materially and adversely impact our results of operations.
We have historically implemented policies, referred to as no-surcharge rules, in certain jurisdictions, including the United States and Canada, that prohibit merchants from charging higher prices to consumers who pay using our products instead of other means. Authorities in several jurisdictions have acted to end or limit the application of these no-surcharge rules (or indicated interest in doing so). Additionally, we have modified our no-surcharge rules to permit U.S. and Canadian merchants to surcharge credit cards, subject to certain limitations. It is possible that over time merchants in some or all merchant categories in these jurisdictions may choose to surcharge as permitted by the rule change. This could result in consumers viewing our products less favorably and/or using alternative means of payment instead of electronic products, which could result in a decrease in our overall transaction volumes, and which in turn could materially and adversely impact our results of operations.
Preferential or Protective Government Actions
Preferential and protective government actions related to domestic payment services could adversely affect our ability to maintain or increase our revenues.
Governments in some countries have acted, or in the future may act, to provide resources, preferential treatment or other protection to selected national payment and switching providers, or have created, or may in the future create, their own national provider. This action may displace us from, prevent us from entering into, or substantially restrict us from participating in, particular geographies, and may prevent us from competing effectively against those providers. For example:
-
Governments in some countries have implemented, or may implement, regulatory requirements that mandate switching of domestic payments either entirely in that country or by only domestic companies.
-
Some jurisdictions have implemented, or are considering, requirements to collect, process and/or store data within their borders, as well as prohibitions on the transfer of data abroad, leading to technological and operational implications as well as increased compliance burdens and other costs.
-
Geopolitical events (such as Russia’s invasion of Ukraine) and resulting OFAC sanctions, adverse trade policies, enforcement of U.S. laws related to counter financing of terrorism, economic sanctions and anti-corruption, or other types of government actions could lead affected or other jurisdictions to take actions in response that could adversely affect our business. Moreover, given our decision to suspend business operations in Russia, other separate jurisdictions may decide to increase their focus on growing local payment networks and other solutions.
-
Regional groups of countries are considering, or may consider, efforts to restrict our participation in the switching of regional transactions.
Such developments prevent us from utilizing our global switching capabilities for domestic or regional customers. In addition, to the extent a jurisdiction determines us not to be in compliance with regulatory requirements (including those related to data localization), we have, and may continue to be, subject to resource and time pressures in order to come back into compliance. Our inability to effect change in, or work with, these jurisdictions could adversely affect our ability to maintain or increase our revenues and extend our global brand.
Additionally, some jurisdictions have implemented, or may implement, foreign ownership restrictions, which could potentially have the effect of forcing or inducing the transfer of our technology and proprietary information as a condition of access to their markets. Such restrictions could adversely impact our ability to compete in these markets.
MASTERCARD 2022 FORM 10-K 27
PART I
ITEM 1A. RISK FACTORS
Privacy, Data and Security
Regulation of privacy, data, security and the digital economy could increase our costs, as well as negatively impact our growth.
We are subject to increasingly complex regulations related to privacy, data and information security in the jurisdictions in which we do business. These regulations could result in negative impacts to our business. As we continue to develop integrated and personalized products and services to meet the needs of a changing marketplace (as well as acquire new companies), we have expanded our information profile through the collection of additional data from additional sources and across multiple channels. This expansion has amplified the impact of these regulations on our business. This regulation requires monitoring of and changes to our data practices in regard to the collection, use, disclosure, storage, transfer and/or protection of personal and sensitive information, as well as increased care in our data management, governance and quality practices. We are also subject to enhanced compliance and operational requirements in the European Union, and policymakers around the globe are or are considering adopting new or updated privacy laws that have resulted or could result in similar or stricter requirements in other jurisdictions. For example, some jurisdictions have implemented or are otherwise considering requirements to collect, process and/or store data within their borders, as well as prohibitions on the transfer of data abroad, leading to technological and operational implications. Other jurisdictions have adopted or are otherwise considering adopting sector-specific regulations for the payments industry, including forced data sharing requirements or additional verification requirements, as well as regulations on artificial intelligence and data governance, that overlap or conflict with, or diverge from, general privacy rules. Failure to comply with these laws, regulations and requirements could result in fines, sanctions or other penalties, which could materially and adversely affect our results of operations and overall business, as well as have an impact on our reputation.
New requirements or changing interpretations of existing requirements in these areas, or the development of new regulatory schemes related to the digital economy in general, may also increase our costs and/or restrict our ability to leverage data for innovation. This could impact the products and services we offer and other aspects of our business, such as fraud monitoring, the need for improved data management, governance and quality practices, the development of information-based products and solutions, and technology operations. In addition, these requirements may increase the costs to our customers of issuing payment products, which may, in turn, decrease the number of our payment products that they issue. Moreover, due to account data compromise events and privacy abuses by other companies, as well as the disclosure of monitoring activities by certain governmental agencies in combination with the use of artificial intelligence and new technologies, there has been heightened legislative and regulatory scrutiny around the world that could lead to further regulation and requirements and/or future enforcement. Those developments have also raised public attention on companies’ data practices and have changed consumer and societal expectations for enhanced privacy and data protection. While we make every effort to comply with all regulatory requirements and we deploy a Privacy by Design and Data by Design approach to all of our product development, the speed and pace of changes in laws (as well as stakeholder interests) may not allow us to meet rapidly evolving regulatory and stakeholder expectations. Any of these developments could materially and adversely affect our overall business and results of operations.
In addition, fraudulent activity and increasing cyberattacks have encouraged legislative and regulatory intervention, and could damage our reputation and reduce the use and acceptance of our integrated products and services or increase our compliance costs. Criminals are using increasingly sophisticated methods to capture consumer personal information to engage in illegal activities such as counterfeiting or other fraud. As outsourcing and specialization become common in the payments industry, there are more third parties involved in processing transactions using our payment products. While we are taking measures to make card and digital payments more secure, increased fraud levels involving our integrated products and services, or misconduct or negligence by third parties switching or otherwise servicing our integrated products and services, could lead to legislative or regulatory intervention, such as enhanced security requirements and liabilities, as well as damage to our reputation.
Other Regulation
Regulations that directly or indirectly apply to Mastercard as a result of our participation in the global payments industry may materially and adversely affect our overall business and results of operations.
We are subject to regulations that affect the payments industry in the many jurisdictions in which our integrated products and services are used. Many of our customers are also subject to regulations applicable to banks and other financial institutions that, at times, consequently affect us. Such regulation has increased significantly in the last several years (as described in “Business - Government Regulation” in Part I, Item 1). Examples include:
- Anti-Money Laundering, Counter Financing of Terrorism, Economic Sanctions and Anti-Corruption** - We are subject to AML and CFT laws and regulations globally. Economic sanctions programs administered by OFAC restrict financial transactions and other dealings with certain countries and geographies, and persons and entities. We are also subject to anti-corruption laws and regulations globally, which, among other things, generally prohibit giving or offering payments or anything of value for the purpose of improperly influencing a business decision or to gain an unfair business advantage.
28 MASTERCARD 2022 FORM 10-K
PART I
ITEM 1A. RISK FACTORS
-
Account-based Payments Systems** - In the U.K., aspects of our Vocalink business are subject to the U.K. payment system oversight regime and are directly overseen by the Bank of England.
-
Issuer and Acquirer Practices Legislation and Regulation** - Certain regulations (such as PSD2 in the EEA) may impact various aspects of our business. For example, PSD2’s strong authentication requirement could increase the number of transactions that consumers abandon if we are unable to secure a frictionless authentication experience under these standards. An increase in the rate of abandoned transactions could adversely impact our volumes or other operational metrics.
Increased regulatory focus on us has resulted and may continue to result in significant compliance and governance burdens or otherwise increase our costs. Similarly, increased regulatory focus on our customers may cause such customers to reduce the volume of transactions processed through our systems, or may otherwise impact the competitiveness of our products. Actions by regulators could influence other organizations around the world to enact or consider adopting similar measures, amplifying any potential compliance burden. Additionally, our compliance with new economic sanctions and related laws with respect to particular jurisdictions or customers could result in a loss of business, which could be significant. Moreover, while our risk-based compliance program obligates issuers and acquirers to comply with their local sanctions programs (among other obligations), the failure of those issuers and acquirers to identify potential non-compliance issues either during or after their customer onboarding processes could ultimately impact our compliance with economic sanctions and related laws. Finally, failure to comply with the laws and regulations discussed above to which we are subject could result in fines, sanctions or other penalties. In particular, a violation and subsequent judgment or settlement against us, or those with whom we may be associated, under economic sanctions and AML, CFT, and anti-corruption laws could subject us to substantial monetary penalties, damages, and/or have a significant reputational impact. Each instance may individually or collectively materially and adversely affect our financial performance and/or our overall business and results of operations, as well as have an impact on our reputation.
We could be subject to adverse changes in tax laws, regulations and interpretations or challenges to our tax positions.
We are subject to tax laws and regulations of the U.S. federal, state and local governments as well as various non-U.S. jurisdictions. Current and potential future changes in existing tax laws, including regulatory guidance, are continuously being considered and have been or may be enacted (such as new guidelines issued by the Organization for Economic Cooperation and Development (OECD) which could impact how multinational enterprises are taxed on their global profits). These changes have or may in the future impact our effective income tax rate and tax payments. Similarly, changes in tax laws and regulations that impact our customers and counterparties, or the economy generally, have and can continue to impact us as well.
In addition, tax laws and regulations are complex and subject to varying interpretations, and any significant failure to comply with applicable tax laws and regulations in all relevant jurisdictions could give rise to substantial penalties and liabilities. Jurisdictions around the globe have also increased tax-related audits, which require time and resources to resolve.
Any changes in enacted tax laws, rules or regulatory or judicial interpretations or guidance; any adverse outcome in connection with tax audits in any jurisdiction; or any changes in the pronouncements relating to accounting for income taxes could materially and adversely impact our effective income tax rate, tax payments, financial condition and results of operations.
Litigation
Liabilities we may incur or limitations on our business related to any litigation or litigation settlements could materially and adversely affect our results of operations.
We are a defendant in a number of civil litigations and regulatory proceedings and investigations, including among others, those alleging violations of competition and antitrust law and those involving intellectual property claims (as described in Note 21 (Legal and Regulatory Proceedings) to the consolidated financial statements included in Part II, Item 8). In the event we are found liable in any material litigations or proceedings (particularly in a large class-action lawsuit or on the basis of an antitrust claim entitling the plaintiff to treble damages or under which we were jointly and severally liable), we could be subject to significant damages, which could have a material adverse impact on our overall business and results of operations.
Certain limitations have been placed on our business in recent years because of litigation and litigation settlements, such as changes to our no-surcharge rule in the United States and Canada. Any future limitations on our business resulting from the outcomes of any litigation or regulatory proceeding, including any changes to our rules or business practices, could impact our relationships with our customers, including reducing the volume of business that we do with them, which may materially and adversely affect our overall business and results of operations.
MASTERCARD 2022 FORM 10-K 29
PART I
ITEM 1A. RISK FACTORS
Business and Operations
Competition and Technology
Substantial and intense competition worldwide in the global payments industry may materially and adversely affect our overall business and results of operations.
The global payments industry is highly competitive. Our payment programs compete against competitors both within and outside of the global payments industry and compete in all payment categories, including paper-based payments and all forms of electronic payments. We compete against general purpose payments networks, debit and local networks, ACH and real-time account-based payments systems, alternative payments systems and new entrants (focused on online activity across various channels and processing payments using in-house capabilities), government-backed networks and digital currencies. We also face competition from companies that provide alternatives to our value-added services and new adjacent network capabilities (including open banking and digital identity).
Our traditional competitors may have substantially greater financial and other resources than we have, may offer a wider range of programs, services, and payment capabilities than we offer or may use more effective advertising and marketing strategies to achieve broader brand recognition and merchant acceptance than we have. They may also introduce their own innovative programs, value-added services and capabilities that adversely impact our growth.
Certain of our competitors to our core payment network operate three-party payments systems with direct connections to both merchants and consumers and these competitors may derive competitive advantages from their business models. If we continue to attract more regulatory scrutiny than these competitors because we operate a four-party system, or we are regulated because of the system we operate in a way in which our competitors are not, we could lose business to these competitors. See “Business - Competition” in Part I, Item 1.
New entrants against whom we compete have developed alternative payments systems, e-commerce payments systems and payments systems for mobile devices, as well as physical store locations. A number of these new entrants rely principally on technology to support their services that provides cost advantages, and as a result may enjoy lower costs than we do, which could put us at a competitive disadvantage.
Our ability to compete may also be affected by regulatory and legislative initiatives, as well as the outcomes of litigation, competition-related regulatory proceedings and central bank activity and legislative activity. Moreover, the suspension of our business operations in Russia may provide the opportunity for competitors to grow their business and increase their market share and relative competitive position in other jurisdictions.
If we are not able to differentiate ourselves from our competitors, drive value for our customers and/or effectively align our resources with our goals and objectives, we may not be able to compete effectively against these threats. Our failure to compete effectively against any of the foregoing competitive threats could materially and adversely affect our overall business and results of operations.
Disintermediation from stakeholders both within and outside of the payments value chain could harm our business.
As the payments industry continues to develop and change, we face disintermediation and related risks, including:
-
Parties that process our transactions in certain countries may try to eliminate our position as an intermediary in the payment process. For example, merchants could switch (and in some cases are switching) transactions directly with issuers. Additionally, processors could process transactions directly between issuers and acquirers. Large scale consolidation within processors could result in these processors developing bilateral agreements or in some cases switching the entire transaction on their own network, thereby disintermediating us.
-
Industry participants continue to invest in and develop alternative capabilities, such as account-to-account payments, which could facilitate P2M transactions that compete with both our core payments network and our additional payment capabilities.
-
Regulation (such as PSD2 in the EEA) may disintermediate issuers by enabling third-party providers opportunities to route payment transactions away from our network and products and towards other forms of payment by offering account information or payment initiation services directly to those who currently use our products. Such regulation may also provide these processors with the opportunity to commoditize the data that are included in the transactions they are servicing. If our customers are disintermediated in their business, we could face diminished demand for our integrated products and services.
-
Although we partner with fintechs and technology companies (such as digital players and mobile providers) that leverage our technology, platforms and networks to deliver their products, they could develop platforms or networks that disintermediate us from digital payments and impact our ability to compete in the digital economy. These companies may also develop products or
30 MASTERCARD 2022 FORM 10-K
PART I
ITEM 1A. RISK FACTORS
services that compete with our customers within the payments ecosystem and, as a result, could diminish demand for our products and services. When we do partner with fintechs and technology companies, we face a heightened risk when we share data as part of those relationships. While we share this data in a controlled manner subject to applicable anonymization and privacy and data standards, sharing this data without proper oversight could provide partners with a competitive advantage.
-
Competitors, customers, fintechs, technology companies, governments and other industry participants may develop products that compete with or replace value-added products and services we currently provide to support our switched transaction and payments offerings. These products could either replace, or force us to change our pricing or practices, for these offerings. In addition, governments that develop or encourage the creation of national or international payments platforms may promote their platforms in such a way that could put us at a competitive disadvantage in those markets, or require us to compete differently.
-
Participants in the payments industry may merge, create joint ventures or form other business combinations that may strengthen their existing business services or create new payment products and services that compete with our products and services.
Our failure to compete effectively against any of the foregoing competitive threats could materially and adversely affect our overall business and results of operations.
Continued intense pricing pressure may materially and adversely affect our overall business and results of operations.
In order to increase transaction volumes, enter new markets and expand our products and services, we seek to enter into business agreements with customers through which we offer incentives, pricing discounts and other support that promote our products. In order to stay competitive, we may have to increase the amount of these incentives and pricing discounts. We continue to experience pricing pressure. The demand from our customers for better pricing arrangements and greater rebates and incentives moderates our growth. We may not be able to continue our expansion strategy to switch additional transaction volumes or to provide additional services to our customers at levels sufficient to compensate for such lower fees or increased costs in the future, which could materially and adversely affect our overall business and results of operations. In addition, increased pressure on prices increases the importance of cost containment and productivity initiatives in areas other than those relating to customer incentives.
In the future, we may not be able to enter into agreements with our customers if they require terms that we are unable or unwilling to offer, and we may be required to modify existing agreements in order to maintain relationships and to compete with others in the industry. Some of our competitors are larger with greater financial resources and accordingly may be able to charge lower prices to our customers. In addition, to the extent that we offer discounts or incentives under such agreements, we will need to further increase transaction volumes or the amount of services provided thereunder in order to benefit incrementally from such agreements and to increase revenue and profit, and we may not be successful in doing so, particularly in the current regulatory environment. Our customers also may implement cost reduction initiatives that reduce or eliminate payment product marketing or increase requests for greater incentives or greater cost stability. These factors could have a material adverse impact on our overall business and results of operations.
Additionally, we face pricing pressure related to real-time account-based payment schemes and cross-border payments. These pressures include the increased use of domestic real-time account-based payment schemes offering increasingly lower or subsidized pricing for P2M transactions as well as continued downward pressure on pricing for cross-border payments resulting from competition from real-time account-based payment schemes and from initiatives to lower the cost of cross-border payments to end users (such as the G20 Roadmap for Enhancing Cross-border Payments). These factors could have a material adverse impact on our overall business and results of operations.
Rapid and significant technological developments and changes could negatively impact our overall business and results of operations or limit our future growth.
The payments industry is subject to rapid and significant technological changes, which can impact our business in several ways:
-
Technological changes, including continuing developments of technologies in the areas of smart cards and devices, contactless and mobile payments, e-commerce, cryptocurrency and blockchain technology, machine learning and AI, could result in new technologies that may be superior to, or render obsolete, the technologies we currently use in our programs and services. Moreover, these changes could result in new and innovative payment methods and products that could place us at a competitive disadvantage and that could reduce the use of our products.
-
We rely in part on third parties (including some of our competitors and potential competitors) for the development of and access to new technologies. The inability of these companies to keep pace with technological developments, or the acquisition of these companies by competitors, could negatively impact our offerings.
MASTERCARD 2022 FORM 10-K 31
PART I
ITEM 1A. RISK FACTORS
-
Our ability to develop and adopt new services and technologies may be inhibited by industry-wide solutions and standards (such as those related to EMV, tokenization or other safety and security technologies), and by resistance from customers or merchants to such changes.
-
Our ability to develop evolving systems and products may be inhibited by any difficulty we may experience in attracting and retaining employees with technology expertise.
-
Our ability to adopt these technologies can also be inhibited by intellectual property rights of third parties. We have received, and we may in the future receive, notices or inquiries from patent holders (for example, other operating companies or non-practicing entities) suggesting that we may be infringing certain patents or that we need to license the use of their patents to avoid infringement. Such notices may, among other things, threaten litigation against us or our customers or demand significant license fees.
-
Our ability to develop new technologies and reflect technological changes in our payments offerings requires resources, which has resulted in and may further result in additional expenses.
-
We work with fintechs, technology companies (such as digital players and mobile providers) and traditional customers that use our technology to enhance payment safety and security and to deliver their payment-related products and services quickly and efficiently to consumers. Our inability to keep pace technologically could negatively impact the willingness of these customers to work with us, and could encourage them to use their own technology and compete against us.
-
Regulatory or government requirements have and could continue to require us to host and deliver certain products and services on-soil in certain markets, requiring us to alter our technology and delivery model, potentially resulting in additional expenses.
-
Various central banks are experimenting with digital currencies called Central Bank Digital Currencies (CBDCs). CBDCs may be launched with their own networks to transfer money between participants. Policy and design considerations that governments adopt could impact the extent of our role in facilitating CBDC-based payment transactions, potentially impacting the transactions that we may process over our network.
We cannot predict the effect of future technological changes on our business, and our future success will depend, in part, on our ability to anticipate, develop or adapt to technological changes and evolving industry standards. Failure to keep pace with these technological developments or otherwise bring to market products that reflect these technologies could lead to a decline in the use of our products, which could have a material adverse impact on our overall business and results of operations.
Operating a real-time account-based payments network presents risks that could materially affect our business.
U.K. regulators have designated Vocalink, our real-time account-based payments network platform, to be a “specified service provider” and regulators in other countries may in the future expand their regulatory oversight of real-time account-based payments systems in similar ways. In addition, any prolonged service outage on this network could result in quickly escalating impacts, including potential intervention by the Bank of England and significant reputational risk to Vocalink and us. For a discussion of the regulatory risks related to our real-time account-based payments platform and oversight by regulators, see our risk factor in “Risk Factors - Payments Industry Regulation” in this Part I, Item 1A. Furthermore, the complexity of this payment technology requires careful management to address security vulnerabilities that are different from those faced on our core payment network. Operational difficulties, such as the temporary unavailability of our services or products, or security breaches on our real-time account-based payments network could cause a loss of business for these products and services, result in potential liability for us and adversely affect our reputation.
Working with new customers and end users as we expand our multi-rail solutions and integrated products and services can present operational and onboarding challenges, be costly and result in reputational damage if the new products or services do not perform as intended.
The payments markets in which we compete are characterized by rapid technological change, new product introductions, evolving industry standards and changing customer and consumer needs. In order to remain competitive and meet the needs of the payments markets, we are continually involved in developing complex multi-rail solutions and diversifying our integrated products and services. These efforts carry the risks associated with any diversification initiative, including cost overruns, delays in delivery and performance problems. These projects also carry risks associated with working with different types of customers, for example organizations such as corporations that are not financial institutions and non-governmental organizations (“NGOs”), and end users other than those we have traditionally worked with. These differences may present new operational challenges in the development and implementation of our new products or services. These new customers are typically less regulated, and as a result, enhanced infrastructure and monitoring is required.
32 MASTERCARD 2022 FORM 10-K
PART I
Item 1A. RISK FACTORS
Our failure to effectively design and deliver these multi-rail solutions and integrated products and services could make our other offerings less desirable to these customers, or put us at a competitive disadvantage. In addition, if there is a delay in the implementation of our products or services (which could include compliance obligations, such as AML and CFT, and licensing requirements for our products and services that operate under regulatory licenses), if our products or services do not perform as anticipated, or we are unable to otherwise adequately anticipate risks related to new types of customers, we could face additional regulatory scrutiny, fines, sanctions or other penalties, which could materially and adversely affect our overall business and results of operations, as well as negatively impact our brand and reputation.
Information Security and Operational Resilience
Information security incidents or account data compromise events could disrupt our business, damage our reputation, increase our costs and cause losses.
Information security risks for payments and technology companies such as ours have significantly increased in recent years in part because of the proliferation of new technologies, the use of the Internet and telecommunications technologies to conduct financial transactions, and the increased sophistication and activities of organized crime, hackers, terrorists and other external parties. These threats may derive from fraud or malice on the part of our employees or third parties, or may result from human error or accidental technological failure. These threats include cyber-attacks such as computer viruses, malicious code (including ransomware), phishing attacks or information security breaches and could lead to the misappropriation of consumer account and other information and identity theft. These types of threats have risen significantly due to a significant portion of our workforce working in a remote or hybrid environment.
Our operations rely on the secure processing, transmission and storage of confidential, proprietary and other information and technology in our computer systems and networks, as well as the systems of our third-party providers. Our customers and other parties in the payments value chain, as well as account holders, rely on our digital technologies, computer systems, software and networks to conduct their operations. In addition, to access our integrated products and services, our customers and account holders increasingly use personal smartphones, tablet PCs and other mobile devices that may be beyond our control. We, like other financial technology organizations, routinely are subject to cyber-threats and our technologies, systems and networks, as well as the systems of our third-party providers, have been subject to attempted cyber-attacks. Because of our position in the payments value chain, we believe that we are likely to continue to be a target of such threats and attacks. In response to U.S. and European sanctions against Russia earlier this year, we saw increased information security threats from state sponsored actors. Other geopolitical events and resulting government activity could also lead to information security threats and attacks by affected or sympathizing jurisdictions or other actors, which could put our information and assets at risk, as well as result in network disruption.
To date, we have not experienced any material impact relating to cyber-attacks or other information security breaches. However, future attacks or breaches could lead to security breaches of the networks, systems (including third-party provider systems) or devices that our customers use to access our integrated products and services, which in turn could result in the unauthorized disclosure, release, gathering, monitoring, misuse, loss or destruction of confidential, proprietary and other information (including account data information) or data security compromises. Such attacks or breaches could also cause service interruptions, malfunctions or other failures in the physical infrastructure or operations systems that support our businesses and customers (such as the lack of availability of our value-added services), as well as the operations of our customers or other third parties. In addition, they could lead to damage to our reputation with our customers, other stakeholders and the broader payments ecosystem, additional costs to us (such as repairing systems, adding new personnel or protection technologies or compliance costs), regulatory penalties, financial losses to both us and our customers and partners and the loss of customers and business opportunities. These consequences could be further pronounced in jurisdictions in which we are deemed critical national infrastructure. If such attacks are not detected immediately, their effect could be compounded.
Despite various mitigation efforts that we undertake, there can be no assurance that we will be immune to these risks and not suffer material breaches and resulting losses in the future, or that our insurance coverage would be sufficient to cover all losses. Our risk and exposure to these matters remain heightened because of, among other things, the evolving nature of these threats, our prominent size and scale and our role in the global payments and technology industries, our plans to continue to implement our digital and mobile channel strategies and develop additional remote connectivity solutions to serve our customers and account holders when and how they want to be served, our global presence, our extensive use of third-party vendors and future joint venture and merger and acquisition opportunities. As a result, information security and the continued development and enhancement of our controls, processes and practices designed to protect our systems, computers, software, data and networks from attack, damage or unauthorized access remain a priority for us. As cyber-threats continue to evolve, we may be required to expend significant additional resources to continue to modify or enhance our protective measures or to investigate and remediate any information security vulnerabilities. Any of the risks described above could materially adversely affect our overall business and results of operations.
MASTERCARD 2022 FORM 10-K 33
PART I
ITEM 1A. RISK FACTORS
In addition to information security risks for our systems, we also routinely encounter account data compromise events involving merchants and third-party payment processors that process, store or transmit payment transaction data, which affect millions of Mastercard, Visa, Discover, American Express and other types of account holders. Further events of this type may subject us to reputational damage and/or lawsuits involving payment products carrying our brands. Damage to our reputation or that of our brands resulting from an account data breach of either our systems or the systems of our customers, merchants and other third parties could decrease the use and acceptance of our integrated products and services. Such events could also slow or reverse the trend toward electronic payments. In addition to reputational concerns, the cumulative impact of multiple account data compromise events could increase the impact of the fraud resulting from such events by, among other things, making it more difficult to identify consumers. Moreover, while most of the lawsuits resulting from account data breaches do not involve direct claims against us and while we have releases from many issuers and acquirers, we could still face damage claims, which, if upheld, could materially and adversely affect our results of operations. Such events could have a material adverse impact on our transaction volumes, results of operations and prospects for future growth, or increase our costs by leading to additional regulatory burdens being imposed on us.
Service disruptions that cause us to be unable to process transactions or service our customers could reduce our operational resilience and materially affect our overall business and results of operations.
Our transaction switching systems and other offerings have experienced in limited instances and may continue to experience interruptions as a result of technology malfunctions, fire, weather events, power outages, telecommunications disruptions, terrorism, workplace violence, accidents or other catastrophic events (including those related to climate change). Our visibility in the global payments industry may also put us at greater risk of attack by terrorists, activists, or hackers who intend to disrupt our facilities and/or systems. Additionally, we rely on third-party service providers for the timely transmission of information across our global data network. Inadequate infrastructure in lesser-developed markets could also result in service disruptions, which could impact our ability to do business in those markets. If one of our service providers fails to provide the communications capacity or services we require, as a result of natural disaster, operational disruptions, terrorism, hacking or any other reason, the failure could interrupt our services. Although we maintain an enterprise resiliency program to analyze risk, assess potential impacts, and develop effective response strategies, we cannot ensure that our business would be immune to these risks, because of the intrinsic importance of our switching systems to our business, any interruption or degradation could adversely affect the perception of the reliability of products carrying our brands and materially adversely affect our overall business and our results of operations.
Stakeholder Relationships
Losing a significant portion of business from one or more of our largest customers could lead to significant revenue decreases in the longer term, which could have a material adverse impact on our business and our results of operations.
Many of our customer relationships are not exclusive. Our customers can reassess their future commitments to us subject to the terms of our contracts, and they separately may develop their own services that compete with ours. Our business agreements with these customers may not ultimately reduce the risk inherent in our business that customers may terminate their relationships with us in favor of relationships with our competitors, or for other reasons, or might not meet their contractual obligations to us.
In addition, a significant portion of our revenue is concentrated among our five largest customers. Loss of business from any of our large customers could have a material adverse impact on our overall business and results of operations.
Exclusive/near exclusive relationships certain customers have with our competitors may have a material adverse impact on our business.
While we have exclusive, or nearly-exclusive, relationships with certain of our customers to issue payment products, other customers have similar exclusive, or nearly-exclusive, relationships with our competitors. These relationships may make it difficult or cost-prohibitive for us to do significant amounts of business with these customers to increase our revenues. In addition, these customers may be more successful and may grow faster than the customers that primarily issue our payment products, which could put us at a competitive disadvantage. Furthermore, we earn substantial revenue from customers with nearly-exclusive relationships with our competitors. Such relationships could provide advantages to the customers to shift business from us to the competitors with which they are principally aligned. A significant loss of our existing revenue or transaction volumes from these customers could have a material adverse impact on our business.
34 MASTERCARD 2022 FORM 10-K
PART I
ITEM 1A. RISK FACTORS
Consolidation amongst our customers could materially and adversely affect our overall business and results of operations.
Our customers’ industries have undergone substantial, accelerated consolidation in the past. These consolidations have included customers with a substantial Mastercard portfolio being acquired by institutions with a strong relationship with a competitor. If significant consolidation among customers were to continue, it could result in the substantial loss of business for us, which could have a material adverse impact on our business and prospects. In addition, one or more of our customers could seek to merge with, or acquire, one of our competitors, and any such transaction could also have a material adverse impact on our overall business. Consolidation could also produce a smaller number of large customers, which could increase their bargaining power and lead to lower prices and/or more favorable terms for our customers. These developments could materially and adversely affect our results of operations.
Our business significantly depends on the continued success and competitiveness of our issuing and acquiring customers and, in many jurisdictions, their ability to effectively manage or help manage our brands.
While we work directly with many stakeholders in the payments system, including merchants, governments, fintechs and large digital companies and other technology companies, we are, and will continue to be, significantly dependent on our relationships with our issuers and acquirers and their respective relationships with account holders and merchants to support our programs and services. Furthermore, we depend on our issuing partners and acquirers to continue to innovate to maintain competitiveness in the market. We do not issue cards or other payment devices, extend credit to account holders or determine the interest rates or other fees charged to account holders. Each issuer determines these and most other competitive payment program features. In addition, we do not establish the discount rate that merchants are charged for acceptance, which is the responsibility of our acquiring customers. As a result, our business significantly depends on the continued success and competitiveness of our issuing and acquiring customers and the strength of our relationships with them. In turn, our customers’ success depends on a variety of factors over which we have little or no influence, including economic conditions in global financial markets or their disintermediation by competitors or emerging technologies, as well as regulation. If our customers become financially unstable, we may lose revenue or we may be exposed to settlement risk. See our risk factor in “Risk Factors - Settlement and Third-Party Obligations” in this Part I, Item 1A with respect to how we guarantee certain third-party obligations for further discussion.
With the exception of the United States and a select number of other jurisdictions, most in-country (as opposed to cross-border) transactions conducted using Mastercard, Maestro and Cirrus cards are authorized, cleared and settled by our customers or other processors. Because we do not provide domestic switching services in these countries and do not, as described above, have direct relationships with account holders, we depend on our close working relationships with our customers to effectively manage our brands, and the perception of our payments system, among consumers in these countries. We also rely on these customers to help manage our brands and perception among regulators and merchants in these countries, alongside our own relationships with them. From time to time, our customers may take actions that we do not believe to be in the best interests of our payments system overall, which may materially and adversely impact our business.
Merchants’ continued focus on acceptance costs may lead to additional litigation and regulatory proceedings and increase our incentive program costs, which could materially and adversely affect our profitability.
Merchants are important constituents in our payments system. We rely on both our relationships with them, as well as their relationships with our issuer and acquirer customers, to continue to expand the acceptance of our integrated products and services. We also work with merchants to help them enable new sales channels, create better purchase experiences, improve efficiencies, increase revenues and fight fraud. In the retail industry, there is a set of larger merchants with increasingly global scope and influence that we believe are having a significant impact on all participants in the global payments industry, including Mastercard. Some large merchants have supported the legal, regulatory and legislative challenges to interchange fees that Mastercard has been defending, including the U.S. merchant litigations. Some merchants are increasingly asking regulators to review and potentially regulate our own network fees, in addition to interchange. See our risk factor in “Risk Factors – Other Regulation” in this Part I, Item 1A with respect to payments industry regulation, including interchange fees. The continued focus of merchants on the costs of accepting various forms of payment, including in connection with the growth of digital payments, may lead to additional litigation and regulatory proceedings.
Certain larger merchants are also able to negotiate incentives from us and pricing concessions from our issuer and acquirer customers as a condition to accepting our products. We also make payments to certain merchants to incentivize them to create co-branded payment programs with us. As merchants consolidate and become even larger, we may have to increase the amount of incentives that we provide to certain merchants, which could materially and adversely affect our results of operations. Competitive and regulatory pressures on pricing could make it difficult to offset the costs of these incentives. Additionally, if the rate of merchant acceptance growth slows our business could suffer.
MASTERCARD 2022 FORM 10-K 35
PART I
ITEM 1A. RISK FACTORS
Our work with governments exposes us to unique risks that could have a material impact on our business and results of operations.
As we increase our work with national, state and local governments, both indirectly through financial institutions and with them directly as our customers, we may face various risks inherent in associating or contracting directly with governments. These risks include, but are not limited to, the following:
-
Governmental entities typically fund projects through appropriated monies. Changes in governmental priorities or other political developments, including disruptions in governmental operations, could impact approved funding and result in changes in the scope, or lead to the termination, of the arrangements or contracts we or financial institutions enter into with respect to our payment products and services.
-
Our work with governments subjects us to U.S. and international anti-corruption laws, including the U.S. Foreign Corrupt Practices Act and the U.K. Bribery Act. A violation and subsequent judgment or settlement under these laws could subject us to substantial monetary penalties and damages and have a significant reputational impact.
-
Working or contracting with governments, either directly or via our financial institution customers, can subject us to heightened reputational risks, including extensive scrutiny and publicity, as well as a potential association with the policies of a government as a result of a business arrangement with that government. Any negative publicity or negative association with a government entity, regardless of its accuracy, may adversely affect our reputation.
Global Economic and Political Environment
Global economic, political, financial and societal events or conditions could result in a material and adverse impact on our overall business and results of operations.
Adverse economic trends. Adverse economic trends in key countries in which we operate may adversely affect our financial performance. Such impact may include, but is not limited to, the following:
-
Customers mitigating their economic exposure by limiting the issuance of new Mastercard products and requesting greater incentive or greater cost stability from us
-
Consumers and businesses lowering spending, which could impact domestic and cross-border spend
-
Government intervention (including the effect of laws, regulations and/or government investments on or in our financial institution customers), as well as uncertainty due to changing political regimes in executive, legislative and/or judicial branches of government, that may have potential negative effects on our business and our relationships with customers or otherwise alter their strategic direction away from our products
-
Tightening of credit availability that could impact the ability of participating financial institutions to lend to us under the terms of our credit facility
Cross-border transactions. We switch substantially all cross-border transactions using Mastercard, Maestro and Cirrus-branded cards and generate a significant amount of revenue from cross-border volume fees and fees related to switched transactions. Revenue from switching cross-border and currency conversion transactions for our customers fluctuates with the levels and destinations of cross-border travel and our customers’ need for transactions to be converted into their base currency. Cross-border activity has, and may continue to be, adversely affected by world geopolitical, economic, health, weather and other conditions. These include COVID-19, as well as the threat of terrorism and separate outbreaks of flu, viruses and other diseases (any of which could result in future epidemics or pandemics), as well as major environmental and extreme weather events, including those related to climate change. The impact of and uncertainty that could result from any of these events or factors could ultimately decrease cross-border activity. Additionally, any regulation of interregional interchange fees could also negatively impact our cross-border activity (for example, the targets announced by the G20 Financial Stability Board related to cross-border payments). In each case, decreased cross-border activity could decrease the revenue we receive.
Russia’s invasion of Ukraine. In response to the Russian invasion of Ukraine, the United States, the European Union and other governments imposed sanctions and other restrictive measures on certain Russian-related entities and individuals and we suspended our business operations in Russia. We have experienced loss of revenue in this fast-growing market as a result of both the implementation of sanctions and the suspension of our business operations, as well as related impacts in Ukraine and throughout the region. Future developments (including the expansion or extension of the war, future sanctions and/or actions taken by others globally, and other macroeconomic factors) could result in further negative impacts on our business and financial results. As customers, merchants and other business partners are impacted by the invasion, it can further negatively affect the environment in which we operate. Moreover, our compliance with sanctions and our decision to suspend business operations has led, and could further lead, to other legal ramifications and operational challenges, including fines, the nationalization of our subsidiary and any resulting impacts, and/or lawsuits.
36 MASTERCARD 2022 FORM 10-K
PART I
ITEM 1A. RISK FACTORS
Standards. Our operations as a global payments network rely in part on global interoperable standards to help facilitate safe and simple payments. To the extent geopolitical events result in jurisdictions no longer participating in the creation or adoption of these standards, or the creation of competing standards, the products and services we offer could be negatively impacted.
Any of these developments could have a material adverse impact on our overall business and results of operations.
The global COVID-19 pandemic and measures taken in response have adversely impacted our business, results of operations and financial condition, and may continue to do so depending on future developments, which are uncertain.
While conditions related to the global COVID-19 pandemic generally improved in 2022, the pandemic continues to have negative effects on the global economy and has affected business activity, in particular, in areas such as travel and supply chains. These impacts have continued to adversely impact consumers, our customers, suppliers and business partners, as well as our workforce. Governments, businesses and consumers continue to react to changing conditions, including the emergence of variants of the virus, the severity of infections on a regional basis and the global administration of vaccines and boosters. Such reactions have included tightening or loosening safety measures and border restrictions or voluntarily making personal safety decisions, as applicable, based on the current environment of their location.
The COVID-19 pandemic has adversely impacted our business, results of operations and financial condition. There are no comparable recent events which may provide guidance as to the future effects of a global pandemic such as COVID-19, and, as a result, the ultimate impact of this pandemic or a similar health epidemic in the future is uncertain and subject to change. The full extent to which the COVID-19 pandemic, and measures taken in response, further impacts our business, results of operations and financial condition will depend on future developments, which are uncertain, including, but not limited to, the duration of the pandemic and its impact on the global economy, including the extent to which we can continue to progress toward and maintain more consistent economic and operating conditions. Even after the COVID-19 pandemic has subsided, we may continue to experience materially adverse impacts to our business and our results of operations as a result of its global economic impact, including any recession that has occurred or may occur in the future.
Adverse currency fluctuations and foreign exchange controls could negatively impact our results of operations.
During 2022, approximately 67% of our revenue was generated from activities outside the United States. This revenue (and the related expense) could be transacted in a non-functional currency or valued based on a currency other than the functional currency of the entity generating the revenues. Resulting exchange gains and losses are included in our net income. Our risk management activities provide protection with respect to adverse changes in the value of only a limited number of currencies and are based on estimates of exposures to these currencies.
In addition, some of the revenue we generate outside the United States is subject to unpredictable currency fluctuations including devaluation of currencies where the values of other currencies change relative to the U.S. dollar. If the U.S. dollar strengthens compared to currencies in which we generate revenue, this revenue may be translated at a materially lower amount than expected. Furthermore, we may become subject to exchange control regulations that might restrict or prohibit the conversion of our other revenue currencies into U.S. dollars, such as what we have experienced in Venezuela.
The occurrence of currency fluctuations or exchange controls could have a material adverse impact on our results of operations.
Brand, Reputational Impact and ESG
Negative brand perception may materially and adversely affect our overall business.
Our brands and their attributes are key assets of our business. The ability to attract consumers to our branded products and retain them depends upon the external perception of us and our industry:
-
Our business may be affected by actions taken by our customers, merchants or other organizations that impact the perception of our brands or the payments industry in general. From time to time, our customers may take actions that we do not believe to be in the best interests of our brands, such as creditor practices that may be viewed as “predatory”. Moreover, adverse developments with respect to our industry or the industries of our customers or other companies and organizations that use our products and services (including certain legally permissible but high- risk merchant categories, such as adult content, firearms, alcohol and tobacco) may also, by association, impair our reputation, or result in greater public, regulatory or legislative scrutiny, as well as potential litigation. We may also face similar scrutiny to the extent that we are unable to detect and/or prevent illegal activities using our payment products or otherwise occurring over our network.
-
We have been pursuing the use of social media channels at an increasingly rapid pace. Under some circumstances, our use of social media, or the use of social media by others as a channel for criticism or other purposes, could also cause rapid, widespread reputational harm to our brands by disseminating rapidly and globally actual or perceived damaging information about us, our products or merchants or other end users who utilize our products.
MASTERCARD 2022 FORM 10-K 37
PART I
ITEM 1A. RISK FACTORS
- We are headquartered in the United States. As such, a negative perception of the United States could impact the perception of our company, which could adversely affect our business.
Any of the above issues could have a material and adverse effect on our overall business.
Lack of visibility of our brand in our products and services, or in the products and services of our partners who use our technology, may materially and adversely affect our business.
As more players enter the global payments ecosystem, the layers between our brand and consumers and merchants increase. In order to compete with other powerful consumer brands that are also becoming part of the consumer payment experience, we often partner with those brands on payment solutions. These brands include large digital companies and other technology companies who are our customers and use our networks to build their own acceptance brands. In some cases, our brand may not be featured in the payment solution or may be secondary to other brands. Additionally, as part of our relationships with some issuers, our payment brand is only included on the back of the card. As a result, our brand may either be invisible to consumers or may not be the primary brand with which consumers associate the payment experience. This brand invisibility, or any consumer confusion as to our role in the consumer payment experience, could decrease the value of our brand, which could adversely affect our business.
ESG matters and related stakeholder reaction may impact our reputation, expose us to legal requirements and liability and/or have other business impacts, which could adversely affect our overall business and/or results of operations.
Our brand and reputation are associated with our public commitments to various ESG initiatives, including our goals relating to climate (e.g., our commitment to achieve net-zero emissions by 2040), financial inclusion, and diversity, equity and inclusion. Consumers, investors, employees and other stakeholders are increasingly focused on ESG practices, and to the extent any of our ESG disclosures, public statements and metrics are subsequently viewed as inaccurate, or we are unable to execute on our sustainability initiatives, we may be viewed negatively by stakeholders concerned about these matters. These stakeholders may also have a negative view of us to the extent we have been or in the future are perceived to have not responded appropriately to growing concerns with respect to ESG matters or take or do not take positions that are unpopular with them.
In addition, various jurisdictions are increasingly adopting or considering laws and regulations that have or would impact us pertaining to ESG governance, strategy, risk management and metrics/targets. Regulations already adopted or being considered include required corporate reporting and disclosures on specific topics (such as climate and human rights) as well as broader matters (such as other environmental matters, treatment of employees and diversity of workforce). These requirements would likely result in increased compliance costs for our business and supply chain, which may increase our operating costs.
Moreover, as governments, investors and other stakeholders face pressure to address climate change and other ESG matters, these stakeholders may express new expectations and focus investments in ways that could cause significant shifts in commerce and consumption behaviors. The impact of and uncertainty that could result from such shifts could ultimately impact our business.
Any of the above issues could have a material or adverse impact to our overall business and/or results of operations.
Talent and Culture
We may not be able to attract and retain a highly qualified and diverse workforce, or maintain our corporate culture, which could harm our overall business and results of operations.
Our performance largely depends on the talents and efforts of our employees (including our people leaders), as well as the environment we create for them to enable them to perform their jobs effectively. The market for specialized skill-sets is highly competitive, particularly in technology and other areas that are important to the growth of our business. Our inability to meet candidate demands has led in recent years, and may continue to lead, to an increase in declined offers. In addition, high inflation has impacted both cost structure and employee demand for wage growth, which may lead to talent attrition. Moreover, changes in and enforcement of immigration and work permit laws and visa regulations have made it difficult for employees to work in, or transfer among, jurisdictions where we operate, potentially impairing our ability to attract and retain talent.
In the wake of the global COVID-19 pandemic and the influence of work flexibility on candidate decisions, we have adapted our policies and practices to allow for flexible team-driven work arrangements (including both remote and hybrid). This approach may impact the nature of relationships among our workforce, which in turn could have a negative impact on the quality of our corporate culture and our ability to innovate. To the extent the arrangements we provide do not meet candidate or employee expectations for flexibility, this could also impact our ability to attract and retain talent.
38 MASTERCARD 2022 FORM 10-K
PART I
ITEM 1A. RISK FACTORS
Failure to attract, hire, develop, motivate and retain highly qualified and diverse employee talent could leave us vulnerable to not anticipating or identifying emerging customer or market opportunities. We also rely on our people leaders to display integrity and decency. To the extent our leaders behave in a manner that is not consistent with our values, we could experience significant impact to our brand and reputation, as well as to our corporate culture.
Any one or more of the above could harm our overall business and results of operations.
Acquisitions
Our efforts to enter into acquisitions, strategic investments or entry into new businesses could be impacted or prevented by regulatory scrutiny and could otherwise result in issues that could disrupt our business and harm our results of operations or reputation.
We continue to evaluate our strategic acquisitions of complementary businesses, products or technologies, as well as acquiring interests in related joint ventures or other entities. As we do so, we face increasing regulatory scrutiny with respect to antitrust, national security and other considerations that could impact these efforts. We also face competition for acquisition targets due to the nature of the market for technology companies. As a result, we could be prevented from successfully completing such acquisitions in the future. If we are not successful in these efforts, we could lose strategic opportunities that are dependent, in part, on inorganic growth.
To the extent we do make these acquisitions, we may not be able to successfully partner with or integrate them, despite original intentions and focused efforts. In addition, such an integration may divert management’s time and resources from our core business and disrupt our operations. Moreover, we may spend time and money on acquisitions or projects that do not meet our expectations or increase our revenue. To the extent we pay the purchase price of any acquisition in cash, it would reduce our cash reserves available to us for other uses, and to the extent the purchase price is paid with our stock, it could be dilutive to our stockholders. Furthermore, we may inherit litigation risk which may increase our post-acquisition costs of operations and impact our ability to successfully finance that business.
Any acquisition or entry into a new business could subject us to new regulations, both directly as a result of the new business as well as in the other existing parts of our business, with which we would need to comply. This compliance could increase our costs, and we could be subject to liability or reputational harm to the extent we cannot meet any such compliance requirements. Additionally, targets that we acquire may have data practices that do not initially conform to our privacy and data protection standards and data governance model, which could lead to regulatory scrutiny and reputational harm.
Settlement and Third-Party Obligations
Our role as guarantor, as well as other contractual obligations, expose us to risk of loss or illiquidity.
We are a guarantor of certain third-party obligations, including those of certain of our customers. In this capacity, we are exposed to credit and liquidity risk from these customers and certain service providers. We may incur significant losses in connection with transaction settlements if a customer fails to fund its daily settlement obligations due to technical problems, liquidity shortfalls, insolvency or other reasons. Concurrent settlement failures of more than one of our larger customers or of several of our smaller customers either on a given day or over a condensed period of time may exceed our available resources and could materially and adversely affect our results of operations.
We have significant contractual indemnification obligations with certain customers. Should an event occur that triggers these obligations, such an event could materially and adversely affect our overall business and results of operations.
Class A Common Stock and Governance Structure
Provisions in our organizational documents and Delaware law could be considered anti-takeover provisions and have an impact on change-in-control.
Provisions contained in our amended and restated certificate of incorporation and bylaws and Delaware law could be considered anti-takeover provisions, including provisions that could delay or prevent entirely a merger or acquisition that our stockholders consider favorable. These provisions may also discourage acquisition proposals or have the effect of delaying or preventing entirely a change in control, which could harm our stock price. For example, subject to limited exceptions, our amended and restated certificate of incorporation prohibits any person from beneficially owning more than 15% of any of the Class A common stock or any other class or series of our stock with general voting power, or more than 15% of our total voting power. In addition:
MASTERCARD 2022 FORM 10-K 39
PART I
ITEM 1A. RISK FACTORS
-
our stockholders are not entitled to the right to cumulate votes in the election of directors
-
our stockholders are not entitled to act by written consent
-
any representative of a competitor of Mastercard or of Mastercard Foundation is disqualified from service on our board of directors
Mastercard Foundation’s substantial stock ownership, and restrictions on its sales, may impact corporate actions or acquisition proposals favorable to, or favored by, the other public stockholders.
As of February 8, 2023, Mastercard Foundation owned 101,253,283 shares of Class A common stock, representing approximately 10.7% of our general voting power. Currently, Mastercard Foundation may not sell or otherwise transfer its shares of Class A common stock prior to May 1, 2027, except to the extent necessary to satisfy its charitable disbursement requirements, for which purpose earlier sales are permitted and have occurred. Based on that timing, Mastercard Foundation would be permitted to sell all of its remaining shares beginning May 1, 2027, subject to certain conditions. The directors of Mastercard Foundation are required to be independent of us and our customers. The ownership of Class A common stock by Mastercard Foundation, together with the restrictions on transfer, could discourage or make more difficult acquisition proposals favored by the other holders of the Class A common stock. In addition, because Mastercard Foundation is restricted from selling its shares for an extended period of time, it may not have the same interest in short or medium-term movements in our stock price as, or incentive to approve a corporate action that may be favorable to, our other stockholders.
Item 1B. Unresolved staff comments
Not applicable.
Item 2. Properties
We own our corporate headquarters, located in Purchase, New York, and our principal technology and operations center, located in O’Fallon, Missouri. As of December 31, 2022, Mastercard and its subsidiaries owned or leased commercial properties throughout the U.S. and other countries around the world, consisting of corporate and regional offices, as well as our operations centers.
We believe that our facilities are suitable and adequate for the business that we currently conduct. However, we periodically review our space requirements and may acquire or lease new space to meet the needs of our business and address climate-related impacts, or consolidate and dispose of facilities that are no longer required.
Item 3. Legal proceedings
Refer to Note 13 (Accrued Expenses and Accrued Litigation) and Note 21 (Legal and Regulatory Proceedings) to the consolidated financial statements included in Part II, Item 8.
Item 4. Mine safety disclosures
Not applicable.
40 MASTERCARD 2022 FORM 10-K
PART I
EXECUTIVE OFFICERS
Information about our executive officers
(as of February 14, 2023)
| Name Current Position | Age | Previous Mastercard Experience | Previous Business Experience | |||||||||||||||||
| Ajay BhallaPresident, Cyber and**Intelligence Solutionssince November 2018 | 57 | President, Enterprise Security Solutions (2014-2018) President, Digital Gateway Services (2011-2013) President, South Asia and Southeast Asia (2008-2011) Various senior leadership positions, including President, Southeast Asia; Country Manager, Singapore and Head of Marketing, Southeast Asia; Vice President | Various leadership positions at HSBC and Xerox Corporation | |||||||||||||||||
| Michael Froman Vice Chairman and President, Strategic Growth since April 2018 | 60 | Mr. Froman joined the Company in 2018 in his current role | U.S. Trade Representative in the Executive Office of President Obama (2013-2017) Assistant to the President and Deputy National Security Advisor for International Economic Policy (2009-2013) Various senior leadership positions at Citigroup, including CEO, CitiInsurance and COO of Citigroup’s alternative investments business | |||||||||||||||||
| Linda Kirkpatrick President, North America since January 2021 | 46 | President, U.S. Issuers (2020) Executive Vice President, Merchants and Acceptance (2016-2020) Senior Vice President, Core Merchants (2013-2016) Senior Vice President, Franchise Development (2011-2013) Vice President, U.S. Region (2008-2011) Vice President, Investor Relations | ||||||||||||||||||
| Hai LingCo-President International Marketssince January 2022 | 52 | Co-President, Asia Pacific (2015-2021) President, Enterprise Development (2014-2015) President, Greater China (2010-2014) | Various roles at Booz Allen Hamilton and Bank of America | |||||||||||||||||
| Raghu MalhotraCo-President International Marketssince January 2022 | 53 | President, Middle East and Africa (2016-2021) Division President, Middle East and North Africa (2012-2015) Various leadership roles (2000-2005) | Various roles at Citicorp, American Express and ANZ Grindlays Bank (1992-2000) | |||||||||||||||||
| Edward McLaughlinPresident and Chief Technology Officer, Mastercard Technologysince May 2017 | 57 | Chief Information Officer (2016-2017) Chief Emerging Payments Officer (2010-2015) Various senior leadership roles, including Chief Franchise Development Officer and Senior Vice President, Bill Payment and Healthcare | Group Vice President, Product and Strategy, Metavante Corporation Co-Founder and CEO, Paytrust, Inc. | |||||||||||||||||
MASTERCARD 2022 FORM 10-K 41
PART I
EXECUTIVE OFFICERS
| Name Current Position | Age | Previous Mastercard Experience | Previous Business Experience | |||||||||||||||||
| Sachin MehraChief Financial Officersince April 2019 | 52 | Chief Financial Operations Officer (2018-2019) Executive Vice President, Commercial Products (2015-2018) Executive Vice President and Business Financial Officer, North America (2013-2015) Corporate Treasurer (2010-2013) | Various senior positions at Hess Corporation, including Vice President and Treasurer Various senior treasury and finance positions, General Motors Corporation and GMAC | |||||||||||||||||
| Michael Miebach President and Chief Executive Officer since January 2021 | 55 | President (2020) Chief Product Officer (2016-2020) President, Middle East and Africa (2010-2015) | Managing Director, Middle East and North Africa and Managing Director, Sub-Saharan Africa, Barclays Bank PLC Various executive positions at Citigroup in Germany, Austria, U.K. and Turkey | |||||||||||||||||
| Tim MurphyChief Administrative Officersince April 2021 | 55 | General Counsel (2014-2021) Chief Product Officer (2009-2014) Various senior leadership roles, including President, U.S. Region; Executive Vice President, Customer Business Planning and Analysis; and Senior Vice President and Associate General Counsel | Associate, Cleary, Gottlieb, Steen and Hamilton, New York and London | |||||||||||||||||
| Raja RajamannarChief Marketing and Communications Officer and President, Healthcaresince January 2016 | 61 | Chief Marketing Officer (2013-2015) | Executive Vice President-Senior Business and Chief Transformation Officer, Anthem (formerly, WellPoint, Inc.) (2012- 2013) Senior Vice President and Chief Innovation and Marketing Officer, Humana Inc. (2009-2012) Various management positions at Citigroup, including Executive Vice President and Chief Marketing Officer-Citi Global Cards | |||||||||||||||||
| Raj SeshadriPresident, Data and Servicessince January 2020 | 57 | President, U.S. Issuers (2016-2019) | Managing Director, Head of iShares U.S. Wealth Advisory business, BlackRock (2014-2016) Managing Director, Global Marketing Officer of iShares, BlackRock, Inc. (2012-2014) Various leadership positions at Citigroup, U.S. Trust Company and McKinsey & Company, Inc. | |||||||||||||||||
| Craig VosburgChief Product Officersince January 2021 | 55 | President, North America (2016-2020) Chief Product Officer (2014-2015) Executive Vice President, U.S. Market Development (2010-2014) Various senior leadership roles, including Head of Mastercard Advisors, U.S. and Canada and Head of Mastercard Advisors, Southeast Asia, Greater China and South Asia/Middle East/Africa | Senior member-financial services practice, Bain & Company and A.T. Kearney Vice President, CoreStates Financial Corporation |
42 MASTERCARD 2022 FORM 10-K
PART II
ITEM 5. MARKET FOR REGISTRANT'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUES PURCHASES OF EQUITY SECURITIES
Item 5. Market for registrant’s common equity, related stockholder matters and issuer purchases of equity securities
Our Class A common stock trades on the New York Stock Exchange under the symbol “MA”. At February 8, 2023, we had 71 stockholders of record for our Class A common stock. We believe that the number of beneficial owners is substantially greater than the number of record holders because a large portion of our Class A common stock is held in “street name” by brokers.
There is currently no established public trading market for our Class B common stock. There were approximately 233 holders of record of our non-voting Class B common stock as of February 8, 2023, constituting approximately 0.8% of our total outstanding equity.
Stock Performance Graph
The graph and table below compare the cumulative total stockholder return of Mastercard’s Class A common stock, the S&P 500 and the S&P 500 Financials for the five-year period ended December 31, 2022. The graph assumes a $100 investment in our Class A common stock and both of the indices and the reinvestment of dividends. Mastercard’s Class B common stock is not publicly traded or listed on any exchange or dealer quotation system.
Comparison of cumulative five-year total return
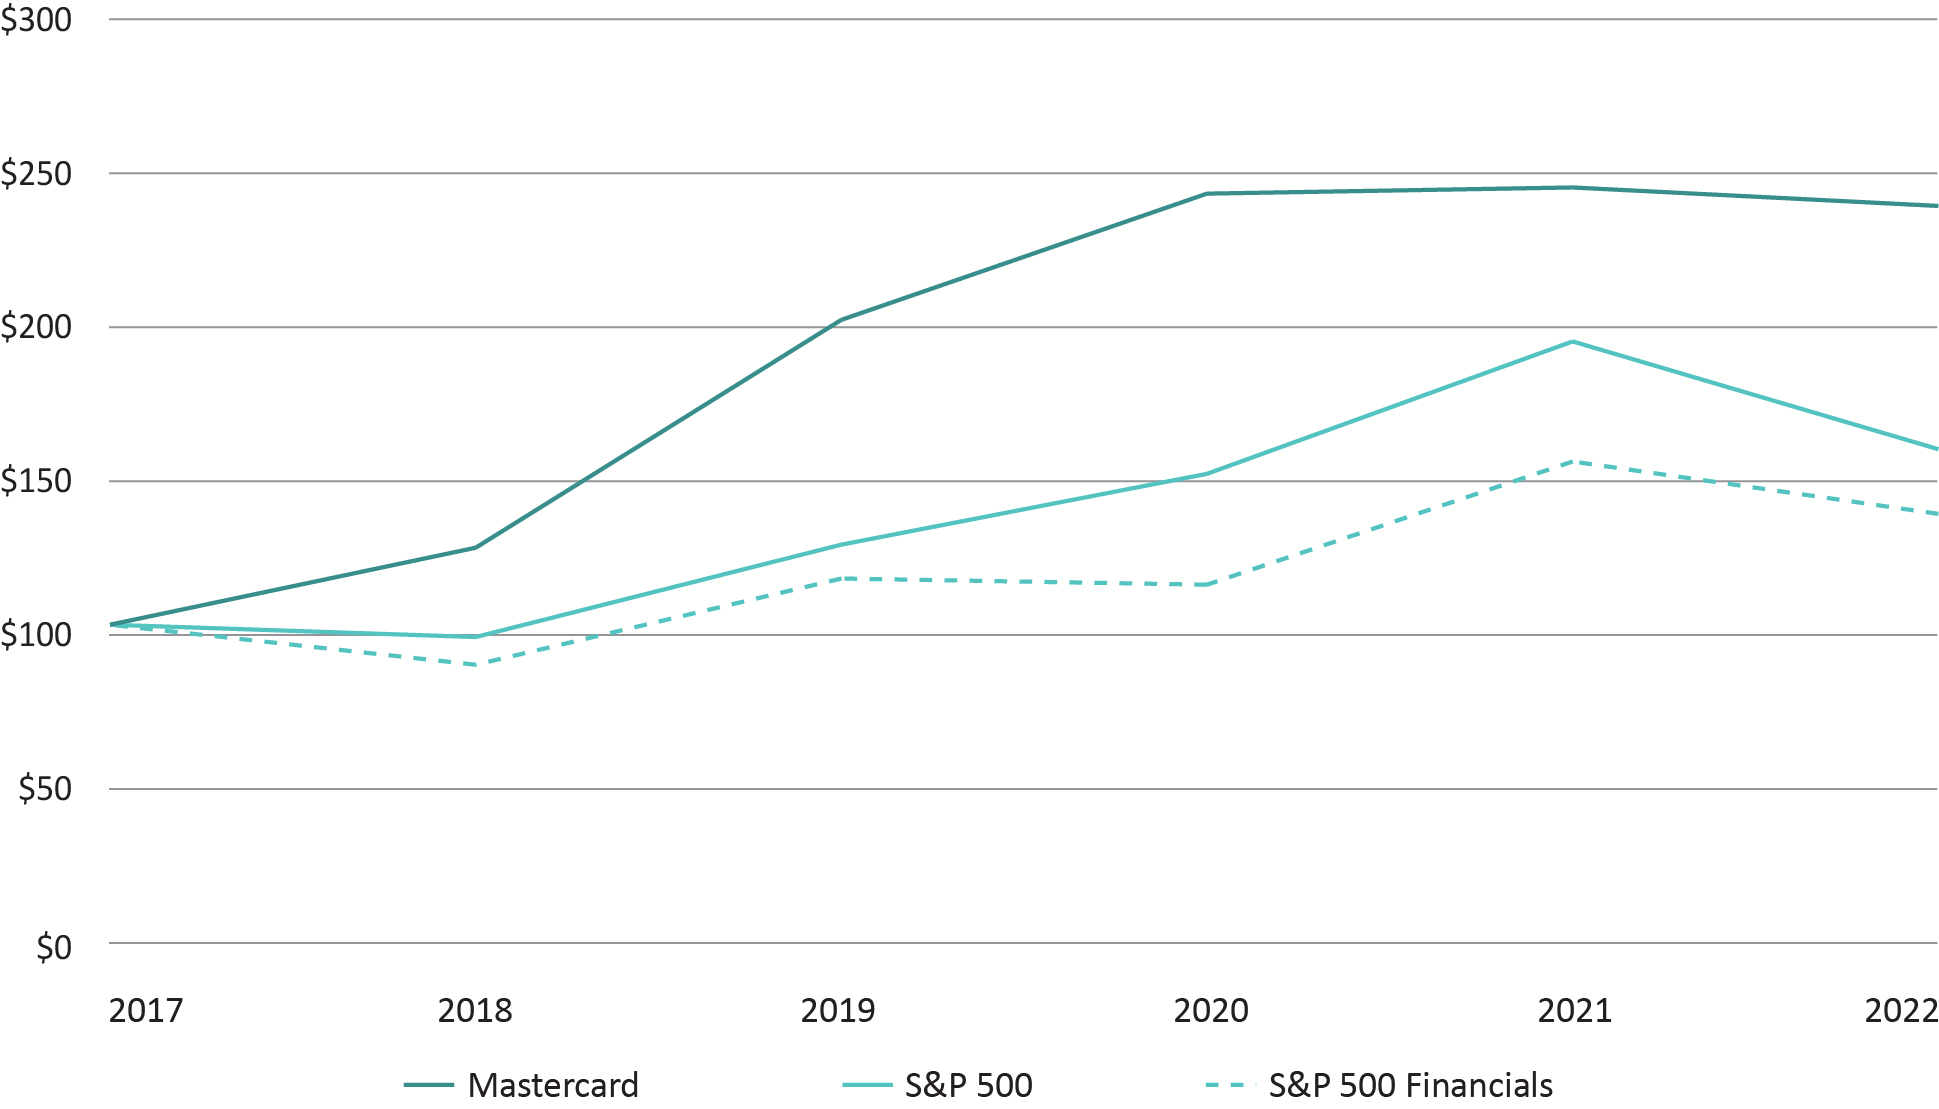
Total returns to stockholders for each of the years presented were as follows:
| Base period | Indexed Returns | |||||||||||||||||||||||||||||||||||||
| For the Years Ended December 31, | ||||||||||||||||||||||||||||||||||||||
| Company/Index | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | ||||||||||||||||||||||||||||||||
| Mastercard | $ | 100.00 | $ | 125.32 | $ | 199.46 | $ | 239.70 | $ | 242.47 | $ | 236.03 | ||||||||||||||||||||||||||
| S&P 500 | 100.00 | 95.62 | 125.72 | 148.85 | 191.58 | 156.88 | ||||||||||||||||||||||||||||||||
| S&P 500 Financials | 100.00 | 86.97 | 114.91 | 112.96 | 152.54 | 136.48 |
Dividend Declaration and Policy
On December 6, 2022, our Board of Directors declared a quarterly cash dividend of $0.57 per share paid on February 9, 2023 to holders of record on January 9, 2023 of our Class A common stock and Class B common stock. On February 14, 2023, our Board of Directors declared a quarterly cash dividend of $0.57 per share payable on May 9, 2023 to holders of record on April 7, 2023 of our Class A common stock and Class B common stock.
Subject to legally available funds, we intend to continue to pay a quarterly cash dividend on our outstanding Class A common stock and Class B common stock. However, the declaration and payment of future dividends is at the sole discretion of our Board of Directors after taking into account various factors, including our financial condition, operating results, available cash and current and anticipated cash needs.
Issuer Purchases of Equity Securities
During the fourth quarter of 2022, we repurchased 7.4 million shares for $2.4 billion at an average price of $328.26 per share of Class A common stock. See Note 16 (Stockholders' Equity) to the consolidated financial statements included in Part II, Item 8 for further discussion with respect to our share repurchase programs. The following table presents our repurchase activity on a cash basis during the fourth quarter of 2022:
| Period | Total Number of Shares Purchased | Average Price Paid per Share (including commission cost) | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Dollar Value of Shares that may yet be Purchased under the Plans or Programs 1 | ||||||||||||||||||||||
| October 1 – 31 | 2,170,087 | $ | 297.01 | 2,170,087 | $ | 4,943,927,887 | ||||||||||||||||||||
| November 1 – 30 | 2,444,959 | $ | 333.87 | 2,444,959 | $ | 4,127,621,138 | ||||||||||||||||||||
| December 1 – 31 | 2,740,325 | $ | 348.01 | 2,740,325 | $ | 12,173,961,341 | ||||||||||||||||||||
| Total | 7,355,371 | $ | 328.26 | 7,355,371 |
1Dollar value of shares that may yet be purchased under the share repurchase programs is as of the end of the period.
2In December 2022 and November 2021, our Board of Directors approved share repurchase programs of our Class A common stock authorizing us to repurchase up to $9.0 billion and $8.0 billion, respectively.
Item 6. [Reserved]
MASTERCARD 2022 FORM 10-K 44
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Item 7. Management’s discussion and analysis of financial condition and results of operations
The following discussion should be read in conjunction with the consolidated financial statements and notes of Mastercard Incorporated and its consolidated subsidiaries, including Mastercard International Incorporated (“Mastercard International”) (together, “Mastercard” or the “Company”), included elsewhere in this Report. Percentage changes provided throughout “Management’s Discussion and Analysis of Financial Condition and Results of Operations” were calculated on amounts rounded to the nearest thousand. For discussion related to the results of operations for the year ended December 31, 2021 compared to the year ended December 31, 2020, please see Part II, Item 7 of our Annual Report on Form 10-K for the year ended December 31, 2021. During 2022, the Company updated its disaggregated net revenue presentation by category and geography to reflect the nature of its payment services and to align such information with the way in which management will prospectively view its categories of net revenue. Prior period amounts have been reclassified to conform to the 2022 presentation. The reclassification had no impact on previously reported total net revenue, operating income or net income.
Business Overview
Mastercard is a technology company in the global payments industry. We connect consumers, financial institutions, merchants, governments, digital partners, businesses and other organizations worldwide by enabling electronic payments instead of cash and checks and making those payment transactions safe, simple, smart, and accessible. We make payments easier and more efficient by providing a wide range of payment solutions and services using our family of well-known and trusted brands, including Mastercard®, Maestro® and Cirrus®. We operate a multi-rail payments network that provides choice and flexibility for consumers, merchants and our customers. Through our unique and proprietary core global payments network, we switch (authorize, clear and settle) payment transactions. We have additional payment capabilities that include automated clearing house (“ACH”) transactions (both batch and real-time account-based payments). Using these capabilities, we offer integrated payment products and services and capture new payment flows. Our value-added services include, among others, cyber and intelligence solutions to allow all parties to transact easily and with confidence, as well as other services that provide proprietary insights, drawing on our principled use of secure consumer and merchant data. Our investments in new networks, such as open banking solutions and digital identity capabilities, support and strengthen our payments and services solutions. Our franchise model sets the standards and ground-rules for our core global payments network that balance value and risk across all stakeholders and allows for interoperability among them. Our payment solutions are designed to ensure safety and security for the global payments ecosystem.
Mastercard is not a financial institution. We do not issue cards, extend credit, determine or receive revenue from interest rates or other fees charged to account holders by issuers, or establish the rates charged by acquirers in connection with merchants’ acceptance of our products. In most cases, account holder relationships belong to, and are managed by, our customers.
Russia and Ukraine
Beginning in February 2022, in response to the Russian invasion of Ukraine, the United States, the European Union and other governments imposed sanctions and other restrictive measures on certain Russian-related entities and individuals and, in March 2022, we suspended our business operations in Russia1. We have taken steps necessary to ensure compliance with all applicable regulatory restrictions with sanctioned entities and individuals and have suspended our business operations with non-sanctioned customers in Russia. Throughout this process, our priority has been the safety and well-being of our employees and their families.
These actions have impacted our full year 2022 performance. As a point of reference, for the year ended December 31, 2021, approximately 4% of our net revenues were derived from business conducted within, into and out of Russia. Additional financial implications directly related to these actions include, but are not limited to, incremental employee-related costs, reserves on uncollectible balances with certain customers and impacts to net revenue, primarily related to rebates and incentives as a result of revised estimates of customer performance through the date of the suspension of our business operations.
We continue to monitor the effects of the Russian invasion of Ukraine and the related impacts to regional and global economies. The full extent to which this matter affects our business, results of operations and financial condition will depend on future developments, including the duration of the invasion and the impacts on regional and global economies, which are uncertain, and cannot be predicted at this time.
1 As a result of the suspension of our business operations, which included the suspension of our network services, cards issued by Russian banks are no longer supported by the Mastercard network regardless of where the cards are used, inside or outside of Russia. In addition, any Mastercard issued outside of Russia will not work at merchants or ATMs located in Russia.
45 MASTERCARD 2022 FORM 10-K
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Financial Results Overview
The following table provides a summary of our key GAAP operating results, as reported:
| Year ended December 31, | 2022 Increase/ (Decrease) | 2021 Increase/ (Decrease) | ||||||||||||||||||||||||||||||
| 2022 | 2021 | 2020 | ||||||||||||||||||||||||||||||
| ($ in millions, except per share data) | ||||||||||||||||||||||||||||||||
| Net revenue | $ | 22,237 | $ | 18,884 | $ | 15,301 | 18% | 23% | ||||||||||||||||||||||||
| Operating expenses | $ | 9,973 | $ | 8,802 | $ | 7,220 | 13% | 22% | ||||||||||||||||||||||||
| Operating income | $ | 12,264 | $ | 10,082 | $ | 8,081 | 22% | 25% | ||||||||||||||||||||||||
| Operating margin | 55.2 | % | 53.4 | % | 52.8 | % | 1.8 ppt | 0.6 ppt | ||||||||||||||||||||||||
| Income tax expense | $ | 1,802 | $ | 1,620 | $ | 1,349 | 11% | 20% | ||||||||||||||||||||||||
| Effective income tax rate | 15.4 | % | 15.7 | % | 17.4 | % | (0.4) ppt | (1.7) ppt | ||||||||||||||||||||||||
| Net income | $ | 9,930 | $ | 8,687 | $ | 6,411 | 14% | 35% | ||||||||||||||||||||||||
| Diluted earnings per share | $ | 10.22 | $ | 8.76 | $ | 6.37 | 17% | 38% | ||||||||||||||||||||||||
| Diluted weighted-average shares outstanding | 971 | 992 | 1,006 | (2)% | (1)% |
The following table provides a summary of our key non-GAAP operating results1, adjusted to exclude the impact of gains and losses on our equity investments, Special Items (which represent litigation judgments and settlements and certain one-time items) and the related tax impacts on our non-GAAP adjustments. In addition, we have presented growth rates, adjusted for the impact of currency:
| Year ended December 31, | 2022 Increase/(Decrease) | 2021 Increase/(Decrease) | ||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2020 | As adjusted | Currency-neutral | As adjusted | Currency-neutral | ||||||||||||||||||||||||||||||||||||||
| ($ in millions, except per share data) | ||||||||||||||||||||||||||||||||||||||||||||
| Adjusted net revenue | $ | 22,200 | $ | 18,884 | $ | 15,301 | 18% | 23% | 23% | 22% | ||||||||||||||||||||||||||||||||||
| Adjusted operating expenses | $ | 9,549 | $ | 8,627 | $ | 7,147 | 11% | 14% | 21% | 19% | ||||||||||||||||||||||||||||||||||
| Adjusted operating margin | 57.0 | % | 54.3 | % | 53.3 | % | 2.7 ppt | 3.4 ppt | 1.0 ppt | 1.2 ppt | ||||||||||||||||||||||||||||||||||
| Adjusted effective income tax rate | 15.7 | % | 15.4 | % | 17.2 | % | 0.3 ppt | 0.5 ppt | (1.8) ppt | (1.8) ppt | ||||||||||||||||||||||||||||||||||
| Adjusted net income | $ | 10,342 | $ | 8,333 | $ | 6,463 | 24% | 32% | 29% | 28% | ||||||||||||||||||||||||||||||||||
| Adjusted diluted earnings per share | $ | 10.65 | $ | 8.40 | $ | 6.43 | 27% | 34% | 31% | 30% |
Note: Tables may not sum due to rounding.
1 See “Non-GAAP Financial Information” for further information on our non-GAAP adjustments and the reconciliation to GAAP reported amounts.
MASTERCARD 2022 FORM 10-K 46
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Key highlights for 2022 as compared to 2021 were as follows:
| Net revenue | Adjusted net revenue | ||||||||||
| GAAP | Non-GAAP (currency-neutral) | Adjusted net revenue increased 23% on a currency-neutral basis. The increase was attributable to our payment network and our value-added services and solutions, which increased 26% and 18%, on a currency-neutral basis, respectively. | |||||||||
| up 18% | up 23% | ||||||||||
| Operating expenses | Adjusted operating expenses | ||||||||||
| GAAP | Non-GAAP (currency-neutral) | Adjusted operating expenses increased 14% on a currency-neutral basis, which includes 4 percentage points of growth due to acquisitions. The remaining increase was primarily due to higher personnel costs, travel and meeting costs, and unfavorable foreign exchange activity. | |||||||||
| up 13% | up 14% | ||||||||||
| Effective income tax rate | Adjusted effective income tax rate | ||||||||||
| GAAP | Non-GAAP (currency-neutral) | The adjusted effective income tax rate of 15.7% was higher than prior year due to the recognition of U.S. tax benefits in 2021 (the majority of which were discrete), a discrete tax benefit in 2021 related to the remeasurement of our net deferred tax asset in the U.K. and a discrete tax expense related to an unfavorable court ruling in 2022, all of which were partially offset by a discrete tax benefit in the first quarter of 2022 due to final U.S. tax regulations published in the current year. | |||||||||
| 15.4% | 15.7% | ||||||||||
Other 2022 financial highlights were as follows:
-
We generated net cash flows from operations of $11.2 billion.
-
We completed the acquisition of a business for total consideration of $0.3 billion.
-
We repurchased 25.7 million shares of our common stock for $8.8 billion and paid dividends of $1.9 billion.
-
We completed a euro-denominated debt offering for an aggregate principal amount of $0.8 billion and entered into an Indian rupee-denominated term loan for $0.3 billion.
Non-GAAP Financial Information
Non-GAAP financial information is defined as a numerical measure of a company’s performance that excludes or includes amounts so as to be different than the most comparable measure calculated and presented in accordance with accounting principles generally accepted in the United States (“GAAP”). Our non-GAAP financial measures exclude the impact of gains and losses on our equity investments which includes mark-to-market fair value adjustments, impairments and gains and losses upon disposition and the related tax impacts. Our non-GAAP financial measures also exclude the impact of special items, where applicable, which represent litigation judgments and settlements and certain one-time items, as well as the related tax impacts (“Special Items”). Our non-GAAP financial measures for the comparable periods exclude the impact of the following:
Gains and Losses on Equity Investments
- During 2022, 2021 and 2020, we recorded net losses of $145 million ($126 million after tax, or $0.13 per diluted share), net gains of $645 million ($497 million after tax, or $0.50 per diluted share) and net gains of $30 million ($15 million after tax, or $0.01 per diluted share), respectively. These net gains and losses were primarily related to unrealized fair market value adjustments on marketable and nonmarketable equity securities. In addition, in 2021, net gains also included realized gains on sales of marketable equity securities.
47 MASTERCARD 2022 FORM 10-K
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Special Items
Litigation provisions
- During 2022, we recorded pre-tax charges of $356 million ($263 million after tax, or $0.27 per diluted share) related to litigation provisions which included pre-tax charges of:
◦$223 million as a result of settlements (both final and agreements in principle) with a number of U.K. merchants, and
◦$133 million as a result of a change in estimate related to the claims of merchants who opted out of the U.S. merchant class litigation.
-
During 2021, we recorded pre-tax charges of $94 million ($74 million after tax, or $0.07 per diluted share) related to litigation settlements and estimated attorneys’ fees with U.K. and Pan-European merchants.
-
During 2020, we recorded pre-tax charges of $73 million ($67 million after tax, or $0.07 per diluted share) related to litigation provisions which included pre-tax charges of:
◦$45 million related to a legal matter associated with our prepaid cards in the U.K., and
◦$28 million related to estimated attorneys’ fees and litigation settlements with U.K. and Pan-European merchants.
Russia-related impacts
- During 2022, we recorded a net charge of $30 million ($24 million after tax, or $0.02 per diluted share), directly related to imposed sanctions and the suspension of our business operations in Russia. The net charge is comprised of general and administrative expenses of $67 million, primarily related to incremental employee-related costs and reserves on uncollectible balances with certain sanctioned customers. These charges are offset by net benefits of $37 million in net revenue, primarily related to a reduction in rebates and incentives liabilities as a result of lower estimates of customer performance for certain customer business agreements due to the suspension of our business operations in Russia.
Indirect tax matter
- During 2021, we recorded a charge of $88 million ($69 million after tax, or $0.07 per diluted share) to resolve a foreign indirect tax matter for 2015 through 2021 and the related interest expense. The charge is comprised of general and administrative expenses of $82 million and other income (expense) of $6 million.
See Note 7 (Investments) and Note 21 (Legal and Regulatory Proceedings) to the consolidated financial statements included in Part II, Item 8 and “Key Developments” above for further discussion related to certain of our non-GAAP financial measures. We excluded these items because management evaluates the underlying operations and performance of the Company separately from these recurring and nonrecurring items.
We believe that the non-GAAP financial measures presented facilitate an understanding of our operating performance and provide a meaningful comparison of our results between periods. We use non-GAAP financial measures to, among other things, evaluate our ongoing operations in relation to historical results, for internal planning and forecasting purposes and in the calculation of performance-based compensation.
Currency-neutral Growth Rates
We present growth rates adjusted for the impact of currency, which is a non-GAAP financial measure. Currency-neutral growth rates are calculated by remeasuring the prior period’s results using the current period’s exchange rates for both the translational and transactional impacts on operating results. The impact of currency translation represents the effect of translating operating results where the functional currency is different than our U.S. dollar reporting currency. The impact of the transactional currency represents the effect of converting revenue and expenses occurring in a currency other than the functional currency of the entity. The impact of the related realized gains and losses resulting from our foreign exchange derivative contracts designated as cash flow hedging instruments is recognized in the respective financial statement line item on the statement of operations when the underlying forecasted transactions impact earnings. We believe the presentation of currency-neutral growth rates provides relevant information to facilitate an understanding of our operating results.
The translational and transactional impact of currency and the related impact of our foreign exchange derivative contracts designated as cash flow hedging instruments (“Currency impact”) has been excluded from our currency-neutral growth rates and has been identified in our “Drivers of Change” tables. See “Foreign Currency - Currency Impact” for further information on our currency impacts and “Financial Results - Revenue and Operating Expenses” for our “Drivers of Change” tables.
Net revenue, operating expenses, operating margin, other income (expense), effective income tax rate, net income and diluted earnings per share adjusted for the impact of gains and losses on our equity investments, Special Items and/or the impact of
MASTERCARD 2022 FORM 10-K 48
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
currency, are non-GAAP financial measures and should not be relied upon as substitutes for measures calculated in accordance with GAAP.
The following tables reconcile our reported financial measures calculated in accordance with GAAP to the respective adjusted non-GAAP financial measures:
| Year ended December 31, 2022 | ||||||||||||||||||||||||||||||||||||||||||||
| Net revenue | Operating expenses | Operating margin | Other income (expense) | Effective income tax rate | Net income | Diluted earnings per share | ||||||||||||||||||||||||||||||||||||||
| ($ in millions, except per share data) | ||||||||||||||||||||||||||||||||||||||||||||
| Reported - GAAP | $ | 22,237 | $ | 9,973 | 55.2 | % | $ | (532) | 15.4 | % | $ | 9,930 | $ | 10.22 | ||||||||||||||||||||||||||||||
| (Gains) losses on equity investments | ** | ** | ** | 145 | — | % | 126 | 0.13 | ||||||||||||||||||||||||||||||||||||
| Litigation provisions | ** | (356) | 1.6 | % | ** | 0.3 | % | 263 | 0.27 | |||||||||||||||||||||||||||||||||||
| Russia-related impacts | (37) | (67) | 0.2 | % | ** | — | % | 24 | 0.02 | |||||||||||||||||||||||||||||||||||
| Adjusted - Non-GAAP | $ | 22,200 | $ | 9,549 | 57.0 | % | $ | (387) | 15.7 | % | $ | 10,342 | $ | 10.65 |
| Year ended December 31, 2021 | ||||||||||||||||||||||||||||||||||||||||||||
| Net revenue | Operating expenses | Operating margin | Other income (expense) | Effective income tax rate | Net income | Diluted earnings per share | ||||||||||||||||||||||||||||||||||||||
| ($ in millions, except per share data) | ||||||||||||||||||||||||||||||||||||||||||||
| Reported - GAAP | $ | 18,884 | $ | 8,802 | 53.4 | % | $ | 225 | 15.7 | % | $ | 8,687 | $ | 8.76 | ||||||||||||||||||||||||||||||
| (Gains) losses on equity investments | ** | ** | ** | (645) | (0.5) | % | (497) | (0.50) | ||||||||||||||||||||||||||||||||||||
| Litigation provisions | ** | (94) | 0.5 | % | ** | 0.1 | % | 74 | 0.07 | |||||||||||||||||||||||||||||||||||
| Indirect tax matter | ** | (82) | 0.4 | % | 6 | 0.1 | % | 69 | 0.07 | |||||||||||||||||||||||||||||||||||
| Adjusted - Non-GAAP | $ | 18,884 | $ | 8,627 | 54.3 | % | $ | (413) | 15.4 | % | $ | 8,333 | $ | 8.40 |
| Year ended December 31, 2020 | ||||||||||||||||||||||||||||||||||||||||||||
| Net revenue | Operating expenses | Operating margin | Other income (expense) | Effective income tax rate | Net income | Diluted earnings per share | ||||||||||||||||||||||||||||||||||||||
| ($ in millions, except per share data) | ||||||||||||||||||||||||||||||||||||||||||||
| Reported - GAAP | $ | 15,301 | $ | 7,220 | 52.8 | % | $ | (321) | 17.4 | % | $ | 6,411 | 6.37 | |||||||||||||||||||||||||||||||
| (Gains) losses on equity investments | ** | ** | ** | (30) | (0.1) | % | (15) | (0.01) | ||||||||||||||||||||||||||||||||||||
| Litigation provisions | ** | (73) | 0.5 | % | ** | (0.1) | % | 67 | 0.07 | |||||||||||||||||||||||||||||||||||
| Adjusted - Non-GAAP | $ | 15,301 | $ | 7,147 | 53.3 | % | $ | (351) | 17.2 | % | $ | 6,463 | $ | 6.43 |
Note: Tables may not sum due to rounding.
** Not applicable
49 MASTERCARD 2022 FORM 10-K
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following tables represent the reconciliation of our growth rates reported under GAAP to our non-GAAP growth rates:
| Year Ended December 31, 2022 as compared to the Year Ended December 31, 2021 | ||||||||||||||||||||||||||||||||||||||
| Increase/(Decrease) | ||||||||||||||||||||||||||||||||||||||
| Net revenue | Operating expenses | Operating margin | Effective income tax rate | Net income | Diluted earnings per share | |||||||||||||||||||||||||||||||||
| Reported - GAAP | 18 | % | 13 | % | 1.8 | ppt | (0.4) | ppt | 14 | % | 17 | % | ||||||||||||||||||||||||||
| (Gains) losses on equity investments | ** | ** | ** | 0.5 ppt | 8 | % | 9 | % | ||||||||||||||||||||||||||||||
| Litigation provisions | ** | (3) | % | 1.1 | ppt | 0.3 ppt | 2 | % | 2 | % | ||||||||||||||||||||||||||||
| Russia-related impacts | — | (1) | % | 0.2 ppt | — ppt | — | % | — | % | |||||||||||||||||||||||||||||
| Indirect tax matter | ** | 1 | % | (0.4) ppt | (0.1) ppt | (1) | % | (1) | % | |||||||||||||||||||||||||||||
| Adjusted - Non-GAAP | 18 | % | 11 | % | 2.7 | ppt | 0.3 ppt | 24 | % | 27 | % | |||||||||||||||||||||||||||
| Currency impact 1 | 5 | % | 3 | % | 0.8 | ppt | 0.2 ppt | 8 | % | 8 | % | |||||||||||||||||||||||||||
| Adjusted - Non-GAAP - currency-neutral | 23 | % | 14 | % | 3.4 | ppt | 0.5 ppt | 32 | % | 34 | % |
| Year Ended December 31, 2021 as compared to the Year Ended December 31, 2020 | ||||||||||||||||||||||||||||||||||||||
| Increase/(Decrease) | ||||||||||||||||||||||||||||||||||||||
| Net revenue | Operating expenses | Operating margin | Effective income tax rate | Net income | Diluted earnings per share | |||||||||||||||||||||||||||||||||
| Reported - GAAP | 23 | % | 22 | % | 0.6 | ppt | (1.7) | ppt | 35 | % | 38 | % | ||||||||||||||||||||||||||
| (Gains) losses on equity investments | ** | ** | ** | (0.4) ppt | (7) | % | (8) | % | ||||||||||||||||||||||||||||||
| Litigation provisions | ** | — | % | — ppt | 0.1 ppt | — | % | — | % | |||||||||||||||||||||||||||||
| Indirect tax matter | ** | (1) | % | 0.4 ppt | 0.1 ppt | 1 | % | 1 | % | |||||||||||||||||||||||||||||
| Adjusted - Non-GAAP | 23 | % | 21 | % | 1.0 ppt | (1.8) ppt | 29 | % | 31 | % | ||||||||||||||||||||||||||||
| Currency impact 1 | (1) | % | (2) | % | 0.2 ppt | — ppt | (1) | % | (1) | % | ||||||||||||||||||||||||||||
| Adjusted - Non-GAAP - currency-neutral | 22 | % | 19 | % | 1.2 ppt | (1.8) ppt | 28 | % | 30 | % |
Note: Tables may not sum due to rounding.
** Not applicable
1See “Non-GAAP Financial Information” for further information on Currency impact.
Key Metrics
In addition to the financial measures described above in “Financial Results Overview”, we review the following metrics to evaluate and identify trends in our business, measure our performance, prepare financial projections and make strategic decisions. We believe that the key metrics presented facilitate an understanding of our operating and financial performance and provide a meaningful comparison of our results between periods.
Operating Margin measures how much profit we make on each dollar of sales after our operating costs but before other income (expense) and income tax expense. Operating margin is calculated by dividing our operating income by net revenue.
Key Drivers
**Gross Dollar Volume (“GDV”)**1 measures dollar volume of activity, including both domestic and cross-border volume, on cards carrying our brands during the period, on a local currency basis and U.S. dollar-converted basis. GDV represents purchase volume plus cash volume; “purchase volume” means the aggregate dollar amount of purchases made with Mastercard-branded cards for the relevant period; and “cash volume” means the aggregate dollar amount of cash disbursements and includes the impact of balance transfers and convenience checks obtained with Mastercard-branded cards for the relevant period. Information denominated in U.S. dollars relating to GDV is calculated by applying an established U.S. dollar/local currency exchange rate for each local currency in which our volumes are reported. These exchange rates are calculated on a quarterly basis using the average exchange rate for each quarter. We report period-over-period rates of change in purchase volume and cash volume on the basis of local currency information, in order to eliminate the impact of changes in the value of currencies against the U.S. dollar in calculating such rates of change.
MASTERCARD 2022 FORM 10-K 50
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Cross-border Volume Growth2 measures the growth of cross-border dollar volume during the period, on a local currency basis and U.S. dollar-converted basis, for all Mastercard-branded programs.
Switched Transactions2 measures the number of transactions switched by Mastercard, which is defined as the number of transactions initiated and switched through our network during the period.
1 Data used in the calculation of GDV is provided by Mastercard customers and is subject to verification by Mastercard and partial cross-checking against information provided by Mastercard’s transaction switching systems. All data is subject to revision and amendment by Mastercard or Mastercard’s customers. Starting in the first quarter of 2022, data related to sanctioned Russian banks was not reported to us and therefore such amounts are not included. Subsequent to the suspension of our business operations in Russia in March 2022, there is no Russian data to be reported.
2 Growth rates are normalized to eliminate the effects of differing switching and carryover days between periods. Carryover days are those where transactions and volumes from days where the Company does not clear and settle are processed. In the fourth quarter of 2021, we began clearing and settling transactions and volumes on a daily basis.
The following tables provide a summary of the growth trends in our key drivers.
| For the Years Ended December 31, | ||||||||||||||||||||||||||
| 2022 | 2021 | |||||||||||||||||||||||||
| Increase/(Decrease) | ||||||||||||||||||||||||||
| USD | Local | USD | Local | |||||||||||||||||||||||
| Mastercard-branded GDV growth 1 | 6% | 12% | 22% | 21% | ||||||||||||||||||||||
| United States | 10% | 10% | 23% | 23% | ||||||||||||||||||||||
| Worldwide less United States | 4% | 13% | 22% | 20% | ||||||||||||||||||||||
| Cross-border volume growth 1 | 33% | 45% | 35% | 32% | ||||||||||||||||||||||
| Mastercard-branded GDV growth adjusted for Russia 1,2 | 10% | 18% | 22% | 20% | ||||||||||||||||||||||
| Worldwide less United States GDV growth adjusted for Russia 1,2 | 10% | 22% | 22% | 19% | ||||||||||||||||||||||
| Cross-border volume growth adjusted for Russia 1,2 | 37% | 50% | 35% | 31% | ||||||||||||||||||||||
| For the Years Ended December 31, | ||||||||||||||
| Increase/(Decrease) | ||||||||||||||
| 2022 | 2021 | |||||||||||||
| Switched transactions growth | 12% | 25% | ||||||||||||
| Switched transactions growth adjusted for Russia 2 | 21% | 24% |
1 Excludes volume generated by Maestro and Cirrus cards.
2 Starting in the first quarter of 2022, as a result of imposed sanctions and the suspension of our business operations in Russia, we have provided adjusted growth rates for our key drivers excluding activity from Russian issued cards from the current and prior periods.
Key Metrics related to the Payment Network
Assessments represent agreed upon standard pricing provided to our customers based on various forms of payment-related activity. Assessments are used internally by management to monitor operating performance as it allows for comparability and provides visibility into cardholder trends. Assessments do not represent our net revenue.
The following provides additional information on our key metrics related to the payment network:
-
Domestic assessments** are charges based on activity related to cards that carry the Company’s brands where the merchant country and the country of issuance are the same. These assessments are primarily driven by the domestic dollar volume of activity (e.g., domestic purchase volume, domestic cash volume) or the number of cards issued.
-
Cross-border assessments** are charges based on activity related to cards that carry the Company’s brands where the merchant country and the country of issuance are different. These assessments are primarily driven by the cross-border dollar volume of activity (e.g., cross-border purchase volume, cross-border cash volume).
51 MASTERCARD 2022 FORM 10-K
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
- Transaction processing assessments** are charges primarily driven by the number of switched transactions on our payment network. Switching activities include:
◦Authorization, the process by which a transaction is routed to the issuer for approval
◦Clearing, the determination and exchange of financial transaction information between issuers and acquirers after a transaction has been successfully conducted at the point of interaction
◦Settlement, which facilitates the determination and exchange of funds between parties
These assessments can also include connectivity services and network access which are based on the volume of data transmitted and the number of authorization and settlement messages.
- Other network assessments** are charges for licensing, implementation and other franchise fees.
The following table provides a summary of our key metrics related to the payment network.
| Year ended December 31, | 2022 | 2021 | ||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2020 | Increase/(Decrease) | Currency-neutral Increase/(Decrease) | Increase/(Decrease) | Currency-neutral Increase/(Decrease) | ||||||||||||||||||||||||||||||||||||||
| ($ in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| Domestic assessments | $ | 8,794 | $ | 8,064 | $ | 6,598 | 9% | 12% | 22% | 22% | ||||||||||||||||||||||||||||||||||
| Cross-border assessments | 6,597 | 4,646 | 3,498 | 42% | 53% | 33% | 30% | |||||||||||||||||||||||||||||||||||||
| Transaction processing assessments | 10,646 | 9,041 | 7,137 | 18% | 23% | 27% | 26% | |||||||||||||||||||||||||||||||||||||
| Other network assessments | 766 | 668 | 659 | 15% | 14% | 1% | 4% | |||||||||||||||||||||||||||||||||||||
Foreign Currency
Currency Impact
Our primary revenue functional currencies are the U.S. dollar, euro, Brazilian real and the British pound. Our overall operating results are impacted by currency translation, which represents the effect of translating operating results where the functional currency is different than our U.S. dollar reporting currency.
Our operating results are also impacted by transactional currency. The impact of the transactional currency represents the effect of converting revenue and expense transactions occurring in a currency other than the functional currency. Changes in currency exchange rates directly impact the calculation of gross dollar volume (“GDV”) and gross euro volume (“GEV”), which are used in the calculation of our key metrics related to domestic assessments and cross-border assessments as well as certain volume-related rebates and incentives. In most non-European regions, GDV is calculated based on local currency spending volume converted to U.S. dollars using average exchange rates for the period. In Europe, GEV is calculated based on local currency spending volume converted to euros using average exchange rates for the period. As a result, our key metrics related to domestic assessments and cross-border assessments as well as certain volume-related rebates and incentives are impacted by the strengthening or weakening of the U.S. dollar versus non-European local currencies and the strengthening or weakening of the euro versus other European local currencies. For example, our billing in Australia is in the U.S. dollar, however, consumer spend in Australia is in the Australian dollar. The currency transactional impact of converting Australian dollars to our U.S. dollar billing currency will have an impact on the revenue generated. The strengthening or weakening of the U.S. dollar is evident when GDV growth on a U.S. dollar-converted basis is compared to GDV growth on a local currency basis. In 2022, GDV on a U.S. dollar-converted basis increased 5.9%, while GDV on a local currency basis increased 12.3% versus 2021. In 2021, GDV on a U.S. dollar-converted basis increased 22.0%, while GDV on a local currency basis increased 20.6% versus 2020. Further, the impact from transactional currency occurs in transaction processing revenue, other revenue and operating expenses when the local currency of these items is different than the functional currency of the entity.
Through December 31, 2020, our approach to managing transactional currency exposure consisted of hedging a portion of anticipated revenues impacted by transactional currencies by entering into foreign exchange derivative contracts, and recording the related changes in fair value in general and administrative expenses on the consolidated statement of operations. During the first quarter of 2021, we started to formally designate certain newly-executed foreign exchange derivative contracts, which meet the established accounting criteria, as cash flow hedges. Gains and losses resulting from changes in fair value of these designated
MASTERCARD 2022 FORM 10-K 52
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
contracts are deferred in accumulated other comprehensive income (loss) and subsequently recognized in the respective component of net revenue when the underlying forecasted transactions impact earnings.
Foreign Exchange Activity
We incur foreign currency gains and losses from remeasuring monetary assets and liabilities, including settlement assets and obligations, that are denominated in a currency other than the functional currency of the entity. To manage this foreign exchange risk, we may enter into foreign exchange derivative contracts to economically hedge the foreign currency exposure of a portion of our nonfunctional currency monetary assets and liabilities. The gains or losses resulting from the changes in fair value of these contracts are intended to reduce the potential effect of the underlying hedged exposure and are recorded net within general and administrative expenses on the consolidated statement of operations. The impact of this foreign exchange activity, including the related hedging activities, has not been eliminated in our currency-neutral results.
Our foreign exchange risk management activities are discussed further in Note 23 (Derivative and Hedging Instruments) to the consolidated financial statements included in Part II, Item 8.
Risk of Currency Devaluation
We are exposed to currency devaluation in certain countries. In addition, we are subject to exchange control regulations that restrict the conversion of financial assets into U.S. dollars. While these revenues and assets are not material to us on a consolidated basis, we can be negatively impacted should there be a continued and sustained devaluation of local currencies relative to the U.S. dollar and/or a continued and sustained deterioration of economic conditions in these countries.
Financial Results
Net Revenue
The components of net revenue were as follows:
| For the Years Ended December 31, | Increase (Decrease) | |||||||||||||||||||||||||||||||
| 2022 | 2021 | 2020 | 2022 | 2021 | ||||||||||||||||||||||||||||
| ($ in millions) | ||||||||||||||||||||||||||||||||
| Payment network | $ | 14,358 | $ | 11,943 | $ | 9,897 | 20% | 21% | ||||||||||||||||||||||||
| Value-added services and solutions | 7,879 | 6,941 | 5,404 | 14% | 28% | |||||||||||||||||||||||||||
| Net revenue | $ | 22,237 | $ | 18,884 | $ | 15,301 | 18% | 23% |
2022
For the year ended December 31, 2022, net revenue increased 18% versus the comparable period in 2021. Adjusted net revenue increased 18%, or 23% on a currency-neutral basis. The increase in net revenue was attributable to both our payment network and our value-added services and solutions and included 1 percentage point of growth from acquisitions. Net revenue includes $13,084 million of rebates and incentives provided to our customers, an increase of 19%, or 23% on a currency-neutral basis, in 2022 versus 2021.
Net revenue from our payment network increased 20%, or 26% on a currency-neutral basis, in 2022 versus 2021. The increase was primarily driven by growth in domestic and cross-border dollar volumes and an increase in the number of switched transactions, reflecting trends of growth in our key drivers. Net revenue from our payment network includes $12,445 million of rebates and incentives provided to customers, which increased 19%, or 23% on a currency-neutral basis, in 2022 versus 2021, primarily due to an increase in our key drivers as well as new and renewed deals.
Net revenue from our value-added services and solutions increased 14%, or 18% on a currency-neutral basis, in 2022 versus 2021, which includes a 4 percentage point increase from acquisitions. The remaining increase was primarily driven by our cyber and intelligence and data and services solutions.
2021
For the year ended December 31, 2021, net revenue increased 23%, or 22% on a currency neutral basis, versus the comparable period in 2020. The increase in net revenue was attributable to both our payment network and our value-added services and solutions and included 2 percentage points of growth from acquisitions. Net revenue includes $10,961 million of rebates and incentives provided to our customers, an increase of 32%, or 31% on a currency-neutral basis, in 2021 versus 2020.
53 MASTERCARD 2022 FORM 10-K
PART II
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Net revenue from our payment network increased 21%, or 20% on a currency-neutral basis, in 2021 versus 2020. The increase was primarily driven by growth in domestic and cross-border dollar volumes and an increase in the number of switched transactions, reflecting trends of growth in our key drivers. Net revenue from our payment network include $10,476 million of rebates and incentives provided to customers, which increased 31%, or 30% on a currency-neutral basis, in 2021 versus 2020, primarily due to an increase in our key drivers as well as new and renewed deals.
Net revenue from our value-added services and solutions increased 28%, or 27% on a currency-neutral basis, in 2021 versus 2020, which includes a 6 percentage point increase from acquisitions. The remaining increase was primarily driven by our cyber and intelligence and data and services solutions.
See Note 3 (Revenue) to the consolidated financial statements included in Part II, Item 8 for a further discussion of how we recognize revenue.
Drivers of Change
The following table summarizes the drivers of change in net revenue:
| For the Years Ended December 31, | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Operational | Acquisitions | Currency Impact 3 | Special Items 4 | Total | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Payment network | 26% | 1 | 20% | 1 | —% | —% | (6)% | 1% | —% | —% | 20 | % | 21 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Value-added services and solutions | 15% | 2 | 21% | 2 | 4% | 6% | (4)% | 1% | ** | —% | 14 | % | 28 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net revenue | 22% | 20% | 1% | 2% | (5)% | 1% | —% | —% | 18 | % | 23 | % |
Note: Table may not sum due to rounding
1Includes impacts from our key drivers and metrics, offset by rebates and incentives.
2 Includes impacts from cyber and intelligence, data and services, processing and gateway, ACH batch and real-time account-based domestic and cross-border payments and solutions, opening banking and digital identity, offset by rebates and incentives.
3 Includes the translational and transactional impact of currency and the related impact of our foreign exchange derivative contracts designated as cash flow hedging instruments.
4 See “Non-GAAP Financial Information” for further information on our non-GAAP adjustments and the reconciliation to GAAP reported amounts.
No individual country, other than the United States, generated more than 10% of net revenue in any such period. A significant portion of our net revenue is concentrated among our five largest customers. In 2022, the net revenue from these customers was approximately $4.7 billion, or 21%, of total net revenue. The loss of any of these customers or their significant card programs could adversely impact our revenue.
Operating Expenses
Operating expenses increased 13% in 2022 versus the prior year. Adjusted operating expenses increased 11%, or 14% on a currency-neutral basis, versus the prior year, which includes a 4 percentage point increase from acquisitions. The remaining increase was primarily due to higher personnel costs, travel and meeting costs and unfavorable foreign exchange activity.
The components of operating expenses were as follows:
| For the Years Ended December 31, | Increase (Decrease) | |||||||||||||||||||||||||||||||
| 2022 | 2021 | 2020 | 2022 | 2021 | ||||||||||||||||||||||||||||
| ($ in millions) | ||||||||||||||||||||||||||||||||
| General and administrative | $ | 8,078 | $ | 7,087 | $ | 5,910 | 14 | % | 20 | % | ||||||||||||||||||||||
| Advertising and marketing | 789 | 895 | 657 | (12) | % | 36 | % | |||||||||||||||||||||||||
| Depreciation and amortization | 750 | 726 | 580 | 3 | % | 25 | % | |||||||||||||||||||||||||
| Provision for litigation | 356 | 94 | 73 | ** | ** | |||||||||||||||||||||||||||
| Total operating expenses | 9,973 | 8,802 | 7,220 | 13 | % | 22 | % | |||||||||||||||||||||||||
| Special Items 1 | (423) | (176) | (73) | ** | ** | |||||||||||||||||||||||||||
| Adjusted operating expenses (excluding Special Items 1) | $ | 9,549 | $ | 8,627 | $ | 7,147 | 11 | % | 21 | % |
Note: Table may not sum due to rounding.
** Not meaningful
1See “Non-GAAP Financial Information” for further information on our non-GAAP adjustments and the reconciliation to GAAP reported amounts.
MASTERCARD 2022 FORM 10-K 54
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following table summarizes the drivers of changes in operating expenses:
| For the Years Ended December 31, | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Operational | Acquisitions | Currency Impact 1 | Special Items 2 | Total | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| General and administrative | 13% | 11 | % | 4 | % | 6 | % | (3) | % | 2 | % | — | % | 1 | % | 14 | % | 20 | % | |||||||||||||||||||||||||||||||||||||||||||
| Advertising and marketing | (9)% | 35 | % | 1 | % | 1 | % | (4) | % | 1 | % | ** | ** | (12) | % | 36 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Depreciation and amortization | (1)% | 3 | % | 8 | % | 20 | % | (4) | % | 2 | % | ** | ** | 3 | % | 25 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Provision for litigation | ** | ** | ** | ** | ** | ** | ** | ** | ** | ** | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total operating expenses | 10% | 12 | % | 4 | % | 7 | % | (3) | % | 2 | % | 3 | % | 1 | % | 13 | % | 22 | % |
Note: Table may not sum due to rounding.
** Not meaningful
1Represents the translational and transactional impact of currency.
2See “Non-GAAP Financial Information” for further information on our non-GAAP adjustments and the reconciliation to GAAP reported amounts.
General and Administrative
General and administrative expenses increased 14%, or 17% on a currency-neutral basis, in 2022 versus the prior year. Current year results include growth of 4 percentage points from acquisitions. The remaining increase was primarily due to higher personnel costs to support our continued investment in our strategic initiatives across payments, services and new networks, increased travel and meeting costs and balance sheet remeasurement losses due to unfavorable foreign exchange activity.
The components of general and administrative expenses were as follows:
| For the Years Ended December 31, | Increase (Decrease) | |||||||||||||||||||||||||||||||
| 2022 | 2021 | 2020 | 2022 | 2021 | ||||||||||||||||||||||||||||
| ($ in millions) | ||||||||||||||||||||||||||||||||
| Personnel 1 | $ | 5,263 | $ | 4,489 | $ | 3,787 | 17% | 19% | ||||||||||||||||||||||||
| Professional fees | 480 | 433 | 384 | 11% | 13% | |||||||||||||||||||||||||||
| Data processing and telecommunications | 926 | 898 | 756 | 3% | 19% | |||||||||||||||||||||||||||
| Foreign exchange activity 2 | 102 | 51 | 9 | ** | ** | |||||||||||||||||||||||||||
| Other 1, 3 | 1,307 | 1,216 | 974 | 7% | 25% | |||||||||||||||||||||||||||
| Total general and administrative expenses | $ | 8,078 | $ | 7,087 | $ | 5,910 | 14% | 20% | ||||||||||||||||||||||||
Note: Table may not sum due to rounding.
** Not meaningful
1For the year ended December 31, 2022, total general and administrative expenses includes a Special Item for Russia-related impacts of $67 million, of which $35 million is included within Personnel and $32 million is included within Other. See “Non-GAAP Financial Information” for further information on our non-GAAP adjustments and the reconciliation to GAAP reported amounts.
2 Foreign exchange activity includes the impact of remeasurement of assets and liabilities denominated in foreign currencies net of the impact of gains and losses on foreign exchange derivative contracts. See Note 23 (Derivative and Hedging Instruments) to the consolidated financial statements included in Part II, Item 8 for further discussion.
3 Includes a Special Item related to a foreign indirect tax matter of $82 million for the year ended December 31, 2021. See “Non-GAAP Financial Information” for further information on our non-GAAP adjustments and the reconciliation to GAAP reported amounts.
Advertising and Marketing
Advertising and marketing expenses decreased 12%, or 8% on a currency-neutral basis, in 2022 versus the prior year, primarily due to lower spending on marketing campaigns.
Depreciation and Amortization
Depreciation and amortization expenses increased 3%, or 7% on a currency-neutral basis, in 2022 versus the prior year, due to the amortization of acquired intangible assets from acquisitions.
55 MASTERCARD 2022 FORM 10-K
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Provision for Litigation
In 2022, 2021 and 2020, we recorded $356 million, $94 million and $73 million, respectively, related to various legal proceedings. See “Non-GAAP Financial Information” in this section and Note 21 (Legal and Regulatory Proceedings) to the consolidated financial statements included in Part II, Item 8 for further discussion.
Other Income (Expense)
Other income (expense) was unfavorable $757 million in 2022 versus the prior year, primarily due to net losses in the current year versus net gains in the prior year related to unrealized fair market value adjustments on marketable and nonmarketable equity securities and realized gains on sales of marketable equity securities in 2021. Adjusted other income (expense) was favorable $26 million versus the prior year, primarily due to an increase in our investment income, partially offset by increased interest expense related to our 2022 debt issuances.
The components of other income (expense) were as follows:
| For the Years Ended December 31, | Increase (Decrease) | |||||||||||||||||||||||||||||||
| 2022 | 2021 | 2020 | 2022 | 2021 | ||||||||||||||||||||||||||||
| ($ in millions) | ||||||||||||||||||||||||||||||||
| Investment income | $ | 61 | $ | 11 | $ | 24 | ** | (52) | % | |||||||||||||||||||||||
| Gains (losses) on equity investments, net | (145) | 645 | 30 | ** | ** | |||||||||||||||||||||||||||
| Interest expense | (471) | (431) | (380) | 9 | % | 13 | % | |||||||||||||||||||||||||
| Other income (expense), net | 23 | — | 5 | ** | ** | |||||||||||||||||||||||||||
| Total other income (expense) | (532) | 225 | (321) | ** | ** | |||||||||||||||||||||||||||
| (Gains) losses on equity investments 1 | 145 | (645) | (30) | ** | ** | |||||||||||||||||||||||||||
| Special Items 1 | — | 6 | — | ** | ** | |||||||||||||||||||||||||||
| Adjusted total other income (expense) 1 | $ | (387) | $ | (413) | $ | (351) | (6) | % | 18 | % |
Note: Table may not sum due to rounding.
** Not meaningful
1 See “Non-GAAP Financial Information” for further information on our non-GAAP adjustments and the reconciliation to GAAP reported amounts.
Income Taxes
The effective income tax rates for the years ended December 31, 2022 and 2021 were 15.4% and 15.7%, respectively. The adjusted effective income tax rates for the years ended December 31, 2022 and 2021 were 15.7% and 15.4%, respectively. The effective income tax rate was lower in 2022 primarily due to a discrete tax benefit in the first quarter of 2022 related to final U.S. tax regulations published in the current year. These regulations resulted in a valuation allowance release of $333 million associated with the U.S. foreign tax credit carryforward deferred tax asset. The regulations limit Mastercard’s ability to generate foreign tax credits starting in 2022 for certain foreign taxes paid, resulting in additional U.S. tax expense. Additionally, a more favorable geographic mix of earnings in 2022 contributed to the lower effective tax rate. The lower effective income tax rate was partially offset by:
-
the recognition of U.S. tax benefits in 2021 (the majority of which were discrete) resulting from a higher foreign derived intangible income deduction and greater utilization of foreign tax credits in the U.S.
-
a discrete tax benefit in 2021 related to the remeasurement of the our net deferred tax asset in the U.K. due to an enacted tax rate change in 2021
-
a discrete tax expense related to an unfavorable court ruling in 2022
The adjusted effective income tax rate was higher in 2022 primarily due to:
-
the recognition of U.S. tax benefits in 2021 (the majority of which were discrete) resulting from a higher foreign derived intangible income deduction and greater utilization of foreign tax credits in the U.S.
-
a discrete tax benefit in 2021 related to the remeasurement of the our net deferred tax asset in the U.K. due to an enacted tax rate change in 2021
-
a discrete tax expense related to an unfavorable court ruling in 2022
MASTERCARD 2022 FORM 10-K 56
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
All of the above impacts were partially offset by a discrete tax benefit in the first quarter of 2022 related to final U.S. tax regulations published in the current year. These regulations resulted in a valuation allowance release of $333 million associated with the U.S. foreign tax credit carryforward deferred tax asset. The regulations limit Mastercard’s ability to generate foreign tax credits starting in 2022 for certain foreign taxes paid, resulting in additional U.S. tax expense.
See Note 20 (Income Taxes) to the consolidated financial statements included in Part II, Item 8 for further discussion.
In August 2022, the U.S. enacted the Inflation Reduction Act (the “IRA”). The IRA includes a corporate alternative minimum tax of 15% on the adjusted financial statement income of corporations for years beginning after December 31, 2022, and an excise tax of 1% on the fair market value of annual net stock repurchases made after December 31, 2022. We continue to analyze the impacts of the IRA, however, it is not expected to have a material impact on our financial statements.
Liquidity and Capital Resources
We rely on existing liquidity, cash generated from operations and access to capital to fund our global operations, credit and settlement exposure, capital expenditures, investments in our business and current and potential obligations. The following table summarizes the cash, cash equivalents, investments and credit available to us at December 31:
| 2022 | 2021 | |||||||||||||
| (in billions) | ||||||||||||||
| Cash, cash equivalents and investments 1 | $ | 7.4 | $ | 7.9 | ||||||||||
| Unused line of credit | 8.0 | 6.0 |
1Investments include available-for-sale securities and held-to-maturity securities. This amount excludes restricted cash and restricted cash equivalents of $2.2 billion and $2.5 billion at December 31, 2022 and 2021, respectively.
We believe that our existing cash, cash equivalents and investment securities balances, our cash flow generating capabilities, and our access to capital resources are sufficient to satisfy our future operating cash needs, capital asset purchases, outstanding commitments and other liquidity requirements associated with our existing operations and potential obligations which include litigation provisions and credit and settlement exposure.
Our liquidity and access to capital could be negatively impacted by global credit market conditions. We guarantee the settlement of many of the transactions between our customers. Historically, payments under these guarantees have not been significant; however, historical trends may not be an indication of potential future losses. The risk of loss on these guarantees is specific to individual customers, but may also be driven by regional or global economic conditions, including, but not limited to the health of the financial institutions in a country or region. See Note 22 (Settlement and Other Risk Management) to the consolidated financial statements in Part II, Item 8 for a description of these guarantees.
Our liquidity and access to capital could also be negatively impacted by the outcome of any of the legal or regulatory proceedings to which we are a party. For additional discussion of these and other risks facing our business, see Part I, Item 1A - Risk Factors - Legal and Regulatory Risks and Note 21 (Legal and Regulatory Proceedings) to the consolidated financial statements included in Part II, Item 8.
Cash Flow
The table below shows a summary of the cash flows from operating, investing and financing activities:
| For the Years Ended December 31, | ||||||||||||||||||||
| 2022 | 2021 | 2020 | ||||||||||||||||||
| (in millions) | ||||||||||||||||||||
| Net cash provided by operating activities | $ | 11,195 | $ | 9,463 | $ | 7,224 | ||||||||||||||
| Net cash used in investing activities | (1,470) | (5,272) | (1,879) | |||||||||||||||||
| Net cash used in financing activities | (10,328) | (6,555) | (2,152) |
Net cash provided by operating activities increased $1.7 billion in 2022 versus the prior year, primarily due to higher net income adjusted for non-cash items and timing of settlement with customers.
Net cash used in investing activities decreased $3.8 billion in 2022 versus the prior year, primarily due to lower business acquisition activity in the current year.
57 MASTERCARD 2022 FORM 10-K
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Net cash used in financing activities increased $3.8 billion in 2022 versus the prior year, primarily due to higher repurchases of our Class A common stock in the current year.
Debt and Credit Availability
In February 2022, we issued €750 million ($800 million as of December 31, 2022) principal amount of notes due February 2029 (the “2022 EUR Notes”). In July 2022, we entered into an unsecured INR22.7 billion ($275 million as of December 31, 2022) term loan due July 2023 (the “INR Term Loan”). During 2022, €700 million ($724 million as of the maturity date) of principal related to the 2015 Euro Notes matured and was paid. Our total debt outstanding was $14.0 billion at December 31, 2022, with the earliest maturity of INR22.7 billion ($275 million as of December 31, 2022) of principal occurring in July 2023.
As of December 31, 2022, we have a commercial paper program (the “Commercial Paper Program”), under which we are authorized to issue up to $6 billion in outstanding notes, with maturities up to 397 days from the date of issuance. On January 27, 2023, we increased our Commercial Paper Program from $6 billion to $8 billion. In conjunction with the Commercial Paper Program, we have a committed unsecured $8 billion revolving credit facility (the “Credit Facility”) which now expires in November 2027.
Borrowings under the Commercial Paper Program and the Credit Facility are to be used to provide liquidity for general corporate purposes, including providing liquidity in the event of one or more settlement failures by our customers. In addition, we may borrow and repay amounts under these facilities for business continuity purposes. We had no borrowings outstanding under the Commercial Paper Program or the Credit Facility at December 31, 2022.
See Note 15 (Debt) to the consolidated financial statements included in Part II, Item 8 for further discussion on our debt, the Commercial Paper Program and the Credit Facility.
Dividends and Share Repurchases
We have historically paid quarterly dividends on our outstanding Class A common stock and Class B common stock. Subject to legally available funds, we intend to continue to pay a quarterly cash dividend. The declaration and payment of future dividends is at the sole discretion of our Board of Directors after taking into account various factors, including our financial condition, operating results, available cash and current and anticipated cash needs.
The following table summarizes the annual, per share dividends paid in the years reflected:
| For the Years Ended December 31, | ||||||||||||||||||||
| 2022 | 2021 | 2020 | ||||||||||||||||||
| (in millions, except per share data) | ||||||||||||||||||||
| Cash dividend, per share | $ | 1.96 | $ | 1.76 | $ | 1.60 | ||||||||||||||
| Cash dividends paid | $ | 1,903 | $ | 1,741 | $ | 1,605 |
On December 6, 2022, our Board of Directors declared a quarterly cash dividend of $0.57 per share paid on February 9, 2023 to holders of record on January 9, 2023 of our Class A common stock and Class B common stock. The aggregate amount of this dividend was $545 million.
On February 14, 2023, our Board of Directors declared a quarterly cash dividend of $0.57 per share payable on May 9, 2023 to holders of record on April 7, 2023 of our Class A common stock and Class B common stock. The aggregate amount of this dividend is estimated to be $543 million.
MASTERCARD 2022 FORM 10-K 58
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Repurchased shares of our common stock are considered treasury stock. In December 2022, November 2021 and December 2020, our Board of Directors approved share repurchase programs of our Class A common stock authorizing us to repurchase up to $9.0 billion, $8.0 billion and $6.0 billion, respectively. The program approved in 2022 will become effective after completion of the share repurchase program approved in 2021. The timing and actual number of additional shares repurchased will depend on a variety of factors, including cash requirements to meet the operating needs of the business, legal requirements, as well as the share price and economic and market conditions. The following table summarizes our share repurchase authorizations and repurchase activity of our Class A common stock through December 31, 2022:
| (in millions, except per share data) | ||||||||
| Remaining authorization at December 31, 2021 | $ | 11,927 | ||||||
| Dollar-value of shares repurchased in 2022 | $ | 8,753 | ||||||
| Remaining authorization at December 31, 2022 | $ | 12,174 | ||||||
| Shares repurchased in 2022 | 25.7 | |||||||
| Average price paid per share in 2022 | $ | 340.60 | ||||||
See Note 16 (Stockholders' Equity) to the consolidated financial statements included in Part II, Item 8 for further discussion.
Critical Accounting Estimates
The application of GAAP requires us to make estimates and assumptions about certain items and future events that directly affect our reported financial condition. Our significant accounting policies, including recent accounting pronouncements, are described in Note 1 (Summary of Significant Accounting Policies) to the consolidated financial statements included in Part II, Item 8.
Revenue Recognition - Rebates and Incentives
We enter into business agreements with certain customers that provide for rebates and incentives when customers meet certain volume thresholds or other incentives tied to customer performance. We consider various factors in estimating customer performance, including forecasted transactions, card issuance and card conversion volumes, expected payments and historical experience with that customer. Rebates and incentives are recorded within net revenue based on these estimates primarily when volume- and transaction- based revenues are recognized over the contractual term. Differences between actual results and our estimates are adjusted in the period the customer reports actual performance. If our customers’ actual performance is not consistent with our estimates of their performance, net revenue may be materially different.
Loss Contingencies
We are currently involved in various claims and legal proceedings. We regularly review the status of each significant matter and assess its potential financial exposure. If the potential loss from any claim or legal proceeding is considered probable and the amount can be reasonably estimated, we accrue a liability for the estimated loss. Significant judgment is required in both the determination of probability and whether an exposure is reasonably estimable. Our judgments are subjective based on the status of the legal or regulatory proceedings, the merits of our defenses and consultation with in-house and outside legal counsel. Because of uncertainties related to these matters, accruals are based only on the best information available at the time. As additional information becomes available, we reassess the potential liability related to pending claims and litigation and may revise our estimates. Due to the inherent uncertainties of the legal and regulatory process in the multiple jurisdictions in which we operate, our judgments may be materially different than the actual outcomes.
Income Taxes
In calculating our effective income tax rate, estimates are required regarding the timing and amount of taxable and deductible items which will adjust the pretax income earned in various tax jurisdictions. Through our interpretation of local tax regulations, adjustments to pretax income for income earned in various tax jurisdictions are reflected within various tax filings. Although we believe that our estimates and judgments discussed herein are reasonable, actual results may be materially different than the estimated amounts.
We record a valuation allowance to reduce our deferred tax assets to the amount that is more likely than not to be realized. Significant judgment is required in determining the valuation allowance. In assessing the need for a valuation allowance, we consider all sources of taxable income, including projected future taxable income, reversing taxable temporary differences and ongoing tax planning strategies. If it is determined that we are able to realize deferred tax assets in excess of the net carrying value
59 MASTERCARD 2022 FORM 10-K
PART II
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
or to the extent we are unable to realize a deferred tax asset, we would adjust the valuation allowance in the period in which such a determination is made, with a corresponding increase or decrease to earnings.
We record tax liabilities for uncertain tax positions taken, or expected to be taken, which may not be sustained or may only be partially sustained, upon examination by the relevant taxing authorities. We consider all relevant facts and current authorities in the tax law in assessing whether any benefit resulting from an uncertain tax position is more likely than not to be sustained and, if so, how current law impacts the amount reflected within these financial statements. If upon examination, we realize a tax benefit which is not fully sustained or is more favorably sustained, this would generally increase earnings in the period. In certain situations, we will have offsetting tax credits or taxes in other jurisdictions.
Deferred taxes are established on the estimated foreign exchange gains or losses for foreign earnings that are not considered permanently reinvested, which will be recognized through cumulative translation adjustments as incurred. Ultimately, the working capital requirements of foreign affiliates will determine the amount of cash to be remitted from respective jurisdictions.
Business Combinations
We account for our business combinations using the acquisition method of accounting. The acquisition purchase price, including contingent consideration, if any, is allocated to the underlying identified, tangible and intangible assets, liabilities assumed and any non-controlling interest in the acquiree, based on their respective estimated fair values on the acquisition date. Any excess of purchase price over the fair value of net assets acquired, including identifiable intangible assets, is recorded as goodwill. The amounts and useful lives assigned to acquisition-related tangible and intangible assets impact the amount and timing of future amortization expense. We use various valuation techniques to determine fair value, primarily discounted cash flows analysis, relief-from-royalty and multi-period excess earnings for estimating the value of intangible assets. These valuation techniques include comparable company multiples, discount rates, growth projections and other assumptions of future business conditions. Determining the fair value of assets acquired, liabilities assumed, any non-controlling interest in the acquiree and the expected useful lives, requires management’s judgment. The significance of management’s estimates and assumptions is relative to the size of the acquisition. Our estimates are based upon assumptions believed to be reasonable, but which are inherently uncertain and unpredictable.
Item 7A. Quantitative and qualitative disclosures about market risk
Market risk is the potential for economic losses to be incurred on market risk sensitive instruments arising from adverse changes in factors such as interest rates and foreign currency exchange rates. Our exposure to market risk from changes in interest rates and foreign exchange rates is limited. Management monitors risk exposures on an ongoing basis and establishes and oversees the implementation of policies governing our funding, investments and use of derivative financial instruments to manage these risks.
Foreign currency and interest rate exposures are managed through our risk management activities, which are discussed further in Note 23 (Derivative and Hedging Instruments) to the consolidated financial statements included in Part II, Item 8.
Foreign Exchange Risk
We enter into foreign exchange derivative contracts to manage currency exposure associated with anticipated receipts and disbursements occurring in a currency other than the functional currency of the entity. We may also enter into foreign currency derivative contracts to offset possible changes in value of assets and liabilities due to foreign exchange fluctuations. The objective of these activities is to reduce our exposure to transaction gains and losses resulting from fluctuations of foreign currencies against our functional currencies, principally the U.S. dollar and euro. The effect of a hypothetical 10% adverse change in the value of the functional currencies could result in a fair value loss of approximately $94 million and $70 million on our foreign exchange derivative contracts outstanding at December 31, 2022 and 2021, respectively, before considering the offsetting effect of the underlying hedged activity.
We are also subject to foreign exchange risk as part of our daily settlement activities. To manage this risk, we enter into short duration foreign exchange contracts based upon anticipated receipts and disbursements for the respective currency position. This risk is typically limited to a few days between when a payment transaction takes place and the subsequent settlement with our customers. The effect of a hypothetical 10% adverse change in the value of the functional currencies would not have a material impact to the fair value of our short duration foreign exchange derivative contracts outstanding at December 31, 2022 and 2021, respectively.
MASTERCARD 2022 FORM 10-K 60
PART II
ITEM 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
We are further exposed to foreign exchange rate risk related to translation of our net investment in foreign subsidiaries where the functional currency is different than our U.S. dollar reporting currency. To manage this risk, we may enter into foreign exchange derivative contracts to hedge a portion of our net investment in foreign subsidiaries. The effect of a hypothetical 10% adverse change in the value of the U.S. dollar could result in a fair value loss of approximately $203 million and $165 million on our foreign exchange derivative contracts designated as a net investment hedge at December 31, 2022 and 2021, respectively, before considering the offsetting effect of the underlying hedged activity.
Interest Rate Risk
Our available-for-sale debt investments include fixed and variable rate securities that are sensitive to interest rate fluctuations. Our policy is to invest in high quality securities, while providing adequate liquidity and maintaining diversification to avoid significant exposure. A hypothetical 100 basis point adverse change in interest rates would not have a material impact to the fair value of our investments at December 31, 2022 and 2021.
We are also exposed to interest rate risk related to our fixed-rate debt. To manage this risk, we may enter into interest rate derivative contracts to hedge a portion of our fixed-rate debt that is exposed to changes in fair value attributable to changes in a benchmark interest rate. The effect of a hypothetical 100 basis point adverse change in interest rates could result in a fair value loss of approximately $36 million and $49 million on our interest rate derivative contracts designated as a fair value hedge of our fixed-rate debt at December 31, 2022 and 2021, respectively, before considering the offsetting effect of the underlying hedged activity.
61 MASTERCARD 2022 FORM 10-K
PART II
ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
Item 8. Financial statements and supplementary data
Mastercard Incorporated
Index to consolidated financial statements
| Page | |||||||||||
| As of December 31, 2022 and 2021 and for the years ended December 31, 2022, 2021 and 2020 | |||||||||||
| Management’s report on internal control over financial reporting | 63 | ||||||||||
| Report of independent registered public accounting firm (PCAOB ID 238) | 64 | ||||||||||
| Consolidated Statement of Operations | 66 | ||||||||||
| Consolidated Statement of Comprehensive Income | 67 | ||||||||||
| Consolidated Balance Sheet | 68 | ||||||||||
| Consolidated Statement of Changes in Equity | 69 | ||||||||||
| Consolidated Statement of Cash Flows | 71 | ||||||||||
| Notes to consolidated financial statements | 72 |
MASTERCARD 2022 FORM 10-K 62
PART II
ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
Management’s report on internal control over financial reporting
The management of Mastercard Incorporated (“Mastercard”) is responsible for establishing and maintaining adequate internal control over financial reporting. Internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external reporting purposes in accordance with accounting principles generally accepted in the United States of America. Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. As required by Section 404 of the Sarbanes-Oxley Act of 2002, management has assessed the effectiveness of Mastercard’s internal control over financial reporting as of December 31, 2022. In making its assessment, management has utilized the criteria set forth in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). Management has concluded that, based on its assessment, Mastercard’s internal control over financial reporting was effective as of December 31, 2022. The effectiveness of Mastercard’s internal control over financial reporting as of December 31, 2022 has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report which appears on the next page.
63 MASTERCARD 2022 FORM 10-K
PART II
ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Stockholders of Mastercard Incorporated
*Opinions on the Financial Statements and Inter
Showing the first 8K of 121K characters. Open the full section
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA - NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
Financial Instruments - Recurring Measurements
The distribution of the Company’s financial instruments measured at fair value on a recurring basis within the Valuation Hierarchy were as follows:
| December 31, 2022 | December 31, 2021 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Quoted Prices in Active Markets (Level 1) | Significant Other Observable Inputs (Level 2) | Significant Unobservable Inputs (Level 3) | Total | Quoted Prices in Active Markets (Level 1) | Significant Other Observable Inputs (Level 2) | Significant Unobservable Inputs (Level 3) | Total | |||||||||||||||||||||||||||||||||||||||||||
| (in millions) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Investment securities available-for-sale 1**:** | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Municipal securities | $ | — | $ | — | $ | — | $ | — | $ | — | $ | 2 | $ | — | $ | 2 | ||||||||||||||||||||||||||||||||||
| Government and agency securities | 35 | 54 | — | 89 | 35 | 63 | — | 98 | ||||||||||||||||||||||||||||||||||||||||||
| Corporate securities | — | 183 | — | 183 | — | 214 | — | 214 | ||||||||||||||||||||||||||||||||||||||||||
| Derivative instruments 2**:** | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Foreign exchange contracts | — | 108 | — | 108 | — | 8 | — | 8 | ||||||||||||||||||||||||||||||||||||||||||
| Interest rate contracts | — | — | — | — | — | 6 | — | 6 | ||||||||||||||||||||||||||||||||||||||||||
| Marketable securities 3**:** | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity securities | 399 | — | — | 399 | 627 | — | — | 627 | ||||||||||||||||||||||||||||||||||||||||||
| Deferred compensation plan 4**:** | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Deferred compensation assets | 74 | — | — | 74 | 89 | — | — | 89 | ||||||||||||||||||||||||||||||||||||||||||
| Liabilities | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Derivative instruments 2**:** | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Foreign exchange contracts | $ | — | $ | 21 | $ | — | $ | 21 | $ | — | $ | 15 | $ | — | $ | 15 | ||||||||||||||||||||||||||||||||||
| Interest rate contracts | — | 105 | — | 105 | — | 8 | — | 8 | ||||||||||||||||||||||||||||||||||||||||||
| Deferred compensation plan 5**:** | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Deferred compensation liabilities | 73 | — | — | 73 | 89 | — | — | 89 |
1The Company’s U.S. government securities are classified within Level 1 of the Valuation Hierarchy as the fair values are based on unadjusted quoted prices for identical assets in active markets. The fair value of the Company’s available-for-sale municipal securities, non-U.S. government and agency securities and corporate securities are based on observable inputs such as quoted prices, benchmark yields and issuer spreads for similar assets in active markets and are therefore included in Level 2 of the Valuation Hierarchy.
2The Company’s foreign exchange and interest rate derivative asset and liability contracts have been classified within Level 2 of the Valuation Hierarchy as the fair value is based on observable inputs such as broker quotes for similar derivative instruments. See Note 23 (Derivative and Hedging Instruments) for further details.
3The Company’s Marketable securities are publicly held and classified within Level 1 of the Valuation Hierarchy as the fair values are based on unadjusted quoted prices in their respective active markets.
4The Company has a nonqualified deferred compensation plan where assets are invested primarily in mutual funds held in a rabbi trust, which is restricted for payments to participants of the plan. The Company has elected to use the fair value option for these mutual funds, which are measured using quoted prices of identical instruments in active markets and are included in prepaid expenses and other current assets on the consolidated balance sheet.
5The deferred compensation liabilities are measured at fair value based on the quoted prices of identical instruments to the investment vehicles selected by the participants. These are included in other liabilities on the consolidated balance sheet.
85 MASTERCARD 2022 FORM 10-K
PART II
ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA - NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
Financial Instruments - Nonrecurring Measurements
Nonmarketable Securities
The Company’s Nonmarketable securities are recorded at fair value on a nonrecurring basis in periods after initial recognition under the equity method or measurement alternative method. Nonmarketable securities are classified within Level 3 of the Valuation Hierarchy due to the absence of quoted market prices, the inherent lack of liquidity and unobservable inputs used to measure fair value that require management’s judgment. The Company uses discounted cash flows and market assumptions to estimate the fair value of its Nonmarketable securities when certain events or circumstances indicate that imp
Showing the first 8K of 143K characters. Open the full section
Item 9. Changes in and disagreements with accountants on accounting and financial disclosure
Not applicable.
Item 9A. Controls and procedures
Evaluation of Disclosure Controls and Procedures
Our disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934, as amended (the “Exchange Act”)) are designed to ensure that information required to be disclosed in the reports that we file or submit under the Exchange Act is recorded, processed, summarized and reported within the time periods specified in the rules and forms of the Securities and Exchange Commission and to ensure that information required to be disclosed is accumulated and communicated to management, including our President and Chief Executive Officer and our Chief Financial Officer, to allow timely decisions regarding disclosure. The President and Chief Executive Officer and the Chief Financial Officer, with assistance from other members of management, have reviewed the effectiveness of our disclosure controls and procedures as of December 31, 2022 and, based on their evaluation, have concluded that the disclosure controls and procedures were effective as of such date.
Internal Control over Financial Reporting
In addition, Mastercard Incorporated’s management assessed the effectiveness of Mastercard’s internal control over financial reporting as of December 31, 2022. Management’s report on internal control over financial reporting is included in Part II, Item 8. PricewaterhouseCoopers LLP, an independent registered public accounting firm, has audited the consolidated financial statements included in this Annual Report on Form 10-K and, as part of their audit, has issued their report, included herein, on the effectiveness of our internal control over financial reporting.
Changes in Internal Control over Financial Reporting
There was no change in Mastercard’s internal control over financial reporting that occurred during the three months ended December 31, 2022 that has materially affected, or is reasonably likely to materially affect, Mastercard’s internal control over financial reporting.
Item 9B. Other information
Pursuant to Section 219 of the Iran Threat Reduction and Syria Human Rights Act of 2012, we hereby incorporate by reference herein the disclosure contained in Exhibit 99.1 of this Report.
113 MASTERCARD 2022 FORM 10-K
PART III
ITEM 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
Item 10. Directors, executive officers and corporate governance
Information regarding our executive officers is included in section “Information about our executive officers” in Part I of this Report. Additional information required by this Item with respect to our directors and executive officers, code of ethics, procedures for recommending nominees, audit committee, audit committee financial experts and compliance with Section 16(a) of the Exchange Act will appear in our definitive proxy statement to be filed with the SEC and delivered to stockholders in connection with our 2023 annual meeting of stockholders (the “Proxy Statement”).
The aforementioned information in the Proxy Statement is incorporated by reference into this Report.
Item 11. Executive compensation
The information required by this Item with respect to executive officer and director compensation will appear in the Proxy Statement and is incorporated by reference into this Report.
Item 12. Security ownership of certain beneficial owners and management and related stockholder matters
The information required by this Item with respect to security ownership of certain beneficial owners and management equity and compensation plans will appear in the Proxy Statement and is incorporated by reference into this Report.
Item 13. Certain relationships and related transactions, and director independence
The information required by this Item with respect to transactions with related persons, the review, approval or ratification of such transactions and director independence will appear in the Proxy Statement and is incorporated by reference into this Report.
Item 14. Principal accountant fees and services
The information required by this Item with respect to auditors’ services and fees will appear in the Proxy Statement and is incorporated by reference into this Report.
115 MASTERCARD 2022 FORM 10-K
| PART IV | |||||||||||||||||
| Item 15. Exhibits and financial statement schedules | |||||||||||||||||
| Item 16. Form 10-K summary | |||||||||||||||||
PART IV
ITEM 15. EXHIBITS AND FINANCIAL STATEMENTS
Item 15. Exhibits and financial statement schedules
(a)The following documents are filed as part of this Report:
1Consolidated Financial Statements
See Index to Consolidated Financial Statements in Part II, Item 8.
2Consolidated Financial Statement Schedules
None.
3The following exhibits are filed as part of this Report or, where indicated, were previously filed and are hereby incorporated by reference:
Refer to the Exhibit Index included herein.
Item 16. Form 10-K summary
None.
117 MASTERCARD 2022 FORM 10-K
Exhibit index
+ Management contracts or compensatory plans or arrangements.
- Filed or furnished herewith.
** Exhibit omits certain information that has been filed separately with the U.S. Securities and Exchange Commission and has been granted confidential treatment.
The agreements and other documents filed as exhibits to this report are not intended to provide factual information or other disclosure other than with respect to the terms of the agreements or other documents themselves, and should not be relied upon for that purpose. In particular, any representations and warranties made by the Company in these agreements or other documents were made solely within the specific context of the relevant agreement or document and may not describe the actual state of affairs as of the date they were made or at any other time.
MASTERCARD 2022 FORM 10-K 118
Signatures
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this Annual Report on Form 10-K to be signed on its behalf by the undersigned, thereunto duly authorized.
| MASTERCARD INCORPORATED | ||||||||||||||
| (Registrant) | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ MICHAEL MIEBACH | |||||||||||
| Michael Miebach | ||||||||||||||
| President and Chief Executive Officer | ||||||||||||||
| (Principal Executive Officer) |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated:
| Date: | February 14, 2023 | By: | /s/ MICHAEL MIEBACH | |||||||||||
| Michael Miebach | ||||||||||||||
| President and Chief Executive Officer; Director | ||||||||||||||
| (Principal Executive Officer) | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ SACHIN MEHRA | |||||||||||
| Sachin Mehra | ||||||||||||||
| Chief Financial Officer | ||||||||||||||
| (Principal Financial Officer) | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ SANDRA ARKELL | |||||||||||
| Sandra Arkell | ||||||||||||||
| Corporate Controller | ||||||||||||||
| (Principal Accounting Officer) | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ CANDIDO BRACHER | |||||||||||
| Candido Bracher | ||||||||||||||
| Director | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ RICHARD K. DAVIS | |||||||||||
| Richard K. Davis | ||||||||||||||
| Director | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ JULIUS GENACHOWSKI | |||||||||||
| Julius Genachowski | ||||||||||||||
| Director | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ CHOON PHONG GOH | |||||||||||
| Choon Phong Goh | ||||||||||||||
| Director | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ MERIT E. JANOW | |||||||||||
| Merit E. Janow | ||||||||||||||
| Chairman of the Board; Director | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ OKI MATSUMOTO | |||||||||||
| Oki Matsumoto | ||||||||||||||
| Director | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ YOUNGME MOON | |||||||||||
| Youngme Moon | ||||||||||||||
| Director | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ RIMA QURESHI | |||||||||||
| Rima Qureshi | ||||||||||||||
| Director | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ GABRIELLE SULZBERGER | |||||||||||
| Gabrielle Sulzberger | ||||||||||||||
| Director | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ JACKSON TAI | |||||||||||
| Jackson Tai | ||||||||||||||
| Director | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ HARIT TALWAR | |||||||||||
| Harit Talwar | ||||||||||||||
| Director | ||||||||||||||
| Date: | February 14, 2023 | By: | /s/ LANCE UGGLA | |||||||||||
| Lance Uggla | ||||||||||||||
| Director | ||||||||||||||
MASTERCARD 2022 FORM 10-K 119