 filings.tools
Mid-America Apartment Communities 10-K 2018-12-31
Filed 2019-02-21. 22 sections, 507K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 maa12312018-10k.htm 10-K
| UNITED STATES | |||||
| SECURITIES AND EXCHANGE COMMISSION | |||||
| Washington, D.C. 20549 | |||||
| FORM 10-K | |||||
| (Mark One) | |||||
| ý | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 For the fiscal year ended December 31, 2018 | ||||
| OR | |||||
| o | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 For the transition period from __________ to ___________ | ||||
| Commission File Number 001-12762 (Mid-America Apartment Communities, Inc.) | |||||
| Commission File Number 333-190028-01 (Mid-America Apartments, L.P.) | |||||
| MID-AMERICA APARTMENT COMMUNITIES, INC. | |||||
| MID-AMERICA APARTMENTS, L.P. | |||||
| (Exact name of registrant as specified in its charter) | |||||
| Tennessee (Mid-America Apartment Communities, Inc.) | 62-1543819 | ||||
| Tennessee (Mid-America Apartments, L.P.) | 62-1543816 | ||||
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | ||||
| 6815 Poplar Avenue, Suite 500, Germantown, Tennessee, 38138 | |||||
| (Address of principal executive offices) (Zip Code) | |||||
| Registrant's telephone number, including area code: (901) 682-6600 | |||||
| Securities registered pursuant to Section 12(b) of the Act: | |||||
| Title of each class | Name of each exchange on which registered | ||||
| Common Stock, par value $.01 per share (Mid-America Apartment Communities, Inc.) | New York Stock Exchange | ||||
| 8.50% Series I Cumulative Redeemable Preferred Stock, $.01 par value per share (Mid-America Apartment Communities, Inc.) | New York Stock Exchange |
| Securities registered pursuant to Section 12(g) of the Act: None. | |||
| Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. | |||
| Mid-America Apartment Communities, Inc. | Yes ý | No o | |
| Mid-America Apartments, L.P. | Yes o | No ý | |
| Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. | |||
| Mid-America Apartment Communities, Inc. | Yes o | No ý | |
| Mid-America Apartments, L.P. | Yes o | No ý | |
| Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding | |||
| 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. | |||
| Mid-America Apartment Communities, Inc. | Yes ý | No o | |
| Mid-America Apartments, L.P. | Yes ý | No o | |
| Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) | |||
| during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). | |||
| Mid-America Apartment Communities, Inc. | Yes ý | No o | |
| Mid-America Apartments, L.P. | Yes ý | No o | |
| Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§229.405 of this chapter) is not contained herein, and will not be contained, to the best of | |||
| registrant's knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. o | |||
| Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the | |||
| definitions of "large accelerated filer," "accelerated filer," "smaller reporting company," and "emerging growth company" in Rule 12b-2 of the Exchange Act. |
| Mid-America Apartment Communities, Inc. | ||||
| Large accelerated filer ý | Accelerated filer o | Non-accelerated filer o | Smaller reporting company o | Emerging growth company o |
| Mid-America Apartments, L.P. | ||||
| Large accelerated filer o | Accelerated filer o | Non-accelerated filer ý | Smaller reporting company o | Emerging growth company o |
| If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. o |
| Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). | |||
| Mid-America Apartment Communities, Inc. | Yes o | No ý | |
| Mid-America Apartments, L.P. | Yes o | No ý |
The aggregate market value of the 80,246,503 shares of common stock of Mid-America Apartment Communities, Inc. held by non-affiliates was approximately $8.1 billion based on the closing price of $100.67 as reported on the New York Stock Exchange on June 29, 2018. This calculation excludes shares of common stock held by the registrant's officers and directors and each person known by the registrant to beneficially own more than 5% of the registrant's outstanding shares, as such persons may be deemed to be affiliates. This determination of affiliate status should not be deemed conclusive for any other purpose. As of February 18, 2019 there were 113,888,340 shares of Mid-America Apartment Communities, Inc. common stock outstanding.
There is no public trading market for the partnership units of Mid-America Apartments, L.P. As a result, an aggregate market value of the partnership units of Mid-America Apartments, L.P. cannot be determined.
Documents Incorporated by Reference
Portions of the proxy statement for the annual shareholders meeting of Mid-America Apartment Communities, Inc. to be held on May 21, 2019 are incorporated by reference into Part III of this report. We expect to file our proxy statement within 120 days after December 31, 2018.
Explanatory Note
This report combines the Annual Reports on Form 10-K for the year ended December 31, 2018 of Mid-America Apartment Communities, Inc., a Tennessee corporation, and Mid-America Apartments, L.P., a Tennessee limited partnership, of which Mid-America Apartment Communities, Inc. is the sole general partner. Mid-America Apartment Communities, Inc. and its 96.5% owned subsidiary, Mid-America Apartments, L.P., are both required to file annual reports under the Securities Exchange Act of 1934, as amended.
Unless the context otherwise requires, all references in this Annual Report on Form 10-K to "MAA" refer only to Mid-America Apartment Communities, Inc., and not any of its consolidated subsidiaries. Unless the context otherwise requires, all references in this report to "we," "us," "our," or the "Company" refer collectively to Mid-America Apartment Communities, Inc., together with its consolidated subsidiaries, including Mid-America Apartments, L.P. Unless the context otherwise requires, all references in this report to the "Operating Partnership" or "MAALP" refer to Mid-America Apartments, L.P. together with its consolidated subsidiaries. "Common stock" refers to the common stock of MAA, "preferred stock" refers to the preferred stock of MAA, and "shareholders" refers to the holders of shares of MAA’s common stock or preferred stock, as applicable. The common units of limited partnership interest in the Operating Partnership are referred to as "OP Units" and the holders of the OP Units are referred to as "common unitholders".
As of December 31, 2018, MAA owned 113,844,267 OP Units (96.5% of the total number of OP Units). MAA conducts substantially all of its business and holds substantially all of its assets, directly or indirectly, through the Operating Partnership, and by virtue of its ownership of the OP Units and being the Operating Partnership's sole general partner, MAA has the ability to control all of the day-to-day operations of the Operating Partnership.
We believe combining the Annual Reports on Form 10-K of MAA and the Operating Partnership, including the notes to the consolidated financial statements, into this report results in the following benefits:
| • | enhances investors' understanding of MAA and the Operating Partnership by enabling investors to view the business as a whole in the same manner that management views and operates the business; |
| • | eliminates duplicative disclosure and provides a more streamlined and readable presentation since a substantial portion of the disclosure in this report applies to both MAA and the Operating Partnership; and |
| • | creates time and cost efficiencies through the preparation of one combined report instead of two separate reports. |
MAA is a multifamily focused, self-administered and self-managed real estate investment trust, or REIT. Management operates MAA and the Operating Partnership as one business. We believe it is important to understand the few differences between MAA and the Operating Partnership in the context of how MAA and the Operating Partnership operate as a consolidated company. MAA and the Operating Partnership are structured as an "umbrella partnership REIT," or UPREIT. MAA's interest in the Operating Partnership entitles MAA to share in cash distributions from, and in the profits and losses of, the Operating Partnership in proportion to MAA's percentage interest therein and entitles MAA to vote on substantially all matters requiring a vote of the partners. MAA's only material asset is its ownership of limited partnership interests in the Operating Partnership (other than cash held by MAA from time-to-time); therefore, MAA does not conduct business itself, other than acting as the sole general partner of the Operating Partnership, issuing public equity from time-to-time and guaranteeing certain debt of the Operating Partnership. The Operating Partnership holds, directly or indirectly, all of the real estate assets. Except for net proceeds from public equity issuances by MAA, which are contributed to the Operating Partnership in exchange for limited partnership interests, the Operating Partnership generates the capital required by the Company's business through the Operating Partnership's operations, direct or indirect incurrence of indebtedness and issuance of OP Units.
The presentation of MAA's shareholders' equity and the Operating Partnership's capital are the principal areas of difference between the consolidated financial statements of MAA and those of the Operating Partnership. MAA's shareholders' equity may include shares of preferred stock, shares of common stock, additional paid-in capital, cumulative earnings, cumulative distributions, noncontrolling interest, treasury shares, accumulated other comprehensive income and redeemable common stock. The Operating Partnership's capital may include common capital and preferred capital of the general partner (MAA), limited partners' common capital and preferred capital, noncontrolling interest, accumulated other comprehensive income and redeemable common units. Holders of OP Units (other than MAA and its subsidiaries) may require the Operating Partnership to redeem their OP Units from time to time, in which case the Operating Partnership may, at its option, pay the redemption price either in cash (in an amount per OP Unit equal, in general, to the average closing price of MAA's common stock on the New York Stock Exchange, or NYSE, over a specified period prior to the redemption date) or by delivering one share of MAA's common stock (subject to adjustment under specified circumstances) for each OP Unit so redeemed.
In order to highlight the material differences between MAA and the Operating Partnership, this Annual Report on Form 10-K includes sections that separately present and discuss areas that are materially different between MAA and the Operating Partnership, including:
| • | the selected financial data in Item 6 of this report; |
| • | the consolidated financial statements in Item 8 of this report; |
| • | certain accompanying notes to the consolidated financial statements, including Note 3 - Earnings per Common Share of MAA and Note 4 - Earnings per OP Unit of MAALP; Note 9 - Shareholders' Equity of MAA and Note 10 - Partners' Capital of MAALP; and Note 16 - Selected Quarterly Financial Information of MAA (Unaudited) and Note 17 - Selected Quarterly Financial Information of MAALP (Unaudited); |
| • | the controls and procedures in Item 9A of this report; and |
| • | the certifications included as Exhibits 31 and 32 to this report. |
In the sections that combine disclosures for MAA and the Operating Partnership, this report refers to actions or holdings as being actions or holdings of the Company. Although the Operating Partnership (directly or indirectly through one of its subsidiaries) is generally the entity that enters into contracts, holds assets and issues debt, management believes this presentation is appropriate for the reasons set forth above and because the business is one enterprise, in that we operate the business through the Operating Partnership.
PART I
Risks Associated with Forward Looking Statements
We consider this and other sections of this Annual Report on Form 10-K to contain forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, or the Securities Act, and Section 21E of the Securities Exchange Act of 1934, as amended, or the Exchange Act, with respect to our expectations for future periods. Forward-looking statements do not discuss historical fact, but instead include statements related to expectations, projections, intentions or other items related to the future. Such forward-looking statements include, without limitation, statements concerning forecasted operating performance and results, property acquisitions and dispositions, joint venture activity, development and renovation activity as well as other capital expenditures, capital raising activities, rent and expense growth, occupancy, financing activities, and interest rate and other economic expectations. Words such as "expects," "anticipates," "intends," "plans," "believes," "seeks," "estimates," and variations of such words and similar expressions are intended to identify such forward-looking statements. Such forward-looking statements involve known and unknown risks, uncertainties and other factors, as described below, which may cause our actual results, performance or achievements to be materially different from the results of operations, financial conditions or plans expressed or implied by such forward-looking statements. Although we believe that the assumptions underlying the forward-looking statements contained herein are reasonable, any of the assumptions could be inaccurate, and therefore such forward-looking statements included in this report may not prove to be accurate. In light of the significant uncertainties inherent in the forward-looking statements included herein, the inclusion of such information should not be regarded as a representation by us or any other person that the results or conditions described in such statements or our objectives and plans will be achieved.
The following factors, among others, could cause our actual results, performance or achievements to differ materially from those expressed or implied in the forward-looking statements:
| • | inability to generate sufficient cash flows due to market conditions, changes in supply and/or demand, competition, uninsured losses, changes in tax and housing laws, or other factors; |
| • | exposure, as a multifamily focused REIT, to risks inherent in investments in a single industry and sector; |
| • | adverse changes in real estate markets, including, but not limited to, the extent of future demand for multifamily units in our significant markets, barriers of entry into new markets which we may seek to enter in the future, limitations on our ability to increase rental rates, competition, our ability to identify and consummate attractive acquisitions or development projects on favorable terms, our ability to consummate any planned dispositions in a timely manner on acceptable terms, and our ability to reinvest sale proceeds in a manner that generates favorable returns; |
| • | failure of new acquisitions to achieve anticipated results or be efficiently integrated; |
| • | failure of development communities to be completed, if at all, within budget and on a timely basis or to lease-up as anticipated; |
| • | unexpected capital needs; |
| • | changes in operating costs, including real estate taxes, utilities and insurance costs; |
| • | losses from catastrophes in excess of our insurance coverage; |
| • | ability to obtain financing at favorable rates, if at all, and refinance existing debt as it matures; |
| • | level and volatility of interest or capitalization rates or capital market conditions; |
| • | loss of hedge accounting treatment for interest rate swaps; |
| • | the continuation of the good credit of our interest rate swap providers; |
| • | price volatility, dislocations and liquidity disruptions in the financial markets and the resulting impact on financing; |
| • | the effect of any rating agency actions on the cost and availability of new debt financing; |
| • | significant decline in market value of real estate serving as collateral for mortgage obligations; |
| • | significant change in the mortgage financing market that would cause single-family housing, either as an owned or rental product, to become a more significant competitive product; |
| • | our ability to continue to satisfy complex rules in order to maintain our status as a REIT for federal income tax purposes, the ability of the Operating Partnership to satisfy the rules to maintain its status as a partnership for federal income tax purposes, the ability of our taxable REIT subsidiaries to maintain their status as such for federal income tax purposes, and our ability and the ability of our subsidiaries to operate effectively within the limitations imposed by these rules; |
| • | inability to attract and retain qualified personnel; |
| • | cyber liability or potential liability for breaches of our privacy or information security systems; |
| • | potential liability for environmental contamination; |
| • | adverse legislative or regulatory tax changes; |
| • | legal proceedings relating to various issues, which, among other things, could result in a class action lawsuit; |
| • | compliance costs associated with laws requiring access for disabled persons; and |
| • | other risks identified in this Annual Report on Form 10-K including under the caption "Item 1A. Risk Factors" and, from time to time, in other reports we file with the Securities and Exchange Commission, or the SEC, or in other documents that we publicly disseminate. |
New factors may also emerge from time to time that could have a material adverse effect on our business. Except as required by law, we undertake no obligation to publicly update or revise forward-looking statements contained in this Annual Report on Form 10-K to reflect events, circumstances or changes in expectations after the date on which this Annual Report on Form 10-K is filed.
Item 1. Business.
Overview
MAA is a multifamily focused, self-administered and self-managed real estate investment trust, or REIT. We own, operate, acquire and selectively develop apartment communities located in the Southeast, Southwest and Mid-Atlantic regions of the United States. As of December 31, 2018, we maintained full or partial ownership of apartment communities and commercial properties across 17 states and the District of Columbia, summarized as follows:
| Multifamily | Communities | Units | |||
| Consolidated | 303 | 100,595 | |||
| Unconsolidated | 1 | 269 | |||
| Total | 304 | 100,864 | |||
| Commercial | Properties | Sq. Ft. (1) | |||
| Consolidated | 4 | 260,000 |
(1) Excludes commercial space located at our multifamily apartment communities, which totals approximately 615,000 square feet of gross leasable space.
Our business is conducted principally through the Operating Partnership. MAA is the sole general partner of the Operating Partnership, holding 113,844,267 OP Units, comprising a 96.5% partnership interest in the Operating Partnership as of December 31, 2018. MAA and MAALP were formed in Tennessee in 1993. As of December 31, 2018, we had 2,508 full-time employees and 44 part-time employees.
Business Objectives
Our primary business objectives are to protect and grow existing property values, to maintain a stable and increasing cash flow that will fund our dividends and distributions through all parts of the real estate investment cycle, and to create shareholder value by growing in a disciplined manner. To achieve these objectives, we intend to continue to pursue the following goals and strategies:
| • | effectively and efficiently operate our existing properties with an intense property and asset management focus and a decentralized structure; |
| • | manage real estate investment cycles by taking an opportunistic approach to buying, selling, developing and renovating apartment communities; |
| • | diversify investment capital across markets in which we operate to achieve a balanced portfolio and minimize volatile operating performance; and |
| • | actively manage our capital structure to enhance predictability of earnings to fund our dividends and distributions. |
Operations
Our goal is to generate return on investment collectively and in each apartment community by increasing revenues, controlling operating expenses, maintaining high occupancy levels and reinvesting in the income producing capacity of each apartment community as appropriate. The steps taken to meet these objectives include:
| • | providing management information and improved customer services through technology innovations; |
| • | utilizing systems to enhance property managers’ ability to optimize revenue by adjusting rental rates in response to local market conditions and individual unit amenities; |
| • | implementing programs to control expenses through investment in cost-saving initiatives; |
| • | analyzing individual asset productivity performances to identify best practices and improvement areas; |
| • | maintaining the physical condition of each property through ongoing capital investments; |
| • | improving the "curb appeal" of the apartment communities through extensive landscaping and exterior improvements, and repositioning apartment communities from time-to-time to enhance or maintain market positions; |
| • | managing lease expirations to align with peak leasing traffic patterns and to maximize productivity of property staffing; |
| • | allocating additional capital, including capital for selective interior and exterior improvements; |
| • | compensating employees through performance-based compensation and stock ownership programs; and |
| • | maintaining a hands-on management style and "flat" organizational structure that emphasizes property level decision making coupled with asset management and senior management's monitoring. |
We believe that our decentralized operating structure capitalizes on specific market knowledge, provides greater personal accountability than a centralized structure and is beneficial in the acquisition and redevelopment processes. To support this decentralized operational structure, senior management, along with various asset management functions, are proactively involved in supporting and reviewing property management through extensive reporting processes and frequent on-site visits. To maximize the amount of information shared between senior management and the properties on a real-time basis, we utilize a web-based property management system. The system contains property and accounting modules that allow for operating efficiencies and continued expense control, provide for various expanded revenue management practices, and improve the support provided to on-site property operations. We use a "yield management" pricing program that helps our property managers optimize rental revenues, and we also utilize purchase order and accounts payable software to provide improved controls and management information.
Investment in technology continues to drive operating efficiencies in our business and help us to better meet the changing needs of our residents. Our residents have the ability to conduct business with us 24 hours a day, 7 days a week and complete online leasing applications and renewals via the use of our web-based resident Internet portal. Interacting with our residents through such technology has allowed us to improve resident satisfaction ratings and increase the efficiency of our operating teams.
Acquisitions
One of our growth strategies is to acquire apartment communities that are located in various markets throughout the Southeast, Southwest and Mid-Atlantic regions of the United States. Acquisitions, along with dispositions, help us achieve and maintain our desired product mix, geographic diversification and asset allocation. Portfolio growth allows for maximizing the efficiency of the existing management and overhead structure. We have extensive experience in the acquisition of apartment
communities. We will continue to evaluate opportunities that arise, and we will utilize this strategy to increase our number of apartment communities in strong and growing markets.
We acquired the following properties during the year ended December 31, 2018:
| Multifamily Acquisition | Market | Units | Closing Date | |||
| Sync 36 | Denver, CO | 374 | April 26, 2018 | |||
| Commercial Acquisition | Market | Sq Ft | Closing Date | |||
| Hue Retail(1) | Raleigh, NC | 7,500 | August 1, 2018 | |||
| Land Acquisition | Market | Acres | Closing Date | |||
| Westminster | Denver, CO | 10 | October 1, 2018 | |||
| Long Point Road | Houston, TX | 9 | November 1, 2018 |
(1) We acquired the ground floor retail portion of one of our existing multifamily apartment communities.
Dispositions
We sell apartment communities and other assets that no longer meet our long-term strategy or when market conditions are favorable, and we redeploy the proceeds from those sales to acquire, develop and redevelop additional apartment communities and rebalance our portfolio across or within geographic regions. Dispositions also allow us to realize a portion of the value created through our investments and provide additional liquidity. We are then able to redeploy the net proceeds from our dispositions in lieu of raising additional capital. In deciding to sell an apartment community, we consider current market conditions and generally solicit competing bids from unrelated parties for these individual properties, considering the sales price and other key terms of each proposal. We also consider portfolio dispositions when such a structure is useful to maximize proceeds and efficiency of execution. During the year ended December 31, 2018, we disposed of five land parcels totaling approximately 76 acres.
Development
As another part of our growth strategy, we invest in a limited number of development projects. Development activities may be conducted through wholly-owned affiliated companies or through joint ventures with unaffiliated parties. Typically, fixed price construction contracts are signed with unrelated parties to minimize construction risk. We typically manage the leasing portion of the project as units become available for lease. We may also engage in limited expansion development opportunities on existing communities in which we typically serve as the developer. While we seek opportunistic new development investments offering attractive long-term investment returns, we intend to maintain a total development commitment that we consider modest in relation to our total balance sheet and investment portfolio. During the year ended December 31, 2018, we incurred $57.1 million in development costs and completed 3 development projects.
The following multifamily projects were under development as of December 31, 2018 (dollars in thousands):
| Project: | Market | Total Units | Units Completed | Cost to Date | Budgeted Cost | Estimated Cost Per Unit | Expected Completion | |||||||||
| Post Parkside at Wade III | Raleigh, NC | 150 | — | $ | 7,235 | $ | 25,000 | $ | 167 | 4th Quarter 2019 | ||||||
| Post Sierra at Frisco Bridges II | Dallas, TX | 348 | — | 12,013 | 69,000 | 198 | 3rd Quarter 2020 | |||||||||
| Sync 36 II | Denver, CO | 79 | — | 11,685 | 24,500 | 310 | 4th Quarter 2019 | |||||||||
| 577 | — | $ | 30,933 | $ | 118,500 |
Redevelopment
We focus on both interior unit upgrades and exterior amenities above and beyond routine capital upkeep on existing apartment communities across our portfolio that we believe have the ability to support additional rent growth. During the year ended December 31, 2018, we renovated 8,155 units at an average cost of $6,138 per unit, achieving average rental rate increases of 10.5% above the normal market rate for similar but non-renovated units.
Capital Structure
We use a combination of debt and equity sources to fund our business objectives. We maintain a capital structure, focused on maintaining access, flexibility and low costs, that we believe allows us to proactively source potential investment
opportunities in the marketplace. We structure our debt maturities to avoid disproportionate exposure in any given year. Our primary debt financing strategy is to access the unsecured debt markets to provide our debt capital needs, but we also maintain a limited amount of secured debt and maintain our access to both the secured and unsecured debt markets for maximum flexibility. We also believe that we have significant access to the equity capital markets.
As of December 31, 2018, 28.6% of our total market capitalization consisted of debt borrowings, including 25.6% under unsecured credit facilities and unsecured senior notes and 3.0% under secured borrowings. We currently intend to target our total debt, net of cash held, to a range of approximately 32% to 38% of the undepreciated book value of our assets. Our charter and bylaws do not limit our debt levels and our Board of Directors can modify this policy at any time. We may issue new equity to maintain our debt within the target range. Covenants for our unsecured senior notes limit our total debt to 60% or less of our adjusted total assets (as defined in the covenants for the bonds issued by MAALP). As of December 31, 2018, our total debt was approximately 32.6% of our adjusted total assets. We continuously review opportunities for lowering our cost of capital. We plan to continue using unsecured debt in order to take advantage of the lower cost of capital and flexibility provided by these markets. We will evaluate opportunities to repurchase shares when we believe that our share price is significantly below our net present value. We also look for opportunities where we can acquire or develop apartment communities, selectively funded or partially funded by sales of equity securities, when appropriate opportunities arise. We focus on improving the net present value of our investments by generating cash flows from our portfolio of assets above the estimated total cost of debt and equity capital. We routinely make new investments when we believe it will be accretive to shareholder value over the life of the investments.
Competition
All of our apartment communities are located in areas that include other apartment communities. Occupancy and rental rates are affected by the number of competitive apartment communities in a particular area. The owners of competing apartment communities may have greater resources than us, and the managers of these apartment communities may have more experience than our management. Moreover, single-family rental housing, manufactured housing, condominiums and the new and existing home markets provide housing alternatives to potential residents of apartment communities. Competition for new residents is generally intense across all of our markets. Some competing apartment communities offer features that our apartment communities do not have. Competing apartment communities can use concessions or lower rents to obtain temporary competitive advantages. Also, some competing apartment communities are larger or newer than our apartment communities. The competitive position of each apartment community is different depending upon many factors including sub-market supply and demand. In addition, other real estate investors compete with us to acquire existing properties and to develop new properties. These competitors include insurance companies, pension and investment funds, public and private real estate companies, investment companies and other public and private apartment REITs, some of which may have greater resources or lower capital costs than we do.
We believe, however, that we are generally well-positioned to compete effectively for residents and investments. We believe our competitive advantages include:
| • | a fully integrated organization with property management, development, redevelopment, acquisition, marketing, sales and financing expertise; |
| • | scalable operating and support systems, which include automated systems to meet the changing technological needs of our residents; |
| • | access to a wide variety of debt and equity capital sources; |
| • | geographic diversification with a presence in 38 defined Metropolitan Statistical Areas across the Southeast, Southwest and Mid-Atlantic regions of the United States; and |
| • | significant presence in many of our major markets that allows us to be a local operating expert. |
Moving forward, we plan to continue to optimize lease expiration management, improve expense control, increase resident retention efforts and align employee incentive plans with our performance. We also plan to continue to make capital improvements to both our apartment communities and individual units on a regular basis in order to maintain a competitive position in each individual market. We believe this plan of operation, coupled with the portfolio’s strengths in targeting residents across a geographically diverse platform, should position us for continued operational upside.
Environmental Matters
As a part of our standard apartment community acquisition and development processes, we generally obtain environmental studies of the sites from outside environmental engineering firms. The purpose of these studies is to identify potential sources of contamination at the site and to assess the status of environmental regulatory compliance. These studies
generally include historical reviews of the site, reviews of certain public records, preliminary investigations of the site and surrounding properties, inspection for the presence of asbestos, poly-chlorinated biphenyls and underground storage tanks and the preparation and issuance of written reports. Depending on the results of these studies, more invasive procedures, such as soil sampling or ground water analysis, may be performed to investigate potential sources of contamination. These studies must be satisfactorily completed before we take ownership of an acquisition or development property; however, no assurance can be given that the studies or additional documents reviewed identify all significant environmental risks. See "Risk Factors - Risks Relating to Our Real Estate Investments and Our Operations - Environmental problems are possible and can be costly."
The environmental studies we received on properties that we have acquired have not revealed any material environmental liabilities. Should any potential environmental risks or conditions be discovered during our due diligence process, the potential costs of remediation will be assessed carefully and factored into the cost of acquisition, assuming the identified risks and factors are deemed to be manageable and within reason. We are not aware of any existing conditions that we believe would be considered a material environmental liability. Nevertheless, it is possible that the studies do not reveal all environmental risks or that there are material environmental liabilities of which we are not aware. Moreover, no assurance can be given concerning future laws, ordinances or regulations, or the potential introduction of hazardous or toxic substances by neighboring properties or residents.
Merger with Post Properties
We completed our merger with Post Properties, Inc., or Post Properties, on December 1, 2016. Accordingly, the consolidated net assets and results of operations of Post Properties are included in our consolidated financial statements from and after the merger closing date.
Qualification as a Real Estate Investment Trust
MAA has elected to be taxed as a REIT under the Internal Revenue Code of 1986, as amended, or the Code. To continue to qualify as a REIT, MAA must continue to meet certain tests which, among other things, generally require that our assets consist primarily of real estate assets, our income be derived primarily from real estate assets, and that we distribute at least 90% of our REIT taxable income (other than our net capital gains) to our shareholders annually. If MAA maintains its qualification as a REIT, MAA generally will not be subject to U.S. federal income taxes at the corporate level on its net income to the extent it distributes such net income to its shareholders annually. Even if MAA continues to qualify as a REIT, it will continue to be subject to certain federal, state and local taxes on its income and its property. In 2018, MAA paid total distributions of $3.69 per share of common stock to its shareholders, which was above the 90% REIT distribution requirement and was in excess of REIT taxable income.
Recent Developments
In February 2019, we closed on the disposition of a 0.4 acre land parcel located in the Atlanta, Georgia market, resulting in a net gain of $9.0 million on the sale of non-depreciable real estate assets recognized in the first quarter of 2019. The gain on sale of non-depreciable real estate assets was not reflected in our initial earnings guidance for the first quarter of 2019 or the full year of 2019. We will review our 2019 earnings guidance in our earnings release and conference call discussing results for the quarter ending March 31, 2019.
In February 2019, we entered into a $191.3 million fixed rate secured property mortgage with a fixed rate of 4.43%, maturing in February 2049.
Website Access to Our Reports
MAA and the Operating Partnership file combined periodic reports with the SEC. Our Annual Reports on Form 10-K, along with our Quarterly Reports on Form 10-Q, Current Reports on Form 8-K and any amendments to those reports, are available on our website at https://www.maac.com as soon as reasonably practicable after such material is electronically filed with, or furnished to, the SEC. Reference to our website does not constitute incorporation by reference of the information contained on the site and should not be considered part of this Annual Report on Form 10-K. All of the aforementioned materials may also be obtained free of charge by contacting our Investor Relations Department, 6815 Poplar Avenue, Suite 500, Germantown, TN 38138.
Item 1A. Risk Factors.
In addition to the other information contained in this Annual Report on Form 10-K, we have identified the following additional risks and uncertainties that may have a material adverse effect on our business prospects, financial condition or results of operations. Investors should carefully consider the risks described below before making an investment decision. Our business faces significant risks and the risks described below may not be the only risks we face. Additional risks not presently known to us or that we currently believe are immaterial may also significantly impact our business operations. If any of these risks occur, our business prospects, financial condition or results of operations could suffer, the market price of our capital stock and the trading price of our debt securities could decline and you could lose all or part of your investment in our capital stock or debt securities.
Risks Related to Our Real Estate Investments and Our Operations
Unfavorable market and economic conditions could adversely affect occupancy levels, rental revenues and the value of our properties.
Unfavorable market conditions in the areas in which we operate and unfavorable economic conditions may significantly affect our occupancy levels, our rental rates and collections, the value of the properties and our ability to acquire or dispose of apartment communities on economically favorable terms. Our ability to lease our apartment communities at favorable rates is adversely affected by the increase in supply in the multifamily and other rental markets and is dependent upon the overall level in the economy, which is adversely affected by, among other things, job losses and unemployment levels, personal debt levels, a downturn in the housing market, stock market volatility and uncertainty about the future. Some of our major expenses generally do not decline when related rents decline. We would expect that declines in our occupancy levels, rental revenues and/or the values of our apartment communities would cause us to have less cash available to make payments on our debt and to make distributions, which could adversely affect our financial condition or the market value of our securities. Factors that may affect our occupancy levels, our rental revenues, and/or the value of our apartment communities include the following, among others:
| • | downturns in global, national, regional and local economic conditions, particularly increases in unemployment; |
| • | declines in mortgage interest rates and home pricing, making alternative housing more affordable; |
| • | government or builder incentives with respect to home ownership, making alternative housing options more attractive; |
| • | local real estate market conditions, including oversupply of apartments or other housing available for rent, or a reduction in demand for apartments in the area; |
| • | declines in the financial condition of our residents, which may make it more difficult for us to collect rents from some residents; |
| • | declines in market rental rates; |
| • | declines in household formation; and |
| • | increases in operating costs, if these costs cannot be passed through to our residents. |
Failure to generate sufficient cash flows could limit our ability to make payments on our debt and to make distributions.
Our ability to make payments on our debt and to make distributions depends on our ability to generate cash flow in excess of operating costs and capital expenditure requirements and/or to have access to the markets for debt and equity financing. Our funds from operations may be insufficient because of factors that are beyond our control. Such events or conditions could include:
| • | competition from other apartment communities; |
| • | overbuilding of new apartments or oversupply of available apartments in our markets, which might adversely affect occupancy or rental rates and/or require rent concessions in order to lease apartments; |
| • | conversion of condominiums and single family houses to rental use or the increase in the number of condominiums and single family homes available for sale; |
| • | weakness in the overall economy, which lowers job growth and the associated demand for apartment housing; |
| • | increases in operating costs (including real estate taxes, utilities and insurance premiums) due to inflation and other factors, which may not be offset by increased rental rates; |
| • | inability to initially, or subsequently after lease terminations, rent apartments on favorable economic terms; |
| • | failure of development communities to be completed, if at all, within budget and on a timely basis or to lease-up as anticipated; |
| • | changes in governmental regulations and the related costs of compliance; |
| • | changes in laws including, but not limited to, tax laws and housing laws including the enactment of rent control laws or other laws regulating multifamily housing; |
| • | withdrawal of government support of apartment financing through its financial backing of the Federal National Mortgage Association, or Fannie Mae, or the Federal Home Loan Mortgage Corporation, or Freddie Mac; |
| • | an uninsured loss, including those resulting from a catastrophic storm, earthquake, or act of terrorism; |
| • | changes in interest rate levels and the availability of financing, borrower credit standards, and down-payment requirements which could lead renters to purchase homes (if interest rates decrease and home loans are more readily available) or increase our acquisition and operating costs (if interest rates increase and financing is less readily available); and |
| • | the relative illiquidity of real estate investments. |
At times, we have relied on external funding sources to fully fund the payment of distributions to shareholders and our capital investment program, including our existing property developments. While we have sufficient liquidity to permit distributions at current rates through additional borrowings, if necessary, any significant and sustained deterioration in operations could result in our financial resources being insufficient to make payments on our debt and to make distributions at the current rate, in which event we would be required to reduce the distribution rate. Any decline in our funds from operations could adversely affect our ability to make distributions or to meet our loan covenants and could have a material adverse effect on our stock price or the trading price of our debt securities.
We are dependent on a concentration of our investments in a single asset class, making our results of operations more vulnerable to a downturn or slowdown in the sector or other economic factors.
As of December 31, 2018, substantially all of our investments are concentrated in the multifamily sector. As a result, we will be subject to risks inherent in investments in a single type of property. A downturn or slowdown in the demand for multifamily housing may have more pronounced effects on our results of operations or on the value of our assets than if we had diversified our investments into more than one asset class.
Our operations are concentrated in the Southeast, Southwest and Mid-Atlantic regions of the United States; we are subject to general economic conditions in the regions in which we operate.
As of December 31, 2018, approximately 39.4% of our portfolio is located in our top five markets: Atlanta, Georgia; Dallas, Texas; Austin, Texas; Charlotte, North Carolina; a
Showing the first 8K of 73K characters. Open the full section
Item 1B. Unresolved Staff Comments.
None.
Item 2. Properties.
We seek to acquire newer apartment communities and those with opportunities for repositioning through capital additions and management improvement located in the Southeast, Southwest and Mid-Atlantic regions of the United States with the potential for above average growth and return on investment. Approximately 68% of our apartment units are located in the Florida, Georgia, North Carolina, and Texas markets. Our strategic focus is to provide our residents high quality apartment units in attractive community settings, characterized by upscale amenities, extensive landscaping and attention to aesthetic detail.
The following table summarizes our apartment community portfolio and occupancy levels by location, as of December 31, 2018:
| Number of Communities | Number of Units (1) | Average Unit Size (Square Footage) | Average Occupancy(2) | |||||||||
| Atlanta, GA | 28 | 10,664 | 1,040.4 | 95.9 | % | |||||||
| Dallas, TX | 29 | 9,404 | 884.2 | 95.3 | % | |||||||
| Austin, TX | 21 | 6,475 | 935.6 | 95.8 | % | |||||||
| Charlotte, NC | 21 | 6,149 | 965.0 | 96.2 | % | |||||||
| Tampa, FL | 14 | 5,220 | 1,015.6 | 96.3 | % | |||||||
| Orlando, FL | 12 | 4,498 | 1,027.4 | 96.2 | % | |||||||
| Houston, TX | 14 | 4,479 | 882.4 | 96.2 | % | |||||||
| Raleigh/ Durham, NC | 14 | 4,397 | 1,016.5 | 96.3 | % | |||||||
| Fort Worth, TX | 11 | 4,249 | 902.9 | 95.8 | % | |||||||
| Washington, DC | 10 | 4,080 | 926.4 | 96.7 | % | |||||||
| Nashville, TN | 10 | 3,776 | 1,019.6 | 95.6 | % | |||||||
| Jacksonville, FL | 10 | 3,496 | 964.4 | 96.6 | % | |||||||
| Charleston, SC | 10 | 2,726 | 956.9 | 95.8 | % | |||||||
| Phoenix, AZ | 7 | 2,301 | 980.2 | 96.7 | % | |||||||
| Savannah, GA | 9 | 2,219 | 1,021.3 | 96.6 | % | |||||||
| Memphis, TN | 4 | 1,811 | 974.2 | 95.7 | % | |||||||
| Greenville, SC | 8 | 1,748 | 902.0 | 96.4 | % | |||||||
| Richmond, VA | 6 | 1,668 | 862.3 | 96.7 | % | |||||||
| San Antonio, TX | 4 | 1,504 | 910.3 | 96.0 | % | |||||||
| Birmingham, AL | 5 | 1,462 | 1,054.8 | 96.2 | % | |||||||
| Little Rock, AR | 5 | 1,368 | 981.5 | 95.4 | % | |||||||
| Jackson, MS | 4 | 1,241 | 970.1 | 96.2 | % | |||||||
| Huntsville, AL | 3 | 1,228 | 1,089.9 | 97.3 | % | |||||||
| Chattanooga, TN | 4 | 943 | 905.7 | 96.2 | % | |||||||
| Lexington, KY | 4 | 924 | 914.4 | 96.2 | % | |||||||
| Norfolk / Hampton / Virginia Beach, VA | 3 | 788 | 924.5 | 96.9 | % | |||||||
| Las Vegas, NV | 2 | 721 | 953.5 | 96.3 | % | |||||||
| Tallahassee, FL | 2 | 604 | 1,111.2 | 96.1 | % | |||||||
| Kansas City, MO / KS | 2 | 603 | 965.9 | 95.9 | % | |||||||
| Columbia, SC | 2 | 576 | 1,028.6 | 96.8 | % | |||||||
| South Florida, FL | 1 | 480 | 1,189.4 | 96.2 | % | |||||||
| Gainesville, FL | 2 | 468 | 1,137.7 | 97.3 | % | |||||||
| Louisville, KY | 1 | 384 | 845.7 | 96.2 | % | |||||||
| Gulf Shores, AL | 1 | 324 | 993.0 | 96.9 | % | |||||||
| Panama City, FL | 1 | 254 | 1,117.5 | 97.6 | % | |||||||
| Charlottesville, VA | 1 | 251 | 943.5 | 97.3 | % | |||||||
| Same Store | 285 | 93,483 | 968.3 | 96.1 | % | |||||||
| Atlanta, GA | 2 | 770 | 859.1 | 61.5 | % | |||||||
| Austin, TX | 1 | 642 | 788.9 | 94.4 | % | |||||||
| Charleston, SC | 1 | 442 | 939.5 | 81.6 | % | |||||||
| Dallas, TX | 2 | 362 | 957.4 | 93.9 | % | |||||||
| Denver, CO | 2 | 733 | 832.1 | 61.6 | % | |||||||
| Greenville, SC | 1 | 336 | 1,029.5 | 94.6 | % | |||||||
| Gulf Shores, AL | 1 | 96 | 2,145.8 | 96.7 | % | |||||||
| Houston, TX | 1 | 388 | 866.4 | 96.2 | % | |||||||
| Kansas City, MO | 1 | 507 | 1,008.1 | 86.3 | % | |||||||
| Nashville, TN | 2 | 599 | 811.2 | 88.1 | % | |||||||
| Orlando, FL | 1 | 776 | 986.9 | 94.9 | % | |||||||
| Phoenix, AZ | 1 | 322 | 901.3 | 95.7 | % | |||||||
| Raleigh/Durham, NC | 1 | 803 | 892.6 | 95.7 | % | |||||||
| Richmond, VA | 1 | 336 | 994.2 | 96.7 | % | |||||||
| Non-Same Store (3) | 18 | 7,112 | 918.4 | 86.5 | % | |||||||
| Total | 303 | 100,595 |
| (1) | Number of Units excludes development units not yet delivered. |
| (2) | Average Occupancy is calculated by dividing the average daily number of units occupied in 2018 by the average daily total number of units available in 2018 at each apartment community. |
| (3) | Non-Same Store total excludes 269 units in a joint venture property in Washington, D.C. |
Thirty of our multifamily properties reflected in the above table also include commercial components totaling approximately 615,000 square feet of gross leasable space. We also owned four commercial properties totaling approximately 260,000 square feet of combined gross leasable space as of December 31, 2018. See "Management's Discussion and Analysis of Financial Condition and Results of Operations" for a discussion of our Same Store and Non-Same Store portfolios.
Mortgage Financing
As of December 31, 2018, we had $476.2 million of indebtedness collateralized, secured, and outstanding as set forth in Schedule III, Real Estate and Accumulated Depreciation included elsewhere in this Annual Report on Form 10-K.
Item 3. Legal Proceedings.
In September 2010, the United States Department of Justice, or the DOJ, filed suit against Post Properties (and by virtue of the merger with Post Properties, MAA) in United States District Court for the District of Columbia alleging that certain of Post Properties' apartments violated accessibility requirements of the FHA and the ADA. The DOJ sought, among other things, an injunction against us, requiring us to retrofit the properties and comply with FHA and ADA standards in future design and construction, as well as monetary damages and civil penalties. In October 2018, we reached an agreement in principle with the DOJ to settle the lawsuit. In November 2018, the settlement agreement was fully executed. In December 2018, a stipulation of dismissal of the case with prejudice was filed with the District Court, concluding the case.
In December 2017, the Equal Rights Center, a non-profit civil rights organization, filed suit against MAA and the Operating Partnership in the United States District Court for the District of Columbia. This suit alleged that we maintained and enforced a criminal records screening policy at certain of our apartment communities, all of which we acquired in the Post Properties merger, which violated the FHA. The suit sought injunctive relief, actual and punitive damages and attorneys' fees and costs. In October 2018, the parties agreed to a settlement, and the District Court entered a Consent Order concluding the case.
In June 2016, plaintiffs Cathi Cleven and Tara Cleven, on behalf of a purported class of plaintiffs, filed a complaint against MAA and the Operating Partnership in the United States District Court for the Western District of Texas, Austin Division. In January 2017, Areli Arellano and Joe L. Martinez joined the lawsuit as additional plaintiffs. The lawsuit alleges that we (but not Post Properties) charged late fees at our Texas properties that violate Section 92.019 of the Texas Property Code, or Section 92.019, which provides that a landlord may not charge a tenant a late fee for failing to pay rent unless, among other things, the fee is a reasonable estimate of uncertain damages to the landlord that are incapable of precise calculation and result from the late payment of rent. The plaintiffs are seeking monetary damages and attorneys' fees and costs. In September 2018, the District Court certified a class proposed by the plaintiffs. Additionally, in September 2018, the District Court denied our motion for summary judgment and granted the plaintiffs’ motion for partial summary judgment. Because the District Court certified a class prior to granting the plaintiffs’ motion for partial summary judgment, the District Court’s ruling applies to the entire class. In October 2018, the Fifth Circuit Court of Appeals accepted our petition to review the District Court’s order granting class certification. We intend to appeal the District Court’s order granting plaintiff’s motion for summary judgment to the Fifth Circuit Court of Appeals if permission to appeal is granted. We will continue to vigorously defend the action and pursue such appeals.
In April 2017, plaintiff Nathaniel Brown, on behalf of a purported class of plaintiffs, filed a complaint against the Operating Partnership, as the successor by merger to Post Properties' primary operating partnership, and MAA in the United States District Court for the Western District of Texas, Austin Division. The lawsuit alleges that Post Properties (and, following the Post Properties merger, the Operating Partnership) charged late fees at its Texas properties that violate Section 92.019. The plaintiffs are seeking monetary damages and attorneys' fees and costs. In September 2018, the District Court certified a class proposed by the plaintiff. Additionally, in September 2018, the District Court denied our motion for summary judgment and granted the plaintiff’s motion for partial summary judgment. Because the District Court certified a class prior to granting the plaintiff’s motion for partial summary judgment, the District Court’s ruling applies to the entire class. In October 2018, the Fifth Circuit Court of Appeals accepted our petition to review the District Court's order granting class certification. We intend to appeal the District Court’s order granting plaintiff’s motion for summary judgment to the Fifth Circuit Court of Appeals if permission to appeal is granted. We will continue to vigorously defend the action and pursue such appeals.
In addition, we are subject to various other legal proceedings arising in the course of our business operations. While no assurances can be given, we do not currently believe that any of these other outstanding matters will have a material adverse effect on our financial condition, results of operations or cash flows in the event of a negative outcome.
Item 4. Mine Safety Disclosures.
Not applicable.
PART II
Item 5. Market for Registrant's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
Mid-America Apartment Communities, Inc.
Market Information
MAA's common stock has been listed and traded on the NYSE under the symbol "MAA" since its initial public offering in February 1994. On February 18, 2019, there were approximately 2,700 holders of record of the common stock. MAA believes it has a significantly larger number of beneficial owners of its common stock.
Direct Stock Purchase and Distribution Reinvestment Plan
We have established the dividend and distribution reinvestment stock purchase plan, or DRSPP, under which holders of common stock, preferred stock and OP Units can elect to automatically reinvest their distributions in shares of MAA common stock. The DRSPP also allows for the optional purchase of MAA common stock of at least $250, but not more than$5,000 in any given month, free of brokerage commissions and charges. In our absolute discretion, we may grant waivers to allow for optional cash payments in excess of $5,000. To fulfill our obligations under the DRSPP, we may either issue additional shares of common stock or repurchase common stock in the open market. We may elect to sell shares under the DRSPP at up to a 5% discount. In 2018, 2017, and 2016, we had issuances with no discounts through our DRSPP of 9,721 shares, 9,568 shares, and 7,906 shares, respectively.
Mid-America Apartments, L.P.
Operating Partnership Units
There is no established public trading market for the Operating Partnership's OP Units. From time-to-time, we issue shares of MAA's common stock in exchange for OP Units tendered to the Operating Partnership for redemption in accordance with the provisions of the Operating Partnership’s limited partnership agreement. As of December 31, 2018, there were 117,955,568 OP Units outstanding in the Operating Partnership, of which 113,844,267 OP Units, or 96.5%, were owned by MAA and 4,111,301 OP Units, or 3.5%, were owned by limited partners. Under the terms of the Operating Partnership’s limited partnership agreement, the limited partner holders of OP Units have the right to require the Operating Partnership to redeem all or a portion of the OP Units held by the holder in exchange for one share of MAA common stock per one OP Unit or a cash payment based on the market value of MAA's common stock at the time of redemption, at the option of MAA. During the year ended December 31, 2018, MAA issued a total of 80,283 shares of common stock upon redemption of OP Units.
At-the-Market Offering
We have entered into distribution agreements with J.P. Morgan Securities LLC, BMO Capital Markets Corp. and KeyBanc Capital Markets Inc. to sell up to an aggregate of 4.0 million shares of common stock, from time-to-time in at-the-market offerings or negotiated transactions through controlled equity offering programs, or ATMs. As of December 31, 2018, there were 4.0 million shares available to be sold under the ATMs.
Stock Repurchase Plan
On December 8, 2015, MAA's Board of Directors authorized the repurchase of up to 4.0 million shares of MAA common stock, which represented approximately 5.3% of MAA's common stock outstanding at the time of such authorization. The December 2015 authorization replaced and superseded any previous authorization. From time to time, we may repurchase shares under the current authorization when we believe that shareholder value would be enhanced. Factors affecting this determination include, among others, the share price and expected rates of return. As of December 31, 2018, no shares have been repurchased under the current authorization.
Purchases of Equity Securities
The following table reflects repurchases of shares of MAA's common stock during the three months ended December 31, 2018:
| Total Number of Shares Purchased(1) | Average Price Paid per Share(2) | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Maximum Number of Shares That May Yet be Purchased Under the Plans or Programs(3) | ||||||||
| October 1, 2018 - October 31, 2018 | — | $ | — | — | 4,000,000 | ||||||
| November 1, 2018 - November 30, 2018 | — | $ | — | — | 4,000,000 | ||||||
| December 1, 2018 - December 31, 2018 | 93 | $ | 97.20 | — | 4,000,000 | ||||||
| Total | 93 | — | 4,000,000 |
| (1) | This column reflects the shares of common stock surrendered by employees to satisfy their statutory minimum federal and state tax obligations associated with the vesting of restricted shares under the Second Amended and Restated 2013 Stock Incentive Plan. |
| (2) | The price per share is based on the closing price of MAA's common stock as of the date of determination of the statutory minimum for federal and state tax obligations. |
| (3) | This column reflects the number of shares of MAA's common stock that are available for purchase under the 4.0 million share repurchase program authorized by MAA's Board of Directors in December 2015. |
Comparison of Five-year Cumulative Total Returns
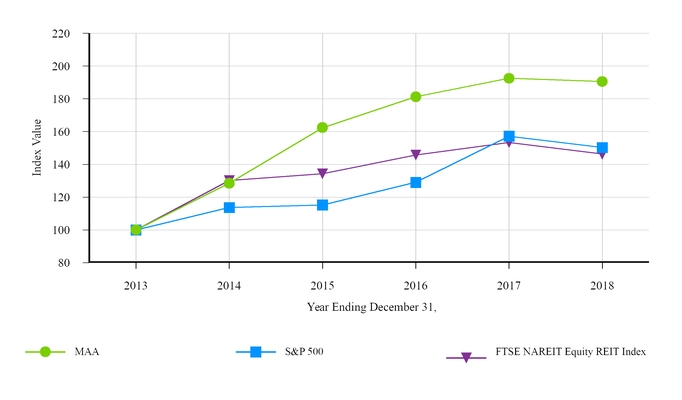
The following graph compares the cumulative total returns of the shareholders of MAA since December 31, 2013 with the S&P 500 Index and the FTSE NAREIT Equity REIT Index. The graph assumes that the base share price for our common stock and each index is $100 and that all dividends are reinvested. The performance graph is not necessarily indicative of future investment performance.
| Year Ending December 31, | ||||||||||||||||||||||||
| 2013 | 2014 | 2015 | 2016 | 2017 | 2018 | |||||||||||||||||||
| MAA | $ | 100.00 | $ | 128.42 | $ | 162.40 | $ | 181.23 | $ | 192.59 | $ | 190.58 | ||||||||||||
| S&P 500 | 100.00 | 113.69 | 115.26 | 129.05 | 157.22 | 150.33 | ||||||||||||||||||
| FTSE NAREIT Equity REIT Index | 100.00 | 130.14 | 134.30 | 145.74 | 153.36 | 146.27 |
Item 6. Selected Financial Data.
The following tables set forth selected financial data on a historical basis for MAA and the Operating Partnership. This data should be read in conjunction with the consolidated financial statements and notes thereto and "Management's Discussion and Analysis of Financial Condition and Results of Operations" included elsewhere in this Annual Report on Form 10-K.
Mid-America Apartment Communities, Inc.
Selected Financial Data
(In thousands, except per share data)
| Year Ended December 31, | |||||||||||||||||||
| 2018 | 2017 | 2016 | 2015 | 2014 | |||||||||||||||
| Operating Data: | |||||||||||||||||||
| Rental and other property revenues | $ | 1,571,346 | $ | 1,528,987 | $ | 1,125,348 | $ | 1,042,779 | $ | 992,332 | |||||||||
| Income from continuing operations | 231,022 | 340,536 | 224,402 | 350,745 | 150,946 | ||||||||||||||
| Discontinued operations: | |||||||||||||||||||
| Loss from discontinued operations before gain on sale | — | — | — | — | (63 | ) | |||||||||||||
| Gain on sale of discontinued operations | — | — | — | — | 5,394 | ||||||||||||||
| Net income | 231,022 | 340,536 | 224,402 | 350,745 | 156,277 | ||||||||||||||
| Net income attributable to noncontrolling interests | 8,123 | 12,157 | 12,180 | 18,458 | 8,297 | ||||||||||||||
| Dividends to MAA Series I preferred shareholders | 3,688 | 3,688 | 307 | — | — | ||||||||||||||
| Net income available for MAA common shareholders | $ | 219,211 | $ | 324,691 | $ | 211,915 | $ | 332,287 | $ | 147,980 | |||||||||
| Per Common Share Data: | |||||||||||||||||||
| Weighted average shares outstanding: | |||||||||||||||||||
| Basic | 113,638 | 113,407 | 78,502 | 75,176 | 74,982 | ||||||||||||||
| Effect of dilutive securities (1) | 198 | 280 | 298 | — | — | ||||||||||||||
| Diluted | 113,836 | 113,687 | 78,800 | 75,176 | 74,982 | ||||||||||||||
| Earnings per common share - basic: | |||||||||||||||||||
| Income from continuing operations available for common shareholders | $ | 1.93 | $ | 2.86 | $ | 2.69 | $ | 4.41 | $ | 1.90 | |||||||||
| Discontinued property operations | — | — | — | — | 0.07 | ||||||||||||||
| Net income available for common shareholders | $ | 1.93 | $ | 2.86 | $ | 2.69 | $ | 4.41 | $ | 1.97 | |||||||||
| Earnings per common share - diluted: | |||||||||||||||||||
| Income from continuing operations available for common shareholders | $ | 1.93 | $ | 2.86 | $ | 2.69 | $ | 4.41 | $ | 1.90 | |||||||||
| Discontinued property operations | — | — | — | — | 0.07 | ||||||||||||||
| Net income available for common shareholders | $ | 1.93 | $ | 2.86 | $ | 2.69 | $ | 4.41 | $ | 1.97 | |||||||||
| Dividends declared per common share(2) | $ | 3.7275 | $ | 3.5325 | $ | 3.3300 | $ | 3.1300 | $ | 2.9600 | |||||||||
| Balance Sheet Data: | |||||||||||||||||||
| Real estate owned, at cost | $ | 13,700,988 | $ | 13,336,995 | $ | 13,016,663 | $ | 8,217,579 | $ | 8,071,187 | |||||||||
| Real estate assets, net | 11,151,701 | 11,261,924 | 11,341,862 | 6,718,366 | 6,697,508 | ||||||||||||||
| Total assets | 11,323,781 | 11,491,919 | 11,604,491 | 6,847,781 | 6,821,778 | ||||||||||||||
| Total debt | 4,528,328 | 4,502,057 | 4,499,712 | 3,427,568 | 3,512,699 | ||||||||||||||
| Noncontrolling interest | 222,349 | 233,982 | 238,282 | 165,726 | 161,287 | ||||||||||||||
| Total MAA shareholders' equity and redeemable stock | 6,159,254 | 6,350,320 | 6,413,892 | 3,000,347 | 2,896,435 | ||||||||||||||
| Other Data (at end of period): | |||||||||||||||||||
| Funds from operations | $ | 712,690 | $ | 699,561 | $ | 463,385 | $ | 452,372 | $ | 404,087 | |||||||||
| Market capitalization (shares and units) (3) | $ | 11,288,348 | $ | 11,849,463 | $ | 11,528,965 | $ | 7,225,894 | $ | 5,933,985 | |||||||||
| Ratio of total debt to total capitalization (4) | 28.6 | % | 27.5 | % | 28.1 | % | 32.2 | % | 37.3 | % | |||||||||
| Number of multifamily apartment communities, including joint venture ownership interest (5) | 304 | 302 | 303 | 254 | 268 | ||||||||||||||
| Number of multifamily units, including joint venture ownership interest (5) | 100,864 | 99,792 | 99,393 | 79,496 | 82,316 |
(1) See Note 3 to the consolidated financial statements included elsewhere in this Annual Report on Form 10-K.
(2) Beginning in 2006, at their regularly scheduled meetings, our Board of Directors began routinely declaring dividends for payment in the following quarter. This can result in dividends declared during a calendar year being different from dividends paid during a calendar year.
(3) Market capitalization includes all shares of common stock, regardless of classification on the balance sheet, as well as OP Units (value based on common stock equivalency).
(4) Total capitalization is market capitalization plus total debt.
(5) Multifamily apartment communities and unit totals have not been adjusted to exclude properties held for sale.
Mid-America Apartments, L.P.
Selected Financial Data
(In thousands, except per unit data)
| Year Ended December 31, | |||||||||||||||||||
| 2018 | 2017 | 2016 | 2015 | 2014 | |||||||||||||||
| Operating Data: | |||||||||||||||||||
| Rental and other property revenues | $ | 1,571,346 | $ | 1,528,987 | $ | 1,125,348 | $ | 1,042,779 | $ | 992,332 | |||||||||
| Income from continuing operations | 231,022 | 340,536 | 224,402 | 350,745 | 150,946 | ||||||||||||||
| Discontinued operations: | |||||||||||||||||||
| Loss from discontinued operations before gain on sale | — | — | — | — | (63 | ) | |||||||||||||
| Gain on sale of discontinued operations | — | — | — | — | 5,394 | ||||||||||||||
| Net income | 231,022 | 340,536 | 224,402 | 350,745 | 156,277 | ||||||||||||||
| Dividends to preferred unitholders | 3,688 | 3,688 | 307 | — | — | ||||||||||||||
| Net income available for MAALP common unitholders | $ | 227,334 | $ | 336,848 | $ | 224,095 | $ | 350,745 | $ | 156,277 | |||||||||
| Per Common Unit Data: | |||||||||||||||||||
| Weighted average units outstanding: | |||||||||||||||||||
| Basic | 117,777 | 117,617 | 82,661 | 79,361 | 79,188 | ||||||||||||||
| Effect of dilutive securities(1) | 198 | 280 | 298 | — | — | ||||||||||||||
| Diluted | 117,975 | 117,897 | 82,959 | 79,361 | 79,188 | ||||||||||||||
| Earnings per common unit - basic: | |||||||||||||||||||
| Income from continuing operations available for common unitholders | $ | 1.93 | $ | 2.86 | $ | 2.70 | $ | 4.41 | $ | 1.90 | |||||||||
| Discontinued property operations | — | — | — | — | 0.07 | ||||||||||||||
| Net income available for common unitholders | $ | 1.93 | $ | 2.86 | $ | 2.70 | $ | 4.41 | $ | 1.97 | |||||||||
| Earnings per common unit - diluted: | |||||||||||||||||||
| Income from continuing operations available for common unitholders | $ | 1.93 | $ | 2.86 | $ | 2.70 | $ | 4.41 | $ | 1.90 | |||||||||
| Discontinued property operations | — | — | — | — | 0.07 | ||||||||||||||
| Net income available for common unitholders | $ | 1.93 | $ | 2.86 | $ | 2.70 | $ | 4.41 | $ | 1.97 | |||||||||
| Distributions declared per common unit (2) | $ | 3.7275 | $ | 3.5325 | $ | 3.3300 | $ | 3.1300 | $ | 2.9600 | |||||||||
| Balance Sheet Data: | |||||||||||||||||||
| Real estate owned, at cost | $ | 13,700,988 | $ | 13,336,995 | $ | 13,016,663 | $ | 8,217,579 | $ | 8,071,187 | |||||||||
| Real estate assets, net | 11,151,701 | 11,261,924 | 11,341,862 | 6,718,366 | 6,697,508 | ||||||||||||||
| Total assets | 11,323,781 | 11,491,919 | 11,604,491 | 6,847,781 | 6,821,778 | ||||||||||||||
| Total debt | 4,528,328 | 4,502,057 | 4,499,712 | 3,427,568 | 3,512,699 | ||||||||||||||
| Total Operating Partnership capital and redeemable units | 6,379,278 | 6,581,977 | 6,649,849 | 3,166,054 | 3,057,703 | ||||||||||||||
| Other Data (at end of period): | |||||||||||||||||||
| Number of multifamily apartment communities, including joint venture ownership interest (3) | 304 | 302 | 303 | 254 | 268 | ||||||||||||||
| Number of multifamily units, including joint venture ownership interest (3) | 100,864 | 99,792 | 99,393 | 79,496 | 82,316 |
(1) See Note 4 to the consolidated financial statements included elsewhere in this Annual Report on Form 10-K.
(2) Beginning in 2006, at their regularly scheduled meetings, the Board of Directors began routinely declaring distributions for payment in the following quarter. This can result in distributions declared during a calendar year being different from distributions paid during a calendar year.
(3) Multifamily apartment communities and unit totals have not been adjusted to exclude properties held for sale.
As previously discussed, the consolidated assets, liabilities, and results of operations of Post Properties are included in MAA's selected financial data from the closing date of the merger, December 1, 2016, through the end of MAA's fiscal year, December 31, 2018. Likewise, the consolidated assets, liabilities, and results of operations of Post Properties’ primary operating partnership are included in the Operating Partnership's selected financial data from the closing date of the merger, December 1, 2016, through the end of the Operating Partnership's fiscal year, December 31, 2018.
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations.
The following discussion analyzes the financial condition and results of operations of both MAA and the Operating Partnership, of which MAA is the sole general partner and in which MAA owned a 96.5% limited partner interest as of December 31, 2018. MAA conducts all of its business through the Operating Partnership and its various subsidiaries. This discussion should be read in conjunction with the consolidated financial statements included elsewhere in this Annual Report on Form 10-K.
MAA is a multifamily focused, self-administered and self-managed real estate investment trust, or REIT. We own, operate, acquire and selectively develop apartment communities located in the Southeast, Southwest and Mid-Atlantic regions of the United States. As of December 31, 2018, we owned and operated 303 apartment communities through the Operating Partnership and its subsidiaries, and we had an ownership interest in one apartment community through an unconsolidated real estate joint venture. In addition, as of December 31, 2018, we owned four commercial properties, and 30 of our apartment communities included retail components. Our multifamily and commercial properties are located across 17 states and the District of Columbia.
We report in two segments, Same Store communities and Non-Same Store and Other. Our Same Store segment represents those communities that have been owned and stabilized for at least 12 months as of the first day of the calendar year. Our Non-Same Store and Other segment includes recently acquired communities, communities being developed or in lease-up, communities undergoing extensive renovations, communities identified for disposition, and communities that have incurred a significant casualty loss. Also included in our Non-Same Store and Other segment are non-multifamily activities.
Effective January 1, 2018, we revised our reportable segment presentation. The revision eliminated the prior distinction between large and secondary same store markets and combined the two previously reportable segments into the Same Store reportable segment referred to above. Additional information regarding the composition of our segments is included in Note 14 to the consolidated financial statements included elsewhere in this Annual Report on Form 10-K.
Overview
For the year ended December 31, 2018, net income available for MAA common shareholders was $219.2 million compared to $324.7 million for the year ended December 31, 2017. Results for the year ended December 31, 2018 included $2.6 million of expense related to the mark-to-market adjustment of the bifurcated embedded derivative related to the MAA Series I preferred stock issued in the merger with Post Properties and $4.5 million of gains related to the sale of real estate assets. Results for the year ended December 31, 2017 included $8.8 million of income related to the adjustment of the bifurcated embedded derivative and $127.4 million of gains related to the sale of real estate assets. Revenues for the year ended December 31, 2018 increased 2.8% compared to the year ended December 31, 2017, driven by a 1.9% increase in our Same Store segment and a 13.5% increase in our Non-Same Store and Other segment. Property operating expenses, excluding depreciation and amortization, for the year ended December 31, 2018 increased by 3.1% compared to the year ended December 31, 2017, due to a 2.0% increase in our Same Store segment and to a 14.6% increase in our Non-Same Store and Other segment. The drivers of these increases are discussed below in the "Results of Operations" section.
Over the past three years, our growth has been driven by our acquisition strategy to invest in growing markets in the Southeast, Southwest and Mid-Atlantic regions of the United States. As a result of the merger with Post Properties, we acquired 61 apartment communities in 2016. We acquired one apartment community in 2018, two in 2017, and five in 2016 apart from the merger with Post Properties. No apartment communities were disposed in 2018. We disposed of five apartment communities in 2017 and 12 in 2016.
Trends
During the year ended December 31, 2018, demand for apartments continued to be relatively strong, as it was during the year ended December 31, 2017. Average daily physical occupancy for our Same Store portfolio was 96.1% for the year ended December 31, 2018, in line with the 96.1% average daily physical occupancy achieved during the year ended December 31, 2017. Average effective rent per unit from our Same Store portfolio continued to increase, up 1.9% for the year ended December 31, 2018 as compared to the year ended December 31, 2017.
An important part of our portfolio strategy is to maintain diversity of markets, submarkets, product types and price points in the Southeast, Southwest and Mid-Atlantic regions of the United States. This diversity tends to mitigate exposure to economic issues in any one geographic market or area. We believe that a well-balanced portfolio, including inner loop, suburban and downtown/central business district locations and various monthly rent price points, will perform well in “up” cycles as well as weather “down” cycles better. Through our investment in 38 defined Metropolitan Statistical Areas, we are diversified across markets, urban and suburban submarkets, and a variety of monthly rent pricing points.
Though overall demand continues to be strong, the current elevated supply levels are impacting rent growth for our portfolio, particularly for apartment communities located in urban submarkets. Properties in suburban submarkets have been impacted somewhat less by supply, primarily because less new development has occurred in those submarkets. Multifamily permitting is typically a leading indicator of future supply levels. While multifamily permitting across our markets was down in 2017 as compared to 2016, to date, the U.S. Census Bureau's data for 2018 suggested multifamily permitting across our markets was up as compared to 2017. It is difficult to project supply levels based on this data because not all permitted projects are ultimately built. However, given the current supply level and the 2018 permitting data, it is possible that supply in some of our markets could remain elevated over the next couple of years.
Demand for our apartments is primarily driven by general economic conditions in our markets. In particular, job growth relative to new supply is a critical factor in our ability to maintain occupancy and increase rents. To the extent that economic conditions continue to support increased job growth, we believe that we may be able to maintain occupancy more effectively and increase rents. Also, we believe that more disciplined credit terms for residential mortgages should continue to
favor rental demand at existing multifamily apartment communities. Furthermore, rental competition from single family homes has not been a major competitive factor impacting our portfolio. For the year ended December 31, 2018, total move outs attributable to single family home rentals for our portfolio represented less than 7% of total move outs, as it did in the year ended December 31, 2017. We have seen significant rental competition from single family homes in only a few of our submarkets. Long term, we expect demographic trends (including the growth of prime age groups for rentals and immigration and population movement to the Southeast, Southwest and Mid-Atlantic regions) will continue to support apartment rental demand in our markets.
Rising interest rates may have a significant impact on our business and results of operations. As of December 31, 2018, we had approximately $4.5 billion of debt, of which 25% had variable rate interest and 75% had fixed or hedged interest rates. To the extent interest rates rise, our net interest expense on variable rate debt will increase as will potentially our net interest expense on any debt refinancing. Given the short-term nature of our leases, to the extent interest rates rise due to general economic growth, we would expect increases in interest expense to be somewhat offset by positive leasing trends.
Our focus is on maintaining strong physical occupancy while increasing pricing where possible through our revenue management system. As noted above, average daily physical occupancy for the year ended December 31, 2018 was sustained at 96.1%. As we continue through the typically slower winter leasing season, we believe that the current level of physical occupancy and continued strong job growth in our markets position us well for this period and sets us up to achieve modestly improved pricing growth in 2019.
Results of Operations
Comparison of the Year Ended December 31, 2018 to the Year Ended December 31, 2017
For the year ended December 31, 2018, we achieved net income available for MAA common shareholders of $219.2 million, a 32.5% decrease as compared to the year ended December 31, 2017, and total revenue growth of $42.4 million, representing a 2.8% increase in property revenues as compared to the year ended December 31, 2017. The following discussion describes the primary drivers of the decrease in net income available for MAA common shareholders for the year ended December 31, 2018 as compared to the year ended December 31, 2017.
Property Revenues
The following table reflects our property revenues by segment for the years ended December 31, 2018 and December 31, 2017 (dollars in thousands):
| December 31, 2018 | December 31, 2017 | Increase | % Increase | |||||||||||
| Same Store | $ | 1,441,811 | $ | 1,414,839 | $ | 26,972 | 1.9 | % | ||||||
| Non-Same Store and Other | 129,535 | 114,148 | 15,387 | 13.5 | % | |||||||||
| Total | $ | 1,571,346 | $ | 1,528,987 | $ | 42,359 | 2.8 | % |
The increase in property revenues for our Same Store segment as compared to the year ended December 31, 2017 was the primary driver of total property revenue growth. The Same Store segment generated a 1.9% increase in revenues for the year ended December 31, 2018, primarily a result of average effective rent per unit growth of 1.9% and stable occupancy as compared to the year ended December 31, 2017. The increase in property revenues from the Non-Same Store and Other segment for the year ended December 31, 2018 as compared to year ended December 31, 2017 was primarily the result of recent property acquisitions and continued lease-up of recent development communities.
Property Operating Expenses
Property operating expenses include costs for property personnel, building repairs and maintenance, real estate taxes and insurance, utilities, landscaping, and other operating expenses. The following table reflects our property operating expenses by segment for the years ended December 31, 2018 and December 31, 2017 (dollars in thousands):
| December 31, 2018 | December 31, 2017 | Increase | % Increase | |||||||||||
| Same Store | $ | 536,055 | $ | 525,663 | $ | 10,392 | 2.0 | % | ||||||
| Non-Same Store and Other | 58,533 | 51,068 | 7,465 | 14.6 | % | |||||||||
| Total | $ | 594,588 | $ | 576,731 | $ | 17,857 | 3.1 | % |
The increase in property operating expenses for our Same Store segment as compared to the year ended December 31, 2017 was primarily driven by increases in real estate tax expense of $7.7 million and personnel expenses of $4.4 million, partially offset by a decrease in building repairs and maintenance expense of $2.5 million. The increase in property operating expenses from our Non-Same Store and Other segment was primarily the result of increases in real estate tax expense of $4.2 million driven by recently completed communities previously in our development pipeline and other operating expense of $3.0 million.
Depreciation and Amortization
Depreciation and amortization expense for the year ended December 31, 2018 was $489.8 million, a decrease of $3.9 million as compared to the year ended December 31, 2017. The decrease was primarily due to a $25.8 million decrease in amortization expense, which was driven by certain intangible assets acquired as a result of the merger with Post Properties becoming fully amortized in the second quarter of 2017. As a result, we recognized no amortization expense for those assets in the year ended December 31, 2018. The decrease in amortization expense was partially offset by a $21.9 million increase to depreciation expense for the year ended December 31, 2018 as compared to the year ended December 31, 2017. The increase in depreciation expense was primarily driven by the recognition of depreciation expense associated with our capital asset spend during the year ended December 31, 2018, which was related to our development and redevelopment activities made in the normal course of business as well as property acquisitions during the year ended December 31, 2018.
Other Income and Expenses
Property management expenses for the year ended December 31, 2018 were $47.6 million, an increase of $4.0 million as compared to the year ended December 31, 2017. The increase was primarily due to increases in personnel costs. General and administrative expenses for the year ended December 31, 2018 were $34.8 million, a decrease of $5.4 million as compared to the year ended December 31, 2017, primarily due to decreases in legal expense. Merger and integration expenses for the year ended December 31, 2018 were $9.1 million, a decrease of $10.9 million as compared to the year ended December 31, 2017, primarily due to declining year-over-year integration activities related to the merger with Post Properties.
Interest expense for the year ended December 31, 2018 was $173.6 million, an increase of $18.8 million as compared to the year ended December 31, 2017. The increase was primarily due to an increase of approximately 18 basis points in our effective interest rate during the year ended December 31, 2018 compared to the year ended December 31, 2017 combined with a decrease in interest capitalized from our development pipeline during the year ended December 31, 2018 compared to the year ended December 31, 2017.
We did not dispose of any apartment communities during the year ended December 31, 2018. For the year ended December 31, 2017, we disposed of five apartment communities, resulting in gains on sale of depreciable real estate assets of $127.4 million. Gain on sale of non-depreciable assets for the year ended December 31, 2018 was $4.5 million, an increase of $4.5 million as compared to the year ended December 31, 2017. Although we disposed of only one land parcel more in the year ended December 31, 2018 as compared to the year ended December 31, 2017, the gain on sale of non-depreciable assets increased primarily due to the nature of the real estate assets sold.
Other non-operating income for the year ended December 31, 2018 was $5.4 million, a decrease of $8.9 million as compared to the year ended December 31, 2017. The decrease was primarily due to the recognition of $2.6 million of expense from the net mark-to-market adjustment of the bifurcated embedded derivative related to the MAA Series I preferred stock during the year ended December 31, 2018 as compared to the recognition of $8.8 million of income from the net mark-to-market adjustment of the bifurcated embedded derivative during the year ended December 31, 2017.
Comparison of the Year Ended December 31, 2017 to the Year Ended December 31, 2016
For the year ended December 31, 2017, we achieved net income available for MAA common shareholders of $324.7 million, as compared to $211.9 million for the year ended December 31, 2016. Total revenue grew $403.6 million for the year ended December 31, 2017 as compared to the year ended December 31, 2016, representing a 35.9% increase in property revenues. The following discussion describes the primary drivers of the increase in net income available for MAA common shareholders for the year ended December 31, 2017 as compared to the year ended December 31, 2016. The comparison of the year ended December 31, 2017 to the year ended December 31, 2016 shows the segment break down based on our Same Store portfolio for the year ended December 31, 2017. A comparison using our 2018 Same Store portfolio would not be comparative due to the nature of the classifications.
Property Revenues
The following table reflects our property revenues by segment for the years ended December 31, 2017 and December 31, 2016 (dollars in thousands):
| December 31, 2017 | December 31, 2016 | Increase | % Increase | |||||||||||
| Same Store | $ | 1,021,138 | $ | 992,721 | $ | 28,417 | 2.9 | % | ||||||
| Non-Same Store and Other | 507,849 | 132,627 | 375,222 | 282.9 | % | |||||||||
| Total | $ | 1,528,987 | $ | 1,125,348 | $ | 403,639 | 35.9 | % |
The Same Store segment generated a 2.9% increase in revenues for the year ended December 31, 2017, primarily a result of average effective rent per unit growth of 3.0% as compared to the year ended December 31, 2016. The increase in property revenues for the year ended December 31, 2017 as compared to the year ended December 31, 2016 from our Non-Same Store and Other segment was primarily the result of the merger with Post Properties, as we classified the properties we acquired in the merger in our Non-Same Store and Other segment.
Property Operating Expenses
Property operating expenses include costs for property personnel, building repairs and maintenance, real estate taxes and insurance, utilities, landscaping and other operating expenses. The following table reflects our property operating expenses by segment for the years ended December 31, 2017 and December 31, 2016 (dollars in thousands):
| December 31, 2017 | December 31, 2016 | Increase | % Increase | |||||||||||
| Same Store | $ | 380,390 | $ | 372,154 | $ | 8,236 | 2.2 | % | ||||||
| Non-Same Store and Other | 196,341 | 51,202 | 145,139 | 283.5 | % | |||||||||
| Total | $ | 576,731 | $ | 423,356 | $ | 153,375 | 36.2 | % |
The increase in property operating expenses for our Same Store segment as compared to the year ended December 31, 2016 was primarily driven by increases in real estate tax expense of $6.2 million and personnel expenses of $2.3 million. The increase in property operating expenses for our Non-Same Store and Other segment was primarily due to the merger with Post Properties.
Depreciation and Amortization
Depreciation and amortization expense for the year ended December 31, 2017 was $493.7 million, an increase of $170.8 million as compared to the year ended December 31, 2016. The increase was primarily driven by the full year of depreciation and amortization expense resulting from the merger with Post Properties compared to only one month of comparable depreciation and amortization in 2016. As a result of the merger with Post Properties, depreciation expense and amortization expense increased $138.2 million and $23.2 million, respectively, for the year ended December 31, 2017 as compared to the year ended December 31, 2016. The remaining increase was primarily driven by our capital asset spend and other asset acquisition activity.
Other Income and Expenses
Property management expenses for the year ended December 31, 2017 were $43.6 million, an increase of $9.5 million as compared to the year ended December 31, 2016. The increase was primarily due to the growth in our portfolio as a result of the merger with Post Properties. General and administrative expenses for the year ended December 31, 2017 were $40.2 million, an increase of $11.2 million as compared to the year ended December 31, 2016, primarily due to increases in legal expense. Merger and integration expenses for the year ended December 31, 2017 were $20.0 million, a decrease of $20.8 million as compared to the year ended December 31, 2016, as we incurred significant merger related expenses in 2016 to complete the merger with Post Properties on December 1, 2016.
Interest expense for the year ended December 31, 2017 was $154.8 million, an increase of $24.8 million as compared to the year ended December 31, 2016. The increase was primarily due to increased borrowing as we assumed several loans as a result of the merger with Post Properties, including a secured loan with a face value of $186.0 million and two unsecured loans with face values of $150.0 million and $250.0 million, respectively. We also entered into a new $300.0 million term loan on the closing date of the merger with Post Properties. Interest expense for the year ended December 31, 2017 increased $16.0 million due to these borrowings resulting from the merger with Post Properties.
Gains on sale of depreciable assets totaled $127.4 million for the year ended December 31, 2017, an increase of $47.0 million as compared to the year ended December 31, 2016. Although disposition activity decreased year-over-year, the gain on sale of depreciable assets increased primarily due to the nature of the real estate assets sold.
Other non-operating income for the year ended December 31, 2017 was $14.4 million, an increase of $16.2 million as compared to the year ended December 31, 2016. The increase was primarily due to an $8.8 million increase in income from the net mark-to-market adjustment of the bifurcated embedded derivative related to the MAA Series I preferred stock issued in the merger with Post Properties. The increase in other non-operating income was also driven by a $3.3 million net gain on debt extinguishment.
During the year ended December 31, 2017, we recorded quarterly dividend distributions to holders of MAA's Series I preferred stock totaling $3.7 million. As there were no shares of MAA Series I preferred stock issued and outstanding until completion of the merger with Post Properties on December 1, 2016, preferred dividends only impacted our results of operations for one month totaling $0.3 million for the year ended December 31, 2016.
Funds from Operations
Funds from operations, or FFO, a non-GAAP financial measure, represent net income available for MAA common shareholders (computed in accordance with the United States generally accepted accounting principles, or GAAP) excluding extraordinary items, asset impairment and gains or losses on disposition of operating properties, plus net income attributable to noncontrolling interests, depreciation and amortization of real estate, and adjustments for joint ventures. Because noncontrolling interest is added back, FFO, when used in this Annual Report on Form 10-K, represents FFO attributable to the Company.
FFO should not be considered as an alternative to net income or any other GAAP measurement, as an indicator of operating performance or as an alternative to cash flow from operating, investing, and financing activities as a measure of liquidity. Management believes that FFO is helpful to investors in understanding our operating performance primarily because its calculation excludes depreciation and amortization expense on real estate assets. We believe that GAAP historical cost depreciation of real estate assets is generally not correlated with changes in the value of those assets, whose value does not diminish predictably over time, as historical cost depreciation implies. While our calculation of FFO is in accordance with the National Association of Real Estate Trust's, or NAREIT's, definition, it may differ from the methodology for calculating FFO utilized by other REITs and, accordingly, may not be comparable to such other REITs.
The following table presents a reconciliation of net income available for MAA common shareholders to FFO for the years ended December 31, 2018, 2017 and 2016, as we believe net income available for MAA common shareholders is the most directly comparable GAAP measure (dollars in thousands):
| Year ended December 31, | |||||||||||
| 2018 | 2017 | 2016 | |||||||||
| Net income available for MAA common shareholders | $ | 219,211 | $ | 324,691 | $ | 211,915 | |||||
| Depreciation and amortization of real estate assets | 484,722 | 489,503 | 319,528 | ||||||||
| Loss (gain) on sale of depreciable real estate assets | 39 | (127,386 | ) | (80,397 | ) | ||||||
| Loss on disposition within unconsolidated entities | — | — | 98 | ||||||||
| Depreciation and amortization of real estate assets of real estate joint venture | 595 | 596 | 61 | ||||||||
| Net income attributable to noncontrolling interests | 8,123 | 12,157 | 12,180 | ||||||||
| Funds from operations attributable to the Company | $ | 712,690 | $ | 699,561 | $ | 463,385 |
FFO for the year ended December 31, 2018 were $712.7 million, an increase of $13.1 million as compared to the year ended December 31, 2017, primarily as a result of increases in property revenues of $42.4 million and gain on sale of non-depreciable assets of $4.5 million, in addition to a decrease in merger and integration expenses of $10.9 million. The increases to FFO were offset by increases in interest expense of $18.8 million and property operating expenses, excluding depreciation and amortization, of $17.9 million, in addition to a decrease in other non-operating income of $8.9 million.
FFO for the year ended December 31, 2017 were $699.6 million, an increase of $236.2 million as compared to the year ended December 31, 2016, primarily as a result of increases in property revenues of $403.6 million and other non-operating income of $16.2 million, in addition to a decrease in merger and integration expenses of $20.8 million. The increases to FFO were offset by increases in property operating expenses, excluding depreciation and amortization, of $153.4 million, interest expense of $24.8 million, general and administrative expenses of $11.2 million, property management expenses of $9.5 million and preferred dividends of $3.4 million.
Liquidity and Capital Resources
Our cash flows from operating, investing and financing activities, as well as general economic and market conditions, are the principal factors affecting our liquidity and capital resources.
Operating Activities
Net cash provided by operating activities was $734.3 million for the year ended December 31, 2018, as compared to $660.8 million for the year ended December 31, 2017. The increase in operating cash flows was primarily driven by our operating performance as well as the timing of cash payments.
Investing Activities
Net cash used in investing activities was $366.4 million for the year ended December 31, 2018, as compared to net cash used in investing activities of $294.2 million for the year ended December 31, 2017. The primary drivers of the change were as follows (dollars in thousands):
| Primary drivers of cash (outflow) inflow | Increase (Decrease) in Net Cash | ||||||||||
| during the year ended December 31, | |||||||||||
| 2018 | 2017 | ||||||||||
| Purchases of real estate and other assets | $ | (129,487 | ) | $ | (136,065 | ) | $ | 6,578 | |||
| Capital improvements, development and other | (254,715 | ) | (343,890 | ) | 89,175 | ||||||
| Proceeds from disposition of real estate assets | 19,982 | 187,245 | (167,263 | ) |
The decrease in cash outflows for purchases of real estate and other assets was driven by the acquisition activity during the year ended December 31, 2018 as compared to the year ended December 31, 2017. The decrease in cash outflows for capital improvements, development and other as compared to the prior year was primarily due to the decrease in activity in our development pipeline during the year ended December 31, 2018 as compared to the prior year. The decrease in cash inflows related to proceeds from disposition of real estate assets was primarily due to the sale of five land parcels during the year ended December 31, 2018, as compared to the sale of five apartment communities and four land parcels during the prior year.
Financing Activities
Net cash used in financing activities was $405.1 million for the year ended December 31, 2018, as compared to net cash used in financing activities of $399.5 million for the year ended December 31, 2017. The primary drivers of the change were as follows (dollars in thousands):
| Primary drivers of cash inflow (outflow) | Increase (Decrease) in Net Cash | ||||||||||
| during the year ended December 31, | |||||||||||
| 2018 | 2017 | ||||||||||
| Net change in credit lines | $ | 50,000 | $ | (160,000 | ) | $ | 210,000 | ||||
| Proceeds from notes payable | 869,630 | 597,480 | 272,150 | ||||||||
| Principal payments on notes payable | (878,610 | ) | (413,557 | ) | (465,053 | ) | |||||
| Dividends paid on common shares | (419,849 | ) | (395,294 | ) | (24,555 | ) |
The increase in cash inflow related to the net change in credit lines resulted from the increase in net borrowings of $50.0 million on our unsecured revolving credit facility during the year ended December 31, 2018, as compared to the decrease in net borrowings of $160.0 million on the unsecured revolving credit facility during the year ended December 31, 2017. The increase in cash inflows from proceeds from notes payable primarily resulted from the issuances of $400.0 million of senior unsecured notes, $172.0 million of secured property mortgages and a $300.0 million unsecured term loan during the year ended December 31, 2018, compared to the issuance of $600.0 million of senior unsecured notes during the year ended December 31, 2017. The increase in cash outflows from principal payments on notes payable primarily resulted from the retirement of $568.0 million of secured property mortgages and an $80.0 million secured credit facility during the year ended December 31, 2018, as compared to the retirement of $233.6 million of secured property mortgages and $168.0 million of senior unsecured notes during the year ended December 31, 2017. The increase in cash outflows from dividends paid on common shares primarily resulted from the increase in the annual dividend rate to $3.69 per share during the year ended December 31, 2018, as compared to the annual dividend rate of $3.48 per share during the year ended December 31, 2017.
Equity
As of December 31, 2018, MAA owned 113,844,267 OP Units, comprising a 96.5% limited partnership interest in MAALP, while the remaining 4,111,301 outstanding OP Units were held by limited partners of MAALP other than MAA and its subsidiaries. Holders of OP Units (other than MAA and its subsidiaries) may require us to redeem their OP Units from time to time, in which case MAA may, at its option, pay the redemption price either in cash (in an amount per OP Unit equal, in general, to the average closing price of MAA's common stock on the NYSE over a specified period prior to the redemption date) or by delivering one share of MAA's common stock (subject to adjustment under specified circumstances) for each OP Unit so redeemed. In addition, MAA has registered under the Securities Act 4,111,301 shares of its common stock that, as of December 31, 2018, were issuable upon redemption of OP Units, in order for those shares to be sold freely in the public markets.
For more information regarding our equity capital resources, see Note 9 and Note 10 to the consolidated financial statements included elsewhere in this Annual Report on Form 10-K.
Debt
The following schedule reflects our fixed and variable rate debt, including the impact of our interest rate swaps, outstanding as of December 31, 2018 (dollars in thousands):
| Principal Balance | Average Years to Rate Maturity | Effective Rate | |||||||
| Unsecured debt | |||||||||
| Fixed rate or swapped | $ | 2,942,000 | 6.0 | 3.8 | % | ||||
| Variable rate | 1,140,000 | 0.1 | 3.4 | % | |||||
| Fair market value adjustments, debt issuance costs and discounts | (28,698 | ) | |||||||
| Total unsecured rate maturity | $ | 4,053,302 | 4.3 | 3.7 | % | ||||
| Secured debt | |||||||||
| Conventional - fixed rate | $ | 476,161 | 12.2 | 4.6 | % | ||||
| Fair market value adjustments and debt issuance costs | (1,135 | ) | |||||||
| Total secured rate maturity | $ | 475,026 | 12.2 | 4.6 | % | ||||
| Total debt | $ | 4,528,328 | 5.1 | 3.8 | % | ||||
| Total fixed or hedged debt | $ | 3,389,249 | 6.8 | 3.9 | % |
As of December 31, 2018, we had entered into interest rate swaps totaling a notional amount of $600.0 million, of which $300.0 million related to issued debt, while the remaining $300.0 million hedges the first 10 years of interest payments on debt we anticipate will be issued in 2019. To date, we believe the interest rate swaps have proven to be highly effective hedges.
The following schedule presents the contractual maturity dates of our outstanding debt, net of fair market value adjustments, debt issuance costs and discounts, as of December 31, 2018 (dollars in thousands):
| Unsecured Revolving Credit Facility | Public Bonds | Other Unsecured | Secured | Total | |||||||||||||||
| 2019 | $ | — | $ | — | $ | 319,508 | $ | 13,524 | $ | 333,032 | |||||||||
| 2020 | 540,000 | — | 149,883 | 159,097 | 848,980 | ||||||||||||||
| 2021 | — | — | 222,294 | 122,837 | 345,131 | ||||||||||||||
| 2022 | — | 248,522 | 416,075 | — | 664,597 | ||||||||||||||
| 2023 | — | 346,826 | 12,217 | — | 359,043 | ||||||||||||||
| Thereafter | — | 1,778,037 | 19,940 | 179,568 | 1,977,545 | ||||||||||||||
| Total | $ | 540,000 | $ | 2,373,385 | $ | 1,139,917 | $ | 475,026 | $ | 4,528,328 |
The following schedule reflects the interest rate maturities of our outstanding fixed or hedged debt, net of fair market value adjustments, debt issuance costs and discounts, as of December 31, 2018 (dollars in thousands):
| Fixed Rate Debt | Interest Rate Swaps | Total Fixed Rate Balances | Contract Rate | ||||||||||||
| 2019 | $ | 33,508 | $ | — | $ | 33,508 | 4.4 | % | |||||||
| 2020 | 159,097 | 299,353 | 458,450 | 3.2 | % | ||||||||||
| 2021 | 195,459 | — | 195,459 | 5.2 | % | ||||||||||
| 2022 | 365,244 | — | 365,244 | 3.6 | % | ||||||||||
| 2023 | 359,043 | — | 359,043 | 4.3 | % | ||||||||||
| Thereafter | 1,977,545 | — | 1,977,545 | 3.9 | % | ||||||||||
| Total | $ | 3,089,896 | $ | 299,353 | $ | 3,389,249 | 3.9 | % |
Unsecured Revolving Credit Facility
In October 2015, the Operating Partnership entered into an unsecured revolving credit facility agreement with a syndicate of banks led by KeyBank National Association, or KeyBank, and fifteen other banks, which we refer to as the KeyBank Facility. The KeyBank Facility replaced the Operating Partnership's previous unsecured credit facility with KeyBank. The interest rate is determined using an investment grade pricing grid using LIBOR plus a spread of 0.85% to 1.55%. In December 2016, the Operating Partnership amended the KeyBank Facility by increasing the borrowing capacity from $750.0 million to $1.0 billion. As of December 31, 2018, we had $540.0 million borrowed under the KeyBank Facility, bearing interest at a rate of one month LIBOR plus 0.90%. The KeyBank Facility serves as our primary source of short-term liquidity and has an accordion feature that we may use to expand its capacity to $1.5 billion. The KeyBank Facility matures in April 2020, with an option to extend for an additional six months.
Senior Unsecured Notes
We have issued both public and private unsecured notes. As of December 31, 2018, we had approximately $2.4 billion (face value) of publicly issued unsecured notes and $242.0 million of unsecured notes issued in two private placements. In October 2013, we publicly issued $350.0 million of senior unsecured notes due October 2023 with a coupon of 4.30%, paid semi-annually on April 15 and October 15. In June 2014, we publicly issued $400.0 million of senior unsecured notes due June 2024 with a coupon of 3.75%, paid semi-annually on June 15 and December 15. In November 2015, we publicly issued $400.0 million senior unsecured notes due November 2025 with a coupon of 4.00%, paid semi-annually on May 15 and November 15. As a result of the merger with Post Properties in December 2016, we assumed $250.0 million of senior unsecured notes due December 2022 with a coupon of 3.38%, paid semi-annually on June 1 and December 1. In May 2017, we publicly issued $600.0 million of senior unsecured notes due June 2027 with a coupon of 3.60%, paid semi-annually on June 1 and December 1. In May 2018, we publicly issued $400.0 million of senior unsecured notes due June 2028 with a coupon of 4.20%, paid semi-annually on June 15 and December 15. The proceeds from the senior unsecured notes issued in May 2018 were used to pay down outstanding amounts under the Key Bank Facility. As of December 31, 2018, all of these amounts remained outstanding.
In July 2011, we issued $135.0 million of senior unsecured notes. The notes were offered and sold in a private placement with three maturity tranches: $50.0 million at 4.7% maturing in July 2018, $72.8 million at 5.4% maturing in July 2021; and $12.3 million at 5.6% maturing in July 2023. The $50.0 million tranche was paid off on its maturity date. In August 2012, we issued $175.0 million of senior unsecured notes. The notes were offered and sold in a private placement with four tranches: $18.0 million at 3.15% maturing in November 2017; $20.0 million at 3.61% maturing in November 2019; $117.0 million at 4.17% maturing in November 2022; and $20.0 million at 4.33% maturing in November 2024. The $18.0 million tranche was paid off on its maturity date. The remaining tranches were outstanding as of December 31, 2018.
Unsecured Term Loans
In addition to the KeyBank Facility and senior unsecured notes, we maintain four unsecured term loans. We had total borrowings of $900.0 million outstanding under these term loan agreements as of December 31, 2018, comprised of:
A $300.0 million term loan with Wells Fargo, N.A., or Wells Fargo, that bears interest at a rate of LIBOR plus a spread of 0.75% to 1.65% based on the credit ratings of our unsecured debt. We entered into the six month term loan in December 2018, and the loan matures in June 2019, with an option to extend for an additional six months. As of December 31, 2018, this loan was bearing interest at a rate of one month LIBOR plus 0.90%.
A $150.0 million term loan with U.S. Bank National Association, or U.S. Bank, that bears interest at a rate of LIBOR plus a spread of 0.90% to 1.90% based on the credit ratings of our unsecured debt. The loan matures in March 2020. As of December 31, 2018, this loan was bearing interest at a rate of one month LIBOR plus 0.98%.
A $150.0 million term loan with KeyBank that bears interest at a rate of LIBOR plus a spread of 0.90% to 1.75% based on the credit ratings of our unsecured debt. The loan matures in February 2021. As of December 31, 2018, this loan was bearing interest at a rate of one month LIBOR plus 0.95%.
A $300.0 million term loan with Wells Fargo that bears interest at a rate of LIBOR plus a spread of 0.90% to 1.75% based on the credit ratings of our unsecured debt. The loan matures in March 2022. As of December 31, 2018, this loan was bearing interest at a rate of one month LIBOR plus 0.95%.
We retired a $250.0 million unsecured term loan with Wells Fargo on its maturity date in August 2018.
Secured Property Mortgages
We maintain secured property mortgages with Fannie Mae, Freddie Mac and various life insurance companies. These mortgages are usually fixed rate and can range from five to 30 years in maturity. As of December 31, 2018, we had $476.2 million of secured property mortgages. In December 2018, we issued $172.0 million in secured property mortgages with a fixed rate of 4.44%. During the year ended December 31, 2018, we retired $568.0 million of secured property mortgages.
For more information regarding our debt capital resources, see Note 6 to the consolidated financial statements included elsewhere in this Annual Report on Form 10-K.
Contractual Obligations
The following table reflects our total contractual cash obligations as of December 31, 2018, which consist of principal and interest on our long-term debt as well as operating leases (dollars in thousands):
| Contractual Obligations | 2019 | 2020 | 2021 | 2022 | 2023 | Thereafter | Total | |||||||||||||||||||||
| Long-term debt obligations (1) | $ | 340,446 | $ | 848,281 | $ | 342,903 | $ | 668,401 | $ | 363,731 | $ | 1,994,399 | $ | 4,558,161 | ||||||||||||||
| Fixed rate or swapped interest (2) | 130,639 | 122,459 | 113,892 | 107,209 | 93,756 | 394,048 | 962,003 | |||||||||||||||||||||
| Variable rate interest (3) | 32,992 | 20,755 | 10,681 | 1,650 | — | — | 66,078 | |||||||||||||||||||||
| Operating lease obligations (4) | 2,729 | 2,744 | 2,771 | 2,767 | 2,761 | 68,516 | 82,288 | |||||||||||||||||||||
| Total | $ | 506,806 | $ | 994,239 | $ | 470,247 | $ | 780,027 | $ | 460,248 | $ | 2,456,963 | $ | 5,668,530 |
(1) Represents principal payments gross of discounts, debt issuance costs and fair market value adjustments of debt assumed.
(2) Swapped interest is subject to the ineffective portion of cash flow hedges as described in Note 7 to the consolidated financial statements included elsewhere in this Annual Report on Form 10-K.
(3) Interest payments on variable rate debt instruments not subject to interest rate swaps are based on each debt instrument's respective interest rate as of December 31, 2018, which is assumed to be in effect through the maturity date of the respective debt instrument.
(4) Primarily comprised of a ground lease underlying one apartment community we own and the lease for our corporate headquarters.
We have a commitment, which is not reflected in the table above, to make additional capital contributions to a limited partnership in which we hold an equity interest. The capital contributions may be called by the general partner at any time until September 2022 after giving appropriate notice. As of December 31, 2018, we had committed to make additional capital contributions totaling up to $13.6 million if and when called by the general partner of the limited partnership and until September 2022.
Off-Balance Sheet Arrangements
As of December 31, 2018 and 2017, we had a 35.0% ownership interest in a limited liability company, which owns one apartment community comprised of 269 units, located in Washington, D.C. We also had a 20.7% ownership interest in a limited partnership as of December 31, 2018. Our interests in these investments are unconsolidated and are recorded using the equity method as we do not have a controlling interest.
As of December 31, 2018 and 2017, we did not have any relationships, including those with unconsolidated entities or financial partnerships, for the purpose of facilitating off-balance sheet arrangements or other contractually narrow or limited purposes. In addition, we do not engage in trading activities involving non-exchange traded contracts. As such, we are not
materially exposed to any financing, liquidity, market or credit risk that could arise if we had engaged in such relationships. We do not have any relationships or transactions with persons or entities that derive benefits from their non-independent relationships with us or our related parties other than those disclosed in Note 13 to the consolidated financial statements included elsewhere in this Annual Report on Form 10-K.
Insurance
We carry comprehensive general liability coverage on our apartment communities, with limits of liability we believe are customary within the multifamily apartment industry, to insure against liability claims and related defense costs. We also maintain insurance against the risk of direct physical damage to reimburse us on a replacement cost basis for costs incurred to repair or rebuild any property, including loss of rental income during the reconstruction period.
We renegotiated our insurance programs effective July 1, 2018. We believe that the current property and casualty insurance program in place provides appropriate insurance coverage for financial protection against insurable risks such that any insurable loss experienced that can be reasonably anticipated would not have a significant impact on our liquidity, financial position or results of operations.
Inflation
Our resident leases at our apartment communities allow, at the time of renewal, for adjustments in the rent payable thereunder, and thus may enable us to seek rent increases. The majority of our leases are for approximately one year or less. The short-term nature of these leases generally serves to reduce our risk to adverse effects of inflation.
Critical Accounting Policies and Estimates
A critical accounting policy is one that is both important to our financial condition and results of operations and that involves some degree of uncertainty. The preceding discussion and analysis of our financial condition and results of operations are based upon our consolidated financial statements and the notes thereto, which have been prepared in accordance with GAAP. The preparation of financial statements in conformity with GAAP requires management to make a number of estimates and assumptions that affect the reported amounts and disclosures in the consolidated financial statements. On an ongoing basis, we evaluate our estimates and assumptions based upon historical experience and various other factors and circumstances. We believe that our estimates and assumptions are reasonable under the circumstances; however, actual results may differ from these estimates and assumptions.
We believe that the estimates and assumptions listed below are most important to the portrayal of our financial condition and results of operations because they require the greatest subjective determinations and form the basis of accounting policies deemed to be most critical.
Acquisition of real estate assets
We account for our acquisitions of investments in real estate as asset acquisitions in accordance with ASU 2017-01, Business Combinations (Topic 805): Clarifying the Definition of a Business, which requires the cost of the real estate acquired to be allocated to the individual acquired tangible assets, consisting of land, buildings and improvements and other, and identified intangible assets, consisting of the value of in-place leases and other contracts, on a relative fair value basis. In calculating the total asset value of acquired tangible assets, management uses stabilized net operating income, or NOI, and market specific capitalization and discount rates. Management analyzes historical stabilized NOI to determine its estimate for forecasted NOI. Management estimates the market capitalization rate by analyzing the market capitalization rates for properties with comparable ages in similarly sized markets. Management then allocates the purchase price of the asset acquisition based on the relative fair value of the individual components as a proportion of the total assets acquired.
Impairment of long-lived assets
We account for long-lived assets in accordance with the provisions of accounting standards for the impairment or disposal of long-lived assets. Management periodically evaluates long-lived assets, including investments in real estate, for indicators that would suggest that the carrying amount of the assets may not be recoverable. The judgments regarding the existence of such indicators are based on factors such as operating performance, market conditions and legal factors. Long-lived assets, such as real estate assets, equipment and purchased intangibles subject to amortization, are reviewed for impairment whenever events or changes in circumstances indicate that the carrying amount of an asset may not be recoverable. Recoverability of assets to be held and used is measured by a comparison of the carrying amount of an asset to estimated
undiscounted future cash flows expected to be generated by the asset, which is estimated by analyzing historical cash flows of the asset. If the carrying amount of an asset exceeds its estimated future cash flows, an impairment charge is recognized for the amount by which the carrying amount of the asset exceeds the fair value of the asset. Management calculates the fair value of an asset by dividing historical operating cash flows by a market capitalization rate. Management estimates the market capitalization rate by analyzing the market capitalization rates for properties with comparable ages in similarly sized markets. No material impairment losses have been recognized during the years ended December 31, 2018, 2017, and 2016.
Cost capitalization
In conformity with GAAP, we capitalize those expenditures that materially enhance the value of an existing asset or substantially extend the useful life of an existing asset. Expenditures necessary to maintain an existing property in ordinary operating condition are expensed as incurred. Therefore, repairs and maintenance costs are expensed as incurred while significant improvements, renovations and replacements are capitalized. The cost to complete any deferred repairs and maintenance at properties acquired by us in order to elevate the condition of the property to our standards are capitalized as incurred. The carrying costs related to development projects, including interest, property taxes, insurance and allocated direct development salary cost during the construction period, are capitalized. Management uses judgment in determining whether costs should be expensed or capitalized. See Note 1 to the consolidated financial statements included elsewhere in this Annual Report on Form 10-K for additional detail.
Loss contingencies
The outcomes of claims, disputes and legal proceedings are subject to significant uncertainty. Management records an accrual for loss contingencies when a loss is probable and the amount of the loss can be reasonably estimated. We also accrue an estimate of defense costs expected to be incurred in connection with legal matters. Management reviews these accruals quarterly and makes revisions based on changes in facts and circumstances. When a loss contingency is not both probable and reasonably estimable, then we do not accrue the loss. However, for material loss contingencies, if the unrecorded loss (or an additional loss in excess of the accrual) is at least a reasonable possibility and material, then management discloses a reasonable estimate of the possible loss, or range of loss, if such reasonable estimate can be made. If we cannot make a reasonable estimate of the possible loss, or range of loss, then that is disclosed.
The assessment of whether a loss is probable or a reasonable possibility, and whether the loss or range of loss is reasonably estimable, often involves a series of complex judgments about future events. Among the factors that we consider in this assessment, including with respect to the matters disclosed in this Annual Report on Form 10-K, are the nature of existing legal proceedings and claims, the asserted or possible damages or loss contingency (if reasonably estimable), the progress of the matter, existing law and precedent, the opinions or views of legal counsel and other advisers, our experience in similar matters, the facts available to us at the time of assessment, and how we intend to respond, or have responded, to the proceeding or claim. Management's assessment of these factors may change over time as individual proceedings or claims progress. For matters where we are not currently able to reasonably estimate a range of reasonably possible loss, the factors that have contributed to this determination include the following: (i) the damages sought are indeterminate; (ii) the proceedings are in the early stages; (iii) the matters involve novel or unsettled legal theories or a large or uncertain number of actual or potential cases or parties; and/or (iv) discussions with the parties in matters that are expected ultimately to be resolved through negotiation and settlement have not reached the point where we believe a reasonable estimate of loss, or range of loss, can be made. In such instances, management believes that there is considerable uncertainty regarding the timing or ultimate resolution of such matters, including a possible eventual loss or business impact, if any.
For more information regarding our significant accounting policies, including a brief description of recent accounting pronouncements that could have a material impact on our financial statements, see Note 1 to the consolidated financial statements included elsewhere in this Annual Report on Form 10-K.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
Market risk includes risks that arise from changes in interest rates, foreign currency exchange rates, commodity prices, equity prices and other market changes that affect market sensitive instruments. Our primary market risk exposure is to changes in interest rates on our borrowings. As of December 31, 2018, 28.6% of our total capitalization consisted of borrowings. Our interest rate risk objective is to limit the impact of interest rate fluctuations on earnings and cash flows and to lower our overall borrowing costs. To achieve this objective, we manage our exposure to fluctuations in market interest rates for borrowings through the use of fixed rate debt instruments and interest rate swaps, which mitigate our interest rate risk on a related financial instrument and effectively fix the interest rate on a portion of our variable debt or on future refinancings. We use our best efforts to have our debt instruments mature across multiple years, which we believe limits our exposure to interest rate changes in any one year. We do not
enter into derivative instruments for trading or other speculative purposes. As of December 31, 2018, 74.8% of our outstanding debt was subject to fixed rates after considering related derivative instruments. We regularly review interest rate exposure on outstanding borrowings in an effort to minimize the risk of interest rate fluctuations.
The table below provides information about our financial instruments that are sensitive to changes in interest rates. For debt obligations, the table presents principal cash flows and related weighted average interest rates by expected maturity dates. For our interest rate swaps, the table presents the notional amount of the swaps and the years in which they expire. Weighted average variable rates are based on rates in effect as of December 31, 2018 (dollars in thousands).
| 2019 | 2020 | 2021 | 2022 | 2023 | Total Thereafter | Total | Fair Value Liability | ||||||||||||||||||||||||
| Long-term debt | |||||||||||||||||||||||||||||||
| Fixed rate | $ | 40,446 | $ | 158,281 | $ | 192,903 | $ | 368,401 | $ | 363,731 | $ | 1,994,399 | $ | 3,118,161 | $ | 3,066,546 | |||||||||||||||
| Average interest rate | 4.40 | % | 4.80 | % | 5.20 | % | 3.64 | % | 4.35 | % | 3.91 | % | 4.06 | % | |||||||||||||||||
| Variable rate (1) | $ | 300,000 | $ | 690,000 | $ | 150,000 | $ | — | $ | — | $ | — | $ | 1,140,000 | $ | 1,143,795 | |||||||||||||||
| Average interest rate | 3.36 | % | 3.38 | % | 3.30 | % | — | % | — | % | — | % | 3.36 | % | |||||||||||||||||
| Interest rate swaps | |||||||||||||||||||||||||||||||
| Variable to fixed | $ | — | $ | 300,000 | $ | — | $ | — | $ | — | $ | 300,000 | (2) | $ | 600,000 | $ | 1,623 | ||||||||||||||
| Average pay rate | — | % | 2.32 | % | — | % | — | % | — | % | 2.91 | % | 2.62 | % |
(1) Excluding the effect of interest rate swap agreements.
(2) Includes six forward rate swaps totaling $300.0 million, which hedge the first 10 years of interest payments on debt we anticipate issuing in 2019.
Item 8. Financial Statements and Supplementary Data.
The consolidated financial statements and related financial information required to be filed are set forth on pages F-1 to F-44 of this Annual Report on Form 10-K.
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure.
None.
Item 9A. Controls and Procedures.
Mid-America Apartment Communities, Inc.
(a) Evaluation of Disclosure Controls and Procedures
MAA is required to maintain disclosure controls and procedures, within the meaning of Exchange Act Rules 13a-15 and 15d-15. MAA's management, with the participation of MAA’s Chief Executive Officer and Chief Financial Officer, carried out an evaluation of the effectiveness of MAA's disclosure controls and procedures as of December 31, 2018. Based on that evaluation, MAA’s Chief Executive Officer and Chief Financial Officer concluded that the disclosure controls and procedures were effective as of December 31, 2018 to ensure that information required to be disclosed by MAA in its Exchange Act filings is accurately recorded, processed, summarized and reported within the time periods specified in the SEC’s rules and forms and is accumulated and communicated to MAA's management, including the Chief Executive Officer and Chief Financial Officer, as appropriate to allow timely decisions regarding required disclosure.
(b) Management’s Report on Internal Control over Financial Reporting
MAA's management is responsible for establishing and maintaining adequate internal control over financial reporting within the meaning of Exchange Act Rules 13a-15 and 15d-15. MAA's management, with the participation of MAA's Chief Executive Officer and Chief Financial Officer, conducted an evaluation of the effectiveness of MAA's internal control over financial reporting as of December 31, 2018 based on the framework specified in Internal Control - Integrated Framework (2013) published by the Committee of Sponsoring Organizations of the Treadway Commission. Based on such evaluation, MAA's management concluded that MAA's internal control over financial reporting was effective as of December 31, 2018.
Ernst & Young LLP, the independent registered public accounting firm that has audited the consolidated financial statements included elsewhere in this Annual Report on Form 10-K, has issued an attestation report on MAA’s internal control
over financial reporting, which is included herein.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Therefore, even those systems determined to be effective can only provide reasonable assurance with respect to financial statement preparation and presentation.
(c) Changes in Internal Control over Financial Reporting
There was no change to MAA’s internal control over financial reporting, within the meaning of Exchange Act Rules 13a-15 and 15d-15, that occurred during the quarter ended December 31, 2018 that has materially affected, or is reasonably likely to materially affect, MAA’s internal control over financial reporting.
Mid-America Apartments, L.P.
(a) Evaluation of Disclosure Controls and Procedures
The Operating Partnership is required to maintain disclosure controls and procedures, within the meaning of Exchange Act Rules 13a-15 and 15d-15. Management of the Operating Partnership, with the participation of the Chief Executive Officer and Chief Financial Officer of MAA, as the general partner of the Operating Partnership, carried out an evaluation of the effectiveness of the Operating Partnership's disclosure controls and procedures as of December 31, 2018. Based on that evaluation, the Chief Executive Officer and Chief Financial Officer of MAA, as the general partner of the Operating Partnership, concluded that the disclosure controls and procedures were effective as of December 31, 2018 to ensure that information required to be disclosed by the Operating Partnership in its in Exchange Act filings is accurately recorded, processed, summarized and reported within the time periods specified in the SEC’s rules and forms and is accumulated and communicated to the Operating Partnership's management, including the Chief Executive Officer and Chief Financial Officer of MAA, as the general partner of the Operating Partnership, as appropriate to allow timely decisions regarding required disclosure.
(b) Management’s Report on Internal Control over Financial Reporting
Management of the Operating Partnership is responsible for establishing and maintaining adequate internal control over financial reporting within the meaning of Exchange Act Rule 13a-15 and 15d-15. Management of the Operating Partnership, with the participation of the Chief Executive Officer and Chief Financial Officer of MAA, as the general partner of the Operating Partnership, conducted an evaluation of the effectiveness of the Operating Partnership’s internal control over financial reporting as of December 31, 2018 based on the framework specified in Internal Control - Integrated Framework (2013) published by the Committee of Sponsoring Organizations of the Treadway Commission. Based on such evaluation, management of the Operating Partnership has concluded that the Operating Partnership's internal control over financial reporting was effective as of December 31, 2018. An attestation report of the independent registered public accounting firm of the Operating Partnership will not be required as long as the Operating Partnership is a non-accelerated filer.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Therefore, even those systems determined to be effective can only provide reasonable assurance with respect to financial statement preparation and presentation.
(c) Changes in Internal Control over Financial Reporting
There was no change to the Operating Partnership’s internal control over financial reporting, within the meaning of Exchange Act Rules 13a-15 and 15d-15, that occurred during the quarter ended December 31, 2018 that has materially affected, or is reasonably likely to materially affect, the Operating Partnership’s internal control over financial reporting.
Item 9B. Other Information.
None.
PART III
Item 10. Directors, Executive Officers and Corporate Governance.
The information contained in MAA's 2019 Proxy Statement in the sections entitled "Board Structure", "Nominees for Election", "Executive Officers of the Registrant" and "Section 16(a) Beneficial Ownership Reporting Compliance," is incorporated herein by reference in response to this Item 10.
Our Board of Directors has adopted a Code of Conduct applicable to all officers, directors and employees, which can be found on our website at https://www.maac.com, on the For Investors page in the "Governance Documents" section under "Corporate Overview". We will provide a copy of this document to any person, without charge, upon request, by writing to the Legal Department at MAA, 6815 Poplar Avenue, Suite 500, Germantown, TN 38138. We intend to satisfy the disclosure requirement under Item 5.05 of Form 8-K regarding an amendment to, or waiver from, a provision of the Code of Conduct by posting such information on our website at the address and the locations specified above. Reference to our website does not constitute incorporation by reference of the information contained on the site and should not be considered part of this Annual Report on Form 10-K.
Item 11. Executive Compensation.
The information contained in MAA's 2019 Proxy Statement in the sections entitled "Executive Compensation Tables", "Director Compensation", "Compensation Committee Interlocks and Insider Participation", "Compensation Committee Report" and "Compensation Discussion and Analysis" is incorporated herein by reference in response to this Item 11.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
The information contained in MAA's 2019 Proxy Statement in the sections entitled "Security Ownership of Management", "Security Ownership of Certain Beneficial Owners" and "Securities Authorized for Issuance Under Equity Compensation Plans" is incorporated herein by reference in response to this Item 12.
Item 13. Certain Relationships and Related Transactions, and Director Independence.
The information contained in MAA's 2019 Proxy Statement in the sections entitled "Certain Relationships and Related Transactions" and "Indebtedness of Management" is incorporated herein by reference in response to this Item 13.
Item 14. Principal Accounting Fees and Services.
The information contained in MAA's 2019 Proxy Statement in the section entitled "Audit and Non-Audit Fees," is incorporated herein by reference in response to this Item 14.
PART IV
Item 15. Exhibits, Financial Statement Schedules.
| (a) | The following documents are filed as part of this Annual Report on Form 10-K: |
| 32.3* | MAALP Certification of Chief Executive Officer Pursuant to 18 U.S.C. Section 1350, as Adopted Pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. |
| 32.4* | MAALP Certification of Chief Financial Officer Pursuant to 18 U.S.C. Section 1350, as Adopted Pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. |
| 101 | The following financial information from Mid-America Apartment Communities, Inc.’s and Mid-America Apartments, L.P.'s Annual Report on Form 10-K for the period ended December 31, 2018, filed with the SEC on February 21, 2019, formatted in XBRL (eXtensible Business Reporting Language): (i) the Consolidated Balance Sheets as of December 31, 2018 and December 31, 2017; (ii) the Consolidated Statements of Operations for the years ended December 31, 2018, 2017 and 2016; (iii) the Consolidated Statements of Comprehensive Income for the years ended December 31, 2018, 2017 and 2016; (iv) the Consolidated Statements of Equity/Changes in Capital for the years ended December 31, 2018, 2017 and 2016; (v) the Consolidated Statements of Cash Flows for the years ended December 31, 2018, 2017 and 2016; (vi) Notes to Consolidated Financial Statements; and (vii) Schedule III - Real Estate and Accumulated Depreciation as of December 31, 2018. |
† Management contract or compensatory plan or arrangement.
- This certification is being furnished solely to accompany this Annual Report on Form 10-K pursuant to 18 U.S.C. Section 1350, and is not being filed for purposes of Section 18 of the Securities Exchange Act of 1934 and is not to be incorporated by reference into any filing of MAA or MAALP, whether made before or after the date hereof, regardless of any general incorporation language in such filings.
| (b) | Exhibits: See Item 15(a)(3) above. |
| (c) | Financial Statement Schedule: See Item 15(a)(2) above. |
Item 16. Form 10-K Summary.
None.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| MID-AMERICA APARTMENT COMMUNITIES, INC. | ||
| Date: | February 21, 2019 | /s/ H. Eric Bolton, Jr. |
| H. Eric Bolton, Jr. Chairman of the Board of Directors Chief Executive Officer (Principal Executive Officer) |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| Date: | February 21, 2019 | /s/ H. Eric Bolton, Jr. |
| H. Eric Bolton, Jr. Chairman of the Board of Directors Chief Executive Officer (Principal Executive Officer) | ||
| Date: | February 21, 2019 | /s/ Albert M. Campbell, III |
| Albert M. Campbell, III Executive Vice President and Chief Financial Officer (Principal Financial Officer) | ||
| Date: | February 21, 2019 | /s/ A. Clay Holder |
| A. Clay Holder Senior Vice President and Chief Accounting Officer (Principal Accounting Officer) | ||
| Date: | February 21, 2019 | /s/ Russell R. French |
| Russell R. French Director | ||
| Date: | February 21, 2019 | /s/ Alan B. Graf, Jr. |
| Alan B. Graf, Jr. Director | ||
| Date: | February 21, 2019 | /s/ Toni Jennings |
| Toni Jennings Director | ||
| Date: | February 21, 2019 | /s/ James K. Lowder |
| James K. Lowder Director | ||
| Date: | February 21, 2019 | /s/ Thomas H. Lowder |
| Thomas H. Lowder Director | ||
| Date: | February 21, 2019 | /s/ Monica McGurk |
| Monica McGurk Director | ||
| Date: | February 21, 2019 | /s/ Claude B. Nielsen |
| Claude B. Nielsen Director | ||
| Date: | February 21, 2019 | /s/ Philip W. Norwood |
| Philip W. Norwood Director | ||
| Date: | February 21, 2019 | /s/ W. Reid Sanders |
| W. Reid Sanders Director | ||
| Date: | February 21, 2019 | /s/ Gary Shorb |
| Gary Shorb Director | ||
| Date: | February 21, 2019 | /s/ David P. Stockert |
| David P. Stockert Director |
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| MID-AMERICA APARTMENTS, L.P. | ||
| a Tennessee Limited Partnership | ||
| By: Mid-America Apartment Communities, Inc., its general partner | ||
| Date: | February 21, 2019 | /s/ H. Eric Bolton, Jr. |
| H. Eric Bolton, Jr. Chairman of the Board of Directors Chief Executive Officer (Principal Executive Officer) |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant as an officer or director of Mid-America Apartment Communities, Inc., in its capacity as the general partner of the registrant and on the dates indicated.
| Date: | February 21, 2019 | /s/ H. Eric Bolton, Jr. |
| H. Eric Bolton, Jr. Chairman of the Board of Directors Chief Executive Officer (Principal Executive Officer) | ||
| Date: | February 21, 2019 | /s/ Albert M. Campbell, III |
| Albert M. Campbell, III Executive Vice President and Chief Financial Officer (Principal Financial Officer) | ||
| Date: | February 21, 2019 | /s/ A. Clay Holder |
| A. Clay Holder Senior Vice President and Chief Accounting Officer (Principal Accounting Officer) | ||
| Date: | February 21, 2019 | /s/ Russell R. French |
| Russell R. French Director | ||
| Date: | February 21, 2019 | /s/ Alan B. Graf, Jr. |
| Alan B. Graf, Jr. Director | ||
| Date: | February 21, 2019 | /s/ Toni Jennings |
| Toni Jennings Director | ||
| Date: | February 21, 2019 | /s/ James K. Lowder |
| James K. Lowder Director | ||
| Date: | February 21, 2019 | /s/ Thomas H. Lowder |
| Thomas H. Lowder Director | ||
| Date: | February 21, 2019 | /s/ Monica McGurk |
| Monica McGurk Director | ||
| Date: | February 21, 2019 | /s/ Claude B. Nielsen |
| Claude B. Nielsen Director | ||
| Date: | February 21, 2019 | /s/ Philip W. Norwood |
| Philip W. Norwood Director | ||
| Date: | February 21, 2019 | /s/ W. Reid Sanders |
| W. Reid Sanders Director | ||
| Date: | February 21, 2019 | /s/ Gary Shorb |
| Gary Shorb Director | ||
| Date: | February 21, 2019 | /s/ David P. Stockert |
| David P. Stockert Director |
Report of Independent Registered Public Accounting Firm
To the Shareholders and the Board of Directors of Mid-America Apartment Communities, Inc.
Opinion on the Financial Statements
We have audited the accompanying consolidated balance sheets of Mid-America Apartment Communities, Inc. (the Company) as of December 31, 2018 and 2017, the related consolidated statements of operations, comprehensive income, equity, and cash flows for each of the three years in the period ended December 31, 2018, and the related notes and financial statement schedule listed in the Index at Item 15(a)(2) (collectively referred to as the "consolidated financial statements"). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company at December 31, 2018 and 2017, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2018, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company’s internal control over financial reporting as of December 31, 2018, based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated February 21, 2019 expressed an unqualified opinion thereon.
Basis for Opinion
These financial statements are the responsibility of the Company's management. Our responsibility is to express an opinion on the Company's financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements. We believe that our audits provide a reasonable basis for our opinion.
/s/ Ernst & Young LLP
We have served as the Company's auditor since 2005.
Memphis, Tennessee
February 21, 2019
F-1
Report of Independent Registered Public Accounting Firm
To the Partners of Mid-America Apartments, L.P.
Opinion on the Financ
Showing the first 8K of 268K characters. Open the full section