 filings.tools
Mid-America Apartment Communities (MAA) 10-K risk factor changes: FY2023 vs FY2022
The 2023-12-31 10-K against the 2022-12-31 one, compared heading by heading and sentence by sentence.
Item 1A86 rewritten33 added20 removed293 unchanged
All filing items1,039 rewritten533 added277 removed1,791 unchanged
Summary
counted, not written
- Item 1A lists 43 risk factor headings: 2 new, 4 reworded and 37 unchanged since FY2022. 1 heading from FY2022 no longer appears.
- Sentence by sentence, 533 added, 277 removed, 1,039 rewritten and 1,791 unchanged across 17 items that differ.
- New this year: Item 1C. Cybersecurity..
New Item 1A headings (2)
- Our implementation of long-standing succession planning could have adverse effects.
- Extreme weather or natural disasters may cause significant damage to our properties.
Removed Item 1A headings (1)
- Extreme weather or natural disasters may cause significant damage to our properties and losses from catastrophes could exceed our insurance coverage.
Reworded Item 1A headings (4)
- We are dependent on a concentration of our investments in a single asset class, making our results of operations more vulnerable to a downturn or slowdown in the [added: multifamily] sector or other economic factors.
- Substantial competition
[removed: among apartment communities and real estate companies]may adversely affect our revenues and [added: limit our] acquisition and development opportunities. - Increasing real estate taxes, utilities and insurance
[removed: premiums][added: premiums, as well as changes in the terms and conditions of our insurance policies,] may negatively impact operating results. [removed: Disease outbreaks and other public health events, such as the COVID-19 pandemic, have materially impacted our business, and our][added: Our] financial condition, results of operations and cash flows could be materially adversely affected by factors relating to[removed: a pandemic.][added: disease outbreaks and other public health events.]
A heading is new when no FY2022 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
23 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2022. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors.
86 rewritten, 33 added, 20 removed, 293 unchanged
[removed: Disease outbreaks and other public health events, such as the COVID-19 pandemic, have materially impacted our business, and our] [added: Our] financial condition, results of operations and cash flows could be materially adversely affected by factors relating to [removed: a pandemic.][added: disease outbreaks and other public health events.]
[removed: The pandemic led governments and other authorities around] [added: For example, in response to] the [removed: world, including] [added: COVID-19 pandemic, extraordinary actions were taken by] federal, state and local governmental authorities [removed: in the U.S.] to [removed: take extraordinary actions to] combat the spread of COVID-19, including issuance of “stay-at-home” directives and similar mandates for many individuals to substantially restrict daily activities and for many businesses to curtail or cease normal operations.
The impact of a disease outbreak or other public health [removed: event, including the COVID-19 pandemic and restrictions intended to prevent its spread could have significant adverse impacts] [added: event] on our business, financial condition, results of operations and cash flows [removed: that are] [added: is] difficult to [removed: predict.][added: predict and, as was demonstrated by the COVID-19 pandemic, will depend on a number of factors, including:]
our residents’ [added: and commercial tenants’] ability or willingness to pay rent in full on a timely basis;
federal, state, local and industry-initiated efforts that may adversely affect the ability of landlords, including us, to collect rent and customary fees, adjust rental rates and enforce remedies for the failure to pay rent, such as the various orders that were issued by governmental authorities and public officials [added: during the COVID-19 pandemic] to temporarily halt residential [removed: evictions to prevent further spread of the disease;][added: evictions;]
the [removed: legacy of the] regulatory focus on landlords [removed: during the public health event] as distinguished from other providers of essential services;
our ability to renew leases or relet units on favorable terms, or at all, including as a result of unfavorable economic and market conditions in those markets where our [removed: apartment communities] [added: properties] are located;
our ability to successfully complete the lease-up of properties in our lease-up portfolio and attain expected rental and occupancy rates due to social distancing or other restrictions that may frustrate our leasing [removed: activities;][added: activities, which, for example, led us to temporarily close property amenities and temporarily prohibit public access in our property leasing offices during the COVID-19 pandemic;]
our ability to continue our apartment unit redevelopment programs and attain increased rental rates for renovated or upgraded units due to social distancing or other [removed: restrictions;][added: restrictions, which, for example, caused us to temporarily suspend our apartment unit redevelopment activities during the COVID-19 pandemic;]
[removed: severe and prolonged] disruption and instability in the financial markets, [removed: including the debt and equity capital markets,] which [removed: have already] experienced [removed: and may continue to experience] significant [removed: volatility,] [added: volatility during the COVID-19 pandemic,] or deteriorations in credit and financing conditions (or a refusal or failure of one or more lenders under our unsecured revolving credit facility to fund their respective financing commitment to us), which [removed: may] [added: could] affect our ability to access capital necessary to fund our business operations or refinance maturing debt on a timely basis, on attractive terms, or at all, which would adversely affect our ability to meet liquidity and capital expenditure requirements;
[removed: sustained] stock market volatility that negatively affects the market price of our securities, including market conditions unrelated to our operating performance or prospects;
our ability to manage our business to the extent our management or other personnel are impacted in significant numbers [removed: by such public health event] and are not willing, available or allowed to conduct work.
To the extent a [removed: future] disease outbreak or other public health [removed: event, such as the COVID-19 pandemic,] [added: event] adversely [removed: affect] [added: affects] our business, financial condition, results of [removed: operation] [added: operations] and cash flows, it may also have the effect of heightening many of the other [removed: risks] [added: risk] described in this Annual Report on Form 10-K.
General economic conditions in the U.S. have fluctuated significantly in recent quarters with the U.S. experiencing negative macroeconomic conditions such as [removed: increasing] inflationary and labor market concerns.
Unfavorable market and economic [removed: conditions, including as a result of public health events in the areas in which we operate] [added: conditions] may significantly affect our occupancy levels, our rental rates and collections, the value of our properties and our ability to acquire or dispose of [removed: apartment communities] [added: properties] on economically favorable terms.
Our ability to lease our [removed: apartment communities] [added: properties] at favorable rates is adversely affected by the increase in supply in the multifamily and other rental markets and is dependent upon the overall level in the economy, which [removed: may continue to be] [added: is] adversely affected by, among other things, job losses and unemployment levels, personal debt levels, a downturn in the housing market, stock market volatility, inflationary conditions and uncertainty about the future.
We would expect that declines in our occupancy levels, rental revenues and/or the values of our [removed: apartment communities] [added: properties] would cause us to have less cash available to make payments on our debt and to make distributions, which could adversely affect our financial condition or the market value of our securities.
Factors that may affect our occupancy levels, our rental revenues and/or the value of our [removed: apartment communities] [added: properties] include the following, among others:
declines in mortgage interest rates and home pricing, making alternative housing [added: options] more affordable;
declines in the financial condition of our [removed: residents,] [added: residents or commercial tenants,] which may make it more difficult for us to collect rents from some [removed: residents;][added: residents or commercial tenants;]
increases in operating costs, if these costs cannot be passed through to our [removed: residents.][added: residents or commercial tenants.]
Such [removed: events or conditions] [added: factors] could include:
overbuilding of new apartments or oversupply of available apartments or alternative housing options [removed: (i.e. condominiums or single-family houses for rent or sale)] in our markets, which might adversely affect occupancy or rental rates and/or require rent concessions in order to lease apartments;
inability to [removed: initially, or subsequently after lease terminations,] rent apartments on favorable economic terms;
other changes in laws, [removed: including, but not limited to,] [added: including] tax laws and housing laws;
changes in interest rate levels and the availability of financing, borrower credit standards and down-payment requirements which could lead renters to purchase homes (if interest rates decrease and home loans are more readily [removed: available) or increase our acquisition and operating costs (if interest rates increase and financing is less readily available); and]
At times, we have relied on external funding sources to fully fund the payment of distributions to shareholders and our capital investment program, including our [removed: existing] property developments.
We are dependent on a concentration of our investments in a single asset class, making our results of operations more vulnerable to a downturn or slowdown in the [added: multifamily] sector or other economic factors.
As of December 31, [removed: 2022,] [added: 2023,] substantially all of our investments are concentrated in the multifamily sector.
A downturn or slowdown in the demand for multifamily housing [removed: may] [added: will] have more pronounced effects on our results of operations [removed: or] [added: and] on the value of our assets than if we had diversified our investments into more than one asset class.
As of December 31, [removed: 2022,] [added: 2023,] approximately [removed: 41.1%] [added: 41.4%] of our portfolio [added: (based on the number of completed apartment units)] was located in our top five markets: Atlanta, Georgia; Dallas, Texas; Austin, Texas; [removed: Orlando, Florida; and] Charlotte, North [removed: Carolina.][added: Carolina; and Orlando, Florida.]
In addition, our overall operations are concentrated in the Southeast, Southwest and Mid-Atlantic regions of the U.S. Our performance could be adversely affected by economic conditions in, and other factors relating to, these geographic areas, including supply and demand for apartments in these areas, zoning and other regulatory conditions and competition from other communities and alternative [removed: forms of housing.][added: housing options.]
[added: To the extent the economic conditions, job growth and] unemployment in any of these markets deteriorate or any of these areas experiences natural disasters, the value of our portfolio, our results of operations and our ability to make payments on our debt and to make distributions could be adversely affected.
Substantial competition [removed: among apartment communities and real estate companies] may adversely affect our revenues and [added: limit our] acquisition and development opportunities.
There are numerous [removed: other apartment communities and real estate companies, some of which may have greater financial and other resources than we have,] [added: alternative housing options] within the market area of each of our communities that compete with us for [removed: residents and acquisition] [added: residents, including other apartment communities, condominiums] and [removed: development opportunities.][added: single-family homes.]
We may make acquisitions [added: or pursue developments] outside of our existing market areas if appropriate opportunities arise.
We may be exposed to a variety of risks if we choose to enter new markets, including an inability to accurately evaluate local market conditions and local economies, [added: an inability] to identify appropriate acquisition [added: or development] opportunities, [added: an inability] to hire and retain key personnel and a lack of familiarity with local governmental and permitting procedures.
The presence of, or failure to properly remediate, [removed: hazardous,] [added: hazardous or] toxic substances or petroleum product releases may adversely affect the owner’s or operator’s ability to sell or rent the affected property or to borrow using the property as collateral.
[removed: We cannot assure you, however,] [added: However, there can be no assurance] that the Phase I environmental studies or other environmental studies undertaken with respect to any of our current or future apartment communities will reveal:
We have obtained a separate pollution insurance policy that covers mold-related claims and have adopted programs designed to minimize the existence of mold in any of our apartment communities as well as guidelines for promptly [added: addressing and resolving reports of mold.]
competition from other apartment communities or alternative housing options (including condominiums and single-family houses for rent or sale);
available) or increase our acquisition and operating costs (if interest rates increase and financing is less readily available); and
Competitive housing in a particular area, particularly new supply (and especially during early lease up efforts), could adversely affect our ability to retain residents, rent our apartments and increase or maintain rents, which could materially adversely affect our results of operations and financial condition.
Similarly, some of our competitors may have loan covenants or fund requirements that encourage decisions on occupancy targets or rental rates that vary from decisions based on market conditions, which could require us to react in ways that may affect our strategy or negatively affect our performance.
We also face competition from other businesses for acquisition and development opportunities.
Likewise, we may acquire properties that are subject to liabilities or that have problems relating to environmental condition, state of title, physical condition or compliance with zoning laws, building codes or other legal requirements.
Our implementation of long-standing succession planning could have adverse effects.
To reduce the risk of disruption from the planned retirement and unexpected departure of long-term employees and board members, we engage in succession planning to identify and develop in-house candidates for leadership and key executive positions within the company, recruit talented associates to fill areas of expertise needed within the company, and continually assess the needs of MAA’s Board of Directors to ensure stable governance of the company.
In the last two years, we have transformed our executive team by elevating internal candidates to the offices of President, Chief Financial Officer, Chief Administrative Officer, Chief Strategy and Analysis Officer and Chief Technology and Innovation Officer.
In addition, at the 2023 annual meeting of MAA’s shareholders, we added three new members to MAA’s Board of Directors.
Such significant changes over a relatively short period of time could result in unintended negative effects, such as creating employee dissatisfaction that could affect retention of key employees or impacting short-term strategic initiatives, which could adversely affect our business.
Additionally, “social inflation” has resulted in the cost of general liability claims increasing at a rate well above general economic inflation due to a trend in increasing litigation costs related to unpredictable jury verdicts for plaintiffs seeking large monetary relief for their injuries.
Premises liability is of particular concern for multifamily apartment owners.
In general, these factors have put pressure on insurance premiums and contributed to an inability to obtain appropriate insurance coverage at reasonable rates without the assumption of increasingly higher levels of self-retained risk.
These laws and regulations include landlord-tenant laws, employment laws, laws benefitting disabled persons, antitrust and other competition laws, privacy laws, tax laws, environmental laws, zoning laws, building codes and other laws regulating housing or that are generally applicable to our business and operations.
Noncompliance with laws and regulations could expose us to liability, such as the imposition of fines by the government or the award of damages to private litigants, and could require us to make significant unanticipated expenditures, such as making modifications to our existing apartment communities or increasing construction costs for development communities.
For example, there are legislative efforts underway at the local, state and federal levels related to tenant screening limitations, affordable housing mandates, increased eviction notice periods, mandatory alternative dispute resolution and access to legal counsel for unrepresented tenants.
In addition, other multifamily apartment owners could become involved in legal proceedings, the outcome of which could affect the way we conduct our business.
We may incur losses that are not covered by our insurance.
We have a comprehensive insurance program covering our properties and operations with limits of liability, deductibles and self-insured retentions that we negotiated with our insurance carriers.
While we believe the terms and insured limits of these policies are appropriate for our business, there are certain types of losses, generally of a catastrophic nature, such as losses due to environmental matters, extreme weather or natural disasters, that are uninsurable or not economically insurable, or that may be insured subject to limitations, and therefore may be uninsured.
Despite our insurance coverage, we may incur material losses due to uninsured risks, deductibles, self-insured retentions and/or losses in excess of coverage limits.
In addition, certain casualties or losses incurred may expose us in the future to higher insurance premiums.
We insure our properties and operations with insurance carriers that we believe have a good rating at the time our policies are put into effect.
However, the financial condition of one or more of our insurance carriers may be negatively impacted, which would result in their inability to cover the full amount of any insured losses for which we submit a claim.
Any such inability to pay future claims could have an adverse impact on our operating results.
In addition, the failure, or exit or partial exit from an insurance market, of one or more insurance carriers may adversely affect our ability to obtain insurance in the amounts that we seek, increase our costs to renew or replace our insurance policies, or cause us to self-insure a greater portion of the risk.
The U.S. has experienced, and may experience in the future, outbreaks of contagious diseases that affect public health and public perception of health risk.
Our rental revenues and operating results depend significantly on the occupancy levels at our properties and the ability of our residents and commercial tenants to meet their rent obligations to us, which could be adversely affected by such disease outbreak or other public health events.
These measures, while intended to protect human life, led to significantly reduced economic activity and a surge in unemployment throughout the U.S., including the markets where our properties are located, and they materially affected our ability to lease our properties and collect rental revenues.
the duration and scope of the event in the U.S.;
Interest rates increased significantly in 2022 and 2023.
Also, as of December 31, 2023, MAA owned approximately 97.4% of the OP Units.
While many of the restrictions have eased across the country, no assurance can be given that similar closures or restrictions will not be reinstated or new restrictions imposed in the future in response to changes in COVID-19 or new public health events.
Our ability to lease our apartments and collect rental revenues is dependent upon national, regional and local economic conditions, particularly unemployment levels and personal income levels.
As unemployment rises and incomes fall, fewer people,
including both current and prospective residents, may be able to afford our apartment communities, and it may be difficult for some of our residents to make timely rental payments to us under their leases.
Such adverse impacts will depend on, among other factors:
The potential impact that future disease outbreaks or other public health events, such as the COVID-19 pandemic, will have on our business, financial condition, results of operation and cash flows is difficult to predict.
competition from other apartment communities;
To the extent the economic conditions, job growth and
The number of competitive apartment communities and real estate companies in these areas could have a material effect on (1) our ability to rent our apartments and generate revenues, and (2) acquisition and development opportunities.
addressing and resolving reports of mold.
For example, the Americans with Disabilities Act of 1990, the Fair Housing Act of 1988 and other federal, state and local laws generally require that public accommodations be made accessible to disabled persons.
Noncompliance could result in the imposition of fines by the government or the award of damages to private litigants.
These laws may require us to modify our existing apartment communities.
These laws may also restrict renovations by requiring improved access to such buildings by disabled persons or may require us to add other structural features that increase our construction costs.
We cannot ascertain the costs of compliance with these laws, which may be substantial.
For example, as the eviction moratoria enacted in light of the COVID-19 pandemic began to lapse in 2021, many state and local governments implemented policies to prevent or delay formal eviction proceedings.
Likewise, the federal government has urged all states to adopt eviction diversion strategies, including, among others, a requirement for landlords to apply for rental assistance prior to filing for eviction and the extension of pending eviction cases to provide sufficient time for rental assistance applications to be processed, while also recommending creation of more robust eviction diversion programs over the longer term that include a combination of rental assistance, mandatory alternative dispute resolution and access to legal counsel for unrepresented tenants.
We carry property insurance on our apartment communities and intend to obtain similar coverage for apartment communities we acquire in the future.
However, some losses, generally of a catastrophic nature, such as losses from floods, tornados, hurricanes or earthquakes, are subject to limitations, and therefore may be uninsured.
Any losses we experience that are not fully covered by our insurance may negatively impact our results of operations and may reduce the value of our properties.
An excerpt. Shown here: 40 of 86 rewritten, all 33 added and all 20 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors. in the FY2023 filing and the FY2022 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
140 rewritten, 119 added, 56 removed, 139 unchanged
The following discussion analyzes the financial condition and results of operations of both MAA and the Operating Partnership, of which MAA is the sole general partner and in which MAA owned a [removed: 97.3%] [added: 97.4%] interest as of December 31, [removed: 2022.][added: 2023.]
[added: We own, operate, acquire and selectively develop apartment communities primarily located in the Southeast, Southwest and Mid-Atlantic regions of the U.S.] As of December 31, [removed: 2022,] [added: 2023,] we owned and operated 290 apartment communities (which does not include development [removed: properties] [added: communities] under construction) through the Operating Partnership and its subsidiaries, and had an ownership interest in one apartment community through an unconsolidated real estate joint venture.
In addition, as of December 31, [removed: 2022,] [added: 2023,] we had [removed: six] [added: five] development communities under construction, and 34 of our apartment communities included retail components.
Our apartment communities, including development communities under construction, were located across 16 states and the District of Columbia as of December 31, [removed: 2022.][added: 2023.]
Our Non-Same Store and Other segment includes recently acquired communities, communities being developed or in lease-up, communities [added: that have been disposed of or] identified for disposition, communities that have incurred a significant casualty loss and stabilized communities that do not meet the requirements to be Same Store communities.
For the year ended December 31, [removed: 2022,] [added: 2023,] net income available for MAA common shareholders was [removed: $633.7] [added: $549.1] million as compared to [removed: $530.1] [added: $633.7] million for the year ended December 31, [removed: 2021.][added: 2022.]
Results for the year ended December 31, [removed: 2021] [added: 2023] included [removed: $221.2] [added: $18.5] million of [added: non-cash] gain related to the [removed: sale] [added: fair value adjustment] of [removed: real estate assets] [added: the embedded derivative in the MAA Series I preferred shares] and [removed: $40.9] [added: $3.5] million of non-cash gain, net of tax, from investments.
Revenues for the year ended December 31, [removed: 2022] [added: 2023] increased [removed: 13.6%] [added: 6.4%] as compared to the year ended December 31, [removed: 2021,] [added: 2022,] driven by a [removed: 13.5%] [added: 6.2%] increase in our Same Store segment.
Property operating expenses, excluding depreciation and amortization, for the year ended December 31, [removed: 2022] [added: 2023] increased by [removed: 7.8%] [added: 6.1%] as compared to the year ended December 31, [removed: 2021,] [added: 2022,] driven by a [removed: 7.6%] [added: 6.5%] increase in our Same Store segment.
During the year ended December 31, [removed: 2022,] [added: 2023,] revenue growth for our Same Store segment continued to be primarily driven by growth in average effective rent per unit.
The average effective rent per unit for our Same Store segment continued to increase from the prior year, up [removed: 14.6%] [added: 7.0%] for the year ended December 31, [removed: 2022] [added: 2023] as compared to the year ended December 31, [removed: 2021.][added: 2022.]
For the year ended December 31, [removed: 2022,] [added: 2023,] average physical occupancy for our Same Store segment was [removed: 95.7%,] [added: 95.6%,] as compared to [removed: 96.1%] [added: 95.8%] for the year ended December 31, [removed: 2021.][added: 2022.]
An important part of our portfolio strategy is to maintain diversity of markets, submarkets, product types and price points in the Southeast, Southwest and Mid-Atlantic regions of the U.S. [removed: This diversity tends to mitigate exposure to economic issues] [added: We have multifamily assets] in [removed: any one geographic market or area.][added: 39 defined markets, with a presence in approximately 150 submarkets and a mixture of garden-style, mid-rise and high-rise communities.]
We believe demand for apartments is primarily driven by general economic conditions in our markets and is particularly correlated to job [added: growth, population growth, household formation and in-migration over the long term.]
While our rent [removed: growth] [added: growth, occupancy] and [removed: rent collection] [added: turnover] trends [removed: during] [added: in] the [removed: year ended December 31, 2022] [added: fourth quarter of 2023] were [removed: strong,] [added: solid,] we continue to monitor pressures surrounding [added: housing supply,] inflation [removed: trends,] [added: trends and] general economic [removed: conditions and housing supply.][added: conditions.]
A worsening of the current environment could contribute to uncertain rent collections going [removed: forward and] [added: forward,] suppress demand for apartments and could drive lower rent growth on new leases and renewals than what we achieved [removed: during] [added: in] the year ended December 31, [removed: 2022.][added: 2023.]
Supply chain and inflationary pressures have driven higher operating expenses during the year ended December 31, [removed: 2022,] [added: 2023,] particularly in personnel, repairs and maintenance and real estate taxes, and this trend may continue going forward.
Access to the financial markets remains available for [removed: high credit] [added: high-credit] rated [removed: borrowers.][added: borrowers, such as ourselves.]
For the year ended December 31, [removed: 2022,] [added: 2023,] we achieved net income available for MAA common shareholders of [removed: $633.7] [added: $549.1] million, a [removed: 19.6% increase] [added: 13.4% decrease] as compared to the year ended December 31, [removed: 2021,] [added: 2022,] and total revenue growth of [removed: $241.8] [added: $128.6] million, representing a [removed: 13.6%] [added: 6.4%] increase in property revenues as compared to the year ended December 31, [removed: 2021.][added: 2022.]
The following discussion describes the primary drivers of the [removed: increase] [added: decrease] in net income available for MAA common shareholders for the year ended December 31, [removed: 2022] [added: 2023] as compared to the year ended December 31, [removed: 2021.][added: 2022.]
A discussion of the results of operations for the year ended December 31, [removed: 2021] [added: 2022] as compared to the year ended December 31, [removed: 2020] [added: 2021] is found in Item 7 of Part II of our Annual Report on Form 10-K for the year ended December 31, [removed: 2021,] [added: 2022,] filed with the SEC on February [removed: 17, 2022,] [added: 14, 2023,] which is available free of charge on the SEC’s website at https://www.sec.gov and on our website at https://www.maac.com, on the “For Investors” page under “Filings and Financials—Annual Reports.”
The following table reflects our property revenues by segment for the [removed: year] [added: years] ended December 31, [added: 2023 and] 2022 (dollars in thousands):
| | | December 31, [removed: 2022] [added: 2023] | | | | December 31, [removed: 2021] [added: 2022] | | | | Increase | | | | % [removed: Change] [added: Increase] | | |
The increase in rental revenues for our Same Store segment for the year ended December 31, [removed: 2022] [added: 2023] as compared to the year ended December 31, [removed: 2021] [added: 2022] was the primary driver of total property revenue growth.
The Same Store segment generated a [removed: 13.5%] [added: 6.2%] increase in revenues for the year ended December 31, [removed: 2022,] [added: 2023,] primarily the result of average effective rent per unit growth of [removed: 14.6%] [added: 7.0%] as compared to the year ended December 31, [removed: 2021,] [added: 2022,] partially offset by lower average physical occupancy.
The increase in property revenues from the Non-Same Store and Other segment for the year ended December 31, [removed: 2022] [added: 2023] as compared to the year ended December 31, [removed: 2021] [added: 2022] was primarily the result of increased revenues from [removed: recently] completed development communities and acquired communities, partially offset by decreased revenues from [removed: recently] disposed [removed: communities.][added: communities during the year ended December 31, 2022.]
The following table reflects our property operating expenses by segment for the [removed: year] [added: years] ended December 31, [added: 2023 and] 2022 (dollars in thousands):
The increase in property operating expenses for our Same Store segment for the year ended December 31, [removed: 2022] [added: 2023] as compared to the year ended December 31, [removed: 2021] [added: 2022] was primarily driven by increases in real estate tax expense of [removed: $15.0 million, personnel expense of $9.6] [added: $13.6] million, building repairs and maintenance of [removed: $9.2] [added: $8.4] million, [removed: utilities] [added: personnel] expense of [removed: $6.9] [added: $7.9] million, [removed: office operations] [added: utilities] expense of [removed: $4.3] [added: $6.1] million, [removed: and] insurance expense of [removed: $3.1] [added: $3.8 million and office operations expense of $2.5] million.
Depreciation and amortization expense for the year ended December 31, [removed: 2022] [added: 2023] was [removed: $543.0] [added: $565.1] million, an increase of [removed: $9.6] [added: $22.1] million as compared to the year ended December 31, [removed: 2021.][added: 2022.]
The increase was primarily driven by the recognition of depreciation expense associated with our [removed: recently] completed development communities and capital spend activities made in the normal course of business during the year ended December 31, [removed: 2022,] [added: 2023,] partially offset from decreased depreciation expense from [removed: recently] disposed [removed: communities.][added: communities during the year ended December 31, 2022.]
Property management expenses for the year ended December 31, [removed: 2022] [added: 2023] were [removed: $65.5] [added: $67.8] million, an increase of [removed: $9.7] [added: $2.3] million as compared to the year ended December 31, [removed: 2021.][added: 2022.]
General and administrative expenses for the year ended December 31, [removed: 2022] [added: 2023] were [removed: $58.8] [added: $58.6] million, [removed: an increase] [added: a decrease] of [removed: $5.9] [added: $0.3] million as compared to the year ended December 31, [removed: 2021.][added: 2022.]
Interest expense for the year ended December 31, [removed: 2022] [added: 2023] was [removed: $154.7] [added: $149.2] million, a decrease of [removed: $2.1] [added: $5.5] million as compared to the year ended December 31, [removed: 2021.][added: 2022.]
The decrease was primarily due to a decrease in our average outstanding debt balance during the year ended December 31, [removed: 2022] [added: 2023] as compared to the year ended December 31, [removed: 2021.][added: 2022.]
During the year ended December 31, [removed: 2021,] [added: 2023,] we disposed of [removed: five] [added: one] land [removed: parcels] [added: parcel,] resulting in [added: the recognition of] a [added: negligible] gain on sale of non-depreciable real estate [removed: assets of $0.8 million.][added: assets.]
Other non-operating [removed: expense] (income) [added: expense] for the year ended December 31, [removed: 2022] [added: 2023] was [removed: $42.7] [added: $31.2] million of [removed: expense,] [added: income,] as compared to [removed: $33.9] [added: $42.7] million of [removed: income] [added: expense] for the year ended December 31, [removed: 2021.][added: 2022.]
The expense for the year ended December 31, 2022 was driven by $45.4 million of non-cash loss from [removed: investments,] [added: investments and] $21.1 million of non-cash loss related to the fair value adjustment of the embedded derivative in the MAA Series I preferred shares, partially offset by $29.9 million in net casualty gain primarily due to winter storm Uri.
The income for the year ended December 31, [removed: 2021] [added: 2023] was driven by [removed: $51.7] [added: $18.5] million of non-cash gain [removed: from investments, partially offset by $13.4 million in debt extinguishment costs and $4.6 million of non-cash loss] related to the fair value adjustment of the embedded [removed: derivative.][added: derivative in the MAA Series I preferred shares, $4.4 million of non-cash gain from investments, $5.5 million of miscellaneous income and $3.4 million of interest income, partially offset by $1.0 million in net casualty loss.]
Funds from operations, or FFO, a non-GAAP financial measure, represents net income available for MAA common shareholders (computed in accordance with [removed: the U.S. generally accepted accounting principles, or] GAAP) excluding gains or losses on disposition of operating properties and asset impairment, plus depreciation and amortization of real estate assets, net income attributable to noncontrolling interests and adjustments for joint ventures.
Because net income attributable to noncontrolling interests is added back, FFO, when used in this Annual Report on Form 10-K, represents FFO attributable to [removed: the Company.][added: common shareholders and unitholders.]
This diversity tends to mitigate exposure to economic issues, including supply and demand factors, in any one geographic market or area.
Demand for apartments in our markets was solid during the fourth quarter of 2023, as evidenced by prospect traffic levels and the revenue growth achieved during the quarter.
Current elevated supply levels are impacting rent growth performance in certain markets of our portfolio.
While we expect this pressure to persist for another few quarters, we expect the demand side to continue to be more impactful over the long term.
However, overall borrowing costs remain at elevated levels and we expect this trend to continue.
As of December 31, 2023, 89.1% of our outstanding debt borrowings was subject to fixed rates.
We may be further exposed to elevated interest rates as a result of additional variable rate borrowings or refinancing activities.
| Same Store | | $ | 2,024,751 | | | $ | 1,907,003 | | | $ | 117,748 | | | | 6.2 | % |
| Non-Same Store and Other | | | 123,717 | | | | 112,863 | | | | 10,854 | | | | 9.6 | % |
| Total | | $ | 2,148,468 | | | $ | 2,019,866 | | | $ | 128,602 | | | | 6.4 | % |
| | | December 31, 2023 | | | | December 31, 2022 | | | | Increase | | | | % Increase | | |
| Same Store | | $ | 717,812 | | | $ | 674,110 | | | $ | 43,702 | | | | 6.5 | % |
| Non-Same Store and Other | | | 50,329 | | | | 49,584 | | | | 745 | | | | 1.5 | % |
| Total | | $ | 768,141 | | | $ | 723,694 | | | $ | 44,447 | | | | 6.1 | % |
For the year ended December 31, 2023, we did not dispose of any apartment communities.
Non-GAAP Financial Measures
Because net income attributable to noncontrolling interests is added back to FFO, Core FFO, when used in this Annual Report on Form 10-K, represents Core FFO attributable to common shareholders and unitholders.
| | | 2023 | | | | 2022 | | | |
| FFO attributable to common shareholders and unitholders | | | 1,123,789 | | | | 972,782 | | |
| Core FFO attributable to common shareholders and unitholders | | $ | 1,098,120 | | | $ | 1,008,206 | | |
For the year ended December 31, 2023, gain on investments is presented net of tax expense of $0.9 million.
Net Debt, EBITDA, EBITDAre, and Adjusted EBITDAre
Net debt, a non-GAAP financial measure, represents unsecured notes payable and secured notes payable less cash and cash equivalents and 1031(b) exchange proceeds included in restricted cash.
Management considers net debt a helpful tool in evaluating our debt position.
Net debt should not be considered as an alternative to any GAAP measurement, as an indicator of operating performance or as an alternative to cash flow from operating, investing and financing activities as a measure of liquidity.
Earnings before interest, taxes, depreciation and amortization, or EBITDA, a non-GAAP financial measure, represents net income (computed in accordance with GAAP) plus depreciation and amortization, interest expense, and income taxes.
As an owner and operator of real estate, management considers EBITDA to be an important measure of performance from core operations because EBITDA does not include various expense items that are not indicative of operating performance.
EBITDA should not be considered as an alternative to net income, or any other GAAP measurement, as an indicator of operating performance or as an alternative to cash flow from operating, investing and financing activities as a measure of liquidity.
EBITDA*re* is composed of EBITDA adjusted for the gain or loss on sale of depreciable assets and adjustments to reflect our share of EBITDA*re* of an unconsolidated affiliate.
As an owner and operator of real estate, management considers EBITDA*re* to be an important measure of performance from core operations because EBITDA*re* does not include various expense items that are not indicative of operating performance.
While our definition of EBITDA*re* is in accordance with NAREIT’s definition, it may differ from the methodology utilized by other REITs to calculate EBITDA*re* and, accordingly, may not be comparable to such other REITs.
EBITDA*re* should not be considered as an alternative to net income, or any other GAAP measurement, as an indicator of operating performance or as an alternative to cash flow from operating, investing and financing activities as a measure of liquidity.
Adjusted EBITDA*re* is comprised of EBITDA*re* further adjusted for items that are not considered part of our core operations such as adjustments related to the fair value of the embedded derivative in the MAA Series I preferred shares; gain or loss on sale of non-depreciable assets; gain or loss on investments; casualty related charges (recoveries), net; gain or loss on debt extinguishment; legal (recoveries), costs and settlements, net; and COVID-19 related costs.
As an owner and operator of real estate, management considers Adjusted EBITDA*re* to be an important measure of performance from core operations because Adjusted EBITDA*re* does not include various income and expense items that are not indicative of operating performance.
Our computation of Adjusted EBITDA*re* may differ from the methodology utilized by other REITs to calculate Adjusted EBITDA*re*.
Adjusted EBITDA*re* should not be considered as an alternative to net income, or any other GAAP measurement, as an indicator of operating performance or as an alternative to cash flow from operating, investing and financing activities as a measure of liquidity.
Management monitors its debt levels to a ratio of net debt to Adjusted EBITDA*re* in order to maintain our investment grade credit ratings.
We believe this is an important factor in the management of our debt levels to maintain an optimal capital structure, and it is also considered in the assignment of our credit ratings.
Adjusted EBITDA*re* is measured on a trailing twelve-month basis.
The following table presents a reconciliation of unsecured notes payable and secured notes payable to net debt as of December 31, 2023 and 2022, as we believe unsecured notes payable and secured notes payable, combined, is the most directly comparable GAAP measure (dollars in thousands):
We own, operate, acquire and selectively develop apartment communities primarily located in the Southeast, Southwest and Mid-Atlantic regions of the United States.
Through our investment in 39 defined markets, we are diversified across markets, urban and suburban submarkets, and a variety of product types and monthly rent price points.
Though demand for apartments moderated during the second half of 2022, we were able to maintain strong rent growth.
growth, population growth, household formation and in-migration.
Current elevated supply levels could further affect rent growth for our portfolio, though we expect the demand side to continue to be more impactful over the long term.
However, a prolonged disruption of the markets or a decline in credit and financing conditions could negatively affect our ability to access capital necessary to fund our operations or refinance maturing debt in the future.
Additionally, rising interest rates could negatively impact our borrowing costs for any variable rate borrowings or refinancing activity.
| Same Store | | $ | 1,924,709 | | | $ | 1,695,234 | | | $ | 229,475 | | | | 13.5 | % |
| Non-Same Store and Other | | | 95,157 | | | | 82,848 | | | | 12,309 | | | | 14.9 | % |
| Total | | $ | 2,019,866 | | | $ | 1,778,082 | | | $ | 241,784 | | | | 13.6 | % |
| Same Store | | $ | 682,014 | | | $ | 633,662 | | | $ | 48,352 | | | | 7.6 | % |
| Non-Same Store and Other | | | 41,680 | | | | 37,503 | | | | 4,177 | | | | 11.1 | % |
| Total | | $ | 723,694 | | | $ | 671,165 | | | $ | 52,529 | | | | 7.8 | % |
The increase in property operating expenses from the Non-Same Store and Other segment for the year ended December 31, 2022 as compared to the year ended December 31, 2021 was primarily the result of $1.8 million of storm-related expenses related to hurricanes and increased property operating expenses from recently completed development communities and acquired communities, partially offset by decreased property operating expenses from recently disposed communities.
For the year ended December 31, 2021, we disposed of seven apartment communities, resulting in a gain on sale of depreciable real estate assets of $220.4 million.
| | | 2022 | | | | 2021 | | | |
| FFO attributable to the Company | | | 972,782 | | | | 853,422 | | |
| Core FFO | | $ | 1,008,206 | | | $ | 830,615 | | |
During the year ended December 31, 2022, MAA incurred $5.8 million in casualty losses related to winter storm Elliot (primarily building repairs, landscaping and asset write-offs).
During the year ended December 31, 2021, MAA incurred $26.0 million in casualty losses related to winter storm Uri.
The majority of the storm costs are expected to be or have been reimbursed through insurance coverage.
An insurance recovery was recognized in Other non-operating expense (income) in the amount of the recognized losses that MAA expects to recover.
Additional costs related to the storms that are not expected to be recovered through insurance coverage, along with other unrelated casualty losses and recoveries, including the receipt of insurance proceeds that exceeded the recognized casualty losses from winter storm Uri, are reflected in Casualty related (recoveries) charges, net.
During the year ended December 31, 2022, we sold four apartment communities as compared to seven apartment communities during the year ended December 31, 2021.
| Proceeds from notes payable | | | — | | | | 594,423 | | | | (594,423 | ) |
The decrease in cash outflows from principal payments on notes payable primarily resulted from the retirement of $125.0 million of unsecured senior notes during the year ended December 31, 2022 as compared to the retirement of $222.0 million of senior unsecured private placement notes, $125.0 million of unsecured senior notes and $118.6 million of property mortgages during the year ended December 31, 2021.
during the year ended December 31, 2021.
| Total unsecured debt | | $ | 4,050,910 | | | | 6.3 | | | | 3.4 | % |
| 2023 | | $ | 20,000 | | | $ | 349,509 | | | $ | — | | | $ | 369,509 | |
| 2024 | | | — | | | | 398,842 | | | | — | | | | 398,842 | |
| 2025 | | | — | | | | 397,773 | | | | 3,978 | | | | 401,751 | |
| 2027 | | | — | | | | 596,548 | | | | — | | | | 596,548 | |
| 2028 | | | — | | | | 396,695 | | | | — | | | | 396,695 | |
| 2029 | | | — | | | | 559,082 | | | | — | | | | 559,082 | |
| 2031 | | | — | | | | 444,985 | | | | — | | | | 444,985 | |
| Thereafter | | | — | | | | 292,732 | | | | 360,015 | | | | 652,747 | |
| Total | | $ | 20,000 | | | $ | 4,030,910 | | | $ | 363,993 | | | $ | 4,414,903 | |
| 2023 | | $ | 349,509 | | | | 4.2 | % |
| 2024 | | | 398,842 | | | | 4.0 | % |
| 2025 | | | 401,751 | | | | 4.2 | % |
An excerpt. Shown here: 40 of 140 rewritten, 40 of 119 added and 40 of 56 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations. in the FY2023 filing and the FY2022 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
2 rewritten, 0 added, 0 removed, 7 unchanged
As of December 31, [removed: 2022, 19.2%] [added: 2023, 22.0%] of our total market capitalization consisted of debt borrowings.
As of December 31, [removed: 2022, 99.5%] [added: 2023, 89.1%] of our outstanding debt was subject to fixed rates.
Item 1. Business.
32 rewritten, 15 added, 21 removed, 173 unchanged
We own, operate, acquire and selectively develop apartment communities primarily located in the Southeast, Southwest and Mid-Atlantic regions of the [removed: United States.][added: U.S. As of December 31, 2023, we maintained full or partial ownership of apartment communities, including communities currently in development, across 16 states and the District of Columbia, summarized as follows:]
As of December 31, [removed: 2022,] [added: 2023,] 34 of the Company’s apartment communities included retail components.
Number of communities includes [removed: six] [added: five] communities under development as of December 31, [removed: 2022.][added: 2023.]
Number of units excludes development units not yet delivered as of December 31, [removed: 2022.][added: 2023.]
MAA is the sole general partner of the Operating Partnership, holding [removed: 115,480,336] [added: 116,694,124] OP Units, comprising a [removed: 97.3%] [added: 97.4%] partnership interest in the Operating Partnership as of December 31, [removed: 2022.][added: 2023.]
Our external growth strategy is to acquire existing apartment communities, utilize our internal development team to develop our own apartment communities and partner with [removed: local] [added: select] developers to develop apartment communities that we will own completely after stabilization, which we refer to as a pre-purchase transaction.
We acquired the following properties during the year ended December 31, [removed: 2022:][added: 2023:]
| MAA Packing District [added: II] | | Orlando, FL | | [removed: 4] [added: 6] | | [removed: May 2022] [added: February 2023] |
| MAA Nixie | | Raleigh, NC | | [removed: 6] [added: 0.4] | | November [removed: 2022] [added: 2023] |
During the year ended December 31, [removed: 2022,] [added: 2023,] we incurred [removed: $172.1] [added: $198.2] million in development costs and completed [removed: three] [added: one] development [removed: projects.][added: project.]
The following multifamily projects were under development as of December 31, [removed: 2022] [added: 2023] (dollars in thousands):
| Novel Val Vista (1) | | Phoenix, AZ | | | 317 | | | [removed: —] | [added: 3] | | | | [removed: 57,646] [added: 71,227] | | | | [removed: 77,200] [added: 79,800] | | | | [removed: 244] [added: 252] | | | [removed: 1st] [added: 4th] Quarter 2024 |
| MAA Milepost 35 | | Denver, CO | | | 352 | | | [removed: —] | [added: 3] | | | | [removed: 41,324] [added: 92,980] | | | | 125,000 | | | | 355 | | | 4th Quarter 2024 |
| MAA Nixie | | Raleigh, NC | | | 406 | | | [removed: —] | [added: —] | | | | [removed: 13,445] [added: 45,932] | | | | 145,500 | | | | 358 | | | 3rd Quarter 2025 |
| MAA Breakwater | | Tampa, FL | | | 495 | | | [removed: —] | [added: —] | | | | [removed: 32,553] [added: 89,851] | | | | 197,500 | | | | 399 | | | 4th Quarter 2025 |
During the year ended December 31, [removed: 2022,] [added: 2023,] we disposed of [removed: four multifamily communities totaling 1,414 units, and two] [added: one] land [removed: parcels] [added: parcel] totaling approximately [removed: five] [added: 21] acres.
During the year ended December 31, [removed: 2022,] [added: 2023,] we renovated the kitchen and bathroom of [removed: 6,574] [added: 6,858] apartment units at an average cost of [removed: $6,109] [added: $6,453] per apartment unit, achieving average rental rate increases of [removed: 10.0%] [added: 7.1%] above the normal market rate for similar but non-renovated apartment units.
During the year ended December 31, [removed: 2022,] [added: 2023,] we installed smart devices in [removed: 24,029] [added: 21,159] apartment units at an average cost of [removed: $1,535] [added: $1,533] per apartment unit and a projected average monthly rent increase of approximately [removed: $25] [added: $20] per unit upon lease renewal or unit turnover.
As of December 31, [removed: 2022,] [added: 2023,] we have completed installation of smart home technology at [removed: nearly 75%] [added: more than 90%] of our existing [removed: properties] [added: apartment units] and are employing smart home technology in all of our new developments.
Separately, we continued our property repositioning program to upgrade and reposition the amenity and common areas at [removed: many] [added: certain] of our apartment communities.
For the year ended December 31, [removed: 2022,] [added: 2023,] we spent [removed: $19.3] [added: $17.0] million on this program.
As of December 31, [removed: 2022,] [added: 2023,] we employed [removed: 2,387] [added: 2,427] associates.
As of December 31, [removed: 2022,] [added: 2023,] ethnic/cultural minorities represented approximately [removed: 50%] [added: 53%] of our workforce, [removed: 40%] [added: 42%] of our collective corporate, regional and property leadership positions and [removed: 51%] [added: 50%] of our associates promoted during the year ended December 31, [removed: 2022.][added: 2023.]
Also, as of December 31, [removed: 2022,] [added: 2023,] females represented approximately 46% of our workforce, 56% of our collective corporate, regional and property leadership positions and 53% of our associates promoted during the year ended December 31, [removed: 2022.][added: 2023.]
Our associates are eligible for [added: many benefit plans and programs for which we pay part or all of the cost, such as] medical, dental and vision insurance, life and disability insurance, various wellness [removed: programs,] [added: programs and] an employee assistance [removed: program, for which we pay part or all the cost, as well as other benefits.][added: program.]
[removed: At MAA, we] [added: We] place an emphasis on communication to ensure associates feel informed and connected as an organization.
We utilize a variety of [removed: communications] [added: communication] channels to provide associates with timely information that is relevant to their role in the company, to company-wide initiatives and their professional interests.
We [removed: currently] intend to target our total debt, net of cash held, to a range of approximately 30% to 36% of our adjusted total assets (as defined in the covenants for the bonds issued by MAALP).
As of December 31, [removed: 2022,] [added: 2023,] our total debt was [removed: approximately 28.4%] [added: 27.8%] of our adjusted total assets.
We must own, operate, manage, acquire, develop and redevelop our properties in compliance with [removed: the laws and regulations of the United States, as well as] [added: numerous federal,] state and local laws and [removed: regulations in the markets where our properties are located,] [added: regulations, some of] which may [removed: differ among jurisdictions.][added: conflict with one another or are subject to limited judicial or regulatory interpretations.]
Compliance with the various laws and regulations we are subject to did not have a material effect on our capital expenditures, results of operations and competitive position for the year ended December 31, [removed: 2022] [added: 2023] as compared to prior periods.
For the year ended December 31, [removed: 2022,] [added: 2023,] MAA paid total distributions of [removed: $4.675] [added: $5.600] per share of common stock to its shareholders, which was above the 90% REIT distribution [removed: requirement and was in excess of REIT taxable income.][added: requirement.]
| Consolidated | | | 295 | | (2) | | 100,625 | | (3) |
| Total | | | 296 | | | | 100,894 | | |
| MAA Central Ave | | Phoenix, AZ | | 323 | | October 2023 |
| MAA Optimist Park | | Charlotte, NC | | 352 | | November 2023 |
| Novel Daybreak (1) | | Salt Lake City, UT | | | 400 | | | | 196 | | | $ | 91,620 | | | $ | 99,450 | | | $ | 249 | | | 3rd Quarter 2024 |
| Total | | | | | 1,970 | | | | 202 | | | $ | 391,610 | | | $ | 647,250 | | | | | | | |
In addition, we offer several supplemental and voluntary benefit plans, paid sick leave, paid vacation and other paid time off benefits to support our associates’ overall well-being.
We intend to target the ratio of our net debt to Adjusted EBITDA*re* to a range of 4.5x to 5.5x.
We monitor our debt levels to a ratio of net debt to Adjusted EBITDA*re* in order to maintain our investment grade credit ratings.
We believe this is an important factor in the management of our debt levels to maintain an optimal capital structure, and it is also considered in the assignment of our credit ratings.
Adjusted EBITDA*re* is measured on a trailing twelve-month basis.
As of December 31, 2023, our net debt to Adjusted EBITDA*re* ratio was 3.6x.
For additional information on net debt and Adjusted EBITDA*re*, including reconciliations of the most directly comparable U.S. generally accepted accounting principles, or GAAP, measures to both net debt and Adjusted EBITDA*re*, see “Management’s Discussion and Analysis of Financial Condition and Results of Operation - Non-GAAP Financial Measures - Net Debt, EBITDA, EBITDA*re*, and Adjusted EBITDA*re*” in this Annual Report on Form 10-K.
These laws and regulation include landlord-tenant laws, employment laws, antitrust and other competition laws, laws benefitting disabled persons, privacy laws, tax laws, environmental laws, zoning laws, building codes and other laws regulating housing or that are generally applicable to our business and operations.
Noncompliance with laws and regulations could expose us to liability, such as the imposition of fines by the government or the award of damages to private litigants, and could require us to make significant unanticipated expenditures, such as making modifications to our existing apartment communities or increasing construction costs for development communities.
As of December 31, 2022, we maintained full or partial ownership of apartment communities, including communities currently in development, across 16 states and the District of Columbia, summarized as follows:
| Consolidated | | | 296 | | (2) | | 99,407 | | (3) |
| Total | | | 297 | | | | 99,676 | | |
(1)
| MAA Hampton Preserve II | | Tampa, FL | | 196 | | July 2022 |
| MAA LoSo | | Charlotte, NC | | 344 | | September 2022 |
| MAA Florida Street Station | | Denver, CO | | 4 | | March 2022 |
| MAA Panorama | | Denver, CO | | 6 | | July 2022 |
| Alta 10th (1) | | Charlotte, NC | | 3 | | December 2022 |
Represents a pre-purchase multifamily development.
Approximately $10 million has been funded as of December 31, 2022, primarily related to land, with development expected to begin in the second half of 2023.
MAA owns 95% of the joint venture that owns this property.
| Novel West Midtown (1) | | Atlanta, GA | | | 340 | | | — | | | | $ | 72,536 | | | $ | 89,500 | | | $ | 263 | | | 3rd Quarter 2023 |
| Novel Daybreak (1) | | Salt Lake City, UT | | | 400 | | | — | | | | | 74,195 | | | | 94,000 | | | | 235 | | | 4th Quarter 2023 |
| Total | | | | | 2,310 | | | | — | | | $ | 291,699 | | | $ | 728,700 | | | | | | | |
We continue to offer several measures to support our associates’ overall well-being in response to the pandemic, including supplemental leave and sick time policies, additional paid time off and coverage for testing and vaccination under our health plan.
As of December 31, 2022, 19.2% of our total market capitalization consisted of debt borrowings, including 17.6% under unsecured borrowings and 1.5% under secured borrowings.
For example, the Americans with Disabilities Act of 1990, the Fair Housing Act of 1988 and other federal, state and local laws generally require that public accommodations be made accessible to disabled persons.
Noncompliance could result in the imposition of fines by the government or the award of damages to private litigants.
These laws may require us to modify our existing apartment communities.
These laws may also restrict renovations by requiring improved access to such buildings by disabled persons or may require us to add other structural features that increase our construction costs.
Cover and table of contents
34 rewritten, 2 added, 0 removed, 165 unchanged
| | | For the fiscal year ended December 31, [removed: 2022] [added: 2023] |
The aggregate market value of the [removed: 79,918,312] [added: 70,492,194] shares of common stock of Mid-America Apartment Communities, Inc. held by non-affiliates was approximately [removed: $14.0] [added: $10.7] billion based on the closing price of [removed: $174.67] [added: $151.86] as reported on the New York Stock Exchange on June 30, [removed: 2022.][added: 2023.]
As of February [removed: 9, 2023,] [added: 6, 2024,] there were [removed: 116,598,821] [added: 116,715,633] shares of Mid-America Apartment Communities, Inc. common stock outstanding.
Portions of the proxy statement for the annual shareholders meeting of Mid-America Apartment Communities, Inc. to be held on May [removed: 16, 2023] [added: 21, 2024] are incorporated by reference into Part III of this report.
We expect to file our proxy statement within 120 days after December 31, [removed: 2022.][added: 2023.]
| 1A. | [Risk Factors.](#item_1a_risk_factors) | [removed: 9] [added: 10] |
| 1B. | [Unresolved Staff Comments.](#item_1b_unresolved_staff_comments) | [removed: 23] [added: 24] |
| 2. | [Properties.](#item_2_properties) | [removed: 23] [added: 27] |
| 3. | [Legal Proceedings.](#item_3_legal_proceedings) | [removed: 25] [added: 28] |
| 4. | [Mine Safety Disclosures.](#item_4_mine_safety_disclosures) | [removed: 25] [added: 28] |
| 5. | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.](#item_5_market_for_registrants_common_equ) | [removed: 25] [added: 28] |
| 6. | [\[Reserved\].](#item_6) | [removed: 26] [added: 30] |
| 7. | [Management’s Discussion and Analysis of Financial Condition and Results of Operations.](#item_7_managements_discussion_analysis_f) | [removed: 27] [added: 31] |
| 7A. | [Quantitative and Qualitative Disclosures About Market Risk.](#item_7a__quantitative_and_qualitative_di) | [removed: 36] [added: 42] |
| 8. | [Financial Statements and Supplementary Data.](#item_8__financial_statements_and_supplem) | [removed: 36] [added: 42] |
| 9. | [Changes in and Disagreements With Accountants on Accounting and Financial Disclosure.](#item_9__changes_in_and_disagreements_wit) | [removed: 36] [added: 42] |
| 9A. | [Controls and Procedures.](#item_9a__controls_and_procedures) | [removed: 37] [added: 42] |
| 9B. | [Other Information.](#item_9b__other_information) | [removed: 38] [added: 43] |
| 9C. | [Disclosure Regarding Foreign Jurisdictions that Prevent Inspections.](#item_9c_foreign_jurisdiction_disclosures) | [removed: 38] [added: 43] |
| 10. | [Directors, Executive Officers and Corporate Governance.](#item_10_directors_executive_ficers_corpo) | [removed: 38] [added: 44] |
| 11. | [Executive Compensation.](#item_11_executive_compensation) | [removed: 38] [added: 44] |
| 12. | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.](#item_12_security_ownership_certain_benef) | [removed: 38] [added: 44] |
| 13. | [Certain Relationships and Related Transactions, and Director Independence.](#item_13_certain_relationships_related_tr) | [removed: 38] [added: 44] |
| 14. | [Principal Accountant Fees and Services.](#item_14_principal_accounting_fees_servic) | [removed: 38] [added: 44] |
| 15. | [Exhibits and Financial Statement Schedules.](#item_15_exhibits_financial_statement_sch) | [removed: 39] [added: 45] |
| 16. | [Form 10-K Summary](#item_16_form_10k_summary). | [removed: 43] [added: 49] |
This report combines the Annual Reports on Form 10-K for the year ended December 31, [removed: 2022] [added: 2023] of Mid-America Apartment Communities, Inc., a Tennessee corporation, and Mid-America Apartments, L.P., a Tennessee limited partnership, of which Mid-America Apartment Communities, Inc. is the sole general partner.
Mid-America Apartment Communities, Inc. and its [removed: 97.3%] [added: 97.4%] owned subsidiary, Mid-America Apartments, L.P., are both required to file annual reports under the Securities Exchange Act of 1934, as amended.
As of December 31, [removed: 2022,] [added: 2023,] MAA owned [removed: 115,480,336] [added: 116,694,124] OP Units [removed: (97.3%] [added: (97.4%] of the total number of OP Units).
[removed: Note Regarding Forward-Looking] [added: Forward-Looking] Statements
Although we believe that the assumptions underlying the forward-looking statements contained herein are reasonable, any of the assumptions could be inaccurate, and therefore such forward-looking statements included in this [removed: report] [added: Annual Report on Form 10-K] may not prove to be accurate.
inability to obtain appropriate insurance coverage at reasonable rates, or at all, [added: losses due to uninsured risks, deductibles and self-insured retentions,] or losses from catastrophes in excess of [removed: our insurance coverage;][added: coverage limits;]
ability to continue to satisfy complex rules in order to maintain our status as a REIT for federal income tax purposes, the ability of the Operating Partnership to satisfy the rules to maintain its status as a partnership for federal income tax purposes, the ability of our taxable REIT subsidiaries to maintain their status as such for federal income tax [removed: purposes] [added: purposes,] and our ability and the ability of our subsidiaries to operate effectively within the limitations imposed by these rules;
disease outbreaks and other public health events, and measures that are taken by federal, [removed: state,] [added: state] and local governmental authorities in response to such outbreaks and events;
| 1C. | [Cybersecurity.](#item_1c_cybersecurity_through_item_4) | 24 |
the impact of adverse developments affecting the U.S. or global banking industry, including bank failures and liquidity concerns, which could cause continued or worsening economic and market volatility, and regulatory responses thereto;
Item 1C. Cybersecurity.
0 rewritten, 40 added, 0 removed, 0 unchanged
New section this year
Cybersecurity Risk Management Program
We recognize the importance of maintaining the integrity of our information systems and safeguarding the confidential business and personal information we receive and store about our residents, prospective residents, employees and suppliers.
As such, we have implemented a cybersecurity risk management program designed to assess, identify and manage material risks from cybersecurity threats.
Our cybersecurity risk management program is designed to employ what we believe are industry best practices, including monitoring and analysis of the threat environment, vulnerability assessments and third-party cybersecurity risks; detecting and responding to cyber attacks, cybersecurity incidents and data breaches; cybersecurity crisis preparedness, incident response plans, and business continuity and disaster recovery capabilities; and investments in cybersecurity infrastructure and program needs.
Key processes in our program include:
regular cybersecurity training and testing for employees with company email and access to connected devices;
continuous security event monitoring, management and incident response;
regular testing of incident response procedures;
regular internal reporting;
regular consulting with external advisors and specialists regarding opportunities and enhancements to strengthen our cyber practices and policies and enhance our cybersecurity maturity;
independent third-party testing of our information technology controls and defenses, including penetration tests;
independent third-party audits of our cybersecurity controls; and
annual independent third-party reviews of program maturity based on the National Institute of Standards and Technology (NIST) cybersecurity framework.
In addition, as part of our cybersecurity risk management program, we have processes designed to oversee and identify material risks from cybersecurity threats associated with our use of third-party service providers, and our cybersecurity risk management program takes into account third-party systems through which we could be impacted by the compromise of the security of a third-party service provider.
In this regard, we conduct due diligence on third-party service providers with respect to cybersecurity risks prior to entering into relationships with them, and we regularly assess security risks associated with our use of third-party service providers, including onboarding contract employees through the same process we onboard our own employees.
In addition, we contractually require third-party service providers to promptly notify us of any actual or suspected breach impacting our data or operations, and we continuously track mission critical vendors using a third-party monitoring service.
We maintain a cyber insurance policy, we periodically meet with our insurer to discuss emerging trends in cybersecurity and we utilize self-assessment tools and other services provided by our insurance broker and insurer, including annual tabletop exercises conducted by cybersecurity experts.
Our cybersecurity risk management program is integrated into our overall risk management system.
To help identify, assess and manage material risks from cybersecurity threats, we include cyber risk in our enterprise risk management, or ERM, evaluation and strategy process.
Our ERM process takes a top-down, enterprise view of risks; it is an ongoing process consisting of risk identification, risk rating, analysis and action plans, and reporting and monitoring.
Our Vice President Cyber Security has a dotted line reporting relationship to our Chief Administrative Officer and General Counsel to help ensure that risks from cybersecurity threats are considered as part of the broader ERM process.
At a management level, our Chief Administrative Officer and General Counsel leads our ERM process.
We do not believe that any risks from cybersecurity threats of which we are aware, including as a result of any previous cybersecurity incidents, have materially affected or are reasonably likely to materially affect us, including our business strategy, results of operations or financial condition.
For information regarding the risks we face associated with cybersecurity incidents, see “Risk Factors – We rely on information technology systems in our operations, and any breach or security failure of those systems could materially adversely affect our business, financial condition, results of operations and reputation” included in this Annual Report on Form 10-K.
Governance
The Audit Committee of our Board of Directors is responsible for oversight of risks from cybersecurity threats.
At a management level, our cybersecurity risk management program is led by our Chief Technology and Innovation Officer who has over 20 years experience providing business and information technology, or IT, process consulting and regulatory compliance services, including founding a cyber-security consulting and regulatory compliance firm, and whose certifications include Big 4 SOX Global Subject Matter Specialist, Certified Public Accountant and Certified Information Systems Auditor.
Partnering with our Chief Technology and Innovations Officer is our Vice President Cyber Security, who has over 30 years of IT technical and IT business process experience, has been an IT and cyber security leader for multiple financial services companies and has certifications including training in Ethical Hacking, serving as the local IT Sector Chief for the Federal Bureau of Investigation’s, or FBI, InfraGard Program, FBI Secret Clearance for all IT related incidents/cybersecurity initiatives, and FBI Citizens Academy Alumni.
Collectively, our cybersecurity team consists of 11 professionals with an average cybersecurity tenure of 17 years and certifications including CISSP, AWS Trainer, AWS Architect, Okta administrator, Splunk administrator, CCNP and CCDA, Microsoft Security, Compliance and Identity, Azure CompTIA Security+ and Splunk, information systems auditor, Red Hat Enterprise Linux certification, among other degrees, certifications and work-related experience.
Members of our cybersecurity team deliver regular updates to our Chief Technology and Innovation Officer and Chief Administrative Officer and General Counsel.
The Audit Committee of our Board of Directors receives regular reports, including an annual cybersecurity maturity assessment and quarterly scorecards, from our Chief Technology and Innovation Officer.
Those reports cover topics related to information security, privacy, and cyber risks and our risk management processes, including the status of any recent cybersecurity events, the emerging threat landscape, and the status of capital investments in our information security infrastructure.
The Audit Committee provides regular reports to the full Board of Directors.
In addition, the Audit Committee and the full Board of Directors have authority to engage external consultants, including legal, accounting or other advisors, such as cybersecurity firms, in carrying out its oversight of our cybersecurity risk management program.
Likewise, the Audit Committee or the Board of Directors may request members of management or others to attend meetings at which cybersecurity risk management is addressed.
As part of our cybersecurity risk management program, we have adopted an incident response plan which provides for controls and procedures upon the occurrence of a cybersecurity event.
In connection with that plan, we have established a cross-functional critical response team, comprised of members of management under the direction of our Chief Technology and Innovation Officer and Chief Administrative Officer and General Counsel, which is responsible for monitoring our cybersecurity incident response.
In addition, this critical response team performs an impact assessment in the event of the occurrence of a cybersecurity event meeting certain criteria, which is elevated for the team’s review and, if any such cybersecurity event is determined by the critical response team to have the potential to have a material impact on the Company, the cybersecurity event is elevated for further review and assessment by a senior management team, which includes all of the members of our standing crises control committee, and, under certain circumstances, the Audit Committee and/or the full Board of Directors.
Cybersecurity risks are part of the broader ERM process overseen by our Board of Directors.
ERM risk assessment results are presented annually to the Board of Directors, and status updates are delivered quarterly to the Audit Committee.
Item 2. Properties.
43 rewritten, 11 added, 12 removed, 18 unchanged
We own, operate, acquire and selectively develop apartment communities primarily located in the Southeast, Southwest and Mid-Atlantic regions of the [removed: United States] [added: U.S.] with the potential for above average growth and return on investment.
The following schedule summarizes our apartment community portfolio and occupancy levels by location, as of December 31, [removed: 2022:][added: 2023:]
| Atlanta, GA | | | 29 | | | | 11,434 | | | | [removed: 95.4] [added: 94.5] | % |
| Dallas, TX | | | 27 | | | | [removed: 9,767] [added: 10,116] | | | | 95.6 | % |
| Austin, TX | | | 20 | | | | 6,829 | | | | [removed: 95.2] [added: 95.1] | % |
| Raleigh/Durham, NC | | | 15 | | | | 5,350 | | | | [removed: 95.6] [added: 95.9] | % |
| Orlando, FL | | | [removed: 13] [added: 12] | | | | 5,274 | | | | [removed: 96.2] [added: 96.0] | % |
| Tampa, FL | | | [removed: 15] [added: 14] | | | | 5,220 | | | | [removed: 96.0] [added: 95.8] | % |
| Jacksonville, FL | | | [removed: 9] [added: 10] | | | | 3,496 | | | | [removed: 96.5] [added: 95.7] | % |
| Phoenix, AZ | | | 8 | | | | 2,623 | | | | [removed: 95.9] [added: 95.5] | % |
| Greenville, SC | | | 10 | | | | 2,355 | | | | [removed: 96.3] [added: 96.1] | % |
| Northern Virginia | | | 4 | | | | 1,888 | | | | [removed: 95.7] [added: 96.2] | % |
| Savannah, GA | | | [removed: 7] [added: 6] | | | | 1,837 | | | | [removed: 96.7] [added: 96.2] | % |
| Memphis, TN | | | 4 | | | | 1,811 | | | | [removed: 95.0] [added: 94.7] | % |
| San Antonio, TX | | | 4 | | | | 1,504 | | | | [removed: 95.6] [added: 95.8] | % |
| Birmingham, AL | | | 5 | | | | 1,462 | | | | [removed: 95.8] [added: 96.2] | % |
| Fredericksburg, VA | | | 4 | | | | 1,435 | | | | [removed: 96.3] [added: 96.4] | % |
| Huntsville, AL | | | 3 | | | | 1,228 | | | | [removed: 95.6] [added: 95.3] | % |
| Kansas City, MO-KS | | | 3 | | | | 1,110 | | | | [removed: 95.7] [added: 95.9] | % |
| Chattanooga, TN | | | 4 | | | | 943 | | | | [removed: 96.5] [added: 95.7] | % |
| Lexington, KY | | | 4 | | | | 924 | | | | [removed: 96.3] [added: 96.7] | % |
| Denver, CO | | | 2 | | | | 812 | | | | [removed: 95.7] [added: 95.4] | % |
| Norfolk / Hampton / Virginia Beach, VA | | | 3 | | | | 788 | | | | [removed: 96.9] [added: 95.9] | % |
| Las Vegas, NV | | | 2 | | | | 721 | | | | [removed: 95.1] [added: 95.8] | % |
| Tallahassee, FL | | | 2 | | | | 604 | | | | [removed: 96.2] [added: 95.2] | % |
| Columbia, SC | | | 2 | | | | 576 | | | | [removed: 94.3] [added: 95.2] | % |
| South Florida, FL | | | 1 | | | | 480 | | | | [removed: 95.4] [added: 95.3] | % |
| Gainesville, FL | | | 2 | | | | 468 | | | | [removed: 95.6] [added: 95.7] | % |
| Louisville, KY | | | 1 | | | | 384 | | | | [removed: 96.6] [added: 95.9] | % |
| Maryland | | | 1 | | | | 361 | | | | [removed: 95.7] [added: 96.4] | % |
| Gulf Shores, AL | | | 1 | | | | 324 | | | | [removed: 96.1] [added: 95.7] | % |
| Panama City, FL | | | 1 | | | | 254 | | | | [removed: 96.1] [added: 95.5] | % |
| Charlottesville, VA | | | 1 | | | | 251 | | | | [removed: 96.8] [added: 96.6] | % |
| Orlando, FL | | | 2 | | | | 633 | | | | [removed: 80.7] [added: 90.9] | % |
| Austin, TX | | | 1 | | | | 350 | | | | [removed: 54.8] [added: 83.0] | % |
| Houston, TX | | | 1 | | | | 308 | | | | [removed: 70.8] [added: 94.7] | % |
| Tampa, FL | | | [removed: 2] [added: 1] | | [added: (4)] | | 196 | | | | [removed: 83.5] [added: 94.9] | % |
| Gulf Shores, AL | | | 1 | | | | 96 | | | | [removed: 97.7] [added: 97.0] | % |
| Salt Lake City, UT | | | 1 | | | [removed: —] | [added: 196] | | | | [removed: —] [added: 30.3] | [added: %] |
Number of communities includes [removed: six] [added: five] communities under development as of December 31, [removed: 2022.][added: 2023.]
| Charlotte, NC | | | 19 | | | | 5,651 | | | | 95.6 | % |
| Fort Worth, TX | | | 9 | | | | 3,687 | | | | 95.6 | % |
| Richmond, VA | | | 6 | | | | 1,732 | | | | 95.9 | % |
| Same Store | | | 274 | | | | 95,286 | | | | 95.6 | % |
| Charlotte, NC | | | 3 | | | | 912 | | | | 87.9 | % |
| Phoenix, AZ | | | 3 | | | | 671 | | | | 91.1 | % |
| Atlanta, GA | | | 1 | | | | 340 | | | | 39.7 | % |
| Denver, CO | | | 2 | | | | 309 | | | | 95.5 | % |
| Richmond, VA | | | 1 | | | | 272 | | | | 96.5 | % |
| Total (5) | | | 295 | | | | 100,625 | | | | 95.1 | % |
Includes a completed MAA multifamily apartment community expansion development and a new multifamily apartment community development that has not yet delivered any units.
| Charlotte, NC | | | 20 | | | | 5,867 | | | | 95.8 | % |
| Fort Worth, TX | | | 9 | | | | 3,519 | | | | 95.5 | % |
| Richmond, VA | | | 7 | | | | 2,004 | | | | 96.1 | % |
| Same Store | | | 281 | | | | 96,313 | | | | 95.7 | % |
| Dallas, TX | | | — | | (4) | | 348 | | | | 95.6 | % |
| Phoenix, AZ | | | 2 | | | | 345 | | | | 93.7 | % |
| Charlotte, NC | | | 1 | | | | 344 | | | | 88.8 | % |
| Denver, CO | | | 2 | | | | 306 | | | | 80.9 | % |
| Fort Worth, TX | | | — | | (4) | | 168 | | | | 96.4 | % |
| Atlanta, GA | | | 1 | | | | — | | | | — | |
| Total (5) | | | 296 | | | | 99,407 | | | | 95.3 | % |
Represents a MAA multifamily apartment community expansion development.
An excerpt. Shown here: 40 of 43 rewritten, all 11 added and all 12 removed. The counts are complete. For every sentence, read Item 2. Properties. in the FY2023 filing and the FY2022 filing.
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
14 rewritten, 9 added, 5 removed, 39 unchanged
As of February [removed: 9, 2023,] [added: 6, 2024,] there were approximately [removed: 2,200] [added: 2,100] holders of record of the common stock.
The DRSPP also allows for the optional purchase of MAA common stock of at least $250, but not more than $5,000 in any given [removed: month, free of brokerage commissions and charges.][added: month.]
During the year ended December 31, [removed: 2022,] [added: 2023,] MAA issued a total of 41,184 shares of common stock upon redemption of OP Units.
During the year ended December 31, [removed: 2022,] [added: 2023,] MAA did not sell any shares of common stock under its ATM program.
As of December 31, [removed: 2022,] [added: 2023,] there were 4.0 million shares remaining under the current ATM program.
As of December 31, [removed: 2022,] [added: 2023,] no shares have been repurchased under the authorization.
The following table reflects repurchases of shares of MAA’s common stock during the three months ended December 31, [removed: 2022:][added: 2023:]
| Period | | Total Number of Shares Purchased [added: (1)] | | | | Average Price Paid per Share [added: (2)] | | | | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | | | | Maximum Number of Shares That May Yet be Purchased Under the Plans or Programs [removed: (1)] [added: (3)] | | |
| October 1, [removed: 2022] [added: 2023] - October 31, [removed: 2022] [added: 2023] | | | [removed: —] [added: 62] | | | $ | [removed: —] [added: 129.23] | | | | — | | | | 4,000,000 | |
| November 1, [removed: 2022] [added: 2023] - November 30, [removed: 2022] [added: 2023] | | | — | | | $ | — | | | | — | | | | 4,000,000 | |
| December 1, [removed: 2022] [added: 2023] - December 31, [removed: 2022] [added: 2023] | | | — | | | $ | — | | | | — | | | | 4,000,000 | |
The following graph compares the cumulative total returns of the shareholders of MAA since December 31, [removed: 2017] [added: 2018] with the S&P 500 Index and the Dow Jones U.S. Real Estate Apartments Index.
[removed: ][added: 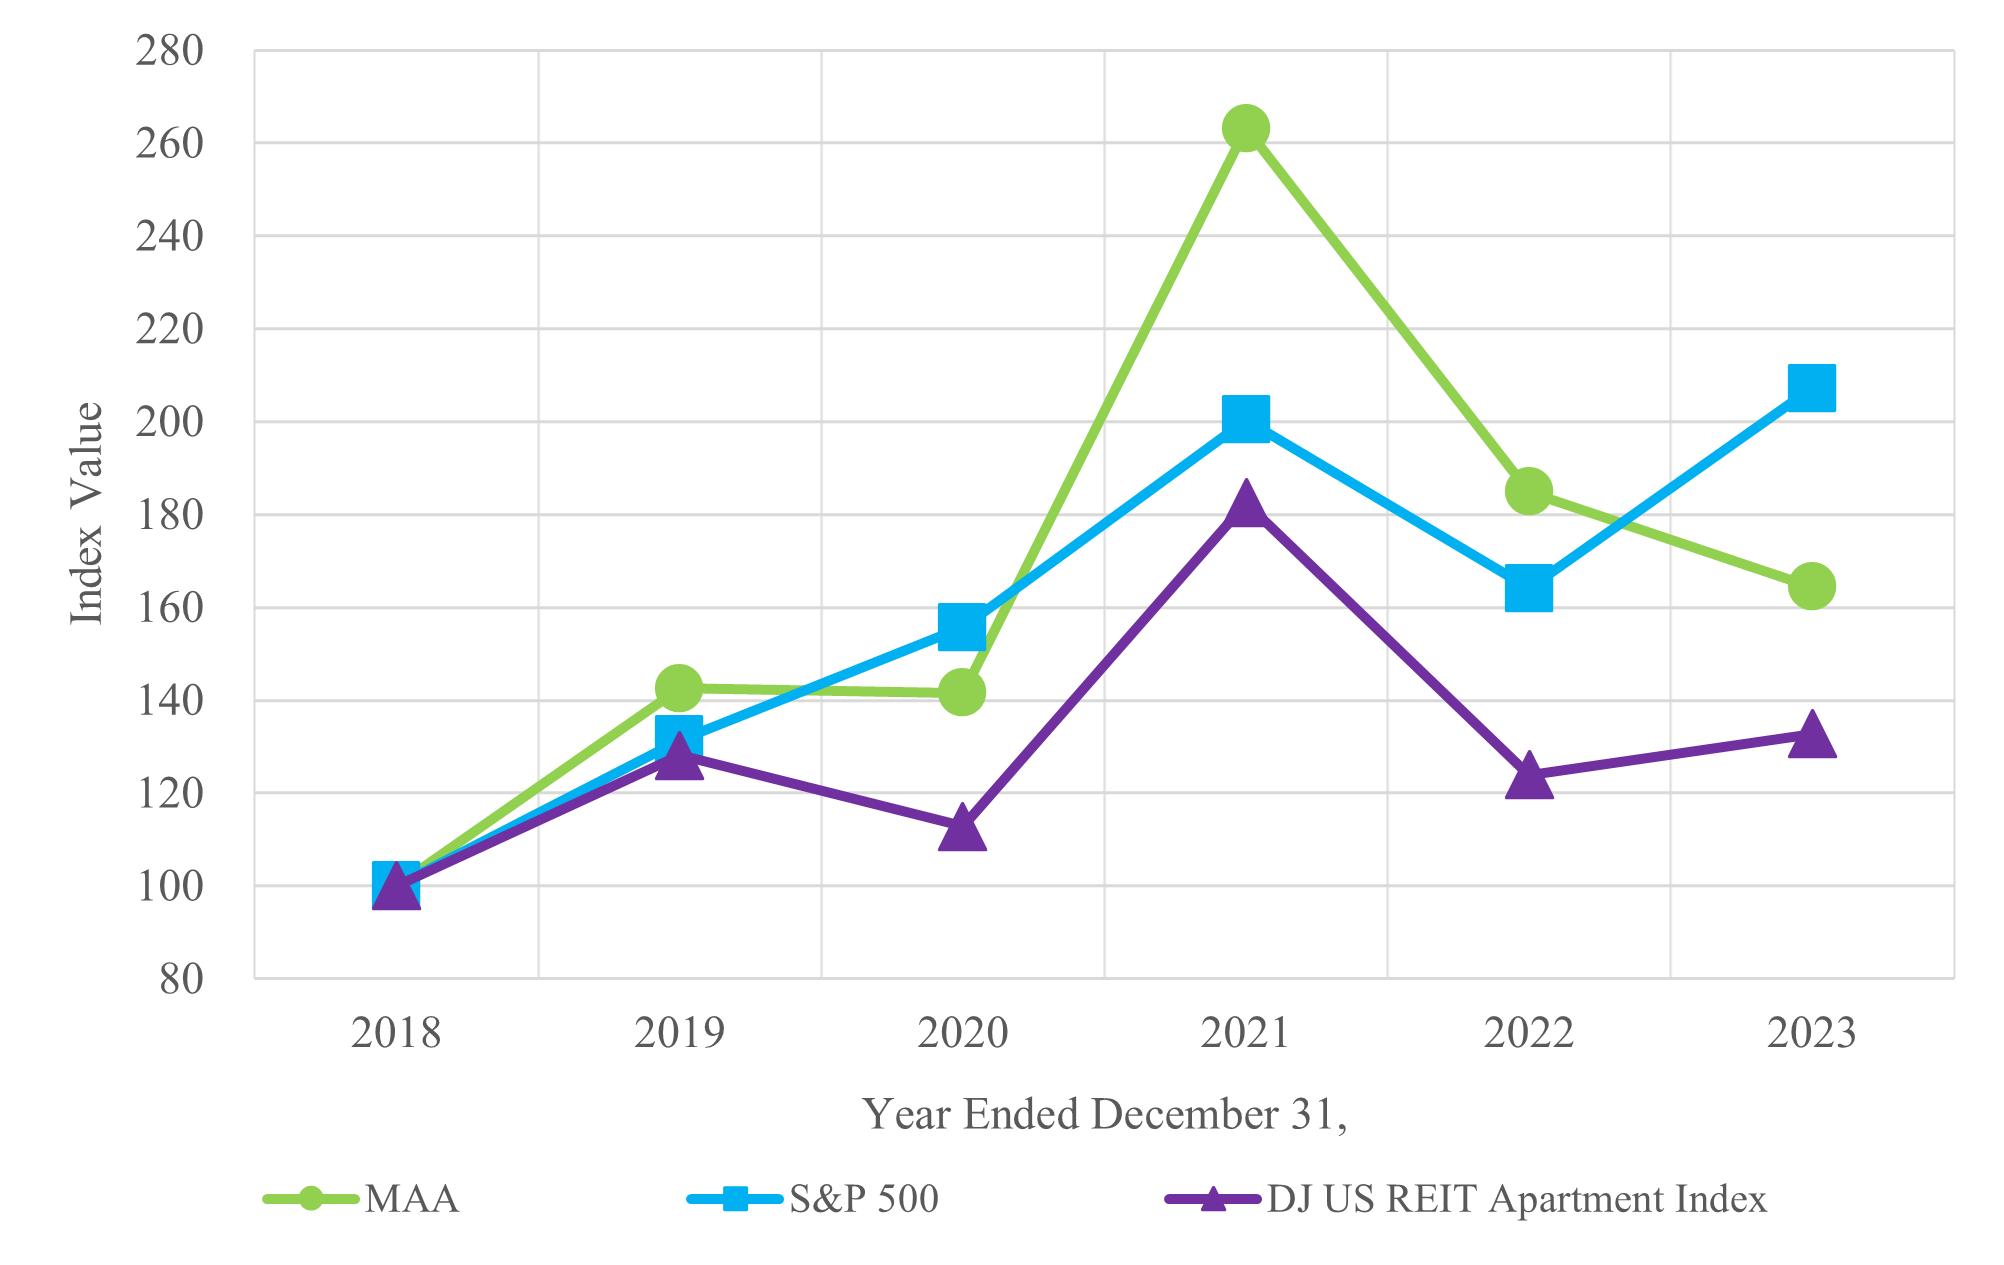]
| | | [removed: 2017 | | | |] 2018 | | | | 2019 | | | | 2020 | | | | 2021 | | | | 2022 | | | | [added: 2023 | | | |]
During the year ended December 31, 2023, we issued 9,787 shares through our DRSPP and no shares were issued at a discount.
As of December 31, 2023, there were 119,838,096 OP Units outstanding in the Operating Partnership, of which 116,694,124 OP Units, or 97.4%, were owned by MAA and 3,143,972 OP Units, or 2.6%, were owned by limited partners.
The shares reflected in this column are shares of MAA’s common stock surrendered by employees to satisfy their statutory minimum federal and state tax obligations associated with the vesting of restricted shares.
(2)
The price per share is based on the closing price of MAA’s common stock as of the date of determination of the statutory minimum for federal and state tax obligations.
(3)
| Mid-America Apartment Communities, Inc. | | $ | 100.00 | | | $ | 142.52 | | | $ | 141.60 | | | $ | 263.20 | | | $ | 184.90 | | | $ | 164.44 | | |
| S&P 500 Index | | | 100.00 | | | | 131.49 | | | | 155.68 | | | | 200.37 | | | | 164.08 | | | | 207.21 | | |
| DJ US REIT Apartment Index | | | 100.00 | | | | 128.11 | | | | 112.83 | | | | 182.52 | | | | 123.96 | | | | 132.77 | | |
During the year ended December 31, 2022 we had issuances with no discounts through our DRSPP of 6,547 shares.
As of December 31, 2022, there were 118,645,269 OP Units outstanding in the Operating Partnership, of which 115,480,336 OP Units, or 97.3%, were owned by MAA and 3,164,933 OP Units, or 2.7%, were owned by limited partners.
| Mid-America Apartment Communities, Inc. | | $ | 100.00 | | | $ | 98.94 | | | $ | 141.00 | | | $ | 140.10 | | | $ | 260.40 | | | $ | 182.93 | | |
| S&P 500 Index | | | 100.00 | | | | 95.62 | | | | 125.72 | | | | 148.85 | | | | 191.58 | | | | 156.88 | | |
| DJ US REIT Apartment Index | | | 100.00 | | | | 102.19 | | | | 130.92 | | | | 115.30 | | | | 186.51 | | | | 126.67 | | |
Item 9A. Controls and Procedures.
10 rewritten, 0 added, 0 removed, 18 unchanged
MAA’s management, with the participation of MAA’s Chief Executive Officer and Chief Financial Officer, carried out an evaluation of the effectiveness of MAA’s disclosure controls and procedures as of December 31, [removed: 2022.][added: 2023.]
Based on that evaluation, MAA’s Chief Executive Officer and Chief Financial Officer concluded that the disclosure controls and procedures were effective as of December 31, [removed: 2022] [added: 2023] to ensure that information required to be disclosed by MAA in its Exchange Act filings is accurately recorded, processed, summarized and reported within the time periods specified in the SEC’s rules and forms and is accumulated and communicated to MAA’s management, including the Chief Executive Officer and Chief Financial Officer, as appropriate to allow timely decisions regarding required disclosure.
MAA’s management, with the participation of MAA’s Chief Executive Officer and Chief Financial Officer, conducted an evaluation of the effectiveness of MAA’s internal control over financial reporting as of December 31, [removed: 2022] [added: 2023] based on the framework specified in Internal Control - Integrated Framework (2013) published by the Committee of Sponsoring Organizations of the Treadway Commission.
Based on such evaluation, MAA’s management concluded that MAA’s internal control over financial reporting was effective as of December 31, [removed: 2022.][added: 2023.]
There was no change to MAA’s internal control over financial reporting, within the meaning of Exchange Act Rules 13a-15 and 15d-15, that occurred during the quarter ended December 31, [removed: 2022] [added: 2023] that has materially affected, or is reasonably likely to materially affect, MAA’s internal control over financial reporting.
Management of the Operating Partnership, with the participation of the Chief Executive Officer and Chief Financial Officer of MAA, as the general partner of the Operating Partnership, carried out an evaluation of the effectiveness of the Operating Partnership’s disclosure controls and procedures as of December 31, [removed: 2022.][added: 2023.]
Based on that evaluation, the Chief Executive Officer and Chief Financial Officer of MAA, as the general partner of the Operating Partnership, concluded that the disclosure controls and procedures were effective as of December 31, [removed: 2022] [added: 2023] to ensure that information required to be disclosed by the Operating Partnership in its in Exchange Act filings is accurately recorded, processed, summarized and reported within the time periods specified in the SEC’s rules and forms and is accumulated and communicated to the Operating Partnership’s management, including the Chief Executive Officer and Chief Financial Officer of MAA, as the general partner of the Operating Partnership, as appropriate to allow timely decisions regarding required disclosure.
Management of the Operating Partnership, with the participation of the Chief Executive Officer and Chief Financial Officer of MAA, as the general partner of the Operating Partnership, conducted an evaluation of the effectiveness of the Operating Partnership’s internal control over financial reporting as of December 31, [removed: 2022] [added: 2023] based on the framework specified in Internal Control - Integrated Framework (2013) published by the Committee of Sponsoring Organizations of the Treadway Commission.
Based on such evaluation, management of the Operating Partnership has concluded that the Operating Partnership’s internal control over financial reporting was effective as of December 31, [removed: 2022.][added: 2023.]
There was no change to the Operating Partnership’s internal control over financial reporting, within the meaning of Exchange Act Rules 13a-15 and 15d-15, that occurred during the quarter ended December 31, [removed: 2022] [added: 2023] that has materially affected, or is reasonably likely to materially affect, the Operating Partnership’s internal control over financial reporting.
Item 9B. Other Information.
0 rewritten, 4 added, 1 removed, 0 unchanged
Rule 10b5-1 Trading Arrangements.
During the quarter ended December 31, 2023, no director or officer of the Company adopted or terminated any “Rule 10b5-1 trading arrangement” as that term is defined in Item 408(a) of Regulation S-K.
Non-Rule 10b5-1 Trading Arrangements.
During the quarter ended December 31, 2023, no director or officer of the Company adopted or terminated any “non-Rule 10b5-1 trading arrangement” as that term is defined in Item 408(a) of Regulation S-K.
None.
Item 10. Directors, Executive Officers and Corporate Governance.
2 rewritten, 0 added, 1 removed, 2 unchanged
The information contained in MAA’s [removed: 2023] [added: 2024] Proxy Statement in the sections entitled “Current Board [removed: Composition”,] [added: Composition,”] “Director Nominees for Election” and “Executive Officers of the [removed: Registrant”] [added: Registrant,”] is incorporated herein by reference in response to this Item 10.
Our Board of Directors has adopted a Code of Conduct applicable to all officers, directors and employees, including the CEO, CFO and principal accounting officer, which can be found on our website at https://www.maac.com, on the “For Investors” page in the “Corporate Documents” section under “Overview—Corporate [removed: Governance”.][added: Governance.” We will provide a copy of this document to any person, without charge, upon request, by writing to the Legal Department at MAA, 6815 Poplar Avenue, Suite 500, Germantown, Tennessee 38138.]
We will provide a copy of this document to any person, without charge, upon request, by writing to the Legal Department at MAA, 6815 Poplar Avenue, Suite 500, Germantown, Tennessee 38138.
Item 11. Executive Compensation.
1 rewritten, 0 added, 0 removed, 0 unchanged
The information contained in MAA’s [removed: 2023] [added: 2024] Proxy Statement in the sections entitled “Executive Compensation [removed: Tables”,] [added: Tables,”] “Director Compensation [removed: Table”,] [added: Table,”] “Compensation Committee Interlocks and Insider [removed: Participation”,] [added: Participation,”] “Compensation Committee Report” and “Compensation Discussion and Analysis” is incorporated herein by reference in response to this Item 11.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
1 rewritten, 0 added, 0 removed, 0 unchanged
The information contained in MAA’s [removed: 2023] [added: 2024] Proxy Statement in the sections entitled “Security Ownership of [removed: Management”,] [added: Management,”] “Security Ownership of Certain Beneficial Owners” and “Securities Authorized for Issuance Under Equity Compensation Plans” is incorporated herein by reference in response to this Item 12.
Item 13. Certain Relationships and Related Transactions, and Director Independence.
1 rewritten, 0 added, 0 removed, 0 unchanged
The information contained in MAA’s [removed: 2023] [added: 2024] Proxy Statement in the sections entitled “Certain Relationships and Related Transactions” and “Indebtedness of Management” is incorporated herein by reference in response to this Item 13.
Item 14. Principal Accountant Fees and Services.
1 rewritten, 0 added, 0 removed, 1 unchanged
The information contained in MAA’s [removed: 2023] [added: 2024] Proxy Statement in the section entitled “Audit and Non-Audit Fees” is incorporated herein by reference in response to this Item 14.
Item 15. Exhibits and Financial Statement Schedules.
26 rewritten, 17 added, 1 removed, 121 unchanged
| | [Consolidated Balance Sheets as of December 31, [removed: 2022] [added: 2023] and [removed: 2021](#consolidated_balance_sheets)] [added: 2022](#consolidated_balance_sheets)] | F-4 |
| | [Consolidated Statements of Operations for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#consolidated_statements_operations)] [added: 2021](#consolidated_statements_operations)] | F-5 |
| | [Consolidated Statements of Comprehensive Income for the](#consolidated_statements_comprehensive_in) [years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#consolidated_statements_operations)] [added: 2021](#consolidated_statements_operations)] | F-6 |
| | [Consolidated Statements of Equity for the](#consolidated_statements_equity) [years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#consolidated_statements_operations)] [added: 2021](#consolidated_statements_operations)] | F-7 |
| | [Consolidated Statements of Cash Flows for the](#consolidated_statements_cash_flows) years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020] [added: 2021] | F-8 |
| | [Consolidated Balance Sheets as of](#consolidated_balance_sheets2) December 31, [removed: 2022] [added: 2023] and [removed: 2021] [added: 2022] | F-9 |
| | [Consolidated Statements of Operations for the](#consolidated_statements_operations2) years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020] [added: 2021] | F-10 |
| | [Consolidated Statements of Comprehensive Income for the](#comprehensive_in2) years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020] [added: 2021] | F-11 |
| | [Consolidated Statements of Changes in Capital for the](#consolidated_statements_changes_in_capit) years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020] [added: 2021] | F-12 |
| | [Consolidated Statements of Cash Flows for the](#consolidated_statements_cash_flows2) years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020] [added: 2021] | F-13 |
| | [Notes to Consolidated Financial Statements for the](#notes_to_consolidated_financial_statemen) years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020] [added: 2021] | F-14 |
| | [Schedule III – Real Estate and Accumulated Depreciation as of](#schedule_iii_real_estate_accumulated_dep) December 31, [removed: 2022] [added: 2023] | F-33 |
| 3.2 | | | [removed: [Fourth] [added: [Fifth] Amended and Restated Bylaws of Mid-America Apartment Communities, Inc., dated as of [removed: March 13, 2018] [added: December 12, 2023] (Filed as Exhibit [removed: 3.2(i)] [added: 3.1] to the Registrant’s Current Report on Form 8-K filed on [removed: March 14, 2018] [added: December 13, 2023] and incorporated herein by [removed: reference).](https://www.sec.gov/Archives/edgar/data/912595/000091259518000015/exhibit32i-fourthamendedan.htm)] [added: reference).](https://www.sec.gov/ix?doc=/Archives/edgar/data/912595/000095017023070045/maa-20231212.htm)] |
| [removed: 4.17] [added: 4.18] | | [Description of Securities (Filed as Exhibit 4.15 to the Registrant’s Annual Report on Form 10-K filed on February 20, 2020 and incorporated herein by reference).](https://www.sec.gov/Archives/edgar/data/912595/000156459020005582/maa-ex415_1341.htm) |
| 21.1 | | [List of [removed: Subsidiaries.](https://www.sec.gov/Archives/edgar/data/912595/000095017023002778/maa-ex21_1.htm)] [added: Subsidiaries.](https://www.sec.gov/Archives/edgar/data/912595/000095017024013275/maa-ex21_1.htm)] |
| 23.1 | | [Consent of Independent Registered Public Accounting Firm, Ernst & Young LLP for [removed: MAA.](https://www.sec.gov/Archives/edgar/data/912595/000095017023002778/maa-ex23_1.htm)] [added: MAA.](https://www.sec.gov/Archives/edgar/data/912595/000095017024013275/maa-ex23_1.htm)] |
| 23.2 | | [Consent of Independent Registered Public Accounting Firm, Ernst & Young LLP for [removed: MAALP.](https://www.sec.gov/Archives/edgar/data/912595/000095017023002778/maa-ex23_2.htm)] [added: MAALP.](https://www.sec.gov/Archives/edgar/data/912595/000095017024013275/maa-ex23_2.htm)] |
| 31.1 | | [MAA Certification of Chief Executive Officer Pursuant to Section 302 of the Sarbanes-Oxley Act of [removed: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017023002778/maa-ex31_1.htm)] [added: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017024013275/maa-ex31_1.htm)] |
| 31.2 | | [MAA Certification of Chief Financial Officer Pursuant to Section 302 of the Sarbanes-Oxley Act of [removed: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017023002778/maa-ex31_2.htm)] [added: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017024013275/maa-ex31_2.htm)] |
| 31.3 | | [MAALP Certification of Chief Executive Officer Pursuant to Section 302 of the Sarbanes-Oxley Act of [removed: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017023002778/maa-ex31_3.htm)] [added: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017024013275/maa-ex31_3.htm)] |
| 31.4 | | [MAALP Certification of Chief Financial Officer Pursuant to Section 302 of the Sarbanes-Oxley Act of [removed: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017023002778/maa-ex31_4.htm)] [added: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017024013275/maa-ex31_4.htm)] |
| 32.1* | | [MAA Certification of Chief Executive Officer Pursuant to 18 U.S.C. Section 1350, as Adopted Pursuant to Section 906 of the Sarbanes-Oxley Act of [removed: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017023002778/maa-ex32_1.htm)] [added: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017024013275/maa-ex32_1.htm)] |
| 32.2* | | [MAA Certification of Chief Financial Officer Pursuant to 18 U.S.C. Section 1350, as Adopted Pursuant to Section 906 of the Sarbanes-Oxley Act of [removed: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017023002778/maa-ex32_2.htm)] [added: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017024013275/maa-ex32_2.htm)] |
| 32.3* | | [MAALP Certification of Chief Executive Officer Pursuant to 18 U.S.C. Section 1350, as Adopted Pursuant to Section 906 of the Sarbanes-Oxley Act of [removed: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017023002778/maa-ex32_3.htm)] [added: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017024013275/maa-ex32_3.htm)] |
| 32.4* | | [MAALP Certification of Chief Financial Officer Pursuant to 18 U.S.C. Section 1350, as Adopted Pursuant to Section 906 of the Sarbanes-Oxley Act of [removed: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017023002778/maa-ex32_4.htm)] [added: 2002.](https://www.sec.gov/Archives/edgar/data/912595/000095017024013275/maa-ex32_4.htm)] |
| 101 | | The following financial information from Mid-America Apartment Communities, Inc.’s and Mid-America Apartments, L.P.’s Annual Report on Form 10-K for the period ended December 31, [removed: 2022,] [added: 2023,] filed with the SEC on February [removed: 14, 2023,] [added: 9, 2024,] formatted in iXBRL (Inline Extensible Business Reporting Language): (i) the Consolidated Balance Sheets as of December 31, [removed: 2022] [added: 2023] and December 31, [removed: 2021;] [added: 2022;] (ii) the Consolidated Statements of Operations for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020;] [added: 2021;] (iii) the Consolidated Statements of Comprehensive Income for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020;] [added: 2021;] (iv) the Consolidated Statements of Equity/Changes in Capital for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020;] [added: 2021;] (v) the Consolidated Statements of Cash Flows for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020;] [added: 2021;] (vi) Notes to Consolidated Financial Statements; and (vii) Schedule III - Real Estate and Accumulated Depreciation as of December 31, [removed: 2022.] [added: 2023.] |
| | All other financial statement schedules for which provision is made in the applicable accounting regulations of the SEC are not required under the related instructions or are inapplicable and, therefore, have been omitted. | |
| 4.17 | | [Seventh Supplemental Indenture, dated as of January 10, 2024, by and between Mid-America Apartments, L.P. and U.S. Bank Trust Company, National Association (Filed as Exhibit 4.2 to the Registrant’s Current Report on Form 8-K filed on January 10, 2024 and incorporated herein by reference).](https://www.sec.gov/ix?doc=/Archives/edgar/data/912595/000119312524005931/d865882d8k.htm) |
| 10.18† | | [Mid-America Apartment Communities, Inc. 2023 OMNIBUS Incentive Plan (filed as Exhibit A to the Registrant’s Definitive Proxy Statement on Schedule 14A filed on April 3, 2023 and incorporated herein by reference).](https://www.sec.gov/ix?doc=/Archives/edgar/data/912595/000114036123015626/ny20006766x1_def14a.htm) |
| 10.19† | | [Form of Restricted Stock Award Agreement Under the Mid-America Apartment Communities, Inc. 2023 OMNIBUS Incentive Plan (Filed as Exhibit 10.2 to the Registrant’s Quarterly Report on Form 10-Q filed on July 27, 2023 and incorporated herein by reference).](https://www.sec.gov/Archives/edgar/data/912595/000095017023035158/maa-ex10_2.htm) |
| 10.20† | | [Form of Non-Qualified Stock Option Agreement for Company Employees Under the Mid-America Apartment Communities, Inc. 2023 OMNIBUS Incentive Plan (Filed as Exhibit 10.3 to the Registrant’s Quarterly Report on Form 10-Q filed on July 27, 2023 and incorporated herein by reference)](https://www.sec.gov/Archives/edgar/data/912595/000095017023035158/maa-ex10_3.htm). |
| 10.21† | | [Form of Incentive Stock Option Agreement for Company Employees Under the Mid-America Apartment Communities, Inc. 2023 OMNIBUS Incentive Plan (Filed as Exhibit 10.4 to the Registrant’s Quarterly Report on Form 10-Q filed on July 27, 2023 and incorporated herein by reference).](https://www.sec.gov/Archives/edgar/data/912595/000095017023035158/maa-ex10_4.htm) |
| 10.22† | | [Form of Restricted Stock Unit Award Agreement Under the Mid-America Apartment Communities, Inc. 2023 OMNIBUS Incentive Plan (Filed as Exhibit 10.5 to the Registrant’s Quarterly Report on Form 10-Q filed on July 27, 2023 and incorporated herein by reference).](https://www.sec.gov/Archives/edgar/data/912595/000095017023035158/maa-ex10_5.htm) |
| 10.23† | | [Retirement and Transition Services Agreement by and between Albert M. Campbell, III and Mid-America Apartment Communities, Inc. and Mid-America Apartments, L.P. (Filed as Exhibit 10.1 to the Registrant’s Quarterly Report on Form 8-K filed on December 13, 2023 and incorporated herein by reference).](https://www.sec.gov/Archives/edgar/data/912595/000095017023070045/maa-ex10_1.htm) |
| | | |
| | | |
| | | |
| | | |
| | | |
| 97 | | [MAA Compensation Recoupment Policy](https://www.sec.gov/Archives/edgar/data/912595/000095017024013275/maa-ex97.htm) |
| | | |
| | | |
| | | |
| 10.18† | | [Retirement and Transition Services Agreement by and between the Registrants and Thomas L. Grimes, Jr.](https://www.sec.gov/Archives/edgar/data/912595/000095017022020325/maa-ex10_2.htm) |
Item 16. Form 10-K Summary.
646 rewritten, 283 added, 160 removed, 807 unchanged
| Date: | February [removed: 14, 2023] [added: 9, 2024] | /s/ H. Eric Bolton, Jr. |
| Date: | February [removed: 14, 2023] [added: 9, 2024] | /s/ Albert M. Campbell, III |
| Date: | February [removed: 14, 2023] [added: 9, 2024] | /s/ A. Clay Holder |
| Date: | February [removed: 14, 2023] [added: 9, 2024] | /s/ Alan B. Graf, Jr. |
| Date: | February [removed: 14, 2023] [added: 9, 2024] | /s/ Edith Kelly-Green |
| Date: | February [removed: 14, 2023] [added: 9, 2024] | /s/ Toni Jennings |
| Date: | February [removed: 14, 2023] [added: 9, 2024] | /s/ James K. Lowder |
| Date: | February [removed: 14, 2023] [added: 9, 2024] | /s/ Thomas H. Lowder |
| Date: | February [removed: 14, 2023] [added: 9, 2024] | /s/ Claude B. Nielsen |
| Date: | February [removed: 14, 2023] [added: 9, 2024] | /s/ W. Reid Sanders |
| Date: | February [removed: 14, 2023] [added: 9, 2024] | /s/ Gary Shorb |
| Date: | February [removed: 14, 2023] [added: 9, 2024] | /s/ David P. Stockert |
We have audited the accompanying consolidated balance sheets of Mid-America Apartment Communities, Inc. (the Company) as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] the related consolidated statements of operations, comprehensive income, equity, and cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] and the related notes and financial statement schedule listed in the Index at Item 15(a)(2) (collectively referred to as the “consolidated financial statements”).
In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company at December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company’s internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated February [removed: 14, 2023] [added: 9, 2024] expressed an unqualified opinion thereon.
| *Description of the Matter* | | As disclosed in Notes 6 and 8 to the consolidated financial statements, the Series I Preferred Stock shares (“preferred shares”) include a redemption feature which represents an embedded call option exercisable at the Company’s option beginning on October 1, 2026 at the redemption price of $50 per share. The embedded call option has been bifurcated as a separate asset and is valued at fair value each reporting period with changes in its fair value reported in earnings. At each reporting date, management performs an analysis which compares the perpetual value of the preferred shares to the value of the preferred shares assuming the call option is exercised, with the value of the bifurcated call option as the difference between the two values. At December 31, [removed: 2022,] [added: 2023,] the fair value of the Company’s embedded derivative asset was [removed: $13.4] [added: $31.9] million. Auditing the Company’s valuation of this bifurcated embedded derivative was challenging as the Company uses a complex valuation methodology that incorporates various inputs, including trading data available on the preferred shares, treasury rates and estimated coupon yields on preferred stock instruments from REITs with similar credit ratings, and includes significant assumptions about economic and market conditions with uncertain future outcomes. |
| *How We Addressed the Matter in Our Audit* | | We obtained an understanding, evaluated the design and tested the operating effectiveness of the Company’s controls over the risks of material misstatement relating to the valuation of the bifurcated embedded derivative asset. For example, we tested controls over management’s review of the valuation model and the underlying inputs and assumptions noted above. To test the valuation of the embedded derivative asset, our audit procedures included, among others, assessing the methodology used in the valuation model and testing the significant assumptions discussed above. For example, we evaluated management’s assumptions by comparing the [removed: coupon rate] [added: rates] that [removed: was] [added: were] used to discount future dividend payments from the preferred stock to observable market data. We also assessed the completeness and accuracy of the underlying data used by the Company in its valuation. In addition, we involved our valuation specialists to assist in our evaluation of the methodology used by the Company and the underlying inputs and assumptions noted above. |
We have audited the accompanying consolidated balance sheets of Mid-America Apartments, L.P. (the Operating Partnership) as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] the related consolidated statements of operations, comprehensive income, changes in capital, and cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] and the related notes and financial statement schedule listed in the Index at Item 15(a)(2) (collectively referred to as the “consolidated financial statements”).
In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Operating Partnership at December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] in conformity with U.S. generally accepted accounting principles.
| *Description of the Matter* | | As disclosed in Notes 6 and 9 to the consolidated financial statements, the MAALP Series I Preferred Units (“preferred units”) have the same characteristics as the MAA Series I Preferred Stock shares (“preferred shares”), and thus include a redemption feature which represents an embedded call option exercisable at the Operating Partnership’s option beginning on October 1, 2026 at the redemption price of $50 per unit. The embedded call option has been bifurcated as a separate asset and is valued at fair value each reporting period with changes in its fair value reported in earnings. At each reporting date, management performs an analysis which compares the perpetual value of the preferred units to the value of the preferred units assuming the call option is exercised, with the value of the bifurcated call option as the difference between the two values. At December 31, [removed: 2022,] [added: 2023,] the fair value of the Operating Partnership’s embedded derivative asset was [removed: $13.4] [added: $31.9] million. Auditing the Operating Partnership’s valuation of this bifurcated embedded derivative was challenging as the Operating Partnership uses a complex valuation methodology that incorporates various inputs, including trading data available on the respective MAA preferred shares, treasury rates and estimated coupon yields on preferred stock instruments from REITs with similar credit ratings, and includes significant assumptions about economic and market conditions with uncertain future outcomes. |
| *How We Addressed the Matter in Our Audit* | | We obtained an understanding, evaluated the design and tested the operating effectiveness of the Operating Partnership’s controls over the risks of material misstatement relating to the valuation of the bifurcated embedded derivative asset. For example, we tested controls over management’s review of the valuation model and the underlying inputs and assumptions noted above. To test the valuation of the embedded derivative asset, our audit procedures included, among others, assessing the methodology used in the valuation model and testing the significant assumptions discussed above. For example, we evaluated management’s assumptions by comparing the [removed: coupon rate] [added: rates] that [removed: was] [added: were] used to discount future dividend payments from the preferred units to observable market data. We also assessed the completeness and accuracy of the underlying data used by the Operating Partnership in its valuation. In addition, we involved our valuation specialists to assist in our evaluation of the methodology used by the Operating Partnership and the underlying inputs and assumptions noted above. |
We have audited Mid-America Apartment Communities, Inc.’s internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria).
In our opinion, Mid-America Apartment Communities, Inc. (the Company) maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of the Company as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] the related consolidated statements of operations, comprehensive income, shareholders’ equity, and cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] and the related notes and financial statement schedule listed in the Index at Item 15(a)(2) and our report dated February [removed: 14, 2023] [added: 9, 2024] expressed an unqualified opinion thereon.
December 31, [removed: 2022] [added: 2023] and [removed: 2021][added: 2022]
| | | December 31, [removed: 2022] [added: 2023] | | | | December 31, [removed: 2021] [added: 2022] | | |
| Land | | $ | [removed: 2,008,364] [added: 2,031,403] | | | $ | [removed: 1,977,813] [added: 2,008,364] | |
| Buildings and improvements and other | | | [removed: 12,841,947] [added: 13,515,949] | | | | [removed: 12,454,439] [added: 12,841,947] | |
| Development and capital improvements in progress | | | [removed: 332,035] [added: 385,405] | | | | [removed: 247,970] [added: 332,035] | |
| Less: Accumulated depreciation | | | [removed: (4,302,747] [added: (4,864,690] | ) | | | [removed: (3,848,161] [added: (4,302,747] | ) |
| Undeveloped land | | | [removed: 64,312] [added: 73,861] | | | | [removed: 24,015] [added: 64,312] | |
| Investment in real estate joint venture | | | [removed: 42,290] [added: 41,977] | | | | [removed: 42,827] [added: 42,290] | |
| Real estate assets, net | | | [removed: 10,986,201] [added: 11,183,905] | | | | [removed: 10,898,903] [added: 10,986,201] | |
| Cash and cash equivalents | | [added: $] | [added: 41,314 | | | $ |] 38,659 | | | [added: $] | 54,302 | |
| Restricted cash | | | [added: 13,777 | | | |] 22,412 | | | | 76,296 | |
| Other assets | | | [removed: 193,893] [added: 245,507] | | | | [removed: 255,681] [added: 193,893] | |
| Total assets | | $ | [removed: 11,241,165] [added: 11,484,503] | | | $ | [removed: 11,285,182] [added: 11,241,165] | |
| Unsecured notes payable | | $ | [removed: 4,050,910] [added: 4,180,084] | | | $ | [removed: 4,151,375] [added: 4,050,910] | |
| Secured notes payable | | | [removed: 363,993] [added: 360,141] | | | | [removed: 365,315] [added: 363,993] | |
| Accrued expenses and other liabilities | | | [removed: 615,843] [added: 645,156] | | | | [removed: 584,400] [added: 615,843] | |
| Date: | February 9, 2024 | /s/ H. Eric Bolton, Jr. |
| Date: | February 9, 2024 | /s/ Deborah H. Caplan |
| | | Deborah H. Caplan Director |
| Date: | February 9, 2024 | /s/ John P. Case |
| | | John P. Case Director |
| Date: | February 9, 2024 | /s/ Tamara Fischer |
| | | Tamara Fischer Director |
| Date: | February 9, 2024 | /s/ H. Eric Bolton, Jr. |
| Date: | February 9, 2024 | /s/ H. Eric Bolton, Jr. |
| Date: | February 9, 2024 | /s/ Albert M. Campbell, III |
| Date: | February 9, 2024 | /s/ A. Clay Holder |
| Date: | February 9, 2024 | /s/ Alan B. Graf, Jr. |
| Date: | February 9, 2024 | /s/ Deborah H. Caplan |
| | | Deborah H. Caplan Director |
| Date: | February 9, 2024 | /s/ John P. Case |
| | | John P. Case Director |
| Date: | February 9, 2024 | /s/ Tamara Fischer |
| | | Tamara Fischer Director |
| Date: | February 9, 2024 | /s/ Toni Jennings |
| Date: | February 9, 2024 | /s/ Edith Kelly-Green |
| Date: | February 9, 2024 | /s/ James K. Lowder |
| Date: | February 9, 2024 | /s/ Thomas H. Lowder |
| Date: | February 9, 2024 | /s/ Claude B. Nielsen |
| Date: | February 9, 2024 | /s/ W. Reid Sanders |
| | | |
| Date: | February 9, 2024 | /s/ Gary Shorb |
| | | |
| Date: | February 9, 2024 | /s/ David P. Stockert |
| | | |
February 9, 2024
| | | |
February 9, 2024
February 9, 2024
| | | | 15,932,757 | | | | 15,182,346 | |
| | | | 11,068,067 | | | | 10,879,599 | |
| Cash and cash equivalents | | | 41,314 | | | | 38,659 | |
| Restricted cash | | | 13,777 | | | | 22,412 | |
Years ended December 31, 2023, 2022 and 2021
Years ended December 31, 2023, 2022 and 2021
| Net income | | | — | | | | — | | | | — | | | | — | | | | — | | | | 552,806 | | | | — | | | | 14,963 | | | | 62 | | | | 567,831 | | | | | — | |
| Date: | February 14, 2023 | /s/ Philip W. Norwood |
| | | Philip W. Norwood Director |
February 14, 2023
| | | | 15,182,346 | | | | 14,680,222 | |
| | | | 10,879,599 | | | | 10,832,061 | |
(1)
| EQUITY BALANCE DECEMBER 31, 2019 | | | 868 | | | $ | 9 | | | | 114,139 | | | $ | 1,140 | | | $ | 7,166,073 | | | $ | (1,085,479 | ) | | $ | (13,178 | ) | | $ | 214,647 | | | $ | 6,247 | | | $ | 6,289,459 | | | | $ | 14,131 | |
| Net income | | | — | | | | — | | | | — | | | | — | | | | — | | | | 254,962 | | | | — | | | | 9,053 | | | | — | | | | 264,015 | | | | | — | |
| Issuance and registration of common shares | | | — | | | | — | | | | 157 | | | | 1 | | | | (209 | ) | | | — | | | | — | | | | — | | | | — | | | | (208 | ) | | | | 1,629 | |
| Exercise of stock options | | | — | | | | — | | | | 1 | | | | — | | | | 71 | | | | — | | | | — | | | | — | | | | — | | | | 71 | | | | | — | |
| Proceeds from revolving credit facility | | | — | | | | — | | | | 255,000 | |
| Repayments of revolving credit facility | | | — | | | | — | | | | (255,000 | ) |
| CAPITAL BALANCE DECEMBER 31, 2019 | | $ | 214,647 | | | $ | 6,015,290 | | | $ | 66,840 | | | $ | (13,584 | ) | | $ | 6,247 | | | $ | 6,289,440 | | | | $ | 14,131 | |
| Net income | | | 9,053 | | | | 251,274 | | | | 3,688 | | | | — | | | | — | | | | 264,015 | | | | | — | |
| Issuance of units | | | — | | | | (208 | ) | | | — | | | | — | | | | — | | | | (208 | ) | | | | 1,629 | |
| Exercise of unit options | | | — | | | | 71 | | | | — | | | | — | | | | — | | | | 71 | | | | | — | |
| Distributions to common unitholders ($4.0250 per unit) | | | (16,334 | ) | | | (460,340 | ) | | | — | | | | — | | | | — | | | | (476,674 | ) | | | | — | |
Total expected costs for the six development projects are $728.7 million, of which $291.7 million had been incurred through December 31, 2022.
to sell and are no longer depreciated.
The assets and liabilities of a disposed group or a property classified as held for sale are presented separately in the appropriate asset and liability sections of the Consolidated Balance Sheets.
The decrease in the Company’s investments in the limited partnerships was driven by the recognition of unrealized losses, which were primarily a result of a decrease in the valuation of an underlying investment that recently became publicly traded and the distribution of publicly traded marketable securities.
Also included in other assets are the fair market value of in-place leases and resident relationships, net of accumulated amortization.
| Accrued construction in progress | | | 16,484 | | | | 15,123 | |
Rental Costs
| | | | | | | |
| --- | --- | --- | --- | --- | --- | --- |
| Nonvested as of January 1, 2022 | | | 161,896 | | | $ | 115.70 | |
| Issued | | | 160,638 | | | | 91.21 | |
| Vested | | | (195,526 | ) | | | 82.04 | |
| Forfeited | | | (1,243 | ) | | | 130.46 | |
In September 2022, MAALP retired the remaining $125.0 million portion of its publicly issued unsecured senior notes due in December 2022.
In July 2021, MAALP retired a $72.8 million tranche of privately placed unsecured senior notes at maturity.
MAALP also publicly issued $300 million in aggregate principal amount of unsecured senior notes maturing 2051 with interest payable semi-annually in arrears and a coupon rate of 2.875% per annum, or the 2051 Notes.
Both the 2026 Notes and 2051 Notes are general unsecured senior obligations of MAALP and rank equally in right of payment with all other unsecured senior indebtedness of MAALP.
The combined net proceeds of the offerings were $590.0 million, after deducting the combined original issue discounts and underwriting commissions totaling $10.0 million.
In September 2021, MAALP retired $149.3 million of privately placed unsecured senior notes and $125.0 million of publicly issued unsecured senior notes.
MAALP incurred $13.4 million in prepayment penalties and write-offs of unamortized costs resulting from the debt retirements during the year ended December 31, 2021.
These costs are included in “Other non-operating expense (income)” in the accompanying Consolidated Statements of Operations.
In February 2021, MAALP retired a $118.6 million mortgage associated with eight apartment communities.
| 2023 | | $ | 370,000 | | | $ | (491 | ) | | $ | 369,509 | |
An excerpt. Shown here: 40 of 646 rewritten, 40 of 283 added and 40 of 160 removed. The counts are complete. For every sentence, read Item 16. Form 10-K Summary. in the FY2023 filing and the FY2022 filing.