 filings.tools
Item 5. Market for Medtronic’s Common Equity, Related Shareholder Matters, and Issuer Purchases of Equity Securities
7K characters. Original on sec.gov · Markdown
Item 5. Market for Medtronic’s Common Equity, Related Shareholder Matters, and Issuer Purchases of Equity Securities
The Company’s ordinary shares are listed on the New York Stock Exchange under the symbol “MDT.”
The following table provides information about the shares repurchased by the Company during the fourth quarter of fiscal year 2020:
| Fiscal Period | Total Number of Shares Purchased | Average Price Paid per Share | Total Number of Shares Purchased as a Part of Publicly Announced Program | Maximum Approximate Dollar Value of Shares that may yet be Purchased Under the Program | ||||||||||||||||||||||
| 1/25/2020-2/21/2020 | 950,308 | $ | 118.23 | 950,308 | $ | 5,950,169,124 | ||||||||||||||||||||
| 2/22/2020-3/27/2020 | — | — | — | 5,950,169,124 | ||||||||||||||||||||||
| 3/28/2020-4/24/2020 | — | — | — | 5,950,169,124 | ||||||||||||||||||||||
| Total | 950,308 | $ | 118.23 | 950,308 | 5,950,169,124 |
In June 2017, the Company's Board of Directors authorized the repurchase of $5.0 billion of the Company’s ordinary shares. In March 2019, the Company's Board of Directors authorized an incremental $6.0 billion for repurchase of the Company's ordinary shares. There is no specific time-period associated with these repurchase authorizations. The Company has deprioritized repurchases of ordinary shares as a result of the COVID-19 pandemic.
On June 17, 2020, there were approximately 24,933 shareholders of record of the Company’s ordinary shares. Ordinary cash dividends declared and paid totaled 54.0 cents per share for each quarter of fiscal year 2020 and 50.0 cents per share for each quarter of fiscal year 2019.
Stock Performance Graph
The following graph compares the cumulative total shareholder return on Medtronic’s ordinary shares with the cumulative total shareholder return on the Standard & Poor’s (S&P) 500 Index and the S&P 500 Health Care Equipment Index for the last five fiscal years. The graph assumes that $100 was invested at market close on April 24, 2015 in Medtronic’s ordinary shares, the S&P 500 Index, and the S&P 500 Health Care Equipment Index and that all dividends were reinvested.
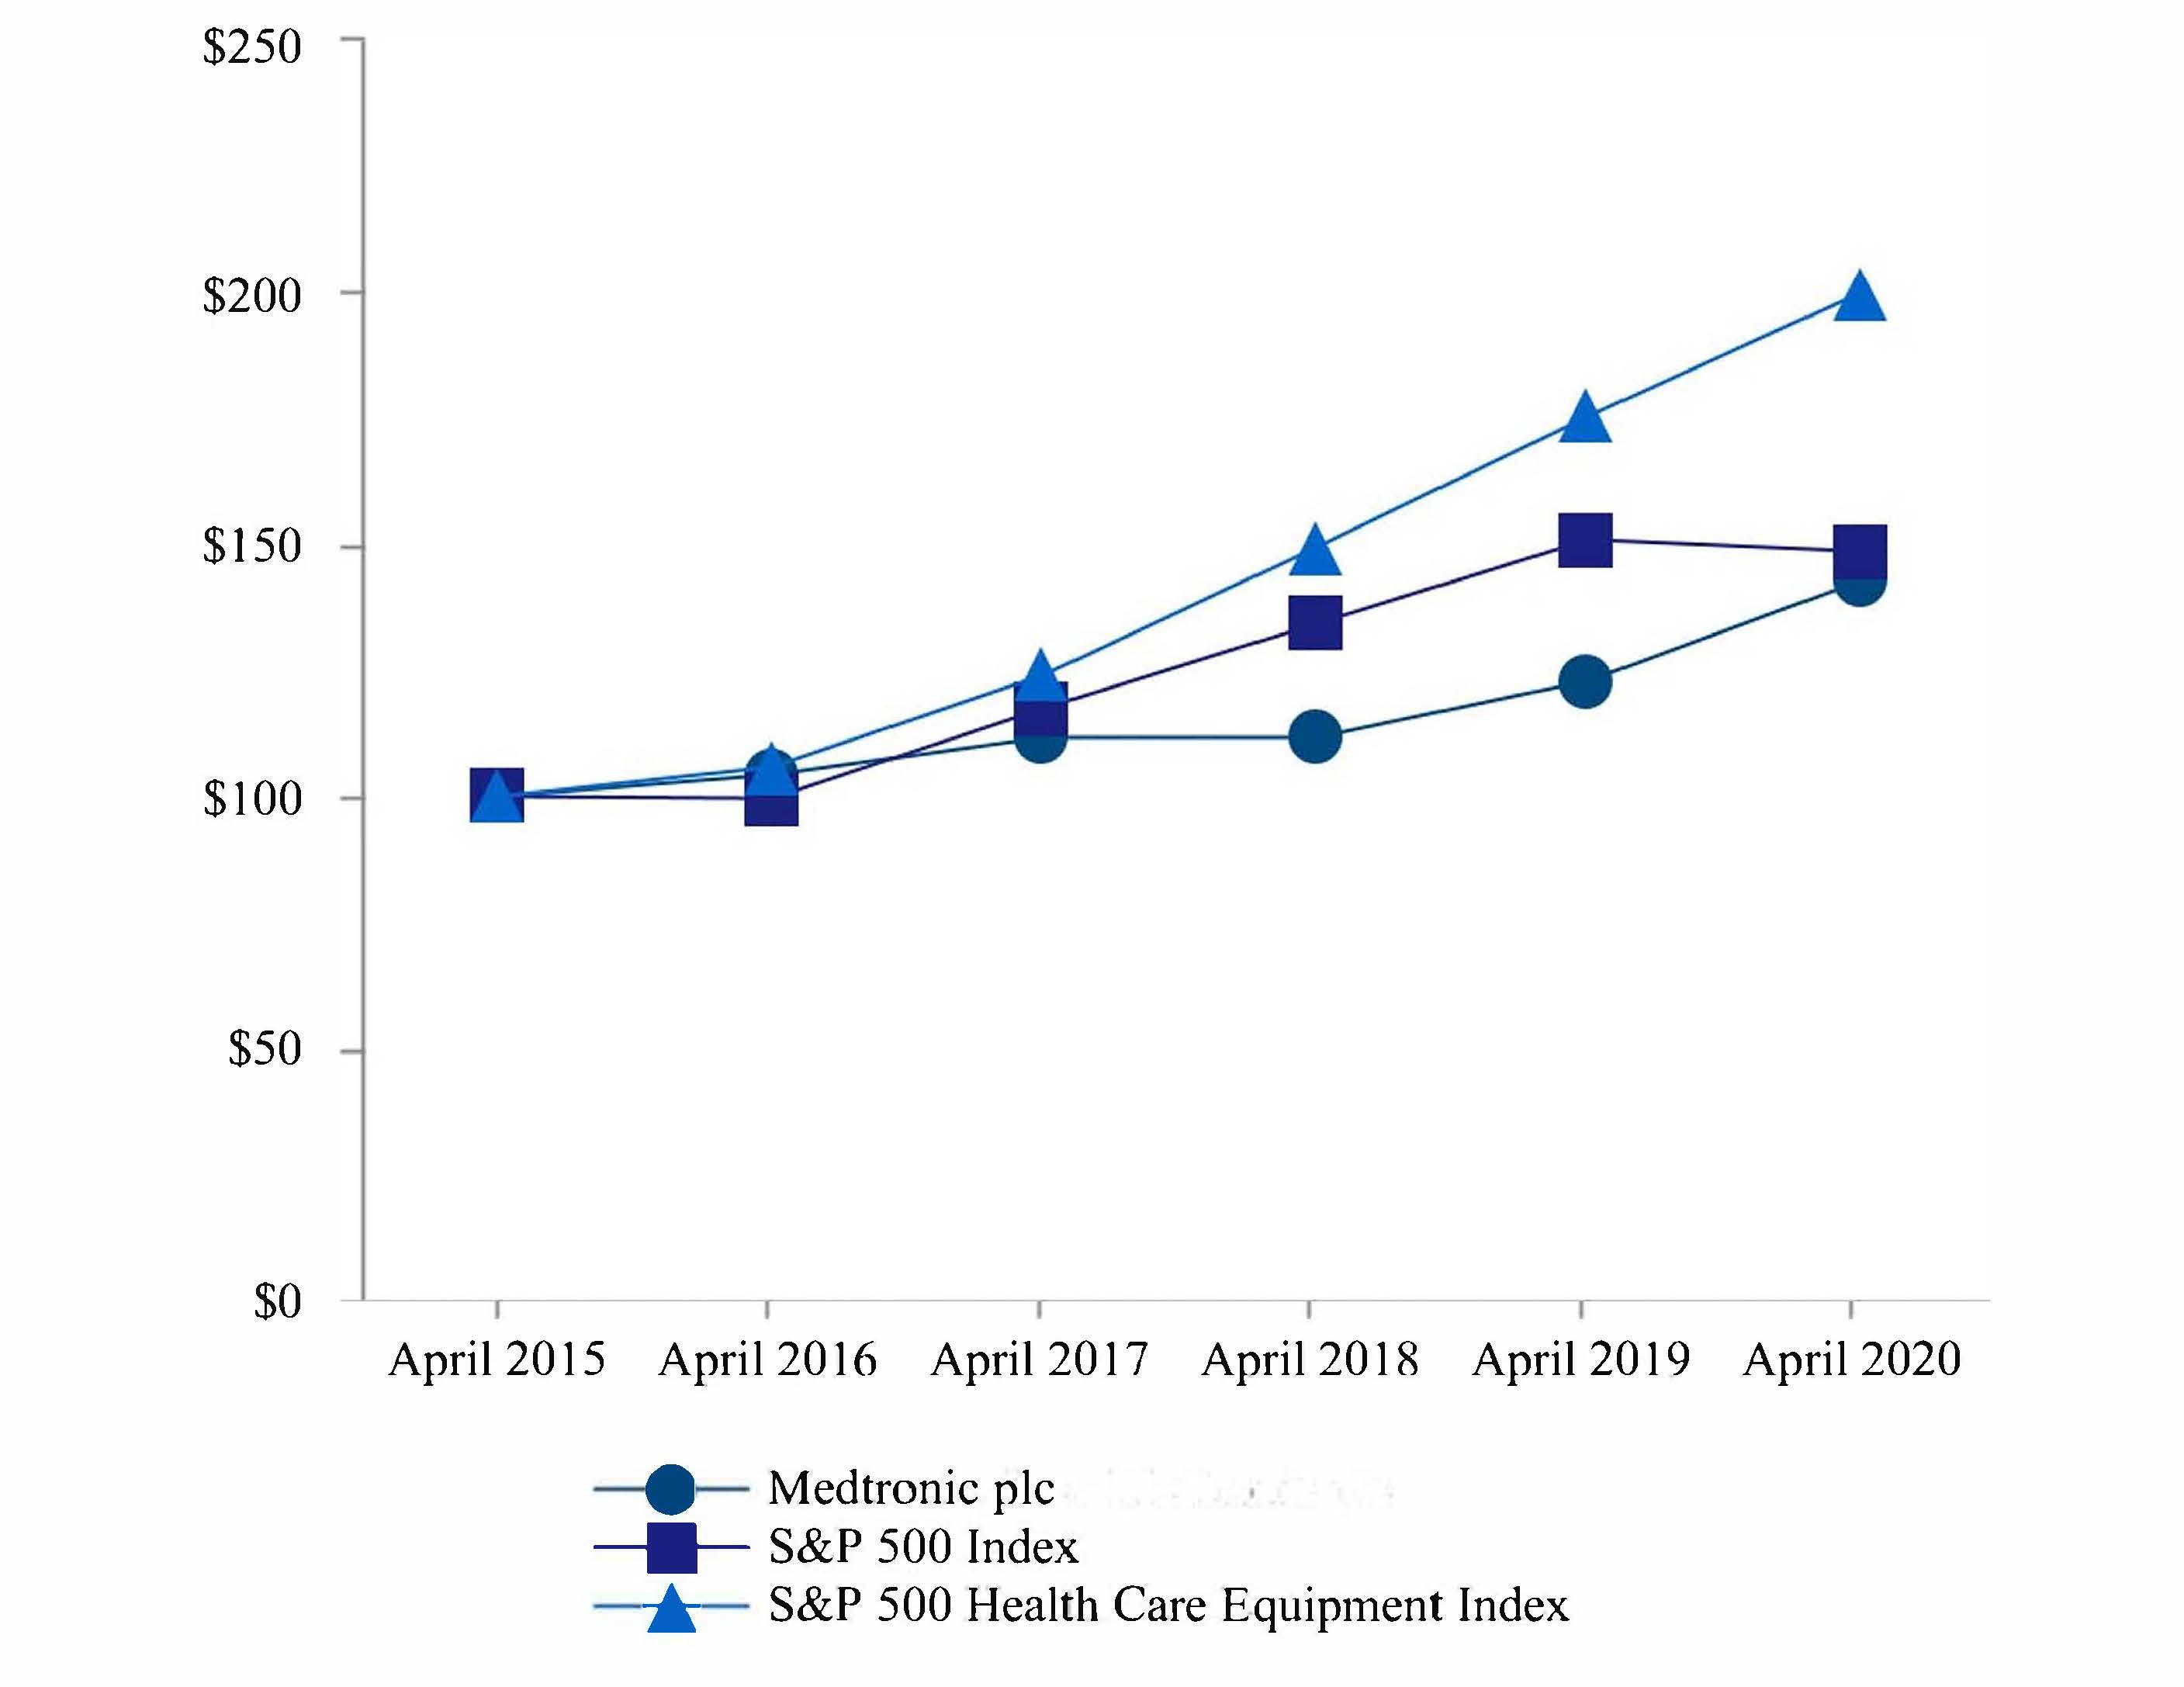
| Company/Index | April 2015 | April 2016 | April 2017 | April 2018 | April 2019 | April 2020 | ||||||||||||||||||||||||||||||||
| Medtronic plc | $ | 100.00 | $ | 104.10 | $ | 111.62 | $ | 111.69 | $ | 122.69 | $ | 142.51 | ||||||||||||||||||||||||||
| S&P 500 Index | 100.00 | 99.69 | 117.55 | 134.24 | 150.80 | 148.44 | ||||||||||||||||||||||||||||||||
| S&P 500 Health Care Equipment Index | 100.00 | 105.96 | 124.14 | 149.40 | 175.35 | 199.55 |
For information on the Company's equity compensation plans, see "Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Shareholder Matters" in this Annual Report on Form 10-K.
Irish Restrictions on Import and Export of Capital
Except as indicated below, there are no restrictions on non-residents of Ireland dealing in Irish domestic securities, which includes ordinary shares of Irish companies. Except as indicated below, dividends and redemption proceeds also continue to be freely transferable to non-resident holders of such securities. The Financial Transfers Act, 1992, provides that the Irish Minister for Finance can make provision for the restriction of financial transfers between Ireland and other countries. For the purposes of this Act, “financial transfers” include all transfers which would be movements of capital or payments within the meaning of the treaties governing the E.U. if they had been made between Member States of the E.U. This Act has been used by the Minister for Finance to implement European Council Directives, which provide for the restriction of financial transfers to certain countries, organizations and people including the Al-Qaeda network and the Taliban, Afghanistan, Belarus, Burma (Myanmar), Democratic People’s Republic of Korea, Democratic Republic of Congo, Egypt, Iran, Iraq, Ivory Coast, Lebanon, Liberia, Libya, Republic of Guinea, Somalia, Sudan, Syria, Tunisia, Ukraine and Zimbabwe.
Any transfer of, or payment in respect of, a share or interest in a share involving the government of any country that is currently the subject of United Nations sanctions, any person or body controlled by any of the foregoing, or by any person acting on behalf of the foregoing, may be subject to restrictions pursuant to such sanctions as implemented into Irish law.
Irish Taxes Applicable to U.S. Holders
Dividends paid by Medtronic will generally be subject to Irish dividend withholding tax (currently at a rate of 25 percent) unless an exemption applies.
Dividends paid to U.S. residents will not be subject to Irish dividend withholding tax provided that:
-
in the case of a beneficial owner of Medtronic shares held in the Depository Trust Company (DTC), the address of the beneficial owner in the records of his or her broker is in the United States and this information is provided by the broker to the Company’s qualifying intermediary; or
-
in the case of a record owner, the record owner has provided to the Company’s transfer agent a valid U.S. Certification of Residence (Form 6166) or valid Irish Non-Resident Form V2.
Irish income tax may also arise with respect to dividends paid on Medtronic’s ordinary shares. A U.S. resident who meets one of the exemptions from dividend withholding tax described above and who does not hold Medtronic shares through a branch or agency in Ireland through which a trade is carried on generally will not have any Irish income tax liability on a dividend paid by Medtronic. In addition, if a U.S. shareholder is subject to the dividend withholding tax, the withholding payment discharges any Irish income tax liability, provided the shareholder furnishes to the Irish Revenue authorities a statement of the dividend withholding tax imposed.
While the U.S./Ireland Double Tax Treaty contains provisions regarding withholding, due to the wide scope of the exemptions from dividend withholding tax available under Irish domestic law, it would generally be unnecessary for a U.S. resident shareholder to rely on the treaty provisions.
Previous: Item 4. Mine Safety Disclosures · Next: Item 6. Selected Financial Data