 filings.tools
MGM Resorts International (MGM) 10-K risk factor changes: FY2020 vs FY2019
The 2020-12-31 10-K against the 2019-12-31 one, compared heading by heading and sentence by sentence.
Item 1A73 rewritten162 added31 removed366 unchanged
All filing items1,153 rewritten854 added890 removed1,800 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 854 added, 890 removed, 1,153 rewritten and 1,800 unchanged across 16 items that differ.
Sentences by item
22 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2020; struck-through words were in FY2019. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
73 rewritten, 162 added, 31 removed, 366 unchanged
[added: | | • |] Our substantial indebtedness and significant financial commitments, including the fixed component of our rent [removed: payments,] [added: payments] and [removed: our debt] guarantees [added: we provide on the indebtedness of the Bellagio BREIT Venture and the MGP BREIT Venture] could adversely affect our operations and financial results and impact our ability to satisfy our obligations. [added: |]
[removed: Moreover, our] [added: Our] leases with MGP, the Bellagio BREIT Venture, and the MGP BREIT Venture have fixed rental payments (with annual escalators) and also require us to apply a percentage of net revenues generated at the leased properties to capital expenditures at those properties.
Similarly, development projects, including any potential future development of an integrated resort in Japan, [added: strategic initiatives, including positioning BetMGM as a leader in online sports betting] and [added: iGaming, and] acquisitions could require significant capital commitments, the incurrence of additional debt, guarantees of third-party debt or the incurrence of contingent liabilities, any or all of which could have an adverse effect on our business, financial [removed: condition and] [added: condition,] results of [removed: operations.][added: operations and cash flows.]
[removed: In addition,] [added: Finally,] our senior credit facility calculates interest on outstanding balances using the London Inter-Bank Offered Rate (“LIBOR”).
[added: | | • |] Current and future economic, capital and credit market conditions could adversely affect our ability to service [removed: or refinance] our [added: substantial] indebtedness and [removed: to] [added: significant financial commitments or] make planned expenditures. [added: |]
Our ability to make payments [removed: on, and to refinance, our indebtedness, make] [added: on] our [added: substantial indebtedness and other significant financial commitments, including the] rent payments under our [removed: leases] [added: leases,] and to fund planned or committed capital expenditures and other investments depends on our ability to generate cash flow, receive distributions from our unconsolidated affiliates (including CityCenter) and subsidiaries (including MGM China and the Operating Partnership), [added: and] borrow under our senior credit facility or incur new indebtedness.
[removed: We cannot assure you that our business will generate sufficient cash flow from operations,] [added: needs] or [removed: continue to receive distributions from] [added: satisfy the financial and other covenants in] our [removed: unconsolidated affiliates] [added: debt] and [removed: subsidiaries, nor can] [added: lease instruments,] we [added: cannot] assure you that future borrowings will be available to us under our senior secured credit facility in an amount sufficient to enable us to pay our indebtedness or [removed: to] fund our other liquidity needs or that we will be able to access the capital markets in the future to borrow additional [removed: indebtedness] [added: debt] on terms [removed: that are] favorable to [removed: us.][added: us, or at all.]
[removed: We] [added: In addition, we] have a significant amount of indebtedness maturing in 2022, and thereafter.
Our ability to timely refinance and replace our indebtedness [removed: in the future] will depend upon the economic and credit market conditions discussed above.
Any default under our senior credit facility or the indentures governing our other debt could adversely affect our growth, our financial condition, our results of operations and our ability to make payments on our [removed: debt.][added: debt and other financial commitments.]
[added: | | • |] We are required to pay a significant portion of our cash flows as rent, which could adversely affect our ability to fund our operations and [removed: growth,] [added: growth initiatives,] service our indebtedness and limit our ability to react to competitive and economic changes. [added: |]
As of December 31, [removed: 2019] [added: 2020] we are required to make annual rent payments of [removed: $946] [added: $828] million under the master lease with [removed: MGP and] [added: MGP,] annual rent payments of [removed: $245] [added: $250] million under the lease with Bellagio BREIT Venture, and [removed: will be required to make] annual rent payments of $292 million under the lease with MGP BREIT Venture, which leases are also subject to annual escalators as described elsewhere in this Annual Report on Form 10-K.
Any of the above factors could have a material adverse effect on our business, financial [removed: condition and] [added: condition,] results of [removed: operations.][added: operations and cash flows.]
We currently [added: also] provide [removed: a] shortfall [removed: guarantee] [added: guarantees] of the $3.01 billion and $3.0 billion principal amount of indebtedness (and any interest accrued and unpaid thereon) of the Bellagio BREIT Venture and MGP BREIT Venture, respectively.
[added: | | • |] We face significant competition with respect to destination travel locations generally and with respect to our peers in the industries in which we compete, [added: including increased competition through online sports betting] and [added: iGaming, and] failure to compete effectively could materially adversely affect our business, financial condition, results of operations and cash [removed: flow.][added: flows. |]
We do not believe that our competition is limited to a particular geographic area, and hotel, resort, entertainment, and gaming operations in other states or [removed: countries] [added: countries, as well as the increased availability of online sports betting and iGaming,] could attract our customers.
Also, the growth of gaming in areas outside Las [removed: Vegas, including California,] [added: Vegas] has increased the competition faced by our operations in Las Vegas and elsewhere.
For example, while our Macau operations compete to some extent with casinos located elsewhere in or near Asia, certain countries in the region have legalized casino gaming (including Japan) and others (such as Taiwan and Thailand) may legalize casino gaming (or [removed: online gaming)] [added: iGaming)] in the future.
[removed: The] [added: In addition, the] expansion of [added: iGaming,] online [removed: gaming,] sports betting, and other types of gaming [removed: in these and other jurisdictions] may further compete with our [added: land-based] operations by reducing customer visitation and spend [removed: in] [added: at] our [removed: casino resorts.][added: properties.]
Our failure to compete successfully in our various markets and to continue to attract customers could adversely affect our business, financial condition, results of operations and cash [removed: flow.][added: flows.]
[removed: Our] [added: | | • | Our] businesses are subject to extensive regulation and the cost of compliance or failure to comply with such regulations may adversely affect our business and results of [removed: operations.][added: operations. |]
In June 2019, a federal district court in New Hampshire ruled that the DOJ’s new interpretation of the Wire Act was erroneous and vacated DOJ’s new [removed: opinion.]
An adverse ruling in the Court of Appeals or other disposition of the case may impact our ability to engage in [removed: online internet gaming] [added: iGaming] in the future.
For instance, we are subject to certain federal, state and local environmental laws, regulations and ordinances, including the Clean Air Act, the Clean Water Act, the Resource Conservation Recovery Act, the Comprehensive Environmental Response, Compensation and Liability [removed: Act and] [added: Act,] the [added: Energy Policy Act, the Safe Drinking Water Act, Renewable Portfolio Standards, the] Oil Pollution Act of [removed: 1990.][added: 1990, and many others.]
In addition, effective January 1, 2019, smoking in casinos in Macau, including MGM Macau and MGM Cotai, [removed: will] [added: is] only [removed: be] permitted inside specially ventilated smoking rooms, rather than outside smoking areas or VIP areas.
For instance, we are subject to regulation under the Currency and Foreign Transactions Reporting Act of 1970, commonly known as the “Bank Secrecy [removed: Act,”] [added: Act”,] which, among other things, requires us to report to the Internal Revenue Service (“IRS”) any currency transactions in excess of $10,000 that occur within a 24-hour gaming day, including identification of the individual(s) involved in the currency transaction.
[removed: Our success depends in part on our ability to anticipate the] preferences of consumers and timely react to these trends, and any failure to do so may negatively impact our results of operations.
The [added: full] extent to which [removed: the coronavirus] [added: COVID-19] impacts [removed: the Company’s] [added: our] results will depend on future developments, which are highly uncertain and cannot be [removed: predicted, including new information which may emerge concerning the severity of the coronavirus and any additional actions taken to contain it from spreading.][added: predicted.]
In addition, since we expect a significant number of customers to come to MGM Macau and MGM Cotai (and, to a lesser extent, our domestic properties) from mainland China, general [removed: economic] [added: economic, regulatory] and market conditions in China could impact our financial prospects.
Any slowdown in economic growth or changes to China’s current restrictions on travel and currency conversion or movements, including [added: continued] market impacts [added: of the COVID-19 outbreak and market impacts] resulting from China’s recent anti-corruption campaign and related tightening of liquidity provided by non-bank lending entities and cross-border currency monitoring (including increased restrictions on Union Pay withdrawals and other ATM limits on the withdrawal of patacas imposed by the government), could disrupt the number of visitors from mainland China and/or the amounts they are willing to spend at our properties.
While we seek employees from outside of Macau to adequately staff our resorts, certain Macau government policies limit our ability to import labor in certain job classifications (for instance, the Macau government requires that we only hire Macau residents as dealers in our casinos) and any future government policies that freeze or cancel our ability to import labor could cause labor costs to [removed: increase.][added: increase (including limitations on our ability to import labor as a result of temporary travel restrictions adopted as part of the COVID-19 mitigation efforts).]
[added: | | • |] We may not realize all of the anticipated benefits of our [added: cost savings initiatives, including those associated with our] MGM 2020 Plan. [added: |]
[removed: We have undertaken, and plan to undertake, several initiatives to implement the first phase] [added: As part] of our MGM 2020 [removed: Plan] [added: Plan, we undertook several initiatives] to reduce costs and further position us for [removed: growth.][added: growth by the end of 2020.]
[removed: We] [added: Although we] intend to pay ongoing regular quarterly cash dividends on our common stock; [removed: however,] our board of directors may, in its sole discretion, change the amount or frequency of dividends or discontinue the payment of dividends entirely.
[removed: We expect our subsidiaries will continue to generate significant cash flow necessary to maintain quarterly dividend payments on] [added: In addition,] our [removed: common stock; however, their] [added: subsidiaries’] ability to [removed: generate funds will be] [added: make distributions to us is] subject to [removed: their operating results, cash requirements and financial condition,] any applicable provisions of state law that may limit the amount of funds available to us, and compliance with covenants and financial ratios related to existing or future agreements governing any indebtedness at such subsidiaries and any limitations in other agreements such subsidiaries may have with third parties.
As a consequence of these various limitations and restrictions, future dividend payments may be [added: further] reduced or [removed: eliminated.][added: eliminated in their entirety.]
In addition, we could incur special charges relating to the closing of such facilities including sublease termination costs, impairment charges and other special charges that would reduce our net income and could have a material adverse effect on our business, financial [removed: condition and] [added: condition,] results of [removed: operations.][added: operations and cash flows.]
[removed: Murren,] [added: Paul Salem,] our Chairman, Daniel J.
Taylor, one of our directors, and [removed: William J.][added: Corey Sanders, and John M.]
[removed: Murren] [added: Paul Salem] serves as our Chairman and as the Chairman of MGP.
Summary of Risk Factors
The following is a summary of the principal risks that could adversely affect our business, operations and financial results.
| | • | The agreements governing our senior credit facility and other senior indebtedness contain restrictions and limitations that could significantly affect our ability to operate our business, as well as significantly affect our liquidity, and therefore could adversely affect our results of operations. |
| | • | The global COVID-19 pandemic has continued to materially impact our business, financial results and liquidity, and such impact could worsen and last for an unknown period of time. |
| | • | Although all of our properties are open to the public, they are operating without certain amenities and subject to certain occupancy limitations, and we are unable to predict the length of time it will take for our open properties to return to normal operations or if such properties will be required to close again due to the COVID-19 pandemic. |
| | • | We have undertaken aggressive actions to reduce costs and improve efficiencies to mitigate losses as a result of the COVID-19 pandemic, which could negatively impact guest loyalty and our ability to attract and retain employees. |
| | • | Our business is affected by economic and market conditions in the jurisdictions in which we operate and in the locations in which our customers reside. |
| | • | The anticipated benefits of our asset light strategy, including the Bellagio sale-leaseback transaction and MGP BREIT Venture Transaction, may take longer to realize than expected or may not be realized at all. |
| | • | Our ability to pay ongoing regular dividends to our stockholders is subject to the discretion of our board of directors and may be limited by our holding company structure, existing and future debt agreements entered into by us or our subsidiaries and state law requirements. |
| | • | Nearly all of our domestic gaming facilities are leased and could experience risks associated with leased property, including risks relating to lease termination, lease extensions, charges and our relationship with the lessor, which could have a material adverse effect on our business, financial position or results of operations. |
| | • | Paul Salem, our Chairman, Daniel J. Taylor, one of our directors, and Corey Sanders, and John M. McManus, members of our senior management, may have actual or potential conflicts of interest because of their positions at MGP. |
| | • | Despite our ability to exercise control over the affairs of MGP as a result of our ownership of the single outstanding Class B share of MGP, MGP has adopted a policy under which certain transactions with us, including transactions |
| | | involving consideration in excess of $25 million, must be approved in accordance with certain specified procedures, which could affect our ability to execute our operational and strategic objectives. |
| | • | We have agreed not to have any interest or involvement in gaming businesses in China, Macau, Hong Kong and Taiwan, other than through MGM China. |
| | • | The Macau government can terminate MGM Grand Paradise’s subconcession under certain circumstances without compensating MGM Grand Paradise, exercise its redemption right with respect to the subconcession, or refuse to grant MGM Grand Paradise an extension of the subconcession in 2022, any of which would have a material adverse effect on our business, financial condition, results of operations and cash flows. |
| | • | MGM Grand Paradise is dependent upon gaming promoters for a significant portion of gaming revenues in Macau. |
| | • | The future recognition of our foreign tax credit deferred tax asset is uncertain, and the amount of valuation allowance we may apply against such deferred tax asset may change materially in future periods. |
| | • | We are subject to risks related to climate change. |
| | • | Because a significant number of our major gaming resorts are concentrated on the Las Vegas Strip, we are subject to greater risks than a gaming company that is more geographically diversified. |
| | • | We extend credit to a large portion of our customers and we may not be able to collect gaming receivables. |
| | • | We may incur impairments to goodwill, indefinite-lived intangible assets, or long-lived assets which could negatively affect our future profits. |
| | • | Any of our future construction, development or expansion projects will be subject to significant development and construction risks, which could have a material adverse impact on related project timetables, costs and our ability to complete the projects. |
| | • | Our insurance coverage may not be adequate to cover all possible losses that our properties could suffer. In addition, our insurance costs may increase and we may not be able to obtain similar insurance coverage in the future. |
| | • | Any failure to protect our trademarks could have a negative impact on the value of our brand names and adversely affect our business. |
| | • | We are subject to risks associated with doing business outside of the United States. |
| | • | Any violation of the Foreign Corrupt Practices Act or any other similar anti-corruption laws could have a negative impact on us. |
| | • | We face risks related to pending claims that have been, or future claims that may be, brought against us. |
| | • | A significant portion of our labor force is covered by collective bargaining agreements. |
| | • | Our business is particularly sensitive to energy prices and a rise in energy prices could harm our operating results. |
| | • | The failure to maintain the integrity of our computer systems and customer information could result in damage to our reputation and/or subject us to fines, payment of damages, lawsuits and restrictions on our use of data. |
| | • | We are subject to risks related to corporate social responsibility and reputation. |
| | • | If the jurisdictions in which we operate increase gaming taxes and fees, as well as other taxes and fees, our results could be adversely affected. |
| | • | Conflicts of interest may arise because certain of our directors and officers are also directors of MGM China, the holding company for MGM Grand Paradise which owns and operates MGM Macau and MGM Cotai. |
For a more complete discussion of the material risks facing our business, please see below.
Risks Relating to Our Substantial Indebtedness
Our substantial indebtedness and significant financial commitments, including the fixed component of our rent payments and guarantees we provide of the indebtedness of the Bellagio BREIT Venture and the MGP BREIT Venture could adversely affect our operations and financial results and impact our ability to satisfy our obligations.
As of December 31, 2020, we had approximately $12.5 billion of principal amount of indebtedness outstanding on a consolidated basis, including $4.2 billion of outstanding indebtedness of the Operating Partnership and $2.8 billion of outstanding indebtedness of MGM China.
Current and future economic, capital and credit market conditions could adversely affect our ability to service our substantial indebtedness and significant financial commitments or make planned expenditures.
The COVID-19 pandemic has resulted in significant deterioration to regional, national and international economic conditions, which has resulted in substantial declines in our revenues from our operations and expected distributions from our unconsolidated affiliates and subsidiaries.
We expect that the pandemic will continue to impact consumer spending levels in 2021 and potentially thereafter, and if we fail to generate cash sufficient to fund our liquidity
As of December 31, 2019, we had approximately $11.3 billion of principal amount of indebtedness outstanding on a consolidated basis.
The Operating Partnership and MGM China, our consolidated subsidiaries, had $4.4 billion and $2.2 billion, respectively, of indebtedness outstanding.
If regional and national economic conditions deteriorate, revenues from our operations could decline as consumer spending levels decrease and we could fail to generate cash sufficient to fund our liquidity needs or satisfy the financial and other restrictive covenants in our debt and lease instruments.
In addition, our senior secured credit facility requires us to satisfy certain financial covenants, including a maximum total net leverage ratio, a maximum first lien net leverage ratio and a minimum interest coverage ratio.
The Company provides a guarantee of the indebtedness of the Bellagio BREIT Venture and MGP BREIT Venture.
Furthermore, certain jurisdictions, including Nevada and New Jersey, have also legalized forms of online gaming and other jurisdictions, including Illinois, have legalized video gaming terminals.
Additionally, in May 2018, the United States Supreme Court overturned a federal ban on sports betting that had prohibited single-game gambling in most states, raising the potential for increased competition in sports betting should additional states pass legislation to legalize it.
For example, Illinois has enacted a ban on smoking in nearly all public places, including bars, restaurants, work places, schools and casinos.
For example, in December 2019 a new strain of coronavirus (Covid-19) was reported in Wuhan, China.
In order to mitigate the spread of the virus, China has placed certain cities under quarantine and advised its citizens to avoid all non-essential travel and other countries, including the U.S., have also restricted inbound travel from China.
In addition, China implemented a temporary suspension of its visa scheme that permits mainland Chinese to travel to Macau, and on February 4, 2020 the Hong Kong SAR government temporarily suspended all ferry service from Hong Kong to Macau until further notice.
The government of Macau also asked that all gaming operators in Macau suspend casino operations for a 15-day period that commenced on February 5, 2020.
As a result, MGM Macau and MGM Cotai suspended all operations at their properties other than operations that were necessary to provide sufficient non-gaming facilities to serve any remaining hotel guests.
Operations at MGM Macau and MGM Cotai resumed on February 20, 2020; however, there are currently limits on the number of gaming tables allowed to operate and restrictions on the number of seats available at each table, and the temporary suspension of the visa scheme and ferry service to Macau remains in place.
The Company is currently unable to predict the duration of the business disruption in Macau or the impact of the reduced customer traffic at the Company’s properties as a result, but we expect the impact could have a material effect on MGM China’s results of operations for the first quarter of 2020 and potentially thereafter.
Although the outbreak has been largely concentrated in China, to the extent that the virus impacts the willingness or ability of customers to travel to the Company’s properties in the United States (due to travel restrictions, or otherwise), the Company’s domestic results of operations could also be negatively impacted.
While we believe these initiatives will exceed $200 million of annual Adjusted EBITDAR uplift by the end of 2020, compared to 2018 results, our efforts may fail to achieve expected results.
As part of the second phase of our MGM 2020 Plan, we also expect to invest in our digital transformation to drive customer-centric strategy for revenue growth to drive additional EBITDAR uplift, which efforts may also fail to achieve expected results.
Execution of our MGM 2020 Plan is subject to numerous risks and uncertainties that may change at any time, and, therefore, our actual Adjusted EBITDAR uplift may differ materially from what we anticipate.
James J.
Hornbuckle, and John M.
Taylor, one of our directors, is
also a director of MGP and William J.
any revenues from these operations.
changes to our assumptions could result in a material change in the valuation allowance with a corresponding impact on the provision for income taxes in the period including such change.
For instance, the coronavirus outbreak has resulted in several countries, including United States, issuing travel warnings and suspending flights to and from China.
In addition, on February 4, 2020, the Hong Kong SAR government temporarily suspended all ferry service from Hong Kong to Macau, until further notice.
We are unable to predict the extent to which disruptions to travel as a result of the coronavirus will impact our results of operations but we expect that the current disruption will have an adverse effect on MGM China’s results of operations for the first quarter of 2020 and potentially thereafter.
For instance, income generated from gaming operations of MGM Grand Paradise currently has the benefit of a corporate tax exemption in Macau through March 31, 2020, which exempts us from paying the 12% complementary tax on profits generated by the operation of casino games.
We have applied for an extension of such exemption to June 26, 2022 to run concurrent with its extended sub-concession.
While our competitors have received additional extensions of their complementary tax exemptions through June 26, 2022, which runs concurrent with the end of the term of their gaming concessions, and we believe MGM Grand Paradise should also be entitled to such extension in order to ensure non-discriminatory treatment among gaming concessionaires and sub-concessionaires, a requirement under Macanese law, due to the uncertainty concerning taxation after the subconcession renewal process, we cannot assure you that any extensions of the tax exemption will be granted beyond March 31, 2020.
An excerpt. Shown here: 40 of 73 rewritten, 40 of 162 added and all 31 removed. The counts are complete. For every sentence, read Item 1A. RISK FACTORS in the FY2020 filing and the FY2019 filing.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
206 rewritten, 230 added, 152 removed, 207 unchanged
This management’s discussion and analysis of financial condition and results of operations includes discussion as of and for the year ended December 31, [removed: 2019] [added: 2020] compared to December 31, [removed: 2018.][added: 2019.]
Discussion of our financial condition and results of operations as of and for the year ended December 31, [removed: 2018] [added: 2019] compared to December 31, [removed: 2017] [added: 2018] can be found in our Annual Report on Form 10-K for the fiscal year ended December 31, [removed: 2018,] [added: 2019,] filed with the Securities and Exchange Commission (“SEC”) on February 27, [removed: 2019.][added: 2020.]
During the year ended December 31, [removed: 2019,] [added: 2020,] Las Vegas visitor volume [removed: increased 1%] [added: decreased 55%] compared to the prior year period according to information published by the Las Vegas Convention and Visitors Authority.
[removed: The] [added: Although the] Las Vegas market [removed: is growing and diversifying with] [added: has had] the addition of new sporting events and venues, the expansion of convention centers, as well as music and entertainment [removed: events.][added: events, the COVID-19 pandemic has drastically impacted visitation.]
During the year ended December 31, [removed: 2019] [added: 2020] Macau visitor arrivals [removed: increased 10%] [added: decreased 85%] compared to the prior year period according to statistics published by the Statistics and Census Service of the Macau [removed: Government.][added: Government, as a result of the disruption caused by the COVID-19 pandemic.]
While our results do not depend on key individual customers, a significant portion of our operating income is generated from high-end gaming customers, which can cause variability in our [removed: results as evidenced by the recent weakness in Far East baccarat, which we expect to continue in 2020.][added: results.]
As of December 31, [removed: 2019,] [added: 2020,] pursuant to a master lease agreement with MGP, we lease the real estate assets of The Mirage, [removed: Mandalay Bay,] Luxor, New York-New York, Park MGM, Excalibur, The Park, Gold Strike Tunica, MGM Grand Detroit, Beau Rivage, Borgata, Empire City, MGM National Harbor, and MGM Northfield Park.
As further discussed below, pursuant to a lease agreement with the Bellagio BREIT Venture, we lease the real estate assets of [removed: Bellagio.][added: Bellagio, and pursuant to a lease agreement with the MGP BREIT Venture, we lease the real estate assets of Mandalay Bay and MGM Grand Las Vegas.]
We then rebranded the property to MGM Northfield Park, [removed: which was then] [added: and] added [added: it] to the [removed: existing] master lease between us and MGP.
Subsequently, MGP acquired the developed real property associated with Empire City from us and Empire City was added to the [removed: existing] master lease between us and MGP.
In March 2019, we entered into an amendment to the [removed: existing] master lease between us and MGP with respect to [removed: investments] [added: improvements] made by us related to [removed: improvements at] [added: rebranding of the] Park MGM and NoMad Las Vegas.
In November 2019, we completed the Bellagio [removed: Sale-Leaseback Transaction,] [added: transaction,] pursuant to which [removed: we formed] the Bellagio BREIT [removed: Venture,] [added: Venture was formed,] which acquired the Bellagio real estate assets from us and entered into a lease agreement to lease the real estate assets back to us.
The [added: Bellagio] lease provides for [added: a term of 30 years with two ten-year renewal options and has] initial annual [added: base] rent of $245 million with a fixed 2% escalator for the first ten years and, thereafter, an escalator equal to the greater of 2% and the CPI increase during the prior year, subject to a cap of 3% during the 11th through 20th years and 4% thereafter.
[removed: We received $4.25 billion consideration] [added: In exchange] for the [removed: sale,] [added: contribution of the real estate assets, we received total consideration of $4.25 billion,] which consisted of a 5% equity interest in the venture [removed: with the remaining consideration of] [added: and] approximately $4.2 billion in cash.
We also provide a shortfall guarantee of the principal amount of indebtedness of the Bellagio BREIT [removed: Venture’s $3.01 billion of debt] [added: Venture] (and any interest accrued and unpaid thereon).
See Note [removed: 1 and Note 12] [added: 11] in the accompanying financial statements for information regarding this [removed: transaction and] lease agreement.
See Note 1 and Note 16 in the accompanying [added: consolidated] financial statements for information regarding this transaction.
In exchange for the contribution of the real estate assets, MGM and MGP received total consideration of $4.6 billion, which was comprised of $2.5 billion of cash, $1.3 billion of the Operating Partnership’s secured indebtedness assumed by [added: the] MGP BREIT Venture, and the Operating Partnership’s 50.1% equity interest in the MGP BREIT Venture.
In addition, the Operating Partnership issued approximately 3 million Operating Partnership units to us representing 5% of the equity value of [added: the] MGP BREIT Venture.
[removed: In connection with the transactions, we provided] [added: We also provide] a shortfall [removed: guaranty] [added: guarantee] of the principal amount of indebtedness of the MGP BREIT Venture (and any interest accrued and unpaid thereon).
In connection with the [removed: transactions,] MGP BREIT Venture [added: Transaction, MGP BREIT Venture] entered into a lease with us for the real estate assets of Mandalay Bay and MGM Grand Las Vegas.
In addition, the lease [removed: will require] [added: obligates] us to spend [removed: 3.5%] [added: a specified percentage] of net revenues [removed: over a rolling five-year period] at the properties on capital expenditures and [removed: for us to] [added: that we] comply with certain financial covenants, which, if not met, [removed: will] [added: would] require us to maintain cash security or provide one or more letters of credit in favor of the landlord in an amount equal to the rent for the succeeding one-year period.
In connection with the MGP BREIT Venture Transaction, the [removed: existing] master lease with MGP was modified to remove the Mandalay Bay property and the annual [added: cash] rent under the MGP master lease was reduced by $133 million.
The waiver [removed: terminates] [added: was scheduled to terminate] on the earlier of 24 months following the closing of the MGP BREIT Venture Transaction [removed: and us receiving] [added: or upon our receipt of] cash proceeds of $1.4 billion as consideration for the redemption of our Operating Partnership units.
In January 2019, we announced the implementation of a company-wide business optimization initiative (the “MGM 2020 Plan”) to further reduce costs, improve efficiencies and position us for [removed: growth, which yielded over $130 million of Adjusted EBITDAR uplift in 2019 compared to 2018 results.][added: growth.]
| | • | Gaming revenue indicators: table games drop and slots handle (volume indicators); “win” or “hold” percentage, which is not fully controllable by us. Our normal table games hold percentage at our Las Vegas Strip Resorts is in the range of 25.0% to 35.0% of table games drop for Baccarat and 19.0% to 23.0% for non-Baccarat; [added: however, reduced gaming volumes as a result of the COVID-19 pandemic could cause volatility in our hold percentages;] and |
| | • | Hotel revenue indicators: hotel occupancy (a volume indicator); average daily rate (“ADR,” a price indicator); and revenue per available room (“REVPAR,” a summary measure of hotel results, combining ADR and occupancy rate). Our calculation of ADR, which is the average price of occupied rooms per day, includes the impact of complimentary rooms. Complimentary room rates are determined based on standalone selling price. Because the mix of rooms provided on a complimentary basis, particularly to casino customers, includes a disproportionate suite component, the composite ADR including complimentary rooms is slightly higher than the ADR for cash rooms, reflecting the higher retail value of suites. [added: Rooms that were out of service during the year ended December 31, 2020 as a result of property closures due to the COVID-19 pandemic were excluded from the available room count when calculating hotel occupancy and REVPAR.] |
| | • | Gaming revenue indicators: MGM China utilizes “turnover,” which is the sum of nonnegotiable chip wagers won by MGM China calculated as nonnegotiable chips purchased plus nonnegotiable chips exchanged less nonnegotiable chips returned. Turnover provides a basis for measuring VIP casino win percentage. Win for VIP gaming operations at MGM China is typically in the range of 2.6% to 3.3% of [removed: turnover.] [added: turnover; however, reduced gaming volumes as a result of the COVID-19 pandemic could cause volatility in MGM China’s hold percentages.] |
The following discussion is based on our consolidated financial statements for the years ended December 31, [removed: 2019, 2018] [added: 2020, 2019] and [removed: 2017.][added: 2018.]
| | [removed: |] Year Ended December 31, | | | | | | | | | | |
| | [removed: | 2019] [added: 2020] | | | | [removed: 2018] [added: 2019] | | | | [removed: 2017] [added: 2018] | | |
| | [removed: |] (In thousands) | | | | | | | | | | |
| Net revenues | [removed: |] $ | [removed: 12,899,672] [added: 5,162,082] | | | $ | [removed: 11,763,096] [added: 12,899,672] | | | $ | [removed: 10,797,479] [added: 11,763,096] | |
| Operating income [removed: |] [added: (loss)] | | [removed: 3,940,215] [added: (642,434] | [added: )] | | | [removed: 1,469,486] [added: 3,940,215] | | | | [removed: 1,712,527] [added: 1,469,486] | |
| Net income [removed: |] [added: (loss)] | | [removed: 2,214,380] [added: (1,319,907] | [added: )] | | | [removed: 583,894] [added: 2,214,380] | | | | [removed: 2,088,184] [added: 583,894] | |
| Net income [added: (loss)] attributable to MGM Resorts International | | [removed: | 2,049,146] [added: (1,032,724] | [added: )] | | | [removed: 466,772] [added: 2,049,146] | | | | [removed: 1,952,052] [added: 466,772] | |
[removed: *Summary] [added: Summary] Operating [removed: Results*][added: Results]
[removed: The current] [added: Corporate expense in the prior] year period included $20 million of Empire City acquisition costs, primarily related to transfer taxes and advisory fees, $29 million in costs incurred to implement the MGM 2020 Plan, [removed: of which $12 million is included in the restructuring costs discussed above,] and $11 million in finance modernization initiative costs.
| Table games win | | $ | [removed: 789,330] [added: 470,432] | | | $ | [removed: 949,055] [added: 789,330] | | | $ | [removed: 931,508] [added: 949,055] | |
| Slots win | | | [removed: 1,193,607] [added: 649,229] | | | | [removed: 1,140,269] [added: 1,193,607] | | | | [removed: 1,106,192] [added: 1,140,269] | |
Description of our business and key performance indicators
Financial Impact of COVID-19
The spread of COVID-19 and developments surrounding the global pandemic have had, and we expect will continue to have, a significant impact on our business, financial condition, results of operations and cash flows in 2021.
In March 2020, all of our domestic properties were temporarily closed pursuant to state and local government restrictions imposed as a result of COVID-19.
Throughout the second and third quarters of 2020 all of our properties that were temporarily closed re-opened to the public but continue to operate without certain amenities and subject to certain occupancy limitations, with restrictions varying by jurisdiction and with further temporary re-closures and re-openings occurring for our properties or portions of our properties into the first quarter of 2021.
In response to reduced demand, we temporarily closed the hotel tower operations at Mandalay Bay and Park MGM midweek and temporarily closed The Mirage midweek, which are expected to resume full week operations on March 3, 2021.
Accordingly, our properties continued to generate revenues that are significantly lower than historical results.
In addition, as a result of the continued impact of the COVID-19 pandemic and the emergence of variant strains, our properties may be subject to temporary, complete, or partial shutdowns in the future.
At this time, we cannot predict whether the jurisdictions in which our properties are located, states or the federal government will continue to impose operating restrictions on us or adopt similar or more restrictive measures in the future, including stay-at-home orders or ordering the temporary closures of all or a portion of our properties.
We have implemented certain measures to mitigate the spread of COVID-19, including limitations on the number of gaming tables allowed to operate and on the number of seats at each table game, as well as slot machine spacing, temperature checks, mask protection, limitations on restaurant capacity, entertainment events and conventions as well as other measures to enforce social distancing.
In addition, following a temporary closure of our properties in Macau on February 5, 2020, operations resumed on February 20, 2020, subject to certain health safeguards, such as limiting the number of gaming tables allowed to operate and the number of seats available at each table game, slot machine spacing, reduced operating hours at a number of restaurants and bars, temperature checks, mask protection and the need to present negative COVID-19 test results and health declarations submitted through the Macau Health Code system which remain in effect.
Effective July 15, 2020, all guests entering our casinos were required to provide a negative nucleic acid test result with a valid ‘green’ Macau Health Code.
Although the issuance of tourist visas (including the IVS) for residents of Zhuhai, Guangdong Province and all other provinces in mainland China to travel to Macau resumed on August 12, 2020, August 26, 2020 and September 23, 2020, respectively, several travel and entry restrictions in Macau, Hong Kong and mainland China remain in place (including the temporary suspension of ferry services from Hong Kong to Macau, the nucleic acid test result certificate and mandatory quarantine requirements
for visitors from Hong Kong and Taiwan, and bans on entry or enhanced quarantine requirements on other visitors into Macau), which have significantly impacted visitation to our Macau properties.
During 2020, we engaged in aggressive cost reduction efforts to minimize cash outflows while our properties were initially closed and have continued to engage in such efforts as the properties have re-opened, we still face significant fixed and variable expenses.
Our efforts included:
| | • | reducing or deferring at least 50% of planned domestic capital expenditures in 2020; |
| | • | reducing employee costs, including through hiring freezes, headcount reductions and substantial furloughs of employees (which have resulted in a number of employees being separated from us) and cancellation of merit pay increases; |
| | • | midweek closures of certain hotel towers and properties in response to reduced demand; |
| | • | initiating a program where certain senior executives and directors voluntarily elected to receive all or a portion of their remaining base salary during 2020 in the form of restricted stock units in lieu of cash; and |
| | • | starting with our dividend for the second quarter of 2020, our Board approved a nominal annual dividend of $0.01 per share. |
On March 27, 2020, the Coronavirus Aid, Relief, and Economic Security Act (the “CARES Act”) was signed into law.
The CARES Act provides opportunities for additional liquidity, loan guarantees, and other government programs to support companies affected by the COVID-19 pandemic and their employees.
Based on a preliminary analysis of the CARES Act, the benefits we expect to recognize include:
| | • | refund of federal income taxes due to a five-year carryback of net operating loss incurred in 2020 that we estimate will result in a $205 million to $215 million refund; |
| --- | --- | --- |
| | • | relaxation of interest expense deduction limitation for income tax purposes, which is included in the estimate above; |
| --- | --- | --- |
| | • | reduction of employer Federal Insurance Contributions Act (“FICA”) taxes equal to 50% of wages paid and health care coverage provided to furloughed employees during 2020, which resulted in permanent savings of approximately $121 million that was recorded in the year ended December 31, 2020, including our share of the savings recorded by CityCenter; and |
| --- | --- | --- |
| | • | deferral of all employer FICA taxes from the date of enactment through December 31, 2020, 50% payable by December 2021 and the remainder payable by December 2022, which resulted in a deferral of approximately $51 million. |
| --- | --- | --- |
In addition, we have seen and continue to expect to see weakened demand at our properties as a result of continued domestic and international travel restrictions or warnings, restrictions on amenity use, such as gaming, restaurant and pool capacity limitations, consumer fears and reduced consumer discretionary spending, general economic uncertainty, and increased rates of unemployment.
In light of the foregoing, we are unable to determine when our properties will return to pre-pandemic demand or pricing, or if our properties will remain re-opened.
The COVID-19 pandemic has had a material impact on our consolidated results of operations during 2020 and we expect that it will continue to have a material impact on our consolidated results of operations during 2021 and potentially thereafter.
*Other Developments*
In July 2018, we and Entain formed BetMGM, a venture that is owned 50% by each party.
In connection with its formation, we provided BetMGM with exclusive access to all of our domestic land-based and online sports betting, major tournament poker, and online gaming operations and Entain provided BetMGM with exclusive access to its technology in the United States.
See Note 1, Note 11, and Note 12 in the accompanying consolidated financial statements for information regarding this transaction, lease agreement, and shortfall guarantee.
See Note 1, Note 11, and Note 12 in the accompanying consolidated financial statements for information regarding this transaction, lease agreement, and shortfall guarantee.
| --- | --- |
Executive Overview
In early 2020, the rapid spread of a respiratory illness caused by a novel coronavirus (Covid-19) identified as originating in Wuhan, Hubei Province, China led to certain cities in China being placed under quarantine and citizens across China were advised to avoid non-essential travel.
Certain countries, including the U.S., have restricted inbound travel from mainland China to mitigate the spread of the virus.
In addition, China implemented a temporary suspension of its visa scheme that permits mainland Chinese to travel to Macau, and on February 4, 2020 the Hong Kong SAR government temporarily suspended all ferry service from Hong Kong to Macau, until further notice.
The Macau Government Tourism Office disclosed total visitation from mainland China to Macau decreased 83% and total visitor arrivals decreased 78% during Chinese New Year as compared to the same period in 2019.
On February 4, 2020, the government of Macau asked that all gaming operators in Macau suspend casino operations for a 15-day period that commenced on February 5, 2020.
As a result, MGM Macau and MGM Cotai suspended all operations at their properties other than operations that were necessary to provide sufficient non-gaming facilities to serve any remaining hotel guests.
Operations at MGM Macau and MGM Cotai resumed on February 20, 2020; however, there are currently limits on the number of gaming tables allowed to operate and restrictions on the number of seats available at each table, and the temporary suspension of the visa scheme and ferry service to Macau remains in place.
As a result of these measures, we expect material declines in MGM China’s operating results during the first quarter of 2020 and potentially thereafter.
Additionally, to the extent that the virus impacts the willingness or ability of customers to travel to our properties in the United States (due to travel restrictions, or otherwise), our domestic results of operations could also be negatively impacted.
We are continuing to evaluate the nature and extent of the impacts to our business, which could have a material effect on our consolidated operating results for the first quarter of 2020 and potentially thereafter.
Given the uncertain nature of these circumstances, the related impact on our results of operations, cash flows and financial condition cannot be reasonably estimated at this time.
The Bellagio lease has an initial term of 30 years with two subsequent ten-year renewal periods, exercisable at our option.
We expect the initiatives associated with the MGM 2020 Plan to exceed Adjusted EBITDAR uplift of $200 million by the end of 2020 compared to 2018 results, which includes operating model changes to improve efficiency.
We currently anticipate achieving this target.
As part of the second phase, we plan to invest in our digital transformation to drive revenue growth through a customer-centric strategy aimed at increasing customer spend, increasing our wallet share, and attracting our most valuable customers.
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
Consolidated net revenues in 2019 increased 10% compared to 2018 due primarily to continued ramp-up of operations at MGM Cotai following its opening in February 2018, a full year of operating results at MGM Springfield, which opened in August 2018, the acquisition of Empire City in January 2019, a full year of operating results at MGM Northfield Park, which MGP acquired in July 2018, and an increase in revenues as a result of the ramp-up of operations at Park MGM, partially offset by a decrease in casino revenues at certain of our other Las Vegas Strip Resorts.
Consolidated operating income increased $2.5 billion to $3.9 billion in 2019, compared to $1.5 billion in 2018.
The current year included a $2.7 billion gain related to the Bellagio Sale-Leaseback Transaction, a $220 million loss related to the sale of Circus Circus Las Vegas and adjacent land, included in property transactions, net, as well as $92 million in restructuring costs related to severance, accelerated stock compensation expense and consulting fees directly related to the operating model component of the MGM 2020 Plan.
In comparison, consolidated operating income in 2018 included a $45 million gain related to the sale of Grand Victoria and $24 million in business interruption insurance proceeds primarily at Mandalay Bay.
During 2019, consolidated operating income was positively impacted by the increase in net revenues described above and a decrease in preopening and start-up expenses, partially offset by increases in general and administrative, depreciation and amortization, and corporate expenses, further discussed below.
Preopening and start-up expenses decreased by $144 million in 2019 compared to 2018 due primarily to the openings of MGM Springfield and MGM Cotai and the completion of the Park MGM rebranding project.
Corporate expense, including share-based compensation for corporate employees, increased $45 million compared to the prior year period.
The prior year period included $27 million of corporate brand campaign expenses, $19 million in transaction costs, and $8 million in costs incurred to implement the MGM 2020 Plan and finance modernization initiatives.
Depreciation and amortization expense, and general and administrative expense increased compared to the prior year due primarily to the operations of MGM Cotai, MGM Springfield and Empire City.
Las Vegas Strip Resorts casino revenue decreased 8% in 2019 compared to 2018, primarily due to a 17% decrease in table games win resulting from a 9% decrease in table games drop, driven by Far East baccarat, and an increase in incentives, partially offset by a 5% increase in slots win.
Las Vegas Strip Resorts rooms revenue increased 5% in 2019 compared to 2018, primarily due to a 4% increase in REVPAR.
Las Vegas Strip Resorts food and beverage revenue increased 8% in 2019 compared to 2018 due primarily to the ramp-up of newly opened outlets at Park MGM and NoMad Las Vegas and an increase in catering and banquets revenue driven by the completion of the expansion of MGM Grand’s Conference Center in 2019.
Las Vegas Strip Resorts entertainment, retail and other revenue increased 2% in 2019 compared to 2018 due primarily to an increase in entertainment revenue related to events at Park Theater, partially offset by a decrease in revenue from Cirque du Soleil production shows.
Regional Operations casino revenue increased 25% in 2019 compared to 2018 primarily due to the acquisition of Empire City in 2019, for which its video lottery terminal revenue is included in other casino revenue, the acquisition of MGM Northfield Park’s operations from MGP, and a full year of operations at MGM Springfield.
Regional Operations food and beverage revenue increased 15% in 2019 compared to 2018 due primarily to full year of operations at MGM Springfield, the acquisition of Empire City, and the acquisition of MGM Northfield Park’s operations from MGP.
Regional Operations entertainment, retail and other revenue increased 25% in 2019 compared to 2018 due primarily to entertainment revenue at MGM Springfield and MGM Northfield Park, ATM fees from the operations of MGM Springfield, Empire City and MGM Northfield Park, and parking fees from the operations of Empire City.
MGM China net revenue increased 19% in 2019 compared to 2018 primarily as a result of the continued ramp-up of operations at MGM Cotai and an increase in main floor table games win percentage.
Main floor table games win increased 37% compared to the prior year due to the addition of 25 new-to-market tables at MGM Cotai in 2019 and a 472 basis point increase in win percentage.
VIP table games win increased slightly in 2019 compared to 2018 due to the opening of VIP junket rooms at the end of the third quarter of 2018 at MGM Cotai and an increase in the VIP table games win percentage, offset by a 34% decrease in turnover at MGM Macau.
Corporate and other
Corporate and other revenue for 2018 included $133 million in net revenues from MGP Northfield’s casino.
See “Non-GAAP Measures” for additional information.
An excerpt. Shown here: 40 of 206 rewritten, 40 of 230 added and 40 of 152 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS in the FY2020 filing and the FY2019 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
6 rewritten, 3 added, 3 removed, 18 unchanged
As of December 31, [removed: 2019,] [added: 2020,] variable rate borrowings represented approximately [removed: 10%] [added: 6%] of our total borrowings after giving effect [removed: to] [added: on] the [added: Operating Partnership’s borrowings for the] currently effective interest rate swap agreements on which the Operating Partnership pays a weighted average of 1.821% on a total notional amount of $1.9 billion.
| | | Debt maturing [removed: in,] [added: in] | | | | | | | | | | | | | | | | | | | | | | | | | | | | December 31, | | |
| | | [removed: 2020 | | | |] 2021 | | | | 2022 | | | | 2023 | | | | 2024 | | | | [added: 2025 | | | |] Thereafter | | | | Total | | | | [removed: 2019] [added: 2020] | | |
| Fixed-rate | | $ | — | | | $ | [removed: —] [added: 1,000] | | | $ | [removed: 1,000] [added: 1,250] | | | $ | [removed: 1,250] [added: 1,800] | | | $ | [removed: 1,800] [added: 2,725] | | | $ | [removed: 4,851] [added: 4,926] | | | $ | [removed: 8,901] [added: 11,701] | | | $ | [removed: 9,759] [added: 12,425] | |
| Average interest rate | | N/A | | | | [removed: N/A] | [added: 7.8] | [added: %] | | | [removed: 7.8] [added: 6.0] | % | | | [removed: 6.0] [added: 5.5] | % | | | [removed: 5.5] [added: 5.6] | % | | | [removed: 5.4] [added: 5.0] | % | | | [removed: 5.8] [added: 5.6] | % | | | | |
As of December 31, [removed: 2019,] [added: 2020,] a 1% weakening of the Hong Kong dollar (the functional currency of MGM China) to the U.S. dollar would result in a foreign currency transaction loss of [removed: $15] [added: $20] million.
| | | (In millions except interest rates) | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Variable rate | | $ | — | | | $ | — | | | $ | 10 | | | $ | 770 | | | $ | — | | | $ | — | | | $ | 780 | | | $ | 780 | |
| Average interest rate | | N/A | | | | N/A | | | | | 1.9 | % | | | 3.0 | % | | N/A | | | | N/A | | | | | 3.0 | % | | | | |
| | | (In millions) | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Variable rate | | $ | — | | | $ | — | | | $ | — | | | $ | 399 | | | $ | 667 | | | $ | 1,305 | | | $ | 2,371 | | | $ | 2,377 | |
| Average interest rate | | N/A | | | | N/A | | | | N/A | | | | | 3.5 | % | | | 4.9 | % | | | 3.8 | % | | | 4.1 | % | | | | |
Item 1. BUSINESS
101 rewritten, 105 added, 73 removed, 239 unchanged
As of December 31, [removed: 2019,] [added: 2020,] pursuant to a master lease agreement between a subsidiary of [removed: the Company] [added: ours] and a subsidiary of the Operating Partnership, we lease the real estate assets of The Mirage, [removed: Mandalay Bay,] Luxor, New York-New York, Park MGM, Excalibur, The Park, Gold Strike Tunica, MGM Grand Detroit, Beau Rivage, Borgata, Empire City, MGM National Harbor, and MGM [removed: Northfield.][added: Northfield Park.]
[removed: As further discussed below, pursuant] [added: Pursuant] to a lease [removed: agreement, we lease the real estate assets] [added: agreement between a subsidiary] of [removed: Bellagio from] [added: ours and] a venture that [removed: we formed with] [added: is 5% owned by such subsidiary and 95% owned by a subsidiary of] Blackstone Real Estate [added: Income] Trust, Inc. [removed: (“BREIT”).][added: (“BREIT”, and such venture, the “Bellagio BREIT Venture”), we lease the real estate assets of Bellagio.]
In August 2016, we acquired the remaining 50% ownership interest in Borgata, at which time Borgata became a [removed: wholly-owned] [added: wholly owned] consolidated subsidiary of ours.
Subsequently, MGP acquired Borgata’s real property from us and Borgata was added to the [removed: existing] master lease between us and MGP.
In December 2016, we opened MGM National Harbor and, in October 2017, MGP also acquired the long-term leasehold interest and real property associated with MGM National Harbor from us and MGM National Harbor was added to the [removed: existing] master lease between us and MGP.
We then rebranded the property to MGM Northfield [removed: Park, which was then] [added: Park and] added [added: it] to the [removed: existing] master lease between us and MGP.
Subsequently, MGP acquired Empire City’s developed real property from us and Empire City was [removed: then] added to the [removed: existing] master lease between us and MGP.
In March 2019, we entered into an amendment to the [removed: existing] master lease between us and MGP with respect to [removed: investments] [added: improvements] made by us related to the [added: rebranding of the] Park MGM and NoMad Las Vegas property (the “Park MGM [removed: Lease] Transaction”).
Additionally, in November 2019, [removed: we formed a venture (the “Bellagio] [added: the Bellagio] BREIT [removed: Venture”) with BREIT,] [added: Venture was formed,] which acquired the Bellagio real estate assets from us and leased such assets back to us pursuant to a [removed: long-term] lease [removed: agreement (the “Bellagio Sale-Leaseback Transaction”).][added: agreement.]
The lease [removed: has an initial] [added: provides for a] term of thirty years with [removed: the potential to extend for] two ten year [removed: terms thereafter] [added: renewal options] and [removed: provides for] [added: has] an initial [added: annual base] rent of $245 million, escalating annually at a rate of 2% per annum for the first ten years and thereafter equal to [added: the greater of 2% and the CPI increase during the prior year subject to a cap of 3% during the 11th through 20th years and 4% thereafter.]
In addition, the lease obligates us to spend a specified percentage of net revenues at the property on capital expenditures and that we comply with certain financial covenants, which, if not met, would require us to maintain cash security or [removed: a letter] [added: provide one or more letters] of credit in favor of the landlord in an amount equal to rent for the succeeding two year period.
[removed: We received $4.25 billion consideration] [added: In exchange] for the [removed: sale,] [added: contribution of the real estate assets, we received total consideration of $4.25 billion,] which consisted of a 5% equity interest in the venture [removed: with the remaining consideration of] [added: and] approximately $4.2 billion in cash.
We also provide a shortfall guarantee of the principal amount of indebtedness of [added: the] Bellagio BREIT [removed: Venture’s $3.01 billion of debt] [added: Venture] (and any interest accrued and unpaid thereon).
On February 14, 2020, we completed a series of transactions (collectively the “MGP BREIT Venture Transaction”) pursuant to which the real estate assets of MGM Grand Las Vegas and Mandalay Bay (including Mandalay Place) were contributed to [removed: a] [added: the] newly formed [removed: entity (“MGP] [added: MGP] BREIT [removed: Venture”), owned 50.1% by the Operating Partnership and 49.9% by a subsidiary of BREIT.][added: Venture.]
In exchange for the contribution of the real estate assets, MGM and MGP received total consideration of $4.6 billion, which was comprised of $2.5 billion of cash, $1.3 billion of the Operating Partnership’s secured indebtedness assumed by [added: the] MGP BREIT Venture, and the Operating Partnership’s 50.1% equity interest in the MGP BREIT Venture.
In addition, the Operating Partnership issued approximately 3 million Operating Partnership units to us representing 5% of the equity value of [added: the] MGP BREIT Venture.
[removed: In connection with the transactions, we provided] [added: We also provide] a shortfall [removed: guaranty] [added: guarantee] of the principal amount of indebtedness of the MGP BREIT Venture (and any interest accrued and unpaid thereon).
In connection with the [removed: transactions,] MGP BREIT Venture [added: Transaction, MGP BREIT Venture] entered into a lease with us for the real estate assets of Mandalay Bay and MGM Grand Las Vegas.
In addition, the lease [removed: will require] [added: obligates] us to spend [removed: 3.5%] [added: a specified percentage] of net revenues [removed: over a rolling five-year period] at the properties on capital expenditures and [removed: for us to] [added: that we] comply with certain financial covenants, which, if not met, [removed: will] [added: would] require us to maintain cash security or provide one or more letters of credit in favor of the landlord in an amount equal to the rent for the succeeding one-year period.
[removed: In connection with the MGP BREIT Venture Transaction,] [added: Additionally,] the [removed: existing] master lease with MGP was modified to remove the Mandalay Bay property and the annual [added: cash] rent under the MGP master lease was reduced by $133 million.
Also, on January 14, 2020, we, the Operating Partnership, and MGP entered into an agreement for the Operating Partnership to waive its right [added: following the closing of the MGP BREIT Venture Transaction] to issue MGP Class A shares, in lieu of cash, to us in connection with us exercising our right to require the Operating Partnership to redeem the Operating Partnership units [added: that] we hold, at a price per unit equal to a 3% discount to the [removed: applicable cash amount as calculated in accordance with] [added: ten day average closing price prior to] the [removed: operating agreement.][added: date of the notice of redemption.]
The waiver [removed: terminates] [added: was effective upon closing of the transaction] on [added: February 14, 2020 and was scheduled to terminate on] the earlier of [removed: 24 months following the closing] [added: February 14, 2022 or upon our receipt] of [removed: the MGP BREIT Venture Transaction and us receiving] cash proceeds of $1.4 billion as consideration for the redemption of our Operating Partnership units.
We [added: also] lease space to [added: third party] retail and food and beverage operators, particularly for branding opportunities.
As of December 31, [removed: 2019,] [added: 2020,] we have three reportable segments: Las Vegas Strip Resorts, Regional Operations, and MGM China.
[removed: *Las] [added: Las] Vegas Strip Resorts and Regional [removed: Operations*][added: Operations]
Over half of the net revenue from our domestic resorts is [added: typically] derived from non-gaming operations, including hotel, food and beverage, entertainment and other non-gaming amenities.
[removed: We] [added: Although we have been operating without certain amenities and subject to certain limitations as a result of the COVID-19 pandemic, our long-term strategy is to] market to different customers and utilize our significant convention and meeting facilities to allow us to maximize hotel occupancy and customer volumes which also leads to better labor utilization.
Our operating results are highly dependent on the volume of customers at our [removed: resorts,] [added: properties,] which in turn affects the price we can charge for our hotel rooms and other amenities.
Our casino operations feature a variety of [removed: slots,] [added: slots and] table games, [removed: and race and] [added: and, through BetMGM, we offer online] sports [removed: book wagering.][added: betting and iGaming in certain jurisdictions in the United States.]
In addition, we [removed: offer] [added: provide] our premium players access to high-limit rooms and lounge experiences where players may enjoy an upscale atmosphere.
[removed: Macau is] [added: Although visitation during 2020 was significantly reduced by] the [removed: world’s largest gaming destination in terms of revenue and] [added: COVID-19 pandemic,] we expect [added: the long-term] future growth [removed: in] [added: of] the Asian gaming market to drive additional visitation at MGM Macau and MGM Cotai.
The Macau government currently prohibits additional concessions and subconcessions, but does not place a limit on the number of casinos or gaming areas operated by the concessionaires and subconcessionaires, though additional casinos [added: or gaming areas] require government approval prior to commencing operations.
We have provided certain information below about our resorts as of December 31, [removed: 2019.][added: 2020.]
| Bellagio | | | 3,933 | | | | 155,000 | | | | [removed: 1,692] [added: 1,415] | | | | [removed: 147] [added: 148] | |
| MGM Grand Las Vegas (4) | | | 6,071 | | | | 169,000 | | | | [removed: 1,553] [added: 1,270] | | | | [removed: 128] [added: 98] | |
| Mandalay Bay (5) | | | 4,750 | | | | 152,000 | | | | [removed: 1,232] [added: 1,117] | | | | [removed: 71] [added: 60] | |
| The Mirage | | | 3,044 | | | | 94,000 | | | | [removed: 1,195] [added: 819] | | | | [removed: 75] [added: 69] | |
| Luxor | | | 4,397 | | | | 101,000 | | | | [removed: 1,049] [added: 859] | | | | [removed: 53] [added: 48] | |
| Excalibur | | | 3,981 | | | | 94,000 | | | | [removed: 1,161] [added: 927] | | | | [removed: 50] [added: 41] | |
| New York-New York | | | 2,024 | | | | 81,000 | | | | [removed: 1,139] [added: 992] | | | | [removed: 62] [added: 51] | |
Additionally, pursuant to a lease agreement between a subsidiary of ours and a venture that is 50.1% owned by a subsidiary of the Operating Partnership and 49.9% by a subsidiary of BREIT (such venture, the “MGP BREIT Venture”), we lease the real estate assets of Mandalay Bay and MGM Grand Las Vegas.
Refer to Note 11 for further discussion of the leases.
In July 2018, we and Entain plc (“Entain”) formed BetMGM LLC (“BetMGM”), a venture that is owned 50% by each party.
In connection with its formation, we provided BetMGM with exclusive access to all of our domestic land-based and online sports betting, major tournament poker, and online gaming operations and Entain provided BetMGM with exclusive access to its technology in the United States.
On May 18, 2020 the Operating Partnership redeemed approximately 30 million Operating Partnership units that we held for $700 million, or $23.10 per unit, and on December 2, 2020, the Operating Partnership redeemed approximately 24 million Operating Partnership units that we held for the remaining $700 million, or $29.78 per unit.
As a result, the waiver terminated in accordance with its terms.
Financial Impact of COVID-19.
The spread of the novel 2019 coronavirus (“COVID-19”) and developments surrounding the global pandemic have had, and we expect will continue to have, a significant impact on our business, financial condition, results of operations and cash flows in 2021.
In March 2020, all of our domestic properties temporarily closed pursuant to state and local government restrictions imposed as a result of COVID-19.
Throughout the second and third quarters of 2020, all of our properties re-opened to the public but continue to operate without certain amenities and subject to certain occupancy limitations, with restrictions varying by jurisdiction and with further temporary re-closures and re-openings occurring for our properties or portions of our properties into the first quarter of 2021.
In response to reduced demand, we temporarily closed the hotel tower operations at Mandalay Bay and Park MGM midweek and temporarily closed The Mirage midweek, which are expected to resume full week operations on March 3, 2021.
Accordingly, our properties have continued to generate revenues that are significantly lower than historical results.
In addition, as a result of the continued impact of the COVID-19 pandemic and the emergence of variant strains, our properties may be subject to temporary, complete, or partial shutdowns in the future.
At this time, we cannot predict whether the jurisdictions in which our properties are located, states or the federal government will continue to impose operating restrictions on us or adopt similar or more restrictive measures in the future, including stay-at-home orders or ordering the temporary closures of all or a portion of our
properties.
We have implemented certain measures to mitigate the spread of COVID-19, including limitations on the number of gaming tables allowed to operate and on the number of seats at each table game, as well as slot machine spacing, temperature checks, mask protection, limitations on restaurant capacity, entertainment events and conventions, as well as other measures to enforce social distancing.
In addition, following a temporary closure of our properties in Macau on February 5, 2020, operations resumed on February 20, 2020, subject to certain health safeguards, such as limiting the number of gaming tables allowed to operate and the number of seats available at each table game, slot machine spacing, reduced operating hours at a number of restaurants and bars, temperature checks, mask protection and the need to present negative COVID-19 test results and health declarations submitted through the Macau Health Code system which remain in effect.
Effective July 15, 2020, all guests entering our casinos were required to provide a negative nucleic acid test result with a valid ‘green’ Macau Health Code.
Although the issuance of tourist visas (including the individual visa scheme (“IVS”)) for residents of Zhuhai, Guangdong Province and all other provinces in mainland China to travel to Macau resumed on August 12, 2020, August 26, 2020 and September 23, 2020, respectively, several travel and entry restrictions in Macau, Hong Kong and mainland China remain in place (including the temporary suspension of ferry services from Hong Kong to Macau, the nucleic acid test result certificate and mandatory quarantine requirements for visitors from Hong Kong and Taiwan, and bans on entry or enhanced quarantine requirements on other visitors into Macau), which have significantly impacted visitation to our Macau properties.
While we have engaged in aggressive cost reduction efforts to minimize cash outflows while our properties were initially closed, and have continued to engage in such efforts as the properties have re-opened, we still have significant fixed and variable expenses, which have and will continue to adversely affect our profitability.
In addition, we have seen, and expect to continue to see, weakened demand at our properties as a result of continued domestic and international travel restrictions or warnings, restrictions on amenity use, such as gaming, restaurant and pool capacity limitations, consumer fears and reduced consumer discretionary spending, general economic uncertainty, and increased rates of unemployment.
In light of the foregoing, we are unable to determine when our properties will return to pre-pandemic demand and pricing, or if our properties will remain re-opened.
The COVID-19 pandemic has had a material impact on our consolidated results of operations during 2020 and we expect that it will continue to have a material impact on our consolidated results of operations during 2021 and potentially thereafter.
Our results of operations do not tend to be seasonal in nature as all of our casino resorts, except as otherwise described related to the impact of COVID-19, typically operate 24 hours a day, every day of the year, with the exception of Empire City Casino which operates 20 hours a day, every day of the year, though a variety of factors may affect the results of any interim period, including the timing of major conventions, Far East baccarat volumes, the amount and timing of marketing and special events for our high-end gaming customers, and the level of play during major holidays, including New Year and Lunar New Year.
See “Risk Factors — Risks Related to our Business — The Macau government can terminate MGM Grand Paradise’s subconcession under certain circumstances without compensating MGM Grand Paradise, exercise its redemption right with respect to the subconcession, or refuse to grant MGM Grand Paradise an extension of the subconcession in 2022, any of which would have a material adverse effect on our business, financial condition, results of operations and cash flows.”
Our unconsolidated affiliates include the ventures with BREIT discussed elsewhere, BetMGM, and CityCenter Holdings, LLC (“CityCenter”), which we also manage for a fee, among others.
| Subtotal | | | 6,588 | | | | 947,000 | | | | 19,570 | | | | 666 | |
We strive to be a leader in the global gaming, entertainment and hospitality industry that delivers extraordinary entertainment across a portfolio of properties in the United States and Macau.
| | • | *People.* Implement programs to enhance recruitment, talent management and development, as well as diversity and inclusion, to support the achievement of key business drivers including guest experience, community engagement and financial goals. |
| | • | *Operational excellence.* Exceed customer expectations through tailored experiences, innovative solutions and quality service to maximize financial results. |
| | • | *Growth.* Execute a targeted approach to growth to become a premier global omni-channel gaming, hospitality and entertainment company, increasing global brand presence in international markets and through establishing ourselves as a data driven company focused on identifying high value customers, enhancing guest experiences through technology and service, growing brand loyalty and capturing greater market share. |
| | • | *Capital allocation.* Disciplined investment of cashflows in growth opportunities. |
through strategic partnerships and international expansion opportunities.
During 2019 and 2020, we delivered on our “MGM 2020 Plan”, a portfolio of improvement initiatives designed to improve the results of our operations, which were primarily comprised of labor, sourcing and revenue programs.
In addition, as a result of the COVID-19 pandemic, we implemented several cost cutting initiatives in 2020 that have further improved our operating model and will, together with our MGM 2020 Plan, position us as a stronger company when our business volumes return to 2019 levels.
Further detail on these cost reduction efforts can be found elsewhere in this Annual Report Form 10-K.
We believe that BetMGM is positioned as a long-term leader in the U.S. online sports betting and iGaming industries with growing market access and market share.
As part of our commitment to the success of our BetMGM joint venture, we have integrated our M life program with BetMGM and have BetMGM branded on-property sportsbooks and kiosks to drive higher value customers at lower acquisition costs through a robust omni-channel strategy.
Keeping health and safety in mind, we accelerated and reimagined several aspects of the guest experience this year through self-service technology.
This includes a newly revamped contactless check-in, which allows guests to complete the check-in process entirely themselves through our mobile app, digital menus, and virtual queues for guests when immediate seating is unavailable or for controlling occupancy at food and beverage outlets, pools and spa, and salon facilities.
| --- | --- |
See Note 11 in the accompanying consolidated financial statements for information regarding the lease with BREIT.
the greater of 2% and the CPI increase during the prior year subject to a cap of 3% during the 11th through 20th years and 4% thereafter.
Our results of operations do not tend to be seasonal in nature as all of our casino resorts operate 24 hours a day, every day of the year, with the exception of Empire City Casino which operates 20 hours a day, every day of the year.
We utilize third-party management for specific expertise in operations of restaurants and nightclubs.
CityCenter Holdings, LLC (“CityCenter”) is our most significant unconsolidated affiliate, which we also manage for a fee.
| Subtotal | | | 6,588 | | | | 887,000 | | | | 20,880 | | | | 711 | |
We strive to be the recognized global leader in entertainment and hospitality, embracing innovation and diversity to inspire excellence.
| | • | *Operational enhancements.* Drive continuous improvements in operational performance to support enterprise-wide increases in revenue, market share, cash flow, and margins; |
| | • | *Financial strength.* Accelerate financial performance through optimal capital structure and disciplined investment of cash flows; |
| | • | *Corporate social responsibility.* Continue to solidify the Company’s reputation as a global leader in the principles of Corporate Social Responsibility; |
| | • | *Geographic expansion.* Execute a targeted approach to domestic and international expansion to increase global brand presence; and |
| | • | *Business model innovation.* Explore the evolution of the existing business model into new lines of business and key adjacencies. |
We regularly evaluate possible expansion and acquisition opportunities in domestic and international markets.
During 2019, we launched the (“MGM 2020 Plan”), a portfolio of Adjusted EBITDAR (as defined herein) improvement initiatives that yielded over $130 million of Adjusted EBITDAR uplift in 2019.
We expect to exceed $200 million by the end of 2020 compared to 2018 results.
The initiatives are primarily comprised of labor, sourcing and revenue initiatives.
As part of the second phase of our MGM 2020 Plan, we expect to invest in our digital transformation to drive customer-centric strategy for revenue growth.
While we continue to automate various aspects of operations in an effort to control costs, we are also investing in infrastructure and platforms unique to MGM such as self-service technology, advanced pricing systems and a host of other platform-based customer and employee services.
Our team of world class product leaders and technologists leverage the newest advancements in technology including cloud, advanced analytics, and other methods to ensure speed to market and security of our platforms.
For example, our commerce and digital platforms provide our customers the ability to create an itinerary of experiences including self-service booking of accommodations, dining and entertainment, with pricing options unique and specific to them based on their relationship or loyalty status with us.
We expect continued and incremental investment in this area as part of the second phase of our MGM 2020 Plan.
Commitment to Employees
We believe that knowledgeable, friendly and dedicated employees are a primary success factor in the hospitality industry.
Therefore, we invest heavily in recruiting, training, motivating and retaining exceptional employees, and we seek to hire and promote the strongest management team possible.
We have numerous programs, both at the corporate and business unit level, designed to achieve these objectives.
We believe in the importance of developing our employees through training and advanced education.
Our Pathways Educational Program provides tuition reimbursement and our College Opportunity Program, in partnership with the Nevada System of Higher Education, provides online education at no cost to eligible MGM Resorts employees in the United States.
We also offer a student Loan Debt Assistance Program that will match a portion of monthly student loan debt payments for qualifying employees.
The MGM Resorts Scholarship Program for Children of Employees awards scholarships to selected children of our full-time domestic employees (excluding executives) based on financial need and academic performance.
We believe that profitability and social responsibility can be linked for long-term sustainability and profitability in furtherance of value to all our stakeholders – our shareholders, our employees, our customers and our communities.
We have a bold vision for how our company will lead the way in social impact and environmental sustainability in the years to come.
Focused on What Matters: Embracing Humanity and Protecting the Planet articulates our purpose and our commitment to a set of priorities and goals that we hope can have an enduring impact on the world.
We have aligned our efforts with a growing interest from investors to define a set of Environmental, Social and Governance criteria that assists in identifying companies with values that match their own.
Focused on What Matters: Embracing Humanity and Protecting the Planet defines our environmental sustainability and social impact strategy in four critical areas: Fostering Diversity and Inclusion, Investing in Community, Caring for One Another and Protecting the Planet.
In each of these areas we have adopted goals against which we will chart our progress.
We have aligned our goals and our social impact and environmental sustainability priorities to the United Nations Sustainable Development Goals.
Focused on What Matters reaffirms our commitment to our guests, employees and partners; to the communities we call home and to the planet we must protect.
Through investment of many years of dedicated effort and resources, our evolving social impact strategy – grounded in prudent fiscal management and long-term focused strategies – have advanced us beyond leadership in the gaming and hospitality industry to national recognition for our accomplishments.
Our core values of integrity, inclusion, teamwork and excellence shape our character and culture, the way we do business, and our CSR practices.
An excerpt. Shown here: 40 of 101 rewritten, 40 of 105 added and 40 of 73 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2020 filing and the FY2019 filing.
Item 3. LEGAL PROCEEDINGS
0 rewritten, 1 added, 28 removed, 1 unchanged
See discussion of legal proceedings in Note 12 – *Commitments and Contingencies* in the accompanying consolidated financial statements.
October 1 litigation.
We and/or certain of our subsidiaries were named as defendants in a number of lawsuits related to the October 1, 2017 shooting in Las Vegas.
The matters involve in large degree the same legal and factual issues, each case being filed on behalf of individuals who are seeking damages for emotional distress, physical injury, medical expenses, economic damages and/or wrongful death.
Lawsuits were first filed in October 2017 and include actions originally filed in the District Court of Clark County, Nevada and in the Superior Court of Los Angeles County, California.
In June 2018, we removed to federal court all actions that remained pending in California and Nevada state courts.
We also initiated declaratory relief actions in federal courts in various districts against individuals who had sued or stated an intent to sue.
In connection with the mediation of these matters, we and law firms representing plaintiffs in the majority of pending matters and purporting to represent substantially all claimants known to us (collectively, the “Claimants”) have entered into a settlement agreement (the “Settlement Agreement”) whereby, subject to the satisfaction of certain monetary and non-monetary conditions, our insurance carriers will deposit funds into a settlement fund covering the plaintiffs and certain other cases that emerged or were filed prior to October 1, 2019.
Pursuant to the terms of the Settlement Agreement, we expect that the total amount placed in the fund to be between $735 million and $800 million, subject to and depending on obtaining a minimum level of participation with escalators based on greater participation increasing the amount payable up to $800 million in the event of 100% participation by certain categories of claimants, as defined in the Settlement Agreement.
We have $751 million of insurance coverage available to fund.
Following the mediation a few additional lawsuits were filed against us and/or certain of our subsidiaries.
While it is possible that these lawsuits may be resolved as part of the Settlement Agreement, no assurances can be made that they will be included.
Although we continue to believe we are not legally responsible for the perpetrator’s criminal acts, in the interest of avoiding protracted litigation and the related impact on the community, we believed it was in the best interests of all parties involved to negotiate and enter into the Settlement Agreement.
As a result of the foregoing, we believe that it is probable a loss will be incurred and, as of December 31, 2019, we accrued a liability of $735 million, which represents the low end of the range of probable loss.
In addition, we recorded an insurance receivable of $735 million, which represents the entire amount of the liability recorded for the settlement of these cases.
While we intend for substantially all claimants to be covered by the Settlement Agreement, it remains possible that certain claimants may not join the settlement.
In addition, no assurances can be given that the significant conditions to the Settlement Agreement will be satisfied by the Claimants.
If the conditions in the Settlement Agreement are not satisfied and the mediation stay is lifted, we are currently unable to reliably predict the future developments in, outcome of, and economic costs and other consequences of any such litigation related to this matter.
We will continue to investigate the factual and legal defenses, and evaluate these matters based on subsequent events, new information and future circumstances.
We intend to defend against any such lawsuits and believe we ultimately should prevail, but litigation of this type is inherently unpredictable.
Although there are significant procedural, factual and legal issues to be resolved that could significantly affect our belief as to the possibility of liability, we currently believe that it is reasonably possible that we could incur liability in connection with certain of these lawsuits.
The foregoing determination was made in accordance with generally accepted accounting principles, as codified in ASC 450-20, and is not an admission of any liability on our part or any of our affiliates.
Given that these cases would be in the early stages, and in light of the uncertainties surrounding them, we do not currently possess sufficient information to determine a range of reasonably possible liability.
The insurance carriers have not expressed a reservation of rights or coverage defense that affects our evaluation of potential losses in connection with these claims.
Our general liability insurance coverage provides, as part of the contractual “duty to defend”, payment of legal fees and associated costs incurred to defend covered lawsuits that are filed arising from the October 1, 2017 shooting in Las Vegas.
Payment of such fees and costs is in addition to (and not limited by) the limits of the insurance policies and does not erode the total liability coverage available.
Other.
We are a party to various legal proceedings, most of which relate to routine matters incidental to our business.
Management does not believe that the outcome of such proceedings will have a material adverse effect on our financial position, results of operations or cash flows.
Cover and table of contents
26 rewritten, 3 added, 2 removed, 52 unchanged
For the fiscal year ended December 31, [removed: 2019][added: 2020]
The aggregate market value of the Registrant’s Common Stock held by non-affiliates of the Registrant as of June [removed: 28, 2019] [added: 30, 2020] (based on the closing price on the New York Stock Exchange Composite Tape on June [removed: 28, 2019)] [added: 30, 2020)] was [removed: $14.4] [added: $7.9] billion.
As of February [removed: 24, 2020, 492,434,341] [added: 23, 2021, 494,853,355] shares of Registrant’s Common Stock, $0.01 par value, were outstanding.
Portions of the Registrant’s definitive Proxy Statement for its [removed: 2019] [added: 2021] Annual Meeting of Stockholders are incorporated by reference into Part III of this Form 10-K.
| Item 1A. | [Risk Factors](#ITEM_1A_RISK_FACTORS) | [removed: 12] [added: 14] |
| Item 1B. | [Unresolved Staff Comments](#ITEM_1B__UNRESOLVED_STAFF_COMMENTS) | [removed: 25] [added: 31] |
| Item 2. | [Properties](#ITEM_2_PROPERTIES) | [removed: 26] [added: 32] |
| Item 3. | [Legal Proceedings](#ITEM_3_LEGAL_PROCEEDINGS) | [removed: 27] [added: 33] |
| Item 4. | [Mine Safety Disclosures](#ITEM_4_MINE_SAFETY_DISCLOSURES) | [removed: 27] [added: 33] |
| Item 5. | [Market for Registrant's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities](#ITEM_5_MARKET_FOR_REGISTRANTS_COMMON_EQU) | [removed: 28] [added: 34] |
| Item 7. | [Management's Discussion and Analysis of Financial Condition and Results of Operations](#ITEM_7_MANAGEMENTS_DISCUSSION_ANALYSIS_F) | [removed: 31] [added: 36] |
| Item 7A. | [Quantitative and Qualitative Disclosures About Market Risk](#ITEM_7A_QUANTITATIVE_QUALITATIVE_DISCLOS) | [removed: 50] [added: 57] |
| Item 8. | [Financial Statements and Supplementary Data](#ITEM_8_FINANCIAL_STATEMENTS_SUPPLEMENTAR) | [removed: 51] [added: 58] |
| | [Consolidated Financial Statements](#Consolidated_Balance_Sheets) | [removed: 55] [added: 62] |
| | [Notes to Consolidated Financial [removed: Statements](#NOTES_TO_CONSOLIDATED_FINANCIAL)] [added: Statements](#NOTES_TO_CONSOLIDATED_FINANCIAL_STATEMEN)] | [removed: 60] [added: 67] |
| | [Schedule II – Valuation and Qualifying Accounts](#SCHEDULE_II_VALUATION_QUALIFYING_ACCOUNT) | [removed: 104] [added: 103] |
| Item 9. | [Changes In and Disagreements with Accountants on Accounting and Financial Disclosure](#ITEM_9_CHANGES_IN_DISAGREEMENTS_WITH_ACC) | [removed: 105] [added: 104] |
| Item 9A. | [Controls and Procedures](#ITEM_9A_CONTROLS_PROCEDURES) | [removed: 106] [added: 104] |
| Item 9B. | [Other Information](#ITEM_9B__OR_INFORMATION) | [removed: 107] [added: 104] |
| Item 10. | [Directors, Executive Officers and Corporate Governance](#ITEM_10_DIRECTORS_EXECUTIVE_FICERS_CORPO) | [removed: 108] [added: 105] |
| Item 11. | [Executive Compensation](#ITEM_11_EXECUTIVE_COMPENSATION) | [removed: 108] [added: 105] |
| Item 12. | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters](#ITEM_12_SECURITY_OWNERSHIP_CERTAIN_BENEF) | [removed: 108] [added: 105] |
| Item 13. | [Certain Relationships and Related Transactions, and Director Independence](#ITEM_13_CERTAIN_RELATIONSHIPS_RELATED_TR) | [removed: 108] [added: 105] |
| Item 14. | [Principal Accounting Fees and Services](#ITEM_14_PRINCIPAL_ACCOUNTING_FEES_SERVIC) | [removed: 108] [added: 105] |
| Item 15. | [Exhibits, Financial Statements Schedules](#ITEM_15_EXHIBITS_FINANCIAL_STATEMENT_SCH) | [removed: 109] [added: 106] |
| Item 16. | [Form 10-K Summary](#ITEM_16_FORM_10K_SUMMARY) | [removed: 116] [added: 114] |
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report.
| Item 6. | [Removed and Reserved](#ITEM_6_REMOVED_RESERVED) | 36 |
| | [Signatures](#SIGNATURES) | 115 |
| Item 6. | [Selected Financial Data](#ITEM_6_SELECTED_FINANCIAL_DATA) | 30 |
| | [Signatures](#SIGNATURES) | 117 |
Item 2. PROPERTIES
25 rewritten, 12 added, 8 removed, 14 unchanged
The following table lists certain of our land holdings as of December 31, [removed: 2019.][added: 2020.]
| | | Approximate | [removed: | |]
| Name and Location | | Acres | [removed: | Notes |]
| Las Vegas Strip Resorts | | | [removed: | |]
| [removed: Bellagio(1) | | 77 |] [added: (9)] | [removed: Approximately two] [added: 11] acres [removed: of the site] are subject to [removed: two] ground [removed: leases.(4)] [added: leases.] |
| MGM Grand Las [removed: Vegas(5)] [added: Vegas(4)] | | 102 | [removed: | |]
| Mandalay [removed: Bay(2)(5)] [added: Bay(4)] | | 124 | [removed: | |]
| The Mirage(2) | | 77 | [removed: | |]
| [removed: Luxor(2) | | 73 |] [added: (5)] | Includes 15 acres of land located across the Las Vegas Strip from Luxor. |
| Excalibur(2) | | 51 | [removed: | |]
| [removed: New York-New York(2) | | 23 |] [added: (6)] | Includes [removed: three] [added: 3] acres of land related to The Park entertainment district development located between Park MGM and New York-New York. |
| Park MGM(2) | | 21 | [removed: | |]
| Regional Operations | | | [removed: | |]
| MGM Grand Detroit (Detroit, Michigan)(2) | | 27 | [removed: | |]
| [removed: Beau Rivage (Biloxi, Mississippi)(2) | | 42 |] [added: (7)] | 10 acres are subject to a tidelands lease. |
| Gold Strike (Tunica, Mississippi)(2) | | 24 | [removed: | |]
| MGM National Harbor (Prince George's County, [removed: Maryland)(2) | | 23] [added: Maryland)(2)(8)] | | [removed: All] 23 [removed: acres are subject to a ground lease.] |
| Borgata (Atlantic City, New [removed: Jersey)(2)] [added: Jersey)(2)(9)] | | 46 | [removed: | 11 acres are subject to ground leases. |]
| MGM Springfield (Springfield, Massachusetts) | | 14 | [removed: | |]
| MGM Northfield Park (Northfield, Ohio)(2) | | 113 | [removed: | |]
| [removed: Empire City (Yonkers, New York)(2) | | 97 |] [added: (10)] | Includes 57 acres of land adjacent to the property. |
| MGM China | | | [removed: | |]
| MGM Macau(3) | | 10 | [removed: | |]
| MGM Cotai(3) | | 18 | [removed: | |]
| [removed: (5)] [added: (4)] | [removed: Beginning February 14, 2020, subject] [added: Subject] to a master lease agreement between a subsidiary of ours and MGP BREIT Venture, in which the land and the real estate assets are leased from MGP BREIT Venture. |
| --- | --- | --- |
| Bellagio(1) | | 75 |
| Luxor(2)(5) | | 73 |
| New York-New York(2)(6) | | 23 |
| Beau Rivage (Biloxi, Mississippi)(2)(7) | | 42 |
| Empire City (Yonkers, New York)(2)(10) | | 97 |
| --- | --- |
| --- | --- |
| (8) | All 23 acres are subject to a ground lease. |
| --- | --- |
| --- | --- |
| --- | --- |
| --- | --- | --- | --- | --- |
| (4) | Beginning January 1, 2020, approximately two acres subject to a ground lease with a third party expired, reducing the total acres to approximately 75 acres. |
As of December 31, 2019, the land and substantially all of the assets of MGM Grand Las Vegas secured the obligations under our senior credit facility.
In addition, the senior credit facility was secured by a pledge of the equity or limited liability company interests of the subsidiaries that own MGM Grand Las Vegas and Bellagio.
In connection with the MGP BREIT Venture Transaction, on February 14, 2020, we entered into a new unsecured credit agreement which provides that we will grant a security interest in our Operating Partnership units in the future to the extent our leverage ratio exceeds certain thresholds.
The land and substantially all of the assets of Bellagio secure the obligations under the Bellagio BREIT Venture indebtedness.
We provide a shortfall guarantee on the principal amount of such indebtedness (and any interest accrued and unpaid thereon) as further described within “Risk Factors – Risks Related to Our Business.”
The land and substantially all of the assets of MGM Grand Las Vegas and Mandalay Bay secure the obligations under MGP BREIT Venture’s indebtedness.
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
4 rewritten, 1 added, 17 removed, 13 unchanged
There were approximately [removed: 3,483] [added: 3,446] record holders of our common stock as of February [removed: 24, 2020.][added: 23, 2021.]
In addition, as a holding company with no independent operations, our ability to pay dividends will depend upon the receipt of cash from our operating subsidiaries to generate the funds from operations necessary to pay dividends on our common [removed: stock.][added: stock, which has been significantly impacted by the COVID-19 pandemic.]
The graph tracks the performance of a $100 investment in our common stock and in each index (with the reinvestment of all dividends as required by the SEC) from December 31, [removed: 2014] [added: 2015] to December 31, [removed: 2019.][added: 2020.]
[removed: ][added: 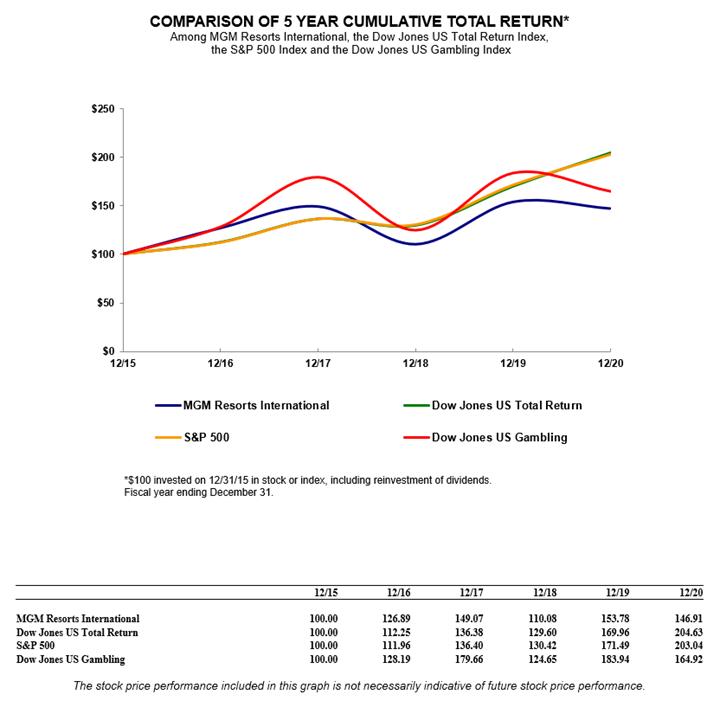]
To preserve liquidity in light of the impact of COVID-19 on its business operations, the Company temporarily reduced its dividend to an annual dividend of $0.01 per share starting with the dividend for the second quarter of 2020.
Purchases of Equity Securities by the Issuer
The following table provides information about share repurchases made by the Company of its common stock during the quarter ended December 31, 2019:
| | | | | | | | | | Total Number | | | | Dollar Value of | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | Total | | | | | | | | of Shares | | | | Shares that May | | |
| | Number of | | | | Average | | | | Purchased as | | | | Yet be Purchased | | |
| | Shares | | | | Price Paid | | | | Part of a Publicly | | | | Under the Program | | |
| Period | Purchased | | | | per Share | | | | Announced Program | | | | (In thousands) | | |
| October 1, 2019 — October 31, 2019 | | — | | | $ | — | | | | — | | | $ | 750,216 | |
| November 1, 2019 — November 30, 2019 | | 4,964,502 | | | $ | 31.23 | | | | 4,964,502 | | | $ | 595,162 | |
| December 1, 2019 — December 31, 2019 | | 7,284,817 | | | $ | 32.62 | | | | 7,284,817 | | | $ | 357,496 | |
On May 10, 2018, the Company announced that its Board of Directors had adopted a $2.0 billion stock repurchase program.
Additionally, in February 2020, upon substantial completion of the prior program, the Company announced that its Board of Directors had adopted a $3.0 billion stock repurchase program.
Under the stock repurchase program the Company may repurchase shares from time to time in the open market or in privately negotiated agreements.
Repurchases of common stock may also be made under a Rule 10b5-1 plan, which would permit common stock to be repurchased when the Company might otherwise be precluded from doing so under insider trading laws.
The timing, volume and nature of stock repurchases will be at the sole discretion of management, dependent on market conditions, applicable securities laws, and other factors, and may be suspended or discontinued at any time.
All shares repurchased by the Company during the quarter ended December 31, 2019 were purchased pursuant to the Company’s publicly announced stock repurchase programs and have been retired.
Item 6. REMOVED AND RESERVED
0 rewritten, 0 added, 33 removed, 1 unchanged
The following reflects selected historical financial data that should be read in conjunction with “Item 7 – Management’s Discussion and Analysis of Financial Condition and Results of Operations” and the consolidated financial statements and notes thereto included elsewhere in this Annual Report on Form 10-K.
The historical results are not necessarily indicative of the results of operations to be expected in the future.
| | | 2019 | | | | 2018 | | | | 2017 | | | | 2016 | | | | 2015 | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | (In thousands, except per share data) | | | | | | | | | | | | | | | | | | |
| Net revenues | | $ | 12,899,672 | | | $ | 11,763,096 | | | $ | 10,797,479 | | | $ | 9,478,269 | | | $ | 9,179,590 | |
| Operating income (loss) | | | 3,940,215 | | | | 1,469,486 | | | | 1,712,527 | | | | 2,078,199 | | | | (152,838 | ) |
| Net income (loss) | | | 2,214,380 | | | | 583,894 | | | | 2,088,184 | | | | 1,235,846 | | | | (1,037,444 | ) |
| Net income (loss) attributable to MGM Resorts International | | | 2,049,146 | | | | 466,772 | | | | 1,952,052 | | | | 1,100,408 | | | | (445,515 | ) |
| Earnings (loss) per share - Basic | | $ | 3.90 | | | $ | 0.82 | | | $ | 3.38 | | | $ | 1.94 | | | $ | (0.82 | ) |
| Earnings (loss) per share - Diluted | | $ | 3.88 | | | $ | 0.81 | | | $ | 3.34 | | | $ | 1.92 | | | $ | (0.82 | ) |
| Dividends declared per common share | | $ | 0.52 | | | $ | 0.48 | | | $ | 0.44 | | | $ | — | | | $ | — | |
| Total assets | | $ | 33,876,356 | | | $ | 30,210,706 | | | $ | 29,160,042 | | | $ | 28,174,400 | | | $ | 25,215,178 | |
| Long-term obligations(1) | | | 15,915,508 | | | | 15,449,495 | | | | 13,115,246 | | | | 13,359,339 | | | | 12,532,224 | |
| MGM Resorts International stockholders' equity | | | 7,727,265 | | | | 6,512,283 | | | | 7,577,061 | | | | 6,192,825 | | | | 5,119,927 | |
| (1) | Includes long-term debt, operating lease liabilities, other long-term obligations (which includes finance lease liabilities), and redeemable noncontrolling interests. |
The following events/transactions affect the year-to-year comparability of the selected financial data presented above:
Acquisitions, Dispositions, and Significant Transactions
| | • | In 2016, we recorded a $401 million gain for our share of CityCenter’s gain on the sale of the Shops at Crystals (“Crystals”) and also recorded a $430 million gain on our acquisition of the remaining 50% ownership interest in Borgata on August 1, 2016, and began to consolidate Borgata beginning on that date. |
| --- | --- | --- |
| | • | In 2016, we received net proceeds of $1.1 billion in connection with MGP’s IPO. |
| | • | In 2016, we opened MGM National Harbor. |
| | • | In 2018, we opened MGM Cotai and MGM Springfield; MGP acquired Northfield. |
| | • | In 2019, we acquired Empire City. |
| | • | In 2019, we recorded a loss of $220 million related to the sale of Circus Circus Las Vegas and adjacent land and a gain of $2.7 billion related to the Bellagio transaction. |
Other
| | • | In 2015, we recorded a goodwill impairment charge of $1.5 billion at MGM China. We also recorded an $80 million gain for our share of CityCenter’s gain resulting from the final resolution of its construction litigation and related settlements. |
| | • | In 2016, we recorded a $152 million expense related to our strategic decision to exit the fully bundled sales system of NV Energy. In 2017, we then recorded a gain of $45 million related to the NV Energy exit fee modification. |
| | • | In 2017, we began declaring dividends. |
| | • | In 2017, we recorded a $1.4 billion tax benefit related to the enactment of the U.S. Tax Cuts and Jobs Act (“Tax Act”). In 2018, we then recorded a $20 million tax expense related to the Tax Act. |
| | • | In 2018, we adopted the new accounting standard relating to revenue recognition on a full retrospective basis. Accordingly, financial data as of and for the years ended December 31, 2018, 2017, and 2016, and for the year ended December 31, 2015, reflect such retrospective adoption within the chart above. Financial data as of December 31, 2015 does not reflect such adoption. |
| | • | In 2019, we adopted the new accounting standard related to leases utilizing the simplified transition method and accordingly did not recast comparative period financial information. |
| | • | In 2019, we recorded a $198 million loss on early retirement of debt. |
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
618 rewritten, 301 added, 531 removed, 733 unchanged
| [Report of Independent Registered Public Accounting Firm on Internal Control Over Financial Reporting](#REPORT_INDEPENDENT_REGISTERED_PUBLIC_2) | | [removed: 52] [added: 59] |
| [Report of Independent Registered Public Accounting Firm on Consolidated Financial Statements](#REPORT_INDEPENDENT_REGISTERED_PUBLIC_ACC) | | [removed: 53] [added: 60] |
| [Consolidated Balance Sheets — December 31, [removed: 2019] [added: 2020] and [removed: 2018](#Consolidated_Balance_Sheets)] [added: 2019](#Consolidated_Balance_Sheets)] | | [removed: 55] [added: 62] |
| Years Ended December 31, [removed: 2019, 2018] [added: 2020, 2019] and [removed: 2017] [added: 2018] | | |
| [Consolidated Statements of Operations](#Statements_of_Operations) | | [removed: 56] [added: 63] |
| [Consolidated Statements of Comprehensive Income (Loss)](#Comprehensive_Income_Loss) | | [removed: 57] [added: 64] |
| [Consolidated Statements of Cash Flows](#CONSOLIDATED_STATEMENTS_CASH_FLOWS) | | [removed: 58] [added: 65] |
| [Consolidated Statements of Stockholders’ Equity](#CONSOLIDATED_STATEMENTS_STOCKHOLDERS_EQU) | | [removed: 59] [added: 66] |
| [Notes to Consolidated Financial [removed: Statements](#NOTES_TO_CONSOLIDATED_FINANCIAL)] [added: Statements](#NOTES_TO_CONSOLIDATED_FINANCIAL_STATEMEN)] | | [removed: 60] [added: 67] |
| [Schedule II — Valuation and Qualifying Accounts](#SCHEDULE_II_VALUATION_QUALIFYING_ACCOUNT) | | [removed: 104] [added: 103] |
We have audited the internal control over financial reporting of MGM Resorts International and subsidiaries (the “Company”) as of December 31, [removed: 2019,] [added: 2020,] based on criteria established in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2019,] [added: 2020,] based on criteria established in Internal Control — Integrated Framework (2013) issued by COSO.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated financial statements and financial statement schedule as of and for the year ended December 31, [removed: 2019,] [added: 2020,] of the Company and our report dated February [removed: 27, 2020,] [added: 26, 2021,] expressed an unqualified opinion on those financial [removed: statements and included an explanatory paragraph regarding the Company’s change in accounting principle.][added: statements.]
We have audited the accompanying consolidated balance sheets of MGM Resorts International and subsidiaries (the "Company") as of December 31, [removed: 2019] [added: 2020] and [removed: 2018,] [added: 2019,] the related consolidated statements of operations and comprehensive income (loss), cash flows and [removed: stockholders’] [added: stockholders'] equity for each of the three years in the period ended December 31, [removed: 2019,] [added: 2020,] and the related notes and the financial statement schedule of Valuation and Qualifying Accounts included in Item 15(a)(2), (collectively referred to as the "financial statements").
In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2019] [added: 2020] and [removed: 2018,] [added: 2019,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2019,] [added: 2020,] in conformity with accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, [removed: 2019,] [added: 2020,] based on criteria established in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February [removed: 27, 2020,] [added: 26, 2021,] expressed an unqualified opinion on the Company's internal control over financial reporting.
[removed: As discussed in Note 2 to the financial statements, effective] [added: Effective] January 1, 2019, the Company adopted FASB ASC Topic 842, Leases, using the modified retrospective approach.
| | | [added: 2020 | | | |] 2019 | | | | 2018 | | |
| Cash and cash equivalents | | $ | [removed: 2,329,604] [added: 5,101,637] | | | $ | [removed: 1,526,762] [added: 2,329,604] | |
| Accounts receivable, net | | | [removed: 612,717] [added: 316,502] | | | | [removed: 657,206] [added: 612,717] | |
| Inventories | | | [removed: 102,888] [added: 88,323] | | | | [removed: 110,831] [added: 102,888] | |
| Income tax receivable | | | [removed: 27,167] [added: 243,415] | | | | [removed: 28,431] [added: 27,167] | |
| October 1 litigation insurance receivable | | | [removed: 735,000] [added: —] | | | | [removed: —] [added: 735,000] | |
| Prepaid expenses and other | | | [removed: 200,317] [added: 200,782] | | | | [removed: 203,548] [added: 200,317] | |
| Total current assets | | | [removed: 4,007,693] [added: 5,950,659] | | | | [removed: 2,526,778] [added: 4,007,693] | |
| Property and equipment, net | | | [removed: 18,285,955] [added: 14,632,091] | | | | [removed: 20,729,888] [added: 18,285,955] | |
| Investments in and advances to unconsolidated affiliates | | | [removed: 822,366] [added: 1,447,043] | | | | [removed: 732,867] [added: 822,366] | |
| Goodwill | | | [removed: 2,084,564] [added: 2,091,278] | | | | [removed: 1,821,392] [added: 2,084,564] | |
| Other intangible assets, net | | | [removed: 3,826,504] [added: 3,643,748] | | | | [removed: 3,944,463] [added: 3,826,504] | |
| Operating lease right-of-use assets, net | | | [removed: 4,392,481] [added: 8,286,694] | | | | [removed: —] [added: 4,392,481] | |
| Other long-term assets, net | | | [removed: 456,793] [added: 443,421] | | | | [removed: 455,318] [added: 456,793] | |
| Total other assets | | | [removed: 11,582,708] [added: 15,912,184] | | | | [removed: 6,954,040] [added: 11,582,708] | |
| Accounts payable | | $ | [removed: 235,437] [added: 142,523] | | | $ | [removed: 302,578] [added: 235,437] | |
| Construction payable | | | [removed: 74,734] [added: 30,149] | | | | [removed: 311,793] [added: 74,734] | |
| Accrued interest on long-term debt | | | [removed: 122,250] [added: 138,832] | | | | [removed: 140,046] [added: 122,250] | |
| October 1 litigation liability | | | [removed: 735,000] [added: —] | | | | [removed: —] [added: 735,000] | |
| Other accrued liabilities | | | [removed: 2,024,002] [added: 1,545,079] | | | | [removed: 2,151,054] [added: 2,024,002] | |
| Total current liabilities | | | [removed: 3,191,423] [added: 1,856,583] | | | | [removed: 2,948,882] [added: 3,191,423] | |
| Deferred income taxes, net | | | [removed: 2,106,506] [added: 2,153,016] | | | | [removed: 1,342,538] [added: 2,106,506] | |
| Long-term debt, net | | | [removed: 11,168,904] [added: 12,376,684] | | | | [removed: 15,088,005] [added: 11,168,904] | |
February 26, 2021
“MGP BREIT Venture Transaction – Investment in MGP BREIT Venture” — Refer to Notes 1, 2, and 6 to the financial statements
During the year ended December 31, 2020, the Company completed the MGP BREIT Venture Transaction and in connection with the transaction, formed MGP BREIT Venture, which, following the transaction, is owned 50.1% by the MGM Growth Properties Operating Partnership LP and 49.9% by a subsidiary of Blackstone Real Estate Income Trust, Inc. The 50.1% equity interest in MGP BREIT Venture was obtained as partial consideration for the contribution of the real estate assets.
The assessment of whether an investment is a variable interest entity (“VIE”) and whether the Company has a controlling financial interest in the investment involves management’s judgment and analysis.
The Company concluded that the investment in MGP BREIT Venture did not meet the definition of a VIE and did not qualify for consolidation under the voting interest entity model since MGP BREIT Venture is structured with substantive participating rights whereby both owners of MGP BREIT Venture participate in the decision making
process, thereby preventing the Company from exerting a controlling financial interest, as defined in ASC 810.
The Company concluded that the MGP BREIT Venture is therefore accounted for under the equity method.
We identified the assessment of whether the investment in MGP BREIT Venture is a VIE and whether it qualifies for consolidation under the voting interest entity model as a critical audit matter because the VIE and consolidation accounting guidance under ASC 810 is complex and requires management to make significant judgments and assumptions to determine if the Company has a controlling financial interest, as defined in ASC 810, in MGP BREIT Venture based upon the terms of the ownership agreements.
Specifically, the significant judgments made by management include evaluating and concluding MGP BREIT Venture does not meet the definition of a VIE or qualify for consolidation under the voting interest entity model and included the application of consolidation accounting guidance.
Given these significant judgments, performing audit procedures to evaluate the reasonableness of management’s evaluation of whether the MGP BREIT Venture does not meet the definition of a VIE or qualify for consolidation under the voting interest entity model required a high degree of auditor judgment, including the need to involve technical accounting specialists.
Our audit procedures related to the Company’s evaluation of whether an investment is a VIE and whether an investment qualifies for consolidation under the voting interest entity model in connection with the MGP BREIT Venture Transaction under ASC 810 included the following, among others:
| | • | We tested the effectiveness of the control over management’s assessment of the investment in MGP BREIT Venture for consolidation, including the judgments and factors used in determining that the MGP BREIT Venture did not meet the definition of a VIE and did not qualify for consolidation under the voting interest entity model. |
| | • | We inspected the underlying agreements and evaluated the reasonableness of the application of consolidation accounting guidance. With the assistance of technical accounting specialists, we evaluated the assumptions and judgments used by management to determine whether the investment in MGP BREIT Venture is a VIE and whether it qualifies for consolidation. |
February 26, 2021
| | | $ | 36,494,934 | | | $ | 33,876,356 | |
| | | $ | 36,494,934 | | | $ | 33,876,356 | |
| Reimbursed costs | | | 244,949 | | | | 436,887 | | | | 425,492 | |
| Gain on REIT transactions, net | | | (1,491,945 | ) | | | (2,677,996 | ) | | | — | |
| Net income (loss) | | $ | (1,319,907 | ) | | $ | 2,214,380 | | | $ | 583,894 | |
| Gain on REIT transactions, net | | | (1,491,945 | ) | | | (2,677,996 | ) | | | — | |
| Proceeds from Mandalay Bay and MGM Grand Las Vegas transaction | | | 2,455,839 | | | | — | | | | — | |
| Proceeds from issuance of bridge loan facility | | | 1,304,625 | | | | — | | | | — | |
| Investment in MGP BREIT Venture | | | 802,000 | | | | — | | | | — | |
| MGP BREIT Venture assumption of bridge loan facility | | | 1,304,625 | | | | — | | | | — | |
| Net loss | | | — | | | | — | | | | — | | | | (1,032,724 | ) | | | — | | | | (1,032,724 | ) | | | (293,401 | ) | | | (1,326,125 | ) |
| Currency translation adjustment | | | — | | | | — | | | | — | | | | — | | | | 15,711 | | | | 15,711 | | | | 12,051 | | | | 27,762 | |
| Cash flow hedges | | | — | | | | — | | | | — | | | | — | | | | (44,528 | ) | | | (44,528 | ) | | | (34,837 | ) | | | (79,365 | ) |
| Stock-based compensation | | | — | | | | — | | | | 100,907 | | | | — | | | | — | | | | 100,907 | | | | 6,049 | | | | 106,956 | |
| Issuance of restricted stock units | | | — | | | | — | | | | 2,142 | | | | — | | | | — | | | | 2,142 | | | | — | | | | 2,142 | |
| Repurchases of common stock | | | (10,861 | ) | | | (109 | ) | | | (353,611 | ) | | | — | | | | — | | | | (353,720 | ) | | | — | | | | (353,720 | ) |
| MGP Class A share issuances | | | — | | | | — | | | | 64,188 | | | | — | | | | 646 | | | | 64,834 | | | | 442,717 | | | | 507,551 | |
| MGP BREIT Venture Transaction | | | — | | | | — | | | | (6,503 | ) | | | — | | | | (59 | ) | | | (6,562 | ) | | | 8,287 | | | | 1,725 | |
| Redemption of Operating Partnership units | | | — | | | | — | | | | 83,859 | | | | — | | | | 8,773 | | | | 92,632 | | | | (114,924 | ) | | | (22,292 | ) |
| Other | | | — | | | | — | | | | (1,724 | ) | | | — | | | | (1,018 | ) | | | (2,742 | ) | | | (638 | ) | | | (3,380 | ) |
| Balances, December 31, 2020 | | | 494,318 | | | $ | 4,943 | | | $ | 3,439,453 | | | $ | 3,091,007 | | | $ | (30,677 | ) | | $ | 6,504,726 | | | $ | 4,675,182 | | | $ | 11,179,908 | |
The determination of settlement method is at the option of MGP’s independent conflicts committee.
Additionally, pursuant to a lease agreement between a subsidiary of the Company and a venture that is 50.1% owned by a subsidiary of the Operating Partnership and 49.9% by a subsidiary of BREIT (such venture, the “MGP BREIT Venture”), the Company leases the real estate assets of Mandalay Bay and MGM Grand Las Vegas.
The Company recorded the difference between consideration received of $2.5 billion and the carrying value of the MGM Grand Las Vegas real estate assets of $733 million and selling costs of $27 million as a net gain on sale of assets of $1.7 billion, which is reflected within “Gain on REIT transactions, net” in the consolidated statements of operations.
The Company also recorded the difference between consideration received of $2.1 billion and the carrying value of the Mandalay Bay real estate assets of $2.3 billion and selling costs of $10 million as a net loss on sale of assets of $252 million, which is reflected within “Gain on REIT transactions, net” in the consolidated statements of operations.
On May 18, 2020, the Operating Partnership redeemed approximately 30 million Operating Partnership units that the Company held for $700 million, or $23.10 per unit, and on December 2, 2020, the Operating Partnership redeemed approximately 24 million of the Operating Partnership units that the Company held for the remaining $700 million, or $29.78 per unit.
| --- | --- | --- |
February 27, 2020
Acquisition and Goodwill and Other Intangible Assets Valuation of Empire City – Refer to Notes 4 and 7 to the financial statements
The Company’s evaluation of goodwill for impairment at the Empire City reporting unit (“Empire City”) involves the comparison of the fair value of the reporting unit to its carrying value.
The Company determines the fair value of its reporting units using a combination of income-based and market-based approaches and incorporates assumptions it believes market participants would utilize.
Under the income-based approach, the Company uses a discounted cash flow model to estimate the fair value of the reporting unit, which requires management to make subjective estimates and assumptions, particularly related to the forecast of future revenues and EBITDA, as well as in the selection of the company specific risk premium utilized in the calculation of the discount rate.
The fair value of Empire City reporting unit exceeded its carrying value as of the measurement date and, therefore, no impairment was recognized.
The Company’s goodwill balance was $2.1 billion as of December 31, 2019, of which $256 million relates to the Empire City acquisition completed in January 2019.
The sensitivity of operating results for Empire City to changes in the regulatory environment and competition required the application of a high degree of auditor judgment and an increased extent of effort, including the need to involve our fair value specialists, when performing audit procedures to evaluate the reasonableness of management’s estimates and assumptions related to the forecast of future revenues and EBITDA, as well as in determining the reasonableness of the selection of the company specific risk premium utilized in the calculation of the discount rate.
Our audit procedures related to management’s estimate of the forecast of future revenues and EBITDA, as well as the company specific risk premium utilized in the discount rate included the following, among others:
| | • | We tested the operating effectiveness of controls over management’s goodwill impairment evaluation, including the controls related to management’s forecast of future revenues and EBITDA, as well as the controls related to management’s selection of the company specific risk premium utilized in the calculation of the discount rate. |
| | • | We evaluated management’s ability to accurately forecast future revenues and EBITDA and assessed the reasonableness of the forecasted future revenues and EBITDA by comparing the forecast to: |
| | o | Historical revenues and EBITDA |
| | o | Forecast information included in analyst and industry reports |
| | o | Internal communications to management and the Board of Directors |
| | o | Subsequent forecasts, to evaluate for changes made by management since the annual measurement date through issuance of the financial statements. |
| | • | With the assistance of our fair value specialists, we evaluated the reasonableness of the company specific risk premium utilized in the discount rate by gaining an understanding of the estimated company specific risk premium, gathering and analyzing relevant facts and objective evidence provided by the Company, and gathering and analyzing additional facts and objective evidence obtained through independent research. |
| | | | | | | | | |
| | | $ | 33,876,356 | | | $ | 30,210,706 | |
| Current portion of long-term debt | | | — | | | | 43,411 | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| NV Energy exit expense | | | — | | | | — | | | | (40,629 | ) |
| Gain on Bellagio transaction | | | (2,677,996 | ) | | | — | | | | — | |
| | | | | | | | | | | | | |
| Increase in construction accounts payable | | | — | | | | — | | | | 204,466 | |
| Balances, January 1, 2017 | | | 574,124 | | | $ | 5,741 | | | $ | 5,653,575 | | | $ | 518,456 | | | $ | 15,053 | | | $ | 6,192,825 | | | $ | 3,749,132 | | | $ | 9,941,957 | |
| Net income | | | — | | | | — | | | | — | | | | 1,952,052 | | | | — | | | | 1,952,052 | | | | 128,320 | | | | 2,080,372 | |
| Currency translation adjustment | | | — | | | | — | | | | — | | | | — | | | | (23,995 | ) | | | (23,995 | ) | | | (19,193 | ) | | | (43,188 | ) |
| Other comprehensive income - cash flow hedges | | | — | | | | — | | | | — | | | | — | | | | 5,234 | | | | 5,234 | | | | 2,761 | | | | 7,995 | |
| Stock-based compensation | | | — | | | | — | | | | 57,531 | | | | — | | | | — | | | | 57,531 | | | | 4,991 | | | | 62,522 | |
| Issuance of performance share units | | | — | | | | — | | | | 9,648 | | | | — | | | | — | | | | 9,648 | | | | 95 | | | | 9,743 | |
| Repurchase of common stock | | | (10,000 | ) | | | (100 | ) | | | (327,400 | ) | | | — | | | | — | | | | (327,500 | ) | | | — | | | | (327,500 | ) |
| MGP Class A share issuance | | | — | | | | — | | | | 35,029 | | | | — | | | | 109 | | | | 35,138 | | | | 326,484 | | | | 361,622 | |
| MGM National Harbor transaction | | | — | | | | — | | | | (12,486 | ) | | | — | | | | (11 | ) | | | (12,497 | ) | | | 19,383 | | | | 6,886 | |
| Other | | | — | | | | — | | | | (6,106 | ) | | | (1,195 | ) | | | — | | | | (7,301 | ) | | | (448 | ) | | | (7,749 | ) |
The determination of settlement method is at the option of MGP’s independent conflicts committee; refer to discussion below as to the agreement entered into in February 2020 which allows the Company to receive cash of up to $1.4 billion in exchange for its Operating Partnership units, should the Company elect to have its units redeemed for a 24 month period following the closing of the MGP BREIT Venture Transaction (as defined below).
The Company and MGP’s ownership interest percentage in the Operating Partnership have varied based upon the transactions that MGP has completed, as discussed in Note 18.
The real estate assets of Mandalay Bay and MGM Grand Las Vegas were classified as held and used in the consolidated balance sheets at December 31, 2019 as the held for sale criteria were not met as of the balance sheet date.
In early 2020, the rapid spread of a respiratory illness caused by a novel coronavirus (Covid-19) identified as originating in Wuhan, Hubei Province, China led to certain actions taken by the Chinese government and other countries to attempt to mitigate the spread of the virus.
Among the actions taken were the implementation of travel restrictions, such as the temporary suspension of China’s visa scheme that permits mainland Chinese to travel to Macau, the temporary suspension of all ferry service from Hong Kong to Macau, the suspension of casino operations in Macau for a 15-day period that commenced on February 5, 2020, and restrictions placed on inbound travel from mainland China to the U.S. Although operations at MGM Macau and MGM Cotai resumed on February 20, 2020, there are currently limits on the number of gaming tables allowed to operate and restrictions on the number of seats available at each table, and the temporary suspension of the visa scheme and ferry service to Macau remains in place.
An excerpt. Shown here: 40 of 618 rewritten, 40 of 301 added and 40 of 531 removed. The counts are complete. For every sentence, read Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA in the FY2020 filing and the FY2019 filing.
Item 9A. CONTROLS AND PROCEDURES
3 rewritten, 0 added, 2 removed, 25 unchanged
Our Chief Executive Officer (principal executive officer) and Chief Financial Officer (principal financial officer) have concluded that our disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934, as amended (“the Exchange Act”)) were effective as of December 31, [removed: 2019] [added: 2020] to provide reasonable assurance that information required to be disclosed in the Company’s reports under the Exchange Act is recorded, processed, summarized and reported within the time periods specified in the SEC rules and regulations and to provide that such information is accumulated and communicated to management to allow timely decisions regarding required disclosures.
During the quarter ended December 31, [removed: 2019,] [added: 2020,] there were no changes in our internal control over financial reporting that materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Based on its evaluation as of December 31, [removed: 2019,] [added: 2020,] management believes that the Company’s internal control over financial reporting is effective in achieving the objectives described above.
We have commenced finance modernization initiatives to implement new accounting systems, which are expected to improve the efficiency of certain business processes.
We will continue to monitor and evaluate our internal control over financial reporting throughout the transformation.
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
1 rewritten, 0 added, 0 removed, 1 unchanged
We incorporate by reference the information appearing under “Information about our Executive Officers” in Item 1 of this Form 10-K and under “Election of Directors” and “Corporate Governance” in our definitive Proxy Statement for our [removed: 2020] [added: 2021] Annual Meeting of Stockholders, which we expect to file with the SEC [removed: on or before March 27,] [added: within 120 days after December 31,] 2020 (the “Proxy Statement”).
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
3 rewritten, 0 added, 0 removed, 11 unchanged
The following table includes information about our equity compensation plans at December 31, [removed: 2019:][added: 2020:]
| Equity compensation plans approved by security holders (1) | | | [removed: 10,991] [added: 9,227] | | | $ | [removed: 23.16] [added: 23.87] | | | | [removed: 20,310] [added: 19,573] | |
| (1) | As of December 31, [removed: 2019,] [added: 2020,] we had [removed: 4.3] [added: 4.7] million restricted stock units and [removed: 2.5] [added: 2.0] million performance share units outstanding that do not have an exercise price; therefore, the weighted average per share exercise price only relates to outstanding stock appreciation rights. The amount included in the securities outstanding above for performance share units assumes that each target price is achieved. |
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
1 rewritten, 0 added, 0 removed, 2 unchanged
We incorporate by reference the information appearing under [removed: “Selection] [added: “Ratification] of [added: Selection of] Independent Registered Public Accounting Firm” in the Proxy Statement.
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES
72 rewritten, 24 added, 3 removed, 81 unchanged
| [Report of Independent Registered Public Accounting Firm on Internal Control Over Financial Reporting](#REPORT_INDEPENDENT_REGISTERED_PUBLIC_2) | | [removed: 52] [added: 59] |
| [Report of Independent Registered Public Accounting Firm on Consolidated Financial Statements](#REPORT_INDEPENDENT_REGISTERED_PUBLIC_ACC) | | [removed: 53] [added: 60] |
| [Consolidated Balance Sheets — December 31, [removed: 2019] [added: 2020] and [removed: 2018](#Consolidated_Balance_Sheets)] [added: 2019](#Consolidated_Balance_Sheets)] | | [removed: 55] [added: 62] |
| Years Ended December 31, [removed: 2019, 2018] [added: 2020, 2019] and [removed: 2017] [added: 2018] | | |
| [Consolidated Statements of Operations](#Statements_of_Operations) | | [removed: 56] [added: 63] |
| [Consolidated Statements of Comprehensive Income (Loss)](#Comprehensive_Income_Loss) | | [removed: 57] [added: 64] |
| [Consolidated Statements of Cash Flows](#CONSOLIDATED_STATEMENTS_CASH_FLOWS) | | [removed: 58] [added: 65] |
| [Consolidated Statements of Stockholders’ Equity](#CONSOLIDATED_STATEMENTS_STOCKHOLDERS_EQU) | | [removed: 59] [added: 66] |
| [Notes to Consolidated Financial [removed: Statements](#NOTES_TO_CONSOLIDATED_FINANCIAL)] [added: Statements](#NOTES_TO_CONSOLIDATED_FINANCIAL_STATEMEN)] | | [removed: 60] [added: 67] |
| [Schedule II — Valuation and Qualifying Accounts](#SCHEDULE_II_VALUATION_QUALIFYING_ACCOUNT) | | [removed: 104] [added: 103] |
| 3.2 | | [Amended and Restated Bylaws of the Company, effective January 13, [removed: 2016] [added: 2021] (incorporated by reference to Exhibit 3.1 to the Company’s Current Report on Form 8-K filed on January 15, [removed: 2016).](http://www.sec.gov/Archives/edgar/data/789570/000119312516431231/d117513dex31.htm)] [added: 2021).](http://www.sec.gov/Archives/edgar/data/789570/000119312521010197/d53546dex31.htm)] |
| [removed: 4.1(10)] [added: 4.1(12)] | | [Indenture, dated as of August 12, 2016, among MGM Growth Properties Operating Partnership LP, MGP Finance Co-Issuer, Inc., the subsidiary guarantors party thereto and U.S. Bank National Association, as trustee (incorporated by reference to Exhibit 4.1 of the Current Report on Form 8-K of MGM Growth Properties LLC filed on August 12, 2016)](http://www.sec.gov/Archives/edgar/data/1656936/000119312516680168/d51988dex41.htm). |
| [removed: 4.1(11)] [added: 4.1(13)] | | [Indenture, dated as of April 20, 2016, among MGP Escrow Issuer, LLC and MGP Escrow Co-Issuer, Inc. and U.S. Bank National Association, as Trustee (incorporated by reference to Exhibit 4.1 to the Company’s Current Report on Form 8-K filed April 21, 2016).](http://www.sec.gov/Archives/edgar/data/789570/000119312516549310/d177305dex41.htm) |
| [removed: 4.1(12)] [added: 4.1(14)] | | [Indenture, dated as of September 21, 2017, among MGM Growth Properties Operating Partnership LP, MGP Finance Co-Issuer, Inc., the subsidiary guarantors party thereto and U.S. Bank National Association, as trustee (incorporated by reference to Exhibit 4.1 of the Current Report on Form 8-K of MGM Growth Properties LLC and MGM Growth Properties Operating Partnership LP filed on September 21, 2017).](http://www.sec.gov/Archives/edgar/data/1656936/000119312517290490/d450326dex41.htm) |
| [removed: 4.1(13)] [added: 4.1(15)] | | [Indenture, dated as of January 25, 2019, among MGM Growth Properties Operating Partnership LP, MGP Finance Co-Issuer, Inc., the subsidiary guarantors party thereto and U.S. Bank National Association, as trustee (incorporated by reference to Exhibit 4.1 of the Current Report on Form 8-K of MGM Growth Properties LLC and MGM Growth Properties Operating Partnership LP filed on January 25, 2019).](http://www.sec.gov/Archives/edgar/data/1656936/000119312519017149/d697852dex41.htm) |
| [removed: 4.1(14)] [added: 4.1(16)] | | [Supplemental Indenture to the Indentures, dated as of June 15, 2018, among MGP OH, Inc., MGP Finance Co-Issuer, Inc. and MGM Growth Properties Operating Partnership LP (incorporated by reference to Exhibit 4.1 to the Quarterly Report on Form 10-Q of MGM Growth Properties LLC and MGM Growth Properties Operating Partnership LP filed on August 7, 2018).](http://www.sec.gov/Archives/edgar/data/1656936/000162828018010642/mgp06302018ex-41.htm) |
| [removed: 4.1(15)] [added: 4.1(17)] | | [Second Supplemental Indenture to the Indentures, dated as of July 10, 2018, among Northfield Park Associates LLC, Cedar Downs OTB, LLC, MGP Finance Co-Issuer, Inc. and MGM Growth Properties Operating Partnership LP (incorporated by reference to Exhibit 4.1 to the Quarterly Report on Form 10-Q of MGM Growth Properties LLC and MGM Growth Properties Operating Partnership LP filed on November 6, 2018).](http://www.sec.gov/Archives/edgar/data/1656936/000162828018013662/mgp09302018ex-41.htm) |
| [removed: 4.1(16)] [added: 4.1(18)] | | [Third Supplemental Indenture to the Indentures, dated as of January 29, 2019, among MGP Yonkers Realty Sub, LLC, YRL Associates, L.P., MGP Finance Co-Issuer, Inc., MGM Growth Properties Operating Partnership LP, the Subsidiary Guarantors named therein, and U.S. Bank National Association, as Trustee (incorporated by reference to Exhibit 4.2 to the Company’s Quarterly Report on Form 10-Q filed on May 7, 2019).](http://www.sec.gov/Archives/edgar/data/1656936/000162828019006077/mgp03312019ex-42.htm) |
| [removed: 4.1(17)] [added: 4.1(19)] | | [Fourth Supplemental Indenture to the Indentures, dated as of March 29, 2019, among MGP, MGP OH Propco, LLC, MGP Finance Co-Issuer, Inc., MGM Growth Properties Operating Partnership LP, the Subsidiary Guarantors named therein, and U.S. Bank National Association, as Trustee (incorporated by reference to Exhibit 4.3 to the Company’s Quarterly Report on Form 10-Q filed on May 7, 2019).](http://www.sec.gov/Archives/edgar/data/1656936/000162828019006077/mgp03312019ex-43.htm) |
| [removed: 4.1(18)] [added: 4.1(20)] | | [Indenture governing the 5.375% senior notes due 2024, dated as of May 16, 2019, between MGM China Holdings Limited and U.S. Bank National Association, as trustee (incorporated by reference to Exhibit 4.1 of the Company’s Current Report on Form 8-K filed on May 16, 2019).](http://www.sec.gov/Archives/edgar/data/789570/000119312519149526/d746400dex41.htm) |
| [removed: 4.1(19)] [added: 4.1(21)] | | [Indenture governing the 5.875% senior notes due 2026, dated as of May 16, 2019, between MGM China Holdings Limited and U.S. Bank National Association, as trustee (incorporated by reference to Exhibit 4.2 of the Company’s Current Report on Form 8-K filed on May 16, 2019).](http://www.sec.gov/Archives/edgar/data/789570/000119312519149526/d746400dex42.htm) |
| 4.4 | | [Description of MGM Common [removed: Stock](https://www.sec.gov/Archives/edgar/data/789570/000156459020007393/mgm-ex44_1341.htm)] [added: Stock](https://www.sec.gov/Archives/edgar/data/789570/000156459021009205/mgm-ex44_10.htm)] |
| [removed: 10.1(1)] [added: 10.1(7)] | | [removed: [Amended and Restated Credit] [added: [Credit] Agreement, dated as of [removed: April 25, 2016,] [added: February 14, 2020,] among MGM Resorts International, the Lenders from time to time party thereto and Bank of America, N.A., as Administrative Agent (incorporated by reference to Exhibit [removed: 10.2 to the Company’s] [added: 10.5 of MGM Resort International’s] Current Report on Form 8-K filed [removed: April 25, 2016).](http://www.sec.gov/Archives/edgar/data/789570/000119312516554391/d171299dex102.htm)] [added: with the Commission on February 18, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000119312520040601/d882756dex105.htm)] |
| [removed: 10.1(2)] [added: 10.1(8)] | | [First [removed: Amendment, dated as of December 21, 2018,] [added: Amendment] to [removed: the Amended and Restated] Credit Agreement, dated as of April [removed: 25, 2016] [added: 29, 2020,] among the Company, [removed: the Administrative Agent] [added: Bank of America, N.A., as administrative agent,] and [removed: the other parties] [added: certain] lenders [added: party] thereto (incorporated by reference to Exhibit 10.1 [removed: to] [added: of] the Company’s [removed: Current] [added: Quarterly] Report on Form [removed: 8-K] [added: 10-Q] filed [removed: December 28, 2018).](http://www.sec.gov/Archives/edgar/data/789570/000119312518361057/d677417dex101.htm)] [added: on August 3, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000156459020035299/mgm-ex101_354.htm)] |
| [removed: 10.1(3)] [added: 10.1(9)] | | [removed: [Second Amendment, dated as of November 14, 2019, to the Amended and Restated] [added: [Revolving] Credit [added: Facility] Agreement, dated [removed: as of April 25, 2016] [added: August 12, 2019 (the “2019 Revolving Credit Facility”), by and] among [removed: MGM, the lenders from time to time] [added: MGM China Holdings Limited and certain Arrangers and Lenders] party thereto [removed: and the Administrative Agent] (incorporated by reference to Exhibit [removed: 10.4 to] [added: 10.1 of] the Company’s Current Report on Form 8-K filed on [removed: November 18, 2019).](http://www.sec.gov/Archives/edgar/data/789570/000119312519294790/d832650dex104.htm)] [added: August 13, 2019).](http://www.sec.gov/Archives/edgar/data/789570/000119312519220072/d764268dex101.htm)] |
| [removed: 10.1(4)] [added: 10.1(1)] | | [Credit Agreement, dated as of April 25, 2016, among MGM Growth Properties Operating Partnership LP, the financial institutions referred to as Lenders therein and Bank of America, N.A., as Administrative Agent (incorporated by reference to Exhibit 10.17 of the Current Report on Form 8-K of MGM Growth Properties LLC filed on April 25, 2016).](http://www.sec.gov/Archives/edgar/data/1656936/000119312516554368/d178144dex1017.htm) |
| [removed: 10.1(5)] [added: 10.1(2)] | | [First Amendment to Credit Agreement, dated October 26, 2016, among MGM Growth Properties Operating Partnership LP, the other loan parties and lenders named therein and Bank of America, N.A., as administrative agent (incorporated by reference to Exhibit 10.1 of the Current Report on Form 8-K of MGM Growth Properties LLC filed on October 26, 2016).](http://www.sec.gov/Archives/edgar/data/1656936/000119312516748022/d273419dex101.htm) |
| [removed: 10.1(6)] [added: 10.1(3)] | | [Second Amendment to Credit Agreement, dated May 1, 2017, among MGM Growth Properties Operating Partnership LP, the other loan parties and lenders named therein and Bank of America, N.A., as administrative agent (incorporated by reference to Exhibit 10.1 of the Current Report on Form 8-K of MGM Growth Properties LLC filed on May 1, 2017).](http://www.sec.gov/Archives/edgar/data/1656936/000119312517152109/d376024dex101.htm) |
| [removed: 10.1(7)] [added: 10.1(4)] | | [Third Amendment to Credit Agreement, dated March 23, 2018, among MGM Growth Properties Operating Partnership LP, the other loan parties and lenders named therein and Bank of America, N.A., as administrative agent (incorporated by reference to Exhibit 10.1 of the Current Report on Form 8-K of MGM Growth Properties LLC filed on March 26, 2018).](http://www.sec.gov/Archives/edgar/data/1656936/000119312518096093/d558827dex101.htm) |
| [removed: 10.1(8)] [added: 10.1(5)] | | [Fourth Amendment to Credit Agreement, dated June 14, 2018, among MGM Growth Properties Operating Partnership LP, the other loan parties and lenders named therein and Bank of America, N.A., as administrative agent (incorporated by reference to Exhibit 10.1 of the Current Report on Form 8-K of MGM Growth Properties LLC filed on June 18, 2018).](http://www.sec.gov/Archives/edgar/data/1656936/000119312518195756/d598380dex101.htm) |
| [removed: 10.1(9)] [added: 10.1(11)] | | [removed: [Sixth Supplemental] [added: [Amendment Letter to the 2019 Revolving Credit Facility] Agreement, dated April [removed: 15, 2019, between] [added: 9, 2020, by and among] MGM China Holdings [removed: Limited, MGM Grand Paradise (HK) Limited, Superemprego Limitada, MGM – Security Services, LTD.] [added: Limited] and [removed: Bank of America, N.A., as Facility Agent] [added: certain Arrangers and Lenders Party thereto] (incorporated by reference to Exhibit [removed: 10.1] [added: 10.3] of the Company’s Quarterly Report on Form 10-Q filed on August [removed: 8, 2019).](http://www.sec.gov/Archives/edgar/data/789570/000156459019030264/mgm-ex101_103.htm)] [added: 3, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000156459020035299/mgm-ex103_42.htm)] |
| 10.1(10) | | [removed: [Revolving] [added: [Amendment Letter to the 2019 Revolving] Credit Facility Agreement, dated [removed: August 12, 2019,] [added: February 18, 2020,] by and among MGM China Holdings Limited and certain Arrangers and Lenders [removed: party] [added: Party] thereto (incorporated by reference to Exhibit 10.1 of the Company’s [removed: Current] [added: Quarterly] Report on Form [removed: 8-K] [added: 10-Q] filed on [removed: August 13, 2019).](http://www.sec.gov/Archives/edgar/data/789570/000119312519220072/d764268dex101.htm)] [added: May 1, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000156459020020518/mgm-ex101_132.htm)] |
| [removed: 10.1(11)] [added: 10.1(16)] | | [Guaranty Agreement, dated as of November 15, 2019 (incorporated by reference to Exhibit 10.3 to the Company’s Current Report on Form 8-K filed on November 18, 2019).](http://www.sec.gov/Archives/edgar/data/789570/000119312519294790/d832650dex103.htm) |
| [removed: 10.4(7)] [added: 10.4(8)] | | [Lease, by and between BCORE Paradise LLC and Bellagio, LLC, dated as of November 15, 2019 (incorporated by reference to Exhibit 10.1 to the Company’s Current Report on Form 8-K filed on November 18, 2019).](http://www.sec.gov/Archives/edgar/data/789570/000119312519294790/d832650dex101.htm) |
| [removed: 10.4(8)] [added: 10.4(10)] | | [Tax Protection Agreement, by and among Bellagio, LLC, BCORE Paradise Parent LLC and BCORE Paradise JV LLC, dated as of November 15, 2019 (incorporated by reference to Exhibit 10.2 to the Company’s Current Report on Form 8-K filed on November 18, 2019).](http://www.sec.gov/Archives/edgar/data/789570/000119312519294790/d832650dex102.htm) |
| [removed: *10.5(11)] [added: *10.5(12)] | | [Employment Agreement, effective as of [removed: November 15, 2016,] [added: April 1, 2020, by and] between the Company and Corey Sanders (incorporated by reference to Exhibit 10.2 [removed: to the Company’s] [added: of MGM Resort International’s] Current Report on Form 8-K filed [added: with the Commission] on [removed: December 7, 2016).](http://www.sec.gov/Archives/edgar/data/789570/000119312516787475/d291794dex102.htm)] [added: March 31, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000156459020014548/mgm-ex102_11.htm)] |
| [removed: *10.5(12)] [added: *10.5(14)] | | [Employment Agreement, effective as of [removed: November 15, 2016,] [added: July 29, 2020, by and] between the Company and William Hornbuckle (incorporated by reference to Exhibit 10.1 of [removed: the Company’s] [added: MGM Resorts International’s] Current Report on Form 8-K filed [added: with the Commission] on [removed: December 7, 2016).](http://www.sec.gov/Archives/edgar/data/789570/000119312516787475/d291794dex101.htm)] [added: July 31, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000119312520206660/d25463dex101.htm)] |
| [removed: *10.5(13)] [added: *10.5(11)] | | [Employment Agreement, effective as of [removed: November 15, 2016,] [added: March 25, 2019,] between the Company and [removed: John McManus] [added: Atif Rafiq] (incorporated by [removed: references] [added: reference] to Exhibit 10.5(14) of the Company’s Annual Report on Form 10-K filed on February 27, [removed: 2019).](http://www.sec.gov/Archives/edgar/data/789570/000156459019004807/mgm-ex10514_592.htm)] [added: 2020).](http://www.sec.gov/Archives/edgar/data/789570/000156459020007393/mgm-ex10514_563.htm)] |
| [removed: *10.5(19)] [added: *10.5(23)] | | [Form of Performance Share Units Agreement of the Company, effective for bonus awards granted in March 2014 through March 2015 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q filed on May 8, 2014).](http://www.sec.gov/Archives/edgar/data/789570/000119312514187861/d704515dex101.htm) |
| [removed: *10.5(20)] [added: *10.5(24)] | | [Form of Performance Share Units Agreement of the Company effective for awards granted in October 2015 and thereafter (incorporated by reference to Exhibit 10.6 to the Company’s Quarterly Report on Form 10-Q filed on November 6, 2015).](http://www.sec.gov/Archives/edgar/data/789570/000156459015009822/mgm-ex106_98.htm) |
| Years Ended December 31, 2020, 2019 and 2018 | | |
| 2.2 | | [Master Transaction Agreement by and among MGM Resorts International, MGM Growth Properties Operating Partnership LP and BCORE Windmill Parent LLC, and, solely with respect to certain sections therein, MGM Growth Properties LLC, dated as of January 14, 2020 (incorporated by reference to Exhibit 2.1 of MGM Resort International’s Current Report on Form 8-K filed with the Commission on January 14, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000119312520007281/d866492dex21.htm) |
| 4.1(10) | | [Eighth Supplemental Indenture, dated May 4, 2020, among MGM Resorts International, the guarantors named therein and U.S. Bank National Association, as trustee, to the Indenture, dated as of March 22, 2012, among MGM Resorts International and U.S. Bank National Association, as trustee, relating to the 6.750% senior notes due 2025 (incorporated by reference to Exhibit 4.1 of the Company’s Current Report on Form 8-K filed with the Commission on May 4, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000119312520132417/d924955dex41.htm) |
| 4.1(11) | | [Ninth Supplemental Indenture, dated October 13, 2020, among MGM Resorts International, the guarantors named therein and U.S. Bank National Association, as trustee, to the Indenture, dated as of March 22, 2012, among MGM Resorts International and U.S. Bank National Association, as trustee, relating to the 4.750% senior notes due 2028 (incorporated by reference to Exhibit 4.1 of the Company’s Current Report on Form 8-K filed with the Commission on October 13, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000119312520268537/d205040dex41.htm) |
| 4.1(22) | | [Indenture, dated as of June 5, 2020, among MGM Growth Properties Operating Partnership LP, MGP Finance Co-Issuer, Inc., the subsidiary guarantors party thereto and U.S. Bank National Association, as trustee (incorporated by reference to Exhibit 4.1 of the Current Report on Form 8-K of MGM Growth Properties LLC and MGM Growth Properties Operating Partnership LP filed on June 5, 2020).](http://www.sec.gov/Archives/edgar/data/1656936/000119312520162252/d927045dex41.htm) |
| 4.1(23) | | [Indenture governing the 5.25% senior notes due 2025, dated as of June 18. 2020, between MGM China Holdings Limited and Wilmington Savings Fund Society, FSB, as trustee (incorporated by reference to Exhibit 4.1 of MGM Resorts International’s Current Report on Form 8-K filed with the Commission on June 22, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000156459020030137/mgm-ex41_6.htm) |
| 4.1(24) | | [Indenture, dated as of November 19, 2020, among MGM Growth Properties Operating Partnership LP, MGP Finance Co-Issuer, Inc., the subsidiary guarantors party thereto and U.S. Bank National Association, as trustee (incorporated by reference to Exhibit 4.1 of the Current Report on Form 8-K of MGM Growth Properties LLC and MGM Growth Properties Operating Partnership LP filed on November 20, 2020).](http://www.sec.gov/Archives/edgar/data/1656936/000119312520299440/d95985dex41.htm) |
| 10.1(6) | | [Fifth Amendment to Credit Agreement, dated as of February 14, 2020, among MGM Growth Properties Operating Partnership LP, the other loan parties and lenders named therein and Bank of America, N.A., as administrative agent (incorporated by reference to Exhibit 10.5 of MGM Growth Properties LLC Current Report on Form 8-K filed with the Commission on February 18, 2020).](http://www.sec.gov/Archives/edgar/data/1656936/000119312520040600/d850473dex105.htm) |
| 10.1(12) | | [Revolving Credit Facility Agreement, dated May 26, 2020 (the “2020” Revolving Credit Facility”), by and among MGM China Holdings Limited and certain Lenders party thereto (incorporated by reference to Exhibit 10.1 of MGM Resorts International’s Current Report on Form 8-K filed with the Commission on May 29, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000119312520155922/d893837dex101.htm) |
| 10.1(13) | | [Increase Confirmation to 2020 Revolving Credit Facility dated as of June 29, 2020 between the Increase Lender and the Facility Agent.](https://www.sec.gov/Archives/edgar/data/789570/000156459021009205/mgm-ex10_202.htm) |
| 10.1(14) | | [Amendment Letter to the 2019 Revolving Credit Facility, dated October 5, 2020, by and among MGM China Holdings Limited and certain Arrangers and Lenders Party thereto.](https://www.sec.gov/Archives/edgar/data/789570/000156459021009205/mgm-ex10_16.htm) |
| 10.1(15) | | [Amendment Letter to the 2020 Revolving Credit Facility, dated October 5, 2020, by and among MGM China Holdings Limited and certain Arrangers and Lenders Party thereto.](https://www.sec.gov/Archives/edgar/data/789570/000156459021009205/mgm-ex10_7.htm) |
| 10.1(17) | | [Guaranty Agreement, dated as of February 14, 2020 (incorporated by reference to Exhibit 10.2 of the Company’s Quarterly Report on Form 10-Q filed on May 1, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000156459020020518/mgm-ex102_131.htm) |
| 10.4(7) | | [Sixth Amendment to Master Lease, by and between MGP Lessor, LLC and MGP Lessee, LLC, dated as of February 14, 2020 (incorporated by reference to Exhibit 10.2 of MGM Resort International’s Current Report on Form 8-K filed with the Commission on February 18, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000119312520040601/d882756dex102.htm) |
| 10.4(9) | | [Lease, by and between Mandalay PropCo, LLC, MGM Grand PropCo, LLC and MGM Lessee II, LLC, dated as of February 14, 2020 (incorporated by reference to Exhibit 10.1 of MGM Resort International’s Current Report on Form 8-K filed with the Commission on February 18, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000119312520040601/d882756dex101.htm) |
| 10.4(11) | | [Tax Protection Agreement, by and among MGM Resorts International, MGM Growth Properties Operating Partnership LP and MGP BREIT Venture 1 LLC, dated as of February 14, 2020 (incorporated by reference to Exhibit 10.3 of MGM Resort International’s Current Report on Form 8-K filed with the Commission on February 18, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000119312520040601/d882756dex103.htm) |
| *10.5(19) | | [Form of RSU Agreement (Named Executive Officer Employment Agreement Awards) (incorporated by reference to Exhibit 10.4 of MGM Resort International’s Current Report on Form 8-K filed with the Commission on March 31, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000156459020014548/mgm-ex104_8.htm) |
| *10.5(20) | | [Form of RSU Agreement (Hornbuckle) (incorporated by reference to Exhibit 10.5 of MGM Resort International’s Current Report on Form 8-K filed with the Commission on March 31, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000156459020014548/mgm-ex105_7.htm) |
| *10.5(21) | | [Form of RSU Agreement (Equity Election Program) (incorporated by reference to Exhibit 10.14 of the Company’s Quarterly Report on Form 10-Q filed on May 1, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000156459020020518/mgm-ex1014_129.htm) |
| *10.5(22) | | [Form of RSU Agreement (Director Equity Election Program) (incorporated by reference to Exhibit 10.15 of the Company’s Quarterly Report on Form 10-Q filed on May 1, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000156459020020518/mgm-ex1015_130.htm) |
| | | |
| --- | --- | --- |
| *10.5(48) | | [CEO Transition Agreement, between MGM Resorts International and James J. Murren, dated February 11, 2020 (incorporated by reference to Exhibit 10.1 of MGM Resort International’s Current Report on Form 8-K filed with the Commission on February 14, 2020).](http://www.sec.gov/Archives/edgar/data/789570/000119312520038441/d870226dex101.htm) |
| 22 | | [Subsidiary Guarantors.](https://www.sec.gov/Archives/edgar/data/789570/000156459021009205/mgm-ex22_6.htm) |
| *10.5(14) | | [Employment Agreement, effective as of March 25, 2019, between the Company and Atif Rafiq.](https://www.sec.gov/Archives/edgar/data/789570/000156459020007393/mgm-ex10514_563.htm) |
| *10.5(24) | | [Form of Freestanding Stock Appreciation Right Agreement of the Company effective for awards granted in October 2013 and thereafter (incorporated by reference to Exhibit 10.4(43) of the Company’s Annual Report on Form 10-K for the year ended December 31, 2013).](http://www.sec.gov/Archives/edgar/data/789570/000119312514078072/d656757dex10443.htm) |
| *10.5(25) | | [Amendment to all Stock Appreciation Right Agreements adopted by the Compensation Committee of the Board of Directors on October 7, 2013 (incorporated by reference to Exhibit 10.4(44) of the Company’s Annual Report on Form 10-K for the year ended December 31, 2013).](http://www.sec.gov/Archives/edgar/data/789570/000119312514078072/d656757dex10444.htm) |
An excerpt. Shown here: 40 of 72 rewritten, all 24 added and all 3 removed. The counts are complete. For every sentence, read Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES in the FY2020 filing and the FY2019 filing.
Item 16. FORM 10-K SUMMARY
14 rewritten, 12 added, 7 removed, 22 unchanged
| | | [removed: Chairman of the Board and] Chief Executive Officer [added: and President] |
Dated: February [removed: 27, 2020][added: 26, 2021]
| /s/ [removed: Corey I. Sanders] [added: Jonathan S. Halkyard] | | Chief Financial Officer and Treasurer (Principal Financial Officer) | | February [removed: 27, 2020] [added: 26, 2021] |
| /s/ [removed: Robert C. Selwood] [added: Todd R. Meinert] | | [removed: Executive] [added: Senior] Vice President and Chief Accounting Officer (Principal Accounting Officer) | | February [removed: 27, 2020] [added: 26, 2021] |
| /s/ Mary Chris Jammet | | Director | | February [removed: 27, 2020] [added: 26, 2021] |
| /s/ William W. Grounds | | Director | | February [removed: 27, 2020] [added: 26, 2021] |
| /s/ Alexis M. Herman | | Director | | February [removed: 27, 2020] [added: 26, 2021] |
| /s/ Roland Hernandez | | Director | | February [removed: 27, 2020] [added: 26, 2021] |
| /s/ John B. Kilroy, Jr. | | Director | | February [removed: 27, 2020] [added: 26, 2021] |
| /s/ Rose McKinney-James | | Director | | February [removed: 27, 2020] [added: 26, 2021] |
| /s/ Keith A. Meister | | Director | | February [removed: 27, 2020] [added: 26, 2021] |
| /s/ Gregory M. Spierkel | | Director | | February [removed: 27, 2020] [added: 26, 2021] |
| /s/ Jan Swartz | | Director | | February [removed: 27, 2020] [added: 26, 2021] |
| /s/ Daniel J. Taylor | | Director | | February [removed: 27, 2020] [added: 26, 2021] |
| By: | | /s/ WILLIAM J. HORNBUCKLE |
| | | William J. Hornbuckle |
| /s/ William J. Hornbuckle | | Chief Executive Officer and President (Principal Executive Officer) | | February 26, 2021 |
| William J. Hornbuckle | | | | |
| Jonathan S. Halkyard | | | | |
| Todd R. Meinert | | | | |
| /s/ Paul Salem | | Chairman of the Board | | February 26, 2021 |
| /s/ Barry Diller | | Director | | February 26, 2021 |
| Barry Diller | | | | |
| Signature | | Title | | Date |
| /s/ Joey Levin | | Director | | February 26, 2021 |
| Joey Levin | | | | |
| By: | | /s/ JAMES J. MURREN |
| | | James J. Murren |
| /s/ James J. Murren | | Chairman of the Board and Chief Executive Officer (Principal Executive Officer) | | February 27, 2020 |
| James J. Murren | | | | |
| Corey I. Sanders | | | | |
| Robert C. Selwood | | | | |
| /s/ Paul Salem | | Director | | February 27, 2020 |