 filings.tools
Martin Marietta Materials 10-K 2022-12-31
Filed 2023-02-24. 22 sections, 550K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
c9
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 10-K
**(**Mark One)
☒ ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended December 31, 2022
OR
☐ TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the transition period from to
Commission file number 1-12744
MARTIN MARIETTA MATERIALS, INC.
(Exact name of registrant as specified in its charter)
| North Carolina | 56-1848578 | |
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | |
| 4123 Parklake Avenue**,** Raleigh**,** North Carolina | 27612 | |
| (Address of principal executive offices) | (Zip Code) |
(919) 781-4550
(Registrant’s telephone number, including area code)
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||
| Common Stock (par value $.01 per share) | MLM | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Exchange Act. Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☒ | Accelerated filer | ☐ |
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ |
| Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☒
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements. ☐
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b). ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ☐ No ☒
As of June 30, 2022, the last business day of the registrant’s most recently completed second fiscal quarter, the aggregate market value of the registrant’s common stock held by non-affiliates of the registrant was **$**16,524,714,169 based on the closing sale price as reported on the New York Stock Exchange.
Indicate the number of shares outstanding of each of the issuer’s classes of common stock on the latest practicable date.
| Class | Outstanding at February 17, 2023 | |
| Common Stock, $.01 par value per share | 62,103,551 shares |
DOCUMENTS INCORPORATED BY REFERENCE
| Document | Parts Into Which Incorporated | |
| Proxy Statement for the Annual Meeting of Shareholders to be held May 11, 2023 (Proxy Statement) | Part III | |
| Auditor Firm Id: | 238 | Auditor Name: | PricewaterhouseCoopers LLP | Auditor Location: | Raleigh, North Carolina, United States |
TABLE OF CONTENTS
| PART IV | 116 | |
| ITEM 15. | EXHIBITS AND FINANCIAL STATEMENT SCHEDULES | 116 |
| ITEM 16. | FORM 10-K SUMMARY | 122 |
| SIGNATURES | 123 |
Part I ♦ Item 1 – Business
PART I
Item 1. BUSINESS
General
Martin Marietta Materials, Inc. (the Company or Martin Marietta) is a natural resource-based building materials company. The Company supplies aggregates (crushed stone, sand and gravel) through its network of approximately 350 quarries, mines and distribution yards in 28 states, Canada and The Bahamas. In 2022, aggregates product gross profit accounted for 69% of the Company’s consolidated total products and services gross profit. Martin Marietta also provides cement and downstream products, namely, ready mixed concrete, asphalt and paving services, in markets that are naturally vertically integrated and where the Company has a leading aggregates position. The Company’s heavy-side building materials are used in infrastructure, nonresidential and residential construction projects. Aggregates are also used in agricultural, utility and environmental applications and as railroad ballast. The aggregates, cement, ready mixed concrete and asphalt and paving operations are reported collectively as the “Building Materials business”. The Company also operates a Magnesia Specialties business with production facilities in Michigan and Ohio. The Magnesia Specialties business produces magnesia-based chemical products that are used in industrial, agricultural and environmental applications. It also produces dolomitic lime sold primarily to customers for steel production and soil stabilization. Magnesia Specialties’ products are shipped to customers domestically and worldwide.
On April 30, 2021, the Company acquired Tiller Corporation (Tiller), a leading aggregates and hot mix asphalt supplier in the Minneapolis/St. Paul area, a large and fast-growing midwestern metropolitan area. The Tiller acquisition complemented the Company’s existing product offerings in the surrounding areas. Additionally, Tiller sells asphalt solely as a materials provider and does not offer paving or other associated services. Tiller is reported in the Company’s East Group.
On July 30, 2021, the Company acquired assets of Southern Crushed Concrete (SCC). SCC was a leading producer of recycled concrete in the Houston area, one of the country’s largest aggregates markets. Recycled concrete is principally used as a base aggregates product in infrastructure, commercial and residential construction applications. SCC is reported in the Company’s West Group.
On October 1, 2021, the Company acquired the Lehigh Hanson West Region business (Lehigh West Region) for $2.26 billion in cash. The acquisition included a portfolio of 17 active aggregates quarries, two cement plants with related distribution terminals, and targeted downstream operations in California, Arizona, Nevada and Oregon. These operations provided a new upstream, materials-led growth platform across several of the nation’s largest megaregions in California and Arizona, solidifying the Company’s position as a leading coast-to-coast aggregates producer. The acquired cement plants, distribution terminals and California ready mixed concrete operations are classified as assets held for sale and discontinued operations as of and for the years ended December 31, 2022 and 2021. The Lehigh West Region business is reported in the Company’s West Group.
On April 1, 2022, the Company divested its Colorado and Central Texas ready mixed concrete operations to Smyrna Ready Mix Concrete LLC. This transaction optimized the Company’s aggregates-led portfolio and improved its ability to generate more attractive margins over the long term by reducing both business cyclicality and exposure to raw material cost inflation. The transaction resulted in a pretax gain of $151.9 million, inclusive of expenses incurred due to the divestiture. The divested operations and the gain on divestiture are all reported in the West Group in the Company's consolidated financial statements included in Item 8.
On June 30, 2022, the Company divested the Redding, California cement plant, related cement distribution terminals and 14 California ready mix operations for $235.0 million in cash. In addition, on July 15, 2022, the Company sold its interest in a joint venture that operates a cement distribution terminal for $15.0 million. These assets were acquired in connection with the acquisition of the Lehigh West Region business in 2021.
On August 9, 2022, the Company announced a definitive agreement to sell the Tehachapi, California cement plant and related distribution terminals for $350.0 million in cash, subject to regulatory approval and customary closing conditions. These assets were acquired in connection with the acquisition of the Lehigh West Region.
FOR FURTHER INFORMATION WITH RESPECT TO THE DEVELOPMENT OF THE COMPANY’S BUSINESS PRIOR TO 2021, SEE THE INFORMATION APPEARING UNDER THE HEADING “GENERAL” INCLUDED IN PART I, ITEM 1 OF THE COMPANY’S FORM 10-K FOR THE YEAR ENDED DECEMBER 31, 2019, WHICH INFORMATION IS INCORPORATED BY REFERENCE.
| Form 10-K ♦ Page 1 |  |
Part I ♦ Item 1 – Business
Business Segment Information
The Company conducts its Building Materials business through two reportable segments, organized by geography: East Group and West Group. The East Group provides aggregates and asphalt products. The West Group provides aggregates, cement, downstream products and paving services. The ten largest revenue-generating states accounted for 83% of the Building Materials business' total revenues in 2022: Texas, Colorado, North Carolina, Minnesota, California, Georgia, Arizona, Iowa, Florida and Indiana. The Company’s Magnesia Specialties business is reported as a separate segment, which includes its magnesia-based chemicals and dolomitic lime businesses. For more information on the organization and geographic area of the Company’s business segments, see “Note A: Accounting Policies” and “Note P: Segments” of the “Notes to Financial Statements” of the Company’s consolidated financial statements, which appear in Item 8, “Financial Statements and Supplementary Data,” of this Annual Report on Form 10-K (this Form 10-K), which information is incorporated by reference.
Building Materials Business
The profitability of the Building Materials business, which serves customers in the construction marketplace, is sensitive to national, regional and local economic conditions and construction cyclicality, which are in turn affected by fluctuations in levels of public-sector infrastructure funding; interest rates; access to capital markets; and demographic, geographic, employment and population dynamics. The heavy-side construction business is conducted outdoors, as are much of the Building Materials business’s operations. Therefore, erratic weather patterns, seasonal changes, and other weather-related conditions, including precipitation, flooding, hurricanes, snowstorms, extreme temperatures, wildfires, earthquakes and droughts, can significantly affect production schedules, shipments, costs, efficiencies and profitability. Generally, the financial results for the first and fourth quarters are subject to the impacts of winter weather, while the second and third quarters are subject to the impacts of heavy precipitation.
The Building Materials business markets its products primarily to the construction industry, with 35% of its 2022 aggregates shipments sold to contractors in connection with highway and other public infrastructure projects and the balance of its shipments sold primarily to contractors for nonresidential and residential construction projects. The Company believes the business’ mix of public sector-related shipments lessens the impacts of fluctuations in nonresidential and residential, or p
Showing the first 8K of 136K characters. Open the full section
Item 1B. UNRESOLVED STAFF COMMENTS
There are no unresolved written comments that were received from the staff of the SEC one hundred and eighty (180) days or more before the end of the Company's fiscal year relating to its periodic or current reports under the Exchange Act.
| Form 10-K ♦ Page 26 | |
Part I ♦ Item 2 – Properties
Item 2. PROPERTIES
Building Materials Business
As of December 31, 2022, the Company processed or shipped aggregates from 344 quarries, mines and distribution terminals in 28 states, Canada and The Bahamas. No individual quarry or mine is material to the Company’s business or financial condition. The Company’s aggregates reserves, on average, represent approximately 75 years at the 2022 annual production level. However, certain locations may be subject to more limited reserves and may not be able to expand. As of December 31, 2022, the Company operated 78 aggregates distribution terminals. In total, aggregates locations (quarries, mines and distribution terminals) include 154 located on land owned by the Company free of major encumbrances, 63 on land owned in part and leased in part, 114 on leased land, and 13 on facilities neither owned nor leased where raw materials are removed under an agreement. In addition, as of December 31, 2022, the Company processed and shipped ready mixed concrete and asphalt products from 132 properties in five states, of which 98 are located on land owned by the Company free of major encumbrances, 3 are on land owned in part and leased in part, 28 are on leased land and 3 are at facilities neither owned nor leased.
An overview of the Company’s quarrying and mining operations is included in “Business—Building Materials Business” and “Business—Environmental and Governmental Regulations,” included in Item 1, “Business” of this Form 10-K, which is incorporated herein by reference. The following map presents the locations of these quarries and underground mines, including the limestone reserves adjacent to the California cement plant that is classified as held for sale:

Mineral reserves and mineral resources for the Company’s aggregates and cement businesses have been prepared in accordance with the disclosure requirements of subpart 1300 of U.S. Securities and Exchange Commission Regulation S-K. Mineral resources represent concentrations or occurrences of material of economic interest in or on the Earth's crust in such form, grade or quality, and quantity that there are reasonable prospects for economic extraction. A mineral resource is a reasonable estimate of mineralization, taking into account relevant factors such as cut-off grade, likely mining dimensions, location or continuity, that, with the assumed and justifiable technical and economic conditions, is likely to, in whole or in part, become economically extractable. A measured mineral resource is that part of the mineral resource for which quantity and grade or quality are estimated on the basis of conclusive geological evidence and sampling in sufficient detail to support detailed extraction planning and final evaluation of the economic viability of the deposit to be quarried or mined. An indicated mineral resource is that part of a mineral resource for which quantity and grade or quality are estimated on the basis of
| Form 10-K ♦ Page 27 | |
Part I ♦ Item 2 – Properties
adequate geological evidence and sampling in sufficient detail to support mine planning and evaluation of the economic viability of the deposit of the material to be quarried or mined. Inferred mineral resources are that part of a mineral resource for which quantity and grade or quality are estimated on the basis of limited geological evidence and sampling. The Company has no inferred resources as of December 31, 2022.
A mineral reserve is an estimate of tonnage and grade or quality of indicated and measured mineral resources that, in the opinion of the qualified person, can be the basis of an economically viable project. More specifically, it is the economically mineable part of a measured or indicated mineral resource, which includes diluting materials and allowances for losses that may occur when the material is mined or extracted. A probable mineral reserve is the economically mineable part of an indicated and, in some cases, a measured mineral resource. A proven mineral reserve is the economically mineable part of a measured mineral resource and can only result from the conversion of a measured mineral resource. The Company estimates proven and probable mineral reserves based on the results of drilling and testing completed by or under the supervision of qualified persons.
The Company uses various exploratory drilling methods, depending on the type of deposit, to estimate mineral reserves that are economically mineable. The extent of drilling varies depending on the complexity of the mineral deposit and whether the location is a potential new site (greensite), an existing location or a potential acquisition. More extensive drilling is performed for potential greensites and acquisitions, and, in rare cases, the Company may rely on existing geological data or results of prior drilling by reputable third parties. Subsequent to drilling, selected drill samples are tested by an accredited laboratory for soundness, abrasion resistance and other physical properties relevant to the aggregates industry. If the mineral reserves meet the Company’s standards and are economically mineable, they are either leased or purchased. Once in operation, routine quality control testing is performed to ensure the quality grade of aggregates continues to meet specifications.
In determining the amount of reserves, evaluations are completed by or under the supervision of qualified Company personnel using industry best practices and internal controls defined by the Company. Reserve estimates represent net tons after consideration of applicable losses incurred during mining and plant processing. The Company’s policy is to exclude from reserve estimates the portions of a mineral deposit that are not available due to property boundaries, set-backs and plant configurations, as deemed appropriate when estimating reserves. The Company uses the same methods of analysis to evaluate and estimate the amount of its mineral reserves used in the cement manufacturing process for its cement operations as it does for its aggregates operations. For additional information on the Company’s assessment of reserves, see “Management’s Discussion and Analysis of Financial Condition and Results of Operations – Other Financial Information - Critical Accounting Policies and Estimates - Property, Plant and Equipment” included under Item 7, “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” of this Form 10-K. While the mineral reserve and resource classification categories (proven and probable) identify relative confidence of reserve estimates, there is inherent risk associated with such estimates. The Company bases estimates on the information known at the time of determination and regularly reevaluates reserves whenever new information indicates a material change in reserves at one of the Company’s sites.
In general, quarry and mining facilities must comply with air quality, water quality, noise regulations, zoning and special-use permitting requirements, applicable mining regulations, and federal health and safety requirements. As new quarry and mining sites are located and acquired, the Company works closely with local authorities during the zoning and permitting processes to design new quarries and mines in such a way as to minimize disturbances. The Company frequently acquires large tracts of land so that quarry, mine and production facilities can be situated substantial distances from surrounding property owners.
Set forth in the tables below are the Company’s estimates as of December 31, 2022 of proven and probable mineral reserves of aggregates (crushed stone and sand and gravel) and measured, indicated and inferred mineral resources of aggregates (exclusive of proven and probable reserves), shown on a geographic division basis. The East Division includes Alabama, Florida, Georgia, Maryland, North Carolina, Pennsylvania, South Carolina, Tennessee, Virginia, Canada and The Bahamas. The Central Division includes Indiana, Iowa, Kansas, Kentucky, Minnesota, Missouri, Nebraska, Ohio and West Virginia. The Southwest Division includes Arkansas, Louisiana, Oklahoma and Texas. The West Division includes Arizona, California, Colorado, Utah, Washington and Wyoming. The reserve estimates shown were determined to be economically mineable using a reasonable and justifiable price for salable product as of December 31, 2021 with respect to each division for each product category of aggregates resources. The Company’s estimate of resources and reserves of aggregates shown in the tables below includes resources and reserves that would be devoted for use in the Company’s cement product line and Magnesia Specialties business.
| Form 10-K ♦ Page 28 | |
Part I ♦ Item 2 – Properties
| Summary Mineral Resources At End of Fiscal Year Ended December 31, 2022****1,2 | ||||||||||||||||
| Measured Mineral Resources | Indicated Mineral Resources | Measured + Indicated Mineral Resources | Inferred Mineral Resources | |||||||||||||
| Tons (in thousands) | Grades/Qualities | Tons (in thousands) | Grades/Qualities | Tons (in thousands) | Grades/Qualities | Tons (in thousands) | Grades/Qualities | |||||||||
| Crushed Stone | ||||||||||||||||
| East Division | 144,299 | Crushed Stone | 30,584 | Crushed Stone | 174,883 | Crushed Stone | — | Crushed Stone | ||||||||
| Central Division | — | Crushed Stone | 22,730 | Crushed Stone | 22,730 | Crushed Stone | — | Crushed Stone | ||||||||
| Southwest Division | — | Crushed Stone | — | Crushed Stone | — | Crushed Stone | — | Crushed Stone | ||||||||
| West Division | 61,320 | Crushed Stone | 152,137 | Crushed Stone | 213,457 | Crushed Stone | — | Crushed Stone | ||||||||
| Total crushed stone | 205,619 | 205,451 | 411,070 | — | ||||||||||||
| Sand and Gravel | ||||||||||||||||
| East Division | — | Sand & Gravel | — | Sand & Gravel | — | Sand & Gravel | — | Sand & Gravel | ||||||||
| Central Division | 1,102 | Sand & Gravel | 35,390 | Sand & Gravel | 36,492 | Sand & Gravel | — | Sand & Gravel | ||||||||
| Southwest Division | — | Sand & Gravel | — | Sand & Gravel | — | Sand & Gravel | — | Sand & Gravel | ||||||||
| West Division | 59,839 | Sand & Gravel | 143,191 | Sand & Gravel | 203,030 | Sand & Gravel | — | Sand & Gravel | ||||||||
| Total sand and gravel | 60,941 | 178,581 | 239,522 | — |
| Summary Mineral Reserves****At End of Fiscal Year Ended December 31, 2022 1,2 | ||||||||||||
| Proven Mineral Reserves | Probable Mineral Reserves | Total Mineral Reserves | ||||||||||
| Tons (in thousands) | Grades/Qualities | Tons (in thousands) | Grades/Qualities | Tons (in thousands) | Grades/Qualities | |||||||
| Crushed Stone | ||||||||||||
| East Division | 4,608,483 | Crushed Stone | 3,643,381 | Crushed Stone | 8,251,864 | Crushed Stone | ||||||
| Central Division | 1,472,296 | Crushed Stone | 1,418,537 | Crushed Stone | 2,890,833 | Crushed Stone | ||||||
| Southwest Division | 2,253,444 | Crushed Stone | 1,711,836 | Crushed Stone | 3,965,280 | Crushed Stone | ||||||
| West Division | 351,196 | Crushed Stone | 600,000 | Crushed Stone | 951,196 | Crushed Stone | ||||||
| Total crushed stone | 8,685,419 | 7,373,754 | 16,059,173 | |||||||||
| Sand and Gravel | ||||||||||||
| East Division | 63,500 | Sand and Gravel | 110,046 | Sand and Gravel | 173,546 | Sand and Gravel | ||||||
| Central Division | 226,350 | Sand and Gravel | 69,562 | Sand and Gravel | 295,912 | Sand and Gravel | ||||||
| Southwest Division | 55,196 | Sand and Gravel | 80,557 | Sand and Gravel | 135,753 | Sand and Gravel | ||||||
| West Division | 170,288 | Sand and Gravel | 41,436 | Sand and Gravel | 211,724 | Sand and Gravel | ||||||
| Total sand and gravel | 515,334 | 301,601 | 816,935 |
The tons presented were determined to be economically mineable using the 2021 average selling price per ton for that product category in that geographic division. There is a range of selling prices for each product category and each geography that depend on the type of product, whether it is washed or not, and its end use. The average selling price per ton used for crushed stone for the East Division, Central Division, Southwest Division and West Division was $15.65, $14.08, $10.46 and $11.53, respectively. The average selling price per ton used for sand and gravel for the East Division, Central Division, Southwest Division and West Division was $10.66, $10.73, $13.28 and $13.52, respectively. These prices exclude any portion of revenues allocated to freight, including internal freight to ship products from a producing quarry to a distribution terminal and third-party freight to deliver product to a customer.
For the purposes of this table, the Company calculates its mineral reserves based on land that has been zoned for quarrying and land for which the Company has determined zoning is not required. The Company's reserves presented in the Central Division include dolomitic limestone reserves used in the Magnesia Specialties business. The Company's reserves presented in the Southwest Division and the West Division include limestone reserves used in the business of the cement product line.
The following presents the Company’s total annual production for the last three years, shown on a product line-by-product line basis.
| **Total Annual Production (tons in millions)**For year ended December 31 | ||||||||||||
| 2022 | 2021 | 2020 | ||||||||||
| Aggregates | 214.5 | 199.6 | 191.2 | |||||||||
| Cement limestone | 6.6 | 5.4 | 5.1 | |||||||||
| Magnesia Specialties limestone | 2.9 | 3.0 | 2.8 | |||||||||
| Total | 224.0 | 208.0 | 199.1 |
Cement
As of December 31, 2022, the Company processed or shipped cement from 14 properties in two states, of which 7 are located on land owned by the Company free of major encumbrances, 1 is located on land owned in part and leased in part and 6 are
| Form 10-K ♦ Page 29 | |
Part I ♦ Item 2 – Properties
on leased land. The Company’s cement operations have production facilities located at three sites: Midlothian, Texas, south of Dallas/Fort Worth; Hunter, Texas, north of San Antonio; and Tehachapi, California. Tehachapi was acquired on October 1, 2021 in connection with the Lehigh Hanson West Region acquisition and is classified as held for sale as of December 31, 2022. The following table summarizes certain information about the Company’s cement manufacturing facilities at December 31, 2022:
| Plant | Rated Annual Productive Capacity-Tons of Clinker (in millions) | Manufacturing Process | Service Date | Internally Estimated Reserves—Years | ||||
| Midlothian, TX | 2.4 | Dry | 2001 | 60 | ||||
| Hunter, TX | 2.1 | Dry | 2013, 1981 | 140 | ||||
| Tehachapi, CA | 0.9 | Dry | 2018, 1990, 1908 | 30 | ||||
| Total | 5.4 |
Reserves identified with the facilities shown above are contained on approximately 3,000 acres of land owned by the Company. As of December 31, 2022, the Company estimated its total proven and probable limestone reserves on such land to be approximately 717 million tons, which are included in the Summary Mineral Reserves table.
The Company’s cement manufacturing facilities include kilns, crushers, pre-heaters/calciners, coolers, finish mills and other equipment used to process limestone and other raw materials into cement, as well as equipment used to extract and transport the limestone from the adjacent quarries. These cement manufacturing facilities are served by rail and truck.
As of December 31, 2022, the Company also operated, directly or through third parties, 11 cement distribution terminals, of which six are classified as assets held for sale.
Magnesia Specialties Business
The Magnesia Specialties business currently operates major manufacturing facilities in Manistee, Michigan, and Woodville, Ohio. Both of these facilities are owned.
Other Properties
The Company’s principal corporate office, which it leases, is located in Raleigh, North Carolina. The Company owns and leases various administrative offices for its five operating business segments.
Condition and Utilization
The Company’s principal properties, which are of varying ages and construction types, are believed to be generally in good condition, are generally well maintained, and are generally suitable and adequate for the purposes for which they are used.
During 2022, the principal properties of the aggregates operations were believed to be utilized at average productive capacities of approximately 75% and were capable of supporting a higher level of market demand. The Company adjusts its production schedules to meet volume demand for its products.
During 2022, the Texas cement kilns operated on average at 77% utilization. The Portland Cement Association (PCA) has projected that Texas cement consumption will increase 2.0% in 2023 over 2022. The cement business’ leadership, in collaboration with the aggregates and ready mixed concrete teams, has developed strategic plans regarding inter-plant efficiencies, as well as tactical plans addressing plant utilization and efficiency.
The Company’s Magnesia Specialties business expects future organic earnings growth to result from increased pricing, product mix optimization, capacity expansion projects and/or cost reductions. In the current operating environment, where steel utilization is between 72% and 77%, any unplanned change in costs or customers introduces volatility to the earnings of the Magnesia Specialties segment. The dolomitic lime business of the Magnesia Specialties segment operated at 77% utilization in 2022.
| Form 10-K ♦ Page 30 | |
♦ Information About Our Executive Officers
Item 3. LEGAL PROCEEDINGS
From time to time, claims of various types are asserted against the Company arising out of its operations in the normal course of business, including claims relating to land use and permits, safety, health, and environmental matters (such as noise abatement, blasting, vibrations, air emissions, and water discharges). Such matters are subject to many uncertainties, and it is not possible to determine the probable outcome of, or the amount of liability, if any, from these matters. In the opinion of management of the Company (which opinion is based in part upon consideration of the opinion of counsel), based upon currently-available facts, it is remote that the ultimate outcome of any litigation and other proceedings will have a material adverse effect on the overall results of the Company's operations, its cash flows or its financial condition. However, management cannot assure that an adverse outcome in any of such litigation would not have a material adverse effect on the Company or its operating segments.
The Company was not required to pay any penalties in 2022 for failure to disclose certain “reportable transactions” under Section 6707A of the Internal Revenue Code.
See also “Note O: Commitments and Contingencies” of the “Notes to Financial Statements” of the Company’s consolidated financial statements included under Item 8, “Financial Statements and Supplemental Data,” of this Form 10-K and the “Environmental Regulation and Litigation” section included under Item 7, “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” of this Form 10-K.
Item 4. MINE SAFETY DISCLOSURES
The information concerning mine safety violations or other regulatory matters required by Section 1503(a) of the Dodd-Frank Wall Street Reform and Consumer Protection Act and Item 104 of Regulation S-K (17 CFR 229.104) is included in Exhibit 95 to this Form 10-K.
In****formation about our Executive Officers
The following sets forth certain information regarding the executive officers of Martin Marietta as of February 24, 2023:
| Name | Age | Present Position | Year Assumed Present Position | Other Positions and Other Business Experience Within the Last Five Years |
| C. Howard Nye | 60 | Chairman of the Board; | 2014 | |
| Chief Executive Officer; | 2010 | |||
| President; | 2006 | |||
| President of Aggregates Business; | 2010 | |||
| Chairman of Magnesia Specialties Business | 2007 | |||
| James A. J. Nickolas | 52 | Senior Vice President, Chief Financial Officer | 2017 | Principal Accounting Officer (2019) |
| Roselyn R. Bar | 64 | Executive Vice President; | 2015 | |
| General Counsel; | 2001 | |||
| Corporate Secretary | 1997 | |||
| Oliver W. Brooks | 37 | Senior Vice President, Enterprise Excellence | 2022 | Vice President, Strategic Planning for Southwest Division (2020-2022); General Manager, North Texas/Oklahoma District (2018-2020); General Manager, Denver Metro Ready Mix (2016-2018) |
| Robert J. Cardin | 59 | Senior Vice President, Controller and Chief Accounting Officer | 2019 | Vice President and Corporate Controller (2019); Chief Accounting Officer, SWM International (2013-2019) |
| Craig M. LaTorre | 55 | Senior Vice President, Chief Human Resource Officer | 2019 | Vice President, Human Resources (2018-2019); Senior Vice President and Chief Human Resources Officer (2013-2018), Andeavor (formerly known as Tesoro Corporation) |
| John P. Mohr | 58 | Senior Vice President; | 2017 | |
| Chief Information Officer | 2015 | |||
| Michael J. Petro | 39 | Senior Vice President, Strategy & Development | 2021 | Vice President, Strategy and Development (2018-2021); Director, Strategy and Development (2015-2018) |
| Form 10-K ♦ Page 31 | |
Part II ♦ Item 5 – Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
PART II
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Market Information and Holders
The Company’s common stock, $0.01 par value, is traded on the New York Stock Exchange (NYSE) (Symbol: MLM). There were 739 holders of record of the Company’s common stock as of February 15, 2023.
| Form 10-K ♦ Page 32 |  |
Part II ♦ Item 5 – Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Common Stock Performance Graph
The following graph and accompanying table compare the five-year cumulative total return from December 31, 2017 to December 31, 2022 for (a) the Company’s common stock, (b) the Standard & Poor’s 500 Composite Stock Index, and (c) the Standard & Poor’s 500 Materials Index.

Recent Sales of Unregistered Securities
None.
| Form 10-K ♦ Page 33 | |
Part II ♦ Item 5 – Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Issuer Purchases of Equity Securities
| Period | Total Number of Shares Purchased | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs**(1)** | Maximum Number of Shares that May Yet be Purchased Under the Plans or Programs | ||||||||||||
| October 1, 2022 — October 31, 2022 | — | $ | — | — | 13,102,616 | |||||||||||
| November 1, 2022 — November 30, 2022 | — | $ | — | — | 13,102,616 | |||||||||||
| December 1, 2022 — December 31, 2022 | — | $ | — | — | 13,102,616 | |||||||||||
| Total | — | $ | — | — | 13,102,616 |
The Company’s stock repurchase program, which currently authorizes the repurchase of 20 million shares of common stock, is approved by the Board of Directors from time to time, and updated as appropriate by the Board of Directors, and announced to the public by press release. The latest announcement on this topic was the Company’s press release dated February 10, 2015 that its Board of Directors had authorized the repurchase of up to 20 million shares of its outstanding common stock, which included 5 million shares authorized under the Company’s previous share repurchase program. Previous press releases announcing prior share repurchase programs and the related amounts of common stock included under the share repurchase authorizations were as follows: (i) press release dated August 15, 2007 (5 million shares); (ii) press release dated February 22, 2006 (5 million shares); and (iii) May 6, 1994 (2.5 million shares).
Item 6. RESERVED
Not required.
| Form 10-K ♦ Page 34 | |
Part II ♦ Item 7 – Management’s Discussion and Analysis of Financial Condition and Results of Operations
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
INTRODUCTORY OVERVIEW

Martin Marietta Materials, Inc. (the Company or Martin Marietta) is a natural resource-based building materials company, with 2022 total revenues of $6.16 billion and 2022 net earnings from continuing operations attributable to Martin Marietta of $856.3 million. These results were achieved in part by supplying aggregates (crushed stone, sand and gravel) through its network of approximately 350 quarries, mines and distribution yards in 28 states, Canada and The Bahamas. Martin Marietta also provides cement and downstream products, namely ready mixed concrete, asphalt and paving services, in certain markets where the Company has a leading aggregates position. Specifically, the Company has two cement plants in Texas, ready mixed concrete operations in Arizona, California and Texas, and asphalt operations in Arizona, California, Colorado and Minnesota. Paving services are offered in California and Colorado. The Company also has one cement plant, related cement distribution terminals and ready mixed concrete operations in California that are classified as assets held for sale and reported as discontinued operations as of and for the years ended December 31, 2022 and 2021.
The Company’s heavy-side building materials are used in infrastructure, nonresidential and residential construction projects. Aggregates are also used in agricultural, utility and environmental applications and as railroad ballast. The aggregates, cement, ready mixed concrete and asphalt and paving product lines are reported collectively as the “Building Materials” business.
As more fully discussed in the Consolidated Strategic Objectives section, geography is critically important for the Building Materials business. The Company conducts its Building Materials business through two reportable segments, organized by geography: East Group and West Group. The East Group, consisting of the East and Central divisions, provides aggregates and asphalt products. The West Group is comprised of the Southwest and West divisions and provides aggregates, cement, downstream products and paving services. Further, the following five states accounted for 64% of the Building Materials business 2022 total revenues: Texas, Colorado, North Carolina, Minnesota and California.
| Form 10-K ♦ Page 35 |  |
Part II ♦ Item 7 – Management’s Discussion and Analysis of Financial Condition and Results of Operations

Magnesia Specialties
The Company operates a Magnesia Specialties business with production facilities in Michigan and Ohio. The Magnesia Specialties business produces magnesia-based chemicals products used in industrial, agricultural and environmental applications. It also produces dolomitic lime sold primarily to customers for steel production and soil stabilization. Magnesia Specialties’ products are shipped to customers domestically and worldwide.
Consolidated Strategic Objectives
The Company’s strategic planning process, or Strategic Operating Analysis and Review (SOAR), provides the framework for execution of Martin Marietta’s long-term strategic plan. Guided by this framework and considering the cyclicality of the Building Materials business, the Company determines capital allocation priorities to maximize long-term shareholder value creation. The Company’s strategy includes ongoing evaluation of aggregates-led opportunities of scale in new domestic markets (i.e., platform acquisitions) and expansion through acquisitions that complement existing operations (i.e., bolt-on acquisitions). To that effect, the Company has invested nearly $8.0 billion in acquisitions since the launch of SOAR in 2010. The Company finances such opportunities with the goal of preserving its financial flexibility by having a leverage ratio (consolidated net debt-to-consolidated earnings before interest, taxes, depreciation, depletion and amortization, or EBITDA) within a range of 2.0 times to 2.5 times within a reasonable period of time, typically within 18 months, following the completion of a debt-financed transaction. SOAR also includes the identification and potential disposition of assets that are not consistent with stated strategic goals. Notably, in 2022, the Company divested its Colorado and Central Texas ready mixed concrete businesses and certain West Coast cement and ready mixed concrete operations, refining its product mix and improving margin profile, while providing balance sheet flexibility.
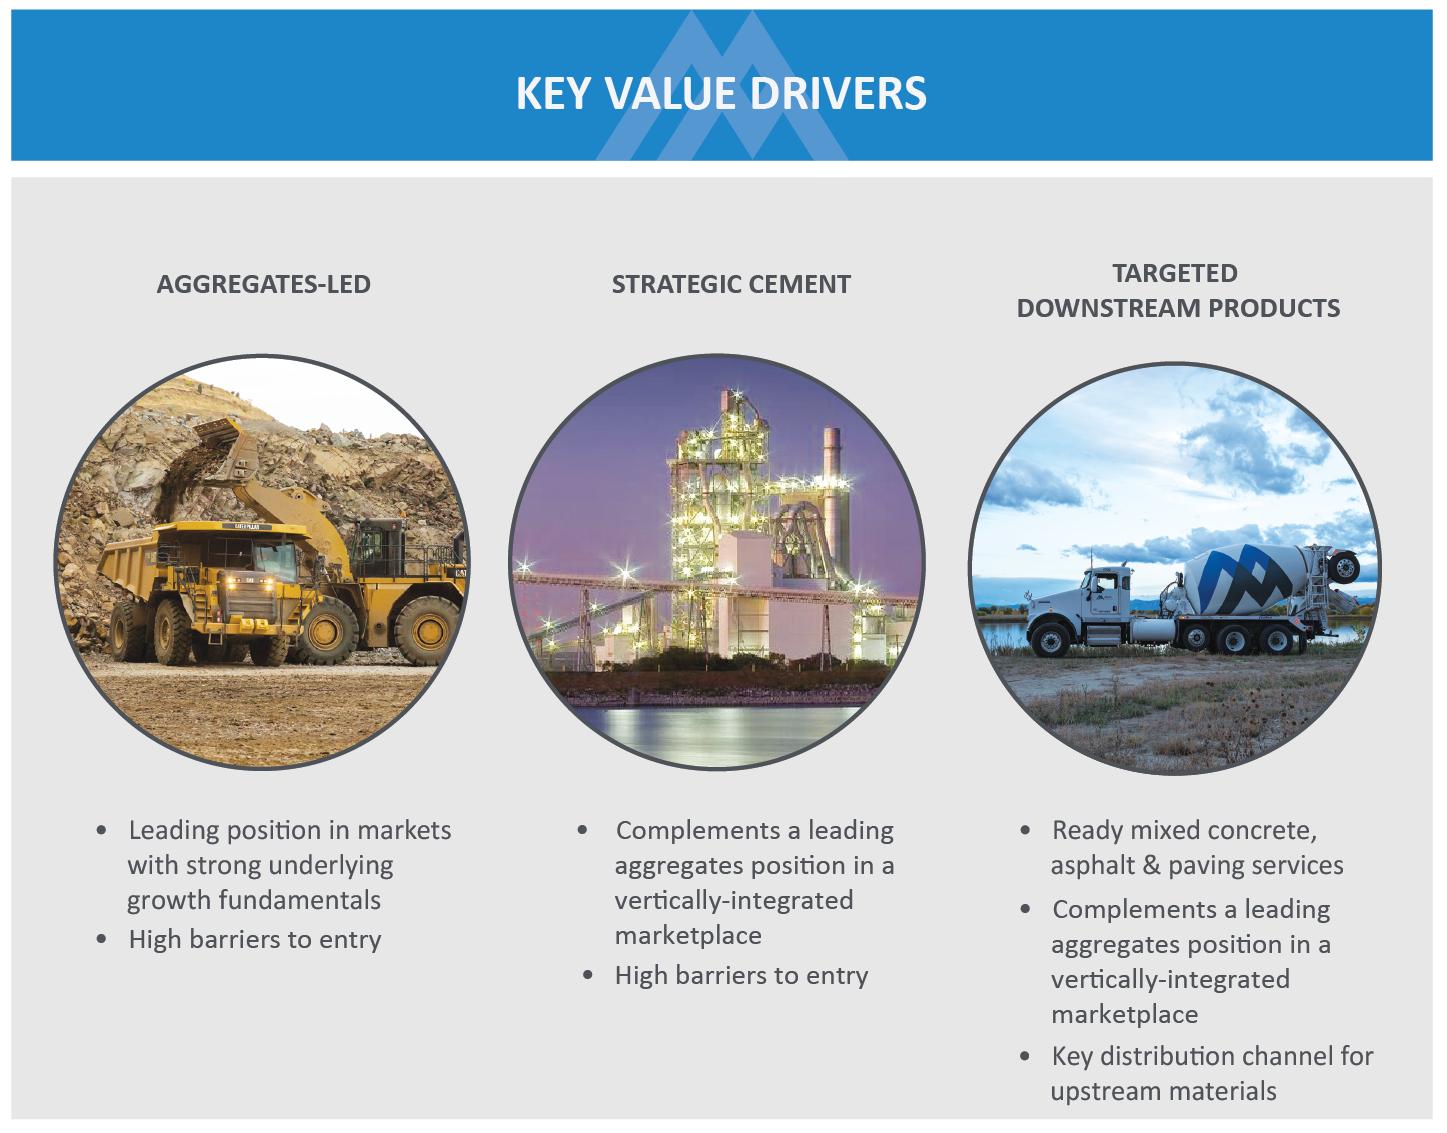
The Company, by purposeful design, will continue to be an aggregates-led business that focuses on markets with strong, underlying growth fundamentals where it can sustain or achieve a leading market position. In fact, aggregates product gross profit represented 69% of 2022 total consolidated products and services gross profit. As part of its long-term strategic plan, the Company may also pursue strategic cement and targeted downstream opportunities. For Martin Marietta, strategic cement and targeted downstream operations are located in vertically-integrated markets where the Company has, or envisions, among other things, a clear path toward a leading aggregates position.
| Form 10-K ♦ Page 36 | |
Part II ♦ Item 7 – Management’s Discussion and Analysis of Financial Condition and Results of Operations
Generally, the Company’s building materials are both sourced and sold locally. As a result, geography is critically important when assessing market attractiveness and growth opportunities. Attractive geographies generally exhibit (a) population growth and/or high population density, both of which are drivers of heavy-side building materials consumption; (b) business and employment diversity, drivers of greater economic stability; and (c) a superior state financial position, a driver of public infrastructure investment.
Population growth and density are assessed based on a site’s proximity to one of the megaregions in the United States. Megaregions are large networks of metropolitan population centers covering thousands of square miles. According to America 2050, a planning and policy program of the Regional Plan Association, a majority of the nation’s population and economic growth through 2050 will occur in 11 megaregions. The Company has a meaningful presence in ten of the megaregions. As evidence of the successful execution of SOAR, the Company’s leading positions in the Texas Triangle, Colorado’s Front Range, northern and southern California and Arizona’s Sun Corridor megaregions, its growth platform in the southern portion of the Northeast megaregion and its enhanced position in the Piedmont Atlantic megaregion, primarily in the Atlanta area, are the results of acquisitions since 2011. The Company has a legacy presence in the southeastern portion of the Great Lakes megaregion, encompassing operations in Indiana and Ohio, as well as the Florida megaregion and the Gulf Coast megaregion in Texas.
| Form 10-K ♦ Page 37 | |
Part II ♦ Item 7 – Management’s Discussion and Analysis of Financial Condition and Results of Operations

With respect to business and employment diversity, the Company focuses its geographic footp
Showing the first 8K of 142K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
As discussed earlier, the Company’s operations are highly dependent upon the interest rate-sensitive construction and steelmaking industries. Consequently, these marketplaces could experience lower levels of economic activity in an environment of rising interest rates or escalating costs (see Business Environment section included under Item 7 – MD&A of this Form 10-K).
Management has considered the current economic environment and its potential impact to the Company’s business. Demand for aggregates products, particularly in the infrastructure construction market, is affected by federal, state and local budget and deficit issues. Further, delays or cancellations of capital projects in the nonresidential and residential construction markets could occur if companies and consumers are unable to obtain affordable financing for construction projects or if consumer confidence is eroded by economic uncertainty.
Demand in the residential and nonresidential construction markets, which combined accounted for 60% of the Company's 2022 aggregates shipments, is affected by interest rates. During 2022, the Federal Reserve raised the target federal funds rate 425 basis points.
Aside from these inherent risks from within its operations, the Company’s earnings are also affected by changes in short-term interest rates and changes in enacted tax laws.
Variable-Rate Borrowing Facilities
At December 31, 2022, the Company had an $800.0 million Revolving Facility and a $400.0 million Trade Receivable Facility. Borrowings under these facilities bear interest at a variable interest rate. As of December 31, 2022, the Company did not have any outstanding variable-rate debt. However, any future borrowings under the credit facilities or outstanding variable-rate debt are exposed to interest rate risk.
Pension Expense
The Company’s results of operations are affected by its pension expense. Assumptions that affect pension expense include the discount rate and, for the qualified defined benefit pension plan only, the expected long-term rate of return on assets. Therefore, the Company has interest rate risk associated with these factors. The impact of hypothetical changes in these assumptions on the Company’s annual pension expense and accrued pension obligation is discussed in the Critical Accounting Policies and Estimates – Pension Expense – Selection of Assumptions section included under Item 7 – MD&A of this Form 10-K.
Income Tax
Any changes in enacted tax laws, rules or regulatory or judicial interpretation, or any change in the pronouncements relating to accounting for income taxes, could materially impact the Company's effective tax rate, tax payments, financial condition and results of operations.
Energy Costs
Energy costs, including diesel fuel, natural gas, electricity, coal, petroleum coke and liquid asphalt, represent significant production costs of the Company. The Company may be unable to pass along increases in the costs of energy to customers in the form of price increases for the Company’s products. The cement product line and Magnesia Specialties business each have varying fixed-price agreements for a portion of their future energy requirements. A hypothetical 10% change in the Company’s energy prices in 2023 as compared with 2022, assuming constant volumes, would change 2023 energy expense by $50.0 million.
Commodity Risk
Cement is a commodity and competition is based principally on price, which is highly sensitive to changes in supply and demand. Prices are often subject to material changes in response to relatively minor fluctuations in supply and demand, general economic conditions and other market conditions beyond the Company’s control. Increases in the production capacity of industry participants or increases in cement imports tend to create an oversupply of such products leading to an imbalance between supply and demand, which can have a negative impact on product prices. There can be no assurance that product prices will not decline in the future or that such declines will not have a material adverse effect on the Company’s business, financial condition and results of operations. A hypothetical 10% change in sales price of the cement product line would impact cement product line revenues by $60.2 million.
| Form 10-K ♦ Page 68 |  |
Part II ♦ Item 7A – Quantitative and Qualitative Disclosures About Market Risk
Cement is a key raw material in the production of ready mixed concrete. The Company may be unable to pass along increases in the costs of cement and raw materials to customers in the form of price increases for the Company’s products. A hypothetical 10% change in cement costs in 2023 compared with 2022, assuming constant volumes, would change the ready mixed concrete product line cost of sales by $26.2 million. While increases in cement pricing may negatively impact the profitability of the ready mixed concrete operations, the cement business would benefit, although the positive impact may not reflect a direct correlation to the impact to the ready mixed concrete business.
| Form 10-K ♦ Page 69 | |
Part II ♦ Item 8 – Financial Statements and Supplementary Data
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
Statement of Responsibility and Management’s Report on Internal Control over Financial Reporting
Management’s Statement of Responsibility
The management of Martin Marietta Materials, Inc. (the Company or Martin Marietta) is responsible for the consolidated financial statements, the related financial information contained in this Form 10-K and the establishment and maintenance of adequate internal control over financial reporting. The consolidated balance sheets for Martin Marietta, at December 31, 2022 and 2021, and the related consolidated statements of earnings, comprehensive earnings, total equity and cash flows for each of the three years in the period ended December 31, 2022, include amounts based on estimates and judgments and have been prepared in accordance with accounting principles generally accepted in the United States applied on a consistent basis.
A system of internal control over financial reporting is designed to provide reasonable assurance, in a cost-effective manner, that assets are safeguarded, transactions are executed and recorded in accordance with management’s authorization, accountability for assets is maintained and financial statements are prepared and presented fairly in accordance with accounting principles generally accepted in the United States. Internal control systems over financial reporting have inherent limitations and may not prevent or detect misstatements. Therefore, even those systems determined to be effective can provide only reasonable assurance with respect to financial statement preparation and presentation.
The Company operates in an environment that establishes an appropriate system of internal control over financial reporting and ensures that the system is maintained, assessed and monitored on a periodic basis. This internal control system includes examinations by internal audit staff and oversight by the Audit Committee of the Board of Directors.
The Company’s management recognizes its responsibility to foster a strong ethical climate. Management has issued written policy statements that document the Company’s business code of ethics. The importance of ethical behavior is regularly communicated to all employees through the distribution of the Code of Ethical Business Conduct and through ongoing education and review programs designed to create a strong commitment to ethical business practices.
The Audit Committee of the Board of Directors, which consists of four independent, nonemployee directors, meets periodically and separately with management, the independent auditors and the internal auditors to review the activities of each. The Audit
| Form 10-K ♦ Page 70 | |
Part II ♦ Item 8 – Financial Statements and Supplementary Data
Committee meets standards established by the Securities and Exchange Commission (SEC) and the New York Stock Exchange as they relate to the composition and practices of audit committees.
Management’s Report on Internal Control over Financial Reporting
The management of Martin Marietta is responsible for establishing and maintaining adequate internal control over financial reporting. Management assessed the effectiveness of the Company’s internal control over financial reporting as of December 31, 2022. In making this assessment, management used the criteria set forth in Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework). Based on management’s assessment under the 2013 framework, management concluded that the Company’s internal control over financial reporting was effective as of December 31, 2022.
The consolidated financial statements of the Company as of December 31, 2022 and 2021, and for each of the three years in the period ended December 31, 2022, and the effectiveness of the Company’s internal control over financial reporting as of December 31, 2022, have been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, whose report appears on the following pages.
 |  |
| C. Howard Nye, Chairman, President and Chief Executive Officer | James A. J. Nickolas, Senior Vice President and Chief Financial Officer |
February 24, 2023
| Form 10-K ♦ Page 71 | |
Part II ♦ Item 8 – Financial Statements and Supplementary Data
Report of Independent Registe****red Public Accounting Firm
To the Board of Directors and Shareholders of Martin Marietta Materials, Inc.
Opinions on the Financial Statements and Internal Control over Financial Reporting
We have audited the accompanying consolidated balance sheets of Martin Marietta Materials, Inc. and its subsidiaries (the Company) as of December 31, 2022 and 2021, and the related consolidated statements of earnings, of comprehensive earnings, of total equity and of cash flows for each of the three years in the period ended December 31, 2022, including the related notes and schedule of valuation and qualifying accounts for each of the three years in the period ended December 31, 2022 appearing under Item 15(c) (collectively referred to as the “consolidated financial statements”). We also have audited the Company's internal control over financial reporting as of December 31, 2022, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, 2022 and 2021, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2022 in conformity with accounting principles generally accepted in the United States of America. Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2022, based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
Showing the first 8K of 184K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Evaluation of Disclosure Controls and Procedures
As of December 31, 2022, an evaluation was performed under the supervision and with the participation of the Company’s management, including the Chief Executive Officer (CEO) and Chief Financial Officer (CFO), of the effectiveness of the design and operation of the Company’s disclosure controls and procedures. Based on that evaluation, the Company’s CEO and CFO concluded that the Company’s disclosure controls and procedures were effective at the reasonable assurance level.
The foregoing evaluation of the Company’s disclosure controls and procedures was based on the definition in Exchange Act Rule 13a-15(e), which requires that disclosure controls and procedures are effectively designed to provide reasonable assurance that information required to be disclosed by an issuer in the reports that it files or submits with the SEC under the Exchange Act is recorded, processed, summarized and reported, within the time periods specified in the SEC’s rules and forms, and is accumulated and communicated to the issuer’s management, including its principal executive and principal financial officers, or persons performing similar functions, as appropriate to allow timely decisions regarding required disclosure.
Management’s Report on Internal Control over Financial Reporting
Our management’s report on internal control over financial reporting is included as the “Statement of Financial Responsibility and Management’s Report on Internal Controls over Financial Reporting” in Item 8, “Financial Statements and Supplemental Data,” of this Form 10-K. The Company’s management concluded that the Company’s internal control over financial reporting was effective in providing reasonable assurance regarding the reliability of financial reporting and the preparation of the Company’s financial statements for external purposes in accordance with generally accepted accounting principles as of December 31, 2022. PricewaterhouseCoopers LLP, the independent registered public accounting firm that audited the Company’s consolidated financial statements contained herein, also audited the Company’s internal control over financial reporting as of December 31, 2022. The audit report is included in Item 8, “Financial Statements and Supplementary Data,” of this Form 10-K.
Changes in Internal Control over Financial Reporting
There were no changes in the Company’s internal control over financial reporting during the most recently completed fiscal quarter ended December 31, 2022 that materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.
Limitations on the Effectiveness of Controls
The Company's management, including the CEO and CFO, does not expect that the Company’s control system will prevent all error and all fraud. A control system, no matter how well conceived and operated, can provide only reasonable, not absolute, assurance that the objectives of the control system are met. Further, the design of a control system must reflect the fact that there are resource constraints, and the benefits of controls must be considered relative to their costs. Because of the inherent limitations in all control systems, no evaluation of controls can provide absolute assurance that all control issues and instances of fraud, if any, within the Company have been detected. These inherent limitations include the realities that judgments in decision making can be faulty and that breakdowns can occur because of simple error or mistake. Additionally, controls can be circumvented by the individual acts of some persons, by collusion of two or more people, or by management override of the control. The design of any system of controls is based in part upon certain assumptions about the likelihood of future events, and there can be no assurance that any design will succeed in achieving its stated goals under all potential future conditions. Over time, controls may become inadequate because of changes in conditions, or the degree of compliance with the policies or procedures may deteriorate. Because of the inherent limitations in a cost-effective control system, misstatements due to error or fraud may occur and not be detected.
| Form 10-K ♦ Page 113 |  |
Part II ♦ Item 9 – Changes In and Disagreements with Accountants on Accounting and Financial Disclosure
CEO and CFO Certifications
Included among the exhibits to this Form 10-K are forms of “Certifications” of the Company’s CEO and CFO as required in accordance with Section 302 of the Sarbanes-Oxley Act of 2002 (the “Section 302 Certification”). The Section 302 Certifications refer to this evaluation of the Company’s disclosure policies and procedures and internal control over financial reporting. The information in this section should be read in conjunction with the Section 302 Certifications for a more complete understanding of the topics presented.
Item 9B. OTHER INFORMATION
None.
Item 9C. DISCLOSURE REGARDING FOREIGN JURISDICTIONS THAT PREVENT INSPECTIONS
Not Applicable.
| Form 10-K ♦ Page 114 | |
Part III ♦ Item 10 – Directors, Executive Officers and Corporate Governance
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
The information concerning directors of the Company, the Audit Committee of the Board of Directors, and the Audit Committee financial expert serving on the Audit Committee, all as required in response to this Item 10, is included under the captions “Corporate Governance Matters” in the Company’s definitive proxy statement to be filed with the SEC pursuant to Regulation 14A within 120 days after the close of the Company’s fiscal year ended December 31, 2022 (the “2023 Proxy Statement”), and that information is hereby incorporated by reference in this Form 10-K. Information concerning Section 16(a) reporting compliance is incorporated by reference to the information appearing under the caption “Section 16(a) Reports” in the 2023 Proxy Statement. Information concerning executive officers of the Company required in response to this Item 10 is included in Part I, under the heading “Information about our Executive Officers,” of this Form 10-K. The information concerning the Company’s code of ethics required in response to this Item 10 is included in Part I, under the heading “Available Information,” of this Form 10‑K.
Item 11. EXECUTIVE COMPENSATION
The information required in response to this Item 11 is included under the captions “Executive Compensation,” “Compensation Discussion and Analysis,” “Pay Versus Performance,” “Corporate Governance Matters,” “Management Development and Compensation Committee Report,” and “Compensation Committee Interlocks and Insider Participation” in the Company’s 2023 Proxy Statement, and that information is hereby incorporated by reference in this Form 10-K.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
The information required in response to this Item 12 is included under the captions “General Information,” “Security Ownership of Certain Beneficial Owners and Management,” and “Securities Authorized for Issuance Under Equity Compensation Plans” in the Company’s 2023 Proxy Statement, and that information is hereby incorporated by reference in this Form 10-K.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
The information required in response to this Item 13 is included under the captions “Compensation Committee Interlocks and Insider Participation in Compensation Decisions” and “Corporate Governance Matters” in the Company’s 2023 Proxy Statement, and that information is hereby incorporated by reference in this Form 10-K.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
The information required in response to this Item 14 is included under the caption “Independent Auditors” in the Company’s 2023 Proxy Statement, and that information is hereby incorporated by reference in this Form 10-K.
| Form 10-K ♦ 115 |  |
Part IV ♦ Item 15 – Exhibits and Financial Statement Schedules
PART IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
(a) (1) List of financial statements filed as part of this Form 10-K
The consolidated financial statements of Martin Marietta and consolidated subsidiaries, and related notes, appear in Item 8, “Financial Statements and Supplemental Data,” of this Form 10-K.
(2) List of financial statement schedules filed as part of this Form 10-K
The following financial statement schedule of Martin Marietta and consolidated subsidiaries is included in Item 15(c) of this Form 10-K.
Schedule II - Valuation and Qualifying Accounts
All other schedules have been omitted because they are not applicable, not required, or the information has been otherwise supplied in the financial statements or notes to the financial statements.
The report of the Company’s independent registered public accounting firm with respect to the above-referenced financial statements is included in Item 8, “Financial Statements and Supplemental Data,” of this Form 10-K. The consent of the Company’s independent registered public accounting firm is attached as Exhibit 23.01 to this Form 10-K.
(3) Exhibits
The list of Exhibits on the accompanying Index of Exhibits included in Item 15(b) of this Form 10-K is hereby incorporated by reference. Each management contract or compensatory plan or arrangement required to be filed as an exhibit is indicated by asterisks.
(b) Index of Exhibits
| Form 10-K ♦ 116 | |
Part IV ♦ Item 15 – Exhibits and Financial Statement Schedules
| Form 10-K ♦ 117 | |
Part IV ♦ Item 15 – Exhibits and Financial Statement Schedules
| Form 10-K ♦ 118 | |
Part IV ♦ Item 15 – Exhibits and Financial Statement Schedules
| Form 10-K ♦ 119 | |
Part IV ♦ Item 15 – Exhibits and Financial Statement Schedules
| Form 10-K ♦ 120 | |
Part IV ♦ Item 15 – Exhibits and Financial Statement Schedules
Other material incorporated by reference:
Martin Marietta Materials, Inc.’s 2023 Proxy Statement to be filed pursuant to Regulation 14A, portions of which are incorporated by reference in this Form 10-K. Those portions of the 2023 Proxy Statement which are not incorporated by reference shall not be deemed to be “filed” as part of this report.
- Filed herewith
** Management contract or compensatory plan or arrangement required to be filed as an exhibit pursuant to Item 14(c) of Form 10-K
| Form 10-K ♦ 121 | |
Part IV ♦ Item 15 – Exhibits and Financial Statement Schedules
(c) Financial Statement Schedule
SCHEDULE II – VALUATION AND QUALIFYING ACCOUNTS
MARTIN MARIETTA MATERIALS, INC. AND CONSOLIDATED SUBSIDIARIES
| Col A | Col B | Col C | Col D | Col E | ||||||||||||||||||
| Additions | ||||||||||||||||||||||
| Description | Balance at beginning of period | (1) Charged to costs and expenses | (2) Charged to other accounts- describe | Deductions- describe | Balance at end of period | |||||||||||||||||
| (Amounts in Millions) | ||||||||||||||||||||||
| Year ended December 31, 2022 | ||||||||||||||||||||||
| Allowance for estimated credit losses | $ | 5.8 | $ | 5.2 | $ | — | $ | — | $ | 11.0 | ||||||||||||
| Allowance for estimated credit losses on notes receivable | $ | 0.1 | $ | — | $ | — | $ | 0.1 | (a) | $ | — | |||||||||||
| Inventory valuation allowance | $ | 214.3 | $ | 145.0 | $ | 2.2 | (b) | $ | 53.2 | (c) | $ | 308.3 | ||||||||||
| Year ended December 31, 2021 | ||||||||||||||||||||||
| Allowance for estimated credit losses | $ | 5.9 | $ | — | $ | — | $ | 0.1 | (a) | $ | 5.8 | |||||||||||
| Allowance for estimated credit losses on notes receivable | $ | 0.4 | $ | — | $ | — | $ | 0.3 | (a) | $ | 0.1 | |||||||||||
| Inventory valuation allowance | $ | 180.3 | $ | 65.2 | $ | 9.6 | (b) | $ | 40.8 | (c) | $ | 214.3 | ||||||||||
| Year ended December 31, 2020 | ||||||||||||||||||||||
| Allowance for estimated credit losses | $ | 4.7 | $ | 1.2 | $ | — | $ | — | $ | 5.9 | ||||||||||||
| Allowance for estimated credit losses on notes receivable | $ | — | $ | 0.4 | $ | — | $ | — | $ | 0.4 | ||||||||||||
| Inventory valuation allowance | $ | 168.6 | $ | 51.3 | $ | — | $ | 39.6 | (c) | $ | 180.3 |
a.
Change in estimates
b.
Application of reserve policy to acquired inventories/customer receivables
c.
Sale of reserved inventory and divestitures
Item 16. FORM 10-K SUMMARY
The Company has chosen not to include an optional summary of the information required by this Form 10-K. For a reference to the information in this Form 10-K, investors should refer to the Table of Contents to this Form 10-K.
| Form 10-K ♦ 122 | |
♦ Signatures
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| MARTIN MARIETTA MATERIALS, INC. | ||
| By: | /s/ Roselyn R. Bar | |
| Roselyn R. Bar | ||
| Executive Vice President, General Counsel and Corporate Secretary |
Dated: February 24, 2023
POWER OF ATTORNEY
KNOW ALL PERSONS BY THESE PRESENTS, that each person whose signature appears below appoints Roselyn R. Bar as her true and lawful attorney-in-fact, each with full power of substitution and resubstitution, for him or her and in his or her name, place and stead, in any and all capacities, to sign any and all amendments to this Annual Report on Form 10-K, and to file the same, with all exhibits thereto, and other documents in connection therewith, with the Securities and Exchange Commission, granting unto said attorney-in-fact, full power and authority to do and perform each in connection therewith, as fully to all intents and purposes as he or she might or could do in person, hereby ratifying and confirming all that said attorney-in-fact, or her substitute or substitutes, may lawfully do or cause to be done by virtue hereof.
Pursuant to the requirements of the Securities and Exchange Act of 1934, this report has been signed by the following persons on behalf of the registrant and in the capacities and on the dates indicated:
| Form 10-K ♦ 123 | |
♦ Signatures
| Signature | Title | Date | ||
| /s/ C. Howard Nye | Chairman of the Board, | February 24, 2023 | ||
| C. Howard Nye | President and Chief Executive Officer | |||
| /s/ James A. J. Nickolas | Senior Vice President | February 24, 2023 | ||
| James A. J. Nickolas | and Chief Financial Officer | |||
| /s/ Robert J. Cardin | Senior Vice President, | February 24, 2023 | ||
| Robert J. Cardin | Controller and Chief Accounting Officer | |||
| /s/ Dorothy M. Ables | Director | February 24, 2023 | ||
| Dorothy M. Ables | ||||
| /s/ Sue W. Cole | Director | February 24, 2023 | ||
| Sue W. Cole | ||||
| /s/ Smith W. Davis | Director | February 24, 2023 | ||
| Smith W. Davis | ||||
| /s/ Anthony R. Foxx | Director | February 24, 2023 | ||
| Anthony R. Foxx | ||||
| /s/ John J. Koraleski | Director | February 24, 2023 | ||
| John J. Koraleski | ||||
| /s/ Laree E. Perez | Director | February 24, 2023 | ||
| Laree E. Perez | ||||
| /s/ Thomas H. Pike | Director | February 24, 2023 | ||
| Thomas H. Pike | ||||
| /s/ Michael J. Quillen | Director | February 24, 2023 | ||
| Michael J. Quillen | ||||
| /s/ Donald W. Slager | Director | February 24, 2023 | ||
| Donald W. Slager | ||||
| /s/ David C. Wajsgras | Director | February 24, 2023 | ||
| David C. Wajsgras |
| Form 10-K ♦ 124 | |