 filings.tools
Item 1. Business.
93K characters. Original on sec.gov · Markdown
Item 1. Business.
OVERVIEW
The Mosaic Company is the world’s leading producer and marketer of concentrated phosphate and potash crop nutrients. Through our broad product offering, we are a single source supplier of phosphate- and potash-based crop nutrients and animal feed ingredients. We serve customers in approximately 40 countries. We are the second largest integrated phosphate producer in the world and one of the largest producers and marketers of phosphate-based animal feed ingredients in North America and Brazil. We are the leading fertilizer production and distribution company in Brazil. We mine phosphate rock in Florida, Brazil and Peru. We process rock into finished phosphate products at facilities in Florida, Louisiana and Brazil. We are one of the four largest potash producers in the world. We mine potash in Saskatchewan, New Mexico and Brazil. We have other production, blending or distribution operations in Brazil, China, India and Paraguay, as well as a strategic equity investment in a joint venture that operates a phosphate rock mine and chemical complexes in the Kingdom of Saudi Arabia. Our distribution operations serve the top four nutrient-consuming countries in the world: China, India, the United States and Brazil.
The Mosaic Company is a Delaware corporation that was incorporated in March 2004 and serves as the parent company of the business that was formed through the October 2004 combination of IMC Global Inc. (“IMC”) and the fertilizer businesses of Cargill, Incorporated. We are publicly traded on the New York Stock Exchange under the ticker symbol “MOS” and are headquartered in Tampa, Florida.
We conduct our business through wholly and majority-owned subsidiaries as well as businesses in which we own less than a majority or a non-controlling interest. We are organized into three reportable business segments: Phosphates, Potash and Mosaic Fertilizantes. Intersegment eliminations, unrealized mark-to-market gains/losses on derivatives, debt expenses, Streamsong Resort® results of operations, and the results of the China and India distribution businesses are included within Corporate, Eliminations and Other.
The following charts show the respective contributions to 2021 sales volumes, net sales and gross margin for each of our business segments in effect at December 31, 2021:
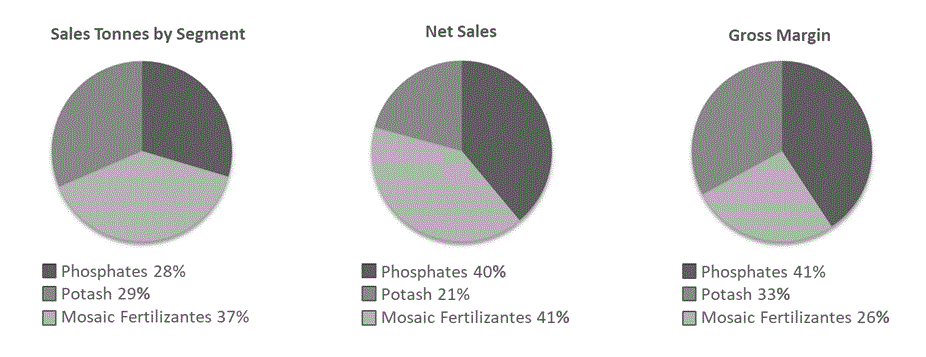
We account for approximately 12% of estimated global annual phosphate production. We also account for approximately 12% of estimated global annual potash production.
Phosphates Segment–We sell phosphate-based crop nutrients and animal feed ingredients throughout North America and internationally. We account for approximately 70% of estimated North American annual production of concentrated phosphate crop nutrients.
Potash Segment–We sell potash throughout North America and internationally, principally as fertilizer, but also for use in industrial applications and, to a lesser degree, as animal feed ingredients. We account for approximately 33% of estimated North American annual potash production.
Mosaic Fertilizantes Segment–We produce and sell phosphate and potash-based crop nutrients, and animal feed ingredients, in Brazil. In addition to five phosphate rock mines, four chemical plants and a potash mine in Brazil, this segment consists of sales offices, crop nutrient blending and bagging facilities, port terminals and warehouses in Brazil and Paraguay. The Mosaic Fertilizantes segment also serves as a distribution outlet for our Phosphates and Potash segments. We account for approximately 65% of estimated annual production of concentrated phosphate crop nutrients in Brazil and 100% of estimated annual potash production in Brazil.
As used in this report:
-
“Mosaic” or “Company” means The Mosaic Company;
-
“we*,” “us,*” and “our” refer to Mosaic and its direct and indirect subsidiaries, individually or in any combination;
-
“Cargill” means Cargill, Incorporated and its direct and indirect subsidiaries, individually or in any combination;
-
“Cargill Crop Nutrition” means the crop nutrient business we acquired from Cargill in the Combination;
-
“Combination” means the October 22, 2004 combination of IMC and Cargill Crop Nutrition; and
statements as to our industry position reflect information from the most recent period available.
Business Developments during 2021
-
During the second quarter of 2021, due to increased brine inflows, we made the decision to accelerate the timing of the shutdown of our K1 and K2 mine shafts at our Esterhazy, Saskatchewan potash mine. Closing the K1 and K2 shafts are key pieces of the transition to the K3 shaft, but the timeline for the closure was accelerated by approximately nine months. We recognized pre-tax costs of $158.1 million related to the permanent closure of these facilities. In the third quarter of 2021, we resumed production at our previously idled Colonsay potash mine to offset a portion of the production lost by the early closure of the K1 and K2 shafts at Esterhazy. In December 2021, the K3 shaft became fully operational and is expected to reach full operating capacity in the first quarter of 2022. The closure of the K1 and K2 shafts will eliminate future brine management expenses at these sites.
-
In August 2021 we entered into a new, unsecured five-year credit facility of up to $2.5 billion, with a maturity date of August 19, 2026, which replaces our prior $2.2 billion line of credit. This increase in size provides additional security and flexibility and reflects the growth in our business.
-
In August 2021 we prepaid the outstanding balance of $450 million on our 3.75% senior notes, due November 15, 2021, without premium or penalty.
*•*During the third quarter of 2021, our Board of Directors approved a new $1 billion share repurchase authorization (the “2021 Repurchase Program”), replacing our previous $1.5 billion authorization (the “2015 Repurchase Program”) that had $700 million remaining. This new, expanded authorization reflects our unchanged commitment to a balanced deployment of excess capital that includes returning capital to stockholders. During 2021, we repurchased 11,200,371 shares of Common Stock, including 8,544,144 shares that we purchased in an underwritten secondary offering by Vale S.A., at an average price of $36.69, for a total of approximately $410.9 million.
-
In November 2021, Vale S.A. sold its 34,176,574 shares of common stock of Mosaic in an underwritten secondary offering. Vale S.A. no longer holds any shares of Mosaic common stock.
-
In the fourth quarter of 2021, our Board of Directors approved a 50% increase in our annual dividend, to $0.45 per share, beginning in 2022.
-
In 2020, we filed petitions with the U.S. Department of Commerce (“DOC”) and the U.S. International Trade Commission (“ITC”) that requested the initiation of countervailing duty investigations into imports of phosphate fertilizers from Morocco and Russia. The purpose of the petitions was to remedy the distortions that we believe foreign subsidies have caused or are causing in the U.S. market for phosphate fertilizers, and thereby restore fair competition. During the first quarter of 2021, the DOC made final affirmative determinations that countervailable subsidies were being provided by those governments and the ITC made final affirmative determinations that the U.S.
phosphate fertilizer industry is materially injured by reason of subsidized phosphate fertilizer imports from Morocco and Russia. As a result of these determinations, the DOC issued countervailing duty orders on phosphate fertilizer imports from Russia and Morocco, which are scheduled to remain in place for at least five years. Currently, the cash deposit rates for such imports are approximately 20 percent for Moroccan producer OCP, 9 percent and 47 percent for Russian producers PhosAgro and Eurochem, respectively, and 17 percent for all other Russian producers. The final determinations in the DOC and ITC investigations are subject to possible challenges before U.S. federal courts and the World Trade Organization, and Mosaic has initiated actions at the U.S. Court of International Trade contesting certain aspects of the DOC’s final determinations that, we believe, failed to capture the full extent of Moroccan and Russian phosphate fertilizer subsidies. Moroccan and Russian producers have also initiated U.S. Court of International Trade actions, seeking lower cash deposit rates and revocation of the countervailing duty orders. Further, the cash deposit rates and the amount of countervailing duties owed by importers on such imports could change based on the results of the DOC’s annual administrative review proceedings.
- In response to Covid-19, we continued to implement measures in 2021 that were intended to provide for the immediate health and safety of our employees, including working remotely and alternating work schedules, in order to minimize the number of employees at a single location. Businesses have been impacted by short-term labor shortages due to illness, transportation issues such as trucking delays and port congestion which are slowing delivery of inputs to facilities and products to end customers. At this time, we have experienced limited adverse financial or operational impacts related to Covid-19.
Subsequent to December 31, 2021, we expect to enter into an accelerated share repurchase (“ASR”) of $400 million, which would be initiated in February 2022. Following the completion of the current authorization, our Board of Directors has approved the establishment of a new $1 billion share repurchase authorization, which will go into effect following completion of this ASR. The Board of Directors has also approved a regular dividend increase to $0.60 per share annually from $0.45, beginning with the second quarter 2022 payment.
We have included additional information about these and other developments in our business during 2021 in our Management’s Discussion and Analysis of Financial Condition and Results of Operations (“Management’s Analysis”) and in the Notes to Consolidated Financial Statements.
Throughout the discussion below, we measure units of production, sales and raw materials in metric tonnes, which are the equivalent of 2,205 pounds, or 1.102 tons (U.S. standard), unless we specifically state that we mean short or long ton(s), which are the equivalent of 2,000 pounds and 2,240 pounds, respectively. In addition, we measure natural gas, a raw material used in the production of our products, in MM BTU, which stands for one million British Thermal Units (“BTU”). One BTU is equivalent to 1.06 Joules.
This report includes market share and industry data and forecasts that we obtained from publicly available information and industry publications, surveys, market research, internal company surveys and consultant surveys. We believe these sources to be reliable, but there can be no assurance as to the accuracy and completeness of such information. We have not independently verified the data from third-party sources, nor have we ascertained the underlying economic assumptions relied upon therein. Similarly, internal company surveys, industry forecasts and market research, which we believe to be reliable based upon management’s knowledge of the industry, have not been verified by any independent sources.
Application of SEC’s New Mining Rules Under Regulation S-K 1300
On October 31, 2018, The U.S. Securities Exchange Commission (the “SEC”) adopted Subpart 1300 of Regulation S-K (“S-K 1300”) to modernize the property disclosure requirements for mining registrants. Information concerning our mining properties in this Form 10-K has been prepared in accordance with these requirements. These requirements differ significantly from the previously applicable disclosure requirements of SEC Industry Guide 7. Among other differences, S-K 1300 requires us to disclose our mineral resources, in addition to our mineral reserves, as of the end of our most recently completed fiscal year both in the aggregate and for each of our individually material mining properties. The calculation of mineral reserves under SEC Industry Guide 7 and under S-K 1300 are significantly different which may lead to differences in reserve reporting. We have four material properties: Belle Plaine, Esterhazy, Florida and Tapira. See Item 2. “Properties,” for further information regarding mineral reserves and resource and discussion of our material mining properties.
BUSINESS SEGMENT INFORMATION
The discussion below of our business segment operations should be read in conjunction with the following information that we have included in this report:
-
The risk factors discussed in this report in Part I, Item 1A, “Risk Factors”.
-
Our Management’s Analysis.
-
The financial statements and supplementary financial information in our Consolidated Financial Statements (“Consolidated Financial Statements”).
This information is incorporated by reference into this section from Part II, Item 8, “Financial Statements and Supplementary Data”.
Phosphates Segment
Our Phosphates business segment owns and operates mines and production facilities in Florida which produce concentrated phosphate crop nutrients and phosphate-based animal feed ingredients, and processing plants in Louisiana which produce concentrated phosphate crop nutrients. We have a 75% economic interest in the Miski Mayo Phosphate Mine in Peru “Miski Mayo Mine”), which is included in the results of our Phosphates segment. On June 18, 2019, we permanently closed our Plant City, Florida production facility. On September 24, 2019, Mosaic entered into a long-term lease agreement with Anuvia Plant Nutrition to lease certain assets at that location.
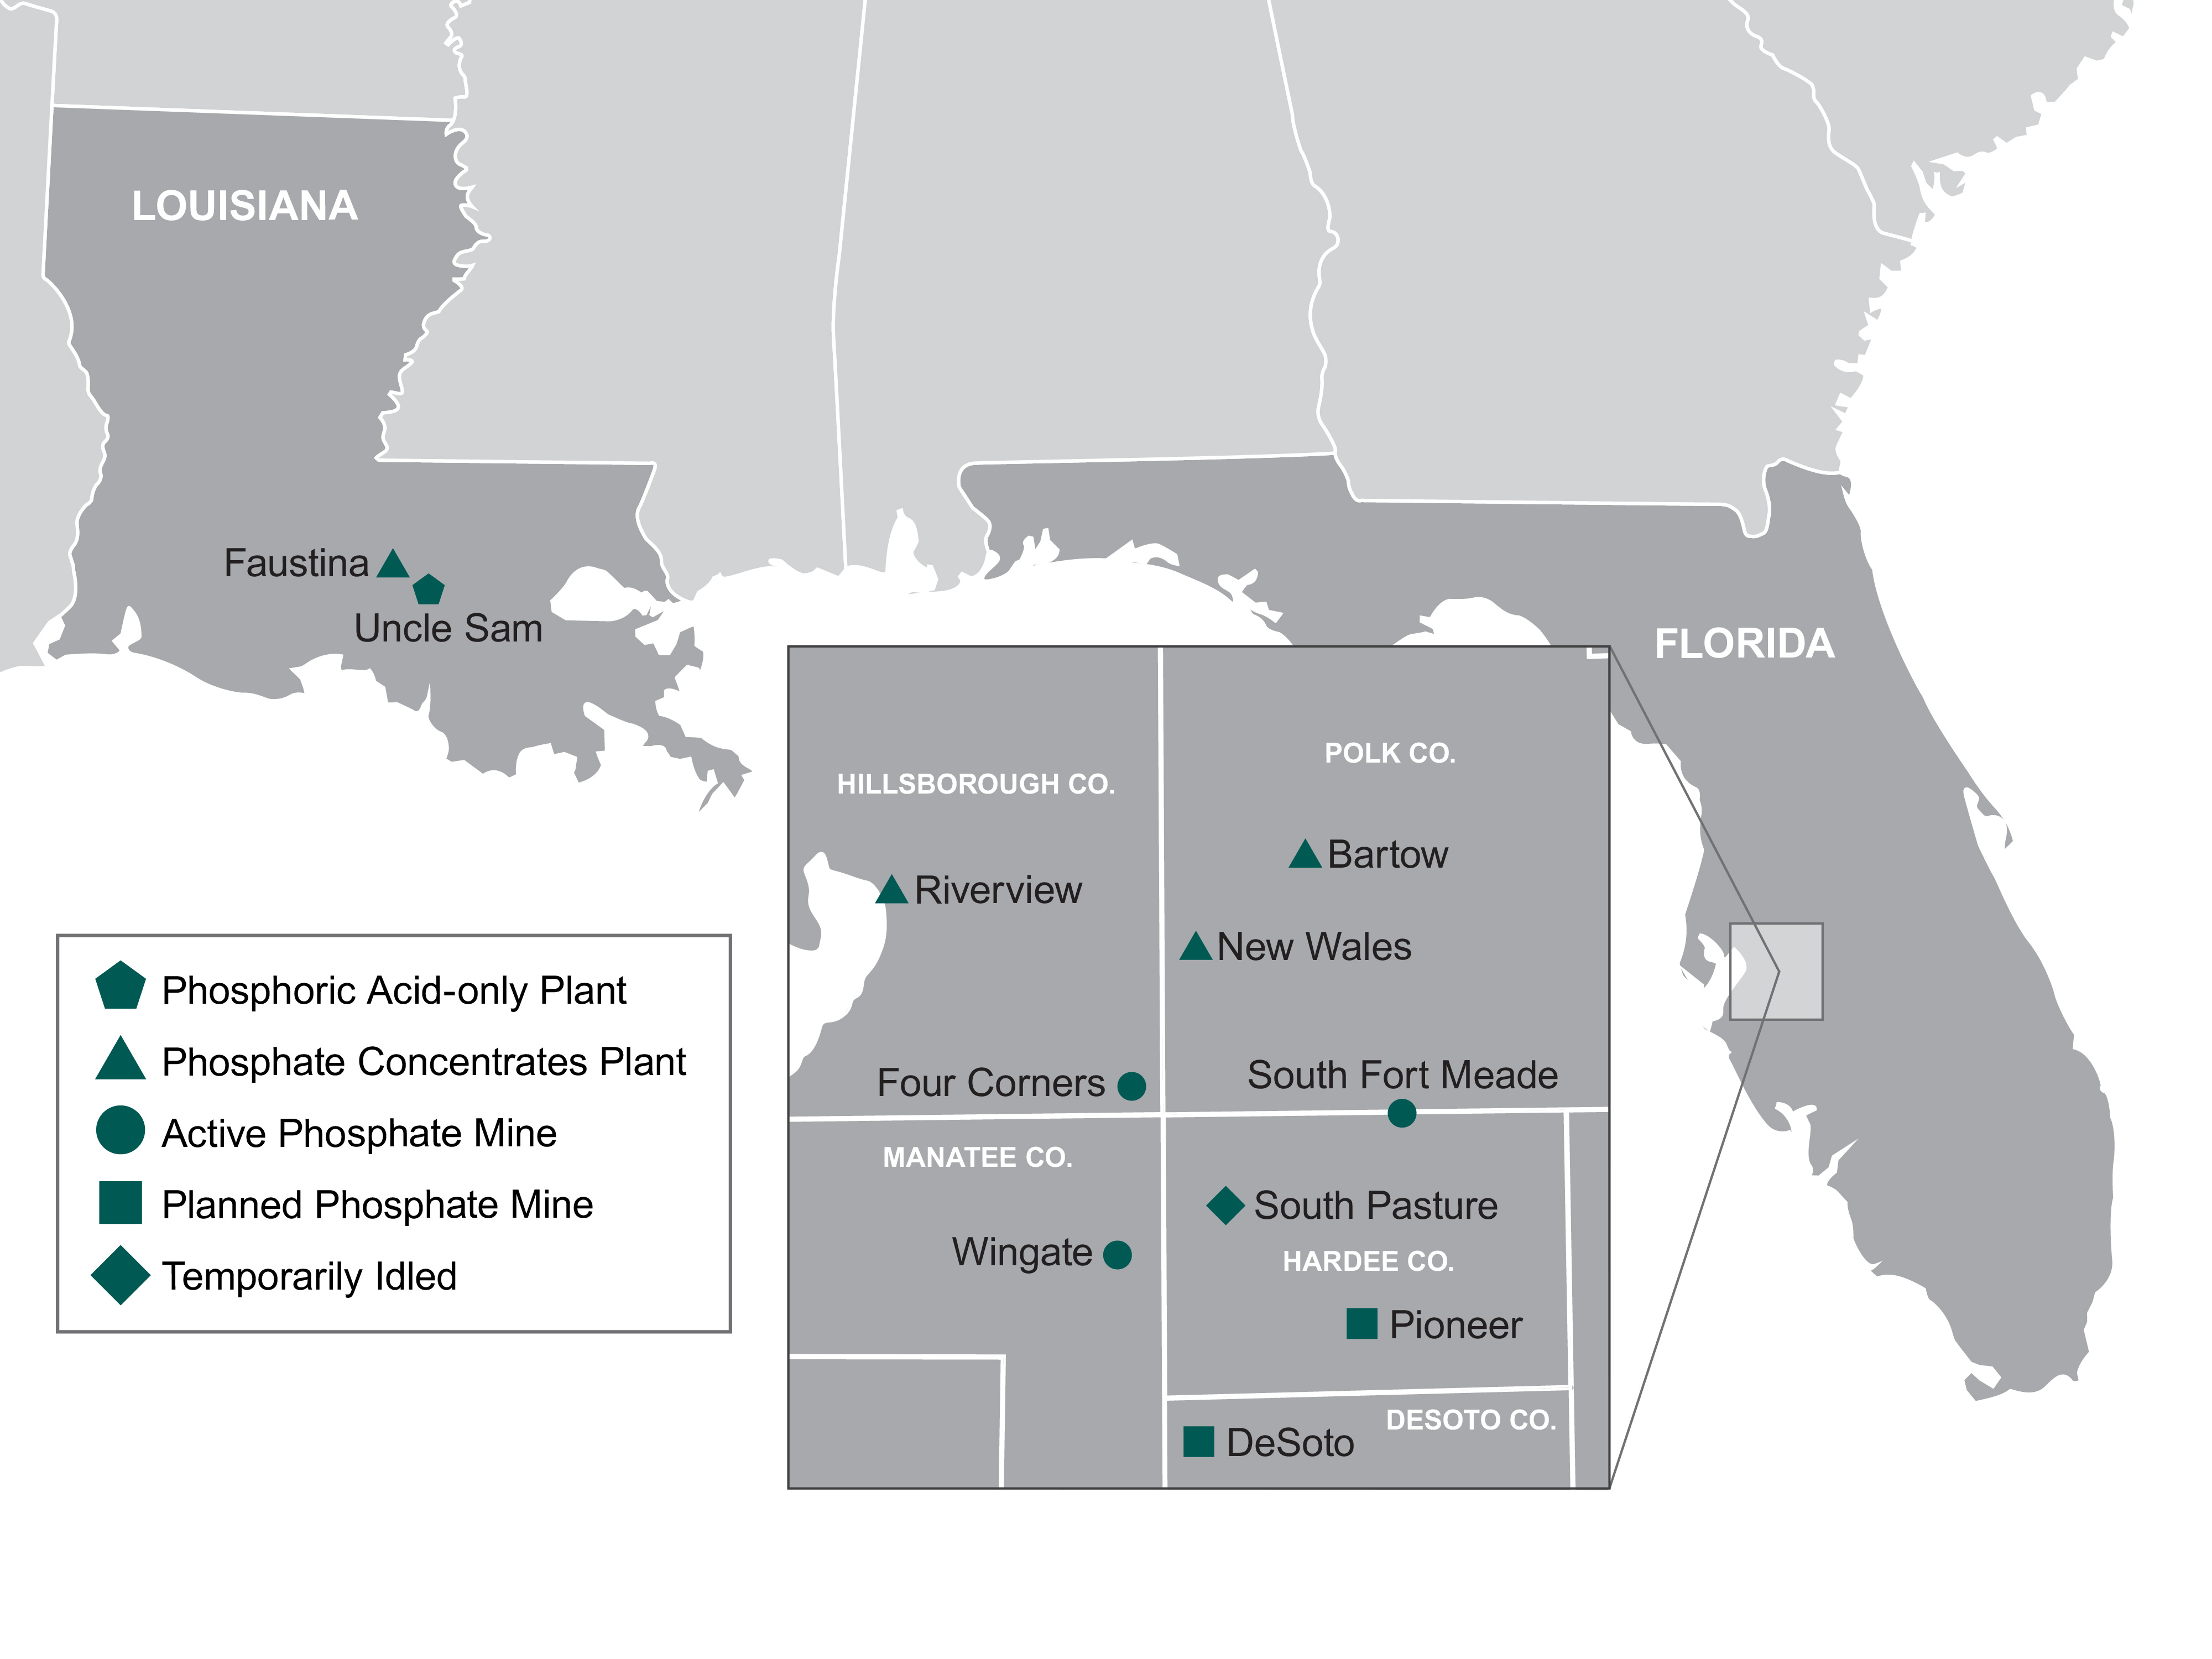
The following map shows the locations of each of our phosphate concentrates plants in the United States and each of our active, temporarily idled, and planned phosphate mine locations, including beneficiation plants, in Florida. The reserves associated with our Ona location have been allocated to other active mines based on our future mining plans:
U.S. Phosphate Crop Nutrients and Animal Feed Ingredients
Our U.S. phosphates operations have capacity to produce approximately 4.5 million tonnes of phosphoric acid (“P2O****5”) per year, or about 7% of world annual capacity and about 60% of North American annual capacity. P2O5 is produced by reacting finely ground phosphate rock with sulfuric acid. P2O5 is the key building block for the production of high analysis or concentrated phosphate crop nutrients and animal feed products, and is the most comprehensive measure of phosphate capacity and production and a commonly used benchmark in our industry. Our U.S. P2O5 production totaled approximately 3.4 million tonnes during 2021. Our U.S. operations account for approximately 7% of estimated global annual production and 51% of estimated North American annual output.
Our phosphate crop nutrient products are marketed worldwide to crop nutrient manufacturers, distributors, retailers and farmers. Our principal phosphate crop nutrient products are:
-
Diammonium Phosphate (18-46-0)** Diammonium Phosphate (“DAP”) is the most widely used high-analysis phosphate crop nutrient worldwide. DAP is produced by first combining phosphoric acid with anhydrous ammonia in a reaction vessel. This initial reaction creates a slurry that is then pumped into a granulation plant where it is reacted with additional ammonia to produce DAP. DAP is a solid granular product that is applied directly or blended with other solid plant nutrient products, such as urea and potash.
-
Monoammonium Phosphate (11-52-0)** Monoammonium Phosphate (“MAP”) is the second most widely used high-analysis phosphate crop nutrient and the fastest growing phosphate product worldwide. MAP is also produced by first combining phosphoric acid with anhydrous ammonia in a reaction vessel. The resulting slurry is then pumped into the granulation plant where it is reacted with additional P2O5 to produce MAP. MAP is a solid granular product that is applied directly or blended with other solid plant nutrient products.
-
MicroEssentials**® is a value-added ammoniated phosphate product that is enhanced through a patented process that creates very thin platelets of sulfur and other micronutrients, such as zinc, on the granulated product. The patented process incorporates both the sulfate and elemental forms of sulfur, providing season-long availability to crops.
Production of our animal feed ingredients products is located at our New Wales, Florida facility. We market our feed phosphate primarily under the leading brand names of Biofos® and Nexfos®.
Annual capacity by plant as of December 31, 2021 and production volumes by plant for 2021 are listed below:
| (tonnes in millions) | Phosphoric Acid | Processed Phosphate**(a)/DAP/MAP/ MicroEssentials®****/Feed Phosphate** | ||||||||||||||||||||||||
| Operational Capacity**(b)** | Operational Capacity**(b)** | |||||||||||||||||||||||||
| Facility | Production**(c)** | Production**(c)** | ||||||||||||||||||||||||
| Florida: | ||||||||||||||||||||||||||
| Bartow | 1.1 | 1.0 | 2.5 | 2.2 | ||||||||||||||||||||||
| New Wales | 1.7 | 1.2 | 4.0 | 2.6 | ||||||||||||||||||||||
| Riverview | 0.9 | 0.8 | 1.8 | 1.6 | ||||||||||||||||||||||
| 3.7 | 3.0 | 8.3 | 6.4 | |||||||||||||||||||||||
| Louisiana: | ||||||||||||||||||||||||||
| Faustina(d) | — | — | 1.6 | 0.9 | ||||||||||||||||||||||
| Uncle Sam(d) | 0.8 | 0.4 | — | — | ||||||||||||||||||||||
| 0.8 | 0.4 | 1.6 | 0.9 | |||||||||||||||||||||||
| Total | 4.5 | 3.4 | 9.9 | 7.3 |
______________________________
(a)Our ability to produce processed phosphates has been less than our annual operational capacity stated in the table above, except to the extent we purchase P2O5. Factors affecting actual production are described in note (c) below.
(b)Operational capacity is our estimated long-term capacity based on an average amount of scheduled down time, including maintenance and scheduled turnaround time, and product mix, and no significant modifications to operating conditions, equipment or facilities.
(c)Actual production varies from annual operational capacity shown in the above table due to factors that include, among others, the level of demand for our products, maintenance and turnaround time, accidents, mechanical failure, product mix, and other operating conditions.
(d)Our Louisiana facilities experienced lower production as a result of downtime from sulfur supply constraints and damage from Hurricane Ida.
The P2O5 produced at Uncle Sam is shipped to Faustina, where it is used to produce DAP, MAP and MicroEssentials®. Our Faustina plant also manufactures ammonia that is mostly consumed in our concentrate plants.
We produced approximately 6.9 million tonnes of concentrated phosphate crop nutrients during 2021 and accounted for approximately 70% of estimated North American annual production.
Phosphate Rock
Phosphate rock is the key mineral used to produce phosphate crop nutrients and feed phosphate. Our Florida phosphate rock mines produced approximately 12.2 million tonnes in 2021 and accounted for approximately 51% of estimated North American annual production. We are the world’s second largest miner of phosphate rock (excluding China) and currently operate four mines in North America with a combined annual capacity of approximately 18.0 million tonnes. Additionally, we own 75% of the Miski Mayo Mine in Peru, which has an annual capacity of 4.0 million tonnes. Production of one tonne of DAP requires between 1.6 and 1.7 tonnes of phosphate rock.
All of our wholly owned phosphate mines and related mining operations in North America are located in central Florida. During 2021, we operated three active mines in Florida: Four Corners, South Fort Meade and Wingate. We plan to explore and develop the DeSoto property and the South Pasture property, which was previously idled, to offset future depletion at our Florida properties. We have a 75% economic interest in the Miski Mayo Mine in Peru, which allows us to supplement our other produced rock to meet our overall fertilizer production needs and is the primary source of rock for our Louisiana operations. We have the right to use or sell to third parties 75% of Miski Mayo’s annual production.
See Item 2. “Properties” for a discussion of our phosphate mining properties, including processing methods, facilities, production and summaries of our mineral resources and reserves, both in the aggregate and for our individual material phosphate mining properties.
Investment in Ma’aden Wa’ad Al Shamal Phosphate Company (“MWSPC”)
We own a 25% interest in MWSPC and, in connection with our equity share, we are entitled to market approximately 25% of MWSPC’s production. MWSPC consists of a mine and two chemical complexes (the “Project”) that produce phosphate fertilizers and other downstream phosphates products in the Kingdom of Saudi Arabia. The greenfield project was built in the northern region of Saudi Arabia at Wa’ad Al Shamal Minerals Industrial City, and included further expansion of processing plants in Ras Al Khair Minerals Industrial City, which is located on the east coast of Saudi Arabia. Ammonia operations commenced in late 2016 and on December 1, 2018, MWSPC commenced commercial operations of the phosphate plant, thereby bringing the entire project to the commercial production phase. Phosphate production will gradually ramp-up until it reaches an expected 3.0 million tonnes in annual production capacity. Actual phosphate production was 2.4 million tonnes in 2021. The Project benefits from the availability of key raw nutrients from sources within Saudi Arabia.
Our cash investment in the Project was $770 million at December 31, 2021. Our obligation to contribute additional equity was eliminated as part of the Project debt refinancing in 2020.
Sulfur
We use molten sulfur at our phosphates concentrates plants to produce sulfuric acid, primarily for use in our production of P2O5. We purchased approximately 3.7 million long tons of sulfur during 2021. We purchase the majority of this sulfur from North American oil and natural gas refiners who are required to remove or recover sulfur during the refining process. Production of one tonne of DAP requires approximately 0.40 long tons of sulfur. We procure our sulfur from multiple sources and receive it by truck, rail, barge and vessel, either directly at our phosphate plants or have it sent for gathering to terminals that are located on the U.S. gulf coast. In addition, we use formed sulfur received through Tampa, Florida ports, which are delivered by truck to our New Wales facility and melted through our sulfur melter.
We own and operate a sulfur terminal in Riverview, Florida. We also lease terminal space in Tampa, Florida and Galveston and Beaumont, Texas. We have long-term time charters on two ocean-going tugs/barges and one ocean-going vessel that transports molten sulfur from the Texas terminals to Tampa. We then further transport by truck to our Florida phosphate plants. In addition, we own a 50% equity interest in Gulf Sulphur Services Ltd., LLLP (“Gulf Sulphur Services”), which is operated by our joint venture partner. Gulf Sulphur Services has a sulfur transportation and terminaling business in the Gulf
of Mexico, and handles these functions for a substantial portion of our Florida sulfur volume. Our sulfur logistic assets also include a large fleet of leased railcars that supplement our marine sulfur logistic system. Our Louisiana operations are served by truck from nearby refineries.
Although sulfur is readily available from many different suppliers and can be transported to our phosphate facilities by a variety of means, sulfur is an important raw material used in our business that has in the past been, and may in the future, be the subject of volatile pricing and availability. Alternative transportation and terminaling facilities might not have sufficient capacity to fully serve all of our facilities in the event of a disruption to current transportation or terminaling facilities. Changes in the price of sulfur or disruptions to sulfur transportation or terminaling facilities could have a material impact on our business. We have included a discussion of sulfur prices in our Management’s Analysis.
Ammonia
We use ammonia together with P2O5 to produce DAP, MAP and MicroEssentials®. We consumed approximately 1.1 million tonnes of ammonia during 2021. Production of one tonne of DAP requires approximately 0.23 tonnes of ammonia. We purchase approximately one-third of our ammonia from various suppliers in the spot market with the remaining two-thirds either purchased through our ammonia supply agreement (the “CF Ammonia Supply Agreement”) with an affiliate of CF Industries Inc. (“CF”) or produced internally at our Faustina, Louisiana location.
Our Florida ammonia needs are currently supplied under multi-year contracts with both domestic and offshore producers. Ammonia for our Bartow and Riverview plants is terminaled through owned ammonia facilities at the Port of Tampa and Port Sutton, Florida. Ammonia for our New Wales plant is terminaled through another ammonia facility owned and operated by a third party at Port Sutton, Florida pursuant to an agreement that provides for service through 2022, with automatic renewal for an additional two-year period unless either party terminates, as provided in the agreement. Ammonia is transported by pipeline from the terminals to our production facilities. We have service agreements with the operators of the pipelines for Bartow, New Wales, and Riverview, which provide service through June 30, 2022 with annual auto-renewal provisions unless either party objects.
Under the CF Ammonia Supply Agreement, Mosaic agreed to purchase approximately 523,000 to 725,000 metric tonnes of ammonia per year during a term that commenced in 2017 and may extend until December 31, 2032, at a price tied to the prevailing price of U.S. natural gas. The contract provides for early termination at certain dates. For 2021, our minimum purchase obligation was approximately 523,000 metric tonnes, and actual purchases were 580,000 metric tonnes. A specialized tug and barge unit transports ammonia for Mosaic between a load location at Donaldsonville, Louisiana and a discharge location at Tampa, Florida. Additional information about this chartered unit and its financing is provided in Note 23 of our Consolidated Financial Statements. We expect a majority of the ammonia purchased under the CF Ammonia Supply Agreement to be received by barge at the Port of Tampa and delivered to our Florida facilities as described in the preceding paragraph. While the market prices of natural gas and ammonia have changed since we executed the CF Ammonia Supply Agreement in 2013 and will continue to change, we expect that the agreement will provide us a competitive advantage over its term, including by providing a reliable long-term ammonia supply.
We produce ammonia at Faustina, Louisiana primarily for our own consumption. Our annual capacity is approximately 530,000 tonnes. From time to time, we sell surplus ammonia to unrelated parties and/or may transport surplus ammonia to the Port of Tampa. In addition, under certain circumstances we are permitted to receive ammonia at Faustina under the CF Ammonia Supply Agreement.
Although ammonia is readily available from many different suppliers and can be transported to our phosphates facilities by a variety of means, ammonia is an important raw material used in our business that has in the past been, and may in the future be, the subject of volatile pricing. In addition, alternative transportation and terminaling facilities might not have sufficient capacity to fully serve all of our facilities in the event of a disruption to existing transportation or terminaling facilities. Changes in the price of ammonia or disruptions to ammonia transportation or terminaling could have a material impact on our business. We have included a discussion of ammonia prices in our Management’s Analysis.
Natural Gas for Phosphates
Natural gas is the primary raw material used to manufacture ammonia. At our Faustina facility, ammonia is manufactured on site. The majority of natural gas is purchased through firm delivery contracts based on published index-based prices and is sourced from Texas and Louisiana via pipelines interconnected to the Henry Hub. We use over-the-counter swap and/or
option contracts to forward price portions of future natural gas purchases. We typically purchase approximately 11.3 million MM Btu of natural gas per year for use in ammonia production at Faustina.
Our ammonia requirements for our Florida operations are purchased rather than manufactured on site. Therefore, while we typically purchase approximately 2.5 million MM Btu of natural gas per year in Florida, it is only used as a thermal fuel for various phosphate production processes.
Florida Land Holdings
We are a significant landowner in the State of Florida, which has in the past been considered one of the fastest areas of population growth in the United States. We own land comprising over 317,000 acres held in fee simple title in central Florida, and have the right to mine additional properties which contain phosphate rock reserves. Some of our land holdings are needed to operate our Phosphates business, while a portion of our land assets, such as certain reclaimed properties, are no longer required for our ongoing operations. As a general matter, more of our reclaimed property becomes available for uses other than for phosphate operations each year. Our real property assets are generally comprised of concentrates plants, port facilities, phosphate mines and other property which we have acquired through our presence in Florida. Our long-term future land use strategy is to optimize the value of our land assets. For example, we developed Streamsong Resort® (the “Resort”), a destination resort and conference center, in an area of previously mined land as part of our long-term business strategy to maximize the value and utility of our extensive land holdings in Florida. In addition to the hotel and conference center, the Resort includes three golf courses, a clubhouse and ancillary facilities.
Potash Segment
We are one of the leading potash producers in the world. We mine and process potash in Canada and the United States and sell potash in North America and internationally. The term “potash” applies generally to the common salts of potassium. Muriate of potash (“MOP”) is the primary source of potassium for the crop nutrient industry. Red MOP has traces of iron oxide. The granular and standard grade red MOP products are well suited for direct fertilizer application and bulk blending. White MOP has a higher percent potassium oxide (“K2O”). White MOP, besides being well suited for the agricultural market, is used in many industrial applications. We also produce a double sulfate of potash magnesia product, which we market under our brand name K-Mag®, at our Carlsbad, New Mexico facility.
Our potash products are marketed worldwide to crop nutrient manufacturers, distributors and retailers and are also used in the manufacturing of mixed crop nutrients and, to a lesser extent, in animal feed ingredients. We also sell potash to customers for industrial use. In addition, our potash products are used for de-icing and as a water softener regenerant.
In the first half of 2021, we operated two potash mines in Canada, including one shaft mine with a total of three production shafts and one solution mine, as well as one potash shaft mine in the United States. During the second quarter of 2021, due to increased brine inflows, we made the decision to accelerate the timing of the shutdown of our K1 and K2 mine shafts at our Esterhazy, Saskatchewan mine by approximately nine months. In the third quarter, we resumed production at our previously idled Colonsay potash mine to offset a portion of the production lost by the early closure of the K1 and K2 shafts. In December, the K3 shaft became fully operational. Currently, work is underway to decommission the K1 and K2 underground mines. Due to this closure, we have eliminated future brine management costs at these locations. We own related mills or refineries at our mines.
We also own a greenfield potash project in Kronau, Saskatchewan, approximately 27 kilometers southeast of Regina, Saskatchewan. In addition, Mosaic leases approximately 291,500 acres of mineral rights from the government of Saskatchewan, and approximately 99,700 acres of freehold mineral rights in the Kronau/Regina area, which have not been developed.
We pay Canadian resource taxes consisting of the Potash Production Tax and resource surcharge. The Potash Production Tax is a Saskatchewan provincial tax on potash production and consists of a base payment and a profits tax. We also pay a percentage of the value of resource sales from our Saskatchewan mines. In addition to the Canadian resource taxes, royalties are payable to the mineral owners in respect of potash reserves or production of potash. We have included a further discussion of the Canadian resource taxes and royalties in our Management’s Analysis.
The map below shows the location of each of our potash properties:
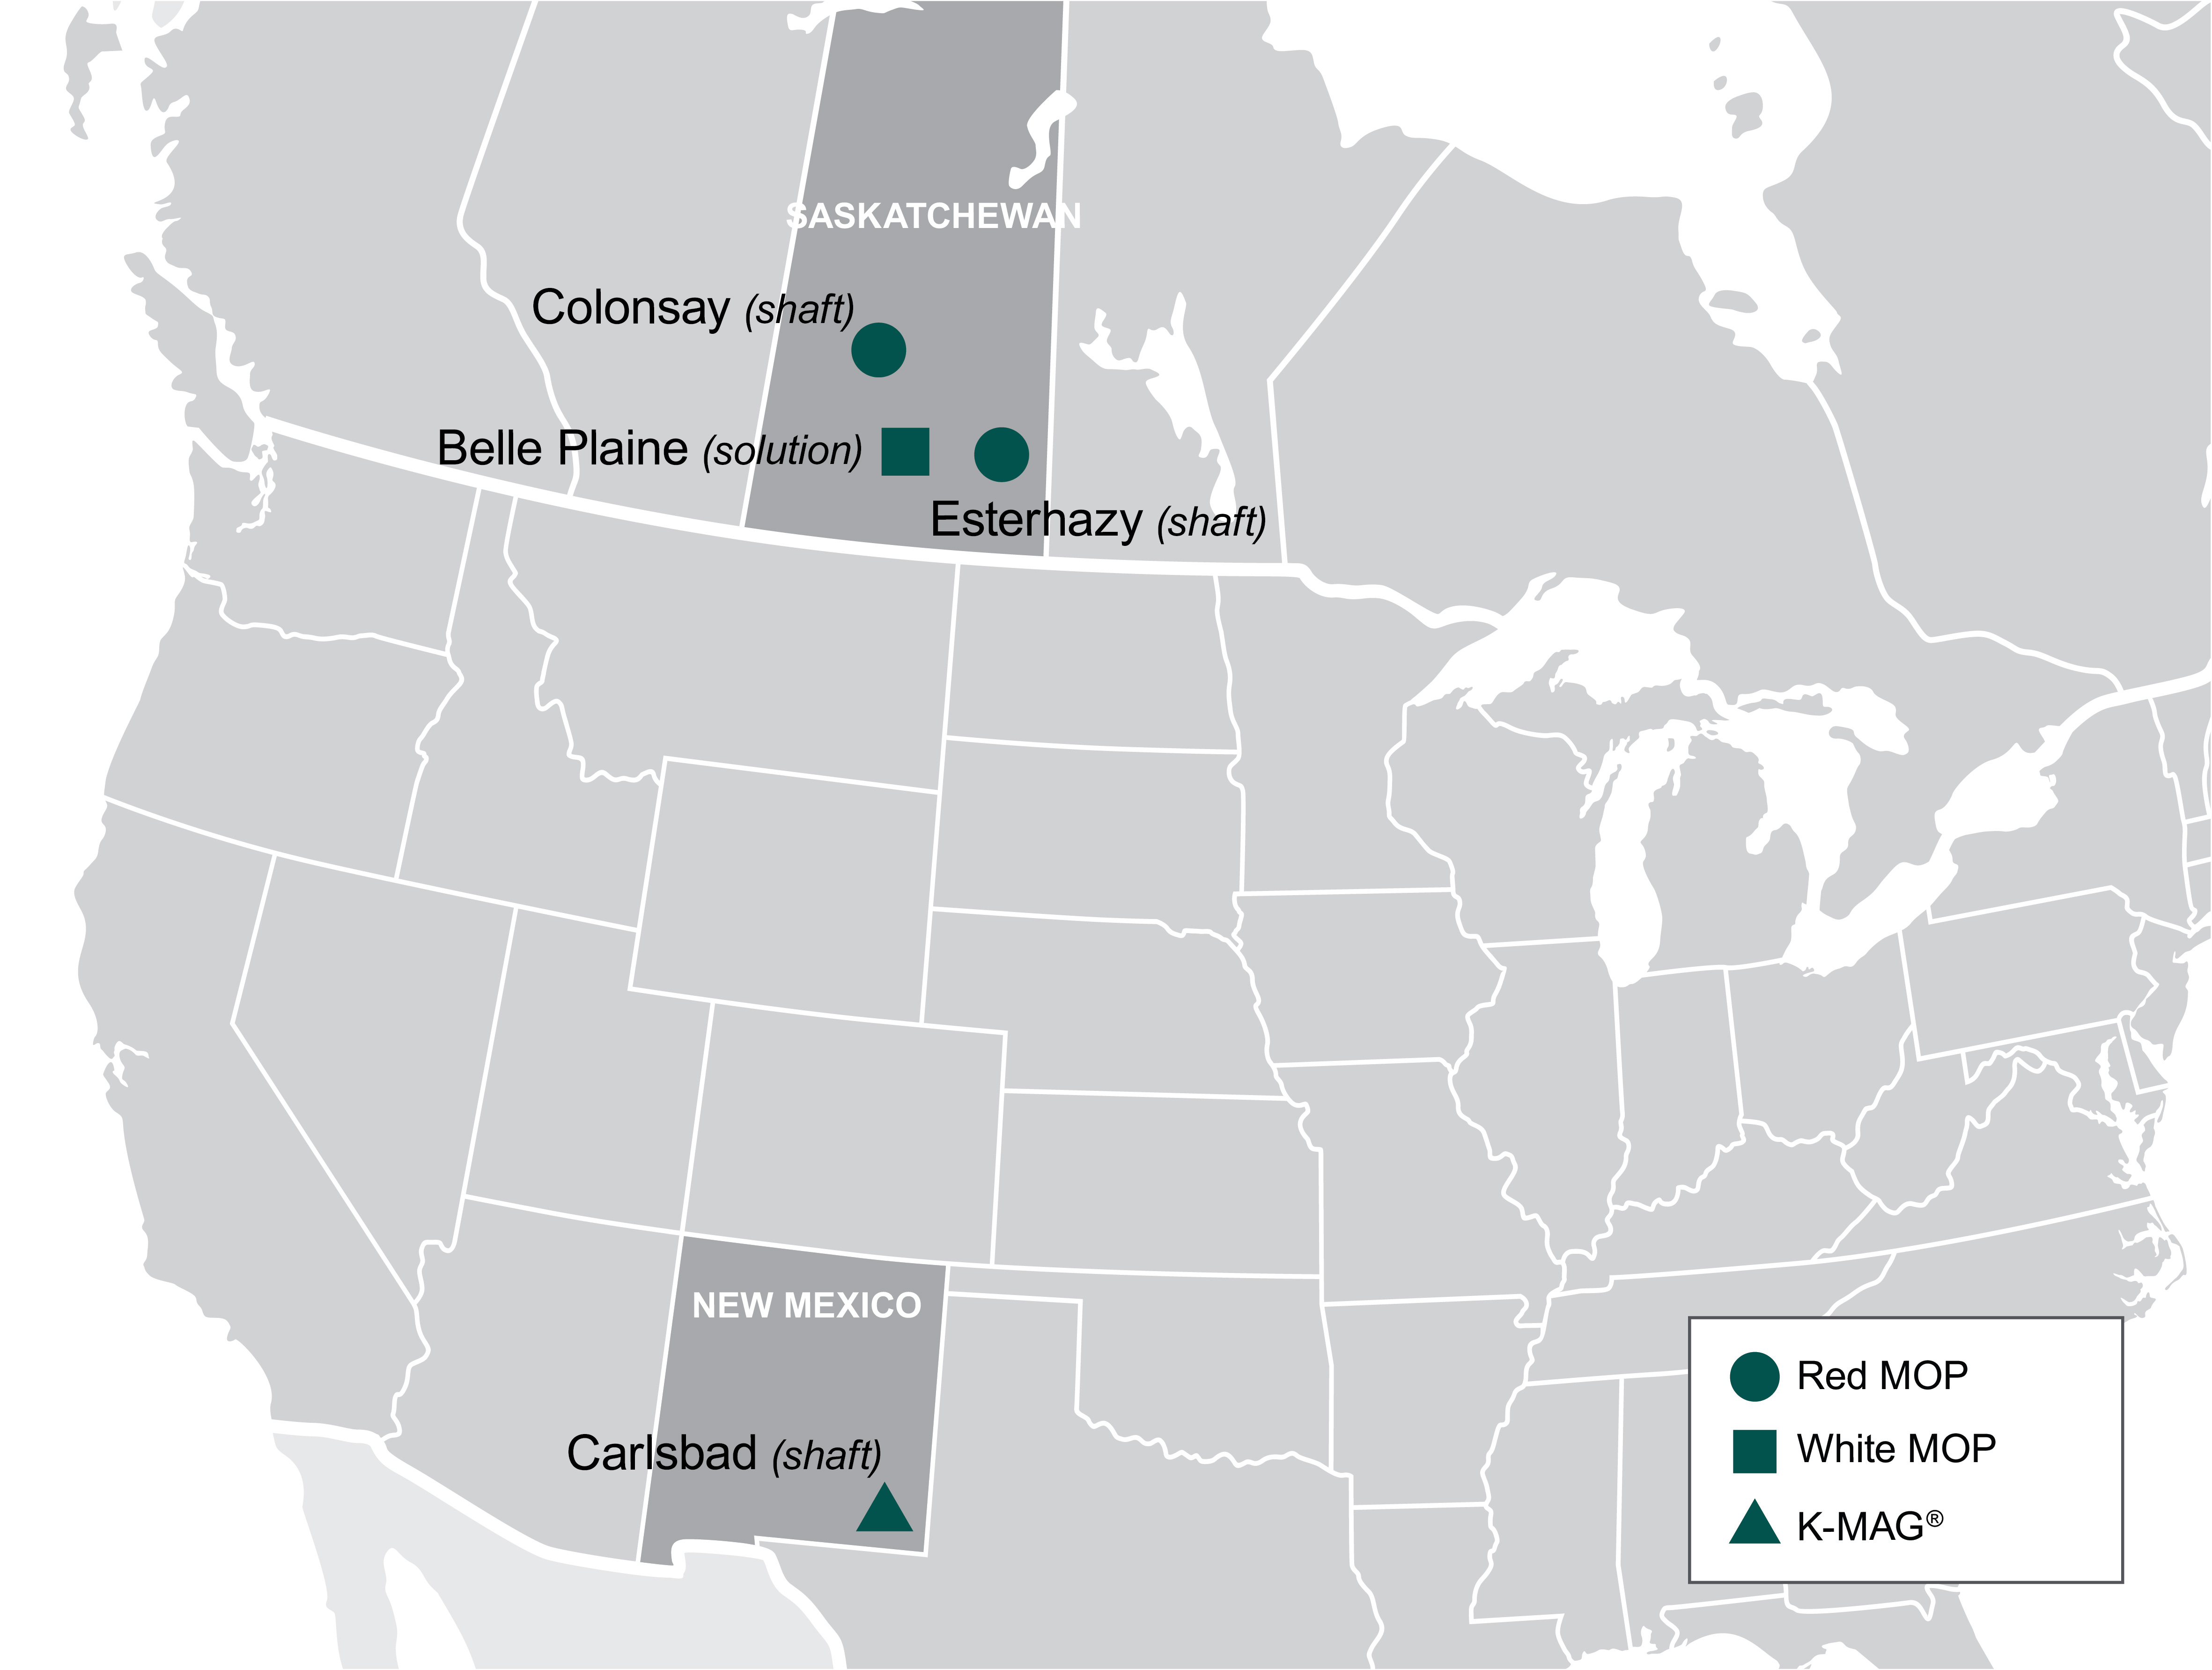
Our North American potash annualized operational capacity totals 11.2 million tonnes of product per year and accounts for approximately 14% of world annual capacity and 32% of North American annual capacity. Production during 2021 totaled 8.2 million tonnes. We account for approximately 12% of estimated world annual production and 33% of estimated North American annual production.
The following table shows, for each of our potash mines, annual capacity as of December 31, 2021 and finished product output for 2021:
| (tonnes in millions) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Facility | Annualized Proven Peaking Capacity (a)(c)(d) | Annual Operational Capacity (a)(b)(d)(e) | Finished Product**(b)** | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Canada | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Belle Plaine—MOP | 3.9 | 3.0 | 2.8 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Colonsay—MOP (f) | 2.6 | 1.5 | 0.4 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Esterhazy—MOP(g) | 6.3 | 6.0 | 4.4 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Canadian Total | 12.8 | 10.5 | 7.6 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| United States | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Carlsbad—K-Mag®(h) | 0.9 | 0.7 | 0.6 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| United States Total | 0.9 | 0.7 | 0.6 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Totals | 13.7 | 11.2 | 8.2 |
______________________________
(a)Finished product.
(b)Actual production varies from annual operational capacity shown in the above table due to factors that include, among others, the level of demand for our products, maintenance and turnaround time, the quality of the reserves and the nature of the geologic formations we are mining at any particular time, accidents, mechanical failure, product mix, and other operating conditions.
(c)Represents full capacity assuming no turnaround or maintenance time.
(d)The annualized proven peaking capacity shown above is the capacity currently used to determine our share of Canpotex, Limited (“Canpotex”) sales. Canpotex members’ respective shares of Canpotex sales are based upon the members’ respective proven peaking capacities for producing potash. When a Canpotex member expands its production capacity, the new capacity is added to that member’s proven peaking capacity based on a proving run at the maximum production level. Alternatively, after January 2017, Canpotex members may elect to rely on an independent engineering firm and approved protocols to calculate their proven peaking capacity. The annual operational capacity reported in the table above can exceed the annualized proven peaking capacity until the proving run has been completed. Our entitlement percentage of Canpotex is 36.2%. In 2021 our realized percentage was 33% due to lower shipments as a result of the early closure of the K1 and K2 mine shafts at Esterhazy.
(e)Annual operational capacity is our estimated long-term potash capacity based on the quality of reserves and the nature of the geologic formations expected to be mined, milled and/or processed over the long term, average amount of scheduled down time, including maintenance and scheduled turnaround time, and product mix, and no significant modifications to operating conditions, equipment or facilities. Operational capacities will continue to be updated to the extent new production results impact ore grades assumptions.
(f)We have the ability to reach an annual operating capacity of 2.1 million tonnes over time by increasing our staffing levels and investment in mine development activities. In August 2019, we indefinitely idled our Colonsay, Saskatchewan mine. In the third quarter of 2021, we restarted operations at Colonsay to offset a portion of the production lost by the early closure of K1 and K2.
(g)In June, 2021, we permanently ceased operations at the K1 and K2 mine shafts. The annual operational capacity of Esterhazy has remained consistent following the K1 and K2 closures based on the accelerated ramp-up in capacity from the K3 mine shafts.
(h)K-Mag® is a specialty product that we produce at our Carlsbad facility.
See Item 2, “Properties” for a discussion of our potash mining properties, including processing methods, facilities, production and summaries of our mineral resources and reserves, both in the aggregate and for our individual material potash mining properties.
Natural Gas
Natural gas is used at our Belle Plaine solution mine as a fuel to produce steam and to dry potash products. The steam is used to generate electricity and provide thermal energy to the evaporation, crystallization and solution mining processes. The Belle Plaine solution mine typically accounts for approximately 80% of our Potash segment’s total natural gas requirements for potash production. At our shaft mines, natural gas is used as a fuel to heat fresh air supplied to the shaft mines and for drying potash products. Combined natural gas usage for both the solution and shaft mines totaled 17 million MM Btu during 2021. We purchase our natural gas requirements on firm delivery index price-based physical contracts and on short-term spot-priced physical contracts. Our Canadian operations purchase physical natural gas from Alberta and Saskatchewan using AECO price indices references and transport the gas to our plants via the TransGas pipeline system. The U.S. potash operation in New Mexico purchases physical gas in the southwest respective regional market using the El Paso San Juan Basin market pricing reference. We use financial derivative contracts to manage the pricing on portions of our natural gas
requirements.
Mosaic Fertilizantes Segment
Our Mosaic Fertilizantes segment owns and operates mines, chemical plants, crop nutrient blending and bagging facilities, port terminals and warehouses in Brazil and Paraguay, which produce and sell concentrated phosphates crop nutrients, phosphate-based animal feed ingredients and potash fertilizer. The following map shows the locations of our operations in Brazil and Paraguay:
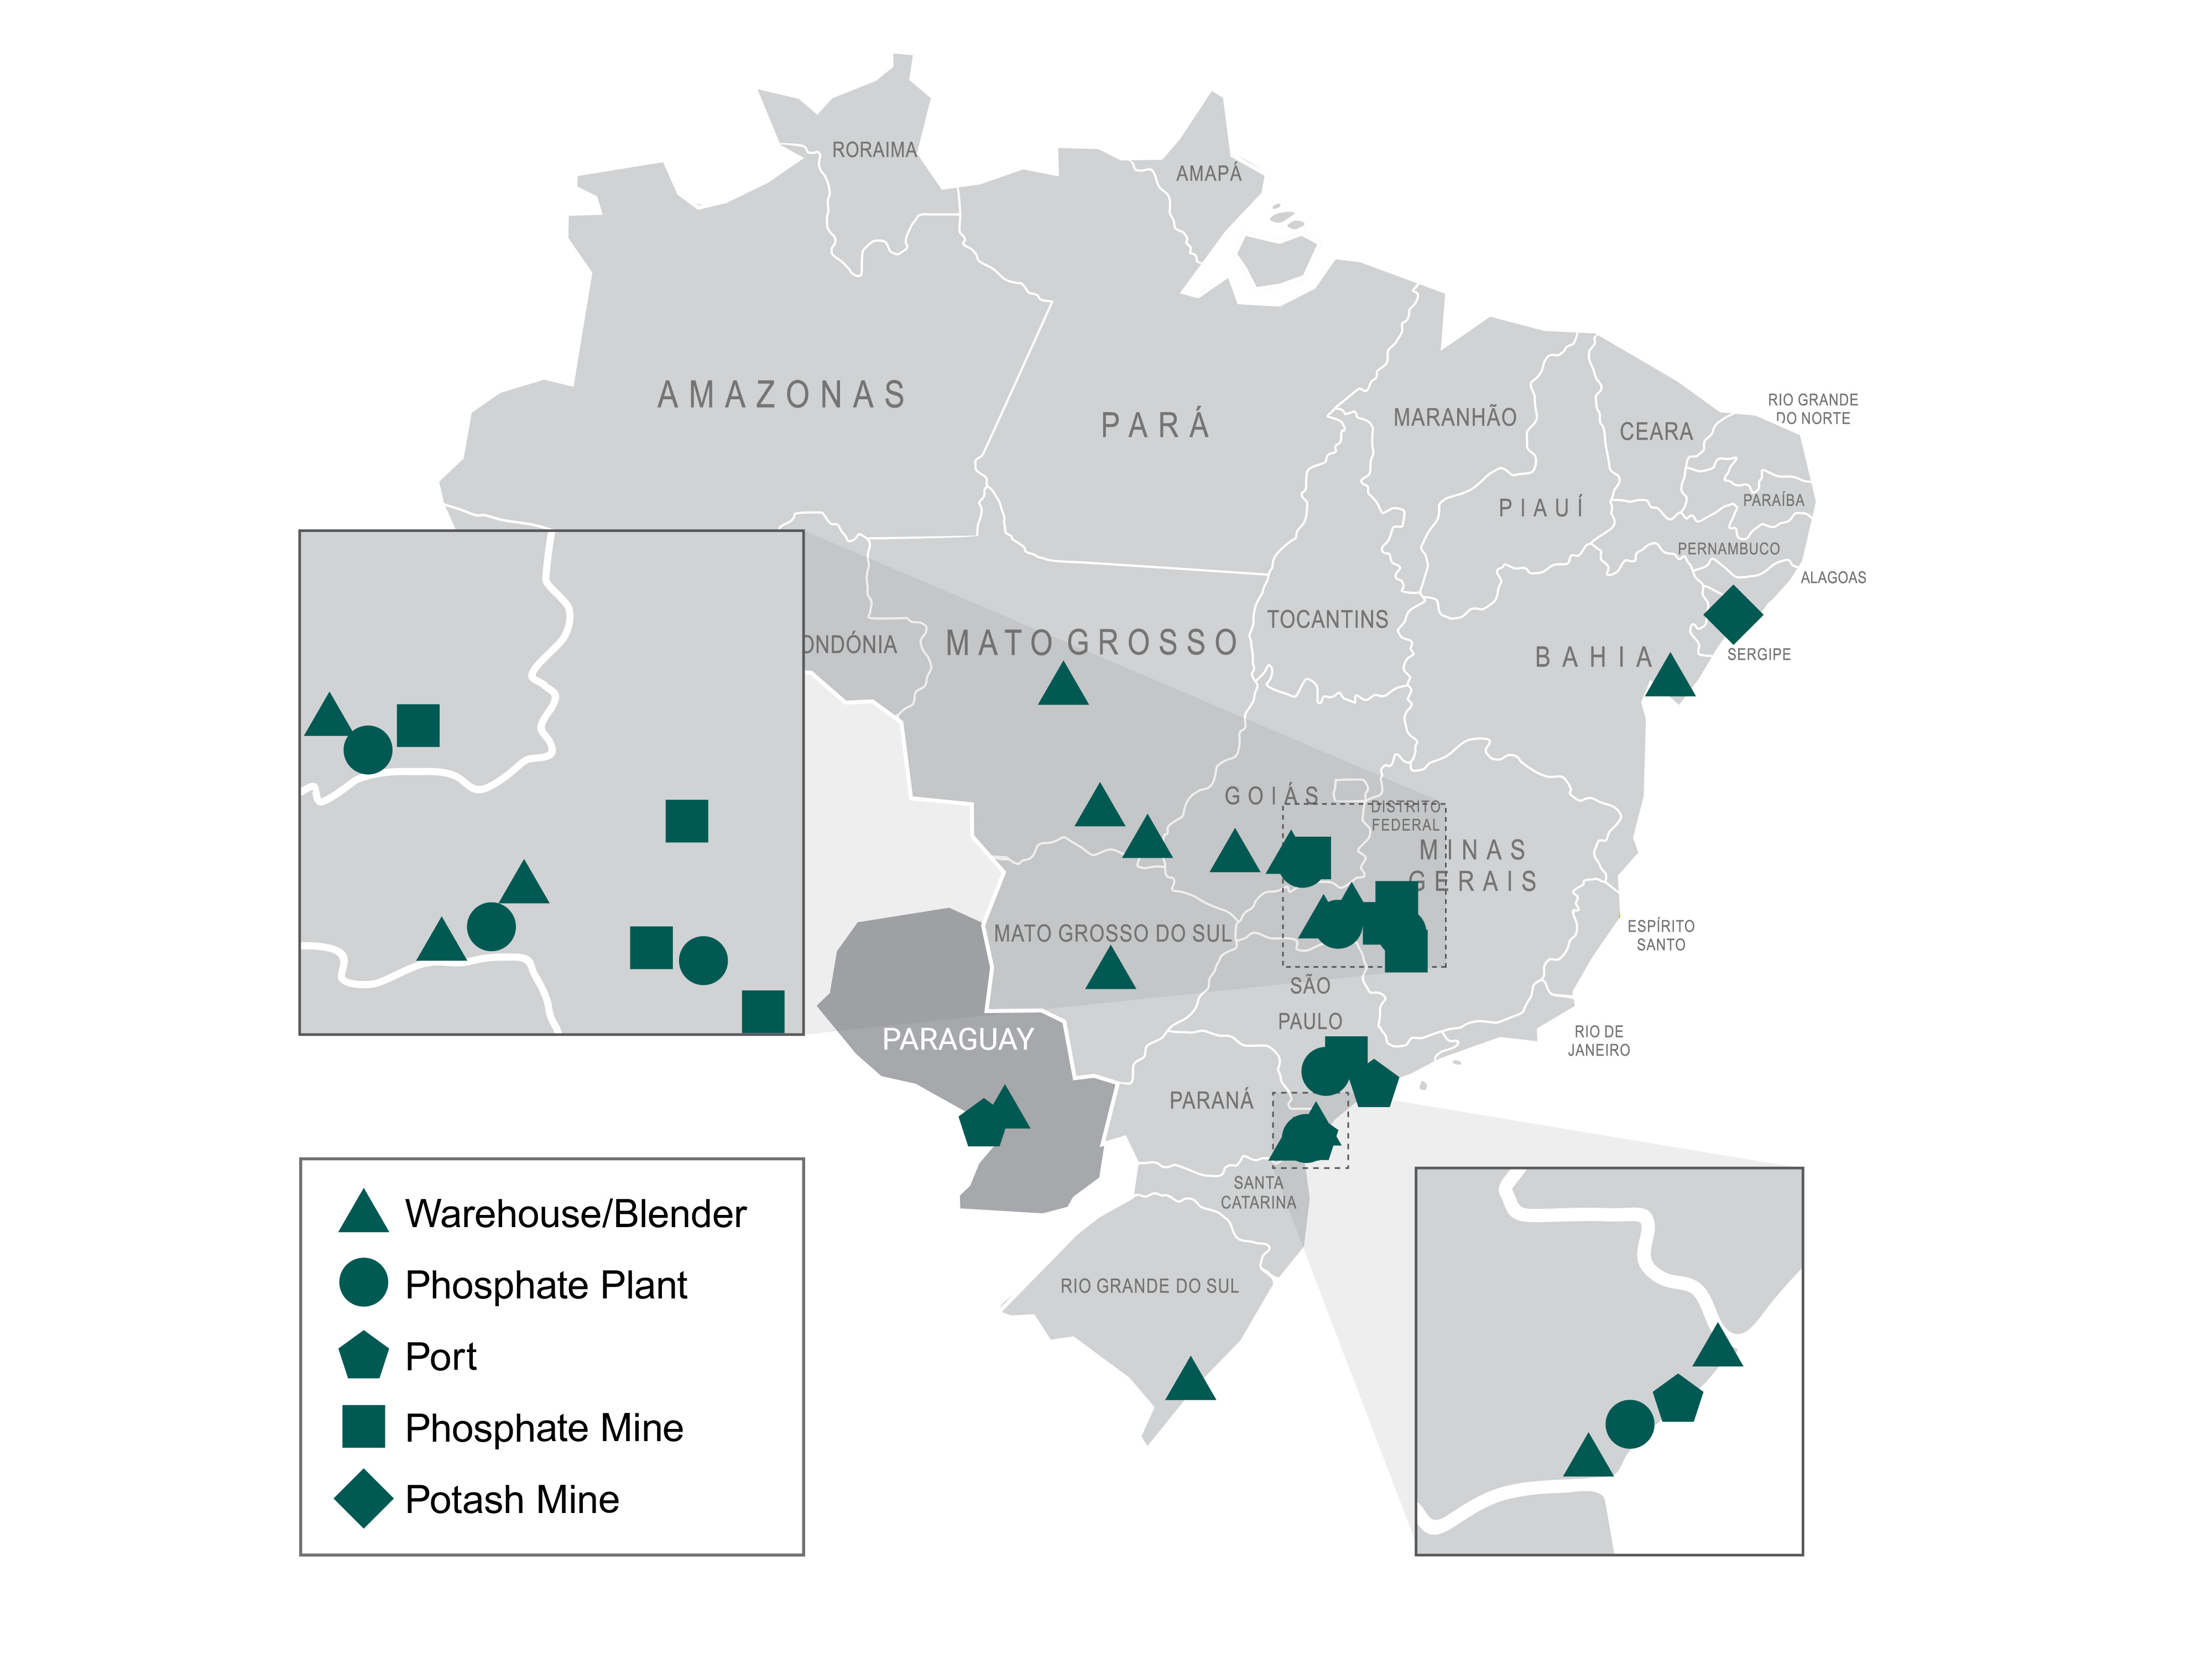
We are the largest producer and one of the largest distributors of blended crop nutrients for agricultural use in Brazil. We produce and sell phosphate-and potash-based crop nutrients, and animal feed ingredients through our operations. Our operations in Brazil include five phosphate mines, four chemical plants and a potash mine. We own and operate ten blending plants in Brazil and one blending plant and port in Paraguay. In addition, we lease several other warehouses and blending units depending on sales and production levels. We also have a 62% ownership interest in Fospar, S.A. (“Fospar”). Fospar owns and operates an SSP (defined below) granulation plant, which produces approximately 0.5 million tonnes of SSP per year, and a deep-water port and throughput warehouse terminal facility in Paranagua, Brazil. The port facility at Paranagua handles approximately 3.6 million tonnes of imported crop nutrients. In 2021, Mosaic Fertilizantes sold approximately 10.1 million tonnes of crop nutrient products and accounted for approximately 20% of fertilizer shipments in Brazil.
We have the capability to annually produce approximately 4.4 million tonnes of phosphate-and potash-based crop nutrients and animal feed ingredients. Crop nutrient products produced are marketed to crop nutrient manufacturers, distributors, retailers and farmers.
In addition to producing crop nutrients, Mosaic Fertilizantes purchases phosphates, potash and nitrogen products which are either used to produce blended crop nutrients (“Blends”) or for resale. In 2021, Mosaic Fertilizantes purchased 2.1 million
tonnes of phosphate-based products, primarily MicroEssentials®, from our Phosphates segment, and 2.5 million tonnes of potash products from our Potash segment and Canpotex.
Phosphate Crop Nutrients and Animal Feed Ingredients
Our Brazilian phosphates operations have capacity to produce approximately 1.1 million tonnes of P2O5 per year, or about 69% of Brazilian annual capacity. Phosphoric acid is produced by reacting ground phosphate rock with sulfuric acid. P2O5 is the key building block for the production of high analysis or concentrated phosphate crop nutrients and animal feed products and is the most comprehensive measure of phosphate capacity and production and a commonly used benchmark in our industry. Our Brazilian P2O5 production totaled approximately 1.0 million tonnes in 2021 and accounted for approximately 90% of Brazilian annual output.
Our principal phosphate crop nutrient products are:
-
Monoammonium Phosphate (11-52-0) (“MAP”) MAP is a crop nutrient composed of two macronutrients, nitrogen and phosphoric acid. This slurry is added inside a rotary drum type granulator with ammonia to complete the neutralization reaction and produce MAP.
-
Triple superphosphate (“TSP”) TSP is a highly concentrated phosphate crop nutrient. TSP is produced from the phosphate rock reaction with phosphoric acid in a kuhlmann type reactor. The process for the production of TSP in Brazil is run of pile where the product undergoes a curing process of approximately seven days for later granulation.
-
Single superphosphate (“SSP”) SSP is a crop nutrient with a low concentration of phosphorus that is used in agriculture because of the sulfur content in its formulation. SSP is produced from mixing phosphate rock with sulfuric acid in a kuhlmann or malaxador type reactor. After the reaction, the product goes to the curing process and then feeds the granulation units.
-
Dicalcium phosphate (“DCP”) Dicalcium phosphate is produced by the reaction of desulphurized phosphoric acid with limestone. At Uberaba, it is produced from the reaction of concentrated phosphoric acid with limestone slurry. At Cajati the phosphoric acid is diluted with dry limestone. The reaction of the DCP occurs in a kuhlmann or spinden type reactor.
Our primary mines and chemical plants are located in the states of Minas Gerais, São Paulo, and Goias. Production of our animal feed ingredients products is located at our Uberaba, Minas Gerais, and Cajati, São Paulo facilities. We market our feed phosphate primarily under the brand name Foscálcio.
Annual capacity and production volume by plant as of December 31, 2021 are listed below:
| (tonnes of ore in millions) | Phosphoric acid | Processed Phosphate**(a)** (MAP/TSP/SSP/DCP/Feed) | |||||||||||||||||||||
| Facility | Capacity**(b)** | Production**(c)** | Capacity**(b)** | Production**(c)** | |||||||||||||||||||
| Phosphate | |||||||||||||||||||||||
| Uberaba | 0.9 | 0.8 | 1.8 | 1.5 | |||||||||||||||||||
| Cajati | 0.2 | 0.1 | 0.5 | 0.4 | |||||||||||||||||||
| Araxá | — | — | 1.0 | 1.0 | |||||||||||||||||||
| Catalão | — | — | 0.4 | 0.4 | |||||||||||||||||||
| Total | 1.1 | 0.9 | 3.7 | 3.3 |
______________________________
(a)Our ability to produce processed phosphates has been less than our annual operational capacity as stated in the table above, except to the extent we purchase phosphoric acid. Factors affecting actual production are described in note (c) below.
(b)The annual production capacity was calculated using the hourly capacity, days stopped for annual maintenance and OEE (historical utilization factor and capacity factor).
(c)Actual production varies from annual operational capacity shown in the table above due to factors that include, among others, the level of demand for our products, maintenance and turnaround time, accidents and mechanical failure.
The phosphoric acid produced at Cajati is used to produce DCP. The phosphoric acid produced at Uberaba is used to produce MAP, TSP and DCP.
We produced approximately 2.9 million tonnes of concentrated phosphate crop nutrients during 2021 which accounted for approximately 51% of estimated Brazilian annual production.
Phosphate Rock
Phosphate rock is the key mineral used to produce phosphate crop nutrients and animal feed product. Our phosphate rock production in Brazil totaled approximately 4.0 million tonnes in 2021, which accounted for approximately 73% of estimated Brazilian annual production. We are the largest producer of phosphate rock in Brazil and currently operate five properties with a combined annual capacity of approximately 4.6 million tonnes. Production of one tonne of MAP requires 1.6 to 1.7 tonnes of phosphate rock. Production of one tonne of SSP requires between 0.6 to 0.7 tonnes of phosphate rock. Production of one tonne of TSP requires 1.4 tonnes of phosphate rock.
During 2021, we operated five properties; Araxá, Patrocínio and Tapira, in the state of Minas Gerais; Catalão, in the state of Goiás; and Cajati, in the state of São Paulo.
See Item 2, “Properties” for a discussion of our Brazilian mining properties, including processing methods, facilities, production and summaries of our mineral resources and reserves, both in the aggregate and for our individually material Brazilian properties.
We are required to pay royalties to mineral owners and resource taxes to the Brazilian government for phosphate and potash production. The resource taxes, known as Compensação Financeira pela Exploração de Recursos Minerais or CFEM*,* are regulated by the National Mining Agency. In 2021, we paid royalties and resource taxes of approximately $9.3 million.
Sulfur
We use molten sulfur at our phosphates concentrates plants to produce sulfuric acid, one of the key components used in the production of phosphoric acid. We consumed approximately 1.2 million long tons of sulfur for our own production during 2021. We purchase approximately 26% of the volume under annual supply agreements from oil and natural gas refiners, who are required to remove or recover sulfur during the refining process. The remaining 74% is purchased in the spot market. Sulfur is imported through the Tiplam port and transported by rail to the Uberaba plant and by truck to the Araxá and Cajati locations.
Although sulfur is readily available from many different suppliers and can be transported to our phosphate facilities by a variety of means, sulfur is an important raw material used in our business that has in the past been, and could in the future be, subject to volatile pricing and availability. Alternative transportation and terminaling facilities might not have sufficient capacity to fully serve all of our facilities in the event of a disruption to current transportation or terminaling facilities. Changes in the price of sulfur or disruptions or sulfur transportation or terminaling facilities could have a material impact on our business.
Ammonia
We use ammonia, together with phosphoric acid, to produce MAP, and to a lesser extent for SSP production. We consumed approximately 133,507 tonnes of ammonia during 2021. Production of one tonne of MAP requires approximately 0.137 tonnes of ammonia. We purchase all of our ammonia under a long-term supply agreement with two suppliers. Ammonia is imported through the Tiplam port and transported by truck to Uberaba, Araxá and Catalão.
We own approximately 1% of the Tiplam terminal in Santos, São Paulo. Our ownership percentage, along with a contractual agreement, guarantee us unloading priority for ammonia and also provide us unloading capacity for rock, sulfur and crop nutrients.
Although ammonia is readily available from many different suppliers and can be transported to our phosphates facilities by a variety of means, ammonia is an important raw material used in our business that has in the past been, and in the future could be, subject to volatile pricing. Alternative transportation and terminaling facilities might not have sufficient capacity to fully serve all of our facilities in the event of a disruption to existing transportation or terminaling facilities. Changes in the price of ammonia or disruptions to ammonia transportation of terminaling could have a material impact on our business.
Brazilian Potash
We conduct potash operations through the leased Taquari-Vassouras shaft mine, which is the only potash mine in Brazil, located in Rosário do Catete in the Brazilian state of Sergipe. We also own a related refinery at the site. We produce and sell potash product domestically. MOP is the primary source of potassium for the crop nutrient industry in Brazil. Red MOP has traces of iron oxide. The granular and standard grade red MOP products are well-suited for direct fertilizer application and bulk blending. Our potash product is marketed in Brazil to crop nutrient manufacturers, distributors and retailers and is also used in the manufacturing of crop nutrients.
In 2021, we paid royalties of approximately $7 million related to the leasing of potash assets and mining rights for Taquari.
Land Holdings
Mosaic Fertilizantes owns properties and the surface rights of certain additional rural lands comprising over 35,000 hectares (86,500 acres) in the States of São Paulo, Minas Gerais, Goiás, Paraná, Mato Grosso, Santa Catarina, Bahia and Sergipe, and has the right to mine additional properties which contain phosphate rock or potash reserves. Most of our land holdings are needed to operate our phosphate and potash production and fertilizer distribution businesses. A portion of our land assets may no longer be required for our current operations and may be leased to third parties, for agricultural or other purposes, or may be set aside for mineral or environmental conservation. Our real property assets are generally comprised of concentrates plants, port facilities and phosphate and potash mines, crop nutrient blending and bagging facilities and other properties which we have acquired through our presence in Brazil.
India and China Distribution Businesses
Our China and India distribution businesses market phosphate-, potash- and nitrogen-based crop nutrients and provide other ancillary services to wholesalers, cooperatives, independent retailers, and farmers in the Asia-Pacific regions. These operations provide our Phosphates and Potash segments access to key markets outside of North and South America and serve as a marketing agent for our Phosphates segment. In 2021, the India and China operations purchased 294,729 tonnes of phosphate-based products from our Phosphates segment and MWSPC, and 1,105,257 tonnes of potash products from our Potash segment and Canpotex. They also purchase phosphates, potash and nitrogen products from unrelated third parties, which we either use to produce blended crop nutrients or for resale.
In China, we own two 300,000-tonne per year capacity blending plants. In 2021, we sold approximately 175,000 tonnes of Blends and distributed another 815,000 tonnes of phosphate and potash crop nutrients in China.
In India, we have distribution facilities to import and sell crop nutrients. In 2021, we distributed approximately 635,000 tonnes of phosphate and potash crop nutrient products in India.
SALES AND DISTRIBUTION ACTIVITIES
United States and Canada
We have a United States and Canada sales and marketing team that serves our business segments. We sell to wholesale distributors, retail chains, cooperatives, independent retailers and national accounts.
Customer service and the ability to effectively minimize the overall supply chain costs are key competitive factors in the crop nutrient and animal feed ingredients businesses. In addition to our production facilities, to service the needs of our customers, we own or have contractual throughput or other arrangements at strategically located distribution warehouses along or near the Mississippi and Ohio Rivers as well as in other key agricultural regions of the United States and Canada. From these facilities, we distribute Mosaic-produced phosphate and potash products for customers who in turn resell the product into the distribution channel or directly to farmers in the United States and Canada.
We own port facilities in Tampa, Florida, which have deep water berth capabilities providing access to the Gulf of Mexico. We also own warehouse distribution facilities in Savage, Minnesota; Rosemount, Minnesota; Pekin, Illinois; and Henderson, Kentucky. The Savage, Minnesota facility has been idled awaiting decisions on future use or sale.
In addition to the facilities that we own, our U.S. distribution operations also include leased distribution space or contractual throughput agreements in other key geographical areas including California, Florida, Illinois, Indiana, Iowa, Kentucky, Louisiana, Minnesota, Missouri, Nebraska, North Dakota, Ohio, Oklahoma, Texas and Wisconsin.
Our Canadian customers include independent dealers and national accounts. We also lease or own warehouse facilities in Saskatchewan, Ontario, Quebec and Manitoba in Canada.
International
Outside of the United States and Canada, we market our Phosphates segment’s products through our Mosaic Fertilizantes segment and our China and India distribution businesses, as well as a salesforce focused on geographies outside of North America. The countries that account for the largest amount of our phosphates sales outside the United States, by volume, are Brazil, Canada, Colombia and Mexico.
Our sales outside of the United States and Canada of potash products are made through Canpotex. Canpotex sales are allocated between its members based on peaking capacity. In 2021, our entitlement percentage of Canpotex is 36.2%.
Our potash exports from Carlsbad are sold through our own sales force. We also market our Potash segment’s products through our Mosaic Fertilizantes segment and our China and India distribution businesses, which acquire potash primarily through Canpotex. The countries that account for the largest amount of international potash sales, by volume, are Brazil, China, Indonesia, India and Malaysia.
To service the needs of our customers, our Mosaic Fertilizantes segment includes a network of strategically located sales offices, crop nutrient blending and bagging facilities, port terminals and warehouse distribution facilities that we own and operate. The blending and bagging facilities primarily produce Blends from phosphate, potash and nitrogen. The average product mix in our Blends (by volume) contains approximately 18% nitrogen, 50% phosphate, and 32% potash, although this mix differs based on seasonal and other factors. All of our production in Brazil is consumed within the country.
Our India and China distribution businesses also includes a network of strategically located sales offices, crop nutrient blending and bagging facilities, port terminals and warehouse distribution facilities. These businesses serve primarily as a sales outlet for our North American phosphates production, as well as additional phosphate production we market from our MWSPC joint venture, both for resale and as an input for Blends. Our Potash segment also has historically furnished the majority of the raw materials needs for the production of Blends, primarily via Canpotex, and is expected to continue to do so in the future.
Other Products
With a strong brand position in a multi-billion dollar animal feed ingredients global market, our Phosphates segment supplies animal feed ingredients for poultry and livestock to customers in North America, Latin America and Asia. Our potash sales to non-agricultural users are primarily to large industrial accounts and the animal feed industry. Additionally, in North America, we sell potash for de-icing and as a water softener regenerant. In Brazil, we also sell phosphogypsum.
COMPETITION
Because crop nutrients are global commodities available from numerous sources, crop nutrition companies compete primarily on the basis of delivered price. Other competitive factors include product quality, cost and availability of raw materials, customer service, plant efficiency and availability of product. As a result, markets for our products are highly competitive. We compete with a broad range of domestic and international producers, including farmer cooperatives, subsidiaries of larger companies, and independent crop nutrient companies. Foreign competitors may have access to cheaper raw materials, may not have to comply with as stringent regulatory requirements or are owned or subsidized by governments and, as a result, may have cost advantages over North American companies. We believe that our extensive North American and international production and distribution system provides us with a competitive advantage by allowing us to achieve economies of scale, transportation and storage efficiencies, and obtain market intelligence. Also, we believe our performance products, such as MicroEssentials®, provide us a competitive advantage with customers in North and South America.
Unlike many of our competitors, we have our own distribution system to sell phosphate- and potash-based crop nutrients and animal feed ingredients, whether produced by us or by other third parties, around the globe. In North America, we have one of the largest and most strategically located distribution systems for crop nutrients, including warehouse facilities in key agricultural regions. We also have an extensive network of distribution facilities internationally, including in the key growth regions of South America and Asia, with port terminals, warehouses, and blending plants in Brazil, Paraguay, China, and India. Our global presence allows us to efficiently serve customers in approximately 40 countries.
Phosphates Segment
Our Phosphates segment operates in a highly competitive global market. Among the competitors in the global phosphate industry are domestic and foreign companies, as well as foreign government-supported producers in Asia and North Africa. Phosphate producers compete primarily based on price, as well as product quality, service and innovation. Major integrated producers of feed phosphates are located in the United States, Europe and China. Many smaller producers are located in emerging markets around the world. Many of these smaller producers are not miners of phosphate rock or manufacturers of phosphoric acid and are required to purchase this material on the open market.
We believe that we are a low-cost integrated producer of phosphate-based crop nutrients, due in part to our scale, vertical integration and strategic network of production and distribution facilities. As the world’s second largest producer of concentrated phosphates, as well as the second largest miner of phosphate rock in the world and the largest in the United States, we maintain an advantage over some competitors as the scale of operations effectively reduces production costs per unit. We are also vertically integrated to captively supply one of our key inputs, phosphate rock, to our phosphate production facilities. We believe that our position as an integrated producer of phosphate rock provides us with a significant cost advantage over competitors that are non-integrated phosphate producers. In addition, our ownership in the Miski Mayo Mine allows us to supplement our overall phosphate rock needs. We also sell approximately 25% of Miski Mayo production to third parties. MWSPC enables us to not only further diversify our sources of phosphates but also improve our access to key agricultural countries in Asia and the Middle East.
We produce ammonia at our Faustina, Louisiana concentrates plant in quantities sufficient to meet approximately one third of our total ammonia needs in North America. We do not have ammonia production capacity within Florida to serve our Florida operations, but we have capacity to supply a portion of our requirements by transporting produced ammonia from Louisiana to Florida. We purchase additional ammonia from world markets and thus are subject to significant volatility in our purchase price of ammonia. The CF Ammonia Supply Agreement provides us with a long-term supply of a substantial volume of ammonia at prices based on the price of natural gas.
With our dedicated sulfur transportation barges and tugs, and our 50% ownership interest in Gulf Sulphur Services, we are also well-positioned to source an adequate, flexible and cost-effective supply of sulfur, our third key input, to our Florida and Louisiana phosphate production facilities. We believe that our investments in sulfur logistical and melting assets continue to afford us a competitive advantage compared to other producers in cost and access to sulfur.
With facilities in both central Florida and Louisiana, we are logistically well positioned to fulfill our material needs at very competitive prices. Those multiple production points also afford us the flexibility to optimally balance supply and demand.
Potash Segment
Potash is a commodity available from several geographical regions around the world and, consequently, the market is highly competitive. Through our participation in Canpotex, we compete outside of North America against various independent and state-owned potash producers. Canpotex has substantial expertise and logistical resources for the international distribution of potash, including strategically located export assets in Portland, Oregon, St. John, New Brunswick, and Vancouver, British Columbia. Our principal methods of competition with respect to the sale of potash include product pricing, and offering consistent, high-quality products and superior service. We believe that our potash cost structure is competitive in the industry and should improve as we continue to complete our potash expansion projects.
Mosaic Fertilizantes
The Mosaic Fertilizantes segment operates in a highly competitive market in Brazil. We compete with a broad range of domestic and international producers, including farmer cooperatives, subsidiaries of larger companies, and independent crop nutrient companies. We believe that having a vertically integrated business, internationally but also in Brazil, provides us with a competitive advantage by allowing us to achieve economies of scale, transportation and storage efficiencies, and obtain market intelligence.
Mosaic Fertilizantes has a wide variety of customers including farmers, blenders, and other local distributors. We compete with local businesses that offer a wide variety of products that are available from many sources. We believe the strategic location of our mines and chemical plants, in close proximity to our customers, and the benefit of our own distribution network, gives us an advantage over most of our competitors. The vertical integration of our wholly-owned production, along with our distribution network, as well as our focus on product innovation and customer solutions, position us with an
advantage over many of our competitors. We have a strong brand in Brazil. In addition to having access to our own production, our distribution activities have the capability to supply a wide variety of crop nutrients to our dealer/farmer customer base.
FACTORS AFFECTING DEMAND
Our results of operations historically have reflected the effects of several external factors which are beyond our control and have in the past produced significant downward and upward swings in operating results. Revenues are highly dependent upon conditions in the agriculture industry and can be affected by, among other factors: crop conditions; changes in agricultural production practices; worldwide economic conditions, including the increasing world population, household incomes, and demand for more protein-rich food, particularly in developing regions such as China, India and Latin America; changing demand for biofuels; variability in commodity pricing; governmental policies; the level of inventories in the crop nutrient distribution channels; customer expectations about farmer economics, future crop nutrient prices and availability, and transportation costs, among other matters; market trends in raw material costs; market prices for crop nutrients; and weather. Furthermore, our crop nutrients business is seasonal to the extent farmers and agricultural enterprises in the markets in which we compete purchase more crop nutrient products during the spring and fall. The international scope of our business, spanning the northern and southern hemispheres, reduces to some extent the seasonal impact on our business. The degree of seasonality of our business can change significantly from year to year due to conditions in the agricultural industry and other factors. The seasonal nature of our businesses requires significant working capital for inventory in advance of the planting seasons.
We sell products throughout the world. Unfavorable changes in trade protection laws, policies and measures, government policies and other regulatory requirements affecting trade; unexpected changes in tax and trade treaties; and strengthening or weakening of foreign economies as well as political relations with the United States may cause sales trends to customers in one or more foreign countries to differ from sales trends in the United States.
Our international operations are subject to risks from changes in foreign currencies, or government policy, which can affect local farmer economics.
OTHER MATTERS
Employees
We had 12,525 employees as of December 31, 2021, consisting of approximately 9,300 salaried and 3,200 hourly employees. There are also approximately 200 salaried and 500 hourly employees at the Miski Mayo Mine, of which we own 75% and its results are consolidated within our results of operations.
Labor Relations
As of December 31, 2021:
-
We had twenty collective bargaining agreements with unions covering certain hourly employees in the U.S. and Canada. Of these employees, approximately 49% are covered under collective bargaining agreements which expire in 2022. All are expected to collectively bargain for new contracts in 2022.
-
We had agreements with 34 unions covering all employees in Brazil. More than one agreement may govern our relations with each of these unions. In general, the agreements are renewable on an annual basis.
Failure to renew any of our union agreements could result in a strike or labor stoppage that could have a material adverse effect on our operations. However, we have not experienced a significant work stoppage in many years and historically have had good labor relations.
Information Available on our Website
Our annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments thereto, filed with the SEC pursuant to Section 13(a) of the Securities Exchange Act of 1934, as amended, and the rules and regulations thereunder are made available free of charge on our website (www.mosaicco.com) as soon as reasonably practicable after we electronically file such material with, or furnish it to, the SEC. These reports are also available on the SEC’s website (www.sec.gov). The information contained on our website and the SEC’s website is not being incorporated in
this report.
HUMAN CAPITAL
Our employees are the foundation of our Company. Our 12,525 colleagues embody Mosaic’s core values of innovation, collaboration, drive and responsibility, and are the key to enabling us to execute our mission to help the world grow the food it needs.
As of December 31, 2021, our regular employee base was made up of the following:
| Country | Male | Female | Total | ||||||||||||||
| Brazil | 5,621 | 1,008 | 6,629 | ||||||||||||||
| Canada | 1,612 | 277 | 1,889 | ||||||||||||||
| China | 105 | 51 | 156 | ||||||||||||||
| India | 56 | 9 | 65 | ||||||||||||||
| Paraguay | 41 | 13 | 54 | ||||||||||||||
| United States | 3,146 | 585 | 3,731 | ||||||||||||||
| Saudi Arabia | 1 | — | 1 | ||||||||||||||
| Total | 10,582 | 1,943 | 12,525 |
Mosaic is committed to the well-being and development of our employees by creating and cultivating an innovative and collaborative workplace that welcomes, values and respects diversity of people, thoughts, and perspectives; a workplace free of discrimination and intolerant of bias. As part of Mosaic’s strategic priorities, we are committed to prioritizing our internal culture and external partnerships to meet our commitments to our employees and stakeholders and to be an employer of choice for generations to come.
Employee Health and Safety–safety is non-negotiable. We strive for zero harm to people and zero environmental incidents. Through the implementation of the Mosaic Management System, we have established a structured approach to effectively manage and control risk for the safety and well-being of our colleagues, the environment and our stockholders. The management system defines processes that help support a safe work environment and establishes a continuous improvement cycle to adjust for changing conditions and identified risks.
Global Worker Wellness–extending beyond safety, our wellness programs seek to improve the well-being of our employees – and their families – in the areas of physical and psychological health, and financial security. These programs include health screenings, insurance plans and mental health resources, as well as our Environmental, Health and Safety (“EHS”) Risk Reduction Program, various trainings and flexible schedules.
- In 2021, we continued to build more flexibility into our pay and leave policies and medical plans to help our employees with any potential or confirmed exposure to Covid-19. We limited the number of employees to those who critically needed to be on site and allowed others to work remotely. We also put a significant amount of preventative measures in place globally to reduce the exposure risk to employees and contractors, including mask requirements, social distancing policies, travel limitations, virtual audits, ultraviolet (UV) light installation, filter upgrades, increased sanitization, ongoing incentives to encourage vaccination and much more.
Development–Mosaic believes in continually investing in people and their lifelong learning. Mosaic holds training events throughout the year across all of our locations, and hosts an online education platform, GrowingU, which all employees are encouraged to access. Mosaic offers companywide educational reimbursement programs to help employees in each of our operating companies acquire new skills and capabilities to better meet their job responsibilities and provide for future career opportunities within the Company. Mosaic supports membership in numerous professional associations and encourages participation in work-related external networking groups.
*•*In 2021, Mosaic continued its pilot programs to help employees gain the knowledge and skills that we believe will be necessary for the next evolution of our business. Like any company, Mosaic experiences turnover and the need to replace talent related to retirement and succession. Mosaic seeks to minimize unwanted turnover through its talent review, succession management, performance management, and compensation processes. For certain roles critical to
our operations, such as engineering, operations, and employee health and safety professionals, we maintain specific talent programs, internal development strategies, and recruitment pipelines.
Community–Mosaic is an active contributor to the communities in which we operate. In addition to philanthropic grants and sponsorships of local programs, we also support and facilitate volunteerism by our employees. We also participate on local committees and associations focused on contributing to the vitality of the people and communities around us.
*•*In 2021, we initiated the Mosaic Employee Giving Program that provides employees with greater flexibility in leveraging matching funds from The Mosaic Company Foundation and aligns to Mosaic’s strategic priorities and our 2025 Environmental, Social and Governance performance targets. Employees can take advantage of matching funds through financial contributions, volunteering, or both - up to $2,000 annually. The opportunity to offer volunteering incentives is an exciting addition we hope provides employees equal opportunity to participate in helping our communities prosper. We also participate on local committees and associations focused on contributing to the vitality of the people and the communities around us.
Diversity, Inclusion and Equal Opportunities–In 2021, Mosaic’s Diversity and Inclusion Task Force engaged in several initiatives to advance Mosaic’s commitments to our employees and stakeholders to do more to ensure a diverse and inclusive environment. Initiatives included conducting a global listening strategy to ascertain the current culture as well as conducting Conscious Inclusion training for all salaried and graded employees globally.
- Pay equity is fundamental to our compensation philosophy and our commitment to diversity and inclusion. Mosaic annually evaluates pay equity and compensation practices to ensure fair and equitable treatment of employees based on our pay-for-performance framework. In 2020, Mosaic retained an independent consultant to assist with our pay equity analysis on the basis of both gender and ethnicity across our global operations. The results revealed fewer than .05% outliers without adequate business justifications. Mosaic addressed each of the instances during our 2021 compensation cycle. We expect to conduct external independent reviews every three years.
Looking ahead to 2022, Mosaic will continue to evolve and build upon current initiatives to ensure inclusion and diversity across our global operations, including driving diversity and inclusion education deeper into the organization, concentrating on attracting a more diverse pipeline of talent and introduction of Employee Inclusion Networks to facilitate increased awareness, engagement and inclusion within our employee populations. Additional information about our human capital, including our recently announced diversity and inclusion goals for 2030, will be available in the sustainability report posted on our website. The information contained on our website is not being incorporated in this report.
INFORMATION ABOUT OUR EXECUTIVE OFFICERS
Information regarding our executive officers as of February 23, 2022 is set forth below:
| Name | Age | Position | ||||||||||||
| Bruce M. Bodine Jr. | 50 | Senior Vice President - North America | ||||||||||||
| Clint C. Freeland | 53 | Senior Vice President and Chief Financial Officer | ||||||||||||
| Mark J. Isaacson | 59 | Senior Vice President, General Counsel and Corporate Secretary | ||||||||||||
| Christopher A. Lewis | 59 | Senior Vice President - Human Resources | ||||||||||||
| James “Joc” C. O’Rourke | 61 | Chief Executive Officer, President and Director | ||||||||||||
| Benjamin J. Pratt | 55 | Senior Vice President - Government and Public Affairs | ||||||||||||
| Walter F. Precourt III | 57 | Senior Vice President - Strategy and Growth | ||||||||||||
| Corrine D. Ricard | 58 | Senior Vice President - Mosaic Fertilizantes | ||||||||||||
| Karen A. Swager | 51 | Senior Vice President - Supply Chain | ||||||||||||
| Yijun (“Jenny”) Wang | 54 | Senior Vice President - Global Strategic Marketing, Head of China and India |
Bruce M. Bodine Jr. Mr. Bodine was named Senior Vice President - North America effective April 1, 2020. From January 1, 2019 until his appointment as Senior Vice President - North America, Mr. Bodine served as our Senior Vice President - Phosphates and, also provided executive oversight for the corporate procurement organization. Prior to that, he served as our Senior Vice President - Potash (from June 2016 to December 31, 2018); as our Vice President - Potash (from April to May 2016); as our Vice President - Supply Chain (from August 2015 to March 2016); as our Vice President - Operations Business
Development (from October 2014 to August 2015); as Vice President - Operations for our Esterhazy and Colonsay potash production facilities (from July 2013 to October 2014); as the General Manager, Esterhazy (from September 2012 to June 2013); and as the General Manager, Four Corners (from March 2010 to August 2012). Before that, Mr. Bodine held various plant and mine development management positions in the Phosphates segment beginning with Mosaic’s formation in 2004. Mr. Bodine serves as a director of MVM Resources International, B.V., the general partner of Compañia Minera Miski Mayo S.R.L., the joint venture that operates the mines in Peru.
Clint C. Freeland. Mr. Freeland was named Senior Vice President and Chief Financial Officer in June 2018. Prior to joining Mosaic, Mr. Freeland served as Executive Vice President and Chief Financial Officer of Dynegy Inc. from July 2011 until Dynegy’s merger with Vistra Energy Corp. in April 2018. Mr. Freeland was responsible for Dynegy’s financial affairs, including finance and accounting, treasury, tax and banking and credit agency relationships. In November 2011, as part of a reorganization of its subsidiaries, certain of Dynegy’s affiliates filed voluntary petitions for reorganization under Chapter 11 of the U.S. Bankruptcy Code (the “Code”) and, in July 2012, Dynegy filed a voluntary petition for reorganization under Chapter 11 of the Code. Dynegy emerged from Bankruptcy in October 2012. Prior to joining Dynegy, Mr. Freeland served as Senior Vice President, Strategy & Financial Structure of NRG Energy, Inc. from February 2009 to July 2011. Mr. Freeland served as NRG’s Senior Vice President and Chief Financial Officer from February 2008 to February 2009 and its Vice President and Treasurer from April 2006 to February 2008. Prior to joining NRG, Mr. Freeland held various key financial roles within the energy sector.
Mark J. Isaacson. Mr. Isaacson was named Senior Vice President, General Counsel and Corporate Secretary in August 2015 and previously served as our Vice President, General Counsel and Corporate Secretary since August 2014. Mr. Isaacson joined Mosaic upon its formation in 2004 as its Chief Phosphates Counsel before being promoted to Vice President, Associate General Counsel and Chief Compliance Officer in 2011 and to Vice President, Acting General Counsel and Corporate Secretary in June 2014. Prior to joining Mosaic, Mr. Isaacson worked for 15 years at Cargill, Inc., where he served as Senior Attorney for a number of its business units.
Christopher A. Lewis. Mr. Lewis was named Senior Vice President - Human Resources in June 2019. Prior to joining Mosaic, Mr. Lewis held the role of Vice President, Project Execution for Spectra Energy Corporation’s merger into Calgary, Alberta, Canada-based Enbridge, Inc. where he led construction of the companies’ energy assets throughout North America, as well as a synergy capture program post acquisition. Prior to that role, Lewis held roles at DCP Midstream, LLC, a natural gas company based in Denver, where he started as the head of Human Resources while the company was formed as a spin-off from Duke Energy in 2007. From 2010 to 2016, he was DCP’s Chief Corporate Officer, a multi-functional role that included leadership of the human resources function. Earlier in his career, Lewis held regional and global senior human resources positions at Thomson Multimedia (formerly RCA, GE consumer electronics) and DHL, Inc.
James “Joc” C. O’Rourke. Mr. O’Rourke was promoted to President and Chief Executive Officer effective in August 2015. Previously, he served as Executive Vice President - Operations and Chief Operating Officer since August 2012 and before that as Executive Vice President - Operations since January 2009. Prior to joining Mosaic, Mr. O’Rourke was President, Australia Pacific for Barrick Gold Corporation, the largest gold producer in Australia, since May 2006, where he was responsible for the Australia Pacific Business Unit, consisting of ten gold and copper mines in Australia and Papua New Guinea. Before that, Mr. O’Rourke was Executive General Manager in Australia and Managing Director of Placer Dome Asia Pacific Ltd., the second largest gold producer in Australia, from December 2004, where he was responsible for the Australia Business Unit, consisting of five gold and copper mines; and General Manager of Western Australia Operations for Iluka Resources Ltd., the world’s largest zircon and second largest titanium producer, from September 2003, where he was responsible for six mining and concentrating operations and two mineral separation/synthetic rutile refineries. Mr. O’Rourke had previously held various management, engineering and other roles in the mining industry in Canada and Australia since 1984. Mr. O’Rourke has served on our Board of Directors since May 2015 and is also a director of The Toro Company.
Benjamin J. Pratt. Ben Pratt was named Senior Vice President - Government and Public Affairs in April 2020. Previously, Mr. Pratt held the position of Vice President - Corporate Public Affairs, leading corporate communications and U.S. Federal Government relations, as well as Mosaic’s corporate social responsibility activities. In addition, Mr. Pratt serves as Owner’s Representative to Streamsong Resort. Prior to joining Mosaic in February 2012, Mr. Pratt was Senior Vice President, Corporate Communications at Ameriprise Financial, Inc., in Minneapolis. Earlier in his career, he worked in a variety of communications and investor relations capacities at The PNC Financial Services Group in Pittsburgh, and at Lehman Brothers and Bear Stearns, both in New York.
Walter F. Precourt III. Mr. Precourt was named Senior Vice President - Strategy and Growth effective January 1, 2019. From June 2016 through March 2020 he also provided executive oversight for the EHS organization. He previously served as Senior Vice President - Phosphates and provided executive oversight for the corporate procurement organization from June 2016 until January 1, 2019, as our Senior Vice President - Potash Operations from May 2012 to June 2016, and before that he led our Environment, Health and Safety organization since joining Mosaic in 2009. Prior to joining Mosaic, Mr. Precourt was employed by cement and mineral component producer Holcim (U.S.) where he initially led its safety transformation and later became Vice President of Environment and Government Affairs. Mr. Precourt started his career at The Dow Chemical Company where he served in a variety of roles in Operations, Technology, Capital Project Management, and Environmental, Health and Safety. Mr. Precourt served as a director and was the past Chairman of the Board of the Saskatchewan Potash Producers Association and was a director of Fertilizer Canada.
Corrine D. Ricard. Ms. Ricard was appointed Senior Vice President - Mosaic Fertilizantes effective November 15, 2019. Prior to that she served as Senior Vice President - Commercial since February 2017, Senior Vice President - Human Resources from April 2012 to February 2017, and before that she held a number of other leadership positions at Mosaic, including Vice President - International Distribution, Vice President - Business Development and Vice President - Supply Chain. Prior to Mosaic’s formation, Ms. Ricard worked for Cargill in various roles, including risk management, supply chain and commodity trading.
Karen A. Swager. Ms. Swager was named Senior Vice President - Supply Chain effective April 1, 2020, and also provides executive oversite for the Procurement and corporate EHS teams. From January 1, 2019 until her appointment as Senior Vice President - Supply Chain, she served as Senior Vice President - Potash. Previously, Ms. Swager held leadership positions at Mosaic, including Vice President - Minerals, Vice President - Mining Operations and General Manager in our Phosphates business. She also led the mine planning and strategy group for the Phosphates business.
Yijun (“Jenny”) Wang. Ms. Wang was named Senior Vice President - Global Strategic Marketing, Head of China and India effective January 1, 2022. From October 15, 2020 until her appointment as Senior Vice President - Global Strategic Marketing, Head of China and India, Ms. Wang served as Vice President - Global Strategic Marketing. Prior to October 2020, Ms. Wang served as Vice President - Global Product Management and International Distribution and before May 2019, Ms. Wang served as Country Head for China. Ms. Wang has served on the Board of Directors at Canpotex.
Our executive officers are generally elected to serve until their respective successors are elected and qualified or until their earlier death, resignation or removal. No “family relationships,” as that term is defined in Item 401(d) of Regulation S-K, exist among any of the listed officers or between any such officer and any member of our board of directors.
Previous: Cover and table of contents · Next: Item 1A. Risk Factors.