 filings.tools
Item 2. Management’s Discussion and Analysis of Financial Condition and Results of Operations
80K characters. Original on sec.gov · Markdown
Item 2. Management’s Discussion and Analysis of Financial Condition and Results of Operations
This section should also be read in conjunction with the unaudited consolidated financial statements and accompanying footnotes included under Item 1. Financial Statements and in conjunction with our Annual Report on Form 10-K for the year ended December 31, 2022.
DISCLOSURES REGARDING FORWARD-LOOKING STATEMENTS
This Quarterly Report on Form 10-Q, particularly Management’s Discussion and Analysis of Financial Condition and Results of Operations and Quantitative and Qualitative Disclosures about Market Risk, includes forward-looking statements that are subject to risks, contingencies or uncertainties. You can identify forward-looking statements by words such as “anticipate,” “believe,” “commitment,” “could,” “design,” “estimate,” “expect,” “forecast,” “goal,” “guidance,” “intend,” “may,” “objective,” “opportunity,” “outlook,” “plan,” “policy,” “position,” “potential,” “predict,” “priority,” “project,” “prospective,” “pursue,” “seek,” “should,” “strategy,” “target,” “will,” “would” or other similar expressions that convey the uncertainty of future events or outcomes.
Forward-looking statements include, among other things, statements regarding:
-
future financial and operating results;
-
environmental, social and governance (“ESG”) plans and goals, including those related to greenhouse gas emissions, diversity and inclusion and ESG reporting;
-
future levels of capital, environmental or maintenance expenditures, general and administrative and other expenses;
-
the success or timing of completion of ongoing or anticipated capital or maintenance projects;
-
business strategies, growth opportunities and expected investments;
-
consumer demand for refined products, natural gas, renewables and NGLs;
-
the timing, amount and form of any future capital return transactions at MPC or MPLX; and
-
the anticipated effects of actions of third parties such as competitors, activist investors, federal, foreign, state or local regulatory authorities, or plaintiffs in litigation.
Our forward-looking statements are not guarantees of future performance, and you should not rely unduly on them, as they involve risks, uncertainties and assumptions that we cannot predict. Forward-looking and other statements regarding our ESG plans and goals are not an indication that these statements are material to investors or required to be disclosed in our filings with the SEC. In addition, historical, current, and forward-looking ESG-related statements may be based on standards for measuring progress that are still developing, internal controls and processes that continue to evolve, and assumptions that are subject to change in the future. Material differences between actual results and any future performance suggested in our forward-looking statements could result from a variety of factors, including the following:
-
general economic, political or regulatory developments, including inflation, interest rates, changes in governmental policies relating to refined petroleum products, crude oil, natural gas, NGLs or renewables, or taxation;
-
the regional, national and worldwide availability and pricing of refined products, crude oil, natural gas, renewables, NGLs and other feedstocks;
-
disruptions in credit markets or changes to credit ratings;
-
the adequacy of capital resources and liquidity, including availability, timing and amounts of free cash flow necessary to execute business plans and to effect any share repurchases or to maintain or increase the dividend;
-
the potential effects of judicial or other proceedings on the business, financial condition, results of operations and cash flows;
-
the timing and extent of changes in commodity prices and demand for crude oil, refined products, feedstocks or other hydrocarbon-based products, or renewables;
-
volatility in or degradation of general economic, market, industry or business conditions as a result of the COVID-19 pandemic, other infectious disease outbreaks, natural hazards, extreme weather events, the military conflict between Russia and Ukraine, other conflicts, inflation, rising interest rates or otherwise;
-
compliance with federal and state environmental, economic, health and safety, energy and other policies and regulations and enforcement actions initiated thereunder;
-
adverse market conditions or other risks affecting MPLX;
-
refining industry overcapacity or under capacity;
-
foreign imports and exports of crude oil, refined products, natural gas and NGLs;
-
changes in producer customers’ drilling plans or in volumes of throughput of crude oil, natural gas, NGLs, refined products, other hydrocarbon-based products or renewables;
-
non-payment or non-performance by our customers;
-
changes in the cost or availability of third-party vessels, pipelines, railcars and other means of transportation for crude oil, natural gas, NGLs, feedstocks, refined products and renewables;
-
the price, availability and acceptance of alternative fuels and alternative-fuel vehicles and laws mandating such fuels or vehicles;
-
political and economic conditions in nations that consume refined products, natural gas, renewables and NGLs, including the United States and Mexico, and in crude oil producing regions, including the Middle East, Russia, Africa, Canada and South America;
-
actions taken by our competitors, including pricing adjustments, the expansion and retirement of refining capacity and the expansion and retirement of pipeline capacity, processing, fractionation and treating facilities in response to market conditions;
-
completion of pipeline projects within the United States;
-
changes in fuel and utility costs for our facilities;
-
accidents or other unscheduled shutdowns affecting our refineries, machinery, pipelines, processing, fractionation and treating facilities or equipment, means of transportation, or those of our suppliers or customers;
-
acts of war, terrorism or civil unrest that could impair our ability to produce refined products, receive feedstocks or to gather, process, fractionate or transport crude oil, natural gas, NGLs, refined products or renewables;
-
political pressure and influence of environmental groups and other stakeholders upon policies and decisions related to the production, gathering, refining, processing, fractionation, transportation and marketing of crude oil or other feedstocks, refined products, natural gas, NGLs, other hydrocarbon-based products or renewables;
-
labor and material shortages;
-
our ability to successfully achieve our ESG goals and targets within the expected timeframe, if at all;
-
the costs, disruption and diversion of management’s attention associated with campaigns commenced by activist investors;
-
personnel changes; and
-
the imposition of windfall profit taxes or maximum refining margin penalties on companies operating in the energy industry in California or other jurisdictions.
For additional risk factors affecting our business, see the risk factors described in our Annual Report on Form 10-K for the year ended December 31, 2022. We undertake no obligation to update any forward-looking statements except to the extent required by applicable law.
EXECUTIVE SUMMARY
Business Update
Our results through the first three months of 2023 as compared to the first three months of 2022, were favorably impacted by the strong demand environment in which our business operates. The increase in global demand for refined products and global commodity supply constraints have continued to drive market prices of petroleum-based transportation fuels, Refining & Marketing margins and Midstream throughputs. Supply has remained constrained for a variety of reasons, including, but not limited to, effects from refinery closures and disruptions in the crude oil and petroleum-based products markets resulting from the Russia-Ukraine conflict. We are unable to predict the potential effects that the continuance or escalation of the military conflict between Russia and Ukraine, and related sanctions or market disruptions, may have on our financial position and results. It remains uncertain how long these conditions may last or how severe they may become.
Strategic Updates
LF Bioenergy Acquisition
On March 8, 2023, MPC announced the acquisition of a 49.9 percent equity interest in LF Bioenergy, an emerging producer of renewable natural gas (“RNG”) in the U.S., for approximately $56 million, which included funding for on-going operations and project development. LF Bioenergy has been focused on developing and growing a portfolio of dairy farm-based, low carbon intensity RNG projects. Current projects are under various stages of development, with the first facility nearing completion and expected to be in service in the first half of 2023. LF Bioenergy's management and origination teams continue to expand the portfolio with additional sanctioned projects while progressing their existing pipeline of opportunities toward final investment decisions. As specific project milestones are achieved, MPC is expected to fund its share of capital expenditures to build out the portfolio.
Martinez Renewable Fuels Project Joint Venture
The Martinez Renewable Fuels facility reached full Phase I production capacity of 260 million gallons per year of renewable fuels during the first quarter of 2023. Pretreatment capabilities are expected to come online in the second half of 2023 and the facility is expected to be capable of producing 730 million gallons per year by the end of 2023.
South Texas Asset Repositioning (“STAR”) Project
We completed the STAR project at our Galveston Bay refinery, which is expected to add 40 mbpd of incremental crude capacity and 17 mbpd of resid processing capacity. Start-up activities are progressing with utilization expected to increase throughout the second quarter of 2023.
Share Repurchase Authorization
On January 31, 2023, the company announced that its board of directors had approved a $5.0 billion share repurchase authorization. Future repurchases under this authorization will depend on the macro environment, cash available after opportunities for capital investment and growth of the business and market conditions. The authorization has no expiration date. As of March 31, 2023, MPC had $5.13 billion remaining under its share repurchase authorizations.
See Note 8 to the unaudited consolidated financial statements for further discussion of our share repurchase authorizations.
Results
Our CODM evaluates the performance of our segments using segment adjusted EBITDA. Amounts included in income before income taxes and excluded from segment adjusted EBITDA include: (i) depreciation and amortization; (ii) net interest and other financial costs; (iii) turnaround expenses and (iv) other adjustments as deemed necessary. These items are either: (i) believed to be non-recurring in nature; (ii) not believed to be allocable or controlled by the segment; or (iii) are not tied to the operational performance of the segment.
Select results are reflected in the following table.
| Three Months Ended March 31, | |||||||||||||||||||||||
| (Millions of dollars) | 2022 | 2021 | |||||||||||||||||||||
| Segment adjusted EBITDA for reportable segments | |||||||||||||||||||||||
| Refining & Marketing | $ | 3,853 | $ | 1,374 | |||||||||||||||||||
| Midstream | 1,530 | 1,403 | |||||||||||||||||||||
| Total reportable segments | $ | 5,383 | $ | 2,777 | |||||||||||||||||||
| Reconciliation of segment adjusted EBITDA for reportable segments to income before income taxes | |||||||||||||||||||||||
| Total reportable segments | $ | 5,383 | $ | 2,777 | |||||||||||||||||||
| Corporate | (165) | (138) | |||||||||||||||||||||
| Refining planned turnaround costs | (357) | (145) | |||||||||||||||||||||
| Litigation | — | 27 | |||||||||||||||||||||
| Depreciation and amortization(c) | (800) | (805) | |||||||||||||||||||||
| Net interest and other financial costs | (154) | (262) | |||||||||||||||||||||
| Income before income taxes | $ | 3,907 | $ | 1,454 | |||||||||||||||||||
| Net income attributable to MPC per diluted share | $ | 6.09 | $ | 1.49 |
Net income attributable to MPC was $2.72 billion, or $6.09 per diluted share, in the first quarter of 2023 compared to $845 million, or $1.49 per diluted share, for the first quarter of 2022. The increase in net income attributable to MPC was largely due higher Refining & Marketing margins.
Refer to the Results of Operations section for a discussion of consolidated financial results and segment results for the first quarter of 2023 as compared to the first quarter of 2022.
MPLX
We owned approximately 647 million MPLX common units as of March 31, 2023, with a market value of $22.30 billion based on the March 31, 2023 closing price of $34.45 per common unit. On April 25, 2023, MPLX declared a quarterly cash distribution of $0.7750 per common unit payable on May 15, 2023, to unitholders of record on May 5, 2023. As a result, MPC’s portion of this distribution is approximately $501 million.
We received limited partner distributions of $502 million from MPLX in the three months ended March 31, 2023 and $456 million in the three months ended March 31, 2022.
During the three months ended March 31, 2023, no MPLX units were repurchased. As of March 31, 2023, approximately $846 million remained available under the authorization for future unit repurchases.
On February 9, 2023, MPLX issued $1.1 billion aggregate principal amount of 5.00 percent senior notes due 2033 and $500 million aggregate principal amount of 5.65 percent senior notes due 2053 in an underwritten public offering.
On February 15, 2023, MPLX redeemed all of its 600,000 outstanding Series B preferred units at the redemption price of $1,000 per unit. The semi-annual distribution due to Series B unitholders on February 15, 2023, was also paid on that date, in the usual manner. On March 13, 2023, MPLX redeemed all of MPLX’s and MarkWest’s $1.0 billion aggregate principal amount of 4.50 percent senior notes due July 2023 at par, plus accrued and unpaid interest.
See Note 4 to the unaudited consolidated financial statements for additional information on MPLX.
OVERVIEW OF SEGMENTS
Refining & Marketing
Refining & Marketing segment adjusted EBITDA depends largely on our refinery throughputs, Refining & Marketing margin, refining operating costs and distribution costs.
Refining & Marketing margin is the difference between the prices of refined products sold and the costs of crude oil and other charge and blendstocks refined, including the costs to transport these inputs to our refineries and the costs of products purchased for resale. The crack spread is a measure of the difference between market prices for refined products and crude oil, commonly used by the industry as a proxy for the refining margin. Crack spreads can fluctuate significantly, particularly when prices of refined products do not move in the same direction as the cost of crude oil. As a performance benchmark and a comparison with other industry participants, we calculate Gulf Coast, Mid-Continent and West Coast crack spreads that we believe most closely track our operations and slate of products. The following are used for these crack spread calculations:
-
The Gulf Coast crack spread uses three barrels of MEH crude producing two barrels of USGC CBOB gasoline and one barrel of USGC ULSD;
-
The Mid-Continent crack spread uses three barrels of WTI crude producing two barrels of Chicago CBOB gasoline and one barrel of Chicago ULSD; and
-
The West Coast crack spread uses three barrels of ANS crude producing two barrels of LA CARBOB and one barrel of LA CARB Diesel.
Our refineries can process significant amounts of sweet and sour crude oil, which typically can be purchased at a discount to crude oil referenced in our Gulf Coast, Mid-Continent and West Coast crack spreads. The amount of these discounts, which we refer to as the sweet differential and sour differential, can vary significantly, causing our Refining & Marketing margin to differ from blended crack spreads. In general, larger sweet and sour differentials will enhance our Refining & Marketing margin.
Future crude oil differentials will be dependent on a variety of market and economic factors, as well as U.S. energy policy.
The following table provides sensitivities showing an estimated change in annual Refining & Marketing segment adjusted EBITDA due to potential changes in market conditions.
| (In millions) | ||||||||
| Blended crack spread sensitivity(a) (per $1.00/barrel change) | $ | 1,080 | ||||||
| Sour differential sensitivity(b) (per $1.00/barrel change) | 500 | |||||||
| Sweet differential sensitivity(c) (per $1.00/barrel change) | 500 | |||||||
| Natural gas price sensitivity(d) (per $1.00/MMBtu) | 310 |
(a)Crack spread based on 40 percent MEH, 40 percent WTI and 20 percent ANS with Gulf Coast, Mid-Continent and West Coast product pricing, respectively, and assumes all other differentials and pricing relationships remain unchanged.
(b)Sour crude oil basket consists of the following crudes: ANS, Argus Sour Crude Index, Maya and Western Canadian Select. We assume approximately 50 percent of the crude processed at our refineries in 2023 will be sour crude.
(c)Sweet crude oil basket consists of the following crudes: Bakken, Brent, MEH, WTI-Cushing and WTI-Midland. We assume approximately 50 percent of the crude processed at our refineries in 2023 will be sweet crude.
(d)This is consumption-based exposure for our Refining & Marketing segment and does not include the sales exposure for our Midstream segment.
In addition to the market changes indicated by the crack spreads, the sour differential and the sweet differential, our Refining & Marketing margin is impacted by factors such as:
-
the selling prices realized for refined products;
-
the types of crude oil and other charge and blendstocks processed;
-
our refinery yields;
-
the cost of products purchased for resale;
-
the impact of commodity derivative instruments used to hedge price risk;
-
the potential impact of lower of cost or market adjustments to inventories in periods of declining prices;
-
the potential impact of LIFO charges due to changes in historic inventory levels; and
-
the cost of purchasing RINs in the open market to comply with RFS2 requirements.
Refining & Marketing segment adjusted EBITDA is also affected by changes in refinery operating costs in addition to committed distribution costs. Changes in operating costs are primarily driven by the cost of energy used by our refineries, including purchased natural gas, and the level of maintenance costs. Distribution costs primarily include long-term agreements with MPLX, which as discussed below include minimum commitments to MPLX, and will negatively impact segment adjusted EBITDA in periods when throughput or sales are lower or refineries are idled.
We have various long-term, fee-based commercial agreements with MPLX. Under these agreements, MPLX, which is reported in our Midstream segment, provides transportation, storage, distribution and marketing services to our Refining & Marketing segment. Certain of these agreements include commitments for minimum quarterly throughput and distribution volumes of crude oil and refined products and minimum storage volumes of crude oil, refined products and other products. Certain other agreements include commitments to pay for 100 percent of available capacity for certain marine transportation and refining logistics assets.
Midstream
Our Midstream segment gathers, transports, stores and distributes crude oil, refined products, including renewable diesel, and other hydrocarbon-based products, principally for our Refining & Marketing segment. Additionally, the segment markets refined products. The profitability of our pipeline transportation operations primarily depends on tariff rates and the volumes shipped through the pipelines. The profitability of our marine operations primarily depends on the quantity and availability of our vessels and barges. The profitability of our light product terminal operations primarily depends on the throughput volumes at these terminals. The profitability of our fuels distribution services primarily depends on the sales volumes of certain refined products. The profitability of our refining logistics operations depends on the quantity and availability of our refining logistics assets. A majority of the crude oil and refined product shipments on our pipelines and marine vessels and the refined product throughput at our terminals serve our Refining & Marketing segment and our refining logistics assets and fuels distribution services are used solely by our Refining & Marketing segment. As discussed above in the Refining & Marketing section, MPLX, which is reported in our Midstream segment, has various long-term, fee-based commercial agreements related to services provided to our Refining & Marketing segment. Under these agreements, MPLX has received various commitments of minimum throughput, storage and distribution volumes as well as commitments to pay for all available capacity of certain assets. The volume of crude oil that we transport is directly affected by the supply of, and refiner demand for, crude oil in the markets served directly by our crude oil pipelines, terminals and marine operations. Key factors in this supply and demand balance are the production levels of crude oil by producers in various regions or fields, the availability and cost of alternative modes of transportation, the volumes of crude oil processed at refineries and refinery and transportation system maintenance levels. The volume of refined products that we transport, store, distribute and market is directly affected by the production levels of, and user demand for, refined products in the markets served by our refined product pipelines and marine operations. In most of our markets, demand for gasoline and distillate peaks during the summer driving season, which extends from May through September of each year, and declines during the fall and winter months. As with crude oil, other transportation alternatives and system maintenance levels influence refined product movements.
Our Midstream segment also gathers, processes and transports natural gas and transports, fractionates, stores and markets NGLs. NGL and natural gas prices are volatile and are impacted by changes in fundamental supply and demand, as well as market uncertainty, availability of NGL transportation and fractionation capacity and a variety of additional factors that are beyond our control. Our Midstream segment profitability is affected by prevailing commodity prices primarily as a result of processing or conditioning at our own or third‑party processing plants, purchasing and selling or gathering and transporting volumes of natural gas at index‑related prices and the cost of third‑party transportation and fractionation services. To the extent that commodity prices influence the level of natural gas drilling by our producer customers, such prices also affect profitability.
RESULTS OF OPERATIONS
The following discussion includes comments and analysis relating to our results of operations. This discussion should be read in conjunction with Item 1. Financial Statements and is intended to provide investors with a reasonable basis for assessing our historical operations, but should not serve as the only criteria for predicting our future performance.
Consolidated Results of Operations
| Three Months Ended March 31, | ||||||||||||||||||||||||||||||||||||||
| (Millions of dollars) | 2023 | 2022 | Variance | |||||||||||||||||||||||||||||||||||
| Revenues and other income: | ||||||||||||||||||||||||||||||||||||||
| Sales and other operating revenues | $ | 34,864 | $ | 38,058 | $ | (3,194) | ||||||||||||||||||||||||||||||||
| Income from equity method investments | 133 | 142 | (9) | |||||||||||||||||||||||||||||||||||
| Net gain on disposal of assets | 3 | (18) | 21 | |||||||||||||||||||||||||||||||||||
| Other income | 77 | 202 | (125) | |||||||||||||||||||||||||||||||||||
| Total revenues and other income | 35,077 | 38,384 | (3,307) | |||||||||||||||||||||||||||||||||||
| Costs and expenses: | ||||||||||||||||||||||||||||||||||||||
| Cost of revenues (excludes items below) | 29,294 | 35,068 | (5,774) | |||||||||||||||||||||||||||||||||||
| Depreciation and amortization | 800 | 805 | (5) | |||||||||||||||||||||||||||||||||||
| Selling, general and administrative expenses | 691 | 603 | 88 | |||||||||||||||||||||||||||||||||||
| Other taxes | 231 | 192 | 39 | |||||||||||||||||||||||||||||||||||
| Total costs and expenses | 31,016 | 36,668 | (5,652) | |||||||||||||||||||||||||||||||||||
| Income from operations | 4,061 | 1,716 | 2,345 | |||||||||||||||||||||||||||||||||||
| Net interest and other financial costs | 154 | 262 | (108) | |||||||||||||||||||||||||||||||||||
| Income before income taxes | 3,907 | 1,454 | 2,453 | |||||||||||||||||||||||||||||||||||
| Provision for income taxes | 823 | 282 | 541 | |||||||||||||||||||||||||||||||||||
| Net income | 3,084 | 1,172 | 1,912 | |||||||||||||||||||||||||||||||||||
| Less net income attributable to: | ||||||||||||||||||||||||||||||||||||||
| Redeemable noncontrolling interest | 23 | 21 | 2 | |||||||||||||||||||||||||||||||||||
| Noncontrolling interests | 337 | 306 | 31 | |||||||||||||||||||||||||||||||||||
| Net income attributable to MPC | $ | 2,724 | $ | 845 | $ | 1,879 |
First Quarter 2023 Compared to First Quarter 2022
Net income attributable to MPC increased $1.88 billion in the first quarter of 2023 compared to the first quarter of 2022 primarily due to higher Refining & Marketing margins in the first quarter of 2023.
Revenues and other income decreased $3.31 billion primarily due to:
-
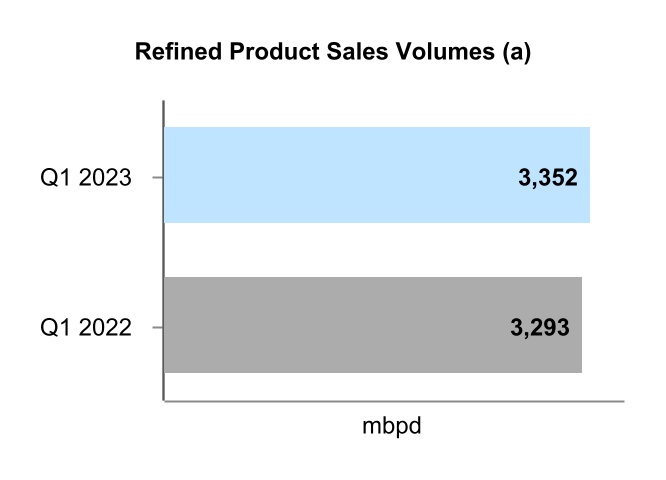
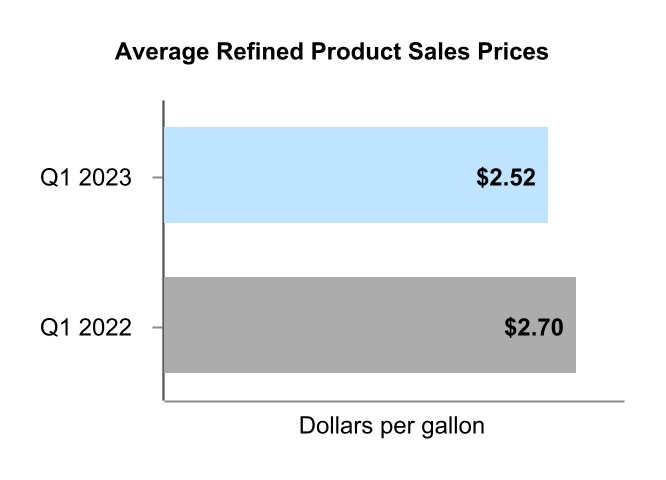
decreased sales and other operating revenues of $3.19 billion primarily due to decreased Refining & Marketing segment average refined product sales prices of $0.18 per gallon, partially offset by increased refined product sales volumes of 59 mbpd; and
-
decreased other income of $125 million primarily due to lower income on RIN sales.
Costs and expenses decreased $5.65 billion primarily due to:
-
decreased cost of revenues of $5.77 billion mainly due to lower crude oil costs:
-
increased selling, general and administrative expenses of $88 million largely due to increased salaries and employee related costs, equity compensation, office expenses and insurance expenses, partially offset by decreased employee benefit costs: and
-
increased other taxes of $39 million primarily due to the reinstated Petroleum Superfund Tax which was effective January 1, 2023.
Net interest and other financial costs decreased $108 million largely due to increased interest income, partially offset by increased interest expense due to higher MPLX borrowings.
We recorded a combined federal, state and foreign income tax provision of $823 million for the three months ended March 31, 2023, which was higher than the tax computed at the U.S. statutory rate primarily due to state taxes offset by permanent tax benefits related to net income attributable to noncontrolling interests. We recorded a combined federal, state and foreign income tax provision of $282 million for the three months ended March 31, 2022, which was lower than the tax computed at the U.S. statutory rate primarily due to certain permanent tax benefits related to net income attributable to noncontrolling interests offset by state taxes.
Net income attributable to noncontrolling interests increased $31 million primarily due to an increase in MPLX’s net income in the first quarter of 2023.
Segment Results
We classify our business in the following reportable segments: Refining & Marketing and Midstream. Segment adjusted EBITDA represents adjusted EBITDA attributable to the reportable segments. Amounts included in income before income taxes and excluded from segment adjusted EBITDA include: (i) depreciation and amortization; (ii) net interest and other financial costs; (iii) turnaround expenses and (iv) other adjustments as deemed necessary. These items are either: (i) believed to be non-recurring in nature; (ii) not believed to be allocable or controlled by the segment; or (iii) are not tied to the operational performance of the segment.
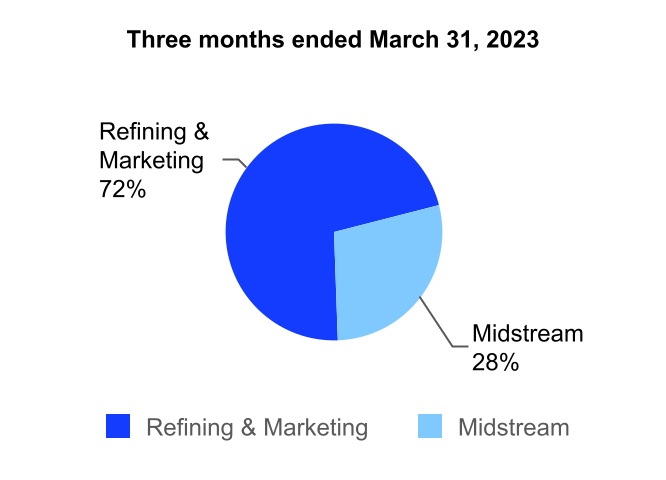
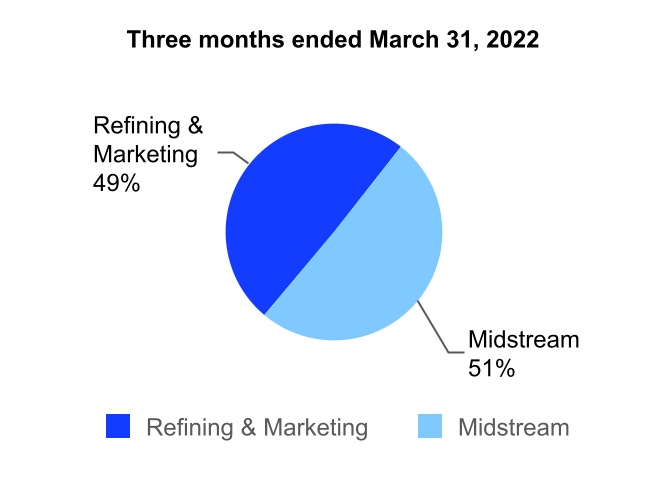
The following shows the percentage of segment adjusted EBITDA by segment for the three months ended March 31, 2023 and 2022.
Refining & Marketing
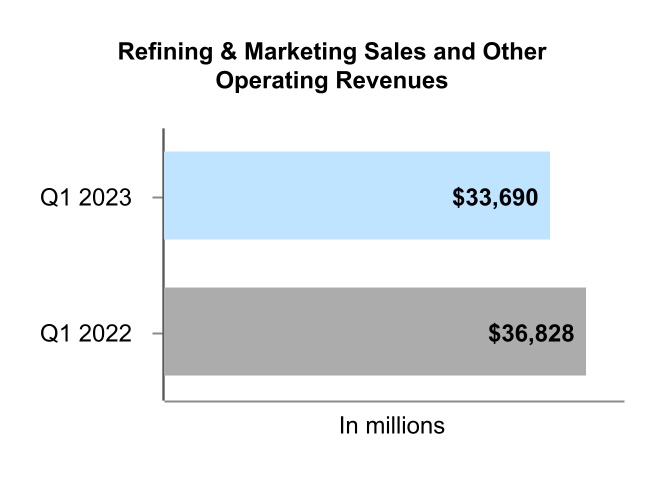
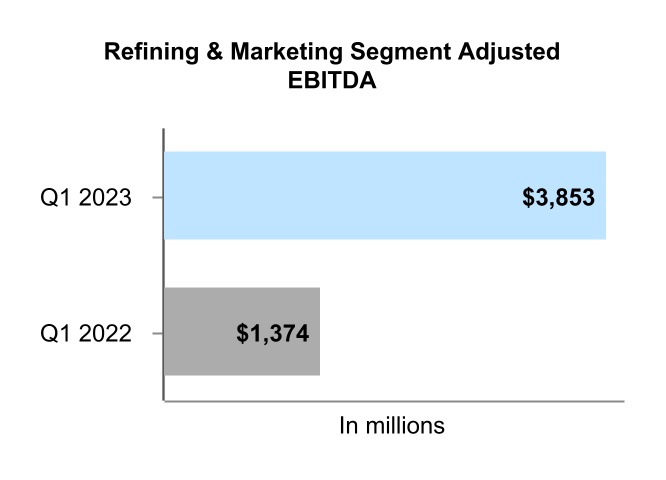
The following includes key financial and operating data for the first quarter of 2023 compared to the first quarter of 2022.
(a)Includes intersegment sales to Midstream and sales destined for export.
| Three Months Ended March 31, | ||||||||||||||||||||||||||
| 2023 | 2022 | |||||||||||||||||||||||||
| Refining & Marketing Operating Statistics | ||||||||||||||||||||||||||
| Net refinery throughput (mbpd) | 2,837 | 2,833 | ||||||||||||||||||||||||
| Refining & Marketing margin per barrel(a)(b) | $ | 26.15 | $ | 15.31 | ||||||||||||||||||||||
| Less: | ||||||||||||||||||||||||||
| Refining operating costs per barrel(c) | 5.68 | 5.22 | ||||||||||||||||||||||||
| Distribution costs per barrel | 5.26 | 4.79 | ||||||||||||||||||||||||
| Other income per barrel(d) | 0.12 | (0.09) | ||||||||||||||||||||||||
| Refining & Marketing segment adjusted EBITDA per barrel | $ | 15.09 | $ | 5.39 | ||||||||||||||||||||||
| Less: | ||||||||||||||||||||||||||
| Refining planned turnaround costs per barrel | 1.40 | 0.57 | ||||||||||||||||||||||||
| Depreciation and amortization per barrel | 1.82 | 1.81 | ||||||||||||||||||||||||
| Refining & Marketing segment income per barrel | $ | 11.87 | $ | 3.01 | ||||||||||||||||||||||
| Fees paid to MPLX per barrel included in distribution costs above | 3.66 | 3.46 |
(a)Sales revenue less cost of refinery inputs and purchased products, divided by net refinery throughput.
(b)See “Non-GAAP Measures” section for reconciliation and further information regarding this non-GAAP measure.
(c)Includes refining operating costs and major maintenance costs. Excludes planned turnaround and depreciation and amortization expense.
(d)Includes income (loss) from equity method investments, net gain (loss) on disposal of assets and other income.
The following information presents certain benchmark prices in our marketing areas and market indicators that we believe are helpful in understanding the results of our Refining & Marketing segment. The benchmark crack spreads below do not reflect the market cost of RINs necessary to meet EPA renewable volume obligations for attributable products under the Renewable Fuel Standard.
| Three Months Ended March 31, | ||||||||||||||||||||||||||
| 2023 | 2022 | |||||||||||||||||||||||||
| Benchmark Spot Prices (dollars per gallon) | ||||||||||||||||||||||||||
| Chicago CBOB unleaded regular gasoline | $ | 2.38 | $ | 2.60 | ||||||||||||||||||||||
| Chicago ULSD | 2.75 | 2.85 | ||||||||||||||||||||||||
| USGC CBOB unleaded regular gasoline | 2.39 | 2.69 | ||||||||||||||||||||||||
| USGC ULSD | 2.87 | 2.98 | ||||||||||||||||||||||||
| LA CARBOB | 2.73 | 3.04 | ||||||||||||||||||||||||
| LA CARB diesel | 2.91 | 3.04 | ||||||||||||||||||||||||
| Market Indicators (dollars per barrel) | ||||||||||||||||||||||||||
| WTI | $ | 75.99 | $ | 95.01 | ||||||||||||||||||||||
| MEH | 77.74 | 96.77 | ||||||||||||||||||||||||
| ANS | 79.02 | 96.31 | ||||||||||||||||||||||||
| Crack Spreads: | ||||||||||||||||||||||||||
| Mid-Continent WTI 3-2-1 | $ | 22.41 | $ | 13.14 | ||||||||||||||||||||||
| USGC MEH 3-2-1 | 21.19 | 14.96 | ||||||||||||||||||||||||
| West Coast ANS 3-2-1 | 29.63 | 26.46 | ||||||||||||||||||||||||
| Blended 3-2-1(a) | 23.36 | 16.53 | ||||||||||||||||||||||||
| Crude Oil Differentials: | ||||||||||||||||||||||||||
| Sweet | $ | 0.28 | $ | 0.11 | ||||||||||||||||||||||
| Sour | (9.23) | (4.88) |
(a) Blended 3-2-1 Mid-Continent/USGC/West Coast crack spread is 40/40/20 percent in 2023 and 2022.
First Quarter 2023 Compared to First Quarter 2022
Refining & Marketing segment revenues decreased $3.14 billion primarily due to decreased average refined product sales prices of $0.18 per gallon, partially offset by increased refined product sales volumes of 59 mbpd.
Net refinery throughputs increased 4 mbpd during the first quarter of 2023.
Refining & Marketing segment adjusted EBITDA increased $2.48 billion primarily due to higher per barrel margins, partially offset by increased refining operating costs and distribution costs, both excluding depreciation and amortization. Refining & Marketing segment adjusted EBITDA was $15.09 per barrel for the first quarter of 2023, versus $5.39 per barrel for the first quarter of 2022.
Refining & Marketing margin was $26.15 per barrel for the first quarter of 2023 compared to $15.31 per barrel for the first quarter of 2022. Refining & Marketing margin is affected by our performance against the market indicators shown earlier, which use spot market values and an estimated mix of crude purchases and product sales. Based on the market indicators and our crude oil throughput, we estimate a net positive impact of approximately $2 billion on Refining & Marketing margin for the first quarter of 2023 compared to the first quarter of 2022, primarily due to wider crack spreads and sour differentials. Our reported Refining & Marketing margin differs from market indicators due to the mix of crudes purchased and their costs, the effect of market structure on our crude oil acquisition prices, the effect of RIN prices on the crack spread, and other items like refinery yields, other feedstock variances and fuel margin from sales to direct dealers. These factors had an estimated net positive effect of approximately $600 million on Refining & Marketing segment income in the first quarter of 2023 compared to the first quarter of 2022.
For the three months ended March 31, 2023, refining operating costs, excluding depreciation and amortization, increased $120 million, or $0.46 per barrel, compared to the three months ended March 31, 2022, largely due to project expense associated with higher turnaround activity.
Distribution costs, excluding depreciation and amortization, increased $123 million, or $0.47 per barrel, and include fees paid to MPLX of $935 million and $882 million for the first quarter of 2023 and 2022, respectively.
Refining planned turnaround costs increased $212 million, or $0.83 per barrel, due to the scope and timing of turnaround activity.
Depreciation and amortization increased $0.01 per barrel.
We purchase RINs to satisfy a portion of our RFS2 compliance. Our expenses associated with purchased RINs were $467 million and $574 million in the first three months of 2023 and 2022, respectively. The RINs expense is included in Refining & Marketing margin. The decrease in the first three months of 2023 was primarily due to lower weighted average RIN costs.
Supplemental Refining & Marketing Statistics
| Three Months Ended March 31, | |||||||||||||||||||||||
| 2023 | 2022 | ||||||||||||||||||||||
| Refining & Marketing Operating Statistics | |||||||||||||||||||||||
| Crude oil capacity utilization percent(a) | 89 | 91 | |||||||||||||||||||||
| Refinery throughputs (mbpd): | |||||||||||||||||||||||
| Crude oil refined | 2,566 | 2,624 | |||||||||||||||||||||
| Other charge and blendstocks | 271 | 209 | |||||||||||||||||||||
| Net refinery throughput | 2,837 | 2,833 | |||||||||||||||||||||
| Sour crude oil throughput percent | 41 | 47 | |||||||||||||||||||||
| Sweet crude oil throughput percent | 59 | 53 | |||||||||||||||||||||
| Refined product yields (mbpd): | |||||||||||||||||||||||
| Gasoline(b) | 1,508 | 1,483 | |||||||||||||||||||||
| Distillates(b) | 1,024 | 978 | |||||||||||||||||||||
| Propane | 67 | 69 | |||||||||||||||||||||
| NGLs and petrochemicals(b) | 157 | 161 | |||||||||||||||||||||
| Heavy fuel oil | 31 | 86 | |||||||||||||||||||||
| Asphalt | 84 | 87 | |||||||||||||||||||||
| Total | 2,871 | 2,864 | |||||||||||||||||||||
| Refined product export sales volumes (mbpd)(b) | 298 | 270 |
(a)Based on calendar-day capacity, which is an annual average that includes down time for planned maintenance and other normal operating activities.
(b)Product yields include renewable production.
(c)Represents fully loaded export cargoes for each time period. These sales volumes are included in the total sales volume amounts.
Midstream
The following includes key financial and operating data for the first quarter of 2023 compared to the first quarter of 2022.
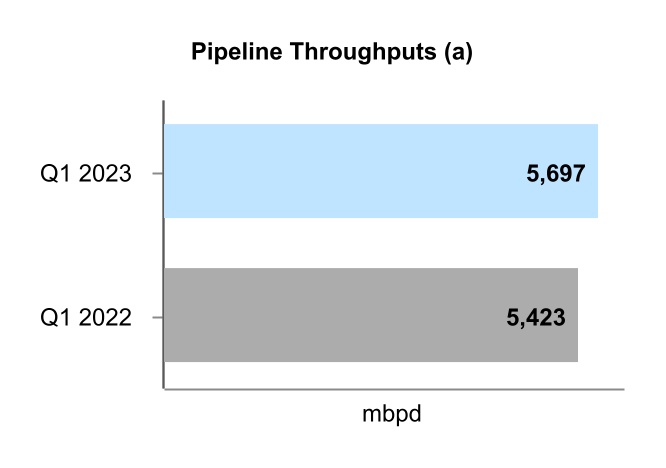
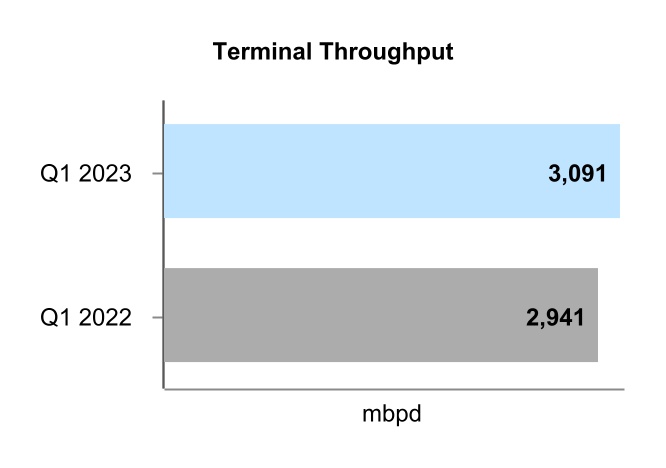
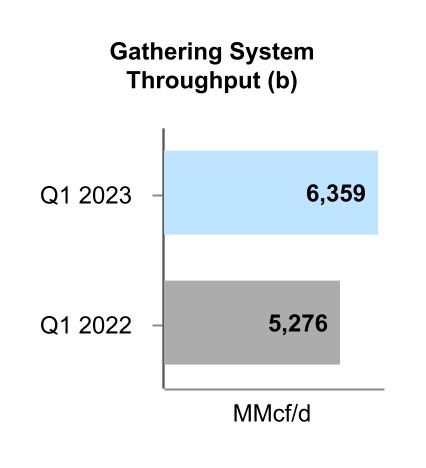
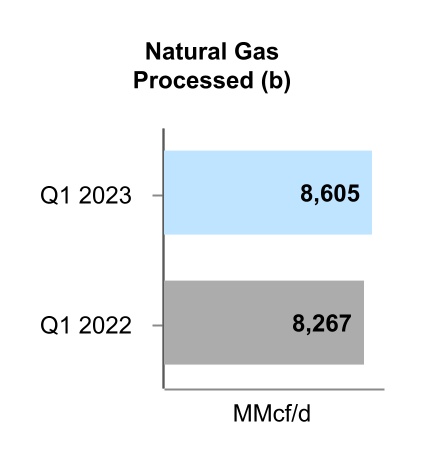
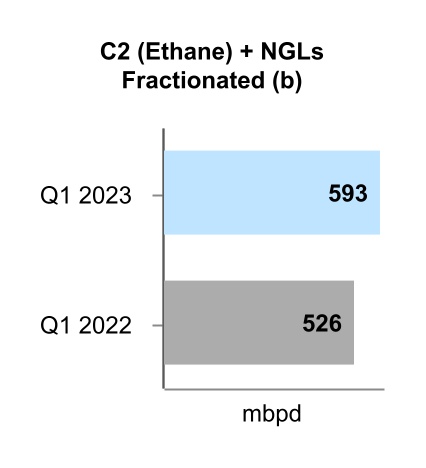
(a)On owned common-carrier pipelines, excluding equity method investments.
(b)Includes amounts related to MPLX operated unconsolidated equity method investments on a 100 percent basis.
| Three Months Ended March 31, | ||||||||||||||||||||||||||
| Benchmark Prices | 2023 | 2022 | ||||||||||||||||||||||||
| Natural Gas NYMEX HH (per MMBtu) | $ | 2.77 | $ | 4.57 | ||||||||||||||||||||||
| C2 + NGL Pricing (per gallon)(a) | $ | 0.77 | $ | 1.15 |
(a)C2 + NGL pricing based on Mont Belvieu prices assuming an NGL barrel of approximately 35 percent ethane, 35 percent propane, 6 percent iso-butane, 12 percent normal butane and 12 percent natural gasoline.
First Quarter 2023 Compared to First Quarter 2022
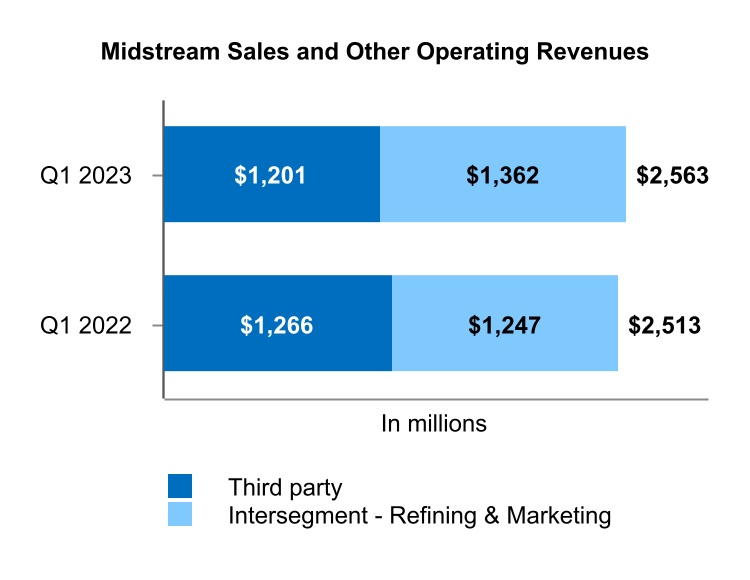
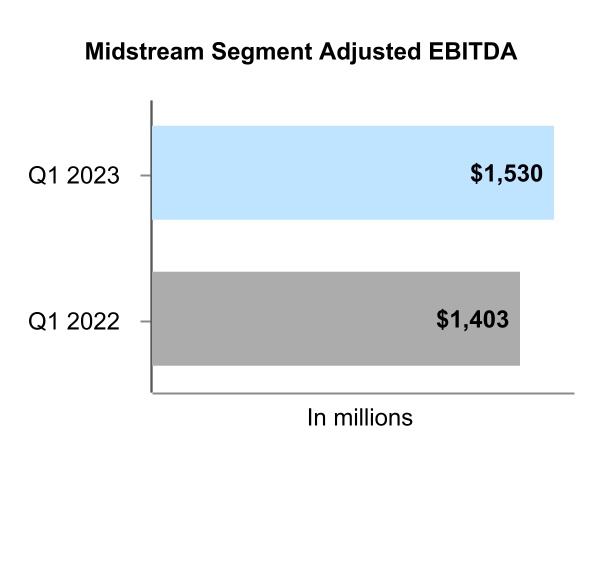
In the first quarter of 2023, Midstream segment adjusted EBITDA increased $127 million. Results for the quarter benefited from higher throughputs of approximately $51 million, higher rates of $45 million and increased income from equity method investments of $38 million, partially offset by lower NGL prices of $41 million.
Corporate
| Key Financial Information (millions of dollars) | Three Months Ended March 31, | |||||||||||||||||||||||||
| 2023 | 2022 | |||||||||||||||||||||||||
| Corporate(a) | $ | (184) | $ | (151) |
(a)Corporate costs consist primarily of MPC’s corporate administrative expenses and costs related to certain non-operating assets, except for corporate overhead expenses attributable to MPLX, which are included in the Midstream segment. Corporate costs include depreciation and amortization of $19 million and $13 million for the first quarter of 2023 and 2022, respectively.
First Quarter 2023 Compared to First Quarter 2022
In the first quarter of 2023, corporate expenses increased $33 million due to higher compensation expenses primarily associated with performance-based equity awards, in addition to increases in technology and communication expenses.
Items not Allocated to Segments
| Key Financial Information (millions of dollars) | Three Months Ended March 31, | |||||||||||||||||||||||||
| 2023 | 2022 | |||||||||||||||||||||||||
| Items not allocated to segments: | ||||||||||||||||||||||||||
| Litigation | $ | — | $ | 27 | ||||||||||||||||||||||
Non-GAAP Financial Measure
Management uses a financial measure to evaluate our operating performance that is calculated and presented on the basis of a methodology other than in accordance with GAAP. The non-GAAP financial measure we use is as follows:
Refining & Marketing Margin
Refining & Marketing margin is defined as sales revenue less cost of refinery inputs and purchased products. We believe this non-GAAP financial measure is used to evaluate our Refining & Marketing segment’s operating and financial performance as it is the most comparable measure to the industry’s market reference product margins. This measure should not be considered a substitute for, or superior to, Refining & Marketing gross margin or other measures of financial performance prepared in accordance with GAAP, and our calculations thereof may not be comparable to similarly titled measures reported by other companies.
Reconciliation of Refining & Marketing segment adjusted EBITDA to Refining & Marketing gross margin and Refining & Marketing margin
| Three Months Ended March 31, | |||||||||||||||||||||||||||||
| (Millions of dollars) | 2023 | 2022 | |||||||||||||||||||||||||||
| Refining & Marketing segment adjusted EBITDA | $ | 3,853 | $ | 1,374 | |||||||||||||||||||||||||
| Plus (Less): | |||||||||||||||||||||||||||||
| Depreciation and amortization | (464) | (461) | |||||||||||||||||||||||||||
| Refining planned turnaround costs | (357) | (145) | |||||||||||||||||||||||||||
| Selling, general and administrative expenses | 592 | 508 | |||||||||||||||||||||||||||
| (Income) loss from equity method investments | 36 | (12) | |||||||||||||||||||||||||||
| Net gain on disposal of assets | (3) | — | |||||||||||||||||||||||||||
| Other income | (51) | (181) | |||||||||||||||||||||||||||
| Refining & Marketing gross margin | 3,606 | 1,083 | |||||||||||||||||||||||||||
| Plus (Less): | |||||||||||||||||||||||||||||
| Operating expenses (excluding depreciation and amortization) | 2,745 | 2,389 | |||||||||||||||||||||||||||
| Depreciation and amortization | 464 | 461 | |||||||||||||||||||||||||||
| Gross margin excluded from and other income included in Refining & Marketing margin(a) | (67) | 14 | |||||||||||||||||||||||||||
| Other taxes included in Refining & Marketing margin | (71) | (43) | |||||||||||||||||||||||||||
| Refining & Marketing margin | $ | 6,677 | $ | 3,904 | |||||||||||||||||||||||||
(a)Reflects the gross margin, excluding depreciation and amortization, of other related operations included in the Refining & Marketing segment and processing of credit card transactions on behalf of certain of our marketing customers, net of other income.
LIQUIDITY AND CAPITAL RESOURCES
Cash Flows
Our consolidated cash and cash equivalents balance was approximately $7.96 billion at March 31, 2023 compared to $8.63 billion at December 31, 2022. Net cash provided by (used in) operating activities, investing activities and financing activities are presented in the following table.
| Three Months Ended March 31, | ||||||||||||||
| (Millions of dollars) | 2023 | 2022 | ||||||||||||
| Net cash provided by (used in): | ||||||||||||||
| Operating activities | $ | 4,057 | $ | 2,513 | ||||||||||
| Investing activities | (816) | 1,708 | ||||||||||||
| Financing activities | (3,907) | (2,364) | ||||||||||||
| Total increase (decrease) in cash | $ | (666) | $ | 1,857 |
Operating Activities
Net cash provided by operations increased $1.54 billion in the first three months of 2023 compared to the first three months of 2022. The change in net cash provided by operations is primarily due to an increase in operating results and an unfavorable change in working capital of $696 million when comparing the change in working capital in both periods.
For the first three months of 2023, changes in working capital, excluding changes in short-term debt, were a net $98 million use of cash primarily due to the effects of decreasing energy commodity volumes and prices at the end of the period on working capital. Accounts payable decreased primarily due to decreases in crude volumes and prices. Inventories increased primarily due to increases in crude and refined product inventory volumes. Current receivables decreased primarily due to decreases in crude volumes and prices.
For the first three months of 2022, changes in working capital, excluding changes in short-term debt, were a net $598 million source of cash primarily due to the effects of increasing energy commodity prices and volumes at the end of the period on working capital. Accounts payable increased primarily due to increases in crude prices and volumes. Current receivables increased primarily due to higher crude and refined product prices and volumes. Inventories increased primarily due to an increase in refined product inventories.
Investing Activities
Net cash used in investing activities was $816 million in the first three months of 2023 compared to net cash provided by investing activities of $1.71 billion in the first three months of 2022.
-
The change in net cash used in investing activities is primarily due to purchases of short-term investments of $2.11 billion, partially offset by maturities and sales of short-term investments of $1.16 billion and $631 million, respectively, in the first three months of 2023.
-
Additions to property, plant and equipment decreased $38 million primarily due to decreased Corporate and Refining & Marketing capital expenditures. See the “Capital Requirements” section for additional information on our capital investment plan.
-
Cash used in net investments was $207 million for the first three months of 2023 compared to $112 million for the first three months of 2022. In 2023, investments primarily included the Martinez Renewable Fuels joint venture and the acquisition of a 49.9 percent equity interest in LF Bioenergy for approximately $56 million. In 2022, increased MPLX contributions to equity method investments included a $60 million contribution to its Bakken Pipeline joint venture to fund its share of a debt repayment by the joint venture.
The consolidated statements of cash flows exclude changes to the consolidated balance sheets that did not affect cash. A reconciliation of additions to property, plant and equipment per the consolidated statements of cash flows to reported total capital expenditures and investments follows.
| Three Months Ended March 31, | ||||||||||||||
| (Millions of dollars) | 2023 | 2022 | ||||||||||||
| Additions to property, plant and equipment per the consolidated statements of cash flows | $ | 457 | $ | 495 | ||||||||||
| Increase (decrease) in capital accruals | 26 | (34) | ||||||||||||
| Total capital expenditures | 483 | 461 | ||||||||||||
| Investments in equity method investees | 207 | 112 | ||||||||||||
| Total capital expenditures and investments | $ | 690 | $ | 573 |
Financing Activities
Financing activities were a net $3.91 billion use of cash in the first three months of 2023 compared to a net $2.36 billion use of cash in the first three months of 2022.
- Long-term debt borrowings and repayments were a net $553 million source of cash in the first three months of 2023 compared to a net $1.15 billion source of cash in the first three months of 2022. During the first three months of 2023, MPLX issued $1.6 billion of senior notes and redeemed $1.0 billion of senior notes.
During the first three months of 2022, MPLX issued $1.5 billion of senior notes and had net payments of $300 million under its revolving credit facility.
-
Cash used in common stock repurchases, including fees and expenses, totaled $3.18 billion in the first three months of 2023 compared to $2.85 billion in the first three months of 2022. See the “Capital Requirements” section for further discussion of our stock repurchases.
-
Cash used in repurchases of noncontrolling interests was $100 million in the first three months of 2022 related to the repurchase of MPLX common units. See Note 4 to the unaudited consolidated financial statements for further discussion of MPLX.
-
During the first three months of 2023, MPLX redeemed all of its outstanding Series B preferred units for $600 million.
Derivative Instruments
See Item 3. Quantitative and Qualitative Disclosures about Market Risk for a discussion of derivative instruments and associated market risk.
Capital Resources
MPC, Excluding MPLX
We control MPLX through our ownership of the general partner; however, the creditors of MPLX do not have recourse to MPC’s general credit through guarantees or other financial arrangements, except as noted. MPC has effectively guaranteed certain indebtedness of LOOP and LOCAP, in which MPLX holds an interest. Therefore, in the following table, we present the liquidity of MPC, excluding MPLX. MPLX liquidity is discussed in the following section.
Our liquidity, excluding MPLX, totaled $16.06 billion at March 31, 2023 consisting of:
| March 31, 2023 | ||||||||||||||||||||||||||
| (Millions of dollars) | Total Capacity | Outstanding Borrowings | Outstanding Letters of Credit | Available Capacity | ||||||||||||||||||||||
| Bank revolving credit facility | $ | 5,000 | $ | — | $ | 1 | $ | 4,999 | ||||||||||||||||||
| Trade receivables facility(a) | 100 | — | 100 | — | ||||||||||||||||||||||
| Total | $ | 5,100 | $ | — | $ | 101 | $ | 4,999 | ||||||||||||||||||
| Cash and cash equivalents and short-term investments(b) | 11,059 | |||||||||||||||||||||||||
| Total liquidity | $ | 16,058 |
(a)The committed borrowing and letter of credit issuance capacity of the trade receivables securitization facility is $100 million. In addition, the facility allows for the issuance of letters of credit in excess of the committed capacity at the discretion of the issuing banks. As of March 31, 2023, letters of credit in the total amount of $533 million were issued and outstanding under the facility to secure contracts awarded by the Department of Energy to purchase crude oil from the Strategic Petroleum Reserve.
(b)Excludes cash and cash equivalents of MPLX of $393 million.
Because of the alternatives available to us, including internally generated cash flow and access to capital markets and a commercial paper program, we believe that our short-term and long-term liquidity is adequate to fund not only our current operations, but also our near-term and long-term funding requirements, including capital spending programs, the repurchase of shares of our common stock, dividend payments, defined benefit plan contributions, repayment of debt maturities and other amounts that may ultimately be paid in connection with contingencies.
We have a commercial paper program that allows us to have a maximum of $2.0 billion in commercial paper outstanding. We do not intend to have outstanding commercial paper borrowings in excess of available capacity under our bank revolving credit facility. At March 31, 2023, we had no borrowings outstanding under the commercial paper program.
The MPC Credit Agreement and trade receivables facility contain representations and warranties, affirmative and negative covenants and events of default that we consider usual and customary for agreements of these types. The financial covenant included in the MPC Credit Agreement requires us to maintain, as of the last day of each fiscal quarter, a ratio of Consolidated Net Debt to Total Capitalization (as defined in the MPC Credit Agreement) of no greater than 0.65 to 1.00. As of March 31, 2023, we were in compliance with the covenants contained in the MPC Credit Agreement and our trade receivables facility, including the financial covenant with a ratio of Consolidated Net Debt to Total Capitalization of approximately 0.00 to 1.00.
Our intention is to maintain an investment-grade credit profile. As of March 31, 2023, the credit ratings on our senior unsecured debt are as follows.
| Company | Rating Agency | Rating | ||||||
| MPC | Moody’s | Baa2 (stable outlook) | ||||||
| Standard & Poor’s | BBB (stable outlook) | |||||||
| Fitch | BBB (stable outlook) |
The ratings reflect the respective views of the rating agencies. Although it is our intention to maintain a credit profile that supports an investment grade rating, there is no assurance that these ratings will continue for any given period of time. The ratings may be revised or withdrawn entirely by the rating agencies if, in their respective judgments, circumstances so warrant.
The MPC Credit Agreement does not contain credit rating triggers that would result in the acceleration of interest, principal or other payments in the event that our credit ratings are downgraded. However, any downgrades of our senior unsecured debt could increase the applicable interest rates, yields and other fees payable thereunder and may limit our flexibility to obtain financing in the future, including to refinance existing indebtedness. In addition, a downgrade of our senior unsecured debt rating to below investment-grade levels could, under certain circumstances, impact our ability to purchase crude oil on an unsecured basis and could result in us having to post letters of credit under existing transportation services or other agreements.
See Note 17 to the unaudited consolidated financial statements for further discussion of our debt.
MPLX
MPLX’s liquidity totaled $3.89 billion at March 31, 2023 consisting of:
| March 31, 2023 | ||||||||||||||||||||||||||
| (Millions of dollars) | Total Capacity | Outstanding Borrowings | Outstanding Letters of Credit | Available Capacity | ||||||||||||||||||||||
| MPLX LP - bank revolving credit facility(a) | $ | 2,000 | $ | — | $ | — | $ | 2,000 | ||||||||||||||||||
| MPC intercompany loan agreement | 1,500 | — | — | 1,500 | ||||||||||||||||||||||
| Total | $ | 3,500 | $ | — | $ | — | $ | 3,500 | ||||||||||||||||||
| Cash and cash equivalents | 393 | |||||||||||||||||||||||||
| Total liquidity | $ | 3,893 |
(a) Outstanding borrowings include less than $1 million in letters of credit outstanding under this facility.
On February 9, 2023, MPLX issued $1.6 billion aggregate principal amount of senior notes in a public offering, consisting of $1.1 billion aggregate principal amount of 5.00 percent senior notes due March 2033 and $500 million aggregate principal amount of 5.65 percent senior notes due March 2053. On February 15, 2023, MPLX used $600 million of the net proceeds to redeem all of its outstanding Series B preferred units. On March 13, 2023, MPLX used the remaining proceeds to redeem all of MPLX’s and MarkWest’s $1.0 billion aggregate principal amount of 4.50 percent senior notes due July 2023.
The MPLX Credit Agreement contains certain representations and warranties, affirmative and restrictive covenants and events of default that we consider to be usual and customary for an agreement of this type. The financial covenant requires MPLX to maintain a ratio of Consolidated Total Debt as of the end of each fiscal quarter to Consolidated EBITDA (both as defined in the MPLX credit agreement) for the prior four fiscal quarters of no greater than 5.0 to 1.0 (or 5.5 to 1.0 during the six-month period following certain acquisitions). Consolidated EBITDA is subject to adjustments for certain acquisitions completed and capital projects undertaken during the relevant period. Other covenants restrict MPLX and/or certain of its subsidiaries from incurring debt, creating liens on assets and entering into transactions with affiliates. As of March 31, 2023, MPLX was in compliance with the covenants, including the financial covenant with a ratio of Consolidated Total Debt to Consolidated EBITDA of 3.52 to 1.0.
Our intention is to maintain an investment-grade credit profile for MPLX. As of March 31, 2023, the credit ratings on MPLX’s senior unsecured debt are as follows.
| Company | Rating Agency | Rating | ||||||
| MPLX | Moody’s | Baa2 (stable outlook) | ||||||
| Standard & Poor’s | BBB (stable outlook) | |||||||
| Fitch | BBB (stable outlook) |
The ratings reflect the respective views of the rating agencies. Although it is our intention to maintain a credit profile that supports an investment grade rating for MPLX, there is no assurance that these ratings will continue for any given period of time. The ratings may be revised or withdrawn entirely by the rating agencies if, in their respective judgments, circumstances so warrant.
The agreements governing MPLX’s debt obligations do not contain credit rating triggers that would result in the acceleration of interest, principal or other payments in the event that MPLX credit ratings are downgraded. However, any downgrades of MPLX senior unsecured debt to below investment grade ratings could increase the applicable interest rates, yields and other fees payable under such agreements. In addition, a downgrade of MPLX senior unsecured debt ratings to below investment-grade levels may limit MPLX’s ability to obtain future financing, including to refinance existing indebtedness.
See Note 17 to the unaudited consolidated financial statements for further discussion of MPLX’s debt.
Capital Requirements
Capital Investment Plan
MPC's capital investment plan for 2023 totals approximately $1.3 billion for capital projects and investments, excluding capitalized interest, potential acquisitions and MPLX’s capital investment plan. MPC’s capital investment plan includes all of the planned capital spending for Refining & Marketing and Corporate, as well as a portion of the planned capital investments for Midstream. The remainder of the planned capital spending for Midstream reflects the capital investment plan for MPLX, which totals $950 million, excluding reimbursable capital. We continuously evaluate our capital investment plan and make changes as conditions warrant.
Capital expenditures and investments for MPC and MPLX are summarized below.
| Three Months Ended March 31, | ||||||||||||||
| (Millions of dollars) | 2023 | 2022 | ||||||||||||
| Capital expenditures and investments:(a) | ||||||||||||||
| MPC, excluding MPLX | ||||||||||||||
| Refining & Marketing | $ | 421 | $ | 244 | ||||||||||
| Midstream - Other | 2 | 3 | ||||||||||||
| Corporate and Other(b) | 7 | 23 | ||||||||||||
| Total MPC, excluding MPLX | $ | 430 | $ | 270 | ||||||||||
| Midstream - MPLX | $ | 239 | $ | 280 |
(a) Capital expenditures include changes in capital accruals.
(b) Excludes capitalized interest of $21 million and $23 million for the three months ended March 31, 2023 and 2022, respectively.
Capital expenditures and investments in affiliates during the three months ended March 31, 2023, were primarily for Refining & Marketing and Midstream projects. Major Refining & Marketing projects include renewables projects, primarily the Martinez facility conversion and an emissions reduction program at our Los Angeles refinery, the STAR project, which commenced operations, and projects that we expect will help us reduce future operating costs and improve the competitive position of our assets.
Major Midstream projects were primarily for MPLX for gas processing plants and gathering projects in the Marcellus and Permian basins.
Share Repurchases
On January 31, 2023, the company announced that its board of directors had approved a $5.0 billion share repurchase authorization. The authorization has no expiration date.
Total share repurchases were as follows for the respective periods:
| Three Months Ended March 31, | |||||||||||||||||||||||
| (In millions, except per share data) | 2023 | 2022 | |||||||||||||||||||||
| Number of shares repurchased | 25 | 37 | |||||||||||||||||||||
| Cash paid for shares repurchased | $ | 3,180 | $ | 2,846 | |||||||||||||||||||
| Average cost per share | $ | 126.56 | $ | 75.88 |
From January 1, 2012 through March 31, 2023, our board of directors has approved $40.05 billion in total share repurchase authorizations and we have repurchased a total of $34.92 billion of our common stock. As of March 31, 2023, MPC has $5.13 billion remaining under its share repurchase authorizations, which reflects the repurchase of 910,402 common shares for $122 million that were transacted in the first quarter of 2023 and settled in the second quarter of 2023.
We may utilize various methods to effect the repurchases, which could include open market repurchases, negotiated block transactions, tender offers, accelerated share repurchases or open market solicitations for shares, some of which may be effected through Rule 10b5-1 plans. The timing and amount of future repurchases, if any, will depend upon several factors, including market and business conditions, and such repurchases may be discontinued at any time.
See Note 8 to the unaudited consolidated financial statements for further discussion of our share repurchase authorizations.
MPLX Unit Repurchases
Total unit repurchases were as follows for the respective periods:
| Three Months Ended March 31, | |||||||||||||||||||||||
| (In millions, except per share data) | 2023 | 2022 | |||||||||||||||||||||
| Number of common units repurchased | — | 3 | |||||||||||||||||||||
| Cash paid for common units repurchased | $ | — | $ | 100 | |||||||||||||||||||
| Average cost per unit | $ | — | $ | 32.06 |
As of March 31, 2023, approximately $846 million remained available under the authorization for future unit repurchases.
MPLX may utilize various methods to effect the repurchases, which could include open market repurchases, negotiated block transactions, tender offers, accelerated share repurchases or open market solicitations for units, some of which may be effected through Rule 10b5-1 plans. The timing and amount of future repurchases, if any, will depend upon several factors, including market and business conditions, and such repurchases may be discontinued at any time.
Cash Commitments
Contractual Obligations
As of March 31, 2023, our purchase commitments primarily consist of obligations to purchase and transport crude oil used in our refining operations. During the first three months of 2023, there were no material changes to our contractual obligations outside the ordinary course of business since December 31, 2022.
Our other contractual obligations primarily consist of long-term debt and pension and post-retirement obligations, for which additional information is included in Notes 17 and 21, respectively, to the unaudited consolidated financial statements, and financing and operating leases.
Other Cash Commitments
On April 26, 2023, our board of directors declared a dividend of $0.75 per share on common stock. The dividend is payable June 12, 2023, to shareholders of record as of the close of business on May 17, 2023.
During the three months ended March 31, 2023, we made no contributions to our funded pension plans. We have no required funding for 2023, but may make voluntary contributions of approximately $200 million at our discretion depending on the anticipated funding status and plan asset performance.
We may, from time to time, repurchase our senior notes in the open market, in tender offers, in privately-negotiated transactions or otherwise in such volumes, at such prices and upon such other terms as we deem appropriate.
ENVIRONMENTAL MATTERS AND COMPLIANCE COST****S
We have incurred and may continue to incur substantial capital, operating and maintenance, and remediation expenditures as a result of environmental laws and regulations. If these expenditures, as with all costs, are not ultimately reflected in the prices of our products and services, our operating results will be adversely affected. We believe that substantially all of our competitors must comply with similar environmental laws and regulations. However, the specific impact on each competitor may vary depending on a number of factors, including the age and location of its operating facilities, marketing areas, production processes and whether it is also engaged in the petrochemical business or the marine transportation of crude oil and refined products.
As previously disclosed in our Annual Report on Form 10-K for the year ended December 31, 2022, actual expenditures may vary as the number and scope of environmental projects are revised as a result of improved technology or changes in regulatory requirements.
There have been no additional significant changes to our environmental matters and compliance costs during the three months ended March 31, 2023.
CRITICAL ACCOUNTING ESTIMATES
As of March 31, 2023, there have been no significant changes to our critical accounting estimates since our Annual Report on Form 10-K for the year ended December 31, 2022.
ACCOUNTING STANDARDS NOT YET ADOPTED
We have not identified any recent accounting pronouncements that are expected to have a material impact on our financial condition, results of operations or cash flows upon adoption.
Previous: Item 1. Financial Statements · Next: Item 3. Quantitative and Qualitative Disclosures about Market Risk