 filings.tools
Micron Technology 10-K 2020-09-03
Filed 2020-10-19. 22 sections, 403K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
| (Mark One) | |||||
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended September 3, 2020
OR
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the transition period from to
Commission file number 1-10658
Micron Technology, Inc.
(Exact name of registrant as specified in its charter)
| Delaware | 75-1618004 | |||||||||||||||||||||||||
| (State or other jurisdiction of incorporation or organization) | (IRS Employer Identification No.) | |||||||||||||||||||||||||
| 8000 S. Federal Way, Boise, Idaho | 83716-9632 | |||||||||||||||||||||||||
| (Address of principal executive offices) | (Zip Code) | |||||||||||||||||||||||||
| Registrant’s telephone number, including area code | (208) 368-4000 | |||||||||||||||||||||||||
| Securities registered pursuant to Section 12(b) of the Act: | ||||||||||||||||||||||||||
| Title of each class | Trading Symbol | Name of each exchange on which registered | ||||||||||||||||||||||||
| Common Stock, par value $0.10 per share | MU | Nasdaq Global Select Market |
Securities registered pursuant to Section 12(g) of the Act: None
| Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. | Yes | ☒ | No | ☐ | ||||||||||||||||||||||||||||||||||||||||||||||
| Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or 15(d) of the Act. | Yes | ☐ | No | ☒ | ||||||||||||||||||||||||||||||||||||||||||||||
| Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. | Yes | ☒ | No | ☐ | ||||||||||||||||||||||||||||||||||||||||||||||
| Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). | Yes | ☒ | No | ☐ | ||||||||||||||||||||||||||||||||||||||||||||||
| Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act. | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Large Accelerated Filer | Accelerated Filer | Non-Accelerated Filer | Smaller Reporting Company | Emerging Growth Company | ||||||||||||||||||||||||||||||||||||||||||||||
| ☒ | ☐ | ☐ | ☐ | ☐ | ||||||||||||||||||||||||||||||||||||||||||||||
| If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. | ☐ | |||||||||||||||||||||||||||||||||||||||||||||||||
| Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. | ☒ | |||||||||||||||||||||||||||||||||||||||||||||||||
| Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). | Yes | ☐ | No | ☒ |
The aggregate market value of the voting and non-voting common equity held by non-affiliates was $44.8 billion based on the closing price reported on the Nasdaq Global Select Market on February 27, 2020. Shares of common stock held by each executive officer and director and by each person who owns 5% or more of the outstanding common stock were excluded as they may be deemed to be affiliates. This determination of affiliate status is not necessarily a conclusive determination for other purposes.
The number of outstanding shares of the registrant’s common stock as of October 9, 2020 was 1,113,221,799.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of the Proxy Statement for the registrant’s Fiscal 2020 Annual Meeting of Shareholders to be held on January 14, 2021 are incorporated by reference into Part III of this Annual Report on Form 10-K.
| Micron Company Profile |  | |||||||||||||
| Founded over 40 years ago on October 5, 1978 Headquartered in Boise, Idaho, USA 4th Largest semiconductor company in the world, excluding IP/software revenue* 134 On the 2020 Fortune 500 44,000 Patents granted and growing** 17 Countries** 13 Manufacturing sites and 14 customer labs** 40,000 Team members** | It’s All About Data | |||||||||||||
| Data is today’s new business currency, and memory and storage are emerging as strategic differentiators that will redefine how we extract value from data to learn, explore, communicate, and experience. | ||||||||||||||
| Who We Are | ||||||||||||||
| Micron designs and manufactures the industry’s broadest portfolio of memory and storage products for the latest applications, including artificial intelligence, 5G, machine learning and autonomous vehicles, in key market segments like mobile, data center, client, consumer, industrial, graphics, automotive, and networking. Our technology and expertise are central to breakthrough computing applications and new business models that are disrupting entire industries. | ||||||||||||||
| Our Vision | ||||||||||||||
| As a global leader in memory and storage solutions, we are transforming how the world uses information to enrich life for all by enabling technologies to collect, store, and manage data with unprecedented speed and efficiency. We are accelerating the transformation of information into intelligence – inspiring the world to learn, communicate, and advance faster than ever. | ||||||||||||||
| Our Commitment | ||||||||||||||
| Our day-to-day operations wouldn’t be possible without our team members’ commitment to business integrity and environmental sustainability. Whether it’s adhering to our professional values or valuing the communities we work in, for us, doing business better means doing business right. | ||||||||||||||
| *Gartner Market Share: Semiconductors by End Market, Worldwide, 2019 (April 2020) **Micron data as of September 3, 2020. | ||||||||||||||
| Media Inquiries mediarelations@micron.com Government Inquiries govaffairs@micron.com Investor Inquiries investorrelations@micron.com | Global Product Portfolio | |||||||||||||
| DRAM | NAND | 3D XPointTM Memory | NOR | Solid-State Drives High Bandwidth Memory (HBM) | Multichip Packages | Advanced Solutions | ||||||||||||||
| Connect with us on micron.com |
© 2020 Micron Technology, Inc. Micron, the Micron logo, the M orbit logo, Intelligence AcceleratedTM, and other Micron trademarks are the property of Micron Technology, Inc. All other trademarks are the property of their respective owners. Products and specifications are subject to change without notice. Rev 09/20
Micron’s Global Footprint
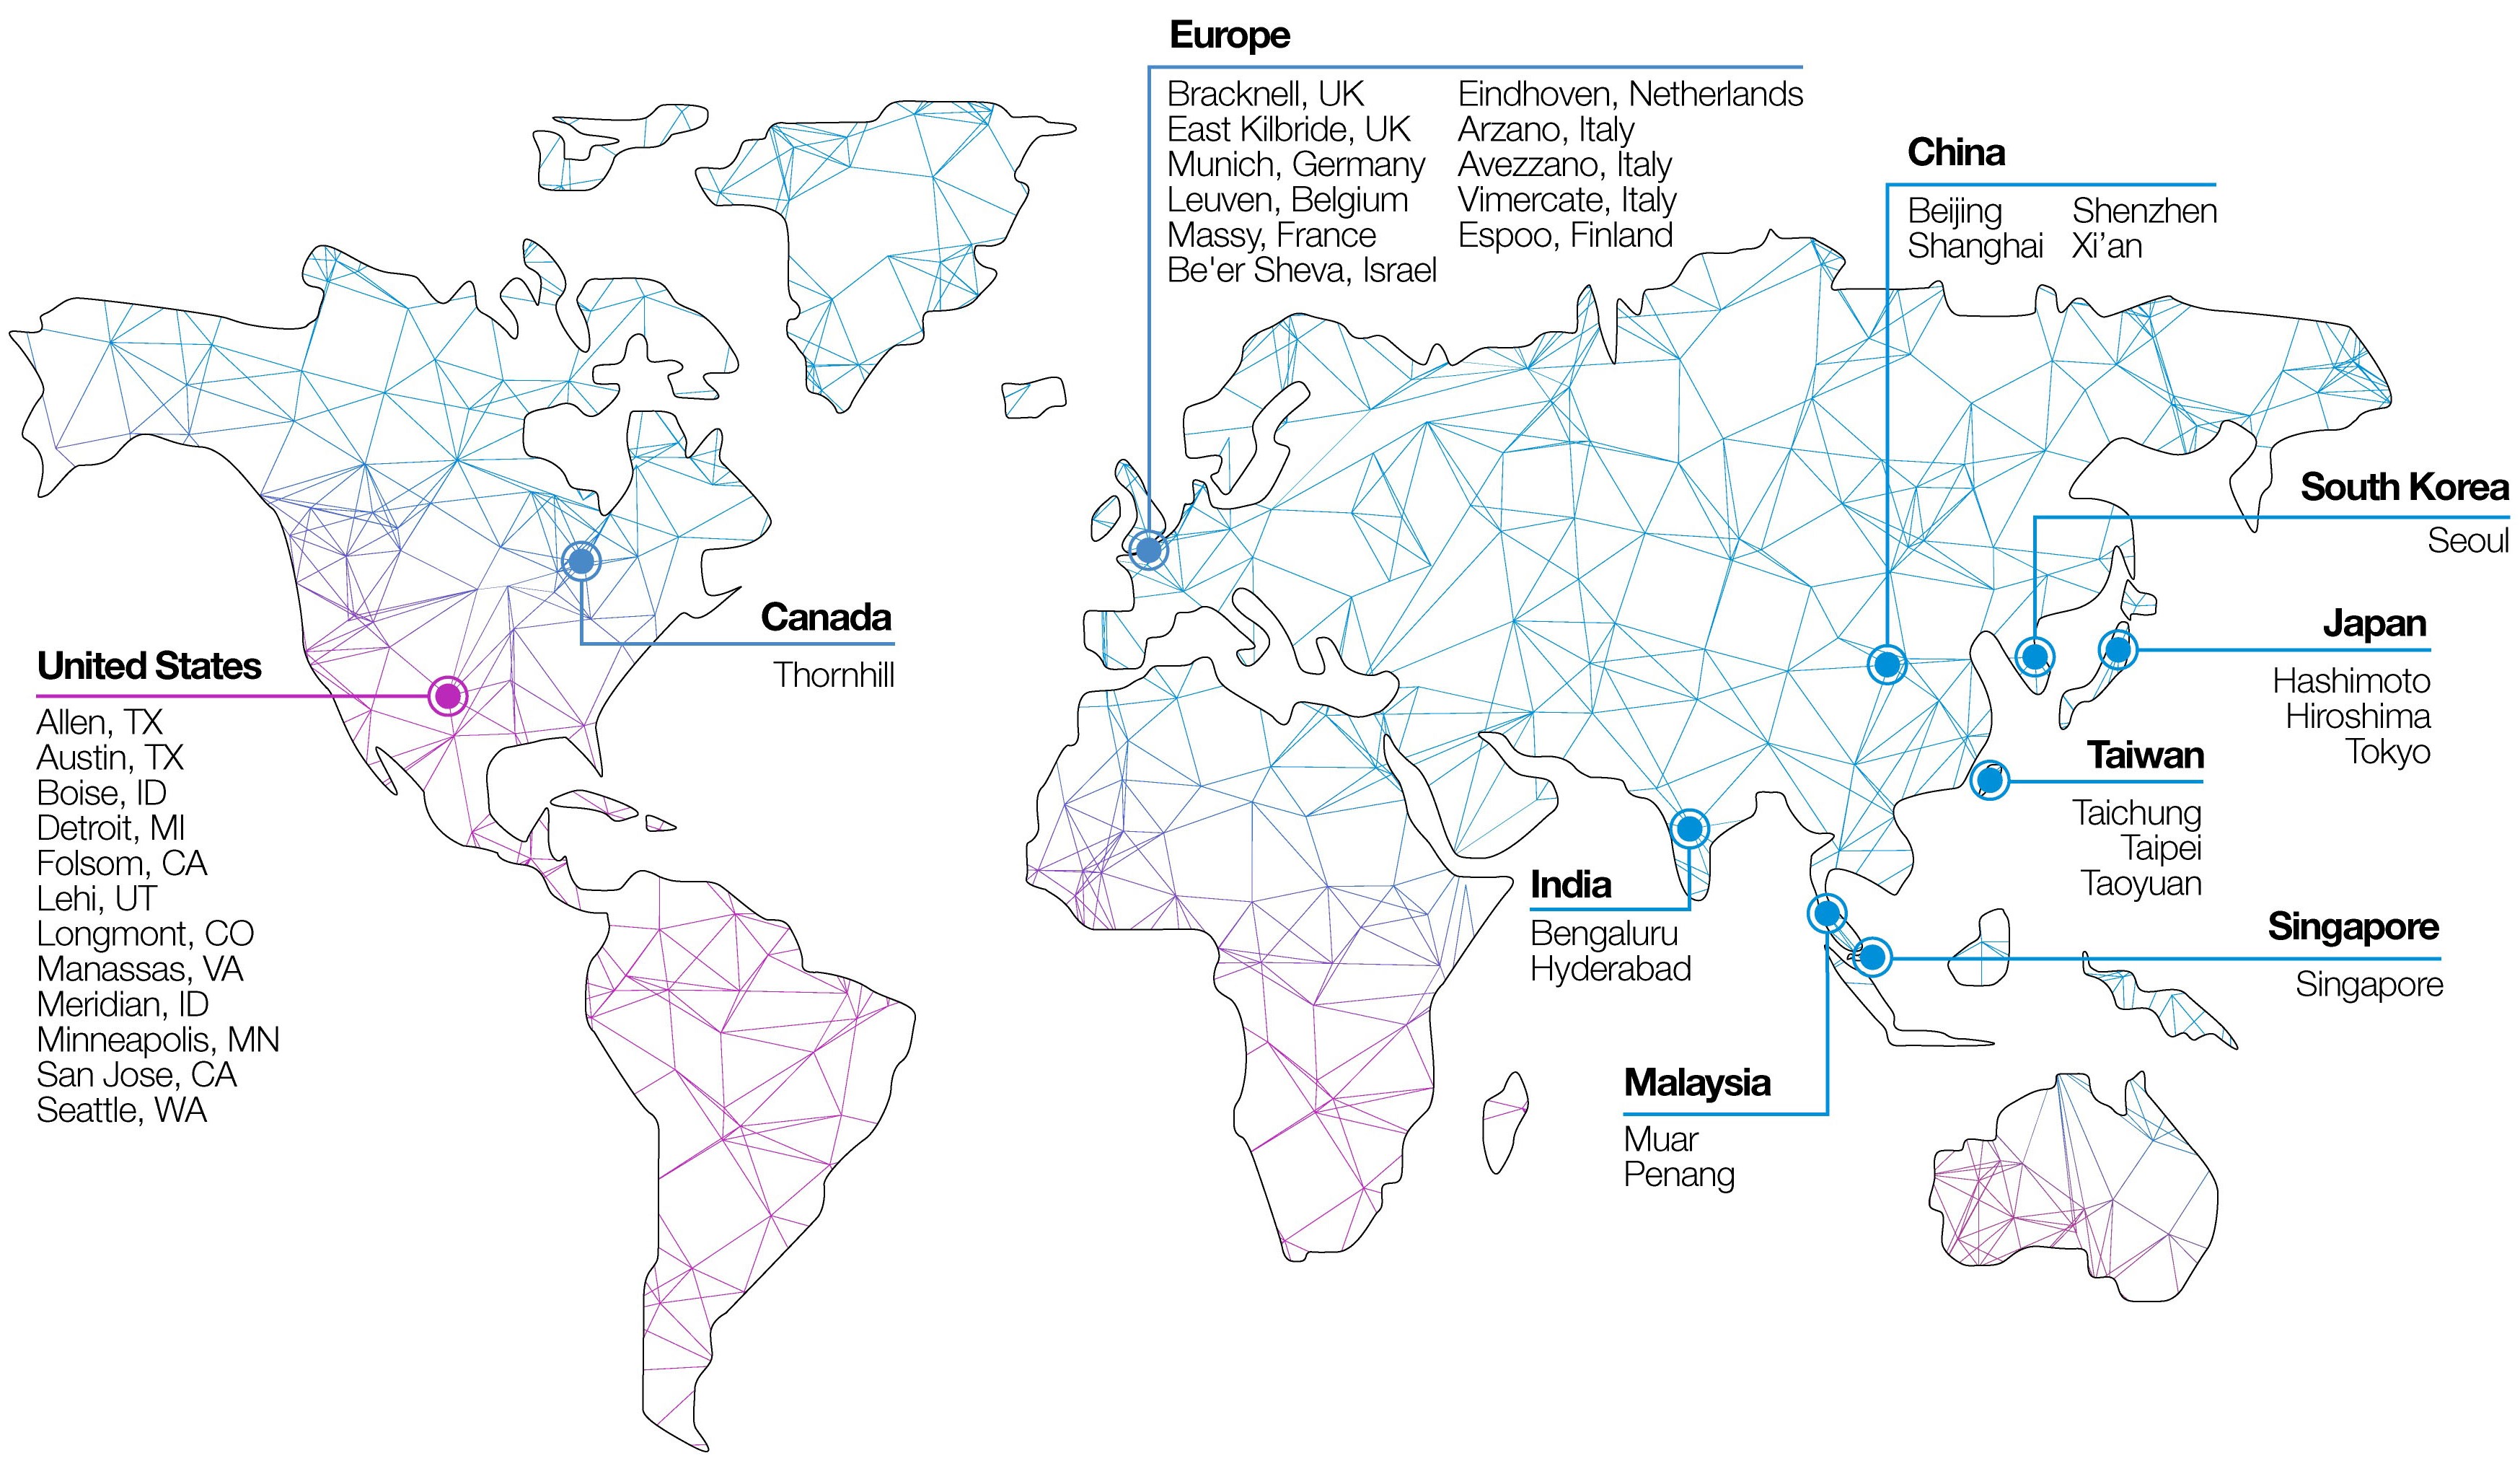
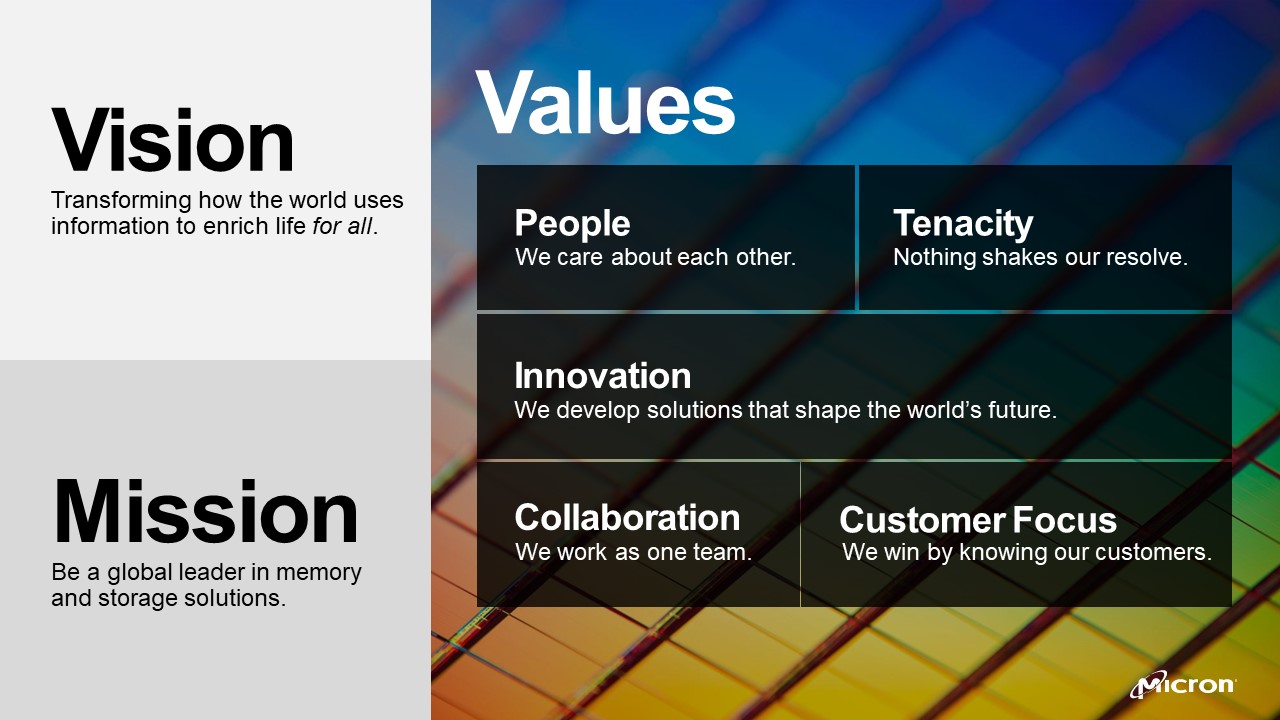
Table of Contents
| Introduction | |||||||||||
| PART I | |||||||||||
| Item 1. | Business | 3 | |||||||||
| Item 1A. | Risk Factors | 14 | |||||||||
| Item 1B. | Unresolved Staff Comments | 30 | |||||||||
| Item 2. | Properties | 31 | |||||||||
| Item 3. | Legal Proceedings | 31 | |||||||||
| Item 4. | Mine Safety Disclosure | 32 | |||||||||
| PART II | |||||||||||
| Item 5. | Market for Registrant’s Common Equity, Related Stockholder Matters, and Issuer Purchases of Equity Securities | 32 | |||||||||
| Item 6. | Selected Financial Data | 34 | |||||||||
| Item 7. | Management’s Discussion and Analysis of Financial Condition and Results of Operations | 34 | |||||||||
| Item 7A. | Quantitative and Qualitative Disclosures About Market Risk | 45 | |||||||||
| Item 8. | Financial Statements and Supplementary Data | 47 | |||||||||
| Item 9. | Changes in and Disagreements With Accountants on Accounting and Financial Disclosure | 86 | |||||||||
| Item 9A. | Controls and Procedures | 86 | |||||||||
| Item 9B. | Other Information | 86 | |||||||||
| PART III | |||||||||||
| Item 10. | Directors, Executive Officers, and Corporate Governance | 87 | |||||||||
| Item 11. | Executive Compensation | 87 | |||||||||
| Item 12. | Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters | 87 | |||||||||
| Item 13. | Certain Relationships and Related Transactions, and Director Independence | 87 | |||||||||
| Item 14. | Principal Accountant Fees and Services | 87 | |||||||||
| PART IV | |||||||||||
| Item 15. | Exhibits and Financial Statement Schedule | 88 | |||||||||
| Item 16. | Form 10-K Summary | 92 | |||||||||
| Signatures | 93 |
1 | 2020 10-K
Forward-Looking Statements
This Form 10-K contains trend information and other forward-looking statements that involve a number of risks and uncertainties. Such forward-looking statements may be identified by words such as "anticipate," "expect," "intend," "pledge," "committed," "plans," "opportunities," "future," "believe," "target," "on track," "estimate," "continue," "likely," "may," "will," "would," "should," "could," and variations of such words and similar expressions. Specific forward-looking statements include, but are not limited to, statements such as those made regarding the impact of coronavirus disease 2019 (“COVID-19”) to our business; the timing of introduction of new technology nodes; underutilization of MTU manufacturing capacity; the sufficiency of our cash and investments; and capital spending in 2021. Our actual results could differ materially from our historical results and those discussed in the forward-looking statements. Factors that could cause actual results to differ materially include, but are not limited to, those identified in “Part I – Item 1A. Risk Factors.”
Definitions of Commonly Used Terms
As used herein, “we,” “our,” “us,” and similar terms include Micron Technology, Inc. and our consolidated subsidiaries, unless the context indicates otherwise. Abbreviations, terms, or acronyms are commonly used or found in multiple locations throughout this report and include the following:
| Term | Definition | Term | Definition | |||||||||||
| 2023 Notes | 2.497% Senior Notes due 2023 | MMJ | Micron Memory Japan, G.K. | |||||||||||
| 2024 Notes | 4.640% Senior Notes due 2024 | MMJ Companies | MAI and MMJ | |||||||||||
| 2024 Term Loan A | Senior Term Loan A due 2024 | MMJ Group | MMJ and its subsidiaries | |||||||||||
| 2025 Notes | 5.500% Senior Notes due 2025 | MMT | Micron Memory Taiwan Co., Ltd. | |||||||||||
| 2026 Notes | 4.975% Senior Notes due 2026 | MSP | Micron Semiconductor Products, Inc. | |||||||||||
| 2027 Notes | 4.185% Senior Notes due 2027 | MTTW | Micron Technology Taiwan, Inc. | |||||||||||
| 2029 Notes | 5.327% Senior Notes due 2029 | MTU | Micron Technology Utah, LLC | |||||||||||
| 2030 Notes | 4.663% Senior Notes due 2030 | NVMe | Hardware interface for SSDs that connect via a PCIe bus. | |||||||||||
| 2032D Notes | 3.125% Convertible Senior Notes due 2032 | OEM | Original Equipment Manufacturer | |||||||||||
| 2033F Notes | 2.125% Convertible Senior Notes due 2033 | PCIe | High-speed motherboard connection for peripheral devices such as storage drives. | |||||||||||
| DDR | Double Data Rate | Qimonda | Qimonda AG | |||||||||||
| GDDR | Graphics Double Data Rate | QLC | Quad-Level Cell (four bits per cell) | |||||||||||
| IMFT | IM Flash Technologies, LLC | Revolving Credit Facility | $2.5 billion Revolving Credit Facility due July 2023 | |||||||||||
| Inotera | Inotera Memories, Inc. | SATA | Hardware interface for connecting to storage devices such as hard disk drives and SSDs. | |||||||||||
| Intel | Intel Corporation | SLC | Single-Level Cell (one bit per cell) | |||||||||||
| LPDDR | Low Power Double Data Rate | SSD | Solid State Drive | |||||||||||
| MAI | Micron Akita, Inc. | TLC | Triple-Level Cell (three bits per cell) | |||||||||||
| MCP | Multi-Chip Package | UFS | Universal Flash Storage | |||||||||||
| Micron | Micron Technology, Inc. (Parent Company) | uMCP | UFS-based MCP |
Micron, Crucial, any associated logos, and all other Micron trademarks are the property of Micron. Intel and 3D XPoint are trademarks of Intel Corporation or its subsidiaries. Other product names or trademarks that are not owned by Micron are for identification purposes only and may be the trademarks of their respective owners.
All period references are to our fiscal periods unless otherwise indicated. Our fiscal year is the 52 or 53-week period ending on the Thursday closest to August 31. Fiscal 2020 contained 53 weeks and fiscal 2019 and 2018 each contained 52 weeks.
 2
PART I
Item 1. BUSINESS
Overview
Micron Technology, Inc., including its consolidated subsidiaries, is an industry leader in innovative memory and storage solutions. Through our global brands — Micron® and Crucial® — our broad portfolio of high-performance memory and storage technologies, including DRAM, NAND, 3D XPointTM memory, and NOR, is transforming how the world uses information to enrich life for all. Backed by more than 40 years of technology leadership, our memory and storage solutions enable disruptive trends, including artificial intelligence, 5G, machine learning, and autonomous vehicles, in key market segments like mobile, data center, client, consumer, industrial, graphics, automotive, and networking.
We manufacture our products at wholly-owned facilities and also utilize subcontractors to perform certain manufacturing processes. In recent years, we have increased our manufacturing scale and product diversity through strategic acquisitions, expansion, and various partnering arrangements.
We make significant investments to develop proprietary product and process technology, which are implemented in our manufacturing facilities, and generally increase the density per wafer and reduce manufacturing costs of each generation of product through advancements in product and process technology, such as our leading-edge line-width process technology and 3D NAND architecture. We continue to introduce new generations of products that offer improved performance characteristics, including higher data transfer rates, advanced packaging solutions to meet industry standards, lower power consumption, improved read/write reliability, and increased memory density. A significant portion of our revenues are from sales of managed NAND and SSD products, which incorporate NAND, a controller, and firmware. An increasing portion of our SSDs incorporate proprietary controllers and firmware that we have developed. Development of advanced technologies enables us to diversify our product portfolio toward a richer mix of differentiated, high-value solutions and to target high-growth markets.
We face intense competition in the semiconductor memory and storage markets and, to remain competitive, we must continuously develop and implement new products and technologies and decrease manufacturing costs. Our success is largely dependent on obtaining returns on our R&D investments, efficient utilization of our manufacturing infrastructure, development and integration of advanced product and process technologies, market acceptance of our diversified portfolio of semiconductor-based memory and storage solutions, and return-driven capital spending.
Impact of COVID-19 on Our Business
Events surrounding the ongoing COVID-19 outbreak have resulted in a reduction in economic activity across the globe. The ultimate severity and duration of these economic repercussions, including any resulting impact on our business, remain largely unknown and will depend on many factors, including the speed and effectiveness of the containment efforts and economic intervention throughout the world.
From the start of the COVID-19 outbreak, we proactively implemented preventative protocols intended to safeguard our team members, contractors, suppliers, customers, distributors, and communities, and to ensure business continuity in the event government restrictions or severe outbreaks impact our operations at certain sites. While all our global sites are currently operational, our facilities could be required to temporarily curtail production levels or temporarily cease operations based on actions we deem to be prudent or as a result of government mandates. We remain committed to providing a healthy and safe environment and continue to actively monitor the situation. We may take further actions to alter our business operations to ensure the health and safety of all our stakeholders, or as required by government authorities.
3 | 2020 10-K
Products
We are relentlessly focused on evolving our product portfolio to a richer mix of high-value solutions and cultivating deeper relationships with customers. Our position as a developer and manufacturer of DRAM, NAND, 3D XPoint memory, NOR, and other emerging memory technologies uniquely enables us to collaborate with our customers to ensure our technology and engineering roadmaps deliver critical features. We continuously introduce new products on our advanced technologies, delivering performance, quality, and cost advantages to our customers. Across our entire portfolio of products, we continue to focus on product differentiation and portfolio expansion to grow our share of industry profits while maintaining stable bit share.
Our product portfolio of memory and storage solutions, advanced solutions, and storage platforms is based on our high-performance semiconductor memory and storage technologies, including DRAM, NAND, 3D XPoint memory, NOR, and other technologies. We sell our products into various markets through our business units in numerous forms, including wafers, components, modules, SSDs, managed NAND, and MCP products. Our system-level solutions, including SSDs, managed NAND, and MCPs, typically include a controller and firmware and in some cases combine DRAM, NAND, and/or NOR.
Product Technologies
DRAM**:** DRAM products are dynamic random access memory semiconductor devices with low latency that provide high-speed data retrieval with a variety of performance characteristics. DRAM products lose content when power is turned off (“volatile”) and are most commonly used in client, cloud server, enterprise, networking, graphics, industrial, and automotive markets. Low-power DRAM (“LPDRAM”) products, which are engineered to meet standards for performance and power consumption, are sold into smartphone and other mobile-device markets, as well as into the automotive, industrial, and consumer markets.
NAND**:** NAND products are non-volatile, re-writeable semiconductor storage devices that provide high-capacity, low-cost storage with a variety of performance characteristics. NAND is used in SSDs for the enterprise and cloud, client, and consumer markets and in removable storage markets. Managed NAND is used in smartphones and other mobile devices, and in consumer, automotive, and embedded markets. Low-density NAND is ideal for applications like automotive, surveillance, machine-to-machine, automation, printer, and home networking.
3D XPoint**:** 3D XPoint is a new class of non-volatile technology between DRAM and NAND in the memory and storage hierarchy, offering higher capacity and non-volatility over DRAM along with lower latency and higher endurance as compared to NAND. 3D XPoint technology is ideal for data center and other markets requiring high-bandwidth storage and low-latency performance.
NOR**:** NOR products are non-volatile re-writable semiconductor memory devices that provide fast read speeds. NOR is most commonly used for reliable code storage (e.g., boot, application, operating system, and execute-in-place code in an embedded system) and for frequently changing small data storage and is ideal for automotive, industrial, and consumer applications.
Products by Business Unit and Market
Compute and Networking Business Unit (“CNBU”)
CNBU includes memory products and solutions sold into client, cloud server, enterprise, graphics, and networking markets. CNBU reported revenue of $9.18 billion in 2020, $9.97 billion in 2019, and $15.25 billion in 2018. In late 2019, we were the first to introduce volume production of 1Znm DRAM which, at the time, was the industry's most advanced node. In 2020, we began ramping our 1Znm technology and achieved bit production crossover in the second half of 2020 with the aggregate of our 1Ynm and 1Znm nodes comprising more than 50% of our DRAM bit production. We began sampling 1Znm DDR5 modules and are on track to introduce high bandwidth memory in calendar 2020. We continue to make meaningful progress on our 1-alpha nm node, which we expect to introduce in 2021. During 2020, we began sampling our first high-bandwidth DRAM memory product, which is competitive with the industry's most advanced products, to enable expansion of our AI data center opportunities.
4
Client: CNBU sales to the client market in 2020 consisted primarily of 1Xnm and 1Ynm DDR4 DRAM products. In 2020, we also achieved significant production and sales to the client market of our DDR4 DRAM products from our 1Znm technology. Our products sold to the client market support both commercial and consumer PC growth, with growth driven by the rapid deployment of PCs to support the work-from-home and e-learning environments as the world responded to the COVID-19 pandemic.
Cloud Server: CNBU sales to the cloud market in 2020 consisted primarily of our 1Xnm, 1Ynm, and 1Znm DDR4 DRAM products. The cloud server market continued to experience significant growth in 2020 due to strong demand from the work-from-home and e-learning environments, video streaming, and significant increases in e-commerce activity around the world. The cloud server market has also been driven, in part, by intelligent edge devices capable of artificial intelligence and augmented reality that store and access data in the cloud. Cloud servers supporting artificial intelligence workloads require significantly increasing quantities of DRAM and, as the number and capabilities of these intelligent edge devices increase, more data is stored, processed, and accessed in the cloud, creating a virtuous cycle between the cloud and edge devices.
Enterprise: CNBU sales to the enterprise market in 2020 consisted primarily of our 1Xnm and 1Ynm DDR4 DRAM products. In 2020, we started providing early engineering samples of 1Znm DDR5 products for enterprise applications. The enterprise market is experiencing demand from intelligent edge devices requiring rapid data analysis and storage to enable machine learning, training, and inference.
Graphics: CNBU sales to the graphics market in 2020 consisted primarily of GDDR6 and GDDR5 graphics products. In addition, in 2020, we started shipping GDDR6 DRAM products for next-generation gaming consoles and also introduced our leading-edge GDDR6X graphics memory, which delivers unprecedented speed, power, and bandwidth for high-performance graphics and computing. The graphics market is driven by the need for high-performance, high-bandwidth, and cost-effective memory solutions. Our GDDR6 and GDDR5 DRAM graphics products are incorporated into game consoles, PC graphics cards, and graphics processing unit-based data center solutions, which are the driving force behind applications such as artificial intelligence, virtual and augmented reality, 4K and 8K gaming, and professional design. Our GDDR6X products feature innovative signal transmission technology enabling over 1-terabyte of memory bandwidth to deliver an immersive, real-life gaming experience.
Networking: CNBU sales to the networking market in 2020 consisted primarily of DDR4 and DDR3 DRAM products. In 2020, demand was driven, in part, by rapid work-from-home infrastructure deployment, as well as increased 5G build-out in certain geographic locations to further support the growth of the advanced 5G networking infrastructure. The networking memory market has relatively long life-cycle DRAM products and, accordingly, a significant portion of our sales consisted of products manufactured on our legacy DRAM technology.
3D XPoint: CNBU sales of 3D XPoint memory consisted primarily of wafers sold to Intel. In 2020, we introduced our X100 NVMe SSD, the fastest storage device in the world. The X100 NVMe SSD is the first product in a new family of high-performance memory solutions based on 3D XPoint technology, which has higher chip density than DRAM, up to 1,000 times lower latency, and exponentially greater endurance than NAND. These specifications create a significant value opportunity for 3D XPoint technology in solutions between DRAM and NAND in the memory and storage hierarchy. Trends in machine learning, big data analytics, and artificial intelligence are driving demand for the features offered by 3D XPoint technology.
Mobile Business Unit (“MBU”)
MBU includes memory products sold into smartphone and other mobile-device markets and includes discrete NAND, DRAM, and managed NAND. MBU managed NAND includes embedded multi-media controller (“e.MMC”) and universal flash storage (“UFS”) solutions, each of which combine high-capacity NAND with a high-speed controller and firmware, and eMCP/uMCP products, which combine an e.MMC/UFS solution with LPDRAM. MBU reported revenue of $5.70 billion in 2020, $6.40 billion in 2019, and $6.58 billion in 2018. In 2020, we were the first company to deliver LPDDR5 mobile DRAM products to customers, including our LPDDR5 products in select 5G-capable smartphones, in capacities up to 12GB. We also began sampling the world's first LPDDR5 DRAM-based UFS MCPs, which enable longer smartphone battery life and high-performance image processing and utilize our advanced 1Ynm DRAM process technology and the world’s smallest 512Gb 96-layer 3D NAND die.
Smartphone: MBU sales to the smartphone market in 2020 consisted primarily of our 1Xnm and 1Ynm LPDDR4, LPDDR5, and managed NAND solutions. In the first quarter of 2020, we ramped our 1Znm LPDDR4 DRAM-based uMCP, which at the time had the fastest revenue ramp of any product in the history of our mobile business. High-
5 | 2020 10-K
end smartphones incorporate higher levels of NAND and LPDRAM that enable features such as larger 4K displays, multiple high-resolution cameras, and 4K high-dynamic range video recording. Additionally, our smartphone products are utilized by OEMs to enable artificial intelligence, augmented reality, and life-like virtual reality capabilities into high-end phones, including facial and voice recognition, real-time translation, fast image search, and scene detection.
Other: MBU sales in 2020 also included products sold into the feature and disposable phone markets, mobile PC, and tablet markets. Sales primarily consisted of LPDDR4, LPDDR3, and eMCPs.
Storage Business Unit (“SBU”)
SBU includes SSDs and component-level solutions sold into enterprise and cloud, client, and consumer storage markets and other discrete storage products sold in component and wafer forms to removable storage markets. SBU reported revenue of $3.77 billion in 2020, $3.83 billion in 2019, and $5.02 billion in 2018. In 2020, we significantly increased the mix of our high-value solutions in NAND.
In 2020, we continued to transition to our NAND QLC technology, representing nearly 20% of our overall NAND sales in the fourth quarter of 2020. The low cost per bit of our NAND QLC technology enables us to offer SSD products at a price point competitive with hard disk drives in a number of market segments. A meaningful portion of our consumer SSDs shipped in the second half of 2020 included NAND with our QLC technology.
In 2020, we started volume production of our first-generation 128-layer 3D NAND using replacement gate technology and began shipping products to customers in the fourth quarter of 2020. We continue to make progress on our second-generation replacement gate node, which we expect to broadly deploy across our product portfolio, and remain on track for replacement gate production to comprise a meaningful portion of our NAND output by the end of calendar 2020.
SSDs: SSD storage products incorporate NAND, a controller, and firmware and offer significant performance and features over hard disk drives, including smaller form factors, faster read and write speeds, higher reliability, and lower power consumption. We offer SSD solutions utilizing our NAND technology to the enterprise and cloud, client, and consumer markets.
Enterprise and Cloud SSDs: SBU sales to the enterprise and cloud SSD markets in 2020 consisted primarily of our 5300, 5200, and 5100 series SATA SSDs. In 2020, we offered new capacity and features with our 5210 ION SATA SSD, continuing our leadership in QLC NAND-based SSDs and accelerating the transition from hard disk drives to QLC SSDs in data centers. Similar to trends in the memory market, the enterprise and cloud storage markets have been driven by advanced edge devices capable of artificial intelligence, augmented reality, and other features that store, access, and analyze data in the cloud. Artificial intelligence servers require fast access to data with low latency, predictable performance, and high storage capacities. Our technology is providing cost-optimized storage solutions at a significantly lower total cost of ownership for demanding workloads.
Client SSDs: SBU sales to the client SSD market in 2020 consisted primarily of our 2200 and 1300 series SATA Client SSDs with our 96- and 64-layer TLC 3D NAND. Our client SSDs, targeted for leading personal computer OEMs as a replacement to hard disk drives, are used in notebooks, desktops, workstations, and other consumer applications, and deliver high performance, power efficiency, security, and capacity. In 2020, we launched our client 2300 NVMe SSD, which uses our 96-layer 3D NAND technology and a single-sided M.2 form factor to provide flexibility in design with industry-leading capacities of up to 2TB. In early 2020, we launched our client 2210 NVMe SSD, which uses our 96-layer QLC NAND technology for higher storage capacity and SLC NAND technology for write-performance, with M.2 form factor to bridge the gap between the low cost of hard disk drives and the performance, reliability, low power, and security of SSDs.
Consumer SSDs: SBU sales to the consumer SSD market in 2020 consisted primarily of our Crucial-branded MX500/BX500 SATA SSDs and our P1/P2 PCIe SSDs, which utilize our NAND QLC and TLC technologies. We had record consumer SSD revenue in 2020, assisted by the growth of our QLC NVMe SSDs, and we continue transitioning our product line of consumer SSDs from SATA to NVMe. In 2020, we expanded into the consumer portable SSD market by introducing the Crucial X8 and X6 portable SSDs and also began shipments of our BX500 SATA SSD, utilizing our 128-layer TLC 3D NAND with replacement gate technology. Similar to the client SSD market, our consumer SSD solutions are replacing hard disk drives as end users seek the higher performance, power savings, and reliability of SSDs.
6
Components and Wafers: SBU sales of components in 2020 included NAND products and consisted primarily of our 64-layer and 96-layer TLC and QLC NAND technology sold into storage markets, which include custom and consumer SSDs and all flash arrays by advanced enterprise users, broadening our footprint into diverse market segments and enabling greater output flexibility.
Embedded Business Unit (“EBU”)
EBU includes memory and storage products sold into industrial, automotive, and consumer markets and includes discrete and module DRAM, discrete NAND, managed NAND, SSDs, and NOR. EBU reported revenue of $2.76 billion in 2020, $3.14 billion in 2019, and $3.48 billion in 2018. The embedded market has traditionally been characterized by long life-cycle DRAM and non-volatile products manufactured on mature process technologies. With strong trends of digitization, connectivity, and intelligence in every device, demand continues to grow for leading-edge products from newer process technologies emerging in the embedded market. Our embedded products enable edge devices to store, connect, and share information in the internet of things (“IoT”) market and are utilized in a diverse set of applications in the automotive, industrial, and consumer markets.
Industrial: EBU sales to the industrial market in 2020 consisted primarily of DDR4 and DDR3 DRAM, LPDDR4 DRAM, SLC NAND, NAND MCPs, and NOR. Our products enable applications in the growing industrial IoT market, including machine-to-machine communication, factory automation, transportation, surveillance, retail, and smart infrastructure.
Automotive: EBU sales to the automotive market in 2020 consisted primarily of DDR3 DRAM, e.MMC managed NAND, and LPDDR4 and LPDDR2 DRAM. Our leading 1TB automotive-grade PCIe NVMe SSD delivers faster, more reliable, and cost-effective storage for next-generation autonomous vehicles. Advancements in autonomous driving and advanced driver-assistance systems continue to increase the requirements for high-performing memory and storage products, with higher reliability requirements for leading-edge products. Automotive memory and storage products enable connected, large display infotainment systems and higher definition 4K displays and support improved voice and gesture control in automotive applications. Our comprehensive and expanding portfolio of DRAM, NAND, and NOR solutions to the automotive market, as well as our extensive customer support network, enable us to maintain our strong leadership position in this market.
Consumer: EBU sales to the consumer market in 2020 consisted primarily of our DDR4 and DDR3 DRAM, LPDDR4 DRAM, managed NAND, SLC NAND, NOR, and secure digital (“SD”) cards. These embedded memory and storage solutions are used in a diverse set of consumer products, including service provider and IP set-top boxes, digital home assistants, digital still and video cameras, home networking, ultra-high definition televisions, and many more applications. Our embedded memory and storage solutions enable edge devices in the consumer products market to store, connect, and share information in the IoT.
Manufacturing
We manufacture our products within our own facilities located in Taiwan, Singapore, Japan, the United States, China, and Malaysia and also utilize subcontractors to perform certain manufacturing processes. Our products are manufactured on 300mm wafers in facilities that generally operate 24 hours per day, seven days per week. Semiconductor manufacturing is extremely capital intensive, requiring large investments in sophisticated facilities and equipment. Our DRAM, NAND, 3D XPoint memory, and NOR products share a number of common manufacturing processes, enabling us to leverage our product and process technology and certain resources and manufacturing infrastructure across these product lines.
Our process for manufacturing semiconductor products is complex and involves numerous precise steps, including wafer fabrication, assembly, and test. Efficient production of semiconductor products requires utilization of advanced semiconductor manufacturing techniques and effectively deploying those techniques across multiple facilities. The primary determinants of manufacturing cost are process line-width, 3D non-volatile layers, NAND cell levels, process complexity (including the number of mask layers and fabrication steps), and manufacturing yield. Other factors include the cost and sophistication of manufacturing equipment, equipment utilization, cost of raw materials, labor productivity, package type, cleanliness of our manufacturing environment, and utilization of subcontractors to
7 | 2020 10-K
perform certain manufacturing processes. As we continue to increase our production of high value products and solutions, manufacturing costs are increasingly affected by the costs of ASIC controllers, advanced and complex packaging configurations, and testing at progressively higher performance speeds and quality levels. We continuously enhance our production processes, increase bits per wafer, transition to higher density products, and utilize advanced testing and assembly processes.
Wafer fabrication occurs in a highly-controlled clean environment to minimize yield loss from contaminants. Despite stringent manufacturing controls, individual circuits may be nonfunctional or wafers may be scrapped due to equipment errors, minute impurities in materials, defects in photomasks, circuit design marginalities or defects, and contamination from airborne particles. Success of our manufacturing operations depends largely on minimizing defects and improving process margin to maximize yield of high-quality circuits. In this regard, we employ rigorous quality controls throughout the manufacturing, screening, and testing processes. We continue to heighten quality control as our product offerings expand into higher-end segments that require increasing performance targets.
Our products are manufactured and sold in both packaged form and as unpackaged bare die. Our packaged products include packaged die, memory modules, and system-level solutions, such as SSDs, managed NAND, and MCPs. We assemble many products in-house and, in some cases, outsource assembly services for certain packaged die, memory modules, SSDs, and MCPs. We test our products at various stages in the manufacturing process, conduct numerous quality control inspections throughout the entire production flow, and perform high temperature burn-in on finished products. In addition, we use our proprietary AMBYX™ line of intelligent test and burn-in systems to perform simultaneous circuit tests of semiconductor die, capturing quality and reliability data and reducing testing time and cost.
In recent years, we have produced an increasingly broad portfolio of products and system solutions, which enhances our ability to allocate resources to our most profitable products but also increases the complexity of our manufacturing and supply chain operations. Although our product lines generally use similar manufacturing processes, our costs can be affected by frequent conversions to new products, the allocation of manufacturing capacity to more complex, smaller-volume products, and the reallocation of manufacturing capacity across various product lines.
Arrangements with Intel
Since 2006, we and Intel owned and operated IMFT, a joint venture that manufactured semiconductor products exclusively for its members under long-term supply agreements at prices approximating cost. Through 2018, IMFT manufactured NAND memory and, subsequent to that time, manufactured 3D XPoint memory. In the first quarter of 2020, we acquired Intel’s interest in IMFT. (See “Part II – Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements – Equity,” “– Debt,” and “– Research and Development.”)
Supply Chain, Materials, and Third-Party Service Providers
Our supply chain and operations are dependent on the availability of materials that meet exacting standards and the use of third parties to provide us with components and services. We generally have multiple sources of supply for our materials and services. However, only a limited number of suppliers are capable of delivering certain materials and services that meet our standards and, in some cases, materials, components, or services are provided by a single supplier. Various factors could reduce the availability of materials or components such as chemicals, silicon wafers, gases, photoresist, controllers, substrates, lead frames, printed circuit boards, targets, and reticle glass blanks. Shortages or increases in lead times may occur from time to time in the future. Our manufacturing processes are also dependent on our relationships with third-party manufacturers of controllers used in a number of our products and with outsourced semiconductor assembly and test providers, contract manufacturers, logistic carriers, and other service providers. We monitor and manage supply-chain activities to mitigate risks associated with raw materials and service providers. Certain materials are primarily available in certain countries, including rare earth elements, minerals, and metals available primarily from China. Trade disputes or other political conditions, economic conditions, or public health issues, such as COVID-19, may limit our ability to obtain such materials. Although these rare earth and other materials are generally available from multiple suppliers, China is the
8
predominant producer of certain of these materials. In addition, we and/or our suppliers and service providers could be affected by tariffs, embargoes, or other trade restrictions, as well as laws and regulations enacted in response to concerns regarding climate change, conflict minerals, responsible sourcing practices, public health crises, or contagious disease outbreaks, which can limit the supply of our materials and/or increase the cost.
Marketing and Customers
We continue to transform how we interact with our customers from transactional opportunistic sales of standardized memory components to collaborative relationships where we work with our customers to understand their unique opportunities and challenges. Many of our customers require thorough review or qualification of our products. By engaging with our customers early in the product life-cycle to identify and design features and performance characteristics into our products, we are able to manufacture products that anticipate and address our customers’ changing needs. Collaborating with our customers on their design needs in changing end markets allows us to differentiate our memory and storage solutions, which provides greater value to our customers.
Our semiconductor memory and storage products are offered under our Micron and Crucial brand names and through private labels. We market our semiconductor memory and storage products primarily through our own direct sales force and maintain sales or representative offices in our primary markets around the world. We sell our Crucial-branded products through a web-based customer direct sales channel as well as through channel and distribution partners. Our products are also offered through independent sales representatives, distributors, and retailers. Our independent sales representatives obtain orders, subject to final acceptance by us, and we then make shipments against these orders directly to customers or through our distributors. Our distributors carry our products in inventory and typically sell a variety of other semiconductor products, including competitors’ products. We maintain inventory at locations in close proximity to certain key customers to facilitate rapid delivery of products.
In each of the last three years, approximately one-half of our total net sales were to our top ten customers. For other information regarding our concentrations and customers, see “Part II – Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements – Certain Concentrations.”
Sales of our memory and storage products, and the transfer of related technical information and know-how, including support, are subject to laws and regulations governing international trade, including, but not limited to, export control, customs, and sanctions regulations administered by U.S. government agencies such as the Bureau of Industry and Security (“BIS”) of the U.S. Department of Commerce and the Office of Foreign Asset Control of the U.S. Department of the Treasury. Other jurisdictions, such as the European Union or China, also maintain, or may implement, similar laws and regulations with which we must comply. Any such laws or regulations may require that we either obtain licenses or other authorizations to export certain of our products or sell them to certain countries, companies, or individuals, or, in the absence of such licenses or authorizations, not export or sell the applicable products or transfer the related technical information and know-how to the affected countries, companies, or individuals. In addition, increased tariffs imposed by the countries in which our products are sold can increase the cost of our product to our customers. The laws and regulations that govern international trade change frequently, sometimes without advance notice. See “Item 1A. Risk Factors – Trade regulations have restricted our ability to sell our products to several customers, could restrict our ability to sell our products to other customers or in certain markets, or could otherwise restrict our ability to conduct operations” and “ – We face risks associated with our international sales and operations that could materially adversely affect our business, results of operations, or financial condition.”
Backlog
Because of volatile industry conditions, our customers are generally reluctant to enter into long-term, fixed-price contracts. Accordingly, new order volumes for our memory and storage products may fluctuate significantly. We typically accept orders with acknowledgment that the terms may be adjusted to reflect market conditions at the time of shipment. For these reasons, we do not believe that our order backlog as of any particular date is a reliable indicator of actual sales for any succeeding period.
9 | 2020 10-K
Product Warranty
The design and manufacturing process for semiconductor products is highly complex and, as a result, it is possible that we may produce products that do not comply with applicable specifications, contain defects, or are otherwise incompatible with end uses. In accordance with industry practice, we generally provide a limited warranty that our products comply with applicable specifications existing at the time of delivery and will operate to those specifications during a stated warranty period. Under our standard terms and conditions of sale, liability for certain failures of product during a stated warranty period is usually limited to repair or replacement of defective items or return of, or a credit with respect to, amounts paid for such items. Under certain circumstances, we provide more extensive limited warranty coverage than that provided under our standard terms and conditions.
Competition
We face intense competition in the semiconductor memory and storage markets from a number of companies, including Intel; Kioxia Holdings Corporation (formerly Toshiba Memory Corporation); Samsung Electronics Co., Ltd.; SK Hynix Inc.; and Western Digital Corporation. Some of our competitors are large corporations or conglomerates that may have greater resources to invest in technology, capitalize on growth opportunities, and withstand downturns in the semiconductor markets in which we compete. Consolidation of industry competitors could put us at a competitive disadvantage. Our competitors generally seek to increase wafer capacity, improve yields, and reduce die size in their product designs which may result in significant increases in worldwide supply and downward pressure on prices. Increases in worldwide supply of semiconductor memory and storage also result from fabrication capacity expansions, either by way of new facilities, increased capacity utilization, or reallocation of other semiconductor production to semiconductor memory and storage production. Our competitors may increase capital expenditures resulting in future increases in worldwide supply. We, and some of our competitors, have plans to ramp, or are constructing or ramping, production at new fabrication facilities. If competitors are more successful at developing or implementing new product or process technology, their products could have cost or performance advantages. Certain of our memory and storage products are manufactured to industry standard specifications and, as such, have similar performance characteristics to those of our competitors. For these products, the principal competitive factors are generally price and performance characteristics including operating speed, power consumption, reliability, compatibility, size, and form factor. In addition, some of our competitors may benefit from policies and regulations that favor domestic companies or may not be subject to certain regulations or restrictions to which we are subject, which may allow them access to certain sales opportunities from which we may be restricted.
Some governments may provide, or have provided, and may continue to provide, significant assistance, financial or otherwise, to some of our competitors or to new entrants and may intervene in support of national industries and/or competitors. In particular, we face the threat of increasing competition as a result of significant investment in the semiconductor industry by the Chinese government and various state-owned or affiliated entities that is intended to advance China’s stated national policy objectives. In addition, the Chinese government may restrict us from participating in the China market or may prevent us from competing effectively with Chinese companies. Some of our competitors may use aggressive pricing to obtain market share or take business of our key customers. Additionally, our customers may redirect their business to our competitors based on government policy, national preference, or other factors.
Research and Development
Our R&D efforts are focused primarily on development of industry leading memory and storage solutions that enable continuous improvement in performance and cost structure for our products. We are focused on developing new fundamentally different memory structures, materials, and packages designed to facilitate our transition to next generation products. Additional R&D efforts focus on the enablement of advanced computing, storage, and mobile memory architectures and the investigation of new opportunities that leverage our core semiconductor expertise. Product design and development efforts include high-density DDR4, DDR5, LPDDR4, LPDDR5, high-bandwidth memory, and advanced graphics DRAM; 3D NAND (including TLC and QLC technologies); 3D XPoint technology; mobile and storage solutions (including firmware and controllers); managed NAND; and other memory technologies and systems.
To compete in the semiconductor memory and storage markets, we must continue to develop technologically advanced products and processes. The continued evolution of our semiconductor product offerings is necessary to meet expected market demand for memory and storage products and solutions. Our process, design, firmware, controller, package, and system development efforts occur at multiple locations across the world. Our primary R&D centers are located in Boise, Idaho, Singapore, Japan, Taiwan, Italy, China, India, Germany, and other sites in the United States.
R&D expenses vary primarily with the number of development and pre-qualification wafers processed and end-product solutions developed, the cost of advanced equipment dedicated to new product and process development, and personnel costs. Because of the lead times necessary to manufacture our products, we typically begin to process wafers before completion of performance and reliability testing. Development of a product is deemed complete when it is qualified through reviews and tests for performance and reliability. R&D expenses can vary significantly depending on the timing of product qualification.
Patents and Licenses
As of September 3, 2020, we owned approximately 14,200 active U.S. patents and 6,500 active foreign patents. In addition, we have thousands of U.S. and foreign patent applications pending. Our patents have various terms expiring through 2040.
From time to time, we sell and/or license our technology to other parties and continue to pursue opportunities to monetize our investments in our intellectual property through partnering and other arrangements. We have also jointly developed memory and storage product and process technology with third parties on a limited basis.
We have a number of patent and intellectual property license agreements and have, from time to time, licensed or sold our intellectual property to third parties. Some of these license agreements require us to make one-time or periodic payments while others have resulted in us receiving payments. We may need to obtain additional licenses or renew existing license agreements in the future, and we may enter into additional sales or licenses of intellectual property and partnering arrangements. We are unable to predict whether these license agreements can be obtained or renewed on terms acceptable to us.
Employees
As of September 3, 2020, we had approximately 40,000 employees.
11 | 2020 10-K
Environmental Compliance
We approach environmental stewardship and sustainability proactively to ensure we meet all government regulations regarding use of raw materials, discharges, climate change and energy use, emissions, and wastes from our manufacturing processes and address the evolving expectations of our investors, customers, team members, and other stakeholders. Compliance with the law and other compliance obligations is considered a minimum environmental expectation at Micron. Our wafer fabrication facilities continued to conform to the requirements of the International Organization for Standardization (“ISO”) 14001 environmental management systems standard to ensure we are continuously improving our performance. As part of the ISO 14001 framework, we have established a global environmental policy and meet requirements in terms of environmental aspects evaluation and control, compliance obligations, commitment, training, communication, control of documented information, operational control, emergency preparedness and response, and management review. While we have not experienced any material adverse effects to our operations from environmental regulations, changes in regulations could necessitate additional capital expenditures, modification of our operations, or other compliance actions.
Information About Our Executive Officers
Our executive officers are appointed annually by our Board of Directors and our directors are elected annually by our shareholders. All officers serve until their successors are duly chosen or elected and qualified, except in the case of earlier death, resignation, or removal.
The following presents information, as of September 3, 2020, about our executive officers:
 | April S. Arnzen | ||||||||||
| Senior Vice President, Human Resources | |||||||||||
| Ms. Arnzen, 49, joined us in December 1996 and has served in various leadership positions since that time. Ms. Arnzen was named Senior Vice President, Human Resources in June 2017. Ms. Arnzen holds a BS in Human Resource Management and Marketing from the University of Idaho and is a graduate of the Stanford Graduate School of Business Executive Program. | |||||||||||
 | Manish Bhatia | ||||||||||
| Executive Vice President, Global Operations | |||||||||||
| Mr. Bhatia, 48, joined us in October 2017 as our Executive Vice President of Global Operations. From May 2016 to October 2017, Mr. Bhatia served as the Executive Vice President of Silicon Operations at Western Digital Corporation. From March 2010 to May 2016, Mr. Bhatia held several executive roles at SanDisk Corporation including Executive Vice President of Worldwide Operations until it was acquired by Western Digital in May 2016. Mr. Bhatia holds a BS and MS in Mechanical Engineering and an MBA, each from the Massachusetts Institute of Technology. | |||||||||||
 | Michael W. Bokan | ||||||||||
| Senior Vice President, Worldwide Sales | |||||||||||
| Mr. Bokan, 59, joined us in 1996 and has served in various leadership positions since that time. Mr. Bokan was named Senior Vice President, Worldwide Sales in October 2018. Mr. Bokan holds a BS in Business Administration from Colorado State University. | |||||||||||
12
 | Scott J. DeBoer | ||||||||||
| Executive Vice President, Technology Development | |||||||||||
| Dr. DeBoer, 54, joined us in February 1995 and has served in various leadership positions since that time. Dr. DeBoer was named Executive Vice President, Technology Development in June 2017. Dr. DeBoer holds a PhD in Electrical Engineering and an MS in Physics from Iowa State University. He completed his undergraduate degree at Hastings College. | |||||||||||
 | ` | Paul Marosvari | |||||||||
| Vice President, Chief Accounting Officer | |||||||||||
| Mr. Marosvari, 54, joined us in March 1996, and has held various leadership positions since that time. Mr. Marosvari was named Vice President, Chief Accounting Officer in October 2019. Mr. Marosvari holds a Bachelor of Business Administration in Accounting from Boise State University. On September 21, 2020, we announced that Mr. Marosvari intends to retire from Micron in early calendar year 2021. Scott Allen, 52, has been appointed by our Board of Directors to succeed Mr. Marosvari as Corporate Vice President and Chief Accounting Officer, effective as of October 26, 2020. | |||||||||||
 | Sanjay Mehrotra | ||||||||||
| President, Chief Executive Officer, and Director | |||||||||||
| Mr. Mehrotra, 62, joined us in May 2017 as our President, Chief Executive Officer, and Director. Mr. Mehrotra co-founded and led SanDisk Corporation as a start-up in 1988 until its eventual sale in May 2016, serving as its President and Chief Executive Officer from January 2011 to May 2016, and as a member of its Board of Directors from July 2010 to May 2016. Mr. Mehrotra served as a member of the Board of Directors for Cavium, Inc. from July 2009 until July 2018 and for Western Digital Corp. from May 2016 to February 2017. Mr. Mehrotra holds a BS and an MS in Electrical Engineering and Computer Science from the University of California, Berkeley and is a graduate of the Stanford Graduate School of Business Executive Program. | |||||||||||
 | Joel L. Poppen | ||||||||||
| Senior Vice President, Legal Affairs, General Counsel, and Corporate Secretary | |||||||||||
| Mr. Poppen, 56, joined us in October 1995 and has held various leadership positions since that time. Mr. Poppen was named Senior Vice President, Legal Affairs, General Counsel, and Corporate Secretary in June 2017. Mr. Poppen holds a BS in Electrical Engineering from the University of Illinois and a JD from the Duke University School of Law. | |||||||||||
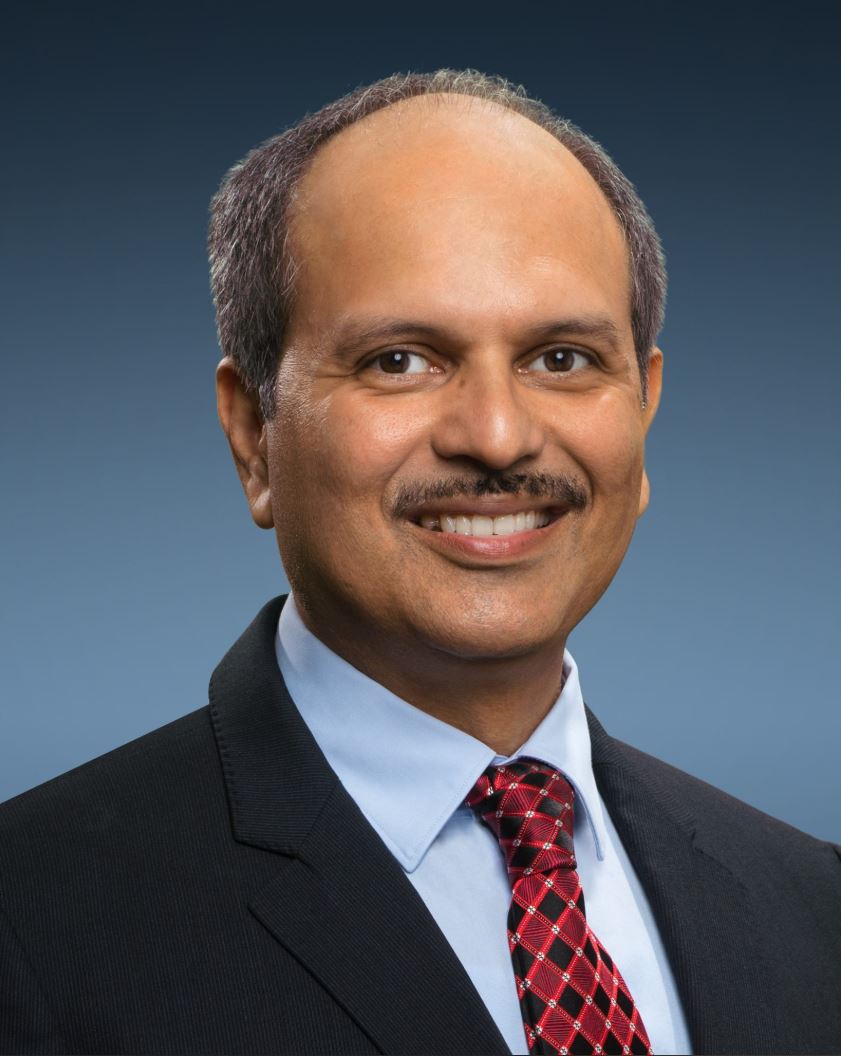 | Sumit Sadana | ||||||||||
| Executive Vice President and Chief Business Officer | |||||||||||
| Mr. Sadana, 51, joined us in June 2017 as our Executive Vice President and Chief Business Officer. From April 2010 to May 2016, Mr. Sadana served in various roles at SanDisk Corporation, including Executive Vice President, Chief Strategy Officer, and General Manager, Enterprise Solutions until it was acquired by Western Digital in May 2016. Mr. Sadana currently serves on the Board of Directors of Silicon Laboratories, Inc. Mr. Sadana holds a B.Tech. in Electrical Engineering from the Indian Institute of Technology, Kharagpur, India and an MS in Electrical Engineering from Stanford University. | |||||||||||
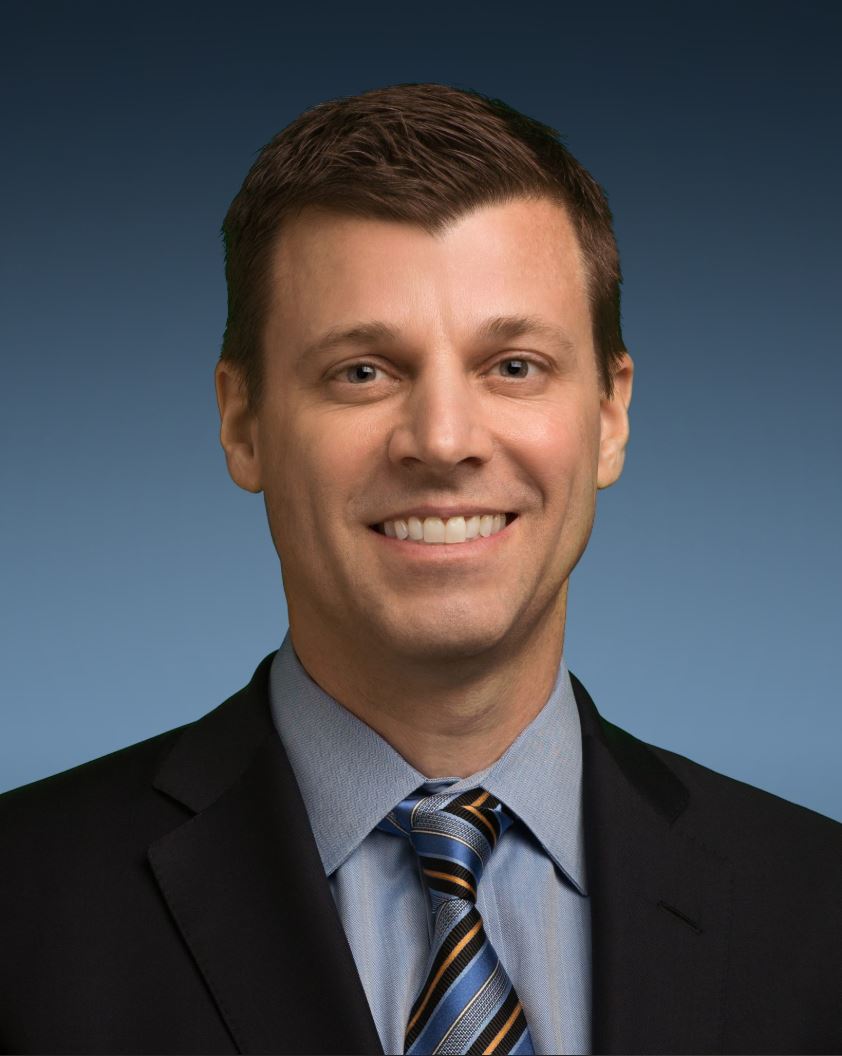 | David A. Zinsner | ||||||||||
| Senior Vice President and Chief Financial Officer | |||||||||||
| Mr. Zinsner, 51, joined us in February 2018 as our Senior Vice President and Chief Financial Officer. From April 2017 to February 2018, Mr. Zinsner served as the President and Chief Operating Officer of Affirmed Networks. From January 2009 to April 2017, Mr. Zinsner served as the Senior Vice President of Finance and Chief Financial Officer of Analog Devices. From July 2005 to January 2009, Mr. Zinsner served as the Senior Vice President and Chief Financial Officer of Intersil Corporation. Mr. Zinsner holds an MBA, Finance and Accounting from Vanderbilt University and a BS in Industrial Management from Carnegie Mellon University. | |||||||||||
There are no family relationships between any of our directors or executive officers.
13 | 2020 10-K
Available Information
Our executive offices are located at 8000 South Federal Way, Boise, Idaho 83716-9632 and our telephone number is (208) 368-4000. Information about us is available at our website, www.micron.com. Also available on our website are our Corporate Governance Guidelines, Governance and Sustainability Committee Charter, Compensation Committee Charter, Audit Committee Charter, Finance Committee Charter, and Code of Business Conduct and Ethics. Any amendments or waivers of our Code of Business Conduct and Ethics will also be posted on our website within four business days of the amendment or waiver. Copies of these documents are available to shareholders upon request. Information contained or referenced on our website is not incorporated by reference and does not form a part of this Annual Report on Form 10-K.
Investors and others should note that we announce material financial information about our business and products through a variety of means, including our investor relations website (investors.micron.com), filings with the U.S. Securities and Exchange Commission (“SEC”), press releases, public conference calls, and webcasts. We use these channels to achieve broad, non-exclusionary distribution of information to the public and for complying with our disclosure obligations under Regulation FD. Therefore, we encourage investors, the media, and others interested in our company to review the information we post on such channels.
Our filings are available free of charge on our website as soon as reasonably practicable after they are electronically filed with, or furnished to, the SEC, including our annual and quarterly reports on Forms 10-K and 10-Q and current reports on Form 8-K, our proxy statements, and any amendments to those reports or statements. The SEC’s website, www.sec.gov, contains reports, proxy and information statements, and other information regarding issuers that file electronically with the SEC. The content on any website referred to in this Form 10-K is not incorporated by reference in this Form 10-K unless expressly noted.
Item 1A. RISK FACTORS
In addition to the factors discussed elsewhere in this Form 10-K, the following are important factors, the order of which is not necessarily indicative of the level of risk that each poses to us, which could cause actual results or events to differ materially from those contained in any forward-looking statements made by us. Any of these factors could have a material adverse effect on our business, results of operations, financial condition, or stock price. Our operations could also be affected by other factors that are presently unknown to us or not considered significant.
The effects of the COVID-19 outbreak could adversely affect our business, results of operations, and financial condition.
The effects of the public health crisis caused by the COVID-19 outbreak and the measures being taken to limit COVID-19’s spread are uncertain and difficult to predict, but may include, and in some cases, have included and may continue to include:
-
A decrease in short-term and/or long-term demand and/or pricing for our products and a global economic recession or depression that could further reduce demand and/or pricing for our products, resulting from actions taken by governments, businesses, and/or the general public in an effort to limit exposure to and the spreading of COVID-19, such as travel restrictions, quarantines, and business shutdowns or slowdowns;
-
Negative impacts to our operations, including:
◦reductions in production levels, R&D activities, product development, technology transitions, yield enhancement activities, and qualification activities with our customers, resulting from our efforts to mitigate the impact of COVID-19 through physical-distancing measures we have enacted at our locations around the world in an effort to protect our employees’ and contractors’ health and well-being, including working from home, limiting the number of meeting attendees, reducing the number of people in certain of our sites at any one time, quarantines of team members, contractors, or vendors who are at risk of contracting, or have contracted, COVID-19, and limiting employee travel;
◦increased costs resulting from our efforts to mitigate the impact of COVID-19 through physical distancing measures, working from home, upgrades to our sites, enhanced cleaning measures, and the increased use of personal protective equipment at our sites;
14
◦increased costs for, or unavailability of, transportation, raw materials, or other inputs necessary for the operation of our business;
◦reductions in or cessation of operations at any site or in any jurisdiction resulting from government restrictions on movement and/or business operations or our failure to prevent and/or adequately mitigate spread of COVID-19 at one or more of our sites;
◦our inability to continue or resume construction projects due to delays in obtaining materials, equipment, labor, engineering services, government permits, or any other essential aspect of projects, which could impact our ability to introduce new technologies, reduce costs, or meet customer demand;
◦disruptions to our supply chain in connection with the sourcing and transportation of materials, equipment and engineering support, and services from or in geographic areas that have been impacted by COVID-19 and by efforts to contain the spread of COVID-19; and
- Deterioration of worldwide credit and financial markets that could limit our ability to obtain external financing to fund our operations and capital expenditures, result in losses on our holdings of cash and investments due to failures of financial institutions and other parties, and result in a higher rate of losses on our accounts receivables due to credit defaults.
The resumption of normal business operations after such interruptions may be delayed or constrained by lingering effects of COVID-19 on our team members, contractors, suppliers, third-party service providers, customers, or distributors.
These effects, alone or taken together, could have a material adverse effect on our business, results of operations, legal exposure, or financial condition. A sustained, prolonged, or recurring outbreak could exacerbate the adverse impact of such measures.
Volatility in average selling prices for our semiconductor memory and storage products may adversely affect our business.
We have experienced significant volatility in our average selling prices, including dramatic declines as noted in the table below, and may continue to experience such volatility in the future. In some prior periods, average selling prices for our products have been below our manufacturing costs and we may experience such circumstances in the future. Average selling prices for our products that decline faster than our costs could have a material adverse effect on our business, results of operations, or financial condition.
| DRAM | NAND | ||||||||||
| (percentage change in average selling prices) | |||||||||||
| 2020 from 2019 | (34) | % | (9) | % | |||||||
| 2019 from 2018 | (30) | % | (47) | % | |||||||
| 2018 from 2017 | 36 | % | (13) | % | |||||||
| 2017 from 2016 | 18 | % | (10) | % | |||||||
| 2016 from 2015 | (34) | % | (16) | % |
Beginning in 2020, revenue and units for MCPs and SSDs, which contain both DRAM and NAND, are disaggregated based on the relative values of each component. Prior periods presented in the table above have been conformed to current period presentation.
We may be unable to maintain or improve gross margins.
Our gross margins are dependent, in part, upon continuing decreases in per gigabit manufacturing costs achieved through improvements in our manufacturing processes and product designs, including, but not limited to, process line-width, additional 3D memory layers, additional bits per cell (i.e., cell levels), architecture, number of mask layers, number of fabrication steps, and yield. In future periods, we may be unable to reduce our per gigabit manufacturing costs at sufficient levels to maintain or improve gross margins. Factors that may limit our ability to maintain or reduce costs include, but are not limited to, strategic product diversification decisions affecting product mix, the increasing complexity of manufacturing processes, difficulties in transitioning to smaller line-width process technologies, 3D memory layers, NAND cell levels, transitioning to replacement gate technology for NAND, process
15 | 2020 10-K
complexity including number of mask layers and fabrication steps, manufacturing yield, technological barriers, changes in process technologies, and new products that may require relatively larger die sizes.
Many factors may result in a reduction of our output or a delay in ramping production, which could lead to underutilization of our production assets. These factors may include, among others, a weak demand environment, industry oversupply, inventory surpluses, our ramp of emerging technologies, declining selling prices, and changes in supply agreements. A significant portion of our manufacturing costs are fixed and do not vary proportionally with changes in production output. As a result, lower utilization and increases in our per gigabit manufacturing costs may adversely affect our gross margins, business, results of operations, or financial condition.
In addition, per gigabit manufacturing costs may also be affected by a broader product portfolio, which may have smaller production quantities and shorter product lifecycles. Our business and the markets we serve are subject to rapid technological changes and material fluctuations in demand based on end-us
Showing the first 8K of 81K characters. Open the full section
Item 1B. UNRESOLVED STAFF COMMENTS
None.
30
Item 2. PROPERTIES
Our corporate headquarters are located in Boise, Idaho. In addition to our principal facilities described below, we own or lease numerous other facilities in locations throughout the world used for design, R&D, and sales and marketing activities. The following is a summary of our principal facilities as of September 3, 2020:
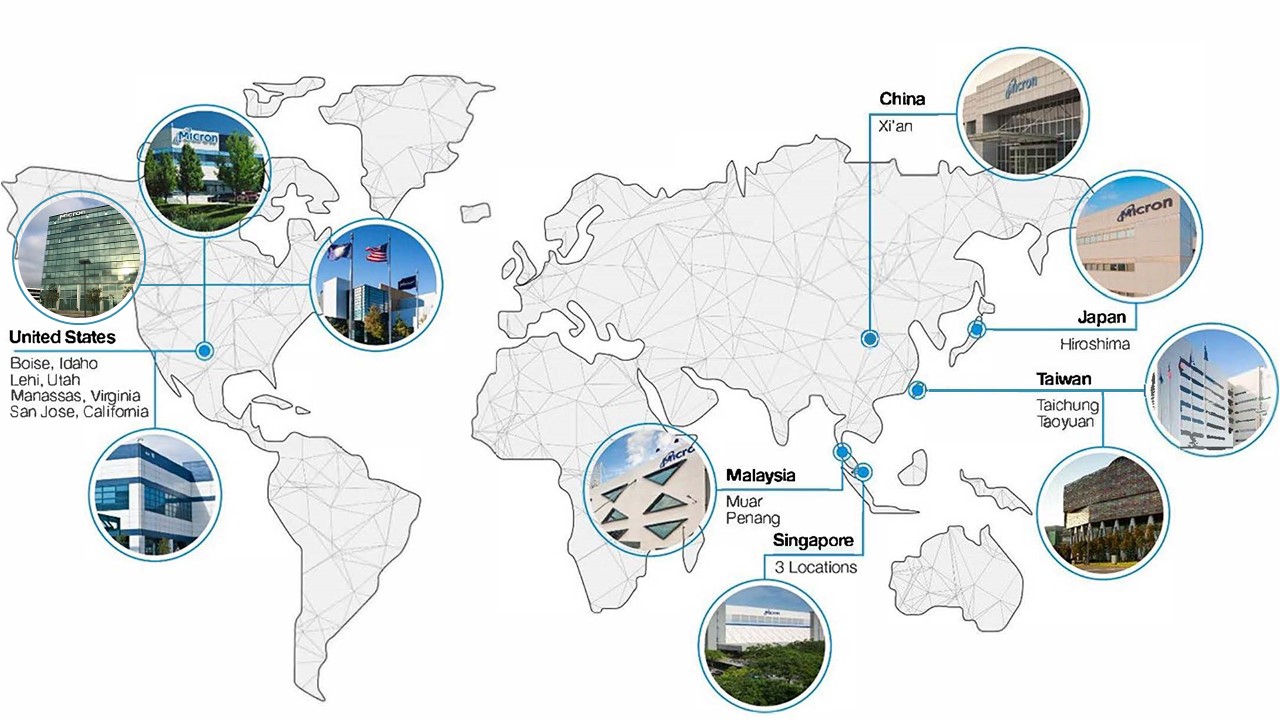
| Location | Principal Operations | ||||
| Taiwan | R&D, wafer fabrication, component assembly and test, module assembly and test | ||||
| Singapore | R&D, wafer fabrication, component assembly and test, module assembly and test | ||||
| Japan | R&D, wafer fabrication | ||||
| United States | R&D, wafer fabrication, reticle manufacturing | ||||
| China | Component assembly and test, module assembly and test | ||||
| Malaysia | Component assembly and test, module assembly and test |
We generally utilize all of our manufacturing capacity; however, a portion of our MTU facility was underutilized for 2020, 2019, and 2018. We believe that our existing facilities are suitable and adequate for our present purposes. We do not identify or allocate assets by operating segment, other than goodwill. (See “Part II – Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements – Geographic Information.”)
Item 3. LEGAL PROCEEDINGS
Reorganization Proceedings of the MMJ Companies
In 2013, we completed the acquisition of Elpida Memory, Inc., now known as MMJ, pursuant to the terms and conditions of an Agreement on Support for Reorganization Companies (the “Sponsor Agreement”) that we entered into in 2012 with the trustees of the MMJ Companies’ pending corporate reorganization proceedings under the Corporate Reorganization Act of Japan. Under the Sponsor Agreement, we agreed to provide certain support for the reorganization of the MMJ Companies and the trustees agreed to seek approval for such support from the Tokyo District Court and the MMJ Companies’ reorganization creditors.
31 | 2020 10-K
The reorganization provided for payments by the MMJ Companies to their secured and unsecured creditors in an aggregate amount of 200 billion yen, less certain expenses. The plan of reorganization also provided for our cash payment at closing of 60 billion yen into MMJ to fund the initial installment payment to the creditors of 60 billion yen in exchange for 100% ownership of MMJ’s equity.
Under MMJ’s plan of reorganization, secured creditors recovered 100% of the amount of their fixed claims on or before the sixth annual installment payment, and unsecured creditors recovered at least 17.4% of the amount of their fixed claims in seven annual installments. In connection with our sale of MAI in 2017, the remaining MAI creditor obligation was paid in full and MAI’s reorganization proceedings were closed at that time.
Because MMJ’s plan of reorganization provided for ongoing payments to creditors, the reorganization proceedings continued following the closing of the MMJ acquisition and MMJ remained subject to the oversight of the Tokyo District Court and two trustees. The final creditor payment under MMJ’s plan of reorganization occurred in December 2019 and, on July 22, 2020, the Tokyo District Court issued a termination order formally closing the reorganization proceedings and ending the oversight of MMJ’s operations by the Tokyo District Court and trustees.
See “Part II – Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements – Contingencies” and “Item 1A. Risk Factors” for a discussion of other legal proceedings.
Item 4. MINE SAFETY DISCLOSURES
Not applicable.
PART II
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS, AND ISSUER PURCHASES OF EQUITY SECURITIES
Our common stock is listed on The Nasdaq Global Select Market under the trading symbol “MU.”
Holders of Record
As of October 9, 2020, there were 1,942 shareholders of record of our common stock.
Equity Compensation Plan Information
The information required by this item is incorporated by reference from the information to be included in our 2020 Proxy Statement under the section entitled “Equity Compensation Plan Information,” which will be filed with the SEC within 120 days after September 3, 2020.
Issuer Purchase of Equity Securities
Common Stock Repurchase Authorization
In May 2018, we announced that our Board of Directors authorized the discretionary repurchase of up to $10 billion of our outstanding common stock through open-market purchases, block trades, privately-negotiated transactions, derivative transactions, and/or pursuant to Rule 10b5-1 trading plans. The repurchase authorization has no expiration date, does not obligate us to acquire any common stock, and is subject to market conditions and our ongoing determination of the best use of available cash.
32
| Period | Total number of shares purchased | Average price paid per share | Total number of shares purchased as part of publicly announced plans or programs | Maximum number (or approximate dollar value) of shares that may yet be purchased under publicly announced plans or programs | ||||||||||||||||||||||
| May 29, 2020 | – | July 2, 2020 | 824,339 | $ | 49.91 | 824,339 | ||||||||||||||||||||
| July 3, 2020 | – | July 30, 2020 | — | — | — | |||||||||||||||||||||
| July 31, 2020 | – | September 3, 2020 | — | — | — | |||||||||||||||||||||
| 824,339 | $ | 49.91 | 824,339 | $7,162,264,784 |
Shares of common stock withheld as payment of withholding taxes and exercise prices in connection with the vesting or exercise of equity awards are also treated as common stock repurchases. Those withheld shares of common stock are not considered common stock repurchases under an authorized common stock repurchase plan and accordingly are excluded from the amounts in the table above.
Performance Graph
The following graph illustrates a five-year comparison of cumulative total returns for our common stock, the S&P 500 Composite Index, and the Philadelphia Semiconductor Index (SOX) from August 31, 2015, through August 31, 2020. We operate on a 52 or 53 week fiscal year which ends on the Thursday closest to August 31. Accordingly, the last day of our fiscal year varies. For consistent presentation and comparison to the industry indices shown herein, we have calculated our stock performance graph assuming an August 31 year end.
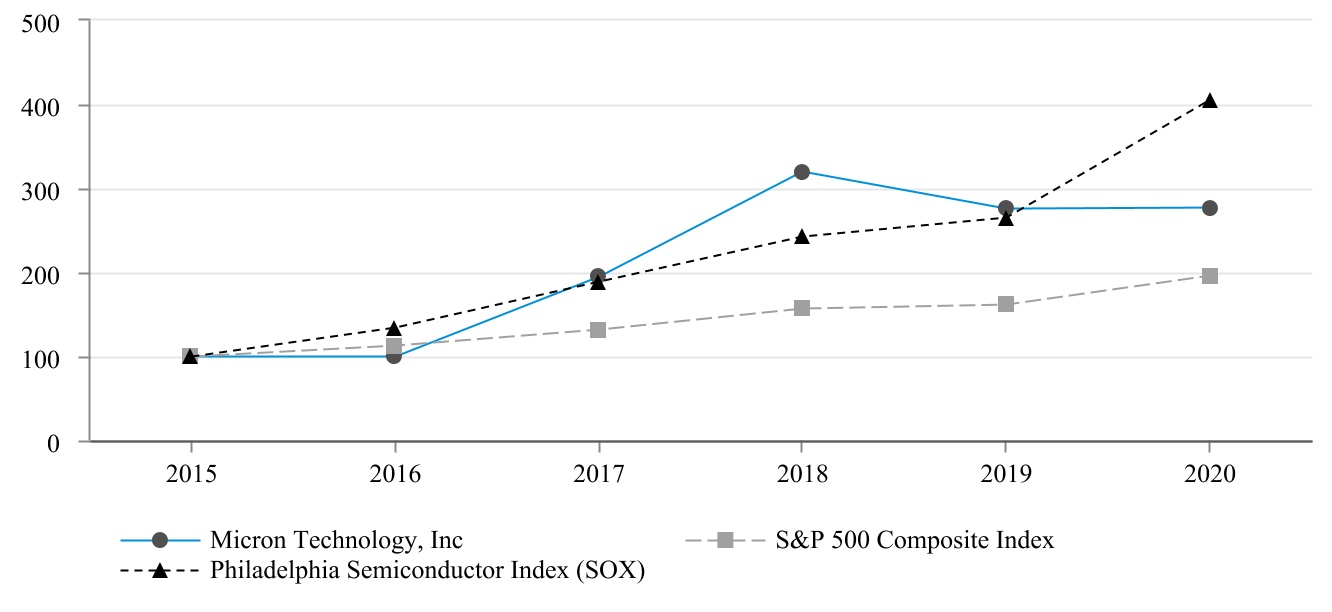
Note: Management cautions that the stock price performance information shown in the graph above may not be indicative of current stock price levels or future stock price performance.
The performance graph above assumes $100 was invested on August 31, 2015 in common stock of Micron Technology, Inc., the S&P 500 Composite Index, and the Philadelphia Semiconductor Index (SOX). Any dividends paid during the period presented were assumed to be reinvested. The performance was plotted using the following data:
| 2015 | 2016 | 2017 | 2018 | 2019 | 2020 | |||||||||||||||
| Micron Technology, Inc. | $ | 100 | $ | 100 | $ | 195 | $ | 320 | $ | 276 | $ | 277 | ||||||||
| S&P 500 Composite Index | 100 | 113 | 131 | 157 | 161 | 196 | ||||||||||||||
| Philadelphia Semiconductor Index (SOX) | 100 | 134 | 189 | 242 | 265 | 405 |
33 | 2020 10-K
Item 6. SELECTED FINANCIAL DATA
| 2020 | 2019 | 2018 | 2017 | 2016 | |||||||||||||||||||||||||
| (in millions, except per share amounts) | |||||||||||||||||||||||||||||
| Revenue | $ | 21,435 | $ | 23,406 | $ | 30,391 | $ | 20,322 | $ | 12,399 | |||||||||||||||||||
| Gross margin | 6,552 | 10,702 | 17,891 | 8,436 | 2,505 | ||||||||||||||||||||||||
| Operating income | 3,003 | 7,376 | 14,994 | 5,868 | 168 | ||||||||||||||||||||||||
| Net income (loss) | 2,710 | 6,358 | 14,138 | 5,090 | (275) | ||||||||||||||||||||||||
| Net income (loss) attributable to Micron | 2,687 | 6,313 | 14,135 | 5,089 | (276) | ||||||||||||||||||||||||
| Diluted earnings (loss) per share | 2.37 | 5.51 | 11.51 | 4.41 | (0.27) | ||||||||||||||||||||||||
| Cash and short-term investments | 8,142 | 7,955 | 6,802 | 5,428 | 4,398 | ||||||||||||||||||||||||
| Total current assets | 17,965 | 16,503 | 16,039 | 12,457 | 9,495 | ||||||||||||||||||||||||
| Property, plant, and equipment | 31,031 | 28,240 | 23,672 | 19,431 | 14,686 | ||||||||||||||||||||||||
| Total assets | 53,678 | 48,887 | 43,376 | 35,336 | 27,540 | ||||||||||||||||||||||||
| Total current liabilities | 6,635 | 6,390 | 5,754 | 5,334 | 4,835 | ||||||||||||||||||||||||
| Long-term debt | 6,373 | 4,541 | 3,777 | 9,872 | 9,154 | ||||||||||||||||||||||||
| Total Micron shareholders’ equity | 38,996 | 35,881 | 32,294 | 18,621 | 12,080 | ||||||||||||||||||||||||
| Noncontrolling interests in subsidiaries | — | 889 | 870 | 849 | 848 | ||||||||||||||||||||||||
| Total equity | 38,996 | 36,770 | 33,164 | 19,470 | 12,928 |
On October 31, 2019, we purchased Intel’s noncontrolling interest in IMFT, now known as MTU, and IMFT Member Debt for $1.25 billion. See “Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements – Debt” and “– Equity.”
In December 2016, we acquired the 67% remaining interest in Inotera and began consolidating Inotera's operating results. In the periods presented above through December 2016, Inotera sold DRAM products exclusively to us through supply agreements. The cash paid for the Inotera Acquisition was funded, in part, with a term loan of 80 billion New Taiwan dollars and $986 million from the sale of 58 million shares of our common stock.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
This discussion should be read in conjunction with the consolidated financial statements and accompanying notes for the year ended September 3, 2020. All period references are to our fiscal periods unless otherwise indicated. Our fiscal year is the 52 or 53-week period ending on the Thursday closest to August 31. Fiscal 2020 contains 53 weeks and our fiscal 2019 and 2018 each contain 52 weeks. Our fourth quarter of fiscal 2020 contained 14 weeks. All tabular dollar amounts are in millions, except per share amounts.
For an overview of our business, see “Part I – Item 1. Business – Overview.”
Impact of COVID-19 on Our Business
Events surrounding the ongoing COVID-19 outbreak have resulted in a reduction in economic activity across the globe, which has affected demand for certain of our products. While we have observed demand increases in some areas of our business that support a stay-at-home economy, such as products used in data center infrastructure, notebook computers, and similar applications, we have also observed demand decreases in other categories such as smartphones, consumer electronics, automotive, desktop PCs, and enterprise markets. The ultimate extent to which COVID-19 will impact demand for our products depends on future developments, which are highly uncertain and very difficult to predict, including new information that may emerge concerning the severity of the coronavirus and actions to contain and treat its impacts.
34
While all our global sites are currently operating with close to full staff and at normal capacity levels, our facilities could be required to temporarily curtail production levels or temporarily cease operations based on government mandates. We may be required to, or deem it to be in the best interest of our employees, customers, partners, suppliers, and stakeholders, to alter our business operations in order to maintain a healthy and safe environment. It is not clear what potential effects any such alterations or modifications may have on our business, including effects on our customers, employees, and prospects, or on our financial results. We are following government policies and recommendations designed to slow the spread of COVID-19 and remain committed to the health and safety of our team members, contractors, suppliers, customers, distributors, and communities.
Our efforts to respond to the COVID-19 outbreak include the following:
-
We have put health screenings in place, required physical distancing, established team separation protocols, and made equipment upgrades at our facilities. We are also prohibiting visitors, have significantly decreased business travel, and are generally requiring team members to work from home where possible. Where work from home is not possible, all on-site team members must pass thermal scanning equipment to ensure they do not have an elevated body temperature and must wear a mask at all times.
-
To respond to changing market conditions, we have shifted some supply from markets which have experienced declines in demand, such as smartphones, consumer electronics, desktop PCs, automotive, and enterprise to markets that have experienced demand increases, such as data center, cloud server, notebooks, and gaming.
-
We have evaluated our supply chain and communicated with our suppliers to identify supply gaps and taken steps to ensure continuity. In some cases, we have added alternative suppliers and increased our on-hand inventory of raw materials needed in our operations.
-
We have added assembly and test capacity to provide redundant manufacturing capability through our network of captive operations and external partners.
-
We are evaluating all our construction projects across our global manufacturing operations and enacting protocols to enhance the safety of our team members, suppliers, and contractors.
-
We have developed strategies and are implementing measures to respond to a variety of potential economic scenarios, such as limitations on new hiring and business travel and reductions of discretionary spending.
-
We are working with government authorities in the jurisdictions where we operate, and continuing to monitor our operations in an effort to ensure we follow government requirements, relevant regulations, industry standards, and best practices to help safeguard our team members, while safely continuing operations at our sites across the globe.
We believe these actions are appropriate and prudent to safeguard our team members, contractors, suppliers, customers, and communities, while allowing us to safely continue operations, but we cannot predict how the steps we, our team members, government entities, suppliers, or customers take in response to the COVID-19 outbreak will ultimately impact our business, outlook, or results of operations.
35 | 2020 10-K
Results of Operations
Consolidated Results
| For the year ended | 2020 | 2019 | 2018 | ||||||||||||||||||||||||||
| Revenue | $ | 21,435 | 100 | % | $ | 23,406 | 100 | % | $ | 30,391 | 100 | % | |||||||||||||||||
| Cost of goods sold | 14,883 | 69 | % | 12,704 | 54 | % | 12,500 | 41 | % | ||||||||||||||||||||
| Gross margin | 6,552 | 31 | % | 10,702 | 46 | % | 17,891 | 59 | % | ||||||||||||||||||||
| Research and development | 2,600 | 12 | % | 2,441 | 10 | % | 2,141 | 7 | % | ||||||||||||||||||||
| Selling, general, and administrative | 881 | 4 | % | 836 | 4 | % | 813 | 3 | % | ||||||||||||||||||||
| Other operating (income) expense, net | 68 | — | % | 49 | — | % | (57) | — | % | ||||||||||||||||||||
| Operating income | 3,003 | 14 | % | 7,376 | 32 | % | 14,994 | 49 | % | ||||||||||||||||||||
| Interest income (expense), net | (80) | — | % | 77 | — | % | (222) | (1) | % | ||||||||||||||||||||
| Other non-operating income (expense), net | 60 | — | % | (405) | (2) | % | (465) | (2) | % | ||||||||||||||||||||
| Income tax (provision) benefit | (280) | (1) | % | (693) | (3) | % | (168) | (1) | % | ||||||||||||||||||||
| Equity in net income (loss) of equity method investees | 7 | — | % | 3 | — | % | (1) | — | % | ||||||||||||||||||||
| Net income attributable to noncontrolling interests | (23) | — | % | (45) | — | % | (3) | — | % | ||||||||||||||||||||
| Net income attributable to Micron | $ | 2,687 | 13 | % | $ | 6,313 | 27 | % | $ | 14,135 | 47 | % |
Total Revenue**:** Total revenue for 2020 decreased 8% as compared to 2019 primarily due to a decline in DRAM sales partially offset by an increase in NAND sales. Sales of DRAM products for 2020 decreased 14% as compared to 2019 as average selling prices declined in the mid-30% range due to challenging market conditions, partially offset by growth in bit shipments in the low-30% range driven by cloud server, enterprise server, and mobile markets. Sales of NAND products for 2020 increased 14% as compared to 2019 primarily due to increases in bit shipments in the mid-20% range driven by sales of SSDs to data center customers and sales of managed NAND products, partially offset by a high-single digit percent decline in average selling prices.
The U.S. Bureau of Industry and Security (“BIS”) enacted broad trade restrictions with respect to Huawei (which represented approximately 10% of our revenue in the fourth quarter of 2020 and 12% in 2019) that took effect on September 15, 2020 and currently prevent us from shipping products to Huawei. We cannot predict the duration these restrictions will remain in place and whether the BIS will grant us licenses to ship products to Huawei. We may not be able to replace the lost revenue opportunities associated with such restrictions.
Total revenue for 2019 decreased 23% as compared to 2018 primarily due to pricing declines resulting from the challenging memory market environment in 2019. Sales of DRAM products for 2019 decreased 28% as compared to 2018 primarily due to declines in average selling prices of approximately 30% resulting from supply and demand imbalances, customer inventory corrections, and CPU shortages. Sales of NAND products for 2019 decreased 12% as compared to 2018 primarily due to declines in average selling prices in the mid-40% range resulting from supply and demand imbalances, which were partially offset by significant increases in sales volumes. In addition, demand for our NAND products was adversely affected by the transition from SATA SSDs to NVMe SSDs. The higher NAND sales volumes in 2019 were driven by increases in sales of high-value mobile managed NAND products as well as discrete NAND products enabled by our execution in ramping 64- and 96-layer TLC 3D NAND.
Overall Gross Margin**:** Our overall gross margin percentage decreased to 31% for 2020 from 46% for 2019, primarily due to declines in average selling prices, partially offset by the effect of decreases in non-cash depreciation expense from the revision in estimated useful lives of equipment in our NAND wafer fabrication facilities described below, cost reductions resulting from strong execution in delivering products featuring advanced technologies, and continuous improvement initiatives to reduce production costs. Our gross margins included the impact of underutilization costs at MTU of $557 million for 2020, $384 million for 2019, and $262 million for 2018. We expect underutilization costs at MTU to gradually decline through 2021 as we redeploy equipment and continue to right-size our capacity.
36
Our overall gross margin percentage decreased to 46% for 2019 from 59% for 2018 primarily due to declines in average selling prices partially offset by cost reductions resulting from strong execution in delivering products featuring advanced technologies and from continuous improvement initiatives to reduce production costs.
We periodically assess the estimated useful lives of our property, plant, and equipment. Based on our assessment of planned technology node transitions, capital spending, and re-use rates, we revised the estimated useful lives of the existing equipment in our NAND wafer fabrication facilities and our research and development facilities from five years to seven years as of the beginning of the first quarter of 2020. The revision in estimated useful lives reduced NAND manufacturing depreciation expense by approximately $565 million in 2020, of which approximately $165 million remained capitalized in inventory as of the end of 2020. Adjusting for the effect of the reduced amount of depreciation expense remaining in inventory, the revision in estimated useful lives benefited cost of goods sold by approximately $400 million for 2020.
Revenue by Business Unit
| For the year ended | 2020 | 2019 | 2018 | ||||||||||||||||||||||||||
| CNBU | $ | 9,184 | 43 | % | $ | 9,968 | 43 | % | $ | 15,252 | 50 | % | |||||||||||||||||
| MBU | 5,702 | 27 | % | 6,403 | 27 | % | 6,579 | 22 | % | ||||||||||||||||||||
| SBU | 3,765 | 18 | % | 3,826 | 16 | % | 5,022 | 17 | % | ||||||||||||||||||||
| EBU | 2,759 | 13 | % | 3,137 | 13 | % | 3,479 | 11 | % | ||||||||||||||||||||
| All Other | 25 | — | % | 72 | — | % | 59 | — | % | ||||||||||||||||||||
| $ | 21,435 | $ | 23,406 | $ | 30,391 |
Percentages of total revenue may not total 100% due to rounding.
Changes in revenue for each business unit for 2020 as compared to 2019 were as follows:
-
CNBU revenue decreased 8% primarily due to DRAM price declines driven by imbalances in supply and demand, partially offset by bit sales growth across key markets, particularly in cloud server and graphics markets. In addition, in the second quarter of 2020, we determined that the 3D XPoint technology and product roadmap are more closely aligned with our CNBU strategy than our SBU strategy and 3D XPoint became an integral part of CNBU. Accordingly, we began to report all 3D XPoint activities within CNBU from that date.
-
MBU revenue decreased 11% primarily due to price declines, partially offset by bit sales growth for high-value mobile MCP products.
-
SBU revenue decreased 2% primarily due to the decline in 3D XPoint revenue in SBU after the first quarter of 2020 as noted above and NAND selling price declines, partially offset by bit sales growth for SSDs. SBU revenue included products manufactured and sold to Intel under a long-term supply agreement at prices approximating cost, which included 3D XPoint memory and NAND, aggregating $124 million, $682 million, and $541 million, for 2020, 2019, and 2018, respectively.
-
EBU revenue decreased 12% primarily due to price declines resulting from the impact of the global COVID-19 pandemic on automotive, industrial, and consumer segments partially offset by bit sales growth from transitions to an increasing mix of high-density DRAM and NAND products.
Changes in revenue for each business unit for 2019 as compared to 2018 were as follows:
-
CNBU revenue decreased 35% due to challenging market conditions in 2019, which led to price declines.
-
MBU revenue decreased 3% primarily due to price declines offset by strong execution in developing and qualifying mobile managed NAND products and continued content growth in smartphones, which combined to drive a significant increase in shipment volumes.
-
SBU revenue decreased 24% primarily due to price declines, partially offset by significant growth in shipment volumes as a result of strong execution in ramping 64-layer and 96-layer TLC NAND products.
-
EBU revenue decreased 10% primarily due to lower sales to consumer markets as a result of weak demand and pricing, partially offset by increases in sales to automotive and industrial markets.
37 | 2020 10-K
Operating Income (Loss) by Business Unit
| For the year ended | 2020 | 2019 | 2018 | ||||||||||||||||||||||||||
| CNBU | $ | 2,010 | 22 | % | $ | 4,645 | 47 | % | $ | 9,773 | 64 | % | |||||||||||||||||
| MBU | 1,074 | 19 | % | 2,606 | 41 | % | 3,033 | 46 | % | ||||||||||||||||||||
| SBU | 36 | 1 | % | (386) | (10) | % | 964 | 19 | % | ||||||||||||||||||||
| EBU | 301 | 11 | % | 923 | 29 | % | 1,473 | 42 | % | ||||||||||||||||||||
| All Other | (2) | (8) | % | 13 | 18 | % | — | — | % | ||||||||||||||||||||
| $ | 3,419 | $ | 7,801 | $ | 15,243 |
Percentages reflect operating income (loss) as a percentage of revenue for each business unit.
Changes in operating income or loss for each business unit for 2020 as compared to 2019 were as follows:
-
CNBU operating income decreased primarily due to declines in DRAM pricing and MTU underutilization costs in 2020 related to 3D XPoint.
-
MBU operating income decreased primarily due to declines in low-power DRAM and NAND pricing, partially offset by increases in sales of high-value MCP products and manufacturing cost reductions.
-
SBU operating margin improved primarily due to lower 3D XPoint underutilization costs, manufacturing cost reductions, increases in sales volumes, and improved product mix, partially offset by declines in selling prices.
-
EBU operating income decreased as a result of declines in pricing, partially offset by increases in sales volumes to the automotive and industrial markets.
Changes in operating income or loss for each business unit for 2019 as compared to 2018 were as follows:
-
CNBU operating income decreased primarily due to declines in pricing and higher R&D costs, partially offset by manufacturing cost reductions.
-
MBU operating income decreased primarily due to declines in pricing partially offset by increases in sales of high-value managed NAND products and manufacturing cost reductions.
-
SBU operating margin declined primarily due to declines in pricing, which were partially offset by manufacturing cost reductions and increases in sales volumes. SBU operating results for 2019 and 2018 were adversely impacted by the underutilization costs at IMFT.
-
EBU operating income decreased as a result of declines in pricing and higher R&D costs partially offset by manufacturing cost reductions and increases in sales volumes.
Operating Expenses and Other
Research and Development**:** R&D expenses vary primarily with the number of development and pre-qualification wafers processed, amounts reimbursed under R&D cost-sharing agreements, the cost of advanced equipment dedicated to new product and process development, and personnel costs. Because of the lead times necessary to manufacture our products, we typically begin to process wafers before completion of performance and reliability testing. Development of a product is deemed complete when it is qualified through reviews and tests for performance and reliability. R&D expenses can vary significantly depending on the timing of product qualification.
R&D expenses for 2020 were 7% higher as compared to 2019 primarily due to increases in volumes of development and pre-qualification wafers, a reduction of R&D reimbursements from our partners, increases in employee compensation, and increases in subcontractor expense, partially offset by lower depreciation expense from the revision of the estimated useful lives of equipment. R&D expenses were reduced by $110 million in 2020 due to the revision of the estimated useful lives of equipment. R&D expenses for 2019 were 14% higher as compared to 2018 primarily due to decreases in reimbursements from our R&D cost-sharing arrangements, increases in depreciation expense as a result of increases in capital spending, and increases in employee compensation.
38
We shared the cost of certain product and process development activities with development partners, including agreements to jointly develop NAND and 3D XPoint technologies with Intel. We substantially completed our cost-sharing agreements with Intel to develop 3D NAND and 3D XPoint technology in 2019 and 2020, respectively. Our R&D expenses were reduced by $60 million for 2019 and $201 million for 2018 from reimbursements under these arrangements. Reimbursements were not significant in 2020.
Selling, General, and Administrative**:** SG&A expenses for 2020 were 5% higher as compared to 2019 due to increases in employee compensation and legal costs, partially offset by a reduction in consulting fees. SG&A expenses for 2019 were 3% higher as compared to 2018 primarily due to increases in legal costs and consulting fees, partially offset by a reduction in employee compensation and sales commissions.
Income Taxes**:** Our income tax (provision) benefit consisted of the following:
| For the year ended | 2020 | 2019 | 2018 | ||||||||
| Income tax (provision) benefit, excluding items below | $ | (117) | $ | (530) | $ | (274) | |||||
| Utilization of and other changes in net deferred tax assets of MMJ, MMT, and MTTW | (163) | (173) | (68) | ||||||||
| Repatriation Tax, net of adjustments related to uncertain tax positions | — | 10 | (1,030) | ||||||||
| Release of the valuation allowance on net deferred tax assets of our U.S. operations | — | — | 1,337 | ||||||||
| Remeasurement of deferred tax assets and liabilities reflecting lower U.S. corporate tax rates | — | — | (133) | ||||||||
| $ | (280) | $ | (693) | $ | (168) | ||||||
| Effective tax rate | 9.4 | % | 9.8 | % | 1.2 | % |
Our income tax provision decreased in 2020 as compared to 2019 primarily as a result of reductions in our profit before tax. Our effective tax rate increased in 2019 as compared to 2018 primarily as a result of the Foreign Minimum Tax. In December 2017, the United States enacted the Tax Cuts and Jobs Act (the “Tax Act”), which imposed a one-time transition tax in 2018 (the “Repatriation Tax”) and, beginning in 2019, created a new minimum tax on certain foreign earnings (the “Foreign Minimum Tax”). We recognize the Foreign Minimum Tax in the period the tax is incurred.
We operate in a number of jurisdictions outside the United States, including Singapore, where we have tax incentive arrangements. These incentives expire, in whole or in part, at various dates through 2034 and are conditional, in part, upon meeting certain business operations and employment thresholds. The effect of tax incentive arrangements reduced our tax provision by $215 million (benefiting our diluted earnings per share by $0.19) for 2020, by $756 million ($0.66 per diluted share) for 2019, and by $1.96 billion ($1.59 per diluted share) for 2018.
(See “Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements – Income Taxes.”)
Other**:** Interest expense for 2020 increased 52% as compared to 2019 primarily due to an increase in the average level of outstanding debt obligations in 2020 as compared to 2019 and to a reduction in the amount of interest expense capitalized in 2020 as compared to 2019 resulting from lower levels of capital projects in process. Interest income for 2020 decreased 44% as compared to 2019 as a result of decreases in interest rates, partially offset by higher average levels of cash and investment balances.
Interest expense for 2019 decreased 63% as compared to 2018 primarily due to prepayments, repurchases, and conversions of debt and to an increase in the amount of interest expense capitalized from higher levels of capital spending, partially offset by increases in debt obligations. Interest income for 2019 increased 71% as compared to 2018 primarily due to increases in interest rates.
39 | 2020 10-K
Further discussion of other operating and non-operating income and expenses can be found in the following notes contained in “Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements”:
-
Equity Plans
-
Research and Development
-
Other Operating Income (Expense), Net
-
Other Non-Operating Income (Expense), Net
Liquidity and Capital Resources
Our primary sources of liquidity are cash generated from operations and financing obtained from capital markets and financial institutions. Cash generated from operations is highly dependent on selling prices for our products, which can vary significantly from period to period. We are continuously evaluating alternatives for efficiently funding our capital expenditures and ongoing operations. We expect, from time to time, to engage in a variety of financing transactions for such purposes, including the issuance of securities. As of September 3, 2020, $2.50 billion was available to draw under our Revolving Credit Facility. We expect that our cash and investments, cash flows from operations, and available financing will be sufficient to meet our requirements at least through the next 12 months.
To develop new product and process technology, support future growth, achieve operating efficiencies, and maintain product quality, we must continue to invest in manufacturing technologies, facilities and equipment, and R&D. We estimate capital expenditures in 2021 for property, plant, and equipment, net of partner contributions, to be approximately $9 billion, focused on technology transitions and product enablement, and expect the timing of our capital expenditures to be more heavily weighted toward the first half of 2021. Actual amounts for 2021 will vary depending on market conditions. As of September 3, 2020, we had purchase obligations of approximately $2.95 billion for the acquisition of property, plant, and equipment, of which approximately $2.76 billion is expected to be paid within one year.
Our Board of Directors has authorized the discretionary repurchase of up to $10 billion of our outstanding common stock through open-market purchases, block trades, privately-negotiated transactions, derivative transactions, and/or pursuant to a Rule 10b5-1 trading plan. The repurchase authorization has no expiration date, does not obligate us to acquire any common stock, and is subject to market conditions and our ongoing determination of the best use of available cash. Through September 3, 2020, we had repurchased an aggregate of $2.84 billion of the authorized amount. See “Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements – Equity.”
Cash and marketable investments totaled $9.19 billion as of September 3, 2020 and $9.12 billion as of August 29, 2019. Our investments consist primarily of bank deposits, money market funds, and liquid investment-grade, fixed-income securities, which are diversified among industries and individual issuers. To mitigate credit risk, we invest through high-credit-quality financial institutions and by policy generally limit the concentration of credit exposure by restricting the amount of investments with any single obligor. As of September 3, 2020, $3.30 billion of our cash and marketable investments was held by our foreign subsidiaries.
Cash Flows**:**
| For the year ended | 2020 | 2019 | 2018 | ||||||||
| Net cash provided by operating activities | $ | 8,306 | $ | 13,189 | $ | 17,400 | |||||
| Net cash provided by (used for) investing activities | (7,589) | (10,085) | (8,216) | ||||||||
| Net cash provided by (used for) financing activities | (317) | (2,438) | (7,776) | ||||||||
| Effect of changes in currency exchange rates on cash, cash equivalents, and restricted cash | 11 | 26 | (37) | ||||||||
| Net increase in cash, cash equivalents, and restricted cash | $ | 411 | $ | 692 | $ | 1,371 |
Operating Activities: Cash provided by operating activities reflects net income adjusted for certain non-cash items, including depreciation expense, amortization of intangible assets, and stock-based compensation, and the effects of changes in operating assets and liabilities. The decrease in cash provided by operating activities for 2020 and 2019 was primarily due to lower net income compared with the prior period and changes in working capital.
40
Investing Activities: For 2020, net cash used for investing activities consisted primarily of $7.91 billion of expenditures for property, plant, and equipment (net of partner contributions), partially offset by $415 million of net inflows from sales, maturities, and purchases of available-for-sale securities.
For 2019, net cash used for investing activities consisted primarily of $9.03 billion of expenditures for property, plant, and equipment (net of partner contributions) and $1.17 billion of net outflows from sales, maturities, and purchases of available-for-sale securities.
For 2018, net cash used for investing activities consisted primarily of $7.99 billion of expenditures for property, plant, and equipment (net of partner contributions), partially offset by $164 million of net inflows from sales, maturities, and purchases of available-for-sale securities.
Financing Activities: For 2020, net cash used for financing activities consisted primarily of $4.37 billion of cash payments to reduce our debt, including $2.50 billion to pay down borrowings under our Revolving Credit Facility, $621 million for IMFT Member Debt repayments, $534 million to prepay our 2025 Notes, $266 million to settle conversions of notes, and $248 million for scheduled repayment of finance leases; $744 million for the acquisition of Intel’s noncontrolling interest in IMFT; and $176 million for the acquisition of 3.6 million shares of our common stock under our $10 billion share repurchase authorization. Cash used for financing activities was partially offset by proceeds of $2.50 billion from our Revolving Credit Facility, $1.25 billion from the 2023 Notes, and $1.25 billion from the 2024 Term Loan A.
For 2019, net cash used for financing activities consisted primarily of $2.66 billion for the acquisition of 67 million shares of treasury stock under our $10 billion share repurchase authorization and cash payments to reduce our debt, including $1.65 billion to settle conversions of notes, $728 million to prepay the 2022 Term Loan B, $316 million for IMFT Member Debt repayments, and $643 million for scheduled repayment of other notes and capital leases. Cash used for financing activities was partially offset by net proceeds of $3.53 billion from the aggregate issuance of the 2024 Notes, 2026 Notes, 2027 Notes, 2029 Notes, and 2030 Notes.
For 2018, net cash used for financing activities consisted primarily of cash payments to reduce our debt, including $9.42 billion to prepay or repurchase debt and settle conversions of notes and $774 million for scheduled repayment of other notes and capital leases. Cash used for financing activities was partially offset by net proceeds of $1.36 billion from the issuance of 34 million shares of our common stock for $41.00 per share in a public offering and $1.01 billion of proceeds from IMFT Member Debt.
See “Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements – Debt.”
Potential Settlement Obligations of Convertible Notes**:** See “Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements – Debt – 2032D Convertible Senior Notes.”
41 | 2020 10-K
Contractual Obligations**:**
| Payments Due by Period | |||||||||||||||||||||||||||||
| As of September 3, 2020 | Total | Less than 1 year | 1-3 years | 3-5 years | More than 5 years | ||||||||||||||||||||||||
| Notes payable(1) | $ | 7,522 | $ | 417 | $ | 1,805 | $ | 1,972 | $ | 3,328 | |||||||||||||||||||
| Finance lease obligations(1) | 589 | 90 | 160 | 91 | 248 | ||||||||||||||||||||||||
| Operating lease obligations(2) | 707 | 70 | 134 | 102 | 401 | ||||||||||||||||||||||||
| Purchase obligations(3) | 5,987 | 4,398 | 871 | 128 | 590 | ||||||||||||||||||||||||
| Other long-term liabilities(4) | 358 | 168 | 161 | 12 | 17 | ||||||||||||||||||||||||
| Total | $ | 15,163 | $ | 5,143 | $ | 3,131 | $ | 2,305 | $ | 4,584 |
(1)Amounts include principal and interest.
(2)Amounts include contractually obligated minimum lease payments for operating leases having an initial noncancelable term in excess of one year.
(3)Purchase obligations include all commitments to purchase goods or services of either a fixed or minimum quantity that meet any of the following criteria: (1) they are noncancelable, (2) we would incur a penalty if the agreement was canceled, or (3) we must make specified minimum payments even if we do not take delivery of the contracted products or services. If the obligation to purchase goods or services is noncancelable, the entire value of the contract was included in the above table. If the obligation is cancelable, but we would incur a penalty if canceled, only the dollar amount of the penalty was included as a purchase obligation. Contracted minimum amounts specified in any take-or-pay contracts were included in the above table as they represent the portion of each contract that is a firm commitment. Purchase obligations also included $838 million for leases that have been executed but have not yet commenced. Such amounts will be reclassified as lease obligations in the table above at the time such assets become available for our use.
(4)Amounts represent future cash payments to satisfy other long-term liabilities recorded on our consolidated balance sheet, including $168 million for the current portion of these long-term liabilities. We are unable to reliably estimate the timing of future certain payments related to uncertain tax positions and deferred tax liabilities; therefore, the amount has been excluded from the preceding table. However, other noncurrent liabilities recorded on our consolidated balance sheet included these uncertain tax positions and deferred tax liabilities.
Critical Accounting Estimates
The preparation of financial statements and related disclosures in conformity with U.S. GAAP requires management to make estimates and judgments that affect the reported amounts of assets, liabilities, revenues, expenses, and related disclosures. Estimates and judgments are based on historical experience, forecasted events, and various other assumptions that we believe to be reasonable under the circumstances. Estimates and judgments may vary under different assumptions or conditions. We evaluate our estimates and judgments on an ongoing basis. Our management believes the accounting policies below are critical in the portrayal of our financial condition and results of operations and require management’s most difficult, subjective, or complex judgments.
Business acquisitions**:** Accounting for acquisitions requires us to estimate the fair value of consideration paid and the individual assets and liabilities acquired, which involves a number of judgments, assumptions, and estimates that could materially affect the amount and timing of costs recognized in subsequent periods. Accounting for acquisitions can also involve significant judgment to determine when control of the acquired entity is transferred. We typically obtain independent third-party valuation studies to assist in determining fair values, including assistance in determining future cash flows, discount rates, and comparable market values. Items involving significant assumptions, estimates, and judgments include the following:
-
Debt, including discount rate and timing of payments;
-
Deferred tax assets, including projections of future taxable income and tax rates;
-
Fair value of consideration paid or transferred;
-
Intangible assets, including valuation methodology, estimations of future revenue and costs, profit allocation rates attributable to the acquired technology, and discount rates;
42
-
Inventory, including estimated future selling prices, timing of product sales, and completion costs for work in process; and
-
Property, plant, and equipment, including determination of values in a continued-use model.
Consolidation**:** We have interests in entities that are Variable Interest Entities (“VIEs”). Determining whether to consolidate a VIE requires judgment in assessing whether an entity is a VIE and if we are the entity’s primary beneficiary. If we are the primary beneficiary of a VIE, we are required to consolidate it. To determine if we are the primary beneficiary, we evaluate whether we have the power to direct the activities that most significantly impact the VIE’s economic performance and the obligation to absorb losses or the right to receive benefits of the VIE that could potentially be significant to the VIE. Our evaluation includes identification of significant activities and an assessment of our ability to direct those activities based on governance provisions and arrangements to provide or receive product and process technology, product supply, operations services, equity funding, financing, and other applicable agreements and circumstances. Our assessments of whether we are the primary beneficiary of our VIEs require significant assumptions and judgments.
Contingencies**:** We are subject to the possibility of losses from various contingencies. Significant judgment is necessary to estimate the probability and amount of a loss, if any, from such contingencies. An accrual is made when it is probable that a liability has been incurred or an asset has been impaired and the amount of loss can be reasonably estimated. In accounting for the resolution of contingencies, significant judgment may be necessary to estimate amounts pertaining to periods prior to the resolution that are charged to operations in the period of resolution and amounts related to future periods.
Goodwill and intangible assets**:** We test goodwill for impairment in our fourth quarter each year, or more frequently if indicators of an impairment exist, to determine whether it is more likely than not that the fair value of the reporting unit with goodwill is less than its carrying value. For reporting units for which this assessment concludes that it is more likely than not that the fair value is more than its carrying value, goodwill is considered not impaired and we are not required to perform the goodwill impairment test. Qualitative factors considered in this assessment include industry and market considerations, overall financial performance, and other relevant events and factors affecting the fair value of the reporting unit. For reporting units for which this assessment concludes that it is more likely than not that the fair value is below the carrying value, goodwill is tested for impairment by determining the fair value of each reporting unit and comparing it to the carrying value of the net assets assigned to the reporting unit. If the fair value of the reporting unit exceeds its carrying value, goodwill is considered not impaired. If the carrying value of the reporting unit exceeds its fair value, we would record an impairment loss up to the difference between the carrying value and implied fair value.
Determining when to test for impairment, the reporting units, the assets and liabilities of the reporting unit, and the fair value of the reporting unit requires significant judgment and involves the use of significant estimates and assumptions. These estimates and assumptions include revenue growth rates, forecasted manufacturing costs, and other expenses and are developed as part of our long-range planning process. The same estimates are used in business planning, forecasting, and capital budgeting as part of our long-term manufacturing capacity analysis. We test the reasonableness of the output of our long-range planning process by calculating an implied value per share and comparing that to current stock prices, analysts’ consensus pricing, and management’s expectations. These estimates and assumptions are used to calculate projected future cash flows for the reporting unit, which are discounted using a risk-adjusted rate to estimate a fair value. The discount rate requires determination of appropriate market comparables. We base fair value estimates on assumptions we believe to be reasonable but that are unpredictable and inherently uncertain. Actual future results may differ from those estimates.
We test other identified intangible assets with definite useful lives when events and circumstances indicate the carrying value may not be recoverable by comparing the carrying amount to the sum of undiscounted cash flows expected to be generated by the asset. We test intangible assets with indefinite lives annually for impairment using a fair value method such as discounted cash flows. Estimating fair values involves significant assumptions, including future sales prices, sales volumes, costs, and discount rates.
Income taxes**:** We are required to estimate our provision for income taxes and amounts ultimately payable or recoverable in numerous tax jurisdictions around the world. These estimates involve significant judgment and interpretations of regulations and are inherently complex. Resolution of income tax treatments in individual jurisdictions may not be known for many years after completion of the applicable year. We are also required to evaluate the realizability of our deferred tax assets on an ongoing basis in accordance with U.S. GAAP, which
43 | 2020 10-K
requires the assessment of our performance and other relevant factors. Realization of deferred tax assets is dependent on our ability to generate future taxable income. In recent periods, our results of operations have benefited from increases in the amount of deferred taxes we expect to realize, primarily from the levels of capital spending and increases in the amount of taxable income we expect to realize in Japan and the United States. Our income tax provision or benefit is dependent, in part, on our ability to forecast future taxable income in these and other jurisdictions. Such forecasts are inherently difficult and involve significant judgments including, among others, projecting future average selling prices and sales volumes, manufacturing and overhead costs, levels of capital spending, and other factors that significantly impact our analyses of the amount of net deferred tax assets that are more likely than not to be realized.
Inventories**:** Inventories are stated at the lower of average cost or net realizable value. Cost includes depreciation, labor, material, and overhead costs, including product and process technology costs. Determining net realizable value of inventories involves significant judgments, including projecting future average selling prices and future sales volumes. To project average selling prices and sales volumes, we review recent sales volumes, existing customer orders, current contract prices, industry analyses of supply and demand, seasonal factors, general economic trends, and other information. When these analyses reflect estimated net realizable values below our manufacturing costs, we record a charge to cost of goods sold in advance of when inventories are actually sold. Differences in forecasted average selling prices used in calculating lower of cost or net realizable value adjustments can result in significant changes in the estimated net realizable value of product inventories and accordingly the amount of write-down recorded. For example, a 5% variance in the estimated selling prices would have changed the estimated net realizable value of our inventory by approximately $525 million as of September 3, 2020. Due to the volatile nature of the semiconductor memory and storage markets, actual selling prices and volumes often vary significantly from projected prices and volumes; as a result, the timing of when product costs are charged to operations can vary significantly.
U.S. GAAP provides for products to be grouped into categories in order to compare costs to net realizable values. The amount of any inventory write-down can vary significantly depending on the determination of inventory categories. We review the major characteristics of product type and markets in determining the unit of account for which we perform the lower of average cost or net realizable value analysis and categorize all inventories (including DRAM, NAND, and other memory) as a single group.
Property, plant, and equipment**:** We periodically assess the estimated useful lives of our property, plant, and equipment based on technology node transitions, capital spending, and equipment re-use rates. Based on our assessment of planned technology node transitions, capital spending, and re-use rates, we revised the estimated useful lives of the existing equipment in our NAND wafer fabrication facilities and our research and development (“R&D”) facilities from five years to seven years as of the beginning of the first quarter of 2020. See “Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements – Property, Plant, and Equipment.”
We also review the carrying value of property, plant, and equipment for impairment when events and circumstances indicate that the carrying value of an asset or group of assets may not be recoverable from the estimated future cash flows expected to result from its use and/or disposition. In cases where undiscounted expected future cash flows are less than the carrying value, an impairment loss is recognized equal to the amount by which the carrying value exceeds the estimated fair value of the assets. The estimate of future cash flows involves numerous assumptions which require significant judgment by us, including, but not limited to, future use of the assets for our operations versus sale or disposal of the assets, future selling prices for our products, and future production and sales volumes. In addition, significant judgment is required in determining the groups of assets for which impairment tests are separately performed.
Research and development**:** Costs related to the conceptual formulation and design of products and processes are expensed as R&D as incurred. Determining when product development is complete requires significant judgment. We deem development of a product complete once the product has been thoroughly reviewed and tested for performance and reliability. Subsequent to product qualification, product costs are included in cost of goods sold.
Revenue recognition**:** Revenue is primarily recognized at a point in time when control of the promised goods is transferred to our customers in an amount that reflects the consideration we expect to be entitled to in exchange for those goods. Contracts with our customers are generally short-term in duration at fixed, negotiated prices with payment generally due shortly after delivery. We estimate a liability for returns using the expected value method
44
based on historical rates of return. In addition, we generally offer price protection to our distributors, which is a form of variable consideration that decreases the transaction price. We use the expected value method, based on historical price adjustments and current pricing trends, to estimate the amount of revenue recognized from sales to distributors. Differences between the estimated and actual amounts are recognized as adjustments to revenue.
Stock-based compensation**:** Stock-based compensation is estimated at the grant date based on the fair value of the award and is recognized as expense using the straight-line amortization method over the requisite service period. For performance-based stock awards, the expense recognized is dependent on our assessment of the likelihood of the performance measure being achieved. We utilize forecasts of future performance to assess these probabilities and this assessment requires significant judgment.
Determining the appropriate fair-value model and calculating the fair value of stock-based awards at the grant date requires significant judgment, including estimating stock price volatility and expected option life. We develop these estimates based on historical data and market information which can change significantly over time. A small change in the estimates used can result in a relatively large change in the estimated valuation. We use the Black-Scholes option valuation model to value employee stock options and awards granted under our employee stock purchase plan. We estimate stock price volatility based on an average of historical volatility and the implied volatility derived from traded options on our stock.
Recently Adopted Accounting Standards
See “Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements – Recently Adopted Accounting Standards.”
Recently Issued Accounting Standards
See “Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements – Recently Issued Accounting Standards.”
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
Interest Rate Risk
We are exposed to interest rate risk related to our indebtedness and our investment portfolio. As of September 3, 2020 and August 29, 2019, we had fixed-rate debt of $4.9 billion and $5.3 billion, respectively, and as a result, the fair value of our debt fluctuates with changes in market interest rates. We estimate that, as of September 3, 2020 and August 29, 2019, a decrease in market interest rates of 1% would increase the fair value of our fixed-rate debt by nearly $300 million. As of September 3, 2020, we had variable-rate debt of $1.25 billion and, therefore, a 1% increase in the interest rates of our variable-rate debt would result in an increase in annual interest expense of approximately $13 million. As of August 29, 2019, we had no variable rate debt.
Foreign Currency Exchange Rate Risk
The information in this section should be read in conjunction with the information related to changes in the currency exchange rates in “Part I – Item 1A. Risk Factors.” Changes in currency exchange rates could materially adversely affect our results of operations or financial condition.
The functional currency for all of our operations is the U.S. dollar. The substantial majority of our sales are transacted in the U.S. dollar; however, significant amounts of our operating expenditures and capital purchases, and certain assets and liabilities, are incurred in or exposed to other currencies, primarily the euro, New Taiwan dollar, Singapore dollar, and yen. We have established currency risk management programs for our monetary assets and liabilities denominated in foreign currencies to hedge against fluctuations in the fair value and volatility of future cash flows caused by changes in currency exchange rates. We generally utilize currency forward contracts in these
45 | 2020 10-K
hedging programs, which reduce, but do not always entirely eliminate, the impact of currency exchange rate movements. We do not use derivative financial instruments for trading or speculative purposes.
Based on monetary assets and liabilities denominated in foreign currencies, we estimate that a 10% adverse change in exchange rates versus the U.S. dollar would result in losses of approximately $98 million as of September 3, 2020 and $149 million as of August 29, 2019. We hedge our exposure to changes in currency exchange rates by utilizing a rolling hedge strategy for our primary currency exposures with currency forward contracts that generally mature within three months. The effectiveness of our hedges is dependent, among other factors, upon our ability to accurately measure exposures on a timely basis. To hedge the exposure of changes in cash flows from changes in currency exchange rates for certain capital expenditures and manufacturing costs, we may utilize currency forward contracts that generally mature within two years. (See “Item 8. Financial Statements and Supplementary Data – Notes to Consolidated Financial Statements – Derivative Instruments.”)
46
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
Micron Technology, Inc.
Consolidated Statements of Operations
(in millions, except per share amounts)
| For the year ended | September 3, 2020 | August 29, 2019 | August 30, 2018 | ||||||||
| Revenue | $ | 21,435 | $ | 23,406 | $ | 30,391 | |||||
| Cost of goods sold | 14,883 | 12,704 | 12,500 | ||||||||
| Gross margin | 6,552 | 10,702 | 17,891 | ||||||||
| Research and development | 2,600 | 2,441 | 2,141 | ||||||||
| Selling, general, and administrative | 881 | 836 | 813 | ||||||||
| Other operating (income) expense, net | 68 | 49 | (57) | ||||||||
| Operating income | 3,003 | 7,376 | 14,994 | ||||||||
| Interest income | 114 | 205 | 120 | ||||||||
| Interest expense | (194) | (128) | (342) | ||||||||
| Other non-operating income (expense), net | 60 | (405) | (465) | ||||||||
| 2,983 | 7,048 | 14,307 | |||||||||
| Income tax (provision) benefit | (280) | (693) | (168) | ||||||||
| Equity in net income (loss) of equity method investees | 7 | 3 | (1) | ||||||||
| Net income | 2,710 | 6,358 | 14,138 | ||||||||
| Net income attributable to noncontrolling interests | (23) | (45) | (3) | ||||||||
| Net income attributable to Micron | $ | 2,687 | $ | 6,313 | $ | 14,135 | |||||
| Earnings per share | |||||||||||
| Basic | $ | 2.42 | $ | 5.67 | $ | 12.27 | |||||
| Diluted | 2.37 | 5.51 | 11.51 | ||||||||
| Number of shares used in per share calculations | |||||||||||
| Basic | 1,110 | 1,114 | 1,152 | ||||||||
| Diluted | 1,131 | 1,143 | 1,229 |
See accompanying notes to consolidated financial statements.
47 | 2020 10-K
Micron Technology, Inc.
Consolidated Statements of Comprehensive Income
(in millions)
| For the year ended | September 3, 2020 | August 29, 2019 | August 30, 2018 | ||||||||
| Net income | $ | 2,710 | $ | 6,358 | $ | 14,138 | |||||
| Other comprehensive income (loss), net of tax | |||||||||||
| Gains (losses) on derivative instruments | 46 | (3) | (15) | ||||||||
| Pension liability adjustments | 15 | (6) | (3) | ||||||||
| Gains (losses) on investments | 1 | 9 | (2) | ||||||||
| Foreign currency translation adjustments | — | (1) | 1 | ||||||||
| Other comprehensive income (loss) | 62 | (1) | (19) | ||||||||
| Total comprehensive income | 2,772 | 6,357 | 14,119 | ||||||||
| Comprehensive income attributable to noncontrolling interests | (23) | (45) | (3) | ||||||||
| Comprehensive income attributable to Micron | $ | 2,749 | $ | 6,312 | $ | 14,116 |
See accompanying notes to consolidated financial statements.
48
Micron Technology, Inc.
Consolidated Balance Sheets
(in millions, except par value amounts)
| As of | September 3, 2020 | August 29, 2019 | ||||||
| Assets | ||||||||
| Cash and equivalents | $ | 7,624 | $ | 7,152 | ||||
| Short-term investments | 518 | 803 | ||||||
| Receivables | 3,912 | 3,195 | ||||||
| Inventories | 5,607 | 5,118 | ||||||
| Other current assets | 304 | 235 | ||||||
| Total current assets | 17,965 | 16,503 | ||||||
| Long-term marketable investments | 1,048 | 1,164 | ||||||
| Property, plant, and equipment | 31,031 | 28,240 | ||||||
| Operating lease right-of-use assets | 584 | — | ||||||
| Intangible assets | 334 | 340 | ||||||
| Deferred tax assets | 707 | 837 | ||||||
| Goodwill | 1,228 | 1,228 | ||||||
| Other noncurrent assets | 781 | 575 | ||||||
| Total assets | $ | 53,678 | $ | 48,887 | ||||
| Liabilities and equity | ||||||||
| Accounts payable and accrued expenses | $ | 5,817 | $ | 4,626 | ||||
| Current debt | 270 | 1,310 | ||||||
| Other current liabilities | 548 | 454 | ||||||
| Total current liabilities | 6,635 | 6,390 | ||||||
| Long-term debt | 6,373 | 4,541 | ||||||
| Noncurrent operating lease liabilities | 533 | — | ||||||
| Noncurrent unearned government incentives | 643 | 636 | ||||||
| Other noncurrent liabilities | 498 | 452 | ||||||
| Total liabilities | 14,682 | 12,019 | ||||||
| Commitments and contingencies | ||||||||
| Redeemable noncontrolling interest | — | 98 | ||||||
| Micron shareholders’ equity | ||||||||
| Common stock, $0.10 par value, 3,000 shares authorized, 1,194 shares issued and 1,113 outstanding (1,182 shares issued and 1,106 outstanding as of August 29, 2019) | 119 | 118 | ||||||
| Additional capital | 8,917 | 8,214 | ||||||
| Retained earnings | 33,384 | 30,761 | ||||||
| Treasury stock, 81 shares held (76 shares as of August 29, 2019) | (3,495) | (3,221) | ||||||
| Accumulated other comprehensive income (loss) | 71 | 9 | ||||||
| Total Micron shareholders’ equity | 38,996 | 35,881 | ||||||
| Noncontrolling interest in subsidiary | — | 889 | ||||||
| Total equity | 38,996 | 36,770 | ||||||
| Total liabilities and equity | $ | 53,678 | $ | 48,887 |
See accompanying notes to consolidated financial statements.
49 | 2020 10-K
Micron Technology, Inc.
Consolidated Statements of Changes in Equity
(in millions)
| Micron Shareholders | |||||||||||||||||||||||||||||||||||||||||||||||
| Common Stock | Additional Capital | Retained Earnings | Treasury Stock | Accumulated Other Comprehensive Income (Loss) | Total Micron Shareholders’ Equity | Noncontrolling Interests in Subsidiaries | Total Equity | ||||||||||||||||||||||||||||||||||||||||
| Number of Shares | Amount | ||||||||||||||||||||||||||||||||||||||||||||||
Showing the first 8K of 155K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
An evaluation was carried out under the supervision and with the participation of our management, including our principal executive officer and principal financial officer, of the effectiveness of the design and operation of our disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934) as of the end of the period covered by this report. Based upon that evaluation, the principal executive officer and principal financial officer concluded that those disclosure controls and procedures were effective to ensure that information required to be disclosed by us in the reports that we file or submit under the Exchange Act are recorded, processed, summarized, and reported within the time periods specified in the Commission’s rules and forms and that such information is accumulated and communicated to our management, including the principal executive officer and principal financial officer, to allow timely decisions regarding disclosure.
During the fourth quarter of 2020, there were no changes in our internal control over financial reporting that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Management’s Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting. Internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with accounting principles generally accepted in the United States of America. Our internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that in reasonable detail accurately reflect the transactions and dispositions of our assets; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that our receipts and expenditures are being made only in accordance with authorizations of our management and directors; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of our assets that could have a material effect on our financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions or that the degree of compliance with the policies or procedures may deteriorate.
Management conducted an evaluation of the effectiveness of our internal control over financial reporting based on the framework in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission. Based on this evaluation, management concluded that our internal control over financial reporting was effective as of September 3, 2020. The effectiveness of our internal control over financial reporting as of September 3, 2020 has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report, which is included in Part II, Item 8, of this Form 10-K.
Item 9B. OTHER INFORMATION
None.
86
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS, AND CORPORATE GOVERNANCE
Item 11. EXECUTIVE COMPENSATION
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
Certain information concerning our executive officers is included under the caption, “Information About Our Executive Officers” in Part I, Item 1 of this report. Other information required by Items 10, 11, 12, 13, and 14 will be contained in our 2020 Proxy Statement which will be filed with the SEC within 120 days after September 3, 2020 and is incorporated herein by reference.
87 | 2020 10-K
PART IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULE
(a) The following documents are filed as part of this report:
| 1 | Financial Statements: See our consolidated financial statements under Item 8. | ||||
| 2 | Financial Statement Schedule: See “Schedule II – Valuation and Qualifying Accounts” within Item 15 below. Certain Financial Statement Schedules have been omitted since they are either not required, not applicable, or the information is otherwise included. | ||||
| 3 | Exhibits. See “Index to Exhibits” within Item 15 below. |
88
SCHEDULE II
VALUATION AND QUALIFYING ACCOUNTS
(in millions)
| Balance at Beginning of Year | Charged (Credited) to Income Tax Provision | Currency Translation and Charges to Other Accounts | Balance at End of Year | |||||||||||
| Deferred Tax Asset Valuation Allowance | ||||||||||||||
| Year ended September 3, 2020 | $ | 277 | $ | 20 | $ | (3) | $ | 294 | ||||||
| Year ended August 29, 2019 | 228 | 40 | 9 | 277 | ||||||||||
| Year ended August 30, 2018 | 2,321 | (2,079) | (14) | 228 |
89 | 2020 10-K
Index to Exhibits
90
- Portions of this exhibit have been omitted pursuant to a request for confidential treatment filed with the Commission.
91 | 2020 10-K
** Indicates management contract or compensatory plan or arrangement.
Item 16. FORM 10-K SUMMARY
None.
92
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| Micron Technology, Inc. | ||||||||||||||
| Date | October 19, 2020 | By: | /s/ David A. Zinsner | |||||||||||
| David A. Zinsner Senior Vice President and Chief Financial Officer | ||||||||||||||
| (Principal Financial Officer) |
Pursuant to the requirements of the Securities Exchange Act of 1934, this Annual Report has been signed below by the following persons on behalf of the Registrant and in the capacities and on the dates indicated.
| Signature | Title | Date | ||||||
| /s/ Sanjay Mehrotra | President and | October 19, 2020 | ||||||
| (Sanjay Mehrotra) | Chief Executive Officer and | |||||||
| Director | ||||||||
| (Principal Executive Officer) | ||||||||
| /s/ David A. Zinsner | Senior Vice President and | October 19, 2020 | ||||||
| (David A. Zinsner) | Chief Financial Officer | |||||||
| (Principal Financial Officer) | ||||||||
| /s/ Paul Marosvari | Vice President and | October 19, 2020 | ||||||
| (Paul Marosvari) | Chief Accounting Officer | |||||||
| (Principal Accounting Officer) | ||||||||
| /s/ Robert L. Bailey | Director | October 19, 2020 | ||||||
| (Robert L. Bailey) | ||||||||
| /s/ Richard M. Beyer | Director | October 19, 2020 | ||||||
| (Richard M. Beyer) | ||||||||
| /s/ Lynn Dugle | Director | October 19, 2020 | ||||||
| (Lynn Dugle) | ||||||||
| /s/ Steve Gomo | Director | October 19, 2020 | ||||||
| (Steve Gomo) | ||||||||
| /s/ Mary Pat McCarthy | Director | October 19, 2020 | ||||||
| (Mary Pat McCarthy) | ||||||||
| /s/ Robert E. Switz | Chairman of the Board | October 19, 2020 | ||||||
| (Robert E. Switz) | Director | |||||||
| /s/ MaryAnn Wright | Director | October 19, 2020 | ||||||
| (MaryAnn Wright) |
93 | 2020 10-K