 filings.tools
Item 2. PROPERTIES (dollars in millions, except per share, per ounce and per pound amounts)
136K characters. Original on sec.gov · Markdown
Item 2. PROPERTIES (dollars in millions, except per share, per ounce and per pound amounts)
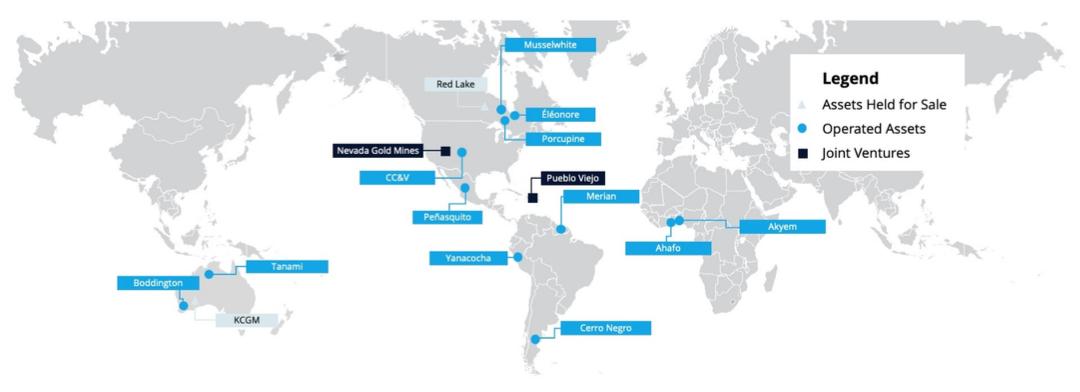
Production and Development Properties
Newmont’s material production and development properties are described below. Operating statistics for each region are presented in a table in the Operating Statistics section. In addition, Newmont holds investment interests in Canada, Mexico, Chile, Argentina and various other locations.
North America
The North America region maintains its headquarters in Vancouver, Canada and operates six sites, Cripple Creek & Victor (“CC&V”), Red Lake, Musselwhite, Porcupine, Éléonore and Peñasquito. The Company entered into a binding agreement dated November 25, 2019, to sell the Red Lake complex in Ontario, Canada, included as part of the Company’s North America segment, to Evolution Mining Limited (“Evolution”). As of December 31, 2019 the sale had not been completed.
Cripple Creek & Victor, Colorado, USA. (100% owned) Cripple Creek & Victor (“CC&V”), located next to the town of Victor, Colorado, is an open pit operation. CC&V is an epithermal alkalic deposit with heap leaching and milling processing facilities located on site. CC&V’s gross property, plant and mine development at December 31, 2019 was $857. CC&V produced 322,000 ounces of gold in 2019 and reported 2.8 million ounces of gold reserves at December 31, 2019.
Red Lake, Canada. (100% owned) Red Lake, located 112 miles (180 kilometers) north of the town of Dryden, Ontario, is an underground operation. Process facilities include two processing plants, an autoclave and a paste fill plant. Red Lake is a mesothermal greenstone-hosted gold deposit. The Red Lake assets and liabilities were classified as held for sale for the year ended December 31,
- Red Lake produced 113,000 ounces of gold in 2019 since the completion of the acquisition of the mine site as part of the Newmont Goldcorp transaction and reported 1.3 million ounces of gold reserves at December 31, 2019.
Musselwhite, Canada. (100% owned) Musselwhite, located approximately 265 miles (430 kilometers) north of Thunder Bay, Ontario, is an underground operation. Process facilities include a conventional mill, which consists of a crushing and grinding circuit, carbon-in-pulp and carbon-in-leach plants and an electrowinning plant. Musselwhite is an iron formation hosted gold deposit. Musselwhite’s gross property, plant and mine development at December 31, 2019 was $1,016. Musselwhite produced 3,000 ounces of gold since the completion of the acquisition of the mine site as part of the Newmont Goldcorp transaction in 2019 and reported 2.1 million ounces of gold reserves at December 31, 2019.
Porcupine, Canada. (100% owned) Porcupine, consists of the Hollinger open pit and Hoyle pond underground operations, located in the city of Timmins, Ontario, as well as the Borden underground operation, located near the town of Chapleau, Ontario. Process facilities, located in the city of Timmins, include a conventional mill, which consists of a crushing and grinding circuit. Mineralization at Hollinger and Hoyle, in Timmins, comprises multiple generations of quartz-carbonate-tourmaline albite veins, associated pyrite alteration envelopes, and disseminated pyrite mineralization. Mineralization at Borden consists of a shear zone containing quartz-vein hosted sulphides within a high-grade metamorphic greenstone package. Porcupine’s gross property, plant and mine development at December 31, 2019 was $1,323. Porcupine produced 223,000 ounces of gold in 2019 since the completion of the acquisition of the mine site as part of the Newmont Goldcorp transaction and reported 2.8 million ounces of gold reserves at December 31, 2019.
Éléonore, Canada. (100% owned) Éléonore, located approximately 510 miles (825 kilometers) north of Montreal in Eeyou Istchee/James Bay in Northern Quebec, is an underground operation. Process facilities include a conventional mill which consists of a crushing and grinding circuit, flotation circuit, and carbon-in-pulp circuits. Éléonore is a clastic sediment-hosted stockwork-disseminated gold deposit. Éléonore’s gross property, plant and mine development at December 31, 2019 was $937. Éléonore produced 246,000 ounces of gold in 2019 since the completion of the acquisition of the mine site as part of the Newmont Goldcorp transaction and reported 1.3 million ounces of gold reserves at December 31, 2019.
Peñasquito, Mexico. (100% owned) Peñasquito is an open pit operation located in the northeast corner of Zacatecas State, Mexico, approximately 125 miles (200 kilometers) northeast of the city of Zacatecas and is accessible by paved roads with a private airport close to the site. The property began production in 2009, with commercial production being achieved in 2010. Goldcorp acquired its ownership in the mine in 2006 when it acquired Glamis and Newmont acquired Peñasquito in 2019 in the Newmont Goldcorp transaction. Peñasquito consists of the Peñasco and Chile Colorado open pit mines. In addition, Peñasquito has one processing plant.
Peñasquito is comprised of 20 mining concessions encompassing approximately 113,231 acres (45,823 hectares). Concessions were granted for durations of 50 years, and will expire between 2045 and 2060, and a second 50-year term can be granted if the applicant has abided by all appropriate regulations and makes the application within five years prior to the expiration date. In order to maintain these concessions, Peñasquito must pay periodic mining rights and file annual mining reports.
Surface rights in the vicinity of the Peñasco and Chile Colorado open pits are held by three ejidos: Ejido Cedros, Ejido Mazapil and Ejido Cerro Gordo. Peñasquito has signed land use agreements with each ejidos, valid through 2035 and 2036, and the relevant private owners. In addition, easements have been granted in association with the La Pardita-Cedros Highway and the El Salero-Peñasquito powerline. All necessary permits have been granted.
In July 2007, Goldcorp and Wheaton Precious Metals Corp. (then Silver Wheaton Corp.) entered into a silver streaming agreement. The Company is obligated to sell 25% of silver production from the Peñasquito mine to Wheaton Precious Metals Corporation at the lesser of market price or a fixed contract price, subject to an annual inflation adjustment of up to 1.65%. Refer to Note 6 to the Consolidated Financial Statements for further information.
A 2% net smelter return royalty is owed to Royal Gold Inc. from both the Chile Colorado and Peñasco open pits of the Peñasquito Mine. Since January 1, 2014, the Mexican Government levies a 7.5% mining royalty that is imposed on earnings before interest, taxes, depreciation, and amortization. There is also a 0.5% environmental erosion fee payable on precious metal production, based on gross revenues. In December 2016, the State of Zacatecas in Mexico approved new environmental taxes that became effective January 1, 2017. Certain operations at the Peñasquito mine may be subject to these taxes. See Item 1A, Risk Factors and Note 32 to the Consolidated Financial Statements for further information.
The mineralization at Peñasquito contains gold, silver, lead and zinc. Deposits currently mined within the Peñasquito operations are considered to be examples of breccia pipes developed as a result of intrusion-related hydrothermal activity.
Process facilities include a sulfide processing plant, comprising four stages of flotation; carbon, lead, zinc and pyrite. The carbon pre-flotation circuit was added in 2018 ahead of lead flotation to remove organic carbon associated with sedimentary ores. In the lead and zinc flotation, the slurry is conditioned with reagents to activate the desired minerals and produce lead and zinc concentrates. The pyrite circuit flotation was added at the end of 2018, which treats the zinc tailings in a pyrite flotation leach, and Merrill Crowe process to recover additional silver and gold in the form of doré. The tailings from the leach circuit undergoes cyanide destruction and combines with final flotation tailings for final deposition in the tailings storage facility.
The available mining fleet consists of five rope shovels, three hydraulic shovels, four loaders, and eighty-five 320 ton haul trucks. The fleet is supported by twelve blast hole production drills, as well as track dozers, rubber tire dozers, excavators, and graders.
Brownfield exploration and development for new reserves is ongoing.
In January 2011, Peñasquito entered into a 20 year power delivery agreement with a subsidiary of InterGen Servicios Mexico (now Saavi Energia) where Peñasquito agreed to purchase electrical power from a gas-fired electricity generating facility located near San Luis de la Paz, Guanajuato, Mexico. Power is also supplied by the Mexican Electricity Federal Commission (Comision Federal de Electricidad) at its central power grid through the El Salero-Peñasquito powerline.
Peñasquito’s gross property, plant and mine development at December 31, 2019 was $5,532. Peñasquito produced 129,000 ounces of gold and 443,000 gold equivalent ounces of other metals since the completion of the acquisition of the mine site as part of the Newmont Goldcorp transaction in 2019 and reported 8.1 million ounces of gold reserves, 471 million ounces of silver reserves, 3,260 million pounds of lead and 7,420 million pounds of zinc at December 31, 2019.
South America
The South America region maintains its headquarters in Miami, Florida and operates three sites, Yanacocha, Merian and Cerro Negro. We also hold a 40% interest in the Pueblo Viejo Mine, an open pit gold mine located in the Dominican Republic. Barrick holds the other 60% interest in, and operates, the Pueblo Viejo Mine.
Yanacocha, Peru. (51.35% owned) Yanacocha is owned by Minera Yanacocha S.R.L. (“Yanacocha” or “MYSRL”), which is 51.35% owned by Newmont. The remaining interest in MYSRL is held by Compañia Minera Condesa S.A, which is 100% owned by Compañia de Minas Buenaventura S.A.A. (“Buenaventura”) (43.65%) and Summit Global Management II VB (5%), a subsidiary of Sumitomo. For further information about ownership transactions during 2017 and 2018, see Note 14 to our Consolidated Financial Statements.
MYSRL and S.M.R.L. Chaupiloma Dos de Cajamarca (“Chaupiloma”) (a related third party) have mining concessions granted by Peru’s Geological, Mining and Metallurgical Institute. Mining concessions grant MYSRL an exclusive and irrevocable right to carry out exploration and exploitation activities within a specified area. In order to maintain these concessions, MYSRL must (i) obtain the appropriate permits and rights over the surface lands, (ii) pay annual license fees and (iii) comply with a minimum annual production obligation. For mining concessions granted prior to 2008, concessions will expire if the production obligations are not met by the end of 2038. For mining concessions granted in 2008 or thereafter, concessions will expire if minimum production is not attained by 2038.
In Peru, a revised royalty and special mining tax was introduced in October 2011. This tax is dependent on whether or not a stabilization agreement is in effect and is based on a sliding scale, between 1% and 12%. A stabilization agreement was in effect through December 2018 for operations in the La Quinua Complex.
Yanacocha is located approximately 375 miles (604 kilometers) north of Lima and 30 miles (48 kilometers) north of the city of Cajamarca and is primarily accessible by paved roads. The Yanacocha property began production in 1993 and consists of the following open pit mines: the La Quinua Complex, the Yanacocha Complex, the Carachugo Complex and Maqui Maqui. In addition, Yanacocha has four leach pads (La Quinua, Yanacocha, Carachugo and Maqui Maqui), three gold processing plants (Pampa Larga, Yanacocha Norte and La Quinua), one limestone processing facility (China Linda) and one mill (Yanacocha Gold Mill).
Yanacocha’s mining activities encompass 301,000 acres (121,810 hectares) that are covered by 185 mining concessions. MYSRL holds the mining rights related to 96,338 acres (38,987 hectares), covered by 73 concessions. Chaupiloma holds the mining rights to the remaining acres and concessions and has assigned these mining concessions to Yanacocha. Each concession has an initial term of 17 to 30 years, which are renewable at Yanacocha’s request for an additional 17 to 20 year term.
The La Quinua Complex is currently mining material from the La Quinua Sur and the Tapado Oeste Layback and is scheduled to finish mining operations in 2020.
The Yanacocha Complex mines material from the Yanacocha Layback and Yanacocha Pinos, which are scheduled to finish mining operations in 2020. The Yanacocha Complex began operations in 1997 and has had limited mining operations in recent years.
The Carachugo Complex and Maqui Maqui mined material from multiple mines that are no longer in operation. In addition, the Carachugo leach pad processes oxide material from the Quecher Main project, which is a new open pit within the existing footprint of Yanacocha. This project went into commercial production in October 2019 and will extend the life of the Yanacocha operation to 2027.
Yanacocha has three processing concessions from Peru’s Ministry of Energy and Mines for its processing facilities: Cerro Yanacocha (La Quinua and Yanacocha leach pads, La Quinua and Yanacocha Norte gold recovery plants and Yanacocha Gold Mill), Yanacocha (Carachugo and Maqui Maqui leach pads and Pampa Larga gold recovery plant) and China Linda (non-metallic processing concessions). Yanacocha’s gold processing plants are located adjacent to the solution storage ponds and are used to process gold-bearing solutions from Yanacocha’s leach pads through a network of solution-pumping facilities. The Yanacocha Gold Mill processes high-grade gold ore to produce a gold-bearing solution for treatment at the La Quinua processing plant. The Yanacocha Gold Mill processes between 5.5 and 6.0 million tonnes per year.
Yanacocha is an epithermal type deposit of high sulfidation hosted in volcanic rock formations. Gold is associated with iron-oxides and pyrite. Material is evaluated for gold grade and cyanide solubility and then placed on leach pads or in stockpiles for processing through the Yanacocha Gold Mill accordingly. Yanacocha’s available mining fleet consists of two shovels, four excavators, two loaders and thirty-one 233-tonne haul trucks.
Brownfield exploration and development for new reserves is ongoing and we continue to evaluate the potential for mining sulfide gold and copper mineralization.
Power is supplied to the operation by Engie Energia Peru SA.
Yanacocha’s gross property, plant and mine development at December 31, 2019 was $4,749. Yanacocha produced 527,000 ounces of gold (270,000 attributable ounces of gold) in 2019 and reported 3.6 million attributable ounces of gold reserves and 740 million attributable pounds of copper reserves at December 31, 2019.
MYSRL also owns the Conga project, which is located approximately 16 miles (25 kilometers) northeast of Yanacocha and is currently in care and maintenance. Due to uncertainty surrounding the project and political risks related to the project’s development, the Company has allocated its exploration and development capital to other projects in recent years. Should the Company be unable to develop the Conga project, the Company may have to consider other alternatives for the project, which may result in a future impairment charge for the project. See Item 1A, Risk Factors, above for further information.
Merian, Suriname. (75% owned) The Merian gold mine (“Merian”) is owned 75% by Newmont Suriname, LLC (“Newmont Suriname”) (formerly known as Suriname Gold Company LLC and 100% indirectly owned by Newmont Corporation) and 25% by Staatsolie (a company wholly owned by the Republic of Suriname).
Merian is located in Suriname, approximately 40 miles (66 kilometers) south of the town of Moengo and 19 miles (30 kilometers) north of the Nassau Mountains, close to the French Guiana border. The site is accessible by paved road from Paramaribo to Moengo and a dirt road maintained mainly by the Company.
Newmont’s interest in the Merian mine was acquired through a Right of Exploitation as defined in a Mineral Agreement. The Right of Exploitation was registered in November 2014, spans a period of 25 years and covers an area of 41,484 acres (16,788 hectares). Newmont Suriname is subject to a 6% net smelter return royalty to the Republic of Suriname payable in gold bullion or cash distributions at the election of the government.
Merian reached commercial production in October 2016 and the operation currently includes the Merian 2 open pit and the Maraba open pit. The Maraba pit was added in January 2018 and the Merian 1 pit is expected to be added in 2021. All of the gold mineralization at Merian is closely associated with quartz veining within siltstone and sandstone formations. Merian’s available mining fleet consists of three shovels, three mining excavators and thirty-six 150-tonne haul trucks.
Merian includes processing facilities that utilize a conventional gold mill, primary crusher and processing plant, consisting of a comminution plant, including gravity and cyanide leach processes, with recovery by carbon-in-leach, elution, electrowinning and induction furnace smelting to produce a gold doré product. It has a nameplate capacity of 12 million tonnes per year, reducing later to 10 million tonnes per year when the mill feed will be predominantly from fresh rock. Maintenance facilities, camp facilities with a capacity of 1,200 workers and various offices complete the site.
Brownfield exploration and development for new reserves is ongoing.
Power for the property is self-generated using on-site heavy fuel oil driven generators.
Merian’s gross property, plant and mine development at December 31, 2019 was $1,079. Merian produced 524,000 ounces of gold (393,000 attributable ounces of gold) in 2019 and reported 3.5 million attributable ounces of gold reserves at December 31, 2019.
Cerro Negro, Argentina. (100% owned) Cerro Negro is located in southern Argentina about 250 miles (400 kilometers) southwest of the coastal city of Comodoro Rivadavia and can be accessed by paved road. Gold was first discovered in the area in 1992. Goldcorp acquired its ownership in the mine in 2010 from Andean Resources Limited and Newmont acquired Cerro Negro in 2019 in the Newmont Goldcorp transaction. Commercial production began in 2015.
The mineral tenure consists of ten mining property titles totaling 53,246 acres (21,548 hectares), and three exploration licenses, covering 13,193 acres (5,339 hectares). We also own significant lands in the Cerro Negro mine area, totaling approximately 27,429 acres (11,100 hectares), which lands overlie the Bajo Negro and Vein Zone deposits and adjacent prospects. The Cerro Negro mine operations hold all required permits to support the current mining operations.
A 3% royalty is payable to the Province of Santa Cruz, subject to certain adjustments. In addition, there is a Provincial Sustainability Fund royalty of up to 2% of gross income, and a Municipality Sustainability Fund royalty of 1% of net earnings.
Cerro Negro consists of the Eureka, Mariana Central and Mariana Norte operating underground mines and the Emilia and San Marcos underground mines, which are currently in development. Deposits within the Cerro Negro mine operations are low-sulphidation, epithermal gold–silver vein deposits.
Cerro Negro’s available underground mining fleet consists of 15 underground loaders, 23 40-tonne haul trucks and additional auxiliary equipment as required.
The processing plant facilities consist of a crushing plant, a grinding circuit, agitated leaching, counter-current decantation, solution clarification, Merril Crowe zinc precipitation and smelting to produce gold/silver doré bars that are shipped to a refinery for further processing.
Brownfield exploration and development for new reserves is ongoing, including the development of the Eastern district.
Electrical power supply for the operation is provided by a 132 kw high voltage line interconnected to the national grid by a transformer station located near the process plant. A 33 kw grid was built to distribute power to the Mariana and Eureka areas.
Cerro Negro’s gross property, plant and mine development at December 31, 2019 was $1,718. Cerro Negro produced 334,000 ounces of gold since the completion of the acquisition of the mine site as part of the Newmont Goldcorp transaction in 2019 and reported 2.6 million ounces of gold reserves at December 31, 2019.
Pueblo Viejo, Dominican Republic. (40% owned) Pueblo Viejo is a joint venture with Barrick, where Barrick is the operator. We report our interest in Pueblo Viejo on an equity method basis. Pueblo Viejo, located approximately 60 miles (100 kilometers) northwest of Santo Domingo, is an open pit operation. Process facilities include a conventional mill which consists of a crushing and grinding circuit, an autoclave, and a carbon-leach circuit. Pueblo Viejo is a high sulphidation, quartz-alunite epithermal gold and silver deposit.
Pueblo Viejo produced 287,000 attributable ounces of gold since the completion of the acquisition of the mine site as part of the Newmont Goldcorp transaction in 2019 and reported 3.8 million ounces of attributable gold reserves at December 31, 2019.
Australia
The Australia region maintains its headquarters in Perth, Australia and operates two sites, Boddington and Tanami. The Company entered into a binding agreement on December 17, 2019, to sell its 50% interest in Kalgoorlie Consolidated Gold Mines (“Kalgoorlie”), included as part of the Company’s Australia segment, to Northern Star Resources Limited (“Northern Star”). The Company completed the sale on January 2, 2020. Pursuant to the terms of the agreement, Newmont will provide transitional services support until June 30, 2020.
Aboriginal land rights in Australia, which recognize the traditional rights and customs of Aboriginal people, are governed by the Commonwealth Native Title Act and certain other Acts specific to individual states and territories. The Commonwealth Native Title Act was enacted in 1993 following a decision in the High Court of Australia, which held that Aboriginal people, who have maintained a continuing connection with their land according to their traditional laws and customs, may hold certain rights which should be recognized under Australian common law. In the Northern Territory, where the Tanami operation is located, the Aboriginal Land Rights Act (“ALRA”) was introduced in 1976, which established an Aboriginal Land rights regime. Under the ALRA, approximately 50% of the land in the Northern Territory is Aboriginal freehold land.
All of Newmont’s operations in Australia take place on land that falls under the custodianship of Aboriginal people. Newmont does not consider that native title claims or determined areas where rights have been established are an impediment to the operation of existing mines. Newmont has existing agreements with the traditional owners of the land utilized by our Tanami and Boddington operations. Any future agreements would depend on a determination of native title, which is likely to take many years. If successful, a native title determination could give rights to compensation claims in the future. Throughout Australia, new exploratory and mining tenements may require native title agreements to be entered into and will be subject to a negotiation process, which often gives rise to compensation payments and heritage survey protocols.
In Australia, various ad valorem royalties and taxes are paid to state and territorial governments, typically based on a percentage of gross revenues or earnings. Aboriginal groups have negotiated compensation/royalty payments as a condition to granting access to areas where native title rights are determined or where they own the land.
Boddington, Australia. (100% owned) Boddington is located 81 miles (130 kilometers) southeast of Perth in Western Australia and is accessible primarily by paved road. Boddington has been wholly owned since June 2009 when Newmont acquired the final 33.33% interest from AngloGold Ashanti Australia Limited.
The Boddington project area comprises 52,506 acres (21,249 hectares) of mining tenure leased from the State of Western Australia, of which 26,910 acres (10,890 hectares) is subleased from the South 32 Worsley Joint Venturers. The total project area is comprised of multiple leases that expire between 2020 and 2039. Royalties are paid to the state government at 2.5% for gold and 5% for copper based on revenue. Shipping and treatment and refining costs are allowable deductions from revenue for royalty calculations for copper. Newmont owns 74,474 acres (30,139 hectares) of rural freehold property, some of which overlaps existing mining tenure.
Boddington consists of greenstone diorite hosted mineralization and activities continue to develop the known reserve. The mine operates two pits (North and South Pits), utilizing two electric rope shovels, an electric hydraulic shovel and a diesel powered face shovel as its prime ex-pit material movers with a fleet of 39 production haul trucks and a fleet of ancillary equipment as required. Boddington has a current capacity to mine approximately 235,000 tonnes of material per day. The milling plant includes a three-stage crushing facility (two primary crushers, six secondary crushers and four high-pressure grinding rolls), four ball mills, a flotation circuit and a carbon-in-leach circuit. The flotation circuit process recovers gold-copper concentrate before the material is then processed by a traditional carbon-in-leach circuit where the remaining gold is recovered to produce doré.
Mining operations consist of two open pit operations located adjacent to each other. The processing plant has a nominal capacity to process approximately 40 million tonnes of ore per year with optimization projects underway to further increase this capacity.
Brownfield exploration and development for new reserves is ongoing.
Power for the operation is sourced through the local power grid under a long-term power purchase agreement with Bluewaters Power.
Boddington’s gross property, plant and mine development at December 31, 2019 was $4,267. Boddington produced 703,000 ounces of gold and 146,000 gold equivalent ounces of other metals in 2019. At December 31, 2019, Boddington reported 11.9 million ounces of gold reserves and 1,230 million pounds of copper reserves.
Tanami, Australia. (100% owned) Tanami is located in the Northern Territory approximately 342 miles (550 kilometers) northwest of Alice Springs. The underground mining infrastructure and operation is located at Dead Bullock Soak (“DBS”). The processing infrastructure is located 25 miles (40 kilometers) to the east of the mining operations at the Granites. Ore is transported by road train from DBS underground to the processing facility at the Granites. Supply of materials for the operations is done primarily by road, while the workforce for Tanami utilizes a fly-in/fly-out program. Gold was first discovered and mined in the area around 1900. Newmont’s landholdings at Tanami consist of mineral leases and exploration licenses. Additionally, Newmont operates through agreements with the Central Land Council who represent the Warlpiri people. Newmont acquired its ownership in the mine in 2002, as a result of the merger with Normandy Mining Limited (“Normandy”).
The Newmont Tanami Operations has an area of 942,597 acres (381,455 hectares) of exploration licenses and 11,025 acres (4,462 hectares) of mineral leases granted pursuant to the Northern Territory Mineral Titles Act. The total project area is comprised of multiple leases and licenses that expire between 2020 and 2036. The operation has been granted authorization via the Northern Territory Mining Management Act to undertake mining activities on these mineral leases. For the exploration licenses, Tanami is required to make annual payments which range from 5% to 7% of the audited exploration expenditure (subject to a minimum payable) to the Central Land Council for each of the Deeds for Exploration.
In accordance with the Northern Territory Mineral Royalties Act, Newmont is obligated to pay a profit based royalty of 20% to the Northern Territory government. The operation is located on Aboriginal Freehold Land granted under the Northern Territory Aboriginal Land Rights Act which requires Newmont to hold a mining agreement with the traditional owners on which the operation is located. The Mining Agreement is managed by the Central Land Council as per the statutory requirements of the Aboriginal Land Rights Act. This agreement also provides for compensation payments to the traditional owners.
Mining operations are predominantly focused on the Callie and Auron ore bodies in the underground mine at DBS. Tanami consists of sediment hosted sheeted quartz vein mineralization. In October 2019, the Board of Directors approved full funding of the Tanami Expansion 2 project comprising a 0.9 mile (1.5 kilometer) hoisting shaft and supporting infrastructure.
Tanami, as an underground mining operation, has a fleet of 10 underground loaders and 20 haul trucks, each with 60 to 65-tonne payloads. The processing plant was originally commissioned in 1986. The processing plant facilities were expanded and upgraded during the third quarter of 2017 and currently consist of a crushing plant, a grinding circuit, gravity carbon in pulp tanks and a conventional tailings disposal facility.
Brownfield exploration and development for new reserves is ongoing with the main focus being underground ore definition drilling of the Auron, Federation and Liberator ore bodies as well as exploration of the Oberon ore body.
The Tanami Power project was completed in March 2019 and includes the installation of two power stations, a 66kV interconnected power line, and a 275 mile (450km) natural gas pipeline connecting the Tanami site to the Amadeus Gas Pipeline. The pipeline was built and will be maintained by Australian Gas Infrastructure Group, while the power stations were constructed and will be operated by Zenith Energy. The gas supply, gas transmission and power purchase agreements are for a ten year term with options to extend.
Tanami’s gross property, plant and mine development at December 31, 2019 was $1,793. Tanami produced 500,000 ounces of gold in 2019 and reported 5.7 million ounces of gold reserves at December 31, 2019.
Kalgoorlie, Australia. (50% owned) Kalgoorlie, located 373 miles (600 kilometers) east of Perth in Western Australia, is an open pit and underground operation. Kalgoorlie is a joint venture with Saracen Mineral Holdings Limited and Newmont is the operator. We report our interest in Kalgoorlie on a pro rata basis. As noted above, we completed the sale of Kalgoorlie on January 2, 2020. The processing plant includes the Fimiston processing plant and the Gidji processing plant. Kalgoorlie consists of greenstone dolerite hosted mineralization. The Kalgoorlie assets and liabilities were classified as held for sale for the year ended December 31, 2019. Kalgoorlie produced 228,000 attributable ounces of gold in 2019 and reported 3.1 million attributable ounces of gold reserves at December 31, 2019.
Africa
The Africa region maintains its headquarters in Accra, Ghana and operates two sites, Ahafo and Akyem.
In December 2003, Ghana’s Parliament unanimously ratified an Investment Agreement (“IA”) between Newmont and the government of Ghana. The IA established a fixed fiscal and legal regime, including fixed royalty and tax rates, for the life of any Newmont project in Ghana. In December 2015, Ghana’s Parliament ratified the Revised Investment Agreements (“Ghana Investment Agreements” or “Revised IAs”). Currently, the maximum corporate income tax rate remains at 32.5% and royalties are paid on a sliding scale system that is based on average monthly gold prices. The rates range from 3% to 5% of revenues (plus an additional 0.6% for any production from forest reserve areas). The government of Ghana is also entitled to receive 10% of a project’s net cash flow after reaching specific production milestones by receiving 1/9th of the total amount paid as dividends to Newmont shareholders. When the average quoted gold price exceeds $1,300 per ounce within a calendar year, an advance payment on these amounts of 0.6% of total revenues is required. The Ghana Investment Agreements also contain commitments with respect to job training for local Ghanaians, community development, purchasing of local goods and services and environmental protection.
The Ghana Investment Agreements also include a change in tax stabilization from life of mine to 15 years from commercial production for each mine. In October 2017, the government of Ghana approved Newmont’s request to extend the stability period of the Revised IAs at the Ahafo operations for five years to December 31, 2025. The extension was approved based on Newmont’s commitment to invest at least $300 for the Subika Underground and Ahafo Mill Expansion projects. This commitment was completed during the fourth quarter of 2018.
See Item 1A, Risk Factors for a description of risks inherent in contracts with governments.
The Ahafo and Akyem mines operate using electrical power generated by the Volta River Authority along with supplemental power generation capacity built by Newmont.
Ahafo, Ghana. (100% owned) Ahafo is located near Kenyasi in the Brong Ahafo Region of Ghana, approximately 180 miles (290 kilometers) northwest of the national capital city of Accra, and is accessible by paved roads. In 2002, Newmont acquired 50% of Ahafo as a result of the merger with Normandy. In 2003, Newmont purchased the remaining interest from Moydow Mines International Inc. (“Moydow”), thereby making it a wholly owned subsidiary. The Ahafo mine commenced commercial production in 2006 and currently operates a mill, two pits and an underground operation.
The Ahafo operations cover an area of approximately 137,000 acres (55,000 hectares) for the mining lease concession with current mine take area of approximately 18,700 acres (7,600 hectares) that has been fully compensated and approximately 6,500 acres (2,600 hectares) of mining area that has not been fully compensated (e.g. payment would be necessary to move people from their land). The Ahafo mine operates on three mining leases between the Government of Ghana and Newmont Ghana Gold Ltd. The leases grant the exclusive rights to work, develop and produce gold in the lease area, including the processing, storing and transportation of ore and materials. The leases require Ahafo to respect or perform certain financial and statutory reporting obligations and expire in approximately 13 years and are renewable subject to certain conditions. Ahafo pays a royalty of 2% on net smelter returns to Franco-Nevada for all gold ounces recovered from areas previously owned by Moydow and a sliding scale royalty based on the average monthly gold price up to 5% on gold production to the government of Ghana.
The Ahafo mine is composed of three orogenic gold deposits that have oxide and primary mineralization. Gold occurs primarily in pyrite and secondarily as native gold in quartz veins. Ahafo has two active open pits, Subika and Awonsu. Subika added an underground operation, which reached commercial production in November 2018, and Awonsu completed a layback in November 2019. The available mining fleet for surface mining consists of three shovels and thirty-eight 141-tonne haul trucks. The available mining fleet for underground mining consists of five underground loaders and eight haul trucks, each with a 60-tonne payload. The daily production rate is approximately 95,000 tonnes. The processing plant was commissioned in 2006 to process 7.5 million tonnes of primary and oxide ore per year. With the depletion of oxide ore, the current plant throughput has decreased to 6.5 million tonnes per year. The processing plant consists of a crushing plant, a grinding circuit, carbon in leach tanks, elution circuit, counter current decantation circuit and a tailings disposal facility.
The Ahafo Mill Expansion was completed in October 2019 that expanded the existing plant by approximately 3.5 million tonnes per year through the installation of a new crusher, a single stage SAG mill and two leach tanks.
Ahafo’s gross property, plant and mine development at December 31, 2019 was $2,473. Ahafo produced 643,000 ounces of gold in 2019 and reported 9.6 million ounces of gold reserves at December 31, 2019.
Akyem, Ghana. (100% owned) Akyem, located in Birim North District of the Eastern Region of Ghana, approximately 80 miles (125 kilometers) northwest of the national capital city of Accra, is an open pit mining operation. Process facilities include a crushing plant, a SAG and ball milling circuit, carbon-in-leach, elution and bullion smelting facilities and a tailings storage facility. The Akyem mine is an orogenic gold deposit that has oxide and primary mineralization. Akyem’s gross property, plant and mine development at December 31, 2019 was $1,458. Akyem produced 422,000 ounces of gold in 2019 and reported 2.6 million ounces of gold reserves at December 31, 2019.
Nevada
On July 1, 2019, the Company contributed its existing Nevada mining operations, which included Carlin, Phoenix, Twin Creeks and Long Canyon, to NGM in exchange for a 38.5% interest in NGM. Prior to the formation of NGM, the Nevada region produced 765,000 ounces of gold and 35 million pounds of copper in 2019. For additional information regarding the formation of NGM, see Note 4 to the Consolidated Financial Statements and the discussion in our Results of Consolidated Operations in Part II Item 7.
NGM, Nevada, USA. (38.5% owned) NGM, located in Elko, Nevada, is a joint venture with Barrick who is the operator. We report our interest in NGM on a pro rata basis. NGM operations include Cortez, Carlin, Turquoise Ridge, Phoenix, and Long Canyon.
In Nevada, mining taxes are assessed on up to 5% of net proceeds of a mine.
NGM owns, or control through long-term mining leases and unpatented mining claims, all of the minerals and surface area within the boundaries of the present Nevada mining operations. The long-term leases extend for at least the anticipated mine life of those deposits. With respect to a significant portion of the Gold Quarry mine at Carlin, NGM pays a royalty equivalent to 16.2% of the mineral production. NGM wholly-owns or controls the remainder of the Gold Quarry mineral rights, in some cases subject to additional royalties. With respect to certain smaller deposits in Nevada, NGM is obligated to pay royalties on production to third parties that vary from 1% to 8% of production.
Cortez, located approximately 60 miles (100 kilometers) southwest of Elko, is an open pit and underground operation. Process facilities include an oxide mill, which consists of a crushing and grinding circuit and carbon-in leach circuit, and two heap leach pads. Refractory ore is transported to Carlin for processing. Mineralization is sedimentary rock-hosted and consists of submicron to micrometer-sized gold particles and gold in solid solution in pyrite. The Cortez available open pit mining fleet consists of six shovels and 46 haul trucks with an average payload of 360 tons. The available underground mining fleet consists of nine underground loaders and 16 haul trucks each with 20 to 40-ton payloads.
Carlin, located 25 miles (40 kilometers) west of Elko, is an open pit and underground operation and includes the former Newmont Carlin operations and the former Barrick Goldstrike operations. Process facilities include an autoclave, roaster, Mill 6, Mill 5 and four heap leach pads. Mill 6 consists of a grinding circuit, roasting circuit and a conventional carbon-in leach circuit and Mill 5 consists of an oxide mill and a floatation circuit. Carlin is a sediment-hosted disseminated gold deposit with an available open pit mining fleet consisting of 12 shovels and 70 haul trucks, which range from 150 to 250 tons. The available underground mining fleet consists of 31 underground loaders and 37 haul trucks each with 20 to 40-ton payloads. Additionally, there is a toll milling agreement with NGM for processing sulfide concentrate produced at CC&V. Under the terms of the agreement, CC&V will deliver a minimum of 4,000 tons and a maximum of 8,333 tons of concentrate per month for milling to NGM. CC&V continues to hold title to the concentrate sent to NGM for processing and receives bullion credits for gold recovered and NGM utilizes the concentrate as a fuel source for the NGM roaster. The agreement expires on December 31, 2020.
Turquoise Ridge, located approximately 25 miles (40 kilometers) northeast of Golconda, is an open pit and underground operation and includes the former Newmont Twin Creeks operations and the former Barrick Turquoise Ridge operations. Process facilities include the Sage autoclave, an oxide mill, and three heap leach pads. Turquoise Ridge is a sediment-hosted disseminated gold deposit. Turquoise Ridge’s available open pit mining fleet consists of two shovels and fourteen 240-ton haul trucks. The available underground mining fleet consists of 11 underground loaders and sixteen haul trucks each with 20 to 40-ton payloads.
Phoenix, located approximately 10 miles (16 kilometers) south of Battle Mountain, is an open pit operation. Process facilities include a flotation mill, a carbon-in-leach plant, a copper leach pad and a solvent extraction electrowinning (“SX/EW”) plant. Phoenix is a skarn-hosted polymetallic massive sulfide replacement deposit. The Phoenix mill produces a gravity gold concentrate and a copper/gold flotation concentrate and recovers additional gold from cyanide leaching of the flotation tails. The Phoenix surface mine’s available mining fleet consists of three shovels and twenty 240-ton haul trucks.
Long Canyon, located approximately 75 miles (120 kilometers) east of Elko, is an open pit operation. Long Canyon is a sediment-hosted disseminated gold deposit. Oxide ore with suitable cyanide solubility is treated on a heap leach pad. The Long Canyon available mining fleet consists of two shovels and twelve 240-ton haul trucks. Gold recovered from the leach pad is transferred as gold-bearing carbon to Carlin for refining and shipment.
Brownfield exploration and development for new reserves is ongoing.
Power is either purchased in the open market or supplied by the power plants owned and operated by NGM.
Newmont’s share of NGM’s gross property, plant and mine development at December 31, 2019 was $7,225. NGM produced 710,000 attributable ounces of gold in 2019 and reported 18.6 million attributable ounces of gold reserves at December 31, 2019.
Operating Statistics
The following tables detail operating statistics related to gold production, ounces sold and production costs per ounce of our continuing operations:
| | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Year Ended December 31, 2019 | North America | South America | Australia | Africa | Nevada | Total Gold | |||||||||||||
| Tons mined (000 dry short tons): | | | | | | | | | | | | | | | | | | | |
| Open pit | | | 135,822 | | | 102,765 | | | 113,031 | | | 75,420 | | | 154,115 | | | 581,153 | |
| Underground | | | 3,082 | | | 1,004 | | | 3,494 | | | 1,342 | | | 2,934 | | | 11,856 | |
| Tons processed (000 dry short tons): | | | | | | | | | | | | | | | | | | | |
| Mill | | | 21,913 | | | 22,408 | | | 53,618 | | | 15,958 | | | 19,722 | | | 133,619 | |
| Leach | | | 21,497 | | | 34,635 | | | — | | | — | | | 15,452 | | | 71,584 | |
| Average ore grade (oz/ton): | | | | | | | | | | | | | | | | | | | |
| Mill | | | 0.045 | | | 0.054 | | | 0.030 | | | 0.071 | | | 0.080 | | | 0.049 | |
| Leach | | | 0.013 | | | 0.011 | | | — | | | — | | | 0.018 | | | 0.013 | |
| Average mill recovery rate | | | 81.6 | % | | 90.0 | % | | 88.8 | % | | 92.7 | % | | 78.3 | % | | 86.1 | % |
| Ounces produced (000): | | | | | | | | | | | | | | | | | | | |
| Mill | | | 782 | | | 1,087 | | | 1,431 | | | 1,051 | | | 1,229 | | | 5,580 | |
| Leach | | | 254 | | | 298 | | | — | | | — | | | 246 | | | 798 | |
| Development (1) | | | — | | | — | | | — | | | 14 | | | — | | | 14 | |
| Consolidated | | | 1,036 | | | 1,385 | | | 1,431 | | | 1,065 | | | 1,475 | | | 6,392 | |
| Attributable | | | 1,036 | | | 997 | | | 1,431 | | | 1,065 | | | 1,475 | | | 6,004 | |
| Consolidated ounces sold (000) | | | 1,080 | | | 1,404 | | | 1,438 | | | 1,051 | | | 1,492 | | | 6,465 | |
| Production costs per ounce sold: (2) | | | | | | | | | | | | | | | | | | | |
| Direct mining and production costs | | $ | 858 | | $ | 606 | | $ | 693 | | $ | 525 | | $ | 765 | | $ | 691 | |
| By-product credits | | | (4) | | | (34) | | | (6) | | | (2) | | | (19) | | | (14) | |
| Royalties and production taxes | | | 22 | | | 65 | | | 36 | | | 88 | | | 13 | | | 43 | |
| Write-downs and inventory change | | | 7 | | | 9 | | | 11 | | | (14) | | | (11) | | | 1 | |
| Costs applicable to sales | | | 883 | | | 646 | | | 734 | | | 597 | | | 748 | | | 721 | |
| Depreciation and amortization | | | 356 | | | 234 | | | 164 | | | 295 | | | 340 | | | 275 | |
| Reclamation accretion | | | 12 | | | 23 | | | 9 | | | 9 | | | 6 | | | 12 | |
| Total production costs | | $ | 1,251 | | $ | 903 | | $ | 907 | | $ | 901 | | $ | 1,094 | | $ | 1,008 | |
| | | | | | | | | | | | | | | | | | | | |
| All-in sustaining costs per ounce sold (3) | | $ | 1,187 | | $ | 814 | | $ | 908 | | $ | 791 | | $ | 935 | | $ | 966 | |
| | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Year Ended December 31, 2018 | North America | South America | Australia | Africa | Nevada | Total Gold | |||||||||||||
| Tons mined (000 dry short tons): | | | | | | | | | | | | | | | | | | | |
| Open pit | | | 41,749 | | | 99,793 | | | 103,192 | | | 71,970 | | | 188,809 | | | 505,513 | |
| Underground | | | — | | | — | | | 3,202 | | | 1,339 | | | 3,024 | | | 7,565 | |
| Tons processed (000 dry short tons): | | | | | | | | | | | | | | | | | | | |
| Mill | | | 1,660 | | | 21,666 | | | 54,337 | | | 15,585 | | | 24,219 | | | 117,467 | |
| Leach | | | 19,513 | | | 25,405 | | | — | | | — | | | 26,521 | | | 71,439 | |
| Average ore grade (oz/ton): | | | | | | | | | | | | | | | | | | | |
| Mill | | | 0.101 | | | 0.042 | | | 0.032 | | | 0.058 | | | 0.073 | | | 0.047 | |
| Leach | | | 0.014 | | | 0.013 | | | — | | | — | | | 0.020 | | | 0.016 | |
| Average mill recovery rate | | | 62.3 | % | | 88.0 | % | | 87.4 | % | | 92.6 | % | | 78.1 | % | | 84.6 | % |
| Ounces produced (000): | | | | | | | | | | | | | | | | | | | |
| Mill | | | 93 | | | 802 | | | 1,523 | | | 850 | | | 1,360 | | | 4,628 | |
| Leach | | | 267 | | | 247 | | | — | | | — | | | 337 | | | 851 | |
| Consolidated | | | 360 | | | 1,049 | | | 1,523 | | | 850 | | | 1,697 | | | 5,479 | |
| Attributable | | | 360 | | | 671 | | | 1,523 | | | 850 | | | 1,697 | | | 5,101 | |
| Consolidated ounces sold (000) | | | 357 | | | 1,060 | | | 1,553 | | | 851 | | | 1,695 | | | 5,516 | |
| Production costs per ounce sold: (2) | | | | | | | | | | | | | | | | | | | |
| Direct mining and production costs | | $ | 712 | | $ | 593 | | $ | 681 | | $ | 592 | | $ | 763 | | $ | 677 | |
| By-product credits | | | (7) | | | (19) | | | (7) | | | (2) | | | (9) | | | (9) | |
| Royalties and production taxes | | | 25 | | | 53 | | | 32 | | | 55 | | | 9 | | | 32 | |
| Write-downs and inventory change | | | (3) | | | 33 | | | 3 | | | — | | | 3 | | | 8 | |
| Costs applicable to sales | | | 727 | | | 660 | | | 709 | | | 645 | | | 766 | | | 708 | |
| Depreciation and amortization | | | 232 | | | 201 | | | 133 | | | 301 | | | 240 | | | 213 | |
| Reclamation accretion | | | 10 | | | 24 | | | 8 | | | 9 | | | 5 | | | 10 | |
| Total production costs | | $ | 969 | | $ | 885 | | $ | 850 | | $ | 955 | | $ | 1,011 | | $ | 931 | |
| | | | | | | | | | | | | | | | | | | | |
| All-in sustaining costs per ounce sold (3) | | $ | 840 | | $ | 804 | | $ | 845 | | $ | 794 | | $ | 928 | | $ | 909 | |
| | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Year Ended December 31, 2017 | North America | South America | Australia | Africa | Nevada | Total Gold | |||||||||||||
| Tons mined (000 dry short tons): | | | | | | | | | | | | | | | | | | | |
| Open pit | | | 43,058 | | | 104,763 | | | 114,371 | | | 74,580 | | | 209,028 | | | 545,800 | |
| Underground | | | — | | | — | | | 3,144 | | | 279 | | | 2,979 | | | 6,402 | |
| Tons processed (000 dry short tons): | | | | | | | | | | | | | | | | | | | |
| Mill | | | 1,496 | | | 20,690 | | | 52,802 | | | 16,884 | | | 23,910 | | | 115,782 | |
| Leach | | | 20,562 | | | 24,082 | | | — | | | — | | | 34,727 | | | 79,371 | |
| Average ore grade (oz/ton): | | | | | | | | | | | | | | | | | | | |
| Mill | | | 0.137 | | | 0.043 | | | 0.035 | | | 0.053 | | | 0.074 | | | 0.048 | |
| Leach | | | 0.021 | | | 0.013 | | | — | | | — | | | 0.020 | | | 0.018 | |
| Average mill recovery rate | | | 60.7 | % | | 87.2 | % | | 86.1 | % | | 92.3 | % | | 78.8 | % | | 84.0 | % |
| Ounces produced (000): | | | | | | | | | | | | | | | | | | | |
| Mill | | | 116 | | | 752 | | | 1,573 | | | 822 | | | 1,369 | | | 4,632 | |
| Leach | | | 335 | | | 296 | | | — | | | — | | | 391 | | | 1,022 | |
| Consolidated | | | 451 | | | 1,048 | | | 1,573 | | | 822 | | | 1,760 | | | 5,654 | |
| Attributable | | | 451 | | | 660 | | | 1,573 | | | 822 | | | 1,760 | | | 5,266 | |
| Consolidated ounces sold (000) | | | 466 | | | 1,046 | | | 1,558 | | | 824 | | | 1,738 | | | 5,632 | |
| Production costs per ounce sold: (2) | | | | | | | | | | | | | | | | | | | |
| Direct mining and production costs | | $ | 519 | | $ | 639 | | $ | 673 | | $ | 573 | | $ | 756 | | $ | 665 | |
| By-product credits | | | (6) | | | (17) | | | (8) | | | (2) | | | (10) | | | (9) | |
| Royalties and production taxes | | | 14 | | | 54 | | | 32 | | | 51 | | | 9 | | | 30 | |
| Write-downs and inventory change | | | 95 | | | 33 | | | (25) | | | 33 | | | (19) | | | 6 | |
| Costs applicable to sales | | | 622 | | | 709 | | | 672 | | | 655 | | | 736 | | | 692 | |
| Depreciation and amortization | | | 272 | | | 229 | | | 134 | | | 277 | | | 236 | | | 217 | |
| Reclamation accretion | | | 8 | | | 45 | | | 7 | | | 9 | | | 5 | | | 14 | |
| Total production costs | | $ | 902 | | $ | 983 | | $ | 813 | | $ | 941 | | $ | 977 | | $ | 923 | |
| | | | | | | | | | | | | | | | | | | | |
| All-in sustaining costs per ounce sold (3) | | $ | 725 | | $ | 870 | | $ | 806 | | $ | 785 | | $ | 918 | | $ | 890 | |
| (1) | Ounces from the removal and production of de minimis saleable materials during development. Related sales are recorded in Other income, net of incremental mining and processing costs. |
|---|
| (2) | Production costs do not include items that are included in sustaining costs such as General and administrative; Exploration; Advanced projects, research and development; Other expense, net and Sustaining capital. |
|---|
| (3) | All-In Sustaining Costs is a non-GAAP financial measure. See Non-GAAP Financial Measures beginning on page 78. |
|---|
The following tables detail operating statistics related to co-product metal production and sales:
| | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| | | Year Ended December 31, 2019 | | ||||||||||||||||
| | | Copper | | Silver | | Lead | | Zinc | | ||||||||||
| | Australia | Nevada | Total | Total (1) | Total (1) | Total (1) | |||||||||||||
| | | (pounds) | | (pounds) | | (pounds) | | (ounces) | | (pounds) | | (pounds) | | ||||||
| Tons milled (000 dry short tons) | | | 43,883 | | | 5,147 | | | 49,030 | | | 15,038 | | | 15,038 | | | 15,038 | |
| Average milled grade (% pounds/ton) / (oz/ton) | | | 0.10 | % | | 0.09 | % | | 0.10 | % | | 1.32 | | | 0.48 | % | | 0.86 | % |
| Average mill recovery rate | | | 80.3 | % | | 59.7 | % | | 78.2 | % | | 87.8 | % | | 78.8 | % | | 84.1 | % |
| Tons leached (000 dry short tons) | | | — | | | 4,074 | | | 4,074 | | | — | | | — | | | — | |
| Average leached grade | | | — | | | 0.25 | % | | 0.25 | % | | — | | | — | | | — | |
| Consolidated pounds (millions)/ ounces (thousands) produced | | | 64 | | | 15 | | | 79 | | | 15,860 | | | 108 | | | 187 | |
| Consolidated pounds (millions)/ ounces (thousands) sold | | | 63 | | | 17 | | | 80 | | | 15,987 | | | 108 | | | 179 | |
| | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| | | Year Ended December 31, 2018 | | Year Ended December 31, 2017 | | ||||||||||||||
| | | Copper | | Copper | | ||||||||||||||
| | Australia | Nevada | Total | Australia | Nevada | Total | |||||||||||||
| Tons milled (000 dry short tons) | | | 44,354 | | | 12,163 | | | 56,517 | | | 42,994 | | | 11,692 | | | 54,686 | |
| Average milled grade | | | 0.12 | % | | 0.09 | % | | 0.11 | % | | 0.13 | % | | 0.10 | % | | 0.12 | % |
| Average mill recovery rate | | | 79.7 | % | | 70.5 | % | | 78.2 | % | | 78.9 | % | | 70.9 | % | | 77.5 | % |
| Tons leached (000 dry short tons) | | | — | | | 7,348 | | | 7,348 | | | — | | | 5,728 | | | 5,728 | |
| Average leached grade | | | — | | | 0.27 | % | | 0.27 | % | | — | | | 0.26 | % | | 0.26 | % |
| Consolidated pounds (millions) produced | | | 77 | | | 32 | | | 109 | | | 80 | | | 33 | | | 113 | |
| Consolidated pounds (millions) sold | | | 80 | | | 30 | | | 110 | | | 79 | | | 32 | | | 111 | |
| (1) | All of our 2019 silver, lead and zinc co-product production came from North America, specifically the Peñasquito Mine. |
|---|
The following tables detail operating statistics related to co-product metal production costs per gold equivalent ounce (“GEO”) sold. Gold equivalent ounces are calculated as pounds or ounces produced multiplied by the ratio of the other metals’ price to the gold price, using Gold ($1,200/oz.), Copper ($2.75/lb.), Silver ($15/oz.), Lead ($0.90/lb.) and Zinc ($1.05/lb.) pricing for 2019, Gold ($1,250/oz.) and Copper ($2.70/lb.) pricing for 2018 and Gold ($1,200/oz.) and Copper ($2.25/lb.) pricing for 2017.
| | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| | | Year Ended December 31, 2019 | ||||||||||
| | North America | Australia | | Nevada | Total / Weighted-Average | |||||||
| Production costs per GEO sold: (1) | | | | | | | | | | | | |
| Costs applicable to sales | | $ | 886 | | $ | 803 | | $ | 750 | | $ | 858 |
| Depreciation and amortization | | | 342 | | | 151 | | | 243 | | | 291 |
| Reclamation and remediation | | | 16 | | | 11 | | | 14 | | | 14 |
| Total production costs | | $ | 1,243 | | $ | 965 | | $ | 1,007 | | $ | 1,164 |
| | | | | | | | | | | | | |
| All-in sustaining costs per GEO sold (2) | | $ | 1,339 | | $ | 954 | | $ | 894 | | $ | 1,222 |
| | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| | | Year Ended December 31, 2018 | | Year Ended December 31, 2017 | ||||||||||||||
| | Australia | Nevada | Total / Weighted-Average | Australia | Nevada | Total / Weighted-Average | ||||||||||||
| Production costs per GEO sold: (1) | | | | | | | | | | | | | | | | | | |
| Costs applicable to sales | | $ | 758 | | $ | 845 | | $ | 782 | | $ | 728 | | $ | 923 | | $ | 784 |
| Depreciation and amortization | | | 138 | | | 227 | | | 162 | | | 146 | | | 245 | | | 174 |
| Reclamation and remediation | | | 10 | | | 20 | | | 12 | | | 8 | | | 20 | | | 11 |
| Total production costs | | $ | 905 | | $ | 1,092 | | $ | 956 | | $ | 882 | | $ | 1,188 | | $ | 970 |
| | | | | | | | | | | | | | | | | | | |
| All-in sustaining costs per GEO sold (2) | | $ | 898 | | $ | 1,035 | | $ | 935 | | $ | 900 | | $ | 1,112 | | $ | 961 |
| (1) | Production costs do not include items that are included in sustaining costs such as General and administrative; Exploration; Advanced projects, research and development; Other expense, net and sustaining capital. |
|---|
| (2) | All-In Sustaining Costs is a non-GAAP financial measure. See Non-GAAP Financial Measures beginning on page 78. |
|---|
Proven and Probable Reserves
On April 18, 2019, we completed the business acquisition of Goldcorp and acquired the Red Lake, Musselwhite, Porcupine, Éléonore, Peñasquito and Cerro Negro operations as well as a 40% interest in the Pueblo Viejo mine and a 50% interest in the NuevaUnión project and the Norte Abierto project, respectively. For further information, see Note 3 to the Consolidated Financial Statements. On July 1, 2019, we contributed our existing Nevada mining operations, which included Carlin, Phoenix, Twin Creeks and Long Canyon, to NGM in exchange for a 38.5% interest in NGM. For further information, see Note 4 to the Consolidated Financial Statements.
We had attributable proven and probable gold reserves of 100.2 million ounces at December 31, 2019. For 2019 and 2018, reserves were calculated at a gold price assumption of $1,200 per ounce. Our 2019 reserves would increase by 6% (6 million ounces), or decline by 6% (6 million ounces), if calculated at a $1,300 and $1,100 per ounce gold price, respectively, with all other assumptions remaining constant.
At December 31, 2019, our attributable proven and probable gold reserves were 18.4 million ounces in North America, 30.2 million ounces in South America, 20.8 million ounces in Australia, 12.2 million ounces in Africa and 18.6 million ounces in Nevada.
Our attributable proven and probable copper reserves at December 31, 2019 were 15,000 million pounds. For 2019, reserves were calculated at a copper price assumption of $2.75 per pound. For 2018, reserves were calculated at a copper price assumption of $2.50 per pound.
Our attributable proven and probable silver reserves at December 31, 2019 were 652 million ounces. For 2019 and 2018, reserves were calculated at a silver price assumption of $16 per ounce. Silver reserves are generally a by-product of gold and/or copper reserves, other than at Peñasquito where silver reserves are accounted for as a co-product, with significant enough levels to be estimated and included in calculations for mine planning and operations.
Our attributable proven and probable lead reserves at December 31, 2019 were 3,260 million pounds. For 2019, reserves were calculated at a lead price assumption of $0.95 per pound.
Our attributable proven and probable zinc reserves at December 31, 2019 were 7,420 million pounds. For 2019, reserves were calculated at a zinc price assumption of $1.20 per pound.
Our attributable proven and probable molybdenum reserves at NuevaUnión at December 31, 2019 were 270 million pounds. For 2019, reserves were estimated based on prices set by the NuevaUnión joint venture.
All of our reserves are located on land that we own or control. The risks that could affect title to our property are included above in Item 1A, Risk Factors.
Proven and probable reserves are based on extensive drilling, sampling, mine modeling and metallurgical testing from which we determined economic feasibility. Metal price assumptions, adjusted for our exchange rate assumption, follow SEC guidance not to exceed a three year trailing average. The price sensitivity of reserves depends upon several factors including grade, metallurgical recovery, operating cost, waste-to-ore ratio and ore type. Metallurgical recovery rates vary depending on the metallurgical properties of each deposit and the production process used. The reserve tables below list the average metallurgical recovery rate for each deposit, which takes into account the relevant processing methods. The cut-off grade, or lowest grade of mineralization considered economic to process, varies with material type, price, metallurgical recoveries, operating costs and co- or by-product credits.
The proven and probable reserve figures presented herein are estimates based on information available at the time of calculation. No assurance can be given that the indicated levels of recovery of gold, copper, silver, lead, zinc and molybdenum will be realized. Ounces of gold or silver or pounds of copper, lead, zinc or molybdenum included in the proven and probable reserves are those contained prior to losses during metallurgical treatment. Reserve estimates may require revision based on actual production. Market fluctuations in the price of gold, copper, silver, lead, zinc and molybdenum, as well as increased production costs or reduced metallurgical recovery rates, could render certain proven and probable reserves containing higher cost reserves uneconomic to exploit and might result in a reduction of reserves.
We publish reserves annually, and will recalculate reserves at December 31, 2020, taking into account metal prices, changes, if any, to future production and capital costs, divestments and depletion as well as any acquisitions and additions during 2020.
The following tables detail gold proven and probable reserves reflecting only those reserves attributable to Newmont’s ownership or economic interest at December 31, 2019 and 2018:
| | | | | | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Gold Reserves At December 31, 2019 (1) | | ||||||||||||||||||||||
| | | | | Proven Reserves | | Probable Reserves | | Proven and Probable Reserves | | | | ||||||||||||
| | | Newmont | | Tonnage (2) | | Grade | | Ounces (3) | | Tonnage (2) | | Grade | | Ounces (3) | | Tonnage (2) | | Grade | | Ounces (3) | | Metallurgical | |
| Deposits/Districts | Share | (000) | (oz/ton) | (000) | (000) | (oz/ton) | (000) | (000) | (oz/ton) | (000) | Recovery (3) | ||||||||||||
| North America | | | | | | | | | | | | | | | | | | | | | | | |
| CC&V Open Pits (4) | | 100% | | 103,800 | | 0.015 | | 1,570 | | 26,900 | | 0.013 | | 340 | | 130,700 | | 0.015 | | 1,910 | | 59% | |
| CC&V Leach Pads (5) | | 100% | | — | | | | — | | 34,800 | | 0.026 | | 890 | | 34,800 | | 0.026 | | 890 | | 59% | |
| Total CC&V, Colorado | | | | 103,800 | | 0.015 | | 1,570 | | 61,700 | | 0.020 | | 1,230 | | 165,500 | | 0.017 | | 2,800 | | 59% | |
| Red Lake, Canada (6) | | 100% | | 1,000 | | 0.254 | | 260 | | 4,100 | | 0.253 | | 1,040 | | 5,100 | | 0.253 | | 1,300 | | 94% | |
| Musselwhite, Canada (7) | | 100% | | 5,400 | | 0.189 | | 1,020 | | 5,500 | | 0.192 | | 1,070 | | 10,900 | | 0.190 | | 2,090 | | 95% | |
| Porcupine Underground (8) | | 100% | | 600 | | 0.307 | | 200 | | 4,700 | | 0.201 | | 950 | | 5,300 | | 0.214 | | 1,150 | | 87% | |
| Porcupine Open Pit (9) | | 100% | | 13,000 | | 0.044 | | 570 | | 36,000 | | 0.030 | | 1,100 | | 49,000 | | 0.034 | | 1,670 | | 88% | |
| Total Porcupine, Canada | | | | 13,600 | | 0.057 | | 770 | | 40,700 | | 0.050 | | 2,050 | | 54,300 | | 0.052 | | 2,820 | | 88% | |
| Éléonore, Canada (10) | | 100% | | 1,700 | | 0.166 | | 280 | | 6,600 | | 0.152 | | 1,000 | | 8,300 | | 0.155 | | 1,280 | | 91% | |
| Peñasquito, Mexico (11) | | 100% | | 121,000 | | 0.018 | | 2,220 | | 365,800 | | 0.016 | | 5,860 | | 486,800 | | 0.017 | | 8,080 | | 77% | |
| | | | | 246,500 | | 0.025 | | 6,120 | | 484,400 | | 0.025 | | 12,250 | | 730,900 | | 0.025 | | 18,370 | | 80% | |
| South America | | | | | | | | | | | | | | | | | | | | | | | |
| Yanacocha Open Pits (12) | | 51.35% | | 12,500 | | 0.021 | | 270 | | 106,500 | | 0.019 | | 1,990 | | 119,000 | | 0.019 | | 2,260 | | 64% | |
| Yanacocha Underground (13) | | 51.35% | | — | | | | — | | 6,500 | | 0.201 | | 1,310 | | 6,500 | | 0.201 | | 1,310 | | 96% | |
| Total Yanacocha, Peru | | | | 12,500 | | 0.021 | | 270 | | 113,000 | | 0.029 | | 3,300 | | 125,500 | | 0.028 | | 3,570 | | 76% | |
| Merian, Suriname (14) | | 75% | | 45,500 | | 0.041 | | 1,860 | | 51,500 | | 0.031 | | 1,620 | | 97,000 | | 0.036 | | 3,480 | | 92% | |
| Cerro Negro, Argentina (15) | | 100% | | 1,200 | | 0.335 | | 400 | | 8,100 | | 0.275 | | 2,200 | | 9,300 | | 0.283 | | 2,600 | | 92% | |
| Pueblo Viejo Open Pits | | 40% | | 7,400 | | 0.078 | | 580 | | 6,200 | | 0.079 | | 490 | | 13,600 | | 0.079 | | 1,070 | | 91% | |
| Pueblo Viejo Stockpiles (16) | | 40% | | — | | | | — | | 38,900 | | 0.070 | | 2,740 | | 38,900 | | 0.070 | | 2,740 | | 90% | |
| Total Pueblo Viejo, Dominican Republic (17) | | | | 7,400 | | 0.078 | | 580 | | 45,100 | | 0.072 | | 3,230 | | 52,500 | | 0.073 | | 3,810 | | 90% | |
| NuevaUnión, Chile (18) | | 50% | | — | | | | — | | 376,000 | | 0.014 | | 5,150 | | 376,000 | | 0.014 | | 5,150 | | 68% | |
| Norte Abierto, Chile (19) | | 50% | | — | | | | — | | 660,100 | | 0.018 | | 11,620 | | 660,100 | | 0.018 | | 11,620 | | 74% | |
| | | | | 66,600 | | 0.047 | | 3,110 | | 1,253,800 | | 0.022 | | 27,120 | | 1,320,400 | | 0.023 | | 30,230 | | 78% | |
| Australia | | | | | | | | | | | | | | | | | | | | | | | |
| Boddington Open Pit (20) | | 100% | | 258,800 | | 0.020 | | 5,260 | | 271,300 | | 0.020 | | 5,460 | | 530,100 | | 0.020 | | 10,720 | | 85% | |
| Boddington Stockpiles (16) | | 100% | | 4,300 | | 0.018 | | 80 | | 89,700 | | 0.013 | | 1,130 | | 94,000 | | 0.013 | | 1,210 | | 78% | |
| Total Boddington, Western Australia | | | | 263,100 | | 0.020 | | 5,340 | | 361,000 | | 0.018 | | 6,590 | | 624,100 | | 0.019 | | 11,930 | | 84% | |
| Tanami, Northern Territory (21) | | 100% | | 14,300 | | 0.151 | | 2,170 | | 22,400 | | 0.157 | | 3,510 | | 36,700 | | 0.155 | | 5,680 | | 97% | |
| Kalgoorlie Open Pit and Underground (22) | | 50% | | 4,000 | | 0.056 | | 230 | | 22,500 | | 0.059 | | 1,330 | | 26,500 | | 0.059 | | 1,560 | | 83% | |
| Kalgoorlie Stockpiles (16) | | 50% | | 15,000 | | 0.031 | | 460 | | 56,800 | | 0.020 | | 1,120 | | 71,800 | | 0.022 | | 1,580 | | 74% | |
| Total Kalgoorlie, Western Australia (23) | | | | 19,000 | | 0.036 | | 690 | | 79,300 | | 0.031 | | 2,450 | | 98,300 | | 0.032 | | 3,140 | | 78% | |
| | | | | 296,400 | | 0.028 | | 8,200 | | 462,700 | | 0.027 | | 12,550 | | 759,100 | | 0.027 | | 20,750 | | 86% | |
| Africa | | | | | | | | | | | | | | | | | | | | | | | |
| Ahafo South Open Pits (24) | | 100% | | 13,500 | | 0.070 | | 940 | | 49,600 | | 0.051 | | 2,550 | | 63,100 | | 0.055 | | 3,490 | | 90% | |
| Ahafo Underground (25) | | 100% | | 1,500 | | 0.140 | | 210 | | 14,500 | | 0.091 | | 1,330 | | 16,000 | | 0.096 | | 1,540 | | 94% | |
| Ahafo Stockpiles (16) | | 100% | | 42,300 | | 0.027 | | 1,140 | | — | | | | — | | 42,300 | | 0.027 | | 1,140 | | 88% | |
| Total Ahafo South, Ghana | | | | 57,300 | | 0.040 | | 2,290 | | 64,100 | | 0.061 | | 3,880 | | 121,400 | | 0.051 | | 6,170 | | 91% | |
| Ahafo North, Ghana (26) | | 100% | | — | | | | — | | 49,600 | | 0.070 | | 3,470 | | 49,600 | | 0.070 | | 3,470 | | 91% | |
| Akyem Open Pit (27) | | 100% | | 20,100 | | 0.048 | | 970 | | 22,700 | | 0.051 | | 1,150 | | 42,800 | | 0.050 | | 2,120 | | 90% | |
| Akyem Stockpiles (16) | | 100% | | 18,000 | | 0.026 | | 460 | | — | | | | — | | 18,000 | | 0.026 | | 460 | | 84% | |
| Total Akyem, Ghana | | | | 38,100 | | 0.037 | | 1,430 | | 22,700 | | 0.051 | | 1,150 | | 60,800 | | 0.042 | | 2,580 | | 89% | |
| | | | | 95,400 | | 0.039 | | 3,720 | | 136,400 | | 0.062 | | 8,500 | | 231,800 | | 0.053 | | 12,220 | | 91% | |
| Nevada | | | | | | | | | | | | | | | | | | | | | | | |
| NGM Open Pits, Nevada | | 38.5% | | 10,800 | | 0.053 | | 570 | | 156,300 | | 0.034 | | 5,370 | | 167,100 | | 0.036 | | 5,940 | | 83% | |
| NGM Stockpiles, Nevada (16) | | 38.5% | | 40,800 | | 0.069 | | 2,830 | | — | | | | — | | 40,800 | | 0.069 | | 2,830 | | 73% | |
| NGM Underground, Nevada | | 38.5% | | 16,200 | | 0.306 | | 5,000 | | 16,800 | | 0.286 | | 4,830 | | 33,000 | | 0.296 | | 9,830 | | 83% | |
| Total NGM, Nevada (28) | | | | 67,800 | | 0.124 | | 8,400 | | 173,100 | | 0.059 | | 10,200 | | 240,900 | | 0.077 | | 18,600 | | 81% | |
| | | | | 67,800 | | 0.124 | | 8,400 | | 173,100 | | 0.059 | | 10,200 | | 240,900 | | 0.077 | | 18,600 | | 81% | |
| Total Gold | | | | 772,700 | | 0.038 | | 29,550 | | 2,510,400 | | 0.028 | | 70,620 | | 3,283,100 | | 0.031 | | 100,170 | | 81% | |
| | | | | | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Gold Reserves At December 31, 2018 (1) | | ||||||||||||||||||||||
| | | | | Proven Reserves | | Probable Reserves | | Proven and Probable Reserves | | | | ||||||||||||
| | | Newmont | | Tonnage (2) | | Grade | | Ounces (3) | | Tonnage (2) | | Grade | | Ounces (3) | | Tonnage (2) | | Grade | | Ounces (3) | | Metallurgical | |
| Deposits/Districts | Share | (000) | (oz/ton) | (000) | (000) | (oz/ton) | (000) | (000) | (oz/ton) | (000) | Recovery (3) | ||||||||||||
| North America | | | | | | | | | | | | | | | | | | | | | | | |
| CC&V Open Pits | | 100% | | 123,900 | | 0.016 | | 2,000 | | 30,900 | | 0.013 | | 400 | | 154,800 | | 0.016 | | 2,400 | | 60% | |
| CC&V Leach Pads (5) | | 100% | | — | | | | — | | 41,900 | | 0.025 | | 1,050 | | 41,900 | | 0.025 | | 1,050 | | 57% | |
| Total CC&V, Colorado | | | | 123,900 | | 0.016 | | 2,000 | | 72,800 | | 0.020 | | 1,450 | | 196,700 | | 0.018 | | 3,450 | | 59% | |
| | | | | 123,900 | | 0.016 | | 2,000 | | 72,800 | | 0.020 | | 1,450 | | 196,700 | | 0.018 | | 3,450 | | 59% | |
| South America | | | | | | | | | | | | | | | | | | | | | | | |
| Yanacocha Open Pits | | 51.35% | | 17,000 | | 0.023 | | 390 | | 113,100 | | 0.019 | | 2,150 | | 130,100 | | 0.020 | | 2,540 | | 64% | |
| Yanacocha Underground | | 51.35% | | — | | | | — | | 6,200 | | 0.204 | | 1,270 | | 6,200 | | 0.204 | | 1,270 | | 97% | |
| Total Yanacocha, Peru | | | | 17,000 | | 0.023 | | 390 | | 119,300 | | 0.029 | | 3,420 | | 136,300 | | 0.028 | | 3,810 | | 76% | |
| Merian, Suriname | | 75% | | 39,200 | | 0.044 | | 1,720 | | 63,400 | | 0.032 | | 2,010 | | 102,600 | | 0.036 | | 3,730 | | 93% | |
| | | | | 56,200 | | 0.038 | | 2,110 | | 182,700 | | 0.030 | | 5,430 | | 238,900 | | 0.032 | | 7,540 | | 82% | |
| Australia | | | | | | | | | | | | | | | | | | | | | | | |
| Boddington Open Pit | | 100% | | 264,900 | | 0.021 | | 5,520 | | 265,000 | | 0.021 | | 5,470 | | 529,900 | | 0.021 | | 10,990 | | 83% | |
| Boddington Stockpiles (16) | | 100% | | 7,600 | | 0.020 | | 150 | | 94,800 | | 0.013 | | 1,210 | | 102,400 | | 0.013 | | 1,360 | | 77% | |
| Total Boddington, Western Australia | | | | 272,500 | | 0.021 | | 5,670 | | 359,800 | | 0.019 | | 6,680 | | 632,300 | | 0.020 | | 12,350 | | 83% | |
| Tanami, Northern Territory | | 100% | | 11,200 | | 0.159 | | 1,780 | | 18,000 | | 0.162 | | 2,910 | | 29,200 | | 0.161 | | 4,690 | | 97% | |
| Kalgoorlie Open Pit and Underground | | 50% | | 4,600 | | 0.059 | | 270 | | 27,500 | | 0.063 | | 1,720 | | 32,100 | | 0.062 | | 1,990 | | 83% | |
| Kalgoorlie Stockpiles (16) | | 50% | | 18,400 | | 0.030 | | 560 | | 55,800 | | 0.020 | | 1,100 | | 74,200 | | 0.022 | | 1,660 | | 74% | |
| Total Kalgoorlie, Western Australia | | | | 23,000 | | 0.036 | | 830 | | 83,300 | | 0.034 | | 2,820 | | 106,300 | | 0.034 | | 3,650 | | 79% | |
| | | | | 306,700 | | 0.027 | | 8,280 | | 461,100 | | 0.027 | | 12,410 | | 767,800 | | 0.027 | | 20,690 | | 84% | |
| Africa | | | | | | | | | | | | | | | | | | | | | | | |
| Ahafo South Open Pits | | 100% | | 17,600 | | 0.070 | | 1,230 | | 53,600 | | 0.054 | | 2,870 | | 71,200 | | 0.058 | | 4,100 | | 91% | |
| Ahafo Underground | | 100% | | — | | | | — | | 8,300 | | 0.138 | | 1,150 | | 8,300 | | 0.138 | | 1,150 | | 94% | |
| Ahafo Stockpiles (16) | | 100% | | 41,700 | | 0.027 | | 1,130 | | — | | | | — | | 41,700 | | 0.027 | | 1,130 | | 87% | |
| Total Ahafo South, Ghana | | | | 59,300 | | 0.040 | | 2,360 | | 61,900 | | 0.065 | | 4,020 | | 121,200 | | 0.053 | | 6,380 | | 91% | |
| Ahafo North, Ghana | | 100% | | — | | | | — | | 48,000 | | 0.070 | | 3,350 | | 48,000 | | 0.070 | | 3,350 | | 91% | |
| Akyem Open Pit | | 100% | | 9,100 | | 0.049 | | 450 | | 28,600 | | 0.049 | | 1,410 | | 37,700 | | 0.049 | | 1,860 | | 90% | |
| Akyem Stockpiles (16) | | 100% | | 14,300 | | 0.026 | | 380 | | — | | | | — | | 14,300 | | 0.026 | | 380 | | 89% | |
| Total Akyem, Ghana | | | | 23,400 | | 0.035 | | 830 | | 28,600 | | 0.049 | | 1,410 | | 52,000 | | 0.043 | | 2,240 | | 89% | |
| | | | | 82,700 | | 0.038 | | 3,190 | | 138,500 | | 0.063 | | 8,780 | | 221,200 | | 0.054 | | 11,970 | | 91% | |
| Nevada (29) | | | | | | | | | | | | | | | | | | | | | | | |
| Carlin Open Pits | | 100% | | 1,700 | | 0.088 | | 140 | | 118,200 | | 0.047 | | 5,550 | | 119,900 | | 0.048 | | 5,690 | | 73% | |
| Carlin Leach Pad (5) | | 100% | | — | | | | — | | 73,500 | | 0.009 | | 650 | | 73,500 | | 0.009 | | 650 | | 51% | |
| Carlin Stockpiles (16) | | 100% | | 18,700 | | 0.067 | | 1,250 | | — | | | | — | | 18,700 | | 0.067 | | 1,250 | | 84% | |
| Carlin Underground | | 100% | | 8,400 | | 0.305 | | 2,580 | | 7,900 | | 0.293 | | 2,290 | | 16,300 | | 0.300 | | 4,870 | | 83% | |
| Total Carlin, Nevada | | | | 28,800 | | 0.138 | | 3,970 | | 199,600 | | 0.043 | | 8,490 | | 228,400 | | 0.055 | | 12,460 | | 77% | |
| Phoenix | | 100% | | 13,200 | | 0.022 | | 290 | | 133,200 | | 0.019 | | 2,530 | | 146,400 | | 0.019 | | 2,820 | | 70% | |
| Lone Tree | | 100% | | 3,900 | | 0.008 | | 30 | | — | | | | — | | 3,900 | | 0.008 | | 30 | | 32% | |
| Total Phoenix, Nevada | | | | 17,100 | | 0.019 | | 320 | | 133,200 | | 0.019 | | 2,530 | | 150,300 | | 0.019 | | 2,850 | | 70% | |
| Turquoise Ridge (30) | | 25% | | 3,300 | | 0.397 | | 1,310 | | 2,700 | | 0.355 | | 960 | | 6,000 | | 0.378 | | 2,270 | | 92% | |
| Twin Creeks | | 100% | | 1,400 | | 0.086 | | 110 | | 26,000 | | 0.047 | | 1,220 | | 27,400 | | 0.049 | | 1,330 | | 77% | |
| Twin Creeks Stockpiles (16) | | 100% | | — | | | | — | | 31,300 | | 0.061 | | 1,910 | | 31,300 | | 0.061 | | 1,910 | | 71% | |
| Total Twin Creeks, Nevada | | | | 4,700 | | 0.302 | | 1,420 | | 60,000 | | 0.068 | | 4,090 | | 64,700 | | 0.085 | | 5,510 | | 81% | |
| Long Canyon, Nevada | | 100% | | 700 | | 0.064 | | 50 | | 23,900 | | 0.038 | | 920 | | 24,600 | | 0.039 | | 970 | | 76% | |
| | | | | 51,300 | | 0.112 | | 5,760 | | 416,700 | | 0.038 | | 16,030 | | 468,000 | | 0.047 | | 21,790 | | 77% | |
| Total Gold | | | | 620,800 | | 0.034 | | 21,340 | | 1,271,800 | | 0.035 | | 44,100 | | 1,892,600 | | 0.035 | | 65,440 | | 83% | |
| (1) | The term “reserve” means that part of a mineral deposit that can be economically and legally extracted or produced at the time of the reserve determination. |
|---|
The term “economically,” as used in the definition of reserve, means that profitable extraction or production has been established or analytically demonstrated in a feasibility study to be viable and justifiable under reasonable investment and market assumptions.
The term “legally,” as used in the definition of reserve, does not imply that all permits needed for mining and processing have been obtained or that other legal issues have been completely resolved. However, for a reserve to exist, Newmont must have a justifiable expectation, based on applicable laws and regulations, that issuance of permits or resolution of legal issues necessary for mining and processing at a particular deposit will be accomplished in the ordinary course and in a timeframe consistent with Newmont’s current mine plans.
The term “proven reserves” means reserves for which (a) quantity is computed from dimensions revealed in outcrops, trenches, workings or drill holes; (b) grade and/or quality are computed from the results of detailed sampling; and (c) the sites for inspection, sampling and measurements
are spaced so closely and the geologic character is sufficiently defined that size, shape, depth and mineral content of reserves are well established.
The term “probable reserves” means reserves for which quantity and grade are computed from information similar to that used for proven reserves, but the sites for sampling are farther apart or are otherwise less closely spaced. The degree of assurance, although lower than that for proven reserves, is high enough to assume continuity between points of observation.
Proven and probable reserves include gold, copper, silver, lead, zinc or molybdenum attributable to Newmont’s ownership or economic interest.
Proven and probable reserves were calculated using the same cut-off grades. The term “cut-off grade” means the lowest grade of mineralized material considered economic to process. Cut-off grades vary between deposits depending upon prevailing economic conditions, mineability of the deposit, by-products, amenability of the ore to gold, copper, silver, lead, zinc or molybdenum extraction and type of milling or leaching facilities available.
2019 and 2018 reserves were calculated at a gold price of $1,200 per ounce unless otherwise noted.
| (2) | Tonnages include allowances for losses resulting from mining methods. Tonnages are rounded to the nearest 100,000. |
|---|
| (3) | Ounces are estimates of metal contained in ore tonnages and do not include allowances for processing losses. Metallurgical recovery rates represent the estimated amount of metal to be recovered through metallurgical extraction processes. Ounces may not recalculate as they are rounded to the nearest 10,000. |
|---|
| (4) | Cut-off grades utilized in 2019 reserves were as follows: oxide mill material not less than 0.030 ounce per ton and leach material not less than 0.007 ounce per ton. |
|---|
| (5) | Leach pad material is the material on leach pads at the end of the year from which gold remains to be recovered. In-process reserves are reported separately where ounces exceed 100,000 and are greater than 5% of the total site-reported reserves. |
|---|
| (6) | Red Lake was classified as held for sale as of December 31, 2019. Cut-off grade utilized in 2019 reserves not less than 0.197 ounce per ton. |
|---|
| (7) | Cut-off grade utilized in 2019 reserves not less than 0.108 ounce per ton. |
|---|
| (8) | Cut-off grade utilized in 2019 reserves not less than 0.118 ounce per ton. |
|---|
| (9) | Cut-off grade utilized in 2019 reserves not less than 0.015 ounce per ton. |
|---|
| (10) | Cut-off grade utilized in 2019 reserves not less than 0.140 ounce per ton. |
|---|
| (11) | Gold cut-off grade varies with level of silver, lead and zinc credits. |
|---|
| (12) | Gold cut-off grades utilized in 2019 reserves were as follows: oxide leach material not less than 0.004 ounce per ton; oxide mill material not less than 0.014 ounce per ton; and refractory mill material not less than 0.042 ounce per ton. |
|---|
| (13) | Gold cut-off grades utilized in 2019 reserves not less than 0.054 ounce per ton. |
|---|
| (14) | Cut-off grade utilized in 2019 reserves not less than 0.011 ounce per ton. |
|---|
| (15) | Cut-off grade utilized in 2019 reserves not less than 0.146 ounce per ton. |
|---|
| (16) | Stockpiles are comprised primarily of material that has been set aside to allow processing of higher grade material in the mills. Stockpiles increase or decrease depending on current mine plans. Stockpile reserves are reported separately where ounces exceed 100,000 and are greater than 5% of the total site-reported reserves. |
|---|
| (17) | The Pueblo Viejo mine, which is 40 percent owned by Newmont, is accounted for as an equity method investment. Reserve estimates provided by Barrick, the operator of Pueblo Viejo. |
|---|
| (18) | Project is currently undeveloped. Reserve estimates provided by the NuevaUnión joint venture. |
|---|
| (19) | Project is currently undeveloped. Reserve estimates provided by the Norte Abierto joint venture. |
|---|
| (20) | Gold cut-off grade varies with level of copper credits. |
|---|
| (21) | Cut-off grade utilized in 2019 reserves not less than 0.047 ounce per ton. |
|---|
| (22) | Cut-off grade utilized in 2019 in situ reserves not less than 0.026 ounce per ton. |
|---|
| (23) | Kalgoorlie was classified as held for sale as of December 31, 2019. |
|---|
| (24) | Cut-off grade utilized in 2019 reserves not less than 0.020 ounce per ton. |
|---|
| (25) | Cut-off grade utilized in 2019 reserves not less than 0.047 ounce per ton. |
|---|
| (26) | Includes undeveloped reserves in the Ahafo trend totaling 3.4 million ounces. Cut-off grade utilized in 2019 reserves not less than 0.015 ounce per ton. |
|---|
| (27) | Cut-off grade utilized in 2019 reserves not less than 0.017 ounce per ton. |
|---|
| (28) | Reserve estimates provided by Barrick, the operator of the NGM joint venture. |
|---|
| (29) | Property was contributed to NGM on July 1, 2019. |
|---|
| (30) | Reserve estimates provided by Barrick, the operator of the Turquoise Ridge joint venture. |
|---|
The following tables detail copper proven and probable reserves reflecting only those reserves attributable to Newmont’s ownership or economic interest at December 31, 2019 and 2018:
| | | | | | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Copper Reserves At December 31, 2019(1) | | ||||||||||||||||||||||
| | | | | Proven Reserves | | Probable Reserves | | Proven and Probable Reserves | | | | ||||||||||||
| | | Newmont | | Tonnage (2) | | Grade | | Pounds (3) | | Tonnage (2) | | Grade | | Pounds (3) | | Tonnage (2) | | Grade | | Pounds (3) | | Metallurgical | |
| Deposits/Districts | Share | (000) | (Cu %) | (millions) | (000) | (Cu %) | (millions) | (000) | (Cu %) | (millions) | Recovery (3) | ||||||||||||
| South America | | | | | | | | | | | | | | | | | | | | | | | |
| Yanacocha Open Pits and Underground, Peru (4) | | 51.35% | | — | | | | — | | 59,000 | | 0.63% | | 740 | | 59,000 | | 0.63% | | 740 | | 83% | |
| NuevaUnión, Chile (5) | | 50% | | — | | | | — | | 1,232,400 | | 0.40% | | 9,760 | | 1,232,400 | | 0.40% | | 9,760 | | 88% | |
| Norte Abierto, Chile (6) | | 50% | | — | | | | — | | 660,100 | | 0.22% | | 2,890 | | 660,100 | | 0.22% | | 2,890 | | 87% | |
| | | | | — | | | | — | | 1,951,500 | | 0.34% | | 13,390 | | 1,951,500 | | 0.34% | | 13,390 | | 87% | |
| Australia | | | | | | | | | | | | | | | | | | | | | | | |
| Boddington Open Pit, Western Australia (7) | | 100% | | 258,800 | | 0.09% | | 480 | | 271,300 | | 0.11% | | 590 | | 530,100 | | 0.10% | | 1,070 | | 78% | |
| Boddington Stockpiles, Western Australia (8) | | 100% | | 4,300 | | 0.09% | | — | | 89,700 | | 0.09% | | 160 | | 94,000 | | 0.09% | | 160 | | 72% | |
| | | | | 263,100 | | 0.09% | | 480 | | 361,000 | | 0.10% | | 750 | | 624,100 | | 0.10% | | 1,230 | | 78% | |
| Nevada | | | | | | | | | | | | | | | | | | | | | | | |
| NGM, Nevada (9) | | 38.5% | | 18,800 | | 0.19% | | 70 | | 88,200 | | 0.17% | | 310 | | 107,000 | | 0.18% | | 380 | | 65% | |
| | | | | 18,800 | | 0.19% | | 70 | | 88,200 | | 0.17% | | 310 | | 107,000 | | 0.18% | | 380 | | 65% | |
| Total Copper | | | | 281,900 | | 0.10% | | 550 | | 2,400,700 | | 0.30% | | 14,450 | | 2,682,600 | | 0.28% | | 15,000 | | 86% | |
| | | | | | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Copper Reserves At December 31, 2018 (1) | | ||||||||||||||||||||||
| | | | | Proven Reserves | | Probable Reserves | | Proven and Probable Reserves | | | | ||||||||||||
| | | Newmont | | Tonnage (2) | | Grade | | Pounds (3) | | Tonnage (2) | | Grade | | Pounds (3) | | Tonnage (2) | | Grade | | Pounds (3) | | Metallurgical | |
| Deposits/Districts | Share | (000) | (Cu %) | (millions) | (000) | (Cu %) | (millions) | (000) | (Cu %) | (millions) | Recovery (3) | ||||||||||||
| South America | | | | | | | | | | | | | | | | | | | | | | | |
| Yanacocha Open Pits and Underground, Peru | | 51.35% | | — | | | | — | | 59,000 | | 0.63% | | 740 | | 59,000 | | 0.63% | | 740 | | 83% | |
| | | | | — | | | | — | | 59,000 | | 0.63% | | 740 | | 59,000 | | 0.63% | | 740 | | 83% | |
| Australia | | | | | | | | | | | | | | | | | | | | | | | |
| Boddington Open Pit, Western Australia | | 100% | | 264,900 | | 0.09% | | 500 | | 265,000 | | 0.11% | | 580 | | 529,900 | | 0.10% | | 1,080 | | 79% | |
| Boddington Stockpiles, Western Australia (8) | | 100% | | 7,600 | | 0.08% | | 10 | | 94,800 | | 0.08% | | 160 | | 102,400 | | 0.08% | | 170 | | 73% | |
| | | | | 272,500 | | 0.09% | | 510 | | 359,800 | | 0.10% | | 740 | | 632,300 | | 0.10% | | 1,250 | | 78% | |
| Nevada | | | | | | | | | | | | | | | | | | | | | | | |
| Phoenix, Nevada (10) | | 100% | | 53,200 | | 0.21% | | 230 | | 189,900 | | 0.17% | | 660 | | 243,100 | | 0.18% | | 890 | | 64% | |
| | | | | 53,200 | | 0.21% | | 230 | | 189,900 | | 0.17% | | 660 | | 243,100 | | 0.18% | | 890 | | 64% | |
| Total Copper | | | | 325,700 | | 0.11% | | 740 | | 608,700 | | 0.18% | | 2,140 | | 934,400 | | 0.15% | | 2,880 | | 77% | |
| (1) | See footnote (1) to the Gold Proven and Probable Reserves tables above. Copper reserves for 2019 were calculated at a copper price of $2.75 per pound. Copper reserves for 2018 were calculated at a copper price of $2.50 per pound. |
|---|
| (2) | See footnote (2) to the Gold Proven and Probable Reserves tables above. Tonnages are rounded to nearest 100,000. |
|---|
| (3) | See footnote (3) to the Gold Proven and Probable Reserves tables above. Pounds may not recalculate as they are rounded to the nearest 10 million. |
|---|
| (4) | Copper cut-off grade varies with level of gold and silver credits. |
|---|
| (5) | Project is currently undeveloped. Reserve estimates provided by the NuevaUnión joint venture. |
|---|
| (6) | Project is currently undeveloped. Reserve estimates provided by the Norte Abierto joint venture. |
|---|
| (7) | Copper cut-off grade varies with level of gold credits. |
|---|
| (8) | Stockpiles are comprised primarily of material that has been set aside to allow processing of higher grade material in the mills. Stockpiles increase or decrease depending on current mine plans. Stockpiles are reported separately where pounds exceed 100 million and are greater than 5% of the total site reported reserves. |
|---|
| (9) | Reserve estimates provided by Barrick, the operator of the NGM joint venture. |
|---|
| (10) | Property was contributed to NGM on July 1, 2019. |
|---|
The following tables detail silver proven and probable reserves reflecting only those reserves attributable to Newmont’s ownership or economic interest at December 31, 2019 and 2018:
| | | | | | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Silver Reserves At December 31, 2019 (1) | | ||||||||||||||||||||||
| | | | | Proven Reserves | | Probable Reserves | | Proven and Probable Reserves | | | | ||||||||||||
| | | Newmont | | Tonnage (2) | | Grade | | Ounces (3) | | Tonnage (2) | | Grade | | Ounces (3) | | Tonnage (2) | | Grade | | Ounces (3) | | Metallurgical | |
| Deposits/Districts | Share | (000) | (oz/ton) | (000) | (000) | (oz/ton) | (000) | (000) | (oz/ton) | (000) | Recovery (3) | ||||||||||||
| North America | | | | | | | | | | | | | | | | | | | | | | | |
| Peñasquito Open Pits, Mexico (4) | | 100% | | 116,000 | | 1.092 | | 126,630 | | 335,700 | | 0.941 | | 315,830 | | 451,700 | | 0.980 | | 442,460 | | 90% | |
| Peñasquito Stockpiles, Mexico (5) | | 100% | | 5,000 | | 1.554 | | 7,730 | | 30,100 | | 0.703 | | 21,170 | | 35,100 | | 0.824 | | 28,900 | | 86% | |
| | | | | 121,000 | | 1.111 | | 134,360 | | 365,800 | | 0.921 | | 337,000 | | 486,800 | | 0.968 | | 471,360 | | 89% | |
| South America | | | | | | | | | | | | | | | | | | | | | | | |
| Yanacocha Open Pits and Underground, Peru (6) | | 51.35% | | 5,000 | | 0.298 | | 1,500 | | 62,500 | | 0.538 | | 33,600 | | 67,500 | | 0.520 | | 35,100 | | 46% | |
| Yanacocha Stockpiles, Peru (5) | | 51.35% | | 1,400 | | 1.162 | | 1,640 | | 1,600 | | 1.217 | | 1,920 | | 3,000 | | 1.191 | | 3,560 | | 58% | |
| Yanacocha Leach Pads, Peru (7) | | 51.35% | | — | | | | — | | 58,400 | | 0.239 | | 13,950 | | 58,400 | | 0.239 | | 13,950 | | 6% | |
| Total Yanacocha, Peru | | | | 6,400 | | 0.488 | | 3,140 | | 122,500 | | 0.404 | | 49,470 | | 128,900 | | 0.408 | | 52,610 | | 36% | |
| Cerro Negro, Argentina (8) | | 100% | | 1,200 | | 2.872 | | 3,400 | | 8,100 | | 2.237 | | 17,940 | | 9,300 | | 2.319 | | 21,340 | | 75% | |
| Pueblo Viejo, Dominican Republic (9) | | 40% | | 7,400 | | 0.421 | | 3,130 | | 45,100 | | 0.476 | | 21,440 | | 52,500 | | 0.468 | | 24,570 | | 77% | |
| NuevaUnión, Chile (10) | | 50% | | — | | | | — | | 856,400 | | 0.045 | | 38,440 | | 856,400 | | 0.045 | | 38,440 | | 65% | |
| Norte Abierto, Chile (11) | | 50% | | — | | | | — | | 660,100 | | 0.044 | | 29,340 | | 660,100 | | 0.044 | | 29,340 | | 74% | |
| | | | | 15,000 | | 0.643 | | 9,670 | | 1,692,200 | | 0.093 | | 156,630 | | 1,707,200 | | 0.097 | | 166,300 | | 60% | |
| Nevada | | | | | | | | | | | | | | | | | | | | | | | |
| NGM, Nevada (12) | | 38.5% | | 6,400 | | 0.239 | | 1,550 | | 64,800 | | 0.204 | | 13,210 | | 71,200 | | 0.207 | | 14,760 | | 38% | |
| | | | | 6,400 | | 0.239 | | 1,550 | | 64,800 | | 0.204 | | 13,210 | | 71,200 | | 0.207 | | 14,760 | | 38% | |
| Total Silver | | | | 142,400 | | 1.022 | | 145,580 | | 2,122,800 | | 0.239 | | 506,840 | | 2,265,200 | | 0.288 | | 652,420 | | 76% | |
| | | | | | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Silver Reserves At December 31, 2018 (1) | | ||||||||||||||||||||||
| | | | | Proven Reserves | | Probable Reserves | | Proven and Probable Reserves | | | | ||||||||||||
| | | Newmont | | Tonnage (2) | | Grade | | Ounces (3) | | Tonnage (2) | | Grade | | Ounces (3) | | Tonnage (2) | | Grade | | Ounces (3) | | Metallurgical | |
| Deposits/Districts | Share | (000) | (oz/ton) | (000) | (000) | (oz/ton) | (000) | (000) | (oz/ton) | (000) | Recovery (3) | ||||||||||||
| South America | | | | | | | | | | | | | | | | | | | | | | | |
| Yanacocha Open Pits, Peru | | 51.35% | | 7,500 | | 0.228 | | 1,710 | | 65,900 | | 0.518 | | 34,110 | | 73,400 | | 0.488 | | 35,820 | | 46% | |
| Yanacocha Stockpiles, Peru (4) | | 51.35% | | 2,400 | | 1.090 | | 2,490 | | 1,600 | | 1.220 | | 2,020 | | 4,000 | | 1.140 | | 4,510 | | 48% | |
| Yanacocha Leach Pads, Peru (5) | | 51.35% | | — | | | | — | | 54,600 | | 0.250 | | 13,460 | | 54,600 | | 0.250 | | 13,460 | | 6% | |
| | | | | 9,900 | | 0.430 | | 4,200 | | 122,100 | | 0.410 | | 49,590 | | 132,000 | | 0.410 | | 53,790 | | 36% | |
| Nevada | | | | | | | | | | | | | | | | | | | | | | | |
| Phoenix, Nevada (13) | | 100% | | 13,200 | | 0.250 | | 3,360 | | 133,200 | | 0.210 | | 28,550 | | 146,400 | | 0.220 | | 31,910 | | 38% | |
| | | | | 13,200 | | 0.250 | | 3,360 | | 133,200 | | 0.210 | | 28,550 | | 146,400 | | 0.220 | | 31,910 | | 38% | |
| Total Silver | | | | 23,100 | | 0.330 | | 7,560 | | 255,300 | | 0.310 | | 78,140 | | 278,400 | | 0.310 | | 85,700 | | 36% | |
| (1) | See footnote (1) to the Gold Proven and Probable Reserves tables above. Silver reserves for 2019 and 2018 were calculated at a silver price of $16 per ounce. |
|---|
| (2) | See footnote (2) to the Gold Proven and Probable Reserves tables above. Tonnages are rounded to nearest 100,000. |
|---|
| (3) | See footnote (3) to the Gold Proven and Probable Reserves tables above. |
|---|
| (4) | Silver cut-off grade varies with gold, lead and zinc credits. |
|---|
| (5) | Stockpiles are comprised primarily of material that has been set aside to allow processing of higher grade material in the mills. Stockpiles increase or decrease depending on current mine plans. Stockpile reserves are reported separately where ounces exceed 100,000 and are greater than 5% of the total site-reported reserves. |
|---|
| (6) | Silver cut-off grade varies with gold and copper credits. |
|---|
| (7) | Leach pad material is the material on leach pads at the end of the year from which silver remains to be recovered. In-process reserves are reported separately where ounces exceed 100,000 and are greater than 5% of the total site-reported reserves. |
|---|
| (8) | Silver cut-off grade varies with gold credits. |
|---|
| (9) | The Pueblo Viejo mine, which is 40 percent owned by Newmont, is accounted for as an equity method investment. Reserve estimates provided by Barrick, the operator of Pueblo Viejo. |
|---|
| (10) | Project is currently undeveloped. Reserve estimates provided by the NuevaUnión joint venture. |
|---|
| (11) | Project is currently undeveloped. Reserve estimates provided by the Norte Abierto joint venture. |
|---|
| (12) | Reserve estimates provided by Barrick, the operator of the NGM joint venture. |
|---|
| (13) | Property was contributed to NGM on July 1, 2019. |
|---|
The following tables detail lead proven and probable reserves reflecting only those reserves attributable to Newmont’s ownership or economic interest at December 31, 2019:
| | | | | | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Lead Reserves At December 31, 2019 (1) | | ||||||||||||||||||||||
| | | | | Proven Reserves | | Probable Reserves | | Proven and Probable Reserves | | | | ||||||||||||
| | | Newmont | | Tonnage (2) | | Grade | | Pounds (3) | | Tonnage (2) | | Grade | | Pounds (3) | | Tonnage (2) | | Grade | | Pounds (3) | | Metallurgical | |
| Deposits/Districts | Share | (000) | (Pb %) | (millions) | (000) | (Pb %) | (millions) | (000) | (Pb %) | (millions) | Recovery (3) | | |||||||||||
| North America | | | | | | | | | | | | | | | | | | | | | | | |
| Peñasquito Open Pits (4) | | 100% | | 114,200 | | 0.39% | | 880 | | 334,200 | | 0.32% | | 2,140 | | 448,400 | | 0.34% | | 3,020 | | 75% | |
| Peñasquito Stockpiles (5) | | 100% | | 5,000 | | 0.54% | | 50 | | 30,100 | | 0.32% | | 190 | | 35,100 | | 0.35% | | 240 | | 64% | |
| Total Lead | | | | 119,200 | | 0.39% | | 930 | | 364,300 | | 0.32% | | 2,330 | | 483,500 | | 0.34% | | 3,260 | | 74% | |
| (1) | See footnote (1) to the Gold Proven and Probable Reserves tables above. Lead reserves for 2019 were calculated at a lead price of $0.95 per pound. |
|---|
| (2) | See footnote (2) to the Gold Proven and Probable Reserves tables above. Tonnages are rounded to nearest 100,000. |
|---|
| (3) | See footnote (3) to the Gold Proven and Probable Reserves tables above. Pounds may not recalculate as they are rounded to the nearest 10 million. |
|---|
| (4) | Lead cut-off grade varies with level of gold, silver and zinc credits. |
|---|
| (5) | Stockpiles are comprised primarily of material that has been set aside to allow processing of higher grade material in the mills. Stockpiles increase or decrease depending on current mine plans. Stockpile reserves are reported separately where pounds exceed 100 million and are greater than 5% of the total site-reported reserves. |
|---|
The following tables detail zinc proven and probable reserves reflecting only those reserves attributable to Newmont’s ownership or economic interest at December 31, 2019:
| | | | | | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Zinc Reserves At December 31, 2019 (1) | | ||||||||||||||||||||||
| | | | | Proven Reserves | | Probable Reserves | | Proven and Probable Reserves | | | | ||||||||||||
| | | Newmont | | Tonnage (2) | | Grade | | Pounds (3) | | Tonnage (2) | | Grade | | Pounds (3) | | Tonnage (2) | | Grade | | Pounds (3) | | Metallurgical | |
| Deposits/Districts | Share | (000) | (Zn %) | (millions) | (000) | (Zn %) | (millions) | (000) | (Zn %) | (millions) | Recovery (3) | | |||||||||||
| North America | | | | | | | | | | | | | | | | | | | | | | | |
| Peñasquito, Mexico (4) | | 100% | | 119,200 | | 0.93% | | 2,210 | | 364,300 | | 0.71% | | 5,210 | | 483,500 | | 0.77% | | 7,420 | | 81% | |
| Total Zinc | | | | 119,200 | | 0.93% | | 2,210 | | 364,300 | | 0.71% | | 5,210 | | 483,500 | | 0.77% | | 7,420 | | 81% | |
| (1) | See footnote (1) to the Gold Proven and Probable Reserves tables above. Zinc reserves for 2019 were calculated at a zinc price of $1.20 per pound. |
|---|
| (2) | See footnote (2) to the Gold Proven and Probable Reserves tables above. Tonnages are rounded to nearest 100,000. |
|---|
| (3) | See footnote (3) to the Gold Proven and Probable Reserves tables above. Pounds may not recalculate as they are rounded to the nearest 10 million. |
|---|
| (4) | Zinc cut-off grade varies with level of gold, silver and lead credits. |
|---|
The following tables detail molybdenum proven and probable reserves reflecting only those reserves attributable to Newmont’s ownership or economic interest at December 31, 2019:
| | | | | | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Molybdenum Reserves At December 31, 2019 (1) | | ||||||||||||||||||||||
| | | | | Proven Reserves | | Probable Reserves | | Proven and Probable Reserves | | | | ||||||||||||
| | | Newmont | | Tonnage (2) | | Grade | | Pounds (3) | | Tonnage (2) | | Grade | | Pounds (3) | | Tonnage (2) | | Grade | | Pounds (3) | | Metallurgical | |
| Deposits/Districts | Share | (000) | (Mo %) | (millions) | (000) | (Mo %) | (millions) | (000) | (Mo %) | (millions) | Recovery (3) | | |||||||||||
| North America | | | | | | | | | | | | | | | | | | | | | | | |
| NuevaUnión, Chile | | 50% | | — | | | | — | | 856,400 | | 0.02% | | 270 | | 856,400 | | 0.02% | | 270 | | 48% | |
| Total Molybdenum | | | | — | | | | — | | 856,400 | | 0.02% | | 270 | | 856,400 | | 0.02% | | 270 | | 48% | |
| (1) | See footnote (1) to the Gold Proven and Probable Reserves tables above. Reserves estimates provided by the NuevaUnión joint venture. The project is currently undeveloped. |
|---|
| (2) | See footnote (2) to the Gold Proven and Probable Reserves tables above. Tonnages are rounded to nearest 100,000. |
|---|
| (3) | See footnote (3) to the Gold Proven and Probable Reserves tables above. Pounds may not recalculate as they are rounded to the nearest 10 million |
|---|
Mineralized Material
On April 18, 2019, we completed the business acquisition of Goldcorp and acquired the Red Lake, Musselwhite, Porcupine, Éléonore, Peñasquito and Cerro Negro operations, a 40% interest in the Pueblo Viejo mine, 50% interest in the Noche Buena project, the NuevaUnión project and the Norte Abierto project, respectively, and a 37.5% interest in the Alumbrera mine. For further information, see Note 3 to the Consolidated Financial Statements. On July 1, 2019, we contributed our existing Nevada mining operations, which included Carlin, Phoenix, Twin Creeks and Long Canyon, to NGM in exchange for a 38.5% interest in NGM. For further information, see Note 4 to the Consolidated Financial Statements.
All of our mineralized material is located on land that we own or control. The risks that could affect title to our property are included above in Item 1A, Risk Factors. Mineralized material is a mineralized ore body which has been intersected by a sufficient number of closely spaced drill holes and/or underground sampling to support sufficient tonnage and average grade of metal(s) to warrant further exploration development work. The deposit does not qualify as a commercially minable ore body until it can be legally and economically extracted or produced at the time of the reserve determination. Metal price assumptions are based on approximately a fifteen to twenty-five percent premium over reserve prices.
Our exploration efforts are directed to the discovery of new mineralized material and converting it into proven and probable reserves. We conduct brownfield exploration around our existing mines and greenfield exploration in other regions globally. Brownfield exploration can result in the discovery of additional deposits, which may receive the economic benefit of existing operating, processing and administrative infrastructures. In contrast, the discovery of mineralization through greenfield exploration efforts will require capital investment to build a stand-alone operation. Our Exploration expense was $265, $197 and $179 in 2019, 2018 and 2017, respectively.
We had attributable gold mineralized material of 3,659 million tons at an average grade of 0.021 ounces per ton at December 31, 2019. For 2019 and 2018, attributable gold mineralized material was calculated at a gold price assumption of $1,400 per ounce.
At December 31, 2019, our gold mineralized material included 1,478 million tons in North America, 1,477 million tons in South America, 453 million tons in Australia, 65 million tons in Africa and 185 million tons in Nevada.
We had attributable copper mineralized material of 2,747 million tons at a grade of 0.27% at December 31, 2019. For 2019 and 2018, attributable copper mineralized material was calculated at a copper price assumption of $3.25 per pound.
We had attributable silver mineralized material of 2,774 million tons at a grade of 0.174 ounces per ton at December 31, 2019. For 2019 and 2018, attributable silver mineralized material was calculated at a silver price assumption of $20 per ounce. Silver mineralized material is generally a by-product of gold and/or copper mineralized material estimates, other than at Peñasquito where silver mineralized material is accounted for as a co-product, with significant enough levels to be estimated and included in future calculations of potential economic extraction.
We had attributable lead mineralized material of 363 million tons at a grade of 0.24% at December 31, 2019. For 2019, attributable lead mineralized material was calculated at a lead price assumption of $1.15 per pound.
We had attributable zinc mineralized material of 363 million tons at a grade of 0.56% at December 31, 2019. For 2019, attributable zinc mineralized material was calculated at a lead price assumption of $1.45 per pound.
We had attributable molybdenum mineralized material at NuevaUnión and Alumbrera of 482 million tons at a grade of 0.01% at December 31, 2019. For 2019, attributable molybdenum mineralized material was calculated based on prices set by the NuevaUnión joint venture and Glencore, respectively.
The mineralized material figures presented herein do not include that part of our mineralized material that has been converted to Proven and Probable Reserves as shown above, as they are reported exclusive of reserves, and have been estimated based on information available at the time of calculation. Market fluctuations in the price of gold, copper, silver, lead, zinc and molybdenum, as well as increased production costs or reduced metallurgical recovery rates, could render certain mineralized material containing lower grades of mineralization uneconomic to exploit and might result in a reduction of mineralized material.
We will publish mineralized materials annually, and will recalculate them at December 31, 2020, taking into account metal prices, changes, if any, in future production and capital costs, divestments and conversion to reserves, as well as any acquisitions and additions during 2020.
Mineralized material is reported exclusive of reserves. Mineralized material as used in this annual report, although permitted by the SEC, does not indicate “reserves” as defined in the SEC’s Industry Guide 7. Newmont cannot be certain that any part of the reported mineralized material will ever be confirmed or converted into SEC Industry Guide 7 compliant “reserves.” Investors are cautioned not to assume that all or any part of the mineralized material will ever be confirmed or converted into reserves or that mineralized material can be economically or legally extracted.
The following tables detail mineralized material reflecting only those that are attributable to Newmont’s ownership or economic interest at December 31, 2019 and 2018:
| | | | | | | | | | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Mineralized Material At December 31, 2019 (1)(2) | | ||||||||||||||||||||||||||
| | | | | Gold | | Copper | | Silver | | Lead | | Zinc | | Molybdenum | | ||||||||||||
| | Newmont | Tonnage | Grade | Tonnage | Grade | Tonnage | Grade | Tonnage | Grade | Tonnage | Grade | Tonnage | Grade | ||||||||||||||
| Deposits/Districts | | Share | | (000) | | (oz/ton) | | (000) | | (Cu %) | | (000) | | (oz/ton) | | (000) | | (Pb %) | | (000) | | (Zn %) | | (000) | | (Mo %) | |
| North America | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| CC&V, Colorado | | 100% | | 122,100 | | 0.014 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Red Lake, Canada | | 100% | | 1,400 | | 0.506 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Musselwhite, Canada | | 100% | | 6,900 | | 0.119 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Porcupine Underground | | 100% | | 900 | | 0.134 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Porcupine Open Pit | | 100% | | 276,800 | | 0.026 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Total Porcupine, Canada | | | | 277,700 | | 0.027 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Éléonore, Canada | | 100% | | 3,100 | | 0.133 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Peñasquito, Mexico | | 100% | | 376,200 | | 0.007 | | — | | | | 376,200 | | 0.723 | | 362,800 | | 0.24% | | 362,800 | | 0.56% | | — | | | |
| Noche Buena, Mexico | | 50% | | 30,300 | | 0.011 | | — | | | | 30,300 | | 0.360 | | — | | | | — | | | | — | | | |
| Sandman, Nevada | | 100% | | 1,300 | | 0.036 | | — | | | | 1,300 | | 0.199 | | — | | | | — | | | | — | | | |
| Coffee, Canada | | 100% | | 51,100 | | 0.042 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Galore Creek, Canada (3) | | 50% | | 608,300 | | 0.008 | | 608,300 | | 0.47% | | 608,300 | | 0.123 | | — | | | | — | | | | — | | | |
| | | | | 1,478,400 | | 0.014 | | 608,300 | | 0.47% | | 1,016,100 | | 0.353 | | 362,800 | | 0.24% | | 362,800 | | 0.56% | | — | | | |
| South America | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Conga, Peru | | 51.35% | | 392,700 | | 0.019 | | 392,700 | | 0.26% | | 392,700 | | 0.060 | | — | | | | — | | | | — | | | |
| Yanacocha Open Pits and Stockpiles | | 51.35% | | 43,100 | | 0.014 | | 3,200 | | 0.32% | | 13,700 | | 0.270 | | — | | | | — | | | | — | | | |
| Yanacocha Underground | | 51.35% | | 1,700 | | 0.190 | | 1,700 | | 0.07% | | 1,700 | | 2.146 | | — | | | | — | | | | — | | | |
| Total Yanacocha, Peru | | | | 44,800 | | 0.021 | | 4,900 | | 0.20% | | 15,400 | | 0.479 | | — | | | | — | | | | — | | | |
| Merian, Suriname | | 75% | | 40,600 | | 0.033 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Cerro Negro, Argentina | | 100% | | 13,400 | | 0.158 | | — | | | | 13,400 | | 0.820 | | — | | | | — | | | | — | | | |
| Pueblo Viejo, Dominican Republic (4) | | 40% | | 97,500 | | 0.065 | | — | | | | 97,500 | | 0.337 | | — | | | | — | | | | — | | | |
| NuevaUnión, Chile (5) | | 50% | | 87,300 | | 0.018 | | 518,300 | | 0.28% | | 431,000 | | 0.033 | | — | | | | — | | | | 431,000 | | 0.01% | |
| Norte Abierto, Chile (6) | | 50% | | 743,200 | | 0.015 | | 671,100 | | 0.20% | | 743,200 | | 0.032 | | — | | | | — | | | | — | | | |
| Alumbrera, Argentina (7) | | 37.5% | | 57,700 | | 0.011 | | 57,700 | | 0.36% | | — | | | | — | | | | — | | | | 50,900 | | 0.01% | |
| | | | | 1,477,200 | | 0.021 | | 1,644,700 | | 0.24% | | 1,693,200 | | 0.066 | | — | | | | — | | | | 481,900 | | 0.01% | |
| Australia | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Boddington, Western Australia | | 100% | | 395,200 | | 0.016 | | 395,200 | | 0.12% | | — | | | | — | | | | — | | | | — | | | |
| Tanami, Northern Territory | | 100% | | 19,500 | | 0.065 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Kalgoorlie, Western Australia | | 50% | | 38,000 | | 0.050 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| | | | | 452,700 | | 0.021 | | 395,200 | | 0.12% | | — | | | | — | | | | — | | | | — | | | |
| Africa | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Ahafo South | | 100% | | 28,900 | | 0.035 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Ahafo Underground | | 100% | | 17,600 | | 0.115 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Total Ahafo South, Ghana | | | | 46,500 | | 0.065 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Ahafo North Open Pits, Ghana | | 100% | | 11,400 | | 0.054 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Akyem Open Pits | | 100% | | 3,300 | | 0.016 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Akyem Underground | | 100% | | 4,200 | | 0.121 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Akyem, Ghana | | | | 7,500 | | 0.075 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| | | | | 65,400 | | 0.064 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Nevada | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| NGM Open Pits, Nevada | | 38.5% | | 154,700 | | 0.033 | | 99,200 | | 0.14% | | 64,500 | | 0.168 | | — | | | | — | | | | — | | | |
| NGM Underground, Nevada | | 38.5% | | 30,300 | | 0.194 | | — | | | | — | | | | — | | | | — | | | | — | | | |
| Total NGM, Nevada (8) | | | | 185,000 | | 0.059 | | 99,200 | | 0.14% | | 64,500 | | 0.168 | | — | | | | — | | | | — | | | |
| Total | | | | 3,658,700 | | 0.021 | | 2,747,400 | | 0.27% | | 2,773,800 | | 0.174 | | 362,800 | | 0.24% | | 362,800 | | 0.56% | | 481,900 | | 0.01% | |
| | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Mineralized Material At December 31, 2018 (1)(2) | | ||||||||||||||
| | | | | Gold | | Copper | | Silver | | ||||||
| | Newmont | Tonnage | Grade | Tonnage | Grade | Tonnage | Grade | ||||||||
| Deposits/Districts | | Share | | (000) | | (oz/ton) | | (000) | | (Cu %) | | (000) | | (oz/ton) | |
| North America | | | | | | | | | | | | | | | |
| CC&V, Colorado | | 100% | | 77,800 | | 0.015 | | — | | | | — | | | |
| Sandman, Nevada | | 100% | | 1,300 | | 0.036 | | — | | | | 1,300 | | 0.200 | |
| Galore Creek, Canada (3) | | 50% | | 608,300 | | 0.008 | | 608,300 | | 0.47% | | 608,300 | | 0.120 | |
| | | | | 687,400 | | 0.009 | | 608,300 | | 0.47% | | 609,600 | | 0.123 | |
| South America | | | | | | | | | | | | | | | |
| Conga, Peru | | 51.35% | | 392,700 | | 0.019 | | 392,700 | | 0.26% | | 392,700 | | 0.060 | |
| Yanacocha Open Pits and Stockpiles | | 51.35% | | 42,700 | | 0.012 | | 2,200 | | 0.12% | | 16,600 | | 0.280 | |
| Yanacocha Underground | | 51.35% | | 2,500 | | 0.161 | | — | | | | 2,200 | | 1.480 | |
| Total Yanacocha, Peru | | | | 45,200 | | 0.020 | | 2,200 | | 0.12% | | 18,800 | | 0.416 | |
| Merian, Suriname | | 75% | | 37,400 | | 0.033 | | — | | | | — | | | |
| | | | | 475,300 | | 0.020 | | 394,900 | | 0.26% | | 411,500 | | 0.080 | |
| Australia | | | | | | | | | | | | | | | |
| Boddington, Western Australia | | 100% | | 384,600 | | 0.016 | | 384,600 | | 0.12% | | — | | | |
| Tanami, Northern Territory | | 100% | | 9,300 | | 0.099 | | — | | | | — | | | |
| Kalgoorlie, Western Australia | | 50% | | 33,800 | | 0.044 | | — | | | | — | | | |
| | | | | 427,700 | | 0.020 | | 384,600 | | 0.12% | | — | | | |
| Africa | | | | | | | | | | | | | | | |
| Ahafo South | | 100% | | 29,700 | | 0.034 | | — | | | | — | | | |
| Ahafo Underground | | 100% | | 11,000 | | 0.140 | | — | | | | — | | | |
| Total Ahafo South, Ghana | | | | 40,700 | | 0.063 | | — | | | | — | | | |
| Ahafo North Open Pits, Ghana | | 100% | | 10,800 | | 0.048 | | — | | | | — | | | |
| Akyem Open Pits | | 100% | | 2,300 | | 0.016 | | — | | | | — | | | |
| Akyem Underground | | 100% | | 4,100 | | 0.134 | | — | | | | — | | | |
| Akyem, Ghana | | | | 6,400 | | 0.089 | | — | | | | — | | | |
| | | | | 57,900 | | 0.063 | | — | | | | — | | | |
| Nevada (9) | | | | | | | | | | | | | | | |
| Carlin Trend Open Pit | | 100% | | 111,500 | | 0.038 | | — | | | | — | | | |
| Carlin Trend Underground | | 100% | | 3,600 | | 0.176 | | — | | | | — | | | |
| Total Carlin, Nevada | | | | 115,100 | | 0.042 | | — | | | | — | | | |
| Phoenix | | 100% | | 113,700 | | 0.014 | | 196,200 | | 0.14% | | 113,700 | | 0.190 | |
| Buffalo Valley | | 70% | | 15,500 | | 0.019 | | — | | | | — | | | |
| Total Phoenix, Nevada | | | | 129,200 | | 0.015 | | 196,200 | | 0.14% | | 113,700 | | 0.190 | |
| Twin Creeks | | 100% | | 36,500 | | 0.063 | | — | | | | — | | | |
| Twin Creeks Stockpiles (10) | | 100% | | 9,000 | | 0.059 | | — | | | | — | | | |
| Turquoise Ridge (11) | | 25% | | 2,000 | | 0.231 | | — | | | | — | | | |
| Total Twin Creeks, Nevada | | | | 47,500 | | 0.069 | | — | | | | — | | | |
| Long Canyon, Nevada | | 100% | | 16,000 | | 0.103 | | — | | | | — | | | |
| | | | | 307,800 | | 0.038 | | 196,200 | | 0.14% | | 113,700 | | 0.190 | |
| Total | | | | 1,956,100 | | 0.020 | | 1,584,000 | | 0.29% | | 1,134,800 | | 0.110 | |
| (1) | Mineralized material is reported exclusive of reserves. “Mineralized material” as used in this annual report, although permitted by the SEC, does not indicate “reserves” as defined in the SEC’s Industry Guide 7. Newmont cannot be certain that any part of the reported mineralized material will ever be confirmed or converted into SEC Industry Guide 7 compliant “reserves.” Investors are cautioned not to assume that all or any part of the mineralized material will ever be confirmed or converted into reserves or that mineralized material can be economically or legally extracted. |
|---|
| (2) | Mineralized material for 2019 and 2018 was calculated at a gold price of $1,400 per ounce. Mineralized material for 2019 and 2018 was calculated at a copper price of $3.25 per pound. Mineralized material for 2019 and 2018 was calculated at a silver price of $20 per ounce. Mineralized material for 2019 was calculated at a lead price of $1.15 per pound and a zinc price of $1.45 per pound. Mineralized material for 2019 was estimated based on molybdenum prices set by the NuevaUnión joint venture and Glencore, respectively. Tonnage amounts have been rounded to the nearest 100,000. |
|---|
| (3) | Project is currently undeveloped. Mineralized material estimates were provided by Teck Resources. |
|---|
| (4) | Mineralized material estimates were provided by Barrick, the operator of Pueblo Viejo. |
|---|
| (5) | Project is currently undeveloped. Mineralized material estimates were provided by the NuevaUnión joint venture. |
|---|
| (6) | Project is currently undeveloped. Mineralized material estimates were provided by the Norte Abierto joint venture. |
|---|
| (7) | Mineralized material estimates were provided by Glencore. |
|---|
| (8) | Mineralized material estimates were provided by Barrick, the operator of the NGM joint venture. |
|---|
| (9) | Property was contributed to NGM on July 1, 2019. |
|---|
| (10) | Stockpiles are comprised primarily of Mineralized material that has been set aside during mining activities. Stockpiles can increase or decrease depending on changes in metal prices and other mining and processing cost and recovery factors. Stockpile Mineralized material are reported separately where tonnage exceeds 100,000 and is greater than 5% of the total site-reported mineralized material. |
|---|
| (11) | Mineralized material estimates were provided by Barrick, the operator of the Turquoise Ridge joint venture. |
|---|
Previous: Item 1A. RISK FACTORS (dollars in millions, except per share, per ounce and per pound amounts) · Next: Item 3. LEGAL PROCEEDINGS