 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
127K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
associated with certain materials and supplies. To the extent that delays occur or our costs increase, our business operations, results of operations, cash flows, and financial condition could be materially adversely affected.
We are faced with increased competition for employee and contractor talent in the current labor market, which has resulted in increased costs to attract and retain talent. We are ensuring that we use all internal human capital programs (development, leadership enablement programs, succession, performance management) to promote retention of our current employees along with having competitive and attractive appeal for potential recruits. With a focus on workforce planning, we are creating flexible work arrangements where we can, and being anticipatory in evaluating our talent footprint for the future to ensure we have the right people, in the right role, and at the right time. To the extent we are unable to execute on our workforce planning initiatives and experience increased employee and contractor costs, our business operations, results of operations, cash flows, and financial condition could be materially adversely affected.
We have also seen an increase in gas costs that we expect to have an effect on customer bills. For the year ended December 31, 2021, we have not seen this increase have a material impact on our results of operations. For more information on our commodity price impacts, see " - Results and Discussion of Segment Operations - Gas Distribution Operations," and " - Market Risk Disclosures."
For more information on global availability of materials for our renewable projects, see " - Results and Discussion of Segment Operations - Electric Operations - Electric Supply and Generation Transition."
Summary of Consolidated Financial Results
A summary of our consolidated financial results for the years ended December 31, 2021, 2020 and 2019, are presented below:
| Favorable (Unfavorable) | |||||||||||||||||||||||||||||
| Year Ended December 31*,* (in millions, except per share amounts) | 2021 | 2020 | 2019 | 2021 vs. 2020 | 2020 vs. 2019 | ||||||||||||||||||||||||
| Operating Revenues | $ | 4,899.6 | $ | 4,681.7 | $ | 5,208.9 | $ | 217.9 | $ | (527.2) | |||||||||||||||||||
| Operating Expenses | |||||||||||||||||||||||||||||
| Cost of energy | 1,392.3 | 1,109.3 | 1,534.8 | (283.0) | 425.5 | ||||||||||||||||||||||||
| Other Operating Expenses | 2,500.4 | 3,021.6 | 2,783.4 | 521.2 | (238.2) | ||||||||||||||||||||||||
| Total Operating Expenses | 3,892.7 | 4,130.9 | 4,318.2 | 238.2 | 187.3 | ||||||||||||||||||||||||
| Operating Income | 1,006.9 | 550.8 | 890.7 | 456.1 | (339.9) | ||||||||||||||||||||||||
| Total Other Deductions, Net | (300.3) | (582.1) | (384.1) | 281.8 | (198.0) | ||||||||||||||||||||||||
| Income Taxes | 117.8 | (17.1) | 123.5 | (134.9) | 140.6 | ||||||||||||||||||||||||
| Net Income (Loss) | 588.8 | (14.2) | 383.1 | 603.0 | (397.3) | ||||||||||||||||||||||||
| Net income (loss) attributable to noncontrolling interest | 3.9 | 3.4 | — | (0.5) | (3.4) | ||||||||||||||||||||||||
| Net Income (Loss) attributable to NiSource | 584.9 | (17.6) | 383.1 | 602.5 | (400.7) | ||||||||||||||||||||||||
| Preferred dividends | (55.1) | (55.1) | (55.1) | — | — | ||||||||||||||||||||||||
| Net Income (Loss) Available to Common Shareholders | 529.8 | (72.7) | 328.0 | 602.5 | (400.7) | ||||||||||||||||||||||||
| Basic Earnings (Loss) Per Share | $ | 1.35 | $ | (0.19) | $ | 0.88 | $ | 1.54 | $ | (1.07) | |||||||||||||||||||
| Diluted Earnings (Loss) Per Share | $ | 1.27 | $ | (0.19) | $ | 0.87 | $ | 1.46 | $ | (1.06) |
The majority of the costs of energy in both segments are tracked costs that are passed through directly to the customer, resulting in an equal and offsetting amount reflected in operating revenues.
The increase in net income available to common shareholders during 2021 was primarily due to higher operating income for the year ended December 31, 2021 compared to the same period in 2020. Operating revenues were higher due to favorable rate case outcomes in 2021. Operating expenses were lower as we did not have expenses associated with the Massachusetts business in 2021, and the loss on sale of the Massachusetts business was primarily incurred in 2020. For additional information on operating income variance drivers see "Results and Discussion of Segment Operations" for Gas and Electric Operations in this Management's Discussion. In addition, we recognized a favorable change in total other deductions, which was partially offset by an increase in income tax expense in 2021. See below for the primary drivers of this change.
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Other Deductions, Net
The change in Other deductions, net in 2021 compared to 2020 is primarily driven by the loss on early extinguishment of debt in 2020, lower long-term and short-term debt interest in 2021 and higher non-service pension benefits partially offset by charitable contributions in 2021. The lower interest in 2021 was due to the early extinguishment of high rate debt in 2020 and lower balances on short-term debt during the year ended December 31, 2021 compared to the same period in 2020. See Note 15, "Long-Term Debt," Note 16, "Short-Term Borrowings," and Note 12, "Pension and Other Postretirement Benefits," in the Notes to the Consolidated Financial Statements for additional information.
Income Taxes
The increase in income tax expense in 2021 compared to the same period in 2020 is primarily attributable to higher pre-tax income, resulting from the items discussed above, state jurisdictional mix of pre-tax income in 2021 tax effected at statutory tax rates and increased amortization of excess deferred federal income taxes in 2021 compared to 2020. These items are offset by decreased deferred tax expense recognized on the sale of the Columbia of Massachusetts' regulatory liability in 2020, established due to TCJA in 2017, that would have otherwise been recognized over the amortization period and one-time adjustments to deferred tax balances.
Refer to Note 11, "Income Taxes," in the Notes to Consolidated Financial Statements for additional information on income taxes and the change in the effective tax rate.
RESULTS AND DISCUSSION OF OPERATIONS
Presentation of Segment Information
Our operations are divided into two primary reportable segments: Gas Distribution Operations and Electric Operations. The remainder of our operations, which are not significant enough on a stand-alone basis to warrant treatment as an operating segment, are presented as "Corporate and Other" within the Notes to the Consolidated Financial Statements and primarily are comprised of interest expense on holding company debt, and unallocated corporate costs and activities.
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Gas Distribution Operations
Financial and operational data for the Gas Distribution Operations segment for the years ended December 31, 2021, 2020 and 2019, are presented below:
| Favorable (Unfavorable) | |||||||||||||||||||||||||||||
| Year Ended December 31, (in millions) | 2021 | 2020 | 2019 | 2021 vs. 2020 | 2020 vs. 2019 | ||||||||||||||||||||||||
| Operating Revenues | $ | 3,183.5 | $ | 3,140.1 | $ | 3,522.8 | $ | 43.4 | $ | (382.7) | |||||||||||||||||||
| Operating Expenses | |||||||||||||||||||||||||||||
| Cost of energy | 962.7 | 794.2 | 1,067.6 | (168.5) | 273.4 | ||||||||||||||||||||||||
| Operation and maintenance | 993.8 | 1,138.0 | 935.7 | 144.2 | (202.3) | ||||||||||||||||||||||||
| Depreciation and amortization | 383.0 | 363.1 | 403.2 | (19.9) | 40.1 | ||||||||||||||||||||||||
| Impairment of intangible assets | — | — | 209.7 | — | 209.7 | ||||||||||||||||||||||||
| Loss on sale of fixed assets and impairments, net | 8.7 | 412.4 | 0.1 | 403.7 | (412.3) | ||||||||||||||||||||||||
| Other taxes | 217.8 | 233.3 | 231.1 | 15.5 | (2.2) | ||||||||||||||||||||||||
| Total Operating Expenses | 2,566.0 | 2,941.0 | 2,847.4 | 375.0 | (93.6) | ||||||||||||||||||||||||
| Operating Income | $ | 617.5 | $ | 199.1 | $ | 675.4 | $ | 418.4 | $ | (476.3) | |||||||||||||||||||
| Revenues | |||||||||||||||||||||||||||||
| Residential | $ | 2,143.4 | $ | 2,110.6 | $ | 2,317.2 | $ | 32.8 | $ | (206.6) | |||||||||||||||||||
| Commercial | 731.0 | 679.7 | 775.1 | 51.3 | (95.4) | ||||||||||||||||||||||||
| Industrial | 197.2 | 213.8 | 245.8 | (16.6) | (32.0) | ||||||||||||||||||||||||
| Off-System | 71.3 | 41.0 | 77.7 | 30.3 | (36.7) | ||||||||||||||||||||||||
| Other | 40.6 | 95.0 | 107.0 | (54.4) | (12.0) | ||||||||||||||||||||||||
| Total | $ | 3,183.5 | $ | 3,140.1 | $ | 3,522.8 | $ | 43.4 | $ | (382.7) | |||||||||||||||||||
| Sales and Transportation (MMDth) | |||||||||||||||||||||||||||||
| Residential | 231.2 | 249.5 | 274.9 | (18.3) | (25.4) | ||||||||||||||||||||||||
| Commercial | 167.0 | 170.5 | 189.6 | (3.5) | (19.1) | ||||||||||||||||||||||||
| Industrial | 507.1 | 538.1 | 542.5 | (31.0) | (4.4) | ||||||||||||||||||||||||
| Off-System | 21.6 | 23.3 | 32.9 | (1.7) | (9.6) | ||||||||||||||||||||||||
| Other | 0.3 | 0.3 | 0.3 | — | — | ||||||||||||||||||||||||
| Total | 927.2 | 981.7 | 1,040.2 | (54.5) | (58.5) | ||||||||||||||||||||||||
| Heating Degree Days | 5,002 | 5,097 | 5,375 | (95) | (278) | ||||||||||||||||||||||||
| Normal Heating Degree Days | 5,427 | 5,485 | 5,452 | (58) | 33 | ||||||||||||||||||||||||
| % Warmer than Normal | (8) | % | (7) | % | (1) | % | |||||||||||||||||||||||
| % Warmer than Prior Year | (2) | % | (5) | % | |||||||||||||||||||||||||
| Gas Distribution Customers | |||||||||||||||||||||||||||||
| Residential | 2,970,157 | 2,954,478 | 3,221,178 | 15,679 | (266,700) | ||||||||||||||||||||||||
| Commercial | 253,987 | 253,184 | 282,778 | 803 | (29,594) | ||||||||||||||||||||||||
| Industrial | 4,921 | 4,968 | 5,982 | (47) | (1,014) | ||||||||||||||||||||||||
| Other | 4 | 3 | 3 | 1 | — | ||||||||||||||||||||||||
| Total | 3,229,069 | 3,212,633 | 3,509,941 | 16,436 | (297,308) |
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Gas Distribution Operations (continued)
Comparability of operation and maintenance expenses, depreciation and amortization, and other taxes may be impacted by regulatory, depreciation and tax trackers that allow for the recovery in rates of certain costs.
The underlying reasons for changes in our operating revenues and expenses from 2021 to 2020 are presented in the respective tables below. Please refer to Part II, Item 7, "Management's Discussion and Analysis of Financial Condition and Results of Operations - Results and Discussion of Segment Operations - Gas Distribution Operations," of the Company's 2020 Annual Report on Form 10-K for discussion of underlying reasons for changes in our operating revenues and expenses for 2020 versus 2019.
| Favorable (Unfavorable) | |||||
| Changes in Operating Revenues (in millions) | 2021 vs 2020 | ||||
| Revenues associated with the Massachusetts Business in 2020 | $ | (223.1) | |||
| New rates from base rate proceedings and regulatory capital programs | 115.9 | ||||
| The effects of customer growth | 5.3 | ||||
| Higher revenue due to the effects of resuming common credit mitigation practices | 5.0 | ||||
| The effects of weather fluctuations in 2021 compared to 2020 | 4.8 | ||||
| Other | 3.8 | ||||
| Change in operating revenues (before cost of energy and other tracked items) | $ | (88.3) | |||
| Operating revenues offset in operating expense | |||||
| Higher cost of energy billed to customers | 277.3 | ||||
| Cost of energy associated with the Massachusetts Business in 2020 | (108.8) | ||||
| Operation and maintenance trackers associated with the Massachusetts Business in 2020 | (36.8) | ||||
| Total change in operating revenues | $ | 43.4 |
Weather
In general, we calculate the weather-related revenue variance based on changing customer demand driven by weather variance from normal heating degree days, net of weather normalization mechanisms. Our composite heating degree days reported do not directly correlate to the weather-related dollar impact on the results of Gas Distribution Operations. Heating degree days experienced during different times of the year or in different operating locations may have more or less impact on volume and dollars depending on when and where they occur. When the detailed results are combined for reporting, there may be weather-related dollar impacts on operations when there is not an apparent or significant change in our aggregated composite heating degree day comparison.
Throughput
The decrease in total volumes sold and transported in 2021 compared to 2020 of 54.5 MMDth is primarily attributable to the sale of the Massachusetts Business in 2020.
Commodity Price Impact
Cost of energy for the Gas Distribution Operations segment is principally comprised of the cost of natural gas used while providing transportation and distribution services to customers. All of our Gas Distribution Operations companies have state-approved recovery mechanisms that provide a means for full recovery of prudently incurred gas costs. These are tracked costs that are passed through directly to the customer, and the gas costs included in revenues are matched with the gas cost expense recorded in the period. The difference is recorded on the Consolidated Balance Sheets as under-recovered or over-recovered gas cost to be included in future customer billings. Therefore, increases in these tracked operating expenses are offset by increases in operating revenues and have essentially no impact on net income.
Certain Gas Distribution Operations companies continue to offer choice opportunities, where customers can choose to purchase gas from a third-party supplier, through regulatory initiatives in their respective jurisdictions.
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Gas Distribution Operations (continued)
| Favorable (Unfavorable) | |||||
| Changes in Operating Expenses (in millions) | 2021 vs 2020 | ||||
| Loss on sale of the Massachusetts Business of $6.8 million in 2021 compared to $412.4 million in 2020 | $ | 405.6 | |||
| Operating expenses associated with the Massachusetts Business in 2020 | 202.2 | ||||
| Lower expense related to the NiSource Next initiative in 2021 compared to 2020 | 3.6 | ||||
| Higher employee and administrative related expenses | (31.7) | ||||
| Higher depreciation and amortization expense | (27.8) | ||||
| Higher outside services expenses | (17.3) | ||||
| Higher unrecoverable environmental remediation costs | (12.7) | ||||
| Higher other than income taxes primarily related to property tax expense | (12.1) | ||||
| Other | (3.1) | ||||
| Change in operating expenses (before cost of energy and other tracked items) | $ | 506.7 | |||
| Operating expenses offset in operating revenue | |||||
| Higher cost of energy billed to customers | (277.3) | ||||
| Cost of energy associated with the Massachusetts Business in 2020 | 108.8 | ||||
| Operation and maintenance trackers associated with the Massachusetts Business in 2020 | 36.8 | ||||
| Total change in operating expense | $ | 375.0 |
Columbia of Massachusetts Asset Sale
On October 9, 2020, we completed the sale of our Massachusetts Business. In March 2021, we reached an agreement with Eversource regarding the final purchase price, including net working capital adjustments. This resulted in a pre-tax loss for the years ended December 31, 2021 and 2020 of $6.8 million and $412.4 million, respectively, based on asset and liability balances as of the close of the transaction on October 9, 2020, transaction costs and the final purchase price. The pre-tax loss is presented as "Loss on sale of assets, net" on the Statements of Consolidated Income (Loss).
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Electric Operations
Financial and operational data for the Electric Operations segment for the years ended December 31, 2021, 2020 and 2019, are presented below:
| Favorable (Unfavorable) | |||||||||||||||||||||||||||||
| Year Ended December 31, (in millions) | 2021 | 2020 | 2019 | 2021 vs. 2020 | 2020 vs. 2019 | ||||||||||||||||||||||||
| Operating Revenues | $ | 1,697.1 | $ | 1,536.6 | $ | 1,699.2 | $ | 160.5 | $ | (162.6) | |||||||||||||||||||
| Operating Expenses | |||||||||||||||||||||||||||||
| Cost of energy | 429.7 | 315.2 | 467.3 | (114.5) | 152.1 | ||||||||||||||||||||||||
| Operation and maintenance | 493.6 | 497.6 | 495.0 | 4.0 | (2.6) | ||||||||||||||||||||||||
| Depreciation and amortization | 329.4 | 321.3 | 277.3 | (8.1) | (44.0) | ||||||||||||||||||||||||
| Gain on sale of fixed assets and impairments, net | (0.9) | — | (0.1) | 0.9 | (0.1) | ||||||||||||||||||||||||
| Other taxes | 57.5 | 53.7 | 52.9 | (3.8) | (0.8) | ||||||||||||||||||||||||
| Total Operating Expenses | 1,309.3 | 1,187.8 | 1,292.4 | (121.5) | 104.6 | ||||||||||||||||||||||||
| Operating Income | $ | 387.8 | $ | 348.8 | $ | 406.8 | $ | 39.0 | $ | (58.0) | |||||||||||||||||||
| Revenues | |||||||||||||||||||||||||||||
| Residential | $ | 568.0 | $ | 527.8 | $ | 481.6 | $ | 40.2 | $ | 46.2 | |||||||||||||||||||
| Commercial | 534.9 | 480.3 | 486.7 | 54.6 | (6.4) | ||||||||||||||||||||||||
| Industrial | 494.1 | 412.9 | 608.4 | 81.2 | (195.5) | ||||||||||||||||||||||||
| Wholesale | 15.7 | 12.3 | 11.7 | 3.4 | 0.6 | ||||||||||||||||||||||||
| Other | 84.4 | 103.3 | 110.8 | (18.9) | (7.5) | ||||||||||||||||||||||||
| Total | $ | 1,697.1 | $ | 1,536.6 | $ | 1,699.2 | $ | 160.5 | $ | (162.6) | |||||||||||||||||||
| Sales (Gigawatt Hours) | |||||||||||||||||||||||||||||
| Residential | 3,546.8 | 3,484.0 | 3,369.5 | 62.8 | 114.5 | ||||||||||||||||||||||||
| Commercial | 3,698.0 | 3,550.0 | 3,760.3 | 148.0 | (210.3) | ||||||||||||||||||||||||
| Industrial | 8,253.7 | 7,480.3 | 8,466.1 | 773.4 | (985.8) | ||||||||||||||||||||||||
| Wholesale | 124.7 | 83.6 | 8.2 | 41.1 | 75.4 | ||||||||||||||||||||||||
| Other | 108.5 | 106.0 | 117.2 | 2.5 | (11.2) | ||||||||||||||||||||||||
| Total | 15,731.7 | 14,703.9 | 15,721.3 | 1,027.8 | (1,017.4) | ||||||||||||||||||||||||
| Cooling Degree Days | 1,020 | 900 | 962 | 120 | (62) | ||||||||||||||||||||||||
| Normal Cooling Degree Days | 803 | 803 | 803 | — | — | ||||||||||||||||||||||||
| % Warmer than Normal | 27 | % | 12 | % | 20 | % | |||||||||||||||||||||||
| % Warmer (Colder) than prior year | 13 | % | (6) | % | |||||||||||||||||||||||||
| Electric Customers | |||||||||||||||||||||||||||||
| Residential | 422,436 | 418,871 | 415,534 | 3,565 | 3,337 | ||||||||||||||||||||||||
| Commercial | 58,010 | 57,435 | 57,058 | 575 | 377 | ||||||||||||||||||||||||
| Industrial | 2,137 | 2,154 | 2,256 | (17) | (102) | ||||||||||||||||||||||||
| Wholesale | 714 | 722 | 726 | (8) | (4) | ||||||||||||||||||||||||
| Other | 2 | 2 | 2 | — | — | ||||||||||||||||||||||||
| Total | 483,299 | 479,184 | 475,576 | 4,115 | 3,608 |
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Electric Operations (continued)
Comparability of operation and maintenance expenses and depreciation and amortization may be impacted by regulatory and depreciation trackers that allow for the recovery in rates of certain costs.
The underlying reasons for changes in our operating revenues and expenses from 2021 to 2020 are presented in the respective tables below. Please refer to Part II, Item 7, "Management's Discussion and Analysis of Financial Condition and Results of Operations - Results and Discussion of Segment Operations - Electric Operations," of the Company's 2020 Annual Report on Form 10-K for discussion of underlying reasons for changes in our operating revenues and expenses for 2020 versus 2019.
| Favorable (Unfavorable) | |||||
| Changes in Operating Revenues (in millions) | 2021 vs 2020 | ||||
| The effects of warmer weather in 2021 compared to 2020 | $ | 17.4 | |||
| Increased customer usage | 13.9 | ||||
| New rates from regulatory capital and DSM programs | 10.4 | ||||
| The effects of customer growth | 5.0 | ||||
| Higher revenue due to the effects of resuming common credit mitigation practices | 2.9 | ||||
| Increased fuel handling costs | (10.5) | ||||
| Other | 2.6 | ||||
| Change in operating revenues (before cost of energy and other tracked items) | $ | 41.7 | |||
| Operating revenues offset in operating expense | |||||
| Higher cost of energy billed to customers | 114.5 | ||||
| Higher tracker deferrals within operation and maintenance, depreciation and tax | 4.3 | ||||
| Total change in operating revenues | $ | 160.5 |
Weather
In general, we calculate the weather-related revenue variance based on changing customer demand driven by weather variance from normal heating or cooling degree days. Our composite heating or cooling degree days reported do not directly correlate to the weather-related dollar impact on the results of Electric Operations. Heating or cooling degree days experienced during different times of the year may have more or less impact on volume and dollars depending on when they occur. When the detailed results are combined for reporting, there may be weather-related dollar impacts on operations when there is not an apparent or significant change in our aggregated composite heating or cooling degree day comparison.
Sales
The increase in total volumes sold in 2021 compared to 2020 of 1,027.8 GWh was primarily attributable to decreased usage by industrial and commercial customers during the second and third quarters of 2020 due to COVID-19. There was no significant variance during the first three months and last three months of 2021 compared to the same period in 2020.
Commodity Price Impact
Cost of energy for the Electric Operations segment is principally comprised of the cost of coal, natural gas purchased for internal generation of electricity at NIPSCO, and the cost of power purchased from third-party generators of electricity. NIPSCO has a state-approved recovery mechanism that provides a means for full recovery of prudently incurred fuel costs. The majority of these fuel costs are passed through directly to the customer, and the fuel costs included in operating revenues are matched with the fuel cost expense recorded in the period. The difference is recorded on the Consolidated Balance Sheets as under-recovered or over-recovered fuel cost to be included in future customer billings. Therefore, increases in these tracked operating expenses are offset by increases in operating revenues and have essentially no impact on net income.
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Electric Operations (continued)
NIPSCO's performance remains closely linked to the performance of the steel industry. NIPSCO’s MWh sales to steel-related industries accounted for approximately 48.1% and 45.9% of the total industrial MWh sales for the years ended December 31, 2021 and 2020, respectively.
| Favorable (Unfavorable) | |||||
| Changes in Operating Expenses (in millions) | 2021 vs 2020 | ||||
| Increased operating expenses related to the retirement of the R.M. Schahfer Generating Station's coal Units 14 and 15 | $ | (9.5) | |||
| Higher depreciation and amortization expense | (6.8) | ||||
| Higher other than income taxes primarily related to property tax and gross receipts tax expense | (3.8) | ||||
| Higher employee and administrative expenses | (2.6) | ||||
| Higher corporate insurance costs | (1.7) | ||||
| Lower outside services expenses | 15.1 | ||||
| Lower environmental costs | 8.6 | ||||
| Other | (2.0) | ||||
| Change in operating expenses (before cost of energy and other tracked items) | $ | (2.7) | |||
| Operating expenses offset in operating revenue | |||||
| Higher cost of energy billed to customers | (114.5) | ||||
| Higher tracker deferrals within operation and maintenance, depreciation and tax | (4.3) | ||||
| Total change in operating expense | $ | (121.5) |
Electric Supply and Generation Transition
NIPSCO continues to execute on an electric generation transition consistent with the preferred pathway from its 2018 Integrated Resource Plan, which outlines plans to retire its remaining coal-fired generation by 2028, to be replaced by lower-cost, reliable and cleaner options. We expect to have capital investment requirements of approximately $2.0 billion, primarily in 2022 and 2023, to replace the generation capacity of R.M. Schahfer Generating Station's coal-fired units. We retired R.M. Schahfer Generating Station Units 14 and 15 on October 1, 2021. The remaining two units are still scheduled to be retired in 2023. Refer to Note 6, "Property, Plant and Equipment," and Note 19-F, "Other Matters," in the Notes to Consolidated Financial Statements for further information.
The current replacement plan primarily includes renewable sources of energy, including wind, solar, and battery storage to be obtained through a combination of NIPSCO ownership and PPAs. NIPSCO has sold, and may in the future sell, renewable energy credits from this generation to third parties because this helps keep the cost of energy more affordable for our customers. NIPSCO has executed several PPAs to purchase 100% of the output from renewable generation facilities at a fixed price per MWh. Each facility supplying the energy will have an associated nameplate capacity, and payments under the PPAs will not begin until the associated generation facility is constructed by the owner/seller. NIPSCO has also executed several BTAs with developers to construct renewable generation facilities. Our current replacement program will be augmented by the Preferred Energy Resource Plan outlined in our 2021 Integrated Resource Plan. See "Executive Summary - Your Energy, Your Future" in this Management's Discussion for additional information.
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Electric Operations (continued)
The following table summarizes the executed PPAs and BTAs from our generation transition:
| Project Name | Transaction Type | Technology | Nameplate Capacity (MW) | Storage Capacity (MW) | IURC Approval | Targeted Construction Completion | |||||||||||||||||
| Jordan Creek | 20 year PPA | Wind | 400 | — | 6/05/2019 | In Service (12/10/2020) | |||||||||||||||||
| Rosewater(1) | BTA | Wind | 102 | — | 8/07/2019 | In Service (12/29/2020) | |||||||||||||||||
| Indiana Crossroads Wind(1) | BTA | Wind | 302 | — | 2/19/2020 | In Service (12/17/2021) | |||||||||||||||||
| Greensboro | 20 year PPA | Solar & Storage | 100 | 30 | 1/27/2021 | Q4 2022 | |||||||||||||||||
| Brickyard | 20 year PPA | Solar | 200 | — | 1/27/2021 | Q4 2022 | |||||||||||||||||
| Cavalry(2) | BTA | Solar & Storage | 200 | 60 | 5/5/2021 | Q4 2023 | |||||||||||||||||
| Dunn's Bridge I(2) | BTA | Solar | 265 | — | 5/5/2021 | Q4 2022 | |||||||||||||||||
| Dunn's Bridge II(2) | BTA | Solar & Storage | 435 | 75 | 5/5/2021 | Q4 2023 | |||||||||||||||||
| Green River | 20 year PPA | Solar | 200 | — | 5/5/2021 | Q2 2023 | |||||||||||||||||
| Gibson | 22 year PPA | Solar | 280 | — | 6/29/2021 | Q2 2023 | |||||||||||||||||
| Fairbanks(2) | BTA | Solar | 250 | — | 6/29/2021 | Q3 2023 | |||||||||||||||||
| Indiana Crossroads Solar(2) | BTA | Solar | 200 | — | 7/28/2021 | Q4 2022 | |||||||||||||||||
| Elliott(2) | BTA | Solar | 200 | — | 7/28/2021 | Q2 2023 | |||||||||||||||||
| Indiana Crossroads II | 15 year PPA | Wind | 204 | — | 9/1/2021 | Q4 2023 |
(1) Refer to Note 4, "Variable Interest Entities," in the Notes to Consolidated Financial Statements for additional information.
(2) Ownership of the facilities will be transferred to joint ventures whose members include NIPSCO and an unrelated tax equity partner.
To date, we have been informed of potential delays related to renewable energy projects, including delays related to the delivery of solar panels, local permitting processes and obtaining interconnection rights. The potential delays to solar panel deliveries relate to the U.S. Department of Homeland Security's June 24, 2021 Withhold Release Order on silica-based products made by Hoshine Silicon Industry Co., Ltd. For all affected projects, the sellers have informed us that they are working diligently to mitigate potential impacts and determine recovery plans, where applicable, in order to minimize potential delays or failures to perform under the agreements. We are also evaluating what, if any, additional flexibility can be afforded to the sellers under these agreements to aid in mitigating, or minimizing, potential delays or failures to perform under the agreements. We, along with the sellers of these generation projects, are continuously evaluating potential impacts to the targeted completion date of each project. At this time, the impact of any delays to materials, permitting or interconnection on the targeted completion dates has not been determined but could include a delay in the financial return of certain investments and timing of our electric generation transition.
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Liquidity and Capital Resources
We continually evaluate the availability of adequate financing to fund our ongoing business operations, working capital and core safety and infrastructure investment programs. Our financing is sourced through cash flow from operations and the issuance of debt and/or equity. External debt financing is provided primarily through the issuance of long-term debt, accounts receivable securitization programs and our $1.5 billion commercial paper program, which is backstopped by our committed revolving credit facility with a total availability from third-party lenders of $1.85 billion. On February 18, 2022, we amended our revolving credit agreement to, among other things, extend its term to February 18, 2027. The commercial paper program and credit facility provide cost-effective, short-term financing until it can be replaced with a balance of long-term debt and equity financing that achieves our desired capital structure. We utilize an ATM equity program that allows us to issue and sell shares of our common stock up to an aggregate issuance of $750.0 million through December 31, 2023. As of December 31, 2021, the ATM program (including the impact of the forward sale agreement) had approximately $300.0 million of equity available for issuance. On April 19, 2021, we completed the sale of 8.625 million Equity Units, which provided net proceeds of $835.5 million, after underwriting and issuance costs. We intend to use the net proceeds from the offering for renewable generation investments and general corporate purposes, including additions to working capital and repayment of existing indebtedness. See Note 13, ''Equity,'' in the Notes to Consolidated Financial Statements for more information on our ATM program and Equity Units.
We believe these sources provide adequate capital to fund our operating activities and capital expenditures in 2022 and beyond.
Greater Lawrence Incident. As discussed in Part I, Item 1A, "Risk Factors," and in Note 19, "Other Commitments and Contingencies," in the Notes to Consolidated Financial Statements, due to the inherent uncertainty of litigation, there can be no assurance that the outcome or resolution of any particular claim related to the Greater Lawrence Incident will not continue to have an adverse impact on our cash flows. Through income generated from operating activities, amounts available under the short-term revolving credit facility, and our ability to access capital markets, we believe we have adequate capital available to settle remaining anticipated claims associated with the Greater Lawrence Incident.
Operating Activities
Net cash from operating activities for the year ended December 31, 2021 was $1,217.9 million, an increase of $113.9 million from 2020. This increase was primarily driven by a year over year decrease in net payments related to the Greater Lawrence Incident. During 2021, we paid $15.6 million compared to $226.7 million of payments during the same period in 2020. This was offset by increased cash outflows related to inventory balances primarily due to lower purchasing and prices in 2020 as well as decreased cash inflows related to the under collection of gas and fuel costs.
Investing Activities
Net cash used for investing activities for the year ended December 31, 2021 was $2,204.9 million, an increase of $1,325.8 million from 2020. In 2020, our investing outflows were lower by $1,115.9 million as a result of proceeds from the sale of the Massachusetts Business. Our current year investing activities were comprised of capital expenditures related to system growth and reliability and payments made to the developers of our renewable generation assets.
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Capital Expenditures. The table below reflects actual capital expenditures and certain other investing activities by segment for 2021.
| Actual | |||||||||||||||||||||||
| (in millions) | 2021 | ||||||||||||||||||||||
| Gas Distribution Operations | |||||||||||||||||||||||
| System Growth and Tracker | $ | 1,060.8 | |||||||||||||||||||||
| Maintenance | 235.6 | ||||||||||||||||||||||
| Total Gas Distribution Operations(1) | 1,296.4 | ||||||||||||||||||||||
| Electric Operations | |||||||||||||||||||||||
| System Growth and Tracker | 248.6 | ||||||||||||||||||||||
| Maintenance | 172.0 | ||||||||||||||||||||||
| Generation Transition Investments | 62.5 | ||||||||||||||||||||||
| Total Electric Operations(1) | 483.1 | ||||||||||||||||||||||
| Corporate and Other Operations - Maintenance(1) | 160.9 | ||||||||||||||||||||||
| Total(2) | $ | 1,940.4 |
(1)Amounts differ from those presented in Note 23, "Segments of Business," in the Notes to Consolidated Financial Statements due to the allocation of Corporate and Other Maintenance Costs to the Gas Distribution and Electric Operations segments.
(2)Amounts differ from those presented on the Statements of Consolidated Cash Flows primarily due to the capitalized portion of the Corporate Incentive Plan payout, inclusion of capital expenditures included in current liabilities and AFUDC Equity.
We expect to make capital investments totaling approximately $10 billion during the 2021-2024 period, comprised of annual investments of $1.9 to $2.2 billion for growth, safety and reliability, and an additional $2.0 billion in renewable generation to replace the retiring coal-fired generation capacity of Schahfer Generating Station.
The following graph illustrates, in billions, the midpoint of forecasted capital investments by expected recovery period for the next three years:
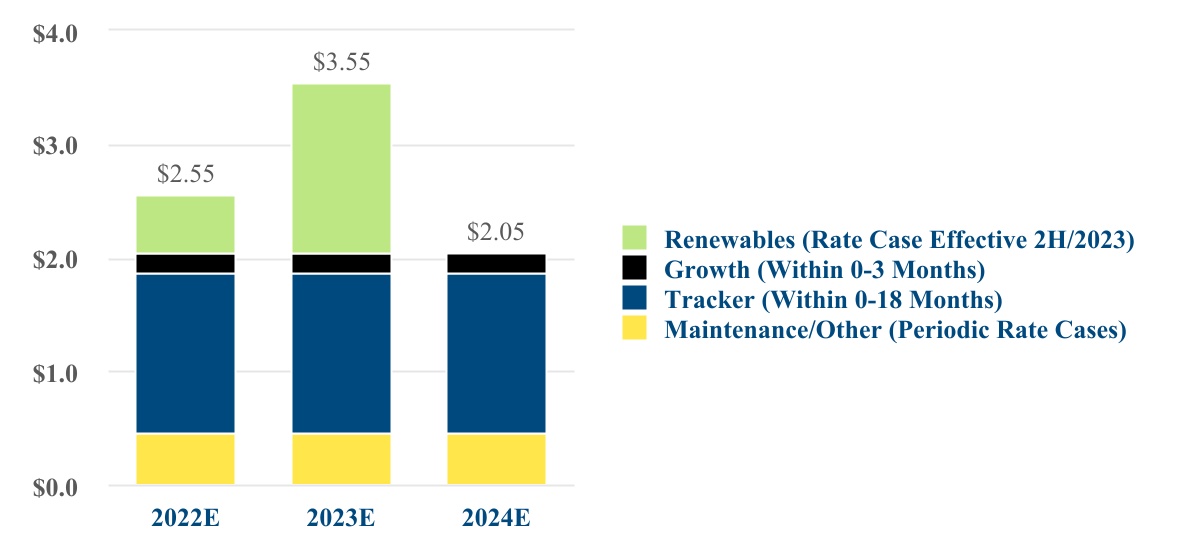
Regulatory Capital Programs. We replace pipe and modernize our gas infrastructure to enhance safety and reliability by reducing leaks, which subsequently reduces GHG emissions. In 2021, we continued to move forward on core infrastructure and environmental investment programs supported by complementary regulatory and customer initiatives across all six states of our operating area.
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
The following table describes the most recent vintage of our regulatory programs to recover infrastructure replacement and other federally mandated compliance investments currently in rates or pending commission approval:
| (in millions) | ||||||||||||||||||||
| Company | Program | Incremental Revenue | Incremental Capital Investment | Investment Period | Costs Covered(1) | Rates Effective | ||||||||||||||
| Columbia of Ohio | IRP - 2021 | $ | 22.2 | $ | 212.6 | 1/20-12/20 | Replacement of (1) hazardous service lines, (2) cast iron, wrought iron, uncoated steel, and bare steel pipe, (3) natural gas risers prone to failure and (4) installation of AMR devices. | May 2021 | ||||||||||||
| Columbia of Ohio | CEP - 2021 | $ | 18.0 | $ | 177.2 | 1/20-12/20 | Assets not included in the IRP. | September 2021 | ||||||||||||
| NIPSCO - Gas | TDSIC 3 | $ | 0.2 | $ | 52.1 | 1/21-6/21 | New or replacement projects undertaken for the purpose of safety, reliability, system modernization or economic development. | January 2022 | ||||||||||||
| NIPSCO - Gas | FMCA 7 | $ | 0.5 | $ | 32.8 | 4/21-9/21 | Project costs to comply with federal mandates. | April 2022 | ||||||||||||
| Columbia of Virginia(2) | SAVE - 2022 | $ | 4.0 | $ | 63.0 | 1/22-12/22 | Replacement projects that (1) enhance system safety or reliability, or (2) reduce, or potentially reduce, greenhouse gas emissions. | January 2022 | ||||||||||||
| Columbia of Kentucky | SMRP - 2021 | $ | 2.6 | $ | 40.0 | 1/21-12/21 | Replacement of mains and inclusion of system safety investments. | May 2021 | ||||||||||||
| Columbia of Maryland | STRIDE - 2022 | $ | 1.3 | $ | 17.5 | 1/22-12/22 | Pipeline upgrades designed to improve public safety or infrastructure reliability. | January 2022 | ||||||||||||
| NIPSCO - Electric(3) | TDSIC - 9 | $ | 0.2 | $ | 42.7 | 2/21-5/21 | New or replacement projects undertaken for the purpose of safety, reliability, system modernization or economic development. | February 2022 |
(1)Programs do not include any costs already included in base rates.
(2)Columbia of Virginia filed its application to amend and extend its SAVE program with the Virginia SCC on August 12, 2021, requesting approval of a two-year SAVE program for calendar years 2022-2023 that includes incremental capital investments of $63.0 million and $72.0 million, respectively. The Commission approved the Company's application in its December 6, 2021 Order Approving SAVE Rider.
(3)On April 1, 2021, NIPSCO filed a notice with the IURC that it intended to terminate its current Electric TDSIC plan effective May 31, 2021. NIPSCO filed for a new electric TDSIC plan on June 1, 2021. An order approving NIPSCO's new electric TDSIC plan was received on December 28, 2021. NIPSCO filed the TDSIC-9 petition on September 28, 2021, and received an order on January 26, 2022 approving TDSIC-9.
Refer to Note 9, "Regulatory Matters," in the Notes to Consolidated Financial Statements for a further discussion of regulatory developments during 2021.
Financing Activities
Common Stock, Preferred Stock and Equity Unit Sale. Refer to Note 13, ''Equity,'' in the Notes to Consolidated Financial Statements for information on common stock, preferred stock and equity units activity.
Short-term Debt and Sale of Trade Accounts Receivables. Refer to Note 16, "Short-Term Borrowings," in the Notes to Consolidated Financial Statements for information on short-term debt.
Long-term Debt. Refer to Note 15, "Long-Term Debt," in the Notes to Consolidated Financial Statements for information on long-term debt.
Non-controlling Interest. Refer to Note 4, "Variable Interest Entities," in the Notes to Consolidated Financial Statements for information on contributions from noncontrolling interest activity.
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Sources of Liquidity
The following table displays our liquidity position as of December 31, 2021 and 2020:
| Year Ended December 31, (in millions) | 2021 | 2020 | ||||||
| Current Liquidity | ||||||||
| Revolving Credit Facility | $ | 1,850.0 | $ | 1,850.0 | ||||
| Accounts Receivable Programs(1) | 251.2 | 273.3 | ||||||
| Less: | ||||||||
| Commercial Paper | 560.0 | 503.0 | ||||||
| Letters of Credit Outstanding Under Credit Facility | 18.9 | 15.2 | ||||||
| Add: | ||||||||
| Cash and Cash Equivalents | 84.2 | 116.5 | ||||||
| Net Available Liquidity | $ | 1,606.5 | $ | 1,721.6 |
(1)Represents the lesser of the seasonal limit or maximum borrowings supportable by the underlying receivables. Our accounts receivable programs' utilization was zero as of December 31, 2021 and 2020.
Debt Covenants**.** We are subject to a financial covenant under our revolving credit facility, which requires us to maintain a debt to capitalization ratio that does not exceed 70%. As of December 31, 2021, the ratio was 57.4%.
Credit Ratings**.** The credit rating agencies periodically review our ratings, taking into account factors such as our capital structure and earnings profile. The following table includes our and NIPSCO's credit ratings and ratings outlook as of December 31, 2021. There have been no changes to our credit ratings or outlooks since February 2020.
A credit rating is not a recommendation to buy, sell or hold securities, and may be subject to revision or withdrawal at any time by the assigning rating organization.
| S&P | Moody's | Fitch | ||||||||||||||||||
| Rating | Outlook | Rating | Outlook | Rating | Outlook | |||||||||||||||
| NiSource | BBB+ | Stable | Baa2 | Stable | BBB | Stable | ||||||||||||||
| NIPSCO | BBB+ | Stable | Baa1 | Stable | BBB | Stable | ||||||||||||||
| Commercial Paper | A-2 | Stable | P-2 | Stable | F2 | Stable |
Certain of our subsidiaries have agreements that contain “ratings triggers” that require increased collateral if our credit ratings or the credit ratings of certain of our subsidiaries are below investment grade. These agreements are primarily for insurance purposes and for the physical purchase or sale of power. As of December 31, 2021, a collateral requirement of approximately $56.2 million would be required in the event of a downgrade below investment grade. In addition to agreements with ratings triggers, there are other agreements that contain “adequate assurance” or “material adverse change” provisions that could necessitate additional credit support such as letters of credit and cash collateral to transact business.
Equity. Our authorized capital stock consists of 620,000,000 shares, $0.01 par value, of which 600,000,000 are common stock and 20,000,000 are preferred stock. As of December 31, 2021, 405,303,023 shares of common stock and 1,302,500 shares of preferred stock were outstanding. For more information regarding our common and preferred stock, see Note 13, "Equity," in the Notes to Consolidated Financial Statements.
Contractual Obligations, Cash Requirements and Off-Balance Sheet Arrangements
We have certain contractual obligations requiring payments at specified periods. Our material cash requirements are detailed below. We intend to use funds from the liquidity sources referenced above to meet these cash requirements.
Our calculated estimated interest payments for long-term debt are based on the stated coupon and payment dates. For 2022, we project that we will be required to make interest payments of approximately $338.5 million, which includes $335.7 million of interest payments related to our long-term debt outstanding as of December 31, 2021. At December 31, 2021, we had $560.0 million in short-term borrowings outstanding. Refer to Note 15, "Long-Term Debt," and Note 16, "Short-Term Borrowings," in the Notes to Consolidated Financial Statements for further information on long-term debt and short-term borrowings, respectively.
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
During 2022 and 2023, we expect to make cash payments of $610.5 million and $366.0 million, respectively, related to pipeline service obligations including demand for gas transportation, gas storage and gas purchases.
We expect to have capital investment requirements of approximately $2.0 billion, primarily in 2022 and 2023, to replace the generation capacity of all R.M. Schahfer Generating Station's coal-fired units. These investments include our portion of the joint venture obligations including construction milestone payments included in the agreements.
Our expected payments include employer contributions to pension and other postretirement benefits plans expected to be made in 2022. Plan contributions beyond 2022 are dependent upon a number of factors, including actual returns on plan assets, which cannot be reliably estimated at this time. In 2022, we expect to make contributions of approximately $2.8 million to our pension plans and approximately $21.5 million to our postretirement medical and life plans. Refer to Note 12, "Pension and Other Postretirement Benefits," in the Notes to Consolidated Financial Statements for more information.
We cannot reasonably estimate the settlement amounts or timing of cash flows related to certain of our long-term obligations classified as "Total Other Liabilities" on the Consolidated Balance Sheets.
We also have obligations associated with income, property, gross receipts, franchise, sales and use, and various other taxes and expect to make tax payments of approximately $291.1 million in 2022. In addition, we have uncertain income tax positions for which we are unable to predict when the matters will be resolved. Refer to Note 11, "Income Taxes," in the Notes to Consolidated Financial Statements for more information.
NIPSCO has executed several PPAs to purchase 100% of the output from renewable generation facilities at a fixed price per MWh. NIPSCO has also executed several BTAs with developers to construct renewable generation facilities. See Note 19-A, "Contractual Obligations," and Note 19-F, "Other Matters - Generation Transition," in the Notes to Consolidated Financial Statements for additional information.
In addition, we, along with certain of our subsidiaries, enter into various agreements providing financial or performance assurance to third parties on behalf of certain subsidiaries. Such agreements include guarantees and stand-by letters of credit.
Refer to Note 19, "Other Commitments and Contingencies," in the Notes to Consolidated Financial Statements for additional information regarding our contractual obligations over the next 5 years and thereafter and our off-balance sheet arrangements.
Environmental and Safety Matters
PHMSA Regulations
On December 27, 2020, the Protecting Our Infrastructure of Pipelines and Enhancing Safety (PIPES) Act of 2020 was signed into law, reauthorizing funding for federal pipeline safety programs through September 30, 2023. Among other things, the PIPES Act requires that PHMSA revise the pipeline safety regulations to require operators to update, as needed, their existing distribution integrity management plans, emergency response plans, and operation and maintenance plans. The PIPES Act also requires PHMSA to adopt new requirements for managing records and updating, as necessary, existing district regulator stations to eliminate common modes of failure that can lead to overpressurization. PHMSA must also require that operators implement and utilize advanced leak detection technologies that enable the location and categorization of all leaks that are hazardous, or potentially hazardous, to human safety or the environment. Natural gas companies, including NiSource and our subsidiaries, may see increased costs depending on how PHMSA implements the new mandates resulting from the PIPES Act.
Climate Change Issues
Increased frequency of severe and extreme weather events associated with climate change could materially impact our facilities, energy sales, and results of operations. We are unable to predict these events. However, we perform ongoing assessments of physical risk, including physical climate risk, to our business. More extreme and volatile temperatures, increased storm intensity and flooding, and more volatile precipitation leading to changes in lake and river levels are among the weather events that are most likely to impact our business. Efforts to mitigate these physical risks continue to be implemented on an ongoing basis.
Future legislative and regulatory programs, at both the federal and state levels, could significantly limit allowed GHG emissions or impose a cost or tax on GHG emissions. Revised or additional future GHG legislation and/or regulation related to the generation of electricity or the extraction, production, distribution, transmission, storage and end use of natural gas could materially impact our gas supply, financial position, financial results and cash flows. We continue to monitor the implementation of final and proposed legislation and regulations, including the Infrastructure Investment and Jobs Act, Build
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Back Better legislation and the EPA's proposed methane regulations for the oil and natural gas industry, but we cannot predict their final form or impact on our business at this time.
On July 8, 2019, the EPA published the final ACE rule, which establishes emission guidelines for states to use when developing plans to limit carbon dioxide at coal-fired electric generating units based on heat rate improvement measures. The U.S. Court of Appeals for the D.C. Circuit vacated and remanded the rule on January 19, 2021. On October 29, 2021, the U.S. Supreme Court agreed to review the scope of the EPA’s authority to impose GHG emission standards under the Clean Air Act. We will continue to monitor this matter.
In February 2021, the United States rejoined the Paris Agreement, an international treaty through which parties set nationally determined contributions to reduce GHG emissions, build resilience, and adapt to the impacts of climate change. Subsequently, the Biden Administration released a target for the United States to achieve a 50%-52% GHG reduction from 2005 levels by 2030, which supports the President's goals to create a carbon-free power sector by 2035 and net zero emissions economy no later than 2050. There are many pathways to reach these goals.
In 2021, the Maryland Commission of Climate Change published a Building Energy Transition Plan. Policy recommendations included in this plan, such as the adoption of an all-electric construction code, are supported by the Commission but do not necessarily reflect current state policy. The report is intended to guide Maryland policy makers on decisions related to reducing GHG emissions from buildings in pursuit of achieving targets in Maryland's 2030 Greenhouse Gas Reduction Act Plan and the Commission's recommendation that Maryland achieve net-zero emissions by 2045. Columbia of Maryland will continue to monitor this matter, but we cannot predict its final impact on our business at this time.
In response to these transition risks, we continue to actively implement our plans to reduce Scope 1 GHG emissions by 90% from 2005 levels by 2030, and to significantly reduce methane emissions, a component of Scope 1 GHG emissions. These plans include the retirement of coal-fired electric generation, increased sourcing of renewable energy, and methane reductions from priority pipeline replacement, traditional leak detection and repair, and deployment of advanced leak detection and repair. As discussed above in this Management's Discussion within "Results and Discussion of Segment Operations - Electric Operations," NIPSCO continues to execute on an electric generation transition consistent with the preferred pathways identified in its 2018 and 2021 Integrated Resource Plans. We expect to have capital investment requirements of approximately $2.0 billion, primarily in 2022 and 2023, to replace the generation capacity previously supplied by R.M. Schahfer. We continue to expect to retire Michigan City Generating Station between 2026 and 2028. The preferred path of the 2021 Integrated Resource plan outlined new generation investments estimated to be up to $750 million, and we are currently evaluating future projects in line with the preferred path.
Additionally, we are active in several efforts to accelerate the development and demonstration of lower-carbon energy technologies and resources, such as hydrogen and renewable natural gas (RNG), to enable affordable pathways to economy-wide decarbonization.
Market Risk Disclosures
Risk is an inherent part of our businesses. The extent to which we properly and effectively identify, assess, monitor and manage each of the various types of risk involved in our businesses is critical to our profitability. We seek to identify, assess, monitor and manage, in accordance with defined policies and procedures, the following principal market risks that are involved in our businesses: commodity price risk, interest rate risk and credit risk. We manage risk through a multi-faceted process with oversight by the Risk Management Committee that requires constant communication, judgment and knowledge of specialized products and markets. Our senior management takes an active role in the risk management process and has developed policies and procedures that require specific administrative and business functions to assist in the identification, assessment and control of various risks. These may include, but are not limited to market, operational, financial, compliance and strategic risk types. In recognition of the increasingly varied and complex nature of the energy business, our risk management process, policies and procedures continue to evolve and are subject to ongoing review and modification.
Commodity Price Risk
Our Gas and Electric Operations have commodity price risk primarily related to the purchases of natural gas and power. To manage this market risk, our subsidiaries use derivatives, including commodity futures contracts, swaps, forwards and options. We do not participate in speculative energy trading activity.
Commodity price risk resulting from derivative activities at our rate-regulated subsidiaries is limited and does not bear signification exposure to earnings risk, since regulations allow recovery of prudently incurred purchased power, fuel and gas
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
costs through the rate-making process, including gains or losses on these derivative instruments. These changes are included in the GCA and FAC regulatory rate-recovery mechanisms. If these mechanisms were to be adjusted or eliminated, these subsidiaries may begin providing services without the benefit of the traditional rate-making process and may be more exposed to commodity price risk.
Our subsidiaries are required to make cash margin deposits with their brokers to cover actual and potential losses in the value of outstanding exchange traded derivative contracts. The amount of these deposits, some of which is reflected in our restricted cash balance, may fluctuate significantly during periods of high volatility in the energy commodity markets.
Refer to Note 10, "Risk Management Activities," in the Notes to the Consolidated Financial Statements for further information on our commodity price risk assets and liabilities as of December 31, 2021 and 2020.
Interest Rate Risk
We are exposed to interest rate risk as a result of changes in interest rates on borrowings under our revolving credit agreement, commercial paper program and accounts receivable programs, which have interest rates that are indexed to short-term market interest rates. Based upon average borrowings and debt obligations subject to fluctuations in short-term market interest rates, an increase (or decrease) in short-term interest rates of 100 basis points (1%) would have increased (or decreased) interest expense by $3.1 million and $12.3 million for 2021 and 2020, respectively. We are also exposed to interest rate risk as a result of changes in benchmark rates that can influence the interest rates of future debt issuances. From time to time we may enter into forward interest rate instruments to lock in long term interest costs and/ or rates.
Refer to Note 10, "Risk Management Activities," in the Notes to Consolidated Financial Statements for further information on our interest rate risk assets and liabilities as of December 31, 2021 and 2020.
Credit Risk
Due to the nature of the industry, credit risk is embedded in many of our business activities. Our extension of credit is governed by a Corporate Credit Risk Policy. In addition, our Risk Management Committee has put guidelines in place which document management approval levels for credit limits, evaluation of creditworthiness, and credit risk mitigation efforts. Exposures to credit risks are monitored by the risk management function, which is independent of commercial operations. Credit risk arises due to the possibility that a customer, supplier or counterparty will not be able or willing to fulfill its obligations on a transaction on or before the settlement date. For derivative-related contracts, credit risk arises when counterparties are obligated to deliver or purchase defined commodity units of gas or power to us at a future date per execution of contractual terms and conditions. Exposure to credit risk is measured in terms of both current obligations and the market value of forward positions net of any posted collateral such as cash and letters of credit.
We closely monitor the financial status of our banking credit providers. We evaluate the financial status of our banking partners through the use of market-based metrics such as credit default swap pricing levels, and also through traditional credit ratings provided by major credit rating agencies.
Certain individual state regulatory commissions instituted regulatory moratoriums in connection with the COVID-19 pandemic that impacted our ability to pursue our credit risk mitigation practices for customer accounts receivable. Following the issuances of these moratoriums, certain of our regulated operations have been authorized to recognize a regulatory asset for bad debt costs above levels currently in rates. We have now resumed our common credit mitigation practices in all jurisdictions as these moratoriums have expired. See the COVID-19 discussion in Part I, Item 1A, "Risk Factors" for risks that have been identified related to the pandemic and refer to Note 9, "Regulatory Matters," in the Notes to Consolidated Financial Statements for state specific regulatory moratoriums.
Other Information
Critical Accounting Policies and Estimates
We apply certain accounting policies in accordance with GAAP, which require that we make estimates and judgments that have had, and may continue to have, significant impacts on our operations and Consolidated Financial Statements. We evaluate our estimates on an ongoing basis. We base our estimates on historical experience and on various other assumptions that we believe are reasonable under the circumstances, the results of which form the basis for making judgments about the carrying values of assets and liabilities that are not readily apparent from other sources. Actual results may differ from these estimates. We believe the following represent the more significant items requiring the use of judgment in preparing our Consolidated Financial Statements:
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Basis of Accounting for Rate-Regulated Subsidiaries. ASC Topic 980, Regulated Operations, provides that rate-regulated subsidiaries account for and report assets and liabilities consistent with the economic effect of the way in which regulators establish rates, if the rates established are designed to recover the costs of providing the regulated service and if the competitive environment makes it probable that such rates can be charged and collected. Certain expenses and credits subject to utility regulation or rate determination normally reflected in income are deferred on the Consolidated Balance Sheets and are recognized in income as the related amounts are included in service rates and recovered from or refunded to customers. The total amounts of regulatory assets and liabilities reflected on the Consolidated Balance Sheets were $2,492.2 million and $1,980.0 million at December 31, 2021, and $1,930.5 million and $2,065.5 million at December 31, 2020, respectively. For additional information, refer to Note 9, “Regulatory Matters,” in the Notes to Consolidated Financial Statements.
In the event that regulation significantly changes the opportunity for us to recover our costs in the future, all or a portion of our regulated operations may no longer meet the criteria for the application of ASC Topic 980, Regulated Operations. In such event, a write-down of all or a portion of our existing regulatory assets and liabilities could result. If transition cost recovery is approved by the appropriate regulatory bodies that would meet the requirements under GAAP for continued accounting as regulatory assets and liabilities during such recovery period, the regulatory assets and liabilities would be reported at the recoverable amounts. If we were unable to continue to apply the provisions of ASC Topic 980, Regulated Operations, we would be required to apply the provisions of ASC Topic 980-20, Discontinuation of Rate-Regulated Accounting. In management’s opinion, our regulated subsidiaries will be subject to ASC Topic 980, Regulated Operations for the foreseeable future.
Certain of the regulatory assets reflected on our Consolidated Balance Sheets require specific regulatory action in order to be included in future service rates. Although recovery of these amounts is not guaranteed, we believe that these costs meet the requirements for deferral as regulatory assets. If we determine that the amounts included as regulatory assets are no longer recoverable, a charge to income would immediately be required to the extent of the unrecoverable amounts.
One of the more significant items recorded through the application of this accounting guidance is the regulatory overlay for JV accounting. The application of HLBV to consolidated VIEs generally results in the recognition of profit from the related joint ventures over a time frame that is different from when the regulatory return is earned. In accordance with the principles of ASC 980, we have recognized a regulatory deferral of certain amounts representing the timing difference between the profit earned from the joint ventures and the amount included in regulated rates to recover our approved investments in consolidated joint ventures. For additional information, refer to Note 1-S, "VIEs and Allocation of Earnings," in the Notes to Consolidated Financial Statements.
Equity Unit Transactions. We record the Series C Mandatory Convertible Preferred Stock and forward purchase contracts that comprise the Corporate Units as a single unit of account and classify the Corporate Units as equity under the provisions of ASC 480 and ASC 815. Significant judgments regarding the economic linkage between the preferred stock and the forward purchase contracts, as well as the substance of the terms and conditions of the Corporate Units, were required by management in making these determinations.
The initial classification of the Corporate Units, whether viewed as a single unit of account or as two freestanding financial instruments, would affect our financial results. If determined to be two units of account, the forward purchase contracts underlying the Corporate Units would be classified as a derivative and result in impacts to net income through the recognition of interest expense and mark-to-market adjustments. If determined to be one unit of account,the equity classification of the Corporate Units would have no material impact on net income. Each classification has differing impacts to the numerator in the computation of EPS.
We consider that there are a small number of similar equity hosted unit structures and that our unit structure is unique. We also consider that the provisions of ASC 480 and ASC 815 that govern the determination of unit of account are highly complex and that alternate conclusions reached under this guidance would result in materially different financial results. See Note 13, "Equity," in the Notes to Consolidated Financial Statements for additional details of the equity unit transaction.
Pension and Postretirement Benefits. We have defined benefit plans for both pension and other postretirement benefits. The calculation of the net obligations and annual expense related to the plans requires a significant degree of judgment regarding the discount rates to be used in bringing the liabilities to present value, expected long-term rates of return on plan assets, health care trend rates, and mortality rates, among other assumptions. Due to the size of the plans and the long-term nature of the associated liabilities, changes in the assumptions used in the actuarial estimates could have material impacts on the measurement of the net obligations and annual expense recognition. Differences between actuarial assumptions and actual plan results are deferred into
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
AOCI or a regulatory balance sheet account, depending on the jurisdiction of our entity. These deferred gains or losses are then amortized into the income statement when the accumulated differences exceed 10% of the greater of the projected benefit obligation or the fair value of plan assets (known in GAAP as the “corridor” method) or when settlement accounting is triggered.
The discount rates, expected long-term rates of return on plan assets, health care cost trend rates and mortality rates are critical assumptions. Methods used to develop these assumptions are described below. While a third party actuarial firm assists with the development of many of these assumptions, we are ultimately responsible for selecting the final assumptions.
The discount rate is utilized principally in calculating the actuarial present value of pension and other postretirement benefit obligations and net periodic pension and other postretirement benefit plan costs. Our discount rates for both pension and other postretirement benefits are determined using spot rates along an AA-rated above median yield curve with cash flows matching the expected duration of benefit payments to be made to plan participants.
The expected long-term rate of return on plan assets is a component utilized in calculating annual pension and other postretirement benefit plan costs. We estimate the expected return on plan assets by evaluating expected bond returns, equity risk premiums, target asset allocations, the effects of active plan management, the impact of periodic plan asset rebalancing and historical performance. We also consider the guidance from our investment advisors in making a final determination of our expected rate of return on assets. For measurement of 2021 net periodic benefit cost, we selected an expected pre-tax long-term rate of return of 5.20% and 5.50% for our pension and other postretirement benefit plan assets, respectively.
We estimate the assumed health care cost trend rate, which is used in determining our other postretirement benefit net expense, based upon our actual health care cost experience, the effects of recently enacted legislation, third-party actuarial surveys and general economic conditions.
We utilize a full yield curve approach to estimate the service and interest components of net periodic benefit cost for pension and other postretirement benefits by applying the specific spot rates along the yield curve used in the determination of the benefit obligation to the relevant projected cash flows. For further discussion of our pension and other postretirement benefits, see Note 12, “Pension and Other Postretirement Benefits,” in the Notes to Consolidated Financial Statements.
Typically, we use the Society of Actuaries’ most recently published mortality data in developing a best estimate of mortality as part of the calculation of the pension and other postretirement benefit obligations. Due to the ongoing COVID-19 pandemic, we adjusted our mortality assumption through 2023 to reflect anticipated slow recovery.
The following tables illustrate the effects of changes in these actuarial assumptions while holding all other assumptions constant:
| Impact on December 31, 2021 Projected Benefit Obligation Increase/(Decrease) | |||||||||||
| Change in Assumptions (in millions) | Pension Benefits | Other Postretirement Benefits | |||||||||
| +50 basis points change in discount rate | $ | (80.0) | $ | (27.7) | |||||||
| -50 basis points change in discount rate | 84.8 | 30.3 | |||||||||
| Impact on 2021 Expense Increase/(Decrease)(1) | |||||||||||
| Change in Assumptions (in millions) | Pension Benefits | Other Postretirement Benefits | |||||||||
| +50 basis points change in discount rate | $ | (1.6) | $ | (0.8) | |||||||
| -50 basis points change in discount rate | 1.6 | 0.8 | |||||||||
| +50 basis points change in expected long-term rate of return on plan assets | (9.9) | (1.4) | |||||||||
| -50 basis points change in expected long-term rate of return on plan assets | 9.9 | 1.4 | |||||||||
(1)Before labor capitalization and regulatory deferrals.
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Goodwill and Other Intangible Assets. We have six goodwill reporting units, comprised of the six state operating companies within the Gas Distribution Operations reportable segment. Our goodwill assets at December 31, 2021 were $1,486 million, most of which resulted from the acquisition of Columbia on November 1, 2000.
As required by GAAP, we test for impairment of goodwill on an annual basis and on an interim basis when events or circumstances indicate that a potential impairment may exist. Our annual goodwill test takes place in the second quarter of each year and was performed on May 1, 2021. A qualitative ("step 0") test was completed on May 1, 2021 for all reporting units. In the Step 0 analysis, we assessed various assumptions, events and circumstances that would have affected the estimated fair value of the applicable reporting units as compared to their baseline May 1, 2020 "step 1" fair value measurement. The results of this assessment indicated that it was more likely than not that the estimated fair value of the reporting unit substantially exceeded the related carrying value of our reporting unit; therefore, no "step 1" analysis was required and no impairment charges were indicated. Since the annual evaluation, there have been no indications that the fair values of the goodwill reporting units have decreased below the carrying values.
As noted above, application of the qualitative goodwill impairment test requires evaluating various events and circumstances to determine whether it is not more likely than not that the fair value of a reporting unit is less than its carrying amount. Although we believe all relevant factors were considered in the qualitative impairment analysis to reach the conclusion that goodwill is not impaired, significant changes in any one of the assumptions could potentially result in the recording of an impairment that could have significant impacts on the Consolidated Financial Statements.
See Note 7, "Goodwill and Other Intangible Assets," in the Notes to Consolidated Financial Statements for further information.
Unbilled Revenue. We record utility operating revenues when energy is delivered to our customers. However, the determination of energy sales to individual customers is based upon the reading of their meters, which occurs on a systematic basis throughout the month. At the end of each month, amounts of energy delivered to customers since the date of their last meter reading are estimated and corresponding unbilled revenues are calculated. This unbilled revenue is estimated each month based upon historical usage, customer rates and weather. Significant fluctuations in energy demand for the unbilled period or changes in the composition of customer classes could impact the accuracy of the unbilled revenue estimate. Refer to Note 3, "Revenue Recognition," in the Notes to Consolidated Financial Statements for additional information regarding our significant judgments and estimates related to unbilled revenue recognition.
Income Taxes. The consolidated income tax provision and deferred income tax assets and liabilities, as well as any unrecognized tax benefits and valuation allowances, require use of estimates and significant management judgement. Although we believe that current estimates for deferred tax assets and liabilities are reasonable, actual results could differ from these estimates for a variety of reasons, including reasonable projections of taxable income, the ability and intent to implement tax planning strategies if necessary, and interpretations of applicable tax laws and regulations across multiple taxing jurisdictions. Ultimate resolution or clarification of income tax matters may result in favorable or unfavorable impacts to net income and cash flows, and adjustments to tax-related assets and liabilities could be material.
We account for uncertain income tax positions using a benefit recognition model with a two-step approach including a more-likely-than-not recognition threshold and a measurement approach based on the largest amount of tax benefit that is greater than 50% likely of being realized upon ultimate settlement. We evaluate each position based solely on the technical merits and facts and circumstances of the position, assuming the position will be examined by a taxing authority having full knowledge of all relevant information. Significant judgment is required to determine whether the recognition threshold has been met and, if so, the appropriate amount of tax benefits to be recorded in the consolidated financial statements. At December 31, 2021 we had $21.7 million of unrecognized tax benefits. Changes in these unrecognized tax benefits may result from remeasurement of amounts expected to be realized, settlements with tax authorities and expiration of statutes of limitations.
Valuation allowances against deferred tax assets are recorded when we conclude it is more likely than not such asset will not be realized in future periods. Accounting for income taxes also requires that only tax benefits for positions taken or expected to be taken on tax returns that meet the more-likely-than-not recognition threshold can be recognized or continue to be recognized. We evaluate each position solely on the technical merits and facts and circumstances of the position, assuming that the position will be examined by a taxing authority that has full knowledge of all relevant information. Significant judgment is required to determine recognition thresholds and the related amount of tax benefits to be recognized. At December 31, 2021, we had established $7.8 million of valuation allowances related to certain state NOL carryforwards. Refer to Note 11, "Income Taxes," in the Notes to Consolidated Financial Statements for additional information.
ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (continued)
NIS****OURCE INC.
Recently Issued Accounting Pronouncements
Refer to Note 2, "Recent Accounting Pronouncements," in the Notes to Consolidated Financial Statements.
Quantitative and Qualitative Disclosures about Market Risk are reported in Item 7, “Management’s Discussion and Analysis of Financial Condition and Results of Operations – Market Risk Disclosures.”
ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
NIS****OURCE INC.
ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA (continued)
NIS****OURCE INC.
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the shareholders and the Board of Directors of NiSource Inc.
Opinion on the Financial Statements
We have audited the accompanying consolidated balance sheets of NiSource Inc. and subsidiaries (the "Company") as of December 31, 2021 and 2020, the related statements of consolidated income (loss), comprehensive income (loss), stockholders' equity, and cash flows for each of the three years in the period ended December 31, 2021, and the related notes and the schedule listed in the Index at Item 15 (collectively referred to as the "financial statements"). In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company as of December 31, 2021 and 2020, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2021, in conformity with accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, 2021, based on criteria established in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February 23, 2022, expressed an unqualified opinion on the Company's internal control over financial reporting.
Basis for Opinion
These financial statements are the responsibility of the Company's management. Our responsibility is to express an opinion on the Company's financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements. We believe that our audits provide a reasonable basis for our opinion.
Critical Audit Matters
The critical audit matters communicated below are matters arising from the current-period audit of the financial statements that were communicated or required to be communicated to the audit committee and that (1) relate to accounts or disclosures that are material to the financial statements and (2) involved our especially challenging, subjective, or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the financial statements, taken as a whole, and we are not, by communicating the critical audit matters below, providing separate opinions on the critical audit matters or on the accounts or disclosures to which they relate.
Impact of Rate Regulation on the Financial Statements - Refer to Notes 1 and 9 to the consolidated financial statements
Critical Audit Matter Description
The Company’s subsidiaries are fully regulated natural gas and electric utility companies serving customers in six states. These rate-regulated subsidiaries account for and report assets and liabilities consistent with the economic effect of the manner in which regulators establish rates, if the rates established are designed to recover the costs of providing the regulated service and it is probable that such rates can be charged to and collected from customers. Certain expenses and credits subject to utility regulation or rate determination normally reflected in income are deferred on the consolidated balance sheets and are later recognized in income as the related amounts are included in customer rates and recovered from or refunded to customers.
The Company’s subsidiaries’ rates are subject to regulatory rate-setting processes. Rates are determined and approved in regulatory proceedings based on an analysis of the subsidiaries’ costs to provide utility service and a return on, and recovery of, the subsidiaries’ investment in the utility business. Regulatory decisions can have an impact on the recovery of costs, the rate of return earned on investment, and the timing and amount of assets to be recovered by rates. The respective commission’s regulation of rates is premised on the full recovery of prudently incurred costs and a reasonable rate of return on invested
ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA (continued)
NIS****OURCE INC.
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
capital. Decisions to be made by the commission in the future will impact the accounting for regulated operations, including decisions about the amount of allowable costs and return on invested capital included in rates and any refunds that may be required. While the Company has indicated it expects to recover costs from customers through regulated rates, there is a risk that the commission will not approve: (1) full recovery of the costs of providing utility service, or (2) full recovery of all amounts invested in the utility business and a reasonable return on that investment.
We identified the accounting for rate-regulated subsidiaries as a critical audit matter due to the significant judgments made by management to support its assertions about impacted account balances and disclosures and the high degree of subjectivity involved in assessing the impact of future regulatory orders on the financial statements. Management judgments include assessing (1) the likelihood of recovery in future rates of incurred costs and (2) the likelihood of refund of amounts previously collected from customers. Given that management’s accounting judgments are based on assumptions about the outcome of future decisions by regulatory commissions, auditing these judgments required specialized knowledge of accounting for rate regulation and the rate making process due its inherent complexities.
How the Critical Audit Matter Was Addressed in the Audit
Our audit procedures related to the uncertainty of future decisions by the commissions included the following, among others:
-
We tested the effectiveness of management’s controls over the evaluation of the likelihood of (1) the recovery in future rates of costs incurred as property, plant, and equipment and deferred as regulatory assets, and (2) a refund or a future reduction in rates that should be reported as regulatory liabilities. We also tested the effectiveness of management’s controls over the initial recognition of amounts as property, plant, and equipment; regulatory assets or liabilities; and the monitoring and evaluation of regulatory developments, that may affect the likelihood of recovering costs in future rates or of a future reduction in rates.
-
We evaluated the Company’s disclosures related to the impacts of rate regulation, including the balances recorded and regulatory developments.
-
We read relevant regulatory orders issued by the commissions for the Company, regulatory statutes, interpretations, procedural memorandums, filings made by interveners, and other publicly available information to assess the likelihood of recovery in future rates or of a future reduction in rates based on precedents of the commissions’ treatment of similar costs under similar circumstances. We evaluated the external information and compared to management’s recorded regulatory asset and liability balances for completeness.
-
For regulatory matters in process, we inspected the Company’s filings with the commissions and the filings with the commissions by intervenors that may impact the Company’s future rates, for any evidence that might contradict management’s assertions related to recoverability of recorded assets*.*
-
We inquired of management about property, plant, and equipment that may be abandoned. For assets that were abandoned, we inquired of management about their considerations regarding the abandonment. We inspected minutes of the board of directors and regulatory orders and other filings with the commissions to identify evidence that may contradict management’s assertion regarding probability of an abandonment.
-
With the assistance of professionals in our firm with expertise in the application of ASC Topic 980, Regulated Operations, we evaluated management’s conclusions regarding the application of ASC Topic 980 to the timing differences between the amount of profit from the consolidated joint ventures and the amount included in regulated rates.
-
We read the relevant regulatory orders issued by the Commission for the Company’s renewable energy investments. We evaluated the appropriateness of recognizing a regulatory liability or asset representing timing differences between the profit allocated under the Hypothetical Liquidation at Book Value (HLBV) method related to the consolidated joint ventures and the allowed earnings included in regulatory rates. We also evaluated the appropriateness of the offset to the regulatory liability or asset recorded in depreciation expense.
-
We evaluated the Company’s disclosures related to the application of ASC Topic 980 to consolidated joint venture accounting.
ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA (continued)
NIS****OURCE INC.
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
Preferred Stock—2021 Equity Units - Refer to Notes 5, 13, 18 and 24 to the consolidated financial statements
Critical Audit Matter Description
On April 19, 2021, the Company completed the sale of 8.625 million equity units, initially consisting of corporate units, each with a stated amount of $100. Each corporate unit consists of a forward contract to purchase shares of the Company's common stock in the future (“Forward Contract”) and a 1/10th, or 10%, undivided beneficial ownership interest in one share of Series C Mandatory Convertible Preferred Stock (“Preferred Stock”) (collectively the “Equity Units”).
The Forward Contract obligates holders to purchase shares of the Company's common stock on December 1, 2023, subject to early settlement in certain situations. The purchase price to be paid under the Forward Contract is $100 per Equity Unit and the number of shares to be purchased will be determined near the settlement date, subject to a maximum settlement rate. The Preferred Stock was pledged upon issuance as collateral to secure the purchase of the Company's common stock under the related Forward Contract. The Company will pay quarterly contract adjustment payments at the rate of 7.75% per year on the stated amount of $100 per Equity Unit.
The Preferred Stock initially will not bear any dividends and is expected to be remarketed prior to December 1, 2023. Following a successful remarketing, dividends may become payable on the Preferred Stock and/or the minimum conversion rate of the Preferred Stock may be increased. Each share of Preferred Stock will automatically convert based on a conversion rate on the mandatory conversion date, which is expected to be on or about March 1, 2024, unless previously converted. If no successful remarketing of the Preferred Stock has previously occurred, effective as of December 1, 2023, the conversion rate will be zero, no shares of the Company's common stock will be delivered upon automatic conversion, and each share of Preferred Stock will be automatically transferred to the Company on the mandatory conversion date without any payment of cash or shares of the Company's common stock thereon. In the event of such a remarketing failure, any share of Preferred Stock held as part of Equity Units will be automatically delivered to the Company on December 1, 2023 in full satisfaction of the relevant holder’s obligation under the related Forward Contracts.
The Company has concluded that the Forward Contracts and the Preferred Stock host represent a single unit of account and has recorded the Equity Units in equity as Preferred Stock. The present value of the quarterly contract adjustment payments was recorded as a liability, with the offset recorded in Preferred Stock.
We identified the accounting for the Equity Units as a critical audit matter due to the significant judgments made by management in the application of accounting guidance. Auditing these judgments required specialized knowledge of accounting for financial instruments and extensive audit procedures to evaluate the accounting treatment associated with the Equity Units.
How the Critical Audit Matter Was Addressed in the Audit
Our audit procedures related to the accounting for the Equity Units included the following, among others:
-
We tested the effectiveness of controls over management’s accounting assessment of the Equity Units.
-
We read the applicable agreements and compared the key terms from the agreements to management’s analysis of the transaction.
-
With the assistance of professionals in our firm with expertise in 1) accounting for financial instruments and 2) assessing probability of certain outcomes underlying the key accounting judgments, we evaluated management’s conclusions regarding the application of the appropriate accounting standards.
-
We evaluated the Company's disclosure of the Equity Units transaction, including the related impacts to the financial statements.
/s/ DELOITTE & TOUCHE LLP
Columbus, Ohio
February 23, 2022
We have served as the Company's auditor since 2002.
ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA (continued)
NIS****OURCE INC.
STATEMENTS OF CONSOLIDATED INCOME (LOSS)
| Year Ended December 31*, (in millions, except per share amounts)* | 2021 | 2020 | 2019 | ||||||||||||||
| Operating Revenues | |||||||||||||||||
| Customer revenues | $ | 4,731.3 | $ | 4,473.2 | $ | 5,053.4 | |||||||||||
| Other revenues | 168.3 | 208.5 | 155.5 | ||||||||||||||
| Total Operating Revenues | 4,899.6 | 4,681.7 | 5,208.9 | ||||||||||||||
| Operating Expenses | |||||||||||||||||
| Cost of energy | 1,392.3 | 1,109.3 | 1,534.8 | ||||||||||||||
| Operation and maintenance | 1,456.0 | 1,585.9 | 1,354.7 | ||||||||||||||
| Depreciation and amortization | 748.4 | 725.9 | 717.4 | ||||||||||||||
| Impairment of goodwill and intangible assets | — | — | 414.5 | ||||||||||||||
| Loss on sale of assets, net | 7.7 | 410.6 | — | ||||||||||||||
| Other taxes | 288.3 | 299.2 | 296.8 | ||||||||||||||
| Total Operating Expenses | 3,892.7 | 4,130.9 | 4,318.2 | ||||||||||||||
| Operating Income | 1,006.9 | 550.8 | 890.7 | ||||||||||||||
| Other Income (Deductions) | |||||||||||||||||
| Interest expense, net | (341.1) | (370.7) | (378.9) | ||||||||||||||
| Other, net | 40.8 | 32.1 | (5.2) | ||||||||||||||
| Loss on early extinguishment of long-term debt | — | (243.5) | — | ||||||||||||||
| Total Other Deductions, Net | (300.3) | (582.1) | (384.1) | ||||||||||||||
| Income (Loss) before Income Taxes | 706.6 | (31.3) | 506.6 | ||||||||||||||
| Income Taxes | 117.8 | (17.1) | 123.5 | ||||||||||||||
| Net Income (Loss) | 588.8 | (14.2) | 383.1 | ||||||||||||||
| Net income attributable to noncontrolling interest | 3.9 | 3.4 | — | ||||||||||||||
| Net Income (Loss) attributable to NiSource | 584.9 | (17.6) | 383.1 | ||||||||||||||
| Preferred dividends | (55.1) | (55.1) | (55.1) | ||||||||||||||
| Net Income (Loss) Available to Common Shareholders | 529.8 | (72.7) | 328.0 | ||||||||||||||
| Earnings (Loss) Per Share | |||||||||||||||||
| Basic Earnings (Loss) Per Share | $ | 1.35 | $ | (0.19) | $ | 0.88 | |||||||||||
| Diluted Earnings (Loss) Per Share | $ | 1.27 | $ | (0.19) | $ | 0.87 | |||||||||||
| Basic Average Common Shares Outstanding | 393.6 | 384.3 | 374.6 | ||||||||||||||
| Diluted Average Common Shares | 417.3 | 384.3 | 376.0 |
The accompanying Notes to Consolidated Financial Statements are an integral part of these statements.
ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA (continued)
NIS****OURCE INC.
STATEMENTS OF CONSOLIDATED COMPREHENSIVE INCOME (LOSS)
| Year Ended December 31, (in millions, net of taxes) | 2021 | 2020 | 2019 | ||||||||||||||
| Net Income (Loss) | $ | 588.8 | $ | (14.2) | $ | 383.1 | |||||||||||
| Other comprehensive income (loss): | |||||||||||||||||
| Net unrealized gain (loss) on available-for-sale securities(1) | (3.9) | 2.7 | 5.7 | ||||||||||||||
| Net unrealized gain (loss) on cash flow hedges(2) | 25.4 | (70.7) | (64.2) | ||||||||||||||
| Unrecognized pension and OPEB benefit(3) | 8.4 | 3.9 | 3.1 | ||||||||||||||
| Total other comprehensive income (loss) | 29.9 | (64.1) | (55.4) | ||||||||||||||
| Total Comprehensive Income (Loss) | $ | 618.7 | $ | (78.3) | $ | 327.7 | |||||||||||
(1) Net unrealized gain (loss) on available-for-sale securities, net of $1.0 million tax benefit, $0.7 million tax expense and $1.5 million tax expense in 2021, 2020 and 2019, respectively.
(2) Net unrealized gain (loss) on derivatives qualifying as cash flow hedges, net of $8.4 million tax expense, $23.4 million tax benefit and $21.2 million tax benefit in 2021, 2020 and 2019, respectively.
(3) Unrecognized pension and OPEB benefit, net of $3.8 million tax expense, $0.1 million tax benefit and $1.6 million tax expense in 2021, 2020 and 2019, respectively.
The accompanying Notes to Consolidated Financial Statements are an integral part of these statements.
ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA (continued)
NIS****OURCE INC.
CONSOLIDATED BALANCE SHEETS
| (in millions) | December 31, 2021 | December 31, 2020 | |||||||||
| ASSETS | |||||||||||
| Property, Plant and Equipment | |||||||||||
| Plant | $ | 25,171.3 | $ | 24,179.9 | |||||||
| Accumulated depreciation and amortization | (7,289.5) | (7,560.4) | |||||||||
| Net Property, Plant and Equipment(1) | 17,881.8 | 16,619.5 | |||||||||
| Investments and Other Assets | |||||||||||
| Unconsolidated affiliates | 0.8 | — | |||||||||
| Available-for-sale debt securities (amortized cost of $169.3 and $163.9, allowance for credit losses of $0.2 and $0.5, respectively) | 171.8 | 170.9 | |||||||||
| Other investments | 87.1 | 81.1 | |||||||||
| Total Investments and Other Assets | 259.7 | 252.0 | |||||||||
| Current Assets | |||||||||||
| Cash and cash equivalents | 84.2 | 116.5 | |||||||||
| Restricted cash | 10.7 | 9.1 | |||||||||
| Accounts receivable | 849.1 | 843.6 | |||||||||
| Allowance for credit losses | (23.5) | (52.3) | |||||||||
| Accounts receivable, net | 825.6 | 791.3 | |||||||||
| Gas inventory | 327.4 | 191.2 | |||||||||
| Materials and supplies, at average cost | 139.1 | 141.5 | |||||||||
| Electric production fuel, at average cost | 32.2 | 68.4 | |||||||||
| Exchange gas receivable | 99.6 | 34.1 | |||||||||
| Regulatory assets | 206.2 | 135.7 | |||||||||
| Deferred property taxes | 91.0 | 85.6 | |||||||||
| Prepayments and other | 104.8 | 86.0 | |||||||||
| Total Current Assets(1) | 1,920.8 | 1,659.4 | |||||||||
| Other Assets | |||||||||||
| Regulatory assets | 2,286.0 | 1,794.8 | |||||||||
| Goodwill | 1,485.9 | 1,485.9 | |||||||||
| Deferred charges and other | 322.7 | 228.9 | |||||||||
| Total Other Assets | 4,094.6 | 3,509.6 | |||||||||
| Total Assets | $ | 24,156.9 | $ | 22,040.5 |
(1)Includes $695.9 million and $175.6 million in 2021 and 2020, respectively, of net property, plant and equipment assets and $14.3 million and $1.7 million in 2021 and 2020, respectively, of current assets of consolidated VIEs that may be used only to settle obligations of the consolidated VIEs. Refer to Note 4, "Variable Interest Entities" for additional information.
The accompanying Notes to Consolidated Financial Statements are an integral part of these statements.
ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA (continued)
NIS****OURCE INC.
CONSOLIDATED BALANCE SHEETS
| (in millions, except share amounts) | December 31, 2021 | December 31, 2020 | |||||||||
| CAPITALIZATION AND LIABILITIES | |||||||||||
| Capitalization | |||||||||||
| Stockholders’ Equity | |||||||||||
| Common stock - $0.01 par value, 600,000,000 shares authorized; 405,303,023 and 391,760,051 shares outstanding, respectively | $ | 4.1 | $ | 3.9 | |||||||
| Preferred stock - $0.01 par value, 20,000,000 shares authorized; 1,302,500 and 440,000 shares outstanding, respectively | 1,546.5 | 880.0 | |||||||||
| Treasury stock | (99.9) | (99.9) | |||||||||
| Additional paid-in capital | 7,204.3 | 6,890.1 | |||||||||
| Retained deficit | (1,580.9) | (1,765.2) | |||||||||
| Accumulated other comprehensive loss | (126.8) | (156.7) | |||||||||
| Total NiSource Stockholders' Equity | 6,947.3 | 5,752.2 | |||||||||
| Noncontrolling interest in consolidated subsidiaries | 325.6 | 85.6 | |||||||||
| Total Stockholders’ Equity | 7,272.9 | 5,837.8 | |||||||||
| Long-term debt, excluding amounts due within one year | 9,183.4 | 9,219.8 | |||||||||
| Total Capitalization | 16,456.3 | 15,057.6 | |||||||||
| Current Liabilities | |||||||||||
| Current portion of long-term debt | 58.1 | 23.3 | |||||||||
| Short-term borrowings | 560.0 | 503.0 | |||||||||
| Accounts payable | 697.8 | 589.0 | |||||||||
| Customer deposits and credits | 237.9 | 243.3 | |||||||||
| Taxes accrued | 277.1 | 244.1 | |||||||||
| Interest accrued | 105.5 | 104.7 | |||||||||
| Exchange gas payable | 107.7 | 48.5 | |||||||||
| Regulatory liabilities | 137.4 | 161.3 | |||||||||
| Accrued compensation and employee benefits | 182.7 | 141.8 | |||||||||
| Other accruals | 382.0 | 220.4 | |||||||||
| Total Current Liabilities(1) | 2,746.2 | 2,279.4 | |||||||||
| Other Liabilities | |||||||||||
| Deferred income taxes | 1,659.4 | 1,470.6 | |||||||||
| Accrued liability for postretirement and postemployment benefits | 292.5 | 336.1 | |||||||||
| Regulatory liabilities | 1,842.6 | 1,904.2 | |||||||||
| Asset retirement obligations | 469.7 | 477.1 | |||||||||
| Other noncurrent liabilities | 690.2 | 515.5 | |||||||||
| Total Other Liabilities(1) | 4,954.4 | 4,703.5 | |||||||||
| Commitments and Contingencies (Refer to Note 19, "Other Commitments and Contingencies") | |||||||||||
| Total Capitalization and Liabilities | $ | 24,156.9 | $ | 22,040.5 |
(1)Includes $10.0 million and $15.3 million in 2021 and 2020, respectively, of current liabilities and $20.5 million and $5.6 million in 2021 and 2020, respectively, of other liabilities of consolidated VIEs that creditors do not have recourse to our general credit. Refer to Note 4, "Variable Interest Entities," for additional information.
The accompanying Notes to Consolidated Financial Statements are an integral part of these statements.
ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA (continued)
NIS****OURCE INC.
STATEMENTS OF CONSOLIDATED CASH FLOWS
| Year Ended December 31, (in millions) | 2021 | 2020 | 2019 | ||||||||||||||
| Operating Activities | |||||||||||||||||
| Net Income (Loss) | $ | 588.8 | $ | (14.2) | $ | 383.1 | |||||||||||
| Adjustments to Reconcile Net Income (Loss) to Net Cash from Operating Activities: | |||||||||||||||||
| Loss on early extinguishment of debt | — | 243.5 | — | ||||||||||||||
| Depreciation and amortization | 748.4 | 725.9 | 717.4 | ||||||||||||||
| Deferred income taxes and investment tax credits | 111.9 | (29.0) | 118.2 | ||||||||||||||
| Stock compensation expense and 401(k) profit sharing contribution | 24.3 | 17.4 | 25.9 | ||||||||||||||
| Impairment of goodwill and intangible assets | — | — | 414.5 | ||||||||||||||
| Loss (gain) on sale of assets | 5.6 | 409.8 | (0.6) | ||||||||||||||
| Other adjustments | (0.7) | (0.3) | (0.1) | ||||||||||||||
| Changes in Assets and Liabilities: | |||||||||||||||||
| Accounts receivable | (40.3) | (3.9) | 187.8 | ||||||||||||||
| Inventories | (112.9) | (1.5) | (2.0) | ||||||||||||||
| Accounts payable | 54.9 | (29.7) | (299.9) | ||||||||||||||
| Exchange gas receivable/payable | (114.2) | (6.9) | 55.5 | ||||||||||||||
| Other accruals | 43.0 | (175.1) | 138.3 | ||||||||||||||
| Prepayments and other current assets | (36.6) | (5.9) | (33.6) | ||||||||||||||
| Regulatory assets/liabilities | 76.8 | 70.8 | (85.6) | ||||||||||||||
| Postretirement and postemployment benefits | (96.4) | (103.6) | (21.1) | ||||||||||||||
| Deferred charges and other noncurrent assets | (4.7) | (15.0) | (76.1) | ||||||||||||||
| Other noncurrent liabilities | (30.0) | 21.7 | 61.6 | ||||||||||||||
| Net Cash Flows from Operating Activities | 1,217.9 | 1,104.0 | 1,583.3 | ||||||||||||||
| Investing Activities | |||||||||||||||||
| Capital expenditures | (1,838.0) | (1,758.1) | (1,802.4) | ||||||||||||||
| Cost of removal | (121.1) | (138.2) | (113.2) | ||||||||||||||
| Proceeds from disposition of assets | 0.7 | 1,115.9 | 0.4 | ||||||||||||||
| Purchases of available-for-sale securities | (102.9) | (144.7) | (140.4) | ||||||||||||||
| Sales of available-for-sale securities | 97.8 | 131.4 | 132.1 | ||||||||||||||
| Payment to renewable generation asset developer | (240.4) | (85.3) | — | ||||||||||||||
| Other investing activities | (1.0) | (0.1) | 1.1 | ||||||||||||||
| Net Cash Flows used for Investing Activities | (2,204.9) | (879.1) | (1,922.4) | ||||||||||||||
| Financing Activities | |||||||||||||||||
| Proceeds from issuance of long-term debt | — | 2,974.0 | 750.0 | ||||||||||||||
| Repayments of long-term debt and finance lease obligations | (25.7) | (1,622.0) | (51.6) | ||||||||||||||
| Issuance of short-term debt (maturity > 90 days) | — | 1,350.0 | 600.0 | ||||||||||||||
| Repayment of short-term debt (maturity > 90 days) | — | (2,200.0) | (700.0) | ||||||||||||||
| Change in short-term borrowings, net (maturity ≤ 90 days) | 57.0 | (420.1) | (104.0) | ||||||||||||||
| Issuance of common stock, net of issuance costs | 299.6 | 211.4 | 244.4 | ||||||||||||||
| Equity costs, premiums and other debt related costs | (18.2) | (246.5) | (17.8) | ||||||||||||||
| Contributions from noncontrolling interest | 245.1 | 82.2 | — | ||||||||||||||
| Distributions to noncontrolling interest | (0.6) | — | — | ||||||||||||||
| Issuance of equity units, net of underwriting costs | 839.9 | — | — | ||||||||||||||
| Dividends paid - common stock | (345.2) | (321.6) | (298.5) | ||||||||||||||
| Dividends paid - preferred stock | (55.1) | (55.1) | (56.1) | ||||||||||||||
| Contract liability payment | (40.5) | — | — | ||||||||||||||
| Net Cash Flows from Financing Activities | 956.3 | (247.7) | 366.4 | ||||||||||||||
| Change in cash, cash equivalents and restricted cash | (30.7) | (22.8) | 27.3 | ||||||||||||||
| Cash, cash equivalents and restricted cash at beginning of period | 125.6 | 148.4 | 121.1 | ||||||||||||||
| Cash, Cash Equivalents and Restricted Cash at End of Period | $ | 94.9 | $ | 125.6 | $ | 148.4 |
| Reconciliation to Balance Sheet | 2021 | 2020 | 2019 | ||||||||||||||
| Cash and cash equivalents | 84.2 | 116.5 | 139.3 | ||||||||||||||
| Restricted Cash | 10.7 | 9.1 | 9.1 | ||||||||||||||
| Total Cash, Cash Equivalents and Restricted Cash | 94.9 | 125.6 | 148.4 |
The accompanying Notes to Consolidated Financial Statements are an integral part of these statements.
Previous: Item 6. RESERVED · Next: Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA (continued)