 filings.tools
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
93K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
NIKE designs, develops, markets and sells athletic footwear, apparel, equipment, accessories and services worldwide. We are the largest seller of athletic footwear and apparel in the world. We sell our products through NIKE-owned retail stores and through digital platforms (which we refer to collectively as our “NIKE Direct” operations), to retail accounts and to a mix of independent distributors, licensees and sales representatives in virtually all countries around the world. Our goal is to deliver value to our shareholders by building a profitable global portfolio of branded footwear, apparel, equipment and accessories businesses. Our strategy is to achieve long-term revenue growth by creating innovative, “must-have” products, building deep personal consumer connections with our brands and delivering compelling consumer experiences through digital platforms and at retail.
Through the Consumer Direct Offense, we are focusing on our Triple Double strategy, with the objective of doubling the impact of innovation, increasing our speed to market and growing our direct connections with consumers. As a result of the execution of this strategy, our long-term financial goals through fiscal 2023, on average, per year, are as follows:
| • | High single-digit revenue growth; |
| • | Gross margin expansion of as much as 50 basis points; |
| • | Slight selling and administrative expense leverage; |
| • | Mid-teens earnings per share growth; and |
| • | Low-thirties percentage rate of return on invested capital. |
Fiscal 2019 was our first full year executing against our new strategy and our results demonstrated the power of the NIKE, Inc. portfolio to generate revenue growth, while investing in capabilities to fuel our next phase of long-term growth and profitability. We achieved record revenues in fiscal 2019, growing 7% to $39.1 billion. The NIKE Brand, which represents over 90% of NIKE, Inc. Revenues, delivered 8% revenue growth fueled by investments in innovative products and digital platforms. On a currency-neutral basis, NIKE Brand revenues grew 11%, driven by growth across all geographies, NIKE Direct and wholesale, nearly all key categories and double-digit growth across footwear and apparel. Within our NIKE Direct business, digital outpaced all other channels, growing at 35% in fiscal 2019. Revenues for Converse increased 1% and 3% on a reported and currency-neutral basis, respectively, primarily driven by double-digit growth in Asia and digital, which was partially offset by declines in the U.S. and Europe.
Income before income taxes increased 11% for fiscal 2019, as revenue growth and gross margin expansion were partially offset by higher selling and administrative expense. NIKE, Inc. gross margin increased 90 basis points primarily due to higher full-price average selling price (ASP), on a wholesale equivalent basis, favorable changes in foreign currency exchange rates and growth in NIKE Direct. These benefits were partially offset by higher product costs. Selling and administrative expense was higher as a percent of revenues, reflecting investments in data and analytics capabilities, digital commerce platforms and an initial investment in a new enterprise resource planning tool to accelerate our end-to-end digital transformation. Additionally, we prioritized investments in global brand campaigns aimed at deepening our connection with consumers.
Diluted earnings per common share reflects a 2% decline in the weighted average diluted common shares outstanding, driven by our share repurchase program.
While foreign currency markets remain volatile, in part due to geopolitical dynamics leading to a stronger U.S. Dollar, we continue to see opportunities to drive future growth and profitability, and remain committed to effectively managing our business to achieve our financial goals over the long-term by executing against the operational strategies outlined above.
24 NIKE, INC.
For discussion related to the results of operations and changes in financial condition for fiscal 2018 compared to fiscal 2017 refer to Part II, Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations in our fiscal 2018 Form 10-K, which was filed with the United States Securities and Exchange Commission on July 25, 2018.
USE OF NON-GAAP FINANCIAL MEASURES
Throughout this Annual Report on Form 10-K, we discuss non-GAAP financial measures, including references to wholesale equivalent revenues and currency-neutral revenues, which should be considered in addition to, and not in lieu of, the financial measures calculated and presented in accordance with accounting principles generally accepted in the United States of America (“U.S. GAAP”). References to wholesale equivalent revenues are intended to provide context as to the total size of our NIKE Brand market footprint if we had no NIKE Direct operations. NIKE Brand wholesale equivalent revenues consist of (1) sales to external wholesale customers and (2) internal sales from our wholesale operations to our NIKE Direct operations, which are charged at prices comparable to those charged to external wholesale customers. Additionally, currency-neutral revenues are calculated using actual exchange rates in use during the comparative prior year period to enhance the visibility of the underlying business trends excluding the impact of translation arising from foreign currency exchange rate fluctuations.
Management uses these non-GAAP financial measures when evaluating the Company's performance, including when making financial and operating decisions. Additionally, management believes these non-GAAP financial measures provide investors with additional financial information that should be considered when assessing our underlying business performance and trends. However, references to wholesale equivalent revenues and currency-neutral revenues should not be considered in isolation or as a substitute for other financial measures calculated and presented in accordance with U.S. GAAP and may not be comparable to similarly titled non-GAAP measures used by other companies.
2019 FORM 10-K 25
RESULTS OF OPERATIONS
| (Dollars in millions, except per share data) | FISCAL 2019 | FISCAL 2018(1) | % CHANGE | FISCAL 2017 | % CHANGE | ||||||||
| Revenues | $ | 39,117 | $ | 36,397 | 7 | % | $ | 34,350 | 6 | % | |||
| Cost of sales | 21,643 | 20,441 | 6 | % | 19,038 | 7 | % | ||||||
| Gross profit | 17,474 | 15,956 | 10 | % | 15,312 | 4 | % | ||||||
| Gross margin | 44.7 | % | 43.8 | % | 44.6 | % | |||||||
| Demand creation expense | 3,753 | 3,577 | 5 | % | 3,341 | 7 | % | ||||||
| Operating overhead expense | 8,949 | 7,934 | 13 | % | 7,222 | 10 | % | ||||||
| Total selling and administrative expense | 12,702 | 11,511 | 10 | % | 10,563 | 9 | % | ||||||
| % of revenues | 32.5 | % | 31.6 | % | 30.8 | % | |||||||
| Interest expense (income), net | 49 | 54 | — | 59 | — | ||||||||
| Other (income) expense, net | (78 | ) | 66 | — | (196 | ) | — | ||||||
| Income before income taxes | 4,801 | 4,325 | 11 | % | 4,886 | -11 | % | ||||||
| Income tax expense | 772 | 2,392 | -68 | % | 646 | 270 | % | ||||||
| Effective tax rate | 16.1 | % | 55.3 | % | 13.2 | % | |||||||
| NET INCOME | $ | 4,029 | $ | 1,933 | 108 | % | $ | 4,240 | -54 | % | |||
| Diluted earnings per common share | $ | 2.49 | $ | 1.17 | 113 | % | $ | 2.51 | -53 | % |
| (1) | Fiscal 2018 reflects the impact from the enactment of the Tax Cuts and Jobs Act. Refer to Note 9 — Income Taxes in the accompanying Notes to the Consolidated Financial Statements for additional information. |
26 NIKE, INC.
CONSOLIDATED OPERATING RESULTS
REVENUES
| (Dollars in millions) | FISCAL 2019 | FISCAL 2018(1) | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES(2) | FISCAL 2017(1) | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES(2) | ||||||||||
| NIKE, Inc. Revenues: | |||||||||||||||||
| NIKE Brand Revenues by: | |||||||||||||||||
| Footwear | $ | 24,222 | $ | 22,268 | 9 | % | 12 | % | $ | 21,081 | 6 | % | 4 | % | |||
| Apparel | 11,550 | 10,733 | 8 | % | 11 | % | 9,654 | 11 | % | 9 | % | ||||||
| Equipment | 1,404 | 1,396 | 1 | % | 4 | % | 1,425 | -2 | % | -4 | % | ||||||
| Global Brand Divisions(3) | 42 | 88 | -52 | % | -53 | % | 73 | 21 | % | 12 | % | ||||||
| Total NIKE Brand Revenues | 37,218 | 34,485 | 8 | % | 11 | % | 32,233 | 7 | % | 5 | % | ||||||
| Converse | 1,906 | 1,886 | 1 | % | 3 | % | 2,042 | -8 | % | -11 | % | ||||||
| Corporate(4) | (7 | ) | 26 | — | — | 75 | — | — | |||||||||
| TOTAL NIKE, INC. REVENUES | $ | 39,117 | $ | 36,397 | 7 | % | 11 | % | $ | 34,350 | 6 | % | 4 | % | |||
| Supplemental NIKE Brand Revenues Details: | |||||||||||||||||
| NIKE Brand Revenues by: | |||||||||||||||||
| Sales to Wholesale Customers | $ | 25,423 | $ | 23,969 | 6 | % | 10 | % | $ | 23,078 | 4 | % | 2 | % | |||
| Sales through NIKE Direct | 11,753 | 10,428 | 13 | % | 16 | % | 9,082 | 15 | % | 12 | % | ||||||
| Global Brand Divisions(3) | 42 | 88 | -52 | % | -53 | % | 73 | 21 | % | 12 | % | ||||||
| TOTAL NIKE BRAND REVENUES | $ | 37,218 | $ | 34,485 | 8 | % | 11 | % | $ | 32,233 | 7 | % | 5 | % | |||
| NIKE Brand Revenues on a Wholesale Equivalent Basis:(2) | |||||||||||||||||
| Sales to Wholesale Customers | $ | 25,423 | $ | 23,969 | 6 | % | 10 | % | $ | 23,078 | 4 | % | 2 | % | |||
| Sales from our Wholesale Operations to NIKE Direct Operations | 7,127 | 6,332 | 13 | % | 16 | % | 5,616 | 13 | % | 10 | % | ||||||
| TOTAL NIKE BRAND WHOLESALE EQUIVALENT REVENUES | $ | 32,550 | $ | 30,301 | 7 | % | 11 | % | $ | 28,694 | 6 | % | 4 | % | |||
| NIKE Brand Wholesale Equivalent Revenues by:(2) | |||||||||||||||||
| Men's | $ | 17,737 | $ | 16,698 | 6 | % | 10 | % | $ | 15,819 | 6 | % | 4 | % | |||
| Women's | 7,380 | 6,913 | 7 | % | 11 | % | 6,637 | 4 | % | 2 | % | ||||||
| NIKE Kids' | 5,283 | 4,906 | 8 | % | 11 | % | 4,838 | 1 | % | -1 | % | ||||||
| Others(5) | 2,150 | 1,784 | 21 | % | 25 | % | 1,400 | 27 | % | 14 | % | ||||||
| TOTAL NIKE BRAND WHOLESALE EQUIVALENT REVENUES | $ | 32,550 | $ | 30,301 | 7 | % | 11 | % | $ | 28,694 | 6 | % | 4 | % | |||
| NIKE Brand Wholesale Equivalent Revenues by:(2) | |||||||||||||||||
| Running | $ | 4,488 | $ | 4,496 | 0 | % | 4 | % | $ | 4,576 | -2 | % | -4 | % | |||
| NIKE Basketball | 1,597 | 1,494 | 7 | % | 9 | % | 1,292 | 16 | % | 14 | % | ||||||
| Jordan Brand | 3,138 | 2,856 | 10 | % | 12 | % | 3,098 | -8 | % | -9 | % | ||||||
| Football (Soccer) | 1,894 | 2,146 | -12 | % | -6 | % | 1,984 | 8 | % | 5 | % | ||||||
| Training | 3,137 | 3,126 | 0 | % | 3 | % | 3,080 | 1 | % | 0 | % | ||||||
| Sportswear | 12,442 | 10,720 | 16 | % | 21 | % | 9,272 | 16 | % | 13 | % | ||||||
| Others(6) | 5,854 | 5,463 | 7 | % | 9 | % | 5,392 | 1 | % | 0 | % | ||||||
| TOTAL NIKE BRAND WHOLESALE EQUIVALENT REVENUES | $ | 32,550 | $ | 30,301 | 7 | % | 11 | % | $ | 28,694 | 6 | % | 4 | % |
| (1) | Certain prior year amounts have been reclassified to conform to fiscal 2019 presentation. These changes had no impact on previously reported consolidated results of operations or shareholders' equity. |
| (2) | The percent change excluding currency changes and the presentation of wholesale equivalent revenues represent non-GAAP financial measures. See "Use of Non-GAAP Financial Measures" for further information. |
| (3) | Global Brand Divisions revenues are primarily attributable to NIKE Brand licensing businesses that are not part of a geographic operating segment. |
2019 FORM 10-K 27
| (4) | Corporate revenues primarily consist of foreign currency hedge gains and losses related to revenues generated by entities within the NIKE Brand geographic operating segments and Converse, but managed through our central foreign exchange risk management program. |
| (5) | Others include all unisex products, equipment and other products not allocated to Men's, Women's and NIKE Kids', as well as certain adjustments that are not allocated to products designated by gender or age. |
| (6) | Others include all other categories and certain adjustments that are not allocated at the category level. |
FISCAL 2019 NIKE BRAND REVENUE HIGHLIGHTS
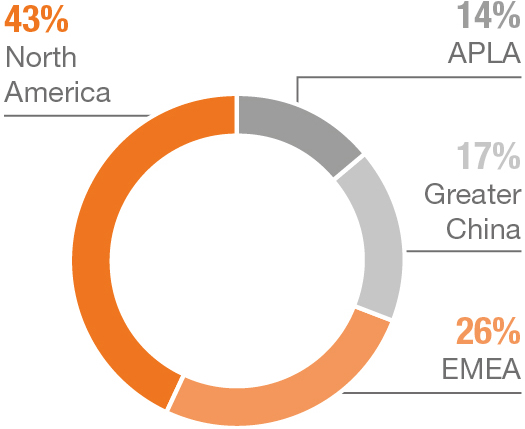
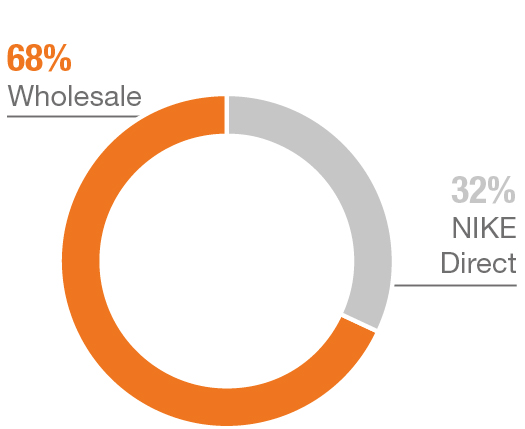
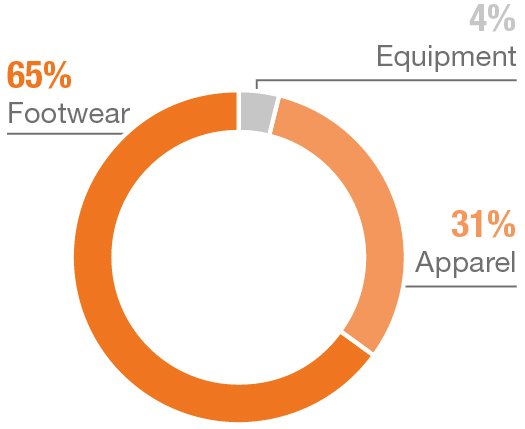
The following tables present NIKE Brand revenues disaggregated by reportable operating segment, distribution channel and major product line:
 |  |  |
FISCAL 2019 COMPARED TO FISCAL 2018
On a currency-neutral basis, NIKE, Inc. Revenues grew 11% for fiscal 2019, driven by growth in both the NIKE Brand and Converse. All NIKE Brand geographies delivered higher revenues for fiscal 2019 as our Consumer Direct Offense continued to deliver innovative products, deep brand connections and compelling retail experiences to consumers through NIKE.com and related mobile applications, digital partner platforms, NIKE-owned and partner stores, as well as through our wholesale customers. Revenue growth was broad-based as Greater China, North America and EMEA each contributed approximately 3 percentage points of growth to NIKE, Inc. Revenues, with APLA contributing approximately 2 percentage points of growth.
On a currency-neutral basis, NIKE Brand footwear and apparel revenues increased 12% and 11%, respectively, for fiscal 2019, while NIKE Brand equipment revenues grew 4%. On a category basis, the increase in NIKE Brand footwear revenues was driven by growth in nearly all key categories, led by Sportswear and, to a lesser extent, the Jordan Brand and Running. Unit sales of footwear increased 8% and higher ASP per pair contributed approximately 4 percentage points of footwear revenue growth, primarily due to higher full-price and NIKE Direct ASPs.
The currency-neutral increase in NIKE Brand apparel revenues for fiscal 2019 was fueled by growth in nearly all key categories, most notably Sportswear. Unit sales of apparel increased 6% and higher ASP per unit contributed approximately 5 percentage points of apparel revenue growth, primarily due to higher full-price ASP, in part reflecting lower discounts, as well as higher NIKE Direct ASP.
On a reported basis, NIKE Direct revenues represented approximately 32% of our total NIKE Brand revenues for fiscal 2019 compared to 30% for fiscal 2018. Digital commerce sales were $3.8 billion for fiscal 2019 compared to $2.8 billion for fiscal 2018. On a currency-neutral basis, NIKE Direct revenues increased 16% for fiscal 2019, driven by strong digital commerce sales growth of 35%, comparable store sales growth of 6% and the addition of new stores. Comparable store sales, which exclude digital commerce sales, comprises revenue from NIKE-owned in-line and factory stores for which all three of the following requirements have been met: (1) the store has been open at least one year, (2) square footage has not changed by more than 15% within the past year and (3) the store has not been permanently repositioned within the past year.
On a wholesale equivalent and currency-neutral basis, fiscal 2019 NIKE Brand Men's and Women's revenues increased 10% and 11%, respectively, both driven by growth in nearly all key categories, led by Sportswear. During fiscal 2019, the growth in Women's was fueled by our focus on compelling design, creating female-focused brand campaigns globally and a shift towards digital-led distribution. Revenues for our NIKE Kids' business increased 11%, as all key categories, except Football (Soccer), experienced growth.
28 NIKE, INC.
GROSS MARGIN
FISCAL 2019 COMPARED TO FISCAL 2018
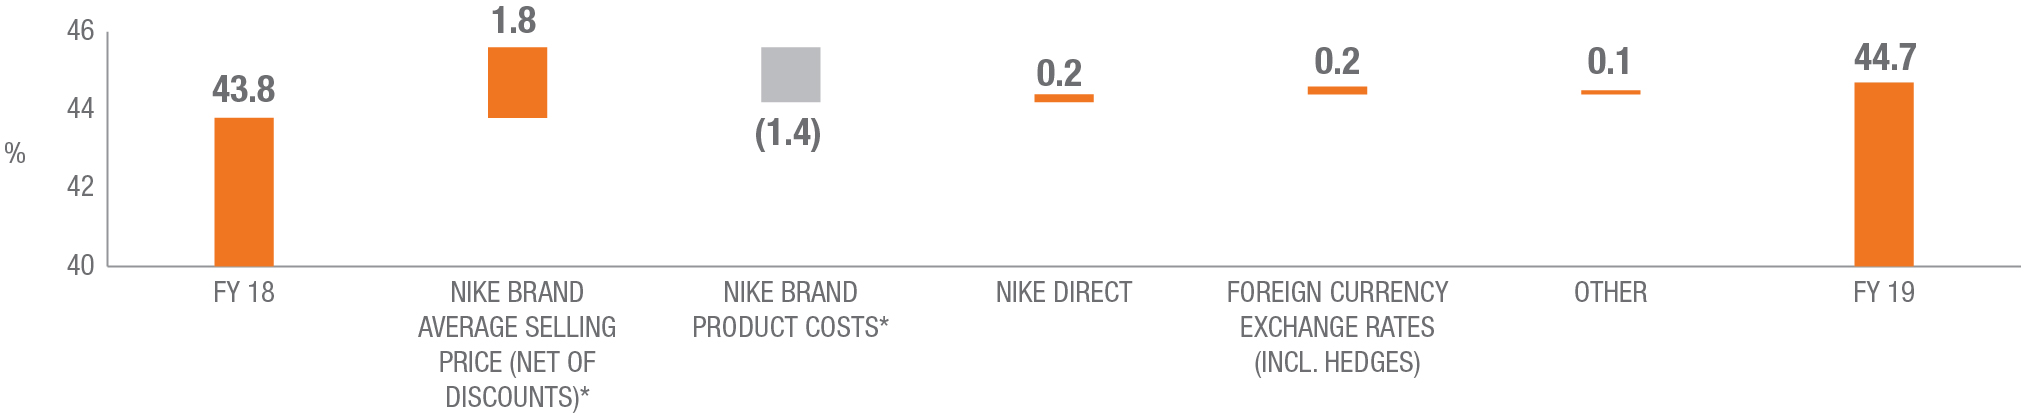
For fiscal 2019, our consolidated gross profit increased 10% to $17,474 million compared to $15,956 million for fiscal 2018. Gross margin increased 90 basis points to 44.7% for fiscal 2019 compared to 43.8% for fiscal 2018 due to the following:
 |
| *Wholesale equivalent |
Higher NIKE Brand product costs are primarily due to shifts in mix to higher-cost products and an increase in labor rates compared to fiscal 2018. Additionally, gross margin was favorably impacted by growth in our higher-margin NIKE Direct business.
TOTAL SELLING AND ADMINISTRATIVE EXPENSE
| (Dollars in millions) | FISCAL 2019 | FISCAL 2018 | % CHANGE | FISCAL 2017 | % CHANGE | ||||||||
| Demand creation expense(1) | $ | 3,753 | $ | 3,577 | 5 | % | $ | 3,341 | 7 | % | |||
| Operating overhead expense | 8,949 | 7,934 | 13 | % | 7,222 | 10 | % | ||||||
| Total selling and administrative expense | $ | 12,702 | $ | 11,511 | 10 | % | $ | 10,563 | 9 | % | |||
| % of revenues | 32.5 | % | 31.6 | % | 90 | bps | 30.8 | % | 80 | bps |
| (1) | Demand creation expense consists of advertising and promotion costs, including costs of endorsement contracts, complimentary product, television, digital and print advertising and media costs, brand events and retail brand presentation. |
FISCAL 2019 COMPARED TO FISCAL 2018
Demand creation expense increased 5% for fiscal 2019 compared to fiscal 2018, due to sports marketing investments, as well as higher advertising and marketing expenses to support global brand campaigns, key sports moments and new product launches. Changes in foreign currency exchange rates decreased Demand creation expense by approximately 2 percentage points for fiscal 2019.
Operating overhead expense increased 13% for fiscal 2019 compared to fiscal 2018, driven primarily by higher wage-related and administrative expenses, which reflect critical investments in innovation, data and analytics capabilities, digital commerce platforms and an initial investment in a new enterprise resource planning tool to accelerate our end-to-end digital transformation. Changes in foreign currency exchange rates decreased Operating overhead expense by approximately 2 percentage points for fiscal 2019.
OTHER (INCOME) EXPENSE, NET
| (Dollars In millions) | FISCAL 2019 | FISCAL 2018 | FISCAL 2017 | |||||||||
| Other (income) expense, net | $ | (78 | ) | $ | 66 | $ | (196 | ) |
Other (income) expense, net comprises foreign currency conversion gains and losses from the re-measurement of monetary assets and liabilities denominated in non-functional currencies and the impact of certain foreign currency derivative instruments, as well as unusual or non-operating transactions that are outside the normal course of business.
FISCAL 2019 COMPARED TO FISCAL 2018
Other (income) expense, net changed from $66 million of other expense, net for fiscal 2018 to $78 million of other income, net for fiscal 2019, primarily due to a $136 million net beneficial change in foreign currency conversion gains and losses, including hedges.
We estimate the combination of the translation of foreign currency-denominated profits from our international businesses and the year-over-year change in foreign currency-related gains and losses included in Other (income) expense, net had an unfavorable impact on our Income before income taxes of $97 million for fiscal 2019.
2019 FORM 10-K 29
INCOME TAXES
| FISCAL 2019 | FISCAL 2018 | % CHANGE | FISCAL 2017 | % CHANGE | |||||
| Effective tax rate | 16.1 | % | 55.3 | % | (3,920) bps | 13.2 | % | 4,210 | bps |
FISCAL 2019 COMPARED TO FISCAL 2018
Our effective tax rate was 16.1% for fiscal 2019, compared to 55.3% for fiscal 2018 due to significant changes related to the enactment of the U.S. Tax Cuts and Jobs Act (the “Tax Act”) in the prior year and a reduction in the U.S. federal statutory rate to 21% in the current year. These decreases were partially offset by an increase in U.S. tax on foreign earnings due to the impact of global intangible low-taxed income (GILTI).
Refer to Note 9 — Income Taxes in the accompanying Notes to the Consolidated Financial Statements for additional information on the impact of the Tax Act.
OPERATING SEGMENTS
Our operating segments are evidence of the structure of the Company's internal organization. The NIKE Brand segments are defined by geographic regions for operations participating in NIKE Brand sales activity.
Each NIKE Brand geographic segment operates predominantly in one industry: the design, development, marketing and selling of athletic footwear, apparel and equipment. The Company's reportable operating segments for the NIKE Brand are: North America; Europe, Middle East & Africa (EMEA); Greater China; and Asia Pacific & Latin America (APLA), and include results for the NIKE, Jordan and Hurley brands. The Company's NIKE Direct operations are managed within each geographic operating segment. Converse is also a reportable operating segment for the Company, and operates predominately in one industry: the design, marketing, licensing and selling of casual sneakers, apparel and accessories.
As part of our centrally managed foreign exchange risk management program, standard foreign currency exchange rates are assigned twice per year to each NIKE Brand entity in our geographic operating segments and Converse. These rates are set approximately nine and twelve months in advance of the future selling seasons to which they relate (specifically, for each currency, one standard rate applies to the fall and holiday selling seasons and one standard rate applies to the spring and summer selling seasons) based on average market spot rates in the calendar month preceding the date they are established. Inventories and Cost of sales for geographic operating segments and Converse reflect the use of these standard rates to record non-functional currency product purchases into the entity's functional currency. Differences between assigned standard foreign currency exchange rates and actual market rates are included in Corporate, together with foreign currency hedge gains and losses generated from our centrally managed foreign exchange risk management program and other conversion gains and losses.
The breakdown of revenues is as follows:
| (Dollars in millions) | FISCAL 2019 | FISCAL 2018 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES(1) | FISCAL 2017 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES(1) | ||||||||||
| North America | $ | 15,902 | $ | 14,855 | 7 | % | 7 | % | $ | 15,216 | -2 | % | -2 | % | |||
| Europe, Middle East & Africa | 9,812 | 9,242 | 6 | % | 11 | % | 7,970 | 16 | % | 9 | % | ||||||
| Greater China | 6,208 | 5,134 | 21 | % | 24 | % | 4,237 | 21 | % | 18 | % | ||||||
| Asia Pacific & Latin America | 5,254 | 5,166 | 2 | % | 13 | % | 4,737 | 9 | % | 10 | % | ||||||
| Global Brand Divisions(2) | 42 | 88 | -52 | % | -53 | % | 73 | 21 | % | 12 | % | ||||||
| TOTAL NIKE BRAND | 37,218 | 34,485 | 8 | % | 11 | % | 32,233 | 7 | % | 5 | % | ||||||
| Converse | 1,906 | 1,886 | 1 | % | 3 | % | 2,042 | -8 | % | -11 | % | ||||||
| Corporate(3) | (7 | ) | 26 | — | — | 75 | — | — | |||||||||
| TOTAL NIKE, INC. REVENUES | $ | 39,117 | $ | 36,397 | 7 | % | 11 | % | $ | 34,350 | 6 | % | 4 | % |
| (1) | The percent change excluding currency changes represents a non-GAAP financial measure. See "Use of Non-GAAP Financial Measures" for further information. |
| (2) | Global Brand Divisions revenues are primarily attributable to NIKE Brand licensing businesses that are not part of a geographic operating segment. |
| (3) | Corporate revenues primarily consist of foreign currency hedge gains and losses related to revenues generated by entities within the NIKE Brand geographic operating segments and Converse, but managed through our central foreign exchange risk management program. |
30 NIKE, INC.
The primary financial measure used by the Company to evaluate performance of individual operating segments is earnings before interest and taxes (commonly referred to as “EBIT”), which represents Net income before Interest expense (income), net and Income tax expense in the Consolidated Statements of Income. As discussed in Note 17 — Operating Segments and Related Information in the accompanying Notes to the Consolidated Financial Statements, certain corporate costs are not included in EBIT of our operating segments.
The breakdown of earnings before interest and taxes is as follows:
| (Dollars in millions) | FISCAL 2019 | FISCAL 2018 | % CHANGE | FISCAL 2017 | % CHANGE | ||||||||||||
| North America | $ | 3,925 | $ | 3,600 | 9 | % | $ | 3,875 | -7 | % | |||||||
| Europe, Middle East & Africa | 1,995 | 1,587 | 26 | % | 1,507 | 5 | % | ||||||||||
| Greater China | 2,376 | 1,807 | 31 | % | 1,507 | 20 | % | ||||||||||
| Asia Pacific & Latin America | 1,323 | 1,189 | 11 | % | 980 | 21 | % | ||||||||||
| Global Brand Divisions | (3,262 | ) | (2,658 | ) | -23 | % | (2,677 | ) | 1 | % | |||||||
| TOTAL NIKE BRAND | 6,357 | 5,525 | 15 | % | 5,192 | 6 | % | ||||||||||
| Converse | 303 | 310 | -2 | % | 477 | -35 | % | ||||||||||
| Corporate | (1,810 | ) | (1,456 | ) | -24 | % | (724 | ) | -101 | % | |||||||
| TOTAL NIKE, INC. EARNINGS BEFORE INTEREST AND TAXES | 4,850 | 4,379 | 11 | % | 4,945 | -11 | % | ||||||||||
| Interest expense (income), net | 49 | 54 | — | 59 | — | ||||||||||||
| TOTAL NIKE, INC. INCOME BEFORE INCOME TAXES | $ | 4,801 | $ | 4,325 | 11 | % | $ | 4,886 | -11 | % |
NORTH AMERICA
| (Dollars in millions) | FISCAL 2019 | FISCAL 2018 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES | FISCAL 2017 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES | ||||||||||
| Revenues by: | |||||||||||||||||
| Footwear | $ | 10,045 | $ | 9,322 | 8 | % | 8 | % | $ | 9,684 | -4 | % | -4 | % | |||
| Apparel | 5,260 | 4,938 | 7 | % | 7 | % | 4,886 | 1 | % | 1 | % | ||||||
| Equipment | 597 | 595 | 0 | % | 0 | % | 646 | -8 | % | -8 | % | ||||||
| TOTAL REVENUES | $ | 15,902 | $ | 14,855 | 7 | % | 7 | % | $ | 15,216 | -2 | % | -2 | % | |||
| Revenues by: | |||||||||||||||||
| Sales to Wholesale Customers | $ | 10,875 | $ | 10,159 | 7 | % | 7 | % | $ | 10,756 | -6 | % | -6 | % | |||
| Sales through NIKE Direct | 5,027 | 4,696 | 7 | % | 7 | % | 4,460 | 5 | % | 5 | % | ||||||
| TOTAL REVENUES | $ | 15,902 | $ | 14,855 | 7 | % | 7 | % | $ | 15,216 | -2 | % | -2 | % | |||
| EARNINGS BEFORE INTEREST AND TAXES | $ | 3,925 | $ | 3,600 | 9 | % | $ | 3,875 | -7 | % |
In the current marketplace environment, we believe there continues to be a meaningful shift in the way consumers shop for product and make purchasing decisions. Consumers are demanding a constant flow of fresh and innovative product, and have an expectation for superior service and rapid delivery, all fueled by the shift toward digital and mono-brand experiences in NIKE Direct. Specifically, in North America we anticipate continued evolution within the retail landscape, driven by shifting consumer traffic patterns across digital and physical channels. The evolution of the North America marketplace is resulting in third-party retail store closures; however, we are currently seeing stabilization and momentum building with our strategic wholesale customers, fueled by innovative product and NIKE Brand consumer experiences, leveraging digital.
FISCAL 2019 COMPARED TO FISCAL 2018
On a currency-neutral basis, North America revenues increased 7%, driven by growth in nearly all key categories, led by Sportswear. NIKE Direct revenues increased 7% for fiscal 2019 as strong digital commerce sales growth of 29% and the addition of new stores more than offset a 3% decline in comparable store sales. The decline in comparable store sales was primarily due to higher sales in NIKE Brand in-line stores being more than offset by declines in NIKE Brand Factory Stores ("NFS"), as growth in our full-price channel has impacted the availability and composition of off-price inventory for sale within NFS.
2019 FORM 10-K 31
Footwear revenues increased 8% on a currency-neutral basis for fiscal 2019, driven by growth in most key categories, led by Sportswear. Unit sales of footwear increased 4%, while higher ASP per pair contributed approximately 4 percentage points of footwear revenue growth. Higher ASP per pair was primarily due to higher full-price ASP, in part reflecting lower discounts, as well as higher ASP in our NIKE Direct business.
On a currency-neutral basis, apparel revenues increased 7% for fiscal 2019, driven by higher revenues in all key categories, led by Sportswear, followed by NIKE Basketball. Unit sales of apparel increased 5%, while higher ASP per unit contributed approximately 2 percentage points of apparel revenue growth. The increase in ASP per unit was primarily a result of higher full-price ASP, in part reflecting lower discounts.
Reported EBIT increased 9% for fiscal 2019, reflecting higher revenues, gross margin expansion and selling and administrative expense leverage. Gross margin increased 30 basis points as higher full-price ASP, in part reflecting lower discounts, as well as favorable full-price mix more than offset higher product costs. Selling and administrative expense grew due to higher demand creation and operating overhead expenses. The increase in demand creation expense was primarily due to higher advertising and marketing costs. Operating overhead expense increased as a result of higher wage-related costs, including investments in our NIKE Direct operations.
EUROPE, MIDDLE EAST & AFRICA
| (Dollars in millions) | FISCAL 2019 | FISCAL 2018 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES | FISCAL 2017 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES | ||||||||||
| Revenues by: | |||||||||||||||||
| Footwear | $ | 6,293 | $ | 5,875 | 7 | % | 12 | % | $ | 5,192 | 13 | % | 6 | % | |||
| Apparel | 3,087 | 2,940 | 5 | % | 9 | % | 2,395 | 23 | % | 16 | % | ||||||
| Equipment | 432 | 427 | 1 | % | 5 | % | 383 | 11 | % | 6 | % | ||||||
| TOTAL REVENUES | $ | 9,812 | $ | 9,242 | 6 | % | 11 | % | $ | 7,970 | 16 | % | 9 | % | |||
| Revenues by: | |||||||||||||||||
| Sales to Wholesale Customers | $ | 7,076 | $ | 6,765 | 5 | % | 9 | % | $ | 5,917 | 14 | % | 8 | % | |||
| Sales through NIKE Direct | 2,736 | 2,477 | 10 | % | 15 | % | 2,053 | 21 | % | 13 | % | ||||||
| TOTAL REVENUES | $ | 9,812 | $ | 9,242 | 6 | % | 11 | % | $ | 7,970 | 16 | % | 9 | % | |||
| EARNINGS BEFORE INTEREST AND TAXES | $ | 1,995 | $ | 1,587 | 26 | % | $ | 1,507 | 5 | % |
FISCAL 2019 COMPARED TO FISCAL 2018
On a currency-neutral basis, EMEA revenues for fiscal 2019 grew 11%, reflecting balanced growth across all territories. Revenues increased in nearly all key categories, led by Sportswear. NIKE Direct revenues increased 15%, driven by strong digital commerce sales growth of 28%, comparable store sales growth of 10% and the addition of new stores.
Currency-neutral footwear revenues grew 12% for fiscal 2019, driven by higher revenues in nearly all key categories, led by Sportswear. Unit sales of footwear increased 9% and higher ASP per pair contributed approximately 3 percentage points of footwear revenue growth. Higher ASP per pair primarily resulted from higher full-price and NIKE Direct ASPs.
For fiscal 2019, currency-neutral apparel revenues increased 9% due to growth in most key categories, led by Sportswear. Unit sales of apparel increased 6% and higher ASP per unit contributed approximately 3 percentage points of apparel revenue growth. Higher ASP per unit was primarily due to higher NIKE Direct and full-price ASPs.
Reported EBIT increased 26% for fiscal 2019, primarily due to strong revenue growth, gross margin expansion and selling and administrative expense leverage. Gross margin increased 280 basis points as favorable standard foreign currency exchange rates and higher full-price ASP more than offset higher product costs. Selling and administrative expense increased due to higher operating overhead and demand creation expense. Growth in operating overhead expense was primarily due to higher wage-related and administrative costs, including investments in our NIKE Direct operations. The increase in demand creation expense was primarily driven by higher advertising and marketing expenses, as well as higher sports marketing costs. The growth in demand creation and operating overhead expense was favorably impacted by changes in foreign currency exchange rates, specifically the Euro.
32 NIKE, INC.
GREATER CHINA
| (Dollars in millions) | FISCAL 2019 | FISCAL 2018 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES | FISCAL 2017 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES | ||||||||||
| Revenues by: | |||||||||||||||||
| Footwear | $ | 4,262 | $ | 3,496 | 22 | % | 25 | % | $ | 2,920 | 20 | % | 16 | % | |||
| Apparel | 1,808 | 1,508 | 20 | % | 23 | % | 1,188 | 27 | % | 23 | % | ||||||
| Equipment | 138 | 130 | 6 | % | 8 | % | 129 | 1 | % | -1 | % | ||||||
| TOTAL REVENUES | $ | 6,208 | $ | 5,134 | 21 | % | 24 | % | $ | 4,237 | 21 | % | 18 | % | |||
| Revenues by: | |||||||||||||||||
| Sales to Wholesale Customers | $ | 3,726 | $ | 3,216 | 16 | % | 19 | % | $ | 2,774 | 16 | % | 13 | % | |||
| Sales through NIKE Direct | 2,482 | 1,918 | 29 | % | 33 | % | 1,463 | 31 | % | 27 | % | ||||||
| TOTAL REVENUES | $ | 6,208 | $ | 5,134 | 21 | % | 24 | % | $ | 4,237 | 21 | % | 18 | % | |||
| EARNINGS BEFORE INTEREST AND TAXES | $ | 2,376 | $ | 1,807 | 31 | % | $ | 1,507 | 20 | % |
FISCAL 2019 COMPARED TO FISCAL 2018
On a currency-neutral basis, Greater China revenues for fiscal 2019 increased 24%, driven by higher revenues in nearly all key categories, led by Sportswear, the Jordan Brand and NIKE Basketball. NIKE Direct revenues increased 33%, driven by strong digital commerce sales growth of 47%, comparable store sales growth of 23% and the addition of new stores.
Currency-neutral footwear revenues increased 25% for fiscal 2019, driven by growth in most key categories, led by Sportswear and, to a lesser extent, the Jordan Brand and NIKE Basketball. Unit sales of footwear increased 20% and higher ASP per pair contributed approximately 5 percentage points to footwear revenue growth, driven by higher NIKE Direct and full-price ASPs.
The currency-neutral apparel revenue growth of 23% for fiscal 2019 was fueled by higher revenues in nearly all key categories, most notably Sportswear and the Jordan Brand. Unit sales of apparel increased 14% and higher ASP per unit increased apparel revenue growth by approximately 9 percentage points, primarily driven by higher full-price and NIKE Direct ASPs.
Reported EBIT increased 31% for fiscal 2019, driven by higher revenues, gross margin expansion and selling and administrative expense leverage. Gross margin increased 210 basis points as higher full-price ASP, in part reflecting lower discounts, as well as favorable standard foreign currency exchange rates and higher NIKE Direct margins more than offset higher product costs. Selling and administrative expense increased due to higher demand creation and operating overhead expenses. Demand creation expense increased primarily due to higher retail brand presentation, advertising and marketing costs, as well as higher sports marketing expenses. Growth in operating overhead expense was driven by higher wage-related and administrative costs, including investments in our NIKE Direct operations.
ASIA PACIFIC & LATIN AMERICA
| (Dollars in millions) | FISCAL 2019 | FISCAL 2018 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES | FISCAL 2017 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES | ||||||||||
| Revenues by: | |||||||||||||||||
| Footwear | $ | 3,622 | $ | 3,575 | 1 | % | 12 | % | $ | 3,285 | 9 | % | 9 | % | |||
| Apparel | 1,395 | 1,347 | 4 | % | 15 | % | 1,185 | 14 | % | 15 | % | ||||||
| Equipment | 237 | 244 | -3 | % | 8 | % | 267 | -9 | % | -8 | % | ||||||
| TOTAL REVENUES | $ | 5,254 | $ | 5,166 | 2 | % | 13 | % | $ | 4,737 | 9 | % | 10 | % | |||
| Revenues by: | |||||||||||||||||
| Sales to Wholesale Customers | $ | 3,746 | $ | 3,829 | -2 | % | 9 | % | $ | 3,631 | 5 | % | 6 | % | |||
| Sales through NIKE Direct | 1,508 | 1,337 | 13 | % | 23 | % | 1,106 | 21 | % | 21 | % | ||||||
| TOTAL REVENUES | $ | 5,254 | $ | 5,166 | 2 | % | 13 | % | $ | 4,737 | 9 | % | 10 | % | |||
| EARNINGS BEFORE INTEREST AND TAXES | $ | 1,323 | $ | 1,189 | 11 | % | $ | 980 | 21 | % |
2019 FORM 10-K 33
FISCAL 2019 COMPARED TO FISCAL 2018
On a currency-neutral basis, APLA revenues increased 13% for fiscal 2019, driven by higher revenues in every territory. Territory revenue growth was led by SOCO (which comprises Argentina, Uruguay and Chile), Korea and Japan, which increased 19%, 16% and 11%, respectively. Revenues increased in nearly all key categories, led by Sportswear and Running. NIKE Direct revenues increased 23%, fueled by strong digital commerce sales growth of 61%, comparable store sales growth of 14% and the addition of new stores.
The 12% increase in currency-neutral footwear revenues for fiscal 2019 was attributable to growth in most key categories, led by Sportswear, followed by Running. Unit sales of footwear increased 6% and higher ASP per pair contributed approximately 6 percentage points of footwear revenue growth, driven by higher full-price and NIKE Direct ASPs, in part reflecting inflationary conditions in our SOCO territory.
Currency-neutral apparel revenues grew 15% for fiscal 2019, driven by higher revenues in nearly all key categories, most notably Sportswear, followed by Training. Unit sales of apparel increased 7% and higher ASP per unit contributed approximately 8 percentage points of apparel revenue growth, primarily driven by higher full-price and NIKE Direct ASPs, in part reflecting inflationary conditions in our SOCO territory.
Reported EBIT increased 11% for fiscal 2019 due to revenue growth, gross margin expansion and slightly lower selling and administrative expense. Gross margin increased 170 basis points as higher full-price ASP, as well as the favorable impact of growth and margin expansion in our NIKE Direct business, more than offset higher product costs. Demand creation expense decreased slightly as higher retail brand presentation and sports marketing costs were more than offset by the favorable impact of changes in foreign currency exchange rates, primarily the Argentine Peso (ARS) and Brazilian Real (BRL). Operating overhead expense decreased slightly as higher wage-related and administrative costs in our NIKE Direct operations were more than offset by the favorable impact of changes in foreign currency exchange rates, primarily the ARS and BRL.
GLOBAL BRAND DIVISIONS
| (Dollars in millions) | FISCAL 2019 | FISCAL 2018 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES | FISCAL 2017 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES | ||||||||||
| Revenues | $ | 42 | $ | 88 | -52 | % | -53 | % | $ | 73 | 21 | % | 12 | % | |||
| Earnings (Loss) Before Interest and Taxes | $ | (3,262 | ) | $ | (2,658 | ) | -23 | % | $ | (2,677 | ) | 1 | % |
Global Brand Divisions primarily represent demand creation and operating overhead expense, including product creation and design expenses that are centrally managed for the NIKE Brand, as well as costs associated with NIKE Direct global digital operations and enterprise technology. Revenues for Global Brand Divisions are primarily attributable to NIKE Brand licensing businesses that are not part of a geographic operating segment.
FISCAL 2019 COMPARED TO FISCAL 2018
Global Brand Divisions' loss before interest and taxes increased 23% for fiscal 2019 as total selling and administrative expense increased compared to fiscal 2018. Operating overhead expense growth was primarily driven by higher wage-related and administrative costs resulting from investments in data and analytics capabilities, digital commerce platforms and our initial investment in a new enterprise resource planning tool, all of which are in an effort to accelerate our end-to-end digital transformation. Lower demand creation expense was primarily due to lower advertising and marketing costs.
CONVERSE
| (Dollars in millions) | FISCAL 2019 | FISCAL 2018 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES | FISCAL 2017 | % CHANGE | % CHANGE EXCLUDING CURRENCY CHANGES | ||||||||||
| Revenues | $ | 1,906 | $ | 1,886 | 1 | % | 3 | % | $ | 2,042 | -8 | % | -11 | % | |||
| Earnings Before Interest and Taxes | $ | 303 | $ | 310 | -2 | % | $ | 477 | -35 | % |
34 NIKE, INC.
In territories we define as “direct distribution markets,” Converse designs, markets and sells products directly to distributors, wholesale customers and to consumers through direct to consumer operations. The largest direct distribution markets are the United States, the United Kingdom and China. We do not own the Converse trademarks in Japan and accordingly do not earn revenues in Japan. Territories other than direct distribution markets and Japan are serviced by third-party licensees who pay royalty revenues to Converse for the use of its registered trademarks and other intellectual property rights.
FISCAL 2019 COMPARED TO FISCAL 2018
On a currency-neutral basis, Converse revenues increased 3% for fiscal 2019. Comparable direct distribution markets (i.e., markets served under a direct distribution model for comparable periods in the current and prior fiscal years) increased 2%, which drove the majority of total Converse revenue growth. Comparable direct distribution market unit sales decreased 3% for fiscal 2019, while higher ASP per unit contributed approximately 5 percentage points of direct distribution markets revenue growth. On a territory basis, the increase in comparable direct distribution markets revenues for the year was primarily attributable to revenue growth in Asia across all distribution channels, partially offset by lower revenues in the U.S. and Europe. Conversion of markets from licensed to direct distribution had minimal impact on total Converse revenues for fiscal 2019. Revenues from comparable licensed markets grew 6% for fiscal 2019, primarily due to revenue growth in Asia and Brazil, but had minimal impact on total Converse revenue growth.
Reported EBIT for Converse decreased 2% for fiscal 2019 as higher selling and administrative expense more than offset gross margin expansion and revenue growth. Gross margin increased 180 basis points, driven by higher margin in our direct to consumer business, favorable standard foreign currency exchange rates and higher full-price ASP due to changes in product mix. Selling and administrative expense increased due to higher operating overhead and higher demand creation expense. Higher operating overhead expense was due to an increase in wage-related and administrative costs, primarily to support investments in our digital business. Higher demand creation expense was primarily due to an increase in advertising and marketing costs associated with our digital platform.
CORPORATE
| (Dollars in millions) | FISCAL 2019 | FISCAL 2018 | % CHANGE | FISCAL 2017 | % CHANGE | ||||||||
| Revenues | $ | (7 | ) | $ | 26 | — | $ | 75 | — | ||||
| Earnings (Loss) Before Interest and Taxes | $ | (1,810 | ) | $ | (1,456 | ) | -24 | % | $ | (724 | ) | -101 | % |
Corporate revenues primarily consist of foreign currency hedge gains and losses related to revenues generated by entities within the NIKE Brand geographic operating segments and Converse, but managed through our central foreign exchange risk management program.
The Corporate loss before interest and taxes largely consists of unallocated general and administrative expenses, including expenses associated with centrally managed departments; depreciation and amortization related to our corporate headquarters; unallocated insurance, benefit and compensation programs, including stock-based compensation; and certain foreign currency gains and losses.
In addition to the foreign currency gains and losses recognized in Corporate revenues, foreign currency results in Corporate include gains and losses resulting from the difference between actual foreign currency exchange rates and standard rates used to record non-functional currency denominated product purchases within the NIKE Brand geographic operating segments and Converse; related foreign currency hedge results; conversion gains and losses arising from re-measurement of monetary assets and liabilities in non-functional currencies; and certain other foreign currency derivative instruments.
FISCAL 2019 COMPARED TO FISCAL 2018
For fiscal 2019, Corporate's loss before interest and taxes increased $354 million primarily due to the following:
| • | an unfavorable change of $276 million related to the difference between actual foreign currency exchange rates and standard foreign currency exchange rates assigned to the NIKE Brand geographic operating segments and Converse, net of hedge gains and losses; these results are reported as a component of consolidated gross margin; |
| • | an unfavorable change of $210 million, primarily due to higher operating overhead expense driven by higher wage-related and administrative costs; and |
| • | a favorable change in net foreign currency gains and losses of $132 million related to the re-measurement of monetary assets and liabilities denominated in non-functional currencies and the impact of certain foreign currency derivative instruments, reported as a component of consolidated Other (income) expense, net. |
2019 FORM 10-K 35
FOREIGN CURRENCY EXPOSURES AND HEDGING PRACTICES
OVERVIEW
As a global company with significant operations outside the United States, in the normal course of business we are exposed to risk arising from changes in currency exchange rates. Our primary foreign currency exposures arise from the recording of transactions denominated in non-functional currencies and the translation of foreign currency denominated results of operations, financial position and cash flows into U.S. Dollars.
Our foreign exchange risk management program is intended to lessen both the positive and negative effects of currency fluctuations on our consolidated results of operations, financial position and cash flows. We manage global foreign exchange risk centrally on a portfolio basis to address those risks material to NIKE, Inc. We manage these exposures by taking advantage of natural offsets and currency correlations existing within the portfolio and, where practical and material, by hedging a portion of the remaining exposures using derivative instruments such as forward contracts and options. As described below, the implementation of the NIKE Trading Company (NTC) and our foreign currency adjustment program enhanced our ability to manage our foreign exchange risk by increasing the natural offsets and currency correlation benefits existing within our portfolio of foreign exchange exposures. Our hedging policy is designed to partially or entirely offset the impact of exchange rate changes on the underlying net exposures being hedged. Where exposures are hedged, our program has the effect of delaying the impact of exchange rate movements on our Consolidated Financial Statements; the length of the delay is dependent upon hedge horizons. We do not hold or issue derivative instruments for trading or speculative purposes.
Refer to Note 6 — Fair Value Measurements and Note 14 — Risk Management and Derivatives in the accompanying Notes to the Consolidated Financial Statements for additional description of how the above financial instruments are valued and recorded, as well as the fair value of outstanding derivatives at each reported period end.
TRANSACTIONAL EXPOSURES
We conduct business in various currencies and have transactions which subject us to foreign currency risk. Our most significant transactional foreign currency exposures are:
| • | Product Costs — NIKE's product costs are exposed to fluctuations in foreign currencies in the following ways: |
| 1. | Product purchases denominated in currencies other than the functional currency of the transacting entity: |
| a. | Certain NIKE entities purchase product from the NTC, a wholly-owned sourcing hub that buys NIKE branded products from third-party factories, predominantly in U.S. Dollars. The NTC, whose functional currency is the U.S. Dollar, then sells the products to NIKE entities in their respective functional currencies. NTC sales to a NIKE entity with a different functional currency results in a foreign currency exposure for the NTC. |
| b. | Other NIKE entities purchase product directly from third-party factories in U.S. Dollars. These purchases generate a foreign currency exposure for those NIKE entities with a functional currency other than the U.S. Dollar. |
In both purchasing scenarios, a weaker U.S. Dollar reduces inventory costs incurred by NIKE whereas a stronger U.S. Dollar increases its cost.
| 2. | Factory input costs: NIKE operates a foreign currency adjustment program with certain factories. The program is designed to more effectively manage foreign currency risk by assuming certain of the factories' foreign currency exposures, some of which are natural offsets to our existing foreign currency exposures. Under this program, our payments to these factories are adjusted for rate fluctuations in the basket of currencies (“factory currency exposure index”) in which the labor, materials and overhead costs incurred by the factories in the production of NIKE branded products (“factory input costs”) are denominated. |
For the currency within the factory currency exposure indices that is the local or functional currency of the factory, the currency rate fluctuation affecting the product cost is recorded within Inventories and is recognized in Cost of sales when the related product is sold to a third-party. All currencies within the indices, excluding the U.S. Dollar and the local or functional currency of the factory, are recognized as embedded derivative contracts and are recorded at fair value through Other (income) expense, net. Refer to Note 14 — Risk Management and Derivatives in the accompanying Notes to the Consolidated Financial Statements for additional detail.
As an offset to the impacts of the fluctuating U.S. Dollar on our non-functional currency denominated product purchases described above, a strengthening U.S. Dollar against the foreign currencies within the factory currency exposure indices reduces NIKE's U.S. Dollar inventory cost. Conversely, a weakening U.S. Dollar against the indexed foreign currencies increases our inventory cost.
36 NIKE, INC.
| • | Non-Functional Currency Denominated External Sales — A portion of our NIKE Brand and Converse revenues associated with European operations are earned in currencies other than the Euro (e.g., the British Pound) but are recognized at a subsidiary that uses the Euro as its functional currency. These sales generate a foreign currency exposure. |
| • | Other Costs — Non-functional currency denominated costs, such as endorsement contracts, also generate foreign currency risk, though to a lesser extent. In certain cases, the Company has entered into contractual agreements which have payments indexed to foreign currencies that create embedded derivative contracts recorded at fair value through Other (income) expense, net. Refer to Note 14 — Risk Management and Derivatives in the accompanying Notes to the Consolidated Financial Statements for additional detail. |
| • | Non-Functional Currency Denominated Monetary Assets and Liabilities — Our global subsidiaries have various assets and liabilities, primarily receivables and payables, including intercompany receivables and payables, denominated in currencies other than their functional currencies. These balance sheet items are subject to re-measurement which may create fluctuations in Other (income) expense, net within our consolidated results of operations. |
MANAGING TRANSACTIONAL EXPOSURES
Transactional exposures are managed on a portfolio basis within our foreign currency risk management program. We manage these exposures by taking advantage of natural offsets and currency correlations that exist within the portfolio and may also elect to use currency forward and option contracts to hedge the remaining effect of exchange rate fluctuations on probable forecasted future cash flows, including certain product cost exposures, non-functional currency denominated external sales and other costs described above. Generally, these are accounted for as cash flow hedges, except for hedges of the embedded derivative components of the product cost exposures and other contractual agreements.
Certain currency forward contracts used to manage the foreign exchange exposure of non-functional currency denominated monetary assets and liabilities subject to re-measurement and embedded derivative contracts are not formally designated as hedging instruments. Accordingly, changes in fair value of these instruments are recognized in Other (income) expense, net and are intended to offset the foreign currency impact of the re-measurement of the related non-functional currency denominated asset or liability or the embedded derivative contract being hedged.
TRANSLATIONAL EXPOSURES
Many of our foreign subsidiaries operate in functional currencies other than the U.S. Dollar. Fluctuations in currency exchange rates create volatility in our reported results as we are required to translate the balance sheets, operational results and cash flows of these subsidiaries into U.S. Dollars for consolidated reporting. The translation of foreign subsidiaries' non-U.S. Dollar denominated balance sheets into U.S. Dollars for consolidated reporting results in a cumulative translation adjustment to Accumulated other comprehensive income (loss) within Shareholders' equity. In the translation of our Consolidated Statements of Income, a weaker U.S. Dollar in relation to foreign functional currencies benefits our consolidated earnings whereas a stronger U.S. Dollar reduces our consolidated earnings. The impact of foreign exchange rate fluctuations on the translation of our consolidated Revenues was a detriment of approximately $1,236 million, a benefit of approximately $832 million and a detriment of approximately $542 million for the years ended May 31, 2019, 2018 and 2017, respectively. The impact of foreign exchange rate fluctuations on the translation of our Income before income taxes was a detriment of approximately $233 million, a benefit of approximately $177 million and a detriment of approximately $115 million for the years ended May 31, 2019, 2018 and 2017, respectively.
Management generally identifies hyper-inflationary markets as those markets whose cumulative inflation rate over a three-year period exceeds 100%. Management has concluded our Argentina subsidiary within our APLA operating segment is operating in a hyper-inflationary market. As a result, beginning in the second quarter of fiscal 2019, the functional currency of our Argentina subsidiary changed from the local currency to the U.S. Dollar. As of and for the period ended May 31, 2019, this change did not have a material impact on our results of operations or financial condition and we do not anticipate it will have a material impact in future periods based on current rates.
MANAGING TRANSLATIONAL EXPOSURES
To minimize the impact of translating foreign currency denominated revenues and expenses into U.S. Dollars for consolidated reporting, certain foreign subsidiaries use excess cash to purchase U.S. Dollar denominated available-for-sale investments. The variable future cash flows associated with the purchase and subsequent sale of these U.S. Dollar denominated investments at non-U.S. Dollar functional currency subsidiaries creates a foreign currency exposure that qualifies for hedge accounting under U.S. GAAP. We utilize forward contracts and/or options to mitigate the variability of the forecasted future purchases and sales of these U.S. Dollar investments. The combination of the purchase and sale of the U.S. Dollar investment and the hedging instrument has the effect of partially offsetting the year-over-year foreign currency translation impact on net earnings in the period the investments are sold. Hedges of the purchase of U.S. Dollar denominated available-for-sale investments are accounted for as cash flow hedges.
2019 FORM 10-K 37
We estimate the combination of translation of foreign currency-denominated profits from our international businesses and the year-over-year change in foreign currency related gains and losses included in Other (income) expense, net had an unfavorable impact of approximately $97 million, $110 million and $59 million on our Income before income taxes for the years ended May 31, 2019, 2018 and 2017, respectively.
NET INVESTMENTS IN FOREIGN SUBSIDIARIES
We are also exposed to the impact of foreign exchange fluctuations on our investments in wholly-owned foreign subsidiaries denominated in a currency other than the U.S. Dollar, which could adversely impact the U.S. Dollar value of these investments and therefore the value of future repatriated earnings. We have, in the past, hedged and may, in the future, hedge net investment positions in certain foreign subsidiaries to mitigate the effects of foreign exchange fluctuations on these net investments. These hedges are accounted for as net investment hedges in accordance with U.S. GAAP. There were no outstanding net investment hedges as of May 31, 2019 and 2018. There were no cash flows from net investment hedge settlements for the years ended May 31, 2019, 2018 and 2017.
LIQUIDITY AND CAPITAL RESOURCES
CASH FLOW ACTIVITY
Cash provided by operations was $5,903 million for fiscal 2019 compared to $4,955 million for fiscal 2018. Net income, adjusted for non-cash items, generated $5,341 million of operating cash flow for fiscal 2019 compared to $3,473 million for fiscal 2018. The net change in working capital and other assets and liabilities resulted in an increase to Cash provided by operations of $562 million for fiscal 2019, compared to an increase to Cash provided by operations of $1,482 million for fiscal 2018. The primary driver of the change in working capital relates to the accrual of $1,172 million for the transition tax under the Tax Act during fiscal 2018. Refer to Note 9 — Income Taxes for additional information on the Tax Act. Cash provided by operations in fiscal 2019 was further impacted by the net change in cash collateral with derivative counterparties as a result of hedging transactions. During fiscal 2019, we received cash collateral of $266 million compared to $23 million in fiscal 2018. In addition, the change in Accounts receivable, net, decreased Cash provided by operations by $457 million in fiscal 2019, primarily driven by revenue growth.
Cash provided (used) by investing activities was an outflow of $264 million for fiscal 2019, compared to an inflow of $276 million for fiscal 2018, driven primarily by the net change in short-term investments. During fiscal 2019, the net change in investments (including sales, maturities and purchases) resulted in a cash inflow of $850 million compared to an inflow of $1,326 million in fiscal 2018.
In fiscal 2020, we plan to continue investing in our infrastructure to support future growth, including corporate facilities, expanding our digital capabilities and new NIKE Direct stores. We continue to expect such investments to approximate 3% to 4% of revenues, on average.
Cash used by financing activities was $5,293 million for fiscal 2019 compared to $4,835 million for fiscal 2018 with the increase primarily impacted by the repayment of Notes payable during fiscal 2019.
In fiscal 2019, we purchased 54.3 million shares of NIKE's Class B Common Stock for $4,283 million (an average price of $78.86 per share). During the third quarter of fiscal 2019, we concluded the four-year, $12 billion program authorized by our Board of Directors in November 2015. Throughout this program we purchased a total of 192.1 million shares for $12 billion (an average price of $62.47 per share). Immediately following the completion of this program, we began repurchasing shares under the new four-year, $15 billion program authorized by our Board of Directors in June 2018.
As of May 31, 2019, we had repurchased 11.6 million shares at a cost of $986 million (an average price of $84.72 per share) under this new program. We continue to expect funding of share repurchases will come from operating cash flows, excess cash and/or proceeds from debt. The timing and the amount of share repurchases will be dictated by our capital needs and stock market conditions.
CAPITAL RESOURCES
On July 21, 2016, we filed a shelf registration statement (the “Shelf”) with the SEC which permits us to issue an unlimited amount of debt securities from time to time. The Shelf expired on July 21, 2019 and we plan to file a new shelf registration statement with the SEC in July 2019. For additional information regarding our long-term debt refer to Note 8 — Long-Term Debt in the accompanying Notes to the Consolidated Financial Statements.
38 NIKE, INC.
On August 28, 2015, we entered into a committed credit facility agreement with a syndicate of banks, which provides for up to $2 billion of borrowings. The facility matures August 28, 2020, with a one-year extension option prior to any anniversary of the closing date, provided that in no event shall it extend beyond August 28, 2022. As of and for the periods ended May 31, 2019 and 2018, we had no amounts outstanding under the committed credit facility.
We currently have long-term debt ratings of AA- and A1 from Standard and Poor's Corporation and Moody's Investor Services, respectively. If our long-term debt ratings were to decline, the facility fee and interest rate under our committed credit facility would increase. Conversely, if our long-term debt ratings were to improve, the facility fee and interest rate would decrease. Changes in our long-term debt ratings would not trigger acceleration of maturity of any then-outstanding borrowings or any future borrowings under the committed credit facility. Under this facility, we have agreed to various covenants. These covenants include limits on our disposal of fixed assets and the amount of debt secured by liens we may incur as well as limits on the indebtedness we can incur relative to our net worth. In the event we were to have any borrowings outstanding under this facility and failed to meet any covenant, and were unable to obtain a waiver from a majority of the banks in the syndicate, any borrowings would become immediately due and payable. As of May 31, 2019, we were in full compliance with each of these covenants and believe it is unlikely we will fail to meet any of these covenants in the foreseeable future.
Liquidity is also provided by our $2 billion commercial paper program. On June 1, 2018, we repaid $325 million and had no additional borrowings under this program as of and for the year ended May 31, 2019. We may continue to issue commercial paper or other debt securities depending on general corporate needs. We currently have short-term debt ratings of A1+ and P1 from Standard and Poor's Corporation and Moody's Investor Services, respectively.
To date, in fiscal 2019, we have not experienced difficulty accessing the credit markets or incurred higher interest costs; however, future volatility in the capital markets may increase costs associated with issuing commercial paper or other debt instruments or affect our ability to access those markets.
As of May 31, 2019, we had cash, cash equivalents and short-term investments totaling $4.7 billion, primarily consisting of deposits held at major banks, money market funds, commercial paper, corporate notes, U.S. Treasury obligations, U.S. government sponsored enterprise obligations and other investment grade fixed-income securities. Our fixed-income investments are exposed to both credit and interest rate risk. All of our investments are investment grade to minimize our credit risk. While individual securities have varying durations, as of May 31, 2019, the weighted-average days to maturity of our cash equivalents and short-term investments portfolio was 32 days.
We believe that existing cash, cash equivalents, short-term investments and cash generated by operations, together with access to external sources of funds as described above, will be sufficient to meet our domestic and foreign capital needs in the foreseeable future.
OFF-BALANCE SHEET ARRANGEMENTS
In connection with various contracts and agreements, we routinely provide indemnification relating to the enforceability of intellectual property rights, coverage for legal issues that arise and other items where we are acting as the guarantor. Currently, we have several such agreements in place. Based on our historical experience and the estimated probability of future loss, we have determined that the fair value of such indemnification is not material to our financial position or results of operations.
CONTRACTUAL OBLIGATIONS
Our significant long-term contractual obligations as of May 31, 2019, and significant endorsement contracts, including related marketing commitments, entered into through the date of this report are as follows:
| DESCRIPTION OF COMMITMENT | CASH PAYMENTS DUE DURING THE YEAR ENDING MAY 31, | ||||||||||||||||||||
| (Dollars in millions) | 2020 | 2021 | 2022 | 2023 | 2024 | THEREAFTER | TOTAL | ||||||||||||||
| Operating Leases | $ | 553 | $ | 513 | $ | 441 | $ | 386 | $ | 345 | $ | 1,494 | $ | 3,732 | |||||||
| Capital Leases and Other Financing Obligations (1) | 32 | 34 | 40 | 37 | 34 | 197 | 374 | ||||||||||||||
| Long-Term Debt (2) | 115 | 112 | 109 | 609 | 98 | 4,617 | 5,660 | ||||||||||||||
| Endorsement Contracts (3) | 1,382 | 1,274 | 1,360 | 1,077 | 968 | 4,148 | 10,209 | ||||||||||||||
| Product Purchase Obligations (4) | 5,203 | — | — | — | — | — | 5,203 | ||||||||||||||
| Other Purchase Obligations (5) | 1,331 | 411 | 225 | 166 | 135 | 492 | 2,760 | ||||||||||||||
| Transition Tax Related to the Tax Act (6) | 86 | 86 | 86 | 86 | 161 | 483 | 988 | ||||||||||||||
| TOTAL | $ | 8,702 | $ | 2,430 | $ | 2,261 | $ | 2,361 | $ | 1,741 | $ | 11,431 | $ | 28,926 |
| (1) | Capital leases and other financing obligations include payments related to build-to-suit lease arrangements. |
2019 FORM 10-K 39
| (2) | The cash payments due for long-term debt include estimated interest payments. Estimates of interest payments are based on outstanding principal amounts, applicable fixed interest rates or currently effective interest rates as of May 31, 2019 (if variable), timing of scheduled payments and the term of the debt obligations. |
| (3) | The amounts listed for endorsement contracts represent approximate amounts of base compensation and minimum guaranteed royalty fees we are obligated to pay athlete, public figure, sport team and league endorsers of our products. Actual payments under some contracts may be higher than the amounts listed as these contracts provide for bonuses to be paid to the endorsers based upon athletic achievements and/or royalties on product sales in future periods. Actual payments under some contracts may also be lower as these contracts include provisions for reduced payments if athletic performance declines in future periods. |
In addition to the cash payments, we are obligated to furnish our endorsers with NIKE product for their use. It is not possible to determine how much we will spend on this product on an annual basis as the contracts generally do not stipulate a specific amount of cash to be spent on the product. The amount of product provided to the endorsers will depend on many factors, including general playing conditions, the number of sporting events in which they participate and our own decisions regarding product and marketing initiatives. In addition, the costs to design, develop, source and purchase the products furnished to the endorsers are incurred over a period of time and are not necessarily tracked separately from similar costs incurred for products sold to customers.
| (4) | We generally order product at least four to five months in advance of sale based primarily on advanced orders received from external wholesale customers and internal orders from our NIKE Direct in-line stores and digital commerce operations. The amounts listed for product purchase obligations represent agreements (including open purchase orders) to purchase products in the ordinary course of business that are enforceable and legally binding and specify all significant terms. In some cases, prices are subject to change throughout the production process. |
| (5) | Other purchase obligations primarily include construction, service and marketing commitments, including marketing commitments associated with endorsement contracts, made in the ordinary course of business. The amounts represent the minimum payments required by legally binding contracts and agreements that specify all significant terms, including open purchase orders for non-product purchases. |
| (6) | Represents the future cash payments due as part of the transition tax on deemed repatriation of undistributed earnings of foreign subsidiaries, which is reflected net of foreign tax credits we utilized. Refer to Note 9 — Income Taxes in the accompanying Notes to the Consolidated Financial Statements for additional information. |
In addition to the above, we have long-term obligations for uncertain tax positions and various post-retirement benefits for which we are not able to reasonably estimate when cash payments will occur. Refer to Note 9 — Income Taxes and Note 13 — Benefit Plans in the accompanying Notes to the Consolidated Financial Statements for further information related to uncertain tax positions and post-retirement benefits, respectively.
We also have the following outstanding short-term debt obligations as of May 31, 2019. Refer to Note 7 — Short-Term Borrowings and Credit Lines in the accompanying Notes to the Consolidated Financial Statements for further description and interest rates related to the short-term debt obligations listed below.
| (Dollars in millions) | AS OF MAY 31, 2019 | ||
| Notes payable, due at mutually agreed-upon dates within one year of issuance or on demand | $ | 9 | |
| Payable to Sojitz America for the purchase of inventories, generally due 60 days after shipment of goods from a foreign port | $ | 75 |
As of May 31, 2019, the Company had bank guarantees and letters of credit outstanding totaling $215 million, issued primarily for real estate agreements, self-insurance programs and other general business obligations.
NEW ACCOUNTING PRONOUNCEMENTS
Refer to Note 1 — Summary of Significant Accounting Policies in the accompanying Notes to the Consolidated Financial Statements for recently adopted and recently issued accounting standards.
CRITICAL ACCOUNTING POLICIES
Our previous discussion and analysis of our financial condition and results of operations are based upon our Consolidated Financial Statements, which have been prepared in accordance with accounting principles generally accepted in the United States of America. The preparation of these financial statements requires us to make estimates and judgments that affect the reported amounts of assets, liabilities, revenues and expenses and related disclosure of contingent assets and liabilities. Note 1 — Summary of Significant Accounting Policies in the accompanying Notes to the Consolidated Financial Statements describes the significant accounting policies and methods used in the preparation of our Consolidated Financial Statements.
We believe the estimates, assumptions and judgments involved in the accounting policies described below have the greatest potential impact on our Consolidated Financial Statements, so we consider these to be our critical accounting policies and estimates. Management has reviewed and discussed these critical accounting policies with the Audit & Finance Committee of the Board of Directors.
40 NIKE, INC.
These policies require that we make estimates in the preparation of our Consolidated Financial Statements as of a given date. Because of the uncertainty inherent in these matters, actual results could differ from the estimates we use in applying the critical accounting policies. Within the context of these critical accounting policies, we are not currently aware of any reasonably likely events or circumstances that would result in materially different amounts being reported.
REVENUE RECOGNITION
On June 1, 2018, we adopted Accounting Standards Update (ASU) No. 2014-09, Revenue from Contracts with Customers (Topic 606), using the modified retrospective method of adoption. Prior period amounts have not been restated and continue to be reported in accordance with our historical accounting policies. Our revenue recognition polices under Topic 606 are described in the following paragraphs and references to prior period policies under Accounting Standard Codification Topic 605 — Revenue Recognition, are included below in the event they are substantially different.
Revenue transactions associated with the sale of NIKE Brand footwear, apparel and equipment, as well as Converse products, comprise a single performance obligation, which consists of the sale of products to customers either through wholesale or direct to consumer channels. We satisfy the performance obligation and record revenues when transfer of control has passed to the customer, based on the terms of sale. A customer is considered to have control once they are able to direct the use and receive substantially all of the benefits of the product. Transfer of control passes to wholesale customers upon shipment or upon receipt depending on the country of the sale and the agreement with the customer. Control passes to retail store customers at the time of sale and to substantially all digital commerce customers upon shipment. Prior to June 1, 2018, the requirements for recognizing revenue were met upon delivery to the customer. The transaction price is determined based upon the invoiced sales price, less anticipated sales returns, discounts and miscellaneous claims from customers. Payment terms for wholesale transactions depend on the country of sale or agreement with the customer and payment is generally required within 90 days or less of shipment to or receipt by the wholesale customer. Payment is due at the time of sale for retail store and digital commerce transactions.
As part of our revenue recognition policy, consideration promised in our contracts with customers is variable due to anticipated reductions such as sales returns, discounts and miscellaneous claims from customers. We estimate the most likely amount we will be entitled to receive and record an anticipated reduction against Revenues, with an offsetting increase to Accrued liabilities at the time revenues are recognized. The estimated cost of inventory for product returns is recorded in Prepaid expenses and other current assets on the Consolidated Balance Sheets. Prior to June 1, 2018, the Company's reserve balances were reported net of the estimated cost of inventory for product returns and recognized within Accounts receivable, net for wholesale transactions and Accrued liabilities for our direct to consumer business, on the Consolidated Balance Sheets.
The provision for anticipated sales returns consists of both contractual return rights and discretionary authorized returns. Provisions for post-invoice sales discounts consist of both contractual programs and discretionary discounts that are expected to be granted at a later date.
Estimates of discretionary authorized returns, discounts and claims are based on (1) historical rates, (2) specific identification of outstanding returns not yet received from customers and outstanding discounts and claims and (3) estimated returns, discounts and claims expected but not yet finalized with customers. Actual returns, discounts and claims in any future period are inherently uncertain and may differ from estimates recorded. If actual or expected future returns, discounts or claims were significantly different than reserves established, a reduction or increase to net revenues would be recorded in the period in which such determination was made.
Refer also to Note 1 — Summary of Significant Accounting Policies and Note 16 — Revenues for additional information in the accompanying Notes to the Consolidated Financial Statements.
INVENTORY RESERVES
We also make ongoing estimates relating to the net realizable value of inventories based upon our assumptions about future demand and market conditions. If we estimate the net realizable value of our inventory is less than the cost of the inventory recorded on our books, we record a reserve equal to the difference between the cost of the inventory and the estimated net realizable value. This reserve is recorded as a charge to Cost of sales. If changes in market conditions result in reductions to the estimated net realizable value of our inventory below our previous estimate, we would increase our reserve in the period in which we made such a determination.
2019 FORM 10-K 41
CONTINGENT PAYMENTS UNDER ENDORSEMENT CONTRACTS
A significant amount of our Demand creation expense relates to payments under endorsement contracts. In general, endorsement payments are expensed on a straight-line basis over the term of the contract. However, certain contract elements may be accounted for differently based upon the facts and circumstances of each individual contract.
Certain contracts provide for contingent payments to endorsers based upon specific achievements in their sports (e.g., winning a championship). We record demand creation expense for these amounts when the endorser achieves the specific goal.
Certain contracts provide for variable payments based upon endorsers maintaining a level of performance in their sport over an extended period of time (e.g., maintaining a specified ranking in a sport for a year). When we determine payments are probable, the amounts are reported in Demand creation expense ratably over the contract period based on our best estimate of the endorser's performance. In these instances, to the extent actual payments to the endorser differ from our estimate due to changes in the endorser's performance, adjustments to Demand creation expense may be recorded in a future period.
Certain contracts provide for royalty payments to endorsers based upon a predetermined percent of sales of particular products, which we record in Cost of sales as the related sales occur. For contracts containing minimum guaranteed royalty payments, we record the amount of any guaranteed payment in excess of that earned through sales of product within Demand creation expense.
PROPERTY, PLANT AND EQUIPMENT AND DEFINITE-LIVED ASSETS
We review the carrying value of long-lived assets or asset groups to be used in operations whenever events or changes in circumstances indicate the carrying amount of the assets might not be recoverable. Factors that would necessitate an impairment assessment include a significant adverse change in the extent or manner in which an asset is used, a significant adverse change in legal factors or the business climate that could affect the value of the asset or a significant decline in the observable market value of an asset, among others. If such facts indicate a potential impairment, we would assess the recoverability of an asset group by determining if the carrying value of the asset group exceeds the sum of the projected undiscounted cash flows expected to result from the use and eventual disposition of the assets over the remaining economic life of the primary asset in the asset group. If the recoverability test indicates the carrying value of the asset group is not recoverable, we will estimate the fair value of the asset group using appropriate valuation methodologies that would typically include an estimate of discounted cash flows. Any impairment would be measured as the difference between the asset group's carrying amount and its estimated fair value.
HEDGE ACCOUNTING FOR DERIVATIVES
We use derivative contracts to hedge certain anticipated foreign currency and interest rate transactions as well as certain non-functional currency monetary assets and liabilities. When the specific criteria to qualify for hedge accounting has been met, changes in the fair value of contracts hedging probable forecasted future cash flows are recorded in Accumulated other comprehensive income (loss), rather than Net income, until the underlying hedged transaction affects Net income. In most cases, this results in gains and losses on hedge derivatives being released from Accumulated other comprehensive income (loss) into Net income sometime after the maturity of the derivative. One of the criteria for this accounting treatment is that the notional value of these derivative contracts should not be in excess of specifically identified anticipated transactions. By their very nature, our estimates of anticipated transactions may fluctuate over time and may ultimately vary from actual transactions. When anticipated transaction estimates or actual transaction amounts decline below hedged levels, or if it is no longer probable a forecasted transaction will occur by the end of the originally specified time period or within an additional two-month period of time thereafter, we are required to reclassify the cumulative change in fair value of the over-hedged portion of the related hedge contract from Accumulated other comprehensive income (loss) to Other (income) expense, net during the quarter in which the decrease occurs.
INCOME TAXES
We are subject to taxation in the United States, as well as various state and foreign jurisdictions. The determination of our provision for income taxes requires significant judgment, the use of estimates and the interpretation and application of complex tax laws. On an interim basis, we estimate our effective tax rate for the full fiscal year. This estimated annual effective tax rate is then applied to the year-to-date Income before income taxes excluding infrequently occurring or unusual items, to determine the year-to-date Income tax expense. The income tax effects of infrequent or unusual items are recognized in the interim period in which they occur. As the fiscal year progresses, we continually refine our estimate based upon actual events and earnings by jurisdiction during the year. This continual estimation process periodically results in a change to our expected effective tax rate for the fiscal year. When this occurs, we adjust the income tax provision during the quarter in which the change in estimate occurs.
42 NIKE, INC.
We record valuation allowances against our deferred tax assets, when necessary. Realization of deferred tax assets (such as net operating loss carry-forwards) is dependent on future taxable earnings and is therefore uncertain. At least quarterly, we assess the likelihood that our deferred tax asset balance will be recovered from future taxable income. To the extent we believe that recovery is not likely, we establish a valuation allowance against our net deferred tax asset, which increases our Income tax expense in the period when such determination is made.
On a quarterly basis, we evaluate the probability a tax position will be effectively sustained and the appropriateness of the amount recognized for uncertain tax positions based on factors including changes in facts or circumstances, changes in tax law, settled audit issues and new audit activity. Changes in our assessment may result in the recognition of a tax benefit or an additional charge to the tax provision in the period our assessment changes. We recognize interest and penalties related to income tax matters in Income tax expense.
On December 22, 2017, the United States enacted the Tax Act, which significantly changed previous U.S. tax laws, including provisions for a one-time transition tax on deemed repatriation of undistributed foreign earnings, and a reduction in the corporate tax rate from 35% to 21% for tax years beginning after December 31, 2017, among other changes. The Tax Act also transitions U.S. international taxation from a worldwide system to a modified territorial system and includes base erosion prevention measures on non-U.S. earnings, which has the effect of subjecting certain earnings of our foreign subsidiaries to U.S. taxation. Certain provisions of the Tax Act, including a provision to tax global intangible low-taxed income (GILTI) of foreign subsidiaries, were not effective for the Company until fiscal 2019. In accordance with U.S. GAAP, the Company has made an accounting policy election to treat taxes due under the GILTI provision as a current period expense.
Implementation of the Tax Act required us to record incremental provisional tax expense in fiscal 2018, which increased our effective tax rate in fiscal 2018. We completed our analysis of the Tax Act in the second quarter of fiscal 2019 and no adjustments were made to the provisional amounts recorded.
Refer to Note 9 — Income Taxes in the accompanying Notes to the Consolidated Financial Statements for additional information.
OTHER CONTINGENCIES
In the ordinary course of business, we are involved in legal proceedings regarding contractual and employment relationships, product liability claims, trademark rights and a variety of other matters. We record contingent liabilities resulting from claims against us when a loss is assessed to be probable and the amount of the loss is reasonably estimable. Assessing probability of loss and estimating probable losses requires analysis of multiple factors, including in some cases judgments about the potential actions of third-party claimants and courts. Recorded contingent liabilities are based on the best information available and actual losses in any future period are inherently uncertain. If future adjustments to estimated probable future losses or actual losses exceed our recorded liability for such claims, we would record additional charges during the period in which the actual loss or change in estimate occurred. In addition to contingent liabilities recorded for probable losses, we disclose contingent liabilities when there is a reasonable possibility the ultimate loss will materially exceed the recorded liability. While we cannot predict the outcome of pending legal matters with certainty, we do not believe any currently identified claim, proceeding or litigation, either individually or in aggregate, will have a material impact on our results of operations, financial position or cash flows.
2019 FORM 10-K 43
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK