 filings.tools
Northern Trust 10-K 2021-12-31
Filed 2022-02-28. 23 sections, 941K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2021
OR
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the transition period from to
Commission File No. 001-36609
NORTHERN TRUST CORPORATION
(Exact name of registrant as specified in its charter)
| Delaware | 36-2723087 | ||||
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
| 50 South La Salle Street | ||||||||
| Chicago, | Illinois | 60603 | ||||||
| (Address of principal executive offices) | (Zip Code) |
Registrant’s telephone number, including area code: (312) 630-6000
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Trading Symbol | Name of Each Exchange On Which Registered | ||||||
| Common Stock, $1.66 2/3 Par Value | NTRS | The NASDAQ Stock Market LLC | ||||||
| Depositary Shares, each representing 1/1,000th interest in a share of Series E Non-Cumulative Perpetual Preferred Stock | NTRSO | The NASDAQ Stock Market LLC |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☒
Indicate by check mark whether the registrant: (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☒ | Accelerated filer | ☐ | Emerging growth company | ☐ | ||||||||||||
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☒
Indicate by check mark whether the registrant is a shell company (as defined in Exchange Act Rule 12b-2). Yes ☐ No ☒
The aggregate market value of the registrant’s common stock as of June 30, 2021 (the last business day of the registrant’s most recently completed second quarter), based upon the last sale price of the common stock at June 30, 2021 as reported by The NASDAQ Stock Market LLC, held by non-affiliates was approximately $24.0 billion. Determination of stock ownership by non-affiliates was made solely for the purpose of responding to this requirement and the registrant is not bound by this determination for any other purpose.
At January 31, 2022, 207,898,329 shares of common stock, $1.66 2/3 par value, were outstanding.
Portions of the registrant’s Proxy Statement for its 2022 Annual Meeting of Stockholders are incorporated by reference into Part III hereof.
NORTHERN TRUST CORPORATION
FORM 10-K
ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
| i 2021 Annual Report | Northern Trust Corporation |
Glossary of Terms
When the following terms and abbreviations appear in the text of this report, they have the meanings indicated below:
| AFS | Available for Sale | ||||
| AIFMD | Alternative Investment Fund Managers Directive | ||||
| ALCO | Asset and Liability Management Committee | ||||
| AMA | Basel Advanced Measurement Approach | ||||
| AML | Anti-Money Laundering | ||||
| AOCI | Accumulated Other Comprehensive Income | ||||
| ARRC | Alternative Reference Rate Committee | ||||
| ASC | Accounting Standards Codification | ||||
| ASU | Accounting Standards Update | ||||
| AUC/A | Assets Under Custody/Administration | ||||
| Bank | The Northern Trust Company | ||||
| Banking book | Northern Trust’s structural assets, liabilities, net investments, and off-balance sheet instruments subject to interest rate risk and/or foreign currency risk. It is distinct from the trading book. | ||||
| Basel Committee | International Basel Committee on Banking Supervision | ||||
| BMR | European Union Benchmarks Regulation | ||||
| BRRD | Bank Recovery and Resolution Directive (EU) | ||||
| C&IS | Corporate & Institutional Services | ||||
| CARES | Coronavirus Aid, Relief, and Economic Security Act | ||||
| CCAR | Comprehensive Capital Analysis and Review | ||||
| CCPA | California Consumer Privacy Act | ||||
| CDFIs | Community Development Financial Institutions | ||||
| CEOC | Compliance & Ethics Oversight Committee | ||||
| CFA | Criminal Finances Act (UK) | ||||
| CFPB | Consumer Financial Protection Bureau | ||||
| CFTC | U.S. Commodity Futures Trading Commission | ||||
| Commission | European Commission | ||||
| Corporation | Northern Trust Corporation | ||||
| CPRA | California Privacy Rights Act of 2020 | ||||
| CRA | Community Reinvestment Act | ||||
| CRC | Credit Risk Committee | ||||
| CRD | Capital Requirements Directive of June 26, 2013 (EU) | ||||
| CRD V | European Commission revisions to the CRD, effective December 29, 2020 | ||||
| CRO | Chief Risk Officer | ||||
| CRR | Capital Requirements Regulation of June 26, 2013 (EU) | ||||
| CRR II | European Commission revisions to the CRR, effective June 28, 2021 | ||||
| CSDR | Central Securities Depositories Regulation (EU) | ||||
| CSSF | Commission de Surveillance du Secteur Financier (Luxembourg) | ||||
| DE&I | Diversity, Equity, and Inclusion | ||||
| DFAST | Dodd-Frank Act Stress Tests | ||||
| DGS | Deposit Guarantee Schemes | ||||
| DGSD | Deposit Guarantee Schemes Directive | ||||
| Dodd-Frank Act | Dodd-Frank Wall Street Reform and Consumer Protection Act | ||||
| EBA | European Banking Authority | ||||
| ECB | European Central Bank | ||||
| Economic Aid Act | The Economic Aid to Hard-Hit Small Businesses, Nonprofits and Venues Act | ||||
| EEA | European Economic Area |
| ii 2021 Annual Report | Northern Trust Corporation |
Glossary of Terms (continued)
| EMIR | European Market Infrastructure Regulation 648/2012 | ||||
| EOP | End of Period | ||||
| ESG | Environmental, Social and Governance | ||||
| EU | European Union | ||||
| Exchange Act | Securities Exchange Act of 1934, as amended | ||||
| FASB | Financial Accounting Standards Board | ||||
| FCA | Financial Conduct Authority | ||||
| FDIA | Federal Deposit Insurance Act | ||||
| FDIC | Federal Deposit Insurance Corporation | ||||
| Federal Reserve Board | The Board of Governors of the Federal Reserve System | ||||
| FICC | Fixed Income Clearing Corporation | ||||
| FINRA | Financial Industry Regulatory Authority | ||||
| FRC | Fiduciary Risk Committee | ||||
| FTE | Fully Taxable Equivalent | ||||
| FTP | Funds Transfer Pricing | ||||
| FX | Foreign Exchange | ||||
| GAAP | Generally Accepted Accounting Principles | ||||
| GDPR | General Data Protection Regulation | ||||
| GERC | Global Enterprise Risk Committee | ||||
| GFX | Global Foreign Exchange | ||||
| GILTI | Global Intangible Low-Taxed Income | ||||
| HTM | Held to Maturity | ||||
| HQLAs | High-Quality Liquid Assets | ||||
| IBA | ICE Benchmark Administration | ||||
| IBOR | Interbank Offered Rates | ||||
| IR | Interest Rate | ||||
| ISTRC | Information Security and Technology Risk Committee | ||||
| ITS | Implementing Technical Standards | ||||
| LCR | Liquidity Coverage Ratio | ||||
| LGD | Loss Given Default | ||||
| LIBOR | London Interbank Offered Rate | ||||
| MD&A | Management’s Discussion and Analysis | ||||
| MIFID | Market in Financial Instruments Directive | ||||
| MIFIR | Markets in Financial Instruments Regulation | ||||
| MLD5 | Fifth EU Money Laundering Directive | ||||
| MLRC | Market & Liquidity Risk Committee | ||||
| MREL | Minimum requirements for own funds and eligible liabilities (EU) | ||||
| MROC | Model Risk Oversight Committee | ||||
| MSDC | Macroeconomic Scenario Development Committee | ||||
| MVE | Market Value of Equity | ||||
| NAICS | North American Industry Classification System | ||||
| NAV | Net Asset Value | ||||
| NFA | National Futures Association | ||||
| NFTS | Northern Trust Fiduciary Services (Guernsey) Limited | ||||
| NII | Net Interest Income | ||||
| N/M | Not Meaningful | ||||
| NSFR | Net Stable Funding Ratio | ||||
| ORC | Operational Risk Committee |
| iii 2021 Annual Report | Northern Trust Corporation |
Glossary of Terms (continued)
| OREO | Other Real Estate Owned | ||||
| OTC | Over-the-Counter | ||||
| OTTI | Other-Than-Temporary Impairment | ||||
| PD | Probability of Default | ||||
| PPP | Paycheck Protection Program | ||||
| PRA | Prudential Regulation Authority | ||||
| Regulatory Relief Act | Economic Growth, Regulatory Relief, and Consumer Protection Act | ||||
| ROU | Right-of-use | ||||
| RTS | Regulatory Technical Standards | ||||
| RWA | Risk Weighted Assets | ||||
| SBA | U.S. Small Business Administration | ||||
| SEC | U.S. Securities and Exchange Commission | ||||
| Series D Preferred Stock | Series D Non-Cumulative Perpetual Preferred Stock | ||||
| Series E Preferred Stock | Series E Non-Cumulative Perpetual Preferred Stock | ||||
| SOFR | Secured Overnight Finance Rate | ||||
| SFDR | Sustainable Finance Disclosure Regulations (EU) | ||||
| SRD II | Shareholder Rights Directive (EU) | ||||
| SFTR | Securities Financing Transactions and Reuse of Collateral | ||||
| Taxonomy Regulations | Regulation (EU) 2020/852 | ||||
| TDR | Troubled Debt Restructuring | ||||
| Trading book | Foreign (non-U.S.) currency trading positions subject to foreign currency risk, as well as trading securities and interest rate derivative transactions, both subject to interest rate risk. | ||||
| UCITS | Undertakings for the Collective Investment in Transferable Securities | ||||
| UK | United Kingdom | ||||
| USD LIBOR | U.S. Dollar LIBOR | ||||
| VaR | Value-at-Risk | ||||
| VIE | Variable Interest Entity | ||||
| WM | Wealth Management |
| iv 2021 Annual Report | Northern Trust Corporation |
PART I
Item 1. BUSINESS
Northern Trust Corporation
Northern Trust Corporation (Corporation) is a leading provider of wealth management, asset servicing, asset management and banking solutions to corporations, institutions, families and individuals. The Corporation is a financial holding company conducting business through various U.S. and non-U.S. subsidiaries, including The Northern Trust Company (Bank).
The Bank is an Illinois banking corporation headquartered in Chicago and the Corporation’s principal subsidiary. Founded in 1889, the Bank conducts its business through its U.S. operations and its various U.S. and non-U.S. branches and subsidiaries. At December 31, 2021, the Bank had consolidated assets of $183.7 billion and common bank equity capital of $11.1 billion.
The Corporation was formed as a holding company for the Bank in 1971. The Corporation has a global presence with offices in 23 U.S. states and Washington, D.C., and across 23 locations in Canada, Europe, the Middle East and the Asia-Pacific region. At December 31, 2021, the Corporation had consolidated total assets of $183.9 billion and stockholders’ equity of $12.0 billion.
The Corporation expects that the Bank will continue in the foreseeable future to be the major source of the Corporation’s consolidated assets, revenues, and net income. Except where the context otherwise requires, references to “Northern Trust,” “we,” “us,” “our,” “its,” or similar terms mean Northern Trust Corporation and its subsidiaries on a consolidated basis.
Business Overview
Northern Trust focuses on managing and servicing client assets through its two client-focused reporting segments: Corporate & Institutional Services (C&IS) and Wealth Management. Asset management and related services are provided to C&IS and Wealth Management clients primarily by the Asset Management business. The revenue and expenses of Asset Management and certain other support functions are allocated fully to C&IS and Wealth Management. Northern Trust reports certain income and expense items not allocated to C&IS and Wealth Management in a third reporting segment, Other.
CORPORATE & INSTITUTIONAL SERVICES
C&IS is a leading global provider of asset servicing and related services to corporate and public retirement funds, foundations, endowments, fund managers, insurance companies, sovereign wealth funds, and other institutional investors around the globe. Asset servicing and related services encompass a full range of capabilities including but not limited to: custody; fund administration; investment operations outsourcing; investment management; investment risk and analytical services; employee benefit services; securities lending; foreign exchange; treasury management; brokerage services; transition management services; banking; and cash management. Client relationships are managed through the Bank and the Bank’s and the Corporation’s other subsidiaries, including support from locations in North America, Europe, the Middle East, and the Asia-Pacific region. At December 31, 2021, total C&IS assets under custody/administration, assets under custody, and assets under management were $15.18 trillion, $11.55 trillion, and $1.19 trillion, respectively.
WEALTH MANAGEMENT
Wealth Management focuses on high-net-worth individuals and families, business owners, executives, professionals, retirees, and established privately-held businesses in its target markets. In supporting these targeted segments, Wealth Management provides trust, investment management, custody, and philanthropic services; financial consulting; guardianship and estate administration; family business consulting; family financial education; brokerage services; and private and business banking. Wealth Management also includes Global Family Office, which provides customized services, including but not limited to: investment consulting; global custody; fiduciary; and private banking to meet the complex financial needs of ultra-high-net-worth individuals and family offices across the globe.
Wealth Management is one of the largest providers of advisory services in the United States, with assets under custody/administration, assets under custody, and assets under management of $1.07 trillion, $1.06 trillion, and $416.1 billion, respectively, at December 31, 2021. Wealth Management services are delivered by multidisciplinary teams through a network of offices in 19 U.S. states and Washington, D.C., as well as offices in London, Guernsey, and Abu Dhabi.
ASSET MANAGEMENT
Asset Management, through the Corporation’s various subsidiaries, supports the C&IS and Wealth Management reporting segments by providing a broad range of asset management and related services and other products to clients around the world. Investment solutions are delivered through separately managed accounts, bank common and collective
| 2021 Annual Report | Northern Trust Corporation 1 |
funds, registered investment companies, exchange traded funds, non-U.S. collective investment funds, and unregistered private investment funds. Asset Management’s capabilities include active and passive equity; active and passive fixed income; cash management; multi-asset and alternative asset classes (such as private equity and hedge funds of funds); and multi-manager advisory services and products. Asset Management’s activities also include overlay services and other risk management services. Asset Management operates internationally through subsidiaries and distribution arrangements and its revenue and expense are fully allocated to C&IS and Wealth Management. As discussed above, Northern Trust managed $1.61 trillion in assets as of December 31, 2021, including $1.19 trillion for C&IS clients and $416.1 billion for Wealth Management clients.
Competition
Northern Trust faces intense competition in all aspects and areas of its business. Competition comes from both regulated and unregulated financial services organizations, whose products and services span the local, national, and global markets in which Northern Trust conducts operations. Our competitors include a broad range of financial institutions and service companies, including other custodial banks, deposit-taking institutions, asset management firms, benefits consultants, trust companies, investment banking firms, insurance companies, investment counseling firms, and various financial technology companies, including software providers and data services firms. As our businesses grow and markets evolve, we may encounter increasing and new forms of competition around the world.
Northern Trust’s business strategy is to provide quality financial services to targeted market segments in which it believes it has a competitive advantage and favorable growth prospects. As part of this strategy, Northern Trust seeks to differentiate itself from its competitors with premier, holistic solutions and exceptional experiences tailored to meet clients’ needs. In addition, Northern Trust emphasizes the development and growth of recurring sources of fee-based income and continual productivity improvements. Northern Trust also seeks to maintain its foundational strength with a strong, conservative balance sheet and a globally respected brand.
Economic Conditions And Government Policies
The earnings of Northern Trust are affected by numerous external influences. Chief among these are general economic conditions, both domestic and international, and actions that governments and their central banks take in managing their economies. These general conditions affect all of Northern Trust’s businesses, as well as the quality, value, and profitability of its loan and investment portfolios.
The Board of Governors of the Federal Reserve System (Federal Reserve Board) implements monetary policy through its open market operations
Showing the first 8K of 67K characters. Open the full section
Item 1A. RISK FACTORS
In the normal course of our business activities, we are exposed to a variety of risks. The following discussion sets forth the risk factors that we have identified as being most significant to Northern Trust. Although we discuss these risk factors primarily in the context of their potential effects on our business, financial condition or results of operations, you should understand that these effects can have further negative implications such as: reducing the price of our common stock and other securities; reducing our capital, which can have regulatory and other consequences; affecting the confidence that clients, counterparties and/or applicable regulators have in us, with a resulting negative effect on our ability to conduct and grow our businesses; and reducing the attractiveness of our securities to rating agencies and potential purchasers, which may affect adversely our ability to raise capital and secure other funding or the cost at which we are able to do so. Additional risks beyond those discussed below, elsewhere in this Annual Report on Form 10-K or in other of our reports filed with, or furnished to, the SEC also could affect us adversely. Further, we cannot assure you that the risk factors herein or elsewhere in our other reports address all potential risks that we may face and you should not interpret discussion of any risk to imply that such risk has not already materialized.
These risk factors also serve to describe factors which may cause our results to differ materially from those described in forward-looking statements included herein or in other documents or statements that make reference to this Annual Report on Form 10-K. Forward-looking statements and other factors that may affect future results are discussed under “Forward-Looking Statements” included in Item 7, “Management’s Discussion and Analysis of Financial Condition and Results of Operations.”
COVID-19 Pandemic-Related Risks
Our business and results of operations generally have been, and may continue to be, adversely affected by the ongoing COVID-19 pandemic.
The ongoing COVID-19 pandemic, and governmental and societal responses thereto, have had a severe impact on global economic and market conditions, including heightened volatility in financial markets; global supply chain disruptions; and the institution of social distancing and travel restrictions that resulted in temporary closures of many businesses, lost revenues, and lower levels of employment. Although certain economic conditions have improved since their worst levels during the pandemic, the pandemic continues to evolve, as recently experienced with the rapid spread of variants and continuing outbreaks, and certain of the impacts of the pandemic may continue to affect aspects of our business and results of operations in the future.
These conditions have impacted—or may in the future impact—our business, results of operations, and financial condition negatively, including through lower net interest income resulting from lower interest rates; increased provisions for credit losses; lower revenue from certain of our fee-based businesses; impairments on the securities we hold; and decreased demand for certain of our products and services. Additionally, our liquidity and regulatory capital could be adversely impacted by volatility and disruptions in the capital and credit markets; volatility in foreign exchange rates; deposit flows; and client draws on lines of credit. Our business operations may also be disrupted if significant portions of our workforce are unable to work effectively, including because of illness, quarantines, government actions, or other restrictions in connection with the pandemic. In some cases, the COVID-19 pandemic has accelerated the transition from traditional to digital financial services and heightened customer expectations in this area, and this transition may require us to invest greater resources in technological advancements. Further, work-from-home and other modified business practices may introduce additional operational risks, including resiliency, cybersecurity, and execution risks, which may result in inefficiencies or delays, and may affect our ability to, or the manner in which we, conduct our business activities.
Governments have taken, and may in the future continue to take, measures to provide economic assistance to individual households and businesses, stabilize the markets, and support economic growth; the ultimate impact of these measures is unknown and they may not be sufficient to mitigate fully the negative impact of the ongoing pandemic and/or may result in consequences—intended or unintended—that negatively impact our business.
The extent to which the COVID-19 pandemic continues to impact our business, results of operations and financial condition will depend on future developments, which are highly uncertain and are difficult to predict, including, but not limited to, the duration, spread and severity of COVID-19 and the rise of variants, the actions to contain the virus or treat its impact, including vaccine and testing mandates, the acceptance and efficacy of a global vaccine distribution plan, and
| 12 2021 Annual Report | Northern Trust Corporation |
the timing and extent that normal economic and operating conditions resume. The ongoing pandemic may also have the effect of heightening many of the other risks described in this section entitled “Risk Factors” and any subsequent filings with the SEC.
Market Risks
We are dependent on fee-based business for a majority of our revenues, which may be affected adversely by market volatility, a downturn in economic conditions, underperformance and/or negative trends in investment preferences.
Our principal operational focus is on fee-based business, which is distinct from commercial banking institutions that earn most of their revenues from loans and other traditional interest-generating products and services. Fees for many of our products and services are based on the market value of assets under management, custody or administration; the volume of transactions processed; securities lending volume and spreads; and fees for other services rendered, all of which may be impacted negatively by market volatility, a downturn in economic conditions, underperformance and/or negative trends in investment preferences. For example, downturns in equity markets and decreases in the value of debt-related investments resulting from market disruption, illiquidity or other factors historically have reduced the valuations of the assets we manage or service for others, which generally impacted our earnings negatively. Market volatility and/or weak economic conditions also may affect wealth creation, investment preferences, trading activities, and savings patterns, which impact demand for certain products and services that we provide.
Our earnings also may be affected by poor investment returns or changes in investment preferences driven by factors beyond market volatility or weak economic conditions. For example, poor absolute or relative investment performance in funds or client accounts that we manage or in investment products that we design or provide could result in declines in the market values of portfolios that we manage and/or administer and may affect our ability to retain existing assets and to attract new clients or additional assets from existing clients. Further, broader changes in investment preferences that lead to less investment in mutual funds or other collective funds, such as the shift in investor preference to lower fee products, could impact our earnings negatively.
Changes in interest rates can affect our earnings negatively.
The direction and level of interest rates are important factors in our earnings. In response to the COV
Showing the first 8K of 85K characters. Open the full section
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 2. PROPERTIES
The executive offices of the Corporation and the Bank are located at 50 South La Salle Street in Chicago. This Bank-owned building is occupied by various divisions of Northern Trust’s businesses. Adjacent to this building is one office building in which the Bank leases space principally for corporate support functions. Financial services are provided by the Bank and other subsidiaries of the Corporation through a network of offices in 23 U.S. states and Washington, D.C., and across 23 locations in Canada, Europe, the Middle East and the Asia-Pacific region. The majority of those offices are leased. The Bank’s other primary U.S. operations are located in five facilities: a leased facility at 333 South Wabash Avenue in Chicago; a leased facility in Tempe, Arizona; and one leased and two Bank-owned supplementary operations/data center buildings located in the western suburbs of Chicago. A majority of the Bank’s London-based staff is located at a leased facility at Canary Wharf in London. Additional support and operations activity originates from four facilities in India, two facilities in Ireland, and one facility in the Philippines, all of which are leased. The Bank and the Corporation’s other subsidiaries operate from various other facilities in North America, Europe, the Asia-Pacific region, and the Middle East, most of which are leased.
The Corporation believes that its owned and leased facilities are suitable and adequate for its business needs. The Corporation continues to evaluate its owned and leased facilities and may determine from time to time that certain of its facilities are no longer necessary for its operations. There is no assurance that the Corporation will be able to dispose of any excess facilities or that it will not incur costs in connection with such dispositions, which could be material to its operating results in a given period.
For additional information relating to properties and lease commitments, refer to Note 9, “Buildings and Equipment” and Note 10, “Lease Commitments,” included under Item 8, “Financial Statements and Supplementary Data,” and which information is incorporated herein by reference.
Item 3. LEGAL PROCEEDINGS
The information presented under the caption “Legal Proceedings” in Note 26, “Commitments and Contingent Liabilities,” included under Item 8, “Financial Statements and Supplementary Data,” is incorporated herein by reference.
Item 4. MINE SAFETY DISCLOSURES
Not applicable.
SUPPLEMENTAL ITEM – INFORMATION ABOUT OUR EXECUTIVE OFFICERS
The following sets forth certain information with regard to each executive officer of the Corporation.
Michael G. O’Grady - Mr. O’Grady, age 56, joined Northern Trust in 2011 and has served as Chairman of the Board since January 2019, as Chief Executive Officer since 2018 and as President since 2017. Prior to that, Mr. O’Grady served as Executive Vice President and President of Corporate & Institutional Services from 2014 to 2016 and as Chief Financial
| 26 2021 Annual Report | Northern Trust Corporation |
Officer from 2011 to 2014. Before joining Northern Trust, Mr. O’Grady served as a Managing Director in Bank of America Merrill Lynch’s Investment Banking Group.
Lauren E. Allnutt - Ms. Allnutt, age 45, joined Northern Trust in 2008 and has served as an Executive Vice President since November 2020 and as Controller since May 2019. Prior to that, Ms. Allnutt served as manager of Global Financial Control from 2014 to April 2019 and led International Accounting Policy and Control from 2013 to 2014.
Peter B. Cherecwich - Mr. Cherecwich, age 57, joined Northern Trust in 2007 and has served as Executive Vice President and President of Corporate & Institutional Services since 2017. Prior to that, Mr. Cherecwich served as Executive Vice President and President of Global Fund Services from 2010 to 2017 and as Chief Operating Officer of Corporate & Institutional Services from 2008 to 2014. From 2007 to 2008, he served as Head of Institutional Strategy & Product Development. Before joining Northern Trust, Mr. Cherecwich served in several executive and operational roles at State Street Corporation.
Steven L. Fradkin - Mr. Fradkin, age 60, joined Northern Trust in 1985 and has served as Executive Vice President and President of Wealth Management since 2014. Prior to that, Mr. Fradkin served as President of Corporate & Institutional Services from 2009 to 2014. From 2004 to 2009, he served as Chief Financial Officer.
Mark C. Gossett - Mr. Gossett, age 60, joined Northern Trust in 1983 and has served as Executive Vice President and Chief Risk Officer since 2020. Prior to that, Mr. Gossett served as Chief Credit Officer and Head of Market and Liquidity Risk from 2014 to 2020 and as Co-Head of Global Foreign Exchange from 2012 to 2014. Mr. Gossett also previously served as the Chief Risk Officer of Asset Management from 2009 to 2012 and as the Chief Operating Officer of Asset Management from 2005 to 2009.
Susan C. Levy - Ms. Levy, age 64, joined Northern Trust in 2014 and has served as Executive Vice President and General Counsel since that time. Ms. Levy also previously served as Corporate Secretary from 2018 to April 2021. Before joining Northern Trust, Ms. Levy served as Managing Partner of the law firm Jenner & Block from 2008 to 2014, where she was a partner since 1990.
Teresa A. Parker - Ms. Parker, age 61, joined Northern Trust in 1982 and has served as Executive Vice President and President of Europe, Middle East and Africa since 2017. Prior to that, Ms. Parker served as Chief Operating Officer of Corporate & Institutional Services from 2014 to 2017. From 2009 to 2014, she served as Executive Vice President, Corporate & Institutional Services for the Asia-Pacific region.
Thomas A. South - Mr. South, age 52, joined Northern Trust in 1999 and has served as Executive Vice President and Chief Information Officer since 2018. Prior to that, Mr. South served as Chief Business Architect from 2014 to 2018 and as Chief Operating Officer of Operations & Technology from 2013 to 2014.
Joyce M. St. Clair - Ms. St. Clair, age 62, joined Northern Trust in 1992 and has served as Executive Vice President and Chief Human Resources Officer since 2018. Prior to that, Ms. St. Clair served as Executive Vice President and Chief Capital Management Officer from 2015 to 2018, as President of Enterprise Operations from 2014 to 2015, as President of Operations & Technology from 2011 to 2014, and as Chief Risk Officer from 2007 to 2011.
Shundrawn A. Thomas - Mr. Thomas, age 48, joined Northern Trust in 2004 and has served as Executive Vice President and President of Asset Management since 2017. Prior to that, Mr. Thomas served as Executive Vice President and Head of the Funds and Managed Accounts Group from 2014 to 2017 and as Head of the Exchange-Traded Funds Group from 2010 to 2014. Mr. Thomas also previously served as President and Chief Executive Officer of Northern Trust Securities, Inc. from 2009 to 2010 and as Head of Corporate Strategy from 2006 to 2009.
Jason J. Tyler - Mr. Tyler, age 50, joined Northern Trust in 2011 and has served as Executive Vice President and Chief Financial Officer since 2020. Prior to that, Mr. Tyler served as Chief Financial Officer of Wealth Management from 2018 to December 2019, as Global Head of Asset Management’s Institutional Group from 2014 to 2018, and as Global Head of Strategy from 2011 to 2014. Before joining Northern Trust, Mr. Tyler served in certain executive and operational roles at Ariel Investments and Bank One/American National Bank.
All officers are appointed annually by the Board of Directors. Officers continue to hold office until their successors are duly elected or until their death, resignation or removal by the Board.
| 2021 Annual Report | Northern Trust Corporation 27 |
PART II
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Our common stock is listed on The NASDAQ Stock Market LLC under the symbol “NTRS.” There were 1,582 shareholders of record as of January 31, 2022.
The following table shows certain information relating to the Corporation’s purchases of common stock for the three months ended December 31, 2021.
TABLE 3: REPURCHASES OF COMMON STOCK IN THE FOURTH QUARTER OF 2021
| PERIOD | TOTAL NUMBER OF SHARES PURCHASED | AVERAGE PRICE PAID PER SHARE | TOTAL NUMBER OF SHARES PURCHASED AS PART OF A PUBLICLY ANNOUNCED PLAN | MAXIMUM NUMBER OF SHARES THAT MAY YET BE PURCHASED UNDER THE PLAN | ||||||||||
| October 1 - 31, 2021 | — | $ | — | — | 25,000,000 | |||||||||
| November 1 - 30, 2021 | — | — | — | 25,000,000 | ||||||||||
| December 1 - 31, 2021 | — | — | — | 25,000,000 | ||||||||||
| Total (Fourth Quarter) | — | $ | — | — | 25,000,000 |
Repurchases prior to October 19, 2021 were made pursuant to the repurchase program announced by the Corporation on July 17, 2018, under which the Corporation’s Board of Directors authorized the Corporation to repurchase up to 25.0 million shares of the Corporation’s common stock. On October 19, 2021, this program was terminated and replaced with a new repurchase program, under which the Corporation’s Board of Directors authorized the Corporation to repurchase up to 25.0 million shares of the Corporation’s common stock. The repurchase authorization approved by the Board of Directors has no expiration date, thus the Corporation retains the ability to repurchase when circumstances warrant and applicable regulation permits. For more information, please refer to Note 15, “Stockholders’ Equity,” provided in Item 8, “Financial Statements and Supplementary Data.”
| 28 2021 Annual Report | Northern Trust Corporation |
COMPARISON OF FIVE-YEAR CUMULATIVE TOTAL RETURN
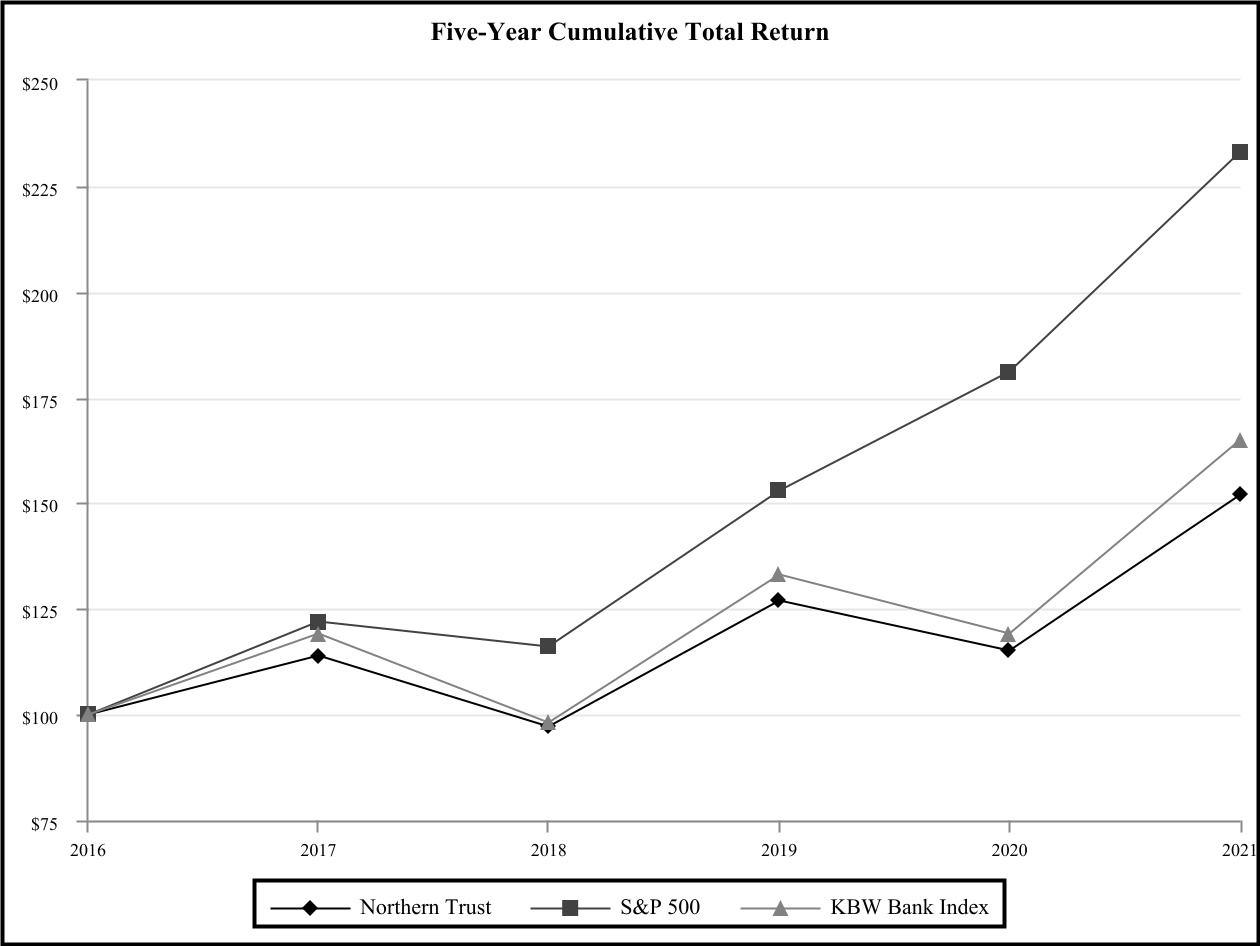
The following graph compares the cumulative total stockholder return on the Corporation’s common stock to the cumulative total return of the S&P 500 Index and the KBW Bank Index for the five fiscal years ended December 31, 2021. The cumulative total stockholder return assumes the investment of $100 in the Corporation’s common stock and in each index on December 31, 2016 and assumes reinvestment of dividends. The KBW Bank Index is a modified-capitalization-weighted index made up of 24 of the largest banking companies in the United States. The Corporation is included in the S&P 500 Index and the KBW Bank Index.
Total Return Assumes $100 Invested on
December 31, 2016 with Reinvestment of Dividends
| DECEMBER 31, | ||||||||||||||||||||
| 2016 | 2017 | 2018 | 2019 | 2020 | 2021 | |||||||||||||||
| Northern Trust | $ | 100 | $ | 114 | $ | 97 | $ | 127 | $ | 115 | $ | 152 | ||||||||
| S&P 500 | 100 | 122 | 116 | 153 | 181 | 233 | ||||||||||||||
| KBW Bank Index | 100 | 119 | 98 | 133 | 119 | 165 |
Item 6. [RESERVED]
| 2021 Annual Report | Northern Trust Corporation 29 |
MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following is management’s discussion and analysis of the financial condition and results of operations (MD&A) of Northern Trust Corporation (Corporation) for the year ended December 31, 2021. The following should be read in conjunction with the consolidated financial statements and related footnotes included in this report. Investors also should read the section entitled “Forward-Looking Statements.”
BUSINESS OVERVIEW
The Corporation is a leading provider of wealth management, asset servicing, asset management and banking solutions to corporations, institutions, families and individuals. The Corporation focuses on managing and servicing client assets through its two client-focused reporting segments: Corporate & Institutional Services (C&IS) and Wealth Management. Asset management and related services are provided to C&IS and Wealth Management clients primarily by the Asset Management business.
The Corporation conducts business through various U.S. and non-U.S. subsidiaries, including The Northern Trust Company (the Bank). The Corporation was formed as a holding company for the Bank in 1971. The Corporation has a global presence with offices in 23 U.S. states and Washington, D.C., and across 23 locations in Canada, Europe, the Middle East and the Asia-Pacific region. Except where the context requires otherwise, the terms “Northern Trust,” “we,” “us,” “our,” “its,” or similar terms refers to the Corporation and its subsidiaries on a consolidated basis.
COVID-19 PANDEMIC AND RECENT EVENTS
During the COVID-19 pandemic, Northern Trust has remained focused on the health and well-being of its workforce, meeting its clients’ needs and supporting its communities. The majority of Northern Trust’s workforce continues to work remotely and the Corporation continues to adjust its response to the pandemic as needed. The timing of any return to office for our workforce will be driven by the operational, business, and client needs of each location, and will be guided by health and safety guidelines and relevant government mandates. In addition, as the prolonged public health crisis has unfolded, Northern Trust has responded by providing additional health and well-being resources to its employees, including expanded virtual access to health care and well-being programs and diversity, equity, and inclusion resources; a well-being learning center with tools for working effectively in a virtual environment; and virtual focus groups allowing employees to provide feedback and build connections with colleagues. Northern Trust also provided additional paid-time-off for a COVID-19 diagnosis and supported all employees electing to receive the COVID-19 vaccine with additional paid-time-off to obtain and recover from the primary series vaccine or booster shot. To facilitate COVID-19 vaccinations in India and the Philippines, Northern Trust hosted on-site vaccine drives (in India) and participated in a program which provided access to vaccines for our employees (in the Philippines). Northern Trust also reimbursed vaccine costs for employees and their immediate family members in India.
During the pandemic, Northern Trust offered credit assistance to impacted clients under a government lending program and provided payment deferrals. In addition, there have been two forms of relief provided to lenders exempting certain loan modifications which would otherwise be classified as troubled debt restructuring from such classification. Northern Trust elected to apply each of these forms of relief, when applicable, in providing borrowers with qualifying loan modifications, including payment deferrals, in response to the COVID-19 pandemic. Both of these assistance measures have declined since the start of the pandemic. For further information, please refer to Note 6, “Loans and Leases,” provided in Item 8. “Financial Statements and Supplementary Data.”
| 30 2021 Annual Report | Northern Trust Corporation |
MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
FINANCIAL OVERVIEW
TABLE 4: FINANCIAL HIGHLIGHTS
| FOR THE YEAR ENDED DECEMBER 31, | |||||||||||
| ($ In Millions) | 2021 | 2020 | 2019 | ||||||||
| Noninterest Income | $ | 5,081.8 | $ | 4,657.6 | $ | 4,395.2 | |||||
| Net Interest Income | 1,382.7 | 1,443.2 | 1,677.9 | ||||||||
| Total Revenue | $ | 6,464.5 | $ | 6,100.8 | $ | 6,073.1 | |||||
| Provision for Credit Losses | (81.5) | 125.0 | (14.5) | ||||||||
| Noninterest Expense | 4,535.9 | 4,348.2 | 4,143.5 | ||||||||
| Income before Income Taxes | $ | 2,010.1 | $ | 1,627.6 | $ | 1,944.1 | |||||
| Provision for Income Taxes | 464.8 | 418.3 | 451.9 | ||||||||
| Net Income | $ | 1,545.3 | $ | 1,209.3 | $ | 1,492.2 | |||||
| Preferred Stock Dividends | 41.8 | 56.2 | 46.4 | ||||||||
| Net Income Applicable to Common Stock | $ | 1,503.5 | $ | 1,153.1 | $ | 1,445.8 | |||||
| PER COMMON SHARE | |||||||||||
| Net Income – Basic | $ | 7.16 | $ | 5.48 | $ | 6.66 | |||||
| – Diluted | 7.14 | 5.46 | 6.63 | ||||||||
| Cash Dividends Declared Per Common Share | 2.80 | 2.80 | 2.60 | ||||||||
| Book Value – End of Period (EOP) | 53.58 | 51.87 | 46.82 | ||||||||
| Market Price – EOP | 119.61 | 93.14 | 106.24 | ||||||||
| SELECTED RATIOS AND METRICS | |||||||||||
| Return on Average Common Equity | 13.9 | % | 11.2 | % | 14.9 | % | |||||
| Return on Average Assets | 0.99 | 0.88 | 1.27 | ||||||||
| Dividend Payout Ratio | 39.2 | 51.3 | 39.2 | ||||||||
| Average Stockholders’ Equity to Average Assets | 7.5 | 8.2 | 9.1 |
Net Income increased $336.0 million, or 28%, to $1.55 billion in 2021 from $1.21 billion in 2020. Earnings per diluted common share was $7.14 in 2021 compared to $5.46 in 2020. Return on average common equity increased to 13.9% in 2021 from 11.2% in 2020.
Revenue increased $363.7 million to $6.46 billion in 2021 from $6.10 billion in the prior year, primarily driven by increases in Trust, Investment and Other Servicing Fees of 9% and Other Operating Income of 26%, partially offset by a decrease in Net Interest Income of 4%.
Client assets under custody/administration (AUC/A) increased 12% from $14.53 trillion as of December 31, 2020 to $16.25 trillion as of December 31, 2021, primarily reflecting favorable markets and net inflows, partially offset by unfavorable currency translation. Client assets under custody, a component of AUC/A, increased 12% from $11.26 trillion as of December 31, 2020 to $12.61 trillion as of December 31, 2021. Client assets under custody included $8.24 trillion of global custody assets as of December 31, 2021, which increased 11% from $7.42 trillion as of December 31, 2020. Client assets under management increased 14% to $1.61 trillion as of December 31, 2021 from $1.41 trillion at December 31, 2020 due to favorable markets and net inflows.
The Provision for Credit Losses in 2021 was a release of credit reserves of $81.5 million as compared to a provision of $125.0 million in 2020. The release of credit reserves during 2021 was primarily due to a decrease in the reserve evaluated on a collective basis, which relates to pooled financial assets sharing similar risk characteristics, and was driven by improvements in projected economic conditions and portfolio credit quality, partially offset by port
Showing the first 8K of 284K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
The information called for by this item is incorporated herein by reference to the “Risk Management” section of Item 7, “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in this Annual Report on Form 10-K.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
Report of Independent Registered Public Accounting Firm
To the Stockholders and Board of Directors
Northern Trust Corporation:
Opinion on the Consolidated Financial Statements
We have audited the accompanying consolidated balance sheets of Northern Trust Corporation and subsidiaries (the Corporation) as of December 31, 2021 and 2020, the related consolidated statements of income, comprehensive income, changes in stockholders’ equity, and cash flows for each of the years in the three-year period ended December 31, 2021, and the related notes (collectively, the consolidated financial statements). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Corporation as of December 31, 2021 and 2020, and the results of its operations and its cash flows for each of the years in the three-year period ended December 31, 2021, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Corporation’s internal control over financial reporting as of December 31, 2021, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission, and our report dated February 28, 2022 expressed an unqualified opinion on the effectiveness of the Corporation’s internal control over financial reporting.
Change in Accounting Principle
As discussed in Note 1 to the consolidated financial statements, the Corporation has changed its method of accounting for the recognition and measurement of credit losses as of January 1, 2020 due to the adoption of ASC Topic 326, Financial Instruments – Credit Losses.
Basis for Opinion
These consolidated financial statements are the responsibility of the Corporation’s management. Our responsibility is to express an opinion on these consolidated financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Corporation in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. We believe that our audits provide a reasonable basis for our opinion.
Critical Audit Matter
The critical audit matter communicated below is a matter arising from the current period audit of the consolidated financial statements that was communicated or required to be communicated to the audit committee and that: (1) relates to accounts or disclosures that are material to the consolidated financial statements and (2) involved our especially challenging, subjective, or complex judgments. The communication of a critical audit matter does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
| 86 2021 Annual Report | Northern Trust Corporation |
Assessment of the allowance for credit losses for commercial loans and leases evaluated on a collective basis
As discussed in Notes 1 and 7 to the consolidated financial statements, the Corporation’s allowance for credit losses for commercial loans and leases evaluated on a collective basis (the collective ACL) was $95.5 million of a total allowance for credit losses assigned to loans and leases of $138.4 million as of December 31, 2021. Expected credit losses are measured on a collective basis as long as the financial assets included in the respective pool share similar risk characteristics. The allowance estimation methodology for the collective assessment is based on data representative of the Corporation’s financial asset portfolio from a historical observation period that includes both expansionary and recessionary periods. The estimation methodology and the related qualitative adjustment framework segregate the loan and lease portfolio into segments based on loan and obligor specific factors, including loan type, borrower type, collateral type, loan size, and borrower credit quality. The estimation methodology applies probability of default and loss given default assumptions to the projected exposure at default on a pool basis. For each segment, the probability of default (PD) and loss given default (LGD) are derived for each quarter of the remaining life of each instrument. For the first two years (the reasonable and supportable period), these factors are derived by applying quarterly macroeconomic projections using models developed from historical data on macroeconomic factors and loans with similar factors, including the borrower rating assigned to individual obligors, as applicable. For periods beyond the reasonable and supportable period, the Corporation reverts to its own long-run historical loss experience on a straight-line basis over four quarters. The projected exposure at default for every quarter is based on contractual balance projections as of each quarter-end. Estimating expected lifetime credit losses requires the consideration of the effect of future economic conditions. The Corporation employs multiple scenarios over a reasonable and supportable period to project future conditions. The Corporation determines the probability weights assigned to each scenario at each quarter-end. The quantitative allowance is then reviewed within the qualitative adjustment framework, through which the Corporation applies judgment by assessing internal risk factors, potential limitations in the quantitative methodology, and environmental factors that are not fully contemplated in the forecast to compute adjustments to the quantitative allowance that may impact individual or multiple segments of the loan portfolio.
We identified the assessment of the quantitative component of the collective ACL as a critical audit matter. A high degree of audit effort, including specialized skills and knowledge, and subjective and complex auditor judgment was involved in the assessment of the quantitative component of the collective ACL due to significant measurement uncertainty. Specifically, the assessment encompassed the evaluation of the quantitative component of the collective ACL methodology, including the methods and models used to estimate the PD and LGD and their significant assumptions, the multiple economic forecast scenarios and macroeconomic factors and their respective weightings, and borrower ratings for certain commercial loans and leases. In addition, auditor judgment was required to evaluate the sufficiency of audit evidence obtained.
The following are the primary procedures we performed to address this critical audit matter. We evaluated the design and operating effectiveness of certain internal controls related to the critical audit
Showing the first 8K of 427K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Disclosure Controls and Procedures
As of December 31, 2021, the Corporation’s management, with the participation of the Corporation’s Chief Executive Officer and Chief Financial Officer, evaluated the effectiveness of the Corporation’s disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Exchange Act) that are designed to ensure that information required to be disclosed by the Corporation in the reports that it files or submits under the Exchange Act is recorded, processed, summarized and reported within the time periods specified in the SEC’s rules and forms. Based on such evaluation, such officers have concluded that, as of December 31, 2021, the Corporation’s disclosure controls and procedures are effective.
Management’s Report on Internal Control Over Financial Reporting
Management of the Corporation is responsible for establishing and maintaining adequate internal control over financial reporting (as defined in Rules 13a-15(f) and 15d-15(f) under the Exchange Act) to provide reasonable assurance to the Corporation’s management and Board of Directors regarding the preparation of reliable published financial statements. This internal control includes monitoring mechanisms, and actions are taken to correct deficiencies identified.
Management assessed the Corporation’s internal control over financial reporting as of December 31, 2021, based on the criteria for effective internal control over financial reporting described in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission. Based on this assessment, management concluded that, as of December 31, 2021, the Corporation maintained effective internal control over financial reporting. Additionally, KPMG LLP, the independent registered public accounting firm that audited the Corporation’s consolidated financial statements as of, and for the year ended, December 31, 2021, included in this Annual Report on Form 10-K, has issued an attestation report on the effectiveness of the Corporation’s internal control over financial reporting as of December 31, 2021.
Changes in Internal Control Over Financial Reporting
There have been no changes in the Corporation’s internal control over financial reporting identified in connection with the evaluation required by Rules 13a-15 and 15d-15 under the Exchange Act during the last fiscal quarter that have materially affected, or are reasonably likely to materially affect, the Corporation’s internal control over financial reporting.
| 2021 Annual Report | Northern Trust Corporation 167 |
Report of Independent Registered Public Accounting Firm
To the Stockholders and Board of Directors
Northern Trust Corporation:
Opinion on Internal Control Over Financial Reporting
We have audited Northern Trust Corporation and subsidiaries’ (the Corporation) internal control over financial reporting as of December 31, 2021, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission. In our opinion, the Corporation maintained, in all material respects, effective internal control over financial reporting as of December 31, 2021, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of the Corporation as of December 31, 2021 and 2020, the related consolidated statements of income, comprehensive income, changes in stockholders’ equity, and cash flows for each of the years in the three-year period ended December 31, 2021, and the related notes (collectively, the consolidated financial statements), and our report dated February 28, 2022 expressed an unqualified opinion on those consolidated financial statements.
Basis for Opinion
The Corporation’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management’s Report on Internal Control Over Financial Reporting. Our responsibility is to express an opinion on the Corporation’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Corporation in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audit also included performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control Over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Chicago, Illinois
February 28, 2022
| 168 2021 Annual Report | Northern Trust Corporation |
Item 9B. OTHER INFORMATION
Not applicable.
Item 9C. DISCLOSURE REGARDING FOREIGN JURISDICTIONS THAT PREVENT INSPECTIONS
Not applicable.
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
The information called for by this item is incorporated by reference to “Supplemental Item – Information About Our Executive Officers” in Part I of this Annual Report on Form 10-K, as well as the following sections of the Corporation’s definitive Proxy Statement for the 2022 Annual Meeting of Stockholders: “Item 1 – Election of Directors,” “Information about the Nominees for Director,” “Security Ownership by Directors and Executive Officers,” “Corporate Governance – Code of Business Conduct and Ethics,” “Corporate Governance – Director Nominations and Qualifications and Proxy Access,” “Board and Board Committee Information – Audit Committee” and “Board and Board Committee Information – Board Committees.”
Item 11. EXECUTIVE COMPENSATION
The information called for by this item is incorporated herein by reference to the “Compensation Discussion and Analysis,” “Compensation and Benefits Committee Report,” “Executive Compensation,” and “Director Compensation” sections of the Corporation’s definitive Proxy Statement for the 2022 Annual Meeting of Stockholders.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
The information called for by this item is incorporated herein by reference to the “Security Ownership by Directors and Executive Officers,” “Security Ownership of Certain Beneficial Owners,” and “Equity Compensation Plan Information” sections of the Corporation’s definitive Proxy Statement for the 2022 Annual Meeting of Stockholders.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
The information called for by this item is incorporated herein by reference to the “Board and Board Committee Information,” “Corporate Governance – Director Independence” and the “Corporate Governance – Related Person Transactions Policy” sections of the Corporation’s definitive Proxy Statement for the 2022 Annual Meeting of Stockholders.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
The information called for by this item is incorporated herein by reference to the “Audit Matters” section of the Corporation’s definitive Proxy Statement for the 2022 Annual Meeting of Stockholders.
| 2021 Annual Report | Northern Trust Corporation 169 |
PART IV
ITEM 15 – EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
ITEM 15(a)(1) AND (2) – NORTHERN TRUST CORPORATION AND SUBSIDIARIES LIST OF FINANCIAL STATEMENTS AND FINANCIAL STATEMENT SCHEDULES
The following financial statements of the Corporation and its Subsidiaries included in Item 8, “Financial Statements and Supplementary Data,” of this Annual Report on Form 10-K are incorporated herein by reference.
| For Northern Trust Corporation and Subsidiaries: | ||
| Consolidated Balance Sheets - December 31, 2021 and 2020 | ||
| Consolidated Statements of Income - Years Ended December 31, 2021, 2020, and 2019 | ||
| Consolidated Statements of Comprehensive Income - Years Ended December 31, 2021, 2020, and 2019 | ||
| Consolidated Statements of Changes in Stockholders’ Equity - Years Ended December 31, 2021, 2020, and 2019 | ||
| Consolidated Statements of Cash Flows - Years Ended December 31, 2021, 2020, and 2019 | ||
| Notes to Consolidated Financial Statements | ||
| Report of Independent Registered Public Accounting Firm (KPMG LLP, Chicago, IL, Auditor Firm ID: 185) |
Financial statement schedules have been omitted for the reason that they are not required or are not applicable.
Item 15. (a)(3) – EXHIBITS
| 170 2021 Annual Report | Northern Trust Corporation |
| 2021 Annual Report | Northern Trust Corporation 171 |
| 172 2021 Annual Report | Northern Trust Corporation |
*** Indicates a management contract or a compensatory plan or agreement.*
Item 16. FORM 10-K SUMMARY
None.
| 2021 Annual Report | Northern Trust Corporation 173 |
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this Annual Report on Form 10-K to be signed on its behalf by the undersigned, thereunto duly authorized.
Date: February 28, 2022
| Northern Trust Corporation | |||||
| (Registrant) | |||||
| By: | /s/ Michael G. O’Grady | ||||
| Michael G. O’Grady | |||||
| Chairman and Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this Annual Report on Form 10-K has been signed below by the following persons on behalf of the Registrant and in the capacities and on the date indicated.
| 174 2021 Annual Report | Northern Trust Corporation |
| Signature | Capacity | |||||||
| /s/ Michael G. O'Grady | Chairman and Chief Executive Officer (Principal Executive Officer) | |||||||
| Michael G. O’Grady | ||||||||
| /s/ Jason J. Tyler | Executive Vice President and Chief Financial Officer (Principal Financial Officer) | |||||||
| Jason J. Tyler | ||||||||
| /s/ Lauren Allnutt | Executive Vice President and Controller (Principal Accounting Officer) | |||||||
| Lauren Allnutt | ||||||||
| /s/ Linda Walker Bynoe | Director | |||||||
| Linda Walker Bynoe | ||||||||
| /s/ Susan Crown | Director | |||||||
| Susan Crown | ||||||||
| /s/ Dean M. Harrison | Director | |||||||
| Dean M. Harrison | ||||||||
| /s/ Jay L. Henderson | Director | |||||||
| Jay L. Henderson | ||||||||
| /s/ Marcy S. Klevorn | Director | |||||||
| Marcy S. Klevorn | ||||||||
| /s/ Siddharth N. (Bobby) Mehta | Director | |||||||
| Siddharth N. (Bobby) Mehta | ||||||||
| /s/ Jose Luis Prado | Director | |||||||
| Jose Luis Prado | ||||||||
| /s/ Martin P. Slark | Director | |||||||
| Martin P. Slark | ||||||||
| /s/ David H.B. Smith, Jr. | Director | |||||||
| David H.B. Smith, Jr. | ||||||||
| /s/ Donald Thompson | Director | |||||||
| Donald Thompson | ||||||||
| /s/ Charles A. Tribbett, III | Director | |||||||
| Charles A. Tribbett, III |
Date: February 28, 2022
| 2021 Annual Report | Northern Trust Corporation 175 |