 filings.tools
Item 1. Business
92K characters. Original on sec.gov · Markdown
Item 1. Business
| --- | --- |
Overview
Nucor Corporation, a Delaware corporation incorporated in 1958, and its affiliates (“Nucor,” the “Company,” “we,” “us” or “our”) manufacture steel and steel products. The Company also produces direct reduced iron (“DRI”) for use in its steel mills. Through The David J. Joseph Company and its affiliates (“DJJ”), the Company also processes ferrous and nonferrous metals and brokers ferrous and nonferrous metals, pig iron, hot briquetted iron (“HBI”) and DRI. Most of the Company’s operating facilities and customers are located in North America. The Company’s operations include international trading and sales companies that buy and sell steel and steel products manufactured by the Company and others.
Nucor is North America’s largest recycler, using scrap steel as the primary raw material in producing steel and steel products. In 2021, we recycled approximately 20.4 million gross tons of scrap steel.
Segments, Principal Products Produced, and Markets and Marketing
Nucor reports its results in three segments: steel mills, steel products and raw materials. The steel mills segment is Nucor’s largest segment, representing 66% of the Company’s sales to external customers in the year ended December 31, 2021.
We market products from the steel mills and steel products segments mainly through in-house sales forces. We also utilize our internal distribution and trading companies to market our products abroad. The markets for these products are largely tied to capital and durable goods spending and are affected by changes in general economic conditions.
We are a leading domestic provider for most of the products we supply, and, in many cases (e.g., structural steel, merchant bar steel, steel joist and deck, pre-engineered metal buildings, steel piling, cold finish bar steel, steel electrical conduit pipe and insulated metal panels), we are the leading supplier.
Steel mills segment
In the steel mills segment, Nucor produces sheet steel (hot-rolled, cold-rolled and galvanized), plate steel, structural steel (wide-flange beams, beam blanks, H-piling and sheet piling) and bar steel (blooms, billets, concrete reinforcing bar, merchant bar and engineered special bar quality (“SBQ”)). Nucor manufactures steel principally from scrap steel and scrap steel substitutes using electric arc furnaces (“EAFs”), continuous casting and automated rolling mills. The steel mills segment also includes Nucor’s equity method investments in NuMit LLC (“NuMit”) and Nucor-JFE Steel Mexico, S. de R.L. de C.V. (“Nucor-JFE”), as well as international trading and distribution companies that buy and sell steel manufactured by the Company and other steel producers.
The steel mills segment sells its products primarily to steel service centers, fabricators and manufacturers located throughout the United States, Canada and Mexico. The steel mills segment sold approximately 20,296,000 tons to outside customers in 2021.
The following chart shows our outside steel shipments by end market:
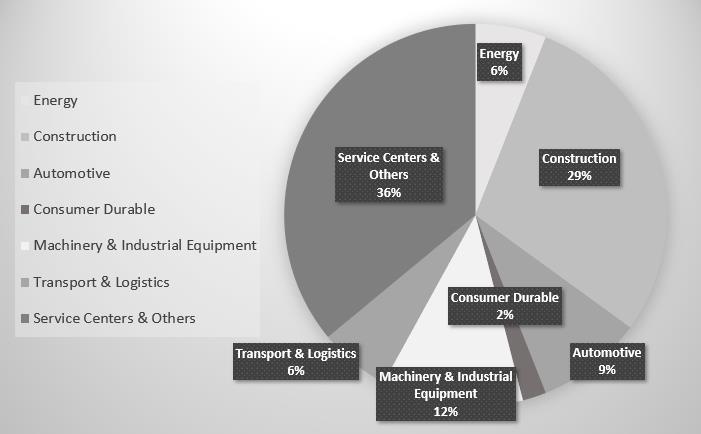
In 2021, 79% of the shipments made by our steel mills segment were to external customers. The remaining 21% of the steel mills segment’s shipments went to our steel products segment.
| • | Bar mills - Nucor has 15 bar mills strategically located across the United States that manufacture a broad range of steel products, including concrete reinforcing bars, hot-rolled bars, rounds, light shapes, structural angles, channels, wire rod and highway products in carbon and alloy steels. Four of the bar mills have a significant focus on manufacturing SBQ and wire rod products. |
|---|
Steel produced by our bar mills has a wide usage serving end markets, including the agricultural, automotive, construction, energy, furniture, machinery, metal building, railroad, recreational equipment, shipbuilding, heavy truck and trailer market segments. Considering Nucor’s production capabilities and the mix of bar products generally produced and marketed, the capacity of the bar mills is estimated at approximately 9,560,000 tons per year.
Reinforcing and merchant bar steel are sold in standard sizes and grades, which allows us to maintain inventory levels of these products to meet our customers’ expected orders. Our SBQ products are hot-rolled to exacting specifications primarily servicing the automotive, energy, agricultural, heavy equipment and transportation sectors.
In December 2021, Nucor announced that it expects to build a rebar micro mill at a to-be-determined location in the South Atlantic region.
| • | Sheet mills - Nucor operates five strategically located sheet mills that utilize thin slab casters to produce flat-rolled steel for automotive, appliance, construction, pipe and tube and many other industrial and consumer applications. Considering Nucor’s production capabilities and the mix of flat-rolled products generally produced and marketed, the capacity of the sheet mills is estimated at approximately 11,300,000 tons per year. All of our sheet mills are equipped with galvanizing lines and four of them are equipped with cold rolling mills for the further processing of hot-rolled sheet steel. |
|---|
Nucor produces hot-rolled, cold-rolled and galvanized sheet steel to customers’ specifications. Contract sales within the steel mills segment are most notable in our sheet operations, as it is common for contract sales to account for the majority of sheet sales in a given year. We estimate that greater than 80% of our sheet steel sales in 2021 were to contract customers. The balance of our sheet steel sales were made in the spot market at prevailing prices at the time of sale. The amount of tons sold to contract customers at any given time depends on a variety of factors, including our consideration of current and future market conditions, our strategy to appropriately balance spot and contract tons in a manner to meet our customers’ requirements while considering the expected profitability, our desire to sustain a diversified customer base, and our end-use customers’ perceptions about future market conditions. These sheet sales contracts are noncancellable agreements that generally incorporate monthly or quarterly price adjustments reflecting changes in the current market-based indices and/or raw material cost, and typically have terms ranging from six to 12 months.
In January 2022, Nucor announced that it expects to build a new, state-of-the-art sheet mill in West Virginia. In February 2022, Nucor completed its acquisition of a majority ownership position in California Steel Industries, Inc. (“CSI”), a flat-rolled steel converter, based in Fontana, California, expanding the reach of Nucor’s sheet mill group to the west coast of the United States.
| • | Structural mills - Nucor operates two structural mills that produce wide-flange steel beams, pilings and heavy structural steel products for fabricators, construction companies, manufacturers and steel service centers. Nucor owns a 51% interest in Nucor-Yamato Steel Company (Limited Partnership) (“Nucor-Yamato”) located in Blytheville, Arkansas. Nucor-Yamato is the only North American producer of high-strength, low-alloy beams. Common applications for the high-strength, low-alloy beams include gravity columns for high-rise buildings, long-span trusses for stadiums and convention centers, and for all projects where seismic design is a critical factor. The benefits of high strength, low alloy beams are increasingly recognized by Nucor’s customers in the construction sector. These include savings in terms of construction time, weight, space, and overall environmental impact. Nucor sells its high-strength, low alloy beams under the trade name AEOSTM. |
|---|
Nucor also owns a steel beam mill in Berkeley County, South Carolina. Considering Nucor’s production capabilities and the mix of structural products generally produced and marketed, the capacity of the two structural mills is estimated at approximately 3,250,000 tons per year. Both mills use a special continuous casting method that produces a beam blank closer in shape to that of the finished beam than traditional methods.
Structural steel products come in standard sizes and grades, which allows us to maintain inventory levels of these products to meet our customers’ expected orders.
| • | Plate mills - Nucor operates three plate mills that produce plate for manufacturers of barges, bridges, heavy equipment, rail cars, refinery tanks, ships, wind towers and other items. Our products are further used in the pipe and tube, pressure vessel, transportation and construction industries. Considering Nucor’s production capabilities and the mix of plate products generally produced and marketed, the capacity of the plate mills is estimated at approximately 2,925,000 tons per year. Nucor is currently constructing a state-of-the-art plate mill in Brandenburg, Kentucky with an anticipated start-up date of late 2022. |
|---|
Plate steel products come in standard sizes and grades, which allows us to maintain inventory levels of these products to meet our customers’ expected orders.
| • | Steel joint ventures - Nucor owns 50% interests in a North American sheet steel processing joint venture and a galvanized sheet steel plant in Mexico. |
|---|
Nucor owns a 50% economic and voting interest in NuMit, a company that owns 100% of the equity interest in Steel Technologies LLC (“Steel Technologies”), an operator of 30 strategically located sheet processing facilities in the United States, Canada and Mexico. Steel Technologies transforms flat-rolled steel into products that meet the exact specifications for customers in a wide range of industries, including the automotive, agricultural and consumer goods markets.
Nucor owns a 50% economic and voting interest in Nucor-JFE, a joint venture with JFE Steel Corporation (“JFE”) of Japan that operates a galvanized sheet steel plant in central Mexico that is expected to supply the country’s automotive market with an annual capacity of approximately 400,000 tons.
Steel products segment
In the steel products segment, Nucor produces hollow structural section (“HSS”) steel tubing, electrical conduit, steel racking, steel joists and joist girders, steel deck, fabricated concrete reinforcing steel, cold finished steel, steel fasteners, metal building systems, insulated metal panels, steel grating and expanded metal, and wire and wire mesh. The steel products segment also includes our piling distributor. These products are sold primarily for use in nonresidential construction applications.
| • | Tubular Products – The Nucor Tubular Products (“NTP”) group has eight tubular facilities that are strategically located in close proximity to Nucor’s sheet mills as they are a consumer of hot-rolled coil. The NTP group produces HSS steel tubing, mechanical steel tubing, galvanized solar torque tube, piling, sprinkler pipe, heat-treated tubing and electrical conduit. HSS steel tubing, mechanical steel tubing and sprinkler pipe are used in structural and mechanical applications, including nonresidential construction, infrastructure, agricultural, automotive and construction equipment end-use markets. Heat-treated tubing and electrical conduit are primarily used to protect and route electrical wiring in various nonresidential structures such as hospitals, schools, office buildings, hotels, stadiums and shopping malls. Solar torque tube is an essential component for ground-mount solar systems. |
|---|
In August 2021, Nucor acquired Hannibal Industries, Inc. (Hannibal), a leading national provider of steel racking solutions. Total annual NTP capacity is approximately 1,500,000 tons. In March 2021, Nucor announced that it expects to build a new tube mill on the site of its Kentucky sheet mill.
| • | Rebar fabrication - Harris Steel (“Harris”) fabricates, installs and distributes rebar for a wide variety of construction work classified as infrastructure (e.g., highways, bridges, reservoirs, utilities and airports) and various building projects, including hospitals, schools, stadiums, commercial office buildings and multi-tenant residential construction. We sell and install fabricated reinforcing products primarily on a construction contract bid basis. |
|---|
Reinforcing products are essential to concrete construction. They supply tensile strength, as well as additional compressive strength, and protect the concrete from cracking. In many markets, Harris sells reinforcing products on an installed basis (i.e., Harris fabricates the reinforcing products for a specific application and performs the installation). Harris operates nearly 70 fabrication facilities across the United States and Canada, with each facility serving a local market. Total annual rebar fabrication capacity is approximately 1,686,000 tons.
| • | Vulcraft/Verco – The Vulcraft/Verco group is the nation’s largest producer and leading innovator of open-web steel joists, joist girders and steel decking, which are used primarily for nonresidential building construction. Steel joists and joist girders are produced and marketed throughout the United States by seven domestic Vulcraft facilities. The Vulcraft/Verco group’s steel decking is produced and marketed throughout the United States by nine domestic plants. Six of these plants are adjacent to Vulcraft joist facilities. The Vulcraft/Verco group also has two plants in Canada, one in Eastern Canada and one in Western Canada, that produce both joist and deck. The annual joist production capacity is approximately 745,000 tons and the annual deck production capacity is approximately 560,000 tons. |
|---|
Sales of steel joists, joist girders and steel decking are dependent on the nonresidential building construction market. The majority of steel joists, joist girders and steel decking are used extensively as part of the roof and floor structural support systems in warehouses, data centers, manufacturing buildings, retail stores, shopping centers, schools, hospitals, and, to a lesser extent, in multi-story buildings and apartments. We make these products to the customers’ specifications and do not sell these finished steel products out of inventory. The majority of these contracts are firm, fixed-price contracts that are, in most cases, competitively bid against other suppliers.
| • | Piling products - Skyline Steel LLC and its subsidiaries (“Skyline”) are primarily a steel foundation distributor serving the North American market. Skyline distributes products to service marine construction, bridge and highway construction, heavy civil construction, storm protection, underground commercial parking and environmental containment projects in the infrastructure and construction industries. Skyline also manufactures a complete line of geostructural foundation solutions, including threaded bar, micropile, strand anchors and hollow bar. It also processes and fabricates spiral weld pipe piling, rolled and welded pipe piling, cold-formed sheet piling and threaded bar. |
|---|
| • | Cold finish - Nucor Cold Finish (“NCF”) is the largest and most diversified producer of cold finished bar products for a wide range of industrial markets in North America, with assets in Canada, Mexico and throughout the United States. The total capacity of the Nucor cold finished bar and wire facilities exceeds approximately 1,069,000 tons per year. |
|---|
Nucor’s cold finished facilities are among the most modern in the world, producing cold finished bars for the most demanding applications. NCF obtains most of its steel from the Nucor bar mills, ensuring consistent quality and supply through all market conditions. These facilities produce cold-drawn, turned, ground and polished steel bars that are used extensively for shafting and other precision machined applications. NCF produces rounds, hexagons, flats and squares in carbon, alloy and leaded steels. These bars are purchased by the appliance, automotive, construction equipment, electric motor, farm machinery and fluid power industries, as well as by service centers. NCF bars are used in tens of thousands of products. A few examples include anchor bolts, hydraulic cylinders and shafting for air conditioner compressors, ceiling fan motors, garage door openers, electric motors and lawn mowers.
Nucor owns a fully integrated precision castings company, Corporacion POK, S.A. de C.V. (“POK”), with a facility in Guadalajara, Mexico. POK produces complex castings and precision machined products used by the oil and gas, mining and sugar processing industries. POK produces a wide array of precision castings using steel, bronze, iron and specialty exotic alloys. POK complements NCF’s businesses and Nucor’s cold finish facility in Monterrey.
| • | Buildings group – Nucor produces metal buildings and components throughout the United States under the following brands: Nucor Building Systems, American Buildings Company, Kirby Building Systems and CBC Steel Buildings. In total, the Nucor Buildings group currently has an annual capacity of approximately 360,000 tons. |
|---|
The sizes of the buildings that can be produced range from less than 1,000 square feet to more than 1,000,000 square feet. Complete metal building packages can be customized and combined with other materials such as glass, wood and masonry to produce cost-effective, energy efficient, aesthetically pleasing buildings designed to the customers’ special requirements. The buildings are sold primarily through independent builder distribution networks in order to provide fast-track, customized solutions for building owners. The primary markets served are commercial, industrial and institutional buildings, including distribution centers, data centers, automobile dealerships, retail centers, schools and manufacturing facilities.
| • | Insulated Metal Panels – In August 2021, Nucor purchased the assets of the insulated metal panels business (“IMP”) of Cornerstone Building Brands, Inc. (“Cornerstone”), which is comprised of two industry leading brands, CENTRIA and Metl-Span. This acquisition, combined with Nucor’s existing IMP business, TrueCore, LLC (“TrueCore”), form the Nucor Insulated Panel Group. The Nucor Insulated Panel group has nine manufacturing locations and has an annual capacity of approximately 92,000 tons. |
|---|
| • | Steel mesh, grating and fasteners – Nucor manufactures wire products, grating and industrial fasteners. |
|---|
Nucor produces mesh at Nucor Steel Connecticut, Inc. and Nucor Wire Products Utah. Nucor also produces mesh in Canada at the Harris operations of Laurel Steel. The combined annual production capacity of the steel mesh facilities is approximately 128,000 tons.
Our grating business manufactures and fabricates steel and aluminum bar grating products at facilities located in North America and serves the new construction and maintenance-related markets. The annual production capacity for our grating business is approximately 46,500 tons.
Nucor Fastener’s bolt-making facility in Indiana produces carbon and alloy steel hex head cap screws, hex bolts, structural bolts, nuts and washers, finished hex nuts and custom-engineered fasteners. Nucor fasteners are used in a broad range of markets, including automotive, machine tool, farm implement, construction and military applications. The annual production capacity of this facility is approximately 75,000 tons.
Raw materials segment
In the raw materials segment, Nucor produces DRI; brokers ferrous and nonferrous metals, pig iron, HBI and DRI; supplies ferro-alloys; and processes ferrous and nonferrous scrap metal. The raw materials segment also includes our natural gas drilling operations. Nucor’s raw materials investments are focused on creating an advantage for its steelmaking operations, through a global information network and a multi-pronged and flexible approach to metallics supply.
| • | Scrap recycling and brokerage operations - DJJ operates six regional scrap recycling companies across the United States that together have shredders capable of processing approximately 5,478,000 tons of ferrous scrap annually. DJJ’s scrap recycling operations use industry-leading expertise and technology to maximize metal recovery and minimize waste. DJJ also operates 12 self-serve used auto parts stores called U Pull-&-Pay that complement its recycling operations. |
|---|
DJJ is the leading broker of ferrous scrap in North America and is a global trader of scrap metal, pig iron and other metallics. In addition to sourcing steel scrap for Nucor’s mills, DJJ is a global trader of ferro-alloys and nonferrous metals. DJJ’s logistics team owns and operates one of the largest independent fleets of railcars in the United States dedicated to the movement of scrap and steel and also offers railcar leasing and railcar fleet management services. These activities have strategic value to Nucor as the leading and most diversified North American steel producer.
Our primary external customers for ferrous scrap are EAF steel mills and foundries that use ferrous scrap as a raw material in their manufacturing process. External customers purchasing nonferrous scrap metal include aluminum can producers, secondary aluminum smelters, steel mills, and other processors and consumers of various nonferrous metals. We market scrap metal products and related services to our external customers through in-house sales forces. In 2021, approximately 9% of the ferrous and nonferrous metals and scrap substitute tons we brokered and processed were sold to external customers. We consumed the balance in our steel mills.
| • | Direct reduced iron operations - DRI is a substitute material for high-quality grades of scrap and pig iron. Nucor operates two DRI plants with a combined annual capacity of approximately 4,500,000 metric tons of material with world-class metallization rates and carbon content. Nucor’s wholly owned subsidiary, Nu-Iron Unlimited, is in Trinidad and benefits from a low-cost supply of natural gas and favorable logistics for inbound iron ore and shipment of DRI to the United States. Nucor’s second DRI plant in Louisiana also benefits from favorable logistics and proximity to its steel mill customers. |
|---|
Nucor’s DRI production and brokering capabilities provide our steel mills flexibility to quickly adjust their metallic input mix to changing market conditions, enabling them to maintain cost competitiveness in the often-volatile ferrous scrap market. With the potential for high-quality scrap to become scarcer, coupled with the risk of third-party supplier disruptions, Nucor’s DRI facilities provide a greater degree of certainty over metallics supply to its steel mills.
| • | Natural gas drilling programs - Nucor owns leasehold interests in natural gas properties in the Piceance Basin in the Western Slope of Colorado. |
|---|
Nucor’s access to a long-term, low-cost supply of natural gas is a component in the execution of Nucor’s raw material strategy. Natural gas produced by Nucor’s drilling operations is being sold to third parties to partially offset our exposure to changes in the price of natural gas consumed by our DRI plant in Louisiana and our steel mills in the United States.
| • | Universal Industrial Gases (UIG) – Nucor acquired UIG in 2019 so that we would have the capability to build and operate our own air separation units (“ASU”) to serve our steel mills, providing us with an alternative to long term service contracts with outside providers. Where economies of scale and regional market conditions warrant, we can also sell excess output from these plants on a merchant basis. We have one ASU in operation at our plate mill in Hertford County, North Carolina and three additional stand-alone facilities that are currently operating. Three more facilities are currently under construction at Nucor facilities. |
|---|
Customers and Markets
We have a diverse customer base and are not dependent on any single customer. Our largest single customer in 2021 represented approximately 5% of sales and consistently pays within terms. Our steel mills use a significant portion of the products of the raw materials segment.
We believe that nonresidential construction is the largest end-use market that we serve. Products from our steel mills and steel products segment are used in a variety of nonresidential construction applications (e.g., commercial, industrial, infrastructure).
In recent years we have come to see our EAF-based steelmaking method, with its lower greenhouse gas (“GHG”) intensity when compared with blast furnace technology, as a competitive advantage for reasons beyond its flexible, highly variable cost base. Many of our customers are expressing greater concern for the GHG emissions in their supply chains and are prioritizing sourcing their steel requirements from EAF-based steelmakers for incorporation into their projects and products.
We have developed branded product lines to leverage this, and other advantages conferred by our specialized capabilities.
| • | Our AEOSTM line of high strength, low alloy steel beams is one such example. AEOSTM’s benefits are increasingly recognized by Nucor’s customers in the construction sector. These include savings in terms of construction time, weight, space and overall environmental impact. |
|---|
| • | Our ECONIQTM line of net zero carbon steel is another example. We launched ECONIQTM during 2021 and have found strong interest from customers in both the automotive and construction end-use markets. These are the two largest end-use markets for steel in the United States. |
|---|
We have also invested in people and processes to organize more of our commercial activities around large customers and end-use markets (e.g., automotive, construction, wind energy and solar energy). We have developed dedicated teams who are tasked with developing relationships and educating decision makers in these sectors. We believe this has resulted in earlier and more thoughtful consideration being given to steel-based solutions from Nucor, and a better appreciation for some our unique products and capabilities, such as AEOSTM and ECONIQTM.
General Development of Our Business in Recent Years
Nucor has invested significant capital in recent years to expand our product portfolio to include more value-added steel mill products and capabilities, improve our cost structure, enhance our operational flexibility and increase our exposure to markets with attractive growth prospects; such as datacenters, warehouses and renewable energy. These investments totaled approximately $6.34 billion over the last three years, with approximately 75% going to capital expenditures and the remainder going to acquisitions. We believe that these investments will help us deliver profitable long-term growth. Further, we believe shifting our product mix to a greater proportion of value-added products will make us less susceptible to being negatively impacted by imports.
Nucor has several new capital projects and an acquisition of majority ownership position a joint venture in the steel mills segment that support our expansion of value-added product offerings and cost-reduction strategies.
| • | Nucor has completed construction of a new $325 million third generation flexible galvanizing line with an annual capacity of approximately 500,000 tons at our Nucor Steel Arkansas facility. We believe this project, combined with Nucor Steel Arkansas’ specialty cold mill that has been in operation for more than two years, uniquely positions Nucor among North American EAF steelmakers to provide the high-strength, light-weight steels that are increasingly in demand from the automotive and other sectors. |
|---|
| • | Nucor has completed construction of its approximately $650 million investment to modernize and expand the production capability at its Gallatin flat-rolled sheet mill located in Ghent, Kentucky. The project is expected to begin start-up in the first quarter of 2022 and will increase the production capability of the mill from approximately 1,400,000 tons to approximately 3,000,000 tons annually once fully online. This project gives the Gallatin mill new, thicker slab casting and wider coil capabilities, expanding our product portfolio into markets currently served by higher-cost competitors. |
|---|
| • | Construction continues on our $1.70 billion state-of-the-art plate mill in Brandenburg, Kentucky on the Ohio river. We expect that the new plate mill will begin production in the fourth quarter of 2022. The mill will be capable of producing approximately 1,200,000 tons per year of steel plate products. With the capability to manufacture nearly all the different types of plate products consumed in the United States, we believe this mill will position Nucor as the supplier of choice in the domestic plate market. We expect domestic demand for steel plate to grow in the coming years as offshore wind farms are permitted and developed with increasing frequency. Steel plate is essential to constructing offshore wind towers, as is steel rebar. |
|---|
| • | In January 2022, Nucor announced that its new state-of-the-art sheet mill will be located in Mason County, West Virginia. Nucor’s West Virginia mill will have an annual capacity of 3,000,000 tons, with related total expected capital expenditures of approximately $2.70 billion. Construction is expected to take two years pending permit and regulatory approvals. |
|---|
The new mill will be equipped to produce 84-inch sheet products, and among other features, will include a 76-inch tandem cold mill and two galvanizing lines. Galvanizing capabilities will include an advanced high-end automotive line with full inspection capabilities as well as a construction-grade line. In addition to its advanced capabilities and strategic location, the new greenfield mill’s product mix is anticipated to have a significantly lower GHG intensity than competitors who have historically supplied the region.
| • | In December 2021, Nucor announced construction of a rebar micro mill, with spooling capabilities, which is expected to be located in the South Atlantic region. This would be Nucor's third rebar micro mill, joining its existing micro mills in Missouri and Florida, both of which began operations in 2020. This $350 million investment will have an annual capacity of approximately 430,000 tons and is expected to be in operation in 2023. |
|---|
These mills are referred to as micro mills because they have a smaller operational footprint than our older rebar mills, as well as less productive capacity – typically about 400,000 tons per year. This makes them suitable for smaller regional markets and enables to us serve these markets with a logistics cost advantage relative to competitors operating from further away. Micro mills also have a lower environmental footprint due to their smaller size and the fact that their plant design does not typically include a natural gas fired reheat furnace that is common in many steel mills.
| • | In February 2022, Nucor completed its acquisition of a majority ownership position in CSI by purchasing a 50% equity ownership interest from a subsidiary of Vale S.A. (Vale) for a cash purchase price of $400 million, adjusted for net debt and working capital at closing, as well as a 1% equity ownership stake from JFE. CSI is a flat-rolled steel converter based in Fontana, California. |
|---|
Our acquisition of CSI expands the reach of Nucor’s sheet mill group to the west coast of the United States and increases our exposure to more value-added sheet steel. CSI’s product capabilities include hot rolled, pickled & oiled, cold rolled and galvanized sheet steels, as well as electric resistance welded (ERW) pipe. Its annual capacity is estimated at more than 2,000,000 tons.
During 2021, Nucor made two strategic acquisitions in the steel products segment.
| • | In August 2021, Nucor acquired the assets of the IMP business of Cornerstone for a cash purchase price of approximately $1.00 billion. The acquired IMP business that we acquired is comprised of two industry leading brands, CENTRIA and Metl-Span. The brands are now part of the Nucor Insulated Panel group, which also includes the Company's initial IMP business, TrueCore. We believe this acquisition will broaden the value-added solutions that the Nucor Buildings group provides to targeted end markets such as warehousing, distribution and data centers. We expect these end-use markets to continue to grow in the coming years and that the use of IMP products within them will also increase. IMPs facilitate cost-effective climate control in the built environment and reduce energy usage and overall operations-related GHG emissions for owners and lessees. |
|---|
| • | In August 2021, Nucor acquired Hannibal for $370 million. Hannibal is a leading national provider of racking solutions to warehouses and serves the e-commerce, industrial, food storage and retail segments. Hannibal has manufacturing facilities in Los Angeles and Houston, as well as three distribution centers. It utilizes sheet and bar steel, as well as steel decking, wire deck and fasteners to produce its racking solutions, providing potential supply chain efficiencies with other Nucor businesses. In addition to manufacturing racking solutions, Hannibal works closely with customers during the construction and design phases of a warehouse build-out by offering turn-key services such as installation, procurement and facility integration. |
|---|
Capital Allocation Strategy
The significant developments in Nucor’s business in recent years have largely been driven by our capital allocation strategy. Our highest capital allocation priority is to invest in our business for profitable long-term growth through our multi-pronged strategy of optimizing existing operations, greenfield expansions and acquisitions.
Our second priority is to return capital to our stockholders through cash dividends and share repurchases. Nucor has paid $1.47 billion in dividends to its stockholders during the past three years. That dividend payout represents 13% of cash flows from operations during that three-year period. The Company repurchased $3.28 billion of its common stock in 2021 ($39.5 million in 2020 and $298.5 million in 2019).
We intend to return at least 40% of our net income to stockholders over time via a combination of both cash dividends and share repurchases. Over the past three years, we have returned approximately 58% of our net income in this manner. At December 31, 2021, the Company had approximately $3.85 billion available for share repurchases under the currently authorized share repurchase program.
We intend to execute on our capital allocation strategy while maintaining a strong balance sheet, with relatively low financial leverage, as measured in terms of net debt to total capital, as well as ample liquidity. At year-end 2021, our net debt to total capital was approximately 14% and we had cash and cash equivalents, short-term investments and restricted cash and cash equivalents on hand of $2.76 billion. At the end of 2021, Nucor had the strongest credit ratings in the North American steel sector (Baa1/A-) with stable outlooks at both Moody’s and Standard & Poor’s.
Competition
We compete in a variety of steel and metal markets, including markets for finished steel products, unfinished steel products and raw materials. These markets are highly competitive with many domestic and foreign firms participating, and, as a result of this highly competitive environment, we find that we primarily compete on price and service.
In our steel mills segment, our EAF steel mills face many different forms of competition, including domestic integrated steel producers (who use iron ore converted into liquid form in a blast furnace as their basic raw material instead of scrap steel), other domestic EAF steel mills, steel imports and alternative materials. Large domestic integrated steel producers have the ability to manufacture a variety of products but face significantly higher energy costs and are often burdened with higher capital and fixed operating costs. EAF-based steel producers, such as Nucor, are sensitive to increases in scrap prices but tend to have lower capital and fixed operating costs compared with large integrated steel producers. EAF-based steel producers also typically emit fewer GHGs per ton of steel produced than integrated steel producers.
Global steel production overcapacity continues to be an ongoing risk to Nucor and the entire steel industry. The Organisation for Economic Cooperation and Development (“OECD”) estimates that global steel production overcapacity is currently approximately 500,000,000 tons, which is down slightly from previous years. However, additional capacity continues to come online and China’s steel production, the largest steel producing country, is still near record levels. In 2021, China’s steel production was 1.13 billion tons compared to the record amount of 1.16 billion tons the previous year.
Circumvention of trade duties also continues to pose a risk. Besides producing record amounts of steel in its own country, China is investing heavily in steel production in neighboring countries which is one way it tries to avoid being subject to trade duties. State-owned Chinese steel companies are involved in new steel capacity projects in Indonesia, the Philippines and Malaysia. The South East Asia Iron and Steel Institute (SEAISI) has estimated that by 2026 there will be significant production overcapacity in the region, noting it will take 20 years for demand to catch up with the projected capacity levels.
Strong trade enforcement has led to a structural change in the U.S. steel market. The Section 232 steel tariffs and successful trade cases have been effective in keeping unfairly traded imports out of the U.S. market. In November 2021, the U.S. government reached an agreement with Europe to end the Section 232 imports on steel from the European Union and replace them with a tariff rate quota. The U.S. government is also negotiating potential deals to end the tariffs with the United Kingdom and Japan. Imports of finished steel in 2021 were up approximately 48% from 2020 levels and accounted for approximately 22% of U.S. market share.
At the end of 2021, Congress passed a significant infrastructure spending bill. The bill will result in an estimated 4 million to 6 million tons of additional steel demand per year, and contains strong Buy America requirements to ensure domestically produced steel is used to rebuild U.S. infrastructure. Approximately 50% of Nucor products are shipped into the construction market, and Nucor’s lower carbon footprint is expected to provide an additional advantage as states and localities look to rebuild infrastructure in a sustainable manner.
We also experience competition from other materials. Depending on our customers’ end use of our products, there are often other materials, such as concrete, aluminum, plastics, composites and wood that compete with our steel products. When the price of steel relative to other raw materials rises, these alternatives can become more attractive to our customers.
Competition in our scrap and raw materials business is also vigorous. The scrap metals market consists of many firms and is highly fragmented. Firms typically compete on price and geographic proximity to the sources of scrap metal.
Backlog
In the steel mills segment, Nucor’s backlog of orders was approximately $3.79 billion and $2.58 billion at December 31, 2021 and 2020, respectively. Order backlog for the steel mills segment includes only orders from external customers and excludes orders from other Nucor businesses. Nucor’s backlog of orders in the steel products segment was approximately $8.12 billion and $2.66 billion at December 31, 2021 and 2020, respectively. The increase in backlogs for the steel products segment is due to several businesses within the steel products segment having record backlog volume and pricing at December 31, 2021. The majority of these orders are expected to be filled within one year. Order backlog within our raw materials segment is not meaningful because the vast majority of the raw materials that segment produces are used internally.
Sources and Availability of Raw Materials
An ample supply of high-quality scrap and scrap substitutes is critical to support Nucor’s ability to produce high-quality steel. Nucor’s raw materials segment safely produces, sources, trades and transports steelmaking raw materials. Nucor’s raw materials investments are focused on creating an advantage for our steelmaking operations, through a global information network and a multi-pronged and flexible approach to metallics supply.
Scrap and scrap substitutes are the most significant element in the total cost of steel production. The average cost of scrap and scrap substitutes used in our steel mills segment increased 62% from $290 per gross ton used in 2020 to $469 per gross ton used in 2021. On average, it takes approximately 1.1 tons of scrap and scrap substitutes to produce one ton of steel. Depending on the market conditions at the time, a raw material surcharge or variable steel pricing mechanism may be implemented to assist Nucor in maintaining operating margins and in meeting our customer commitments during periods of rapidly changing scrap and scrap substitute costs.
For the past decade, Nucor has focused on securing access to low-cost raw material inputs as they are the Company’s largest expense. We believe Nucor’s broad, balanced supply chain is an important strength which allows us to reduce the cost of our steelmaking operations, create a shorter supply chain and have greater optionality over our metallic inputs. Our investment in DRI production facilities and scrap yards, as well as our access to international raw materials markets, provides Nucor with significant flexibility in optimizing our raw material costs. Additionally, having a significant portion of our raw materials supply under our control minimizes risk associated with the global sourcing of raw materials, particularly since a good deal of scrap substitutes comes from regions of the world that have historically experienced greater political turmoil, such as Ukraine, Russia and Brazil. We believe the continued successful implementation of our raw material strategy, including key investments in DRI production, as well as in the scrap brokerage and processing services performed by our team at DJJ, gives us greater control over our metallic inputs and thus helps us mitigate the risk of significant fluctuations in the availability and costs of critical inputs.
DJJ acquires ferrous scrap from numerous sources, including manufacturers of products made from steel, industrial plants, scrap dealers, peddlers, auto wreckers and demolition firms. We purchase pig iron as needed primarily from overseas sources including Russia, Ukraine and Brazil. We received over 2,800,000 gross tons of pig iron in 2021. Our DRI plants in Trinidad and Louisiana have respective annual production capacities of approximately 2,000,000 and 2,500,000 metric tons. The primary raw material for our DRI facilities is pelletized iron ore, which we purchase from various international suppliers.
The primary raw material for our steel products segment is steel produced by Nucor’s steel mills.
Energy Consumption and Costs
Steel manufacturing is considered an energy-intensive, trade exposed industry. As a result, we continuously strive to make our operations in all three of our business segments more energy efficient. In addition, we proactively engage with suppliers, regulators and other energy industry participants to ensure the continued availability of reliable, low-cost sources of energy in various forms.
Our steel mills utilize EAFs for 100% of their steel production, with approximately 50% of their total energy consumed as electricity. The total energy consumed by Nucor also includes natural gas, oxygen and carbon raw material inputs. For the scrap melting process, electricity is the primary energy source, with natural gas combustion serving as the fuel for reheat furnaces and other pre-heating operations. Our DRI facilities in Trinidad and Louisiana are also large consumers of natural gas.
The availability and prices of electricity and natural gas are influenced today by many factors, including changes in supply and demand, the regulatory environment and pipeline/transmission infrastructure.
We use a variety of strategies to manage our exposure to price risk of natural gas, including cash flow hedges, as well as our owned natural gas drilling operations. In addition to the currently producing wells in the Piceance Basin, Nucor owns leasehold interests in natural gas properties in the South Piceance Basin, in the Western Slope of Colorado. To support Nucor’s operating wells and potential future well developments on these properties, Nucor has entered into long-term agreements directly with third-party gathering and processing service providers. Natural gas produced by Nucor’s drilling operations is being sold to partially offset our exposure to changes in the price of natural gas consumed by our DRI plant in Louisiana, and by our steel mills in the United States. Nucor has full discretion on its participation in all future drilling capital investments.
We closely monitor developments in public policy relating to energy production and consumption. We engage with policymakers to provide technical information that can inform policy decisions and avoid unintended adverse consequences of legislative and regulatory actions. We believe that a thoughtful approach to domestic energy policy can help ensure that steel and steel products manufactured in the United States remain competitive in the increasingly global marketplace.
Reducing Greenhouse Gas Emissions
GHG emissions by the energy sector have received an increasing amount of attention in recent years, as more people become concerned that these emissions are a significant contributor to climate change. This has led to increasing support for, and investment in, low or zero carbon energy generation technologies such as solar, wind and nuclear. As a result, the development of these technologies has accelerated, and in many cases, they are now more cost competitive with traditional, fossil fuel-based power generation. We believe that this ongoing diversification of power generation technologies is fundamentally positive, but without careful planning and investment there is some risk to the reliability of the domestic power grid as this transition continues. In particular, legacy fossil fuel-based assets will remain essential for some time to come and the U.S. transmission grid is broadly in need of substantial upgrades to take full advantage of these newer, more intermittent power sources. We are also optimistic about the related demand for our products as transmission grid upgrades are executed and newer power generation assets are developed using steel.
In July 2021, we announced a commitment to lower the GHG emissions intensity from our steel mill operations by 35% in 2030, measured against a 2015 baseline - the year the Paris Climate Agreement was adopted. As a result, Nucor’s GHG intensity in 2030 is expected to be 77% less than today’s global average. We expect to achieve these goals with a multi-pronged approach that includes utilization of renewable energy, carbon substitutes, more efficient operations and carbon sequestration.
In 2020 and 2021, we entered into three Virtual Power Purchase Agreements (“VPPAs”). Under each VPPAs, we have agreed to purchase for a fixed price a portion of the output of both solar and wind renewable power projects being developed in the United States. The VPPAs will be settled financially on a monthly basis. We have undertaken these initiatives to support the ongoing transition of the U.S. power grid to a greater reliance on renewable power. As part of these arrangements, we will also receive Renewable Energy Credits (“RECs”) commensurate with the power we purchase. These RECs can be applied against a portion of our GHG emissions, enabling us to receive credit for reducing them. The pay fixed, received floating nature of this arrangement also offsets a portion of our exposure to higher prices for electricity over the life of the contract. We are evaluating and considering similar transactions. One VPPA started delivering RECs to us in June 2021 and the other two VPPAs may be delayed as a result of supply chain disruptions and permitting delays and interconnection delays.
Government and Environmental Regulations
Our business operations are subject to numerous federal, state and local laws and regulations, the most significant of which are intended to protect our teammates and the environment. Due to the nature of the steel industry, we are subject to substantial regulations related to safety in the workplace. In addition to the requirements of the state and local governments of the communities in which we operate, we must comply with federal health and safety regulations, the most significant of which are enforced by the Occupational Safety and Health Administration (“OSHA”). Because safety and safety compliance is one of our primary values, its effect on our capital expenditures, earnings and competitive position is not estimable.
Nucor operates a robust and sustainable environmental program that incorporates the concept of each individual teammate, as well as management, being responsible for environmental performance. All of Nucor’s steel mills that have been in operation for over five years are ISO 14001 certified. Achieving ISO 14001 certification requires Nucor’s steel mills to implement an environmental management system with measurable targets and objectives, such as reducing the use of oil and grease and minimizing electricity use.
The principal federal environmental laws that regulate our business include the Clean Air Act (the “CAA”), which regulates air emissions; the Clean Water Act (the “CWA”), which regulates water withdrawals and discharges; the Resource Conservation and Recovery Act (the “RCRA”), which addresses solid and hazardous waste treatment, storage and disposal; and the Comprehensive Environmental Response, Compensation and Liability Act (the “CERCLA”), which governs releases of hazardous substances, and remediation of contaminated sites. Our operations are also subject to state and local environmental laws and regulations.
As it relates to air emission rates, EAFs are the most efficient and cleanest steel making process commercially available today. In comparison to blast furnaces, emissions of sulfur oxides from EAFs are approximately 14% of the amount emitted from blast furnaces. EAFs emit less than 1% of the particulate emissions compared to blast furnace operations. Importantly, EAF emissions of GHGs per ton of steel average less than half of the rates typically generated by blast furnaces. Operating EAFs instead of blast furnaces is a proven air quality improvement strategy. In addition, each of our steel mills operates air pollution control devices (baghouses) to collect and capture particulate emissions (“EAF dust”) from the steel making process. We strive to maintain compliance with all applicable CAA requirements.
The primary raw material of Nucor’s steelmaking operations is scrap metal. The process of recycling scrap metal generates particulate matter emissions that includes contaminants such as paint, zinc, lead, chrome and other metals. Initially, the particulate matter captured and collected is classified as a listed hazardous waste under the RCRA. Because these contaminants contain valuable metals, the EAF dust is recycled to recover these metals. Nucor sends all but a small fraction of the EAF dust it collects to recycling facilities that recover the zinc, lead, chrome and other valuable metals from this dust. By recycling this material, Nucor believes it is not only acting in a sustainable, responsible manner but it is also substantially limiting its potential for future liability under both the CERCLA and the RCRA.
In addition to recycling EAF dust, Nucor mills beneficially reuse steel slag in road materials as a granular base, embankments, engineered fill, highway shoulders, and hot mix asphalt pavement. The physical, chemical, mechanical and thermal properties of steel slag provide a vital resource for construction companies and activities. We take considerable pride in our recycling efforts.
Not only does the RCRA establish standards for the management of solid and hazardous wastes, the RCRA also addresses the environmental impact of contamination from waste disposal activities and from recycling and storage of most wastes. Periodically, past waste disposal activities that were legal when conducted but now may pose a contamination threat are discovered. When the U.S. Environmental Protection Agency determines these off-site properties are contaminated, Nucor quickly evaluates such claims and, if Nucor is determined to be responsible, we do our part to remediate our share of such issues. Nucor believes all identified liabilities under the RCRA are either currently being resolved or have been fully resolved.
Because Nucor has historically implemented environmental practices that have resulted in the responsible disposal of waste materials, Nucor is also not presently considered a major contributor to any major cleanups under the CERCLA for which Nucor has been named a potentially responsible party. Nucor regularly evaluates these types of potential liabilities and, if appropriate, maintains reserves sufficient to remediate the identified liabilities. Under the RCRA, private citizens may also bring an action against the operator of a regulated facility for potential damages and payment of cleanup costs. Nucor believes that its system of internal evaluation and due diligence has sufficiently identified these types of potential liabilities so that compliance with these regulations will not have a material adverse effect on our results of operations, cash flows or financial condition beyond that already reflected in the reserves established for them.
To protect water resources, the CWA regulates water withdrawals and discharges. When applicable, Nucor maintains water withdrawal and discharge permits at its facilities under the national pollutant discharge elimination system program of the CWA and conducts its operations in compliance with those permits. Nucor also maintains permits from local governments if the facility discharges into publicly owned treatment works.
Capital expenditures at our facilities that are associated with environmental regulation compliance for 2021 and 2022 are estimated to be less than $100 million per year.
Human Capital Resources
Culture, Organization and Compensation
We consider our teammates the most important part of Nucor and believe that our culture – and the encouragement that we provide to our teammates to “grow the core; expand beyond; and live our culture” – provides us with a competitive advantage. Our culture’s key principles are: Safety First, Trust, Open Communications, Teamwork, Community Stewardship and Results.
Nucor has a simple, streamlined organizational structure that allows our teammates to make quick decisions and innovate. Our organization is also highly decentralized, with most day-to-day operating decisions made by our division general managers and their teams. With nearly 29,000 teammates, fewer than 200 work in our principal executive offices in Charlotte, North Carolina. By empowering our teammates, our goal is to foster an entrepreneurial mindset, along with a strong sense of personal responsibility and a culture of accountability. This empowerment is reinforced by our compensation policies (see “Pay for Performance” discussion in Our Teammates, Compensation, Training & Development section below) to drive results and contribute to our success.
Teammate input is essential for us to maintain our culture of empowering teammates to make operational decisions. Aside from our practice of everyday open communication, we periodically ask our teammates to formally provide feedback. Beginning in 1986, we have asked our teammates to complete a comprehensive survey in order to gather feedback on a range of topics, including matters relating to the effectiveness of our culture. We view the survey as an important tool we use to continually improve our company and ensure our teammates remain engaged and satisfied. This survey is conducted every three years, the last of which was conducted in 2019. In the most recent survey, 90% of the responses were favorable in the category of “Satisfaction & Commitment.” The overall percentage of negative responses in the most recent survey has dropped by 25 percentage points since the survey began in 1986. The next survey will be conducted in the summer of 2022. Teammates of certain previously acquired businesses – most notably Harris, which accounted for approximately 15% of our workforce as of December 31, 2021 – complete a comparable survey that has also shown an improving trend over time.
Safety, Diversity, Equity & Inclusion
One of Nucor’s core values is our teammates’ well-being and safety, and it is our goal to become the safest steel company in the world. Our foremost responsibility is to work safely, which requires our teammates to identify unsafe conditions and activities and mitigate these hazards. We will continue working to eliminate exposures that can lead to injury and encourage our teammates to share their ideas for safety improvement. Two key metrics Nucor uses to measure safety are: the Injury/Illness Rate and Days Away, Restricted and Transfer (“DART”) Case Rate.
Nucor calculates the annual Injury/Illness Rate by dividing the number of work-related injuries and illnesses by the total number of hours worked by all Nucor teammates in a given year, and then multiplying the resulting percentage by 200,000, the equivalent of 100 full-time employees working 40 hours per week, 50 weeks per year. In 2021, we achieved an annual Injury/Illness Rate of 1.04, which marks the safest year in the Company’s history. This marks an improvement over our annual Injury/Illness Rate of 1.10 in 2020, which was the Company’s previous record.
Nucor uses the DART Case Rate to assess and manage the risk of serious injury in the workplace. Nucor calculates the annual DART Case Rate by dividing the number of cases resulting in days away from work, restricted work activity and/or job transfers by the total number of hours worked by all Nucor teammates in a given year, and then multiplying the resulting percentage by 200,000, the equivalent of 100 full-time employees working 40 hours per week, 50 weeks per year. In 2021, we achieved an annual DART Case Rate of 0.50 (0.59 in 2020).
Beginning in 1998, Nucor has used the President’s Safety Award to recognize divisions that achieve strong records of safety performance based on objective metrics. The President’s Safety Award has the following three levels: Platinum, which is awarded to divisions with zero recordable illnesses or injuries; Gold, which is awarded to divisions that have an Illness/Injury Rate below 0.6 and a DART Case Rate below one-third of the national average for their NAICS code; and Silver, which is awarded to divisions that achieve one-third the national average on Illness/Injury Rate and DART Case Rate. In 2021, 16 divisions achieved the Platinum level award, 14 divisions achieved the Gold level award and 17 divisions achieved the Silver level award. Nucor also has 25 OSHA Voluntary Protection Program Sites, OSHA’s highest level of recognition.
In 2020, the Company introduced the Nucor President’s Safety Cup as a way to foster more safety benchmarking throughout the Company. The President’s Safety Cup is an additional annual award that is presented to the region that has the best safety record across all of Nucor. Not only does this reward a facility for exceeding their individual safety goals, but it encourages our teams to work with their regional teammates to share ideas and improve safety as a group. The President’s Safety Cup trophy travels among the mills and divisions that make up the winning region.
We believe however, that Safety is about more than just avoiding injuries. At Nucor, safety means making sure our teammates feel safe, welcome and valued when they come to work each day. We are accelerating our diversity, equity and inclusion efforts with the objective of ensuring that each teammate feels a sense of belonging at Nucor. By creating an inclusive workplace, we believe we will attract top talent and achieve greater diversity in our workforce and leadership, which will make Nucor a stronger company. Some of the initiatives focused on inclusion, equity and diversity we have launched include:
| • | Conducting focused discussion groups to share experiences of the workplace and the effects of race and gender |
|---|
| • | Taking feedback onboard to enhance training and development |
|---|
| • | Webcasts by diverse senior leaders sharing their career progression and life experiences |
|---|
| • | Increasing tempo and intensity of engagement with supportive external partners, such as |
|---|
| • | Society of Black Engineers |
|---|
| • | Society of Women Engineers |
|---|
| • | Tuskegee University |
|---|
| • | INROADS (non-profit focused on addressing the lack of diversity in corporate America) |
|---|
| • | More proactive senior executive support for career development opportunities for diverse employees |
|---|
Our Teammates - Compensation, Training & Development
Nucor had approximately 28,800 teammates as of December 31, 2021. The vast majority of our teammates are located in the United States, with only a small number of teammates located outside of North America. Our operations are highly automated, allowing us to take advantage of lower employment costs while still providing our teammates with compensation that we believe is highly competitive as compared to businesses in our industry. At Nucor, we believe in “Pay-for-Performance.” Nucor teammates typically earn a significant part of their compensation based on their productivity. Production teammates work under group incentives that provide increased earnings for increased production. This additional incentive compensation is paid weekly in most cases. Nucor has also historically contributed 10% of earnings before federal taxes to a profit sharing plan for the majority of teammates below the officer level. We believe such compensation practices incentivize our workforce and reinforce our culture. For 2021, this profit sharing contribution, was the largest in our history and amounted to approximately $861 million.
While Nucor seeks to hire qualified and talented individuals as teammates, we also believe in developing the skills of our workforce by providing educational and on-the-job training, in addition to safety training. Further, Nucor believes it is important for senior management to also be familiar with, and have had direct experience running, Nucor’s mills and other operational divisions. The vast majority of our teammates are not represented by labor unions and we believe our teammate turnover is low.
At Nucor, we believe that a diversity of perspectives and background helps to facilitate the “Nucor Way” as we work to “grow the core; expand beyond; and live our culture.” We also believe that recruiting and hiring the best talent available will continue to provide us with a more diverse and capable workforce.
Policies
Nucor has a long history of conducting our businesses in a manner consistent with high standards of social responsibility. We have adopted a comprehensive Human Rights Policy, which operates in conjunction with many other Nucor policies related to ethical conduct and human rights, including our Standards of Business Conduct and Ethics, Code of Ethics for Senior Financial Professionals, Supplier Code of Conduct and Policy on Eliminating Forced Labor from our Supply Chain.
Available Information
Nucor’s Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K, and any amendments to these reports, as well as proxy statements and other information, are available on our website at www.nucor.com, as soon as reasonably practicable after Nucor files these documents electronically with, or furnishes them to, the U.S. Securities and Exchange Commission (the “SEC”).
We use the investor relations portion of our website, www.nucor.com/investors, to distribute information, including as a means of disclosing material, non-public information and for complying with our disclosure obligations under Regulation FD. We routinely post and make accessible financial and other information regarding the Company on our website. Accordingly, investors should monitor the investor relations portion of our website, in addition to our press releases, SEC filings and other public communications. Except as otherwise expressly stated in these documents, the information contained on our website or available by hyperlink from our website is not a part of this report and is not incorporated into this report or any other documents we file with, or furnish to, the SEC.
| Item 1A**.** | Risk Factors |
|---|
Many of the factors that affect our business and operations involve risk and uncertainty. The factors described below are some of the risks that could materially negatively affect our business, financial condition, results of operations and cash flows.
Industry Specific Risk Factors
Overcapacity in the global steel industry could increase the level of steel imports, which may negatively affect our business, results of operations, financial condition and cash flows.
Global steel production overcapacity continues to be an ongoing risk to Nucor and the entire steel industry. The OECD estimates that global steel production overcapacity currently approximately 500,000,000 tons, with additional capacity expected to come online over the next few years. China continues to be a significant contributor to excess steelmaking capacity, producing more than 1 billion tons of steel in each of the past two years. China is also investing in new steelmaking capacity in several countries in southeast Asia.
During periods of global economic weakness, this overcapacity is amplified because of weaker global demand for steel and steel products. This excess capacity often results in manufacturers in certain countries exporting significant amounts of steel and steel products at prices that are at or below their costs of production. In some countries the steel industry is subsidized or owned in whole or in part by the government, giving imported steel from those countries certain cost advantages. These imports, which are also affected by demand in the domestic market, international currency conversion rates, and domestic and international government actions, can result in downward pressure on steel prices, which could materially adversely affect our business, results of operations, financial condition and cash flows.
Our business requires substantial capital investment and maintenance expenditures, and our capital resources may not be adequate to provide for all of our cash requirements.
Our operations are capital intensive. For the three-year period ended December 31, 2021, our total capital expenditures were approximately $4.74 billion. Our business requires substantial expenditures for routine maintenance. We also recently announced substantial capital projects that we expect will increase production capacity, increase the efficiency of our operations and enhance our product offerings. Although we expect requirements for our business needs, including the funding of capital expenditures, debt service for financings and any contingencies, will be financed by internally generated funds, short-term commercial paper issuance, offerings of our debt and equity securities or from borrowings under our $1.75 billion unsecured revolving credit facility, we cannot guarantee that this will be the case. Additional acquisitions, increases in interest rates or unforeseen events could require financing from additional sources.
Changes in the availability and cost of electricity and natural gas are subject to volatile market conditions that could adversely affect our business.
Our steel mills are large consumers of electricity and natural gas. In addition, our DRI facilities are also large consumers of natural gas. We rely upon third parties for our supply of energy resources consumed in the manufacture of our products. The prices for and availability of electricity and natural gas are subject to volatile market conditions. These market conditions often are affected by weather, political, regulatory and economic factors beyond our control, and we may be unable to raise the price of our products to cover increased energy costs. Disruptions, including physical or information systems related issues, that impact the supply of our energy resources could temporarily impair our ability to manufacture our products for our customers. Increases in our energy costs resulting from market fluctuations or regulations that are not equally applicable across the entire global steel market could materially adversely affect our business, results of operations, financial condition and cash flows.
Competition from other steel producers, imports or alternative materials may adversely affect our business.
We face strong competition from other steel producers and imports that compete with our products on price, quality and service. The steel markets are highly competitive and a number of firms, domestic and foreign, participate in the steel, steel products and raw materials markets. Depending on a variety of factors, including the cost and availability of raw materials, energy, technology, labor, transportation and capital costs, currency exchange rates, government subsidies of foreign steel producers and other global political and economic factors, our business may be materially adversely affected by competitive forces.
In many applications, steel competes with other materials, such as concrete, aluminum, plastics, composites and wood. Increased use or availability of these materials in substitution for steel products could have a material adverse effect on prices and demand for our steel products.
Since 2011, automobile producers have begun taking steps towards complying with new Corporate Average Fuel Economy mileage requirements for new cars and light trucks that they produce. As automobile producers work to produce vehicles in compliance with these new standards, they may seek to reduce the amount of steel they incorporate in their vehicles, require different types or higher grades of steel products, or begin utilizing alternative materials in cars and light trucks to improve fuel economy, thereby reducing their demand for steel. Certain automakers have begun to use greater amounts of aluminum and smaller proportions of steel in some models since 2015. Additional shifts in demand for steel products by automobile producers could materially adversely affect our business, results of operations, financial condition and cash flows.
Our industry is cyclical and both recessions and prolonged periods of slow economic growth could have an adverse effect on our business.
Demand for most of our products is cyclical in nature and sensitive to general economic conditions. Our business supports cyclical industries, such as the commercial construction, energy, metals service centers, appliance and automotive industries. As a result, downturns in the U.S. economy or any of these industries could materially adversely affect our results of operations, financial condition and cash flows.
The U.S. economy has experienced a strong recovery from the conditions experienced at the onset of the COVID-19 pandemic, but new variants of COVID-19 and the continued abatement of the COVID-19 pandemic, labor shortages, supply chain disruptions, new or proposed legislation related to governmental spending, inflation and increases in interest rates have impacted, and will continue to impact, economic growth. Even with this economic recovery, challenges from global production overcapacity in the steel industry and ongoing uncertainties, both in the United States and in other regions of the world, remain.
We are unable to predict with certainty the duration of current economic conditions or the magnitude and timing of changes in economic activity. Future economic downturns, prolonged slow growth or stagnation in the economy, a sector-specific slowdown in one of our key end-use markets, such as nonresidential construction, or changes in inflation could materially adversely affect our business, results of operations, financial condition and cash flows, especially in light of the capital-intensive nature of our business.
The results of our operations are sensitive to volatility in steel prices and the cost and availability of raw materials, particularly scrap steel.
We rely to an extent on outside vendors to supply us with key consumables such as graphite electrodes and raw materials, including both scrap and scrap substitutes that are critical to the manufacture of our steel products. The raw material required to produce DRI is pelletized iron ore. Although we have vertically integrated our business by constructing our DRI facilities in Trinidad and Louisiana and also by acquiring DJJ in 2008, we still must purchase most of our primary raw material, steel scrap, from numerous other sources located throughout the United States and internationally. Although we believe that the supply of scrap and scrap substitutes is adequate to operate our facilities, prices of these critical raw materials are volatile and are influenced by changes in scrap exports in response to changes in the scrap, scrap substitutes and iron ore demands of our global competitors, as well as volatility in currency rates and political conditions. For example, we source a substantial amount of our scrap and scrap substitutes from countries in Europe such as Russia and Ukraine. If political conditions in those countries or their relations with the United States or each other further deteriorate, or such countries were to become subject to sanctions or other restrictions or interruptions in trade with the United States, it may materially affect the price and availability of scrap and scrap substitutes.
At any given time, we may be unable to obtain an adequate supply of these critical raw materials with price and other terms acceptable to us. The availability and prices of raw materials may also be negatively affected by new laws and regulations, allocation by suppliers, interruptions in production, accidents or natural disasters, war and other forms of armed conflict or political instability, changes in exchange rates, worldwide price fluctuations, including due to global political and economic factors, changes in governmental, business and consumer spending, inflation, increases in interest rates, labor shortages, and the availability and cost of transportation, including as a result of the COVID-19 pandemic. Many countries that export steel into our markets restrict the export of scrap, protecting the supply chain of some foreign competitors. This trade practice creates an artificial competitive advantage for foreign producers that could limit our ability to compete in the U.S. market.
If our suppliers increase the prices of our critical raw materials, we may not have alternative sources of supply. In addition, to the extent that we have quoted prices to our customers and accepted customer orders for our products prior to purchasing necessary raw materials, we may be unable to raise the price of our products to cover all or part of the increased cost of the raw materials or pass along increased transportation costs. Also, if we are unable to obtain adequate, cost-effective and timely deliveries of our required raw materials, we may be unable to timely manufacture sufficient quantities of our products. This could cause us to lose sales, incur additional costs, experience margin compressions or suffer harm to our reputation and customer relationships.
Our steelmaking processes, our DRI processes, and the manufacturing processes of many of our suppliers, customers and competitors are energy intensive and generate carbon dioxide and other GHGs. The regulation of these GHGs could have a material adverse impact on our results of operations, financial condition and cash flows.
Our operations are subject to numerous federal, state and local laws and regulations relating to the protection of the environment, and, accordingly, we make provision in our financial statements for the estimated costs of compliance. There are inherent uncertainties in these estimates. Most notably, the uncertainty of policies, enforcement priorities, legislation and regulations related to climate change mitigation strategies pose the greatest risk.
As a carbon steel producer, Nucor could be increasingly affected both directly and indirectly if carbon policy decisions and mandates are not properly implemented. Carbon is an essential raw material in Nucor’s steel production processes. Furthermore, Nucor steel mills utilize EAFs for 100% of their steel melting operations and the costs associated with the decarbonization of electricity generation is a significant concern. Significant new rulemaking or legislation could have a material adverse impact on our results of operations, financial condition and cash flows.
Environmental regulation compliance and remediation could result in substantially increased costs and materially adversely impact our competitive position.
We incur significant costs in meeting our environmental regulation compliance and remediation obligations. The principal federal environmental laws include the CAA, which regulates air emissions; the CWA which regulates water withdrawals and discharges; the RCRA, which addresses solid and hazardous waste treatment, storage and disposal; and the CERCLA, which governs releases of hazardous substances, and remediation of contaminated sites. Our operations are also subject to state and local environmental laws and regulations. Capital expenditures at our facilities that are associated with environmental regulation compliance for 2022 and 2023 are estimated to be less than $100 million per year.
In addition to the above mentioned statutes, certain revisions to National Air Ambient Quality Standards could make it significantly more difficult for us to obtain construction permits and permits to expand existing operations. Resulting cancellations, delays or unanticipated costs to these projects could negatively impact our ability to generate expected returns on our investments. These regulations can also increase our cost of energy, primarily electricity, which we use extensively in the steelmaking process. We may in the future incur substantially increased costs complying with such regulations, particularly if federal regulatory agencies were to change their enforcement posture with respect to such regulations.
Emerging customer preferences for greater product transparency and less GHG intensive materials may put us at a competitive disadvantage or reduce demand for our products.
Numerous states, including Washington, Oregon and New York, are considering establishing requirements for Environmental Product Declarations (“EPDs”) to evaluate environmental impacts of products. California has enacted the “Buy Clean California Act” and California has established Global Warming Potential (GWP) benchmarks through EPDs for certain materials, including certain steel products. Currently, the federal government is considering similar legislation. To provide for greater product transparency, Nucor contracted an independent, third-party to evaluate and publish EPDs for many of its products. Nucor’s EPDs extend beyond what is required under the “Buy Clean California Act”, which requires EPDs for four steel products. The following Nucor products have been evaluated and issued a corresponding EPD: fabricated hot-rolled structural steel sections; fabricated steel concrete reinforcing bar and merchant bar products; steel reinforcing bar and merchant bar products; fabricated steel hollow structural sections; fabricated structural plate; fabricated open web steel joist and joist girders; and fabricated steel roof and floor deck.
EPD legislation has the potential to put domestic steel manufacturers at a disadvantage to foreign competitors unless standardized mechanisms are used to fully evaluate products produced by foreign steel producers.
General Risk Factors
The COVID-19 pandemic, as well as similar epidemics and other public health emergencies in the future, could have a material adverse effect on our business, results of operations, financial condition and cash flows.
Our operations expose us to risks associated with pandemics, epidemics and other public health emergencies, such as the ongoing COVID-19 pandemic which spread from China to many other countries including the United States. The COVID-19 pandemic has had and may have further negative impacts on our operations, supply chain, transportation networks and customers, which may compress our margins or impact demand for our steel products, including as a result of preventative and precautionary measures that we, other businesses and governments have taken or may take in the future. The COVID-19 pandemic and governmental actions in response have adversely affected the economies of many countries and caused periodic disruption to and increased volatility in financial markets. The progression of the COVID-19 pandemic, including due to new variants of COVID-19, could also negatively impact our business or results of operations through the temporary closure of our operating facilities or those of our customers or suppliers.
In addition, the ability of our teammates and our suppliers’ and customers’ teammates to work may be significantly impacted by individuals contracting or being exposed to COVID-19. Our customers may be directly impacted by business interruptions or weak market conditions and may not be willing or able to fulfill their contractual obligations. Furthermore, the progression of and global response to the COVID-19 pandemic has caused and increased the risk of further delays in construction activities and equipment deliveries related to our capital projects, including potential delays in obtaining permits from government agencies, as well as changes in the prices and availability of labor and equipment for capital projects. The extent of such delays and other effects of COVID-19 on our capital projects, certain of which are outside of our control, is unknown, but they could impact or delay the timing of anticipated benefits on capital projects.
The extent to which COVID-19 may adversely impact our business depends on future developments, which are highly uncertain and unpredictable, including new variants of the virus, information concerning the severity of the pandemic, the adoption rate of vaccines, and the effectiveness of actions globally to contain or mitigate the effects of the pandemic. The current level of uncertainty over the economic and operational impacts of COVID-19 means the related financial impact cannot be reasonably estimated at this time.
We are subject to information technology and cyber security threats which could have an adverse effect on our business and results of operations.
We utilize various information technology systems to efficiently address business functions ranging from the operation of our production equipment to administrative computation to the storage of data such as intellectual property and proprietary business information. We also utilize third-party service providers for certain information technology services that are important to our operations. We continuously evaluate our cyber security systems and practices, assess potential threats, and improve our information technology networks, policies and procedures to address potential vulnerabilities. Despite efforts to assure secure and uninterrupted operations, threats from increasingly sophisticated cyber-attacks or system failures could result in materially adverse operational disruptions or security breaches of our systems or those of our third-party service providers. These risks could result in disclosure or destruction of key proprietary information or personal data or reputational damage, theft of assets or trade secrets, or could adversely affect our ability to physically produce or transport steel, resulting in lost revenues, as well as delays in reporting our financial results. We also could be required to spend significant financial and other resources to remedy the damage caused by a cyber security breach, including to repair or replace networks and information technology systems. We may also contend with potential liability for stolen information, increased cyber security protection costs, litigation expense and increased insurance premiums.
Our operations are subject to business interruptions and casualty losses.
The steelmaking business is subject to numerous inherent risks, particularly unplanned events such as explosions, fires, other accidents, natural disasters such as floods or earthquakes, critical equipment failures, acts of terrorism, inclement weather and transportation interruptions. While our insurance coverage could offset a portion of the losses relating to some of those types of events, our results of operations and cash flows could be adversely impacted to the extent that any such losses are not covered by our insurance, or that there are significant delays in resolving our claims with our insurance providers.
We acquire businesses and enter into joint ventures from time to time and we may encounter difficulties in integrating businesses we acquire.
We plan to continue to seek attractive opportunities to acquire businesses, enter into joint ventures and make other investments that strengthen Nucor. Realizing the anticipated benefits of acquisitions or other transactions will depend on our ability to operate these businesses and integrate them with our operations effectively identify and manage risks, and cooperate with our strategic partners. Our business, results of operations, financial condition and cash flows could be materially adversely affected if we are unable to successfully integrate these businesses or otherwise fail to realize the anticipated benefits of acquisitions or other transactions.
Risks associated with operating in international markets could adversely affect our business, financial position and results of operations.
Certain of our businesses and investments are located outside of the United States, in Canada, Mexico and in emerging markets. There are a number of risks inherent in doing business in or sourcing raw materials from such markets. These risks include, but are not limited to: unfavorable political or economic factors; local labor and social issues; changes in regulatory requirements; fluctuations in foreign currency exchange rates, interest rates and inflation; and complex foreign laws, treaties including tax laws, and the Foreign Corrupt Practices Act of 1977 (FCPA). These risks could restrict our ability to operate our international businesses profitably and therefore have a negative impact on our financial position and results of operations. In addition, our reported results of operations and financial position could also be negatively affected by exchange rates when the activities and balances of our foreign operations are translated into U.S. dollars for financial reporting purposes.
The accounting treatment of equity method investments, goodwill and other long-lived assets could result in future asset impairments, which would reduce our earnings.
We periodically test our equity method investments, goodwill and other long-lived assets to determine whether their estimated fair value is less than their value recorded on our balance sheet. The results of this testing for potential impairment may be adversely affected by uncertain market conditions for the global steel industry, as well as changes in interest rates, commodity prices and general economic conditions. If we determine that the fair value of any of these assets is less than the value recorded on our balance sheet, and, in the case of equity method investments the decline is other than temporary, we would likely incur a non-cash impairment loss that would negatively impact our results of operations.
Tax increases and changes in tax laws and regulations or exposure to additional tax liabilities could adversely affect our financial results.
The steel industry and our business are sensitive to changes in taxes. As a company based in the United States, Nucor is more exposed to the effects of changes in U.S. tax laws than some of our major competitors. Our provision for income taxes and cash tax liability in the future could be adversely affected by changes in U.S. tax laws.
Nucor recognizes the effect of income tax positions only if those positions are believed to be more likely than not of being sustained. We cannot predict whether taxing authorities will conduct an audit challenging any of our tax positions and there can be no assurance as to the outcome of any challenges. If we are unsuccessful in any of these matters, we may be required to pay taxes for prior periods, interest, fines or penalties.
We are subject to legal proceedings and legal compliance risks.
We spend substantial resources ensuring that we comply with domestic and foreign regulations, contractual obligations and other legal standards. Notwithstanding this, we are subject to a variety of legal proceedings and legal compliance risks in respect of various issues, including regulatory, safety, environmental, employment, transportation, intellectual property, contractual, import/export, international trade and governmental matters that arise in the course of our business and in our industry. For information regarding our current significant legal proceedings, see “Item 3. Legal Proceedings.” A negative outcome in an unusual or significant legal proceeding or compliance investigation could adversely affect our financial condition and results of operations. While we believe that we have adopted appropriate risk management and compliance programs, the nature of our operations means that legal compliance risks will continue to exist and additional legal proceedings and other contingencies, the outcome of which cannot be predicted with certainty, will arise from time to time.
Previous: Cover and table of contents · Next: Item 1B. Unresolved Staff Comments