 filings.tools
Item 1. BUSINESS
92K characters. Original on sec.gov · Markdown
Item 1. BUSINESS
GENERAL
We are incorporated under the laws of the state of Oklahoma, and our common stock is listed on the NYSE under the trading symbol “OKE.” We deliver energy products and services vital to an advancing world. We are a leading midstream service provider of gathering, processing, fractionation, transportation, storage and marine export services. As one of the largest diversified energy infrastructure companies in North America, we are delivering energy that makes a difference in the lives of people in the U.S. and around the world. Through our more than 50,000-mile pipeline network, we transport the natural gas, NGLs, Refined Products and crude oil that help meet domestic and international energy demand, contribute to energy security and provide safe, reliable and responsible energy solutions needed today and into the future.
Midstream Value Chain
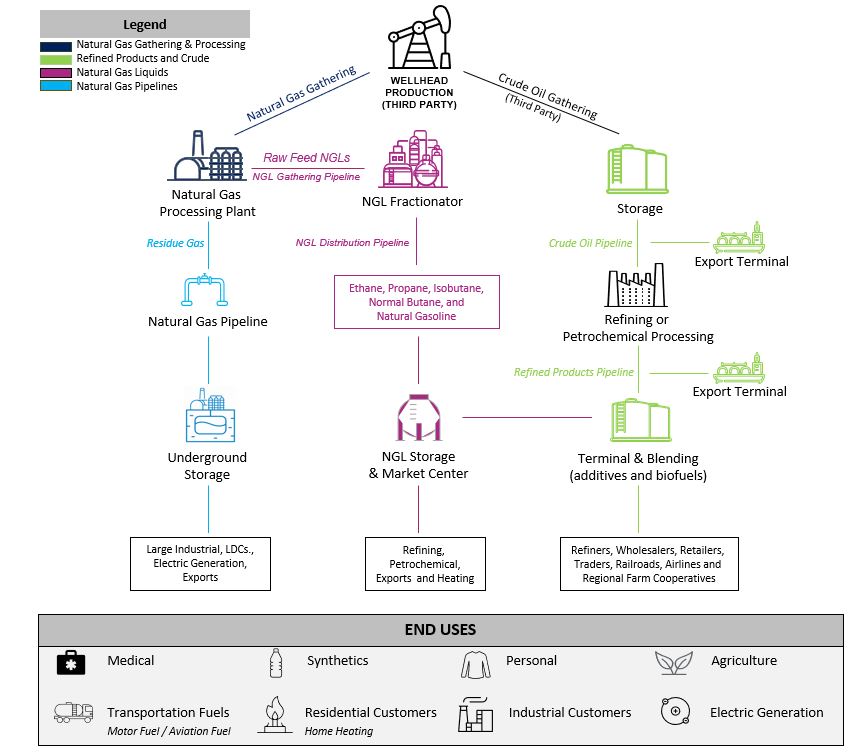
The midstream value chain is a vital part of the energy industry. After crude oil and natural gas are produced from upstream wells, we use our extensive infrastructure to process and transport these raw materials, readying them for end use. For transportation of crude oil, natural gas, Refined Products and NGLs, pipelines are generally the most reliable, lowest cost, least carbon intensive and safest alternative for intermediate and long-haul movements between markets.
EXECUTIVE SUMMARY
Magellan Acquisition - On September 25, 2023, we completed the Magellan Acquisition. The acquisition strategically diversifies our complementary asset base and allows for significant expected synergies. Pursuant to the Merger Agreement, each common unit of Magellan was exchanged for a fixed ratio of 0.667 shares of ONEOK common stock and $25.00 of cash, for a total consideration of $14.1 billion. In addition, we assumed Magellan’s debt at the fair value of $4.0 billion. We issued approximately 135 million shares of common stock, with a fair value of approximately $9.0 billion as of the closing date of the Magellan Acquisition. We funded the cash portion of the acquisition with an underwritten public offering of $5.25 billion senior unsecured notes.
For additional information on the Magellan Acquisition, see Part II, Item 8, Note B of the Notes to Consolidated Financial Statements in this Annual Report. See Part 1, Item 1A “Risk Factors” for further discussion of risks related to the Magellan Acquisition.
Business Update and Market Conditions - We experienced increased volumes across our system in 2023, compared with 2022, highlighting our extensive and integrated assets located in, and connected with, some of the most productive shale basins, refining regions and demand centers in the United States. Although the energy industry has experienced many commodity cycles, we have positioned ourselves to reduce exposure to direct commodity price volatility. Each of our four reportable segments are primarily fee-based, and our consolidated earnings were more than 85% fee-based in 2023.
Medford Incident - In January 2023, we reached an agreement with our insurers to settle all claims for physical damage and business interruption related to the Medford incident that occurred at our 210 MBbl/d Medford, Oklahoma, NGL fractionation facility in July 2022. Under the terms of the settlement agreement, we agreed to resolve the claims for total insurance payments of $930 million, $100 million of which was received in 2022. The remaining $830 million was received in the first quarter of 2023, resulting in a one-time settlement gain of $779 million. The proceeds serve as settlement for property damage, business interruption claims to the date of settlement and as payment in lieu of future business interruption insurance claims.
Due to market demand and a more favorable completion schedule, in January 2023, we announced plans to construct a new 125 MBbl/d MB-6 NGL fractionator in Mont Belvieu, Texas, instead of immediately rebuilding our Medford NGL fractionator. The MB-6 fractionator is expected to be in service in the first quarter of 2025 and will produce purity ethane instead of the ethane/propane mix previously produced at the Medford facility. The 125 MBbl/d capacity of the MB-6 fractionator is expected to be economically comparable to the capacity lost at Medford. In addition, our 125 MBbl/d MB-5 NGL fractionator was completed in April 2023, which has reduced the need for third-party fractionation while the new MB-6 fractionator is being constructed.
For additional information on the Medford Incident, see Part II, Item 8, Note C of the Notes to Consolidated Financial Statements in this Annual Report.
Capital Allocation - We continue to focus on maintaining prudent financial strength and flexibility. In January 2024, our Board of Directors increased our quarterly dividend to 99 cents per share and announced a targeted 3% to 4% annual dividend growth rate. Our Board of Directors also authorized a share repurchase program to buy up to $2.0 billion of our outstanding common stock and targets it to be largely utilized over the next four years. Additionally, in the fourth quarter of 2023, we opportunistically repurchased in the open market $322 million of our senior notes at a discount to par value using operating cash flows. At December 31, 2023, we had $338 million of cash and cash equivalents and no borrowings under our $2.5 Billion Credit Agreement.
Sustainability and Social Responsibility - Through our participation in the 2023 S&P Global Corporate Sustainability Assessment, we qualified for inclusion in the S&P Global Sustainability Yearbook for the fourth consecutive year, scoring within the top 15% of the Oil and Gas Storage and Transportation industry. In 2023, we qualified for inclusion in the Dow Jones Sustainability North American Index, part of the Dow Jones Sustainability Indices, which recognizes global sustainability leaders. Additionally, in 2023, we received an MSCI ESG Rating of AAA, and our ESG Risk Rating, as assessed by Morningstar Sustainalytics, was in the top 20% of the refiners and pipelines industry.
In 2021, we announced a companywide absolute GHG emissions reduction target of 2.2 million metric tons of carbon dioxide equivalents from our combined Scope 1 and Scope 2 GHG emissions by 2030. The target represents a 30% reduction in combined operational Scope 1 and location-based Scope 2 GHG emissions attributable to ONEOK assets as of December 31, 2019. We have achieved reductions totaling approximately 1.1 million metric tons of the targeted 2.2 million metric tons of carbon dioxide equivalents, primarily as a result of methane emissions mitigation, system optimizations, electrification of certain natural gas compression equipment and lower carbon-based electricity in states in which we operate. We continue to
look for ways to reduce our GHG emissions and utilize more efficient technologies. We are evaluating the development of renewable energy and low-carbon projects, including opportunities that may complement our extensive midstream assets and expertise.
For more information on our GHG emissions, see “GHG emissions” in the “Regulatory, Environmental and Safety Matters” section.
Natural Gas - In our Natural Gas Gathering and Processing segment, processed volumes increased in 2023, compared with 2022, due primarily to increased producer activity in the Rocky Mountain and Mid-Continent regions and the impact of winter weather in the Rocky Mountain region in the second and fourth quarters of 2022.
In our Natural Gas Pipelines segment, we completed an expansion of the injection capabilities of our Oklahoma natural gas storage facilities, which allowed us to utilize and subscribe an additional 4 Bcf of existing storage capacity, which is fully subscribed through 2027 and 90% subscribed through 2029. In addition, we completed the electrification of certain compression assets on Viking to maintain reliability of our operations while lowering our Scope 1 emissions from this equipment. Viking is seeking to recover its investment in the project through a proposed increase in rates filed in July 2023.
In February 2024, the FERC approved our Saguaro Connector Pipeline, L.L.C.’s Presidential Permit application to construct and operate new international border-crossing facilities at the U.S. and Mexico border. The proposed border facilities would connect upstream with a potential intrastate pipeline, the Saguaro Connector pipeline. Additionally, the proposed border facilities would connect at the international boundary with a new pipeline under development in Mexico for delivery to a liquefied natural gas export facility on the west coast of Mexico. The final investment decision on the Saguaro Connector pipeline is expected by mid-year 2024.
NGLs - In our Natural Gas Liquids segment, we benefited from increased volumes in 2023, compared with 2022, due primarily to increased production in the Permian Basin and Rocky Mountain region.
In addition to construction of our MB-6 fractionator, activities are underway to complete the looping of the West Texas NGL pipeline, which will more than double our NGL capacity out of the Permian Basin. The full loop is expected to be in service in the first quarter of 2025. We also have begun initial work, primarily on long-lead-time components, towards expanding the Elk Creek pipeline to 435 MBbl/d to provide capacity for growing volumes in the Rocky Mountain region, which will bring our total pipeline capacity out of the Rocky Mountain region to 575 MBbl/d. The Elk Creek pipeline expansion is expected to be in service in the first quarter of 2025.
Refined Products and Crude - Our 2023 results include the period from September 25, 2023, to December 31, 2023. During this time, we benefited from mid-year tariff increases and long-haul shipments of Refined Products, as well as increased shipments on our crude oil system compared to the pre-acquisition period. Additionally, our liquids blending margins have remained strong due to favorable commodity market conditions.
Progress continues on the expansion of our Refined Products pipeline to El Paso, Texas, which is expected to be completed in early 2024. This expansion will connect more supply to growing markets in Texas, New Mexico, Arizona and Mexico and the majority of the capital associated with this expansion is supported by volume commitments.
See Part II, Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations, in this Annual Report for more information on our capital projects, results of operations, liquidity and capital resources.
BUSINESS STRATEGY
Our mission is to deliver energy products and services vital to an advancing world. Our vision is to create exceptional value for our stakeholders by providing solutions for a transforming energy future. Our business strategy is focused on:
-
Zero incidents - We commit to developing processes to drive a zero-incident culture for the well-being of our employees, contractors and communities. Safety and environmental responsibility continue to be primary areas of focus for us, and our emphasis on safety has produced improving trends in the key indicators we track.
-
Highly engaged workforce - We strive to be an employer of choice and continue to focus on attracting, selecting and retaining talent, advancing an inclusive, diverse and engaged culture and developing individuals and leaders.
-
Sustainable business model - We aim to maintain prudent financial strength and flexibility while operating a safe, reliable and resilient asset base. We seek to maintain investment-grade credit ratings and a strong balance sheet. We expect our internally generated cash flows will allow us to fund high-return capital projects in our existing operating
regions, grow our dividend, reduce debt and fund our $2.0 billion share repurchase program. We aim to focus on capital projects that provide value-added products and services that contribute to long-term growth, profitability and business diversification. We continue to actively research opportunities that will complement our extensive assets and expertise, strengthening the role we expect to play in the transformation to a lower-carbon economy.
- Maximizing total shareholder return - We plan to grow earnings through high-return capital projects that will allow us to increase our dividend and repurchase shares under our $2.0 billion share repurchase program. We expect consistent and strong returns on invested capital will allow us to reward our shareholders and provide the means and opportunity to serve our additional stakeholders, including employees, communities and the environment.
NARRATIVE DESCRIPTION OF BUSINESS
We report operations in the following four business segments:
-
Natural Gas Gathering and Processing;
-
Natural Gas Liquids;
-
Natural Gas Pipelines; and
-
Refined Products and Crude.
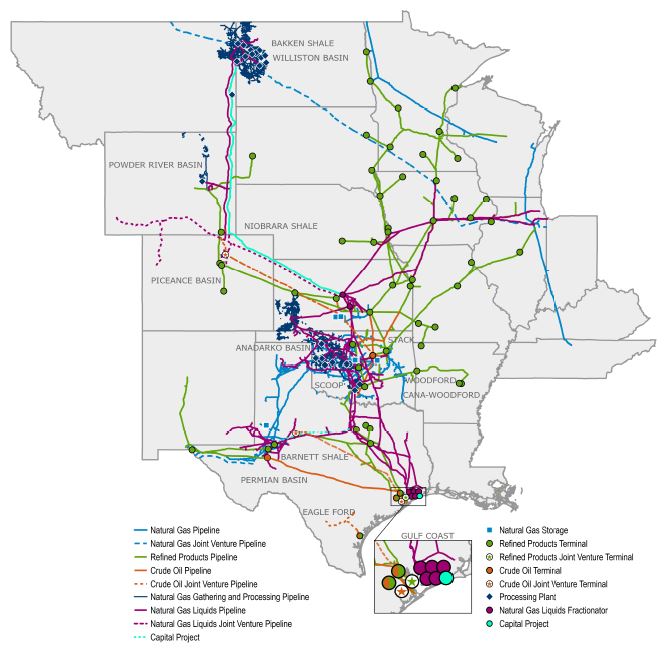
Natural Gas Gathering and Processing
Overview of Operations - In our Natural Gas Gathering and Processing segment, raw natural gas is typically gathered at the wellhead, compressed and transported through pipelines to our processing facilities. Most raw natural gas produced at the wellhead also contains a mixture of NGL components, including ethane, propane, iso-butane, normal butane and natural gasoline. Gathered wellhead natural gas is directed to our processing plants to remove NGLs resulting in residue natural gas (primarily methane). Residue natural gas is then recompressed and delivered to natural gas pipelines, storage facilities and end users. The NGLs separated from the raw natural gas are delivered through NGL pipelines to fractionation facilities for further processing. Some of the heavier NGLs may separate upstream of processing and fractionation and are sold as condensate at NGL or crude oil markets. Our Natural Gas Gathering and Processing segment provides these midstream services to producers in North Dakota, Montana, Wyoming, Kansas and Oklahoma.
Rocky Mountain region - The Williston Basin is located in portions of North Dakota and Montana and includes the oil-producing, NGL-rich Bakken Shale and Three Forks formations. We have more than 3 million dedicated acres in the Williston Basin.
The Powder River Basin is primarily located in Wyoming, which includes the NGL-rich Niobrara, Frontier, Turner and Mowry formations where we provide gathering and processing services to customers in the eastern portion of the state.
Mid-Continent region - The Mid-Continent region includes the gas and oil-producing Anadarko Basin, which includes the NGL-rich SCOOP and STACK areas, including the Cana-Woodford Shale, Woodford Shale, Springer Shale, Meramec, Granite Wash and Mississippian Lime formations of Oklahoma and the Hugoton Basin in Kansas. We have more than 600,000 dedicated acres in the Anadarko Basin.
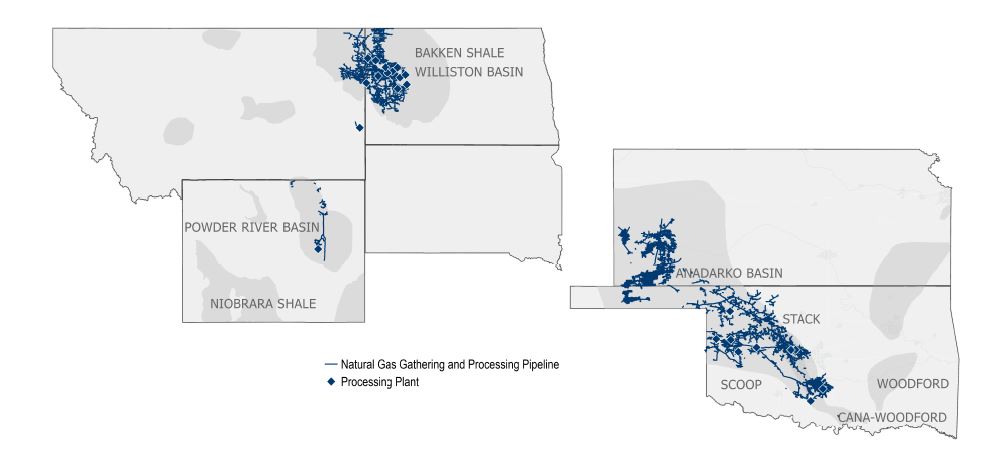
Property - Our Natural Gas Gathering and Processing segment includes the following assets, which are wholly owned, except where noted:
-
17,400 miles of natural gas gathering pipelines;
-
14 natural gas processing plants with 1.9 Bcf/d of processing capacity in the Rocky Mountain region, and nine natural gas processing plants with 0.9 Bcf/d of processing capacity in the Mid-Continent region, and up to 150 MMcf/d of processing capacity in the Mid-Continent region through a long-term processing services agreement with an unaffiliated third party; and
-
14 MBbl/d of NGL fractionation capacity and 26 MBbl/d of de-ethanizer capacity at various natural gas processing plants.
The utilization rates for our natural gas processing plants were 77% and 70% for 2023 and 2022, respectively. The increase was due primarily to increased producer activity in the Rocky Mountain and the Mid-Continent regions. Our 2022 utilization rates were impacted by winter weather in the Rocky Mountain region in the second and fourth quarters of 2022. We calculate utilization rates using a weighted-average approach, adjusting for the dates that assets were placed in or removed from service.
Sources of Earnings - Earnings for this segment are derived primarily from the following types of service contracts:
-
Fee with POP contracts with no producer take-in-kind rights - We purchase raw natural gas and charge contractual fees for providing midstream services, which include gathering, treating, compressing and processing the producer’s natural gas. After performing these services, we sell the commodities and remit a portion of the commodity sales proceeds to the producer less our contractual fees. This type of contract represented 72% and 73% of supply volumes in this segment for 2023 and 2022, respectively.
-
Fee with POP contracts with producer take-in-kind rights - We purchase a portion of the raw natural gas stream, charge fees for providing the midstream services listed above, return primarily the residue natural gas to the producer, sell the remaining commodities and remit a portion of the commodity sales proceeds to the producer less our contractual fees. This type of contract represented 19% and 20% of supply volumes in this segment for 2023 and 2022, respectively.
-
Fee-only - Under this type of contract, we charge a fee for the midstream services we provide, based on volumes gathered, processed, treated and/or compressed. Our fee-only contracts represented 9% and 7% of supply volumes in this segment for 2023 and 2022, respectively.
For commodity sales, we contract to deliver residue natural gas, condensate and/or unfractionated NGLs to downstream customers at a specified delivery point. Our sales of NGLs are primarily to our affiliate in the Natural Gas Liquids segment.
Unconsolidated Affiliates - Our unconsolidated affiliates in this segment are not material.
See Note N of the Notes to Consolidated Financial Statements in this Annual Report for additional discussion of our unconsolidated affiliates.
Government Regulation - The FERC traditionally has maintained that a natural gas processing plant is not a facility for the transportation or sale of natural gas in interstate commerce and, therefore, is not subject to jurisdiction under the Natural Gas Act. Although the FERC has made no specific declaration as to the jurisdictional status of our natural gas processing operations or facilities, our natural gas processing plants are primarily involved in extracting NGLs and, therefore, are exempt from FERC jurisdiction. The Natural Gas Act also exempts natural gas gathering facilities from the jurisdiction of the FERC. We believe our natural gas gathering facilities, upstream of our natural gas processing plants, meet the criteria used by the FERC for non-jurisdictional natural gas gathering facility status. Interstate transmission facilities remain subject to FERC jurisdiction. The FERC has historically distinguished between these two types of facilities, either interstate or intrastate, on a fact-specific basis. We transport residue natural gas from certain of our natural gas processing plants to interstate pipelines in accordance with Section 311(a) of the Natural Gas Policy Act. Oklahoma, Kansas, Wyoming, Montana and North Dakota also have statutes regulating, to varying degrees, the gathering of natural gas in those states. In each state, regulation is applied on a case-by-case basis if a complaint is filed against the gatherer with the appropriate state regulatory agency.
See further discussion in the “Regulatory, Environmental and Safety Matters” section.
Natural Gas Liquids
Overview of Operations - In our Natural Gas Liquids segment, NGLs that are extracted at natural gas processing plants, both third-party and our own, are gathered by our NGL gathering pipelines. Gathered NGLs are directed to our downstream fractionators in the Mid-Continent and Gulf Coast regions to be separated into Purity NGLs. Purity NGLs are stored or distributed to our customers, such as petrochemical companies, propane distributors, heating fuel users, ethanol producers, refineries and exporters.
We own and operate facilities primarily in Oklahoma, Kansas, Texas, New Mexico and the Rocky Mountain region, which includes the Williston, Powder River and DJ Basins. We provide midstream services to producers of NGLs and deliver those products to the two primary market centers: one in the Mid-Continent in Conway, Kansas, and the other in the Gulf Coast in Mont Belvieu, Texas. We own or have an ownership interest in FERC-regulated NGL gathering and distribution pipelines in Oklahoma, Kansas, Texas, New Mexico, Montana, North Dakota, Wyoming and Colorado, and terminal and storage facilities in Kansas, Nebraska, Iowa and Illinois. We have a 50% ownership interest in Overland Pass, which operates an interstate NGL pipeline originating in Wyoming and Colorado and terminating in Kansas. The majority of the pipeline-connected natural gas processing plants in the Williston Basin, Oklahoma, Kansas and the Texas Panhandle are connected to our NGL gathering systems. We lease rail cars and own and operate truck- and rail-loading and -unloading facilities connected to our NGL fractionation, storage and pipeline assets. We also own FERC-regulated NGL distribution pipelines in Kansas, Nebraska, Iowa, Illinois and Indiana that connect our Mid-Continent assets with Midwest markets, including Chicago, Illinois. A portion of our ONEOK North System transports Refined Products, including unleaded gasoline and diesel.
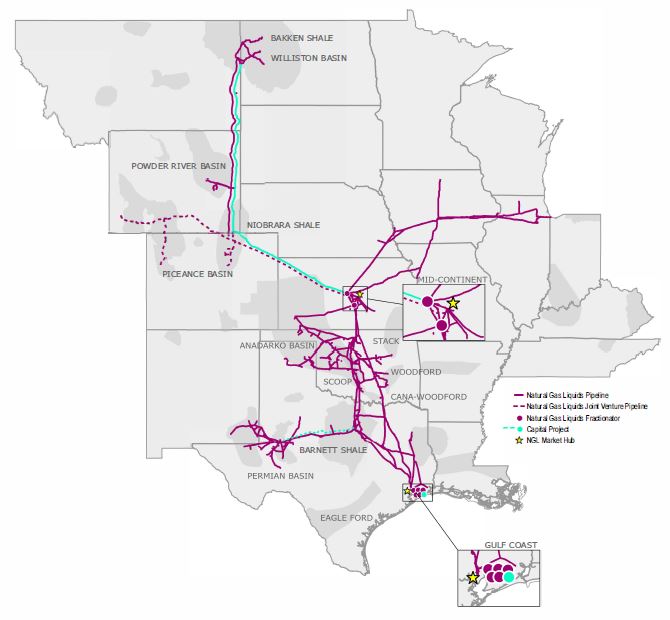
Property - Our Natural Gas Liquids segment includes the following assets, which are wholly owned, except where noted:
-
9,160 miles of gathering pipelines;
-
4,350 miles of distribution pipelines;
-
eight NGL fractionators with combined operating capacity of 835 MBbl/d (includes interests in our proportional share of operating capacity), including 310 MBbl/d in the Mid-Continent region and 525 MBbl/d in the Gulf Coast region, which are 98% utilized;
-
one isomerization unit with operating capacity of 10 MBbl/d;
-
one ethane/propane splitter with operating capacity of 40 MBbl/d;
-
six NGL storage facilities with operating storage capacity of 30 MMBbl; and
-
eight Purity NGLs terminals.
In addition, we have access to 5 MMBbl of combined NGL storage capacity at facilities in Kansas and Texas and 60 MBbl/d of NGL fractionation capacity in the Gulf Coast through service agreements.
The operating capacity of our pipelines varies depending on pipeline diameter, product composition and segment of the system. As a result, we consider throughput a more useful measure of utilization, which is provided within “Selected Financial Results and Operating Information” in Part II, Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations, in this Annual Report.
We are in the process of constructing our 125 MBbl/d MB-6 NGL fractionator in Mont Belvieu, Texas, the full looping of our West Texas NGL pipeline and expansion of our Elk Creek pipeline. These projects are excluded from the assets listed above. As a result of the Medford incident, our 210 MBbl/d NGL fractionator in Medford, Oklahoma, is not currently operational and is excluded from the assets listed above.
See “Recent Developments” in Part II, Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations, in this Annual Report for more information on our capital projects.
Sources of Earnings - Earnings for our Natural Gas Liquids segment are derived primarily from commodity sales and purchases and fee-based services. We purchase NGLs and condensate from third parties, as well as from our Natural Gas Gathering and Processing segment. Our business activities are categorized as follows:
-
Exchange services - We utilize our assets to gather, transport, treat and fractionate NGLs, thereby converting them into marketable Purity NGLs and deliver them to a market center or customer-designated location. Some of these exchange volumes are under contracts with minimum volume commitments that provide a minimum level of revenues regardless of volumetric throughput. Our exchange services activities are primarily fee-based and include some rate-regulated tariffs; however, we also capture certain product price differentials through the fractionation process.
-
Transportation and storage services - We transport Purity NGLs and certain Refined Products, primarily under FERC-regulated tariffs. Tariffs specify the maximum rates we may charge our customers and the general terms and conditions for transportation service on our pipelines. Our storage activities consist primarily of fee-based NGL storage services at our Mid-Continent and Gulf Coast storage facilities.
-
Optimization and marketing - We utilize our assets, contract portfolio and market knowledge to capture location, product and seasonal price differentials through the purchase and sale of unfractionated NGLs and Purity NGLs. We primarily transport Purity NGLs between Conway, Kansas, and Mont Belvieu, Texas, to capture the location price differentials between the two market centers. Our marketing activities also include utilizing our NGL storage facilities to capture seasonal price differentials and serving truck and rail markets. Our isomerization activities capture the price differential when normal butane is converted into the more valuable iso-butane at our isomerization unit in Conway, Kansas.
In the majority of our exchange services contracts, we purchase the unfractionated NGLs at the tailgate of the processing plant and deduct contractual fees related to the transportation and fractionation services we must perform before we can sell them as Purity NGLs. To the extent we hold unfractionated NGLs in inventory, the related contractual fees are not recognized until the unfractionated inventory is fractionated and sold.
Unconsolidated Affiliates - We have a 50% ownership interest in Overland Pass, which operates an interstate NGL pipeline system extending 760 miles, originating in Wyoming and Colorado and terminating in Kansas. Our other unconsolidated affiliates in this segment are not material.
See Note N of the Notes to Consolidated Financial Statements in this Annual Report for additional discussion of unconsolidated affiliates.
Government Regulation - The operations and revenues of our NGL pipelines are regulated by various state and federal government agencies. Our interstate NGL pipelines are regulated under the Interstate Commerce Act, which gives the FERC jurisdiction to regulate the terms and conditions of service, rates, including depreciation and amortization policies, and initiation of service. In Oklahoma, Kansas and Texas, certain aspects of our intrastate NGL pipelines that provide common carrier service are subject to the jurisdiction of the OCC, KCC and RRC, respectively.
See further discussion in the “Regulatory, Environmental and Safety Matters” section.
Natural Gas Pipelines
Overview of Operations - In our Natural Gas Pipelines segment, we receive residue natural gas from third parties and our own natural gas processing plants and interconnecting pipelines. Residue natural gas is transported or stored for end users, such as large industrial customers, natural gas and electric utilities serving commercial and residential consumers and can ultimately reach international markets through liquified natural gas exports and cross border pipelines.
Our assets are connected to key supply areas and demand centers, including export markets in Mexico via Roadrunner and supply areas in Canada and the United States via our interstate and intrastate natural gas pipelines and Northern Border, which enables us to provide essential natural gas transportation and storage services. Continued demand from LDCs, electric-
generation facilities and large industrial companies supported low-cost expansions that position us well to provide additional services to our customers when needed.
Intrastate Pipelines and Storage - Our intrastate natural gas pipeline and storage assets are located in Oklahoma, Texas and Kansas. Our intrastate pipeline and storage companies primarily include:
-
ONEOK Gas Transportation, which transports natural gas throughout the state of Oklahoma and has access to the major natural gas production areas in the Mid-Continent region, which include the SCOOP and STACK areas and the Cana-Woodford Shale, Woodford Shale, Springer Shale, Meramec, Granite Wash and Mississippian Lime formations. ONEOK Gas Transportation is connected to our ONEOK Gas Storage facilities in Oklahoma, which provide 50 Bcf of working gas storage capacity; and
-
ONEOK WesTex Transmission, which transports natural gas throughout the western portion of the state of Texas, including the Waha Hub area where other pipelines may be accessed for transportation to western markets, exports to Mexico, several markets to the southeast along the Gulf Coast, including the Houston Ship Channel and the Mid-Continent market to the north. It has access to major natural gas producing formations in the Texas Panhandle, including the Granite Wash formation and Delaware and Midland Basins in the Permian Basin. ONEOK WesTex Transmission is connected to our ONEOK Texas Gas Storage facilities, which provide 5 Bcf of working gas storage capacity.
Interstate Pipelines - Our interstate pipelines are regulated by the FERC and are located in North Dakota, Minnesota, Wisconsin, Illinois, Indiana, Kentucky, Tennessee, Oklahoma, Texas and New Mexico. Our interstate pipeline companies include:
-
Guardian, which interconnects with several pipelines at the Chicago Hub near Joliet, Illinois, and with local natural gas distribution and electric generation companies in Wisconsin;
-
Midwestern Gas Transmission, which is a bidirectional system that interconnects with Tennessee Gas Transmission Company’s pipeline near Portland, Tennessee, and with multiple interstate pipelines that have access to both the Utica Shale and the Marcellus Shale, and multiple interstate pipelines at the Chicago Hub near Joliet, Illinois;
-
Viking, which is a bidirectional system that interconnects with TC Energy Corporation’s Canadian Mainline System at the United States border near Emerson, Canada, and ANR Pipeline Company near Marshfield, Wisconsin; and
-
OkTex Pipeline, which has interconnections with several pipelines in Oklahoma, Texas and New Mexico.

Property - Our Natural Gas Pipelines segment includes the following wholly owned assets:
-
5,100 miles of state-regulated intrastate transmission pipelines with transportation capacity of 4.5 Bcf/d;
-
1,500 miles of FERC-regulated interstate natural gas pipelines with 3.7 Bcf/d of transportation capacity; and
-
six underground natural gas storage facilities with 57.4 Bcf of total active working natural gas storage capacity.
Our storage includes two underground natural gas storage facilities in Oklahoma, two underground natural gas storage facilities in Kansas and two underground natural gas storage facilities in Texas. In 2023, we completed an expansion of our injection capabilities of our Oklahoma natural gas storage facilities which allowed us to utilize and subscribe an additional 4 Bcf of our existing storage capacity.
We are reactivating previously idled storage facilities with 3 Bcf of working gas storage capacity in Texas, which is not included in the capacity above. We are also further expanding our injection capabilities in Oklahoma to allow us to subscribe additional firm storage capacity.
Our natural gas pipelines were 96% and 94% subscribed in 2023 and 2022, respectively, and our natural gas storage facilities were 76% and 77% subscribed in 2023 and 2022, respectively.
Sources of Earnings - Earnings in this segment are derived primarily from transportation and storage services.
Our transportation earnings are primarily fee-based from the following types of services:
- Firm service - Customers reserve a fixed quantity of pipeline capacity for a specified period of time, which obligates the customer to pay regardless of usage. Under this type of contract, the customer pays a monthly fixed fee and incremental fees, known as commodity charges, which are based on the actual volumes of natural gas they transport or store. Under the firm service contract, the customer generally is guaranteed access to the capacity they reserve.
- Interruptible service - Under interruptible service transportation agreements, the customer may utilize available capacity after firm service requests are satisfied. The customer is not guaranteed use of our pipelines unless excess capacity is available.
Our regulated natural gas transportation services contracts are based upon rates stated in the respective tariffs, which have generally been established through shipper specific negotiation, discounts and negotiated settlements. The rates are filed with FERC or the appropriate state jurisdictional agencies. In addition, customers typically are assessed fees, such as a commodity charge, and we may retain a percentage of natural gas in-kind for our compression services.
Our storage earnings are primarily fee-based from the following types of services:
-
Firm service - Customers reserve a specific quantity of storage capacity, including injection and withdrawal rights, and generally pay fixed fees based on the quantity of capacity reserved plus an injection and withdrawal fee based on actual usage. Our firm storage contracts typically have terms longer than one year.
-
Park-and-loan service - An interruptible storage service offered to customers providing the ability to park (inject) or loan (withdraw) natural gas into or out of our storage, typically for monthly or seasonal terms. Customers reserve the right to park or loan natural gas based on a specified quantity, including injection and withdrawal rights when capacity is available.
Unconsolidated Affiliates - Our Natural Gas Pipelines segment includes the following unconsolidated affiliates:
-
50% ownership interest in Northern Border, which owns a FERC-regulated interstate pipeline that transports natural gas from the Montana-Saskatchewan border near Port of Morgan, Montana, and the Williston Basin in North Dakota to a terminus near North Hayden, Indiana.
-
50% ownership interest in Roadrunner, a bidirectional pipeline, which has the capacity to transport 570 MMcf/d of natural gas from the Permian Basin in West Texas to the Mexican border near El Paso, Texas, and has capacity to transport approximately 1.0 Bcf/d of natural gas from the Delaware Basin to the Waha Hub area. We are the operator of Roadrunner.
In February 2024, the FERC approved our Saguaro Connector Pipeline, L.L.C.’s Presidential Permit application to construct and operate new international border-crossing facilities at the U.S. and Mexico border. The proposed border facilities would connect upstream with a potential intrastate pipeline, the Saguaro Connector pipeline. Additionally, the proposed border facilities would connect at the international boundary with a new pipeline under development in Mexico for delivery to a liquefied natural gas export facility on the west coast of Mexico. The final investment decision on the Saguaro Connector pipeline is expected by mid-year 2024.
See Note N of the Notes to Consolidated Financial Statements in this Annual Report for additional discussion of unconsolidated affiliates.
Government Regulation - Interstate - Our interstate natural gas pipelines are regulated under the Natural Gas Act, which gives the FERC jurisdiction to regulate virtually all aspects of this business, such as transportation of natural gas, rates and charges for services, construction of new facilities, depreciation and amortization policies, acquisition and disposition of facilities and the initiation and discontinuation of services.
Intrastate - Our intrastate natural gas pipelines in Oklahoma, Kansas and Texas are regulated by the OCC, KCC and RRC, respectively, and by the FERC under the Natural Gas Policy Act for certain services where we deliver natural gas into FERC-regulated natural gas pipelines. While we have flexibility in establishing natural gas transportation rates with customers, there is a maximum rate that we can charge our customers in Oklahoma and Kansas and for the services regulated by the FERC. In Texas and Kansas, natural gas storage may be regulated by the state and by the FERC for certain types of services. In Oklahoma, natural gas storage operations are not subject to rate regulation by the state, and we have market-based rate authority from the FERC for certain types of intrastate services.
See further discussion in the “Regulatory, Environmental and Safety Matters” section.
Refined Products and Crude
Overview of Operations - Our Refined Products and Crude segment is principally engaged in the transportation, storage and distribution of Refined Products and crude oil. This new reportable business segment was added in conjunction with the Magellan Acquisition. Our Refined Products pipeline system is one of the longest common carrier pipeline systems for Refined Products in the United States, extending approximately 9,800 miles from the Texas Gulf Coast and covering a 15-state area
across the central and western United States. Our crude oil pipelines transport crude oil to refineries, export facilities and demand centers. Throughout our distribution system, terminals play a key role in facilitating product movements and marketing by providing storage, distribution, blending and other ancillary services. Products transported on our Refined Products pipeline system include gasoline, distillates, aviation fuel and certain NGLs. Shipments originate on our Refined Products pipeline system from direct connections to refineries or through interconnections with other pipelines or terminals for transportation and ultimate distribution to retail fueling stations, convenience stores, travel centers, railroads, airports and other end users.
Our crude oil assets are strategically located to transport and store crude oil supply and are connected with multiple trading and demand centers. Our 450-mile Longhorn pipeline has the capacity to transport approximately 275 MBbl/d of crude oil from the Permian Basin in West Texas to our East Houston terminal. Our Houston distribution system consists of more than 100 miles of pipeline that connect our East Houston terminal through several interchanges to various points, including multiple refineries throughout the Houston area and crude oil import and export facilities. Our East Houston terminal is a primary delivery point for the HOU futures contract traded on ICE, and certain price quotes are based on trades at our terminal. We own approximately 400 miles of pipeline in Kansas and Oklahoma used for crude oil transportation service. Our Cushing terminal primarily receives and distributes crude oil via the multiple common carrier pipelines that terminate in and originate from the Cushing crude oil trading hub. Our Corpus Christi terminal receives product primarily from barges and pipelines that connect to our terminal for further distribution to end users by trucks, pipeline or waterborne vessels.
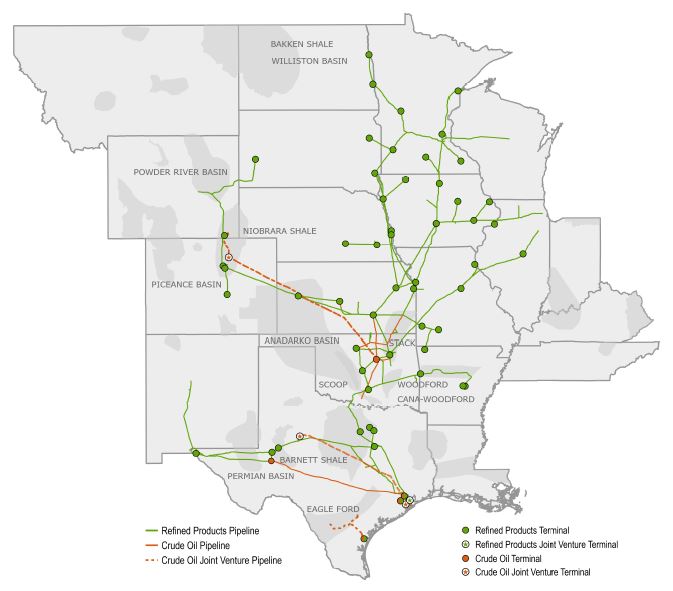
Property - Our Refined Products and Crude segment includes the following wholly owned assets:
-
9,800 miles of Refined Products pipelines;
-
1,000 miles of crude oil pipelines;
-
54 Refined Products terminals;
-
two marine terminals; and
-
91 MMBbl of operating storage capacity.
The operating capacity of our pipelines varies depending on pipeline diameter, product composition and segment of the system. As a result, we consider volumes shipped a more useful measure of utilization, which is provided within “Selected Financial Results and Operating Information” in Part II, Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations, in this Annual Report.
Sources of Earnings - Earnings in this segment are derived primarily from transportation, storage and terminal services and product sales:
*•*Transportation services - We generate revenue from transportation tariffs on volumes shipped on our Refined Products and crude oil pipeline systems. These transportation tariffs vary depending upon where the product originates, where ultimate delivery occurs and any applicable discounts. Transportation fees and discounts are in published tariffs filed with the FERC or the appropriate state agency or established by negotiated rates.
-
Storage and terminal services - We generate additional revenue from providing pipeline capacity and tank storage services, as well as providing services such as terminalling, ethanol and biodiesel unloading and loading, and additive injection, which are performed under a mix of as needed, monthly and long-term agreements.
-
Optimization and marketing - At times, we obtain Refined Products and crude oil and utilize our assets, contract portfolio and market knowledge to capture location, product and seasonal price differentials through purchases and sales of product and liquids blending.
Unconsolidated Affiliates - Our Refined Products and Crude segment has the following unconsolidated affiliates:
-
a 30% ownership interest in BridgeTex, which owns an approximately 400-mile crude oil pipeline with transport capacity of up to 440 MBbl/d that connects Permian Basin crude oil to our East Houston terminal;
-
a 30% ownership interest in Saddlehorn, which owns an undivided joint interest in an approximately 600-mile pipeline, with transport capacity of up to 290 MBbl/d of crude oil from the DJ Basin and Rocky Mountain region to storage facilities in Cushing, including our Cushing terminal; and
-
a 25% ownership in MVP, which owns a Refined Products marine storage terminal along the Houston Ship Channel in Pasadena, Texas, including more than 5 MMBbl of storage, two ship docks and truck loading facilities.
Our other unconsolidated affiliates in this segment are not material.
See Note N of the Notes to Consolidated Financial Statements in this Annual Report for additional discussion of unconsolidated affiliates.
Government Regulation - Our interstate common carrier pipeline operations are subject to rate regulation by the FERC under the Interstate Commerce Act, the Energy Policy Act of 1992 and related rules and orders. Most of the tariffs on our long-haul crude oil pipelines are established by negotiated rates that generally provide for annual adjustments in line with changes in the FERC index applicable to liquids pipelines, subject to certain modifications. Some shipments on our pipeline systems that move within a single state are considered to be in intrastate commerce. The rates, terms and conditions of intrastate service are subject to certain regulations with respect to such intrastate transportation by state regulatory authorities in the states of Colorado, Kansas, Minnesota, Oklahoma, Texas and Wyoming. The FERC or state regulatory authorities could limit our ability to increase our rates or to set rates based on our costs or could order us to reduce our rates and require the payment of refunds to shippers if our rates are found to have been unjust.
See further discussion in the “Regulatory, Environmental and Safety Matters” section.
Market Conditions and Seasonality
Supply and Demand - Supply for each of our segments depends on crude oil and natural gas drilling and production activities, which are driven by the strength of the economy and impacts of geopolitical events; crude oil, natural gas, NGL and Refined Products prices; the demand for each of these products from end users; changes in gas-to-oil ratios and the decline rate of
existing production; refinery maintenance cycles; producer access to capital and investment in the industry; connections to pipelines and refineries; and producer firm commitments to transportation pipelines.
Demand for gathering and processing services is dependent on natural gas production by producers in the regions in which we operate. Demand for NGLs and the ability of natural gas processors to sustain their operations successfully and economically affect the volume of unfractionated NGLs produced by natural gas processing plants, thereby affecting the demand for NGL gathering, transportation and fractionation services. Natural gas and Purity NGLs are affected by the demand associated with the various industries that utilize the commodities, such as butanes and natural gasoline used by the refining industry as blending stocks for motor fuel, denaturant for ethanol and diluents for crude oil. Ethane, propane, butanes and natural gasoline are also used by the petrochemical industry to produce chemical components, used for a range of products that improve our daily lives and promote economic growth, including health care products, recyclable food packaging, clothing, technology, building materials, industrial, manufacturing and energy infrastructure, lightweight vehicle components and batteries. Propane is also used to heat homes and businesses. Demand for Refined Products is influenced by many factors, including driving patterns, consumer preferences, economic conditions, population changes, government regulations, changes in vehicle fuel efficiency and the development of alternative energy sources. The demand for Refined Products in the market areas served by our pipeline system has historically been stable. Demand for shipments on our crude oil pipelines is driven primarily by crude oil production in the regions in which we operate, as well as by takeaway demand in the Houston and Cushing areas. Demand for natural gas, NGLs, Refined Products and crude oil is also impacted by global macroeconomic factors.
Commodity Prices - Our earnings are primarily fee-based in all of our segments; however, we are exposed to some commodity price risk. As part of our hedging strategy, we use commodity derivative financial instruments and physical-forward contracts to reduce the impact of price fluctuations related to natural gas, NGLs, Refined Products and crude oil. Our Natural Gas Gathering and Processing segment is exposed to commodity price risk as a result of retaining a portion of the commodity sales proceeds associated with our fee with POP contracts. We have hedged approximately 60% of our forecasted equity volumes for our Natural Gas Gathering and Processing segment in 2024. Under certain fee with POP contracts, our contractual fees and POP percentage may increase or decrease if production volumes, delivery pressures or commodity prices change relative to specified thresholds. In our Natural Gas Liquids segment, we are exposed to commodity price risk associated with changes in the price of NGLs; the location differential between the Mid-Continent, Chicago, Illinois, and Gulf Coast regions; and the relative price differential between natural gas, NGLs and individual Purity NGLs, which affect our NGL purchases and sales, our exchange services, transportation and storage services, and optimization and marketing financial results. NGL storage revenue may be affected by price volatility and forward pricing of NGL physical contracts versus the current price of NGLs on the spot market. In our Natural Gas Pipelines segment, we are exposed to minimal commodity price risk associated with (i) changes in the price of natural gas, which impact our fuel costs and retained fuel in-kind received for our compression services; and (ii) the differential between forward pricing of natural gas physical contracts and the price of natural gas on the spot market, which may affect our customer demand for our natural gas storage services. In our Refined Products and Crude segment, we are exposed to commodity price risk, including product price and location differentials from our liquids blending and marketing activities, as well as product retained during the operations of our pipelines and terminals.
See additional discussion regarding our commodity price risk and related hedging activities under “Commodity Price Risk” in Part II, Item 7A, Quantitative and Qualitative Disclosures about Market Risk, in this Annual Report.
Seasonality - Cold temperatures usually increase demand for natural gas and certain Purity NGLs, such as propane, a heating fuel for homes and businesses. Warm temperatures usually increase demand for natural gas used in gas-fired electric generation for residential and commercial cooling, as well as agriculture-related equipment like irrigation pumps and crop dryers. Demand for butanes and natural gasoline, which are used by the refining industry as blending stocks for motor fuel, denaturant for ethanol and diluents for crude oil, are also subject to some variability during seasonal periods when certain government restrictions on motor fuel blending products change. Additionally, our liquids blending activities are limited by seasonal changes in gasoline vapor pressure specifications and by the varying quantity of the gasoline delivered to us. During periods of peak demand for a certain commodity, prices for that product typically increase.
Extreme weather conditions, seasonal temperature changes and the impact of temperature and humidity on the mechanical abilities of equipment impact the volumes of natural gas gathered and processed, NGL volumes gathered, transported and fractionated, and Refined Products and crude oil volumes transported and stored. Power interruptions and inaccessible well sites as a result of severe storms or freeze-offs, a phenomenon where water vapor from the well bore freezes at the wellhead or within the natural gas gathering system, may cause a temporary interruption in the flow of natural gas, NGLs, Refined Products and crude oil.
In our Natural Gas Pipelines segment, natural gas storage is necessary to balance the relatively steady natural gas supply with the seasonal demand of our local natural gas distribution and electric-generation customers as a result of the demand from their residential and commercial customers.
Competition - We compete for natural gas, NGL, Refined Products and crude oil volumes with other midstream companies, major integrated oil companies and independent exploration and production companies that have gathering and processing assets, fractionators, pipelines, terminals and storage facilities. The factors that typically affect our ability to compete for natural gas, NGL, Refined Products and crude oil volumes are:
-
quality of services provided;
-
producer drilling activity;
-
proceeds remitted and/or fees charged under our contracts;
-
proximity of our assets to natural gas, NGL, Refined Products and crude oil supply areas and markets;
-
proximity of our assets to alternative energy production;
-
location of our assets relative to those of our competitors;
-
efficiency and reliability of our operations;
-
receipt and delivery capabilities for natural gas, NGLs, Refined Products and crude oil that exist in each pipeline system, plant, fractionator, terminal and storage location;
-
the petrochemical industry’s level of capacity utilization and feedstock requirements;
-
current and forward natural gas, NGLs, Refined Products and crude oil prices; and
-
cost of and access to capital.
We have remained competitive by making capital investments to access and connect new supplies with end-user demand; increasing gathering, processing, fractionation and pipeline capacity; increasing storage, withdrawal and injection capabilities; and improving operating efficiency. Our and our competitors’ infrastructure projects may affect commodity prices and could displace supply volumes from the Mid-Continent and Rocky Mountain regions and the Permian Basin where our assets are located. We believe our assets are located strategically, connecting diverse supply areas to market and demand centers.
Customers - Our Natural Gas Gathering and Processing, Natural Gas Liquids and Refined Products and Crude segments derive services revenue from major and independent crude oil and natural gas producers. Our Natural Gas Liquids segment’s customers also include other NGL and natural gas gathering and processing companies. Our downstream commodity sales customers are primarily petrochemical, refining and marketing companies, utilities, large industrial companies, natural gasoline distributors, propane distributors and municipalities. Our Refined Products and Crude segment’s customers also include crude oil producers, refiners, wholesalers, retailers, traders, railroads, airlines and regional farm cooperatives. End markets for Refined Products deliveries are primarily retail gasoline stations, truck stops, farm cooperatives, railroad fueling depots, military bases and commercial airports. Our Natural Gas Pipeline segment’s assets primarily serve LDCs, electric-generation facilities, large industrial companies, municipalities, producers, processors and marketing companies. Our utility customers generally require our services regardless of commodity prices. See discussion regarding our customer credit risk under “Counterparty Credit Risk” in Part II, Item 7A, Quantitative and Qualitative Disclosures about Market Risk, in this Annual Report.
Other
Through ONEOK Leasing Company, L.L.C. and ONEOK Parking Company, L.L.C., we own a 17-story office building (ONEOK Plaza) and a parking garage in downtown Tulsa, Oklahoma, where our headquarters are located. ONEOK Leasing Company, L.L.C. leases excess office space, if any, to others and operates our headquarters office building. ONEOK Parking Company, L.L.C. owns and operates a parking garage adjacent to our headquarters. We have a wholly owned captive insurance company, which was formed in 2022.
REGULATORY, ENVIRONMENTAL AND SAFETY MATTERS
We are subject to a variety of historical preservation and environmental laws and/or regulations that affect many aspects of our present and future operations. Regulated activities include, but are not limited to, those involving air emissions, storm water and wastewater discharges, handling and disposal of solid and hazardous waste, wetland and waterway preservation, wildlife conservation, cultural resource protection, hazardous materials transportation and pipeline and facility construction. These laws and regulations require us to obtain and/or comply with a wide variety of environmental clearances, registrations, licenses, permits and other approvals. Failure to comply with these laws, regulations, licenses and permits may expose us to fines, penalties, reputational harm and/or interruptions in our operations that could be material to our results of operations or financial condition. In addition, emissions controls and/or other regulatory or permitting mandates under the Clean Air Act and other
similar federal and state laws could require unexpected capital expenditures at our facilities. We cannot ensure that existing environmental statutes and regulations will not be revised or that new regulations will not be adopted or become applicable to us. We also cannot ensure that existing permits will not be revised or cancelled, potentially impacting facility construction activities or ongoing operations.
Air and Water Emissions - The Clean Air Act, the Clean Water Act, the Oil Pollution Act of 1990 and analogous state laws and/or regulations impose restrictions and controls regarding the discharge of pollutants into the air and water in the United States. Under the Clean Air Act, a federal operating permit is required for sources of significant air emissions. We may be required to incur certain capital expenditures for air pollution-control equipment in connection with obtaining or maintaining permits and approvals for sources of air emissions. The Clean Water Act imposes substantial potential liability for pollutants discharged into waters of the United States and requires remediation of waters affected by such discharge. The Oil Pollution Act aims at preventing and responding to oil spills in U.S. waters and shorelines.
GHG Emissions - 2022 GHG emissions were approximately 3.7 million metric tons of carbon dioxide equivalents of Scope 1 emissions and 2.9 million metric tons of carbon dioxide equivalents of Scope 2 emissions. Scope 1 emissions originate from the combustion of fuel in our equipment, such as compressor engines and heaters, as well as fugitive methane emissions. Scope 2 emissions are generated from purchased power sources.
In 2021, we announced a companywide absolute GHG emissions reduction target of 2.2 million metric tons of carbon dioxide equivalents from our combined Scope 1 and Scope 2 GHG emissions by 2030 for our legacy ONEOK assets. The target represents a 30% reduction in combined operational Scope 1 and location-based Scope 2 GHG emissions attributable to ONEOK assets as of December 31, 2019. As of December, 31, 2023, we have achieved reductions totaling approximately 1.1 million metric tons of the targeted 2.2 million metric tons of carbon dioxide equivalents, primarily as a result of methane emissions mitigation, system optimizations, electrification of certain natural gas compression equipment and lower carbon-based electricity in states in which we operate. GHG emission reductions as reported may be modified, updated, changed or supplemented based on available information. For the years ended December 31, 2023, 2022 and 2021, we did not have any material dedicated capital expenditures specifically for climate-related projects, nor did we purchase or sell carbon credits or offsets. Progress to date on our goal has been accomplished through routine capital projects and asset optimizations that were primarily performed for operational improvements that inherently improved our emissions profile. We continue to anticipate several potential pathways toward achieving our emissions reduction target. In 2024, we anticipate reduction in our emissions toward our target to be primarily a result of improved methane management practices and system optimization that will not require material capital expenditures. We do not anticipate purchasing or selling carbon credits or offsets in 2024.
We currently participate in Our Nation’s Energy (ONE) Future Coalition to voluntarily report methane emission reductions and to calculate our methane intensity for our natural gas transmission and storage assets. We continue to focus on maintaining low methane gas release rates through expanded implementation of improved practices to limit the release of natural gas during pipeline and facility maintenance and operations.
In 2023, we became a participant in American Petroleum Institute’s The Environmental Partnership and enrolled in environmental performance programs that are designed to further reduce emissions using proven, cost-effective controls.
Regulation
PHMSA - The PHMSA has submitted to the Federal Register an advisory bulletin underscoring to pipeline and pipeline facility operators requirements to minimize methane emissions in the Protecting our Infrastructure of Pipelines and Enhancing Safety (PIPES) Act of 2020. The PIPES Act directs pipeline operators to update their inspection and maintenance plans to address the elimination of hazardous leaks and to minimize natural gas releases from pipeline facilities. The updated plans must also address the replacement or remediation at facilities that historically have been known to experience leaks. We have completed and continue to update our pipeline maintenance procedures to identify and reduce methane leaks.
EPA - The EPA’s Mandatory Greenhouse Gas Reporting Rule requires annual GHG emissions reporting from our affected facilities and the carbon dioxide emission equivalents for all hydrocarbon liquids produced by us as if all of these products were combusted, even if they are used otherwise. The additional cost to gather and report this emission data did not have, and we do not expect it to have, a material impact on our results of operations, financial position or cash flows.
Recently, the EPA has released the pre-publication of the New Source Performance Standards Subpart OOOOb regulations to further reduce methane emissions, which includes increased monitoring frequency and more stringent repair requirements for new and modified oil and gas facilities. In addition, the EPA is proposing new nationwide emission guidelines, OOOOc, for states to limit methane emissions from existing oil and gas facilities. At this time, we do not anticipate a material impact to our
planned capital, operations and maintenance costs resulting from compliance with the current or pending regulations and proposed EPA actions. However, the EPA and/or state regulators may issue additional regulations, responses, amendments and/or policy guidance, which could alter our present expectations.
We are an obligated party under the Renewable Fuel Standard (RFS) promulgated by the EPA and are required to satisfy our Renewable Volume Obligation (RVO) on an annual basis. To meet our RVO, the transportation fuel we produce in our liquids blending activities must either contain the mandated renewable fuel components, or credits must be purchased to cover any shortfall. We generally satisfy our RVO requirements through the purchase of renewable energy credits, known as RINs. RINs are generated when a gallon of renewable fuel is produced and may be separated when the renewable fuel is blended into gasoline or diesel fuel, at which point the RIN is available for use in compliance or available for sale on the open market. As the RFS program is currently structured, the RVO of all obligated parties may increase over time unless adjusted by the EPA. The ability to incorporate increasing volumes of renewable fuel components into fuel products and the availability of RINs may be limited, which could increase our costs to comply with the RFS standards or limit our ability to blend.
The EPA has proposed changes to the federal gasoline distribution regulations. We do not anticipate a material impact to our planned capital, operations and maintenance costs resulting from compliance with the current or pending regulations and proposed EPA actions.
Additionally, we are subject to the EPA’s fuels compliance regulations. These regulations include standards for fuel parameters and require rigorous product sampling and testing, recordkeeping and reporting. Our ongoing compliance with these regulations is not expected to have a material adverse effect on our business.
Federal Regulation - In August 2022, the IRA was signed into law. The IRA includes tax credits and other incentives intended to combat climate change by advancing decarbonization and promoting increased investment in renewable and low carbon intensity energy. In addition, the IRA directed the EPA to impose and collect “Waste Emissions Charges,” or “Methane Fees,” for specific facilities that report more than 25,000 metric tons of carbon dioxide equivalent of GHG emissions per year and have a methane emissions intensity in excess of the relevant statutory threshold. Based on text in the IRA and a related rule that the EPA proposed in January 2024 that will require payment of Methane Fees to the EPA beginning in 2025 (for 2024 reported emissions), we do not believe the Methane Fees will have a material impact on our results of operations, financial position or cash flows.
We believe it is likely that continued future governmental legislation and/or regulation may require us to limit GHG emissions associated with our operations, pay additional fees associated with our GHG emissions or purchase allowances for such emissions. However, we cannot predict precisely what form these future regulations will take, the stringency of the regulations, when they will become effective or the impact on our capital expenditures, competitive position and results of operations. In addition to activities on the federal level, state and regional initiatives could also lead to the regulation of GHG emissions sooner than or independent of federal regulation. These regulations could be more stringent than any federal legislation that may be adopted. We monitor all relevant legislation and regulatory initiatives to assess the potential impact on our operations and otherwise take steps to limit GHG emissions from our facilities, including methane.
For additional information regarding the potential impact of laws and regulations on our operations see Item 1A “Risk Factors.”
Waste - Our operations generate waste, including hazardous waste, that is subject to the requirements of the RCRA and comparable state statutes. We are not currently required to comply with a substantial portion of the RCRA requirements as our operations routinely generate only small quantities of hazardous waste, and we are not a hazardous waste treatment, storage or disposal facility operator that is required to obtain a RCRA permit. While the RCRA currently exempts a number of waste from being subject to hazardous waste requirements, including many oil and gas exploration and production waste, the EPA could consider the adoption of stricter disposal standards for non-hazardous waste. Moreover, it is possible that additional waste, which could include non-hazardous waste currently generated during operations, may be designated as hazardous waste. Hazardous waste is subject to more rigorous and costly storage and disposal requirements than non-hazardous waste. Changes in the regulations could materially increase our expenses.
We own or lease properties where hydrocarbons have been handled for many years, during which operating and disposal standards have evolved. Although we believe we have utilized operating and disposal practices that meet prevailing industry standards, hydrocarbons or other waste may have been disposed of or released on, under or from the properties owned or leased by us or at offsite disposal facilities. In addition, many of these properties were previously operated by third parties whose treatment and disposal or release of hydrocarbons or other waste was not under our control. These properties and waste disposal facilities may be subject to CERCLA, RCRA and analogous state laws. Under these laws, we could be required to
remove or remediate previously disposed waste, including waste disposed of or released by prior owners or operators, to remediate contaminated property, including groundwater contaminated by prior owners or operators, or to make capital improvements to prevent future contamination.
Pipeline and Facility Safety - We are subject to PHMSA safety regulations, including pipeline asset integrity-management regulations. The Pipeline Safety Improvement Act of 2002 requires pipeline companies operating high-pressure pipelines to perform integrity assessments on pipeline segments that pass through densely populated areas or near specifically designated high-consequence areas (HCAs). The Pipeline Safety, Regulatory Certainty and Job Creation Act of 2011 (the 2011 Pipeline Safety Act) increased maximum penalties for violating federal pipeline safety regulations, directs the DOT and Secretary of Transportation to conduct further review or studies on issues that may or may not be material to us and may result in the imposition of more stringent regulations.
In 2015, PHMSA issued notices of proposed rulemaking for hazardous liquid pipeline safety regulations, natural gas transmission and gathering lines and underground natural gas storage facilities. For natural gas and natural gas gathering pipelines, the new proposed regulations became known as “the Mega Rule.” Due to the large number of rules being considered, PHMSA partitioned the new rulemaking into three sections. The first section of rules was finalized and published in 2019 in the Federal Register and became effective in July 2020. These final rules mostly address congressional mandates due to former pipeline safety reauthorizations and established criteria for verifying current operating pressures. The second section of the Mega Rule, which was published in August 2022 and became effective in May 2023, focuses on natural gas transmission pipelines and includes enhancements to management requirements for risk and integrity assessments, guidance for corrosion and mitigation timelines, pipeline inspections following extreme weather events and repair requirements for HCAs and non-HCAs. The third section of the Mega Rule establishes new regulations for certain gas gathering lines, which were formerly unregulated, and was published in November 2021 and became effective in May 2022.
Coupled together, these new sections of the Mega Rule provide increased requirements for operating and maintenance, integrity management, public awareness and civil/criminal penalties; however, we do not anticipate a material impact to our planned capital or operations and maintenance costs resulting from compliance with the newly published regulations.
Our NGL, Refined Products and crude oil pipeline systems are subject to regulation by the DOT and PHMSA under the Hazardous Liquid Pipeline Safety Act of 1979, as amended (HLPSA). The HLPSA prescribes and enforces minimum federal safety standards for the transportation of hazardous liquids by pipeline, including the design, construction, testing, operation and maintenance, spill response planning and overall reporting and management related to our pipeline facilities. In addition to the amended HLPSA covered in Title 49 of the Code of Federal Regulations, subsequent statutes provide the framework for the pipeline hazardous liquid safety program and include provisions related to PHMSA’s authorities, administration and regulatory activities. During 2022, PHMSA published expanded regulations for the installation of rupture mitigation valves and the establishment of a minimum rupture detection standard. We believe that compliance with such regulatory changes will not have a material adverse effect on our business.
Our marine terminals along coastal waterways are subject to U.S. Coast Guard regulations and comparable state and municipal statutes relating to the design, installation, construction, testing, operation, replacement and management of these assets.
In 2020, legislation was passed to reauthorize PHMSA through 2024. Certain requirements for operations and maintenance, integrity management, leak detection and public awareness will be subject to future rulemaking as a result. The potential capital and operating expenditures related to the new regulations are not fully known, but we do not anticipate a material impact to our planned capital or operations and maintenance costs resulting from compliance with the new regulations.
In July 2022, a fire occurred at our 210 MBbl/d Medford, Oklahoma, natural gas liquids fractionation facility. All personnel were safe and accounted for with temporary evacuations of local residents taken as a precautionary measure. As a result of the incident, the United States Chemical Safety and Hazard Investigation Board (CSB) requested information including the incident investigation report and causal factors of the incident, which we submitted to the CSB. This inquiry is still active with the CSB.
Pipeline Security - Homeland Security’s Transportation Security Administration (TSA) released new pipeline security guidelines that included broader definitions for the determination of pipeline “critical facilities.” We have reviewed our pipeline facilities according to the new guidelines and met the timelines associated with TSA reporting. The cost of compliance did not have a material impact on our operations, financial position or cash flows.
In 2021, the TSA began issuing pipeline security directives to owners and/or operators of critical pipeline systems or facilities. The most recent version of the security directive included a requirement to provide on an annual basis an assessment plan for
the Cybersecurity Implementation Plan. While compliance with the security directives requires significant internal and external resources, we do not expect it to have a material impact on our results of operations, financial position or cash flows.
HUMAN CAPITAL
The long-term sustainability of our business is dependent on our continued ability to maintain a highly engaged workforce. To accomplish this, our business strategy includes attracting, selecting and retaining talent, advancing an inclusive, diverse and engaged culture and developing individuals and leaders.
Leaders continued to execute on employee engagement action plans in 2023 to build on the strong 2022 employee engagement survey results. We did not complete a survey in 2023 as we began the process to stabilize and integrate our employee base following the Magellan Acquisition. We expect to conduct a survey of the combined company in 2024.
As of December 31, 2023, we had 4,775 employees. Listed below is a summary of our human capital resources, measures and objectives that are collectively important to our success as an organization.
Values - Our success relies on the skills, experience and dedication of our employees. We are committed to cultivating an inclusive and dynamic work environment where people can find opportunities to succeed, grow and contribute to the success of the company. Our employees work each day to provide safe and reliable services to a wide range of customers in the states where we operate. Our core values, listed below, guide our employee behaviors and the ways in which we conduct our business and operations.
-
Safety & Environmental: we commit to a zero-incident culture for the well-being of our employees, contractors and communities and to operate in an environmentally responsible manner.
-
Ethics: we act with honesty, integrity and adherence to the highest standards of personal and professional conduct.
-
Diversity & Inclusion: we respect the uniqueness and worth of each employee, and believe that a diverse, inclusive workforce is essential for a sense of belonging, engagement and performance.
-
Excellence: we hold ourselves and others accountable to a standard of excellence through continuous improvement and teamwork.
-
Service: we invest our time, effort and resources to serve each other, our customers and communities.
-
Innovation: we seek to develop creative solutions by leveraging collaboration through ingenuity and technology.
Diversity and Inclusion - Our diversity and inclusion (D&I) strategy is a cross-functional effort that draws upon contributions from employees at all levels of the organization and is focused on enhancing the workplace to attract and retain talent. The strategy is guided by a D&I Council composed of a diverse group of employees who represent different demographics, work locations, points of view, roles and levels of seniority. We also have a team within our human resources department that is wholly dedicated to supporting our D&I efforts.
In early 2023, we introduced a Racial Inclusion Collective Resource Group that combines our legacy race- and ethnicity-focused business resource groups (BRGs), along with new resources and support for our Asian-American and Pacific Islander employees and allies, into a single organization to facilitate collaboration on topics relevant to all groups while reserving opportunities for more identity-focused programming where appropriate. We provide funding and support for this group as well as our other employee-led BRGs: a Veterans Resource Group, a Women’s Resource Group and a LGBTQ+ Resource Group (Lesbian, Gay, Bisexual, Transgender, Queer and others). The purpose of these groups is to promote the attraction, development, motivation and retention of members of traditionally underrepresented groups in our industry and workplace in an effort to drive positive business outcomes. A key factor in the success of our BRGs is the active participation by officer-level executive sponsors and allies from outside the BRG’s underrepresented populations. All employees are invited to become a supporter of our BRGs.
We embed D&I concepts into our core leadership development curriculum and sponsor a number of internal programs intended to promote D&I. In addition, we seek to give back to the communities where we operate by partnering on initiatives to support underrepresented community members and local charitable organizations.
Employee Safety - The safety of our employees is critical to our operations and success. By promoting the safety of our employees and monitoring the integrity of our assets, we are investing in the long-term sustainability of our businesses. We continuously assess the risks our employees face in their jobs, and we work to mitigate those risks through training, appropriate engineering controls, work procedures and other preventive safety programs. Reducing incidents and improving our personal safety incident rates are important, but we are not focused only on statistics. Low personal safety incident rates alone cannot prevent a large-scale incident, which is why we continue to focus on enhancing our Environmental, Safety and Health
management systems and process safety programs, such as key risk/key control identification and knowledge sharing. We endeavor to operate our assets safely, reliably and in an environmentally responsible manner. We maintain mature and robust programs that guide trained staff in the completion of these activities, and we continue to enhance and improve these programs and our internal capabilities.
Health and Welfare - We provide a variety of benefits to help promote the health and welfare of our employees and their families. These benefits include medical, dental and vision plans, virtual health visits and engagement of third-party service providers to offer company on-site and near-site clinics in several of our operating areas. Eligible employees also have access, at no charge, to an employee assistance program, a medical second opinion service and a health care concierge service to assist with finding in-network providers and billing resolution. We offer full pay for maternity, paternity or adoption leave of up to 240 hours per qualifying event. We also provide up to $10,000 for reasonable and necessary expenses of a qualifying adoption and/or surrogacy. Additional benefits available for the welfare of our employees include, among others, life insurance and long-term disability plans, health and dependent care flexible spending accounts, fertility benefits, disease prevention and management programs and full pay while on bereavement, military or personal and family care leave.
We also provide the opportunity for our employees to help fellow employees through the ONE Trust Fund by contributing donated vacation hours or monetary donations. The ONE Trust Fund is a nonprofit, charitable organization run entirely by employee volunteers, that serves our employees in times of personal crises due to natural disasters, medical emergencies or other hardships. Further, we provide volunteer opportunities and volunteer grants, as well as $10,000 of charitable giving matching, annually, through the ONEOK Foundation.
Personal and Professional Development - We provide various options to assist with career growth and development. For employees just entering the workforce who desire to advance their career and continue to learn or for the professional who is interested in developing their skills, we provide education and training in a variety of areas, including leadership, functional and industry-specific topics, professional development and skill-building opportunities. Our organizational development and D&I teams provide live in-person and virtual classroom training, computer-based self-study and one-on-one coaching that is available to all employees.
We value education and assist eligible employees with the expense of furthering their education in job-related fields, including up to $5,250 per year in qualifying tuition expenses. We also may reimburse employees for certain job-related professional certification examination fees.
Recruiting - We make it a priority to attract, select, develop, motivate, challenge and retain the talent necessary to support our key business strategies. We use targeted recruitment events, maintain strong relationships with area technical schools, colleges and universities, and we offer compensation benefits and career opportunities that are designed to position us as an employer of choice. D&I continues to be a priority in recruiting, and we deploy sourcing strategies designed to access talent from groups that are historically underrepresented in our industry and workplace.
Retirement - We maintain a 401(k) Plan for our employees and match 100% of employee contributions up to 6% of eligible compensation each payroll period, subject to applicable tax limits. We have a legacy defined benefit pension plan covering certain employees and former employees, which closed to new participants in 2005. In addition, as a result of the Magellan Acquisition, we assumed the pension and postretirement benefit obligations for Magellan employees and former employees. These obligations are composed of two defined benefit pension plans, including one for non-union employees and one for union employees, as well as a postretirement welfare benefit plan for certain employees. The pension plan for non-union employees closed to new participants upon the closing of the Magellan Acquisition. The pension plan for union employees closed to new participants in January 2024. Employees who do not participate in our defined benefit pension plan are eligible to receive quarterly and annual profit-sharing contributions under our 401(k) Plan. As of December 31, 2023, 96% of eligible employees were contributing to our 401(k) Plan. For additional information about our retirement benefits, see Note L of the Notes to Consolidated Financial Statements in this Annual Report.
INFORMATION ABOUT OUR EXECUTIVE OFFICERS
All executive officers are elected annually by our Board of Directors. Our executive officers listed below include the officers who have been designated by our Board of Directors as our Section 16 executive officers.
| Name and Position | Age | Business Experience in Past Five Years | ||||||||||||||||||
| Julie H. Edwards | 65 | 2022 to present | Board Chair, ONEOK | |||||||||||||||||
| Board Chair | 2007 to 2022 | Board Director, ONEOK | ||||||||||||||||||
| Pierce H. Norton II | 64 | 2021 to present | President and Chief Executive Officer, ONEOK | |||||||||||||||||
| President and Chief Executive Officer | 2021 to present | Member of the Board of Directors, ONEOK | ||||||||||||||||||
| 2014 to 2021 | President and Chief Executive Officer, ONE Gas, Inc. | |||||||||||||||||||
| 2014 to 2021 | Member of the Board of Directors, ONE Gas, Inc. | |||||||||||||||||||
| Walter S. Hulse III | 60 | 2022 to present | Chief Financial Officer, Treasurer and Executive Vice President, Investor Relations and Corporate Development, ONEOK | |||||||||||||||||
| Chief Financial Officer, Treasurer and Executive Vice President, Investor Relations and Corporate Development | 2019 to 2021 | Chief Financial Officer, Treasurer and Executive Vice President, Strategy and Corporate Affairs, ONEOK | ||||||||||||||||||
| 2017 to 2019 | Chief Financial Officer and Executive Vice President, Strategic Planning and Corporate Affairs, ONEOK | |||||||||||||||||||
| Kevin L. Burdick | 59 | 2023 to present | Executive Vice President and Chief Enterprise Services Officer, ONEOK | |||||||||||||||||
| Executive Vice President and Chief Enterprise Services Officer | 2022 to 2023 | Executive Vice President and Chief Commercial Officer, ONEOK | ||||||||||||||||||
| 2017 to 2022 | Executive Vice President and Chief Operating Officer, ONEOK | |||||||||||||||||||
| Sheridan C. Swords | 54 | 2023 to present | Executive Vice President, Commercial Liquids and Gathering and Processing, ONEOK | |||||||||||||||||
| Executive Vice President, Commercial Liquids and Gathering and Processing | 2022 to 2023 | Senior Vice President, Natural Gas Liquids and Natural Gas Gathering and Processing, ONEOK | ||||||||||||||||||
| 2017 to 2022 | Senior Vice President, Natural Gas Liquids, ONEOK | |||||||||||||||||||
| Lyndon C. Taylor | 65 | 2023 to present | Executive Vice President, Chief Legal Officer and Assistant Secretary, ONEOK | |||||||||||||||||
| Executive Vice President, Chief Legal Officer and Assistant Secretary | 2005 to 2021 | Executive Vice President and Chief Legal and Administrative Officer, Devon Energy Corporation | ||||||||||||||||||
| Charles M. Kelley | 65 | 2022 to present | Senior Vice President, Natural Gas Pipelines, ONEOK | |||||||||||||||||
| Senior Vice President, Natural Gas Pipelines | 2018 to 2022 | Senior Vice President, Natural Gas, ONEOK | ||||||||||||||||||
| Mary M. Spears | 44 | 2022 to present | Senior Vice President and Chief Accounting Officer, Finance and Tax, ONEOK | |||||||||||||||||
| Senior Vice President and Chief Accounting Officer, Finance and Tax | 2019 to 2021 | Vice President and Chief Accounting Officer, ONEOK | ||||||||||||||||||
| 2015 to 2019 | Director, SEC Reporting, ONEOK | |||||||||||||||||||
| Scott D. Schingen | 50 | 2023 to present | Senior Vice President, Natural Gas Liquids and Natural Gas Operations, ONEOK | |||||||||||||||||
| Senior Vice President, Natural Gas Liquids and Natural Gas Operations | 2021 to 2023 | Senior Vice President, Operations, ONEOK | ||||||||||||||||||
| 2017 to 2021 | Vice President, Natural Gas Liquids Operations, ONEOK | |||||||||||||||||||
| James R. Hoskin | 52 | 2023 to present | Senior Vice President, Refined Products and Crude Operations, ONEOK | |||||||||||||||||
| Senior Vice President, Refined Products and Crude Operations | 2023 to 2023 | Senior Vice President Operations, Magellan Midstream Partners | ||||||||||||||||||
| 2021 to 2023 | Vice President of Operations, Magellan Midstream Partners | |||||||||||||||||||
| 2019 to 2021 | Director of Operations, Magellan Midstream Partners |
No family relationships exist between any of the executive officers, nor is there any arrangement or understanding between any executive officer and any other person pursuant to which the officer was selected.
INFORMATION AVAILABLE ON OUR WEBSITE
We make available, free of charge, on our website (www.oneok.com) copies of our Annual Reports, Quarterly Reports, Current Reports on Form 8-K, amendments to those reports filed or furnished to the SEC pursuant to Section 13(a) or 15(d) of the Exchange Act and reports of holdings of our securities filed by our officers and directors under Section 16 of the Exchange Act as soon as reasonably practicable after filing such material electronically or otherwise furnishing it to the SEC. Copies of our Code of Business Conduct and Ethics, Corporate Governance Guidelines, Director Independence Guidelines, Corporate Sustainability Report and the written charters of our Board Committees also are available on our website, and we provide copies of these documents upon request.
In addition to our filings with the SEC and materials posted on our website, we also use social media platforms as additional channels of distribution to reach public investors. Information contained on our website, posted on our social media accounts, and any corresponding applications, are not incorporated by reference into this report.
Previous: Cover and table of contents · Next: Item 1A. RISK FACTORS