 filings.tools
Item 16. Form 10-K Summary
324K characters. Original on sec.gov · Markdown
Item 16. Form 10-K Summary
None.
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, the Registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| OTIS WORLDWIDE CORPORATION (Registrant) | |||||||||||
| Dated: | February 5, 2021 | by: | /s/ RAHUL GHAI | ||||||||
| Rahul Ghai | |||||||||||
| Executive Vice President and Chief Financial Officer | |||||||||||
| (on behalf of the Registrant and as the Registrant's Principal Financial Officer) | |||||||||||
| Dated: | February 5, 2021 | by: | /s/ MICHAEL P. RYAN | ||||||||
| Michael P. Ryan | |||||||||||
| Vice President and Chief Accounting Officer | |||||||||||
| (on behalf of the Registrant and as the Registrant's Principal Accounting Officer) |
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, this report has been signed below by the following persons on behalf of the Registrant and in the capacities and on the dates indicated.
| Signature | Title | Date | ||||||
| /s/ JUDITH F. MARKS | Director, President and Chief Executive Officer | February 5, 2021 | ||||||
| Judith F. Marks | ||||||||
| /s/ RAHUL GHAI | Executive Vice President and Chief Financial Officer | February 5, 2021 | ||||||
| Rahul Ghai | ||||||||
| /s/ MICHAEL P. RYAN | Vice President and Chief Accounting Officer | February 5, 2021 | ||||||
| Michael P. Ryan | ||||||||
| /s/ JEFFREY H. BLACK* | Director | |||||||
| Jeffrey H. Black | ||||||||
| /s/ KATHY HOPINKAH HANNAN* | Director | |||||||
| Kathy Hopinkah Hannan | ||||||||
| /s/ SHAILESH G. JEJURIKAR* | Director | |||||||
| Shailesh G. Jejurikar | ||||||||
| /s/ CHRISTOPHER J. KEARNEY* | Director | |||||||
| Christopher J. Kearney | ||||||||
| /s/ HAROLD W. MCGRAW III* | Director | |||||||
| Harold W. McGraw III | ||||||||
| /s/ MARGARET M.V. PRESTON* | Director | |||||||
| Margaret M.V. Preston | ||||||||
| /s/ SHELLEY STEWART, JR.* | Director | |||||||
| Shelley Stewart, Jr. | ||||||||
| /s/ JOHN H. WALKER* | Director | |||||||
| John H. Walker | ||||||||
| *By: /s/ NORA E. LAFRENIERE | ||||||||
| Executive Vice President & Chief General Counsel, as Attorney-in-fact | ||||||||
| Date: February 5, 2021 |
Report of Independent Registered Public Accounting Firm on
Financial Statement Schedule
To the Board of Directors and Shareholders of Otis Worldwide Corporation
Our audits of the consolidated financial statements referred to in our report dated February 5, 2021 appearing in the 2020 Annual Report to Shareholders of Otis Worldwide Corporation (which report and consolidated financial statements are incorporated by reference in this Annual Report on Form 10-K) also included an audit of the financial statement schedule listed in Item 15(a)(2) of this Form 10-K. In our opinion, this financial statement schedule presents fairly, in all material respects, the information set forth therein when read in conjunction with the related consolidated financial statements.
/s/ PricewaterhouseCoopers LLP
Hartford, Connecticut
February 5, 2021
I
OTIS WORLDWIDE CORPORATION
SCHEDULE II - Valuation and Qualifying Accounts
Three years ended December 31, 2020
(Dollars in millions)
| Allowance for Doubtful Accounts and Expected Credit Losses: | |||||
| Balance, December 31, 2017 | $ | 90 | |||
| Provision charged to income | 10 | ||||
| Doubtful accounts written off | (6) | ||||
| Other | (10) | ||||
| Balance, December 31, 2018 | 84 | ||||
| Provision charged to income | 26 | ||||
| Doubtful accounts written off | (19) | ||||
| Other | (8) | ||||
| Balance, December 31, 2019 | 83 | ||||
| Impact of credit standard adoption | 28 | ||||
| Current period provision for expected credit losses | 40 | ||||
| Write-offs charged against the allowance for expected credit losses | (20) | ||||
| Other | 30 | ||||
| Balance, December 31, 2020 | $ | 161 | |||
| Future Income Tax Benefits - Valuation Allowance | |||||
| Balance, December 31, 2017 | $ | 20 | |||
| Additions charged to income tax expense | 15 | ||||
| Reductions credited to income tax expense | (5) | ||||
| Other adjustments | (1) | ||||
| Balance, December 31, 2018 | 29 | ||||
| Additions charged to income tax expense | 28 | ||||
| Reductions credited to income tax expense | — | ||||
| Other adjustments | (2) | ||||
| Balance, December 31, 2019 | 55 | ||||
| Additions charged to income tax expense | 63 | ||||
| Reductions credited to income tax expense | (13) | ||||
| Other adjustments, including Separation activity | 137 | ||||
| Balance, December 31, 2020 | $ | 242 |
II
Exhibit 13
Excerpt from Otis' 2020 Annual Report to Shareholders for the Year Ended December 31, 2020
| Five-Year Summary | ||||||||||||||||||||||||||||||||
| (dollars in millions, except per share amounts; shares in millions) | 2020 | 2019 | 2018 | 2017 | 2016 (Unaudited) | |||||||||||||||||||||||||||
| For The Year | ||||||||||||||||||||||||||||||||
| Net sales | $ | 12,756 | $ | 13,118 | $ | 12,915 | $ | 12,323 | $ | 11,886 | ||||||||||||||||||||||
| Net income (1) | 1,056 | 1,267 | 1,210 | 809 | 1,397 | |||||||||||||||||||||||||||
| Net income attributable to common shareholders (1) | 906 | 1,116 | 1,049 | 636 | 1,197 | |||||||||||||||||||||||||||
| Basic earnings per share—Net income attributable to common shareholders (2) | 2.09 | 2.58 | 2.42 | 1.47 | 2.76 | |||||||||||||||||||||||||||
| Diluted earnings per share—Net income attributable to common shareholders (2) | 2.08 | 2.58 | 2.42 | 1.47 | 2.76 | |||||||||||||||||||||||||||
| Cash dividends per common share | 0.60 | — | — | — | — | |||||||||||||||||||||||||||
| At December 31, | ||||||||||||||||||||||||||||||||
| Total assets (3) | $ | 10,710 | $ | 9,687 | $ | 9,135 | $ | 9,089 | $ | 8,584 | ||||||||||||||||||||||
| Total debt (4) | 5,963 | 39 | 28 | 18 | 18 |
| (1) | 2020 amounts include the impact of interest expense on debt, incremental standalone public company costs and non-recurring Separation-related costs. 2019 reflects the absence of unfavorable tax charges incurred in 2018, offset by $69 million of non-recurring costs associated with Otis’ separation from UTC. 2018 amounts include a tax charge of $143 million that will become due when previously reinvested earnings of certain international subsidiaries are remitted. 2017 amounts include a $507 million tax charge, representing the U.S. Tax Cuts and Jobs Act (“TCJA”) related adjustments. This amount relates to U.S. income tax attributable to previously undistributed earnings of Otis’ international subsidiaries, equity investments and the revaluation of the U.S. deferred income taxes. | ||||
| (2) | On April 3, 2020, the date of consummation of the Separation, 433,079,455 shares of the Common Stock, were distributed to UTC shareholders of record as of March 19, 2020. This share amount is being utilized for the calculation of basic and diluted earnings per share for all periods presented prior to the Separation. | ||||
| (3) | The increase in total assets as of December 31, 2020 primarily relates to the impact of foreign exchange rates on foreign-denominated assets and cash provided by operating activities in excess of cash used in investing and financing activities. The increase in total assets as of December 31, 2019 primarily relates to the adoption of Accounting Standards Update (“ASU”) No. 2016-02—Leases (Topic 842), which Otis adopted as of January 1, 2019. | ||||
| (4) | The increase in Total Debt as of December 31, 2020 primarily reflects the issuance of $6.3 billion in debt during the year ended December 31, 2020. |
Management's Discussion and Analysis of Financial Condition and Results of Operations
BUSINESS OVERVIEW
We are the world’s leading elevator and escalator manufacturing, installation and service company. Our Company is organized into two segments, New Equipment and Service. Through our New Equipment segment, we design, manufacture, sell and install a wide range of passenger and freight elevators, as well as escalators and moving walkways for residential and commercial buildings and infrastructure projects. Our New Equipment customers include real-estate and building developers and general contractors who develop and/or design buildings for residential, commercial, retail or mixed-use activity. We sell our New Equipment directly to customers, as well as through agents and distributors.
Through our Service segment, we perform maintenance and repair services for both our own products and those of other manufacturers and provide modernization services to upgrade elevators and escalators. Maintenance services include inspections to ensure code compliance, preventive maintenance offerings and other customized maintenance offerings tailored to meet customer needs, as well as repair services to address equipment and component wear and tear and breakdowns. Modernization services enhance equipment operation and improve building functionality. Modernization offerings can range from relatively simple upgrades of interior finishes and aesthetics to complex upgrades of larger components and sub-systems. Our typical Service customers include building owners, facility managers, housing associations and government agencies that operate buildings where elevators and escalators are installed.
We serve our customers through a global network of approximately 69,000 employees. These include sales personnel, field technicians with separate skills in performing installation and service, as well as engineers driving our continued product development and innovation. We function under a centralized operating model whereby we pursue a global strategy set around New Equipment and Service because we seek to grow our maintenance portfolio, in part, through the conversion of new elevator and escalator installations into service contracts. Accordingly, we benefit from an integrated global strategy, which sets priorities and establishes accountability across the full product lifecycle.
For additional discussion, refer to the "Business Overview" section in our Form 10-K.
Separation from United Technologies Corporation
On April 3, 2020, the Separation of each of Otis and Carrier Global Corporation ("Carrier") from United Technologies Corporation, subsequently renamed Raytheon Technologies Corporation ("UTC" or "RTX", as applicable), into separate independent publicly-traded companies was completed through the distribution of 100% of the outstanding common stock of each of Otis and Carrier to holders of UTC common stock as of the close of business on the record date of March 19, 2020. UTC distributed 433,079,455 shares of Otis' common stock, par value $0.01 per share ("Common Stock") in the Distribution, which was effective at 12:01 a.m. Eastern Time, on April 3, 2020. As a result of the Distribution, UTC shareholders of record received 0.5 shares of Common Stock for every share of UTC common stock. As a result of the Distribution, Otis became an independent, publicly-traded company and its Common Stock is listed under the symbol "OTIS" on the New York Stock Exchange ("NYSE").
Prior to the Separation on April 3, 2020, our historical financial statements were prepared on a standalone combined basis and were derived from the consolidated financial statements and accounting records of UTC. For the period subsequent to April 3, 2020, our financial statements are presented on a consolidated basis as the Company became a standalone public company. The Consolidated Financial Statements have been prepared in accordance with accounting principles generally accepted in the United States of America.
As a result of the Separation during the year ended December 31, 2020 and our becoming an independent, publicly-traded company, we have incurred non-recurring Separation-related costs and ongoing costs consisting primarily of employee-related costs, costs to establish certain standalone functions and information technology systems, professional services fees, equity award conversions, tax-related items, transaction-related costs and other services. We believe our cash flows from operations will continue to be sufficient to fund any incremental corporate expenses.
We entered into a transition services agreement ("TSA") with our former parent UTC and Carrier on April 2, 2020, in connection with the Separation pursuant to which RTX provides us with certain services and we provide certain services to RTX for a limited time to help ensure an orderly transition following the Separation. We received and continue to receive services for information technology, technical and engineering support, application support for operations, general administrative services and other support services. Prior to the Separation, costs for these services were allocated from UTC and included in the Company's historical operating expenses and cash flow. For additional discussion, see Note 5 "Related Parties" to the Consolidated Financial Statements.
In connection with the Separation, we entered into a tax matters agreement ("TMA") with our former parent UTC and Carrier on April 2, 2020, that governs the parties’ respective rights, responsibilities and obligations with respect to tax matters (including responsibility for taxes, entitlement to refunds, allocation of tax attributes, preparation of tax returns, control of tax contests and other tax matters).
Subject to certain exceptions set forth in the TMA, the Company generally is responsible for federal, state and foreign taxes imposed on a separate return basis on the Company (or any of its subsidiaries) with respect to taxable periods (or portions thereof) that ended on or prior to the date of the Distribution.
The TMA provides special rules that allocate responsibility for tax liabilities arising from a failure of the Separation and certain related transactions to qualify for tax-free treatment based on the reasons for such failure. The TMA also imposes restrictions on each of Otis and Carrier during the two-year period following the Distribution that are intended to prevent certain transactions from failing to qualify as transactions that are generally tax-free.
On December 22, 2017, the TCJA was enacted which significantly changed U.S. tax law. This new legislation imposed a one-time toll charge, paid in installments over an 8-year period, on deemed repatriated earnings of foreign subsidiaries as of December 31, 2017. Under the terms of the TMA, Otis is required to indemnify RTX for a percentage of the toll charge installment payments (and any adjustments to any prior toll charge installment payments) due after April 3, 2020. As a result, a portion of the future income tax obligations corresponding to the toll charge has been reclassified as a contractual indemnity obligation within Other long-term liabilities on the Consolidated Balance Sheet. For additional discussion, see Note 15 "Income Taxes" to the Consolidated Financial Statements.
In connection with the Separation, we entered into an Employee Matters Agreement ("EMA") and Intellectual Property Agreement with UTC and Carrier on April 2, 2020. These agreements are not expected to have a material impact on the financial results of Otis.
Impact of COVID-19 on our Company
The results of our operations and overall financial performance were impacted due to the COVID-19 pandemic during the year ended December 31, 2020. COVID-19 could have a negative impact to our business, including net sales and overall financial performance in 2021, as a result of the following:
-
Customer liquidity constraints and related credit reserves
-
Temporary closure or reduced capacity of our factory operations and those of our suppliers
-
Limited new equipment job site closures
-
Cancellations or delays of customer orders
-
Challenges in accessing units to provide maintenance and repair services
-
Customer demand impacting our new equipment, maintenance and repair, and modernization businesses
We currently do not expect any significant impact to our capital and financial resources, including our overall liquidity position based on our available cash and cash equivalents and our access to credit facilities and the capital markets, from the COVID-19 pandemic. We are focused on navigating these challenges presented by COVID-19 by continuing to preserve our liquidity and manage our cash flow by taking the necessary measures to meet our short-term liquidity needs. Our cost containment actions have included, and could include in the future, but are not limited to, reducing our discretionary spending, reducing payroll costs and restructuring.
See the Liquidity and Financial Condition section for further detail.
We have not experienced during the year-ended December 31, 2020 any material impairments to our goodwill, intangible asset and long-lived asset balances as a result of the COVID-19 pandemic and do not currently anticipate any as a result of the COVID-19 pandemic in the future.
Germany Fire
In the quarter ended June 30, 2020 there was a fire at the Company’s manufacturing facility in Germany. As a result of the fire, the Company initially recognized immaterial losses related to the write-down of related fixed assets and facilities and incurred immaterial impacts to operating income due to business interruption during the year ended December 31, 2020. The Company has submitted an insurance claim related to the fire for both property damage and business interruption insurance.
Based on the developments of the insurance claim, the Company has recorded a gain on an expected insurance recovery relating to property damage of approximately $17 million, that is recorded in Other (expense) income, net on the Consolidated Statement of Operations for the year ended December 31, 2020. The Company is continuing to work with insurers to determine the final amounts recoverable for both impacted assets and business interruption. We do not anticipate any additional material impact to our operations in the future from this event.
See Part I, Item 1A,"Risk Factors" in the Form 10-K for further discussion.
RESULTS OF OPERATIONS
Net Sales
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Net sales | $ | 12,756 | $ | 13,118 | $ | 12,915 | |||||||||||
| Percentage change year-over-year | (2.8) | % | 1.6 | % | 4.8 | % |
The factors contributing to the total percentage change year-over-year in total Net sales are as follows:
| 2020 | 2019 | ||||||||||
| Organic volume | (2.1) | % | 4.7 | % | |||||||
| Foreign currency translation | (0.4) | % | (3.1) | % | |||||||
| Acquisitions and divestitures, net | (0.2) | % | (0.1) | % | |||||||
| Other | (0.1) | % | 0.1 | % | |||||||
| Total % change | (2.8) | % | 1.6 | % |
The Organic volume decrease of (2.1)% for 2020 was driven by decreases in organic sales of (4.0)% in the New Equipment segment and (0.7)% in the Service segment.
The Organic volume increase of 4.7% for 2019 was driven by increases in organic sales of 4.2% in the New Equipment segment and 5.1% in the Service segment.
See "Segment Review" below for a discussion of Net sales by segment.
Cost of Products and Services Sold
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Cost of products and services sold | $ | 8,977 | $ | 9,292 | $ | 9,189 | |||||||||||
| Percentage change year-over-year | (3.4) | % | 1.1 | % | 6.6 | % |
The factors contributing to the percentage change year-over-year in total cost of products and services sold are as follows:
| 2020 | 2019 | ||||||||||
| Organic volume | (2.7) | % | 4.6 | % | |||||||
| Foreign currency translation | (0.5) | % | (3.3) | % | |||||||
| Acquisitions and divestitures, net | (0.2) | % | (0.1) | % | |||||||
| Restructuring | — | % | (0.1) | % | |||||||
| Total % change | (3.4) | % | 1.1 | % |
The organic volume decrease in total cost of products and services sold in 2020 was driven by the organic sales decrease noted above, productivity and cost containment actions.
The organic volume increase in cost of products and services sold in 2019 was primarily driven by the organic sales increase above.
Gross Margin
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Gross margin | $ | 3,779 | $ | 3,826 | $ | 3,726 | |||||||||||
| Gross margin percentage | 29.6 | % | 29.2 | % | 28.9 | % |
Gross margin increased 40 basis points in 2020 when compared to 2019, primarily driven by an increase in the Service margin rate and overall segment mix, partially offset by a decrease in the New Equipment margin rate.
Gross margin increased 30 basis points in 2019 when compared to 2018, primarily driven by an increase in the Service margin rate, partially offset by a decrease in the New Equipment margin rate.
See the Segment Review below for discussion of operating results by segment.
Research and Development
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Research and development | $ | 152 | $ | 163 | $ | 181 | |||||||||||
| Percentage of Net sales | 1.2 | % | 1.2 | % | 1.4 | % |
Research and development spending decreased approximately $11 million, or (6.7)%, in 2020 compared to 2019 primarily as a result of cost containment actions taken in the current year. Research and development expenses remained relatively consistent as a percentage of Net sales. We continue to fund our strategic investment projects and focus on our commitment to Internet of Things technology developing the next generation of connected elevators and escalators.
Research and development in 2019 reflects the benefit of organizational optimization and lower cost allocations from UTC in 2019 compared to 2018.
Selling, General and Administrative
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Selling, general and administrative | $ | 1,924 | $ | 1,810 | $ | 1,735 | |||||||||||
| Percentage of Net sales | 15.1 | % | 13.8 | % | 13.4 | % |
Selling, general and administrative expenses increased approximately $114 million, or 6.3%, in 2020, with lower employment costs and lower discretionary spending, including cost containment actions taken in response to COVID-19, and the absence of corporate allocations from UTC, being more than offset by non-recurring Separation-related costs and incremental standalone public company costs. Selling, general and administrative expenses increased as a percentage of Net sales in 2020, primarily driven by the increase in non-recurring Separation-related costs, incremental standalone public company costs and lower Net sales.
Selling, general and administrative expenses increased approximately $75 million, or 4.3%, in 2019. Excluding the favorable impact of foreign exchange fluctuations (3%), the increase is primarily driven by costs in preparation of our Separation from UTC and higher employment and digital technology costs. See Note 5, "Related Parties" for further discussion on costs related to the Separation.
We are continuously evaluating our cost structure and have implemented restructuring actions as a method of keeping our cost structure competitive. For further discussion, see “Restructuring Costs” below and Note 16, "Restructuring Costs" to the Consolidated Financial Statements.
Restructuring Cos****ts
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Restructuring costs | $ | 77 | $ | 54 | $ | 69 |
We initiate restructuring actions to keep our cost structure competitive. Charges generally arise from severance related to workforce reductions, and to a lesser degree, facility exit and lease termination costs associated with the consolidation of field and manufacturing operations. We continue to closely monitor the economic environment, especially in light of the economic impact of COVID-19, and may undertake further restructuring actions to keep our cost structure aligned with the demands of the prevailing market conditions. Total 2020 restructuring costs include $71 million of costs related to 2020 actions and $6 million of costs related to 2019.
2020 Actions. During 2020, we recorded net pre-tax restructuring charges of $71 million relating to cost reduction actions initiated in 2020. We are targeting to complete in 2021 the majority of the remaining workforce cost reduction actions initiated in 2020. Approximately 97% of the total expected pre-tax charges will require cash payments, which we have funded and expect to continue to fund with cash generated from operations. During 2020, we had cash outflows of approximately $29 million related to the 2020 actions. We expect to incur additional restructuring charges of $15 million to complete these actions. We expect recurring pre-tax savings in continuing operations to increase to approximately $57 million annually over the two-year period subsequent to initiating the actions.
2019 Actions. During 2020 and 2019, we recorded net pre-tax restructuring charges of $6 million and $45 million, respectively, for actions initiated in 2019. Approximately 100% of the total pre-tax charge will require cash payments, which we have and expect to continue to fund with cash generated from operations. During 2020, we had cash outflows of approximately $15 million related to the 2019 actions. We expect to incur additional restructuring charges of $3 million to complete these actions. We expect recurring pre-tax savings to increase over the two-year period after initiating the actions to be approximately $45 million annually, of which approximately $35 million was realized during 2020, net of the current year charges.
In addition, we recorded net pre-tax restructuring costs totaling $0 and $9 million in 2020 and 2019, respectively, for restructuring actions initiated in 2018 and prior years. For additional discussion of restructuring, see Note 16, "Restructuring Costs" in the Consolidated Financial Statements.
Other Income (Expense), Net
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Other income (expense), net | $ | (64) | $ | (39) | $ | 25 |
Other income (expense), net primarily includes the impact of changes in the fair value and settlement of embedded and foreign exchange derivatives, gains or losses on sale of businesses and fixed assets, earnings from equity method investments, fair value changes on equity securities, impairments, non-recurring Separation-related expenses, gains on expected insurance recoveries and certain other infrequent operating income and expense items.
The year-over-year increase in Other income (expense), net in 2020 when compared to 2019 is driven by current year fixed asset impairments of approximately $(71) million and associated license costs of approximately $(14) million and non-recurring Separation-related expenses. These were partially offset by favorable mark-to-market adjustments on foreign currency derivatives of approximately $46 million when compared to the prior year, the absence of the loss on the sale of a business of approximately $19 million included in the 2019 results and a non-recurring gain of approximately $17 million related to an expected insurance recovery recognized for property damage as a result of the fire in our manufacturing facility in Germany in the current year.
The year-over-year change in Other income (expense), net in 2019 when compared to 2018 is primarily due to an increase in unfavorable mark-to-market adjustments on foreign currency derivatives, non-recurring charges in 2019 related to our Separation from UTC and lower gains on sales of certain fixed assets.
See Note 5, "Related Parties" to the Consolidated Financial Statements for further discussion on costs related to the Separation.
Interest Expense (Income), Net
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Interest expense (income), net | $ | 122 | $ | (14) | $ | (14) |
Interest expense (income), net primarily relates to interest expense on our external debt, offset by interest income earned on cash balances, short-term investments and related party activity between Otis and UTC in the prior years.
The increase in Interest expense (income), net in 2020 compared to 2019 was primarily driven by interest expense of $124 million on our external debt for the year ended December 31, 2020 and debt issuance cost amortization of $5 million. These expenses were offset by interest income on short-term investments. The average interest rate on our external long-term debt for 2020 is 2.3%.
Interest expense (income), net remained flat in 2019 in comparison to 2018.
For additional discussion of borrowings, see Note 10, "Borrowings and Lines of Credit" to the Consolidated Financial Statements.
Income Taxes
| 2020 | 2019 | 2018 | |||||||||||||||
| Effective tax rate | 30.1 | % | 31.9 | % | 36.1 | % |
The 2020 effective tax rate is higher than the statutory U.S. rate primarily due to higher international tax rates as compared to the lower U.S. federal statutory rate and foreign earnings subject to U.S. tax under the provisions of the TCJA.
The 2020 effective tax rate compared to the 2019 effective tax rate reflects a tax benefit of $10 million related to our change in assertion of no longer intending to reinvest certain undistributed earnings made during the year as compared to the liability previously recorded by UTC, a decrease as a result of tax regulations related to the TCJA that were enacted during the
year, as well as a recognition of a Separation-related foreign tax loss. These were partially offset by incremental withholding taxes in 2020.
The 2019 effective tax rate is higher than the statutory U.S. rate primarily due to higher international tax rates as compared to the lower U.S. federal statutory rate, and the full phase-in of the TCJA.
The 2019 effective tax rate compared to the 2018 effective tax rate reflects a decrease in the cost of U.S. and foreign tax on international activities primarily attributable to the absence of the net tax charge of $143 million as a result of UTC’s change of assertion of no longer intending to reinvest certain undistributed earnings of its international subsidiaries, offset by the full phase-in of the TCJA.
The 2018 effective tax rate is higher than the statutory U.S. rate as it reflects a net tax charge of $143 million as a result of UTC’s change of assertion of no longer intending to reinvest certain undistributed earnings of its international subsidiaries.
For additional discussion of income taxes and the effective income tax rate, see Note 15, "Income Taxes" to the Consolidated Financial Statements.
Noncontrolling Interest in Subsidiaries' Earnings
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Noncontrolling interest in subsidiaries' earnings | $ | 150 | $ | 151 | $ | 161 |
Noncontrolling interest in subsidiaries' earnings remained consistent in 2020 in comparison to 2019.
Net income attributable to noncontrolling interest decreased in 2019 when compared with 2018 primarily due to a decrease in the net income of certain subsidiaries with noncontrolling interest.
Ownership interest in the underlying entities has remained generally consistent year-over-year.
Net Income Attributable to Common Shareholders
| (dollars in millions, except per share amounts) | 2020 | 2019 | 2018 | ||||||||||||||
| Net income attributable to common shareholders | $ | 906 | $ | 1,116 | $ | 1,049 | |||||||||||
| Diluted earnings per share from operations | $ | 2.08 | $ | 2.58 | $ | 2.42 |
Net income attributable to common shareholders for the year ended December 31, 2020 includes restructuring charges, net of taxes, of $58 million ($77 million pre-tax), as well as charges relating to significant non-operational and/or non-recurring items, net of taxes, of approximately $132 million ($203 million pre-tax) which include non-recurring Separation-related costs, fixed asset impairments, non-recurring Separation-related tax benefits and the impact of non-recurring tax items. These significant non-operational and/or non-recurring items, along with incremental standalone public company costs were the primary contributors to lower Net income attributable to common shareholders for the year ended December 31, 2020 when compared to the same period in 2019. The effects of the restructuring and the non-operational and non-recurring items above resulted in an impact of $0.44 on diluted earnings per share for the year ended December 31, 2020.
Net income attributable to common shareholders for the year ended December 31, 2019 includes restructuring charges, net of tax benefit, of $39 million ($54 million pre-tax) as well as charges relating to significant non-operational and/or non-recurring items, net of taxes, of approximately $51 million ($69 million pre-tax), which primarily consist of employee-related costs, costs to establish certain standalone functions, information technology systems, professional services fees and other transaction-related costs for our transition to being a standalone public company, in addition to non-recurring losses on disposals of businesses.
Net income attributable to common shareholders for the year ended December 31, 2018 includes restructuring charges, net of tax benefit, of $53 million ($69 million pre-tax) as well as a net charge for certain non-operational and/or non-recurring items, primarily driven by a tax charge of $143 million that will become due when previously reinvested earnings of certain international subsidiaries are remitted.
Segment Review
| Net Sales | Operating Profit | Operating Profit Margin | |||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in millions) | 2020 | 2019 | 2018 | 2020 | 2019 | 2018 | 2020 | 2019 | 2018 | ||||||||||||||||||||||||||||||||||||||||||||
| New Equipment | $ | 5,371 | $ | 5,648 | $ | 5,596 | $ | 318 | $ | 393 | $ | 390 | 5.9 | % | 7.0 | % | 7.0 | % | |||||||||||||||||||||||||||||||||||
| Service | 7,385 | 7,470 | 7,319 | 1,611 | 1,603 | 1,516 | 21.8 | % | 21.5 | % | 20.7 | % | |||||||||||||||||||||||||||||||||||||||||
| Total segment | 12,756 | 13,118 | 12,915 | 1,929 | 1,996 | 1,906 | 15.1 | % | 15.2 | % | 14.8 | % | |||||||||||||||||||||||||||||||||||||||||
| General corporate expenses and other | — | — | — | (290) | (182) | (71) | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||
| Total | $ | 12,756 | $ | 13,118 | $ | 12,915 | $ | 1,639 | $ | 1,814 | $ | 1,835 | 12.8 | % | 13.8 | % | 14.2 | % | |||||||||||||||||||||||||||||||||||
New Equipment
The New Equipment segment designs, manufactures, sells and installs a wide range of passenger and freight elevators, as well as escalators and moving walkways in residential and commercial buildings and infrastructure projects. Our New Equipment customers include real-estate and building developers and general contractors who develop and/or design buildings for residential, commercial, retail or mixed-use activity. We sell directly to customers as well as through agents and distributors.
| Total Increase (Decrease) Year-Over-Year for: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in millions) | 2020 | 2019 | 2018 | 2020 compared with 2019 | 2019 compared with 2018 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net sales | $ | 5,371 | $ | 5,648 | $ | 5,596 | $ | (277) | (4.9) | % | $ | 52 | 0.9 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Cost of sales | 4,439 | 4,640 | 4,586 | (201) | (4.3) | % | 54 | 1.2 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 932 | 1,008 | 1,010 | (76) | (7.5) | % | (2) | (0.2) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Operating expenses and other | 614 | 615 | 620 | (1) | (0.2) | % | (5) | (0.8) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Operating profit | $ | 318 | $ | 393 | $ | 390 | $ | (75) | (19.1) | % | $ | 3 | 0.8 | % |
| 2020 | 2019 | |||||||||||||||||||||||||||||||||||||
| Net Sales | Cost of Sales | Operating Profit | Net Sales | Cost of Sales | Operating Profit | |||||||||||||||||||||||||||||||||
| Organic/Operational | (4.0) | % | (3.7) | % | (12.7) | % | 4.2 | % | 4.8 | % | 2.6 | % | ||||||||||||||||||||||||||
| Foreign currency translation | (0.8) | % | (0.7) | % | (2.3) | % | (3.4) | % | (3.6) | % | (4.3) | % | ||||||||||||||||||||||||||
| Acquisitions/Divestitures, net | — | % | — | % | — | % | — | % | — | % | — | % | ||||||||||||||||||||||||||
| Restructuring cost | — | % | 0.1 | % | (2.8) | % | — | % | — | % | 1.5 | % | ||||||||||||||||||||||||||
| Other | (0.1) | % | — | % | (1.3) | % | 0.1 | % | — | % | 1.0 | % | ||||||||||||||||||||||||||
| Total % change | (4.9) | % | (4.3) | % | (19.1) | % | 0.9 | % | 1.2 | % | 0.8 | % |
2020 Compared with 2019
The organic sales decrease of (4.0)% was primarily driven by organic sales declines in all regions primarily due to impacts of the COVID-19 pandemic.
New Equipment operational profit decreased (12.7)%, as strong material productivity 15.8% and cost containment actions, were more than offset by the impact of lower volume (8.9)% and unfavorable rate drivers (25.1)% due to under-absorption, field inefficiencies, price and mix and higher bad debt expense. New Equipment operating profit was also impacted by foreign currency headwinds, higher restructuring costs and incremental public company standalone costs.
2019 Compared with 2018
The organic sales increase of 4.2% primarily reflects growth in Asia.
New Equipment operational profit increased 2.6% driven by higher volume 6.8% and lower research and development expenses 3.1%, partially offset by higher selling, general and administrative expenses (7.1)%.
Service
The Service segment performs maintenance and repair services for both our products and those of other manufacturers and provides modernization services to upgrade elevators and escalators. Maintenance services include inspections to ensure code compliance, preventive maintenance offerings and other customized maintenance offerings tailored to meet customer needs, as well as repair services that address equipment and component wear and tear, and breakdowns. Modernization services enhance equipment operation and improve building functionality. Modernization offerings can range from relatively simple upgrades of interior finishes and aesthetics, to complex upgrades of larger components and sub-systems. Our typical Service customers include building owners, facility managers, housing associations and government agencies that operate buildings where elevators and escalators are installed.
| Total Increase (Decrease) Year-Over-Year for: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in millions) | 2020 | 2019 | 2018 | 2020 compared with 2019 | 2019 compared with 2018 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net sales | $ | 7,385 | $ | 7,470 | $ | 7,319 | $ | (85) | (1.1) | % | $ | 151 | 2.1 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Cost of sales | 4,538 | 4,652 | 4,603 | (114) | (2.5) | % | 49 | 1.1 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 2,847 | 2,818 | 2,716 | 29 | 1.0 | % | 102 | 3.8 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Operating expenses and other | 1,236 | 1,215 | 1,200 | 21 | 1.7 | % | 15 | 1.3 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Operating profit | $ | 1,611 | $ | 1,603 | $ | 1,516 | $ | 8 | 0.5 | % | $ | 87 | 5.7 | % |
| 2020 | 2019 | |||||||||||||||||||||||||||||||||||||
| Net Sales | Cost of Sales | Operating Profit | Net Sales | Cost of Sales | Operating Profit | |||||||||||||||||||||||||||||||||
| Organic/Operational | (0.7) | % | (1.8) | % | 0.9 | % | 5.1 | % | 4.4 | % | 8.3 | % | ||||||||||||||||||||||||||
| Foreign currency translation | (0.1) | % | (0.1) | % | 0.2 | % | (3.0) | % | (3.0) | % | (3.4) | % | ||||||||||||||||||||||||||
| Acquisitions/Divestitures, net | (0.3) | % | (0.6) | % | (0.1) | % | — | % | (0.2) | % | (0.1) | % | ||||||||||||||||||||||||||
| Restructuring cost | — | % | (0.1) | % | (0.7) | % | — | % | — | % | 0.6 | % | ||||||||||||||||||||||||||
| Other | — | % | 0.1 | % | 0.2 | % | — | % | (0.1) | % | 0.3 | % | ||||||||||||||||||||||||||
| Total % change | (1.1) | % | (2.5) | % | 0.5 | % | 2.1 | % | 1.1 | % | 5.7 | % |
2020 Compared with 2019
Service sales declined (1.1)% with an organic sales decline of (0.7)% and the remaining decrease due to foreign currency headwinds and the net impact from acquisitions and divestitures. The organic sales decrease (0.7)% primarily consists of organic sales decrease in maintenance and repair of (0.9)%, with organic sales for modernization remaining flat.
Maintenance and repair net sales decreased (1.2)% year over year and was comprised of a (0.9)% organic sales decrease, foreign currency headwinds of (0.1)% and decreases related to net acquisitions and divestitures of (0.2)%.
Modernization net sales decreased (0.9)% year over year and was comprised of a 0.1% organic sales increase, foreign currency tailwinds of 0.1%, more than offset by decreases related to net acquisitions and divestitures (1.1)%.
Service operational profit increased 0.9% with the benefit of favorable productivity 4.2%, pricing and mix 2.3%, and cost containment actions, more than offsetting the combined impact of price concessions and lower volume (3.4)% and higher bad debt expense. Service operating profit was also favorably impacted by foreign currency, offset by higher restructuring costs and incremental public company standalone costs.
2019 Compared with 2018
The organic sales increase of 5.1% primarily consists of organic increases in maintenance and repair 4.9% and modernization 6.2%.
Maintenance and repair net sales increased 1.7% year over year and was comprised of a 4.9% organic sales increase, offset by foreign currency headwinds of (3.2)%.
Modernization net sales increased 3.6% year over year and was comprised of a 6.2% organic sales increase, offset by foreign currency headwinds of (2.2)% and decreases related to acquisitions and divestitures, net of (0.4)%.
Service operational profit increased 8.3%, driven by higher volume 7.8% and favorable price and mix 6.0%, partially offset by higher selling, general and administrative expenses (4.1)%.
General Corporate Expenses and Other
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||||||||||||||||||||
| General corporate expenses and other | (290) | (182) | (71) |
General corporate expenses and other increased approximately $108 million in 2020 compared to the same period in 2019, primarily driven by current year fixed asset impairments of $71 million and associated license costs of approximately $14 million, non-recurring Separation-related costs of $119 million in the current year and incremental standalone public company costs. These were partially offset by favorable mark-to-market adjustments on foreign currency derivatives of $46 million when compared to the prior period, the absence of losses on the sale of a business of $19 million that occurred during 2019 and a non-recurring gain of approximately $17 million related to an expected insurance recovery for property damage as a result of the fire in our manufacturing facility in Germany recognized in the current year.
General corporate expenses and other increased approximately $111 million in 2019 compared to the same period in 2018, primarily driven by non-recurring Separation costs and the changes in Other (expense) income, net previously discussed above.
LIQUIDITY AND FINANCIAL CONDITION
| (dollars in millions) | December 31, 2020 | December 31, 2019 | ||||||||||||||||||
| Cash and cash equivalents | $ | 1,782 | $ | 1,446 | ||||||||||||||||
| Total debt | 5,963 | 39 | ||||||||||||||||||
| Net debt (total debt less cash and cash equivalents) | 4,181 | (1,407) | ||||||||||||||||||
| Total equity | (3,284) | 2,231 | ||||||||||||||||||
| Total capitalization (total debt plus total equity) | 2,679 | 2,270 | ||||||||||||||||||
| Net capitalization (total debt plus total equity less cash and cash equivalents) | 897 | 824 | ||||||||||||||||||
| Total debt to total capitalization | 223 | % | 2 | % | ||||||||||||||||
| Net debt to net capitalization | 466 | % | (171) | % |
At December 31, 2020, we had cash and cash equivalents of approximately $1.8 billion, of which approximately 88% was held by the Company's foreign subsidiaries. We manage our worldwide cash requirements by reviewing available funds among the many subsidiaries through which we conduct our business and the cost effectiveness with which those funds can be accessed. On occasion, we are required to maintain cash deposits with certain banks with respect to contractual obligations related to acquisitions and divestitures or other legal obligations. As of December 31, 2020 and 2019, the amount of such restricted cash was approximately $19 million and $13 million, respectively.
From time to time we may need to access the capital markets to obtain financing. We may incur indebtedness or issue equity as needed. Although we believe that the arrangements in place as of December 31, 2020 permit us to finance our operations on acceptable terms and conditions, our access to, and the availability of, financing on acceptable terms and conditions in the future could be impacted by many factors, including (1) our credit ratings or absence of a credit rating, (2) the liquidity of the overall capital markets and (3) the current state of the economy, including the impact of COVID-19. There can be no assurance that we will continue to have access to the capital markets on terms acceptable to us.
The following is a summary of the debt issuances in 2020:
| (dollars in millions) | ||||||||||||||
| Issuance Date | Description of Debt | Aggregate Principal Balance | ||||||||||||
| 03-27-2020 | LIBOR plus 112.5 bps term loan due 2023 | $ | 1,000 | |||||||||||
| 02-27-2020 | LIBOR plus 45 bps floating rate notes due 2023 | 500 | ||||||||||||
| 02-27-2020 | 2.056% notes due 2025 | 1,300 | ||||||||||||
| 02-27-2020 | 2.293% notes due 2027 | 500 | ||||||||||||
| 02-27-2020 | 2.565% notes due 2030 | 1,500 | ||||||||||||
| 02-27-2020 | 3.112% notes due 2040 | 750 | ||||||||||||
| 02-27-2020 | 3.362% notes due 2050 | 750 |
The following is a summary of the debt repayments in 2020:
| (dollars in millions) | ||||||||||||||
| Payment Date | Description of Debt | Total Principal Payments | ||||||||||||
| 09-28-2020 | LIBOR plus 112.5 bps term loan due 2023 | $ | 750 | |||||||||||
| 11-20-2020 | LIBOR plus 112.5 bps term loan due 2023 | $ | 250 |
In 2020 we repaid the $1.0 billion term loan in full, using cash from operations and proceeds from the issuance of Euro denominated and US Dollar denominated commercial paper.
The net proceeds from the above February and March debt issuances totaling $6.3 billion were used to distribute cash to UTC as part of the Separation in 2020.
For additional discussion of borrowings, see Note 10, "Borrowings and Lines of Credit" to the Consolidated Financial Statements.
Following the enactment of the TCJA, and after reassessing as part of the Separation, the Company determined that it no longer intends to reinvest certain undistributed earnings of our international subsidiaries that have been previously taxed in the U.S. For the remainder of the Company’s undistributed international earnings, unless tax effective to repatriate, we will continue to permanently reinvest these earnings.
We expect to fund our ongoing operating, investing and financing requirements mainly through cash flows from operations, available liquidity through cash on hand and available bank lines of credit and access to the capital markets.
On April 27, 2020, our Board of Directors authorized a share repurchase program for up to $1.0 billion of Common Stock. Under this program, shares may be purchased on the open market, in privately negotiated transactions, under accelerated share repurchase programs, or under plans complying with rules 10b5-1 and 10b-18 under the Securities Exchange Act of 1934, as amended. We expect to commence share repurchases under the program in 2021.
Cash Flow - Operating Activities
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Net cash flows provided by operating activities | $ | 1,480 | $ | 1,469 | $ | 1,550 |
2020 Compared with 2019
Cash generated from operating activities in 2020 was $11 million higher than 2019, primarily due to increased cash inflows related to current assets and current liabilities activity of $109 million, as described below. There were also increased Other operating activities of $106 million compared to the same period in 2019, primarily due to increased long-term accruals. These were partially offset by lower net income of $211 million, which includes the impact of interest expense on debt, incremental standalone public company costs and non-recurring Separation-related costs in 2020.
2020 Changes in Working Capital
The 2020 cash inflows related to current assets and current liabilities operating activity were $77 million. These cash inflows were primarily driven by:
-
Contract assets, current and Contract liabilities, current, net change of $282 million, driven by the timing of billings on contracts compared to the progression on current contracts; and
-
Accounts payable, which increased by $20 million primarily due to the timing of payments to suppliers.
The cash inflows were partially offset by cash outflows related to:
-
Inventories, net, which increased $76 million, due to the impact of higher production inventory levels related to the timing of deliveries to construction sites; and
-
Accounts receivable, net, which increased $163 million due to slower collections and increased customer financing activity.
Additionally, Other current assets decreased by $28 million due to the receipt of indemnification pursuant to the TMA in order to pay foreign tax obligations, partially offset by tax prepayments in certain tax jurisdictions, while Accrued liabilities decreased $14 million largely due to the payment of foreign tax obligations pursuant to the TMA described above and income tax liabilities in certain tax jurisdictions, partially offset by accruals for interest in excess of interest payments. The receipt and payment of indemnification assets and foreign tax obligations resulted in no net cash flow for 2020. See Note 5, "Related Parties" to the Consolidated Financial Statements for further discussion on transactions with our former parent UTC.
2019 Compared with 2018
Cash generated from operating activities in 2019 was $81 million lower than 2018, primarily due to higher income taxes settled with UTC. Cash outflows for working capital increased by $24 million over the prior period to support higher organic sales.
2019 Changes in Working Capital
The 2019 cash outflows related to current assets and current liabilities operating activity were $32 million. These cash outflows were primarily driven by:
- Accounts receivable, net, which increased $191 million due to increased sales volume and timing of receipts of payments;
The cash outflows were partially offset by cash inflows related to:
-
Net change in Contract assets, current and Contract liabilities, current of $97 million due to the timing of billings on contracts compared to the progression on current contracts; and
-
Inventories, net, which decreased $60 million due to lower production inventory.
Cash Flow - Investing Activities
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Net cash flows used in investing activities | $ | (353) | $ | (203) | $ | (201) |
Cash flows used in investing activities primarily reflect capital expenditures, investments in businesses and securities, proceeds received on the sale of fixed assets, and settlement of derivative contracts.
2020 compared to 2019
| (dollars in millions) | 2020 | 2019 | Change | ||||||||||||||
| Investing Activities: | |||||||||||||||||
| Capital expenditures | $ | (183) | $ | (145) | $ | (38) | |||||||||||
| Investments in businesses, net of cash acquired | (53) | (47) | (6) | ||||||||||||||
| Investments in equity securities | (51) | — | (51) | ||||||||||||||
| Receipts (payments) on settlements of derivative contracts | (69) | (5) | (64) | ||||||||||||||
| Other investing activities, net | 3 | (6) | 9 | ||||||||||||||
| Net cash flows used in investing activities | $ | (353) | $ | (203) | $ | (150) | |||||||||||
Cash flows used in investing activities in 2020 compared to 2019 increased $150 million, including a $64 million increase in payments on settlements of derivative contracts, a $51 million investment in the current year related to equity securities, a $38 million increase in capital expenditures, and a $6 million increase in investments in businesses. Increases in our capital expenditures reflect investments in assets to support the Separation, as well as investments in software for internal use to support our digital and strategic initiatives.
As discussed in Note 17, "Financial Instruments" to the Consolidated Financial Statements, we enter into derivative instruments for risk management purposes. We operate internationally and, in the normal course of business, are exposed to fluctuations in interest rates and foreign exchange rates. These fluctuations can increase the costs of financing, investing and operating the business. We use derivative instruments, including forward contracts and options, to manage certain foreign currency exposures. The settlement of these derivative instruments resulted in a net cash outflow of $69 million in 2020, which includes $21 million of payments associated with the hedges of foreign-denominated TMA indemnification assets.
2019 compared to 2018
Cash flows used in investing activities in 2019 compared to 2018 remained relatively flat, primarily due to a $27 million decrease in capital expenditures, offset by a $15 million decrease in proceeds received on the sale of certain fixed assets and a $15 million increase in short-term investing activity.
Cash Flow - Financing Activities
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Net cash flows used in financing activities | $ | (844) | $ | (1,133) | $ | (1,497) |
Financing activities primarily include issuance of long-term debt, increases (decreases) in short-term borrowings, dividends paid to common shareholders, dividends paid to noncontrolling interest and transfers to and from UTC, consisting of, among other things, cash transfers, distributions, cash investments and changes in receivables and payables between Otis and UTC. See Note 5, "Related Parties" to the Consolidated Financial Statements for further discussion on transactions with UTC.
2020 compared to 2019
Net cash used in financing activities decreased $289 million in 2020 compared to 2019, primarily due to the issuance of long-term notes of $5.3 billion, the draw of $1.0 billion from the term loan, and an increase in short-term borrowings of
$641 million primarily from the issuance of commercial paper in 2020. These were partially offset by a $5.4 billion increase in net transfers to UTC related to the Separation, the full repayment of the $1.0 billion term loan, a $260 million increase in dividends paid on Common Stock, and $43 million in payments of long-term debt issuance costs in 2020. See Note 10, "Borrowings and Lines of Credit" to the Consolidated Financial Statements for further discussion on borrowings.
2019 compared to 2018
Net cash used in financing activities decreased $364 million in 2019 compared to 2018 primarily due to a decrease in Net transfers to UTC.
CRITICAL ACCOUNTING ESTIMATES
Preparation of the financial statements requires management to make estimates and assumptions that affect the reported amounts of assets, liabilities, revenues and expenses. Note 2, "Summary of Significant Accounting Policies" to the Consolidated Financial Statements describes the significant accounting policies used in preparation of the Consolidated Financial Statements. Management believes the most complex and sensitive judgments, because of their significance to the Consolidated Financial Statements, result primarily from the need to make estimates about the effects of matters that are inherently uncertain. The most significant areas involving management judgments and estimates are described below. Actual results in these areas could differ from management’s estimates.
Revenue Recognition from Contracts with Customers
Effective January 1, 2018, we adopted Accounting Standards Update (“ASU”) 2014-09 and its related amendments (referred to as "ASC 606”) and elected the modified retrospective approach. The impact of ASC 606 did not significantly change the revenue recognition model for us nor our policies and procedures. For new equipment and modernization contracts, equipment and installation are typically procured in a single contract providing the customer with a complete installed elevator or escalator unit. The combination of equipment and installation promises are typically a single performance obligation. For these performance obligations, revenue is typically recognized over time using costs incurred to date relative to total estimated costs at completion to measure progress. Contract costs are usually incurred over a period of time, which can be several years, and the estimation of these costs requires management’s judgment. Contract costs included in the calculation are comprised of labor, materials, subcontractors’ costs or other direct costs and indirect costs, which include indirect labor costs.
The long-term nature of the contracts, the complexity of the products and the scale of the projects can affect our ability to estimate costs precisely. We review cost estimates on significant new equipment and modernization contracts on a quarterly basis and, for others, no less frequently than annually or when circumstances change and warrant a modification to a previous estimate. We record changes in contract estimates using the cumulative catch-up method and we review changes in contract estimates for their impact on net sales or operating profit in the Consolidated Financial Statements. Modifications are recognized as a cumulative catch-up or treated as a separate accounting contract if the modification adds distinct goods or services and the modification is priced at its stand-alone selling price.
See Note 2, "Summary of Significant Accounting Policies" and Note 4, "Revenue Recognition" to the Consolidated Financial Statements for further discussion.
Income Taxes
The future tax benefit arising from deductible temporary differences and tax carryforwards was $642 million at December 31, 2020 and $619 million at December 31, 2019. Management estimates that our earnings during the periods when the temporary differences become deductible will be generally sufficient to realize the related future income tax benefits, which may be realized over an extended period of time. For those jurisdictions where the expiration date of tax carryforwards or the projected operating results indicate that realization is not likely, a valuation allowance is provided.
In assessing the need for a valuation allowance, we estimate future taxable income, considering the feasibility of ongoing tax planning strategies and the realizability of tax loss carryforwards. Valuation allowances related to deferred tax assets can be affected by changes to tax laws, changes to statutory tax rates and future taxable income levels. In the event we were to determine that we would not be able to realize all or a portion of our deferred tax assets in the future, we would reduce such amounts through an increase to tax expense in the period in which that determination is made or when tax law changes are
enacted. Conversely, if we were to determine that we would be able to realize our deferred tax assets in the future in excess of the net carrying amounts, we would decrease the recorded valuation allowance through a decrease to tax expense in the period in which that determination is made.
In the ordinary course of business there is inherent uncertainty in quantifying our income tax positions. We assess our income tax positions and record tax benefits for all years subject to examination based upon management’s evaluation of the facts, circumstances and information available at the reporting date. For those tax positions where it is more likely than not that a tax benefit will be sustained, we have recorded the largest amount of tax benefit with a greater than 50% likelihood of being realized upon ultimate settlement with a taxing authority that has full knowledge of all relevant information. For those income tax positions where it is not more likely than not that a tax benefit will be sustained, no tax benefit has been recognized in the Consolidated Financial Statements. See Notes 3, "Earnings Per Share" and 14, "Accumulated Other Comprehensive Income (Loss)" to the Consolidated Financial Statements for further discussion. Additionally, see Note 21, "Contingent Liabilities" to the Consolidated Financial Statements for discussion of administrative review proceedings with the German Tax Office.
Goodwill
We have generated goodwill as a result of our acquisitions. At the time of acquisition, we account for business acquisitions using the purchase method of accounting, in accordance with which assets acquired and liabilities assumed are recorded at their respective fair values at the acquisition date. The fair value of the consideration paid, including contingent consideration, is assigned to the assets acquired and liabilities assumed based on their respective fair values. Goodwill represents the excess of the purchase price over the estimated fair values of the assets acquired and liabilities assumed.
We review our goodwill for impairment on an annual basis at July 1 or more frequently if events or a change in circumstances indicate that the carrying amount may not be recoverable. We test goodwill for impairment at a level within the Company referred to as the reporting unit, which is one level below the business segment level. We have determined there to be three reporting units within each business segment.
In accordance with Accounting Standards Codification (“ASC”) 350, Intangibles – Goodwill and Other, we initially perform a qualitative assessment (commonly known as “step zero”) to determine whether further impairment testing is necessary before performing the two-step test. The qualitative assessment requires judgments by management about economic conditions including the entity’s operating environment, its industry and other market considerations, entity-specific events related to financial performance or loss of key personnel and other events that could impact the reporting unit. If management concludes, based on assessment of relevant events, facts and circumstances, that it is more likely than not that a reporting unit’s fair value is greater than its carrying value, no further impairment testing is required. If we determine, based on this assessment, that it is more likely than not that the fair value of the reporting unit is less than its carrying value, we perform a quantitative goodwill impairment test by comparing the reporting unit’s fair value with its carrying value. An impairment loss is recognized for the amount by which the reporting unit’s carrying value exceeds its fair value, up to the total amount of goodwill allocated to the reporting unit. No impairment loss is recognized if the fair value of the reporting exceeds its carrying value.
We completed the annual goodwill impairment test for all of our reporting units as of July 1, 2020 and determined that no adjustment to goodwill was necessary as the fair value of each reporting unit was significantly in excess of the carrying value of each reporting unit.
Contingent Liabilities
Otis is party to litigation related to a number of matters as described in Note 21, "Contingent Liabilities" to the Consolidated Financial Statements. In particular, they may include risks associated with contractual, regulatory and other matters, which may arise in the ordinary course of business. The outcome of these matters may have a material effect on the financial position, results of operations or cash flows. Management regularly analyzes current information about these matters and accrues for contingent losses that are probable and reasonably estimable. To assess the exposure to potential liability, we consult with relevant internal and external counsel. In making the decision regarding the need for loss accruals, management considers the degree of probability of an unfavorable outcome and the ability to make a sufficiently reliable estimate of the amount of loss. See Part I, Item 1A, "Risk Factors" in the Form 10-K for further discussion.
Employee Benefit Plans
We sponsor domestic and international defined benefit pension and other postretirement plans. Major assumptions used in the accounting for these employee benefit plans include the discount rate, expected return on plan assets, rate of increase in employee compensation levels and mortality rates. Assumptions are determined based on company data and appropriate market indicators, and are evaluated each year at December 31. A change in any of these assumptions would have an effect on net periodic pension and postretirement benefit costs reported in the Consolidated Financial Statements.
In the following table, we show the sensitivity of our pension and other postretirement benefit plan liabilities and net periodic cost to a 25 basis point change in the discount rates for benefit obligations, as of December 31, 2020:
| (dollars in millions) | Increase in Discount Rate of 25 bps | Decrease in Discount Rate of 25 bps | |||||||||
| Pension plans | |||||||||||
| Projected benefit obligation | $ | (33) | $ | 34 | |||||||
| Net periodic pension (benefit) cost | (1) | 2 | |||||||||
The impact on the accumulated postretirement benefit obligation and on the net periodic postretirement (benefit) cost is less than $1 million.
Pension expense is also sensitive to changes in the expected long-term rate of asset return. An increase or decrease of 25 basis points in the expected long-term rate of asset return would have decreased or increased 2020 pension expense by approximately $2 million.
The weighted-average discount rates used to measure pension liabilities and costs utilize each plan’s specific cash flows and are then compared to high-quality bond indices for reasonableness. Global market interest rates decreased in 2020 as compared with 2019, and, as a result, the weighted-average discount rate used to measure pension liabilities was 1.05% in 2020 and 1.50% in 2019.
See Note 13, "Employee Benefit Plans" to the Consolidated Financial Statements for further discussion.
Off-Balance Sheet Arrangements and Contractual Obligations
We extend a variety of financial guarantees to third parties in support of our business. We also have obligations arising from environmental, health and safety, tax and employment matters. Circumstances that could cause the contingent obligations and liabilities arising from these arrangements to come to fruition include changes in the underlying transaction, non-performance under a contract or deterioration in the financial condition of the guaranteed party.
Below is a summary of our contractual obligations and commitments as of December 31, 2020:
| Payments Due by Period | ||||||||||||||||||||||||||||||||
| (dollars in millions) | Total | 2021 | 2022-2023 | 2024-2025 | Thereafter | |||||||||||||||||||||||||||
| Long-term debt - principal | $ | 5,305 | $ | — | $ | 503 | $ | 1,302 | $ | 3,500 | ||||||||||||||||||||||
| Long-term debt - future interest | 1,770 | 130 | 256 | 237 | 1,147 | |||||||||||||||||||||||||||
| Purchase obligations | 1,194 | 935 | 181 | 67 | 11 | |||||||||||||||||||||||||||
| Other long-term liabilities | 406 | 81 | 70 | 131 | 124 | |||||||||||||||||||||||||||
| Total contractual obligations | $ | 8,675 | $ | 1,146 | $ | 1,010 | $ | 1,737 | $ | 4,782 | ||||||||||||||||||||||
Purchase obligations include amounts committed for the purchase of goods and services under legally enforceable contracts or purchase orders. Where it is not practically feasible to determine the legally enforceable portion of our obligation under certain of our long-term purchase agreements, we include additional expected purchase obligations beyond what may be legally enforceable. In connection with the Separation and transition to a standalone public company, we entered into contractual purchase commitments with suppliers, service vendors, and various transition services agreements to support our information technology that are either necessary to operate as a standalone business or are resulting from implementing
strategic initiatives.
Other long-term liabilities primarily include amounts on our December 31, 2020 Consolidated Balance Sheet representing obligations under product service and warranty policies, estimated remediation costs, expected contributions under employee benefit programs and $239 million of payables to RTX for reimbursement of tax payments RTX is responsible to pay after the Separation pursuant to the TMA. The timing of expected cash flows associated with these obligations is based upon management's estimates over the terms of these agreements and is largely based upon historical experience.
The above table excludes unrecognized tax benefits of $397 million, the timing of which is uncertain to become payable. See Note 15, "Income Taxes" to the Consolidated Financial Statements for additional discussion on unrecognized tax benefits.
Market Risk and Risk Management
We are exposed to fluctuations in foreign currency exchange rates and commodity prices. To manage certain of those exposures, we use derivative instruments, including forward contracts. Derivative instruments utilized by us in our hedging activities are viewed as risk management tools, involve relatively little complexity and are not used for trading or speculative purposes. We diversify the counterparties used and monitor the concentration of risk to limit our counterparty exposure.
We have evaluated our exposure to changes in foreign currency exchange rates and interest rates in our market risk sensitive instruments, which are primarily cash, debt and derivative instruments, using a value at risk analysis. Based on a 95% confidence level and one-day holding period, at December 31, 2020, the potential loss in fair value on our market risk sensitive instruments was not material in relation to our financial position, results of operations or cash flows. Our calculated value at risk exposure represents an estimate of reasonably possible net losses based on volatilities and correlations, and is not necessarily indicative of actual results. Additionally, any losses or gains on derivative instruments would be mostly offset by corresponding gains or losses in the remeasurement of the underlying transactions being hedged.
Refer to Note 2, "Summary of Significant Accounting Policies", Note 10, "Borrowings and Lines of Credit" and Note 17, "Financial Instruments" to the Consolidated Financial Statements for additional discussion of foreign currency exchange, interest rates and financial instruments, including the aggregate notional amount of our outstanding foreign currency hedges.
Foreign Currency Exposures
The value of certain foreign currencies as compared to the U.S. Dollar may impact Otis’ financial results. We have a high volume of foreign currency exposures that result from our international sales, purchases, investments and other international transactions. International sales were approximately $9.3 billion, $9.5 billion and $9.5 billion in 2020, 2019 and 2018, respectively. We manage foreign currency exposures that are associated with committed foreign currency purchases and sales as well as foreign currency denominated assets and liabilities that are created in the ordinary course of business. More than insignificant exposures, that cannot be naturally offset, are generally hedged with foreign currency derivatives.
For our non-U.S. based entities, a substantial portion of revenues are generated and costs are incurred in local currencies. We transact business in various foreign currencies. which exposes our cash flows and earnings to changes in foreign currency exchange rates. We periodically enter into sales contracts denominated in currencies other than the functional currency of the parties to the transaction, which can create foreign exchange exposure. While the objective of the hedging program is to minimize the foreign currency exchange impact on operating results, there are typically variances between the hedging gains or losses and the translational impact due to the length of hedging contracts, changes in the sales profile, volatility in the exchange rates and other such operational considerations. Otis does not enter into hedging contracts for speculative purposes.
As discussed in Note 17, "Financial Instruments" to the Consolidated Financial Statements as of December 31, 2020, we have €420 million of euro-denominated commercial paper, which qualifies as a net investment hedge against our investments in European businesses. As of December 31, 2020, the net investment hedge is deemed to be effective.
Interest Rate Risk
Our long-term debt portfolio primarily consists of fixed-rate instruments. For any variable rate debt, interest rate changes in the London Interbank Offered Rate ("LIBOR") will impact future earnings and cash flows. From time to time, we may hedge floating rates using interest rate swaps. The hedges would be designated as fair value hedges and the gains and losses on the swaps would be reported in interest expense, reflecting that portion of interest expense at a variable rate.
Cautionary Note Concerning Factors That May Affect Future Results
This 2020 Annual Report to Shareholders (2020 Annual Report) contains statements which, to the extent they are not statements of historical or present fact, constitute “forward-looking statements” under the securities laws. From time to time, oral or written forward-looking statements may also be included in other information released to the public. These forward-looking statements are intended to provide management’s current expectations or plans for Otis’ future operating and financial performance, based on assumptions currently believed to be valid. Forward-looking statements can be identified by the use of words such as “believe,” “expect,” “expectations,” “plans,” “strategy,” “prospects,” “estimate,” “project,” “target,” “anticipate,” “will,” “should,” “see,” “guidance,” “outlook,” “confident” and other words of similar meaning in connection with a discussion of future operating or financial performance or the Separation. Forward-looking statements may include, among other things, statements relating to future sales, earnings, cash flow, results of operations, uses of cash, dividends, share repurchases, tax rates and other measures of financial performance or potential future plans, strategies or transactions of Otis following the Separation, including the estimated costs associated with the Separation and other statements that are not historical facts. All forward-looking statements involve risks, uncertainties and other factors that may cause actual results to differ materially from those expressed or implied in the forward-looking statements. For those statements, Otis claims the protection of the safe harbor for forward-looking statements contained in the U.S. Private Securities Litigation Reform Act of 1995. Such risks, uncertainties and other factors include, without limitation:
-
the effect of economic conditions in the industries and markets in which Otis and its businesses operate in the U.S. and globally and any changes therein, including financial market conditions, fluctuations in commodity prices, interest rates and foreign currency exchange rates, levels of end market demand in construction, the impact of weather conditions, pandemic health issues (including COVID-19 and its effects, among other things, on global supply, demand, and distribution disruptions as the coronavirus outbreak continues and results in an increasingly prolonged period of travel, commercial and/or other similar restrictions and limitations), natural disasters and the financial condition of Otis’ customers and suppliers;
-
challenges in the development, production, delivery, support, performance and realization of the anticipated benefits of advanced technologies and new products and services;
-
future levels of indebtedness, capital spending and research and development spending;
-
future availability of credit and factors that may affect such availability, including credit market conditions and Otis’ capital structure;
-
the timing and scope of future repurchases of Otis’ common stock ("Common Stock"), which, if commenced, may be suspended at any time due to various factors, including market conditions and the level of other investing activities and uses of cash;
-
delays and disruption in delivery of materials and services from suppliers;
-
cost reduction or containment actions, restructuring costs and related savings and other consequences thereof;
-
new business and investment opportunities;
-
the anticipated benefits of moving away from diversification and balance of operations across product lines, regions and industries;
-
the outcome of legal proceedings, investigations and other contingencies;
-
pension plan assumptions and future contributions;
-
the impact of the negotiation of collective bargaining agreements and labor disputes;
-
the effect of changes in political conditions in the U.S., including the new U.S. Administration, and other countries in which Otis and its businesses operate, including the United Kingdom’s recent withdrawal from the European Union, on general market conditions, global trade policies and currency exchange rates in the near term and beyond;
-
the effect of changes in tax, environmental, regulatory (including among other things import/export) and other laws and regulations in the U.S. and other countries in which Otis and its businesses operate, including changes as a result of the new U.S. Administration;
-
the ability of Otis to retain and hire key personnel;
-
the scope, nature, impact or timing of acquisition and divestiture activity, including among other things integration of acquired businesses into existing businesses and realization of synergies and opportunities for growth and innovation and incurrence of related costs;
-
the expected benefits of the Separation and the timing thereof;
-
a determination by the Internal Revenue Service and other tax authorities that the distribution or certain related transactions should be treated as taxable transactions;
-
risks associated with indebtedness incurred as a result of financing transactions undertaken in connection with the Separation;
-
the risk that dis-synergy costs, costs of restructuring transactions and other costs incurred in connection with the Separation will exceed Otis’ estimates; and
-
the impact of the Separation on Otis’ businesses, resources, systems, procedures and controls, diversion of management’s attention and the impact on relationships with customers, suppliers, employees and other business counterparties.
In addition, this 2020 Annual Report includes important information as to risks, uncertainties and other factors that may cause actual results to differ materially from those expressed or implied in the forward-looking statements. See the "Notes to Consolidated Financial Statements" under the heading "Note 1: Description of Business" and "Note 22: Segment Financial Data" and the section titled "Management's Discussion and Analysis of Financial Condition and Results of Operations" under the headings "Business Overview," "Results of Operations," "Liquidity and Financial Condition," and "Critical Accounting Estimates." Our Annual Report on Form 10-K for 2020 also includes important information as to these factors in "Item 1. Business" under the headings "General," "Description of Business by Segment" and "Other Matters Relating to Our Business as a Whole," and in "Item 1A. Risk Factors". We undertake no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, future events or otherwise, except as required by applicable law. Additional information as to factors that may cause actual results to differ materially from those expressed or implied in the forward-looking statements is disclosed from time to time in our other filings with the SEC.
Management's Report on Internal Control over Financial Reporting
The management of Otis is responsible for establishing and maintaining adequate internal control over financial reporting. Internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external reporting purposes in accordance with accounting principles generally accepted in the United States of America. Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements.
Management has assessed the effectiveness of Otis' internal control over financial reporting as of December 31, 2020. In making its assessment, management has utilized the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission in Internal Control - Integrated Framework (2013). Management concluded that based on its assessment, Otis' internal control over financial reporting was effective as of December 31, 2020. The effectiveness of Otis' internal control over financial reporting, as of December 31, 2020, has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report which is included herein.
| OTIS WORLDWIDE CORPORATION (Registrant) | |||||
| by: | /s/ JUDITH F. MARKS | ||||
| Judith F. Marks | |||||
| President and Chief Executive Officer | |||||
| by: | /s/ RAHUL GHAI | ||||
| Rahul Ghai | |||||
| Executive Vice President and Chief Financial Officer | |||||
| by: | /s/ MICHAEL P. RYAN | ||||
| Michael P. Ryan | |||||
| Vice President and Chief Accounting Officer | |||||
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Shareholders of Otis Worldwide Corporation
Opinions on the Financial Statements and Internal Control over Financial Reporting
We have audited the accompanying consolidated balance sheets of Otis Worldwide Corporation and its subsidiaries (the “Company”) as of December 31, 2020 and 2019, and the related consolidated statements of operations, of comprehensive income, of changes in equity and of cash flows for each of the three years in the period ended December 31, 2020, including the related notes (collectively referred to as the “consolidated financial statements”). We also have audited the Company's internal control over financial reporting as of December 31, 2020, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, 2020 and 2019, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2020 in conformity with accounting principles generally accepted in the United States of America. Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2020, based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
Basis for Opinions
The Company's management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management’s Report on Internal Control over Financial Reporting. Our responsibility is to express opinions on the Company’s consolidated financial statements and on the Company's internal control over financial reporting based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud, and whether effective internal control over financial reporting was maintained in all material respects.
Our audits of the consolidated financial statements included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.
Definition and Limitations of Internal Control over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Critical Audit Matters
The critical audit matter communicated below is a matter arising from the current period audit of the consolidated financial statements that was communicated or required to be communicated to the audit committee and that (i) relates to accounts or disclosures that are material to the consolidated financial statements and (ii) involved our especially challenging, subjective, or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
Revenue Recognition - Estimated Costs at Completion for New Equipment Contracts
As described in Notes 2 and 22, to the consolidated financial statements, the Company recognized $5.4 billion of revenue from new equipment contracts for the year ended December 31, 2020. For new equipment contracts, equipment and installation are typically procured in a single contract providing the customer with a complete installed elevator or escalator unit. The combination of equipment and installation promises are typically a single performance obligation. For these performance obligations, revenue is typically recognized over time using costs incurred to date relative to total estimated costs at completion to measure progress. As disclosed by management, contract costs are usually incurred over a period of time, which can be several years, and the estimation of these costs requires management’s judgment. The long-term nature of the contracts, the complexity of the products and the scale of the projects can affect management’s ability to estimate costs precisely. Management reviews cost estimates on significant new equipment contracts on a quarterly basis and, for others, no less frequently than annually or when circumstances change and warrant a modification to a previous estimate. Management records changes in contract estimates using the cumulative catch-up method and reviews changes in contract estimates for their impact on net sales or operating profit in the consolidated financial statements. Contract costs included in the calculation are comprised of labor, materials, subcontractors’ costs or other direct costs and indirect costs, which include indirect labor costs.
The principal considerations for our determination that performing procedures relating to revenue recognition - estimated costs at completion for new equipment contracts is a critical audit matter are the significant judgment by management to determine the estimated costs at contract completion, which in turn led to significant auditor judgment, subjectivity and effort in performing procedures and evaluating audit evidence related to the estimated expected labor and indirect labor costs used in the development of estimated costs at contract completion.
Addressing the matter involved performing procedures and evaluating audit evidence in connection with forming our overall opinion on the consolidated financial statements. These procedures included testing the effectiveness of controls relating to the revenue recognition process, including controls over the determination of the estimated costs at contract completion and development of the significant assumptions related to the estimated expected labor and indirect labor costs. These procedures also included, among others, evaluating and testing management’s process for developing and modifying estimated costs at contract completion for a sample of contracts, which included evaluating the reasonableness of significant assumptions related to the estimated expected labor and indirect labor costs considered by management specific to each contract. Evaluating the reasonableness of the estimated expected labor and indirect labor costs involved assessing management’s ability to reasonably estimate costs at completion by (i) testing costs incurred to date and obtaining a sample of executed contracts and related change orders, (ii) performing a comparison of the originally estimated and actual costs incurred on similar completed equipment contracts, and (iii) evaluating the timely identification of circumstances that may warrant a modification to estimated total cost to complete.
/s/ PricewaterhouseCoopers LLP
Hartford, Connecticut
February 5, 2021
We have served as the Company’s auditor since 2019.
OTIS WORLDWIDE CORPORATION
CONSOLIDATED STATEMENTS OF OPERATIONS
| (dollars in millions, except per share amounts) | 2020 | 2019 | 2018 | |||||||||||||||||
| Net sales: | ||||||||||||||||||||
| Product sales | $ | 5,371 | $ | 5,648 | $ | 5,596 | ||||||||||||||
| Service sales | 7,385 | 7,470 | 7,319 | |||||||||||||||||
| 12,756 | 13,118 | 12,915 | ||||||||||||||||||
| Costs and expenses: | ||||||||||||||||||||
| Cost of products sold | 4,439 | 4,640 | 4,586 | |||||||||||||||||
| Cost of services sold | 4,538 | 4,652 | 4,603 | |||||||||||||||||
| Research and development | 152 | 163 | 181 | |||||||||||||||||
| Selling, general and administrative | 1,924 | 1,810 | 1,735 | |||||||||||||||||
| 11,053 | 11,265 | 11,105 | ||||||||||||||||||
| Other income (expense), net | (64) | (39) | 25 | |||||||||||||||||
| Operating profit | 1,639 | 1,814 | 1,835 | |||||||||||||||||
| Non-service pension cost (benefit) | 6 | (33) | (44) | |||||||||||||||||
| Interest expense (income), net | 122 | (14) | (14) | |||||||||||||||||
| Net income before income taxes | 1,511 | 1,861 | 1,893 | |||||||||||||||||
| Income tax expense | 455 | 594 | 683 | |||||||||||||||||
| Net income | 1,056 | 1,267 | 1,210 | |||||||||||||||||
| Less: Noncontrolling interest in subsidiaries' earnings | 150 | 151 | 161 | |||||||||||||||||
| Net income attributable to common shareholders | $ | 906 | $ | 1,116 | $ | 1,049 | ||||||||||||||
| Earnings per share (Note 3): | ||||||||||||||||||||
| Basic | $ | 2.09 | $ | 2.58 | $ | 2.42 | ||||||||||||||
| Diluted | $ | 2.08 | $ | 2.58 | $ | 2.42 | ||||||||||||||
| Weighted average number of shares outstanding | ||||||||||||||||||||
| Basic shares | 433.2 | 433.1 | 433.1 | |||||||||||||||||
| Diluted shares | 434.6 | 433.1 | 433.1 |
See accompanying Notes to Consolidated Financial Statements
OTIS WORLDWIDE CORPORATION
CONSOLIDATED STATEMENTS OF COMPREHENSIVE INCOME
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||||||||||||||
| Net income | $ | 1,056 | $ | 1,267 | $ | 1,210 | |||||||||||||||||||||||
| Other comprehensive income (loss): | |||||||||||||||||||||||||||||
| Foreign currency translation adjustments, net of tax | 8 | (26) | (126) | ||||||||||||||||||||||||||
| Pension and postretirement benefit plan adjustments: | |||||||||||||||||||||||||||||
| Net actuarial gain (loss) | (43) | (28) | (37) | ||||||||||||||||||||||||||
| Prior service credit | — | — | 1 | ||||||||||||||||||||||||||
| Amortization of actuarial loss and prior service credit | 15 | 9 | 11 | ||||||||||||||||||||||||||
| Other | (19) | (22) | 5 | ||||||||||||||||||||||||||
| (47) | (41) | (20) | |||||||||||||||||||||||||||
| Tax benefit (expense) | 11 | 9 | 4 | ||||||||||||||||||||||||||
| Pension and postretirement benefit plan adjustments, net of tax | (36) | (32) | (16) | ||||||||||||||||||||||||||
| Change in unrealized cash flow hedging: | |||||||||||||||||||||||||||||
| Unrealized cash flow hedging gain (loss) | 10 | (3) | — | ||||||||||||||||||||||||||
| Adjustment for net (gain) loss realized and included in net income | (3) | — | — | ||||||||||||||||||||||||||
| Change in unrealized cash flow hedging, net of tax | 7 | (3) | — | ||||||||||||||||||||||||||
| Other comprehensive income (loss), net of tax | (21) | (61) | (142) | ||||||||||||||||||||||||||
| Comprehensive income | 1,035 | 1,206 | 1,068 | ||||||||||||||||||||||||||
| Less: Comprehensive income attributable to noncontrolling interest | (186) | (140) | (140) | ||||||||||||||||||||||||||
| Comprehensive income attributable to common shareholders | $ | 849 | $ | 1,066 | $ | 928 | |||||||||||||||||||||||
See accompanying Notes to Consolidated Financial Statements
OTIS WORLDWIDE CORPORATION
CONSOLIDATED BALANCE SHEETS
| (amounts in millions, except par value) | 2020 | 2019 | |||||||||
| Assets | |||||||||||
| Cash and cash equivalents | $ | 1,782 | $ | 1,446 | |||||||
| Accounts receivable (net of allowance for expected credit losses of $161 and $83) | 3,148 | 2,861 | |||||||||
| Contract assets | 458 | 529 | |||||||||
| Inventories, net | 659 | 571 | |||||||||
| Other current assets | 446 | 251 | |||||||||
| Total Current Assets | 6,493 | 5,658 | |||||||||
| Future income tax benefits | 334 | 373 | |||||||||
| Fixed assets, net | 774 | 721 | |||||||||
| Operating lease right-of-use assets | 542 | 535 | |||||||||
| Intangible assets, net | 484 | 490 | |||||||||
| Goodwill | 1,773 | 1,647 | |||||||||
| Other assets | 310 | 263 | |||||||||
| Total Assets | $ | 10,710 | $ | 9,687 | |||||||
| Liabilities and (Deficit) Equity | |||||||||||
| Short-term borrowings | $ | 701 | $ | 34 | |||||||
| Accounts payable | 1,453 | 1,331 | |||||||||
| Accrued liabilities | 1,977 | 1,739 | |||||||||
| Contract liabilities | 2,542 | 2,270 | |||||||||
| Total Current Liabilities | 6,673 | 5,374 | |||||||||
| Long-term debt | 5,262 | 5 | |||||||||
| Future pension and postretirement benefit obligations | 654 | 590 | |||||||||
| Operating lease liabilities | 367 | 386 | |||||||||
| Future income tax obligations | 321 | 695 | |||||||||
| Other long-term liabilities | 634 | 311 | |||||||||
| Total Liabilities | 13,911 | 7,361 | |||||||||
| Commitments and contingent liabilities (Note 21) | |||||||||||
| Redeemable noncontrolling interest | 83 | 95 | |||||||||
| Shareholders' (Deficit) Equity: | |||||||||||
| Preferred Stock, $0.01 par value, 125 shares authorized; None issued or outstanding | — | — | |||||||||
| Common Stock and additional paid-in capital, $0.01 par value, 2,000 shares authorized; 433.4 shares issued and outstanding | 59 | — | |||||||||
| Accumulated deficit | (3,076) | — | |||||||||
| UTC Net Investment | — | 2,458 | |||||||||
| Accumulated other comprehensive income (loss) | (815) | (758) | |||||||||
| Total Shareholders' (Deficit) Equity | (3,832) | 1,700 | |||||||||
| Noncontrolling interest | 548 | 531 | |||||||||
| Total (Deficit) Equity | (3,284) | 2,231 | |||||||||
| Total Liabilities and (Deficit) Equity | $ | 10,710 | $ | 9,687 |
See accompanying Notes to Consolidated Financial Statements
OTIS WORLDWIDE CORPORATION
CONSOLIDATED STATEMENTS OF CHANGES IN EQUITY
| (dollars in millions, except per share amounts) | 2020 | 2019 | 2018 | |||||||||||||||||
| Total (Deficit) Equity at January 1 | $ | 2,231 | $ | 2,106 | $ | 2,532 | ||||||||||||||
| Common Stock and Additional Paid-In Capital | ||||||||||||||||||||
| Balance at January 1 | — | — | — | |||||||||||||||||
| Issuance of common stock (a) | 4 | — | — | |||||||||||||||||
| Stock-based compensation | 52 | — | — | |||||||||||||||||
| Common Stock issued under employee plans | 3 | — | — | |||||||||||||||||
| Balance at December 31 | 59 | — | — | |||||||||||||||||
| Accumulated Deficit | ||||||||||||||||||||
| Balance at January 1 | — | — | — | |||||||||||||||||
| Reclassification of UTC Net Investment (Deficit) (a) | (3,556) | — | — | |||||||||||||||||
| Net income | 741 | — | — | |||||||||||||||||
| Cash dividends declared ($0.60, $0.00 and $0.00 per common share) | (260) | — | — | |||||||||||||||||
| Acquisitions, disposals and other changes in noncontrolling interest | 4 | — | — | |||||||||||||||||
| Other | (5) | — | — | |||||||||||||||||
| Balance at December 31 | (3,076) | — | — | |||||||||||||||||
| UTC Net Investment (Deficit) | ||||||||||||||||||||
| Balance at January 1 | 2,458 | 2,277 | 2,552 | |||||||||||||||||
| Net transfers (to) from UTC and Separation-related transactions | (6,150) | (935) | (1,274) | |||||||||||||||||
| Net income | 165 | 1,116 | 1,049 | |||||||||||||||||
| Acquisitions, disposals and other changes in noncontrolling interest | — | — | (1) | |||||||||||||||||
| Adoption of credit loss standard, net of tax (Note 6) | (25) | — | — | |||||||||||||||||
| Adoption of revenue standard, net of tax (Note 2) | — | — | (49) | |||||||||||||||||
| Issuance of common stock and reclassification of UTC Net Investment (Deficit) (a) | 3,552 | — | — | |||||||||||||||||
| Balance at December 31 | — | 2,458 | 2,277 | |||||||||||||||||
| Accumulated Other Comprehensive Income (Loss) | ||||||||||||||||||||
| Balance at January 1 | (758) | (708) | (587) | |||||||||||||||||
| Other comprehensive income (loss), net of tax | (57) | (50) | (121) | |||||||||||||||||
| Balance at December 31 | (815) | (758) | (708) | |||||||||||||||||
| Noncontrolling Interest | ||||||||||||||||||||
| Balance at January 1 | 531 | 537 | 567 | |||||||||||||||||
| Net income | 150 | 151 | 161 | |||||||||||||||||
| Other comprehensive income (loss), net of tax | 38 | (8) | (13) | |||||||||||||||||
| Dividends attributable to noncontrolling interest | (147) | (163) | (173) | |||||||||||||||||
| Acquisitions, disposals and other changes in noncontrolling interest | (23) | 7 | (1) | |||||||||||||||||
| Redeemable noncontrolling interest in subsidiaries earnings | (1) | 7 | (4) | |||||||||||||||||
| Balance at December 31 | 548 | 531 | 537 | |||||||||||||||||
| Total (Deficit) Equity at December 31 | $ | (3,284) | $ | 2,231 | $ | 2,106 | ||||||||||||||
| Redeemable Noncontrolling Interest | ||||||||||||||||||||
| Balance at January 1 | $ | 95 | $ | 109 | $ | 131 | ||||||||||||||
| Redeemable noncontrolling interest in subsidiaries' earnings | 1 | (7) | 4 | |||||||||||||||||
| Other comprehensive income (loss), net of tax | (2) | (3) | (8) | |||||||||||||||||
| Acquisitions, disposals and other changes in redeemable noncontrolling interest | (13) | — | (11) | |||||||||||||||||
| Changes in redeemable noncontrolling interest redemption value | 2 | (4) | (7) | |||||||||||||||||
| Balance at December 31 | $ | 83 | $ | 95 | $ | 109 |
(a) Upon Separation from UTC
See accompanying Notes to Consolidated Financial Statements
OTIS WORLDWIDE CORPORATION
CONSOLIDATED STATEMENTS OF CASH FLOWS
| (dollars in millions) | 2020 | 2019 | 2018 | |||||||||||||||||
| Operating Activities: | ||||||||||||||||||||
| Net income | $ | 1,056 | $ | 1,267 | $ | 1,210 | ||||||||||||||
| Adjustments to reconcile net income to net cash flows provided by operating activities, net of acquisitions: | ||||||||||||||||||||
| Depreciation and amortization | 191 | 180 | 190 | |||||||||||||||||
| Deferred income tax benefit | (51) | (8) | 127 | |||||||||||||||||
| Stock compensation cost | 63 | 37 | 38 | |||||||||||||||||
| Loss on fixed asset impairment | 71 | — | — | |||||||||||||||||
| Loss on disposal of business | — | 26 | — | |||||||||||||||||
| Change in: | ||||||||||||||||||||
| Accounts receivable, net | (163) | (191) | (196) | |||||||||||||||||
| Contract assets and liabilities, current | 282 | 97 | 9 | |||||||||||||||||
| Inventories, net | (76) | 60 | 24 | |||||||||||||||||
| Other current assets | 28 | 30 | (11) | |||||||||||||||||
| Accounts payable | 20 | 6 | 124 | |||||||||||||||||
| Accrued liabilities | (14) | (34) | 42 | |||||||||||||||||
| Pension contributions | (64) | (32) | (34) | |||||||||||||||||
| Other operating activities, net | 137 | 31 | 27 | |||||||||||||||||
| Net cash flows provided by operating activities | 1,480 | 1,469 | 1,550 | |||||||||||||||||
| Investing Activities: | ||||||||||||||||||||
| Capital expenditures | (183) | (145) | (172) | |||||||||||||||||
| Investments in businesses, net of cash acquired (Note 9) | (53) | (47) | (50) | |||||||||||||||||
| Investments in equity securities | (51) | — | — | |||||||||||||||||
| Receipts (payments) on settlements of derivative contracts | (69) | (5) | 3 | |||||||||||||||||
| Other investing activities, net | 3 | (6) | 18 | |||||||||||||||||
| Net cash flows used in investing activities | (353) | (203) | (201) | |||||||||||||||||
| Financing Activities: | ||||||||||||||||||||
| Proceeds from issuance of long-term debt | 6,300 | — | — | |||||||||||||||||
| Payment of long-term debt issuance costs | (43) | — | — | |||||||||||||||||
| Repayment of long-term debt | (1,000) | — | — | |||||||||||||||||
| Increase in short-term borrowings, net | 647 | 6 | 11 | |||||||||||||||||
| Net transfers to UTC | (6,330) | (972) | (1,312) | |||||||||||||||||
| Dividends paid on Common Stock | (260) | — | — | |||||||||||||||||
| Dividends paid to noncontrolling interest | (149) | (163) | (173) | |||||||||||||||||
| Other financing activities, net | (9) | (4) | (23) | |||||||||||||||||
| Net cash flows used in financing activities | (844) | (1,133) | (1,497) | |||||||||||||||||
| Effect of foreign exchange rate changes on cash and cash equivalents | 59 | (20) | (77) | |||||||||||||||||
| Net increase in cash and cash equivalents | 342 | 113 | (225) | |||||||||||||||||
| Cash, cash equivalents and restricted cash, beginning of year | 1,459 | 1,346 | 1,571 | |||||||||||||||||
| Cash, cash equivalents and restricted cash, end of year | 1,801 | 1,459 | 1,346 | |||||||||||||||||
| Less: Restricted cash | 19 | 13 | 17 | |||||||||||||||||
| Cash and cash equivalents, end of period | $ | 1,782 | $ | 1,446 | $ | 1,329 | ||||||||||||||
| Supplemental cash flow information: | ||||||||||||||||||||
| Interest paid (including related party of $0, $18 and $20) | $ | 81 | $ | 18 | $ | 20 | ||||||||||||||
| Income taxes paid, net of (refunds) (including related party of $(15), $255 and $186) | 561 | 632 | 607 |
See accompanying Notes to Consolidated Financial Statements
OTIS WORLDWIDE CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
Note 1: Business Overview and Separation from United Technologies Corporation
Otis (as defined below) is the world’s largest elevator and escalator manufacturing, installation and service company. Our operations are classified into two segments: New Equipment and Service. Through the New Equipment segment, we design, manufacture, sell and install a wide range of passenger and freight elevators, as well as escalators and moving walkways, for residential and commercial building and infrastructure projects. The Service segment provides maintenance and repair services for both our products and those of other manufacturers, and provides modernization services to upgrade elevators and escalators.
On November 26, 2018, United Technologies Corporation, subsequently renamed to Raytheon Technologies Corporation on April 3, 2020 ("UTC" or "RTX", as applicable), announced its intention to spin-off its Otis reportable segment and its Carrier reportable segment into two separate publicly-traded companies (the "Separation"). On April 3, 2020, the Company became an independent publicly-traded company through a pro-rata distribution of 0.5 shares of Common Stock for every share of UTC common stock held at the close of business on the record date of March 19, 2020 ("Distribution"). Otis began to trade as a separate public company (New York Stock Exchange ("NYSE"): OTIS) on April 3, 2020.
Unless the context otherwise requires, references to "Otis", "we", "us", "our" and "the Company" refer to (i) Otis Worldwide Corporation's business ("Business") prior to the Separation and (ii) Otis Worldwide Corporation and its subsidiaries following the Separation, as applicable. References to "UTC" relate to pre-Separation matters, and references to "RTX" relate to post-Separation matters.
The Separation was completed pursuant to a Separation and Distribution Agreement ("Separation Agreement") and other agreements with UTC related to the Separation, including but not limited to a transition services agreement (the "Transition Services Agreement" or "TSA"), a tax matters agreement (the "Tax Matters Agreement" or "TMA"), an employee matters agreement (the "Employee Matters Agreement" or "EMA") and an intellectual property agreement (the "Intellectual Property Agreement"). For further discussion on these agreements, see Note 5, "Related Parties".
Note 2: Summary of Significant Accounting Policies
Principles of Consolidation and Basis of Presentation. Prior to the Separation on April 3, 2020, our historical financial statements were prepared on a standalone combined basis and were derived from the consolidated financial statements and accounting records of UTC. For the period subsequent to April 3, 2020, our financial statements are presented on a consolidated basis as the Company became a standalone public company (collectively, the financial statements for all periods presented, including the historical results of the Company prior to April 3, 2020, are now referred to as "Consolidated Financial Statements" to reflect this change). They have been prepared in accordance with the instructions to Form 10-K.
Prior to the Separation on April 3, 2020, the Consolidated Statements of Operations included all revenues and costs directly attributable to Otis, including costs for facilities, functions and services used by Otis. Costs for certain functions and services performed by centralized UTC organizations were directly charged to Otis based on specific identification when possible or based on a reasonable allocation driver such as net sales, headcount, usage or other allocation methods. All charges and allocations for facilities, functions and services performed by UTC organizations have been deemed settled in cash by Otis to UTC in the period in which the cost was recorded on the Consolidated Statements of Operations. Current and deferred income taxes were determined based on the standalone results of Otis. However, because the Company was included in our former parent UTC’s tax group in certain jurisdictions, the Company's actual tax balances may differ from those reported. The Company's portion of its domestic income taxes and certain income taxes for jurisdictions outside the U.S. are deemed to have been settled in the period the related tax expense was recorded prior to the Separation.
The Consolidated Financial Statements include the accounts of Otis and its controlled subsidiaries, as well as entities where Otis has a variable interest and is the primary beneficiary as defined by Financial Accounting Standards Board (“FASB”) Accounting Standards Codification (“ASC”) Topic 810, Consolidation. The factors we use to determine the primary beneficiary of a variable interest entity ("VIE") may include decision authority, control over management of day-to-day operations and the amount of our equity investments in relation to others' investments.
All significant intracompany accounts and transactions within the Company have been eliminated in the preparation of the Consolidated Financial Statements. Prior to the Separation, the Consolidated Financial Statements of the Company include assets and liabilities that have been determined to be specifically or otherwise attributable to the Company.
Certain amounts for prior years have been reclassified to conform to the current year presentation, which are immaterial.
Use of Estimates. The preparation of the Consolidated Financial Statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities. In addition, estimates and assumptions may impact the disclosure of contingent assets and liabilities at the date of the financial statements, as well as the reported amounts of revenues and expenses during the reporting period. Actual results could differ from those estimates.
We assessed certain accounting matters that generally require consideration of forecasted financial information in the context of the information reasonably available to us and the unknown future impacts of coronavirus ("COVID-19") at December 31, 2020 and through the date of this report. The accounting matters assessed included, but were not limited to, our allowance for credit losses, the carrying value of our goodwill and other long-lived assets, financial assets and revenue recognition. While there was not a material impact to our Consolidated Financial Statements as of and for the year ended December 31, 2020 resulting from our assessments of these matters, future assessment of our current expectations at that time of the magnitude and duration of COVID-19, as well as other factors, could result in material impacts to our Consolidated Financial Statements in future reporting periods.
Risks and Uncertainties. In March 2020, the World Health Organization declared the outbreak of the novel strain of COVID-19, a global pandemic and recommended a number of restrictive measures to contain the spread, which were implemented to different degrees by governments across the world. As the global pandemic continues, the Company continues to closely monitor and manage the impact of the COVID-19 pandemic on its business globally. It is difficult to estimate at this time the duration and extent of the continued impact of the pandemic on the Company's business, financial position, cash flow and results of operations. The results of our operations and overall financial performance were impacted during the year ended December 31, 2020.
Due to existing conditions and uncertainty, COVID-19 could have an impact on our business, cash flow and results of operations into 2021. The extent of the impact will depend largely on future developments, which are highly uncertain, including the emergence of additional information concerning the severity of the outbreak, timing, efficacy, availability and distribution of vaccines, actions taken by government authorities to further contain the outbreak or address its impact and its longer-term impacts on the global economy, among other factors.
Cash and Cash Equivalents. Cash and cash equivalents includes cash on hand, demand deposits and short-term cash investments that are highly liquid in nature and have original maturities of three months or less. Prior to the Separation, the Company participated in UTC’s centralized cash management and financing programs. See Note 5, "Related Parties" for additional information.
On occasion, we are required to maintain cash deposits with certain banks with respect to contractual or other legal obligations. Included in Other current assets and Other assets on the Consolidated Balance Sheets is approximately $19 million and $13 million of such restricted cash as of December 31, 2020 and 2019, respectively.
Accounts Receivable. The Company records accounts receivables when the right to consideration becomes unconditional. We regularly evaluate the collectability of our accounts receivable and maintain reserves for expected credit losses. See Note 6, "Accounts Receivable, Net" for additional information on the Company's policy for evaluation of expected credit losses. We do not believe that accounts receivable represent significant concentrations of credit risk because of the diversified portfolio of individual customers and geographic areas.
Retainage and Unbilled Receivables. Current and long-term accounts receivable as of December 31, 2020 and 2019 include retainage of $61 million and $59 million, respectively, and unbilled receivables of $104 million and $108 million, respectively. Retainage represents amounts that, pursuant to the applicable contract, are not due until after project completion and acceptance by the customer. Unbilled receivables represent revenues that are earned but not currently billable to the customer under the terms of the contract. These items are expected to be billed and collected in the ordinary course of business. Unbilled receivables where we have an unconditional right to payment are included in Accounts receivable, net as of December 31, 2020 and 2019.
Customer Financing Notes Receivable. Through financing arrangements with our customers, we extend payment terms, which are generally not more than one year in duration. See Note 6, "Accounts Receivable, Net" for additional information.
Factoring. The Company may sell certain trade accounts and notes receivable to lending institutions to manage credit risk. Financial assets sold under these arrangements are excluded from Accounts receivable, net in the Company’s Consolidated Balance Sheets at the time of sale if the Company has surrendered control over the related assets. Whether control has been relinquished requires, among other things, an evaluation of relevant legal considerations and an assessment of the nature and extent of the Company’s continuing involvement with the assets transferred. Gains and losses stemming from transfers reported as sales are included in Interest expense (income), net in the accompanying Consolidated Statements of Operations.
Contract Assets and Liabilities. Contract assets and liabilities represent the difference in the timing of revenue recognition from receipt of cash from our customers and billings. Contract assets reflect revenue recognized and performance obligations satisfied in advance of customer billing. Performance obligations partially satisfied in advance of customer billings are included in Contract assets, current.
Contract liabilities relate to payments received in advance of the satisfaction of performance under the contract. We receive payments from customers based on the terms established in our contracts. See Note 4, "Revenue Recognition" for further discussion of contract assets and liabilities.
Inventories. Inventories are stated at the lower of cost or estimated realizable value and are primarily based on a first-in, first-out (“FIFO”) method. Valuation reserves for excess, obsolete and slow-moving inventory are estimated by comparing the inventory levels of individual parts to both future sales forecasts or production requirements and historical usage rates in order to identify inventory where the resale value or replacement value is less than inventoriable cost.
Fixed Assets. Fixed assets, including software capitalized for internal-use, are recorded at cost. Depreciation of fixed assets is computed over the fixed assets' useful lives on a straight-line basis, unless another systematic and rational basis is more representative of the fixed asset's pattern of use. See Note 8, "Fixed Assets" for further details of useful lives.
Internal-use software. The Company capitalizes direct costs of services used in the development of, and external software acquired for use as, internal-use software. Amounts capitalized are amortized over a period ranging from three to five years, on a straight-line basis, unless another systematic and rational basis is more representative of the software's use. Amounts are reported as a component of Machinery and equipment.
Asset Retirement Obligations. The Company records the fair value of legal obligations associated with the retirement of tangible long-lived assets in the period in which the legal obligations are determined to exist. Upon initial recognition of a liability, the Company capitalizes the cost of the asset retirement obligation by increasing the carrying amount of the related long-lived asset. Over time, the liability is adjusted for changes in its present value and the capitalized cost is depreciated over the useful life of the related asset.
Fair Value of Financial Instruments. The fair value hierarchy is based on inputs to valuation techniques that are used to measure fair value that are either observable or unobservable. Observable inputs reflect assumptions market participants would use in pricing an asset or liability based on market data obtained from independent sources, while unobservable inputs reflect a reporting entity’s pricing based upon their own market assumptions. The fair value hierarchy consists of the following three levels:
Level I – Quoted prices for identical instruments in active markets.
Level II – Quoted prices for similar instruments in active markets; quoted prices for identical or similar instruments in markets that are not active; and model-derived valuations whose inputs are observable or whose significant value drivers are observable.
Level III – Instruments whose significant value drivers are unobservable.
The carrying amount of current trade receivables, accounts payable and accrued expenses approximates fair value due to the short maturity (less than one year) of the instruments.
Equity Method Investments. Investments in which we have the ability to exercise significant influence, but do not control, are accounted for under the equity method of accounting and are included in Other assets on the Consolidated Balance Sheets. Under this method of accounting, our share of the net earnings or losses of the investee is included in Other income (expense), net in the Consolidated Statements of Operations since the activities of the investee are closely aligned with the operations of the Company. We evaluate our equity method investments whenever events or changes in circumstance indicate that the carrying amounts of such investments may be impaired. If a decline in the value of an equity method investment is determined to be other than temporary, a loss is recorded in earnings in the current period.
Business Combinations. We account for transactions that are classified as business combinations in accordance with the FASB ASC Topic 805: Business Combinations. Once a business is acquired, the fair values of the identifiable assets acquired and liabilities assumed are determined with the excess cost recorded to goodwill. As required, preliminary fair values are determined once a business is acquired, with the final determination of the fair values being completed within the one-year measurement period from the date of acquisition.
Goodwill, Intangible Assets and Long-Lived Assets. Goodwill represents costs in excess of fair values assigned to the underlying net assets of acquired businesses. Intangible assets consist of service portfolios, patents, trademarks/trade names, customer relationships and other intangible assets. Acquired intangible assets are recognized at fair value during acquisition accounting and then amortized to Cost of products and services sold and Selling, general and administrative over the applicable useful lives.
Goodwill and Indefinite-Lived Intangible Assets. Goodwill and intangible assets deemed to have indefinite lives are not amortized. Goodwill and indefinite-lived intangible assets are subject to impairment testing annually or when a triggering event occurs using the guidance and criteria described in FASB ASC Topic 350: Intangibles – Goodwill and Other. This testing compares carrying values to fair values and, when appropriate, the carrying value of these assets is reduced to fair value.
We test goodwill for impairment at a level within the Company referred to as the reporting unit, which is one level below the business segment level. When testing goodwill for impairment, the Company may first assess qualitative factors. If an initial qualitative assessment identified that it is more likely than not that the fair value of a reporting unit is less than its carrying value, additional quantitative testing is performed. The Company may also elect to skip the qualitative testing and proceed directly to the quantitative testing. If the quantitative testing indicates that goodwill is impaired, an impairment charge is recognized based on the difference between the reporting unit's carrying value and its fair value. When it is determined that a quantitative analysis is required, the Company primarily utilizes a discounted cash flow methodology to calculate the fair value of its reporting units. The Company completed its most recent annual impairment testing as of July 1, 2020, and determined that no adjustment to goodwill was necessary since the fair value of each reporting unit was significantly in excess of its respective carrying value.
Finite-Lived Intangible Assets and Long-Lived Assets. Useful lives of finite-lived intangible assets are estimated based upon the nature of the intangible asset. These intangible assets are amortized based on the pattern in which the economic benefits of the intangible assets are consumed or if straight-line amortization approximates the pattern of economic benefit, a straight-line amortization method may be used. The range of estimated useful lives is as follows:
| Purchased service portfolios | 5 to 25 years | ||||
| Patents, trademarks/trade names | 4 to 40 years | ||||
| Customer relationships and other | 1 to 20 years |
The Company evaluates the potential impairment of long-lived assets, including finite-lived intangible assets whenever events or changes in circumstances indicate that the related carrying amounts may not be recoverable. If the carrying value of other long-lived assets held and used exceeds the sum of the undiscounted expected future cash flows, the carrying value is written down to fair value. See Note 8, "Fixed Assets" and Note 9, "Business Acquisitions, Goodwill and Intangible Assets" for additional information regarding intangible assets and other long-lived assets.
Income Taxes. Income taxes as presented in the Consolidated Financial Statements of the Company for periods prior to the Separation attribute current and deferred income taxes of UTC to the Company's stand-alone financial statements in a manner that is systematic, rational and consistent with the asset and liability method prescribed by FASB ASC Topic 740: Income Taxes (“ASC 740”). Accordingly, the Company's income tax provision for periods prior to the Separation was prepared following the separate return method. The separate return method applies ASC 740 to the stand-alone financial statements of each member of the consolidated group as if the group members were a separate taxpayer and a stand-alone enterprise. The
calculation of our income taxes on a separate return basis requires a considerable amount of judgment and use of both estimates and allocations. As a result, actual transactions included in the consolidated financial statements of UTC may not be included in the Consolidated Financial Statements of the Company. Similarly, the tax treatment of certain items reflected in the Consolidated Financial Statements of the Company may not be reflected in the consolidated financial statements and tax returns of UTC. Therefore, such items as net operating losses, credit carry-forwards and valuation allowances may exist in the stand-alone financial statements that may or may not exist in UTC’s consolidated financial statements. As such, the income taxes of the Company as presented in the Consolidated Financial Statements prior to the Separation may not be indicative of the income taxes that the Company will report in the future.
Certain operations of the Company have historically been included in a combined return with other UTC entities before the Separation. Current obligations for taxes in certain jurisdictions, where the Company files a combined tax return with UTC, are deemed settled with UTC for purposes of the Consolidated Financial Statements for periods prior to the Separation. Current obligations for tax in jurisdictions where the Company does not file a combined return with UTC, including certain foreign jurisdictions and certain U.S. states, are recorded within Accrued liabilities on the Consolidated Balance Sheets. On December 22, 2017, the U.S. Tax Cuts and Jobs Act (“TCJA”) was enacted. As a result, income tax attributable to previously undistributed earnings of the Company's international subsidiaries recognized in 2017 is recorded within Accrued liabilities and Future income tax obligations on the Consolidated Balance Sheets pursuant to UTC’s election to pay the tax over time, for which Otis will settle with UTC (or RTX). Additionally, under the terms of the TMA, Otis will indemnify RTX for a percentage of the toll charge installment payments due after the Separation. As a result, a portion of Otis' Future income tax obligations corresponding to the toll charge has been reclassified as a contractual indemnity obligation within Other long-term liabilities on the Consolidated Balance Sheet as of December 31, 2020. See Note 5, "Related Parties" and Note 15, "Income Taxes" for additional information.
In the ordinary course of business, there is inherent uncertainty in quantifying our income tax positions. We assess our income tax positions and record tax benefits for all years subject to examination based upon management’s evaluation of the facts, circumstances and information available at the reporting date. For those tax positions where it is more-likely-than-not that a tax benefit will be sustained, we have recorded the largest amount of tax benefit with a greater than 50% likelihood of being realized upon ultimate settlement with a taxing authority that has full knowledge of all relevant information. For those income tax positions where it is not more-likely-than-not that a tax benefit will be sustained, no tax benefit has been recognized in the financial statements. Where applicable, associated interest expense has also been recognized. We recognize accrued interest related to unrecognized tax benefits in Interest expense (income), net. Penalties, if incurred, would be recognized as a component of Income tax expense.
The TCJA contains a new law that subjects the Company to a tax on Global Intangible Low-Taxed Income (“GILTI”), beginning in 2018. GILTI is a tax on foreign income in excess of a deemed return on tangible assets of foreign corporations. The FASB has provided that companies subject to GILTI have the option to account for the GILTI tax as a period cost if and when incurred, or to recognize deferred taxes for temporary differences, including outside basis differences, expected to reverse as GILTI. We have elected to account for GILTI as a period cost as incurred.
Revenue Recognition. We adopted the FASB ASC Topic 606: Revenue from Contracts with Customers and its related amendments, (referred to, collectively, as "ASC 606”) effective January 1, 2018, and elected the modified retrospective approach. The results for periods before 2018 were not adjusted for the new standard and the cumulative effect of the change in accounting was recognized through UTC Net Investment at the date of adoption.
The Company's revenue streams include new equipment, maintenance and repair, and modernization. New equipment, modernization and repair services revenue are typically recognized over time as we are enhancing an asset the customer controls. Maintenance revenue is recognized on a straight-line basis over the life of the maintenance contract.
New Equipment, Modernization and Repair services. For new equipment and modernization transactions, equipment and installation are typically procured in a single contract providing the customer with a complete installed elevator or escalator unit. The combination of equipment and installation promises are typically a single performance obligation. For repair services, the customer typically contracts for specific short-term services which form a single performance obligation.
For these performance obligations, revenue is recognized over time using costs incurred to date relative to total estimated costs at completion to measure progress. Incurred costs represent work performed, which corresponds with and best depicts transfer of control or the enhancement of the customer’s assets. Contract costs included in the calculation are comprised of labor, materials, subcontractors’ costs or other direct costs and indirect costs, which include indirect labor costs. Specific to new equipment and modernization arrangements, the Company, based on project progression, reviews cost estimates on significant
contracts on a quarterly basis, and for others, no less frequently than annually or when circumstances change and warrant a modification to a previous estimate. These estimates form the basis for the amount of revenue to be recognized and include the latest updated total transaction price, costs and risks for each contract. These estimates for our ongoing contracts may materially change due to the change and completions of the contract scopes, cost estimates and customers' plans, among other factors.
For performance obligations recognized under the cost to cost method, we record changes in contract estimates using the cumulative catch-up method. Modifications are recognized as a cumulative catch-up or treated as a separate accounting contract if the modification adds distinct goods or services and the modification is priced at its stand-alone selling price.
Maintenance. Our customers purchase maintenance contracts which include services such as required periodic maintenance procedures, preventive services and stand ready obligations to remediate issues with the elevator/escalator when and if they arise. Given the continuous nature of these services throughout the year, we recognize revenue on maintenance contracts on a straight-line basis which aligns with the cost profile of these services. Contractual changes are typically recognized prospectively as most modifications are extensions of the existing arrangement.
Transaction Price Considerations. Our contracts typically include fixed payments which are generally received as we progress under our contracts. As a result, we have not identified any significant financing elements in our contract, and our contracts do not have significant estimates related to variable consideration except in the case of a project having an underlying performance issue, which is rare. In situations where multiple performance obligations in a single contract (e.g., new equipment and maintenance) exist, the transaction price is allocated to each performance obligation in proportion to their stand-alone selling prices. Estimates are made to account for changes in transaction prices attributable to pricing disputes that occur subsequent to the inception of contracts, based upon historical experience and the status of contracts.
Certain costs to obtain or fulfill contracts. Certain costs to obtain or fulfill a contract with a customer must be capitalized, to the extent recoverable from the associated contract margin, and subsequently amortized as the products or services are delivered to the customer. Sales commissions related to new equipment, modernization and maintenance contracts, excluding renewals, are capitalized as contract fulfillment costs and are amortized consistent with the pattern of transfer of the goods or services. Customer contract costs, which do not qualify for capitalization as contract fulfillment costs, are expensed as incurred.
Loss Contracts. Loss provisions on contracts are recognized to the extent that estimated contract costs exceed the estimated consideration from the products contemplated under the contractual arrangement. For new commitments, we generally record loss provisions at contract signing. For existing commitments, anticipated losses on contractual arrangements are recognized in the period in which losses become probable.
Self-Insurance. The Company is primarily self-insured for a number of risks including, but not limited to, workers’ compensation, general liability, automobile liability, property and employee-related healthcare benefits. The Company has obtained insurance coverage for amounts exceeding individual and aggregate loss limits. The Company accrues for known future claims and incurred but not reported losses within Accrued liabilities and Other long-term liabilities on the Consolidated Balance Sheets, totaling $299 million and $269 million as of December 31, 2020 and 2019, respectively.
Derivatives and Hedging Activity. We have used derivative instruments, principally forward contracts, to help manage certain foreign currency exposures. Derivative instruments are viewed as risk management tools by us and are not used for trading or speculative purposes. By their nature, all financial instruments involve market and credit risks. We enter into derivative and other financial instruments with major investment grade financial institutions and have policies to monitor the credit risk of those counterparties. We limit counterparty exposure and concentration of risk by diversifying counterparties. While there can be no assurance, we do not anticipate any material non-performance by any of these counterparties.
Derivatives used for hedging purposes may be designated and effective as a hedge of the identified risk exposure at the inception of the contract. All derivative instruments are recorded on the Consolidated Balance Sheets at fair value. Derivatives used to hedge foreign currency denominated balance sheet items are reported directly in earnings along with offsetting transaction gains and losses on the items being hedged. Derivatives used to hedge forecasted cash flows associated with foreign currency commitments or forecasted commodity purchases may be accounted for as cash flow hedges, as deemed appropriate. Gains and losses on derivatives designated as cash flow hedges are recorded in other comprehensive income (loss), net of tax and reclassified to earnings as a component of product sales or expenses, as applicable, when the hedged transaction occurs. Gains and losses on derivatives designated as cash flow hedges are recorded in Other operating activities, net within the Consolidated Statement of Cash Flows. To the extent that a previously designated hedging transaction is no longer an effective hedge, any ineffectiveness measured in the hedging relationship is recorded currently in earnings in the period it occurs.
As discussed in Note 17, "Financial Instruments" to the Consolidated Financial Statements as of December 31, 2020 we have €420 million of euro-denominated commercial paper, which qualifies as a net investment hedge against our investments in European businesses. We evaluate the effectiveness of the net investment hedge each quarter, and as of December 31, 2020, the net investment hedge is deemed to be effective.
In addition, the Company periodically enters into sales contracts denominated in currencies other than the functional currency of the parties to the transaction. The Company accounts for these transactions separately valuing the embedded derivative component of these contracts. The changes in the fair value of these embedded derivatives are recorded in Other income (expense), net in the Consolidated Statements of Operations. For the years ended December 31, 2020, 2019 and 2018, Other income (expense), net included a loss of $3 million, a loss of $27 million and a gain of $12 million, respectively, related to the changes in fair value of embedded derivatives.
To the extent the hedge accounting criteria are not met, the foreign currency forward contracts are utilized as economic hedges and changes in the fair value of these contracts are recorded currently in earnings in the period in which they occur. Additional information pertaining to foreign currency forward contracts and net investment hedging is included in Note 17, "Financial Instruments".
Environmental. Environmental investigatory, remediation, operating and maintenance costs are accrued when it is probable that a liability has been incurred and the amount can be reasonably estimated. The most likely cost to be incurred is accrued based on an evaluation of currently available facts with respect to each individual site, including current laws, regulations and prior remediation experience. Where no amount within a range of estimates is more likely, the minimum is accrued. Liabilities with fixed or reliably determinable future cash payments are discounted. Accrued environmental liabilities are not reduced by potential insurance reimbursements. See Note 21, "Contingent Liabilities" for additional details on the environmental remediation activities.
Research and Development. These costs are expensed in the period incurred and are shown on a separate line of the Consolidated Statements of Operations. Research and development expenses, covering research and the advancement of potential new and improved products and their uses, primarily include salaries and other employment costs.
Other Income (Expense), Net. Other income (expense), net includes the impact of changes in the fair value and settlement of embedded and foreign exchange derivatives, gains or losses on sale of businesses and fixed assets, earnings from equity method investments, fair value changes on equity securities, impairments, non-recurring Separation-related expenses, gains on insurance recoveries and certain other infrequent operating income and expense items.
Foreign Exchange. We conduct business in many different currencies and, accordingly, are subject to the inherent risks associated with foreign exchange rate movements. The financial position and results of operations of substantially all of our foreign subsidiaries are measured using the local currency as the functional currency. Foreign currency denominated assets and liabilities are translated into U.S. Dollars at the exchange rates existing at the respective balance sheet dates, and income and expense items are translated at the average exchange rates during the respective periods. The aggregate effects of translating the balance sheets of these subsidiaries are deferred within Accumulated other comprehensive income (loss).
Pension and Postretirement Obligations. Guidance under FASB ASC Topic 715: Compensation – Retirement Benefits requires balance sheet recognition of the overfunded or underfunded status of pension and postretirement benefit plans. Under this guidance, actuarial gains and losses, prior service costs or credits and any remaining transition assets or obligations that have not been recognized under previous accounting standards must be recognized in other comprehensive income (loss), net of tax effects, until they are amortized as a component of net periodic benefit cost. Pension and postretirement obligation balances and related costs reflected within the Consolidated Financial Statements include both costs directly attributable to plans dedicated to Otis, as well as an allocation of costs for Otis employees’ participation in UTC’s plans prior to Separation. See Note 13, "Employee Benefit Plans" for additional information.
Noncontrolling Interest. Ownership interest in the Company's subsidiaries held by parties other than the Company are presented separately from Shareholders' (Deficit) Equity as “Noncontrolling interest” within equity on the Consolidated Balance Sheets. The amount of net income attributable to common shareholders and the noncontrolling interest are both presented on the Consolidated Statements of Operations.
All noncontrolling interest with redemption features, such as put options, that are not solely within our control (redeemable noncontrolling interest) are reported in the mezzanine section of the Consolidated Balance Sheets, between Liabilities and equity (deficit), at the greater of redemption value or initial carrying value.
The activity attributable to noncontrolling interest and redeemable noncontrolling interest for the years ended December 31, 2020, 2019 and 2018 are presented in the Consolidated Statements of Changes in Equity.
UTC Net Investment. For periods prior to the Separation, UTC’s Net Investment in the Company is presented as “UTC Net Investment” on the Consolidated Balance Sheets. The Consolidated Statements of Changes in Equity include corporate allocations, net cash transfers and other property transfers between our former parent UTC and the Company, as well as related party receivables, payables and long-term debt between the Company and other UTC affiliates that were settled on a current basis. Prior to the Separation, UTC performed cash management and other treasury-related functions on a centralized basis for nearly all of its legal entities, which includes the Company, and, consequently, the net cash generated by the Company in legal entities that participated in UTC’s centralized cash management and financing programs was transferred to UTC through the related party accounts. See Note 5, "Related Parties" for additional information.
Recent Accounting Pronouncements
In June 2016, the FASB issued ASU 2016-13, Financial Instruments - Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments. We adopted this standard effective January 1, 2020 utilizing a modified retrospective approach, resulting in recording a cumulative-effect non-cash after-tax adjustment to retained earnings as of January 1, 2020, as discussed further in Note 6, "Accounts Receivable, Net."
In August 2018, the FASB issued ASU 2018-13, Fair Value Measurement (Topic 820): Disclosure Framework—Changes to the Disclosure Requirements for Fair Value Measurement. The new standard removes the disclosure requirements for the amount of and reasons for transfers between Level 1 and Level 2 of the fair value hierarchy. The provisions of this ASU are effective for years beginning after December 15, 2019, with early adoption permitted. The Company adopted this standard effective January 1, 2020. The adoption of this ASU did not have a material impact on our Consolidated Financial Statements.
In August 2018, the FASB issued ASU 2018-15, Intangibles—Goodwill and Other—Internal-Use Software (Subtopic 350-40): Customer’s Accounting for Implementation Costs Incurred in a Cloud Computing Arrangement That Is a Service Contract. The new standard provides updated guidance surrounding implementation costs associated with cloud computing arrangements that are service contracts. The provisions of this ASU are effective for years beginning after December 15, 2019. The Company adopted this standard prospectively effective January 1, 2020. The adoption of this ASU did not have a material impact on our Consolidated Financial Statements.
In February 2018, the FASB issued ASU 2018-02, Reclassification of Certain Tax Effects from Accumulated Other Comprehensive Income (Topic 220). The new standard allows companies to reclassify to retained earnings the stranded tax effects in Accumulated other comprehensive income from the then-newly-enacted TCJA. The new standard is effective for fiscal years beginning after December 15, 2018, including interim periods within those fiscal years, with early adoption permitted. The Company adopted the standard and elected to reclassify the income tax effects of the TCJA from Accumulated other comprehensive (loss) to UTC Net Investment effective January 1, 2019. The adoption of this standard did not have a material impact on our Consolidated Financial Statements.
In August 2018, the FASB issued ASU 2018-14, Compensation—Retirement Benefits—Defined Benefit Plans - General (Subtopic 715-20): Disclosure Framework—Changes to the Disclosure Requirements for Defined Benefit Plans. The new standard includes updates to the disclosure requirements for defined benefit plans including several additions, deletions and modifications to the disclosure requirements. The provisions of this ASU are effective for years ending after December 15, 2020, with early adoption permitted. The Company adopted this standard effective January 1, 2020. The adoption of this ASU did not have a material impact on our Consolidated Financial Statements.
Future Accounting Pronouncements
In December 2019, the FASB issued ASU 2019-12, Income Taxes (Topic 740): Simplifying the Accounting for Income Taxes. The amendments in this update remove certain exceptions of Topic 740 including: exception to the incremental approach for intraperiod tax allocation when there is a loss from continuing operations and income or gain from other items; exception to the requirement to recognize a deferred tax liability for equity method investments when a foreign subsidiary becomes an equity method investment; exception to the ability not to recognize a deferred tax liability for a foreign subsidiary when a foreign equity method investment becomes a subsidiary; exception to the general methodology for calculating income taxes in an interim period when a year-to-date loss exceeds the anticipated loss for the year. There are also additional areas of guidance in regards to: franchise and other taxes partially based on income and the interim recognition of enactment of tax laws and rate
changes. The provisions of this ASU are effective for years beginning after December 15, 2020, with early adoption permitted. We do not expect this standard to have a material impact on our Consolidated Financial Statements.
In March 2020, the FASB issued ASU 2020-04*,* Reference Rate Reform (Topic 848): Facilitation of the Effects of Reference Rate Reform on Financial Reporting ("ASU 2020-04"), which provides temporary optional expedients and exceptions for applying generally accepted accounting principles to contracts, hedging relationships and other transactions affected by reference rate reform if certain criteria are met. The amendments in ASU 2020-04 apply only to contracts, hedging relationships, and other transactions that reference LIBOR or another reference rate expected to be discontinued because of reference rate reform. ASU 2020-04 is currently effective and upon adoption may be applied prospectively to contract modifications made on or before December 31, 2022. We are currently evaluating the impact of adopting this standard but do not expect it to have a material impact on our Consolidated Financial Statements.
Note 3: Earnings per Share
On April 3, 2020, the date of consummation of the Separation, 433,079,455 shares of the Common Stock, par value $0.01 per share, were distributed to UTC shareholders of record as of March 19, 2020. This share amount is being utilized for the calculation of basic and diluted earnings per share for all periods presented prior to the Separation as all shares were owned by UTC prior to the Separation. For the 2019 and 2018 calculations, these shares are treated as issued and outstanding at January 1, 2019 and 2018 for purposes of calculating historical basic and diluted earnings per share.
Prior to the Separation, Otis employees participated in UTC's equity incentive plans, pursuant to which they were granted stock options, stock appreciation rights, restricted stock units, and performance-based restricted stock units. All awards granted under these plans were related to UTC common shares. Upon Separation, outstanding awards held by Otis employees under UTC's equity incentive plans were converted in accordance with the EMA using the conversion ratios set forth in the EMA. Depending on whether the awards held on the Separation date were in an unvested or vested status, Otis employees either received converted awards solely in Otis based shares (unvested status) or a combination of Otis, UTC and Carrier share based awards (vested status). Former Otis employees, and current and former legacy UTC and Carrier employees, who on the Separation date were holding outstanding UTC awards in a vested status also received a combination of Otis, UTC and Carrier awards post-spin. The conversion methodology used was calculated in accordance with the EMA and with the purpose of maintaining the aggregate intrinsic value of the award immediately after the Separation when compared to the aggregate intrinsic value immediately prior to the Separation. See Note 13, "Employee Benefit Plans" for further detail.
For the purpose of the below diluted earnings per share computation, we only included the units associated with the converted Otis share-based awards. These awards were assumed to be outstanding beginning from the Separation date.
| (dollars in millions, except per share amounts; shares in millions) | 2020 | 2019 | 2018 | ||||||||||||||||||||||||||
| Net income attributable to common shareholders | $ | 906 | $ | 1,116 | $ | 1,049 | |||||||||||||||||||||||
| Basic weighted average number of shares outstanding | 433.2 | 433.1 | 433.1 | ||||||||||||||||||||||||||
| Stock awards and equity units (share equivalent) | 1.4 | — | — | ||||||||||||||||||||||||||
| Diluted weighted average number of shares outstanding | 434.6 | 433.1 | 433.1 | ||||||||||||||||||||||||||
| Earnings Per Share of Common Stock: | |||||||||||||||||||||||||||||
| Basic | $ | 2.09 | $ | 2.58 | $ | 2.42 | |||||||||||||||||||||||
| Diluted | $ | 2.08 | $ | 2.58 | $ | 2.42 |
The computation of diluted earnings per share excludes the effect of the potential exercise of stock awards, including stock appreciation rights and stock options, when the average market price of the Common Stock is lower than the exercise price of the related stock awards during the period because the effect would be anti-dilutive. In addition, the computation of diluted earnings per share excludes the effect of the potential exercise of stock awards when the awards assumed proceeds exceed the average market price of the common shares during the period. For 2020, there were 4.6 million of anti-dilutive stock awards excluded from the computation.
Note 4: Revenue Recognition
We account for revenue in accordance with ASC 606. In addition to the following disclosures, Note 22, "Segment Financial Data" provides additional disclosures required by ASC 606, including disaggregation of revenue into categories that depict how the nature, amount, timing and uncertainty of revenue and cash flows are affected by economic factors.
Contract Assets and Liabilities. Contract assets reflect revenue recognized in advance of customer billing. Contract liabilities are recognized when a customer pays consideration, or we have a right to receive an amount of unconditional consideration, in advance of the satisfaction of performance obligations under the contract. We typically receive progress payments from our customers as we perform our work over time.
Total Contract assets and Contract liabilities at December 31, 2020 and 2019 are as follows:
| (dollars in millions) | 2020 | 2019 | ||||||||||||
| Contract assets, current | $ | 458 | $ | 529 | ||||||||||
| Total contract assets | 458 | 529 | ||||||||||||
| Contract liabilities, current | 2,542 | 2,270 | ||||||||||||
| Contract liabilities, noncurrent (included within Other long-term liabilities) | 44 | 18 | ||||||||||||
| Total contract liabilities | 2,586 | 2,288 | ||||||||||||
| Net contract liabilities | $ | 2,128 | $ | 1,759 |
Contract assets decreased by $71 million during the year ended December 31, 2020 as a result of the progression of current contracts and timing of billing on customer contracts. Contract liabilities increased by $298 million during the year ended December 31, 2020 primarily due to contract billings in excess of revenue earned. During the year ended December 31, 2020 and 2019, we recognized revenue of $1.6 billion and $1.7 billion related to the contract liabilities as of January 1, 2020 and as of January 1, 2019, respectively.
Remaining Performance Obligations ("RPO"). RPO represents the aggregate amount of total contract transaction price that is unsatisfied or partially unsatisfied. As of December 31, 2020, our total RPO was approximately $17.2 billion. Of the total RPO as of December 31, 2020, we expect approximately 90% will be recognized as sales over the following 24 months. On December 31, 2019, we had approximately $16.4 billion of remaining performance obligations, at which time we expected to recognize approximately 91% of these remaining performance obligations as sales in the next 24 months.
Note 5: Related Parties
In connection with the Separation as further described in Note 1, "Description of Business and Separation from United Technologies Corporation", the Company entered into several agreements with our former parent UTC and Carrier. These agreements include a separation and distribution agreement that sets forth certain agreements with UTC and Carrier regarding the principal actions to be taken in connection with the Separation, including identifying the assets transferred, the liabilities assumed and the contracts transferred to each of UTC, Carrier and Otis as part of the Separation, and when and how these transfers and assumptions occurred. Other agreements that we entered into that govern aspects of our relationship with RTX and Carrier following the Separation include:
-
TSA. We entered into the TSA under which RTX provides the Company with certain services and we provide certain services to RTX for a limited time to help ensure an orderly transition following the Separation.
-
TMA. We entered into the TMA with our former parent UTC and Carrier that governs the parties’ respective rights, responsibilities and obligations with respect to tax matters (including responsibility for taxes, entitlement to refunds, allocation of tax attributes, preparation of tax returns, control of tax contests and other tax matters). Subject to certain exceptions set forth in the TMA, Otis generally is responsible for federal, state and foreign taxes imposed on a separate return basis on Otis (or any of its subsidiaries) with respect to taxable periods (or portions thereof) that ended on or prior to the date of the Distribution. The TMA provides special rules that allocate responsibility for tax liabilities arising from a failure of the Separation transactions to qualify for tax-free treatment based on the reasons for such failure. The TMA
also imposes restrictions on Otis during the two-year period following the Distribution that are intended to prevent certain transactions from failing to qualify as transactions that are generally tax-free.
- EMA and Intellectual Property Agreement. We also entered into the EMA, which allocated among Otis, UTC and Carrier the liabilities and responsibilities relating to employment matters, employee compensation and benefit plans, benefit programs and other related matters, as well as an intellectual property agreement with UTC and Carrier in connection with the Separation.
Net Transfers from (to) UTC and Separation Transactions. In connection with the Separation, certain assets and liabilities were contributed to the Company by our former parent UTC leading up to and at the time of the Separation. During 2020 and prior to the Separation, net liabilities of $43 million were contributed to the Company by UTC, primarily consisting of deferred tax assets and liabilities and fixed assets. Prior to the Separation, these non-cash contributions were recorded as Net transfers (to) from UTC on the Consolidated Statements of Changes in Equity through UTC Net Investment.
Upon Separation, the following were recorded as Net transfers (to) from UTC and Separation-related transactions on the Consolidated Statements of Changes in Equity through UTC Net Investment:
| (dollars in millions) | |||||
| Cash and cash equivalents | $ | 220 | |||
| Taxes and other | 187 | ||||
| Total | $ | 407 |
Prior to the Separation, UTC paid Otis Cash and cash equivalents of $190 million in connection with the Separation Agreement, and approximately $30 million as settlement of related party receivables due from UTC to Otis as a result of a cash overdraft as of March 31, 2020.
Additionally, the TCJA imposed a non-recurring toll charge, to be paid in installments over an 8-year period, on deemed repatriated earnings of foreign subsidiaries as of December 31, 2017. Under the terms of the TMA, Otis will indemnify RTX for a percentage of the toll charge installment payments due after April 3, 2020. As a result, a portion of Otis' Future income tax obligations corresponding to the toll charge has been reclassified as a contractual indemnity obligation within Other long-term liabilities on the Consolidated Balance Sheets. The TMA also provides for RTX to indemnify Otis for certain foreign tax obligations as a result of Otis' inclusion in certain foreign consolidated tax returns prior to the Separation. As a result, Otis has reflected this contractual indemnification asset within Other current assets and the related tax obligations within Accrued liabilities on the Consolidated Balance Sheets. As a result of the Separation and the provisions of the TMA, Otis' total net tax-related liabilities on April 3, 2020 were reduced by $191 million, comprising the following impacts to the Consolidated Balance Sheets:
| (dollars in millions) | Increase (Decrease) | ||||
| Assets | |||||
| Other current assets | $ | 167 | |||
| Total Current Assets | 167 | ||||
| Future income tax benefits | (4) | ||||
| Total Assets | $ | 163 | |||
| Liabilities and (Deficit) Equity | |||||
| Accrued liabilities | $ | 110 | |||
| Total Current Liabilities | 110 | ||||
| Future income tax obligations | (377) | ||||
| Other long-term liabilities | 239 | ||||
| Total Liabilities | (28) | ||||
| Total Shareholders' (Deficit) Equity | 191 | ||||
| Total (Deficit) Equity | 191 | ||||
| Total Liabilities and (Deficit) Equity | $ | 163 |
There were also $4 million of Other long-term liabilities recorded upon Separation on the Consolidated Balance Sheet.
In addition to Income taxes paid, net of (refunds) on the Consolidated Statements of Cash Flows, as a result of the TMA the Company made a payment of $86 million for foreign tax obligations that was reimbursed by RTX in 2020.
Shared Costs. The Consolidated Financial Statements have been prepared on a standalone basis for the periods prior to the Separation on April 3, 2020, and for those periods are derived from the consolidated financial statements and accounting records of UTC. Prior to the Separation, the Company had been managed and operated in the normal course of business with other affiliates of UTC. Accordingly, for periods prior to the Separation on April 3, 2020, certain shared costs were allocated to the Company and reflected as expenses in these Consolidated Financial Statements.
Allocated centralized costs were incurred as follows:
| (dollars in millions) | 2020 | 2019 | 2018 | |||||||||||||||||||||||
| Allocated centralized costs | $ | 16 | $ | 80 | $ | 90 |
Prior to the Separation, UTC incurred significant corporate costs such as treasury, tax, accounting, human resources, audit, legal, purchasing, information technology and other such services. The costs associated with these services generally included all payroll and benefit costs, as well as overhead costs related to certain functions. All such amounts have been deemed to have been incurred and settled by the Company in the period in which the costs were recorded. These expenses are primarily included in Selling, general and administrative expense on the Consolidated Statements of Operations. The future results of operations, financial position and cash flows could differ materially from the historical results presented herein. There were no allocated centralized costs for the periods after the Separation.
Separation Costs. In connection with the Separation as further described in Note 1, "Description of Business and Separation from United Technologies Corporation", we incurred Separation costs as follows:
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||||||||||||||
| Separation costs | $ | 119 | $ | 43 | $ | — | |||||||||||||||||||||||
We incurred non-recurring Separation-related costs of $119 million and $43 million in 2020 and 2019, respectively, of which $106 million and $43 million, respectively, are recorded in Selling, general and administrative expense and the remaining costs are recorded in Other income (expense), net on the Consolidated Statements of Operations. The Selling, general and administrative expenses primarily consist of employee-related costs, costs to establish certain standalone functions and information technology systems, professional services fees, costs to exit from certain services previously provided under the TSA, equity-based awards and other transaction-related costs to transition to being a standalone public company. The costs recorded in Other income (expense), net primarily consist of the finalization of tax returns and tax payments made after the Separation, partially offset in the tax provision, due to differences between the estimated indemnity recorded upon spin and final indemnity payment received relative to the overall tax liability and payments previously submitted.
Cash Management and Financing. Prior to the Separation, the Company participated in UTC's centralized cash management and financing programs. Disbursements were made through centralized accounts payable systems which were operated by UTC. Cash receipts were transferred to centralized accounts, which were also maintained by UTC. As cash was received and disbursed by UTC, it was accounted for by the Company through UTC Net Investment. All short and long-term debt was financed by UTC prior to the issuance of the notes and the term loan in connection with the Separation, and the financing decisions for wholly and majority owned subsidiaries were determined by UTC. The cash reflected on the Consolidated Balance Sheets as of December 31, 2019 represents cash on hand at certain foreign entities that did not participate in the centralized cash management program and were specifically identifiable to the Company.
Long-Term Debt, Accounts Receivable and Accounts Payable. Certain related party transactions between the Company and our former parent UTC have been included within UTC Net Investment on the Consolidated Balance Sheets in the historical periods presented prior to the Separation. The UTC Net Investment includes related party receivables due from UTC and its affiliates of $7.7 billion as of December 31, 2019. The UTC Net Investment includes related party payables due to UTC and its affiliates of $750 million as of December 31, 2019, which primarily related to centralized cash management and financing programs. The UTC Net Investment includes related party debt due to UTC and its affiliates of $100 million as of
December 31, 2019. The interest income and expense related to the activity with UTC that was included in Otis' results is presented on a net basis in the Consolidated Statements of Operations as this is settled in cash. Interest income on the activity with our former parent UTC was $23 million and $25 million in 2019 and 2018, respectively. Interest expense on the activity with our former parent UTC was $18 million and $20 million in 2019 and 2018, respectively. There was no interest income or interest expense activity with our former parent UTC in 2020. The total effect of the settlement of these related party transactions is reflected as a financing activity on the Consolidated Statements of Cash Flows for the historical periods presented.
Additionally, prior to the Separation, certain related party trade transactions between Otis and UTC and affiliate businesses were cash-settled on a current basis, and therefore, are reflected in the Consolidated Balance Sheets as Accounts payable and amounted to $11 million as of December 31, 2019.
Guarantees. Prior to the Separation, UTC and its affiliates issued parent company guarantees to certain customers or other third parties regarding the product performance obligations of Otis under certain installation and long-term maintenance contracts, as well as parent guarantees on behalf of Otis to guarantee ordinary course of business performance obligations as required by certain Otis customers and banks to support credit facilities to Otis' affiliates. Typically, contract performance guarantees provided to Otis customers are in amounts equal to a portion or the entire value of the awarded contract and remain in place through the completion of a contract or warranty period. At December 31, 2019, the total outstanding parent guarantees were approximately $1.8 billion, and all such parent guarantees were terminated in connection with the Separation.
There were no costs charged to Otis by our former parent UTC related to these guarantees. Payouts under these guarantees were not significant for 2020, 2019 and 2018.
UTC also provided parent guarantees of Otis' long-term debt, which terminated upon Separation.
Note 6: Accounts Receivable, Net
Adoption of Credit Loss Standard
In June 2016, the FASB issued ASU 2016-13, Financial Instruments - Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments. This ASU and its related amendments (collectively, the "Credit Loss Standard") modifies the impairment model to utilize an expected loss methodology in place of the incurred loss methodology for financial instruments including trade receivables, contract assets, long term receivables and off-balance sheet credit exposures. The Credit Loss Standard requires consideration of a broader range of information to estimate expected credit losses, including historical information and current conditions through a reasonable forecast period. The Credit Loss Standard requires that the income statement reflect the measurement of credit losses for newly recognized financial assets as well as the expected increase or decrease of expected credit losses that have taken place during the period, which may result in earlier recognition of certain losses. We adopted this standard effective January 1, 2020 utilizing a modified retrospective approach. A cumulative-effect non-cash after-tax adjustment to retained earnings as of January 1, 2020 was recorded in the amount of approximately $25 million.
We are exposed to credit losses primarily through our net sales of products and services to our customers which are recorded as Accounts Receivable, net on the Consolidated Balance Sheets. We evaluate each customer's ability to pay through assessing customer creditworthiness, historical experience and current economic conditions through a reasonable forecast period. Factors considered in our evaluation of assessing collectability and risk include: underlying value of any collateral or security interests, significant past due balances, historical losses and existing economic conditions including country and political risk. There can be no assurance that actual results will not differ from estimates or that consideration of these factors in the future will not result in an increase or decrease to the allowance for credit losses. We may require collateral or prepayment to mitigate credit risk.
We estimate expected credit losses of financial assets with similar risk characteristics. We determine an asset is impaired when our assessment identifies there is a risk that we will be unable to collect amounts due according to the contractual terms of the agreement. We monitor our ongoing credit exposure through reviews of customer balances against contract terms and due dates, current economic conditions and dispute resolution. Estimated credit losses are written off in the period in which the financial asset is no longer collectible.
Accounts receivable, net consisted of the following as of December 31:
| (dollars in millions) | 2020 | 2019 | |||||||||
| Trade receivables | $ | 2,987 | $ | 2,671 | |||||||
| Customer financing notes receivable | 130 | 52 | |||||||||
| Unbilled receivables | 104 | 108 | |||||||||
| Miscellaneous receivables | 88 | 113 | |||||||||
| 3,309 | 2,944 | ||||||||||
| Less: allowance for expected credit losses 1 | 161 | 83 | |||||||||
| Balance | $ | 3,148 | $ | 2,861 |
1 Prior to January 1, 2020 allowances for doubtful accounts were recorded when accounts receivable were determined to be uncollectible.
The changes in allowance for credit losses related to Accounts receivable, net for the year ended December 31, 2020 is as follows:
| (dollars in millions) | 2020 | ||||||||||
| Balance as of January 1 | $ | 83 | |||||||||
| Impact of credit standard adoption | 28 | ||||||||||
| Current period provision for expected credit losses | 40 | ||||||||||
| Write-offs charged against the allowance for expected credit losses | (20) | ||||||||||
| Other | 30 | ||||||||||
| Balance as of December 31 | $ | 161 | |||||||||
During 2020, there was approximately $26 million of previously reserved balances moved into allowance for credit losses. As a result of this activity, there was no impact to the Consolidated Statements of Operations for 2020.
Note 7: Inventories, net
| (dollars in millions) | 2020 | 2019 | |||||||||
| Raw materials and work-in-process | $ | 113 | $ | 103 | |||||||
| Finished goods | 546 | 468 | |||||||||
| Total | $ | 659 | $ | 571 |
Raw materials and work-in-process and Finished goods are net of valuation reserves of $112 million and $103 million as of December 31, 2020 and 2019, respectively.
Note 8: Fixed Assets
| (dollars in millions) | Estimated Useful Lives | 2020 | 2019 | ||||||||||||||
| Land | $ | 48 | $ | 45 | |||||||||||||
| Buildings and improvements | 20 - 40 Years | 616 | 574 | ||||||||||||||
| Machinery and equipment | 3 - 12 Years | 1,175 | 1,043 | ||||||||||||||
| Assets under construction | 132 | 141 | |||||||||||||||
| 1,971 | 1,803 | ||||||||||||||||
| Less: Accumulated depreciation | (1,197) | (1,082) | |||||||||||||||
| $ | 774 | $ | 721 |
Depreciation expense was $100 million, $85 million and $86 million in 2020, 2019 and 2018, respectively.
In 2020, as a result of reviewing our technology strategies following the Separation, the Company recorded a pre-tax loss for the write-off of Assets under construction of approximately $71 million within Other income (expense), net in the Consolidated Statements of Operations.
Non-cash investing activities involving fixed assets resulted in a net increase to Accounts payable of $7 million and $4 million during 2020 and 2019, respectively.
Note 9: Business Acquisitions, Goodwill and Intangible Assets
Business Acquisitions. Our investments in businesses, net of cash acquired, totaled $55 million (including debt assumed), $47 million and $50 million in 2020, 2019 and 2018, respectively. The acquisitions in each year consisted of a number of immaterial acquisitions in our Service segment. Transaction costs incurred were not considered significant.
In 2019, the Company recorded a pre-tax loss on the sale of a business of $19 million within Other income (expense), net on the Consolidated Statement of Operations. There were no significant disposals of businesses for the years ended December 31, 2020 or 2018.
Goodwill. Changes in our Goodwill balances in 2020 were as follows:
| (dollars in millions) | Balance as of January 1, 2020 | Goodwill Resulting From Business Combinations | Foreign Currency Translation and Other | Balance as of December 31, 2020 | |||||||||||||||||||||||||
| New Equipment | $ | 337 | $ | — | $ | 20 | $ | 357 | |||||||||||||||||||||
| Service | 1,310 | 30 | 76 | 1,416 | |||||||||||||||||||||||||
| Total | $ | 1,647 | $ | 30 | $ | 96 | $ | 1,773 |
Changes in our Goodwill balances in 2019 were as follows:
| (dollars in millions) | Balance as of January 1, 2019 | Goodwill Resulting From Business Combinations | Business Disposals | Foreign Currency Translation and Other | Balance at December 31, 2019 | ||||||||||||||||||||||||
| New Equipment | $ | 345 | $ | — | $ | — | $ | (8) | $ | 337 | |||||||||||||||||||
| Service | 1,343 | 16 | (16) | (33) | 1,310 | ||||||||||||||||||||||||
| Total | $ | 1,688 | $ | 16 | $ | (16) | $ | (41) | $ | 1,647 |
Intangible Assets. Identifiable intangible assets are comprised of the following:
| 2020 | 2019 | ||||||||||||||||||||||||||||
| (dollars in millions) | Gross Amount | Accumulated Amortization | Gross Amount | Accumulated Amortization | |||||||||||||||||||||||||
| Amortized: | |||||||||||||||||||||||||||||
| Purchased service portfolios | $ | 2,123 | $ | (1,661) | $ | 2,069 | $ | (1,598) | |||||||||||||||||||||
| Patents, trademarks/trade names | 22 | (16) | 21 | (15) | |||||||||||||||||||||||||
| Customer relationships and other | 54 | (45) | 46 | (40) | |||||||||||||||||||||||||
| 2,199 | (1,722) | 2,136 | (1,653) | ||||||||||||||||||||||||||
| Unamortized: | |||||||||||||||||||||||||||||
| Trademarks and other | 7 | — | 7 | — | |||||||||||||||||||||||||
| Total | $ | 2,206 | $ | (1,722) | $ | 2,143 | $ | (1,653) |
Fully amortized service portfolios of $117 million were written off during 2020.
Amortization expense of intangible assets was $91 million, $95 million and $104 million for the years ended December 31, 2020, 2019 and 2018, respectively. The estimated future amortization of intangible assets is as follows:
| (dollars in millions) | 2021 | 2022 | 2023 | 2024 | 2025 | ||||||||||||||||||||||||
| Future amortization | $ | 83 | $ | 71 | $ | 61 | $ | 53 | $ | 47 |
Note 10: Borrowings and Lines of Credit
| (dollars in millions) | 2020 | 2019 | |||||||||
| Commercial paper | $ | 664 | $ | — | |||||||
| Other borrowings | 37 | 34 | |||||||||
| Total short-term borrowings | $ | 701 | $ | 34 |
As of December 31, 2020, we had an aggregate of $1.5 billion unsecured, unsubordinated commercial paper programs in place. We use our commercial paper borrowings for general corporate purposes including to finance acquisitions, pay dividends and for debt refinancing. The need for commercial paper borrowings may arise if the use of domestic cash for general corporate purposes exceeds the sum of domestic cash generation and foreign cash repatriated to the U.S. In September 2020, we issued €420 million of Euro denominated commercial paper. The Company used the proceeds from the commercial paper issuance to pay down a portion of the principal balance of the term loan described below. The Euro denominated commercial paper qualifies as a net investment hedge against our investments in European businesses. As of December 31, 2020, the net investment hedge is deemed to be effective. In November 2020, we issued $150 million of U.S. Dollar commercial paper to pay down the remaining balance of the term loan described below.
As of December 31, 2020, we had a credit agreement, as amended, with various banks providing for a $1.5 billion unsecured, unsubordinated 5-year revolving credit facility, effective as of April 3, 2020, with an interest rate of LIBOR plus 125 basis points and a commitment fee rate of 12.5 basis points. As of December 31, 2020, there were no borrowings under the revolving credit facility. The undrawn portion of the revolving credit facility serves as a backstop for the issuance of commercial paper.
On February 10, 2020, the Company entered into a term loan credit agreement, as amended, providing for a $1.0 billion unsecured, unsubordinated 3-year term loan credit facility (the "term loan"). On March 27, 2020, the Company drew on the full amount of the term loan. On September 28, 2020, we made a $750 million prepayment of our term loan and paid the remaining balance of approximately $250 million on November 20, 2020, resulting in the payment in full and termination of the term loan credit agreement.
Additionally, on February 27, 2020, we issued $5.3 billion unsecured, unsubordinated notes.
The net proceeds of the term loan and the notes described above of approximately $6.3 billion in the aggregate were distributed to UTC prior to the Separation.
The revolving credit agreement, term loan credit agreement and indenture contain affirmative and negative covenants customary for financings of these types that, among other things, limit the Company's and its subsidiaries’ ability to incur additional liens, to make certain fundamental changes and to enter into sale and leaseback transactions. In addition, the revolving credit agreement and the term loan credit agreement require that we maintain a maximum consolidated leverage ratio as defined in the agreements, commencing with the test period ending September 30, 2020. The revolving credit agreement, term loan credit agreement and indenture also contain events of default customary for financings of these types. The Company was in compliance with all covenants in 2020.
Long-term debt consisted of the following as of December 31:
| (dollars in millions) | 2020 | 2019 | |||||||||
| LIBOR plus 45 bps floating rate notes due 2023 1,2 | $ | 500 | $ | — | |||||||
| 2.056% notes due 2025 2 | 1,300 | — | |||||||||
| 2.293% notes due 2027 2 | 500 | — | |||||||||
| 2.565% notes due 2030 2 | 1,500 | — | |||||||||
| 3.112% notes due 2040 2 | 750 | — | |||||||||
| 3.362% notes due 2050 2 | 750 | — | |||||||||
| Other (including finance leases) | 5 | 5 | |||||||||
| Total principal long-term debt | 5,305 | 5 | |||||||||
| Other (discounts and debt issuance costs) | (43) | — | |||||||||
| Total long-term debt | 5,262 | 5 | |||||||||
| Less: current portion | — | — | |||||||||
| Long-term debt, net of current portion | $ | 5,262 | $ | 5 |
1 The three-month LIBOR rate at December 31, 2020 was approximately 0.24%.
2 On February 27, 2020, we issued $5.3 billion of unsecured, unsubordinated notes. We may redeem these notes at our option pursuant to certain terms.
Debt issuance costs are presented as a reduction of debt on the Consolidated Balance Sheets and are amortized as a component of interest expense over the term of the related debt using the effective interest method. Debt issuance costs amortization reflected in the Statements of Operations for the year ended December 31, 2020 is $5 million, and the total interest expense recorded on our external debt for the year ended December 31, 2020 was $124 million. The unamortized debt issuance costs at December 31, 2020 is approximately $43 million.
The average maturity of our long-term debt at December 31, 2020 is approximately 11.2 years. The average interest rate on our debt for 2020 is as follows:
| 2020 | |||||
| Average interest rate - average outstanding borrowings during the year: | |||||
| Short-term borrowings | (0.2) | % | |||
| Total long-term debt | 2.3 | % | |||
| Average interest rate - average outstanding borrowings as of December 31: | |||||
| Short-term borrowings | (0.2) | % | |||
| Total long-term debt | 2.4 | % |
The schedule of principal payments required on long-term debt for the next five years and thereafter is:
| (dollars in millions) | |||||
| 2021 | $ | — | |||
| 2022 | 3 | ||||
| 2023 | 500 | ||||
| 2024 | — | ||||
| 2025 | 1,302 | ||||
| Thereafter | 3,500 | ||||
| Total | $ | 5,305 |
Note 11: Accrued Liabilities
| (dollars in millions) | 2020 | 2019 | |||||||||
| Accrued salaries, wages and employee benefits | $ | 556 | $ | 516 | |||||||
| Accrued interest | 223 | 165 | |||||||||
| Accrued income taxes payable | 182 | 157 | |||||||||
| Operating lease liabilities | 167 | 140 | |||||||||
| VAT and other non-income tax payables | 102 | 116 | |||||||||
| Other liabilities | 747 | 645 | |||||||||
| Total | $ | 1,977 | $ | 1,739 |
Accrued interest primarily consists of interest accrued for uncertain tax positions and the German tax litigation as described in Note 21, "Contingent Liabilities", as well as $45 million of interest accrued for borrowings as described in Note 10, "Borrowings and Lines of Credit".
Note 12: Other Long-term Liabilities
| (dollars in millions) | 2020 | 2019 | |||||||||
| Contractual indemnity obligation | $ | 239 | $ | — | |||||||
| General, product and auto liability | 152 | 145 | |||||||||
| Employee benefits | 113 | 97 | |||||||||
| Other liabilities | 130 | 69 | |||||||||
| Total | $ | 634 | $ | 311 |
The Contractual indemnity obligation consists of a payable to RTX, resulting from the TMA. See Note 5, "Related Parties" for further details.
Note 13: Employee Benefit Plans
The Company sponsors numerous single-employer domestic and international employee benefit plans and, prior to the Separation, certain of our employees participated in employee benefit plans (“Shared Plans”) sponsored by UTC that included participants of the other UTC businesses. We have accounted for our participation in the Shared Plans prior to the Separation as multiemployer benefit plans, as discussed below.
Employee Savings Plans. We sponsor various employee savings plans. Prior to the Separation, UTC also sponsored and contributed to defined contribution employee savings plans. Prior to the Separation, certain employees of Otis participated in these plans. Our contributions to employer-sponsored defined contribution plans were $54 million, $41 million and $38 million for 2020, 2019, and 2018, respectively.
Pension Plans. We sponsor both funded and unfunded domestic and international defined benefit pension plans that cover a large number of our employees. Our plans use a December 31 measurement date consistent with our fiscal year.
| (dollars in millions) | 2020 | 2019 | |||||||||
| Change in benefit obligation: | |||||||||||
| Beginning balance | $ | 1,092 | $ | 869 | |||||||
| Service cost | 40 | 33 | |||||||||
| Interest cost | 16 | 21 | |||||||||
| Actuarial (gain) loss | 40 | 81 | |||||||||
| Benefits paid | (28) | (30) | |||||||||
| Net settlement, curtailment and special termination benefits | (26) | (23) | |||||||||
| Other | 91 | 141 | |||||||||
| Ending balance | $ | 1,225 | $ | 1,092 | |||||||
| Change in plan assets: | |||||||||||
| Beginning balance | $ | 622 | $ | 444 | |||||||
| Actual return on plan assets | 24 | 76 | |||||||||
| Employer contributions | 64 | 32 | |||||||||
| Benefits paid | (28) | (30) | |||||||||
| Settlements | (26) | (23) | |||||||||
| Other | 47 | 123 | |||||||||
| Ending balance | $ | 703 | $ | 622 | |||||||
| Funded status: | |||||||||||
| Fair value of plan assets | $ | 703 | $ | 622 | |||||||
| Benefit obligations | (1,225) | (1,092) | |||||||||
| Funded status of plan | $ | (522) | $ | (470) | |||||||
| Amounts recognized in the Consolidated Balance Sheets consist of: | |||||||||||
| Noncurrent assets | $ | 87 | $ | 83 | |||||||
| Current liability | (21) | (20) | |||||||||
| Noncurrent liability | (588) | (533) | |||||||||
| Net amount recognized | $ | (522) | $ | (470) | |||||||
| Amounts recognized in Accumulated other comprehensive loss consist of: | |||||||||||
| Net actuarial loss | $ | 280 | $ | 236 | |||||||
| Prior service credit | (1) | (2) | |||||||||
| Net amount recognized | $ | 279 | $ | 234 |
The amounts included in "actuarial loss" in the above table primarily are due to changes in discount rate assumptions driven by decreases in corporate bond yields. The amounts included in “Other” in the above table primarily reflect the impact of foreign exchange translation, primarily for plans in Australia, Canada, Germany, Spain and Switzerland, and in 2019 an additional foreign defined benefit plan. Domestic pension plans provide retirement benefits to certain employees and are not a material component of the projected benefit obligation.
In 2020, 2019 and 2018 we made cash contributions to our defined benefit pension plans of $64 million, $32 million and $34 million, respectively.
Information for pension plans with accumulated benefit obligations in excess of plan assets:
| (dollars in millions) | 2020 | 2019 | |||||||||
| Projected benefit obligation | $ | 787 | $ | 697 | |||||||
| Accumulated benefit obligation | 685 | 609 | |||||||||
| Fair value of plan assets | 205 | 157 |
Information for pension plans with projected benefit obligations in excess of plan assets:
| (dollars in millions) | 2020 | 2019 | |||||||||
| Projected benefit obligation | $ | 991 | $ | 966 | |||||||
| Accumulated benefit obligation | 846 | 846 | |||||||||
| Fair value of plan assets | 383 | 413 |
The accumulated benefit obligation for all defined benefit pension plans was $1.1 billion and $1.0 billion at December 31, 2020, and 2019, respectively.
The components of the net periodic pension cost are as follows:
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Pension benefits: | |||||||||||||||||
| Service cost | $ | 40 | $ | 33 | $ | 33 | |||||||||||
| Interest cost | 16 | 21 | 21 | ||||||||||||||
| Expected return on plan assets | (25) | (24) | (23) | ||||||||||||||
| Amortization of prior service credit | (1) | (1) | (1) | ||||||||||||||
| Recognized actuarial net loss | 16 | 10 | 12 | ||||||||||||||
| Net settlement, curtailment and special termination benefits loss (gain) | 5 | 2 | (3) | ||||||||||||||
| Net periodic pension cost – employer | $ | 51 | $ | 41 | $ | 39 |
Other changes in plan assets and benefit obligations recognized in other comprehensive loss are as follows:
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Current year actuarial loss | $ | 41 | $ | 28 | $ | 37 | |||||||||||
| Prior service credit arising during period | — | — | (1) | ||||||||||||||
| Amortization of actuarial loss | (16) | (10) | (12) | ||||||||||||||
| Amortization of prior service credit | 1 | 1 | 1 | ||||||||||||||
| Net settlement and curtailment (loss) gain | (5) | (2) | 3 | ||||||||||||||
| Other | 24 | 27 | (8) | ||||||||||||||
| Total recognized in other comprehensive loss | $ | 45 | $ | 44 | $ | 20 | |||||||||||
| Net recognized in net periodic pension cost and other comprehensive loss | $ | 96 | $ | 85 | $ | 59 |
The amounts included in “Other” in the above table primarily reflect the impact of foreign exchange translation, primarily for plans in Australia, Germany, Canada and Switzerland, and in 2019, an additional foreign defined benefit plan.
Major assumptions used in determining the benefit obligation and net cost for pension plans are presented in the following table as weighted-averages:
| Benefit Obligation | Net Cost | ||||||||||||||||||||||||||||
| (dollars in millions) | 2020 | 2019 | 2020 | 2019 | 2018 | ||||||||||||||||||||||||
| Discount rate: | |||||||||||||||||||||||||||||
| Projected benefit obligation | 1.1 | % | 1.5 | % | 1.5 | % | 2.5 | % | 2.4 | % | |||||||||||||||||||
| Salary scale | 3.0 | % | 3.1 | % | 3.1 | % | 3.3 | % | 3.3 | % | |||||||||||||||||||
| Expected return on plan assets | — | — | 4.5 | % | 5.2 | % | 5.2 | % | |||||||||||||||||||||
| Interest crediting rate | 0.6 | % | 0.7 | % | 0.7 | % | 1.5 | % | 1.5 | % |
The weighted-average discount rates used to measure pension benefit obligations and net costs are set by reference to specific analyses using each plan’s specific cash flows and are then comparing them to high-quality bond indices for reasonableness.
In determining the expected return on plan assets, we consider the relative weighting of plan assets, the historical performance of total plan assets and individual asset classes, and economic and other indicators of future performance. In addition, we may consult with, and consider the opinions of, financial and other professionals in developing appropriate capital market assumptions. Return projections are also validated using a simulation model that incorporates yield curves, credit spreads and risk premiums to project long-term prospective returns.
The plans’ investment management objectives include providing the liquidity and asset levels needed to meet current and future benefit payments, while maintaining a prudent degree of portfolio diversification considering interest rate risk and market volatility. Globally, investment strategies target a mix of approximately 50% of growth-seeking assets and 50% of income-generating and hedging assets using a wide diversification of asset types, fund strategies and investment managers. The growth seeking allocation consists of global public equities in developed and emerging countries, and alternative-asset class strategies. Within the income-generating assets, the fixed income portfolio consists of mainly government and broadly diversified high-quality corporate bonds.
The fair values of pension plan assets at December 31, 2020 and 2019 by asset category are as follows:
| (dollars in millions) | Quoted Prices in Active Markets for Identical Assets (Level 1) | Significant Observable Inputs (Level 2) | Significant Unobservable Inputs (Level 3) | Not Subject to Leveling | Total | ||||||||||||||||||||||||
| Asset category | |||||||||||||||||||||||||||||
| Public equities: | |||||||||||||||||||||||||||||
| Global Equity Commingled Funds (1) | $ | 52 | $ | 39 | $ | — | $ | — | $ | 91 | |||||||||||||||||||
| Global Equity Funds at net asset value (5) | — | — | — | 154 | 154 | ||||||||||||||||||||||||
| Fixed income securities: | |||||||||||||||||||||||||||||
| Governments | 20 | 41 | — | — | 61 | ||||||||||||||||||||||||
| Corporate Bonds | 49 | 4 | — | — | 53 | ||||||||||||||||||||||||
| Fixed income securities at net asset value (5) | — | — | — | 90 | 90 | ||||||||||||||||||||||||
| Real estate (2) (5) | 12 | 6 | — | 12 | 30 | ||||||||||||||||||||||||
| Other (3) (5) | 2 | 129 | — | 25 | 156 | ||||||||||||||||||||||||
| Cash and cash equivalents (4) (5) | 6 | 1 | — | 41 | 48 | ||||||||||||||||||||||||
| Total | $ | 141 | $ | 220 | $ | — | $ | 322 | 683 | ||||||||||||||||||||
| Other assets and liabilities (6) | 20 | ||||||||||||||||||||||||||||
| Total at December 31, 2020 | $ | 703 |
| (dollars in millions) | Quoted Prices in Active Markets for Identical Assets (Level 1) | Significant Observable Inputs (Level 2) | Significant Unobservable Inputs (Level 3) | Not Subject to Leveling | Total | ||||||||||||||||||||||||
| Asset category | |||||||||||||||||||||||||||||
| Public equities: | |||||||||||||||||||||||||||||
| Global Equity Commingled Funds (1) | $ | — | $ | 183 | $ | — | $ | — | $ | 183 | |||||||||||||||||||
| Global Equity Funds at net asset value (5) | — | — | — | 78 | 78 | ||||||||||||||||||||||||
| Fixed income securities: | |||||||||||||||||||||||||||||
| Governments | — | 54 | — | — | 54 | ||||||||||||||||||||||||
| Corporate Bonds | — | 87 | — | — | 87 | ||||||||||||||||||||||||
| Fixed income securities at net asset value (5) | — | — | — | 47 | 47 | ||||||||||||||||||||||||
| Real estate(2) (5) | — | 26 | — | 1 | 27 | ||||||||||||||||||||||||
| Other (3) | — | 138 | — | — | 138 | ||||||||||||||||||||||||
| Cash and cash equivalents (4)(5) | — | 8 | — | — | 8 | ||||||||||||||||||||||||
| Total at December 31, 2019 | $ | — | $ | 496 | $ | — | $ | 126 | $ | 622 |
(1) Represents investments in mutual funds and investments in commingled funds that invest primarily in common stocks.
(2) Represents investments in real estate including commingled funds and directly-held properties.
(3) Represents insurance contracts and global-balanced-risk commingled funds consisting mainly of equity, bonds and some commodities.
(4) Represents short-term commercial paper, bonds and other cash or cash-like instruments.
(5) In accordance with FASB ASU 2015-07, Fair Value Measurement (Topic 820), certain investments that are measured at fair value using the net asset value per share (or its equivalent) practical expedient have not been classified in the fair value hierarchy. The fair value amounts presented in this table are intended to permit reconciliation of the fair value hierarchy to the amounts presented for the total pension benefits plan assets.
(6) Represents trust receivables and payables that are not leveled.
Quoted market prices are used to value investments when available. Investments in securities traded on exchanges, including listed futures and options, are valued at the last reported sale prices on the last business day of the year or, if not available, the last reported bid prices. Fixed income securities are primarily measured using a market approach pricing methodology, where observable prices are obtained by market transactions involving identical or comparable securities of issuers with similar credit ratings. Over-the-counter securities and government obligations are valued at the bid prices or the average of the bid and ask prices on the last business day of the year from published sources or, if not available, from other sources considered reliable, generally broker quotes. Temporary cash investments are stated at cost, which approximates fair value.
We expect to make total contributions of approximately $30 million to our global defined benefit pension plans in 2021, including benefit payments to be paid directly from corporate assets.
Benefit payments, including amounts to be paid from corporate assets, and reflecting expected future service, as appropriate, are expected to be paid as follows: $56 million in 2021, $59 million in 2022, $62 million in 2023, $59 million in 2024, $61 million in 2025, and $353 million from 2026 through 2030.
Postretirement Benefit Plans. We sponsor postretirement benefit plans that provide health and life benefits to eligible retirees. The postretirement plans are unfunded. The benefit obligation was $11 million and $9 million at December 31, 2020, and 2019, respectively. The net periodic cost was $1 million for 2020, 2019 and 2018, respectively. Other comprehensive loss of $2 million was recognized during 2020 related to changes in benefit obligations.
The projected benefit obligation discount rate was 4.3% and 4.7% at December 31, 2020 and 2019, respectively. The Net Cost discount rate was 4.7%, 5.3% and 5.3% for 2020, 2019 and 2018, respectively.
Benefit payments, including amounts to be paid from corporate assets, and reflecting expected future service, as appropriate, are expected to be paid as follows: $1 million each year from 2021 through 2025, and $3 million from 2026 through 2030.
Multiemployer Benefit Plans. We contribute to various domestic and international multiemployer defined benefit pension plans. The risks of participating in these multiemployer plans are different from single-employer plans in that assets contributed are pooled and may be used to provide benefits to employees of other participating employers. If a participating employer stops contributing to the plan, the unfunded obligations of the plan may be borne by the remaining participating employers. Lastly, if we choose to stop participating in some of our multiemployer plans, we may be required to pay those plans a withdrawal liability based on the underfunded status of the plan.
Our participation in these plans for the annual periods ended December 31 is outlined in the table below. Unless otherwise noted, the most recent Pension Protection Act (“PPA”) zone status available in 2020 and 2019 is for the plan’s year-end at June 30, 2019 and June 30, 2018, respectively. The zone status is based on information that we received from the plan and is certified by the plan’s actuary. Our significant plan is in the green zone which represents a plan that is at least 80% funded and does not require a financial improvement plan (“FIP”) or a rehabilitation plan (“RP”). An extended amortization provision of ten years was utilized to recognize investment gains or losses for our significant plan through June 30, 2019.
| (dollars in millions) | PPA Zone Status | FIP/RP Status | Contributions | Surcharge Imposed | Expiration Date of Collective-Bargaining Agreement | ||||||||||||||||||||||||||||||||||||||||||||||||
| Pension Fund | EIN/Pension Plan Number | 2020 | 2019 | Pending/Implemented | 2020 | 2019 | 2018 | ||||||||||||||||||||||||||||||||||||||||||||||
| National Elevator Industry Pension Plan | 23-2694291 | Green | Green | No | $ | 131 | $ | 127 | $ | 120 | No | 7/8/2022 | |||||||||||||||||||||||||||||||||||||||||
| Other funds | 7 | 9 | 8 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | 138 | $ | 136 | $ | 128 |
For the plan years ended June 30, 2019 and 2018, respectively, we were listed in the National Elevator Industry Pension Plan’s Forms 5500 as providing more than 5% of the total contributions for the plan. At the date these financial statements were issued, the Form 5500 was not available for the plan year ending June 30, 2020.
In addition, we participate in multiemployer arrangements that provide postretirement benefits other than pensions, with the National Elevator Industry Health Benefit Plan being the most significant. These arrangements generally provide medical and life benefits for eligible active employees and retirees and their dependents. Contributions to multiemployer plans that provide postretirement benefits other than pensions were $20 million, $21 million and $20 million for 2020, 2019 and 2018, respectively.
UTC Sponsored Defined Benefit Plans. Defined benefit pension and postretirement benefit plans that were sponsored by our former parent UTC have been accounted for as multi-employer plans in these Consolidated Financial Statements pre-Separation, in accordance with FASB ASC Topic 715-30: Defined Benefit Plans – Pension and FASB ASC Topic 715-60: Defined Benefit Plans – Other Postretirement. FASB ASC Topic 715: Compensation-Retirement Benefits provides that an employer that participates in a multi-employer defined benefit plan is not required to report a liability beyond the contributions currently due and unpaid to the plan. Therefore, no assets or liabilities related to these plans have been included on the Consolidated Balance Sheets.
These pension and post retirement expenses were allocated to the Company and reported in Cost of products and services sold, Selling, general and administrative and Non-service pension cost (benefit) on the Consolidated Statements of Operations. The Company's participation in the defined pension and postretirement benefit plans sponsored by our former parent UTC concluded upon the completion of the Separation on April 3, 2020. The amounts for pension and postretirement expenses for the years ended December 31 were as follows:
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Service cost | $ | 1 | $ | 15 | $ | 18 | |||||||||||
| Non-service pension benefit | (5) | (42) | (49) | ||||||||||||||
| $ | (4) | $ | (27) | $ | (31) |
Stock-based Compensation. Prior to the Separation, certain of the Company's employees participated in stock-based compensation plans sponsored by our former parent UTC. The UTC stock-based compensation plans included various types of market and performance-based incentive awards, including stock options, stock appreciation rights, restricted stock units, and performance-based share units. All awards granted under the plans were based on UTC common shares, and only the activity attributable to Otis employees from these awards is reflected in the accompanying Consolidated Financial Statements for the year ended December 31, 2020.
In connection with the Separation, the Company adopted the 2020 Long-Term Incentive Plan (the "Plan"). The Plan became effective on April 3, 2020. A total of 45 million shares of common stock are authorized under the Plan. The Plan provides for the grant of various types of awards including restricted share unit awards, stock appreciation rights, stock options, and performance-based awards. Under the Plan, the exercise price of awards, if any, is set on the grant date and may not be less than the fair market value per share on that date. Generally, stock appreciation rights and stock options have a term of ten years and a three-year vesting period, subject to limited exceptions. In the event of retirement, annual stock appreciation rights, stock options, and restricted share units held for more than one year may become vested and exercisable (if applicable), subject to certain terms and conditions. Awards with performance-based vesting generally have a minimum three-year vesting period and vest based on actual performance against pre-established metrics. In the event of retirement, performance-based awards held for more than one year remain eligible to vest based on actual performance relative to target metrics. We currently intend to issue new shares for share option exercises and conversions under our equity compensation arrangements, and will continue to evaluate this policy in connection with our share repurchase program.
In connection with the Separation, and in accordance with the EMA, the Company's employees with outstanding former UTC stock-based awards received replacement stock-based awards under the Plan at Separation. The value of the replaced stock-based awards was designed to preserve the aggregate intrinsic value of the award immediately after the Separation when compared to the aggregate intrinsic value of the award immediately prior to Separation. The incremental expense incurred by the Company was not material. As of December 31, 2020, approximately 28 million shares remain available for awards under the 2020 Plan.
Stock-based Compensation Expense
We measure the cost of all share-based payments, including stock options, at fair value on the grant date and recognize this cost in the Consolidated Statements of Operations. A forfeiture rate assumption is applied on grant date to adjust the expense recognition for awards that are not expected to vest. For periods prior to the Separation, stock-based compensation expense includes expense attributable to Otis, and the fair value assumptions are based on the awards and terms previously granted under the UTC incentive compensation plan to Otis employees. Accordingly, the amounts presented for the years ended December 31, 2020, 2019 and 2018 are not necessarily indicative of future awards and do not necessarily reflect the results that Otis would have experienced as an independent publicly-traded company.
Stock-based compensation expense and the resulting tax benefits were as follows:
| Year Ended | |||||||||||||||||
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Stock-based compensation expense (Share-based) | $ | 63 | $ | 37 | $ | 38 | |||||||||||
| Stock-based compensation expense (Cash-based) | (4) | 10 | (1) | ||||||||||||||
| Total gross stock-based compensation expense | $ | 59 | $ | 47 | $ | 37 | |||||||||||
| Less: future tax benefit | 7 | 5 | 4 | ||||||||||||||
| Stock-based compensation expense, net of tax | $ | 52 | $ | 42 | $ | 33 |
For the years ended December 31, 2020, 2019 and 2018, the amount of cash received from the exercise of stock options was $3 million, $10 million and $25 million, respectively, with an associated tax benefit realized of $2 million, $6 million and $5 million, respectively. In addition, for the years ended December 31, 2020, 2019 and 2018, the associated tax benefit realized from the vesting of performance share units and other restricted awards was $1 million, $4 million and $1 million, respectively. The 2020 amount was computed using current U.S. federal and state tax rates.
As of December 31, 2020, there was approximately $60 million of total unrecognized compensation cost related to non-vested equity awards granted under the Plan. This cost is expected to be recognized ratably over a weighted-average period of 2.3 years.
A summary of the transactions under the new Otis Plan for the year ended December 31, 2020 follows:
| Stock Appreciation Rights | Restricted Share Units | Performance Share Units | Stock Options | ||||||||||||||||||||||||||||||||||||||||||||
| (shares in thousands) | Shares | Average Price* | Shares | Average Price** | Shares | Average Price** | Shares | Average Price** | |||||||||||||||||||||||||||||||||||||||
| Outstanding at: | |||||||||||||||||||||||||||||||||||||||||||||||
| December 31, 2019 | — | $ | — | — | $ | — | — | $ | — | — | $ | — | |||||||||||||||||||||||||||||||||||
| Converted from UTC (1) | 12,782 | 60.16 | 1,376 | 68.14 | 38 | 67.53 | 520 | 53.99 | |||||||||||||||||||||||||||||||||||||||
| Granted (2) | 179 | 53.25 | 607 | 54.21 | 5 | 65.45 | — | — | |||||||||||||||||||||||||||||||||||||||
| Exercised / Earned (2) | (609) | 45.19 | (201) | 61.89 | (43) | 67.29 | (57) | 45.39 | |||||||||||||||||||||||||||||||||||||||
| Cancelled | (175) | 72.82 | (72) | 67.56 | — | 69.79 | (9) | 41.42 | |||||||||||||||||||||||||||||||||||||||
| December 31, 2020 | 12,177 | $ | 60.63 | 1,710 | $ | 63.94 | — | $ | — | 454 | $ | 55.31 |
- Weighted-average grant price
** Weighted-average grant fair value
(1) Converted shares as of April 3, 2020 include Carrier and Legacy UTC employees receiving Otis awards on Separation
(2) Includes annual retainer awards issued to the Board of Directors
The weighted-average grant date fair value of stock options and stock appreciation rights granted by Otis and UTC during 2020, 2019 and 2018 was $10.38, $20.92 and $20.18, respectively. The weighted-average grant date fair value of performance share units, which vest upon achieving certain performance metrics, and other restricted stock awards granted by Otis and UTC during 2020, 2019 and 2018 was $54.29, $109.17 and $131.47, respectively. The total intrinsic value (which is the amount by which the stock price exceeded the exercise price on the date of exercise) of stock options and stock appreciation rights exercised during 2020, 2019 and 2018 was $13 million, $53 million and $36 million, respectively. The total fair value (which is the stock price at vesting) of performance share units and other restricted awards vested was $10 million, $33 million and $11 million during the years ended December 31, 2020, 2019 and 2018, respectively.
The following table summarizes information about equity awards outstanding that are vested and expected to vest and equity awards outstanding that are exercisable at December 31, 2020:
| Equity Awards Vested and Expected to Vest | Equity Awards That Are Exercisable | ||||||||||||||||||||||||||||||||||||||||||||||
| (shares in thousands; aggregate intrinsic value in millions) | Awards | Average Price* | Aggregate Intrinsic Value | Remaining Term** | Awards | Average Price* | Aggregate Intrinsic Value | Remaining Term** | |||||||||||||||||||||||||||||||||||||||
| Stock Options/Stock Appreciation Rights | 12,506 | $ | 60.30 | $ | 115 | 5.6 years | 7,964 | $ | 54.16 | $ | 107 | 4.1 years | |||||||||||||||||||||||||||||||||||
| Performance Share Units/Restricted Stock | 1,639 | — | $ | 111 | 1.7 years | ||||||||||||||||||||||||||||||||||||||||||
- Weighted-average grant price per share
** Weighted-average contractual remaining term in years
The fair value of each option award is estimated on the date of grant using a binomial lattice model. The following table indicates the assumptions used in estimating fair value for the years ended December 31, 2020, 2019 and 2018. For periods prior to the Separation, these assumptions represent those utilized by UTC and are not necessarily indicative of assumptions that would be used by Otis as a standalone company. Lattice-based option models incorporate ranges of assumptions for inputs; those ranges are as follows:
| 2020 | 2019 | 2018 | |||||||||||||||
| Expected volatility | 25.5% | 18.8% - 19.7% | 17.5% - 21.1% | ||||||||||||||
| Weighted-average volatility | 25.5% | 19.5% | 18.0% | ||||||||||||||
| Expected term (in years) | 6.8 | 6.5 - 6.6 | 6.5 - 6.6 | ||||||||||||||
| Expected dividend yield | 1.8% | 2.4% | 2.2% | ||||||||||||||
| Risk-free rate | 0.5% | 2.3% - 2.7% | 1.3% - 2.7% |
Due to the lack of trading history of Otis' stock at the time of valuation efforts, the expected volatility for Otis was calculated based on the average of the volatility of the peer group within the industry. UTC's historical data for Otis employees was used to estimate equity award exercise and employee termination behavior within the valuation model. The expected term represents an estimate of the period of time equity awards are expected to remain outstanding. The risk-free rate is based on the term structure of interest rates at the time of equity award grant.
Note 14: Accumulated Other Comprehensive Income (Loss)
A summary of the changes in each component of Accumulated other comprehensive income (loss), net of tax for the years ended December 31, 2020, 2019 and 2018 is provided below:
| (dollars in millions) | Foreign Currency Translation | Defined Benefit Pension and Postretirement Plans | Unrealized Hedging Gains (Losses) | Accumulated Other Comprehensive Income (Loss) | |||||||||||||||||||
| Balance at December 31, 2017 | $ | (468) | $ | (119) | $ | — | $ | (587) | |||||||||||||||
| Other comprehensive income (loss) before reclassifications, net | (105) | (31) | — | (136) | |||||||||||||||||||
| Amounts reclassified, pre-tax | — | 11 | — | 11 | |||||||||||||||||||
| Tax expense reclassified | — | 4 | — | 4 | |||||||||||||||||||
| Balance at December 31, 2018 | $ | (573) | $ | (135) | $ | — | $ | (708) | |||||||||||||||
| Other comprehensive income (loss) before reclassifications, net | (15) | (50) | (3) | (68) | |||||||||||||||||||
| Amounts reclassified, pre-tax | — | 9 | — | 9 | |||||||||||||||||||
| Tax expense reclassified | — | 9 | — | 9 | |||||||||||||||||||
| Balance at December 31, 2019 | $ | (588) | $ | (167) | $ | (3) | $ | (758) | |||||||||||||||
| Other comprehensive income (loss) before reclassifications, net | (28) | (47) | 10 | (65) | |||||||||||||||||||
| Amounts reclassified, pre-tax | — | 15 | (3) | 12 | |||||||||||||||||||
| Tax benefit reclassified | — | (4) | — | (4) | |||||||||||||||||||
| Balance at December 31, 2020 | $ | (616) | $ | (203) | $ | 4 | $ | (815) | |||||||||||||||
Amounts reclassified that relate to defined benefit pension and postretirement plans include amortization of prior service costs and actuarial net losses recognized during each period presented. These costs are recorded as components of net periodic pension cost for each period presented. See Note 13, "Employee Benefit Plans" for additional information.
Note 15: Income Taxes
Income Before Income Taxes. The sources of income from operations before income taxes are:
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| United States | $ | 105 | $ | 470 | $ | 504 | |||||||||||
| Foreign | 1,406 | 1,391 | 1,389 | ||||||||||||||
| $ | 1,511 | $ | 1,861 | $ | 1,893 |
Following enactment of the TCJA, and as part of the historical UTC assertion, the Company determined that it no longer intends to reinvest certain undistributed earnings of its international subsidiaries that have been previously taxed in the U.S. As such, in 2018 Otis recorded the international taxes associated with the future remittance of these earnings. As part of the Separation process, the Company re-assessed this position as a standalone company. The Company no longer intends to reinvest certain undistributed earnings of its international subsidiaries that have been previously taxed in the U.S. The international taxes recorded relative to this assertion differ from those recorded in 2018. As a result of the change in assertion, the Company recognized a one-time tax benefit of $10 million during the year resulting from an overall reduction in the liability previously recorded by UTC. For the remainder of the Company's undistributed international earnings, unless tax effective to repatriate, Otis will continue to permanently reinvest these earnings. As of December 31, 2020, such undistributed earnings were approximately $3.5 billion, excluding other comprehensive income amounts. It is not practicable to estimate the amount of tax that might be payable on the remaining amounts.
Provision for Income Taxes. The income tax expense (benefit) for the years ended December 31, 2020, 2019 and 2018 consisted of the following components:
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Current: | |||||||||||||||||
| United States: | |||||||||||||||||
| Federal | $ | 42 | $ | 103 | $ | 59 | |||||||||||
| State | 26 | 38 | 38 | ||||||||||||||
| Foreign | 438 | 461 | 459 | ||||||||||||||
| 506 | 602 | 556 | |||||||||||||||
| Future: | |||||||||||||||||
| United States: | |||||||||||||||||
| Federal | 8 | 11 | (11) | ||||||||||||||
| State | (8) | — | 7 | ||||||||||||||
| Foreign | (51) | (19) | 131 | ||||||||||||||
| (51) | (8) | 127 | |||||||||||||||
| Income tax expense | $ | 455 | $ | 594 | $ | 683 | |||||||||||
| Attributable to items (charged) credited to (deficit) equity | $ | (6) | $ | (14) | $ | (4) |
Reconciliation of Effective Income Tax Rate. Differences between effective income tax rates and the statutory U.S. federal income tax rate are as follows:
| 2020 | 2019 | 2018 | |||||||||||||||
| Statutory U.S. federal income tax rate | 21.0 | % | 21.0 | % | 21.0 | % | |||||||||||
| State income taxes | 0.9 | % | 1.7 | % | 1.6 | % | |||||||||||
| Tax on international activities | 4.4 | % | 6.5 | % | 14.0 | % | |||||||||||
| U.S. tax effect of foreign earnings | 3.4 | % | 2.9 | % | (0.1) | % | |||||||||||
| Other | 0.4 | % | (0.2) | % | (0.4) | % | |||||||||||
| Effective income tax rate | 30.1 | % | 31.9 | % | 36.1 | % |
The 2020 effective tax rate is higher than the statutory U.S. rate primarily due to higher international tax rates as compared to the lower U.S. federal statutory rate and foreign earnings subject to U.S. tax under the provisions of the TCJA.
The 2020 effective tax rate compared to the 2019 effective tax rate reflects a tax benefit of $10 million related to our change in assertion of no longer intending to reinvest certain undistributed earnings of our international subsidiaries made during the year as compared to the liability previously recorded by UTC, a decrease as a result of tax regulations related to the TCJA that were enacted during the year, as well as a recognition of a Separation-related foreign tax loss. These were partially offset by incremental withholding taxes in 2020.
The 2019 effective tax rate is higher than the statutory U.S. rate primarily due to higher international tax rates as compared to the lower U.S. federal statutory rate, and the full phase-in of the TCJA.
The 2019 effective tax rate compared to the 2018 effective tax rate reflects a decrease in the cost of U.S. and foreign tax on international activities primarily attributable to the absence of the net tax charge of $143 million as a result of UTC’s change of assertion of no longer intending to reinvest certain undistributed earnings of its international subsidiaries, offset by the full phase-in of the TCJA.
The 2018 effective tax rate is higher than the statutory U.S. rate as it reflects a net tax charge of $143 million as a result of UTC’s change of assertion of no longer intending to reinvest certain undistributed earnings of its international subsidiaries.
Deferred Tax Assets and Liabilities. Future income taxes represent the tax effects of transactions which are reported in different periods for tax and financial reporting purposes. These amounts consist of the tax effects of temporary differences between the tax and financial reporting balance sheets and tax carryforwards. Future income tax benefits and payables within the same tax paying component of a particular jurisdiction are offset for presentation in the Consolidated Balance Sheets.
The tax effects of temporary differences and tax carryforwards which gave rise to future income tax benefits and payables as of December 31, 2020 and 2019 are as follows:
| (dollars in millions) | 2020 | 2019 | |||||||||
| Future income tax benefits: | |||||||||||
| Insurance and employee benefits | $ | 201 | $ | 159 | |||||||
| Other asset basis differences | 149 | 121 | |||||||||
| Other liability basis differences | 299 | 335 | |||||||||
| Tax loss carryforwards | 197 | 45 | |||||||||
| Tax credit carryforwards | 38 | 14 | |||||||||
| Valuation allowances | (242) | (55) | |||||||||
| $ | 642 | $ | 619 | ||||||||
| Future income taxes payable: | |||||||||||
| Intangible assets | $ | 182 | $ | 174 | |||||||
| Other assets basis differences | 335 | 298 | |||||||||
| $ | 517 | $ | 472 |
Valuation allowances have been established primarily for tax credit carryforwards, tax loss carryforwards, and certain foreign temporary differences to reduce the future income tax benefits to expected realizable amounts. The table above includes impacts recorded as part of the Separation.
Tax Credit and Loss Carryforwards. As of December 31, 2020, tax credit carryforwards, principally state and foreign, and tax loss carryforwards, principally state and foreign, were as follows:
| (dollars in millions) | Tax Credit Carryforwards | Tax Loss Carryforwards | |||||||||
| Expiration period: | |||||||||||
| 2021-2025 | $ | — | $ | 39 | |||||||
| 2026-2030 | 7 | 33 | |||||||||
| 2031-2040 | 1 | 22 | |||||||||
| Indefinite | 30 | 720 | |||||||||
| $ | 38 | $ | 814 |
Unrecognized Tax Benefits. As of December 31, 2020, the Company had gross tax-effected unrecognized tax benefits of $397 million, all of which, if recognized, would impact the effective tax rate. A reconciliation of the beginning and ending amounts of unrecognized tax benefits and interest expense related to unrecognized tax benefits for the years ended December 31, 2020, 2019 and 2018 is as follows:
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Balance at January 1 | $ | 379 | $ | 380 | $ | 392 | |||||||||||
| Additions for tax positions related to the current year | 16 | 18 | 3 | ||||||||||||||
| Additions for tax positions of prior years | 41 | 15 | 1 | ||||||||||||||
| Reductions for tax positions of prior years | (31) | (15) | (16) | ||||||||||||||
| Settlements | (8) | (19) | — | ||||||||||||||
| Balance at December 31 | $ | 397 | $ | 379 | $ | 380 | |||||||||||
| Gross interest expense related to unrecognized tax benefits | $ | 10 | $ | 8 | $ | 10 | |||||||||||
| Total accrued interest balance at December 31 | $ | 153 | $ | 141 | $ | 136 |
Otis conducts business globally and, as a result, Otis or one or more of its subsidiaries files income tax returns in the U.S. federal jurisdiction and various state and foreign jurisdictions.
In the ordinary course of business, Otis could be subject to examination by taxing authorities throughout the world, including such major jurisdictions as Austria, Belgium, Brazil, Canada, China, France, Germany, Hong Kong, India, Italy, Japan, Mexico, Netherlands, Portugal, Russia, South Korea, Spain, Switzerland, the United Kingdom and the U.S. With few exceptions, Otis is no longer subject to U.S. federal, state and local, or non-U.S. income tax examinations for years before 2010.
A subsidiary of Otis engaged in litigation in Belgium received a favorable appellate court decision in 2018. The Belgian Tax Authorities appealed the decision to the Court of Cassation (the equivalent of Supreme Court in Belgium). On December 4, 2020, the Court of Cassation overturned the decision of the appellate court and remanded the case to the appellate court for reconsideration. It is not known how much time will elapse prior to the issuance of the appellate court’s decision. The associated tax and interest have been fully reserved.
In the ordinary course of business, there is inherent uncertainty in quantifying our income tax positions. We assess our income tax positions and record tax benefits for all years subject to examination based upon management’s evaluation of the facts, circumstances, and information available at the reporting date. It is reasonably possible that a range of a $10 million increase to a $380 million reduction of unrecognized tax benefits and a range of a $10 million increase to a $150 million reduction in associated interest may occur within the next 12 months as a result of additional worldwide uncertain tax positions, the closure of tax statutes, or the revaluation of current uncertain tax positions arising from the issuance of legislation, regulatory or other guidance or developments in examinations, in appeals or in the courts.
See Note 21, "Contingent Liabilities" for discussion regarding uncertain tax positions, included in the above range, related to pending litigation with respect to certain deductions claimed in Germany.
Note 16: Restructuring Costs
During the years ended December 31, 2020, 2019 and 2018, we recorded pre-tax restructuring costs totaling $77 million, $54 million and $69 million, respectively, for new and ongoing restructuring actions. We recorded restructuring charges in our operating segments as follows:
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||||||||
| New Equipment | $ | 30 | $ | 19 | $ | 25 | |||||||||||||||||
| Service | 47 | 35 | 44 | ||||||||||||||||||||
| Total | $ | 77 | $ | 54 | $ | 69 |
Restructuring charges incurred in the years ended December 31, 2020, 2019 and 2018 primarily relate to actions initiated during 2020, 2019 and 2018, and were recorded as follows:
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||||||||
| Cost of products and services sold | $ | 22 | $ | 19 | $ | 23 | |||||||||||||||||
| Selling, general and administrative | 55 | 35 | 48 | ||||||||||||||||||||
| Non-service pension (benefit) | — | — | (2) | ||||||||||||||||||||
| Total | $ | 77 | $ | 54 | $ | 69 |
2020 and 2019 Actions**.** During 2020, we recorded net pre-tax restructuring costs of $71 million for restructuring actions initiated in 2020, consisting of $21 million in Cost of products and services sold and $50 million in Selling, general and administrative expenses. During 2020, we recorded net pre-tax restructuring costs totaling $6 million for restructuring actions initiated in 2019, primarily included in Selling, general and administrative expenses. The 2020 and 2019 actions relate to ongoing cost reduction efforts, including workforce reductions.
We are targeting to complete in 2021 the majority of remaining restructuring actions initiated in 2020 and 2019. The following table summarizes the accrual balance and utilization for the 2020 and 2019 restructuring actions, which are primarily for severance costs:
| (dollars in millions) | 2020 Actions | 2019 Actions | |||||||||||||||
| Restructuring accruals at January 1, 2020 | $ | — | $ | 16 | |||||||||||||
| Net pre-tax restructuring costs | 71 | 6 | |||||||||||||||
| Utilization, foreign exchange and other costs | (29) | (14) | |||||||||||||||
| Balance at December 31, 2020 | $ | 42 | $ | 8 | |||||||||||||
The following table summarizes expected, incurred and remaining costs for the 2020 and 2019 restructuring actions by segment:
| (dollars in millions) | Expected Costs | Cost Incurred During 2019 | Costs Incurred During 2020 | Remaining Costs at December 31, 2020 | |||||||||||||||||||||||||||||||
| New Equipment | $ | 33 | $ | — | $ | (29) | $ | 4 | |||||||||||||||||||||||||||
| Service | 53 | — | (42) | 11 | |||||||||||||||||||||||||||||||
| Total 2020 Actions | $ | 86 | $ | — | $ | (71) | $ | 15 | |||||||||||||||||||||||||||
| New Equipment | $ | 20 | $ | (17) | $ | (2) | $ | 1 | |||||||||||||||||||||||||||
| Service | 37 | (28) | (4) | 5 | |||||||||||||||||||||||||||||||
| Total 2019 Actions | $ | 57 | $ | (45) | $ | (6) | $ | 6 | |||||||||||||||||||||||||||
2018 and Prior Actions. During 2020, no pre-tax restructuring costs were recorded for restructuring actions initiated in 2018 and prior.
Note 17: Financial Instruments
We enter into derivative instruments primarily for risk management purposes, including derivatives designated as hedging instruments under ASC 820, Fair Value Measurement. We operate internationally and, in the normal course of business, are exposed to fluctuations in interest rates and foreign exchange rates. These fluctuations can increase the costs of financing, investing in and operating the business. We may use derivative instruments, including swaps, forward contracts and options, to manage certain foreign currency and interest rate exposures.
The average of the notional amount of foreign exchange contracts hedging foreign currency transactions was $3.0 billion and $1.0 billion at December 31, 2020 and 2019, respectively.
The following table summarizes the fair value and presentation on the Consolidated Balance Sheets for derivative instruments as of December 31, 2020 and 2019:
| (dollars in millions) | Balance Sheet Classification | December 31, 2020 | December 31, 2019 | ||||||||||||||
| Derivatives designated as Cash flow hedging instruments: | |||||||||||||||||
| Foreign exchange contracts | Asset Derivatives: | ||||||||||||||||
| Other current assets | $ | 9 | $ | — | |||||||||||||
| Other assets | 4 | — | |||||||||||||||
| Total asset derivatives | $ | 13 | $ | — | |||||||||||||
| Liability Derivatives: | |||||||||||||||||
| Accrued liabilities | $ | (7) | $ | (1) | |||||||||||||
| Other long-term liabilities | (4) | — | |||||||||||||||
| Total liability derivatives | $ | (11) | $ | (1) | |||||||||||||
| Derivatives not designated as Cash flow hedging instruments: | |||||||||||||||||
| Foreign exchange contracts | Asset Derivatives: | ||||||||||||||||
| Other current assets | $ | 23 | $ | 8 | |||||||||||||
| Other assets | 10 | 1 | |||||||||||||||
| Total asset derivatives | $ | 33 | $ | 9 | |||||||||||||
| Liability Derivatives: | |||||||||||||||||
| Accrued liabilities | (24) | (5) | |||||||||||||||
| Other long-term liabilities | (8) | — | |||||||||||||||
| Total liability derivatives | $ | (32) | $ | (5) |
The amount of gain or (loss) attributable to foreign exchange contract activity reclassified from Accumulated other comprehensive income (loss) was immaterial for the years ended December 31, 2020 and 2019, respectively.
The effect of cash flow hedging relationships on Accumulated other comprehensive income (loss) as of December 31, 2020 and 2019 are presented in the table below.
| December 31, | |||||||||||||||||||||||
| (dollars in millions) | 2020 | 2019 | |||||||||||||||||||||
| Gain (loss) recorded in Accumulated other comprehensive income (loss) | $ | 4 | $ | (3) | |||||||||||||||||||
The Company utilizes the critical terms match method in assessing firm commitment derivatives for hedge effectiveness. Accordingly, the hedged items and derivatives designated as hedging instruments are highly effective.
We have €420 million of euro denominated commercial paper, which qualifies as a net investment hedge against our investments in European businesses. As of December 31, 2020, the net investment hedge is deemed to be effective. We have recognized $18 million of losses associated with this net investment hedge in Other comprehensive income (loss) during 2020 and in Accumulated other comprehensive income (loss) at December 31, 2020.
Assuming current market conditions continue, a $2 million pre-tax loss is expected to be reclassified from Accumulated other comprehensive income (loss) into Product sales to reflect the fixed prices obtained from foreign exchange hedging within the next 12 months. At December 31, 2020, all derivative contracts accounted for as cash flow hedges will mature by December 2024.
The effect of derivatives not designated as Cash flow hedging instruments within Other income (expense) net, on the Consolidated Statements of Operations was as follows:
| Year Ended December 31, | |||||||||||||||||||||||
| (dollars in millions) | 2020 | 2019 | |||||||||||||||||||||
| Foreign exchange contracts | $ | (4) | $ | (9) |
Note 18: Fair Value Measurements
In accordance with the provisions of ASC 820: Fair Value Measurements, the following tables provide the valuation hierarchy classification of assets and liabilities that are carried at fair value and measured on a recurring and non-recurring basis in our Consolidated Balance Sheets as of December 31, 2020 and 2019:
| December 31, 2020 | |||||||||||||||||||||||
| (dollars in millions) | Total | Level 1 | Level 2 | Level 3 | |||||||||||||||||||
| Recurring fair value measurements: | |||||||||||||||||||||||
| Equity securities | $ | 59 | $ | 59 | $ | — | $ | — | |||||||||||||||
| Derivative assets | 46 | — | 46 | — | |||||||||||||||||||
| Derivative liabilities | (43) | — | (43) | — | |||||||||||||||||||
| December 31, 2019 | |||||||||||||||||||||||
| (dollars in millions) | Total | Level 1 | Level 2 | Level 3 | |||||||||||||||||||
| Recurring fair value measurements: | |||||||||||||||||||||||
| Equity securities | $ | 3 | $ | 3 | $ | — | $ | — | |||||||||||||||
| Derivative assets | 9 | — | 9 | — | |||||||||||||||||||
| Derivative liabilities | (5) | — | (5) | — | |||||||||||||||||||
Valuation Techniques. Our equity securities include equity investments that are traded in active markets, either domestically or internationally, and are measured at fair value using closing stock prices from active markets. The fair value gains or losses related to our equity securities are recorded through net income. Our derivative assets and liabilities include foreign exchange contracts that are measured at fair value using internal models based on observable market inputs such as forward rates, interest rates, our own credit risk and our counterparties' credit risks. Our notes, as described in Note 10, "Borrowings and Lines of Credit", are measured at fair value using closing bond prices from active markets.
As of December 31, 2020, there has not been any significant impact to the fair value of our derivative liabilities due to our own credit risk. Similarly, there has not been any significant adverse impact to our derivative assets based on our evaluation of our counterparties' credit risks.
The following table provides carrying amounts and fair values of financial instruments that are not carried at fair value in our Consolidated Balance Sheets at December 31, 2020 and 2019:
| December 31, 2020 | December 31, 2019 | ||||||||||||||||||||||
| (dollars in millions) | Carrying Amount | Fair Value | Carrying Amount | Fair Value | |||||||||||||||||||
| Long-term receivables, net | $ | 65 | $ | 62 | $ | 62 | $ | 62 | |||||||||||||||
| Customer financing notes receivable, net | 128 | 126 | 62 | 62 | |||||||||||||||||||
| Short-term borrowings | (701) | (701) | (34) | (34) | |||||||||||||||||||
| Long-term debt (excluding leases and other) | (5,300) | (5,717) | — | — | |||||||||||||||||||
| Long-term liabilities | (263) | (234) | (4) | (4) |
Long-term liabilities as of December 31, 2020 includes $239 million of payables to RTX for reimbursement of tax payments RTX is responsible to pay after the Separation as a result of the TMA.
The following tables provide the valuation hierarchy classification of assets and liabilities that are not carried at fair value in the Consolidated Balance Sheets at December 31, 2020 and 2019:
| December 31, 2020 | |||||||||||||||||||||||
| (dollars in millions) | Total | Level 1 | Level 2 | Level 3 | |||||||||||||||||||
| Long-term receivables, net | $ | 62 | $ | — | $ | 62 | $ | — | |||||||||||||||
| Customer financing notes receivable, net | 126 | — | 126 | — | |||||||||||||||||||
| Short-term borrowings | (701) | — | (701) | — | |||||||||||||||||||
| Long-term debt (excluding leases and other) | (5,717) | — | (5,717) | ||||||||||||||||||||
| Long-term liabilities | (234) | — | (234) | — |
| December 31, 2019 | |||||||||||||||||||||||
| (dollars in millions) | Total | Level 1 | Level 2 | Level 3 | |||||||||||||||||||
| Long-term receivables | $ | 62 | $ | — | $ | 62 | $ | — | |||||||||||||||
| Customer financing notes receivable, net | 62 | — | 62 | — | |||||||||||||||||||
| Short-term borrowings | (34) | — | (34) | — | |||||||||||||||||||
| Long-term liabilities | (4) | — | (4) | — |
Note 19: Guarantees
The Company provides service and warranty on its products beyond normal service and warranty policies. The changes in the carrying amount of service and product guarantees for the years ended December 31, 2020 and 2019 are as follows:
| (dollars in millions) | 2020 | 2019 | |||||||||
| Balance as of January 1 | $ | 27 | $ | 47 | |||||||
| Warranties | 12 | 10 | |||||||||
| Settlements made | (14) | (18) | |||||||||
| Other | — | (12) | |||||||||
| Balance as of December 31 | $ | 25 | $ | 27 |
The Company provides certain financial guarantees to third parties. As of December 31, 2020, Otis has stand-by letters of credit with maximum potential payment totaling $185 million. We accrue costs associated with guarantees when it is probable that a liability has been incurred and the amount can be reasonably estimated. The most likely cost to be incurred is accrued based on an evaluation of currently available facts, and where no amount within a range of estimates is more likely, the minimum is accrued. In accordance with the FASB ASC Topic 460: Guarantees, we record these liabilities at fair value. As of December 31, 2020, Otis has determined there are no estimated costs probable under these guarantees.
Note 20: Leases
ASU 2016-02, Leases (Topic 842) and its related amendments (collectively, "Lease Accounting Standard") were effective for reporting periods beginning after December 15, 2018. We adopted the Lease Accounting Standard effective January 1, 2019 and elected the modified retrospective approach in which results for periods before 2019 were not adjusted for the new standard and the cumulative effect of the change in accounting was recognized through retained earnings at the date of adoption.
The Lease Accounting Standard establishes a right-of-use ("ROU") model that requires a lessee to record a ROU asset and a lease liability on the Consolidated Balance Sheets for all leases with terms longer than 12 months. Leases are classified as either finance or operating, with classification affecting the pattern of expense recognition on the Consolidated Statements of Operations. In addition, this standard requires a lessor to classify leases as either sales-type, finance or operating. A lease will be treated as a sale if it transfers all of the risks and rewards, as well as control of the underlying asset, to the lessee. If risks and rewards are conveyed without the transfer of control, the lease is treated as financing. If the lessor doesn’t convey risks and rewards or control, the lease is treated as operating.
We elected certain of the practical expedients available under the Lease Accounting Standard upon adoption. We applied the practical expedient which allows prospective transition to the Lease Accounting Standard on January 1, 2019. Under the transition practical expedient, we did not reassess lease classification, embedded leases or initial direct costs. We have applied the practical expedient for short-term leases, whereby a lease ROU asset and liability is not recognized and the expense is recognized in a straight-line basis over the lease term. In addition, we have lease agreements with lease and non-lease components, for which we have elected the practical expedients to combine these components for certain equipment leases. The adoption of the Lease Accounting Standard did not have a material effect on our Consolidated Financial Statements. Upon adoption, we recorded a $530 million ROU asset and a $523 million lease liability.
We enter into lease agreements for the use of real estate space, vehicles and certain other equipment under operating and finance leases. We determine if an arrangement contains a lease at inception. Operating leases are included in Operating lease ROU assets, Accrued liabilities, and Operating lease liabilities in our Consolidated Balance Sheets. Finance leases are not considered significant to our Consolidated Balance Sheets or Consolidated Statements of Operations.
ROU assets represent our right to use an underlying asset for the lease term and lease liabilities represent our obligation to make lease payments arising from the lease. Lease ROU assets and liabilities are recognized at commencement date based on the present value of lease payments over the lease term. As most of our leases do not provide an implicit rate, we use our incremental borrowing rate based on the information available at commencement date in determining the present value of lease payments, and use the implicit rate when readily determinable. We determine our incremental borrowing rate through market sources including relevant industry rates. Our lease ROU assets also include any lease pre-payments and exclude lease incentives. Certain of our leases include variable payments, which may vary based upon changes in facts or circumstances after the start of the lease. We exclude variable payments from lease ROU assets and lease liabilities, to the extent not considered fixed, and instead, expense variable payments as incurred. Variable lease expense and lease expense for short duration contracts is not a material component of lease expense. Our leases generally have remaining lease terms of 1 to 20 years, some of which include options to extend leases. The majority of our leases with options to extend are up to five years with the ability to terminate the lease within one year. The exercise of lease renewal options is at our sole discretion and our lease ROU assets and liabilities reflect only the options we are reasonably certain that we will exercise. Lease expense is recognized on a straight-line basis over the lease term.
Operating lease expense for the years ended December 31, 2020 and 2019 was $186 million and $191 million, respectively. Prior to the adoption of the New Lease Accounting Standard, rent expense was $161 million in 2018.
Supplemental cash flow information related to operating leases for the years ended December 31, 2020 and 2019 were as follows:
| (dollars in millions) | 2020 | 2019 | |||||||||
| Operating cash flows used for the measurement of operating lease liabilities | $ | (162) | $ | (134) | |||||||
| Operating lease ROU assets obtained in exchange for operating lease obligations | 126 | 157 | |||||||||
Operating lease ROU assets and liabilities are reflected on our Consolidated Balance Sheets as follows:
| December 31, | |||||||||||
| (dollars in millions) | 2020 | 2019 | |||||||||
| Operating lease ROU assets | $ | 542 | $ | 535 | |||||||
| Accrued liabilities | $ | 167 | $ | 140 | |||||||
| Operating lease liabilities | 367 | 386 | |||||||||
| Total operating lease liabilities | $ | 534 | $ | 526 | |||||||
Supplemental information related to operating leases was as follows:
| December 31, | |||||||||||
| 2020 | 2019 | ||||||||||
| Weighted Average Remaining Lease Term (in years) | 5.0 | 5.3 | |||||||||
| Weighted Average Discount Rate | 2.9 | % | 3.4 | % | |||||||
Undiscounted maturities of operating lease liabilities, including options to extend lease terms that are reasonably certain of being exercised, as of December 31, 2020 are as follows:
| (dollars in millions) | Total | ||||||||||||||||
| 2021 | $ | 172 | |||||||||||||||
| 2022 | 134 | ||||||||||||||||
| 2023 | 95 | ||||||||||||||||
| 2024 | 63 | ||||||||||||||||
| 2025 | 42 | ||||||||||||||||
| Thereafter | 84 | ||||||||||||||||
| Total undiscounted lease payments | 590 | ||||||||||||||||
| Less: imputed interest | (56) | ||||||||||||||||
| Total discounted lease payments | $ | 534 |
Note 21: Contingent Liabilities
Except as otherwise noted, while we are unable to predict the final outcome, based on information currently available, we do not believe that resolution of any of the following matters will have a material adverse effect upon our competitive position, results of operations, cash flows or financial condition. Legal costs generally are expensed when incurred.
Environmental. As previously disclosed, the Company's operations are subject to environmental regulation by authorities with jurisdiction over its operations. The Company has accrued for the costs of environmental remediation activities, including, but not limited to, investigatory, remediation, operating and maintenance costs and performance guarantees, and periodically reassesses these amounts. Management believes that the likelihood of incurring losses materially in excess of amounts accrued is remote. The outstanding liability for environmental obligations was $12 million as of December 31, 2020 and December 31, 2019, and is included in Accrued liabilities and Other long-term liabilities on the Consolidated Balance Sheets.
Legal Proceedings.
German Tax Litigation
As previously disclosed, we have been involved in administrative review proceedings with the German Tax Office, which concern approximately €215 million (approximately $264 million as of December 31, 2020) of tax benefits that we have claimed related to a 1998 reorganization of the corporate structure of our operations in Germany. Upon audit, these tax benefits were disallowed by the German Tax Office. We estimate interest associated with the aforementioned tax benefits is an additional approximately €118 million (approximately $145 million as of December 31, 2020).
On August 3, 2012, a suit was filed in the local German Tax Court (Berlin-Brandenburg). In 2015, our former parent UTC made tax and interest payments to German tax authorities of €275 million (approximately $300 million) in order to avoid additional interest accruals pending final resolution of this matter. In March 2016, the local German Tax Court dismissed the suit, and we appealed this decision to the German Federal Tax Court. Following a hearing on July 24, 2018, the German Federal Tax Court remanded the matter to the local German Tax Court for further proceedings. On December 7, 2020, the local Tax Court ruled against the Company. We have filed an appeal with the Federal Tax Court; however there is no assurance that the Federal Tax Court will agree to hear the appeal or, if it does, rule in the Company's favor, and it is possible that the decision of the German Tax Office ultimately could be sustained.
Pursuant to the TMA, the Company retains the liability associated with the remaining interest, and has recorded an interest accrual of €45 million (approximately $55 million as of December 31, 2020), net of payments and other deductions, included within Accrued liabilities on the Consolidated Balance Sheets at December 31, 2020. In the event that RTX and the Company prevail in this matter, any recoveries would be allocated between RTX and the Company pursuant to the terms of the TMA.
Asbestos Matters
As previously disclosed, we have been named as defendants in lawsuits alleging personal injury as a result of exposure to asbestos. While we have never manufactured any asbestos-containing component parts, and no longer incorporate asbestos in any current products, certain of our historical products have contained components manufactured by third parties incorporating asbestos. A substantial majority of these asbestos-related claims have been dismissed without payment or were covered in full or in part by insurance or other forms of indemnity. Additional cases were litigated and settled without any insurance reimbursement. The amounts involved in asbestos related claims were not material individually or in the aggregate as of, and for the periods ended, December 31, 2020 and December 31, 2019.
The estimated range of total liabilities to resolve all pending and unasserted potential future asbestos claims through 2059 is $23 million to $45 million as of December 31, 2020, and $24 million to $45 million as of December 31, 2019. Because no amount within the range of estimates is more likely to occur than any other, we recorded the minimum amount of $23 million and $24 million as of December 31, 2020 and 2019, respectively, which is principally recorded in Other long-term liabilities on our Consolidated Balance Sheets. Amounts are on a pre-tax basis, not discounted, and excludes the Company's legal fees to defend the asbestos claims (which will continue to be expensed as they are incurred). In addition, the Company has an insurance recovery receivable for probable asbestos related recoveries of approximately $5 million, which is principally recorded in Other assets on our Consolidated Balance Sheets as of December 31, 2020 and December 31, 2019.
Putative Class Action Lawsuit
On August 12, 2020, a putative class action lawsuit, (Geraud Darnis et al. v. Raytheon Technologies Corporation et al.), was filed in the United States District Court for the District of Connecticut against Otis, Raytheon Technologies Corporation ("RTX"), Carrier, each of their directors, and various incentive and deferred compensation plans. The named plaintiffs are former employees of UTC and its current and former subsidiaries, including Otis and Carrier. They seek to recover monetary damages, as well as related declaratory and equitable relief, based on claimed decreases in the value of long-term incentive awards and deferred compensation under nonqualified deferred compensation plans allegedly caused by the formula used to calculate the adjustments to such awards and deferred compensation from RTX, Carrier, and Otis following the spin-offs of Carrier and Otis and the subsequent combination of UTC and Raytheon Company. Otis believes that the claims against the Company are without merit. At this time, Otis is unable to predict the outcome, or the possible loss or range of loss, if any, which could result from this action.
Other.
As previously disclosed, we have commitments and contingent liabilities related to legal proceedings, self-insurance programs and matters arising out of the normal course of business. We accrue contingencies based on a range of possible outcomes. If no amount within this range is a better estimate than any other, we accrue the minimum amount. While it is not possible to determine the ultimate disposition of each of these claims and whether they will be resolved consistent with our beliefs, we expect that the outcome of such claims, individually or in the aggregate, will not have a material adverse effect on our business, financial condition, cash flows or results of operations.
As previously disclosed, in certain European countries, claims for overcharges on elevators and escalators related to civil cartel cases have been made, which we have accrued for based on our evaluation of the claims. While it is not possible to determine the ultimate disposition of each of these claims and whether they will be resolved consistent with our beliefs, historical settlement experience of these cases have not been material to the business, financial condition, cash flows or results of operations, however the future outcome of these cases cannot be determined.
As previously disclosed, in the ordinary course of business, the Company is also routinely a defendant in, party to or otherwise subject to many pending and threatened legal actions, claims, disputes and proceedings. These matters are often based on alleged violations of contract, product liability, warranty, regulatory, environmental, health and safety, employment, intellectual property, tax and other laws. In some of these proceedings, claims for substantial monetary damages are asserted against the Company and its subsidiaries and could result in fines, penalties, compensatory or treble damages or non-monetary relief. We do not believe that these matters will have a material adverse effect upon our competitive position, results of operations, cash flows or financial condition.
Note 22: Segment Financial Data
Our operations are classified into two operating segments: New Equipment and Service. Through the New Equipment segment, we design, manufacture, sell and install a wide range of passenger and freight elevators as well as escalators and moving walkways to customers in the residential and commercial building and infrastructure projects. The Service segment provides maintenance and repair services for both our products and those of other manufacturers, and provides modernization services to upgrade elevators and escalators. The operating segments are generally based on the management structure of the Company, how management allocates resources, assesses performance and makes strategic and operational decisions.
Segment Information. Segment information for the years ended December 31 are as follows:
| Net Sales | Operating Profit | ||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in millions) | 2020 | 2019 | 2018 | 2020 | 2019 | 2018 | |||||||||||||||||||||||||||||||||||||||||
| New Equipment | $ | 5,371 | $ | 5,648 | $ | 5,596 | $ | 318 | $ | 393 | $ | 390 | |||||||||||||||||||||||||||||||||||
| Service | 7,385 | 7,470 | 7,319 | 1,611 | 1,603 | 1,516 | |||||||||||||||||||||||||||||||||||||||||
| Total segments | 12,756 | 13,118 | 12,915 | 1,929 | 1,996 | 1,906 | |||||||||||||||||||||||||||||||||||||||||
| General corporate expenses and other 1 | — | — | — | (290) | (182) | (71) | |||||||||||||||||||||||||||||||||||||||||
| Total | $ | 12,756 | $ | 13,118 | $ | 12,915 | $ | 1,639 | $ | 1,814 | $ | 1,835 |
1 The increase in General corporate expenses and other during 2020 compared to 2019 is primarily driven by current year fixed asset impairments of $71 million and associated license costs of $14 million, incremental standalone public company costs, as well as $76 million higher non-recurring Separation-related expenses in 2020. These were partially offset by favorable foreign exchange activity during 2020 compared to 2019 of $46 million.
Total assets are not presented for each segment as they are not presented to, or reviewed by, the Chief Operating Decision Maker.
Geographic External Sales. Geographic Net sales are attributed to the geographic regions based on their location of origin. With the exception of the U.S. and China, there were no individually significant countries with sales exceeding 10% of Net sales during the years ended December 31, 2020, 2019 and 2018.
| External Net Sales | Long Lived Assets | ||||||||||||||||||||||||||||||||||
| (dollars in millions) | 2020 | 2019 | 2018 | 2020 | 2019 | 2018 | |||||||||||||||||||||||||||||
| United States Operations | $ | 3,462 | $ | 3,594 | $ | 3,429 | $ | 309 | $ | 295 | $ | 246 | |||||||||||||||||||||||
| International Operations | |||||||||||||||||||||||||||||||||||
| China | 2,135 | 2,113 | 1,919 | 113 | 105 | 113 | |||||||||||||||||||||||||||||
| Other | 7,159 | 7,411 | 7,567 | 352 | 321 | 319 | |||||||||||||||||||||||||||||
| Total | $ | 12,756 | $ | 13,118 | $ | 12,915 | $ | 774 | $ | 721 | $ | 678 | |||||||||||||||||||||||
Segment Net sales disaggregated by product and service type for the years ended December 31, 2020, 2019 and 2018 are as follows:
| (dollars in millions) | 2020 | 2019 | 2018 | ||||||||||||||
| Disaggregated Net sales by type | |||||||||||||||||
| New Equipment | $ | 5,371 | $ | 5,648 | $ | 5,596 | |||||||||||
| Maintenance and Repair | 6,047 | 6,120 | 6,017 | ||||||||||||||
| Modernization | 1,338 | 1,350 | 1,302 | ||||||||||||||
| Total Service | 7,385 | 7,470 | 7,319 | ||||||||||||||
| Total | $ | 12,756 | $ | 13,118 | $ | 12,915 | |||||||||||
Major Customers. There were no customers that individually accounted for 10% or more of the Company's consolidated Net sales for the years ended December 31, 2020, 2019 and 2018.
Selected Quarterly Financial Data (Unaudited)
The following tables show a summary of the Company's quarterly financial information for each of the four quarters of 2020 and 2019 (in millions, except per share amounts):
| Fourth Quarter | Third Quarter | Second Quarter | First Quarter | ||||||||||||||||||||
| 2020: | |||||||||||||||||||||||
| Net sales | $ | 3,493 | $ | 3,268 | $ | 3,029 | $ | 2,966 | |||||||||||||||
| Gross margin | 1,012 | 979 | 891 | 897 | |||||||||||||||||||
| Net income attributable to shareholders | 251 | 266 | 224 | 165 | |||||||||||||||||||
| Earnings per share of Common Stock (1): | |||||||||||||||||||||||
| Basic - net income attributable to shareholders | $ | 0.58 | $ | 0.61 | $ | 0.52 | $ | 0.38 | |||||||||||||||
| Diluted - net income attributable to shareholders | $ | 0.58 | $ | 0.61 | $ | 0.52 | $ | 0.38 |
| Fourth Quarter | Third Quarter | Second Quarter | First Quarter | ||||||||||||||||||||
| 2019: | |||||||||||||||||||||||
| Net sales | $ | 3,353 | $ | 3,313 | $ | 3,351 | $ | 3,101 | |||||||||||||||
| Gross margin | 966 | 975 | 984 | 901 | |||||||||||||||||||
| Net income attributable to shareholders | 218 | 317 | 308 | 273 | |||||||||||||||||||
| Earnings per share of Common Stock (1): | |||||||||||||||||||||||
| Basic - net income attributable to shareholders | $ | 0.50 | $ | 0.73 | $ | 0.71 | $ | 0.63 | |||||||||||||||
| Diluted - net income attributable to shareholders | $ | 0.50 | $ | 0.73 | $ | 0.71 | $ | 0.63 |
(1) Basic and diluted earnings per share are computed independently for each of the quarters presented. Therefore, the sum of quarterly basic and diluted per share information may not equal annual basic and diluted earnings per share.
Performance Graph (Unaudited)
The following graph and table illustrate the total return from April 3, 2020 (date of Separation) through December 31, 2020, for (i) our Common Stock, (ii) the Standard and Poor's ("S&P") 500 Index, and (iii) the S&P 500 Industrial Select Sector Index. The graph and table assume that $100 was invested on April 3, 2020 in each of our Common Stock, the S&P 500 Index and the S&P 500 Industrial Select Sector Index, and that any dividends were reinvested. The comparison reflected in the graph and the table are not intended to forecast the future performance of our Common Stock and may not be indicative of our future performance.
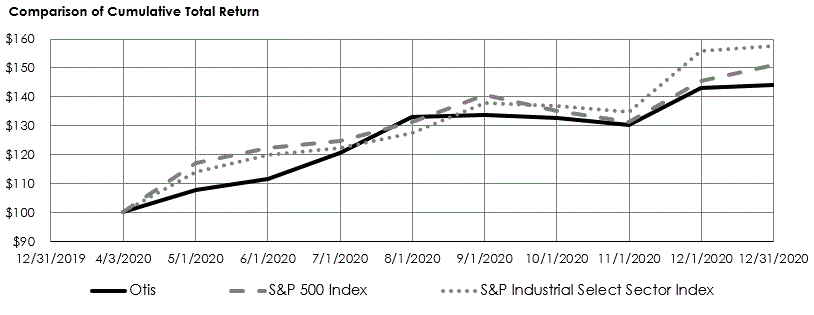
| April 3, 2020 | June 30, 2020 | September 30, 2020 | December 31, 2020 | |||||||||||
| Otis | $ | 100 | $ | 121 | $ | 133 | $ | 144 | ||||||
| S&P 500 Index | 100 | 125 | 135 | 151 | ||||||||||
| S&P 500 Industrial Select Sector Index | 100 | 122 | 137 | 158 |
Previous: Item 15. Exhibits and Financial Statement Schedule