 filings.tools
PulteGroup 10-K 2013-12-31
Filed 2014-02-05. 21 sections, 374K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 a201310-k.htm 10-K
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
[X] ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended December 31, 2013
OR
[ ] TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
Commission File Number 1-9804
PULTEGROUP, INC.
(Exact name of registrant as specified in its charter)
| MICHIGAN | 38-2766606 | |
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
100 Bloomfield Hills Parkway, Suite 300
Bloomfield Hills, Michigan 48304
(Address of principal executive offices) (Zip Code)
Registrant’s telephone number, including area code: (248) 647-2750
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Name of each exchange on which registered | |
| Common Stock, par value $0.01 | New York Stock Exchange | |
| PulteGroup, Inc. 7.375% Senior Notes due 2046 | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act:
NONE
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. YES [X] NO [ ]
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. YES [ ] NO [X]
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. YES [X] NO [ ]
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Act. YES [X] NO [ ]
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. [X]
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See the definitions of “large accelerated filer”, “accelerated filer”, and “smaller reporting company” in Rule 12b-2 of the Exchange Act. (Check one):
Large accelerated filer [X] Accelerated filer [ ] Non-accelerated filer [ ] Smaller reporting company [ ]
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). YES [ ] NO [X]
The aggregate market value of the registrant’s voting stock held by nonaffiliates of the registrant as of June 30, 2013, based on the closing sale price per share as reported by the New York Stock Exchange on such date, was $7,299,008,871.
As of February 1, 2014, the registrant had 381,299,600 shares of common stock outstanding.
Documents Incorporated by Reference
Applicable portions of the Proxy Statement for the 2014 Annual Meeting of Shareholders are incorporated by reference in Part III of this Form.
PULTEGROUP, INC.
TABLE OF CONTENTS
PART I
ITEM I. BUSINESS
PulteGroup, Inc.
PulteGroup, Inc. is a Michigan corporation organized in 1956. We are one of the largest homebuilders in the United States ("U.S."), and our common stock trades on the New York Stock Exchange under the ticker symbol “PHM”. Unless the context otherwise requires, the terms "PulteGroup", the "Company", "we", "us", and "our" used herein refer to PulteGroup, Inc. and its subsidiaries. While our subsidiaries engage primarily in the homebuilding business, we also have mortgage banking operations, conducted principally through Pulte Mortgage LLC (“Pulte Mortgage”), and title operations.
Homebuilding, our core business, includes the acquisition and development of land primarily for residential purposes within the U.S. and the construction of housing on such land. Homebuilding offers a broad product line to meet the needs of home buyers in our targeted markets. Through our brands, which include Pulte Homes, Del Webb, and Centex (acquired through our merger with Centex Corporation ("Centex") in 2009), we offer a wide variety of home designs, including single-family detached, townhouses, condominiums, and duplexes at different prices and with varying levels of options and amenities to our major customer groups: entry-level, move-up, and active adult. Over our history, we have delivered over 625,000 homes.
As of December 31, 2013, we conducted our operations in 48 markets located throughout 27 states. For reporting purposes, our Homebuilding operations are aggregated into six reportable segments:
| Northeast: | Connecticut, Delaware, Maryland, Massachusetts, New Jersey, New York, Pennsylvania, Rhode Island, Virginia | |
| Southeast: | Georgia, North Carolina, South Carolina, Tennessee | |
| Florida: | Florida | |
| Texas: | Texas | |
| North: | Illinois, Indiana, Michigan, Minnesota, Missouri, Northern California, Ohio, Oregon, Washington | |
| Southwest: | Arizona, Nevada, New Mexico, Southern California |
We also have a reportable segment for our financial services operations, which consist principally of mortgage banking and title operations. Our Financial Services segment operates generally in the same geographic markets as our Homebuilding segments.
Financial information for each of our reportable business segments is included in Note 5 to our Consolidated Financial Statements.
Available information
Our internet website address is www.pultegroupinc.com. Our annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Exchange Act are available free of charge through our website as soon as reasonably practicable after we electronically file them with or furnish them to the Securities and Exchange Commission. Our code of ethics for principal officers, our code of ethical business conduct, our corporate governance guidelines, and the charters of the Audit, Compensation and Management Development, Nominating and Governance, and Finance and Investment committees of our Board of Directors are also posted on our website and are available in print, free of charge, upon request.
Homebuilding Operations
| Years Ended December 31, ($000’s omitted) | |||||||||||||||||||
| 2013 | 2012 | 2011 | 2010 | 2009 | |||||||||||||||
| Home sale revenues | $ | 5,424,309 | $ | 4,552,412 | $ | 3,950,743 | $ | 4,419,812 | $ | 3,869,297 | |||||||||
| Home closings | 17,766 | 16,505 | 15,275 | 17,095 | 15,013 |
Beginning in 2006 and continuing through 2011, the U.S. housing market experienced a significant decline in the demand for new homes as well as a sharp decline in overall residential real estate values. U.S. new home sales in 2011 were the lowest since 1962. As a result of this industry-wide downturn, we suffered net losses in each year between 2007 - 2011 from a combination of reduced operational profitability and significant asset impairments. In response to these market conditions, we restructured our operations, including making significant reductions in employee headcount and overhead costs, and managed our business to generate cash, including curtailing our investments in inventory. We used this positive cash flow to, among other things, increase our cash reserves as well as retire outstanding debt.
In 2012, new home sales in the U.S. increased for the first time since 2005. In 2013, this trend continued as new home sales in the U.S. rose 16% to approximately 428,000 homes, an approximate 40% increase from the bottom of the housing cycle in 2011. Additionally, mortgage interest rates remain near historic lows and the overall inventory of homes available for sale, especially new homes, remains low. Although current industry volume remains low compared with historical levels, the improved environment and the actions we have taken contributed to our return to profitability in 2012 and a significant increase in our profitability in 2013. In the long term, we continue to believe that the national publicly-traded builders will have a competitive advantage over local builders through their ability to leverage economies of scale, access to more reliable and lower cost financing through the capital markets, ability to control and entitle large land positions, and greater geographic and product diversification. Among the national publicly-traded peer group, we believe that builders with broad geographic and product diversity, and sustainable capital positions will benefit as market conditions recover. In the short-term, we expect that overall market conditions will continue to improve but that improvements will occur unevenly across our markets. Our strategy to enhance shareholder value is centered around the following operational objectives:
| • | Improving our inventory turns; |
| • | More effectively allocating the capital we invest in our business using a risk-based portfolio approach; |
| • | Enhancing revenues by: establishing clear product offerings for each of our brands based on systematic, consumer-driven input, optimizing our pricing through the expanded use of options and lot premiums, and lessening our reliance on speculative home sales; |
| • | Reducing our house costs through common house plan management, value-engineering our house plans, and working with suppliers to reduce costs; and |
| • | Maintaining an efficient overhead structure. |
Our Homebuilding operations are geographically diverse within the U.S. As of December 31, 2013, we had 577 active communities. Sales prices of unit closings during 2013 ranged from less than $100,000 to greater than $1,200,000, with 86% falling within the range of $100,000 to $450,000. The average unit selling price in 2013 was $305,000, compared with $276,000 in 2012, $259,000 in 2011, $259,000 in 2010, and $258,000 in 2009. The increase in average selling price in recent years resulted from a number of factors, including improved market conditions and a shift in our sales mix toward move-up and active adult homebuyers.
Sales of single-family detached homes, as a percentage of total unit sales, were 85% in 2013, compared with 81% in 2012, 79% in 2011, 79% in 2010, and 77% in 2009. The increase in the percentage of single-family detached homes can be attributed to a weakened demand for townhouses, condominiums, and other attached housing, as prices for detached new homes have become more affordable for entry-level and active adult homebuyers.
Ending backlog, which represents orders for homes that have not yet closed, was $1.9 billion (5,772 units) at December 31, 2013 and $1.9 billion (6,458 units) at December 31, 2012. For each order in backlog, we have received a signed customer contract and customer deposit, which is refundable in certain instances. Of the orders in backlog at December 31, 2013, substantially all are scheduled to be closed during 2014, though all orders are subject to potential cancellation by or final negotiations with the customer. In the event of cancellation, the majority of our sales contracts stipulate that we have the right to retain the customer’s deposit, though we may choose to refund the deposit in certain instances.
Land acquisition and development
We acquire land primarily for the construction of homes for sale to homebuyers. We select locations for development of homebuilding communities after completing a feasibility study, which includes, among other things, soil tests, independent environmental studies and other engineering work, an evaluation of necessary zoning and other governmental entitlements, and extensive market research that enables us to match the location with our product offering to targeted consumer groups. We consider factors such as proximity to developed areas, population and job growth patterns and, if applicable, estimated development costs. We frequently manage a portion of the risk of controlling our land positions through the use of land option contracts, which enable us to defer acquiring portions of properties owned by land sellers until we have determined whether and when to exercise our option. Our use of land option agreements reduces our financial risks associated with long-term land holdings. We typically acquire land with the intent to complete sales of housing units within 24 to 36 months from the date of opening a community, except in the case of certain Del Webb active adult developments and other large master-planned projects for which the completion of community build-out requires a longer time period. While our overall supply of controlled land is in excess of our short-term needs in many of our markets, some of our controlled land consists of long-term positions that will not be converted to home sales in the near term. Accordingly, we remain active in our pursuit of new land investment. We may also periodically sell select parcels of land to third parties for commercial or other development. Additionally, we may determine that certain land assets no longer fit into our strategic operating plans.
Land is generally purchased after it is properly zoned and developed or is ready for development. In the normal course of business, we dispose of owned land not required by our homebuilding operations through sales to appropriate end users. Where we develop land, we engage directly in many phases of the development process, including: land and site planning; obtaining environmental and other regulatory approvals; and constructing roads, sewers, water and drainage facilities, and community amenities, such as parks, pools, and clubhouses. We use our staff and the services of independent engineers and consultants for land development activities. Land development work is performed primarily by independent contractors and local government authorities who construct sewer and water systems in some areas. At December 31, 2013, we controlled 123,478 lots, of which 95,212 were owned and 28,266 were under option agreements.
Sales and marketing
We are dedicated to improving the quality and value of our homes through innovative architectural and community designs. Analyzing various qualitative and quantitative data obtained through extensive market research, we stratify our potential customers into well-defined buyer groups. Such stratification provides a method for understanding the business opportunities and risks across the full spectrum of consumer groups in each market. Once the demands of potential buyers are understood, we link our home design and community development efforts to the specific lifestyle of each targeted consumer group. Through our portfolio of brands, each serving unique consumer groups, we are able to provide a distinct experience to potential customers:
| Centex | Pulte Homes | Del Webb | |
| Targeted consumer group | Entry-level buyers | Move-up buyers | Active adults |
| Portion of 2013 home closings | 25% | 46% | 29% |
The move-up buyers in our Pulte Homes communities tend to place more of a premium on location and amenities. These communities typically offer larger homes at higher price points. Our Centex brand is targeted to entry-level buyers, and these homes tend to be smaller with product offerings geared toward lower average selling prices. Through our Del Webb brand, we are better able to address the needs of active adults. Our Del Webb brand offers both destination communities and “in place” communities, for those buyers who prefer to remain in their current geographic area. These highly amenitized communities offer a variety of features, including golf courses, recreational centers, and educational classes, to the age fifty-five and over buyer to maintain an active lifestyle. In order to make the cost of these highly amenitized communities affordable to the individual homeowner, Del Webb communities tend to be larger than entry-level or move-up communities.
We market our homes to prospective buyers through media advertising, illustrated brochures, Internet listings and link placements, mobile applications, and other advertising displays. We have made significant enhancements in our tools and business practices to adapt our selling efforts to today's mobile customers. In addition, our websites, www.pulte.com, www.delwebb.com, and www.centex.com, provide tools to help users find a home that meets their needs, investigate financing alternatives, communicate moving plans, maintain a home, learn more about us, and communicate directly with us. There were approximately 9.2 million unique visits to our websites during 2013, compared with approximately 8.0 million in 2012.
To meet the demands of our various customers, we have established design expertise for a wide array of product lines. We believe that we are an innovator in consumer-inspired home design, and we view our design capabilities as an integral aspect of our marketing strategy. Our in-house architectural services teams and management, supplemented by outside consultants, create distinctive design features, both in exterior facades and interior options and features. We typically offer a variety of potential options and upgrades, such as different flooring, countertop, and appliance choices, and design our base house and option packages to meet the needs of our customers as defined through rigorous market research. Energy efficiency represents an important source of value for new homes compared with existing homes and represents a key area of focus for our home designs, including high efficiency HVAC systems and insulation, low-emissivity windows, solar power in certain geographies, and other energy-efficient features.
Typically, our sales teams, together with outside sales brokers, are responsible for guiding the customer through the sales process. We are committed to industry-leading customer service through a variety of quality initiatives, including our customer care program, which ensures that homeowners are comfortable at every stage of the building process. Fully furnished and landscaped model homes are generally used to showcase our homes and their distinctive design features.
Construction
The construction of our homes is conducted under the supervision of our on-site construction field managers. Substantially all of our construction work is performed by independent subcontractors under contracts that, in many instances, cover both labor and materials on a fixed-price basis. Using a selective process, we have teamed up with what we believe are premier subcontractors and suppliers to deliver all aspects of the house construction process.
Continuous improvement in our house construction process is a key area of focus. We maintain efficient construction operations by using standard materials and components from a variety of sources and utilizing standard construction practices. Beginning in 2011, we implemented an intensive effort to improve our product offerings and production processes through the following programs:
| • | A 12-step product development process to introduce new features and technologies based on customer-validated data; |
| • | Common management of house plans in order to focus on building those house designs that customers value the most and that can be built at the highest quality and an efficient cost; |
| • | Value engineering our house plans to optimize house designs in terms of material content and ease of construction while still providing a clear value to the customer (value engineering eliminates items that add cost but that have little to no value to the customer); and |
| • | Working with our suppliers to establish the "should cost", a data driven, collaborative effort to reduce construction costs to what the associated construction activities or materials “should cost” in the market. |
The availability of labor and materials at reasonable prices is becoming an increasing concern for certain trades and building materials in some markets as the supply chain responds to uneven industry growth. Additionally, the cost of certain building materials, especially lumber, steel, concrete, copper, and petroleum-based materials, is influenced by changes in global commodity prices. To minimize the effects of changes in construction costs, the contracting and purchasing of building supplies and materials generally is negotiated at or near the time when related sales contracts are signed with customers. In addition, we leverage our size by actively negotiating certain materials on a national or regional basis to minimize production component cost. We are also working to establish a more integrated system that can effectively link suppliers, contractors, and the production schedule. However, we cannot determine the extent to which necessary building materials and labor will be available at reasonable prices in the future.
Competition
The housing industry in the U.S. is fragmented and highly competitive. While we are one of the largest homebuilders in the U.S., our national market share represented only approximately 4% of U.S. new home sales in 2013. In each of our local markets, there are numerous national, regional, and local homebuilders with whom we compete. Additionally, new home sales have traditionally represented less than 15% of overall U.S. home sales (new and existing homes). Therefore, we also compete with sales of existing house inventory, and any provider of housing units, for sale or to rent, including apartment operators, may be considered a competitor. Conversion of apartments to condominiums further provides an alternative to traditional housing, as does manufactured housing. We compete primarily on the basis of location, price, quality, reputation, design, community amenities, and our customers' overall sales and homeownership experiences.
Seasonality
Our homebuilding operating cycle historically reflected increased revenues, profitability, and cash flow from operations during the fourth quarter based on the timing of home closings. While the challenging market conditions experienced in recent years lessened the seasonal variations of our results, we have experienced a return to a more traditional demand pattern as new orders were higher in the first half of the year and home closings increased in each quarter throughout the year. If and when the homebuilding industry more fully recovers from the recent downturn, we believe these traditional seasonal patterns will continue.
Regulation and environmental matters
Our operations are subject to extensive regulations imposed and enforced by various federal, state, and local governing authorities. These regulations are complex and include building codes, land zoning and other entitlement restrictions, health and safety regulations, labor practices, marketing and sales practices, environmental regulations, rules and regulations relating to mortgage financing and title operations, and various other laws, rules, and regulations. Collectively, these regulations have a significant impact on the site selection and development of our communities, our house design and construction techniques, our relationships with customers, employees, and suppliers / subcontractors, and many other aspects of our business. The applicable governing authorities frequently have broad discretion in administering these regulations, including inspections of our homes prior to closing with the customer in the majority of municipalities in which we operate.
Financial Services Operations
We conduct our financial services business, which includes mortgage and title operations, through Pulte Mortgage and other subsidiaries. Pulte Mortgage arranges financing through the origination of mortgage loans primarily for the benefit of our homebuyers. We are a lender approved by the FHA and VA and are a seller/servicer approved by Government National Mortgage Association ("Ginnie Mae"), Federal National Mortgage Association ("Fannie Mae"), Federal Home Loan Mortgage Corporation ("Freddie Mac"), and other investors. In our conventional mortgage lending activities, we follow underwriting guidelines established by Fannie Mae, Freddie Mac, and private investors. We believe that our customers’ use of our in-house mortgage and title operations provides us with a competitive advantage by enabling more control over the quality of the overall home buying process for our customers while also helping us align the timing of the house construction process with our customers’ financing needs.
Operating as a captive business model primarily targeted to supporting our Homebuilding operations, the business levels of our Financial Services operations are highly correlated to Homebuilding. During 2013, 2012, and 2011, we originated mortgage loans for 64%, 67%, and 61%, respectively, of the homes we sold. Such originations represented substantially all of our total originations in each of those years. Our capture rate, which we define as loan originations from our homebuilding business as a percentage of total loan opportunities from our homebuilding business excluding cash settlements, was 80.2% in 2013, 81.9% in 2012, and 78.5% in 2011.
In originating mortgage loans, we initially use our own funds, including funds available pursuant to credit agreements with third parties, and subsequently sell such mortgage loans to third party investors in the secondary market. Substantially all of the loans we originate are sold in the secondary market within a short period of time after origination, generally within 30 days. We also sell the servicing rights for the loans we originate through fixed price servicing sales contracts to reduce the risks and costs inherent in servicing loans. This strategy results in owning the servicing rights for only a short period of time.
The mortgage industry in the U.S. is highly competitive. We compete with other mortgage companies and financial institutions to provide attractive mortgage financing to our homebuyers. We utilize a centralized fulfillment center staffed with loan consultants to perform our mortgage underwriting, processing, and closing functions. We believe centralizing both the fulfillment and origination of our loans improves the speed, efficiency, and quality of our mortgage operations, improving our profitability and allowing us to focus on providing attractive mortgage financing opportunities for our customers.
In originating and servicing mortgage loans, we are subject to the rules and regulations of the government-sponsored investors and other investors that purchase the loans we originate, as well as to those of other government agencies that have oversight of the government-sponsored investors or consumer lending rules in the U.S. In addition to being affected by changes in these programs, our mortgage banking business is also affected by many of the same factors that impact our homebuilding business.
Our mortgage operations may be responsible for losses associated with mortgage loans originated and sold to investors in the event of errors or omissions relating to representations and warranties made by us that the loans met certain requirements, including representations as to underwriting standards, the existence of primary mortgage insurance, and the validity of certain borrower representations in connection with the loan. If a loan is determined to be faulty, we either repurchase the loan from the investors or reimburse the investors' losses (a "make-whole" payment). Historically, our overall losses related to this risk were not significant. Beginning in 2009, however, we experienced a significant increase in losses as a result of the high level of loan defaults and related losses in the mortgage industry and increasing aggressiveness by investors in presenting such claims to us. To date, the significant majority of these losses relates to loans originated in 2006 and 2007, during which period inherently riskier loan products became more common in the mortgage origination market. Given the volatility in the mortgage industry and the uncertainty regarding the ultimate resolution of these claims, actual costs could differ from our current estimates.
Our subsidiary title insurance companies serve as title insurance agents and underwriters in select markets by providing title insurance policies and examination and closing services to buyers of homes we sell. Historically, we have not experienced significant claims related to our title operations.
Financial Information About Geographic Areas
Substantially all of our operations are located within the U.S. However, we have some non-operating foreign subsidiaries and affiliates, which are insignificant to our consolidated financial results.
Organization/Employees
All subsidiaries and operating units operate independently with respect to daily operations. Homebuilding real estate purchases and other significant homebuilding, mortgage banking, financing activities, and similar operating decisions must be approved by the business unit’s management and/or corporate senior management.
At December 31, 2013, we employed 3,843 people, of which 709 people were employed in our Financial Services operations. Except for a small group of employees in our St. Louis homebuilding division, our employees are not represented by any union. Contracted work, however, may be performed by union contractors. Our local and corporate management personnel are paid incentive compensation based on a combination of individual performance and the performance of the applicable business unit or the Company. Each business unit is given a level of autonomy regarding employment of personnel, although our senior corporate management acts in an advisory capacity in the employment of subsidiary officers. We consider our employee and contractor relations to be satisfactory.
Item 1A. RISK FACTORS
Discussion of our business and operations included in this annual report on Form 10-K should be read together with the risk factors set forth below. They describe various risks and uncertainties to which we are, or may become, subject. These risks and uncertainties, together with other factors described elsewhere in this report, have the potential to affect our business, financial condition, results of operations, cash flows, strategies, or prospects in a material and adverse manner.
Downward changes in general economic, real estate construction, or other business conditions could adversely affect our business or our financial results.
The residential homebuilding industry is sensitive to changes in economic conditions and other factors, such as the level of employment, consumer confidence, consumer income, availability of financing, and interest rate levels. Adverse changes in any of these conditions generally, or in the markets where we operate, could decrease demand and pricing for new homes in these areas or result in customer cancellations of pending contracts, which could adversely affect the number of home deliveries we make or reduce the prices we can charge for homes, either of which could result in a decrease in our revenues and earnings and would adversely affect our financial condition.
The homebuilding industry experienced a significant downturn in recent years. Although industry conditions improved during 2012 and 2013, the overall U.S. economy, while improving, remains challenged and consumer demand in the industry remains volatile. A deterioration in industry conditions could adversely affect our business and results of operations.
Beginning in 2006 and continuing through 2011, the U.S. housing market was unfavorably impacted by severe weakness in new home sales attributable to, among other factors, weak consumer confidence, tightened mortgage standards, significant foreclosure activity, a more challenging appraisal environment, higher than normal unemployment levels, and significant uncertainty in the global economy. These conditions contributed to sharply weakened demand for new homes and heightened pricing pressures on new and existing home sales. As a result of these factors, we experienced significant decreases in our revenues and profitability during the period 2007 - 2011. We also incurred substantial impairments of our land inventory and certain other assets during this period. During 2012 and 2013, overall industry new home sales increased, and we returned to profitability. However, the overall demand for new homes remains below historical levels. Accordingly, we can provide no assurances that the adjustments we have made in our operating strategy will be successful.
If the market value of our land and homes drops significantly, our profits could decrease.
The market value of land, building lots, and housing inventories can fluctuate significantly as a result of changing market conditions, and the measures we employ to manage inventory risk may not be adequate to insulate our operations from a severe drop in inventory values. We acquire land for expansion into new markets and for replacement of land inventory and expansion within our current markets. If housing demand decreases below what we anticipated when we acquired our inventory, we may not be able to make profits similar to what we have made in the past, we may experience less than anticipated profits, and/or we may not be able to recover our costs when we sell and build homes. When market conditions are such that land values are not appreciating, option arrangements previously entered into may become less desirable, at which time we may elect to forego deposits and pre-acquisition costs and terminate the agreement. In the face of adverse market conditions, we may have substantial inventory carrying costs, we may have to write down our inventory to its fair value, and/or we may have to sell land or homes at a loss.
Our success depends on our ability to acquire land suitable for residential homebuilding at reasonable prices, in accordance with our land investment criteria.
The homebuilding industry is highly competitive for suitable land. The availability of finished and partially finished developed lots and undeveloped land for purchase that meet our internal criteria depends on a number of factors outside our control, including land availability in general, competition with other homebuilders and land buyers for desirable property, inflation in land prices, zoning, allowable housing density, and other regulatory requirements. Should suitable lots or land become less available, the number of homes we may be able to build and sell could be reduced, and the cost of land could be increased, perhaps substantially, which could adversely impact our results of operations.
Our long-term ability to build homes depends on our acquiring land suitable for residential building at reasonable prices in locations where we want to build. In the past, we experienced significant competition for suitable land as a result of land constraints in many of our markets. As competition for suitable land increases, and as available land is developed, the cost of acquiring suitable remaining land could rise, and the availability of suitable land at acceptable prices may decline. Any land shortages or any decrease in the supply of suitable land at reasonable prices could limit our ability to develop new communities or result in increased land costs. We may not be able to pass through to our customers any increased land costs, which could adversely impact our revenues, earnings, and margins.
We are subject to claims related to mortgage loans we sold in the secondary mortgage market that may be significant.
Our mortgage operations may be responsible for losses associated with mortgage loans originated and sold to investors in the event of errors or omissions relating to certain representations and warranties made by us that the loans met certain requirements, including representations as to underwriting standards, the type of collateral, the existence of primary mortgage insurance, and the validity of certain borrower representations in connection with the loan. We may also be required to indemnify underwriters that purchased and securitized loans originated by a former subsidiary of Centex for losses incurred by investors in those securitized loans based on similar breaches of representations and warranties.
To date, the significant majority of these losses relate to loans originated in 2006 and 2007, during which period inherently riskier loan products became more common in the origination market. In 2006 and 2007, we originated $39.5 billion of loans, excluding loans originated by Centex's former subprime loan business sold by Centex in 2006.
In addition, we entered into an agreement in conjunction with the wind down of Centex’s mortgage operations, which ceased loan origination activities in December 2009, that provides a guaranty for one major investor of loans originated by Centex. This guaranty provides that we will honor the potential repurchase obligations of Centex’s mortgage operations related to breaches of similar representations in the origination of a certain pool of loans.
The resolution of claims related to alleged breaches of these representations and warranties and repurchase claims could have a material adverse effect on our financial condition, cash flows and results of operations, and could exceed existing estimates and accruals. The repurchase liability we have recorded is estimated based on several factors, including the level of current unresolved repurchase requests, the volume of estimated probable future repurchase requests, our ability to cure the defects identified in the repurchase requests, and the severity of the estimated loss upon repurchase. The factors referred to above are subject to change in light of market developments, the economic environment, and other circumstances, some of which are beyond our control. Accordingly, there can be no assurance that such reserves will not need to be increased in the future.
Future increases in interest rates, reductions in mortgage availability, or other increases in the effective costs of owning a home could prevent potential customers from buying our homes and adversely affect our business and financial results.
A large majority of our customers finance their home purchases through mortgage loans, many through our mortgage bank. Interest rates have been near historical lows for several years, which has made new homes more affordable. Increases in interest rates or decreases in the availability of mortgage financing, however, could adversely affect the market for new homes. Potential homebuyers may be less willing or able to pay the increased monthly costs or to obtain mortgage financing. Lenders may increase the qualifications needed for mortgages or adjust their terms to address any increased credit risk. Even if potential customers do not need financing, changes in interest rates and mortgage availability could make it harder for them to sell their current homes to potential buyers who need financing. These factors could adversely affect the sales or pricing of our homes and could also reduce the volume or margins in our financial services business. Our financial services business could also be impacted to the extent we are unable to match interest rates and amounts on loans we have committed to originate through the various hedging strategies we employ. These developments have had, and may continue to have, a material adverse effect on the overall demand for new housing and thereby on the results of operations for our homebuilding business.
We also believe that the availability of FHA and VA mortgage financing is an important factor in marketing some of our homes. The FHA has and may continue to impose stricter loan qualification standards, raise minimum down payment requirements, impose higher mortgage insurance premiums and other costs, and/or limit the number of mortgages it insures. The liquidity provided by Fannie Mae and Freddie Mac to the mortgage industry is also critical to the housing market. The impact of the federal government’s conservatorship of Fannie Mae and Freddie Mac on the short-term and long-term demand for new housing remains unclear. Any limitations or restrictions on the availability of financing by these agencies could adversely affect interest rates, mortgage financing, and our sales of new homes and mortgage loans.
Significant costs of homeownership include mortgage interest expense and real estate taxes, both of which are generally deductible for an individual’s federal and, in some cases, state income taxes. Any changes to income tax laws by the federal government or a state government to eliminate or substantially reduce these income tax deductions, as has been considered from time to time, would increase the after-tax cost of owning a home. Increases in real estate taxes by local governmental authorities also increase the cost of homeownership. Any such increases to the cost of homeownership could adversely impact the demand for and sales prices of new homes.
Adverse capital and credit market conditions may significantly affect our access to capital and cost of capital.
The capital and credit markets have experienced significant volatility in recent years. In many cases, the markets have exerted downward pressure on the availability of liquidity and credit capacity for issuers. We may need credit-related liquidity for future growth and development of our business. Without sufficient liquidity, we may not be able to purchase additional land or develop land, which could adversely affect our financial results. At December 31, 2013, we had cash and equivalents of $1.6 billion as well as restricted cash totaling $72.7 million. However, our internal sources of liquidity may prove to be insufficient, and in such case, we may not be able to successfully obtain additional financing on terms acceptable to us, or at all.
Another source of liquidity includes our ability to use letters of credit and surety bonds pursuant to certain performance-related obligations and as security for certain land option agreements and under various insurance programs. The majority of these letters of credit and surety bonds are in support of our land development and construction obligations to various municipalities, other government agencies, and utility companies related to the construction of roads, sewers, and other infrastructure. At December 31, 2013, we had outstanding letters of credit and surety bonds totaling $183.1 million and $958.3 million, respectively. Of these amounts outstanding, $58.7 million of the letters of credit were subject to cash-collateralized agreements while the remaining letters of credit and surety bonds were unsecured. If we are unable to obtain letters of credit or surety bonds when required, or the conditions imposed by issuers increase significantly, our financial condition and results of operations could be adversely affected.
Competition for homebuyers could reduce our deliveries or decrease our profitability.
The housing industry in the U.S. is highly competitive. We compete primarily on the basis of location, price, quality, reputation, design, community amenities, and our customers' overall sales and homeownership experiences. We compete in each of our markets with numerous national, regional, and local homebuilders. This competition with other homebuilders could reduce the number of homes we deliver or cause us to accept reduced margins in order to maintain sales volume.
We also compete with resales of existing or foreclosed homes, housing speculators, and available rental housing. Increased competitive conditions in the residential resale or rental market in the regions where we operate could decrease demand for new homes or unfavorably impact pricing for new homes.
Supply shortages and other risks related to the demand for skilled labor and building materials could increase costs and delay deliveries.
The homebuilding industry is highly competitive for skilled labor and materials. Additionally, the cost of certain building materials, especially lumber, steel, concrete, copper, and petroleum-based materials, is influenced by changes in global commodity prices. Increased costs or shortages of skilled labor and/or materials could cause increases in construction costs and construction delays. We may not be able to pass on increases in construction costs to customers and generally are unable to pass on any such increases to customers who have already entered into sales contracts as those sales contracts generally fix the price of the home at the time the contract is signed, which may be well in advance of the construction of the home. Sustained increases in construction costs may, over time, erode our margins, and pricing competition may restrict our ability to pass on any such additional costs, thereby decreasing our margins.
Our income tax provision and tax reserves may be insufficient if a taxing authority is successful in asserting positions that are contrary to our interpretations and related reserves, if any.
Significant judgment is required in determining our provision for income taxes and our reserves for federal, state, and local taxes. In the ordinary course of business, there may be matters for which the ultimate outcome is uncertain. Our evaluation of our tax matters is based on a number of factors, including changes in facts or circumstances, changes in tax law, correspondence with tax authorities during the course of audits, and effective settlement of audit issues. Although we believe our approach to determining the tax treatment for such items is appropriate, no assurance can be given that the final tax authority review will not be materially different than that which is reflected in our income tax provision and related tax reserves. Such differences could have a material adverse effect on our income tax provision in the period in which such determination is made and, consequently, on our financial position, cash flows, or net income for such period.
We are periodically audited by various federal, state, and local authorities regarding tax matters. Our current audits are in various stages of completion; however, no outcome for a particular audit can be determined with certainty prior to the conclusion of the audit, appeal and, in some cases, litigation process. As each audit is concluded, adjustments, if any, are recorded in our financial statements in the period determined. To provide for potential tax exposures, we maintain tax reserves based on reasonable estimates of potential audit results. If these reserves are insufficient upon completion of an audit, there could be an adverse impact on our financial position, cash flows, and results of operations.
We may not realize our deferred income tax assets.
As of December 31, 2013, we had deferred income tax assets, net of deferred tax liabilities, of $2.2 billion, against which we provided a valuation allowance of $157.3 million. The ultimate realization of our deferred income tax assets is dependent upon generating future taxable income and executing tax planning strategies. While we have recorded valuation allowances against certain of our deferred income tax assets, the valuation allowances are subject to change as facts and circumstances change.
Our ability to utilize net operating losses (“NOLs”), built-in losses (“BILs”), and tax credit carryforwards to offset our future taxable income would be limited if we were to undergo an “ownership change” within the meaning of Section 382 of the Internal Revenue Code (the “IRC”). In general, an “ownership change” occurs whenever the percentage of the stock of a corporation owned by “5-percent shareholders” (within the meaning of Section 382 of the IRC) increases by more than 50 percentage points over the lowest percentage of the stock of such corporation owned by such “5-percent shareholders” at any time over the testing period.
An ownership change under Section 382 of the IRC would establish an annual limitation to the amount of NOLs, BILs, and tax credit carryforwards we could utilize to offset our taxable income in any single year. The application of these limitations might prevent full utilization of the deferred tax assets attributable to our NOLs, BILs, and tax credit carryforwards. We have not experienced an ownership change as defined by Section 382. To preserve our ability to utilize NOLs, BILs, and other tax benefits in the future without a Section 382 limitation, we adopted a shareholder rights plan, which is triggered upon certain transfers of our securities, and amended our by-laws to prohibit certain transfers of our securities. Notwithstanding the foregoing measures, there can be no assurance that we will not undergo an ownership change within the meaning of Section 382.
As a result of the merger with Centex in August 2009, our ability to use certain of Centex’s pre-ownership change NOLs, BILs, and deductions is limited under Section 382 of the Internal Revenue Code. The applicable Section 382 limitation is approximately $67.4 million per year for NOLs, losses realized on built-in loss assets that are sold within 60 months of the ownership change (i.e. before August 2014), and certain deductions. We do not believe that the Section 382 limitation will prevent the Company from using Centex's pre-ownership change NOL carryforwards and built-in losses or deductions.
The value of our deferred tax assets is also dependent upon the tax rates expected to be in effect at the time taxable income is expected to be generated. A decrease in enacted corporate tax rates in our major jurisdictions, especially the U.S. federal corporate tax rate, would decrease the value of our deferred tax assets, which could be material.
We have significant intangible assets. If these assets become impaired, then our profits and shareholders’ equity may be reduced.
We have significant intangible assets related to prior business combinations. We evaluate the recoverability of intangible assets whenever facts and circumstances indicate the carrying amount may not be recoverable. If the carrying value of intangible assets is deemed impaired, the carrying value is written down to fair value. This would result in a charge to our operating earnings. If management’s expectations of future results and cash flows decrease significantly, impairments of the remaining intangible assets may occur.
Government regulations could increase the cost and limit the availability of our development and homebuilding projects or affect our related financial services operations and adversely affect our business or financial results.
Our operations are subject to building, environmental, and other regulations imposed and enforced by various federal, state, and local governing authorities. New housing developments may also be subject to various assessments for schools, parks, streets, and other public improvements. These can cause an increase in the effective cost of our homes.
We also are subject to a variety of local, state, and federal laws and regulations concerning protection of health, safety, and the environment. The impact of environmental laws varies depending upon the prior uses of the building site or adjoining properties and may be greater in areas with less supply where undeveloped land or desirable alternatives are less available. These matters may result in delays, may cause us to incur substantial compliance, remediation and other costs, and can prohibit or severely restrict development and homebuilding activity in environmentally sensitive regions or areas. More stringent requirements could be imposed in the future on homebuilders and developers, thereby increasing the cost of compliance.
Our financial services operations are also subject to numerous federal, state, and local laws and regulations. These include eligibility requirements for participation in federal loan programs and compliance with consumer lending and similar requirements such as disclosure requirements, prohibitions against discrimination, and real estate settlement procedures. They also subject our operations to examination by applicable agencies, pursuant to which those agencies may limit our ability to provide mortgage financing or title services to potential purchasers of our homes. For our homes to qualify for FHA or VA mortgages, we must satisfy valuation standards and site, material, and construction requirements of those agencies.
In January 2013, the Consumer Financial Protection Bureau adopted new rules regarding the origination of mortgages, including the criteria for “qualified mortgages”, rules for lender practices regarding assessing borrowers’ ability to repay, and limitations on certain fees and incentive arrangements. Such rules went into effect in January 2014. While we have adjusted our operations to comply with the new rules, the impact such rules will have on our business remains unclear. Additionally, many other rules required by the Dodd-Frank Act of 2010 have not yet been completed or implemented, which has created uncertainty in the overall U.S. financial services and mortgage industries as to their long-term impact.
Homebuilding is subject to warranty and other claims in the ordinary course of business that can be significant.
As a homebuilder, we are subject to home warranty, construction defect, and other claims arising in the ordinary course of business. We record warranty and other reserves for the homes we sell based on historical experience in our markets and our judgment of the qualitative risks associated with the types of homes built. We have, and require our subcontractors to have, general liability, property, errors and omissions, workers compensation, and other business insurance. These insurance policies protect us against a portion of our risk of loss from claims, subject to certain self-insured per occurrence and aggregate retentions, deductibles, and available policy limits. We reserve for costs to cover our self-insured and deductible amounts under these policies and for any costs of claims and lawsuits based on an analysis of our historical claims, which includes an estimate of claims incurred but not yet reported. Because of the uncertainties inherent in these matters, we cannot provide assurance that our insurance coverage, our subcontractor arrangements, and our reserves will be adequate to address all our warranty and construction defect claims in the future. Contractual indemnities can be difficult to enforce, we may be responsible for applicable self-insured retentions, and some types of claims may not be covered by insurance or may exceed applicable coverage limits. Additionally, the coverage offered by and the availability of general liability insurance for construction defects are currently costly and limited. We have responded to increases in insurance costs and coverage limitations by increasing our self-insured retentions and claim reserves. There can be no assurance that coverage will not be further restricted and become more costly. Additionally, we are exposed to counterparty default risk related to our subcontractors and our and our subcontractors’ insurance carriers.
Natural disasters and severe weather conditions could delay deliveries, increase costs, and decrease demand for new homes in affected areas.
Our homebuilding operations are located in many areas that are subject to natural disasters and severe weather. The occurrence of natural disasters or severe weather conditions can delay new home deliveries, increase costs by damaging inventories, reduce the availability of materials, and negatively impact the demand for new homes in affected areas. Furthermore, if our insurance does not fully cover business interruptions or losses resulting from these events, our earnings, liquidity, or capital resources could be adversely affected.
Inflation may result in increased costs that we may not be able to recoup.
Inflation can have a long-term impact on us because increasing costs of land, materials, and labor may require us to increase the sales prices of homes in order to maintain satisfactory margins. However, we may not be able to raise home prices sufficiently to keep up with the rate of inflation and our margins could decrease. In addition, inflation is often accompanied by higher interest rates, which could have a negative impact on housing demand.
Information technology failures or data security breaches could harm our business.
We use information technology and other computer resources to carry out important operational activities and to maintain our business records. Our computer systems, including our back-up systems, are subject to damage or interruption from power outages, computer and telecommunications failures, computer viruses, security breaches (through cyber-attacks from computer hackers and sophisticated organizations), catastrophic events such as fires, tornadoes and hurricanes, and usage errors by our associates. If our computer systems and our back-up systems are damaged, breached, or cease to function properly, we could suffer interruptions in our operations or unintentionally allow misappropriation of proprietary or confidential information (including information about our homebuyers and business partners), which could require us to incur significant costs to remediate or otherwise resolve these issues.
Future terrorist attacks against the U.S. or increased domestic and international instability could have an adverse effect on our operations.
A future terrorist attack against the U.S. could cause a sharp decrease in the number of new contracts signed for homes and an increase in the cancellation of existing contracts. Accordingly, adverse developments in the war on terrorism, future terrorist attacks against the U.S., or increased domestic and international instability could adversely affect our business.
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 2. PROPERTIES
Our homebuilding and corporate headquarters are located in leased office facilities at 100 Bloomfield Hills Parkway, Bloomfield Hills, Michigan 48304. Pulte Mortgage leases its primary office facilities in Englewood, Colorado. We also maintain various support functions in leased facilities near Phoenix, Arizona and Atlanta, Georgia. Our homebuilding divisions and financial services branches lease office space in the geographic locations in which they conduct their day-to-day operations.
Because of the nature of our homebuilding operations, significant amounts of property are held as inventory in the ordinary course. Such properties are not included in response to this Item.
Item 3. LEGAL PROCEEDINGS
We are involved in various legal and governmental proceedings incidental to our continuing business operations, many involving claims related to certain construction defects. The consequences of these matters are not presently determinable but, in our opinion, after consulting with legal counsel and taking into account insurance and reserves, the ultimate liability is not expected to have a material adverse impact on our results of operations, financial position, or cash flows. However, to the extent the liability arising from the ultimate resolution of any matter exceeds our estimates reflected in the recorded reserves relating to such matter, we could incur additional charges that could be significant.
Item 4. MINE SAFETY DISCLOSURES
This Item is not applicable.
Item 4A. EXECUTIVE OFFICERS OF THE REGISTRANT
Set forth below is certain information with respect to our executive officers.
| Name | Age | Position | Year Became An Executive Officer | |||
| Richard J. Dugas, Jr. | 48 | Chairman, President and Chief Executive Officer | 2002 | |||
| Robert T. O'Shaughnessy | 48 | Executive Vice President and Chief Financial Officer | 2011 | |||
| Harmon D. Smith | 50 | Executive Vice President - Homebuilding Operations and Area President, Texas | 2011 | |||
| James R. Ellinghausen | 55 | Executive Vice President, Human Resources | 2005 | |||
| Steven M. Cook | 55 | Senior Vice President, General Counsel and Secretary | 2006 | |||
| Stephen P. Schlageter | 43 | Area President, Northeast | 2012 | |||
| Ryan R. Marshall | 39 | Area President, Southeast | 2012 | |||
| Patrick J. Beirne | 50 | Area President, Central | 2011 | |||
| John J. Chadwick | 52 | Area President, Southwest | 2012 | |||
| James L. Ossowski | 45 | Vice President, Finance and Controller | 2013 |
The following is a brief account of the business experience of each officer during the past five years:
Mr. Dugas was appointed Chairman in August 2009 and President and Chief Executive Officer in July 2003. Previously, he was appointed Chief Operating Officer in May 2002 and Executive Vice President in December 2002. Since joining our company in 1994, he has served in a variety of management positions.
Mr. O'Shaughnessy was appointed Executive Vice President and Chief Financial Officer in May 2011. Prior to joining our company, he held a number of financial roles at Penske Automotive Group from 1997 to 2011, most recently as Executive Vice President and Chief Financial Officer.
Mr. Smith was appointed Executive Vice President - Homebuilding Operations and Area President, Texas, in May 2012, and previously held the position of Area President, Gulf Coast since 2008. He has served as an Area President over various geographical markets since 2006.
Mr. Ellinghausen was appointed Executive Vice President, Human Resources in December 2006.
Mr. Cook was appointed Senior Vice President, General Counsel and Secretary in December 2008 and previously held the position of Vice President, General Counsel and Secretary since February 2006.
Mr. Schlageter was appointed Area President, Northeast in November 2012 and previously held the positions of Vice President, Strategic Planning since October 2010 and Division President, Raleigh since November 2003.
Mr. Marshall was appointed Area President, Southeast in November 2012 and previously held the positions of Area President, Florida since May 2012 and Division President, South Florida since 2006.
Mr. Beirne was appointed Area President, Central in 2012 and has served as an Area President over various geographical markets since 2006.
Mr. Chadwick was appointed Area President, Southwest in 2012 and previously served as Division President, Arizona. Since 2006, Mr. Chadwick has held the position of Area President or Division President over various geographical markets.
Mr. Ossowski was appointed Vice President, Finance and Controller in February 2013 and previously held the position of Vice President, Finance - Homebuilding Operations since August 2010. Since 2002, Mr. Ossowski has held various finance positions of increasing responsibility with the Company.
There is no family relationship between any of the officers. Each officer serves at the pleasure of the Board of Directors.
PART II
Item 5. MARKET FOR THE REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Our common shares are listed on the New York Stock Exchange (Symbol: PHM).
Related Stockholder Matters
The table below sets forth, for the quarterly periods indicated, the range of high and low closing prices for our common shares and dividend per share information:
| December 31, 2013 | December 31, 2012 | ||||||||||||||||||||||
| High | Low | Declared Dividend | High | Low | Declared Dividend | ||||||||||||||||||
| 1st Quarter | $ | 21.67 | $ | 18.02 | $ | — | $ | 9.61 | $ | 6.52 | $ | — | |||||||||||
| 2nd Quarter | 24.25 | 17.54 | — | 10.70 | 7.69 | — | |||||||||||||||||
| 3rd Quarter | 20.39 | 15.11 | 0.10 | 16.98 | 10.02 | — | |||||||||||||||||
| 4th Quarter | 20.37 | 15.54 | 0.05 | 18.61 | 15.24 | — |
At February 1, 2014, there were 2,868 shareholders of record.
Issuer Purchases of Equity Securities
| (a) Total number of shares purchased (1) | (b) Average price paid per share (1) | (c) Total number of shares purchased as part of publicly announced plans or programs | (d) Approximate dollar value of shares that may yet be purchased under the plans or programs ($000’s omitted) | |||||||||||
| October 1, 2013 to October 31, 2013 | — | $ | — | — | $ | 269,321 | (2) | |||||||
| November 1, 2013 to November 30, 2013 | 894,286 | 16.77 | 886,509 | $ | 254,467 | (2) | ||||||||
| December 1, 2013 to December 31, 2013 | 1,238,872 | 18.34 | 1,100,000 | $ | 234,290 | (2) | ||||||||
| Total | 2,133,158 | $ | 17.68 | 1,986,509 |
| (1) | During the fourth quarter of 2013, a total of 146,649 shares were surrendered by employees for payment of minimum tax obligations upon the vesting or exercise of previously granted stock-based compensation awards. Such shares were not repurchased as part of our publicly-announced stock repurchase programs. |
| (2) | Pursuant to the two $100 million share repurchase programs authorized and announced by our Board of Directors in October 2002 and October 2005, the $200 million share repurchase authorized and announced in February 2006, and the $250 million share repurchase authorized and announced in July 2013 (for a total share repurchase authorization of $650 million), we have repurchased a total of 16,925,409 shares for a total of $415.8 million. We have fully utilized the authorizations provided by the 2002, 2005, and 2006 share repurchase authorizations and will no longer conduct share repurchases under these programs. The July 2013 share repurchase authorization has $234.3 million remaining as of December 31, 2013. There is no expiration date for this program. |
The information required by this item with respect to equity compensation plans is set forth under Item 12 of this annual report on Form 10-K and is incorporated herein by reference.
Performance Graph
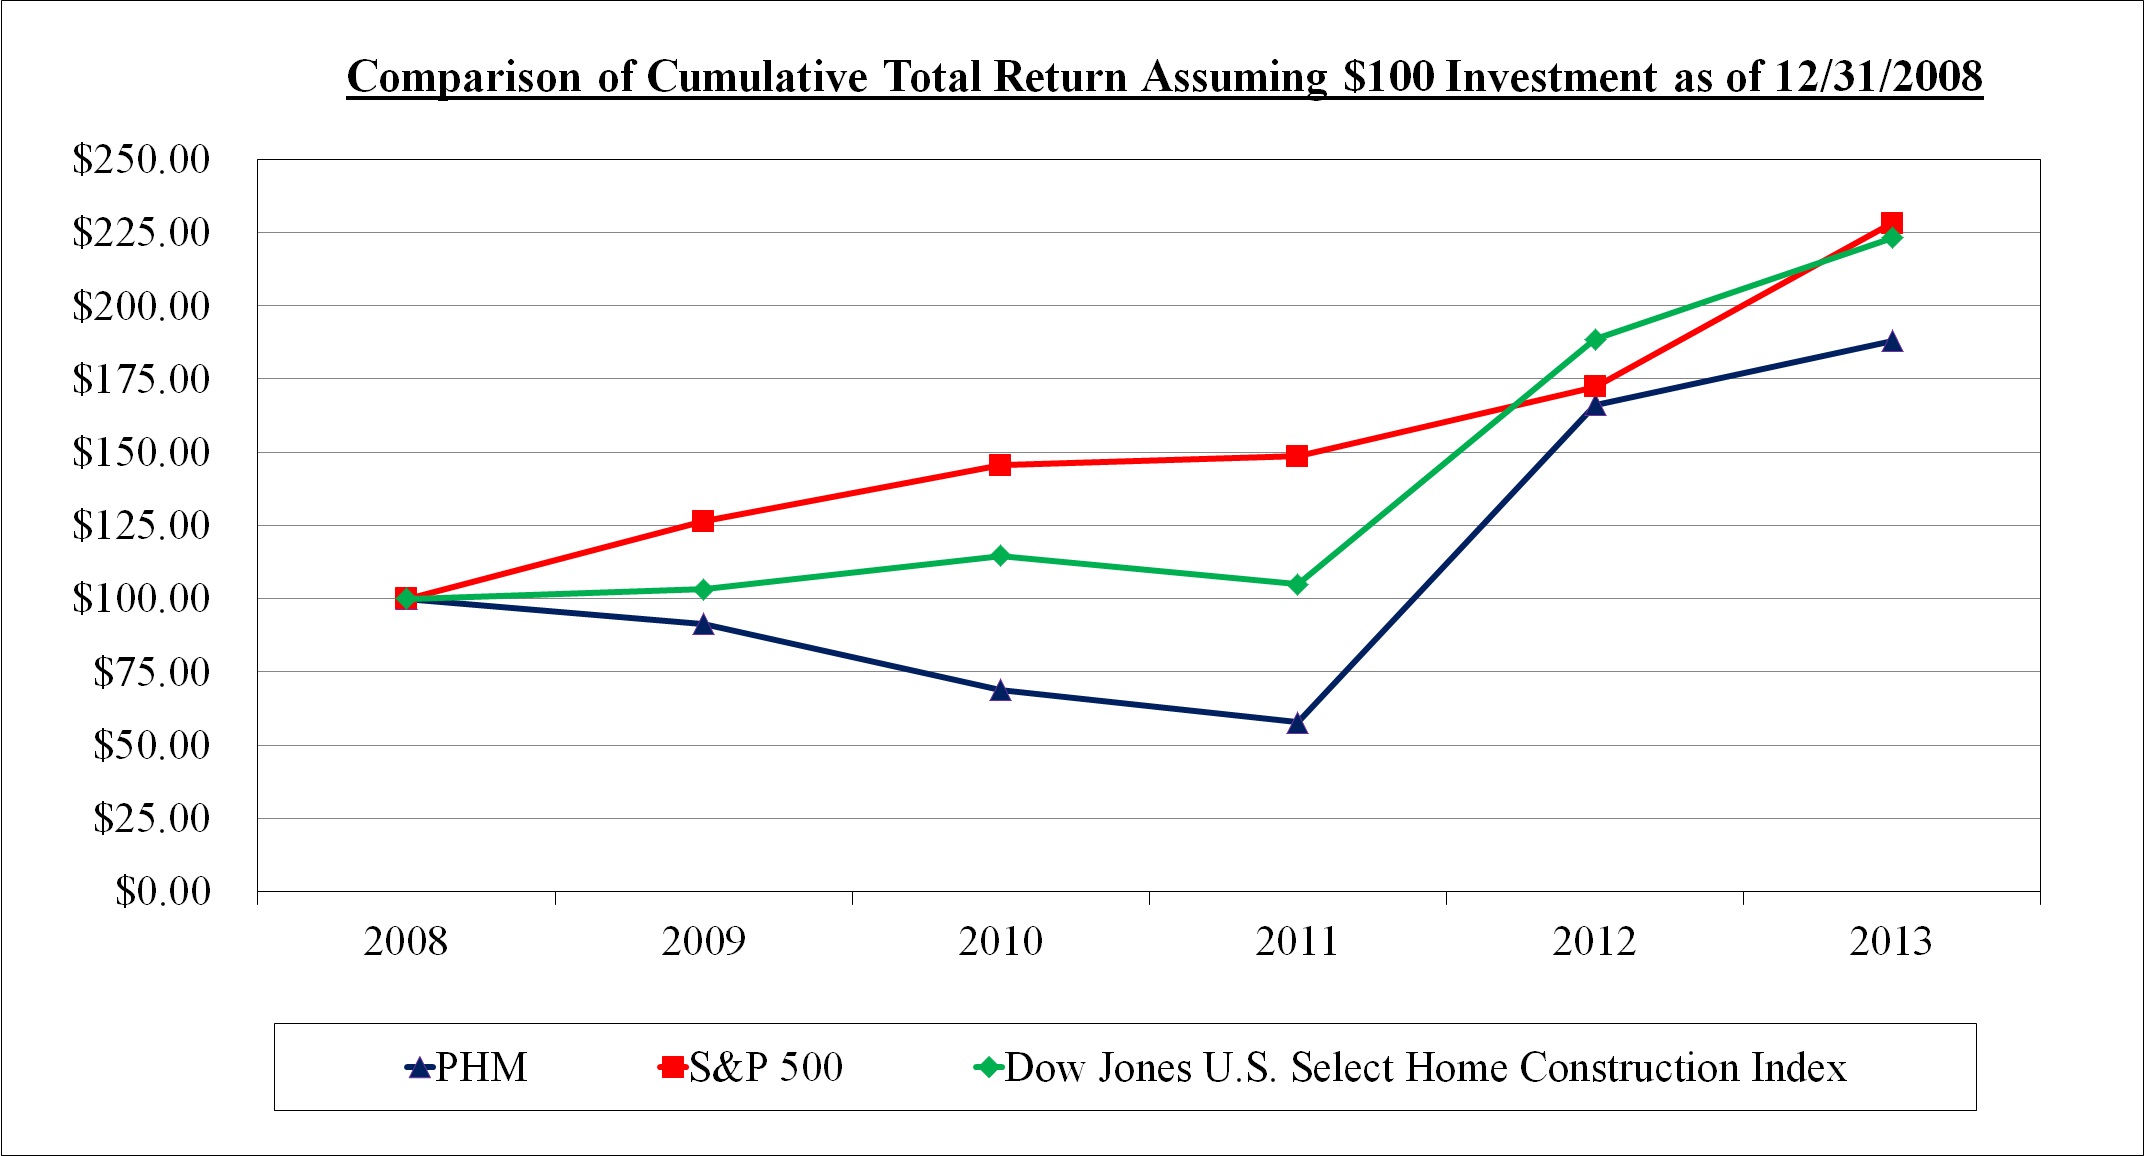
The following line graph compares for the fiscal years ended December 31, 2009, 2010, 2011, 2012, and 2013 (a) the yearly cumulative total shareholder return (i.e., the change in share price plus the cumulative amount of dividends, assuming dividend reinvestment, divided by the initial share price, expressed as a percentage) on PulteGroup’s common shares, with (b) the cumulative total return of the Standard & Poor’s 500 Stock Index, and with (c) the Dow Jones U.S. Select Home Construction Index. The Dow Jones U.S. Select Home Construction Index is a widely-recognized index comprised primarily of large national homebuilders. We believe comparison of our shareholder return to this index represents a meaningful analysis for investors.
COMPARISON OF FIVE YEAR CUMULATIVE TOTAL RETURN*
AMONG PULTEGROUP, INC., S&P 500 INDEX, AND PEER INDEX
Fiscal Year Ended December 31, 2013
| 2008 | 2009 | 2010 | 2011 | 2012 | 2013 | |||||||||||||
| PULTEGROUP, INC. | 100.00 | 91.49 | 68.80 | 57.73 | 166.15 | 187.99 | ||||||||||||
| S&P 500 Index - Total Return | 100.00 | 126.47 | 145.52 | 148.59 | 172.37 | 228.17 | ||||||||||||
| Dow Jones U.S. Select Home Construction Index | 100.00 | 103.13 | 114.65 | 104.90 | 188.49 | 223.18 |
- Assumes $100 invested on December 31, 2008, and the reinvestment of dividends.
Item 6. SELECTED FINANCIAL DATA
Set forth below is selected consolidated financial data for each of the past five fiscal years. The selected financial data should be read in conjunction with Management’s Discussion and Analysis of Financial Condition and Results of Operations and our Consolidated Financial Statements and Notes thereto included elsewhere in this report.
| Years Ended December 31, (000’s omitted, except per share data) | |||||||||||||||||||
| 2013 | 2012 | 2011 | 2010 | 2009 (a) | |||||||||||||||
| OPERATING DATA: | |||||||||||||||||||
| Homebuilding: | |||||||||||||||||||
| Revenues | $ | 5,538,644 | $ | 4,659,110 | $ | 4,033,596 | $ | 4,447,627 | $ | 3,966,589 | |||||||||
| Income (loss) before income taxes | $ | 479,113 | $ | 157,991 | $ | (275,830 | ) | $ | (1,240,155 | ) | $ | (1,920,081 | ) | ||||||
| Financial Services: | |||||||||||||||||||
| Revenues | $ | 140,951 | $ | 160,888 | $ | 103,094 | $ | 121,663 | $ | 117,800 | |||||||||
| Income (loss) before income taxes | $ | 48,709 | $ | 25,563 | $ | (34,470 | ) | $ | 5,609 | $ | (55,038 | ) | |||||||
| Consolidated results: | |||||||||||||||||||
| Revenues | $ | 5,679,595 | $ | 4,819,998 | $ | 4,136,690 | $ | 4,569,290 | $ | 4,084,389 | |||||||||
| Income (loss) before income taxes | $ | 527,822 | $ | 183,554 | $ | (310,300 | ) | $ | (1,234,546 | ) | $ | (1,975,119 | ) | ||||||
| Income tax expense (benefit) | (2,092,294 | ) | (22,591 | ) | (99,912 | ) | (137,817 | ) | (792,552 | ) | |||||||||
| Net income (loss) | $ | 2,620,116 | $ | 206,145 | $ | (210,388 | ) | $ | (1,096,729 | ) | $ | (1,182,567 | ) | ||||||
| PER SHARE DATA: | |||||||||||||||||||
| Net income (loss) per share: | |||||||||||||||||||
| Basic | $ | 6.79 | $ | 0.54 | $ | (0.55 | ) | $ | (2.90 | ) | $ | (3.94 | ) | ||||||
| Diluted | $ | 6.72 | $ | 0.54 | $ | (0.55 | ) | $ | (2.90 | ) | $ | (3.94 | ) | ||||||
| Number of shares used in calculation: | |||||||||||||||||||
| Basic | 383,077 | 381,562 | 379,877 | 378,585 | 300,179 | ||||||||||||||
| Effect of dilutive securities | 3,789 | 3,002 | — | — | — | ||||||||||||||
| Diluted | 386,866 | 384,564 | 379,877 | 378,585 | 300,179 | ||||||||||||||
| Shareholders’ equity | $ | 12.19 | $ | 5.66 | $ | 5.07 | $ | 5.59 | $ | 8.39 | |||||||||
| Cash dividends declared | $ | 0.15 | $ | — | $ | — | $ | — | $ | — |
| (a) | Includes operations of Centex since August 18, 2009. |
| December 31, ($000’s omitted) | |||||||||||||||||||
| 2013 | 2012 | 2011 | 2010 | 2009 (a) | |||||||||||||||
| BALANCE SHEET DATA: | |||||||||||||||||||
| House and land inventory | $ | 3,978,561 | $ | 4,214,046 | $ | 4,636,468 | $ | 4,781,813 | $ | 4,940,358 | |||||||||
| Total assets | 8,734,143 | 6,734,409 | 6,885,620 | 7,699,376 | 10,051,222 | ||||||||||||||
| Senior notes | 2,058,168 | 2,509,613 | 3,088,344 | 3,391,668 | 4,281,532 | ||||||||||||||
| Shareholders’ equity | 4,648,952 | 2,189,616 | 1,938,615 | 2,135,167 | 3,194,440 | ||||||||||||||
| Years Ended December 31, | |||||||||||||||||||
| 2013 | 2012 | 2011 | 2010 | 2009 (a) | |||||||||||||||
| OTHER DATA: | |||||||||||||||||||
| Markets, at year-end | 48 | 58 | 61 | 67 | 69 | ||||||||||||||
| Active communities, at year-end | 577 | 670 | 700 | 786 | 882 | ||||||||||||||
| Closings (units) | 17,766 | 16,505 | 15,275 | 17,095 | 15,013 | ||||||||||||||
| Net new orders (units) | 17,080 | 19,039 | 15,215 | 15,148 | 14,185 | ||||||||||||||
| Backlog (units), at year-end | 5,772 | 6,458 | 3,924 | 3,984 | 5,931 | ||||||||||||||
| Average selling price (per unit) | $ | 305,000 | $ | 276,000 | $ | 259,000 | $ | 259,000 | $ | 258,000 | |||||||||
| Gross margin from home sales (b) | 20.5 | % | 15.8 | % | 12.8 | % | 9.4 | % | (10.5 | )% |
| (a) | Includes operations of Centex Corporation since August 18, 2009. |
| (b) | Homebuilding interest expense, which represents the amortization of capitalized interest, and land impairment charges are included in home sale cost of revenues. |
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Overview
The underlying trends in U.S. housing point toward an ongoing multi-year recovery supported by favorable demographics, an improving economy, mortgage interest rates near historic lows, and limited supplies of new and existing home inventories. Our results in 2013 showed significant improvement in the majority of our key operating metrics in the first half of the year, while demand conditions slowed for us in the second half of the year as consumers adjusted to higher home prices and a moderate rise in mortgage interest rates. For the full year 2013, the overall improvement in market conditions, in concert with our own tactical actions, contributed to our seventh consecutive profitable quarter. Home closings, revenues, average selling price, inventory turns, gross margin, overhead leverage, and income before income taxes all improved in 2013 compared with 2012.
Our net new orders declined 10% in 2013 compared with 2012. A lower number of active communities contributed to the decline in net new orders as we maintained 14% fewer active communities in 2013 compared with 2012. The lower active community count resulted from the close-out of a number of long-term projects and is consistent with our more disciplined land investment strategy. In addition, demand slowed in the second half of 2013 in response to higher home prices and a rise in mortgage interest rates. We will continue to calibrate sales pace in each community to improve our gross margins and maximize returns on invested capital. We expect that this approach will continue to result in a moderation in our net new order volume in the short-term relative to overall growth in the U.S. homebuilding industry and relative to certain of our competitors. While we believe higher mortgage interest rates are inevitable and may have a moderating effect on demand and pricing, we believe this impact will be outweighed in the long-term by other factors driving increased sales volume as overall new home sales in the U.S. remain low compared with historical levels.
The significant improvements reported for 2013 also allowed us to continue to enhance our financial position. We generated significant positive cash flow from operations in each of the last two years via a combination of improved profitability and inventory management. Our improved financial position provided additional flexibility to retire debt early and increase our planned future investments in new communities, while also paying a dividend and selectively repurchasing our common shares. Specifically, we accomplished the following during 2013:
| • | Increased our total cash balance to $1.7 billion; |
| • | Proactively reduced our outstanding debt by $461.4 million; |
| • | Increased our existing share repurchase authorization by $250.0 million and retired $127.7 million of shares; |
| • | Reinstated a quarterly dividend; |
| • | Increased our land investment spending to support future growth; and |
| • | Lowered our ratio of debt to total capitalization from 53.4% to 30.7%, in part due to the reversal of a valuation allowance against our deferred tax assets. |
In the short-term, we will continue to focus on maximizing our operating margins, despite the possibility of rising house cost pressures from material and labor prices, by using our existing land assets more effectively, allocating capital more effectively, and aggressively controlling unsold "spec" inventory to enhance our balance sheet. We believe we have positioned ourselves to deliver improved long-term returns. In planning for the longer term, we continue to maintain confidence that we are in the early stages of a broad, sustainable recovery in the U.S. new home market. While the U.S. macroeconomic environment continues to face challenges and each local market will experience varying results, we are continuing to pursue strategic land positions that meet our underwriting requirements in well-positioned submarkets and believe that sustained execution of our strategy will continue to result in increased profits and improved returns on invested capital over the housing cycle.
The following is a summary of our operating results by line of business ($000's omitted, except per share data):
| Years Ended December 31, | |||||||||||
| 2013 | 2012 | 2011 | |||||||||
| Income (loss) before income taxes: | |||||||||||
| Homebuilding | $ | 479,113 | $ | 157,991 | $ | (275,830 | ) | ||||
| Financial Services | 48,709 | 25,563 | (34,470 | ) | |||||||
| Income (loss) from continuing operations before income taxes | 527,822 | 183,554 | (310,300 | ) | |||||||
| Income tax expense (benefit) | (2,092,294 | ) | (22,591 | ) | (99,912 | ) | |||||
| Net income (loss) | $ | 2,620,116 | $ | 206,145 | $ | (210,388 | ) | ||||
| Per share data - assuming dilution: | |||||||||||
| Net income (loss) | $ | 6.72 | $ | 0.54 | $ | (0.55 | ) |
| • | The Homebuilding income (loss) before income taxes included charges related to the following items ($000's omitted): |
| 2013 | 2012 | 2011 | |||||||||
| Land-related charges (see Note 4) | $ | 9,672 | $ | 17,195 | $ | 35,786 | |||||
| Loss on debt retirements (see Note 7) | 26,930 | 32,071 | 5,638 | ||||||||
| Settlement of contractual dispute at a closed-out community (see Note 13) | 41,170 | — | — | ||||||||
| Goodwill impairments (see Note 2) | — | — | 240,541 | ||||||||
| $ | 77,772 | $ | 49,266 | $ | 281,965 |
For additional information on each of the above, see the applicable Notes to the Consolidated Financial Statements.
Our Homebuilding operating results in 2013 and 2012 improved significantly from the loss experienced in 2011 due to higher revenues and gross margins, improved overhead leverage, and lower charges, as listed in the above table.
| • | The increase in Financial Services income in 2013 compared with 2012 and 2011 was primarily due to lower loan loss reserves. There were no such loss reserves in 2013 compared with $49.0 million in 2012 and $59.3 million in 2011 (see Note 13 to the Consolidated Financial Statements). Additionally, loan origination volume increased in 2013 compared with 2012 and 2011, primarily as the result of increased Homebuilding closings. These favorable factors were partially offset in 2013 by margin compression caused by heightened competition in the mortgage industry compared with 2012. |
| • | The income tax benefit in 2013 includes $2.1 billion related to the reversal of substantially all of the valuation allowance previously recorded against our deferred tax assets. See Note 10 to the Condensed Consolidated Financial Statements for additional information. The income tax benefits in 2012 and 2011 were attributable primarily to the favorable resolution of certain federal and state income tax matters. |
Homebuilding Operations
The following is a summary of income (loss) before income taxes for our Homebuilding operations ($000’s omitted):
| | | | | | | | | | | | | | | | | | | | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | ---
Showing the first 8K of 99K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
We are subject to interest rate risk on our rate-sensitive financings to the extent long-term rates decline. The following tables set forth, as of December 31, 2013 and 2012, our rate-sensitive financing obligations, principal cash flows by scheduled maturity, weighted-average interest rates, and estimated fair value ($000’s omitted).
| As of December 31, 2013 for the Years ending December 31, | |||||||||||||||||||||||||||||||
| 2014 | 2015 | 2016 | 2017 | 2018 | Thereafter | Total | Fair Value | ||||||||||||||||||||||||
| Rate-sensitive liabilities: | |||||||||||||||||||||||||||||||
| Fixed interest rate debt: | |||||||||||||||||||||||||||||||
| Senior notes | $ | — | $ | 333,647 | $ | 465,245 | $ | 123,000 | $ | — | $ | 1,150,000 | $ | 2,071,892 | $ | 2,070,744 | |||||||||||||||
| Average interest rate | — | % | 5.24 | % | 6.50 | % | 7.63 | % | — | % | 6.80 | % | 6.53 | % | |||||||||||||||||
| As of December 31, 2012 for the Years ending December 31, | |||||||||||||||||||||||||||||||
| 2013 | 2014 | 2015 | 2016 | 2017 | Thereafter | Total | Fair Value | ||||||||||||||||||||||||
| Rate-sensitive liabilities: | |||||||||||||||||||||||||||||||
| Fixed interest rate debt: | |||||||||||||||||||||||||||||||
| Senior notes | $ | — | $ | 398,852 | $ | 369,222 | $ | 465,245 | $ | 150,000 | $ | 1,150,000 | $ | 2,533,319 | $ | 2,663,451 | |||||||||||||||
| Average interest rate | — | % | 5.49 | % | 5.24 | % | 6.50 | % | 7.63 | % | 6.80 | % | 6.36 | % |
Derivative instruments and hedging activities
Pulte Mortgage is exposed to market risks from commitments to lend, movements in interest rates, and canceled or modified commitments to lend. A commitment to lend at a specific interest rate (an interest rate lock commitment) is a derivative financial instrument (interest rate is locked to the borrower). The interest rate risk continues through the loan closing and until the loan is sold to an investor. We are generally not exposed to variability in cash flows of derivative instruments for more than approximately 75 days. In periods of rising interest rates, the length of exposure will generally increase due to customers locking in an interest rate sooner as opposed to letting the interest rate float.
In order to reduce these risks, we use other derivative financial instruments, principally cash forward placement contracts on mortgage-backed securities and whole loan investor commitments, to economically hedge the interest rate lock commitment. We enter into one of the aforementioned derivative financial instruments upon accepting interest rate lock commitments. Changes in the fair value of interest rate lock commitments and the other derivative financial instruments are recognized in Financial Services revenues. We do not use any derivative financial instruments for trading purposes.
Hypothetical changes in the fair values of our financial instruments arising from immediate parallel shifts in long-term mortgage rates of 50, 100, and 150 basis points would not be material to our financial results.
SPECIAL NOTES CONCERNING FORWARD-LOOKING STATEMENTS
As a cautionary note, except for the historical information contained herein, certain matters discussed in Item 7, Management's Discussion and Analysis of Financial Condition and Results of Operations, and Item 7a, Quantitative and Qualitative Disclosures About Market Risk, are “forward-looking” statements within the meaning of the Private Securities Litigation Reform Act of 1995. Such forward-looking statements are subject to a number of risks, uncertainties and other factors that could cause our actual results, performance, prospects or opportunities, as well as those of the markets we serve or intend to serve, to differ materially from those expressed in, or implied by, these statements. You can identify these statements by the fact that they do not relate to matters of a strictly factual or historical nature and generally discuss or relate to forecasts, estimates or other expectations regarding future events. Generally, the words “believe,” “expect,” “intend,” “estimate,” “anticipate,” “project,” “may,” “can,” “could,” “might,” “will” and similar expressions identify forward-looking statements, including statements related to expected operating and performing results, planned transactions, planned objectives of management, future developments or conditions in the industries in which we participate and other trends, developments and uncertainties that may affect our business in the future.
Such risks, uncertainties and other factors include, among other things: interest rate changes and the availability of mortgage financing; continued volatility in the debt and equity markets; competition within the industries in which we operate; the availability and cost of land and other raw materials used by us in our homebuilding operations; the impact of any changes to our strategy in responding to the cyclical nature of the industry, including any changes regarding our land positions; the availability and cost of insurance covering risks associated with our businesses; shortages and the cost of labor; weather related slowdowns; slow growth initiatives and/or local building moratoria; governmental regulation directed at or affecting the housing market, the homebuilding industry or construction activities; uncertainty in the mortgage lending industry, including revisions to underwriting standards and repurchase requirements associated with the sale of mortgage loans; the interpretation of or changes to tax, labor and environmental laws; economic changes nationally or in our local markets, including inflation, deflation, changes in consumer confidence and preferences and the state of the market for homes in general; legal or regulatory proceedings or claims; required accounting changes; terrorist acts and other acts of war; and other factors of national, regional and global scale, including those of a political, economic, business and competitive nature. See Item 1A – Risk Factors for a further discussion of these and other risks and uncertainties applicable to our businesses. We undertake no duty to update any forward-looking statement, whether as a result of new information, future events or changes in our expectations.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
PULTEGROUP, INC.
CONSOLIDATED BALANCE SHEETS
December 31, 2013 and 2012
($000’s omitted, except per share data)
| 2013 | 2012 | ||||||
| ASSETS | |||||||
| Cash and equivalents | $ | 1,580,329 | $ | 1,404,760 | |||
| Restricted cash | 72,715 | 71,950 | |||||
| House and land inventory | 3,978,561 | 4,214,046 | |||||
| Land held for sale | 61,735 | 91,104 | |||||
| Land, not owned, under option agreements | 24,024 | 31,066 | |||||
| Residential mortgage loans available-for-sale | 287,933 | 318,931 | |||||
| Investments in unconsolidated entities | 45,323 | 45,629 | |||||
| Other assets | 460,621 | 407,675 | |||||
| Intangible assets | 136,148 | 149,248 | |||||
| Deferred tax assets, net | 2,086,754 | — | |||||
| $ | 8,734,143 | $ | 6,734,409 | ||||
| LIABILITIES AND SHAREHOLDERS’ EQUITY | |||||||
| Liabilities: | |||||||
| Accounts payable, including book overdrafts of $35,827 and $42,053 in 2013 and 2012, respectively | $ | 202,736 | $ | 178,274 | |||
| Customer deposits | 134,858 | 101,183 | |||||
| Accrued and other liabilities | 1,377,750 | 1,418,063 | |||||
| Income tax liabilities | 206,015 | 198,865 | |||||
| Financial Services debt | 105,664 | 138,795 | |||||
| Senior notes | 2,058,168 | 2,509,613 | |||||
| Total liabilities | 4,085,191 | 4,544,793 | |||||
| Shareholders’ equity: | |||||||
| Preferred stock, $0.01 par value; 25,000,000 shares authorized, none issued | $ | — | $ | — | |||
| Common stock, $0.01 par value; 500,000,000 shares authorized, 381,299,600 and 386,608,436 shares issued and outstanding at December 31, 2013 and 2012, respectively | 3,813 | 3,866 | |||||
| Additional paid-in capital | 3,052,016 | 3,030,889 | |||||
| Accumulated other comprehensive loss | (795 | ) | (992 | ) | |||
| Retained earnings (accumulated deficit) | 1,593,918 | (844,147 | ) | ||||
| Total shareholders’ equity | 4,648,952 | 2,189,616 | |||||
| $ | 8,734,143 | $ | 6,734,409 |
See Notes to Consolidated Financial Statements.
PULTEGROUP, INC.
CONSOLIDATED STATEMENTS OF OPERATIONS
For the years ended December 31, 2013, 2012, and 2011
(000’s omitted, except per share data)
| 2013 | 2012 | 2011 | |||||||||
| Revenues: | |||||||||||
| Homebuilding | |||||||||||
| Home sale revenues | $ | 5,424,309 | $ | 4,552,412 | $ | 3,950,743 | |||||
| Land sale revenues | 114,335 | 106,698 | 82,853 | ||||||||
| 5,538,644 | 4,659,110 | 4,033,596 | |||||||||
| Financial Services | 140,951 | 160,888 | 103,094 | ||||||||
| Total revenues | 5,679,595 | 4,819,998 | 4,136,690 | ||||||||
| Homebuilding Cost of Revenues: | |||||||||||
| Home sale cost of revenues | 4,310,528 | 3,833,451 | 3,444,398 | ||||||||
| Land sale cost of revenues | 104,426 | 94,880 | 59,279 | ||||||||
| 4,414,954 | 3,928,331 | 3,503,677 | |||||||||
| Financial Services expenses | 92,379 | 135,511 | 137,666 | ||||||||
| Selling, general, and administrative expenses | 568,500 | 514,457 | 519,583 | ||||||||
| Other expense, net | 80,753 | 66,298 | 293,102 | ||||||||
| Interest income | (4,395 | ) | (4,913 | ) | (5,055 | ) | |||||
| Interest expense | 712 | 819 | 1,313 | ||||||||
| Equity in earnings of unconsolidated entities | (1,130 | ) | (4,059 | ) | (3,296 | ) | |||||
| Income (loss) before income taxes | 527,822 | 183,554 | (310,300 | ) | |||||||
| Income tax expense (benefit) | (2,092,294 | ) | (22,591 | ) | (99,912 | ) | |||||
| Net income (loss) | $ | 2,620,116 | $ | 206,145 | $ | (210,388 | ) | ||||
| Net income (loss) per share: | |||||||||||
| Basic | $ | 6.79 | $ | 0.54 | $ | (0.55 | ) | ||||
| Diluted | $ | 6.72 | $ | 0.54 | $ | (0.55 | ) | ||||
| Cash dividends declared | $ | 0.15 | $ | — | $ | — | |||||
| Number of shares used in calculation: | |||||||||||
| Basic | 383,077 | 381,562 | 379,877 | ||||||||
| Effect of dilutive securities | 3,789 | 3,002 | — | ||||||||
| Diluted | 386,866 | 384,564 | 379,877 |
See Notes to Consolidated Financial Statements.
PULTEGROUP, INC.
CONSOLIDATED STATEMENTS OF COMPREHENSIVE INCOME (LOSS)
For the years ended December 31, 2013, 2012, and 2011
(000’s omitted)
| 2013 | 2012 | 2011 | |||||||||
| Net income (loss) | $ | 2,620,116 | $ | 206,145 | $ | (210,388 | ) | ||||
| Other comprehensive income, net of tax: | |||||||||||
| Change in fair value of derivatives | 197 | 314 | 213 | ||||||||
| Other comprehensive income | 197 | 314 | 213 | ||||||||
| Comprehensive income (loss) | $ | 2,620,313 | $ | 206,459 | $ | (210,175 | ) |
See Notes to Consolidated Financial Statements.
PULTEGROUP, INC.
CONSOLIDATED STATEMENTS OF SHAREHOLDERS’ EQUITY
For the years ended December 31, 2013, 2012, and 2011
(000’s omitted, except per share data)
| Common Stock | Additional Paid-in Capital | Accumulated Other Comprehensive Income (Loss) | Retained Earnings (Accumulated Deficit) | Total | ||||||||||||||||||
| Shares | $ | |||||||||||||||||||||
| Shareholders' Equity, January 1, 2011 | 382,028 | $ | 3,820 | $ | 2,972,919 | $ | (1,519 | ) | $ | (840,053 | ) | $ | 2,135,167 | |||||||||
| Stock option exercises | — | — | — | |||||||||||||||||||
| Stock awards, net of cancellations | 944 | 10 | (10 | ) | — | — | — | |||||||||||||||
| Stock repurchases | (364 | ) | (4 | ) | (3,128 | ) | — | 296 | (2,836 | ) | ||||||||||||
| Stock-based compensation | — | — | 16,459 | — | — | 16,459 | ||||||||||||||||
| Net income (loss) | — | — | — | — | (210,388 | ) | (210,388 | ) | ||||||||||||||
| Other comprehensive income | — | — | — | 213 | — | 213 | ||||||||||||||||
| Shareholders' Equity, December 31, 2011 | 382,608 | $ | 3,826 | $ | 2,986,240 | $ | (1,306 | ) | $ | (1,050,145 | ) | $ | 1,938,615 | |||||||||
| Stock option exercises | 2,877 | 29 | 32,780 | — | — | 32,809 | ||||||||||||||||
| Stock awards, net of cancellations | 1,228 | 12 | (12 | ) | — | — | — | |||||||||||||||
| Stock repurchases | (105 | ) | (1 | ) | (813 | ) | — | (147 | ) | (961 | ) | |||||||||||
| Stock-based compensation | — | — | 12,694 | — | — | 12,694 | ||||||||||||||||
| Net income (loss) | — | — | — |
Showing the first 8K of 162K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
This Item is not applicable.
Item 9A. CONTROLS AND PROCEDURES
Disclosure Controls and Procedures
Management, including our Chairman, President and Chief Executive Officer and Executive Vice President and Chief Financial Officer, evaluated the effectiveness of the design and operation of our disclosure controls and procedures as of December 31, 2013. Based upon, and as of the date of that evaluation, our Chairman, President and Chief Executive Officer and Executive Vice President and Chief Financial Officer concluded that the disclosure controls and procedures were effective as of December 31, 2013.
Internal Control Over Financial Reporting
| (a) | Management’s Annual Report on Internal Control Over Financial Reporting |
Management is responsible for the preparation and fair presentation of the consolidated financial statements included in this annual report. The consolidated financial statements have been prepared in conformity with U.S. generally accepted accounting principles and reflect management’s judgments and estimates concerning events and transactions that are accounted for or disclosed.
Management is also responsible for establishing and maintaining effective internal control over financial reporting, as such term is defined in Exchange Act Rule 13a-15(f). Management recognizes that there are inherent limitations in the effectiveness of any internal control and effective internal control over financial reporting can provide only reasonable assurance with respect to financial statement preparation. Additionally, because of changes in conditions, the effectiveness of internal control over financial reporting may vary over time.
In order to ensure that the Company’s internal control over financial reporting is effective, management regularly assesses such controls and did so most recently for its financial reporting as of December 31, 2013. Management’s assessment was based on criteria for effective internal control over financial reporting described in Internal Control – Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (1992 Framework). Based on this assessment, management asserts that the Company has maintained effective internal control over financial reporting as of December 31, 2013.
Ernst & Young LLP, the independent registered public accounting firm that audited the Company’s consolidated financial statements included in this annual report, has issued its report on the effectiveness of the Company’s internal control over financial reporting as of December 31, 2013.
| (b) | Report of Independent Registered Public Accounting Firm |
The Board of Directors and Shareholders of PulteGroup, Inc.
We have audited PulteGroup, Inc.’s internal control over financial reporting as of December 31, 2013, based on criteria established in Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (1992 Framework) (the COSO criteria). PulteGroup, Inc.’s management is responsible for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management’s Annual Report on Internal Control Over Financial Reporting. Our responsibility is to express an opinion on the company’s internal control over financial reporting based on our audit.
We conducted our audit in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
In our opinion, PulteGroup, Inc. maintained, in all material respects, effective internal control over financial reporting as of December 31, 2013, based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated balance sheets of PulteGroup, Inc. as of December 31, 2013 and 2012, and the related consolidated statements of operations, comprehensive income (loss), shareholders’ equity, and cash flows for each of the three years in the period ended December 31, 2013 and our report dated February 5, 2014 expressed an unqualified opinion thereon.
/s/ Ernst & Young LLP
Detroit, Michigan
February 5, 2014
| (c) | Changes in Internal Control Over Financial Reporting |
There has been no change in our internal control over financial reporting during the quarter ended December 31, 2013 that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. OTHER INFORMATION
This Item is not applicable.
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
Information required by this Item with respect to our executive officers is set forth in Item 4A of this Annual Report on Form 10-K. Information required by this Item with respect to members of our Board of Directors and with respect to our audit committee will be contained in the Proxy Statement for the 2014 Annual Meeting of Shareholders (“2014 Proxy Statement”) under the captions “Election of Directors” and “Committees of the Board of Directors - Audit Committee” and in the chart disclosing Audit Committee membership and is incorporated herein by this reference. Information required by this Item with respect to compliance with Section 16(a) of the Securities Exchange Act of 1934 will be contained in the 2014 Proxy Statement under the caption “Beneficial Security Ownership - Section 16(a) Beneficial Ownership Reporting Compliance,” and is incorporated herein by this reference. Information required by this Item with respect to our code of ethics will be contained in the 2014 Proxy Statement under the caption “Corporate Governance - Governance Guidelines; Code of Ethical Business Conduct; Code of Ethics” and is incorporated herein by this reference.
Our code of ethics for principal officers, our code of ethical business conduct, our corporate governance guidelines, and the charters of the Audit, Compensation and Management Development, Nominating and Governance, and Finance and Investment committees of our Board of Directors are also posted on our website and are available in print, free of charge, upon request.
Item 11. EXECUTIVE COMPENSATION
Information required by this Item will be contained in the 2014 Proxy Statement under the captions “2013 Executive Compensation” and “2013 Director Compensation” and is incorporated herein by this reference, provided that the Compensation and Management Development Committee Report shall not be deemed to be “filed” with this Annual Report on Form 10-K.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLER MATTERS
Information required by this Item will be contained in the 2014 Proxy Statement under the captions “Beneficial Security Ownership” and “Equity Compensation Plan Information” and is incorporated herein by this reference.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS AND DIRECTOR INDEPENDENCE
Information required by this Item will be contained in the 2014 Proxy Statement under the captions “Certain Relationships and Related Transactions” and “Election of Directors - Independence” and is incorporated herein by this reference.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
Information required by this Item will be contained in the 2014 Proxy Statement under the captions “Audit and Non-Audit Fees” and “Audit Committee Preapproval Policies” and is incorporated herein by reference.
PART IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
| (a) | The following documents are filed as part of this Annual Report on Form 10-K: |
(1) Financial Statements
| (2) | Financial Statement Schedules |
All schedules are omitted because the required information is not present, is not present in amounts sufficient to require submission of the schedule, or because the required information is included in the financial statements or notes thereto.
| (3) | Exhibits |
The following exhibits are filed with this Annual Report on Form 10-K or are incorporated herein by reference:
Exhibit Number and Description
| (3) | (a) | Restated Articles of Incorporation, of PulteGroup, Inc. (Incorporated by reference to Exhibit 3.1 of our Current Report on Form 8-K, filed with the SEC on August 18, 2009) | ||
| (b) | Certificate of Amendment to the Articles of Incorporation, dated March 18, 2010 (Incorporated by reference to Exhibit 3(b) of our Quarterly Report on Form 10-Q for the quarter ended March 31, 2010) | |||
| (c) | Certificate of Amendment to the Articles of Incorporation, dated May 21, 2010 (Incorporated by reference to Exhibit 3(c) of our Quarterly Report on Form 10-Q for the quarter ended September 30, 2010) | |||
| (d) | By-laws, as amended, of PulteGroup, Inc. (Incorporated by reference to Exhibit 3.1 of our Current Report on Form 8-K, filed with the SEC on April 8, 2009) | |||
| (e) | Certificate of Designation of Series A Junior Participating Preferred Shares, dated August 6, 2009 (Incorporated by reference to Exhibit 3(b) of our Registration Statement on Form 8-A, filed with the SEC on August 18, 2009) | |||
| (4) | (a) | Any instrument with respect to long-term debt, where the securities authorized thereunder do not exceed 10% of the total assets of PulteGroup, Inc. and its subsidiaries, has not been filed. The Company agrees to furnish a copy of such instruments to the SEC upon request. | ||
| (b) | Amended and Restated Section 382 Rights Agreement, dated as of March 18, 2010, between PulteGroup, Inc. and Computershare Trust Company, N.A., as rights agent, which includes the Form of Rights Certificate as Exhibit B thereto (Incorporated by reference to Exhibit 4 of PulteGroup, Inc.’s Registration Statement on Form 8-A/A filed with the SEC on March 23, 2010) | |||
| (c) | First Amendment to Amended and Restated Section 382 Rights Agreement, dated as of March 14, 2013, between PulteGroup, Inc. and Computershare Trust Company, N.A., as rights agent (Incorporated by reference to Exhibit 4-1 of our Current Report on Form 8-K, filed with the SEC on March 15, 2013) | |||
| (10) | (a) | 1995 Stock Incentive Plan for Key Employees (Incorporated by reference to our Proxy Statement dated March 31, 1995, and as Exhibit 4.1 of our Registration Statement on Form S-8, Registration No. 33-99218) | ||
| (b) | PulteGroup, Inc. 401(k) Plan (Incorporated by reference to Exhibit 4.3 of our Registration Statement on Form S-8, No. 333-115570) | |||
| (c) | Facility Agreement dated as of June 23, 2009 among PulteGroup, Inc., Various Financial Institutions, and Deutsche Bank AG, New York Branch (Incorporated by reference to Exhibit 10.1 of our Current Report on Form 8-K, filed with the SEC on June 26, 2009) | |||
| (d) | PulteGroup, Inc. 2000 Stock Incentive Plan for Key Employees (Incorporated by reference to Exhibit 4.3 of our Registration Statement on Form S-8, Registration No. 333-66284) | |||
| (e) | PulteGroup, Inc. 2000 Stock Plan for Nonemployee Directors (Incorporated by reference to Exhibit 4.3 of our Registration Statement on Form S-8, Registration No. 333-66284) | |||
| (f) | PulteGroup, Inc. 2002 Stock Incentive Plan (Incorporated by reference to our Proxy Statement dated April 3, 2002 and as Exhibit 4.3 of our Registration Statement on Form S-8, No. 333-123223) | |||
| (g) | PulteGroup, Inc. 2008 Senior Management Incentive Plan (Incorporated by reference to our Proxy Statement dated April 7, 2008) | |||
| (h) | PulteGroup, Inc. 2013 Senior Management Incentive Plan (Incorporated by reference to Exhibit 10.2 of our Current Report on Form 8-K, filed with the SEC on May 13, 2013) | |||
| (i) | PulteGroup, Inc. Long-Term Incentive Program (Incorporated by reference to Exhibit 10.2 of our Current Report on Form 8-K, filed with the SEC on May 20, 2008) | |||
| (j) | Form of PulteGroup, Inc. Long Term Incentive Award Agreement (Incorporated by reference to Exhibit 10.3 of our Current Report on Form 8-K, filed with the SEC on May 20, 2008) | |||
| (k) | Form of PulteGroup, Inc. 2008-2010 Grant Acceptance Agreement - Company Performance Measures (Incorporated by reference to Exhibit 10.4 of our Current Report on Form 8-K, filed with the SEC on May 20, 2008) | |||
| (l) | Form of PulteGroup, Inc. 2008-2010 Grant Acceptance Agreement - Individual Performance Measures (Incorporated by reference to Exhibit 10.5 of our Current Report on Form 8-K, filed with the SEC on May 20, 2008) | |||
| (m) | PulteGroup, Inc. 2013 Stock Incentive Plan (Incorporated by reference to Exhibit 10.1 of our Current Report on Form 8-K, filed with the SEC on May 13, 2013) | |||
| (n) | PulteGroup, Inc. 2004 Stock Incentive Plan (as Amended and Restated as of July 9, 2009) (Incorporated by reference to Exhibit 10(a) of our Quarterly Report on Form 10-Q for the quarter ended September 30, 2009) | |||
| (o) | Form of Restricted Stock Award Agreement (as amended) under PulteGroup, Inc. 2004 Stock Incentive Plan (Incorporated by reference to Exhibit 10(a) of our Quarterly Report on Form 10-Q for the quarter ended March 31, 2010) | |||
| (p) | Form of Restricted Stock Award Agreement (as amended) under PulteGroup, Inc. 2004 Stock Incentive Plan (Filed herewith) | |||
| (q) | Form of Restricted Stock Award Agreement (as amended) under PulteGroup, Inc. 2000 Stock Incentive Plan for Key Employees ( Incorporated by reference to Exhibit 10(b) of our Quarterly Report on Form 10-Q for the quarter ended March 31, 2010) | |||
| (r) | Form of Stock Option Agreement under PulteGroup, Inc. 2002 and 2004 Stock Incentive Plans (Incorporated by reference to Exhibit 10(s) of our Annual Report on Form 10-K for the year ended December 31, 2007) | |||
| (s) | Form of Stock Option Agreement (as amended) under PulteGroup, Inc. 2002 and 2004 Stock Incentive Plans (Incorporated by reference to Exhibit 10(t) of our Annual Report on Form 10-K for the year ended December 31, 2007) | |||
| (t) | Form of Performance Share Award Agreement under PulteGroup, Inc. 2004 Stock Incentive Plan (Incorporated by reference to Exhibit 10(w) of our Annual Report on Form 10-K for the year ended December 31, 2011 ) | |||
| (u) | Centex Corporation Amended and Restated 1987 Stock Option Plan (Amended and Restated Effective February 11, 2009) (Incorporated by reference to Exhibit 10.4 of Centex’s Current Report on Form 8-K, filed with the SEC on February 13, 2009) | |||
| (v) | Amended and Restated Centex Corporation 2001 Stock Plan (Amended and Restated Effective February 11, 2009) (Incorporated by reference to Exhibit 10.2 of Centex’s Current Report on Form 8-K, filed with the SEC on February 13, 2009) | |||
| (w) | Form of stock option agreement for the Amended and Restated Centex Corporation 2001 Stock Plan (Incorporated by reference to Exhibit 10.5 of Centex’s Current Report on Form 8-K, filed with the SEC on May 13, 2008) | |||
| (x) | Centex Corporation 2003 Equity Incentive Plan (Amended and Restated Effective February 11, 2009) (Incorporated by reference to Exhibit 10.1 of Centex’s Current Report on Form 8-K, filed with the SEC on February 13, 2009) | |||
| (y) | Form of stock option agreement for the Centex Corporation 2003 Equity Incentive Plan (Incorporated by reference to Exhibit 10.6 of Centex’s Current Report on Form 8-K, filed with the SEC on May 13, 2008) | |||
| (z) | PulteGroup, Inc. Long Term Compensation Deferral Plan (As Amended and Restated Effective January 1, 2004) (Incorporated by reference to Exhibit 10(a) of our Quarterly Report on Form 10-Q for the quarter ended March 31, 2006) | |||
| (aa) | PulteGroup, Inc. Deferred Compensation Plan for Non-Employee Directors (as Amended and Restated Effective December 8, 2009) (Incorporated by reference to Exhibit 10(al) of our Annual Report on Form 10-K for the year ended December 31, 2009) | |||
| (ab) | Assignment and Assumption Agreement dated as of August 18, 2009 between PulteGroup, Inc. and Centex Corporation (Incorporated by reference to Exhibit 10.2 of our Current Report on Form 8-K, filed with the SEC on August 20, 2009) | |||
| (ac) | Form of Performance Award Agreement under PulteGroup, Inc. 2008 Senior Management Incentive Plan (Incorporated by reference to Exhibit 10(a) of our Quarterly Report on Form 10-Q for the quarter ended March 31, 2012) | |||
| (ad) | PulteGroup, Inc. Executive Severance Policy (Incorporated by reference to Exhibit 10.1 of our Current Report on Form 8-K, filed with the SEC on February 12, 2013) | |||
| (ae) | PulteGroup, Inc. Retirement Policy (Incorporated by reference to Exhibit 10.2 of our Current Report on Form 8-K, filed with the SEC on February 12, 2013) | |||
| (af) | Master Repurchase Agreement dated as of September 28, 2012 among Comerica Bank, as Agent and a Buyer, the other Buyers party hereto and Pulte Mortgage LLC, as Seller (Incorporated by reference to Exhibit 10.1 of our Current Report on Form 8-K filed with the SEC on October 2, 2012) | |||
| (ag) | First Amendment to Master Repurchase Agreement dated as of September 13, 2013 among Comerica Bank, as Agent and a Buyer, the other Buyers party hereto and Pulte Mortgage LLC, as Seller (Incorporated by reference to Exhibit 10.1 of our Current Report on Form 8-K filed with the SEC on September 18, 2013) | |||
| (ah) | Second Amendment to Master Repurchase Agreement dated as of January 9, 2014 among Comerica Bank, as Agent and a Buyer, the other Buyers party hereto and Pulte Mortgage LLC, as Seller (Incorporated by reference to Exhibit 10.1 of our Current Report on Form 8-K filed with the SEC on January 13, 2014) | |||
| (ai) | Third Amendment to Master Repurchase Agreement dated as of September 13, 2013 among Comerica Bank, as Agent and a Buyer, the other Buyers party hereto and Pulte Mortgage LLC, as Seller (filed herewith) | |||
| (aj) | Separation Agreement dated as of November 30, 2012, between PulteGroup, Inc. and John B. Bertero III (Incorporated by referenced to Exhibit 10.1 of our Current Report on Form 8-K filed with the SEC on December 4, 2012) | |||
| (12) | Ratio of Earnings to Fixed Charges at December 31, 2013 (Filed herewith) | |||
| (21) | Subsidiaries of the Registrant (Filed herewith) | |||
| (23) | Consent of Independent Registered Public Accounting Firm (Filed herewith) | |||
| (31) | (a) | Rule 13a-14(a) Certification by Richard J. Dugas, Jr., Chairman, President, and Chief Executive Officer (Filed herewith) | ||
| (b) | Rule 13a-14(a) Certification by Robert T. O'Shaughnessy, Executive Vice President and Chief Financial Officer (Filed herewith) | |||
| (32) | Certification Pursuant to 18 United States Code § 1350 and Rule 13a-14(b) of the Securities Exchange Act of 1934 (Filed herewith) | |||
| 101.INS | XBRL Instance Document |
| 101.SCH | XBRL Taxonomy Extension Schema Document | |||
| 101.CAL | XBRL Taxonomy Extension Calculation Linkbase Document | |||
| 101.DEF | XBRL Taxonomy Extension Definition Linkbase Document | |||
| 101.LAB | XBRL Taxonomy Extension Label Linkbase Document | |||
| 101.PRE | XBRL Taxonomy Extension Presentation Linkbase Document |
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
PULTEGROUP, INC.
(Registrant)
| February 5, 2014 | By: | /s/ Robert T. O'Shaughnessy | |
| Robert T. O'Shaughnessy | |||
| Executive Vice President | |||
| and Chief Financial Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the Registrant and in the capabilities and on the dates indicated:
| Signature | Title | Date | ||
| /s/ Richard J. Dugas, Jr. | Chairman of the Board of Directors, President, and Chief Executive Officer (Principal Executive Officer) | February 5, 2014 | ||
| Richard J. Dugas, Jr. | ||||
| /s/ Robert T. O'Shaughnessy | Executive Vice President and Chief Financial Officer (Principal Financial Officer) | February 5, 2014 | ||
| Robert T. O'Shaughnessy | ||||
| /s/ James L. Ossowski | Vice President, Finance and Controller (Principal Accounting Officer) | February 5, 2014 | ||
| James L. Ossowski | ||||
| /s/ Brian P. Anderson | Member of Board of Directors | February 5, 2014 | ||
| Brian P. Anderson | ||||
| /s/ Bryce Blair | Member of Board of Directors | February 5, 2014 | ||
| Bryce Blair | ||||
| /s/ Thomas J. Folliard | Member of Board of Directors | February 5, 2014 | ||
| Thomas J. Folliard | ||||
| /s/ Cheryl W. Grisé | Member of Board of Directors | February 5, 2014 | ||
| Cheryl W. Grisé | ||||
| /s/ André J. Hawaux | Member of Board of Directors | February 5, 2014 | ||
| André J. Hawaux | ||||
| /s/ Debra J. Kelly-Ennis | Member of Board of Directors | February 5, 2014 | ||
| Debra J. Kelly-Ennis | ||||
| /s/ Patrick J. O’Leary | Member of Board of Directors | February 5, 2014 | ||
| Patrick J. O’Leary | ||||
| /s/ James J. Postl | Member of Board of Directors | February 5, 2014 | ||
| James J. Postl | ||||