 filings.tools
PulteGroup 10-K 2020-12-31
Filed 2021-02-02. 22 sections, 379K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2020
OR
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
Commission File Number 1-9804
PULTEGROUP, INC.
(Exact name of registrant as specified in its charter)
| Michigan | 38-2766606 | |||||||
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
| 3350 Peachtree Road NE, Suite 150 | ||||||||
| Atlanta, | Georgia | 30326 | ||||||
| (Address of principal executive offices) (Zip Code) |
| Registrant’s telephone number, including area code: | 404 | 978-6400 |
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol | Name of each exchange on which registered | ||||||
| Common Shares, par value $0.01 | PHM | New York Stock Exchange | ||||||
| Series A Junior Participating Preferred Share Purchase Rights | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act:
NONE
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer”, “accelerated filer”, “smaller reporting company”, and "emerging growth company" in Rule 12b-2 of the Exchange Act
| Large accelerated filer | Accelerated filer | Non-accelerated filer | Smaller reporting company | Emerging growth company | ||||||||||
| ☒ | ☐ | ☐ | ☐ | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. [ ]
Indicate by check mark whether the registrant has filed a report on and attestation to its management's assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☑
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ☐ No ☒
The aggregate market value of the registrant’s voting shares held by nonaffiliates of the registrant as of June 30, 2020, based on the closing sale price per share as reported by the New York Stock Exchange on such date, was $9,077,356,567. As of January 21, 2021, the registrant had 265,894,240 shares of common shares outstanding.
Documents Incorporated by Reference
Applicable portions of the Proxy Statement for the 2021 Annual Meeting of Shareholders are incorporated by reference in Part III of this Form.
PULTEGROUP, INC.
TABLE OF CONTENTS
PART I
ITEM I. BUSINESS
PulteGroup, Inc. is a Michigan corporation organized in 1956. We are one of the largest homebuilders in the United States ("U.S."), and our common shares are included in the S&P 500 Index and trade on the New York Stock Exchange under the ticker symbol “PHM”. Unless the context otherwise requires, the terms "PulteGroup", the "Company", "we", "us", and "our" used herein refer to PulteGroup, Inc. and its subsidiaries. While our subsidiaries engage primarily in the homebuilding business, we also have financial services businesses, including mortgage banking, conducted principally through Pulte Mortgage LLC (“Pulte Mortgage”), title, and insurance brokerage operations.
Homebuilding, our core business, which includes the acquisition and development of land primarily for residential purposes within the U.S. and the construction of housing on such land, generated 97% of our consolidated revenues of $11.0 billion in 2020 and 98% of our consolidated revenues of $10.2 billion in 2019 and 2018, respectively.
Available information
We file annual, quarterly, and current reports, proxy statements, and other information with the Securities and Exchange Commission (the “SEC”). These filings are available at the SEC’s website at www.sec.gov. Our internet website address is www.pultegroupinc.com. Our annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Securities Exchange Act are available free of charge through our website as soon as reasonably practicable after we electronically file them with or furnish them to the SEC. Our code of ethics for principal officers, our code of ethical business conduct, our corporate governance guidelines, and the charters of the Audit, Compensation and Management Development, Nominating and Governance, and Finance and Investment Committees of our Board of Directors are also posted on our website and are available in print, free of charge, upon request.
Homebuilding Operations
Our Homebuilding operations are geographically diverse within the U.S. As of December 31, 2020, we operated out of 874 active communities in 40 markets across 23 states. We offer a broad product line to meet the needs of homebuyers in our targeted markets. Through our brands, which include Centex, Pulte Homes, Del Webb, DiVosta Homes, John Wieland Homes and Neighborhoods, and American West, we offer a wide variety of home designs at different prices and with varying levels of options and amenities to our major customer groups: first-time, move-up, and active adult. During 2020, we delivered home closings totaling 24,624 homes, compared with 23,232 homes in 2019 and 23,107 homes in 2018. Over our history, we have delivered nearly 750,000 homes.
We predominantly sell single-family detached homes, which represented 85% of our home closings in 2020, 2019, and 2018. The remaining units consist of attached homes, such as townhomes, condominiums, and duplexes. Sales prices of home closings during 2020 ranged from approximately $150,000 to over $2,500,000, with 92% falling within the range of $200,000 to $750,000. The average unit selling price in 2020 was $430,000, compared with $427,000 in 2019, and $425,000 in 2018.
Strategy
We believe that national publicly-traded builders have a competitive advantage over local builders through their ability to: access more reliable and lower cost financing through the capital markets; control and entitle large land positions; gain better access to scarce labor resources; and achieve greater geographic and product diversification. Among our national publicly-traded peer group, we believe that builders with broad geographic and product diversity and sustainable capital positions will benefit from this scale and diversification in any market conditions. Our strategy to enhance shareholder value is centered around the following operational objectives:
-
Drive operational gains and asset efficiency in support of high returns over the housing cycle;
-
Shorten the duration of our owned land pipeline to improve returns and reduce risks, including targeting a long-term balance of approximately three years of supply each for owned and optioned land (approximately six years of supply in total);
-
Maintain disciplined business practices to maximize returns on investment;
-
Increase scale within our existing markets by appropriately expanding market share among our primary buyer groups: first-time, move-up, and active adult;
-
Focus on building-to-order while maintaining an appropriate balance of speculative homes; and
-
Manage the Company's capital consistent with our stated priorities: invest in the business, fund our dividend, maintain a long-term debt-to-capital ratio within a targeted range of 30.0% to 40.0%, and routinely return excess funds to shareholders through share repurchases.
Land acquisition and development
We acquire land primarily for the construction of homes for sale. We select locations for development of homebuilding communities after completing a feasibility study, which includes, among other things, soil tests, independent environmental studies and other engineering work, an evaluation of necessary zoning and other governmental entitlements, and extensive market research that enables us to match the location with our product offering to meet the needs of consumers. We consider factors such as proximity to developed areas, population and job growth patterns, and, if applicable, estimated development costs. We frequently manage a portion of the risk of controlling our land positions through the use of land option agreements, which enable us to defer acquiring portions of properties owned by land sellers until we have determined whether and when to exercise our option. Our use of land option agreements can serve to enhance our expected returns on our land investments and reduce the financial risk associated with long-term land holdings. We typically acquire land with the intent to complete sales of housing units within 24 to 36 months from the date of opening a community, except in the case of certain Del Webb active adult developments and other large master-planned projects for which the completion of community build-out requires a longer time period. While our overall supply of controlled land is in excess of our short-term needs in certain of our markets, some of our controlled land consists of long-term positions that will not be converted to home sales in the near term. Accordingly, we remain active in our pursuit of new land investment. We also periodically sell select parcels of land to third parties for commercial or other development or if we determine that such parcels no longer fit into our strategic operating plans.
Land is generally purchased after it is zoned and developed, or is ready for development, for our intended use. Where we develop land, we engage directly in many phases of the development process, including: land and site planning; obtaining environmental and other regulatory approvals; and constructing roads, sewers, water and drainage facilities, and community amenities, such as parks, pools, and clubhouses. We use our staff and the services of independent engineers and consultants for land development activities. Land development work is performed primarily by independent contractors and, when needed, local government authorities who construct sewer and water systems in some areas. At December 31, 2020, we controlled 180,352 lots, of which 91,363 were owned and 88,989 were under land option agreements.
Sales and marketing
We are dedicated to improving the quality and value of our homes through innovative architectural and community designs. Analyzing various qualitative and quantitative data obtained through extensive market research, we stratify our potential customers into well-defined homebuyer groups. Such stratification provides a method for understanding the business opportunities and risks across the full spectrum of consumer groups in each market. Once the needs of potential homebuyers are understood, we link our home design and community development efforts to the specific lifestyle of each consumer group. Through our understanding of each consumer group, we seek to provide homes that better meet the needs and wants of each homebuyer.
Our homes targeted to first-time homebuyers tend to be smaller with product offerings geared toward lower average selling prices and higher density. Move-up homebuyers tend to place more of a premium on location and amenities. These communities typically offer larger homes at higher price points. Through our Del Webb brand, we address the needs of active adults. Many of these active adult communities are age-restricted to homebuyers aged fifty-five and over and are highly amenitized, offering a variety of features, including athletic facilities, recreational centers, and educational classes, to facilitate the homebuyer maintaining an active lifestyle. In order to make the cost of these highly amenitized communities affordable to the individual homeowner, Del Webb communities tend to be larger than first-time or move-up homebuyer communities. During 2020, 31%, 45%, and 24% of our home closings were to first-time, move-up, and active adult customers, respectively, which reflects a slight increase toward first-time buyers since 2019 consistent with our continued investment in serving first-time buyers.
We believe that we are an innovator in home design, and we view our design capabilities as an integral aspect of our marketing strategy. Our in-house architectural services teams, supplemented by outside consultants, follow a disciplined product development process to introduce new features and technologies based on customer-validated data. Following this disciplined process results in distinctive design features, both in exterior facades and interior options and features. We typically offer a variety of house floor plans and elevations in each community, including potential options and upgrades, such as different flooring, countertop, fixture, and appliance choices, and design our base house and option packages to meet the needs of our
customers as defined through rigorous market research. Energy efficiency represents an important source of value for new homes compared with existing homes and represents a key area of focus for our home designs, including high efficiency heating, ventilation, and air conditioning systems and insulation, low-emissivity windows, solar power in certain geographies, and other energy-efficient features.
We market our homes to prospective homebuyers through internet listings and link placements, mobile applications, media advertising, illustrated brochures, and other advertising displays. We have made significant enhancements in our tools and business practices to adapt our selling efforts to today's tech-enabled customers. This includes our websites (www.centex.com, www.pulte.com, www.delwebb.com, www.divosta.com, www.americanwesthomes.com, and www.jwhomes.com), which provide tools to help users find a home that meets their needs, investigate financing alternatives, communicate moving plans, maintain a home, learn more about us, and communicate directly with us.
Our sales teams consist primarily of commissioned employees, and the majority of our home closings also involve independent third-party sales brokers. Our sales consultants are responsible for guiding the customer through the sales process, including selecting the community, house floor plan, and options that meet the customer's needs. We are committed to industry-leading customer service through a variety of quality initiatives, including our customer care program, which seeks to ensure that homebuyers are engaged and satisfied at every stage of the process. Fully furnished and landscaped model homes physically located in our communities, which leverage the expertise of our interior designers, are generally used to showcase our homes and their distinctive design features. We have also introduced virtual reality walkthroughs of our house floor plans in certain communities to provide prospective homebuyers a more cost-effective means to provide a realistic vision of our homes.
The majority of our homes are sold on a built-to-order basis where we do not begin construction of the home until we have a signed contract with a customer. However, we also build speculative ("spec") homes in most of our communities, which allow us to compete more effectively with existing homes available in the market, especially for homebuyers that require a home within a short time frame. We determine our spec home strategy for each community based on local market factors and maintain a level of spec home inventory based on our current and planned sales pace and construction cadence for the community.
Our sales contracts with customers generally require payment of a deposit at the time of contract signing and sometimes additional deposits upon selection of certain options or upgrade features for their homes. Our sales contracts also typically include a financing contingency that provides customers with the right to cancel if they cannot obtain mortgage financing at specified interest rates within a specified period. Our contracts may also include other contingencies, such as the sale of an existing home. Backlog, which represents orders for homes that have not yet closed, was $6.8 billion (15,158 units) at December 31, 2020 and $4.5 billion (10,507 units) at December 31, 2019. For orders in backlog, we have received a signed customer contract and customer deposit, which is refundable in certain instances. Of the orders in backlog at December 31, 2020, substantially all are scheduled to be closed during 2021, though all orders are subject to potential cancellation by or final negotiations with the customer. In the event of contract cancellation, the majority of our sales contracts stipulate that we have the right to retain the customer’s deposit, though we may choose to refund the deposit in certain instances.
Construction
The construction of our homes is conducted under the supervision of our on-site construction field managers. Substantially all of our construction work is performed by independent subcontractors under contracts that establish a specific scope of work at an agreed-upon price. Using a selective process, we have aligned with what we believe are premier subcontractors and suppliers to deliver quality throughout all aspects of the house construction process. In addition, our construction field managers and customer care associates interact with our homebuyers throughout the construction process and instruct homebuyers on post-closing home maintenance.
Continuous improvement in our house construction process is a key area of focus. We seek to build superior quality homes while maintaining efficient construction operations by using standard materials and components from a variety of sources and by following industry and company-specific construction practices. We maintain high quality product offerings and production processes through the following programs:
-
Common management of house plans to deliver house designs that customers value the most and that can be built at the highest quality and at an efficient cost;
-
Value engineering our house plans to optimize house designs in terms of material content and ease of construction while still providing a clear value to the customer;
-
Utilizing our proprietary construction standards and practices, training of our field leadership and construction personnel, communication with our suppliers, and auditing our compliance through the use of both internal and third party construction experts; and
-
Working with our suppliers using a data driven, collaborative method to reduce construction costs.
Generally, the construction materials used in our operations are readily available from numerous sources. However, the cost of certain building materials, especially lumber, steel, concrete, copper, and petroleum-based materials, is influenced by changes in global commodity prices, national tariffs, and other foreign trade factors. Additionally, the ability to consistently source qualified labor at reasonable prices remains challenging as labor supply growth has not kept pace with construction demand. To protect against changes in construction costs, labor and materials costs are generally established prior to or near the time when related sales contracts are signed with customers. In addition, we leverage our size by actively negotiating for certain materials on a national or regional basis to minimize costs. We are also working to establish a more integrated system that can effectively link suppliers, contractors, and the production schedule. However, we cannot determine the extent to which necessary building materials and labor will be available at reasonable prices in the future.
Competition
The housing industry in the U.S. is fragmented and highly competitive. While we are one of the largest homebuilders in the U.S., our national market share represented only approximately 3% of U.S. new home sales in 2020. In each of our local markets, there are numerous national, regional, and local homebuilders with whom we compete. Additionally, new home sales have traditionally represented less than 15% of overall U.S. home sales (new and existing homes). Therefore, we also compete with sales of existing house inventory and any provider of for sale or rental housing units, including apartment operators. We compete primarily on the basis of location, price, quality, reputation, design, community amenities, and our customers' overall sales and homeownership experiences.
Seasonality
Although significant changes in market conditions have impacted our seasonal patterns in the past and could do so again, we historically experience variability in our quarterly results from operations due to the seasonal nature of the homebuilding industry. We generally experience increases in revenues and cash flow from operations during the fourth quarter based on the timing of home closings. This seasonal activity increases our working capital requirements in our third and fourth quarters to support our home production and loan origination volumes. As a result of the seasonality of our operations, our quarterly results of operations are not necessarily indicative of the results that may be expected for the full year. Additionally, given the disruption in economic activity caused by the COVID-19 pandemic, our quarterly results in 2020 are not necessarily indicative of results that may be achieved in the future.
Regulation and environmental matters
Our operations are subject to extensive regulations imposed and enforced by various federal, state, and local governing authorities. These regulations are complex and include building codes, land zoning and other entitlement restrictions, health and safety regulations, labor practices, marketing and sales practices, environmental regulations, rules and regulations relating to mortgage financing and title operations, and various other laws, rules, and regulations. Collectively, these regulations have a significant impact on the site selection and development of our communities; our house design and construction techniques; our relationships with customers, employees, suppliers, and subcontractors; and many other aspects of our business. The applicable governing authorities frequently have broad discretion in administering these regulations, including inspections of our homes prior to closing with the customer in the majority of municipalities in which we operate. Additionally, we may experience extended timelines for receiving required approvals from municipalities or other government agencies that can delay our anticipated development and construction activities in our communities.
Financial Services Operations
We conduct our financial services business, which includes mortgage banking, title, and insurance brokerage operations, through Pulte Mortgage and other subsidiaries. Pulte Mortgage arranges financing through the origination of mortgage loans primarily for the benefit of our homebuyers. We are a lender approved by the Federal Housing Administration ("FHA") and Department of Veterans Affairs ("VA") and are a seller/servicer approved by Government National Mortgage Association ("Ginnie Mae"), Federal National Mortgage Association ("Fannie Mae"), Federal Home Loan Mortgage Corporation ("Freddie Mac"), and other investors. In our conventional mortgage lending activities, we follow underwriting guidelines established by Fannie Mae, Freddie Mac, and private investors. We believe that our customers’ use of our in-house mortgage and title operations provides us with a competitive advantage by enabling more control over the quality of the overall home buying process for our customers, while also helping us align the timing of the house construction process with our customers’ financing needs.
Operating through a captive business model targeted to supporting our Homebuilding operations, the business levels of our Financial Services operations are highly correlated to Homebuilding. Our Homebuilding customers continue to account for substantially all of our loan production. We originated the mortgage loans for 73% of the homes we closed in 2020, 67% in 2019, and 62% in 2018. Other home closings are settled via either cash, which typically represent approximately 20% of home closings, or third party lenders.
In originating mortgage loans, we initially use our own funds, including funds available pursuant to credit agreements with third parties, and subsequently sell such mortgage loans to third party investors in the secondary market. Substantially all of the loans we originate are sold in the secondary market within a short period of time after origination, generally within 30 days. We also sell the servicing rights for the loans we originate through fixed price servicing sales contracts to reduce the risks and costs inherent in servicing loans. This strategy results in owning the loans and related servicing rights for only a short period of time.
The mortgage industry in the U.S. is highly competitive. We compete with other mortgage companies and financial institutions to provide attractive mortgage financing to our homebuyers. We utilize a centralized fulfillment center for our mortgage operations that performs underwriting, processing, and closing functions. We believe centralizing both the fulfillment and origination of our loans improves the speed, efficiency, and quality of our mortgage operations, improving our profitability and allowing us to focus on providing attractive mortgage financing opportunities for our customers.
In originating and servicing mortgage loans, we are subject to the rules and regulations of the government-sponsored investors and other investors that purchase the loans we originate, as well as to those of other government agencies that have oversight of the government-sponsored investors or consumer lending rules in the U.S. In addition to being affected by changes in these programs, our mortgage banking business is also affected by many of the same factors that impact our homebuilding business.
Our mortgage operations may be responsible for losses associated with mortgage loans originated and sold to investors in the event of errors or omissions relating to representations and warranties made by us that the loans met certain requirements, including representations as to underwriting standards, the existence of primary mortgage insurance, and the validity of certain borrower representations in connection with the loan. If a loan is determined to be faulty, we either indemnify the investor for potential future losses, repurchase the loan from the investor, or reimburse the investor's actual losses.
Our subsidiary title insurance companies serve as title insurance agents and underwriters in select markets by providing title insurance policies and examination and closing services to buyers of homes we sell. Historically, we have not experienced significant claims related to our title operations.
Our insurance brokerage operations serve as a broker for home, auto, and other personal insurance policies in select markets to buyers of homes we sell. All such insurance policies are placed with third party insurance carriers.
Human Capital Resources
The Company's key human capital management objectives are to attract, develop, and retain top industry talent that reflects the diversity of the communities in which we build. To support this goal, the Company's human resources programs are designed to develop talent to prepare for key roles and leadership positions for the future; reward employees through competitive industry pay, benefits, and other programs; instill the Company's culture with a focus on diversity and ethical behavior; and enhance our employees' performance through investment in current technology, tools, and training to enable our employees to operate at a
high level. The Company's commitment to the aforementioned goals is evidenced through its certification as a Great Place to Work® and recent formation of a national diversity council.
At December 31, 2020, we employed 5,249 people, of which 945 were employed in our Financial Services operations. Of our homebuilding employees, 282 are involved in land acquisition and development functions, 1,752 are involved in construction and and post-closing customer care functions; 1,189 are involved in the sales function; and 1,081 are involved in procurement, corporate, and other functions. Our employees are not represented by any union. Contracted work, however, may be performed by union contractors. We consider our employee relations to be good.
We offer our employees a broad range of company-paid benefits, and we believe our compensation package and benefits are competitive with others in our industry.
Our management team supports a culture of developing future leaders from our existing workforce, enabling us to promote from within for many leadership positions. We believe this provides long-term focus and continuity to our operations while also providing opportunities for the growth and advancement of our employees. Our focus on retention is evident in the length of service of our executive, area, and divisional management teams. The average tenure of our executive team and homebuilding area presidents is 20 years and the average tenure of our homebuilding division presidents is 15 years.
We are committed to hiring, developing and supporting a diverse and inclusive workplace. Our management teams are expected to exhibit and promote honest, ethical and respectful conduct in the workplace. All of our employees must adhere to a code of conduct that sets standards for appropriate ethical behavior.
Item 1A. RISK FACTORS
Discussion of our business and operations included in this annual report on Form 10-K should be read together with the risk factors set forth below. They describe various risks and uncertainties to which we are, or may become, subject. These risks and uncertainties, together with other factors described elsewhere in this report, have the potential to affect our business, financial condition, results of operations, cash flows, strategies, or prospects in a material and adverse manner.
Risks Related to the COVID-19 Pandemic
Our business has been materially and adversely disrupted by the present outbreak and worldwide spread of COVID-19 and could be materially and adversely disrupted by another epidemic or pandemic, or similar public threat, or fear of such an event, and the measures that international, federal, state and local governments, agencies, law enforcement and/or health authorities implement to address it.
An epidemic, pandemic, or similar serious public health issue, and the measures undertaken by governmental authorities to address it, could significantly disrupt or prevent us from operating our business in the ordinary course for an extended period, and thereby, and/or along with any associated economic and/or social instability or distress, have a significant adverse impact on our consolidated financial statements.
On March 11, 2020, the World Health Organization characterized the outbreak of COVID-19 as a global pandemic and recommended containment and mitigation measures worldwide. On March 13, 2020, the United States declared a national emergency concerning the COVID-19 outbreak, and shortly thereafter many states and municipalities also declared public health emergencies. Along with these declarations, extraordinary and wide-ranging actions were taken by international, federal, state, and local public health and governmental authorities to contain and combat the outbreak and spread of COVID-19 in regions across the United States and the world, including quarantines, “shelter-in-place” orders and similar mandates for many individuals to substantially restrict daily activities and for many businesses to curtail or cease normal operations. For instance, our business was impacted by restrictions on travel, the inability to keep our sales centers open for in-person customer interactions, limits on our ability to continue physical construction of homes and adjustments to many of our other business processes to limit direct interactions.
The severity of these restrictions and the extent of their impact on our operations has varied by market based upon the scope of "shelter in place" orders and public health conditions. While all of the above-referenced steps were necessary and appropriate in light of the COVID-19 pandemic, they have impacted our ability to operate our business in its ordinary and traditional course. Those restrictions, combined with a reduction in the availability, capacity, and efficiency of municipal and private services
necessary to progress land development, homebuilding, mortgage loan originations, and home sales, which in each case varied by market depending on the scope of the restrictions local authorities have established, tempered our sales pace and delayed home construction and deliveries. The inconsistent pace of recovery from the cessation of normal activities in the second quarter of 2020 impacted our ability to start homes in that quarter, which impacts our ability to advance production at typical paces in some markets through the date of this report.
While our operations are now fully functioning, subject to regulated restrictions and safety constraints we have enacted in order to protect our employees, trade contractors, and customers, the current resurgence of the COVID pandemic in key areas of our operations may require us to implement restrictions on our operations. The potential magnitude or duration of the business and economic impacts from the unprecedented public health effort to contain and combat the spread of COVID-19 are uncertain and could include, among other things, significant volatility in financial markets. The COVID-19 public health effort may be intensified to such an extent that we will not be able to conduct any business operations in certain of our served markets or at all for an indefinite period. In addition, efforts by local governments and agencies to lift restrictions on individuals’ daily activities and businesses’ normal operations may result in a resurgence of a pandemic or epidemic like COVID-19 and potentially prolong and intensify the impact of the crisis. Despite the development of a vaccine and more effective treatments for the physical impacts of COVID-19, there are no reliable estimates of how long the COVID-19 pandemic will last, and therefore, the unpredictability of the current economic and public health conditions will continue to evolve.
Our business has also been impacted by constraints to the labor and supply chain we rely on to construct our homes. The continuing pandemic has caused our employees and those of our trade partners to miss workdays due to illness or quarantine. In addition, our supply chain has been impacted by similar labor interruptions slowing production capacity and by increased demand on raw materials generated in part by the COVID pandemic. The combination of these factors can lead to increased costs and reductions in our production times.
Our business could also be negatively impacted over the medium-to-longer term if the disruptions related to COVID-19 decrease consumer confidence generally or with respect to purchasing a home; cause civil unrest; precipitate a prolonged economic downturn and/or an extended rise in unemployment or tempering of wage growth, any of which could lower demand for our products, impair our ability to sell and build homes in a typical manner or at all, generate revenues and cash flows, and/or access the capital or lending markets (or significantly increase the costs of doing so), as may be necessary to sustain our business; increase the costs or decrease the supply of building materials or the availability of subcontractors and other talent, including as a result of infections or medically necessary or recommended self-quarantining, or governmental mandates to direct production activities to support public health efforts; and/or result in our recognizing charges in future periods, which may be material, for inventory impairments or land option contract abandonments, or both, related to our current inventory assets. The unprecedented uncertainty surrounding COVID-19, due to rapidly changing governmental directives, public health challenges and progress, macroeconomic consequences, and market reactions thereto, also makes it more challenging for our management to estimate the future performance of our business and develop strategies to generate growth or achieve our objectives for 2021 and beyond.
Should the adverse impacts described above (or others that are currently unknown) occur, whether individually or collectively, we would expect to experience, among other things, increases in the cancellation rates for homes in our backlog, and decreases in our net orders, homes delivered, revenues, and profitability, as we experienced in the first few weeks of our second quarter of 2020. Such impacts could be material to our consolidated financial statements in future reporting periods. We could also be forced to reduce our average selling prices in order to generate consumer demand or in reaction to competitive pressures. In addition, should the COVID-19 public health effort and governmental restrictions in response to the pandemic instensify to such an extent that we cannot operate in most or all of our served markets, we could generate few or no orders and deliver few, if any, homes during the applicable period, which could be prolonged. Along with a potential increase in cancellations of home purchase contracts, if there are prolonged government restrictions on our business and our customers, and/or an extended economic recession, we could be unable to produce revenues and cash flows sufficient to conduct our business; meet the terms of our covenants and other requirements under our debt obligations, and/or mortgages and land contracts due to land sellers and other loans; service our outstanding debt; or pay any dividends to our stockholders. Such circumstances could, among other things, exhaust our available liquidity (and ability to access liquidity sources) and/or trigger an acceleration to pay a significant portion or all of our then-outstanding debt obligations, which we may be unable to do.
While the economic impact of COVID-19 may be reduced by financial assistance under the Coronavirus Aid, Relief, and Economic Security (CARES) Act; the Consolidated Appropriations Act, 2021; or other similar COVID-19 related federal and state programs, such programs may not be sufficient to have a positive impact on our business.
Risks Associated With Our Industry
The homebuilding industry is cyclical and a deterioration in industry conditions or downward changes in general economic or other business conditions could adversely affect our business or our financial results.
The residential homebuilding industry is sensitive to changes in economic conditions and other factors, such as the level of employment, consumer confidence, consumer income, availability of financing, and interest rate levels. Adverse changes in any of these conditions generally, or in the markets where we operate, could decrease demand and pricing for new homes in these areas or result in customer cancellations of pending contracts, which could adversely affect the number of home deliveries we make or reduce the prices we can charge for homes, either of which could result in a significant decrease in our revenues and earnings that could materially and adversely affect our financial condition.
For example, beginning in 2006 and continuing through 2011, the U.S. housing market was unfavorably impacted by severe weakness in new home sales attributable to, among other factors, weak consumer confidence, tightened mortgage standards, significant foreclosure activity, a more challenging appraisal environment, higher than normal unemployment levels, and significant uncertainty in the global economy. During this period, we incurred significant losses, including impairments of our land inventory and certain other assets, and some aspects of the housing industry have yet to return to pre-2007 production levels.
Future increases in interest rates, reductions in mortgage availability, or other increases in the effective costs of owning a home could prevent potential customers from buying our homes and adversely affect our business and financial results.
A large majority of our customers finance their home purchases through mortgage loans, many through Pulte Mortgage. Mortgage interest rates in recent years have been at or near historic lows, thereby making new homes more affordable. Increases in interest rates or decreases in the availability of mortgage financing could adversely affect the market for new homes. Potential homebuyers may be less willing or able to pay the increased monthly costs resulting from higher interest rates or to obtain mortgage financing. Lenders may increase the qualifications needed for mortgages or adjust their terms to address any increased credit risk. Even if potential customers do not need financing, changes in interest rates and mortgage availability could make it harder for them to sell their current homes to potential buyers who need financing. These factors could adversely affect the sales or pricing of our homes and could also reduce the volume or margins in our financial services business. Our financial services business could also be impacted to the extent we are unable to match interest rates and amounts on loans we have committed to originate through the various hedging strategies we employ. These developments have had, and may continue to have, a material adverse effect on the overall demand for new housing and thereby on the results of operations of our business. For example, during 2018, we experienced lower than expected conversions of traffic to signups, especially among first-time and move-up buyers, beginning in May 2018 when mortgage rates increased.
The liquidity provided by Fannie Mae and Freddie Mac to the mortgage industry is also critical to the housing market. The impact of the federal government’s conservatorship of Fannie Mae and Freddie Mac on the short-term and long-term demand for new housing remains unclear. Any limitations or restrictions on the availability of financing by these agencies could adversely affect interest rates, mortgage financing, and our sales of new homes and mortgage loans. Additionally, the availability of FHA and VA mortgage financing is an important factor in marketing some of our homes.
Mortgage interest expense and real estate taxes represent significant costs of homeownership, both of which were historically generally deductible for an individual’s federal and, in some cases, state income taxes. In December 2017, a law commonly known as the Tax Cuts and Jobs Act (the "Tax Act") was enacted. While the Tax Act lowered the tax rates applicable to many businesses and individuals, it also, among other things, (i) limits the federal deduction for mortgage interest so that it only applies to the first $750,000 of a new mortgage (as compared to $1 million under previous tax law), (ii) introduced a $10,000 cap on the federal deduction for state and local taxes, including real estate taxes, and (iii) eliminated the federal deduction for interest on certain home equity loans. The Tax Act also increased the standard deduction for individuals. As a result, fewer individuals are expected to itemize their income tax deductions, which would reduce the income tax advantages associated with homeownership for those individuals. Any further changes in income tax law which eliminate or further reduce the income tax benefits associated with home ownership could have an adverse impact on our business.
Inflation may result in increased costs that we may not be able to recoup.
Inflation can adversely affect us by increasing costs of land, materials, and labor. In addition, significant inflation is often accompanied by higher interest rates, which may have a negative impact on demand for our homes. In an inflationary environment, economic conditions and other market factors may make it difficult for us to raise home prices enough to keep up with the rate of inflation, which would reduce our profit margins. Although the rate of inflation has been historically low for the last several years, we currently are experiencing increases in the prices of labor and certain materials above the general inflation rate.
Our success depends on our ability to acquire land suitable for residential homebuilding in accordance with our land investment criteria.
The homebuilding industry is highly competitive for suitable land. The availability of finished and partially finished developed lots and undeveloped land for purchase that meet our internal criteria depends on a number of factors outside our control, including land availability in general, competition with other homebuilders and land buyers for desirable property, inflation in land prices, zoning, allowable housing density, and other regulatory requirements. Should suitable lots or land become less available, the number of homes we may be able to build and sell could be reduced, and the cost of land could be increased, perhaps substantially, which could adversely impact our results of operations.
Our long-term ability to build homes depends on our acquiring land suitable for residential building at reasonable prices in locations where we want to build. We experience significant competition for suitable land as a result of land constraints in many of our markets. As competition for suitable land increases, and as available land is developed, the cost of acquiring suitable remaining land could rise, and the availability of suitable land at acceptable prices may decline. Any land shortages or any decrease in the supply of suitable land at reasonable prices could limit our ability to develop new communities or result in increased land costs. We may not be able to pass through to our customers any increased land costs, which could adversely impact our revenues, earnings, and margins.
If the market value of our land drops significantly, our profits could decrease and result in write-downs of the carrying values of land we own.
The market value of land can fluctuate significantly as a result of changing market conditions, and the measures we employ to manage inventory risk may not be adequate to insulate our operations from a severe drop in inventory values. We acquire land for expansion into new markets and for replacement of land inventory and expansion within our current markets. If housing demand decreases below what we anticipated when we acquired our inventory, we may not be able to make profits similar to what we have made in the past, we may experience less than anticipated profits, and/or we may not be able to recover our costs when we sell and build homes. When market conditions are such that land values are not appreciating, land option arrangements previously entered into may become less desirable, at which time we may elect to forego deposits and pre-acquisition costs and terminate the agreement. In the face of adverse market conditions, we may have substantial inventory carrying costs, we may have to write down our inventory to its fair value, and/or we may have to sell land or homes at a loss. At times we have been required to record significant write-downs of the carrying value of our land inventory, and we have elected not to exercise options to purchase land, even though that required us to forfeit deposits and write-off pre-acquisition costs. For example, we incurred land-related charges totaling $20.3 million, $27.1 million, and $99.4 million in 2020, 2019, and 2018, respectively. If market conditions were to deteriorate in the future, we could again be required to record significant write downs to our land inventory, which would decrease the asset values reflected on our balance sheet and materially and adversely affect our earnings and our stockholders' equity.
Supply shortages and other risks related to the demand for skilled labor and building materials could increase costs and delay deliveries.
The homebuilding industry is highly competitive for skilled labor. Labor shortages in certain of our markets have become more acute in recent years as the supply chain adjusts to industry growth. Additionally, the cost of certain building materials, especially lumber, steel, concrete, copper, and petroleum-based materials, is influenced by changes in local and global commodity prices as well as government regulation, such as government-imposed tariffs or trade restrictions on supplies such as steel and lumber. During 2020 and 2019, we experienced supply chain constraints, increases in the prices of some building materials, and shortages of skilled labor in some areas. Increased costs or shortages of skilled labor and/or materials cause increases in construction costs and/or could cause construction delays. We may not be able to pass on increases in construction
costs to customers and generally are unable to pass on any such increases to customers who have already entered into sales contracts as those sales contracts generally fix the price of the home at the time the contract is signed, which may be well in advance of the construction of the home. Sustained increases in construction costs may, over time, erode our margins, and pricing competition may restrict our ability to pass on any such additional costs, thereby decreasing our margins.
Competition for homebuyers could reduce our deliveries or decrease our profitability.
The U.S. housing industry is highly competitive. Homebuilders compete for homebuyers in each of our markets with numerous national, regional, and local homebuilders on the basis of location, price, quality, reputation, design, community amenities, and our customers' overall sales and homeownership experiences. This competition with other homebuilders could reduce the number of homes we deliver or cause us to accept reduced margins to maintain sales volume.
We also compete with resales of existing or foreclosed homes, housing speculators, and available rental housing. Increased competitive conditions in the residential resale or rental market in the regions where we operate could decrease demand for new homes or unfavorably impact pricing for new homes.
Government regulations could increase the cost and limit the availability of our development and homebuilding projects or affect our related financial services operations and adversely affect our business or financial results.
Our operations are subject to building, safety, environmental, and other regulations imposed and enforced by various federal, state, and local governing authorities. New housing developments may also be subject to various assessments for schools, parks, streets, and other public improvements. These assessments have increased over recent years as other funding mechanisms have decreased causing local governing authorities to seek greater contributions from homebuilders. All of these factors can cause an increase in the effective cost of our homes.
We also are subject to a variety of local, state, and federal laws and regulations concerning protection of health, safety, and the environment. The impact of environmental laws varies depending upon the prior uses of the building site or adjoining properties and may be greater in areas with less supply where undeveloped land or desirable alternatives are less available. These matters may result in delays, may cause us to incur substantial compliance, remediation and other costs, and can prohibit or severely restrict development and homebuilding activity in environmentally sensitive regions or areas. More stringent requirements could be imposed in the future on homebuilders and developers, thereby increasing the cost of compliance.
Our financial services operations are also subject to numerous federal, state, and local laws and regulations. These include eligibility requirements for participation in federal loan programs and compliance with consumer lending and similar requirements such as disclosure requirements, prohibitions against discrimination, and real estate settlement procedures. They also subject our operations to examination by applicable agencies, pursuant to which those agencies may limit our ability to provide mortgage financing or title services to potential purchasers of our homes. For our homes to qualify for FHA or VA mortgages, we must satisfy valuation standards and site, material, and construction requirements of those agencies.
Homebuilding is subject to warranty and other claims in the ordinary course of business that can be significant.
As a homebuilder, we are subject to home warranty, construction defect, and other claims arising in the ordinary course of business. We rely on subcontractors to perform the actual construction of our homes and, in some cases, to select and obtain building materials. Despite our detailed specifications and quality control procedures, in some cases, subcontractors may use improper construction processes or defective materials. In such cases, it can result in the need to perform extensive repairs to large numbers of homes. We record warranty and other reserves relating to the homes we sell based on historical experience in our markets and our judgment of the qualitative risks associated with the types of homes built.
We have, and require our subcontractors to have, general liability, property, errors and omissions, workers compensation, and other business insurance. These insurance policies protect us against a portion of our risk of loss from claims, subject to certain self-insured per occurrence and aggregate retentions, deductibles, and available policy limits. In certain instances, we may offer our subcontractors the opportunity to purchase insurance through one of our captive insurance subsidiaries or participate in a project-specific insurance program provided by us. Policies issued by our captive insurance subsidiaries represent self-insurance of these risks by us. We reserve for costs to cover our self-insured and deductible amounts under these policies and for any costs of claims and lawsuits based on an analysis of our historical claims, which includes an estimate of claims incurred
but not yet reported. Our insurance coverage, our subcontractor arrangements, and our reserves may not be adequate to address all our warranty and construction defect claims in the future. Contractual indemnities can be difficult to enforce, we may be responsible for applicable self-insured retentions, and some types of claims may not be covered by insurance or may exceed applicable coverage limits. Additionally, the coverage offered by and the availability of general liability insurance for construction defects are currently costly and limited. We have responded to increases in insurance costs and coverage limitations by increasing our self-insured retentions. There can be no assurance that coverage will not be further restricted or become more costly. Additionally, we are exposed to counterparty default risk related to our subcontractors, our insurance carriers, and our subcontractors’ insurance carriers.
We can be injured by improper acts of persons over whom we do not have control or by the attempt to impose liabilities or obligations of third parties on us.
Although we expect all of our subcontractors, employees, officers, and directors to comply at all times with all applicable laws, rules, and regulations, there may be instances in which subcontractors or others through whom we do business engage in practices that do not comply with applicable laws, regulations, or governmental guidelines. When we learn of practices that do not comply with applicable laws or regulations, including practices relating to homes, buildings, or multifamily properties we build or finance, we move to stop the non-complying practices as soon as possible, and we have taken disciplinary action regarding subcontractors and employees of ours who were aware of non-complying practices and did not take steps to address them, including in some instances terminating their employment. However, regardless of the steps we take after we learn of practices that do not comply with applicable laws or regulations, we can in some instances be subject to fines or other governmental penalties, and our reputation can be injured, due to the practices' having taken place.
The homes we sell are built by employees of subcontractors and other contract parties. We do not have the ability to control what these contract parties pay their employees or subcontractors or the work rules they impose on their employees or subcontractors. However, various governmental agencies are trying to hold contract parties like us responsible for violations of wage and hour laws and other work-related laws by firms whose employees are performing contracted services. Governmental rulings or changes in state or local laws that make us responsible for labor practices by our subcontractors could create substantial exposures for us in situations that are not within our control.
Natural disasters, severe weather conditions and changing climate patterns could delay deliveries, increase costs, and decrease demand for new homes in affected areas.
Our homebuilding operations are located in many areas that are subject to natural disasters and severe weather. The occurrence of natural disasters or severe weather conditions can delay new home deliveries, increase costs by damaging inventories, reduce the availability of materials, and negatively impact the demand for new homes in affected areas. For instance, in 2019 and 2018, several hurricanes caused disruptions in our southeastern coastal markets but did not result in a material impact to our results of operations. In addition, while they also did not have a material impact on our business in 2020 or 2019, the increased prevalence of forest fires in our western markets have caused disruptions to our sales operations and development delays. Furthermore, if our insurance does not fully cover business interruptions or losses resulting from these events, our earnings, liquidity, or capital resources could be adversely affected.
Government restrictions, standards, or regulations intended to reduce greenhouse gas emissions or potential climate change impacts are likely to result in restrictions on land development in certain areas and may increase energy, transportation, or raw material costs, which could reduce our housing gross profit margins and adversely affect our results of operations. For example, as the risk of flooding in coastal and other flood prone areas increases, local governments may increase the requirements on new home builders for zoning approvals and restrict areas where new homes may be built, resulting in increased development costs and greater competition for more desirable land parcels. In addition, as local governmental authorities and utilities are required to spend increasing amounts of their resources responding to and remediating weather and climate related events, their ability to provide approvals and service to new housing communities may be impaired.
Risks Related to our Business Model and Capital Structure
Adverse capital and credit market conditions may significantly affect our access to capital and cost of capital.
The capital and credit markets can experience significant volatility. We may need credit-related liquidity for the future development of our business and other capital needs. Without sufficient liquidity, we may not be able to purchase additional land or develop land, which could adversely affect our financial results. At December 31, 2020, we had cash, cash equivalents, and restricted cash of $2.6 billion as well as $750.3 million available under our revolving credit facility ("Revolving Credit Facility"), less any outstanding letters of credit issued under the terms of our credit facilities. However, our internal sources of liquidity and Revolving Credit Facility may prove to be insufficient, and, in such case, we may not be able to successfully obtain additional financing on terms acceptable to us, or at all.
Another source of liquidity includes our ability to use letters of credit and surety bonds relating to certain performance-related obligations and as security for certain land option agreements and insurance programs. The majority of these letters of credit and surety bonds are in support of our land development and construction obligations to various municipalities, other government agencies, and utility companies related to the construction of roads, sewers, and other infrastructure. At December 31, 2020, we had outstanding letters of credit and surety bonds totaling $249.7 million and $1.5 billion, respectively. These letters of credit are generally issued via our unsecured Revolving Credit Facility, which contains certain financial covenants and other limitations. If we are unable to obtain letters of credit or surety bonds when required, or the conditions imposed by issuers increase significantly, our liquidity could be adversely affected.
Our income tax provision and tax reserves may be insufficient if a taxing authority is successful in asserting positions that are contrary to our interpretations and related reserves, if any.
Significant judgment is required in determining our provision for income taxes and our reserves for federal, state, and local taxes. In the ordinary course of business, there may be matters for which the ultimate outcome is uncertain. Our evaluation of our tax matters is based on a number of factors, including relevant facts and circumstances, applicable tax law, correspondence with tax authorities during the course of audits, and effective settlement of audit issues. Although we believe our approach to determining the tax treatment for such items is appropriate, no assurance can be given that the final tax authority review will not be materially different than that which is reflected in our income tax provision and related tax reserves. Such differences could have a material adverse effect on our income tax provision in the period in which such determination is made and, consequently, on our financial position, cash flows, or net income.
We are periodically audited by various federal, state, and local authorities regarding tax matters. Our current audits are in various stages of completion; however, no outcome for a particular audit can be determined with certainty prior to the conclusion of the audit, appeal, and, in some cases, litigation process. As each audit is concluded, adjustments, if any, are recorded in our financial statements in the period determined. To provide for potential tax exposures, we consider a variety of factors, including relevant facts and circumstances, applicable tax law, correspondence with taxing authorities, and effective settlement of audit issues. If these reserves are insufficient upon completion of an audit, there could be an adverse impact on our financial position, cash flows, and results of operations.
We may not realize our deferred tax assets.
As of December 31, 2020, we had deferred tax assets, net of deferred tax liabilities, of $102.5 million, against which we provided a valuation allowance of $69.8 million. The ultimate realization of our deferred tax assets is dependent upon generating future taxable income. While we have recorded valuation allowances against certain of our deferred tax assets, the valuation allowances are subject to change as facts and circumstances change.
Our ability to utilize net operating losses (“NOLs”), built-in losses (“BILs”), and tax credit carryforwards to offset our future taxable income or income tax would be limited if we were to undergo an “ownership change” within the meaning of Section 382 of the Internal Revenue Code (the “IRC”). In general, an “ownership change” occurs whenever the percentage of the stock of a corporation owned by “5-percent shareholders” (within the meaning of Section 382 of the IRC) increases by more than 50 percentage points over the lowest percentage of the stock of such corporation owned by such “5-percent shareholders” at any time over the testing period.
An ownership change under Section 382 of the IRC would establish an annual limitation to the amount of NOLs, BILs, and tax credit carryforwards we could utilize to offset our taxable income or income tax in any single year. The application of these limitations might prevent full utilization of the deferred tax assets attributable to our NOLs, BILs, and tax credit carryforwards. To preserve our ability to utilize NOLs, BILs, and other tax benefits in the future without a Section 382 limitation, we adopted a shareholder rights plan, which is triggered upon certain transfers of our securities, and amended our by-laws to prohibit certain transfers of our securities. Our shareholder rights plan, as amended, expires June 1, 2022, unless our Board of Directors and shareholders approve an amendment to extend the term prior thereto. Notwithstanding the foregoing measures, there can be no assurance that we will not undergo an ownership change within the meaning of Section 382.
The value of our deferred tax assets and liabilities are also dependent upon the tax rates expected to be in effect at the time they are realized. A change in enacted corporate tax rates in our major jurisdictions, especially the U.S. federal corporate tax rate, would change the value of our deferred taxes, which could be material.
Our inability to sell mortgages into the secondary market could significantly reduce our ability to sell homes unless we are willing to become a long-term investor in loans we originate.
We sell substantially all of the residential mortgage loans we originate within a short period in the secondary mortgage market. If we were unable to sell loans into the secondary mortgage market or directly to Fannie Mae and Freddie Mac, we would have to either (a) curtail our origination of residential mortgage loans, which among other things, could significantly reduce our ability to sell homes, or (b) commit our own funds to long term investments in mortgage loans, which, in addition to requiring us to deploy substantial amounts of our own funds, could delay the time when we recognize revenues from home sales on our statements of operations.
We are subject to claims related to mortgage loans we sold in the secondary mortgage market that may be significant.
Our mortgage operations may be responsible for losses arising out of claims associated with mortgage loans originated and sold to investors in the event of errors or omissions relating to certain representations and warranties made by us that the loans met certain requirements, including representations as to underwriting standards, the type of collateral, the existence of primary mortgage insurance, and the validity of certain borrower representations in connection with the loan. To date, the significant majority of these claims made by investors against our mortgage operations relate to loans originated prior to 2009, during which inherently riskier loan products became more common in the origination market. We may also be asked to indemnify underwriters that purchased and securitized loans originated by a former subsidiary of Centex Corporation ("Centex"), which we acquired in 2009, for losses incurred by investors in those securitized loans based on similar breaches of representations and warranties.
The resolution of claims related to alleged breaches of these representations and warranties and repurchase claims could have a material adverse effect on our financial condition, cash flows and results of operations. Given the unsettled nature of these claims, changes in values of underlying collateral over time, and other uncertainties regarding the ultimate resolution of these claims, actual costs could differ from our current estimates. Accordingly, there can be no assurance that such reserves will not need to be increased in the future.
General Risk Factors
Information technology failures or data security breaches could harm our business.
We use information technology and other computer resources to carry out important operational activities and to maintain our business records. Our computer systems, including our back-up systems, are subject to damage or interruption from power outages, computer and telecommunications failures, computer viruses, security breaches (through cyberattacks from computer hackers and sophisticated organizations), catastrophic events such as fires, tornadoes and hurricanes, usage errors by our employees, or cyber-attacks or errors by third party vendors who have access to our confidential data or that of our customers. While to our knowledge we have not experienced a significant cyber-attack, we are continuously working to improve our information technology systems and provide employee awareness training around phishing, malware, and other cyber risks to enhance our levels of protection, to the extent possible, against cyber risks and security breaches, and monitor to prevent, detect, address and mitigate the risk of unauthorized access, misuse, computer viruses and other events that could have an impact on our business, there is no assurance that advances in computer capabilities, new technologies, methods or other developments will detect or prevent security breaches and safeguard access to proprietary or confidential information. The
frequency and sophistication of cyber-attacks on companies has increased over the last year with significant ransomware attacks and foreign attacks on prominent computer software systems impacting a wide variety of companies and industries. If our computer systems and our back-up systems are damaged, breached, or cease to function properly, or if there are intrusions or failures of critical infrastructure such as the power grid or communications systems, we could suffer extended interruptions in our operations or unintentionally allow misappropriation of proprietary or confidential information (including information about our employees, homebuyers and business partners). Any such disruption could damage our reputation, result in market value declines, lead to legal proceedings against us by affected third parties resulting in penalties or fines, and require us to incur significant costs to remediate or otherwise resolve these issues.
Negative publicity could negatively impact sales, which could cause our revenues or results of operations to decline.
Our business strategy relies heavily on our reputation and brands, which are critical to our success. Unfavorable media or investor and analyst reports related to our industry, company, brand, marketing, personnel, operations, business performance, or prospects may affect our stock price and the performance of our business, regardless of its accuracy or inaccuracy. Furthermore, the speed at which negative publicity is disseminated has increased dramatically through the use of electronic communication, including social media outlets, websites and other digital platforms. Our success in maintaining and enhancing our brand depends on our ability to adapt to this rapidly changing media environment. Adverse publicity or negative commentary from any media outlets could damage our reputation and reduce the demand for our homes, which would adversely affect our business.
In addition, we can be affected by poor relations with the residents of communities we develop because efforts made by us to resolve issues or disputes that may arise in connection with the operation or development of their communities, or in connection with the transition of a homeowners association, could be deemed unsatisfactory by the affected residents and subsequent actions by these residents could adversely affect sales or our reputation. In addition, we could decide or be required to make material expenditures related to the settlement of such issues or disputes, which could adversely affect our results of operations.
The loss of the services of members of our senior management or a significant number of our operating employees could negatively affect our business.
Our success depends upon the skills, experience, and active participation of our senior management, many of whom have been with the Company for a significant number of years. If we were to lose members of our senior management, we might not be able to find appropriate replacements on a timely basis, and our operations could be negatively affected. Also, the loss of a significant number of operating employees in key roles or geographies where we are not able to hire qualified replacements could have a material adverse effect on our business.
We have significant intangible assets. If these assets become impaired, then our profits and shareholders’ equity may be reduced.
We have significant intangible assets related to business combinations. If the carrying value of intangible assets is deemed impaired, the carrying value is written down to fair value. This would result in a charge to our earnings. If management’s expectations of future results and cash flows decrease significantly, impairments of the remaining intangible assets may occur.
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 2. PROPERTIES
Our homebuilding and corporate headquarters are located in leased office facilities at 3350 Peachtree Road NE, Suite 150, Atlanta, Georgia 30326. Pulte Mortgage leases its primary office facilities in Englewood, Colorado. We also maintain various support functions in leased facilities in Tempe, Arizona. Our homebuilding divisions and financial services branches lease office space in the geographic locations in which they conduct their daily operations. In total across our organization, we lease approximately 1.1 million square feet of office space. The Company considers its properties suitable and adequate for its current business operations.
Because of the nature of our homebuilding operations, significant amounts of property are held as inventory in the ordinary course. Such properties are not included in response to this Item.
Item 3. LEGAL PROCEEDINGS
We are involved in various legal and governmental proceedings incidental to our continuing business operations, many involving claims related to certain construction defects. The consequences of these matters are not presently determinable but, in our opinion, after consulting with legal counsel and taking into account insurance and reserves, the ultimate liability is not expected to have a material adverse impact on our results of operations, financial position, or cash flows. However, to the extent the liability arising from the ultimate resolution of any matter exceeds our estimates reflected in the recorded reserves relating to such matter, we could incur additional charges that could be significant.
Item 4. MINE SAFETY DISCLOSURES
This Item is not applicable.
Item 4A. INFORMATION ABOUT OUR EXECUTIVE OFFICERS
Set forth below is certain information with respect to our executive officers.
| Name | Age | Position | Year Became An Executive Officer | |||||||||||||||||
| Ryan R. Marshall | 46 | President and Chief Executive Officer | 2012 | |||||||||||||||||
| John J. Chadwick | 59 | Executive Vice President and Chief Operating Officer | 2019 | |||||||||||||||||
| Robert T. O'Shaughnessy | 55 | Executive Vice President and Chief Financial Officer | 2011 | |||||||||||||||||
| Todd N. Sheldon | 53 | Executive Vice President, General Counsel and Corporate Secretary | 2017 | |||||||||||||||||
| Michelle Hairston | 44 | Senior Vice President, Human Resources | 2018 | |||||||||||||||||
| Brien P. O'Meara | 48 | Vice President and Controller | 2020 |
The following is a brief account of the business experience of each officer during the past five years:
Mr. Marshall was appointed Chief Executive Officer in September 2016. Previously, he held the positions of President since February 2016 and Executive Vice President, Homebuilding Operations since May 2014.
Mr. Chadwick was appointed Executive Vice President and Chief Operating Officer in April 2019 and previously held the position of Area President over various geographical markets since 2012.
Mr. O'Shaughnessy was appointed Executive Vice President and Chief Financial Officer in May 2011.
Mr. Sheldon was appointed Executive Vice President, General Counsel and Corporate Secretary in March 2017. Prior to joining our company, he served as Executive Vice President, General Counsel and Secretary at Americold Realty Trust from June 2013 to March 2017.
Ms. Hairston was appointed Senior Vice President, Human Resources in April 2018 and previously held the positions of Area Vice President of Human Resources, for the East and Midwest Areas since May 2015 and Vice President of Human Resources, Talent Acquisition between May 2015 and September 2016.
Mr. O'Meara was appointed Vice President and Controller in February 2017 and previously held the position of Assistant Controller since January 2013.
There is no family relationship between any of the officers. Each officer serves at the pleasure of the Board of Directors.
PART II
Item 5. MARKET FOR THE REGISTRANT’S COMMON EQUITY, RELATED SHAREHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Our common shares are listed on the New York Stock Exchange (Symbol: PHM). At January 21, 2021, there were 2,110 shareholders of record.
Issuer Purchases of Equity Securities
| Total number of shares purchased (1) | Average price paid per share | Total number of shares purchased as part of publicly announced plans or programs | Approximate dollar value of shares that may yet be purchased under the plans or programs ($000’s omitted) | |||||||||||||||||||||||
| October 1, 2020 to October 31, 2020 | 347,737 | $ | 46.38 | 347,737 | $ | 413,744 | (2) | |||||||||||||||||||
| November 1, 2020 to November 30, 2020 | 746,242 | 42.96 | 746,242 | $ | 381,684 | (2) | ||||||||||||||||||||
| December 1, 2020 to December 31, 2020 | 622,773 | 43.05 | 622,773 | $ | 354,873 | (2) | ||||||||||||||||||||
| Total | 1,716,752 | $ | 43.69 | 1,716,752 |
(1)During 2020, participants surrendered 0.3 million shares for payment of minimum tax obligations upon the vesting or exercise of previously granted share-based compensation awards. Such shares were not repurchased as part of our publicly-announced share repurchase programs and are excluded from the table above.
(2)The Board of Directors approved a share repurchase authorization totaling $500.0 million in January 2018 and an increase of $500.0 million to such authorization in May 2019. There is no expiration date for this program, under which $354.9 million remained available as of December 31, 2020. During 2020, we repurchased 4.5 million shares for a total of $170.7 million under this program.
The information required by this item with respect to equity compensation plans is set forth under Item 12 of this annual report on Form 10-K and is incorporated herein by reference.
Performance Graph
The following line graph compares, for the fiscal years ended December 31, 2016, 2017, 2018, 2019, and 2020, (a) the yearly cumulative total shareholder return (i.e., the change in share price plus the cumulative amount of dividends, assuming dividend reinvestment, divided by the initial share price, expressed as a percentage) on PulteGroup’s common shares, with (b) the cumulative total return of the Standard & Poor’s 500 Stock Index and with (c) the Dow Jones U.S. Select Home Construction Index. The Dow Jones U.S. Select Home Construction Index is a widely-recognized index comprised primarily of large national homebuilders. We believe comparison of our shareholder return to this index represents a meaningful analysis for investors.
COMPARISON OF FIVE YEAR CUMULATIVE TOTAL RETURN*
AMONG PULTEGROUP, INC., S&P 500 INDEX, AND PEER INDEX
Fiscal Year Ended December 31, 2020
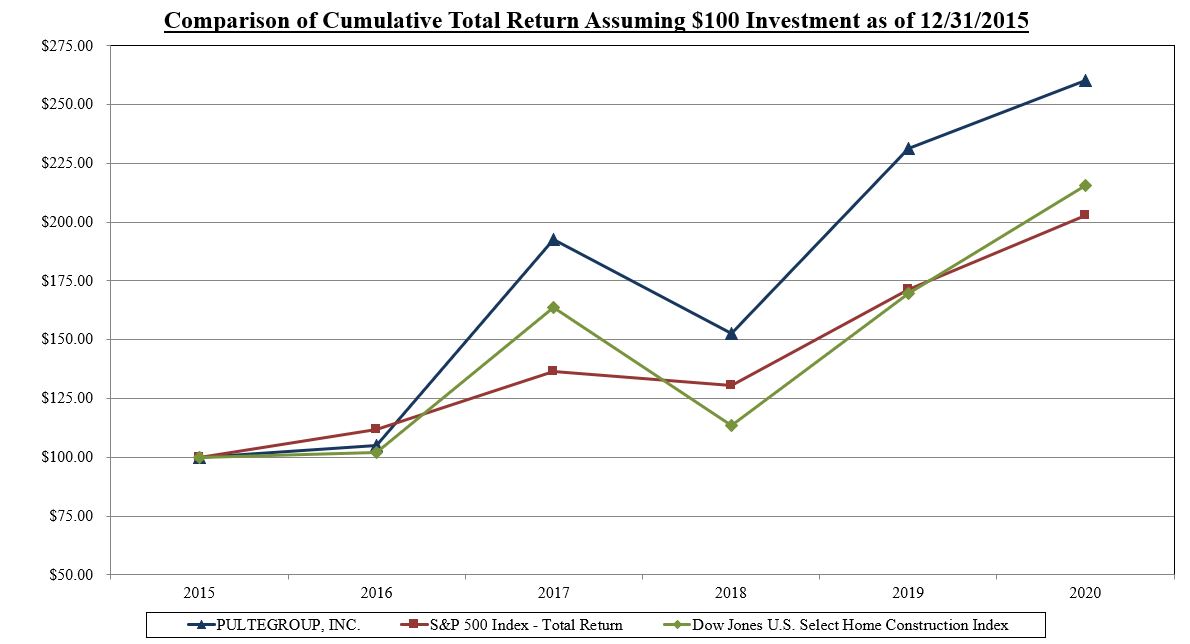
| 2015 | 2016 | 2017 | 2018 | 2019 | 2020 | |||||||||||||||||||||||||||||||||
| PULTEGROUP, INC. | $ | 100.00 | $ | 105.12 | $ | 192.81 | $ | 152.78 | $ | 231.20 | $ | 260.44 | ||||||||||||||||||||||||||
| S&P 500 Index - Total Return | 100.00 | 111.96 | 136.40 | 130.42 | 171.49 | 203.04 | ||||||||||||||||||||||||||||||||
| Dow Jones U.S. Select Home Construction Index | 100.00 | 102.22 | 163.71 | 113.40 | 169.65 | 215.44 |
- Assumes $100 invested on December 31, 2015, and the reinvestment of dividends.
Item 6. SELECTED FINANCIAL DATA
Set forth below is selected consolidated financial data for each of the past five fiscal years. The selected financial data should be read in conjunction with Management’s Discussion and Analysis of Financial Condition and Results of Operations and our Consolidated Financial Statements and Notes thereto included elsewhere in this report.
| Years Ended December 31, (000’s omitted, except per share data) | |||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | 2017 | 2016 | |||||||||||||||||||||||||
| OPERATING DATA: | |||||||||||||||||||||||||||||
| Homebuilding: | |||||||||||||||||||||||||||||
| Revenues | $ | 10,673,913 | $ | 9,978,526 | $ | 9,982,949 | $ | 8,385,526 | $ | 7,495,404 | |||||||||||||||||||
| Income before income taxes | $ | 1,542,057 | $ | 1,236,261 | $ | 1,288,804 | $ | 865,332 | $ | 860,766 | |||||||||||||||||||
| Financial Services: | |||||||||||||||||||||||||||||
| Revenues | $ | 362,169 | $ | 234,431 | $ | 205,382 | $ | 192,160 | $ | 181,126 | |||||||||||||||||||
| Income before income taxes | $ | 186,637 | $ | 103,315 | $ | 58,736 | $ | 73,496 | $ | 73,084 | |||||||||||||||||||
| Consolidated results: | |||||||||||||||||||||||||||||
| Revenues | $ | 11,036,082 | $ | 10,212,957 | $ | 10,188,331 | $ | 8,577,686 | $ | 7,676,530 | |||||||||||||||||||
| Income before income taxes | $ | 1,728,694 | $ | 1,339,576 | $ | 1,347,540 | $ | 938,828 | $ | 933,850 | |||||||||||||||||||
| Income tax expense | (321,855) | (322,876) | (325,517) | (491,607) | (331,147) | ||||||||||||||||||||||||
| Net income | $ | 1,406,839 | $ | 1,016,700 | $ | 1,022,023 | $ | 447,221 | $ | 602,703 | |||||||||||||||||||
| PER SHARE DATA: | |||||||||||||||||||||||||||||
| Net income per share: | |||||||||||||||||||||||||||||
| Basic | $ | 5.19 | $ | 3.67 | $ | 3.56 | $ | 1.45 | $ | 1.76 | |||||||||||||||||||
| Diluted | $ | 5.18 | $ | 3.66 | $ | 3.55 | $ | 1.44 | $ | 1.75 | |||||||||||||||||||
| Number of shares used in calculation: | |||||||||||||||||||||||||||||
| Basic | 268,553 | 274,495 | 283,578 | 305,089 | 339,747 | ||||||||||||||||||||||||
| Effect of dilutive securities | 861 | 802 | 1,287 | 1,725 | 2,376 | ||||||||||||||||||||||||
| Diluted | 269,414 | 275,297 | 284,865 | 306,814 | 342,123 | ||||||||||||||||||||||||
| Shareholders’ equity | $ | 24.66 | $ | 20.20 | $ | 17.39 | $ | 14.60 | $ | 13.63 | |||||||||||||||||||
| Cash dividends declared | $ | 0.50 | $ | 0.45 | $ | 0.38 | $ | 0.36 | $ | 0.36 |
| December 31, ($000’s omitted) | |||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | 2017 | 2016 | |||||||||||||||||||||||||
| BALANCE SHEET DATA: | |||||||||||||||||||||||||||||
| House and land inventory | $ | 7,721,798 | $ | 7,680,614 | $ | 7,253,353 | $ | 7,147,130 | $ | 6,770,655 | |||||||||||||||||||
| Total assets | 12,205,498 | 10,715,597 | 10,172,976 | 9,686,649 | 10,178,200 | ||||||||||||||||||||||||
| Notes payable | 2,752,302 | 2,765,040 | 3,028,066 | 3,006,967 | 3,129,298 | ||||||||||||||||||||||||
| Shareholders’ equity | 6,569,989 | 5,458,180 | 4,817,782 | 4,154,026 | 4,659,363 | ||||||||||||||||||||||||
| Years Ended December 31, | |||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | 2017 | 2016 | |||||||||||||||||||||||||
| OTHER DATA: | |||||||||||||||||||||||||||||
| Markets, at year-end | 40 | 42 | 44 | 47 | 49 | ||||||||||||||||||||||||
| Average active communities | 874 | 863 | 832 | 779 | 705 | ||||||||||||||||||||||||
| Closings (units) | 24,624 | 23,232 | 23,107 | 21,052 | 19,951 | ||||||||||||||||||||||||
| Net new orders (units) | 29,275 | 24,977 | 22,833 | 22,626 | 20,326 | ||||||||||||||||||||||||
| Backlog (units), at year-end | 15,158 | 10,507 | 8,722 | 8,996 | 7,422 | ||||||||||||||||||||||||
| Average selling price (per unit) | $ | 430,000 | $ | 427,000 | $ | 425,000 | $ | 395,000 | $ | 373,000 |
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Overview
We experienced significant volatility in market conditions during 2020. We ended 2019 and began 2020 in an environment exhibiting strong demand conditions. However, on March 11, 2020, the World Health Organization declared COVID-19 a global pandemic, and the various containment and mitigation measures adopted by governments and institutions globally and in the U.S. began to have a severe economic impact, including causing the U.S. to enter into an economic recession that continues through the date of this report.
In response to the COVID-19 pandemic and various state and local orders, we instituted the following actions in March:
-
Placed restrictions on business travel for our employees;
-
Closed our sales centers, model homes, and design centers to the general public and shifted to appointment-only interactions with our customers where permitted, following recommended distancing and other health and safety protocols when meeting in person with a customer;
-
Enhanced our virtual sales tools to give customers the ability to shop for a new home online;
-
Closed the public gathering spaces of our amenity centers as well as community pools and athletic facilities;
-
Modified our corporate and division office functions in order to allow all of our employees to work remotely except for essential minimum basic operations which could only be done in an office setting;
-
Eliminated non-emergency warranty work in our customers’ homes;
-
Modified much of our customer interactions around the mortgage origination and closing process to be virtual and minimize in-person interactions; and
-
Modified our construction operations to enforce enhanced safety protocols around social distancing, hygiene, and health screening.
The severity of these restrictions and the date we resumed more normal operations have varied by market based on the reduction in restrictions under "shelter in place" orders and improvement in public health conditions. While all of the above-referenced steps were, and some remain, necessary and appropriate in light of the COVID-19 pandemic, they impacted our ability to operate our business in its ordinary and traditional course. However, residential construction and financial services have been designated as essential services in almost all of our markets, which has allowed us to continue operations.
As the result of the COVID-19 pandemic, our net new orders declined significantly in late March through April. As the pandemic spread and government and business responses expanded, we focused on protecting our liquidity and closely managing our cash flows, including through the following actions:
-
Delaying the acquisition of certain land parcels and slowing land development where practical;
-
Limiting our investment in house construction, including strictly limiting production of new unsold "speculative" homes, and contacting backlog customers to reconfirm status before beginning construction of sold homes;
-
As a precautionary measure, proactively drawing $700.0 million under the Revolving Credit Facility in March;
-
Suspending the repurchase of shares under our share repurchase program; and
-
Reducing headcount and other overhead expenses.
However, demand began to stabilize in May and then rebounded sharply in June and has remained strong through the date of this report. This resulted in a 17% increase in net new orders for the full year 2020 over 2019, including a 24% increase in net new orders in the fourth quarter of 2020 over the fourth quarter of 2019. We believe the recovery in demand reflects a number of factors, including historically low mortgage interest rates, a limited supply of new and existing home inventory, an increased appeal for homeownership and single-family living, and a desire among some buyers to exit more densely populated urban centers. In addition to the improved demand, all of our operations are now functioning at effectively full capacity subject to health and safety protocols necessitated by the ongoing pandemic. However, we have experienced periodic disruptions in our supply chain, including the availability of skilled labor as industry demand increases, which have elongated the production cycles in certain markets. We are also facing cost pressures related to labor and materials, especially lumber, although we believe that we will be able to increase pricing to offset the majority of such cost increases.
Despite the volatility in 2020, the resurgence of demand resulted in the second highest annual pre-tax income and the highest year-end backlog (as measured in dollars) in our history. These financial results, combined with the favorable outlook, have allowed us to:
-
Fully repay the $700.0 million drawn on the Revolving Credit Facility;
-
Reinstate our share repurchase program, including the repurchase of $75.0 million of shares in the fourth quarter of 2020;
-
Increase our quarterly dividend by 17% to $0.14 per share in the fourth quarter of 2020;
-
Announce a tender offer expected to be completed in March 2021 for $300 million of our senior notes scheduled to mature in 2026 and 2027;
-
Increase our investments in new communities via land acquisition and development expenditures; and
-
Improve our available liquidity to $3.4 billion, consisting of $2.6 billion of cash and cash equivalents and $750.3 million available under our Revolving Credit Facility as of December 31, 2020.
The following tables and related discussion set forth key operating and financial data for our Homebuilding and Financial Services operations as of and for the fiscal years ended December 31, 2020 and 2019. For similar operating and financial data and discussion of our fiscal 2019 results compared to our fiscal 2018 results, refer to Item 7, “Management’s Discussion and Analysis of Financial Condition and Results of Operations” under Part II of our annual report on Form 10-K for the fiscal year ended December 31, 2019, which was filed with the SEC on January 30, 2020.
The following is a summary of our operating results by line of business ($000's omitted, except per share data):
| Years Ended December 31, | |||||||||||
| 2020 | 2019 | ||||||||||
| Income before income taxes: | |||||||||||
| Homebuilding | $ | 1,542,057 | $ | 1,236,261 | |||||||
| Financial Services | 186,637 | 103,315 | |||||||||
| Income before income taxes | 1,728,694 | 1,339,576 | |||||||||
| Income tax expense | (321,855) | (322,876) | |||||||||
| Net income | $ | 1,406,839 | $ | 1,016,700 | |||||||
| Per share data - assuming dilution: | |||||||||||
| Net income | $ | 5.18 | $ | 3.66 |
-
Homebuilding income before income taxes increased 25% in 2020, primarily as the result of higher revenues, improved gross margins, and strong overhead management. Homebuilding results also included a goodwill impairment charge of $20.2 million in 2020 (see Note 1) and net favorable insurance-related adjustments totaling $75.7 million and $26.8 million in 2020 and 2019, respectively (see Note 11).
-
The increase in Financial Services income in 2020 compared with 2019 was primarily the result of the Homebuilding volume growth, an improved capture rate of homebuyers from our Homebuilding operations, and a low mortgage interest rate environment. Mortgage interest rates continued at or near historically low levels during 2020, which resulted in higher gains from the sale of mortgages in the secondary market. These improvements were partially offset by $26.4 million of mortgage repurchase reserve charges (see Note 11 ).
-
Our eff
Showing the first 8K of 84K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
We are subject to market risk on our debt instruments primarily due to fluctuations in interest rates. We utilize both fixed-rate and variable-rate debt. For fixed-rate debt, changes in interest rates generally affect the fair value of the debt instrument but not our earnings or cash flows. Conversely, for variable-rate debt, changes in interest rates generally do not affect the fair value of the debt instrument but could affect our earnings and cash flows. Except in very limited circumstances, we do not have an obligation to prepay our debt prior to maturity. As a result, interest rate risk and changes in fair value should not have a significant impact on our fixed-rate debt until we are required or elect to refinance or repurchase such debt.
The following table sets forth the principal cash flows by scheduled maturity, weighted-average interest rates, and estimated fair value of our debt obligations as of December 31, 2020 and 2019 ($000’s omitted).
| As of December 31, 2020 for the Years ending December 31, | |||||||||||||||||||||||||||||||||||||||||||||||
| 2021 | 2022 | 2023 | 2024 | 2025 | Thereafter | Total | Fair Value | ||||||||||||||||||||||||||||||||||||||||
| Rate-sensitive liabilities: | |||||||||||||||||||||||||||||||||||||||||||||||
| Fixed rate debt | $ | 451,596 | $ | 14,456 | $ | — | $ | — | $ | — | $ | 2,300,000 | $ | 2,766,052 | $ | 3,415,662 | |||||||||||||||||||||||||||||||
| Average interest rate | 4.10 | % | 0.28 | % | — | % | — | % | — | % | 5.90 | % | 5.57 | % | |||||||||||||||||||||||||||||||||
| Variable rate debt (a) | $ | 411,821 | $ | — | $ | — | $ | — | $ | — | $ | — | $ | 411,821 | $ | 411,821 | |||||||||||||||||||||||||||||||
| Average interest rate | 2.55 | % | — | % | — | % | — | % | — | % | — | % | 2.55 | % | |||||||||||||||||||||||||||||||||
| As of December 31, 2019 for the Years ending December 31, | |||||||||||||||||||||||||||||||||||||||||||||||
| 2020 | 2021 | 2022 | 2023 | 2024 | Thereafter | Total | Fair Value | ||||||||||||||||||||||||||||||||||||||||
| Rate-sensitive liabilities: | |||||||||||||||||||||||||||||||||||||||||||||||
| Fixed rate debt | $ | 21,327 | $ | 447,712 | $ | 10,295 | $ | — | $ | — | $ | 2,300,000 | $ | 2,779,334 | $ | 3,152,046 | |||||||||||||||||||||||||||||||
| Average interest rate | 2.09 | % | 4.17 | % | 0.39 | % | — | % | — | % | 5.90 | % | 5.57 | % | |||||||||||||||||||||||||||||||||
| Variable rate debt (a) | $ | 326,573 | $ | — | $ | — | $ | — | $ | — | $ | — | $ | 326,573 | $ | 326,573 | |||||||||||||||||||||||||||||||
| Average interest rate | 3.59 | % | — | % | — | % | — | % | — | % | — | % | 3.59 | % |
(a) Includes the Pulte Mortgage Repurchase Agreement. There were no borrowings outstanding under our Revolving Credit Facility at either December 31, 2020 or 2019.
Derivative instruments and hedging activities
Pulte Mortgage is exposed to market risks from commitments to lend, movements in interest rates, and canceled or modified commitments to lend. A commitment to lend at a specific interest rate (an interest rate lock commitment) is a derivative financial instrument (interest rate is locked to the borrower). The interest rate risk continues through the loan closing and until the loan is sold to an investor. We are generally not exposed to variability in cash flows of derivative instruments for more than approximately 60 days. In periods of rising interest rates, the length of exposure will generally increase due to customers locking in an interest rate sooner as opposed to letting the interest rate float. In periods of low or decreasing interest rates, the length of exposure will also generally increase as customers desire to lock before the possibility of rising rates.
In order to reduce these risks, we use other derivative financial instruments, principally cash forward placement contracts on mortgage-backed securities and whole loan investor commitments, to economically hedge the interest rate lock commitment. We generally enter into one of the aforementioned derivative financial instruments upon accepting interest rate lock commitments. Changes in the fair value of interest rate lock commitments and the other derivative financial instruments are recognized in Financial Services revenues. We do not use any derivative financial instruments for trading purposes.
At December 31, 2020 and 2019, residential mortgage loans available-for-sale had an aggregate fair value of $565.0 million and $509.0 million, respectively. At December 31, 2020 and 2019, we had aggregate interest rate lock commitments of $367.2 million and $255.3 million, respectively, which were originated at interest rates prevailing at the date of commitment. Unexpired forward contracts totaled $686.4 million and $518.2 million at December 31, 2020 and 2019, respectively, and whole loan investor commitments totaled $169.6 million and $200.7 million, respectively, at such dates. Hypothetical changes in the fair values of our financial instruments arising from immediate parallel shifts in long-term mortgage rates would not be material to our financial results due to the offsetting nature in the movements in fair value of our financial instruments.
SPECIAL NOTES CONCERNING FORWARD-LOOKING STATEMENTS
As a cautionary note, except for the historical information contained herein, certain matters discussed in Item 7, Management's Discussion and Analysis of Financial Condition and Results of Operations, and Item 7A, Quantitative and Qualitative Disclosures About Market Risk, are “forward-looking” statements within the meaning of the Private Securities Litigation Reform Act of 1995. Such forward-looking statements are subject to a number of risks, uncertainties and other factors that could cause our actual results, performance, prospects or opportunities, as well as those of the markets we serve or intend to serve, to differ materially from those expressed in, or implied by, these statements. You can identify these statements by the fact that they do not relate to matters of a strictly factual or historical nature and generally discuss or relate to forecasts, estimates or other expectations regarding future events. Generally, the words “believe,” “expect,” “intend,” “estimate,” “anticipate,” “plan,” “project,” “may,” “can,” “could,” “might,” "should", “will” and similar expressions identify forward-looking statements, including statements related to any potential impairment charges and the impacts or effects thereof, expected operating and performing results, planned transactions, planned objectives of management, future developments or conditions in the industries in which we participate and other trends, developments and uncertainties that may affect our business in the future.
Such risks, uncertainties and other factors include, among other things: interest rate changes and the availability of mortgage financing; competition within the industries in which we operate; the availability and cost of land and other raw materials used by us in our homebuilding operations; the impact of any changes to our strategy in responding to the cyclical nature of the industry, including any changes regarding our land positions and the levels of our land spend; the availability and cost of insurance covering risks associated with our businesses; shortages and the cost of labor; weather related slowdowns; slow growth initiatives and/or local building moratoria; governmental regulation directed at or affecting the housing market, the homebuilding industry or construction activities; uncertainty in the mortgage lending industry, including revisions to underwriting standards and repurchase requirements associated with the sale of mortgage loans; the interpretation of or changes to tax, labor and environmental laws which could have a greater impact on our effective tax rate or the value of our deferred tax assets than we anticipate; economic changes nationally or in our local markets, including inflation, deflation, changes in consumer confidence and preferences and the state of the market for homes in general; legal or regulatory proceedings or claims; our ability to generate sufficient cash flow in order to successfully implement our capital allocation priorities; required accounting changes; terrorist acts and other acts of war; the negative impact of the COVID-19 pandemic on our financial position and ability to continue our Homebuilding or Financial Services activities at normal levels or at all in impacted areas; the duration, effect and severity of the COVID-19 pandemic; the measures that governmental authorities take to address the COVID-19 pandemic which may precipitate or exacerbate one or more of the above-mentioned and/or other risks and significantly disrupt or prevent us from operating our business in the ordinary course for an extended period of time; and other factors of national, regional and global scale, including those of a political, economic, business and competitive nature. See Item 1A – Risk Factors for a further discussion of these and other risks and uncertainties applicable to our businesses. We undertake no duty to update any forward-looking statement, whether as a result of new information, future events or changes in our expectations.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
PULTEGROUP, INC.
CONSOLIDATED BALANCE SHEETS
December 31, 2020 and 2019
($000’s omitted, except per share data)
| 2020 | 2019 | ||||||||||
| ASSETS | |||||||||||
| Cash and equivalents | $ | 2,582,205 | $ | 1,217,913 | |||||||
| Restricted cash | 50,030 | 33,543 | |||||||||
| Total cash, cash equivalents, and restricted cash | 2,632,235 | 1,251,456 | |||||||||
| House and land inventory | 7,721,798 | 7,680,614 | |||||||||
| Land held for sale | 27,962 | 24,009 | |||||||||
| Residential mortgage loans available-for-sale | 564,979 | 508,967 | |||||||||
| Investments in unconsolidated entities | 35,562 | 59,766 | |||||||||
| Other assets | 923,270 | 895,686 | |||||||||
| Intangible assets | 163,425 | 124,992 | |||||||||
| Deferred tax assets | 136,267 | 170,107 | |||||||||
| $ | 12,205,498 | $ | 10,715,597 | ||||||||
| LIABILITIES AND SHAREHOLDERS’ EQUITY | |||||||||||
| Liabilities: | |||||||||||
| Accounts payable, including book overdrafts of $84,505 and $51,827 at December 31, 2020 and 2019, respectively | $ | 511,321 | $ | 435,916 | |||||||
| Customer deposits | 449,474 | 294,427 | |||||||||
| Deferred tax liabilities | 103,548 | — | |||||||||
| Accrued and other liabilities | 1,407,043 | 1,435,461 | |||||||||
| Financial Services debt | 411,821 | 326,573 | |||||||||
| Notes payable | 2,752,302 | 2,765,040 | |||||||||
| Total liabilities | 5,635,509 | 5,257,417 | |||||||||
| Shareholders’ equity: | |||||||||||
| Preferred shares, $0.01 par value; 25,000,000 shares authorized, none issued | $ | — | $ | — | |||||||
| Common shares, $0.01 par value; 500,000,000 shares authorized, 266,464,063 and 270,235,297 shares issued and outstanding at December 31, 2020 and 2019, respectively | 2,665 | 2,702 | |||||||||
| Additional paid-in capital | 3,261,412 | 3,235,149 | |||||||||
| Accumulated other comprehensive loss | (145) | (245) | |||||||||
| Retained earnings | 3,306,057 | 2,220,574 | |||||||||
| Total shareholders’ equity | 6,569,989 | 5,458,180 | |||||||||
| $ | 12,205,498 | $ | 10,715,597 |
See Notes to Consolidated Financial Statements.
PULTEGROUP, INC.
CONSOLIDATED STATEMENTS OF OPERATIONS
For the years ended December 31, 2020, 2019, and 2018
(000’s omitted, except per share data)
| 2020 | 2019 | 2018 | |||||||||||||||
| Revenues: | |||||||||||||||||
| Homebuilding | |||||||||||||||||
| Home sale revenues | $ | 10,579,896 | $ | 9,915,705 | $ | 9,818,445 | |||||||||||
| Land sale and other revenues | 94,017 | 62,821 | 164,504 | ||||||||||||||
| 10,673,913 | 9,978,526 | 9,982,949 | |||||||||||||||
| Financial Services | 362,169 | 234,431 | 205,382 | ||||||||||||||
| Total revenues | 11,036,082 | 10,212,957 | 10,188,331 | ||||||||||||||
| Homebuilding Cost of Revenues: | |||||||||||||||||
| Home sale cost of revenues | (8,004,823) | (7,628,700) | (7,540,937) | ||||||||||||||
| Land sale and other cost of revenues | (77,626) | (56,098) | (126,560) | ||||||||||||||
| (8,082,449) | (7,684,798) | (7,667,497) | |||||||||||||||
| Financial Services expenses | (175,481) | (130,770) | (147,422) | ||||||||||||||
| Selling, general, and administrative expenses | (1,011,442) | (1,044,337) | (1,012,023) | ||||||||||||||
| Goodwill impairment | (20,190) | — | — | ||||||||||||||
| Other expense, net | (17,826) | (13,476) | (13,849) | ||||||||||||||
| Income before income taxes | 1,728,694 | 1,339,576 | 1,347,540 | ||||||||||||||
| Income tax expense | (321,855) | (322,876) | (325,517) | ||||||||||||||
| Net income | $ | 1,406,839 | $ | 1,016,700 | $ | 1,022,023 | |||||||||||
| Net income per share: | |||||||||||||||||
| Basic | $ | 5.19 | $ | 3.67 | $ | 3.56 | |||||||||||
| Diluted | $ | 5.18 | $ | 3.66 | $ | 3.55 | |||||||||||
| Cash dividends declared | $ | 0.50 | $ | 0.45 | $ | 0.38 | |||||||||||
| Number of shares used in calculation: | |||||||||||||||||
| Basic | 268,553 | 274,495 | 283,578 | ||||||||||||||
| Effect of dilutive securities | 861 | 802 | 1,287 | ||||||||||||||
| Diluted | 269,414 | 275,297 | 284,865 |
See Notes to Consolidated Financial Statements.
PULTEGROUP, INC.
CONSOLIDATED STATEMENTS OF COMPREHENSIVE INCOME
For the years ended December 31, 2020, 2019, and 2018
($000’s omitted)
| 2020 | 2019 | 2018 | |||||||||||||||
| Net income | $ | 1,406,839 | $ | 1,016,700 | $ | 1,022,023 | |||||||||||
| Other comprehensive income, net of tax: | |||||||||||||||||
| Change in value of derivatives | 100 | 100 | 100 | ||||||||||||||
| Other comprehensive income | 100 | 100 | 100 | ||||||||||||||
| Comprehensive income | $ | 1,406,939 | $ | 1,016,800 | $ | 1,022,123 |
See Notes to Consolidated Financial Statements.
PULTEGROUP, INC.
CONSOLIDATED STATEMENTS OF SHAREHOLDERS’ EQUITY
For the years ended December 31, 2020, 2019, and 2018
(000’s omitted)
| Common Shares | Additional Paid-in Capital | Accumulated Other Comprehensive Income (Loss) | Retained Earnings | Total | |||||||||||||||||||||||||||||||
| Shares | $ | ||||||||||||||||||||||||||||||||||
| Shareholders' equity, December 31, 2017 | 286,752 | $ | 2,868 |
Showing the first 8K of 148K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
This Item is not applicable.
Item 9A. CONTROLS AND PROCEDURES
Disclosure Controls and Procedures
Management, including our President and Chief Executive Officer and Executive Vice President and Chief Financial Officer, evaluated the effectiveness of the design and operation of our disclosure controls and procedures as of December 31, 2020. Based upon, and as of the date of that evaluation, our President and Chief Executive Officer and Executive Vice President and Chief Financial Officer concluded that the disclosure controls and procedures were effective as of December 31, 2020.
Internal Control Over Financial Reporting
**(a)**Management’s Annual Report on Internal Control Over Financial Reporting
Management is responsible for the preparation and fair presentation of the consolidated financial statements included in this annual report. The consolidated financial statements have been prepared in conformity with U.S. generally accepted accounting principles and reflect management’s judgments and estimates concerning events and transactions that are accounted for or disclosed.
Management is also responsible for establishing and maintaining effective internal control over financial reporting, as such term is defined in Exchange Act Rule 13a-15(f). Management recognizes that there are inherent limitations in the effectiveness of any internal control and effective internal control over financial reporting can provide only reasonable assurance with respect to financial statement preparation. Additionally, because of changes in conditions, the effectiveness of internal control over financial reporting may vary over time.
In order to ensure that the Company’s internal control over financial reporting is effective, management regularly assesses such controls and did so most recently for its financial reporting as of December 31, 2020. Management’s assessment was based on criteria for effective internal control over financial reporting described in Internal Control – Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 Framework). Based on this assessment, management asserts that the Company has maintained effective internal control over financial reporting as of December 31, 2020. On January 24, 2020, the Company acquired the operations of Innovative Construction Group. As permitted by the Securities and Exchange Commission, management excluded such operations from its assessment of internal control over financial reporting as of December 31, 2020. Such operations constituted less than 1% of the Company’s consolidated total assets as of December 31, 2020, and less than 1% of the Company’s consolidated total revenues for the year then ended.
Ernst & Young LLP, the independent registered public accounting firm that audited the Company’s consolidated financial statements included in this annual report, has issued its report on the effectiveness of the Company’s internal control over financial reporting as of December 31, 2020.
**(b)**Report of Independent Registered Public Accounting Firm
To the Shareholders and the Board of Directors of PulteGroup, Inc.
Opinion on Internal Control over Financial Reporting
We have audited PulteGroup, Inc.’s internal control over financial reporting as of December 31, 2020, based on criteria established in Internal Control— Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria). In our opinion, PulteGroup, Inc. (the Company) maintained, in all material respects, effective internal control over financial reporting as of December 31, 2020, based on the COSO criteria.
As indicated in the accompanying Management’s Annual Report on Internal Control Over Financial Reporting, management’s assessment of and conclusion on the effectiveness of internal control over financial reporting did not include the internal controls of Innovative Construction Group, which is included in the 2020 consolidated financial statements of the Company and constituted less than 1% of consolidated total assets as of December 31, 2020 and less than 1% of consolidated total revenues for the year then ended. Our audit of internal control over financial reporting of the Company also did not include an evaluation of the internal control over financial reporting of Innovative Construction Group.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of the Company as of December 31, 2020 and 2019, the related consolidated statements of operations, comprehensive income, shareholders’ equity and cash flows for each of the three years in the period ended December 31, 2020, and the related notes and our report dated February 2, 2021 expressed an unqualified opinion thereon.
Basis for Opinion
The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management’s Annual Report on Internal Control Over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects.
Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control Over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/ Ernst & Young LLP
Atlanta, GA
February 2, 2021
**(c)**Changes in Internal Control Over Financial Reporting
There has been no change in our internal control over financial reporting during the quarter ended December 31, 2020 that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. OTHER INFORMATION
This Item is not applicable.
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
Information required by this Item with respect to our executive officers is set forth in Item 4A of this Annual Report on Form 10-K. Information required by this Item with respect to members of our Board of Directors and with respect to our audit committee will be contained in the Proxy Statement for the 2021 Annual Meeting of Shareholders (“2021 Proxy Statement”), which will be filed no later than 120 days after December 31, 2020, under the captions “Election of Directors” and “Committees of the Board of Directors - Audit Committee” and in the chart disclosing Audit Committee membership and is incorporated herein by this reference. Information required by this Item with respect to compliance with Section 16(a) of the Securities Exchange Act of 1934 will be contained in the 2021 Proxy Statement under the caption “Delinquent Section 16(a) Reports,” and is incorporated herein by this reference. Information required by this Item with respect to our code of ethics will be contained in the 2021 Proxy Statement under the caption “Corporate Governance - Governance Guidelines; Code of Ethical Business Conduct; Code of Ethics” and is incorporated herein by this reference.
Our code of ethics for principal officers, our code of ethical business conduct, our corporate governance guidelines, and the charters of the Audit, Compensation and Management Development, Nominating and Governance, and Finance and Investment committees of our Board of Directors are also posted on our website and are available in print, free of charge, upon request.
Item 11. EXECUTIVE COMPENSATION
Information required by this Item will be contained in the 2021 Proxy Statement under the captions “2020 Executive Compensation” and “2020 Director Compensation” and is incorporated herein by this reference, provided that the Compensation and Management Development Committee Report shall not be deemed to be “filed” with this Annual Report on Form 10-K.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
Information required by this Item will be contained in the 2021 Proxy Statement under the captions “Beneficial Security Ownership” and “Equity Compensation Plan Information” and is incorporated herein by this reference.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS AND DIRECTOR INDEPENDENCE
Information required by this Item will be contained in the 2021 Proxy Statement under the captions “Certain Relationships and Related Transactions” and “Board of Directors Information” and is incorporated herein by this reference.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
Information required by this Item will be contained in the 2021 Proxy Statement under the captions “Audit and Non-Audit Fees” and “Audit Committee Preapproval Policies” and is incorporated herein by reference.
PART IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
(a) The following documents are filed as part of this Annual Report on Form 10-K:
(1) Financial Statements
**(2)**Financial Statement Schedules
All schedules are omitted because the required information is not present, is not present in amounts sufficient to require submission of the schedule, or because the required information is included in the financial statements or notes thereto.
(3) Exhibits
The following exhibits are filed with this Annual Report on Form 10-K or are incorporated herein by reference:
Exhibit Number and Description
| (21) | Subsidiaries of the Registrant (Filed herewith) | |||||||||||||
| (22) | List of Guarantor Subsidiaries | |||||||||||||
| (23) | Consent of Independent Registered Public Accounting Firm (Filed herewith) | |||||||||||||
| (24) | Power of Attorney (Filed herewith) | |||||||||||||
| (31) | (a) | Rule 13a-14(a) Certification by Ryan R. Marshall, President and Chief Executive Officer (Filed herewith) | ||||||||||||
| (b) | Rule 13a-14(a) Certification by Robert T. O'Shaughnessy, Executive Vice President and Chief Financial Officer (Filed herewith) | |||||||||||||
| (32) | Certification Pursuant to 18 United States Code § 1350 and Rule 13a-14(b) of the Securities Exchange Act of 1934 (Furnished herewith) | |||||||||||||
| 101.INS | Inline XBRL Instance Document - the instance document does not appear in the Interactive Data File because its XBRL tags are embedded within the inline XBRL document. | |||||||||||||
| 101.SCH | Inline XBRL Taxonomy Extension Schema Document | |||||||||||||
| 101.CAL | Inline XBRL Taxonomy Extension Calculation Linkbase Document | |||||||||||||
| 101.DEF | InlineXBRL Taxonomy Extension Definition Linkbase Document | |||||||||||||
| 101.LAB | Inline XBRL Taxonomy Extension Label Linkbase Document | |||||||||||||
| 101.PRE | Inline XBRL Taxonomy Extension Presentation Linkbase Document | |||||||||||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) |
- Indicates a management contract or compensatory plan or arrangement
Item 16. FORM 10-K SUMMARY
None.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
PULTEGROUP, INC.
(Registrant)
| February 2, 2021 | By: | /s/ Robert T. O'Shaughnessy | |||||||||
| Robert T. O'Shaughnessy | |||||||||||
| Executive Vice President and Chief Financial Officer | |||||||||||
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the Registrant and in the capacities and on the date indicated:
| February 2, 2021 | ||||||||||||||||||||
| /s/ Ryan R. Marshall | /s/ Robert T. O'Shaughnessy | /s/ Brien P. O'Meara | ||||||||||||||||||
| Ryan R. Marshall | Robert T. O'Shaughnessy | Brien P. O'Meara | ||||||||||||||||||
| President and Chief Executive Officer (Principal Executive Officer) and Member of Board of Directors | Executive Vice President and Chief Financial Officer (Principal Financial Officer) | Vice President and Controller (Principal Accounting Officer) | ||||||||||||||||||
| Brian P. Anderson | Member of Board of Directors | } | ||||||||||||||||||
| Bryce Blair | Non-Executive Chairman of Board of Directors | } | ||||||||||||||||||
| Richard W. Dreiling | Member of Board of Directors | } | ||||||||||||||||||
| Thomas J. Folliard | Member of Board of Directors | } | /s/ Robert T. O'Shaughnessy | |||||||||||||||||
| Cheryl W. Grisé | Member of Board of Directors | } | Robert T. O'Shaughnessy | |||||||||||||||||
| André J. Hawaux | Member of Board of Directors | } | Executive Vice President and Chief Financial Officer | |||||||||||||||||
| J. Phillip Holloman | Member of Board of Directors | } | ||||||||||||||||||
| John R. Peshkin | Member of Board of Directors | } | ||||||||||||||||||
| Scott F. Powers | Member of Board of Directors | } | ||||||||||||||||||
| Lila Snyder | Member of Board of Directors | } | ||||||||||||||||||