 filings.tools
Item 1. BUSINESS
29K characters. Original on sec.gov ·
Item 1. BUSINESS
| --- | --- |
Packaging Corporation of America (“we,” “us,” “our,” “PCA,” or the “Company”) is the third largest producer of containerboard products and the third largest producer of uncoated freesheet (UFS) paper in North America. We operate six containerboard mills, two uncoated freesheet (UFS) paper mills, and 90 corrugated products manufacturing plants. We are headquartered in Lake Forest, Illinois and operate primarily in the United States.
We report in three reportable segments: Packaging, Paper and Corporate and Other. For segment financial information see Note 19, Segment Information, of the Notes to Consolidated Financial Statements in “Part II, Item 8, Financial Statements and Supplementary Data” of this Form 10-K.
During the fourth quarter of 2020, due to an increase in demand for our corrugated products and as part of our assessment of a potential conversion to produce containerboard, we began producing high-performance, virgin kraft linerboard on the No. 3 machine at our Jackson, Alabama mill on a trial basis. Before October 2020, operating results for the Jackson mill were included in the Paper segment. Beginning in October 2020, operating results for the Jackson mill are included in both the Packaging and Paper segments.
During the second quarter of 2018, we discontinued the production of paper grades at the Wallula, Washington mill and converted the No. 3 machine to production of virgin kraft linerboard. Before May 2018, operating results for the Wallula mill were included in the Paper segment. After May 2018, operating results for the Wallula mill are primarily included in the Packaging segment.
Production and Shipments
The following table summarizes the Packaging segment's containerboard production and corrugated products shipments and the Paper segment's UFS production.
| First Quarter | Second Quarter | Third Quarter | Fourth Quarter | Full Year | ||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Containerboard Production | 2020 | 1,047 | 1,072 | 1,048 | 1,174 | 4,341 | ||||||||||||||||||
| (thousand tons) | 2019 | 1,037 | 1,063 | 1,070 | 1,079 | 4,249 | ||||||||||||||||||
| 2018 | 953 | 1,020 | 1,087 | 1,021 | 4,081 | |||||||||||||||||||
| Corrugated Shipments (BSF) | 2020 | 15.3 | 15.1 | 16.0 | 16.4 | 62.8 | ||||||||||||||||||
| 2019 | 14.5 | 14.9 | 15.1 | 14.9 | 59.4 | |||||||||||||||||||
| 2018 | 14.4 | 15.1 | 14.8 | 14.6 | 58.9 | |||||||||||||||||||
| UFS Production | 2020 | 224 | 148 | 129 | 147 | 648 | ||||||||||||||||||
| (thousand tons) | 2019 | 239 | 236 | 236 | 236 | 947 | ||||||||||||||||||
| 2018 | 279 | 252 | 239 | 247 | 1,017 |
Below is a map of our locations:
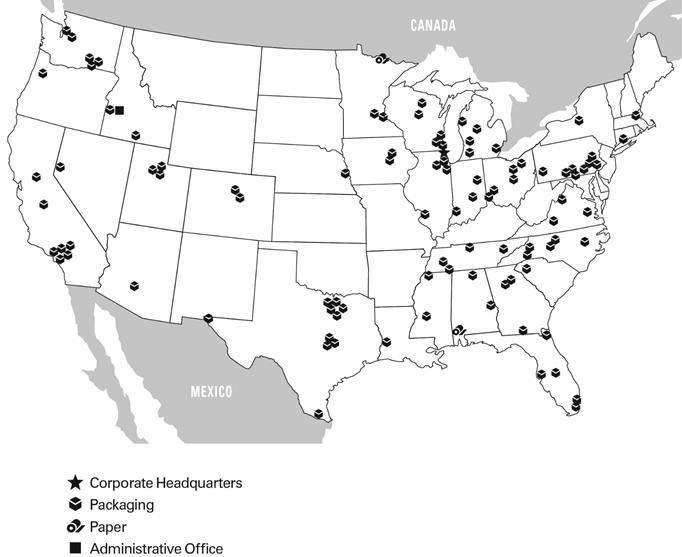
Packaging
Packaging Products
Our containerboard mills produce linerboard and corrugating medium, which are primarily used in the production of corrugated products. Our corrugated products manufacturing plants produce a wide variety of corrugated packaging products, including conventional shipping containers used to protect and transport manufactured goods, multi-color boxes and displays with strong visual appeal that help to merchandise the packaged product in retail locations, and honeycomb protective packaging. In addition, we are a large producer of packaging for meat, fresh fruit and vegetables, processed food, beverages, and other industrial and consumer products.
During the year ended December 31, 2020, our Packaging segment produced 4.3 million tons of containerboard at our mills. Our corrugated products manufacturing plants sold 62.8 billion square feet (BSF) of corrugated products. The Packaging segment’s net sales to third parties totaled $5.9 billion in 2020.
Facilities
We manufacture containerboard, which includes a variety of performance and specialty grades, at six containerboard mills. Total annual containerboard capacity was approximately 4.3 million tons as of December 31, 2020. We also produce corrugated and protective packaging products at 90 manufacturing locations. The following provides more details of our operations:
Counce. Our Counce, Tennessee mill produces kraft linerboard on two machines. The mill can produce basis weights from 26 lb. to 90 lb.
DeRidder. Our DeRidder, Louisiana mill produces kraft linerboard on its No. 1 machine and kraft linerboard and corrugating medium on its No. 2 machine. The mill can produce linerboard in basis weights of 26 lb. to 69 lb. and medium in basis weights of 23 lb. to 33 lb.
Valdosta. Our Valdosta, Georgia mill produces kraft linerboard on one machine. The mill can produce basis weights from 35 lb. to 96 lb.
Tomahawk. Our Tomahawk, Wisconsin mill produces corrugating medium on two machines. The mill can produce basis weights from 23 lb. to 47 lb.
Filer City. Our Filer City, Michigan mill produces corrugating medium on three machines. The mill can produce basis weights from 20 lb. to 47 lb.
Wallula. Our Wallula, Washington mill produces corrugating medium on its No. 2 machine and kraft linerboard on its No. 3 machine. The mill can produce medium in basis weights from 23 lb. to 33 lb. and linerboard in basis weights from 31 lb. to 52 lb.
We operate 90 corrugated manufacturing and protective packaging operations, a technical and development center, 10 regional design centers, a rotogravure printing operation, and a complement of packaging supplies and distribution centers. Of the 90 manufacturing facilities, 58 operate as combining operations, commonly called corrugated plants, which manufacture corrugated sheets and finished corrugated packaging products, 31 are sheet plants, which procure combined sheets and manufacture finished corrugated packaging products, and one is a corrugated sheet-only manufacturer.
Corrugated products plants tend to be located in close proximity to customers to minimize freight costs. Each of our plants serve a market radius of approximately 150 miles. Our sheet plants are generally located in close proximity to our larger corrugated plants, which enables us to offer additional services and converting capabilities such as small volume and quick turnaround items.
Major Raw Materials Used
Fiber supply. Fiber is the largest raw material cost to manufacture containerboard. We consume both wood fiber and recycled fiber in our containerboard mills. Our mill system has the capability to shift a portion of its fiber consumption between softwood, hardwood, and recycled sources. All of our mills can utilize virgin wood fiber and all of our mills, other than the Valdosta mill, can utilize some recycled fiber in their containerboard production. Our corrugated manufacturing operations generate recycled fiber as a by-product from the manufacturing process, which is consumed by our mills. In 2020, our usage of recycled fiber, net of internal generation, represents 17% of our containerboard production.
We procure wood fiber through leases of cutting rights, long-term supply agreements, and market purchases and believe we have adequate sources of fiber supply for the foreseeable future.
We participate in the Sustainable Forestry Initiative® (SFI), the Programme for the Endorsement of Forest Certification (PEFC), as well as the Forest Stewardship Council® (FSC®), and we are certified under their sourcing and chain of custody standards. These standards are aimed at ensuring the long-term health and conservation of forestry resources. We are committed to sourcing wood fiber through environmentally, socially, and economically sustainable practices and promoting resource and conservation stewardship ethics.
Energy supply. Energy at our packaging mills is obtained through self-generated or purchased fuels and electricity. Fuel sources include by-products of the containerboard manufacturing and pulping process (including black liquor and wood waste), natural gas, purchased wood waste, and other purchased fuels. Each of our mills self-generates process steam requirements from by-products (black liquor and wood waste), as well as from the various purchased fuels. The process steam is used throughout the production process and also to generate electricity.
In 2020, our packaging mills consumed about 74 million MMBTUs of fuel to produce both steam and electricity. Of the 74 million MMBTUs consumed, about 63% was from mill generated by-products and 37% was from purchased fuels. Of the purchased fuels, 78% was from natural gas, 20% was from purchased wood waste and 2% was from other purchased fuels.
Chemical supply. We consume various chemicals in the production of containerboard, including caustic soda, sulfuric acid, soda ash, and lime. Most of our chemicals are purchased under contracts, which are bid or negotiated periodically.
Sales, Marketing, and Distribution
Our corrugated products are sold through our direct sales and marketing organization, independent brokers, and distribution partners. We have sales representatives and a sales manager at most of our corrugated manufacturing operations and also have corporate account managers who serve customer accounts with a national presence. Additionally, our design centers maintain an on-site dedicated graphics sales force. In addition to direct sales and marketing personnel, we utilize new product development engineers and product graphics and design specialists. These individuals are located at both the corrugated plants and the design centers. General marketing support is located at our corporate headquarters.
Our containerboard sales group is responsible for linerboard and corrugating medium order processing and sales to our corrugated plants, to outside domestic customers, and to export customers. These personnel also coordinate and execute all containerboard trade agreements with other containerboard manufacturers.
Containerboard produced in our mills is shipped by rail or truck. Our corrugated products are delivered by truck due to our large number of customers and their demand for timely service. Our corrugated manufacturing operations typically serve customers within a 150-mile radius. We sometimes use third-party warehouses for short-term storage of corrugated products.
Customers
We sell containerboard and corrugated products to approximately 16,000 customers in approximately 33,000 locations. About 70% of our corrugated products sales are to regional and local accounts, which are broadly diversified across industries and geographic locations. The remaining 30% of our customer base consists primarily of national accounts that have multiple locations and are served by a number of PCA plants. No single customer exceeds 10% of segment sales.
The primary end-use markets in the United States for corrugated products are shown below as reported in the 2019 Fibre Box Association annual report:
| Food, beverages, and agricultural products | 45 | % | ||
|---|---|---|---|---|
| Retail and wholesale trade | 22 | % | ||
| Paper and other products | 14 | % | ||
| Chemical, plastic, and rubber products | 10 | % | ||
| Miscellaneous manufacturing | 9 | % |
Competition
As of December 31, 2020, we were the third largest producer of containerboard products in North America, according to industry sources and our own estimates. According to industry sources, corrugated products are produced by about 450 U.S. companies operating approximately 1,200 plants. The primary basis for competition for most of our packaging products includes quality, service, price, product design, and innovation. Most corrugated products are manufactured to the customer’s specifications. Corrugated producers generally sell within a 150-mile radius of their plants and compete with other corrugated producers in their local region. Competition in our corrugated products operations tends to be regional, although we also face competition from competitors with significant national account presence.
On a national level, our primary competitors are International Paper Company, WestRock Company, Georgia-Pacific LLC, and Pratt Industries. However, with our strategic focus on regional and local accounts, we also compete with the smaller, local producers.
Paper
We are the third largest manufacturer of UFS in North America, according to industry sources and our own estimates. We manufacture and sell papers, including both commodity and specialty papers, which may have custom or specialized features such as colors, coatings, high brightness, and recycled content. Our papers consist of communication papers, including cut-size office papers, and printing and converting papers.
Facilities
We currently have two paper mills located in the United States. Total annual UFS capacity is 964,000 tons. Our operations include the following:
Jackson. Our Jackson, Alabama mill produces both commodity and specialty papers on two paper machines.
International Falls. Our International Falls, Minnesota mill produces both commodity and specialty papers on two paper machines.
Major Raw Materials Used
Fiber supply. Fiber is the largest raw material cost in this segment. We consume wood fiber, recycled fiber, and purchased pulp. Our Jackson mill purchases recycled fiber to produce our line of recycled office papers. We purchase wood fiber through contracts and open-market purchase, and we purchase recycled fiber and pulp from third parties pursuant to contractual agreements.
We participate in the Sustainable Forestry Initiative® (SFI), the Programme for the Endorsement of Forest Certification (PEFC), as well as the Forest Stewardship Council® (FSC®), and we are certified under their sourcing and chain of custody standards. These standards are aimed at ensuring the long-term health and conservation of forestry resources. We are committed to sourcing wood fiber through environmentally, socially, and economically sustainable practices and promoting resource and conservation stewardship ethics.
Energy supply. We obtain energy through self-generated or purchased fuels and electricity. Fuel sources include by-products of the manufacturing and pulping process (including black liquor and wood waste), natural gas, electricity, and purchased wood waste. Each of the paper mills self-generates process steam requirements from by-products (black liquor and wood waste), as well as from the various purchased fuels. The process steam is used throughout the production process and to generate electricity.
In 2020, our paper mills consumed about 19 million MMBTUs of fuel to produce both steam and electricity. Of the 19 million MMBTUs consumed, about 75% was from mill generated by-products and 25% was from purchased fuels. Of the purchased fuels, 89% was from natural gas and 11% from purchased wood waste.
Chemical supply. We consume various chemicals in the production of white papers, including starch, precipitated calcium carbonate, caustic soda, and sodium chlorate. Most of our chemicals are purchased under contracts, which are bid or negotiated periodically.
Sales, Marketing, and Distribution
Our papers are sold primarily through our sales and marketing organization. We ship to customers both directly from our mills and through distribution centers and a network of outside warehouses by rail or truck. This allows us to respond quickly to customer requirements.
Customers
We have over 100 customers in approximately 400 locations. These customers include office products distributors and retailers, paper merchants, and envelope and other converters. We have established long-term relationships with many of our
customers. Office Depot, Inc. is our largest customer in the Paper segment. Effective January 1, 2020, we have a revised agreement with Office Depot in which we will continue to supply commodity and non-commodity office papers to Office Depot through December 31, 2022. Office Depot is not subject to a minimum volume commitment and is entitled to receive rebates for achieving certain volume thresholds. If the agreement is not renewed by the parties, Office Depot’s obligation to purchase paper would phase down over a two-year period beginning on January 1, 2023. In 2020, our sales revenue to Office Depot represented 45% of our Paper segment sales revenue and 5% of our consolidated sales revenue.
Competition
The markets in which our Paper segment competes are large and highly competitive. Commodity grades of UFS paper are globally traded, with numerous worldwide manufacturers, and as a result, these products compete primarily on the basis of price. All of our paper manufacturing facilities are located in the United States, and although we compete primarily in the domestic market, we do face competition from foreign producers. In 2016, as a result of a case brought by us and other domestic producers before United States international trade authorities, antidumping and countervailing duties at various levels were imposed on producers of uncoated freesheet papers produced in Australia, Brazil, China, Indonesia, and Portugal. These duties remain in effect and are subject to review in 2021. Other factors influencing competition from overseas producers include domestic and foreign demand and foreign currency exchange rates.
Our largest competitors include Domtar Corporation and International Paper Company. We also face competition from foreign producers. Although price is the primary basis for competition in most of our paper grades, quality and service are also important competitive determinants. Our papers compete with electronic data transmission, e-readers, electronic document storage alternatives, and paper grades we do not produce. Increasing shifts to these alternatives have had, and are likely to continue to have, an adverse effect on traditional print media and paper usage and lower demand for communication papers.
Corporate and Other
Our Corporate and Other segment includes corporate support staff services and related assets and liabilities. This segment also includes transportation assets, such as rail cars and trucks, which we use to transport some of our products to and from our manufacturing sites, and assets related to a 50% owned variable interest entity, Louisiana Timber Procurement Company, L.L.C. (LTP).
Human Capital
PCA’s success depends on a highly engaged, results-oriented workforce operating in an entrepreneurial culture. Our primary objective is to place the right people in the right roles, and empower them to succeed.
Safety is a core value at PCA and we believe that all accidents are preventable and an injury-free environment is achievable. We have implemented a robust occupational health and safety management system to assure accountability throughout the organization for safe work practices. Key components to our system include commitment from management, extensive training of employees, hazard identification and communication and regular safety audits.
During 2020, we were committed to conducting safe operations through the COVID-19 pandemic in accordance with the guidelines of the Center for Disease Control and applicable health and safety regulations. As PCA’s operations continued to operate as “essential businesses,” we adopted measures to protect the health and safety of our employees, including social distancing practices, health screening procedures, enhanced sanitation procedures and enhanced absence pay policies. These practices will continue into 2021 as the effects of the pandemic continue. PCA did not experience significant disruptions in its operations as a result of the pandemic and has maintained adequate availability of its workforce and supply of raw materials and services to continue to serve its customers.
We have extensive recruiting, training and development programs designed to attract and retain a highly talented workforce aligned with our objectives to relentlessly serve our customers and achieve operational excellence throughout our organization. As demand for qualified personnel is increasing, we are expanding our efforts in these critical areas along with efforts to continue to develop, promote and maintain a diverse workforce with a culture and an environment of respect and inclusion. These principles are designed to develop and promote strong and increasing engagement of all PCA employees.
As of December 31, 2020, we had approximately 15,200 employees, including 4,500 salaried and 10,700 hourly employees. Approximately 62% of our hourly employees worked pursuant to collective bargaining agreements. The majority of our unionized employees are represented by the United Steel Workers (USW), the International Brotherhood of Teamsters (IBT), the International Association of Machinists (IAM), and the Association of Western Pulp and Paper Workers (AWPPW). We are currently in negotiations to renew or extend union contracts that have recently expired or are expiring in the near future. During 2020, we experienced no work stoppages, and we believe we have satisfactory labor relations with our employees.
Regulatory and Environmental Matters
A discussion of the financial impact of our compliance with environmental laws is presented under the caption “Regulatory and Environmental Matters” in “Part II, Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations” of this Form 10-K.
Executive Officers of the Registrant
Brief statements setting forth the age at February 24, 2021, the principal occupation, employment during the past five years, the year in which such person first became an officer of PCA, and other information concerning each of our executive officers appears below.
Mark W. Kowlzan, 65, Chairman and Chief Executive Officer - Mr. Kowlzan has served as PCA's Chairman since January 2016 and as Chief Executive Officer and a director since July 2010. From 1998 through June 2010, Mr. Kowlzan led the company’s containerboard mill system, first as Vice President and General Manager and then as Senior Vice President - Containerboard. From 1996 through 1998, Mr. Kowlzan served in various senior mill-related operating positions with PCA and Tenneco Packaging, including as manager of the Counce linerboard mill. Prior to joining Tenneco Packaging, Mr. Kowlzan spent 15 years at International Paper Company, a global paper and packaging company, where he held a series of operational and managerial positions within its mill organization. Mr. Kowlzan is a member of the board of American Forest and Paper Association.
Thomas A. Hassfurther, 65, Executive Vice President - Corrugated Products - Mr. Hassfurther has served as Executive Vice President - Corrugated Products of PCA since September 2009. From February 2005 to September 2009, Mr. Hassfurther served as Senior Vice President - Sales and Marketing, Corrugated Products. Prior to this he held various senior-level management and sales positions at PCA and Tenneco Packaging. Mr. Hassfurther joined the company in 1977.
Robert P. Mundy, 59, Executive Vice President and Chief Financial Officer - Mr. Mundy has served as Executive Vice President and Chief Financial Officer since May 2019. Mr. Mundy previously served as PCA’s Senior Vice President and Chief Financial Officer from 2015 to 2019. He previously served as Senior Vice President and Chief Financial Officer of Verso Corporation, a leading North American supplier of coated papers to catalog and magazine publishers, from 2006 to June 2015. Verso Corporation filed for Chapter 11 bankruptcy in January 2016. Prior to that, he worked at International Paper Company, from 1983 to 2006, where he was Director of Finance of the Coated and Supercalendered Papers division from 2002 to 2006, Director of Finance Projects from 2001 to 2002, Controller of Masonite Corporation from 1999 to 2001, and Controller of the Petroleum and Minerals business from 1996 to 1999. He served in various business positions at International Paper from 1983 to 1996.
Pamela A. Barnes, 56, Senior Vice President – Finance and Controller - Ms. Barnes has served as Senior Vice President – Finance and Controller since May 2019. Ms. Barnes previously served as a Vice President in PCA’s finance organization from 2012 to 2019. After joining the company in 1992, she has held various positions of increasing responsibility, including serving as PCA’s Treasurer since 1999. Before joining PCA, Ms. Barnes worked for Deloitte & Touche.
Charles J. Carter, 61, Senior Vice President - Containerboard Mill Operations - Mr. Carter has served as Senior Vice President - Containerboard Mill Operations since July 2013. Prior to this, he served as Vice President – Containerboard Mill Operations since January 2011. From March 2010 to January 2011, Mr. Carter served as PCA’s Director of Papermaking Technology. Prior to joining PCA in 2010, Mr. Carter spent 28 years with various pulp and paper companies in managerial and technical positions of increasing responsibility, most recently as Vice President and General Manager of the Calhoun, Tennessee mill of Abitibi Bowater from 2007 to 2010 and as manager of SP Newsprint’s Dublin, Georgia mill from 1999 to 2007.
Jeff S. Kaser, 55, Senior Vice President – Corrugated Products - Mr. Kaser has served as Senior Vice President — Corrugated Products since May 2020. Prior to this, he served as Vice President and Area General Manager of PCA’s Midwest Area, Mid-Atlantic Area and Pennsylvania Region. Mr. Kaser joined PCA in 1987 and has also held plant positions in sales, sales management and general management.
Kent A. Pflederer, 50, Senior Vice President, General Counsel and Secretary - Mr. Pflederer has served as Senior Vice President, General Counsel and Corporate Secretary since January 2013 and has led our legal department since June 2007. Prior to joining PCA, Mr. Pflederer served as Senior Counsel, Corporate and Securities, at Hospira, Inc. from 2004 to 2007 and served in the corporate and securities practice at Mayer Brown, LLP from 1996 to 2004.
Bruce A. Ridley, 65, Senior Vice President – Environmental Health and Safety and Operational Services - Mr. Ridley has served as Senior Vice President – Environmental Health and Safety and Operational Services since May 2019. Mr. Ridley previously served as Vice President of Operations from 2012 to 2019 and at PCA’s Tomahawk, Wisconsin containerboard mill as the Operations Manager and Mill Manager from 1999 to 2011. Before joining PCA, he held several positions of increasing responsibility at multiple locations during his 19 years with International Paper Co. and two years with Champion International.
Robert A. Schneider, 55, Senior Vice President and Chief Information Officer - Mr. Schneider has served as Senior Vice President and Chief Information Officer since May 2019. He previously served as Vice President and Chief Information Officer from 2000 to 2019. Mr. Schneider joined the company in 1989 and has held various management and other positions of increasing responsibility in information systems for PCA.
D. Ray Shirley, 49, Senior Vice President – Corporate Engineering and Process Technology - Mr. Shirley has served as PCA’s Senior Vice President – Corporate Engineering and Process Technology since May 2019. Mr. Shirley previously served as PCA’s Vice President – Containerboard Mills Engineering and Process Technology from 2012 to 2019 and as Mill Manager at PCA’s Counce, Tennessee containerboard mill from 2010 to 2012. He has served in various management roles within the company, including the Operations Manager at the Filer City, Michigan containerboard mill. Before joining PCA in 1996, Mr. Shirley worked for Georgia-Pacific Corporation.
Thomas W.H. Walton, 61, Senior Vice President - Sales and Marketing, Corrugated Products - Mr. Walton has served as Senior Vice President - Sales and Marketing, Corrugated Products since October 2009. Prior to this, he served as a Vice President and Area General Manager within the Corrugated Products Group since 1998. Mr. Walton joined the company in 1981 and has also held positions in production, sales, and general management.
Available Information
PCA’s internet website address is www.packagingcorp.com. Our annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments to those reports filed or furnished pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934 are available free of charge through our website as soon as reasonably practicable after they are electronically filed with, or furnished to, the Securities and Exchange Commission. In addition, our Code of Ethics may be accessed in the Investor Relations section of PCA’s website. PCA’s website and the information contained or incorporated therein are not intended to be incorporated into this report.
Previous: Cover and table of contents · Next: Item 1A. RISK FACTORS