 filings.tools
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
80K characters. Original on sec.gov · Markdown
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
The following discussion should be read in conjunction with the Consolidated Financial Statements included in Item 8. Financial Statements and Supplementary Data of this report and the matters described under Item 1A. Risk Factors.
A discussion regarding our financial condition and results of operations for 2019 compared to 2018 is presented below. Information on 2017 is included in graphs only to show year over year trends in our results of operations. Our financial condition for 2017 and results of operations for 2017 and 2018 compared to 2017 can be found under Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations which is incorporated by reference herein to our Annual Report on Form 10-K for the fiscal year ended December 31, 2018, filed with the SEC on February 13, 2019, and is available on the SEC’s website at www.sec.gov and our Investor Relations website at www.ir.prologis.com.
MANAGEMENT’S OVERVIEW
Summary of 2019
During the year ended December 31, 2019, operating fundamentals remained strong for our O&M portfolio. Our occupancy decreased to 96.5% at December 31, 2019 as compared to 97.5% at December 31, 2018 due to our focus on rental rate growth as evidenced by our weighted average net effective rent change of 23.7% in our O&M portfolio during 2019.
In 2019, we completed the following significant activities as described in the Notes to the Consolidated Financial Statements:
| • | In January, we formed PBLV, a Brazilian unconsolidated co-investment venture, with one partner. We contributed an initial portfolio of real estate properties to PBLV consisting of 14 operating properties totaling 7 million square feet and 371 acres of land. We received total proceeds of $620 million, including cash and units, which represents a 20% equity interest. |
|---|
| • | Excluding the contribution to PBLV, we generated net proceeds of $2.4 billion and realized net gains of $719 million, primarily from the contribution of properties to our unconsolidated co-investment ventures in Europe, Japan and the U.S. |
|---|
| • | In February, we redeemed a portion of our investment in a European unconsolidated co-investment venture for proceeds of €278 million ($313 million). |
|---|
| • | In December, we formed PCCLF, an unconsolidated co-investment venture investing in properties in China, with eight partners. At that time, we and our existing partner in Prologis China Logistics Venture I, LP received equity interests in PCCLF for the contribution of the existing portfolio of assets consisting of 79 properties totaling 22 million square feet. The seven new partners contributed cash, which was used to redeem a portion of our existing partner’s investment in PCCLF. We maintained our ownership percentage in these assets subsequent to the contribution and therefore did not recognize a gain. |
|---|
| • | We earned promotes aggregating $181 million ($121 million net of related expenses), of which $166 million was recorded in Strategic Capital Revenues, primarily from PELF, and $15 million was recorded in Net Earnings Attributable to Noncontrolling Interests. |
|---|
| • | We completed the following financing activities that resulted in extending our debt maturities to 7.8 years and lowering our effective interest rate to 2.2%, both on a weighted average basis at December 31, 2019. |
|---|
| • | In January, we upsized our global senior credit facility to $3.5 billion, maturing in January 2023. |
|---|
| • | In January, we also entered into two unsecured Japanese yen term loans for a total of ¥15.0 billion ($137 million) that bear interest of Yen LIBOR plus 0.5% to 0.6% and mature in January 2028 and 2030. |
|---|
| • | In March, we entered into an unsecured Japanese yen term loan agreement (the “March 2019 Yen Term Loan”) under which we can draw Japanese yen in an aggregate amount not to exceed ¥85.0 billion ($783 million at December 31, 2019). The March 2019 Yen Term Loan bears interest at Yen LIBOR plus 0.4% and matures in March 2026. We used the proceeds to repay the majority of the outstanding balance of ¥100.0 billion ($897 million) on our 2016 Japanese yen term loan. |
|---|
| • | In March, we also completed a private placement for ¥10.0 billion ($91 million) of senior notes with a stated interest rate of 1.2%, maturing in March 2039. |
|---|
| • | In September, we issued three series of senior notes for a total of €1.8 billion ($2.0 billion), bearing a weighted-average fixed interest rate of 0.7% and maturing in September 2027 through 2049. We utilized the proceeds to pay off senior notes of €600 million ($656 million) bearing an interest rate of 1.4% and maturing in October 2020 and $499 million on our multi-currency term loan. |
|---|
| • | At December 31, 2019, we had $3.7 billion of available borrowing capacity under our credit facilities and total liquidity of $4.8 billion, including unrestricted cash balances. |
|---|
Subsequent to year end, we closed the following transactions in 2020:
| • | On January 3rd, we redeemed €400 million ($446 million) of senior notes bearing a floating rate of Euribor plus 0.3%. |
|---|
| • | On January 8th, our two U.S. co-investment ventures acquired the wholly-owned real estate assets of IPT for approximately $4 billion (our investment was approximately $1.6 billion). See Notes 5 and 11 to our Consolidated Financial Statements for more information on this transaction. |
|---|
| • | On February 4th, we completed the Liberty Transaction for approximately $13 billion through the issuance of equity and the assumption of debt. See Note 20 to our Consolidated Financial Statements for more information on this transaction. |
|---|
RESULTS OF OPERATIONS
We evaluate our business operations based on the NOI of our two operating segments: Real Estate Operations and Strategic Capital. NOI by segment is a non-GAAP performance measure that is calculated using revenues and expenses directly from our financial statements. We consider NOI by segment to be an appropriate supplemental measure of our performance because it helps management and investors understand our operating results.
Below is a reconciliation of our NOI by segment to Operating Income per the Consolidated Financial Statements (in millions). Each segment’s NOI is reconciled to a line item in the Consolidated Financial Statements in their respective segment discussions below.
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Real Estate Operations – NOI | $ | 2,091 | $ | 1,784 | ||||
| Strategic Capital – NOI | 307 | 249 | ||||||
| General and administrative expenses | (266 | ) | (239 | ) | ||||
| Depreciation and amortization expenses | (1,140 | ) | (947 | ) | ||||
| Operating income before gains on real estate transactions, net | 992 | 847 | ||||||
| Gains on dispositions of development properties and land, net | 468 | 470 | ||||||
| Gains on other dispositions of investments in real estate, net | 390 | 371 | ||||||
| Operating income | $ | 1,850 | $ | 1,688 | ||||
See Note 17 to the Consolidated Financial Statements for more information on our segments and a reconciliation of each business segment’s NOI to Operating Income and Earnings Before Income Taxes.
Real Estate Operations
This operating segment principally includes rental revenue and rental expenses recognized from our consolidated properties. We allocate the costs of our property management and leasing functions to the Real Estate Operations segment through Rental Expenses and the Strategic Capital segment through Strategic Capital Expenses based on the square footage of the relative portfolios. The operating fundamentals in the markets in which we operate continue to be strong, which has increased rents and kept occupancies high. In addition, this segment is impacted by our development, acquisition and disposition activities.
Below are the components of Real Estate Operations revenues, expenses and NOI (in millions), derived directly from the Consolidated Financial Statements.
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Rental revenues (1) | $ | 2,832 | $ | 2,389 | ||||
| Development management and other revenues | 6 | 9 | ||||||
| Rental expenses | (734 | ) | (601 | ) | ||||
| Other expenses | (13 | ) | (13 | ) | ||||
| Real Estate Operations – NOI | $ | 2,091 | $ | 1,784 |
| (1) | As disclosed in Note 2 to the Consolidated Financial Statements, under the new lease standard, we adopted the practical expedient to present rental revenue and rental recoveries as a single component under Rental Revenues in our Consolidated Statements of Income. |
|---|
The change in Real Estate Operations NOI in 2019 compared to 2018 was impacted by the following items (dollars in millions):
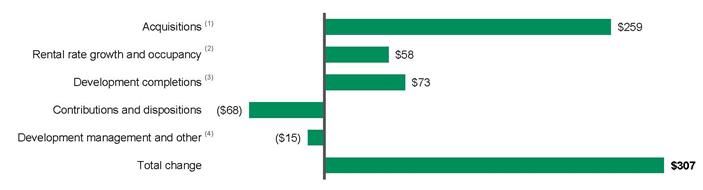
| (1) | Acquisition activity increased NOI in 2019, compared to 2018, primarily due to the acquisition of DCT Industrial Trust Inc. and DCT Industrial Operating Partnership LP (collectively “DCT”), which was completed for $8.5 billion on August 22, 2018 (“DCT Transaction”). |
|---|
| (2) | During both years, we experienced positive rental rate growth. Rental rate growth (or rent change) is a combination of the rollover of existing leases to higher rental rates and contractual rent increases on existing leases. If a lease has a contractual rent increase driven by a metric that is not known at the time the lease commences, such as the consumer price index or a similar metric, the rent increase is not included in rent leveling and therefore, impacts the rental revenue we recognize. We experienced an increase in NER change from 29.4% in 2018 to 32.8% in 2019, that was marginally reduced by a decrease in average occupancy of 0.6% during the same period. See below for key metrics on rent change on rollover and occupancy for the consolidated operating portfolio. |
|---|
| (3) | We calculate changes in NOI from development completions period over period by comparing the change in NOI generated on the pool of developments that completed on or after January 1, 2018 through December 31, 2019 year over year. |
|---|
| (4) | Other activity decreased NOI in 2019, compared to 2018, primarily due to internal costs of $25 million related to leasing activities, partially reduced by lower non-recoverable expenses, both in 2019, and changes in foreign currency exchange rates. Beginning in 2019 with the adoption of the new lease accounting standard, we no longer capitalize internal costs related to our leasing activities. |
|---|
Below are key operating metrics of our consolidated operating portfolio.
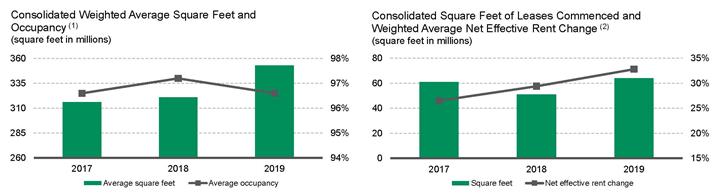
| (1) | In August 2018, we completed the DCT Transaction and acquired a portfolio of logistics real estate assets aggregating 68 million square feet. |
|---|
| (2) | Consolidated square feet of leases commenced and weighted average net effective rent change were calculated for leases with initial terms of one year or greater. |
|---|
Development Activity
The following table summarizes consolidated development activity (dollars and square feet in millions):
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Starts: | ||||||||
| Number of new development projects during the period | 74 | 67 | ||||||
| Square feet | 25 | 26 | ||||||
| TEI | $ | 2,741 | $ | 2,408 | ||||
| Percentage of build-to-suits based on TEI | 44.0 | % | 40.8 | % | ||||
| Stabilizations: | ||||||||
| Number of development projects stabilized during the period | 72 | 60 | ||||||
| Square feet | 26 | 21 | ||||||
| TEI | $ | 2,422 | $ | 1,824 | ||||
| Weighted average stabilized yield (1) | 6.3 | % | 6.5 | % | ||||
| Estimated value at completion | $ | 3,313 | $ | 2,459 | ||||
| Estimated weighted average margin | 36.8 | % | 34.8 | % |
| (1) | We calculate the weighted average stabilized yield as estimated NOI assuming stabilized occupancy divided by TEI. |
|---|
At December 31, 2019, our consolidated development portfolio, including properties under development and prestabilized properties with a TEI of $4.0 billion, was 50.0% leased and expected to be completed before December 2021. For additional information on our development portfolio at December 31, 2019, see Item 2. Properties.
Capital Expenditures
We capitalize costs incurred in renovating and improving our operating properties as part of the investment basis or within other assets. The following graph summarizes our total capital expenditures, excluding development costs, and property improvements per average square foot of our consolidated operating properties during each year:
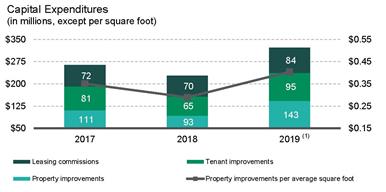
| (1) | In 2019, total capital expenditures increased primarily due to a larger portfolio and leasing our operating properties at higher rental rates and longer lease terms. |
|---|
Strategic Capital
This operating segment includes revenues from asset and property management, other fees for services performed and promote revenue earned from the unconsolidated entities. Revenues associated with the Strategic Capital segment fluctuate because of changes in the size of the portfolios through acquisitions and dispositions, the fair value of the properties and other transactional activity including foreign currency exchange rates and timing of promotes. These revenues are reduced by the direct costs associated with the asset and property-level management expenses for the properties owned by these ventures. We allocate the costs of our property management and leasing functions to the Strategic Capital segment through Strategic Capital Expenses and to the Real Estate Operations segment through Rental Expenses based on the square footage of the relative portfolios.
Below are the components of Strategic Capital revenues, expenses and NOI, derived directly from the Consolidated Financial Statements (in millions):
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Strategic capital revenues | $ | 492 | $ | 406 | ||||
| Strategic capital expenses | (185 | ) | (157 | ) | ||||
| Strategic Capital – NOI | $ | 307 | $ | 249 | ||||
Below is additional detail of our Strategic Capital revenues, expenses and NOI (in millions):
| U.S. (1) | Other Americas | Europe | Asia | Total | |||||||||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2019 | 2018 | 2019 | 2018 | 2019 | 2018 | 2019 | 2018 | 2019 | 2018 | ||||||||||||||||||||||||||||||||
| Strategic capital revenues ($) | |||||||||||||||||||||||||||||||||||||||||
| Recurring fees (2) | 75 | 65 | 31 | 23 | 106 | 95 | 56 | 48 | 268 | 231 | |||||||||||||||||||||||||||||||
| Transactional fees (3) | 11 | 9 | 5 | 3 | 17 | 23 | 25 | 22 | 58 | 57 | |||||||||||||||||||||||||||||||
| Promote revenue (4) | - | 1 | 5 | 6 | 161 | 57 | - | 54 | 166 | 118 | |||||||||||||||||||||||||||||||
| Total strategic capital revenues ($) | 86 | 75 | 41 | 32 | 284 | 175 | 81 | 124 | 492 | 406 | |||||||||||||||||||||||||||||||
| Strategic capital expenses ($) | (97 | ) | (70 | ) | (14 | ) | (12 | ) | (38 | ) | (39 | ) | (36 | ) | (36 | ) | (185 | ) | (157 | ) | |||||||||||||||||||||
| Strategic Capital - NOI ($) | (11 | ) | 5 | 27 | 20 | 246 | 136 | 45 | 88 | 307 | 249 | ||||||||||||||||||||||||||||||
| (1) | The U.S. expenses include compensation, personnel costs and PPP awards for employees who were based in the U.S. but also support other geographies. |
|---|
| (2) | Recurring fees include asset and property management fees. |
|---|
| (3) | Transactional fees include leasing commission, acquisition, development and other fees. |
|---|
| (4) | We generally earn promote revenue directly from third-party investors in the co-investment ventures and occasionally from the venture. The promote is generally based on cumulative returns over a three-year period. Under either structure, when the promote is earned we recognize the third-party investors’ share of the promote. Approximately 40% of the promote earned by us is paid to our employees as a combination of cash and stock awards pursuant to the terms of the PPP and expensed through Strategic Capital Expenses, as vested. |
|---|
The following real estate investments were held through our unconsolidated co-investment ventures based on historical cost at December 31 (dollars and square feet in millions):
| U.S. | Other Americas | Europe | Asia | Total | ||||||||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2019 | 2018 | 2019 (1) | 2018 | 2019 | 2018 | 2019 (2) | 2018 | 2019 | 2018 | |||||||||||||||||||||||||||||||
| Ventures | 1 | 1 | 2 | 2 | 3 | 3 | 3 | 2 | 9 | 8 | ||||||||||||||||||||||||||||||
| Operating properties | 605 | 566 | 214 | 209 | 731 | 669 | 144 | 125 | 1,694 | 1,569 | ||||||||||||||||||||||||||||||
| Square feet | 99 | 91 | 44 | 39 | 176 | 159 | 59 | 51 | 378 | 340 | ||||||||||||||||||||||||||||||
| Total assets ($) | 8,408 | 7,303 | 2,707 | 2,137 | 14,677 | 13,028 | 8,758 | 7,089 | 34,550 | 29,557 | ||||||||||||||||||||||||||||||
| (1) | PBLV and our other Brazilian joint ventures are combined as one venture for the purpose of this table. |
|---|
| (2) | In December, we formed PCCLF, an unconsolidated co-investment venture investing in properties in China, with eight partners. At that time, we and our existing partner in Prologis China Logistics Venture I, LP contributed the existing portfolio of assets to PCCLF. |
|---|
See Note 5 to the Consolidated Financial Statements for additional information on our unconsolidated co-investment ventures.
G&A Expenses
G&A expenses were $266 million and $239 million for 2019 and 2018, respectively. G&A expenses increased in 2019 as compared to 2018, due to higher compensation expenses based largely on the increase in our share price.
We capitalize certain internal costs, including salaries and related expenses, directly related to our development activities. We previously capitalized G&A related to our internal leasing activities, however, beginning January 1, 2019 these costs were expensed and recorded to Rental Expenses in the Consolidated Statements of Income.
The following table summarizes capitalized G&A amounts (in millions):
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Building and land development activities | $ | 68 | $ | 63 | ||||
| Leasing activities | - | 21 | ||||||
| Operating building improvements and other | 20 | 16 | ||||||
| Total capitalized G&A expenses | $ | 88 | $ | 100 | ||||
| Capitalized salaries and related costs as a percent of total salaries and related costs | 19.5 | % | 24.5 | % |
Depreciation and Amortization Expenses
Depreciation and amortization expenses were $1.1 billion and $947 million for 2019 and 2018, respectively.
The following table highlights the key changes in depreciation and amortization expenses in 2019 as compared to 2018 (dollars in millions):
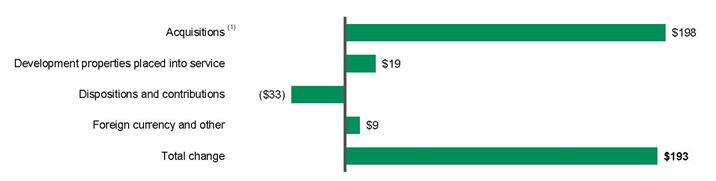
| (1) | The acquisition of properties primarily includes the DCT Transaction through which we acquired operating properties and the related intangible assets in the third quarter of 2018. See Note 3 to the Consolidated Financial Statements for more information on the DCT Transaction. |
|---|
Gains on Real Estate Transactions, Net
The following table summarizes our Gains on Dispositions of Development Properties and Land, net and Gains on Other Dispositions of Investments in Real Estate, net, which includes sales of non-developed properties (primarily operating properties) and other real estate transactions, for the years ended December 31 (in millions):
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Gains on dispositions of development properties and land, net | ||||||||
| Contributions to unconsolidated entities | $ | 403 | $ | 423 | ||||
| Dispositions to third parties | 65 | 47 | ||||||
| Total gains on dispositions of development properties and land, net | $ | 468 | $ | 470 | ||||
| Gains on other dispositions of investments in real estate, net | ||||||||
| Contributions to unconsolidated entities | $ | 98 | $ | 36 | ||||
| Dispositions to third parties | 157 | 335 | ||||||
| Total gains on contributions and dispositions, net | $ | 255 | $ | 371 | ||||
| Gains on partial redemptions of investment in an unconsolidated co-investment venture | 135 | - | ||||||
| Total gains on other dispositions of investments in real estate, net | $ | 390 | $ | 371 |
We utilized the proceeds from these transactions primarily to fund our capital investments during both periods. See Note 4 to the Consolidated Financial Statements for further information on these transactions.
Our Owned and Managed (“O&M”) Operating Portfolio
We manage our business and review our operating fundamentals on an O&M basis, which includes properties wholly owned by us or owned by one of our co-investment ventures. We believe reviewing the fundamentals this way allows management to understand the entire impact to the financial statements, as it will affect both the Real Estate Operations and Strategic Capital segments, as well as the net earnings we recognize from our unconsolidated co-investment ventures based on our ownership. We do not control the unconsolidated co-investment ventures for purposes of GAAP and the presentation of the ventures’ operating information does not represent a legal claim.
Our O&M operating portfolio does not include our development portfolio, value-added properties, non-industrial properties or properties held for sale to third parties and was as follows at December 31 (square feet in millions):
| 2019 | 2018 | ||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Number of Properties | Square Feet | Percentage Occupied | Number of Properties | Square Feet | Percentage Occupied | ||||||||||||||||||
| Consolidated | 1,882 | 359 | 96.1 | % | 1,835 | 348 | 97.2 | % | |||||||||||||||
| Unconsolidated | 1,676 | 376 | 96.8 | % | 1,561 | 339 | 97.8 | % | |||||||||||||||
| Total | 3,558 | 735 | 96.5 | % | 3,396 | 687 | 97.5 | % |
Below are the key operating metrics summarizing the leasing activity of our O&M operating portfolio.
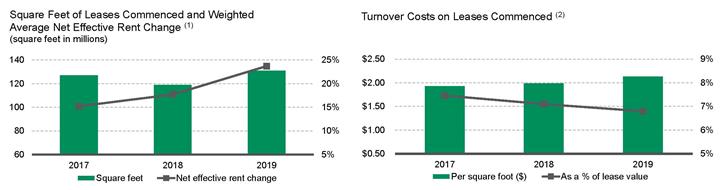
| (1) | Square feet of leases commenced and weighted average net effective rent change were calculated for leases with initial terms of one year or greater. We retained more than 70% of our customers, based on the total square feet of leases commenced, for each year. |
|---|
| (2) | Turnover costs are defined as leasing commissions and tenant improvements and represent the obligations incurred in connection with the lease commencement for leases greater than one year. In 2019 and 2018, turnover costs per square foot |
|---|
| increased, however, due to the longer terms and higher rents on leases commenced, this resulted in a lower cost as a percentage of lease value. |
|---|
Same Store Analysis
Our same store metrics are non-GAAP financial measures, which are commonly used in the real estate industry and expected from the financial community, on both a net effective and cash basis. We evaluate the performance of the operating properties we own and manage using a “same store” analysis because the population of properties in this analysis is consistent from period to period, which allows us and investors to analyze our ongoing business operations. We determine our same store metrics on property NOI, which is calculated as rental revenue less rental expense for the applicable properties in the same store population for both consolidated and unconsolidated properties based on our ownership interest, as further defined below.
We define our same store population for the three months ended December 31, 2019 as the properties in our O&M operating portfolio, including the property NOI for both consolidated properties and properties owned by the unconsolidated co-investment ventures at January 1, 2018 and owned throughout the same three-month period in both 2018 and 2019. We believe the drivers of property NOI for the consolidated portfolio are generally the same for the properties owned by the ventures in which we invest and therefore we evaluate the same store metrics of the O&M portfolio based on Prologis’ ownership in the properties (“Prologis Share”). The same store population excludes properties held for sale to third parties, along with development properties that were not stabilized at the beginning of the period (January 1, 2018) and properties acquired or disposed of to third parties during the period. To derive an appropriate measure of period-to-period operating performance, we remove the effects of foreign currency exchange rate movements by using the reported period-end exchange rate to translate from local currency into the U.S. dollar, for both periods.
As non-GAAP financial measures, the same store metrics have certain limitations as an analytical tool and may vary among real estate companies. As a result, we provide a reconciliation of Rental Revenues less Rental Expenses (“Property NOI”) (from our Consolidated Financial Statements prepared in accordance with U.S. GAAP) to our Same Store Property NOI measures.
We evaluate the results of our same store portfolio on a quarterly basis. The following is a reconciliation of our consolidated rental revenues, rental expenses and property NOI for each quarter in 2019 and 2018 to the full year, as included in the Consolidated Statements of Income and within Note 19 to the Consolidated Financial Statements and to the respective amounts in our same store portfolio analysis for the three months ended December 31 (dollars in millions):
| Three Months Ended | ||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| March 31, | June 30, | September 30, | December 31, | Full Year | ||||||||||||||||
| 2019 | ||||||||||||||||||||
| Rental revenues | $ | 697 | $ | 701 | $ | 711 | $ | 723 | $ | 2,832 | ||||||||||
| Rental expenses | (188 | ) | (181 | ) | (181 | ) | (184 | ) | (734 | ) | ||||||||||
| Property NOI | $ | 509 | $ | 520 | $ | 530 | $ | 539 | $ | 2,098 | ||||||||||
| 2018 | ||||||||||||||||||||
| Rental revenues | $ | 556 | $ | 545 | $ | 609 | $ | 679 | $ | 2,389 | ||||||||||
| Rental expenses | (143 | ) | (133 | ) | (147 | ) | (178 | ) | (601 | ) | ||||||||||
| Property NOI | $ | 413 | $ | 412 | $ | 462 | $ | 501 | $ | 1,788 |
| Three Months Ended December 31, | |||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|
| 2019 | 2018 | % Change | |||||||||
| Reconciliation of Consolidated Property NOI to Same Store Property NOI measures: | |||||||||||
| Rental revenues | $ | 723 | $ | 679 | |||||||
| Rental expenses | (184 | ) | (178 | ) | |||||||
| Consolidated Property NOI | $ | 539 | $ | 501 | |||||||
| Adjustments to derive same store results: | |||||||||||
| Property NOI from consolidated properties not included in same store portfolio and other adjustments (1)(2) | (157 | ) | (128 | ) | |||||||
| Property NOI from unconsolidated co-investment ventures included in same store portfolio (1)(2) | 452 | 434 | |||||||||
| Third parties' share of Property NOI from properties included in same store portfolio (1)(2) | (364 | ) | (355 | ) | |||||||
| Prologis Share of Same Store Property NOI – Net Effective (2) | $ | 470 | $ | 452 | 4.0 | % | |||||
| Consolidated properties straight-line rent and fair value lease adjustments included in same store portfolio (3) | (3 | ) | (5 | ) | |||||||
| Unconsolidated co-investment ventures straight-line rent and fair value lease adjustments included in same store portfolio (3) | (5 | ) | (5 | ) | |||||||
| Third parties' share of straight-line rent and fair value lease adjustments included in same store portfolio (2)(3) | 4 | 4 | |||||||||
| Prologis Share of Same Store Property NOI – Cash (2)(3) | $ | 466 | $ | 446 | 4.6 | % |
| (1) | We exclude properties held for sale to third parties, along with development properties that were not stabilized at the beginning of the period and properties acquired or disposed of to third parties during the period. We also exclude net termination and renegotiation fees to allow us to evaluate the growth or decline in each property’s rental revenues without regard to one-time items that are not indicative of the property’s recurring operating performance. Net termination and renegotiation fees represent the gross fee negotiated to allow a customer to terminate or renegotiate their lease, offset by the write-off of the asset recorded due to the adjustment to straight-line rents over the lease term. Same Store Property NOI is adjusted to include an allocation of property management expenses for our consolidated properties based on the property management services provided to each property (generally, based on a percentage of revenues). On consolidation, these amounts are eliminated and the actual costs of providing property management services are recognized as part of our consolidated rental expense. |
|---|
| (2) | We include the Property NOI for the same store portfolio for both consolidated properties and properties owned by the co-investment ventures based on our investment in the underlying properties. In order to calculate our share of Same Store Property NOI from the co-investment ventures in which we own less than 100%, we use the co-investment ventures’ underlying Property NOI for the same store portfolio and apply our ownership percentage at December 31, 2019 to the Property NOI for both periods, including the properties contributed during the period. We adjust the total Property NOI from the same store portfolio of the co-investment ventures by subtracting the third parties’ share of both consolidated and unconsolidated co-investment ventures. |
|---|
During the periods presented, certain wholly owned properties were contributed to a co-investment venture and are included in the same store portfolio. Neither our consolidated results nor those of the co-investment ventures, when viewed individually, would be comparable on a same store basis because of the changes in composition of the respective portfolios from period to period (e.g. the results of a contributed property are included in our consolidated results through the contribution date and in the results of the venture subsequent to the contribution date based on our ownership interest at the end of the period). As a result, only line items labeled “Prologis Share of Same Store Property NOI” are comparable period over period.
| (3) | We further remove certain noncash items (straight-line rent and amortization of fair value lease adjustments) included in the financial statements prepared in accordance with U.S. GAAP to reflect a Same Store Property NOI – Cash measure. |
|---|
We manage our business and compensate our executives based on the same store results of our O&M portfolio at 100% as we manage our portfolio on an ownership blind basis. We calculate those results by including 100% of the properties included in our same store portfolio.
Other Components of Income (Expense)
Earnings from Unconsolidated Entities, Net
We recognized net earnings from unconsolidated entities, which are accounted for using the equity method, of $200 million and $298 million during 2019 and 2018, respectively. The decrease in earnings year over year was primarily due to significant gains recognized in 2018 on real estate dispositions in Europe. The earnings we recognize can be impacted by: (i) variances in revenues and expenses of each venture; (ii) the size and occupancy rate of the portfolio of properties owned by each venture; (iii) gains or losses from the dispositions of properties and extinguishment of debt; (iv) our ownership interest in each venture; and (v) fluctuations in foreign currency exchange rates used to translate our share of net earnings to U.S. dollars.
See the discussion of our unconsolidated entities above in the Strategic Capital segment discussion and in Note 5 to the Consolidated Financial Statements for a further breakdown of our share of net earnings recognized.
Interest Expense
The following table details our net interest expense (dollars in millions):
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Gross interest expense | $ | 271 | $ | 269 | ||||
| Amortization of debt discount and debt issuance costs, net | 17 | 12 | ||||||
| Capitalized amounts | (48 | ) | (52 | ) | ||||
| Net interest expense | $ | 240 | $ | 229 | ||||
| Weighted average effective interest rate during the year | 2.4 | % | 3.0 | % |
Net interest expense increased by $11 million, primarily due to higher average debt balances in 2019 as compared to 2018. The increase in debt year over year was due to the assumption of debt in the DCT Transaction in August 2018 that was mostly refinanced with debt at lower interest rates. Additionally, we recognized a gain upon settlement of the interest rate swaps on the Canadian term loan in 2018.
See Note 8 to the Consolidated Financial Statements and the Liquidity and Capital Resources section, for further discussion of our debt and borrowing costs.
Foreign Currency and Derivative Gains (Losses), Net
We are exposed to foreign currency exchange risk related to investments in and earnings from our foreign investments. We may use derivative financial instruments to manage foreign currency exchange rate risk. We recognize the change in fair value of the undesignated derivative contracts in unrealized gains and losses. Upon settlement of these transactions, we recognize realized gains or losses.
We primarily hedge our foreign currency risk by borrowing in the currencies in which we invest thereby providing a natural hedge. We may also issue debt in a currency that is not the same functional currency of the borrowing entity and we generally designate the debt as a nonderivative net investment hedge. We recognize the remeasurement and settlement of the unhedged portion of the debt and accrued interest in unrealized gains or losses. We also recognize the change in fair value and settlement of any undesignated derivative contracts to hedge the eventual payment of these borrowings in a foreign currency in unrealized gains or losses.
The following table details our foreign currency and derivative gains (losses), net included in earnings (in millions):
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Realized foreign currency and derivative gains (losses), net: | ||||||||
| Gains (losses) on the settlement of undesignated derivatives | $ | 28 | $ | (3 | ) | |||
| Gains on the settlement of transactions with third parties | 1 | - | ||||||
| Total realized foreign currency and derivative gains (losses), net | 29 | (3 | ) | |||||
| Unrealized foreign currency and derivative gains (losses), net: | ||||||||
| Gains (losses) on the change in fair value of undesignated derivatives and unhedged debt | (74 | ) | 125 | |||||
| Gains (losses) on remeasurement of certain assets and liabilities | 3 | (5 | ) | |||||
| Total unrealized foreign currency and derivative gains (losses), net | (71 | ) | 120 | |||||
| Total foreign currency and derivative gains (losses), net | $ | (42 | ) | $ | 117 |
See Note 2 to the Consolidated Financial Statements for more information about our foreign currency and derivative financial instrument policies and Note 15 to the Consolidated Financial Statements for more information about our derivative and nonderivative transactions.
Losses on Early Extinguishment of Debt, Net
We recognized a loss of $16 million and $3 million upon extinguishment of debt in 2019 and 2018, respectively. Through our financing activities in both 2019 and 2018 we reduced our effective interest rate and lengthened the maturities of our debt. See Note 8 to the Consolidated Financial Statements and the Liquidity and Capital Resources section, for more information regarding our debt repurchases.
Income Tax Expense
We recognize income tax expense related to our taxable REIT subsidiaries and in certain local, state and foreign jurisdictions in which we operate. Our current income tax expense fluctuates from period to period based primarily on the timing of our taxable income.
Deferred income tax expense (benefit) is generally a function of the period’s temporary differences and the utilization of net operating losses generated in prior years that had been previously recognized as deferred income tax assets in taxable subsidiaries.
The following table summarizes our income tax expense (benefit) (in millions):
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Current income tax expense: | ||||||||
| Income tax expense | $ | 48 | $ | 44 | ||||
| Income tax expense on dispositions | 15 | 17 | ||||||
| Income tax expense on dispositions related to acquired tax liabilities | - | 1 | ||||||
| Total current income tax expense | 63 | 62 | ||||||
| Deferred income tax expense (benefit): | ||||||||
| Income tax expense | 12 | 2 | ||||||
| Income tax benefit on dispositions related to acquired tax liabilities | - | (1 | ) | |||||
| Total deferred income tax expense | 12 | 1 | ||||||
| Total income tax expense | $ | 75 | $ | 63 |
Our income taxes are discussed in more detail in Note 13 to the Consolidated Financial Statements.
Net Earnings Attributable to Noncontrolling Interests
This amount represents the third-party investors’ share of the earnings generated in consolidated entities in which we do not own 100% of the equity, reduced by the third-party share of fees or promotes payable to us and earned during the period. We had net earnings attributable to noncontrolling interests of $129 million and $174 million in 2019 and 2018, respectively. Included in these amounts were $47 million and $49 million in 2019 and 2018, respectively, of net earnings attributable to the common limited partnership unitholders of Prologis, L.P.
See Note 11 to the Consolidated Financial Statements for further information on our noncontrolling interests.
Other Comprehensive Income (Loss)
See Note 2 to the Consolidated Financial Statements for more information about our foreign currency and derivative financial instrument policies and Note 15 to the Consolidated Financial Statements for more information about our derivative and nonderivative transactions and other comprehensive income (loss).
ENVIRONMENTAL MATTERS
See Note 16 in the Consolidated Financial Statements for further information about environmental liabilities.
LIQUIDITY AND CAPITAL RESOURCES
Overview
We consider our ability to generate cash from operating activities, distributions from our co-investment ventures, contributions and dispositions of properties and available financing sources to be adequate to meet our anticipated future development, acquisition, operating, debt service, dividend and distribution requirements.
Near-Term Principal Cash Sources and Uses
In addition to dividends and distributions, we expect our primary cash needs may consist of the following:
| • | completion of the development and leasing of the properties in our consolidated development portfolio (at December 31, 2019, 105 properties in our development portfolio were 50.0% leased with a current investment of $1.9 billion and a TEI of $4.0 billion when completed and leased, leaving $2.1 billion of estimated additional required investment); |
|---|
| • | development of new properties which we may hold for long-term investment or subsequently contribute to unconsolidated co-investment ventures, including the acquisition of land in certain markets; |
|---|
| • | capital expenditures and leasing costs on properties in our operating portfolio; |
|---|
| • | repayment of debt and scheduled principal payments of $536 million in 2020, of which $446 million of senior notes were redeemed in January 2020; |
|---|
| • | additional investments in current unconsolidated entities or new investments in future unconsolidated entities; |
|---|
| • | acquisition of operating properties or portfolios of operating properties, including the acquisition of IPT described above, (depending on market and other conditions) for direct, long-term investment in our consolidated portfolio (this might include acquisitions from our co-investment ventures); and |
|---|
| • | repurchase of our outstanding debt or equity securities (depending on prevailing market conditions, our liquidity, contractual restrictions and other factors) through cash purchases, open-market purchases, privately negotiated transactions, tender offers or otherwise. |
|---|
We expect to fund our cash needs principally from the following sources (subject to market conditions):
| • | available unrestricted cash balances ($1.1 billion at December 31, 2019); |
|---|
| • | net cash flow from property operations; |
|---|
| • | fees earned for services performed on behalf of the co-investment ventures, including promotes; |
|---|
| • | distributions received from the co-investment ventures; |
|---|
| • | proceeds from the disposition of properties, land parcels or other investments to third parties; |
|---|
| • | proceeds from the contributions of properties to current or future co-investment ventures; |
|---|
| • | proceeds from the sale of a portion of our investments in co-investment ventures to achieve long-term ownership targets; |
|---|
| • | borrowing capacity under our current credit facility arrangements, other facilities or borrowing arrangements ($3.7 billion available at December 31, 2019); and |
|---|
| • | proceeds from the issuance of debt. |
|---|
We may also generate proceeds from the issuance of equity securities, subject to market conditions. In February 2020, we completed the Liberty Transaction for approximately $13 billion through the issuance of equity and the assumption of debt.
Debt
The following table summarizes information about our consolidated debt by currency at December 31 (dollars in millions):
| 2019 | 2018 | |||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Weighted Average Interest Rate | Amount Outstanding | % of Total | Weighted Average Interest Rate | Amount Outstanding | % of Total | |||||||||||||||||||
| British pound sterling | 2.3 | % | $ | 657 | 5.5 | % | 2.3 | % | $ | 636 | 5.8 | % | ||||||||||||
| Canadian dollar | 3.4 | % | 280 | 2.3 | % | 3.6 | % | 266 | 2.4 | % | ||||||||||||||
| Euro | 1.9 | % | 6,129 | 51.5 | % | 2.2 | % | 4,894 | 44.1 | % | ||||||||||||||
| Japanese yen | 0.7 | % | 2,329 | 19.6 | % | 0.9 | % | 1,952 | 17.6 | % | ||||||||||||||
| U.S. dollar | 4.4 | % | 2,511 | 21.1 | % | 4.5 | % | 3,342 | 30.1 | % | ||||||||||||||
| Total debt (1) | 2.2 | % | $ | 11,906 | 2.7 | % | $ | 11,090 |
| (1) | The weighted average maturity for total debt outstanding at December 31, 2019 and 2018 was 94 and 76 months, respectively. |
|---|
Our credit ratings at December 31, 2019, were A3 from Moody’s and A- from Standard & Poor’s, both with stable outlook. These ratings allow us to borrow at an advantageous rate. Adverse changes in our credit ratings could negatively impact our business and, in particular, our refinancing and other capital market activities, our ability to manage debt maturities, our future growth and our development and acquisition activity. A securities rating is not a recommendation to buy, sell or hold securities and is subject to revision or withdrawal at any time by the rating organization.
At December 31, 2019, we were in compliance with all of our financial debt covenants. These covenants include customary financial covenants for total debt, encumbered debt and fixed charge coverage ratios.
See Note 8 to the Consolidated Financial Statements for further discussion on our debt.
Equity Commitments Related to Certain Co-Investment Ventures
Certain co-investment ventures have equity commitments from us and our venture partners. Our venture partners fulfill their equity commitment with cash. We may fulfill our equity commitment through contributions of properties or cash.
The following table summarizes the remaining equity commitments at December 31, 2019 (in millions):
| Equity Commitments | ||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Prologis | Venture Partners | Total | Exchange Rate | Expiration Date | ||||||||||||
| Prologis Targeted U.S. Logistics Fund | $ | - | $ | 1,919 | $ | 1,919 | N/A | 2022 | ||||||||
| Prologis European Logistics Fund | - | 747 | 747 | 1.12 U.S. dollar/ 1 euro | 2022 | |||||||||||
| Prologis UK Logistics Venture | 11 | 59 | 70 | 1.32 U.S. dollar/ 1 British pound sterling | 2021 | |||||||||||
| Prologis China Core Logistics Fund (1) | - | 311 | 311 | 0.14 U.S. dollar/ 1 Chinese renminbi | 2022 | |||||||||||
| Prologis China Logistics Venture (1) | 321 | 1,818 | 2,139 | N/A | 2020 – 2024 | |||||||||||
| Prologis Brazil Logistics Venture | 48 | 193 | 241 | 0.25 U.S. dollar/ 1 Brazilian real | 2026 | |||||||||||
| Total | $ | 380 | $ | 5,047 | $ | 5,427 |
| (1) | As discussed above, in December 2019 we formed PCCLF with eight venture partners with initial equity commitments of ¥4,622 million ($657 million). At that time, we and our existing partner in Prologis China Logistics Venture I, LP contributed the real estate portfolio to PCCLF in exchange for equity interests. The contributions from the seven new partners were used to redeem a portion of our existing partner’s investment in PCCLF. |
|---|
See the Cash Flow Summary below for more information about our investment activity in the co-investment ventures.
Cash Flow Summary
The following table summarizes our cash flow activity (in millions):
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Net cash provided by operating activities | $ | 2,264 | $ | 1,804 | ||||
| Net cash used in investing activities | $ | (685 | ) | $ | (664 | ) | ||
| Net cash used in financing activities | $ | (840 | ) | $ | (1,232 | ) | ||
| Net increase (decrease) in cash and cash equivalents, including the effect of foreign currency exchange rates | $ | 745 | $ | (103 | ) |
Operating Activities
Cash provided by operating activities, exclusive of changes in receivables and payables, was impacted by the following significant activities:
| • | Real estate operations. We receive the majority of our operating cash through the net revenues of our Real Estate Operations segment. See the Results of Operations section above for further explanation on our Real Estate Operations segment. The revenues from this segment include noncash adjustments for straight-lined rents and amortization of above and below market leases of $98 million and $67 million for 2019 and 2018, respectively. |
|---|
| • | Strategic capital. We also generate operating cash through our Strategic Capital segment by providing asset and property management and other services to our unconsolidated co-investment ventures. See the Results of Operations section above for the key drivers of the net revenues from our Strategic Capital segment. Included in Strategic Capital Revenues is the third-party investors’ share that is owed for fees and promotes, which is recognized in operating activities in the period the cash is received. |
|---|
| • | G&A expenses and equity-based compensation awards. We incurred $266 million and $239 million of G&A costs in 2019 and 2018, respectively. Included in these amounts are equity-based, noncash compensation expenses of $98 million and $76 million in 2019 and 2018, respectively, which were recorded to Rental Expenses in the Real Estate Operations segment, Strategic Capital Expenses in the Strategic Capital segment and G&A Expenses. |
|---|
| • | Operating distributions from unconsolidated entities. We received $347 million and $350 million of distributions from our unconsolidated entities in 2019 and 2018, respectively. Certain unconsolidated co-investment ventures distribute the total promote, including our share, that is recorded to Investment In and Advances to Unconsolidated Entities and is included in operating activities in the period the cash is received. |
|---|
| • | Cash paid for interest and income taxes, net. We paid combined amounts for interest and income taxes, net of amounts received, of $277 million and $266 million in 2019 and 2018, respectively. See Note 8 and Note 13 to the Consolidated Financial Statements for further information on this activity. |
|---|
Investing Activities
Cash provided by investing activities is driven by proceeds from contributions and dispositions of real estate properties, including the contribution of the initial portfolio of properties to PBLV. Cash used in investing activities is principally driven by our capital deployment activities of investing in real estate development, acquisitions and capital expenditures. See Note 4 to the Consolidated Financial Statements for further information on these activities. In addition, the following significant transactions also impacted our cash provided by or used in investing activities:
| • | DCT Transaction, net of cash acquired. We paid net cash of $46 million to complete the DCT Transaction in 2018, primarily due to transaction costs. The acquisition was financed through the issuance of equity and assumption of debt. See Notes 3 and 18 to the Consolidated Financial Statements for more detail on the DCT Transaction. |
|---|
| • | Investments in and advances to. We invested cash in our unconsolidated entities that represented our proportionate share, of $276 million and $160 million in 2019 and 2018, respectively. The ventures used the funds for the acquisition of properties, development and repayment of debt. See Note 5 to the Consolidated Financial Statements for more detail on our unconsolidated co-investment ventures. |
|---|
| • | Return of investment. We received distributions from unconsolidated entities as a return of investment of $389 million and $360 million during 2019 and 2018, respectively. Included in these amounts were distributions from venture activities including proceeds from property sales, debt refinancing and the redemption of our investment in certain unconsolidated entities. |
|---|
| • | Proceeds from repayment of notes receivable backed by real estate. We received $34 million for the repayment of notes received in connection with the disposition of real estate to third parties in 2018. |
|---|
| • | Settlement of net investment hedges. We paid net cash of $7 million and received $18 million from the settlement of net investment hedges during 2019 and 2018, respectively. See Note 15 to the Consolidated Financial Statements for further information on our derivative transactions. |
|---|
Financing Activities
Cash provided by and used in financing activities is principally driven by proceeds from and payments on credit facilities and other debt, along with dividends paid on common and preferred stock and noncontrolling interest contributions and distributions.
Our repurchase of and payments on debt and proceeds from the issuance of debt consisted of the following activity (in millions):
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Repurchase of and payments on debt (including extinguishment costs) (1) | ||||||||
| Regularly scheduled debt principal payments and payments at maturity | $ | 29 | $ | 201 | ||||
| Secured mortgage debt | 433 | 508 | ||||||
| Senior notes | 669 | 973 | ||||||
| Term loans | 2,171 | 2,484 | ||||||
| Total | $ | 3,302 | $ | 4,166 | ||||
| Proceeds from the issuance of debt | ||||||||
| Secured mortgage debt | $ | 250 | $ | 229 | ||||
| Senior notes | 2,053 | 2,493 | ||||||
| Term loans | 1,674 | 2,178 | ||||||
| Total | $ | 3,977 | $ | 4,900 |
| (1) | We completed the DCT Transaction in 2018 and assumed $1.9 billion of debt, of which $1.8 billion was paid off with the proceeds from the issuance of senior notes. The assumption of $1.9 billion of debt was excluded from the table above. |
|---|
OFF-BALANCE SHEET ARRANGEMENTS
Unconsolidated Co-Investment Venture Debt
We had investments in and advances to our unconsolidated co-investment ventures, at December 31, 2019, of $5.9 billion. The ventures listed below had total third-party debt of $9.4 billion at December 31, 2019. Certain of our ventures do not have third-party debt and are therefore excluded. This debt is non-recourse to Prologis and other investors in the co-investment ventures and matures and bears interest as follows at December 31, 2019 (dollars in millions):
| Total (1) | Weighted Average Interest Rate | Gross Book Value (1) | Ownership % | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Prologis Targeted U.S. Logistics Fund | $ | 2,130 | 3.8% | $ | 8,920 | 27.3% | ||||||||||
| FIBRA Prologis | 769 | 4.6% | 2,112 | 47.1% | ||||||||||||
| Prologis European Logistics Fund | 2,749 | 2.1% | 10,854 | 24.1% | ||||||||||||
| Prologis UK Logistics Venture | 464 | 3.3% | 862 | 15.0% | ||||||||||||
| Nippon Prologis REIT | 2,199 | 0.7% | 5,980 | 15.1% | ||||||||||||
| Prologis China Core Logistics Fund | 597 | 6.0% | 1,749 | 15.6% | ||||||||||||
| Prologis China Logistics Venture | 500 | 3.8% | 948 | 15.0% | ||||||||||||
| Total | $ | 9,408 | $ | 31,425 | ||||||||||||
| (1) | The weighted average loan-to-value ratio for all unconsolidated co-investment ventures was 26.0% at December 31, 2019. Loan-to-value, a non-GAAP measure, was calculated as the percentage of total third-party debt to the gross book value of real estate for each venture and weighted based on the cumulative gross book value of all unconsolidated co-investment ventures. |
|---|
At December 31, 2019, we did not guarantee any third-party debt of the unconsolidated co-investment ventures. In our role as the manager or sponsor, we work with the co-investment ventures to maintain sufficient liquidity and refinance their maturing debt. There can be no assurance that the co-investment ventures will be able to refinance any maturing indebtedness on terms as favorable as the maturing debt, or at all. If the ventures are unable to refinance the maturing indebtedness with newly issued debt, they may be able to obtain funds by voluntary capital contributions from us and our partners or by selling assets. Certain of our ventures also have credit facilities, or unencumbered properties, both of which may be used to obtain funds.
CONTRACTUAL OBLIGATIONS
Long-Term Contractual Obligations
The following table summarizes our long-term contractual obligations at December 31, 2019 (in millions):
| Payments Due by Period | |||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Less than 1 Year | 1 to 3 Years | 3 to 5 Years | More than 5 Years | Total | |||||||||||||||
| Debt obligations, other than credit facilities | $ | 536 | $ | 1,680 | $ | 2,064 | $ | 7,530 | $ | 11,810 | |||||||||
| Interest on debt obligations, other than credit facilities | 257 | 468 | 345 | 867 | 1,937 | ||||||||||||||
| Unfunded commitments on the development portfolio (1) | 1,647 | 454 | - | - | 2,101 | ||||||||||||||
| Operating and financing lease payments (2) | 44 | 88 | 75 | 776 | 983 | ||||||||||||||
| Total | $ | 2,484 | $ | 2,690 | $ | 2,484 | $ | 9,173 | $ | 16,831 |
| (1) | We had properties in our consolidated development portfolio (completed and under development) at December 31, 2019, with a TEI of $4.0 billion. The unfunded commitments presented include not only those costs that we are obligated to fund under construction contracts, but all costs necessary to place the property into service, including the estimated costs of tenant improvements, marketing and leasing costs that we expect to incur as the property is leased. |
|---|
| (2) | Beginning January 1, 2019, as a lessee we were required to record both a right-of-use asset and lease liability for our ground and office space leases based on the present value of our future minimum lease payments. See Note 2 to the Consolidated Financial Statements for additional information. |
|---|
Distribution and Dividend Requirements
Our dividend policy on our common stock is to distribute a percentage of our cash flow to ensure that we will meet the dividend requirements of the IRC, relative to maintaining our REIT status, while still allowing us to retain cash to fund capital improvements and other investment activities.
Under the IRC, REITs may be subject to certain federal income and excise taxes on our undistributed taxable income.
We paid quarterly cash dividends of $0.53 and $0.48 per common share in 2019 and 2018, respectively. Our future common stock dividends, if and as declared, may vary and will be determined by the Board based upon the circumstances prevailing at the time,
including our financial condition, operating results and REIT distribution requirements, and may be adjusted at the discretion of the Board during the year.
We make distributions on the common limited partnership units outstanding at the same per unit amount as our common stock dividend. The Class A Units in the OP are entitled to a quarterly distribution equal to $0.64665 per unit so long as the common units receive a quarterly distribution of at least $0.40 per unit. We paid a quarterly distribution of $0.64665 per Class A Unit in 2019 and 2018.
At December 31, 2019, we had 1.4 million shares of Series Q preferred stock outstanding with a liquidation preference of $50 per share. The annual dividend rate is 8.54% per share and dividends are payable quarterly in arrears. Pursuant to the terms of our preferred stock, we are restricted from declaring or paying any dividend with respect to our common stock unless and until all cumulative dividends with respect to the preferred stock have been paid and sufficient funds have been set aside for dividends that have been declared for the relevant dividend period with respect to the preferred stock.
Other Commitments
On a continuing basis, we are engaged in various stages of negotiations for the acquisition or disposition of individual properties or portfolios of properties.
CRITICAL ACCOUNTING POLICIES
A critical accounting policy is one that involves an estimate or assumption that is subjective and requires management judgment about the effect of a matter that is inherently uncertain and material to an entity’s financial condition and results of operations. Management’s best judgment considers historical and current economic conditions and expectations for the future. Changes in estimates could affect our financial position and specific items in our results of operations that are used by stockholders, potential investors, industry analysts and lenders in their evaluation of our performance. Of the significant accounting policies discussed in Note 2 to the Consolidated Financial Statements, those presented below have been identified by us as meeting the criteria to be considered critical accounting policies. Refer to Note 2 for more information on these critical accounting policies.
Acquisitions
We generally account for an acquisition of a single property or portfolio of properties as an asset acquisition. We measure the real estate assets acquired through an asset acquisition based on their cost or total consideration exchanged and any excess consideration or bargain purchase amount is allocated to the real estate properties, excluding those identified as held for sale, on a relative fair value basis.
We make estimates as part of our valuation of the assumed assets and liabilities at the acquisition date. The components of an acquisition typically include buildings, land, improvements, intangible assets or liabilities related to the acquired leases, debt, deferred tax assets and liabilities and other assumed assets and liabilities. The purchase price allocation is based on the expected future cash flows of the property and various characteristics of the markets where the property is located utilizing an income approach methodology, which may be a discounted cash flow analysis or applying a capitalization rate to the estimated NOI of a property. Key assumptions include market rents, growth rates, and discount and capitalization rates. Estimates of future cash flows are based on a number of factors including historical operating results, known trends and market and economic conditions. We determine discount and capitalization rates by market based on recent transactions and other market data. The fair value of land is generally based on relevant market data, such as a comparison of the subject site to similar parcels that have recently been sold or are currently being offered on the market for sale. The use of different assumptions to value the acquired properties and intangible assets and assumed liabilities could affect the future revenues and expenses we recognize over the estimated remaining useful life or lease term.
Recoverability of Real Estate Assets
We assess the carrying values of our respective long-lived assets whenever events or changes in circumstances indicate that the carrying amounts of these assets may not be fully recoverable.
Recoverability of real estate assets is measured by comparison of the carrying amount of the asset to the estimated future undiscounted cash flows. To review our real estate assets for recoverability, we consider current market conditions and property-level operating results, as well as our intent with respect to holding or disposing of the asset. Our intent with regard to the underlying assets might change as market conditions change. Fair value is determined through various valuation techniques, including discounted cash flow models, applying a capitalization rate to the estimated NOI of a property, quoted market values and third-party appraisals, where considered necessary. The use of projected future cash flows is based on assumptions that are consistent with our estimates of future expectations and the strategic plan we use to manage our underlying business. If our analysis indicates that the carrying value of a property that we expect to hold is not recoverable on an undiscounted cash flow basis, we recognize an impairment charge for the amount by which the carrying value exceeds the current estimated fair value of the property. Assumptions and estimates used in the recoverability analyses for future cash flows, including market rents, discount rates and capitalization rates are complex and subjective. Changes in economic and operating conditions or our intent with regard to our investment that occurs subsequent to our impairment analyses could impact these assumptions and result in future impairment.
NEW ACCOUN****TING PRONOUNCEMENTS
See Note 2 to the Consolidated Financial Statements.
FUNDS FROM OPERATIONS ATTRIBUTABLE TO COMMON STOCKHOLDERS/UNITHOLDERS (“FFO”)
FFO is a non-GAAP financial measure that is commonly used in the real estate industry. The most directly comparable GAAP measure to FFO is net earnings.
The National Association of Real Estate Investment Trusts (“NAREIT”) defines FFO as earnings computed under GAAP to exclude historical cost depreciation and gains and losses from the sales, along with impairment charges, of previously depreciated properties. We also exclude the gains on revaluation of equity investments upon acquisition of a controlling interest and the gain recognized from a partial sale of our investment, as these are similar to gains from the sales of previously depreciated properties. We exclude similar adjustments from our unconsolidated entities and the third parties’ share of our consolidated co-investment ventures.
Our FFO Measures
Our FFO measures begin with NAREIT’s definition and we make certain adjustments to reflect our business and the way that management plans and executes our business strategy. While not infrequent or unusual, the additional items we adjust for in calculating FFO, as modified by Prologis and Core FFO, both as defined below, are subject to significant fluctuations from period to period. Although these items may have a material impact on our operations and are reflected in our financial statements, the removal of the effects of these items allows us to better understand the core operating performance of our properties over the long term. These items have both positive and negative short-term effects on our results of operations in inconsistent and unpredictable directions that are not relevant to our long-term outlook.
We calculate our FFO measures, as defined below, based on our proportionate ownership share of both our unconsolidated and consolidated ventures. We reflect our share of our FFO measures for unconsolidated ventures by applying our average ownership percentage for the period to the applicable reconciling items on an entity by entity basis. We reflect our share for consolidated ventures in which we do not own 100% of the equity by adjusting our FFO measures to remove the noncontrolling interests share of the applicable reconciling items based on our average ownership percentage for the applicable periods.
These FFO measures are used by management as supplemental financial measures of operating performance and we believe that it is important that stockholders, potential investors and financial analysts understand the measures management uses. We do not use our FFO measures as, nor should they be considered to be, alternatives to net earnings computed under GAAP, as indicators of our operating performance, as alternatives to cash from operating activities computed under GAAP or as indicators of our ability to fund our cash needs.
We analyze our operating performance principally by the rental revenue of our real estate and the revenues from our strategic capital business, net of operating, administrative and financing expenses. This income stream is not directly impacted by fluctuations in the market value of our investments in real estate or debt securities.
FFO, as modified by Prologis attributable to common stockholders/unitholders (“FFO, as modified by Prologis”)
To arrive at FFO, as modified by Prologis, we adjust the NAREIT defined FFO measure to exclude the impact of foreign currency related items and deferred tax, specifically:
| • | deferred income tax benefits and deferred income tax expenses recognized by our subsidiaries; |
|---|
| • | current income tax expense related to acquired tax liabilities that were recorded as deferred tax liabilities in an acquisition, to the extent the expense is offset with a deferred income tax benefit in earnings that is excluded from our defined FFO measure; and |
|---|
| • | foreign currency exchange gains and losses resulting from (i) debt transactions between us and our foreign entities, (ii) third-party debt that is used to hedge our investment in foreign entities, (iii) derivative financial instruments related to any such debt transactions, and (iv) mark-to-market adjustments associated with other derivative financial instruments. |
|---|
We use FFO, as modified by Prologis, so that management, analysts and investors are able to evaluate our performance against other REITs that do not have similar operations or operations in jurisdictions outside the U.S.
Core FFO attributable to common stockholders/unitholders (“Core FFO”)
In addition to FFO, as modified by Prologis, we also use Core FFO. To arrive at Core FFO, we adjust FFO, as modified by Prologis, to exclude the following recurring and nonrecurring items that we recognized directly in FFO, as modified by Prologis:
| • | gains or losses from the disposition of land and development properties that were developed with the intent to contribute or sell; |
|---|
| • | income tax expense related to the sale of investments in real estate; |
|---|
| • | impairment charges recognized related to our investments in real estate generally as a result of our change in intent to contribute or sell these properties; |
|---|
| • | gains or losses from the early extinguishment of debt and redemption and repurchase of preferred stock; and |
|---|
| • | expenses related to natural disasters. |
|---|
We use Core FFO, including by segment and geographies, to: (i) assess our operating performance as compared to other real estate companies; (ii) evaluate our performance and the performance of our properties in comparison with expected results and results of previous periods; (iii) evaluate the performance of our management; (iv) budget and forecast future results to assist in the allocation of resources; (v) provide guidance to the financial markets to understand our expected operating performance; and (vi) evaluate how a specific potential investment will impact our future results.
Limitations on the use of our FFO measures
While we believe our modified FFO measures are important supplemental measures, neither NAREIT’s nor our measures of FFO should be used alone because they exclude significant economic components of net earnings computed under GAAP and are, therefore, limited as an analytical tool. Accordingly, these are only a few of the many measures we use when analyzing our business. Some of the limitations are:
| • | The current income tax expenses that are excluded from our modified FFO measures represent the taxes and transaction costs that are payable. |
|---|
| • | Depreciation and amortization of real estate assets are economic costs that are excluded from FFO. FFO is limited, as it does not reflect the cash requirements that may be necessary for future replacements of the real estate assets. Furthermore, the amortization of capital expenditures and leasing costs necessary to maintain the operating performance of logistics facilities are not reflected in FFO. |
|---|
| • | Gains or losses from non-development property dispositions and impairment charges related to expected dispositions represent changes in value of the properties. By excluding these gains and losses, FFO does not capture realized changes in the value of disposed properties arising from changes in market conditions. |
|---|
| • | The deferred income tax benefits and expenses that are excluded from our modified FFO measures result from the creation of a deferred income tax asset or liability that may have to be settled at some future point. Our modified FFO measures do not currently reflect any income or expense that may result from such settlement. |
|---|
| • | The foreign currency exchange gains and losses that are excluded from our modified FFO measures are generally recognized based on movements in foreign currency exchange rates through a specific point in time. The ultimate settlement of our foreign currency-denominated net assets is indefinite as to timing and amount. Our FFO measures are limited in that they do not reflect the current period changes in these net assets that result from periodic foreign currency exchange rate movements. |
|---|
| • | The gains and losses on extinguishment of debt or preferred stock that we exclude from our Core FFO, may provide a benefit or cost to us as we may be settling our obligation at less or more than our future obligation. |
|---|
| • | The natural disaster expenses that we exclude from Core FFO are costs that we have incurred. |
|---|
We compensate for these limitations by using our FFO measures only in conjunction with net earnings computed under GAAP when making our decisions. This information should be read with our complete Consolidated Financial Statements prepared under GAAP. To assist investors in compensating for these limitations, we reconcile our modified FFO measures to our net earnings computed under GAAP as follows (in millions):
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Reconciliation of net earnings attributable to common stockholders/unitholders to FFO measures: | ||||||||
| Net earnings attributable to common stockholders | $ | 1,567 | $ | 1,643 | ||||
| Add (deduct) NAREIT defined adjustments: | ||||||||
| Real estate related depreciation and amortization | 1,102 | 913 | ||||||
| Gains on other dispositions of investments in real estate, net | (390 | ) | (371 | ) | ||||
| Reconciling items related to noncontrolling interests | (8 | ) | 23 | |||||
| Our share of reconciling items included in earnings related to unconsolidated entities | 246 | 142 | ||||||
| NAREIT defined FFO attributable to common stockholders/unitholders | 2,517 | 2,350 | ||||||
| Add (deduct) our modified adjustments: | ||||||||
| Unrealized foreign currency and derivative losses (gains), net | 69 | (120 | ) | |||||
| Deferred income tax expense | 12 | 1 | ||||||
| Current income tax expense on dispositions related to acquired tax liabilities | - | 1 | ||||||
| Our share of reconciling items included in earnings related to unconsolidated entities | (7 | ) | - | |||||
| FFO, as modified by Prologis attributable to common stockholders/unitholders | 2,591 | 2,232 | ||||||
| Adjustments to arrive at Core FFO: | ||||||||
| Gains on dispositions of development properties and land, net | (468 | ) | (470 | ) | ||||
| Current income tax expense on dispositions | 15 | 17 | ||||||
| Losses on early extinguishment of debt, net | 16 | 3 | ||||||
| Reconciling items related to noncontrolling interests | - | 6 | ||||||
| Our share of reconciling items included in earnings related to unconsolidated entities | 10 | - | ||||||
| Core FFO attributable to common stockholders/unitholders | $ | 2,164 | $ | 1,788 |
Previous: Item 6. Selected Financial Data · Next: Item 7A. Quantitative and Qualitative Disclosures About Market Risk