 filings.tools
Philip Morris International 10-K 2019-12-31
Filed 2020-02-07. 21 sections, 509K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2019
OR
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the transition period from to
Commission File Number: 001-33708
PHILIP MORRIS INTERNATIONAL INC.
(Exact name of registrant as specified in its charter)
| Virginia | 13-3435103 | |
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | |
| 120 Park Avenue | ||
| New York | ||
| New York | 10017 | |
| (Address of principal executive offices) | (Zip Code) |
917**-**663-2000
(Registrant’s telephone number, including area code)
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||
| Common Stock, no par value | PM | New York Stock Exchange | ||
| 2.000% Notes due 2020 | PM20B | New York Stock Exchange | ||
| Floating Notes due 2020 | PM20C | New York Stock Exchange | ||
| 1.750% Notes due 2020 | PM20A | New York Stock Exchange | ||
| 4.500% Notes due 2020 | PM20 | New York Stock Exchange | ||
| 1.875% Notes due 2021 | PM21B | New York Stock Exchange | ||
| 1.875% Notes due 2021 | PM21C | New York Stock Exchange | ||
| 4.125% Notes due 2021 | PM21 | New York Stock Exchange | ||
| 2.900% Notes due 2021 | PM21A | New York Stock Exchange | ||
| 2.625% Notes due 2022 | PM22A | New York Stock Exchange | ||
| 2.375% Notes due 2022 | PM22B | New York Stock Exchange | ||
| 2.500% Notes due 2022 | PM22 | New York Stock Exchange | ||
| 2.500% Notes due 2022 | PM22C | New York Stock Exchange | ||
| 2.625% Notes due 2023 | PM23 | New York Stock Exchange | ||
| 2.125% Notes due 2023 | PM23B | New York Stock Exchange | ||
| 3.600% Notes due 2023 | PM23A | New York Stock Exchange | ||
| 2.875% Notes due 2024 | PM24 | New York Stock Exchange | ||
| 2.875% Notes due 2024 | PM24C | New York Stock Exchange | ||
| 0.625% Notes due 2024 | PM24B | New York Stock Exchange |
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||
| 3.250% Notes due 2024 | PM24A | New York Stock Exchange | ||
| 2.750% Notes due 2025 | PM25 | New York Stock Exchange | ||
| 3.375% Notes due 2025 | PM25A | New York Stock Exchange | ||
| 2.750% Notes due 2026 | PM26A | New York Stock Exchange | ||
| 2.875% Notes due 2026 | PM26 | New York Stock Exchange | ||
| 0.125% Notes due 2026 | PM26B | New York Stock Exchange | ||
| 3.125% Notes due 2027 | PM27 | New York Stock Exchange | ||
| 3.125% Notes due 2028 | PM28 | New York Stock Exchange | ||
| 2.875% Notes due 2029 | PM29 | New York Stock Exchange | ||
| 3.375% Notes due 2029 | PM29A | New York Stock Exchange | ||
| 0.800% Notes due 2031 | PM31 | New York Stock Exchange | ||
| 3.125% Notes due 2033 | PM33 | New York Stock Exchange | ||
| 2.000% Notes due 2036 | PM36 | New York Stock Exchange | ||
| 1.875% Notes due 2037 | PM37A | New York Stock Exchange | ||
| 6.375% Notes due 2038 | PM38 | New York Stock Exchange | ||
| 1.450% Notes due 2039 | PM39 | New York Stock Exchange | ||
| 4.375% Notes due 2041 | PM41 | New York Stock Exchange | ||
| 4.500% Notes due 2042 | PM42 | New York Stock Exchange | ||
| 3.875% Notes due 2042 | PM42A | New York Stock Exchange | ||
| 4.125% Notes due 2043 | PM43 | New York Stock Exchange | ||
| 4.875% Notes due 2043 | PM43A | New York Stock Exchange | ||
| 4.250% Notes due 2044 | PM44 | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☑ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☑
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☑ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☑ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
Large accelerated filer ☑ Accelerated filer ☐
Non-accelerated filer ☐ Smaller reporting company ☐
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ☐ No ☑
As of June 30, 2019, the aggregate market value of the registrant’s common stock held by non-affiliates of the registrant was approximately $122 billion based on the closing sale price of the common stock as reported on the New York Stock Exchange.
| Class | Outstanding at | January 31, 2020 | ||
| Common Stock, no par value | 1,555,911,930 | shares |
DOCUMENTS INCORPORATED BY REFERENCE
| Document | Parts Into Which Incorporated |
| Portions of the registrant’s definitive proxy statement for use in connection with its annual meeting of shareholders to be held on May 6, 2020, to be filed with the Securities and Exchange Commission (“SEC”) on or about March 26, 2020. | Part III |
TABLE OF CONTENTS
In this report, “PMI,” “we,” “us” and “our” refers to Philip Morris International Inc. and its subsidiaries.
Trademarks and service marks in this report are the registered property of, or licensed by, the subsidiaries of Philip Morris International Inc. and are italicized.
PART I
Item 1. Business.
General Development of Business
General
Philip Morris International Inc. is a Virginia holding company incorporated in 1987. We are a leading international tobacco company engaged in the manufacture and sale of cigarettes, smoke-free products and associated electronic devices and accessories, and other nicotine-containing products in markets outside the United States of America. In addition, we ship a version of our Platform 1 device and its consumables authorized by the U.S. Food and Drug Administration ("FDA") to Altria Group, Inc., for sale in the United States under license.
We are leading a transformation in the tobacco industry to create a smoke-free future, based on a new category of reduced-risk products that, while not risk free, are a much better choice than continuing to smoke. Our goal is to ultimately replace cigarettes with smoke-free products to the benefit of adults who would otherwise continue to smoke, society, the company and its shareholders.
Reduced-risk products ("RRPs") is the term we use to refer to products that present, are likely to present, or have the potential to present less risk of harm to smokers who switch to these products versus continuing smoking. We have a range of RRPs in various stages of development, scientific assessment and commercialization. Because our RRPs do not burn tobacco, they produce an aerosol that contains far lower quantities of harmful and potentially harmful constituents than found in cigarette smoke. Through multidisciplinary capabilities in product development, state-of-the-art facilities and scientific substantiation, we aim to ensure that our RRPs meet adult consumer preferences and rigorous regulatory requirements.
Our IQOS smoke-free product brand portfolio includes heated tobacco and nicotine-containing vapor products. Our leading smoke-free platform ("Platform 1") is a precisely controlled device into which a specially designed heated tobacco unit is inserted and heated to generate an aerosol. We market our heated tobacco units under the brand names HEETS, HEETS Marlboro and HEETS FROM MARLBORO, defined collectively as HEETS, as well as Marlboro HeatSticks and Parliament HeatSticks. Platform 1 was first introduced in Nagoya, Japan, in 2014. As of December 31, 2019, Platform 1 is available for sale in 52 markets in key cities or nationwide.
Our cigarettes are sold in more than 180 markets, and in many of these markets they hold the number one or number two market share position. We have a wide range of premium, mid-price and low-price brands. Our portfolio comprises both international and local brands and is led by Marlboro, the world’s best-selling international cigarette, which accounted for approximately 37% of our total 2019 cigarette shipment volume. Marlboro is complemented in the premium-price category by Parliament. Our other leading international cigarette brands are Bond Street, Chesterfield, L&M, Lark and Philip Morris. These seven international cigarette brands contributed approximately 78% of our cigarette shipment volume in 2019. We also own a number of important local cigarette brands, such as Dji Sam Soe, Sampoerna A and Sampoerna U in Indonesia, and Fortune and Jackpot in the Philippines.
Source of Funds — Dividends
We are a legal entity separate and distinct from our direct and indirect subsidiaries. Accordingly, our right, and thus the right of our creditors and stockholders, to participate in any distribution of the assets or earnings of any subsidiary is subject to the prior rights of creditors of such subsidiary, except to the extent that claims of our company itself as a creditor may be recognized. As a holding company, our principal sources of funds, including funds to make payment on our debt securities, are from the receipt of dividends and repayment of debt from our subsidiaries. Our principal wholly owned and majority-owned subsidiaries currently are not limited by long-term debt or other agreements in their ability to pay cash dividends or to make other distributions with respect to their common stock that are otherwise compliant with law.
Description of Business
We manage our business in six operating segments as follows:
| • | The European Union Region (“EU”) is headquartered in Lausanne, Switzerland, and covers all the European Union countries and also Switzerland, Norway, Iceland and the United Kingdom; |
| • | The Eastern Europe Region (“EE”) is also headquartered in Lausanne and includes Southeast Europe, Central Asia, Ukraine, Israel and Russia; |
| • | The Middle East & Africa Region (“ME&A”) is also headquartered in Lausanne and covers the African continent, the Middle East, Turkey and our international duty free business; |
| • | The South & Southeast Asia Region (“S&SA”) is headquartered in Hong Kong and includes Indonesia, the Philippines and other markets in this region; |
| • | The East Asia & Australia Region (“EA&A”) is also headquartered in Hong Kong and includes Australia, Japan, South Korea, the People's Republic of China and other markets in this region, as well as Malaysia and Singapore; and |
| • | The Latin America & Canada Region (“LA&C”) is headquartered in New York and covers the South American continent, Central America, Mexico, the Caribbean and Canada. LA&C also includes transactions under license with Altria Group, Inc., for the distribution of our Platform 1 product in the United States. |
As of March 22, 2019, we deconsolidated the financial results of our Canadian subsidiary, Rothmans, Benson & Hedges Inc. ("RBH") from our financial statements. For further details, see Item 8, Note 22. Deconsolidation of RBH.
Following the deconsolidation of our Canadian subsidiary, we will continue to report the volume of brands sold by RBH for which other PMI subsidiaries are the trademark owners. These include HEETS, Next, Philip Morris and Rooftop, which together accounted for approximately 40% of RBH's total shipment volume in 2018.
References to total international market, defined as worldwide cigarette and heated tobacco unit volume excluding the United States, total industry, total market and market shares in this Form 10-K are our estimates for tax-paid products based on the latest available data from a number of internal and external sources and may, in defined instances, exclude the People's Republic of China and/or our duty free business. In addition, to reflect the deconsolidation of RBH, effective March 22, 2019, PMI's total market share has been restated for previous periods.
Our total shipments, including cigarettes and heated tobacco units, decreased by 2.0% in 2019 to 766.4 billion units. We estimate that international industry volumes, including cigarettes and heated tobacco units, were approximately 5.1 trillion units in 2019, a 0.9% decrease from 2018. Excluding the People’s Republic of China (“PRC”), we estimate that international cigarette and heated tobacco unit volume was 2.7 trillion units in 2019, a 2.0% decrease from 2018. We estimate that our reported share of the international market (which is defined as worldwide cigarette and heated tobacco unit volume, excluding the United States of America) was approximately 15.1% in 2019, 15.2% in 2018 and 15.1% in 2017. Excluding the PRC, we estimate that our reported share of the international market was approximately 28.4%, 28.3%, and 27.8% in 2019, 2018 and 2017, respectively.
Shipments of our principal cigarette brand, Marlboro, decreased by 0.6% in 2019 and represented approximately 10.0% of the international cigarette market, excluding the PRC, in 2019, 9.7% in 2018 and 9.7% in 2017.
Total shipment volume of heated tobacco units reached 59.7 billion units in 2019, up from 41.4 billion units in 2018.
We have a market share of at least 15% and, in a number of instances, substantially more than 15%, in approximately 95 markets, including Algeria, Argentina, Australia, Austria, Belgium, Brazil, the Czech Republic, Egypt, France, Germany, Hong Kong, Hungary, Indonesia, Israel, Italy, Japan, Kazakhstan, Korea, Kuwait, Mexico, the Netherlands, the Philippines, Poland, Portugal, Russia, Saudi Arabia, the Slovak Republic, Spain, Switzerland, Turkey and Ukraine.
Distribution & Sales
Our main types of distribution are tailored to the characteristics of each market and are often used simultaneously:
| • | Direct sales and distribution, where we have set up our own distribution selling directly to the retailers (including gas stations and other key accounts); |
| • | Distribution through independent distributors that often distribute other fast-moving consumer goods and are responsible for distribution in a particular market; |
| • | Exclusive zonified distribution, where the distributors are dedicated to us in tobacco products distribution and assigned to exclusive territories within a market; |
| • | Distribution through national or regional wholesalers that then supply the retail trade; and |
| • | Our own brand retail and e-commerce infrastructures for our RRP products and accessories. |
Competition
We are subject to highly competitive conditions in all aspects of our business. We compete primarily on the basis of product quality, brand recognition, brand loyalty, taste, R&D, innovation, packaging, customer service, marketing, advertising and retail price and, increasingly, adult smoker willingness to convert to our RRPs. In the combustible product category, we predominantly sell American blend cigarette brands, such as Marlboro, L&M, Parliament, Philip Morris and Chesterfield, which are the most popular across many of our markets. In the RRP product category, we predominantly sell Platform 1 devices and heated tobacco units under the IQOS brand umbrella. We seek to compete in all profitable retail price categories, although our brand portfolio is weighted towards the premium-price category.
The competitive environment and our competitive position can be significantly influenced by weak economic conditions, erosion of consumer confidence, competitors' introduction of lower-price products or innovative products, higher tobacco product taxes, higher absolute prices and larger gaps between retail price categories, and product regulation that diminishes the ability to differentiate tobacco products and restricts adult consumer access to truthful and non-misleading information about our RRPs. Competitors include three large international tobacco companies, new market entrants, particularly with respect to innovative products, several regional and local tobacco companies and, in some instances, state-owned tobacco enterprises, principally in Algeria, Egypt, the PRC, Taiwan, Thailand and Vietnam. Industry consolidation and privatizations of state-owned enterprises have led to an overall increase in competitive pressures. Some competitors have different profit and volume objectives, and some international competitors are susceptible to changes in different currency exchange rates. Certain new market entrants may alienate consumers from innovative products through inappropriate marketing campaigns and messaging and inferior product satisfaction, while not relying on scientific substantiation based on appropriate R&D protocols and standards. The growing use of digital media could increase the speed and extent of the dissemination of inaccurate and misleading information about our RRPs.
Procurement and Raw Materials
We purchase tobacco leaf of various types, grades and styles throughout the world, mostly through independent tobacco suppliers. In 2019, we also contracted directly with farmers in several countries, including Argentina, Brazil, Colombia, Ecuador, Italy, Pakistan, the Philippines and Poland. In 2019, direct sourcing from farmers represented approximately 23% of PMI’s global leaf requirements. The largest supplies of tobacco leaf are sourced from Argentina, Brazil, China, Italy, Indonesia (mostly for domestic use in kretek products), Malawi, Mozambique, the Philippines, Turkey and the United States.
We believe that there is an adequate supply of tobacco leaf in the world markets to satisfy our current and anticipated production requirements.
In addition to tobacco leaf, we purchase a wide variety of direct materials from a total of approximately 400 suppliers. In 2019, our top ten suppliers of direct materials combined represented approximately 50% of our total direct materials purchases. The three most significant direct materials that we purchase are printed paper board used in packaging, acetate tow used in filter making and fine paper used in the manufacturing of cigarettes and heated tobacco units. In addition, the adequate supply and procurement of cloves are of particular importance to our Indonesian business.
The adequate supply chain for our RRP portfolio, including the supply of electronic devices, is important to our business. We work with two electronics manufacturing service providers for the supply of our Platform 1 devices and a small number of other providers for other products in our RRP portfolio and related accessories. Although we work closely with these service providers on monitoring their
production capability and financial health, the commercialization of our RRPs could be adversely affected if they are unable to meet their commitments. The production of our RRP portfolio requires various metals, and we believe that there is an adequate supply of such metals in the world markets to satisfy our current and anticipated production requirements. However, some components and materials necessary for the production of our RRPs are obtained from single or limited sources, and can be subject to industry-wide shortages and price fluctuations. Our inability to secure an adequate supply of such components and materials could negatively impact the commercialization of our RRPs.
Our IQOS devices are subject to product warranties, which are described in more detail in Item 8. Financial Statements and Supplementary Data of this Annual Report on Form 10-K (“Item 8”) in Note 5. Product Warranty to our consolidated financial statements. We discuss our RRP products in more detail in Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations of this Annual Report on Form 10-K (“Item 7”) in Business Environment—Reduced-Risk Products.
Business Environment
Information called for by this Item is hereby incorporated by reference to the paragraphs in Item 7, Business Environment.
Other Matters
Customers
As described in more detail in “Distribution & Sales” above, in many of our markets we sell our products to distributors. In 2019, sales to a distributor in the European Union Region and a distributor in the East Asia & Australia Region each amounted to 10 percent or more of our consolidated net revenues. See Item 8, Note 12. Segment Reporting for more information. We believe that none of our business segments is dependent upon a single customer or a few customers, the loss of which would have a material adverse effect on our consolidated results of operations. In some of our markets, particularly in the European Union and in the East Asia & Australia Regions, a loss of a distributor may result in a temporary market disruption.
Employees
At December 31, 2019, we employed approximately 73,500 people worldwide, including full-time, temporary and part-time staff. Our businesses are subject to a number of laws and regulations relating to our relationship with our employees. Generally, these laws and regulations are specific to the location of each business. In addition, in accordance with European Union requirements, we have established a European Works Council composed of management and elected members of our workforce. We believe that our relations with our employees and their representative organizations are excellent.
Information About Our Executive Officers
The disclosure regarding executive officers is hereby incorporated by reference to the discussion under the heading “Information about our Executive Officers as of February 6, 2020” in Part III, Item 10. Directors, Executive Officers and Corporate Governance of this Annual Report on Form 10-K (“Item 10”).
Intellectual Property
Our trademarks are valuable assets, and their protection and reputation are essential to us. We own the trademark rights to all of our principal brands, including Marlboro, HEETS and IQOS, or have the right to use them in all countries where we use them.
In addition, we have a large number of granted patents and pending patent applications worldwide. Our patent portfolio, as a whole, is material to our business. However, no one patent, or group of related patents, is material to us. We also have registered industrial designs, as well as unregistered proprietary trade secrets, technology, know-how, processes and other unregistered intellectual property rights.
Effective January 1, 2008, PMI entered into an Intellectual Property Agreement with Philip Morris USA Inc. (“PM USA”), a wholly owned subsidiary of Altria Group, Inc. The Intellectual Property Agreement allocates ownership of jointly funded intellectual property as follows:
| • | PMI owns all rights to jointly funded intellectual property outside the United States, its territories and possessions; and |
| • | PM USA owns all rights to jointly funded intellectual property in the United States, its territories and possessions. |
The parties agreed to submit disputes under the Intellectual Property Agreement first to negotiation between senior executives and then to binding arbitration.
Seasonality
Our business segments are not significantly affected by seasonality, although in certain markets cigarette consumption trends may rise during the summer months due to outdoor use, longer daylight, and tourism.
Environmental Regulation
We are subject to international, national and local environmental laws and regulations in the countries in which we do business. We have specific programs across our business units designed to meet applicable environmental compliance requirements and reduce our carbon footprint and wastage as well as water and energy consumption. We report externally about our climate change mitigation strategy, together with associated targets and results in reducing our carbon footprint, through CDP (formerly, the Carbon Disclosure Project), the leading international non-governmental organization assessing the work of thousands of companies worldwide in the area of environmental impact, including climate change. Our environmental and occupational health and safety management system includes policies, standard practices and procedures at all our manufacturing centers. We also conduct regular safety assessments at our offices, warehouses and car fleet organizations. Furthermore, we have engaged an external certification body to validate the effectiveness of this management system at our manufacturing centers around the world, in accordance with internationally recognized standards for safety and environmental management. The environmental performance data we report externally is also verified by a qualified third party. Our subsidiaries expect to continue to make investments in order to drive improved performance and maintain compliance with environmental laws and regulations. We assess and report the compliance status of all our legal entities on a regular basis. Based on the management and controls we have in place and our review of climate change risks (both physical and regulatory), environmental expenditures have not had, and are not expected to have, a material adverse effect on our consolidated results of operations, capital expenditures, financial position, earnings or competitive position.
Available Information
We are required to file with the SEC annual, quarterly and current reports, proxy statements and other information required by the Securities Exchange Act of 1934, as amended (the “Exchange Act”). The SEC maintains an Internet website at http://www.sec.gov that contains reports, proxy and information statements, and other information regarding issuers that file electronically with the SEC, from which investors can electronically access our SEC filings.
We make available free of charge on, or through, our website at www.pmi.com our Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Exchange Act as soon as reasonably practicable after we electronically file such material with, or furnish it to, the SEC. Investors can access our filings with the SEC by visiting www.pmi.com.
The information on our website is not, and shall not be deemed to be, a part of this report or incorporated into any other filings we make with the SEC.
Item 1A. Risk Factors.
The following risk factors should be read carefully in connection with evaluating our business and the forward-looking statements contained in this Annual Report on Form 10-K. Any of the following risks could materially adversely affect our business, our operating results, our financial condition and the actual outcome of matters as to which forward-looking statements are made in this Annual Report on Form 10-K.
Forward-Looking and Cautionary Statements
We may from time to time make written or oral forward-looking statements, including statements contained in this Annual Report on Form 10-K and other filings with the SEC, in reports to stockholders and in press releases and investor webcasts. You can identify these forward-looking statements by use of words such as "strategy," "expects," "continues," "plans," "anticipates," "believes," "will," "estimates," "intends," "projects," "goals," "targets" and other words of similar meaning. You can also identify them by the fact that they do not relate strictly to historical or current facts.
We cannot guarantee that any forward-looking statement will be realized, although we believe we have been prudent in our plans and assumptions. Our RRPs constitute a new product category in its early stages that is less predictable than our mature cigarette business. Achievement of future results is subject to risks, uncertainties and inaccurate assumptions. Should known or unknown risks or uncertainties materialize, or should underlying assumptions prove inaccurate, actual results could vary materially from those anticipated, estimated or projected. Investors should bear this in mind as they consider forward-looking statements and whether to invest in or remain invested in our securities. In connection with the “safe harbor” provisions of the Private Securities Litigation Reform Act of 1995, we are identifying important factors that, individually or in the aggregate, could cause actual results and outcomes to differ materially from those contained in any forward-looking statements made by us; any such statement is qualified by reference to the following cautionary statements. We elaborate on these and other risks we face throughout this document, particularly in Item 7, Business Environment. You should understand that it is not possible to predict or identify all risk factors. Consequently, you should not consider the following to be a complete discussion of all potential risks or uncertainties. We do not undertake to update any forward-looking statement that we may make from time to time, except in the normal course of our public disclosure obligations.
Risks Related to Our Business and Industry
| • | Consumption of tax-paid cigarettes continues to decline in many of our markets. |
This decline is due to multiple factors, including increased taxes and pricing, governmental actions, the diminishing social acceptance of smoking, continuing economic and geopolitical uncertainty, and the continuing prevalence of illicit products. These factors and their potential consequences are discussed more fully below and in Item 7, Business Environment.
| • | Cigarettes are subject to substantial taxes. Significant increases in cigarette-related taxes have been proposed or enacted and are likely to continue to be proposed or enacted in numerous jurisdictions. These tax increases may disproportionately affect our profitability and make us less competitive versus certain of our competitors. |
Tax regimes, including excise taxes, sales taxes and import duties, can disproportionately affect the retail price of cigarettes versus other combustible tobacco products, or disproportionately affect the relative retail price of our cigarette brands versus cigarette brands manufactured by certain of our competitors. Because our portfolio is weighted toward the premium-price cigarette category, tax regimes based on sales price can place us at a competitive disadvantage in certain markets. As a result, our volume and profitability may be adversely affected in these markets.
Increases in cigarette taxes are expected to continue to have an adverse impact on our sales of cigarettes, due to resulting lower consumption levels, a shift in sales from manufactured cigarettes to other combustible tobacco products and from the premium-price to the mid-price or low-price cigarette categories, where we may be under-represented, from local sales to legal cross-border purchases of lower price products, or to illicit products such as contraband, counterfeit and "illicit whites."
| • | Our business faces significant governmental action aimed at increasing regulatory requirements with the goal of reducing or preventing the use of tobacco products. |
Governmental actions, combined with the diminishing social acceptance of smoking and private actions to restrict smoking, have resulted in reduced industry volume in many of our markets, and we expect that such factors will continue to reduce consumption levels and will increase down-trading and the risk of counterfeiting, contraband, "illicit whites" and legal cross-border purchases. Significant regulatory developments will continue to take place over the next few years in most of our markets, driven principally by the World Health Organization's Framework Convention on Tobacco Control (“FCTC”). Since it came into force in 2005, the FCTC has led to increased efforts by tobacco control advocates and public health organizations to promote increasingly restrictive regulatory measures on the marketing and sale of tobacco products to adult smokers. Regulatory initiatives that have been proposed, introduced or enacted include:
| • | restrictions on or licensing of outlets permitted to sell cigarettes; |
| • | the levying of substantial and increasing tax and duty charges; |
| • | restrictions or bans on advertising, marketing and sponsorship; |
| • | the display of larger health warnings, graphic health warnings and other labeling requirements; |
| • | restrictions on packaging design, including the use of colors, and plain packaging; |
| • | restrictions on packaging and cigarette formats and dimensions; |
| • | restrictions or bans on the display of tobacco product packaging at the point of sale and restrictions or bans on cigarette vending machines; |
| • | requirements regarding testing, disclosure and performance standards for tar, nicotine, carbon monoxide and other smoke constituents; |
| • | disclosure, restrictions, or bans of tobacco product ingredients; |
| • | increased restrictions on smoking in public and work places and, in some instances, in private places and outdoors; |
| • | regulation, restrictions or prohibitions of novel tobacco or nicotine-containing products; |
| • | elimination of duty free sales and duty free allowances for travelers; |
| • | encouraging litigation against tobacco companies; and |
| • | excluding tobacco companies from transparent public dialogue regarding public health and other policy matters. |
Our financial results could be significantly affected by regulatory initiatives resulting in a significant decrease in demand for our brands, in particular requirements that lead to a commoditization of tobacco products or impede adult consumers' ability to convert to our RRPs, as well as any significant increase in the cost of complying with new regulatory requirements.
| • | Litigation related to tobacco use and exposure to environmental tobacco smoke could substantially reduce our profitability and could severely impair our liquidity. |
There is litigation related to tobacco products pending in certain jurisdictions. Damages claimed in some tobacco-related litigation are significant and, in certain cases in Brazil, Canada, and Nigeria, range into the billions of U.S. dollars. We anticipate that new cases will continue to be filed. The FCTC encourages litigation against tobacco product manufacturers. It is possible that our consolidated results of operations, cash flows or financial position could be materially affected in a particular fiscal quarter or fiscal year by an unfavorable outcome or settlement of certain pending litigation. See Item 8, Note 18. Contingencies to our consolidated financial statements for a discussion of pending litigation and Item 7, Business Environment—Reduced-Risk Products (RRPs)—Legal Challenges to RRPs.
| • | We face intense competition, and our failure to compete effectively could have a material adverse effect on our profitability and results of operations. |
We compete primarily on the basis of product quality, brand recognition, brand loyalty, taste, R&D, innovation, packaging, customer service, marketing, advertising and retail price and, increasingly, adult smoker willingness to convert to our RRPs. We are subject to highly competitive conditions in all aspects of our business. The competitive environment and our competitive position can be significantly influenced by weak economic conditions, erosion of consumer confidence, competitors' introduction of lower-price products or innovative products, higher tobacco product taxes, higher absolute prices and larger gaps between retail price categories, and product regulation that diminishes the ability to differentiate tobacco products and restricts adult consumer access to truthful and non-misleading information about our RRPs. Competitors include three large international tobacco companies, new market entrants, particularly with respect to innovative products, several regional and local tobacco companies and, in some instances, state-owned tobacco enterprises, principally in Algeria, Egypt, the PRC, Taiwan, Thailand and Vietnam. Industry consolidation and privatizations of state-owned enterprises have led to an overall increase in competitive pressures. Some competitors have different profit and volume objectives, and some international competitors are susceptible to changes in different currency exchange rates. Certain new market entrants may alienate consumers from innovative products through inappropriate marketing campaigns and messaging and inferior product satisfaction, while not relying on scientific substantiation based on appropriate R&D protocols and standards. The growing use of digital media could increase the speed and extent of the dissemination of inaccurate and misleading information about our RRPs.
| • | Because we have operations in numerous countries, our results may be influenced by economic, regulatory and political developments, natural disasters, pandemics or conflicts. |
Some of the countries in which we operate face the threat of civil unrest and can be subject to regime changes. In others, nationalization, terrorism, conflict and the threat of war may have a significant impact on the business environment. Natural disasters, pandemics, economic, political, regulatory or other developments could disrupt our supply chain, manufacturing capabilities or distribution capabilities. In addition, such developments could lead to loss of property or equipment that are critical to our business in certain markets and difficulty in staffing and managing our operations, which could reduce our volumes, revenues and net earnings.
In certain markets, we are dependent on governmental approvals of various actions such as price changes, and failure to obtain such approvals could impair growth of our profitability.
In addition, despite our high ethical standards and rigorous control and compliance procedures aimed at preventing and detecting unlawful conduct, given the breadth and scope of our international operations, we may not be able to detect all potential improper or unlawful conduct by our employees and partners.
| • | We may be unable to anticipate changes in adult consumer preferences. |
Our business is subject to changes in adult consumer preferences, which may be influenced by local economic conditions. To be successful, we must:
| • | promote brand equity successfully; |
| • | anticipate and respond to new adult consumer trends; |
| • | develop new products and markets and broaden brand portfolios; |
| • | improve productivity; |
| • | convince adult smokers to convert to our RRPs; |
| • | ensure adequate production capacity to meet demand for our products; and |
| • | be able to protect or enhance margins through price increases. |
In periods of economic uncertainty, adult consumers may tend to purchase lower-price brands, and the volume of our premium-price and mid-price brands and our profitability could suffer accordingly. Such down-trading trends may be reinforced by regulation that limits branding, communication and product differentiation.
| • | The financial and business performance of our reduced-risk products is less predictable than our cigarette business. |
Our RRPs are novel products in a new category, and the pace at which adult smokers adopt them may vary, depending on the competitive, regulatory, fiscal and cultural environment, and other factors in a specific market. There may be periods of accelerated growth and periods of slower growth for these products, the timing and drivers of which may be more difficult for us to predict versus our mature cigarette business. The impact of this lower predictability on our projected results for a specific period may be significant, particularly during the early stages of this new product category.
| • | We lose revenues as a result of counterfeiting, contraband, cross-border purchases, “illicit whites,” non-tax-paid volume produced by local manufacturers, and counterfeiting of our Platform 1 device and heated tobacco units. |
Large quantities of counterfeit cigarettes are sold in the international market. We believe that Marlboro is the most heavily counterfeited international cigarette brand, although we cannot quantify the revenues we lose as a result of this activity. In addition, our revenues are reduced by contraband, legal cross-border purchases, “illicit whites” and non-tax-paid volume produced by local manufacturers. Our revenues and consumer satisfaction with our Platform 1 device and heated tobacco units may be adversely affected by counterfeit products that do not meet our product quality standards and scientific validation procedures.
| • | From time to time, we are subject to governmental investigations on a range of matters. |
Investigations include allegations of contraband shipments of cigarettes, allegations of unlawful pricing activities within certain markets, allegations of underpayment of income taxes, customs duties and/or excise taxes, allegations of false and misleading usage of descriptors, allegations of unlawful advertising, and allegations of unlawful labor practices. We cannot predict the outcome of those investigations or whether additional investigations may be commenced, and it is possible that our business could be materially affected by an unfavorable outcome of pending or future investigations. See Item, 8, Note 18. Contingencies—Other Litigation and Item 7, Business Environment—Governmental Investigations for a description of certain governmental investigations to which we are subject.
| • | We may be unsuccessful in our attempts to introduce reduced-risk products, and regulators may not permit the commercialization of these products or the communication of scientifically substantiated risk-reduction claims. |
Our key strategic priorities are: to develop and commercialize products that present less risk of harm to adult smokers who switch to those products versus continued smoking; and to convince current adult smokers who would otherwise continue to smoke to switch to those RRPs. For our efforts to be successful, we must: develop RRPs that such adult smokers find acceptable alternatives to smoking; conduct rigorous scientific studies to substantiate that they reduce exposure to harmful and potentially harmful constituents in smoke and, ultimately, that these products present, are likely to present, or have the potential to present less risk of harm to adult smokers who switch to them versus continued smoking; and effectively advocate for the development of science-based regulatory frameworks for the development and commercialization of RRPs, including communication of scientifically substantiated information to enable adult smokers to make better consumer choices. We might not succeed in our efforts. If we do not succeed, but others do, or if heat-not-burn products are inequitably regulated compared to other RRP categories without regard to the totality of the scientific evidence available for such products, we may be at a competitive disadvantage. In addition, actions of some market entrants, such as the inappropriate marketing of e-vapor products to youth, as well as alleged health consequences associated with the use of certain e-vapor products, may unfavorably impact public opinion and/or mischaracterize all e-vapor products or other RRPs to consumers, regulators and policy makers
without regard to the totality of scientific evidence for specific products. This may impede our efforts to advocate for the development of science-based regulatory frameworks for the development and commercialization of RRPs. We cannot predict whether regulators will permit the sale and/or marketing of RRPs with scientifically substantiated risk-reduction claims. Such restrictions could limit the success of our RRPs. Moreover, the FDA’s premarket tobacco product authorization of a version of our Platform 1 product is subject to strict marketing, reporting and other requirements and is not a guarantee that the product will remain authorized, particularly if there is a significant uptake in youth initiation.
| • | We may be unsuccessful in our efforts to differentiate reduced-risk products and cigarettes with respect to taxation. |
To date, we have been largely successful in demonstrating to regulators that our RRPs are not cigarettes, and as such they are generally taxed either as a separate category or as other tobacco products, which typically yields more favorable tax rates than cigarettes. If we cease to be successful in these efforts, RRP unit margins may be adversely affected.
| • | Our reported results could be adversely affected by unfavorable currency exchange rates, and currency devaluations could impair our competitiveness. |
We conduct our business primarily in local currency and, for purposes of financial reporting, the local currency results are translated into U.S. dollars based on average exchange rates prevailing during a reporting period. During times of a strengthening U.S. dollar, our reported net revenues, operating income and EPS will be reduced because the local currency translates into fewer U.S. dollars. During periods of local economic crises, foreign currencies may be devalued significantly against the U.S. dollar, reducing our margins. Actions to recover margins may result in lower volume and a weaker competitive position.
| • | Changes in the earnings mix and changes in tax laws may result in significant variability in our effective tax rates. Our ability to receive payments from foreign subsidiaries or to repatriate royalties and dividends could be restricted by local country currency exchange controls. |
The Tax Cuts and Jobs Act that was signed into law in December 2017 constitutes a major change to the U.S. tax system. Our estimated impact of the Tax Cuts and Jobs Act is based on management’s current interpretations, and our analysis is ongoing. Our final tax liability may be materially different from current estimates due to developments such as implementing regulations and clarifications. In future periods, our effective tax rate and our ability to recover deferred tax assets could be subject to additional uncertainty as a result of such developments. Furthermore, changes in the earnings mix or applicable foreign tax laws may result in significant variability in our effective tax rates. Because we are a U.S. holding company, our most significant source of funds is distributions from our non-U.S. subsidiaries. Certain countries in which we operate have adopted or could institute currency exchange controls that limit or prohibit our local subsidiaries' ability to convert local currency into U.S. dollars or to make payments outside the country. This could subject us to the risks of local currency devaluation and business disruption.
| • | Our ability to grow profitability may be limited by our inability to introduce new products, enter new markets or improve our margins through higher pricing and improvements in our brand and geographic mix. |
Our profit growth may suffer if we are unable to introduce new products or enter new markets successfully, to raise prices or to improve the proportion of our sales of higher margin products and in higher margin geographies.
| • | We may be unable to expand our brand portfolio through successful acquisitions or the development of strategic business relationships. |
One element of our growth strategy is to strengthen our brand portfolio and market positions through selective acquisitions and the development of strategic business relationships. Acquisition and strategic business development opportunities are limited and present risks of failing to achieve efficient and effective integration, strategic objectives and anticipated revenue improvements and cost savings. There is no assurance that we will be able to acquire attractive businesses on favorable terms, or that future acquisitions or strategic business developments will be accretive to earnings.
| • | Government mandated prices, production control programs, shifts in crops driven by economic conditions and the impact of climate change may increase the cost or reduce the quality of the tobacco and other agricultural products used to manufacture our products. |
As with other agricultural commodities, the price of tobacco leaf and cloves can be influenced by imbalances in supply and demand, and crop quality can be influenced by variations in weather patterns, including those caused by climate change. Tobacco production in certain countries is subject to a variety of controls, including government mandated prices and production control programs. Changes in the
patterns of demand for agricultural products could cause farmers to produce less tobacco or cloves. Any significant change in tobacco leaf and clove prices, quality and quantity could affect our profitability and our business.
| • | Our ability to achieve our strategic goals may be impaired if we fail to attract and retain the best global talent. |
To be successful, we must continue transforming our culture and ways of working, align our talent with our business needs, innovate and transform to a consumer-centric business. We compete for talent, including in areas that are new to us, such as digital and technical solutions, with companies in the consumer products, technology and other sectors that enjoy greater societal acceptance. As a result, we may be unable to attract and retain the best global talent with the right degree of diversity, experience and skills to achieve our strategic goals.
| • | The failure of our information systems to function as intended or their penetration by outside parties with the intent to corrupt them or our failure to comply with privacy laws and regulations could result in business disruption, litigation and regulatory action, and loss of revenue, assets or personal or other confidential data. |
We use information systems to help manage business processes, collect and interpret data and communicate internally and externally with employees, suppliers, consumers, customers and others. Some of these information systems are managed by third-party service providers. We have backup systems and business continuity plans in place, and we take care to protect our systems and data from unauthorized access. Nevertheless, failure of our systems to function as intended, or penetration of our systems by outside parties intent on extracting or corrupting information or otherwise disrupting business processes, could place us at a competitive disadvantage, result in a loss of revenue, assets or personal or other sensitive data, litigation and regulatory action, cause damage to our reputation and that of our brands and result in significant remediation and other costs. Failure to protect personal data, respect the rights of data subjects, and adhere to strict cybersecurity protocols could subject us to substantial fines and other legal challenges under regulations such as the EU General Data Protection Regulation. As we are increasingly relying on digital platforms in our business, the magnitude of these risks is likely to increase.
| • | We may be unable to adequately protect our intellectual property rights, and disputes relating to intellectual property rights could harm our business. |
Our intellectual property rights are valuable assets, and their protection is important to our business. If the steps we take to protect our intellectual property rights globally, including through a combination of trademark, design, patent and other intellectual property rights, are inadequate, or if others infringe or misappropriate our intellectual property rights, notwithstanding legal protection, our business could suffer. Intellectual property rights of third parties may limit our ability to introduce new products or improve the quality of existing products in one or more markets. Competitors or other third parties may claim that we infringe their intellectual property rights. Any such claims, regardless of merit, could divert management’s attention, be costly, disruptive, time-consuming and unpredictable and expose us to litigation costs and damages, and impede our ability to manufacture and sell new products or improve existing products. If, as a result, we are unable to manufacture or sell our RRPs or improve their quality in one or more markets, our ability to convert adult smokers to our RRPs in such markets would be adversely affected.
| • | We may be required to replace third-party contract manufacturers or service providers with our own resources. |
In certain instances, we contract with third parties to manufacture some of our products or product parts or to provide other services. We may be unable to renew these agreements on satisfactory terms for numerous reasons, including government regulations. Accordingly, our costs may increase significantly if we must replace such third parties with our own resources.
Item 1B. Unresolved Staff Comments.
None.
Item 2. . Properties.
We own or lease various manufacturing, office and research and development facilities in locations primarily outside the United States. We own properties in Switzerland where our operations center and state-of-the-art research and development facility are located.
At December 31, 2019, we operated and owned a total of 38 manufacturing facilities across our six operating segments. Among them, 7 factories produced heated tobacco units.
In 2019, certain facilities each manufactured over 30 billion units (cigarettes and heated tobacco units combined). The largest manufacturing facilities, in terms of volume, are located in Indonesia (S&SA), Turkey (ME&A), the Philippines (S&SA), Russia (EE), Poland (EU), Lithuania (EU), and Italy (EU). As part of our global operating model, products manufactured in a particular manufacturing facility are not necessarily distributed in the operating segment where the facility is located.
We have integrated the production of our heated tobacco units into a number of our existing manufacturing facilities, and we are progressing with our plans to build manufacturing capacity for our other RRP platforms. We will continue to optimize our manufacturing infrastructure.
We believe the properties owned or leased by our subsidiaries are maintained in good condition and are believed to be suitable and adequate for our present needs.
Item 3. Legal Proceedings.
The information called for by this Item is incorporated herein by reference to Item 8, Note 18. Contingencies.
Item 4. Mine Safety Disclosures.
Not applicable.
PART II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
The principal stock exchange on which our common stock (no par value) is listed is the New York Stock Exchange (ticker symbol "PM"). At January 31, 2020, there were approximately 50,800 holders of record of our common stock.
Performance Graph
The graph below compares the cumulative total shareholder return on PMI's common stock with the cumulative total return for the same period of PMI's Peer Group and the S&P 500 Index. The graph assumes the investment of $100 as of December 31, 2014, in PMI common stock (at prices quoted on the New York Stock Exchange) and each of the indices as of the market close and reinvestment of dividends on a quarterly basis.

| Date | PMI | PMI Peer Group (1) | S&P 500 Index | ||||
| December 31, 2014 | $100.00 | $100.00 | $100.00 | ||||
| December 31, 2015 | $113.40 | $108.20 | $101.40 | ||||
| December 31, 2016 | $123.10 | $109.70 | $113.50 | ||||
| December 31, 2017 | $147.60 | $130.20 | $138.30 | ||||
| December 31, 2018 | $98.60 | $118.30 | $132.20 | ||||
| December 31, 2019 | $133.00 | $146.40 | $173.90 |
(1) The PMI Peer Group presented in this graph is the same as that used in the prior year. The PMI Peer Group was established based on a review of four characteristics: global presence; a focus on consumer products; and net revenues and a market capitalization of a similar size to those of PMI. The review also considered the primary international tobacco companies. As a result of this review, the following companies constitute the PMI Peer Group: Altria Group, Inc., Anheuser-Busch InBev SA/NV, British American Tobacco p.l.c., The Coca-Cola Company, Colgate-Palmolive Co., Diageo plc, Heineken N.V., Imperial Brands PLC, Japan Tobacco Inc., Johnson & Johnson, Kimberly-Clark Corporation, The Kraft-Heinz Company, McDonald's Corp., Mondelēz International, Inc., Nestlé S.A., PepsiCo, Inc., The Procter & Gamble Company, Roche Holding AG, and Unilever NV and PLC.
Note: Figures are rounded to the nearest $0.10.
Issuer Purchases of Equity Securities During the Quarter Ended December 31, 2019
Our share repurchase activity for each of the three months in the quarter ended December 31, 2019, was as follows:
| Period | Total Number of Shares Repurchased | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Approximate Dollar Value of Shares that May Yet be Purchased Under the Plans or Programs | ||||||||||
| October 1, 2019 – October 31, 2019 (1) | — | $ | — | — | $ | — | ||||||||
| November 1, 2019 – November 30, 2019 (1) | — | $ | — | — | $ | — | ||||||||
| December 1, 2019 – December 31, 2019 (1) | — | $ | — | — | $ | — | ||||||||
| Pursuant to Publicly Announced Plans or Programs | — | $ | — | |||||||||||
| October 1, 2019 – October 31, 2019 (2) | 897 | $ | 75.37 | |||||||||||
| November 1, 2019 – November 30, 2019 (2) | 690 | $ | 81.33 | |||||||||||
| December 1, 2019 – December 31, 2019 (2) | 1,186 | $ | 82.69 | |||||||||||
| For the Quarter Ended December 31, 2019 | 2,773 | $ | 79.98 |
| (1) | During this reporting period, we did not have an authorized share repurchase program. |
| (2) | Shares repurchased represent shares tendered to us by employees who vested in restricted and performance share unit awards and used shares to pay all, or a portion of, the related taxes. |
Item 6. Selected Financial Data.
(in millions of dollars, except per share data)
| 2019 | 2018 | 2017 | 2016 | 2015 | |||||||||||||||
| Summary of Operations: | |||||||||||||||||||
| Revenues including excise taxes | $ | 77,921 | $ | 79,823 | $ | 78,098 | $ | 74,953 | $ | 73,908 | |||||||||
| Excise taxes on products | 48,116 | 50,198 | 49,350 | 48,268 | 47,114 | ||||||||||||||
| Net revenues | 29,805 | 29,625 | 28,748 | 26,685 | 26,794 | ||||||||||||||
| Operating income | 10,531 | 11,377 | 11,581 | 10,903 | 10,745 | ||||||||||||||
| Net earnings attributable to PMI | 7,185 | 7,911 | 6,035 | 6,967 | 6,873 | ||||||||||||||
| Basic earnings per share | 4.61 | 5.08 | 3.88 | 4.48 | 4.42 | ||||||||||||||
| Diluted earnings per share | 4.61 | 5.08 | 3.88 | 4.48 | 4.42 | ||||||||||||||
| Dividends declared per share | 4.62 | 4.49 | 4.22 | 4.12 | 4.04 | ||||||||||||||
| Total assets | 42,875 | 39,801 | 42,968 | 36,851 | 33,956 | ||||||||||||||
| Long-term debt (1) | 26,656 | 26,975 | 31,334 | 25,851 | 25,250 | ||||||||||||||
| Total debt | 31,045 | 31,759 | 34,339 | 29,067 | 28,480 |
(1) Excluding current portion of long-term debt.
This Selected Financial Data should be read in conjunction with Item 7 and Item 8.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
The following discussion should be read in conjunction with the other sections of this Annual Report on Form 10-K, including the consolidated financial statements and related notes contained in Item 8, and the discussion of risks and cautionary factors that may affect future results in Item 1A. Risk Factors.
Description of Our Company
We are leading a transformation in the tobacco industry to create a smoke-free future and ultimately replace cigarettes with smoke-free products to the benefit of adults who would otherwise continue to smoke, society, the company and its shareholders. We are a leading international tobacco company engaged in the manufacture and sale of cigarettes, as well as smoke-free products and associated electronic devices and accessories, and other nicotine-containing products in markets outside the United States. In addition, we ship a version of our Platform 1 device and its consumables authorized by the U.S. Food and Drug Administration ("FDA") to Altria Group, Inc., for sale in the United States under license. We are building a future on a new category of smoke-free products that, while not risk free, are a much better choice than continuing to smoke. Through multidisciplinary capabilities in product development, state-of-the-art facilities and scientific substantiation, we aim to ensure that our smoke-free products meet adult consumer preferences and rigorous regulatory requirements. Our IQOS smoke-free product brand portfolio includes heat-not-burn tobacco and nicotine-containing vapor products.
We manage our business in six operating segments:
| • | European Union ("EU"); |
| • | Eastern Europe ("EE"); |
| • | Middle East & Africa ("ME&A"), which includes our international duty free business; |
| • | South & Southeast Asia ("S&SA"); |
| • | East Asia & Australia ("EA&A"); and |
| • | Latin America & Canada ("LA&C"), which includes transactions under license with Altria Group, Inc. for the distribution of our Platform 1 product in the United States. |
Our cigarettes are sold in more than 180 markets, and in many of these markets they hold the number one or number two market share position. We have a wide range of premium, mid-price and low-price brands. Our portfolio comprises both international and local brands. In addition to the manufacture and sale of cigarettes, we are engaged in the development and commercialization of reduced-risk products ("RRPs"). RRPs is the term we use to refer to products that present, are likely to present, or have the potential to present less risk of harm to smokers who switch to these products versus continuing smoking.
We use the term net revenues to refer to our operating revenues from the sale of our products, including shipping and handling charges billed to customers, net of sales and promotion incentives, and excise taxes. Our net revenues and operating income are affected by various factors, including the volume of products we sell, the price of our products, changes in currency exchange rates and the mix of products we sell. Mix is a term used to refer to the proportionate value of premium-price brands to mid-price or low-price brands in any given market (product mix). Mix can also refer to the proportion of shipment volume in more profitable markets versus shipment volume in less profitable markets (geographic mix).
Our cost of sales consists principally of: tobacco leaf, non-tobacco raw materials, labor and manufacturing costs; shipping and handling costs; and the cost of the IQOS devices produced by third-party electronics manufacturing service providers. Estimated costs associated with IQOS warranty programs are generally provided for in cost of sales in the period the related revenues are recognized.
Our marketing, administration and research costs include the costs of marketing and selling our products, other costs generally not related to the manufacture of our products (including general corporate expenses), and costs incurred to develop new products. The most significant components of our marketing, administration and research costs are marketing and sales expenses and general and administrative expenses.
Philip Morris International Inc. is a legal entity separate and distinct from its direct and indirect subsidiaries. Accordingly, our right, and thus the right of our creditors and stockholders, to participate in any distribution of the assets or earnings of any subsidiary is subject to the prior rights of creditors of such subsidiary, except to the extent that claims of our company itself as a creditor may be recognized. As a holding company, our principal sources of funds, including funds to make payment on our debt securities, are from the receipt of
dividends and repayment of debt from our subsidiaries. Our principal wholly owned and majority-owned subsidiaries currently are not limited by long-term debt or other agreements in their ability to pay cash dividends or to make other distributions with respect to their common stock that are otherwise compliant with law.
Executive Summary
The following executive summary provides significant highlights from the Discussion and Analysis that follows.
Consolidated Operating Results
| • | Net Revenues – Net revenues of $29.8 billion for the year ended December 31, 2019, increased by $0.2 billion, or 0.6%, from the comparable 2018 amount. The change in our net revenues from the comparable 2018 amount was driven by the following (variances not to scale with year-to-date results): |

Net revenues, excluding unfavorable currency, increased by 3.8%, mainly reflecting: a favorable pricing variance, notably in Germany, Indonesia, Japan, the Philippines and Turkey; and favorable volume/mix, mainly driven by heated tobacco unit and IQOS device volume in the EU and Russia, and heated tobacco unit volume in Japan, partly offset by unfavorable volume/mix of cigarettes, notably in Australia, the EU, Indonesia, Japan and Russia, unfavorable heated tobacco unit volume in PMI Duty Free, and unfavorable IQOS device volume in Japan and Korea. The currency-neutral growth in net revenues of 3.8% came despite the unfavorable impact of $763 million, shown in "Other" above, predominantly resulting from the deconsolidation of our Canadian subsidiary, Rothmans, Benson & Hedges, Inc. ("RBH"), effective March 22, 2019. For further details on the deconsolidation of RBH, see Item 8, Note 18. Contingencies and Note 22. Deconsolidation of RBH.
Net revenues by product category for the years ended December 31, 2019 and 2018, are shown below:
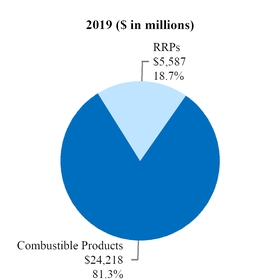
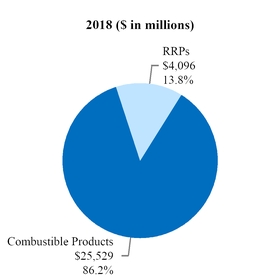
| • | Diluted Earnings Per Share – The changes in our reported diluted earnings per share (“diluted EPS”) for the year ended December 31, 2019, from the comparable 2018 amounts, were as follows: |
| Diluted EPS | % Growth (Decline) | ||||
| For the year ended December 31, 2018 | $ | 5.08 | |||
| 2018 Asset impairment and exit costs | — | ||||
| 2018 Tax items | 0.02 | ||||
| Subtotal of 2018 items | 0.02 | ||||
| 2019 Asset impairment and exit costs | (0.23 | ) | |||
| 2019 Canadian tobacco litigation-related expense | (0.09 | ) | |||
| 2019 Loss on deconsolidation of RBH | (0.12 | **) |
Showing the first 8K of 167K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
The information called for by this Item is included in Item 7, Market Risk.
Item 8. Financial Statements and Supplementary Data.
Consolidated Statements of Earnings
(in millions of dollars, except per share data)
| for the years ended December 31, | 2019 | 2018 | 2017 | ||||||||
| Revenues including excise taxes | $ | 77,921 | $ | 79,823 | $ | 78,098 | |||||
| Excise taxes on products | 48,116 | 50,198 | 49,350 | ||||||||
| Net revenues | 29,805 | 29,625 | 28,748 | ||||||||
| Cost of sales | 10,513 | 10,758 | 10,432 | ||||||||
| Gross profit | 19,292 | 18,867 | 18,316 | ||||||||
| Marketing, administration and research costs (Notes 18, 21 & 22) | 8,695 | 7,408 | 6,647 | ||||||||
| Amortization of intangibles | 66 | 82 | 88 | ||||||||
| Operating income | 10,531 | 11,377 | 11,581 | ||||||||
| Interest expense, net (Note 14) | 570 | 665 | 914 | ||||||||
| Pension and other employee benefit costs (Note 13) | 89 | 41 | 78 | ||||||||
| Earnings before income taxes | 9,872 | 10,671 | 10,589 | ||||||||
| Provision for income taxes (Note 11) | 2,293 | 2,445 | 4,307 | ||||||||
| Equity investments and securities (income)/loss, net | (149 | ) | (60 | ) | (59 | ) | |||||
| Net earnings | 7,728 | 8,286 | 6,341 | ||||||||
| Net earnings attributable to noncontrolling interests | 543 | 375 | 306 | ||||||||
| Net earnings attributable to PMI | $ | 7,185 | $ | 7,911 | $ | 6,035 | |||||
| Per share data (Note 10): | |||||||||||
| Basic earnings per share | $ | 4.61 | $ | 5.08 | $ | 3.88 | |||||
| Diluted earnings per share | $ | 4.61 | $ | 5.08 | $ | 3.88 |
See notes to consolidated financial statements.
Consolidated Statements of Comprehensive Earnings
(in millions of dollars)
| for the years ended December 31, | 2019 | 2018 | 2017 | ||||||||
| Net earnings | $ | 7,728 | $ | 8,286 | $ | 6,341 | |||||
| Other comprehensive earnings (losses), net of income taxes: | |||||||||||
| Change in currency translation adjustments: | |||||||||||
| Unrealized gains (losses), net of income taxes of ($161) in 2019, ($47) in 2018 and $620 in 2017 | 505 | (812 | ) | 330 | |||||||
| (Gains)/losses transferred to earnings, net of income taxes of $0 in 2019, 2018 and 2017 | — | — | (2 | ) | |||||||
| (Gains)/losses transferred to earnings - deconsolidation of RBH, net of income taxes of $0 in 2019, 2018 and 2017 (Note 22) | 502 | — | — | ||||||||
| Change in net loss and prior service cost: | |||||||||||
| Net gains (losses) and prior service costs, net of income taxes of $247 in 2019, $65 in 2018 and ($17) in 2017 | (454 | ) | (1,046 | ) | 523 | ||||||
| Amortization of net losses, prior service costs and net transition costs, net of income taxes of ($69) in 2019, ($43) in 2018 and ($31) in 2017 | 243 | 218 | 228 | ||||||||
| (Gains)/losses transferred to earnings - deconsolidation of RBH, net of income taxes of ($15) in 2019, $0 in 2018 and $0 in 2017 (Note 22) | 27 | — | — | ||||||||
| Change in fair value of derivatives accounted for as hedges: | |||||||||||
| Gains (losses) recognized, net of income taxes of $2 in 2019, ($4) in 2018 and $8 in 2017 | (18 | ) | 24 | (44 | ) | ||||||
| (Gains) losses transferred to earnings, net of income taxes of $3 in 2019, $5 in 2018 and $2 in 2017 | (14 | ) | (31 | ) | (11 | ) | |||||
| Total other comprehensive earnings (losses) | 791 | (1,647 | ) | 1,024 | |||||||
| Total comprehensive earnings | 8,519 | 6,639 | 7,365 | ||||||||
| Less comprehensive earnings attributable to: | |||||||||||
| Noncontrolling interests | 586 | 304 | 306 | ||||||||
| Comprehensive earnings attributable to PMI | $ | 7,933 | $ | 6,335 | $ | 7,059 |
See notes to consolidated financial statements.
Consolidated Balance Sheets
(in millions of dollars, except share data)
| at December 31, | 2019 | 2018 | |||||
| Assets | |||||||
| Cash and cash equivalents | $ | 6,861 | $ | 6,593 | |||
| Trade receivables (less allowances of $20 in 2019 and $25 in 2018) | 3,080 | 2,950 | |||||
| Other receivables | 637 | 614 | |||||
| Inventories: | |||||||
| Leaf tobacco | 2,052 | 2,318 | |||||
| Other raw materials | 1,596 | 1,405 | |||||
| Finished product | 5,587 | 5,081 | |||||
| 9,235 | 8,804 | ||||||
| Other current assets | 701 | 481 | |||||
| Total current assets | 20,514 | 19,442 | |||||
| Property, plant and equipment, at cost: | |||||||
| Land and land improvements | 566 | 600 | |||||
| Buildings and building equipment | 4,132 | 3,975 | |||||
| Machinery and equipment | 9,354 | 9,096 | |||||
| Construction in progress | 394 | 886 | |||||
| 14,446 | 14,557 | ||||||
| Less: accumulated depreciation | 7,815 | 7,356 | |||||
| 6,631 | 7,201 | ||||||
| Goodwill (Note 3) | 5,858 | 7,189 | |||||
| Other intangible assets, net (Note 3) | 2,113 | 2,278 | |||||
| Investments in unconsolidated subsidiaries and equity securities (Notes 4 & 16) | 4,635 | 1,269 | |||||
| Deferred income taxes | 1,153 | 977 | |||||
| Other assets | 1,971 | 1,445 | |||||
| Total Assets | $ | 42,875 | $ | 39,801 |
See notes to consolidated financial statements.
| at December 31, | 2019 | 2018 | |||||
| Liabilities | |||||||
| Short-term borrowings (Note 7) | $ | 338 | $ | 730 | |||
| Current portion of long-term debt (Note 7) | 4,051 | 4,054 | |||||
| Accounts payable | 2,299 | 2,068 | |||||
| Accrued liabilities: | |||||||
| Marketing and selling | 666 | 732 | |||||
| Taxes, except income taxes | 5,837 | 5,088 | |||||
| Employment costs | 1,042 | 794 | |||||
| Dividends payable | 1,831 | 1,783 | |||||
| Other | 1,973 | 1,366 | |||||
| Income taxes (Note 11) | 796 | 576 | |||||
| Total current liabilities | 18,833 | 17,191 | |||||
| Long-term debt (Note 7) | 26,656 | 26,975 | |||||
| Deferred income taxes | 908 | 898 | |||||
| Employment costs | 3,634 | 3,083 | |||||
| Income taxes and other liabilities (Note 11) | 2,443 | 2,393 | |||||
| Total liabilities | 52,474 | 50,540 | |||||
| Contingencies (Note 18) | |||||||
| Stockholders’ (Deficit) Equity | |||||||
| Common stock, no par value (2,109,316,331 shares issued in 2019 and 2018) | — | — | |||||
| Additional paid-in capital | 2,019 | 1,939 | |||||
| Earnings reinvested in the business | 30,987 | 31,014 | |||||
| Accumulated other comprehensive losses |
Showing the first 8K of 238K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure.
None.
Item 9A. Controls and Procedures.
PMI carried out an evaluation, with the participation of PMI’s management, including PMI’s Chief Executive Officer and Chief Financial Officer, of the effectiveness of PMI’s disclosure controls and procedures (as defined in Rule 13a-15(e) under the Securities Exchange Act of 1934, as amended) as of the end of the period covered by this report. Based upon that evaluation, PMI’s Chief Executive Officer and Chief Financial Officer concluded that PMI’s disclosure controls and procedures are effective. There have been no changes in PMI’s internal control over financial reporting during the most recent fiscal quarter that have materially affected, or are reasonably likely to materially affect, PMI’s internal control over financial reporting.
The Report of Management on Internal Control over Financial Reporting and the Report of Independent Registered Public Accounting Firm are included in Item 8.
Item 9B. Other Information.
None.
PART III
Except for the information relating to the executive officers set forth in Item 10 and the information relating to equity compensation plans set forth in Item 12, the information called for by Items 10-14 is hereby incorporated by reference to PMI’s definitive proxy statement for use in connection with its annual meeting of stockholders to be held on May 6, 2020, that will be filed with the SEC on or about March 26, 2020 (the “proxy statement”), and, except as indicated therein, made a part hereof.
Item 10. Directors, Executive Officers and Corporate Governance.
Information About Our Executive Officers as of February 6, 2020**:**
| Name | Office | Age | ||||
| André Calantzopoulos | Chief Executive Officer | 62 | ||||
| Massimo Andolina | Senior Vice President, Operations | 51 | ||||
| Drago Azinovic | President, Middle East & Africa Region and PMI Duty Free | 57 | ||||
| Werner Barth | Senior Vice President, Commercial | 55 | ||||
| Charles Bendotti | Senior Vice President, People and Culture | 47 | ||||
| Frank de Rooij | Vice President, Treasury and Corporate Finance | 54 | ||||
| Frederic de Wilde | President, European Union Region | 52 | ||||
| Marc S. Firestone | President, External Affairs and General Counsel | 60 | ||||
| Stacey Kennedy | President, South and Southeast Asia Region | 47 | ||||
| Martin G. King | Chief Financial Officer | 55 | ||||
| Michael Kunst | Senior Vice President, Commercial Transformation | 51 | ||||
| Andreas Kurali | Vice President and Controller | 54 | ||||
| Bin Li | Chief Product Officer | 48 | ||||
| Marco Mariotti | President, Eastern Europe Region | 55 | ||||
| Mario Masseroli | President, Latin America & Canada Region | 49 | ||||
| Deepak Mishra | Chief Strategy Officer | 48 | ||||
| John O'Mullane | Chief Life Sciences Officer | 66 | ||||
| Jacek Olczak | Chief Operating Officer | 55 | ||||
| Paul Riley | President, East Asia and Australia Region | 54 | ||||
| Marian Salzman | Senior Vice President, Global Communications | 61 | ||||
| Jaime Suarez | Chief Digital Officer | 46 | ||||
| Michael Voegele | Chief Technology Officer | 47 | ||||
| Stefano Volpetti | Chief Consumer Officer | 48 | ||||
| Jerry E. Whitson | Deputy General Counsel and Corporate Secretary | 64 | ||||
| Miroslaw Zielinski | Chief New Ventures Officer | 58 |
All of the above-mentioned officers, except Ms. Salzman, Mr. Mishra, Mr. Kunst, Mr. Voegele, Mr. O'Mullane, Mr. Volpetti and Mr. Li, have been employed by us in various capacities during the past five years.
Before joining Philip Morris International Inc. in April 2018, Ms. Salzman headed Havas PR North America, where she had served as Chief Executive Officer from 2011.
Before joining Philip Morris International Inc. in September 2018, Mr. Mishra was Managing Director, Portfolio Operations at Centerbridge Partners, a private equity firm, from 2014, where he led commercial, operational and digital transformation in various business sectors. From 2001 to 2014, Mr. Mishra was Partner and part of the Consumer Goods, Retail and Operations leadership team of McKinsey & Co, where he supported clients in their transformation projects.
Before joining Philip Morris International Inc. in January 2019, Mr. Kunst was Partner at Bain & Company from 2009, most recently working with us on our transformation projects.
Before joining Philip Morris International Inc. in February 2019, Mr. Voegele had served in various senior capacities at Adidas Group from 2011, most recently, as Global CIO and part of the core leadership team at Adidas Group.
Before joining Philip Morris International Inc. in May 2019, Mr. O'Mullane was Global Head SVP Innovation and Development for Consumer Health at Bayer AG from 2014.
Before joining Philip Morris International Inc. in June 2019, Mr. Volpetti served in various executive capacities at the Procter & Gamble Company from 1996, most recently, as Vice President of a global business unit. He also served as Chief Marketing Officer at Luxottica Group S.p.A. in 2015.
Before joining Philip Morris International Inc. in August 2019, Mr. Li served in various executive capacities at Harman International, a subsidiary of Samsung Electronics Co. Ltd., from 2010, most recently, as Senior Vice President and General Manager, Consumer Audio Product Development and Operations.
Codes of Conduct and Corporate Governance
We have adopted the Philip Morris International Code of Conduct, which complies with requirements set forth in Item 406 of Regulation S-K. This Code of Conduct applies to all of our employees, including our principal executive officer, principal financial officer, principal accounting officer or controller, and persons performing similar functions. We have also adopted a code of business conduct and ethics that applies to the members of our Board of Directors. These documents are available free of charge on our website at www.pmi.com.
In addition, we have adopted corporate governance guidelines and charters for our Audit, Finance, Compensation and Leadership Development, Product Innovation and Regulatory Affairs and Nominating and Corporate Governance committees of the Board of Directors. All of these documents are available free of charge on our website at www.pmi.com. Any waiver granted by Philip Morris International Inc. to its principal executive officer, principal financial officer or controller or any person performing similar functions under the Code of Conduct, or certain amendments to the Code of Conduct, will be disclosed on our website at www.pmi.com.
The information on our website is not, and shall not be deemed to be, a part of this Report or incorporated into any other filings made with the SEC.
Also refer to Board Operations and Governance—Committees of the Board, Election of Directors—Process for Nominating Directors and Election of Directors—Director Nominees and Delinquent Section 16(a) Reports sections of the proxy statement.
Item 11. Executive Compensation.
Refer to Compensation Discussion and Analysis and Compensation of Directors sections of the proxy statement.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
The number of shares to be issued upon exercise or vesting and the number of shares remaining available for future issuance under PMI’s equity compensation plans at December 31, 2019, were as follows:
| Number of Securities to be Issued upon Exercise of Outstanding Options and Vesting of RSUs and PSUs (a) | Weighted Average Exercise Price of Outstanding Options (b) | Number of Securities Remaining Available for Future Issuance Under Equity Compensation Plans (excluding Securities reflected in column (a)) (c) | |||||||
| Equity compensation plans approved by stockholders | 6,289,960 (1) | $ | — | 21,081,444 |
(1) Represents 3,725,870 shares of common stock that may be issued upon vesting of the restricted share units and 2,564,090 shares that may be issued upon vesting of the performance share units if maximum performance targets are achieved for each performance cycle. PMI has not granted options since the spin-off from Altria on March 28, 2008.
Also refer to Stock Ownership Information—Ownership of Equity Securities section of the proxy statement.
Item 13. Certain Relationships and Related Transactions, and Director Independence.
Refer to Related Person Transactions and Code of Conduct and Election of Directors—Independence of Nominees sections of the proxy statement.
Item 14. Principal Accounting Fees and Services.
Refer to Audit Committee Matters section of the proxy statement.
PART IV
Item 15. Exhibits and Financial Statement Schedules.
(a) Index to Consolidated Financial Statements and Schedules
| Page | |
| Consolidated Statements of Earnings for the years ended December 31, 2019, 2018 and 2017 | 53 |
| Consolidated Statements of Comprehensive Earnings for the years ended December 31, 2019, 2018 and 2017 | 54 |
| Consolidated Balance Sheets at December 31, 2019 and 2018 | 55 - 56 |
| Consolidated Statements of Cash Flows for the years ended December 31, 2019, 2018 and 2017 | 57 - 58 |
| Consolidated Statements of Stockholders’ (Deficit) Equity for the years ended December 31, 2019, 2018 and 2017 | 59 |
| Notes to Consolidated Financial Statements | 60 - 109 |
| Report of Independent Registered Public Accounting Firm | 110 - 112 |
| Report of Management on Internal Control Over Financial Reporting | 113 |
Schedules have been omitted either because such schedules are not required or are not applicable.
(b) The following exhibits are filed as part of this Report:
| 4.6 | — | The Registrant agrees to furnish copies of any instruments defining the rights of holders of long-term debt of the Registrant and its consolidated subsidiaries that does not exceed 10 percent of the total assets of the Registrant and its consolidated subsidiaries to the Commission upon request. | ||
| 10.1 | — | Employee Matters Agreement between Altria Group, Inc. and Philip Morris International Inc., dated as of March 28, 2008 (incorporated by reference to Exhibit 10.2 to the Current Report on Form 8-K filed March 31, 2008). | ||
| 10.2 | — | Intellectual Property Agreement between Philip Morris International Inc. and Philip Morris USA Inc., dated as of January 1, 2008 (incorporated by reference to Exhibit 10.4 to the Registration Statement on Form 10 filed March 5, 2008). |
| 101.CAL | — | XBRL Taxonomy Extension Calculation Linkbase. | ||
| 101.DEF | — | XBRL Taxonomy Extension Definition Linkbase. | ||
| 101.LAB | — | XBRL Taxonomy Extension Label Linkbase. | ||
| 101.PRE | — | XBRL Taxonomy Extension Presentation Linkbase. | ||
| 104 | — | Cover Page Interactive Data File (formatted as Inline XBRL and contained in Exhibit 101) |
| * | Denotes management contract or compensatory plan or arrangement in which directors or executive officers are eligible to participate. |
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| PHILIP MORRIS INTERNATIONAL INC. | |
| By: | /s/ ANDRÉ CALANTZOPOULOS |
| (André Calantzopoulos Chief Executive Officer) |
Date: February 7, 2020
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the date indicated:
| Signature | Title | Date |
| /s/ ANDRÉ CALANTZOPOULOS | Chief Executive Officer | February 7, 2020 |
| (André Calantzopoulos) | ||
| /s/ MARTIN G. KING | Chief Financial Officer | February 7, 2020 |
| (Martin G. King) | ||
| /s/ ANDREAS KURALI | Vice President and Controller | February 7, 2020 |
| (Andreas Kurali) | ||
| *LOUIS C. CAMILLERI, MASSIMO FERRAGAMO, WERNER GEISSLER, LISA A. HOOK, JENNIFER LI, JUN MAKIHARA, KALPANA MORPARIA, LUCIO A. NOTO, FREDERIK PAULSEN, ROBERT B. POLET, STEPHEN M. WOLF | Directors |
| *By: | /s/ ANDRÉ CALANTZOPOULOS | February 7, 2020 | |
| (André Calantzopoulos Attorney-in-fact) |