 filings.tools
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
131K characters. Original on sec.gov · Markdown
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
Forward-Looking Statements
Statements in this Annual Report about anticipated financial results and growth, as well as about the development of our products and markets, are forward-looking statements that are based on our current plans and assumptions. Important information about the bases for these plans and assumptions and factors that may cause our actual results to differ materially from these statements is contained below and in Item 1A. “Risk Factors” of this Annual Report.
Unless otherwise indicated, all references to a year reflect our fiscal year that ends on September 30.
Operating and Non-GAAP Financial Measures
Our discussion of results includes discussion of our operating measures (including "ARR," “license and subscription bookings” and other subscription-related measures) and non-GAAP financial measures. Our operating measures and non-GAAP financial measures, including the reasons we use those measures, are described below in Results of Operations - Operating Measures and Results of Operations - Non-GAAP Financial Measures, respectively. You should read those sections to understand our operating and non-GAAP financial measures.
Revenue Sources and Recognition
We sell software subscription and perpetual licenses, support for perpetual licenses, cloud services and professional services.
Subscription revenue is comprised of time-based licenses whereby customers use our software and receive related support for a specified term. Results for reporting periods beginning on or after October 1, 2018 are presented under the Accounting Standards Update No. 2014-09, Revenue from Contracts with Customers: Topic 606 (ASC 606), while prior period amounts are not adjusted and continue to be reported in accordance with the guidance provided by ASC 985-605, Software-Revenue Recognition and revenues for non-software deliverables in accordance with ASC 605-25, Revenue Recognition, Multiple-Element Arrangements (ASC 605). Through 2018, revenue for our subscription contracts was recognized ratably over the term of the contract under ASC 605; this differs from how revenue for such contracts is recognized under ASC 606. Our contracts with customers may include multiple goods and services. Under ASC 606, revenue is recognized for each performance obligation that can be separately identified under the contract. Accordingly, our on-premise subscription contracts are unbundled into multiple performance obligations (i.e., license, cloud and support). Determining whether the software licenses and the cloud services are distinct from each other, and therefore performance obligations to be accounted for separately, or not distinct from each other, and therefore part of a single performance obligation, may require significant judgment. To date, for the majority of our products, we have concluded that the on-premise software licenses and cloud services provided in our subscription offerings are distinct from each other such that revenue from each performance obligation within the offering should be recognized separately. We will continue to review this conclusion as the cloud services that we deliver in combination with our on-premise subscriptions continue to evolve, which could result in changes to how we recognize revenue for such products. The license portion of our on-premise subscription contracts (approximately 50% to 55%) is recognized upfront and the cloud and support portions (approximately 45% to 50%) are recognized ratably over the term. Software as a Service (SaaS) and cloud services for which revenue is generally recognized ratably over the term of the contract are included in subscription revenue and have been immaterial to date.
Perpetual licenses are a perpetual right to use the software, for which revenue is generally recognized up front upon shipment to the customer. Support revenue is comprised of contracts to maintain new and/or previously purchased licenses, for which revenue is recognized ratably over the
term of the contract. Professional services engagements typically result from sales of new licenses, and for which revenue is recognized as the services are performed.
Our revenue recognition practices and the effects of our adoption of ASC 606, including adjustments to accumulated deficit related to billed and unbilled deferred revenue, are described in "revenue Recognition" and "Recently Adopted Accounting Pronouncements" in Note 2. Summary of Significant Accounting Policies and in Note 3. Revenue from Contracts with Customers in the Notes to Consolidated Financial Statements in this Annual Report.
Our adoption of ASC 606 has increased the volatility of our revenue results as a significant portion of subscription revenue is recognized at the time of delivery, rather than being recognized ratably over the contract period.
Executive Overview
ARR increased 10% to $1,116 million ($1,134 million and 12% at the guidance rate) as of the end of 2019 reflecting solid growth for this metric across all our businesses, particularly in our IoT and AR businesses.
Operating cash flow was $285 million, up 15% in 2019 compared to 2018. We made $22 million more in restructuring payments in 2019 compared to 2018 related to our workforce realignment and headquarters relocation.
Our 2019 results reflect continued demand for our PLM and CAD products as well as growing demand for our IoT and Augmented Reality (AR) products. License and subscription bookings in the fourth quarter of 2019 were $150 million, higher than anticipated, driven by strong bookings in IoT and AR, including a mega deal (bookings greater than $5 million) with our strategic alliance partner, Rockwell Automation. License and subscription bookings were $472 million, up 1% (4% constant currency) in 2019 compared to 2018, primarily driven by strong IoT and AR bookings growth, offset by declines in PLM and CAD bookings.
Under ASC 605, total revenue, software revenue and subscription revenue grew in 2019 compared to 2018, despite an 800 basis point increase in subscription mix in 2019. Under ASC 605, recurring software revenue was $1,079 million, an increase of 10% (13% constant currency) in 2019 compared to 2018. Under ASC 605, recurring revenue as a percentage of software revenue was 94% in 2019 compared to 90% in 2018. Under ASC 605, perpetual license and support revenue decreased year over year because we discontinued offering perpetual licenses for most of our solutions effective January 1, 2019. Operating margin under ASC 605 increased 200 basis points in 2019 resulting from the compounding effect of subscription licenses and lower operating expenses due to effective cost discipline. EPS declined under ASC 605 in 2019 primarily due to a higher tax provision.
Summary Revenue and Earnings Results
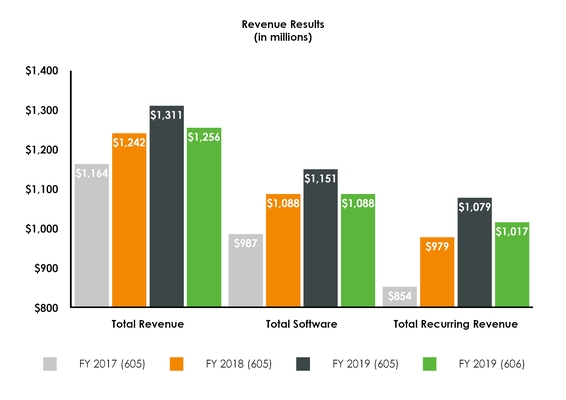
| Year Ended September 30, | ||||||||||||||||||
| Percent change | ||||||||||||||||||
| ASC 605 | ||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | 2019 vs 2018 | |||||||||||||||
| Revenue (in thousands) | 2019 | 2019 | 2018 | Change | Constant Currency | |||||||||||||
| Subscription license | $ | 253.7 | ||||||||||||||||
| Subscription support & cloud services | 348.5 | |||||||||||||||||
| Total subscription | 602.2 | 667.6 | 482.0 | 38 | % | 41 | % | |||||||||||
| Perpetual support | 415.2 | 411.0 | 496.8 | (17 | )% | (15 | )% | |||||||||||
| Total recurring revenue | 1,017.4 | 1,078.6 | 978.9 | 10 | % | 13 | % | |||||||||||
| Perpetual license | 70.7 | 72.2 | 109.6 | (34 | )% | (32 | )% | |||||||||||
| Total software revenue (1) | 1,088.1 | 1,150.8 | 1,088.5 | 6 | % | 8 | % | |||||||||||
| Professional services | 167.5 | 160.7 | 153.3 | 5 | % | 9 | % | |||||||||||
| Total revenue | $ | 1,255.6 | $ | 1,311.5 | $ | 1,241.8 | 6 | % | 8 | % | ||||||||
| (1) Total software revenue includes: | ||||||||||||||||||
| License (2) | $ | 324.4 | $ | 666.8 | $ | 529.3 | 26 | % | 29 | % | ||||||||
| Support and cloud services | 763.7 | 484.0 | 559.2 | (13 | )% | (11 | )% | |||||||||||
| Total software revenue | $ | 1,088.1 | $ | 1,150.8 | $ | 1,088.5 | 6 | % | 8 | % |
(2) Under ASC 605, we have classified all subscription revenue as subscription license revenue.
| Year Ended September 30, | |||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | ASC 605 | ||||||||||||
| Earnings Measures | 2019 | 2019 | 2018 | Change | |||||||||||
| Operating Margin | 5.0 | % | 7.7 | % | 5.8 | % | 33 | % | |||||||
| Earnings (Loss) Per Share | $ | (0.23 | ) | $ | 0.03 | $ | 0.44 | (94 | )% | ||||||
| Non-GAAP Operating Margin(1) | 20.3 | % | 22.4 | % | 18.3 | % | 22 | % | |||||||
| Non-GAAP Earnings Per Share(1) | $ | 1.64 | $ | 1.74 | $ | 1.45 | 20 | % |
(1) Non-GAAP financial measures are reconciled to GAAP results under Results of Operations - Non-GAAP Measures below.
We ended 2019 with cash, cash equivalents and marketable securities of $327 million, up from $316 million at the end of 2018. We generated $285 million of cash from operations in 2019 compared to $248 million in 2018. Cash from operations in 2019 includes $25 million of restructuring payments compared to $3 million in the year-ago period. In 2019, we also used cash from operations to repurchase $115 million of common stock. As of September 30, 2019, the balance outstanding under our credit facility was $173 million and total debt outstanding was $673 million.
Operating Measures
We provide these measures to help investors understand the progress of our subscription transition. These measures are not necessarily indicative of revenue for the period or any future period.
ARR
ARR at the end of 2019 grew 10% (12% constant currency) compared to the end of 2018, reflecting the strength of our products and solutions and the value we provide to our customers. Our CAD and PLM businesses saw combined ARR growth of 8% (10% constant currency). Our IoT and AR businesses delivered 26% ARR growth (28% constant currency). With the combination of IoT and AR exiting fiscal 2019 at greater than 12% of total ARR and one-third of total bookings, these businesses represent a growing portion of the PTC business. Our focused solutions group closed the year stronger than expected, delivering 8% (10% constant currency) ARR growth for the year.
License and Subscription Bookings
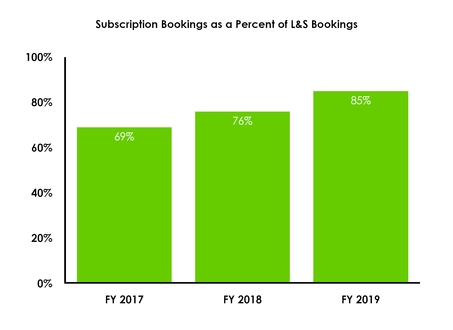
License and subscription bookings for 2019 were $472 million, up 1% over 2018 (4% on a constant currency basis). In the fourth quarter of 2019 we had a mega deal (bookings greater than $5 million) with Rockwell Automation. The mega deal from Rockwell Automation was issued to satisfy a portion of
expected 2020 demand and will be credited against committed ACV minimums due in 2020 under the parties’ strategic alliance agreement, as amended.
Subscription ACV
New subscription ACV increased 13% over 2018 to $199 million due to continued adoption of our subscription offerings around the globe.
Deferred Revenue and Backlog (Unbilled Deferred Revenue)
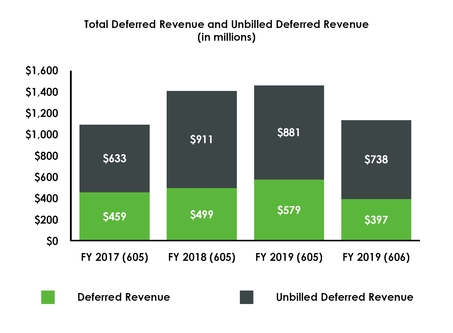
Deferred revenue primarily relates to software agreements invoiced to customers for which the revenue has not yet been recognized. Unbilled deferred revenue (backlog) is the aggregate of booked orders for license, support and subscription (including multi-year subscription contracts with start dates after October 1, 2018 through the third quarter of 2019 that were subject to a limited annual cancellation right, of which approximately $158 million was cancellable at September 30, 2019) for which the associated revenue has not been recognized and the customer has not yet been invoiced. Early in the fourth quarter of 2019, we discontinued the cancellation right for substantially all new contracts. We do not record unbilled deferred revenue on our Consolidated Balance Sheets; such amounts are recorded as deferred revenue when we invoice the customer. We provide this view of deferred revenue and backlog to enable investors to understand the significant contractual commitments we have to customers and to provide a view of future revenue that we expect will be recognized, even if those commitments are not reflected on our balance sheet.
| (Dollar amounts in millions) | September 30, | |||||||||||||||
| ASC 606 (1) | ASC 605 | ASC 605 | ASC 605 | |||||||||||||
| 2019 | 2019 | 2018 | 2017 | |||||||||||||
| Deferred revenue | $ | 397 | $ | 579 | $ | 499 | $ | 459 | ||||||||
| Unbilled deferred revenue | 738 | 881 | 911 | 633 | ||||||||||||
| Total | $ | 1,135 | $ | 1,460 | $ | 1,410 | $ | 1,092 |
(1) Upon adoption of ASC 606, approximately $367 million of total deferred revenue was recorded as a decrease to accumulated deficit with an offsetting $219 million increase to unbilled accounts receivable, a $143 million decrease to deferred revenue and a $5 million increase in other assets net of liabilities, primarily as a result of the acceleration of subscription license revenue under ASC 606.
Of the unbilled deferred revenue balance at September 30, 2019, we expect to invoice customers approximately $504 million within the next twelve months. Unbilled deferred revenue decreased by 3% year over year due to initial multi-year contracts renewing for shorter periods.
We expect that the amount of deferred revenue and unbilled deferred revenue will fluctuate from quarter to quarter due to the specific timing, duration and size of customer subscription and support agreements, varying billing cycles of such agreements, the specific timing of customer renewals (which are typically for one year), foreign currency fluctuations, the timing of when deferred revenue is recognized as revenue and the timing of our fiscal quarter ends. The average contract duration was approximately 2 years for new subscription contracts in 2019, 2018 and 2017.
The effects of our adoption of ASC 606, including the adjustments to accumulated deficit related to billed and unbilled deferred revenue, are described in Note 3. Revenue from Contracts with Customers in the Notes to Consolidated Financial Statements.
Subsequent Events
On November 1, 2019, PTC acquired Onshape, creators of the first Software as a Service (SaaS) product development platform that unites robust CAD with powerful data management and collaboration tools, for approximately $470 million, net of cash acquired. The acquisition is expected to accelerate PTC's ability to attract new customers with a SaaS-based product offering and position the company to capitalize on the inevitable industry transition to SaaS. In connection with the acquisition, PTC borrowed $455 million under its existing credit facility.
On November 13, 2019 we increased the revolving loan commitment under the credit facility to $1 billion and made other administrative amendments to the credit facility.
Future Expectations, Strategies and Risks
Our transition to a subscription model has been a headwind for revenue and earnings in 2019 with an increase in our subscription bookings mix of 800 basis points as compared to 2018. We expect the effect of the transition to moderate in fiscal 2020. We expect to grow revenue and expand our margins in fiscal 2020. We anticipate that IoT and AR adoption rates will continue to expand and will be the most significant driver to growth. In addition, we believe the recent acquisition of Onshape will provide us an opportunity to participate in the higher growth CAD and PLM markets serving small and medium businesses where we traditionally have not had a presence.
PTC remains committed to long-term development of Creo and Windchill. We want to be best-in-class with both the on-premise and SaaS deployment models in the CAD market. We will continue our pursuits of real-time simulation, generative design, additive manufacturing, and embedded IoT and AR capabilities.
With the growth opportunity in the SaaS-based CAD market and other strategic initiatives we have undertaken, as well as our continued commitment to operating margin improvement, we are realigning our workforce in 2020 to shift investment to support these strategic, high growth opportunities. We expect this realignment will result in a restructuring charge of up to $25 million in 2020. The effect of the realignment is reflected in our 2020 guidance.
As we move into 2020, our three overriding goals are:
 | Sustainable Growth | We are focused on driving ARR growth both in the high-growth Industrial IoT and AR markets and in our core CAD and PLM markets. |
 | Cost Controls and Margin Expansion | Our goal is to drive continued margin expansion over the long term. We continue to proactively manage our cost structure and invest in what we believe are high return opportunities in our business. We expect to deliver continued long-term operating margin expansion, as we drive ARR growth and realize the compounding benefit of our maturing subscription business. |
 | Expand Free Cash Flow | Our goal is to grow our free cash flow. PTC's free cash flow is driven primarily by increasing operating profit and efficiently managing both working capital and capital expenditures. Our plan for 2020 is to increase operating profit by expanding ARR and maintaining an efficient cost structure. |
Results of Operations
The following table shows the financial measures that we consider the most significant indicators of the performance of our business. In addition to providing measures calculated under generally accepted accounting principles (“GAAP”), we also provide non-GAAP financial measures for the reported periods. Investors should use these non-GAAP financial measures only in conjunction with our GAAP results.
For discussion of 2018 results and comparison with 2017 results refer to "Management's Discussion and Analysis of Financial Conditions and Results of Operations" in our Annual Report on Form 10-K for the fiscal year ended September 30, 2018.
| (Dollar amounts in millions, except per share data) | Year ended September 30, | ||||||||||||||||||||||||||
| Percent Change | |||||||||||||||||||||||||||
| ASC 605 | |||||||||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | Actual | Constant Currency | Actual | Constant Currency | ||||||||||||||||||||
| Subscription | $ | 602.2 | $ | 667.6 | $ | 482.0 | $ | 279.2 | 38 | % | 41 | % | 73 | % | 69 | % | |||||||||||
| Perpetual support | 415.2 | 411.0 | 496.8 | 574.7 | (17 | )% | (15 | )% | (14 | )% | (16 | )% | |||||||||||||||
| Total recurring revenue | 1,017.4 | 1,078.6 | 978.9 | 853.9 | 10 | % | 13 | % | 15 | % | 12 | % | |||||||||||||||
| Perpetual license | 70.7 | 72.2 | 109.6 | 133.4 | (34 | )% | (32 | )% | (18 | )% | (20 | )% | |||||||||||||||
| Total software revenue | 1,088.1 | 1,150.8 | 1,088.5 | 987.3 | 6 | % | 8 | % | 10 | % | 8 | % | |||||||||||||||
| Professional services | 167.5 | 160.7 | 153.3 | 176.7 | 5 | % | 9 | % | (13 | )% | (16 | )% | |||||||||||||||
| Total revenue | 1,255.6 | 1,311.5 | 1,241.8 | 1,164.0 | 6 | % | 8 | % | 7 | % | 4 | % | |||||||||||||||
| Total cost of revenue | 325.4 | 318.2 | 326.5 | 328.5 | (3 | )% | (1 | )% | |||||||||||||||||||
| Gross margin | 930.3 | 993.3 | 915.3 | 835.5 | 9 | % | 10 | % | |||||||||||||||||||
| Operating expenses | 867.2 | 891.7 | 842.7 | 793.8 | 6 | % | 6 | % | |||||||||||||||||||
| Total costs and expenses | 1,192.6 | 1,209.9 | 1,169.2 | 1,122.3 | 3 | % | 5 | % | 4 | % | 2 | % | |||||||||||||||
| Operating income | $ | 63.0 | $ | 101.6 | $ | 72.6 | $ | 41.8 | 40 | % | 55 | % | 74 | % | 52 | % | |||||||||||
| Non-GAAP operating income (1) | $ | 255.3 | $ | 293.9 | $ | 229.4 | $ | 189.3 | 28 | % | 33 | % | 21 | % | 15 | % | |||||||||||
| Operating margin | 5.0 | % | 7.7 | % | 5.8 | % | 3.6 | % | |||||||||||||||||||
| Non-GAAP operating margin (1) | 20.3 | % | 22.4 | % | 18.3 | % | 16.2 | % | |||||||||||||||||||
| Diluted earnings (loss) per share (2) | $ | (0.23 | ) | $ | 0.03 | $ | 0.44 | $ | 0.05 | ||||||||||||||||||
| Non-GAAP diluted earnings per share (2) | $ | 1.64 | $ | 1.74 | $ | 1.45 | $ | 1.17 | |||||||||||||||||||
| Cash flow from operations (3) | $ | 285.1 | $ | 285.1 | $ | 247.8 | $ | 135.2 |
(1) See Non-GAAP Financial Measures below for a reconciliation of our GAAP results to our non-GAAP measures.
(2) We have a full valuation allowance against our U.S. net deferred tax assets and a valuation allowance against net deferred tax assets in certain foreign jurisdictions. As we are profitable on a non-GAAP basis, the 2019 - 2017 non-GAAP tax provisions are calculated assuming there is no valuation allowance. Income tax adjustments reflect the tax effects of non-GAAP adjustments which are calculated by applying the applicable tax rate by jurisdiction to the non-GAAP adjustments listed above. We recorded the impact of the Tax Cuts and Jobs Act in our 2018 GAAP earnings, resulting in a non-cash benefit of approximately $12 million. We have excluded this benefit from our non-GAAP results.
(3) Cash flow from operations for 2019 includes $25 million of restructuring payments. Cash flow from operations for 2018 includes $3 million of restructuring payments. Cash flow from operations for 2017 includes $37 million of restructuring payments, a $12 million payment related to a Korea tax audit and $3 million of legal settlement payments.
Impact of Foreign Currency Exchange on Results of Operations
Approximately 60% of our revenue and 40% of our expenses are transacted in currencies other than the U.S. dollar. Currency translation affects our reported results, which are in U.S. Dollars. If 2019 reported results were converted into U.S. dollars based on the corresponding prior year’s foreign currency exchange rates, 2019 revenue would have been higher by $34 million and expenses would have been higher by $22 million. The net impact on year-over-year results would have been an increase in operating income of $12 million in 2019. The results of operations, revenue by line of business and revenue by geographic region in the tables that follow present both actual percentage changes year over year and percentage changes on a constant currency basis.
Revenue
We discuss our revenue results by line of business, by product group and by geographic region below. Our discussion is focused on our results under ASC 605 for purposes of comparability. In 2019 our ASC 606 software revenue results were lower than under ASC 605 primarily as a result of the acceleration of our on-premise subscription revenue associated with the retained earnings adoption adjustment recorded in the first quarter, offset by revenue recognized in 2019, which would otherwise have been recognized ratably over future years under ASC 605. Professional services revenue under ASC 606 was higher than under ASC 605 due to the requirement to separately identify certain performance obligations, which would have otherwise been combined and recognized ratably under ASC 605, but instead were recognized in 2019.
Revenue by Line of Business


Software
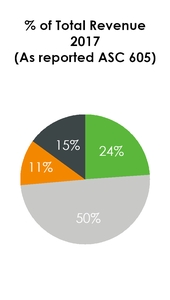
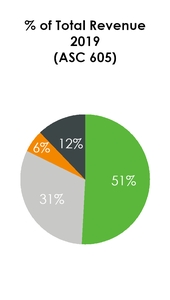
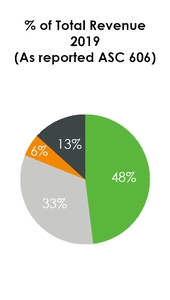
Software revenue consists of subscription, support, and perpetual license revenue. Under ASC 605, recurring software revenue consists of subscription and support revenue and was 82% of total revenue and 94% of software revenue for 2019. Our subscription revenue includes an immaterial amount of Software as a Service (SaaS) and cloud services revenue.
As our mix of subscription sales relative to perpetual license sales has increased, perpetual license revenue and support revenue have declined and are expected to continue to decline as customers purchase our solutions as subscriptions and convert existing perpetual licenses with support contracts to
subscriptions. Effective January 1, 2019, new software licenses for our core solutions and ThingWorx solutions became available only by subscription worldwide.
Our results have been impacted, and we expect will continue to be impacted, by our ability to close large transactions. The amount of bookings and revenue, particularly license and subscriptions, attributable to large transactions, and the number of such transactions, may vary significantly from quarter to quarter based on customer purchasing decisions and macroeconomic conditions. Such transactions may have long lead times as they often follow a lengthy product selection and evaluation process and, for existing customers, are influenced by contract expiration cycles. This may cause volatility in our results.
Professional Services
Professional services engagements typically result from sales of new licenses; revenue is recognized over the term of the engagement. Under ASC 605 professional services revenue was up 5% (9% constant currency) in 2019 compared to 2018. Professional services revenue in 2018 includes a $14.5 million write-down related to a settlement of a customer dispute concerning a receivable. Excluding the impact of this write-down, professional services revenue in 2019 would have declined 4% year over year. We expect that professional services revenue will trend flat-to-down over time due to our strategy to expand margins by migrating services engagements to our partners and delivering products that require less consulting and training services.
Revenue by Product Group
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||||||||
| Percent Change | |||||||||||||||||||||||||||
| ASC 605 | |||||||||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | Actual | Constant Currency | Actual | Constant Currency | ||||||||||||||||||||
| Solutions Products | |||||||||||||||||||||||||||
| Software revenue | $ | 947.9 | $ | 1,000.2 | $ | 964.6 | $ | 893.6 | 4 | % | 6 | % | 8 | % | 5 | % | |||||||||||
| Professional services | 151.9 | 135.7 | 137.9 | 167.1 | (2 | )% | 2 | % | (17 | )% | (20 | )% | |||||||||||||||
| Total revenue | $ | 1,099.8 | $ | 1,135.9 | $ | 1,102.5 | $ | 1,060.7 | 3 | % | 6 | % | 4 | % | 1 | % | |||||||||||
| IoT Products | |||||||||||||||||||||||||||
| Software revenue | $ | 140.2 | $ | 150.6 | $ | 123.9 | $ | 93.7 | 22 | % | 24 | % | 32 | % | 31 | % | |||||||||||
| Professional services | 15.6 | 25.0 | 15.4 | 9.6 | 62 | % | 65 | % | 60 | % | 57 | % | |||||||||||||||
| Total revenue | $ | 155.8 | $ | 175.6 | $ | 139.3 | $ | 103.3 | 26 | % | 28 | % | 35 | % | 33 | % |
Solutions Group
Under ASC 605, Solutions Group software revenue grew in 2019 compared to 2018, driven by growth in subscription revenue, which was up 41% (44% on a constant currency basis) year over year. This growth was offset in part by the 49% (46% on a constant currency basis) decline in perpetual license revenue in 2019 due to the end of life of perpetual licenses.
Solutions professional services revenue in 2018 reflects the $14.5 million write-down described above. Excluding the impact of this write-down, Solutions professional services revenue would have declined 11% year over year. Solutions professional services revenue for 2019 declined compared to 2018 due to our strategy to limit the amount of professional services we provide.
IoT Group
Under ASC 605, IoT recurring software revenue grew by 25% (27% on a constant currency basis) in 2019, reflecting the strong bookings growth over the past several years and the compounding benefit of our maturing subscription model. IoT software revenue in 2018 reflects $5.2 million of new subscription revenue related to the customer dispute settlement described above, which settlement included the purchase of new subscription licenses.
IoT professional services revenue increased in 2019 due to implementation and adoption services we sell in connection with new software licenses as part of our efforts to help customers' IoT initiatives succeed.
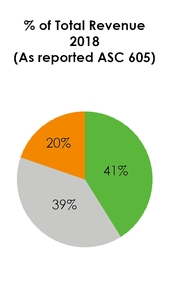
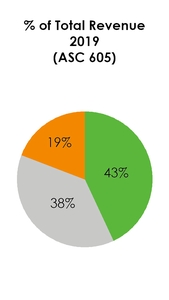
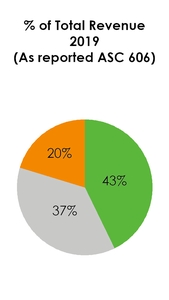
Revenue by Geographic Region
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||||||||
| Percent Change | |||||||||||||||||||||||||||
| ASC 605 | |||||||||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | AS Reported ASC 605 | AS Reported ASC 605 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | Actual | Constant Currency | Actual | Constant Currency | ||||||||||||||||||||
| Americas | |||||||||||||||||||||||||||
| Software revenue | $ | 484.1 | $ | 512.3 | $ | 468.3 | $ | 433.7 | 9 | % | 10 | % | 8 | % | 8 | % | |||||||||||
| Professional services revenue | 53.4 | 53.0 | 42.9 | 67.2 | 24 | % | 24 | % | (36 | )% | (36 | )% | |||||||||||||||
| Total Revenue | $ | 537.5 | $ | 565.3 | $ | 511.2 | $ | 500.9 | 11 | % | 11 | % | 2 | % | 2 | % | |||||||||||
| Europe | |||||||||||||||||||||||||||
| Software revenue | $ | 379.9 | $ | 417.2 | $ | 402.9 | $ | 356.5 | 4 | % | 9 | % | 13 | % | 7 | % | |||||||||||
| Professional services revenue | 84.8 | 77.7 | 83.0 | 78.7 | (6 | )% | (1 | )% | 5 | % | (1 | )% | |||||||||||||||
| Total Revenue | $ | 464.7 | $ | 494.9 | $ | 485.9 | $ | 435.2 | 2 | % | 7 | % | 12 | % | 5 | % | |||||||||||
| Asia Pacific | |||||||||||||||||||||||||||
| Software revenue | $ | 224.1 | $ | 221.3 | $ | 217.3 | $ | 197.1 | 2 | % | 4 | % | 10 | % | 8 | % | |||||||||||
| Professional services revenue | 29.4 | 29.9 | 27.4 | 30.9 | 9 | % | 12 | % | (11 | )% | (13 | )% | |||||||||||||||
| Total Revenue | $ | 253.4 | $ | 251.3 | $ | 244.7 | $ | 228.0 | 3 | % | 5 | % | 7 | % | 5 | % |
Americas
The growth in ASC 605 software revenue in 2019 was due to growth of subscription revenue, which was up 37% over 2018. This growth was offset in part by a decline of 9% (8% on a constant currency basis) in perpetual license revenue in 2019 due to the end of life of perpetual licenses in the Americas as of January 1, 2018.
Professional services revenue in 2018 reflects the $14.5 million write-down related to the customer dispute settlement described above. Excluding the impact of this write-down, professional services revenue in the Americas would have declined 8% year over year.
Europe
Under ASC 605, software revenue in 2019 grew over 2018 driven by the growth in subscription revenue, which was up 37% (44% on a constant currency basis) year over year. This growth was offset in part by the decline of 51% (47% on a constant currency basis) in perpetual license revenue in 2019 due to the end of life of perpetual licenses in Europe as of January 1, 2018.
Year-over-year declines in foreign currency exchange rates, particularly the Euro, impacted European revenue unfavorably in 2019 by $26 million.
Asia Pacific
Under ASC 605, software revenue in 2019 grew slightly over 2018 driven by growth in subscription revenue of 49% (51% on a constant currency basis) year over year. This growth was offset in part by the decline of 38% (36% on a constant currency basis) in perpetual license revenue in 2019 due to the end of life of perpetual licenses in Asia Pacific as of January 1, 2019.
Year-over-year changes in foreign currency exchange rates unfavorably impacted Asia Pacific revenue by $6 million in 2019.
Gross Margin

| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | Percent Change | |||||||||||||||||
| ASC 605 | |||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||
| Gross margin | $ | 930.3 | $ | 993.3 | $ | 915.3 | $ | 835.5 | 9 | % | 10 | % | |||||||||
| Non-GAAP gross margin | 970.0 | 1,033.1 | 963.7 | 877.0 | 7 | % | 10 | % | |||||||||||||
| Gross margin as a % of revenue: | |||||||||||||||||||||
| License | 84 | % | 92 | % | 91 | % | 81 | % | |||||||||||||
| Support and cloud services | 83 | % | 73 | % | 76 | % | 82 | % | |||||||||||||
| Professional services | 16 | % | 16 | % | 6 | % | 15 | % | |||||||||||||
| Gross margin as a % of total revenue | 74 | % | 76 | % | 74 | % | 72 | % | |||||||||||||
| Non-GAAP gross margin as a % of total non-GAAP revenue | 77 | % | 79 | % | 77 | % | 75 | % |
Under ASC 605, the increase in total gross margin in 2019 compared to 2018 reflects higher software revenue driven by the increase in recurring subscription revenue. Margins for license and subscription are beginning to expand as the subscription model matures and revenue that has been deferred begins to contribute to each quarterly period. Under ASC 605, support gross margins are down in 2019 compared 2018 due to the decrease in perpetual support revenue due to conversions of support to subscription and the end of life of perpetual licenses.
Professional services revenue in 2018 reflects the $14.5 million revenue write-down associated with the customer dispute described above. Without the revenue write-down, professional services gross margin would have been 17% in 2018.
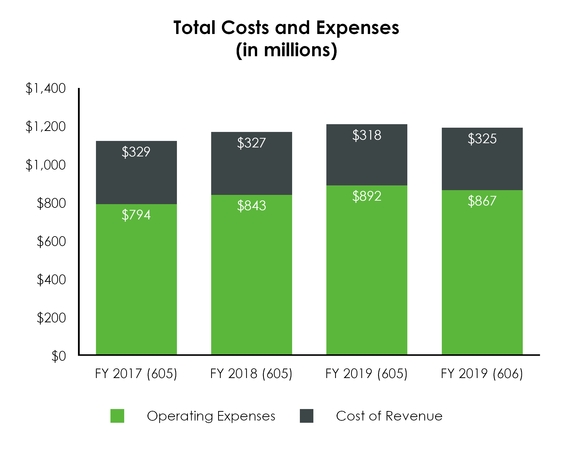
Total Costs and Expenses
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | Percent Change | |||||||||||||||||||
| ASC 605 | |||||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||||
| Cost of license revenue | 51.9 | 50.2 | 47.7 | 66.8 | 5 | % | (29 | )% | |||||||||||||||
| Cost of support and cloud services revenue | 133.5 | 133.0 | 135.1 | 110.9 | (2 | )% | 22 | % | |||||||||||||||
| Cost of professional services revenue | 140.0 | 134.9 | 143.7 | 150.7 | (6 | )% | (5 | )% | |||||||||||||||
| Sales and marketing | 417.4 | 442.0 | 414.8 | 372.7 | 7 | % | 11 | % | |||||||||||||||
| Research and development | 246.9 | 246.9 | 249.8 | 236.0 | (1 | )% | 6 | % | |||||||||||||||
| General and administrative | 127.9 | 127.9 | 143.0 | 145.0 | (11 | )% | (1 | )% | |||||||||||||||
| Amortization of acquired intangible assets | 23.8 | 23.8 | 31.4 | 32.1 | (24 | )% | (2 | )% | |||||||||||||||
| Restructuring and other charges, net | 51.1 | 51.1 | 3.8 | 7.9 | 1,258 | % | (53 | )% | |||||||||||||||
| Total costs and expenses | $ | 1,192.6 | $ | 1,209.8 | $ | 1,169.2 | $ | 1,122.3 | 3 | % | (1) | 4 | % | (1) | |||||||||
| Total headcount at end of period | 6,055 | 6,055 | 6,110 | 6,041 | (1 | )% | 1 | % |
| (1) | On a constant currency basis from the prior period, total costs and expenses increased 5% from 2018 to 2019 and increased 2% from 2017 to 2018. |
2019 compared to 2018
ASC 605 costs and expenses in 2019 compared to 2018 increased primarily due to the following:
| • | a $32.7 million restructuring charge associated with exiting our Needham headquarters facility in the second quarter of 2019 and a $15.7 million restructuring charge for our workforce realignment in the first quarter of 2019, |
| • | a $9.3 million increase in cloud services hosting costs, |
| • | a $3.6 million increase in royalty expense, |
| • | a $2.4 million increase in rent expense partially due to one month of overlapping rent in Needham and the new Seaport location in January 2019, and |
| • | a $2.1 million increase in marketing expenses. |
The increases above were partially offset by:
| • | a $15.0 million decrease in total compensation benefit costs and travel expenses, primarily driven by a $12.5 million decrease in performance-based compensation and a $4.7 million decrease in salaries, benefits and travel costs, partially offset by a $2.2 million increase in commissions expense, and |
| • | a $9.6 million decrease in amortization of intangible assets and depreciation of fixed assets expenses, which were higher in 2018 due to the accelerated depreciation associated with the headquarters relocation, and |
Costs and expenses for 2019 compared to 2018 include a $22.2 million decrease due to changes in foreign currency exchange rates.
Cost of License Revenue
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | Percent Change | |||||||||||||||||
| ASC 605 | |||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||
| Cost of license revenue | $ | 51.9 | $ | 50.2 | $ | 47.7 | $ | 66.8 | 5 | % | (29 | )% | |||||||||
| % of total revenue | 4 | % | 4 | % | 4 | % | 6 | % | |||||||||||||
| % of total license revenue | 16 | % | 8 | % | 9 | % | 19 | % |
Our cost of license revenue consists of fixed and variable costs associated with reproducing and distributing software and documentation, as well as royalties paid to third parties for technology embedded in or licensed with our software products, amortization of intangible assets associated with acquired products, and cost of subscription licensing. Costs associated with providing post-contract support such as providing software updates and technical support for both our subscription offerings and our perpetual licenses are included in cost of support and cloud service revenue. Cost of license revenue as a percentage of license revenue can vary depending on the subscription mix percentage, the product mix sold, the effect of fixed and variable royalties, headcount and the level of amortization of acquired software intangible assets.
Cost of license revenue in 2019 under ASC 606 is higher than under ASC 605 due to the timing of revenue recognition under ASC 606, resulting in earlier recognition of the associated royalty costs. Under ASC 605, the support component of subscription revenue is included in license revenue, which reduces cost of license as a percentage of total license revenue.
Cost of license revenue in 2019 compared to 2018 increased primarily due to a $3.2 million increase in royalty expense, offset by $2.8 million lower compensation costs.
Cost of license revenue as a percentage of license revenue under ASC 605 decreased in 2019 compared to 2018 due to higher revenue as recurring subscription revenue increased.
Cost of Support and Cloud Services Revenue
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | Percent Change | |||||||||||||||||
| ASC 605 | |||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||
| Cost of support and cloud services revenue | $ | 133.5 | $ | 133.0 | $ | 135.1 | $ | 110.9 | (2 | )% | 22 | % | |||||||||
| % of total revenue | 11 | % | 10 | % | 11 | % | 10 | % | |||||||||||||
| % of total support and cloud services revenue | 17 | % | 27 | % | 24 | % | 18 | % |
Our cost of support and cloud services revenue includes costs associated with providing post-contract support such as providing software updates and technical support for both our subscription offerings and our perpetual licenses, cost of cloud services (including third party hosting costs), and cost of software as a service revenue. Cost of support and cloud services revenue consists of costs such as salaries, benefits, and computer equipment and facilities associated with customer support and cloud services and the release of support updates (including related royalty costs).
Under ASC 605, the support component of subscription revenue is included in license revenue, which increases the cost of support and cloud services as a percentage of total support and cloud services revenue.
In 2019 compared to 2018, cloud services hosting costs increased 32% ($4.5 million), offset by a decrease in total support and cloud services compensation, benefit costs and travel expenses of 1% ($1.2 million) and in third-party consulting costs of 23% ($1.5 million).
Cost of Professional Services Revenue
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | Percent Change | |||||||||||||||||
| ASC 605 | |||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||
| Cost of professional service revenue | $ | 140.0 | $ | 134.9 | $ | 143.7 | $ | 150.7 | (6 | )% | (5 | )% | |||||||||
| % of total revenue | 11 | % | 10 | % | 12 | % | 13 | % | |||||||||||||
| % of total professional service revenue | 84 | % | 84 | % | 94 | % | 85 | % |
Our cost of professional services revenue includes costs such as salaries, benefits, information technology costs and facilities expenses for our training and consulting personnel, and third-party subcontractor fees.
Cost of professional services revenue is higher in 2019 under ASC 606 than under ASC 605 due to the timing of professional services revenue recognition and associated professional service costs.
In 2019 compared to 2018, total professional services compensation, benefit costs and travel expenses decreased by 11% ($11.6 million), partially offset by higher third-party subcontractor fees, which increased by 20% ($5.3 million).
Sales and Marketing
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | Percent Change | |||||||||||||||||
| ASC 605 | |||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||
| Sales and marketing expenses | $ | 417.4 | $ | 442.0 | $ | 414.8 | $ | 372.7 | 7 | % | 11 | % | |||||||||
| % of total revenue | 33 | % | 34 | % | 33 | % | 32 | % |
Our sales and marketing expenses primarily include salaries and benefits, sales commissions, advertising and marketing programs, travel and facility costs.
Sales and marketing costs are lower under ASC 606 than under ASC 605 due to the deferral of ongoing commission expenses, offset by the amortization of commission costs capitalized upon adoption of ASC 606.
In 2019 compared to 2018, total sales and marketing compensation, benefit costs and travel expenses under ASC 605 increased 6% ($19.8 million) due to an increase in headcount, and marketing expenses increased by 7% ($2.1 million).
Research and Development
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | Percent Change | |||||||||||||||||
| ASC 605 | |||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||
| Research and development expenses | $ | 246.9 | $ | 246.9 | $ | 249.8 | $ | 236.0 | (1 | )% | 6 | % | |||||||||
| % of total revenue | 20 | % | 19 | % | 20 | % | 20 | % |
Our research and development expenses consist principally of salaries and benefits, costs of computer equipment and facility expenses. Major research and development activities include developing new products and releases and updates of our software that enhance functionality and add features.
In 2019 compared to 2018, total research and development compensation, benefit costs and travel expenses decreased 1% ($2.9 million) primarily due to decreases in headcount, and third-party consulting services decreased by 33% ($2.5 million). Offsetting these lower costs is a 62% ($2.5 million) increase in cloud services hosting costs.
General and Administrative
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | Percent Change | |||||||||||||||||
| ASC 605 | |||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||
| General and administrative expenses | $ | 127.9 | $ | 127.9 | $ | 143.0 | $ | 145.0 | (11 | )% | (1 | )% | |||||||||
| % of total revenue | 10 | % | 10 | % | 12 | % | 12 | % |
Our general and administrative expenses include the costs of our corporate, finance, information technology, human resources, legal and administrative functions, as well as acquisition-related charges, bad debt expense and outside professional services, including accounting and legal fees.
In 2019 compared to 2018, total general and administrative compensation, benefit costs and travel expenses decreased by 14% ($16.3 million) primarily due to a decrease in performance-based
compensation, and third-party consulting services declined by 56% ($2.6 million). Offsetting these lower costs is a 11% ($1.4 million) increase in hosted subscription costs.
Amortization of Acquired Intangible Assets
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | Percent Change | |||||||||||||||||
| ASC 605 | |||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||
| Amortization of acquired intangible assets | $ | 23.8 | $ | 23.8 | $ | 31.4 | $ | 32.1 | (24 | )% | (2 | )% | |||||||||
| % of total revenue | 2 | % | 2 | % | 3 | % | 3 | % |
Amortization of acquired intangible assets reflects the amortization of acquired non-product related intangible assets, primarily customer and trademark-related intangible assets, recorded in connection with completed acquisitions. The decrease in amortization of acquired intangible assets in 2019 compared to 2018 is due to some assets being fully amortized as well as the impact of foreign currency exchange rates.
Restructuring and Other Charges, net
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | Percent Change | |||||||||||||||||
| ASC 605 | |||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||
| Restructuring charges (credits), net | $ | 48.6 | $ | 48.6 | $ | (1.0 | ) | $ | 7.9 | (4,947 | )% | (113 | )% | ||||||||
| Headquarters relocation charges | 2.5 | 2.5 | 4.8 | — | (48 | )% | - | ||||||||||||||
| Restructuring and Other Charges, Net | 51.1 | 51.1 | 3.8 | 7.9 | 1,258 | % | (53 | )% | |||||||||||||
| % of total revenue | 4 | % | 4 | % | — | % | 1 | % |
In January 2019, we relocated to our new worldwide headquarters in the Boston Seaport District. Our prior headquarters lease expires in November 2022. As a result, we have overlapping rent obligations for those premises and in 2019 we recorded a restructuring charge of $32.7 million associated with the restructuring of that lease. The facility restructuring charge is based on the net present value of remaining lease commitments net of estimated sublease income of $7.6 million, of which $3.9 million is committed as of the end of fiscal 2019. We continue to seek additional subtenants for the space. Restructuring charges and estimated cash outflows could increase if we are unable to sublease our prior headquarters as we expect.
The headquarters relocation charges include accelerated depreciation expense and duplicate rent for January associated with exiting our prior headquarters facility.
In the first quarter of 2019, we initiated a restructuring plan to realign our workforce to shift investment to support Industrial Internet of Things and Augmented Reality strategic opportunities. As this was a realignment of resources rather than a cost-savings initiative, it did not result in significant cost savings. The restructuring plan was completed in the first quarter of 2019. In 2019 we recorded restructuring charges of $15.7 million related to this restructuring plan.
In 2019, we made cash payments related to restructuring charges of $24.7 million. At September 30, 2019, accrued restructuring totaled $31.1 million, of which we expect to pay $12 million within the next twelve months.
Interest Expense
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | Percent Change | |||||||||||||||||
| ASC 605 | |||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||
| Interest expense | $ | (43.0 | ) | $ | (43.0 | ) | $ | (41.7 | ) | $ | (42.4 | ) | 3 | % | (2 | )% |
Interest expense includes interest under our credit facility and senior notes. We had $673 million of total debt at September 30, 2019, compared to $648 million at September 30, 2018.
The average interest rate on our total borrowings was 5.4% in 2019, 5.2% in 2018 and 4.9% in 2017.
Other Income (Expense), net
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | Percent Change | |||||||||||||||||
| ASC 605 | |||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||
| Foreign currency losses, net | $ | (3.2 | ) | $ | (3.3 | ) | $ | (7.0 | ) | $ | (5.7 | ) | (52 | )% | 23 | % | |||||
| Interest income | 4.1 | 4.1 | 3.8 | 3.2 | 7 | % | 18 | % | |||||||||||||
| Other non-operating income (expense), net | (0.6 | ) | (0.6 | ) | 0.9 | 1.7 | (172 | )% | (47 | )% | |||||||||||
| Other income (expense), net | $ | 0.3 | $ | 0.1 | $ | (2.3 | ) | $ | (0.8 | ) | (106 | )% | 196 | % |
Foreign currency net losses include costs of hedging contracts, certain realized and unrealized foreign currency transaction gains or losses, and foreign exchange gains or losses resulting from the required period-end currency re-measurement of the assets and liabilities of our subsidiaries that use the U.S. dollar as their functional currency. Because a large portion of our revenue and expenses is transacted in foreign currencies, we engage in hedging transactions involving the use of foreign currency forward contracts to reduce our exposure to fluctuations in foreign exchange rates. Changes in the balance year over year are due to required period-end currency re-measurement of the assets and liabilities of our subsidiaries that use the U.S. Dollar as their functional currency. Hedging costs decreased $4.0 million in 2019 compared to 2018 due to implementation of favorable net investment hedges of foreign currency exposure.
Interest income represents earnings on the investment of our available cash balances.
Other non-operating income (expense), net is primarily made up of other non-operating gains and losses.
Income Taxes
Tax Provision and Effective Income Tax Rate
| (Dollar amounts in millions) | Year ended September 30, | ||||||||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | Percent Change | |||||||||||||||||
| ASC 605 | |||||||||||||||||||||
| 2019 | 2019 | 2018 | 2017 | 2019 vs. 2018 | 2018 vs. 2017 | ||||||||||||||||
| Income (loss) before income taxes | $ | 20.3 | $ | 58.7 | $ | 28.7 | $ | (1.4 | ) | 105 | % | (2,138 | )% | ||||||||
| Provision (benefit) for income taxes | 47.8 | 55.7 | (23.3 | ) | (7.6 | ) | (339 | )% | 205 | % | |||||||||||
| Effective income tax rate | 235 | % | 95 | % | (81 | )% | 544 | % |
In 2019, our tax rate is higher than the statutory federal income tax rate of 21% due in large part, to the scheduling of the reversal of existing temporary differences resulting in deferred tax liabilities that
cannot be offset against deferred tax assets requiring an increase to the U.S. valuation allowance, U.S. tax reform (as described below) and foreign withholding taxes, an obligation of the U.S. parent. This is offset by our corporate structure in which our foreign taxes are at a net effective tax rate lower than the U.S. rate, the excess tax benefit related to stock-based compensation and the indirect effects of the adoption of ASC 606. A significant amount of our foreign earnings is generated by our subsidiaries organized in Ireland. In 2019 the foreign rate differential predominantly relates to these Irish earnings.
On December 22, 2017, the United States enacted tax reform legislation through the Tax Cuts and Jobs Act, (the "Tax Act"), which significantly changed existing U.S. tax laws by a reduction of the corporate tax rate, the implementation of a new system of taxation for non-U.S. earnings, the imposition of a one-time tax on the deemed repatriation of undistributed earnings of non-U.S. subsidiaries, and the expansion of the limitations on the deductibility of executive compensation and interest expense. As we have a September 30 fiscal year-end, a blended U.S. statutory federal rate of approximately 24.5% applies for our fiscal year ended September 30, 2018 and 21% for subsequent fiscal years. The Tax Act also provides that net operating losses generated in years ending after December 31, 2017 (our fiscal 2018) will be carried forward indefinitely and can no longer be carried back, and that net operating losses generated in years beginning after December 31, 2017 can only reduce taxable income by up to 80% when utilized in a future period. The Tax Act includes a provision to tax global intangible low-tax income (GILTI) of foreign subsidiaries, a deduction for Foreign-Derived Intangible Income (FDII), and the base erosion anti-abuse tax (BEAT) measure that taxes certain payments between a U.S. corporation and its foreign subsidiaries. The GILTI, FDII and BEAT provisions were effective for us beginning October 1, 2018. Our accounting policy is to treat tax on GILTI as a current period cost included in tax expense in the year incurred.
In 2018, we provided no federal income taxes payable as a result of the deemed repatriation of undistributed earnings as the tax was offset by a combination of current year losses and existing attributes which had a full valuation allowance recorded against the related deferred tax assets. In 2018, we recorded a state income taxes payable on the deemed repatriation of $1.7 million. We also recorded a deferred tax benefit of $14.1 million for the impact of the Tax Act on our net U.S. deferred income tax balances. This was primarily attributable to the reduction of the federal tax rate on the net deferred tax liability in the U.S., and the ability to realize net operating losses from the reversal of existing deferred tax assets which can now be carried forward indefinitely and can therefore be netted against deferred tax liabilities for indefinite lived intangible assets.
The U.S. Securities and Exchange Commission issued rules that allow for a period of up to one year after the enactment date of the Tax Act to finalize the recording of the related tax impacts. We finalized recording the impacts of the Tax Act in the quarter ended December 29, 2018 and did not record any significant adjustments.
In October 2016, the Financial Accounting Standards Board (FASB) issued Accounting Standards Update (ASU) 2016-16, Income Taxes (Topic 740): Intra-Entity Transfers of Assets Other Than Inventory. The purpose of ASU 2016-16 is to simplify the income tax accounting of an intra-entity transfer of an asset other than inventory and to record its effect when the transfer occurs. We adopted this amendment beginning in the first quarter of 2019 using the modified retrospective method with a cumulate effect adjustment to accumulated deficit of $72.3 million, with a corresponding increase of $75.3 million to deferred tax assets, a $6.0 million decrease to income tax assets and a $3.0 million decrease to income tax liabilities. The adjustment primarily relates to deductible amortization of intangible assets in Ireland. Post adoption, our effective tax rate no longer includes the benefit of this amortization.
Valuation Allowance
We have concluded, based on the weight of available evidence, that a full valuation allowance continues to be required against our U.S. net deferred tax assets as they are not more likely than not to be realized in the future. We will continue to reassess our valuation allowance requirements each financial reporting period. However, we believe that there is a reasonable possibility that within the next 12 months, sufficient positive evidence may become available to allow us to reach a conclusion that a significant portion of the valuation allowance will no longer be needed. Release of the valuation allowance would result in the recognition of certain deferred tax assets and a decrease to income tax expense for the period the release is recorded. However, the exact timing and amount of the valuation allowance release are subject to change on the basis of the level of profitability that we are able to actually achieve.
Tax Audits and Examinations
In the normal course of business, PTC and its subsidiaries are examined by various taxing authorities, including the Internal Revenue Service (IRS) in the U. S. We regularly assess the likelihood of additional assessments by tax authorities and provide for these matters as appropriate. We are currently under audit by tax authorities in several jurisdictions. Audits by tax authorities typically involve examination of the deductibility of certain permanent items, transfer pricing, limitations on net operating losses and tax credits. Although we believe our tax estimates are appropriate, the final determination of tax audits and any related litigation could result in material changes in our estimates.
In the fourth quarter of 2016, we received an assessment of approximately $12 million from the tax authorities in South Korea. The assessment relates to various tax issues, primarily foreign withholding taxes. We have appealed and intend to vigorously defend our positions. We believe that upon completion of a multi-level appeal process it is more likely than not that our positions will be sustained. Accordingly, we have not recorded a tax reserve for this matter. We paid this assessment in the first quarter of 2017, pending resolution of the appeal process. If the South Korean tax authorities were to prevail the potential additional exposure through 2019 would be approximately $13 million.
Our Future Effective Income Tax Rate
Our future effective income tax rate may be materially impacted by the amount of income taxes associated with our foreign earnings, which are taxed at rates different from the U.S. federal statutory income tax rate, as well as the timing and extent of the realization of deferred tax assets and changes in the tax law. Further, our tax rate may fluctuate within a fiscal year, including from quarter to quarter, due to items arising from discrete events, including settlements of tax audits and assessments, the resolution or identification of tax position uncertainties, and acquisitions of other companies.
In July 2015, the U.S. Tax Court issued an opinion in Altera Corp. v. Commissioner related to the treatment of stock-based compensation expense in an intercompany cost-sharing arrangement. The opinion invalidated part of a treasury regulation requiring stock-based compensation to be included in any qualified intercompany cost-sharing arrangement. The Company previously recorded a tax benefit based on the opinion in the case, which was offset by a corresponding increase in the valuation allowance against U.S. deferred tax assets. On June 7, 2019, the U.S. Court of Appeals for the Ninth Circuit reversed the U.S. Tax Court’s decision. On July 22, 2019, Altera Corp. filed a petition for an en banc rehearing before the U.S. Court of Appeals for the Ninth Circuit, which was denied on November 12, 2019. Altera Corp. has 90 days from this date to petition the U.S. Supreme Court for review of the decision. Due to the fact that the Altera decision is not yet final, as well as uncertainty surrounding the status of the current regulations and questions related to jurisdiction given the Company does not reside in the Ninth Circuit, we have determined no adjustment is required to the consolidated financial statements as a result of this ruling. The Company will continue to monitor ongoing developments and potential impacts to its consolidated financial statements.
Operating Measures
ARR
To help investors understand and assess the success of our subscription transition, we provide an ARR operating measure. On September 5, 2019, we revised the ARR definition. ARR represents the annualized value of our portfolio of recurring customer arrangements as of the end of the reporting period, including subscription software, cloud, and support contracts. This is a change from our prior definition where ARR for a quarter was calculated by dividing the portion of non-GAAP software revenue attributable to subscription and support under ASC 605 for the quarter by the number of days in the quarter and multiplying by 365. The definition change did not materially change the amount of ARR reported under ASC 605 for the period.
We believe ARR is a valuable operating metric to measure the health of a subscription business because it captures expected subscription and support cash generation from new customers, existing customer expansions and includes the impact of total churn, which reflects churn, offset by the impact of any pricing increases.
Because this measure represents the annualized value of recurring customer contracts as of the end of a reporting period, ARR does not represent revenue for any particular period or remaining revenue that will be recognized in future periods.
Subscription Bookings and Subscription ACV
On September 5, 2019, we announced a revision to our reporting measures. Effective in 2020, we will no longer provide bookings but instead we will provide ARR, which we believe provides a more comprehensive view of a subscription business.
Given the difference in revenue recognition between the sale of a perpetual software license and a subscription, during our transition to a subscription business model we used bookings for internal planning, forecasting and reporting of new license and cloud services transactions (as subscription bookings includes cloud services bookings).
In order to normalize between perpetual and subscription licenses, we define subscription bookings as the subscription annualized contract value (subscription ACV) of new subscription contracts multiplied by a conversion factor of 2. We arrived at the conversion factor of 2 by considering a number of variables, including pricing, support, length of term, and renewal rates. In 2019, 2018 and 2017, the average subscription contract term was approximately two years.
We define subscription ACV as the total value of a new subscription contract (which may include annual values that increase over time and without regard to contractual termination options) divided by the term of the contract (in days), multiplied by 365. If the term of the subscription contract is less than a year, and is not associated with an existing contract, the booking is equal to the total contract value. Beginning in the third quarter of 2018, minimum ACV commitments under our Strategic Alliance Agreement with Rockwell Automation are included in subscription ACV if the period-to-date minimum ACV commitment exceeds actual ACV sold under the Agreement.
We define license and subscription bookings as subscription bookings plus perpetual license bookings.
Because subscription bookings is a metric we use to approximate the value of subscription sales if sold as perpetual licenses, it does not represent the actual revenue that will be recognized with respect to subscription sales or that would be recognized if the sales were perpetual licenses, nor does the annualized value of monthly software rental bookings represent the value of any such booking.
Non-GAAP Financial Measures
The non-GAAP financial measures presented in the discussion of our results of operations and the respective most directly comparable GAAP measures are:
| • | non-GAAP revenue—GAAP revenue |
| • | non-GAAP gross margin—GAAP gross margin |
| • | non-GAAP operating income—GAAP operating income |
| • | non-GAAP operating margin—GAAP operating margin |
| • | non-GAAP net income—GAAP net income |
| • | non-GAAP diluted earnings per share—GAAP diluted earnings per share |
The non-GAAP financial measures exclude fair value adjustments related to acquired deferred revenue and deferred costs, stock-based compensation expense, amortization of acquired intangible assets expense, acquisition-related charges, pension plan termination-related costs, a legal accrual, restructuring charges, non-operating credit facility refinancing costs, identified discrete charges included in non-operating other expense, net and the related tax effects of the preceding items, and any other identified tax items.
These items are normally included in the comparable measures calculated and presented in accordance with GAAP. Our management excludes these items when evaluating our ongoing performance and/or predicting our earnings trends, and therefore excludes them when presenting non-GAAP financial measures. Management uses non-GAAP financial measures in conjunction with our GAAP results, as should investors.
Settlement Revenue Exclusions. In Q4'18, we settled a previously disclosed dispute with respect to a customer receivable. The settlement included partial payment of the receivable and new software purchases. The net revenue write-down recorded in Q4'18 was $9.3 million, comprised of a $14.5 million professional services revenue write-down, partially offset by new subscription revenue of $5.2 million. We excluded the professional services revenue write-down because the write-down related to revenue that was recorded in periods prior to fiscal 2017 and is not reflective of current operating performance and
excluded the new subscription revenue because it mitigated the impact of the professional services revenue write-down.
Fair value of acquired deferred revenue is a purchase accounting adjustment recorded to reduce acquired deferred revenue to the fair value of the remaining obligation, so our GAAP revenue after an acquisition does not reflect the full amount of revenue that would have been reported if the acquired deferred revenue was not written down to fair value. We believe excluding these adjustments to revenue from these contracts (and associated costs in fair value adjustment to deferred services cost) is useful to investors as an additional means to assess revenue trends of our business.
Stock-based compensation is a non-cash expense relating to stock-based awards issued to executive officers, employees and outside directors, consisting of restricted stock, stock options and restricted stock units. We exclude this expense as it is a non-cash expense and we assess our internal operations excluding this expense and believe it facilitates comparisons to the performance of other companies in our industry.
Amortization of acquired intangible assets is a non-cash expense that is impacted by the timing and magnitude of our acquisitions. We believe the assessment of our operations excluding these costs is relevant to our assessment of internal operations and comparisons to the performance of other companies in our industry.
Acquisition-related and other transactional charges included in general and administrative costs are direct costs of potential and completed acquisitions and expenses related to acquisition integration activities, including transaction fees, due diligence costs, severance and professional fees. Subsequent adjustments to our initial estimated amount of contingent consideration associated with specific acquisitions are also included within acquisition-related charges. Other transactional charges include third-party costs related to structuring unusual transactions. We do not include these costs when reviewing our operating results internally. The occurrence and amount of these costs will vary depending on the timing and size of acquisitions.
U.S. pension plan termination-related costs include charges related to our plan that we began terminating in the second quarter of 2014. Costs associated with termination of the plan are not considered part of our regular operations.
Restructuring and other charges, net include excess facility restructuring charges, headquarters relocation charges and severance costs resulting from reductions of personnel driven by modifications to our business strategy. Headquarters relocation charges are non-cash accelerated depreciation expense recorded in anticipation of exiting our prior headquarters facility due to changes in the estimated useful lives of fixed assets. We do not include these costs when reviewing our operating results internally. These costs may vary in size based on our restructuring plan.
Non-operating credit facility refinancing costs are non-operating charges we record as a result of the refinancing of our credit facility. We assess our internal operations excluding these costs and believe it facilitates comparisons to the performance of other companies in our industry.
Income tax adjustments include the tax impact of the items above and assumes that we are profitable on a non-GAAP basis in the U.S. and one foreign jurisdiction. It also eliminates the effect of the valuation allowance recorded against our net deferred tax assets in those jurisdictions. Additionally, we exclude other material tax items that we do not include when reviewing our operating results internally.
We use these non-GAAP financial measures, and we believe that they assist our investors, to make period-to-period comparisons of our operational performance because they provide a view of our operating results without items that are not, in our view, indicative of our core operating results. We believe that these non-GAAP financial measures help illustrate underlying trends in our business, and we use the measures to establish budgets and operational goals (communicated internally and externally) for managing our business and evaluating our performance. We believe that providing non-GAAP financial measures also affords investors a view of our operating results that may be more easily compared to the results of other companies in our industry that use similar financial measures to supplement their GAAP results.
The items excluded from the non-GAAP financial measures often have a material impact on our financial results and such items often recur. Accordingly, the non-GAAP financial measures included in this Annual Report should be considered in addition to, and not as a substitute for or superior to, the
comparable measures prepared in accordance with GAAP. The following tables reconcile each of these non-GAAP financial measures to its most closely comparable GAAP measure on our financial statements.
| (in millions, except per share amounts) | Year ended September 30, | ||||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | ||||||||||||
| 2019 | 2019 | 2018 | 2017 | ||||||||||||
| GAAP revenue | $ | 1,255.6 | $ | 1,311.5 | $ | 1,241.8 | $ | 1,164.0 | |||||||
| Settlement revenue exclusion | — | — | 9.3 | — | |||||||||||
| Fair value of acquired deferred revenue | 0.8 | 0.8 | 1.3 | 2.7 | |||||||||||
| Non-GAAP revenue | $ | 1,256.4 | $ | 1,312.3 | $ | 1,252.4 | $ | 1,166.8 | |||||||
| GAAP gross margin | $ | 930.3 | $ | 993.3 | $ | 915.3 | $ | 835.5 | |||||||
| Settlement revenue exclusion | — | — | 9.3 | — | |||||||||||
| Fair value of acquired deferred revenue | 0.8 | 0.8 | 1.3 | 2.7 | |||||||||||
| Fair value to acquired deferred costs | (0.3 | ) | (0.3 | ) | (0.4 | ) | (0.4 | ) | |||||||
| Stock-based compensation | 11.9 | 11.9 | 11.5 | 12.6 | |||||||||||
| Amortization of acquired intangible assets included in cost of revenue | 27.3 | 27.3 | 26.7 | 26.6 | |||||||||||
| Non-GAAP gross margin | $ | 970.0 | $ | 1,033.1 | $ | 963.7 | $ | 877.0 | |||||||
| GAAP operating income (loss) | $ | 63.0 | $ | 101.6 | $ | 72.6 | $ | 41.8 | |||||||
| Settlement revenue exclusion | — | — | 9.3 | — | |||||||||||
| Fair value of acquired deferred revenue | 0.8 | 0.8 | 1.3 | 2.7 | |||||||||||
| Fair value to acquired deferred costs | (0.3 | ) | (0.3 | ) | (0.4 | ) | (0.4 | ) | |||||||
| Stock-based compensation | 86.4 | 86.4 | 82.9 | 76.7 | |||||||||||
| Amortization of acquired intangible assets included in cost of revenue | 27.3 | 27.3 | 26.7 | 26.6 | |||||||||||
| Amortization of acquired intangible assets | 23.8 | 23.8 | 31.4 | 32.1 | |||||||||||
| Acquisition-related and other transactional charges included in general and administrative expenses | 3.1 | 3.1 | 1.9 | 1.6 | |||||||||||
| U.S. pension plan termination-related costs | — | — | — | 0.3 | |||||||||||
| Restructuring and other charges, net | 51.1 | 51.1 | 3.8 | 7.9 | |||||||||||
| Non-GAAP operating income | $ | 255.3 | $ | 293.9 | $ | 229.4 | $ | 189.3 | |||||||
| GAAP net income (loss) | $ | (27.5 | ) | $ | 3.0 | $ | 52.0 | $ | 6.2 | ||||||
| Settlement revenue exclusion | — | — | 9.3 | — | |||||||||||
| Fair value of acquired deferred revenue | 0.8 | 0.8 | 1.3 | 2.7 | |||||||||||
| Fair value to acquired deferred costs | (0.3 | ) | (0.3 | ) | (0.4 | ) | (0.4 | ) | |||||||
| Stock-based compensation | 86.4 | 86.4 | 82.9 | 76.7 | |||||||||||
| Amortization of acquired intangible assets included in cost of revenue | 27.3 | 27.3 | 26.7 | 26.6 | |||||||||||
| Amortization of acquired intangible assets | 23.8 | 23.8 | 31.4 | 32.1 | |||||||||||
| Acquisition-related and other transactional charges included in general and administrative expenses | 3.1 | 3.1 | 1.9 | 1.6 | |||||||||||
| U.S. pension plan termination-related costs | — | — | — | 0.3 | |||||||||||
| Restructuring and other charges, net | 51.1 | 51.1 | 3.8 | 7.9 | |||||||||||
| Non-operating credit facility refinancing costs | — | — | — | 1.2 | |||||||||||
| Income tax adjustments (1) | 29.7 | 11.8 | (37.6 | ) | (17.4 | ) | |||||||||
| Non-GAAP net income | $ | 194.5 | $ | 207.0 | $ | 171.2 | $ | 137.6 | |||||||
| GAAP diluted earnings (loss) per share | $ | (0.23 | ) | $ | 0.03 | $ | 0.44 | $ | 0.05 | ||||||
| Settlement revenue exclusion | — | — | 0.08 | — | |||||||||||
| Fair value of acquired deferred revenue | 0.01 | 0.01 | 0.01 | 0.02 | |||||||||||
| Stock-based compensation | 0.73 | 0.73 | 0.70 | 0.65 | |||||||||||
| Total amortization of acquired intangible assets | 0.43 | 0.43 | 0.49 | 0.50 |
| Acquisition-related and other transactional charges included in general and administrative expenses | 0.03 | 0.03 | 0.02 | 0.01 | |||||||||||
| Restructuring and other charges, net | 0.43 | 0.43 | 0.03 | 0.07 | |||||||||||
| Non-operating credit facility refinancing costs | — | — | — | 0.01 | |||||||||||
| Income tax adjustments (1) | 0.25 | 0.10 | (0.32 | ) | (0.15 | ) | |||||||||
| Non-GAAP diluted earnings per share (2) | $ | 1.64 | $ | 1.74 | $ | 1.45 | $ | 1.17 |
| (1) | We have a full valuation allowance against our U.S. net deferred tax assets and a valuation allowance against net deferred tax assets in certain foreign jurisdictions. As we are profitable on a non-GAAP basis, the 2019, 2018 and 2017 non-GAAP tax provisions are being calculated assuming there is no valuation allowance. Income tax adjustments reflect the tax effects of non-GAAP adjustments which are calculated by applying the applicable tax rate by jurisdiction to the non-GAAP adjustments listed above. We recorded the impact of the Tax Cuts and Jobs Act in 2018 GAAP earnings, resulting in a non-cash benefit of approximately $12 million. We have excluded these benefits from our non-GAAP results. |
| (2) | Diluted earnings per share impact of non-GAAP adjustments is calculated by dividing the dollar amount of the non-GAAP adjustment by the diluted weighted average shares outstanding for the respective year. |
| Year ended September 30, | ||||||||||||
| As Reported ASC 606 | ASC 605 | As Reported ASC 605 | As Reported ASC 605 | |||||||||
| Operating margin impact of non-GAAP adjustments: | 2019 | 2019 | 2018 | 2017 | ||||||||
| GAAP operating margin | 5.0 | % | 7.7 | % | 5.8 | % | 3.6 | % | ||||
| Settlement revenue exclusion | — | % | — | % | 0.6 | % | — | % | ||||
| Fair value of acquired deferred revenue | 0.1 | % | 0.1 | % | 0.1 | % | 0.2 | % | ||||
| Stock-based compensation | 6.9 | % | 6.6 | % | 6.7 | % | 6.6 | % | ||||
| Total amortization of acquired intangible assets | 4.1 | % | 3.9 | % | 4.7 | % | 5.0 | % | ||||
| Acquisition-related and other transactional charges included in general and administrative expenses | 0.2 | % | 0.2 | % | 0.1 | % | 0.1 | % | ||||
| Restructuring and other charges, net | 4.1 | % | 3.9 | % | 0.3 | % | 0.7 | % | ||||
| Non-GAAP operating margin | 20.3 | % | 22.4 | % | 18.3 | % | 16.2 | % |
Critical Accounting Policies and Estimates
We have prepared our consolidated financial statements in accordance with accounting principles generally accepted in the United States of America. In preparing our financial statements, we make estimates, assumptions and judgments that can have a significant impact on our reported revenues, results of operations, and net income, as well as on the value of certain assets and liabilities on our balance sheet. These estimates, assumptions and judgments are made based on our historical experience and on other assumptions that we believe to be reasonable under the circumstances. These estimates may change as new events occur or additional information is obtained, and we may periodically be faced with uncertainties, the outcomes of which are not within our control and may not be known for a prolonged period of time.
The accounting policies, methods and estimates used to prepare our financial statements are described generally in Note 2. Summary of Significant Accounting Policies of Notes to Consolidated Financial Statements in this Annual Report. The most important accounting judgments and estimates that we made in preparing the financial statements involved:
| • | revenue recognition; |
| • | accounting for income taxes; and |
| • | valuation of assets and liabilities acquired in business combinations. |
A critical accounting policy is one that is both material to the presentation of our financial statements and requires us to make subjective or complex judgments that could have a material effect on our financial condition and results of operations. Critical accounting policies require us to make assumptions about matters that are uncertain at the time of the estimate, and different estimates that we could have used, or changes in the estimates that are reasonably likely to occur, may have a material impact on our financial condition or results of operations. Because the use of estimates is inherent in the financial reporting process, actual results could differ from those estimates.
Accounting policies, guidelines and interpretations related to our critical accounting policies and estimates are generally subject to numerous sources of authoritative guidance and are often reexamined by accounting standards rule makers and regulators. These rule makers and/or regulators may promulgate interpretations, guidance or regulations that may result in changes to our accounting policies, which could have a material impact on our financial position and results of operations.
Revenue Recognition
Nature of Products and Services
Our sources of revenue include: (1) subscription, (2) perpetual license, (3) support for perpetual licenses and (4) professional services. Revenue is derived from the licensing of computer software products and from related support and/or professional services contracts. Effective October 1, 2018, we record revenues in accordance with the guidance provided by ASC 606, Revenue from Contracts with Customer. In accordance with ASC 606, revenue is recognized when a customer obtains control of promised products or services. The amount of revenue recognized reflects the consideration that we expect to be entitled to receive in exchange for these products or services. To achieve the core principle of this standard, we apply the following five steps:
(1) Identify the contract with the customer,
(2) identify the performance obligations in the contract,
(3) determine the transaction price,
(4) allocation the transaction price to performance obligations in the contract,
(5) recognize revenue when or as we satisfy a performance obligation.
We enter into contracts that include combinations of products, support and professional services, which are accounted for as separate performance obligations with differing revenue recognition patterns referenced below.
| Performance Obligation | When Performance Obligation is Typically Satisfied |
| Term-based subscriptions | |
| On-premise software licenses | Point in Time: Upon the later of when the software is made available or the subscription term commences |
| Support and cloud-based offerings | Over Time: Ratably over the contractual term; commencing upon the later of when the software is made available or the subscription term commences |
| Perpetual software licenses | Point in Time: when the software is made available |
| Support for perpetual software licenses | Over Time: Ratably over the contractual term |
| Professional services | Over time: As services are provided |
Through 2018, we recorded revenues for software related deliverables in accordance with the guidance provided by ASC 985-605, Software-Revenue Recognition and revenues for non-software deliverables in accordance with ASC 605-25*, Revenue Recognition, Multiple-Element Arrangements.* Under those standards, revenue is recorded when the following criteria are met: (1) persuasive evidence of an arrangement exists, (2) delivery has occurred (generally, FOB shipping point or electronic distribution), (3) the fee is fixed or determinable, and (4) collection is probable. We exercise judgment and use estimates in connection with determining the amounts of software license and services revenues to be recognized in each accounting period.
Judgments and Estimates
Our contracts with customers for subscriptions typically include commitments to transfer term-based, on-premise software licenses bundled with support and/or cloud services. On-premise software is determined to be a distinct performance obligation from support which is sold for the same term of the subscription. For subscription arrangements which include cloud services, we assess whether the cloud
component is highly interrelated with on-premise term software licenses. Other than a limited population of subscriptions, the cloud component is not currently deemed to be interrelated with the on-premise term software and, as a result, cloud services are accounted for as a distinct performance obligation from the software and support components of the subscription.
Judgment is required to allocate the transaction price to each performance obligation. We use the estimated standalone selling price method to allocate the transaction price for items that are not sold separately. The estimated standalone selling price is determined using all information reasonably available to us, including market conditions and other observable inputs. The corresponding revenues are recognized as the related performance obligations are satisfied. We determined that 50% to 55% of the estimated standalone selling price for subscriptions that contain distinct license and support performance obligations are attributable to software licenses and 45% to 50%, depending upon the product offering, is attributable to support for those licenses.
Our multi-year, non-cancellable on-premise subscription contracts provide customers with an annual right to exchange software within the original subscription with other software. Although the exchange right is limited to software products within a similar product grouping, the exchange right is not limited to products with substantially similar features and functionality as those originally delivered. We determined that this right to exchange previously delivered software for different software represents variable consideration to be accounted for as a liability. We have identified a standard portfolio of contracts with common characteristics and applied the expected value method of determining variable consideration associated with this right. Additionally, where there are isolated situations that are outside of the standard portfolio of contracts due to contract size, longer contract duration, or other unique contractual terms, we use the most likely amount method to determine the amount of variable consideration. In both circumstances, the variable consideration included in the transaction price is constrained to the extent it is probable that a significant reversal in the amount of cumulative revenue recognized will not occur when the uncertainty associated with the variable consideration is subsequently resolved.
Accounting for Income Taxes
As part of the process of preparing our consolidated financial statements, we are required to calculate our income tax expense based on taxable income by jurisdiction. There are many transactions and calculations about which the ultimate tax outcome is uncertain; as a result, our calculations involve estimates by management. Some of these uncertainties arise as a consequence of revenue-sharing, cost-reimbursement and transfer pricing arrangements among related entities and the differing tax treatment of revenue and cost items across various jurisdictions. If we were compelled to revise or to account differently for our arrangements, that revision could affect our tax liability.
The income tax accounting process also involves estimating our actual current tax liability, together with assessing temporary differences resulting from differing treatment of items for tax and accounting purposes. These differences result in deferred tax assets and liabilities, which are included within our consolidated balance sheets. We must then assess the likelihood that our deferred tax assets will be recovered from future taxable income and, to the extent we believe that it is more likely than not that all or a portion of our deferred tax assets will not be realized, we must establish a valuation allowance as a charge to income tax expense.
As of September 30, 2019, we have a valuation allowance of $146.1 million against net deferred tax assets in the U.S. and a valuation allowance of $31.6 million against net deferred tax assets in certain foreign jurisdictions. We have concluded, based on the weight of available evidence, that a full valuation allowance continues to be required against our U.S. net deferred tax assets as they are not more likely than not to be realized in the future. We will continue to reassess our valuation allowance requirements each financial reporting period.
The valuation allowance recorded against net deferred tax assets of certain foreign jurisdictions is established primarily for our net operating loss carryforwards, the majority of which do not expire. There are limitations imposed on the utilization of such net operating losses that could further restrict the recognition of any tax benefits.
Prior to the passage of the U.S. Tax Act, the Company asserted that substantially all of the undistributed earnings of its foreign subsidiaries were considered indefinitely invested and accordingly, no deferred taxes were provided. Pursuant to the provisions of the U.S. Tax Act, these earnings were subjected to a one-time transition tax. We maintain our assertion to permanently reinvest these earnings outside the U.S. unless repatriation can be done with no significant tax cost, with the exception of a
foreign holding company formed in 2018 and our Taiwan subsidiary. If we decide to repatriate any additional non-U.S. earnings in the future, we may be required to establish a deferred tax liability on such earnings. The amount of unrecognized deferred tax liability on the undistributed earnings would not be material.
In the normal course of business, PTC and its subsidiaries are examined by various taxing authorities, including the Internal Revenue Service (IRS) in the U.S. We regularly assess the likelihood of additional assessments by tax authorities and provide for these matters as appropriate. We are currently under audit by tax authorities in several jurisdictions. Audits by tax authorities typically involve examination of the deductibility of certain permanent items, transfer pricing, limitations on net operating losses and tax credits. Although we believe our tax estimates are appropriate, the final determination of tax audits and any related litigation could result in material changes in our estimates.
Valuation of Assets and Liabilities Acquired in Business Combinations
In accordance with business combination accounting, we allocate the purchase price of acquired companies to the tangible and intangible assets acquired and liabilities assumed based on their estimated fair values. Determining these fair values requires management to make significant estimates and assumptions, especially with respect to intangible assets.
Our identifiable intangible assets acquired consist of developed technology, core technology, tradenames, customer lists and contracts, and software support agreements and related relationships. Developed technology consists of products that have reached technological feasibility. Core technology represents a combination of processes, inventions and trade secrets related to the design and development of acquired products. Customer lists and contracts and software support agreements and related relationships represent the underlying relationships and agreements with customers of the acquired company’s installed base. We have generally valued intangible assets using a discounted cash flow model. Critical estimates in valuing certain of the intangible assets include but are not limited to:
| • | future expected cash flows from software license sales, customer support agreements, customer contracts and related customer relationships and acquired developed technologies and trademarks and trade names; |
| • | expected costs to develop the in-process research and development into commercially viable products and estimating cash flows from the projects when completed; |
| • | the acquired company’s brand awareness and market position, as well as assumptions about the period of time the acquired brand will continue to be used by the combined company; and |
| • | discount rates used to determine the present value of estimated future cash flows. |
In addition, we estimate the useful lives of our intangible assets based upon the expected period over which we anticipate generating economic benefits from the related intangible asset.
Net tangible assets consist of the fair values of tangible assets less the fair values of assumed liabilities and obligations. Except for deferred revenues, net tangible assets were generally valued by us at the respective carrying amounts recorded by the acquired company, if we believed that their carrying values approximated their fair values at the acquisition date. The values assigned to deferred revenue reflect an amount equivalent to the estimated cost plus an appropriate profit margin to perform the services related to the acquired company’s software support contracts.
In addition, uncertain tax positions and tax related valuation allowances assumed in connection with a business combination are initially estimated as of the acquisition date and we reevaluate these items quarterly with any adjustments to our preliminary estimates being recorded to goodwill provided that we are within the measurement period (up to one year from the acquisition date) and we continue to collect information in order to determine their estimated values. Subsequent to the measurement period or our final determination of the estimated value of uncertain tax positions or tax related valuation allowances, whichever comes first, changes to these uncertain tax positions and tax related valuation allowances will affect our provision for income taxes in our Consolidated Statements of Operations.
Our estimates of fair value are based upon assumptions believed to be reasonable at that time, but which are inherently uncertain and unpredictable. Assumptions may be incomplete or inaccurate, and unanticipated events and circumstances may occur, which may affect the accuracy or validity of such assumptions, estimates or actual results.
When events or changes in circumstances indicate that the carrying value of a finite-lived intangible asset may not be recoverable, we perform an assessment of the asset for potential impairment. This assessment is based on projected undiscounted future cash flows over the asset’s remaining life. If the carrying value of the asset exceeds its undiscounted cash flows, we record an impairment loss equal to the excess of the carrying value over the fair value of the asset, determined using projected discounted future cash flows of the asset.
Liquidity and Capital Resources
| (in thousands) | September 30, | ||||||||||
| 2019 | 2018 | 2017 | |||||||||
| Cash and cash equivalents | $ | 269,579 | $ | 259,946 | $ | 280,003 | |||||
| Marketable securities | 57,435 | 55,951 | 50,315 | ||||||||
| Total | $ | 327,014 | $ | 315,897 | $ | 330,318 | |||||
| Activity for the year included the following: | |||||||||||
| Cash provided by operating activities | $ | 285,145 | $ | 247,752 | $ | 135,203 | |||||
| Cash used by investing activities | (150,024 | ) | (49,212 | ) | (16,127 | ) | |||||
| Cash used by financing activities | (122,960 | ) | (210,846 | ) | (118,105 | ) |
Cash and cash equivalents
We invest our cash with highly rated financial institutions and in diversified domestic and international money market mutual funds. Cash and cash equivalents include highly liquid investments with original maturities of three months or less. In addition, we hold investments in marketable securities totaling approximately $57 million with an average maturity of 12 months. At September 30, 2019, cash and cash equivalents totaled $270 million, compared to $260 million at September 30, 2018, reflecting $285 million in operating cash flow, $25 million of net borrowings under our credit facility, $13 million in proceeds from issuance of common stock, and $10 million from settlements of net investment hedges, offset by $115 million used for repurchases of common stock, $87 million used for acquisitions, $64 million used for capital expenditures, $44 million used to pay withholding taxes on stock-based awards that vested in the period, $8 million used for purchases of investments, $2 million used for the payment of contingent consideration, and $1 million used to purchase marketable securities, net of proceeds from maturities.
Cash provided by operating activities
Cash provided by operating activities was $285 million in 2019 compared to $248 million in 2018. The increase in 2019 is primarily due to higher cash collection of accounts receivable of approximately $80 million, offset by an increase in payments related to payables and accruals due to timing, a decrease in net income of $79 million, and an increase in restructuring payments of $22 million (year over year).
Restructuring payments totaled $25 million in 2019, compared to $3 million in 2018. Cash paid for income taxes was $39 million in 2019 compared to $23 million in 2018.
Cash used by investing activities
| (in thousands) | Year ended September 30, | ||||||||||
| 2019 | 2018 | 2017 | |||||||||
| Acquisitions of businesses, net of cash acquired | $ | (86,737 | ) | $ | (3,000 | ) | $ | (4,960 | ) | ||
| Additions to property and equipment | (64,411 | ) | (36,041 | ) | (25,444 | ) | |||||
| Purchases of short- and long-term marketable securities | (33,027 | ) | (24,311 | ) | (19,726 | ) | |||||
| Proceeds from maturities of short- and long-term marketable securities | 31,976 | 18,140 | 18,785 | ||||||||
| Proceeds from sales of investments | — | — | 15,218 | ||||||||
| Purchase on intangible asset | — | (3,000 | ) | — | |||||||
| Settlement of net investment hedges | 9,675 | — | — | ||||||||
| Purchases of investments | (7,500 | ) | (1,000 | ) | — | ||||||
| $ | (150,024 | ) | $ | (49,212 | ) | $ | (16,127 | ) |
The 2019 increase in property, plant and equipment payments is primarily attributable to capitalized expenditures related to construction of our new worldwide headquarters in the Boston Seaport District (a portion of which is offset by landlord reimbursements included in cash from operations above). We used $70 million to acquire Frustum and an additional $17 million for two smaller acquisitions as described in Note 6. Acquisitions included in the Notes to Consolidated Financial Statements in this Annual Report.
Our expenditures for property and equipment consist primarily of facility improvements, office equipment, computer equipment, and software.
Cash used by financing activities
| (in thousands) | Year ended September 30, | ||||||||||
| 2019 | 2018 | 2017 | |||||||||
| Borrowings under debt agreements | $ | 205,000 | $ | 250,000 | $ | 150,000 | |||||
| Repayments of borrowings under credit facility | (180,000 | ) | (320,000 | ) | (190,000 | ) | |||||
| Repurchases of common stock | (114,994 | ) | (1,100,000 | ) | (50,991 | ) | |||||
| Proceeds from issuance of common stock | 12,975 | 1,015,654 | 10,778 | ||||||||
| Payments of withholding taxes in connection with vesting of stock-based awards | (44,366 | ) | (45,374 | ) | (26,654 | ) | |||||
| Credit facility origination costs | — | (2,851 | ) | (184 | ) | ||||||
| Contingent consideration | (1,575 | ) | (8,275 | ) | (11,054 | ) | |||||
| $ | (122,960 | ) | $ | (210,846 | ) | $ | (118,105 | ) |
The net borrowings in 2019 reflect borrowings of $205 million under our credit facility to fund the working capital requirements and Frustum acquisition, offset by repayments of $180 million. In 2019 we repurchased $115 million of our common stock, paid $44 million in withholding taxes in connection with stock-based awards, received $13 million in proceeds from issuance of common stock under our ESPP, and made $2 million in contingent consideration payments.
Credit Agreement
In November 2019, we amended and restated our existing credit facility to increase the revolving loan commitment from $700 million to $1 billion and amend other provisions. The credit facility is a multi-currency credit facility with a syndicate of sixteen banks for which JPMorgan Chase Bank, N.A. acts as Administrative Agent. Outstanding revolving loan amounts may be repaid in whole or in part, without penalty or premium, prior to the September 13, 2023 maturity date, when all remaining amounts outstanding will be due and payable in full.
We use the credit facility for general corporate purposes, including acquisitions of businesses, share repurchases and working capital requirements. As of September 30, 2019, we had $173.1 million in revolving loans outstanding under the credit facility, the fair value of which approximated its book value. As of September 30, 2019, we had approximately $527 million undrawn, of which $512 million would be available to borrow, the availability of which is reduced by letters of credit and certain other long-term liabilities. Giving effect to the Onshape acquisition and the amendment to the credit facility, we had approximately $357 million available to borrow.
Any borrowings by PTC Inc. or certain of our foreign subsidiaries under the credit facility would be guaranteed, respectively, by our material domestic subsidiaries that become parties to the subsidiary guaranty, if any, and/or by PTC Inc. Borrowings are also secured by first priority liens on property of PTC and certain of our material domestic subsidiaries, including 100% of the voting equity interests of certain of our domestic subsidiaries and 65% of our material first-tier foreign subsidiaries. Loans under the credit facility bear interest at variable rates that reset every 30 to 180 days depending on the rate and period selected by us and based upon our total leverage ratio. During 2019, the weighted average annual interest rate for all borrowings outstanding was 5.38% and, as of September 30, 2019, the rate on the credit facility was 3.44%. We also pay a quarterly commitment fee on the undrawn portion of the credit facility ranging from 0.175% to 0.30% per year based on our total leverage ratio.
The credit facility imposes customary covenants that limit our ability to incur liens or guarantee obligations, pay dividends and make other distributions, make investments and engage in certain other transactions. In addition, we and our material domestic subsidiaries may not invest in, or loan to, our foreign subsidiaries in aggregate amounts exceeding $100 million for any purpose and an additional $200 million for acquisitions of businesses. We also must maintain the following financial ratios:
| Required Ratio | Ratio as of September 30, 2019 | ||
| Total Leverage Ratio Ratio of consolidated total indebtedness to the consolidated trailing four quarters EBITDA. | Not > 4.50:1.00 | 1.73:1:00 | |
| Interest Coverage Ratio Ratio of consolidated trailing four quarters EBITDA to consolidated trailing four quarters cash basis interest expense. | > 3.00:1.00 | 9.76:1.00 | |
| Senior Secured Leverage Ratio Ratio of senior consolidated total indebtedness (which excludes unsecured indebtedness) to consolidated trailing four quarters EBITDA as of the last day of any fiscal quarter. | Not > 3.00:1.00 | 0.47:1.00 |
Any failure to comply with such covenants would prevent us from being able to borrow additional funds, and would constitute a default, permitting the lenders to, among other things, accelerate the amounts outstanding and terminate the credit facility. As of September 30, 2019, we were in compliance with all financial and operating covenants of the credit facility.
Outstanding Notes
On May 12, 2016, we issued $500 million of 6.00% Senior Notes due 2024 (the “2024 6% Notes”) in a registered offering and used the net proceeds to repay indebtedness under our senior credit facility. As of September 30, 2019, unamortized deferred financing fees associated with the offering and presented as a direct reduction from the carrying amount of the 2024 6% Notes were $4.0 million.
The 2024 6% Notes are unsecured, mature on May 15, 2024, and bear interest at a rate of 6.00% per annum, payable semi-annually (November and May). We may redeem some or all of the 2024 6% Notes at redemption prices specified in the 2024 6% Notes plus accrued and unpaid interest. In addition, if we undergo a change of control, we will be required to make an offer to purchase all the 2024 6% Notes at a price equal to 101% of the principal amount of the 2024 6% Notes plus accrued and unpaid interest.
The notes were issued under an indenture that contains customary covenants. Subject to certain exceptions, our ability to incur certain additional debt is limited unless, after giving pro forma effect to such incurrence and the application of the proceeds thereof, the ratio of our EBITDA to our Consolidated Fixed Charges (as both terms are defined in the indenture) is not greater than 2.00 to 1.00. The indenture also restricts our ability to incur liens, pay dividends or make certain other distributions, sell assets or engage in sale/leaseback transactions. Any failure to comply with these and other covenants included in the indenture could constitute an event of default that could result in the acceleration of the payment of the aggregate principal amount of 2024 6% Notes then outstanding and accrued interest. As of September 30, 2019, we were in compliance with all such covenants.
Share Repurchase Authorization
Our Articles of Organization authorize us to issue up to 500 million shares of our common stock. Our Board of Directors has authorized us to repurchase up to $1,500 million of our common stock for the October 1, 2017 through September 30, 2020 period. We use cash from operations and borrowings under our credit facility to make such repurchases. All shares of our common stock repurchased are automatically restored to the status of authorized and unissued.
In 2019, we repurchased 1.4 million shares in the open market for $115 million. In addition, in 2019 and 2018, we repurchased 3.0 million and 9.4 million shares, respectively, under accelerated share repurchase agreements.
Expectations for Fiscal 2020
We believe that existing cash and cash equivalents, together with cash generated from operations and amounts available under the credit facility, will be sufficient to meet our working capital and capital expenditure requirements (which we expect to be $28 million in 2020) through at least the next twelve months and to meet our known long-term capital requirements.
On November 1, 2019, we acquired Onshape for approximately $470 million, net of cash acquired. In connection with the acquisition, we borrowed $455 million under our existing credit facility, and we also increased the loan commitment to $1 billion on November 13, 2019. We plan to suspend our share repurchase program in 2020 in order to accelerate debt repayments.
Our expected uses of cash could change, our cash position could be reduced, and we could incur additional debt obligations if we purchase our outstanding shares or retire debt or engage in strategic transactions, any of which could be commenced, suspended or completed at any time. Any such purchases or retirement of debt will depend on prevailing market conditions, our liquidity requirements, contractual restrictions and other factors. We also evaluate possible strategic transactions on an ongoing basis and at any given time may be engaged in discussions or negotiations with respect to possible strategic transactions. The amounts involved in any share or debt repurchases or strategic transactions may be material.
We ended 2019 with a cash balance of $270 million and marketable securities of $57 million. A significant portion of our cash is generated and held outside of the United States. At September 30, 2019, we had cash and cash equivalents of $40.0 million in the United States, $83.0 million in Europe, $122.0 million in Asia Pacific Rim (including India) and $25.0 million in other non-U.S. countries. All of the marketable securities are held in Europe. We have substantial cash requirements in the United States, but we believe that the combination of our existing U.S. cash and cash equivalents, marketable securities, and future U.S. operating cash flows and cash available under our credit facility, will be sufficient to meet our ongoing U.S. operating expenses and known capital requirements.
Contractual Obligations
At September 30, 2019, our contractual obligations were as follows:
| Payments due by period | ||||||||||||||||||||
| Contractual Obligations (in millions) | Total | Less than 1 year | 1-3 years | 3-5 years | More than 5 years | |||||||||||||||
| Debt (1) | $ | 851.7 | $ | 37.2 | $ | 74.4 | $ | 740.0 | $ | — | ||||||||||
| Operating leases (2) | 312.8 | 31.9 | 58.7 | 36.2 | 186.0 | |||||||||||||||
| Purchase obligations (3) | 101.8 | 67.6 | 34.0 | 0.2 | — | |||||||||||||||
| Pension liabilities (4) | 25.1 | 2.7 | 6.1 | 6.7 | 9.6 | |||||||||||||||
| Unrecognized tax benefits (5) | 11.5 | |||||||||||||||||||
| Total | $ | 1,302.9 | $ | 139.4 | $ | 173.2 | $ | 783.1 | $ | 195.7 |
| (1) | Includes required principal repayments and interest and commitment fees on our 2024 6% Notes and our revolving credit facility based on the balance outstanding as of September 30, 2019 and the interest rates in effect as of September 30, 2019, 6.0% for our 2024 6% Notes and 3.44% for our revolving credit facility. The credit facility matures on September 13, 2023, when all remaining amounts outstanding will be due and payable in full. Principal and interest on any additional borrowing that may be required to refinance the credit facility upon its maturity are not included in the contractual obligations above. |
| (2) | The future minimum lease payments above include minimum future lease payments for excess facilities under non-cancellable operating leases. These leases qualify for operating lease accounting treatment and, as such, are not included on our balance sheet. See Note 10. Commitments and Contingencies of Notes to Consolidated Financial Statements in this Annual Report for additional information regarding our operating leases. On September 7, 2017, we entered into a lease for approximately 250,000 square feet located at 121 Seaport Boulevard, Boston, Massachusetts. The term of the lease is expected to run from January 1, 2019 through June 30, 2037. Base rent for the first year of the lease is $11.0 million and will increase by $1 per square foot leased per year thereafter ($0.3 million per year). Base rent first becomes payable on July 1, 2020. In addition to the future minimum lease payments above, for a majority of leases we are required to pay a pro rata portions of building operating costs and real estate taxes (together, “Additional Rent”). Additional rent is variable in nature and is not included in the operating lease payments above. |
| (3) | Purchase obligations represent minimum commitments due to third parties, including royalty contracts, research and development contracts, telecommunication contracts, information technology maintenance contracts in support of internal-use software and hardware and other marketing and consulting contracts. Contracts for which our commitment is variable, based on volumes, with no fixed minimum quantities, and contracts that can be canceled without payment penalties have been excluded. The purchase obligations included above are in addition to amounts included in current liabilities and prepaid expenses recorded on our September 30, 2019 consolidated balance sheet. |
| (4) | These obligations relate to our international pension plans and are not subject to fixed payment terms. Payments have been estimated based on the plans’ current funded status, planned employer contributions and actuarial assumptions. In addition, we may, at our discretion, make additional voluntary contributions to the plans. See Note 14. Pension Plans of Notes to Consolidated Financial Statements in this Annual Report for further discussion. |
| (5) | As of September 30, 2019, we had recorded total unrecognized tax benefits of $11.5 million. This liability is not subject to fixed payment terms and the amount and timing of payments, if any, which we will make related to this liability, are not known. See Note 8. Income Taxes of Notes to Consolidated Financial Statements in this Annual Report for additional information. |
As of September 30, 2019, we had letters of credit and bank guarantees outstanding of approximately $15.1 million (of which $1.1 million was collateralized).
Off-Balance Sheet Arrangements
We have not created, and are not party to, any special-purpose or off-balance sheet entities for the purpose of raising capital, incurring debt or operating parts of our business that are not consolidated (to
the extent of our ownership interest therein) into our financial statements. We have not entered into any transactions with unconsolidated entities whereby we have subordinated retained interests, derivative instruments or other contingent arrangements that expose us to material continuing risks, contingent liabilities, or any other obligation under a variable interest in an unconsolidated entity that provides financing, liquidity, market risk or credit risk support to us.
Recent Accounting Pronouncements
In accordance with recently issued accounting pronouncements, we will be required to comply with certain changes in accounting rules and regulations, some of which are expected to have a material impact on our consolidated financial statements. Refer to Note 2. Summary of Significant Accounting Policies to the Condensed Consolidated Financial Statements in this Form 10-K for all recently issued accounting pronouncements, which is incorporated herein by reference.
Previous: Item 6. Selected Financial Data · Next: Item 7A. Quantitative and Qualitative Disclosures about Market Risk