 filings.tools
Item 1. BUSINESS
35K characters. Original on sec.gov · Markdown
Item 1. BUSINESS
Overview
PayPal Holdings, Inc. was incorporated in Delaware in January 2015 and is a leading technology platform and digital payments company that enables digital and mobile payments on behalf of consumers and merchants worldwide. Our vision is to democratize financial services, as we believe that managing and moving money is a right for all people, not just the affluent. Our goal is to increase our relevance for consumers and merchants to manage and move their money anywhere in the world, anytime, on any platform and using any device. Our combined payment solutions, including our PayPal, PayPal Credit, Braintree, Venmo, Xoom, and Paydiant products, compose our proprietary Payments Platform.
We operate a two-sided proprietary global technology platform that links our customers, which consist of both merchants and consumers, around the globe to facilitate the processing of payment transactions, allowing us to connect millions of merchants and consumers worldwide. We offer our customers the flexibility to use their account to both purchase and receive payment for goods and services, as well as to transfer and withdraw funds. We enable consumers to more safely exchange funds with merchants using a variety of funding sources, which may include a bank account, a PayPal account balance, a PayPal Credit account, a credit or debit card or other stored value products such as coupons and gift cards. Our PayPal, Venmo and Xoom products also make it safer and simpler for friends and family to transfer funds to each other. We offer merchants an end-to-end payments solution that provides authorization and settlement capabilities, as well as instant access to funds. We help merchants connect with their customers and manage risk. We enable consumers to engage in cross-border shopping and merchants to extend their global reach while reducing the complexity and friction involved in enabling overseas and cross-border trade.
We generate revenues by charging fees for providing transaction processing and other payment-related services based primarily on the volume of activity processed through our Payments Platform. We generally do not charge consumers to fund or draw from their accounts; however, we generate revenue from consumers on fees charged for foreign currency exchange. We also earn revenue by providing value added services to consumers and merchants, such as our PayPal Credit and gateway services. Our gateway services, which include our Payflow Gateway services and Braintree Gateway services, provide the technology that links a merchant’s website to its processing network and merchant account and enable merchants to accept payments online with credit or debit cards.
Strategy
Our ability to grow revenue is affected by, among other things, consumer spending patterns, merchant and consumer adoption of digital payment methods, the expansion of multiple commerce channels, the growth of mobile devices and merchant and consumer applications on those devices, the growth of consumers globally with Internet and mobile access, the pace of transition from cash and checks to digital forms of payment, our share of the digital payments market, and our ability to innovate new methods of payment that merchants and consumers value. Our strategy to drive growth in our business includes the following:
| • | Growing our core: through expanding our global capabilities, customer base and scale, increasing our customers' use of our products and services by better addressing their everyday needs related to accessing, managing and moving money and expanding the adoption of our solutions by new merchants and consumers; |
| • | Expanding our value proposition for customers: by focusing on trust and simplicity, providing risk management and insights from our two-sided Payments Platform and being technology and platform agnostic; |
| • | Extending through strategic partnerships: by building new strategic partnerships to provide better experiences for our customers, offering greater choice and flexibility, acquiring new customers and reinforcing our role in the ecosystem; and |
| • | Seeking new areas of growth: through new international markets around the world and focusing on innovation both in the digital and the physical world. |
Key Performance Metrics
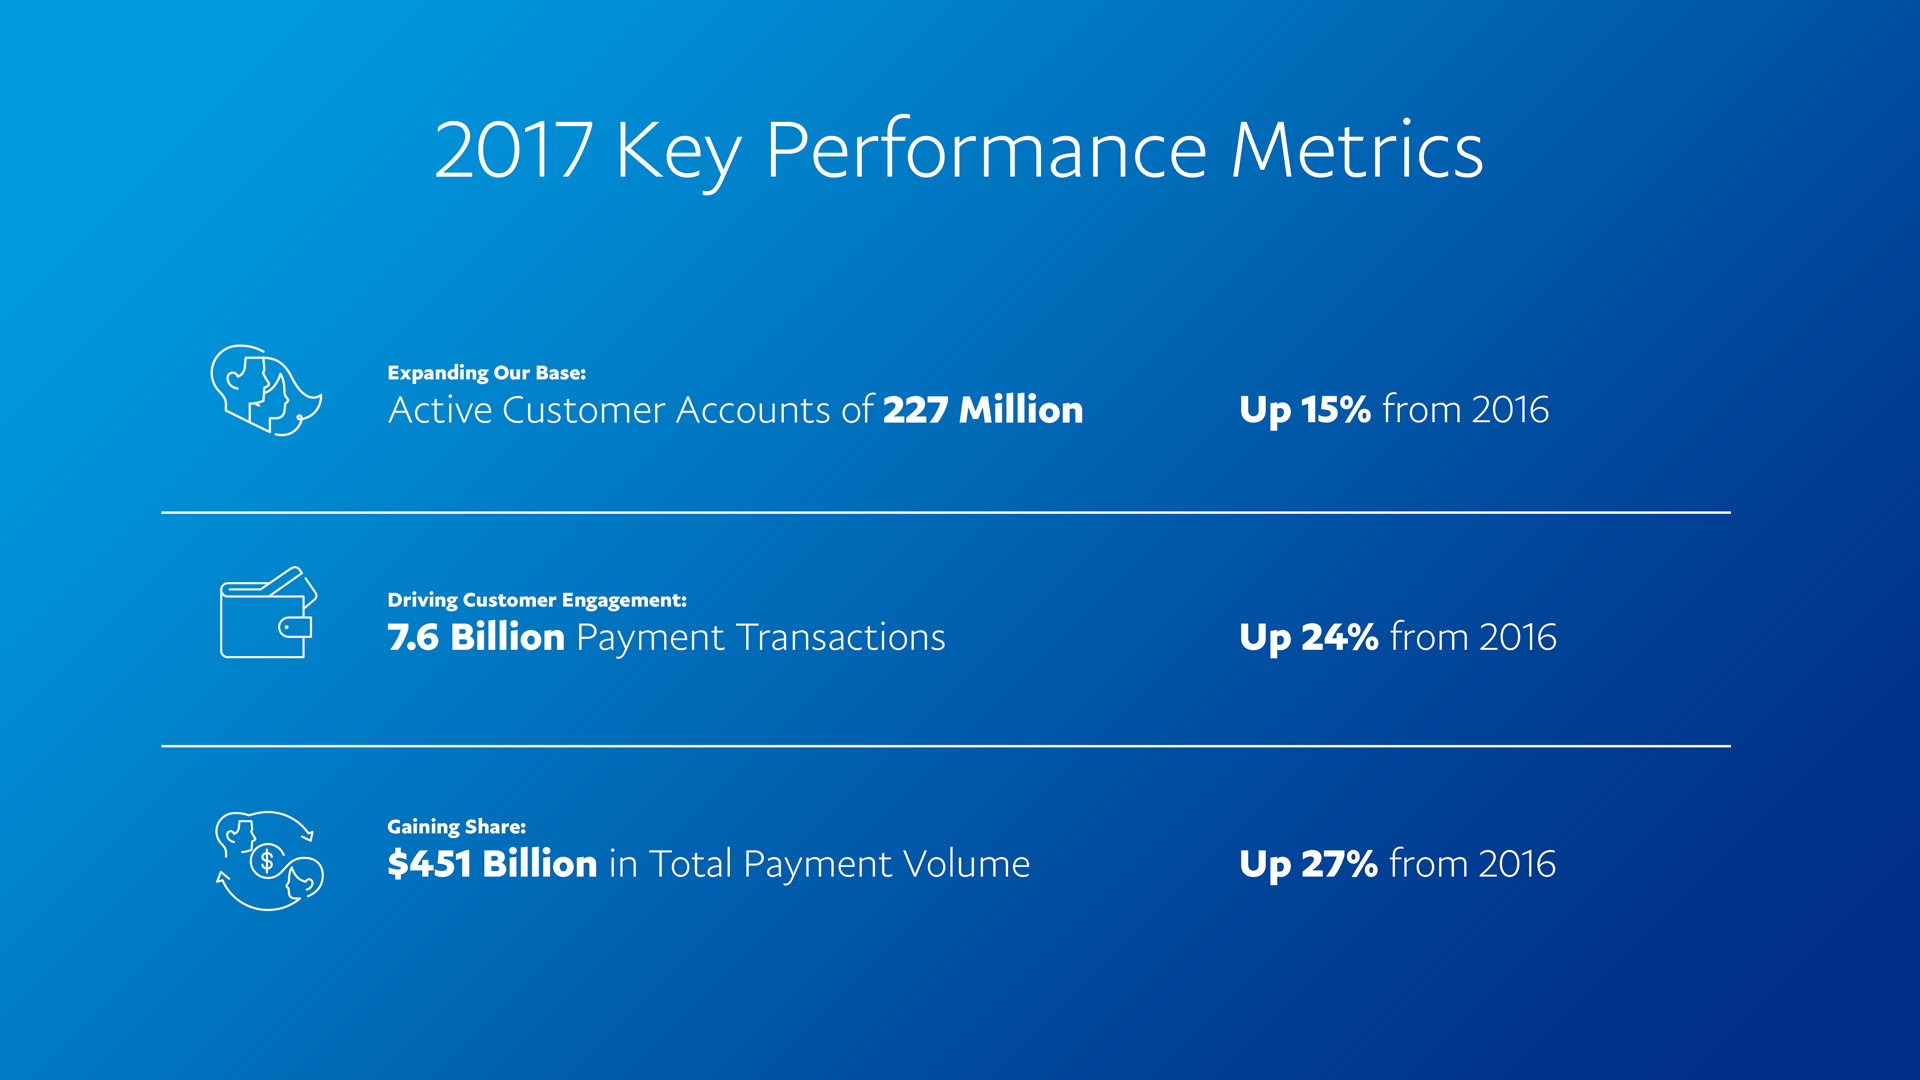
We measure the relevance of our products to our customers, and therefore the success of our business, through active customer accounts, payment volume and payment transactions:
Active Customer Accounts: An active customer account is a registered account that successfully sent or received at least one payment or payment reversal through our Payments Platform, excluding transactions processed through our gateway and Paydiant products, in the past 12 months. As of December 31, 2017, we had approximately 227 million active customer accounts across more than 200 markets. A market is a geographic area or political jurisdiction, such as a country, territory, or protectorate, in which we offer our services. A country, territory or protectorate is identified by a distinct set of laws and regulations.
Number of Payment Transactions: Number of payment transactions is defined as the total number of payments, net of payment reversals, successfully completed through our Payments Platform, excluding transactions processed through our gateway and Paydiant products.
Total Payment Volume (“TPV”): TPV is the value of payments, net of payment reversals, successfully completed through our Payments Platform, excluding transactions processed through our gateway and Paydiant products.
Our Strengths
Our business is built on a strong foundation designed to drive growth and differentiate us from our competitors. We believe that our competitive strengths include the following:
| • | Two-sided Platform - our platform connecting merchants and consumers enables PayPal to offer unique end-to-end product experiences while gaining valuable insights into customer behavior through our data. Our platform provides for simple digital and mobile transactions while being both brand and technology agnostic. |
| • | Scale - our global scale allows us to drive organic growth. As of December 31, 2017, we had 227 million active customer accounts, which included 18 million active merchant accounts. In 2017, we processed $451 billion of TPV in more than 200 markets around the world. |
| • | Brand - we have built a well-recognized and trusted brand. Our marketing efforts play an important role in building brand visibility, usage and overall preference among customers. |
| • | Risk Management - our risk management system and tokenization usage are designed to keep our customers safe and to ensure we process legitimate transactions around the world, while reducing illegal, high-risk, or fraudulent transactions. |
| • | Regulatory - we believe that our regulatory licenses, which enable us to operate in markets around the world, are a distinct advantage and support business growth. |
Technology
Our Payments Platform utilizes a combination of proprietary technologies and services as well as technologies and services provided by third parties to efficiently and securely facilitate transactions between millions of merchants and consumers worldwide across different channels, markets and networks. Our Payments Platform connects with financial institutions around the world and allows consumers to make purchases using a wide range of payment methods, regardless of where a merchant is located. Consumers who use our Payments Platform can send payments in more than 200 markets across the globe and in more than 100 currencies, withdraw funds to their bank accounts in 56 currencies and hold balances in their PayPal accounts in 25 currencies.
A transaction on our Payments Platform can involve multiple participants in addition to us including a merchant, a consumer and the consumer’s funding source provider. We have developed intuitive user interfaces, customer tools on our Payments Platform, transaction processing, and database and network applications that help our customers utilize our suite of products and services. Our Payments Platform, open application programming interfaces, and developer tools are designed to enable developers to innovate with ease and offer robust applications to our global ecosystem of merchants and consumers, while at the same time maintaining the security of our customers’ financial information.
The technology infrastructure supporting our Payments Platform simplifies the storage and processing of large amounts of data, and facilitates the deployment and operation of large-scale global products and services and automates much of the administration of large-scale clusters of computers. Our technology infrastructure has been designed around industry-standard architectures to reduce downtime in the event of outages or catastrophic occurrences. Our Payments Platform incorporates multiple layers of protection, both for continuity and system redundancy purposes and to help address cybersecurity challenges. We engage in multiple efforts to protect our technology infrastructure and Payments Platform against these challenges, including regularly testing our systems to address potential vulnerabilities. We strive to continually improve our technology infrastructure and Payments Platform to enhance the customer experience and to increase efficiency, scalability and security.
Merchant and Consumer Payment Solutions
Our combined payment solution capabilities offer our merchants and consumers a broad range of products and services, enabling our merchants to safely and simply receive payments from their customers while allowing our consumers to make seamless transactions across different markets and networks.
We partner with our merchants to help grow and expand their businesses by improving sales conversion, providing global reach, offering alternative payment methods, reducing losses through proprietary protection programs and leveraging data analytics. Merchants can onboard quickly with PayPal and are not required to invest in new or specialized hardware. For our standard service, we do not charge merchants setup or recurring fees. We offer access to credit products for certain small and medium-sized merchants through PayPal Working Capital and, with the recent acquisition of Swift Financial Corporation ("Swift"), other business loan products. Our PayPal Working Capital product allows businesses to borrow a certain percentage of their annual payment volume
processed by PayPal for a fee. Our Swift business loan products provide businesses with access to short-term business financing based on an evaluation of both the applying business as well as the business owner. We believe that our business financing offerings allow us to deepen our engagement with our small and medium-sized business merchants by providing them with access to capital to grow their business that they may not otherwise be able to effectively or efficiently access from traditional banks or other lending providers. Our recent acquisition of Swift also enables us to enhance our underwriting capabilities and strengthen our business financing offerings, helping us to deepen relationships with our existing merchants and expand services to new merchants.
PayPal is a popular form of payment for mobile commerce, and our business has grown with the increased adoption of mobile devices. We believe our Braintree products strengthen our position in mobile payments and extend our coverage to a new class of retailers and service providers that offer their services primarily through mobile applications. Through a single Braintree integration, a merchant can begin accepting payments with credit or debit cards, PayPal, Android Pay, Apple Pay, Samsung Pay and other payment solutions. We also offer gateway services, including our Payflow Gateway services and Braintree Gateway services, that enable merchants to accept payments online with credit or debit cards. Our gateway services provide the payment gateway technology that links a merchant’s website to its processing network and enable merchants to accept payments online with credit and debit cards.
We focus on providing affordable consumer products intended to democratize the management and movement of money. We offer our customers the flexibility to use their account to both purchase and receive payment for goods and services, as well as transfer and withdraw funds. We enable consumers to more safely exchange funds with merchants using a variety of financial resources, which may include a bank account, a PayPal account balance, a PayPal Credit account, a credit or debit card or other stored value products such as coupons and gift cards. We generally do not charge consumers to fund or draw from their accounts. We generate revenue from consumers on fees charged for foreign currency exchange and on interest and fees from our PayPal Credit product. We offer our PayPal Credit product to consumers as a potential funding source at checkout. Once a consumer is approved for credit, PayPal Credit is made available as a funding source in their account. We believe that our consumer credit products allow us to increase engagement with both consumers and merchants on our two-sided network as well as differentiate ourselves from rival payment processors by helping merchants drive incremental sales through products like PayPal Credit. We are responsible for all servicing functions related to all of our credit products. In the U.S., credit originated through our PayPal Credit, PayPal Working Capital and Swift business loan products is currently extended through third-party financial institutions, from whom we purchase the related receivables. For our consumer and merchant credit products outside the U.S., we extend credit through certain international PayPal subsidiaries.
During the fourth quarter of 2017, we expanded our strategic consumer credit relationship with Synchrony Financial ("Synchrony") and agreed to sell our U.S. consumer credit receivables portfolio to Synchrony Bank. Following the closing of this transaction, which is expected to occur in the third quarter of 2018, Synchrony Bank will become the exclusive issuer of the PayPal Credit online consumer financing program in the U.S. and we will no longer hold any participation interest in the receivables generated through the program (other than charged off receivables).
We offer consumers person-to-person (“P2P”) payment solutions through our PayPal, Venmo and Xoom products. PayPal continues to drive the majority of our total P2P volumes, enabling both domestic and international P2P transfers across our Payments Platform. Our Venmo app in the U.S. is a leading mobile application used to move money between friends and family. Xoom is an international money transfer service that enables our customers to send money to, pay bills for and send prepaid mobile phone reloads for family and friends around the world in a secure, fast and cost-effective way, using their mobile device or personal computers. P2P is a significant customer acquisition channel with network effects that helps us to establish relationships with potential PayPal users by allowing them to join our Payments Platform at the time of making or receiving P2P payments, which drives organic growth.
Protecting Merchants and Consumers
Protecting merchants and consumers on our Payments Platform from financial and data loss is imperative to successfully competing in the payments industry and sustainably growing our business. Fraudulent activities, such as account takeover, identity theft and counterparty malicious activities, represent a significant and growing risk to merchants and consumers, as well as their payment partners. We provide merchants and consumers with protection programs on most purchase transactions completed through our Payments Platform, except for transactions using our gateway and Paydiant products. We believe that these programs, which protect both merchants and consumers from financial and data loss due primarily to fraud and counterparty non-performance, are generally much broader than similar protections provided by other participants in the payments industry. Many payment providers do not offer merchant protection in general, and those that do generally do not provide protection for online or card not present transactions. As a result, merchants may incur losses for chargebacks and other claims on certain transactions when using other payments providers that they would not incur if they used our payments services. We also provide consumer protection against losses on qualifying purchases and accept claims for 180 days post transaction in the markets that we serve. We believe that this protection is generally consistent with, or better than, that offered by other payments providers. We believe that as a result of these
programs, consumers can be confident that they will only be required to pay if they receive the product in the condition as described, and merchants can be confident that they will receive payment for the product that they are delivering to the customer.
Our ability to protect both consumers and merchants is based largely on our proprietary end-to-end payments platform and our ability to leverage the data we collect on both sides of the transactions on our two-sided network (i.e., from buyers and sellers, and from senders and receivers of payments). We believe mobile devices will continue to play a significant and increasing role in commerce, including by creating the opportunities to make our ecosystem safer. For example, PayPal is able to use location data from mobile devices and growing protection for the mobile operating environment to reduce risk to merchants and consumers. Our ongoing investment in systems and processes, designed to enhance the safety and security of our products, reflects our goal of having PayPal recognized as one of the world’s most trusted payments brands.
Competition
The global payments industry is highly competitive. We compete against a wide range of businesses, including banks, credit card providers, technology and ecommerce companies and traditional retailers, many of which are larger than we are, have a dominant and secure position, or offer other products and services to consumers and merchants which we do not offer. We compete against all forms of payments, including credit and debit cards; automated clearing house and bank transfers; other online payment services; mobile payments; and offline payment methods, including cash and check.
We compete primarily on the basis of the following:
| • | ability to attract, retain and engage both merchants and consumers with our two-sided platform; |
| • | ability to show merchants that they may achieve incremental sales by offering our end-to-end services; |
| • | consumer confidence in safety and security of transactions on our Payments Platform, including the ability for consumers to use our products and services without sharing their financial information with the merchant or the party they are paying; |
| • | simplicity of our fee structure; |
| • | ability to develop products and services across multiple commerce channels, including mobile payments, credit products and payments at the retail point of sale; |
| • | trust in our dispute resolution and buyer and seller protection programs; |
| • | customer service; |
| • | brand recognition and preference; |
| • | website, mobile platform and application onboarding, ease-of-use, speed, availability, and dependability; |
| • | the technology and payment agnostic nature of our Payments Platform; |
| • | system reliability and data security; |
| • | ease and quality of integration into third-party mobile applications and operating systems; and |
| • | quality of developer tools such as our application programming interfaces and software development kits. |
In addition to the discussion in this section, see “Item 1A. Risk Factors” under the caption “Substantial and increasingly intense competition worldwide in the global payments industry may harm our business” for further discussion of the potential impact of competition on our business.
Research and Development
Total research and development expense was $953 million, $834 million and $792 million in 2017, 2016 and 2015, respectively.
Intellectual Property
The protection of our intellectual property, including our trademarks (particularly those covering the PayPal name), patents, copyrights, domain names, trade dress and trade secrets is important to the success of our business. We seek to protect our intellectual property rights by relying on applicable laws and regulations in the U.S. and internationally, as well as a variety of administrative procedures. We also rely on contractual restrictions to protect our proprietary rights when offering or procuring products and services. We have routinely entered into confidentiality and invention assignment agreements with our employees and contractors and non-disclosure agreements with parties with whom we conduct business to control access to and limit disclosure of our proprietary information.
We pursue the registration of our domain names, trademarks and service marks in the U.S. and internationally. Additionally, we have filed U.S. and international patent applications covering certain aspects of our proprietary technology. We have registered our core brands as trademarks and domain names in the U.S. and a large number of other jurisdictions and have in place an active program to continue to secure trademarks and domain names that correspond to our brands in markets of interest.
For additional information regarding some of the risks relating to our intellectual property, including costs of protecting our intellectual property, see the information in “Item 1A. Risk Factors” under the captions “We are subject to patent litigation” and “We may be unable to adequately protect or enforce our intellectual property rights, or third parties may allege that we are infringing their intellectual property rights.”
Government Regulation
We operate globally and in a rapidly evolving regulatory environment characterized by a heightened regulatory focus on all aspects of the payments industry. That focus continues to become even more heightened as regulators on a global basis focus on such important issues as countering terrorist financing, anti-money laundering, privacy and consumer protection. Some of the laws and regulations to which we are subject were enacted recently, and the laws and regulations applicable to us, including those enacted prior to the advent of digital and mobile payments, are continuing to evolve through legislative and regulatory action and judicial interpretation. Non-compliance with laws and regulations, increased penalties and enforcement actions related to non-compliance, changes in laws and regulations, or their interpretation, and the enactment of new laws and regulations applicable to us could have a material adverse impact on our business, results of operations and financial condition. Therefore, we monitor these areas closely to design compliant solutions for our customers who depend on us.
Government regulation impacts key aspects of our business. We are subject to regulations that affect the payments industry in the markets we operate.
Payments Regulation. Various laws and regulations govern the payments industry in the U.S. and internationally. In the U.S., PayPal, Inc. holds licenses to operate as a money transmitter (or its equivalent), which, among other things, subjects PayPal, Inc. to reporting requirements, bonding requirements, limitations on the investment of customer funds and inspection by state regulatory agencies. Outside the U.S., we provide localized versions of our service to customers through various foreign subsidiaries. The activities of those non-U.S. entities are, or may be, supervised by a financial regulatory authority in the jurisdictions in which they operate. Among other regulatory authorities, the Luxembourg Commission de Surveillance du Secteur Financier (the “CSSF”), the Australian Securities and Investment Commission, the Monetary Authority of Singapore, the Reserve Bank of India, and the Central Bank of Russia have asserted jurisdiction over some or all of our activities in country. This list is not exhaustive, as there are numerous other regulatory agencies that have or may assert jurisdiction over our activities. The laws and regulations applicable to the payments industry in any given jurisdiction are subject to interpretation and change.
Banking Agency Supervision. We serve our customers in the European Union through PayPal (Europe) S.à.r.l. et Cie, SCA, a wholly-owned subsidiary that is licensed and subject to regulation as a bank in Luxembourg by the CSSF. Consequently, we must comply with rules and regulations of the banking industry, including those related to capitalization, funds management, corporate governance, anti-money laundering, disclosure, reporting and inspection. We also are, or may be, subject to banking-related regulations in other countries now or in the future related to our role in the financial industry. In addition, based on our relationships with our partner financial institutions, we are, or may be, subject to indirect regulation and examination by these financial institutions’ regulators.
Consumer Financial Protection Bureau. The Consumer Financial Protection Bureau (the “CFPB”) has significant authority to regulate consumer financial products in the United States, including consumer credit, deposit, payment, and similar products. As a large market participant of remittance transfers, the CFPB has direct supervisory authority over our business. The CFPB and other similar regulatory agencies in other jurisdictions may have broad consumer protection mandates that could result in the promulgation and interpretation of rules and regulations that may affect our business.
Anti-Money Laundering and Counter-Terrorist Financing. PayPal is subject to anti-money laundering (“AML”) laws and regulations in the U.S. and other jurisdictions, as well as laws designed to prevent the use of the financial systems to facilitate terrorist activities. Our AML program is designed to prevent our payment network from being used to facilitate money laundering, terrorist financing, and other illicit activities, or to do business in countries or with persons and entities included on designated country or person lists promulgated by the U.S. Department of the Treasury’s Office of Foreign Assets Controls (“OFAC”) and equivalent authorities in other countries. Our AML compliance program, overseen by our AML/Bank Secrecy Act Officer, is composed of policies, procedures and internal controls, and is designed to address these legal and regulatory requirements and assist in managing money laundering and terrorist financing risks.
Interchange Fees. Interchange fees associated with four-party payments systems are being reviewed or challenged in various jurisdictions. For example, in the European Union ("EU"), the Multilateral Interchange Fee (“MIF”) Regulation caps credit and debit interchange fees for cards payments and provides for business rules to be complied with by any company dealing with card
transactions, including PayPal. As a result, the fees that we collect in certain jurisdictions may become the subject of regulatory challenge.
Data Protection and Information Security. Aspects of our operations or business are subject to privacy and data protection regulation in the United States ("U.S."), the EU and elsewhere. For example, the EU has adopted a comprehensive General Data Protection Regulation (the "GDPR"), which comes into effect in May 2018 and expands the scope of the EU data protection law to all foreign companies processing personal data of EU residents, imposes a strict data protection compliance regime, and includes new rights. In the United States, we are subject to information safeguarding requirements under the Gramm-Leach-Bliley Act that require the maintenance of a written, comprehensive information security program and in Europe, the operations of our Luxembourg bank are subject to information safeguarding requirements under the Luxembourg Banking Act, among other laws. Regulatory authorities around the world are considering numerous legislative and regulatory proposals concerning privacy and data protection. In addition, the interpretation and application of these privacy and data protection laws in the United States, Europe and elsewhere are often uncertain and in a state of flux.
Anti-Corruption. PayPal is subject to applicable anti-corruption laws, such as the U.S. Foreign Corrupt Practices Act and the U.K. Bribery Act, and similar anti-corruption laws in the jurisdictions in which it operates. Anti-corruption laws generally prohibit offering, promising, giving, accepting or authorizing others to provide anything of value, either directly or indirectly, to or from a government official or private party in order to influence official action or otherwise gain an unfair business advantage, such as to obtain or retain business. We have implemented policies, procedures, and internal controls that are designed to comply with these laws and regulations.
Additional Regulatory Developments. Various regulatory agencies continue to examine a wide variety of issues, including virtual currencies, identity theft, account management guidelines, privacy, disclosure rules, security and marketing that may impact PayPal's business.
For an additional discussion on governmental regulation affecting our business, please see the risk factors related to regulation of our payments business and regulation in the areas of consumer privacy, data use and/or security in “Item 1A. Risk Factors” under the caption “Risk Factors That May Affect Our Business, Results of Operations and Financial Condition” and “Item 3. Legal Proceedings” included elsewhere in this Annual Report on Form 10-K.
Seasonality
The Company does not experience meaningful seasonality with respect to net revenues. No individual quarter in 2017, 2016 or 2015 accounted for more than 30% of annual net revenue.
Financial Information About Segments
We operate in one business segment and have one reportable segment. See “Note 11—Segment and Geographical Information” to the consolidated financial statements included elsewhere in this Annual Report on Form 10-K for additional information including certain financial information about our operations in the U.S. and internationally. Additionally, please see the information in “Item 1A. Risk Factors” under the caption “Our international operations are subject to increased risks, which could harm our business,” which describes risks associated with our foreign operations.
Employees
As of December 31, 2017, we employed approximately 18,700 people globally, of whom approximately 10,600 were located in the U.S. We consider our relationship with our employees to be good.
Separation from eBay Inc.
PayPal Holdings, Inc. was incorporated in Delaware in January 2015 for the purpose of owning and operating eBay’s Payments business in connection with the separation and distribution described below. Prior to the contribution of this business to PayPal Holdings, Inc., which occurred prior to the distribution in July 2015, PayPal Holdings, Inc. had no operations. On July 17, 2015 (the “distribution date”), PayPal became an independent publicly traded company through the pro rata distribution by eBay of 100% of the outstanding common stock of PayPal to eBay stockholders (which we refer to as the “separation” or the “distribution”). Each eBay stockholder of record as of the close of business on July 8, 2015 received one share of PayPal common stock for every share of eBay common stock held on the record date. Approximately 1.2 billion shares of PayPal common stock were distributed on July 17, 2015 to eBay stockholders. PayPal’s common stock began “regular way” trading under the ticker symbol “PYPL” on
the NASDAQ Stock Market on July 20, 2015. Prior to the separation, eBay transferred substantially all of the assets and liabilities and operations of eBay’s payments business to PayPal, which was completed in June 2015.
Available Information
The address of our principal executive offices is PayPal Holdings, Inc., 2211 North First Street, San Jose, California 95131. Our website is located at www.paypal.com, and our investor relations website is located at http://investor.paypal-corp.com. From time to time, we may use our investor relations site and other online and social media channels, including our PayPal Stories Blog (https://www.paypal.com/stories/us), Twitter handle (@PayPal), LinkedIn page (https://www.linkedin.com/company/paypal), Facebook page (https://www.facebook.com/PayPalUSA/), YouTube channel (https://www.youtube.com/paypal), Dan Schulman's LinkedIn profile (https://www.linkedin.com/in/dan-schulman/) and Dan Schulman's Facebook profile (https://www.facebook.com/DanSchulmanPayPal/) to disclose material non-public information and comply with our disclosure obligations under Regulation Fair Disclosure. Our Annual Report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K and amendments to those reports are available free of charge on our investor relations website as soon as reasonably practicable after they are electronically filed with, or furnished to, the SEC. The content of our websites and information that we may post on or provide to online and social media channels, including those mentioned above, and information that can be accessed through our websites or these online and social media channels is not incorporated by reference into this Annual Report on Form 10-K or in any other report or document we file with the SEC, and any references to our websites or these online and social media channels are intended to be inactive textual references only.
Previous: Cover and table of contents · Next: Item 1A. RISK FACTORS