 filings.tools
Regency Centers 10-K 2019-12-31
Filed 2020-02-18. 21 sections, 653K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, DC 20549
FORM 10-K
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the fiscal year ended December 31, 2019
or
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the transition period from to
Commission File Number 1-12298 (Regency Centers Corporation)
Commission File Number 0-24763 (Regency Centers, L.P.)
REGENCY CENTERS CORPORATION
REGENCY CENTERS, L.P.
(Exact name of registrant as specified in its charter)
| Florida (REGENCY CENTERS CORPORATION) | 59-3191743 | |
|---|---|---|
| Delaware (REGENCY CENTERS, L.P.) |  | 59-3429602 |
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | |
| One Independent Drive, Suite 114 Jacksonville, Florida 32202 | (904) 598-7000 | |
| (Address of principal executive offices) (zip code) | (Registrant's telephone number, including area code) |
Securities registered pursuant to Section 12(b) of the Act:
Regency Centers Corporation
| Title of each class | Trading Symbol | Name of each exchange on which registered | ||
|---|---|---|---|---|
| Common Stock, $.01 par value | REG | The Nasdaq Stock Market LLC |
Regency Centers, L.P.
| Title of each class | Trading Symbol | Name of each exchange on which registered | ||
|---|---|---|---|---|
| None | N/A | N/A |
Securities registered pursuant to Section 12(g) of the Act:
Regency Centers Corporation: None
Regency Centers, L.P.: Units of Partnership Interest
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act.
Regency Centers Corporation YES ☒ NO ☐ Regency Centers, L.P. YES ☒ NO ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act
Regency Centers Corporation YES ☐ NO ☒ Regency Centers, L.P. YES ☐ NO ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days.
Regency Centers Corporation YES ☒ NO ☐ Regency Centers, L.P. YES ☒ NO ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files).
Regency Centers Corporation YES ☒ NO ☐ Regency Centers, L.P. YES ☒ NO ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act. (Check one):
Regency Centers Corporation:
| Large accelerated filer | ☒ | Accelerated filer | ☐ | Emerging growth company | ☐ |
|---|---|---|---|---|---|
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ |
Regency Centers, L.P.:
| Large accelerated filer | ☐ | Accelerated filer | ☒ | Emerging growth company | ☐ |
|---|---|---|---|---|---|
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
Regency Centers Corporation ☐ Regency Centers, L.P. ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act).
Regency Centers Corporation YES ☐ NO ☒ Regency Centers, L.P. YES ☐ NO ☒
State the aggregate market value of the voting and non-voting common equity held by non-affiliates computed by reference to the price at which the common equity was last sold, or the average bid and asked price of such common equity, as of the last business day of the registrants' most recently completed second fiscal quarter.
Regency Centers Corporation $11.1 billion Regency Centers, L.P. N/A
The number of shares outstanding of the Regency Centers Corporation’s common stock was 167,715,882 as of February 12, 2020.
Documents Incorporated by Reference
Portions of Regency Centers Corporation's proxy statement in connection with its 2020 Annual Meeting of Stockholders are incorporated by reference in Part III.
EXPLANATORY NOTE
This report combines the annual reports on Form 10-K for the year ended December 31, 2019 of Regency Centers Corporation and Regency Centers, L.P. Unless stated otherwise or the context otherwise requires, references to “Regency Centers Corporation” or the “Parent Company” mean Regency Centers Corporation and its controlled subsidiaries and references to “Regency Centers, L.P.” or the “Operating Partnership” mean Regency Centers, L.P. and its controlled subsidiaries. The term “the Company”, “Regency Centers” or “Regency” means the Parent Company and the Operating Partnership, collectively.
The Parent Company is a real estate investment trust (“REIT”) and the general partner of the Operating Partnership. The Operating Partnership's capital includes general and limited common Partnership Units (“Units”). As of December 31, 2019, the Parent Company owned approximately 99.6% of the Units in the Operating Partnership. The remaining limited Units are owned by investors. As the sole general partner of the Operating Partnership, the Parent Company has exclusive control of the Operating Partnership's day-to-day management.
The Company believes combining the annual reports on Form 10-K of the Parent Company and the Operating Partnership into this single report provides the following benefits:
| • | Enhances investors' understanding of the Parent Company and the Operating Partnership by enabling investors to view the business as a whole in the same manner as management views and operates the business; |
|---|
| • | Eliminates duplicative disclosure and provides a more streamlined and readable presentation; and |
|---|
| • | Creates time and cost efficiencies through the preparation of one combined report instead of two separate reports. |
|---|
Management operates the Parent Company and the Operating Partnership as one business. The management of the Parent Company consists of the same individuals as the management of the Operating Partnership. These individuals are officers of the Parent Company and employees of the Operating Partnership.
The Company believes it is important to understand the key differences between the Parent Company and the Operating Partnership in the context of how the Parent Company and the Operating Partnership operate as a consolidated company. The Parent Company is a REIT, whose only material asset is its ownership of partnership interests of the Operating Partnership. As a result, the Parent Company does not conduct business itself, other than acting as the sole general partner of the Operating Partnership, issuing public equity from time to time and guaranteeing certain debt of the Operating Partnership. Except for $500 million of unsecured public and private placement debt, the Parent Company does not hold any indebtedness, but guarantees all of the unsecured debt of the Operating Partnership. The Operating Partnership is also the co-issuer and guarantees the $500 million of Parent Company debt. The Operating Partnership holds all the assets of the Company and retains the ownership interests in the Company's joint ventures. Except for net proceeds from public equity issuances by the Parent Company, which are contributed to the Operating Partnership in exchange for partnership units, the Operating Partnership generates all remaining capital required by the Company's business. These sources include the Operating Partnership's operations, its direct or indirect incurrence of indebtedness, and the issuance of partnership units.
Stockholders' equity, partners' capital, and noncontrolling interests are the main areas of difference between the consolidated financial statements of the Parent Company and those of the Operating Partnership. The Operating Partnership's capital includes general and limited common Partnership Units. The limited partners' units in the Operating Partnership owned by third parties are accounted for in partners' capital in the Operating Partnership's financial statements and outside of stockholders' equity in noncontrolling interests in the Parent Company's financial statements.
In order to highlight the differences between the Parent Company and the Operating Partnership, there are sections in this report that separately discuss the Parent Company and the Operating Partnership, including separate financial statements, controls and procedures sections, and separate Exhibit 31 and 32 certifications. In the sections that combine disclosure for the Parent Company and the Operating Partnership, this report refers to actions or holdings as being actions or holdings of the Company.
As general partner with control of the Operating Partnership, the Parent Company consolidates the Operating Partnership for financial reporting purposes, and the Parent Company does not have assets other than its investment in the Operating Partnership. Therefore, while stockholders' equity and partners' capital differ as discussed above, the assets and liabilities of the Parent Company and the Operating Partnership are the same on their respective financial statements.
TABLE OF CONTENTS
Forward-Looking Statements
In addition to historical information, information in this Form 10-K contains forward-looking statements as defined under federal securities laws. These forward-looking statements include statements about anticipated changes in our revenues, the size of our development and redevelopment program, earnings per share and unit, returns and portfolio value, and expectations about our liquidity. These statements are based on current expectations, estimates and projections about the real estate industry and markets in which the Company operates, and management's beliefs and assumptions. Forward-looking statements are not guarantees of future performance and involve certain known and unknown risks and uncertainties that could cause actual results to differ materially from those expressed or implied by such statements. Known risks and uncertainties are described further in the Item 1A. Risk Factors below. The following discussion should be read in conjunction with the accompanying Consolidated Financial Statements and Notes thereto of Regency Centers Corporation and Regency Centers, L.P. appearing elsewhere herein. We do not undertake any obligation to release publicly any revisions to such forward-looking statements to reflect events or uncertainties after the date hereof or to reflect the occurrence of uncertain events.
PART I
Item 1. Business
Regency Centers Corporation is a fully integrated real estate company and self-administered and self-managed real estate investment trust that began its operations as a publicly-traded REIT in 1993. Regency Centers L.P. is the entity through which Regency Centers Corporation conducts substantially all of its operations and owns substantially all of its assets. Our business consists of acquiring, developing, owning and operating income-producing retail real estate principally located in many of the top markets in the United States. We generate revenues by leasing space to retail tenants such as highly productive grocers, restaurants, service providers, and best-in-class retailers. Following our merger with Equity One Inc. (“Equity One”) in 2017, Regency became an S&P 500 Index member.
As of December 31, 2019, we had full or partial ownership interests in 419 properties, primarily anchored by market leading grocery stores, encompassing 52.6 million square feet (“SF”) of gross leasable area (“GLA”). Our Pro-rata share of this GLA is 42.8 million square feet, including our share of the partially owned properties.
Our mission is to be the preeminent national owner, operator, and developer of shopping centers, creating places that provide a thriving environment for outstanding retailers and service providers to connect with the surrounding neighborhoods and communities. Our goals are to:
| • | Own and manage a portfolio of high-quality neighborhood and community shopping centers anchored by market leading grocers and located in affluent suburban and near urban trade areas in the country’s most desirable metro areas. We expect that this combination will produce highly desirable and attractive centers with best-in-class retailers. These centers should command higher rental and occupancy rates resulting in excellent prospects to grow net operating income (“NOI”); |
|---|
| • | Maintain an industry leading and disciplined development and redevelopment platform to deliver exceptional retail centers at higher returns as compared to acquisitions; |
|---|
| • | Support our business activities with a conservative capital structure, including a strong balance sheet; |
|---|
| • | Attain best-in-class environmental, social, and governance practices; |
|---|
| • | Engage an exceptional and diverse team that is guided by our strong values and special culture, while fostering an environment of innovation and continuous improvement that will deploy industry-leading operating standards; and |
|---|
| • | Increase earnings per share and dividends and generate total returns at or near the top of our shopping center peers. |
|---|
Key strategies to achieve our goals are to:
| • | Sustain same property NOI growth that over the long-term consistently ranks at or near the top of our shopping center peers; |
|---|
| • | Develop and redevelop high quality shopping centers at attractive returns on investment; |
|---|
| • | Maintain a conservative balance sheet providing financial flexibility to cost effectively fund investment opportunities and debt maturities on a favorable basis, and to weather economic downturns; |
|---|
| • | Maintain the highest standards for corporate governance and act as good stewards of our communities and the environment; and |
|---|
| • | Attract and motivate an exceptional team of employees who operate efficiently and are recognized as industry leaders. |
|---|
Corporate Responsibility
Our vision is to be the preeminent national owner, operator and developer of shopping centers, connecting outstanding retailers and service providers with their neighborhoods and communities while practicing best-in-class corporate responsibility. We have established four pillars for our corporate responsibility program that we believe support our vision and mission:
| • | Our People; |
|---|
| • | Our Communities; |
|---|
| • | Ethics and Governance; and |
|---|
| • | Environmental Stewardship. |
|---|
Our people are our greatest asset and we work to support our highly engaged team that drives our business and is critical to achieving our strategic objectives. We maintain a safe and pleasant workspace, promote employee well-being, and empower our employees by focusing on health and benefits, training and education, safety, and diversity.
Our team is also passionate about investing in and connecting with the communities in which we live and work. Philanthropy and giving back are cornerstones of what we do and who we are. Our local teams personally customize and cultivate our centers by bringing tenants and shoppers together and continually engage with the communities in which we operate.
As stewards of our investors’ capital, we are committed to best-in-class corporate governance practice. We place great emphasis on integrity and transparency, which extends to our reporting practices, long-term value creation for our stakeholders, and strong culture of business compliance.
We believe sustainability is in the best interest of our tenants, investors, employees, and the communities in which we operate. We have five strategic priorities when it comes to identifying and implementing sustainable business practices and minimizing our environmental impact: green building, energy efficiency, greenhouse gas emissions reduction, water conservation, and waste minimization and management. We believe these commitments are not only the right thing to do to address material environmental topics such as air pollution, climate change, and resource scarcity, but also support us in achieving key strategic objectives in operations and development.
We are committed to transparency with regard to our corporate responsibility and sustainability performance, risks and opportunities, and will continue to enhance disclosures using industry accepted reporting frameworks. More information about our corporate responsibility strategy, goals, performance, and formal disclosures are available on our website at www.regencycenters.com. The content of our website is not incorporated by reference into this Annual Report on Form 10-K or in any other report or document we file with the SEC, and any references to our website are intended to be inactive textual references only.
Competition
We are among the largest owners of shopping centers in the nation based on revenues, number of properties, GLA, and market capitalization. There are numerous companies and individuals engaged in the ownership, development, acquisition, and operation of shopping centers that compete with us in our targeted markets, including grocery store chains that also anchor some of our shopping centers. This results in competition for attracting tenants, as well as the acquisition of existing shopping centers and new development sites. We believe that our competitive advantages are driven by:
| • | our locations within our market areas; |
|---|
| • | the design and high quality of our shopping centers; |
|---|
| • | the strong demographics surrounding our shopping centers; |
|---|
| • | our relationships with our anchor tenants and our side-shop and out-parcel retailers; |
|---|
| • | our practice of maintaining and renovating our shopping centers; and |
|---|
| • | our ability to source and develop new shopping centers. |
|---|
Employees
Our corporate headquarters are located at One Independent Drive, Suite 114, Jacksonville, Florida. We presently maintain 22 market offices nationwide, including our corporate headquarters, where we conduct management, leasing, construction, and investment activities. We have 450 employees throughout the United States and we believe that our relations with our employees are good.
Compliance with Governmental Regulations
Under various federal, state and local laws, ordinances and regulations, we may be liable for the cost to remove certain hazardous substances at our shopping centers that generally arise from dry cleaners, gas stations, and historic land use practices. These laws often impose liability without regard to whether the owner knew of, or was responsible for, the presence of the hazardous substances. The presence of such substances, or the failure to properly address such substances, may adversely affect our ability to sell or lease the property or borrow using the property as collateral. Although we have a number of properties that could require or are currently undergoing varying levels of clean up, known environmental corrective actions are not currently expected to have a material financial impact on us due to our environmental insurance programs, various state-regulated programs that shift the responsibility and cost to the state, and existing accrued liabilities.
Executive Officers
Our executive officers are appointed each year by our Board of Directors. Each of our executive officers has been employed by us for more than five years and, as of December 31, 2019, included the following:
| Name | Age | Title | Executive Officer in Position Shown Since |
|---|---|---|---|
| Martin E. Stein, Jr. | 67 | Chairman and Chief Executive Officer | 1993(1) |
| Lisa Palmer | 52 | President | 2016 (2) |
| Michael J. Mas | 44 | Executive Vice President, Chief Financial Officer | 2019 (3) |
| Dan M. Chandler, III | 52 | Executive Vice President, Chief Investment Officer | 2019 (4) |
| James D. Thompson | 64 | Executive Vice President, Chief Operating Officer | 2019 (5) |
| (1) | Mr. Stein was appointed Executive Chairman of the Board effective January 1, 2020. Prior to this appointment, Mr. Stein served as Chief Executive Officer since 1993 and Chairman of the Board since 1999. |
|---|
| (2) | Ms. Palmer was named Chief Executive Officer effective January 1, 2020, in addition to her responsibilities as President, which position she has held since January 2016. Prior to this appointment, Ms. Palmer served as Chief Financial Officer since January 2013. Prior to that, Ms. Palmer served as Senior Vice President of Capital Markets since 2003 and has been with the Company since 1996. |
|---|
| (3) | Mr. Mas assumed the responsibilities of Executive Vice President and Chief Financial Officer effective August 2019. Prior to this appointment, Mr. Mas served as Managing Director, Finance, since February 2017, and Senior Vice President, Capital Markets, since 2013. |
|---|
| (4) | Mr. Chandler assumed the role of Chief Investment Officer, effective August 2019, and Executive Vice President of Investments in 2016. Mr. Chandler previously served as Managing Director since 2006. Prior to that, Mr. Chandler served in various investment officer positions since 1999. |
|---|
| (5) | Mr. Thompson assumed the role of Chief Operating Officer, effective August 2019, and Executive Vice President of Operations in 2016. Mr. Thompson previously served as our Managing Director - East since 1993. |
|---|
Company Website Access and SEC Filings
Our website may be accessed at www.regencycenters.com. All of our filings with the Securities and Exchange Commission (“SEC”) can be accessed free of charge through our website promptly after filing; however, in the event that the website is inaccessible, we will provide paper copies of our most recent annual report on Form 10-K, the most recent quarterly report on Form 10-Q, current reports filed or furnished on Form 8-K, and all related amendments, excluding exhibits, free of charge upon request. These filings are also accessible on the SEC's website at www.sec.gov. The content of our website is not incorporated by reference into this Annual Report on Form 10-K or in any other report or document we file with the SEC, and any references to our website are intended to be inactive textual references only.
General Information
Our registrar and stock transfer agent is Broadridge Corporate Issuer Solutions, Inc. (“Broadridge”), Philadelphia, PA. We offer a dividend reinvestment plan (“DRIP”) that enables our shareholders to reinvest dividends automatically, as well as to make voluntary cash payments toward the purchase of additional shares. For more information, contact Broadridge toll free at (855) 449-0975 or our Shareholder Relations Department at (904) 598-7000.
The Company's common stock is listed on NASDAQ and trades under the stock symbol “REG”.
Our independent registered public accounting firm is KPMG LLP, Jacksonville, Florida. Our legal counsel is Foley & Lardner LLP, Jacksonville, Florida.
Annual Meeting of Shareholders
Our 2020 annual meeting of shareholders will be held at the Ponte Vedra Inn and Club, 200 Ponte Vedra Blvd., Ponte Vedra Beach, Florida, at 9:00 a.m. on Wednesday, April 29, 2020.
Defined Terms
In addition to the required Generally Accepted Accounting Principles (“GAAP”) presentations, we use certain non-GAAP performance measures as we believe these measures improve the understanding of our operational results. We continually evaluate the usefulness, relevance, limitations, and calculation of our reported non-GAAP performance measures to determine how best to provide relevant information to the public, and thus such reported measures could change.
The following terms, as defined, are commonly used by management and the investing public to understand and evaluate our operational results:
| • | Development Completion is a property in development that is deemed complete upon the earliest of: (i) 90% of total estimated net development costs have been incurred and percent leased equals or exceeds 95%, or (ii) the property features at least two years of anchor operations, or (iii) three years have passed since the start of construction. Once deemed complete, the property is termed a Retail Operating Property the following calendar year. |
|---|
| • | Fixed Charge Coverage Ratio is defined as Operating EBITDAre divided by the sum of the gross interest and scheduled mortgage principal paid to our lenders. |
|---|
| • | NAREIT EBITDAre is a measure of REIT performance, which the National Association of Real Estate Investment Trusts (“NAREIT”) defines as net income, computed in accordance with GAAP, excluding (i) interest expense, (ii) income tax expense, (iii) depreciation and amortization, (iv) gains on sales of real estate, (v) impairments of real estate, and (vi) adjustments to reflect the Company's share of unconsolidated partnerships and joint ventures. We provide a reconciliation of Net Income to NAREIT EBITDAre. |
|---|
| • | NAREIT Funds from Operations (“NAREIT FFO”) is a commonly used measure of REIT performance, which NAREIT defines as net income, computed in accordance with GAAP, excluding gains on sales and impairments of real estate, net of tax, plus depreciation and amortization, and after adjustments for unconsolidated partnerships and joint ventures. We compute NAREIT FFO for all periods presented in accordance with NAREIT's definition in effect during that period. Effective January 1, 2019, we prospectively adopted the NAREIT FFO White Paper – 2018 Restatement (“2018 FFO White Paper”), and elected the option of excluding gains on sale and impairments of land, which are considered incidental to our main business. Prior period amounts were not restated to conform to the current year presentation, and therefore are calculated as described above, and also include gains on sale and impairments of land. |
|---|
Companies use different depreciable lives and methods, and real estate values historically fluctuate with market conditions. Since NAREIT FFO excludes depreciation and amortization and gains on sales and impairments of real estate, it provides a performance measure that, when compared year over year, reflects the impact on operations from trends in occupancy rates, rental rates, operating costs, acquisition and development activities, and financing costs. This provides a perspective of our financial performance not immediately apparent from net income determined in accordance with GAAP. Thus, NAREIT FFO is a supplemental non-GAAP financial measure of our operating performance, which does not represent cash generated from operating activities in accordance with GAAP; and, therefore, should not be considered a substitute measure of cash flows from operations. We provide a reconciliation of Net Income Attributable to Common Stockholders to NAREIT FFO.
| • | Net Operating Income (“NOI”) is the sum of base rent, percentage rent, recoveries from tenants, other lease income, and other property income, less operating and maintenance expenses, real estate taxes, ground rent, and uncollectible lease income / provision for doubtful accounts. NOI excludes straight-line rental income and expense, above and below market |
|---|
| rent and ground rent amortization, tenant lease inducement amortization, and other fees. We also provide disclosure of NOI excluding termination fees, which excludes both termination fee income and expenses. |
|---|
| • | Non-Same Property is any property, during either calendar year period being compared, that was acquired, sold, a Property in Development, a Development Completion, or a property under, or being positioned for, significant redevelopment that distorts comparability between periods. Non-retail properties and corporate activities, including the captive insurance program, are part of Non-Same Property. |
|---|
| • | Operating EBITDAre begins with the NAREIT EBITDAre and excludes certain non-cash components of earnings derived from above and below market rent amortization and straight-line rents. We provide a reconciliation of Net Income to NAREIT EBITDAre to Operating EBITDAre. |
|---|
| • | Pro-rata information includes 100% of our consolidated properties plus our economic share (based on our ownership interest) in our unconsolidated real estate investment partnerships. |
|---|
We provide Pro-rata financial information because we believe it assists investors and analysts in estimating our economic interest in our consolidated and unconsolidated partnerships, when read in conjunction with the Company’s reported results under GAAP. We believe presenting our Pro-rata share of assets, liabilities, operating results, and certain operating metrics, along with other non-GAAP measures, makes comparisons of other REITs' operating results to ours more meaningful. The Pro-rata information provided is not, nor is it intended to be, presented in accordance with GAAP. The Pro-rata supplemental details of assets and liabilities and supplemental details of operations reflect our proportionate economic ownership of the assets, liabilities and operating results of the properties in our portfolio
The Pro-rata information is prepared on a basis consistent with the comparable consolidated amounts and is intended to more accurately reflect our proportionate economic interest in the assets, liabilities, and operating results of properties in our portfolio. We do not control the unconsolidated investment partnerships, and the Pro-rata presentations of the assets and liabilities, and revenues and expenses do not represent our legal claim to such items. The partners are entitled to profit or loss allocations and distributions of cash flows according to the operating agreements, which generally provide for such allocations according to their invested capital. Our share of invested capital establishes the ownership interests we use to prepare our Pro-rata share.
The presentation of Pro-rata information has limitations which include, but are not limited to, the following:
| o | The amounts shown on the individual line items were derived by applying our overall economic ownership interest percentage determined when applying the equity method of accounting or allocating noncontrolling interests, and do not necessarily represent our legal claim to the assets and liabilities, or the revenues and expenses; and |
|---|
| o | Other companies in our industry may calculate their Pro-rata interest differently, limiting the comparability of Pro-rata information. |
|---|
Because of these limitations, the Pro-rata financial information should not be considered independently or as a substitute for our financial statements as reported under GAAP. We compensate for these limitations by relying primarily on our GAAP financial statements, using the Pro-rata information as a supplement.
| • | Property In Development includes properties in various stages of ground-up development. |
|---|
| • | Property In Redevelopment includes Retail Operating Properties under redevelopment or being positioned for redevelopment. Unless otherwise indicated, a Property in Redevelopment is included in the Same Property pool. |
|---|
| • | Retail Operating Property is any retail property not termed a Property in Development. A retail property is any property where the majority of the income is generated from retail uses. |
|---|
| • | Same Property is a Retail Operating Property that was owned and operated for the entirety of both calendar year periods being compared. This term excludes Properties in Development, prior year Development Completions, and Non-Same Properties. Properties in Redevelopment are included unless otherwise indicated. |
|---|
Item 1A. Risk Factors
Risk Factors Related to the Retail Industry
Economic and market conditions may adversely affect the retail industry and consequently reduce our revenues and cash flow, and increase our operating expenses.
Our properties are leased primarily to retail tenants from whom we derive most of our revenue in the form of base rent, expense recoveries and other income. Therefore, our performance and operating results are directly linked to the economic and market conditions occurring in the retail industry. We are subject to the risks that, upon expiration, leases for space in our properties are not renewed by existing tenants, vacant space is not leased to new tenants, or tenants demand new lease terms, including costs for renovations or concessions. The market for leasing retail space in our properties may be adversely affected by any of the following:
| • | changes in national, regional and local economic conditions; |
|---|
| • | changes in population and migration patterns to/from the markets in which we operate; |
|---|
| • | deterioration in the competitiveness and creditworthiness of our retail tenants; |
|---|
| • | increased competition from the use of e-commerce by retailers and consumers as well as other concepts such as super-stores and warehouse clubs; |
|---|
| • | tenant bankruptcies and subsequent rejections of our leases; |
|---|
| • | reductions in consumer spending and retail sales; |
|---|
| • | reduced tenant demand for retail space; |
|---|
| • | oversupply of retail space; |
|---|
| • | reduced consumer demand for certain retail categories; |
|---|
| • | consolidation within the retail sector; |
|---|
| • | increased operating costs; |
|---|
| • | perceptions by retailers and shoppers of the safety, convenience and attractiveness of our properties; and |
|---|
| • | acts of terrorism and war, natural disasters and other physical and weather-related damages to our properties. |
|---|
To the extent that any of these conditions occur they are likely to impact the retail industry, our retail tenants, the demand and market rents for retail space, the occupancy levels of our properties, our ability to sell, acquire or develop properties, our operating results and our cash available for distributions to stock and unit holders.
Shifts in retail sales and delivery methods between brick and mortar stores, e-commerce, home delivery, and curbside pick-up may adversely impact our revenues and cash flows.
Retailers are increasingly impacted by e-commerce and changes in customer buying habits, including the delivery or curbside pick-up of items ordered online. Retailers are considering these e-commerce trends when making decisions regarding their bricks and mortar stores and how they will compete and innovate in a rapidly changing retail environment. Many retailers in our shopping centers provide services or sell goods, which have historically been less likely to be purchased online; however, the continuing increase in e-commerce sales in all retail categories may cause retailers to adjust the size or number of retail locations in the future or close stores. Our grocer tenants are incorporating e-commerce concepts through home delivery and curbside pick-up, which could reduce foot traffic at our centers. In certain higher-income markets, foot traffic at our centers may be impacted more by these alternative delivery methods if consumers are willing to pay premiums for such services. This shift may adversely impact our occupancy and rental rates, which would impact our revenues and cash flows. Changes in shopping trends as a result of the growth in e-commerce may also impact the profitability of retailers that do not adapt to changes in market conditions. These conditions may adversely impact our results of operations and cash flows if we are unable to meet the needs of our tenants or if our tenants encounter financial difficulties as a result of changing market conditions.
Changing economic and retail market conditions in geographic areas where our properties are concentrated may reduce our revenues and cash flow.
Economic conditions in markets where our properties are concentrated can greatly influence our financial performance. During the year ended December 31, 2019, our properties in California, Florida, Texas, New York and Virginia accounted for 29.0%, 21.0%, 6.9%, 5.7%, and 5.0% respectively, of our NOI from Consolidated Properties plus our Pro-rata share from Unconsolidated Properties (“Pro-rata basis”). Our revenues and cash flow may be adversely affected by this geographic concentration if market conditions, such as supply of or demand for retail space, deteriorate more significantly in these states compared to other geographic areas.
Our success depends on the success and continued presence of our “anchor” tenants.
“Anchor Tenants” (tenants occupying 10,000 square feet or more) occupy large stores in our shopping centers, pay a significant portion of the total rent at a property and contribute to the success of other tenants by attracting shoppers to the property. We derive significant revenues from anchor tenants such as Publix, Kroger Co., Albertsons Companies, Inc., TJX Companies, Inc., and Whole Foods who accounted for 3.2%, 3.0%, 2.8%, 2.4%, and 2.4%, respectively, of our total annualized base rent on a Pro-rata basis, for the year ended December 31, 2019. Additionally, other tenants with significant lease obligations at a singular location could also have a material impact on our earnings if they are unable to fulfill their lease obligations or fail to renew their leases. Our net income and cash flow may be adversely affected by the loss of revenues and additional costs in the event a significant anchor tenant:
| • | becomes bankrupt or insolvent; |
|---|
| • | experiences a downturn in its business; |
|---|
| • | materially defaults on its leases; |
|---|
| • | does not renew its leases as they expire; |
|---|
| • | renews at lower rental rates and/or requires a tenant improvement allowance; or |
|---|
| • | renews but reduces its store size, which results in down-time and additional tenant improvement costs to the landlord to re-lease the vacated space. |
|---|
Some anchors have the right to vacate their space and may prevent us from re-tenanting by continuing to comply and pay rent in accordance with their lease agreement. Vacated anchor space, including space owned by the anchor, can reduce rental revenues generated by the shopping center in other spaces because of the loss of the departed anchor's customer drawing power. If a significant tenant vacates a property, co-tenancy clauses in select lease contracts may allow other tenants to modify or terminate their rent or lease obligations. Co-tenancy clauses have several variants: they may allow a tenant to postpone a store opening if certain other tenants fail to open their stores; they may allow a tenant to close its store prior to lease expiration if another tenant closes its store prior to lease expiration; or more commonly, they may allow a tenant to pay reduced levels of rent until a certain number of tenants open their stores within the same shopping center.
Additionally, many of our shopping centers are anchored by retailers who own their space whose location is within or immediately adjacent to our shopping center (“shadow anchors”). In those cases, the shadow anchors appear to the consumer as a retail tenant of the shopping center and, as a result, attract additional consumer traffic to the center. In the event that a shadow anchor were to close, it could negatively impact our center as consumer traffic would likely be red
Showing the first 8K of 66K characters. Open the full section
Item 1B. Unresolved Staff Comments
None.
Item 2. Properties
The following table is a list of the shopping centers, summarized by state and in order of largest holdings by number of properties, presented for Consolidated Properties (excludes properties owned by unconsolidated co-investment partnerships):
| December 31, 2019 | December 31, 2018 | |||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Location | Number of Properties | GLA (in thousands) | Percent of Total GLA | Percent Leased | Number of Properties | GLA (in thousands) | Percent of Total GLA | Percent Leased | ||||||||||||||||||||||||
| Florida | 89 | 10,629 | 28.3 | % | 94.0 | % | 90 | 10,745 | 28.3 | % | 94.7 | % | ||||||||||||||||||||
| California | 57 | 8,633 | 23.0 | % | 96.8 | % | 54 | 8,168 | 21.5 | % | 96.6 | % | ||||||||||||||||||||
| Texas | 23 | 3,050 | 8.1 | % | 90.7 | % | 23 | 3,019 | 8.0 | % | 97.3 | % | ||||||||||||||||||||
| Georgia | 21 | 2,048 | 5.5 | % | 94.6 | % | 21 | 2,048 | 5.4 | % | 95.5 | % | ||||||||||||||||||||
| Connecticut | 14 | 1,453 | 3.9 | % | 95.0 | % | 14 | 1,453 | 3.8 | % | 95.6 | % | ||||||||||||||||||||
| Colorado | 14 | 1,146 | 3.1 | % | 96.5 | % | 14 | 1,146 | 3.0 | % | 96.2 | % | ||||||||||||||||||||
| New York | 11 | 1,367 | 3.6 | % | 93.4 | % | 11 | 1,367 | 3.6 | % | 97.8 | % | ||||||||||||||||||||
| North Carolina | 10 | 901 | 2.4 | % | 95.5 | % | 10 | 895 | 2.3 | % | 96.8 | % | ||||||||||||||||||||
| Massachusetts | 9 | 931 | 2.5 | % | 91.7 | % | 9 | 907 | 2.4 | % | 98.9 | % | ||||||||||||||||||||
| Washington | 9 | 857 | 2.3 | % | 98.3 | % | 7 | 825 | 2.2 | % | 99.4 | % | ||||||||||||||||||||
| Ohio | 8 | 1,209 | 3.2 | % | 98.6 | % | 8 | 1,205 | 3.2 | % | 99.4 | % | ||||||||||||||||||||
| Virginia | 7 | 1,256 | 3.3 | % | 84.2 | % | 8 | 1,332 | 3.5 | % | 83.8 | % | ||||||||||||||||||||
| Oregon | 7 | 741 | 2.0 | % | 95.4 | % | 7 | 741 | 2.0 | % | 96.1 | % | ||||||||||||||||||||
| Illinois | 6 | 1,081 | 2.9 | % | 95.5 | % | 6 | 1,075 | 2.8 | % | 91.2 | % | ||||||||||||||||||||
| Missouri | 4 | 408 | 1.1 | % | 100.0 | % | 4 | 408 | 1.1 | % | 100.0 | % | ||||||||||||||||||||
| Maryland | 3 | 334 | 0.9 | % | 93.4 | % | 3 | 372 | 1.0 | % | 85.4 | % | ||||||||||||||||||||
| Tennessee | 3 | 318 | 0.8 | % | 100.0 | % | 3 | 318 | 0.8 | % | 99.1 | % | ||||||||||||||||||||
| Pennsylvania | 3 | 317 | 0.8 | % | 97.6 | % | 3 | 317 | 0.8 | % | 98.1 | % | ||||||||||||||||||||
| Indiana | 1 | 279 | 0.7 | % | 100.0 | % | 1 | 254 | 0.7 | % | 98.4 | % | ||||||||||||||||||||
| Delaware | 1 | 232 | 0.6 | % | 95.3 | % | 1 | 232 | 0.6 | % | 95.6 | % | ||||||||||||||||||||
| New Jersey | 1 | 218 | 0.6 | % | 99.0 | % | 1 | 218 | 0.6 | % | 96.9 | % | ||||||||||||||||||||
| Michigan | 1 | 97 | 0.3 | % | 100.0 | % | 1 | 97 | 0.3 | % | 100.0 | % | ||||||||||||||||||||
| South Carolina | 1 | 51 | 0.1 | % | 97.4 | % | 1 | 51 | 0.1 | % | 94.8 | % | ||||||||||||||||||||
| Louisiana | — | — | — | — | 5 | 753 | 2.0 | % | 92.8 | % | ||||||||||||||||||||||
| Total | 303 | 37,556 | 100.0 | % | 94.7 | % | 305 | 37,946 | 100.0 | % | 95.5 | % |
Certain Consolidated Properties are encumbered by mortgage loans of $486.3 million, excluding debt issuance costs and premiums and discounts, as of December 31, 2019.
The weighted average annual effective rent for the consolidated portfolio of properties, net of tenant concessions, is $22.38 and $21.51 PSF as of December 31, 2019 and 2018, respectively.
The following table is a list of the shopping centers, summarized by state and in order of largest holdings by number of properties, presented for Unconsolidated Properties (includes properties owned by unconsolidated co-investment partnerships):
| December 31, 2019 | December 31, 2018 | |||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Location | Number of Properties | GLA (in thousands) | Percent of Total GLA | Percent Leased | Number of Properties | GLA (in thousands) | Percent of Total GLA | Percent Leased | ||||||||||||||||||||||||
| California | 22 | 3,017 | 20.1 | % | 93.8 | % | 22 | 3,017 | 19.3 | % | 94.2 | % | ||||||||||||||||||||
| Virginia | 15 | 2,075 | 13.8 | % | 96.4 | % | 17 | 2,403 | 15.4 | % | 94.8 | % | ||||||||||||||||||||
| Maryland | 10 | 1,066 | 7.1 | % | 94.1 | % | 11 | 1,184 | 7.6 | % | 96.2 | % | ||||||||||||||||||||
| Florida | 10 | 1,045 | 6.9 | % | 97.7 | % | 10 | 1,045 | 6.7 | % | 98.8 | % | ||||||||||||||||||||
| North Carolina | 8 | 1,269 | 8.4 | % | 94.8 | % | 9 | 1,417 | 9.1 | % | 94.1 | % | ||||||||||||||||||||
| Texas | 7 | 933 | 6.2 | % | 98.1 | % | 7 | 933 | 6.0 | % | 98.2 | % | ||||||||||||||||||||
| Washington | 7 | 878 | 5.8 | % | 96.7 | % | 7 | 859 | 5.5 | % | 95.1 | % | ||||||||||||||||||||
| Colorado | 6 | 854 | 5.7 | % | 93.1 | % | 6 | 854 | 5.5 | % | 93.2 | % | ||||||||||||||||||||
| Pennsylvania | 6 | 669 | 4.5 | % | 86.5 | % | 6 | 666 | 4.2 | % | 94.4 | % | ||||||||||||||||||||
| Minnesota | 5 | 665 | 4.4 | % | 97.0 | % | 5 | 665 | 4.2 | % | 99.0 | % | ||||||||||||||||||||
| Illinois | 4 | 671 | 4.5 | % | 97.7 | % | 4 | 671 | 4.3 | % | 97.1 | % | ||||||||||||||||||||
| New Jersey | 4 | 353 | 2.3 | % | 94.1 | % | 4 | 353 | 2.3 | % | 96.4 | % | ||||||||||||||||||||
| Massachusetts | 2 | 726 | 4.8 | % | 97.0 | % | 2 | 726 | 4.6 | % | 98.4 | % | ||||||||||||||||||||
| Indiana | 2 | 139 | 0.9 | % | 88.4 | % | 2 | 139 | 0.9 | % | 100.0 | % | ||||||||||||||||||||
| District of Columbia | 2 | 40 | 0.3 | % | 92.5 | % | 2 | 40 | 0.3 | % | 84.4 | % | ||||||||||||||||||||
| Connecticut | 1 | 186 | 1.2 | % | 95.8 | % | 1 | 186 | 1.2 | % | 80.1 | % | ||||||||||||||||||||
| New York | 1 | 141 | 0.9 | % | 100.0 | % | 1 | 141 | 0.9 | % | 100.0 | % | ||||||||||||||||||||
| Oregon | 1 | 93 | 0.7 | % | 100.0 | % | 1 | 93 | 0.6 | % | 100.0 | % | ||||||||||||||||||||
| Georgia |
Showing the first 8K of 105K characters. Open the full section
Item 3. Legal Proceedings
We are a party to various legal proceedings that arise in the ordinary course of our business. We are not currently involved in any litigation, nor to our knowledge is any litigation threatened against us, the outcome of which would, in our judgment based on information currently available to us, have a material adverse effect on our financial position or results of operations.
Item 4. Mine Safety Disclosures
N/A
PART II
Item 5. Market for the Registrant's Common Equity, Related Stockholder Matters, and Issuer Purchases of Equity Securities
Since November 13, 2018, our common stock has traded on NASDAQ under the symbol “REG.” Before November 13, 2018, our common stock traded on the NYSE, also under the symbol “REG.”
As of February 7, 2020, there were 65,795 holders of common equity.
We intend to pay regular quarterly distributions to Regency Centers Corporation's common stockholders. Future distributions will be declared and paid at the discretion of our Board of Directors and will depend upon cash generated by operating activities, our financial condition, capital requirements, annual dividend requirements under the REIT provisions of the Internal Revenue Code of 1986, as amended, and such other factors as our Board of Directors deems relevant. In order to maintain Regency Centers Corporation's qualification as a REIT for federal income tax purposes, we are generally required to make annual distributions at least equal to 90% of our real estate investment trust taxable income for the taxable year. Under certain circumstances, which we do not expect to occur, we could be required to make distributions in excess of cash available for distributions in order to meet such requirements. We have a dividend reinvestment plan under which shareholders may elect to reinvest their dividends automatically in common stock. Under the plan, we may elect to purchase common stock in the open market on behalf of shareholders or may issue new common stock to such stockholders.
Under the revolving credit agreement of our line of credit, in the event of any monetary default, we may not make distributions to stockholders except to the extent necessary to maintain our REIT status.
There were no unregistered sales of equity securities during the quarter ended December 31, 2019.
The following table represents information with respect to purchases by the Parent Company of its common stock during the months in the three month period ended December 31, 2019:
| Period | Total number of shares purchased (1) | Total number of shares purchased as part of publicly announced plans or programs (2) | Average price paid per share | Maximum number or approximate dollar value of shares that may yet be purchased under the plans or programs (2) | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| October 1, 2019, through October 31, 2019 | — | — | $ | — | $ | 250,000,000 | ||||||||||
| November 1, 2019, through November 30, 2019 | — | — | $ | — | $ | 250,000,000 | ||||||||||
| December 1, 2019, through December 31, 2019 | 640 | — | $ | 60.91 | $ | 250,000,000 |
| (1) | Represents shares repurchased to cover payment of withholding taxes in connection with restricted stock vesting by participants under Regency's Long-Term Omnibus Plan. |
|---|
| (2) | On February 4, 2020, the Company's Board authorized a new common share repurchase program under which the Company may purchase, from time to time, up to a maximum of $250 million of its outstanding common stock through open market purchases and/or in privately negotiated transactions. Any shares purchased will be retired. The program is scheduled to expire on February 5, 2021. No shares have been repurchased under this new share repurchase program and no shares have been purchased under the program that expired in 2020. |
|---|
The performance graph furnished below shows Regency's cumulative total stockholder return to the S&P 500 Index, the FTSE NAREIT Equity REIT Index, and the FTSE NAREIT Equity Shopping Centers index since December 31, 2014. The stock performance graph should not be deemed filed or incorporated by reference into any other filing made by us under the Securities Act of 1933 or the Securities Exchange Act of 1934, except to the extent that we specifically incorporate the stock performance graph by reference in another filing.
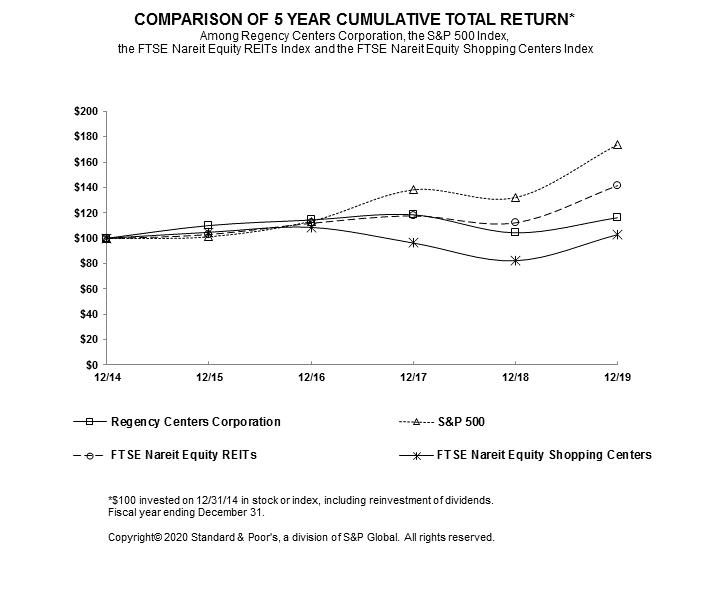
| 12/31/14 | 12/31/15 | 12/31/16 | 12/31/17 | 12/31/18 | 12/31/19 | |||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Regency Centers Corporation | $ | 100.00 | 110.03 | 114.39 | 118.50 | 104.26 | 116.17 | |||||||||||||||||
| S&P 500 | 100.00 | 101.38 | 113.51 | 138.29 | 132.23 | 173.86 | ||||||||||||||||||
| FTSE NAREIT Equity REITs | 100.00 | 103.20 | 111.99 | 117.84 | 112.39 | 141.61 | ||||||||||||||||||
| FTSE NAREIT Equity Shopping Centers | 100.00 | 104.72 | 108.57 | 96.23 | 82.23 | 102.81 |
Item 6. Selected Financial Data
The following table sets forth Selected Financial Data for the Company on a historical basis for the five years ended December 31, 2019 (in thousands, except per share and unit data, number of properties, and ratio of earnings to fixed charges). This historical Selected Financial Data has been derived from the audited consolidated financial statements. This information should be read in conjunction with the consolidated financial statements of Regency Centers Corporation and Regency Centers, L.P. (including the related notes thereto) and Management's Discussion and Analysis of the Financial Condition and Results of Operations, each included elsewhere in this Form 10-K.
Parent Company
| 2019 | 2018 | 2017 (1) | 2016 | 2015 | ||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating data: | ||||||||||||||||||||
| Revenues | $ | 1,133,138 | 1,120,975 | 984,326 | 614,371 | 569,763 | ||||||||||||||
| Operating expenses | 763,226 | 740,806 | 744,763 | 403,152 | 365,098 | |||||||||||||||
| Total other expense (income) | 187,610 | 170,818 | 113,661 | 100,745 | 74,630 | |||||||||||||||
| Income from operations before equity in income of investments in real estate partnerships and income taxes | 182,302 | 209,351 | 125,902 | 110,474 | 130,035 | |||||||||||||||
| Equity in income of investments in real estate partnerships | 60,956 | 42,974 | 43,341 | 56,518 | 22,508 | |||||||||||||||
| Deferred income tax benefit of taxable REIT subsidiary | — | — | (9,737 | ) | — | — | ||||||||||||||
| Net income | 243,258 | 252,325 | 178,980 | 166,992 | 152,543 | |||||||||||||||
| Income attributable to noncontrolling interests | (3,828 | ) | (3,198 | ) | (2,903 | ) | (2,070 | ) | (2,487 | ) | ||||||||||
| Net income attributable to the Company | 239,430 | 249,127 | 176,077 | 164,922 | 150,056 | |||||||||||||||
| Preferred stock dividends and issuance costs | — | — | (16,128 | ) | (21,062 | ) | (21,062 | ) | ||||||||||||
| Net income attributable to common stockholders | $ | 239,430 | 249,127 | 159,949 | 143,860 | 128,994 | ||||||||||||||
| Income per common share - diluted | $ | 1.43 | 1.46 | 1.00 | 1.42 | 1.36 | ||||||||||||||
| NAREIT FFO (2) | 654,362 | 652,857 | 494,843 | 277,301 | 276,515 | |||||||||||||||
| Other information: | ||||||||||||||||||||
| Net cash provided by operating activities | $ | 621,271 | 610,327 | 469,784 | 297,177 | 285,543 | ||||||||||||||
| Net cash used in investing activities | (282,693 | ) | (106,024 | ) | (1,007,230 | ) | (408,632 | ) | (139,346 | ) | ||||||||||
| Net cash (used in) provided by financing activities | (268,206 | ) | (508,494 | ) | 568,948 | 88,711 | (223,117 | ) | ||||||||||||
| Cash dividends paid to common stockholders and unit holders | 391,649 | 376,755 | 323,285 | 201,336 | 181,691 | |||||||||||||||
| Common dividends declared per share | 2.34 | 2.22 | 2.10 | 2.00 | 1.94 | |||||||||||||||
| Common stock outstanding including exchangeable operating partnership units | 168,318 | 168,254 | 171,715 | 104,651 | 97,367 | |||||||||||||||
| Balance sheet data: | ||||||||||||||||||||
| Real estate investments before accumulated depreciation (3) | $ | 11,564,816 | 11,326,163 | 11,279,125 | 5,230,198 | 4,852,106 | ||||||||||||||
| Total assets | 11,132,253 | 10,944,663 | 11,145,717 | 4,488,906 | 4,182,881 | |||||||||||||||
| Total debt | 3,919,544 | 3,715,212 | 3,594,977 | 1,642,420 | 1,864,285 | |||||||||||||||
| Total liabilities | 4,842,292 | 4,494,495 | 4,412,663 | 1,864,404 | 2,100,261 | |||||||||||||||
| Total stockholders’ equity | 6,213,348 | 6,397,970 | 6,692,052 | 2,591,301 | 2,054,109 | |||||||||||||||
| Total noncontrolling interests | 76,613 | 52,198 | 41,002 | 33,201 | 28,511 |
| (1) | 2017 reflects the results of our merger with Equity One on March 1, 2017, and therefore only includes ten months of operating results for the Equity One portfolio, but also includes merger and integration related costs within Operating expenses. |
|---|
| (2) | See Item 1, Defined Terms, for the definition of NAREIT FFO and Item 7, Supplemental Earnings Information, for a reconciliation to the nearest GAAP measure. |
|---|
| (3) | Includes our Investments in real estate partnerships. |
|---|
Operating Partnership
| 2019 | 2018 | 2017 (1) | 2016 | 2015 | ||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating data: | ||||||||||||||||||||
| Revenues | $ | 1,133,138 | 1,120,975 | 984,326 | 614,371 | 569,763 | ||||||||||||||
| Operating expenses | 763,226 | 740,806 | 744,763 | 403,152 | 365,098 | |||||||||||||||
| Total other expense (income) | 187,610 | 170,818 | 113,661 | 100,745 | 74,630 | |||||||||||||||
| Income from operations before equity in income of investments in real estate partnerships and income taxes | 182,302 | 209,351 | 125,902 | 110,474 | 130,035 | |||||||||||||||
| Equity in income of investments in real estate partnerships | 60,956 | 42,974 | 43,341 | 56,518 | 22,508 | |||||||||||||||
| Deferred income tax (benefit) of taxable REIT subsidiary | — | — | (9,737 | ) | — | — | ||||||||||||||
| Net income | 243,258 | 252,325 | 178,980 | 166,992 | 152,543 | |||||||||||||||
| Income attributable to noncontrolling interests | (3,194 | ) | (2,673 | ) | (2,515 | ) | (1,813 | ) | (2,247 | ) | ||||||||||
| Net income attributable to the Partnership | 240,064 | 249,652 | 176,465 | 165,179 | 150,296 | |||||||||||||||
| Preferred unit distributions and issuance costs | — | — | (16,128 | ) | (21,062 | ) | (21,062 | ) | ||||||||||||
| Net income attributable to common unit holders | $ | 240,064 | 249,652 | 160,337 | 144,117 | 129,234 | ||||||||||||||
| Income per common unit - diluted: | $ | 1.43 | 1.46 | 1.00 | 1.42 | 1.36 | ||||||||||||||
| NAREIT FFO (2) | 654,362 | 652,857 | 494,843 | 277,301 | 276,515 | |||||||||||||||
| Other information: | ||||||||||||||||||||
| Net cash provided by operating activities | $ | 621,271 | 610,327 | 469,784 | 297,177 | 285,543 | ||||||||||||||
| Net cash used in investing activities | (282,693 | ) | (106,024 | ) | (1,007,230 | ) | (408,632 | ) | (139,346 | ) | ||||||||||
| Net cash (used in) provided by financing activities | (268,206 | ) | (508,494 | ) | 568,948 | 88,711 | (223,117 | ) | ||||||||||||
| Distributions paid on common and limited partnership units | 391,649 | 376,755 | 323,285 | 201,336 | 181,691 | |||||||||||||||
| Balance sheet data: | ||||||||||||||||||||
| Real estate investments before accumulated depreciation (3) | $ | 11,564,816 | 11,326,163 | 11,279,125 | 5,230,198 | 4,852,106 | ||||||||||||||
| Total assets | 11,132,253 | 10,944,663 | 11,145,717 | 4,488,906 | 4,182,881 | |||||||||||||||
| Total debt | 3,919,544 | 3,715,212 | 3,594,977 | 1,642,420 | 1,864,285 | |||||||||||||||
| Total liabilities | 4,842,292 | 4,494,495 | 4,412,663 | 1,864,404 | 2,100,261 | |||||||||||||||
| Total partners’ capital | 6,249,448 | 6,408,636 | 6,702,959 | 2,589,334 | 2,052,134 | |||||||||||||||
| Total noncontrolling interests | 40,513 | 41,532 | 30,095 | 35,168 | 30,486 |
| (1) | 2017 reflects the results of our merger with Equity One on March 1, 2017, and therefore only includes ten months of operating results for the Equity One portfolio, but also includes merger and integration related costs within Operating expenses. |
|---|
| (2) | See Item 1, Defined Terms, for the definition of NAREIT FFO and Item 7, Supplemental Earnings Information, for a reconciliation to the nearest GAAP measure. |
|---|
| (3) | Includes our Investments in real estate partnerships. |
|---|
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
Executing on our Strategy
We had Net income attributable to the Company of $239.4 million during the year ended December 31, 2019, as compared to $249.1 million during the year ended December 31, 2018.
We sustained same property NOI growth:
| • | We attained Pro-rata same property NOI growth, excluding termination fees, of 2.1%. |
|---|
| • | We executed 1,702 leasing transactions representing 6.1 million Pro-rata SF of new and renewal leasing with trailing twelve month rent spreads of 8.5% on comparable retail operating property spaces. |
|---|
| • | At December 31, 2019, our total property portfolio was 94.8% leased while our same property portfolio was 95.1% leased. |
|---|
We continued our development and redevelopment of high quality shopping centers at attractive returns on investment:
| • | We started a new development representing a total Pro-rata investment of $27.3 million upon completion with a projected return on investment of 6.0%. |
|---|
| • | We started 11 new redevelopments representing a total incremental Pro-rata investment of $237.2 million upon completion with a weighted average projected return on investment of 6.9%, including $74.7 million for two future phases at Serramonte Center. |
|---|
| • | Including these projects, a total of 22 properties were in the process of development or redevelopment as of December 31, 2019 representing a Pro-rata investment upon completion of $350.8 million. |
|---|
| • | We completed six new developments during 2019 representing a total Pro-rata investment of $223.2 million with a weighted average return on investment of 7.2%. |
|---|
| • | We completed three new redevelopments during 2019 representing a total incremental Pro-rata investment of $7.6 million with a weighted average return on investment of 7.0%. |
|---|
We maintained a conservative balance sheet providing financial flexibility to cost effectively fund investment opportunities and debt maturities:
| • | On March 6, 2019, we issued $300.0 million of 4.65% senior unsecured public notes, which priced at 99.661%, and mature in March 2049. The net proceeds of the offering were used to repay in full our $250 million 4.8% notes due April 15, 2021, including a make-whole premium of approximately $9.6 million and accrued interest. The remaining proceeds were used toward repaying in full two mortgages for $52.7 million with interest rates ranging between 6.25% and 7.25%, including a repayment premium of $1.0 million. |
|---|
| • | On August 13, 2019, we issued $425.0 million of 2.95% senior unsecured public notes, which priced at 99.903% and mature in September 2029. The net proceeds of the offering were used to repay in full our $300.0 million term loan that was due to mature in December 2020, including an interest rate swap breakage fee of approximately $1.1 million, and to reduce the outstanding balance on our Line. |
|---|
| • | During September 2019, we entered into forward sale agreements under our ATM program through which we will issue 1,894,845 shares of common stock at an average offering price of $67.99. The shares under the forward sales agreements may be settled at any time before the required settlement date of September 12, 2020. Proceeds from the issuance of shares are expected to be used to fund acquisitions of operating properties, to fund developments and redevelopments, and for general corporate purposes. No shares have been settled through December 31, 2019. |
|---|
| • | At December 31, 2019, our annualized net debt-to-operating EBITDAre ratio on a Pro-rata basis was 5.4x. |
|---|
Leasing Activity and Significant Tenants
We believe our high-quality, grocery anchored shopping centers located in densely populated, desirable infill trade areas create attractive spaces for retail tenants.
Pro-rata Occupancy
The following table summarizes Pro-rata occupancy rates of our combined Consolidated and Unconsolidated shopping center portfolio:
| December 31, 2019 | December 31, 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| % Leased – All properties | 94.8 | % | 95.6 | % | ||||
| Anchor space | 97.3 | % | 98.4 | % | ||||
| Shop space | 90.6 | % | 90.9 | % |
The decline in both anchor and shop space percent leased is primarily attributable to bankruptcy filings.
Pro-rata Leasing Activity
The following table summarizes leasing activity, including our Pro-rata share of activity within the portfolio of our co-investment partnerships:
| Year ended December 31, 2019 | ||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Leasing Transactions | SF (in thousands) | Base Rent PSF | Tenant Allowance and Landlord Work PSF | Leasing Commissions PSF (1) | ||||||||||||||||
| Anchor Leases | ||||||||||||||||||||
| New | 32 | 633 | $ | 20.78 | $ | 48.64 | $ | 4.88 | ||||||||||||
| Renewal | 107 | 2,756 | 13.89 | 0.60 | 0.13 | |||||||||||||||
| Total Anchor Leases | 139 | 3,389 | $ | 15.18 | $ | 9.57 | $ | 1.02 | ||||||||||||
| Shop Space | ||||||||||||||||||||
| New | 506 | 921 | $ | 33.60 | $ | 29.75 | $ | 9.67 | ||||||||||||
| Renewal | 1,057 | 1,819 | 33.59 | 1.04 | 0.61 | |||||||||||||||
| Total Shop Space Leases | 1,563 | 2,740 | $ | 33.59 | $ | 10.69 | $ | 3.65 | ||||||||||||
| Total Leases | 1,702 | 6,129 | $ | 23.41 | $ | 10.07 | $ | 2.20 |
| (1) | On January 1, 2019, the Company adopted ASC Topic 842, Leases, under which non-contingent internal leasing costs can no longer be capitalized. |
|---|
| Year Ended December 31, 2018 | ||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Leasing Transactions | SF (in thousands) | Base Rent PSF | Tenant Allowance and Landlord Work PSF | Leasing Commissions PSF | ||||||||||||||||
| Anchor Leases | ||||||||||||||||||||
| New | 38 | 625 | $ | 18.75 | $ | 29.78 | $ | 6.96 | ||||||||||||
| Renewal | 99 | 2,886 | 15.18 | 0.60 | 0.35 | |||||||||||||||
| Total Anchor Leases | 137 | 3,511 | $ | 15.82 | $ | 5.79 | $ | 1.52 | ||||||||||||
| Shop Space | ||||||||||||||||||||
| New | 519 | 890 | $ | 33.05 | $ | 28.17 | $ | 13.86 | ||||||||||||
| Renewal | 1,146 | 1,838 | 33.65 | 0.83 | 2.13 | |||||||||||||||
| Total Shop Space Leases | 1,665 | 2,728 | $ | 33.45 | $ | 9.75 | $ | 5.96 | ||||||||||||
| Total Leases | 1,802 | 6,239 | $ | 23.53 | $ | 7.52 | $ | 3.46 |
Total weighted average base rent on signed shop space leases during 2019 was $33.59 PSF and exceeds the average annual base rent of all shop space leases due to expire during the next 12 months of $32.56 PSF. The increase in tenant allowance and landlord work committed on new anchor leases signed in 2019 is attributable to anchor deals that include costs to either convert units to a specialized use, deliver new GLA, or demise units to accommodate smaller tenant formats.
Significant Tenants and Concentrations of Risk
We seek to reduce our operating and leasing risks through geographic diversificatio
Showing the first 8K of 82K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures about Market Risk
We are exposed to two significant components of interest rate risk:
| • | We have a Line commitment, as further described in note 9 to the Consolidated Financial Statements, which has a variable interest rate that is based upon an annual rate of LIBOR plus 0.875%. LIBOR rates charged on our Line change monthly and the spread on the Line is dependent upon maintaining specific credit ratings. If our credit ratings are downgraded, the spread on the Line would increase, resulting in higher interest costs. The interest rate spread based on our credit rating ranges from LIBOR plus 0.700% to LIBOR plus 1.550%. |
|---|
| • | We are also exposed to changes in interest rates when we refinance our existing long-term fixed rate debt. The objective of our interest rate risk management program is to limit the impact of interest rate changes on earnings and cash flows. To achieve these objectives, we borrow primarily at fixed interest rates and may enter into derivative financial instruments such as interest rate swaps, caps, or treasury locks in order to mitigate our interest rate risk on a related financial instrument. We do not enter into derivative or interest rate transactions for speculative purposes. Our interest rate swaps are structured solely for the purpose of interest rate protection. |
|---|
We continuously monitor the capital markets and evaluate our ability to issue new debt, to repay maturing debt, or fund our commitments. Based upon the current capital markets, our credit ratings, our capacity under our unsecured credit facilities, and the number of high quality, unencumbered properties that we own which could collateralize borrowings, we expect that we will be able to successfully issue new secured or unsecured debt to fund maturing debt obligations.
Our interest rate risk is monitored using a variety of techniques. The table below presents the principal cash flows, weighted average interest rates of remaining debt, and the fair value of total debt as of December 31, 2019. For variable rate mortgages and unsecured credit facilities for which we have interest rate swaps in place to fix the interest rate, they are included in the Fixed rate debt section below at their all-in fixed rate. The table is presented by year of expected maturity to evaluate the expected cash flows and sensitivity to interest rate changes. Although the average interest rate for variable rate debt is included in the table, those rates represent rates that existed as of December 31, 2019, and are subject to change on a monthly basis. In addition, the Company continually assesses the market risk for its floating rate debt and believes that a 1% increase in interest rates would decrease future earnings and cash flows by approximately $2.6 million per year based on $35.1 million of floating rate mortgage debt and $220.0 million of floating rate line of credit balance outstanding at December 31, 2019. If the Company increases its line of credit balance in the future, additional decreases to future earnings and cash flows could occur.
Further, the table below incorporates only those exposures that exist as of December 31, 2019, and does not consider exposures or positions that could arise after that date. Since firm commitments are not presented, the table has limited predictive value. As a result, our ultimate realized gain or loss with respect to interest rate fluctuations will depend on the exposures that arise during the period, our hedging strategies at that time, and actual interest rates.
The table below presents the principal cash flow payments associated with our outstanding debt by year, weighted average interest rates on debt outstanding at each year-end, and fair value of total debt as of December 31, 2019.
| (dollars in thousands) | 2020 | 2021 | 2022 | 2023 | 2024 | Thereafter | Total | Fair Value | ||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Fixed rate debt (1) | $ | 50,360 | 50,599 | 582,645 | 69,498 | 346,043 | 2,592,015 | 3,691,160 | 3,920,909 | |||||||||||||||||||||||
| Average interest rate for all fixed rate debt (2) | 3.74 | % | 3.72 | % | 3.85 | % | 3.86 | % | 3.87 | % | 3.87 | % | ||||||||||||||||||||
| Variable rate LIBOR debt (1) | $ | — | 35,100 | 220,000 | — | — | — | 255,100 | 257,191 | |||||||||||||||||||||||
| Average interest rate for all variable rate debt (2) | 3.17 | % | 3.14 | % | — | % | — | % | — | % | — | % | — | % |
| (1) | Reflects amount of debt maturities during each of the years presented as of December 31, 2019. |
|---|
| (2) | Reflects weighted average interest rates of debt outstanding at the end of each year presented. For variable rate debt, the benchmark interest rate (LIBOR), as of December 31, 2019, was used to determine the average rate for all future periods. |
|---|
Item 8. Consolidated Financial Statements and Supplementary Data
Regency Centers Corporation and Regency Centers, L.P.
Index to Financial Statements
All other schedules are omitted because of the absence of conditions under which they are required, materiality or because information required therein is shown in the consolidated financial statements or notes thereto.
Report of Independent Registered Public Accounting Firm
To the Stockholders and Board of Directors
Regency Centers Corporation:
Opinion on the Consolidated Financial Statements
We have audited the accompanying consolidated balance sheets of Regency Centers Corporation and subsidiaries (the Company) as of December 31, 2019 and 2018, the related consolidated statements of operations, comprehensive income, equity, and cash flows for each of the years in the three-year period ended December 31, 2019, and the related notes and financial statement schedule III – Consolidated Real Estate and Accumulated Depreciation (collectively, the consolidated financial statements). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company as of December 31, 2019 and 2018, and the results of its operations and its cash flows for each of the years in the three-year period ended December 31, 2019, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company’s internal control over financial reporting as of December 31, 2019, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission, and our report dated February 14, 2020 expressed an unqualified opinion on the effectiveness of the Company’s internal control over financial reporting.
Change in Accounting Principle
As discussed in Note 1 to the consolidated financial statements, the Company has changed its method of accounting for leases as of January 1, 2019 due to the adoption of Accounting Standards Codification Topic 842, Leases.
Basis for Opinion
These consolidated financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on these consolidated financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. We believe that our audits provide a reasonable basis for our opinion.
Critical Audit Matters
The critical audit matters communicated below are matters arising from the current period audit of the consolidated financial statements that were communicated or required to be communicated to the audit committee and that: (1) relate to accounts or disclosures that are material to the consolidated financial statements and (2) involved our especially challenging, subjective, or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matters below, providing separate opinions on the critical audit matters or on the accounts or disclosures to which they relate.
Evaluation of real estate properties for impairment
As discussed in Note 1 to the consolidated financial statements and presented on the consolidated balance sheet, real estate assets, less accumulated depreciation was $9.3 billion as of December 31, 2019. The Company evaluates real estate properties for impairment whenever there are indicators that the carrying value of the real estate properties may not be recoverable. To the extent that the carrying value of a real estate property exceeds the estimate of its undiscounted cash flows, an impairment loss is recognized equal to the excess of carrying value over its fair value. Fair value of real estate properties is determined through a comparable sales approach or a discounted cash flow approach. As discussed in Note 11 to the consolidated financial statements, the Company determined that one property’s carrying value exceeded its fair value through the use of a discounted cash flow analysis, and recorded an impairment charge of $40.3 million.
We identified the evaluation of real estate properties for impairment as a critical audit matter. Evaluating the Company’s judgments regarding the identification of potential indicators that the carrying value of the real estate properties may not be recoverable involved a high degree of subjective auditor judgment. Changes in assumptions regarding property conditions, occupancy rates, net operating income, and anticipated hold periods could have an impact on the determination of the existence of impairment indicators and the need to further evaluate the real estate properties for impairment. In addition, the evaluation of the fair value of the real estate property that resulted in the $40.3 million impairment charge, in particular, the key assumptions over the property’s highest and best use, terminal capitalization rate, and the hold period, required a high degree of auditor judgment. The evaluation of these key assumptions required an increased extent of effort, including the need to involve valuation professionals with specialized skills and knowledge.
The primary procedures we performed to address these critical audit matters incl
Showing the first 8K of 302K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
None.
Item 9A. Controls and Procedures
Controls and Procedures (Regency Centers Corporation)
Conclusion Regarding the Effectiveness of Disclosure Controls and Procedures
Under the supervision and with the participation of the Parent Company's management, including its chief executive officer and chief financial officer, the Parent Company conducted an evaluation of its disclosure controls and procedures, as such term is defined under Rule 13a-15(e) and 15d-15(e) promulgated under the Securities Exchange Act of 1934, as amended (the “Exchange Act”). Based on this evaluation, the Parent Company's chief executive officer and chief financial officer concluded that its disclosure controls and procedures were effective as of the end of the period covered by this annual report on Form 10-K to ensure information required to be disclosed in the reports filed or submitted under the Exchange Act is recorded, processed, summarized and reported, within the time period specified in the SEC's rules and forms. These disclosure controls and procedures include controls and procedures designed to ensure that information required to be disclosed by the Parent Company in the reports it files or submits is accumulated and communicated to management, including its chief executive officer and chief financial officer, as appropriate, to allow timely decisions regarding required disclosure.
Management's Report on Internal Control over Financial Reporting
The Parent Company's management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Exchange Act Rules 13a-15(f) and 15d-15(f). Under the supervision and with the participation of its management, including its chief executive officer and chief financial officer, the Parent Company conducted an evaluation of the effectiveness of its internal control over financial reporting based on the framework in Internal Control - Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission. Based on its evaluation under the framework in Internal Control - Integrated Framework (2013), the Parent Company's management concluded that its internal control over financial reporting was effective as of December 31, 2019.
KPMG LLP, an independent registered public accounting firm, has audited the consolidated financial statements included in this annual report on Form 10-K and, as part of their audit, has issued a report, included herein, on the effectiveness of the Parent Company's internal control over financial reporting.
The Parent Company's system of internal control over financial reporting was designed to provide reasonable assurance regarding the preparation and fair presentation of published financial statements in accordance with accounting principles generally accepted in the United States. All internal control systems, no matter how well designed, have inherent limitations. Therefore, even those systems determined to be effective can provide only reasonable assurance and may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Changes in Internal Controls
There have been no changes in the Parent Company's internal controls over financial reporting identified in connection with this evaluation that occurred during the fourth quarter of 2019 that have materially affected, or are reasonably likely to materially affect, our internal controls over financial reporting.
Controls and Procedures (Regency Centers, L.P.)
Conclusion Regarding the Effectiveness of Disclosure Controls and Procedures
Under the supervision and with the participation of the Operating Partnership's management, including the chief executive officer and chief financial officer of its general partner, the Operating Partnership conducted an evaluation of its disclosure controls and procedures, as such term is defined under Rule 13a-15(e) and 15d-15(e) promulgated under the Exchange Act. Based on this evaluation, the chief executive officer and chief financial officer of its general partner concluded that its disclosure controls and procedures were effective as of the end of the period covered by this annual report on Form 10-K to ensure information required to be disclosed in the reports filed or submitted under the Exchange Act is recorded, processed, summarized and reported, within the time period specified in the SEC's rules and forms. These disclosure controls and procedures include controls and procedures designed to ensure that information required to be disclosed by the Operating Partnership in the reports it files or submits is accumulated and communicated to management, including the chief executive officer and chief financial officer of its general partner, as appropriate, to allow timely decisions regarding required disclosure.
Management's Report on Internal Control over Financial Reporting
The Operating Partnership's management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Exchange Act Rules 13a-15(f) and 15d-15(f). Under the supervision and with the participation of its management, including the chief executive officer and chief financial officer of its general partner, the Operating Partnership conducted an evaluation of the effectiveness of its internal control over financial reporting based on the framework in Internal Control - Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission. Based on its evaluation under the framework in Internal Control - Integrated Framework (2013), the Operating Partnership's management concluded that its internal control over financial reporting was effective as of December 31, 2019.
KPMG LLP, an independent registered public accounting firm, has audited the consolidated financial statements included in this annual report on Form 10-K and, as part of their audit, has issued a report, included herein, on the effectiveness of the Operating Partnership's internal control over financial reporting.
The Operating Partnership's system of internal control over financial reporting was designed to provide reasonable assurance regarding the preparation and fair presentation of published financial statements in accordance with accounting principles generally accepted in the United States. All internal control systems, no matter how well designed, have inherent limitations. Therefore, even those systems determined to be effective can provide only reasonable assurance and may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Changes in Internal Controls
There have been no changes in the Operating Partnership's internal controls over financial reporting identified in connection with this evaluation that occurred during the fourth quarter of 2019 that have materially affected, or are reasonably likely to materially affect, our internal controls over financial reporting.
Item 9B. Other Information
Not applicable
PART III
Item 10. Directors, Executive Officers, and Corporate Governance
Information concerning our directors, executive officers, and corporate governance is incorporated herein by reference to our definitive proxy statement to be filed with the Securities and Exchange Commission within 120 days after the end of the fiscal year covered by this Form 10-K with respect to the 2020 Annual Meeting of Stockholders. Information regarding executive officers is included in Part I of this Form 10-K as permitted by General Instruction G(3).
Code of Ethics.
We have a code of ethics applicable to our Board of Directors, principal executive officers, principal financial officer, principal accounting officer and persons performing similar functions. The text of this code of ethics may be found on our web site at www.regencycenters.com. We will post a notice of any waiver from, or amendment to, any provision of our code of ethics on our web site.
Item 11. Executive Compensation
Incorporated herein by reference to our definitive proxy statement to be filed with the Securities and Exchange Commission within 120 days after the end of the fiscal year covered by this Form 10-K with respect to the 2020 Annual Meeting of Stockholders.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
Equity Compensation Plan Information
(as of December 31, 2019)
| (a) | (b) | (c) | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Plan Category | Number of securities to be issued upon exercise of outstanding options, warrants and rights (1) | Weighted-average exercise price of outstanding options, warrants and rights (2) | Number of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in column a) (3) | |||||||||
| Equity compensation plans approved by security holders | — | $ | — | 4,962,651 | ||||||||
| Equity compensation plans not approved by security holders | N/A | N/A | N/A | |||||||||
| Total | — | $ | — | 4,962,651 |
| (1) | This column does not include 623,090 shares that may be issued pursuant to unvested restricted stock and performance share awards. |
|---|
| (2) | The weighted average exercise price excludes stock rights awards, which we sometimes refer to as unvested restricted stock. |
|---|
| (3) | The Regency Centers Corporation Omnibus Incentive Plan, (“Omnibus Plan”), as approved by stockholders at our 2019 annual meeting, provides that an aggregate maximum of 5.6 million shares of our common stock are reserved for issuance under the Omnibus Plan. |
|---|
Information about security ownership is incorporated herein by reference to our definitive proxy statement to be filed with the Securities and Exchange Commission within 120 days after the end of the fiscal year covered by this Form 10-K with respect to the 2020 Annual Meeting of Stockholders.
Item 13. Certain Relationships and Related Transactions, and Director Independence
Incorporated herein by reference to our definitive proxy statement to be filed with the Securities and Exchange Commission within 120 days after the end of the fiscal year covered by this Form 10-K with respect to the 2020 Annual Meeting of Stockholders.
Item 14. Principal Accountant Fees and Services
Incorporated herein by reference to our definitive proxy statement to be filed with the Securities and Exchange Commission within 120 days after the end of the fiscal year covered by this Form 10-K with respect to the 2020 Annual Meeting of Stockholders.
PART IV
Item 15. Exhibits and Financial Statement Schedules
| (a) | Financial Statements and Financial Statement Schedules: |
|---|
Regency Centers Corporation and Regency Centers, L.P. 2019 financial statements and financial statement schedule, together with the reports of KPMG LLP are listed on the index immediately preceding the financial statements in Item 8, Consolidated Financial Statements and Supplemental Data.
| (b) | Exhibits: |
|---|
In reviewing the agreements included as exhibits to this report, please remember they are included to provide you with information regarding their terms and are not intended to provide any other factual or disclosure information about the Company, its subsidiaries or other parties to the agreements. The Agreements contain representations and warranties by each of the parties to the applicable agreement. These representations and warranties have been made solely for the benefit of the other parties to the applicable agreement and:
| • | should not in all instances be treated as categorical statements of fact, but rather as a way of allocating the risk to one of the parties if those statements prove to be inaccurate; |
|---|
| • | have been qualified by disclosures that were made to the other party in connection with the negotiation of the applicable agreement, which disclosures are not necessarily reflected in the agreement; |
|---|
| • | may apply standards of materiality in a way that is different from what may be viewed as material to you or other investors; and |
|---|
| • | were made only as of the date of the applicable agreement or such other date or dates as may be specified in the agreement and are subject to more recent developments. |
|---|
Accordingly, these representations and warranties may not describe the actual state of affairs as of the date they were made or at any other time. We acknowledge that, notwithstanding the inclusion of the foregoing cautionary statements, we are responsible for considering whether additional specific disclosures of material information regarding material contractual provisions are required to make the statements in this report not misleading. Additional information about the Company may be found elsewhere in this report and the Company's other public files, which are available without charge through the SEC's website at http://www.sec.gov .
Unless otherwise indicated below, the Commission file number to the exhibit is No. 001-12298.
| 1. | Underwriting Agreement | |||
|---|---|---|---|---|
| (a) | Form of Equity Distribution Agreement dated May 17, 2017 among Regency Centers Corporation, Regency Centers, L.P. and the parties listed below (incorporated by reference to Exhibit 1.1 to the Company’s Form 8-K filed on May 17, 2017). The Equity Distribution Agreements listed below are substantially identical in all material respects to the Form of Equity Distribution Agreement, except for the identities of the parties, and have not been filed as exhibits to the Company’s 1934 Act reports pursuant to Instruction 2 to item 601 of Regulation S-K: | |||
| (i) | Equity Distribution Agreement dated May 17, 2017 among Regency Centers Corporation, Regency Centers, L.P. and Wells Fargo Securities, LLC; | |||
| (ii) | Equity Distribution Agreement dated May 17, 2017 among Regency Centers Corporation, Regency Centers, L.P. and J.P. Morgan Securities LLC; | |||
| (iii) | Equity Distribution Agreement dated May 17, 2017 among Regency Centers Corporation, Regency Centers, L.P. and Merrill Lynch, Pierce, Fenner & Smith Incorporated; | |||
| (iv) | Equity Distribution Agreement dated May 17, 2017 among Regency Centers Corporation, Regency Centers, L.P. and BB&T Capital Markets, a division of BB&T Securities, LLC; | |||
| (v) | Equity Distribution Agreement dated May 17, 2017 among Regency Centers Corporation, Regency Centers, L.P. and BTIG, LLC; | |||
The certifications in this exhibit 32 are being furnished solely to accompany this report pursuant to 18 U.S.C. § 1350, and are not being filed for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, and are not to be incorporated by reference into any of the Company's filings, whether made before or after the date hereof, regardless of any general incorporation language in such filing.
| 32.1 | 18 U.S.C. § 1350 Certification of Chief Executive Officer for Regency Centers Corporation. | |
|---|---|---|
| 32.2 | 18 U.S.C. § 1350 Certification of Chief Financial Officer for Regency Centers Corporation. | |
| 32.3 | 18 U.S.C. § 1350 Certification of Chief Executive Officer for Regency Centers, L.P. | |
| 32.4 | 18 U.S.C. § 1350 Certification of Chief Financial Officer for Regency Centers, L.P. | |
| 101. | Interactive Data Files | |
| 101.INS+ | Inline XBRL Instance Document - the instance document does not appear in the Interactive Data File because its XBRL tags are embedded within the Inline XBRL document | |
| 101.SCH+ | Inline XBRL Taxonomy Extension Schema Document | |
| 101.CAL+ | Inline XBRL Taxonomy Extension Calculation Linkbase Document | |
| 101.DEF+ | Inline XBRL Taxonomy Definition Linkbase Document | |
| 101.LAB+ | Inline XBRL Taxonomy Extension Label Linkbase Document | |
| 101.PRE+ | Inline XBRL Taxonomy Extension Presentation Linkbase Document | |
| 104. | Cover Page Interactive Data File (formatted as inline XBRL and contained in Exhibit 101) |
| + Submitted electronically with this Annual Report |
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| February 14, 2020 | REGENCY CENTERS CORPORATION | |||
| By: | /s/ Lisa Palmer | |||
| Lisa Palmer, President and Chief Executive Officer |
| February 14, 2020 | REGENCY CENTERS, L.P. | ||
| By: | Regency Centers Corporation, General Partner | ||
| By: | /s/ Lisa Palmer | ||
| Lisa Palmer, President and Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| February 14, 2020 | /s/ Martin E. Stein, Jr. | |
| Martin E. Stein. Jr., Executive Chairman of the Board | ||
| February 14, 2020 | /s/ Lisa Palmer | |
| Lisa Palmer, President, Chief Executive Officer, and Director | ||
| February 14, 2020 | /s/ Michael J. Mas | |
| Michael J. Mas, Executive Vice President, Chief Financial Officer (Principal Financial Officer) | ||
| February 14, 2020 | /s/ J. Christian Leavitt | |
| J. Christian Leavitt, Senior Vice President and Treasurer (Principal Accounting Officer) | ||
| February 14, 2020 | /s/ Joseph Azrack | |
| Joseph Azrack, Director | ||
| February 14, 2020 | /s/ Bryce Blair | |
| Bryce Blair, Director | ||
| February 14, 2020 | /s/ C. Ronald Blankenship | |
| C. Ronald Blankenship, Director | ||
| February 14, 2020 | /s/ Deirdre J. Evens | |
| Deirdre J. Evens, Director | ||
| February 14, 2020 | /s/ Thomas W. Furphy | |
| Tom W. Furphy, Director | ||
| February 14, 2020 | /s/ Karin M. Klein | |
| Karin M. Klein, Director | ||
| February 14, 2020 | /s/ Peter Linneman | |
| Peter Linneman, Director | ||
| February 14, 2020 | /s/ David P. O'Connor | |
| David P. O'Connor, Director | ||
| February 14, 2020 | /s/ Thomas G. Wattles | |
| Thomas G. Wattles, Director |