 filings.tools
Item 1. BUSINESS
72K characters. Original on sec.gov · Markdown
Item 1. BUSINESS
Raymond James Financial, Inc. (“RJF” or the “firm”) is a leading diversified financial services company providing private client group, capital markets, asset management, banking and other services to individuals, corporations and municipalities. The firm, together with its subsidiaries, is engaged in various financial services activities, including providing investment management services to retail and institutional clients, merger & acquisition and advisory services, the underwriting, distribution, trading and brokerage of equity and debt securities, and the sale of mutual funds and other investment products. The firm also provides corporate and retail banking services, and trust services. The firm operates predominantly in the United States (“U.S.”) and, to a lesser extent, in Canada, the United Kingdom (“U.K.”), and other parts of Europe. As used herein, the terms “our,” “we,” or “us” refer to RJF and/or one or more of its subsidiaries.
Established in 1962 and public since 1983, RJF is listed on the New York Stock Exchange (the “NYSE”) under the symbol “RJF.” As a bank holding company (“BHC”) and financial holding company (“FHC”), RJF is subject to supervision, examination and regulation by the Board of Governors of the Federal Reserve System (“the Fed”).
Among the keys to our historical and continued success, our emphasis on putting the client first is at the core of our corporate values. We also believe in maintaining a conservative, long-term focus in our decision making. We believe that this disciplined decision-making approach translates to a strong, stable financial services firm for clients, associates, and shareholders.
REPORTABLE SEGMENTS
We currently operate through the following five segments: Private Client Group (“PCG”); Capital Markets; Asset Management; Bank; and Other.
The following graph depicts the relative net revenue contribution of each of our business segments for the fiscal year ended September 30, 2022.
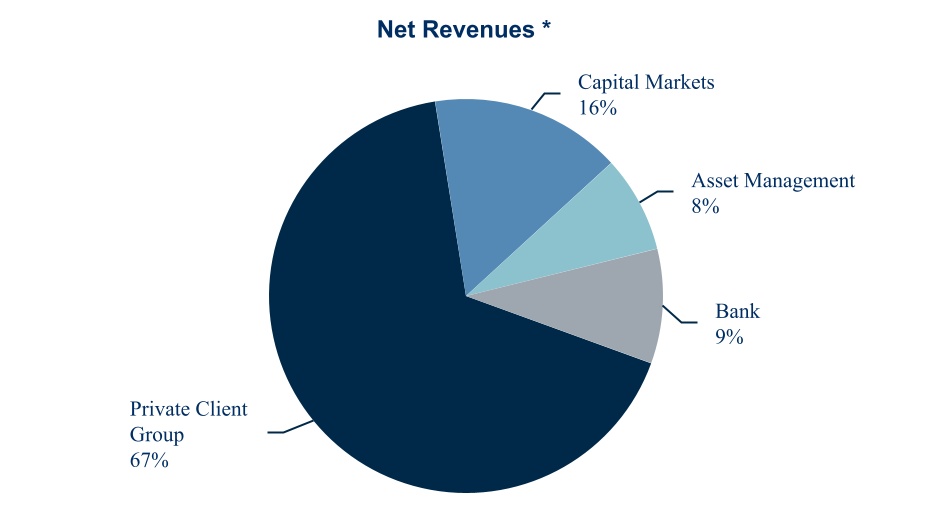
- The preceding chart does not include intersegment eliminations or the Other segment.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
Private Client Group
We provide financial planning, investment advisory and securities transaction services to clients through financial advisors. Total client assets under administration (“AUA”) in our PCG segment as of September 30, 2022 were $1.04 trillion, of which $586.0 billion related to fee-based accounts (“fee-based AUA”). We had 8,681 employee and independent contractor financial advisors affiliated with us as of September 30, 2022.
Affiliation
We offer multiple affiliation options, which we refer to as AdvisorChoice. Financial advisors primarily affiliate with us directly as either employees or independent contractors, or as employees of the third-party Registered Investment Advisors (“RIAs”) and broker-dealers to which we provide services through our RIA and Custody Services (“RCS”) division.
Employee financial advisors
Employee financial advisors work in a traditional branch supported by local management and administrative staff. They provide services predominantly to retail clients. Compensation for these financial advisors primarily includes a payout on revenues they generate and such advisors also participate in the firm’s employee benefit plans.
Independent contractor financial advisors
Our financial advisors who are independent contractors are responsible for all of their direct costs and, accordingly, receive a higher payout percentage on the revenues they generate than employee financial advisors. Our independent contractor financial advisor options are designed to help our advisors build their businesses with as much or as little of our support as they determine they need. Independent contractor financial advisors may affiliate with us directly or through an affiliated bank or credit union in our Financial Institutions Division. With specific approval, and on a limited basis, they are permitted to conduct certain other approved business activities, such as offering insurance products, independent registered investment advisory services, and accounting and tax services.
RIA and Custody Services
Through our domestic RCS division, we offer third-party RIAs and broker-dealers a range of products and services including custodial services, trade execution, research and other support and services (including access to clients’ account information and the services of the Asset Management segment) for which we receive fees, which may be either transactional or based on AUA. Firms affiliated with us through RCS retain the fees they charge to their clients and are responsible for all of their direct costs. Financial advisors associated with firms in RCS are not included in our financial advisor counts, although their client assets are included in our AUA. AUA associated with firms in our RCS division totaled $108.5 billion as of September 30, 2022.
Products and services
We offer a broad range of third-party and proprietary investment products and services to meet our clients’ various investment and financial needs. Revenues from this segment are typically driven by AUA and are generally either asset-based or transactional in nature.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
PCG segment net revenues for the fiscal year ended September 30, 2022 are presented in the following graph.
Net Revenues — $7.71 billion
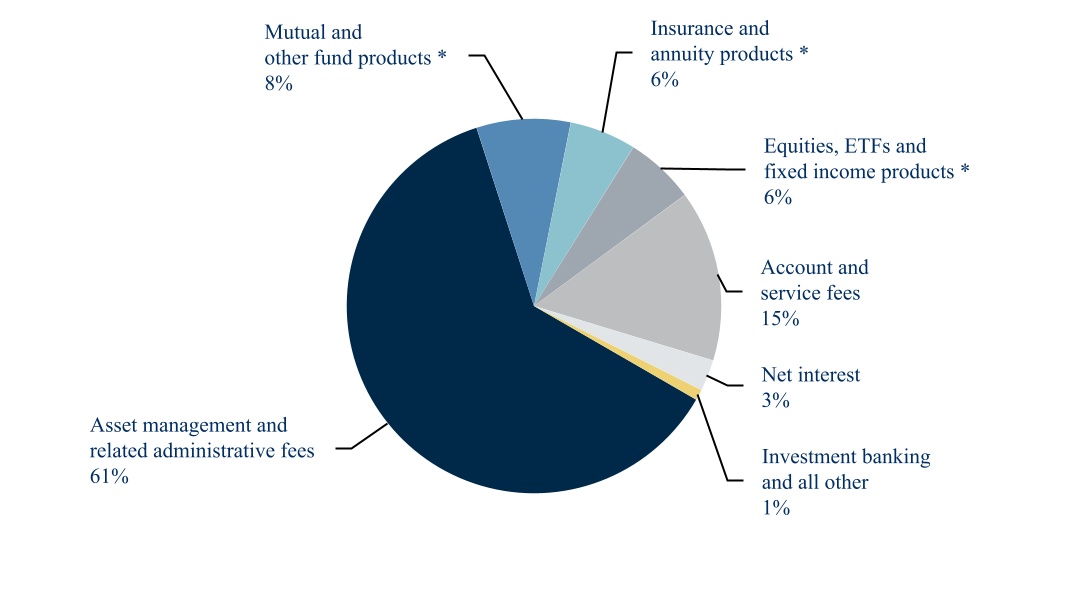
- Included in “Brokerage revenues” on our Consolidated Statements of Income and Comprehensive Income.
We provide the following products and services through this segment:
-
Investment services for which we charge sales commissions or asset-based fees based on established schedules.
-
Portfolio management services for which we charge either a fee computed as a percentage of the assets in the client’s account or a flat periodic fee.
-
Insurance and annuity products.
-
Mutual funds.
-
Support to third-party mutual fund and annuity companies, including sales and marketing support, distribution, and accounting and administrative services.
-
Administrative services to banks to which we sweep a portion of our clients’ cash deposits as part of the Raymond James Bank Deposit Program (“RJBDP”), our multi-bank sweep program. Fees received from third-party banks for these services are variable in nature and fluctuate based on client cash balances in the program, as well as the level of short-term interest rates relative to interest paid to clients by the third-party banks on balances in the RJBDP. PCG also earns fees from our Bank segment, which are based on the greater of a base servicing fee or net yield equivalent to the average yield that the firm would otherwise receive from third-party banks in the RJBDP. These fees are eliminated in consolidation.
-
Margin loans to clients that are collateralized by the securities purchased or by other securities owned by the client. Interest is charged to clients on the amount borrowed based on current interest rates.
-
Securities borrowing and lending activities with other broker-dealers, financial institutions and other counterparties. The net revenues of this business generally consist of the interest spreads generated on these activities.
-
Diversification strategies and alternative investment products to qualified clients of our affiliated financial advisors.
-
Custodial services, trade execution, research and other support and services to third-party RIAs and broker-dealers.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
Capital Markets
Our Capital Markets segment conducts investment banking, institutional sales, securities trading, equity research, and the syndication and management of investments in low-income housing funds and funds of a similar nature, the majority of which qualify for tax credits (referred to as our “affordable housing investments” business).
Capital Markets segment net revenues for the fiscal year ended September 30, 2022 are presented in the following graph.
Net Revenues — $1.81 billion
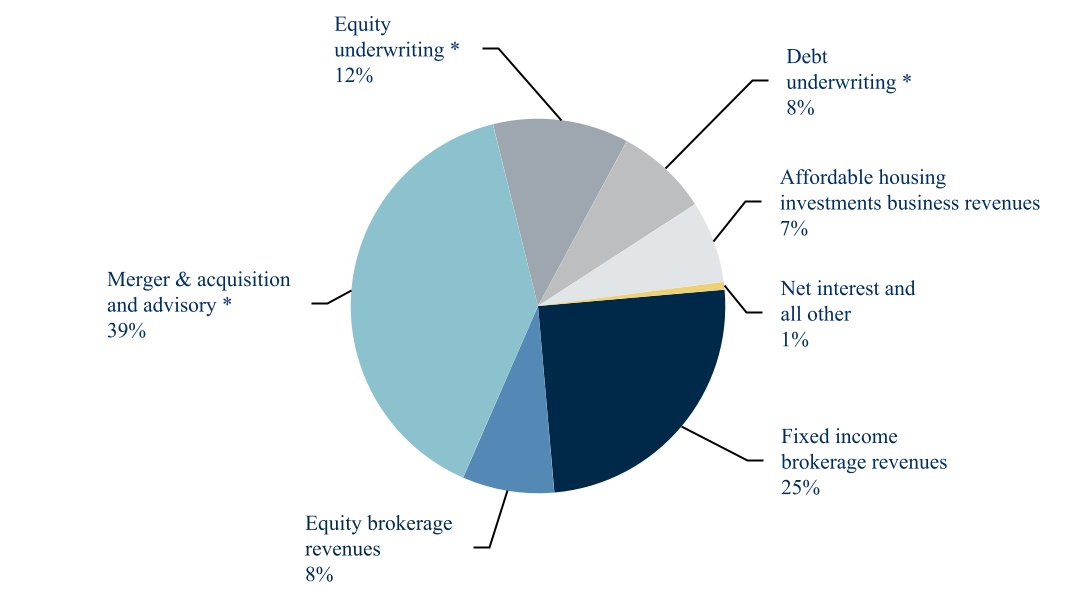
- Included in “Investment banking” on our Consolidated Statements of Income and Comprehensive Income.
We provide the following products and services through this segment.
Investment banking
-
Merger & acquisition and advisory - We provide a comprehensive range of strategic and financial advisory assignments, including with respect to mergers and acquisitions, divestitures and restructurings, across a number of industries throughout the U.S., Canada, and Europe.
-
Equity underwriting - We provide public and private equity financing services, including the underwriting and placement of common and preferred stock and other equity securities, to corporate clients throughout the U.S., Canada, and Europe across a number of industries.
-
Debt underwriting - Our services include public finance and debt underwriting activities where we serve as a placement agent or underwriter to various issuers, including private and public corporate entities, state and local government agencies (and their political subdivisions), and non-profit entities including healthcare and higher education institutions.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
Brokerage
- Fixed income - We earn revenues from institutional clients who purchase and sell both taxable and tax-exempt fixed income products, municipal, corporate, government agency and mortgage-backed bonds, and whole loans, as well as from our market-making activities in fixed income debt securities. We carry inventories of debt securities to facilitate such transactions.
We also enter into interest rate derivatives to facilitate client transactions or to actively manage risk exposures that arise from our client activity, including a portion of our trading inventory. In addition, we conduct a “matched book” derivatives business where we may enter into interest rate derivative transactions with clients. In this matched book business, for every derivative transaction we enter into with a client, we enter into an offsetting derivative transaction with a credit support provider that is a third-party financial institution.
- Equity - We earn brokerage revenues on the sale of equity products to institutional clients. Client activity is influenced by a combination of general market activity and our ability to identify attractive investment opportunities for our institutional clients. Revenues on equity transactions are generally based on trade size and the amount of business conducted annually with each institution.
Our global research department supports our institutional and retail sales efforts and publishes research on a wide variety of companies. This research primarily focuses on U.S. and Canadian companies across a multitude of industries. Research reports are made available to both institutional and retail clients.
Affordable housing investments business
We act as the general partner or managing member in partnerships and limited liability companies that invest in real estate entities, the majority of which qualify for tax credits under Section 42 of the Internal Revenue Code and/or provide a mechanism for banks and other institutions to meet their Community Reinvestment Act (“CRA”) obligations throughout the U.S. We earn fees for the origination and sale of these investment products as well as for the oversight and management of the investments, including over the statutory tax credit compliance period when applicable.
Asset Management
Our Asset Management segment earns asset management and related administrative fees for providing asset management, portfolio management and related administrative services to retail and institutional clients. This segment oversees a portion of our fee-based AUA for our PCG clients through our Asset Management Services division (“AMS”) and through Raymond James Trust, N.A. (“RJ Trust”). This segment also provides asset management services through our Raymond James Investment Management division (“Raymond James Investment Management,” formerly referred to as Carillon Tower Advisers), for certain retail accounts managed on behalf of third-party institutions, institutional accounts, and proprietary mutual funds that we manage, generally using active portfolio management strategies.
Management fees in this segment are generally calculated as a percentage of the value of our fee-billable financial assets under management (“AUM”) in both AMS, which includes the portion of fee-based AUA in PCG that is overseen by AMS, and Raymond James Investment Management, where investment decisions are made by in-house or third-party portfolio managers or investment committees. The fee rates applied are dependent upon various factors, including the distinct services provided and the level of assets within each client relationship. The fee rates applied in Raymond James Investment Management may also vary based on the account objective (i.e., equity, fixed income, or balanced). Our AUM are impacted by market fluctuations and net inflows or outflows of assets, including transfers between fee-based accounts and transaction-based accounts within our PCG segment. Fees are generally collected quarterly and are based on balances as of the beginning of the quarter (particularly in AMS) or the end of the quarter, or based on average daily balances throughout the quarter.
Our Asset Management segment also earns administrative fees on certain fee-based assets within PCG that are not overseen by our Asset Management segment, but for which the segment provides administrative support (e.g., record-keeping).
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
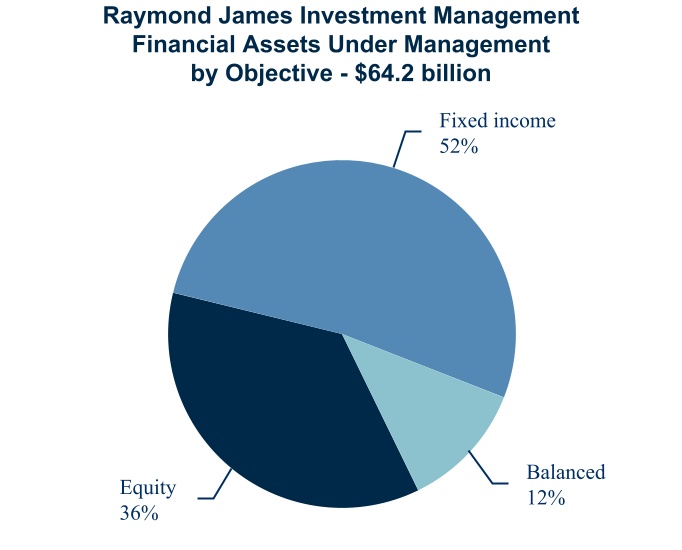
Our AUM and our Raymond James Investment Management AUM by objective as of September 30, 2022 are presented in the following graphs.

Bank
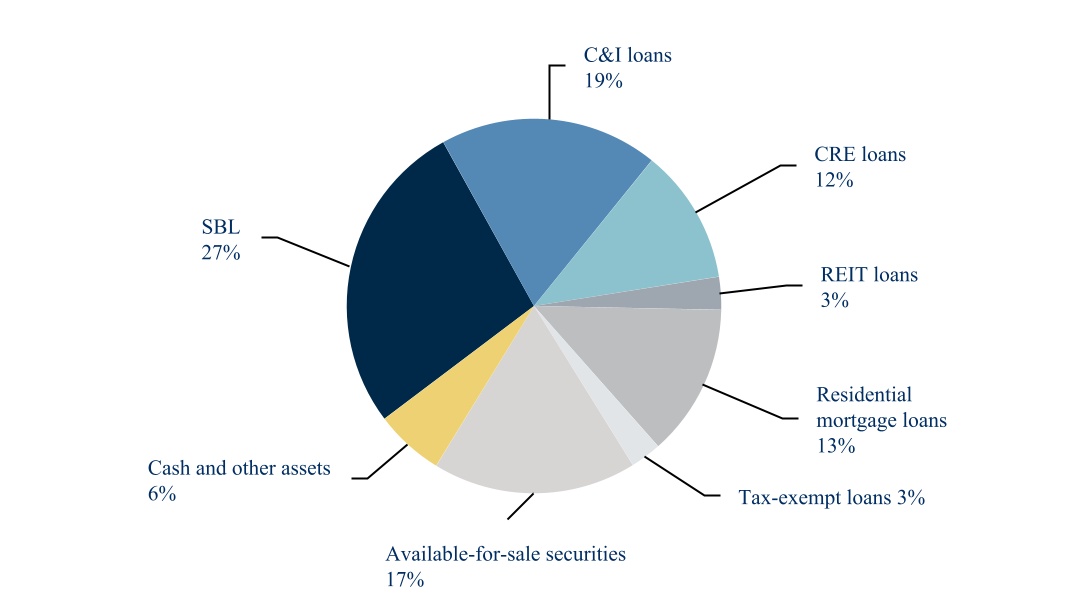
Our Bank segment reflects the results of our banking operations, including the results of Raymond James Bank, a Florida-chartered state bank and Fed member bank, and TriState Capital Bank, a Pennsylvania-chartered state bank, which was acquired on June 1, 2022 in our acquisition of TriState Capital Holdings, Inc. (“TriState Capital”). We provide various types of loans, including securities-based loans (“SBL”), corporate loans (commercial and industrial (“C&I”), commercial real estate (“CRE”) and real estate investment trust (“REIT”) loans), residential mortgage loans, and tax-exempt loans. Our Bank segment is active in corporate loan syndications and participations and lending directly to clients. We also provide Federal Deposit Insurance Corporation (“FDIC”)-insured deposit accounts, including to clients of our broker-dealer subsidiaries, and other deposit and liquidity management products and services. The Bank segment generates net interest income principally through the interest income earned on loans and an investment portfolio of available-for-sale securities, which is offset by the interest expense it pays on client deposits and on its borrowings.
As of September 30, 2022, corporate and tax-exempt loans represented approximately 37% of the Bank segment’s total assets, and 73% of such loans were U.S. and Canadian syndicated loans. Residential mortgage loans are originated or purchased and held for investment or sold in the secondary market. The Bank segment’s investment portfolio is primarily comprised of agency mortgage-backed securities (“MBS”) and agency collateralized mortgage obligations (“CMOs”) and is classified as available-for-sale. The Bank segment’s liabilities primarily consist of cash deposits, including those at Raymond James Bank that are primarily swept from the investment accounts of PCG clients through the RJBDP, as well as those at TriState Capital Bank, which are primarily money market and interest-bearing checking accounts. The Bank segment’s liabilities also include borrowings from the Federal Home Loan Bank (“FHLB”).
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
The following graph details the composition of our Bank segment’s total assets as of September 30, 2022.
Bank Segment Total Assets — $56.74 billion
Other
Our Other segment includes our private equity investments, which predominantly consist of investments in third-party funds, interest income on certain corporate cash balances, certain acquisition-related expenses, primarily comprised of professional fees, and certain corporate overhead costs of RJF, including the interest costs on our public debt and any losses on extinguishment of such debt.
HUMAN CAPITAL
Our “associates” (which include our employee financial advisors and all of our other employees) and our independent contractor financial advisors (which we call our “independent advisors”) are vital to our success in the financial services industry. As a human capital-intensive business, our ability to attract, develop, and retain exceptional and diverse associates and independent advisors is critical, not only in the current competitive labor market, but also to our long-term success. It is important to us to maintain a strong commitment to diversity and inclusion. To compete effectively, we must offer attractive compensation and health and wellness programs and workplace flexibility, as well as provide formal and informal opportunities for associates and advisors to develop their capabilities and reach their full potential. We also endeavor to foster and maintain our unique and long-standing values-based culture.
As of September 30, 2022, we had approximately 17,000 associates (including 3,638 employee financial advisors) and 5,043 independent advisors. The growth in the number of associates compared to the prior year was due in part to our acquisitions completed during fiscal 2022. Our associates are spread across four countries in North America and Europe. However, the vast majority of our associates are located in the U.S. Of our global associates, 44% self-identify as women, and among our U.S.-based associates, 19% self-identify as ethnically diverse.
Culture
We strive to attract individuals who are people-focused and share our values. Our values are memorialized in a document we refer to as our culture “blueprint” that is communicated to all associates. Our culture is people-focused and rooted in the values established at the firm’s foundation. Our pledge to clients, to our advisors, and to all our other associates is that:
-
we put clients first,
-
we act with integrity,
-
we think long term, and
-
we value independence.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
One way in which we measure the health of our culture is through firmwide short and targeted surveys in which we routinely ask our associates about their experiences at the firm. Feedback provided through these surveys is also used to create and continually enhance programs that support our associates’ needs.
Diversity, equity, and inclusion
We are committed to maintaining a diverse workforce, and an inclusive work environment is a natural extension of our culture. We are committed to ensuring that all our associates feel welcomed, valued, respected, and heard, so that they can fully contribute their unique talents for the benefit of their careers, our clients, our firm, and our communities. Our diversity strategy is centered on three pillars: the workplace, the workforce, and the community. In our recruiting efforts, we seek to identify a diverse group of candidates for each role we seek to fill. To that end, we have built strong relationships with a variety of industry associations that represent diverse professionals, as well as with diversity groups at the colleges and universities where we recruit. We have firmwide and business unit-specific diversity and inclusion networks, which are open to all professionals at the firm and are designed to promote and advance inclusion, understanding, and belonging. These networks also host various events and conferences to educate and provide avenues for all associates and independent advisors to contribute to an inclusive work environment, and offer mentorship opportunities to our associates. In order to continue to promote and advance inclusion, we have recently launched or expanded certain programs, such as:
-
the Pride Financial Advisor Network, which provides support and resources for LGBTQ+ advisors through educational programs, interactive networking and business development opportunities;
-
the Encore Inclusion Network, which provides support and opportunities for the growing mature workforce; and
-
the Veteran Financial Advisors Network, which is dedicated to supporting armed services veterans in the development of their careers as financial advisors.
We also invest in community-supporting organizations that are dedicated to improving the lives of diverse individuals. Our firmwide diversity, equity, and inclusion advisory council stewards the firm’s efforts and provides guidance on priorities. This council is composed of associate representatives from all areas of our business and across geographic locations. In all of our diversity efforts, we strive to create opportunities for allies of diverse communities to participate, contribute, and grow. We believe that to truly achieve all of the benefits of having a diverse and inclusive workforce, all associates and advisors need to be engaged in these discussions.
Recruitment, talent development, and retention
We seek to build a workforce that provides outstanding client service and helps clients achieve their financial goals. We have competitive programs dedicated to selecting new talent and enhancing the skills of our associates. Among other opportunities, we offer internships to selected college students, professionals returning to the workforce, and veterans, which may lead to permanent roles, and we offer pipeline programs which accelerate the progression from entry level positions for recent graduates across many areas of the firm. We are also committed to supporting associates in reaching their professional goals. We conduct a formal annual goal setting and performance review process for each employee, which includes touch points throughout the year. We also offer associates the opportunity to participate in a variety of professional development programs. Our extensive program catalog includes courses designed to expand our associates’ industry, product, technical, professional, business development, and regulatory knowledge. The firm also provides leadership development programs that prepare our leaders for challenges they will face in new roles or with expanded responsibilities. To provide associates equal opportunity to compete for new positions, we require that all roles, with the exception of certain revenue-generating positions and certain senior-level roles, be posted on our internal online career platform. We conduct ongoing and robust succession planning for roles that are within two levels of our Executive Committee, and we strive to ensure we have a diverse pool of candidates for such roles. We discuss the results with executive leadership and the Board of Directors several times per year.
An important driver of our success is the continuous recruitment and retention of financial advisors. Our ability to attract high quality advisors is based on our values-based culture, our commitment to service, and the unique ways in which we provide services to our financial advisors. Individuals who want to become financial advisors can gain relevant branch experience through our Wealth Management Associate Program or move to our Advisor Mastery Program and begin building their client base. We have a department dedicated to providing practice education and management resources to our financial advisors. We also offer these advisors the opportunity to participate in conferences and workshops, and we offer resources and coaching at all levels to help them grow their businesses. These include separate national conferences for our employee and independent contractor financial advisor channels, each of which is attended by thousands of advisors each year.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
We also monitor and evaluate various turnover and attrition metrics. Our overarching commitment to the attraction, development, and retention of our associates results in a relatively low annualized voluntary turnover rate. Importantly, our financial advisor regrettable attrition rate for the fiscal year ending September 30, 2022, was approximately 1%.
Compensation
We have designed a compensation structure, including an array of benefit plans and programs, that is intended to be attractive to current and prospective associates, while also reinforcing our core values and mitigating excessive risk taking. Our competitive pay packages include base salary, incentive bonus, and equity compensation programs. Additionally, the firm makes annual contributions to support the retirement goals of each associate through our employee stock ownership plan and our profit sharing plan, in addition to a matching contribution program for the 401(k) retirement savings plan. We also offer associates the opportunity to participate in an employee stock purchase plan that enables them to acquire our common stock at a discount, further increasing their ability to participate in the growth and success of the firm. As an additional retention tool, we may grant equity awards in connection with initial employment or under various retention programs for individuals who are responsible for contributing to our management, growth, and/or profitability. For certain employees who meet compensation, production, or other criteria, we also offer various non-qualified deferred compensation plans that provide a return to the participant, as well as a retention tool to the firm.
We strive to ensure that our programs are designed to promote equitable rewards for all associates. We have enhanced our compensation practices with the goal of achieving pay equity at all levels of the organization for female and ethnically diverse associates. Every year, we conduct pay equity studies in the U.S., U.K., and Canada and make adjustments in situations if there is a pay equity gap.
The physical, emotional, and financial well-being of our associates is a high priority of the firm. To that end, programs including healthcare insurance, health and flexible savings accounts, paid time off, family leave, flexible work schedules, tuition assistance, counseling services, as well as on-site services at our corporate offices in St. Petersburg, Florida and Memphis, Tennessee, which include health clinics and a fitness center. Additionally, following our return to office from the COVID-19 pandemic, we have offered more workplace flexibility to our associates as we continue to evaluate our long-term workplace strategy.
OPERATIONS AND INFORMATION PROCESSING
We have operations personnel at various locations who are responsible for processing securities transactions, custody of client securities, support of client accounts, the receipt, identification and delivery of funds and securities, and compliance with regulatory and legal requirements for most of our securities brokerage operations.
The information technology department develops and supports the integrated solutions that provide a customized platform for our businesses. These include a platform for financial advisors designed to allow them to spend more time with their clients and enhance and grow their businesses; systems that support institutional and retail sales and trading activity from initiation to settlement and custody; and thorough security protocols to protect firm and client information. In the area of information security, we have developed and implemented a framework of principles, policies and technology to protect our own information and that of our clients. We apply numerous safeguards to maintain the confidentiality, integrity and availability of both client and firm information.
Our business continuity program has been developed to provide reasonable assurance that we will continue to operate in the event of disruptions at our critical facilities or other business disruptions. We have developed operational plans for such disruptions, and we have devoted significant resources to maintaining those plans. Our business continuity plan continues to be enhanced and tested to allow for continuous operations in the event of weather-related or other interruptions at our corporate headquarters in Florida, one of our operations processing or data center sites (located in Florida, Colorado, Tennessee or Michigan), and our branch and office locations throughout the U.S., Canada and Europe.
After successfully implementing business continuity protocols at the onset of the COVID-19 pandemic, and the following period of working remotely, we implemented our return to office strategy during our fiscal second quarter of 2022. We have offered more workplace flexibility to our associates as we continue to evaluate our long-term workplace strategy.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
COMPETITION
The financial services industry is intensely competitive. We compete with many other financial services firms, including a number of larger securities firms, most of which are affiliated with major financial services companies, insurance companies, banking institutions and other organizations. We also compete with companies that offer web-based financial services and discount brokerage services to individual clients, usually with lower levels of service, and, more recently, financial technology companies (“fintechs”). We compete principally on the basis of the quality of our associates, services, product selection, performance records, location and reputation in local markets.
Our ability to compete effectively is substantially dependent on our continuing ability to develop or attract, retain and motivate qualified financial advisors, investment bankers, trading professionals, portfolio managers and other revenue-producing or specialized personnel. Furthermore, the labor market continues to experience elevated levels of turnover in the aftermath of the pandemic and an extremely competitive labor market, including increased competition for talent across all areas of our business, as well as increased competition with non-traditional competitors, such as technology companies. Employers are increasingly offering guaranteed contracts, upfront payments, increased compensation and increased opportunities to work with greater flexibility, including remote work, on a permanent basis.
REGULATION
The following summarizes the principal elements of the regulatory and supervisory framework applicable to us as a participant in the financial services industry. The framework includes extensive regulation under U.S. federal and state laws, as well as the applicable laws of the jurisdictions outside the U.S. in which we do business. While this framework is intended to protect our clients, the integrity of the financial markets, our depositors, and the Federal Deposit Insurance Fund, it is not intended to protect our creditors or shareholders. These rules and regulations limit our ability to engage in certain activities, as well as our ability to fund RJF from our regulated subsidiaries, which include our bank subsidiaries, Raymond James Bank and TriState Capital Bank, our broker-dealer subsidiaries, and our trust subsidiaries. To the extent that the following information describes statutory and regulatory provisions, it is qualified in its entirety by reference to the particular statutory and regulatory provisions that are referenced. A change in applicable statutes or regulations or in regulatory or supervisory policy may have a material effect on our business.
We continue to experience a period of notable changes in financial regulation and supervision. Changes in business regulations, as well as in both corporate and individual taxation, could have a significant impact on our business, financial condition, results of operations, and cash flows in the future; however, we cannot predict the exact changes or quantify their potential impacts (see “Item 1A - Risk Factors” of this Form 10-K for further discussion of the potential future impact on our operations).
Banking supervision and regulation
RJF is a BHC under the Bank Holding Company Act of 1956, as amended (the “BHC Act”), that has made an election to be a FHC and is subject to regulation, oversight and consolidated supervision, including periodic examination, by the Fed. Under the system of “functional regulation” established under the BHC Act, the primary regulators of our U.S. non-bank subsidiaries directly regulate the activities of those subsidiaries, with the Fed exercising a supervisory role. Such “functionally regulated” subsidiaries include our broker-dealers registered with the Securities and Exchange Commission (“SEC”), such as Raymond James & Associates, Inc. (“RJ&A”) and Raymond James Financial Services, Inc. (“RJFS”), and investment advisors registered with the SEC with respect to their investment advisory activities, among other subsidiaries.
We have two depository institutions, Raymond James Bank and TriState Capital Bank (collectively, “our bank subsidiaries”). Raymond James Bank is an FDIC-insured depository institution and a Florida-chartered state member bank of the Fed that is primarily supervised by both the Fed and the Florida Office of Financial Regulation (“OFR”). TriState Capital Bank is a FDIC-insured depository institution and a Pennsylvania-chartered state non-member bank that is primarily supervised by both the FDIC and the Pennsylvania Department of Banking and Securities (“PDBS”). Both Raymond James Bank and TriState Capital Bank are also subject to supervision by the Consumer Financial Protection Bureau (“CFPB”).
We also have two non-depository trust company subsidiaries: RJ Trust, which is regulated, supervised, and examined by the Office of the Comptroller of the Currency (“OCC”), and Raymond James Trust Company of New Hampshire (“RJTCNH”) which is regulated, supervised, and examined by the New Hampshire Banking Department (“NHBD”). RJTCNH provides Individual Retirement Account custodial services and trust services for our PCG clients.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
Collectively, the rules and regulations of the Fed, the FDIC, the OFR, the PDBS, the CFPB, the OCC and the NHBD result in extensive regulation and supervision covering all aspects of our banking and trust businesses, including, for example, lending practices, the receipt of deposits, capital structure, transactions with affiliates, conduct and qualifications of personnel and, as discussed further in the following sections, capital requirements. This regulatory, supervisory and oversight framework is subject to significant changes that can affect the operating costs and permissible businesses of RJF and our subsidiaries. As a part of their supervisory functions, the Fed, the FDIC, the OFR, the PDBS, the CFPB, the OCC and the NHBD conduct extensive examinations of our operations and also have the power to bring enforcement actions for violations of law and, in the case of the Fed, the FDIC, the OFR, the PDBS, the OCC, and the NHBD for unsafe or unsound practices.
Basel III and U.S. capital rules
RJF and Raymond James Bank are subject to the Fed’s capital rules and TriState Capital Bank is subject to the FDIC’s capital rules. These rules establish an integrated regulatory capital framework and implement, in the U.S., the Basel III capital framework developed by the Basel Committee on Banking Supervision and certain Dodd-Frank Wall Street Reform and Consumer Protection Act (“Dodd-Frank Act”) and other capital provisions, and, for insured depository institutions, set the prompt corrective action framework discussed below to reflect the regulatory capital requirements (the “U.S. Basel III Rules”). The U.S. Basel III Rules: (i) establish minimum requirements for both the quantity and quality of regulatory capital; (ii) set forth a capital conservation buffer; and (iii) define the calculation of risk-weighted assets. These capital requirements could restrict our ability to grow, including during favorable market conditions, and to return capital to shareholders, or require us to raise additional capital. As a result, our business, results of operations, financial condition and future prospects could be adversely affected. See “Item 1A - Risk Factors” of this Form 10-K for more information. See Note 24 of the Notes to Consolidated Financial Statements of this Form 10-K for further information.
Failure to meet minimum capital requirements can trigger discretionary, and in certain cases, mandatory actions by regulators that could have a direct material effect on the financial results of RJF, Raymond James Bank, and TriState Capital Bank. In addition, failure to maintain the capital conservation buffer would result in constraints on distributions, including limitations on dividend payments and stock repurchases, and certain discretionary bonus payments based on the amount of the shortfall and eligible retained income. Under the capital adequacy rules, RJF, Raymond James Bank, and TriState Capital Bank must meet specific capital ratio requirements that involve quantitative measures of assets, liabilities and certain off-balance sheet items as calculated under the rules. The capital amounts and classification for RJF, Raymond James Bank, and TriState Capital Bank are also subject to the qualitative judgments of U.S. regulators based on components of capital, risk-weightings of assets, off-balance sheet transactions and other factors.
Under applicable capital rules, RJF would need to obtain prior approval from the Fed if its repurchases or redemptions of equity securities over a twelve-month period would reduce its net worth by ten percent or more and an exemption were not available. Guidance from the Fed also provides that RJF would need to inform the Fed in advance of repurchasing common stock in certain prescribed situations, such as if it were experiencing, or at risk of experiencing, financial weaknesses or considering expansion, either through acquisitions or other new activities, or if the repurchase would result in a net reduction in common equity over a quarter. Further, Fed guidance indicates that, pursuant to the Fed’s general supervisory and enforcement authority, Fed supervisory staff should prevent a BHC from repurchasing its common stock if such action would be inconsistent with the BHC’s prospective capital needs and safe and sound operation.
Source of strength
The Fed requires that BHCs, such as RJF, serve as a source of financial strength for any of its subsidiary depository institutions. The term “source of financial strength” is defined as the ability of a company to provide financial assistance to its insured depository institution subsidiaries in the event of financial distress at such subsidiaries. Under this requirement, RJF could be required to provide financial assistance to Raymond James Bank and TriState Capital Bank in the future should either bank experience financial distress.
Transactions between affiliates
Transactions between (i) Raymond James Bank, TriState Capital Bank, RJ Trust, or their subsidiaries on the one hand and (ii) RJF or its other subsidiaries or affiliates on the other hand are subject to compliance with Sections 23A and 23B of the Federal Reserve Act and Regulation W issued by the Fed, which generally limit the types and amounts of such transactions that may take place and generally require those transactions to be on market terms. These laws generally do not apply to transactions between Raymond James Bank, TriState Capital Bank, RJ Trust, and any subsidiaries they may have.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
The Volcker Rule, a provision of the Dodd-Frank Act, generally prohibits certain transactions and imposes a market terms requirement on certain other transactions between (i) RJF or its affiliates on the one hand and (ii) covered funds for which RJF or its affiliates serve as the investment manager, investment advisor, commodity trading advisor or sponsor, or other covered funds organized and offered by RJF or its affiliates on the other hand. See “The Volcker Rule” in the following section.
Deposit insurance
Raymond James Bank and TriState Capital Bank are subject to the Federal Deposit Insurance Act because they provide deposits covered by FDIC insurance, generally up to $250,000 per account ownership type. For banks with greater than $10 billion in assets, which includes Raymond James Bank and TriState Capital Bank, the FDIC’s current assessment rate calculation relies on a scorecard designed to measure a bank’s financial performance and ability to withstand stress, in addition to measuring the FDIC’s exposure should Raymond James Bank or TriState Capital Bank fail.
Prompt corrective action
The U.S. Federal Deposit Insurance Corporation Improvement Act of 1991 (“FDICIA”) requires the U.S. federal bank regulatory agencies to take “prompt corrective action” with respect to depository institutions that do not meet specified capital requirements. FDICIA establishes five capital categories for FDIC-insured banks, such as Raymond James Bank and TriState Capital Bank: well-capitalized, adequately capitalized, undercapitalized, significantly undercapitalized and critically undercapitalized.
An institution may be downgraded to, or deemed to be in, a capital category that is lower than the category indicated by its capital ratios if the institution is determined to be in an unsafe or unsound condition or if it receives an unsatisfactory examination rating with respect to certain matters. FDICIA imposes progressively more restrictive constraints on operations, management and capital distributions, as the capital category of an institution declines. Failure to meet the capital requirements could also require a depository institution to raise capital. Ultimately, critically undercapitalized institutions are subject to the appointment of a receiver or conservator.
Although the prompt corrective action regulations do not apply to BHCs, such as RJF, the Fed is authorized to take appropriate action at the BHC level, based upon the undercapitalized status of the BHC’s depository institution subsidiaries. In certain instances related to an undercapitalized depository institution subsidiary, the BHC would be required to guarantee the performance of the undercapitalized subsidiary’s capital restoration plan and might be liable for civil money damages for failure to fulfill its commitments on that guarantee. Furthermore, in the event of the bankruptcy of the BHC, this guarantee would take priority over the BHC’s general unsecured creditors. As of September 30, 2022, Raymond James Bank and TriState Capital Bank were well-capitalized.
The Volcker Rule
RJF is subject to the Volcker Rule, which generally prohibits BHCs and their subsidiaries and affiliates from engaging in proprietary trading, but permits underwriting, market making, and risk-mitigating hedging activities. The Volcker Rule also prohibits BHCs and their subsidiaries and affiliates from acquiring or retaining ownership interests in, sponsoring, or having certain relationships with “covered funds” (as defined in the rule), including hedge funds and private equity funds, subject to certain exceptions.
Compensation practices
Our compensation practices are subject to oversight by the Fed. Compensation regulation in the financial industry continues to evolve, and we expect these regulations to change over a number of years. The U.S. federal bank regulatory agencies have provided guidance designed to ensure incentive compensation policies do not encourage imprudent risk-taking and are consistent with safety and soundness. As required by SEC rules, we disclose in our proxy statements for each annual meeting of shareholders the relationship of our compensation policies and practices to risk management initiatives, to the extent that the risks arising from such policies and practices are reasonably likely to have a material adverse effect on the firm.
On August 25, 2022, the SEC adopted the final “pay-for-performance” rule mandated by the Dodd-Frank Act. Among other disclosure requirements, the rule requires companies to disclose the relationships among named executive officer compensation “actually paid,” total shareholder return and certain financial performance measures that the company uses to link compensation to company performance for its five most recent fiscal years. The rule will first apply to disclosures in our proxy statement for the 2024 annual shareholders meeting.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
Community Reinvestment Act regulations
Raymond James Bank and TriState Capital Bank are subject to the CRA, which is intended to encourage banks to help meet the credit needs of their communities, including low and moderate income neighborhoods, consistent with safe and sound bank operations. Under the CRA, federal banking regulators are required to periodically examine and assign to each bank a public CRA rating. If any insured depository institution subsidiary of a FHC fails to maintain at least a “satisfactory” rating under the CRA, the FHC would be subject to restrictions on certain new activities and acquisitions.
On May 5, 2022, federal banking regulators requested comment on a joint notice of proposed rulemaking on the CRA. Until the proposed rulemaking is final and effective, Raymond James Bank and TriState Capital Bank will continue to operate under the CRA regulations currently in effect. At this time, it is uncertain what effect the impending CRA regulations will have on Raymond James Bank, TriState Capital Bank, and other depositories with respect to their CRA activities.
Other restrictions
FHCs, such as RJF, generally can engage in a broader range of financial and related activities than are otherwise permissible for BHCs as long as they continue to meet the eligibility requirements for FHCs. Among other things, the broader range of permissible activities for FHCs includes underwriting, dealing and making markets in securities and making investments in non-FHCs or merchant banking activities. We are required to obtain Fed approval before engaging in certain banking and other financial activities both within and outside the U.S.
The Fed, however, has the authority to limit an FHC’s ability to conduct activities that would otherwise be permissible, and will likely do so if the FHC does not satisfactorily meet certain requirements of the Fed. For example, if an FHC or any of its U.S. depository institution subsidiaries ceases to maintain its status as “well-capitalized” or “well-managed,” the Fed may impose corrective capital and/or managerial requirements, as well as additional limitations or conditions. If the deficiencies persist, the FHC may be required to divest its U.S. depository institution subsidiaries or to cease engaging in activities other than the business of banking and certain closely related activities.
Broker-dealer and securities regulation
The SEC is the federal agency charged with administration of the federal securities laws in the U.S. Our U.S. broker-dealer subsidiaries are subject to SEC regulations relating to their business operations, including sales and trading practices, public offerings, publication of research reports, use and safekeeping of client funds and securities, capital structure, record-keeping, privacy requirements, and the conduct of directors, officers and employees. Financial services firms are also subject to regulation by state securities commissions in those states in which they conduct business. Our most significant U.S. broker-dealers, RJ&A, RJFS, and SumRidge Partners, LLC (“SumRidge Partners”), are currently registered as broker-dealers in all 50 states.
Financial services firms are also subject to regulation by various foreign governments, securities exchanges, central banks and regulatory bodies, particularly in those countries where they have established offices. Outside of the U.S., we have additional offices primarily in Canada, the U.K., and Germany and are subject to regulations in those areas. Much of the regulation of broker-dealers in the U.S. and Canada, however, has been delegated to self-regulatory organizations (“SROs”), such as the Financial Industry Regulatory Authority (“FINRA”) in the U.S., the Investment Industry Regulatory Organization of Canada (“IIROC”), and securities exchanges. These SROs adopt and amend rules for regulating the industry, subject to the approval of government agencies. These SROs also conduct periodic examinations of member broker-dealers. The single primary regulator with respect to our conduct of financial services in the U.K. is the Financial Conduct Authority (“FCA”), which operates on a statutory basis.
The SEC, SROs and state securities regulators may conduct administrative proceedings that can result in censure, fine, suspension or expulsion of a broker-dealer, its officers, employees or other associated persons. Such administrative proceedings, whether or not resulting in adverse findings, can require substantial expenditures and may adversely impact the reputation of a broker-dealer.
Our U.S. broker-dealer subsidiaries are subject to the Securities Investor Protection Act (“SIPA”) and are required by federal law to be members of the Securities Investors Protection Corporation (“SIPC”). The SIPC was established under SIPA, and oversees the liquidation of broker-dealers during liquidation or financial distress. The SIPC fund provides protection for cash and securities held in client accounts up to $500,000 per client, with a limitation of $250,000 on claims for cash balances.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
U.S. broker-dealer capital
Our broker-dealer subsidiaries are subject to certain of the SEC’s financial stability rules, including the: (i) net capital rule; (ii) customer protection rule; (iii) record-keeping rules; and (iv) notification rules. Broker-dealers are required to maintain the minimum net capital deemed necessary to meet their continuing commitments to customers and others, and are required to keep their assets in relatively liquid form. These rules also limit the ability of broker-dealers to transfer capital to parent companies and other affiliates. See Note 24 of the Notes to Consolidated Financial Statements of this Form 10-K for further information pertaining to our broker-dealer regulatory minimum net capital requirements.
Standard of care
Pursuant to the Dodd-Frank Act, the SEC was charged with considering whether broker-dealers should be subject to a standard of care similar to the fiduciary standard applicable to RIAs. In June 2019, the SEC adopted a package of rule-makings and interpretations related to the provision of advice by broker-dealers and investment advisers, including Regulation Best Interest and Form CRS. Among other things, Regulation Best Interest requires a broker-dealer to act in the best interest of a retail client when making a recommendation to that client of any securities transaction or investment strategy involving securities. Form CRS requires that broker-dealers and investment advisers provide retail investors with a brief summary document containing simple, easy-to-understand information about the nature of the relationship between the parties. Our implementation of these regulations resulted in the review and modification of certain of our policies and procedures and associated supervisory and compliance controls, as well as the implementation of additional client disclosures, which included us providing related education and training to financial advisors.
Various states have also proposed, or adopted, laws and regulations seeking to impose new standards of conduct on broker-dealers that may differ from the SEC’s new regulations, which may lead to additional implementation costs. The Department of Labor (“DOL”) has also reinstated the historical “five-part test” for determining who is an investment advice “fiduciary” when dealing with certain retirement plans and accounts. In 2022, the DOL promulgated a new exemption that enables investment advice fiduciaries to receive transaction-based compensation and engage in certain otherwise prohibited transactions, subject to compliance with the exemption’s requirements. In addition, the DOL is expected to amend the five-part test by the end of 2023 so that the fiduciary standard would apply to a broader range of client relationships. Imposing such a new standard of care on additional client relationships could result in incremental costs for our business and we are evaluating how these regulatory changes may further impact our business.
Other non-U.S. regulation
Raymond James Ltd. (“RJ Ltd.”) is currently registered as an investment dealer in all provinces and territories in Canada. The financial services industry in Canada is subject to comprehensive regulation under both federal and provincial laws. Securities commissions have been established in all provinces and territorial jurisdictions, which are charged with the administration of securities laws. Investment dealers in Canada are subject to regulation by IIROC, a SRO under the oversight of the securities commissions that make up the Canadian Securities Administrators. IIROC is responsible for the enforcement of, and conformity with, securities legislation for their members and has been granted the powers to prescribe their own rules of conduct and financial requirements of members, including RJ Ltd. IIROC also requires that RJ Ltd. be a member of the Canadian Investors Protection Fund, whose primary role is investor protection. This fund provides protection for securities and cash held in client accounts up to 1 million Canadian dollars (“CAD”) per client, with additional coverage of CAD 1 million for certain types of accounts.
Certain of our subsidiaries are registered in, and operate from, the U.K. which has a highly developed and comprehensive regulatory regime. These subsidiaries are authorized and regulated by the FCA and have limited permissions to carry out business in certain European Union (“E.U.”) countries as part of treaty arrangements. The FCA operates on a statutory basis and creates rules which are largely principles-based. These regulated U.K. subsidiaries and their senior managers are registered with the FCA, and wealth managers and certain other staff are subject to certification requirements. Certain of these subsidiaries operate in the retail sector, providing investment and financial planning services to high-net-worth individuals, while others provide brokerage and investment banking services to institutional clients. Retail clients of our U.K. subsidiaries benefit from the Financial Ombudsman Service, which settles complaints between consumers and business that provide financial services, as well as the Financial Services Compensation Scheme, which is the U.K.’s statutory deposit insurance and investors compensation scheme for customers of authorized financial services firms.
In Germany, our subsidiary Raymond James Corporate Finance GmbH is licensed by the German Federal Financial Supervisory Authority (Bundesanstalt für Finanzdienstleistungsaufsicht, or "BaFin") to conduct the regulated activities of investment advice and investment brokerage. Among other requirements, BaFin requires Raymond James Corporate Finance
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
GmbH, as a regulated entity, to comply with certain capital, liquidity, governance, and business conduct requirements, and has a range of supervisory and disciplinary powers which it is able to use in overseeing the activities of this subsidiary.
Investment management regulation
Our investment advisory operations, including the mutual funds that we sponsor, are also subject to extensive regulation in the U.S. The majority of our asset managers are registered as investment advisers with the SEC under the Investment Advisers Act of 1940 as amended, and are also required to make notice filings in certain states. Virtually all aspects of our asset management business are subject to various federal and state laws and regulations. These laws and regulations are primarily intended for the benefit of our clients.
Anti-money laundering, economic sanctions, and anti-bribery and corruption regulation
The U.S. Bank Secrecy Act (“BSA”), as amended by the USA PATRIOT Act of 2001 (“PATRIOT Act”), the Customer Due Diligence Rule, and the Anti-Money Laundering Act of 2020 (“AMLA”), contains anti-money laundering and financial transparency laws and mandates the implementation of various regulations applicable to all financial institutions, including standards for verifying client identification at account opening, and obligations to monitor client transactions and report suspicious activities. Through these and other provisions, the BSA, the PATRIOT Act, and AMLA seek to promote the identification of parties that may be involved in terrorism, money laundering or other suspicious activities. Anti-money laundering laws outside the U.S. contain some similar provisions.
The U.S. Treasury’s Office of Foreign Assets Control administers economic and trade sanctions programs and enforces sanctions regulations with which all U.S. persons must comply. The E.U. as well as various countries have also adopted economic sanctions programs targeted at countries, entities and individuals that are involved in terrorism, hostilities, embezzlement or human rights violations.
In addition, various countries have adopted laws and regulations, including the U.S. Foreign Corrupt Practices Act and the U.K. Bribery Act, related to corrupt and illegal payments to, and hiring practices with regard to, government officials and others. The scope of the types of payments or other benefits covered by these laws is very broad and is subject to significant uncertainties that may be clarified only in the context of further regulatory guidance or enforcement proceedings.
RJF and its affiliates have implemented and maintain internal policies, procedures, and controls to meet the compliance obligations imposed by such U.S. and non-U.S. laws and regulations concerning anti-money laundering, economic sanctions, and anti-bribery and corruption. Failure to continue to meet the requirements of these regulations could result in supervisory action, including fines.
Privacy and data protection
U.S. federal law establishes minimum federal standards for financial privacy by, among other provisions, requiring financial institutions to adopt and disclose privacy policies with respect to consumer information and setting forth certain limitations on disclosure to third parties of consumer information. U.S. state laws and regulations adopted under U.S. federal law impose obligations on RJF and its subsidiaries for protecting the confidentiality, integrity and availability of client information, and require notice of data breaches to certain U.S. regulators and to clients. The Fair Credit Reporting Act of 1970, as amended, mandates the development and implementation of a written identity theft prevention program that is designed to detect, prevent, and mitigate identity theft.
The California Privacy Rights Act amends the California Consumer Privacy Act of 2020 and is expected to be enforced beginning in July 2023. New regulations under the statute have not yet been published. The new regulations will update the existing privacy protections for the personal information of California residents, including by requiring companies to provide certain additional disclosures to California consumers, and provides for a number of specific additional data subject rights for California residents.
Similarly, the General Data Protection Regulation (“GDPR”) imposes requirements for companies that collect or store personal data of E.U. residents, as well as residents of the U.K. GDPR’s legal requirements extend to all foreign companies that solicit and process personal data of E.U. and U.K. residents, imposing a strict data protection compliance regime that includes consumer rights actions that must be responded to by organizations. Canadian data privacy laws contain many provisions similar to U.S. financial privacy laws and are currently undergoing legislative reform at a federal and provincial level. In September 2021, Quebec enacted Bill C-64, a comprehensive privacy law with extraterritorial application modeled after GDPR and which imposes fines for non-compliance. The law includes staggered implementation dates (running from September 2022
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
through September 2024) for various provisions. The firm intends to implement Bill C-64 through its privacy program framework. We have implemented policies, processes, and training with regard to communicating to our clients and business partners required information relating to financial privacy and data security. We continue to monitor regulatory developments on both a domestic and international level to assess requirements and potential impacts on our global business operations.
The multitude of data privacy laws and regulations adds complexity and cost to managing compliance and data management capabilities and can result in potential litigation, regulatory fines and reputational harm. Data privacy requirements compel companies to track personal information use and provide greater transparency on data practices to consumers. In addition, technology advances in the areas of artificial intelligence, mobile applications, and remote connectivity solutions have increased the collection and processing of personal information as well as the risks associated with unauthorized disclosure and access to personal information.
Alternative reference rate transition
Central banks and regulators in the U.S. and other jurisdictions are working to implement the transition from the London Interbank Offered Rate (“LIBOR”) to replacement interest rate benchmarks. On March 5, 2021, the FCA, which regulates LIBOR, announced it would cease publication of the less commonly used tenors after December 31, 2021, while it would cease publication of the most commonly used U.S. dollar LIBOR tenors after June 30, 2023. As a result, U.S. federal banking agencies issued guidance strongly encouraging institutions to cease entering into contracts that reference LIBOR as soon as practicable, and no later than December 31, 2021. There have been several pronouncements released during our fiscal year ended September 30, 2022 that have provided additional guidance related to the transition away from LIBOR and reduced uncertainty across the industry, including the International Swaps and Derivatives Association (ISDA) Fallback Protocol, the Adjustable Interest Rate (LIBOR) Act, and a proposal released by the Fed.
Consistent with the preceding guidance, as of December 31, 2021, we phased out the use of LIBOR as a reference rate in new financial instruments and converted our FHLB borrowings and SBL from LIBOR-based interest rates to Secured Overnight Financing Rate-based interest rates, resulting in an insignificant impact on interest income, interest expense, and cash flows. We continue to make progress on the transition away from LIBOR, as coordinated by our enterprise-wide team established to facilitate the transition. We continue to focus on monitoring the impacts of LIBOR across our business operations and products, ensuring that legacy instruments contain appropriate fallback language, modifying instruments that require amendments, engaging with financial advisors and clients on the impact of the transition, and working through infrastructure enhancements (e.g., systems and models) to ensure operational readiness. We continue to evaluate the anticipated effect of the alternative reference rate transition and, at this time, we expect minimal financial impact.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
INFORMATION ABOUT OUR EXECUTIVE OFFICERS
Executive officers of the registrant (which includes officers of certain significant subsidiaries) are as follows:
| Christopher S. Aisenbrey | 53 | Chief Human Resources Officer since October 2019; Senior Vice President, Organization and Talent Development - Raymond James & Associates, Inc., January 2019 - October 2019; Vice President, Organization and Talent Development - Raymond James & Associates, Inc., November 2014 - December 2018 | ||||||
| James E. Bunn | 49 | President - Global Equities and Investment Banking - Raymond James & Associates, Inc. since December 2018 and Head of Investment Banking - Raymond James & Associates, Inc. since January 2014; Co-President - Global Equities and Investment Banking - Raymond James & Associates, Inc., October 2017 - December 2018 | ||||||
| Horace L. Carter | 51 | President - Fixed Income - Raymond James & Associates, Inc. since January 2022; President - SumRidge Partners, LLC since July 2022; Executive Vice President, Head of Fixed Income Capital Markets - Raymond James & Associates, Inc., October 2019 - December 2021; Managing Director, Co-Head of Fixed Income Capital Markets - Raymond James & Associates, Inc., January 2019 - September 2019; Managing Director, Head of Fixed Income Trading - Raymond James & Associates, Inc., April 2012 - December 2018 | ||||||
| George Catanese | 63 | Chief Risk Officer since February 2006 | ||||||
| James R. E. Coulter | 53 | Chief Executive Officer - Raymond James Ltd. since January 2022; Executive Vice President, Head of Wealth Management - Private Client Group - Raymond James Ltd., December 2019 - December 2021; Senior Vice President, Branch Manager - Private Client Group - Raymond James Ltd., October 2014 - December 2019 | ||||||
| Scott A. Curtis | 60 | President - Private Client Group since June 2018; President - Raymond James Financial Services, Inc. since January 2012 | ||||||
| Jeffrey A. Dowdle | 58 | Chief Operating Officer since October 2019 and President - Asset Management Group since May 2016; Chief Administrative Officer, August 2018 - October 2019 | ||||||
| Tashtego S. Elwyn | 51 | Chief Executive Officer and President - Raymond James & Associates, Inc. since June 2018; President - Private Client Group - Raymond James & Associates, Inc., January 2012 - June 2018 | ||||||
| Thomas A. James | 80 | Chair Emeritus since February 2017 | ||||||
| Bella Loykhter Allaire | 69 | Executive Vice President - Technology and Operations - Raymond James & Associates, Inc. since June 2011 | ||||||
| Jodi L. Perry | 51 | President - Independent Contractor Division - Raymond James Financial Services, Inc. since June 2018; Senior Vice President, National Director - ICD - Raymond James Financial Services, Inc., May 2018 - June 2018; Senior Vice President, ICD Regional Director - Raymond James Financial Services, Inc., June 2012 - May 2018 | ||||||
| Steven M. Raney | 57 | Chair - Raymond James Bank, since November 2020; President and CEO - Raymond James Bank since January 2006 | ||||||
| Paul C. Reilly | 68 | Chair since February 2017 and Chief Executive Officer since May 2010; Director since January 2006 | ||||||
| Jonathan N. Santelli | 51 | Executive Vice President, General Counsel and Secretary since May 2016 | ||||||
| Paul M. Shoukry | 39 | Chief Financial Officer since January 2020 and Treasurer since February 2018; Senior Vice President - Finance and Investor Relations, January 2017 - December 2019; Senior Vice President - Treasury, January 2017 - February 2018 |
Except where otherwise indicated, the executive officer has held his or her current position for more than five years.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
ADDITIONAL INFORMATION
Our Internet address is www.raymondjames.com. We make available on our website, free of charge and in printer-friendly format including “.pdf” file extensions, our Annual Reports on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Securities Exchange Act of 1934, as soon as reasonably practicable after we electronically file such material with, or furnish it to, the SEC. Our reports and other information that we electronically file with the SEC are also available free of charge on the SEC’s website at www.sec.gov.
FACTORS AFFECTING “FORWARD-LOOKING STATEMENTS”
Certain statements made in this Annual Report on Form 10-K may constitute “forward-looking statements” under the Private Securities Litigation Reform Act of 1995. Forward-looking statements include information concerning future strategic objectives, business prospects, anticipated savings, financial results (including expenses, earnings, liquidity, cash flow and capital expenditures), industry or market conditions, demand for and pricing of our products, acquisitions, divestitures, anticipated results of litigation, regulatory developments, and general economic conditions. In addition, words such as “believes,” “expects,” “anticipates,” “projects,” and future or conditional verbs such as “will,” “may,” “could,” “should,” and “would,” as well as any other statement that necessarily depends on future events, are intended to identify forward-looking statements. Forward-looking statements are not guarantees, and they involve risks, uncertainties and assumptions. Although we make such statements based on assumptions that we believe to be reasonable, there can be no assurance that actual results will not differ materially from those expressed in the forward-looking statements. We caution investors not to rely unduly on any forward-looking statements and urge you to carefully consider the risks described in “Item 1A - Risk Factors” of this report. We expressly disclaim any obligation to update any forward-looking statement in the event it later turns out to be inaccurate, whether as a result of new information, future events, or otherwise.
RAYMOND JAMES FINANCIAL, INC. AND SUBSIDIARIES
Previous: Cover and table of contents · Next: Item 1A. RISK FACTORS