 filings.tools
Rollins (ROL) 10-K risk factor changes: FY2022 vs FY2021
The 2022-12-31 10-K against the 2021-12-31 one, compared heading by heading and sentence by sentence.
All filing items607 rewritten579 added458 removed879 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: the parser did not find an Item 1A in both filings.
- Sentence by sentence, 579 added, 458 removed, 607 rewritten and 879 unchanged across 15 items that differ.
Sentences by item
20 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2022; struck-through words were in FY2021. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
56 rewritten, 71 added, 54 removed, 56 unchanged
Discussions of [removed: 2019] [added: 2020] items and year-to-year comparisons of [removed: 2020] [added: 2021] and [removed: 2019] [added: 2020] that are not included in this Form 10-K can be found in “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in Part II, Item 7 on our Annual report on Form 10-K for the year ended December 31, [removed: 2020.][added: 2021.]
Income before income taxes increased [removed: 33.9%] [added: 3.4%] to [removed: $474.8] [added: $498.9] million compared to [removed: $354.7] [added: $482.5] million the prior year.
Net income increased [removed: 34.5%] [added: 3.4%] to [removed: $350.7] [added: $368.6] million, with earnings per diluted share of [removed: $0.71] [added: $0.75] compared to [removed: $260.8] [added: $356.6] million, or [removed: $0.53] [added: $0.72] per diluted share for the prior year.
The Company [removed: has continued to increase] [added: paid] dividends to investors [removed: with $0.42] [added: of $0.43] per diluted share [removed: paid] in [removed: 2021] [added: 2022] as compared to [removed: $0.33] [added: $0.42] per diluted share for the prior year, resulting in a [removed: 27%] [added: 2.4%] increase in dividends per share.
The global spread and unprecedented impact of [removed: the] COVID-19 [removed: pandemic (“COVID-19”) continues] [added: has continued] to create [removed: significant volatility,] uncertainty and economic disruption around the [removed: world.][added: world during 2022.]
We [added: have and] will continue to [removed: actively] monitor [removed: the rapidly evolving situation related to] COVID-19 and may [added: again] take actions that may alter our operations, including those that may be required by federal, state, or local authorities, or that we determine are in the best interests of our [removed: employees, customers] [added: employees] and [removed: communities.][added: customers.]
We do not know when, or if, it will become practical to [removed: relax or] eliminate [removed: some or] all of these measures entirely as there is no guarantee that COVID-19 will be fully contained.
The Company’s [added: condensed] consolidated financial statements reflect estimates and assumptions made by management that affect the reported amounts of assets and liabilities and related disclosures as of the date of the [added: condensed] consolidated financial statements.
The Company considered the impact of COVID-19 [added: and other economic trends] on the assumptions and estimates used in preparing the [added: condensed] consolidated financial statements.
In the opinion of management, all [added: material] adjustments necessary for a fair presentation of the Company’s financial results for the year have been made.
These adjustments are of a normal recurring nature but complicated by the [added: continued] uncertainty surrounding [removed: the global] [added: COVID-19 and other] economic [removed: impact of COVID-19.][added: trends.]
The severity, magnitude and [removed: duration,] [added: duration of certain economic trends,] as well as the economic consequences of COVID-19, [removed: are uncertain, rapidly changing] [added: continue to be uncertain] and [added: are] difficult to predict.
Therefore, our accounting estimates and assumptions may change over time in response to COVID-19 and [added: other economic trends and] may change materially in future periods.
Results of [removed: Operations—2021] [added: Operations—2022] Versus [removed: 2020][added: 2021]
| (in thousands) | | [removed: 2021] [added: 2022] | | | [removed: 2020] [added: 2021] | | | $ | | % | | [removed: 2021] [added: 2022] | | [removed: 2020] [added: 2021] |
| Cost of services provided (exclusive of depreciation and amortization below) | | | [removed: 1,162,617] [added: 1,308,399] | | | [removed: 1,048,592] [added: 1,162,617] | | [removed: 114,025] [added: 145,782] | | [removed: 10.9] [added: 12.5] | | [removed: 48.0] [added: 48.5] | | [removed: 48.5] [added: 48.0] |
| Sales, general and administrative | | | [removed: 727,489] [added: 802,710] | | | [removed: 656,207] [added: 727,489] | | [removed: 71,282] [added: 75,221] | | [removed: 10.9] [added: 10.3] | | [removed: 30.0] [added: 29.8] | | [removed: 30.4] [added: 30.0] |
| Interest expense, net | | | [removed: 830] [added: 2,638] | | | [removed: 5,082] [added: 830] | | [removed: (4,252)] [added: 1,808] | | [removed: NM] [added: 217.8] | | [removed: 0.0] [added: 0.1] | | [removed: 0.2] [added: 0.0] |
Revenues for the year ended December 31, [removed: 2021] [added: 2022] were [removed: $2.4] [added: $2.7] billion, an increase of [removed: $263.1] [added: $271.5] million, or [removed: 12.2%,] [added: 11.2%,] from [removed: 2020] [added: 2021] revenues of [removed: $2.2] [added: $2.4] billion.
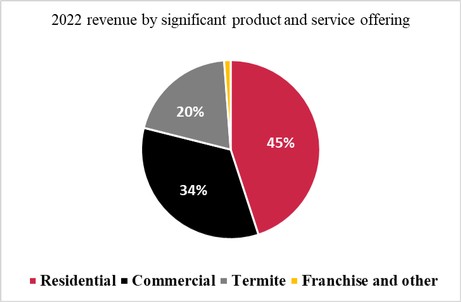
Comparing [removed: 2021] [added: 2022] to [removed: 2020,] [added: 2021,] residential pest control revenue increased [removed: 13%,] [added: 10%,] commercial pest control revenue increased 10% and termite and ancillary services grew [removed: 14%.][added: 15%.]
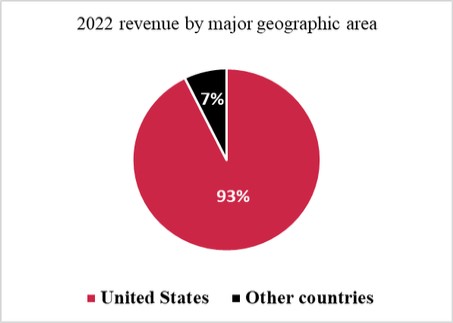
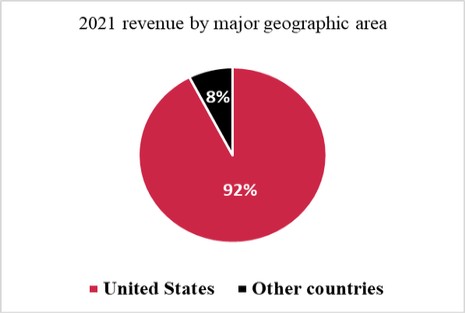
The Company’s foreign operations accounted for approximately [removed: 8% and] 7% [added: and 8%] of total revenues for the years ended December 31, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] respectively.
[removed: Sales,] [added: _Sales,] General and [removed: Administrative][added: Administrative_]
For the twelve months ended December 31, [removed: 2021,] [added: 2022,] sales, general and administrative (SG&A) expenses increased [removed: $71.3] [added: $75.2] million, or [removed: 10.9%,] [added: 10.3%,] compared to the twelve months ended December 31, [removed: 2020.][added: 2021.]
For the twelve months ended December 31, [removed: 2021,] [added: 2022,] depreciation and amortization increased [removed: $5.9] [added: $4.8] million, or [removed: 6.7%,] [added: 5.5%,] compared to the twelve months ended December 31, [removed: 2020.][added: 2021.]
The increase was due to the additional amortization of customer contracts from several [removed: acquisitions.][added: acquisitions offset by a decrease in the depreciation of operating equipment and internal-use software.]
Other [removed: (Income) Expense][added: Income, Net]
[removed: The current year gain is] [added: During the twelve months ended December 31, 2022, other income decreased $27.5 million] primarily [added: due to the Company recognizing a $31.5 million gain in the prior year] related to multiple sale-leaseback transactions where the Company sold and leased back properties that it acquired in 2019 with the Clark Pest Control acquisition.
The most significant operating use of cash is to pay our suppliers, employees, [removed: tax authorities] and [removed: others for a wide range of material] [added: tax] and [removed: services.][added: regulatory authorities.]
| | | [removed: Years ended] [added: Year Ended] December 31, | | | | | | Variance | | |
| (in thousands) | | [removed: 2021] [added: 2022] | | | [removed: 2020] [added: 2021] | | | $ | | % |
| Net cash provided by operating activities | | $ | [removed: 401,805] [added: 465,930] | | $ | [removed: 435,785] [added: 401,805] | | [removed: (33,980)] [added: 64,125] | | [removed: (7.8)] [added: 16.0] |
| Net cash used in investing activities | | | [removed: (98,965)] [added: (134,141)] | | | [removed: (162,395)] [added: (98,965)] | | [removed: 63,430] [added: (35,176)] | | [removed: (39.1)] [added: (35.5)] |
| Net cash used in financing activities | | | [removed: (290,159)] [added: (336,017)] | | | [removed: (281,273)] [added: (290,159)] | | [removed: (8,886)] [added: (45,858)] | | [removed: 3.2] [added: (15.8)] |
| Effect of exchange rate on cash | | | [removed: (5,857)] [added: (5,727)] | | | [removed: 12,084] [added: (5,857)] | | [removed: (17,941)] [added: 130] | | [removed: NM] [added: 2.2] |
| Net [added: (decrease)] increase in cash and cash equivalents | | $ | [removed: 6,824] [added: (9,955)] | | $ | [removed: 4,201] [added: 6,824] | | [removed: ] [added: (16,779)] | | [removed: ] [added: (245.9)] |
The Company’s operations generated cash of [removed: $401.8] [added: $465.9] million for the year ended December 31, [removed: 2021 primarily from net income of $350.7 million,] [added: 2022] compared with cash provided by operating activities of [removed: $435.8] [added: $401.8] million in [removed: 2020.][added: 2021.]
The Company believes its current cash and cash equivalents balances, future cash flows expected to be generated from operating activities, and available borrowings under its $175 million revolving credit facility and [removed: $250] [added: $300] million term loan [removed: facility, (which was amended in January 2022 to $300 million)] [added: facility] will be sufficient to finance its current operations and obligations, and fund expansion of the business for the foreseeable future.
The Company used [removed: $99.0] [added: $134.1] million [added: of cash] in investing activities for the year ended December 31, [removed: 2021] [added: 2022] and used [removed: $162.4] [added: $99.0] million for the year ended December 31, [removed: 2020.][added: 2021.]
The Company invested approximately [removed: $27.2] [added: $30.6] million in capital expenditures during [removed: 2021] [added: 2022] compared to [removed: $23.2] [added: $27.2] million during [removed: 2020.][added: 2021.]
Cash paid for acquisitions totaled [removed: $146.1] [added: $119.2] million for the year ended December 31, [removed: 2021] [added: 2022] as compared to [removed: $147.6] [added: $146.1] million for the year ended December 31, [removed: 2020.][added: 2021.]
We finished 2022 with record revenue of $2.7 billion.
We have consistently grown revenue and 2022 represented another strong year for growth.
We experienced strong growth across all major service lines driving 11% total growth in revenues.
Residential service revenue increased 10%, commercial revenue growth was also 10% and termite and ancillary revenue growth was 15%.
Operating cash flow remained strong in 2022 and finished at $465.9 million up from $401.8 million in 2021.
We repaid debt by $100 million in 2022, we paid $119 million for 31 acquisitions in 2022 and a final payment on a 2021 acquisition, and continued to increase dividends to investors.
While we continue to monitor macro-economic and other risks facing our business, we are starting 2023 with a strong foundation.
Demand remains strong in our business with revenue growth of 11% in January 2023.
Our balance sheet also provides us flexibility with debt remaining at very low levels to start the new year.
We plan to evaluate opportunities to renegotiate our current credit facility that will be expiring in April 2024.
Our pipeline for acquisitions is strong and we remain very well positioned to drive growth across all of our service lines in 2023.
IMPACT OF THE PANDEMIC AND OTHER ECONOMIC TRENDS
In addition, continued disruption in economic markets due to high inflation, increases in interest rates, increased fuel costs, business interruptions due to natural disasters, employee shortages and supply chain issues, all pose challenges which may adversely affect our future performance.
The Company continues to carry out various strategies previously implemented to help mitigate the impact of these economic disruptors, including revamping its routing and scheduling process to decrease the number of miles per stop, advanced scheduling to compensate for employee and vehicle shortages, and maintaining higher purchasing levels to allow for sufficient inventory.
However, the Company cannot reasonably estimate whether these strategies will help mitigate the impact of these economic disruptors in the future.
The extent to which COVID-19, increasing interest rates, inflation and other economic trends will continue to impact the Company’s business, financial condition and results of operations is uncertain.
Therefore, we cannot reasonably estimate the full future impacts of these matters at this time.
| Revenues | | $ | 2,695,823 | | $ | 2,424,300 | | 271,523 | | 11.2 | | 100.0 | | 100.0 |
| Gross profit | | | 1,387,424 | | | 1,261,683 | | 125,741 | | 10.0 | | 51.5 | | 52.0 |
| Depreciation and amortization | | | 91,326 | | | 86,558 | | 4,768 | | 5.5 | | 3.4 | | 3.6 |
| Operating income | | | 493,388 | | | 447,636 | | 45,752 | | 10.2 | | 18.3 | | 18.5 |
| Other income, net | | | (8,167) | | | (35,679) | | 27,512 | | (77.1) | | 0.3 | | 1.5 |
| Consolidated income before income taxes | | | 498,917 | | | 482,485 | | 16,432 | | 3.4 | | 18.5 | | 19.9 |
| Provision for income taxes | | | 130,318 | | | 125,920 | | 4,398 | | 3.5 | | 4.8 | | 5.2 |
| Net income | | $ | 368,599 | | $ | 356,565 | | 12,034 | | 3.4 | | 13.7 | | 14.7 |
**
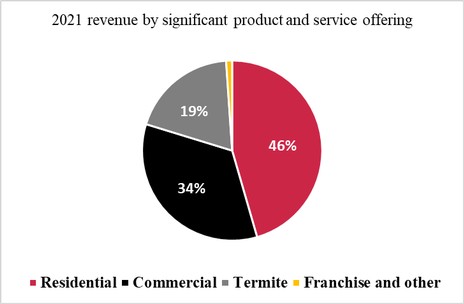
The following presents a summary of revenues by product and service offering and revenues by geography:
Gross Profit
Gross profit for the year ended December 31, 2022 was $1.4 billion, an increase of $125.7 million, or 10.0%, compared to $1.3 billion for the year ended December 31, 2021.
Gross margin was 51.5% in 2022 compared to 52.0% in 2021.
For the year, we saw higher expenses associated with casualty reserves and people cost, notably medical costs.
Excluding the increases we experienced in these areas, strategic pricing efforts helped offset inflationary pressures we experienced in fleet, material and other people associated costs.
We remain focused on executing our pricing strategies and expect to pull forward our price increase again in 2023 and expect to raise prices for services in the first quarter.
As a percentage of revenue, SG&A decreased to 29.8% from 30.0% in the prior year.
Despite investing in additional people, advertising and other customer facing activities to drive growth, we saw an
improvement in SG&A as a percentage of sales as we continue to manage our cost structure.
Although casualty reserves and people costs, notably medical costs, had an impact on SG&A, they had a lesser impact on SG&A than cost of services.
Operating Income
2021 marked the Company’s 24th consecutive year of increased revenues.
Revenues for the year rose 12.2% percent to $2.4 billion compared to $2.2 billion for the prior year.
In 2020, the dividend was reduced due to the uncertainty surrounding the effects of the COVID-19 pandemic (“COVID-19”) to our business.
Cybersecurity Incident
In October 2021, a third-party information technology Managed Service Provider (“MSP”) of the Company was the target of a cybersecurity incident (the “Incident”) resulting in the shutdown of the Company’s third-party Customer Relationship Management software used by certain of our subsidiaries whose aggregate annual revenues comprise less than 11% of our total revenues.
Upon notice of the Incident from the MSP, the Company immediately initiated its incident response protocols.
There was no known material day-to-day impact to our ability to provide normal service to customers and there was no known indication that the information of our customers or employees was compromised as a result of the Incident.
The Incident did not have a material adverse effect on our business, results of operation or financial condition; however, we may continue to be the target of further cybersecurity incidents that could possibly have a material adverse effect on our business, reputation, results of operation or financial condition.
More information about our cybersecurity risks is discussed under Item 1A., “Risk Factors,” of Part I of this Annual Report on Form 10-K.
COVID-19
In 2020, the pest control industry was designated as “essential” by the Department of Homeland Security.
The Company has been able to remain operational in every part of the world in which it operates.
With the availability of vaccinations, many COVID-19 restrictions have been lifted; however, public hesitancy regarding the vaccinations and the continued spread of COVID-19, may result in additional restrictions and mandates being imposed.
The situation related to COVID-19 continues to be complex and dynamic.
We cannot reasonably estimate the duration of the pandemic or fully ascertain its impact to
our future results.
The results of operations for the year ended December 31, 2021 are not necessarily indicative of results for future years.
| REVENUES | | | | | | | | | | | | | | |
| Customer services | | $ | 2,424,300 | | $ | 2,161,220 | | 263,080 | | 12.2 | | 100.0 | | 100.0 |
| COSTS AND EXPENSES | | | | | | | | | | | | | | |
| Depreciation and amortization | | | 94,205 | | | 88,329 | | 5,876 | | 6.7 | | 3.9 | | 4.1 |
| Total operating expenses | | | 1,984,311 | | | 1,793,128 | | 191,183 | | 10.7 | | 81.9 | | 83.0 |
| OPERATING INCOME | | | 439,989 | | | 368,092 | | 71,897 | | 19.5 | | 18.1 | | 17.0 |
| Other (income) expense, net | | | (35,679) | | | 8,290 | | (43,969) | | NM | | 1.5 | | 0.4 |
| CONSOLIDATED INCOME BEFORE INCOME TAXES | | | 474,838 | | | 354,720 | | 120,118 | | 33.9 | | 19.6 | | 16.4 |
| PROVISION FOR INCOME TAXES | | | 124,151 | | | 93,896 | | 30,255 | | 32.2 | | 5.1 | | 4.3 |
| NET INCOME | | $ | 350,687 | | $ | 260,824 | | 89,863 | | 34.5 | | 14.5 | | 12.1 |
The Company’s revenue mix for the year ended December 31, 2021 consisted primarily of 46% residential pest control, 34% commercial pest control and 20% termite and ancillary revenues (such as moisture control, insulation, deck and gutter work).
Cost of Services Provided
For the twelve months ended December 31, 2021, cost of services provided increased $114.0 million, or 10.9%, compared to the twelve months ended December 31, 2020.
The increase was driven by increased people costs and materials and supplies due to the increase in revenues.
Additionally, fleet costs increased mainly driven by an increase in fuel costs.
The increases were driven by increased people costs mostly due to sales personnel, directly related to our increase in revenues.
Additionally, SG&A increased due to the accrual related to the potential settlement of the ongoing SEC matter of $8.0 million, increased advertising costs and the charitable donation of certain excess personal protection equipment.
During the twelve months ended December 31, 2021, other income increased $44.0 million primarily due to the Company recognizing a gain of $35.7 million compared to a loss of $1.6 million in the prior year.
Additionally, 2020 included $6.7 million of accelerated stock compensation vesting expense that did not occur in 2021.
Interest expense, net for the years ended December 31, 2021 and 2020 was $0.8 million and $5.1 million respectively.
The decrease was primarily driven by the lower average debt balance in 2021 compared to the same period in 2020.
The Company’s effective tax rate decreased to 26.1% in 2021 compared to 26.5% in 2020.
An excerpt. Shown here: 40 of 56 rewritten, 40 of 71 added and 40 of 54 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations. in the FY2022 filing and the FY2021 filing.
Item 7A. Quantitative and Qualitative Disclosures about Market Risk
6 rewritten, 0 added, 0 removed, 5 unchanged
The Company maintained an investment portfolio (included in cash and cash equivalents) subject to short-term interest rate risk [removed: exposure.][added: exposure; and other current and long-term investments.]
The Company is subject to interest rate risk exposure through borrowings on its $175.0 million revolving credit facility and amended $300.0 million term loan [removed: facility that was amended effective January 27, 2022.][added: facility.]
As of December 31, [removed: 2021,] [added: 2022,] the [removed: revolving commitment] [added: Company] had outstanding borrowings of [removed: $107.0] [added: $54.9] million [removed: and] [added: under] the [removed: term loan had] [added: Term Loan and there were no] outstanding borrowings [removed: of $48.0 million.][added: under the Revolving Commitment.]
Additionally, the Company maintained [removed: $37.2] [added: $71.3] million in Letters of Credit.
See Note [removed: 4] [added: 10] to the accompanying financial statements for further details regarding debt.
These letters of credit are required by the Company’s [removed: fronting] insurance [removed: companies and/or certain states,] [added: companies,] due to the Company’s [removed: self-insured status,] [added: high deductible insurance program,] to secure various workers’ compensation and casualty insurance contracts coverage.
Item 1. Business
29 rewritten, 217 added, 51 removed, 90 unchanged
We believe that the principal competitive factors in the market areas that we serve are quality [added: and speed] of service, customer proximity, [added: customer satisfaction, brand awareness and reputation,] terms of guarantees, [removed: reputation for] safety, technical proficiency and price.
Although we believe that our [removed: experience and reputation for] [added: experience,] safety and quality service are excellent, we cannot assure investors that we will be able to maintain our competitive position in the future and any competitive pressures we may face could have a material adverse effect on our reputation, [added: business,] financial condition, results of operations and cash flows.
We cannot assure investors that we will be able to identify and acquire acceptable acquisition [removed: candidates] [added: targets] on terms favorable to us in the future, or that any acquisitions will achieve the anticipated financial benefits.
An element of our [removed: strategy] [added: business] includes further expansion into international markets.
Our strong brands, [removed: Rollins,] Orkin, [removed: HomeTeam,] [added: HomeTeam Pest Defense,] Clark Pest Control, [removed: Western,] Northwest Exterminating, Trutech, [added: Western Pest Services, The Industrial Fumigant Company (IFC), Waltham Services, Okolona Pest Control (OPC),] Critter Control, [removed: IFC, Waltham,] and [removed: others] [added: others,] have significantly [removed: contributed to the success of our business.]
Further, if our brands are significantly damaged, our [added: reputation,] business, results of operations, and financial condition could be materially adversely affected.
Maintaining and enhancing our brands will depend largely on our [added: brands’] ability to remain a service leader and continue to provide high-quality pest control services that are truly beneficial and play a meaningful role in people’s lives.
This could materially adversely impact our [added: reputation,] business, financial condition, results of operations and cash flows.
These strains in our relationships or any resulting claims could have a material adverse effect on our reputation, [added: business,] financial condition, results of operations and cash flows.
Our ability to remain productive and profitable will depend substantially on our ability to [added: compete with other pest control companies to] attract and retain skilled workers, create leadership opportunities and successfully implement diversity, equity and inclusion initiatives.
[removed: COVID-19 has exacerbated labor shortages and the enforcement of COVID-19 mandates may result in additional] [added: Ongoing] labor shortages [removed: which] could negatively affect our ability to efficiently operate at full capacity or lead to increased costs, such as increased overtime to meet demand and increased wage rates to attract and retain employees.
The increase in pest presence and activity, as well as the metamorphosis of termites in the spring and summer (the occurrence of which is determined by the timing of the change in seasons), has historically resulted in an increase in the revenue [removed: and income] of our pest and termite control operations during such [removed: periods.][added: periods as evidenced by the following chart.]
[added: Because of the uncertainty of weather volatility related to climate change and any] resulting unfavorable weather conditions, we cannot predict its potential impact on our business, financial condition, results of operations and cash flows.
_Adverse economic conditions, including inflation and restrictions in customer discretionary expenditures, [added: increases in interest rates or other] disruptions in credit or financial markets, increases in fuel prices, raw material costs, or other operating costs could materially adversely affect our business._
[removed: Our IT systems also contain the Company’s and its wholly-owned] subsidiaries’ proprietary and other confidential information related to our business, such as business plans, customer lists and product and service development initiatives.
[added: Furthermore, while we maintain cybersecurity insurance, our insurance may not cover all] liabilities incurred due to a security breach or incident and this could have a material adverse effect on our reputation, financial condition, results of operations and cash flows.
_Our brand recognition [added: or reputation] could be impacted if we are not able to adequately protect our intellectual property and other proprietary rights that are material to our business._
[removed: _We] [added: We] are from time to time subject to lawsuits, investigations and other proceedings which could have a material adverse effect on our business, financial condition and results of [removed: operations, and our operations may be adversely affected if we fail to comply with applicable law or other governmental regulations, including environmental and other regulations relating to the pest control industry._][added: operations.]
In the normal course of business, we are involved in various claims, contractual disputes, investigations, arbitrations and litigation, including claims that our acts, omissions, services or vehicles caused damage or injury, claims that our services did not achieve the desired results, claims related to acquisitions, allegations by federal, state or local authorities, including the [removed: SEC,] [added: Securities and Exchange Commission,] of violations of regulations or statutes, claims related to wage and hour law violations and claims related to environmental matters.
We are unable to predict whether such laws will, in the future, materially affect our operations and financial [removed: condition or whether any changes will require us to incur substantial increases in costs in order to comply with such changes.][added: condition.]
Penalties for noncompliance with these laws may include [removed: investigations,] criminal sanctions or civil remedies, including, but not limited to, cancellation of licenses, fines, and other corrective actions, which could negatively affect our [removed: reputation,] [added: business,] financial condition, results of operations [removed: and cash flows.][added: or reputation.]
[removed: The] [added: A control group that includes members of] Company’s [added: Board of Directors and] management has a [removed: substantial] [added: majority] ownership interest; public stockholders may have no effective voice in the Company’s management.
The Company is a “Controlled Company” because a group that includes the Company’s [added: Executive] Chairman of the [removed: Board and Chief Executive Officer,] [added: Board,] Gary W.
Rollins, [added: Board member, Pam Rollins,] and certain [removed: companies under his control] [added: persons acting as a group with them] (the “Controlling Group”), controls in excess of fifty percent of the Company’s voting power.
[removed: Rollins, Inc.’s executive officers, directors and their affiliates hold] [added: The Controlling Group holds] directly, or through indirect beneficial ownership, in the aggregate, approximately [removed: 53] [added: 51] percent of the Company’s outstanding shares of common stock as of December 31, [removed: 2021.][added: 2022.]
[removed: As a result, these persons will effectively control the] operations of the Company, including the election of directors and approval of significant corporate transactions such as acquisitions and approval of matters requiring stockholder approval.
[removed: Our management] [added: A Controlling Group] has a substantial ownership interest, and the availability of the Company’s common stock to the investing public may be limited.
The availability of Rollins’ common stock to the investing public is limited to those shares not held by the [removed: executive officers, directors and their affiliates,] [added: Controlling Group,] which could negatively impact Rollins’ stock trading prices and affect the ability of minority stockholders to sell their shares.
Future sales by [removed: executive officers, directors and their affiliates] [added: the Controlling Group] of all or a portion of their shares could also negatively affect the trading price of our common stock.
General Overview
Rollins, Inc. (“Rollins,” “we,” “us,” “our,” or the “Company”), is an international services company headquartered in Atlanta, Georgia.
Through our family of leading brands, we provide essential pest and wildlife control services and protection against termite damage, rodents and insects to more than two million residential and commercial customers from more than 800 Company-owned and franchised locations in approximately 70 countries.
Over the course of our lengthy operating history, we have garnered a reputation for providing great customer service.
The contracted and recurring nature of our services provide us with visibility into a significant portion of our future earnings.
In 1964, brothers O.
Wayne and John Rollins acquired Orkin Exterminating Company and in 1965 we changed our name from Rollins Broadcasting, Inc to Rollins, Inc. In 1968, Rollins began trading on the New York Stock Exchange under the symbol “ROL.” Since then, we have grown into a premier consumer and commercial services business with numerous industry leading brands including the world renowned Orkin, as well as HomeTeam Pest Defense, Clark Pest Control, Western Pest Services, Critter Control Wildlife, and Northwest Exterminating, among others.
We operate under one reportable segment which contains our three business lines:
| | ● | _Residential_: Pest control services protecting residential properties from common pests, including rodents, insects and wildlife; |
| --- | --- | --- |
| | ● | _Commercial_: Workplace pest control solutions for customers across diverse end markets such as healthcare, foodservice, logistics; and |
| --- | --- | --- |
| | ● | _Termite_: Termite protection services and ancillary services for both residential and commercial customers. |
| --- | --- | --- |
Our Competitive Strengths
Rollins is a global leader in pest control.
We have established a portfolio of premier brands with extensive service capabilities across a deep operating network.
Our scale enables delivery of great service and provides a significant and reinforcing competitive advantage through (i) comprehensive capabilities to win new residential and commercial accounts, (ii) technology investments for operations optimization and enhanced customer experience, (iii) route density to manage variable costs, and (iv) financial flexibility to generate organic growth and pursue M&A.
Robust Operating Platform with Proprietary Technology
Our extensive footprint creates an efficient and scalable operating platform to facilitate exceptional customer service delivery, increased cross-selling opportunities, and cost efficiencies.
We have strategically invested in proprietary routing and scheduling technologies to increase our competitive advantage, which includes real-time service tracking and customer internet communication to personalize the customer experience.
We run our proprietary Branch Operating Support System (“BOSS”), which offers a back-end interface to facilitate service tracking and payment processing for technicians.
BOSS also provides virtual route management tools to increase route efficiency across our network, reducing miles driven and associated costs while increasing customer retention through on-time and rapid response service.
Differentiated Employee Base and Service Delivery
Our employees are critical to delivering an outstanding customer experience, and we are highly focused on providing our team with best-in-class training and development opportunities.
We operate the 27,000 square foot Rollins Learning Center training facility located in Atlanta, GA, which is a distance-learning and global broadcast facility with simulated environments and classrooms for training.
In addition to in-person training, the Rollins Learning Center offers on-demand training sessions that employees can access from anywhere in the world that are produced at our on-site, state-of-the-art broadcast studio.
Our unique programs contribute to our position as an
employer of choice and have earned us recognition from Training magazine among the Top 125 U.S. Training Companies 17 times in the past 20 years.
We were also recognized by the Top Workplaces program as a top workplace on both a national and local level.
This marks the seventh consecutive year to be recognized in Atlanta.
We continuously monitor co-worker engagement and customer loyalty.
Experienced Management Team
Our management team combines extensive business and consumer services experience with robust local pest control leadership.
Consistent with our culture of attracting, developing and progressing talented individuals, our senior leadership team consists of a combination of long-term internal leaders and strategic hires from well-respected external platforms.
Our Chairman, Gary Rollins, is the son of Rollins, Inc. co-founder O.
Wayne Rollins and has spent his entire career with the Company, serving as Chief Executive Officer (“CEO”) from 2001 to 2022.
Effective January 1, 2023, Jerry Gahlhoff, Jr. assumed the role of CEO and now serves as President and CEO.
International Business
We continue to expand our international presence through organic growth, acquisitions, and our international franchise programs.
Because of the uncertainty of weather volatility related to climate change and any
_Our business, results of operations and financial condition are impacted by the coronavirus (COVID-19) pandemic and the restrictions put in place in connection therewith._
We have responded and continue to respond to the global outbreak of COVID-19 by taking steps to mitigate the potential risks posed to us by its spread and the impact of the restrictions put in place by the local, state and federal governments to protect the population.
We continue to execute our comprehensive set of protocols for the health and safety of our employees, customers, and business partners, such as wearing masks, gloves, and other personal protective equipment, social distancing and utilizing electronic documents, among others.
However, due to the unprecedented uncertainty surrounding the duration of COVID-19, COVID-19 variants, rapidly changing governmental directives, public health challenges and progress, macroeconomic consequences, and market reactions thereto, we are not able at this time to predict the extent to which the COVID-19 pandemic may have a material adverse effect on our results of operations or financial condition, and it continues to be challenging for our management to estimate the future performance of our business and develop strategies to generate growth or achieve our objectives for 2022 and beyond.
In September 2021, the federal government issued an executive order requiring United States based employees, contractors, and subcontractors that work on or in support of United States government contracts, to be fully vaccinated by January 4, 2022, and it only permits limited exceptions for medical and religious reasons (the “COVID-19 Executive Order”).
On December 7, 2021, the United States District Court for the Southern District of Georgia issued a preliminary nationwide injunction enjoining the enforcement of the COVID-19 Executive Order.
The government appealed the order to the United States Court of Appeals for the Eleventh Circuit and briefing is due to the Eleventh Circuit by April 4, 2022.
As a result of the COVID-19 Executive Order, we may be forced to terminate relationships with various United States government agencies we provide services to.
Furthermore, certain customers have issued vaccine requirements with respect to our technicians who provide on-site services at our commercial customer’s facilities.
The COVID-19 Executive Order along with any customer-specific mandates or rules could result in labor shortages as well as difficulty securing future labor needs, which could impact our ability to provide services to our customers, potentially resulting in material adverse impacts to our reputation, results of operations, financial condition and cash flows.
For example, in October 2021, one of our third-party information technology Managed Service Providers (“MSP”) was the target of a cybersecurity incident (the “Incident”) resulting in the shutdown of our third-party Customer Relationship Management software used by certain subsidiaries whose aggregate annual revenues comprise less than 11% of our total revenues.
There was no known material day-to-day impact to our ability to provide normal service to customers and there was no known indication that the information of our customers or employees was compromised as a result of the Incident.
The Incident did not have a material adverse effect on our business, reputation, results of operation or financial condition; however, we may continue to be the target of further cybersecurity incidents that could possibly have a material adverse effect on our business, reputation, results of operation or financial condition.
We are also subject to risks associated with attacks involving our supply chain, such as the vulnerabilities of IT infrastructure management software provided by SolarWinds Corporation.
During 2021, we have observed an increase in ransomware attacks in our supply chain.
In December 2021, a vulnerability named “Log4Shell” was reported for the widely used Java logging library, ApacheLog4j2.
We have reviewed the use of this library within our software product portfolio and in our IT environment and have taken steps to mitigate the vulnerability; however, there can be no assurances that other similar vulnerabilities or cybersecurity incidents may not occur in the future or may not have a material adverse effect on our business, reputation, results of operation or financial condition.
Furthermore, while we maintain cybersecurity insurance, our insurance may not cover all
Our ability to compete effectively depends in part on our rights to service marks, trademarks, trade names and other intellectual property rights we own or license, particularly our registered brand names and service marks, Orkin®, Orkin Canada®, HomeTeam Pest Defense®, TAEXX®, Clark Pest Control®, Western Pest Services®, Northwest Exterminating®, Critter Control®, IFC®, Trutech®, Waltham Pest Services®, OPC Services®, Perma Treat Pest and Termite Control®, Crane Pest Control®, Murray Pest Control®, Allpest®, Statewide Pest Control®, Safeguard the Pest Control People®, Aardwolf Pestkare®, Adams Pest Control™, McCall® and others.
The ongoing SEC investigation and any potential related litigation entail risks and uncertainties.
As we previously disclosed, the SEC is conducting an investigation (the “SEC Investigation”).
We believe the SEC Investigation is primarily focused on how the Company established accruals and reserves at period-ends for periods beginning January 1, 2016 through December 31, 2018 and the impact of those accruals and reserves on reported earnings per share, specifically, in the first quarter of 2016 and the second quarter of 2017.
The Company is in ongoing discussions with the SEC staff regarding a potential resolution of the SEC Investigation.
In light of the foregoing, in accordance with the accounting guidance in ASC 450, “Contingencies,” the Company recorded an accrual for $8.0 million related to the SEC Investigation in the third and fourth quarters of 2021, which is reflected in other current liabilities in our consolidated statements of financial position.
The ultimate amount of any liability related to the potential resolution of the SEC Investigation could be different from the $8.0 million accrued as of December 31, 2021.
The Company will continue to cooperate with the SEC in working towards a final resolution of the SEC Investigation.
As we previously reported during the third quarter of 2021, the Audit Committee of the Company’s Board of Directors initiated a related, supplemental internal investigation.
This supplemental investigation was concluded in the fourth quarter of 2021.
The Company believes that no restatement of its prior period financial statements will be required as a result of the SEC Investigation or matters related thereto.
There can be no assurance that the SEC or another regulatory body will not make further regulatory inquiries or pursue action against the Company and its directors or senior officers that could result in potentially significant sanctions and penalties, or that could require the Company to take additional remedial steps, which could include revising or restating portions of our historical net income and earnings per share for the impacted quarterly periods.
Potential sanctions against the Company and/or individuals include penalties, injunctions, and cease-and-desist orders.
In addition, the Company and its current or former senior officers and directors may be subject to litigation, including by the Company’s stockholders, related to the matters under review by the SEC.
Accordingly, the SEC investigation and any potential related litigation in connection with the SEC Investigation entail risks and uncertainties the outcome of which could materially adversely affect our reputation, results of operations, financial position and liquidity, and stock price.
Our insurance coverage may be inadequate to cover all significant risk exposures.
We are exposed to liabilities that are unique to our business and the services we provide.
We maintain commercial liability insurance that extends to products liability.
In addition, we also maintain other insurance and other traditional risk transfer tools to respond to certain types of liabilities and risks.
However, such tools are subject to terms such as deductibles, retentions, limits and policy exclusions, as well as risk of denial of coverage, default or insolvency.
If we suffer unexpected or uncovered losses, or if any of our insurance policies are terminated for any reason or are not effective in mitigating our risks, we may incur losses that are not covered or that exceed our coverage limits which could adversely affect our results of operations, financial condition, and cash flows.
An excerpt. Shown here: all 29 rewritten, 40 of 217 added and 40 of 51 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2022 filing and the FY2021 filing.
Item 3. Legal Proceedings.
3 rewritten, 8 added, 11 removed, 3 unchanged
In the normal course of business, the Company and its subsidiaries are involved in, and will continue to be involved in, various claims, arbitrations, contractual disputes, investigations, [added: litigation, environmental] and [removed: regulatory] [added: tax] and [removed: litigation] [added: other regulatory] matters relating to, and arising out of, our businesses and our operations.
These matters may involve, but are not limited to, allegations that our services or vehicles caused damage or injury, claims that our services did not achieve the desired results, claims related to acquisitions and allegations by federal, state or local [removed: authorities] [added: authorities, including taxing authorities,] of violations of regulations or statutes.
We are also involved from time to time in certain environmental [added: and tax] matters primarily arising in the normal course of business.
The Company retains, up to specified limits, certain risks related to general liability, workers’ compensation and auto liability.
The estimated costs of existing and future claims under the retained loss program are accrued based upon historical trends as incidents occur, whether reported or unreported (although actual settlement of the claims may not be made until future periods) and may be subsequently revised based on developments relating to such claims.
The Company contracts with an independent third party to provide the Company an estimated liability based upon historical claims information.
The actuarial study is a major consideration in establishing the reserve, along with management’s knowledge of changes in business practice and existing claims compared to current balances.
Management’s judgment is inherently subjective as a number of factors are outside management’s knowledge and control.
Additionally, historical information is not always an accurate indication of future events.
The accruals and reserves we hold are based on estimates that involve a degree of judgment and are inherently variable and could be overestimated or insufficient.
If actual claims exceed our estimates, our operating results could be materially affected, and our ability to take timely corrective actions to limit future costs may be limited.
As we previously disclosed, the SEC is conducting an investigation (the “SEC Investigation”).
We believe the SEC Investigation is primarily focused on how the Company established accruals and reserves at period-ends for periods beginning January 1, 2016 through December 31, 2018 and the impact of those accruals and reserves on reported earnings per share, specifically, in the first quarter of 2016 and the second quarter of 2017.
The Company is in ongoing discussions with the SEC staff regarding a potential resolution of the SEC Investigation.
In light of the foregoing, in accordance with the accounting guidance in ASC 450, “Contingencies,” the Company recorded an accrual for $8.0 million related to the SEC Investigation in the third and fourth quarters of 2021, which is reflected in other current liabilities in our consolidated statements of financial position.
The ultimate amount of any liability related to the potential resolution of the SEC Investigation could be different from the $8.0 million accrued as of December 31, 2021.
The Company will continue to cooperate with the SEC in working towards a final resolution of the SEC Investigation.
As we previously reported during the third quarter of 2021, the Audit Committee of the Company’s Board of Directors initiated a related, supplemental internal investigation.
This supplemental investigation was concluded in the fourth quarter of 2021.
The Company believes that no restatement of its prior period financial statements will be required as a result of the SEC Investigation or matters related thereto.
See “Item 1A.
Risk Factors-- Risks Related to Legal, Regulatory and Risk Management Matters -- The ongoing SEC investigation and any potential related litigation entail risks and uncertainties.”
Cover and table of contents
11 rewritten, 2 added, 163 removed, 82 unchanged
FOR THE FISCAL YEAR ENDED DECEMBER 31, [removed: 2021][added: 2022]
The aggregate market value of Rollins, Inc. Common Stock held by non-affiliates on June 30, [removed: 2021] [added: 2022] was [removed: $7,888,772,207] [added: $8,027,727,333] based on the reported last sale price of common stock on June 30, [removed: 2021,] [added: 2022,] which is the last business day of the registrant’s most recently completed second fiscal quarter.
Rollins, Inc. had [removed: 492,085,707] [added: 492,280,053] shares of Common Stock outstanding as of January 31, [removed: 2022.][added: 2023.]
Portions of the Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Stockholders of Rollins, Inc. are incorporated by reference into Part III, Items 10-14.
For the Year Ended December 31, [removed: 2021][added: 2022]
| [Item 1.A.](#Item1ARiskFactors_4050) | | [Risk Factors.](#Item1ARiskFactors_4050) | | [removed: 9] [added: 10] |
| [Item 1.B.](#Item1BUnresolvedStaffComments_801686) | | [Unresolved Staff Comments.](#Item1BUnresolvedStaffComments_801686) | | [removed: 16] [added: 15] |
| [Item 2.](#Item2Properties_348308) | | [Properties.](#Item2Properties_348308) | | [removed: 16] [added: 15] |
| [Part II](#PARTII_487076) | | | | [removed: 17] [added: 16] |
| [Item 5.](#Item5MarketforRegistrantsCommonEquityRel) | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.](#Item5MarketforRegistrantsCommonEquityRel) | | [removed: 17] [added: 16] |
| [Item 9.A.](#Item9AControlsandProcedures_187269) | | [Controls and Procedures.](#Item9AControlsandProcedures_187269) | | [removed: 61] [added: 63] |
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements.
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b).
| --- | --- | --- |
| | | [Schedule II.](#SCHEDULEIIVALUATIONANDQUALIFYINGACCOUNTS) | | 67 |
Item 1.
Business
General Overview
Rollins, Inc. (“Rollins,” “we,” “us,” “our,” or the “Company”), is an international services company headquartered in Atlanta, Georgia.
Through our family of leading brands, we provide essential pest and wildlife control services and protection against termite damage, rodents and insects to more than two million residential and commercial customers from more than 800 Company-owned and franchised locations in over 70 countries.
Over the course of our lengthy operating history, we have garnered a reputation for providing great customer service.
The contracted and recurring nature of our services provide us with visibility into a significant portion of our future earnings.
In 1964, brothers O.
Wayne and John Rollins acquired Orkin Exterminating Company and in 1965 we changed our name from Rollins Broadcasting, Inc to Rollins, Inc. In 1968, Rollins began trading on the New York Stock Exchange under the symbol “ROL”.
Since then, we have grown into a premier consumer and commercial services business with numerous industry leading brands including the world renowned Orkin, as well as HomeTeam Pest Defense, Clark Pest Control, Western Pest Services, Critter Control Wildlife, and Northwest Pest Control, among others.
We operate under one reportable segment which contains our three business lines:
| | ● | _Residential_: Pest control services protecting residential properties from common pests, including rodents, insects and wildlife; |
| | ● | _Commercial_: Workplace pest control solutions for customers across diverse end markets such as healthcare, foodservice, logistics; and |
| | ● | _Termite_: Traditional and baiting termite protection services and ancillary services for both residential and commercial customers. |
Our Competitive Strengths
Rollins is a global leader in pest control.
We have established a portfolio of premier brands with extensive service capabilities across a deep operating network.
Our scale enables delivery of great service and provides a significant and reinforcing competitive advantage through (i) comprehensive capabilities to win new residential and commercial accounts, (ii) technology investments for operations optimization and enhanced customer experience, (iii) route density to manage variable costs, and (iv) financial flexibility to generate organic growth and pursue M&A.
Robust Operating Platform with Proprietary Technology
Our extensive footprint creates an efficient and scalable operating platform to facilitate exceptional customer service delivery, increased cross-selling opportunities, and cost efficiencies.
We have strategically invested in proprietary routing and scheduling technologies to increase our competitive advantage, which includes real-time service tracking and customer Internet communication to personalize the customer experience.
We also developed and launched our proprietary Branch Operating Support System (“BOSS”), which offers a back-end interface to facilitate service tracking and payment processing for technicians.
BOSS also provides virtual route management tools to increase route efficiency across our network, reducing miles driven and associated costs while increasing customer retention through on-time and rapid response service.
Differentiated Employee Base and Service Delivery
Our employees are critical to delivering an outstanding customer experience, and we are highly focused on providing our team with best-in-class training and development opportunities.
We operate the 27,000 square foot Rollins Learning Center training facility located in Atlanta, GA, which is a distance-learning and global broadcast facility with simulated environments and classrooms for training.
In addition to in-person training, the Rollins Learning Center offers on-demand training sessions that employees can access from anywhere
in the world that are produced at our on-site, state-of-the-art broadcast studio.
Our unique programs contribute to our position as an employer of choice and have earned us recognition from Training magazine among the Top 125 U.S. Training Companies 16 times in the past 19 years.
We continuously monitor co-worker engagement and customer loyalty.
Experienced Management Team
Our management team combines extensive business and consumer services experience with robust local pest control leadership.
Consistent with our culture of attracting, developing and progressing talented individuals, our senior leadership team consists of a combination of long-term internal leaders and strategic hires from well-respected external platforms.
Our Chairman and CEO, Gary Rollins, is the son of Rollins, Inc. co-founder O.
Wayne Rollins and has spent his entire career with the Company, serving as CEO since 2001.
International Business
We continue to expand our international presence through organic growth, international acquisitions, and our international franchise programs.
In 2021, we saw revenue growth in our operations in Canada, Australia, the United Kingdom, and Singapore.
An excerpt. Shown here: all 11 rewritten, all 2 added and 40 of 163 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2022 filing and the FY2021 filing.
Item 2. Properties.
1 rewritten, 1 added, 0 removed, 3 unchanged
[removed: None of the] branch offices, individually considered, represents a materially important physical property of the Company.
None of the
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
10 rewritten, 4 added, 6 removed, 20 unchanged
As of January 31, [removed: 2022,] [added: 2023,] there were [removed: 7,747] [added: 177,950] holders of record of the Company’s common stock.
During the years ended December 31, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] the Company did not repurchase shares on the open market.
| Period | | [removed: purchased (1)] [added: purchased(1)] | | per share | | | repurchases (2) | | repurchase plan (2) |
| October 1 to 31, [removed: 2021] [added: 2022] | | — | | $ | — | | — | | 11,415,625 |
| December 1 to 31, [removed: 2021] [added: 2022] | | — | | | — | | — | | 11,415,625 |
| Total | | [removed: 2,429] [added: 3,062] | | $ | [removed: 39.34] [added: 34.37] | | — | | 11,415,625 |
| (2) | [removed: In 2012, the Company’s Board authorized] [added: The Company has] a share repurchase [removed: plan] [added: plan, adopted in 2012,] to repurchase up to [removed: 5.0] [added: 16.9] million shares of the Company’s common stock. [removed: The split-adjusted authorized] [added: There are 11.4 million] shares [added: authorized to be repurchased] under [removed: the share] [added: prior board approval. The] repurchase plan [removed: are 16.9 million shares.] [added: has no expiration date.] |
The indices included in the following graph are the S&P 500 Index and the S&P 500 Commercial Services [added: & Supplies] Index.
[removed: 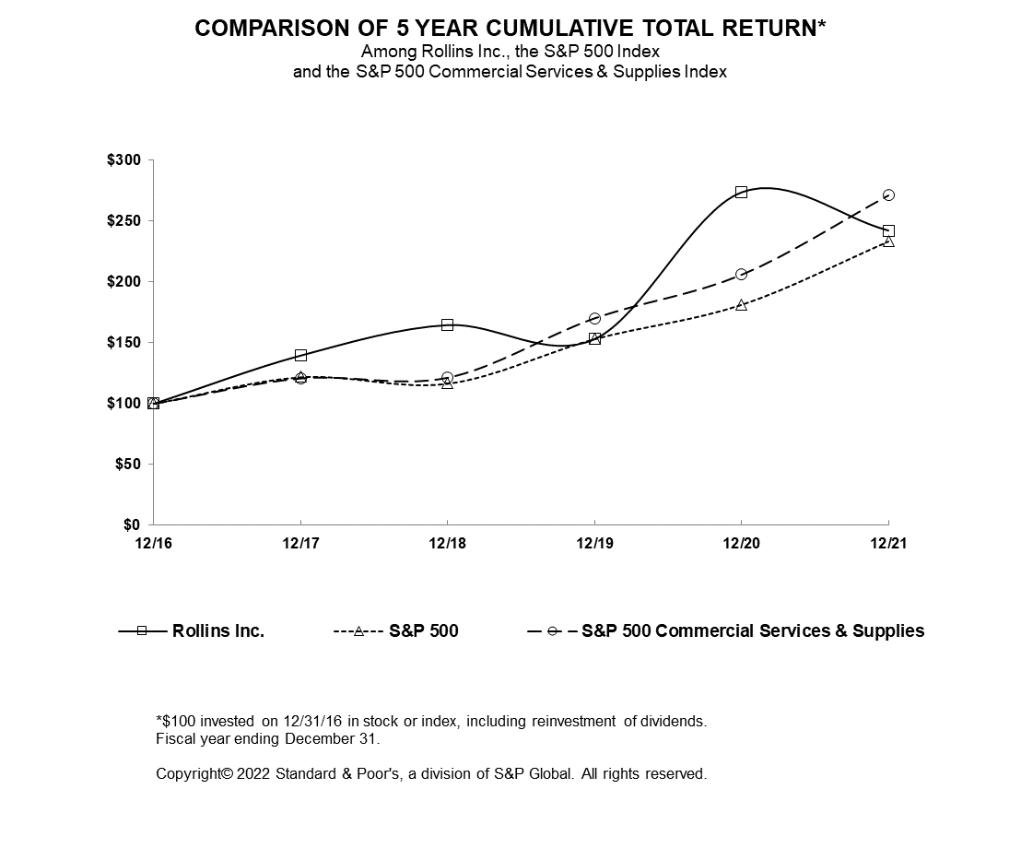][added: 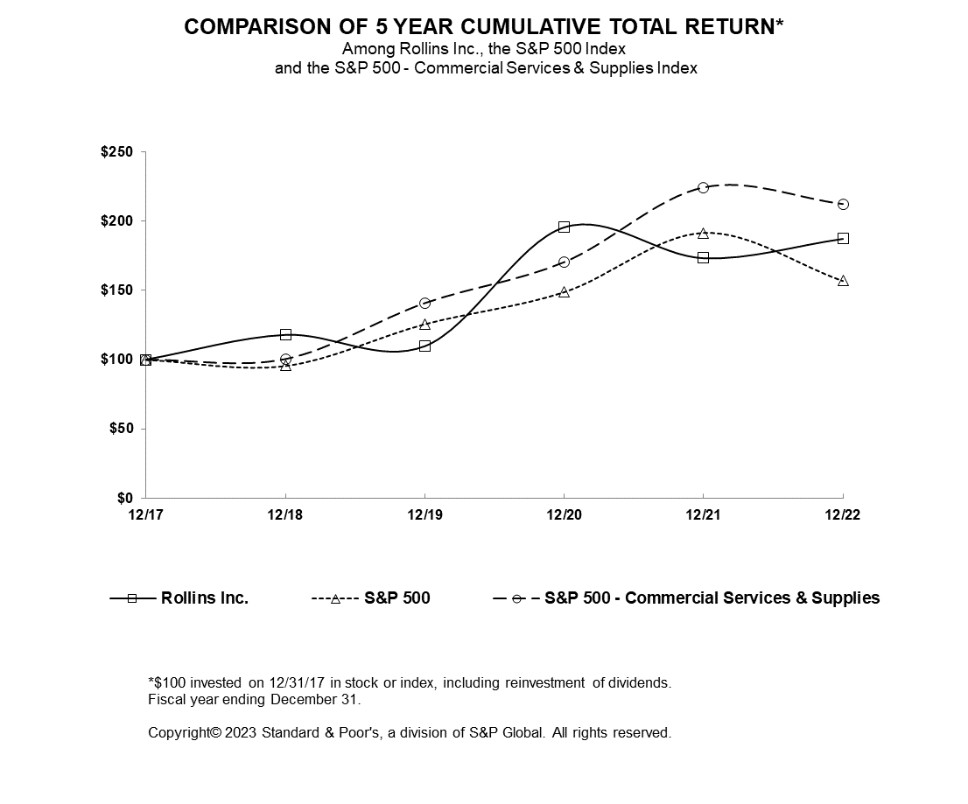]
| | | [removed: 2016 | |] 2017 | | 2018 | | 2019 | | 2020 | | 2021 | [added: | 2022 |]
| November 1 to 30, 2022 | | 3,062 | | | 34.37 | | — | | 11,415,625 |
| Rollins Inc. | | 100.00 | | 117.89 | | 109.68 | | 195.81 | | 173.43 | | 187.47 |
| S&P 500 | | 100.00 | | 95.62 | | 125.72 | | 148.85 | | 191.58 | | 156.89 |
| S&P 500 Commercial Services & Supplies | | 100.00 | | 100.49 | | 140.84 | | 170.39 | | 224.30 | | 212.33 |
In total, there remains 11.4 million additional shares authorized to be repurchased under prior Board approval.
The repurchase program does not have an expiration date.
| November 1 to 30, 2021 | | 2,429 | | | 39.34 | | — | | 11,415,625 |
| Rollins Inc. | | 100.00 | | 137.74 | | 160.30 | | 147.25 | | 260.24 | | 227.86 |
| S&P500 | | 100.00 | | 119.42 | | 111.97 | | 144.31 | | 167.77 | | 212.89 |
| S&P 500 Commercial Services & Supplies | | 100.00 | | 118.67 | | 117.37 | | 162.24 | | 193.66 | | 252.11 |
Item 8. Financial Statements and Supplementary Data
444 rewritten, 253 added, 149 removed, 535 unchanged
Under the supervision and with the participation of our management, including our principal executive officer and principal financial and [added: principal] accounting officer, we conducted an evaluation of the effectiveness of the design and operation of internal controls over financial reporting, as of December 31, [removed: 2021] [added: 2022] based on criteria established in the 2013 Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission.
Based on this evaluation, management’s assessment is that Rollins, Inc. maintained effective internal control over financial reporting as of December 31, [removed: 2021.][added: 2022.]
The independent registered public accounting firm, Grant Thornton LLP has audited the consolidated financial statements as of and for the year ended December 31, [removed: 2021,] [added: 2022,] and has also issued their report on the effectiveness of the Company’s internal control over financial reporting, included in this report on page 27.
| [removed: Chairman] [added: President] and Chief Executive Officer | | [removed: Interim] [added: Executive Vice President,] Chief Financial Officer and Treasurer |
| Principal Executive Officer | | Principal Financial [removed: and Accounting] Officer |
[removed: | | | |] Board of Directors and Stockholders [removed: Rollins, Inc. |]
[removed: | | | |] Opinion on internal control over financial reporting [removed: |]
[removed: | | | |] We have audited the internal control over financial reporting of Rollins, Inc. (a Delaware corporation) and subsidiaries (the “Company”) as of December 31, [removed: 2021,] [added: 2022,] based on criteria established in the 2013 Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (“COSO”). [removed: In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2021, based on criteria established in the 2013 Internal Control—Integrated Framework issued by COSO. |]
[removed: | | | |] We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (“PCAOB”), the consolidated financial statements of the Company as of and for the year ended December 31, [removed: 2021,] [added: 2022,] and our report dated February [removed: 25, 2022] [added: 16, 2023] expressed an unqualified opinion on those financial statements. [removed: |]
[removed: | | | |] Basis for opinion [removed: |]
[removed: | | | | The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management’s Report on Internal Control over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit.] We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB. [removed: |]
[removed: | | | | We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects.] Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. [removed: We believe that our audit provides a reasonable basis for our opinion. |]
[removed: | | | |] Definition and limitations of internal control over financial reporting [removed: |]
[removed: | | | |] A company’s internal control over financial reporting [removed: is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting] includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements. [removed: |]
[removed: | | | | Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements.] Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate. [removed: |]
[removed: | | | |] /s/ GRANT THORNTON LLP [removed: Atlanta, Georgia February 25, 2022 |]
[removed: | | |] Board of Directors and Stockholders [removed: Rollins, Inc. |]
[removed: | | |] Opinion on the financial statements [removed: |]
[removed: | | | We have audited the accompanying consolidated statements of financial position of Rollins, Inc. (a Delaware corporation) and subsidiaries (the “Company”) as of December 31, 2021 and 2020, the related consolidated statements of income, comprehensive earnings, stockholders’ equity, and cash flows for each of the three years in the period ended December 31, 2021, and the related notes and financial statement schedule included under Item 15 (collectively referred to as the “financial statements”).] In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2021,] [added: 2022,] in conformity with accounting principles generally accepted in the United States of America. [removed: |]
[removed: | | |] We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (“PCAOB”), the Company’s internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] based on criteria established in the 2013 Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (“COSO”), and our report dated February [removed: 25, 2022] [added: 16, 2023] expressed an unqualified opinion. [removed: |]
[removed: | | |] Basis for opinion [removed: |]
[removed: | | | These financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s financial statements based on our audits.] We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB. [removed: |]
[removed: | | |] Critical audit matter [removed: |]
[removed: | | |] The critical audit matter communicated below is a matter arising from the current period audit of the financial statements that was communicated or required to be communicated to the audit committee and that: (1) relates to accounts or disclosures that are material to the financial statements and (2) involved our especially challenging, subjective, or complex judgments. [removed: The communication of critical audit matters does not alter in any way our opinion on the financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates. |]
[removed: | | |] _Accrued Insurance – [added: general liability,] workers’ compensation and [removed: vehicle] [added: auto] liability_ [removed: |]
[removed: | | | As described further in Note 1 to the financial statements, the Company retains, up to certain policy-specified limits, certain risks related to workers’ compensation and vehicle liability.] The estimated costs of existing and future claims under the retained loss [removed: programs] [added: program] are accrued based upon historical trends as incidents occur, whether reported or unreported (although actual settlement of the claims may not be made until future periods) and may be subsequently revised based on developments relating to such claims. [removed: We identified accrued insurance - workers’ compensation and vehicle liability (“accrued insurance”) as a critical audit matter. |]
[removed: | | |] The principal considerations for our determination that accrued insurance is a critical audit matter are that [added: the] accrued insurance liability has [added: a] higher risk of estimation uncertainty due to the [added: utilization of] loss development factors and [removed: inherent] assumptions in actuarial methods used in determining the required liability. [removed: The estimation uncertainty and complexity of the actuarial methods utilized involved especially subjective auditor judgment and an increased extent of effort, including the need to involve an auditor-engaged actuarial specialist. |]
[removed: | | |] Our audit procedures related to [removed: the] accrued insurance [removed: reserve] included the following, among others: [removed: |]
| [removed: ] | [removed: |] ● [removed: Obtained] [added: | We obtained] an understanding, evaluated the design and tested [added: the] operating effectiveness of key [removed: controls relating to accrued insurance,] [added: controls,] including, but not limited to, controls that (1) determine that claims were reported and submitted accurately and timely, (2) determine the underlying data maintained by the Company and the third-party administrator used to develop the accrued insurance reserve was complete and accurate, and (3) determine the third-party actuarial [removed: report] [added: report, including the assumptions,] used in developing [added: and recording] the accrued insurance reserve was reviewed by the Company’s management. |
| [removed: ] | [removed: |] ● [removed: Utilized] [added: | We utilized] an auditor-engaged specialist in evaluating management’s methods and assumptions, including the reasonableness of the selected loss development [removed: factors utilized by management] [added: factors, as well as performed a comparison of actual versus expected claims development] to identify indicators of potential bias. [removed: We also performed retrospective reviews to evaluate the assumptions utilized by management in the determination] [added: The auditor-engaged specialist developed an independent estimate] of the [removed: prior year] [added: range of potential losses] and [removed: current year liability.] [added: compared to the accrued insurance reserve recorded by management.] |
| [removed: ] | [removed: |] ● [removed: Tested] [added: | We tested] the [added: completeness and accuracy of the] underlying data maintained by the Company and the third-party administrator, which was submitted to the Company’s actuary to develop the accrued insurance [removed: reserve, for completeness and accuracy.] [added: reserve.] |
[removed: | | |] /s/ GRANT THORNTON LLP [removed: |]
[removed: | | |] We have served as the Company’s auditor since [removed: 2004. |][added: 2004]
[removed: | | |] Atlanta, Georgia [removed: February 25, 2022 |]
| | [added: ] | [removed: 2021] [added: 2022] | | | [added: 2021 | | |] 2020 | |
| Cash and cash equivalents | | $ | [removed: 105,301] [added: 95,346] | | $ | [removed: 98,477] [added: 105,301] |
| Trade receivables, net of allowance for expected credit losses of [removed: $13,885] [added: $14,073] and [removed: $16,854,] [added: $13,885,] respectively | | | [removed: 139,579] [added: 155,759] | | | [removed: 126,337] [added: 139,579] |
| Financed receivables, short-term, net of allowance for expected credit losses of [removed: $1,463] [added: $1,768] and [removed: $1,297,] [added: $1,463,] respectively | | | [removed: 26,152] [added: 33,618] | | | [removed: 23,716] [added: 26,152] |
| Materials and supplies | | | [removed: 28,926] [added: 29,745] | | | [removed: 30,843] [added: 28,926] |
| Other current assets | | | [removed: 52,422] [added: 34,151] | | | [removed: 35,404] [added: 52,422] |
| /s/ Jerry E. Gahlhoff, Jr. | | /s/ Kenneth D. Krause |
| Jerry E. Gahlhoff, Jr. | | Kenneth D. Krause |
| February 16, 2023 | | |
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
Rollins, Inc.
In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2022, based on criteria established in the 2013 Internal Control—Integrated Framework issued by COSO.
The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management’s Report on Internal Control over Financial Reporting.
Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit.
We conducted our audit in accordance with the standards of the PCAOB.
Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects.
We believe that our audit provides a reasonable basis for our opinion.
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements.
February 16, 2023
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
Rollins, Inc.
We have audited the accompanying consolidated statements of financial position of Rollins, Inc. (a Delaware corporation) and subsidiaries (the “Company”) as of December 31, 2022 and 2021, the related consolidated statements of income, comprehensive income, stockholders’ equity, and cash flows for each of the three years in the period ended December 31, 2022, and the related notes (collectively referred to as the “financial statements”).
These financial statements are the responsibility of the Company’s management.
Our responsibility is to express an opinion on the Company’s financial statements based on our audits.
We conducted our audits in accordance with the standards of the PCAOB.
Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud.
Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks.
Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements.
Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements.
We believe that our audits provide a reasonable basis for our opinion.
The communication of critical audit matters does not alter in any way our opinion on the financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
As described further in note 1 to the financial statements, the Company retains, up to certain policy-specified limits, risks related to claims under general liability, workers’ compensation and auto liability programs (“accrued insurance”).
Historical claims experience is utilized to estimate the current year accrual and the underlying provision for future claims under the retained loss programs.
This actuarially determined accrual and provision includes both reported and unreported claims and may be subsequently revised based on future developments relating to such claims.
We identified accrued insurance as a critical audit matter.
The estimation uncertainty and complexity of the actuarial methods utilized involved especially subjective auditor judgment and an increased level of effort, including the involvement of an auditor-engaged actuarial specialist.
| --- | --- | --- |
Atlanta, Georgia
February 16, 2023
| | | 2022 | | | 2021 | |
| Goodwill | | | 846,704 | | | 786,504 |
| Total assets | | $ | 2,122,028 | | $ | 2,021,540 |
| Total liabilities | | | 854,831 | | | 910,323 |
| Retained earnings | | | 687,069 | | | 530,088 |
| /s/ Gary W. Rollins | | /s/ Julie Bimmerman |
| Gary W. Rollins | | Julie Bimmerman |
| | | |
| February 25, 2022 | | |
| | | | |
| --- | --- | --- | --- |
|  | | | |
 |
| GRANT THORNTON LLP1100 Peachtree St.NE, Suite 1200 Atlanta, GA 30309 D +1 404 330 2000 F +1 404 330 2047 | | | REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM ON INTERNAL CONTROL OVER FINANCIAL REPORTING |
| | | | |
| GT.COM | | | Grant Thornton LLP is the U.S. member firm of Grant Thornton International Ltd (GTIL). GTIL and each of its member firms are separate legal entities and are not a worldwide partnership. |
| | | |
|  | | |
| GRANT THORNTON LLP1100 Peachtree St.NE, Suite 1200 Atlanta, GA 30309 D +1 404 330 2000 F +1 404 330 2047 | | REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM ON CONSOLIDATED FINANCIAL STATEMENTS AND SCHEDULE |
| | | |
| | | We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements. We believe that our audits provide a reasonable basis for our opinion. |
| GT.COM | | Grant Thornton LLP is the U.S. member firm of Grant Thornton International Ltd (GTIL). GTIL and each of its member firms are separate legal entities and are not a worldwide partnership. |
| HIDDEN_ROW | | |
|  | | |
| Goodwill | | | 721,819 | | | 653,176 |
| Deferred income tax liabilities | | | 13,255 | | | 10,612 |
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Balance at December 31, 2018 | | 490,962 | | $ | 490,962 | | — | | $ | — | | $ | 85,386 | | $ | (71,078) | | $ | 206,638 | | $ | 711,908 |
| Net income | | | | | | | | | | | | | | | | | | | 203,347 | | | 203,347 |
| Pension settlement loss, net of tax | | | | | | | | | | | | | | | | 46,022 | | | | | | |
| Cash dividends | | | | | | | | | | | | | | | | | | | (153,836) | | | (153,836) |
| Stock compensation | | 580 | | | 580 | | | | | | | | 13,772 | | | | | | (193) | | | 14,159 |
| Employee stock buybacks | | (396) | | | (396) | | | | | | | | (9,745) | | | | | | 132 | | | (10,009) |
| Impact of adoption of ASC 326 | | | | | | | | | | | | | | | | | | | 2,486 | | | 2,486 |
| Interest rate swaps, net of tax | | | | | | | | | | | | | | | | (104) | | | | | | (104) |
| Pension settlement loss | | | — | | | — | | | 49,898 |
Supplemental Disclosures of Non-Cash Items
Pension—Non-cash decreases/(increases) in the minimum pension liability which were charged/(credited) to other comprehensive income were $0 million, $(0.2) million, and $75.4 million in 2021, 2020, and 2019, respectively.
Business Combinations —There were $17.7 million ($14.5 million of which relates to acquisition holdback and earnout liabilities) in non-cash acquisitions of assets in business combinations for the year ended December 31, 2021, $12.6 million in 2020 and $34.2 million for 2019.
Traditional termite protection uses “Termidor” liquid treatment and/or dry foam and Orkin foam to treat voids and spaces around the property, while baiting termite protection uses baits to disrupt the molting process termites require for growth and offers ongoing protection.
product or service.
There were no large recoveries in 2021, 2020, and 2019.
The Company’s international business is expanding, and we intend to continue to grow the business in foreign markets in the future through reinvestment of foreign deposits and future earnings as well as potential acquisitions of unrelated companies.
Repatriation of cash from the Company’s foreign subsidiaries is not a part of the Company’s current business plan.
An excerpt. Shown here: 40 of 444 rewritten, 40 of 253 added and 40 of 149 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data in the FY2022 filing and the FY2021 filing.
Item 9A. Controls and Procedures
4 rewritten, 0 added, 0 removed, 4 unchanged
The Company has a Disclosure Committee, consisting of certain members of management to assist our Chief Executive Officer (principal executive officer) and [removed: Interim] Chief Financial Officer (principal financial officer) in preparing the disclosures required under the SEC rules and to help ensure that the Company’s disclosure controls and procedures are properly implemented.
The Disclosure Committee, with the participation of our principal executive officer and principal financial officer, conducted an evaluation of the effectiveness of the design and operation of our disclosure controls and procedures, as defined in rules 13a 15(e) and 15d-15(e) under the Securities Exchange Act of 1934, as amended (the “Exchange Act”) as of December 31, [removed: 2021] [added: 2022] (the “Evaluation Date”).
The effectiveness of our internal control over financial reporting as of December 31, [removed: 2021] [added: 2022] has been audited by Grant Thornton LLP, an independent registered public accounting firm, as stated in its report on page 27.
Changes in Internal Controls—There were no changes in our internal control over financial reporting during the fourth quarter of [removed: 2021] [added: 2022] that materially affected or are reasonably likely to materially affect these controls.
Item 10. Directors, Executive Officers and Corporate Governance.
3 rewritten, 0 added, 0 removed, 3 unchanged
The information required by this Item, except that set forth below regarding the Company’s code of ethics, will be set forth in our Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Stockholders and is incorporated herein by reference.
The Proxy Statement will be filed with the SEC within 120 days of the fiscal year ended December 31, [removed: 2021,] [added: 2022,] or by the following business day.
The Company intends to satisfy the disclosure requirement under Item 5.05 of Form [removed: 8-K1] [added: 8-K] regarding an amendment to, or waiver from, a provision of its code of ethics that relates to any elements of the code of ethics definition enumerated in SEC rules by posting such information on its internet website, the address of which is provided above.
Item 11. Executive Compensation.
2 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this Item will be set forth in our Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Stockholders and is incorporated herein by reference.
The Proxy Statement will be filed with the SEC within 120 days of the fiscal year ended December 31, [removed: 2021,] [added: 2022,] or by the following business day.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
2 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this Item will be set forth in our Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Stockholders and is incorporated herein by reference.
The Proxy Statement will be filed with the SEC within 120 days of the fiscal year ended December 31, [removed: 2021,] [added: 2022,] or by the following business day.
Item 13. Certain Relationships and Related Party Transactions, and Director Independence.
1 rewritten, 0 added, 0 removed, 0 unchanged
Information concerning certain relationships and related party transactions and director independence will be included in the Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Stockholders and is incorporated herein by reference.
Item 14. Principal Accounting Fees and Services.
1 rewritten, 0 added, 0 removed, 1 unchanged
Information regarding principal accounting fees and services will be included in the Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Stockholders and is incorporated herein by reference.
Item 15. Exhibits and Financial Statement Schedules
34 rewritten, 23 added, 24 removed, 71 unchanged
| [removed: 3.] [added: 2.] | | Exhibits listed in the accompanying Index to Exhibits are filed as part of this report. The following such exhibits are management contracts or compensatory plans or arrangements: |
| [removed: 10.5*] [added: 10.4*] | [Forms of award agreements under the 2013 Cash Incentive Plan](https://www.sec.gov/Archives/edgar/data/84839/000117120017000077/i17072_ex10-d1.htm) | 10-K | February 24, 2017 | 10(d) | |
| [removed: 10.6*] [added: 10.5*] | [2018 Stock Incentive Plan](https://www.sec.gov/Archives/edgar/data/84839/000008483918000081/rol2018proxy.htm) | DEF 14A | March 21, 2018 | Appendix A | |
| [removed: 10.7*] [added: 10.6*] | [Form of Restricted Stock Grant Agreement](https://www.sec.gov/Archives/edgar/data/84839/000008483908000071/exh10d.htm) | 8-K | April 28, 2008 | 10(d) | |
| [removed: 10.8*] [added: 10.7*] | [Form of Time-Lapse Restricted Stock Agreement](https://www.sec.gov/Archives/edgar/data/84839/000110465912029465/a12-8764_1ex10d1.htm) | 10-Q | April 27, 2012 | 10.1 | |
| [removed: 10.11] [added: 10.17] | [Revolving Credit Agreement dated as of April 30, 2019 between Rollins, Inc. and SunTrust Bank and Bank of America, [removed: N.A](https://www.sec.gov/Archives/edgar/data/84839/000117120019000278/i19356_ex10-1.htm).] [added: N.A](https://www.sec.gov/Archives/edgar/data/84839/000117120019000278/i19356_ex10-1.htm)] | 10-K | February 28, 2020 | [removed: 10.1] [added: (10)(j)] | |
| [removed: 10.12] [added: 10.18] | [Amended Credit Agreement dated as of January 27, 2022 between Rollins, Inc. and Truist Bank in its capacity as Administrative Agent and as a Lender and Bank of America, N.A. as a [removed: Lender*](https://www.sec.gov/Archives/edgar/data/84839/000008483922000011/rol-20211231ex10126165b.htm)] [added: Lender*](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex10d12.htm)] | [removed: ] [added: 10-K] | [removed: ] [added: February 25, 2022] | [removed: ] [added: 10.12] | [removed: X] |
| [removed: 10.13] [added: 10.19] | [Annex A to the Credit Agreement dated as of January 27, 2022 between Rollins, Inc. and Truist Bank in its capacity as Administrative Agent and as a Lender and Bank of America, N.A. as a [removed: Lender](https://www.sec.gov/Archives/edgar/data/84839/000008483922000011/rol-20211231ex101321859.htm)] [added: Lender](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex10d13.htm)] | [removed: ] [added: 10-K] | [removed: ] [added: February 25, 2022] | [removed: ] [added: 10.13] | [removed: X] |
| [removed: 10.14] [added: 10.20] | [Annex B to the Credit Agreement dated as of January 27, 2022 between Rollins, Inc. and Truist Bank in its capacity as Administrative Agent and as a Lender and Bank of America, N.A. as a [removed: Lender](https://www.sec.gov/Archives/edgar/data/84839/000008483922000011/rol-20211231ex1014dc534.htm)] [added: Lender](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex10d14.htm)] | [removed: ] [added: 10-K] | [removed: ] [added: February 25, 2022] | [removed: ] [added: 10.14] | [removed: X] |
| 10.15* | [removed: [Form of Rollins,] [added: [Rollins,] Inc. [removed: 2022] [added: 2023] Executive Bonus [removed: Plan](https://www.sec.gov/Archives/edgar/data/84839/000008483922000011/rol-20211231ex101561e72.htm)] [added: Agreement–Elizabeth B. Chandler](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex10d15.htm)] | | | | X |
| [removed: 10.16*] [added: 10.12*] | [Rollins, Inc. [removed: 2022] [added: 2023] Executive Bonus [removed: Plan - Jerry Gahlhoff](https://www.sec.gov/Archives/edgar/data/84839/000008483922000011/rol-20211231ex10161de0b.htm)] [added: Agreement–Jerry E. Gahlhoff, Jr.](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex10d12.htm)] | | | | X |
| 21 | [Subsidiaries of [removed: Registrant](https://www.sec.gov/Archives/edgar/data/84839/000008483922000011/rol-20211231xex21.htm)] [added: Registrant](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex21.htm)] | | | | X |
| 23.1 | [Consent of Grant Thornton LLP, Independent Registered Public Accounting [removed: Firm](https://www.sec.gov/Archives/edgar/data/84839/000008483922000011/rol-20211231ex231028094.htm)] [added: Firm](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex23d1.htm)] | | | | X |
| 24 | [Powers of Attorney for [removed: Directors](https://www.sec.gov/Archives/edgar/data/84839/000008483922000011/rol-20211231xex24.htm)] [added: Directors](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex24.htm)] | | | | X |
| 31.1 | [Certification of Chief Executive Officer Pursuant to Item 601(b)(31) of Regulation S-K, as adopted pursuant to Section 302 of the Sarbanes-Oxley Act of [removed: 2002](https://www.sec.gov/Archives/edgar/data/84839/000008483922000011/rol-20211231ex3119ad1b7.htm)] [added: 2002](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex31d1.htm)] | | | | X |
| 31.2 | [Certification of Chief Financial Officer Pursuant to Item 601(b)(31) of Regulation S-K, as adopted pursuant to Section 302 of the Sarbanes-Oxley Act of [removed: 2002](https://www.sec.gov/Archives/edgar/data/84839/000008483922000011/rol-20211231ex312fdf033.htm)] [added: 2002](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex31d2.htm)] | | | | X |
| 32.1 | [Certification of Chief Executive Officer and Chief Financial Officer Pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of [removed: 2002](https://www.sec.gov/Archives/edgar/data/84839/000008483922000011/rol-20211231ex321c8b3d3.htm)] [added: 2002](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex32d1.htm)] | | | | X |
| [removed: | | By:] [added: ] | [removed: /s/] Gary W. [removed: Rollins] [added: Rollins, Chairman] | [added: |]
| | | | [removed: Chairman] [added: President] and Chief Executive Officer |
| | | Date: | February [removed: 25, 2022] [added: 16, 2023] |
| | [removed: Chairman] [added: President] and Chief Executive Officer | | | [removed: Interim] [added: Executive Vice President,] Chief Financial Officer and Treasurer |
| | (Principal Executive Officer) | | | [removed: (Principal] [added: Principal] Financial [removed: and Accounting Officer)] [added: Officer] |
| Date: | February [removed: 25, 2022] [added: 16, 2023] | | Date: | February [removed: 25, 2022] [added: 16, 2023] |
The Directors of Rollins, Inc. (listed below) executed a power of attorney appointing [removed: Gary W.][added: Jerry E.]
[removed: Rollins] [added: Gahlhoff, Jr.] their attorney-in-fact, empowering him to sign this report on their behalf.
| [Management’s Report on Internal Control Over Financial Reporting](#MANAGEMENTSREPORTONINTERNALCONTROLOVERFI) | | [removed: 26] [added: 25] |
| [Reports of Independent Registered Public Accounting Firm](#report) (PCAOB ID Number 248) | | [removed: 27] [added: 26] |
| [Consolidated Statements of Financial Position as of December 31, [removed: 2020] [added: 2022] and [removed: 2019](#CONSOLIDATEDSTATEMENTSOFFINANCIALPOSITIO)] [added: 2021](#CONSOLIDATEDSTATEMENTSOFFINANCIALPOSITIO)] | | [removed: 31] [added: 29] |
| [Consolidated Statements of Income for each of the three years in the period ended December 31, [removed: 2020](#CONSOLIDATEDSTATEMENTSOFINCOME_877052)] [added: 2022](#CONSOLIDATEDSTATEMENTSOFINCOME_877052)] | | [removed: 32] [added: 30] |
| [Consolidated Statements of Comprehensive [removed: Earnings] [added: Income] for each of the three years in the period ended December 31, [removed: 2020](#CONSOLIDATEDSTATEMENTSOFCOMPREHENSIVEEAR)] [added: 2022](#CONSOLIDATEDSTATEMENTSOFCOMPREHENSIVEEAR)] | | [removed: 33] [added: 31] |
| [Consolidated Statements of Stockholders’ Equity for each of the three years in the period ended December 31, [removed: 2020](#CONSOLIDATEDSTATEMENTSOFSTOCKHOLDERSEQUI)] [added: 2022](#CONSOLIDATEDSTATEMENTSOFSTOCKHOLDERSEQUI)] | | [removed: 34] [added: 32] |
| [Consolidated Statements of Cash Flows for each of the three years in the period ended December 31, [removed: 2020](#CONSOLIDATEDSTATEMENTSOFCASHFLOWS_411057)] [added: 2022](#CONSOLIDATEDSTATEMENTSOFCASHFLOWS_411057)] | | [removed: 35] [added: 33] |
| [Notes to Consolidated Financial Statements](#NOTESTOCONSOLIDATEDFINANCIALSTATEMENTS_1) | | [removed: 37-66] [added: 34-60] |
| [removed: Schedules not listed above] [added: All schedules] have been omitted as not applicable, immaterial or disclosed in the Consolidated Financial Statements or notes thereto. | | |
| 10.8* | [Form of Time-Lapse Restricted Stock Agreement of Non-Section 16 Reporting Persons](https://www.sec.gov/Archives/edgar/data/84839/000008483922000059/rol-20220930xex10d17.htm) | 10-Q | October 27, 2022 | 10.17 | |
| 10.9* | [Form of Time-Lapse Restricted Stock Agreement for Section 16 Reporting Persons](https://www.sec.gov/Archives/edgar/data/84839/000008483922000059/rol-20220930xex10d18.htm) | 10-Q | October 27, 2022 | 10.18 | |
| 10.10* | [Form of Rollins, Inc. Performance Share Unit Award Agreement](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex10d10.htm) | | | | X |
| 10.11* | [Rollins, Inc. 2023 Executive Bonus Agreement–Gary W. Rollins](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex10d11.htm) | | | | X |
| 10.13* | [Rollins, Inc. 2023 Executive Bonus Agreement–Kenneth D. Krause](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex10d13.htm) | | | | X |
| 10.14* | [Rollins, Inc. 2023 Executive Bonus Agreement–John F. Wilson](https://www.sec.gov/Archives/edgar/data/84839/000008483923000006/rol-20221231xex10d14.htm) | | | | X |
| 10.16* | [Offer Letter dated July 25, 2022, between Kenneth D. Krause and the Company](https://www.sec.gov/Archives/edgar/data/84839/000008483922000059/rol-20220930xex10d19.htm) | 10-Q | October 27, 2022 | 10.19 | |
| | | By: | /s/ Jerry E. Gahlhoff, Jr. |
| | | | Jerry E. Gahlhoff, Jr. |
| By: | /s/ Jerry E. Gahlhoff, Jr. | | By: | /s/ Kenneth D. Krause |
| | Jerry E. Gahlhoff, Jr. | | | Kenneth D. Krause |
| | | | | |
| By: | /s/ Traci Hornfeck | | | |
| | Traci Hornfeck | | | |
| | Chief Accounting Officer | | | |
| | (Principal Accounting Officer) | | | |
| | | | | |
| Date: | February 16, 2023 | | | |
| | | | | |
| | Louise S. Sams, Director | |
| /s/ Jerry E. Gahlhoff, Jr. | | |
| Jerry E. Gahlhoff, Jr. | | |
| February 16, 2023 | | |
| 2. | | The financial statement schedule listed in the accompanying Index to Consolidated Financial Statements and Schedule is filed as part of this report. |
| 10.4* | [Written description of Rollins, Inc. Performance-Based Incentive Cash Compensation Plan for Executive Officer](https://www.sec.gov/Archives/edgar/data/84839/000117120021000049/i21043_ex10-a.htm) | 8-K | February 1, 2021 | 10(a) | |
| 10.9* | [Summary of Compensation Arrangements with Executive Officers](https://www.sec.gov/Archives/edgar/data/84839/000104746911001349/a2202150zex-10_q.htm) | 10-K | February 25, 2011 | (10)(q) | |
| 10.10* | [Summary of Compensation Arrangements with Non-Employee Directors](https://www.sec.gov/Archives/edgar/data/84839/000155278115000273/e00088_ex10i.htm) | 10-K | February 25, 2015 | 10(i) | |
| | | | Gary W. Rollins |
| By: | /s/ Gary W. Rollins | | By: | /s/ Julie Bimmerman |
| | Gary W. Rollins | | | Julie Bimmerman |
| | Thomas J. Lawley, MD, Director | |
| /s/ Gary W. Rollins | | |
| Gary W. Rollins | | |
| February 25, 2022 | | |
ROLLINS, INC. AND SUBSIDIARIES
| [Schedule II – Valuation and Qualifying Accounts](#SCHEDULEIIVALUATIONANDQUALIFYINGACCOUNTS) | | 67 |
SCHEDULE II – VALUATION AND QUALIFYING ACCOUNTS
| | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | Allowance for Expected Credit Losses | | | | | | | | | | | | | |
| | | Balance at | | | | | | Charged to | | | Net | | | | |
| | | Beginning of | | | Adoption of | | | Costs and | | | (Deductions) | | | Balance at | |
| (in thousands) | | Year | | | ASC 326 | | | Expenses | | | Recoveries | | | End of Year | |
| 2021 | | $ | 20,085 | | $ | — | | $ | 15,285 | | $ | (17,500) | | $ | 17,870 |
| 2020 | | $ | 19,658 | | $ | (3,330) | | $ | 17,536 | | $ | (13,779) | | $ | 20,085 |
| 2019 | | $ | 16,666 | | $ | — | | $ | 15,145 | | $ | (12,153) | | $ | 19,658 |