 filings.tools
Item 2. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
69K characters. Original on sec.gov · Markdown
Item 2. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following discussion should be read in conjunction with our financial statements and the related notes that appear elsewhere in this quarterly report on Form 10-Q.
GENERAL OPERATING COMMENTS
Below is a summary of the key operating results for the three months ended September 30, 2024:
-
Third quarter revenues were $916.3 million, an increase of 9.0% over the third quarter of 2023 with organic revenues* increasing 7.7%.
-
Quarterly operating income was $191.8 million, an increase of 8.3% over the third quarter of 2023. Quarterly operating margin was 20.9%, a decrease of 20 basis points versus the third quarter of 2023. Adjusted operating income* was $196.0 million, an increase of 4.5% over the prior year. Adjusted operating income margin* was 21.4%, a decrease of 90 basis points compared to the prior year.
-
Adjusted EBITDA* was $219.5 million, an increase of 5.5% over the prior year. Adjusted EBITDA margin* was 24.0%, a decrease of 80 basis points versus the third quarter of 2023.
-
Quarterly net income was $136.9 million, an increase of 7.1% over the prior year. Adjusted net income* was $139.6 million, an increase of 3.3% over the prior year.
-
Quarterly EPS was $0.28 per diluted share, a 7.7% increase over the prior year EPS of $0.26. Adjusted EPS* was $0.29 per diluted share, an increase of 3.6% over the prior year.
-
Operating cash flow was $146.9 million for the quarter, an increase of 15.4% compared to the prior year. The Company invested $23.9 million in acquisitions, $7.5 million in capital expenditures, and paid dividends totaling $72.8 million.
Demand remains favorable to start the fourth quarter and the pipeline of acquisition activity remains healthy. Although we continue to navigate a highly uncertain macro-environment, we believe we are well positioned to continue to deliver strong results in the last quarter of 2024.
We remain focused on driving 7% to 8% organic revenue growth while adding 2% to 3% of inorganic revenue growth for 2024. While we believe this goal is achievable, we acknowledge the potential impact weather as well as volatility in one-time business, and staffing levels, amongst other factors, might have on revenue performance. We continue to focus on improving the efficiency of our business model while investing in programs aimed at growing our business across our service offerings.
*Amounts are non-GAAP financial measures. See the schedules below for a discussion of non-GAAP financial metrics including a reconciliation of the most directly comparable GAAP measure.
IMPACT OF ECONOMIC TRENDS
The continued disruption in economic markets due to inflation, changing interest rates, business interruptions due to natural disasters and changes in weather patterns, employee shortages, and supply chain issues, all pose challenges which may adversely affect our future performance. The Company continues to execute various strategies previously implemented to help mitigate the impact of these economic disruptors.
However, the Company cannot reasonably estimate whether these strategies will help mitigate the impact of these economic disruptors in the future.
The Company’s condensed consolidated financial statements reflect estimates and assumptions made by management that affect the reported amounts of assets and liabilities and related disclosures as of the date of the condensed consolidated financial statements. The Company considered the impact of economic trends on the assumptions and estimates used in preparing the condensed consolidated financial statements. In the opinion of management, all material adjustments necessary for a fair presentation of the Company’s financial results for the quarter have been made. These adjustments are of a normal recurring nature but are complicated by the continued uncertainty surrounding these macro economic trends.
ROLLINS, INC. AND SUBSIDIARIES
The severity, magnitude and duration of certain economic trends continue to be uncertain and are difficult to predict. Therefore, our accounting estimates and assumptions may change over time in response to economic trends and may change materially in future periods.
The extent to which changing interest rates, inflation and other economic trends will continue to impact the Company’s business, financial condition and results of operations is uncertain. Therefore, we cannot reasonably estimate the full future impacts of these matters at this time.
Tax Legislation Developments
The Organization for Economic Co-operation and Development ("OECD") has proposed a global minimum tax of 15% of reported profits ("Pillar Two") for multinational enterprises with annual global revenues exceeding €750 million. Pillar Two has been agreed upon in principle by over 140 countries and is intended to apply for tax years beginning in 2024. The OECD has issued administrative guidance (including transitional safe harbor rules) in conjunction with the implementation of the Pillar Two global minimum tax. The Company has evaluated the impact of these rules and currently believes they will not have any material impact on financial results in 2024 due to certain transitional safe harbors. The Company will continue to monitor the potential impact of Pillar Two proposals and developments on our condensed consolidated financial statements and related disclosures as various tax jurisdictions begin enacting such legislation.
RESULTS OF OPERATIONS
Quarter ended September 30, 2024 compared to quarter ended September 30, 2023
| Three Months Ended September 30, | ||||||||||||||||||||
| Variance | ||||||||||||||||||||
| (in thousands, except per share data) | 2024 | 2023 | $ | % | ||||||||||||||||
| GAAP Metrics | ||||||||||||||||||||
| Revenues | $ | 916,270 | $ | 840,427 | $ | 75,843 | 9.0 | % | ||||||||||||
| Gross profit (1) | $ | 494,378 | $ | 451,894 | $ | 42,484 | 9.4 | % | ||||||||||||
| Gross profit margin (1) | 54.0 | % | 53.8 | % | 20 | bps | ||||||||||||||
| Operating income | $ | 191,796 | $ | 177,124 | $ | 14,672 | 8.3 | % | ||||||||||||
| Operating income margin | 20.9 | % | 21.1 | % | (20) | bps | ||||||||||||||
| Net income | $ | 136,913 | $ | 127,777 | $ | 9,136 | 7.1 | % | ||||||||||||
| EPS | $ | 0.28 | $ | 0.26 | $ | 0.02 | 7.7 | % | ||||||||||||
| Operating cash flow | $ | 146,947 | $ | 127,355 | $ | 19,592 | 15.4 | % | ||||||||||||
| Non-GAAP Metrics | ||||||||||||||||||||
| Adjusted operating income (2) | $ | 196,012 | $ | 187,582 | $ | 8,430 | 4.5 | % | ||||||||||||
| Adjusted operating margin (2) | 21.4 | % | 22.3 | % | (90) | bps | ||||||||||||||
| Adjusted net income (2) | $ | 139,617 | $ | 135,191 | $ | 4,426 | 3.3 | % | ||||||||||||
| Adjusted EPS (2) | $ | 0.29 | $ | 0.28 | $ | 0.01 | 3.6 | % | ||||||||||||
| Adjusted EBITDA (2) | $ | 219,460 | $ | 208,038 | $ | 11,422 | 5.5 | % | ||||||||||||
| Adjusted EBITDA margin (2) | 24.0 | % | 24.8 | % | (80) | bps | ||||||||||||||
| Free cash flow (2) | $ | 139,425 | $ | 120,487 | $ | 18,938 | 15.7 | % |
(1) Exclusive of depreciation and amortization
(2) Amounts are non-GAAP financial measures. See "Non-GAAP Financial Measures" of this Form 10-Q for a discussion of non-GAAP financial metrics including a reconciliation of the most directly comparable GAAP measure.
ROLLINS, INC. AND SUBSIDIARIES
Revenues
The following presents a summary of revenues by product and service offering:
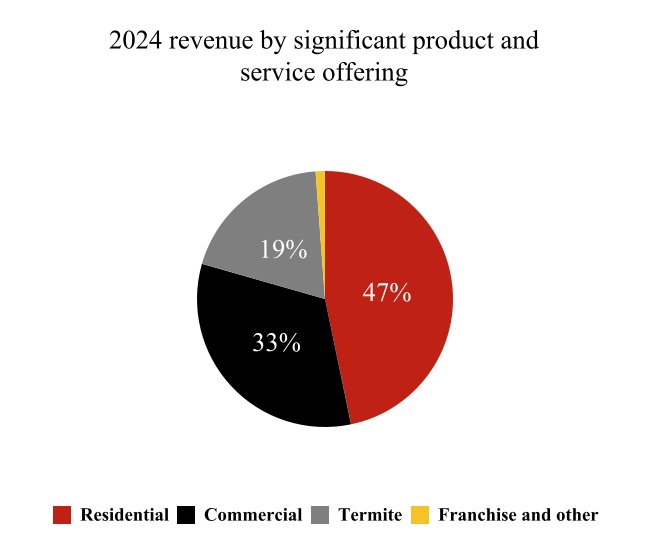
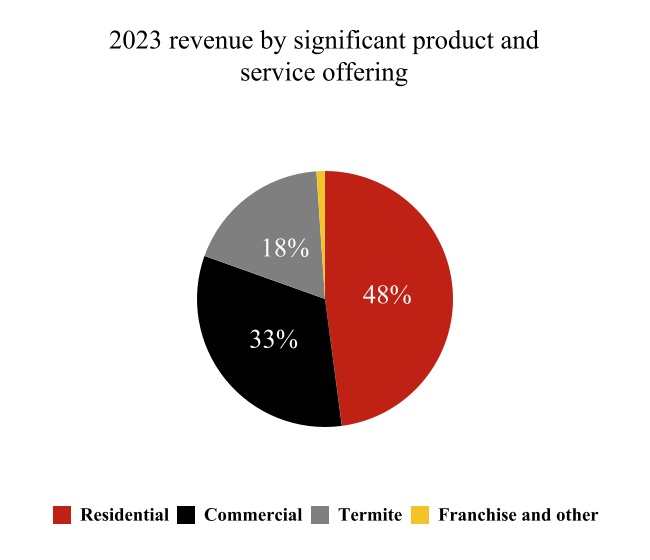
Revenues for the quarter ended September 30, 2024 were $916.3 million, an increase of $75.8 million, or 9.0%, from 2023 revenues of $840.4 million. The increase in revenues was driven by demand from our customers across all major service offerings, partially offset by weakness late in the quarter associated with hurricane activity. Organic revenue* growth was 7.7% with acquisitions adding 2.1% in the quarter, offset by divestitures of 0.8%. Residential pest control revenue increased 6.4%, commercial pest control revenue increased 9.4% and termite and ancillary services grew 14.5% including both organic and acquisition-related growth in each area. Organic revenue* growth was strong across our service offerings, growing 4.9% in residential, 8.1% in commercial, and 13.7% in termite and ancillary activity. Residential organic revenue* growth was driven by stronger recurring revenue growth but was offset by slower one-time business.
Revenues are impacted by the seasonal nature of the Company’s pest and termite control services. The increase in pest activity, as well as the metamorphosis of termites in the spring and summer (the occurrence of which is determined by the change in seasons), has historically resulted in an increase in the Company’s revenues as evidenced by the following table:
| Consolidated Net Revenues | |||||||||||||||||
| (in thousands) | 2024 | 2023 | 2022 | ||||||||||||||
| First Quarter | $ | 748,349 | $ | 658,015 | $ | 590,680 | |||||||||||
| Second Quarter | 891,920 | 820,750 | 714,049 | ||||||||||||||
| Third Quarter | 916,270 | 840,427 | 729,704 | ||||||||||||||
| Fourth Quarter | — | 754,086 | 661,390 | ||||||||||||||
| Year to date | $ | 2,556,539 | $ | 3,073,278 | $ | 2,695,823 |
Gross Profit (exclusive of Depreciation and Amortization)
Gross profit for the quarter ended September 30, 2024 was $494.4 million, an increase of $42.5 million, or 9.4%, compared to $451.9 million for the quarter ended September 30, 2023. Gross margin improved 20 basis points to 54.0% in 2024 compared to 53.8% in 2023, as pricing more than offset inflationary pressures. We saw good leverage across a number of cost categories with the most significant leverage in fleet costs and materials and supplies, partially offset by investments in people and less favorable insurance and claims.
ROLLINS, INC. AND SUBSIDIARIES
Sales, General and Administrative
For the quarter ended September 30, 2024, sales, general and administrative ("SG&A") expenses were $274.9 million and increased $30.0 million, or 12.3%, compared to the quarter ended September 30, 2023.
As a percentage of revenue, SG&A increased to 30.0% from 29.1% in the prior year. Selling and marketing costs have increased as we continue to invest in growth initiatives, including advertising. Insurance and claims costs have also increased, offset by leverage associated with lower administrative costs and fleet costs.
While we are focused on driving improvement in SG&A as a percentage of revenue, we expect to continue to invest in growth initiatives, which may, from time to time, impact this ratio.
Restructuring Costs
For the quarter ended September 30, 2024 restructuring costs decreased by $5.2 million. During the quarter ended September 30, 2023, we executed a restructuring program to modernize our workforce. No such costs were incurred during the quarter ended September 30, 2024.
Depreciation and Amortization
For the quarter ended September 30, 2024, depreciation and amortization increased $3.0 million, or 12.1%, compared to the quarter ended September 30, 2023. The increase was due to higher amortization of intangible assets from acquisitions.
Operating Income
For the quarter ended September 30, 2024, operating income increased $14.7 million, or 8.3%, compared to the prior year.
As a percentage of revenue, operating income was 20.9%, a decrease of 20 basis points compared to the third quarter of 2023. Operating margin declined mostly due to investments in people, growth initiatives, and less favorable insurance and claims.
While we expect to continue to invest in our business in the fourth quarter, we expect the pace of investment to moderate as we go through the final quarter of the year.
Interest Expense, Net
During the quarter ended September 30, 2024, interest expense, net increased $1.6 million compared to the prior year primarily due to the higher average debt balance. The increase was driven by the debt associated with the share repurchase completed in the third quarter of 2023.
Other Income, Net
During the quarter ended September 30, 2024, other income increased $0.1 million primarily due to higher gains on non-operational asset sales.
Income Taxes
The Company’s effective tax rate was 26.1% in the third quarter of 2024 and 25.7% in the third quarter of 2023. The 2024 rate was higher primarily due to an increase in non-deductible expenses and foreign tax expense in 2024.
ROLLINS, INC. AND SUBSIDIARIES
Nine months ended September 30, 2024 compared to nine months ended September 30, 2023
| Nine Months Ended September 30, | ||||||||||||||||||||
| Variance | ||||||||||||||||||||
| (in thousands, except per share data) | 2024 | 2023 | $ | % | ||||||||||||||||
| GAAP Metrics | ||||||||||||||||||||
| Revenues | $ | 2,556,539 | $ | 2,319,192 | $ | 237,347 | 10.2 | % | ||||||||||||
| Gross profit (1) | $ | 1,358,804 | $ | 1,219,626 | $ | 139,178 | 11.4 | % | ||||||||||||
| Gross profit margin (1) | 53.2 | % | 52.6 | % | 60 | bps | ||||||||||||||
| Operating income | $ | 506,597 | $ | 444,153 | $ | 62,444 | 14.1 | % | ||||||||||||
| Operating income margin | 19.8 | % | 19.2 | % | 60 | bps | ||||||||||||||
| Net income | $ | 360,704 | $ | 326,154 | $ | 34,550 | 10.6 | % | ||||||||||||
| EPS | $ | 0.74 | $ | 0.66 | $ | 0.08 | 12.1 | % | ||||||||||||
| Operating cash flow | $ | 419,495 | $ | 375,541 | $ | 43,954 | 11.7 | % | ||||||||||||
| Non-GAAP Metrics | ||||||||||||||||||||
| Adjusted operating income (2) | $ | 520,286 | $ | 459,872 | $ | 60,414 | 13.1 | % | ||||||||||||
| Adjusted operating margin (2) | 20.4 | % | 19.8 | % | 60 | bps | ||||||||||||||
| Adjusted net income (2) | $ | 370,194 | $ | 333,217 | $ | 36,977 | 11.1 | % | ||||||||||||
| Adjusted EPS (2) | $ | 0.76 | $ | 0.68 | $ | 0.08 | 11.8 | % | ||||||||||||
| Adjusted EBITDA (2) | $ | 590,331 | $ | 525,055 | $ | 65,276 | 12.4 | % | ||||||||||||
| Adjusted EBITDA margin (2) | 23.1 | % | 22.6 | % | 50 | bps | ||||||||||||||
| Free cash flow (2) | $ | 396,106 | $ | 354,262 | $ | 41,844 | 11.8 | % |
(1) Exclusive of depreciation and amortization
(2) Amounts are non-GAAP financial measures. See "Non-GAAP Financial Measures" of this Form 10-Q for a discussion of non-GAAP financial metrics including a reconciliation of the most closely correlated GAAP measure.
ROLLINS, INC. AND SUBSIDIARIES
Revenues
The following presents a summary of revenues by product and service offering:


Revenues for the nine months ended September 30, 2024 were $2.6 billion, an increase of $237.3 million, or 10.2%, from 2023 revenues of $2.3 billion. The increase in revenues was driven by demand from our customers across all major service offerings. Organic revenue* growth was 7.7% with acquisitions adding 3.3% in the nine months ended September 30, 2024, offset by divestitures of 0.8%. Residential pest control revenue increased 9.0%, commercial pest control revenue increased 10.2% and termite and ancillary services grew 12.7%, including both organic and acquisition-related growth in each area. Organic revenue* growth was strong across our service offerings, growing 4.9% in residential, 8.9% in commercial, and 11.4% in termite and ancillary activity. Residential organic revenue* growth was driven by stronger recurring revenue growth but was offset by slower one-time business.
Gross Profit (exclusive of Depreciation and Amortization)
Gross profit for the nine months ended September 30, 2024 was $1.4 billion, an increase of $139.2 million, or 11.4%, compared to $1.2 billion for the nine months ended September 30, 2023. Gross margin improved 60 basis points to 53.2% in 2024 compared to 52.6% in 2023, as pricing more than offset inflationary pressures. We saw leverage across several areas, including fleet and materials and supplies.
Sales, General and Administrative
For the nine months ended September 30, 2024, SG&A expenses increased $72.9 million, or 10.5%, compared to the nine months ended September 30, 2023. The increase is driven by expenses associated with growth initiatives aimed at capitalizing on the health of our underlying markets.
As a percentage of revenue, SG&A expenses increased to 30.1% from 30.0% in the prior year. Selling and marketing costs have increased as we continue to invest in growth initiatives, offset by leverage associated with lower administrative costs.
ROLLINS, INC. AND SUBSIDIARIES
Restructuring Costs
For the nine months ended September 30, 2024, restructuring costs decreased by $5.2 million. During the nine months ended September 30, 2023, we executed a restructuring program to modernize our workforce. No such costs were incurred during the nine months ended September 30, 2024.
Depreciation and Amortization
For the nine months ended September 30, 2024, depreciation and amortization increased $9.1 million, or 12.3%, compared to the nine months ended September 30, 2023. The increase was primarily due to higher amortization of intangible assets from acquisitions, most notably from the acquisition of FPC Holdings, LLC ("Fox Pest Control", or "Fox").
Operating Income
For the nine months ended September 30, 2024, operating income increased $62.4 million, or 14.1%, compared to the nine months ended September 30, 2023.
As a percentage of revenue, operating income increased to 19.8% from 19.2% in the prior year. Operating margin improved due to revenue growth and the changes noted in gross profit and SG&A above.
Interest Expense, Net
For the nine months ended September 30, 2024, interest expense, net increased $11.9 million, compared to the nine months ended September 30, 2023, due to the increase in the average debt balance associated with the share repurchase completed in the third quarter of 2023 and the acquisition of Fox Pest Control in the second quarter of 2023.
Other Income, Net
During the nine months ended September 30, 2024, other income decreased $5.3 million compared to the nine months ended September 30, 2023, due to lower gains on non-operational asset sales.
Income Taxes
During the nine months ended September 30, 2024, the Company’s effective tax rate decreased to 25.6% compared to 25.8% in 2023 due to a decrease in foreign tax expense in 2024.
We expect the effective tax rate to approximate 26% for the full year. This implies a fourth quarter rate in excess of 27%.
ROLLINS, INC. AND SUBSIDIARIES
Non-GAAP Financial Measures
Reconciliation of GAAP and non-GAAP Financial Measures
The Company has used the non-GAAP financial measures of organic revenues, organic revenues by type, adjusted operating income, adjusted operating margin, adjusted net income, adjusted earnings per share (“EPS”), earnings before interest, taxes, depreciation and amortization (“EBITDA”), EBITDA margin, Adjusted EBITDA, adjusted EBITDA margin, incremental EBITDA margin, adjusted incremental EBITDA margin, free cash flow, free cash flow conversion, net debt, net leverage ratio, and adjusted sales, general and administrative expenses ("SG&A") in this Form 10-Q. Organic revenue is calculated as revenue less the revenue from acquisitions completed within the prior 12 months and excluding the revenue from divested businesses. Acquisition revenue is based on the trailing 12-month revenue of our acquired entities. Adjusted operating income and adjusted operating income margin are calculated by adding back to the GAAP measures those expenses resulting from the amortization of certain intangible assets, adjustments to the fair value of contingent consideration resulting from the acquisition of Fox, and restructuring costs related to restructuring and workforce reduction plans. Adjusted net income and adjusted EPS are calculated by adding back to the GAAP measure amortization of certain intangible assets, adjustments to the fair value of contingent consideration resulting from the acquisition of Fox, and restructuring costs related to restructuring and workforce reduction plans, and excluding gains and losses on the sale of non-operational assets and by further subtracting the tax impact of those expenses, gains, or losses. Adjusted EBITDA and adjusted EBITDA margin are calculated by adding back to the GAAP measures those expenses resulting from the adjustments to the fair value of contingent consideration resulting from the acquisition of Fox, restructuring costs related to restructuring and workforce reduction plans, and excluding gains and losses on the sale of non-operational assets. Incremental EBITDA margin is calculated as the change in EBITDA divided by the change in revenue. Adjusted incremental EBITDA margin is calculated as the change in adjusted EBITDA divided by the change in revenue. Free cash flow is calculated by subtracting capital expenditures from cash provided by operating activities. Free cash flow conversion is calculated as free cash flow divided by net income. Net debt is calculated as total long-term debt less cash and cash equivalents. Net leverage ratio is calculated by dividing net debt by trailing twelve-month EBITDA. Adjusted SG&A is calculated by removing the adjustments to the fair value of contingent consideration resulting from the acquisition of Fox. These measures should not be considered in isolation or as a substitute for revenues, net income, earnings per share or other performance measures prepared in accordance with GAAP.
Management uses adjusted operating income, adjusted operating income margin, adjusted net income, adjusted EPS, EBITDA, EBITDA margin, adjusted EBITDA, adjusted EBITDA margin, incremental EBITDA margin, adjusted incremental EBITDA margin, and adjusted SG&A as measures of operating performance because these measures allow the Company to compare performance consistently over various periods. Management also uses organic revenues, and organic revenues by type to compare revenues over various periods excluding the impact of acquisitions and divestitures. Management uses free cash flow to demonstrate the Company’s ability to maintain its asset base and generate future cash flows from operations. Management uses free cash flow conversion to demonstrate how much net income is converted into cash. Management uses net debt as an assessment of overall liquidity, financial flexibility, and leverage. Net leverage ratio is useful to investors because it is an indicator of our ability to meet our future financial obligations. Management believes all of these non-GAAP financial measures are useful to provide investors with information about current trends in, and period-over-period comparisons of, the Company's results of operations. An analysis of any non-GAAP financial measure should be used in conjunction with results presented in accordance with GAAP.
A non-GAAP financial measure is a numerical measure of financial performance, financial position, or cash flows that either 1) excludes amounts, or is subject to adjustments that have the effect of excluding amounts, that are included in the most directly comparable measure calculated and presented in accordance with GAAP in the statement of operations, balance sheet or statement of cash flows, or 2) includes amounts, or is subject to adjustments that have the effect of including amounts, that are excluded from the most directly comparable measure so calculated and presented.
Set forth below is a reconciliation of the non-GAAP financial measures contained in this report with their most directly comparable GAAP measures (unaudited, in thousands, except per share data and margins).
ROLLINS, INC. AND SUBSIDIARIES
| Three Months Ended September 30, | Variance | Nine Months Ended September 30, | Variance | ||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2023 | $ | % | 2024 | 2023 | $ | % | ||||||||||||||||||||||||||||||||||||||||
| Reconciliation of Operating Income to Adjusted Operating Income and Adjusted Operating Income Margin | |||||||||||||||||||||||||||||||||||||||||||||||
| Operating income | $ | 191,796 | $ | 177,124 | $ | 506,597 | $ | 444,153 | |||||||||||||||||||||||||||||||||||||||
| Fox acquisition-related expenses (1) | 4,216 | 5,262 | 13,689 | 10,523 | |||||||||||||||||||||||||||||||||||||||||||
| Restructuring costs (2) | — | 5,196 | — | 5,196 | |||||||||||||||||||||||||||||||||||||||||||
| Adjusted operating income | $ | 196,012 | $ | 187,582 | 8,430 | 4.5 | $ | 520,286 | $ | 459,872 | 60,414 | 13.1 | |||||||||||||||||||||||||||||||||||
| Revenues | $ | 916,270 | $ | 840,427 | $ | 2,556,539 | $ | 2,319,192 | |||||||||||||||||||||||||||||||||||||||
| Operating income margin | 20.9 | % | 21.1 | % | 19.8 | % | 19.2 | % | |||||||||||||||||||||||||||||||||||||||
| Adjusted operating margin | 21.4 | % | 22.3 | % | 20.4 | % | 19.8 | % | |||||||||||||||||||||||||||||||||||||||
| Reconciliation of Net Income to Adjusted Net Income and Adjusted EPS (6) | |||||||||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 136,913 | $ | 127,777 | $ | 360,704 | $ | 326,154 | |||||||||||||||||||||||||||||||||||||||
| Fox acquisition-related expenses (1) | 4,216 | 5,262 | 13,689 | 10,523 | |||||||||||||||||||||||||||||||||||||||||||
| Restructuring costs (2) | — | 5,196 | — | 5,196 | |||||||||||||||||||||||||||||||||||||||||||
| Gain on sale of assets, net (3) | (582) | (493) | (933) | (6,226) | |||||||||||||||||||||||||||||||||||||||||||
| Tax impact of adjustments (4) | (930) | (2,551) | (3,266) | (2,430) | |||||||||||||||||||||||||||||||||||||||||||
| Adjusted net income | $ | 139,617 | $ | 135,191 | 4,426 | 3.3 | $ | 370,194 | $ | 333,217 | 36,978 | 11.1 | |||||||||||||||||||||||||||||||||||
| EPS - basic and diluted | $ | 0.28 | $ | 0.26 | $ | 0.74 | $ | 0.66 | |||||||||||||||||||||||||||||||||||||||
| Fox acquisition-related expenses (1) | 0.01 | 0.01 | 0.03 | 0.02 | |||||||||||||||||||||||||||||||||||||||||||
| Restructuring costs (2) | — | 0.01 | — | 0.01 | |||||||||||||||||||||||||||||||||||||||||||
| Gain on sale of assets, net (3) | — | — | — | (0.01) | |||||||||||||||||||||||||||||||||||||||||||
| Tax impact of adjustments (4) | — | (0.01) | (0.01) | — | |||||||||||||||||||||||||||||||||||||||||||
| Adjusted EPS - basic and diluted (5) | $ | 0.29 | $ | 0.28 | 0.01 | 3.6 | $ | 0.76 | $ | 0.68 | 0.08 | 11.8 | |||||||||||||||||||||||||||||||||||
| Weighted average shares outstanding – basic | 484,317 | 490,775 | 484,231 | 491,980 | |||||||||||||||||||||||||||||||||||||||||||
| Weighted average shares outstanding – diluted | 484,359 | 490,965 | 484,270 | 492,158 | |||||||||||||||||||||||||||||||||||||||||||
| Reconciliation of Net Income to EBITDA, Adjusted EBITDA, EBITDA Margin, Incremental EBITDA Margin, Adjusted EBITDA Margin, and Adjusted Incremental EBITDA Margin (6) | |||||||||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 136,913 | $ | 127,777 | $ | 360,704 | $ | 326,154 | |||||||||||||||||||||||||||||||||||||||
| Depreciation and amortization | 27,664 | 24,668 | 82,685 | 73,609 | |||||||||||||||||||||||||||||||||||||||||||
| Interest expense, net | 7,150 | 5,547 | 22,650 | 10,797 | |||||||||||||||||||||||||||||||||||||||||||
| Provision for income taxes | 48,315 | 44,293 | 124,176 | 113,428 | |||||||||||||||||||||||||||||||||||||||||||
| EBITDA | $ | 220,042 | $ | 202,285 | 17,757 | 8.8 | $ | 590,215 | $ | 523,988 | 66,227 | 12.6 | |||||||||||||||||||||||||||||||||||
| Fox acquisition-related expenses (1) | — | 1,050 | 1,049 | 2,097 | |||||||||||||||||||||||||||||||||||||||||||
| Restructuring costs (2) | — | 5,196 | — | 5,196 | |||||||||||||||||||||||||||||||||||||||||||
| Gain on sale of assets, net (3) | (582) | (493) | (933) | (6,226) | |||||||||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA | $ | 219,460 | $ | 208,038 | 11,422 | 5.5 | $ | 590,331 | $ | 525,055 | 65,276 | 12.4 | |||||||||||||||||||||||||||||||||||
| Revenues | $ | 916,270 | $ | 840,427 | $ | 2,556,539 | $ | 2,319,192 | |||||||||||||||||||||||||||||||||||||||
| EBITDA margin | 24.0 | % | 24.1 | % | 23.1 | % | 22.6 | % | |||||||||||||||||||||||||||||||||||||||
| Incremental EBITDA margin | 23.4 | % | 27.9 | % | |||||||||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA margin | 24.0 | % | 24.8 | % | 23.1 | % | 22.6 | % | |||||||||||||||||||||||||||||||||||||||
| Adjusted incremental EBITDA margin | 15.1 | % | 27.5 | % | |||||||||||||||||||||||||||||||||||||||||||
| Reconciliation of Net Cash Provided by Operating Activities to Free Cash Flow and Free Cash Flow Conversion | |||||||||||||||||||||||||||||||||||||||||||||||
| Net cash provided by operating activities | $ | 146,947 | $ | 127,355 | $ | 419,495 | $ | 375,541 | |||||||||||||||||||||||||||||||||||||||
| Capital expenditures | (7,522) | (6,868) | (23,389) | (21,279) | |||||||||||||||||||||||||||||||||||||||||||
| Free cash flow | $ | 139,425 | $ | 120,487 | 18,938 | 15.7 | $ | 396,106 | $ | 354,262 | 41,844 | 11.8 | |||||||||||||||||||||||||||||||||||
| Free cash flow conversion | 101.8 | % | 94.3 | % | 109.8 | % | 108.6 | % |
(1) Consists of expenses resulting from the amortization of certain intangible assets and adjustments to the fair value of contingent consideration resulting from the acquisition of Fox. While we exclude such expenses in this non-GAAP measure, the revenue from the acquired company is reflected in this non-GAAP measure and the acquired assets contribute to revenue generation.
ROLLINS, INC. AND SUBSIDIARIES
(2) Restructuring costs consist of costs primarily related to severance and benefits paid to employees pursuant to restructuring and workforce reduction plans.
(3) Consists of the gain or loss on the sale of non-operational assets.
(4) The tax effect of the adjustments is calculated using the applicable statutory tax rates for the respective periods.
(5) In some cases, the sum of the individual EPS amounts may not equal total non-GAAP EPS calculations due to rounding.
(6) In the first quarter of 2024, we revised the non-GAAP metrics adjusted net income, adjusted EPS, and adjusted EBITDA to exclude gains and losses related to non-operational asset sales. These measures are of operating performance and we believe excluding the gains and losses on non-operational assets allows us to better compare our operating performance consistently over various periods. Refer to our first quarter 2024 press release for fully revised quarterly metrics.
| Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||||||||||
| Variance | Variance | ||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2023 (7) | $ | % | 2024 | 2023 (7) | $ | % | ||||||||||||||||||||||||||||||||||||||||
| Reconciliation of Revenues to Organic Revenues | |||||||||||||||||||||||||||||||||||||||||||||||
| Revenues | $ | 916,270 | $ | 840,427 | 75,843 | 9.0 | $ | 2,556,539 | $ | 2,319,192 | 237,347 | 10.2 | |||||||||||||||||||||||||||||||||||
| Revenues from acquisitions | (17,339) | — | (17,339) | 2.1 | (77,479) | — | (77,479) | 3.3 | |||||||||||||||||||||||||||||||||||||||
| Revenues of divestitures | — | (5,823) | 5,823 | (0.8) | — | (16,500) | 16,500 | (0.8) | |||||||||||||||||||||||||||||||||||||||
| Organic revenues | $ | 898,931 | $ | 834,604 | 64,327 | 7.7 | $ | 2,479,060 | $ | 2,302,692 | 176,368 | 7.7 | |||||||||||||||||||||||||||||||||||
| Reconciliation of Residential Revenues to Organic Residential Revenues | |||||||||||||||||||||||||||||||||||||||||||||||
| Residential revenues | $ | 428,290 | $ | 402,559 | 25,731 | 6.4 | $ | 1,166,042 | $ | 1,069,403 | 96,639 | 9.0 | |||||||||||||||||||||||||||||||||||
| Residential revenues from acquisitions | (9,571) | — | (9,571) | 2.4 | (54,257) | — | (54,257) | 5.1 | |||||||||||||||||||||||||||||||||||||||
| Residential revenues of divestitures | — | (3,263) | 3,263 | (0.9) | — | (9,668) | 9,668 | (1.0) | |||||||||||||||||||||||||||||||||||||||
| Residential organic revenues | $ | 418,719 | $ | 399,296 | 19,423 | 4.9 | $ | 1,111,785 | $ | 1,059,735 | 52,050 | 4.9 | |||||||||||||||||||||||||||||||||||
| Reconciliation of Commercial Revenues to Organic Commercial Revenues | |||||||||||||||||||||||||||||||||||||||||||||||
| Commercial revenues | $ | 299,633 | $ | 273,865 | 25,768 | 9.4 | $ | 845,517 | $ | 767,472 | 78,045 | 10.2 | |||||||||||||||||||||||||||||||||||
| Commercial revenues from acquisitions | (6,434) | — | (6,434) | 2.3 | (17,456) | — | (17,456) | 2.3 | |||||||||||||||||||||||||||||||||||||||
| Commercial revenues of divestitures | — | (2,560) | 2,560 | (1.0) | — | (6,832) | 6,832 | (1.0) | |||||||||||||||||||||||||||||||||||||||
| Commercial organic revenues | $ | 293,199 | $ | 271,305 | 21,894 | 8.1 | $ | 828,061 | $ | 760,640 | 67,421 | 8.9 | |||||||||||||||||||||||||||||||||||
| Reconciliation of Termite and Ancillary Revenues to Organic Termite and Ancillary Revenues | |||||||||||||||||||||||||||||||||||||||||||||||
| Termite and ancillary revenues | $ | 177,674 | $ | 155,135 | 22,539 | 14.5 | $ | 515,758 | $ | 457,664 | 58,094 | 12.7 | |||||||||||||||||||||||||||||||||||
| Termite and ancillary revenues from acquisitions | (1,334) | — | (1,334) | 0.8 | (5,766) | — | (5,766) | 1.3 | |||||||||||||||||||||||||||||||||||||||
| Termite and ancillary organic revenues | $ | 176,340 | $ | 155,135 | 21,205 | 13.7 | $ | 509,992 | $ | 457,664 | 52,328 | 11.4 |
ROLLINS, INC. AND SUBSIDIARIES
| Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||||||||||
| Variance | Variance | ||||||||||||||||||||||||||||||||||||||||||||||
| 2023 (7) | 2022 (7) | $ | % | 2023 (7) | 2022 (7) | $ | % | ||||||||||||||||||||||||||||||||||||||||
| Reconciliation of Revenues to Organic Revenues | |||||||||||||||||||||||||||||||||||||||||||||||
| Revenues | $ | 840,427 | $ | 729,704 | 110,723 | 15.2 | $ | 2,319,192 | $ | 2,034,433 | 284,759 | 14.0 | |||||||||||||||||||||||||||||||||||
| Revenues from acquisitions | (49,971) | — | (49,971) | 6.8 | (114,273) | — | (114,273) | 5.6 | |||||||||||||||||||||||||||||||||||||||
| Organic revenues | $ | 790,456 | $ | 729,704 | 60,752 | 8.4 | $ | 2,204,919 | $ | 2,034,433 | 170,486 | 8.4 | |||||||||||||||||||||||||||||||||||
| Reconciliation of Residential Revenues to Organic Residential Revenues | |||||||||||||||||||||||||||||||||||||||||||||||
| Residential revenues | $ | 402,559 | $ | 336,626 | 65,933 | 19.6 | $ | 1,069,403 | $ | 917,790 | 151,613 | 16.5 | |||||||||||||||||||||||||||||||||||
| Residential revenues from acquisitions | (42,974) | — | (42,974) | 12.8 | (91,067) | — | (91,067) | 9.9 | |||||||||||||||||||||||||||||||||||||||
| Residential organic revenues | $ | 359,585 | $ | 336,626 | 22,959 | 6.8 | $ | 978,336 | $ | 917,790 | 60,546 | 6.6 | |||||||||||||||||||||||||||||||||||
| Reconciliation of Commercial Revenues to Organic Commercial Revenues | |||||||||||||||||||||||||||||||||||||||||||||||
| Commercial revenues | $ | 273,865 | $ | 245,009 | 28,856 | 11.8 | $ | 767,472 | $ | 688,523 | 78,949 | 11.5 | |||||||||||||||||||||||||||||||||||
| Commercial revenues from acquisitions | (3,456) | — | (3,456) | 1.4 | (10,688) | — | (10,688) | 1.6 | |||||||||||||||||||||||||||||||||||||||
| Commercial organic revenues | $ | 270,409 | $ | 245,009 | 25,400 | 10.4 | $ | 756,784 | $ | 688,523 | 68,261 | 9.9 | |||||||||||||||||||||||||||||||||||
| Reconciliation of Termite and Ancillary Revenues to Organic Termite and Ancillary Revenues | |||||||||||||||||||||||||||||||||||||||||||||||
| Termite and ancillary revenues | $ | 155,135 | $ | 139,359 | 15,776 | 11.3 | $ | 457,664 | $ | 405,089 | 52,575 | 13.0 | |||||||||||||||||||||||||||||||||||
| Termite and ancillary revenues from acquisitions | (3,541) | — | (3,541) | 2.5 | (12,518) | — | (12,518) | 3.1 | |||||||||||||||||||||||||||||||||||||||
| Termite and ancillary organic revenues | $ | 151,594 | $ | 139,359 | 12,235 | 8.8 | $ | 445,146 | $ | 405,089 | 40,057 | 9.9 |
(7) Revenues classified by significant product and service offerings for the three and nine months ended September 30, 2023 and 2022 were misstated by an immaterial amount and have been restated from the amounts previously reported to correct the classification of such revenues. There was no impact on our condensed consolidated statements of income, financial position, or cash flows.
| Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||
| 2024 | 2023 | 2024 | 2023 | ||||||||||||||||||||
| Reconciliation of SG&A to Adjusted SG&A | |||||||||||||||||||||||
| SG&A | $ | 274,918 | $ | 244,906 | $ | 769,522 | $ | 696,668 | |||||||||||||||
| Fox acquisition-related expenses | — | 1,050 | 1,049 | 2,097 | |||||||||||||||||||
| Adjusted SG&A | $ | 274,918 | $ | 243,856 | $ | 768,473 | $ | 694,571 | |||||||||||||||
| Revenues | $ | 916,270 | $ | 840,427 | $ | 2,556,539 | $ | 2,319,192 | |||||||||||||||
| Adjusted SG&A as a % of revenues | 30.0 | % | 29.0 | % | 30.1 | % | 29.9 | % |
| Period Ended September 30, 2024 | Period Ended December 31, 2023 | ||||||||||
| Reconciliation of Long-term Debt to Net Debt and Net Leverage Ratio | |||||||||||
| Long-term debt (8) | $ | 447,000 | $ | 493,000 | |||||||
| Less: cash | 95,282 | 103,825 | |||||||||
| Net debt | $ | 351,718 | $ | 389,175 | |||||||
| Trailing twelve-month EBITDA | $ | 771,291 | $ | 705,064 | |||||||
| Net leverage ratio | 0.5x | 0.6x |
(8) As of September 30, 2024, the Company had outstanding borrowings of $447.0 million under the Credit Facility. Borrowings under the Credit Facility are presented under the long-term debt caption of our condensed consolidated balance sheet, net of $1.8 million in unamortized debt issuance costs as of September 30, 2024.
ROLLINS, INC. AND SUBSIDIARIES
LIQUIDITY AND CAPITAL RESOURCES
Cash and Cash Flow
The Company’s $95.3 million of total cash at September 30, 2024 is held at various banking institutions. As of September 30, 2024, approximately $53.5 million is held in cash accounts at international bank institutions and the remaining $41.8 million is primarily held in Federal Deposit Insurance Corporation (“FDIC”) insured non-interest-bearing accounts at various domestic banks which at times exceed federally insured amounts.
We intend to continue to grow the business in the international markets where we have a presence. As it relates to our unremitted earnings in foreign jurisdictions, we assert that foreign cash earnings in excess of working capital and cash needed for strategic investments and acquisitions are not intended to be indefinitely reinvested offshore.
On February 24, 2023, the Company entered into a revolving credit agreement with, among others, JPMorgan Chase Bank, N.A. (“JPMorgan Chase”), as administrative agent (in such capacity, the “Administrative Agent”), which refinanced its previous credit facility.
The Credit Agreement provides for a $1.0 billion revolving Credit Facility, which may be denominated in U.S. Dollars and other currencies, including Euros, Australian Dollars, Canadian Dollars, New Zealand Dollars, Pounds Sterling and Japanese Yen, subject to a $400 million foreign currency sublimit. Rollins has the ability to expand its borrowing availability under the Credit Agreement in the form of increased revolving commitments or one or more tranches of term loans by up to an additional $750 million, subject to the agreement of the participating lenders and certain other customary conditions. The maturity date of the loans under the Credit Agreement is February 24, 2028. Refer to Note 8. Debt, of the Notes to Condensed Consolidated Financial Statements for further details.
As of September 30, 2024, the Company had outstanding borrowings of $447.0 million under the Credit Facility. The aggregate effective interest rate on the debt outstanding as of September 30, 2024 was 6.2%. As of December 31, 2023, the Company had outstanding borrowings of $493.0 million under the Credit Facility. The aggregate effective interest rate on the debt outstanding as of December 31, 2023 was 6.5%.
The Company maintained $72.0 million in letters of credit as of September 30, 2024 and $71.7 million as of December 31, 2023. These letters of credit are required by the Company’s insurance companies, due to the Company’s high deductible insurance program, to secure various workers’ compensation and casualty insurance contracts coverage. The Company believes that it has adequate liquid assets, funding sources and insurance accruals to accommodate potential future insurance claims.
The Company believes its current cash and cash equivalents balances, future cash flows expected to be generated from operating activities, and available borrowings under its Credit Facility will be sufficient to finance its current operations and obligations, and fund expansion of the business for the foreseeable future.
The following table sets forth a summary of our cash flows from operating, investing and financing activities for the nine month periods presented:
| Nine Months Ended September 30, | Variance | ||||||||||||||||||||||
| (in thousands) | 2024 | 2023 | $ | % | |||||||||||||||||||
| Net cash provided by operating activities | $ | 419,495 | $ | 375,541 | 43,954 | 11.7 | |||||||||||||||||
| Net cash used in investing activities | (123,560) | (362,334) | 238,774 | 65.9 | |||||||||||||||||||
| Net cash (used in) provided by financing activities | (305,506) | 33,743 | (339,249) | N/M | |||||||||||||||||||
| Effect of exchange rate on cash | 1,028 | (49) | 1,077 | N/M | |||||||||||||||||||
| Net (decrease) increase in cash and cash equivalents | $ | (8,543) | $ | 46,901 | (55,444) | (118.2) |
N/M - calculation not meaningful
Cash Provided by Operating Activities
Cash from operating activities is the principal source of cash generation for our businesses. The most significant source of cash in our cash flow from operations is customer-related activities, the largest of which is collecting cash resulting from
ROLLINS, INC. AND SUBSIDIARIES
services sold. The most significant operating use of cash is to pay our suppliers, employees, and tax authorities. The Company’s operating activities generated net cash of $419.5 million and $375.5 million for the nine months ended September 30, 2024 and 2023, respectively. The $44.0 million increase was driven primarily by strong operating results and the timing of cash receipts and cash payments to and from customers, vendors, employees, and tax and regulatory authorities.
Cash Used in Investing Activities
The Company’s investing activities used $123.6 million and $362.3 million for the nine months ended September 30, 2024 and 2023, respectively. Cash paid for acquisitions totaled $105.5 million for the nine months ended September 30, 2024, as compared to $349.3 million for the nine months ended September 30, 2023, primarily related to the Fox acquisition. The Company invested $23.4 million in capital expenditures during the year, offset by $3.0 million in cash proceeds from the sale of assets, compared with $21.3 million of capital expenditures and $10.2 million in cash proceeds from asset sales in 2023. The Company’s investing activities were funded through existing cash balances, operating cash flows, and borrowings under the Credit Facility.
Cash Used in or Provided by Financing Activities
Cash of $305.5 million was used in financing activities during the nine months ended September 30, 2024, compared with $33.7 million of cash provided by financing activities during the nine months ended September 30, 2023. A total of $218.0 million was paid in cash dividends ($0.45 per share) during the nine months ended September 30, 2024, compared to $191.8 million in cash dividends paid ($0.39 per share) during the nine months ended September 30, 2023. The Company made net repayments under its credit agreements of $46.0 million during the nine months ended September 30, 2024 compared to net borrowings of $544.0 million during 2023. During the nine months ended September 30, 2024, the Company paid $33.4 million of contingent consideration, primarily related to the Fox acquisition, compared to $9.3 million during the nine months ended September 30, 2023. The Company withheld $11.5 million and $10.7 million of common stock for the nine months ended September 30, 2024 and 2023, respectively, in connection with tax withholding obligations of its employees upon vesting of such employees’ equity awards. In addition, during the nine months ended September 30, 2023, the Company completed the repurchase of 8,724,100 of the shares of common stock from LOR, Inc ("LOR") for $300.0 million in conjunction with the Offering, as defined in our 2023 Annual Report on Form 10-K.
In 2012, the Company’s Board of Directors authorized the purchase of up to 5 million shares of the Company’s common stock. After adjustments for stock splits, the total authorized shares under the share repurchase plan is 16.9 million shares. As of September 30, 2024, 11.4 million additional shares may be purchased under the share repurchase program.
In addition, the Form S-3 on file with the SEC registered $1.5 billion of the Company’s common stock, preferred stock, debt securities, depositary shares, warrants, rights, purchase contracts and units for future issuance. The Company may offer and sell some or all of such securities from to time or to or through underwriters, brokers or dealers, directly to one or more other purchasers, through a block trade, through agents on a best-efforts basis, through a combination of any of the above methods of sale or through other types of transactions described in the Form S-3. The Company has not sold any securities as of the date of this Form 10-Q.
CONTINGENCIES
In the normal course of business, the Company and its subsidiaries are involved in, and will continue to be involved in, various claims, arbitrations, contractual disputes, investigations, litigation, and tax and other regulatory matters relating to, and arising out of, our businesses and our operations. These matters may involve, but are not limited to, allegations that our services or vehicles caused damage or injury, claims that our services did not achieve the desired results, claims related to acquisitions and allegations by federal, state or local authorities, including taxing authorities, of violations of regulations or statutes. In addition, we are parties to employment-related cases and claims from time to time, which may include claims on a representative or class action basis alleging wage and hour law violations. We are also involved from time to time in certain environmental and tax matters primarily arising in the normal course of business or claims filed under California's Private Attorneys General Act. We evaluate pending and threatened claims and establish loss contingency reserves based upon outcomes we currently believe to be probable and reasonably estimable.
The Company retains, up to specified limits, certain risks related to general liability, workers’ compensation and auto liability. The estimated costs of existing and future claims under the retained loss program are accrued based upon historical trends as incidents occur, whether reported or unreported (although actual settlement of the claims may not be
ROLLINS, INC. AND SUBSIDIARIES
made until future periods) and may be subsequently revised based on developments relating to such claims. The Company contracts with an independent third party to provide the Company an estimated liability based upon historical claims information. The actuarial study is a major consideration in establishing the reserve, along with management’s knowledge of changes in business practice and existing claims compared to current balances. Management’s judgment is inherently subjective as a number of factors are outside management’s knowledge and control. Additionally, historical information is not always an accurate indication of future events. The accruals and reserves we hold are based on estimates that involve a degree of judgment and are inherently variable and could be overestimated or insufficient. If actual claims exceed our estimates, our operating results could be materially affected, and our ability to take timely corrective actions to limit future costs may be limited.
Management does not believe that any pending claim, proceeding or litigation, regulatory action or investigation, either alone or in the aggregate, will have a material adverse effect on the Company’s financial position, results of operations or liquidity; however, it is possible that an unfavorable outcome of some or all of the matters could result in a charge that might be material to the results of an individual quarter or year.
CRITICAL ACCOUNTING ESTIMATES
There have been no significant changes in our identified critical accounting estimates as disclosed in Part II, Item 7, "Management's Discussion and Analysis of Financial Condition and Results of Operations - Critical Accounting Estimates" of our 2023 Form 10-K.
CAUTION REGARDING FORWARD-LOOKING STATEMENTS
This Quarterly Report on Form 10-Q as well as other written or oral statements by the Company may contain “forward-looking statements” as defined in the Private Securities Litigation Reform Act of 1995. We have based these forward-looking statements on our current opinions, expectations, intentions, beliefs, plans, objectives, assumptions and projections about future events and financial trends affecting the operating results and financial condition of our business. Although we believe that these forward-looking statements are reasonable, we cannot assure you that we will achieve or realize these plans, intentions, or expectations. Generally, statements that do not relate to historical facts, including statements concerning possible or assumed future actions, business strategies, events or results of operations, are forward-looking statements. The words “believe,” “continue,” “could,” “estimate,” “expect,” “intend,” “may,” “might,” “plan,” “possible,” “potential,” “predict,” “should,” “will,” “would,” and similar expressions may identify forward-looking statements, but the absence of these words does not mean that a statement is not forward-looking. Forward-looking statements in this Quarterly Report on Form 10-Q include, but are not limited to, statements regarding:
-
expectations with respect to our financial and business performance;
-
expansion efforts and growth opportunities, including but not limited to recent and future acquisitions in the United States and in foreign markets;
-
the impact of high inflation, increasing interest rates, business interruptions due to natural disasters and changes in the weather patterns, employee shortages, and supply chain issues;
-
expectations with respect to interest costs and the effective tax rate;
-
sufficiency of current cash and cash equivalents balances, future cash flows, and available borrowings under our Credit Facility to finance our current and future operations;
-
our belief that the Company has adequate liquid assets, funding sources and insurance accruals to accommodate potential future insurance claims;
-
our approach to capital allocation inclusive of our intent to pay cash dividends to common shareholders and to invest in acquisitions;
-
our belief that no pending or threatened claim, proceeding, litigation, regulatory action or investigation, either alone or in the aggregate, including but not limited to the investigation by certain California governmental authorities regarding compliance with environmental regulations and claims filed under California's Private Attorneys General Act, will have a material adverse effect on our financial position, results of operations or liquidity;
ROLLINS, INC. AND SUBSIDIARIES
- estimates, assumptions, and projections related to our application of critical accounting policies, described in more detail under “Critical Accounting Estimates.”
These forward-looking statements are based on information available as of the date of this report, and current expectations, forecasts, and assumptions, and involve a number of judgments, risks and uncertainties. Important factors could cause actual results to differ materially from those indicated or implied by forward-looking statements including, but not limited to, those set forth in the sections entitled “Risk Factors” in our Annual Report on Form 10-K for the fiscal year ended December 31, 2023 and may also be described from time to time in our future reports filed with the SEC.
Accordingly, forward-looking statements should not be relied upon as representing our views as of any subsequent date, and we do not undertake any obligation to update forward-looking statements to reflect events or circumstances after the date they were made, whether as a result of new information, future events or otherwise, except as may be required by law.
Previous: Item 1. FINANCIAL STATEMENTS · Next: Item 3. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK