 filings.tools
Item 1. BUSINESS
62K characters. Original on sec.gov ·
Item 1. BUSINESS
Steel Dynamics, Inc. is one of the largest domestic steel producers and metal recyclers in the United States, based on estimated steelmaking and coating capacity of approximately 13 million tons and actual metals recycling volumes as of December 31, 2020, with one of the most diversified product and end-market portfolios in the domestic steel industry. The company’s primary sources of revenue are from the manufacture and sale of steel products, the processing and sale of recycled ferrous and nonferrous metals, and the fabrication and sale of steel joists and deck products.
We refer to our founding principles as our six core strategic pillars. They bring us together with a common focus, and they provide the foundation upon which we operate and grow. Our unique entrepreneurial culture and business model benefit us operationally, financially, and through the responsible use of our resources in diverse economic environments. Innovation in all forms is essential to our success, and our teams focus on how to do things “smarter” within our current operations as well as how we continue to grow. This means creating solutions for our teammates, customers, suppliers, and other stakeholders. It also includes finding ways to “do business” with fewer resources and less environmental impact. Our six pillars and the team’s execution of them each day has driven our success and sustainability.
| |
|---|
| ● | Safety – Creating and maintaining a safe work environment is the foundation of our decision making. Safety is always at the forefront and is a constant topic of conversation across the company. Our goal is zero injuries—no accidents. |
|---|
| ● | Culture – Our entrepreneurial culture fosters a team of energetic, positive, driven, innovative and diverse individuals by utilizing open communication and meaningful performance-based compensation aligned to our strategic focus. |
|---|
| ● | Customer Commitment – We focus on being a preferred partner of our customers by providing quality products and unique supply-chain solutions to meet their current and future needs. |
|---|
| ● | Growth – We focus on intentional margin expansion and consistency through-the-cycle. |
|---|
| ● | Innovation – Through individual creativity and ingenuity, our teams drive innovation to improve safety, quality, productivity, and resource sustainability. We strive to provide unique, superior products, customer supply chain solutions, and next-generation technologies and processes. |
|---|
| ● | Financial Strength – Through our adaptable value-added product diversification, vertically connected businesses model, coupled with our highly variable operating cost structure and performance-based incentive compensation, along with our continued operating innovations and efficiency, we achieve higher utilization and lower costs, which provide strong cash flow generation through both strong and weak market cycles. |
|---|
Differentiated Model - Uniquely Steel Dynamics
Competitively advantaged differentiation is core to our long-term value creation strategy. We aim to set ourselves apart in every aspect of our business with a spirit of excellence, with the following core values driving our differentiation strategy.
Unique Entrepreneurial Culture
Our entrepreneurial culture is at the core of our success and is driven by our extensive performance-based incentive compensation philosophy for those on the plant floor to senior leadership. Over 60% of a plant floor colleague’s total potential compensation is “at risk” to both quality production and cost-effectiveness. Over 85% of our senior leadership team’s total potential compensation is “at risk” to company-wide financial performance metrics that encourage long-term value creation, including return on equity, growth, cash generation, and return on invested capital metrics. Our common goal of consistently achieving excellence in all we do is reflected in the esprit de corps that permeates our team. We believe diversity within our teams enhances broad-based thinking, innovation, and value creation.
Diversified, Value-Added Product Offerings / Supply-Chain Solutions
We have one of the most diversified, high-margin product offerings of any domestic steel producer. We have a track record of profitable growth, driving diversification in both end markets and product offerings to sustain higher volume and profitability through all market environments. This includes developing premium, value-added steel products, with over 70% of our steel and fabrication sales being considered value-added.
A key competitive advantage is our numerous supply-chain solutions which provide significant advantages to our customers, creating long-lasting relationships and higher through-cycle sales. The majority of our steelmaking operations are in locations near sustainable sources of scrap metals and near our customer base, allowing us to realize freight savings for inbound scrap as well as for outbound steel products destined for our customers. This also allows us to provide consistent on-time delivery to our customer base with relatively short lead times, further solidifying our customer relationships.
This diversified portfolio of products enables us to access a broad range of markets, serve a large customer base, and helps mitigate our market exposure to any one product or sector, resulting in increased through-cycle steel mill utilization. In addition, our value-added steel product offerings help to balance our exposure to commodity grade products supplied by other steel manufacturers. We will continue to seek additional opportunities and to collaborate with our customers to anticipate their future needs by further expanding our range of products and offerings.
Our new Southwest-Sinton Flat Roll Division growth investment is a prime example of our internal growth and differentiated business model. This $1.9 billion electric arc furnace (EAF) flat roll steel mill will have an estimated 3.0 million tons of annual steel production capacity, including value-added coating lines comprised of a galvanizing line with planned annual coating capacity of 550,000 tons with galvalume capability and a paint line with annual coating capacity of 250,000 tons. As with all our growth initiatives, we seek to competitively differentiate ourselves through service, product capability and quality, and supply chain solutions. This investment encompasses each of these elements.
By leveraging our construction and operating expertise, we are building a "next-generation” EAF flat roll steel mill with production capabilities designed to have product size and quality capabilities beyond that of existing domestic EAF flat roll steel producers, competing even more effectively with the integrated steel model and foreign competition. Our new steel mill will have the capability to provide higher-strength, tougher grades of flat roll steel for the energy and automotive markets. These ultra-high-strength steel products are not currently readily available from other domestic steel producers. We will also be producing value-added steel products at the commencement of operations, providing high-margin product and end-market diversification.
Out new steel mill is being strategically located in Sinton, Texas, which has significant competitive advantages—including geographic market positioning, power accessibility, competitive freight for the intended customers, proximity to a deep-water port and site constructability. By locating our new steel mill in Sinton, Texas we are strategically targeting underserved markets that are largely reliant on imports with long lead times and lower product quality capabilities, providing customers throughout the Southwest United States and Mexico significant freight benefits and shorter lead times allowing them to realize working capital advantages. Additionally, our new steel mill site has sufficient acreage to allow for some customers to locate on-site, providing them with logistics savings and our steel mill with volume base-loading opportunities. Three customers have committed to locate onsite, representing over 1.0 million tons of annual processing and consumption capacity, and we expect to secure similar commitments from additional customers.
Our new EAF steel mill is adhering to the same sustainability model as our other steelmaking facilities, utilizing state-of-the-art environmental controls and processes to produce high quality sustainable steel. Our existing EAF steel mills have a fraction of the greenhouse gas emissions (GHG) and energy intensity of average traditional integrated steelmaking technology, resulting in a much more environmentally friendly steel production alternative. Operations are planned to begin mid-year 2021.
Vertically Connected Businesses and Pull-Through Volume Advantage
Our vertically connected businesses contribute to our higher through-cycle steel production and overall profitability. Steel demand that is generated from our internal manufacturing businesses is a significant competitive advantage supporting higher and more stable through-cycle earnings and cash flow generation. Our steel fabrication operations and downstream processing locations use a significant amount of steel in their operations. During weaker demand environments, we source more of their needs internally, and during strong demand environments, we source more of their needs externally at a preferred cost. Ultimately, we optimize our company-wide profitability in all steel demand environments. In 2020, our own steel consuming businesses purchased 1.5 million tons of steel from our steel mills representing 14% of our total 2020 steel shipments.
A strategic synergistic relationship also exists between our steel mills and metals recycling operations, which is the largest supplier of recycled ferrous scrap to our steel operations. This allows us to reduce company-wide working capital, as we retain less scrap inventory at the steel mills, and we are able to source higher-quality scrap for our steel mills, optimizing cost and quality. Additionally, as a consistent consumer of recycled ferrous scrap, our steel operations help maintain steady sales for the metals recycling platform.
Technically Advanced, Low-Cost, Highly-Efficient Operations
We operate some of the most technically advanced and environmentally friendly steel operations when compared to global steelmaking operations. We are focused on maintaining one of the lowest operating cost structures in the North American steel industry. Our value-added product diversification, vertically connected businesses, and performance-based incentive compensation programs drive our efficient, environmentally friendly, and competitively advantaged footprint.
Our low operating costs are primarily a result of our efficient plant designs and operations, our high productivity rate, low ongoing maintenance cost requirements and strategic locations near sources of our primary raw material, ferrous scrap, and near our customers. We will continue to develop innovative ways to use our equipment, enhance our productivity and explore new technologies to further improve our unit costs of production at each of our facilities. As one of the lowest cost producers in each of our three primary operating segments, we are able to better manage through all market cycles, and to consistently maximize our profitability. Additionally, we continuously seek to maximize the variability of our cost structure and to reduce per unit and fixed costs.
Sustainability
Sustainability is a part of our long-term value creation. We are dedicated to our people, our communities and our environment. We are committed to operating our business with the highest integrity and have been since our founding.
We only produce steel using EAF technology, which uses recycled ferrous scrap as the primary raw material. EAF steelmaking technology generates a mere fraction of the carbon emissions produced and energy intensity required by traditional blast furnace steelmaking technology. We believe EAF production is currently the steelmaking technology that provides the least environmental impact, is the most cost effective, and provides the most flexibility, and as such, has been a focus of our growth strategy.
Our intentional growth strategy has focused on increasing through-cycle cash generation and providing growth opportunities for our people, partners, communities, and shareholders, all while keeping sustainability of resources and climate-impact at the fore. We intentionally developed a vertically connected operating model, further strengthening our company by creating a “closed loop” manufacturing life cycle.
Our metals recycling platform collects and processes scrap from manufacturing and from end-of-life items, such as automobiles, appliances, and machinery. This processed scrap is then sold to end-users for reuse, including our EAF steel mills, which produce new steel from the scrapped material. Our steel is then sold to consumers that both further process and manufacture end products. We sell a meaningful amount of steel to our own manufacturing businesses that in turn sell finished products to consumers. Ultimately, when these products reach the end of their life cycle, they can be collected as scrap and used again in our steelmaking operations, creating our “vertically connected sustainable product life cycle.”
We recognize that minimizing the impact of GHG is important to our stakeholders, including local communities and team members. We endeavor for continuous improvement in minimizing carbon dioxide emissions, while maintaining compliance with regulation emission limits. We evaluate our GHG emissions by regularly reviewing furnace performance and efficiency. We analyze the latest available technologies to also determine whether emissions can be minimized. Our carbon mitigation strategy is integral to our overarching sustainability program to address climate-related considerations. Our Board of Directors provides oversight concerning the company’s sustainability strategy, disclosures, and climate-related impact. Our senior leadership, including our President and Chief Executive Officer, Executive Vice President, Chief Financial Officer, and Corporate Secretary, and other operating platform senior executives, establish our near- and long-term strategies related to our climate-related assessments, goals, and programs.
Experienced Leadership Team / Fosters an Entrepreneurial Culture
Our senior leadership team is highly experienced and has a proven track record in the steel, metals recycling, and steel fabrication industries. Our leadership objectives are closely aligned with our stakeholders through meaningful stock ownership positions and performance-based incentive compensation programs that are correlated to the company’s profitability and operational performance in relationship to our steel manufacturing peers. We emphasize decentralized operational decision making and responsibility, while continuing to maintain appropriate corporate governance and risk oversight. We reward teamwork, innovation, and operating efficiency, and focus on maintaining the effectiveness of our performance-driven incentive bonus plans that are designed to maximize overall productivity and align the interests of our leadership and teams with our stakeholders.
| | | | | |
|---|---|---|---|---|
| Name | | Age | | Position |
| Mark D. Millett | | 61 | | President and Chief Executive Officer |
| Theresa E. Wagler | | 50 | | Executive Vice President, Chief Financial Officer, and Corporate Secretary |
| Russ B. Rinn | | 63 | | Executive Vice President, Metals Recycling |
| Miguel Alvarez | | 53 | | Senior Vice President, Southwest United States and Mexico |
| Chris A. Graham | | 56 | | Senior Vice President, Long Products Steel Group |
| Glenn A. Pushis | | 55 | | Senior Vice President, Special Projects |
| Barry T. Schneider | | 52 | | Senior Vice President, Flat Roll Steel Group |
| James S. Anderson | | 60 | | Vice President, Steel Fabrication |
Mark D. Millett, a co-founder of our company and director since inception, has been our President and Chief Executive Officer since January 2012. Prior to that, Mr. Millett has held various positions within the company, including President and Chief Operating Officer, Executive Vice President of Metals Recycling and Ferrous Resources, President and Chief Operating Officer of OmniSource, LLC, and Executive Vice President and Chief Operating Officer for Flat Rolled Steels and Ferrous Resources. Mr. Millett was responsible for the design, construction, and start-up operation of all of our steel mills, including our Butler, Indiana flat roll, melting, and casting operations. Prior to co-founding Steel Dynamics, Mr. Millett served in various leadership roles for the Nucor Corporation. His roles included being charged with developing the world’s first commercially viable thin slab casting process as the manager of the project at Nucor’s Hazelett facility and being given the responsibility by Nucor for the design, construction, staffing, and operation of the melting and casting facility at the world’s first thin slab casting facility at Nucor’s Crawfordsville, Indiana facility.
Theresa E. Wagler has been our Executive Vice President, Chief Financial Officer and Corporate Secretary since May 2007. Ms. Wagler joined the Steel Dynamics corporate finance team in 1998, and has held various finance and accounting positions, including Chief Accounting Officer and Vice President and Corporate Controller, and was appointed to her current position in May 2007. She is responsible for and oversees accounting and taxation, treasury, risk management, legal, information technology and cyber security, health and safety, human resources, sustainability efforts, and strategic business development functions, as well as investor relations, and corporate communications. Ms. Wagler also has various operational responsibilities directly overseeing two operating joint ventures. Prior to joining Steel Dynamics, Ms. Wagler was as a certified public accountant with Ernst & Young LLP.
Russell B. Rinn has been our Executive Vice President for Metals Recycling since July 2011. Mr. Rinn is responsible for OmniSource’s ferrous and nonferrous metals recycling operations including marketing, trading, and logistics activities. OmniSource procures metal scrap, processes it, and markets these recycled metals to external customers and supplies ferrous scrap to the company’s steel mills. Prior to joining Steel Dynamics, Mr. Rinn was an Executive Vice President of Commercial Metals Company, a Texas based mini-mill steel company.
Miguel Alvarez has been our Senior Vice President, Southwest United States and Mexico since February 2019. Mr. Alvarez is responsible for the comprehensive business development and partnerships in the regions, encompassing both steel and recycled metals. Prior to joining Steel Dynamics, Mr. Alvarez served in leadership positions at BlueScope, including leading BlueScope’s North American metal buildings business with manufacturing facilities in the United States and Mexico and being responsible for BlueScope’s only North American electric arc furnace flat roll steel mill as President of North Star BlueScope Steel.
Chris A. Graham has been our Senior Vice President, Long Products Steel Group since February 2019. In this role, Mr. Graham is responsible for the company’s four long product steel mills. Prior to that, Mr. Graham has served as Senior Vice President, Downstream Manufacturing and President of New Millennium Building Systems, responsible for the company’s steel fabrication and downstream manufacturing operations and other operational and leadership roles. Mr. Graham was also a part of the team that constructed the company’s first steel mill in Butler, Indiana, in 1994.
Glenn A. Pushis has been our Senior Vice President, Special Projects since February 2019. Mr. Pushis is responsible for the successful design and construction of the company’s new Southwest-Sinton Flat Roll Division developed to serve the Southwestern United States and Mexico. He has extensive experience in this capacity and has been instrumental in numerous construction projects for Steel Dynamics since its founding. Prior to that, Mr. Pushis served as Senior Vice President, Long Products Steel Group, responsible for the company’s four long product steel mills. Mr. Pushis has been with Steel Dynamics since 1994, holding various operational and leadership roles, including roles within the Engineered Bar Products Division and the Butler Flat Roll Division. He was also part of the team that constructed the company’s first steel mill in Butler, Indiana, in 1994.
Barry T. Schneider has been our Senior Vice President, Flat Roll Steel Group, since March 2016. Mr. Schneider is responsible for the company’s entire flat roll steel operations, including the company’s two flat roll steel mills and numerous flat roll coating operations. Before that, Mr. Schneider served in various operational and leadership roles within the company’s steel operations,
including Engineered Bar Products Division and Butler Flat Roll Division. He was also part of the team that constructed the company’s first steel mill in Butler, Indiana, in 1994.
James S. Anderson is our Vice President, Steel Fabrication, and President of New Millennium Building Systems, since February 2019. In this role, Mr. Anderson is responsible for the company's steel fabrication operations. Prior to that, Mr. Anderson served as the Chief Operating Officer of New Millennium Building Systems, and was the general manager of The Techs three flat roll galvanizing lines.
Human Capital / Valuing People
We value the dedicated people whose passion, innovation, and dedication to excellence have helped successfully grow our company and serve our customers. We have a culture of trust, fostered through individual empowerment and accountability that drives decision-making throughout our businesses. Our performance-based incentive compensation programs align our people with the interests of our strategic long-term growth and our stakeholders, including our customers, communities, and shareholders. We know that our teams will do what is right and that trust comes from effective communication and transparency. The Steel Dynamics team consisted of approximately 9,625 full time team members at December 31, 2020.
Health and Safety
Valuing people includes providing a safe and healthy work environment and creating a culture of safety that extends beyond the workplace, into our homes and communities. Safety is and always will be our primary focus and core value. Our goal is for each individual to arrive at the workplace and return home safely each day — without accident or injury. This is achievable when we all work together. It requires commitment from leadership and team members at every level to take ownership and responsibility for their safety and the safety of others. Under no circumstance does the desire to maximize production or earnings override the priority of individual safety.
Safety is our first core strategic pillar — it is the foundation of our decision making. Safety is always at the forefront and is a constant topic of conversation across the company, whether led by a team member from the plant floor, a supervisor, or a manager. Leadership is engaged and continuously evaluates where we can improve. We believe having every individual engaged in safety will lead to zero injuries. We are committed to achieve world-class safety performance throughout our businesses to ensure everyone goes home safely. The commitment to safety has led to each of our platforms performing better compared to industry benchmarks. Specifically, for 2020, our total recordable injury rate compared to industry benchmarks, and lost time injury and severity rates are as follows:
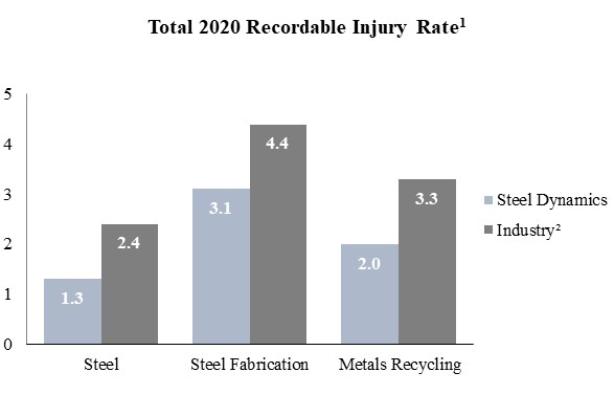
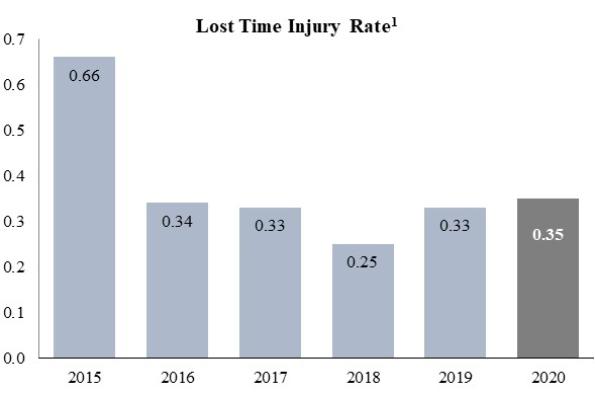
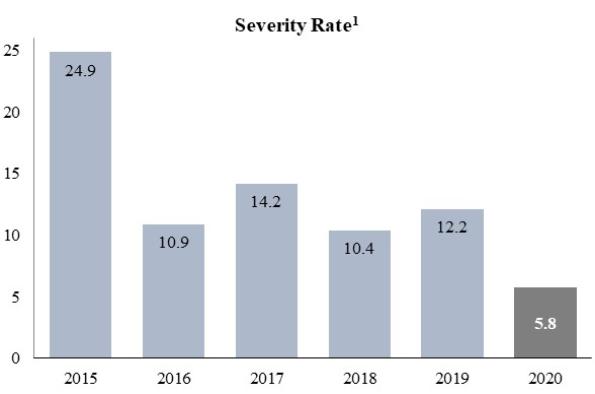
1 Total Recordable Injury Rate is defined as OSHA recordable incidents x 200,000 / hours worked. Lost Time Injury Rate is defined as OSHA days away from work cases x 200,000 / hours worked. Severity Rate is defined as OSHA days away from work x 200,000 / hours worked.
2 Source: 2019 U.S. DOL Bureau of Labor Statistics
Coronavirus (COVID-19)
Our leadership teams, safety professionals, and nursing team have been instrumental in our responsible handling of the COVID-19 pandemic. Steelmaking and its ancillary support businesses are considered a “critical infrastructure industry” by the U.S. Department of Homeland Security and have been deemed an essential business in all of the states in which we operate. As such, our businesses have remained operational throughout the COVID-19 outbreak. Our teams are our most valued priority and we took decisive, conservative actions and implemented numerous additional health-related protocols and policies very early in 2020, when it became apparent there was a risk to our teams. We believe these steps were and remain critical in protecting our teams, their families, and our communities. During 2020, none of our operations has been closed or idled due to the COVID-19 pandemic.
Talent Development and Educational Opportunities
Our people represent the foundation of our six strategic pillars. Their continued education and talent development is paramount to our success. Our education assistance and development programs encourage personal growth so individuals can remain current in their areas of responsibility, as well as develop new skills for advancement. Our senior leadership plays a key role in our development programs, linking our culture to critical, proven leadership concepts. As we continue to grow, building talent and creating opportunities within our teams is one of our most important tasks and is critical to our long-term success. We have numerous programs and development initiatives designed to develop our employees.
Compensation Structure
We believe in empowering our teams and rewarding them for their achievements through a four-tiered, performance-based compensation framework. The various components of our compensation programs promote a balance of high-return growth, effective capital investment, low-cost operations, and risk mitigation. By rewarding our teams based on their performance as an individual, as a team, as a company, and based on shareholder concerns, we believe we have the ultimate alignment with our stakeholders. This is achieved through the following methods:
| ● | Individual performance awards consist of an individual’s base compensation, which is determined by their individual performance, responsibilities, and skills. |
|---|
| ● | Team performance awards are based on departmental results, rewarding cost effectiveness and quality production. Our performance-based incentive programs reward team members for reducing waste and increasing efficiency, while also producing quality products for our customers. These awards can be well over 100% of base wages, based on strong performance and on the teams doing things that are within their control. |
|---|
| ● | Company-wide performance awards unite everyone through our profit-sharing program, which is based on consolidated pretax profitability, and our 401(k) match, which is based on consolidated return on assets. |
|---|
| ● | Alignment with our shareholders and the pursuit of long-term value creation is fostered through the issuance of restricted stock units. Each full-time, non-union, United States-based team member receives annual equity awards. These awards generally have a two-year vesting period, supporting retention and company-wide strategy alignment. |
|---|
Our compensation framework helps ensure that we remain strong with best-in-class performance and retain top talent even in economic downturns. We all share in the company’s success, as well as the challenges.
Workplace Philosophy
Our people are the foundation of our success and are our most important resource. Our culture safeguards all people and requires each person to be treated fairly and with dignity. We have equal employment opportunity, no tolerance for harassment of any kind, respect for human rights, diversity, and inclusion – all of which focus on our expectations of treating every person with the utmost respect. Our leadership is reminded of these expectations and receives recurring training on these critical topics.
We work together as a unified team and respect each other as individuals. Our team-based compensation structure reinforces this philosophy. We strive to create an open and inclusive environment, ensuring the best ideas are recognized regardless of the position or the individual. We believe these ideals will continue to drive our success.
Given the value our team members provide, retention is a key metric to our company. In 2020, our overall employee retention was approximately 86%, with steel operations retention of 94%.
Segments
We have three reporting segments: steel operations, metals recycling operations, and steel fabrication operations. Refer to Notes 1 and 13 in the notes to consolidated financial statements in Part II, Item 8 of this Form 10-K for more thorough segment information.
| |
|---|
| |
| Steel Operations Segment |
Steel operations consist of our six EAF steel mills, producing steel from ferrous scrap and scrap substitutes, utilizing continuous casting, automated rolling mills and numerous steel coating and processing lines. Our steel operations sell directly to end-users, steel fabricators, and service centers. These products are used in numerous industry sectors, including the construction, automotive, manufacturing, transportation, heavy and agriculture equipment, and pipe and tube (including OCTG) markets. Our steel operations
accounted for 74%, 76%, and 75% of our consolidated net sales during 2020, 2019 and 2018, respectively. We currently are predominantly a domestic steel company, with exported sales representing 4% of our steel segment net sales during 2020 and 2019, and 5% in 2018.
Our steel operations consist primarily of steelmaking and numerous coating operations. We have approximately 8.4 million tons of flat roll steel annual shipping capacity, comprised of 6.4 million tons of flat roll steel capacity at our Butler and Columbus Flat Roll Divisions. We have additional 2.0 million tons of flat roll steel shipping capacity through The Techs and our Heartland Flat Roll Division – acquired June 29, 2018, as well as distribution of metallic coated and pre-paint products through United Steel Supply (USS) – acquired 75% equity interest March 1, 2019. We have annual flat roll galvanizing capability of 3.9 million tons and painting capability of 1.2 million tons. We also have approximately 4.4 million tons of long product steel capacity at our long products divisions. Once completed, our new Southwest-Sinton Flat Roll Division will increase our total annual steel capacity by over 25%.
Capacities represent manufacturing capabilities based on steel mill configuration and related employee support. These capacities do not represent expected volumes in a given year. In addition, estimates of steel mill capacity are highly dependent on the specific product mix manufactured. Each of our steel mills can and do roll many different types and sizes of products; therefore, our capacity estimates assume a typical product mix.
The following chart summarizes our steel operations primary products and the estimated percentage of tons sold by end market:

SHEET STEEL PRODUCTS
Our sheet steel products, consisting of hot roll, cold roll and coated steel products are currently produced by our Butler and Columbus Flat Roll Divisions, and our numerous downstream coating lines, including The Techs, Heartland Flat Roll Division and USS. Our sheet steel operations represented 69% of steel operations net sales in 2020, and 70% in 2019 and 2018. We produced 7.6 million, 7.8 million, and 7.5 million tons of sheet steel at these facilities in 2020, 2019, and 2018, respectively.
We shipped the following sheet steel products volumes at each of these facilities (tons):
| | | | | | | | | |
|---|---|---|---|---|---|---|---|---|
| | | | | | | | | |
| | | 2020 | | 2019 | | 2018 | | |
| | Butler Flat Roll Division | 2,971,548 | | 3,034,254 | | 3,093,419 | | |
| | Columbus Flat Roll Division | 2,918,187 | | 3,106,293 | | 3,113,600 | | |
| | The Techs | 822,101 | | 847,815 | | 806,345 | | |
| | Heartland Flat Roll Division | 525,542 | | 507,319 | | 167,921 | | |
| | United Steel Supply | 351,785 | | 230,523 | | - | | |
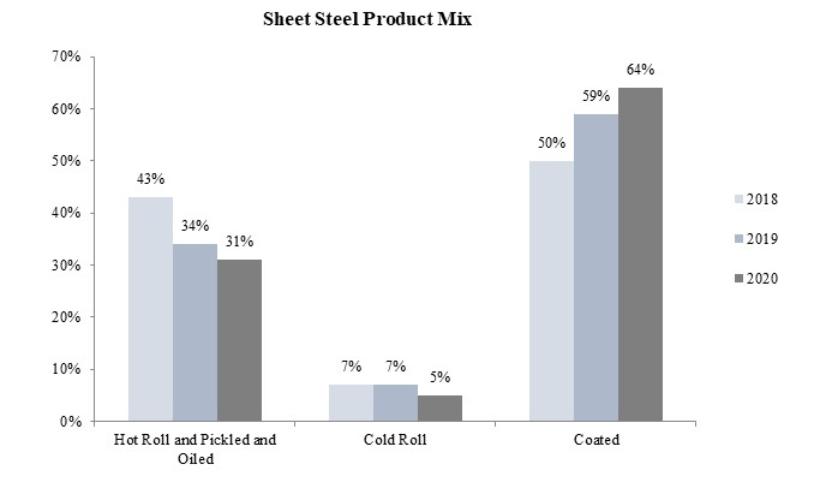
The following chart summarizes the types of sheet steel products sold by sales dollars, during the respective years, with cold roll and coated products representing value-added products:
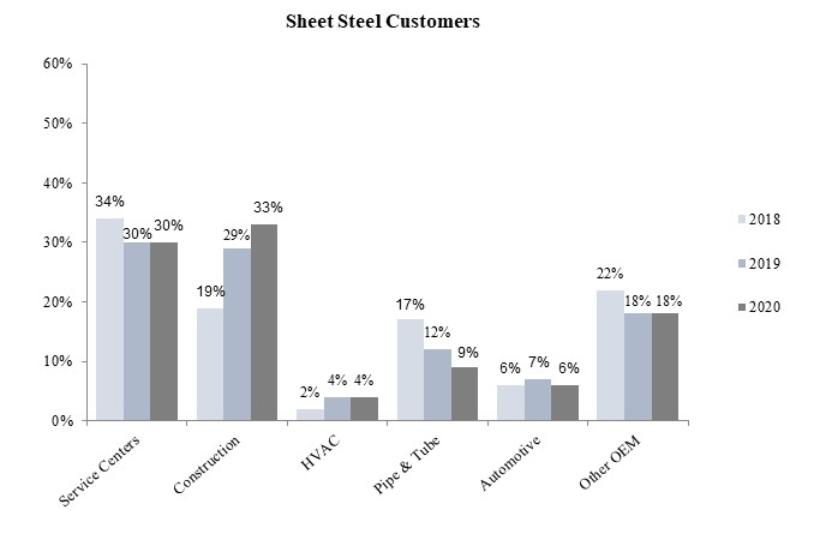
Customers. Steel processors and service centers typically act as intermediaries between primary sheet steel producers and the many end-user manufacturers that require further processing of hot roll coils. The additional processing performed by the intermediate steel processors and service centers include pickling, galvanizing, cutting to length, slitting to size, leveling, blanking, shape correcting, edge rolling, shearing and stamping. We believe that our intermediate steel processor and service center customers will remain an integral part of our customer base. The Columbus Flat Roll Division allows us to capitalize on the industrial markets in the Southern United States and Mexico, as well as further expand our customer base in painted, and line and other pipe products. Galvanized flat roll products produced by our Butler and Columbus Flat Roll Divisions are similar and are sold to a similar customer base. The Techs and Heartland Flat Roll Division specialize in the galvanizing of specific types of flat roll steels in primarily non-automotive applications, servicing a variety of customers in the heating, ventilation and air conditioning (HVAC), construction, agriculture and consumer goods markets. USS adds a complementary distribution channel for metallic coated and pre-paint flat roll steel coils to the niche regional roll-former market, serving the roofing and siding industry. This connected us to a rapidly growing industry segment with customers that do not traditionally purchase steel directly from a steel producer. USS provides continued growth to one of our highest-margin flat roll steel products. Our sheet steel operations also provide a substantial portion of the sheet steel utilized in our steel fabrication operations.
The following chart summarizes the types of end-customers who purchased our sheet steel products, by sales dollars, during the respective years:
LONG PRODUCTS
Our long steel products, consists of a wide array of differentiating products produced by our four mills and Vulcan Threaded Products, Inc. (Vulcan), a downstream finishing operation.
Structural and Rail Division produces a variety of parallel flange beams and channel sections, as well as flat bars and large unequal leg angles, and reinforcing bar including custom cut-to-length, smooth bar, and coiled. We also produce standard strength carbon, intermediate alloy hardness, and premium grade rails in 40 to 320 feet length for the railroad industry. Our state-of-the art heat treating system allows us to produce high quality premium rail, which has been certified by all Class I railroads. In addition, our rail-welding facility has the ability to weld (Continuous Welded Rail) in lengths up to 1,600 feet, which offers substantial savings to the railroads both in terms of initial capital cost and through reduced maintenance. We also utilize Structural and Rail Division’s excess capacity to supply our Engineered Bar Products Division with pull-through volume of billets to utilize its excess rolling capacity.
Engineered Bar Products Division produces a broad range of engineered special-bar-quality (SBQ), merchant-bar-quality (MBQ) and other engineered round steel bars. We also have a bar finishing facility, which provides various downstream finishing operations for SBQ steel bars, including turning, polishing, straightening, chamfering, precision saw-cutting, and heat-treating capabilities. Vulcan produces threaded rod product, and cold drawn and heat treated bar, creating strategic pull-through demand of our special-bar-quality products.
Roanoke Bar Division produces merchant products, including channels, angles, flats, merchant rounds, and reinforcing steel bar. Excess steel billet production is sold to mills without sufficient melting capacities, including our Steel of West Virginia facility. Our steel fabrication operations also purchase angles from Roanoke Bar Division.
Steel of West Virginia produces a wide array of specialty merchant bar products and frequently performs fabrication and finishing operations on those products, such as cutting to length, additional straightening, hole punching, shot blasting, welding, galvanizing, and coating. Through this array of products and additional finishing, we create custom finished products that are generally placed directly into our customers’ assembly operations.
We shipped the following long products volumes at each of these facilities (tons):
| | | | | | | | | |
|---|---|---|---|---|---|---|---|---|
| | | | | | | | | |
| | | 2020 | | 2019 | | 2018 | | |
| | Structural and Rail Division | 1,663,915 | | 1,469,356 | | 1,630,235 | | |
| | Rail production (included above) | 283,141 | | 302,821 | | 295,706 | | |
| | Engineered Bar Products Division | 555,620 | | 650,408 | | 827,049 | | |
| | Roanoke Bar Division | 505,387 | | 529,479 | | 559,801 | | |
| | Steel of West Virginia | 328,998 | | 358,827 | | 315,603 | | |
Customers. The principal customers for our structural steel products are steel service centers, steel fabricators and various manufacturers. Service centers, though not the ultimate end-user, provide valuable mill distribution channels to the fabricators and manufacturers, including small quantity sales, repackaging, cutting, preliminary processing and warehousing. The steel rail marketplace in the United States, Canada and Mexico is specialized and defined, with eight Class I railroads and a large distribution network.
SBQ products are principally consumed by cold finishers, forgers, intermediate processors, OEM manufacturers, steel service centers, and distributors, as well as pull-through volume to Vulcan. Our MBQ products are sold primarily to steel service centers, as well as reinforcing bar distributors, joist producers, and OEMs. Some of the excess steel billet production at the Roanoke Bar Division is sold to mills without sufficient melting capacities, including our Steel of West Virginia facility. Our steel fabrication operations also purchase angles from Roanoke Bar Division. Steel of West Virginia’s customers are primarily OEMs producing truck trailers, industrial lift trucks, merchant products, guardrail posts, manufactured housing, mining, and off-highway construction equipment. Steel of West Virginia’s flexible manufacturing capabilities enable us to meet demand for a variety of custom-ordered and designed products. Many of these products are produced in small quantities for low volume end-uses resulting in a wide variety of customers, the largest of which are in the truck trailer and industrial lift truck industries.
Steel Competition. The markets in which we conduct business are highly competitive with an abundance of competition in the carbon steel industry from North American and foreign integrated and mini-mill steelmaking and processing operations. We compete in numerous industry sections, most significantly tied to the construction, automotive, and other manufacturing sectors. In many applications within these industry sections, steel competes with other materials, such as aluminum, cement, composites, plastics, carbon fiber, glass and wood. Some of our products are commodities, subject to their own cyclical fluctuations in supply and demand. However, we are focused on providing a broad range of diversified value-added products that de-emphasize commodity steel. The primary competitive influences on products we sell are price, quality and value-added services.
| Metals Recycling Operations Segment |
|---|
The metals recycling operations include both ferrous and nonferrous scrap metal processing, transportation, marketing, and brokerage and scrap management services, strategically located primarily in close proximity to our steel mills and other end-user scrap consumers, throughout the United States, and Central and Northern Mexico. In August 2020, we completed the acquisition of Zimmer, S.A. de C.V. (Zimmer), a Mexican metal recycling company, which is an important part of our raw material procurement strategy for our new steel mill in Sinton, Texas. Our metals recycling operations accounted for 11% of our consolidated net sales during 2020 and 2019, and 13% in 2018. Export sales represented 10%, 9% and 8% of metals recycling segment net sales during 2020, 2019 and 2018, respectively.
We shipped the following from our metals recycling operations:
| | | | | | | | | |
|---|---|---|---|---|---|---|---|---|
| | | | | | | | | |
| | | 2020 | | 2019 | | 2018 | | |
| | Ferrous metal total (gross tons) | 4,591,881 | | 4,627,214 | | 5,123,553 | | |
| | Shipments to our steel mills | 3,184,451 | | 3,061,257 | | 3,346,135 | | |
| | Percent of total to our steel mills | 69% | | 66% | | 65% | | |
| | | | | | | | | |
| | Nonferrous metals (thousands of pounds) | 977,882 | | 1,068,208 | | 1,131,412 | | |
We sell various grades of processed ferrous scrap primarily to steel mills and foundries. Ferrous scrap metal is the primary raw material for EAF’s, such as our steel mills. In addition, we sell various grades of nonferrous metals such as copper, brass, aluminum, and stainless steel, to aluminum, steel and ingot manufacturers, brass and bronze ingot makers, copper refineries and mills, smelters, specialty mills, alloy manufacturers, and other consumers.
We purchase processed and unprocessed ferrous and nonferrous scrap metals, in a variety of forms for our metals recycling facilities.
Ferrous scrap comes from two primary sources:
| ● | Manufacturers and industrial plants, metal fabrication plants, machine shops and factories, which generate ferrous scrap referred to as prompt or industrial scrap, and |
|---|
| ● | Scrap dealers, retail individuals, auto wreckers, demolition firms and others who provide steel and iron scrap, referred to as obsolete scrap. Obsolete scrap includes scrap recycled from end-of-life items, such as automobiles, appliances, and machinery. |
|---|
Nonferrous scrap comes from three primary sources:
| ● | Manufacturers and other nonferrous scrap sources, which generate or sell scrap aluminum, copper, stainless steel, and other nonferrous metals, |
|---|
| ● | Producers of items such as electric wire, telecommunication service providers, aerospace, defense and recycling companies that generate nonferrous scrap consisting primarily of copper wire, aluminum beverage cans, and various other metals and alloys, and |
|---|
| ● | Retail individuals who sell material directly to our facilities, which they collect from a variety of sources. |
|---|
We do not purchase a significant amount of scrap metal from a single source or from a limited number of major sources. Market demand and the composition, quality, size, weight, and location of the materials are the primary factors that determine prices.
Products. Our metals recycling operations primarily involve the purchase, processing, and resale of ferrous and nonferrous scrap metals into reusable forms and grades. We process an array of ferrous products through a variety of methods, including sorting, shredding, shearing, cutting, and breaking. Our major ferrous products include heavy melting steel, busheling, bundled scrap, shredded scrap and other scrap metal products, such as steel turnings and cast iron. These products vary in properties or attributes related to cleanness, size of individual pieces, and residual alloys. The necessary characteristics of the ferrous products are determined by the specific needs and requirements of the consumer and affect the individual product’s relative value. We process numerous grades of nonferrous products, including aluminum, brass, copper, stainless steel, and other nonferrous metals. Additionally, we provide transportation logistics (truck, rail, and river barge), marketing, brokerage, and scrap management services, providing competitive price and cost advantages to our suppliers and customers. We design, install, and manage customized scrap management programs for industrial manufacturing companies.
Customers. We sell various grades of processed ferrous scrap to end-users, such as EAF steel mills, integrated steelmakers, foundries, secondary smelters, and metal brokers, who aggregate materials for other large users. Ferrous scrap metal is the primary raw material for electric arc furnaces, such as our steel mills. Most of our ferrous scrap customers purchase processed scrap through negotiated spot sales contracts which establish a quantity purchase for the month. The price we charge for ferrous scrap depends upon market demand and pricing, transportation costs, as well as the quality and grade of the scrap.
Competition. Scrap is a global commodity influenced by conditions in a number of industrialized and emerging markets throughout Asia, Europe and North America. The markets for scrap metals are highly competitive, both in the purchase of raw or unprocessed scrap, and the sale of processed scrap. With regard to the purchase of unprocessed scrap, we compete with numerous independent recyclers, as well as smaller scrap companies engaged only in collecting obsolete scrap. In many cases, we also purchase unprocessed scrap metal from smaller scrap dealers and other processors. Successful procurement of materials is determined primarily by the price offered by the purchaser for the raw scrap and the proximity of our processing facility to the source of the raw scrap. Both ferrous and nonferrous scrap sells as a commodity in both domestic and international markets, which are affected, sometimes significantly, by relative economic conditions, currency fluctuations, and the availability and cost of transportation. Competition for sales of processed scrap is based primarily on the price, quality, and location of the scrap metals, as well as the level of service provided in terms of reliability and timing of delivery.
We also face potential competition for sales of processed scrap from other producers of steel products, such as EAF and integrated steel mills, some of which like us are also vertically integrated in the scrap metals recycling business. In addition, other steel mills may compete with us in attempting to secure scrap supply through direct purchasing from our scrap suppliers. Scrap metal processors also face competition from substitutes for prepared ferrous scrap, such as pig iron, pelletized iron, hot briquetted iron (HBI), direct reduced iron (DRI), and other forms of processed iron. The availability and relative prices of substitutes for ferrous scrap could result in a decreased demand for processed ferrous scrap and could result in lower prices and/or lower demand for our scrap products.
The industry is highly fragmented with many smaller, regional, national and global companies, which have multiple locations in areas in which OmniSource also operates. No single scrap metals recycler has a significant market share in the domestic market.
| Steel Fabrication Operations Segment |
|---|
Our steel fabrication operations include seven New Millennium Building Systems plants that primarily serve the non-residential construction industry throughout the United States. We have a national operating footprint that allows us to serve the entire domestic construction market, as well as national accounts, such as large retail chains.
Steel fabrication operations accounted for 9% of our consolidated net sales during 2020 and 2019, and 8% in 2018. We sold 666,000, 644,000, and 642,000 tons of joist and deck products during 2020, 2019, and 2018, respectively.
Products. Our steel fabrication operations produce steel building components, including steel joists, girders, and trusses, and steel deck. Our joist products include bowstring, arched, scissor, double-pitched and single-pitched joists. Our deck products include a full range of steel decking: roof, form, composite floor, specialty architectural, floor systems, and bridge deck.
Customers and Markets. Our primary steel fabrication operations customers are non-residential steel fabricators, such as metal building companies, general construction contractors, developers, brokers and governmental entities. Our customers are located throughout the United States, including national accounts. Our steel fabrication operations maintain approximately one-third of the total domestic steel joist and deck market of approximately 2.3 million tons in 2020, and 2.1 million tons in 2019 and 2018. We believe we are well positioned with our national footprint as the non-residential construction market remains strong, and we have available capacity that can be deployed as needed.
Competition. We compete with other North American joist and steel deck producers primarily on the basis of price, quality, customer service, and proximity to the customer. Our national footprint allows us to service the entire domestic non-residential construction market, as well as national accounts such as large retail chains, including their related omni-channel distribution centers, and certain specialty deck customers.
| Other Information |
Sources, Availability, and Cost of Steel and Other Operations’ Raw Materials
Scrap Metals. The principal raw material of our steel operations is scrap metal derived from, among other sources "home scrap”, generated internally at steel mills themselves; industrial scrap, generated as a by-product of manufacturing; and obsolete scrap recycled from end-of-life automobiles, appliances, and machinery, and demolition scrap from obsolete structures, containers and machines.
Ferrous scrap typically comprises more than 80% of the metallic melt mix in EAF steelmaking, in contrast to integrated mill steelmaking, where the proportion of scrap has traditionally been approximately 25% to 35%. Depending upon the scrap substitute material that may be available from time to time, and the relative cost of such material, the percentage of scrap used in our steelmaking operations could be increased or reduced in our metallic melt mix.
Many variables can impact ferrous scrap prices, all of which reflect the pushes and pulls of the supply demand equation. These factors include the level of domestic steel production (high quality low-residual scrap is a by-product of steel manufacturing activity), the level of exports of scrap from the United States, and the amount of obsolete scrap production. In addition, domestic ferrous scrap prices generally have a strong correlation and spread to global pig iron pricing. Generally, as domestic steel demand increases, so does scrap demand and resulting scrap prices. The reverse is also normally, but not always, true with scrap prices following steel prices downward when supply exceeds demand. When scrap prices greatly accelerate, this can challenge one of the principal elements of an EAF based steel mill’s traditional lower cost structure—the cost of its metallic raw material.
Iron Units. In addition to scrap, pig iron, DRI, HBI, and internally sourced liquid pig iron are used in our EAF steel mill production. During 2020, 2019, and 2018, we consumed 10.4 million, 10.6 million and 10.9 million tons, respectively, of metallic materials in our steelmaking furnaces, of which, iron units other than scrap, represented approximately 13% of the tons in 2020 and 2019, and 14% in 2018.
Energy Resources
Electricity. Electricity is a significant input required in the EAFs in our steelmaking operations, representing between 4% and 5% of steel production costs of goods sold in 2020, 2019 and 2018. We have entered into fixed price electricity contracts for the Butler Flat Roll Division, Columbus Flat Roll Division, Roanoke Bar Division and Steel of West Virginia, while our Engineered Bar Products Division has a combination of fixed pricing and market pricing for the various components of the electrical services (demand charge, energy charge, riders, etc.). Our Structural and Rail Division purchases electricity at current market prices and through fixed price forward contracts.
Research and Development
Our research and development activities have consisted of efforts to expand, develop and improve our steel products and operating processes, such as our planned Southwest-Sinton Flat Roll Division, and our efforts to develop and improve alternative ironmaking technologies. Most of these research and development efforts have been conducted in-house by our employees.
Environmental Matters
Our operations are subject to substantial and evolving local, state, and federal environmental, health and safety laws and regulations concerning, among other things, emissions to the air, discharges to surface and ground water and to sewer systems, and the generation, handling, storage, transportation, treatment and disposal of solid and hazardous wastes and secondary materials. Our operations are dependent upon permits regulating discharges into the environment or the use and handling of by-products in order to operate our facilities. We dedicate considerable resources aimed at achieving compliance with federal, state and local laws concerning the environment. While we do not currently believe that our future compliance efforts with such provisions will have a material adverse effect on our results of operations, cash flows or financial condition, this is subject to change in the ever-evolving regulatory environment in which we operate.
Since the interpretation and enforcement of environmental laws and regulations that may be enacted from time to time are subject to changing social or political pressures, our environmental capital expenditures and costs for environmental compliance may increase in the future. In addition, due to the possibility of unanticipated regulatory or other developments, the amount and timing of future environmental expenditures may vary substantially from those currently anticipated. The cost of current and future environmental
compliance may also place United States steel producers at a competitive disadvantage with respect to foreign steel producers, which may not be required to undertake equivalent costs in their operations.
Pursuant to the Resource Conservation and Recovery Act (RCRA), which governs the treatment, handling and disposal of solid and hazardous wastes, the United States Environmental Protection Agency, or United States EPA, and authorized state or local environmental agencies may conduct inspections to identify alleged violations or areas where there may have been releases of solid or hazardous constituents into the environment and require the facilities to take corrective action to address any such releases. RCRA also allows citizens to bring certain suits against regulated facilities for potential damages and cleanup. Our steelmaking and certain other facilities generate wastes subject to RCRA. Our operations produce various by-products, some of which, for example EAF dust, are often categorized as hazardous waste, requiring special handling for disposal or for the recovery of metallics. We collect such by-products in pollution control equipment, such as baghouses, and then recycle what’s possible, and appropriately dispose of the remaining unusable by-products. While we cannot predict the future actions of the regulators or other interested parties, the potential exists for required corrective action at these facilities, the costs of which could be substantial.
Under the Comprehensive Environmental Response, Compensation and Liability Act, known as (CERCLA) or (Superfund), the United States EPA, state agencies and, in some instances, private parties have the authority to impose joint and several liability for the remediation of contaminated properties upon generators of waste, current and former site owners and operators, transporters and other potentially responsible parties, regardless of fault or the legality of the original disposal activity. Many states have statutes and regulatory authorities similar to CERCLA that can also apply. We have a number of material handling agreements with various contractors to properly dispose of or recycle our EAF dust and certain other by-products of our operations. However, we cannot assure that, even if there has been no fault by us, we may not still be cited as a waste generator by reason of an environmental cleanup at a site to which our by-products were transported.
The Clean Water Act and similar state and local laws apply to aspects of our operations and impose regulatory restrictions related to the discharge of wastewater, storm water and dredged or fill material. The United States EPA, state agencies and, in certain instances, private parties have the ability to bring suit alleging violations and seeking penalties and damages. The Clean Water Act’s provisions can require new or expanded water treatment investments to be made and can limit or even prohibit certain current or planned activities at our operations.
The Clean Air Act and analogous state and local laws require many of our facilities to obtain and maintain air permits in order to operate. Air permits can impose new or expanded obligations to limit or prevent current or future emissions and to add costly pollution control equipment. Enforcement for alleged violations can be brought by the United States EPA, state agencies, and in certain instances private parties, and can result in substantial penalties and injunctive relief.
In addition, there are a number of other environmental, health and safety laws and regulations that apply to our facilities and may affect our operations. By way of example and not of limitation, certain portions of the federal Toxic Substances Control Act, Oil Pollution Act, Safe Drinking Water Act and Emergency Planning and Community Right-to-Know Act, as well as state and local laws and regulations implemented by the regulatory agencies, apply to aspects of our facilities’ operations. In some instances, we may also be subject to foreign governments’ regulations and international treaties and laws. Many of these laws allow both the governments and citizens to bring certain suits against regulated facilities for alleged environmental violations. Finally, our operations could be subject to certain toxic tort suits brought by citizens or other third parties alleging causes of action such as nuisance, negligence, trespass, infliction of emotional distress, or other claims alleging personal injury or property damage.
Available Information
Our internet website address is www.steeldynamics.com. We make available on our internet website, under "Investors,” free of charge, as soon as reasonably practicable after such materials are electronically filed with, or furnished to, the Securities and Exchange Commission, our Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K and amendments to those reports, as well as press releases, ownership reports pursuant to Section 16(a) of the Securities Act of 1933, our Code of Ethics for Principal Executive Officers and Senior Financial Officers, our Code of Business Conduct and Ethics, and any amendments thereto or waivers thereof, as well as our Audit, Compensation, and Corporate Governance and Nominating Committee Charters. The contents of our or any other website are not incorporated into this report.
Previous: Cover and table of contents · Next: Item 1A. RISK FACTORS