 filings.tools
Stanley Black & Decker 2021 10-K/A Amended Annual Report
SWK · CIK 93556 · Form 10-K/A · Fiscal year ended January 2, 2021 · Filed January 31, 2022
22 sections, 664K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 10-K/A
(Amendment No. 1)
☑ ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended January 2, 2021
or
☐ TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the transition period from ___________ to ___________
Commission File Number 001-05224
STANLEY BLACK & DECKER, INC.
(Exact Name Of Registrant As Specified In Its Charter)
| Connecticut | 06-0548860 | |||||||
| (State or Other Jurisdiction of Incorporation or Organization) | (I.R.S. Employer Identification Number) |
1000 STANLEY DRIVE
NEW BRITAIN, CT 06053
(Address of Principal Executive Offices and Zip Code)
Registrant’s Telephone Number, Including Area Code 860 225-5111
Securities Registered Pursuant to Section 12(b) of the Act:
| Title Of Each Class | Trading Symbol(s) | Name Of Each Exchange on Which Registered | |||||||||
| Common Stock | $2.50 Par Value per Share | SWK | New York Stock Exchange | ||||||||
| Corporate Units | SWT | New York Stock Exchange |
Securities Registered Pursuant To Section 12(g) Of The Act:
None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes þ No ¨
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or 15(d) of the Act. Yes ¨ No þ
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports) and (2) has been subject to such filing requirements for the past 90 days. Yes þ No ¨
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files).
Yes þ No ¨
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and "emerging growth company" in Rule 12b-2 of the Exchange Act.
| Large Accelerated Filer | þ | Accelerated Filer | ¨ | |||||||||||
| Non-Accelerated Filer | ¨ | Smaller Reporting Company | ☐ | |||||||||||
| Emerging Growth Company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report.☑
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ☐ No þ
As of June 26, 2020, the aggregate market value of the voting and non-voting common equity held by non-affiliates of the registrant was $21.8 billion based on the New York Stock Exchange closing price for such shares on that date. On February 15, 2021, the registrant had 160,893,004 shares of common stock outstanding.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of the registrant’s definitive proxy statement relating to its 2021 annual meeting of shareholders (the "2021 Proxy Statement") are incorporated by reference into Part III of this Annual Report on Form 10-K/A where indicated. The 2021 Proxy Statement was filed with the U.S. Securities Exchange Commission within 120 days after the end of the fiscal year to which this report relates.
EXPLANATORY NOTE
Stanley Black & Decker, Inc. (“the Company”) filed its Annual Report on Form 10-K for the fiscal year ended January 2, 2021 with the U.S. Securities and Exchange Commission (“SEC”) on February 18, 2021 (the “Original Form 10-K”). This Amendment No. 1 on Form 10-K (this "Amendment" or "Form 10-K/A") is being filed to restate certain information in the Company's previously issued consolidated financial statements for the fiscal years ended January 2, 2021, December 28, 2019, and December 29, 2018, as well as the summarized unaudited interim financial information for each of the quarters during the years ended January 2, 2021 and December 28, 2019 (collectively, the "Affected Periods"), contained in the Original Form 10-K (the “Restatement”).
Background of Restatement
Subsequent to the filing of the Original Form 10-K, the Company received comments from the SEC Staff regarding its accounting for equity units issued in May 2017 and November 2019 (the “Equity Units”), which were comprised of forward stock purchase contracts and convertible preferred stock. Upon further reflection on the comments received from the SEC Staff and the nature of the Equity Units, the Company determined that errors were made in its original accounting conclusions related to: (a) accounting for the forward stock purchase contracts and convertible preferred stock as separate units of account, and (b) applying the treasury stock method to the shares associated with the forward stock purchase contracts for purposes of calculating diluted earnings per share.
Based on the Company's correspondence with the SEC Staff, the Company re-evaluated its accounting assessment and concluded that the Equity Units should be accounted for as one unit of account based on the economic linkage between the forward stock purchase contracts and convertible preferred stock as well as the Company’s assessment of the applicable accounting guidance relating to combining freestanding instruments. The Equity Units represent mandatorily convertible preferred stock. Accordingly, the shares associated with the combined instrument should be reflected in diluted earnings per share using the if-converted method.
On January 24, 2022, the Company's management and the audit committee of the Company's Board of Directors concluded that the previously issued financial statements during the Affected Periods should be restated. In this Amendment, the Company has restated its basic and diluted earnings per share, as applicable, and the related diluted earnings per share impacts disclosed in this Form 10-K/A, as a result of accounting for the Equity Units as a combined instrument. The shares underlying the forward stock purchase contracts have been included in the denominator of the Company’s diluted earnings per share utilizing the if-converted method, which represents a correction of an error of previously applying the treasury stock method. The Company also corrected the classification of certain amounts in the consolidated balance sheets, statements of cash flows and statements of changes in shareowners' equity to reflect the forward stock purchase contracts and convertible preferred stock as one unit of account, which represents a correction of an error of previously accounting for the instruments as two units of account. The corrections have no impact on the Company’s net earnings, total assets, cash flows from operations or business segment information.
Internal Control Considerations
In connection with the Restatement, management has concluded that the Company had material weaknesses in its internal control over financial reporting as of January 2, 2021, related to its accounting for the Equity Units. For a discussion of management’s considerations of the Company’s disclosures controls and procedures, internal controls over financial reporting, and material weaknesses identified, refer to Controls and Procedures in Part II, Item 9A.
Items Amended in this Amendment
This Amendment sets forth the Original Form 10-K, as modified and superseded where necessary to reflect the Restatement and the related internal control considerations. Accordingly, the following items included in the Original Form 10-K have been amended:
-
Part I, Item 1.A, Risk Factors
-
Part II, Item 6, Selected Financial Data
-
Part II, Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations
-
Part II, Item 8, Financial Statements and Supplementary Data
-
Part II, Item 9A, Controls and Procedures
-
Part IV, Item 15, Exhibits and Financial Statement Schedules
Additionally, in accordance with Rule 12b-15 under the Securities Exchange Act of 1934, as amended, the Company is including with this Amendment currently dated certifications from its Chief Executive Officer and President and Chief Financial Officer. These certifications are filed or furnished, as applicable, as Exhibits 31.1(a), 31.1(b), 32.1 and 32.2.
Except as described above, this Amendment does not amend, update or change any other disclosures in the Original Form 10-K. In addition, the information contained in this Amendment does not reflect events occurring after the Original Form 10-K and does not modify or update the disclosures therein, except to reflect the effects of the Restatement. This Amendment should be read in conjunction with the Company’s other filings with the SEC.
TABLE OF CONTENTS
FORM 10-K/A
PART I
Item 1. BUSINESS
Stanley Black & Decker, Inc. ("the Company") was founded in 1843 by Frederick T. Stanley and incorporated in Connecticut in 1852. In March 2010, the Company completed a merger ("the Merger") with The Black & Decker Corporation (“Black & Decker”), a company founded by S. Duncan Black and Alonzo G. Decker and incorporated in Maryland in 1910. At that time, the Company changed its name from The Stanley Works to Stanley Black & Decker, Inc. The Company’s principal executive office is located at 1000 Stanley Drive, New Britain, Connecticut 06053 and its telephone number is (860) 225-5111.
The Company is a diversified global provider of hand tools, power tools and related accessories, engineered fastening systems and products, services and equipment for oil & gas and infrastructure applications, commercial electronic security and monitoring systems, healthcare solutions, and automatic doors, with 2020 consolidated annual revenues of $14.5 billion. Approximately 61% of the Company’s 2020 revenues were generated in the United States, with the remainder largely from Europe (19%), emerging markets (11%) and Canada (5%).
The Company continues to execute a growth and acquisition strategy that involves industry, geographic and customer diversification to foster sustainable revenue, earnings and cash flow growth. The Company remains focused on delivering above-market organic growth with margin expansion by leveraging its proven and long-standing Stanley Black & Decker Operating Model (“SBD Operating Model”) which has continually evolved over the past 15 years as times have changed. At the center of the SBD Operating Model is the concept of the interrelationship between people and technology, which intersect and interact with the other key elements: Performance Resiliency, Extreme Innovation, Operations Excellence and Extraordinary Customer Experience. Each of these elements co-exists synergistically with the others in a systems-based approach. The Company will leverage the SBD Operating Model to continue making strides towards achieving its vision of delivering top-quartile financial performance, becoming known as one of the world’s leading innovators and elevating its commitment to social responsibility.
The above strategy has also resulted in approximately $11.5 billion of acquisitions since 2002 (excluding the Merger), which was enabled by strong cash flow generation and increased debt capacity. In recent years, the Company completed the acquisitions of Consolidated Aerospace Manufacturing, LLC ("CAM") for approximately $1.4 billion, International Equipment Solutions Attachments Group ("IES Attachments") for approximately $654 million, Nelson Fastener Systems ("Nelson") for approximately $424 million, the Tools business of Newell Brands ("Newell Tools") for approximately $1.8 billion, and the Craftsman® brand from Sears Holdings Corporation ("Sears Holdings") for an estimated cash purchase price of approximately $937 million on a discounted basis. The CAM acquisition further diversifies the Company's presence in the industrial markets and expands its portfolio of specialty fasteners in the aerospace and defense markets. The IES Attachments acquisition further diversified the Company's presence in the industrial markets, expanded its portfolio of attachment solutions and provided a meaningful platform for continued growth. The Nelson acquisition was complementary to the Company's product offerings, enhanced its presence in the general industrial end markets, and expanded its portfolio of highly-engineered fastening solutions. The Newell Tools acquisition, which included the industrial cutting, hand tool and power tool accessory brands IRWIN® and LENOX®, enhanced the Company’s position within the global tools & storage industry and broadened the Company’s product offerings and solutions to customers and end users, particularly within power tool accessories. The Craftsman acquisition provided the Company with the rights to develop, manufacture and sell Craftsman®-branded products in non-Sears Holdings channels.
In January 2019, the Company acquired a 20 percent interest in MTD Holdings Inc. ("MTD"), a privately held global manufacturer of outdoor power equipment, for $234 million in cash. Under the terms of the agreement, the Company has the option to acquire the remaining 80 percent of MTD beginning on July 1, 2021. The investment in MTD increases the Company's presence in the greater than $20 billion lawn and garden segment and enables the two companies to work together to pursue revenue and cost opportunities, improve operational efficiency, and introduce new and innovative products for professional and residential outdoor equipment customers, utilizing each company's respective portfolios of strong brands.
In May 2019, the Company sold its Sargent and Greenleaf mechanical locks business within the Security segment for net proceeds of $79 million. In February 2017, the Company completed the sale of the majority of its mechanical security businesses, which included the commercial hardware brands of Best Access, phi Precision and GMT, for net proceeds of approximately $717 million. These divestitures allowed the Company to invest in other areas of the Company that fit into its long-term growth strategy.
The Company has also divested several smaller businesses in recent years that did not fit into its long-term strategic objectives.
Refer to Note E, Acquisitions and Investments, and Note T, Divestitures, of the Notes to Consolidated Financial Statements in Item 8 for further discussion.
The Company’s growth and acquisition strategy is interdependent with its social responsibility strategy focused on workforce upskilling, product innovation, and environmental preservation including mitigating the impacts of climate change. These are core business issues that ensure the long-term viability of the Company, its customers, suppliers, and communities. The Company has established environmental, social and corporate governance targets embodied in its 2030 Corporate Social Responsibility (“CSR”) strategy that include upskilling 10 million makers and creators, enhancing 500 million lives through purpose driven product innovation, becoming carbon-positive, landfill-free, and reducing water use in water stressed and scarce areas. The carbon positive target includes third-party approved science-based targets to reduce absolute scope 1 and 2 greenhouse gas emissions by greater than 100% by 2030, and to reduce supply chain emissions by 35%. The Company’s CSR strategy considers all life-cycle stages including material procurement from supply chain partners, product design, manufacturing, distribution and transportation, product use, product service and end-of-life. Refer to section "Human Capital Management" for additional information regarding the Company's commitment to upskilling its employees and improving diversity, equity and inclusion.
Description of the Business
The Company’s operations are classified into three reportable business segments, which also represent its operating segments: Tools & Storage, Industrial and Security. All segments have significant international operations and are exposed to translational and transactional impacts from fluctuations in foreign currency exchange rates.
Additional information regarding the Company’s business segments and geographic areas is incorporated herein by reference to the material captioned “Business Segment Results” in Item 7 and Note P, Business Segments and Geographic Areas, of the Notes to Consolidated Financial Statements in Item 8.
Tools & Storage
The Tools & Storage segment is comprised of the Power Tools and Equipment ("PTE") and Hand Tools, Accessories & Storage ("HTAS") businesses. Annual revenues in the Tools & Storage segment were $10.3 billion in 2020, representing 71% of the Company’s total revenues.
The PTE business includes both professional and consumer products. Professional products include professional grade corded and cordless electric power tools and equipment including drills, impact wrenches and drivers, grinders, saws, routers and sanders, as well as pneumatic tools and fasteners including nail guns, nails, staplers and staples, concrete and masonry anchors. Consumer products include corded and cordless electric power tools sold primarily under the BLACK+DECKER® brand, lawn and garden products, including hedge trimmers, string trimmers, lawn mowers, edgers and related accessories, and home products such as hand-held vacuums, paint tools and cleaning appliances.
The HTAS business sells hand tools, power tool accessories and storage products. Hand tools include measuring, leveling and layout tools, planes, hammers, demolition tools, clamps, vises, knives, saws, chisels and industrial and automotive tools. Power tool accessories include drill bits, screwdriver bits, router bits, abrasives, saw blades and threading products. Storage products include tool boxes, sawhorses, medical cabinets and engineered storage solution products.
The segment sells its products to professional end users, distributors, retail consumers and industrial customers in a wide variety of industries and geographies. The majority of sales are distributed through retailers, including home centers, mass merchants, hardware stores, and retail lumber yards, as well as third-party distributors and a direct sales force.
Industrial
The Industrial segment is comprised of the Engineered Fastening and Infrastructure businesses. Annual revenues in the Industrial segment were $2.3 billion in 2020, representing 16% of the Company’s total revenues.
The Engineered Fastening business primarily sells highly engineered components such as fasteners, fittings and various engineered products, which are designed for specific application across multiple verticals. The product lines include externally threaded fasteners, blind rivets and tools, blind inserts and tools, drawn arc weld studs and systems, engineered plastic and mechanical fasteners, self-piercing riveting systems, precision nut running systems, micro fasteners, high-strength structural fasteners, axel swage, latches, heat shields, pins, and couplings. The business sells to customers in the automotive, manufacturing, electronics, construction, and aerospace industries, amongst others, and its products are distributed through direct sales forces and, to a lesser extent, third-party distributors.
The Infrastructure business consists of the Attachment Tools and Oil & Gas product lines. Attachment Tools sells hydraulic tools and high quality, performance-driven heavy equipment attachment tools for off-highway applications. Oil & Gas sells and rents custom pipe handling, joint welding and coating equipment used in the construction of large and small diameter pipelines, and provides pipeline inspection services. The Infrastructure business sells to the oil and natural gas pipeline industry and other industrial customers. The products and services are primarily distributed through a direct sales force and, to a lesser extent, third-party distributors.
Security
The Security segment is comprised of the Convergent Security Solutions ("CSS") and Mechanical Access Solutions ("MAS") businesses. Annual revenues in the Security segment were $1.9 billion in 2020, representing 13% of the Company’s total revenues.
The CSS business designs, supplies and installs commercial electronic security systems and provides electronic security services, including alarm monitoring, video surveillance, fire alarm monitoring, systems integration and system maintenance. Purchasers of these systems typically contract for ongoing security systems monitoring and maintenance at the time of initial equipment installation. The business also sells healthcare solutions, which include asset tracking, infant protection, pediatric protection, patient protection, wander management, fall management, and emergency call products. The CSS business sells to consumers, retailers, educational, financial and healthcare institutions, as well as commercial, governmental and industrial customers. The MAS business primarily sells automatic doors to commercial customers. Products for both businesses are sold predominantly on a direct sales basis.
Other Information
Competition
The Company competes on the basis of its reputation for product quality, its well-known brands, its commitment to customer service, its strong customer relationships, the breadth of its product lines, its innovative products and customer value propositions.
The Company encounters active competition in the Tools & Storage and Industrial segments from both larger and smaller companies that offer the same or similar products and services. Certain large customers offer private label brands (“house brands”) that compete across a wide spectrum of the Company’s Tools & Storage segment product offerings. Competition in the Security segment is generally fragmented via both large international companies and regional providers. Competition tends to be based primarily on price and the quality and comprehensiveness of services offered to customers.
Major Customers
A significant portion of the Company’s Tools & Storage products are sold to home centers and mass merchants in the U.S. and Europe. A consolidation of retailers both in North America and abroad has occurred over time. While this consolidation and the domestic and international expansion of these large retailers have provided the Company with opportunities for growth, the increasing size and importance of individual customers creates a certain degree of exposure to potential sales volume loss. Lowe's accounted for approximately 15%, 15% and 12% of the Company's consolidated net sales in 2020, 2019 and 2018, respectively, while The Home Depot accounted for approximately 12% and 10% of the Company's consolidated net sales in 2020 and 2019, respectively. No other customer exceeded 10% of the Company's consolidated net sales in 2020, 2019 or 2018.
Working Capital
The Company continues to practice the five operating principles encompassed by Operations Excellence, one element of the SBD Operating Model, which work in concert: sales and operations planning, operational lean, complexity reduction, global supply management, order-to-cash excellence, the application of Industry 4.0 and upskilling the Company's workforce. The Company develops standardized business processes and system platforms to reduce costs and provide scalability. The continued focus on the operating principles above have been instrumental in reducing working capital and creating significant opportunities to generate incremental free cash flow (defined as cash flow from operations less capital and software expenditures). Working capital turns were 10.4 at the end of 2020, up 0.6 turns from 2019, reflecting the strong revenue performance in 2020. The Company plans to continue leveraging Operations Excellence to generate ongoing improvements, both in the existing business and future acquisitions, in working capital turns, cycle times, complexity reduction and customer service levels, with a long-term goal of sustaining 10+ working capital turns.
Raw Materials
The Company’s products are manufactured using resins, ferrous and non-ferrous metals including, but not limited to, steel, zinc, copper, brass, aluminum and nickel. The Company also purchases components such as batteries, motors, and electronic components to use in manufacturing and assembly operations along with resin-based molded parts. The raw materials required are procured globally and generally available from multiple sources at competitive prices. As part of the Company's Enterprise Risk Management, the Company has implemented a supplier risk mitigation strategy in order to identify and address any potential supply disruption or material scarcity issues associated with commodities, components, finished goods and critical services. The Company does not anticipate difficulties in obtaining supplies for any raw materials or energy used in its production processes.
Patents and Trademarks
No business segment is solely dependent, to any significant degree, on patents, licenses, franchises or concessions, and the loss of one or several of these patents, licenses, franchises or concessions would not have a material adverse effect on any of the Company's businesses. The Company owns numerous patents, none of which individually is material to the Company's operations as a whole. These patents expire at various times over the next 20 years. The Company holds licenses, franchises and concessions, none of which individually or in the aggregate are material to the Company's operations as a whole. These licenses, franchises and concessions vary in duration, but generally run from one to 40 years.
The Company has numerous trademarks that are used in its businesses worldwide. In the Tools & Storage segment, significant trademarks include STANLEY®, BLACK+DECKER®, DEWALT®, FLEXVOLT®, IRWIN®, LENOX®, CRAFTSMAN®, PORTER-CABLE®, BOSTITCH®, FATMAX®, Powers®, Guaranteed Tough®, MAC TOOLS®, PROTO®, Vidmar®, FACOM®, Expert®, LISTA® and the yellow & black color scheme for power tools and accessories. Significant trademarks in the Industrial segment include STANLEY®, CRC®, NELSON®, LaBounty®, Dubuis®, CribMaster®, POP®, Avdel®, Heli-Coil®, Tucker®, NPR®, Spiralock®, PALADIN®, CAM®, Bristol Industries®, Voss™, Aerofit™, EA Patten™, Integra®, Optia®, PENGO® and STANLEY® Assembly Technologies. The Security segment includes significant trademarks such as STANLEY®, HSM®, SONITROL®, Stanley Access Technologies™, AeroScout®, Hugs®, WanderGuard®, Roam Alert®, MyCall®, Arial® and Bed-Check®. The terms of these trademarks typically vary from 10 to 20 years, with most trademarks being renewable indefinitely for like terms.
Governmental Regulations
The Company's operations are subject to numerous federal, state and local laws and regulations, both within and outside the U.S., in areas such as environmental protection, international trade, data privacy, tax, consumer protection, government contracts, and others. The Company is subject to import and export controls, tariffs, and other trade-related regulations and restrictions in the countries in which it has operations or otherwise does business. These controls, tariffs, regulations, and restrictions have had, and may continue to have, a material impact on the Company's business, including its ability to sell products and to manufacture or source components. Refer to Item 1A. Risk Factors in Part I of this Form 10-K/A for additional information regarding various laws and regulations that affect the Company's business operations.
The Company is also subject to various environmental laws and regulations in the U.S. and foreign countries where it has operations. In the normal course of business, the Company is involved in various legal proceedings relating to environmental issues. The Company’s policy is to accrue environmental investigatory and remediation costs for identified sites when it is probable that a liability has been incurred and the amount of loss can be reasonably estimated. In the event that no amount in the range of probable loss is considered most likely, the minimum loss in the range is accrued. The amount of liability recorded is based on an evaluation of currently available facts with respect to each individual site and includes such factors as existing technology, presently enacted laws and regulations, and prior experience in remediation of contaminated sites. The liabilities recorded do not take into account any claims for recoveries from insurance or third parties. As assessments and remediation progress at individual sites, the amounts recorded are reviewed periodically and adjusted to reflect additional technical and legal information that becomes available. As of January 2, 2021 and December 28, 2019, the Company had reserves of $174.2 million and $213.8 million, respectively, for remediation activities associated with Company-owned properties, as well as for Superfund sites, for losses that are probable and estimable. Of the 2020 amount, $46.7 million is classified as current and $127.5 million as long-term, which is expected to be paid over the estimated remediation period. As of January 2, 2021, the Company has recorded $15.9 million in other assets related to funding by the Environmental Protection Agency ("EPA") and monies received have been placed in trust in accordance with the Consent Decree associated with the West Coast Loading Corporation ("WCLC") proceedings, as further discussed in Note S, Contingencies, of the Notes to Consolidated Financial Statements in Item 8. Accordingly, the Company's net cash obligation as of January 2, 2021 associated with the aforementioned remediation activities is $158.3 million. The range of environmental remediation costs that is reasonably possible is $102.9
million to $245.3 million, which is subject to change in the near term. The Company may be liable for environmental remediation of sites it no longer owns. Liabilities have been recorded on those sites in accordance with the Company's policy.
The amount recorded for identified contingent liabilities is based on estimates. Amounts recorded are reviewed periodically and adjusted to reflect additional technical and legal information that becomes available. Actual costs to be incurred in future periods may vary from the estimates, given the inherent uncertainties in evaluating certain exposures. Subject to the imprecision in estimating future contingent liability costs, the Company does not expect that any sum it may have to pay in connection with these matters in excess of the amounts recorded will have a materially adverse effect on its financial position, results of operations or liquidity. Additional information regarding environmental matters is available in Note S, Contingencies, of the Notes to Consolidated Financial Statements in Item 8.
Compliance with government regulations, including environmental regulations, has not had, and based on current information and the applicable laws and regulations currently in effect, is not expected to have a material effect on the Company's capital expenditures, results of operations or competitive position. However, laws and regulations may be changed, accelerated or adopted that impose significant operational restrictions and compliance requirements upon the Company and which could negatively impact its operating results and financial condition.
Human Capital Management
The Company’s purpose is For Those Who Make the World, which puts employees, customers, communities and plants at the heart of its human capital strategies and practices. The Company defines success as delivering value for all stakeholders. The Company believes its commitment to quality, safety and sustainability enables its vision to be the type of uniquely human-centered global industrial company that strives to keep every stakeholder in mind and the Company's values, operating model and oversight of its human capital support this purpose.
As of January 2, 2021, the Company had approximately 53,100 employees in over 60 countries, approximately one-third of whom were employed in the U.S. In addition, the Company had approximately 10,500 temporary contractors globally, primarily in operations. The workforce is comprised of approximately 68% hourly-paid employees, principally in manufacturing, distribution center and security monitoring operations, and 32% salaried employees. Nearly 1,400 U.S. employees are covered by collective bargaining agreements dispersed among 28 different local labor unions, and a majority of European employees are represented by workers councils. The Company strives to maintain a positive relationship with all its employees, as well as the unions and workers councils representing them where applicable. There have been no significant interruptions of the Company’s operations in recent years due to labor disputes.
Governance and Oversight
The CEO and the management Executive Committee are entrusted with developing and advancing the Company’s key human capital strategy which is reviewed with the Board of Directors. The Chief Human Resource Officer is charged with the development and stewardship of this strategy on an enterprise-wide basis. This incorporates a broad range of dimensions, including culture, values, labor and employee relations, leadership capabilities, performance management and total rewards. Diversity, equity and inclusion are key to successfully achieving business and organizational objectives. Key processes include ongoing performance and development feedback, quarterly diversity, equity and inclusion reviews, and periodic engagement surveys that are reviewed by the management Executive Committee and Board of Directors. Code of Business Ethics, Workplace Harassment Prevention, and Managing Unconscious Bias trainings are provided to employees and the content is regularly reviewed for applicability and improvement, and updated as needed. All employees have access to the INTEGRITY@SBD platform where support, guidance and resources are available on topics regarding integrity, code of ethics, diversity, compliance, and workplace harassment. Employees are encouraged to address any concerns through multiple channels, including anonymously whenever possible, without fear of retaliation or retribution.
Diversity, Equity & Inclusion
The Company's management Executive Committee, Board of Directors and workforce are dedicated to diversity, equity and inclusion and work to ensure that all employees feel valued, heard and are positioned to succeed. As of January 2, 2021, the Company's CEO and his direct staff reside in the U.S. and are comprised of 27% women and 20% of the CEO and his direct staff are racially or ethnically diverse. Women represent approximately 31% of the global workforce. As stated in the Company's Equal Employment Opportunity reporting to the U.S. government, in the U.S., approximately 33% of employees are racially or ethnically diverse.
The Company strives to create a culture of equality that unlocks human potential and uncovers the key drivers of a workplace in which everyone can advance and thrive. The Company is executing initiatives across the global workforce designed to foster an inclusive workplace and facilitate equitable career development opportunities. The Company has nine employee resource
groups ("ERGs") with more than 90 local chapters across the globe. These ERGs are formed around various dimensions of diversity and participation across groups is encouraged. The ERGs include Abilities (including cognitive, social-emotional, and physical abilities), African Ancestry, Asian Heritage, Hispanic/Latinx, Developing Professionals, Pride & Allies (LGBTQ+), Veterans, Women, and Working Parents. Company leaders actively participate, sponsor and engage with the ERGs. Management monitors hiring, retention, promotion and continued progress toward achieving the Company's diversity goals. The Company also prioritizes investing in its communities by supporting individuals and organizations that advance these goals across cities and regions in which it operates. In 2020, the management Executive Committee prioritized a focus on gender and racial/ethnic diversity across the Company. The Company launched an equity campaign designed to reach, inspire, support and engage (“RISE”) women and people of color. Through RISE, the Company has supported ten actions to confront racism and social injustice throughout its communities and across the world, which includes specific goals across culture, career, and community focus areas. In 2019, the Company became a signatory of Paradigm for Parity committing to addressing the gender gap in corporate leadership. The Company has also participated in the Business Roundtable Diversity & Inclusion Index, where the largest U.S.-based employers are committed to building a more inclusive environment. The Company's CEO was among the signatories of the CEO Action for Diversity & Inclusion.
Lifelong Learning
The Company believes a sustainable competitive advantage is achieved through lifelong learning. The employees' rate of learning, resilience, and adaptive performance enables the Company to innovate, operate with excellence, and deliver value to customers and shareholders. Employee learning and development is a key enabler to engage, motivate and inspire the Company's workforce and is supported internally through the Stanley Black & Decker University and externally with key partners. Tailored programs address career advancement, leadership development, and skill development needs of the workforce across the Company. Employees consumed more than 25,000 hours of online voluntary learning in 2020. As a leader in advanced manufacturing the Company also strives to provide meaningful training and development for critical skills, new skills, and ways of working with technology to its labor and factory workforce. This includes new operational skills, maintenance, digital, and management skills. The Company utilizes a broad range of capabilities, modes of learning, and platforms, including the use of artificial intelligence and data analytics to achieve its lifelong learning and advanced manufacturing objectives.
Talent Attraction, Advancement, and Retention
The diversity of skills, ways of working, and adaptability of the Company's operating model continue to increase and are reflected in all aspects of its talent management practices. Approximately 35% of global new hires in 2020 were women, and in the U.S. approximately 47% of new employees were racially or ethnically diverse. Internal talent reviews are conducted annually to manage talent and leadership performance. The Company utilizes feedback provided by employees through multiple channels, including internal social platforms, listening sessions, and periodic surveys to improve the employee experience and aspires to be the employer of choice. Development and succession plans are managed in partnership with Human Resources and business segments. Employee compensation and benefits are globally managed and locally adjusted to maintain market and skill competitiveness to attract and retain talent.
Employee Wellness, Health and Safety
The Company is committed to providing competitive benefits to attract and retain talent, that vary by country, including benefits and programs to support healthy lifestyles, mental health, and retirement readiness. In 2020, the Company's commitment to ensuring the health and safety of its employees and supply chain partners was demonstrated through its agile and adaptive response to the ongoing novel coronavirus (COVID-19) pandemic. The Company was able to sustain business operations by implementing critical safety measures and wellness policies, oversight and systems. These actions proved to be highly effective in protecting critical manufacturing and operating employees in site locations and field operations. The Company also quickly transitioned its office employees around the globe to a nearly complete virtual workforce, providing the necessary technical and collaboration support to enable these employees to adjust to a virtual working environment. The Company believes the adopted hybrid work policies are likely to be a lasting result of the pandemic and will be a key enabler to support the broad needs of critical on-site to fully virtual employees. Additional information regarding the Company's response to COVID-19 is available under the caption “COVID-19 Pandemic” in Item 7.
The Company’s Environmental, Health, and Safety (“EHS”) Management System Plan describes the core elements of health and safety responsibility and accountability, including policies and procedures, designed in alignment with global standards, the Company’s Code of Business Ethics, applicable law and individual facility needs. Health and safety requirements apply to all employees and operating unit locations worldwide, including all manufacturing facilities, distribution centers, warehouses, field service centers, retail, office locations and mobile units, as well as to the Company's subsidiaries and joint ventures (in which the Company exercises decision making control over operations). Legal requirements may vary in different countries in which
the Company’s facilities are located. Primary measures of safety performance include Total Recordable Incident Rate ("TRIR") and the Lost Time Incident Rate ("LTIR") based upon the number of incidents per 100 employees (or per 200,000 work hours). Through December 2020, the Company reported a TRIR of 0.48, a LTIR of 0.17 and zero work-related fatalities. Reported total workforce numbers include employees and supervised contractors.
Additional information regarding the Company's Human Capital programs and initiatives is available in the Company's Annual Sustainability Report located under the Social Responsibility section of the Company’s website. The information on the Company’s website is not, and is not intended to be, part of this Form 10-K/A and is not incorporated into this report by reference.
Research and Development Costs
Research and development costs, which are classified in Selling, general and administrative ("SG&A"), were $211.0 million, $255.2 million and $275.8 million for fiscal years 2020, 2019 and 2018, respectively. The reduction in spending in 2020 versus 2019 was primarily due to the temporary cost actions taken in response to COVID-19 that were broadly reinstated. In 2021, the Company plans to return to historic normalized spend levels consistent with 2019 as the Company continues to focus on becoming known as one of the world's greatest innovators and remains committed to generating new core and breakthrough innovations.
Available Information
The Company’s website is located at http://www.stanleyblackanddecker.com. This URL is intended to be an inactive textual reference only. It is not intended to be an active hyperlink to the Company's website. The information on the Company's website is not, and is not intended to be, part of this Form 10-K/A and is not incorporated into this report by reference. The Company makes its Forms 10-K, 10-Q, 8-K and amendments to each available free of charge on its website as soon as reasonably practicable after filing them with, or furnishing them to, the U.S. Securities and Exchange Commission ("SEC").
Item 1A. RISK FACTORS
The Company’s business, operations and financial condition are subject to various risks and uncertainties. You should carefully consider the risks and uncertainties described below, together with all of the other information in this Annual Report on Form 10-K/A, including those risks set forth under the heading entitled "Cautionary Statements Under the Private Securities Litigation Reform Act of 1995" in Item 7, and in other documents that the Company files with the SEC, before making any investment decision with respect to its securities. If any of the risks or uncertainties actually occur or develop, the Company’s business, financial condition, results of operations and future growth prospects could change. Under these circumstances, the trading prices of the Company’s securities could decline, and you could lose all or part of your investment in the Company’s securities.
Except for the New Risk Factor included below, this Item 1A. Risk Factors section in this Annual Report on Form 10-K/A has not been updated to reflect developments occurring subsequent to the Company’s Original Form 10-K, filed with the SEC on February 18, 2021. All risk factors, however, should be considered in context of the New Risk Factor.
New Risk Factor
The Company has identified material weaknesses in its internal control over financial reporting. If not remediated, the Company’s failure to establish and maintain effective disclosure controls and procedures and internal control over financial reporting could result in material misstatements in its financial statements and a failure to meet its reporting and financial obligations, each of which could have a material adverse effect on the Company’s financial condition and the trading price of its common stock.
Subsequent to the filing of the Original Form 10-K, management identified material weaknesses in its internal control over financial reporting related to its accounting for the equity units issued in May 2017 and November 2019. A material weakness is a deficiency, or a combination of deficiencies, in internal control over financial reporting, such that there is a reasonable possibility that a material misstatement of a company’s annual or interim financial statements will not be prevented or detected on a timely basis.
As discussed in Item 9A. Controls and Procedures of this Annual Report on Form 10-K/A, the Company’s management has re-evaluated its assessment of the effectiveness of internal control over financial reporting and its disclosure controls and procedures and concluded that they were not effective as of January 2, 2021.
The Company is committed to remediating its material weaknesses as promptly as possible. Management is in the process of implementing its remediation plan. However, there can be no assurance as to when the material weaknesses will be remediated or that additional material weaknesses will not arise in the future. If the Company is unable to maintain effective internal control over financial reporting, its ability to record, process and report financial information timely and accurately could be adversely affected, which could subject the Company to litigation or investigations, require management resources, increase costs, negatively affect investor confidence and adversely impact its stock price.
Business and Operational Risks
The continued adverse effects of the COVID-19 pandemic and an indeterminate recovery period could have a materially negative impact on the Company’s business, operations, financial condition, results of operations, and liquidity, the nature and extent of which is highly uncertain.
The impact of the COVID-19 pandemic has resulted in a widespread public health crisis and governmental authorities have implemented numerous measures attempting to contain and mitigate the effects of the virus. These measures have adversely affected, and may continue to adversely affect, the Company’s workforce and operations and the operations of its customers, distributors, suppliers and contractors. There is significant uncertainty regarding such measures and potential future measures, and restrictions on the Company's access to its manufacturing facilities or on its support operations or workforce, or similar limitations for its distributors and suppliers. These measures have limited and could continue to limit customer demand and/or the Company's capacity to meet customer demand, which could have a material negative impact on its financial condition and results of operations. In addition, a sustained downturn in customer demand or other economic conditions could result in material charges related to bad debt or inventory write-offs, restructuring charges, or impairments of long-lived assets, including both tangible and intangible assets. Furthermore, a sustained downturn in financial markets and asset values could adversely affect the Company’s cost of capital, liquidity and access to capital markets, in addition to potentially increasing its pension funding obligations to ensure its pension plans continue to be adequately funded.
The ongoing COVID-19 pandemic has caused the Company to modify its business practices (including employee travel, employee work locations, and cancellation of physical participation in meetings, events and conferences), and the Company may take further actions as may be required by government authorities or that the Company determines are in the best interests of its employees, customers, distributors, suppliers and contractors. There is no certainty that such measures will be sufficient to mitigate the risks posed by the virus, and the Company's ability to perform critical functions could be harmed. Furthermore, as a result of the ongoing COVID-19 pandemic, the Company executed certain temporary and permanent cost reduction measures including adjustments to its supply chain and manufacturing labor base to match the demand environment and reductions in staffing, compensation and benefits in a manner that allows the Company to respond to changes in demand. These cost reduction measures may not prove to be successful and the Company may need to undertake further measures that could adversely impact its business and/or its ability to ramp up operations in a timely manner.
The continued spread of COVID-19 has caused, and may continue to cause, disruptions in the Company's supply chain, cause delay, or limit the ability of, customers to continue to operate and perform, including in making timely payments to the Company, result in the Company's inability to meet its consumers' and customers' needs due to disruptions in manufacturing and supply arrangements caused by the loss or disruption of essential manufacturing and supply elements, and cause other unpredictable events.
In addition, the ongoing COVID-19 pandemic may also limit the Company’s resources or delay the Company’s ability to implement strategic initiatives. If strategic initiatives are delayed, such initiatives may not achieve some or all of the expected benefits, which could have a material adverse effect on the Company’s competitive position, business, financial condition and results of operations and cash flows.
The continued spread of COVID-19 has caused, and may continue to cause, significant reductions in demand or significant volatility in demand for certain of the Company’s products. As lockdowns occurred in the first and second quarters of 2020, those subject to lockdowns engaged in home improvement projects in large numbers, and demand for the Company’s products at its retail partners increased significantly. As different geographical areas anticipate moving into a recovery era, demand for the Company’s products may decrease as focus shifts to activities outside the home. The degree to which COVID-19 ultimately affects the Company’s results and operations will depend on future developments, which are highly uncertain and cannot be predicted, including, but not
Showing the first 8K of 73K characters. Open the full section
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 2. PROPERTIES
As of January 2, 2021, the Company and its subsidiaries owned or leased significant facilities used for manufacturing, distribution and sales offices in 20 states and 18 countries. The Company leases its corporate headquarters in New Britain, Connecticut. The Company has 92 facilities including its corporate headquarters that are larger than 100,000 square feet, as follows:
| Owned | Leased | Total | |||||||||||||||
| Tools & Storage | 43 | 22 | 65 | ||||||||||||||
| Industrial | 15 | 6 | 21 | ||||||||||||||
| Security | 1 | 2 | 3 | ||||||||||||||
| Corporate | 2 | 1 | 3 | ||||||||||||||
| Total | 61 | 31 | 92 |
The combined size of these facilities is approximately 25 million square feet. The buildings are in good condition, suitable for their intended use, adequate to support the Company’s operations, and generally fully utilized.
Item 3. LEGAL PROCEEDINGS
In the normal course of business, the Company is involved in various lawsuits and claims, including product liability, environmental and distributor claims, and administrative proceedings. The Company does not expect that the resolution of these matters will have a materially adverse effect on the Company’s consolidated financial position, results of operations or liquidity.
Item 4. MINE SAFETY DISCLOSURES
Not applicable.
PART II
Item 5. MARKET FOR THE REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
The Company’s common stock is listed and traded on the New York Stock Exchange, Inc. (“NYSE”) under the abbreviated ticker symbol “SWK”, and is a component of the Standard & Poor’s (“S&P”) 500 Composite Stock Price Index. The Company’s high and low quarterly stock prices on the NYSE for the years ended January 2, 2021 and December 28, 2019 follow:
| 2020 | 2019 | |||||||||||||||||||||||||||||||||||||
| High | Low | Dividend Per Common Share | High | Low | Dividend Per Common Share | |||||||||||||||||||||||||||||||||
| QUARTER: | ||||||||||||||||||||||||||||||||||||||
| First | $ | 172.53 | $ | 72.03 | $ | 0.69 | $ | 138.92 | $ | 115.69 | $ | 0.66 | ||||||||||||||||||||||||||
| Second | $ | 148.23 | $ | 92.13 | $ | 0.69 | $ | 153.08 | $ | 127.22 | $ | 0.66 | ||||||||||||||||||||||||||
| Third | $ | 166.25 | $ | 135.61 | $ | 0.70 | $ | 152.51 | $ | 128.85 | $ | 0.69 | ||||||||||||||||||||||||||
| Fourth | $ | 190.94 | $ | 161.48 | $ | 0.70 | $ | 167.76 | $ | 135.09 | $ | 0.69 | ||||||||||||||||||||||||||
| Total | $ | 2.78 | $ | 2.70 |
As of February 5, 2021, there were 9,029 holders of record of the Company’s common stock. Information required by Item 201(d) of Regulation S-K concerning securities authorized for issuance under equity compensation plans can be found under Item 12 of this Annual Report on Form 10-K/A.
Issuer Purchases of Equity Securities
The following table provides information about the Company’s purchases of equity securities that are registered by the Company pursuant to Section 12 of the Securities Exchange Act of 1934 for the three months ended January 2, 2021:
| 2020 | Total Number Of Shares Purchased (a) | Average Price Paid Per Share | Total Number Of Shares Purchased As Part Of A Publicly Announced Plan or Program | Maximum Number Of Shares That May Yet Be Purchased Under The Program (b) | ||||||||||||||||||||||
| September 27 - October 31 | 3,494 | $ | 175.67 | — | 11,450,000 | |||||||||||||||||||||
| November 1 - November 28 | 11 | $ | 164.57 | — | 11,450,000 | |||||||||||||||||||||
| November 29 - January 2 | 79,591 | $ | 176.76 | — | 11,450,000 | |||||||||||||||||||||
| Total | 83,096 | $ | 176.71 | — | 11,450,000 |
(a)The shares of common stock in this column were deemed surrendered to the Company by participants in various benefit plans of the Company to satisfy the participants’ taxes related to vesting or delivery of time-vesting restricted share units under those plans.
(b)On July 20, 2017, the Board of Directors approved a new repurchase program for up to 15.0 million shares of the Company’s common stock and terminated its previously approved repurchase program. As of January 2, 2021, the authorized shares available for repurchase under the new repurchase program totaled approximately 11.5 million shares. The currently authorized shares available for repurchase do not include approximately 3.6 million shares reserved and authorized for purchase under the Company’s previously approved repurchase program relating to a forward share purchase contract entered into in March 2015. Refer to Note J, Capital Stock, of the Notes to Consolidated Financial Statements in Item 8 for further discussion.
Stock Performance Graph
The following line graph compares the yearly percentage change in the Company’s cumulative total shareholder return for the last five years to that of the S&P 500 Index and the S&P 500 Industrials Index. The Company has decided to use the S&P 500 Industrials Index, which is utilized by a number of the Company’s industrial peers, for the purpose of this disclosure.
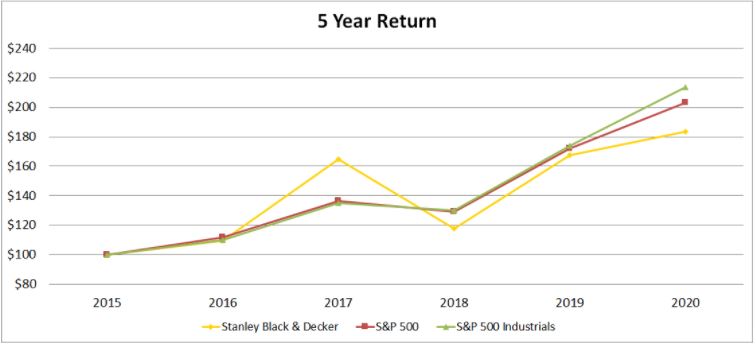
| THE POINTS IN THE ABOVE TABLE ARE AS FOLLOWS: | 2015 | 2016 | 2017 | 2018 | 2019 | 2020 | |||||||||||||||||||||||||||||
| Stanley Black & Decker | $ | 100.00 | $ | 109.65 | $ | 165.01 | $ | 117.68 | $ | 167.54 | $ | 183.69 | |||||||||||||||||||||||
| S&P 500 | $ | 100.00 | $ | 111.95 | $ | 136.38 | $ | 129.28 | $ | 171.90 | $ | 202.96 | |||||||||||||||||||||||
| S&P 500 Industrials | $ | 100.00 | $ | 110.16 | $ | 135.19 | $ | 130.05 | $ | 174.00 | $ | 213.76 |
The comparison assumes $100 invested at the closing price on January 2, 2016 in the Company’s common stock, S&P 500 Index, and S&P 500 Industrials Index. Total return assumes reinvestment of dividends.
Item 6. SELECTED FINANCIAL DATA
Acquisitions and divestitures completed by the Company during the five-year period presented below affect comparability of results. Refer to Note E, Acquisitions and Investments, and Note T, Divestitures, of the Notes to Consolidated Financial Statements in Item 8 and prior year 10-K filings for further information.
| (Millions of Dollars, Except Per Share Amounts) | 2020 (a) (As Restated) (h) | 2019 (b) (As Restated) (h) | 2018 (c) (As Restated) (h) | 2017 (d) (As Restated) (i) | 2016 | |||||||||||||||||||||||||||
| Net sales | $ | 14,535 | $ | 14,442 | $ | 13,982 | $ | 12,967 | $ | 11,594 | ||||||||||||||||||||||
| Net Earnings Attributable to Common Shareowners | $ | 1,210 | $ | 954 | $ | 603 | $ | 1,226 | $ | 968 | ||||||||||||||||||||||
| Net Earnings Attributable to Common Shareowners - Diluted | $ | 1,211 | $ | 956 | $ | 604 | $ | 1,226 | $ | 968 | ||||||||||||||||||||||
| Earnings per share of common stock: | ||||||||||||||||||||||||||||||||
| Basic | $ | 7.85 | $ | 6.43 | $ | 4.05 | $ | 8.19 | $ | 6.63 | ||||||||||||||||||||||
| Diluted | $ | 7.46 | $ | 6.11 | $ | 3.85 | $ | 7.88 | $ | 6.53 | ||||||||||||||||||||||
| Percent of net sales: | ||||||||||||||||||||||||||||||||
| Cost of sales | 65.8 | % | 66.7 | % | 65.3 | % | 63.1 | % | 63.2 | % | ||||||||||||||||||||||
| Selling, general and administrative(e) | 21.3 | % | 21.1 | % | 22.7 | % | 23.1 | % | 22.7 | % | ||||||||||||||||||||||
| Other, net | 1.8 | % | 1.7 | % | 2.1 | % | 2.1 | % | 1.6 | % | ||||||||||||||||||||||
| Restructuring charges | 0.6 | % | 1.1 | % | 1.1 | % | 0.4 | % | 0.4 | % | ||||||||||||||||||||||
| Interest, net | 1.4 | % | 1.6 | % | 1.5 | % | 1.4 | % | 1.5 | % | ||||||||||||||||||||||
| Earnings before income taxes and equity interest | 8.7 | % | 7.8 | % | 7.3 | % | 11.8 | % | 10.6 | % | ||||||||||||||||||||||
| Net Earnings Attributable to Common Shareowners | 8.3 | % | 6.6 | % | 4.3 | % | 9.5 | % | 8.3 | % | ||||||||||||||||||||||
| Balance sheet data: | ||||||||||||||||||||||||||||||||
| Total assets(f) | $ | 23,566 | $ | 20,597 | $ | 19,408 | $ | 19,098 | $ | 15,655 | ||||||||||||||||||||||
| Long-term debt, including current maturities | $ | 4,245 | $ | 3,180 | $ | 3,822 | $ | 3,806 | $ | 3,806 | ||||||||||||||||||||||
| Stanley Black & Decker, Inc.’s shareowners’ equity | $ | 11,060 | $ | 9,136 | $ | 7,836 | $ | 8,302 | $ | 6,374 | ||||||||||||||||||||||
| Ratios: | ||||||||||||||||||||||||||||||||
| Total debt to total capital | 27.7 | % | 27.8 | % | 34.9 | % | 31.5 | % | 37.4 | % | ||||||||||||||||||||||
| Income tax rate | 3.3 | % | 14.2 | % | 40.7 | % | 19.7 | % | 21.3 | % | ||||||||||||||||||||||
| Common stock data: | ||||||||||||||||||||||||||||||||
| Dividends per share | $ | 2.78 | $ | 2.70 | $ | 2.58 | $ | 2.42 | $ | 2.26 | ||||||||||||||||||||||
| Equity per basic share at year-end | $ | 70.40 | $ | 60.97 | $ | 53.07 | $ | 55.20 | $ | 42.80 | ||||||||||||||||||||||
| Market price per share — high | $ | 190.94 | $ | 167.76 | $ | 175.91 | $ | 170.03 | $ | 125.78 | ||||||||||||||||||||||
| Market price per share — low | $ | 72.03 | $ | 115.69 | $ | 108.45 | $ | 115.75 | $ | 90.14 | ||||||||||||||||||||||
| Weighted-average shares outstanding (in 000’s): | ||||||||||||||||||||||||||||||||
| Basic | 154,176 | 148,365 | 148,919 | 149,629 | 146,041 | |||||||||||||||||||||||||||
| Diluted | 162,427 | 156,381 | 156,780 | 155,573 | 148,207 | |||||||||||||||||||||||||||
| Other information: | ||||||||||||||||||||||||||||||||
| Average number of employees(g) | 62,606 | 61,755 | 60,785 | 57,076 | 53,231 | |||||||||||||||||||||||||||
| Shareowners of record at end of year | 9,064 | 9,360 | 9,727 | 10,014 | 10,313 |
(a)The Company's 2020 results include $400 million of pre-tax charges related to a cost reduction program, loss on extinguishment of debt, inventory step-up charges, deal costs, Security business transformation and margin resiliency initiatives, and a net loss related to the sales of businesses, partially offset by a release of a contingent consideration liability relating to the CAM acquisition. As a result, as a percentage of Net sales, Cost of sales was 49 basis points higher, Selling, general, & administrative was 121 basis points higher, Other, net was 6 basis points higher, Restructuring charges was 57 basis points higher, and Earnings before income taxes and equity interest was 275 basis points lower. The Company also recorded a tax benefit of $211 million, which is comprised of a $119 million one-time tax benefit associated with a supply chain reorganization and a $92 million tax benefit of the above pre-tax charges. In addition, the Company's share of MTD's net earnings included an after-tax charge of approximately $10 million. Overall, the amounts described above resulted in a decrease to the Company's 2020 Net earnings attributable to common shareowners of $199 million (or $1.22 per diluted share).
(b)The Company's 2019 results include $363 million of pre-tax charges related to restructuring, deal and integration costs, loss on extinguishment of debt, Security business transformation and margin resiliency initiatives, and a gain on a sale of a
business. As a result, as a percentage of Net sales, Cost of sales was 27 basis points higher, Selling, general, & administrative was 97 basis points higher, Other, net was 21 basis points higher, Restructuring charges was 106 basis points higher, and Earnings before income taxes and equity interest was 251 basis points lower. In addition, the Company's share of MTD's net earnings included an after-tax charge of approximately $24 million. Overall, the amounts described above resulted in a decrease to the Company's 2019 Net earnings attributable to common shareowners of $309 million (or $1.98 per diluted share).
(c)The Company's 2018 results include $450 million of pre-tax charges related to acquisitions, an environmental remediation settlement, a non-cash fair value adjustment, a cost reduction program, an incremental freight charge related to a service provider's bankruptcy, and a loss related to a previously divested business. As a result, as a percentage of Net sales, Cost of sales was 47 basis points higher, Selling, general, & administrative was 113 basis points higher, Other, net was 77 basis points higher, Restructuring charges was 84 basis points higher, and Earnings before income taxes was 322 basis points lower. The Company also recorded a net tax charge of $181 million, which is comprised of charges related to the Tax Cuts and Jobs Act ("the Act"), partially offset by the tax benefit of the above pre-tax charges. Overall, the amounts described above resulted in a decrease to the Company's 2018 Net earnings attributable to common shareowners of $631 million (or $4.03 per diluted share).
(d)The Company's 2017 results include $156 million of pre-tax acquisition-related charges and a $264 million pre-tax gain on sales of businesses, primarily related to the divestiture of the mechanical security businesses. As a result, as a percentage of Net sales, Cost of sales was 36 basis points higher, Selling, general, & administrative was 29 basis points higher, Other, net was 45 basis points higher, Restructuring charges was 11 basis points higher, and Earnings before income taxes was 83 basis points higher. The net tax benefit of the acquisition-related charges and gain on sales of businesses was $7 million. Income taxes for 2017 also includes a one-time net tax charge of $24 million related to the Act. Overall, the acquisition-related charges, gain on sales of businesses, and one-time net tax charge related to the Act resulted in a net increase to the Company's 2017 Net earnings attributable to common shareowners of $91 million (or $0.58 per diluted share).
(e)SG&A is inclusive of the Provision for credit losses.
(f)In the first quarter of 2019, the Company adopted ASU 2016-02, Leases (Topic 842) ("new lease standard") utilizing the transition method, which allowed the new lease standard to be applied as of the adoption date with no adjustment for periods prior to fiscal year 2019. As a result, total assets as of January 2, 2021 and as of December 28, 2019 reflect a lease right-of-use asset of approximately $523 million and $535 million, respectively.
(g)The average number of employees includes temporary contractors.
(h)Refer to Note A, Significant Accounting Policies - Restatement, of the Notes to Consolidated Financial Statements in Item 8 for further discussion regarding the impacts of the Restatement.
(i)The Restatement had the following impacts on fiscal year 2017 results: (1) a decrease of $1 million to Net Earnings Attributable to Common Shareowners, (2) a $0.01 decrease to basic earnings per share, (3) a $0.17 decrease to diluted earnings per share, and (4) an increase to weighted-average diluted shares outstanding of approximately 3.1 million shares. Refer to Note A, Significant Accounting Policies - Restatement, of the Notes to Consolidated Financial Statements in Item 8, for further discussion regarding the nature of the Restatement.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Restatement
As discussed in the Explanatory Note to this Annual Report on Form 10-K/A and Note A, Significant Accounting Policies - Restatement, the Company is restating its consolidated financial statements and related financial information for the years ended January 2, 2021, December 28, 2019 and December 29, 2018. The Restatement relates to the correction of basic and diluted earnings per share, as applicable, and the classification of certain amounts in the consolidated balance sheets, statements of cash flows and statements of changes in shareowners’ equity. The corrections have no impact on the Company’s net earnings, total assets, cash flows from operations or business segment information. Furthermore, any forward-looking statements herein are as of the Original Form 10-K filed with the SEC on February 18, 2021. Refer to Note A, Significant Accounting Policies - Restatement, which accompany the financial statements in Item 8 of this Annual Report on Form 10-K/A, for further discussion regarding the restatement impacts. In addition, for further information regarding the matters leading to the restatement and related findings with respect to the Company’s internal control over financial reporting, refer to Item 9A. Controls and Procedures in Part II of this Annual Report on Form 10-K/A.
The financial and business analysis below provides information which the Company believes is relevant to an assessment and understanding of its consolidated financial position, results of operations and cash flows. This financial and business analysis should be read in conjunction with the Consolidated Financial Statements and related notes. All references to “Notes” in this Item 7 refer to the Notes to Consolidated Financial Statements included in Item 8 of this Annual Report.
The following discussion and certain other sections of this Annual Report on Form 10-K/A contain statements reflecting the Company’s views about its future performance that constitute “forward-looking statements” under the Private Securities Litigation Reform Act of 1995. These forward-looking statements are based on current expectations, estimates, forecasts and projections about the industry and markets in which the Company operates as well as management’s beliefs and assumptions. Any statements contained herein (including without limitation statements to the effect that Stanley Black & Decker, Inc. or its management “believes,” “expects,” “anticipates,” “plans” and similar expressions) that are not statements of historical fact should be considered forward-looking statements. These statements are not guarantees of future performance and involve certain risks, uncertainties and assumptions that are difficult to predict. There are a number of important factors that could cause actual results to differ materially from those indicated by such forward-looking statements. These factors include, without limitation, those set forth, or incorporated by reference, below under the heading “Cautionary Statements Under The Private Securities Litigation Reform Act Of 1995.” The Company does not intend to update publicly any forward-looking statements whether as a result of new information, future events or otherwise.
Strategic Objectives
The Company continues to pursue a growth and acquisition strategy, which involves industry, geographic and customer diversification to foster sustainable revenue, earnings and cash flow growth, and employ the following strategic framework in pursuit of its vision to deliver top-quartile financial performance, become known as one of the world’s leading innovators and elevate its commitment to social responsibility:
-
Continue organic growth momentum by leveraging the SBD Operating Model to drive innovation and commercial excellence, while diversifying toward higher-growth, higher-margin businesses;
-
Be selective and operate in markets where brand is meaningful, the value proposition is definable and sustainable through innovation, and global cost leadership is achievable; and
-
Pursue acquisitive growth on multiple fronts by building upon its existing global tools platform, expanding the Industrial platform in Engineered Fastening and Infrastructure, consolidating the commercial electronic security industry, and pursuing adjacencies with sound industrial logic.
Execution of the above strategy has resulted in approximately $11.5 billion of acquisitions since 2002 (excluding the Black & Decker merger), a 20 percent investment in MTD Holdings Inc. ("MTD"), several divestitures, improved efficiency in the supply chain and manufacturing operations, and enhanced investments in organic growth, enabled by cash flow generation and increased debt capacity. In addition, the Company's continued focus on diversification and organic growth has resulted in improved financial results and an increase in its global presence. The Company also remains focused on leveraging its SBD Operating Model to deliver success in the 2020s and beyond. The latest evolution of the SBD Operating Model builds on the strength of the Company's past while embracing changes in the external environment to ensure the Company has the right
skillsets, incorporates technology advances in all areas, maintains operational excellence, drives efficiency in business processes and resiliency into its culture, delivers extreme innovation and ensures the customer experience is world class. The operating model underpins the Company's ability to deliver above-market organic growth with margin expansion, maintain efficient levels of selling, general and administrative expenses ("SG&A") and deliver top-quartile asset efficiency.
The Company’s long-term financial objectives remain as follows:
-
4-6% organic revenue growth;
-
10-12% total revenue growth;
-
10-12% total EPS growth (7-9% organically) excluding acquisition-related charges;
-
Free cash flow equal to, or exceeding, net income;
-
Sustain 10+ working capital turns; and
-
Cash Flow Return On Investment ("CFROI") between 12-15%.
In terms of capital allocation, the Company remains committed, over time, to returning approximately 50% of free cash flow to shareholders through a strong and growing dividend as well as opportunistically repurchasing shares. The remaining free cash flow (approximately 50%) will be deployed towards acquisitions.
COVID-19 Pandemic
The novel coronavirus (COVID-19) outbreak has adversely affected the Company's workforce and operations, as well as the operations of its customers, distributors, suppliers and contractors. The COVID-19 pandemic has also resulted in significant volatility and uncertainty in the markets in which the Company operates. To successfully navigate through this unprecedented period, the Company has remained focused on the following key priorities:
-
Ensuring the health and safety of its employees and supply chain partners;
-
Maintaining business continuity and financial strength and stability;
-
Serving its customers as they provide essential products and services to the world; and
-
Doing its part to mitigate the impact of the virus across the globe.
To respond to the volatile and uncertain environment, the Company implemented a comprehensive cost reduction and efficiency program, which delivered approximately $500 million of savings in 2020 and is expected to deliver net savings of approximately $125 million in 2021. Cost actions executed under the program included headcount reductions, furloughs, reduced employee work schedules, a voluntary retirement program, and footprint rationalizations. The Company has taken steps to make some of the cost actions permanent while certain employees were returned to full-time status. This ensures the sustainability of the cost reduction program into 2021 while providing more employment stability for the Company's remaining associates.
The program’s primary focus was to: (a) adjust the Company’s supply chain and manufacturing labor
Showing the first 8K of 121K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
The Company incorporates by reference the material captioned “Market Risk” in Item 7 and in Note I, Financial Instruments, of the Notes to Consolidated Financial Statements in Item 8.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
See Item 15 for an index to Financial Statements and Financial Statement Schedule. Such Financial Statements and Financial Statement Schedule are incorporated herein by reference.
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Material Weaknesses in Internal Control Over Financial Reporting
The management of Stanley Black & Decker, Inc. (the "Company") is responsible for establishing and maintaining adequate internal control over financial reporting, as that term is defined under Rules 13a-15(f) and 15d-15(f) of the Securities Exchange Act of 1934, as amended (the “Exchange Act”). Under the supervision and with the participation of management, including the Chief Executive Officer and the President and Chief Financial Officer, the Company has assessed the effectiveness of its internal control over financial reporting as of the end of the period covered by this report based upon the criteria set forth by the Committee of Sponsoring Organizations (COSO) of the Treadway Commission in Internal Control — Integrated Framework (2013 Framework). Based on that assessment, the Chief Executive Officer and the President and Chief Financial Officer concluded that the Company's internal control over financial reporting was not effective to provide reasonable assurance regarding the reliability of its financial reporting and the preparation of its financial statements for external purposes in accordance with accounting principles generally accepted in the United States of America as of January 2, 2021 due to the material weaknesses in internal control described below.
A material weakness, as defined in Rule 12b-2 under the Exchange Act, is a deficiency, or a combination of deficiencies, in internal control over financial reporting, such that there is a reasonable possibility that a material misstatement of a company’s annual or interim financial statements will not be prevented or detected on a timely basis.
As discussed in the Explanatory Note to this Annual Report on Form 10-K/A and Note A, Significant Accounting Policies - Restatement, of the Notes to Consolidated Financial Statements in Item 8, the Company determined that errors were made in its original accounting conclusions related to equity units issued in May 2017 and November 2019 (the “Equity Units”). The Company determined the errors were the result of the following deficiencies in internal control over financial reporting:
1.The design of its control to consider all the relevant authoritative accounting guidance for financial instruments with debt- and equity-like features; and
2.The design of its control to consider financial instruments with debt- and equity-like features in the calculation of earnings per share.
The Company assessed whether there was a reasonable possibility that a material misstatement would not have been prevented or detected on a timely basis as a result of the above control deficiencies. The first control deficiency could result in a determination that there are two units of account in which the forward stock purchase contracts, when evaluated separately as freestanding instruments, would be precluded from equity classification. As a result, the asset or liability related to the forward stock purchase contracts would be subject to mark-to-market accounting, which would be significantly influenced by factors outside of the Company’s control, including fluctuations in its share price. The second control deficiency resulted in material errors in the calculation of diluted earnings per share previously disclosed in the Company’s historical financial statements. Based on these factors, the Company concluded that the deficiencies noted above each rise to the level of a material weakness.
Remediation of Material Weaknesses
The Company acknowledges that its management is responsible for establishing and maintaining adequate internal control over financial reporting and assessing the effectiveness of its internal controls. The Company is committed to maintaining a strong internal control environment and implementing measures to ensure that the control deficiencies identified above are remediated as soon as possible. Management is in the process of implementing its remediation plan, which includes steps to design and implement new controls and expand education and training related to the accounting considerations for complex financing transactions. The Company will consider the material weakness remediated after the applicable controls operate for a sufficient period of time, and management has concluded, through testing, that the controls are operating effectively.
Evaluation of Disclosure Controls and Procedures
The Company’s management is responsible for establishing and maintaining adequate internal control over financial reporting. Internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external reporting purposes in accordance with accounting principles generally accepted in the United States of America. Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements.
As required by Rules 13a-15(b) of the Exchange Act, the Company’s management assessed the effectiveness of its internal control over financial reporting as of January 2, 2021 based upon the criteria set forth by the Committee of Sponsoring Organizations (COSO) of the Treadway Commission in Internal Control — Integrated Framework (2013 Framework). Based upon its original evaluation, as previously disclosed in its Annual Report on Form 10-K for the fiscal year ended January 2, 2021 filed with the Securities and Exchange Commission ("SEC") on February 18, 2021, the Company's President and Chief Executive Officer and its Executive Vice President and Chief Financial Officer concluded that its disclosure controls and procedures were effective as of January 2, 2021. Subsequently, and as a result of the material weaknesses identified in internal control over financial reporting, the Company's Chief Executive Officer and its President and Chief Financial Officer have concluded that its disclosure controls and procedures were not effective as of January 2, 2021 to ensure that information required to be disclosed by the Company in reports filed or submitted under the Exchange Act is reported accurately.
In February 2020, the Company acquired Consolidated Aerospace Manufacturing, LLC ("CAM") for approximately $1.4 billion. Since Stanley Black & Decker, Inc. had not yet fully incorporated the internal controls and procedures of CAM into Stanley Black & Decker, Inc.'s internal control over financial reporting, management excluded this business from its assessment of the effectiveness of internal control over financial reporting as of January 2, 2021. CAM accounted for 6% of Stanley Black & Decker, Inc.'s total assets as of January 2, 2021 and 2% of Stanley Black & Decker, Inc.'s net sales for the year then ended.
Other than those items noted above, there has been no change in the Company’s internal control over financial reporting that occurred during the fiscal year ended January 2, 2021 that has materially affected, or is reasonably likely to materially affect, the Company’s internal control over financial reporting.
Refer to Management’s Report On Internal Control Over Financial Reporting on page 66.
Item 9B. OTHER INFORMATION
None.
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE OF THE REGISTRANT
The information required by this Item, except for certain information with respect to the Company’s Code of Ethics, the identification of the executive officers of the Company and any material changes to the procedures by which security holders may recommend nominees to the Company’s Board of Directors, as set forth below, is incorporated herein by reference to the information set forth in the section of the Company’s definitive proxy statement (which was filed pursuant to Regulation 14A under the Exchange Act within 120 days after the close of the Company’s fiscal year) under the headings “Information Concerning Nominees for Election as Directors,” and “Board of Directors".
Available on the Company's website at http://www.stanleyblackanddecker.com on the “Corporate Governance” section which appears under the “Investors” heading is the Code of Business Ethics applicable to all of its directors, officers and employees worldwide and a Code of Ethics for the Chief Executive Officer and senior financial officers including the Chief Financial Officer and principal accounting officer. The Company intends to post on its website required information regarding any amendment to, or waiver from, the Code of Business Ethics that applies to our Chief Executive Officer and senior financial officers within four business days after any such amendment or waiver.
The following is a list of the executive officers of the Company as of February 18, 2021:
| Name and Age | Office | Date Elected to Office | ||||||||||||
| James M. Loree (62) | President & Chief Executive Officer since August 2016. President & Chief Operating Officer (2013); Executive Vice President and Chief Operating Officer (2009); Executive Vice President Finance and Chief Financial Officer (1999). | 7/19/1999 | ||||||||||||
| Donald Allan, Jr. (56) | Executive Vice President & Chief Financial Officer since October 2016. Senior Vice President & Chief Financial Officer (2010); Vice President & Chief Financial Officer (2009); Vice President & Corporate Controller (2002); Corporate Controller (2000); Assistant Controller (1999). | 10/24/2006 | ||||||||||||
| Jeffery D. Ansell (53) | Executive Vice President, Stanley Black & Decker since July 2020. Executive Vice President & President, Tools & Storage (2016); Senior Vice President and Group Executive, Global Tools & Storage (2015); Senior Vice President and Group Executive, Construction & DIY (2010); Vice President & President, Stanley Consumer Tools Group (2006); President - Consumer Tools and Storage (2004); President of Industrial Tools & Storage (2002); Vice President - Global Consumer Tools Marketing (2001); Vice President Consumer Sales America (1999). | 2/22/2006 | ||||||||||||
| Janet M. Link (51) | Senior Vice President, General Counsel and Secretary since July 2017. Executive Vice President, General Counsel, JC Penney Company, Inc. (2015); Vice President, Deputy General Counsel, JC Penney Company, Inc. (2014); Vice President, Deputy General Counsel, Clear Channel Companies (2013). | 7/19/2017 | ||||||||||||
| Jaime A. Ramirez (53) | Executive Vice President & President, Global Tools & Storage since July 2020. Senior Vice President & Chief Operating Officer, Tools & Storage (2019); Senior Vice President & President, Global Emerging Markets (2012); President, Construction & DIY, Latin America (2010); Vice President and General Manager - Latin America, Power Tools & Accessories, The Black & Decker Corporation (2008); Vice President and General Manager - Andean Region The Black & Decker Corporation (2007). | 3/12/2010 | ||||||||||||
| John H. Wyatt (62) | Senior Vice President & President, Stanley Outdoor since January 2021. Senior Vice President & President, Stanley Outdoor and Aerospace (2020); President, Stanley Engineered Fastening (2016); President, Sales & Marketing - Global Tools & Storage (2015); President, Construction & DIY, Europe and ANZ (2012); President, Construction & DIY, EMEA (2010); President-Europe, Middle East, and Africa, Power Tools and Accessories, The Black & Decker Corporation (2008); Vice President-Consumer Products (Europe, Middle East and Africa), The Black & Decker Corporation (2006). | 3/12/2010 | ||||||||||||
| Robert H. Raff (54) | President, Stanley Security since November 2016. President, Stanley Electronic Security North America (2015); President, North America Sales, Construction & DIY (2010); President, Stanley National Hardware (2007); Vice President of Latin America, Construction & DIY (2005); General Manager, Construction & DIY (2002). | 4/19/2018 | ||||||||||||
| Robert Blackburn (52) | Senior Vice President of Global Operations since May 2019. Hoffman Group, CEO and Chairman of the Executive Board (2017); BASF S.E., President of Supply Chain Operations & Information Services (2007). | 5/6/2019 | ||||||||||||
| Graham N. Robinson (52) | Senior Vice President & President, Stanley Industrial since April 2020. President, Honeywell Industrial Safety (Honeywell International) (2018); President, Honeywell Sensing and Internet of Things (Honeywell International) (2016); Chief Marketing Officer and Vice President, Global Strategy & Marketing, Automation and Control Solutions (Honeywell International) (2014). | 4/17/2020 | ||||||||||||
| Stephen Subasic (52) | Senior Vice President, Chief Human Resources Officer since January 2021. Vice President, Human Resources & Corporate Talent Management (2019); Vice President, Human Resources, Global Tools & Storage (2015); Vice President, Human Resources, Construction & DIY (2011). | 2/18/2021 |
Item 11. EXECUTIVE COMPENSATION
The information required by this Item is incorporated herein by reference to the information set forth under the sections entitled "Compensation Discussion & Analysis" and “2020 Executive Compensation” of the Company’s definitive proxy statement, which was filed pursuant to Regulation 14A under the Exchange Act within 120 days after the close of the Company’s fiscal year.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
The information required by Item 403 of Regulation S-K is incorporated herein by reference to the information set forth under the sections entitled "Security Ownership of Certain Beneficial Owners," "Security Ownership of Directors and Officers," "Compensation Discussion & Analysis" and “2020 Executive Compensation” of the Company’s definitive proxy statement, which was filed pursuant to Regulation 14A under the Exchange Act within 120 days after the close of the Company's fiscal year.
EQUITY COMPENSATION PLAN INFORMATION
Compensation plans under which the Company’s equity securities are authorized for issuance at January 2, 2021 follow:
| (A) | (B) | (C) | |||||||||||||||||||||
| Plan Category | Number of securities to be issued upon exercise of outstanding options and stock awards | Weighted-average exercise price of outstanding options | Number of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in column (A)) | ||||||||||||||||||||
| Equity compensation plans approved by security holders | 8,004,647 | (1) | $ | 138.84 | (2) | 9,594,743 | (3) | ||||||||||||||||
| Equity compensation plans not approved by security holders (4) | — | — | — | ||||||||||||||||||||
| Total | 8,004,647 | $ | 138.84 | 9,594,743 |
(1)Consists of 5,875,246 shares underlying outstanding stock options (whether vested or unvested) with a weighted-average exercise price of $138.84 and a weighted-average term of 7.13 years; 2,033,157 shares underlying time-vesting restricted stock units that have not yet vested and the maximum number of shares that will be issued pursuant to outstanding performance awards if all established goals are met; and 96,244 of shares earned but related to which participants elected deferral of delivery. All stock-based compensation plans are discussed in Note J, Capital Stock, of the Notes to Consolidated Financial Statements in Item 8.
(2)There is no cost to the recipient for shares issued pursuant to time-vesting restricted stock units or performance awards. Because there is no strike price applicable to these stock awards they are excluded from the weighted-average exercise price which pertains solely to outstanding stock options.
(3)Consists of 1,480,962 of shares available for purchase under the employee stock purchase plan ("ESPP") at the election of employees and 8,113,781 securities available for future grants by the Board of Directors under stock-based compensation plans. On January 22, 2018, the Board of Directors adopted the 2018 Omnibus Award Plan (the "2018 Plan") and authorized the issuance of 16,750,000 shares of the Company's common stock in connection with the awards pursuant to the 2018 Plan. No further awards will be issued under the Company's 2013 Long-Term Incentive Plan.
(4)U.S. employees are eligible to contribute from 1% to 25% of their salary to a qualified tax deferred savings plan as described in the Employee Stock Ownership Plan ("ESOP") section of Note L, Employee Benefit Plans, of the Notes to the Consolidated Financial Statements in Item 8. The Company contributes an amount equal to one half of the employee contribution up to the first 7% of salary. There is a non-qualified tax deferred savings plan for highly compensated salaried employees which mirrors the qualified plan provisions, but was not specifically approved by security holders. Eligible highly compensated salaried U.S. employees are eligible to contribute from 1% to 50% of their salary to the non-qualified tax deferred savings plan. The same matching arrangement was provided for highly compensated salaried employees in the non-qualified plan, to the extent the match was not fully met in the qualified plan, except that the arrangement for these employees is outside of the ESOP, and is not funded in advance of distributions. Effective January 1, 2019, the Company, at its discretion, will determine whether matching and core contributions will be made for the non-qualified tax deferred savings plan for a particular year. If the Company decides to make matching contributions for a year, it will make contributions, in an amount determined in its discretion, that may constitute part or all of or more than the matching contributions that would have been made pursuant to the provisions of the Stanley Black & Decker Supplemental Retirement Account Plan that were in effect prior to 2019. For
both qualified and non-qualified plans, the investment of the employee’s contribution and the Company’s contribution is controlled by the employee and may include an election to invest in Company stock. Shares of the Company’s common stock may be issued at the time of a distribution from the qualified plan. The number of securities remaining available for issuance under the plans at January 2, 2021 is not determinable, since the plans do not authorize a maximum number of securities.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
The information required by Items 404 and 407(a) of Regulation S-K is incorporated by reference to the information set forth under the sections entitled "Corporate Governance," "Director Independence" and "Related Party Transactions" of the Company’s definitive proxy statement, which was filed pursuant to Regulation 14A under the Exchange Act within 120 days after the close of the Company's fiscal year.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
The information required by Item 9(e) of Schedule 14A is incorporated herein by reference to the information set forth under the section entitled “Fees of Independent Auditors” of the Company’s definitive proxy statement, which was filed pursuant to Regulation 14A under the Exchange Act within 120 days after the close of the Company's fiscal year.
PART IV
ITEM 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULE
(a) Index to documents filed as part of this report:
- and 2. Financial Statements and Financial Statement Schedule.
The response to this portion of Item 15 is submitted as a separate section of this report beginning with an index thereto on page 62.
- Exhibits
See Exhibit Index in this Form 10-K/A on page 131.
(b) See Exhibit Index in this Form 10-K/A on page 131.
(c) The response in this portion of Item 15 is submitted as a separate section of this Form 10-K/A with an index thereto beginning on page 62.
FORM 10-K/A
Item 15. (a) (1) AND (2)
STANLEY BLACK & DECKER, INC. AND SUBSIDIARIES
INDEX TO FINANCIAL STATEMENTS AND FINANCIAL STATEMENT SCHEDULE
| Schedule II — Valuation and Qualifying Accounts is included in Item 15 (page 65). | ||
| Management’s Report on Internal Control Over Financial Reporting (page 66). | ||
| Report of Independent Registered Public Accounting Firm — Financial Statement Opinion (page 67). | ||
| Report of Independent Registered Public Accounting Firm — Internal Control Opinion (page 70). | ||
| Consolidated Statements of Operations — fiscal years ended January 2, 2021, December 28, 2019, and December 29, 2018 (page 72). | ||
| Consolidated Statements of Comprehensive Income — fiscal years ended January 2, 2021, December 28, 2019, and December 29, 2018 (page 73). | ||
| Consolidated Balance Sheets — January 2, 2021 and December 28, 2019 (page 74). | ||
| Consolidated Statements of Cash Flows — fiscal years ended January 2, 2021, December 28, 2019, and December 29, 2018 (page 75). | ||
| Consolidated Statements of Changes in Shareowners’ Equity — fiscal years ended January 2, 2021, December 28, 2019, and December 29, 2018 (page 77). | ||
| Notes to Consolidated Financial Statements (page 78). | ||
| Selected Quarterly Financial Data (Unaudited) (page 129). | ||
| Consent of Independent Registered Public Accounting Firm (Exhibit 23). |
All other schedules are omitted because either they are not applicable or the required information is shown in the financial statements or the notes thereto.
Item 16. FORM 10-K/A SUMMARY
Not applicable.
SIGNATURE
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Company has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| STANLEY BLACK & DECKER, INC. | ||||||||
| By: | /s/ James M. Loree | |||||||
| James M. Loree, Chief Executive Officer | ||||||||
| Date: | January 31, 2022 |
Schedule II — Valuation and Qualifying Accounts
Stanley Black & Decker, Inc. and Subsidiaries
Fiscal years ended January 2, 2021, December 28, 2019, and December 29, 2018
(Millions of Dollars)
| ADDITIONS | |||||||||||||||||||||||||||||
| Beginning Balance | Charged To Costs And Expenses | Charged To Other Accounts (b) | (a) Deductions | Ending Balance | |||||||||||||||||||||||||
| Allowance for Credit Losses: | |||||||||||||||||||||||||||||
| Year Ended 2020 | $ | 112.4 | $ | 41.1 | $ | 23.7 | $ | (36.1) | $ | 141.1 | |||||||||||||||||||
| Year Ended 2019 | $ | 102.0 | $ | 33.0 | $ | 5.9 | $ | (28.5) | $ | 112.4 | |||||||||||||||||||
| Year Ended 2018 | $ | 80.4 | $ | 28.0 | $ | 12.5 | $ | (18.9) | $ | 102.0 | |||||||||||||||||||
| Tax Valuation Allowance: | |||||||||||||||||||||||||||||
| Year Ended 2020 (c) | $ | 1,065.0 | $ | 312.0 | $ | (8.6) | $ | (309.5) | $ | 1,058.9 | |||||||||||||||||||
| Year Ended 2019 | $ | 626.7 | $ | 461.5 | $ | (0.5) | $ | (22.7) | $ | 1,065.0 | |||||||||||||||||||
| Year Ended 2018 | $ | 516.7 | $ | 146.2 | $ | (6.4) | $ | (29.8) | $ | 626.7 |
(a)With respect to the allowance for credit losses, deductions represent amounts charged-off less recoveries of accounts previously charged-off.
(b)Amounts represent the impact of foreign currency translation, acquisitions and net transfers to/from other accounts.
(c)Refer to Note Q, Income Taxes, of the Notes to Consolidated Financial Statements in Item 8 for further discussion.
MANAGEMENT’S REPORT ON INTERNAL CONTROL OVER FINANCIAL REPORTING
The management of Stanley Black & Decker, Inc. is responsible for establishing and maintaining adequate internal control over financial reporting. Internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external reporting purposes in accordance with accounting principles generally accepted in the United States of America. Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements.
In February 2020, the Company acquired Consolidated Aerospace Manufacturing, LLC ("CAM") for approximately $1.4 billion. Since Stanley Black & Decker, Inc. had not yet fully incorporated the internal controls and procedures of CAM into Stanley Black & Decker, Inc.'s internal control over financial reporting, management excluded this business from its assessment of the effectiveness of internal control over financial reporting as of January 2, 2021. CAM accounted for 6% of Stanley Black & Decker, Inc.'s total assets as of January 2, 2021 and 2% of Stanley Black & Decker, Inc.'s net sales for the year then ended.
Management has assessed the effectiveness of Stanley Black & Decker, Inc.’s internal control over financial reporting as of January 2, 2021. In making its assessment, management has utilized the criteria set forth by the Committee of Sponsoring Organizations (COSO) of the Treadway Commission in Internal Control — Integrated Framework (2013 Framework). Management concluded that based on its assessment, and the existence of material weaknesses related to the accounting for equity units issued in May 2017 and November 2019, Stanley Black & Decker, Inc.’s internal control over financial reporting was not effective as of January 2, 2021. Ernst & Young LLP, Registered Public Accounting Firm included in this annual report, has issued an attestation report on the registrant’s internal control over financial reporting, a copy of which appears on page 70.
| /s/ James M. Loree | |||||
| James M. Loree, Chief Executive Officer |
| /s/ Donald Allan, Jr. | |||||
| Donald Allan, Jr., President and Chief Financial Officer |
Report of Independent Registered Public Accounting Firm
To the Shareowners and Board of Directors of Stanley Black & Decker, Inc.
Opinion on the Financial Statements
We have audited the accompanying consolidated balance sheets of Stanley Black & Decker, Inc. (the Company) as of January 2, 2021 and December 28, 2019, the related consolidated statements of operations, comprehensive income, shareowners’ equity and cash flows for each of the three years in the period ended January 2, 2021, and the related notes and the financial statement schedule listed in the Index at Item 15(a) (collectively referred to as the “consolidated financial statements”). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company at January 2, 2021 and December 28, 2019, and the results of its operations and its cash flows for each of the three years in the period ended January 2, 2021, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company’s internal control over financial reporting as of January 2, 2021, based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated February 18, 2021, except for the effect of the material weaknesses described in the second paragraph as to which the date is January 31, 2022, expressed an adverse opinion thereon.
Restatement of 2020, 2019 and 2018 Financial Statements
As discussed in Note A - Restatement to the consolidated financial statements, the 2020, 2019 and 2018 consolidated financial statements have been restated to correct misstatements related to the Equity Units.
Basis for Opinion
These financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the US federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of mater
Showing the first 8K of 377K characters. Open the full section