 filings.tools
Item 2. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
63K characters. Original on sec.gov · Markdown
Item 2. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Overview
For more than two centuries, we have been brewing beverages that unite people for all life’s moments. From Coors Light, Miller Lite, Molson Canadian, Carling and Staropramen to Coors Banquet, Blue Moon Belgian White, Blue Moon LightSky, Vizzy, Coors Seltzer, Leinenkugel’s Summer Shandy, Creemore Springs, Hop Valley and more, we produce many beloved and iconic beer brands. While our Company's history is rooted in beer, we offer a modern portfolio that expands beyond the beer aisle as well. As a business, our ambition is to be the first choice for our people, our consumers and our customers, and our success depends on our ability to make our products available to meet a wide range of consumer segments and occasions.
Management's Discussion and Analysis of Financial Condition and Results of Operations ("MD&A") in this Quarterly Report on Form 10-Q is provided as a supplement to, and should be read in conjunction with, our audited consolidated financial statements, the accompanying notes and the MD&A included in our Annual Report on Form 10-K for the fiscal year ended December 31, 2021 ("Annual Report"), as well as our unaudited condensed consolidated financial statements and the accompanying notes included in this report. Due to the seasonality of our operating results, quarterly financial results are not an appropriate basis from which to project annual results.
Unless otherwise noted in this report, any description of "we," "us" or "our" includes Molson Coors Beverage Company ("MCBC" or the "Company"), principally a holding company, and its operating and non-operating subsidiaries included within our reporting segments. Our reporting segments include Americas and EMEA&APAC. Our Americas segment operates in the U.S., Canada and various countries in the Caribbean, Latin and South America and our EMEA&APAC segment operates in Bulgaria, Croatia, Czech Republic, Hungary, Montenegro, the Republic of Ireland, Romania, Serbia, the U.K., various other European countries, and certain countries within the Middle East, Africa and Asia Pacific.
Unless otherwise indicated, information in this report is presented in USD and comparisons are to comparable prior periods. Our primary operating currencies, other than the USD, include the CAD, the GBP, and our Central European operating currencies such as the EUR, CZK, HRK and RSD.
Operational Measures
We have certain operational measures, such as STWs and STRs, which we believe are important metrics. STW is a metric that we use in our business to reflect the sales from our operations to our direct customers, generally wholesalers. We believe the STW metric is important because it gives an indication of the amount of beer and adjacent products that we have produced and shipped to customers. STR is a metric that we use in our business to refer to sales closer to the end consumer than STWs, which generally means sales from wholesalers or our company to retailers, who in turn sell to consumers. We believe the STR metric is important because, unlike STWs, it provides the closest indication of the performance of our brands in relation to market and competitor sales trends.
Items Affecting Reported Results
Items Affecting Consolidated Results of Operations
Coronavirus Global Pandemic
We have been actively monitoring the impact of the coronavirus pandemic since it started at the end of the first quarter of 2020. We observed improvements in the marketplace related to the coronavirus global pandemic as on-premise locations began to re-open, with varying degrees of restrictions, across the world beginning in the second quarter of 2021. Despite the improvements in the re-openings of on-premise locations, closures and openings with restrictions impacted our financial results during the three and six months ended June 30, 2021. A new variant of coronavirus, Omicron, created additional uncertainty and negatively impacted our on-premise business at the end of 2021. This uncertainty partially subsided in the first quarter of 2022 as we saw progressive improvements in the on-premise channel. In addition, during the first two months of 2022, certain provinces of Canada endured heavy restrictions which eased significantly towards the end of February 2022. Thus, while an improvement from 2021, the coronavirus global pandemic did have a negative impact to our financial results for the six months ended June 30, 2022.
The extent to which our operations will continue to be impacted by the coronavirus pandemic will depend largely on future developments, which are highly uncertain and cannot be accurately predicted, including, but not limited to, the level of governmental or societal orders or restrictions on public gatherings and on-premise venues including any vaccine mandates or testing requirements, the severity and duration of the coronavirus pandemic by market including continued or prolonged outbreaks of variants, changes in consumer behavior, the rate of vaccination and the efficacy of vaccines against coronavirus
and related variants. We continue to actively monitor the ongoing evolution of the coronavirus pandemic and resulting impacts to our business.
Cost Inflation
We continued to experience significant cost inflation, including higher material, transportation and energy costs, which negatively impacted our results of operations during the three and six months ended June 30, 2022. We expect significant cost inflation to continue to have a negative impact on our results of operations for the remainder of 2022 and potentially beyond. In addition to the cost increases that commenced in the second half of 2021, the Russian invasion of Ukraine in February 2022 has caused a negative impact on the global economy, driving further increases to, among other things, the cost of transportation, energy and materials. Higher transportation costs are a result of increased fuel prices, a short supply of truck drivers worldwide and increased freight costs. In the Americas, we are taking steps to reduce the impact of driver shortages by shipping more beverages via rail. Besides impacting our outbound shipments, our suppliers are facing difficulty in timely delivering the materials we need, and we are also experiencing increased materials costs due to overall cost inflation. The volatility of aluminum prices, inclusive of Midwest Premium and tariffs, significantly impacted our results during the three and six months ended June 30, 2021 and June 30, 2022, respectively. To the extent materials, transportation and energy prices continue to fluctuate, our business and financial results could be materially adversely impacted. We continue to monitor these risks and rely on our risk management hedging program, pricing, our premiumization strategy and cost savings programs to help mitigate some of the inflationary pressures.
Cybersecurity Incident
During March 2021, we experienced a systems outage, that was caused by a cybersecurity incident. We engaged leading forensic information technology firms and legal counsel to assist our investigation into the incident and we restored our systems after working to get the systems back up as quickly as possible. Despite these actions, we experienced delays and disruptions to our business, including brewery operations, production and shipments. This incident caused a shift in production and shipments from the first quarter of 2021 to the balance of fiscal year 2021.
Items Affecting Americas Segment Results of Operations
Montreal/Longueuil, Quebec Brewery and Distribution Centers Labor Strike
From late March 2022 until June 2022, approximately 400 unionized employees in our Montreal/Longueuil, Québec brewery and distribution centers went on strike. This strike adversely affected our business and operations during the second quarter of 2022. We expect to see an impact on our operations in the second half of 2022 as we restart brewery operations, rebuild inventory and replenish retailer shelves. See the risk factor related to this labor strike at Part II.—Item 1A. "Risk Factors".
Keystone Litigation
During March 2022, we accrued a liability of $56 million within marketing, general, and administrative ("MG&A") expenses on the unaudited condensed consolidated statement of operations related to potential losses as a result of the ongoing Keystone litigation case. See Part I. - Item 1. Financial Statements, Note 12, "Commitments and Contingencies" for further information.
Impairment of an Asset Group
During the first quarter of 2022, we recognized an impairment loss of $28.6 million within special items, net in the unaudited condensed consolidated statements of operations, of which $12.1 million was attributable to the noncontrolling interest. See Part I.—Item 1. Financial Statements, Note 5, "Special Items" for further information.
Texas Storm
In February 2021, a winter ice storm severely impacted the southern U.S. In particular, local government authorities in Texas were forced to impose energy restrictions, causing the Fort Worth brewery to be offline which resulted in our inability to produce or ship product during the downtime.
Items Affecting EMEA&APAC Segment Results of Operations
Russia-Ukraine Conflict
In February 2022, Russia invaded Ukraine and the conflict remains ongoing. We had less than 0.2% of our 2021 annual net sales and no physical assets in Russia and Ukraine. While not material to our Company, the Russia-Ukraine conflict negatively impacted our results of operations for the three and six months ended June 30, 2022. We suspended all exports of
any MCBC brands to Russia and also terminated the license to produce any of our brands in Russia. Production and sales of our brands in Ukraine under license arrangements are currently halted as a result of the dangerous environment in the country due to the conflict. In addition, the Russia-Ukraine conflict has caused a negative impact to the global economy which has impacted our Company, driving further increases to the cost of materials, transportation and energy. See the risk factor related to this conflict at Part II.—Item 1A. "Risk Factors".
India Sale
During the first quarter of 2022, we completed the sale of our non-operating India entity in our EMEA&APAC segment resulting in an insignificant loss on disposal recorded in special items, net in the unaudited condensed consolidated statements of operations. The disposal group had previously been classified as held for sale during the fourth quarter of 2021.
Consolidated Results of Operations
The following table highlights summarized components of our unaudited condensed consolidated statements of operations for the three and six months ended June 30, 2022 and June 30, 2021. See Part I.—Item 1. Financial Statements for additional details of our U.S. GAAP results.
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||
| June 30, 2022 | June 30, 2021 | % change | June 30, 2022 | June 30, 2021 | % change | ||||||||||||||||||||||||||||||
| (In millions, except percentages and per share data) | |||||||||||||||||||||||||||||||||||
| Net sales | $ | 2,921.7 | $ | 2,939.4 | (0.6) | % | $ | 5,136.3 | $ | 4,837.8 | 6.2 | % | |||||||||||||||||||||||
| Cost of goods sold | (2,101.7) | (1,667.9) | 26.0 | % | (3,388.5) | (2,835.3) | 19.5 | % | |||||||||||||||||||||||||||
| Gross profit | 820.0 | 1,271.5 | (35.5) | % | 1,747.8 | 2,002.5 | (12.7) | % | |||||||||||||||||||||||||||
| Marketing, general and administrative expenses | (707.6) | (681.7) | 3.8 | % | (1,383.3) | (1,224.6) | 13.0 | % | |||||||||||||||||||||||||||
| Special items, net | (0.6) | (9.0) | (93.3) | % | (28.2) | (19.9) | 41.7 | % | |||||||||||||||||||||||||||
| Equity income (loss) | 2.7 | — | N/M | 2.6 | — | N/M | |||||||||||||||||||||||||||||
| Operating income (loss) | 114.5 | 580.8 | (80.3) | % | 338.9 | 758.0 | (55.3) | % | |||||||||||||||||||||||||||
| Total other income (expense), net | (59.6) | (58.2) | 2.4 | % | (110.3) | (109.1) | 1.1 | % | |||||||||||||||||||||||||||
| Income (loss) before income taxes | 54.9 | 522.6 | (89.5) | % | 228.6 | 648.9 | (64.8) | % | |||||||||||||||||||||||||||
| Income tax benefit (expense) | (7.0) | (132.3) | (94.7) | % | (43.4) | (176.6) | (75.4) | % | |||||||||||||||||||||||||||
| Net income (loss) | 47.9 | 390.3 | (87.7) | % | 185.2 | 472.3 | (60.8) | % | |||||||||||||||||||||||||||
| Net (income) loss attributable to noncontrolling interests | (0.6) | (1.7) | (64.7) | % | 13.6 | 0.4 | N/M | ||||||||||||||||||||||||||||
| Net income (loss) attributable to MCBC | $ | 47.3 | $ | 388.6 | (87.8) | % | $ | 198.8 | $ | 472.7 | (57.9) | % | |||||||||||||||||||||||
| Net income (loss) attributable to MCBC per diluted share | $ | 0.22 | $ | 1.79 | (87.7) | % | $ | 0.91 | $ | 2.17 | (58.1) | % | |||||||||||||||||||||||
| Financial volume in hectoliters | 22.739 | 23.823 | (4.6) | % | 39.776 | 40.040 | (0.7) | % | |||||||||||||||||||||||||||
| Brand volume in hectoliters | 21.740 | 22.131 | (1.8) | % | 38.271 | 38.379 | (0.3) | % |
N/M = Not meaningful
Foreign currency impacts on results
During the three months ended June 30, 2022, foreign currency movements unfavorably impacted our consolidated USD net sales by $82.5 million (EMEA&APAC segment and Americas segment unfavorable impact of $69.2 million and $13.3 million, respectively). During the three months ended June 30, 2022, foreign currency movements unfavorably impacted our consolidated USD income before income taxes by $2.9 million (EMEA&APAC segment and Americas segment unfavorable impact of $6.1 million and $0.4 million, respectively, partially offset by the favorable impact of Unallocated of $3.6 million). The unfavorable impact of foreign currency movements on our consolidated USD net sales and our consolidated USD income before income taxes for the three months ended June 30, 2022 was primarily due to the strengthening of the dollar relative to the GBP, CAD and our Central European operating currencies.
During the six months ended June 30, 2022 foreign currency movements unfavorably impacted our consolidated USD net sales by $99.7 million (EMEA&APAC segment and Americas segment unfavorable impact of $85.9 million and $13.8 million, respectively). During the six months ended June 30, 2022, foreign currency movements unfavorably impacted our consolidated
USD income before income taxes by $3.3 million (EMEA&APAC segment unfavorable impact of $5.1 million, partially offset by the favorable impact of Unallocated of $1.2 million and our Americas segment of $.0.6 million). The unfavorable impact of foreign currency movements on our consolidated USD net sales and our consolidated USD income before income taxes for the six months ended June 30, 2022 was primarily due to the strengthening of the dollar relative to the GBP, CAD and our Central European operating currencies.
Included in the three months and six months ended amounts are both translational and transactional impacts of changes in foreign exchange rates. The impact of transactional foreign currency gains and losses is recorded within other income (expense) in our unaudited condensed consolidated statements of operations.
Volume
Worldwide brand volume (or "brand volume" when discussed by segment) reflects owned or actively managed brands sold to unrelated external customers within our geographic markets (net of returns and allowances), royalty volume and our proportionate share of equity investment worldwide brand volume calculated consistently with MCBC owned volume. Financial volume represents owned brands sold to unrelated external customers within our geographic markets (net of returns and allowances), as well as contract brewing, wholesale/factored non-owned brand volume and company-owned distribution volume. Contract brewing and wholesale/factored volume is included within financial volume, but is removed from worldwide brand volume, as this is non-owned volume for which we do not directly control performance. Factored volume in our EMEA&APAC segment is the distribution of beer, wine, spirits and other products owned and produced by other companies to the on-premise channel, which is a common arrangement in the U.K. Royalty volume consists of our brands produced and sold by third parties under various license and contract-brewing agreements and because this is owned volume, it is included in worldwide brand volume. Our worldwide brand volume definition also includes an adjustment from STW volume to STR volume. We believe the brand volume metric is useful to investors and management because, unlike financial volume and STWs, it provides the closest indication of the performance of our brands in relation to market and competitor sales trends.
As part of the revitalization plan strategy to grow our above premium portfolio and expand beyond the beer aisle, we have de-prioritized and rationalized certain non-core economy stock-keeping units ("SKU"). This strategy is intended to drive sustainable net sales growth and earnings growth, despite potential volume declines as the portfolio mix shifts towards a higher composition of above premium products.
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||
| June 30, 2022 | June 30, 2021 | % change | June 30, 2022 | June 30, 2021 | % change | ||||||||||||||||||||||||||||||
| (In millions, except percentages) | |||||||||||||||||||||||||||||||||||
| Volume in hectoliters | |||||||||||||||||||||||||||||||||||
| Financial volume | 22.739 | 23.823 | (4.6) | % | 39.776 | 40.040 | (0.7) | % | |||||||||||||||||||||||||||
| Less: Contract brewing and wholesale/factored volume | (1.858) | (1.833) | 1.4 | % | (3.360) | (3.071) | 9.4 | % | |||||||||||||||||||||||||||
| Add: Royalty volume | 0.863 | 1.124 | (23.2) | % | 1.783 | 2.050 | (13.0) | % | |||||||||||||||||||||||||||
| Add: STW to STR adjustment | (0.004) | (0.983) | (99.6) | % | 0.072 | (0.640) | N/M | ||||||||||||||||||||||||||||
| Total worldwide brand volume | 21.740 | 22.131 | (1.8) | % | 38.271 | 38.379 | (0.3) | % |
N/M = Not meaningful
Net Sales
The following table highlights the drivers of change in net sales for the three months ended June 30, 2022 versus June 30, 2021, by segment (in percentages):
| Financial Volume | Price and Sales Mix | Currency | Total | ||||||||||||||||||||||||||
| Consolidated | (4.6) | % | 6.8 | % | (2.8) | % | (0.6) | % | |||||||||||||||||||||
| Americas | (8.1) | % | 6.4 | % | (0.6) | % | (2.3) | % | |||||||||||||||||||||
| EMEA&APAC | 6.2 | % | 14.3 | % | (13.3) | % | 7.2 | % |
The following table highlights the drivers of change in net sales for the six months ended June 30, 2022 versus June 30, 2021, by segment (in percentages):
| Financial Volume | Price and Sales Mix | Currency | Total | ||||||||||||||||||||||||||
| Consolidated | (0.7) | % | 8.9 | % | (2.0) | % | 6.2 | % | |||||||||||||||||||||
| Americas | (5.0) | % | 7.5 | % | (0.3) | % | 2.2 | % | |||||||||||||||||||||
| EMEA&APAC | 14.3 | % | 26.7 | % | (11.9) | % | 29.1 | % |
Net sales per hectoliter on a brand volume basis in local currency increased 7.1% and 8.3% for the three and six months ended June 30, 2022, respectively, compared to prior year, primarily due to positive net pricing and favorable brand and channel mix resulting from portfolio premiumization and fewer on-premise channel restrictions. Net sales per hectoliter on a financial volume basis in local currency increased 7.1% and 9.0% for the three and six months ended June 30, 2022, compared to prior year.
Worldwide brand volumes decreased 1.8% and 0.3% for the three and six months ended June 30, 2022, respectively, compared to prior year. Financial volumes decreased 4.6% and 0.7% for the three and six months ended June 30, 2022, respectively, compared to prior year. The decrease in financial volumes for the three months ended June 30, 2022 was primarily due to the cycling of the U.S. distributor inventory recovery in the prior year as a result of the cybersecurity incident and Texas storm in the first quarter of 2021 and lower shipments in Canada this quarter, partially offset by higher EMEA&APAC financial volumes driven by higher brand volumes in Western Europe, as well as Central and Eastern Europe, along with higher factored volumes. Lower shipments in Canada this quarter was a result of the Montreal/Longueuil, Québec brewery and distribution centers labor strike which began at the end of March 2022 and ended in mid-June 2022.
The decrease in financial volumes for the six months ended June 30, 2022 was primarily due to lower brand volumes in Americas and lower shipments in Canada, partially offset by higher brand and factored volumes in EMEA&APAC.
The decrease in brand volumes for the three months ended June 30, 2022 was primarily due to a 2.2% decline in the Americas as a result of softer industry performance and the impacts of the Québec labor strike and a 0.7% decline in EMEA&APAC due to markets impacted by the Russia-Ukraine conflict, largely offset by growth in Western Europe, as well as Central and Eastern Europe.
The decrease in brand volumes for the six months ended June 30, 2022 was primarily due to a 2.6% decrease in Americas brand volumes driven by a decline in the economy portfolio, including the de-prioritization and rationalization of non-core SKUs, as well as softer industry performance and the impacts from the Québec labor strike, partially offset by growth in the above premium portfolio. This was largely offset by a 6.6% increase in EMEA&APAC brand volumes including the cycling of significant on-premise closures that occurred during the first half of 2021, particularly in the U.K.
Cost of goods sold
Cost of goods sold per hectoliter in local currency increased 35.7% and 22.8% for the three and six months ended June 30, 2022, respectively, compared to prior year, primarily due to changes to our unrealized mark-to-market commodity positions which accounted for approximately 66% and 51% of the increase for the three and six months ended June 30, 2022, respectively and are recorded as Unallocated. In addition, the increases were also impacted by cost inflation mainly on materials, transportation and energy costs, volume deleverage and mix impacts from both portfolio premiumization and higher factored volumes, partially offset by lower depreciation expense.
Marketing, general and administrative expenses
MG&A expenses increased 3.8% and 13.0% for the three and six months ended June 30, 2022, respectively, compared to prior year. The increase for the three and six months ended June 30, 2022 was primarily due to higher general and administrative expenses driven by the cycling of lower people related costs in the prior year, including travel and entertainment, and higher marketing investment to support our core brands, new innovations and increased local sponsorship and events, partially offset by the favorable impact of foreign currencies. The increase for the six months ended June 30, 2022 was also impacted by a $56 million accrued liability related to potential losses as a result of the ongoing Keystone litigation as well as higher legal fees associated with the trial.
Special items, net
See Part I.—Item 1. Financial Statements, Note 5, "Special Items" for detail of special items, net.
Total other income (expense), net
Total other expense, net increased 2.4% and 1.1% for the three and six months ended June 30, 2022, respectively, compared to prior year primarily due to higher pension and OPEB non-service costs, partially offset by lower net interest expense.
Income taxes benefit (expense), net
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||
| June 30, 2022 | June 30, 2021 | June 30, 2022 | June 30, 2021 | ||||||||||||||||||||
| Effective tax rate | 13 | % | 25 | % | 19 | % | 27 | % |
The lower effective tax rate for the three and six months ended June 30, 2022, as compared to the same periods in 2021, was primarily due to a decrease in net discrete tax expense in combination with lower income before income taxes. We recognized $3.2 million of net discrete tax benefit through the second quarter of 2022 versus $38.5 million of net discrete tax expense through the second quarter of 2021, with the 2021 expense driven largely by the remeasurement of our deferred tax liabilities in the U.K. following enactment of a tax rate increase in that quarter. For the second quarter of 2022, there was a disproportionate impact from the discrete tax benefit recorded on our effective tax rate due to the lower income before income taxes.
Our tax rate can be volatile and may change with, among other things, the amount and source of income (loss) before income taxes, our ability to utilize foreign tax credits, excess tax benefits or deficiencies from share-based compensation, changes in tax laws and the movement of liabilities established pursuant to accounting guidance for uncertain tax positions as statutes of limitations expire, positions are effectively settled or when additional information becomes available. There are proposed or pending tax law changes in various jurisdictions and other changes to regulatory environments in countries in which we do business that, if enacted, may have an impact on our effective tax rate.
Refer to Part I.—Item 1. Financial Statements, Note 6, "Income Tax" for discussion regarding our effective tax rate.
Segment Results of Operations
Americas Segment
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||
| June 30, 2022 | June 30, 2021 | % change | June 30, 2022 | June 30, 2021 | % change | ||||||||||||||||||||||||||||||
| (In millions, except percentages) | |||||||||||||||||||||||||||||||||||
| Net sales(1) | $ | 2,367.4 | $ | 2,422.4 | (2.3) | % | $ | 4,203.6 | $ | 4,114.4 | 2.2 | % | |||||||||||||||||||||||
| Income (loss) before income taxes | $ | 348.0 | $ | 428.2 | (18.7) | % | $ | 435.1 | $ | 572.4 | (24.0) | % | |||||||||||||||||||||||
| Financial volume in hectoliters(2) | 16.536 | 17.986 | (8.1) | % | 29.535 | 31.088 | (5.0) | % | |||||||||||||||||||||||||||
| Brand volume in hectoliters | 15.639 | 15.986 | (2.2) | % | 28.075 | 28.817 | (2.6) | % |
(1)Includes gross inter-segment sales and volumes which are eliminated in the consolidated totals.
(2)Excludes royalty volume of 0.645 million hectoliters and 1.246 million hectoliters for the three and six months ended June 30, 2022, respectively, and excludes royalty volume of 0.585 million hectoliters and 1.152 million hectoliters for the three and six months ended June 30, 2021, respectively.
Net sales and volume
Net sales per hectoliter on a brand volume basis in local currency increased 6.2% and 7.6% for the three and six months ended June 30, 2022, respectively, compared to prior year, primarily due to positive net pricing and favorable brand mix. Net sales per hectoliter on a financial volume basis in local currency increased 6.9% and 7.9% for the three and six months ended June 30, 2022, respectively, compared to prior year.
Brand volumes decreased 2.2% and 2.6% for the three and six months ended June 30, 2022, respectively, compared to prior year. The decrease for the three months ended June 30, 2022 was primarily due to a 1.7% decline in the U.S. as a result of softer industry performance and an 8.0% decline in Canada due to the impacts of the Québec labor strike more than offsetting growth in certain other provinces, partially offset by growth in the above premium portfolio driven by hard seltzers and the launch of Simply Spiked Lemonade and 1.8% growth in Latin America. The decrease for the six months ended June 30, 2022 was primarily due to a 2.9% decline in the U.S. driven by a decline in the economy portfolio, including the de-prioritization and
rationalization of non-core SKUs, as well as softer industry performance, partially offset by growth in the above premium portfolio driven by hard seltzers and the launch of Simply Spiked Lemonade. Canada brand volumes declined 6.5% for the six months ended June 30, 2022 reflecting softer industry performance and the impacts of the Québec labor strike, while Latin America brand volumes grew 7.5%.
Financial volumes decreased 8.1% and 5.0% for the three and six months ended June 30, 2022, respectively, compared to prior year. The decrease for the three months ended June 30, 2022 was primarily due to an 8.2% decline in U.S. domestic shipments attributed to the cycling of the U.S. distributor inventory recovery in the prior year as a result of the first quarter 2021 cybersecurity incident and Texas storm, as well as lower shipments in Canada this quarter attributed to the Québec labor strike more than offsetting growth in certain other provinces. The decrease for the six months ended June 30, 2022 was primarily due to lower brand volumes and lower shipments in Canada attributed to the Québec labor strike.
Income (loss) before income taxes
Income (loss) before income taxes decreased 18.7% and 24.0% for the three and six months ended June 30, 2022, respectively, compared to prior year. The decrease for the three months ended June 30, 2022 was primarily due to lower financial volumes, cost inflation mainly on materials, transportation and energy costs, and higher MG&A spend, partially offset by positive net pricing, lower depreciation expense and favorable sales mix. The decrease for the six months ended June 30, 2022 was primarily due to lower financial volumes, cost inflation mainly on materials, transportation and energy costs, higher MG&A spend, a $56 million accrued liability related to potential losses as a result of the ongoing Keystone litigation as well as higher legal fees associated with the trial and higher special items, net driven by a non-cash impairment charge taken on our Truss LP joint venture asset group, partially offset by positive net pricing, lower depreciation expense and favorable sales mix. Higher MG&A spend for the three and six months ended June 30, 2022 was primarily due to higher general and administrative expenses driven by the cycling of lower people related costs in the prior year, including travel and entertainment, as well as higher marketing investment in Coors Light, Miller Lite and Topo Chico Hard Seltzer.
EMEA&APAC Segment
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||
| June 30, 2022 | June 30, 2021 | % change | June 30, 2022 | June 30, 2021 | % change | ||||||||||||||||||||||||||||||
| (In millions, except percentages) | |||||||||||||||||||||||||||||||||||
| Net sales(1) | $ | 558.2 | $ | 520.5 | 7.2 | % | $ | 939.4 | $ | 727.4 | 29.1 | % | |||||||||||||||||||||||
| Income (loss) before income taxes | $ | 34.4 | $ | 47.4 | (27.4) | % | $ | 2.2 | $ | (42.0) | N/M | ||||||||||||||||||||||||
| Financial volume in hectoliters(2) | 6.207 | 5.844 | 6.2 | % | 10.246 | 8.966 | 14.3 | % | |||||||||||||||||||||||||||
| Brand volume in hectoliters | 6.101 | 6.145 | (0.7) | % | 10.196 | 9.562 | 6.6 | % |
N/M = Not meaningful
(1)Includes gross inter-segment sales and volumes which are eliminated in the consolidated totals.
(2)Excludes royalty volume of 0.218 million hectoliters and 0.537 million hectoliters for the three and six months ended June 30, 2022, respectively, and excludes royalty volume of 0.539 million hectoliters and 0.898 million hectoliters for the three and six months ended June 30, 2021, respectively.
Net sales and volume
Net sales per hectoliter on a brand volume basis in local currency increased 15.5% and 19.4% for the three and six months ended June 30, 2022, respectively, compared to prior year. The increase for the three and six months ended June 30, 2022 was primarily due to favorable sales mix and positive net pricing. Net sales per hectoliter on a financial volume basis in local currency increased 13.5% and 23.3% for the three and six months ended June 30, 2022, respectively, compared to prior year.
Brand volume decreased 0.7% for the three months ended June 30, 2022 and increased 6.6% for the six months ended June 30, 2022, compared to prior year. The decrease for the three months ended June 30, 2022 was primarily due to volume declines as a result of the Russia-Ukraine conflict, partially offset by higher brand volumes in Western Europe, as well as Central and Eastern Europe. The increase for the six months ended June 30, 2022 was primarily due to growth in our above premium portfolio including the cycling of significant on-premise closures and restrictions that occurred during the first half of 2021, particularly in the U.K., partially offset by volume declines as a result of the Russia-Ukraine conflict.
Financial volumes increased 6.2% and 14.3% for the three and six months ended June 30, 2022, respectively, compared to prior year. The increase for the three and six months ended June 30, 2022 was primarily due to higher brand volumes in Western Europe, as well as Central and Eastern Europe, driven by growth in our above premium portfolio including the cycling of significant on-premise closures and restrictions that occurred during the second quarter of 2021, particularly in the U.K., and higher factored volumes.
Income (loss) before income taxes
Income before income taxes decreased 27.4% for the three months ended June 30, 2022 compared to the prior year, primarily due to cost inflation mainly on materials, transportation and energy costs, higher MG&A spend and unfavorable foreign currency movements, partially offset by higher financial volumes, favorable mix and positive net pricing. Income before income taxes was $2.2 million for the six months ended June 30, 2022, compared to a loss before income taxes of $42.0 million in the prior year. The improvement for the six months ended June 30, 2022 was primarily due to higher financial volumes, favorable sales mix and positive net pricing, partially offset by cost inflation mainly on materials, transportation and energy costs, higher MG&A spend and unfavorable foreign currency movements. Higher MG&A spend for the three and six months ended June 30, 2022 was primarily due to the cycling of lower spend in the prior year due to cost mitigation efforts and increased marketing spend as we accelerate investment behind our brands and as on-premise channel and events return.
Unallocated
We have certain activity that is not allocated to our segments and primarily includes financing-related costs such as interest expense and income, foreign exchange gains and losses on intercompany balances related to financing and other treasury-related activities and the unrealized changes in fair value on our commodity swaps not designated in hedging relationships. Additionally, only the service cost component of net periodic pension and OPEB cost is reported within each operating segment, and all other components remain unallocated.
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||
| June 30, 2022 | June 30, 2021 | % change | June 30, 2022 | June 30, 2021 | % change | ||||||||||||||||||||||||||||||
| (In millions, except percentages) | |||||||||||||||||||||||||||||||||||
| Cost of goods sold | $ | (272.8) | $ | 101.9 | N/M | $ | (102.0) | $ | 223.4 | N/M | |||||||||||||||||||||||||
| Gross profit | (272.8) | 101.9 | N/M | (102.0) | 223.4 | N/M | |||||||||||||||||||||||||||||
| Operating income (loss) | (272.8) | 101.9 | N/M | (102.0) | 223.4 | N/M | |||||||||||||||||||||||||||||
| Total other income (expense), net | (54.7) | (54.9) | (0.4) | % | (106.7) | (104.9) | 1.7 | % | |||||||||||||||||||||||||||
| Income (loss) before income taxes | $ | (327.5) | $ | 47.0 | N/M | $ | (208.7) | $ | 118.5 | N/M |
N/M = Not meaningful
Cost of goods sold
The unrealized changes in fair value on our commodity derivatives, which are economic hedges, make up the entirety of the activity presented within cost of goods sold in the table above for the three and six months ended June 30, 2022 and June 30, 2021, respectively. As the exposure we are managing is realized, we reclassify the gain or loss on our commodity derivatives to the segment in which the underlying exposure resides, allowing our segments to realize the economic effects of the derivative without the resulting unrealized mark-to-market volatility. See Part I.—Item 1. Financial Statements, Note 11, "Derivative Instruments and Hedging Activities" for further information.
Total other income (expense), net
Total other expense, net was nearly flat for the three months ended June 30, 2022 and increased 1.7% for the six months ended June 30, 2022, respectively, compared to prior year.
The increase in total other expense, net for the six months ended June 30, 2022 compared to prior year was primarily due to higher pension and OPEB non-service costs, partially offset by lower net interest expense. See Part I.—Item 1. Financial Statements, Note 8 "Debt" for further details on our debt instruments.
Liquidity and Capital Resources
Liquidity
Overview
Our primary sources of liquidity include cash provided by operating activities and access to external capital. We continue to monitor world events which may create credit or economic challenges that could adversely impact our profit or operating cash flows and our ability to obtain additional liquidity. We currently believe that our cash and cash equivalents, cash flows from operations and cash provided by short-term and long-term borrowings, when necessary, will be adequate to meet our ongoing operating requirements, scheduled principal and interest payments on debt, anticipated dividend payments, capital expenditures and other obligations for the twelve months subsequent to the date of the issuance of this quarterly report and our long-term liquidity requirements. We do not have any restrictions that prevent or limit our ability to declare or pay dividends.
While a significant portion of our cash flows from operating activities is generated within the U.S., our cash balances include cash held outside the U.S. and in currencies other than the USD. As of June 30, 2022 approximately 84% of our cash and cash equivalents were located outside the U.S., largely denominated in foreign currencies. The recent fluctuations in foreign currency exchange rates may have a material impact on these foreign cash balances. Cash balances in foreign countries are often subject to additional restrictions and covenants. We may, therefore, have difficulties repatriating cash held outside the U.S., and such repatriation may be subject to tax. In some countries, repatriation of certain foreign balances is restricted by local laws and could have adverse tax consequences if we were to move the cash to another country. These limitations may affect our ability to fully utilize our cash resources for needs in the U.S. and other countries and may adversely affect our liquidity. When the earnings are considered indefinitely reinvested outside the U.S., we do not accrue taxes. To the extent necessary, we accrue for tax consequences on the earnings of our foreign subsidiaries upon repatriation. We may utilize tax planning and financing strategies in an effort to ensure that our worldwide cash is available in the locations in which it is needed. We periodically review and evaluate these plans and strategies, including externally committed and non-committed credit agreements accessible by our Company and each of our operating subsidiaries. We believe these financing arrangements, along with the cash generated from the operations of our U.S. business are sufficient to fund our current cash needs in the U.S.
Cash Flows and Use of Cash
Our business historically generates positive operating cash flow each year and our debt maturities are of a longer-term nature. However, our liquidity could be impacted significantly by the risk factors we described in Part I—Item 1A. "Risk Factors" in our Annual Report, Part II.—Item 1A. "Risk Factors" in this report and the items listed above.
Cash Flows from Operating Activities
Net cash provided by operating activities of $666.8 million for the six months ended June 30, 2022 decreased $81.7 million compared to $748.5 million for the six months ended June 30, 2021. The decrease in net cash provided by operating activities was primarily due to lower net income adjusted for non-cash items, partially offset by lower income taxes paid as well as lower payments for incentive compensation.
Cash Flows from Investing Activities
Net cash used in investing activities of $369.5 million for the six months ended June 30, 2022 increased $169.4 million compared to $200.1 million for the six months ended June 30, 2021. The increase in net cash used in investing activities was primarily due to higher capital expenditures as a result of the timing of capital projects.
Cash Flows from Financing Activities
Net cash used in financing activities of $469.8 million for the six months ended June 30, 2022 increased $465.9 million compared to $3.9 million for the six months ended June 30, 2021. The increase in net cash used in financing activities was primarily due to the repayment of our $500 million 3.5% USD notes which matured in May 2022, higher dividend payments as well as current year Class B common stock share repurchases, partially offset by higher borrowings under our commercial paper program in the current year.
Capital Resources, including Material Cash Requirements
Cash and Cash Equivalents
We had total cash and cash equivalents of $442.1 million as of June 30, 2022, compared to $637.4 million as of December 31, 2021 and $1,308.9 million as of June 30, 2021. The decrease in cash and cash equivalents from December 31, 2021 was primarily due to net debt repayments, including the repayment of our $500 million 3.5% USD notes which matured in May 2022, capital expenditures, dividend payments and Class B common stock share repurchases, partially offset by net cash
provided by operating activities and proceeds from the sales of properties and other assets. The decrease in cash and cash equivalents from June 30, 2021 was primarily due to net debt repayments, including the repayment of our $1.0 billion 2.1% senior notes which matured in July 2021 and our $500 million 3.5% USD notes which matured in May 2022, capital expenditures, dividend payments and Class B common stock share repurchases, partially offset by net cash provided by operating activities and proceeds from the sales of properties and other assets.
Borrowings
We repaid our $500 million 3.5% USD notes upon maturity on May 1, 2022 using a combination of commercial paper borrowings and cash on hand. Refer to Part I.—Item 1. Financial Statements, Note 8, "Debt" for details.
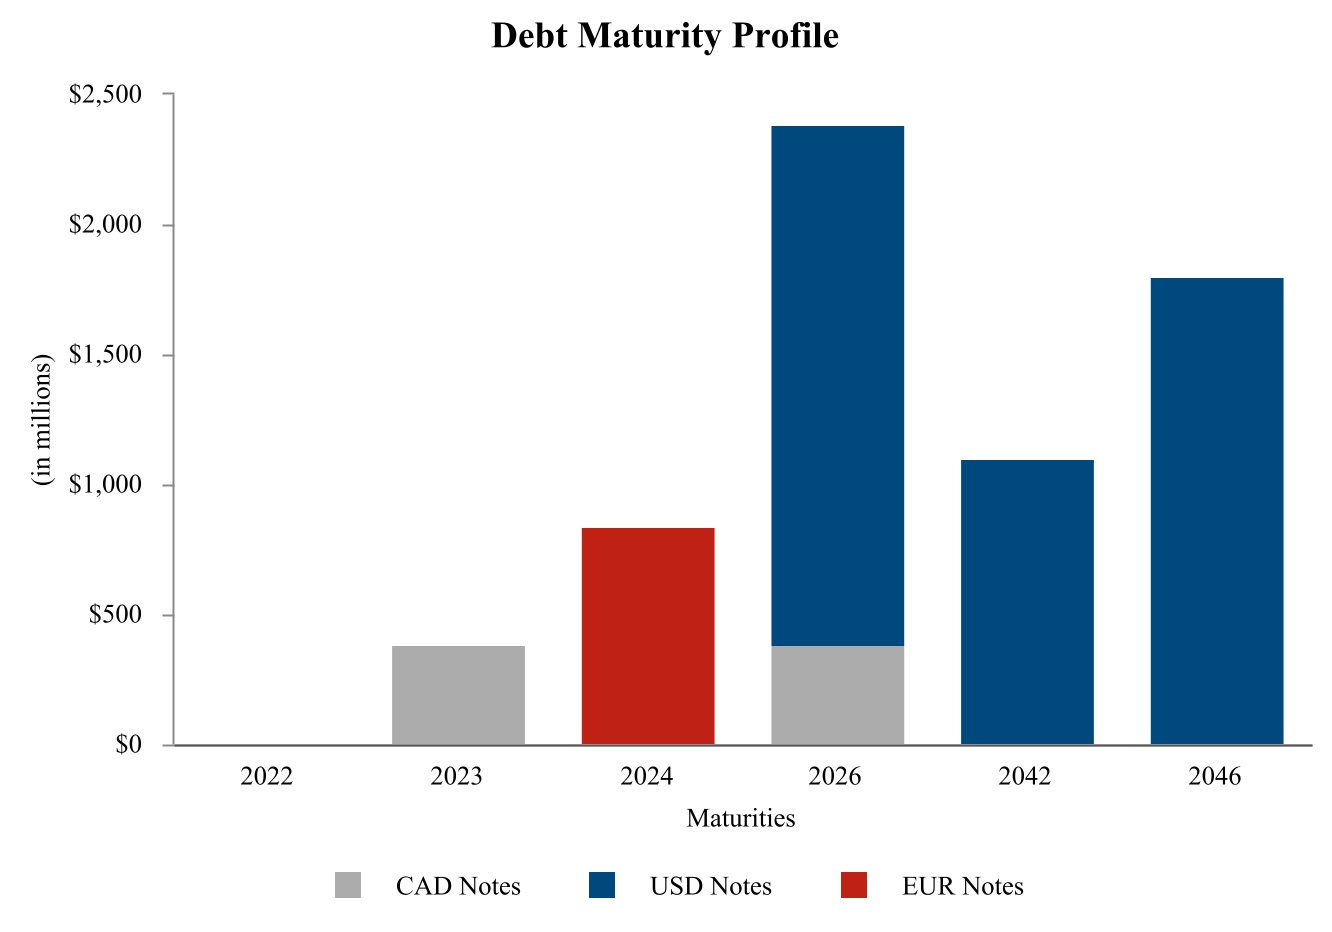
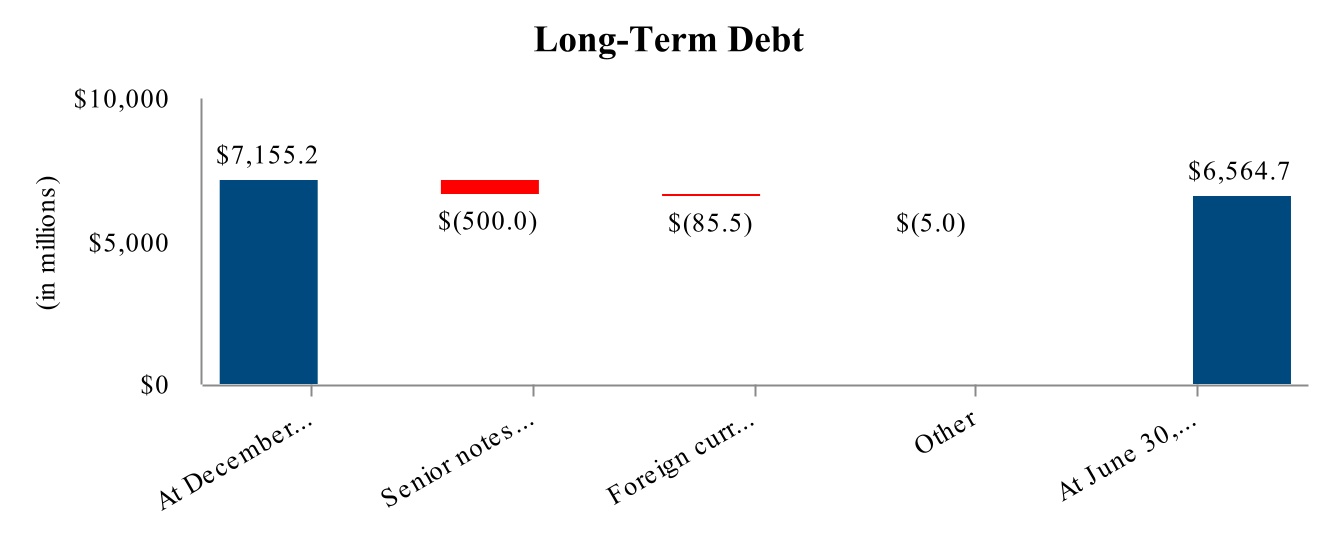
Based on the credit profile of our lenders that are party to our credit facilities, we are confident in our ability to continue to draw on our revolving credit facility if the need arises. As of June 30, 2022, we had $1.3 billion available to draw on our $1.5 billion revolving credit facility. The borrowing capacity is reduced by borrowings under our commercial paper program. As of June 30, 2022, we had total outstanding borrowings under our commercial paper program of approximately $230 million. Subsequent to June 30, 2022, we had net commercial paper repayments that resulted in commercial paper outstanding of approximately $93 million as of August 2, 2022. As such, we have approximately $1.4 billion available to draw on our total $1.5 billion revolving credit facility.
We intend to further utilize our cross-border, cross currency cash pool as well as our commercial paper programs for liquidity as needed. We also have CAD, GBP and USD overdraft facilities across several banks should we need additional short-term liquidity.
Under the terms of each of our debt facilities, we must comply with certain restrictions. These include customary events of default and specified representations, warranties and covenants, as well as covenants that restrict our ability to incur certain additional priority indebtedness (certain thresholds of secured consolidated net tangible assets), certain leverage threshold percentages, create or permit liens on assets and restrictions on mergers, acquisitions and certain types of sale lease-back transactions.
The maximum net debt to EBITDA leverage ratio, as defined by the amended revolving credit facility agreement, was 4.00x as of June 30, 2022 and December 31, 2021. As of June 30, 2022 and December 31, 2021, we were in compliance with all of these restrictions, have met such financial ratios and have met all debt payment obligations. All of our outstanding senior notes as of June 30, 2022 rank pari-passu.
In October 2021, we further amended our existing revolving credit facility agreement to replace LIBOR with designated replacement rates for any future borrowings denominated in EUR or GBP to ensure continued, uninterrupted access to these markets should we need it.
See Part I.—Item 1. Financial Statements, Note 8, "Debt" for further discussion of our borrowings and available sources of borrowing, including lines of credit.
Guarantees
We guarantee indebtedness and other obligations to banks and other third parties for some of our equity method investments and consolidated subsidiaries. See Part I.—Item 1. Financial Statements, Note 12, "Commitments and Contingencies" for further discussion.
Material Cash Requirements from Contractual and Other Obligations
There were no material changes to our material cash requirements from contractual and other obligations outside the ordinary course of business or due to factors similar in nature to inflation, changing prices on operations or changes in the remaining terms of the contracts since December 31, 2021, as reported in Part II.— Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations, "Material Cash Requirements from Contractual and Other Obligations" in our Annual Report.
Credit Rating
Our current long-term credit ratings are BBB-/Stable Outlook, Baa3/Stable Outlook and BBB(Low)/Stable Outlook with Standard & Poor's, Moody's and DBRS, respectively. Our short-term credit ratings are A-3, Prime-3 and R-2(low), respectively. A securities rating is not a recommendation to buy, sell or hold securities, and it may be revised or withdrawn at any time by the applicable rating agency.
Guarantor Information
SEC Registered Securities
For purposes of this disclosure, including the tables, "Parent Issuer" shall mean MCBC. "Subsidiary Guarantors" shall mean certain Canadian and U.S. subsidiaries reflecting the substantial operations of our Americas segment.
Pursuant to the indenture dated May 3, 2012 (as amended, the "May 2012 Indenture"), MCBC issued its outstanding 3.5% senior notes due 2022 (subsequently repaid upon maturity on May 1, 2022) and 5.0% senior notes due 2042. Additionally, pursuant to the indenture dated July 7, 2016, MCBC issued its outstanding 3.0% senior notes due 2026, 4.2% senior notes due 2046 and 1.25% senior notes due 2024. The issuances of the senior notes issued under the May 2012 Indenture and the July
2016 Indenture were registered under the Securities Act of 1933, as amended. These senior notes are guaranteed on a senior unsecured basis by certain subsidiaries of MCBC, which are listed in Exhibit 22 of our Annual Report on Form 10-K (the "Subsidiary Guarantors", and together with the Parent Issuer, the "Obligor Group"). "Parent Issuer" in this section is specifically referring to MCBC in its capacity as the issuer of the senior notes under the May 2012 Indenture and the July 2016 Indenture. Each of the Subsidiary Guarantors is 100% owned by the Parent Issuer. The guarantees are full and unconditional and joint and several.
None of our other outstanding debt was issued in a transaction that was registered with the SEC, and such other outstanding debt is issued or otherwise generally guaranteed on a senior unsecured basis by the Obligor Group or other consolidated subsidiaries of MCBC. These other guarantees are also full and unconditional and joint and several.
The senior notes and related guarantees rank pari-passu with all other unsubordinated debt of the Obligor Group and senior to all future subordinated debt of the Obligor Group. The guarantees can be released upon the sale or transfer of a Subsidiary Guarantors' capital stock or substantially all of its assets, or if such Subsidiary Guarantor ceases to be a guarantor under our other outstanding debt.
See Part I.—Item 1. Financial Statements, Note 8, "Debt" for details of all debt issued and outstanding as of June 30, 2022.
The following summarized financial information relates to the Obligor Group as of June 30, 2022 on a combined basis, after elimination of intercompany transactions and balances between the Obligor Group, and excluding the investments in and equity in the earnings of any non-guarantor subsidiaries. The balances and transactions with non-guarantor subsidiaries have been separately presented.
Summarized Financial Information of Obligor Group
| Six Months Ended | |||||
| June 30, 2022 | |||||
| (in millions) | |||||
| Net sales, out of which: | $ | 4,151.2 | |||
| Intercompany sales to non-guarantor subsidiaries | $ | 17.4 | |||
| Gross profit, out of which: | $ | 1,444.0 | |||
| Intercompany net costs from non-guarantor subsidiaries | $ | (206.5) | |||
| Net interest expense third parties | $ | (127.4) | |||
| Intercompany net interest income from non-guarantor subsidiaries | $ | 58.7 | |||
| Income before income taxes | $ | 327.3 | |||
| Net income | $ | 237.6 |
| As of June 30, 2022 | As of December 31, 2021 | ||||||||||
| (in millions) | |||||||||||
| Total current assets, out of which: | $ | 1,962.6 | $ | 1,834.4 | |||||||
| Intercompany receivables from non-guarantor subsidiaries | $ | 263.8 | $ | 155.5 | |||||||
| Total noncurrent assets, out of which: | $ | 25,230.4 | $ | 25,349.4 | |||||||
| Noncurrent intercompany notes receivable from non-guarantor subsidiaries | $ | 3,904.6 | $ | 3,977.1 | |||||||
| Total current liabilities, out of which: | $ | 2,559.6 | $ | 2,725.8 | |||||||
| Current portion of long-term debt and short-term borrowings | $ | 232.4 | $ | 502.9 | |||||||
| Intercompany payables due to non-guarantor subsidiaries | $ | 98.3 | $ | 87.0 | |||||||
| Total noncurrent liabilities, out of which: | $ | 13,503.7 | $ | 13,714.9 | |||||||
| Long-term debt | $ | 6,491.3 | $ | 6,573.5 | |||||||
| Noncurrent intercompany notes payable due to non-guarantor subsidiaries | $ | 4,230.3 | $ | 4,352.9 |
Capital Expenditures
We incurred $347.3 million, and paid $388.7 million, for capital improvement projects worldwide in the six months ended June 30, 2022, excluding capital spending by equity method joint ventures, representing an increase of $143.0 million from the $204.3 million of capital expenditures incurred in the six months ended June 30, 2021. This increase was primarily due to the timing of capital expenditures. We continue to focus on where and how we employ our planned capital expenditures, with an emphasis on strengthening our focus on required returns on invested capital as we determine how to best allocate cash within the business.
Contingencies
We are party to various legal proceedings arising in the ordinary course of business, environmental litigation and indemnities associated with our sale of Kaiser to FEMSA. See Part I.—Item 1. Financial Statements, Note 12, "Commitments and Contingencies" for further discussion.
Off-Balance Sheet Arrangements
Refer to Part II.—Item 8 Financial Statements, Note 18, "Commitments and Contingencies" in our Annual Report for discussion of off-balance sheet arrangements. As of June 30, 2022, we did not have any other material off-balance sheet arrangements.
Critical Accounting Estimates
Our accounting policies and accounting estimates critical to our financial condition and results of operations are set forth in our Annual Report and did not change during the first half of 2022. See Part I.—Item 1. Financial Statements, Note 2, "New Accounting Pronouncements" for discussion of recently adopted accounting pronouncements. See also Part I.—Item 1. Financial Statements, Note 7, "Goodwill and Intangible Assets" for discussion of the results of our 2021 annual impairment testing analysis, the related risks to our indefinite-lived intangible brand assets and the goodwill amounts associated with our reporting units.
New Accounting Pronouncements Not Yet Adopted
See Part I.—Item 1. Financial Statements, Note 2, "New Accounting Pronouncements" for a description of any new accounting pronouncements that have or could have a significant impact on our financial statements.
Previous: Item 1. FINANCIAL STATEMENTS (UNAUDITED) · Next: Item 3. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK