 filings.tools
Item 2. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
42K characters. Original on sec.gov · Markdown
Item 2. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Overview
For over two centuries, we have been brewing beverages that unite people to celebrate all life’s moments. From our core power brands Coors Light, Miller Lite, Coors Banquet, Molson Canadian, Carling and Ožujsko to our above premium brands including Madri, Staropramen, Blue Moon Belgian White and Leinenkugel’s Summer Shandy, to our economy and value brands like Miller High Life and Keystone, we produce many beloved and iconic beer brands. While our Company’s history is rooted in beer, we offer a modern portfolio that expands beyond the beer aisle as well, including flavored beverages like Vizzy Hard Seltzer, spirits like Five Trail whiskey as well as non-alcoholic beverages. As a business, our ambition is to be the first choice for our people, our consumers and our customers, and our success depends on our ability to make our products available to meet a wide range of consumer segments and occasions.
Management's Discussion and Analysis of Financial Condition and Results of Operations ("MD&A") in this Quarterly Report on Form 10-Q is provided as a supplement to, and should be read in conjunction with, our audited consolidated financial statements, the accompanying notes and the MD&A included in our Annual Report on Form 10-K for the fiscal year ended December 31, 2023 ("Annual Report"), as well as our unaudited condensed consolidated financial statements and the accompanying notes included in this report. Due to the seasonality of our operating results, quarterly financial results are not necessarily indicative of the results that may be achieved for the full year or any other future period.
Unless otherwise noted in this report, any description of "we," "us" or "our" includes Molson Coors Beverage Company ("MCBC" or the "Company"), principally a holding company, and its operating and non-operating subsidiaries included within our reporting segments. Our reporting segments include Americas and EMEA&APAC. Our Americas segment operates in the U.S., Canada and various countries in the Caribbean, Latin and South America and our EMEA&APAC segment operates in Bulgaria, Croatia, Czech Republic, Hungary, Montenegro, the Republic of Ireland, Romania, Serbia, the U.K., various other European countries, and certain countries within the Middle East, Africa and Asia Pacific.
Unless otherwise indicated, information in this report is presented in USD and comparisons are to comparable prior periods. Our primary operating currencies, other than the USD, include the CAD, the GBP, and our Central European operating currencies such as the EUR, CZK, RON and RSD.
Consolidated Results of Operations
The following table highlights summarized components of our unaudited condensed consolidated statements of operations for the three months ended March 31, 2024 and 2023. See Part I.—Item 1. Financial Statements for additional details of our U.S. GAAP results.
| Three Months Ended | |||||||||||||||||||||||||||||||||||
| March 31, 2024 | March 31, 2023 | % change | |||||||||||||||||||||||||||||||||
| (In millions, except percentages and per share data) | |||||||||||||||||||||||||||||||||||
| Net sales | $ | 2,596.4 | $ | 2,346.3 | 10.7 | % | |||||||||||||||||||||||||||||
| Cost of goods sold | (1,632.9) | (1,575.6) | 3.6 | % | |||||||||||||||||||||||||||||||
| Gross profit | 963.5 | 770.7 | 25.0 | % | |||||||||||||||||||||||||||||||
| Marketing, general and administrative expenses | (654.6) | (615.0) | 6.4 | % | |||||||||||||||||||||||||||||||
| Other operating income (expense), net | 6.3 | (0.5) | N/M | ||||||||||||||||||||||||||||||||
| Equity income (loss) | (0.9) | 3.0 | N/M | ||||||||||||||||||||||||||||||||
| Operating income (loss) | 314.3 | 158.2 | 98.7 | % | |||||||||||||||||||||||||||||||
| Total non-operating income (expense), net | (48.9) | (56.3) | (13.1) | % | |||||||||||||||||||||||||||||||
| Income (loss) before income taxes | 265.4 | 101.9 | 160.5 | % | |||||||||||||||||||||||||||||||
| Income tax benefit (expense) | (55.5) | (28.7) | 93.4 | % | |||||||||||||||||||||||||||||||
| Net income (loss) | 209.9 | 73.2 | 186.7 | % | |||||||||||||||||||||||||||||||
| Net (income) loss attributable to noncontrolling interests | (2.1) | (0.7) | 200.0 | % | |||||||||||||||||||||||||||||||
| Net income (loss) attributable to MCBC | $ | 207.8 | $ | 72.5 | 186.6 | % | |||||||||||||||||||||||||||||
| Net income (loss) attributable to MCBC per diluted share | $ | 0.97 | $ | 0.33 | 193.9 | % | |||||||||||||||||||||||||||||
| Financial volume in hectoliters | 17.974 | 17.006 | 5.7 | % |
N/M = Not meaningful
Foreign currency impacts on results
During the three months ended March 31, 2024, foreign currency movements had the following impacts on our USD consolidated results:
-
Net sales - Favorable impact of $12.6 million (favorable impact for EMEA&APAC and Americas of $11.8 million and $0.8 million, respectively).
-
Cost of goods sold - Unfavorable impact of $8.5 million (unfavorable impact for EMEA&APAC and Americas of $8.0 million and $0.6 million, respectively, partially offset by the favorable impact for Unallocated of $0.1 million).
-
MG&A - Unfavorable impact of $3.8 million (unfavorable impact for EMEA&APAC and Americas of $3.6 million and $0.2 million, respectively).
-
Income (loss) before income taxes - Unfavorable impact of $7.6 million (unfavorable impact for Unallocated, EMEA&APAC and Americas of $4.4 million, $1.9 million and $1.3 million, respectively).
The impacts of foreign currency movements on our consolidated USD results described above for the three months ended March 31, 2024 were primarily due to the weakening of the USD compared to the GBP.
Included in these amounts are both translational and transactional impacts of changes in foreign exchange rates. We calculate the impact of foreign exchange by translating our current period local currency results at the average exchange rates used to translate the financial statements in the comparable prior year period during the respective period throughout the year and comparing that amount with the reported amount for the period. The impact of transactional foreign currency gains and losses, including the impact of undesignated foreign currency forwards, is recorded within other non-operating income (expense), net in our unaudited condensed consolidated statements of operations.
Volume
Financial volume represents owned or actively managed brands sold to unrelated external customers within our geographic markets (net of returns and allowances), as well as contract brewing, wholesale/factored non-owned volume and company-owned distribution volume. This metric is presented on an STW basis to reflect the sales from our operations to our direct customers, generally distributors. We believe this metric is important and useful for investors and management because it gives an indication of the amount of beer and adjacent products that we have produced and shipped to customers. This metric excludes royalty volume, which consists of our brands produced and sold under various license and contract brewing agreements. Factored volume in our EMEA&APAC segment is the distribution of beer, wine, spirits and other products owned and produced by other companies to the on-premise channel, which is a common arrangement in the U.K.
Net Sales
The following table highlights the drivers of the change in net sales for the three months ended March 31, 2024 compared to March 31, 2023 (in percentages):
| Financial Volume | Price and Sales Mix | Currency | Total | ||||||||||||||||||||||||||
| Consolidated net sales | 5.7 | % | 4.4 | % | 0.6 | % | 10.7 | % | |||||||||||||||||||||
Net sales increased 10.7% for the three months ended March 31, 2024, compared to prior year, driven by higher financial volumes, favorable price and sales mix and favorable foreign currency impacts.
Financial volumes increased 5.7% for the three months ended March 31, 2024, compared to prior year, primarily due to higher financial volumes in the Americas segment.
Price and sales mix favorably impacted net sales for the three months ended March 31, 2024 by 4.4% primarily due to increased net pricing as well as favorable sales mix as a result of lower contract brewing volume in the the Americas segment.
A discussion of currency impacts on net sales is included in the "Foreign currency impacts on results" section above.
Cost of goods sold
We utilize cost of goods sold per hectoliter, as well as the year over year changes in this metric, as a key metric for analyzing our results. This metric is calculated as cost of goods sold per our unaudited condensed consolidated statements of operations divided by financial volume for the respective period. We believe this metric is important and useful for investors and management because it provides an indication of the trends of sales mix and other cost impacts on our cost of goods sold.
Cost of goods sold increased 3.6% for the three months ended March 31, 2024, compared to prior year, primarily due to higher financial volumes and unfavorable foreign currency impacts, partially offset by lower cost of goods sold per hectoliter. Cost of goods sold per hectoliter improved 1.9% for the three months ended March 31, 2024 compared to prior year, including unfavorable foreign currency impacts of 0.6%, primarily due to the favorable changes in our unrealized mark-to-market derivative positions of $52.6 million, the benefits of cost savings and volume leverage, partially offset by cost inflation related to materials and manufacturing expenses and unfavorable mix driven by lower contract brewing volumes in the Americas segment.
Marketing, general and administrative expenses
MG&A expenses increased 6.4% for the three months ended March 31, 2024 compared to prior year, primarily due to increased marketing investment to support our brands and innovations and unfavorable foreign currency impacts.
Other operating income (expense), net
See Part I.—Item 1. Financial Statements, Note 12, "Other Operating Income (Expense), net" for detail of our other operating income (expense), net.
Total non-operating income (expense), net
Total non-operating expense, net improved 13.1% for the three months ended March 31, 2024, compared to prior year, primarily due to lower net interest expense of 18.1% as a result of higher interest income from higher cash balances and higher interest rates as well as our continued deleveraging actions and higher pension and OPEB non-service net benefit, partially offset by unfavorable transactional foreign currency impacts.
Income taxes benefit (expense)
| Three Months Ended | |||||||||||||||||||||||
| March 31, 2024 | March 31, 2023 | ||||||||||||||||||||||
| Effective tax rate | 21 | % | 28 | % |
The lower effective tax rate for the three months ended March 31, 2024 compared to the same period in the prior year was primarily due to a decrease in net discrete tax expense. We recognized a $5.7 million discrete tax benefit in the three months ended March 31, 2024 compared to $7.5 million discrete tax expense in the three months ended March 31, 2023.
Our tax rate can be volatile and may change with, among other things, the amount and source of pretax income or loss, our ability to utilize foreign tax credits, excess tax benefits or deficiencies from share-based compensation, changes in tax laws and the movement of liabilities established pursuant to accounting guidance for uncertain tax positions as statutes of limitations expire, positions are effectively settled or when additional information becomes available. There are proposed or pending tax law changes in various jurisdictions and other changes to regulatory environments in countries in which we do business that, if enacted, could have an impact on our effective tax rate.
Refer to Part I.—Item 1. Financial Statements, Note 9, "Income Tax" for discussion regarding our effective tax rate.
Segment Results of Operations
Americas Segment
| Three Months Ended | |||||||||||||||||||||||||||||||||||
| March 31, 2024 | March 31, 2023 | % change | |||||||||||||||||||||||||||||||||
| (In millions, except percentages) | |||||||||||||||||||||||||||||||||||
| Net sales(1) | $ | 2,145.4 | $ | 1,939.0 | 10.6 | % | |||||||||||||||||||||||||||||
| Income (loss) before income taxes | $ | 320.6 | $ | 233.4 | 37.4 | % | |||||||||||||||||||||||||||||
| Financial volume in hectoliters(1)(2) | 13.910 | 12.936 | 7.5 | % |
(1)Includes gross inter-segment sales and volumes which are eliminated in the consolidated totals.
(2)Excludes royalty volume of 0.591 million hectoliters and 0.618 million hectoliters for the three months ended March 31, 2024 and March 31, 2023, respectively.
Net sales
The following table highlights the drivers of the change in net sales for the three months ended March 31, 2024 compared to March 31, 2023 (in percentages):
| Financial Volume | Price and Sales Mix | Currency | Total | ||||||||||||||||||||||||||
| Americas net sales | 7.5 | % | 3.1 | % | 0.0 | % | 10.6 | % | |||||||||||||||||||||
Net sales increased 10.6% for the three months ended March 31, 2024, compared to prior year, driven by higher financial volumes and favorable price and sales mix.
Financial volumes increased 7.5% for the three months ended March 31, 2024, compared to prior year, primarily due to an increase in U.S. volumes driven by volume growth in our core brands, partially offset by lower contract brewing volumes related to the wind down of a contract brewing arrangement leading up to the termination by the end of 2024. The increase in U.S. volume was impacted by the continued shifts in consumer purchasing behavior largely within the premium beer segment and the building of distributor inventory levels to support the peak summer selling season and to mitigate the impact of the Fort Worth brewery strike that commenced in mid-February 2024.
Price and sales mix favorably impacted net sales for the three months ended March 31, 2024 by 3.1% primarily due to increased net pricing and favorable sales mix as a result of lower contract brewing volumes in the U.S. related to the wind down of a contract brewing arrangement leading up to the termination by the end of 2024.
A discussion of currency impacts on net sales is included in the "Foreign currency impacts on results" section above.
Income (loss) before income taxes
Income before income taxes improved 37.4% for the three months ended March 31, 2024 compared to prior year, primarily due to higher financial volumes, increased net pricing, favorable sales mix and cost savings initiatives, partially offset by cost inflation related to materials and manufacturing expenses, as well as higher MG&A expense. Higher MG&A spend was primarily due to increased marketing investment to support our brands and innovations.
EMEA&APAC Segment
| Three Months Ended | |||||||||||||||||||||||||||||||||||
| March 31, 2024 | March 31, 2023 | % change | |||||||||||||||||||||||||||||||||
| (In millions, except percentages) | |||||||||||||||||||||||||||||||||||
| Net sales(1) | $ | 454.7 | $ | 410.1 | 10.9 | % | |||||||||||||||||||||||||||||
| Income (loss) before income taxes | $ | (11.0) | $ | (25.4) | (56.7) | % | |||||||||||||||||||||||||||||
| Financial volume in hectoliters(1)(2) | 4.064 | 4.071 | (0.2) | % |
(1)Includes gross inter-segment sales and volumes which are eliminated in the consolidated totals.
(2)Excludes royalty volume of 0.218 million hectoliters and 0.156 million hectoliters for the three months ended March 31, 2024 and March 31, 2023 respectively.
The following table highlights the drivers of the change in net sales for the three months ended March 31, 2024 compared to March 31, 2023 (in percentages):
| Financial Volume | Price and Sales Mix | Currency | Total | ||||||||||||||||||||||||||
| EMEA&APAC net sales | (0.2) | % | 8.2 | % | 2.9 | % | 10.9 | % | |||||||||||||||||||||
Net sales increased 10.9% for the three months ended March 31, 2024, compared to prior year, driven by favorable price and sales mix as well as favorable foreign currency impacts, partially offset by slightly unfavorable financial volumes.
Financial volumes slightly decreased 0.2% for the three months ended March 31, 2024, compared to prior year primarily due to lower volumes in Western Europe impacted by challenges in the U.K. off-premise, partially offset by increased volumes in Central and Eastern Europe as inflation pressures ease for this market.
Price and sales mix favorably impacted net sales for the three months ended March 31, 2024 by 8.2%, primarily due to increased net pricing to customers and favorable sales mix driven by premiumization.
A discussion of currency impacts on net sales is included in the "Foreign currency impacts on results" section above.
Income (loss) before income taxes
Loss before income taxes improved $14.4 million or 56.7% for the three months ended March 31, 2024, compared to the prior year, primarily due to increased net pricing to customers and favorable sales mix, partially offset by higher MG&A expense. Higher MG&A spend was primarily due to increased marketing to support our brands and innovations as well as cost inflation and unfavorable foreign currency impacts.
Unallocated Segment
We have certain activity that is not allocated to our segments, which has been reflected as "Unallocated" below. Specifically, "Unallocated" activity primarily includes financing-related costs such as interest expense and income, foreign exchange gains and losses on intercompany balances and realized and unrealized changes in fair value on instruments not designated in hedging relationships related to financing and other treasury-related activities and the unrealized changes in fair value on our commodity swaps not designated in hedging relationships recorded within cost of goods sold, which are later reclassified when realized to the segment in which the underlying exposure resides. Additionally, only the service cost component of net periodic pension and OPEB cost is reported within each operating segment, and all other components remain unallocated.
| Three Months Ended | |||||||||||||||||||||||||||||||||||
| March 31, 2024 | March 31, 2023 | % change | |||||||||||||||||||||||||||||||||
| (In millions, except percentages) | |||||||||||||||||||||||||||||||||||
| Cost of goods sold | $ | 0.5 | $ | (50.7) | N/M | ||||||||||||||||||||||||||||||
| Gross profit | 0.5 | (50.7) | N/M | ||||||||||||||||||||||||||||||||
| Operating income (loss) | 0.5 | (50.7) | N/M | ||||||||||||||||||||||||||||||||
| Total non-operating income (expense), net | (44.7) | (55.4) | (19.3) | % | |||||||||||||||||||||||||||||||
| Income (loss) before income taxes | $ | (44.2) | $ | (106.1) | (58.3) | % |
N/M = Not meaningful
Cost of goods sold
The unrealized changes in fair value on our commodity derivatives, which are economic hedges, make up substantially all of the activity presented within cost of goods sold in the table above for the three months ended March 31, 2024 and March 31, 2023. As the exposure we are managing is realized, we reclassify the gain or loss on our commodity derivatives to the segment in which the underlying exposure resides, allowing our segments to realize the economic effects of the derivative without the resulting unrealized mark-to-market volatility. See Part I.—Item 1. Financial Statements, Note 8, "Derivative Instruments and Hedging Activities" for further information.
Total non-operating income (expense), net
Total non-operating expense, net improved 19.3% for the three months ended March 31, 2024, compared to prior year, primarily due to lower net interest expense of 17.8% as a result of higher interest income from higher cash balances and higher interest rates as well as our continued deleveraging actions and higher pension and OPEB non-service net benefit, partially offset by the unfavorable impact of transactional foreign currency impacts.
See Part I.—Item 1. Financial Statements, Note 7, "Debt" for further details on our debt instruments.
Liquidity and Capital Resources
Liquidity
Overview
Our primary sources of liquidity include cash provided by operating activities and access to external capital. We continue to monitor world events which may create credit or economic challenges that could adversely impact our profit or operating cash flows and our ability to obtain additional liquidity. We currently believe that our cash and cash equivalents, cash flows from operations and cash provided by short-term and long-term borrowings, when necessary, will be adequate to meet our ongoing operating requirements, scheduled principal and interest payments on debt, anticipated dividend payments, capital expenditures and other obligations for the twelve months subsequent to the date of the issuance of this quarterly report and our long-term liquidity requirements. We do not have any restrictions that prevent or limit our ability to declare or pay dividends.
While a significant portion of our cash flows from operating activities are generated within the U.S., our cash balances include cash held outside the U.S. and in currencies other than the USD. As of March 31, 2024, approximately 54% of our cash and cash equivalents were located outside the U.S., largely denominated in foreign currencies. Fluctuations in foreign currency exchange rates have had and may continue to have a material impact on these foreign cash balances. Cash balances in foreign countries are often subject to additional restrictions. We may, therefore, have difficulties timely repatriating cash held outside the U.S., and such repatriation may be subject to tax. These limitations may affect our ability to fully utilize our cash resources for needs in the U.S. and other countries and may adversely affect our liquidity. To the extent necessary, we accrue for tax consequences on the earnings of our foreign subsidiaries as they are earned. We may utilize tax planning and financing strategies in an effort to ensure that our worldwide cash is available in the locations in which it is needed. We periodically review and evaluate these plans and strategies, including externally committed and non-committed credit agreements accessible by our Company and each of our operating subsidiaries. We believe these financing arrangements, along with the cash generated from the operations of our U.S. business, are sufficient to fund our current cash needs in the U.S.
Cash Flows and Use of Cash
Our business historically generates positive operating cash flows each year and our debt maturities are generally of a longer-term nature. However, our liquidity could be impacted significantly by the risk factors we described in Part I—Item 1A. "Risk Factors" in our Annual Report, Part II.—Item 1A. "Risk Factors" in this report and the items listed above.
Cash Flows from Operating Activities
Net cash provided by operating activities of $25.4 million for the three months ended March 31, 2024 increased $22.0 million compared to $3.4 million for the three months ended March 31, 2023. The increase in net cash provided by operating activities was primarily due to higher net income and lower interest paid, partially offset by the unfavorable timing of working capital. The unfavorable timing of working capital was primarily driven by the timing of cash receipts on trade receivables as well as higher payments for prior year annual incentive compensation.
Cash Flows from Investing Activities
Net cash used in investing activities of $212.5 million for the three months ended March 31, 2024 increased $35.1 million compared to $177.4 million for the three months ended March 31, 2023. The increase in net cash used in investing activities was primarily due to higher capital expenditures driven by the timing of capital projects.
Cash Flows from Financing Activities
Net cash used in financing activities of $216.2 million for the three months ended March 31, 2024 increased $113.7 million compared to $102.5 million for the three months ended March 31, 2023. The increase in net cash used in financing activities was primarily due to higher Class B common stock share repurchases and higher dividend payments.
Capital Resources, including Material Cash Requirements
Cash and Cash Equivalents
As of March 31, 2024, we had total cash and cash equivalents of $458.4 million, compared to $868.9 million as of December 31, 2023 and $328.2 million as of March 31, 2023. The decrease in cash and cash equivalents from December 31, 2023 was primarily due to capital expenditures, Class B common stock share repurchases and dividends paid, partially offset by the net proceeds from operating activities. The increase in cash and cash equivalents from March 31, 2023 was primarily due to the net cash provided by operating activities, partially offset by capital expenditures, net debt repayments, including the repayment of our CAD 500 million 2.84% notes which matured in July 2023, dividend payments, Class B common stock share repurchases as well as cash paid for acquisitions.
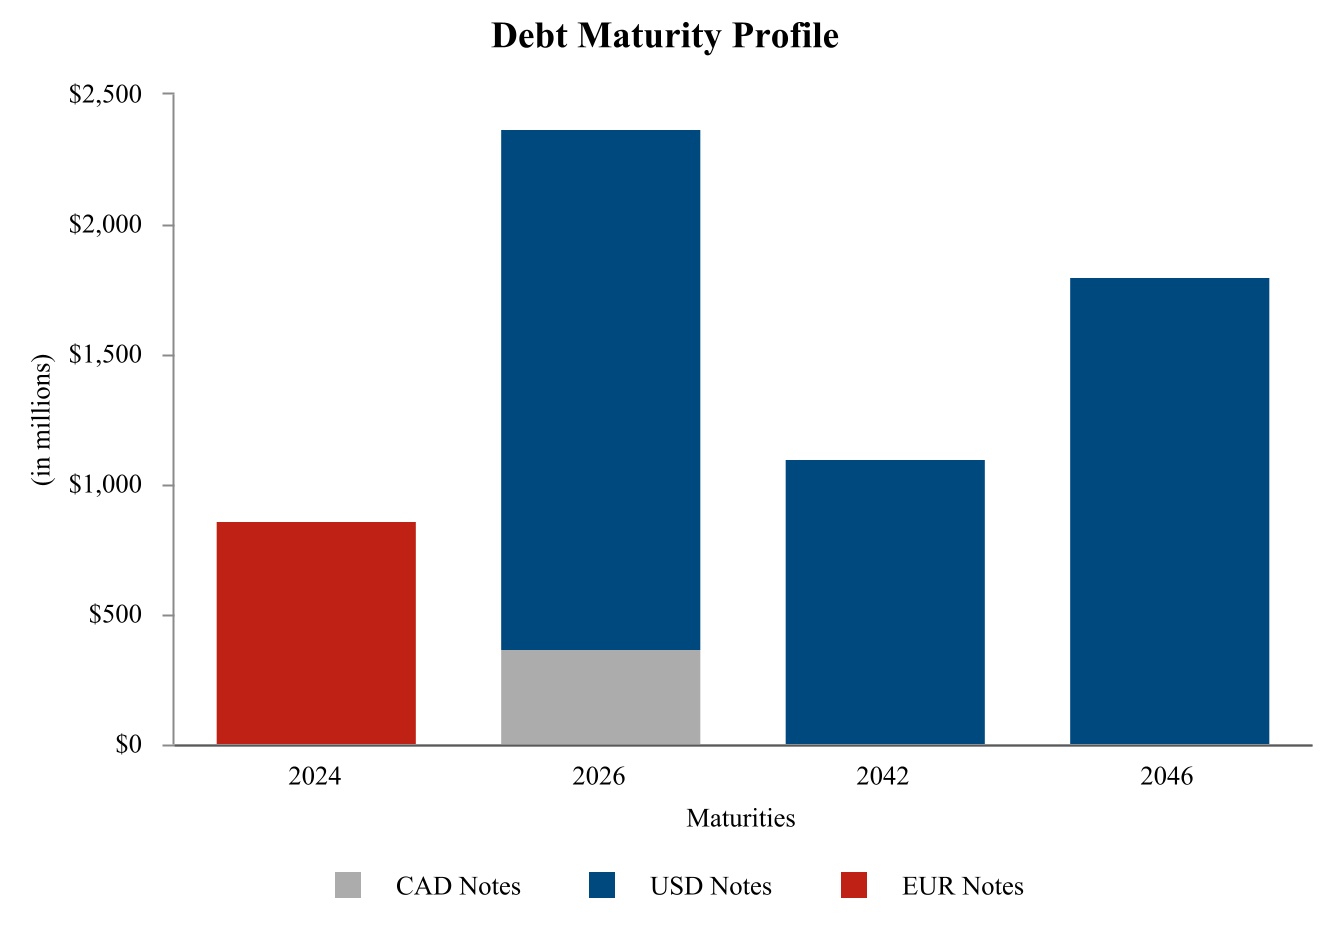
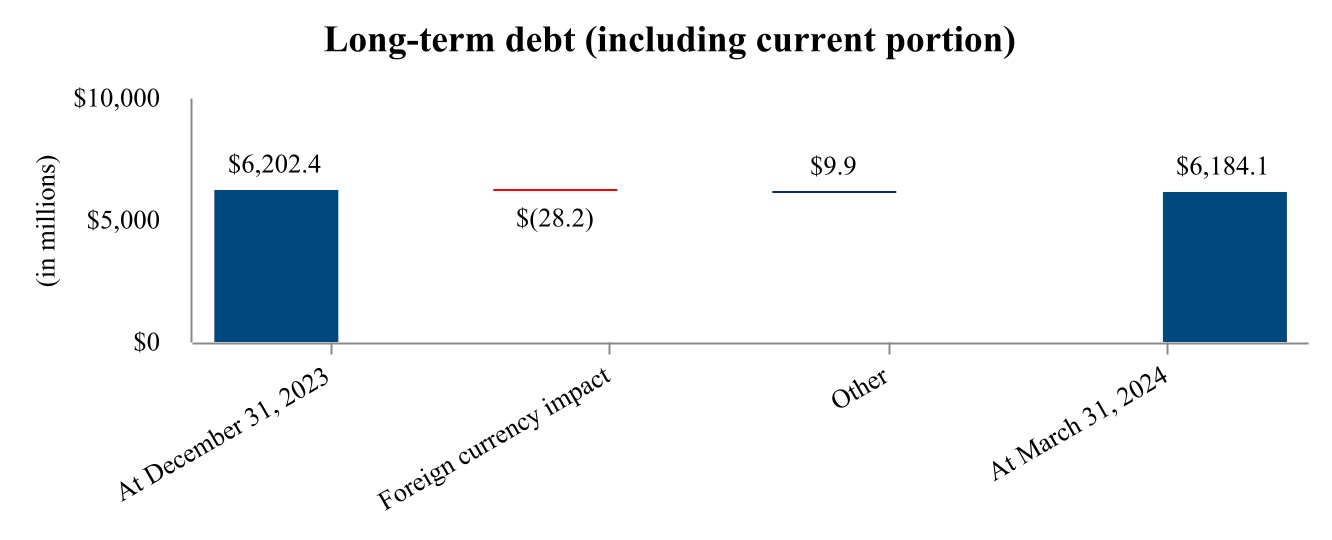
Based on the credit profile of our lenders that are party to our credit facilities, we are confident in our ability to draw on our amended and restated revolving credit facility if the need arises. As of March 31, 2024, we had $2.0 billion available to draw on our $2.0 billion amended and restated revolving credit facility. As of March 31, 2024, we had no borrowings drawn on this amended and restated revolving credit facility and no commercial paper borrowings.
We intend to further utilize our cross-border, cross currency cash pool as well as our commercial paper programs for liquidity as needed. We also have CAD, GBP and USD overdraft facilities across several banks should we need additional short-term liquidity.
Under the terms of each of our debt facilities, we must comply with certain restrictions. These include customary events of default and specified representations, warranties and covenants, as well as covenants that restrict our ability to incur certain additional priority indebtedness (certain thresholds of secured consolidated net tangible assets), certain leverage threshold percentages, create or permit liens on assets and restrictions on mergers, acquisitions and certain types of sale lease-back transactions.
The maximum net debt to EBITDA leverage ratio, as defined by the amended and restated revolving credit facility agreement, was 4.00x as of March 31, 2024 and December 31, 2023. As of March 31, 2024 and December 31, 2023, we were in compliance with all of these restrictions and covenants, have met such financial ratios and have met all debt payment obligations. All of our outstanding senior notes as of March 31, 2024 rank pari-passu.
See Part I.—Item 1. Financial Statements, Note 7, "Debt" for further discussion of our borrowings and available sources of borrowings, including lines of credit.
Guarantees
We guarantee indebtedness and other obligations to banks and other third parties for some of our equity method investments and consolidated subsidiaries. See Part I.—Item 1. Financial Statements, Note 10, "Commitments and Contingencies" for further discussion.
Material Cash Requirements from Contractual and Other Obligations
There were no material changes to our material cash requirements from contractual and other obligations outside the ordinary course of business or due to factors similar in nature to inflation, changing prices on operations or changes in the remaining terms of the contracts since December 31, 2023, as reported in Part II.— Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations, "Material Cash Requirements from Contractual and Other Obligations" in our Annual Report.
Credit Rating
Our current long-term credit ratings are BBB/Stable Outlook, Baa2/Positive Outlook and BBB/Stable Outlook with Standard & Poor's, Moody's and DBRS, respectively. Our short-term credit ratings are A-2, Prime-2 and R-2, respectively. A securities rating is not a recommendation to buy, sell or hold securities, and it may be revised or withdrawn at any time by the applicable rating agency.
Guarantor Information
SEC Registered Securities
For purposes of this disclosure, including the tables, "Parent Issuer" shall mean MCBC in its capacity as the issuer of the senior notes under the May 2012 Indenture and the July 2016 Indenture. "Subsidiary Guarantors" shall mean certain Canadian and U.S. subsidiaries reflecting the substantial operations of our Americas segment.
Pursuant to the indenture dated May 3, 2012 (as amended, the "May 2012 Indenture"), MCBC issued its outstanding 5.0% senior notes due 2042. Additionally, pursuant to the indenture dated July 7, 2016 ("July 2016 Indenture"), MCBC issued its outstanding 3.0% senior notes due 2026, 4.2% senior notes due 2046 and 1.25% senior notes due 2024. The issuances of the senior notes issued under the May 2012 Indenture and the July 2016 Indenture were registered under the Securities Act of 1933, as amended. These senior notes are guaranteed on a senior unsecured basis by certain subsidiaries of MCBC, which are listed in Exhibit 22 of this Quarterly Report on Form 10-Q (the Subsidiary Guarantors, and together with the Parent Issuer, the "Obligor Group"). Each of the Subsidiary Guarantors is 100% owned by the Parent Issuer. The guarantees are full and unconditional and joint and several.
None of our other outstanding debt was issued in a transaction that was registered with the SEC, and such other outstanding debt is issued or otherwise generally guaranteed on a senior unsecured basis by the Obligor Group or other consolidated subsidiaries of MCBC. These other guarantees are also full and unconditional and joint and several.
As of March 31, 2024, the senior notes and related guarantees rank pari-passu with all other unsubordinated debt of the Obligor Group and senior to all future subordinated debt of the Obligor Group. The guarantees can be released upon the sale or transfer of a Subsidiary Guarantors' capital stock or substantially all of its assets, or if such Subsidiary Guarantor ceases to be a guarantor under our other outstanding debt.
See Part I.—Item 1. Financial Statements, Note 7, "Debt" for details of all debt issued and outstanding as of March 31, 2024.
The following summarized financial information relates to the Obligor Group as of March 31, 2024 on a combined basis, after elimination of intercompany transactions and balances between the Obligor Group, and excluding the investments in and equity in the earnings of any non-guarantor subsidiaries. The balances and transactions with non-guarantor subsidiaries have been separately presented.
Summarized Financial Information of Obligor Group
| Three Months Ended | |||||
| March 31, 2024 | |||||
| (in millions) | |||||
| Net sales, out of which: | $ | 2,107.8 | |||
| Intercompany sales to non-guarantor subsidiaries | $ | 24.3 | |||
| Gross profit, out of which: | $ | 803.3 | |||
| Intercompany net costs from non-guarantor subsidiaries | $ | (103.2) | |||
| Net interest expense, out of which: | $ | (35.5) | |||
| Intercompany net interest income from non-guarantor subsidiaries | $ | 13.0 | |||
| Income before income taxes | $ | 278.2 | |||
| Net income | $ | 215.0 |
| As of March 31, 2024 | As of December 31, 2023 | ||||||||||
| (in millions) | |||||||||||
| Total current assets, out of which: | $ | 1,798.2 | $ | 1,814.3 | |||||||
| Intercompany receivables from non-guarantor subsidiaries | $ | 262.7 | $ | 255.7 | |||||||
| Total noncurrent assets, out of which: | $ | 24,507.3 | $ | 24,641.0 | |||||||
| Noncurrent intercompany notes receivable from non-guarantor subsidiaries | $ | 4,094.3 | $ | 4,178.6 | |||||||
| Total current liabilities, out of which: | $ | 2,968.8 | $ | 3,048.4 | |||||||
| Current portion of long-term debt and short-term borrowings | $ | 867.3 | $ | 885.6 | |||||||
| Intercompany payables due to non-guarantor subsidiaries | $ | 148.2 | $ | 117.7 | |||||||
| Total noncurrent liabilities, out of which: | $ | 8,106.4 | $ | 8,094.7 | |||||||
| Long-term debt | $ | 5,257.7 | $ | 5,257.6 | |||||||
Capital Expenditures
We incurred $143.9 million, and paid $214.7 million, for capital improvement projects worldwide in the three months ended March 31, 2024, excluding capital spending by equity method joint ventures, representing a decrease of $5.1 million from the $149.0 million of capital expenditures incurred in the three months ended March 31, 2023. We continue to focus on where and how we employ our planned capital expenditures, with an emphasis on strengthening our focus on required returns on invested capital as we determine how to best allocate cash within the business.
Contingencies
We are party to various legal proceedings arising in the ordinary course of business, environmental litigation and indemnities associated with our sale of Kaiser to FEMSA. See Part I.—Item 1. Financial Statements, Note 10, "Commitments and Contingencies" for further discussion.
Off-Balance Sheet Arrangements
Refer to Part II.—Item 8. Financial Statements, Note 13, "Commitments and Contingencies" in our Annual Report for discussion of off-balance sheet arrangements. As of March 31, 2024, we did not have any other material off-balance sheet arrangements.
Critical Accounting Estimates
Our accounting policies and accounting estimates critical to our financial condition and results of operations are set forth in our Annual Report and did not change during the three months ended March 31, 2024. See Part I.—Item 1. Financial Statements, Note 2, "New Accounting Pronouncements" for discussion of recently adopted accounting pronouncements. See also Part I.—Item 1. Financial Statements, Note 5, "Goodwill and Intangible Assets" for discussion of the results of our 2023 annual impairment testing analysis, the related risks to our indefinite-lived intangible brand assets and the goodwill amounts associated with our reporting units.
New Accounting Pronouncements Not Yet Adopted
See Part I.—Item 1. Financial Statements, Note 2, "New Accounting Pronouncements" for a description of any new accounting pronouncements that have or could have a significant impact on our financial statements.
Previous: Item 1. FINANCIAL STATEMENTS (UNAUDITED) · Next: Item 3. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK