 filings.tools
Truist Financial 10-K 2022-12-31
Filed 2023-02-28. 20 sections, 969K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
_________________________________________________________________
FORM 10-K
_________________________________________________________________
☒ ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d)
OF THE SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended December 31, 2022
Commission File Number: 1-10853
TRUIST FINANCIAL CORPORATION
(Exact name of registrant as specified in its charter)
_________________________________________________________________
| North Carolina | 56-0939887 | ||||||||||
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | ||||||||||
| 214 North Tryon Street | |||||||||||
| Charlotte, | North Carolina | 28202 | |||||||||
| (Address of principal executive offices) | (Zip Code) | ||||||||||
| Registrant’s telephone number, including area code: | (336) | 733-2000 | |||||||||
_________________________________________________________________
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol | Name of each exchange on which registered | ||||||||||||
| Common Stock, $5 par value | TFC | New York Stock Exchange | ||||||||||||
| Depositary Shares each representing 1/4,000th interest in a share of Series I Perpetual Preferred Stock | TFC.PI | New York Stock Exchange | ||||||||||||
| 5.853% Fixed-to-Floating Rate Normal Preferred Purchase Securities each representing 1/100th interest in a share of Series J Perpetual Preferred Stock | TFC.PJ | New York Stock Exchange | ||||||||||||
| Depositary Shares each representing 1/1,000th interest in a share of Series O Non-Cumulative Perpetual Preferred Stock | TFC.PO | New York Stock Exchange | ||||||||||||
| Depositary Shares each representing 1/1,000th interest in a share of Series R Non-Cumulative Perpetual Preferred Stock | TFC.PR | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☐ No ☒
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the Registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☒ | Accelerated filer | ☐ | |||||||||||
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ | |||||||||||
| Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☒
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements. ☐
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b). ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ☐ No ☒
At January 31, 2023, the Company had 1,327,909,982 shares of its common stock, $5 par value, outstanding. As of June 30, 2022, the aggregate market value of voting stock held by nonaffiliates of the Company was approximately $62.7 billion. Documents incorporated by reference: Portions of the definitive proxy statement relating to the registrant’s 2023 annual meeting of stockholders are incorporated by reference in this Form 10-K in response to Items 10, 11, 12, 13 and 14 of Part III.
| TABLE OF CONTENTS | ||||||||||||||
| TRUIST FINANCIAL CORPORATION | ||||||||||||||
| FORM 10-K | ||||||||||||||
| December 31, 2022 | ||||||||||||||
| Page No. | ||||||||||||||
| PART I | ||||||||||||||
| Glossary of Defined Terms | 1 | |||||||||||||
| Forward-Looking Statements | 3 | |||||||||||||
| Item 1 | Business | 4 | ||||||||||||
| Item 1A | Risk Factors | 18 |
Item 1B. Unresolved Staff Comments (None to be reported)
Item 4. Mine Safety Disclosures (Not applicable)
| PART II | | | | | | | | | | | | | | | | Item 5 | | | | | | Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities | | | 37 | | | | | | Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations | | | | | | | Executive Overview | | | 40 | | | | | | | | | | | | | Analysis of Results of Operations | | | 43 | | | | | | | | | | | | | Analysis of Financial Condition | | | 49 | | | | | | | | | | | | | Risk Management | | | 62 | | | | | | | | | | | | | Liquidity | | | 72 | | | | | | | | | | | | | Capital | | | 74 | | | | | | | Item 7A | | | | | | Quantitative and Qualitative Disclosures About Market Risk (see Market Risk) | | | 64 | | | | | | Item 8. Financial Statements and Supplementary Data | | | | | | | Report of Independent Registered Public Accounting Firm (PCAOB ID: 238) | | | 81 | | | | | | | | | | | | | Consolidated Balance Sheets | | | 83 | | | | | | | | | | | | | Consolidated Statements of Income | | | 84 | | | | | | | | | | | | | Consolidated Statements of Comprehensive Income | | | 85 | | | | | | | | | | | | | Consolidated Statements of Changes in Shareholders’ Equity | | | 86 | | | | | | | | | | | | | Consolidated Statements of Cash Flows | | | 87 | | | | | | | | | | | | | Notes to Consolidated Financial Statements | | | | | | | | | | | | | | | | Note 1. Basis of Presentation | | | 88 | | | | | | | | | | | | | Note 2. Business Combinations | | | 102 | | | | | | | | | | | | | Note 3. Securities Financing Activities | | | 102 | | | | | | | | | | | | | Note 4. Investment Securities | | | 103 | | | | | | | | | | | | | Note 5. Loans and ACL | | | 105 | | | | | | | | | | | | | Note 6. Premises and Equipment | | | 111 | | | | | | | | | | | | | Note 7. Goodwill and Other Intangible Assets | | | 111 | | | | | | | | | | | | | Note 8. Loan Servicing | | | 112 | | | | | | | | | | | | | Note 9. Other Assets and Liabilities | | | 113 | | | | | | | | | | | | | Note 10. Deposits | | | 114 | | | | | | | | | | | | | Note 11. Borrowings | | | 114 | | | | | | | | | | | | | Note 12. Shareholders’ Equity | | | 115 | | | | | | | | | | | | | Note 13. AOCI | | | 116 | | | | | | | | | | | | | Note 14. Income Taxes | | | 117 | | | | | | | | | | | | | Note 15. Benefit Plans | | | 118 | | | | | | | | | | | | | Note 16. Commitments and Contingencies | | | 121 | | | | | | | | | | | | | Note 17. Regulatory Requirements and Other Restrictions | | | 126 | | | | | | | | | | | | | Note 18. Fair Value Disclosures | | | 127 | | | | | | | | | | | | | Note 19. Derivative Financial Instruments | | | 132 | | | | | | | | | | | | | Note 20. Computation of EPS | | | 136 | | | | | | | | | | | | | Note 21. Operating Segments | | | 136 | | | | | | | | | | | | | Note 22. Parent Company Financial Information | | | 140 | | | | | | | | | | | | | Note 23. Subsequent Events | | | 141 | | | | | |
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure (None to be reported)
| Item 9A | | | | | | Controls and Procedures | | | 142 | | | | | |
Item 9B. Other Information (None to be reported)
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections (Not applicable)
| PART III | | | | | | | | | | | | | | |
Item 10. Directors, Executive Officers and Corporate Governance
Item 11. Executive Compensation
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
Item 13. Certain Relationships and Related Transactions, and Director Independence
Item 14. Principal Accounting Fees and Services
| PART IV | | | | | | | | | | | | | | | Item 15. Exhibits, Financial Statement Schedules | | | | | | | Financial Statements (see Listing in Item 8 above) | | | | | | | | | | | | | | | | Exhibits | | | 143 | | | | | | | | | | | | | Financial Statement Schedules (None required) | | | | | | | | |
Item 16. Form 10-K Summary (None)
| | | | | | | | | | | | | | | |
| * | For information regarding executive officers, refer to “Executive Officers” in Part I. The other information required by Item 10 is incorporated herein by reference to the information that appears under the headings “Nominees for Election as Directors for a One-Year Term Expiring in 2024,” “Nominating and Governance Committee Director Nominations,” “Ethics at Truist,” “Corporate Governance Guidelines,” “Audit Committee Report” and “Audit Committee” in the Registrant’s Proxy Statement for the 2023 Annual Meeting of Shareholders. The information required by Item 11 is incorporated herein by reference to the information that appears under the headings “Compensation Discussion and Analysis,” “Compensation of Executive Officers,” “Compensation and Human Capital Committee Report on Executive Compensation,” “Compensation and Human Capital Committee Interlocks and Insider Participation” and “Compensation of Directors” in the Registrant’s Proxy Statement for the 2023 Annual Meeting of Shareholders. For information regarding the registrant’s securities authorized for issuance under equity compensation plans, refer to “Equity Compensation Plan Information” in Part II herein. The other information required by Item 12 is incorporated herein by reference to the information that appears under the heading “Stock Ownership Information” in the Registrant’s Proxy Statement for the 2023 Annual Meeting of Shareholders. The information required by Item 13 is incorporated herein by reference to the information that appears under the headings “Director Independence” and “Related Person Transactions” in the Registrant’s Proxy Statement for the 2023 Annual Meeting of Shareholders. The information required by Item 14 is incorporated herein by reference to the information that appears under the headings “Fees to Independent Registered Public Accounting Firm” and “Audit Committee Pre-Approval Policy” in the Registrant’s Proxy Statement for the 2023 Annual Meeting of Shareholders. | |||||||||||||
Glossary of Defined Terms
The following terms may be used throughout this report, including the consolidated financial statements and related notes.
| Term | Definition | ||||
| ACL | Allowance for credit losses | ||||
| AFS | Available-for-sale | ||||
| Agency MBS | Mortgage-backed securities issued by a U.S. government agency or GSE | ||||
| ALLL | Allowance for loan and lease losses | ||||
| ALM | Asset/Liability management | ||||
| ARRC | Alternative Reference Rates Committee of the FRB and the Federal Reserve Bank of New York | ||||
| AOCI | Accumulated other comprehensive income (loss) | ||||
| Basel III Rules | Rules issued by the FRB, OCC, and FDIC on capital adequacy and liquidity requirements in the U.S for banking organizations. | ||||
| BB&T | BB&T Corporation and subsidiaries (changed to “Truist Financial Corporation” effective with the Merger) | ||||
| BCBS | Basel Committee on Banking Supervision | ||||
| BHC | Bank holding company | ||||
| BHCA | Bank Holding Company Act of 1956, as amended | ||||
| Board | Truist’s Board of Directors | ||||
| Branch Bank | Branch Banking and Trust Company (changed to “Truist Bank” effective with the Merger) | ||||
| BSA/AML | Bank Secrecy Act/Anti-Money Laundering | ||||
| C&CB | Corporate and Commercial Banking, an operating segment | ||||
| CARES Act | The Coronavirus Aid, Relief, and Economic Security Act | ||||
| CB&W | Consumer Banking and Wealth, an operating segment | ||||
| CCAR | Comprehensive Capital Analysis and Review | ||||
| CCB | Capital Conservation Buffer | ||||
| CD | Certificate of deposit | ||||
| CDI | Core deposit intangible | ||||
| CECL | Current expected credit loss model | ||||
| CEO | Chief Executive Officer | ||||
| CFTC | Commodity Futures Trading Commission | ||||
| CFO | Chief Financial Officer | ||||
| CET1 | Common equity tier 1 | ||||
| CIB | Corporate and Investment Banking | ||||
| CFPB | Consumer Financial Protection Bureau | ||||
| CMO | Collateralized mortgage obligation | ||||
| Company | Truist Financial Corporation and its subsidiaries (interchangeable with “Truist” below) | ||||
| COVID-19 | Coronavirus disease 2019 | ||||
| CRA | Community Reinvestment Act of 1977 | ||||
| CRE | Commercial real estate | ||||
| CRO | Chief Risk Officer | ||||
| DC | Disclosure Committee | ||||
| DEI | Diversity, Equity & Inclusion | ||||
| DIF | Deposit Insurance Fund administered by the FDIC | ||||
| Dodd-Frank Act | Dodd-Frank Wall Street Reform and Consumer Protection Act | ||||
| DTA | Deferred tax asset | ||||
| DTL | Deferred tax liability | ||||
| EBPCC | Ethics, Business Practices, and Conduct Committee | ||||
| ECRC | Enterprise Credit Risk Committee | ||||
| EGRRCPA | Economic Growth, Regulatory Relief, and Consumer Protection Act | ||||
| ERC | Enterprise Risk Committee | ||||
| ERISA | Employee Retirement Income Security Act of 1974 | ||||
| EPS | Earnings per common share | ||||
| ESG | Environmental, Social, and Governance | ||||
| Exchange Act | Securities Exchange Act of 1934, as amended | ||||
| FASB | Financial Accounting Standards Board | ||||
| FDIC | Federal Deposit Insurance Corporation | ||||
| FHA | Federal Housing Administration | ||||
| FHC | Financial holding company | ||||
| FHLB | Federal Home Loan Bank | ||||
| FHLMC | Federal Home Loan Mortgage Corporation | ||||
| FINRA | Financial Industry Regulatory Authority | ||||
| FNMA | Federal National Mortgage Association | ||||
| FRB | Board of Governors of the Federal Reserve System | ||||
| FTE | Full-time equivalent employee | ||||
| GAAP | Accounting principles generally accepted in the United States of America | ||||
| GDP | Gross Domestic Product | ||||
| GLBA | Gramm-Leach-Bliley Act | ||||
| GNMA | Government National Mortgage Association | ||||
| Grandbridge | Grandbridge Real Estate Capital, LLC | ||||
| GSE | U.S. government-sponsored enterprise | ||||
| HFI | Held for investment | ||||
| HMDA | Home Mortgage Disclosure Act |
Truist Financial Corporation 1
| Term | Definition | ||||
| HQLA | High-quality liquid assets | ||||
| HTM | Held-to-maturity | ||||
| IDI | Insured depository institution | ||||
| IH | Insurance Holdings, an operating segment | ||||
| IPV | Independent price verification | ||||
| IRC | Internal Revenue Code | ||||
| IRS | Internal Revenue Service | ||||
| ISDA | International Swaps and Derivatives Association, Inc. | ||||
| LCR | Liquidity Coverage Ratio | ||||
| LHFS | Loans held for sale | ||||
| LIBOR | London Interbank Offered Rate | ||||
| LOCOM | Lower of cost or market | ||||
| Market Risk Rule | Market risk capital requirements issued jointly by the OCC, U.S. Treasury, FRB, and FDIC | ||||
| MBS | Mortgage-backed securities | ||||
| MD&A | Management’s Discussion and Analysis of Financial Condition and Results of Operations | ||||
| Merger | Merger of BB&T and SunTrust effective December 6, 2019 | ||||
| MRLCC | Market Risk, Liquidity and Capital Committee | ||||
| MRO | Model Risk Oversight | ||||
| MSR | Mortgage servicing right | ||||
| MSRB | Municipal Securities Rulemaking Board | ||||
| NA | Not applicable | ||||
| NCCOB | North Carolina Office of the Commissioner of Banks | ||||
| NFA | National Futures Association | ||||
| NIM | Net interest margin, computed on a TE basis | ||||
| NM | Not meaningful | ||||
| NPA | Nonperforming asset | ||||
| NPL | Nonperforming loan | ||||
| NSFR | Net stable funding ratio | ||||
| NYSE | New York Stock Exchange | ||||
| OAS | Option adjusted spread | ||||
| OCC | Office of the Comptroller of the Currency | ||||
| OCI | Other comprehensive income (loss) | ||||
| OFAC | U.S. Department of the Treasury’s Office of Foreign Assets Control | ||||
| OPEB | Other post-employment benefit | ||||
| OREO | Other real estate owned | ||||
| OT&C | Other, Treasury and Corporate | ||||
| OTC | Over-the-counter | ||||
| Parent Company | Truist Financial Corporation, the parent company of Truist Bank and other subsidiaries | ||||
| Patriot Act | Uniting and Strengthening America by Providing Appropriate Tools Required to Intercept and Obstruct Terrorism Act of 2001 | ||||
| PCD | Purchased credit deteriorated loans | ||||
| PCI | Purchased credit impaired loans | ||||
| PPP | Paycheck Protection Program, established by the CARES Act | ||||
| PSU | Performance share units | ||||
| Re-REMICs | Re-securitizations of Real Estate Mortgage Investment Conduits | ||||
| RMO | Risk Management Organization | ||||
| ROU assets | Right-of-use assets | ||||
| RSA | Restricted stock award | ||||
| RSU | Restricted stock unit | ||||
| RUFC | Reserve for unfunded lending commitments | ||||
| S&P | Standard & Poor’s | ||||
| SBA | Small Business Administration | ||||
| SBIC | Small Business Investment Company | ||||
| SCB | Stress Capital Buffer | ||||
| SEC | Securities and Exchange Commission | ||||
| SOFR | Secured Overnight Financing Rate | ||||
| SunTrust | SunTrust Banks, Inc. | ||||
| Tailoring Rules | The final rules changing the applicability thresholds for regulatory capital and liquidity requirements, issued by the OCC, FRB, and FDIC, together with the final rules changing the applicability thresholds for enhanced prudential standards issued by the FRB | ||||
| TDR | Troubled debt restructuring | ||||
| TE | Taxable-equivalent | ||||
| TMC | Technology Management Committee | ||||
| TRS | Total Return Swap | ||||
| Truist | Truist Financial Corporation and its subsidiaries (interchangeable with the “Company” above) | ||||
| Truist Bank | Truist Bank, formerly Branch Banking and Trust Company | ||||
| U.S. | United States of America | ||||
| U.S. Treasury | United States Department of the Treasury | ||||
| UPB | Unpaid principal balance | ||||
| USAA | United Services Automobile Association | ||||
| UTB | Unrecognized tax benefit | ||||
| VaR | Value-at-risk | ||||
| VIE | Variable interest entity |
2 Truist Financial Corporation
Forward-Looking Statements
This Annual Report on Form 10-K contains “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995, regarding the financial condition, results of operations, business plans and the future performance of Truist. Words such as “anticipates,” “believes,” “estimates,” “expects,” “forecasts,” “intends,” “plans,” “projects,” “may,” “will,” “should,” “would,” “could,” and other similar expressions are intended to identify these forward-looking statements.
Forward-looking statements are not based on historical facts but instead represent management’s expectations and assumptions regarding Truist’s business, the economy, and other future conditions. Such statements involve inherent uncertainties, risks, and changes in circumstances that are difficult to predict. As such, Truist’s actual results may differ materially from those contemplated by forward-looking statements. While there can be no assurance that any list of risks and uncertainties or risk factors is complete, important factors that could cause actual results to differ materially from those contemplated by forward-looking statements include the following, without limitation, as well as the risks and uncertainties more fully discussed in Item 1A-Risk Factors:
-
changes in the interest rate environment, including the replacement of LIBOR as an interest rate benchmark, could adversely affect Truist’s revenue and expenses, the value of assets and obligations, and the availability and cost of capital, cash flows, and liquidity;
-
Truist is subject to credit risk by lending or committing to lend money, may have more credit risk and higher credit losses to the extent that loans are concentrated by loan type, industry segment, borrower type or location of the borrower or collateral, and may suffer losses if the value of collateral declines in stressed market conditions;
-
inability to access short-term funding or liquidity, loss of client deposits or changes in Truist’s credit ratings could increase the cost of funding or limit access to capital markets;
-
general economic or business conditions, either globally, nationally or regionally, may be less favorable than expected, including as a result of supply chain disruptions, inflationary pressures and labor shortages, and instability in global geopolitical matters, including due to an outbreak or escalation of hostilities, or volatility in financial markets could result in, among other things, slower deposit or asset growth, a deterioration in credit quality, or a reduced demand for credit, insurance, or other services;
-
the monetary and fiscal policies of the federal government and its agencies, including in response to rising inflation, could have a material adverse effect on the economy and Truist’s profitability;
-
the effects of COVID-19 adversely impacted the Company’s operations and financial performance and similar adverse impacts resulting from pandemics could occur in future periods;
-
risk management oversight functions may not identify or address risks adequately, and management may not be able to effectively manage credit risk;
-
there are risks resulting from the extensive use of models in Truist’s business, which may impact decisions made by management and regulators;
-
deposit attrition, client loss or revenue loss following completed mergers or acquisitions may be greater than anticipated;
-
Truist could fail to execute on strategic or operational plans, including the ability to successfully complete or integrate mergers and acquisitions;
-
increased competition, including from (i) new or existing competitors that could have greater financial resources or be subject to different regulatory standards or compliance costs, and (ii) products and services offered by non-bank financial technology companies, may reduce Truist’s client base, cause Truist to lower prices for its products and services in order to maintain market share or otherwise adversely impact Truist’s businesses or results of operations;
-
failure to maintain or enhance Truist’s competitive position with respect to new products, services, and technology, whether it fails to anticipate client expectations or because its technological developments fail to perform as desired or do not achieve market acceptance or regulatory approval or for other reasons, may cause Truist to lose market share or incur additional expense;
-
negative public opinion could damage Truist’s reputation and adversely impact business and revenues;
-
regulatory matters, litigation or other legal actions may result in, among other things, costs, fines, penalties, restrictions on Truist’s business activities, reputational harm, negative publicity, or other adverse consequences;
-
Truist faces substantial legal and operational risks in safeguarding personal information;
-
evolving legislative, accounting and regulatory standards, including with respect to climate, capital, and liquidity requirements, and results of regulatory examinations may adversely affect Truist’s financial condition and results of operations;
-
increased scrutiny regarding Truist’s consumer sales practices, training practices, incentive compensation design, and governance could damage its reputation and adversely impact business and revenues;
-
accounting policies and processes require management to make estimates about matters that are uncertain, including the potential write down to goodwill if there is an elongated period of decline in market value for Truist’s stock and adverse economic conditions are sustained over a period of time;
-
Truist faces risks related to originating and selling mortgages, including repurchase and indemnity demands from purchasers related to representations and warranties on loans sold, which could result in an increase in the amount of losses for loan repurchases;
-
there are risks relating to Truist’s role as a loan servicer, including an increase in the scope or costs of the services Truist is required to perform without any corresponding increase in servicing fees or a breach of Truist’s obligations as servicer;
-
Truist’s success depends on hiring and retaining key teammates, and if these individuals leave or change roles without effective replacements, Truist’s operations could be adversely impacted, which could be exacerbated in the increased work-from-home environment as job markets may be less constrained by physical geography;
-
Truist’s operations rely on its ability, and the ability of key external parties, to maintain appropriate-staffed workforces, and on the competence, trustworthiness, health and safety of teammates;
-
Truist faces the risk of fraud or misconduct by internal or external parties, which Truist may not be able to prevent, detect, or mitigate;
-
security risks, including denial of service attacks, hacking, social engineering attacks targeting Truist’s teammates and clients, malware intrusion, data corruption attempts, system breaches, cyberattacks, which have increased in frequency with geopolitical tensions, identity theft, ransomware attacks, and physical security risks, such as natural disasters, environmental conditions, and intentional acts of destruction, could result in the disclosure of confidential information, adversely affect Truist’s business or reputation or create significant legal or financial exposure; and
-
widespread outages of operational, communication, or other systems, whether internal or provided by third parties, natural or other disasters (including acts of terrorism and pandemics), and the effects of climate change, including physical risks, such as more frequent and intense weather events, and risks related to the transition to a lower carbon economy, such as regulatory or technological changes or shifts in market dynamics or consumer preferences, could have an adverse effect on Truist’s financial condition and results of operations, lead to material disruption of Truist’s operations or the ability or willingness of clients to access Truist’s products and services.
Readers are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date they are made. Except to the extent required by applicable law or regulation, Truist undertakes no obligation to revise or update any forward-looking statements.
Truist Financial Corporation 3
Item 1. BUSINESS
Truist Financial Corporation is a purpose-driven financial services company committed to inspiring and building better lives and communities. Truist has leading market share in many high-growth markets in the country. The Company offers a wide range of services. Headquartered in Charlotte, North Carolina, Truist is a top 10 U.S. commercial bank.
Truist Bank, Truist’s largest subsidiary, was chartered in 1872 and is the oldest bank headquartered in North Carolina. Truist Bank provides a wide range of banking and trust services for clients through 2,123 offices as of December 31, 2022 and its digital platform.
Services
Truist’s subsidiaries offer commercial and consumer clients a full array of products and services to meet their financial needs. The following table reflects examples of services provided by Truist:
| Table 1: Services | |||||||||||
| Consumer Services: | Commercial Services: | ||||||||||
| Asset management | Asset based lending | ||||||||||
| Automobile lending | Asset management | ||||||||||
| Credit card lending | Commercial deposit and treasury services | ||||||||||
| Consumer finance | Commercial lending | ||||||||||
| Home equity and other direct retail lending | Floor plan lending | ||||||||||
| Home mortgage lending | Derivatives | ||||||||||
| Insurance | Institutional trust services | ||||||||||
| Investment brokerage services | Insurance | ||||||||||
| Mobile/online banking | Insurance premium finance | ||||||||||
| Payment solutions | International banking | ||||||||||
| Point-of-sale lending | Investment banking and capital markets services | ||||||||||
| Retail and small business deposit products | Leasing | ||||||||||
| Small business lending | Merchant services | ||||||||||
| Student lending | Mortgage warehouse lending | ||||||||||
| Wealth management/private banking | Payment solutions | ||||||||||
| Real estate lending | |||||||||||
| Supply chain financing |
Market Area
The following table reflects Truist’s deposit market share and branch locations by state:
| Table 2: Deposit Market Share and Branch Locations by State | ||||||||||||||||||||
| % of Truist’s Deposits (2) | Deposit Market Share Rank (2) | Number of Branches (3) | ||||||||||||||||||
| Florida | 23 | % | 3rd | 472 | ||||||||||||||||
| Georgia | 19 | 1st | 222 | |||||||||||||||||
| Virginia | 15 | 2nd | 286 | |||||||||||||||||
| North Carolina (1) | 13 | 1st | 297 | |||||||||||||||||
| Maryland | 7 | 3rd | 155 | |||||||||||||||||
| Tennessee | 5 | 4th | 108 | |||||||||||||||||
| Pennsylvania | 4 | 8th | 157 | |||||||||||||||||
| South Carolina | 4 | 3rd | 99 | |||||||||||||||||
| Texas | 2 | 22nd | 106 | |||||||||||||||||
| West Virginia | 2 | 1st | 48 | |||||||||||||||||
| Kentucky | 2 | 4th | 61 | |||||||||||||||||
| Washington, D.C. | 2 | 5th | 24 | |||||||||||||||||
| Alabama | 1 | 7th | 59 | |||||||||||||||||
| New Jersey | 1 | 25th | 23 | |||||||||||||||||
| Other states | NA | NA | 6 | |||||||||||||||||
(1)Deposit market share rank excludes home office deposits.
(2)Source: FDIC.gov data as of June 30, 2022.
(3)As of December 31, 2022.
4 Truist Financial Corporation
Competition
The financial services industry is intensely competitive and constantly evolving. Management believes that Truist’s client-first approach is a competitive advantage that strengthens the Company’s ability to effectively provide financial products and services to businesses and individuals in its markets. In addition, management has made significant investments in recent years to develop Truist’s digital platform and believes that its mobile and online applications are highly competitive in meeting clients’ expectations. Legislative, regulatory, economic, and technological changes, as well as continued consolidation within the industry, could result in increased competition from new and existing market participants. Truist’s subsidiaries compete actively with national, regional, and local financial services providers, including banks, thrifts, securities dealers, mortgage bankers, finance companies, financial technology companies, and insurance companies. The ability of non-banking entities, including financial technology companies, to provide services previously limited to commercial banks has increased competition. Non-banking entities are not subject to the same regulatory framework as banks and BHCs, and therefore, can often operate with greater flexibility and lower costs. In addition, the ability to access and use technology is an increasingly significant competitive factor in the financial services industry. Having the right technology is a critically important component to client satisfaction because it affects the Company’s ability to deliver the products and services that clients desire in a manner that they find convenient and attractive. Management believes that the Company is well positioned to compete and that its continued focus on touch and technology will engender trust among its current and future clients.
General Business Development
Truist seeks to satisfy all of its clients’ financial needs, enabling the Company to grow and diversify its sources of revenue and profitability. Truist’s long-term strategy encompasses both organic and inorganic growth, including mergers or acquisitions of complementary financial institutions or other businesses.
Merger and Acquisition Strategy
The Company operates a diverse set of business lines nationally, with strong market shares concentrated in high growth markets in the Southeast and Mid-Atlantic regions. Truist will continue to pursue strategic mergers and acquisitions to enhance growth, when market conditions, business objectives, profitability, and market share considerations align to create favorable opportunities. Such opportunities might include insurance agencies, financial services businesses that strengthen Truist’s capabilities, and banks that enhance Truist’s market position.
Truist’s merger and acquisition strategy focuses on meeting the following criteria:
- the merger or acquisition must be strategically attractive in that it:
◦enhances scale and increases revenue via expanded markets and/or products;
◦improves the client experience; and
◦solidifies Truist’s position within the future of banking;
-
the organization must be a good fit with Truist’s culture;
-
associated risks must be identifie
Showing the first 8K of 73K characters. Open the full section
Item 1A. RISK FACTORS
Summary of Risk Factors
Market Risks
*•*Changes in interest rates could adversely affect revenue and expenses, the value of assets and liabilities, as well as the availability and cost of capital, and liquidity.
*•*The monetary and fiscal policies of the U.S. federal government could have a material adverse effect on profitability.
*•*Inflation could negatively impact our business, our profitability, and our stock price.
*•*Financial results, lending or other business activities could be materially affected by a deterioration of economic conditions.
*•*Instability in global economic conditions and geopolitical matters, as well as volatility in financial markets, could have a material adverse effect on the Company’s results of operations and financial condition.
- The replacement of LIBOR could adversely affect Truist’s profitability and financial condition.
Credit Risks
*•*The Company is subject to credit risk by lending, committing to lend money, or entering into a letter of credit or other types of contracts with counterparties.
*•*The Company may have more credit risk and higher credit losses to the extent that loans are concentrated by loan type, industry segment, borrower type, or location of the borrower or collateral.
*•*The Company may suffer losses if the value of collateral declines in stressed market conditions.
Liquidity Risks
- Loss of deposits or a change in deposit mix could increase Truist’s funding costs.
*•*Truist’s liquidity could be impaired by an inability to access short-term funding, an unforeseen outflow of cash, or the inability to monetize liquid assets.
*•*Truist relies on the mortgage secondary market and GSEs for some of the Company’s liquidity.
*•*Any reduction in the Company’s credit ratings could increase the Company’s cost of funding or reduce its access to the capital markets.
*•*The Parent Company could have less access to funding sources and its liquidity could be constrained if the Bank becomes unable to pay dividends during a time of stress.
*•*Truist may be impacted by the soundness of other financial institutions.
Technology Risks
- The Company faces cybersecurity risks, including denial of service, phishing, malware and ransomware attacks, potential insider threats, and third-party cybersecurity incidents, which could result in the disclosure of confidential information, adversely affect the Company’s operations, cause reputational damage, and create significant legal and financial exposure.
*•*The Company’s operational capabilities managed or supplied by third parties could fail, be compromised, or be breached, which could disrupt the Company’s business and adversely impact the Company’s results of operations, and financial condition, as well as cause legal exposure or reputational harm.
*•*Truist will continually encounter technological change and must effectively anticipate, develop, and implement new technology.
*•*The Company faces risks associated with quality, availability, and retention of key data for operational, strategic, regulatory, and compliance purposes.
Other External Risks
*•*The effects of COVID-19 adversely impacted the Company’s operations and financial performance and similar adverse impacts resulting from pandemics could occur in future periods.
*•*Physical, transition, or other risks associated with climate change have the potential to negatively impact operations, business results, and clients.
*•*The Company is at risk of increased losses from fraud.
*•*Natural disasters and other catastrophic events, which may increase in frequency and intensity due to climate change, could have a material adverse impact on the Company’s operations or the Company’s financial condition and results.
*•*An outbreak or escalation of hostilities between countries or within a country or region could have a material adverse effect on the U.S. economy and on Truist’s businesses.
18 Truist Financial Corporation
Compliance Risks
*•*Truist is subject to extensive and evolving government regulation and supervision, which could increase the cost of doing business, limit Truist’s ability to make investments and generate revenue, and lead to costly enforcement actions.
*•*Truist is subject to regulatory capital and liquidity standards that affect the Company’s business, operations, and ability to pay dividends, or otherwise return capital to shareholders.
*•*Truist is subject to certain risks related to originating and selling mortgages and may be required to repurchase mortgage loans or indemnify mortgage loan purchasers.
*•*Truist faces risks as a servicer of loans.
- Truist faces substantial legal and operational risks in safeguarding personal information.
*•*Differences in regulation can affect the Company’s ability to compete effectively.
*•*The Company can face risks of non-compliance and incur higher operational and compliance costs under laws and regulations relating to anti-money laundering, economic sanctions, embargo programs, and anti-corruption.
Strategic Risks
*•*Truist may face the risk of financial loss or negative impact resulting from ineffective strategy setting and execution, adverse business decisions, or lack of responsiveness to changes in the external environment.
*•*Competition may reduce Truist’s client base or cause Truist to modify pricing for products and services.
*•*Truist may not be able to complete future mergers or acquisitions.
*•*Truist has businesses other than banking that are subject to a variety of risks.
Regulatory and Legal Risks
*•*The Company may incur fines, penalties and other negative consequences from regulatory violations, including inadvertent or unintentional violations.
*•*Legal proceedings may adversely affect the Company’s results, reputation, and business operations.
Reputational Risks
*•*Negative public opinion could damage the Company’s reputation and adversely impact business and revenues.
*•*Scrutiny of the Company’s sales, training, and incentive compensation practices could damage the Company’s reputation and adversely impact business and revenues.
Talent Management Risks
*•*Truist depends on the expertise of key teammates. If these individuals leave or change their roles without effective replacements, operations may suffer.
*•*The Company depends on the ability to attract and retain qualified teammates while effectively managing recruiting and compensation costs amid highly competitive and rapidly changing market conditions in order to implement and execute upon business strategies.
*•*The Company’s operations rely on its ability, and the ability of key external parties, to maintain appropriately staffed workforces, and on the competence, trustworthiness, health and safety of employees.
Risks Related to Estimates and Assumptions
*•*There are risks resulting from the extensive use of models in Truist’s business, which may impact decisions made by Management and regulators.
*•*The Company’s accounting policies and processes are critical to how the Company reports its financial condition and results of operations and require management to make estimates about matters that are uncertain.
*•*Depressed market values for the Company’s stock and adverse economic conditions sustained over a period of time may require the Company to write down all or some portion of the Company’s goodwill.
Truist Financial Corporation 19
Operational Risks
*•*Truist relies on other companies to provide key components of the Company’s business infrastructure.
*•*The Company’s framework for managing risks may not be effective.
*•*Truist depends on the accuracy and completeness of information about clients and counterparties.
*•**Truist can be negatively affected if it fails to identify and address operational risks associated with the introduction of or changes to products,
Showing the first 8K of 98K characters. Open the full section
Item 2. PROPERTIES
Truist’s owns its headquarters building at 214 North Tryon Street, Charlotte, NC, 28202. Truist owns or leases free-standing operations centers, with its primary operations and information technology centers located in various locations in the Southeastern and Mid-Atlantic United States. Truist owns or leases retail branches and other offices in a number of states, primarily concentrated in the Southeastern and Mid-Atlantic United States. See Table 2 for a list of Truist’s branches by state. Truist also operates numerous insurance agencies and other businesses that occupy facilities throughout the U.S. and Canada. Management believes that these premises, in the aggregate, are well-located and suitably equipped to serve as financial services facilities. See “Note 6. Premises and Equipment” for additional disclosures.
36 Truist Financial Corporation
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Truist’s common stock is traded on the NYSE under the symbol “TFC.” As of December 31, 2022, Truist’s common stock was held by 84,359 registered shareholders.
Common Stock
Truist’s ability to pay dividends is primarily dependent on earnings from operations, the adequacy of capital and the availability of liquid assets for distribution and is subject to its capital plan meeting the SCB requirements from the FRB. Truist’s ability to generate liquid assets for distribution is dependent on the ability of Truist Bank to pay dividends to the Parent Company. The payment of cash dividends is an integral part of providing a competitive return on shareholders’ investments and needs to be balanced with maintaining sufficient capital to support future growth and meet regulatory requirements.
Management’s target common dividend payout ratio (computed by dividing common stock dividends by net income available to common shareholders) is between 30% and 50% during normal economic conditions. Truist’s common dividend payout ratio was 45% in 2022 compared to 41% in 2021 and 58% in 2020. Truist expects common dividend declarations, if made, to occur in January, April, July, and October with payment dates on or about the first of March, June, September, and December. A discussion of dividend restrictions is included in “Note 17. Regulatory Requirements and Other Restrictions” and in the “Regulatory Considerations” section.
Share Repurchases
Truist has periodically repurchased shares of its own common stock and expects to periodically repurchase shares in the future, to the extent the Company has excess capital and does not have sufficient investment opportunities in the form of organic growth and / or acquisitions. In accordance with North Carolina law, repurchased shares cannot be held as treasury stock, but revert to the status of authorized and unissued shares upon repurchase and are therefore available for future issuances. Repurchases may be affected through open market purchases, privately negotiated transactions, trading plans established in accordance with SEC rules, or other means. The timing and exact amount of repurchases are subject to various factors, including the Company’s capital position, liquidity, financial performance, alternative uses of capital, stock trading price and general market conditions, and may be suspended or resumed at any time. During 2022, the Company repurchased 5.1 million shares of common stock totaling $250 million through open market purchases. The following table provides information for share repurchases as part of publicly announced plans and shares exchanged or surrendered in connection with the exercise of equity-based awards:
| Table 5: Share Repurchase Activity | |||||||||||||||||||||||
| (Dollars in millions, except per share data, shares in thousands) | Total Number of Shares Purchased (1) | Average Price Paid Per Share (2) | Total Number of Shares Purchased as part of Publicly Announced Plans (3) | Approximate Dollar Value of Shares that may yet be Purchased Under the Plans (3) | |||||||||||||||||||
| October 1, 2022 to October 31, 2022 | — | $ | — | — | $ | 4,100 | |||||||||||||||||
| November 1, 2022 to November 30, 2022 | 1 | 46.33 | — | 4,100 | |||||||||||||||||||
| December 1, 2022 to December 31, 2022 | — | — | — | 4,100 | |||||||||||||||||||
| Total | 1 | 46.33 | — |
(1)Includes shares exchanged or surrendered in connection with the exercise of equity-based awards under equity-based compensation plans.
(2)Excludes commissions.
(3)In July 2022, the Board of Directors approved, effective October 1, 2022, new repurchase authority to effectuate repurchases up to an aggregate of $4.1 billion in shares of the Company’s common stock through September 30, 2023.
Truist Financial Corporation 37
Preferred Stock
Issuances
During 2020, Truist issued $3.5 billion in series O, series P, series Q, and series R preferred stock, gross of issuance cost, to further strengthen its capital position.
Redemptions
During 2021, the Company redeemed all 18,000 outstanding shares of its perpetual preferred stock series F and the corresponding depositary shares representing fractional interests in such series for $450 million, all 20,000 outstanding shares of its perpetual preferred stock series G and the corresponding depositary shares representing fractional interests in such series for $500 million, and all 18,600 outstanding shares of its perpetual preferred stock series H and the corresponding depositary shares representing fractional interests in such series for $465 million.
During 2020, the Company redeemed all 5,000 outstanding shares of its perpetual preferred stock series K and the corresponding depositary shares representing fractional interests in such series for $500 million plus any unpaid dividends.
These preferred stock redemptions were in accordance with the terms of the Company’s Articles of Incorporation.
See “Note 12. Shareholders’ Equity” for information about preferred stock.
Equity Compensation Plan Information
The following table provides information about equity-based awards as of December 31, 2022:
| Table 6: Equity Compensation Plan Information | ||||||||||||||||||||
| Plan Category | (a)(1)(2) Number of securities to be issued upon exercise of outstanding options, warrants and rights | (b)(3) Weighted-average exercise price of outstanding options, warrants and rights | (c) Number of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in (a)) | |||||||||||||||||
| Approved by security holders | 11,407,677 | $ | 35.02 | 41,980,866 | ||||||||||||||||
| Not approved by security holders | 6,828,634 | 23.89 | — | |||||||||||||||||
| Total | 18,236,311 | $ | 32.22 | 41,980,866 |
(1)Includes 10,995,360 RSUs and PSUs in plans approved by security holders.
(2)Plans not approved by security holders consists of 138,242 options outstanding with a weighted average exercise price of $23.89 and 6,690,392 RSUs for plans that were assumed in mergers and acquisitions and issued prior to shareholder approval of the Truist Financial Corporation 2022 Incentive Plan.
(3)Excludes RSUs and PSUs because they do not have an exercise price.
38 Truist Financial Corporation
Five-Year Common Stock Performance
The following graph and table compare the cumulative total shareholder return of the Company’s common stock, the S&P 500 Index, and the KBW Nasdaq Bank Index for the five-year period ended December 31, 2022. The Company is a component of both indexes. The graph and table assume an initial investment of $100 was made on December 31, 2017 in each of the Company’s common stock and the two indexes, as well as reinvestment of all dividends without commissions.
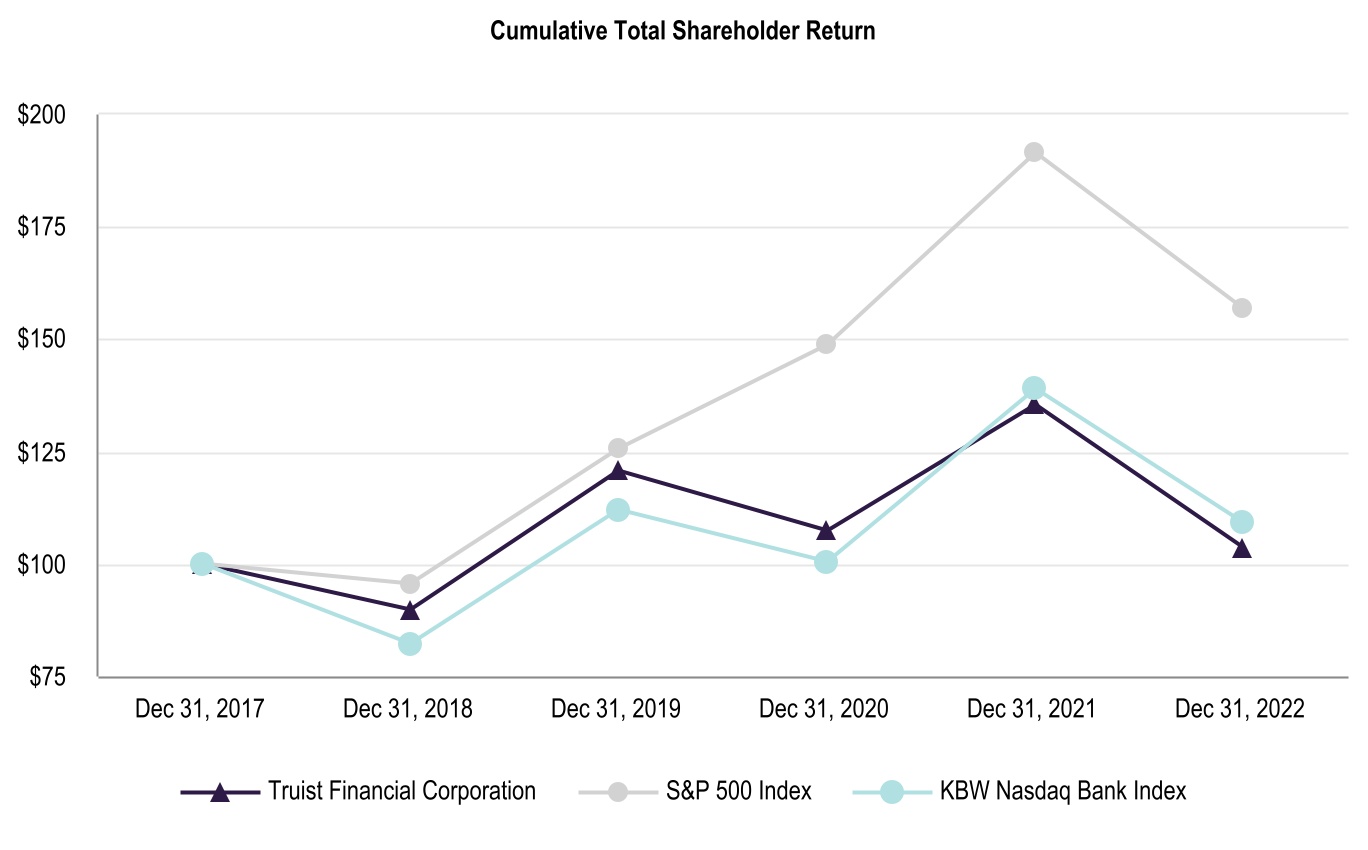
| Table 7: Cumulative Total Shareholder Return | ||||||||||||||||||||||||||||||||||||||||||||
| Invested | Cumulative Total Return | |||||||||||||||||||||||||||||||||||||||||||
| As of / Through December 31, | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | ||||||||||||||||||||||||||||||||||||||
| Truist Financial Corporation | $ | 100.00 | $ | 89.78 | $ | 120.77 | $ | 107.33 | $ | 135.31 | $ | 103.49 | ||||||||||||||||||||||||||||||||
| S&P 500 Index | 100.00 | 95.61 | 125.70 | 148.81 | 191.48 | 156.77 | ||||||||||||||||||||||||||||||||||||||
| KBW Nasdaq Bank Index | 100.00 | 82.29 | 112.01 | 100.47 | 138.99 | 109.25 | ||||||||||||||||||||||||||||||||||||||
Truist Financial Corporation 39
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
MD&A is intended to assist readers in their analysis of the accompanying Consolidated Financial Statements and supplemental financial information. It should be read in conjunction with the Consolidated Financial Statements, the accompanying Notes to the Consolidated Financial Statements in this Form 10-K, and other information contained in this document. For discussion of 2021 results as compared to 2020 results, see “Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations” in the Annual Report on Form 10-K for the year ended December 31, 2021.
A description of certain factors that may affect our future results and risk factors is set forth in Part I, Item 1A-Risk Factors of this report.
Executive Overview
This year was a strategic turning point for Truist as we began to shift our focus to executional excellence and purposeful growth. Results for 2022 were solid, reflecting post-integration momentum and progress in many areas. Robust loan growth, significant margin expansion, and good cost discipline contributed to our strong performance. Credit quality remains strong reflecting our conservative credit culture and diverse business mix. We also delivered on our commitment to achieve positive operating leverage for the full-year 2022.
We fulfilled our purpose to inspire and build better lives and communities in many ways throughout the year. We showed care for our teammates with a bold increase in our minimum wage; created new ways to meet clients’ needs through initiatives like Truist One Banking and enhanced digital offerings like Truist Assist, Truist Invest Pro, and Truist Trade; and supported our communities, including introducing a $120 million commitment to small businesses. In addition, we exceeded our $60 billion Community Benefits Plan commitment that we established at the time of the Merger.
We continued to have strong momentum during the year with regards to other environmental, social and governance initiatives that we have undertaken. We announced our goal to achieve net zero greenhouse gas emissions by 2050, which will help support our clients’ transition to a low-carbon economy. In support of this goal, we joined the Partnership for Carbon Accounting Financials, and set 2030 goals to reduce Scope 1 and Scope 2 emissions by 35% each, and to reduce water consumption by 25%, relative to 2019. With 17.2% of senior leadership roles being held by ethnically diverse teammates, we have exceeded our original goal and we aspire for continued growth in this area, and surpassed our goal of 10% spend with diverse suppliers in 2022. Truist was ranked 5th overall within the JUST 100 list and recognized as one of Fortune Magazine’s Most Admired Companies.
Truist maintained strong capital and liquidity in 2022 and made a number of strategic investments to deploy capital and expand on its businesses. During 2022, Truist made the following acquisitions:
-
BankDirect Capital Finance, the insurance premium finance unit of Texas Capital Bancshares, which resulted in the addition of approximately $3.1 billion of loans;
-
BenefitMall, one of the nation’s leading benefit wholesale general insurance agencies, to broaden the selection of products and services offered by IH’s wholesale insurance broker;
-
Kensington Vanguard National Land Services, one of the largest independent full-service national title insurance agencies, to expand IH’s presence in the title insurance market; and
-
A noncontrolling equity interest in SunTrust Merchant Services, LLC, in exchange for the rights to certain merchant banking relationships, including relationships previously referred by Truist to SunTrust Merchant Services, LLC.
Truist increased the quarterly common dividend 8% during the year and declared total common dividends of $2.00 per share during 2022. The dividend payout ratio for 2022 was 45% compared to 41% for the prior year. The total payout ratio for 2022 was 49% compared to 68% for the prior year.
40 Truist Financial Corporation
Financial Results
Net income available to common shareholders totaled $5.9 billion for 2022, a 1.8% decrease from the prior year. On a diluted per common share basis, earnings for 2022 were $4.43, compared to $4.47 for 2021. Truist’s results of operations for 2022 produced a return on average assets of 1.15% and a return on average common shareholders’ equity of 10.4% compared to prior year ratios of 1.23% and 9.7%, respectively. Results include merger-related and restructuring charges of $513 million ($393 million after-tax) for 2022 compared to $822 million ($631 million after-tax) for 2021, and incremental operating expenses related to the Merger of $465 million ($356 million after-tax) for 2022 compared to $771 million ($592 million after-tax) for 2021. Additionally, the 2022 results include a gain on the redemption of noncontrolling equity interest of $74 million ($57 million after-tax) related to the acquisition of certain merchant services relationships, a gain on the early extinguishment of long-term debt of $39 million ($30 million after-tax), partially offset by net losses on the sales of securities of $71 million ($54 million after-tax). The 2021 results include charitable contributions of $200 million ($153 million after-tax), an acceleration of loss recognition related to certain terminated cash flow hedges of $36 million ($28 million after tax), and a one-time professional fee expense of $30 million ($23 million after tax), partially offset by a small gain on extinguishment of debt.
| Table 8: Earnings Highlights | |||||||||||||||||||||||||||||||||||||||||||||||
| Year Ended December 31, (Dollars in millions) | Change | ||||||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2020 | 2022 vs. 2021 | 2021 vs. 2020 | |||||||||||||||||||||||||||||||||||||||||||
| Net income available to common shareholders | $ | 5,927 | $ | 6,033 | $ | 4,184 | $ | (106) | $ | 1,849 | |||||||||||||||||||||||||||||||||||||
| Diluted earnings per common share | 4.43 | 4.47 | 3.08 | (0.04) | 1.39 | ||||||||||||||||||||||||||||||||||||||||||
| Net interest income - taxable equivalent | $ | 14,4 |
Showing the first 8K of 249K characters. Open the full section
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Shareholders of Truist Financial Corporation
Opinions on the Financial Statements and Internal Control over Financial Reporting
We have audited the accompanying consolidated balance sheets of Truist Financial Corporation and its subsidiaries (the “Company”) as of December 31, 2022 and 2021, and the related consolidated statements of income, comprehensive income, changes in shareholders’ equity and cash flows for each of the three years in the period ended December 31, 2022, including the related notes (collectively referred to as the “consolidated financial statements”). We also have audited the Company’s internal control over financial reporting as of December 31, 2022 based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, 2022 and 2021, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2022 in conformity with accounting principles generally accepted in the United States of America. Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2022, based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
Change in Accounting Principle
As discussed in Note 1 to the consolidated financial statements, the Company changed the manner in which it accounts for the allowance for credit losses in 2020.
Basis for Opinions
The Company’s management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting, included in Management’s Report on Internal Control over Financial Reporting appearing under Item 9A. Our responsibility is to express opinions on the Company’s consolidated financial statements and on the Company’s internal control over financial reporting based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud, and whether effective internal control over financial reporting was maintained in all material respects.
Our audits of the consolidated financial statements included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.
Definition and Limitations of Internal Control over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Truist Financial Corporation 81
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Critical Audit Matters
The critical audit matter communicated below is a matter arising from the current period audit of the consolidated financial statements that was communicated or required to be communicated to the audit committee and that (i) relates to accounts or disclosures that are material to the consolidated financial statements and (ii) involved our especially challenging, subjective, or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
Allowance for Credit Losses for Certain Commercial and Consumer Portfolios
As described in Notes 1 and 5 to the consolidated financial statements, the Company’s allowance for credit losses (ACL) represents management’s best estimate of expected future credit losses related to loan and lease portfolios and off-balance sheet lending commitments at the balance sheet date. The consolidated ACL balance was $4.6 billion as of December 31, 2022, including $1.7 billion for commercial portfolios and $2.3 billion for consumer portfolios. Estimates of expected future credit losses are determined by management using quantitative models and by applying qualitative adjustments to the modeled results. The models are designed to forecast probability of default, exposure at default, and loss given default by correlating certain macroeconomic forecast data to historical experience. The models are applied to pools of loans with similar risk characteristics. The macroeconomic forecast data used in the quantitative models is based on forecasted variables for a reasonable and supportable period. The qualitative adjustments incorporate management judgment and are used to account for limitations in modeled results related to current economic conditions and other risks in the portfolios.
The principal considerations for our determination that performing procedures relating to the ACL for certain commercial and consumer portfolios is a critical audit matter are (i) the significant judgment by management in determining the ACL quantit
Showing the first 8K of 459K characters. Open the full section
Item 9A. CONTROLS AND PROCEDURES
Management’s Report on Internal Control over Financial Reporting and Evaluation of
Disclosure Controls and Procedures
Management’s Report on Internal Control over Financial Reporting
Management of Truist is responsible for establishing and maintaining adequate internal control over financial reporting as defined in Rule 13a-15(f) of the Exchange Act. The Company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with GAAP. Truist’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records, that in reasonable detail, accurately and fairly reflect the transactions and disposition of the Company’s assets; (2) provide reasonable assurance that transactions are recorded as necessary to permit the preparation of financial statements in accordance with GAAP and that receipts and expenditures of the Company are being made only in accordance with the authorizations of Truist’s management and directors; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use or disposition of the Company’s assets that could have a material impact on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate due to changes in conditions, or that the degree of compliance with the policies and procedures may deteriorate.
Under the supervision and with the participation of management, including the Chief Executive Officer and the Chief Financial Officer, the Company conducted an evaluation of the effectiveness of the internal control over financial reporting based on the framework in Internal Control-Integrated Framework (2013) promulgated by the Committee of Sponsoring Organizations of the Treadway Commission, commonly referred to as the “COSO” criteria. Based on this evaluation under the COSO criteria, management concluded that the Company’s internal control over financial reporting was effective as of December 31, 2022.
The effectiveness of the Company’s internal control over financial reporting as of December 31, 2022 has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their accompanying report, which expresses an unqualified opinion on the effectiveness of the Company’s internal control over financial reporting as of December 31, 2022.
Disclosure Controls and Procedures and Changes in Internal Control over Financial Reporting
As of the end of the period covered by this report, the management of the Company, under the supervision and with the participation of the Company’s Chief Executive Officer and Chief Financial Officer, carried out an evaluation of the Company’s disclosure controls and procedures as defined in Rule 13a-15(e) of the Exchange Act. Based on that evaluation, the Chief Executive Officer and Chief Financial Officer concluded that the Company’s disclosure controls and procedures were effective.
There was no change in the Company’s internal control over financial reporting that occurred during the fourth quarter of 2022 that has materially affected, or is likely to materially affect, the Company’s internal control over financial reporting.
142 Truist Financial Corporation
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES
| Exhibit No. | Description | Location | |||||||||||||||
| 3.1 | Articles of Incorporation of the Registrant, as consolidated and restated December 15, 2020. | Incorporated herein by reference to Exhibit 3.1 of the Annual Report on Form 10-K, filed February 24, 2021. | |||||||||||||||
| 3.2 | Amended and Restated Bylaws of Truist Financial Corporation | Incorporated herein by reference to Exhibit 3.1 of the Current Report on Form 8-K, filed October 26, 2022. | |||||||||||||||
| 4.1 | Indenture Regarding Senior Securities (including form of Senior Debt Security) between Registrant and U.S. Bank National Association (as successor in interest to State Street Bank and Trust Company), as trustee, dated as of May 24, 1996. | Incorporated herein by reference to Exhibit 4.1 of the Quarterly Report on Form 10-Q, filed August 14, 1996. | |||||||||||||||
| 4.2 | First Supplemental Indenture, dated May 4, 2009, to the Indenture Regarding Senior Securities, dated as of May 24, 1996, between the Registrant and U.S. Bank National Association. | Incorporated herein by reference to Exhibit 4.2 of the Current Report on Form 8-K, filed May 4, 2009. | |||||||||||||||
| 4.3 | Indenture Regarding Subordinated Securities (including Form of Subordinated Debt Security) between the Registrant and U.S. Bank National Association (as successor in interest to State Street Bank and Trust Company), as trustee, dated as of May 24, 1996. | Incorporated herein by reference to Exhibit 4.2 of the Quarterly Report on Form 10-Q, filed August 14, 1996. | |||||||||||||||
| 4.4 | First Supplemental Indenture, dated as of December 23, 2003, to the Indenture Regarding Subordinated Securities, dated as of May 24, 1996, between the Registrant and U.S. Bank National Association. | Incorporated herein by reference to Exhibit 4.5 of the Annual Report on Form 10-K, filed February 27, 2009. | |||||||||||||||
| 4.5 | Second Supplemental Indenture, dated as of September 24, 2004, to the Indenture Regarding Subordinated Securities, dated as of May 24, 1996, between the Registrant and U.S. Bank National Association. | Incorporated herein by reference to Exhibit 4.7 of the Annual Report on Form 10-K, filed February 26, 2010. | |||||||||||||||
| 4.6 | Third Supplemental Indenture, dated May 4, 2009, to the Indenture Regarding Subordinated Securities, dated as of May 24, 1996, between the Registrant and U.S. Bank National Association. | Incorporated herein by reference to Exhibit 4.6 of the Current Report on Form 8-K, filed May 4, 2009. | |||||||||||||||
| 4.7 | Deposit Agreement, dated as of July 29, 2019, between the Company and Computershare Inc. and Computershare Trust Company, N.A., jointly as depositary. | Incorporated herein by reference to Exhibit 4.2 of the Current Report on Form 8-K, filed July 29, 2019. | |||||||||||||||
| 4.8 | Form of Depositary Receipt. | Incorporated herein by reference to Exhibit 4.2 of the Current Report on Form 8-K, filed July 29, 2019. | |||||||||||||||
| 4.9 | Description of the Securities Registered Pursuant to Section 12 of the Securities Exchange Act of 1934 | Filed herewith. | |||||||||||||||
| 4.10 | Second Supplemental Indenture, dated as of June 6, 2022, between the Company and U.S. Bank Trust Company, National Association. | Incorporated herein by reference to Exhibit 4.1 of the Current Report on Form 8-K, filed June 6, 2022. | |||||||||||||||
| 4.11 | Fourth Supplemental Indenture, dated as of July 28, 2022, between the Company and U.S. Bank Trust Company, National Association. | Incorporated herein by reference to Exhibit 4.1 of the Current Report on Form 8-K, filed July 28, 2022. | |||||||||||||||
| Other instruments defining the rights of holders of long-term debt securities of Truist are omitted pursuant to Section (b)(4)(iii)(A) of Item 601 of Regulation S-K. Truist agrees to furnish copies of these instruments to the SEC upon request. | |||||||||||||||||
| 10.1* | BB&T Corporation Amended and Restated Non-Employee Directors’ Deferred Compensation Plan (amended and restated January 1, 2005). | Incorporated herein by reference to Exhibit 10.1 of the Annual Report on Form 10-K, filed February 28, 2008. | |||||||||||||||
| 10.2* | BB&T Corporation Amended and Restated 2004 Stock Incentive Plan, as amended (as amended through February 24, 2009). | Incorporated herein by reference to the Appendix to the Proxy Statement for the 2009 Annual Meeting of Shareholders on Schedule 14A, filed March 13, 2009. | |||||||||||||||
| 10.3* | BB&T Corporation 2012 Incentive Plan, as amended | Incorporated herein by reference to Exhibit 10.1 of the Registration Statement on Form S-8, filed May 25, 2017. | |||||||||||||||
| 10.4* | Form of Employee Nonqualified Stock Option Agreement for the BB&T Corporation Amended and Restated 2004 Stock Incentive Plan (5-Year Vesting). | Incorporated herein by reference to Exhibit 10.8 of the Annual Report on Form 10-K, filed February 28, 2008. | |||||||||||||||
| 10.5* | Form of Employee Nonqualified Stock Option Agreement for the BB&T Corporation Amended and Restated 2004 Stock Incentive Plan (4-Year Vesting). | Incorporated herein by reference to Exhibit 10.5 of the Quarterly Report on Form 10-Q, filed May 7, 2010. | |||||||||||||||
| 10.6* | Southern National Deferred Compensation Plan for Key Executives including Amendments. | Incorporated herein by reference to Exhibit 10.21 of the Annual Report on Form 10-K, filed February 25, 2011. | |||||||||||||||
| 10.7* | Termination Amendment for the Southern National Deferred Compensation Plan for Key Executives | Filed herewith. | |||||||||||||||
| 10.8* | BB&T Nonqualified Defined Benefit Plan (January 1, 2012 Restatement) | Incorporated herein by reference to Exhibit 10.11 of the Annual Report on Form 10-K, filed February 25, 2016. | |||||||||||||||
| 10.9* | First Amendment to the BB&T Non-Qualified Defined Benefit Plan (January 1, 2012 Restatement). | Incorporated herein by reference to Exhibit 10.12 of the Annual Report on Form 10-K, filed February 25, 2016. | |||||||||||||||
| 10.10* | Second Amendment to the BB&T Non-Qualified Defined Benefit Plan (January 1, 2012 Restatement). | Incorporated herein by reference to Exhibit 10.13 of the Annual Report on Form 10-K, filed February 25, 2016. | |||||||||||||||
| 10.11* | Third Amendment to the BB&T Non-Qualified Defined Benefit Plan (January 1, 2012 Restatement) | Incorporated herein by reference to Exhibit 10.11 of the Annual Report on Form 10-K, filed February 23, 2022. |
Truist Financial Corporation 143
144 Truist Financial Corporation
| Exhibit No. | Description | Location | |||||||||||||||
| 10.37* | SunTrust Banks, Inc. 2018 Omnibus Incentive Compensation Plan | Incorporated herein by reference to Appendix B to SunTrust's definitive Proxy Statement, filed March 9, 2018. | |||||||||||||||
| 10.38* | Form of Performance-Vested Restricted Stock Unit Award Agreement, Type I | Incorporated herein by reference to Exhibit 10.3 to SunTrust’s Quarterly Report on Form 10-Q, filed May 4, 2018. | |||||||||||||||
| 10.39* | Form of Performance-Vested Restricted Stock Unit Award Agreement, Type II | Incorporated herein by reference to Exhibit 10.4 to SunTrust’s Quarterly Report on Form 10-Q, filed May 4, 2018. | |||||||||||||||
| 10.40* | Form of Time-Vested Restricted Stock Unit Award Agreement, Type I | Incorporated herein by reference to Exhibit 10.5 to SunTrust's Quarterly Report on Form 10-Q, filed May 4, 2018. | |||||||||||||||
| 10.41* | Form of Time-Vested Restricted Stock Unit Award Agreement, Type II | Incorporated herein by reference to Exhibit 10.6 to SunTrust's Quarterly Report on Form 10-Q, filed May 4, 2018. | |||||||||||||||
| 10.42* | Form of Time-Vested Restricted Stock Unit Award Agreement, Type III | Incorporated herein by reference to Exhibit 10.7 to SunTrust's Quarterly Report on Form 10-Q, filed May 4, 2018. | |||||||||||||||
| 10.43* | Form of Time-Vested Restricted Stock Unit Award Agreement, Type IV | Incorporated herein by reference to Exhibit 10.8 to SunTrust's Quarterly Report on Form 10-Q, filed May 4, 2018. | |||||||||||||||
| 10.44* | 2019 Employment Agreement by and among BB&T Corporation, Branch Banking and Trust Company and William H. Rogers, Jr. | Incorporated herein by reference to Exhibit 10.90 of the Annual Report on Form 10-K, filed March 3, 2020. | |||||||||||||||
| 10.45* | Form of Restricted Stock Unit Agreement (Non-Employee Directors) for the Truist Financial Corporation 2012 Incentive Plan (effective 2020). | Incorporated herein by reference to Exhibit 10.1 of the Quarterly Report on Form 10-Q, filed May 8, 2020. | |||||||||||||||
| 10.46* | Form of Restricted Stock Unit Agreement (Category 2 Employee) for the Truist Financial Corporation 2012 Incentive Plan (effective 2021). | Incorporated herein by reference to Exhibit 10.1 of the Quarterly Report on Form 10-Q, filed May 3, 2021. | |||||||||||||||
| 10.47* | Form of Restricted Stock Unit Agreement (Senior Executive) for the Truist Financial Corporation 2012 Incentive Plan (effective 2021). | Incorporated herein by reference to Exhibit 10.2 of the Quarterly Report on Form 10-Q, filed May 3, 2021. | |||||||||||||||
| 10.48* | Form of LTIP Award Agreement for the Truist Financial Corporation 2012 Incentive Plan (effective 2021). | Incorporated herein by reference to Exhibit 10.3 of the Quarterly Report on Form 10-Q, filed May 3, 2021. | |||||||||||||||
| 10.49* | Form of Performance Unit Award Agreement for the Truist Financial Corporation 2012 Incentive Plan (effective 2021). | Incorporated herein by reference to Exhibit 10.4 of the Quarterly Report on Form 10-Q, filed May 3, 2021. | |||||||||||||||
| 10.50* | Truist Financial Corporation Nonqualified Defined Contribution Plan | Incorporated herein by reference to Exhibit 10.62 of the Annual Report on Form 10-K, filed February 24, 2021. | |||||||||||||||
| 10.51* | Master Trust Agreement (Nonqualified Plans) between Truist Financial Corporation and Fidelity Management Trust Company | Incorporated herein by reference to Exhibit 10.63 of the Annual Report on Form 10-K, filed February 24, 2021. | |||||||||||||||
| 10.52* | Truist Financial Corporation 401(k) Savings Plan | Incorporated herein by reference to Exhibit 10.64 of the Annual Report on Form 10-K, filed February 24, 2021. | |||||||||||||||
| 10.53* | First Amendment to the Truist Financial Corporation 401(k) Savings Plan (August 1, 2020 Restatement) | Incorporated herein by reference to Exhibit 10.62 of the Annual Report on Form 10-K, filed February 23, 2022. | |||||||||||||||
| 10.54* | Second Amendment to the Truist Financial Corporation 401(k) Saving Plan (August 1, 2020 Restatement) | Incorporated herein by reference to Exhibit 10.63 of the Annual Report on Form 10-K, filed February 23, 2022. | |||||||||||||||
| 10.55* | Third Amendment to the Truist Financial Corporation 401(k) Savings Plan (August 1, 2020 Restatement) | Filed herewith. | |||||||||||||||
| 10.56* | Fourth Amendment to the Truist Financial Corporation 401(k) Savings Plan (August 1, 2020 Restatement) | Filed herewith. | |||||||||||||||
| 10.57* | SunTrust Banks, Inc. Directors Deferred Compensation Plan, amended and restated as of January 1, 2009 | Incorporated by reference to Exhibit 10.1 to the SunTrust Current Report on Form 8-K, filed January 7, 2009. | |||||||||||||||
| 10.58* | Amendment Number One to the SunTrust Banks, Inc. Directors Deferred Compensation Plan, effective as of January 1, 2018 | Incorporated herein by reference to Exhibit 10.14 of SunTrust's Annual Report on Form 10-K, filed February 22, 2019. | |||||||||||||||
| 10.59* | First Amendment to BB&T Corporation Amended and Restated Non-Employee Directors’ Deferred Compensation Plan (Amended and Restated January 1, 2005) | Incorporated herein by reference to Exhibit 10.69 of the Annual Report on Form 10-K, filed February 24, 2021. | |||||||||||||||
| 10.60* | 2020 Amendment to the Truist Financial Corporation Amended and Restated Non-Employee Directors’ Deferred Compensation Plan | Incorporated herein by reference to Exhibit 10.67 of the Annual Report on Form 10-K, filed February 23, 2022. | |||||||||||||||
| 10.61* | Employment Agreement by and between Truist Insurance Holdings, Inc. and John Howard | Incorporated herein by reference to Exhibit 10.68 of the Annual Report on Form 10-K, filed February 23, 2022. | |||||||||||||||
| 10.62* | Qualified Trust Agreement between Truist Financial Corporation and Fidelity Management Trust Company (July 15, 2020) | Incorporated herein by reference to Exhibit 10.65 of the Annual Report on Form 10-K, filed February 24, 2021. |
Truist Financial Corporation 145
| Exhibit No. | Description | Location | |||||||||||||||
| 10.63* | First Amendment to Qualified Trust Agreement between Truist Financial Corporation and Fidelity Management Trust Company (July 15, 2020) | Incorporated herein by reference to Exhibit 10.66 of the Annual Report on Form 10-K, filed February 24, 2021. | |||||||||||||||
| 10.64* | Truist Financial Corporation 2022 Incentive Plan | Incorporated by reference to Annex B to the Corporation’s Definitive Proxy Statement (filed on March 14, 2022). | |||||||||||||||
| 10.65* | Letter to the Board of Directors from William H. Rogers Jr. dated, April 14, 2022, waiving certain rights under his employment agreement | Incorporated herein by reference to Exhibit 10.2 of the Quarterly Report on Form 10-Q, filed May 5, 2022. | |||||||||||||||
| 10.66* | Form of Employee Restricted Stock Unit Agreement for the Truist Financial Corporation 2022 Incentive Plan | Incorporated herein by reference to Exhibit 10.3 of the Quarterly Report on Form 10-Q, filed May 5, 2022. | |||||||||||||||
| 10.67* | Letter from Daryl N. Bible, dated, December 2, 2022 regarding Voluntary Resignation as a Consultant | Filed herewith. | |||||||||||||||
| 10.68* | Retirement and Consulting Agreement between the Company and Daryl N. Bible. | Incorporated herein by reference to Exhibit 10.1 of the Quarterly Report on Form 10-Q, filed August 1, 2022. | |||||||||||||||
| 10.69* | Truist Financial Corporation Management Change of Control, Severance, and Noncompetition Plan. | Incorporated herein by reference to Exhibit 10.1 on Current Report on Form 8-K, filed July 26, 2022. | |||||||||||||||
| 10.70* | Form of Executive Severance and Noncompetition Agreement. | Incorporated herein by reference to Exhibit 10.1 of the Quarterly Report on Form 10-Q, filed October 31, 2022. | |||||||||||||||
| 11 | Statement re computation of earnings per share. | Filed herewith as Computation of EPS note to the consolidated financial statements. | |||||||||||||||
| 21† | Subsidiaries of the Registrant. | Filed herewith. | |||||||||||||||
| 22† | List of Subsidiary Issuers of Guaranteed Securities. | Filed herewith. | |||||||||||||||
| 23† | Consent of Independent Registered Public Accounting Firm. | Filed herewith. | |||||||||||||||
| 31.1 | Certification of Chief Executive Officer pursuant to Rule 13a-14(a) or 15d-14(a) of the Exchange Act, as adopted pursuant to Section 302 of the Sarbanes-Oxley Act of 2002. | Filed herewith. | |||||||||||||||
| 31.2 | Certification of Chief Financial Officer pursuant to Rule 13a-14(a) or 15d-14(a) of the Exchange Act, as adopted pursuant to Section 302 of the Sarbanes-Oxley Act of 2002. | Filed herewith. | |||||||||||||||
| 32 | Certification of Chief Executive Officer and Chief Financial Officer pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. | Filed herewith. | |||||||||||||||
| 101.INS | XBRL Instance Document – the instance document does not appear in the interactive data file because its XBRL tags are embedded within the inline XBRL document. | Filed herewith. | |||||||||||||||
| 101.SCH | XBRL Taxonomy Extension Schema. | Filed herewith. | |||||||||||||||
| 101.CAL | XBRL Taxonomy Extension Calculation Linkbase. | Filed herewith. | |||||||||||||||
| 101.LAB | XBRL Taxonomy Extension Label Linkbase. | Filed herewith. | |||||||||||||||
| 101.PRE | XBRL Taxonomy Extension Presentation Linkbase. | Filed herewith. | |||||||||||||||
| 101.DEF | XBRL Taxonomy Definition Linkbase. | Filed herewith. | |||||||||||||||
| 104 | Cover Page Interactive Data File (formatted as inline XBRL with applicable taxonomy extension information contained in Exhibits101). | Filed herewith. | |||||||||||||||
| † Exhibit filed with the SEC and available upon request. | |||||||||||||||||
| * Management compensatory plan or arrangement. |
146 Truist Financial Corporation
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized, as of February 28, 2023:
| Truist Financial Corporation | ||||||||
| (Registrant) | ||||||||
| /s/ William H. Rogers Jr. | ||||||||
| William H. Rogers Jr. | ||||||||
| Chairman and Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities indicated:
| /s/ William H. Rogers Jr. | Chairman and Chief Executive Officer | February 28, 2023 | ||||||||||||
| William H. Rogers Jr. | ||||||||||||||
| /s/ Michael B. Maguire | Senior Executive Vice President and Chief Financial Officer | February 28, 2023 | ||||||||||||
| Michael B. Maguire | (Principal Financial Officer) | |||||||||||||
| /s/ Cynthia B. Powell | Executive Vice President and Corporate Controller | February 28, 2023 | ||||||||||||
| Cynthia B. Powell | (Principal Accounting Officer) | |||||||||||||
| /s/ Jennifer S. Banner | Director | February 28, 2023 | ||||||||||||
| Jennifer S. Banner | ||||||||||||||
| /s/ K. David Boyer, Jr. | Director | February 28, 2023 | ||||||||||||
| K. David Boyer, Jr. | ||||||||||||||
| /s/ Agnes Bundy Scanlan | Director | February 28, 2023 | ||||||||||||
| Agnes Bundy Scanlan | ||||||||||||||
| /s/ Anna R. Cablik | Director | February 28, 2023 | ||||||||||||
| Anna R. Cablik | ||||||||||||||
| /s/ Dallas S. Clement | Director | February 28, 2023 | ||||||||||||
| Dallas S. Clement | ||||||||||||||
| /s/ Paul D. Donahue | Director | February 28, 2023 | ||||||||||||
| Paul D. Donahue | ||||||||||||||
| /s/ Patrick C. Graney III | Director | February 28, 2023 | ||||||||||||
| Patrick C. Graney III | ||||||||||||||
| /s/ Linnie M. Haynesworth | Director | February 28, 2023 | ||||||||||||
| Linnie M. Haynesworth | ||||||||||||||
| /s/ Kelly S. King | Director | February 28, 2023 | ||||||||||||
| Kelly S. King | ||||||||||||||
| /s/ Easter A. Maynard | Director | February 28, 2023 | ||||||||||||
| Easter A. Maynard | ||||||||||||||
| /s/ Donna S. Morea | Director | February 28, 2023 | ||||||||||||
| Donna S. Morea | ||||||||||||||
| /s/ Charles A. Patton | Director | February 28, 2023 | ||||||||||||
| Charles A. Patton | ||||||||||||||
| /s/ Nido R. Qubein | Director | February 28, 2023 | ||||||||||||
| Nido R. Qubein | ||||||||||||||
| /s/ David M. Ratcliffe | Director | February 28, 2023 | ||||||||||||
| David M. Ratcliffe | ||||||||||||||
| /s/ Frank P. Scruggs, Jr. | Director | February 28, 2023 | ||||||||||||
| Frank P. Scruggs, Jr. | ||||||||||||||
| /s/ Christine Sears | Director | February 28, 2023 | ||||||||||||
| Christine Sears | ||||||||||||||
| /s/ Thomas E. Skains | Director | February 28, 2023 | ||||||||||||
| Thomas E. Skains | ||||||||||||||
| /s/ Bruce L. Tanner | Director | February 28, 2023 | ||||||||||||
| Bruce L. Tanner | ||||||||||||||
| /s/ Thomas N. Thompson | Director | February 28, 2023 | ||||||||||||
| Thomas N. Thompson | ||||||||||||||
| /s/ Steven C. Voorhees | Director | February 28, 2023 | ||||||||||||
| Steven C. Voorhees |
Truist Financial Corporation 147